



Worldwide Diesel Lubricity Improver Market: Why 4.2% CAGR Upsets Old Growth Narratives
By PW Consulting, 2026-09-18
Worldwide Diesel Lubricity Improver Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Snapshot and Core Challenges
The global diesel lubricity improver market has evolved from a compliance-driven niche into a strategically significant segment within the broader fuel additives landscape. Valued at approximately $475 million in 2020, the sector expanded steadily through the mid-2020s, reaching roughly $585 million by 2025. Forward-looking projections place the market on a trajectory to exceed $780 million by 2032, supported by a compound annual growth rate of around 4.2 percent. This growth reflects a structural shift rather than a cyclical uptick, as refiners, additive formulators, and engine manufacturers navigate the persistent tension between emissions reduction mandates and equipment durability. The consistent upward trajectory underscores how lubricity management has become embedded in fuel specification compliance, supply chain planning, and downstream performance expectations across multiple geographies and end-use sectors.
Behind the headline figures, the industry confronts three interconnected challenges that will shape competitive positioning over the next several years. First, the regulatory baseline continues to tighten. Standards such as EN 590 and GB 19147 mandate a maximum HFRR wear scar diameter of 460 μm at 60°C, which effectively compels the use of lubricity enhancers in ultra-low sulfur diesel formulations. While this creates steady baseline demand, it also compresses the value proposition for basic compliance products, pushing suppliers to differentiate through multi-functional performance rather than single-attribute improvement. Second, feedstock economics introduce volatility into cost structures. The production of diesel lubricity improvers commonly relies on fatty acid derivatives and esters, whose pricing is influenced by upstream vegetable oil markets and crude oil-derived feedstocks. Fluctuations in these input costs ripple through manufacturing economics, squeezing margins for formulators that lack robust hedging strategies or diversified sourcing networks. Third, the transition toward advanced combustion technologies and higher biofuel blending rates is altering the performance envelope. Deposit control, oxidation stability, and cold-flow behavior are increasingly intertwined with lubricity requirements, meaning that legacy stand-alone improvers face pressure to integrate into broader additive packages that deliver synergistic engine protection.
For executives and strategists, these dynamics translate into a market where volume growth is relatively predictable but margin and differentiation trajectories are highly contingent on formulation strategy, supply chain agility, and regulatory interpretation. Companies that treat lubricity improvement as a commodity compliance exercise risk being squeezed by price competition and feedstock exposure, while those that position their offerings as integrated performance solutions capture greater resilience and pricing power. The next section examines the drivers intensifying these shifts.
2. Key Drivers Reshaping the Market
Technological Innovation and Formulation Evolution
Advancements in additive chemistry are redefining what a lubricity improver can deliver beyond baseline wear protection. Formulators are increasingly designing molecules and blends that address HFRR wear scar requirements while simultaneously contributing to deposit mitigation, corrosion resistance, and compatibility with higher biofuel content. This multi-functional approach is particularly relevant as engine manufacturers optimize fuel injection systems for efficiency and emissions control, demanding fuels that protect precision components without compromising combustion cleanliness. Recent product launches illustrate this trajectory. In February 2025, TotalEnergies introduced the RUBIA OPTIMA diesel lubricity improver, tailored for ultra-low sulphur diesel engines in Europe. The launch signals a broader industry pattern: rather than offering narrow lubricity additives, leading suppliers are packaging performance attributes that align with real-world operating conditions and regional fuel specifications. For engine and vehicle manufacturers, this evolution means a growing preference for additive partners that can validate performance across multiple parameters, reducing the burden of multi-supplier qualification and simplifying fuel quality assurance.
Policy and Regulatory Environment
Regulation remains the most reliable demand anchor for diesel lubricity improvers. The widespread adoption of ultra-low sulfur diesel has eliminated naturally occurring sulfur compounds that historically contributed to fuel lubricity, making additives essential for protecting fuel pumps, injectors, and cylinder components. Global fuel standards codify this need through measurable HFRR thresholds, creating a consistent compliance pull across mature and emerging markets. In parallel, environmental agencies maintain oversight of additive formulations to ensure that lubricity enhancements do not undermine emissions performance or air quality objectives. The U.S. EPA, for example, maintains a registered diesel additives list updated as of March 2025 that includes multiple approved lubricity improver formulations for commercial use. This registration framework increases transparency for end-users but also raises the bar for product documentation, testing, and ongoing compliance management. For suppliers, the regulatory environment rewards those with established testing infrastructure, clear homologation pathways, and the ability to adapt formulations as regional standards evolve.
Demand-Side Shifts in Vehicle and Industrial Use
Demand patterns are diverging by application, creating distinct opportunity pockets. Heavy-duty vehicles continue to represent the largest application segment, driven by long-haul logistics, commercial fleet operations, and the durability requirements of high-pressure common-rail injection systems. Passenger vehicles, while smaller in absolute volume, benefit from increasing fuel quality expectations and the persistence of diesel in certain regional markets, particularly where total cost of ownership remains favorable. Industrial and stationary engines constitute another meaningful demand base, especially in power generation, agricultural equipment, and remote-site operations where fuel storage duration and variable operating conditions amplify the need for wear protection. Across these segments, the common thread is that lubricity management is no longer a standalone concern; it is integrated into broader fuel reliability and asset-protection strategies. Fleet operators and industrial buyers are increasingly evaluating total cost of ownership, maintenance intervals, and warranty implications, which broadens the relevance of additive performance beyond immediate wear metrics.
Supply Chain and Cost Structure Dynamics
Cost structures in the lubricity improver market are closely tied to raw material availability and pricing. Fatty acids and ester-based feedstocks form the backbone of many formulations, linking production economics to agricultural commodity cycles and petroleum-derived intermediates. When these input costs fluctuate, manufacturers face pressure on margins unless they can adjust blend architectures, optimize process efficiency, or pass through cost changes without losing volume. The implication is clear: competitive advantage is shifting toward companies with geographically diversified sourcing, long-term supplier agreements, and formulation flexibility that allows substitution among functionally equivalent chemistries. Refineries and terminal operators also influence demand patterns through blending economics and logistics. Additive inclusion decisions at the terminal stage can vary by region, season, and fuel specification, meaning that distribution and partnership models matter as much as molecular performance. Suppliers that can integrate technical service, blending guidance, and inventory alignment into their commercial offerings reduce friction for customers and strengthen retention in a market where switching costs are sometimes lower than the operational risk of inconsistent fuel quality.
PW Consulting
3. Competitive Landscape and Leading Strategies
The competitive map in diesel lubricity improvers is characterized by a blend of global specialty chemical companies, fuel additive specialists, and integrated energy suppliers. Market concentration metrics indicate that a limited number of players command a substantial share of revenues, with the top three holding approximately 45.2 percent and the top five reaching around 62.4 percent. This footprint suggests a market where scale, technical credibility, and customer relationships create meaningful barriers, but it also leaves room for regional specialists and application-focused entrants in underserved niches.
Infineum International Limited, headquartered in the United Kingdom, operates as a major global supplier of diesel fuel additives, with dedicated lubricity improvers formulated for ultra-low sulfur diesel to meet HFRR standards such as EN 590 and equivalent specifications. Its strength lies in broad formulation expertise and a global technical support footprint that helps refiners and distributors align additive programs with regional fuel quality requirements. The Lubrizol Corporation, based in the United States, provides comprehensive diesel performance additive packages with lubricity improvers targeting fuel injection equipment protection in low-sulfur diesel fuels. Lubrizol’s differentiation often comes from packaging lubricity within broader performance solutions, giving customers a streamlined route to multi-attribute fuel improvement. Afton Chemical Corporation, also U.S.-based, offers the HiTEC series lubricity improvers and multi-functional diesel additives designed to restore lubricity in ULSD while meeting global fuel specifications. Afton’s emphasis on brand recognition and application-specific formulations supports a strategy centered on validated performance and customer education.
European chemical majors contribute scale and regional regulatory fluency. BASF SE supplies diesel fuel additives including acidic and non-acidic lubricity improvers for automotive, commercial, and industrial diesel applications, leveraging its broad chemical portfolio to support customized solutions. Evonik Industries AG produces performance additives including lubricity enhancers for low-sulfur diesel fuels used in transportation and industrial sectors, combining specialty chemistry capabilities with application engineering. LANXESS AG and Clariant AG further round out the European field, with LANXESS providing chemical additives for fuels, including lubricity improvement solutions for diesel, and Clariant supplying a fuel additives portfolio containing lubricity improvers compliant with global diesel fuel quality standards. These companies often compete on technical depth, compliance documentation, and the ability to support large-volume programs across multiple jurisdictions.
In the United States, Innospec Inc. develops and markets diesel lubricity improvers such as OLI series products for ULSD and biofuel blends to ensure compliance with wear scar diameter requirements, positioning itself around assurance of specification compliance and compatibility with evolving blending trends. Chevron Oronite Company LLC specializes in fuel additives with lubricity improvers for diesel fuels, supporting refinery and terminal blending to meet international lubricity standards. Its refinery-facing orientation reinforces a strategy built on technical service at the point of fuel production and distribution. Baker Hughes Company delivers fuel additives via its specialty chemicals segment, including lubricity improvers for diesel fuel systems, reflecting the broader trend of large industrial groups using diversified platforms to address fuel performance needs.
Regional and emerging-market players add another dimension to the landscape. Dorf Ketal Chemicals, based in India, offers specialized diesel lubricity improvers and fuel treatment chemicals focused on ULSD applications in emerging markets. Its positioning highlights a growing opportunity set in regions where fuel quality improvement programs are expanding, infrastructure is modernizing, and cost-sensitive formulators seek reliable performance at competitive price points. TotalEnergies SE complements this dynamic from the integrated energy side, marketing diesel additives and lubricity improvers through its additives and special fuels division, including products for ultra-low sulfur diesel. Its February 2025 launch of the RUBIA OPTIMA diesel lubricity improver for ultra-low sulphur diesel engines in Europe demonstrates how integrated energy companies can use product updates to reinforce performance positioning in regulated markets.
Strategically, the leaders differentiate along several axes: multi-functional formulation capability, regulatory compliance infrastructure, technical service depth, and supply chain resilience. Some compete by offering broad additive packages that reduce the number of suppliers a customer must manage. Others emphasize application-specific validation for heavy-duty, passenger, or industrial use. A third group focuses on regional execution, tailoring products and service models to local fuel standards, logistics, and price sensitivity. The market is likely to see continued consolidation among players seeking scale and portfolio breadth, while also witnessing targeted entry or expansion by companies that serve specific geographies or application niches with lean, high-value propositions. For customers, this means more choices but also greater importance in evaluating total value rather than price per kilogram alone.
4. Forward Trends for 2026–2032
Looking ahead, three trends are likely to shape the diesel lubricity improver market over the next several years. The first is the shift from single-attribute lubricity additives to integrated performance packages. As engine equipment becomes more sensitive to deposits, corrosion, and compatibility with renewable blends, customers will increasingly favor formulations that address multiple performance parameters in a single addition step. This favors suppliers that can demonstrate cross-attribute synergy and provide validated testing for real-world operating conditions, opening opportunities for premium positioning and longer-term customer partnerships.
Lubricant Viscosity Index Improvers Market
The second trend is the continued expansion of lubricity improvement demand in regions where fuel quality standards are tightening or where biofuel blending is increasing. Regulatory baselines such as EN 590 and GB 19147 provide a durable anchor in established markets, while emerging economies pursuing fuel quality upgrades and cleaner diesel programs create incremental volume opportunities. Suppliers with strong regional technical presence, flexible formulation options, and credible compliance documentation are best placed to capture this growth. At the same time, the relationship between lubricity enhancers and higher biofuel blends remains an area of active development, as oxygenated components and varying oxidation behaviors can influence both wear performance and storage stability.
The third trend is cost discipline and supply chain adaptability becoming competitive differentiators. With feedstock exposure to fatty acid derivatives and petroleum-linked inputs, companies that can manage input volatility through diversified sourcing, formulation flexibility, and efficient blending operations will protect margins more effectively than those dependent on narrow supply paths. This dynamic may accelerate supplier consolidation in some segments while encouraging niche players to compete on agility, localized service, and rapid response to regional specification changes. A related uncertainty is the pace and shape of fuel transition strategies. If diesel demand in certain passenger segments declines faster than expected, growth may concentrate even more heavily in heavy-duty, industrial, and backup power applications, requiring suppliers to align product roadmaps with where durable diesel use persists. Regulatory interpretations, additive registration updates, and sustainability expectations for feedstocks also introduce variability, making scenario planning essential for both manufacturers and buyers.
5. Strategic Guidance for Decision-Makers
For additive manufacturers and formulators, the priority is to move beyond compliance-only positioning and build demonstrable multi-functional value. Invest in testing that connects lubricity performance with deposit control, engine protection, and compatibility with higher biofuel blends, and align product documentation with the regulatory expectations of key markets. Strengthening supply chain flexibility and feedstock diversification will also be critical to protecting margins amid input cost volatility. Building technical service capabilities that help customers optimize blending and fuel handling can create stickier relationships and reduce exposure to pure price competition.
Fuel Additives Market
For investors, the most compelling opportunities lie in companies with credible formulation differentiation, established compliance infrastructure, and exposure to durable demand in heavy-duty, industrial, and regions undergoing fuel quality upgrades. Evaluate cost structure resilience, sourcing strategy, and the ability to scale multi-functional products as indicators of long-term competitiveness. Monitor how product portfolios evolve relative to biofuel blending trends and regional specification shifts, as these will influence both volume growth and margin profiles. Companies that can balance global reach with regional execution are likely to outperform in a market where local fuel standards and logistics matter.
For procurement and fuel quality stakeholders, the focus should be on total value rather than unit price alone. Compare additive programs on HFRR compliance assurance, compatibility with existing fuel handling practices, storage stability, and the supplier’s ability to support blending optimization and documentation needs. Where possible, consolidate supply around partners that can deliver consistent performance across applications and provide reliable technical support during specification changes or feedstock transitions. Treat supplier selection as a risk-management decision that affects maintenance costs, warranty exposure, and operational reliability over time. For those seeking a more granular view of regional dynamics, application splits, and formulation-level segmentation, the full market research report provides detailed breakdowns and tailored recommendations to support planning and procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Diesel Lubricity Improver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Seam Tracking Laser Sensors: Why 7.5% CAGR Reshapes Market|2026-2032
By PW Consulting, 2026-09-18
The Strategic Evolution of the Smart Seam Tracking Laser Sensors Market
The global market for smart seam tracking laser sensors has entered a phase of structurally accelerating growth, expanding from approximately 490.2 million USD in 2020 to an estimated 685.0 million USD in 2025, with momentum carrying toward more than 1.13 billion USD by 2032. This trajectory translates to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window. The growth is neither cyclical nor narrowly tied to a single industrial cycle; rather, it reflects a foundational shift in how automated fabrication, assembly, and inspection workflows are engineered. Seam tracking has transitioned from a niche alignment aid to a core perception layer that enables closed-loop control in robotic welding, hybrid joining, brazing, and precision inspection. As tolerance stacks tighten and production volumes scale across mobility, marine, and advanced manufacturing sectors, the sensor layer has become the differentiating factor between basic automation and adaptive, high-yield processing.
Despite the clear growth path, manufacturers and system integrators are navigating three overlapping challenges that will define competitive outcomes over the next half decade. First, the industry must reconcile performance expectations with real-world variability. Workshop lighting, surface oxidation, gap deviations, and material heterogeneity consistently degrade the robustness of vision-based tracking if algorithms, optics, and illumination are not co-optimized for production environments rather than controlled lab conditions. Second, supply chain fragility has moved from a logistical nuisance to a strategic cost driver. Concentrated sourcing of high-power semiconductor components, laser optics, and specialty substrates introduces exposure to pricing shocks and lead-time elongation, forcing vendors to redesign bill-of-materials strategies and qualification pipelines. Third, integration complexity remains a persistent adoption barrier. While individual sensor specifications are increasingly impressive, the value is realized only when tracking data is fused seamlessly with robot kinematics, process controllers, and quality management systems, a requirement that demands ecosystem readiness rather than stand-alone hardware superiority. Addressing these friction points is no longer an engineering afterthought; it is the central commercial battleground.
Market Architecture and Concentration Dynamics
The revenue base is distributed across a mix of established sensor specialists and application-focused equipment players, with a meaningful share of total volume concentrated among a small group of incumbents. This concentration does not imply a static hierarchy. Instead, it reveals a market where differentiation is increasingly earned through software maturity, cross-platform compatibility, and lifecycle support rather than pure sensor resolution. The three dimensional profile segment commands the largest revenue share, reflecting the broader industry migration from simple line profiling to volumetric perception that can handle complex joint geometries and variable gaps. Two dimensional profile sensors retain strong adoption in high-speed, lower-complexity tasks where cost and cycle time dominate purchasing decisions, while point laser sensors serve targeted displacement and alignment uses. Geographically, demand is broadest across Asia Pacific, followed by Europe and North America, with Latin America and the Middle East and Africa representing smaller but strategically important footprints tied to localized capacity expansion and export-oriented fabrication. Across application domains, automotive manufacturing leads demand formation, reflecting the impact of electrification on joint designs, material mixes, and throughput requirements. Heavy machinery and infrastructure, shipbuilding, and aerospace and defense each contribute sizable demand blocks shaped by durability requirements, regulatory scrutiny, and the rising use of robotic processes in large-scale structures and precision assemblies.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Sensor Intelligence
The most consequential driver is the maturation of sensor intelligence itself. Modern systems are no longer simply delivering better point clouds; they are increasingly capable of adaptive interpretation under imperfect conditions. Advances in image processing pipelines, real-time filtering, and edge-based inference have improved seam detection reliability in environments where joint preparation varies, weld spatter is present, or surface finish is inconsistent. The practical effect is a reduction in false rejects, fewer manual interventions, and higher first-pass yield, which directly improves the economics of automated joining. In parallel, hybrid approaches that combine laser profile data with displacement and groove detection are reducing the need for multiple stand-alone sensors on the end effector, simplifying payload management and lowering integration risk. Recent product refreshes that emphasize enhanced image processing for precise seam tracking in automated welding illustrate how vendors are shifting from hardware-centric specifications toward application-tuned performance. This shift matters commercially because it expands the addressable envelope from ideal applications into broader, less forgiving production settings where the return on automation is most contested.
Policy, Standards, and Strategic Industrial Directives
Regulatory and policy environments are quietly but decisively reshaping demand patterns. In shipbuilding and advanced marine fabrication, national guidelines promoting smart shipyard development have created explicit tailwinds for robotic welding precision and integrated laser seam tracking. These directives do not merely encourage automation in principle; they support procurement strategies, modernization programs, and supplier qualification paths that make sensor-enabled joining more bankable for yard operators and tier suppliers. Equally important, quality assurance expectations in aerospace, defense, and safety-critical mobility segments are tightening, which elevates the role of inspection-grade tracking as part of a unified process rather than a separate quality gate. When seam tracking becomes part of the process control logic rather than a post-process verification step, the sensor transitions from an optional accessory to a core process enabler. For decision-makers, the strategic implication is that adoption is increasingly influenced by compliance roadmaps, export requirements, and program-level quality targets as much as by unit cost or cycle time.
Demand-Side Transformation in Mobility and Heavy Fabrication
On the demand side, the most visible change is the structural shift in joining requirements across e-mobility, vehicle architecture evolution, and large-scale fabrication. Electric drivetrains, battery enclosures, lightweight structural elements, and mixed-material assemblies introduce new gaps, thicker coatings, and more varied joint geometries than legacy body-in-white production. Robotic laser welding and hybrid joining are responding to these requirements because they can achieve consistent results while preserving productivity, but they also demand higher robustness from the tracking layer. In shipbuilding and infrastructure-adjacent heavy fabrication, similar pressures exist: longer structural runs, complex edge conditions, and a need to reduce rework in high-value assemblies. The common thread is that tolerance control and process repeatability are becoming more valuable than raw speed alone. As a result, end users are more willing to invest in sensors that demonstrably reduce rework, support adaptive path correction, and provide inspection-grade confidence. This demand evolution favors suppliers that can articulate total process value rather than sensor-only performance metrics.
Supply Chain Realities and Cost Structure Pressures
Cost structures are undergoing a simultaneous push and pull. On one side, raw material and component pressures have intensified. Restrictions and export dynamics affecting gallium and germanium, alongside broader concentration in high-power semiconductor and optics supply, have driven notable price increases in critical inputs, with ripple effects across laser-based and optics-intensive sensor designs. On the other side, integration complexity and qualification cycles can inflate total cost of ownership if the sensor is treated as an isolated component rather than part of a coordinated system. The resulting dynamic favors vendors that can stabilize performance despite component volatility, offer modular designs, and deliver predictable field performance with minimal recalibration burden. For buyers, the cost conversation is shifting from sticker price to resilience: supply assurance, multi-source readiness, software support longevity, and integration compatibility now weigh heavily in evaluation. Suppliers that overlook these factors risk margin erosion even when their core technology is competitive.
Worldwide Security Laser Scanner Market
Competitive Landscape and Differentiation in Practice
The competitive field blends specialized sensor manufacturers, welding-equipment integrators, and emerging players with regional cost advantages and application-specific engineering depth. A defining feature of the leaders is that they do not compete solely on resolution or scan speed; they compete on how well the sensing capability is packaged into the target process. Some firms anchor their positioning in high-speed, high-accuracy vision systems explicitly engineered for laser welding, hybrid welding, and brazing, where real-time joint guidance must keep pace with rapid thermal cycles and moving workpieces. Others emphasize optical seam tracking tuned for automated arc and laser welding, with particular attention to e-mobility and automotive use cases where tolerances and material variability are elevated. A further group integrates laser seam tracking sensors directly with robotic welding torches and joint guidance systems, aiming to reduce end-effector complexity and shorten deployment cycles. This diversity in go-to-market posture reflects a market that is still maturing from component competition toward solution-level competition.
Several strategic differentiators are increasingly decisive. First, cross-platform compatibility is becoming a practical necessity. As customers standardize on major robot brands and seek to deploy tracking across multiple cell designs, sensors that demonstrate reliable interoperability with common controllers and robot ecosystems reduce integration friction and expand addressable reuse within a facility. Second, the ability to support both real-time tracking and downstream inspection functions is gaining commercial weight. Systems that can guide the weld and then contribute to bead profile inspection or displacement verification offer a more complete value proposition, especially where quality records and traceability are mandatory. Third, application specialization is creating defensible niches. Vendors with focus on zero-gap detection for sheet metal, aerospace-oriented sensor lines, or specialized weld bead profiling are building domain credibility that generic specifications cannot easily replicate. This does not mean broad platforms are losing relevance; rather, the most resilient players are pairing broad compatibility with application-specific tuning and support.
Laser Displacement Sensor Market
The competitive evolution is also being shaped by a mix of consolidation logic and new-entry pressure. On one hand, established players are likely to deepen vertical integration around software, service, and integration support, because those layers increasingly determine retention and expansion within existing accounts. On the other hand, regional manufacturers and sensor-focused entrants continue to expand, particularly where localized price-performance ratios, faster engineering responsiveness, and strong relationships with domestic robot integrators create a viable path to scale. A notable early signal is the emergence of sensor lines targeting high-stakes verticals such as aerospace, which reflects both demand maturation and the willingness of large customers to qualify specialized offerings for demanding tolerances. The net direction is not simply toward fewer competitors; it is toward clearer segmentation between general-purpose tracking platforms and application-hardened solutions, with the most competitive firms capable of bridging both through modular architectures and adaptable software stacks. For customers, this means the evaluation framework should weigh ecosystem fit and support capability as heavily as raw sensing performance.
Forward-Looking Trends and the Shape of Opportunity
Over the next three to five years, the market is likely to consolidate around three interrelated trends. The first is the expansion of perception from tracking to closed-loop process control. Seam tracking will increasingly feed adaptive path correction, dynamic parameter adjustment, and inspection feedback within a single workflow, reducing dependence on offline quality sampling and shortening response time to process drift. This creates commercial opportunities for vendors that can deliver reliable sensor data in a form that controllers and quality systems can consume without heavy middleware or custom integration work. The second trend is the continued migration from hardware differentiation toward software and algorithm differentiation. As baseline optical and scanning performance becomes more comparable across competent suppliers, the edge will increasingly belong to systems that perform better under variable joint gaps, surface conditions, and production noise, and that can be updated and tuned without extensive re-qualification. The third trend is a growing emphasis on supply resilience and modular design. Given ongoing component volatility, customers will reward suppliers that can articulate risk-mitigated sourcing, maintain performance continuity across revisions, and offer flexible configuration options aligned with different payload, cycle-time, and budget constraints.
These trends translate into concrete opportunity spaces. For system integrators and equipment builders, the opportunity lies in embedding sensor capability earlier in the design of welding cells and large-scale fabrication lines, so that tracking is planned as a process layer rather than retrofitted as an add-on. For end users, the opportunity is to use tracking data not simply to improve alignment but to unlock higher automation rates in applications that were previously considered too variable for unattended operation. At the same time, uncertainty remains. Pricing pressure on critical optical and semiconductor inputs could compress margins or slow product iteration in segments where cost sensitivity is high. Adoption may also fragment if integration standards and data interfaces remain inconsistent, forcing repeated customization across robot platforms and cell architectures. Finally, the competitive mix may shift quickly where regional players gain traction through strong local support and cost positioning. These dynamics do not threaten the broader growth path, but they do reward participants who can balance technological ambition with deployment practicality.
Strategic Actions for Decision-Makers
For manufacturers and equipment integrators, the priority is to treat seam tracking as part of the core process architecture rather than a peripheral feature. Selection criteria should emphasize robust performance under real production variability, compatibility with existing robot ecosystems, and the ability to support both guidance and inspection use cases within a manageable integration footprint. Suppliers that can demonstrate repeatable outcomes across joint variation and surface conditions will increasingly capture preference over those competing only on peak specifications or isolated lab results. This is also the moment to evaluate whether in-house tracking capability, partnership with a sensor specialist, or bundled equipment offerings best fit long-term process roadmaps.
For investors and corporate strategists, the key is to differentiate between sensor hardware exposure and solution-level exposure. Revenue tied to recurring software support, integration services, and application-specific qualification is likely to be more durable than revenue dependent solely on unit volume in commoditizing segments. Watching which companies expand across multiple verticals while maintaining integration simplicity and supply resilience will provide an early signal of which positions are likely to scale. Capital and partnership decisions should account for the possibility that value capture shifts toward players capable of combining perception hardware with the software, support, and ecosystem relationships needed to keep systems operating in demanding environments.
For procurement and operations leaders, the emphasis should move toward total cost of ownership and deployment reliability. Where possible, qualification should include tests that reflect actual gap variation, surface finish, and noise conditions rather than idealized setups. Multi-source readiness, lifecycle support expectations, and compatibility with the dominant robot and controller platforms in the facility should weigh heavily in purchasing decisions. Tracking investments will deliver the strongest returns when they are aligned with broader automation and quality objectives, allowing process teams to reduce rework, increase automation coverage, and build more consistent inspection evidence from the same data stream. For organizations seeking deeper segmentation data, competitive benchmarking, and customized adoption roadmaps, the full research report provides the detailed breakdowns and scenario analysis needed to translate these trends into precise procurement, investment, and product strategy decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Seam Tracking Laser Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HYW Self-Adhesive Tape Market: Why 6.12% CAGR Reshapes Regional Dynamics
By PW Consulting, 2026-09-18
The HYW Self-Adhesive Tape Market: Strategic Trends and Commercial Opportunities Through 2032
The global HYW self-adhesive tape market has entered a phase of steady, structurally supported expansion, with total revenue projected to climb from approximately USD 315.4 million in 2025 to USD 478.02 million by 2032. This trajectory reflects a compound annual growth rate of 6.12 percent over the 2026–2032 forecast horizon, building on a consistent upward path from the 2020 baseline of USD 231.5 million. The growth is not merely cyclical but rooted in enduring shifts in packaging logistics, industrial assembly methods, and material performance expectations. Self-adhesive tapes have transitioned from auxiliary sealing commodities to engineered components that influence supply chain efficiency, product safety, and environmental compliance. As end-user industries recalibrate their material specifications and regulatory frameworks tighten around packaging waste, the tape segment is experiencing both demand acceleration and formulation pressure.
Despite the favorable macro trajectory, three structural challenges are reshaping how participants navigate the market. First, raw material cost volatility, particularly in polymer backings and adhesive resins, is compressing margins and forcing continuous price–performance recalibration. Second, the regulatory environment is shifting from voluntary sustainability commitments to enforceable recycled-content and recyclability mandates, requiring reformulation, supply chain transparency, and compliance verification that many mid-tier producers are still building capacity to absorb. Third, the market is exhibiting moderate concentration, with the top three players collectively accounting for just over 42 percent of revenue and the top five reaching approximately 58 percent, leaving substantial room for specialized, regional, and application-focused entrants but also raising the bar for scale, technical service, and compliance infrastructure. These dynamics mean that growth alone is no longer a sufficient strategic narrative; differentiation in material engineering, regulatory readiness, and value-chain integration is becoming the primary determinant of durable competitiveness.
Key Drivers Reshaping the HYW Self-Adhesive Tape Landscape
Material Innovation and Performance Differentiation
The chemistry mix continues to pivot toward adhesives that balance bonding strength, temperature tolerance, and environmental resistance while meeting downstream recyclability expectations. Acrylic-based formulations remain dominant in value terms, reflecting their broad compatibility with automated dispensing, consistent tack profiles, and suitability for high-speed carton sealing and industrial bonding. Rubber-based adhesives maintain a strong position where cost efficiency and initial tack are prioritized, particularly in medium-weight packaging and general industrial applications. Silicone adhesives, while smaller in absolute terms, are gaining traction in specialized contexts requiring extreme temperature stability, clean removal, or compatibility with sensitive substrates. The strategic implication is that tape performance is increasingly evaluated not just on holding force but on process integration, substrate compatibility, and end-of-life behavior, pushing R&D teams to optimize formulations for both manufacturing throughput and compliance footprints.
Regulatory Pressure as a Catalyst for Product Redesign
Policy frameworks are no longer peripheral considerations; they are actively reshaping formulation roadmaps and procurement specifications. Jurisdictions are moving toward explicit recycled-content minimums, recyclability requirements, and producer responsibility obligations that affect both the adhesive layer and the backing film. In India, regulatory requirements have driven early compliance-oriented product updates, with recycled-content BOPP tapes entering the market to align with national plastic waste management mandates. In Europe, packaging regulations are setting recyclability and recycled-content expectations that cascade into tape specifications used on or as part of packaging systems. The strategic signal is clear: compliance is becoming a design parameter rather than a post-production check, and manufacturers that embed regulatory readiness into their development cycles are better positioned to retain spec-in decisions and avoid reformulation scrambles.
Demand-Side Shifts in Packaging and Industrial Assembly
End-user behavior is changing on two fronts: volume and specification. E-commerce and logistics intensification continue to increase the frequency of carton sealing, reinforcing demand for reliable, high-speed compatible packaging tapes. At the same time, industrial and electronics assembly is placing greater emphasis on tapes that support clean processing, substrate safety, and consistent performance under variable environmental conditions. These use cases favor solutions that reduce line stoppages, minimize waste from misapplication, and align with broader sustainability targets in the purchasing organization. The result is a demand profile that rewards suppliers capable of pairing product performance with application engineering, testing support, and documentation that helps buyers justify material choices internally.
Airtight Tapes Market
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by regional divergence in polymer pricing and by the operational implications of sustainability mandates. Backing materials such as BOPP film exhibit meaningful price differences across major markets, influencing where production is routed and how cost-advantaged formulations are sourced. At the same time, polypropylene-linked cost indicators remain elevated, reinforcing the importance of yield optimization, scrap reduction, and adhesive efficiency. Companies are increasingly evaluating not just per-unit material cost but total cost of compliance, including certification, recycled feedstock availability, and the operational burden of managing multiple formulation grades. This broader cost lens is accelerating consolidation of SKUs around platforms that can serve multiple applications while still meeting regional regulatory thresholds.
Competitive Positioning and Market Evolution
The competitive field is anchored by a mix of global scale players and specialized manufacturers, each pursuing distinct strategic positioning. Large diversified companies leverage broad adhesive science capabilities, integrated film and coating operations, and global distribution networks to serve cross-industry demand. Their advantage lies in 일관된 성능 기준, 응용 엔지니어링 지원, 그리고 규모 기반 공급망 복원력입니다. 유럽 기반의 한 주요 업체는 재활용 PET 캐리어와 친환경 포장 테이프 라인을 강조하며 규제 대응형 제품 아키텍처를 구축하고 있으며, 이는 구매팀이 지속 가능성 목표와 성능 요구사항을 동시에 충족하도록 돕는 포지셔닝입니다. 북미와 아시아 지역의 다른 선도 기업들은 이커머스 포장, 중형·중량 박스 실링, 자동화 라인 호환성에 초점을 맞춘 핫멜트 및 아크릴 기반 솔루션을 강화하며 처리 속도와 공정 안정성을 핵심 차별점으로 삼고 있습니다.
PW Consulting Chemical & Energy Research Center
지역 및 니치 플레이어의 전략은 규모 경쟁보다 규제 적합성, 소재 혁신, 비용 효율적 재활용 함량 활용에 기울어져 있습니다. 예를 들어 인도 시장의 한 제조업체는 현지 EPR 요건에 대응하기 위해 재활용 함량 BOPP 테이프 라인을 확대하며 지역 규정 친화적 포트폴리오를 구축하고 있습니다. 이러한 움직임은 규제 민감도가 높은 시장에서 빠른 대응력과 지역 공급망 접근성이 경쟁 우위로 전환될 수 있음을 보여줍니다. 동시에 일본의 소재 및 테이프 전문 기업들은 BOPP와 특수 필름 기반의 포장·산업 용도를 포괄하며, 기판 호환성과 필름 설계 역량에서 차별화를 모색하고 있습니다.
시장 구조의 진화 방향은 수평적 통합과 수직적 전문화가 동시에 진행되는 양상입니다. 상위권 기업들은 제품 플랫폼을 확장해 여러 응용 분야를 커버하고, 지역별 규제 요건에 맞춰 변형 가능한 공통 기반을 구축하며 포트폴리오 복잡도를 관리하는 경향을 보입니다. 반면 중소형 참여자들은 특정 화학군, 특정 지역 규제 시장, 또는 특정 최종 사용 산업의 기술 요구에 집중해 대체 불가능한 포지셔닝을 확보하려는 움직임을 보입니다. 신규 진입의 문은 여전히 열려 있으나, 성공을 위해서는 단순한 가격 경쟁력이 아니라 시험 데이터, 규제 문서, 일관된 품질 관리, 그리고 구매팀의 내부 검토를 통과할 수 있는 기술 신뢰도가 함께 요구됩니다. 이 환경에서 경쟁 우위는 제품 자체의 성능뿐 아니라 구매 여정 전체를 얼마나 매끄럽게 지원하느냐에 의해 점차 결정되고 있습니다.
Forward Outlook: Trends Shaping the Next Three to Five Years
여러 동인이 겹치면서 향후 3~5년 동안 산업 방향을 규정할 몇 가지 흐름이 뚜렷해지고 있습니다. 첫째, 재활용 함량과 재활용 가능성은 선택적 마케팅 요소가 아니라 제품 설계의 기본 조건으로 자리 잡을 것입니다. 구매 조직은 사양서에 규제 적합 증거를 포함하고, 공급업체는 공통 플랫폼에서 지역 변형을 효율적으로 관리할 수 있는 구조를 갖추게 될 것입니다. 이는 준수형 등급과 고성능 등급 사이의 경계가 더 유연하게 연결되는 제품군으로 이어질 가능성이 높습니다.
Seam Sealer Tape Market
둘째, 응용 공학이 상업적 차별화의 중심축으로 부상할 것입니다. 자동화 라인 호환성, 도포 일관성, 기판 손상 최소화, 환경 조건에서의 접착 신뢰성 같은 요소가 구매 결정의 전면에 나서면서, 단순 가격 비교보다 총 공정 비용과 품질 일관성이 더 큰 비중을 차지하게 됩니다. 이 흐름은 기술 지원, 테스트 데이터, 현장 문제 해결 능력을 갖춘 공급업체에 유리하게 작용할 것입니다.
셋째, 비용 구조와 원료 조달의 지역적 분화가 심화되면서 공급망 설계가 제품 전략과 분리될 수 없게 될 것입니다. 폴리오레핀 계열 재료의 지역별 가격 차이와 재활용 원료의 가용성 변동은 생산 거점, 배합 전략, SKU 관리 방식에 직접 영향을 미칠 것입니다. 기업들은 표준화와 현지화 사이의 균형을 더 정교하게 맞추어야 하며, 그렇지 않을 경우 규제 대응과 원가 경쟁력 사이에서 동시에 압박을 받게 됩니다.
이러한 추세 아래에는 불확실성이 남아 있습니다. 규제 시행 시기와 세부 요건은 지역별로 차이가 있을 수 있고, 재활용 원료의 품질 일관성과 공급 안정성은 조성 전환을늦출 수 있으며, 경기 변동은 포장 및 산업 수요 모두에 영향을 줄 수 있습니다. 그럼에도 기본적인 방향은 명확합니다. 성능, 준수, 공정 통합이 함께 평가되는 시장에서 운영 속도와 데이터 투명성을 갖춘 참여자가 유리한 위치를 점할 가능성이 높습니다.
Strategic Implications for Decision-Makers
제조업체에게는 규제 적합성을 사후 조치가 아니라 제품 플랫폼 설계의 입력 변수로 다루는 것이 중요합니다. 공통 베이스를 중심으로 지역별 변형을 관리할 수 있는 구조를 갖추면 복잡도와 준수 리스크를 동시에 줄일 수 있으며, 응용 지원과 테스트 문서를 강화하면 사양 채택 가능성을 높일 수 있습니다. 또한 원료 가격 변동과 재활용 원료 조달 환경을 고려한 배합 및 재고 전략이 마진 방어에 직접적인 영향을 미칩니다.
투자자에게는 왜곡된 성장 수치보다 플랫폼 확장 능력, 규제 대응 속도, 지역 가격 구조를 흡수할 수 있는 운영 역량이 장기 가치 창출의 핵심이라는 점이 중요합니다. 화학군별 수요 강도, 지역 규제 일정, 원재료 조달의 지역적 차이, 그리고 경쟁사가 제품 플랫폼을 어떻게 단순화하고 있는지는 포트폴리오 판단과 진입 시점 평가에 유용한 기준입니다. 빠른 규제 대응이 가능한 지역 강자와, 글로벌 규모에서 성능 일관성을 확보한 기업 사이의 역할 분리가 심화될 가능성을 주목할 필요가 있습니다.
조달 담당자와 구매 리더에게는 총소유비용 관점으로 전환할 때 더 나은 의사결정이 가능합니다. 도포 효율성, 라인 중단 위험, 규격 변경 시 검증 부담, 그리고 문서화된 준수 증거는 가격표 이상의 가치를 만듭니다. 또한 단일 공급원에 대한 의존도를 낮추면서도 사양 일관성을 유지하려면, 동등한 성능 기준을 충족하는 대체 후보군과 검증된 시험 데이터를 사전에 확보하는 것이 유리합니다.
시장 구조와 규제 환경이 빠르게 재조정되는 상황에서는 세분화된 수요 강도, 지역별 규제 이행 일정, 원재료 가격 경로, 주요 기업의 제품 플랫폼 변화에 대한 최신 정보가 의사결정의 질을 좌우합니다. 이러한 세부 데이터는 단기 조달 전략부터 중장기 포트폴리오 재편까지 연결되므로, 지속적인 모니터링과 적용 가능한 형태의 인사이트 확보가 필수적입니다. 보다 상세한 세분화 데이터, 지역별 규제 이행 타임라인, 기업별 제품 전략과 경쟁 포지셔닝에 대한 심층 분석은 전체 연구 보고서에서 확인할 수 있습니다.
For detailed analysis of this topic, please visit the official page: HYW Self-Adhesive Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Asia Pacific's 8.2B Lead and 6.15% CAGR Are Redefining the AC Motor Controllers Market
By PW Consulting, 2026-09-18
Worldwide AC Motor Controllers Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape and Core Challenges
The global AC motor controllers market has matured into a critical enabler of industrial efficiency and electrification. Between 2020 and 2025, the sector expanded from approximately USD 13.7 billion to USD 18.5 billion, reflecting a compound annual growth rate of 6.15% through 2032, when it is projected to reach USD 28.1 billion. This trajectory is not merely incremental; it signals a structural shift where motor control infrastructure is moving from a maintenance-driven commodity to a strategic asset for energy management, process optimization, and automation.
Despite this robust expansion, the industry faces three interconnected challenges that will define competitive positioning in the coming years. First, supply chain fragmentation and component volatility are testing margin resilience. While wide-bandgap semiconductor pricing has shown periodic relief, other critical inputs such as copper-based PCB materials have experienced sharp cost escalations, forcing manufacturers to balance pricing power against volume commitments. Second, regulatory complexity is accelerating fragmentation across regional compliance frameworks. Safety and efficiency mandates are no longer optional; they dictate design architectures, certification pathways, and time-to-market. Firms that treat compliance as an afterthought face escalating rework costs and delayed commercialization. Third, the integration of advanced control algorithms with legacy infrastructure creates deployment friction. End users increasingly expect plug-and-play interoperability, yet many facilities operate mixed-vendor environments with varying communication protocols and cybersecurity baselines. Bridging this gap requires more than hardware performance; it demands ecosystem-level compatibility and lifecycle support.
These pressures are reshaping how value is captured. Companies that can standardize compliance, stabilize component sourcing, and simplify integration are gaining share, while those relying on fragmented product lines or reactive supply strategies are seeing margin compression. The market is no longer growing uniformly; growth is concentrating around application segments that deliver measurable energy savings, process reliability, and scalability.
Key Drivers Shaping Market Dynamics
Technological Innovation and Control Architecture Evolution
The most visible driver is the maturation of intelligent control architectures that embed optimization directly into drive hardware and firmware. Recent product introductions highlight a shift toward self-tuning parameters, adaptive torque control, and built-in energy management functions that reduce the need for external supervisory systems. At major industry exhibitions, manufacturers have demonstrated drives with integrated optimization features that adjust operating profiles based on load conditions, reducing energy waste without requiring extensive re-engineering of existing lines. This evolution lowers the barrier to adoption for mid-tier industrial users and expands the addressable base beyond high-performance automation.
Cybersecurity and functional safety are now first-class design requirements rather than add-on certifications. Updated drive platforms have begun incorporating hardened communication stacks and secure update pathways, responding to the reality that connected motor control systems are increasingly exposed to operational technology threats. As facilities integrate drives into broader industrial networks, vendors that provide verifiable security baselines and clear lifecycle patching policies are differentiating themselves in procurement evaluations.
Policy and Regulatory Momentum
Regulatory frameworks are acting as a powerful demand catalyst, particularly where energy efficiency mandates directly influence equipment selection. Efficiency standards that require higher performance classes for AC motors above defined power thresholds have accelerated the replacement of fixed-speed setups with variable-speed solutions. In parallel, safety regulations for adjustable speed power drive systems remain mandatory across multiple jurisdictions, shaping both product certification and system integration practices. These requirements are not uniform; they vary by region and application, which creates compliance complexity but also rewards vendors with global certification portfolios and regionalized support capabilities.
The cumulative effect is a regulatory tailwind that favors controllers capable of delivering measurable efficiency gains while meeting stringent safety and interoperability criteria. Procurement teams are increasingly aligning equipment specifications with compliance roadmaps, turning regulation from a constraint into a selection filter that narrows the field to vendors with proven adherence and documentation rigor.
Demand-Side Shifts in Industrial and Commercial End Users
On the demand side, operational resilience and total cost of ownership are driving procurement behavior. Industrial operators are prioritizing motor control solutions that reduce maintenance downtime, improve process consistency, and offer remote diagnostics. HVAC and water management sectors are similarly focused on energy consumption reduction, where variable-speed control delivers fast payback through reduced fan, pump, and compressor loads. Meanwhile, electrification trends in mobility and material handling are expanding the use of precision motor control in applications that require responsive torque and regenerative capabilities.
These demand patterns are shifting the evaluation criteria from unit price to lifecycle value. End users are more willing to invest in controllers that provide clearer visibility into operating conditions, predictive maintenance signals, and integration with existing control ecosystems. The result is a market where software-enabled features, service agreements, and deployment support increasingly influence purchasing decisions alongside hardware specifications.
Supply Chain and Cost Structure Realignment
Cost structures are being reshaped by both component dynamics and trade policy. On the input side, power semiconductor pricing has experienced periodic declines due to expanded production capacity, easing pressure on bill-of-materials costs for certain drive categories. However, this relief is uneven; other materials critical to drive construction have seen price increases tied to mining disruptions and logistics constraints. These fluctuations require proactive sourcing strategies, dual-sourcing arrangements, and design flexibility to substitute components without compromising performance or certification status.
Trade policy adds another layer of complexity. Tariff adjustments on specific import categories have altered regional cost comparisons, prompting manufacturers and distributors to reassess sourcing footprints and regional assembly strategies. Companies that maintain diversified supply chains and clear regional compliance documentation are better positioned to navigate these shifts, while those heavily dependent on single-source imports face greater exposure to cost volatility and lead-time risk.
Competitive Landscape and Leading Strategies
The competitive field is defined by a blend of multinational incumbents with broad automation portfolios and specialized players with deep application expertise. Leading firms are pursuing differentiation through a combination of platform breadth, application-specific tuning, and ecosystem integration. Rather than competing solely on hardware specifications, top vendors are expanding their value proposition to include deployment services, firmware lifecycle management, and interoperability with prevailing control architectures.
Strategic positioning varies by company focus. Large industrials leverage integrated drive-and-control platforms to serve complex automation environments, emphasizing precision, scalability, and engineering support. In contrast, specialists often concentrate on high-volume application segments such as HVAC, pumping, and wastewater, where energy efficiency and ease of commissioning drive adoption. Recent product updates have reinforced these strategies: revised drive lines with enhanced security features, expanded low-voltage options, and catalog updates that broaden compatibility with common industrial use cases. Trade show introductions have also highlighted optimization capabilities and process-industry refinements, signaling a market where performance is increasingly defined by how well a controller fits into a specific operational context.
Distribution and regional reach are becoming equally important. Appointment of new distribution partners in key growth regions reflects a deliberate push to improve local availability, technical support, and faster fulfillment. This is particularly relevant where end users expect shorter lead times and on-the-ground application engineering. As a result, competitive advantage is shifting toward vendors that can combine global product consistency with regional responsiveness.
Market consolidation and specialization are unfolding simultaneously. Larger players are strengthening their positions through portfolio alignment and cross-selling into adjacent automation and energy management offerings. At the same time, niche suppliers continue to gain traction by focusing on specific applications, cost-sensitive segments, or unique integration requirements. New entrants face high barriers in certification, reliability validation, and channel development, but opportunities remain in underserved application pockets and regions where localized support is scarce. The overall trend is toward a layered competitive structure: broad-platform leaders at the top, application-focused specialists in the middle, and regional distributors or system integrators extending reach and tailoring solutions to local requirements.
AC Servo Motor Market
Future Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, three trends are likely to shape commercial opportunity. First, intelligent optimization and edge-level analytics will become standard expectations rather than premium features. Drives that can autonomously adjust operating parameters, flag degradation signatures, and communicate efficiently with supervisory systems will be favored in procurement processes. This creates opportunities for vendors that can package control hardware with actionable diagnostics, simplified configuration tools, and clear data interfaces.
Second, regulation-driven adoption will continue to expand the addressable market, especially where efficiency mandates accelerate retrofit and replacement cycles. Regions with active ecodesign and motor efficiency policies will see sustained demand for variable-speed solutions, while safety and interoperability standards will push system designers toward platforms that simplify compliance documentation and multi-vendor integration. Commercial winners will be those that translate regulatory requirements into turnkey deployment pathways rather than leaving end users to assemble compliance pieces independently.
Third, supply chain and cost dynamics will reward agility. Component price cycles will remain uneven, and trade policy will continue to influence regional cost structures. Firms that invest in design modularity, diversified sourcing, and regional inventory positioning will be better equipped to protect margins and maintain service levels. For buyers, this environment favors suppliers with transparent lead-time communication, flexible configuration options, and clear roadmaps for component lifecycle management.
PW Consulting
Potential risks include the possibility that component cost relief could be temporary, that regulatory divergence could increase certification burden for global players, and that rapid feature expansion could outpace end-user readiness for integration and training. Companies that assume uniform adoption or stable input costs may face margin surprises. Conversely, organizations that prepare for variability and invest in deployment simplicity will be better positioned to convert market growth into sustainable commercial gains.
Strategic Recommendations for Decision-Makers
For manufacturers and product leaders, the priority is to align hardware roadmaps with the shifting basis of competition. This means investing in control features that reduce commissioning complexity, strengthening cybersecurity and safety documentation, and building modular designs that can accommodate component substitutions without re-certification delays. Differentiators will increasingly come from how quickly a solution can be deployed, how clearly it communicates operating status, and how well it fits into existing automation ecosystems.
For investors, the market offers opportunities in companies that demonstrate platform cohesion, regional channel strength, and disciplined cost management. Valuation and growth potential will depend less on headline volume and more on the ability to protect margins amid input price fluctuation, expand in regulation-driven segments, and capture share through application-focused solutions. Monitoring product launch cadence, distributor expansion, and compliance readiness provides early signals of competitive momentum.
For procurement and operations leaders, the focus should shift from unit price to total lifecycle value. Evaluation criteria ought to include energy performance under real load profiles, integration effort with current control infrastructure, support availability in the region, and the vendor’s ability to sustain firmware and security updates over the asset life. Supplier diversity and clear service-level expectations can reduce exposure to supply disruptions and configuration delays.
Timely access to detailed segmentation data, regional cost structures, and application-level demand patterns can sharpen these decisions and reduce execution risk. For organizations seeking a deeper view of the market, including component-level cost dynamics, regional policy timelines, and competitive positioning across application segments, a comprehensive market report can provide the granular context needed to align strategy with the next phase of growth.
Electric Vehicle Motor Controller Market
For detailed analysis of this topic, please visit the official page: Worldwide AC Motor Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mobile App Development Platform Market: Why 22.5% CAGR Redefines Growth by 2032
By PW Consulting, 2026-09-18
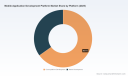
Global Mobile Application Development Platform Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for mobile application development platforms has entered a period of rapid expansion. From a valuation of approximately $10.2 billion in 2020, the sector grew to around $28.5 billion by 2025, reflecting a compound annual growth rate of 22.5 percent over the historical period. Projections indicate that the market will continue its upward trajectory, reaching roughly $117.9 billion by 2032. This acceleration is not merely a byproduct of broader digital adoption; it reflects a fundamental shift in how organizations conceive, build, and deploy mobile experiences. The pace of growth suggests that development platforms are evolving from tactical tools into strategic infrastructure components that determine how quickly enterprises can respond to changing customer expectations and operational demands.
Geographically, the market demonstrates a broad but uneven distribution. North America continues to represent the largest single regional bloc, while Asia Pacific and Europe each command substantial shares of total revenue. Latin America and the Middle East and Africa, though smaller in absolute terms, are growing faster than mature markets as organizations in those regions modernize legacy systems and expand digital service offerings. Deployment models are similarly tilted toward cloud-based solutions, which now account for the majority of platform revenue, though on-premise deployments retain a meaningful presence among organizations with strict security, compliance, or latency requirements. In terms of development approach, cross-platform solutions lead in overall market share, reflecting the broad appeal of unified codebases and faster time-to-market, while native development maintains a solid position in sectors where performance, platform-specific features, and deep ecosystem integration remain decisive.
The market is moderately concentrated. The three largest players collectively hold roughly 41.8 percent of total revenue, and the top five account for approximately 56.4 percent. This concentration indicates that leading platforms have achieved scale advantages in distribution, ecosystem depth, and enterprise trust. Yet the presence of a long tail of specialized and emerging vendors suggests that differentiation is increasingly driven by vertical expertise, workflow-specific capabilities, and integration quality rather than by generic low-code features alone. For decision-makers, this means that platform selection is less about picking the largest name and more about aligning platform strengths with the organization's operating model, compliance posture, and speed-to-value requirements.
IoT Platforms Market
Several structural challenges and inflection points shape the current environment. First, platform Evaluation fatigue is rising as the number of viable options expands and feature overlap increases. Buyers face growing difficulty in assessing which platforms will genuinely accelerate delivery versus those that simply promise flexibility but create hidden integration and maintenance burdens. Second, the cost and reliability of underlying infrastructure are becoming more material. As AI-enabled development assistants, continuous integration pipelines, and cloud-hosted testing environments become standard, demand for compute and storage is intensifying, and organizations must factor rising infrastructure costs into total cost of ownership assessments. Third, regulatory complexity is accelerating. Data sovereignty requirements, consumer privacy laws, and the impending full implementation of the EU AI Act are redefining what constitutes a compliant mobile application, especially for platforms that embed AI-assisted generation, personalization, or automated decisioning. Together, these forces are turning platform procurement into a multi-dimensional decision that balances speed, governance, and long-term operational risk.
Key Drivers of Market Change
The expansion of mobile application development platforms is being propelled by a convergence of technological, regulatory, demand-side, and cost-structure forces. Each of these drivers is reshaping the value proposition of platforms and redefining what buyers expect from their development tooling.
Technological innovation remains the most visible driver. AI-assisted development, model-driven design, and low-code/no-code interfaces are compressing delivery timelines for both enterprise and mid-market teams. Platforms are increasingly embedding generative capabilities that help developers scaffold interfaces, generate business logic, and automate repetitive tasks, while still providing governance hooks for controlled deployment. A notable example is Appian Corporation's version 25.1 release in February 2025, which introduced an AI-powered data fabric that significantly improved document processing speed for enterprise applications. This kind of capability illustrates how platforms are moving beyond simple UI builders to become orchestration layers that handle complex data workflows, document intake, and process acceleration. For organizations, the implication is clear: platforms that combine rapid development with AI-enhanced productivity can shorten project cycles and reduce the reliance on scarce specialized engineering resources.
Regulatory and policy shifts are also reshaping platform design and procurement. As of January 2026, twenty U.S. states had comprehensive consumer privacy laws in effect, requiring mobile applications to address data collection, consent, and processing practices in a consistent and auditable manner. Meanwhile, data sovereignty and localization rules continue to tighten in the EU under GDPR, across parts of Asia-Pacific, and in the Middle East, mandating where user data must be stored and processed. These requirements are pushing platforms to offer stronger controls around data residency, consent management, and audit trails. They are also encouraging enterprises to favor platforms that provide transparent governance and the ability to configure regional data handling without sacrificing speed. For vendors, compliance is no longer a secondary feature; it is a competitive differentiator that can determine win rates in regulated industries and multinational deployments.
PW Consulting
On the demand side, enterprise behavior is shifting toward faster, more continuous delivery of mobile experiences. Companies are increasingly treating mobile applications as living touchpoints rather than static product releases, requiring platforms that support iterative updates, offline-first usage patterns, and tight integration with back-end systems such as CRM, ERP, and data clouds. Salesforce's completion of its Informatica acquisition in May 2025 highlights this trend: by strengthening data and AI capabilities across its Lightning Platform, the company signaled a broader industry move toward unifying application development with deeper data integration and AI-driven insights. For buyers, this convergence means that platform decisions increasingly affect not just development velocity but also the ability to derive actionable insights from the data that mobile applications generate.
Cost and supply-side dynamics are adding both pressure and opportunity. The infrastructure underpinning cloud-based development and deployment is experiencing significant demand growth. U.S. data centers' total electricity demand is projected to nearly double from roughly 80 GW in 2025 to about 150 GW in 2028, driven by AI and cloud workloads that support mobile application development and deployment. This infrastructure strain is likely to translate into higher compute and storage costs over time, particularly for platforms that rely heavily on AI-assisted services and continuous cloud-based testing. At the same time, the shift toward cloud-based deployment is helping many organizations reduce on-premise overhead and gain elasticity. The net effect is that cost optimization is becoming a more sophisticated exercise: enterprises must weigh the savings from cloud elasticity against the risk of rising infrastructure pricing and the need for resilient, well-governed architecture.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a handful of scaled platform providers, a strong presence of ecosystem-led players, and a persistent set of native tooling champions. Each cluster pursues a distinct strategic logic, and understanding these differences is essential for assessing where value is being created and how the landscape may evolve.
Microsoft Corporation has anchored its offering around Power Apps, a low-code mobile application development platform integrated with Microsoft 365, Azure, and Dataverse. Its strategy emphasizes rapid enterprise mobile and web app creation with strong governance and AI capabilities, positioning the platform as a natural fit for organizations already invested in the Microsoft ecosystem. OutSystems, Inc. takes a different approach, offering a full-stack low-code platform specialized in complex, mission-critical mobile and web applications. Its differentiation rests on AI-assisted development, one-click deployment, and enterprise-grade security and scalability, making it attractive to organizations that need to build sophisticated applications without sacrificing control or performance. Mendix, now part of Siemens, focuses on collaborative, model-driven development with strong support for offline-first mobile apps and industrial and enterprise use cases. Its positioning reflects an emphasis on teamwork, model-based design, and scenarios where mobile apps must operate reliably in environments with intermittent connectivity or in close integration with industrial systems.
Appian Corporation supplies a low-code automation platform that combines mobile application development with process management, case management, and AI-powered decision-making for complex enterprise workflows. Its strategic emphasis is on workflow orchestration and decision support, appealing to organizations that view mobile applications as part of broader operational processes rather than isolated digital products. Salesforce, Inc. offers the Lightning Platform and related tools for building custom mobile applications deeply integrated with CRM, data cloud, and AI capabilities. Its strength lies in extending the CRM ecosystem into custom mobile experiences, particularly for enterprise customers that want development to stay closely aligned with customer data and sales/service workflows. Google LLC provides AppSheet as a no-code/low-code platform for building mobile apps directly from data sources such as Google Sheets or databases, with strong integration into Google Workspace and cloud services. This approach targets rapid, data-driven app creation for teams that want to move quickly without heavy engineering investment.
Apple Inc. remains the primary native development anchor through Xcode and associated SDKs for iOS, iPadOS, and related ecosystems. While not a low-code player in the traditional sense, Apple's tooling defines the standard for platform-specific performance, user experience fidelity, and access to device capabilities, and it continues to influence how cross-platform and low-code tools must evolve to meet native expectations. IBM Corporation provides IBM Mobile Foundation as an enterprise mobile application development platform supporting secure mobile app management, backend integration, and hybrid development, which appeals to organizations that need a balance of mobile delivery and enterprise security. Oracle Corporation delivers APEX and related cloud tools as low-code platforms for building mobile-ready enterprise applications integrated with Oracle databases and cloud infrastructure, targeting environments where database-centric development and Oracle ecosystem alignment are strategic priorities. SAP SE offers SAP Mobile Services and low-code capabilities within its Business Technology Platform for developing mobile applications integrated with SAP ERP and enterprise systems, positioning mobile development as part of a broader enterprise transformation strategy.
Several strategic patterns emerge from this landscape. First, ecosystem integration is a powerful differentiator. Platforms that align closely with widely adopted productivity, CRM, ERP, or cloud ecosystems benefit from shorter adoption cycles, familiar governance models, and clearer value narratives for business buyers. Second, AI-assisted development is becoming a central battleground. As platforms embed AI for scaffolding, documentation, testing, and process automation, the winners are likely to be those that balance speed with governance, ensuring that AI-generated outputs remain auditable and controllable. Third, the market is showing signs of both consolidation and specialization. Large players are expanding through acquisitions and capability broadening, as seen with Salesforce's data and AI-focused moves, while specialized vendors compete on vertical depth, workflow complexity, and industrial or regulated-use scenarios. New entrants and niche providers continue to appear, often targeting underserved segments or specific development pain points. The net effect is a market in which scale confers advantages, but differentiation increasingly depends on the ability to solve specific workflow, compliance, and integration problems rather than on generic low-code promises.
Future Trends and Strategic Implications
Looking ahead to the next three to five years, several trends are likely to shape the market's trajectory and create distinct commercial opportunities. These trends are grounded in current data patterns and the regulatory, technological, and cost dynamics already in motion.
One major trend is the shift from generic low-code platforms toward workflow- and industry-aware development environments. As enterprises demand more than simple form builders and UI scaffolds, platforms that embed domain-specific templates, process orchestration, offline-first design, and AI-assisted decisioning will gain preference in complex environments such as healthcare, manufacturing, financial services, and field operations. This creates an opportunity for vendors that can combine rapid development with deep workflow intelligence, and for buyers who can reduce long-term maintenance burdens by choosing platforms aligned with their operational realities rather than generic development needs.
A second trend is the growing importance of governance, compliance, and data handling as core platform selection criteria. With the EU AI Act reaching full implementation in August 2026 and imposing requirements on high-risk AI systems used in mobile application development platforms, and with consumer privacy and data sovereignty rules continuing to tighten, platforms will need to offer transparent controls, auditable AI usage, and configurable data residency. For enterprises, this means that platform evaluations should increasingly include compliance stress-testing, especially for applications handling sensitive data or supporting automated decisions. Vendors that can demonstrate robust governance without sacrificing speed will be well positioned to win in regulated and multinational contexts.
Messaging Platform Market
A third trend is the rising influence of infrastructure economics on platform strategy. As AI workloads and cloud-based development pipelines intensify demand on data center capacity, costs associated with compute, storage, and AI services are likely to become more prominent in total cost of ownership calculations. This may encourage platforms to optimize resource usage, offer more efficient AI assistance modes, or provide hybrid deployment options for cost-sensitive scenarios. For buyers, it suggests that platform comparisons should extend beyond license or subscription pricing to include the likely trajectory of infrastructure and AI service costs over the planning horizon.
These trends carry both opportunity and uncertainty. The outlook is favorable for platforms that can deliver speed, governance, and ecosystem integration in a coherent package, and for enterprises that use development platforms to accelerate digital initiatives while maintaining control over compliance and cost. However, uncertainty remains around the pace of AI regulation, the trajectory of infrastructure pricing, and the degree to which cross-platform tools can continue to narrow the gap with native experiences in performance-critical scenarios. Organizations that monitor these variables closely will be better prepared to adapt their platform strategies as conditions evolve.
Recommendations for Decision-Makers
For platform vendors and product manufacturers, the priority is to reinforce differentiation through depth rather than breadth alone. Investing in workflow-specific capabilities, strong governance and compliance controls, and seamless integration with widely used enterprise systems can create defensibility even in a crowded market. Vendors should also consider how AI-assisted features are packaged and governed, since buyers are increasingly evaluating not just how fast a platform can build an app, but how safely and auditably it can do so.
For investors, the strategic value lies in distinguishing between platforms with genuine enterprise traction and those riding generic low-code narratives. Attention should be paid to governance capabilities, ecosystem integration, vertical specialization, and the ability to manage infrastructure cost pressures. Companies that can demonstrate measurable reductions in development cycle time while maintaining compliance and operational reliability are likely to command stronger positioning as the market matures.
For procurement and technology leadership teams, platform decisions should be approached as multi-year strategic choices rather than short-term productivity purchases. Evaluations should weigh development speed, integration complexity, data handling and compliance posture, offline and field-use requirements, and the likely evolution of AI-related infrastructure costs. Given the pace of change in regulation and platform capabilities, ongoing market intelligence is essential for keeping procurement criteria aligned with shifting risk and value drivers.
For readers seeking a more detailed breakdown of segmentation dynamics, regional nuances, competitive benchmarking, and customized strategic recommendations, the full PW Consulting research report provides a deeper evidence base and structured scenarios to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Application Development Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HUD Film Market: Why 15.25% CAGR and Asia-Pacific Surge Reshape 2026 Strategy
By PW Consulting, 2026-09-18
The HUD Film Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The head-up display (HUD) film market has entered a period of aggressive expansion, driven by the convergence of automotive digitalization and advanced optical materials. Valued at approximately $1.45 billion in 2025, the market has grown consistently from around $645 million in 2020. Projections indicate the sector will reach roughly $3.92 billion by 2032, representing a compound annual growth rate of 15.25 percent over the forecast period. This trajectory reflects a structural shift rather than a cyclical upturn. Vehicle manufacturers are increasingly treating HUD systems not as premium add-ons but as core components of the digital driver interface, particularly in adaptive driving display and augmented reality implementations. The growth is broad-based across vehicle segments, with passenger cars accounting for the majority of volume and commercial vehicles representing a smaller but steadily expanding application area.
Despite the strong upward momentum, the market faces several structural inflection points that will define competitive outcomes over the next several years. The first challenge centers on optical performance versus manufacturing complexity. HUD films must simultaneously manage light projection, eliminate ghosting and reflections, and maintain structural integrity under automotive safety and environmental standards. As HUD systems evolve from combiner reflections to windshield-embedded and large-field-of-view augmented reality configurations, the tolerance for optical distortion and thermal deviation narrows dramatically. Material producers are therefore pushed to deliver films with tighter birefringence control, higher thermal stability, and more precise wedge geometries, all while preserving processing ease for glass laminators.
A second challenge lies in navigating the tension between standardization and customization. The industry has seen a dominant concentration among a small group of suppliers, which reflects the specialized know-how required for HUD-grade interlayers and cover lens films. At the same time, automakers and tier-one suppliers are demanding region-specific adaptations, varying field-of-view requirements, and acoustic or thermal enhancements tailored to specific vehicle architectures. Managing this balance without fragmenting production economics is a persistent operational challenge for both material vendors and integration partners.
A third inflection point involves the pace of technology transitions. Holographic and in-plane transparent display concepts are moving from proof-of-concept stages toward potential commercialization, and large-field-of-view augmented reality HUDs are gaining traction in premium segments. These shifts create a moving target for film suppliers, who must anticipate which optical architectures will scale and which will remain niche. The risk of investing in film formulations or coating processes for architectures that do not achieve volume production is real, especially when automotive development cycles extend across multiple years. The market's trajectory will therefore be shaped not only by demand growth but by how efficiently participants align material innovation with architectural consolidation.
Key Drivers of Market Change
Several interconnected forces are accelerating the HUD film market and reshaping its value chain. Understanding these drivers is essential for mapping where growth will concentrate and which capabilities will command premium positioning.
Technology Innovation and Optical Performance Breakthroughs
Technological advancement remains the primary engine of market expansion. The core function of HUD films has evolved from passive light transmission to active optical management. Wedge-shaped interlayer films are now engineered to minimize ghosting across standard, augmented reality, and dual-plane HUD configurations, enabling cleaner projection without compromising the safety and bonding properties required in laminated windshields. In parallel, cover lens films are gaining sophistication through birefringence control, chatter mark mitigation, and UV resistance, allowing brighter and more stable imagery in high-temperature and high-humidity environments. These material improvements directly support the migration toward larger fields of view and more immersive digital overlays, which consumers and manufacturers increasingly expect from modern cockpit designs.
Light Control Film Market
A notable development in this space is the progress around holographic in-plane transparent display technology. Recent collaborations have focused on laminated hologram solutions that can host multiple transparent HUDs on a single windshield, using photopolymer films paired with specialized interlayer structures and replication processes. Proof-of-concept demonstrations have highlighted the possibility of separate display zones within one windshield, which would allow different information layers to be presented without splitting the driver's attention. While commercialization timing remains contingent on cost, yield, and automaker adoption, the underlying technology illustrates how film and interlayer materials are becoming integral to system architecture rather than mere components.
Policy and Regulatory Environment
Regulatory frameworks and automotive safety standards are both enabling and constraining market dynamics. HUD windshield interlayers must satisfy established automotive glass and safety requirements while delivering optical clarity and impact performance. Compliance with recognized safety specifications ensures that HUD-enabled windshields can be integrated into vehicle type approvals without compromising occupant protection. At the same time, regulatory expectations around driver distraction, visibility, and electronic display placement are influencing how and where HUDs are deployed. As augmented reality and large-field-of-view systems become more prominent, regulators and industry bodies are likely to scrutinize information density, projection alignment, and cognitive load. These considerations do not stifle innovation, but they raise the bar for materials that must perform reliably across a wider set of operating conditions and usage scenarios.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are being reshaped by the premiumization of digital cockpits and the electrification of vehicle fleets. Consumers are increasingly accustomed to connected, software-defined interfaces, and HUDs fit naturally into that expectation by projecting navigation, safety alerts, and vehicle status information into the driver's line of sight. For automakers, HUDs offer a way to differentiate cockpit experiences while reducing reliance on traditional instrument clusters. The push is especially pronounced in electric vehicles, where packaging flexibility and the emphasis on advanced digital features create additional room for HUD integration.
Commercial vehicle applications, while smaller in volume, are also gaining relevance. Fleet operators and commercial OEMs are exploring HUDs for safety enhancement, navigation support, and driver assistance integration, particularly where visibility and workload management are critical. This broadening demand base helps diversify the market beyond passenger car premium segments and provides a pathway for incremental volume growth in segments that were previously conservative in adopting optical display technologies.
Supply Chain and Cost Structure Dynamics
The cost and supply side of the market is evolving as volume scales and material specifications become more demanding. Established suppliers have been expanding production footprints and refining pricing structures to capture growing orders, particularly in regions with strong automotive manufacturing activity. Recent contract updates have signaled more structured volume-based pricing in response to rising demand, which reflects both increased confidence in order pipelines and the need to remain competitive in price-sensitive segments. At the same time, the shift toward more advanced film grades and cover lens solutions introduces cost pressure, since tighter optical tolerances, specialized coatings, and higher durability requirements can raise material and processing expenses.
Supply chain resilience is also becoming a strategic consideration. As HUD film demand expands across multiple regions, suppliers and glass integrators must coordinate capacity, logistics, and quality consistency across dispersed manufacturing sites. The concentration of specialized expertise among a limited number of players makes it important for buying organizations to secure long-term alignment with partners who can scale while maintaining optical and safety performance. This dynamic reinforces the value of partnerships that combine material know-how with regional production capability and responsive technical support.
Competitive Landscape and Leading Strategies
The competitive environment in the HUD film market is defined by a small group of highly specialized material companies that have built long-standing relationships with automotive glass manufacturers and system integrators. Market concentration is high, reflecting the technical barriers to producing HUD-grade interlayers and cover lens films that meet optical, thermal, and safety requirements at scale. Within this landscape, leading participants are differentiating not just on material performance but on ecosystem positioning, geographic reach, and integration with next-generation display architectures.
Strategic Positioning and Differentiation
Several core strategies are visible among the leading suppliers:
-
Wedge interlayer specialization for ghost reduction. One Japanese chemical company has built a recognizable position around wedge-shaped PVB interlayer films designed to eliminate ghosting across standard, augmented reality, and dual-plane HUD systems. Its strategy combines global production presence with broad application coverage, enabling supply across Europe, North America, China, and Japan.
-
Expanded HUD and acoustic interlayer portfolios. A US-based materials company offers wedge PVB interlayers with variant series targeting acoustic performance and large field-of-view augmented reality applications. It has also pursued partnerships that link its interlayer technology with holographic display concepts, positioning itself at the intersection of optical interlayer performance and advanced display integration.
-
Long-established interlayer supply with safety and process focus. A Japanese specialty materials company emphasizes wedge monolayer and acoustic PVB solutions that prevent ghosting while preserving safety, acoustic quality, and processing ease. Its multi-decade track record with automotive glass makers provides a credibility advantage in an industry where qualification cycles are long and performance consistency matters.
-
Cover lens films for display optics and durability. A German polymer company has focused on polycarbonate film grades for HUD cover lenses, emphasizing birefringence control, UV resistance, and durability under demanding environmental conditions. Its strategy includes mass production partnerships with automakers in China, particularly for electric vehicle applications, highlighting a regional acceleration of advanced optical film adoption.
-
Optical and thermal management films for projection systems. A US conglomerate supplies cold mirror and visible-light reflective films used in HUD projection units and assemblies, addressing brightness and thermal management. This capability extends the company's role beyond windshield interlayers into the optics and thermal control layer of HUD hardware.
Market Evolution and Competitive Dynamics
The market structure is evolving along several axes. One is the deepening integration between material suppliers and display technology partners. Recent partnership activity around holographic in-plane transparent display concepts illustrates how interlayer and photopolymer film capabilities are being combined to unlock multi-HUD windshield architectures. This suggests a trajectory in which film suppliers participate earlier in system design, co-developing solutions that span optical film, interlayer performance, and replication or display integration.
A second dynamic is regional competition and capacity deployment. Strong demand growth in Asia-Pacific, especially within China's automotive manufacturing ecosystem, is prompting suppliers to adjust pricing, expand volumes, and prioritize local order fulfillment. Recent contract and production updates underscore the strategic importance of securing share in fast-growing regional markets while maintaining global supply credibility. As electric vehicle adoption and cockpit digitalization continue to rise in these markets, regional scale is likely to become an increasingly important competitive advantage.
PW Consulting Chemical & Energy Research Center
A third dynamic is the tension between consolidation and entry. High market concentration reflects the specialized nature of HUD film technology, but it also creates incentives for partnership, licensing, and targeted entry in adjacent optical film segments. While full-scale disruption is unlikely in the near term given qualification and performance requirements, incremental new entries may emerge through niche film technologies, regional production partnerships, or specialized optical coatings that address particular HUD architectures. The likely outcome is not a fragmented free-for-all but a layered competitive field in which established leaders defend core interlayer and cover lens positions while collaborating on advanced display concepts.
Future Outlook and Strategic Implications
Looking ahead to the 2026 through 2032 window, three trends are likely to shape commercial outcomes and investment decisions.
Automotive Head-up Display (HUD) Market
The first trend is the continued shift from basic HUD implementations toward large-field-of-view and augmented reality configurations in premium and increasingly mainstream segments. As optical requirements become more demanding, films that deliver cleaner projection, improved thermal stability, and stronger durability will capture disproportionate value. Manufacturers that can supply these advanced grades at scale, while maintaining consistent quality across regions, are positioned to benefit from the premiumization of digital cockpits.
The second trend is the gradual maturation of multi-HUD and holographic display concepts. Whether through holographic in-plane transparent displays or other laminated optical approaches, the possibility of hosting multiple transparent display zones on a single windshield creates a strategic opening for suppliers that can combine interlayer performance, photopolymer film capability, and replication know-how. The transition from proof-of-concept to volume production will depend on cost, manufacturability, and automaker commitment, but the direction of travel points toward richer optical integration and new material requirements.
The third trend is regional realignment of demand and production. Asia-Pacific is expected to remain the largest revenue region, reflecting both vehicle production scale and rapid adoption of advanced cockpit features, especially in electric vehicles. Europe and North America will continue as significant markets, but competitive intensity may increase as suppliers expand capacity and pricing structures adapt to volume growth. For companies operating in this space, regional demand patterns will influence not only revenue potential but also the pace of qualification, production localization, and partnership strategies.
These trends carry both opportunity and uncertainty. The upside lies in capturing growth from digital cockpit expansion, electric vehicle adoption, and advanced optical architectures. The risk lies in overcommitting to film configurations or display concepts that do not achieve scale, or in underestimating the cost and yield challenges associated with higher-performance HUD films and multi-HUD systems. Market participants will need to balance innovation investment with disciplined product roadmapping and close alignment to automotive OEM development timelines.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align material and optical strategies with the HUD architectures most likely to scale. Investing in wedge interlayer precision, cover lens durability, and thermal management capabilities will be increasingly important as field-of-view and augmented reality applications expand. Equally important is securing supply commitments and technical collaboration with glass integrators and display partners who can translate film performance into reliable system outcomes.
For investors, the market offers exposure to a high-growth materials segment tied to digital cockpit adoption, but selection matters. The strongest competitive positions are likely to belong to suppliers with proven qualification credibility, diversified regional production, and participation in next-generation optical integration. Monitoring partnership activity around multi-HUD and holographic concepts can provide early signals of where value may migrate beyond conventional interlayer and cover lens products.
For procurement and sourcing leaders, the focus should be on building resilient relationships with suppliers capable of consistent performance at scale. Given the concentration of specialized expertise, long-term alignment, clear quality expectations, and regional capacity planning are critical. Evaluating suppliers on the basis of optical performance, safety compliance, process ease, and ability to support evolving HUD specifications will help reduce qualification risk and support smoother scale-up.
For organizations seeking to translate these trends into detailed segment data, regional volume estimates, pricing dynamics, and tailored sourcing or investment scenarios, a full market research report can provide the deeper granularity needed for planning. Accessing that level of detail enables more precise benchmarking, scenario modeling, and prioritization of the opportunities that best fit a company's capabilities and risk appetite.
For detailed analysis of this topic, please visit the official page: Head-Up Display (HUD) Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bovine Leather Goods Market: 4.25% CAGR Trajectory and Regional Power Shifts Exposed
By PW Consulting, 2026-09-18
Bovine Leather Goods Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The bovine leather goods market has demonstrated resilient growth over the past half-decade, expanding from approximately $234.66 billion in 2020 to $285.5 billion in 2025. This trajectory reflects a compound annual growth rate of 4.25% through the forecast period extending to 2032, with projected revenues reaching $382.08 billion by the end of the outlook window. The market's expansion is not merely a function of population growth or inflation; it represents a structural shift in how bovine leather is positioned across premium, mid-tier, and specialized industrial applications. However, the growth path is neither linear nor without friction. Industry participants navigating this landscape must contend with a set of interconnected challenges that will define competitive positioning over the next several years.
Leather Market
One of the most pressing inflection points lies in the tension between raw material cost volatility and margin preservation. Hides prices have fluctuated in a narrow but persistent band, hovering around 57 to 59 US cents per pound in early 2026, while wholesale raw hides and skins in the United States have traded within a range of approximately $1.38 to $2.76 per kilogram. These fluctuations, though seemingly modest in percentage terms, compound across complex supply chains where tanning, finishing, and craftsmanship add significant value. Manufacturers operating with thin margins or rigid pricing contracts face residual exposure that can erode profitability even when end-market demand remains robust. The ability to hedge, negotiate long-term supply agreements, or vertically integrate upstream has become a differentiating capability rather than a optional efficiency play.
A second challenge centers on regulatory and sustainability expectations that are reshaping procurement criteria across both consumer and industrial buyer segments. The United States and European Union maintain strict environmental and animal welfare standards for bovine leather production and imports, and compliance is increasingly treated as a baseline requirement rather than a discretionary credential. Tariff structures on imported raw leather materials further complicate cost planning for manufacturers reliant on cross-border sourcing, introducing variability that can disrupt otherwise stable production economics. Companies that treat compliance as a reactive exercise risk facing supply disruptions, reputational friction, or lost contracts with buyers who now embed sustainability and traceability requirements directly into vendor selection frameworks.
A third structural tension involves the market's moderate concentration and the resulting fragmentation of competitive dynamics. With a combined share of roughly 18.5% held by the top three firms and approximately 24.4% by the top five, the industry remains broadly distributed across established luxury houses, specialized tanneries, and regional manufacturers. This dispersion fosters innovation and niche specialization but also means that no single entity exerts decisive pricing or supply control. The result is a market where scale advantages are real but not absolute, and where differentiation through craftsmanship, traceability, or application-specific engineering often matters more than pure volume. For decision-makers, this environment rewards clarity of positioning and penalizes undifferentiated competition.
Key Drivers of Market Change
Several interlocking forces are propelling the bovine leather goods market forward, each reinforcing the others in ways that create both opportunity and strategic urgency. Understanding these drivers is essential for aligning production capacity, sourcing strategy, and product development with where demand and regulatory momentum are actually heading.
Technological Innovation and Processing Breakthroughs
Advancements in tanning chemistry, finishing technologies, and grading consistency are reshaping what bovine leather can deliver across applications. Traditional vegetable and chrome tanning methods continue to anchor premium segments, but newer processes are enabling manufacturers to achieve more uniform surface quality, improved durability, and reduced environmental footprints without sacrificing the tactile and aesthetic qualities that buyers expect. These improvements matter because they expand the usable yield from each hide, lower rejection rates, and allow producers to serve demanding applications such as automotive interiors and high-wear footwear with greater confidence. The practical implication is straightforward: firms that invest in process control and finishing innovation can convert raw material volatility into a more predictable cost-per-output equation, while also meeting stricter performance specifications from commercial buyers.
Policy, Regulation, and Standards Evolution
Regulatory frameworks are not merely constraints; they are increasingly shaping the structure of competition. Environmental and animal welfare standards in major markets create a de facto barrier for producers who lack traceability systems, certified sourcing practices, or documented compliance records. At the same time, industry bodies and exhibition platforms are actively promoting sustainable bovine leather goods, signaling that sustainability is becoming a commercial asset rather than a compliance cost. Participation in major industry gatherings and exhibitions has become a channel for showcasing compliant, traceable, and performance-optimized leather goods to buyers who are actively filtering suppliers through sustainability criteria. For manufacturers and brands, the strategic question is no longer whether to engage with these standards but how to use them as a basis for differentiation in buyer negotiations and market positioning.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand patterns are evolving on both the consumer and commercial sides. In consumer markets, there is sustained appreciation for bovine leather goods that combine durability with craftsmanship, particularly in footwear, apparel accessories, and luxury-adjacent categories where material provenance and finish quality influence purchase decisions. In enterprise and industrial applications, buyers are prioritizing consistency, traceability, and lifecycle performance, especially in automotive interiors and furniture upholstery where material specifications are tied to brand promises and warranty exposure. This dual dynamic means that bovine leather is no longer competing solely on tradition or aesthetics; it is increasingly evaluated on measurable performance, supply reliability, and alignment with sustainability expectations. Brands and manufacturers that can articulate these value propositions with evidence are better positioned to defend pricing and secure long-term contracts.
Supply Chain and Cost Structure Dynamics
Supply chain reconfiguration is another significant driver. Tariff impacts on imported raw leather materials have introduced cost variability for manufacturers dependent on cross-border sourcing, prompting some firms to reassess supplier geography, inventory buffers, and contract structures. At the same time, raw material pricing remains sensitive to broader agricultural and livestock market conditions, meaning that even well-structured procurement strategies must accommodate periodic fluctuations. Companies are responding by diversifying supplier bases, strengthening relationships with certified tanneries, and in some cases exploring closer coordination with hide suppliers to improve visibility and reduce lead-time uncertainty. The firms that treat supply chain design as a strategic lever rather than a transactional function are gaining an edge in cost stability and delivery reliability, both of which are increasingly weighted in buyer selection.
Competitive Landscape and Leading Strategies
The competitive environment in the bovine leather goods market is defined by a mix of heritage craftsmanship, brand equity, and specialized manufacturing capability. The presence of large luxury groups alongside focused tanneries and regional manufacturers creates a landscape where multiple pathways to differentiation coexist. Understanding how leading players position themselves reveals where value is being captured and how the market is likely to evolve.
Strategic Positioning Among Leading Players
At the premium end, luxury houses such as Hermès International S.A. and Kering S.A. emphasize full-grain bovine and calf leathers, artisanal craftsmanship, and strong brand heritage. Their strategy centers on maintaining perceived scarcity, controlling the narrative around material quality, and using leather goods as anchor products within broader luxury portfolios. LVMH and Prada similarly leverage bovine leather across handbags, wallets, and travel goods, but with a stronger emphasis on volume coordination across brands and collections. These players benefit from brand-driven pricing power and direct consumer relationships, but they also face ongoing pressure to demonstrate sustainability credentials and supply transparency without diluting the exclusivity that underpins their pricing.
Specialized manufacturers and tanneries occupy a different strategic position. Horween Leather Company, for example, focuses on high-quality vegetable and chrome tanned bovine leathers for footwear, bags, wallets, and belts, relying on traditional methods that appeal to brands and consumers who value pedigree and consistency. Rancourt & Co., The Frye Company, Circa of America, Garrett Leather Corp, and Tanner Goods each serve distinct niches, from footwear and boots to accessories and supply-oriented manufacturing. Their advantages typically lie in application knowledge, production flexibility, and the ability to meet specific performance or aesthetic requirements that broader producers may not prioritize. In a market with moderate concentration, these specialized players can compete effectively by deepening relationships with brand partners and delivering reliable quality rather than competing solely on price.
PW Consulting Health Care Research Center
Market Evolution: Consolidation, Differentiation, and New Entrants
The market's moderate concentration suggests room for both consolidation and continued fragmentation, depending on segment and geography. In premium luxury, brand consolidation and portfolio coordination are likely to persist, as large groups seek to balance exclusivity with scale efficiencies across leather goods categories. In mid-tier and specialized manufacturing, the more probable trajectory is differentiation through capability: firms that can combine consistent quality, traceability, and application-specific engineering will capture preferential access to discerning buyers. New entrants and smaller specialized producers may find opportunity in niches where craftsmanship, limited runs, or sustainability credentials command premiums, though they will need to navigate raw material cost variability and compliance requirements carefully. Overall, the competitive dynamic favors players who can articulate a clear value proposition and execute reliably across sourcing, production, and delivery.
Leather Goods Market
Future Outlook and Emerging Trends
Looking ahead over the next three to five years, several trends are likely to shape how the bovine leather goods market evolves and where commercial opportunities emerge. These trends are not speculative abstractions; they are extensions of current pricing behavior, regulatory direction, and buyer expectations already visible in the market.
One prominent trend is the increasing integration of sustainability and traceability into procurement decisions across both consumer-facing and industrial segments. As environmental and animal welfare standards remain strict in major markets and as industry exhibitions continue to highlight sustainable bovine leather goods, buyers are likely to place greater weight on documented compliance, responsible sourcing, and process transparency. The commercial opportunity lies in building verifiable credentials that can be presented in sales cycles and vendor evaluations, turning sustainability from a cost center into a competitive asset. The associated risk is that firms without credible traceability or compliance infrastructure may find themselves increasingly excluded from preferred supplier lists, particularly in segments where brand reputation and regulatory exposure are high.
A second trend is the ongoing refinement of product performance and finish consistency through processing innovation. As tanning and finishing capabilities improve, bovine leather goods can better meet the demands of automotive interiors, footwear, and upholstery applications where durability, appearance retention, and uniformity are critical. This creates opportunities for manufacturers to expand into higher-specification segments and for brands to market leather goods with clearer performance promises. The risk here is that innovation requires investment and process discipline; companies that delay modernization may face yield inefficiencies and reduced competitiveness against more advanced producers.
A third trend involves continued supply chain recalibration in response to cost variability and trade dynamics. With raw hides prices fluctuating and tariff impacts affecting imported materials, firms are likely to pursue more diversified sourcing, stronger supplier partnerships, and greater inventory or contract flexibility. The opportunity is to reduce exposure to sudden cost shocks and improve delivery reliability, both of which strengthen buyer confidence. The risk is that over-concentration in any single sourcing geography or supplier relationship can leave a company vulnerable if conditions shift, making diversification and contingency planning essential rather than optional.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen process control, traceability, and supplier coordination so that raw material volatility can be managed more predictably. Investing in finishing consistency, grading reliability, and documented compliance will improve both margins and buyer confidence, particularly in segments where performance specifications and sustainability expectations are tightening. Building longer-term supplier relationships and diversifying sourcing where feasible can also reduce exposure to tariff and price fluctuations.
For investors, the most compelling opportunities lie in companies that combine clear differentiation with operational discipline. Luxury and heritage brands with strong demand and pricing power remain attractive, but scrutiny should extend to their sustainability readiness and supply transparency. Specialized manufacturers with application expertise, dependable quality, and flexible production may offer resilient exposure to multiple end-use segments, especially where they serve buyers who value reliability and specification compliance over lowest-cost sourcing.
For procurement and sourcing leaders, the strategic imperative is to evaluate suppliers against a broader set of criteria that includes traceability, consistency, and resilience alongside price. Engaging with suppliers who can demonstrate compliance, stable output, and transparent sourcing practices will reduce downstream risk and support brand-level commitments. Maintaining visibility into raw material pricing trends and regulatory developments will also improve negotiation positioning and inventory planning.
Detailed segmentation data, regional breakdowns, and customized scenario analysis can sharpen these decisions further. For teams that need granular revenue splits, application-specific growth patterns, and company-level benchmarking beyond the overview presented here, the full PW Consulting research report provides the deeper dataset and structured frameworks required to translate these market dynamics into precise action plans.
For detailed analysis of this topic, please visit the official page: Bovine Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Nail Care Packaging Market Shaped by 5.5% CAGR and Glass Lead
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Nail Care Packaging Market
Market Snapshot and Core Challenges
The global nail care packaging market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of $1,532.65 million in 2025. This growth trajectory reflects a compound annual growth rate of 5.48 percent projected through 2032, signaling steady demand despite broader macroeconomic volatility. The sector's foundation rests on a specialized ecosystem where material choices, regional production hubs, and product form factors dictate competitive positioning. Glass continues to dominate material preferences due to its premium aesthetics and barrier properties, while plastic formulations capture significant volume through cost efficiency and design flexibility. Product architecture remains heavily skewed toward bottles, which serve as the primary delivery mechanism, though caps, brushes, tubes, and jars collectively represent a substantial secondary segment that shapes user experience and brand differentiation.
Several structural headwinds are reshaping how manufacturers and brand owners approach capacity planning, material sourcing, and product development. The first challenge stems from escalating raw material volatility, particularly in resin markets where producer price indices have climbed sharply amid energy cost pressures and constrained supply chains. This inflation directly impacts plastic component pricing, forcing converters to navigate margin compression while maintaining competitive retail pricing. The second challenge emerges from an accelerating regulatory environment that demands fundamental redesigns of packaging architectures. Extended producer responsibility frameworks are gaining momentum across multiple jurisdictions, compelling manufacturers to internalize end-of-life management costs and adjust commercial models accordingly. The third challenge lies in balancing sustainability mandates with performance requirements. Nail care products demand precise dispensing mechanisms, chemical compatibility, and tamper evidence, which historically limited material substitution options. Companies now face the complex task of meeting recycled content targets and design-for-recycling criteria without compromising functionality or aesthetic appeal.
These intersecting pressures create a market at an inflection point. Stakeholders must reconcile cost discipline with compliance readiness, while simultaneously responding to evolving consumer expectations around sustainability and premiumization. The companies that successfully navigate this transition will be those that treat regulatory and material shifts not as isolated constraints but as catalysts for structural innovation across their packaging portfolios.
Key Drivers Reshaping the Market
Technological innovation continues to serve as a primary catalyst for market evolution, particularly in the realm of dispensing systems, closure mechanisms, and material engineering. Advanced brush geometries, precision dropper assemblies, and ergonomically optimized caps are redefining application consistency and user satisfaction. Suppliers are increasingly integrating smart manufacturing techniques, including precision molding and automated quality verification, to reduce defect rates and improve batch uniformity. These advancements matter because nail care products rely heavily on tactile and visual cues during application; even minor improvements in flow control or bristle alignment can translate into measurable brand loyalty gains. The trend toward hybrid formulations, including products that blend traditional color delivery with added functional benefits, further reinforces the need for packaging that supports stable ingredient interactions while maintaining clarity and structural integrity.
Policy and regulatory developments are simultaneously restructuring competitive dynamics by imposing new design and compliance obligations. Extended producer responsibility frameworks in several U.S. states are moving from legislative intent to operational requirements, with recycling rate disclosures and fee structures increasingly tied to material choice and packaging complexity. In parallel, the European Union's packaging and packaging waste regulation trajectory is steering manufacturers toward design-for-recycling standards and recycled content thresholds that directly affect cosmetic and nail care containers. These policy shifts are not merely compliance exercises; they influence upstream sourcing strategies, mold investment timelines, and collaboration models between brand owners and packaging suppliers. Companies that anticipate these requirements and build modular design capabilities into their development pipelines are better positioned to avoid retrofitting costs and supply disruptions later in the product lifecycle.
Nail Polish Market
Demand-side behavior is also undergoing a meaningful transformation, driven by a combination of premiumization, sustainability sensibility, and the expansion of professional and at-home nail care usage. Consumers increasingly associate packaging quality with product efficacy and brand credibility, which elevates the strategic importance of bottle clarity, labelability, and closure reliability. At the same time, the rise of hybrid care categories encourages manufacturers to consider packaging that communicates added benefits without complicating the user journey. On the supply chain side, cost structures are being recalibrated by resin price fluctuations, energy inputs, and logistics constraints. These pressures are prompting sourcing diversification, closer coordination between converters and raw material producers, and renewed evaluation of glass-versus-plastic trade-offs based on total cost of ownership rather than unit price alone. Recent trade activity and product introductions illustrate how these forces are converging, with suppliers showcasing material alternatives, refill-compatible configurations, and specialized dispensing components that respond to both performance and regulatory expectations.
Competitive Landscape and Leading Strategies
The market's competitive architecture is characterized by a mix of incumbent packaging specialists, global container manufacturers, and regional suppliers with focused nail care expertise. Concentration levels remain moderate, indicating that no single entity controls the majority of supply and that differentiation is largely achieved through design capability, material specialization, and service integration rather than sheer scale alone. Leading players have positioned themselves along distinct strategic axes, balancing premium aesthetics, sustainability readiness, dispensing innovation, and regional manufacturing proximity. This diversification allows brand owners to select partners based on product positioning, compliance requirements, and speed-to-market considerations.
Worldwide Nail Strips Market
Several companies illustrate the breadth of current strategic approaches. Global cosmetic packaging providers with strong glass and hybrid container capabilities emphasize complete solution offerings, combining bottle design, finish options, and compatibility testing to reduce development friction for nail care brands. European design-driven suppliers focus on customizable, eco-oriented constructions that align with regional regulatory expectations while maintaining premium visual appeal. Specialized glass and plastic container manufacturers prioritize safety, clarity, and aesthetic consistency, appealing to brands where product presentation and chemical stability are paramount. Suppliers centered on dispensing systems, closures, and brushes contribute differentiated value by improving application precision and user experience rather than competing solely on container volume. Meanwhile, manufacturers offering turnkey or private-label capabilities integrate formulation and packaging workflows, creating efficiencies for brands seeking streamlined go-to-market pathways.
The landscape is evolving through a combination of capability consolidation and niche specialization. Larger players are expanding their nail care portfolios through targeted investments in dispensing technology, sustainable material options, and regional production footprints that shorten lead times. At the same time, smaller and mid-sized suppliers are carving out positions by offering highly customizable glass solutions, specialized brush assemblies, or region-specific compliance support. New entrants and adjacent players are also testing the market by leveraging flexible manufacturing and design services to serve emerging brands that prioritize speed, distinctiveness, and sustainability credentials. This dynamic suggests that competition will increasingly hinge on the ability to deliver integrated solutions rather than standalone components, with success measured by how effectively a supplier can align material performance, regulatory readiness, and brand storytelling within a single packaging system.
PW Consulting
Future Outlook and Emerging Opportunities
Over the next three to five years, the market is likely to be shaped by the convergence of regulatory-driven design changes, material innovation, and continued premiumization. One prominent trend will be the broader adoption of recyclable and refill-compatible packaging architectures as extended producer responsibility obligations mature and recycled content expectations become more enforceable. This shift will create opportunities for suppliers that can standardize modular components, simplify material sorting, and demonstrate verifiable end-of-life pathways without sacrificing dispensing accuracy or product protection. Brands that proactively align their packaging roadmaps with these requirements will reduce future reformulation risk and strengthen shelf positioning in markets where sustainability claims are scrutinized.
A second trend will involve the acceleration of functional integration within packaging, including closures and brushes designed to support hybrid product types, precision dosing, and improved application control. As nail care categories expand beyond traditional color cosmetics into care-oriented and hybrid formulations, packaging will need to signal functionality while maintaining the tactile and visual attributes consumers associate with quality. Suppliers that invest in application-specific engineering and user testing will be better equipped to capture premium segments and support brand differentiation. A third trend relates to supply chain reconfiguration, as manufacturers seek to mitigate raw material volatility and compliance complexity through diversified sourcing, regional production, and closer collaboration with converters and resin suppliers. This reconfiguration may favor partners that offer transparency, flexible order structures, and predictable lead times.
These opportunities are not without risk. Material substitution can introduce compatibility challenges, especially when formulations evolve faster than packaging validation cycles. Regulatory timelines may diverge across regions, creating uneven compliance burdens and complicating global product rollouts. Additionally, if resin price pressures persist or recycling infrastructure lags behind policy goals, the economics of sustainable packaging transitions could tighten, rewarding only those players with strong cost control and technical validation capabilities. Strategic foresight will therefore matter as much as execution.
Strategic Implications for Decision-Makers
For packaging manufacturers and converters, the priority is to build modular design capability that can accommodate recycled content, design-for-recycling standards, and changing dispensing requirements without requiring complete toolchain overhauls. Investing in application testing, closure optimization, and glass-plastic integration strategies will help protect margins while meeting evolving brand demands. For investors, the most attractive exposure lies in suppliers that combine regulatory readiness with differentiated dispensing or material solutions, especially those serving premium and hybrid nail care segments where performance and aesthetics command pricing power. For procurement teams and brand owners, the focus should be on supplier partnerships that offer compliance transparency, stable material sourcing, and design flexibility, since these attributes reduce launch risk and support consistent product experience across markets.
Given the pace of regulatory change, material volatility, and product innovation, decision-makers benefit from access to detailed segmentation data, regional compliance mapping, and supplier capability assessments that go beyond high-level market sizing. Deeper Intelligence on volume splits, material transitions, competitive positioning, and scenario-based forecasts can sharpen capacity planning, sourcing decisions, and portfolio prioritization. For organizations seeking a comprehensive view of market structure, company strategies, and forward-looking dynamics, the full PW Consulting research report provides expanded segmentation detail and tailored analysis to support sector-specific planning.
For detailed analysis of this topic, please visit the official page: Worldwide Nail Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


