



Strategic Trends & Commercial Opportunities in the Health Savings Account Provider Market
Market Overview: Scale, Trajectory, and Core Challenges
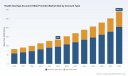
The Health Savings Account (HSA) provider market has matured into a cornerstone of the U.S. consumer-directed healthcare ecosystem, reflecting both structural shifts in insurance design and evolving consumer expectations around health financing. Measured in constant terms over a five-year baseline through 2025, the market has expanded from roughly 82.5 to 135.0 across the referenced period, with projections extending through 2032 pointing to sustained momentum. The forward trajectory implies a compound annual growth rate of approximately 11.55 percent, lifting the market size to nearly 290.1 by the end of the forecast window. This expansion is not merely a function of inflation or administrative growth; it signals a fundamental recalibration of how households and employers approach healthcare spending, savings, and investment.
Worldwide Financial Wellness Benefits Market
Beneath the headline figures, several structural realities define the current operating environment. First, account distribution is heavily weighted toward employer-sponsored arrangements, which dominate the overall composition, while individual-direct accounts represent a meaningful but smaller share. This split underscores the continued reliance on workplace channels for account origination, even as digital enrollment pathways and direct-to-consumer marketing gradually broaden the addressable base. Second, the provider landscape is fragmented across Banks and Financial Institutions, Insurance Carriers, and FinTech and Third-Party Administrators, with no single category achieving outright dominance. That fragmentation creates both distribution frictions and partnership opportunities, as each provider type brings distinct capabilities in compliance, investment access, and user experience. Third, regional concentration remains pronounced, with North America accounting for the overwhelming majority of activity and the rest of the world representing a negligible fraction, highlighting the deeply U.S.-centric nature of the current regulatory and tax framework.
The market also exhibits meaningful concentration at the top, with the largest players collectively holding roughly 48.2 percent of the landscape and the top five approaching 62.4 percent. Such concentration suggests established incumbents have secured durable advantages in employer relationships, compliance infrastructure, and asset accumulation, yet the remaining share leaves considerable room for differentiated entrants and niche platforms. The challenges ahead are equally clear. Providers must navigate the tension between scale-driven margin improvement and the growing expectation for personalized digital experiences, all while operating within a regulatory perimeter that ties account eligibility to qualifying High Deductible Health Plans. Compounding these dynamics, the shift from pure spend accounts to true investment vehicles is reshaping customer expectations, forcing providers to prove out performance, transparency, and long-term value rather than merely facilitating contributions and withdrawals.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Realities
The most visible catalyst for market expansion is the accelerating convergence of financial services and digital health platforms. Modern HSA architectures increasingly embed self-service dashboards, real-time claim adjudication, automatic investment enrollment, and integrated budgeting tools that treat health spending as part of broader household finance. These capabilities reduce administrative burden for employers and improve engagement among account holders, which in turn supports higher asset retention and deeper investment adoption. The trend toward embedding HSA functionality within broader benefits ecosystems—often layered with flexible spending arrangements, health reimbursement arrangements, and emergency savings features—has transformed the account from a standalone tax-advantaged vehicle into a multi-purpose financial hub. Recent industry reporting highlights that assets reached nearly 174 billion across 41.7 million accounts at year-end 2025, with 19 percent year-over-year asset growth and a rising share allocated to investments, signaling that users and sponsors are increasingly comfortable with longer-horizon financial behaviors.
Regulation continues to shape the speed and structure of adoption, not only by defining eligibility but by setting annual contribution limits that influence household behavior and employer design choices. For 2026, the IRS set HSA contribution limits at 4,400 for self-only coverage and 8,750 for family coverage, parameters that guide recurring contributions and encourage year-end planning. Because HSAs must be paired with a qualifying High Deductible Health Plan to preserve tax advantages, any shift in employer insurance strategy, employee cost sensitivity, or plan design directly influences account origination and asset accumulation. The regulatory backdrop also rewards providers that can demonstrate robust compliance, clean reporting, and seamless integration with plan documents and payroll workflows. In practice, the firms that most effectively translate regulatory requirements into friction-free employer onboarding and employee education capture disproportionate share of new accounts and assets.
Demand-side dynamics reinforce this trajectory. Employers are increasingly weighing total rewards packages that blend clinical coverage with financial wellness, recognizing that HSA participation can influence employee retention, productivity, and financial resilience. Individuals, meanwhile, are becoming more deliberate about health spending, investment growth, and portability as job mobility rises and traditional employer relationships become less sticky. This behavioral shift favors platforms that offer clear fee structures, intuitive investment options, and educational support that demystifies contribution strategies, catch-up provisions for older participants, and the interplay between current spending and future growth. The result is a market where user experience and transparency are no longer differentiators but baseline requirements.
Cost structures and operating models are evolving in parallel. As digital onboarding, automated compliance checks, and platform-based integrations reduce marginal handling costs, providers are gaining latitude to compete on value rather than price alone. At the same time, the economics of managing growing asset balances introduce new considerations around recordkeeping, custody, and investment administration. Companies that can align scalable technology with disciplined cost control are better positioned to sustain margins as the market expands, especially when investment assets increasingly represent a meaningful portion of total value. The strategic implication is straightforward: the winners will be those that turn cost efficiency into better user outcomes, not just internal savings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by several well-established players, each leveraging a distinct blend of scale, integration, and product breadth. Fidelity Investments has built a reputation for fee-light HSAs paired with broad investment menus that span stocks, ETFs, and mutual funds, complemented by seamless connectivity to retirement accounts. Its positioning emphasizes low cost and investment flexibility, appealing to account holders who view their HSA as a long-term savings and investment instrument rather than a transactional spend account. HealthEquity has concentrated on employer-sponsored administration at scale, combining compliance rigor with integrated consumer-directed benefits that include FSAs and HRAs. Its strengths lie in analytics, account volume, and enterprise-grade support, and its recent financial results—record revenue of 1.31 billion, over one million new HSAs from sales, and an outlook raised for fiscal 2027 with 17.8 million total accounts and more than 36 billion in assets—illustrate how scale and disciplined execution can compound in a maturing market.
HSA Bank, operating as a division of Webster Bank, blends HSA administration with investment access through brokerage relationships and integrated benefits solutions, while also extending into adjacent pillars of employee financial wellness. Its acquisition of SecureSave to expand into employer-sponsored Emergency Savings Accounts signals a move toward broader financial resilience offerings, allowing employers to bundle health savings with emergency savings in a single wellness narrative. Lively has carved out a modern, digital-first identity with an emphasis on user-friendly tools, transparent pricing, and support for both individuals and small-to-mid employers, positioning itself as an agile alternative to more traditional administrators. Optum Bank leverages its integration within a large health benefits ecosystem to offer HSAs connected to broader care and benefits management, with investment options available through brokerage windows or managed solutions. Bank of America brings a conventional banking footprint with tiered interest rates and basic investment access, appealing to consumers who prioritize familiar banking relationships and integrated account management.
The strategic differences among these players reveal a market that is simultaneously consolidating around scale and differentiating around experience. Incumbents with deep employer relationships and robust compliance infrastructure continue to capture the bulk of new accounts, while newer platforms compete on design, fee clarity, and specialized workflows that reduce administrative overhead for smaller sponsors. The evolution is also visible in product adjacency: providers are extending beyond core HSA administration into emergency savings, wellness incentives, and integrated benefit stacks, recognizing that household financial decisions rarely occur in isolation. This blending of use cases creates opportunities for cross-selling and deeper engagement, but it also raises the bar for operational discipline, as each new feature must be supported by clear governance and reliable user communication.
Concentration patterns suggest that while the largest players enjoy meaningful advantages in distribution and asset accumulation, the market remains open to targeted innovation. The gap between top-tier scale and the long tail of smaller providers creates a natural environment for partnerships, platform integrations, and geographic or segment specialization. At the same time, the expectation for investment adoption and digital fluency is pulling even traditional providers toward more modern interfaces and transparent fee logic. The net effect is a landscape in flux: scale still matters, but differentiation through experience, ecosystem fit, and adjacent financial wellness capabilities is increasingly decisive.
Strategic Outlook: Three Trends Shaping the Next 3-5 Years
First, the HSA will continue its evolution from a spend account to a core investment vehicle within household finance. As assets grow and a larger share is allocated to investments, providers that offer well-structured investment options, clear performance reporting, and educational support will deepen engagement and retention. The commercial opportunity lies in building trust around long-term outcomes, including guidance on contribution strategies, catch-up eligibility, and the interaction between current healthcare spending and future growth. Platforms that can communicate value without complexity are likely to capture more assets and fewer lapses.
Second, financial wellness bundling will become a standard expectation rather than a differentiator. Employers and individuals increasingly view health savings alongside emergency savings, retirement readiness, and benefits transparency as part of a single financial resilience strategy. Providers that can integrate these use cases in a coherent, compliant manner will gain preference in employer selection and individual adoption. The upside is higher engagement and broader account utility; the risk is operational complexity and the potential for feature sprawl that dilutes clarity.
Third, digital experience and fee transparency will increasingly separate leaders from laggards. As account holders compare platforms on usability, investment access, and total cost, providers that invest in self-service design, proactive education, and straightforward fee logic will stand out. The uncertainty here is twofold: regulatory parameters can change with annual limits and eligibility rules, and competitive pressure may compress fee-based economics, pushing providers to rely more on scale, ecosystem partnerships, and value-added services to sustain margins.
Actionable Recommendations for Decision-Makers
For employers and plan sponsors, the priority is to treat HSA design as a strategic component of total rewards rather than an administrative checkbox. That means selecting providers based on integration quality, fee clarity, investment readiness, and employer analytics, while pairing account access with education that improves participation and asset retention. Sponsors should also evaluate adjacent financial wellness capabilities, such as emergency savings integrations, as part of a cohesive offer that supports employee resilience and engagement.
Health Products Market
For investors and market participants, the most durable opportunities lie in platforms that combine scalable compliance infrastructure with modern user experience and credible investment pathways. Attractive theses typically emphasize asset growth, investment adoption trends, and the ability to expand into adjacent wellness use cases without sacrificing operational discipline. Caution is warranted where differentiation rests primarily on marketing claims without transparent fee structures, reliable service levels, or clear employer value.
PW Consulting Information & Electronics Research Center
For technology providers and procurement teams, the mandate is to prioritize interoperability, clean data flows, and enrollment simplicity. Solutions that reduce onboarding friction, automate compliance checks, and deliver actionable reporting will earn preference in a market where scale and experience increasingly converge. Timely, granular intelligence on segment dynamics, provider positioning, and adoption patterns can sharpen procurement decisions and reduce integration risk, especially as the market continues to reward providers that align product design with real user behavior. For those seeking deeper segmentation, competitive benchmarking, and tailored strategic guidance, PW Consulting’s full research report provides detailed breakdowns and customized recommendations to support concrete next steps.
For detailed analysis of this topic, please visit the official page: Health Savings Account (HSA) Provider Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Coffee Concentrate Juice Market: Why 6.12% CAGR Changes Everything
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Coffee Concentrate Market
Market Landscape and Core Challenges
The global coffee concentrate market has demonstrated consistent expansion, with revenue climbing from approximately USD 2,120.45 million in 2020 to an estimated USD 2,842.50 million in 2025. Projections indicate a compound annual growth rate of 6.12 percent through 2032, positioning the sector to reach roughly USD 4,303.18 million by the end of the forecast window. This trajectory reflects a broader reallocation of value within the beverage industry, where convenience, consistency, and scalability are increasingly dictating procurement decisions across both commercial and retail channels. The market's steady expansion suggests that concentrate formats are no longer functioning as a niche input but are becoming a structural component of modern beverage architecture.
Despite the favorable growth backdrop, the industry is navigating several structural friction points that will determine which participants capture disproportionate value in the coming years. First, raw material volatility continues to inject uncertainty into cost planning and margin management. The International Coffee Organization's Composite Indicator Price averaged 296.89 US cents per pound in January 2026, followed by a downward drift toward lows near 262 US cents per pound in February before partial stabilization in the 273–290 US cents per pound range during the spring months. This pattern underscores the sensitivity of concentrate economics to crop cycles, weather outcomes, and supply expectations. When input costs shift rapidly, manufacturers with limited hedging discipline or inflexible procurement structures face compressed profitability, while more adaptive firms can protect margins and even gain share during periods of price dislocation.
Second, regulatory architecture remains uneven and poorly synchronized across markets, creating compliance friction for global operators. Coffee and tea infusions derived from dried ingredients fall outside the scope of FDA Juice HACCP regulation, a distinction that differentiates coffee concentrates from fruit or vegetable juice concentrates intended for beverage use. At the same time, labeling rules for products purporting to contain juice require explicit juice content declarations and mandate that beverages made from concentrate include terms such as "from concentrate" or "reconstituted" where the product name appears. For coffee concentrate manufacturers operating in adjacent or hybrid categories, these overlapping and sometimes contradictory requirements increase formulation complexity, labeling costs, and the risk of misclassification. Firms that invest early in regulatory mapping and documentation discipline will face fewer costly disruptions as product portfolios expand across categories and geographies.
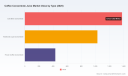
Third, the combination of market concentration and ongoing process innovation is raising the competitive bar. With the top three participants accounting for roughly 38.45 percent of revenue and the top five reaching approximately 52.3 percent, scale, brand equity, and distribution reach continue to confer meaningful advantages. Yet concentration also signals an opportunity for targeted differentiation. As major operators push proprietary processing technologies and customized concentrate variants, smaller or regionally focused players must avoid competing on commodity-like volumes alone. The market is bifurcating: scale players are leveraging volume and branding, while agile suppliers are carving positions through specialty origins, performance-focused processing, and tailored foodservice formats. Recognizing this divergence is essential for any operator planning capacity, partnership, or entry decisions.
Coffee Concentrates Market
Key Growth Drivers
Several interconnected forces are shaping the direction of the coffee concentrate market and creating differentiated opportunities for participants that align their capabilities with structural demand shifts.
Technological Innovation and Processing Differentiation
Process innovation remains one of the most consequential drivers of competitive advantage. Advances in cold-brew extraction, high-Brix concentration, and shelf-stable liquid formulation are enabling manufacturers to deliver concentrates with improved flavor consistency, reduced preparation complexity, and broader application compatibility. Recent product activity illustrates this trajectory clearly. In July 2025, Red Diamond Coffee & Tea introduced the Fitz Cold Brew Coffee Concentrate for foodservice operators, designed to simplify cold brew preparation by providing a ready-to-dilute format that reduces labor, variability, and equipment demands. A few months later, in April 2026, Nestlé and Starbucks unveiled the Starbucks Coffee Craft concentrate, expanding cold coffee availability through a concentrate format engineered for consistent taste and efficient deployment across foodservice and beverage manufacturing applications.
These launches are not isolated product additions; they reflect a broader shift toward concentrates that serve as operational tools rather than raw inputs. For beverage manufacturers and foodservice operators, the commercial appeal of concentrates increasingly rests on repeatability, speed of preparation, and compatibility with existing dispensing or blending infrastructure. Suppliers that can pair flavor integrity with formulation flexibility, such as customized Brix levels or origin-specific profiles, are well positioned to deepen customer relationships and move beyond transactional supply arrangements. The strategic implication is that processing capability is becoming a core differentiator, and investment in extraction, stabilization, and customization technologies is likely to separate market leaders from follow-on competitors.
Demand-Side Transformation and Channel Evolution
Consumer and enterprise behavior is reshaping where and how coffee concentrate is consumed. Cold coffee formats have moved from a seasonal novelty to a sustained category with year-round demand, and the concentrate segment is benefiting directly from this normalization. Foodservice operators are drawn to concentrate formats that reduce preparation variability and labor intensity, particularly in high-turnover environments where consistency and speed are essential. At the same time, retail and household channels are absorbing concentrates as consumers seek convenient, customizable home beverage experiences without the operational burden of brewing from scratch.
This channel divergence is producing distinct demand profiles. Foodservice demand tends to prioritize operational efficiency, portion control, and compatibility with existing equipment. Retail and household demand places greater weight on shelf stability, ease of use, and perceived premium quality. Manufacturers that design concentrate portfolios with these channel-specific requirements in mind can capture value across multiple touchpoints without forcing a single format to carry all use cases. The broader insight is that demand growth is being supported not only by total volume expansion but also by the migration of coffee consumption into formats that are inherently more concentrate-friendly.
Supply Chain Dynamics and Cost Structure Realignment
Coffee concentrate economics are being recalibrated by evolving raw material conditions and supply chain design choices. The recent softening of green coffee pricing, driven by expectations of record Brazilian harvests and broader global supply surpluses, has altered the near-term cost environment. While lower input prices can relieve margin pressure, they also introduce new considerations around procurement timing, inventory strategy, and supplier relationships. Firms that treat raw material volatility as a recurring design parameter rather than an episodic disruption are better equipped to maintain cost discipline. This includes diversifying origin exposure, structuring flexible offtake arrangements, and aligning concentrate specifications with cost-efficient processing routes where feasible.
PW Consulting
Supply chain resilience is increasingly tied to operational flexibility. Concentrate manufacturers are evaluating everything from batch sizing and packaging configurations to logistics networks and regional production footprints. In a market where foodservice and industrial processing customers demand reliable availability and predictable lead times, the ability to balance efficiency with responsiveness is becoming a differentiator. Cost structures that incorporate proactive inventory planning, multi-origin sourcing, and format optimization are more likely to sustain profitability through cycles of input price movement. The practical takeaway is that supply chain design is no longer a back-office concern; it is a strategic lever that shapes pricing power, service levels, and customer retention.
Regulatory Clarity as a Strategic Enabler
Regulatory dynamics are also functioning as a growth enabler by clarifying where concentrate products sit within existing compliance frameworks. The distinction between coffee and tea infusions from dried ingredients and juice-based concentrates under FDA Juice HACCP guidance helps reduce uncertainty for coffee-focused manufacturers, provided that labeling and category positioning are managed carefully. In parallel, customs marking exemptions for roasted and instant coffee and certain coffee preparations can simplify trade documentation and reduce administrative overhead for exporters and importers operating across jurisdictions. Where beverage products include juice claims, however, percentage declarations and from-concentrate labeling requirements still apply and must be integrated into product development and packaging processes.
These regulatory nuances are not merely compliance checkboxes; they influence product architecture, market entry sequencing, and labeling investment. Organizations that build regulatory literacy into their formulation and go-to-market planning can reduce time-to-market, avoid rework, and position products more cleanly within their intended categories. As the concentrate market expands across both coffee-centric and hybrid beverage applications, clarity on classification and labeling will increasingly separate operators that scale smoothly from those that encounter avoidable friction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of global scale players, specialized concentrate suppliers, and foodservice-oriented manufacturers, each pursuing distinct value propositions. Nestlé and Starbucks exemplify a partnership-driven approach to category expansion, leveraging brand equity and distribution muscle to accelerate cold coffee availability through concentrate formats. Their focus on broad availability and recognizable branding targets mass consumption and beverage manufacturing channels where standardization and reach are paramount. This strategy underscores the continued relevance of scale, but it also highlights the importance of product relevance: even large incumbents must ensure that concentrate formats align with specific usage occasions and preparation expectations.
Finlays represents a more customization-oriented posture, supplying tailored coffee concentrates including cold brew and high-Brix variants for beverage manufacturing and ready-to-drink products. Its emphasis on multiple origins and certifications signals a strategy built on formulation flexibility and sourcing credibility. For industrial and beverage manufacturing customers, this profile can translate into stronger partnership potential, particularly where product differentiation depends on origin selection, processing nuance, or certification requirements. In a market where generic concentrate offerings are increasingly commoditized, the ability to adapt specifications to customer needs becomes a meaningful differentiator.
U.S.-based manufacturers such as Westrock Coffee Company, The J.M. Smucker Company, Keurig Dr Pepper, All American Coffee LLC, Red Diamond Coffee & Tea, Chameleon Cold-Brew, CoolBrew, and Jedwards International illustrate the breadth of domestic concentration activity across private label, retail, and foodservice applications. Some participants emphasize proprietary processing for customized formats, while others focus on convenience-driven foodservice concentrates or organic retail-oriented cold brew products. Red Diamond's Fitz Cold Brew launch, for example, reflects a practical service logic: enabling foodservice operators to deliver premium cold brew with simplified preparation. CoolBrew's proprietary cold-drip process and Chameleon's organic positioning point to differentiation through process identity and category authenticity. These approaches demonstrate that U.S. players are competing not only on volume but also on format design, brand narrative, and channel fit.
International and specialty-oriented operators add further texture to the landscape. Jake-Frut & Jake-Café provides custom branding solutions for concentrated juices and liquid coffee, targeting customers that value packaging and brand integration. Cafeahaus AG DEK specializes in soluble coffees and liquid coffee extracts for food industry and vending applications, an area where compatibility, dosing reliability, and machine-friendly formats matter. Batavia Cold Drip Coffee, with operations spanning the Netherlands and Indonesia, offers bulk liquid cold drip concentrates with customizable recipes and packaging options, an appealing profile for buyers seeking scale without sacrificing formulation input. Together, these companies show that the market is not a simple hierarchy of global giants versus niche suppliers; it is a layered ecosystem where competitive advantage can be built through provenance, customization, service model, or application expertise.
The competitive trajectory appears to be moving toward selective consolidation and simultaneous niche differentiation. Scale players will continue to consolidate advantageous distribution, brand recognition, and processing capacity, especially in broad consumer and foodservice segments. At the same time, new entrants and focused incumbents will likely find room by addressing underserved applications, origin narratives, organic or specialty certifications, and operational pain points such as preparation complexity or format incompatibility. The most durable strategies will be those that combine credible processing capability with clear customer value, whether that value is operational efficiency, flavor consistency, customization, or category positioning. A market with this level of strategic diversity rewards companies that define their positioning precisely rather than attempting to compete across every dimension at once.
Future Outlook: Three Signals to Watch
Looking ahead to the 2026–2032 window, several signals point to where strategic attention should be concentrated.
First, cold coffee adoption will continue to anchor concentrate demand, but the growth logic will increasingly shift from novelty to operational integration. As foodservice and beverage manufacturing customers mature in their use of concentrate formats, the value proposition will depend less on introducing cold coffee and more on improving preparation efficiency, consistency, and scalability. Manufacturers that align concentrate specifications with real-world workflow requirements, including dilution ratios, dispensing compatibility, and batch-to-batch stability, are likely to secure stickier customer relationships. The related opportunity is to design concentrate portfolios for repeatable deployment rather than one-off product launches.
Second, a period of lower input prices can reshape competitive behavior if it leads to complacency in cost management or procurement discipline. Lower green coffee pricing may temporarily ease margin pressure, but it can also obscure the need for robust hedging, origin diversification, and specification-to-cost alignment. Operators that use favorable pricing windows to strengthen supply chain resilience and lock in flexible sourcing arrangements will be better positioned when prices cycle back. The risk is that temporary cost relief encourages volume-driven competition without corresponding value or efficiency gains, which can erode profitability over time.
Third, category boundaries will continue to test labeling and regulatory clarity, especially as beverage concepts blur the line between coffee, juice-adjacent, and hybrid formats. Products that incorporate juice claims, from-concentrate language, or multi-ingredient formulations will face tighter scrutiny on declaration accuracy and consumer communication. This creates both a compliance challenge and an opportunity: companies that develop clean, category-appropriate labeling and transparent product narratives can reduce friction and build trust, while those that treat labeling as an afterthought risk rework, market delays, or consumer confusion. The strategic opportunity lies in treating regulatory and labeling design as part of product architecture rather than a downstream task.
Strategic Recommendations for Decision-Makers
For manufacturers, the immediate priority is to align concentrate development with application-specific value. This means prioritizing processing consistency, customization capability, and preparation simplicity where customer workflows demand it. Investment should be directed toward formats and specifications that reduce customer friction, whether that friction is operational, sensory, or regulatory. In parallel, supply chain strategy should incorporate flexible sourcing and inventory planning so that margin protection is not dependent on any single price environment.
Worldwide Citrus Concentrate Market
For investors, the most relevant question is not whether the market is expanding, but which business models are best configured to capture durable margin and share. Comparative evaluation should focus on processing differentiation, channel fit, customer retention logic, and exposure to raw material cycles. Companies that can demonstrate repeatable concentrate performance, clear application relevance, and disciplined cost management are more likely to translate market growth into sustained profitability. Due diligence should also assess regulatory readiness, especially for products operating near category boundaries or with multi-ingredient formulations.
For procurement and sourcing teams, concentrate selection should be evaluated on total operational impact rather than unit price alone. Dilution performance, shelf stability, equipment compatibility, lead-time reliability, and documentation clarity all influence total cost of ownership. Where feasible, buyers should seek suppliers with proven customization capacity and transparent compliance practices, particularly if product portfolios are expected to expand into hybrid or multi-format use cases. Strategic sourcing relationships, rather than transactional purchasing, will increasingly determine how smoothly concentrate programs scale.
Market-level growth is only one part of the story. The more consequential question is which participants will convert that growth into defensible advantage through better processing, smarter sourcing, and sharper category positioning. Detailed segmentation, regional dynamics, and application-level cost structures provide the granularity needed to make those judgments with confidence. Readers seeking a deeper view of segment performance, competitive benchmarking, and forward scenarios can consult the full PW Consulting report on the worldwide coffee concentrate market for more detailed data and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Worldwide Coffee Concentrate Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Air Quality Sensor ICs Market to Hit $1.57B by 2032
By PW Consulting, 2026-09-17
A Strategic Imperative for Semiconductor Leaders: Navigating the Global Air Quality Sensor ICs Market (2026–2032)
The global trajectory of environmental monitoring is no longer defined solely by regulatory compliance; it is increasingly driven by a convergence of consumer health awareness, automotive cabin optimization, and industrial automation. For semiconductor strategists and product leaders, the air quality sensor integrated circuit (IC) market represents a high-growth vector where technological differentiation meets expanding application scope. Our latest research into the Worldwide Air Quality Sensor ICs Market provides a granular, forward-looking intelligence framework designed to support critical investment and portfolio decisions throughout the 2026–2032 forecast horizon.
In a landscape characterized by rapid technological iteration and shifting geopolitical supply chains, relying on historical analogs or fragmented public data is insufficient. This report distills complex market mechanics into actionable strategic insights, enabling stakeholders to identify high-value segments, anticipate competitive disruptions, and align R&D roadmaps with emerging demand patterns. The following analysis outlines the core value proposition of this study, highlighting the macro-economic currents, competitive dynamics, and operational frameworks that will define market leadership in the coming years.
Market Trajectory and Macro-Economic Foundations
The air quality sensor IC industry has demonstrated robust resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has consistently grown its total addressable revenue, culminating in an estimated global valuation of approximately 780.0 million USD in the base year. This upward momentum is not merely cyclical; it is structural, fueled by the integration of sensing technologies into everyday electronic ecosystems and stringent indoor air quality (IAQ) mandates across major built environments.
Looking ahead, the forecast period from 2026 to 2032 projects sustained expansion. By 2026, the market is poised to cross the 868.92 million USD threshold, signaling a decisive acceleration in adoption rates across both mature and emerging application verticals. The compound annual growth rate (CAGR) for this forecast window stands at a compelling 10.51 percent, underscoring the sector's capacity to outperform broader semiconductor segments. As the timeline extends toward 2032, revenue projections escalate significantly, reflecting the maturation of next-generation sensor platforms and the deepening penetration of multi-parameter ICs in high-volume consumer and industrial deployments.
Air Quality Sensor Market
This growth trajectory is underpinned by a fundamental shift from single-function sensing to integrated, intelligent monitoring solutions. Manufacturers are increasingly prioritizing ICs that combine particulate matter detection, volatile organic compound (VOC) analysis, and environmental compensation within unified packages. Our research quantifies the revenue contribution of these converging technology stacks while isolating the specific drivers that will determine market share allocation among key geographies and end-use segments. While precise regional and application-level revenue breakdowns are detailed exclusively within the full report, the strategic narrative is clear: value is migrating toward ecosystems that demand higher accuracy, lower power consumption, and seamless system integration.
Technology Segmentation: From Discrete Sensing to Integrated Intelligence
The architecture of the modern air quality sensor IC market is defined by a multidimensional segmentation structure that spans technology type, application domain, and geographic deployment. At the core of the technology split, the market encompasses gas sensor ICs, particulate matter sensor ICs, and an emerging category of integrated multi-parameter ICs. Each of these technology tracks presents distinct value chains, manufacturing complexities, and performance benchmarks, requiring stakeholders to evaluate investment opportunities through a nuanced lens of risk and return.
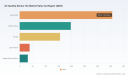
Gas sensor ICs continue to anchor a substantial portion of overall revenue, driven by the persistent demand for VOC and NOx detection in both indoor and outdoor environments. Concurrently, particulate matter sensor ICs are witnessing accelerated adoption as public health initiatives and smart city infrastructure projects mandate real-time PM2.5 and PM10 monitoring. The integrated multi-parameter segment, though currently smaller in absolute scale, represents a critical frontier for differentiation, as system designers increasingly seek consolidated solutions that reduce bill-of-materials complexity and streamline embedded processing requirements.
On the application side, the market is diversified across consumer electronics, automotive cabin monitoring, industrial and smart city infrastructure, and medical and healthcare sectors. Each vertical carries unique performance tolerances, certification pathways, and procurement cycles. Consumer electronics leverage sensor ICs for personal health and home automation, while automotive cabin monitoring demands robust, humidity-tolerant solutions capable of operating in dynamic vehicular environments. Industrial and smart city deployments prioritize scalability, environmental ruggedness, and network interoperability, whereas medical and healthcare applications require exceptional accuracy and calibration stability to support diagnostic and therapeutic workflows.
The report provides a comprehensive mapping of these application segments, analyzing how revenue streams are distributed and where onboarding barriers remain highest. Rather than presenting isolated percentage splits, the study ties application dynamics to broader macro trends—such as the proliferation of energy-efficient HVAC systems in commercial buildings and the regulatory push toward healthier vehicle interiors—enabling readers to assess which verticals will generate the highest marginal returns over the forecast period.
Competitive Landscape: Key Players and Strategic Positioning
The global air quality sensor IC market is characterized by a moderately concentrated competitive environment, where a handful of established incumbents and technology specialists command a significant share of overall revenue. Our analysis indicates that the top three firms collectively account for approximately 42.5 percent of total market revenue, while the top five players extend their combined footprint to roughly 58.8 percent. This concentration level suggests a market where scale advantages and proprietary technology stacks play a decisive role, yet sufficient white space remains for agile entrants and specialized component suppliers to capture value in niche or rapidly evolving subsegments.
Among the recognized leaders shaping this competitive landscape is Sensirion AG, headquartered in Stäfa, Switzerland. Sensirion has built a strong reputation for its CMOSens®-based sensor ICs and modular platforms, including the SGP40 and SGP41 VOC/NOx sensor families and the integrated SEN6x platform that combines PM, CO2, and multi-gas sensing capabilities for indoor air quality monitoring. In December 2025, the company announced next-generation SEN65 and SEN63C indoor air quality sensor platforms, signaling a continued commitment to multi-parameter measurement enhancement and system-level optimization.
Worldwide Air Quality Sensor ICs Market
ScioSense B.V., based in Eindhoven, Netherlands, competes through its specialization in MOX-based air quality sensor ICs, notably the ENS16x, ENS160, and ENS170A series. These products are engineered for VOC, multi-gas, and indoor air quality detection, with certain variants offering integrated processing and automotive-grade qualifications. ScioSense's focus on configurable gas sensing solutions positions it as a flexible supplier for OEMs seeking customized environmental monitoring architectures.
Bosch Sensortec GmbH, operating from Reutlingen, Germany, leverages its MEMS expertise to deliver a diversified portfolio that includes the BME688 and BME690 4-in-1 gas, humidity, temperature, and pressure sensors augmented with AI-driven interpretation capabilities. The company also offers the BMV080, an ultra-compact PM2.5 particulate matter sensor. In June 2025, Bosch Sensortec unveiled the BME690 with up to 50 percent reduced power consumption, specifically optimized for high-condensation environments. Continuing this momentum, the company introduced the BMV080 in January 2026, describing it as the world's smallest fanless PM2.5 particulate matter air quality sensor for ultra-compact IoT devices.
Renesas Electronics Corporation, headquartered in Tokyo, Japan, supplies the ZMOD series of air quality sensor IC modules, including the ZMOD4410 for total VOC and indoor air quality applications and the ZMOD4510 for outdoor monitoring. Renesas differentiates its offerings through a firmware-configurable architecture that simplifies signal conditioning and accelerates time-to-market for end-product developers.
Infineon Technologies AG, based in Neubiberg, Germany, is recognized for its XENSIV™ PAS CO2 sensor ICs, which utilize photoacoustic spectroscopy to deliver accurate indoor air quality and CO2 monitoring within compact form factors. In September 2024, Infineon released the XENSIV PAS CO2 5V sensor for smart buildings, emphasizing real-time air quality data delivery and compliance with IAQ standards.
The competitive field also includes prominent contributors such as Amphenol Advanced Sensors (Telaire) in St. Marys, Pennsylvania, USA, which manufactures CO2, VOC, dust/PM, and humidity sensors leveraging NDIR and other technologies for HVAC, building automation, and automotive use cases. Amphenol SGX Sensortech, based in Corby, United Kingdom, develops MOX and other gas sensor technologies for indoor air quality, with recent introductions including the SGX4410 and SGX4510 series for versatile detection. Additionally, Cubic Sensor and Instrument Co., Ltd. in Wuhan, China, produces integrated air quality sensor modules that combine PM, CO2, VOC, and environmental parameters using NDIR, laser, and other sensing technologies.
Our report goes beyond corporate profiling to examine product portfolio overlaps, pricing strategies, and the strategic implications of recent product launches. By connecting launch timelines to broader market demand shifts, the analysis reveals which technology roadmaps are likely to capture disproportionate adoption and which legacy architectures may face margin compression.
Industry Dynamics: Supply Chain Pressures, Regulatory Shifts, and Environmental Realities
Market growth does not occur in a vacuum. The air quality sensor IC sector is navigating a complex matrix of macro-economic and regulatory forces that will profoundly influence sourcing strategies, cost structures, and regional competitiveness. In January 2026, U.S. Presidential Proclamations imposed a 25 percent tariff on certain advanced computing chips, while directing policy actions on critical minerals supply chains. Although this measure primarily targeted high-performance computing semiconductors, its ripple effects extend to the broader semiconductor ecosystem, potentially affecting the cost and availability of sensor IC components that depend on specialized fabrication processes and advanced packaging technologies.
Simultaneously, geopolitical tensions surrounding critical material access continue to shape the industry's operational calculus. China's restrictions on rare earth and critical mineral exports have raised expectations of supply shortages and increased input costs for materials integral to MEMS and gas sensor production. These constraints are particularly relevant for manufacturers that rely on specific element dependencies for sensor calibration, thermal management, or protective coatings. Strategic procurement and supply chain diversification are no longer optional; they are competitive necessities that will determine which firms can sustain margin stability through the forecast period.
Beyond geopolitical and trade dynamics, the environmental footprint of semiconductor manufacturing itself introduces additional cost and compliance pressures. Semiconductor fabrication processes generate air pollutants, including VOCs, NOx, SOx, and particulate matter, which influence upstream environmental compliance costs for sensor IC production. As regulators worldwide tighten emissions monitoring and enforce more rigorous sustainability standards, sensor manufacturers may face increased capital and operational expenditure requirements to maintain compliant production lines. Our report evaluates how these upstream dynamics intersect with downstream demand, identifying the segments that are best insulated from cost pass-through challenges and the geographies where regulatory alignment may facilitate faster adoption.
What This Research Delivers: An Operational Framework for 2026 Decision-Making
The Worldwide Air Quality Sensor ICs Market research is engineered to function as a strategic decision-support tool, not merely a descriptive data repository. Stakeholders across semiconductor manufacturing, component distribution, systems integration, and venture investment will find the report structured to answer the questions that directly impact capital allocation and product planning.
Key analytical deliverables include a comprehensive historical and forecast revenue assessment across the entire market and within defined segmentation parameters. The study traces the trajectory from 2020 through 2025 to establish baseline momentum, then projects forward through 2032 to map inflection points, growth accelerations, and potential saturation thresholds. By isolating the CAGR for the forecast period and contextualizing it within technology adoption curves, the report enables readers to differentiate between short-term demand spikes and durable secular growth.
The segmentation analysis provides a structured dissection of revenue by region, by type, and by application, allowing decision-makers to pinpoint where value creation is concentrated and where emerging pockets of demand are forming. Rather than exposing granular percentage splits in this preview, the full report delivers the precise regional revenue contributions and application-specific valuation profiles that procurement leaders, product managers, and investment analysts require to build robust market-entry or expansion strategies.
Competitive profiling within the study extends to a detailed examination of the top market participants, their strategic positioning, and the implications of recent innovations. The report evaluates how product launches from Sensirion, Bosch Sensortec, ScioSense, Renesas, Infineon, Amphenol, and Cubic Sensor and Instrument are reshaping performance expectations, power budgets, and form-factor constraints. By cross-referencing launch timelines with market demand signals, the analysis helps readers anticipate which corporate roadmaps will drive consolidation, which may open partnership opportunities, and where disruptor potential resides.
Additionally, the research integrates a critical assessment of industry dynamics, including tariff impacts, critical mineral supply risks, and environmental compliance cost trajectories. These factors are mapped against regional and segment-level demand profiles to identify the operating environments that will yield the most favorable risk-adjusted returns. The objective is to equip readers with a holistic view of the forces that will govern not only market size, but also profitability and long-term competitive resilience.
Positioning Your Organization for the Forecast Horizon
As the air quality sensor IC market advances toward the 2032 horizon, success will depend on the ability to interpret high-level growth signals with precision, align product roadmaps with evolving performance expectations, and navigate a supply environment that is increasingly sensitive to geopolitical and regulatory interventions. The structural expansion reflected in the forecast—a CAGR of 10.51 percent from 2026 through 2032—represents a meaningful opportunity, but it also intensifies competition for market share, talent, and preferred supply chain positioning.
This report is designed to convert that opportunity into executable strategy. By synthesizing historical performance, forward-looking projections, competitive intelligence, and macro-environmental analysis into a single cohesive narrative, it enables stakeholders to move beyond speculation and base their 2026 decisions on rigorously validated market intelligence. Whether the objective is to prioritize R&D investment, evaluate potential acquisition targets, optimize regional sales focus, or assess supply chain vulnerability, the study provides the structured insight necessary to act with confidence.
To access the complete segmentation data, full competitor profiles, detailed forecast tables, and region-specific strategic commentary, we invite you to consult the full Worldwide Air Quality Sensor ICs Market research report. The complete analysis delivers the granular revenue breakdowns, application-level valuation profiles, and competitive dynamics that will inform your most critical strategic choices throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Air Quality Sensor ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Helical Spring Market Hits $3.12B in 2025, Projected to Reach $4.29B by 2032
By PW Consulting, 2026-09-17
Navigating the Automotive Helical Spring Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview
The automotive helical spring market stands at a critical inflection point as global original equipment manufacturers navigate simultaneous pressures from electrification, regulatory tightening, and supply chain realignment. Our latest Worldwide Automotive Helical Spring Market study provides a comprehensive, data-driven foundation for strategic planning through the end of the decade. Built on a rigorous historical baseline spanning 2020 through 2025 and extending forecast visibility to 2032, this intelligence asset translates complex market signals into actionable pathways for procurement leaders, product development teams, and competitive strategy executives. With the global market reaching approximately 3.12 billion USD in 2025 and projected to expand toward 4.29 billion USD by 2032, a compound annual growth rate of 4.65 percent shapes the trajectory that forward-looking organizations must navigate. The following analysis outlines the structural forces defining the sector, the competitive architecture shaping supplier relationships, and the operational dimensions that will separate resilient companies from those left behind. This is a trailer for a deeper intelligence asset. Complete segmentation breakdowns, regional revenue distributions, type-specific growth profiles, and company-by-company financial exposure metrics are available through the full report. Accessing the complete dataset ensures that your strategic planning rests on verified, granular intelligence rather than generalized industry narratives.
Macro Trajectory and Demand Architecture
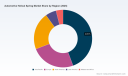
Market expansion over the past half-decade reflects a sector recovering from post-pandemic supply disruptions while absorbing structural shifts in vehicle architecture. Revenue progression from 2.55 billion USD in 2020 through a brief contraction in 2021, followed by recovery and acceleration into 2025, illustrates the resilience of helical spring demand even amid semiconductor constraints, logistics bottlenecks, and raw material volatility. The forecast window extends steady growth across 2026 through 2032, with the market projected to nearly double its 2020 baseline by decade end. Several underlying demand vectors sustain this trajectory. Passenger vehicle production recovery in key Asian and European markets continues to anchor volume, while commercial fleet operators increasingly retrofit and maintain suspension systems to extend asset lifecycles. Light commercial vehicle deployments in urban logistics networks further stimulate replacement and OEM demand. Heavy commercial applications, though smaller in relative volume, contribute to baseline stability due to rigorous maintenance schedules and longer service intervals. The diversity of end-use demand across passenger cars, light commercial vehicles, and heavy commercial vehicles creates a portfolio effect that buffers individual segments against cyclical downturns. Understanding how these application streams interact with regional manufacturing footprints, cost structures, and supplier capabilities forms a central pillar of the full report. Readers seeking precise revenue allocations across application categories and regional markets will find detailed breakdowns in the complete study.
Competitive Architecture and Strategic Positioning
The competitive landscape reflects a concentrated yet fragmented structure where global specialists operate alongside regional cost-optimized manufacturers. Top-three concentration reaches approximately 38.45 percent, while the top five suppliers command roughly 52.6 percent of market revenue. This concentration level indicates meaningful scale advantages among leading players, yet leaves sufficient room for regional specialists to capture niche value through customization, localized service, and application-specific engineering. Japanese firms such as NHK Spring, Showa Corporation, and Chuo Spring maintain strong positions through advanced manufacturing, OEM relationships, and product integration expertise spanning passenger cars, trucks, and motorcycles. NHK Spring recently advanced its portfolio with a product launch in September 2025, introducing high-strength helical springs optimized for electric vehicle suspensions and lightweighting objectives. Showa Corporation completed durability testing validation in April 2025 for helical springs integrated into Honda hybrid vehicle lineups, reinforcing quality assurance narratives aligned with electrified powertrain requirements. Mubea Fahrwerke GmbH continues to strengthen its European OEM footprint, earning supplier nomination from BMW in June 2025 for helical torsion springs in next-generation chassis systems. Its affiliate Lesjöfors Springs extends spring manufacturing capabilities across Europe and Asia, supporting shock absorber and engine valve applications with broad geographic reach. Chinese manufacturers such as Zhejiang Changchun Spring and Huanyu Spring emphasize cost-effective high-volume production and custom helical compression solutions, leveraging steel alloy capabilities and export-oriented supply chains. Industrial Spring Inc. anchors North American heavy-duty truck suspension supply, serving a market segment where durability and load-bearing performance drive purchasing decisions. Competitive differentiation now extends beyond unit pricing. Lightweight design, fatigue resistance, corrosion mitigation, and supply chain responsiveness increasingly determine sourcing outcomes. The full report maps competitive positioning through revenue estimates, product scope, geographic coverage, and recent strategic moves, enabling procurement teams to benchmark supplier alternatives with precision.
Material, Regulatory, and Operational Dynamics Shaping Value Chains
Several interconnected external forces are reshaping how helical springs are specified, manufactured, and validated. Raw material conditions influence production economics and supplier margin structures. Automotive helical springs predominantly rely on SAE 5160 high-carbon spring steel, with prices experiencing fluctuations of 10 to 15 percent due to alloy scrap supply constraints. At the same time, silicon-manganese steel adoption has demonstrated significant corrosion reduction of approximately 30 percent in high-humidity regions, creating engineering incentives for material substitution where environmental exposure is elevated. Regulatory frameworks are also altering design priorities. Euro 7 emission standards mandate lighter suspension components, pushing development teams to redesign helical springs for around 20 percent weight reduction without compromising fatigue performance. These requirements directly impact geometry planning, material selection, and validation testing cycles. Safety standards add additional specification rigor, with FMVSS 209 requiring helical springs in seat belt retractors to withstand 5000 cycles at a 2000N load, reinforcing the importance of certified manufacturing controls and traceability. Labor economics further differentiate regional production strategies. Precision coiling operations require skilled labor, with US hourly rates near 28 USD compared with roughly 6 USD in China. This cost differential shapes make-versus-buy decisions, nearshoring evaluations, and automation investment pacing. Companies that integrate material strategy, compliance readiness, and labor optimization into a cohesive sourcing and design framework gain meaningful competitive advantage. The complete report translates these dynamics into scenario-based implications for procurement, product engineering, and regional capacity planning, with actionable guidance for managing volatility and capturing value from materials innovation.
What the Full Study Delivers
The Worldwide Automotive Helical Spring Market study is structured to support decision-making across multiple functional domains. It provides verified historical data, forward-looking forecasts, and multi-dimensional segmentation that connects market size with strategic interpretation. The analysis is organized to answer practical questions that leaders face when allocating capital, qualifying suppliers, and preparing for regulatory or technological transitions. Key deliverables include a complete market sizing framework covering the historical period and forecast horizon, with consistent methodology that supports trend analysis and benchmarking. Segmentation analysis examines market structure by region, type, and application, offering organizations the ability to align sourcing and product roadmaps with demand concentration patterns. Competitive profiling explores the strategies, geographic reach, product focus, and recent developments of leading suppliers, enabling structure-to-strategy comparisons for procurement and partnership evaluation. The study also integrates material and regulatory context so that engineering and compliance teams can assess how raw material trends and standard requirements influence cost, design, and validation timelines. Scenario interpretations translate data into operational guidance, highlighting where growth is likely to concentrate, where margin pressure may intensify, and where supplier diversification or vertical integration could improve resilience. This report is particularly valuable for organizations planning OEM negotiations, capacity investments, or entry into new application streams. It is designed for teams that need more than top-line estimates: they require structured intelligence that links market behavior to internal planning assumptions, risk registers, and strategic initiatives. Full access to the source data, including detailed regional and application breakdowns and type-level revenue distributions, ensures that decisions are grounded in a complete picture rather than partial indicators.
Worldwide Automotive Helical Spring Market
Strategic Takeaways for 2026 and Beyond
As organizations prepare for 2026 planning cycles, several strategic priorities emerge from the current market architecture. Supplier evaluation must extend beyond unit pricing to include lightweighting capability, fatigue and corrosion performance, compliance readiness, and geographic flexibility. Procurement strategies should assess how raw material volatility, particularly in high-carbon spring steel and alloy scrap availability, will affect cost forecasting and contract structuring. Engineering teams need to anticipate how regulatory pressure, especially around weight reduction and safety validation, will influence spring design, testing cycles, and qualification timelines. Competitive positioning will increasingly reward suppliers that can combine scale, precision manufacturing, and application-specific engineering with reliable delivery and regional responsiveness. Companies that treat the helical spring market as a static commodity segment risk underestimating the value of technical differentiation and supply resilience. Those that align sourcing, product development, and regulatory strategy with verified market intelligence will be better positioned to manage cost, performance, and risk through the forecast period. The full report converts these priorities into detailed benchmarks, regional demand maps, type-level growth outlines, and supplier profiles that support structured decision-making. Accessing the complete study provides the granularity necessary to validate assumptions, compare alternatives, and align cross-functional teams around a shared market view.
Automotive Leaf Spring Assembly Market
The Worldwide Automotive Helical Spring Market study is available now. Complete regional, type, and application breakdowns, supplier financial context, and scenario-based planning guidance are included in the full report. Download the complete intelligence package to equip your 2026 strategy with verified, presentation-ready market insights.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Helical Spring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Utility String Inverter Market Hits $7,505M in 2025, Projected 8.74% CAGR to 2032
By PW Consulting, 2026-09-17
Navigating the 2026 Landscape: Strategic Insights from the Worldwide Utility Scale String Inverter Market
The global energy transition is entering a phase of structural maturation, where the performance, scalability, and regulatory alignment of utility-scale string inverters have become decisive factors in project economics and grid resilience. As solar deployments shift from policy-driven experimentation to commercially optimized infrastructure, procurement teams, technology strategists, and market planners require intelligence that cuts through fragmented signal and isolates actionable trajectory. The latest Worldwide Utility Scale String Inverter Market research report delivers precisely this framework: a rigorously modeled, multi-dimensional analysis designed to anchor 2026 corporate decision-making in verifiable market mechanics rather than speculative narratives.
This executive briefing outlines the core analytical architecture of the study, demonstrates its direct application to 2026 strategic planning, and illustrates how procurement roadmaps, capacity allocation, and competitive positioning can be refined using the report’s proprietary segmentation and scenario modeling. Readers seeking granular regional breakdowns, power-rating revenue distributions, and component-level valuation matrices will find those datasets systematically mapped within the full publication, where they are structured for immediate integration into investment committees, supply chain forecasts, and technology adoption timelines.
The 2026 Inflection Point: Why Utility-Scale String Inverters Demand Refined Strategic Intelligence
The utility-scale inverter segment has evolved from a commoditized balance-of-system component into a highly engineered nexus of grid-forming capability, modular scalability, and software-integrated asset management. Recent industry assessments confirm that string inverter architectures now command a majority share of the utility-scale on-grid inverter market, driven by their inherent flexibility in phased deployments, simplified maintenance logistics, and favorable levelized cost of energy profiles. This structural shift compels stakeholders to reassess procurement criteria, vendor qualification metrics, and long-term service agreements with greater precision than historical centralized-inverter paradigms required.
The research report captures this transition by establishing a continuous historical baseline spanning 2020 through 2025, then projecting forward across a six-year forecast window through 2032. Total market revenue, measured in USD millions, has been reconstructed using shipment-weighted valuation, regional deployment pacing, and component-mix evolution. The trajectory from the early 2020 baseline to the mid-2020s reflects accelerated project pipelines, improved inverter power density, and the compounding effect of utility-scale tender activity across multiple geographies. Forecasts extend this momentum through 2032, with the compound annual growth rate anchoring at 8.74 percent. This growth rate is not presented as a static assumption but as a dynamically stress-tested output that incorporates capacity expansion cycles, module-to-inverter power matching trends, and evolving interconnection standards.
For 2026 decision-makers, this methodology translates into three immediate strategic advantages. First, it isolates the inflection between historical shipment execution and forward-looking capacity commitments, enabling capital planners to distinguish between temporary supply tightness and structural demand expansion. Second, it maps the interaction between hardware deployment and software/service attachment rates, revealing how recurring revenue streams and performance guarantees are reshaping vendor selection criteria. Third, it provides a disciplined baseline against which internal procurement forecasts, regional pipeline assumptions, and technology roadmap milestones can be calibrated, reducing the risk of overcommitting to inventory or underpreparing for specification upgrades.
Research Architecture: How the Report Converts Complexity into Executable Intelligence
The study is engineered to serve cross-functional teams rather than a single procurement silo. Its analytical framework is organized around multiple interdependent dimensions that mirror how enterprise stakeholders actually evaluate utility-scale inverter decisions. Each dimension is built with transparent modeling assumptions, cross-validated against shipment records, tender documentation, and manufacturer capacity disclosures, then stress-tested across macroeconomic and regulatory scenarios.
Segmentation Framework and Analytical Depth
The report dissects the market through three core segmentation axes, each designed to reveal distinct commercial implications. Regional analysis maps deployment concentration, policy-driven pipeline velocity, and supply chain localization trends without reducing complex geographies to simplistic growth rankings. Power-rating segmentation captures the ongoing shift toward higher-current architectures and modular block configurations that align with next-generation photovoltaic module formats and phased plant commissioning strategies. Component-level analysis separates hardware revenue from software and services, illuminating how remote monitoring, predictive maintenance, grid-support firmware, and performance optimization layers are becoming inseparable from the core inverter value proposition.
A dedicated competitive concentration module quantifies market consolidation dynamics, tracking how leading manufacturers balance scale, technological differentiation, and regional service footprints. The analysis contextualizes concentration metrics against recent production expansions, product architecture launches, and grid-forming capability introductions, allowing readers to assess whether market share shifts reflect temporary pricing advantages or durable structural moats.
Operational Content for 2026 Planning Cycles
Beyond high-level sizing, the publication delivers practical instruments that can be embedded directly into internal workflows. These include:
- Pipeline-to-capacity alignment matrices that help procurement and engineering teams match inverter specifications with anticipated module upgrades and site layout changes.
- Vendor capability benchmarking across grid support features, thermal performance thresholds, and modular scalability, enabling systematic shortlisting rather than anecdotal comparison.
- Regulatory exposure mapping that ties incentive phase-out timing, market-based pricing transitions, and interconnection rule updates to deployment windows and margin sensitivity.
- Supply chain cost-pressure indicators that connect raw material pricing movements, labor cost escalation, and manufacturing expansion timelines to component valuation and total installed cost forecasts.
This structuring ensures that the report functions not merely as a market snapshot but as a decision-support system for 2026 budgeting, vendor negotiations, and technology roadmapping. The full report preserves detailed data tables, scenario overlays, and regional granularity so that analysts can extract precisely the slice required for their internal models without reconstructing the underlying methodology from scratch.
Worldwide Utility Scale String Inverter Market
Competitive Positioning and the 2026 Vendor Landscape
The utility-scale string inverter market is contested by a diverse set of manufacturers whose strategies diverge along technology integration, regional service strength, production scalability, and software differentiation. Competitive analysis in the report evaluates these players through a multi-layered lens: shipment momentum, architecture innovation, grid-forming and high-current readiness, service network density, and exposure to regional policy shifts. Rather than presenting a static leaderboard, the research maps how each company’s recent moves position it for specific deployment profiles and procurement priorities in 2026 and beyond.
Major Chinese manufacturers continue to emphasize modular architectures, high power density, and AI-assisted fault detection. Recent product introductions highlight scalable block configurations, enhanced current support for high-power modules, and intelligent arc-fault and grid-forming capabilities designed for large PV plants and elevated ambient operating conditions. These developments signal a clear intent to align inverter design with the next wave of utility-scale projects that prioritize phased construction, higher module currents, and reduced derating risk under temperature stress.
European and other established technology providers are responding with heightened focus on industrial-grade reliability, modular system design, and grid integration solutions that address stringent interconnection requirements and long-term performance guarantees. Recent production expansions and high-capacity inverter line adjustments illustrate how incumbents are scaling to meet global demand while reinforcing perceptions of engineering robustness and service continuity.
Simultaneously, companies with strong regional footholds are leveraging localized supply, specialized high-voltage string platforms, and utility-scale ground-mount expertise to defend or expand share in specific markets. Others are extending their footprint from distributed or commercial segments into larger utility configurations, while integrated industrial and electrification players continue to position inverters within broader energy management and power conversion portfolios.
The report synthesizes these dynamics into a structured competitive matrix that helps buyers evaluate trade-offs among price, technological readiness, service responsiveness, and supply continuity. It also tracks how recent product launches and production expansions alter short-term availability expectations, which is critical for 2026 project timelines where specification changes late in the design cycle can cascade into delivery delays or renegotiation risk.
Regulatory, Cost, and Market Structure Dynamics Shaping 2026 Decisions
No utility-scale procurement strategy in 2026 can ignore the regulatory and cost environment. The research embeds these forces directly into its scenario analysis rather than treating them as peripheral commentary. In the United States, legislative changes affecting clean electricity production and investment tax credits introduce timing sensitivity for facilities with construction commencement and in-service dates beyond specific thresholds. The report translates these policy milestones into deployment pacing implications, helping planners sequence projects to align incentive eligibility with inverter procurement, manufacturing lead times, and interconnection queue realities.
PV Inverters Market
On the cost side, recent movements in global polysilicon pricing and labor cost escalation in North American utility-scale installations feed directly into total system cost modeling. Even when inverter hardware constitutes a defined share of balance-of-system expenditure, upstream material pricing and installation labor dynamics influence bidding environments, margin structures, and the relative attractiveness of higher-efficiency or higher-reliability inverter options. The research incorporates these cost-pressure indicators to illustrate where inverter specification choices can partially offset broader system cost inflation through improved performance, reduced downtime, or simplified commissioning.
Regulatory shifts in other regions similarly reshape project economics and inverter selection logic. Market-based pricing reforms for new wind and solar capacity, restrictions on full-export configurations above certain capacity thresholds, and evolving compensation structures alter how developers value export flexibility, curtailment resilience, and grid-support features. The report analyzes how these policy transitions influence the relative priority of modular designs, software-driven optimization, and inverters capable of operating efficiently under variable compensation and export constraints.
Taken together, these dynamics underscore why deterministic forecasting is insufficient in 2026. The report’s value lies in its ability to connect policy timeline shocks, input-cost volatility, and technology differentiation into a single evaluative framework, enabling stakeholders to test deployment timing, specification selection, and vendor commitments against multiple plausible futures.
From Intelligence to Execution: Translating Findings into 2026 Corporate Strategy
The strategic utility of this research is maximized when organizations move from observation to integration. For procurement and supply chain leaders, the report supports more disciplined vendor shortlisting, contract structuring, and inventory positioning by clarifying where modular scalability, current-class upgrades, and software attachment rates are becoming decisive purchasing criteria. For technology and engineering teams, it offers a structured basis for evaluating grid-forming readiness, thermal performance margins, and compatibility with next-generation module formats. For executives and market planners, the modeled growth trajectory and concentration analysis inform capacity planning, partnership evaluation, and regional prioritization with reduced reliance on fragmented public data.
Because the full dataset preserves detailed regional valuation, power-rating revenue distribution, component-level breakdowns, and competitive event timelines, teams can extract the exact parameters needed for internal financial models, bid strategy documents, and technology roadmaps without reconstructing the underlying market logic. The publication is deliberately organized so that high-level narrative supports strategic alignment while granular tables and scenario overlays enable precise operational use.
Accessing the Full Market Intelligence
The Worldwide Utility Scale String Inverter Market research report is structured as a working intelligence asset for organizations that must make capital, procurement, and technology decisions in a fast-shifting environment. Its combination of historical reconstruction, forward-looking growth modeling, segmentation depth, and competitive event tracking provides a comprehensive foundation for 2026 planning cycles. Stakeholders seeking complete regional data splits, power-rating and component revenue distributions, vendor benchmarking details, and scenario-based projections are encouraged to access the full report through the source page, where the complete intelligence set is available for immediate integration into strategic workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Utility Scale String Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Product Passport Software Market Surges to $285.5M in 2025, 22.5% CAGR to $1.18B by 2032
By PW Consulting, 2026-09-17
The Digital Product Passport Software Market: A Strategic Imperative for 2026 and Beyond
As global regulatory frameworks shift toward unprecedented transparency, the Digital Product Passport Software Market has emerged from a niche sustainability initiative into a core infrastructure requirement for modern enterprises. Based on our latest comprehensive analysis, this sector is not merely growing—it is accelerating at a pace that demands immediate strategic attention from C-suite executives, supply chain leaders, and compliance officers. The transition from voluntary sustainability reporting to mandatory digital traceability represents a fundamental restructuring of how products are manufactured, tracked, and consumed.
Our research indicates that the market revenue, measured in USD Million, has exhibited a compound annual growth rate (CAGR) of 22.5% throughout the forecast period extending from 2026 to 2032. This trajectory underscores a critical reality: Digital Product Passport (DPP) software is no longer a future consideration but a present-day operational necessity. With the overall market size projected to expand significantly from its base year levels in 2025, organizations that delay adoption risk not only regulatory penalties but also competitive obsolescence in increasingly transparent supply chains.
This article serves as a strategic overview of the market dynamics, competitive landscape, and operational considerations detailed in our full report. While we outline the macro-level forces shaping the industry, the specific segmentation data, regional revenue splits, and granular adoption rates are reserved for our licensed intelligence portal. Understanding the breadth of this opportunity requires looking beyond the headline numbers to the structural shifts driving demand.
Regulatory Catalysts and Market Dynamics
The primary engine propelling this market expansion is the tightening regulatory environment, particularly within the European Union. The Ecodesign for Sustainable Products Regulation (ESPR) has established a phased implementation roadmap for Digital Product Passports across priority sectors. Our analysis highlights that batteries are set to become the first mandatory category from 2027, followed by textiles, iron and steel, and other key industries. This regulatory cascade creates a domino effect across global supply chains, compelling manufacturers outside the EU to adopt compliant systems if they wish to maintain access to the European market.
A critical milestone in this regulatory timeline is the operational launch of the central EU DPP Registry. Scheduled to become functional in July 2026, this registry will serve as the central node for market access verification. Organizations must ensure their software infrastructure is interoperable with this registry well before the deadline. The implication for enterprise strategy is clear: compliance is not a checkbox exercise but a data integration challenge that requires robust software architecture capable of communicating with centralized government databases.
However, regulatory pressure is only one side of the coin. The market dynamics are equally influenced by the need for supply chain visibility and consumer engagement. Modern consumers increasingly demand verifiable proof of sustainability claims, driving brands to adopt DPP solutions that offer end-to-end traceability. This dual pressure—regulatory compliance on one end and consumer trust on the other—creates a resilient demand curve that is less susceptible to economic downturns than typical software markets.
Key Industry Developments and Strategic Partnerships
The landscape is evolving rapidly through strategic collaborations and pilot projects that signal the transition from concept to scalable execution. In early 2026, significant moves were observed among key players. For instance, a notable Memorandum of Understanding was signed between DigiProd Pass and Fashion Power Group for a Digital Product Passport pilot project in apparel manufacturing. Such initiatives demonstrate the industry's focus on practical application within the textile sector, which remains a high-priority area for regulation.
Simultaneously, technology giants are entering the fray to provide the infrastructure necessary for scale. A collaboration between Siemens and Accenture has been advancing Digital Product Passports from concept to scalable execution, with a specific focus on data integration. This involvement of major industrial technology firms validates the market's maturity and suggests that DPP software will increasingly become embedded within broader Manufacturing Execution Systems (MES) and Enterprise Resource Planning (ERP) platforms.
Furthermore, sector-specific preparations are underway. Leaders in the textile space have highlighted ongoing DPP pilots and groundwork for production systems ahead of the 2026 registry launch. These updates indicate that early movers are already stress-testing their data pipelines to ensure they can handle the volume and veracity requirements of a fully operational registry. The convergence of regulatory deadlines and technological readiness creates a narrow window for organizations to finalize their vendor selection and implementation strategies.
Market Segmentation and Deployment Preferences
Our report dives deep into how organizations are choosing to deploy DPP solutions. While specific revenue splits are detailed in the full intelligence subscription, the broader trends indicate a strong preference for certain deployment models based on organizational size and complexity. Cloud-based DPP software deployments are becoming the default choice for many entities, particularly Small and Medium-sized Enterprises (SMEs). This preference is driven by lower upfront infrastructure costs and the flexibility of subscription models compared to traditional on-premises solutions.
Digital Product Passport Software Market
The shift toward cloud-based architectures also addresses the scalability challenges inherent in managing vast amounts of product data. However, this introduces new operational considerations. Organizations must remain vigilant about cloud spending efficiency, as reports suggest that unused resources can lead to significant waste in cloud hosting budgets. For scalable DPP platforms reliant on cloud hosting for data management, optimizing these costs is a key operational factor that our research examines in detail.
Industry vertical adoption also varies significantly based on regulatory exposure and supply chain complexity. Sectors such as textiles and apparel, electronics, and automotive batteries are leading the charge. Each sector presents unique challenges regarding data standardization and lifecycle management. For example, the electronics sector must navigate complex chemical compliance data, while the fashion industry focuses heavily on material provenance and labor standards. Our full report provides a comparative analysis of these vertical-specific requirements, helping stakeholders understand which solutions are best tailored to their specific operational context.
Competitive Landscape and Vendor Ecosystem
The market is characterized by a mix of specialized startups, established compliance software providers, and large conglomerates entering the space. Our analysis identifies a fragmented but consolidating landscape, with a handful of key players capturing significant attention. The competitive intensity is high, driven by the race to establish standard-setting positions before the registries go live.
Among the notable entities shaping the market is Spherity, based in Cologne, Germany. Their VERA Digital Product Passport solution is heavily focused on battery passports and compliance with ESPR and REACH regulations. They enable lifecycle management and integrate recycling and resale marketplace functionalities, making them particularly relevant for the battery sector where mandatory compliance begins earliest.
In the textiles and fashion domain, TrusTrace, headquartered in Stockholm, Sweden, delivers an end-to-end DPP compliance solution. Their offering includes supplier traceability, unique IDs, and QR codes designed for standardized consumer interfaces. This focus on verified supply chain data aligns closely with the needs of fashion brands facing intense scrutiny over sustainability claims. Similarly, Arianee, located in Paris, France, offers a blockchain-powered DPP platform specialized in product lifecycle, ownership tracking, and consumer engagement, with a strong foothold in luxury goods and fashion.
Kezzler, from Oslo, Norway, provides a Connected Products Platform (CPP) for digital IDs and DPP across industries including textiles and footwear. Their support for GS1 Digital Link and partnerships for supply chain visibility positions them as a infrastructure-play vendor. On the compliance and chemical safety side, 3E Exchange, based in Carlsbad, California, provides Digital Product Passports integrated with safety, chemical, and regulatory compliance data such as PFAS and RoHS, catering to supply chain visibility and sustainability requirements.
Renoon, operating out of the Netherlands, functions as a DPP infrastructure platform connecting data, compliance, and customer value for fashion and textile brands, with a strong emphasis on operational system integration. iPoint-systems, based in Reutlingen, Germany, offers software solutions for product compliance and sustainability data management supporting DPP requirements, leveraging their long history in compliance software.
Blockchain technology remains a core component for several players. Circularise, also based in the Netherlands, provides blockchain-based Digital Product Passports for material traceability, transparency, and circular economy applications. In the realm of retail and labeling, Avery Dennison, headquartered in Mentor, Ohio, delivers DPP as a Service (DPPaaS) via their atma.io platform for end-to-end product traceability and EU compliance in fashion and retail. Finally, Carbonfact, with a presence in France and the USA, offers an AI-powered platform for LCA-based Digital Product Passports in apparel and footwear, automating environmental data and publishing compliant DPPs.
Market concentration metrics suggest that while no single vendor dominates the entire landscape, there is a moderate level of consolidation among the top players. This fragmentation offers buyers choice but also creates complexity in selecting the right partner. Our full report includes a detailed vendor benchmarking matrix that evaluates these companies based on technology stack, compliance coverage, and scalability.
Strategic Considerations for 2026 Decision Makers
For enterprise leaders planning their 2026 strategies, several critical factors emerge from our analysis. First, the timeline for compliance is non-negotiable. With the EU DPP Registry becoming operational in July 2026, the window for system integration and testing is narrowing. Organizations must prioritize data readiness, ensuring that product information is structured, verifiable, and accessible via API.
Second, data privacy cannot be an afterthought. DPP systems handling personal data must comply with GDPR requirements, including data minimisation, explicit consent, and breach notification within 72 hours. Potential fines can reach up to 4% of global turnover, representing a significant financial risk. Our research outlines the specific data governance frameworks required to mitigate this risk while maintaining the transparency needed for compliance.
Third, the cost of non-compliance is severe. Under ESPR regulations, non-compliance prohibits the market placement of affected products in the EU. Member states are empowered to enforce fines and potential public procurement exclusions. This creates a clear line of sight between DPP software investment and revenue protection. The software is not an IT expense but a license to operate in key markets.
Finally, organizations must consider the long-term scalability of their chosen solution. As the registry expands to include more product categories beyond batteries and textiles, the software must be flexible enough to accommodate new data fields and reporting standards. Vendors that offer modular architectures and strong integration capabilities with existing ERP and PLM systems will likely provide more value over the forecast period.
Conclusion and Access to Full Intelligence
The Digital Product Passport Software Market represents one of the most significant shifts in industrial data management in recent decades. The convergence of regulatory mandates, consumer demand, and technological maturity creates a compelling case for immediate action. With a projected CAGR of 22.5% and a market size expanding into the billions by the end of the decade, the stakes for strategic positioning are high.
However, navigating this landscape requires more than general awareness. Success depends on granular insights into regional adoption rates, specific vendor capabilities, and detailed cost-benefit analyses of deployment models. Our full market research report provides the depth required to make informed investment decisions, including proprietary data on segmentation splits, competitive positioning, and risk assessments that are not available in public summaries.
To access the complete dataset, including detailed regional revenue projections, specific vendor benchmarking scores, and comprehensive regulatory impact analyses, we invite you to explore our dedicated research portal. The intelligence contained within is designed to equip your organization with the precision needed to lead in the era of digital transparency.
Shipping Software Market
For detailed analysis of this topic, please visit the official page: Digital Product Passport Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Water Based Acrylates Copolymer Market to Hit $1,356.55M by 2032 at 5.34% CAGR
By PW Consulting, 2026-09-17
Navigating Growth and Complexity in the Global Water Based Acrylates Copolymer Rheology Modifiers Market
The global landscape for water based acrylates copolymer rheology modifiers is undergoing a period of nuanced transformation. As industries pivot toward sustainable formulations and waterborne solutions, the demand for precise viscosity control and emulsion stability has never been more critical. At PW Consulting, we recognize that making informed strategic decisions in this sector requires more than surface-level data. It demands a granular understanding of market trajectories, competitive maneuvers, and the underlying raw material dynamics that shape profitability. Our latest comprehensive study, the Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market research, offers a definitive look into this evolving space, providing the intelligence necessary to navigate the forecast period from 2026 through 2032.
Market Trajectory and Historical Context
Understanding where the market is going requires a clear view of where it has been. The industry has demonstrated consistent resilience and growth over the past half-decade. Valued at approximately 726.28 million USD in 2020, the market expanded steadily to reach an estimated 942.5 million USD by 2025. This historical progression underscores the steady adoption of acrylates copolymer technologies across various industrial and consumer applications. Looking ahead, the forecast indicates continued expansion, with market value projected to climb toward 1356.55 million USD by the end of 2032.
This growth is not merely linear; it reflects shifting consumer preferences and regulatory pressures favoring water-based systems over solvent-based alternatives. The Compound Annual Growth Rate (CAGR) during the forecast period is estimated at 5.34%, signaling a moderate but robust pace of expansion. For stakeholders, this trajectory suggests a maturing market where competitive advantage will depend on optimization and innovation rather than sheer volume capture alone. The revenue unit throughout our analysis is maintained in Million USD, ensuring consistency and clarity for financial modeling and strategic planning.
Strategic Segmentation Insights
The market is diversified across type, application, and region, each presenting unique opportunities and challenges. Our research dissects these segments to reveal where value is being generated and where potential bottlenecks may arise.
Product Type Dynamics
Within the product landscape, the market is primarily driven by technologies such as Alkali Swellable Emulsions (ASE) and Hydrophobically Modified Alkali Swellable Emulsions (HASE), alongside Cross-linked Acrylic Copolymers. ASE technologies have historically held significant volume due to their versatility in personal care and industrial applications. However, HASE modifiers are gaining traction for their ability to provide high viscosity at low usage levels, particularly in formulations requiring specific sensory profiles or stability under varying pH conditions. Cross-linked acrylic copolymers represent a specialized segment, often utilized where high suspension stability is paramount. The interplay between these types influences formulation costs and performance outcomes, making the choice of rheology modifier a critical R&D decision.
Application Layer Opportunities
The demand pull from downstream applications is a primary engine of growth. Paints and Coatings remain a foundational segment, driven by the global shift toward low-VOC and waterborne coating systems. Personal Care and Cosmetics represent another substantial pillar, where rheology modifiers are essential for texture, stability, and sensory experience in increasingly complex formulations like sulfate-free cleansers and natural-based creams. Adhesives and Sealants, as well as Detergents and Household Cleaning, also contribute significantly to the overall demand profile. Each application segment has distinct technical requirements, and our report details how different rheology modifiers align with these specific needs without compromising on performance or cost-efficiency.
Regional Supply and Demand Patterns
Geographically, the market is distributed across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Asia Pacific continues to be a central hub for both manufacturing and consumption, reflecting the region's massive industrial base and growing consumer goods sector. Europe and North America maintain strong demand driven by stringent environmental regulations and high standards for product performance in personal care and coatings. Emerging regions in Latin America and the Middle East and Africa offer incremental growth opportunities as industrialization and personal care markets expand. Our analysis maps these regional flows to help companies identify where to allocate supply chain resources and where to focus sales efforts for maximum return.
Competitive Landscape and Key Players
The market is moderately concentrated, with the top three competitors holding a combined share of 38.5% and the top five accounting for 52.8%. This structure indicates a competitive environment where major players coexist with specialized niche suppliers. Leading the field are industry giants such as The Dow Chemical Company, BASF SE, and Lubrizol Corporation, each offering flagship product lines like ACULYN, RHEOVIS, and Carbopol respectively. These companies compete not only on price but on technical service, formulation support, and the ability to deliver consistent quality at scale.
Other significant contributors include Arkema, Ashland Global Holdings, and Elementis, which leverage specialized additives to capture specific application niches. Regional specialists and focused innovators like Clariant, BYK Additives & Instruments, Akzo Nobel, Croda International, 3V Sigma, Lamberti Group, and Organik Kimya further diversify the competitive field. These players often compete on agility, regional customization, and specific technical attributes such as clarity in rinse-off systems or compatibility with natural ingredients. Understanding the strategic positioning of these key companies is essential for assessing partnership opportunities, potential consolidation, or competitive threats.
Raw Material Volatility and Cost Dynamics
A critical layer of complexity in this market lies in the upstream supply chain, particularly regarding acrylic acid, the primary feedstock for acrylates copolymers. Price volatility in raw materials directly impacts margins and pricing strategies for rheology modifiers. In 2025, the market for acrylic acid saw significant shifts. In China, prices declined steadily from approximately 8,196 RMB/ton in January to 5,900 RMB/ton by December, indicating a shift toward oversupply conditions in the region. This trend provided temporary cost relief for manufacturers sourcing from Asian supply chains but also signaled potential demand soft ness or capacity expansion pressures.
Conversely, the North American market experienced different dynamics. In Q1 2026, acrylic acid prices fell 4.21% quarter-over-quarter, driven by muted demand and ample supply. However, cost pressures persist elsewhere. In March 2026, BASF implemented price increases on acrylic monomers in North America, raising selling prices for glacial acrylic acid and various acrylates to counter rising raw material, energy, and logistics costs. This divergence in regional cost structures highlights the importance of geographic supply chain management. Companies must navigate these fluctuations carefully to maintain pricing power while protecting profitability.
Rheology Modifiers Market
Recent Industry Developments and Innovation
Innovation remains a key differentiator in a crowded market. Companies are increasingly focusing on sustainability and performance enhancement to justify premium positioning. For instance, in March 2025, Lubrizol unveiled the pre-launch of Carbopol BioSense polymer, a sustainable rheology modifier, with the official launch occurring at in-cosmetics Global in April 2025. This move underscores the industry's shift toward bio-based and environmentally friendly solutions. Further data released in November 2025 confirmed that Carbopol Fusion S-20 polymer performance rivals traditional acrylates copolymer technologies in rinse-off systems, offering improvements in thickening, suspension, and clarity.
Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
Such developments illustrate the rapid pace of technical advancement. Formulators are constantly seeking materials that deliver equivalent or superior performance with improved sustainability profiles or ease of use. Keeping pace with these launches is vital for downstream users who need to maintain competitive product offerings. Our research tracks these developments to provide context on how new introductions might disrupt existing supply relationships or redefine performance benchmarks.
Regulatory and Environmental Pressures
Regulatory frameworks continue to shape market demand. Environmental regulations pushing for reduced volatile organic compounds (VOCs) in coatings and stricter safety standards in personal care products favor water-based systems. This regulatory tailwind supports the long-term growth of water based acrylates copolymer rheology modifiers. However, compliance costs and the need for reformulation can create short-term barriers. Companies that proactively adapt to these regulations by developing compliant additive solutions position themselves favorably. The interplay between regulation, raw material sourcing, and formulation technology creates a complex environment where strategic foresight is invaluable.
Value Proposition of Our Research
Our Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market report is designed to be more than a statistical overview. It is a strategic tool intended to support decision-making at the executive and operational levels. The study provides a deep dive into market sizing, growth drivers, and restraints, contextualized within the historical data from 2020 to 2025 and the forecast horizon through 2032. We analyze the segmentation splits across types, applications, and regions to highlight where growth is most concentrated and where diversification might be warranted.
Furthermore, the report examines the competitive landscape, offering profiles on key companies and their recent strategic moves. By integrating raw material price trends and regulatory updates, we provide a holistic view of the cost environment and risk factors. This allows stakeholders to stress-test their strategies against various scenarios. Whether you are looking to enter the market, expand your product portfolio, or optimize your supply chain, the intelligence contained in this study offers the foundation needed to act with confidence.
For detailed breakdowns of specific segment valuations, regional growth rates, and comprehensive company profiles, we invite you to access the full report. The data provided here serves as an indicator of the depth available, but the complete intelligence lies within the full analysis. In a market defined by technical nuance and cost volatility, having the right data is the first step toward securing a competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Disease CRO Market Set to Hit $12.8B by 2032 with 10.2% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for 2026: Navigating the Rare Disease CRO Service Market
The landscape of clinical research is undergoing a pivotal transformation, driven by the increasing complexity of rare disease development and the urgent need for specialized operational excellence. As we move through 2026, pharmaceutical sponsors and biotech innovators face a critical juncture. The decision of how to partner with Contract Research Organizations (CROs) is no longer merely about cost efficiency; it is about securing access to niche expertise, adaptive trial designs, and global patient networks that can make or break an orphan drug application. Our latest market research report, Rare Disease CRO Service Market, offers a comprehensive lens into this evolving ecosystem, providing the strategic clarity needed to navigate the opportunities and challenges of the forecast period from 2026 to 2032.
This article serves as a strategic preview of our findings. It highlights the macroeconomic trajectory, the shifting competitive dynamics, and the operational realities defining the sector. However, the true depth of our analysis lies in the detailed segmentation, granular regional data, and specific competitive benchmarking available in the full report. For executives planning capital allocation, partnership strategies, or service line expansions in the coming year, this intelligence is not just valuable—it is essential.
Rare Disease CRO Service Market
Macroeconomic Trajectory and Market Momentum
The rare disease CRO service market has demonstrated robust growth over the past half-decade, reflecting the broader industry shift toward specialized therapeutics. Our analysis tracks the market revenue from 2020 through the base year of 2025, projecting a strong upward trend into the next decade. The market reached an estimated value in the mid-six figures million USD range by 2025, building on a consistent compound annual growth rate observed over the historical period. This momentum is expected to accelerate, with the forecast period indicating a sustained CAGR of approximately 10.2 percent.
This growth trajectory is not linear. It is underpinned by specific catalysts that are reshaping demand patterns. The market forecast suggests that revenue volumes will expand significantly by 2032, driven by an increasing pipeline of gene therapies, cell therapies, and targeted small molecules for indications that were previously considered undruggable. For strategic planners, this implies that capacity constraints and specialized talent shortages may become binding factors earlier than anticipated. Understanding where this growth concentrates—whether in specific service lines or therapeutic focuses—is key to anticipating supply-demand imbalances. The full report provides a detailed year-by-year breakdown of these projections, allowing stakeholders to model their resource planning against realistic market expansion scenarios.
Segmentation and Operational Focus
One of the most critical aspects of strategic planning in this sector is understanding where the value is being generated within the CRO service portfolio. The market is not monolithic. It is divided into distinct service categories, each carrying different margin profiles, complexity levels, and strategic importance to sponsors. Our research delineates the market across major service types, including clinical development, regulatory consulting, laboratory services, and patient recruitment.
Clinical development remains a cornerstone of the market, reflecting the heavy lifting required in executing complex protocols. However, the relative weight of regulatory consulting and patient recruitment services is gaining prominence as trials become more intricate. Regulatory pathways for orphan drugs are evolving, and the ability of a CRO to navigate these nuances—from FDA Rare Disease Evidence Principles to EMA guidelines—can add significant value beyond data collection. Similarly, patient recruitment in ultra-rare conditions often dictates the timeline and success of a program, making it a high-stakes service segment.
Therapeutic area segmentation further refines this picture. Oncology has historically dominated rare disease trials, but neurology and metabolic disorders are claiming substantial shares of the CRO landscape. The interplay between these areas and the service types offered is a key focus of our analysis. For instance, the requirements for a metabolic disorder trial may differ significantly from a neurological study in terms of biomarker integration, site selection, and long-term follow-up. By examining the market through these dual lenses—service type and therapeutic area—sponsors can identify partners that offer the right combination of capabilities rather than relying on generalized claims. The complete report offers a detailed split of these segments, enabling a nuanced view of where the largest revenue pools and fastest growth vectors reside.
Competitive Landscape and Strategic Positioning
The competitive environment in the rare disease CRO space is characterized by a mix of established global players and specialized boutiques. Market concentration metrics indicate a moderately fragmented landscape, where a handful of leading firms hold significant share, but numerous niche operators thrive by offering deep domain expertise. Our report profiles a wide array of key companies, analyzing their strategic positioning, service footprints, and recent moves.
Firms like Medpace and Precision for Medicine have built reputations on end-to-end capabilities and specialized approaches such as integrated biomarker and cell/gene therapy services. Others, such as Parexel and PPD (Thermo Fisher Scientific), leverage scale and integrated platforms to support complex trials across diverse indications. The landscape also includes specialized entities like Allucent, Ergomed, and TFS HealthScience, which focus intensely on orphan and rare indications, often providing tailored methodologies for patient location and regulatory success.
Contract Research Organization (CRO) Market
Recent developments in 2025 and 2026 underscore the dynamic nature of this competition. We have observed strategic acquisitions and leadership expansions aimed at bolstering capabilities in advanced therapeutics and broader clinical development support. For example, recent acquisition activity by major players to integrate data solutions, endpoint data platforms, and expanded oncology and FSP capabilities signals a trend toward vertical and horizontal integration. Leadership appointments focused on advanced therapeutics and cell/gene therapy programs highlight the industry's commitment to building centers of expertise for the most challenging indications. These moves are reshaping the competitive hierarchy and altering the value propositions available to sponsors. Our report analyzes these developments in detail, providing context on how each company is positioning itself for the future and what these changes mean for partnership negotiations.
Industry Dynamics and External Pressures
Beyond the core market mechanics, a constellation of external factors is influencing the rare disease CRO sector. Regulatory evolution is a primary driver. Initiatives such as the FDA Rare Disease Innovation Hub and the Rare Disease Evidence Principles introduced in 2025 are providing more flexible evidence standards and harmonized approaches for ultra-rare conditions. These regulatory shifts can reduce barriers to entry for certain programs but also introduce new expectations for data quality and trial design. Similarly, the finalization of ICH E6(R3) Good Clinical Practice guidelines emphasizes risk-based monitoring and flexible designs, which are particularly relevant for complex rare disease trials where traditional monitoring approaches may be impractical.
Data privacy and cross-border complexities remain significant hurdles. Regulatory frameworks like GDPR and HIPAA add layers of complexity and cost to trials involving international patient registries and data sharing, especially when genomic data is involved. Sponsors must weigh the benefits of global patient access against the operational burden of compliance. Additionally, reimbursement landscapes and incentives such as Orphan Drug Act designations and EU equivalents continue to drive outsourcing decisions by offering market exclusivity and development support, making the cost-benefit analysis of CRO partnerships even more critical.
Cost structures in rare disease trials also warrant careful attention. The requirement for specialized navigators, expert clinicians, and tailored recruitment strategies leads to higher per-patient costs. Analysis indicates that per-patient CRO costs for ultra-rare Phase III programs can run significantly higher than standard trials, sometimes reaching multiples of standard rates. This cost differential means that efficiency in trial design, patient retention, and site management is paramount. CROs that can demonstrate superior retention rates, reduced protocol deviations, or faster enrollment in hard-to-reach populations offer a compelling value proposition that goes beyond hourly rates. Our report delves into these dynamics, exploring how cost pressures and regulatory incentives interact to shape outsourcing strategies.
Strategic Implications for 2026 Decision-Makers
As organizations prepare their strategies for the remainder of 2026 and beyond, several actionable insights emerge from our analysis. First, the selection of a CRO partner should be aligned with the specific therapeutic and operational profile of the asset. A one-size-fits-all approach is unlikely to yield optimal results in a market where niche expertise can accelerate development and mitigate risks. Second, the trend toward integration—whether through acquisitions or service bundling—suggests that sponsors may benefit from engaging partners who offer cohesive solutions across clinical, regulatory, and data management functions, reducing the fragmentation that can slow down complex trials.
Third, the growing importance of patient-centric approaches and decentralized models is reshaping recruitment and retention strategies. CROs that have invested in advanced technologies, patient advocacy relationships, and global site networks are better positioned to address the challenges of dispersed patient populations. Fourth, regulatory agility is becoming a competitive differentiator. With evolving evidence standards and guidelines, partners that can anticipate regulatory shifts and incorporate flexible designs into trial protocols will add significant value.
Finally, the market growth trajectory suggests that competition for high-quality sites and specialized talent will intensify. Early engagement with capable partners, clear communication of study requirements, and strategic alignment on milestones can help secure the resources needed for success. The full report provides benchmarking data, detailed company profiles, and segment-specific forecasts that allow decision-makers to evaluate their options with precision.
Conclusion
The Rare Disease CRO Service Market stands at the intersection of scientific innovation, regulatory evolution, and operational complexity. The data indicates strong growth, but realizing value in this environment requires more than just tracking market size. It demands a deep understanding of segmentation, competitive dynamics, regulatory nuances, and cost structures. Our market research report offers a detailed, data-driven exploration of these factors, providing the intelligence needed to make informed strategic decisions.
We invite you to explore the full report to access the complete analysis, including detailed regional breakdowns, precise segment valuations, competitive benchmarking, and actionable recommendations tailored for 2026 planning. The insights contained within are designed to empower your team to navigate the rare disease CRO landscape with confidence and clarity.
For detailed analysis of this topic, please visit the official page: Rare Disease CRO Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


