



PW Consulting: 4K Ultra HD TV Market Hits $118.85M in 2025, Projected 24.38% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizon: Navigating the 4K Ultra HD TV Market in 2026 and Beyond
The 4K Ultra HD television market stands at a critical inflection point as of 2026. Driven by an accelerating compound annual growth rate of 24.38 percent, the sector has transformed from a mature consumer electronics category into a high-velocity growth arena fueled by display innovation, smart ecosystem integration, and shifting viewer behaviors. Our latest 4K Ultra HD TVs Market study compresses the historical trajectory of 2020 through 2025 and extends a disciplined forecast window to 2032, delivering the analytical architecture executives need to calibrate capital allocation, product roadmaps, and supply chain resilience in an increasingly volatile landscape.
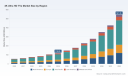
For strategic decision-makers, the overarching narrative is clear: market revenue has climbed from 56.22 million USD in 2020 to an estimated 118.85 million USD in 2025, positioning the base year as a springboard for exponential expansion. Looking forward, the forecast period maps a steep upward curve, projecting revenue to reach 147.92 million USD in 2026, 178.42 million USD in 2027, and accelerating toward 541.36 million USD by 2032. This trajectory is not merely a statistical projection; it is a structural signal that the next wave of growth will be captured by organizations that align product strategy with regional demand patterns, display technology adoption, and application-driven usage models. The purpose of this preview is to illuminate the analytical depth awaiting buyers of the full study, while deliberately withholding the granular breakdowns that only the complete report can provide.
Decoding the Growth Trajectory: From Recovery to Accelerated Expansion
The historical window of 2020 to 2025 reveals a market that has consistently outgrown the broader consumer electronics average. Revenue climbed to 64.76 million USD in 2021, advanced to 76.68 million USD in 2022, and held steady growth at 86.68 million USD in 2023. The acceleration became more pronounced in 2024, when revenue reached 105.39 million USD, before culminating in the 2025 base-year figure of 118.85 million USD. This progression underscores a market that has successfully navigated post-pandemic demand normalization, channel rebalancing, and the early adoption of premium display technologies.
The forecast window from 2026 through 2032 is where strategic planning becomes decisive. Starting at 147.92 million USD in 2026, the market is projected to scale to 228.87 million USD by 2028, then 351.99 million USD by 2030, and ultimately 541.36 million USD by 2032. This stepped expansion signals a market in which technological differentiation, smart-platform monetization, and regional penetration rates will increasingly determine competitive positioning. Executing on this opportunity requires more than a top-line growth assumption; it demands a comprehensive understanding of how product segmentation, regional dynamics, and end-use applications interact over time. The full study unpacks these interactions with a level of granularity that enables scenario planning, market-entry prioritization, and investment sequencing.
Segmentation Architecture: Where Growth Will Concentrate
A market moving at this pace cannot be managed through aggregate figures alone. The report disaggregates the landscape across three critical dimensions, each carrying distinct strategic implications for product planning, pricing architecture, and channel strategy. Understanding how display types compete, how applications evolve, and how regional markets behave is essential for translating a 24.38 percent CAGR into actionable forecasts.
Display Technology Dynamics
The competitive battleground for 4K Ultra HD televisions is increasingly defined by the interplay of advanced display technologies. The study examines OLED, QLED, and LED architectures as distinct value pools, mapping their adoption curves, pricing tiers, and performance positioning. Each technology offers a different value proposition, from premium contrast and color performance to cost-efficient scalability and smart-feature enablement. The analytical framework inside the full report isolates the demand drivers that will determine which technology segments capture share, how pricing pressure evolves, and where manufacturers can secure margin resilience. Because these technology shares are shifting rapidly with new panel supply and consumer preference, the detailed splits and growth trajectories are disclosed only within the complete study.
Application-Driven Demand
Modern 4K Ultra HD TVs are no longer passive display devices; they are content hubs, gaming platforms, and smart-ecosystem endpoints. The report evaluates application categories including Smart TV and Gaming TV environments, alongside other specialized use cases. This segmentation is vital because application mix directly influences feature requirements, connectivity expectations, and retail positioning. Smart TVs, for instance, require deep integration with operating systems, streaming partnerships, and AI-driven user experiences, while gaming-focused models emphasize refresh rates, low latency, and HDR alignment. The study maps demand intensity and growth prospects across these applications, equipping product teams with a demand-side blueprint. Specific proportion breakdowns and revenue attribution by application are reserved for the full report to preserve the precision of the underlying model.
Regional Growth Profiles
Geographic demand is unevenly distributed and increasingly shaped by regulatory conditions, infrastructure readiness, and local pricing dynamics. The research partitions the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each presenting a distinct value-creation path. Asia Pacific represents the largest value concentration, reflecting scale demand and rapid technology adoption, while North America and Europe contribute structurally significant volumes with higher average unit pricing in premium segments. Latin America and the Middle East and Africa present growth opportunities tied to infrastructure expansion, digital content availability, and evolving retail ecosystems. The complete study provides a region-by-region examination of market size trajectories, demand catalysts, and competitive intensity without publishing the detailed regional percentages here, so decision-makers are encouraged to consult the full report for the exact geographic splits required to build accurate regional plans.
Competitive Landscape: Strategic Positioning and Innovation Pressure
The 4K Ultra HD TV market is defined by a dense field of global manufacturers, each pursuing differentiated strategies in display technology, smart-platform integration, and pricing architecture. The report profiles leading enterprises including Samsung Electronics, LG Electronics, Sony Corporation, Hisense, TCL Corporation, Panasonic Corporation, VIZIO, and Skyworth. These companies anchor the market through distinct value propositions: Samsung and LG leverage advanced QLED, OLED, and AI-enhanced smart features; Sony competes on premium picture quality and BRAVIA platform integration; Hisense and TCL push Mini-LED and QD-Mini LED architectures into broader consumer segments with Google TV and smart ecosystem alignment; Panasonic combines OLED and 4K LCD panels with Fire TV integration; VIZIO focuses on accessible 4K UHD smart TVs with Dolby Vision and HDR support; and Skyworth delivers HDR-enabled 4K UHD models targeting value-conscious segments.
Beyond the established incumbents, market dynamics are being reshaped by new entrants and platform-driven expansion. Notably, Amazon announced the W70B Series Smart TV as a core 4K UHD model, emphasizing sleek design and immersive viewing, signaling how platform players are entering the hardware space to deepen ecosystem lock-in. This kind of product launch matters strategically because it intensifies competition for share of attention, smart-services revenue, and retail shelf presence. The full study goes beyond company profiles to map competitive interaction patterns, including how brand portfolios are structured, where pricing pressure is building, and which segments are most vulnerable to disruption. Given the consolidated nature of the industry, competitive analysis must also consider market concentration, and the complete research provides the exact concentration metrics needed to assess barrier-to-entry conditions and pricing power.
Industry Dynamics: Supply Chain Constraints, Regulatory Headwinds, and Cost Volatility
No strategic assessment of the 4K Ultra HD TV market is complete without confronting the operational and regulatory pressures that shape cost structures and supply continuity. As of April 2025, China placed export restrictions on seven categories of medium and heavy rare earths, including dysprosium, samarium, and terbium, which are essential for permanent magnets used in 4K TV displays and components. These restrictions were part of a broader response to tariff escalations and have introduced material price volatility and supply chain uncertainty across electronics production. Further analysis from early 2026 indicates that these controls will continue to affect component availability and cost planning, with additional foreign direct product rule extensions shaping procurement strategies.
The practical implication for manufacturers and channel partners is that cost forecasting can no longer rely solely on historical component pricing. Rare earth constraints and raw material volatility have become structural variables in the cost stack, influencing margin planning, sourcing diversification, and manufacturing geography. The report integrates these dynamics into a broader sustainability and supply chain risk framework, helping executives anticipate where bottlenecks may emerge, how pricing architectures may need to adapt, and which product tiers are most exposed to input-cost fluctuations. Because the precise impact varies by component, component substitution pathways, supplier diversification options, and regional sourcing implications differ across product segments, the complete study supplies the operational detail necessary to translate these macro risks into procurement and product decisions.
Inside the Report: Operational Content Built for Executive Action
This market study is designed to move beyond descriptive trends and deliver decision-grade intelligence. The full version includes product and technology assessments, application-level demand analysis, regional market mapping, and competitive positioning evaluations. It is structured to support multiple functional needs: product managers can use it to prioritize feature roadmaps and display mix decisions; sales and commercial teams can align go-to-market plans with regional demand signals; supply chain and sourcing leaders can evaluate material exposure and supplier diversification paths; and strategy teams can build investment scenarios grounded in forecast-period growth paths.
In addition to the core segmentation and forecast content, the study synthesizes recent industry developments and regulatory milestones, including export control actions and platform-driven product launches, into a practical context for near-term planning. The report is built for readers who need a single analytical reference that connects market size, growth trajectory, competitive intensity, and supply-side risk into one consistent framework. Readers seeking exact regional percentages, application splits, type-based revenue shares, and company-level concentration figures will find those details only in the full release, which is why this preview deliberately highlights the architecture and advisory value without disclosing the embedded figures.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a market view that is simultaneously optimistic about growth and disciplined about risk. A compound annual growth rate of 24.38 percent over the forecast period signals an exceptional opportunity, but capturing that opportunity requires a precise understanding of where growth is concentrated, how competitive pressures are evolving, and which external shocks can alter cost and availability assumptions. The 4K Ultra HD TVs Market study provides that integrated view, linking historical momentum, forecast expansion, segmentation dynamics, and competitive context into a single strategic frame. It is intended to help leadership teams answer the practical questions that shape capital allocation, product portfolio strategy, regional prioritization, and risk mitigation in the year ahead.
For organizations building their 2026 plans, the full report offers the depth required to convert a high-level growth story into actionable strategy. The preview above demonstrates the analytical approach, the scope of coverage, and the strategic context embedded in the research, while preserving the segmented data and competitive metrics for the complete edition. To access the full market size progression by year, the detailed segmentation splits, the comprehensive company profiles, and the operational dynamics analysis, readers are encouraged to obtain the full study from the source page, where the complete intelligence package is available for decision-making across product, commercial, and supply chain functions.
4K Ultra HD TVs Market
UHD TV Market
For detailed analysis of this topic, please visit the official page: 4K Ultra HD TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corporate Travel Insurance Drives 14.75% CAGR in $648.4M Market
By PW Consulting, 2026-09-16
Strategic Imperatives in the Business Travel Insurance Market: A 2026 Outlook
Introduction: The New Risk Landscape for Corporate Travel
Corporate travel has fundamentally transformed over the past half-decade. As organizations navigate a complex environment defined by geopolitical volatility, evolving regulatory frameworks, and heightened duty of care obligations, the business travel insurance market has emerged as a critical component of enterprise risk management strategies. Our latest comprehensive market research provides decision-makers with the intelligence needed to navigate this rapidly expanding landscape through 2032.
The base year analysis (2025) reveals a market that has demonstrated remarkable resilience and growth momentum. Historical data from 2020 through 2025 illustrates consistent upward trajectory, with revenues expanding from 129.74 million USD to 249.8 million USD—a reflection of both increased travel volumes and heightened awareness of comprehensive coverage needs. This growth pattern establishes a robust foundation for the forecast period extending through 2032, where compound annual growth rates are projected at 14.75 percent.
Market Trajectory and Growth Catalysts
The forecast period from 2026 to 2032 presents compelling expansion opportunities that warrant immediate strategic attention. Market valuations are expected to progress from approximately 285.26 million USD in 2026 to reach 648.4 million USD by 2032. This trajectory underscores the accelerating demand for specialized coverage solutions as corporations reassess their travel risk postures in an uncertain global environment.
Structural Market Dynamics and Segment Evolution
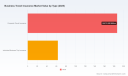
Understanding which coverage categories command the largest share of corporate spending provides essential insight for product development teams and procurement strategists. Within the type-based segmentation, Corporate Travel Insurance represents the dominant category, valued at 186.73 million USD, while Individual Business Trip Insurance accounts for 63.07 million USD. This distribution highlights the strong preference among enterprises for comprehensive group-based solutions that streamline administration and ensure consistent protection across teams.
The application-based analysis further illuminates corporate priorities. Medical and Health Coverage stands at 95.62 million USD, Accident and Liability at 92.19 million USD, and Trip Cancellation and Delay at 61.99 million USD. These figures affirm that health protection and liability management remain paramount concerns for risk managers, while trip disruption coverage continues to gain prominence as travel schedules become increasingly complex and subject to interruption.
Regional deployment patterns reveal distinct maturity profiles across global markets. North America leads with 100.35 million USD in market value, followed by Europe at 74.6 million USD and Asia Pacific at 62.42 million USD. Latin America contributes 12.43 million USD, while the Mideast and Africa region represents an emerging frontier with significant growth potential. These regional distributions correspond closely with corporate travel volumes and maturity of local insurance infrastructure.
Market concentration data indicates that the top three players command 55.2 percent of total market share, while the top five firms control 68.4 percent. This concentrated structure suggests both competitive intensity among established leaders and opportunities for specialized providers to differentiate through niche capabilities, digital innovation, or tailored service models.
Regulatory Environment and Compliance Imperatives
Regulatory considerations increasingly shape procurement decisions within the business travel insurance sector. No federal statute mandates business travel insurance in the United States; however, employers maintain a duty of care obligation under OSHA Section 5(a)(1), creating a compliance-driven rationale for maintaining adequate coverage programs. This obligation extends to organizations operating internationally, where local labor laws and host-country requirements may impose additional expectations.
The ISO 31030:2021 standard for travel risk management provides a framework that requires organizations to document insurance as one control within their broader risk management architecture. Corporations seeking to demonstrate mature risk governance increasingly reference this standard when evaluating provider offerings and structuring their travel protection programs. Adoption of such frameworks correlates strongly with the purchasing patterns observed in larger enterprises.
Evolving data privacy requirements under GDPR and related regulations compel providers to enhance cybersecurity protocols for policyholder data embedded within corporate plans. Organizations must evaluate vendor capabilities not only on coverage breadth and pricing but also on data handling maturity, particularly when policies encompass multinational travel across jurisdictions with divergent privacy expectations. Specialized human labor for claims processing and risk advisory services represents a primary operational cost for business travel insurance providers, a factor that influences both pricing structures and service quality differentiation across the competitive landscape.
Competitive Landscape and Strategic Positioning
The competitive arena features established multinational insurers and specialized providers, each pursuing differentiated value propositions. Allianz, headquartered in Munich, Germany, specializes in Allianz Travel and Allianz Global Assistance business travel insurance plans with digital app-based claims processing, emergency assistance, and corporate/group programs. AXA, based in Paris, France, provides AXA Assistance corporate and digital business travel insurance platforms with multi-trip coverage and real-time traveler support features, emphasizing technology-enabled service delivery.
Travel Insured International, located in Morristown, New Jersey, USA, offers specialized business travel insurance solutions with coverage for trip cancellation, interruption, medical emergencies, and business equipment protection—catering to organizations with diverse asset protection needs. Seven Corners, headquartered in Bloomington, Minnesota, USA, delivers annual multi-trip business travel insurance plans with high limits and features tailored for frequent business travelers and corporate groups, addressing the segment of employees with elevated travel frequency.
International Business Travel Insurance Plans Market
HTH Worldwide, based in Scottsdale, Arizona, USA, provides corporate business travel insurance with long-term and international coverage options for business travelers, serving organizations with extended-duration assignments. Zurich Insurance Group, headquartered in Zurich, Switzerland, offers Zurich Business Travel Solution and Zurich Travel Assist for group business travel insurance with dedicated account management and global claims processing, emphasizing relationship-driven service for complex corporate accounts.
Chubb, also based in Zurich, Switzerland, supplies Chubb Business Travel Insurance plans with group coverage, target market determinations, and integration with corporate risk management—appealing to organizations seeking seamless alignment between travel insurance and broader enterprise risk frameworks. Marsh, headquartered in New York, USA, delivers business travel insurance solutions as part of its risk advisory services, including group plans and corporate risk management integration, positioning insurance within a holistic advisory context.
Aon, based in London, UK, provides Aon Business Travel Insurance solutions with focus on corporate travel programs and integrated risk management services, leveraging its global advisory platform. Berkshire Hathaway Travel Protection, located in Fairfield, Connecticut, USA, specializes in business travel insurance with robust coverage for corporate travelers and group programs, drawing on the financial strength and reputation of its parent organization.
Recent industry developments underscore the evolving governance landscape. In March 2026, the US Travel Insurance Association named a new president to guide the association focused on travel insurance standards, signaling heightened attention to industry self-regulation and best practice dissemination. In February 2026, USTIA released updated resources on why 2026 is the year to travel smart, reinforcing the strategic emphasis on informed coverage decisions as travel activity accelerates.
Report Framework and Analytical Depth
Our market research delivers actionable intelligence across multiple analytical dimensions designed to support evidence-based decision-making. The report structure encompasses comprehensive market sizing with historical baselines and forward-looking projections, segmentation analysis across type, application, and regional dimensions, and granular competitive profiling of key market participants.
Operational cost analysis examines the role of specialized human labor in claims processing and risk advisory services, illuminating cost structures that influence pricing strategies and margin profiles. Coverage architecture assessments evaluate how medical, liability, and trip disruption protections are bundled and priced across different corporate segments, revealing optimization opportunities for procurement teams seeking to align coverage with actual risk exposure.
Business Travel Insurance Market
Technology adoption trends are explored in the context of digital claims processing, real-time traveler support platforms, and integrated risk management dashboards that connect travel insurance data with broader corporate risk ecosystems. The analysis of regulatory developments—including OSHA duty of care obligations, ISO 31030:2021 framework expectations, and GDPR-driven cybersecurity requirements—provides compliance leaders with structured guidance for vendor evaluation and policy design.
The report also incorporates scenario analysis that enables organizations to stress-test their coverage strategies against potential disruptions, from geopolitical events to public health crises and natural disasters. By mapping coverage gaps against plausible disruption scenarios, risk managers can prioritize enhancements that deliver the greatest resilience improvement relative to incremental cost.
Strategic Recommendations for 2026 Decision-Makers
Organizations approaching business travel insurance procurement in 2026 should prioritize several strategic actions. First, assess current coverage alignment with duty of care obligations and ISO 31030:2021 documentation requirements, ensuring that policy structures satisfy both legal expectations and internal governance standards. Second, evaluate provider capabilities in digital claims processing and real-time traveler support, as these service dimensions increasingly differentiate vendor value propositions and influence employee experience during incidents.
Third, consider the integration potential between travel insurance platforms and existing corporate risk management systems, recognizing that seamless data flow enhances both operational efficiency and risk visibility. Fourth, examine regional coverage adequacy in light of expanding travel footprints, particularly as organizations increase engagement with Asia Pacific and Latin American markets where insurance infrastructure continues to mature.
Fifth, benchmark pricing and coverage structures against the competitive landscape, leveraging the detailed vendor analysis provided in this report to identify opportunities for renegotiation or provider diversification. The market concentration data indicates that while large players dominate, specialized providers offer differentiated features that may better suit specific organizational profiles, travel patterns, or risk appetites.
Conclusion: Accessing Comprehensive Market Intelligence
The business travel insurance market stands at an inflection point where growth, regulation, and technology converge to reshape enterprise risk management practices. Our full market research report provides the detailed quantitative analysis, competitive assessments, and strategic recommendations necessary for informed decision-making throughout the 2026–2032 forecast horizon. The insights presented here represent a curated preview of the comprehensive analysis available in the complete study.
Decision-makers seeking granular segmentation data, detailed vendor benchmarking matrices, scenario modeling outputs, and region-specific procurement guidance are invited to access the full report through our platform. The complete intelligence package delivers the depth required to construct resilient, cost-effective, and compliant business travel insurance strategies aligned with organizational objectives.
As corporate travel continues its recovery and expansion trajectory, the organizations that invest in sophisticated risk management frameworks—supported by comprehensive insurance coverage and informed by rigorous market intelligence—will be best positioned to navigate uncertainty while enabling their teams to travel with confidence. We invite you to explore the full research to strengthen your strategic positioning in this dynamic market.
For detailed analysis of this topic, please visit the official page: Business Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: High-Speed Centrifugal Blower Market at $633M in 2025, Forecast 2.9% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the High-Speed Single-stage Centrifugal Blower Market: Strategic Intelligence for 2026 Decision Makers
The industrial air and gas handling sector stands at a critical inflection point. As manufacturing processes become increasingly energy-intensive and environmental regulations tighten globally, the demand for efficient, reliable, and high-performance fluid movement solutions has never been more pronounced. At the heart of this transformation lies the High-Speed Single-stage Centrifugal Blower Market, a specialized segment that serves as a critical enabler for wastewater treatment, industrial gas processing, and emerging clean energy applications.
For executives, investors, and strategic planners operating in 2026, understanding the nuances of this market is no longer optional—it is a prerequisite for sustainable growth. This article serves as a strategic primer, drawing from our comprehensive market research report to illuminate the key dynamics, competitive forces, and growth trajectories that will define the sector through 2032. While we outline the broader landscape here, the full depth of our quantitative analysis and granular segmentation remains a vital resource for those seeking to secure a competitive advantage in this evolving industry.
Market Trajectory and Macroeconomic Context
The High-Speed Single-stage Centrifugal Blower Market has demonstrated resilience and steady expansion over the past half-decade. Analyzing the historical performance from 2020 to 2025 provides a robust baseline for forecasting future demand. The market revenue, denominated in USD Million, has shown a consistent upward trend, reflecting the underlying growth in industrial infrastructure and environmental compliance requirements across key global regions.
Looking forward, the forecast period spanning 2026 to 2032 suggests a continued progression. The compound annual growth rate (CAGR) indicated for this forecast window points to a moderate yet steady expansion. This growth is not merely a function of volume but is increasingly driven by the replacement of older, less efficient technologies with high-speed single-stage solutions that offer superior aerodynamic performance and lower lifecycle costs. For stakeholders, this trajectory implies a market that is mature enough to offer stability but dynamic enough to reward those who can navigate technological shifts and regional demand variations effectively.
Technology Drivers and Application Dynamics
The core value proposition of high-speed single-stage centrifugal blowers lies in their ability to deliver high flows at precise pressures with minimal energy consumption. This capability is essential across several key verticals. In the realm of sewage treatment, these blowers are indispensable for aeration processes, where energy efficiency directly correlates with operational expenditure. Similarly, in off-gas desulfuration and other industrial gas handling applications, the ability to manage variable flow requirements while maintaining system integrity is paramount.
Recent developments in the sector highlight a clear industry focus on efficiency and integration. For instance, major players have launched new ranges specifically targeting energy reduction in wastewater applications, aligning with stricter EU energy efficiency standards. These regulatory pressures are not just constraints; they are catalysts for innovation, forcing manufacturers to refine impeller designs, bearing technologies, and control systems. The integration of magnetic levitation and air-foil bearings represents a significant technological leap, reducing maintenance needs and enhancing reliability in continuous operation environments.
However, the market is not without its headwinds. Sector analysis indicates that material costs, particularly for aluminum and steel, alongside skilled labor shortages for high-speed impeller manufacturing, continue to influence overall blower pricing and availability. Supply chain resilience and local manufacturing capabilities are becoming strategic differentiators. Companies that can balance cost efficiency with quality certification, such as ISO 9001 and API standards, are better positioned to capture market share in a regulated environment.
Competitive Landscape and Strategic Positioning
The competitive arena for high-speed single-stage centrifugal blowers is characterized by a mix of established global industrial giants and specialized manufacturers with deep technical expertise. The market concentration, as reflected by CR3 and CR5 metrics, suggests a fragmented yet competitive landscape where differentiation is key. No single entity dominates completely, allowing for niche players to thrive by focusing on specific applications or regional strengths.
High-Speed Single-stage Centrifugal Blower Market
Leading companies such as Howden (Chart Industries) and Gardner Denver continue to set benchmarks with integrally geared turbo blowers and magnetic-bearing models optimized for large turndown ranges. Their recent product launches and partnerships underscore a commitment to R&D and geographic expansion. For example, Howden's launch of high-efficiency centrifugal blower ranges targeting energy reduction demonstrates the industry's response to regulatory and operational pressures. Similarly, expansions by companies like Greenheck into new corporate campuses signal long-term confidence in market growth.
On the other hand, manufacturers based in China, such as Shandong Zhangqiu Blower and Shenyang Blower Works Group Corporation, leverage lower labor and material costs to offer competitive solutions for wastewater treatment and industrial gas handling. Their export capabilities and domestic-leading designs present both a challenge and an opportunity for global incumbents. Meanwhile, specialized firms like APG-Neuros and Hoffman & Lamson focus on delivering energy savings through advanced air-bearing technologies and plug-and-play installations, catering to customers who prioritize ease of integration and operational savings.
Strategic partnerships are also reshaping the landscape. Recent collaborations aimed at strengthening distribution networks, such as those seen in the Mid-Atlantic region, highlight the importance of local presence and service support. Acquisitions of manufacturing facilities to expand production capacity further indicate that supply security is a top priority for companies aiming to meet rising demand without compromising on lead times.
Regional Perspectives and Growth Opportunities
While global demand is rising, the distribution of market value varies significantly by region. North America and Asia Pacific represent substantial portions of the market revenue, driven by robust industrial activity and infrastructure investments. Europe, while a mature market, remains critical due to stringent environmental regulations that accelerate the replacement of legacy systems. Latin America and the Middle East & Africa, though smaller in relative terms, offer emerging opportunities as industrial capacities expand in these regions.
Understanding the specific demand drivers in each region is essential for tailoring go-to-market strategies. In developed markets, the focus is often on retrofitting and upgrading existing installations to meet energy standards. In developing markets, new infrastructure projects and capacity expansions drive initial equipment sales. Our detailed analysis delves into these regional nuances, providing actionable intelligence on where to allocate resources for maximum impact.
Why This Report Matters for 2026 Strategy
In an environment defined by rapid technological change and regulatory complexity, generic industry overviews are insufficient. Decision-makers need access to precise data on market size, segmentation trends, and competitive movements to formulate effective strategies. This report is designed to bridge the gap between high-level market knowledge and actionable strategic insight.
- Comprehensive Segmentation Analysis: Gain clarity on how revenue is distributed across different blower types, applications, and regions without getting lost in aggregated data.
- Competitive Intelligence: Understand the product portfolios, recent developments, and strategic moves of key players to identify gaps and opportunities in the market.
- Risk and Opportunity Assessment: Evaluate the impact of raw material costs, labor availability, and regulatory standards on pricing and supply chain stability.
- Forecasting Accuracy: Utilize our detailed forecast data from 2026 to 2032 to plan capacity, investment, and R&D initiatives with greater confidence.
The insights contained within this research are tailored for stakeholders who require more than just headline numbers. Whether you are evaluating market entry, assessing competitor threats, or optimizing your product roadmap, the granular data provided in the full report is essential for validating assumptions and mitigating risks.
Conclusion: Empowering Decision-Making in a Dynamic Market
The High-Speed Single-stage Centrifugal Blower Market is poised for continued evolution, driven by the dual engines of industrial efficiency demands and environmental compliance. For organizations operating in this space, staying informed is the first step toward staying ahead. While the overview presented here highlights the critical themes and trends shaping the sector, the full extent of our analysis offers the depth required for precise strategic planning.
Centrifugal Compressors Market
We invite you to explore the complete market intelligence provided in our full report. By accessing the detailed segmentation data, comprehensive company profiles, and forward-looking forecasts, you can equip your team with the knowledge needed to navigate the complexities of 2026 and beyond. The investment in accurate, timely market intelligence is an investment in your organization's ability to thrive in a competitive global landscape.
For detailed analysis of this topic, please visit the official page: High-Speed Single-stage Centrifugal Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pallet Rack Market Hits $11.7B in 2025 with 6.7% CAGR to $18.26B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Modern Warehouse: Navigating the Pallet Rack Market Outlook 2026–2032
In an era defined by volatile supply chains, accelerating e-commerce penetration, and relentless pressure on warehouse throughput, the pallet racking infrastructure is no longer a passive storage utility. It is a strategic asset that dictates inventory velocity, space utilization, and long-term operational scalability. PW Consulting’s newly published Pallet Rack Market research report transforms fragmented industry signals into a structured intelligence framework, equipping executive teams, procurement leaders, and supply chain architects with the analytical rigor required to make confident capital allocation decisions in 2026 and beyond. The report does not merely track historical inventory movements; it maps the structural inflection points that will separate cost-advantaged operators from those burdened by legacy spatial constraints and unpredictable capex cycles.
Pallet Rack Market
The Macro Trajectory: Translating Historical Momentum Into Forward Visibility
Drawing on a comprehensive historical window spanning 2020 through 2025, the research establishes a clear baseline of market resilience and expansion. Over this period, total industry revenue climbed from approximately 8,500 million USD to 11,700 million USD, reflecting sustained demand across both retrofitting initiatives and ground-up facility builds. More importantly, the forward projection window extends through 2032, anchored by a compound annual growth rate of 6.7 percent. This growth trajectory translates the market from a 12.8 billion USD base in 2026 toward an estimated 18.3 billion USD by 2032, signaling a structurally expanding addressable market rather than a cyclical upturn.
For enterprise decision-makers, this macro arc carries immediate strategic implications. First, it underscores that pallet racking procurement can no longer be treated as a commodity purchasing exercise; the scale of projected expansion means capacity planning must account for multi-year infrastructure commitments. Second, the steady CAGR indicates that demand drivers are becoming entrenched in operational realities rather than temporary inventory bulges. The report contextualizes this trajectory by mapping underlying consumption behaviors, durability requirements, and regional deployment rhythms, giving leadership teams a reliable baseline against which to calibrate budgeting, vendor negotiations, and facility expansion timelines.
Decoding the Segment Architecture: Where Capital Meets Operational Leverage
Market growth does not distribute evenly across product configurations or application environments. The research dissects the pallet rack ecosystem across dimensional axes, revealing how structural design choices and operational use cases converge to shape procurement priorities. On the product architecture side, the analysis examines how conventional selective systems continue to anchor baseline storage requirements, while high-density alternatives—driven by space-constrained urban facilities and labor optimization mandates—are reshaping engineering specifications. The report also evaluates secondary configurations that serve specialized throughput profiles, helping procurement teams align rack geometry with actual pallet flow patterns rather than defaulting to historically familiar layouts.
From an application perspective, the study maps demand intensity across warehousing and logistics hubs, retail distribution networks, manufacturing floor environments, and adjacent operational verticals. Rather than presenting static share figures, the report emphasizes how end-use characteristics influence load capacity requirements, seismic and compliance considerations, and lifecycle maintenance expectations. This application-layer analysis is particularly valuable for organizations operating multi-site networks, as it clarifies which facility types are experiencing the most aggressive storage density upgrades and which are prioritizing reconfigurability over maximum vertical utilization. By understanding how segment dynamics interact, executives can anticipate whether their procurement strategy should lean toward standardization, customization, or hybrid deployment models.
Competitive Dynamics and Strategic Positioning in a Consolidating Landscape
The pallet rack manufacturing and distribution ecosystem is characterized by a meaningful degree of concentration, with the top three players accounting for roughly 48.5 percent of market revenue and the top five firms extending that footprint to approximately 62.8 percent. This concentration does not imply a monolithic market; rather, it highlights the importance of differentiating vendor evaluation criteria beyond unit pricing. The research profiles leading operators whose product portfolios and service architectures set the competitive tempo. Steel King Industries, headquartered in Stevens Point, Wisconsin, continues to anchor its market presence through engineered offerings such as the SK2000 boltless tubular pallet rack and the SK3000 structural pallet rack system, emphasizing modular adaptability and load integrity. Ridg-U-Rak, based in North East, Pennsylvania, competes across a broader configuration spectrum, with teardrop and slotted pallet racking complemented by high-density systems including drive-in, push-back, gravity flow, and pick modules. Interlake Mecalux, operating from Chicago, Illinois, pushes integration further by pairing selective and high-density racking platforms with automated warehouse solutions. Nucor Warehouse Systems, headquartered in Monroe, Georgia, contributes patented engineering approaches through its TubeRack platform alongside structural, roll-formed, cantilever, pushback, and drive-in pallet racking systems.
Evaluating these players requires more than a feature-comparison matrix. The report examines how product engineering philosophies, regional service networks, lead-time reliability, and aftermarket support shape total cost of ownership. Because the market exhibits concentrated revenue shares at the top, enterprise buyers must treat vendor selection as a risk-mitigation exercise as much as a procurement decision. The analysis highlights how manufacturers are differentiating through certification alignment, fabrication standards, and installation ecosystems, allowing organizations to align supplier partnerships with their own operational risk tolerances and quality assurance mandates.
Market Dynamics and External Pressures Shaping Procurement Timelines
Structural growth does not occur in a vacuum. The research integrates real-time industry context to show how external pressures are altering quoting behavior, compliance requirements, and deployment urgency. On the material side, steel tariffs and import duties have introduced significant pricing unpredictability into new racking procurement. Recent market observations indicate that quotes can swing by 10 to 20 percent within a matter of weeks, forcing procurement teams to reconsider fixed-budget assumptions and just-in-time purchasing models. This volatility reinforces the report’s emphasis on scenario planning, long-lead negotiations, and inventory buffering strategies for critical structural components.
Regulatory and standards compliance has simultaneously become a more visible differentiator. Recent certification milestones, including fusion welding certifications aligned with CSA Standard W47.1 and the achievement of RMI R-Mark Certifications for manufacturer, system, and installation compliance, illustrate how quality assurance frameworks are reshaping buyer expectations. These developments matter because they influence not only installation safety and load reliability but also insurance considerations, audit readiness, and cross-jurisdiction operational continuity. Companies that require standardized, certifiable supply chains are increasingly factoring compliance credentials into vendor shortlists, and the report maps how these credentials are distributed across the competitive landscape.
Data Center Rack Market
Demand-side momentum is equally pronounced. E-commerce volume expansion and the continued growth of third-party logistics networks are intensifying requirements for heavy-duty pallet racking across the United States, with heavy-duty pallet rack demand alone reaching an estimated 182.40 million USD in 2025. This signal aligns with broader operational trends: faster order cycles, higher throughput expectations, and the need for racking systems that tolerate heavier pallet loads without compromising reconfiguration flexibility. The report synthesizes these dynamics into actionable observations on where procurement urgency is intensifying and which facility typologies are most exposed to capacity constraints.
Recent Industry Movements Signaling 2026 Deployment Priorities
Recent corporate developments provide additional texture for anticipating near-term market behavior. At MODEX 2026, Nucor Warehouse Systems announced a new facility in Monroe, Georgia, signaling expanded manufacturing or service capacity aimed at strengthening regional delivery and installation support. Around the same event window, multiple industry participants, including AR Racking and Frazier Industrial Company, showcased their latest racking technologies and system configurations in Atlanta, highlighting continued investment in product visibility and customer engagement at major trade platforms. Earlier in the year, AR Racking also participated in LogiMAT 2026, presenting galvanized system options that reflect ongoing attention to corrosion resistance and environmental durability.
These movements are not isolated publicity events. They indicate where manufacturers are placing capital, which geographies are receiving infrastructure attention, and how product features such as galvanization, high-density modularity, and automated integration are being positioned for commercial uptake. The report distills these signals into deployment-oriented insights, helping organizations understand whether nearby manufacturing or distribution expansions may improve lead times, whether trade-show announcements foreshadow broader product-line shifts, and how service network density is evolving in regions critical to their operations.
What the Report Delivers: Operational Content for Executive Decision-Making
PW Consulting’s Pallet Rack Market research is structured to move quickly from macro context to decision-ready detail. The report opens with baseline sizing and forward projections that frame the scale of the opportunity and the tempo of expected growth. From there, it transitions into segmentation analysis that clarifies how product configurations and application environments drive divergent procurement requirements. Competitive profiling goes beyond corporate summaries to examine how leading manufacturers differentiate through product engineering, certification alignment, and service ecosystem depth. The dynamics section integrates material pricing volatility, regulatory certification trends, and demand-side momentum from e-commerce and 3PL expansion into a cohesive narrative on procurement risk and timing.
Operational appendices and analytical supplements provide additional leverage for planning teams. These include technology adoption considerations, installation and maintenance lifecycle observations, and scenario-based guidance that helps organizations align rack system selection with throughput projections, space constraints, and compliance expectations. The report is designed to support multiple internal audiences simultaneously: procurement teams can use the competitive and pricing dynamics sections to structure negotiations; operations leaders can reference segmentation and application analysis to refine facility layout decisions; and strategy executives can draw on the macro trajectory and competitive concentration data to evaluate multi-year capital commitments and vendor partnership strategies.
Strategic Imperatives for 2026 and the Years Ahead
The pallet rack market is entering a period where growth is supported by durable operational shifts rather than temporary inventory accumulation. For organizations planning facility upgrades, network expansions, or large-scale racking replacement programs, the strategic question is no longer whether demand will persist, but how to structure procurement, vendor selection, and capacity planning in an environment marked by pricing volatility, concentrated supplier influence, and rising performance expectations. The research underscores several decision-making priorities: aligning rack configuration choices with actual material flow and density requirements rather than historical precedent; evaluating suppliers on total cost of ownership, certification credibility, and service network reliability; and building procurement timelines that account for material price swings and installation lead times.
Organizations that treat racking infrastructure as a long-horizon operational lever will be better positioned to convert space constraints into throughput advantages. Those that continue to approach procurement as a transactional purchasing event risk facing mounting inefficiencies as facility density requirements intensify and compliance expectations rise. The report provides the analytical scaffolding needed to move from reactive purchasing to proactive infrastructure strategy.
Access the Full Intelligence Framework
This article provides a high-level orientation to the trajectory, competitive structure, and operational dynamics shaping the pallet racking sector through 2032. The complete PW Consulting Pallet Rack Market research report extends far beyond these thematic outlines, delivering granular segmentation breakdowns, detailed competitive positioning analyses, scenario-informed procurement guidance, and region-specific deployment insights that enable precise capital planning. To access the full dataset, vendor evaluations, and strategic recommendations that support decisive 2026 action, request the complete report and integrated market intelligence package through our official research portal.
For detailed analysis of this topic, please visit the official page: Pallet Rack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Functional Cooking Food Processors Hit $3.38B in 2025, 5.88% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Multi-Functional Cooking Food Processors Market: Strategic Insights for 2026 Decision-Making
The modern kitchen has evolved from a simple preparation space into a hub of technological integration, where efficiency, versatility, and smart functionality converge. As household consumers and commercial operators alike seek to streamline food preparation workflows, the multi-functional cooking food processor segment has emerged as a critical battleground for appliance manufacturers. This article serves as a strategic preview of the latest PW Consulting market study, designed to equip executives, product managers, and investment analysts with the analytical frameworks needed to navigate the 2026–2032 forecast period. While this overview establishes the macro trajectories and competitive undercurrents shaping the sector, the complete intelligence—including granular segmentation breakdowns, pricing elasticity models, and supplier-tier mapping—resides within the full report.
The Macro Trajectory: A Decade of Measured Expansion
The multi-functional cooking food processor market has demonstrated consistent, compounding growth over the past five years, reflecting a structural shift rather than a transient consumer trend. Historical revenue data from 2020 through 2025 reveals a steady upward curve, as the global market expanded from approximately 2,538 million USD to a projected 3,378 million USD at the close of the base year. This trajectory has been underpinned by broadening appliance adoption, rising disposable incomes in emerging economies, and an increasing consumer preference for space-efficient, multi-tasking kitchen equipment.
Looking forward, the forecast period extending through 2032 indicates sustained momentum. The market is projected to breach the 3,500 million USD threshold in 2026 and accelerate toward the 5,000 million USD mark by the end of the decade. This expansion is anchored by a forecast compound annual growth rate of 5.88 percent, a figure that signals healthy, above-inflation demand across both mature and developing regions. For corporate strategists, this CAGR is not merely a statistical projection; it represents a window of opportunity for product portfolio optimization, supply chain reconfiguration, and targeted geographic penetration. The years ahead will reward firms that can balance volume growth with margin preservation, particularly as input costs and regulatory compliance requirements continue to reshape manufacturing economics.
Market Architecture and Structural Dynamics
Understanding the architecture of this market requires moving beyond headline revenue figures and examining the underlying demand drivers. The industry is characterized by a moderate degree of concentration, with the top three participants collectively commanding roughly 48.5 percent of total industry revenue, while the top five firms extend their combined share to approximately 52.0 percent. This concentration profile suggests a market that is neither fragmented nor monopolistic, but rather one where established incumbents maintain strong brand equity while leaving ample room for niche innovators and regional specialists to capture value through differentiated features or localized distribution networks.
Product design philosophy has increasingly shifted toward all-in-one functionality. The integration of guided smart cooking, precision blending, automated chopping, steaming, and slow-cooking capabilities into single units has fundamentally altered purchasing behavior. Industry utilization data indicates that multi-functional processors achieve an average household utilization rate exceeding 65 percent, a metric that underscores the tangible value proposition of consolidated appliance ecosystems. Consumers are no longer buying isolated tools; they are investing in kitchen workstations that reduce countertop clutter, minimize accessory swaps, and streamline recipe execution. This behavioral shift has direct implications for product engineering roadmaps, warranty cost structures, and after-sales service expectations.
Capacity segmentation remains a critical dimension of consumer and commercial decision-making. The market accommodates a spectrum of volume requirements, ranging from compact units designed for everyday household chopping and mixing, to mid-tier configurations that balance batch flexibility with storage footprint, and finally to larger-capacity systems tailored for high-volume meal preparation. Each tier serves distinct use cases, and the strategic allocation of research and development resources across these capacity bands will determine which manufacturers can effectively capture cross-segment demand without diluting brand positioning.
Strategic Imperatives for 2026 Enterprise Decision-Making
As organizations plan their 2026 product launches, capacity expansions, and market-entry initiatives, several strategic imperatives emerge from the broader market context. First, the convergence of hardware engineering and software-guided culinary workflows demands cross-functional collaboration between mechanical design teams, embedded systems developers, and recipe content creators. Firms that treat smart cooking guidance as a premium differentiator rather than a marketing afterthought will likely secure stronger customer retention and higher average selling prices.
Second, pricing architecture must be calibrated against evolving consumer willingness to pay. Premium multi-functional processors from leading innovators command retail prices that sit 40 to 50 percent above basic models, a premium justified by integrated electronics, precision engineering, and extended functionality. However, this pricing gap also creates a two-tier market dynamic. Mass-market consumers continue to seek reliable, compact units that deliver core chopping, shredding, and mixing capabilities at accessible price points, while enthusiast and premium segments prioritize advanced dicing meshes, wider feed chutes, and guided programming. Successful portfolio strategies will require clear tiering, distinct feature roadmaps, and disciplined channel management to prevent cannibalization.
Multi-Functional Cooking Food Processors Market
Third, compliance and certification have transitioned from back-office obligations to competitive advantages. In the European Union, mandatory CE marking verification remains a prerequisite for retail listing, and leading manufacturers have aligned their products with EU Low Voltage and EMC directives to ensure consumer safety and electromagnetic compatibility. Simultaneously, household kitchen appliances in key export markets are increasingly evaluated against NSF International food-contact material standards. Companies that proactively embed compliance into their design cycles reduce time-to-market friction, minimize regulatory risk, and strengthen retailer confidence. For 2026 planning, compliance readiness should be treated as a strategic enabler rather than a procedural checkpoint.
Competitive Landscape: Incumbents, Innovation Pace, and Differentiators
The competitive field is anchored by a diverse set of multinational appliance manufacturers, each leveraging distinct brand heritage, engineering philosophies, and distribution strengths. Vorwerk, headquartered in Germany, continues to lead the premium segment with its Thermomix lineage, including the TM6 and the recently introduced TM7. The TM7's global rollout in early 2025 reinforced Vorwerk's emphasis on guided smart cooking, blending, chopping, steaming, and slow-cooking within a single integrated device. This holistic approach has cultivated a dedicated user base and positioned the brand as a reference point for smart culinary ecosystems.
Cuisinart, based in the United States, maintains a strong presence through customizable capacity options, including the Custom 14-Cup and Pro Classic 7-Cup configurations. Its product architecture emphasizes chopping, slicing, shredding, and mixing versatility, appealing to consumers who value modular flexibility and recognizable brand reliability. Breville, an Australian manufacturer, has pursued a performance-oriented strategy with its Sous Chef 16 and Sous Chef 9 lines, and in mid-2026 expanded its lineup with the Paradice 9 and Paradice 16 models. These updates introduced wide dicing meshes and extended feed chutes, reflecting a continued focus on precision dicing and throughput efficiency.
KitchenAid contributes to the competitive mosaic through its KFP series, which targets versatile chopping, mixing, and food preparation tasks with a strong emphasis on brand familiarity and kitchen integration. Ninja, also American, has capitalized on everyday utility with its Professional Plus and related models, emphasizing accessible chopping, shredding, and mixing performance for routine household use. Magimix, from France, caters to users seeking professional-grade chopping, slicing, and dough handling, often positioning its 14-Cup configurations as durable, high-performance workhorses. Hamilton Beach addresses the value-conscious segment with compact, easy-assembly designs such as its 12-Cup Stack & Snap line, prioritizing daily food prep convenience and straightforward operation. TAURUS Group, headquartered in Spain, extends its reach through versatile attachments that serve both household and light commercial applications, while Tefal rounds out the competitive field with processors that support chopping, mixing, and general preparation functions.
This competitive diversity creates both opportunities and risks. On one hand, the breadth of design philosophies allows consumers to align purchases with specific kitchen constraints, culinary habits, and budget parameters. On the other hand, it intensifies the need for clear value communication, consistent quality control, and differentiated after-sales support. Firms that invest in user education, recipe ecosystems, and service network reliability will be better positioned to defend market share as feature parity increases across mid-tier segments.
Regulatory, Labor, and Consumer Habit Pressures Shaping the Next Cycle
Beyond product design and competitive positioning, several macro-level pressures will influence market behavior throughout the forecast period. Regulatory compliance remains a persistent operational consideration, particularly for manufacturers exporting across multiple jurisdictions. The requirement for CE marking verification prior to retail listing in the EU, coupled with NSF International food-contact material certifications for household kitchen appliances, establishes a baseline of safety and material integrity that retailers and consumers increasingly expect. Companies that treat these standards as strategic safeguards rather than administrative hurdles will experience fewer supply chain disruptions and faster market access.
Labor cost dynamics and premium pricing structures also warrant attention. As integrated electronics, precision engineering, and smart cooking guidance become more prevalent in premium models, manufacturing complexity rises. This complexity is reflected in retail pricing, with premium units commanding a significant premium over basic alternatives. For 2026 planning, manufacturers must evaluate whether the cost of advanced feature integration can be offset by higher margin capture, reduced return rates, or expanded service revenue streams. Simultaneously, mass-market segments will continue to pressure supply chain efficiency, requiring leaner component sourcing and more scalable assembly processes.
Consumer habit data further reinforces the strategic importance of utilization and satisfaction. The observed average household utilization rate above 65 percent indicates that multi-functional processors are not merely occasional-use gadgets but central components of daily kitchen routines. This pattern suggests that product reliability, ease of cleaning, attachment durability, and software consistency will heavily influence repeat purchase behavior and word-of-mouth advocacy. Brands that prioritize post-purchase experience—through intuitive interfaces, clear maintenance guidance, and responsive warranty support—will likely see stronger lifetime value metrics.
Inside the PW Consulting Market Study: What Decision-Makers Will Find
The complete PW Consulting Multi-Functional Cooking Food Processors Market study is structured to translate macro trends into actionable intelligence. The report opens with a detailed historical reconstruction covering the 2020–2025 period, establishing baseline demand patterns, regional growth rhythms, and capacity-tier performance. From there, the analysis extends through the full 2026–2032 forecast horizon, providing forward-looking revenue trajectories, structural inflection points, and scenario-based sensitivity considerations.
The segmentation framework examines market behavior across multiple dimensions without reducing complexity to oversimplified ratios. Readers will find granular analysis of regional demand characteristics, product capacity preferences, and application-driven usage patterns, all contextualized within broader macroeconomic and consumer behavior trends. The competitive landscape section goes beyond company profiling to evaluate strategic positioning, feature differentiation, pricing architecture, and recent product launch cadence. Regulatory and compliance dynamics are mapped to specific market entry requirements, while labor cost and premium pricing pressures are analyzed in relation to margin sustainability and portfolio tiering.
Importantly, the study integrates real-world product development milestones, including recent launch activity and model updates, to illustrate how incumbents are adapting to shifting consumer expectations. These case-level observations are paired with industry habit data, utilization patterns, and certification requirements to create a multidimensional view of market evolution. The report also provides strategic recommendations for product planning, channel optimization, compliance readiness, and competitive response, enabling executives to align 2026 initiatives with measurable market opportunities.
Kitchen Food Garbage Processors Market
Conclusion: Turning Market Intelligence into 2026 Advantage
The multi-functional cooking food processor market is entering a phase where growth is no longer guaranteed by broad appliance adoption alone. Sustained expansion will depend on product differentiation, compliance agility, pricing discipline, and a deep understanding of how consumers actually use these devices in daily routines. The forecast CAGR of 5.88 percent and the projected revenue progression toward 5,039 million USD by 2032 outline a promising trajectory, but capturing share within that trajectory requires more than top-line optimism.
This article has outlined the strategic contours of the market: the concentration dynamics, the premium-versus-mass segmentation tension, the regulatory and certification expectations, and the competitive diversity that defines the sector. Yet the full depth of the analysis—segment-level revenue splits, application-specific demand drivers, regional growth nuances, and detailed competitor benchmarking—remains within the complete PW Consulting report. For executives preparing 2026 product launches, supply chain adjustments, or market-entry strategies, the full study provides the structured intelligence needed to move from awareness to action. The next step is to access the complete market intelligence and translate these macro insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Multi-Functional Cooking Food Processors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cellophane Market Hits $403M in 2025, Projected to Reach $557M by 2032 at 4.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Regenerated Cellulose Landscape: Strategic Insights for the Cellophane Market Through 2032
Executive Summary
The global cellophane market stands at a critical intersection of sustainability mandates, packaging innovation, and supply chain recalibration. As enterprises navigate the transition from conventional plastics toward bio-based, transparent packaging solutions, regenerated cellulose films are experiencing a measured but definitive resurgence. Our latest Cellophane Market research report provides a comprehensive, data-driven framework designed specifically to support strategic decision-making across procurement, product development, regional expansion, and competitive positioning through 2032.
Built on a rigorous historical foundation spanning 2020 through 2025 and extended forward to 2032, this analysis captures the structural shifts, regulatory tailwinds, and material science advancements that will define commercial viability in the coming years. Below, we outline the strategic architecture of the study, highlight the operational intelligence it delivers, and demonstrate why access to granular market intelligence is no longer optional for organizations competing in the advanced packaging ecosystem.
Market Trajectory and Structural Growth Drivers
The cellophane market has demonstrated consistent expansion over the past half-decade, with global revenue progressing from approximately 322.0 million USD in 2020 to an estimated 403.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 4.8 percent across the analysis window, culminating in projected revenue of 426.65 million USD for 2026. The forward forecast indicates steady momentum, with market valuation expected to approach 557.0 million USD by 2032.
Several structural forces underpin this growth profile. First, regulatory frameworks across major economies are increasingly penalizing conventional plastic packaging while incentivizing compostable, recyclable, and bio-based alternatives. Regenerated cellulose films, which derive their functional properties from wood-pulp-based feedstocks, align closely with these policy directions. Second, consumer-facing brands in food, personal care, and tobacco segments continue to prioritize visual clarity, breathable barrier properties, and eco-credentialing in their packaging architectures, all of which reinforce demand for high-grade cellophane grades. Third, manufacturing capacity expansions in key production hubs are gradually improving supply reliability and cost competitiveness, though regional variations in pellet-to-film conversion efficiency and raw material availability continue to shape localized pricing dynamics.
Our report synthesizes these demand-side, supply-side, and policy-driven variables into a cohesive forecasting model, enabling organizations to stress-test procurement strategies, anticipate capacity utilization cycles, and map growth corridors with greater precision.
Segmentation Intelligence: Where Commercial Value Is Being Concentrated
Effective strategy formulation requires more than top-line market sizing. The cellophane market is inherently segmented across product types, application verticals, and geographic footprints, each presenting distinct margin profiles, regulatory exposures, and growth velocity. This research deconstructs those dimensions with operational granularity.
Cling Film Market
By product type, the market bifurcates into specialty grades optimized for visual transparency and moisture management, alongside variant formulations engineered for enhanced barrier performance, printability, and compatibility with automated packaging lines. Demand patterns across these categories reflect differing end-use requirements: beverage and confectionery applications prioritize clarity and tactile premiumization, while industrial and adhesive-adjacent uses emphasize dimensional stability and coating adhesion. The report evaluates volume shifts, price elasticity, and substitution risks within each product tier.
Application segmentation reveals a diversified consumption base. Food packaging continues to anchor the largest share of industrial demand, driven by regulatory alignment around compostable wraps, breathable confectionery films, and tamper-evident presentation layers. Tobacco packaging maintains a stable, brand-conscious demand profile where cellophane's clarity and sealing characteristics support traditional and premium product positioning. Pharmaceutical packaging leverages the film's moisture-regulating properties and regulatory compliance pathways for blister backing, unit-dose sleeves, and secondary presentation wraps. Personal care and specialty applications, including cosmetic pouches, gift presentation, and industrial wrapping, round out a consumption matrix that demonstrates both resilience and adaptability.
Cellophane Market
Geographically, the market exhibits pronounced regional divergence in consumption intensity, manufacturing localization, and policy exposure. Developed markets with mature packaging ecosystems show steady replacement-driven demand and heightened sensitivity to extended producer responsibility frameworks, while emerging and industrializing regions display faster volume expansion tied to retail formalization, e-commerce logistics, and domestic film manufacturing scale-up. The analysis maps these regional trajectories without relying on surface-level aggregate splits, instead focusing on the structural drivers, trade flow patterns, and capacity deployment strategies that determine where competitive advantage can be sustained.
Raw material sourcing represents a critical supply-side variable. Wood-derived cellulose is projected to account for a dominant share of feedstock input in 2026, reflecting the material's capacity to deliver consistent film strength, commercial throughput, and functional transparency. However, supply continuity remains sensitive to forestry harvest cycles, pulp pricing volatility, and competing industrial demand from textile and paper sectors. The report assesses how feedstock availability, regenerative sourcing certification trends, and alternative cellulose pathways influence cost structures and long-term supply resilience.
Competitive Landscape: Positioning, Capability, and Market Concentration
Market concentration in the cellophane sector reflects a structure where scale, technological differentiation, and regional manufacturing presence converge to shape competitive outcomes. Industry analysis indicates a concentrated landscape in which leading producers capture a substantial share of global throughput, with the top three competitors accounting for approximately 60 percent of market revenue and the top five collectively representing around 70 percent. This concentration underscores the importance of understanding not just who competes, but how they compete across product architecture, sustainability credentials, and downstream customer integration.
Futamura Chemical Co., Ltd., headquartered in Japan, remains a defining reference point for the sector. As a leading producer of cellophane-based and cellulose-derived transparent packaging films, the company has historically anchored its commercial strategy around renewable wood-pulp formulations designed for food, confectionery, and sustainable packaging applications. Its recent product development pathway emphasizes compostable sachet architectures and collaborative engineering with packaging machinery manufacturers, reflecting a broader industry shift toward closing the loop on single-use non-compostable formats.
In China, several manufacturers have scaled cellophane and coated cellulose film production into globally exported volumes. Weifang Henglian Cellophane Co., Ltd., based in Shandong, operates annual capacity exceeding 5,000 metric tons across PT-cellophane, roll cellophane, MST-cellophane, and coated variants, with commercial focus spanning food packaging, adhesives, and printing applications. Zhejiang Koray New Materials Co., Ltd., located in Shaoxing, specializes in cellulose film production including coated grades and markets high-quality transparent films through eco-industrial production lines. Hubei Golden Ring New Materials Tech Ltd., operating from Hubei, integrates viscose and lyocell fiber production with cellulose film manufacturing, supplying regenerated cellulose packaging materials through vertically coordinated pulp-to-film processes. Together, these entities illustrate how regional capacity expansion, cost engineering, and export-oriented supply chains are reshaping the competitive equilibrium.
Recent corporate and policy developments further illuminate the trajectory of competition. Futamura's launch of compostable packaging sachets for liquid products, developed in collaboration with machine producer GK Sondermaschinenbau, signals an industry-wide push to lower dependence on non-compostable formats through advanced cellulose film engineering. Meanwhile, manufacturing participation at major trade platforms such as interpack 2026 demonstrates how suppliers are using exhibition-driven visibility to reinforce green packaging positioning and showcase regenerated cellulose film capabilities to global buyers. These moves are not isolated product launches; they are strategic signals that reshape customer expectations, procurement criteria, and supplier qualification standards.
Regulatory and Operational Dynamics Shaping Procurement and Compliance
Regulatory frameworks are no longer peripheral considerations; they are central determinants of cost allocation, material selection, and market access. The U.S. FDA permits the use of regenerated cellulose film for food packaging under structured conditions, reinforcing the material's eligibility within certified food-contact applications and influencing procurement specifications among North American buyers. In parallel, European and Commonwealth policy architectures are moving toward packaging stewardship models that assign financial responsibility for end-of-life management directly to producers.
The UK government's publication of 2025–2026 base fees for Extended Producer Responsibility for Packaging illustrates this shift in operational terms. The fee structure introduces differentiated rates across material categories, with implications for cellulose film producers classified under broader packaging material designations. Because extended producer responsibility schemes tie compliance costs to material composition and recovery performance, procurement teams must evaluate not only unit pricing and conversion efficiency but also downstream recyclability, compostability claims, and administrative burden associated with fee registration and reporting.
The operational consequence is clear: packaging decisions increasingly require integrated assessments that combine material performance, regulatory cost exposure, supplier documentation readiness, and brand sustainability messaging. Our research maps these regulatory dynamics to real procurement scenarios, enabling teams to anticipate compliance friction, quantify total cost of ownership more accurately, and align material selection with policy trajectories rather than reacting after regulatory thresholds shift.
What the Report Delivers: Practical Intelligence for Cross-Functional Decision-Making
This Cellophane Market study is designed as an executive-grade operational resource rather than a static market summary. It translates macroeconomic trends, segmentation behavior, and competitive dynamics into actionable intelligence across multiple functional domains.
- Historical reconstructions and forward forecasts that establish a defensible baseline for capacity planning, inventory strategy, and revenue modeling through 2032.
- Granular segmentation analysis across product types, application verticals, and geographic markets, enabling teams to isolate high-margin demand pockets and identify substitution pressure points.
- Raw material and supply chain assessments that examine cellulose feedstock reliance, forestry supply sensitivity, and regional pulp-to-film conversion dynamics affecting cost structures and availability risk.
- Competitive profiling of leading producers, with emphasis on manufacturing scale, product differentiation, sustainability positioning, and recent corporate developments that influence customer qualification and supplier selection.
- Regulatory and compliance mapping that connects packaging stewardship frameworks, food-contact permissions, and material classification rules to procurement strategy and total cost evaluation.
- Strategic scenario considerations that help organizations evaluate growth corridors, pricing sensitivity, capacity deployment logic, and portfolio alignment with sustainability-driven procurement mandates.
Each section is structured to support direct integration into commercial planning workflows. Whether the objective is to validate regional expansion assumptions, benchmark supplier capabilities, refine application-specific packaging specifications, or assess the financial impact of extended producer responsibility exposure, the report provides the analytical scaffolding necessary to move from intuition to evidence-based strategy.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle demands more than retrospective market readouts. It requires forward visibility into a market where regulatory cost structures, feedstock availability, consumer packaging expectations, and competitor capability development are evolving simultaneously. The 4.8 percent compound growth trajectory, the progression toward 557.0 million USD by 2032, and the concentration of market revenue among a limited set of scaled producers all point to a sector where timing, positioning, and intelligence quality directly influence commercial outcomes.
Organizations that treat cellophane as a commodity input risk underpricing compliance exposure, overestimating supply flexibility, and missing segment-specific demand shifts. Organizations that treat it as a strategically managed material system, by contrast, can align procurement with sustainability mandates, lock in preferred supplier relationships ahead of capacity constraints, and tailor product specifications to application-level performance requirements. The distinction between these two approaches is often determined by the quality of market intelligence available at the point of decision.
Our report is structured to close that gap. It provides the macro context, segmentation clarity, competitive map, and regulatory overlay needed to support confident choices in sourcing, product development, and market prioritization. The full dataset, scenario analysis, and detailed segmentation breakdowns are reserved for the complete study, where they can be deployed with the precision necessary for capital allocation, supplier negotiation, and long-range planning.
Next Steps: Accessing the Complete Intelligence Framework
For executives, procurement leaders, packaging developers, and strategy teams preparing for 2026 and beyond, partial visibility is a strategic liability. The complete Cellophane Market research report extends far beyond the summary perspective outlined here, offering detailed segmentation depth, regional demand logic, competitive benchmarking, and forward-looking scenario analysis calibrated for operational decision-making.
To obtain the full intelligence package, including granular market size trajectories, application-level demand analysis, supplier capability comparisons, and regulatory impact assessments, we invite you to access the complete report through our official research portal. The comprehensive version is designed to support precise forecasting, procurement strategy refinement, and competitive positioning grounded in data rather than generalization.
In a market defined by sustainability transitions, regulatory recalibration, and concentrated supplier capability, strategic advantage belongs to organizations that make decisions with full context. This research is built to provide that context.
For detailed analysis of this topic, please visit the official page: Cellophane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railroad Tie Market Hits $488.65M in 2025, Poised to Reach $655.95M by 2032 at 4.23% CAGR
By PW Consulting, 2026-09-16
Navigating the 2026 Railroad Tie Landscape: Strategic Intelligence for Infrastructure Leaders
The global railroad infrastructure sector stands at a critical inflection point as we enter 2026. Operators, suppliers, and investors alike are confronted with a complex matrix of aging assets, evolving environmental regulations, and shifting material preferences that will define capital allocation decisions for the next decade. Understanding the underlying market mechanics is no longer a passive exercise—it is a strategic imperative. Our latest comprehensive study on the Railroad Tie Market delivers the granular intelligence required to navigate this terrain with confidence.
Worldwide Composite Railroad Tie Market
This report is designed not merely as a statistical overview, but as a decision-support framework for executives who must balance operational reliability with long-term sustainability. By synthesizing historical performance data with forward-looking projections, the analysis equips stakeholders with the clarity needed to anticipate supply chain disruptions, evaluate competitive positioning, and align procurement strategies with emerging regulatory mandates. The insights presented here are drawn from rigorous primary research and validated industry datasets, ensuring that every recommendation rests on a foundation of verifiable market reality.
Macro Market Trajectory: Growth Anchored in Infrastructure Renewal
The railroad tie market has demonstrated consistent resilience over the past half-decade, driven by sustained capital expenditure on rail network maintenance and expansion. From a baseline valuation of approximately USD 392 million in 2020, the sector has advanced through a series of incremental yet meaningful increments, reaching an estimated USD 458 million by 2024 and climbing to roughly USD 489 million in 2025. This trajectory reflects a compound annual growth rate of 4.23 percent across the forecast horizon extending through 2032, positioning the market to surpass the USD 655 million threshold by the end of the projection period.
Such growth is not accidental. It is intrinsically linked to the ongoing modernization of rail infrastructure across multiple geographies, where aging wooden sleepers are gradually being replaced or supplemented by longer-lasting alternatives. The steady upward curve underscores a market that is maturing rather than experiencing volatile spikes, offering planners a predictable environment for budgetary forecasting. However, the aggregate figures only tell part of the story. Beneath the headline numbers lie nuanced shifts in material adoption, regional procurement patterns, and application-specific demand drivers that require deeper excavation to inform precise strategic moves.
Decoding Market Structure: Segment Dynamics and Material Shifts
Material Preferences in Transition
The composition of the railroad tie market reveals a clear hierarchy of material adoption, yet the edges of this hierarchy are where the most strategic opportunities reside. Traditional wooden ties continue to command a substantial share of overall revenue, reflecting their entrenched role in legacy networks and the sheer scale of ongoing replacement cycles. Concrete alternatives have carved out a significant and growing footprint, particularly in heavy-haul and high-speed corridors where durability and load-bearing capacity are non-negotiable. Steel and emerging composite solutions occupy more specialized niches, but their relevance is expanding as operators seek to mitigate decay-related maintenance costs and comply with increasingly stringent environmental standards.
What makes this material landscape particularly compelling for 2026 decision-makers is the pace at which performance expectations are evolving. Field data and industry benchmarks indicate that conventional wooden crossties typically deliver between eight and twelve years of service life in high-decay environments. By contrast, advanced composite formulations are now demonstrating operational lifespans exceeding fifty years under comparable conditions. This differential is not merely a technical footnote—it translates directly into total cost of ownership, track availability metrics, and long-term asset planning. Procurement teams that understand the cost-benefit calculus across these material categories will be better positioned to negotiate favorable terms and justify capital expenditures to internal stakeholders.
Application and Regional Nuances
Demand generation within the railroad tie ecosystem is heavily influenced by the operational profile of the end-user. Mainline passenger and freight train operations remain the dominant application driver, absorbing the bulk of annual production output. Subway and urban transit networks represent a secondary but strategically important demand channel, where space constraints, noise considerations, and rapid deployment requirements shape material selection. Beyond these core segments, specialized industrial and temporary track applications contribute incremental volume while introducing distinct specification requirements.
Geographically, the market exhibits pronounced concentration patterns that reflect historical infrastructure investment cycles, regulatory environments, and local sourcing capabilities. North America continues to represent the largest revenue contributor, underpinned by extensive Class I railroad networks and ongoing maintenance programs. Europe follows as a mature market with strong emphasis on high-speed rail modernization and environmental compliance. The Asia Pacific region, while currently smaller in absolute terms, presents dynamic growth potential tied to expanding rail corridors and urban transit development. Latin America and the Middle East/Africa markets, though more modest in scale, offer targeted opportunities for suppliers that can navigate localized logistics and specification requirements. Detailed regional and application breakdowns are mapped comprehensively within the full report to enable precise market-entry and expansion planning.
Competitive Landscape: Incumbents, Innovators, and Strategic Moves
Established Players and Supply Chain Anchors
The competitive architecture of the railroad tie market is characterized by a mix of large-scale manufacturers, specialized treatment providers, and national distributors. Firms such as Koppers Inc. and Stella-Jones Inc. have long anchored the North American supply chain, leveraging extensive sawmill sourcing networks and pressure-treatment capabilities to serve Class I, regional, and short-line railroads. Their scale and established relationships provide a baseline of supply reliability that network operators depend upon for routine replacement programs.
On the concrete and composite side, Vossloh AG has built a global reputation for prestressed concrete ties and synthetic sleepers tailored to heavy-haul and high-speed applications. L.B. Foster Company, through its concrete product subsidiary, holds a significant share of the North American concrete tie supply, reinforcing the material's growing relevance in mainline infrastructure. Gross & Janes Corporation and Nisus Corporation contribute specialized pressure-treated wood solutions, with the latter emphasizing copper naphthenate formulations designed to extend service life in demanding field conditions. These companies illustrate how incumbent players are adapting their portfolios to address both traditional performance expectations and emerging longevity requirements.
Innovation Entrants and Sustainability-Driven Investment
A distinct cohort of composite-focused manufacturers is reshaping the competitive perimeter by targeting the intersection of durability and environmental stewardship. TieTek LLC, operating under Axion International, specializes in composite ties manufactured from recycled materials, offering sustainable alternatives that reduce reliance on virgin timber and creosote-based treatments. Evertrak has similarly positioned itself in the recycled-plastic and fiberglass composite space, with its flagship models engineered for extended lifespans in high-decay zones. IntegriCo Composites Inc. expands this segment further by producing composite railroad ties from recycled feedstocks across dedicated manufacturing facilities.
Railroad Tie Market
Strategic capital flows are reinforcing this innovation axis. In early 2025, Sumitomo Corporation of Americas announced a strategic investment and formalized partnership with Evertrak to support production scalability and expand sustainable composite tie manufacturing for North American railroads. Such moves signal growing institutional confidence in composite technologies and suggest that financing environments are increasingly favorable for manufacturers that can demonstrate both performance superiority and circular-economy alignment. Additionally, broad-line suppliers such as A&K Railroad Materials, Inc. and POHL Railroad Materials Corporation LLC continue to play essential roles in distribution and sourcing, maintaining comprehensive catalogs of new and used ties that support diverse procurement needs across the network.
Market Concentration and Competitive Implications
The competitive dynamics of the railroad tie market are further contextualized by its concentration profile. With the top three firms accounting for approximately 21.5 percent of market revenue and the top five reaching roughly 24.8 percent, the sector exhibits a moderately fragmented structure. This configuration carries strategic implications: while no single entity dominates outright, established players benefit from scale advantages in treatment capacity, distribution networks, and long-term contracting leverage. Meanwhile, niche innovators can pursue differentiation through material performance, sustainability credentials, and specialized application targeting. For buyers, this balance means that supplier diversification, qualification processes, and performance benchmarking are essential to securing both cost competitiveness and supply resilience.
Regulatory and Operational Currents Shaping 2026 Strategy
Performance Standards and Environmental Compliance
Regulatory evolution is becoming a decisive force in material specification and disposal practices. In August 2025, the U.S. Federal Railroad Administration developed performance-based specifications for concrete railroad tie freeze-thaw durability, a move designed to ensure track longevity and tighten manufacturing process control. This specification framework directly influences procurement standards, quality assurance protocols, and supplier qualification criteria for concrete tie programs across North American networks.
Environmental considerations are simultaneously reshaping the end-of-life landscape for treated wood ties. The U.S. Department of Transportation's Federal Railroad Administration issued a request for information in 2023 examining potential uses and options for the disposal or repurposing of used creosote-treated railroad ties, reflecting broader concerns about hazardous substance management. At the state level, New Hampshire's Department of Environmental Services implemented requirements in September 2025 mandating proper disposal options for creosote-treated ties to prevent environmental release. These regulatory threads collectively push operators and suppliers toward more transparent disposal pathways, extended service life solutions, and alternative materials that reduce long-term environmental liability.
Raw Material Capacity and Supply Realism
On the supply side, industry capacity data provides important context for procurement planning. Railroad crossties account for the majority of North American wood tie production capacity, which exceeds 24 million units annually, while current industry output stands at just over 19 million ties. This gap between nameplate capacity and realized output highlights both latent production potential and the operational constraints—labor availability, raw material logistics, treatment facility throughput—that influence actual delivery timelines. For network planners, understanding this capacity dynamic is essential when forecasting replacement schedules, negotiating supply agreements, and modeling cost trajectories under varying operational scenarios.
Strategic Takeaways for 2026 Decision-Makers
The railroad tie market in 2026 rewards organizations that approach procurement and investment through a multi-dimensional lens. Several strategic priorities emerge from the current landscape:
- Align material selection with total cost of ownership rather than upfront unit pricing, factoring in service life differentials, maintenance frequency, and disposal compliance costs.
- Evaluate supplier portfolios for both scale reliability and innovation capability, recognizing that established treatment and manufacturing networks remain critical while composite and sustainability-focused entrants are gaining traction.
- Incorporate regulatory developments into specification frameworks early, particularly performance-based durability standards and environmental disposal mandates that will influence eligibility, reporting, and liability exposure.
- Monitor capacity utilization and regional sourcing dynamics to anticipate lead-time variability and identify opportunities for dual-sourcing or localized supply partnerships.
- Leverage strategic investment activity as a signal of where institutional capital is converging, using partnership and funding announcements to inform competitive benchmarking and technology adoption roadmaps.
These considerations are not isolated tactics; they form an integrated approach to navigating a market where material performance, regulatory pressure, and supply chain realism intersect. Organizations that embed these priorities into their planning cycles will be better equipped to manage risk, capture efficiency gains, and position their rail infrastructure assets for long-term operational excellence.
Accessing the Full Strategic Intelligence
The insights summarized here represent a high-level orientation to the railroad tie market's structure, dynamics, and strategic levers. Yet the depth required for enterprise-level decision-making extends well beyond aggregate trends. The complete report delivers detailed segment-level revenue trajectories, application-specific demand breakdowns, regional procurement analyses, and granular competitive profiling that enable precise market-entry assessments, supplier negotiations, and capital planning. It also maps the interplay between regulatory timelines and material adoption curves, offering scenario-based frameworks that help leaders stress-test procurement strategies against evolving compliance requirements and performance expectations.
For executives and strategy teams preparing for 2026 and the forecast window through 2032, the full study provides the empirical foundation necessary to convert market awareness into actionable advantage. To access the complete dataset, competitive deep-dives, and operational recommendation frameworks, we invite you to explore the full report through our official publication channel. There, you will find the detailed tables, methodology notes, and scenario analyses that transform these strategic themes into executable intelligence tailored to your organization's specific rail infrastructure objectives.
For detailed analysis of this topic, please visit the official page: Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CTBN Market Reaches $70M in 2025, Projected 4.98% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the CTBN Market: Navigating Growth, Competition, and Material Innovation in 2026
The specialty chemicals landscape is undergoing a structural recalibration. Among the most consequential segments for advanced manufacturing, the Carboxyl-Terminated Butadiene-Nitrile (CTBN) market is entering a decisive inflection point. Over the past half-decade, demand trajectories have been shaped by automotive lightweighting mandates, adhesive formulation shifts, and the expanding reliance on polymer-modified epoxy systems across industrial and aerospace applications. As we move through 2026, enterprise decision-makers face a more complex calculus: balancing cost-efficient sourcing against performance-grade material specifications, anticipating regional supply chain realignments, and positioning product pipelines ahead of tightening regulatory and sustainability expectations. Our newly released CTBN Market research report has been designed specifically to convert this complexity into actionable intelligence.
The foundational narrative of this market is one of measured but persistent expansion. Historical consumption patterns from 2020 through 2025 reveal a consistent upward arc, with aggregate revenue climbing from 55.2 million USD to 70.0 million USD. Looking forward across the 2026 to 2032 forecast horizon, the sector is projected to continue its growth path, reaching an estimated 97.86 million USD by the terminal year of the analysis window. This progression translates to a compound annual growth rate of 4.98 percent, a pace that underscores durable industrial demand rather than speculative optimism. The implied trajectory signals steady capacity utilization, incremental formulation upgrades, and sustained procurement activity across mature and emerging applications alike. For procurement leaders and R&D directors, these macro indicators are not merely background statistics; they represent the scaffolding upon which sourcing strategies, capacity planning, and product roadmaps must be constructed.
Why This CTBN Market Research Matters for 2026 Enterprise Decisions
Corporate strategy in specialty chemicals rarely succeeds on intuition alone. It requires a granular understanding of where value is created, where margins compress, and where competitive friction is intensifying. The CTBN Market study is built to address precisely these operational and strategic questions. Rather than offering a static snapshot, the report functions as a decision-support instrument calibrated for the realities of 2026 procurement cycles, technology adoption timelines, and regional market access strategies.
Several structural dynamics make this publication particularly timely:
- The CTBN value chain is no longer driven solely by volume expansion; formulation differentiation, reactive toughening performance, and compatibility with advanced resin systems increasingly determine commercial advantage.
- Supply-side geography is evolving in response to logistics costs, raw material availability, and localized regulatory frameworks, forcing manufacturers to weigh concentration risk against cost efficiency.
- Downstream applications are diverging in their technical requirements. Epoxy modification for adhesives and sealants, composite toughening for automotive and industrial assemblies, and polyurethane precursor performance all impose distinct specification thresholds that influence supplier selection.
- Pricing and contractual frameworks are being reshaped by capacity investments, feedstock variability, and the growing premium attached to consistent batch quality and technical service support.
By mapping these forces into a structured analytical framework, the report enables leaders to test assumptions before they commit capital. Whether the objective is to optimize distributor relationships, evaluate a new plant footprint, refine a product-grade strategy, or identify whitespace in a particular application vertical, the research supplies the evidentiary base needed to reduce uncertainty and accelerate approval cycles.
TCB Bonder Market
What the Report Delivers: Analytical Depth and Actionable Frameworks
To support rigorous planning, the CTBN Market report integrates multiple analytical layers that bridge high-level market sizing with granular commercial insight. The structure is designed to serve both strategic and tactical teams, from executive committees to technical sourcing managers. Core deliverables include:
Market Sizing, Historical Baselines, and Forward Estimates
The analysis begins with a comprehensive historical reconstruction covering the 2020 to 2025 period, establishing a defensible baseline against which growth assumptions can be stress-tested. From that foundation, the forecast window extends through 2032, allowing planners to model revenue trajectories, capacity utilization patterns, and demand timing across multiple planning horizons. Every projection is anchored to observable market behavior rather than abstracted trends, ensuring that downstream decisions rest on plausible, internally consistent assumptions.
Segmentation Architecture for Application and Type Dynamics
Because CTBN chemistry is deployed across distinct end-use environments, the report disaggregates demand by type and application to expose where performance requirements and consumption intensity diverge. This segmentation supports more precise portfolio decisions, including whether to prioritize low-acrylonitrile or high-acrylonitrile grades, how to align formulation capabilities with adhesive and sealant markets versus coatings and composite toughening, and where automotive-linked specifications create durable demand pull.
Regional Market Structure and Access Considerations
Geographic distribution is analyzed to clarify where demand concentration creates scale advantages, where regulatory or logistics conditions influence cost structures, and where localized supply capabilities alter competitive positioning. The regional view does not simply rank territories; it helps organizations evaluate import-export exposure, assess nearshoring and regionalization scenarios, and determine which markets warrant dedicated commercial resources versus selective distribution models.
Competitive Benchmarking and Supplier Intelligence
The report profiles the principal participants shaping the CTBN competitive landscape, with attention to product architecture, application focus, and commercial strategy. Featured companies include:
- Emerald Performance Materials , whose Hypro CTBN carboxyl-terminated butadiene-acrylonitrile copolymer is positioned as a reactive toughener in epoxy resins, adhesives, sealants, and composites for aerospace, automotive, and industrial applications.
- Tanyun Aerospace Materials (Yingkou) Technology Co. , which produces carboxy-terminated butadiene-acrylonitrile rubber as an additive for epoxy resins and thermoset polymers, emphasizing toughness, flexibility, and impact resistance in aerospace composites and structural applications.
- Shandong Qilong Chemical Co., Ltd. , a manufacturer of end-carboxyl-terminated butadiene-nitrile rubber liquid rubber and related functional elastomers for adhesives, sealants, and polymer modification.
- Shanghai Theorem Chemical Technology Co., Ltd. , which exports and supplies CTBN as a high-performance polyurethane precursor and toughener in resins for adhesives, sealants, and advanced composites.
Beyond company-level profiles, the research incorporates concentration metrics that illuminate market structure. With a CR3 of 35.2 percent and a CR5 of 52.8 percent, the landscape reflects a competitive environment in which leading suppliers command meaningful share while still leaving substantial room for specialized players and regional specialists. This structure has direct implications for pricing power, negotiation leverage, and supplier diversification strategy.
Strategic Scenario Tools for 2026 and Beyond
The report closes the gap between descriptive analysis and decision execution by providing scenario-oriented tools. These include demand sensitivity frameworks tied to application growth, type-mix shifts, and regional procurement behavior; competitive response simulations that help anticipate supplier pricing or capacity moves; and sourcing risk assessments that connect material performance requirements to supply continuity considerations. The intent is to enable organizations to model alternative pathways rather than rely on a single forecast.
Competitive Positioning in a Fragmented but Concentrating Landscape
A defining feature of the CTBN market is its blend of technical specialization and commercial contestability. The presence of well-established suppliers with distinct formulation capabilities coexists with regional manufacturers that compete on cost, responsiveness, and application-specific service. For enterprises buying or producing CTBN-based systems, this means supplier evaluation cannot be reduced to unit price alone. Performance consistency, technical assistance, regulatory documentation, and compatibility with downstream processing equipment all influence total cost of ownership.
The competitive analysis in the report is structured to help buyers and producers interpret this environment with precision. Rather than treating market share as a static hierarchy, the study examines how supplier positioning varies by application pressure, type-grade specialization, and geographic access. This approach is particularly relevant in 2026, as firms reassess supplier portfolios in response to changing procurement policies, resilience requirements, and formulation roadmaps. Organizations that understand where concentration creates negotiation constraints and where fragmentation creates alternatives will be better equipped to structure contracts, qualify second sources, and manage supply continuity without overpaying for unnecessary redundancy.
Market Dynamics, Demand Drivers, and the Regulatory-Economic Backdrop
CTBN demand is linked to broader trends in advanced materials, structural performance requirements, and formulation evolution. Automotive programs continue to pursue weight reduction and damage-tolerant composite assemblies. Adhesive and sealant formulators are seeking tougher, more flexible polymer modifications that preserve bond integrity under mechanical stress. Coatings and industrial resin systems increasingly depend on reactive tougheners to balance mechanical performance with processing practicality. These application-level drivers are not uniform; they differ by region, by product class, and by the technical maturity of the end market.
At the same time, market participants are operating within a broader industrial and regulatory environment that continues to reshape infrastructure investment, spectrum access frameworks, and connectivity requirements in adjacent sectors. While these dynamics belong to the wider advanced-technology ecosystem, they indirectly influence the operating context for specialized material supply chains by affecting logistics planning, industrial capacity deployment, and the cadence of capital investment across technology-intensive industries. Regulatory coordination in spectrum and network access, neutrality principles, and efforts to streamline cross-border policy burdens all contribute to the background conditions under which industrial procurement and infrastructure programs advance. Public and private investment in network build-out and shared-access frameworks has expanded materially, with operator spending on spectrum and small-cell deployment reaching substantial levels and annual investment in related radio access and transport infrastructure projected to grow at a double-digit pace through the near term. These conditions do not define CTBN chemistry directly, but they shape the industrial tempo, risk appetite, and capital environment in which specialty chemical suppliers and their customers operate.
For CTBN market participants, the practical implication is clear: demand planning must account for both application-specific technical drivers and the wider industrial environment in which capacity, logistics, and compliance costs evolve. The report integrates these considerations into its forward analysis so that strategic assumptions are grounded in current operating reality rather than historical convenience.
How to Use This Research for 2026 Planning Cycles
The report is constructed for multiple internal audiences and planning workflows. Procurement teams can use the segmentation and supplier profiles to refine grade selection and qualification strategies. Commercial leaders can apply the competitive structure and regional analysis to prioritize market access and partnership models. R&D and product management teams can align formulation direction with the most consequential application and type-grade dynamics. Executive planners can rely on the consolidated market sizing and scenario tools to test growth assumptions and capital allocation priorities.
To support this range of use cases, the study is organized around questions that recur in 2026 decision-making:
- Which demand pools are expanding fastest in specification intensity rather than merely in volume?
- Where do type-grade distinctions create sustainable differentiation versus commoditization risk?
- How should supplier portfolios be structured to balance performance assurance with cost competitiveness?
- Which regional markets warrant closer commercial engagement given concentration, logistics, and regulatory conditions?
- What scenario ranges should be assumed for the 2026 to 2032 period when modeling capacity, sourcing, and product strategy?
Answering these questions requires more than summary data. It requires an evidence base that connects market size, segmentation behavior, supplier positioning, and dynamic operating conditions into a single coherent framework. That is the core function of this publication.
Conclusion: Converting Market Uncertainty into Strategic Advantage
The CTBN market is not defined by abrupt disruption; it is defined by cumulative technical demand, evolving supplier capabilities, and a competitive structure that rewards precision in formulation, sourcing, and market selection. The 2026 to 2032 outlook reinforces the case for disciplined strategic planning. With aggregate revenue projected to advance from 75.38 million USD in 2026 toward nearly 98 million USD by 2032 at a CAGR of 4.98 percent, the opportunity lies not simply in participating in growth, but in shaping how a company captures it. That requires clarity on type-grade positioning, application relevance, geographic exposure, and competitive leverage.
The CTBN Market report is designed to provide that clarity. It offers the analytical depth needed to justify decisions internally, the segmentation discipline required to avoid oversimplification, and the competitive context necessary to anticipate supplier and customer behavior. The full research contains detailed segmentation performance, regional market structures, application-level breakdowns, and extended company profiles that cannot be fully reproduced here. To access the complete dataset, scenario tools, and competitive intelligence, visit the official report page and retrieve the full CTBN Market study.
CTBN Market
For organizations preparing for 2026 sourcing cycles, product commitments, and long-range capacity evaluation, the difference between informed positioning and reactive adjustment will come down to the quality of the underlying intelligence. This research is built to supply precisely that advantage.
For detailed analysis of this topic, please visit the official page: CTBN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


