



PW Consulting: Rheology Modifiers Market Hits $11.45B in 2025, Poised to Reach $15.27B by 2032
By PW Consulting, 2026-09-16
The Rheology Modifiers Market in 2026: Navigating Growth, Compliance, and Competitive Complexity
Executive Overview
The global rheology modifiers market has entered a decisive phase of structural expansion, shifting from a period of steady organic growth to one defined by regulatory pressure, raw material volatility, and accelerated formulation innovation. With a 2025 baseline valuation of USD 11.45 billion and a projected valuation of USD 12.17 billion at the close of 2026, the market is on a clear trajectory toward USD 15.27 billion by 2032. At a compound annual growth rate of 4.2 percent across the forecast window, the sector is no longer moving at the pace of incremental capacity additions or routine product refreshes. It is being reshaped by the simultaneous forces of sustainability mandates, performance-driven reformulation, and strategic supply chain repositioning.
For market participants, 2026 is not a simple continuation of historical momentum. It is a year in which segmentation decisions, geographic prioritization, and product portfolio alignment will determine which firms capture disproportionate value and which face margin compression from compliance costs and feedstock uncertainty. The latest Rheology Modifiers Market research from PW Consulting has been built to equip strategic decision-makers with the analytical rigor required to navigate this environment. This article outlines the strategic architecture of the study and explains why its findings should be treated as essential input for 2026 planning cycles.
From Steady Expansion to Structural Realignment: Why 2026 Is a Deviation Year
The historical record from 2020 through 2025 reveals more than a smooth revenue curve. It documents a market that absorbed pandemic-era disruptions, navigated supply bottlenecks, and successfully scaled production to support a rising demand base across coatings, personal care, adhesives, and specialty industrial applications. The journey from USD 9.32 billion in 2020 to USD 11.45 billion in 2025 reflects both volume growth and the increasing technical deployment of rheology modifiers in formulations where viscosity control, suspension stability, and application behavior directly influence end-product performance and regulatory compliance.
Yet the forecast period introduces a more nuanced picture. Growth through 2032 will not be evenly distributed across all segments, nor will it be immune to external pressure points. The forecast profile shows a market that continues to expand but also encounters inflection points tied to regulatory alignment, raw material cost structures, and regional manufacturing footprints. A 4.2 percent CAGR may appear moderate in isolation, but in a market of this scale and technical complexity, it implies substantial absolute value creation and intensifying competition for high-growth pockets within paints and coatings, personal care, and emerging bio-based formulation pathways.
This is precisely why the research has been designed not merely as a top-line forecast tool, but as a decision framework for 2026. Firms that treat 2026 as a year of routine execution risk misallocating R&D, production capacity, and commercial resources. Firms that use the study to anticipate segment acceleration, regional demand migration, and formulation shifts will be better positioned to act before market signals become obvious.
What the Study Delivers: Actionable Intelligence Beyond the Headline Numbers
The full report is structured to translate macro trajectory into operational guidance. It begins with the historical baseline and forward projection, but its greater value lies in the depth of its segmentation logic, competitive mapping, and scenario-ready insights. Decision-makers can expect to access an integrated analysis that connects market size evolution to the underlying demand drivers, formulation trends, and regional dynamics that will shape procurement strategies, capacity investment decisions, and product roadmap planning throughout the forecast horizon.
Rheology Modifiers Market
Specifically, the study addresses several dimensions that are often fragmented across separate analyses:
- A detailed review of market structure by type, including the relative positioning of organic and inorganic rheology modifier categories and their respective relevance to formulation requirements across major end-use industries.
- An application-level reading of demand concentration, highlighting where rheology modifiers are gaining share in core uses and where technical or regulatory friction is reshaping adoption velocity.
- A regional assessment that identifies where mature demand bases are stabilizing and where growth momentum is accelerating due to manufacturing expansion, regulatory transitions, and formulation modernization.
- An evaluation of market concentration and competitive intensity, offering context on how consolidated the landscape is and what that means for pricing behavior, differentiation, and supplier negotiation.
- A review of recent corporate developments, including product launches and capacity expansions, that signal where leading players are betting on future demand.
The report also integrates the external factors that are increasingly inseparable from market forecasts. Feedstock dynamics tied to crude oil price movements, evolving restrictions on synthetic polymer microparticles, VOC-related formulation shifts, and compliance demands linked to REACH, FDA, and food-contact considerations are addressed as market-shaping variables rather than peripheral noise. That means the analysis does not simply project demand; it places demand within the regulatory and cost environment that executives must actually manage.
Competitive Positioning: Where Leading Players Are Investing and Innovating
The competitive landscape is defined by a concentrated group of globally active chemical and specialty materials firms, each competing on technical performance, application specificity, regional presence, and sustainability alignment. The research provides a structured competitive scan of these players, with a focus on how product portfolios are being tailored to water-based, solvent-based, and solvent-free formulations, and how recent moves suggest broader strategic intent.
Among the firms profiled, BASF SE continues to build on a broad rheology modifier platform spanning RHEOVIS®, ATTAGEL®, ATTAFLOW®, and EFKA® products, with a clear emphasis on serving water-based, solvent-based, and solvent-free applications. The April 2025 announcement of a production line expansion for Rheovis HEUR thickeners in Nanjing, China signals a deliberate response to rising demand from architectural and industrial coatings markets. This type of capacity action is significant because it links product availability directly to regional growth dynamics rather than treating supply as a generic global function.
The Dow Chemical Company maintains a focused presence through ACRYSOL™ HASE rheology modifiers and PRIMAL™ RM-7 for latex coatings, positioning itself where performance consistency in latex-based systems remains a priority. Lubrizol Corporation is expanding in personal care and specialty Formulation through Solthix™ and Carbopol® rheology modifiers, and its May 2025 introduction of Arbalon® RC 76 cellulose liquid illustrates a continued push into cationic cellulose-derived solutions for personal care applications. These moves suggest that leading suppliers are not only defending core positions but also refining portfolios toward higher-value formulation niches.
Other major participants reflect similarly differentiated strategies. Elementis plc brings RHEOLATE® associative polyurethane thickeners and BENTONE® clay-based modifiers into competition, while Evonik Industries AG relies on AEROSIL® fumed silica and the TEGO® ViscoPlus series to articulate a performance-led value proposition. Clariant AG maintains a prominent personal care and coatings footprint with Hostagel™ and Aristoflex® lines, and its August 2025 launch of Aristoflex SUN underscores a recent focus on advanced sunscreen formulations with improved stability and SPF performance. Ashland Global Holdings Inc. continues to compete through Aquaflow™ nonionic synthetic associative thickeners and Natrosol® cellulosic products, reinforcing the breadth of its formulation support capabilities.
The competitive scan also includes firms that are shaping regional and application-specific demand with notable precision. Croda International Plc emphasizes high-performance rheology modifiers for aqueous and non-aqueous formulations. Münzing Chemie GmbH contributes TAFIGEL® PUR alongside HEUR/HASE associative modifiers. BYK-Chemie GmbH is active with fumed silica-based and associative additives. Arkema S.A. extends its offering with Coapur® and Rheostyl® waterborne modifiers. AkzoNobel N.V. competes in coatings and industrial applications with formulation-specific rheology solutions. San Nopco Co. rounds out the landscape with its SN-Thickener series polymer and associative modifiers. Taken together, these players illustrate that the market is not a simple contest of scale; it is one where technical differentiation, application specificity, and regional readiness increasingly determine commercial advantage.
The Regulatory and Cost Environment Reshaping Demand Signals
A defining feature of the 2026 outlook is that demand is being steered as much by compliance as by performance. In North America, EPA VOC limits for architectural coatings are accelerating the shift toward waterborne rheology modifiers with lower solvent content. This transition favors suppliers that can deliver effective thickening and suspension in waterborne systems without compromising application characteristics or dry-time behavior. In Europe, EU Regulation 2023/2055 on synthetic polymer microparticles is placing new constraints on certain associative thickeners, increasing the pull toward bio-based alternatives and more sustainable formulation architectures. At the same time, stringent restrictions on APEO-containing thickeners in both the EU and North America are pushing reformulation efforts toward options that satisfy environmental expectations while preserving performance.
Beyond regulation, raw material dynamics remain a critical planning variable. Volatility in crude oil prices directly influences feedstock costs for synthetic acrylic and polyurethane rheology modifiers used in coatings, making cost forecasting and formulation flexibility more important than ever. Meanwhile, escalating technical complexity across REACH and FDA compliance for food-contact applications means that product qualification cycles can become longer and more demanding. These factors do not eliminate growth; they reshape where growth is achievable and which suppliers can serve it efficiently.
This is why the research treats regulatory and feedstock conditions as integral inputs to the forecast environment rather than as disconnected background events. The analysis connects these pressures to operational implications: what they mean for reformulation roadmaps, how they alter the attractiveness of different product types, and where regional demand may shift as end-users adapt to new compliance realities.
Why the Study Is Strategic Input for 2026 Decision-Making
For executives, procurement leaders, R&D directors, and strategy teams, the value of this study lies in its ability to convert market trajectory into decision-ready context. In a market projected to rise from USD 11.45 billion in 2025 to USD 12.17 billion in 2026, and onward toward USD 15.27 billion by 2032, the immediate question is not whether growth exists. The question is where the most defensible growth will originate, which segments will face the steepest technical or regulatory barriers, and how competitive intensity will evolve as leading players align capacity and product portfolios with regional demand shifts.
Worldwide Rheology Modifier Coating Additive Market
The report is designed to support that decision process by clarifying the structural forces behind the numbers. It helps teams evaluate whether current portfolio exposure aligns with the fastest-moving application areas, assess which type categories are likely to gain relevance under evolving formulation and compliance conditions, and understand how regional dynamics may influence sourcing, production, and market-entry priorities. It also provides a competitive baseline that makes it easier to interpret new product launches, capacity announcements, and partnership activity as signals rather than isolated events.
In practical terms, the study supports a range of 2026 uses:
- Refining segment-level growth assumptions before committing to capacity, inventory, or commercial investment.
- Identifying formulation trends that may alter demand for organic versus inorganic rheology modifiers across core applications.
- Anticipating regional shifts tied to regulatory transitions and manufacturing expansion.
- Benchmarking competitive positioning against major global suppliers with differentiated product systems and recent market moves.
- Integrating regulatory and raw material risk into longer-term market planning rather than treating them as after-the-fact constraints.
Conclusion: Treat 2026 as a Year for Informed Strategic Positioning
The rheology modifiers market is entering 2026 with solid momentum, but also with heightened complexity. Growth is real, yet it is increasingly selective. Regulatory evolution is accelerating formulation change, feedstock volatility is complicating cost planning, and competitive players are responding with targeted capacity expansion and application-specific innovation. In this environment, broad market awareness is no longer enough. Decision-makers need a structured, evidence-based view of where value will be created, which segments will be most affected by external pressures, and how the competitive field is shifting beneath the headline numbers.
The full Rheology Modifiers Market research from PW Consulting provides that view. It combines historical context, forward-looking projections, segmentation insight, competitive profiling, and industry-context analysis into a single strategic framework intended for 2026 planning and beyond. The complete report contains the segmented detail, regional interpretation, application-level analysis, and executive recommendations necessary to turn market intelligence into action. For teams preparing for a year in which strategic precision matters more than ever, the research offers the depth required to move from observation to execution.
For detailed analysis of this topic, please visit the official page: Rheology Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Truck-Bus Tire Market Hits $209.2M in 2025, Projects 5.3% CAGR to $301.7M by 2032
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Truck-Bus Tires Market in 2026 and Beyond
Executive Summary
The commercial transportation sector stands at a critical inflection point. As global supply chains recalibrate and regulatory frameworks tighten, the Truck-Bus Tires Market represents a vital component of operational efficiency and cost management for fleet operators. Our latest market research provides a comprehensive strategic compass for navigating this complex landscape through 2032. This report is not merely a collection of statistics; it is a decision-making tool designed to identify risks, uncover growth vectors, and optimize procurement strategies in an increasingly volatile environment.
For strategic planners and procurement leaders, understanding the trajectory of this market is essential. The data indicates a sustained period of growth driven by replacement demand, fleet modernization, and regulatory compliance requirements. However, the margin for error is narrowing. Fluctuating raw material costs, shifting trade policies, and the rapid adoption of alternative powertrains require a nuanced approach to forecasting and inventory management. This article outlines the strategic value of our upcoming analysis, highlighting key market dynamics, competitive forces, and operational challenges that define the current era.
Long-Term Market Trajectory and Growth Drivers
Analyzing the historical performance from 2020 through 2025 provides a foundational understanding of market resilience. The sector has demonstrated consistent expansion, overcoming pandemic-induced disruptions to reach significant valuation milestones. Our forecast period, spanning from 2026 to 2032, projects a continued upward trend, underpinned by a steady compound annual growth rate. This growth is not uniform; it is propelled by specific macroeconomic engines that organizations must monitor closely.
The expansion is largely fueled by the necessity of maintaining operational continuity. As existing vehicle fleets age, the replacement cycle intensifies, ensuring steady demand even when new vehicle production fluctuates. Furthermore, the push towards heavier goods transportation and increased freight volumes across key economic zones contributes to higher tire consumption rates. Organizations that align their inventory planning with these long-term growth trajectories will be better positioned to manage supply chain bottlenecks and capitalize on emerging market opportunities.
Key elements influencing this trajectory include:
- Infrastructure development projects that increase heavy commercial vehicle movement.
- Rising logistics demand in emerging economies requiring robust transport solutions.
- The transition towards higher durability products that last longer but cost more upfront.
- Regulatory pressures forcing fleets to upgrade to compliant tire specifications.
Critical Market Dynamics and Operational Shifts
The landscape is being reshaped by external forces that directly impact production costs and consumer behavior. In the current environment, raw material volatility is a primary concern. Recent industry data highlights significant spikes in natural rubber prices, which have surged substantially over short periods. Since raw materials now comprise a dominant portion of production expenses, manufacturers are facing pressure to adjust pricing structures or absorb costs to maintain market share. This volatility creates uncertainty for downstream buyers who need to budget for long-term contracts.
Regulatory environments are equally transformative. Strict efficiency mandates from bodies such as the United States Environmental Protection Agency are compelling fleet owners to transition toward low-rolling-resistance radial products. This shift is not optional; it is a compliance requirement that directly influences purchasing decisions. Furthermore, trade policies have introduced new cost layers. Recent surges in steel tariffs have contributed to higher costs for imported components, affecting the final price point of tires available in key markets. These macroeconomic variables must be integrated into financial modeling to avoid budget overruns.
The electrification of commercial fleets is another pivotal dynamic. Industry reports indicate that a significant portion of new buses exceeding certain weight classes registered recently were partially or fully electrified. This transition drives demand for sustainable tire solutions designed to handle the unique torque and weight characteristics of electric vehicles. As the powertrain mix changes, the specifications required for optimal performance evolve, creating a niche for specialized tire technologies that support sustainable transportation goals.
- Raw material scarcity leading to price instability and production delays.
- Government mandates accelerating the adoption of fuel-efficient tire technologies.
- Trade policy changes impacting the cost structure of imported goods and steel components.
- Electrification trends requiring specialized tire formulations for electric commercial vehicles.
Segmentation Insights: Type and Application Trends
Understanding the structural composition of the market is vital for targeted strategy development. The market is primarily divided by tire construction type and vehicle application. In terms of type, the radial segment continues to dominate the landscape, reflecting the industry's broad shift towards higher performance and fuel efficiency. While bias tires maintain a presence, particularly in specific regional or heavy-load applications, the momentum is clearly behind radial technology. Our analysis delve into the specific volume splits within these categories, revealing where the highest growth margins are located.
Regarding application, trucks constitute the larger portion of the market volume compared to buses, driven by the sheer scale of freight logistics globally. However, the bus segment is experiencing unique pressures due to urban mobility initiatives and the electrification trends mentioned earlier. Fleet managers must recognize that while the truck segment offers volume, the bus segment may offer faster adoption rates for new technologies. Detailed segmentation data allows organizations to allocate resources effectively, focusing on the high-growth niches rather than treating the market as a monolith.
Strategic implications of these segments include:
- Prioritizing radial tire procurement to meet efficiency standards and reduce total cost of ownership.
- Monitoring truck replacement cycles for steady revenue streams and supply planning.
- Evaluating bus fleet electrification plans to anticipate demand for specialized electric-compatible tires.
- Assessing regional preferences where bias tires may still retain relevance due to road conditions or cost constraints.
Regional Performance and Supply Chain Considerations
Geographic dynamics play a crucial role in supply chain strategy. The market is broad, with significant volume distributed across multiple continents. North America and Asia Pacific represent substantial portions of the market size, reflecting the heavy industrialization and freight movement in these regions. Europe maintains a strong presence driven by stringent environmental regulations and dense logistics networks. Meanwhile, Latin America and the Middle East and Africa offer emerging opportunities that are often overlooked in generalized analyses.
For multinational operators, understanding these regional weights is not about simple market sizing but about risk diversification. Dependence on a single region for supply or demand can be disruptive. Our research provides a granular look at these regional contributions without oversimplifying the nuances. Supply chain managers need to know where production hubs are vulnerable and where demand is most resilient. This geographic intelligence supports decisions on warehousing, logistics partnerships, and localized manufacturing investments.
Regional strategic focus areas include:
- Strengthening supply chain resilience in high-volume regions like North America and Asia Pacific.
- Navigating regulatory landscapes in Europe to ensure compliance with efficiency mandates.
- Exploring growth potential in emerging markets where infrastructure investment is accelerating.
- Mitigating tariff impacts by evaluating local sourcing options versus imported solutions.
Competitive Landscape and Company Strategies
The market is characterized by high concentration, with a few key players controlling a significant majority of the share. This consolidation means that competitive moves by top-tier manufacturers ripple through the entire ecosystem. Our report profiles major industry leaders, analyzing their specific offerings, headquarters locations, and strategic focus areas. Companies such as Michelin and Bridgestone continue to set benchmarks with their comprehensive lines of commercial tires emphasizing safety and cost-effectiveness.
Competitors on the periphery, such as Goodyear and Continental, are also aggressively innovating. Continental, for instance, has been particularly active, appointing new leadership for original equipment roles and releasing new product catalogs. Their focus on sustainability certification and product size extensions demonstrates a commitment to adapting to fleet needs and environmental standards. Other significant players like Apollo Tyres, JK Tyre, and BKT are expanding their footprints, particularly in international markets, offering wide ranges of tires for urban to long-haul operations.
Tire Market
The competitive environment is not static. Recent developments show companies launching specific products for regional fleets and expanding size offerings to cover more vehicle types. Hankook and Giti Tire are also notable for their high-quality offerings for trucks, buses, and commercial vans. Understanding the product roadmaps of these competitors allows businesses to benchmark their own requirements and negotiate better terms with suppliers who are competing for contract retention.
- Monitoring product launches and size extensions from leaders like Michelin, Bridgestone, and Continental.
- Tracking sustainability initiatives and certifications that may become procurement criteria.
- Analyzing the expansion strategies of emerging competitors like Apollo, JK Tyre, and Hankook.
- Identifying leadership changes within key companies that signal shifts in strategic direction.
Strategic Imperatives for 2026 Decision Makers
As organizations plan for the remainder of the decade, several imperatives emerge from the data. First, cost management must be dynamic. With raw material expenses comprising a large share of production costs and trade tariffs fluctuating, static budgeting is insufficient. Procurement teams need flexible contracts that account for material volatility. Second, technology adoption cannot be delayed. The shift toward low-rolling-resistance and electric-compatible tires is accelerating due to regulation and fleet electrification. Early adoption can secure compliance advantages and operational efficiencies.
Third, supply chain diversification is critical. Given the concentration of market share among top players and the geopolitical factors affecting trade, relying on a single supply source is risky. Building relationships with multiple tier suppliers across different regions can buffer against disruptions. Finally, sustainability is becoming a procurement metric. As certification and environmental standards tighten, tires are no longer just rubber components but part of a broader sustainability strategy. Aligning tire procurement with corporate sustainability goals will be increasingly important for public and private fleet operators.
- Implement dynamic pricing models to handle raw material cost fluctuations.
- Accelerate the transition to compliant radial and electric-ready tire technologies.
- Diversify supplier bases to mitigate regional risks and tariff impacts.
- Integrate tire sustainability metrics into broader corporate environmental goals.
Unlock Full Market Intelligence
This overview provides the strategic context necessary to understand the magnitude of the opportunity and the complexity of the challenges facing the Truck-Bus Tires Market. However, successful execution requires depth. To make informed decisions that withstand the volatility of the coming years, leaders need access to granular data, specific segmentation splits, and detailed competitive profiles. Our full report contains the precise valuations, regional percentages, and company-specific forecasts that allow for precise planning.
We invite strategic leaders to access the complete research document to gain the actionable intelligence required to optimize fleet performance, manage costs, and capture growth in the 2026 to 2032 period. The market is moving fast, and the insights within our full analysis are designed to keep your strategy ahead of the curve.
Truck-Bus Tires Market
For detailed analysis of this topic, please visit the official page: Truck-Bus Tires Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Traumatic Brain Injury Diagnostic Market to Hit $769.94M by 2032 at 12.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Brain: Strategic Intelligence in the Traumatic Brain Injury Diagnostic Market (2026-2032)
The landscape of traumatic brain injury (TBI) diagnostics is undergoing a profound transformation, shifting from reliance on subjective clinical assessments and structural imaging toward objective, biomarker-driven, and AI-enhanced diagnostic paradigms. As healthcare systems grapple with the long-term neurological consequences of mild TBI and concussion, the demand for rapid, accurate, and accessible diagnostic tools has never been more critical. For executive leadership, investors, and strategic planners operating in the medical technology and life sciences sectors, understanding the trajectory of this market is not merely an academic exercise—it is a commercial imperative. Our latest comprehensive market research report, covering the historical baseline from 2020 through the forecast horizon to 2032, offers a detailed roadmap of this evolving ecosystem. This article serves as a strategic preview, illustrating the macroeconomic currents, technological inflection points, and competitive dynamics that will define decision-making in 2026 and beyond.
Executive Summary: The Scale and Trajectory of a High-Growth Diagnostic Sector
The global market for TBI diagnostics has demonstrated consistent and accelerating expansion over the past half-decade. Valued at approximately 245.34 million USD in 2020, the market has grown steadily to reach an estimated 335.15 million USD by 2025. This historical progression reflects the gradual but firm integration of novel diagnostic modalities into emergency departments, sports medicine clinics, and specialized neurological care pathways. Looking forward, the sector is projected to maintain a robust compound annual growth rate of 12.7 percent throughout the 2026 to 2032 forecast period. By 2032, the total market revenue is anticipated to approach 769.94 million USD. Such a trajectory underscores a market that is not only expanding in absolute terms but is also maturing in its technological complexity and clinical adoption rates. For corporate strategists, these figures signal a window of opportunity where early positioning, strategic partnerships, and targeted product development can yield disproportionate competitive advantages. The growth is not uniform across all vectors; rather, it is being propelled by specific technological breakthroughs, regulatory clearances, and shifting clinical guidelines that prioritize objective diagnostic confirmation over empirical judgment.
Technological Convergence: Imaging, Biomarkers, and Digital Diagnostics
The architecture of the TBI diagnostic market is defined by a compelling convergence of established imaging technologies and emerging biological and digital assessment tools. Traditional structural imaging, primarily computed tomography and magnetic resonance imaging, has long served as the cornerstone for identifying acute intracranial lesions. However, the diagnostic gap for mild TBI and concussion, where structural abnormalities often remain invisible, has catalyzed innovation in blood-based biomarker assays and neurophysiological monitoring platforms. The market now features a dynamic interplay between these modalities. Blood-based biomarker tests, which detect proteins such as glial fibrillary acidic protein and ubiquitin carboxy-terminal hydrolase L1, offer the promise of rapid, objective triage that can potentially reduce unnecessary imaging referrals and accelerate clinical decision-making. Complementing these biological assays is a new generation of AI-enabled platforms that analyze electroencephalographic patterns, eye-tracking metrics, and multimodal data streams to provide prognostic insights and severity grading. This technological diversification is reshaping procurement strategies, clinical workflows, and reimbursement models. Healthcare providers are increasingly evaluating integrated diagnostic suites rather than standalone devices, while device manufacturers are pursuing cross-platform compatibility and data interoperability to secure long-term market relevance.
Regulatory Catalysts and Clinical Validation: Accelerating Market Readiness
Regulatory milestones have emerged as a critical accelerant for commercialization and clinical adoption in the TBI diagnostics space. Over the past several years, a series of landmark clearances and certifications have validated the clinical utility of biomarker and digital diagnostic tools, providing a regulatory scaffold upon which broader market confidence is being built. The clearance of whole blood testing cartridges for point-of-care biomarker assessment, alongside serum-based automated platforms for ruling out intracranial lesions, has expanded the addressable clinical settings beyond centralized laboratories. Concurrently, digital health devices utilizing eye-movement analysis and AI-driven electroencephalography have secured clearances with increasingly broad labeling indications, enabling objective concussion assessment across diverse age groups and post-injury timeframes. These regulatory achievements are not merely compliance checkpoints; they are market-making events that influence purchasing decisions, insurance coverage trajectories, and clinical guideline updates. Furthermore, ongoing pivotal clinical studies continue to generate the evidence base required to support expanded indications, prognostic claims, and integration into standard-of-care protocols. For market participants, tracking the cadence of regulatory approvals and clinical trial readouts is essential for anticipating shifts in competitive positioning and identifying whitespace opportunities for product iteration or strategic entry.
Competitive Landscape: Specialized Innovators and Diversified Incumbents
The competitive fabric of the TBI diagnostic market is characterized by a blend of focused innovators and broad-based healthcare conglomerates, each pursuing distinct strategic pathways to capture value. A cohort of specialized companies has emerged at the forefront of biomarker and digital diagnostic development, leveraging proprietary assays, algorithmic platforms, and niche clinical expertise to differentiate their offerings. These firms are actively expanding their intellectual property portfolios, advancing pivotal clinical trials, and strengthening commercial leadership to scale their technologies from research and pilot deployments into broader clinical practice. Simultaneously, major diagnostic and life sciences corporations are integrating TBI diagnostic capabilities into their existing immunoassay, point-of-care, and clinical chemistry portfolios, leveraging established distribution networks, regulatory experience, and commercialized product platforms to accelerate market penetration. The result is a landscape where innovation speed, clinical evidence generation, and supply chain robustness are equally vital. Market concentration remains relatively moderate, reflecting the early-stage fragmentation of advanced diagnostic modalities and the ongoing validation of new clinical workflows. This structural characteristic suggests that consolidation, licensing arrangements, and strategic collaborations will likely play an increasingly prominent role as the market matures and clinical adoption curves steepen.
Key organizations shaping the competitive dynamics include:
- Banyan Biomarkers, Inc. – Pioneering blood-based biomarker assays targeting GFAP and UCH-L1 to support mild TBI evaluation and inform imaging triage decisions.
- BrainBox Solutions, Inc. – Developing AI-enabled multi-modality diagnostic and prognostic platforms for concussion and mild TBI, with active advancement of pivotal clinical studies and patent portfolio expansion.
- Oculogica, Inc. – Commercializing eye-tracking diagnostic devices that provide objective, baseline-free concussion assessment across broad pediatric and adult age ranges.
- BrainScope Company, Inc. – Advancing AI-powered electroencephalography-based brain assessment platforms for objective evaluation of mild TBI and concussion as an adjunct to standard clinical practice.
- Quanterix Corporation – Utilizing ultra-sensitive digital immunoassay architectures to support biomarker quantification for TBI-related diagnostic applications.
- bioMérieux – Integrating automated serum-based biomarker testing into clinical microbiology and immunoassay portfolios, with cleared indications for ruling out intracranial lesions in mild TBI.
- ABBOTT – Deploying point-of-care whole blood testing cartridges for rapid biomarker assessment, enabling bedside evaluation and streamlined emergency department workflows.
- Upfront Diagnostics – Focusing on lateral flow assay technologies for point-of-care detection of brain injury biomarkers as a diagnostic adjunct in decentralized care settings.
Demand Drivers: Emergency Care, Sports Medicine, and Defense Applications
Clinical demand for TBI diagnostics is being generated across multiple care settings, each with distinct operational requirements, procurement cycles, and adoption drivers. Emergency care environments represent a primary demand vector, where rapid triage and objective decision support can reduce diagnostic uncertainty, optimize imaging utilization, and improve patient throughput. In parallel, sports medicine and athletic organization settings are increasingly adopting concussion assessment tools to support return-to-play protocols, mitigate liability exposure, and enhance athlete safety through data-driven clinical evaluation. Military and defense applications further contribute to market demand, where field-deployable and ruggedized diagnostic capabilities are valued for rapid injury assessment in austere environments and for supporting long-term neurological health surveillance. The interplay between these application segments creates a diversified demand base that insulates the market from single-sector volatility while simultaneously requiring manufacturers to tailor product specifications, validation evidence, and service models to distinct end-user expectations. Understanding the nuances of each demand channel is essential for companies designing go-to-market strategies, pricing architectures, and clinical education programs.
Traumatic Brain Injury Diagnostic Market
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Market Structure and the Strategic Imperative of Evidence Generation
The current market structure reflects a sector in transition, where early adopters and clinical champions are validating new diagnostic workflows, and broader commercialization depends on the accumulation of robust clinical evidence, reimbursement alignment, and operational integration. The presence of multiple competing technological approaches means that differentiation is increasingly driven by clinical performance data, ease of workflow integration, and the ability to generate actionable prognostic insights rather than diagnostic confirmation alone. For strategic planners, this environment demands a disciplined focus on evidence generation timelines, health economics outcomes research, and real-world performance monitoring. Companies that can demonstrate clear clinical utility, cost-effectiveness, and seamless integration into existing care pathways are best positioned to convert regulatory clearance into sustained commercial traction. Conversely, organizations that underestimate the complexity of clinical adoption or fail to align product capabilities with measurable healthcare value may find market entry slower and more resource-intensive than projected.
Why This Report Matters for 2026 Strategic Decision-Making
As organizations plan capital allocation, product roadmaps, partnership strategies, and market entry initiatives for 2026 and beyond, access to granular, forward-looking market intelligence becomes a decisive competitive asset. This report delivers a structured, data-grounded analysis of the TBI diagnostic market across multiple dimensions: historical performance baselines, forecast trajectories, segment-level demand patterns, regional expansion dynamics, and competitive positioning frameworks. Beyond aggregate market sizing, the analysis provides actionable context for evaluating technology adoption curves, regulatory impact scenarios, and the commercial implications of emerging clinical evidence. It is designed to support executives in identifying high-probability growth corridors, assessing the relative strength of competitor portfolios, and anticipating shifts in procurement behavior across emergency, sports, and defense-related care settings. The report also includes detailed company profiles, recent development timelines, and strategic assessments that enable benchmarking of innovation pipelines, intellectual property positions, and commercialization readiness. By synthesizing macroeconomic growth indicators with operational and competitive intelligence, the research equips decision-makers with the contextual depth required to navigate uncertainty and align strategic investments with market realities.
Conclusion: Positioning for the Next Phase of Diagnostic Innovation
The traumatic brain injury diagnostic market stands at a pivotal juncture where technological innovation, regulatory validation, and clinical demand are converging to redefine how brain injuries are assessed, triaged, and managed. The projected growth trajectory, coupled with the expanding portfolio of biomarker assays, AI-enabled platforms, and point-of-care devices, signals a market that will reward strategic foresight, evidence-driven product development, and disciplined commercial execution. For organizations seeking to capture value in this evolving landscape, the difference between reactive participation and proactive leadership will increasingly depend on the quality of market intelligence guiding strategic choices. This report is structured to provide that intelligence, offering a comprehensive foundation for evaluating opportunities, anticipating competitive shifts, and building resilient strategies for the 2026 to 2032 horizon. To access the full dataset, detailed segment analyses, regional breakdowns, and complete competitive profiles, we invite you to explore the complete market research report.
For detailed analysis of this topic, please visit the official page: Traumatic Brain Injury Diagnostic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chelating Agents Market Set for 6.1% CAGR to Reach $344.8 Million by 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Chelating Agents Market Through 2032
The global chelating agents market stands at a critical inflection point. Based on comprehensive historical analysis from 2020 through 2025 and forward-looking forecasts extending to 2032, the market has demonstrated a trajectory of robust, compound annual growth. For executive leadership teams, procurement directors, and strategic planners, the question is no longer whether demand will expand, but how organizations can position themselves to capture value amidst shifting regulatory tides, raw material volatility, and an increasingly bifurcated product landscape defined by traditional performance versus emerging sustainability mandates. Our latest market research report offers the granular intelligence required to navigate this complexity, transforming macro-level economic signals into actionable strategic roadmaps for the 2026 fiscal year and beyond.
The historical data outlines a market that has steadily accelerated its revenue generation. Reviewing the performance from a base of approximately $163.15 million in 2020, the sector climbed consistently through successive years, reaching $170.07 million in 2021, $172.94 million in 2022, $185.51 million in 2023, and $206.85 million in 2024. Entering the most recent reporting year of 2025, the market total was valued at $215.0 million. This established foundation sets the stage for the forecast period beginning in 2026, where the market size is projected to surge to $236.38 million, followed by projected valuations of $247.57 million in 2027, $257.16 million in 2028, $284.71 million in 2029, $297.93 million in 2030, $312.61 million in 2031, and ultimately reaching $344.8 million by 2032. This trajectory, underpinned by a robust compound annual growth rate (CAGR) of 6.1% across the forecast horizon, signals sustained structural demand. For decision-makers, this growth represents both a significant opportunity for market share expansion and a rising risk of supply chain disruption if capacity investments and procurement strategies are not meticulously aligned with forecasted consumption patterns.
Chelating Agents Market
Chelants Market
However, relying solely on top-line revenue figures is insufficient for sophisticated strategic planning. The true competitive advantage lies in decoding the intricate segmentation dynamics that drive these numbers. Our research dissects the market across multiple critical dimensions, specifically analyzing regional consumption patterns, the evolving dichotomy between application-specific performance chemistries, and the distinct categorization by product nature. While the overall economic signal is strong, the distribution of value is not uniform. Understanding where demand is intensifying, which product archetypes are gaining traction, and how industrial, commercial, and consumer applications are diverging is paramount.
In the realm of geographic consumption, distinct regional economic profiles dictate varied growth drivers. Certain established markets maintain heavy reliance on mature industrial ecosystems, while high-growth regions are accelerating adoption due to expanding manufacturing bases, urban infrastructure development, and stringent environmental compliance requirements. The ability to align supply chain logistics and distribution networks with these disparate regional consumption velocities is a key differentiator. Similarly, the analysis of how demand is partitioned across core verticals reveals critical interdependencies. End-use sectors are the ultimate arbiters of volume. Traditional industrial applications continue to anchor volume, yet we are observing a marked acceleration in segments where water remediation, advanced cleaning formulations, and chemical processing are driving incremental growth. The report delves deep into these application-specific volumes, providing the granular breakdown necessary to identify which sectors offer the highest margin potential and which are susceptible to commoditization pressures. Furthermore, the categorization by product nature presents a strategic crossroads: the market remains anchored by non-biodegradable variants that dominate current volume, yet the share attributable to biodegradable alternatives is expanding at a significantly faster pace, propelled by regulatory pressure and brand owner sustainability commitments. Understanding the precise revenue mix and the elasticity of demand between these two archetypes is essential for portfolio optimization.
The Competitive Architecture: Navigating a Consolidated yet Dynamic Landscape
The chelating agents market is characterized by a moderately concentrated competitive structure. With the top three players accounting for a significant portion of market share and the top five controlling over half of total industry revenue, the landscape is dominated by multinational chemical giants with deep integration capabilities. However, the market remains contestable, with regional specialists and innovators driving disruption through niche product development, cost-competitive manufacturing, and sustainable chemistry alternatives. Our report provides a detailed competitive profiling of the key entities shaping the market trajectory, enabling clients to benchmark their strategic positioning against the moves of the industry's most influential players.
BASF SE, headquartered in Ludwigshafen, Germany, remains a foundational pillar of the global supply chain. As a leading producer of the Trilon® EDTA-series chelating agents, BASF provides comprehensive solutions spanning home care, industrial cleaning, agriculture, and broad industrial applications. The company's extensive product portfolio and brand recognition in the EDTA space make it a benchmark for performance and reliability. In a telling recent development that highlights the cost pressures ravaging the industry, BASF announced in June 2026 a price increase effective July 1, 2026, or as existing contracts allow, raising prices by $0.33 per kilogram for a broad select of its Trilon® chelating agents portfolio in North America. This adjustment affects liquid and solid forms of Trilon B, Trilon BD, Trilon BS, Trilon BX, Trilon C, Trilon CA Food Grade, Trilon D, Trilon G, and Trilon NA Food Grade. The rationale, as stated in BASF's official press release, points to an unrelenting convergence of cost drivers: continued increases in key raw material inputs, spiraling energy costs, and persistent logistics inflation, compounded by ongoing supply chain volatility. For customers and competitors alike, this move is a stark indicator of the margin compression facing traditional chemistry and the necessity for robust hedging strategies and supply diversification.
Dow Inc., based in Midland, Michigan, United States, maintains a formidable presence through its VERSENE™ EDTA and acid chelating agents. Dow's portfolio is engineered for broad pH metal ion control, serving critical functions in detergents, food processing, and complex industrial systems. Their ability to deliver consistent performance across widely varying pH environments positions them as a preferred supplier for applications where process chemistry precision is non-negotiable. Meanwhile, Nippon Shokubai Co., Ltd., operating from Osaka, Japan, distinguishes itself through innovation in high-performance polymeric chelating agents. Their AQUALIC™ line exemplifies this technological focus, targeting detergents, water treatment, and paper/pulp applications. This specialization allows Nippon Shokubai to command premium positioning in segments where efficiency and specific material interactions are valued over commoditized pricing.
On the Asian manufacturing front, Shandong IRO Chelating Chemical Co., Ltd., headquartered in Zaozhuang, Shandong, China, has established itself as a manufacturer of a remarkably full-spectrum chemistry catalog. Their production capabilities encompass the full EDTA-series, DTPA-series, NTA-series, and organophosphine chelating agents. This breadth enables Shandong IRO to serve a vast array of downstream markets including detergents, agriculture, textiles, and food applications, often providing a cost-competitive alternative to western incumbents and catering to the rapid industrialization demands of the Asia Pacific region. In the sustainability corner, two European players stand out for their strategic pivot toward bio-based solutions. Jungbunzlauer, based in Basel, Switzerland, is a recognized producer of biodegradable fermentation-based chelating agents, specifically citrates and gluconates. Their expertise is highly relevant for sensitive applications such as food, beverage, and personal care formulations, where natural origin and safety profiles are paramount. Complementing this, Nouryon, headquartered in Amsterdam, Netherlands, is a manufacturer of advanced biodegradable chelating agents including GLDA, MGDA, IDS, and HBED. These next-generation chemistries are engineered for demanding applications in agriculture, detergents, and industrial processes, offering performance profiles that can rival traditional EDTA while addressing the biodegradability gaps that are increasingly drawing regulatory scrutiny.
The strategic implications of this competitive map are profound. BASF's recent pricing maneuver serves as a case study in the vulnerability of supply chains dependent on petrochemical derivatives and energy-intensive production routes. It underscores the value of contracts with long-term price stabilization clauses and the potential for suppliers of alternative chemistries to gain traction as buyers seek to mitigate cost risk. The divergence between BASF/Dow's commodity-scale EDTA focus and the specialized offerings of Nippon Shokubai, Jungbunzlauer, and Nouryon highlights the market's polarization. Buyers must now evaluate not just price per kilogram, but the total cost of performance, including regulatory compliance costs, consumer perception risks, and the operational flexibility offered by different chemical architectures. Our report dissects these competitive dynamics, analyzing market share concentrations, strategic partnerships, capacity expansions, and the product launch trajectories that will define market winners and losers over the forecast period.
Actionable Intelligence for 2026 Decision-Making
A market research report is only as valuable as its applicability to real-world business challenges. Our Chelating Agents Market study is designed as an executive toolkit, providing the operational intelligence required to make informed decisions in procurement, R&D, M&A, and market entry. The report structure moves beyond descriptive analytics to deliver prescriptive insights. Key components include:
- Detailed Value Chain Mapping: An end-to-end analysis of the supply ecosystem, from key raw material precursors like formaldehyde, sodium cyanide, and ethylene diamine to the manufacturing processes, logistics networks, and downstream consumption loops. This mapping identifies critical bottlenecks, sub-tier supplier dependencies, and points of leverage where supply disruptions or cost pass-through mechanisms are most likely to impact margins.
- Regulatory and Sustainability Deep-Dive: A comprehensive review of the evolving regulatory landscape across major jurisdictions. This includes an assessment of restrictions on EDTA usage in certain household detergents in the European Union and other regions, the growing emphasis on aquatic toxicity profiles, and the incentives driving the adoption of readily biodegradable alternatives. The report evaluates the timeline for regulatory enforcement and its projected impact on demand substitution across different regions and applications.
- Technology and Formulation Trends: An evaluation of emerging chelating technologies and formulation science. This covers the development of hybrid chelants, synergistic blends, and the integration of chelating agents into concentrated and solid detergent formats. Understanding these technical shifts is crucial for product developers aiming to future-proof their formulations against performance degradation or regulatory non-compliance.
- Procurement and Negotiation Intelligence: Drawing on the cost pressure signals exemplified by BASF's recent announcement, the report provides a framework for analyzing supplier pricing power, raw material exposure indices, and the negotiation levers available to buyers. It helps procurement teams anticipate price volatility cycles and structure contracts that balance supply security with cost control.
- Segmentation-Specific Growth Models: While the aggregate market data provides the macro context, this report unlocks the specific regional and application-level drivers. The segmentation data reveals how demand is ordered across the top-five regions, the interplay between type-based consumption of non-biodegradable versus biodegradable chemistries, and the volume distribution across key application verticals. This level of detail is essential for allocating marketing resources, targeting plant expansion, and identifying white-space opportunities in underserved niches.
The Path Forward: Translating Data into Advantage
The chelating agents market of 2026 is not merely a reflection of past industrial activity; it is a complex system influenced by the interplay of chemical engineering, environmental policy, global supply chain resilience, and shifting consumer expectations. The headline growth figures, while impressive, are a composite of divergent underlying forces. Some segments will thrive on volume and cost efficiency, while others will be propelled by performance differentiation and the urgent need for sustainable alternatives. Organizations that treat this market with a one-size-fits-all strategy risk being blindsided by localized disruptions, margin erosion, or regulatory headwinds.
Access to the complete intelligence contained in this report is the bridge between reactive management and proactive strategy. The data on regional consumption velocities, the precise revenue contributions of each product type, and the application-specific volume forecasts allow planning teams to model multiple scenarios with confidence. The competitive profiles provide the context to anticipate competitor moves, whether that involves BASF's pricing adjustments to protect margins or Nouryon's push into bio-based agriculture solutions. The industry context, highlighted by raw material and energy cost dynamics, equips stakeholders with the foresight to manage risk proactively.
We invite you to explore the full scope of this analysis. The insights presented here are a glimpse into a comprehensive body of work designed to empower your executive team with the clarity and depth needed to lead in a dynamic market environment. By leveraging the detailed segmentation data, the granular competitive assessments, and the forward-looking scenario analyses provided in the full report, you can transform the 6.1% CAGR growth trajectory into a tailored strategic advantage. To access the complete dataset, regional and application breakdowns, and the full suite of strategic recommendations, please visit our source page to download the full study. Equip your organization with the intelligence required to navigate the complexities of the chelating agents market and capture the value that lies ahead.
For detailed analysis of this topic, please visit the official page: Chelating Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ozone Analyzer Market to Reach $422.64M by 2032 at 6.0% CAGR
By PW Consulting, 2026-09-16
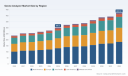
Executive Preview: Navigating the Ozone Analyzer Market in 2026 and Beyond
The global landscape for environmental monitoring and industrial safety is undergoing a significant transformation. As regulatory frameworks tighten and industrial processes become increasingly automated, the demand for precise gas detection and water quality assurance has never been more critical. At PW Consulting, we have compiled a comprehensive strategic analysis of the Ozone Analyzer Market, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 to 2032.
This article serves as an executive preview of our latest research. It outlines the macroeconomic trajectory, the shifting competitive terrain, and the regulatory forces shaping the industry. However, to ensure that our clients make decisions based on the most granular and actionable data, we have intentionally reserved specific segmentation breakdowns and detailed financial models for the full report. This preview establishes the strategic context, demonstrating why access to the complete intelligence suite is vital for 2026 planning.
Market Trajectory and Macroeconomic Context
The ozone analyzer sector is experiencing steady expansion, driven by heightened awareness of environmental compliance and the adoption of ozone-based disinfection technologies. Our analysis tracks market performance from historical baseline years through the current forecast horizon. The data indicates a consistent upward trend in revenue, reflecting both increased unit sales and a shift toward higher-value monitoring solutions.
For the base year 2025, the market established a significant valuation benchmark, setting the stage for accelerated growth in the coming years. The trajectory suggests that by 2032, the total market revenue will reach new heights, underpinned by a compound annual growth rate that underscores the sector's resilience. This growth is not merely linear; it reflects structural changes in how industries monitor ozone concentrations, moving from manual sampling to integrated, real-time digital monitoring systems.
Understanding the aggregate market size is only the first step. The true value for enterprise decision-makers lies in understanding the velocity of this growth across different technological and geographic vectors. While the overall top-line figures indicate a healthy market, the dispersion of value across different segments reveals where the highest margins and fastest adoption rates are occurring. Our full report dissects these layers to identify high-opportunity zones without exposing the company to the risks of generalized industry data.
Technological Segmentation and Application Drivers
The market is diversified across various technological methodologies and end-use applications. In terms of technology, UV photometric methods continue to hold substantial weight due to their precision and regulatory acceptance. Electrochemical solutions also represent a significant portion of the market, particularly where cost-effectiveness and portability are prioritized. The balance between these technologies is shifting as industries demand higher sensitivity and lower maintenance overhead.
Application-wise, the demand is broad but concentrated in specific sectors. Water treatment remains a cornerstone driver, with the Drinking Water Industry and Sewage & Industrial Process Water sectors accounting for a substantial share of adoption. However, growth is also notable in the Cosmetics and Pharmaceutical Industries, where ozone is used for sterilization and process purity. Environmental and Health Industries further contribute to the demand landscape, focusing on ambient air quality monitoring.
Strategic Note: While the broad categories are visible, the specific revenue contribution of each segment varies significantly by region and by vendor capability. Identifying which application segment offers the highest return on investment in a specific geographic territory requires the detailed segmentation matrices provided in the full PW Consulting study. General industry averages often mask local disparities that can make or break a product launch strategy.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established multinational corporations and specialized niche players. Market concentration indicates a moderate level of consolidation, with the top five competitors holding a significant share of the total market revenue. This structure suggests that while there is room for innovation and entry, scale and regulatory certification are becoming increasingly important barriers to entry.
Ozone Generator Market
Key players are differentiating themselves through technology specialization and regulatory compliance. For instance, Teledyne API focuses on UV absorption analyzers such as the Model T400 and T703 series, which are EPA-approved for regulatory compliance. Similarly, 2B Technologies offers ambient and industrial UV-based ozone monitors certified as Federal Equivalent Methods (FEM), making them critical vendors for air quality and generator monitoring sectors.
Other notable entities include Aeroqual, known for portable and fixed ozone gas sensors for perimeter and indoor air quality applications, and HORIBA, which utilizes NDUV technology for ambient ozone monitors in air quality control. Acoem provides precise ambient air ozone measurements with the Serinus 10 analyzer, while BMT MESSTECHNIK GmbH specializes in high-concentration ozone analyzers with temperature and pressure compensation for industrial settings.
In the water treatment space, Hach integrates portable and process ozone analyzers with water treatment monitoring systems, whereas Sailhero targets marine and environmental ozone monitoring instruments. Thermo Fisher Scientific contributes instruments for environmental and laboratory air quality testing, and Eco Sensors focuses on environmental ozone sensors for air quality monitoring. IN USA, Inc. offers UV absorption ozone analyzers for high-concentration gaseous phase monitoring in safety and industrial applications, and Ozone Solutions Inc. provides monitoring systems for semiconductor, water, and industrial applications.
Strategic Note: Evaluating the specific market share and growth rate of each of these competitors requires the detailed competitor benchmarking section of our report. Knowing who leads the market is different from knowing which player is gaining share in high-growth segments like semiconductor manufacturing or pharmaceutical sterilization.
Regulatory Dynamics and Industry Developments
Regulatory frameworks are a primary catalyst for market demand. The U.S. Environmental Protection Agency (EPA) has implemented regulations that promote the use of ozone for disinfection, enhancing market growth in related monitoring solutions. Furthermore, the EPA is supplementing proposals to clarify the intended scope under the Protection of Stratospheric Ozone listing of substitutes. These regulatory actions create a compliance imperative for industries, driving the need for accurate, certified monitoring equipment.
Beyond regulation, industry standards are evolving. Trends in the ozone aging tester market emphasize ISO and ASTM standards for automation and certification in testing solutions. This shift toward standardized, automated testing increases the reliability of data and encourages the adoption of advanced analyzers that can integrate with broader quality management systems.
Recent industry activity also signals shifting dynamics. In May 2025, RainHarvest Systems launched new Pro Series and M Series ozone generator lines with integrated monitoring capabilities for water purification applications. Such product launches indicate a trend toward integrated systems where generation and monitoring are coupled, reducing installation complexity and improving reliability for end-users.
Strategic Value of the 2026-2032 Forecast Period
The forecast period from 2026 to 2032 represents a critical window for strategic investment. The market is expected to grow from a valuation of approximately 324.23 Million USD in 2026 to over 422.64 Million USD by 2032. This growth trajectory offers opportunities for capacity expansion, M&A, and product portfolio optimization. However, capturing this value requires precise timing and segmentation strategy.
Early movers who can align their product offerings with emerging regulatory requirements in North America, Europe, and Asia Pacific will gain a competitive advantage. The regional divergence in growth rates means that a one-size-fits-all strategy is inefficient. Some regions may prioritize ambient air quality monitoring due to urban pollution concerns, while others may focus on industrial process water due to manufacturing expansion.
Ozone Analyzer Market
Our full report provides the necessary depth to tailor strategies to these regional nuances. It includes detailed analysis of supply chain dynamics, pricing trends, and technology adoption curves that are not visible in high-level summaries. For executives planning capital allocation in 2026, understanding these granular drivers is essential to mitigate risk and maximize ROI.
Report Contents and Operational Utility
The PW Consulting Ozone Analyzer Market study is designed for operational utility. It goes beyond macro trends to provide actionable intelligence. The report covers:
- Detailed Segmentation Analysis: Breakdown by type, application, and region with historical and forecast data to identify high-growth pockets.
- Competitive Benchmarking: Profiled assessments of key market players, including their strategic moves, product portfolios, and regional footprints.
- Regulatory Impact Assessment: Analysis of how current and upcoming EPA regulations and ISO/ASTM standards affect demand and compliance costs.
- Market Concentration Metrics: Insights into CR3 and CR5 dynamics to understand competitive intensity and pricing power.
- Risk Factors and Opportunities: Identification of potential market headwinds and strategic avenues for growth.
Each section is crafted to answer specific strategic questions. For product managers, the segmentation data informs R&D priorities. For sales leaders, the regional breakdowns guide territory planning. For investors, the growth projections and competitive landscape assessments support valuation and due diligence processes.
Conclusion: The Case for Deep Intelligence
The Ozone Analyzer Market is poised for sustained growth, driven by regulatory tailwinds, technological advancements, and expanding industrial applications. However, the complexity of the market landscape means that surface-level data is insufficient for high-stakes decision-making. The difference between a successful market entry and a missed opportunity often lies in the details of segmentation performance and competitor positioning.
This preview highlights the structural elements of the market and the strategic importance of the 2026-2032 period. Yet, the specific data points that enable precise targeting and risk assessment are contained within the full PW Consulting report. We invite stakeholders to access the complete study to gain the comprehensive intelligence required to lead in this evolving sector. By leveraging deep-dive insights, enterprises can align their strategies with the most lucrative opportunities and navigate the regulatory complexities with confidence.
For detailed analysis of this topic, please visit the official page: Ozone Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Vacuum Pump Market to Hit $3.04B by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
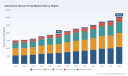
The Automotive Vacuum Pump Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is navigating a structural transformation defined by electrification, stringent emissions regulations, and evolving safety architectures. At the intersection of braking performance, engine management, and thermal integration, the automotive vacuum pump market has emerged as a critical subsystem category. This report provides a comprehensive, decision-ready analysis of market trajectory, competitive positioning, and technology migration patterns across the forecast period from 2026 to 2032.
Our baseline assessment situates the market within a broader historical context spanning 2020 through 2025. Over this six-year window, the global market advanced from 1,520.0 million USD to a projected 1,950.0 million USD in 2025, reflecting sustained adoption of electric vacuum pumping solutions, integration into brake-by-wire architectures, and demand from hybrid and electric vehicle platforms. Looking forward, the forecast window projects continued expansion, with the market reaching 2,121.39 million USD in 2026 and progressing toward 3,043.56 million USD by 2032. This trajectory implies a compound annual growth rate of 6.5 percent, underscoring a market that is not merely growing in absolute terms but is also evolving in capability, supplier concentration, and application complexity.
For executive teams, product planners, procurement leaders, and investment analysts, these figures are not isolated statistics. They represent a signal of where value is moving within the powertrain and chassis subsystems landscape. The market is no longer defined by a linear replacement cycle. Instead, it is being reshaped by regulatory mandates, electrified brake architectures, and the need for on-demand vacuum generation in engine-off and start-stop conditions. Understanding this shift is essential for 2026 planning cycles, supplier negotiations, platform allocation decisions, and long-term portfolio strategy.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will be judged against how well organizations anticipated the convergence of electrification, braking safety, and emissions compliance. The automotive vacuum pump market is no longer a peripheral component category. It sits at the core of brake assist reliability, hybrid energy management, and advanced driver assistance functionality. This research is designed to help leaders cut through short-term noise and focus on durable structural drivers.
The study translates market growth into actionable intelligence. Rather than presenting numbers in isolation, the analysis ties valuation trends to product substitution patterns, architecture shifts, and supplier capability profiles. Decision-makers can use this framework to assess where demand is most likely to intensify, which performance attributes will differentiate winning products, and how supplier ecosystems are consolidating or expanding around key vehicle programs. The report also supports scenario planning by linking technology deployment logic to real-world operational requirements such as low-noise operation, thermal load management, and rapid vacuum buildup during engine-off phases.
Equally important, the report provides context for regulatory and safety developments that influence purchasing and engineering priorities. On-demand vacuum generation has become a relevant factor in meeting CO2 reduction targets, supporting downsized engine architectures, and ensuring brake assist continuity in hybrid and electric applications. At the same time, market participants have had to respond to field performance concerns, including notable recall actions that highlighted the importance of robust vacuum pump reliability in certain brake assist conditions. These events reinforce the strategic value of better data, tighter quality oversight, and more resilient supplier selection.
What the Report Delivers in Practice
This market research is built for operational use. It goes beyond headline figures and provides a structured foundation for product planning, competitive benchmarking, and market entry evaluation. The study is organized to support practical decision-making across multiple functional areas:
- Market sizing and forecast logic that connects historical performance with forward-looking demand assumptions across the 2026 to 2032 period
- Technology segmentation analysis that examines how different pump architectures are positioned across vehicle categories and subsystem requirements
- Application-level demand mapping that identifies where vacuum pumps are most critical within brake systems, engine management, HVAC systems, and emission control domains
- Regional demand context that highlights where volumes are developing and how regional vehicle mix, electrification pace, and OEM sourcing strategies shape opportunity
- Competitive landscape profiling that evaluates major incumbents and emerging contributors by technology focus, geographic footprint, and program relevance
- Recent product and deployment developments that track how suppliers are translating engineering intent into market-facing launches and modular platform strategies
- Regulatory and safety context that frames how compliance requirements and field performance issues influence design priorities and sourcing confidence
The report is intentionally constructed to support both strategic and tactical use cases. Product planners can assess where to allocate development resources. Procurement teams can better understand concentration risk and alternative sourcing options. Commercial teams can identify which applications and regions are likely to generate the strongest demand momentum. Investors and analysts can use the framework to interpret supplier commentary, program wins, and technology migration signals with greater precision.
Competitive Landscape and Technology Leadership
The competitive structure of the market reflects a concentrated but diversified supplier base. Market concentration metrics indicate that the top three participants account for approximately 25.8 percent of market revenue, while the top five participants represent about 35.2 percent. This structure suggests that while scale incumbents remain influential, there is meaningful room for specialist suppliers, regional players, and technology-focused entrants to compete on performance, integration, and program access.
Several European and Asian suppliers are defining the current pace of innovation. Continental AG has been advancing electric vacuum pump solutions for brake systems in passenger cars, commercial vehicles, and hybrid applications, with integration pathways into zone control and brake-by-wire architectures. Robert Bosch GmbH has expanded its electric vacuum pump platform across global SUV programs that rely on brake-by-wire for stable vacuum independent of engine operation, while also supporting modular deployments with adaptive control and regenerative braking compatibility. MAHLE GmbH has focused on high-efficiency electric vacuum pumps with integrated thermal management modules suited to 48V mild-hybrid and electric vehicle architectures.
Valeo SA supplies electric vacuum pumps for brake assist and emissions control in micro-hybrid and electric vehicles, including OEM supply relationships with major Asian manufacturers. Hella GmbH & Co. KGaA provides electric vacuum pump solutions for power brake boosters, including auxiliary and diaphragm-type models for hybrid and internal combustion engine braking systems. Rheinmetall Automotive AG, through its Pierburg division, supplies high-efficiency electric vacuum pumps for hybrid passenger vehicles, optimized for low noise, rapid buildup, and on-demand operation during engine-off phases.
From an Asia-Pacific and emerging-market perspective, Denso Corporation develops diaphragm-type electric vacuum pumps for hybrid and internal combustion engines with adaptive control intended to improve braking and fuel efficiency. Aisin Seiki Co., Ltd. supplies electric vacuum pumps for automotive brake systems integrated with advanced driver assistance and efficiency-related systems. Ningbo Tuopu Group Co., Ltd. produces electric vacuum pumps as part of intelligent brake systems, supporting mass production and OEM supply for passenger and commercial vehicles. Youngshin Precision Co., Ltd. manufactures electric vacuum pumps for automotive braking systems with an emphasis on quality and global OEM supply. Johnson Electric develops electric vacuum pumps for automotive applications including brake assist and hybrid systems. Advik Hi-Tech Pvt Ltd manufactures and supplies advanced electric vacuum pumps for passenger cars and commercial vehicles, including 48V ABS-related applications for hybrid and electric use.
The competitive picture is not static. Recent activity through early 2025 shows how supplier roadmaps are being executed in practice. In January 2025, Advik Hi-Tech unveiled a broader range of automotive components, including advanced electric vacuum pumps for passenger cars and commercial vehicles. Also in January 2025, Robert Bosch GmbH expanded deployment of its electric vacuum pump platform across multiple global SUV programs using brake-by-wire for stable vacuum independent of engine operation. In March 2025, Continental AG unveiled a high-performance electric vacuum pump for passenger internal combustion engines in Europe, featuring adaptive vacuum control for power efficiency and regenerative braking support. In April 2025, Pierburg under Rheinmetall Automotive launched an electric vacuum pump in Germany designed to reduce CO2 emissions and enhance hybrid and brake systems. In the same month, Denso Corporation launched a diaphragm-type electric vacuum pump in Asia-Pacific with adaptive vacuum control for hybrid and internal combustion engines to improve braking and fuel efficiency.
Vacuum Pumps Market
These developments matter because they demonstrate a shift from generic component supply toward application-specific optimization. Suppliers are increasingly designing for engine-off reliability, low parasitic loss, noise reduction, and integration with electrified brake and chassis control systems. That shift has direct implications for sourcing strategy, validation requirements, and long-term supplier partnerships.
Demand Drivers and Market Dynamics
The market's forward momentum is anchored in several reinforcing dynamics. First, electrification and hybridization continue to reshape vacuum requirements. In hybrid and electric vehicles, vacuum can no longer be assumed from a running engine in all operating conditions. Electric vacuum pumps enable on-demand brake vacuum generation, which supports brake assist performance and helps vehicle programs comply with CO2 reduction targets while maintaining safe and predictable braking behavior in downsized and electrified powertrains.
Second, brake-by-wire and advanced driver assistance deployment are increasing the importance of stable vacuum management during engine-off and start-stop events. In 2025, deployments of electric vacuum pumps in brake-by-wire systems have provided stable vacuum for advanced driver assistance functionality during those transitions. This is not merely an efficiency consideration; it is a safety and architecture consideration that influences which pump technologies are selected for next-generation vehicle programs.
Third, integration into 48V mild-hybrid architectures has created new design priorities. Electric vacuum pumps in these systems can reduce thermal load and parasitic losses while maintaining brake booster performance. At the same time, high-efficiency electric vacuum pumps for hybrid passenger vehicles are being optimized for low-noise operation and pulse-width-modulated control to minimize energy draw during intermittent engine phases. These engineering refinements indicate a market that is moving toward higher-performance, more tightly integrated solutions rather than commoditized replacements.
Fourth, safety and reliability scrutiny remains an important market factor. Field events such as the NHTSA recall action in August 2025, which addressed vacuum pump failure that could reduce brake assist performance under specific conditions, highlight the consequences of performance variability in critical brake systems. For sourcing and engineering teams, this reinforces the need for thorough validation, robust quality processes, and supplier selection criteria that account not only for cost and volume, but also for long-term durability and system-level reliability.
These dynamics collectively shape the market's next phase. Demand is not simply increasing; it is becoming more selective. Vehicle programs are increasingly evaluating vacuum pump solutions in the context of electrified braking architectures, thermal constraints, acoustic targets, and regulatory expectations. Suppliers that can demonstrate adaptive control, low energy consumption, rapid vacuum buildup, and integration-ready packaging are better positioned to participate in higher-value programs.
Where the Market Appears to Be Heading
Based on the trajectory documented in this study, the market is likely to continue expanding as vehicle electrification deepens and brake architectures become more dependent on electronically managed vacuum support. Growth is expected to be distributed across multiple application domains, with brake systems and engine management remaining central demand anchors while HVAC and emission control applications contribute additional volume and differentiation opportunities. The relative importance of electric vacuum pumps is expected to rise as hybrid and electric vehicle content increases and as braking safety requirements become more tightly integrated with advanced driver assistance and chassis control logic.
Regional variation will continue to influence market outcomes. Vehicle mix, electrification pace, OEM sourcing preferences, and regulatory exposure differ materially across regions, and these differences shape where demand scales most quickly and which supplier capabilities are most valued. The report examines these regional patterns without reducing them to simplistic rankings. Instead, it situates each region within the broader context of vehicle production, technology adoption, and program timing.
The competitive environment is also likely to evolve through a combination of consolidation, technology specialization, and program-level competition. Incumbents with strong brake system integration and global OEM relationships will continue to play a leading role, while regional and specialist suppliers may gain traction where they can demonstrate differentiated performance in noise, efficiency, packaging, or application-specific control. The market concentration structure suggests that scale matters, but it does not guarantee advantage unless supported by product relevance and reliability.
How to Use This Research in 2026 Planning
This report is intended to support concrete decisions rather than generic market awareness. In 2026, organizations can use the findings to align product roadmaps with demand where it is most likely to grow, assess supplier portfolios against performance and integration requirements, and anticipate how regulation and safety expectations will shape validation and sourcing criteria. The study also supports more disciplined interpretation of supplier announcements, program wins, and technology launches by placing them in a broader market context.
Automotive Vacuum Pump Market
For teams comparing opportunities across applications or regions, the report provides a structured basis for evaluating where vacuum pump demand is most strategically relevant and which technology attributes are gaining importance. For teams managing supplier relationships, it offers a framework for assessing concentration, differentiation, and program readiness. For analysts and investors, it provides a market narrative that connects sizing, growth, and competitive action to underlying automotive trends rather than short-term cycles.
Conclusion
The automotive vacuum pump market is entering a phase in which growth and technology transformation are intertwined. Historical expansion from 2020 through 2025 and the projected path toward 2032 indicate a market that is responding to electrification, brake system modernization, and emissions-driven design constraints. The market is not simply getting larger; it is becoming more performance-sensitive, more application-specific, and more dependent on supplier capability in areas such as adaptive control, thermal integration, and reliability under engine-off conditions.
This report translates that complexity into a usable strategic framework. It combines market sizing, segmentation logic, competitive profiling, and recent industry developments with the regulatory and safety context that influences sourcing and engineering decisions. For organizations preparing for 2026 and beyond, the value of the study lies in its ability to connect market movement with decision-relevant insight.
For the complete dataset, detailed segmentation analysis, regional demand breakdowns, application-level valuation, and full supplier profiles, please access the full report through the source page. The executive summary presented here is designed to demonstrate the scope and analytical depth of the study while preserving the proprietary segmentation and directional intelligence that support informed commercial, engineering, and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Vacuum Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Respiratory Humidifying Equipment Market Hits $7B in 2025, Poised for $11.6B by 2032
By PW Consulting, 2026-09-16
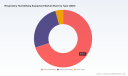
Strategic Intelligence for the Respiratory Humidifying Equipment Market: Navigating the 2026 Decision Landscape
The respiratory humidifying equipment market stands at a critical inflection point. As healthcare systems worldwide recalibrate around patient outcomes, supply chain resilience, and sustainable procurement, the devices that deliver optimal airway hydration have evolved from routine clinical accessories to strategically decisive assets. For executives, procurement leaders, and medical technology strategists, the weeks leading into 2026 demand more than generalized market briefings. They require structurally sound, forward-looking intelligence capable of informing capital allocation, R&D prioritization, competitive positioning, and regulatory compliance roadmaps.
Our latest comprehensive study, Respiratory Humidifying Equipment Market, is engineered to meet that exact requirement. Spanning a rigorous historical retrospective from 2020 through 2025 and projecting systematically across the 2026–2032 forecast horizon, the analysis translates complex clinical, regulatory, and commercial signals into actionable executive guidance. This overview outlines the strategic architecture of the report, demonstrates how macroeconomic and tactical data are synthesized, and clarifies the executive decisions the study is designed to support.
Executive Context: Why the Market Now Demands Precision Intelligence
The structural drivers shaping respiratory humidification are no longer confined to incremental clinical adoption. They intersect with regulatory recalibration, reimbursement architecture, material science breakthroughs, and consolidation pressures within the medical device supply chain. Organizations that continue to rely on fragmented market snapshots or backward-looking incident reports risk misallocating development budgets, underestimating compliance timelines, and misreading competitive velocity.
Respiratory Humidifying Equipment Market
The research is grounded in a disciplined quantitative foundation. Tracking the market’s progression from approximately 5,200 million USD in 2020 to a 2025 baseline of 7,000 million USD, the study documents a trajectory defined by sustained clinical demand, technology maturation, and gradual geographic expansion. The forecast period extends to 2032, reflecting a compound annual growth rate of 7.75 percent. By anchoring analysis in this extended horizon, the report enables decision-makers to evaluate not only near-term operational impacts but also multi-year capacity planning, product portfolio evolution, and strategic partnership timing. Importantly, the narrative treats top-line magnitude and growth velocity as directional compasses rather than isolated metrics, always threading them into the operational conditions that actually determine commercial execution.
Report Architecture: Operational Intelligence Over Abstract Market Commentary
A distinguishing feature of this study is its emphasis on execution-ready content. Rather than cataloguing broad trends, the analysis dissects the operational levers that determine procurement cycles, product roadmaps, and pricing architecture. The report integrates rigorous segmentation perspectives across product architecture, clinical environment, and geographic deployment, while deliberately preserving analytical depth that supports scenario modeling and internal stakeholder alignment.
Worldwide Active Humidifier Devices Market
Product Architecture and Clinical Deployment Dynamics
The study examines how humidifier design philosophies are diverging across clinical workflows. Active heated systems, passive condensation-management configurations, and ancillary accessory categories are analyzed not merely as discrete revenue pools, but as responses to distinct clinical demands, sterilization requirements, and integration constraints. The research explores how product architecture decisions influence procurement frequency, service intensity, and total cost of ownership across acute care, extended-stay facilities, and decentralized care environments.
Equally critical is the report’s treatment of application pathways. By mapping how humidification technologies are deployed across institutional settings, long-term care environments, homecare programs, and specialized respiratory support contexts, the analysis identifies where adoption velocity is being accelerated by workflow integration, reimbursement alignment, or care-delivery restructuring. This application-level perspective helps organizations anticipate where channel strategy, clinical validation, and service infrastructure must be synchronized to capture durable demand.
Geographic Exposure and Regional Commercial Architecture
Market opportunity is not uniformly distributed, and neither is the operational complexity of capturing it. The research builds a regional framework that examines how healthcare infrastructure maturity, procurement governance, regulatory cadence, and distribution ecosystems shape market penetration. By evaluating how different regions absorb product introductions, navigate sterilization and maintenance logistics, and respond to reimbursement mechanisms, the report enables firms to prioritize market-entry sequencing, localization investments, and partnership strategies with greater precision.
Competitive Architecture: Positioning in a Concentrated but Dynamic Field
Concentration in the respiratory humidifying equipment market is substantial, with the three largest participants collectively commanding a dominant share and the top five consolidating an even broader portion of total revenue. Yet concentration does not equate to stagnation. The field remains tactically active, with incumbents upgrading integrated humidification platforms, challengers pursuing regulatory clearances, and component specialists expanding sustainable material capabilities.
The report provides a structured evaluation of the companies defining this competitive environment. Profiles extend beyond descriptive summaries to examine each organization’s product philosophy, integration strategy, geographic footprint, and recent commercial moves. The analysis covers firms with distinct strategic identities: organizations anchoring their position in advanced heated humidification systems for hospital and homecare respiratory support; manufacturers focused on mechanical ventilation gas humidification and patient respiratory support components; suppliers of active heated humidifiers and breathing systems for hospital respiratory care; developers of heated humidification systems for clinical respiratory support; ventilator-integrated humidifier manufacturers serving ICU and respiratory applications; providers of CPAP and NIV humidification systems for sleep and respiratory therapy; companies embedding humidification within BiPAP and ventilator ecosystems; suppliers of humidifiers tailored to intensive care and neonatal respiratory care; firms integrating humidification with adult and pediatric ventilator platforms; developers of respiratory humidification circuits and accessories oriented toward sustainable care; and manufacturers of respiratory care humidification solutions designed for both hospital and homecare environments.
Recent company-level developments illustrate the contours of this competitive dynamism. In late 2025, one manufacturer announced a next-generation humidifier designed to minimize condensate for advanced respiratory support, signaling continued emphasis on workflow efficiency and airway management. Around the same period, a separate medical company secured regulatory clearance for a respiratory humidifier unit, reinforcing the importance of compliance milestones in sustaining commercial momentum. Meanwhile, a component and circuit specialist advanced a series of sustainability-focused milestones, including the launch of a bioplastic-based breathing circuit and humidification component showcased at a major industry trade fair, alongside multiple certifications intended to strengthen quality standards and sustainable innovation credentials within respiratory humidifying equipment. These developments are not presented as isolated announcements; they are interpreted as indicators of how product differentiation, regulatory timing, and material sustainability are converging into competitive advantage.
Market Dynamics: The Operational Forces Shaping Commercial Execution
Commercial outcomes in this sector are increasingly determined by the interplay of regulation, reimbursement, material economics, and infrastructure realities. The report treats these forces not as background context but as primary variables in the competitive equation.
Regulatory and Standards Evolution
The regulatory environment is tightening the operational boundaries within which humidification devices are designed, validated, and deployed. Updated safety and performance specifications are redefining compliance expectations for respiratory humidifiers in medical settings. At the same time, guidance emphasizing proper disinfection, performance testing, and sterilization control standards reinforces the clinical and legal importance of documented hygiene protocols. For manufacturers and procurement organizations alike, these measures alter development timelines, validation burdens, and lifecycle management expectations, making regulatory readiness a strategic asset rather than an administrative task.
Reimbursement Architecture and Commercial Access
Reimbursement structures directly influence adoption speed and procurement predictability. Specific billing codes continue to serve as the operational mechanism for reimbursement of respiratory humidifiers and heated humidifiers under Medicare policies. Understanding how these code categories function, where they facilitate access, and where they create administrative friction is essential for forecasting demand stability and designing commercially viable product configurations. The study examines these reimbursement pathways as enablers or constraints on segment-level growth, especially in settings where cost justification must withstand structured review.
Material Economics, Sterilization, and Procurement Cycles
Material selection and processing costs have become decisive factors in both product design and procurement behavior. Elevated raw material costs intersect with the demand for biocompatible, sterilizable materials featuring antimicrobial coatings, influencing not only production economics but also replacement cycles and service frequency. In parallel, sterilization and maintenance costs remain a persistent constraint, particularly for smaller hospitals and homecare adoption, where operational budgets are tighter and service infrastructure is less centralized. The report analyzes how these cost pressures affect purchasing intervals, product longevity expectations, and the competitive appeal of systems that reduce total lifecycle burden.
Strategic Implications for 2026 Decision-Making
For organizations operating in or entering this market, 2026 is a year of structural choices. Should product strategy prioritize integration with mechanical ventilation and critical care platforms, or expand into decentralized respiratory support and homecare ecosystems? How should R&D resources be divided between performance enhancement, condensate management, and sustainable material adoption? Where should commercial teams concentrate regulatory preparation, reimbursement alignment, and distribution partnerships to minimize time-to-value?
The research is designed to support these decisions through scenario-based interpretation rather than static snapshots. By combining historical trajectory, forward demand projections, segmentation logic, competitor movement analysis, and operational constraint mapping, the study enables leaders to stress-test assumptions. Companies can evaluate how product launches, regulatory updates, certification milestones, and reimbursement clarity may shift competitive positions. Procurement leaders can better anticipate where sterilization, maintenance, and material constraints will influence supplier selection. Strategy teams can identify which geographic and application opportunities warrant earlier investment versus more cautious monitoring.
The report also recognizes that market advantage increasingly depends on anticipating secondary effects. A new product announcement may matter less for its headline presence than for what it reveals about rival engineering priorities. A certification achievement may signal not just compliance status but readiness to expand into regulated channels. A standards update may reshape procurement specifications long before a purchasing cycle formally opens. By reading these signals together, executives can convert market complexity into timing advantage.
How to Use This Study for Enterprise Planning
The study is structured to serve multiple internal audiences without diluting analytical precision. Executive leadership can use the forecast horizon and macro growth trajectory to frame capital allocation and portfolio review. Product and engineering teams can leverage the segmentation architecture, material considerations, and standards developments to prioritize feature roadmaps and manufacturing requirements. Commercial and market access teams can draw on the competitive landscape, reimbursement context, and application-level deployment analysis to refine channel strategy and pricing logic. Regulatory and quality teams can integrate the compliance and sterilization expectations into planning calendars and documentation workflows.
To preserve the strategic integrity of the analysis while ensuring operational relevance, the full report moves beyond directional commentary into detailed segmentation splits, revenue breakdown structures, regional deployment profiles, product-type contributions, application-level demand distribution, and company-specific performance indicators. Those datasets form the quantitative backbone required for board-level reviews, investor communications, go-to-market planning, and competitive benchmarking.
Closing Perspective
The respiratory humidifying equipment market is being reshaped by the convergence of clinical performance expectations, regulatory rigor, reimbursement discipline, and sustainability-driven product innovation. In that environment, strategic decisions made in 2026 will set the trajectory for the remainder of the decade. Organizations that rely on incomplete market narratives risk reacting late to compliance shifts, misreading competitive intent, and underpositioning against evolving procurement economics.
This study provides the depth, structure, and forward orientation necessary to move from reactive awareness to deliberate strategy. By translating historical momentum, forecast growth, competitive maneuvers, and operational constraints into a unified executive framework, it equips decision-makers to align product, commercial, and compliance strategies with the realities of the market ahead. The full intelligence set—segment-level breakdowns, regional deployment figures, application distribution detail, and company-specific indicators—completes the analytical picture required for high-stakes planning.
For leaders seeking to secure a decisive informational advantage, the complete report is available through our official market research portal, where the full dataset, segmentation detail, and competitive profiles can be reviewed in their entirety and integrated directly into enterprise strategy workflows.
For detailed analysis of this topic, please visit the official page: Respiratory Humidifying Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camellia Oil Market to Hit $321.07M by 2032 at 9.1% CAGR
By PW Consulting, 2026-09-16
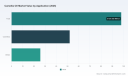
The Camellia Oil Market: Strategic Imperatives for 2026 and Beyond
The global camellia oil landscape stands at a critical inflection point. As consumer preferences shift toward premium, health-oriented edible oils and functional cosmetic ingredients, market participants face a complex matrix of supply chain restructuring, regulatory evolution, and intensifying regional competition. Our newly published Camellia Oil Market research provides executives with the analytical framework needed to navigate this transition with confidence. The study does not merely track historical performance; it constructs a forward-looking decision architecture calibrated for corporate strategy through 2032.
For leadership teams evaluating expansion, acquisition, or product positioning in 2026, the timing of this intelligence is decisive. Structural supply investments, cross-border certification milestones, and technology-driven consolidation are reshaping competitive boundaries faster than traditional market signals can capture. A disciplined, data-grounded view of trajectory, segmentation dynamics, and player positioning is no longer optional; it is foundational to capital allocation and go-to-market design.
Market Trajectory and the Architecture of Growth
Historical data paints a clear picture of sustained expansion. Between 2020 and 2025, total market revenue progressed from approximately 113.4 million USD to 175.7 million USD, reflecting consistent year-over-year appreciation driven by widening adoption in food applications, rising demand for plant-based cosmetic formulations, and improved extraction and branding capabilities across producing regions. The momentum carries decisively into the forecast window. Starting from an estimated 185.6 million USD in 2026, the market advances through a series of compounding steps, reaching 202.8 million USD in 2027, 233.0 million USD in 2028, and continuing upward to 253.1 million USD in 2029, 271.1 million USD in 2030, 292.8 million USD in 2031, and 321.1 million USD by 2032. This pathway corresponds to a compound annual growth rate of 9.1 percent across the 2026 to 2032 forecast period.
Such a rate signals more than incremental expansion. It reflects the convergence of multiple reinforcing forces: maturing consumer appreciation for cold-pressed and single-origin oils, broadening cosmetic formulations leveraging favorable regulatory assessments, and supply-side scaling that reduces unit costs while improving grade consistency. Yet trajectory alone does not dictate strategy. The strategic value lies in understanding which segments and channels capture disproportionate share of this growth, how regional demand patterns diverge, and where capacity, certification, and distribution bottlenecks may create asymmetric advantages for well-positioned operators.
Segmentation Dynamics Without Surface-Level Simplification
The market’s internal structure reveals distinct value pools rather than a uniform growth curve. Demand is distributed across food, cosmetics, and other applications, each with different procurement cycles, pricing sensitivities, and quality thresholds. Edible use remains anchored by traditional culinary consumption and emerging premium positioning, while cosmetic applications benefit from growing formulation diversity and recently expanded safety recognition that eases entry into international personal care channels. The other applications segment captures niche industrial and specialty uses that, while smaller, often command higher margins and longer contract horizons.
Camellia Oil Market
Product differentiation further shapes competitive outcomes. Extra virgin and pure camellia oil categories serve different buyer expectations. The former emphasizes minimal processing, sensory quality, and traceability, aligning with premium retail and gift-channel demand. The latter supports broader functional and blending applications where consistency and scale are prioritized. Understanding the interplay between these product streams, their pricing architectures, and the manufacturing capabilities required to serve them is essential for companies deciding whether to compete on terroir and certification or on volume and cost efficiency.
Regional patterns add another layer of strategic nuance. Production and consumption are not evenly distributed, and supply chain geography heavily influences margin structure, logistics cost, and responsiveness. Some markets function primarily as demand centers with strong import dependence for specialty grades, while others combine cultivation, processing, and export orientation within integrated corridors. The report maps these regional contributions and demand intensities without reducing them to static percentage snapshots, instead emphasizing relative scale, growth direction, and the strategic implications of geographic concentration for sourcing, distribution, and market entry timing.
Competitive Landscape: Integrated Players and Emerging Consolidation
The player base reflects a concentration of vertically integrated producers, especially among leading Chinese manufacturers that coordinate cultivation, processing, refining, and branded sales. Firms such as Hunan Yamei Camellia Oil Co., Ltd. emphasize organic and premium edible positioning with end-to-end control from cultivation to processing. Hunan Jinhao Camellia Oil Co., Ltd. pursues a comparable vertical model, offering fresh-pressed oils and high-end edible products supported by ISO9001 and CNAS accreditation. In Jiangxi Province, multiple enterprises extend the integrated chain with differentiated emphases. Jiangxi YouNiBao Agricultural Science And Technology Co., LTD supplies across multiple provinces with a focus on organic certification and export-grade edible oils. Jiangxi Tianyuan Camellia Oil Co., Ltd. and Jiangxi Wufeng Camellia Oil Co., Ltd. concentrate on single-origin and terroir-differentiated oil, expanding cold-pressing capacity and securing organic and non-GMO certifications targeting premium channels.
Worldwide Wolfberry Oil Market
Other participants complement this landscape with specialized functions. Jiangxi Golden Deer Oil Co., Ltd. operates with an export orientation, maintaining cold-pressing lines certified to international food safety standards and developing partnerships across Japan, South Korea, Singapore, Australia, and the United States. Jiangxi Youjia Oils and Grains Co., Ltd. focuses on refining and packaging, leveraging extensive domestic distribution and growing export operations for bulk ingredients. Hunan Jiufeng Agricultural Development Co., Ltd. represents another vertically integrated model, spanning oil-tea cultivation, raw material processing, pressing, refining, and branded sales, anchored by partnerships with numerous cooperatives.
Market concentration metrics indicate that the top three competitors command roughly 40 percent of revenue, while the top five reach approximately 45 percent. This level of concentration suggests meaningful but not insurmountable consolidation, leaving room for differentiated entrants, regional specialists, and channel-focused operators to compete on quality, certification, or distribution strength. The strategic question for 2026 is not only who leads today, but which capabilities will determine leadership by the end of the forecast period.
Industry Dynamics Shaping the 2026 Decision Environment
Recent developments illustrate how quickly structural change is materializing. Production capacity in China has expanded materially, with annual output reaching approximately 1.1 million metric tons, an increase of about 53 percent since 2020 following a three-year expansion of hundreds of thousands of hectares under a dedicated action plan. This expansion aligns with planting area reaching roughly 75 million mu by the end of 2025, with Hunan Province leading at over 1.58 million hectares and contributing substantial yield. Such scale alters the supply base, improves availability of graded material, and intensifies competition for export and premium-channel positioning.
At the same time, corporate activity signals a shift toward technology-enabled supply chain integration. A recent preliminary acquisition agreement involving a major group and a vertically integrated producer underscores interest in building AI-driven supply chain capabilities around camellia oil production. Parallel industry events have highlighted intelligent harvesting technology and promotional efforts to strengthen camellia oil’s standing as a distinct edible oil category. These moves indicate that operational efficiency, traceability, and category elevation are becoming central competitive battlegrounds.
Regulatory and certification progress is equally consequential. A favorable safety review for camellia oleifera seed oil in cosmetic applications has expanded access to European personal care markets, lowering a historic barrier and opening new formulation opportunities. Simultaneously, clarified quality benchmarks for exports and continued policy support for planting expansion are shaping both supply reliability and market access. For international buyers and exporters, these developments affect conformance requirements, sourcing strategy, and the credibility of premium claims.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is designed as a working instrument rather than a static overview. It connects macro trajectory with segment-level logic, regional demand patterns, and competitive positioning to support concrete decisions in product strategy, sourcing, pricing, and market entry. The report provides:
- A consolidated market size and forecast series that situates current performance within a multi-year growth path and highlights inflection points relevant to capacity planning and investment timing
- Segment-level analysis across product types and application categories that explains relative scale, demand drivers, and the operational implications of serving premium versus volume-oriented channels
- Regional demand and supply context that helps identify where procurement, distribution, and market development efforts are likely to yield the strongest return, without reducing complex geography to decontextualized shares
- A structured competitive assessment of leading manufacturers, including their integration models, certification postures, export orientation, and premium-market positioning, enabling benchmarking and threat assessment
- An integrated view of regulatory, certification, and capacity-expansion developments that affect export readiness, formulation access, and supply reliability
- Strategic scenario framing that links market dynamics to actionable choices in brand architecture, channel selection, partnership design, and technology adoption
Throughout, the report emphasizes decision utility over data volume. Executives will find not only what is changing, but how to interpret those changes in relation to margin goals, risk exposure, and competitive positioning through 2032.
Why 2026 Demands a Disciplined Intelligence Baseline
The coming year will reward organizations that can align product-grade strategy with real demand traction, match sourcing and certification capabilities to target markets, and anticipate consolidation and technology adoption that may redefine cost and speed advantages. Companies that treat camellia oil as a generic commodity risk misreading premiumization trends, regulatory openings, and regional concentration effects. Those that invest in a precise, forward-looking view can better prioritize capacity, refine channel mix, and structure partnerships for durable advantage.
The complete research contains the full segmentation detail, regional breakdowns, competitive benchmarking, and forecast architecture necessary to move from directional awareness to executable strategy. To access the complete dataset, segment-level breakdowns, and full competitive profiles, refer to the source page for the Camellia Oil Market study.
For detailed analysis of this topic, please visit the official page: Camellia Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


