



Vinylphosphonic Acid Market: Why 8.7% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Vinylphosphonic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for vinylphosphonic acid (VPA) has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 10.8 million USD in 2020 to an estimated 16.4 million USD in 2025. The trajectory points toward continued growth, with the market projected to reach nearly 29.3 million USD by 2032, reflecting a compound annual growth rate of 8.7 percent. This scale places VPA in the niche specialty chemicals segment, where volume is modest but value addition through application-specific performance is substantial.
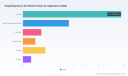
At first glance, the numbers suggest uninterrupted expansion. Closer examination reveals a market that is fragmenting around performance thresholds rather than pure capacity. The revenue distribution across grades, applications, and geographies shows that demand is not uniform. High-purity grades dominate share, while coatings and water treatment applications account for the bulk of consumption. Asia Pacific leads regional contribution, reflecting concentrated industrial activity and manufacturing capacity in the region, while mature markets in North America and Europe sustain steady, high-value demand.
PW Consulting
Despite the positive outlook, the sector faces structural challenges that complicate straightforward growth strategies.
Challenge One: Purity Thresholds and Application-Specific Performance
The market is no longer defined by generic chemical supply. Buyers in coatings, corrosion inhibition, and polymer modification increasingly require tight impurity profiles and consistent batch-to-batch performance. The shift from 80 percent grades toward 90 percent and higher purity thresholds is reshaping procurement logic. Suppliers that cannot demonstrate controlled impurity levels risk being relegated to lower-margin segments, while those that can command premium positioning and longer-term contracts.
Challenge Two: Feedstock Volatility and Cost Structure Pressure
Production economics are tightly coupled to phosphorus-based feedstock availability and pricing. Raw material price volatility affects a significant portion of global producers, placing pressure on margin forecasting and inventory planning. Facilities operating with narrow buffers or inflexible procurement arrangements face heightened exposure to cost swings, which in turn influences pricing stability for downstream buyers. This dynamic is particularly acute in regions where feedstock logistics and storage constraints amplify supply variability.
Challenge Three: Regulatory and Logistics Compliance Burden
Hazardous chemical handling introduces a compliance layer that touches production, storage, transportation, and labor practices. A meaningful share of manufacturers report increased compliance costs tied to storage regulations, while logistics providers face restrictions related to chemical transportation safety standards. Elevated labor and safety costs in production facilities further contribute to operating expense pressure. These factors are not marginal; they influence site selection, capacity expansion timing, and the cost of serving distant markets.
Key Drivers Behind Market Evolution
Growth in the VPA market is not accidental. It is being shaped by a set of reinforcing drivers that alter where value is created and how companies compete. Four forces stand out.
Technical Innovation and Purity Engineering
The most visible driver is the push toward higher purity and application-tuned specifications. Industry developments in 2024 and 2025 illustrate this direction. A high-purity 92 percent grade with 14 percent lower impurities was introduced, reflecting a strategic emphasis on impurity control as a differentiator. This matters because even modest reductions in trace contaminants can translate into improved performance in coatings, corrosion inhibition, and polymer modification. Innovation is increasingly less about new molecule discovery and more about precision manufacturing, analytical control, and specification reliability.
Phosphoric Acid Market
Policy and Regulatory Environment
Regulatory expectations around hazardous chemical storage and transportation continue to tighten. Rather than acting as a uniform brake, these requirements are reshaping competitive dynamics. Companies with mature compliance infrastructure, documented safety processes, and regional distribution capacity are better positioned to absorb regulatory friction. Conversely, organizations with fragmented logistics or limited safety investment face higher relative cost and longer time to market. In practice, compliance is becoming a selection criterion for buyers who need predictable supply and reduced operational risk in their own value chains.
Demand-Side Shifts Across Industrial and Specialty Applications
Demand is broadening but not evenly. Coatings remain a core consumption center, driven by performance needs in corrosion resistance, adhesion, and flame retardancy. Water treatment and oil well applications sustain steady demand linked to industrial infrastructure and resource extraction activity. Fuel cells represent a smaller but strategically important segment, where VPA’s functional properties support research and development pathways even if commercial scale remains nascent. Medical care and printing applications contribute niche volumes with distinct purity and handling requirements.
The common thread is not volume growth in isolation but specification sensitivity. Buyers are less interested in generic availability and more focused on whether a grade reliably meets performance thresholds in their process. This shifts purchasing decisions toward suppliers who can evidence consistency, provide technical support, and align product grades with application outcomes.
Supply Chain and Cost Structure Realignment
Supply chain design is becoming a strategic variable. Regional distribution optimization has reduced delivery lead times by 21 percent across three regional distribution centers for one manufacturer, a change that directly affects service levels and inventory planning for downstream customers. At the same time, upstream feedstock fluctuations continue to drive raw material volatility, influencing production economics. Together, these factors are pushing companies to balance proximity, redundancy, and cost efficiency more deliberately. Supply chains that can flex across regions while maintaining specification integrity are gaining a practical advantage.
Competitive Landscape and Leading Strategies
The competitive structure of the VPA market is moderately concentrated, with the top three players accounting for approximately 28.5 percent of revenue and the top five reaching roughly 35.2 percent. This level of concentration indicates that while no single company controls the market, a small group of established players sets much of the pace in specification development, regional coverage, and compliance posture. The rest of the market is dispersed among regional suppliers, specialty producers, and laboratory-focused vendors, creating a multi-layered landscape rather than a simple oligopoly.
Strategic Positioning Among Leading Companies
Several firms illustrate the different ways competition is being structured.
- One German-based producer emphasizes high-purity VPA in both 80 percent and 90 percent grades, with ISO 9001 certification and a portfolio covering monomer and polymer grades for coatings, corrosion inhibition, flame retardancy, and adhesion. Its positioning centers on specification breadth and certified quality control, which supports use across multiple industrial functions.
- A major European chemical company offers specialty VPA grades aimed at polymer modification, coatings, and water treatment. Its advantage lies in the ability to slot VPA into broader specialty chemical portfolios and leverage existing customer relationships in performance materials and water-related applications.
- A Brussels-based supplier provides VPA grades including a formulation for aluminum pretreatment and corrosion inhibition. Its differentiation is application-solving rather than generic supply, targeting a specific industrial pretreatment need with a branded grade.
- A Tokyo-headquartered chemical supplier markets VPA as a high-purity liquid for laboratory and specialty chemical synthesis. Its role is narrower, serving R&D, pilot-scale, and specialty synthesis demand where purity and traceability matter more than bulk cost.
- An Italian manufacturer focuses on VPA for industrial and pharmaceutical applications, indicating a dual-use orientation that spans conventional industrial demand and higher-specification pharmaceutical relevance.
These profiles show that leadership is not defined by a single formula. Some players win through certified quality and grade variety, others through application-specific formulation, and others through purity and technical service for specialized users.
Differentiation Levers and Recent Moves
In a market where volume is constrained and performance requirements are rising, differentiation tends to appear in three levers: purity and impurity control, application reliability, and service responsiveness. Recent industry developments reinforce this pattern. The introduction of a 92 percent high-purity grade with lower impurities reflects a purity-driven differentiation strategy. The reduction in delivery lead times through regional distribution optimization shows a service-level differentiation strategy that improves reliability for buyers. Meanwhile, upgraded polymer modification testing facilities in Asia-Pacific have increased quality assurance throughput by 25 percent, pointing to investment in process verification and application readiness.
These moves matter because they align with how buyers purchase in specialty chemicals. In coatings and water treatment, batch consistency and impurity control affect end-product performance. In polymer modification, testing throughput and quality assurance affect the speed at which new formulations can be validated. In laboratory and specialty synthesis, purity and documentation support downstream reproducibility. Companies that invest in these levers are not simply selling a chemical; they are selling predictable outcomes.
Market Structure Evolution
The market is likely to evolve along two concurrent paths: selective consolidation and continued niche segmentation. Consolidation will probably remain measured rather than aggressive. Because VPA serves multiple applications with different specification needs, scale alone does not guarantee advantage. However, companies that can combine purity control, compliance readiness, and regional distribution capacity are well placed to acquire share from smaller competitors that lack one or more of these capabilities.
At the same time, segmentation will persist. Laboratory-grade supply, industrial bulk grades, and specialized pretreatment or polymer modification grades each carry different buyer expectations, pricing logic, and service requirements. New entrants are most likely to appear in niche positions where a specific grade, regional service advantage, or technical support capability can create a defensible position without requiring dominant scale. The practical outcome is a market that becomes more tiered, with premium specification players, application-focused specialists, and cost-oriented regional suppliers coexisting.
Strategic Outlook for the Next Three to Five Years
Looking ahead to 2032, three trends are likely to shape commercial opportunity and risk.
Trend One: Purity and Specification As control Become the Default Expectation
As higher-purity grades become more widely available and application performance expectations rise, what is considered acceptable purity will shift upward across more use cases. This will compress the middle ground where generic, lower-specification supply once found a home. Suppliers will need to demonstrate tighter impurity control, stronger analytical documentation, and consistent lot performance. The commercial opportunity lies in grades and services that reduce downstream processing variability, especially in coatings and polymer modification, where small quality differences can have outsized effects on end-use performance.
Trend Two: Regional Service Networks Will Matter More Than Raw Proximity
Lead-time reduction, regional distribution optimization, and improved delivery reliability are becoming competitive differentiators. Buyers increasingly value predictable timing and service consistency as much as unit price, particularly when chemical handling and logistics constraints raise the cost of disruption. Companies that build or strengthen regional service networks will be better positioned to capture share in markets where responsiveness and safety compliance are closely linked. This trend also creates opportunities for partnerships that improve storage, transportation, and inventory buffering without requiring every producer to own the full logistics chain.
Trend Three: Regulatory Friction Will Elevate Compliant Operators
Compliance costs tied to hazardous chemical storage, transportation safety standards, and elevated labor and safety requirements are unlikely to recede. Instead, they will continue to separate operators that have built institutional capability from those that have not. Over the next few years, this will influence which producers can expand efficiently, which can serve certain regions reliably, and which can maintain stable pricing. The strategic opportunity is to treat compliance as part of the value proposition rather than a cost to minimize in isolation. Buyers in sensitive applications may prefer suppliers whose safety and transport readiness lower their own operational exposure.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Feedstock volatility remains a persistent risk; if phosphorus-based feedstock supply fluctuations intensify, production economics could tighten and pricing volatility could increase. Regulatory changes could further raise storage and transportation requirements, reshaping cost structures and market access. Demand may also shift faster than expected in certain applications, particularly where alternative materials, formulation changes, or new process technologies reduce reliance on VPA in specific functions. Finally, capacity additions in Asia-Pacific and other regions could alter supply balance, intensifying competition in some segments while creating export opportunities in others.
Actions for Decision-Makers
The VPA market rewards companies that align their strategy with specification sensitivity, service reliability, and compliance readiness. The following actions are most relevant across different roles.
Phosphonate Market
For Manufacturers and Producers
- Prioritize purity engineering and analytical consistency over undifferentiated capacity expansion. In a market where higher-purity grades and lower impurity levels are gaining traction, the ability to document and replicate performance will shape pricing power and customer retention.
- Invest in regional distribution and lead-time reliability. Reducing delivery friction is not just a logistics improvement; it is a commercial differentiator that supports premium positioning and reduces the likelihood of substitution under pressure.
- Design compliance into operations as a competitive asset. Storage, transportation, and labor safety costs are real, but companies that manage them systematically can use reliability and risk reduction as part of their customer value proposition.
For Investors and Strategic Partners
- Focus on business models that combine specification control with service differentiation rather than volume alone. The strongest growth potential lies in companies that can secure long-term relationships through purity, consistency, and responsiveness, especially in coatings, water treatment, and polymer modification.
- Watch for selective consolidation opportunities where regional or specialty players lack the compliance infrastructure, analytical capability, or distribution reach to compete upward. Value creation may come more from capability alignment than from scale expansion.
- Monitor feedstock exposure and regional capacity dynamics. Margins and pricing stability will depend on how well companies manage raw material volatility and adapt to shifting supply balance across regions.
For Procurement and Supply Chain Leaders
- Evaluate suppliers on specification reliability and service consistency as well as price. In applications where impurity levels and batch consistency affect performance, the lowest headline price may not translate into the lowest total cost if variability creates processing risk.
- Build buffer and logistics strategies that account for hazardous chemical transportation constraints. Where safety standards and transport restrictions raise the cost of disruption, regional distribution capability and documented handling practices can reduce supply risk.
- Align grade selection with application outcomes. The choice between 80 percent, 90 percent, and higher-purity grades should be tied to actual performance requirements and downstream process sensitivity, not just inventory convenience.
The commercial dynamics of vinylphosphonic acid are increasingly defined by precision, service, and compliance rather than by bulk commodity logic. For companies operating in coatings, water treatment, polymer modification, fuel cells, medical care, printing, and related specialty segments, the window to strengthen positioning is now, before specification expectations and regulatory expectations become even more firmly entrenched. Detailed segmentation data, regional breakdowns, grade-level dynamics, and customized scenario analysis are available in the full PW Consulting report on the Vinylphosphonic Acid Market, which provides the deeper quantitative and strategic detail needed for planning beyond high-level trends.
For detailed analysis of this topic, please visit the official page: Vinylphosphonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Bike Market 2026: 10.54% CAGR Trajectory and the Asia Pacific Shift
By PW Consulting, 2026-09-21
Electric Bike Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The electric bike market has transitioned from a niche alternative to a mainstream mobility solution, demonstrating sustained expansion over the past five years. Between 2020 and 2025, industry revenue climbed from approximately 41.9 billion USD to 73.2 billion USD, reflecting a compound annual growth rate that underscores the sector's resilience and accelerating adoption. Forward projections indicate continued momentum, with revenue expected to reach 147.2 billion USD by 2032, translating to a CAGR of 10.54 percent across the 2026-2032 forecast horizon. This trajectory positions electric bikes as one of the fastest-growing segments within the broader micro-mobility and personal transportation landscape, driven by urbanization pressures, sustainability mandates, and evolving consumer preferences for flexible, low-emission transit options.
Despite the robust growth trajectory, the industry stands at a critical inflection point where several structural challenges threaten to reshape competitive dynamics. First, regulatory fragmentation is intensifying across key markets. Jurisdictions are diverging on speed limits, motor power thresholds, battery safety mandates, and classification frameworks, creating compliance complexity for manufacturers operating across multiple regions. Second, raw material volatility is introducing cost uncertainty, particularly in battery component pricing, which directly impacts margin structures and pricing strategies. Third, market concentration remains relatively high, with the top three players holding a substantial share of global revenue and the top five firms commanding an even larger portion, which raises barriers to entry and compresses differentiation opportunities for smaller competitors. These forces collectively demand strategic agility from market participants seeking to capture growth without exposing themselves to excessive regulatory, cost, or competitive risk.
Key Drivers Shaping Market Evolution
Technological Innovation and Performance Differentiation
Technology remains the primary engine of market expansion, with advancements in motor efficiency, battery energy density, and smart connectivity reshaping product expectations. Manufacturers are increasingly embedding proprietary control units, GPS tracking, over-the-air updates, and integrated app ecosystems into their platforms. These features extend beyond novelty; they address safety concerns, enable fleet management capabilities, and create recurring engagement loops that strengthen brand loyalty. Recent model launches illustrate this trajectory: one U.S.-based brand introduced a fat-tire model with enhanced range and a proprietary control unit supporting GPS and OTG functionality, signaling how connectivity and utility features are becoming baseline expectations rather than premium add-ons. Simultaneously, performance-oriented manufacturers are pushing torque outputs and frame materials to cater to aggressive riding styles and demanding terrain, while other players focus on step-through designs and extended range to serve senior and recreational segments. The technological arms race is widening product segmentation and forcing companies to clarify whether they compete on accessibility, performance, or integrated digital experience.
Policy and Regulatory Environment as a Market Accelerant and Constraint
Policy frameworks are actively reshaping demand patterns and compliance requirements. In the United States, reciprocal tariffs on Chinese electric bicycle imports were reduced from 55 percent to 45 percent effective November 2025, easing some cost pressures on imported finished goods while still maintaining a significant trade barrier. This adjustment alters sourcing economics and encourages regional assembly or supply chain diversification strategies. Concurrently, California implemented updated State Fire Marshal safety standards for electric bike batteries effective January 2026, requiring manufacturers to demonstrate enhanced thermal management and certification compliance. In Europe, the European Commission fully enforced the revised EN 15194 standard after August 2025, harmonizing technical requirements but also tightening conformity assessment processes. Meanwhile, the United Kingdom revoked anti-dumping duties on non-folding electric bikes of Chinese origin in February 2025, opening a pathway for cost-competitive imports in that segment. Collectively, these regulatory shifts are creating a patchwork environment where successful players must navigate divergent safety, classification, and trade rules while leveraging favorable policy windows to optimize cost structures.
Demand-Side Shifts in Urban Mobility and Commercial Utility
Consumer and enterprise behavior is evolving beyond recreational use toward practical, daily mobility solutions. City and urban applications continue to dominate usage patterns, reflecting the role of electric bikes in first-mile and last-mile connectivity, commute substitution, and congestion avoidance. At the same time, cargo and utility applications are gaining meaningful traction as businesses and households recognize the cost and efficiency advantages of electric cargo bikes for local deliveries, family transport, and municipal operations. This shift is reinforced by rising fuel costs, parking constraints, and corporate sustainability targets that incentivize fleet electrification at the micro-mobility level. Demand is also becoming more segmented by rider profile: high-performance models appeal to enthusiasts and trail riders, while accessible step-through designs and folding formats attract seniors, multi-modal commuters, and space-constrained urban users. These diverging demand clusters require manufacturers to align product architecture, marketing positioning, and distribution channels with specific use cases rather than relying on generic electric bike positioning.
Supply Chain and Cost Structure Dynamics
The supply chain environment is undergoing a period of recalibration as material costs, logistics constraints, and sourcing strategies interact. Lithium carbonate prices rose sharply in December 2025 and January 2026, with industrial grades increasing by double-digit percentages, placing upward pressure on battery pack costs and, by extension, finished product pricing. This volatility highlights the sensitivity of margin profiles to commodity cycles and underscores the value of long-term supplier agreements, battery chemistry diversification, and design efficiencies that reduce dependency on constrained inputs. At the same time, tariff adjustments and trade remedy decisions are prompting companies to reconsider manufacturing footprints, assembly locations, and inventory strategies. Some manufacturers are responding by emphasizing regional distribution, localized assembly partnerships, or product architectures that optimize shipping efficiency and tariff exposure. The net effect is a market where cost discipline and supply chain resilience are becoming as strategically important as product features in determining competitive outcomes.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of regional specialists, performance-focused incumbents, and accessible-value brands, each pursuing distinct strategic positioning. Premium German manufacturers have built strong reputations around integrated drive systems, advanced battery integration, and high-end frame engineering, targeting customers who prioritize durability, ride quality, and ecosystem alignment with established component suppliers. These firms compete on engineering credibility and residual value, often anchoring their portfolios in eMTB, cargo, and city categories with sophisticated powertrain integration. U.S.-based brands occupy a broad value spectrum, ranging from budget-friendly folding and cruiser models with emphasis on quiet operation and certified electrical safety, to mid-range and premium platforms that differentiate through proprietary app controls, GPS tracking, and over-the-air update capabilities. This stratification allows American manufacturers to address price-sensitive urban riders as well as tech-conscious consumers seeking connected features. Global players such as hybrid bike leaders and Taiwanese high-end manufacturers leverage scale, alloy frame expertise, and battery option flexibility to serve commuter and performance segments with broad geographic reach. A Dutch specialist has carved out a niche in compact folding designs with efficient pedal-assist systems, targeting urban mobility users who prioritize portability and maneuverability.
Recent product activity reinforces the intensity of differentiation. A U.S. brand expanded its fat-tire lineup with enhanced range and GPS/OTG functionality, reinforcing its focus on connected adventure and urban versatility. A Taiwanese manufacturer introduced new eMTB series powered by Bosch CX motors in alloy frames, emphasizing improved affordability while maintaining performance credibility. A major global brand launched a flagship model with a carbon frame and high torque output, signaling continued investment in premium performance segments. These moves illustrate how leaders are contesting multiple battlegrounds simultaneously: range and battery endurance, motor torque and frame material, connectivity and software integration, and price-to-performance ratios across accessibility and premium tiers.
The market structure is evolving along two parallel paths. Consolidation is likely to accelerate among mid-tier players seeking scale, distribution leverage, and cost efficiencies, particularly as compliance and battery cost pressures raise the fixed-cost threshold for sustained competitiveness. At the same time, fragmentation persists in specialized niches such as cargo utility, folding urban formats, senior-focused accessibility designs, and high-performance trail categories, where targeted product architecture and community-driven branding can sustain differentiation. New entrants are most likely to succeed by focusing on underserved use cases, regional compliance advantages, or digital service ecosystems rather than attempting to compete broadly on hardware alone. Companies that combine clear segmentation, disciplined cost structures, and defensible feature sets are best positioned to navigate this environment.
Electric Bicycles Market
Strategic Trends and Outlook for 2026-2032
Several trends are likely to define the market over the next three to five years. First, connectivity and software-defined features will become increasingly central to product value propositions. As GPS tracking, app-based controls, and over-the-air updates move from differentiators to expectations, manufacturers that treat the electric bike as a platform with ongoing digital engagement will have an advantage in retention, service revenue, and fleet integration. This trend creates opportunities for brands that can build reliable software stacks, secure update pathways, and data-informed rider experiences without compromising electrical safety or user privacy.
Second, regulatory alignment and battery safety certification will increasingly shape market access and sourcing decisions. As jurisdictions tighten battery standards and harmonize technical requirements, companies with robust quality assurance processes and transparent compliance documentation will face fewer market entry frictions. The trend also opens opportunities for suppliers and assemblers that can deliver certified battery systems with traceable sourcing and consistent performance. However, the risk lies in uneven enforcement and periodic standard revisions that can disrupt product roadmaps and require rapid design adjustments.
Third, cargo and utility applications are expected to expand beyond early adopters into broader commercial and household use. Local delivery operators, municipal programs, and multi-purpose household users are likely to increase adoption as total cost of ownership advantages become more apparent and as frame, battery, and load-capacity designs improve. This trend presents opportunities for purpose-built cargo architectures, swappable battery configurations, and service networks tailored to commercial uptime requirements. The associated risk is that utility-focused models must withstand higher usage intensity, which places greater demands on component durability, warranty management, and after-sales support.
Underlying these trends are unresolved uncertainties. Commodity price swings can quickly alter margin assumptions, and tariff or trade-remedy shifts may change the cost competitiveness of imported versus regionally assembled products. Demand could also diverge by region if economic conditions affect discretionary spending or if public transport investments alter commute substitution dynamics. Manufacturers and investors should therefore treat growth as achievable but contingent on strategic choices around sourcing, compliance, segmentation, and service infrastructure.
Electric Motorcycle Market
Actionable Recommendations for Decision Makers
For manufacturers, the priority is to reinforce product architecture decisions with clear segmentation and compliance readiness. Rather than broadening portfolios indiscriminately, companies should define whether they compete on accessible value, performance credibility, or connected digital experience, and then align motor, battery, frame, and software choices accordingly. Investing in battery safety certification, traceable sourcing, and design efficiencies that reduce exposure to commodity volatility will help protect margins and ensure continuity across regulatory cycles. Manufacturers should also evaluate assembly and distribution footprints against tariff exposure and shipping efficiency, especially as trade conditions remain fluid. Building proactive after-sales and service capabilities is equally important, particularly for cargo and utility models where uptime and durability directly influence commercial adoption.
For investors, the opportunity lies in identifying players with defensible segmentation, resilient cost structures, and scalable digital or service propositions. Due diligence should extend beyond top-line growth to assess battery supply agreements, certification readiness, tariff sensitivity, and the credibility of software and connectivity roadmaps. Companies that combine clear use-case positioning with disciplined manufacturing and compliance practices are more likely to sustain margins and navigate consolidation pressures. Investors should also monitor regions where regulatory changes create temporary cost advantages or new import pathways, as these conditions can reshape competitive positioning over short to medium horizons.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet decision makers, the focus should be on total cost of ownership, safety compliance, and operational fit rather than upfront price alone. Evaluating battery certification status, warranty structures, service network coverage, and load-capacity suitability for specific urban or cargo tasks will reduce operational risk and support longer asset life. Organizations deploying electric bikes at scale should consider standardized battery and component specifications where possible, while preserving enough flexibility to match different rider profiles and route requirements. Procurement teams should also track regulatory updates in their operating jurisdictions, as changing safety and classification standards can affect model availability, replacement part compatibility, and compliance timelines.
For decision makers seeking deeper granularity on regional demand patterns, segment-level sizing, pricing dynamics, and company-specific competitive benchmarks, the full research report provides detailed quantitative breakdowns and customized strategic guidance. Accessing that level of detail can help narrow strategic options, stress-test sourcing and compliance plans, and prioritize investments in the segments most aligned with specific business objectives.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silver-based Antimicrobial Agent Market: What 6.98% CAGR Means for 2032 Growth
By PW Consulting, 2026-09-21
The Silver-Based Antimicrobial Agent Market: Navigating Growth, Regulation, and Strategic Opportunities Through 2032
The silver-based antimicrobial agent market has evolved from a niche specialty segment into a structurally significant component of the broader biocides and functional materials landscape. Between 2020 and 2025, global revenue expanded from approximately USD 153.44 million to USD 215.0 million, reflecting a compound trajectory shaped by sustained infection-control priorities, material-performance demands, and incremental substitution against conventional chemical biocides. Looking ahead to 2032, the market is projected to reach USD 344.79 million, underpinned by a forecast-period CAGR of 6.98%. This growth rate signals steady, technology-led expansion rather than speculative boom dynamics, making it a market where disciplined positioning, regulatory fluency, and application-specific differentiation will separate long-term winners from cyclical participants.
PW Consulting Health Care Research Center
Despite the positive directional signal, the sector operates at a critical inflection point. Three structural challenges are reshaping how manufacturers, formulators, and end-users approach silver-based antimicrobial solutions. First, feedstock volatility has moved from a background concern to a core planning variable. Silver prices climbed sharply through 2024 and 2025, reaching roughly $50 per ounce amid converging industrial demand pressures, which directly elevated the cost base for silver nitrate and related precursors. Second, regulatory gatekeeping is tightening across major end markets. In the United States, EPA registration requirements for silver or silver-ion applications in textiles now demand rigorous safety, efficacy, and environmental-impact documentation, adding time and compliance cost to product development cycles. Third, downstream sustainability mandates are rewriting formulation rules. China’s Recycled Plastics Standards (GB/T 45091-2024), effective from June 2025, introduced restricted-substance guidelines for antimicrobial additives in recycled polymer streams, forcing suppliers to demonstrate compatibility with circularity goals rather than simply delivering antimicrobial performance. Together, these forces are compressing the window for undifferentiated commodity offerings and elevating the value of technically validated, regulation-ready, and application-optimized products.
Technical Innovation and Carrier Architecture
The most consequential driver of market evolution is not silver itself but the carrier systems that control ion release, durability, and compatibility. Silicate-based carriers continue to anchor a large share of the market because they offer a balanced combination of sustained antimicrobial activity, thermal stability, and processing flexibility across polymers and coatings. Phosphate-based carriers occupy a complementary role where controlled reactivity and specific substrate interactions are prioritized, while titanium dioxide carrier systems are gaining relevance in applications that pair antimicrobial function with photocatalytic or surface-modification benefits. The strategic implication is clear: competitive advantage is shifting from raw silver content to engineered release kinetics, particle morphology, and formulation compatibility. Companies that can demonstrate predictable performance across extrusion, coating, or textile-finishing processes are capturing premium positioning, while those relying on generic silver inputs face margin pressure and heightened customer qualification hurdles.
Regulatory Architecture as a Market Filter
Regulation is no longer a peripheral compliance cost; it functions as a market filter that shapes entry dynamics, product architecture, and go-to-market pacing. EPA registration for silver-based applications in U.S. textiles has raised the evidentiary bar for safety, efficacy, and environmental impact, making regulatory readiness a de facto competitive requirement. At the same time, China’s updated recycled-plastics standards have intensified scrutiny on restricted substances, pushing formulators to align antimicrobial additives with broader material-circularity expectations. For market participants, this means that product pipelines must be built with regulatory trajectory in mind, not simply current technical performance. Early alignment with testing protocols, documentation standards, and regional substance restrictions reduces time-to-market risk and strengthens customer trust, particularly in applications where compliance failures can disrupt entire supply chains.
Demand-Side Shifts and Application Expansion
Demand is being reshaped by a blend of consumer behavior, institutional procurement standards, and functional-material expectations. Textiles remain a dominant application environment, where antimicrobial and odor-control performance supports hygiene-sensitive use cases, performance apparel, and institutional fabric programs. Beyond textiles, coatings and plastics are expanding the addressable surface area for silver-based antimicrobials, particularly where long-lasting protection, surface durability, and low-maintenance operation are valued. Consumer and enterprise buyers increasingly evaluate antimicrobial features not as isolated add-ons but as part of broader product reliability, sustainability, and lifecycle narratives. This shift rewards solutions that can be integrated without compromising material properties, appearance, or recyclability, and it penalizes formulations that create processing friction or end-of-life complications.
Supply-Side Dynamics and Cost Structure
On the supply side, the market is navigating the intersection of precious-metal economics and industrial chemistry. Silver nitrate export prices displayed notable volatility in mid-2025, influenced by Asian production declines and feedstock-level dynamics, reinforcing the need for procurement agility and formulation efficiency. Manufacturers are responding by optimizing carrier loadings, improving dispersion and ion-release efficiency, and diversifying source strategies where feasible. The broader implication is that cost leadership in this market is increasingly derived from process efficiency and application engineering rather than from raw-material arbitrage alone. Companies that can maintain performance while reducing effective silver intensity, or that can offer stable pricing through long-term supply arrangements and technical service support, are better positioned to retain customers through cycles of input-cost volatility.
Strategic Positioning Among Leading Players
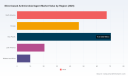
The competitive landscape remains moderately consolidated, with the top three participants holding roughly 24.6% of market revenue and the top five reaching approximately 26.2%. This concentration suggests a market where scale, application breadth, and technical service networks matter, but where meaningful space still exists for specialized players with strong formulation expertise or regional execution capabilities. Leading participants are differentiating along several axes. Some emphasize inorganic silver carrier technologies purpose-built for water treatment, polymers, and resins, positioning around durability and controlled release. Others focus on silver-based additives for textiles, plastics, and coatings, integrating antimicrobial functionality into broader material portfolios. A further group targets disinfectant and hygiene applications through silver-based chemistries such as silver dihydrogen citrate, highlighting food-hygiene and surface-sanitation use cases. There is also notable activity around glass-carrier and inorganic silver systems, where the emphasis is on stability and compatibility in demanding material environments. Rather than competing solely on price, the more defensible strategies combine application-specific validation, regulatory documentation, and technical support that lowers integration risk for customers.
Antimicrobial Peptides Market
M&A, Portfolio Shaping, and New-Entry Dynamics
Recent corporate activity signals an ongoing reshaping of portfolios around silver-based antimicrobial capabilities. BASF’s completion of the Aseptrol biocide business transaction with Oxidium Technologies LLC, including silver-based antimicrobial solutions, illustrates how large chemical and biocides players are consolidating functional-material assets to strengthen application coverage and technology breadth. At the same time, PURE Bioscience’s brand repositioning around its silver dihydrogen citrate technology for food hygiene reflects a strategic attempt to sharpen market identity and align product messaging with specific end-use priorities. These moves point to a broader pattern: incumbents are tightening their focus around differentiated technology platforms, while the entry of new players is likely to occur through targeted application niches, regional distribution partnerships, or specialized carrier chemistry rather than through broad commodity competition. The practical consequence is an environment where customer qualification, regulatory readiness, and proven integration performance increasingly determine market access.
Forecast Trends and Commercial Implications
Over the next three to five years, three interlocking trends are likely to define how value is created in this market. First, application engineering will become the primary battleground. As carrier technologies mature, differentiation will depend on how well antimicrobial performance is maintained across specific processing conditions, substrates, and end-use environments. Companies that invest in application-level validation and offer formulation guidance will capture more resilient demand than those selling generic functional ingredients. Second, regulatory and sustainability integration will move from a compliance exercise to a product-design input. Documentation readiness, restricted-substance alignment, and compatibility with recycled or circularity-driven material flows will influence purchasing decisions, especially among multinational buyers and regulated-industry customers. Third, input-cost volatility will continue to reward efficiency and service depth. Pricing pressure from silver feedstock fluctuations will likely persist, but customers will increasingly prefer partners who can stabilize total cost of ownership through technical optimization, predictable supply, and quality assurance rather than chasing the lowest nominal price point.
These trends translate into tangible commercial opportunities. There is room for growth in high-value application segments where antimicrobial durability and regulatory confidence carry premium value, especially in hygiene-sensitive textiles, performance coatings, and specialized polymer applications. There is also opportunity for suppliers that can provide regionally compliant documentation packages and application-specific testing support, reducing the burden on formulators and procurement teams. At the same time, uncertainty remains. Silver price trajectories, regulatory tightening in key markets, and evolving standards for recycled-content materials could alter relative competitiveness across carrier types and end-use segments. Participants should therefore avoid overcommitting to a single application or carrier architecture without scenario planning for regulatory shifts and feedstock volatility.
Strategic Actions for Manufacturers
For manufacturers and formulators, the priority is to treat silver-based antimicrobial ingredients as engineered system components rather than commoditized additives. That means validating performance under actual processing conditions, building regulatory documentation early, and aligning product design with downstream sustainability requirements. Where possible, optimize carrier loading and ion-release efficiency to protect performance while managing silver intensity. Strengthening technical-service capabilities can also create a durable moat, because customers increasingly value partners who reduce integration risk and accelerate qualification cycles.
Worldwide Smart Antimicrobial Surface Market
Strategic Actions for Investors
For investors, the market offers attractive structural growth, but returns will likely accrue to platforms with defensible application breadth, regulatory readiness, and disciplined feedstock management. Due diligence should focus on the quality of carrier technology, the strength of application validation, and the ability to navigate regional compliance requirements. Visibility into customer concentration, product qualification pipelines, and exposure to silver-input volatility is essential when evaluating long-term resilience. Companies that can demonstrate recurring demand from regulated or hygiene-critical applications are better positioned than those reliant on discretionary or price-sensitive volume.
Strategic Actions for Procurement and Sourcing Leaders
For procurement and sourcing leaders, the strategic task is to balance cost, compliance, and performance stability. Multi-source planning, clear specification of required antimicrobial performance and regulatory documentation, and evaluation of supplier technical support can reduce exposure to both price volatility and compliance disruption. Where applications are regulated or publicly visible, prioritizing suppliers with established registration footprints and robust testing packages can lower downstream risk. In parallel, procurement teams should monitor changing restricted-substance and recycled-material standards to avoid specification mismatches that could affect product acceptability.
The silver-based antimicrobial agent market is entering a phase where informed, application-aware decision-making matters more than ever. Growth is supported by durable demand in hygiene-sensitive and performance-driven applications, but the payoff will go to participants who can integrate technical, regulatory, and supply-side realities into coherent commercial strategies. For executives and planners seeking detailed segmentation data, regional and application-level revenue splits, competitive benchmarking, and scenario-based forecasts, a full research report can provide the granularity needed to translate these market dynamics into specific sourcing, investment, and product-development decisions.
For detailed analysis of this topic, please visit the official page: Silver-based Antimicrobial Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicon Monoxide Market: Why 15.1% CAGR Reshapes Automotive & Electronics Demand
By PW Consulting, 2026-09-21
Silicon Monoxide Market: Strategic Trends and Commercial Opportunities (2025–2032)
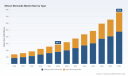
The silicon monoxide market has entered a phase of accelerated expansion, driven by converging demands across advanced electronics, energy storage, and industrial coatings. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenues climbing from approximately $141 million to $285 million. This trajectory is projected to continue through the forecast period ending in 2032, with an estimated compound annual growth rate of 15.1 percent. By the close of the decade, the market is expected to surpass $760 million, reflecting a structural shift rather than a cyclical upswing. The growth is not uniform across all verticals or geographies; it is concentrated in application areas where material purity, thermal stability, and barrier properties are becoming critical differentiators.
For executives and investors tracking specialty materials, this market presents a compelling case study in how a relatively niche inorganic compound is transitioning into a strategic enabler for multiple high-growth industries. The challenge lies in navigating a fragmented supply base, evolving regulatory frameworks, and rapidly changing end-user specifications. Understanding where value is being created—and where vulnerabilities are emerging—requires moving beyond headline figures to examine the underlying technological, policy, and supply chain dynamics.
Market Status and Core Challenges
The current market structure reflects a balance between established industrial uses and emerging high-performance applications. Gaseous and solid forms of silicon monoxide serve distinct processing requirements, with each format catering to specific deposition, coating, or synthesis workflows. The revenue split between these formats underscores a mature but still evolving production ecosystem, where manufacturers are increasingly pressured to deliver consistent purity levels while scaling output. Similarly, demand is distributed across automotive and transportation, consumer electronics, energy and power systems, and a range of secondary applications. This distribution signals that no single industry dominates the growth narrative; instead, multiple sectors are pulling the market forward, each with its own technical thresholds and procurement cycles.
Geographically, the market exhibits a multi-polar character. North America, Europe, and Asia Pacific each command significant shares, while Latin America and the Middle East and Africa represent smaller but gradually expanding footholds. This geographic spread is not merely a reflection of historical manufacturing capacity; it is increasingly shaped by localized supply chain strategies, trade flows, and regional industrial policies. The presence of verified exporters across multiple continents, alongside targeted trade activity in emerging markets, indicates that silicon monoxide is moving through a globalization phase where sourcing flexibility and regulatory compliance are becoming as important as price competitiveness.
Several structural challenges complicate this growth trajectory.
- Purity and consistency requirements are intensifying. As silicon monoxide finds its way into battery anodes, thin-film deposition, and high-barrier packaging, end users are demanding tighter control over impurities and particle morphology. Inconsistent feedstock quality or variable reaction conditions can disrupt downstream performance, making quality assurance a competitive moat rather than a baseline expectation.
- Regulatory and trade compliance is fragmenting. Classification under inorganic compound duty frameworks, coupled with shifting export documentation requirements and country-specific trade data reporting, adds layers of complexity for cross-border procurement. Companies that treat compliance as an afterthought face delays, cost overruns, and potential supply interruptions.
- Supply chain concentration risks are emerging. While the market remains relatively fragmented at the top, with the top three and top five players holding modest combined shares, the underlying production ecosystem depends on high-temperature reaction processes and reliable silicon feedstock. Any disruption in upstream material availability or energy-intensive manufacturing capacity can create bottlenecks that ripple through multiple application sectors.
For decision makers, these challenges are not merely operational headaches; they are strategic inflection points. Companies that proactively address purity standardization, trade compliance, and feedstock resilience will be better positioned to capture premium segments, while those that compete primarily on price risk margin compression as customer expectations rise.
Key Demand Drivers Analysis
Technological Innovation and Material Breakthroughs
The most powerful accelerator for silicon monoxide demand is the ongoing push toward higher-performance materials in energy storage and electronic fabrication. In lithium-ion battery development, silicon-based anodes are attracting sustained attention for their potential to increase energy density compared with conventional graphite formulations. Silicon monoxide plays a role in this ecosystem both as a precursor and as a functional component in coating and synthesis workflows. Manufacturers that can deliver high-purity forms tailored to anode development are aligning themselves with a long-term technological shift rather than a short-term procurement trend.
At the same time, vacuum deposition and sputtering applications continue to rely on silicon monoxide evaporation sources and related deposition materials. As thin-film processing becomes more precise in semiconductor-adjacent and industrial coating environments, the need for stable evaporation behavior, predictable particle size, and reproducible deposition rates is increasing. This is driving suppliers to refine product forms—pieces, powders, and customized evaporation sources—so that downstream users can reduce process variability and improve yield.
Policy and Regulatory Environment
Regulatory conditions are shaping market access and cost structures in subtle but meaningful ways. In key markets such as the United States, silicon monoxide is classified under inorganic compound duty frameworks that generally allow duty-free treatment, lowering the tariff barrier for cross-border trade. While this may appear to be a minor detail, it has practical implications for sourcing strategies, especially for manufacturers that operate across multiple jurisdictions or assemble final products from globally sourced components.
Beyond tariffs, export documentation and trade transparency are becoming more prominent. Verified export activity across multiple shippers and destinations over recent periods indicates that the trade network is active but still relatively dispersed. For companies engaged in import/export operations, the ability to navigate shipment verification, country-of-origin documentation, and destination-specific requirements is increasingly a differentiator. Regulatory clarity can reduce lead times and working capital friction, while ambiguity can create hidden costs that erode competitiveness.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user behavior is changing on two fronts. In consumer electronics, the drive toward smaller, more durable, and better-protected devices is reinforcing interest in barrier materials and thin-film coatings where silicon monoxide can contribute. In industrial and energy sectors, procurement teams are increasingly evaluating materials not just on specification sheets but on total cost of ownership, including process stability, waste reduction, and integration ease. This shift is pushing suppliers to offer more than raw material; it is encouraging value-added formats, technical support, and application-specific packaging.
The automotive and transportation segment reflects a broader transition toward electrification and lightweighting, where material performance and supply reliability matter more than ever. As vehicle manufacturers and their tier suppliers reassess component sourcing in response to electrification roadmaps and regional content requirements, silicon monoxide’s role in battery-related workflows and specialized coatings positions it as a material worth monitoring in procurement strategies.
Supply Chain and Cost Structure Evolution
The production of silicon monoxide typically involves high-temperature reactions between silicon and silicon dioxide, or carbon-based reduction of silicon dioxide, with high-purity silicon feedstock underpinning consistent quality. This process architecture means that energy costs, feedstock availability, and reaction control are central to margin dynamics. As energy markets fluctuate and industrial energy efficiency becomes a broader corporate priority, producers that can optimize thermal processes, reduce waste, and maintain tight purity control will gain an advantage.
At the same time, the supply base is expanding in certain regions, with manufacturers offering silicon monoxide pieces, powders, and chemical-grade products for coating and inorganic chemical portfolios. This diversification increases buyer options but also raises the importance of qualification and vendor evaluation. Buyers that build rigorous technical assessment processes can secure better terms and more reliable supply, while those that rely on spot purchasing without technical due diligence may encounter inconsistent performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized producers, broad-line material suppliers, and regional manufacturers targeting distinct application niches. Rather than competing as a single undifferentiated market, participants are carving out positions based on purity ranges, product forms, application alignment, and geographic reach.
Several companies illustrate the strategic diversity currently shaping the market.
- Osaka Titanium Technologies Co., Ltd. has positioned itself around high-purity silicon monoxide for food packaging barrier applications and lithium-ion battery anode development. This dual focus reflects a strategy of linking material quality to high-value downstream uses, where purity and consistency directly influence customer outcomes.
- RD Mathis Company concentrates on evaporation sources, pieces, and deposition materials for vacuum technology. Its approach emphasizes process enablement, supplying the forms and configurations that deposition users need to reduce setup complexity and improve reproducibility.
- American Elements offers silicon monoxide in multiple purities and forms for research, sputtering targets, and industrial applications. This breadth-based model appeals to customers who require flexibility across R&D and production environments, and who value a supplier capable of supporting varied procurement scenarios.
- Stanford Advanced Materials (SAM) leverages manufacturing experience to supply high-quality silicon monoxide for electronic and industrial uses. Its long-standing production background supports a reliability narrative that resonates with buyers seeking stable supply and predictable specifications.
- Unilong Industry Co., Ltd. focuses on pieces and powder for coating and material applications, targeting customers that need practical forms for surface engineering and coating workflows.
- Hebei Yanxi Chemical Co., Ltd. and Hefei TNJ Chemical Industry Co., Ltd. operate within the inorganic chemical space, supplying silicon monoxide as part of broader chemical portfolios. Their presence highlights how the material is integrated into wider chemical supply chains, where procurement efficiency and portfolio breadth can be as important as isolated product specs.
The strategic positioning of these players reveals several differentiation levers. Some compete on purity and application alignment, others on product form and process support, and still others on portfolio breadth and regional availability. What is notable is that none of these approaches is inherently superior; rather, their effectiveness depends on the customer’s technical requirements, procurement model, and risk tolerance.
Market evolution is likely to follow a path of partial consolidation alongside continued specialization. On one hand, buyers increasingly prefer suppliers that can demonstrate consistent quality, regulatory familiarity, and application expertise, which may favor larger or more integrated players over time. On the other hand, the diversity of end uses—from packaging barriers to battery development to vacuum deposition—creates room for specialized manufacturers that can serve narrow but high-value segments. New entrants may find opportunities by focusing on underserved application niches, offering custom particle or form factors, or building stronger technical service capabilities around deposition and coating processes.
For competitive strategy, the key question is not simply who has the largest footprint, but who can reduce uncertainty for the buyer. Suppliers that combine reliable purity, clear trade documentation support, and application-relevant product forms are better positioned to command preference in procurement decisions, especially as customers move from spot buying toward longer-term supply relationships.
Future Trends Forecast
Looking ahead three to five years, several trends are likely to shape the market’s direction and create actionable opportunities.
Carbon Monoxide Market
1. Higher-purity, application-tailored forms will become the norm in premium segments. As silicon monoxide is integrated into more performance-sensitive workflows, buyers will increasingly differentiate between commodity-grade supply and specification-driven material. This will reward suppliers that invest in controlled reaction conditions, consistent particle morphology, and transparent quality documentation. The commercial opportunity lies in shifting from price-based competition to value-based positioning, where reliability and specification alignment justify premium margins.
2. Battery-related and energy storage workflows will continue to be a strategic growth vector. The broader interest in silicon-based anode development and energy density improvements is not a short-lived trend; it reflects a structural interest in next-generation storage materials. Silicon monoxide’s role in these workflows may evolve as formulations and processing methods mature, but the directional signal is clear: materials that support battery performance and manufacturing consistency will remain in focus. Companies that build application expertise and supply readiness for this vector can capture a growing share of demand, provided they can navigate technical qualification cycles and scale requirements.
3. Trade transparency and regional sourcing strategies will intensify. With active export flows across multiple shippers and destination markets, procurement teams are likely to place greater emphasis on supply visibility, documentation reliability, and regional resilience. This trend creates opportunities for suppliers that can offer predictable lead times, clear compliance support, and flexible sourcing arrangements. At the same time, it introduces risk for companies that rely on opaque supply chains or assume that duty-free classification automatically translates into frictionless trade. Regulatory interpretation, documentation quality, and destination-specific requirements will continue to matter.
PW Consulting
These trends carry inherent uncertainties. Technological adoption in battery anodes may proceed at different speeds across vehicle platforms and cell manufacturers. Energy costs and feedstock availability could affect production economics, particularly for energy-intensive synthesis routes. Trade documentation and compliance expectations may become more stringent in certain jurisdictions, adding cost and administration even where tariffs remain favorable. Decision makers should therefore treat growth opportunities as conditional on operational readiness, not as automatic outcomes of market expansion.
Actionable Guidance for Decision Makers
The market’s direction offers different implications depending on a company’s role in the value chain. The following recommendations are designed to translate market dynamics into practical next steps.
For Manufacturers and Material Suppliers
Focus on specifying and communicating purity, form consistency, and application fit rather than competing solely on unit price. Customers in deposition, coating, and battery-related workflows are increasingly weighing total process performance, so suppliers that provide clear technical documentation, reproducible product forms, and responsive support can differentiate more effectively. At the same time, review production economics with energy efficiency and feedstock reliability in mind, since these factors will influence margin stability as demand scales.
For Investors and Strategic Planners
Evaluate exposure to silicon monoxide not as a single market bet but as a cross-cutting enabler across electronics, energy storage, and industrial coatings. The most resilient opportunities are likely to be tied to suppliers or downstream users that can demonstrate application-specific value, reliable compliance handling, and the ability to serve multiple verticals without diluting quality. When assessing potential investments or partnerships, pay attention to qualification readiness, supply chain transparency, and the company’s ability to navigate trade documentation and regional sourcing requirements.
Silicon 28 Market
For Procurement and Sourcing Leaders
Strengthen technical qualification processes before committing to volume supply. Given the variability in product forms and purity ranges across the supply base, spot purchasing without specification alignment can create downstream variability and hidden costs. Build a shortlist based on documented purity consistency, form suitability for the intended process, and trade compliance reliability. Where possible, favor suppliers that can support predictable documentation and lead times, as these attributes reduce operational friction in multi-source or multi-region procurement strategies.
For organizations that need deeper segmentation, region-specific trade dynamics, and customized scenario planning, a more detailed research view can help translate these strategic signals into precise procurement, investment, and production decisions. A comprehensive report is available for teams that require granular data, application-level breakdowns, and tailored recommendations aligned with specific operational objectives.
For detailed analysis of this topic, please visit the official page: Silicon Monoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
WiFi Modules Market: Why 9.2% CAGR and Asia Pacific's 186.9M Lead Redefine Growth Beyond 2032
By PW Consulting, 2026-09-21
Navigating the WiFi Modules Market: Strategic Trends and Commercial Opportunities Through 2032
The WiFi modules market has evolved from a component-level consideration into a strategic enabler of connectivity across consumer, industrial, and infrastructure applications. Measured in USD across a forecast horizon extending to 2032, the market has demonstrated consistent expansion, with 2025 establishing a baseline around the mid-hundreds of millions and projected revenue climbing steadily toward the high hundreds by the end of the decade. This trajectory reflects more than incremental device proliferation; it signals a structural shift in how products are architected, certified, and deployed. For executives and investors evaluating connectivity roadmaps, the question is no longer whether WiFi modules matter, but how to align product portfolios, supply chains, and partnership strategies with a market that is maturing in capability while fragmenting in application requirements.
The growth profile over the analysis window points to a compound annual rate in the low-to-mid single digits, with revenue curves that accelerate as newer standards penetrate volume markets and legacy designs are refreshed. This pattern suggests a market that is not simply adding units, but progressively shifting toward higher-value configurations that bundle security, software stacks, and pre-certification support. At the same time, the competitive field remains moderately consolidated at the top tier, while the broader supplier base continues to expand through specialized players and regional champions. The result is a landscape where scale, certification readiness, and application-specific engineering increasingly determine who captures durable share.
Current Market Dynamics and Core Challenges
The current phase of the WiFi modules market is defined by three intersecting pressures that are reshaping sourcing decisions and product roadmaps. First, regulatory and trade dynamics are injecting cost and availability uncertainty into the component supply base. Tariff measures targeting advanced semiconductors and critical minerals have raised input costs and complicated procurement planning, while export controls on advanced semiconductors and high-bandwidth memory have extended to additional entities, altering the availability of certain chipset categories. These moves are not abstract policy signals; they directly affect lead times, bill-of-materials stability, and the feasibility of multi-source strategies for designs that depend on specific silicon families.
Second, the raw material and components environment has become more volatile at a time when demand for compute-intensive workloads is pulling memory and analog content in competing directions. Component pricing has experienced upward pressure in recent cycles, with lead times for analog ICs and microcontrollers lengthening meaningfully and memory products reaching multi-year highs. For module designers, this translates into tighter margin control, more frequent redesign risk, and a stronger incentive to lock in qualified alternatives before design freezes.
Third, critical mineral controls are reshaping the upstream economics of semiconductor fabrication used in connectivity products. Licensing requirements on gallium and germanium have introduced new constraints on materials that feed into chip production, reinforcing the importance of supplier diversification and regional sourcing strategies. These pressures are not uniform across all applications, but they raise the strategic cost of single-source dependency and reward companies that build redundancy into their qualification pipelines.
Key Growth Drivers Reshaping the Market
Underlying these challenges, several forces are propelling sustained expansion and redirecting value toward higher-performance, lower-power, and more application-tailored solutions.
Technology innovation and standards evolution. The migration toward newer WiFi generations is reshaping module design around throughput, latency, power efficiency, and coexistence with Bluetooth and other radios. Module suppliers are increasingly bundling SoCs, antennas, and firmware to deliver pre-certified platforms that reduce time-to-market for OEMs. Recent product announcements illustrate this direction: new module series built on advanced IoT SoCs target lower-power applications, while WiFi 7-oriented modules are being positioned for AI-capable PCs, embedded systems, and automotive/industrial environments. At the same time, long-range and low-power variants continue to broaden the addressable set of deployments, especially where battery life and range outweigh peak throughput as primary selection criteria.
PW Consulting Information & Electronics Research Center
Regulatory and certification dynamics. Certification remains a decisive gate for commercial adoption, particularly in regulated verticals and consumer markets where interoperability and security expectations are high. Securing alliance certification for specific module families has become a meaningful commercial milestone because it reduces OEM integration risk and accelerates launch cycles. The strategic implication is that module suppliers that can reliably deliver certified, documented, and supported platforms gain a structural advantage over component-only offerings, especially for customers that lack in-house RF compliance resources.
Demand-side shifts in industrial, smart, and edge applications. Demand is being pulled by expanding deployments in smart environments, industrial automation, and edge-connected devices, where WiFi is increasingly paired with local processing and sensor integration. Consumer electronics continue to anchor volume, but the growth narrative increasingly includes use cases that require robustness, longer lifecycle support, and environmental resilience. This shift is changing procurement priorities: buyers are weighing not only unit price but also temperature ranges, firmware update pathways, lifecycle availability, and the supplier's ability to support certification updates over product lifespans.
Supplychain and cost structure reconfiguration. Cost structures are being re-evaluated in light of component lead-time variability and the increasing value of integration. Modules that consolidate radios, processing, and support services can reduce total integration effort and de-risk compliance, which is especially attractive when internal engineering bandwidth is constrained. For suppliers, the cost equation now favors designs that balance performance with material availability and that offer predictable lifecycle planning, since customers are less willing to accept abrupt obsolescence or unmanaged pin-to-pin replacements.
Competitive Landscape and Leading Strategies
The competitive field combines well-established semiconductor and module specialists with regional players that compete on integration ease, certification readiness, and vertical-specific support. Several patterns define the current landscape and point to where differentiation is being earned.
Embedded Wi Fi Modules Market
Differentiation through pre-certified platforms and ecosystem alignment. Companies that focus on pre-certified WiFi and Bluetooth modules are building advantage by shortening integration cycles and lowering compliance risk for customers. Recent certification milestones and new module series based on leading IoT SoCs demonstrate a strategy centered on pairing proven silicon with turnkey module design, firmware, and documentation. Participation in major industry events further signals a push toward edge AI and IoT use cases, where the value proposition extends beyond connectivity to include ease of integration and application support.
Verticalization and industrial-grade positioning. A parallel strategy emphasizes ruggedized, industrial-grade modules and combo offerings that address harsher environments, longer support horizons, and specialized regulatory requirements. Suppliers in this tier are expanding portfolios to cover WiFi, long-range variants, and cellular-WiFi combos, broadening the set of deployments they can serve. The commercial logic is clear: industrial, medical, and infrastructure customers often prioritize availability, support, and environmental specs over absolute lowest unit cost, which creates room for premium positioning when product reliability is demonstrable.
Silicon-and-module coupling and reference designs. SoC providers that supply reference modules and partner ecosystems are reinforcing their position by enabling faster certification and more predictable performance. This model benefits customers that want consistent behavior across batches and suppliers that can scale volume without reinventing integration for each design. Where SoC vendors and module builders align closely, the market sees faster proliferation of certified designs and tighter control over RF performance and software quality.
Consolidation pressure and new-entry opportunities. The market exhibits moderate concentration at the top, which suggests that scale, portfolio breadth, and certification pipelines increasingly matter. At the same time, fragmentation persists in niche segments, creating openings for specialists that can deliver targeted solutions with strong documentation and lifecycle support. New entrants and regional champions can compete not by matching the broadest portfolios, but by solving specific integration, compliance, or environmental challenges better than generalist suppliers. Over time, the likely evolution is a mix of consolidation among scale players and continued specialization among application-focused vendors, with partnership and acquisition activity linking silicon, module, and vertical expertise.
Forward Outlook: Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to shape where value accumulates and how participants should position themselves.
Shift toward integrated, certified platforms as the default procurement model. As integration complexity and compliance expectations rise, more buyers are expected to favor pre-certified modules and supported platforms over discrete component assemblies. This trend creates opportunities for suppliers that can offer reliable certification, clear documentation, and predictable lifecycle management, while increasing pressure on vendors that rely primarily on price competition without robust support. The commercial upside lies in becoming a trusted integration partner rather than a commodity source, especially in segments where time-to-market and regulatory risk dominate purchasing decisions.
WiFi Home Router Market
Performance-tier segmentation will deepen. The market is moving toward clearer segmentation between high-throughput, low-latency designs for AI-capable compute and premium consumer devices, and low-power, cost-sensitive designs for IoT and battery-operated deployments. This divergence rewards suppliers that can tailor architectures to distinct workloads and environments rather than offering one-size-fits-all products. Opportunity exists in bridging these tiers with modular architectures that allow customers to scale features while maintaining compatibility, and in providing clear migration paths as standards and silicon evolve.
Resilience and multi-source strategies will become procurement priorities. Ongoing trade measures, export controls, and component price volatility are likely to keep supply resilience on the agenda for enterprise and industrial buyers. Companies that can demonstrate qualified alternatives, transparent lead-time communication, and regional sourcing options will be better positioned to retain and expand accounts during periods of disruption. The associated risk is that over-reliance on a narrow set of silicon families or single-region suppliers may expose product lines to sudden redesign costs or launch delays, particularly if controls or material constraints tighten further.
Long-range and specialized connectivity will expand addressable deployments. As deployments extend into smarter infrastructure, industrial monitoring, and longer-range sensing, variants that balance range, power, and cost will find expanding use cases beyond traditional indoor networking. This creates room for suppliers that can pair appropriate radio characteristics with robust mechanical and environmental packaging, along with support for vertical-specific certification and lifecycle needs. The key uncertainty is how quickly standards, spectrum conditions, and ecosystem support converge to make these variants mainstream in volume applications.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat module selection as a platform decision rather than a component transaction. That means evaluating suppliers not only on unit economics, but also on certification status, documentation quality, firmware support, environmental specifications, and lifecycle commitments. Building qualified alternatives into designs early can reduce redesign risk if lead times or controls shift, and partnering with suppliers that provide pre-certified platforms can compress integration timelines while lowering compliance exposure. Where products target industrial, medical, or infrastructure markets, investing in ruggedized requirements and long-term availability planning is likely to pay dividends in customer trust and repeat business.
For investors, the attractive signals are found in suppliers that combine certification readiness with clear vertical focus and disciplined lifecycle management. Companies that can demonstrate recurring value through integration support, application-specific engineering, and reliable supply communication are better positioned to defend margins than those competing solely on price in commoditizing segments. At the same time, it is worth monitoring exposure to regulatory and material constraints, since concentrated dependency on specific silicon or materials can amplify downside if trade or licensing conditions evolve unfavorably. Portfolio breadth, ecosystem partnerships, and evidence of repeat design wins in demanding verticals are useful indicators of durable positioning.
For procurement and sourcing leaders, resilience should be built into the sourcing model through multi-source qualification, clear escalation paths for lead-time changes, and contractual clarity around lifecycle and obsolescence. Where possible, prioritize suppliers that provide transparent roadmaps, predictable certification updates, and documented alternatives for critical designs. Balancing performance requirements with supply reality is especially important in periods when memory, analog, and MCU availability are under pressure, since over-optimizing for a single optimal component can create hidden risk if conditions shift. In practice, the strongest sourcing strategies combine technical fit with redundancy, support quality, and a clear view of how trade and material dynamics may affect future revision cycles.
For organizations that need granular segmentation, customer-level demand signals, and tailored scenario planning across regions, applications, and module types, deeper market data can materially sharpen planning and reduce guesswork in portfolio and sourcing decisions. Detailed breakdowns of revenue by region, type, and application, along with company-level positioning and recent development tracking, provide the resolution needed to prioritize investments, qualify suppliers, and time product refreshes with greater confidence. For teams evaluating next-step connectivity strategies, a more detailed research report can serve as a practical reference for aligning product roadmaps, sourcing plans, and investment theses with where the market is heading through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: WiFi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fire Pump Market to Hit $665M by 2032: Why 4.96% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
Global Fire Pump Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
The fire pump sector has evolved from a commoditized infrastructure component into a strategically differentiated business segment where reliability, regulatory compliance, and technical integration define market positioning. Over the historical review window from 2020 through 2025, global market revenue expanded from approximately 375 million USD to 482 million USD, reflecting a compound annual growth rate of 4.96 percent. Forward projections through 2032 indicate continued expansion toward roughly 665 million USD, driven by sustained capital formation in commercial real estate, industrial facilities, and offshore energy infrastructure. The trajectory is not uniform. Growth phases are shaped by regulatory cycles, regional construction activity, raw material volatility, and the pace at which manufacturers integrate monitoring capabilities, hydraulic efficiency, and application-specific engineering into product portfolios.
The market structure remains moderately concentrated. Three leading players collectively account for approximately 45 percent of total revenue, while the top five capture around 55 percent. This concentration level indicates a sector where established manufacturers hold meaningful share through product breadth, certification expertise, and long-term service relationships, yet it also leaves meaningful room for regional specialists, project-driven integrators, and technology-enabled entrants to capture niche positions. For executive teams evaluating exposure to fire protection equipment, the landscape presents a blend of stable baseline demand, cyclical project volatility, and clear differentiation opportunities for firms that can align product development with compliance evolution and end-user operational expectations.
Core Macro Dynamics and Structural Shifts
The revenue curve over the 2020 to 2025 period demonstrates steady expansion rather than explosive growth, which is typical of essential safety equipment markets where demand is anchored to building codes, industrial capacity additions, and asset life-cycle replacement programs. The moderation in growth velocity after the early post-2020 recovery reflects a normalization phase in which supply chains adjusted to elevated input costs, lead-time variability, and workforce constraints in fabrication and testing operations. As the market moves through the 2026 to 2032 forecast horizon, growth is expected to be sustained by ongoing urban development, industrial modernization, and energy sector projects that require integrated pump skids and high-pressure fire protection systems.
Three structural challenges define the current inflection point. First, raw material cost variability, particularly in steel-intensive pump housings, casings, and skid assemblies, introduces margin pressure and pricing complexity. Recent market data indicates that US steel prices averaged approximately 1,086 USD per metric ton in May 2026, up 3.5 percent from April, with hot-rolled coil near 1,109 USD per ton in June 2026. For manufacturers, this environment demands disciplined cost management, hedging strategies, and product engineering that reduces material intensity without compromising hydraulic performance or code compliance.
Second, regulatory frameworks continue to shape procurement cycles and product qualification requirements. The NFPA 20 Standard for the Installation of Stationary Pumps for Fire Protection remains the foundational reference for selection and installation as of 2026, while ASSE 15010 water-based fire protection certification qualifications and processes are undergoing changes beginning in early 2025 for inspection and testing of fire pumps. For suppliers and specifiers, evolving certification expectations create both administrative burden and competitive advantage for organizations that can streamline compliance, documentation, and field verification.
Third, the market faces an ongoing tension between standardization and customization. End-users in commercial building sectors increasingly favor packaged pump systems and compact configurations that simplify installation and maintenance, while oil and gas, marine, and large industrial facilities require engineered solutions that address site-specific pressure, flow, and environmental conditions. Balancing these demands requires manufacturing flexibility, modular design philosophies, and service teams capable of supporting both off-the-shelf and project-engineered deployments.
Key Drivers Shaping Market Trajectory
Technology Innovation and Monitoring Integration
A defining trend in the fire pump sector is the transition from purely mechanical reliability to connected, condition-aware systems. Historically, fire pumps were evaluated primarily on flow capability, pressure performance, and durability under intermittent duty cycles. Today, manufacturers are embedding telemetry, remote status monitoring, and diagnostic interfaces that enable facility operators and service contractors to track run-hours, alarm states, and performance deviations without manual inspection alone. This shift aligns with broader operational expectations in commercial real estate and industrial facilities, where uptime assurance, predictive maintenance, and rapid response capability are increasingly tied to asset management strategies.
Product launches in recent months illustrate this direction. In January 2026, Armstrong Fluid Technology introduced a new range of Constant Speed Vertical-In-Line Fire Pumps with high-pressure ratings up to 160 PSI for both 60Hz and 50Hz markets. The expansion into higher-pressure vertical in-line configurations reflects demand for compact, high-performance solutions suitable for taller buildings, space-constrained mechanical rooms, and applications where vertical footprint limitations constrain traditional horizontal installations. Vertical in-line designs also appeal to specifiers seeking reduced installation complexity and simplified alignment, provided the hydraulic and reliability requirements are met for the intended duty point.
Regulatory Environment and Certification Evolution
Regulation is not merely a constraint in this market; it is a design parameter and a commercial gate. NFPA 20 continues to define the baseline expectations for stationary fire pump selection and installation, creating a shared technical language across manufacturers, engineering firms, authorities having jurisdiction, and service providers. At the same time, evolving certification processes such as the ASSE 15010 updates introduce new scrutiny around inspection and testing practices. For manufacturers, the practical implication is that product approval, documentation rigor, and test protocol alignment are becoming differentiators in bidding and specification capture. Firms that invest early in certification readiness and clear compliance narratives tend to reduce deployment friction and improve win rates in regulated markets.
For purchasers and engineering teams, regulatory dynamism creates the need for supplier partners who can interpret standards consistently across regions and project types. In practice, this means that product capability alone is insufficient unless accompanied by repeatable installation guidance, commissioning support, and post-installation testing documentation that satisfies jurisdictional requirements. The regulatory layer therefore reinforces the value of established brands and technically credible service networks, while also opening opportunities for manufacturers that can simplify compliance through integrated documentation packages and standardized test evidence.
Demand-Side Changes in Commercial and Industrial Sectors
Demand patterns are shaped by the interplay of construction pipelines, facility modernization programs, and risk management priorities. Commercial buildings remain a dominant application area, with fire pump demand linked to new development, code-driven renovations, and replacement cycles in aging mechanical systems. Industrial facilities represent the second major demand pillar, where fire protection requirements intersect with process safety, hazardous area considerations, and large-scale infrastructure planning. In both segments, purchasers are increasingly focused on lifecycle economics rather than lowest initial equipment cost, which advantages solutions that combine reliability, serviceability, and remote monitoring capabilities.
Water Pumps Market
In parallel, energy sector activity continues to influence demand for engineered fire pump skids and high-pressure systems. Contract awards such as Sulzer’s November 2025 win for multiple integrated pump skids for Petrobras P-84 and P-85 FPSOs, with delivery in early 2026, underscore how offshore and large industrial projects generate specialized demand for integrated packages rather than standalone pump units. These projects reward suppliers with skid integration expertise, application engineering depth, and the ability to deliver systems that meet both fire protection and broader process interface requirements.
Supply Chain Resilience and Cost Structure Adaptation
The sector’s cost structure is sensitive to steel pricing, casting lead times, machining capacity, and the availability of qualified assembly and test labor. Companies that have strengthened supply chain resilience through multi-sourcing, forward inventory positioning, and modular subassembly strategies are better positioned to maintain delivery reliability during input price spikes. Equally important is product design discipline: pumps and skid systems that optimize material usage, standardize components across product lines, and reduce rework in fabrication can absorb input cost pressure more effectively than less standardized designs.
From a commercial standpoint, this environment favors manufacturers that can offer transparent pricing mechanisms, delivery certainty, and configuration flexibility. Procurement teams are increasingly weighing supplier reliability and compliance readiness against unit price, particularly for projects where delay costs and inspection risks are significant. This dynamic reinforces the strategic value of regional manufacturing footprints, localized service capabilities, and strong relationships with distributors and installation contractors.
Competitive Landscape and Strategic Positioning
Differentiation Vectors Among Leading Players
The market’s leading participants compete across several overlapping dimensions: product range breadth, application-specific engineering, certification depth, service networks, and increasingly, digital monitoring and integration. Pentair manufactures Aurora and Fairbanks Nijhuis fire pumps in horizontal and vertical configurations for global fire protection systems, positioning itself around established brand lines and a broad configuration portfolio. Grundfos produces fire pumps within a wider pump portfolio, leveraging its broader hydraulic competence and distribution relationships. NAFFCO offers fire protection pumps and related equipment for commercial and industrial use, often competing on regional responsiveness and bundled system solutions in Middle East and broader project markets.
Flowserve supplies industrial pumps including fire pump solutions, drawing on its broader engineered pump capabilities and industrial service infrastructure. Sulzer provides integrated fire pump skids and solutions for oil and gas and general fire protection, which aligns well with project-based demand where skid-level integration and application engineering matter. Kirloskar Brothers manufactures fire pumps for municipal and industrial applications, reflecting strength in regional manufacturing and cost-competitive engineering. SPP Pumps produces specialist fire pumps for fixed and portable systems, and Peerless Pump Company designs and manufactures horizontal and vertical fire pumps, including its FireConnect monitoring system, which illustrates how traditional pump manufacturers are extending into connected diagnostics to differentiate their offerings.
Armstrong Fluid Technology offers end-suction, horizontal, vertical in-line, and multi-stage fire pumps, giving it coverage across common commercial and industrial configurations. Rosenbauer produces fire pump systems integrated into fire trucks and apparatus, representing a distinct adjacency where pump capability is embedded into mobile fire suppression platforms. Waterous has manufactured US-made fire pumps, engines, and suppression equipment since 1886, competing on legacy, domestic production, and specialized suppression system integration. CET Fire Pumps MFG Inc. produces portable fire pumps with gas and diesel engines, plus skid units and foam systems, addressing niche mobile and specialized suppression needs. Xylem provides fire pumps under the AC brand for municipal and industrial fire protection, leveraging its broader water technology and infrastructure positioning.
Filter Pump Market
Market Concentration and Evolution Patterns
With a three-firm concentration near 45 percent and a five-firm concentration near 55 percent, the market is consolidated enough that scale, certification portfolios, and global distribution matter, yet fragmented enough that specialized players can win on application fit, regional proximity, and service agility. Over the next several years, two evolutionary patterns are likely to persist. The first is selective consolidation through capability acquisition, particularly where a manufacturer seeks broader product coverage, stronger skid integration capabilities, or access to a specialized monitoring or control technology. The second is continued differentiation among regional and application-focused players who compete on responsiveness, local certification expertise, and integration with local engineering and contractor ecosystems.
New entrants face meaningful barriers in this market, including code familiarity, test and certification requirements, service network expectations, and the need for reliable production quality. However, entry opportunities exist where modular packaged systems, compact vertical configurations, and connected monitoring reduce installation complexity and improve service economics. Companies that can demonstrate consistent compliance documentation, predictable lead times, and strong field support can gain traction even in competitive bidding environments.
Forward-Looking Trends and Commercial Implications
Trend One: Connected Diagnostics as a Standard Expectation
Remote monitoring and condition awareness are likely to move from premium option to expected capability in a growing share of commercial and industrial applications. As facility operators consolidate maintenance workflows and seek earlier warning of mechanical or electrical anomalies, pumps equipped with status telemetry, fault logging, and integration-friendly interfaces will be easier to specify and retain in service. The commercial implication is that manufacturers offering genuine monitoring value—rather than superficial connectivity—will improve after-service revenue potential and strengthen customer retention. A practical risk is that monitoring features must be supported by reliable data infrastructure, cybersecurity considerations, and service processes capable of acting on the information collected.
Trend Two: High-Pressure and Compact Vertical Solutions Gaining Share
The expansion of high-pressure vertical in-line options reflects demand for space-efficient, high-performance configurations suitable for tall buildings, constrained mechanical rooms, and applications where footprint and installation simplicity matter. This trend favors manufacturers that can deliver reliable vertical designs with robust sealing, alignment, and bearing arrangements while meeting code requirements across 50Hz and 60Hz regions. For procurement teams, compact and high-pressure solutions can reduce installation cost and improve building layout flexibility, but they require careful specification to ensure duty-point suitability and long-term serviceability.
Trend Three: Integrated Skid and Application-Engineered Packages in Energy and Industrial Projects
Offshore and large industrial projects continue to create demand for integrated skid systems that combine pumps, drivers, controls, and interface engineering into coordinated packages. Contract awards in FPSO and similar large-scale energy projects demonstrate that suppliers with skid integration capability and application-specific design competence can secure high-value projects even in concentrated markets. The commercial opportunity lies in expanding from component supply to system-level value creation, where integration reduces field engineering burden and improves commissioning reliability. A key uncertainty is project timing and capital expenditure variability in energy markets, which can shift demand from steady pipelines to episodic large contracts.
Strategic Implications for Decision-Makers
For Fire Pump Manufacturers and Integrators
- Align product roadmaps with compliance evolution and monitoring expectations. Invest in certification readiness, documentation clarity, and telemetry features that deliver actionable maintenance insight rather than simple data visibility.
- Strengthen cost and supply chain resilience. Standardize key components, manage steel exposure through procurement discipline and design efficiency, and protect delivery reliability during input price volatility.
- Expand toward system-level value where appropriate. Skid integration, packaged systems, and application-specific engineering can improve project margins and differentiate offerings in industrial, energy, and complex commercial deployments.
- Build service-aligned commercial models. In a market where uptime, installation correctness, and compliance documentation matter, service responsiveness and commissioning support can be as decisive as product specifications.
For Investors and Strategic Acquirers
- Prioritize businesses with durable compliance positioning, recurring service relationships, and credible monitoring or integration capabilities. Brand heritage alone is insufficient without modern product support and service economics.
- Evaluate regional specialists for capability tuck-ins. Strong local certification knowledge, contractor relationships, and application focus can complement broader platforms and accelerate entry into specific geographies or end markets.
- Monitor steel cost exposure and margin discipline as part of due diligence. Companies with standardized designs, flexible sourcing, and transparent cost pass-through mechanisms are better positioned to preserve profitability when input prices fluctuate.
- Watch for consolidation driven by product coverage gaps and digital capability needs. Targets that add vertical configurations, packaged systems, or connected diagnostics may offer strategic leverage beyond revenue scale.
For Procurement, Engineering, and Facility Decision-Makers
- Evaluate total lifecycle value rather than initial price alone. Installation complexity, commissioning support, compliance documentation, and serviceability can materially affect operating risk and long-term cost.
- Specify with monitoring and serviceability in mind. Where uptime assurance is critical, select configurations that enable condition tracking and simpler field support, and ensure that service providers can act on the data provided.
- Confirm compliance readiness early. Verify that proposed pump systems align with NFPA 20 expectations and current inspection and testing practices, including any changes to certification processes, to avoid delays during commissioning and jurisdictional review.
- Plan for supply-side variability. Given steel price movements and project timing risk, include delivery certainty, lead-time transparency, and contingency planning in procurement decisions, especially for time-sensitive commercial and industrial projects.
The fire pump market is entering a phase in which growth is supported by steady demand fundamentals, but competitive outcomes will increasingly depend on compliance mastery, product differentiation, and the ability to deliver reliable installation and service performance. The most compelling commercial opportunities will accrue to manufacturers and integrators that combine technical breadth with execution discipline, and to buyers who specify with lifecycle performance and regulatory alignment in mind. For teams that require detailed segmentation data, regional demand patterns, type-level revenue splits, and company-level competitive profiles to support planning and investment decisions, the full research report provides expanded datasets and tailored scenarios that build on the strategic direction outlined here.
PW Consulting
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Iron Ore Market at a Strategic Inflection Point: Navigating Growth, Disruption, and Value Creation
The global iron ore market is entering a phase defined by steady expansion layered with structural volatility. Valued at approximately $215.0 billion in 2025, the market has demonstrated consistent upward momentum since 2020, reflecting a compound annual growth rate of 3.9% through the 2032 forecast horizon. This trajectory projects the sector past the $340 billion threshold by the end of the decade, driven by sustained steel production, evolving metallurgical demands, and shifting trade dynamics. The numbers tell a story of durable demand, but beneath the aggregate figures lies a more complex reality: capacity expansions, regulatory shocks, price normalization, and strategic realignments are reshaping how value is captured across the supply chain. For executives, investors, and procurement leaders, the imperative is no longer simply tracking volume growth. It is understanding where margins will compress, where premium differentiation will emerge, and how supply architecture will reorganize in response to policy and technology shifts.
Market Context and the Core Challenges Defining This Cycle
The iron ore sector’s expansion from roughly $163 billion in 2020 to the $215 billion midpoint in 2025 reflects a market that has absorbed pandemic-era disruptions, supply chain recalibrations, and cyclical price swings while maintaining a clear growth path. Yet the headline trajectory masks three interconnected challenges that will dictate competitive outcomes over the next several years.
First, price normalization is compressing revenue expectations for operators that relied on elevated unit values to justify capital expenditures and margin expansion. After averaging above $112 per ton in the first nine months of 2024, global iron ore unit values declined to approximately $99 per ton in the comparable period of 2025. This pull-back matters because pricing discipline is no longer guaranteed by tight supply alone; buyers are increasingly sophisticated, alternative raw materials are gaining traction in specific metallurgical applications, and freight and logistics costs continue to introduce volatility into realized pricing. Operators and traders must now plan for a regime where volume growth, grade optimization, and cost efficiency matter more than riding a rising price cycle.
Second, regulatory interventions are fragmenting trade flows and forcing regional repositioning. The restoration and escalation of steel tariffs on imports from all countries, raised to a 50% level effective in early 2025, has reshaped the competitive calculus for exporters targeting North American markets. Tariffs of this magnitude do not merely raise costs; they alter sourcing strategies, incentivize domestic production where feasible, and compress the economics of long-distance iron ore shipments into protected markets. This creates a bifurcated landscape: regions with integrated steel ecosystems and policy support can defend share, while export-dependent operators must navigate narrower margins and more complex negotiation dynamics with steelmakers seeking to manage input costs.
Third, the structural transition toward lower-emission steelmaking is introducing both opportunity and friction. Direct reduction pathways and alternative feedstock requirements are growing, but the capital intensity of conversion, the availability of suitable iron ore grades, and the readiness of downstream infrastructure mean that demand shifts will be uneven across regions and customer segments. The market is not moving in a single direction; it is splitting into metallurgical niches where premium fines, specialized pellets, and consistent quality specifications command different pricing logic than commoditized volumes. Companies that treat iron ore as a homogeneous bulk commodity will face increasing difficulty in defending position as customers tailor input strategies to decarbonization targets and operational flexibility.
The Forces Reshaping Supply, Demand, and Competitive Positioning
The iron ore market’s evolution is being driven by a set of interlocking forces that extend beyond cyclical supply and demand. Understanding these drivers is essential for identifying where growth will be durable and where exposure will be most vulnerable.
Technology and metallurgical innovation are redefining what constitutes valuable iron ore. As steelmakers evaluate direct reduction, hydrogen-enabled pathways, and more efficient blast furnace operations, the premium attached to consistent high-grade material, low impurities, and predictable granulometry is increasing. Operations that can deliver concentrate and pellet feed with tight specification control are better positioned to capture margin resilience, particularly in segments where metallurgical performance translates directly into energy savings or emission reductions downstream. Technology-driven differentiation is not limited to the mine site; it extends to beneficiation capabilities, logistics optimization, and the ability to align product specs with customer conversion processes. In this environment, the value of a tonne is increasingly a function of what it enables rather than what it weighs.
Policy and regulatory environments are becoming a decisive competitive variable. Trade policy is no longer a background condition; it is an active determinant of routing, customer mix, and pricing power. The imposition of higher steel import tariffs has intensified the strategic importance of local and regional supply security for steel producers, while simultaneously pressuring exporters to identify alternative demand centers or negotiate terms that account for policy-driven cost structures. Regulatory trajectories around emissions, mining approvals, and indigenous or community agreements also influence the speed and cost of capacity additions. Projects that can align with clear regulatory frameworks and long-term development agreements gain a meaningful advantage in execution certainty, while operators facing shifting approval regimes or policy volatility must price that risk into their expansion plans.
Demand-side behavior is shifting as steel producers balance volume requirements with cost control and decarbonization mandates. The largest application segment for iron ore remains steel production, and that anchor demand provides the market’s underlying stability. However, buyer behavior is becoming more segmented. Large integrated steelmakers are increasingly negotiating around grade consistency, delivery reliability, and total cost of conversion rather than focusing solely on spot price movements. At the same time, direct reduction and other alternative processes are expanding their share of attention, creating incremental demand for materials suited to those pathways. The practical implication is that demand is consolidating around relationships and specifications, not just price. Suppliers that can demonstrate operational consistency and align product attributes with customer process requirements are better positioned to secure longer-term arrangement stability, even in a normalizing price environment.
Supply chain and cost structure dynamics are reshaping where and how iron ore reaches markets. Logistics remains a critical lever in realized economics, particularly for long-haul export routes. Any disruption in port capacity, rail throughput, or maritime freight introduces volatility that can erode the advantage of low-grade-cost production. At the same time, cost structures are being tested by the need to maintain output while managing inflation in energy, labor, and capital equipment. The operators that navigate this phase effectively are those treating the supply chain as an integrated system: mine planning, processing efficiency, stockpile management, and shipping coordination are increasingly evaluated as a single margin equation rather than separate functions. In a market where unit values have moderated, the ability to reduce cost per tonne and protect throughput continuity becomes a primary source of competitive advantage.
Competitive Landscape: Positioning, Differentiation, and the Evolving Structure of the Market
The iron ore market remains concentrative, with a relatively small group of large-scale operators controlling a substantial share of global supply. This concentration creates a landscape where scale, asset quality, and strategic optionality matter enormously. Yet the competitive dynamics are not static. Recent operational milestones, project developments, and regional adjustments illustrate how the leading players are actively reshaping their positions.
The major integrated producers continue to compete on the basis of tonnage reliability, ore quality, and the ability to sustain output through market cycles. Operations anchored in established mining complexes with mature infrastructure benefit from scale economics and logistics familiarity, while also facing the ongoing challenge of maintaining production levels, managing stockpile balances, and responding to cost pressures. In this context, the recent achievement of record Pilbara output by one of the leading Australian producers, alongside the first ore shipment from the Simandou high-grade project in Guinea, highlights two contrasting but complementary strategic thrusts: maximizing the productivity of long-established assets while opening new high-grade supply corridors that can shift grade mix and market access over time. The shipment of a significant cumulative volume milestone from the Pilbara region further underscores how legacy operations remain central to global supply, even as new projects begin to contribute incremental tonnage.
Worldwide Iron Ore Trade Market
In South America, a leading Brazilian producer recently reached a seven-year high in iron ore output, surpassing a key Pilbara-based peer’s volume for the first time since 2018. This reversal is strategically significant because it shows that operational reliability and capacity execution can alter the ranking of major suppliers within a single cycle. For the market, it signals that the balance of supply between established regions is not fixed; it responds to operational performance, infrastructure utilization, and the ability to keep complex mining and logistics systems running at target levels. Premium concentrate, fines, and pellet offerings from major Brazilian and South African operations continue to play a differentiated role, particularly for customers seeking material that supports specific metallurgical outcomes.
The competitive picture also includes producers with more regionally concentrated footprints. In North America, a major domestic steel and mining company’s decision to idle portions of its Minnesota operations as part of a stockpile reduction strategy reflects a more tactical approach to balancing supply, inventory, and market conditions. The resulting decline in U.S. domestic iron ore production illustrates how quickly regional supply can adjust when operators choose inventory discipline or cost management over volume retention. This kind of localized adjustment matters because it interacts directly with policy-driven demand dynamics. When import tariffs raise the cost of foreign material, domestic supply becomes more strategically valuable, but only if it is available at a competitive cost and in sufficient quantity to support steelmaking schedules.
Steelmakers with integrated mining interests add another layer to the competitive landscape. By controlling upstream supply in select assets, these companies can better align raw material availability with steel production planning, reduce exposure to spot market volatility, and support longer-term operational continuity. Recent infrastructure expansion in Liberia, including the completion of a new concentrator facility and the extension of a long-term mineral development agreement, demonstrates how integrated players are building longer-duration supply visibility in emerging regions. This type of move is not merely about adding tonnage; it is about securing a predictable input base that supports downstream strategic planning over decades rather than quarters.
Taken together, the competitive landscape is evolving along several axes. Scale remains essential, but it is no longer sufficient on its own. Differentiation is increasingly tied to grade consistency, logistical reliability, regional access, and the ability to align product specifications with evolving steelmaking requirements. At the same time, the market is not moving toward uniform consolidation. Instead, it is developing pockets of integration around key supply corridors and customer relationships, while leaving room for specialized operators that can serve premium or regionally targeted niches. New entrants and project developers face high barriers in the form of capital intensity, permitting complexity, and the need to establish reliable offtake and logistics arrangements, but targeted projects that can deliver distinctive grade profiles or open new export routes can still alter local competitive dynamics.
What the Next Three to Five Years Will Likely Bring
The iron ore market’s medium-term trajectory will be shaped by the interaction of demand durability, supply execution, policy direction, and metallurgical transition. Several trends are likely to define strategic outcomes over the next three to five years.
Trend one: volume growth will continue, but margin capture will depend on grade and specification management. The market is projected to expand steadily toward the mid-2030s, supported by ongoing steel production and incremental demand from alternative reduction pathways. However, as unit values moderate and buyers become more selective, the ability to command premium realization will increasingly hinge on product consistency, impurity control, and alignment with customer processes. Suppliers that can reliably deliver high-quality fines and pellets with predictable metallurgical behavior will be better positioned to preserve pricing leverage, while those competing primarily on volume may face greater pressure from both substitutes and more demanding procurement standards.
Trend two: trade policy and regional supply security will redraw procurement maps. Tariff structures, domestic production levels, and logistics constraints are likely to keep regional sourcing strategies in sharp focus. In markets where import costs are elevated by policy, steelmakers will continue to weigh the trade-off between domestic supply, established export relationships, and the operational implications of switching sources. This does not mean globalization retreats entirely, but it does mean that supply routing will be more deliberately engineered. Exporters with diversified destination markets, flexible logistics, and credible grade offerings will have more optionality, while those heavily exposed to a single policy-sensitive corridor will need to plan for discontinuity and negotiate accordingly.
Trend three: decarbonization-driven demand segmentation will accelerate, but unevenly. The shift toward lower-emission steelmaking will not unfold at the same pace across every region or producer. Some customers will pursue direct reduction and related pathways more aggressively, increasing interest in materials that support those processes. Others will continue to optimize blast furnace operations and look for iron ore attributes that reduce energy intensity or improve yield. The result will be a more segmented demand environment in which premium product lines, specialized pellets, and consistent concentrate supply gain relative importance. Companies that invest early in understanding customer conversion needs and align product development with those requirements will have an advantage in securing more resilient demand channels.
Carbonate Ore Market
These trends create commercial opportunity, but they also carry risk. Price volatility may persist if macroeconomic conditions, freight markets, or policy adjustments shift quickly. Capital projects can face delays from permitting, community engagement, or cost inflation, altering the timing and composition of new supply. And the pace of metallurgical transition may be slower or faster than anticipated, affecting the trajectory of demand for specific grades and product forms. Strategic planning must therefore account for multiple scenarios rather than a single linear forecast.
Strategic Actions for Decision-Makers
For steel manufacturers and integrated producers, the priority is to treat iron ore procurement as a strategic input system rather than a commodity purchasing function. That means investing in supplier relationships that deliver specification reliability, evaluating total cost of conversion rather than nominal price alone, and building sourcing flexibility that can respond to tariff changes or logistics disruptions. Where feasible, securing longer-term supply visibility through structured agreements or integrated access can reduce exposure to abrupt market shifts, particularly in policy-sensitive regions. At the same time, manufacturers should monitor how customer-facing decarbonization targets affect raw material requirements, and align internal planning with the grade and form factors that support those goals.
For investors and capital allocators, the opportunity lies in distinguishing between operators that are built for volume exposure and those that can capture value through differentiation and execution discipline. Assets with strong logistics integration, consistent high-grade output, and credible cost control are better positioned to perform across a range of price environments. Equally important is the regulatory and project execution profile of new supply. Developments that combine clear alignment with local agreements, defined export routes, and metallurgically valuable product characteristics offer more resilient upside than undifferentiated tonnage additions. Portfolio exposure should also account for regional policy risk, especially where tariff or trade policy changes can rapidly alter the attractiveness of specific supply corridors.
For procurement leaders and supply chain decision-makers, resilience should be designed into sourcing strategies before disruption forces a reaction. That includes maintaining visibility into multiple qualified suppliers, understanding the specification dependencies of internal steelmaking or fabrication processes, and stress-testing the impact of freight fluctuations and policy changes on total landed cost. Stockpile and inventory strategies should be evaluated not only for working capital implications but also for their effect on operational continuity if supply interruptions occur. In an environment where unit values can shift and trade policy can reshape relative costs quickly, the organizations that perform best will be those that combine cost discipline with optionality and deep supplier intelligence.
PW Consulting
The iron ore market is large enough to absorb disruption and flexible enough to reward precision. The winners in the next phase will be those who move beyond aggregate growth assumptions and build decisions around grade strategy, regulatory exposure, logistics resilience, and customer-aligned product value. For organizations that need granular segment data, regional cost structures, and customized scenario planning to support those choices, a full research report with detailed segmentation, competitive benchmarking, and forward-looking market modeling can provide the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Iron Ore Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Irrigation Controllers Market: Why 8.82% CAGR & Sensor Shifts Redefine Growth
By PW Consulting, 2026-09-21
Strategic Outlook: Navigating Growth and Transformation in the Irrigation Controllers Market
Market Trajectory and Core Challenges
The global irrigation controllers market is entering a period of sustained expansion, driven by the intersection of resource scarcity, technological maturity, and regulatory alignment. Measured in USD millions, the market has grown from approximately 200 million in 2020 to 260 million in 2025, reflecting a compound annual growth rate of 8.82 percent across the historical and forecast window extending to 2032. By the end of the outlook period, market revenue is projected to reach 465.56 million, signaling a structural acceleration rather than a cyclical upturn. This trajectory is underpinned by consistent year-over-year gains, with growth steepening notably in the latter half of the forecast as smart controller adoption moves from early-adopter segments into mainstream commercial and agricultural deployments.
Despite the favorable macro outlook, the industry faces several inflection points that will shape competitive outcomes over the next five years. First, regulatory fragmentation is intensifying. Water efficiency mandates, certification requirements, and rebate architectures vary widely across jurisdictions, creating compliance complexity for manufacturers seeking scale. Second, material cost volatility and trade policy shifts are compressing margins in the short term while forcing supply chain reconfiguration. Third, the definition of "connected" is evolving rapidly. Early smart controllers relied on basic scheduling and remote access; the next generation integrates real-time sensor feedback, predictive weather modeling, and interoperability with broader water management ecosystems. Companies that treat connectivity as a feature rather than a platform risk losing relevance as procurement standards rise.
Key Drivers Reshaping the Market
Technology Innovation and the Shift to Adaptive Control
The transition from timer-based and fixed-schedule systems to weather-based and sensor-driven controllers represents the most consequential technical shift in the category. Weather-based controllers currently account for the largest share of product-type revenue, reflecting their broad applicability across residential, commercial, and agricultural settings. Sensor-based systems, however, are gaining traction in applications where precision and automation deliver measurable operational savings. The value proposition has moved beyond water conservation alone. Advanced controllers now enable labor reduction, pressure management, leak detection, and integration with centralized facility or farm management platforms. This evolution is mirrored in recent industry activity: exhibitors at the 2026 Irrigation Show, co-located with Groundwater Week in Las Vegas, showcased a wave of innovations spanning connectivity upgrades, energy-efficient designs, and hybrid control architectures. Startup winners announced at the 2025 show further highlighted emerging product directions, including alkaline battery-powered GSM controllers that extend reliable operation in off-grid or low-infrastructure environments. These developments indicate that the technology frontier is expanding in both connectivity and deployment flexibility, opening new addressable use cases.
Policy and Regulatory Dynamics as a Demand Accelerator
Regulatory frameworks are increasingly acting as both a compliance gate and a demand catalyst. The US EPA's updated WaterSense criteria for irrigation controllers, requiring independent certification for efficiency and performance with new labeled controllers available as of March 2026, establish a clearer benchmark for procurement teams and municipal buyers. Certification is becoming a de facto market access requirement in higher-value segments, particularly where public funding or rebate eligibility is tied to labeled products. At the municipal level, rebate programs are lowering the effective purchase price for end users. Programs such as the 2026 Woodbury, Minnesota initiative and the Hays, USA program offer discounts of up to 100 dollars for WaterSense-labeled smart controllers, directly stimulating adoption among residential and small commercial buyers.
State and local building codes are reinforcing this pull. In Minnesota, for example, WaterSense-certified controllers are required for all new systems installed after 2020, embedding the technology into standard construction and landscaping practice. At the same time, government-sector validation is building confidence in performance claims. The US Department of Energy's Federal Energy Management Program notes that advanced controllers, including both sensor-based and weather-based models, demonstrate water use reductions of 15 to 40 percent in federal applications. This range is significant because it spans diverse climates, system ages, and management practices, suggesting that well-deployed smart controls can deliver consistent savings across varied conditions. For commercial and institutional buyers, these documented outcomes reduce perceived risk and strengthen the business case for upgrade cycles.
Demand-Side Behavior and the Broadening Application Base
Demand is evolving along two reinforcing paths. In agriculture, controllers are increasingly positioned as components of precision farming systems rather than standalone timing devices. The emphasis is on matching irrigation output to crop needs, soil conditions, and evapotranspiration patterns, often in concert with drip and micro-irrigation infrastructure. This application orientation favors controllers that integrate with broader agronomic data flows and can operate reliably in demanding field environments. In non-agricultural settings, demand is driven by a mix of water cost sensitivity, sustainability commitments, and regulatory compliance. Commercial property managers, municipal grounds departments, and landscape contractors are all evaluating controllers through the lens of total cost of ownership, including labor savings from remote management, reduced water billing, and eligibility for incentives. The growing share of non-agricultural applications in market revenue reflects this diversification, as does the continued strength of agricultural demand in regions where irrigation efficiency directly affects yield stability and input costs.
Supply Chain and Cost Structure Pressures
Cost dynamics are introducing both constraints and opportunities. The Irrigation Association reported that a 25 percent tariff on steel and aluminum imports announced in February 2025 will increase costs for irrigation manufacturers and components. For hardware-intensive products, these input cost pressures can affect pricing strategy, margin structure, and the economics of localized production. The impact is not uniform; companies with diversified supplier bases, flexible manufacturing footprints, or higher-value product mixes may absorb or offset cost increases more effectively than those dependent on commodity-driven assemblies. At the same time, the same cost environment is accelerating interest in design efficiencies, component standardization, and software-led value creation that can differentiate offerings without proportionally increasing bill-of-materials expense. Procurement teams are increasingly weighing total cost of ownership against upfront price, which creates room for premium, certified, and integrated solutions when they can demonstrate clear operational returns.
Smart Irrigation Controllers Market
Competitive Landscape and Leading Strategies
Established Players and Divergent Positioning
The competitive set reflects a blend of established irrigation brands, precision agriculture specialists, and software-leaning control innovators. Hunter Industries, headquartered in Tualatin, Oregon, focuses on smart Wi-Fi and internet-connected controllers, including the MCC series and Hydrawise integration. Its positioning emphasizes residential and light commercial usability, remote management, and ecosystem connectivity that lowers the barrier to adoption for contractors and end users. Rain Bird Corporation, based in Glendora, California, offers modular and weather-based smart options through the ESP-ME3, LNK WiFi, and ESP-TM2 series. Its strategy leans on modularity, serviceability, and a broad installed base that supports retrofit and upgrade cycles. The Toro Company, in Bloomington, Minnesota, provides DXi central control and Irritrol Rain Master controllers for commercial and residential applications. Toro's recent catalog release effective January 2026 underscores a focus on clear product segmentation and pricing transparency across central control and distributed controller lines, catering to projects that require scalable management across multiple zones or sites.
Netafim brings a precision agriculture orientation, with digital farming and NMC Junior Pro controllers designed for drip systems and field-level control. Its value proposition is tightly linked to yield optimization, water precision, and integration with broader agricultural management practices. Galcon, operating globally from Israel, specializes in advanced smart controllers for residential, agricultural, and golf applications, emphasizing multi-zone flexibility and application-specific programmability. HydroPoint Data Systems, based in Santa Barbara, California, develops weather-based and sensor-integrated smart controllers for commercial and agricultural use, with a positioning that blends data-driven control logic and connectivity suitable for managed properties and institutional landscapes.
Market Structure and Strategic Implications
Market concentration remains elevated, with the top three companies accounting for approximately 62.5 percent of revenue and the top five representing about 78.2 percent. This concentration indicates that scale, brand recognition, distribution relationships, and installed-base advantages still matter significantly. However, concentration also masks meaningful segmentation in product architecture, application focus, and region-specific demand. The presence of strong regional and application specialists suggests that differentiation is increasingly achieved through fit rather than sheer breadth. Manufacturers that can align certification readiness, connectivity standards, and application-specific features with local rebate and code environments are better positioned to capture share in high-growth pockets. At the same time, the pipeline of startup activity and niche product launches indicates that new entrants can find openings by targeting underserved use cases, such as off-grid power options, simplified installation profiles, or specialized integrations for municipal and institutional procurement.
The competitive trajectory is likely to feature both consolidation and continued specialization. Larger incumbents may pursue tuck-in acquisitions or partnerships to expand software capabilities, sensor integration, or regional service coverage. Specialist players may deepen application expertise and certification compliance to defend and expand niches. The key differentiator over the next several years will be the ability to deliver verified performance, interoperable connectivity, and a clear path to total cost of ownership savings for the buyer, rather than connectivity alone.
Future Trends and Commercial Opportunities
Trend One: Certification-Driven Procurement and Incentive-Linked Adoption
As WaterSense labeling and state or municipal code requirements become more embedded in procurement standards, certified controllers will increasingly function as a baseline expectation in higher-value segments. The commercial opportunity lies in aligning product portfolios, documentation, and channel enablement with certification criteria and incentive architectures. Manufacturers and distributors that can streamline the path to compliant deployment, provide clear performance evidence, and support rebate navigation will gain an advantage in municipal, institutional, and regulated residential channels. For buyers, the practical implication is that selection criteria should incorporate certification status, verified water savings ranges, and compatibility with local incentive programs as standard evaluation factors.
Trend Two: Integrated Control as a Platform for Water Management
Controllers are evolving from isolated scheduling devices into nodes within broader water and site management platforms. The trend toward sensor integration, weather-based adaptation, and centralized control broadens the scope of value that can be delivered, including pressure optimization, leak indication, and multi-site management. This creates opportunities for solutions that emphasize interoperability, data usability, and service-oriented business models. For commercial property portfolios, agricultural operators, and landscape service providers, the upside is in reducing manual oversight, improving consistency across sites, and tying control decisions to operational metrics that matter to finance and sustainability teams. The risk is that fragmented ecosystems or proprietary locks can slow adoption; buyers will increasingly favor solutions that connect to existing infrastructure and reporting workflows without demanding wholesale replacement.
Trend Three: Cost and Supply Chain Realignment shaping Product Architecture
Input cost pressures and trade policy uncertainty are likely to continue influencing product design and sourcing decisions. Over the next three to five years, expect more emphasis on modular architectures, selective localization, and design choices that reduce exposure to volatile commodities while preserving performance. This environment favors companies that can balance cost discipline with differentiation through software, usability, and certified performance. For investors and manufacturers, the strategic question is whether cost pressures will consolidate supply around a smaller set of globally scaled producers or whether regionalized, application-tuned offerings will capture meaningful share by better matching local requirements and incentive environments. The answer will vary by region and application, and both dynamics can coexist.
PW Consulting
Strategic Action Points for Decision Makers
For Manufacturers and Product Leaders
Prioritize certification readiness and total cost of ownership proof. Align product development with the latest WaterSense criteria and other relevant efficiency standards, and prepare clear documentation that supports procurement and rebate eligibility. Invest in connectivity and interoperability that reduce integration friction for contractors and end users, and ensure that field serviceability and supply chain resilience are designed into the product roadmap, not treated as afterthoughts. Where input cost pressure is acute, explore modular design and supplier diversification to protect margins without eroding performance.
For Investors and Strategic Partners
Focus on segments where regulation, incentives, and verified savings converge to create durable demand. The strongest near-term opportunities are likely in certified smart controllers for municipal and institutional procurement, precision agriculture integrations that tie control to yield and input efficiency, and service-oriented models that monetize remote management and analytics. When evaluating targets or partnerships, assess certification posture, channel access, installed-base momentum, and the ability to demonstrate water and labor savings in real-world deployments. Monitor startup activity for novel power, connectivity, and integration approaches that could redefine sub-segments or become acquisition targets.
For Procurement and Operations Leaders
Use efficiency certification and incentive availability as initial screening criteria, then evaluate total cost of ownership across water savings, labor reduction, serviceability, and interoperability. Favor solutions that can integrate with existing management workflows and provide usable data for ongoing optimization. In regions with code mandates or active rebate programs, align replacement and new-install cycles with certified options to secure compliance and financial support. Build internal evaluation standards that reflect documented savings ranges and the operational realities of your sites or portfolios, rather than relying on generic feature checklists.
Worldwide Environment Controllers Market
The irrigation controllers market is moving from a phase of incremental smartification to one where certification, integration, and verified performance determine competitive outcomes. Companies and buyers that treat controllers as part of a broader water management strategy, and that align product and procurement decisions with regulatory and incentive realities, will capture more of the value created by the next wave of adoption. For decision makers seeking deeper segmentation, region-specific dynamics, and customized scenario analysis, the full research report provides detailed breakdowns and extended data to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


