



PW Consulting: Diabetes Drugs Market to Hit $117.7B by 2032, 6.5% CAGR Amid GLP-1 Growth
By PW Consulting, 2026-09-16
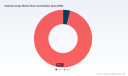
# The Diabetes Drugs Market in 2026: Navigating Growth, Innovation, and Strategic Complexity ## Executive Summary: Why Deep Intelligence Matters Now The global landscape for diabetes management is undergoing a seismic shift, driven by breakthrough therapies, evolving reimbursement models, and persistent supply chain vulnerabilities. For executives, investors, and strategic planners, relying on surface-level data is no longer sufficient. The decisions made in 2026 will dictate competitive positioning for the remainder of the decade. This article provides a high-level strategic overview of the market environment, illustrating the complexity and opportunity that define the sector today. However, true strategic advantage requires granular precision that goes beyond public headlines. Our comprehensive Diabetes Drugs Market research report delivers the specific segmentation volumes, competitive share analysis, and future trajectories necessary to optimize your portfolio and entry strategies. ## Market Trajectory and Scale: A Decade of Expansion The diabetes drugs market has demonstrated consistent resilience and growth over the past half-decade, establishing a robust foundation for the forecast period extending through 2032. Between 2020 and 2025, the market experienced significant expansion, with revenues rising from 51.0 billion USD to 75.9 billion USD. This historical performance underscores the inelastic demand for chronic care solutions and the rapid adoption of newer therapeutic classes. Looking forward, the market is projected to sustain a Compound Annual Growth Rate (CAGR) of 6.5 percent during the 2026 to 2032 forecast period. This trajectory suggests that the market will surpass the 100 billion USD milestone shortly after the turn of the decade, reaching approximately 117.7 billion USD by 2032. Such growth is not uniform; it is fueled by specific innovation waves and regional dynamics that require careful unpacking. While the top-line figures indicate a healthy sector, the distribution of this growth across drug classes, diabetes types, and geographic regions reveals critical niches where value is being created and captured. Understanding where the revenue streams are concentrating is vital for resource allocation, yet these specific breakdowns are detailed within our full proprietary dataset. ## The Innovation Engine: Drug Classes and Therapeutic Shifts The competitive battlefield is defined by the performance of distinct drug classes, each carrying different risk profiles, pricing power, and patient adherence rates. The market has seen a pronounced pivot toward incretin-based therapies, which have reshaped expectations for glycemic control and weight management. Conversely, traditional insulin markets remain foundational but face pressure from biosimilar competition and novel delivery mechanisms. Recent regulatory milestones highlight the pace of innovation. In March 2026, Novo Nordisk received FDA approval for Awiqli (insulin icodec-abae), a once-weekly insulin designed to improve glycemic control for type 2 diabetes. This approval represents a significant advancement in patient convenience and potentially adherence, disrupting the daily injection paradigm. Alongside such developments, the market landscape is being reshaped by key industry players who are leveraging distinct portfolios to capture share. Our report provides an in-depth profiling of the entities driving these changes. Leading manufacturers such as Novo Nordisk A/S, headquartered in Bagsværd, Denmark, continue to dominate with a strong lineup including Ozempic, Wegovy, and Rybelsus. Their strategy focuses heavily on the intersection of diabetes and obesity management. Similarly, Eli Lilly and Company, based in Indianapolis, Indiana, USA, is pushing the envelope with GLP-1 and GIP receptor agonists, including Mounjaro, Zepbound, and the investigational orforglipron, targeting both glycemic control and obesity-related metrics. Traditional insulin leaders remain relevant through formulation innovation. Sanofi, headquartered in Paris, France, maintains a strong presence with long-acting insulins like Lantus and Toujeo. Meanwhile, the SGLT2 inhibitor space is contested by developers like Boehringer Ingelheim, based in Ingelheim am Rhein, Germany, with products such as Jardiance, and Janssen Pharmaceuticals, located in Beerse, Belgium, offering Invokana for type 2 diabetes management. The interplay between these giants involves patent cliffs, pipeline Succession, and strategic partnerships that are meticulously analyzed in our full report to help you anticipate market share shifts. ## Geography and Patient Segmentation: Where the Revenue Lies Revenue distribution is not homogeneous across the globe. Certain regions exhibit higher purchasing power and faster adoption rates for premium therapies, while others offer volume growth potential driven by prevalence rates and improving healthcare infrastructure. The concentration of value in specific geographic zones creates distinct regulatory and pricing challenges for multinational strategies. Similarly, the patient base is segmented by diabetes type, with the vast majority of therapeutic spend directed toward Type 2 diabetes management, reflecting the global burden of metabolic syndrome. Type 1 diabetes, while smaller in terms of total revenue volume, represents a critical area for innovation in insulin delivery and immunosuppression therapies. The nuances of how these segments interact with drug class preferences—for instance, the preference for SGLT2 inhibitors in specific comorbidity profiles versus insulin dependence in advanced cases—require detailed modeling. Our research breaks down these segments to identify high-growth pockets that are often obscured in aggregate market figures. Access to the full segmentation data allows stakeholders to pinpoint exactly where their products fit within the current hierarchy of treatment guidelines. ## Market Concentration and Competitive Intensity The diabetes drugs market is characterized by a moderate level of concentration, suggesting room for niche players while maintaining strong barriers to entry for complex biologics and patented formulations. The top three companies hold a significant portion of the market share, collectively accounting for approximately 50 percent of revenue. Expanding the view to the top five players, the concentration rises to 65 percent. This structure indicates a market dominated by well-capitalized incumbents with extensive distribution networks and regulatory expertise. However, concentration does not imply stagnation. The remaining 35 percent of the market is highly competitive, with opportunities arising from generic entry, biosimilar development, and novel mechanisms of action. Strategic decisions regarding M&A, licensing, or organic pipeline development must account for this concentration risk. Entering a market segment dominated by the top five requires a differentiated value proposition, whether through superior clinical outcomes, cost efficiency, or delivery convenience. Our competitive landscape analysis dives deeper into the strategic moves of these key players, evaluating their R&D pipelines, litigation status, and global expansion strategies to provide a clear picture of the barriers and opportunities ahead. ## Supply Chain and Regulatory Dynamics: Navigating Risk in 2026 Beyond the clinical data and revenue projections, the operational environment for diabetes drugs is fraught with logistical and regulatory complexities. Supply chain resilience has emerged as a critical strategic pillar, particularly concerning the sourcing of key starting materials and active pharmaceutical ingredients (APIs). Recent analysis by the United States Pharmacopeia (USP) highlights a significant vulnerability: nearly half (48 percent) of key starting materials for drugs on the USP vulnerable medicines list are solely manufactured in a single country. This concentration poses acute and chronic risks to the supply of diabetes medications should disruptions occur. Furthermore, the USP emphasizes that upstream starting material sourcing bottlenecks could impact the availability of essential medicines. In the context of raw materials, 48 percent of global API Drug Master Files (DMFs) originate from India. This heavy reliance underscores the need for diversified sourcing strategies and robust contingency planning. Regulatory and reimbursement landscapes are also shifting dynamically. The Centers for Medicare & Medicaid Services (CMS) has introduced the GLP-1 Bridge model, providing access at a $50 copay for eligible Medicare beneficiaries with standardized coverage criteria. Additionally, the Medicare GLP-1 Bridge program offers eligible Part D beneficiaries $50 monthly access to certain GLP-1 medications beginning July 1, 2026. These initiatives are designed to improve patient access but introduce new variables for pricing strategy and demand forecasting. Stakeholders must understand how these reimbursement changes affect volume projections and manufacturer rebates. Our report synthesizes these regulatory developments with market demand models to predict how policy shifts will alter consumption patterns and profitability across different payer segments. ## Strategic Implications for Industry Stakeholders The convergence of robust market growth, therapeutic innovation, and supply chain fragility creates a complex decision matrix for 2026. Manufacturers must balance the urgency of launching new formulations against the risk of supply disruptions. Investors need to discern which drug classes will sustain premium pricing versus those facing imminent generic erosion. Policymakers and payers are grappling with the cost implications of widespread GLP-1 adoption while trying to expand access. To navigate this environment, organizations require more than just top-line growth numbers. They need a granular understanding of how segmentation splits interact with regional regulations, how competitive concentration affects pricing power, and how supply chain dependencies impact product availability. The data provided in public summaries often lacks the depth required to model these scenarios accurately. For instance, knowing the overall market size is useful, but understanding the specific revenue contribution of SGLT2 inhibitors versus GLP-1 receptor agonists in North America versus Asia Pacific is essential for regional market entry or expansion plans. ## Conclusion: The Value of Granular Intelligence The diabetes drugs market is poised for significant expansion through 2032, driven by a CAGR of 6.5 percent and evolving therapeutic standards. However, realizing value in this market requires precise intelligence. The interplay between major pharmaceutical players, regional demand variations, drug class performance, and regulatory policies creates a landscape where general knowledge is insufficient for competitive advantage. Our comprehensive Diabetes Drugs Market research report goes beyond the macro trends to provide the detailed segmentation data, competitive profiles, and strategic analysis necessary for informed decision-making. By uncovering the specific revenue splits, concentration metrics, and dynamic risk factors, this report equips stakeholders to mitigate risk and capitalize on growth opportunities with confidence. We invite you to explore the full findings to gain the actionable insights needed to thrive in this evolving sector.
Diabetes Drugs Market
Fertility Drugs Market
For detailed analysis of this topic, please visit the official page: Diabetes Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Insulating Oil Market Hits $3.41B in 2025, To Reach $5.06B by 2032 at 5.8% CAGR
By PW Consulting, 2026-09-16
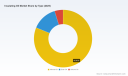
Insulating Oil Market Intelligence Report 2026: Strategic Insights for Power Infrastructure Decision-Makers
The global power transmission and distribution sector stands at a critical inflection point. As aging infrastructure demands modernization and sustainability mandates reshape procurement criteria, insulating oil remains the silent enabler of grid reliability. At PW Consulting, our latest Insulating Oil Market study delivers a comprehensive, data-driven roadmap for corporate strategists, procurement leaders, and engineering executives. This introduction outlines the strategic architecture of the report, highlights the key dynamics that will define the 2026-2032 horizon, and explains why timely, granular market intelligence is no longer optional but essential for competitive positioning.
Executive Overview: Market Trajectory and Strategic Relevance for 2026
Over the historical review window of 2020 through 2025, the insulating oil sector has demonstrated consistent expansion, reflecting steady capital expenditure in electrical infrastructure and a gradual shift toward higher-performance dielectric fluids. The market valuation has progressed from a baseline exceeding two and a half billion USD in 2020 to an estimated base-year valuation approaching three point five billion USD by 2025. This trajectory underscores both the growing electrification footprint across emerging economies and the intensifying maintenance and upgrade cycles in mature grids.
Looking ahead, the 2026-2032 forecast period projects a compound annual growth rate of 5.8 percent. By 2032, the estimated market size is projected to cross the five billion USD threshold. These figures are not merely statistical milestones; they signal structural shifts in fluid chemistry, supply chain diversification, and regulatory compliance pathways. For executives planning capacity investments, supplier negotiations, or product development pipelines, understanding the velocity and direction of this growth is fundamental to mitigating risk and capturing value. The upcoming report translates these macro trends into actionable intelligence, mapping growth pockets, identifying inflection technologies, and quantifying the cost-of-compliance variables that are reshaping procurement economics.
Market Segmentation and Regional Dynamics Decoded
The insulating oil ecosystem is defined by three critical segmentation axes: type, application, and geography. Each dimension carries distinct pricing dynamics, regulatory exposure, and growth profiles that require separate strategic treatment.
By fluid type, the market is anchored by conventional mineral oil formulations, which continue to command the largest share due to legacy infrastructure compatibility and established refining supply chains. Simultaneously, ester-based and silicone-based alternatives are gaining accelerated adoption, driven by heightened fire safety requirements, environmental mandates, and extended equipment lifecycle expectations. The strategic tension between incumbent cost advantages and next-generation performance premiums creates nuanced procurement decisions that demand granular levelized cost analysis.
From an application standpoint, power transformers represent the dominant consumption channel, reflecting their central role in voltage regulation, grid stability, and long-distance transmission. Switchgear, circuit breakers, and reactance assemblies constitute the secondary demand pillar, offering a more specialized but technically demanding application segment where dielectric strength, moisture tolerance, and oxidation stability are non-negotiable performance benchmarks.
Geographically, the market exhibits pronounced divergence. Asia Pacific leads in absolute consumption volume, fueled by rapid grid expansion, industrial electrification, and large-scale infrastructure programs. The North American market reflects a mature but steadily evolving landscape shaped by grid hardening initiatives and aging substation replacements. Europe presents a distinct regulatory-led transition, where sustainability criteria and end-of-life fluid management protocols are accelerating reformulation and recycling investments. Latin American and Middle East and Africa regions operate at lower absolute volumes but exhibit targeted growth pockets tied to specific transmission upgrades and localized industrial demand. The report contains detailed regional demand-to-supply gap analysis, logistics cost modeling, and localized compliance impact assessments that are critical for market entry or capacity allocation decisions.
Insulating Oil Market
Competitive Intelligence: Incumbent Leadership and Strategic Market Maneuvers
The insulating oil sector is characterized by a moderately concentrated competitive landscape. Top-tier players collectively command a substantial share of global production capacity, with the top three and top five firms representing a dominant proportion of the revenue base. This concentration creates a marketplace where scale economies, proprietary refining technologies, and established utility relationships serve as durable moats, while simultaneously leaving space for agile niche players and sustainability-focused innovators to capture differentiated positioning.
The report profiles the core competitive set shaping the market trajectory. Nynas AB, headquartered in Stockholm, continues to reinforce its leadership position in naphthenic transformer oils through the NYTRO brand portfolio, with recent strategic emphasis on bio-based and sustainability-aligned formulations. In May 2025, the company advanced this direction by introducing Nytro Bio 300X, a bio-based ester transformer oil that achieved IEC 62770 vegetable-based fluid classification, delivering dielectric breakdown strength at 800 V/mm and a flash point exceeding 300°C. This launch illustrates how incumbents are leveraging performance credibility to transition legacy customer bases toward eco-compatible alternatives.
APAR Industries Limited, based in Vadodara, India, has built its POWEROIL lineup across naphthenic, iso-paraffinic, and ester-based grades that align with international performance standards. By August 2025, the company secured FM approval for its eco-friendly ester-based natural and synthetic transformer oils, a certification milestone that strengthens its credibility in safety-sensitive procurement environments and opens new addressable segments for sustainable fluid specifications. Savita Oil Technologies Limited, operating from Mumbai with over sixty years of petroleum specialty product experience, remains a recognized producer of TRANSOL transformer oils and insulating fluids, maintaining a strong service orientation for power transmission clients across long operating cycles.
Transformer Oil Market
On the Western hemisphere side, Ergon, Inc. of Jackson, Mississippi, continues to supply dielectric fluids and specialty transformer oils with global distribution reach and rigorous testing infrastructure. In July 2025, the company opened its first Transformer Oil Technology Center in Merak, Indonesia, a strategic facility designed to strengthen quality control, analytical testing, and regional supply responsiveness amid intensifying global energy demand. Aevitas Inc., based in Ayr, Ontario, operates as a specialized supplier and distributor of mineral and silicone insulating oils, complementing its product portfolio with on-site service capabilities and flexible packaging solutions tailored to Canadian and North American transformer operators. Cargill, Incorporated, headquartered in Minneapolis, has intensified its focus on BiO+ FR3 natural ester insulating fluids, emphasizing fire safety and biodegradability. Throughout 2025, the company executed capacity expansion initiatives in the United States to align production capability with rising demand for biodegradable transformer fluid alternatives.
In emerging regional markets, GANELEC of Cape Town delivers IEC-compliant premium transformer oils across Super, High, Standard, and Special grades, supported by filtration services and technical assistance specifically oriented toward African market requirements. The report provides a deeper competitive scoring framework, evaluating each profiled company on manufacturing scale, product breadth, sustainability positioning, certification depth, regional service coverage, and recent strategic capital deployment.
Regulatory Pressures, Environmental Compliance, and Raw Material Volatility
The insulating oil market does not operate in a regulatory vacuum. The 2026 outlook is heavily shaped by overlapping compliance layers that affect formulation choices, supplier qualification, and whole-life cost accounting. In May 2025, the European Union updated its REACH regulation list of Substances of Very High Concern, incorporating certain mineral oil categories used in transformer applications. This update introduces new labeling and reporting obligations with a compliance horizon extending into 2027, compelling distributors, OEMs, and utility operators to reassess inventory strategies, documentation workflows, and substitution pathways.
Beyond Europe, environmental regulations governing the storage, handling, and disposal of used mineral transformer oil are progressively tightening across OECD markets. These evolving standards add compliance overhead and procedural complexity, increasing the relative attractiveness of fluids with reduced environmental persistence and improved end-of-life recoverability. At the same time, crude oil price volatility continues to exert significant influence over the cost structure of petroleum-derived insulating oils. Annual fluctuations approaching thirty percent have been observed, directly affecting pricing predictability for naphthenic and paraffinic variants and reinforcing the case for long-term supply agreements, hedging strategies, and fluid performance optimization that reduces total volume consumption over asset lifecycles.
These dynamics converge to create a decision environment where technical specifications, regulatory foresight, and cost modeling must be integrated rather than evaluated in isolation. The report includes dedicated sections on compliance time horizons, environmental restriction impact mapping, and raw material price sensitivity simulations designed to support scenario planning.
What the Full Report Delivers: Scope, Methodology, and Decision Utility
The PW Consulting Insulating Oil Market study is structured to move beyond surface-level trend description and into operationally actionable intelligence. The full report encompasses historical performance reconstruction for the 2020-2025 period, a forecast model spanning 2026 through 2032, and a multi-layered segmentation framework that enables scenario testing across fluid types, application categories, and regional demand environments.
Key deliverables include:
- A calibrated market size and growth trajectory analysis with sensitivity parameters that reflect regulatory adoption speed, utility capex pacing, and fluid substitution rates.
- Detailed segmentation breakdowns that isolate volume and value dispersion patterns without oversimplifying the strategic differences between mineral, ester, and silicone fluid pathways.
- Competitive landscape assessment covering market share architecture, strategic positioning, product differentiation, certification portfolios, and recent corporate developments across the principal global and regional players.
- Regional market dynamics covering demand drivers, infrastructure investment cycles, import-export logistics considerations, and local compliance burdens that shape opportunity sizing and entry conditions.
- Regulatory and environmental impact analysis that maps impending compliance deadlines, disposal and recycling cost trajectories, and substitution economics for decision-makers evaluating long-term supplier contracts.
- Supply chain and raw material exposure assessment that highlights crude oil linkage, refining margin sensitivity, and logistics cost variability, supporting procurement resilience planning.
- Strategic recommendations tailored for manufacturers, distributors, utility procurement teams, and engineering service providers seeking to align product roadmaps, pricing strategies, and market prioritization with observable demand signals.
The report methodology integrates primary market intelligence, supplier and end-user structural analysis, regulatory tracking, and validated secondary data triangulation. This approach is designed to produce a decision-ready output rather than a passive data collection, ensuring that executive readers can translate findings into investment prioritization, supplier qualification criteria, and regional expansion logic.
Why This Study Matters for 2026 Portfolio and Procurement Strategy
As insulation technologies evolve and environmental expectations harden, organizations that rely on fragmented or outdated market assumptions will face disproportionate exposure to pricing shocks, compliance delays, and specification misalignment. The insulating oil market in 2026 will reward players who can synthesize technical performance, regulatory foresight, and supply chain realism into a coherent commercial strategy. Whether the objective is to secure reliable feedstock access, evaluate entry into ester-based fluid segments, benchmark competitive positioning, or model regional demand growth against infrastructure investment cycles, the underlying data architecture must be robust and current.
The full PW Consulting report provides the analytical depth required to make those decisions with confidence. It connects macro growth signals to segment-specific opportunity sizing, aligns competitive observations with strategic moat analysis, and translates regulatory noise into compliance timelines and cost implications. Most importantly, it preserves the granularity that executive teams need to differentiate viable initiatives from generic assumptions.
To access the complete segmentation models, competitive scoring matrices, regional demand dynamics, and forward-looking scenario frameworks, visit the official PW Consulting Insulating Oil Market research landing page and download the full report. The strategic insights contained within are designed to support informed, timely decision-making throughout the 2026-2032 planning window.
For detailed analysis of this topic, please visit the official page: Insulating Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoked Salmon Market Hits $541 Million in 2025, Projects 5.6% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Smoked Salmon Market Through 2032
The global smoked salmon industry stands at a critical inflection point. As supply chains mature and consumer preferences shift toward premium protein sources, understanding the trajectory of this market is no longer optional for stakeholders operating at scale. Our latest research publication delivers a comprehensive assessment of the sector, distilling twelve years of historical performance and forward-looking projections into an actionable intelligence framework. For executives planning capital allocation, product development, and geographic expansion in 2026, this report serves as the foundational reference for disciplined decision-making.
The value proposition of this study lies not merely in aggregation, but in synthesis. Where many market assessments stop at headline figures, this analysis traces the structural forces that will define competitive positioning over the next seven years. Readers who approach this document as a strategic compass rather than a static dataset will find a clear pathway through an environment characterized by both robust demand fundamentals and intensifying operational complexity.
Industry Trajectory and Structural Momentum
The market has demonstrated consistent expansion across the historical review window, recovering from mid-cycle fluctuations and establishing a higher baseline entering the forecast horizon. After reaching a valuation of 541.0 million USD in the base year of 2025, the sector moves into a projected growth phase that extends through 2032. The compound annual growth rate of 5.6 percent reflects a measured but durable expansion profile, one that rewards participants capable of balancing volume scale with margin discipline.
This trajectory is underpinned by several interlocking dynamics. Consumer demand continues to favor seafood protein as a cornerstone of modern dietary patterns, while retail and food service channels alike are expanding their premium cold-cut and prepared protein assortments. At the same time, the production ecosystem is responding to supply-side pressures ranging from raw material sourcing constraints to evolving regulatory expectations. The interplay between these demand-pull and supply-push forces creates a landscape where operational readiness, rather than market entry alone, determines which organizations capture disproportionate share.
Our forecast framework extends through 2032, tracing a path from the 587.32 million USD expected in 2026 to a projected 788.0 million USD by the terminal year of the analysis window. The progression is not a simple linear extrapolation; it incorporates the shifting weight of channel consumption, the maturation of regional supply networks, and the cadence of product innovation that will redefine value perception among end consumers. Executives who map their internal planning against this progression will be better positioned to synchronize capacity investments, inventory strategies, and go-to-market timing with the actual pace of market absorption.
Competitive Architecture and Strategic Positioning
The competitive landscape is defined by a concentration profile that rewards scale, brand equity, and channel relationships while leaving room for differentiated specialists to capture premium niches. According to the concentration metrics embedded in our analysis, the top three firms account for approximately 32 percent of the market, and the top five together command roughly 45 percent. This structure indicates a moderately consolidated arena where leading incumbents retain meaningful influence over pricing norms, supplier relationships, and category standards, yet where fragmentation below the top tier allows for opportunistic positioning by agile operators.
Across North America, Europe, and select international nodes, a diverse set of manufacturers is shaping the category. Long-established producers such as Acme Smoked Fish Corporation and Haifa Smoked Fish have built distribution footprints that span retail and foodservice, with private label partnerships and broad cold-smoked portfolios anchoring their relevance to large-scale buyers. Operators like Honey Smoked Fish Co., Boston Smoked Fish Co., and Forman & Field emphasize craftsmanship narratives, leveraging traditional smoking methods, local sourcing, and heritage positioning to command premium price points. Meanwhile, vertically integrated and export-oriented players including Bakkafrost Scotland, Trident Seafoods, and Suempol Sp. z o.o. balance volume production with geographic diversification, supplying fresh and smoked salmon variants across multiple destinations.
Recent corporate activity underscores the competitive intensity. In early 2026, Trident Seafoods expanded its smoked salmon line with a premium King Smoked Salmon offering, signaling a direct push into the higher-value tier. Around the same period, Echo Falls Seafoods, operating under Ocean Beauty Seafoods, unveiled flavor and retail packaging innovations for salmon caviar products at Seafood Expo North America, extending the category footprint beyond whole fillet formats. Natural Grocers entered the retail assortment landscape with a private-label Wild Smoked Salmon line featuring sockeye and coho varieties, certified under the Marine Stewardship Council and cold smoked in small batches at a seaside smokehouse. This launch illustrates how retailer-branded offerings continue to pressure branded manufacturers while also raising the bar for quality signaling and traceability.
Not all developments are expansionary. The category has also been shaped by product integrity events that reinforce the centrality of food safety as a strategic asset. In late 2025, both Haifa Smoked Fish and Acme Smoked Fish issued voluntary recalls related to potential Listeria contamination in cold-smoked products, with one involving a private label assortment tied to a major retailer. These episodes highlight the operational accountability that accompanies cold-smoked production, particularly under the FDA's Fish and Fishery Products Hazards and Controls Guidance, which mandates rigorous sanitation and environmental monitoring for Listeria in cold-smoked environments. For decision-makers, the strategic implication is clear: quality assurance infrastructure, supplier oversight, and rapid response capability are competitive differentiators, not merely compliance functions.
Demand Channels and Product Form Evolution
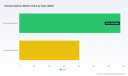
The consumption architecture of the market is distributed across retail and food service channels, each with distinct purchase drivers, format requirements, and price sensitivity profiles. Retail demand favors branded differentiation, convenient packaging, and clear quality credentials, while food service demand emphasizes consistency, portion control, and menu versatility. Our segmentation analysis examines how these channels interact with product types, revealing where margin opportunities concentrate and where volume-led strategies remain viable.
Within product form, cold-smoked and hot-smoked preparations serve different culinary applications and consumer experiences. Cold-smoked offerings generally align with appetizer, deli, and premium retail formats, where texture, aroma, and presentation are primary purchase drivers. Hot-smoked products, by contrast, often connect with ready-to-eat meal occasions and foodservice menus that prioritize warmth, robustness, and ease of preparation. The balance between these forms shapes production planning, smokehouse utilization, and the product innovation agenda of leading manufacturers.
Smoked Salmon Market
Innovation activity in recent months points to a broader category expansion beyond traditional fillet formats. Flavor experimentation, packaging refinement, and the introduction of derivative products such as salmon caviar indicate that manufacturers are seeking incremental growth through differentiation rather than relying solely on volume gains. Retailers and private label operators are simultaneously curating assortments that emphasize species variety, certification signals, and small-batch production narratives. This dual pressure from branded producers and retailer offerings is reshaping shelf strategy and menu integration across both channels.
Regulatory Environment and Trade Friction
Regulatory and trade conditions form a persistent layer of complexity in the smoked salmon market. U.S. import requirements and permitting regimes apply to many fishery products, including smoked salmon from certain origins, driven by disease and health standard considerations. These restrictions can influence sourcing strategies, lengthen lead times, and create volatility in cross-border supply planning. At a regional level, facility-level export constraints have also been observed, with indications that certain operations may face ongoing limitations on shipments to the United States into the first half of 2026. Such disruptions can cascade through downstream distribution networks, making geographic diversification and multi-origin sourcing strategically valuable.
On the domestic compliance side, the enforcement of the FDA's hazard controls guidance places cold-smoked production under continuous scrutiny for sanitation and environmental monitoring. This regulatory backdrop elevates the importance of validated process controls, supplier verification, and documentation rigor. For organizations evaluating capacity investments or supplier partnerships, the compliance burden is not a peripheral concern but a core determinant of operating risk and brand reputation. Our report integrates these regulatory considerations into the broader market framework, enabling readers to assess where friction is likely to persist and how leading operators adapt their operating models in response.
Strategic Relevance for 2026 Decision-Making
The strategic utility of this research for 2026 planning is rooted in its ability to connect macro momentum with operational reality. Executives facing capital allocation decisions can use the growth trajectory and concentration profile to calibrate expectations around market entry difficulty, share capture potential, and the realistic cadence of revenue scaling. Product and innovation teams can align their roadmaps with the observed direction of channel preferences, species and format diversification, and the certification and quality signals that increasingly influence purchase behavior. Supply chain and procurement leaders can benchmark their sourcing strategies against a backdrop of trade restrictions, multi-origin supply dynamics, and the heightened accountability surrounding cold-smoked safety controls.
This report is designed to support scenario-based thinking. Rather than presenting a single predetermined outcome, it structures the evidence so that leadership teams can test assumptions about pricing power, channel mix, capacity expansion, and geographic prioritization. The analysis examines how concentration dynamics affect competitive response times, how regulatory and trade conditions shape the cost and reliability of supply, and how product innovation cycles influence category perception and consumption frequency. Each of these dimensions is mapped to practical decision points, allowing subscribers to translate intelligence into planning inputs with precision.
In a market where the difference between effective and ineffective strategy often comes down to the quality of early-stage information, this study provides the granularity needed to move beyond broad assumptions. The macro outlook establishes the size and pace of the opportunity; the competitive and operational analysis reveals who is acting, how they are acting, and where the structural pressures are most acute; and the channel and product-form discussion clarifies where value creation is most defensible. Together, these elements form a decision-support foundation that is intended to be referenced repeatedly throughout the planning cycle, not merely read once and filed.
Smoked Meats Market
What This Study Delivers
Our methodology combines historical performance review with a seven-year forecast, anchored in a base year of 2025 and extending through 2032. The study examines total market size progression, growth rate assumptions, and the structural components that drive divergence across regions, product types, and applications. Segmentation is presented with the analytical depth required to understand relative scale and strategic relevance, while preserving the confidentiality of the finer breakdowns that constitute the full intelligence asset.
The competitive section profiles the companies that materially influence supply, pricing, and category direction, integrating recent developments such as new product introductions, private label expansions, packaging and flavor innovations, and product integrity events. These developments are contextualized within broader industry dynamics, including macro import patterns for seafood products, the weight and value share of salmon within those imports, and the specific regulatory requirements that shape production and trade. By weaving together company-level action with sector-level conditions, the report enables readers to interpret discrete events as part of a coherent strategic narrative.
Beyond the published segments, the complete study contains detailed regional and application-level breakdowns, type-specific evolution paths, company profiles with operational context, and scenario-oriented interpretation that supports targeted planning. These components are structured to answer the questions that executive teams repeatedly encounter: where growth is concentrated, which players are positioned to benefit, how regulatory and trade conditions alter the cost of participation, and what product and channel moves are most likely to resonate with demand. The report is therefore both an information resource and a planning instrument, intended for use in budgeting, sourcing strategy, product portfolio review, and competitive benchmarking.
Conclusion: Positioning for Durable Advantage
The smoked salmon market in 2026 is neither a nascent category nor a mature commodity play. It is a differentiated protein segment with steady growth characteristics, meaningful concentration among leading operators, and a competitive environment that increasingly rewards quality signaling, channel readiness, and operational discipline. The organizations that navigate the next phase most effectively will be those that treat intelligence as a strategic input rather than a retrospective summary.
This research publication has been designed to support that approach. It provides the scale and trajectory needed to frame opportunity, the competitive and regulatory context needed to manage risk, and the segmentation depth needed to prioritize action. For leaders shaping 2026 strategy, the value lies in using the analysis to pressure-test assumptions, align cross-functional plans, and identify the specific moves that convert market momentum into durable advantage. The full report extends far beyond the outline presented here, offering the complete dataset, company-by-company detail, and interpretive guidance necessary to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Smoked Salmon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasonic Cleaners Market to Hit $1.98B by 2032, 6.8% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Medical Ultrasonic Cleaners Market 2026-2032: A Executive Outlook
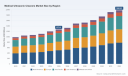
The global medical ultrasonic cleaners market stands at a critical inflection point as healthcare infrastructure modernization, stringent infection control mandates, and evolving regulatory frameworks reshape equipment procurement cycles. Over the 2026–2032 forecast horizon, the sector is projected to advance at a compound annual growth rate of 6.8 percent, translating into a trajectory from 1331.54 million USD in 2026 to 1980.92 million USD by 2032. This sustained expansion is not merely a function of volume replacement; it reflects a structural revaluation of decontamination workflows within sterile processing departments, operating rooms, and centralized instrument reprocessing facilities. For executives navigating medical device manufacturing, healthcare operations, or sterile supply chain management, the current market phase demands more than incremental procurement adjustments. It requires a disciplined, data-informed approach to technology adoption, regional deployment, and competitive positioning. Our newly released Medical Ultrasonic Cleaners Market research delivers precisely that analytical infrastructure, translating macro momentum into actionable enterprise strategy.
Market Trajectory and the 2026 Investment Thesis
Growth in the ultrasonic cleaning sector has accelerated decisively since 2020, when the market was valued at 987.65 million USD. By 2025, revenue had climbed to 1273.5 million USD, reflecting a compound expansion of roughly 6 percent annually across the historical record. The forecast period extends this momentum, with revenue projected to cross 1524.59 million USD in 2028, 1751.76 million USD in 2030, and 1913.12 million USD in 2031, before stabilizing at 1980.92 million USD in 2032. This trajectory is underpinned by three converging forces: the replacement of legacy manual decontamination protocols, the integration of ultrasonic technology into automated reprocessing lines, and the growing recognition of ultrasonic cavitation as a repeatable, validated method for contaminant removal on complex surgical and dental instrument geometries.
Medical Desktop Ultrasonic Equipment Market
For 2026 strategic planning, the most salient implication is that volume growth is increasingly tied to capability upgrades rather than baseline installation counts. Healthcare networks are reassessing capital expenditure priorities in light of labor constraints, throughput bottlenecks, and compliance documentation requirements. Ultrasonic systems that deliver programmable cycles, reproducible rinse profiles, and digital validation outputs are transitioning from optional enhancements to operational necessities. The research emphasizes that organizations which anchor their 2026 procurement roadmaps to process standardization, instrument throughput targets, and total cost of ownership modeling will capture disproportionate efficiency gains relative to peers pursuing ad hoc equipment rotation.
Core Report Architecture: From Data Layers to Decision Frameworks
The study is structured to support multi-functional decision-making across procurement, clinical operations, regulatory affairs, and market development. Rather than presenting isolated statistics, the analysis integrates demand-side drivers, supply-side capacity signals, and operational benchmarks into a cohesive planning environment. Key analytical modules include:
- Demand driver mapping across surgical, dental, laboratory, and medical device reprocessing workflows, with emphasis on throughput requirements, cycle validation expectations, and decontamination chain integration points.
- Product configuration analysis that distinguishes between benchtop, industrial, and specialized formats, linking tank capacity, frequency stability, and control architecture to use-case suitability and procurement risk.
- Regional deployment intelligence that evaluates healthcare spending patterns, manufacturing footprint expansion, and localized compliance expectations across major economic corridors without isolating granular share percentages.
- Competitive benchmarking that profiles product positioning, recent commercial moves, and strategic intent across the leading participants shaping category standards.
- Scenario-based modeling that allows leadership teams to test procurement timing, capacity expansion, and partnership strategies against shifting regulatory and reimbursement conditions.
This architecture is designed for execution. Procurement leaders can calibrate specification thresholds against validated deployment patterns. Clinical operations teams can align decontamination workflows with cycle reproducibility and purity expectations. Commercial teams can identify account segments where digital control upgrades, modular reconfiguration, or eco-friendly agent compatibility directly influence purchasing velocity. The report deliberately refrains from over-disclosing sub-segment percentages and localized valuation breakdowns within this executive preview; those layers remain fully accessible in the complete intelligence package, where the granularity supports precise territory planning and product-mix optimization.
Competitive Architecture and Strategic Orbital Moves
The competitive field is moderately concentrated, with the top three firms accounting for approximately 28.5 percent of category revenue and the top five expanding that footprint to roughly 35.2 percent. This concentration signals a market where scale, application specialization, and compliance readiness increasingly separate leaders from followers. Several manufacturers have moved aggressively to reinforce their positions through targeted product evolution, partnership formation, and regulatory alignment.
Crest Ultrasonics, headquartered in Trenton, New Jersey, has sharpened its focus on precision cleaning for surgical and medical instruments through healthcare-oriented product lines such as the Healthcare Pro Junior series, which incorporates multi-cycle wash and rinse capabilities alongside digital controls tailored for sterile processing environments. In September 2025, the company entered a strategic partnership with a leading hospital network to deliver customized ultrasonic cleaning solutions, a move that underscores the growing preference for networked deployments aligned to institutional workflow specifications.
Elma Schmidbauer GmbH, based in Singen, Germany, continues to advance modular ultrasonic cleaning platforms and has introduced eco-friendly InnoWave PCF models designed to support medical device instrument reprocessing and decontamination under evolving medical device regulation expectations. In July 2025, the company unveiled an eco-friendly ultrasonic cleaner utilizing biodegradable cleaning agents for medical applications, highlighting an industry-wide shift toward agent compatibility, waste stream management, and environmental compliance within sterile decontamination processes. Regulatory documentation reinforces that Elma Schmidbauer medical ultrasonic cleaners are positioned for instrument reprocessing in medical technology applications, with ultrasound cleaning systems expected to provide reproducible processes and the highest purity standards in medical device manufacturing.
Branson Ultrasonics, operating from Danbury, Connecticut, has reinforced its emphasis on digital control sophistication for surgical instrument cleaning. In August 2025, the company announced a new line of ultrasonic cleaners specifically for surgical instruments, incorporating advanced digital controls intended to enhance cleaning efficiency and support validation workflows. This product direction aligns with broader operating-room and sterile processing priorities around cycle repeatability, documentation readiness, and reduced manual intervention.
Ultrasonic Power Corporation, based in New Britain, Connecticut, manufactures industrial and medical-grade ultrasonic cleaners for pharmaceutical and medical applications, including custom systems engineered for precision part cleaning. Ultrasonic LLC, also United States-based, supplies machines designed for medical parts cleaning, handling small batches and complex components across healthcare and aerospace-related requirements. Together, these participants reflect a diversifying supplier base in which application specificity, custom configuration capability, and regulatory awareness increasingly influence purchasing decisions.
For enterprise strategists, these competitive signals carry clear implications. Supplier selection is no longer a function of unit price alone; it incorporates validation readiness, cycle programmability, compliance support, and compatibility with institutional decontamination chains. Organizations that evaluate vendors through a multi-criteria scorecard encompassing traceability, digital output quality, service response, and upgrade pathways will be better positioned to lock in operational resilience as category standards tighten.
Operational, Regulatory, and Labor Economics Shaping Procurement Behavior
Beyond competitive dynamics, the market is being reshaped by operational realities that directly influence specification priorities. High-capacity stainless steel tank models in the 5-liter to 8-liter range have become standard in medical ultrasonic cleaners for instrument pre-cleaning, reflecting a broader shift toward throughput-compatible hardware that can process reusable instrument sets efficiently at the front end of decontamination workflows. This hardware normalization reduces variability in cycle execution while supporting consistent exposure of instrument surfaces to cavitation activity.
Labor economics are also accelerating adoption. Ultrasonic cleaners deliver measurable labor savings by replacing manual cleaning methods for surgical instruments in sterile processing departments. As staffing pressures persist and training consistency becomes a recognized operational risk, automated or semi-automated cleaning cycles offer a practical lever for reducing variability, reducing rework, and improving instrument readiness before sterilization. Reimbursement and compliance structures further reinforce this direction. In practice, instrument cleaning equipment used in healthcare settings must support decontamination prior to autoclaving, and systems that align with established healthcare standards are increasingly favored during procurement reviews and quality audits.
Regulatory context adds another layer of strategic relevance. Medical technology applications are subject to evolving expectations around documentation, process reproducibility, and validation traceability. Organizations are therefore placing greater weight on equipment that supports repeatable cycles, verifiable rinse outcomes, and integration into broader quality management systems. In this environment, procurement decisions are increasingly evaluated not just on cleaning performance in isolation, but on how effectively a system supports downstream compliance and sterilization readiness.
Medical Ultrasonic Cleaners Market
Strategic Playbook for 2026 Enterprise Decision-Makers
Translating these dynamics into executable strategy requires a structured approach. The research outlines several priorities that resonate across healthcare networks, medical device manufacturers, and equipment distributors:
- Define instrument reprocessing targets first, then map equipment specifications to those targets. Throughput, cycle flexibility, and validation output should be treated as interdependent decision variables rather than separate purchasing dimensions.
- Embed total cost of ownership analysis into capital planning. Upfront pricing comparisons should be supplemented with assessments of labor displacement, rework reduction, maintenance expectations, and compliance documentation value.
- Align supplier evaluation with future regulatory and environmental expectations. Preference should be given to platforms that accommodate standardized cycle programs, digital record generation, and compatibility with evolving cleaning agent requirements.
- Treat regional deployment as a strategic variable. Healthcare infrastructure maturity, manufacturing presence, and localized service capacity influence implementation timelines and long-term support reliability, making geography a relevant component of procurement planning.
- Use competitive intelligence to anticipate category direction. Recent product launches, partnerships, and eco-friendly innovations signal where specification expectations are heading, enabling earlier internal alignment and reduced procurement friction.
These priorities are not generic best practices; they are derived from the observed intersection of demand-side operational pressures, supplier innovation cadence, and regulatory reinforcement within the ultrasonic cleaning category. Organizations that operationalize them early in the 2026 planning cycle will have a clearer path to procurement efficiency, reduced implementation risk, and stronger alignment with downstream sterilization and quality requirements.
The Complete Intelligence Layer: What Is Held Back and Why
This executive overview is intentionally structured as a strategic preview. The purpose is to establish analytical credibility, demonstrate sector fluency, and clarify how the full report supports decision-making without dispersing the most granular intelligence across public-facing formats. Core segmentation values, regional revenue distributions, application-level breakdowns, and product-type splits remain embedded in the complete study, where they can be cross-referenced against operational benchmarks, competitive profiles, and scenario models without dilution. That architecture allows procurement and strategy teams to apply precise figures to territory planning, product-mix evaluation, and vendor comparison without exposing sensitive analytical layers prematurely.
In practice, the full report provides the quantitative scaffolding required to convert directional momentum into specific procurement, expansion, and partnership decisions. The macro trajectory, competitive positioning, regulatory context, and operational drivers presented here form the strategic foundation; the detailed segmentation and valuation layers supply the execution-level precision. Together, they create a planning environment that supports both short-term purchasing calibration and multi-year capability roadmapping.
Closing Perspective: Positioning for Measured, High-Value Growth
The medical ultrasonic cleaners market is advancing along a clearly defined growth path, but the strategic opportunity lies less in the headline numbers than in the operational and regulatory conditions that are reshaping procurement logic. As the category moves from 1331.54 million USD in 2026 toward nearly 1980.92 million USD in 2032, the organizations that win will be those that convert that momentum into disciplined specification choices, validated workflow integration, and supplier relationships aligned with compliance, reproducibility, and efficiency goals. The complete Medical Ultrasonic Cleaners Market research is built to support precisely that outcome, offering the depth, structure, and benchmarking context required to move from informed awareness to decisive execution.
For detailed analysis of this topic, please visit the official page: Medical Ultrasonic Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coding Equipment Market Hits $6.75B in 2025, Projects CAGR of 6.12% to $10.27B by 2032
By PW Consulting, 2026-09-16
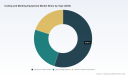
Strategic Imperatives in the Global Coding and Marking Equipment Market: Navigating Growth Through 2032
In an era where supply chain transparency, regulatory compliance, and packaging sustainability dictate competitive advantage, the coding and marking equipment market stands at a critical inflection point. Manufacturing leaders, procurement directors, and automation strategists are no longer asking whether to upgrade their marking infrastructure, but how to align capital allocation with a market that is expanding at a steady pace while simultaneously fragmenting under technological, regulatory, and material-cost pressures. Our latest comprehensive study on the Coding and Marking Equipment Market transforms raw trajectory data into a decision-ready framework, offering executives a clear line of sight into the operational and financial implications of the 2026–2032 forecast window.
The market’s historical foundation provides essential context for forward-looking strategy. Between 2020 and 2025, sector revenue climbed from approximately 5.0 billion USD to 6.75 billion USD, reflecting a period of accelerated line automation, heightened traceability mandates, and widespread adoption of advanced coding technologies across high-volume production environments. This momentum is projected to sustain itself through the end of the decade, with market valuation expected to reach 7.21 billion USD in 2026 and continue its upward trajectory toward 10.27 billion USD by 2032. The forecast period compound annual growth rate of 6.12 percent underscores a mature but structurally resilient industry, one whose expansion is increasingly driven not by volume alone, but by precision, compliance readiness, and lifecycle optimization.
For enterprise decision-makers, these figures represent more than a top-line growth narrative. They signal a shifting capital allocation landscape where legacy equipment refresh cycles, cross-platform compatibility, and total cost of ownership calculations must be recalibrated against a backdrop of evolving packaging substrates, tightening food-safety disclosures, and intensifying competitive consolidation. Our report translates these macro trends into actionable intelligence, enabling strategy teams to stress-test investment theses, benchmark regional performance vectors, and anticipate demand inflection points before they materialize in procurement cycles.
Decoding the Operational Architecture of the Analysis
The study is engineered for practitioners rather than passive observers. It maps the full lifecycle of coding and marking deployment, from technology selection and line integration to maintenance economics and compliance verification. Readers will encounter a methodical dissection of how different printing modalities interact with production throughput, substrate variability, and regulatory labeling requirements. The analysis places particular emphasis on the operational tradeoffs that procurement and engineering teams face daily: balancing ink-based continuity against laser permanence, evaluating thermal transfer durability under abrasive or temperature-fluctuating conditions, and aligning printer head lifecycle with line-speed targets and changeover frequency.
Beyond equipment taxonomy, the report integrates upstream cost dynamics that directly influence capital expenditure planning. Recent shifts in raw material pricing have compressed margins across packaging supply chains, creating ripple effects for coding system operators who must now weigh upfront hardware investments against ongoing consumables volatility. The analysis incorporates these material-cost pressures into scenario modeling, helping executives evaluate whether modular upgrades, ink-substitution strategies, or full-line conversions offer the most defensible path to sustained ROI. This practical orientation ensures that financial teams can align operational roadmaps with realistic cost curves rather than static vendor quotes.
Compliance architecture forms another critical pillar of the study. As labeling requirements become more granular and audit expectations more stringent, the functional scope of coding equipment has expanded beyond simple identifier placement. The report examines how verification workflows, third-party audit readiness, and automated inspection integration are reshaping procurement priorities. Organizations seeking to future-proof their packaging lines will find structured guidance on aligning coding capabilities with traceability mandates, nutrient-disclosure frameworks, and sustainability-driven substrate transitions.
Competitive Dynamics and Strategic Differentiation
The market’s competitive architecture reflects both entrenched 리더십을 and continuous technological repositioning. The sector remains moderately concentrated, with the top three players collectively commanding roughly 45.8 percent of revenue and the top five firms controlling approximately 61.2 percent. This distribution indicates a landscape where scale advantages, service networks, and cross-vertical application expertise create meaningful barriers, yet leave sufficient headroom for specialized innovators and regional specialists to capture value through niche performance differentiation.
At the center of the competitive field are organizations that have built deep application fluency across high-demand verticals. Domino Printing Sciences, headquartered in Cambridge, United Kingdom, has maintained a strong focus on continuous inkjet, laser, and hybrid inkjet coding systems, with dedicated solutions engineered for high-speed traceability on cans, bottles, cartons, and cases. Its recent product cadence illustrates the pace of innovation shaping the market: in March 2026, the company introduced the Cx150i direct-to-box printer utilizing oil-based ink for more sustainable and accessible coding on food packaging, alongside the Ux360i UV Laser Coder designed for high-speed sustainable packaging applications in food and beverage lines. The same period saw the release of the Gx-Series PRO Printhead, built to support the industry’s transition toward 2D coding on food packaging. These developments were preceded by the October 2025 introduction of the Dx1060i CO2 Laser Coder and F-Series fibre lasers, which target permanent code generation on beverage cans, glass, and plastics.
Videojet Technologies, based in Auckland, New Zealand, continues to position its CIJ, TIJ, and laser coder portfolio around permanent, food-safe prints tailored for food and beverage packaging lines. Markem-Imaje, operating from Aubervilliers, France, offers thermal inkjet, continuous inkjet, and laser marking systems calibrated for product- and case-level coding within food and beverage environments. Matthews International Corporation, headquartered in Pittsburgh, Pennsylvania, supplies TIJ, laser, and labeling systems aimed at high-resolution and permanent coding applications, while ID Technology, based in Minneapolis, Minnesota, delivers thermal inkjet coders and integrated systems for direct marking on cans, jugs, and cartons.
The competitive field also includes significant contributions from industrial equipment manufacturers and compliance-adjacent service providers. Hitachi Industrial Equipment Systems, headquartered in Tokyo, Japan, manufactures laser and inkjet coding systems optimized for traceability in industrial food and beverage settings. SATO Holdings Corporation, also based in Tokyo, provides TIJ and thermal transfer coders focused on packaging identification and regulatory compliance. SGS, headquartered in Geneva, Switzerland, extends the ecosystem through third-party verification and audit services for coding and marking systems deployed in food and beverage packaging lines. Rounding out the roster, Gem Gravure, based in the United States, supplies regulation-quality coding equipment specifically engineered for food and beverage packaging applications.
For strategy teams, this competitive mosaic matters because vendor selection is no longer a straightforward equipment-procurement exercise. It is a multi-year partnership decision that encompasses service responsiveness, technology roadmaps, consumables availability, and compliance-support capabilities. The report provides a structured comparison framework that helps organizations evaluate not just hardware specifications, but the broader value chain resilience each supplier brings to high-volume, high-compliance production environments.
Regulatory and Material-Cost Pressures Redefining Market Dynamics
External forces are accelerating the strategic relevance of coding and marking infrastructure. Regulatory evolution is one of the most immediate drivers. In January 2025, the FDA proposed a rule requiring a front-of-package Nutrition Info box on most packaged foods, mandating clear display of saturated fat, sodium, and added sugars categorized as Low, Medium, or High. By April 2025, the agency finalized updates to the healthy nutrient content claim definition, tightening limits on added sugars, saturated fat, and sodium. These developments do not merely change label content; they reshape the precision, legibility, and verification demands placed on coding systems, particularly on high-speed lines where print quality, placement consistency, and audit-ready documentation must remain uncompromised.
Simultaneously, raw material dynamics are injecting cost volatility into packaging production and, by extension, into coding system planning. In 2026, PET, PP, and PS plastic sheet prices rose 15–30 percent due to energy costs and paraxylene supply constraints. Corrugated paperboard and paper packaging costs also increased amid higher pulp and energy prices for food packaging production. For coding and marking operators, these shifts affect substrate compatibility, ink adhesion performance, laser interaction with treated surfaces, and overall line-tuning requirements. Equipment that performs reliably on stable substrate profiles may require recalibration, consumables substitution, or complementary inspection modules when material characteristics fluctuate.
These intersecting pressures are reshaping market dynamics in ways that reward proactive planning. Organizations that treat coding infrastructure as a static cost center risk encountering deployment bottlenecks when regulatory label formats change or when substrate transitions alter print stability. Conversely, enterprises that align their equipment strategy with anticipated regulatory timelines and material-cost trajectories can convert compliance and packaging shifts into efficiency gains, reducing downtime, minimizing rework, and improving audit outcomes.
Why This Study Matters for 2026 Decision-Making
The value of this research lies in its translation of trajectory data into operational clarity. Enterprise leaders operating in 2026 must navigate a market that is simultaneously expanding, consolidating, and being reshaped by compliance mandates and input-cost volatility. Top-line growth figures alone cannot guide capital deployment; they must be paired with segmentation intelligence, competitive capability mapping, regulatory horizon scanning, and total-cost modeling that reflects real-world line conditions.
Coding and Marking Equipment Market
Our report delivers that integrated view. It helps strategy and operations teams identify where demand concentration is forming, which technology pathways align with upcoming packaging and labeling requirements, and how vendor portfolios differ in their capacity to support rapid changeover, substrate variability, and verification workflows. It also contextualizes market concentration dynamics, enabling organizations to evaluate whether partnership with a large-scale incumbent, a specialized technology provider, or a service-oriented verification partner best matches their risk tolerance and growth targets.
Crucially, the study is designed to support decisions that extend beyond the current fiscal year. With a forecast horizon stretching to 2032, executives gain a structured basis for multi-phase investment planning, technology refresh scheduling, and capacity alignment. Rather than reacting to equipment obsolescence or compliance gaps after they emerge, organizations can sequence upgrades, model consumables exposure, and stress-test vendor commitments against plausible regulatory and material-cost scenarios.
Accessing the Full Strategic Blueprint
The coding and marking equipment market is entering a phase where precision, compliance, and cost resilience will separate scalable operators from those burdened by reactive procurement. This study provides the analytical foundation needed to navigate that phase with confidence. It combines market trajectory mapping, technology and application segmentation, competitive profiling, and dynamic cost-and-regulation context into a single decision-support instrument.
Coding and Marking Systems and Solutions Market
To explore the complete segmentation breakdown, detailed vendor capability comparisons, scenario-based cost modeling, and region-specific growth vectors, we invite you to access the full report through our source page. The complete intelligence package is structured for immediate integration into capital planning, procurement strategy, and operational roadmapping, enabling your team to move from market awareness to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Coding and Marking Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Payment Cards Market to Hit $364.76B by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
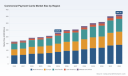
Navigating the Next Wave: Strategic Insights from the Commercial Payment Cards Market Research 2026
The landscape of corporate spending is undergoing a seismic shift. As businesses grapple with inflationary pressures, evolving regulatory frameworks, and the demand for seamless digital integration, the commercial payment card sector has emerged as a critical lever for operational efficiency. For decision-makers navigating the fiscal calendar of 2026, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. PW Consulting is proud to unveil our latest comprehensive market research, designed to equip leaders with the intelligence needed to capitalize on growth opportunities and mitigate emerging risks in the commercial payment ecosystem.
This research is anchored in rigorous data analysis covering historical performance from 2020 through 2025 and extending robust forecasts through 2032. The macro-environment presents a compelling story of resilience and expansion. In 2025, the global revenue for commercial payment cards reached approximately 229.05 billion USD. Looking ahead, the market is projected to climb to 249.66 billion USD in 2026, marking a significant inflection point in corporate adoption rates. Our forecast models indicate a steady compound annual growth rate of 6.98 percent throughout the forecast period, with revenues expected to surpass 364.76 billion USD by 2032. These figures underscore a sustained appetite for flexible payment instruments that bridge the gap between traditional corporate treasury functions and modern procurement needs.
Decoding Market Concentration and Competitive Forces
One of the most critical aspects of our analysis focuses on the competitive dynamics that define the industry. The market is characterized by a moderate level of concentration, where strategic positioning among top-tier players dictates the pace of innovation. Our report details a landscape where the top three companies command a combined market share of roughly 49.5 percent, while the top five entities control approximately 62.8 percent of the revenue pool. This structure suggests that while dominant networks hold significant sway, there remains substantial room for specialized issuers and niche providers to carve out profitable segments.
Plastic Cards Market
The competitive arena is populated by a diverse mix of global network operators and specialized issuers. Giants like American Express, Visa, and Mastercard continue to dominate the infrastructure layer, offering robust networks that support virtual purchase cards and corporate spend management solutions. American Express, headquartered in New York, remains a key player in issuing commercial payment cards including virtual purchase cards for business-to-business procurement. Similarly, Visa, based in San Francisco, operates a global network supporting commercial payment cards including virtual cards for corporate spend management, while Mastercard, located in Purchase, NY, provides network infrastructure with a focus on virtual and single-use variants for B2B transactions.
However, the ecosystem extends far beyond these primary networks. Discover Financial Services, based in Riverwoods, IL, issues commercial payment cards for business expense tracking and virtual solutions, catering to specific expense management needs. International reach is exemplified by JCB in Tokyo and UnionPay in Beijing, the latter facilitating commercial payment cards with contactless and virtual options to support cross-border commerce. On the specialized issuer front, companies like WEX in Minneapolis provide commercial fleet and virtual payment cards for business expenses, whereas Corpay in Nashville issues and manages commercial payment cards for corporate travel and expense programs.
Innovation is also being driven by agile entrants and standards bodies. Engine, based in Denver, recently made waves with the launch of the Engine X Visa-branded corporate charge card specifically for small and mid-sized businesses. This product features spending controls and travel rewards, directly addressing the needs of the SMB segment which often feels overlooked by larger issuers. Furthermore, standards development plays a crucial role in interoperability and security. X9, the standards body in Annapolis, MD, developed and published X9.149 for single-use virtual business-to-business payment cards, aiming to streamline transaction efficiency.
Recent Developments Shaping the 2026 Landscape
Real-time intelligence is vital in a sector moving this fast. Our research integrates the latest developments that are actively reshaping the value proposition for corporate clients. In March 2026, Engine announced the launch of their corporate charge card, featuring spending limits, merchant restrictions, and up to 10 percent rewards on business travel. This move highlights a trend toward incentivizing specific spending categories while maintaining strict control parameters, a balance that many finance teams are seeking.
Simultaneously, the regulatory and standards environment is tightening to support higher efficiency and security. In April 2026, the Accredited Standards Committee X9 published the X9.149 standard for single-use virtual purchase card payment automation. This development is designed to improve B2B transaction efficiency and reconciliation following ISO 20022 messaging standards. Such standardization efforts are critical for reducing friction in accounts payable processes and enhancing the auditability of corporate spending.
Beyond specific product launches, broader industry dynamics are influencing market behavior. The Federal Reserve Board reported on average debit card interchange fees by payment card network in December 2025, providing essential data for cost-benefit analyses of different card programs. Security remains paramount, with the PCI DSS Card Production and Provisioning Physical and Logical Security Requirements defining standards for card manufacturing, transport, and personalization. Additionally, the Payment Card Industry Data Security Standard version 4.0 guides organizations on card data handling and compliance, a critical consideration for any firm integrating payment cards into their IT infrastructure.
Infrastructure costs also play a background role in the economics of payment processing. The American Society of Civil Engineers 2025 Infrastructure Report Card noted that deployment costs for broadband infrastructure increased over 10 percent with materials and labor as primary drivers. While this relates to physical infrastructure, it impacts the broader digital ecosystem supporting payment technologies. Furthermore, macro-level shifts are occurring, as highlighted by the McKinsey Global Payments Report in September 2025, which pointed to growing payment sovereignty initiatives in regions such as Europe and Brazil to reduce reliance on global intermediaries. This trend could influence network selection and localization strategies for multinational corporations.
Segmentation Dynamics and Application Scenarios
Understanding where the revenue is generated is key to allocating resources effectively. Our research delves deep into the segmentation of the market by type and application, revealing distinct growth drivers within each category. The market is segmented by type into Credit Cards, Debit Cards, and Prepaid Cards. Credit cards continue to hold a substantial portion of the market value, reflecting their utility in managing cash flow and earning rewards, while Debit Cards offer a controlled spending mechanism linked directly to funds. Prepaid Cards also represent a significant segment, often utilized for specific budgeting purposes or employee allowances.
From an application perspective, the divide between Large Business Cards and Small Business Cards illustrates the diverse needs across the corporate spectrum. Large Business Cards constitute a major share of the application market, driven by high-volume procurement and complex travel requirements. Small Business Cards, while representing a smaller total revenue share compared to the enterprise segment, are witnessing heightened innovation and competitive pressure from issuers like Engine looking to capture the SME market. Our report provides granular analysis of how these segments interact with regional dynamics and type preferences without exposing the specific numerical splits that constitute our core proprietary intelligence.
Geographic distribution also plays a pivotal role in strategy formulation. The market serves key regions including North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique regulatory environments, adoption rates, and competitive intensities. For instance, payment sovereignty trends may impact strategies in Europe and Latin America differently than in North America. Our analysis contextualizes these regional variations to help clients prioritize market entry or expansion efforts based on their specific risk tolerance and growth objectives.
The Strategic Value of Comprehensive Intelligence
Why does this level of detail matter for your 2026 planning? In a market projected to grow by over 130 billion USD between 2026 and 2032, the margin for error shrinks as competition intensifies. Access to detailed segmentation data, competitive profiling, and regulatory roadmaps allows organizations to move from reactive spending management to proactive financial strategy. Whether you are a issuer looking to refine your product portfolio, a corporate treasurer optimizing expense policies, or an investor assessing the viability of fintech ventures in the payments space, this report provides the foundational knowledge required to make informed decisions.
The report goes beyond high-level numbers to explore the operational realities faced by market participants. It examines how reimbursement dynamics, influenced by factors such as interchange fee structures, affect the total cost of ownership for corporate card programs. It also assesses how compliance with evolving security standards impacts procurement timelines and vendor selection. By synthesizing data on market concentration, company profiles, and recent developments, we offer a 360-degree view of the ecosystem.
Our analysis of key companies includes detailed profiles covering their headquarters, operational focus, and strategic moves. For example, understanding the focus of WEX on fleet and virtual payment cards versus Corpay's emphasis on corporate travel and expense programs helps tailor partnership or benchmarking strategies. Similarly, tracking the standardization efforts of bodies like X9 ensures that technology investments align with future-proof protocols.
Commercial Payment Cards Market
Unlock the Full Intelligence
The insights summarized here represent only the surface of the comprehensive intelligence available in the full PW Consulting Commercial Payment Cards Market Research. To truly leverage the 6.98 percent CAGR opportunity and navigate the complexities of a market reaching 364.76 billion USD by 2032, decision-makers need access to the complete dataset, detailed forecasts, and proprietary analytical models.
We invite you to access the source webpage to download the full report. There you will find the specific regional growth rates, detailed application segment valuations, and deep-dive competitive benchmarking that cannot be fully disclosed in this overview. Equip your team with the precise data needed to outperform in the evolving commercial payment landscape. Visit our report page today to secure your copy and start transforming market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Commercial Payment Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Compact Construction Equipment Market to Reach $311M by 2032, Growing at 5.1% CAGR
By PW Consulting, 2026-09-16
Compact Construction Equipment Market: Strategic Intelligence for 2026 Decision-Makers
The compact construction equipment sector is entering a phase of transformative acceleration, driven by shifting labor dynamics, stringent regulatory frameworks, and rapid technological integration. For enterprise leaders, procurement strategists, and market development teams, the operational environment in 2026 demands more than surface-level awareness. It requires granular, forward-looking intelligence capable of informing capital allocation, product positioning, and competitive response. Our latest comprehensive research report on the Compact Construction Equipment Market delivers precisely this intelligence, translating historical trajectories and forward forecasts into actionable strategic playbooks for the 2026 fiscal landscape and beyond.
The Macro Trajectory: From Recovery to Sustained Expansion
Over the past half-decade, the compact equipment segment has demonstrated remarkable resilience, evolving from post-pandemic supply chain recalibration into a structurally expanding market. The addressable revenue base has grown consistently, reflecting sustained demand across construction, infrastructure, and specialized industrial applications. This growth trajectory is not merely cyclical; it is underpinned by fundamental shifts in how site work is executed, how fleets are optimized, and how operators are trained. With a projected compound annual growth rate of 5.1 percent across the forecast horizon extending to the early 2030s, the market is poised to surpass the 300 million dollar threshold, representing a meaningful expansion from its mid-2020s baseline.
This macro progression masks critical inflection points that will define competitive positioning throughout 2026 and the subsequent years. Understanding where volume is accumulating, how pricing power is shifting among equipment classes, and which operational bottlenecks are reshaping procurement cycles requires a disciplined analytical framework. Our report constructs that framework, offering enterprise teams a structured vantage point from which to evaluate market entry, product portfolio expansion, and commercial strategy.
Market Structure and Competitive Realities in 2026
The competitive architecture of the compact equipment landscape is defined by a concentrated yet highly dynamic environment. Leading manufacturers have entrenched strong market share, with the top three and top five players collectively commanding substantial portions of total industry revenue. This concentration reflects decades of brand equity, distribution network maturity, and service infrastructure investment. Yet, within this consolidated top tier, a wave of strategic repositioning is underway, particularly as electrification, smart automation, and regional market penetration converge to reshape competitive boundaries.
Established industrial leaders continue to leverage their scale, engineering heritage, and financing ecosystems to reinforce their standing. Their compact offerings span tracked loaders, skid steers, and mini excavators, each engineered for versatility across general construction, landscaping, utility work, and material handling. Financing incentives, including promotional terms structured through mid-2026, are actively deployed to stimulate fleet acquisition and lower procurement barriers for contractors and rental operators. At the same time, legacy manufacturers are recalibrating product roadmaps to address evolving operator expectations and compliance mandates.
Compact Construction Equipment Market
Construction Equipment Market
Simultaneously, emerging entrants and regional manufacturers are intensifying their competitive presence. Korean equipment groups, for instance, have been aggressively expanding their compact construction and demolition equipment portfolios, emphasizing hands-on demonstrations, customizable job-site configurations, and brand-led North American market entry strategies. These organizations are signaling long-term commitment through trade show participations, product unveilings, and operational demonstrations designed to capture the attention of procurement teams seeking differentiated value propositions.
Product Innovation and the Strategic Imperative of Electrification
Equipment innovation in the compact segment is no longer a peripheral development track; it is a central driver of commercial differentiation. Recent industry showcases have highlighted a clear pivot toward next-generation smart and automated compact equipment, with manufacturers unveiling concept platforms, enhanced operator-assist technologies, and streamlined mechanical architectures. Electrically powered models are increasingly prominent, reflecting both regulatory tailwinds and end-user demand for quieter, zero-emission site operations. Mini excavator lineups, in particular, have seen notable advancements in chassis engineering, control precision, and modular customization capabilities.
For corporate strategy teams, these product developments carry direct implications. Fleet electrification planning, service network readiness, battery lifecycle considerations, and operator training reconfiguration all intersect with procurement timing and total cost of ownership models. Our analysis dissects these innovation trajectories, mapping them against adoption curves, segment-specific demand patterns, and regional compliance timelines to help decision-makers anticipate where competitive advantage will be captured in the near term.
Regulatory Shifts, Labor Dynamics, and Supply Chain Headwinds
The operational environment for compact equipment operators is being reshaped by intersecting external forces. In Europe, the revised Construction Products Regulation has taken full effect, introducing stricter sustainability and digital compliance requirements that reverberate through equipment specifications, documentation, and certification workflows. Across North America, regional energy codes and space conditioning mandates are altering equipment specification standards, placing renewed emphasis on efficiency-aligned machinery and compliant operational configurations.
Concurrently, labor market realities continue to exert pressure on construction operations. Skilled labor shortages persist, accelerating the adoption of compact equipment that reduces training time, simplifies site workflows, and integrates automation features capable of compensating for workforce constraints. This labor-driven demand signal reinforces the strategic value of compact machinery as a productivity multiplier rather than a mere capacity substitute.
On the supply side, material cost volatility remains a persistent concern. Fluctuations in steel and aluminum pricing, influenced by tariff structures and trade tensions, continue to impact manufacturing margins, inventory planning, and lead-time reliability. At the same time, engineering adaptations such as the incorporation of high-strength steel and advanced alloys in booms and chassis are improving durability and extending service intervals, partially offsetting input cost pressures through performance gains. These interconnected dynamics require scenario-aware planning, and our report structures this complexity into clear strategic considerations for procurement, production, and distribution leadership.
What follows is a curated overview of the analytical depth contained within our full market research publication. The sections below illustrate how each dimension of the study is designed to support concentrated decision-making in 2026.
In-Depth Market Sizing, Segmentation, and Forecast Architecture
Our research constructs a multi-layered sizing and forecasting model that traces historical performance and projects forward market evolution across the defined forecast period. Rather than presenting a single top-line figure, the report decomposes market structure across equipment classifications, application domains, and geographic footprints, enabling stakeholders to identify where volume concentration is strongest and where growth acceleration is most pronounced. Each segmentation layer is examined through the lens of operational relevance, allowing readers to evaluate how product mix decisions, regional expansion initiatives, and application-specific demand signals will interact throughout the planning horizon.
The forecast architecture accounts for base-year baselines, historical trend calibration, and forward projections that incorporate demand elasticity, regulatory pacing, and technology adoption curves. By aligning forecast outputs with strategic planning cycles, enterprise teams can stress-test portfolio assumptions, evaluate market entry timing, and model revenue scenarios with greater precision. The complete segmentation datasets, regional volume distributions, application-level revenue splits, and equipment-class breakdowns are detailed within the full report, providing the quantitative foundation required for board-level presentations, capital planning, and commercial forecasting.
Competitive Intelligence and Strategic Move Analysis
Understanding competitive positioning requires more than a roster of key players. It demands a structured assessment of where manufacturers are deploying capital, how they are differentiating product lines, and which commercial tactics are reshaping buyer behavior. Our competitive analysis maps the strategic activity of leading organizations across the compact equipment ecosystem, examining product specialization, geographic focus, financing programs, and demonstration-driven market engagement.
Analysis covers organizations with broad compact equipment portfolios as well as those executing targeted regional expansions and product launches. The report evaluates how manufacturers are aligning their offerings with application-specific requirements, how they are leveraging trade events and hands-on demonstrations to accelerate adoption, and how new model introductions are influencing competitive pressure points. Recent product unveilings, trade show activations, and electrification-focused launches are contextualized within broader market dynamics, allowing readers to distinguish between tactical visibility and structurally significant strategic moves.
This competitive mapping is designed to support benchmarking, identify white-space opportunities, and inform partnership or distribution strategy decisions. Full competitive profiles, recent development timelines, product positioning summaries, and strategic implication analyses are documented comprehensively within the complete publication.
Operational Dynamics, Risk Factors, and Strategic Response Frameworks
Effective market strategy requires an integrated view of external pressures and internal capability adjustments. Our report synthesizes the most consequential operational dynamics shaping the compact equipment sector, translating regulatory, labor, and supply-chain developments into actionable response frameworks. Rather than treating these factors as isolated constraints, the analysis positions them as interconnected variables that collectively influence pricing strategy, inventory management, product specification decisions, and regional market prioritization.
Labor-driven productivity requirements, compliance deadlines, raw material cost exposure, and material innovation trends are examined as strategic inputs rather than background noise. The report outlines how organizations can structure procurement timing, service readiness, and product mix adjustments to navigate these pressures while preserving margin integrity and market responsiveness. Scenario-based considerations are embedded throughout, helping leadership teams prepare for divergent operating environments and make calibrated decisions under uncertainty.
Why This Research Matters for 2026 Strategic Planning
As market participants navigate a landscape defined by concentrated competition, accelerating product innovation, evolving compliance mandates, and persistent operational constraints, the cost of incomplete information is rising. Strategic decisions made in 2026 will have compounding effects on fleet positioning, regional growth trajectories, and competitive resilience through the remainder of the decade. Access to structured, forward-looking intelligence is therefore not a supplementary advantage but a foundational requirement.
Our Compact Construction Equipment Market research is engineered to serve as that foundation. It consolidates historical context, forecast modeling, competitive mapping, regulatory analysis, and operational dynamics into a unified decision-support resource. The complete report enables leadership teams to move beyond high-level market awareness and into precise, evidence-based strategy formulation. For organizations seeking to refine procurement roadmaps, evaluate product portfolio expansion, benchmark against rival moves, or identify high-opportunity segments and regions, the full publication provides the depth and clarity necessary to act with confidence.
The complete dataset, extended segmentation breakdowns, detailed competitive profiles, and forward scenario analyses are available in the full report. Explore the complete intelligence package to align your 2026 strategy with the structural realities shaping the compact construction equipment market.
For detailed analysis of this topic, please visit the official page: Compact Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Visual Effects Services Market to Reach $344.8M by 2032, Growing at 7.12% CAGR from 2026-2032
By PW Consulting, 2026-09-16
The Visual Effects Services Market in 2026: Strategic Intelligence for Enterprise Decision-Making
Navigating a Transformative Era in Visual Storytelling
The global Visual Effects Services Market has entered a defining phase where artistic ambition, technological acceleration, and financial engineering converge. As production pipelines evolve and audience expectations shift toward immersive, photorealistic storytelling, enterprises across film, television, gaming, and advertising must look beyond creative intuition and ground their strategies in rigorous market intelligence. This new research publication from PW Consulting provides a comprehensive, data-driven examination of the Visual Effects Services Market, offering executives a strategic blueprint for navigating the opportunities and pressures that will shape the industry through the end of the decade.
The market has demonstrated consistent momentum across the historical review period, reflecting sustained demand for high-end visual content and expanding investment in digital production capabilities. Our analysis traces this trajectory from 2020 through the base year of 2025, capturing the structural shifts that have redefined competitive positioning, service delivery models, and revenue generation across the sector. The data underscores a market that has not merely grown but fundamentally restructured itself around new workflows, platform diversification, and the integration of advanced computation into creative processes.
For enterprise leaders, the critical question is no longer whether visual effects will play a central role in content strategy, but how to allocate capital, select partners, and position operations in a landscape characterized by rapid technological change, evolving incentive frameworks, and intensifying competition for specialized talent. This research is designed to answer that question with precision, offering actionable intelligence that supports investment planning, vendor selection, geographic expansion, and long-term portfolio management.
Forecasting Framework: Aligning 2026 Decisions with the 2026–2032 Outlook
The forecast period covered in this report spans from 2026 through 2032, a window that coincides with pivotal developments in production technology, distribution economics, and regulatory incentives. By anchoring strategic planning in a disciplined forward-looking framework, organizations can anticipate demand shifts, assess the ROI of capability investments, and identify the inflection points where competitive advantage will be won or lost.
The report integrates historical demand patterns with forward projections to deliver a coherent view of market evolution. This approach enables decision-makers to stress-test assumptions against multiple scenarios, evaluate the timing of capacity expansions, and understand how macro-level growth translates into sector-specific opportunities. Rather than presenting growth as a monolithic trend, the analysis disentangles the underlying drivers—content volume, platform fragmentation, technological adoption, and regional production migration—to reveal where value is being created and how it is likely to redistribute over time.
Strategic alignment with this forecast horizon is essential for organizations that must commit resources today to capabilities that will mature over the next several years. Whether the objective is to internalize certain production functions, form strategic alliances with specialized vendors, or reallocate budget toward higher-value service tiers, the report provides the contextual foundation needed to make those choices with confidence. The emphasis throughout is on decision relevance: every dataset, every segmentation lens, and every competitive observation is framed to support operational and financial planning in the current fiscal cycle and beyond.
Report Architecture: Operational Depth Across Segments, Competition, and Dynamics
To support rigorous strategic analysis, this research is structured around a set of operational modules that together provide a complete picture of the market environment. The segmentation framework examines the market through multiple dimensions, allowing readers to isolate the demand characteristics, service configurations, and growth profiles that are most relevant to their specific business context. By analyzing the market across type-based and application-based lenses, the report illuminates how different service categories and end-use channels contribute to overall demand patterns and where structural advantages are emerging.
The regional dimension of the analysis adds further granularity, mapping how production activity, vendor ecosystems, and incentive environments vary across major geographic corridors. This regional perspective is particularly valuable for organizations evaluating location strategy, outsourcing partners, or international expansion, as it surfaces the interplay between local production capacity, talent availability, and policy support. Importantly, the report maintains a disciplined focus on strategic interpretation rather than exhaustive enumeration, ensuring that the data serves decision-making rather than overwhelming it.
Complementing the segmentation analysis is a detailed competitive landscape assessment that profiles the leading operators shaping the market. The research examines the positioning, capability strengths, and strategic moves of prominent firms, including Industrial Light & Magic, Weta Digital, Framestore, DNEG, Pixomondo, Animal Logic, Rodeo FX, Cinesite, Method Studios, Deluxe, Digital Domain, The Mill, and Scanline VFX. These profiles are not static company summaries; they are structured to reveal how each organization competes on technology, service breadth, artistic reputation, and operational scale, and how recent consolidation, investment, and partnership activity is reshaping the hierarchy.
The report also incorporates a dedicated dynamics module that captures the forces currently redefining market behavior. This includes an examination of labor cost structures and talent availability, with attention to median compensation levels and employment growth trajectories for visual effects artists and animators in the context of sustained demand across gaming, film, and television. The regulatory landscape receives equal attention, with analysis of incentive programs and policy initiatives that are actively influencing production location decisions and cost structures. Recent developments illustrate how these forces are unfolding in real time, including significant investment activity, acquisitions that consolidate animation and VFX operations, award-recognized creative campaigns, and organizational rebranding efforts that reflect evolving workflow integration.
By integrating these content streams, the report functions as both a reference document and a planning tool. Readers will find a clear path from high-level market context to granular operational insight, enabling them to draw connections between market structure, competitor behavior, and their own strategic priorities.
Competitive Intensity and Strategic Positioning in a Consolidating Landscape
The competitive environment in the Visual Effects Services Market is characterized by a combination of creative differentiation, technological capability, and ongoing consolidation. With a moderately concentrated market structure, the leading firms compete not only on artistic quality but also on their ability to deliver end-to-end solutions that span visual effects, animation, virtual production, and post-production support. This breadth of capability has become increasingly important as producers seek to streamline workflows, reduce integration risk, and maintain consistency across complex, multi-platform projects.
Several of the most prominent operators have pursued strategic moves that signal how they intend to strengthen their competitive position. Investment activity has provided selected companies with the capital to expand technology pipelines, deepen AI-driven workflows, and scale content production capacity. Acquisitions have been used to consolidate complementary capabilities, particularly where animation and visual effects operations can be integrated to offer more complete service offerings. At the same time, high-profile creative recognition continues to serve as a powerful differentiator, reinforcing brand equity and attracting premium client relationships.
For enterprise buyers and investors, this dynamic landscape raises important questions about vendor stability, service continuity, and the long-term implications of consolidation. The report addresses these concerns by evaluating how recent transactions and investments are likely to affect pricing, capacity, and service specialization. It also examines how firms are positioning themselves around emerging capability areas, including simulation, creature work, motion capture, immersive media, and AI-assisted production. Understanding these strategic vectors is essential for organizations that must select partners capable of supporting both current production needs and future content ambitions.
Regulatory and Cost Dynamics: Incentives, Labor, and Operational Strategy
Market behavior in the Visual Effects Services Market is increasingly shaped by the interaction between labor economics and policy incentives. On the labor side, specialized creative and technical roles command significant compensation, and employment growth in animation and visual effects is projected to remain positive over the coming decade, driven by ongoing demand across entertainment and interactive media. This sustained demand places pressure on talent availability and reinforces the strategic importance of workforce planning, retention, and productivity-enhancing technology adoption.
Worldwide CG Visual Service Market
At the same time, a range of incentive programs is actively reshaping where and how visual effects work is performed. Recent policy developments have expanded or clarified credit structures in key production markets, giving producers new options for optimizing cost structures while maintaining access to high-quality service providers. In some jurisdictions, tax credit frameworks have been updated to increase eligible spend or streamline application and audit processes, reducing administrative friction and making incentive capture more predictable. In others, advocacy efforts are pushing for standalone post-production incentives that would better align support with the specific economics of visual effects work.
Visual Effects Services Market
These dynamics create both opportunities and risks for enterprises. Advantages can be gained by aligning production footprints with favorable incentive environments, but such strategies must be balanced against considerations of talent quality, vendor capability, delivery timelines, and long-term relationship strength. The report provides a structured examination of these trade-offs, helping decision-makers evaluate how regulatory and cost factors should inform location strategy, vendor selection, and budget allocation. Rather than treating incentives as isolated financial benefits, the analysis situates them within the broader operational context in which content is produced and delivered.
Strategic Imperatives for 2026 and Beyond
As enterprises move through 2026, the most successful organizations will be those that treat visual effects not as a discretionary enhancement but as a core component of content strategy and operational planning. That shift requires a clear understanding of where the market is heading, which capabilities will command premium value, and how competitive and regulatory forces will influence cost and access over time. This research is designed to provide that understanding in a form that can be directly applied to investment decisions, partnership strategies, and organizational planning.
Among the strategic imperatives highlighted in the report are the need to evaluate vendor partners against long-term capability roadmaps rather than short-term project requirements, the importance of monitoring consolidation and investment activity for signals about market concentration and service availability, and the value of integrating incentive and labor considerations into location and sourcing decisions from the outset. The report also emphasizes the growing relevance of technology adoption, particularly where advanced workflows can improve efficiency, quality, and scalability without compromising artistic integrity.
For executives seeking to translate market intelligence into action, the full study offers a more detailed evidentiary base, including deeper segmentation analysis, competitive profiling, and scenario-based interpretation of demand drivers. The complete research package is available through the source publication, where readers can access the full range of data, analysis, and strategic recommendations that support enterprise decision-making across the 2026–2032 horizon.
In a market defined by rapid change and high creative stakes, disciplined intelligence is the foundation of confident strategy. This report provides the context, structure, and insight needed to make that strategy durable, responsive, and aligned with the realities of the Visual Effects Services Market as it enters its next phase of growth.
For detailed analysis of this topic, please visit the official page: Visual Effects Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


