



PW Consulting: Intravesical BCG Market Hits $195M in 2025, Projected 8.97% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating Supply Chain Complexity and Treatment Demand: Strategic Insights into the Intravesical BCG Market
As the global healthcare landscape continues to evolve, the management of non-muscle invasive bladder cancer remains a critical focal point for urologists, pharmaceutical manufacturers, and healthcare administrators. The Intravesical Bacillus Calmette-Guérin market has experienced steady expansion over the past five years, reflecting both the clinical indispensability of BCG therapy and the structural challenges inherent in biological manufacturing. Our latest market intelligence study provides a comprehensive examination of this evolving landscape, offering executives and strategy teams a rigorous foundation for capital allocation, supply chain planning, and competitive positioning through the 2026 to 2032 forecast horizon.
The therapeutic context for intravesical BCG is unambiguous. Major clinical guidelines continue to position BCG as the preferred adjuvant treatment for intermediate- and high-risk disease presentations, underscoring a durable demand profile that transcends short-term pricing fluctuations or regional reimbursement variations. At the same time, the biological nature of BCG production introduces constraints that have repeatedly tested supply resilience. Understanding how these clinical mandates intersect with manufacturing bottlenecks, regulatory pathways, and regional procurement patterns is precisely the kind of strategic clarity that our research is designed to deliver.
Historical Trajectory and Forecast Outlook
The market has followed a measured but consistent growth curve since the early 2020s, driven by steady adoption in established markets and gradual expansion of access in developing regions. Our historical reconstruction places total market revenue at approximately 150 million dollars in 2020, progressing to 158 million dollars in 2021, 168 million dollars in 2022, 178 million dollars in 2023, and 184 million dollars in 2024. The base year analysis for 2025 reflects continued momentum, with the market reaching 195 million dollars as procurement cycles stabilized and clinical demand maintained its upward trajectory.
Looking forward, our forecast modeling projects the market to exceed 214 million dollars in 2026, followed by progressive expansion toward 237 million dollars in 2027, 241 million dollars in 2028, 279 million dollars in 2029, 292 million dollars in 2030, 315 million dollars in 2031, and 342 million dollars by 2032. The compound annual growth rate across the forecast period is calculated at 8.97 percent, a figure that captures the combined effect of sustained clinical utilization, capacity investments by key manufacturers, and incremental market participation from newly authorized or expanded-access formulations. This trajectory is not merely a statistical projection; it is a strategic signal that underscores the importance of long-term planning for procurement teams, investors, and clinical network operators who must anticipate both volume growth and supply volatility.
Structural Dynamics Shaping Market Behavior
The Intravesical BCG ecosystem is defined by a small number of entrenched manufacturers, each operating within distinct regulatory environments and supply chain architectures. Because BCG is a live biological product, production is inherently sensitive to process validation, strain stability, facility compliance, and distribution logistics. These factors have historically limited the number of viable commercial suppliers and concentrated market participation among a handful of established entities. Our research maps these structural realities in detail, offering decision-makers a clear view of where supply-side constraints originate and how they influence procurement strategies across different clinical settings.
Shortages have been a recurring theme in the market narrative, particularly in regions where a single manufacturer has served as the primary domestic source. This concentration has prompted repeated discussions within clinical guideline bodies regarding dose modification protocols and alternative sourcing strategies when supply disruptions occur. At the same time, recent authorization and supply-agreement developments have begun to diversify the availability landscape, introducing expanded-access programs and cross-border supply arrangements that create new options for treating centers. Our report examines these developments not as isolated announcements, but as interconnected signals that reshape procurement risk, pricing expectations, and competitive dynamics over the forecast period.
The Competitive Landscape: Positioning Among Core Participants
A defining feature of this market is the strategic positioning of its leading commercial participants, each of whom brings a different combination of manufacturing capability, regulatory footprint, and supply-chain response to the table. Our analysis evaluates these participants with a focus on operational readiness, product presentation, and the ability to respond to demand pressure.
One of the most closely watched developments involves the sole U.S.-based manufacturer of a widely recognized intravesical formulation. This company has publicly outlined plans to construct a new production facility intended to significantly expand output capacity, with an operational timeline that positions the expansion to intersect with the later years of our forecast window. The strategic significance of this investment extends beyond volume; it reflects an effort to address persistent supply limitations that have influenced clinical scheduling, procurement planning, and payer discussions for years. Our research explores how this capacity expansion is likely to alter supply risk perceptions and what it implies for market share stability among competing sources.
Alongside this effort, other participants have pursued complementary routes to strengthen availability. One manufacturer and distributor involved in U.S. intravesical administration continues to play a central role in the commercial pathway for a well-established product, maintaining its presence as a key node in the domestic supply chain. In parallel, an Indian-based producer has advanced a lyophilized formulation with broad international authorization for non-muscle invasive bladder cancer treatment, supported by a multi-year shelf-life profile and a presentation designed for practical clinical use. This participant has also been linked to recent regulatory authorization activity that expanded access to a recombinant BCG approach under specific program conditions, signaling a more direct response to shortage-driven demand.
A Japanese manufacturer adds another dimension to the competitive picture through its intravesical offering built on a distinct strain with specific potency characteristics. This supplier's product has been associated with recent supply arrangements intended to broaden availability in key markets, including an exclusive development and supply framework for U.S. activity. These moves illustrate how strain differentiation, dosing conventions, and regional authorization strategies all feed into a competitive environment where supply assurance can be as strategically important as the product itself. Our report unpacks these positioning choices and evaluates how they interact with procurement realities across hospital and clinic settings.
Segmentation Logic and Revenue Concentration Patterns
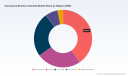
Our segmentation framework is designed to help executives understand where revenue is generated, which product formats dominate commercial activity, and how procurement is distributed across clinical care environments. The study examines product-type dynamics across the principal vial presentations that define commercial supply, with particular attention to how volume concentration differs across dosage forms. The analysis also maps application-level demand patterns, distinguishing between the largest care setting that anchors bulk utilization and the secondary setting that contributes a smaller but strategically meaningful share of total demand.
In addition, the research evaluates regional revenue distribution to identify where commercial activity is most concentrated and where growth potential is emerging. Rather than presenting percentages in isolation, our analysis situates regional data within the broader context of procurement habits, guideline adoption, and supply accessibility, enabling readers to interpret geographic patterns in a way that directly informs market-entry discussions, partnership evaluation, and inventory planning. The report further addresses market concentration metrics to clarify how revenue is distributed among leading participants, providing a realistic picture of the degree to which the market remains consolidated and where competitive pressure may intensify.
Report Contents and Operational Utility for Decision-Makers
This study is structured to support practical decision-making rather than abstract market observation. Readers will find a detailed examination of the demand drivers that shape utilization, the supply-side factors that influence availability, and the regulatory and guideline environment that governs treatment selection. The report includes a comprehensive competitive profiling section that describes each major participant's operational base, product positioning, and strategic response to market constraints. It also provides a forward-looking synthesis of how capacity investments, authorization activity, and supply agreements may alter the balance of availability across the forecast period.
Beyond competitive mapping, the report delivers actionable analytical building blocks for pricing strategy, sourcing diversification, and network planning. Procurement teams can use the segmentation analysis to better understand where demand concentrates and how product formats are distributed across end-use settings. Executive teams can draw on the forecast structure to test scenario assumptions around capacity release, shortage mitigation, and regional expansion. Investors and business development professionals can use the concentration and competitive assessments to evaluate entry feasibility and partnership opportunities without relying on incomplete or anecdotal information.
The study also incorporates discussions of cost considerations and treatment-course economics where relevant to strategic planning, alongside the practical implications of strain potency differences, dosing conventions, and product presentation choices. These details matter because they influence both clinical workflow and procurement behavior, and our report places them in context so that strategic conclusions are grounded in operational reality rather than surface-level market descriptors.
Why This Research Matters for 2026 Strategy
The 2026 to 2032 window represents a period in which the Intravesical BCG market is likely to be shaped as much by supply-side restructuring as by underlying clinical demand. Capacity expansion commitments, authorization pathways, and cross-company supply arrangements are beginning to alter the availability landscape, yet the biological and regulatory complexity of BCG production means that uncertainty will not disappear overnight. In this environment, decision-makers need more than top-line growth figures; they need an integrated view of how product formats, care settings, regional dynamics, and competitive actions combine to create risk and opportunity.
Our report is designed to provide that integrated view. It connects market size progression and forecast expansion to the operational realities behind the numbers, helping organizations anticipate where supply resilience will improve, where dependence on limited sources may persist, and how different procurement strategies may perform under varying shortage and authorization scenarios. For executives planning budgets, sourcing frameworks, or competitive responses in 2026, this research offers the level of detail required to move from reactive positioning to informed strategy.
BCG Vaccine Market
Conclusion and Next Steps
The Intravesical BCG market is at a point where clinical importance, manufacturing complexity, and evolving supply arrangements converge to create both challenge and opportunity. Our study translates that convergence into a structured, forward-looking analysis that supports strategic planning across commercial, operational, and investment decisions. The full report provides the complete segmentation detail, competitive assessment, and forecast architecture needed to evaluate market potential with confidence. Readers interested in the full set of regional breakdowns, application-level revenue patterns, product-type splits, and concentration metrics are encouraged to access the complete study for the comprehensive intelligence required to guide 2026 decision-making.
Intravesical Bacillus Calmette Market
For detailed analysis of this topic, please visit the official page: Intravesical Bacillus Calmette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Auto Hand Dryer Market to Reach $372.52M by 2032, Growing at 8.2% CAGR
By PW Consulting, 2026-09-16
The Automatic Hand Dryers Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: Why Timing Matters
The automatic hand dryer industry stands at a critical inflection point. As commercial facilities, healthcare networks, and hospitality operators recalibrate their capital expenditure priorities for 2026 and beyond, the choice of hygiene infrastructure has evolved from a routine procurement decision to a strategic lever with implications for sustainability targets, regulatory compliance, and occupant experience. Our latest comprehensive research on the Automatic Hand Dryers Market is designed specifically to equip executives, procurement leaders, and industry analysts with the granular intelligence required to navigate this shifting terrain.
The market registered an estimated valuation of USD 215.0 Million in the 2025 base year, reflecting sustained momentum from the post-pandemic acceleration in facility modernization. Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 8.2% , culminating in a market valuation of approximately USD 372.52 Million by the end of the horizon. These figures are not merely retrospective acknowledgments of growth; they represent a structural recalibration of how commercial environments approach hygiene, energy consumption, and operational efficiency. For organizations making procurement bets in 2026, this report provides the evidentiary framework necessary to align tactical purchasing with long-term strategic positioning.
Market Trajectory: Mapping the Growth Arc from 2020 to 2032
Over the historical window from 2020 through 2025, the automatic hand dryer sector demonstrated resilience that outpaced many adjacent facility management categories. Revenue expanded from USD 163.15 Million in 2020 to the aforementioned 2025 baseline, navigating supply chain friction, shifting public awareness of surface-contact transmission, and evolving building code expectations. The progression from year to year reveals a market that has matured beyond its initial pandemic-driven surge into a phase of sustained, utility-driven adoption.
The forward-looking trajectory through 2032 indicates continued expansion, with year-by-year forecasts suggesting incremental gains that compound meaningfully over the forecast horizon. The 2026 opening estimate of approximately USD 225.93 Million sets a foundation for steady growth through subsequent years, reaching the terminal valuation previously noted. This growth arc is underpinned by several structural forces: the replacement cycle of legacy drying equipment, municipal and corporate sustainability mandates that favor high-efficiency electro-mechanical solutions over single-use paper alternatives, and heightened institutional focus on touchless interaction in high-traffic environments. Decision-makers evaluating capital plans for the 2026-2032 window will find our time-series analysis and scenario modeling particularly valuable for aligning budget cycles with anticipated demand shifts.
Segmentation Dynamics: Navigating Category and Application Divergence
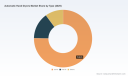
Our research dissects the market across multiple segmentation axes that matter most to product planners and commercial sales teams. At the product-category level, the Jet Air segment commands a distinctly larger share of total revenue compared to Hot Air units and Others categories, reflecting the industry's pivot toward high-velocity, low-cycle-time drying experiences that reduce queue congestion in busy facilities. Hot air variants continue to serve specific retrofit and cost-sensitive applications, while specialized equipment segments maintain relevance in niche institutional contexts.
Application-wise, the Hospitality sector emerges as the most significant demand driver, a finding that aligns with the segment's dual imperatives of guest experience enhancement and operational cost containment. Healthcare facilities represent a strategically important, regulation-intensive application environment where hygiene certification, rapid drying performance, and infection-control protocols converge to shape procurement decisions. The Others application cohort—encompassing educational institutions, corporate offices, and municipal buildings—contributes meaningful volume and serves as a bellwether for broader commercial adoption trends.
Geography further stratifies demand patterns. North America and Asia Pacific collectively anchor the largest revenue pools, while Europe , Latin America , and the Middle East and Africa regions each present distinct regulatory, climate, and procurement dynamics. Our report does not simply partition the market into static regional silos; it contextualizes regional behavior within the frameworks of local building codes, labor cost structures, energy pricing, and institutional procurement cycles. Readers seeking regional-specific procurement insights will find the detailed territorial breakdowns essential for tailoring market entry and expansion strategies.
Regulatory and Operational Dynamics: Compliance as Competitive Moats
The commercial hand dryer landscape is governed by a dense matrix of standards and protocols that directly influence product design, testing, certification, and go-to-market strategy. In the United States, ADA Accessibility Standards require that all commercial automatic hand dryers comply with accessibility and safety requirements, ensuring that deployed units accommodate a broad spectrum of user needs without creating barriers. Simultaneously, the UL 499 Standard for Safety – Electric Heating Appliances governs the construction and operational parameters of heating-element-based devices, establishing baseline electrical and fire-safety expectations that manufacturers must satisfy.
Automatic Hand Dryers Market
International considerations add further complexity. The NSF International Protocol P335 for Hygienic Commercial Hand Dryers is increasingly referenced in safety and hygiene certification frameworks, reflecting the sector's heightened scrutiny around microbial exposure and aerosolization dynamics. In European markets, Directive 2011/65/EU (RoHS 2) restricts the use of specified hazardous substances in electrical and electronic equipment, including hand dryers, compelling manufacturers to adapt material selections, component sourcing, and manufacturing processes accordingly.
These regulatory threads are not peripheral compliance checkboxes. They shape bill of materials decisions, influence total cost of ownership calculations, and determine which products can realistically compete in regulated procurement tenders. Our report maps the regulatory environment with precision, identifying which standards carry the greatest weight in specific application and regional contexts so that product strategists can anticipate certification pathways and commercial barriers before committing R&D or manufacturing resources.
Competitive Landscape: Differentiated Portfolios and Convergent Priorities
The automatic hand dryer market exhibits moderate concentration, with the top three firms collectively representing approximately 24.6% of total market share and the top five firms accounting for roughly 26.2% . This competitive structure indicates a field in which several established players maintain defensible niches while broader adoption creates room for challengers with differentiated value propositions. The profiles of leading participants illustrate how product engineering, compliance positioning, and production capacity decisions collectively define competitive advantage.
Excel Dryer Inc. , headquartered in East Longmeadow, Massachusetts, has continued to invest aggressively in capacity. The company's July 2025 expansion of its manufacturing facility in Massachusetts was explicitly aimed at increasing production capacity for automatic hand dryers, a move that signals both demand confidence and the strategic importance of supply responsiveness. Excel's portfolio centers on the XLERATOR high-speed automatic sensor-activated jet hand dryer, distinguished by HEPA filtration integration, ADA compliance, and eco-variants such as the XLERATOReco . These features reflect a coherent strategy that pairs performance credentials with sustainability and accessibility positioning.
World Dryer Corporation , based in West Bend, Wisconsin, competes with the SMARTdri Plus series, an automatic high-speed hand dryer lineup emphasizing low energy use and optional HEPA filtration. The emphasis on energy efficiency resonates strongly with facility operators managing long-term operating costs and sustainability reporting requirements.
American Dryer, Inc. , operating from Bensenville, Illinois, offers touchless high-speed automatic hand dryers including the Extreme Air and a Global value series tailored for commercial and institutional applications. This dual-track approach addresses both premium performance segments and cost-conscious procurement environments, broadening the addressable market across institution types.
Danish Design A/S , located in Denmark, brings a distinct aesthetic and hygiene-driven identity through its automatic touchless LOKI and BJØRK series. The brand's Danish design heritage is paired with hygiene features that appeal to markets where appearance, ergonomics, and cleanliness narrative converge in procurement criteria.
American Specialties, Inc. , based in the United States, fields the TURBO ADA and Roval series automatic high-speed hand dryers offered in stainless steel and matte black finishes. The emphasis on ADA-compliant touchless designs and finish options positions the company for hospitality and commercial environments where design integration and accessibility both matter.
Beyond these core firms, broader industry activity underscores the directional priorities of the sector. In 2026, the electric Handdryer Initiative highlighted the industry's trajectory during its week at InterClean 2026 in Amsterdam , emphasizing growing demand for touchless and green high-speed hand drying solutions. The initiative's May 2026 activities for World Hand Hygiene Day further reinforced advocacy for high-speed HEPA-filtered automatic hand drying technology. Meanwhile, Dyson Ltd. 's August 2025 launch of a latest hand dryer model featuring advanced HEPA filtration technology illustrated how premium engineering outfits continue to push hygiene and performance benchmarks, exerting downstream pressure on the entire category. Collectively, these developments demonstrate that the competitive field rewards firms that simultaneously deliver touchless operability, energy efficiency, filtration credibility, and installation elegance.
Hair Dryer Market
What Our Research Delivers: A Practical Toolkit for 2026 Decisions
The Automatic Hand Dryers Market research report is structured to translate macro-level intelligence into actionable decision support. Readers will find a rigorous quantitative foundation paired with qualitative analysis that connects data to commercial reality. The report's architecture is designed around several pillars.
- Historical Reconstruction and Forward Modeling: A detailed time-series analysis covering 2020-2025 provides the empirical backbone for understanding how the market behaved through distinct cycles. The 2026-2032 forecast framework extends this foundation with scenario-based projections that account for demand elasticity, replacement cycles, and adoption pacing across application types.
- Segmentation Detail at Category, Application, and Regional Levels: Our segmentation analysis goes beyond aggregate splits to reveal how product categories perform across different end-use environments and geographies. This enables readers to assess where growth concentrates, which segments exhibit resilience during economic variability, and how regional procurement cultures shape product preferences.
- Competitive Intelligence on Major Players: The report profiles leading manufacturers, examines their product strategies, evaluates recent corporate and facility developments, and contextualizes competitive positioning within the moderation of overall market concentration. This section supports benchmarking, partnership evaluation, and competitive response planning.
- Regulatory Mapping and Compliance Roadmaps: A dedicated treatment of relevant standards—including ADA accessibility, UL 499, NSF Protocol P335, and EU RoHS 2—helps product teams, procurement officers, and legal/compliance stakeholders anticipate certification requirements and identify potential barriers to market entry or expansion.
- Demand Drivers, Restraints, and Industry Event Context: The report synthesizes macro drivers such as hygiene awareness, sustainability mandates, and touchless interaction trends alongside constraints including cost sensitivity, installation complexity, and regulatory fragmentation. Recent industry events and association activities from 2025 and 2026 are integrated to ground analysis in current market sentiment and directional signals.
- Executive Decision Frameworks: Beyond raw data, the report provides interpretive guidance on how to prioritize investments, time procurement cycles, evaluate supplier alternatives, and align product selection with corporate sustainability and hygiene objectives for the 2026-2032 horizon.
Conclusion: Turning Market Intelligence into Strategic Advantage
The automatic hand dryer market is no longer a commoditized fixture category. It has become a strategically significant segment where hygiene performance, energy efficiency, regulatory adherence, and design sensibility converge to influence procurement outcomes and long-term operational economics. The 8.2% CAGR projected over the 2026-2032 period, anchored by a market that has grown from 163.15 million USD in 2020 to an estimated 372.52 million USD by 2032, reflects an environment in which informed decision-making can materially affect competitive positioning and total cost of ownership.
For executives, procurement leaders, and product strategists preparing for 2026 and the subsequent years, the detailed intelligence within our full report is purpose-built to reduce uncertainty and sharpen execution. Regional breakdowns, granular segmentation figures, company-level strategic profiles, regulatory pathway analyses, and forward scenario modeling are available in the complete publication. We invite you to access the full report to obtain the precise data and interpretive frameworks required to make confident, evidence-based decisions for the automatic hand dryer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automatic Hand Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Practice Management Software Market Hits $2.68B in 2025, 11.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for Legal Decision-Makers: Navigating the Practice Management Software Market in 2026
The legal technology landscape has reached an inflection point. What was once a fragmented market of niche tools has matured into a consolidated ecosystem where operational efficiency, AI integration, and regulatory compliance converge. For enterprise buyers, law firm managing partners, and institutional investors, understanding the trajectory of legal practice management software is no longer optional. It is a core component of operational strategy.
PW Consulting is pleased to introduce our latest market intelligence study, a comprehensive analysis designed to equip leadership teams with the actionable insights required to navigate the 2026 landscape and beyond. This report does not merely recount historical trends. It constructs a forward-looking framework that aligns technology procurement, competitive positioning, and capital allocation with the structural shifts reshaping legal service delivery.
Market Trajectory and the Case for Strategic Foresight
The legal practice management software sector has demonstrated consistent, above-average growth across the historical analysis window. Revenue expansion has outpaced many adjacent enterprise software categories, driven by a compounding set of operational pressures: rising labor costs, stringent client expectations around transparency, and the accelerating digitization of court and compliance workflows. The market has moved decisively from early-adopter experimentation to mainstream operational dependency.
This maturation is not accidental. It reflects a structural recalibration within legal operations. Firms of all sizes are confronting margin compression and talent scarcity, forcing a shift from manual, paper-heavy processes toward integrated platforms that centralize matter management, financial operations, and client engagement. Cloud-based architectures have become the default deployment model, supported by an increasingly robust security and compliance infrastructure that addresses the sector's unique trust accounting and data privacy requirements.
The forecast horizon captured in our analysis points to continued robust expansion through the end of the decade. However, aggregate growth rates only tell part of the story. The true strategic value of this research lies in its ability to segment that growth into actionable intelligence: where adoption is concentrating, which deployment models are winning, how revenue is shifting across user categories, and what competitive dynamics will determine market leadership over the next several years. These are the questions that separate reactive procurement from proactive strategy.
Inside the Analysis: What the Report Delivers
Our research methodology combines quantitative modeling with on-the-ground industry validation. The resulting publication is structured to serve multiple executive functions simultaneously: situational awareness, vendor evaluation, investment scenario planning, and operational roadmap development.
Readers will find detailed examinations across the dimensions that matter most to decision-makers:
- Market sizing and trajectory modeling spanning historical performance and a forward-looking forecast window, enabling scenario-based planning rather than single-point estimates.
- Deployment architecture analysis comparing cloud-native and on-premises environments, with emphasis on security postures, integration pathways, and total cost of ownership implications.
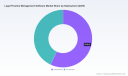
- Application-level segmentation distinguishing demand patterns across law firms and attorneys, court systems, and other institutional users, revealing where procurement momentum is strongest.
- Regional landscape mapping that contextualizes adoption maturity, regulatory environments, and purchasing dynamics across key geographic markets.
- Competitive benchmarking of leading platform providers, evaluating product roadmaps, AI integration depth, pricing architectures, and ecosystem partnerships.
- Operational dynamics assessment covering labor cost pressures, compliance frameworks, reimbursement cycle acceleration, and the evolving ethical boundaries around AI-driven case analysis and document review.
Each section is designed to produce a clear decision artifact. Rather than leaving readers with abstract market commentary, the report translates data into procurement criteria, vendor shortlisting guidance, and implementation sequencing recommendations.
The AI Inflection and Competitive Reconfiguration
No variable has reshaped this market more rapidly than artificial intelligence. Over the past year, AI usage among legal professionals has expanded meaningfully, with practice management platforms absorbing automation capabilities that were previously isolated in point solutions. Document generation, time capture, matter triage, and financial reconciliation are increasingly handled through embedded intelligence rather than manual workflow. This shift is altering vendor value propositions across the board.
The competitive landscape reflects this transformation. Market concentration remains moderate, with leading firms commanding a combined share that underscores both established presence and ongoing consolidation potential. The roster of influential players spans full-suite cloud platforms, specialized matter management systems, and AI-forward tools targeting specific practice verticals.
Analysis of the current vendor ecosystem reveals several distinct strategic postures. Cloud-native leaders such as Clio and MyCase continue to expand their functional breadth, embedding client intake, billing, trust accounting, and compliance tooling within unified workflows. Clio's strategic moves illustrate the scale-up dynamic: the acquisition of vLex in mid-2025 represents the largest legal tech M&A transaction in recent memory, merging AI-powered global legal research directly into practice management infrastructure. Shortly thereafter, the launch of a large-firm platform signaled a deliberate push into more complex case and process management environments.
Medical Practice Management Software Market
Other providers are executing differentiated plays. Rocket Matter and Filevine have emphasized reimagined platforms with stronger analytics and AI-powered case handling, while Smokeball and PracticePanther have doubled down on automated time capture, document automation, and trust accounting for firms seeking operational simplification. Centerbase's partnership to embed accounts payable automation directly into its midsize firm platform highlights a parallel trend: integration with back-office financial ecosystems as a competitive differentiator. Supio's specialization in personal injury and mass tort workflows demonstrates how vertical-specific AI can command premium positioning. Lexzur and Caseflow extend the field with AI-assisted matter management and client communication features, while LeanLaw's focus on QuickBooks-integrated revenue operations points to a growing appetite for financial tooling built around familiar accounting backbones.
These vendor movements matter because they redefine buyer expectations. A practice management decision in 2026 is simultaneously a decision about AI strategy, data residency, financial reconciliation speed, and vendor longevity. The report's competitive analysis maps these trade-offs explicitly, helping organizations match platform capabilities against their operating model rather than adopting a one-size-fits-all framing.
Industry Dynamics Driving Procurement and Adoption
Market growth is not simply a function of technology availability. It is being propelled by a set of interlocking operational and regulatory forces that raise the cost of inaction. Our research distills these dynamics into practical considerations for both buyers and vendors.
Cloud adoption has become the baseline expectation. Recent industry survey data indicates that a substantial majority of law firms now rely on cloud-based legal tools, with practice management and document management software posting the highest utilization rates. This shift is not cosmetic. It reflects reduced on-premises maintenance burdens, improved remote collaboration, and the ability to push updates and security patches without disrupting firm operations. For decision-makers, the question has moved from whether to adopt cloud architecture to how to select platforms that meet rigorous compliance and performance standards.
Security and regulatory compliance have accordingly become central procurement criteria. Cloud-based platforms increasingly emphasize SOC 2 alignment and data privacy standards to support trust accounting integrity and client data protection. These requirements are not uniform across jurisdictions, and the report examines how compliance posture varies by platform and what that means for multi-jurisdiction firms.
Financial workflow acceleration is another powerful driver. Automated billing, trust accounting, and integrated payment capabilities are shortening client payment cycles and reducing administrative overhead. For firms operating on tight margins, faster cash conversion is a direct operational benefit, not merely a feature checkbox. The analysis quantifies how these capabilities influence vendor selection and what performance indicators buyers should track post-implementation.
At the same time, AI integration introduces a new compliance layer. As automation expands into case analysis and document review, firms must navigate evolving professional ethics guidance on the use of AI in legal work. Regulatory bodies are actively updating expectations around supervision, accuracy, and client confidentiality. The report evaluates how leading platforms are addressing these requirements and what risk management frameworks should accompany AI adoption.
Legal Practice Management Software Market
Why This Research Matters for 2026 Decision-Making
The strategic stakes for 2026 are unusually high. Organizations that treat practice management software as a routine IT purchase risk underinvesting in capabilities that directly affect profitability, risk exposure, and client retention. Conversely, organizations that approach the market with structured intelligence can sequence implementations, negotiate from a position of clarity, and avoid vendor lock-in to platforms that lack the roadmap depth required for future growth.
This report is built for that decision environment. It provides the macro context needed to validate market timing, the segmentation detail needed to prioritize investment, and the competitive analysis needed to assess vendor durability. For law firm leadership, it supports operational transformation planning and resource allocation. For technology buyers and institutional stakeholders, it clarifies where durable demand is forming and which platform categories are likely to consolidate further.
Because the full value of this analysis depends on the underlying segmentation models, regional breakdowns, deployment comparisons, and company-level benchmarking, the complete dataset and executive findings are available through our comprehensive market study. The page-length overview presented here is intended as a strategic preview: a demonstration of the analytical rigor and decision-focus that define the full publication.
Next Steps for Strategic Alignment
Market leadership in legal technology is being redefined in real time. Firms that align their practice management strategy with the realities of AI adoption, compliance evolution, and financial workflow acceleration will be best positioned to convert operational software into durable competitive advantage. Those that delay structured evaluation risk entering a more consolidated market with fewer negotiating advantages and higher switching costs.
The complete market research extends well beyond this overview. It delivers the segmented data, vendor assessments, and forward-looking projections required to support confident 2026 decision-making across procurement, investment, and operational transformation initiatives. Readers seeking the full intelligence package, including detailed segmentation splits and competitive benchmarking, are encouraged to access the complete report at the source page, where the full dataset and executive insights are available for direct review.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasound Probe Market Hits $215M in 2025, Projected 3.3% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Pulse: Strategic Intelligence for the 2026 Medical Ultrasound Probe Market
The medical ultrasound probe market stands at a critical inflection point as healthcare delivery models shift toward point-of-care diagnostics and advanced imaging integration. For executives and strategy teams planning capital allocation and product roadmaps through 2032, understanding the nuanced trajectory of this sector is not merely analytical—it is imperative. This article introduces PW Consulting's latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate regulatory shifts, competitive realignments, and evolving clinical demands. The following insights distill the executive summary of our full report, highlighting the strategic value embedded within our analysis while preserving the granular data necessary for precise execution available exclusively in the complete document.
Macroeconomic Trajectory and Market Size Evolution
Our analysis covers a robust historical period from 2020 through 2025, extending a forecast horizon to 2032. This longitudinal view allows for the identification of structural trends rather than transient fluctuations. The market has demonstrated consistent growth over the past half-decade, with revenue figures reflecting a steady expansion in diagnostic imaging adoption globally. In 2020, the market valuation stood at approximately 163.15 Million USD. Year-over-year progression saw increases to 167.51 Million USD in 2021, 175.83 Million USD in 2022, and a notable acceleration to 183.64 Million USD in 2023. The recent past indicates a significant jump to 205.21 Million USD in 2024, culminating in an estimated base year valuation of 215.0 Million USD for 2025.
Looking forward, the forecast period projects the market to reach 222.9 Million USD in 2026. The trajectory suggests continued growth, with valuations anticipated to climb toward 236.95 Million USD by 2027. However, strategic planners must note specific variance points within the forecast window. While growth is the overarching theme, the data indicates a slight contraction to 235.1 Million USD in 2028 before resuming an upward trend toward 252.9 Million USD in 2029. Subsequent years show fluctuation, with dips to 247.5 Million USD in 2030, followed by recovery to 266.77 Million USD in 2031 and a projected stabilization near 268.83 Million USD by 2032. The Compound Annual Growth Rate (CAGR) calculated over this forecast period is 3.3 percent. This moderate yet steady growth rate underscores a mature market environment where competitive advantage is derived from segmentation precision and operational efficiency rather than pure volumetric expansion.
Structural Segmentation Overview
To truly leverage market opportunities, one must understand the underlying architecture of demand and supply. Our research dissects the market across three primary dimensions: Region, Type, and Application. Each dimension reveals distinct behavioral patterns and strategic entry points for stakeholders.
Geographically, the market exhibits significant dispersion. While North American markets have historically commanded strong positions, our data highlights the substantial weight of the Asia Pacific region, followed closely by North America and Europe. Latin America and the Middle East and Africa represent emerging vectors with unique adoption curves. The concentration of revenue across these regions suggests that supply chain resilience and localized regulatory compliance are becoming key differentiators.
In terms of product Type, the landscape is diversified. Convex probes remain a dominant segment, reflecting their broad utility in abdominal and obstetric imaging. Linear probes constitute a significant portion of the revenue mix, driven by vascular and musculoskeletal applications. Specialized categories such as Phased Array and Endocavitary probes serve niche but critical clinical needs, while Other types capture emerging technologies. The distribution across these types indicates that innovation is not solely focused on volume drivers but also on high-value specialized transducers.
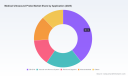
Regarding Clinical Application, the demand is heavily influenced by standard diagnostic protocols. OB-GYN applications represent a substantial share, consistent with the global emphasis on maternal health and routine screening. Vascular and Nervous System applications follow as a major demand driver, supported by the rising prevalence of cardiovascular conditions. Renal, Digestive, and Musculoskeletal applications round out the core demand pillars, with Other applications encompassing emerging use cases in emergency medicine and primary care. Understanding the revenue contribution of each application helps manufacturers prioritize R&D and marketing resources effectively.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive environment. The top three companies hold a combined market concentration of 24.6 percent, while the top five extend this to 26.2 percent. This relatively low concentration ratio implies that no single entity dominates the entire value chain, leaving ample room for specialized players and regional champions to compete on technology, service, and cost.
Our report provides detailed profiles and strategic assessments of key industry participants. Global giants such as GE HealthCare, headquartered in Chicago, Illinois, continue to lead with proprietary diagnostic systems and transducer compatibility, notably within their Voluson Expert series. Koninklijke Philips N.V., based in Amsterdam, maintains a strong presence through its EPIQ and Affiniti series, offering broad diagnostic compatibility. Siemens Healthineers AG, operating from Erlangen, Germany, manufactures MyLab systems and associated probes that serve diverse clinical imaging needs.
Recent Regulatory Milestones and Industry Noise
The regulatory environment remains a pivotal factor in product deployment and market access. Recent months have seen significant activity regarding FDA 510(k) clearances, which directly impact the availability and cycle times for new probe technologies. In January 2025, GE HealthCare announced FDA clearance for enhanced Voluson Expert Series ultrasound systems, including lightweight probes, signaling a push toward ergonomics and portability. Further clearances followed in July 2025 for the Venue Go, Venue Fit, Venue Sprint, and Venue systems, and again in November 2025 for the Voluson Expert 18, 20, and 22 systems under specific K-numbers. Philips also secured FDA clearance in June 2025 for its EPIQ and Affiniti Series diagnostic systems.
Beyond approvals, the industry must also navigate recall dynamics. Recent database entries indicate Class III recalls for multiple Philips ultrasound transducers in early 2026. Such events highlight the importance of quality assurance and risk management in strategic planning. Additionally, service ecosystems are evolving; for instance, in January 2026, Probo Medical secured the inclusion of ultrasound probe repair services on the Federal Supply Schedule via Maclean Group LLC, indicating a growing demand for lifecycle management and repair solutions alongside new equipment sales.
Unlocking Decision-Ready Intelligence
While this overview establishes the strategic context, the full PW Consulting report delivers the depth required for actionable execution. The complete study moves beyond high-level trends to provide specific revenue splits, growth rates by segment, and detailed competitor benchmarking that are essential for tactical planning. By accessing the full intelligence, stakeholders can dissect exactly how regional shifts will impact their supply chains, which probe types offer the highest margin potential in specific clinical settings, and how the competitive moves of entities like FUJIFILM Sonosite, Canon Medical, Samsung Medison, Hitachi Healthcare, Esaote, Mindray, SIUI, and emerging players like Shenzhen Ruqi Technology will reshape the battlefield.
Worldwide Ultrasonic Probe Covers Market
The report integrates real-world data to map out the competitive intensity, identifying where consolidation might occur and where niche players can secure defensible positions. It also analyzes the implications of regulatory clearances on market entry barriers and the strategic value of service contracts in an era of increasing hardware complexity. With the market projected to nearly double from its 2020 levels by the end of the forecast period, the cost of inaction or misinformed strategy is significant.
Medical Ultrasound Probe Market
Call to Action for Strategic Leaders
As we move through 2026, the ability to anticipate market fluctuations—such as the variance projected between 2027 and 2030—will separate market leaders from followers. The data suggests that while the overall CAGR is 3.3 percent, specific segments and regions may outperform or underperform this average based on regulatory adoption and clinical guideline updates. PW Consulting's detailed analysis provides the granular visibility needed to capitalize on these discrepancies.
We invite industry executives, investors, and product strategists to explore the full findings of our Medical Ultrasound Probe Market report. The comprehensive document includes detailed segmentation tables, competitor SWOT analyses, and forward-looking scenarios that go beyond the summary provided here. To gain the competitive edge required for 2026 and beyond, access the complete intelligence package available on the PW Consulting website. Let us guide your strategy with data precision and industry expertise.
For detailed analysis of this topic, please visit the official page: Medical Ultrasound Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 9.5% CAGR for High Speed Oven Market to Hit $7.88B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the High Speed Oven Market: Navigating the 2026–2032 Growth Cycle
The commercial foodservice sector is undergoing a profound operational transformation, driven by acute labor constraints, rising real estate costs, and an unprecedented demand for rapid ticket-to-order fulfillment. In this volatile environment, the high speed oven market has emerged as a critical enabler of kitchen efficiency, bridging the gap between traditional cooking methodologies and the aggressive throughput requirements of modern quick-service and fast-casual operations. As we analyze the trajectory of this sector through 2032, our latest market research provides a comprehensive strategic blueprint for manufacturers, investors, and foodservice operators aiming to capitalize on a projected industry expansion. This article outlines the macro-economic foundations of the sector, highlights the competitive dynamics shaping vendor strategies, and details the actionable intelligence embedded within our full report.
The Macro Trajectory: A High-Growth Window Across 2026–2032
Market data spanning the evaluation period paints a clear picture of sustained acceleration. Following a robust historical baseline, the industry has entered a steep growth phase, with the overall market value reaching $4,370.0 million in 2025 before projected to chart $4,686.06 million in 2026. Our forecast models indicate that this momentum will compound consistently, pushing revenue toward $7,880.0 million by 2032. This represents a compound annual growth rate of 9.5 percent, a figure that significantly outpaces broader commercial kitchen equipment benchmarks and underscores a structural shift in how operators are designing their culinary workflows.
The valuation trajectory does not merely reflect cyclical demand; it signals a permanent reorientation of commercial cooking infrastructure. As high-throughput concepts proliferate and legacy kitchen footprints contract, speed cooking appliances are transitioning from supplementary tools to central production assets. Organizations that align their capital expenditure strategies with this growth pattern stand to secure meaningful first-mover advantages in supply chain positioning, channel partnerships, and menu innovation capabilities.
Market Structure and Demand Drivers Shifting the Landscape
Segmentation Dynamics and End-Use Priorities
The current market architecture reveals a balanced but rapidly evolving distribution of demand across equipment configurations and deployment environments. Operators are increasingly evaluating built-in installation formats against standalone countertop solutions, with the strategic choice heavily dependent on modular kitchen design, ventilation constraints, and throughput targets. Simultaneously, end-use applications are bifurcating between high-volume restaurant environments and a diverse array of other commercial deployments, including corporate cafeterias, educational dining facilities, retail food halls, and airport concessions. This diversification is critical, as it insulates the market from overreliance on a single dining segment and broadens the addressable customer base for manufacturers and distributors.
Geographic Expansion and Infrastructure Maturation
Regional adoption patterns are stabilizing around established commercial foodservice hubs while demonstrating clear upward pressure in emerging markets. North American and European territories continue to anchor substantial share, anchored by mature restaurant supply chains, stringent health and safety compliance frameworks, and widespread adoption of ventless and impingement cooking technologies. Meanwhile, Asia Pacific and Latin American markets are exhibiting accelerating deployment rates as quick-service brands expand internationally and local operators prioritize operational efficiency to offset rising commodity and labor costs. Middle Eastern and African regions, though smaller in absolute valuation, are carving out niche growth corridors driven by hospitality infrastructure projects and tourism-centric foodservice concepts.
Regulatory Compliance and Operational Cost Pressures
The commercial deployment of high speed ovens is strictly governed by a multi-layered certification ecosystem. Equipment destined for U.S. and Canadian commercial kitchens must satisfy UL and NSF safety and sanitation standards, while ETL certification remains mandatory for market entry across North America. Ventless configurations introduce an additional compliance layer, requiring catalytic converter certification to meet stringent emissions thresholds. Furthermore, energy efficiency frameworks, including Energy STAR and related efficiency certifications, are increasingly influencing procurement decisions, particularly for models that integrate convection, microwave, and broil capabilities in a single footprint.
Worldwide Build-in High Speed Oven Market
Beyond regulatory overhead, labor economics are the most potent demand catalyst in the current cycle. High speed ovens routinely deliver cook times up to 80 percent faster than conventional equipment, directly compressing staffing requirements and reducing dependency on highly specialized culinary labor. In an environment where wage inflation and recruitment volatility remain unresolved, this labor efficiency premium is no longer a convenience feature—it is a financial imperative that dictates capital allocation and menu engineering strategies.
High Speed Oven Market
Competitive Arena: Strategic Moves and Product Evolution
Market concentration remains firmly consolidated, with the top three participants commanding a combined 62 percent share and the top five firms extending that footprint to 65 percent. This structure rewards scale, technical differentiation, and robust service networks, while simultaneously raising the barrier for new entrants attempting to disrupt established channel relationships.
Several active manufacturers are currently defining the competitive tempo through targeted product evolution and strategic positioning. Prática Klimaquip, operating out of Minas Gerais, Brazil, has solidified its footprint in commercial rapid-cook applications with stackable configurations such as the FIT XL and Rocket Express, specifically engineered for pizza, wing, and quick-service workflows. The Middleby Corporation, leveraging its TurboChef Technologies subsidiary based in Elgin, Illinois, continues to deploy impingement-based rapid-cook architecture optimized for high-volume foodservice throughput. Hatco Corporation, through its Ovention Ovens brand in Milwaukee, Wisconsin, maintains a strong emphasis on 100 percent ventless impingement systems that integrate seamlessly into constrained kitchen footprints without extensive exhaust infrastructure.
Merrychef Ltd., headquartered in Elkhart, Indiana, remains a pioneer in high-speed oven technology, with its eikon and conneX series reflecting a consistent focus on streamlined kitchen operations and connectivity-driven workflow management. Panasonic Corporation, from its Osaka base, extends its commercial reach through convection-microwave-broil hybrids such as the NE-SCV3 series, targeting restaurants and cafes that require multi-functionality within a single appliance footprint. UNOX S.p.A. contributes a distinct European engineering perspective from Italy, offering commercial speed ovens such as the SPEED.Pro line that merge convection, steam, and microwave capabilities for versatile culinary outputs. Sharp Corporation has also entered the acceleration curve with its Celerity high speed oven, showcasing advanced thermal engineering capable of reducing whole-chicken cook times to roughly one-third of conventional methods. Additionally, Buffalo Equipment has expanded its proprietary portfolio by unveiling two new high-speed models, reinforcing the trend of domestic and regional manufacturers investing heavily in rapid-cook technology differentiation.
2026–2027 Product Cycle: Real-Time Market Signals
The competitive landscape is being actively reshaped by a concentrated wave of product launches, catalog updates, and application-focused messaging during mid-2026. Ovention Ovens recently refreshed its product catalog with detailed guidance on integrating high-speed ovens into modular kitchen designs and optimizing team workflow allocation. TurboChef simultaneously promoted its Bullet Oven for campus dining environments and high-volume service settings, emphasizing throughput efficiency and space-conscious deployment. Merrychef announced an expansion of its conneX high-speed oven range, positioning the new line as a solution for consolidated kitchen operations and reduced equipment sprawl. Buffalo Equipment followed with the unveiling of two new models within its branded cooking range, signaling continued investment in rapid-cook capacity across retail and foodservice channels. These concurrent developments reflect a broader industry pivot toward operational modularity, deployment flexibility, and menu-agnostic performance.
Inside the Report: Operational Intelligence and Decision Frameworks
Our full market research publication extends well beyond macro-valuation summaries to deliver a tactical decision-support architecture. The report systematically deconstructs market sizing across historical baselines and forward-looking forecast periods, enabling precise revenue modeling and capacity planning. It examines structural segmentation splits that illuminate how built-in versus countertop configurations are performing across distinct commercial environments, while also mapping end-use distribution between restaurant-grade deployments and alternative foodservice applications. Geographic coverage is analyzed through a lens of market maturity, infrastructure readiness, and regional adoption velocity, providing a nuanced view of where demand is stabilizing and where it is accelerating.
The competitive intelligence section profiles active market participants, mapping headquarters locations, technological specializations, and recent developmental activity. Recent product launches, catalog revisions, and targeted promotional campaigns are cataloged to reveal how vendors are responding to shifting operator requirements. Beyond hardware and vendor mapping, the report incorporates regulatory and certification pathways, ensuring that compliance planning is integrated directly into procurement and deployment strategies. Labor cost mitigation scenarios are quantified against conventional cooking benchmarks, and energy efficiency considerations are evaluated alongside certification requirements to provide a complete total-cost-of-ownership perspective. This multidimensional framework is designed to support capital planning, channel strategy formulation, competitive positioning, and menu engineering initiatives with minimal reliance on secondary interpretation.
Strategic Imperatives for Stakeholders
For equipment manufacturers and technology developers, the 9.5 percent growth trajectory and concentrated market share structure underscore the necessity of differentiated engineering, robust ventless and hybrid-cooking portfolios, and proactive compliance alignment. For foodservice operators and franchise groups, the immediate priority lies in evaluating kitchen reconfiguration opportunities that leverage 80 percent faster cook times to compress labor dependency, improve ticket throughput, and expand menu flexibility within constrained footprints. For investors and financial analysts, the diversification across end-use environments and regional growth corridors provides a clear framework for assessing exposure, identifying channel expansion opportunities, and monitoring vendor consolidation patterns. The data demonstrates that high speed ovens are transitioning from tactical kitchen tools to strategic infrastructure assets; companies that embed this reality into their planning cycles will be better positioned to navigate the operational and financial demands of the coming half-decade.
Conclusion: Accessing the Complete Strategic Blueprint
The high speed oven market is entering a phase of sustained, structurally driven expansion marked by technological consolidation, regulatory rigor, and intensifying competitive maneuvering. The aggregate market trajectory, segment dispersion patterns, vendor activity cycles, and compliance frameworks documented in our full research publication provide a comprehensive foundation for informed capital allocation, product planning, and operational optimization. While the overview presented here captures the essential strategic contours, the complete report contains granular sizing breakdowns, detailed vendor profiling, segment-level deployment dynamics, regional adoption mappings, and actionable scenario models that are essential for precise decision-making. To access the full intelligence suite and integrate these findings directly into your 2026 planning cycle, please visit the official market research portal and download the complete publication.
For detailed analysis of this topic, please visit the official page: High Speed Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Paper Pallet Market: Strategic Intelligence for 2026 Decision-Makers
As global supply chains recalibrate around sustainability mandates and regulatory pressures, the packaging sector stands at a pivotal inflection point. The paper pallet market, once a niche alternative to traditional wooden and plastic logistics solutions, has matured into a strategic imperative for enterprises managing high-volume freight across international borders. PW Consulting's latest comprehensive study on the Paper Pallet Market delivers actionable intelligence designed to inform capital allocation, supplier partnerships, and regional expansion strategies throughout the 2026–2032 horizon.
This introduction outlines the strategic architecture of our research, demonstrates how macroeconomic indicators translate into operational foresight, and illustrates why forward-looking organizations are treating paper-based palletization as a core component of their supply chain resilience playbook.
The Macro Trajectory: Growth Signals and Structural Shifts
Between 2020 and 2025, the global paper pallet market demonstrated consistent revenue expansion, reflecting a steady migration away from conventional wood-based packaging. Initial valuation benchmarks in the early 2020s established a foundation that subsequent years reinforced through accelerated adoption across logistics-intensive sectors. The market's progression through 2024 and 2025 reflects an ecosystem that has moved beyond early-adopter experimentation into mainstream procurement considerations.
Our forecast model projects continued revenue growth across the 2026–2032 period, with compound annual growth rates indicating a durable expansion path. This trajectory is not merely a reflection of volume displacement; it captures fundamental shifts in how multinational corporations evaluate total cost of ownership, customs compliance, and environmental reporting. Decision-makers who understand the drivers behind this upward curve position themselves to capture margin advantages before commoditization erodes early-mover benefits.
The scale of the opportunity underscores why organizations cannot rely on fragmented industry anecdotes. A structured, data-anchored view of revenue pathways, demand elasticity, and competitive intensity allows procurement leaders and supply chain executives to evaluate whether paper pallet integration belongs in their near-term roadmap or longer-term sustainability pipeline.
Regulatory Tailwinds and the ISPM-15 Advantage
One of the most consequential dynamics shaping the market involves international phytosanitary regulations. Wooden packaging materials entering cross-border trade corridors must comply with ISPM-15 treatment requirements, which mandate heat treatment or fumigation protocols to mitigate pest transmission risks. Paper pallets, by contrast, fall outside these treatment mandates, eliminating a layer of compliance complexity that has historically slowed freight movement and increased administrative overhead.
This regulatory distinction creates measurable operational advantages for shippers managing high-frequency transatlantic, transpacific, and intra-Asia logistics flows. Paper alternatives reduce dwell time at inspection points, lower the risk of shipment rejection, and simplify documentation workflows. As customs enforcement protocols become more stringent in 2026 and beyond, organizations that standardize paper pallet utilization across export lanes can expect smoother clearance cycles and reduced contingency costs.
Wood Pallet Market
The regulatory environment also intersects with corporate sustainability commitments. Enterprises tracking Scope 3 emissions and packaging circularity targets find that paper-based solutions offer clearer end-of-life pathways when paired with recycling infrastructure, reinforcing the business case beyond mere compliance convenience.
Competitive Architecture: Who Shapes the Market and How
Market leadership in the paper pallet sector is defined not by raw production capacity alone but by proprietary engineering, material science capabilities, and the ability to integrate pallet solutions into broader transit and storage ecosystems. Several organizations have emerged as influential players, each pursuing distinct value propositions that appeal to specific supply chain profiles.
Smurfit Kappa Group, headquartered in Dublin, has built a recognizable presence through engineered paper pallet offerings such as PaPillOn strong paper pallet and TOPPSafe™ pallet top systems. Their approach emphasizes load-bearing performance combined with compatibility into existing corrugated supply networks. DS Smith Plc, based in London, advances a complementary yet differentiated position with its patented fibre-based pallet technology, targeting organizations that prioritize structural consistency and manufacturability at scale.
International Paper Company brings extensive raw material and converting infrastructure to the market, offering corrugated and molded paper pallet formats that leverage decades of industrial packaging expertise. Sonoco Products Company, operating from Hartsville, South Carolina, focuses on integrated paper pallet systems designed for specialized transit requirements and operational durability. PALLITE Limited, headquartered in the United Kingdom, has carved a distinct niche through honeycomb paper pallet designs and PIX® storage solutions that appeal to organizations seeking lightweight yet structurally reliable storage and transport alternatives.
Signode, based in Illinois, has positioned itself around paper pallet options designed for transit environments with ISPM-15 compliance considerations, aligning its portfolio with cross-border shippers seeking regulatory simplicity. ATTA Pallet, located in Hungary, emphasizes production and assembly capabilities tailored to paper pallet manufacturing workflows, while EcoDuro Inc., operating in Canada, contributes molded pulp and paper-based pallet options that broaden the material palette available to sustainability-focused procurement teams.
The competitive field reflects a mosaic of engineering priorities, regional strengths, and integration strategies. Understanding which players are expanding capacity, which are locking in proprietary formulations, and which are building partnerships with logistics integrators is essential for organizations evaluating supplier resilience and pricing stability over multi-year contracting cycles.
Recent Developments Reshaping Product Expectations
The pace of product-level innovation has accelerated markedly in recent months, signaling that incumbents are actively responding to shifting procurement criteria. In September 2025, Smurfit Westrock introduced a recyclable paper pallet wrap engineered as a direct replacement for single-use plastic pallet wraps in shipment applications. This launch reflects a growing emphasis on eliminating plastic wrapping without compromising load containment, a concern that has become increasingly prominent among shippers tracking packaging waste reduction targets.
Earlier, in March 2024, Seaman Paper expanded the functional scope of paper-based transit solutions with the launch of SeaStretch™, a patented lightweight paper alternative designed for shipping and storage loads. This development reinforced the viability of paper as a performance-competitive material in contexts where plastic film had previously dominated, particularly when weight reduction and recyclability are weighted heavily in procurement evaluation frameworks.
These launches matter because they illustrate a market trend moving beyond pallet boards alone. The broader product ecosystem now includes wrapping solutions, load stabilization approaches, and storage geometries that collectively influence total logistics cost. Buyers evaluating paper pallet adoption must consider how compatible wrapping, cushioning, and handling practices affect throughput, damage rates, and downstream recycling feasibility.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
PW Consulting's Paper Pallet Market research is structured to support decision-making at multiple organizational levels. Rather than presenting a static snapshot, the study maps revenue evolution, segment dynamics, and competitive interventions across historical and forecast periods, enabling readers to test assumptions against evidence-based scenarios.
The report examines the structural composition of market demand, identifying how different product types and application categories contribute to overall revenue behavior. It explores regional demand patterns without reducing complexity to oversimplified ratios, offering instead a nuanced view of where adoption momentum is strongest and what local regulatory or logistics conditions amplify or constrain growth.
Detailed company profiles analyze strategic positioning, product differentiation, and recent developmental activity across key participants. This competitive mapping is paired with an assessment of concentration dynamics, helping stakeholders gauge pricing influence, supplier dependency risk, and the likelihood of consolidation pressure in the years ahead.
Operational considerations are addressed through analysis of material developments, product launches, and regulatory alignments that affect procurement planning. Readers gain insight into how transit compliance frameworks, sustainability reporting expectations, and packaging innovation cycles intersect with supplier selection and contract structuring. The research also contextualizes supply chain decision points such as total cost comparisons, damage-risk trade-offs, customs efficiency, and recyclability infrastructure readiness.
Because the study spans a defined historical baseline and extends across a multi-year forecast window, it supports scenario-based evaluation. Organizations can assess how shifts in freight volume, regulatory enforcement intensity, or material cost dynamics may alter adoption timing and budget allocation. This forward-looking structure is particularly valuable for teams planning capital-intensive logistics improvements or evaluating multi-year supplier partnerships.
Why 2026 Is a Defining Year for Strategic Action
The convergence of regulatory clarity, product innovation, and expanding adoption creates a window in which strategic choices carry disproportionate long-term effects. Organizations that delay evaluation risk entering supplier negotiations after pricing structures adjust to heightened demand visibility, while those that assess options prematurely may overlook rapid product improvements that reshape performance comparisons.
In 2026, procurement and supply chain leaders must determine whether paper pallet integration belongs within tactical cost-reduction programs or within broader transformation initiatives tied to compliance, sustainability reporting, and international freight efficiency. Answering that question requires a granular understanding of market direction, competitive behavior, and application-specific demand behavior, all of which our research is designed to clarify.
Firms operating across multiple regions face additional complexity. Regional demand intensity varies, and local regulatory expectations, recycling infrastructure availability, and logistics partner capabilities influence whether paper pallet adoption generates the anticipated benefits. A market-level view must therefore be paired with operational realism about implementation readiness, supplier reliability, and internal change management requirements.
The report enables this level of discernment by connecting macro growth signals with actionable procurement implications. Readers can evaluate whether current supplier options align with their technical specifications, whether product innovation timelines match their implementation horizons, and whether market concentration trends suggest a need for diversification or long-term contracting.
From Insight to Execution
Deep market intelligence becomes valuable only when it informs concrete decisions. PW Consulting's Paper Pallet Market study is built to support that translation. It equips strategy teams with evidence-based context, helps procurement groups benchmark supplier claims against market-wide patterns, and gives executive stakeholders the framing needed to prioritize packaging logistics investments alongside other transformation initiatives.
For organizations preparing for the 2026 decision cycle, the critical task is not simply recognizing that the market is expanding. The strategic value lies in understanding which forces are structural rather than cyclical, which supplier capabilities are likely to endure, and where adoption timing will most strongly affect cost and operational outcomes. Our research is designed to illuminate those distinctions without leaving decision-makers to infer them from partial data.
Paper Pallet Market
The complete analysis provides the depth, segmentation clarity, competitive mapping, and scenario-aware forecasting required to move from awareness to action. For teams tasked with evaluating paper pallet integration as part of broader supply chain strategy, the full report offers the intelligence foundation necessary to make informed, timely, and defensible decisions.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Meal Kit Market Hits $39.44B in 2025, Forecast 8.4% CAGR to $69.37B by 2032
By PW Consulting, 2026-09-16
Strategic Compass for the Meal Kit Delivery Services Market: Navigating the 2026–2032 Growth Cycle
The global meal kit delivery services market is entering a decisive phase. As consumer habits around convenience, nutrition, and sustainability continue to reshape home cooking, market participants face a complex matrix of expansion opportunities, cost pressures, and compliance risks. This analysis frames the commercial landscape that will define enterprise strategy through the end of the decade, drawing on a comprehensive market research study designed to support high-stakes decision-making in 2026 and beyond.
Why 2026 Demands a Refined Market View
Meal kit delivery services are no longer an experimental convenience category. They have matured into a structural alternative to traditional grocery and dining-out behaviors. The sector is expanding against a backdrop of shifting household budgets, evolving dietary preferences, and increasing scrutiny of food safety and supply chain resilience. For executives, the central challenge is no longer whether demand exists, but how to position operations, pricing, and portfolio strategy amid volatility.
The most recent market data underscores the scale and momentum of this environment. The global meal kit delivery services market generated approximately USD 39.44 billion in revenue in 2025, up from roughly USD 19.61 billion in 2020. Over that same historical window, the market advanced through a sustained growth trajectory that carried valuations from USD 23.12 billion in 2021 to USD 35.4 billion in 2024, reflecting the category’s deepening penetration across consumer segments. Looking forward, the forecast period from 2026 to 2032 points to continued expansion, with the market projected to reach USD 42.87 billion in 2026 and advance toward USD 69.37 billion by 2032. The implied compound annual growth rate across the forecast horizon is 8.4 percent.
These headline figures matter because they frame the stakes. Growth at this pace is strong enough to justify bold investment, yet not so automatic that it absorbs operational missteps. A company that treats meal kits as a purely transactional offering risks losing share to competitors who integrate brand trust, recipe innovation, and supply chain discipline into a cohesive value proposition. Conversely, operators that align their roadmap to the structural drivers behind this expansion can convert category growth into durable competitive advantage.
Worldwide Pet Food Delivery Market
Macro Signals Shaping the Competitive Terrain
The market’s trajectory is being influenced by more than consumer sentiment alone. Inflationary pressure on raw materials, regulatory scrutiny around food safety, and heightened expectations for quality and transparency are reshaping the operating environment. These forces are not peripheral concerns; they directly affect margin structures, product design, and the credibility of brands that depend on recurring subscription behavior.
On the supply side, farm-level vegetable prices are predicted to increase 20.5 percent in 2026, with a prediction interval ranging from 3.6 percent to 42.7 percent. This degree of uncertainty complicates ingredient planning for providers that rely on fresh produce as a core component of their value proposition. Compounding this, retail fresh vegetable prices increased by 3.1 percent from March 2026 to April 2026 and were 11.5 percent higher in April 2026 than in April 2025. For meal kit companies, the implication is clear: input cost variability can quickly translate into pricing tension, recipe reformulation, or margin erosion if sourcing and hedging strategies are not built for volatility.
At the same time, food safety remains a defining trust factor. A multistate Salmonella outbreak linked to home delivery meals from Metabolic Meals resulted in 16 illnesses and 7 hospitalizations, with the CDC investigation closing after the outbreak was resolved. In a separate event, cheese ingredients included in certain HelloFresh brand meal kits were recalled in Canada due to Listeria monocytogenes contamination. These incidents illustrate how quickly a compliance or quality failure can disrupt brand perception and operational continuity. In a category built on recurring delivery and household trust, such events are not merely reputational setbacks; they are strategic risk signals that should inform vendor oversight, traceability investments, and recall readiness.
What the Research Report Delivers
This market research study is structured to move beyond broad narrative and into actionable intelligence. It is designed for strategy, product, sales, and investor teams that need a shared fact base for planning, prioritization, and external communication. The report brings together market sizing, segmentation logic, competitive profiling, and industry context in a format that supports both internal alignment and external stakeholder engagement.
The analysis covers historical performance from 2020 through 2025 and extends forecast perspective across 2026 to 2032. This dual lens helps organizations distinguish between cyclical fluctuations and structural trends, enabling more disciplined scenario planning. Rather than treating growth as a single line item, the report unpacks the categories, offerings, and meal types that constitute the market’s underlying architecture, allowing decision-makers to identify where demand is concentrated and where variance is likely to emerge.
Throughout the study, attention is given to the practical implications of the data. Market size is presented with the context needed to interpret momentum, while segmentation insights are framed to support portfolio decisions, market-entry logic, and resource allocation. The report also examines market concentration to illuminate the balance between established players and the room available for differentiation. The objective is to provide a stable analytical foundation on which operational strategy can be built.
How the Market Is Structured
The meal kit delivery services market is shaped by multiple overlapping demand drivers. Some consumers prioritize the experience of cooking from scratch with guided recipes and pre-portioned ingredients, while others seek speed and simplicity with minimal preparation. Dietary identity also plays a significant role, with a meaningful portion of demand oriented toward plant-based and vegetarian options, and a larger share anchored in non-vegetarian meals. These preferences influence not only product design, but also customer acquisition messaging, retention dynamics, and the cost profiles of different service models.
Offering formats split the market between services that emphasize cooking from ingredients and those oriented toward quicker, more immediate consumption. The balance between these approaches affects logistics, packaging, customer expectations, and margin potential. Meal type segmentation further differentiates demand, creating distinct strategic paths for brands that compete on variety, culinary authenticity, convenience, or health and sustainability credentials. Regionally, the market reflects varying levels of adoption, with differing consumer expectations around price sensitivity, distribution reach, and brand trust.
In concentrated markets, the behavior of leading providers often sets pace and expectations for the broader field. Concentration patterns can inform how aggressively new entrants can pursue differentiation, how incumbents defend share, and where partnerships or niche positioning may create viable openings. The report contextualizes these structural relationships without reducing them to oversimplified rankings, because competitive advantage in meal kits often depends on execution details that numbers alone cannot capture.
Competitive Landscape: Ten Profiles, Multiple Strategic Playbooks
The competitive field includes a diverse set of operators, each pursuing a distinct interpretation of what consumers should receive from a meal kit service. The companies profiled in the research represent a cross-section of business models, recipe philosophies, and distribution approaches that together define the current market rhythm.
- HelloFresh SE, headquartered in Berlin, Germany, provides meal kit delivery services with more than 100 weekly recipes, alongside add-ons, seasonal boxes, premium meals, and vending machine distribution. Its breadth of format and recipe volume points to a scale-oriented strategy that seeks to serve a wide range of household needs under one brand umbrella.
- Marley Spoon, based in Sydney, Australia, offers meal kit delivery services featuring gourmet recipes, budget plans, and collaborations such as with Martha Stewart. Its profile suggests a dual focus on elevated culinary appeal and accessible price points, using partnerships to extend brand reach and recipe credibility.
- Purple Carrot, headquartered in Santa Barbara, California, specializes in meal kit delivery services focused on plant-based and vegetarian options. Its narrower dietary emphasis positions it within a segment where mission alignment and ingredient storytelling can support loyalty and differentiation.
- Hungryroot, based in Chicago, Illinois, provides fresh meal kit delivery services with customizable recipes and ingredient sourcing. Customization and sourcing transparency indicate a model built around flexibility and consumer control, which can be especially relevant for households balancing dietary preferences with convenience.
- Sunbasket, located in Burlingame, California, delivers organic meal kit services with nutrient-dense recipes and sustainable ingredients. Its emphasis on organic and sustainability attributes aligns with consumers who treat food quality and sourcing as central purchase drivers.
- Gobble, headquartered in Columbus, Ohio, offers meal kit delivery services emphasizing quick and easy home cooking recipes. Its value proposition leans toward time savings and usability, appealing to consumers who want cooking engagement without extended prep burden.
- Freshly Inc., based in New York, New York, provides meal kit delivery services with fresh, pre-portioned ingredients for at-home meals. Its approach reinforces convenience and freshness as core purchase triggers, positioning the service as a practical bridge between groceries and ready-made dining.
- Dinnerly, headquartered in Denver, Colorado, delivers budget-friendly meal kit services with simplified recipes for everyday use. The focus on affordability and simplicity targets cost-conscious households and those seeking repeatable, low-friction meal routines.
- Green Chef, also based in Denver, Colorado, specializes in organic and plant-based meal kit delivery services. By combining organic positioning with plant-centric offerings, it operates at the intersection of health, dietary preference, and ingredient quality.
- Home Chef, located in Chicago, Illinois, offers meal kit delivery services with chef-created recipes and value options. Its combination of culinary identity and value-tiered choices reflects an effort to serve both experience-seeking and price-sensitive consumers.
- Tovala, headquartered in San Francisco, California, provides scan-to-cook meal kit delivery services with smart oven integration for precise heating. This model blends meal kits with connected appliance functionality, illustrating how hardware, software, and food service can converge around convenience and repeatability.
These profiles matter because they show that the market is not converging on a single formula. Some providers compete through scale, recipe variety, and multi-format distribution. Others compete through dietary specialization, sustainability claims, customization, or appliance-linked convenience. For a company planning its next move, the strategic question is less about which model is universally best and more about which combination of audience, operational capability, and brand promise can be sustained at scale.
From Consumer Preference to Operating Risk
Market growth does not happen in a vacuum. The same forces that expand demand can also expose weak points in execution. Ingredient inflation, for example, is not only a cost issue; it is a design issue. If farm-level input prices can swing materially within a single year, then menus, portion sizing, sourcing partnerships, and pricing architecture must be flexible enough to absorb change without eroding consumer trust. Brands that lock themselves into rigid recipes or uncompetitive price points may find themselves squeezed from both sides.
Food safety adds another layer of strategic urgency. The recall events involving HelloFresh and the Salmonella outbreak associated with Metabolic Meals demonstrate that meal kit providers operate in an environment where quality failures can become public quickly and carry both health and business consequences. In this context, operational discipline is a competitive asset. Traceability, supplier vetting, testing protocols, and recall procedures should be treated as part of the core value proposition, not as back-office compliance functions. Companies that institutionalize these practices are better positioned to protect retention and reduce the likelihood that a single incident derails growth momentum.
These dynamics also intersect with customer acquisition and retention economics. Meal kit services depend heavily on recurring engagement, which means the cost of disappointing a customer is multiplied over time. Quality, reliability, and transparent communication can therefore be viewed as retention investments with direct financial returns. In a market projected to grow from USD 42.87 billion in 2026 toward nearly USD 70 billion by 2032, the winners are likely to be those who combine expansion with consistency.
Using the Study to Inform 2026 Decisions
For organizations active in or entering this market, the study functions as a strategic decision-support tool. It helps leadership teams answer questions that are otherwise difficult to resolve with fragmented public information: where demand is accumulating, which segments carry the strongest growth logic, how competitive intensity varies across formats, and what external pressures may shape margin and operational planning in the near term.
The report’s historical and forecast structure supports a range of applications. Strategy teams can use it to evaluate expansion timing and geographic or segment prioritization. Product and operations teams can use it to frame menu architecture, sourcing resilience, and service-model trade-offs. Marketing and brand teams can use the segmentation context to sharpen positioning without relying on broad assumptions. Investors and advisors can use the concentration and growth outlook to assess market maturity and the durability of competitive claims.
Importantly, the study is designed to be actionable without being over-specified at the summary level. It provides the analytical scaffolding needed to make informed choices while leaving room for company-specific interpretation. The most valuable insights often emerge when broad market direction is combined with internal capabilities, customer data, and operational constraints. That is where the research is intended to be most useful: as a reliable base layer for strategic judgment.
What Remains in the Full Analysis
The overview above outlines the strategic context and structural themes that shape the meal kit delivery services market. It also demonstrates why 2026 is a pivotal year for planning: input-cost uncertainty, food safety scrutiny, and continued category expansion are all active at once. Yet the full report contains a deeper level of segmentation value, competitive benchmarking, and scenario-ready detail that cannot be fully reproduced in an executive summary.
Meal Kit Delivery Services Market
For teams that need to move from general market awareness to specific planning assumptions, the complete study provides the granularity required to support concrete decisions. The full analysis examines how the market breaks down across regions, offerings, and meal types, and it contextualizes those splits within the broader growth trajectory. It also expands the competitive and operational picture in ways that help organizations identify where to concentrate resources, where to defend position, and where to experiment responsibly.
If your objective is to align 2026 strategy with a market projected to grow at 8.4 percent through 2032, the complete research offers the evidence base needed to make that alignment precise rather than approximate. The full report is available on the PW Consulting market research page, where the detailed segmentation, competitive profiles, and supporting market context can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Meal Kit Delivery Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Manufacturing Market Hits $215B in 2025, Projected 13.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Intelligent Factory: Strategic Imperatives for the Smart Manufacturing Market in 2026
The industrial landscape is undergoing a fundamental reset. As enterprises transition from pilot projects to enterprise-wide deployment, smart manufacturing has moved from a competitive advantage to an operational necessity. For executives planning capital allocation, technology roadmaps, and supply chain resilience in 2026, the window for strategic action is narrowing. This introduction outlines the strategic framework embedded in our latest market research, designed to equip decision-makers with the analytical rigor required to navigate an increasingly complex ecosystem.
A Market in Accelerated Expansion
The smart manufacturing sector has demonstrated consistent momentum over the past half-decade, evolving from incremental automation to integrated, data-driven production environments. Our analysis tracks this trajectory from 2020 through the base year of 2025, establishing a clear upward curve that sets the stage for the forecast window extending to 2032. The compound annual growth rate of 13.5 percent across the projection period signals more than incremental uptake; it reflects a structural shift in how manufacturers invest in infrastructure, software, and operational intelligence.
Revenue expansion tells a parallel story. The market crossed the two hundred billion dollar threshold in 2024 and reached approximately two hundred fifteen billion dollars by 2025. Forward momentum carries this trajectory through the mid-to-late 2020s, with valuations climbing steadily toward the three hundred forty billion dollar range by 2032. These figures are not abstract metrics; they represent capital deployment patterns, procurement cycles, and technology prioritization decisions that will define competitive positioning for the remainder of the decade.
Yet macro-level growth is only the starting point. The real strategic challenge lies in understanding how capital flows across technology stacks, how regional supply chains are reconfiguring under policy pressures, and which operational models will prove sustainable as deployment scales. This report is built to answer those questions with precision.
Report Architecture and Operational Utility
A market study earns its value only when it translates into actionable strategy. Our research is structured to serve multiple stakeholder functions simultaneously, from executive briefing to operational planning. The core of the analysis is built around four interconnected pillars:
- Technology segmentation analysis that dissects adoption patterns across control systems, execution platforms, and programmable logic architectures, revealing where investment is concentrating and which capabilities are becoming baseline expectations.
- Component-level evaluation distinguishing hardware procurement cycles from software licensing and services integration, helping procurement and IT leaders align budgeting rhythms with deployment realities.
- End-use industry mapping that highlights how automotive, electronics, aerospace, and defense organizations are tailoring smart manufacturing investments to their specific throughput, compliance, and precision requirements.
- Geographic distribution insights that contextualize regional demand intensity, policy acceleration, and supply chain localization trends without reducing complex dynamics to simplistic rankings.
Beyond segmentation, the report delivers competitor profiling, partnership mapping, and a regulatory watch module that tracks how industrial policy is reshaping procurement and localization mandates. Each section is designed to feed directly into scenario planning, vendor evaluation, and capacity expansion decisions. Readers will find executive dashboards, adoption maturity curves, and investment prioritization matrices that convert raw analysis into boardroom-ready narrative.
Competitive Dynamics Among Market Leaders
The smart manufacturing arena is defined by a concentrated but heterogeneous group of players, each anchoring its strategy around distinct value propositions. Our competitive assessment examines how these organizations position themselves across automation, digital factory platforms, and industrial connectivity.
Smart Factory Market
Siemens AG continues to anchor its offering around integrated digital factory ecosystems, bundling automation, production operations, and Industry 4.0 platforms into a unified deployment model. ABB Ltd has carved a parallel path with a focus on robotics, automation, and AI-driven optimization, positioning intelligent control as a differentiator rather than a feature. Rockwell Automation, Inc. emphasizes industrial automation platforms, MES systems, and digital twin technologies, reflecting a growing enterprise appetite for simulation-led process refinement before physical deployment.
Schneider Electric SE brings an energy-centric lens to the market, developing eco-adaptive infrastructure and smart grid solutions that integrate directly into manufacturing environments. Honeywell International Inc. contributes a connective enterprise perspective, pairing industrial cybersecurity with IIoT platforms to address the operational risk dimension that becomes more acute as factories digitize. Emerson Electric Co. reinforces this momentum with automation solutions, digital twins, and smart equipment designed to streamline industrial operations at scale.
GE has maintained leadership in advanced manufacturing technologies, particularly through industrial IoT and predictive maintenance systems that extend asset life and reduce unplanned downtime. Mitsubishi Electric Corporation complements the field with factory automation, robotics, and IoT-enabled smart factory systems, while Robert Bosch GmbH focuses on industrial automation, IoT, and digital transformation solutions that support smart production across diverse manufacturing modalities.
The competitive field also includes specialized and adjacent players that shape niche but high-impact segments. Applied Materials, Inc. delivers semiconductor equipment and smart manufacturing platforms purpose-built for chip production, an industry where precision and process control carry outsized strategic weight. Cimatron Ltd. supplies CAM software and integrated workflow solutions that bridge design and shop-floor execution. HighByte Inc. addresses the data plumbing challenge directly, providing industrial data management and connectivity software that underpins effective smart factory integration.
Together, these players illustrate a market where differentiation is increasingly tied to integration depth, data interoperability, and sector-specific expertise rather than hardware specifications alone. Understanding these positioning strategies is essential for procurement leaders evaluating vendor roadmaps and for operators assessing which ecosystems are most likely to support long-term scalability.
Policy, Regulation, and Regional Dynamics
Market growth does not occur in a policy vacuum. Industrial strategy, trade dynamics, and regulatory frameworks are actively reshaping where and how smart manufacturing investments are deployed. Recent developments provide a clear signal that governments and standards bodies are accelerating their focus on manufacturing modernization.
China's industrial upgrading program continues to influence global supply chain architecture. By mid-2025, assessments documented substantial progress in localization rates across key sectors, including agricultural machinery and basic materials. At the same time, high-performance computing segments have shown more uneven progress, with import dependency remaining elevated in certain categories. The nine implementation paths associated with the initiative prioritize digitalization of manufacturing equipment, intelligent process design, and green standards aimed at reducing resource consumption. These priorities intersect directly with smart manufacturing adoption, especially in energy-intensive sectors where China already holds dominant production share in lithium-ion batteries and solar modules.
On the other side of the Pacific, policy incentives are reinforcing domestic investment. Analysis released in late 2025 highlighted U.S. government incentives and OEM-led digital transformation efforts as key drivers of smart manufacturing adoption, alongside state-level support mechanisms for pilot programs. This alignment between federal encouragement and corporate deployment is creating a more structured pathway for scaling intelligent manufacturing capabilities.
Standards development is also gaining momentum. India's telecommunications engineering framework introduced a technical report in mid-2025 establishing standards for Industry 4.0 and smart manufacturing integration, reflecting a broader international push to harmonize interoperability expectations and reduce fragmentation in connected factory environments.
Meanwhile, industry events and conference agendas are increasingly centered on autonomy, agentic AI integration, and advanced packaging in semiconductor manufacturing, signaling where practitioner attention and R&D emphasis are converging. These developments do not merely contextualize the market; they shape procurement timelines, compliance strategies, and cross-border investment decisions.
Why This Research Matters for 2026 Decision-Making
Executive teams entering 2026 face a set of interlocking decisions: which technology layers to standardize, how to sequence capital deployment, which vendor ecosystems to align with, and how to hedge against regulatory and supply chain volatility. High-level growth projections can inform optimism, but they cannot replace granular intelligence about adoption bottlenecks, segment-specific demand intensity, and competitive maneuvering.
This report is designed to close that gap. It converts market scale into strategic context, situates competitor moves within broader technology trends, and embeds policy developments into operational planning assumptions. For organizations evaluating factory modernization, capacity expansion, or digital transformation roadmaps, the analysis provides a structured reference point for scenario modeling and risk assessment.
The full study goes further than what an introduction can capture. It contains segment-specific adoption trajectories, regional intensity mapping, detailed competitor positioning tables, procurement cycle insights, and scenario-based forecasts that allow leadership teams to test assumptions against multiple future states. Those elements are essential for converting directional awareness into precise investment logic.
Accessing the Complete Intelligence
The smart manufacturing market is expanding at a pace that rewards disciplined analysis. With a sustained growth trajectory, intensifying competition among established and specialized players, and an evolving policy environment that directly affects localization and standards, the cost of incomplete information is rising. Organizations that enter 2026 with a clear view of technology segmentation, competitive positioning, and regulatory direction will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build manufacturing capabilities that remain resilient as the landscape shifts.
Smart Manufacturing Market
To explore the complete dataset, segmentation breakdowns, and competitor profiles in full detail, download the full report. The complete analysis provides the depth required to move from strategic awareness to execution-ready decision-making.
For detailed analysis of this topic, please visit the official page: Smart Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


