



GaN on Diamond Semiconductor Substrates Market 2026: 17% CAGR and Strategic Shifts Redefining RF Power Leadership
By PW Consulting, 2026-09-21
GaN on Diamond Semiconductor Substrates: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The GaN on Diamond semiconductor substrates market has entered a phase of accelerated expansion, driven by the compounding demands of high-frequency communications, defense electronics, and next-generation power systems. Measured in millions of U.S. dollars across a 2020 through 2032 horizon, the sector has moved from niche experimentation to commercial validation. Revenue grew steadily through the early 2020s as proof-of-concept devices gave way to production-grade architectures, and the pace quickened materially once supply ecosystems matured and end-users began certifying GaN-on-diamond components in operational systems. Forward projections indicate continued double-digit compound growth, with the market expected to cross the 90-dollar threshold by the early 2030s as edge deployments scale and thermal management requirements tighten across RF, microwave, and power applications.
This trajectory, however, is not uniform across value chains or geographies. The segment remains concentrated among a small group of established players who have invested early in substrate development, epitaxy compatibility, and bonding processes. Such concentration creates both momentum and friction: incumbents benefit from process know-how and early customer relationships, while the broader industry faces structural bottlenecks that complicate rapid scaling. Production of high-quality diamond wafers, particularly single-crystal variants, demands specialized chemical vapor deposition capabilities, stringent quality control, and capital-intensive cleanroom environments. Bonding GaN layers to diamond substrates without introducing defects or interfacial thermal resistance remains a disciplined engineering challenge, and yield optimization is still a differentiating factor rather than a commodity.
Three structural challenges now define the inflection point for this market. First, the thermal and electrical performance advantages of diamond substrates are well understood, but translating those advantages into repeatable, cost-effective manufacturing at volume remains uneven. Process variability, wafer-scale uniformity, and the economics of bonding and testing constrain the speed at which commercial programs can ramp. Second, demand is fragmenting across application profiles with different performance priorities. Some users prioritize maximum power density and thermal conductivity, while others require reliability at moderate performance levels with lower cost thresholds. This divergence complicates standardization and slows the emergence of common substrate specifications that could accelerate adoption. Third, supply resilience has become a strategic variable. The industry depends on a limited number of specialized synthesis and wafer processing nodes, which intensifies exposure to equipment availability, raw material readiness, and regional logistics dynamics. When those nodes face disruptions, even strong end-demand can be delayed by substrate availability rather than component design.
Taken together, the market is characterized by strong technological pull and uneven commercial readiness. The opportunity lies not only in demonstrating performance but in aligning substrate supply, bonding reliability, and application-specific design to create repeatable value chains.
Key Drivers Shaping the Market
The growth path for GaN on Diamond substrates is anchored in a combination of technical breakthroughs, regulatory momentum, demand-side evolution, and supply-side restructuring. Each driver reinforces the others, but not uniformly, and the interplay between them determines which segments scale first.
Technical innovation remains the primary catalyst. Advances in chemical vapor deposition have improved the purity, grain structure, and thermal conductivity of diamond substrates, which directly supports higher power density and lower junction temperatures in GaN devices. Alongside substrate improvements, progress in wafer bonding, interface engineering, and epi-layer compatibility has reduced the risk of performance degradation at the GaN-to-diamond interface. These advances matter because the value proposition of diamond is not just thermal conductivity in isolation; it is the ability to transport heat away from active regions under high-duty-cycle conditions without compromising RF performance or long-term reliability. Recent product launches and platform demonstrations reflect this trajectory, including new single-crystal wafers optimized for RF and power device applications, and power amplifier unveilings that emphasize reduced thermal resistance for satellite communications. The cumulative effect is closing the gap between laboratory potential and fielded hardware.
Policy and procurement dynamics are adding a second layer of support. Government programs and defense procurement pathways increasingly favor substrate and packaging technologies that extend performance envelopes in latency-sensitive, thermally constrained environments. Contracts and funding initiatives have reinforced interest in GaN-on-diamond integration for defense, radar, and hypersonic-related applications where thermal and power density requirements are explicit. This is not simply a question of subsidies; it shapes demand visibility, encourages investment in domestic capability, and signals long-term procurement preferences. In parallel, broader semiconductor support measures have influenced funding availability for satellite communications and advanced RF ecosystems, helping de-risk early-stage commercialization for companies pursuing diamond-cooling approaches. The practical impact is stronger demand forecasting and a higher tolerance for early-stage supply investment where the end-use case is strategically prioritized.
On the demand side, application behavior is changing in ways that favor higher-performance substrates. Satellite communications is expanding the need for compact, efficient RF front ends that can operate reliably under continuous load and in constrained thermal environments. Radar and millimeter-wave sensing systems increasingly require wideband performance and stable gain under temperature extremes, which makes thermal management a design driver rather than an afterthought. In commercial RF deployment, the push toward higher throughput and denser arrays also raises the thermal bar, encouraging component designs that would be difficult to sustain on conventional substrates alone. These shifts are not abstract; they translate into product roadmaps where substrate selection becomes part of system optimization, not a discrete component choice.
Single Crystal Diamond Market
Supply-side and cost dynamics complete the picture. Fabrication and bonding economics still place a premium on diamond wafer production, and the costs associated with CVD processes and bonding steps influence overall substrate pricing. At the same time, supply chain bottlenecks in diamond wafer production and high production costs constrain commercial scaling unless capacity and process maturity improve together. Regional imbalances in substrate availability have also emerged from geopolitical pressures and logistics disruption, which has prompted customers and manufacturers alike to consider diversification, near-shoring, and vertical integration strategies. These pressures are reshaping how companies plan capacity, qualification, and customer commitments. Notably, consolidation and partnership activity is increasing as firms seek to improve control over critical steps in the value chain, while consortium-based regional facilities are being advanced to support supply resilience.
Worldwide Synthetic Single Crystal Diamond Market
Competitive Landscape and Leading Strategies
The competitive field is defined by a handful of companies that have moved beyond material research into concrete product routes and targeted applications. The differences among them are less about whether GaN-on-diamond is promising and more about where each player chooses to compete: substrate supply, device integration, application focus, or vertical integration.
Element Six has built a reputation around synthetic diamond substrates and GaN-on-diamond technology for high-thermal-conductivity applications in RF, power, and defense electronics. Its strategic positioning leans on deep material expertise and controlled substrate quality, which supports customers seeking consistent performance in demanding environments. By launching ultra-high-purity single-crystal diamond wafers optimized for RF and power device applications, the company has reinforced its emphasis on material-grade differentiation as a foundation for downstream device performance.
Akash Systems has targeted satellite communications technology and related substrates, with a clear link between diamond-cooling concepts and space-grade or satellite RF performance. Securing funding tied to CHIPS Act support to advance diamond-cooling GaN-on-diamond satellite technology indicates a strategy aligned with public-sector programs and long-cycle satellite roadmaps. This positions the company where performance, thermal management, and mission-critical reliability intersect, rather than competing broadly across all RF applications.
Qorvo operates as both a components producer and an integrator in the RF and satellite space, manufacturing GaN-on-diamond transistors and power amplifiers. Its product unveiling of a GaN-on-diamond power amplifier for satellite communications that reduces thermal resistance reflects a device-level strategy: rather than selling substrate capability in isolation, it demonstrates how the substrate improves end-device performance metrics that matter directly to system designers. That route can shorten the adoption cycle because it ties substrate benefits to amplifier behavior customers can measure and specify.
RFHIC Corporation has focused on GaN-on-diamond epi wafers and technology for radar, microwave, and satellite uses. Its profile suggests a strategy oriented toward enabling partners and programs that require tailored epi and substrate combinations for high-frequency applications, including defense and satellite domains. This support-layer positioning can be strategically valuable when customers need integration flexibility or customized device structures rather than standard catalog products alone.
Coherent Corp. has moved into offering GaN-on-diamond wafers scaled for commercial RF applications, which points to a strategy centered on broader commercialization and volume orientation. Scaling for commercial RF implies a different balancing act between performance and cost compared with niche or defense-first approaches, and it suggests attention to process throughput, wafer consistency, and application breadth.
Blue Wave Semiconductor has commercialized GaN-on-diamond substrates for high-power RF and defense electronics, which places it in a space where thermal performance and power handling are central. Its commercial focus aligns with programs that need robust substrate performance under sustained high-power operation, again linking substrate choice to application risk management.
PW Consulting Information & Electronics Research Center
The landscape is evolving along several axes. Vertical integration is becoming more visible, as illustrated by an acquisition in the diamond synthesis space intended to strengthen control over upstream capability for GaN-on-diamond products. That move signals a recognition that substrate and material readiness can be a strategic bottleneck, not just a component specification. At the same time, consortium-based regional facilities are emerging to support supply chain resilience, reflecting a broader shift toward diversified capacity and regional redundancy. These developments suggest the market will likely see further consolidation where material control matters, while also encouraging new regional players or partnerships aimed at reducing dependency on limited supply nodes. Differentiation will increasingly come from application-tailored solutions, process maturity, and the ability to reduce thermal and reliability risk in real systems rather than from substrate claims alone.
Future Outlook and Strategic Opportunities
Looking ahead three to five years, the market is likely to move along a path shaped by scale, specialization, and supply-chain reorganization. The most consequential trend is the gradual shift from performance demonstration to production repeatability. As bonding yields, wafer uniformity, and qualifying standards improve, GaN-on-diamond will become less of an exceptional choice and more of a standard option in selected high-performance RF and power portfolios. That transition creates commercial opportunity for companies that can offer predictable supply, documented reliability, and design support that reduces integration risk for system manufacturers.
A second trend is the deepening linkage between substrate selection and application-specific program requirements. Defense, radar, satellite, and high-end communications will continue to push toward higher power density and thermal resilience, but they will not all value the same trade-offs. Some programs will prioritize maximum performance and tolerate complex supply or cost structures, while others will seek a balanced combination of performance, reliability, and cost. This divergence opens space for tiered offerings, application-focused qualification paths, and partnerships that align substrate supply with end-use certification timelines.
A third trend concerns supply resilience and regionalization. Given the concentration of specialized diamond wafer capability and the exposure created by logistics and geopolitical pressures, more customers and manufacturers are expected to prioritize regional availability, diversified sourcing, and tighter integration across material and device stages. Where that occurs, it creates opportunities for regional capacity initiatives, strategic partnerships, and vertically coordinated offerings that can promise steadier delivery and lower program risk.
These trends carry commercial upside, but they also include uncertainty. Yield and process consistency remain central risks, especially for single-crystal paths where scale-up is technically demanding. Cost structures may persist at elevated levels for advanced substrates, which can slow adoption in price-sensitive branches of the market. Demand timing can also diverge from supply readiness when procurement cycles, qualification requirements, or regional availability issues extend program schedules. The businesses that navigate this period most effectively will be those that treat thermal performance as a system-level advantage while building credible supply and qualification pathways around it.
Actionable Guidance for Decision-Makers
For manufacturers and device developers, the priority is to align substrate strategy with realistic production and qualification pathways rather than with performance claims alone. That means investing early in bonding reliability, thermal interface engineering, and application-specific testing that mirrors field conditions. It also means evaluating whether the target application truly requires the upper end of diamond thermal performance or whether a balanced substrate approach can meet requirements at better cost and availability. The most defensible strategies will connect device architecture, substrate selection, and supply readiness into one plan, so that performance gains do not stall at the interface between design and manufacturing.
For investors, the value lies in distinguishing between material promise and commercial readiness. Platforms with clear application anchors, credible supply strategies, and demonstrable progress in yield or integration tend to offer stronger strategic positioning than those relying on performance narrative alone. Attention should also be paid to consolidation patterns and regional capacity initiatives, since these can reshape competitive advantage by changing who controls critical nodes in the value chain. The key judgment is whether a company is building durable differentiation through process maturity and customer alignment, or whether its position depends on assumptions that have not yet been validated at scale.
For procurement and program leaders, the focus should be on supply risk, qualification timelines, and design support as much as on nominal performance. In applications where thermal limits shape system architecture, substrate availability and reliability can be as decisive as device specs. Evaluating suppliers in terms of consistency, capacity visibility, and integration assistance can reduce later schedule exposure and improve total system outcomes. Where programs span multiple regions or rely on constrained supply nodes, diversification and redundancy planning should be treated as part of the technical decision, not as a separate procurement exercise.
For decision-makers seeking a fuller picture of end-use segmentation, regional dynamics, competitive positioning, and scenario-based projections, a dedicated, detailed research view can provide the granularity needed for planning. In markets moving this quickly, detailed segmentation data and customized strategic interpretation are often what separate reactive positioning from proactive advantage.
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Embedded Non-volatile Memory Market: Why 11.54% CAGR and Automotive Demand Redefine Industry Growth
By PW Consulting, 2026-09-21
The Embedded Non-Volatile Memory Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
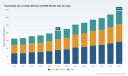
The embedded non-volatile memory market has entered a phase of sustained expansion, underpinned by a compound annual growth rate of 11.54 percent across the forecast horizon. Revenue trajectories from 2020 through 2025 reflect steady acceleration, with the market advancing from approximately 163 million units of currency to 215 million. Forward projections extend this climb, reaching roughly 226 million in 2026 and surpassing 344 million by 2032. This growth is not merely cyclical; it represents a structural realignment in how semiconductor architectures handle persistent data storage, security, and in-field programmability.
Automotive Embedded Storage (eMMC and UFS) Market
Several interconnected challenges are reshaping the competitive baseline. First, the integration of advanced eNVM variants into next-generation system-on-chip designs introduces substantial layout complexity and extended verification cycles. Embedding memory requires additional intellectual property blocks, specialized design rules, and rigorous testing protocols that lengthen development timelines and increase engineering overhead. This friction disproportionately affects fabless design teams and smaller manufacturers that lack established process integration expertise.
PW Consulting
Second, manufacturing economics remain a persistent constraint. High-cost fabrication equipment and process steps that diverge from standard CMOS pathways create integration bottlenecks. Many foundries must adapt existing lines or invest in specialized modules, which raises capital expenditure and narrows the margin window for volume products. As a result, cost-per-bit advantages can be delayed until design maturity and factory yield optimization converge.
Third, reliability and qualification requirements are intensifying across safety-critical verticals. Automotive and industrial eNVM products must satisfy stringent temperature ranges, long-term data retention targets, and grade-level certifications that validate performance under extreme operating conditions. These demands favor mature or thoroughly validated memory technologies, yet simultaneously create barriers for emerging solutions seeking rapid adoption in high-trust segments.
Key Drivers Shaping Market Dynamics
Technological innovation in memory physics and integration methodologies is accelerating the shift toward alternative eNVM types. Resistive, magnetic, and ferroelectric approaches are gaining traction where conventional flash encounters scaling limits or endurance constraints. Demonstrations of embedded ReRAM integrated into mature BCD processes for mixed-signal and high-voltage applications illustrate how non-traditional nodes can host advanced memory for power management, analog-intensive, and high-reliability designs. Similarly, MRAM and RRAM integration into FinFET and FD-SOI platforms shows that memory types once reserved for niche use cases are becoming credible candidates for mainstream microcontroller and SoC implementations.
Regulatory and certification pressures are reinforcing demand for resilient storage in mission-critical applications. Automotive and industrial programs increasingly require qualification frameworks that guarantee operation across wide temperature envelopes and sustained data integrity over extended service life. In parallel, specialized material platforms and testing protocols are gaining attention for aerospace-grade and radiation-tolerant deployments, where memory must withstand environmental stressors that conventional solutions cannot reliably tolerate. These requirements do not simply raise the compliance bar; they reshape procurement priorities and elevate the strategic value of memory suppliers with proven qualification track records.
Demand-side shifts are also redefining the addressable market. The proliferation of connected devices, edge intelligence, and vehicle electrification is expanding the installed base of microcontrollers and processors that require on-chip persistent storage for configuration, firmware updates, cryptographic keys, and calibration data. Consumers and enterprises alike are expecting systems that can be securely updated in the field and that retain essential state information across power cycles. This behavior creates recurring pull for embedded memory that balances performance, endurance, and security without relying on external storage components that add board space, cost, and failure modes.
Supply-chain and cost-structure dynamics are influencing where and how eNVM is adopted. Foundry strategies that embed MRAM and ReRAM directly into advanced and mid-range process nodes are reducing design fragmentation and enabling more efficient IP reuse across product families. At the same time, geopolitical factors continue to diversify sourcing options, with multiple foundry ecosystems offering embedded memory capabilities to global manufacturers. This broadening of supply choices can improve resilience and pricing competitiveness, but it also requires buyers to evaluate process maturity, qualification status, and long-term roadmaps rather than assuming uniformity across vendors.
Competitive Landscape and Leading Strategies
The market features a diverse mix of semiconductor manufacturers, memory specialists, and foundry platforms, each pursuing distinct value-creation strategies. Samsung Electronics continues to develop embedded STT-MRAM and flash eNVM solutions for microcontrollers, systems-on-chip, and high-performance applications, leveraging scale and process expertise to integrate memory across multiple product tiers. STMicroelectronics has focused on embedding PCM and RRAM into FD-SOI microcontrollers for automotive and industrial use cases, emphasizing platform-level integration that aligns memory choice with architecture-level efficiency. Infineon Technologies combines embedded FRAM and RRAM within automotive AURIX controllers and edge ML microprocessors, targeting applications where reliability and real-time processing intersect.
NXP Semiconductors delivers embedded MRAM in automotive microcontrollers built on advanced FinFET processes in collaboration with leading foundries, reinforcing its position in safety-critical vehicle systems. Renesas Electronics offers embedded STT-MRAM and flash for industrial and IoT microcontrollers, aligning memory selection with broad vertical coverage and long product lifecycles. Texas Instruments supplies ferroelectric and flash-based embedded memory across microcontrollers and processors, reflecting a balanced approach that spans mature and emerging technologies. Microchip Technology manufactures embedded flash and NOR eNVM for embedded systems and microcontrollers, maintaining emphasis on broad deployability and design familiarity.
On the IP and specialized memory side, Weebit Nano licenses embedded ReRAM IP for integration into foundry platforms, with recent demonstrations and qualifications spanning multiple process nodes and design environments. Everspin Technologies supplies embedded and standalone MRAM for automotive, aerospace, and industrial applications, and has expanded its high-reliability portfolio to address extended temperature and endurance requirements. TSMC embeds MRAM and ReRAM directly into advanced FinFET processes for microcontrollers and systems-on-chip, enabling designers to access memory capabilities within leading-edge node offerings. GlobalFoundries integrates embedded MRAM and ReRAM into mature and specialized platforms for high-reliability designs, providing an alternative path for applications that prioritize robustness and customization over aggressive scaling.
Leading strategies converge around three themes. The first is platform-level integration, where memory is treated as an intrinsic capability of the process and device family rather than an afterthought, reducing integration risk and enabling repeatable product derivatives. The second is qualification and reliability leadership, particularly in automotive and industrial segments where certifications and long-term retention claims are decisive procurement criteria. The third is ecosystem expansion through licensing and multi-foundry enablement, which broadens adoption by allowing design teams to deploy a consistent memory IP across different manufacturing partners and node options.
The competitive landscape is evolving through a combination of consolidation among integrated suppliers and new entry via IP licensing and specialty memory providers. Established manufacturers continue to strengthen their process roadmaps and portfolio breadth, while memory-technology specialists are expanding the set of supported nodes and design environments. This dual dynamic creates both pressure and opportunity: incumbents must defend their integration advantages and qualification portfolios, while newer entrants can gain relevance by demonstrating multi-platform compatibility, cost-effective integration, and strong technical support. Over time, the market is likely to fragment by application requirements and process node strategy rather than converge into a single dominant memory type.
Outlook for the Next Three to Five Years
One clear trend is the broadening adoption of non-flash embedded memory types in mainstream microcontroller and SoC designs. As MRAM, ReRAM, FRAM, and related technologies demonstrate improved integration maturity and cross-platform compatibility, they are expected to capture additional share in applications that demand higher endurance, lower power during write operations, or enhanced security features. The commercial opportunity lies in enabling product families that can address multiple verticals from a common architecture, reducing time-to-market and simplifying lifecycle management for manufacturers.
A second trend is the deepening of qualification-led competition in automotive and industrial segments. Requirements for wide temperature operation, long data retention, and robust reliability will continue to favor suppliers that can document consistent performance and provide transparent qualification data. This creates an opportunity for differentiated positioning through documented reliability, application-specific reference designs, and support for in-field update and secure-boot scenarios. The risk is that qualification lead times and testing costs may slow adoption of newer memory types in the highest-tier safety applications, creating a bifurcated market where mature technologies retain a multi-year advantage in the most demanding tiers.
A third trend is the increasing strategic importance of foundry and process choice. As multiple ecosystems offer embedded MRAM and ReRAM capabilities, design teams will evaluate memory integration alongside node selection, power targets, and supply resilience. This trend favors suppliers that can provide predictable integration paths, multi-node availability, and clear migration options. The uncertainty arises from the uneven pace of process optimization across foundries and the potential for cost pressures if specialized equipment or steps remain difficult to scale economically. Buyers should therefore treat memory adoption as a joint decision with process strategy rather than a standalone component selection.
Strategic Recommendations for Decision Makers
For semiconductor manufacturers and design-house leaders, the priority is to align memory selection with architecture strategy and process roadmap. Embedding eNVM early in the design cycle can reduce integration complexity later, but only if the chosen memory type has a credible path to the target node and a clear qualification trajectory for the intended applications. Companies should map memory options against product-tier requirements, plan for extended verification where necessary, and invest in reference designs that demonstrate security, endurance, and in-field update capabilities. A disciplined approach that balances emerging memory benefits with proven reliability will improve competitiveness in automotive, industrial, and connected-device markets.
For investors and strategic analysts, the value lies in tracking differentiation signals rather than headline revenue alone. Indicators such as multi-node IP enablement, qualification progress in safety-critical segments, foundry partnerships, and portfolio expansion into high-reliability products provide early insight into which players are building durable advantage. Attention should also be paid to cost dynamics and integration complexity trends, since manufacturing economics can determine whether a promising memory technology achieves volume adoption or remains confined to premium niches. Monitoring these signals helps differentiate cyclical growth from structurally advantaged positions.
Worldwide eMMC Flash Chip Market
For procurement and product-planning teams, the practical move is to evaluate embedded memory as part of a broader system strategy that includes supply resilience, certification status, and lifecycle planning. Given the range of available technologies and node options, buyers should request detailed integration specifications, qualification documentation, and roadmap alignment before committing to a memory choice for long-lifecycle programs. Detailed, segment-level intelligence is essential for comparing alternatives across applications, regions, and process technologies without relying on assumptions that may obscure important differences in cost, reliability, and availability.
Timely access to granular market data, segmentation detail, and company-specific developments can materially improve planning accuracy and reduce execution risk. Comprehensive research that covers segmentation breakdowns, regional dynamics, and recent product and partnership activity provides the context needed to translate broad market growth into specific action plans. For teams evaluating entry, expansion, or sourcing decisions, a full structured study offers the depth required to assess opportunities with greater confidence and to align technology choices with commercial objectives.
For detailed analysis of this topic, please visit the official page: Embedded Non-volatile Memory (eNVM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nitrogen Gas Springs Market: Why the 5.7% CAGR and 657M Outlook Redefine Strategy
By PW Consulting, 2026-09-21
The Nitrogen Gas Springs Market: Strategic Shifts and Commercial Opportunities Through 2032
The nitrogen gas springs market has entered a phase of steady, structurally driven expansion. Valued at approximately 442.3 million USD in 2025, the market is projected to reach 657.3 million USD by 2032, reflecting a compound annual growth rate of 5.7 percent. This trajectory does not represent a cyclical rebound but rather a fundamental realignment of how downstream industries consume, specify, and integrate gas spring technologies. The historical volatility of the early 2020s has given way to a more predictable upward slope, yet the pace and composition of growth are being reshaped by digitalization, regulatory standardization, and shifting end-use demand profiles. For executives and investors navigating this space, the central question is no longer whether the market will expand, but how value will be captured across different segments, geographies, and technology tiers.
At the operational level, nitrogen gas springs have transitioned from commoditized tooling components to integrated elements within broader manufacturing and assembly ecosystems. Their role in metal stamping, injection molding, die making, and industrial machinery has been steadily reinforced by pressures for faster cycle times, higher precision, and safer tool handling. The market structure reflects this maturation, with a moderate concentration that leaves room for differentiated positioning. The top three players account for roughly 38 percent of revenue, while the top five collectively represent about 48 percent. This distribution indicates a landscape where scale matters, but technical specialization, regional proximity, and application-specific engineering remain decisive competitive levers.
Market Landscape and Core Challenges
The current market environment is defined by a tension between steady demand growth and structural friction points that constrain margin expansion and operational predictability. Three challenges stand out as particularly consequential for manufacturers, distributors, and downstream buyers.
First, the standardization framework is simultaneously a stabilizer and a constraint. Global specifications such as ISO 11901 govern dimensions, force ratings, and safety instructions for press tools and dies, while European deployments must align with PED 2014/68/EU compliance requirements. Additional mounting and interchangeability conventions, including VDI 3003 and CNOMO standards, further shape procurement and engineering workflows. These frameworks reduce integration risk and accelerate design cycles, but they also compress differentiation opportunities for suppliers that rely solely on mechanical performance. Companies that cannot embed compliance into their design and documentation processes face increasing friction in multi-region sourcing, while buyers must navigate a landscape where interchangeability is expected but not uniformly achieved across vendors.
Second, input cost volatility continues to pressure production economics. Steel prices fluctuate in response to supply chain disruptions, geopolitical tensions, and shifting demand patterns, and these movements translate directly into manufacturing cost variability for gas springs. Because many components rely on precision steel geometries, valve assemblies, and sealing systems, manufacturers operate in an environment where raw material exposure must be managed through hedging, supplier diversification, or engineered redesigns. The challenge is not simply higher prices, but the unpredictability that complicates long-term pricing commitments, inventory planning, and margin forecasting.
Third, the market is experiencing a functional shift from passive component supply to active performance monitoring and lifecycle management. Industry 4.0 initiatives in die tooling and stamping operations are driving interest in pressure and temperature telemetry, condition tracking, and predictive maintenance signals. This shift creates a transition cost for incumbents that lack digital integration capabilities, while also raising the bar for downstream adoption. Buyers increasingly expect components that can be monitored, serviced, and replaced with minimal downtime, which means the value proposition is expanding beyond force delivery to include reliability data, serviceability, and integration readiness.
Together, these challenges point to a market in which compliance, cost resilience, and digital capability are becoming baseline expectations rather than optional enhancements. Suppliers that treat these as separate initiatives will struggle to keep pace; those that integrate them into product architecture and commercial models will be better positioned to defend margins and capture share.
Key Drivers Reshaping the Market
The expansion path of the nitrogen gas springs market is being propelled by overlapping forces that influence both supply-side capabilities and demand-side behavior. Four drivers are particularly relevant for strategic planning.
Technological innovation and miniaturization pathways are expanding the functional envelope of gas springs. Standard nitrogen gas springs remain the volume backbone of the market, but compact, super compact, and micro variants are gaining relevance in applications where space constraints, weight sensitivity, and higher precision are critical. This is not merely a sizing trend; it reflects broader engineering demands in automotive tooling, aerospace assemblies, and advanced industrial machinery, where component packaging and force consistency must be optimized simultaneously. Manufacturers that can deliver reliable performance at smaller footprints, while maintaining safety and interchangeability, are able to enter design cycles earlier and secure specification preference.
Regulatory and standards-driven adoption is reinforcing demand in established industrial regions while also shaping entry barriers. Compliance with ISO 11901-5:2021, which specifies that only nitrogen in commercial-grade purity class 5.0 should be used to charge gas springs for stamping dies, provides a clear technical baseline and reduces ambiguity in procurement. PED 2014/68/EU requirements add another layer of assurance for European machinery and tooling applications. For suppliers, these standards create a credible quality narrative and reduce the risk of non-conforming installations. For buyers, they simplify specification and reduce integration risk. The net effect is a market where conformance becomes a competitive asset, particularly in sectors where safety, repeatability, and auditability are non-negotiable.
Demand-side shifts in automotive and aerospace tooling are reshaping application priorities. Automotive remains the largest application segment, reflecting the continued intensity of stamping, forming, and mold-based production across vehicle platforms. Aerospace continues to contribute a meaningful share of demand, driven by precision components, stricter performance tolerances, and higher lifecycle expectations. These sectors are not simply buying more gas springs; they are specifying them with greater attention to contamination resistance, slow-return behavior, high-temperature capability, and long-term reliability. As vehicle architectures evolve and aerospace programs demand more consistent tooling performance, gas springs are increasingly evaluated as part of a broader system-level reliability strategy rather than as isolated consumables.
Air Springs Market
Supply chain reconfiguration and cost structure adaptation are altering how manufacturers compete on availability, lead time, and total cost of ownership. In a market where steel price volatility and logistics uncertainty can erode planned margins, suppliers are responding with tighter inventory models, regional warehousing, and broader standard catalogs that enable faster fulfillment. The ability to offer steel and stainless steel variants, standardized mounting dimensions, and interchangeable designs is becoming a practical differentiator for procurement teams seeking to reduce downtime and simplify spare-part management. At the same time, manufacturers are re-examining BOM sensitivity, sealing technologies, and cylinder protection features to reduce vulnerability to contamination and premature wear, which lowers total maintenance burden over the life of the tool.
These drivers interact in practical ways. A compact or micro spring that meets ISO dimensions and is designed for contamination-resistant operation can unlock adoption in tighter industrial layouts. A product line that pairs compliance with stainless or steel variants and rapid fulfillment can reduce procurement risk in regions exposed to input cost swings. A digitally enabled series with integrated monitoring can align gas springs with broader Industry 4.0 tooling strategies. The strategic implication is that competitive advantage is increasingly cumulative: performance, compliance, availability, and intelligence must reinforce one another.
Competitive Landscape and Leadership Strategies
The competitive field is anchored by a mix of specialized manufacturers with strong regional footprints and global reach. Several companies illustrate the strategic directions currently shaping the market.
DADCO has built a broad portfolio spanning micro to very high-force nitrogen gas springs for stamping, injection molding, and tooling, with ISO-compliant series and a strong automotive OEM supply presence. Its recent move into IoT-enabled springs with integrated pressure and temperature monitoring reflects a push toward die tooling solutions aligned with Industry 4.0. The strategic logic is clear: by combining scale, specification breadth, and telemetry, the company positions itself not only as a component supplier but also as a partner in process visibility and tool management.
Special Springs has emphasized in-house manufacturing, safety-oriented designs such as OSAS, OPAS, and SKUDO, and interchangeable replacement capability for heavy-duty industrial and stamping applications. Recent updates include the Skudo-Flex accessory to extend cylinder life, a new US Series catalog, and improved reducer options for contaminated environments. The company is also actively supporting trade exhibitions with dedicated event kits. This approach underscores a strategy centered on durability, serviceability, and market engagement, with particular attention to environments where contamination and heavy-duty cycling raise failure risk.
Gas Spring Market
Hyson Products provides a full line of nitrogen gas springs for metal stamping dies, injection molds, and custom machines, including high-force, slow-return, and contamination-resistant models. Its breadth of force and functional variants suggests a focus on application flexibility and process-specific performance, which is valuable in shops where tooling requirements vary widely across jobs and material types.
Pascal Engineering Corporation supports manufacturers with nitrogen and mini gas springs for stamping dies and injection molding, emphasizing high-quality components that contribute to safety and productivity. Its positioning is aligned with manufacturers seeking dependable, application-focused components in precision workflows.
KALLER offers high-performance nitrogen gas springs for tool and die applications, including high-temperature variants capable of operating up to 250°C for hot stamping. This capability addresses a niche but strategically important requirement in processes where thermal exposure would limit conventional components.
Bordignon, with a history dating back to 1958, is known for longevity, reliability, and innovation in stamping and forming, reinforcing a value proposition built on proven performance and incremental improvement over time.
Isotech, Gemini Gas Springs, AZOLGAS, and FIBRO each contribute distinct angles to the market. Isotech emphasizes complete gas spring lines in steel and stainless steel variants for industrial applications. Gemini focuses on in-house manufactured lift supports and dampers meeting high industrial standards. AZOLGAS provides extensive catalogs and safety-compliant designs for metal stamping and multi-technology applications. FIBRO distinguishes itself through a large standard catalog and same-day delivery from a central European warehouse, which directly addresses availability and lead-time sensitivity.
Taken together, the competitive landscape reveals several differentiation pathways. One is application breadth and force range, where suppliers aim to cover everything from micro springs to very high-force units and thereby become a default specification source across multiple tooling contexts. Another is durability and safety engineering, where cylinder protection, contamination resistance, and interchangeable designs reduce downtime and simplify maintenance. A third is digital and lifecycle integration, where monitoring and telemetry align gas springs with modern tooling and maintenance strategies. A fourth is availability and fulfillment speed, where large standard catalogs, regional warehousing, and same-day delivery reduce procurement friction for time-sensitive production environments.
The market structure suggests a moderate trend toward consolidation at the top, but also continued room for differentiation among specialized players. Larger, broadly positioned suppliers can leverage scale, multi-region presence, and digital features to capture share in standardized, high-volume applications. Specialized manufacturers can compete on heavy-duty reliability, temperature resilience, contamination handling, and custom solutions in niche or demanding contexts. New entrants face a meaningful bar because compliance, interchangeability expectations, and established supplier relationships raise switching costs. At the same time, the growing emphasis on monitoring, safety, and lifecycle service creates openings for companies that can bundle component performance with operational intelligence or service support.
Forward-Looking Trends and Commercial Implications
Looking ahead to 2032, three trends are likely to shape how the nitrogen gas springs market evolves and where commercial opportunities emerge.
Trend one: digital integration will move from pilot adoption to procurement expectation in advanced tooling environments. As stamping and molding operations pursue traceability, condition monitoring, and predictive maintenance, gas springs equipped with pressure and temperature monitoring will become more relevant in high-value tooling programs. The commercial opportunity lies not only in selling smart components, but in linking component data to tool management workflows, service scheduling, and downtime reduction. Suppliers that can demonstrate measurable reliability benefits and seamless integration with existing tooling systems are likely to secure stronger specification preference in automotive, aerospace, and advanced industrial applications. The risk is that digital features may be over-specified in contexts where basic mechanical performance and compliance already suffice, creating cost and complexity without proportional return.
Trend two: high-temperature, contamination-resistant, and compact designs will capture incremental share in demanding applications. Hot stamping, harsh environments, and space-constrained tooling layouts will continue to reward designs that balance force delivery with environmental resilience and packaging efficiency. High-temperature variants, slow-return models, and contamination-resistant configurations are positioned to benefit as manufacturers seek to extend tool life and reduce failure-driven interruptions. The commercial opportunity here is application-led differentiation: suppliers that can validate performance in specific process conditions and offer interchangeable or protective accessories can build sticky relationships with tooling engineers and maintenance teams. The uncertainty lies in how quickly these features become standard expectations versus remaining specialized upgrades, which will affect pricing power and margin trajectories.
Trend three: availability, standardization, and material-cost resilience will become central to competitive positioning. With steel price volatility and supply chain disruption remaining part of the operating environment, the ability to provide steel and stainless variants, standardized dimensions, and fast fulfillment will matter increasingly to procurement teams. Large standard catalogs, regional inventory, and interchangeability aligned with recognized mounting conventions can reduce total sourcing risk and simplify spare-part management. The commercial opportunity is to compete on total cost of ownership rather than unit price alone, especially for buyers managing multiple plants, diverse tooling portfolios, and tight production schedules. The risk is that aggressive standardization may pressure margins if not paired with volume scale, efficient logistics, or value-added services that distinguish one supplier from another.
These trends point to a market where growth is likely to be underpinned by reliability, compliance, and integration rather than by volume expansion alone. The most durable opportunities will be those that align technical features with real operational outcomes: less downtime, safer tool handling, better condition visibility, and lower lifecycle maintenance burden.
Strategic Guidance for Decision Makers
For manufacturers and suppliers, the priority is to align product architecture with the converging demands of compliance, environmental resilience, and digital readiness. Rather than treating ISO conformance, contamination handling, high-temperature capability, and monitoring as separate product lines, companies should design families that can be configured around real application conditions. This includes offering interchangeable designs, protective accessories, and material variants that reduce total maintenance exposure. Equally important is the commercial narrative: positioning gas springs as part of a tool reliability and process visibility strategy can support stronger specification lock-in, especially in automotive and aerospace tooling where downtime and consistency are closely scrutinized.
PW Consulting
For investors, the market offers exposure to a steady-growth industrial component sector, but differentiation in risk-adjusted returns will depend on which business models capture compounding value. Companies with broad catalogs, reliable fulfillment, and credible digital or lifecycle features are better positioned to defend margins in an environment of input cost volatility. Investors should also monitor the pace at which smart monitoring transitions from premium option to standard expectation, since that shift will influence both pricing dynamics and the value of existing product portfolios. Exposure to heavy-duty, high-temperature, and contamination-resistant niches may provide resilience if demand in those areas continues to outpace broader commoditization.
For procurement and engineering leaders, the strategic emphasis should be on specification criteria that reduce total cost of ownership rather than focusing narrowly on upfront price. Interchangeability, compliance documentation, contamination resistance, slow-return options, and availability all contribute to lower downtime and simpler spare-part management. Where tooling environments are complex or multi-site, standardized dimensions and recognized mounting conventions can significantly reduce integration risk. Evaluating suppliers on lifecycle performance, service support, and condition-monitoring readiness can yield more durable value than selecting on unit cost alone.
Given the pace of product updates, regulatory alignment, and application-specific innovation, decision makers benefit from access to detailed segmentation data, regional demand patterns, and company-level benchmarking that go beyond headline market size. A comprehensive research view can help translate these dynamics into segment-level priorities, identify where compliance and digital readiness are becoming table stakes, and map out which supplier profiles are best aligned with specific application portfolios. For teams preparing capacity plans, sourcing strategies, or investment theses, that level of granularity is essential for moving from market awareness to actionable execution.
For detailed analysis of this topic, please visit the official page: Nitrogen Gas Springs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Strength Steel Market: Why 7.8% CAGR from Automotive Demand Redefines 2032 Outlook
By PW Consulting, 2026-09-21
High Strength Steel Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Critical Inflection Points
The global high strength steel market has established itself as a critical enabler of industrial modernization, currently valued at $130.0 million in 2025 and projected to reach $217.2 million by 2032. The sector's 7.8 percent compound annual growth rate reflects a structural shift rather than a cyclical expansion, driven by simultaneous pressures to reduce weight, improve safety, and lower lifecycle emissions across heavy industry and transportation. The market's trajectory is being shaped by concentration dynamics that reward specialized producers while creating volatility for commoditized participants. Industry concentration, with three firms controlling 39 percent of revenue and five firms holding 52 percent, indicates an oligopolistic structure where scale advantages in specialized grade development, capital-intensive processing, and customer qualification programs create meaningful barriers to entry.
PW Consulting Chemical & Energy Research Center
Several inflection points are reshaping how the market operates. First, the price and availability of prime scrap have become central cost drivers, with early-2026 moves by major domestic producers to raise hot-rolled coil prices reflecting underlying raw material inflation. This dynamic compresses margins for buyers while reinforcing the value of high-strength grades that deliver more performance per ton of material consumed. Second, renewed and expanded trade restrictions have altered the competitive geography of steel supply. In the United States, import tariffs on steel were raised to 25 percent in early 2025 and increased to 50 percent by mid-2025, while the European Union moved in early 2026 to reduce duty-free quotas by approximately 47 percent and apply a 50 percent duty above allocated volumes. These measures are rerouting supply patterns, prompting localized production strategies, and elevating the strategic importance of regional manufacturing assets. Third, the technical standards governing high-strength steel applications are evolving in parallel with product innovation. The publication of revised welding electrode classifications under EN ISO 18275:2026 underscores how downstream application ecosystems are maturing, requiring producers and fabricators to align process specifications with new material grades.
For decision-makers, the implication is clear: high strength steel is no longer a commodity input subject to price-only negotiation. It is a performance material whose value depends on grade selection, supply reliability, application engineering support, and alignment with regulatory and technical requirements. Companies that treat the category as a strategic input rather than a purchased commodity are positioned to capture efficiency gains and competitive differentiation.
Key Drivers of Market Evolution
Technological Innovation and Material Performance Breakthroughs
The market's growth is being sustained by a continuous cycle of grade development and application engineering. Producers are moving beyond incremental strength improvements toward multi-functional steels that combine high tensile capability with formability, weldability, and fatigue resistance tailored to specific end-use requirements. In the automotive sector, third-generation advanced high-strength steels and ultra-high-strength grades are enabling designers to consolidate parts, reduce wall thicknesses, and maintain crashworthiness while lowering overall vehicle mass. Recent industry work published by WorldAutoSteel in mid-2026 highlighted how advanced high-strength steels can simplify vehicle architecture by reducing part count and assembly complexity, reinforcing the economic case for grade substitution and design optimization.
Structural and industrial applications are benefiting from parallel advances. Specialized grades optimized for welded structures, offshore environments, and heavy machinery are extending service life and reducing maintenance cycles. The focus has shifted from achieving a single mechanical property to delivering a balanced property set that aligns with the fabrication and operational constraints of each application. This evolution raises the importance of technical collaboration between steel suppliers and engineering teams, turning material selection into a value-creation process rather than a specification exercise.
Policy and Regulatory Environment as a Competitive Variable
Trade policy and regulatory standards are now among the most significant variables shaping market access and competitive positioning. The reinstatement and escalation of import measures in the United States, combined with the European Union's tightened quota and duty framework, have increased the cost of cross-border steel flows and incentivized regional supply strategies. These policies affect everything from mill location decisions to inventory planning, contract structuring, and logistics design. Producers with domestic or near-shore capacity are gaining structural advantages in certain markets, while buyers must navigate a more fragmented and policy-sensitive supply environment.
Regulatory developments also extend into product specifications and compatibility standards. Updated welding classifications and application-specific codes influence how quickly new grades can be qualified and deployed at scale. For manufacturers adopting advanced high-strength steels, the alignment of material grades with fabrication processes, inspection protocols, and certification requirements becomes a critical path item. Companies that invest early in understanding these technical and regulatory interdependencies can reduce time-to-implementation and avoid costly redesign cycles.
High-strength Polyester Thread Market
Demand-Side Shifts in Transportation, Construction, and Energy
Demand is being reshaped by performance and efficiency objectives that transcend any single sector. In transportation, lightweighting and safety compliance remain dominant forces, but the rise of electric vehicle architectures has added new considerations around battery enclosure protection, structural rigidity, and material compatibility with manufacturing processes optimized for new powertrain configurations. Advanced high-strength steels are increasingly evaluated not just for mass reduction but for their ability to support platform simplification, multi-model flexibility, and total cost of ownership.
Structural Steel Market
In construction and infrastructure, demand for high-strength structural steels is tied to durability, span capability, and lifecycle performance. As projects face pressure to use materials more efficiently and extend service intervals, high-strength grades enable lighter sections, faster erection, and reduced material volume without sacrificing load-bearing capacity. In energy applications, high-tensile steels for offshore, pipeline, and infrastructure use continue to be driven by harsh-environment performance requirements and the need to standardize reliable grades across long-duration assets. Across all these segments, the common thread is a demand for materials that deliver measurable operational value over the asset lifecycle, not only at the point of purchase.
Supply Chain and Cost Structure Dynamics
The cost structure of high strength steel production is increasingly sensitive to scrap quality, energy inputs, and capital intensity. Early-2026 pricing actions by domestic producers illustrate how prime scrap cost increases feed directly into mill pricing and customer economics. At the same time, capacity investments in quenching and tempering lines and other specialized processing routes reflect a strategic bet that differentiated grades can command premiums and offset raw material volatility. This dynamic creates a divergence between commoditized volume players and producers with specialized assets, know-how, and customer qualification pipelines.
For procurement and supply planning teams, the operational challenge is to balance cost control with resilience. Concentration in specialized grades means that qualification lead times, supply assurance, and engineering support often matter as much as unit price. Companies that diversify grade options, secure multi-source strategies where feasible, and build closer technical relationships with producers are better positioned to manage both cost and risk in a volatile input environment.
Competitive Landscape and Leading Strategies
Competitive Landscape and Leading Strategies
The market is anchored by a group of globally active producers with distinct strategic footprints. SSAB AB has built a reputation around premium and special steels, including structural grades such as Strenx and automotive advanced high-strength and ultra-high-strength offerings under the Docol brand, positioning itself where performance certification and application engineering matter most. ArcelorMittal operates at scale with high-yield high-strength steels and advanced grades for automotive and construction, and its recent launch of ultra-high-strength steels tailored for electric vehicle chassis reflects a focus on lightweighting and safety compliance. POSCO emphasizes premium structural steels and automotive high-strength products with expanding global sales reach, while Nippon Steel contributes high-tensile offshore plates and ultra-high-tensile sheets for automotive and infrastructure use.
In the North American market, Cleveland-Cliffs stands as a significant supplier of advanced high-strength steels, including third-generation grades for automotive lightweighting, and has announced a substantial investment to expand quenching and tempering capacity at an Alabama facility to support high-strength brands. U.S. Steel complements this landscape with proprietary advanced high-strength grades and ultra-thin lightweight steels designed for electric vehicles and transformers, signaling a focus on differentiated product architecture and emerging application segments.
European and Indian producers round out the competitive field with specialized orientations. thyssenkrupp AG supplies high-strength flat-rolled steels for automotive and industrial applications, and voestalpine AG focuses on premium grades for automotive and machinery, reinforcing the value of application-specific specialization. Tata Steel brings corrosion-resistant high-tensile steels for offshore and maritime applications, extending the market's relevance into demanding environmental conditions.
Recent company actions illustrate how leading producers are translating strategy into tangible moves. In early 2025, ArcelorMittal introduced a line of ultra-high-strength steels for electric vehicle chassis, emphasizing lightweighting and safety compliance. Later in 2025, U.S. Steel outlined a growth-oriented portfolio expansion that included proprietary advanced high-strength steel and ultra-thin lightweight grades for electric vehicles. In late 2025, Cleveland-Cliffs announced a $74 million investment to expand quenching and tempering production capacity for high-strength brands, reinforcing the capital-intensive path to differentiated grade supply. Around the same time, SSAB-related coverage highlighted capacity expansion activity tied to hard-facing and high-strength structural brands, underscoring the alignment between specialized processing assets and premium grade positioning.
The competitive landscape is evolving along several axes. One is consolidation of advantage among producers with specialized assets, strong customer qualification programs, and the ability to co-engineer solutions with end users. Another is the potential for divergence between commoditized volume segments, where price competition remains intense, and premium-grade segments, where performance, certification, and supply assurance differentiate winners. A third dynamic is the role of regional policy in shaping competitive geography; producers with local capacity and compliant supply chains are gaining stature in markets where import costs and quotas have risen sharply. New entrants face steep barriers in high-strength steel because value is created not only through chemistry and processing but also through the long qualification cycles, application testing, and trusted relationships that underpin adoption in automotive, construction, and energy markets.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to define the market's commercial shape. The first is the acceleration of application-driven grade selection. As designers and engineers gain broader access to advanced high-strength steels and as industry studies continue to quantify the benefits of part consolidation and architecture simplification, material selection will become more tightly linked to total system performance. This creates opportunities for producers and service providers that can translate technical properties into application outcomes, offering guidance on grade substitution, fabrication compatibility, and lifecycle value.
The second trend is the deepening influence of trade and regulatory policy on supply strategy. With import duties and quota adjustments already reshaping market access in major regions, companies are likely to place greater weight on regional production, inventory positioning, and contractual flexibility. This environment rewards suppliers with diversified manufacturing footprints and buyers who build supply strategies that account for policy variability rather than assuming stable cross-border flows. The opportunity lies in designing procurement and production networks that remain viable across multiple policy scenarios.
The third trend is the convergence of material innovation with manufacturing process alignment. High-strength steels deliver their greatest value when matched to appropriate welding, forming, and assembly processes, and updated standards such as the revised welding electrode classification increasingly require coordinated planning across material and fabrication choices. Producers and fabricators that invest in joint technical development, process qualification, and education can reduce implementation friction and capture more of the material's potential. This convergence favors participants who operate as solution partners rather than transactional sellers.
These trends point to a set of commercial opportunities. Producers with differentiated grades and strong application support are well positioned to deepen relationships in automotive lightweighting, structural efficiency, and demanding energy environments. Suppliers of fabrication accessories, welding consumables, and process engineering services can benefit from the need to align downstream operations with new grades. Procurement organizations have an opportunity to shift negotiation from unit price to total value, using grade optimization and supply assurance to improve cost-performance outcomes. Investors should watch for capital deployment in specialized processing capacity, regional supply expansion, and portfolio moves that link high-strength steel to growth applications such as electric vehicle platforms and infrastructure modernization.
Risks remain. Raw material volatility can compress margins and create pricing uncertainty, particularly where prime scrap availability and energy costs fluctuate. Policy changes can alter competitive dynamics quickly, rewarding some regions and penalizing others. Technical qualification cycles can slow adoption if fabricators and end users face compatibility or certification hurdles. And in segments where differentiation is limited, price competition may erode returns despite overall market growth. Navigating these risks requires a clear view of where value is created in a given product segment and a disciplined approach to investment, sourcing, and technical collaboration.
Actionable Guidance for Decision-Makers
For manufacturers and engineering-led organizations, the priority is to integrate high-strength steel selection into product development and sourcing strategy rather than treating it as a late-stage specification. Start by mapping where advanced grades can reduce part count, lower assembly complexity, or improve lifecycle performance without compromising manufacturability. Establish early technical dialogue with steel suppliers to align grade choice with welding, forming, and inspection processes, and track evolving standards that affect qualification timelines. Where possible, develop multi-grade options for critical components to preserve design flexibility and mitigate supply risk.
For investors and strategy teams, the focus should be on the structural points of value creation within the market. Differentiated, application-specific grades and specialized processing capacity are likely to command better margins than undifferentiated volume exposure. Regional supply advantages are gaining importance in policy-sensitive markets, making local production footprints and compliant logistics relevant evaluation criteria. Capital allocation decisions should weigh not only demand growth but also the intensity of competition in each segment, the degree of technical differentiation, and the ability of a company to sustain customer qualification programs and application support.
For procurement and supply chain leaders, the effective approach is to balance cost management with resilience and performance. In concentrated, specialized segments, unit price is only one component of total cost; qualification lead time, supply assurance, technical support, and compatibility with fabrication processes often determine the real outcome. Build sourcing strategies that combine competitive negotiation with risk management, including scenario planning around trade policy shifts and raw material cost movements. Where feasible, qualify alternative grades and suppliers for critical applications to preserve optionality and reduce dependence on single points of supply.
For organizations seeking a deeper, customized view of where to focus, a detailed segmentation review can clarify which grade families, applications, and regional pathways offer the strongest alignment with specific business objectives. Fine-grained market sizing, segment-level growth profiles, competitive positioning, and tailored sourcing or investment scenarios help convert the broad market trajectory into concrete action steps. Access to such detailed intelligence supports more precise prioritization, whether the goal is to optimize a material specification, evaluate a supply partnership, assess a capacity investment, or identify the most promising application segments for growth.
The high strength steel market is moving from a period of broad expansion to a phase where advantage is increasingly determined by technical fit, supply resilience, and regional strategy. Companies that align their material choices, partnerships, and sourcing structures with this reality are better positioned to turn a critical input into a durable source of performance and competitive advantage.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lysine Market’s 6.45% CAGR: Animal Feed Demand and Fragmented Competition
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Lysine Market: A 2032 Outlook
The global lysine market has matured from a niche amino acid segment into a critical strategic commodity underpinning animal nutrition, food fortification, and pharmaceutical applications. Between 2020 and 2025, the industry expanded its revenue base from approximately 3.35 billion USD to 4.36 billion USD, reflecting steady demand growth across traditional and emerging application channels. Forward-looking projections indicate a compound annual growth rate of 6.45 percent through 2032, with the market expected to reach 6.7 billion USD by the end of the forecast horizon. This trajectory signals a structural shift rather than a cyclical upturn, driven by demographic pressures, feed formulation optimization, and evolving regulatory frameworks that reshape trade flows and production economics.
Despite the broadly positive growth narrative, the lysine sector sits at a complex inflection point. Supply chain volatility, regulatory friction across major import markets, and persistent raw material cost pressures are redefining competitive advantages and forcing strategic recalibration among producers and downstream users alike. Understanding how these forces interact is essential for executives, investors, and procurement leaders who must navigate capacity allocation, pricing dynamics, and supplier diversification decisions over the coming years.
Market Snapshot and the Pressures Defining the Current Cycle
The market's expansion over the past five years has been anchored by consistent volume growth in animal feed applications, supported by rising livestock production in Asia-Pacific and Latin America, alongside steady formulation shifts in North America and Europe. The revenue progression from 2020 through 2025 reflects a compound growth path that has outpaced several adjacent agricultural input segments, underscoring lysine's entrenched role as a cost-efficiency and nutritional balance lever in feed rations.
Three structural challenges are currently shaping the operating environment. First, the market exhibits a high degree of concentration, with a small group of manufacturers commanding a dominant share of global supply. This concentration creates pricing influence and supply reliability advantages for incumbents, but it also exposes downstream buyers to concentration risk, particularly when production disruptions or trade policy shifts affect the leading facilities. Second, trade policy is introducing new friction into historically integrated supply chains. Multiple jurisdictions have escalated investigative and remedial actions targeting lysine imports from China, altering the cost and routing calculus for buyers who previously leveraged cross-border price differentials. Third, the input cost environment for fermentation-based production remains sensitive to commodity grain markets and nitrogen feedstock dynamics. Fluctuations in corn pricing and related agricultural inputs translate directly into production economics, compressing margins for producers and creating volatility for contract negotiations.
PW Consulting
Together, these forces are pushing the market from a relatively stable growth phase into a period where geopolitical, regulatory, and cost variables carry disproportionate weight in strategic planning. For decision-makers, the implication is that historical supply relationships and price assumptions require continuous revalidation rather than reliance on legacy benchmarks.
Core Drivers Shaping the Market Trajectory
Technological Innovation and Fermentation Efficiency
The lysine industry's competitive edge has increasingly depended on fermentation process optimization, strain efficiency, and scale economics. Leading producers have invested in large-capacity facilities across multiple geographies to capture cost advantages, improve throughput consistency, and reduce exposure to localized operational risk. Process improvements that increase yield per unit of feedstock, lower energy intensity, and enhance purification quality are not merely operational upgrades; they directly influence margin resilience in periods when corn and nitrogen-related inputs become more expensive.
Recent market signals reinforce the importance of cost-efficient production. Corn price levels have placed upward pressure on input costs for lysine manufacturers, highlighting how feedstock sensitivity remains a central factor in profitability. In this environment, producers with diversified feedstock strategies, integrated agricultural exposure, or access to lower-cost production basins are better positioned to absorb cost shocks without eroding competitive positioning. The broader lesson is that fermentation scale alone does not guarantee resilience; it must be paired with input management, logistics optimization, and geographic diversification to sustain advantage through commodity cycles.
Policy and Regulatory Dynamics Reshaping Trade Flows
Regulatory developments are now a defining driver of lysine market structure. The pattern of anti-dumping investigations and duty actions across major Western markets has introduced a new layer of complexity for global sourcing strategies. The European Commission's formal imposition of duties on Chinese lysine imports in the mid-2020s, alongside continuing investigative activity, signals a shift toward heightened scrutiny of pricing practices and import competition in mature markets. In parallel, U.S. trade actions affecting related agricultural inputs have created broader ripple effects across nitrogen supply chains that feed into lysine production economics.
For commercial strategies, these regulatory developments do more than alter unit costs at the border. They reorganize supplier selection criteria, encourage nearshoring and regional supply diversification, and increase the premium placed on documentation, traceability, and compliance readiness. Buyers that previously optimized primarily around spot price differentials are now weighing tariff exposure, lead-time reliability, and source-region resilience as equally important variables. Producers, in turn, are adjusting capacity deployment, export orientation, and market prioritization to align with the evolving duty landscape.
Demand-Side Shifts in Feed, Food, and Pharmaceutical Applications
Demand growth continues to be anchored most strongly by animal nutrition, where lysine remains a foundational amino acid for balancing swine and poultry diets. The scale of this application channel means that even modest formulation intensity improvements or incremental livestock production gains can translate into meaningful volume movement. This demand base has also been reinforced by ongoing efforts to improve feed conversion efficiency and reduce dependency on higher-cost protein sources, positioning lysine as a strategic formulation input rather than a simple commodity additive.
Beyond animal feed, food and dietary supplement applications as well as pharmaceutical uses represent smaller but strategically significant demand pillars. These segments often carry different margin profiles, quality requirements, and customer stickiness. In food and supplement channels, consumer interest in fortified products and protein-supportive formulations can create higher-value demand opportunities for producers able to meet specific purity and quality standards. In pharmaceutical applications, the requirements around consistency, regulatory documentation, and grade specification elevate the importance of supply reliability and technical support. As these channels mature, the ability to serve differentiated quality tiers becomes a clear source of competitive differentiation.
Supply Chain Reconfiguration and Cost Structure Evolution
The lysine supply chain is undergoing a gradual reconfiguration as companies reassess where to concentrate production relative to demand centers and trade risk. The combination of tariff exposure, commodity input volatility, and geopolitical uncertainty has encouraged a more deliberate approach to plant placement, export routing, and inventory strategy. Some producers are expanding in regions that offer feedstock proximity, logistics efficiency, and favorable market access, while others are recalibrating export plans to prioritize destinations with lower trade friction.
This restructuring also affects the cost structure beyond raw materials. Freight volatility, port and logistics bottlenecks, and the cost of maintaining compliance across multiple regulatory regimes all influence total landed cost. For large-scale producers, the ability to manage these layered costs while maintaining service levels is increasingly part of the value proposition offered to downstream customers. For buyers, the consequence is that procurement decisions must account for the full supply chain cost envelope rather than focusing narrowly on production-side pricing.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive environment in lysine remains shaped by a concentrated group of globally active producers with different geographic footprints, product portfolios, and strategic emphases. Their positioning reflects long-term investments in fermentation capacity, regional market access, and application-specific product offerings, and it continues to evolve in response to the regulatory and cost pressures described above.
Ajinomoto has built a strong global profile in amino acid production, with feed-grade lysine hydrochloride and sulfate supported by large-scale fermentation facilities in Brazil, Thailand, and the United States. Its multinational footprint provides exposure to multiple demand regions and offers a degree of supply diversification that can be advantageous in a trade-friction environment. Archer Daniels Midland is another major force in feed-grade lysine hydrochloride and acetate, with fermentation plants oriented toward high-capacity production for animal nutrition across North America and Asia. Its integration into broader agricultural and nutrition operations supports operational scale and supply chain coordination.
Evonik occupies a differentiated position through its branded Biolys offering for animal feed, with fermentation capacity in the United States and Brazil and a clear emphasis on animal nutrition applications. This branded approach and application focus can support value-based positioning where customers prioritize consistency, technical support, and specification reliability. CJ CheilJedang stands among the world's largest lysine producers, supplying feed-grade hydrochloride and sulfate through fermentation facilities in Indonesia, China, Brazil, and the United States. Its multi-region production base reflects a strategy designed to balance scale with geographic flexibility.
On the Chinese side, several producers have expanded fermentation capacity to serve poultry and swine feed markets and broader animal nutrition demand. Meihua Holdings is a leading domestic producer expanding capacity for hydrochloride and sulfate aimed at poultry and swine feed. COFCO Biochemical remains a major amino acid manufacturer with lysine sulfate and hydrochloride production focused on large-scale fermentation in China. Ningxia Eppen Biotech specializes in hydrochloride production for feed and food-grade applications, operating large-scale fermentation facilities domestically. Global Bio-Chem Technology Group produces hydrochloride and sulfate for animal nutrition and maintains fermentation operations in Asia. Collectively, these producers underscore the importance of China as both a production hub and a source of competitive pricing pressure, which in turn has contributed to the trade policy responses seen in several import markets.
ε-Polylysine Market
The strategic differentiation among these players often comes down to scale, geographic reach, product-grade capability, and the ability to manage regulatory and cost complexity. Larger multinational producers leverage diversified facilities and integrated supply chains to reduce concentration risk and serve multiple regions. Branded and application-focused suppliers seek to compete on quality assurance, formulation support, and specification consistency rather than price alone. Chinese producers with extensive fermentation capacity emphasize scale efficiency and regional demand coverage, while also navigating the consequences of heightened trade scrutiny in key export destinations.
Looking ahead, the market structure appears likely to evolve through a combination of consolidation, regional capacity rebalancing, and selective entry or expansion by producers seeking to capitalize on shifting trade routes and demand growth centers. Mature markets may see continued emphasis on supply security and compliance-ready sourcing, while growth markets may attract investment in capacity that aligns with local feed demand and import substitution objectives. New entrants will face the challenge of competing against established fermentation scale, customer relationships, and compliance infrastructure, making differentiation in grade quality, regional service, or niche application focus especially important.
L-Alanine Market
Forward View: Trends and Commercial Implications for 2026 to 2032
Trade Policy as a Structural Cost and Sourcing Variable
One of the clearest trends shaping the next several years is the entrenchment of trade policy as a structural factor in lysine sourcing and pricing. Anti-dumping investigations and duties in major import regions are not isolated events; they are part of a broader pattern that increases the importance of market-specific compliance planning. For producers, this trend creates both risk and opportunity: risk for those heavily dependent on exports to jurisdictions with active remedial measures, and opportunity for those able to redirect supply to less constrained markets or to serve demand through regionally located production.
For commercial actors, the strategic implication is that sourcing maps will increasingly be built around duty exposure, regional supply security, and documentation readiness. Companies that treat trade policy as a temporary disruption rather than a persistent variable may face repeated surprises in landed cost and supply availability. Those that proactively diversify sources, evaluate regional production options, and strengthen compliance capabilities are better positioned to stabilize procurement costs and reduce interruption risk.
Input Cost Sensitivity and the Push for Production Efficiency
The continued sensitivity of lysine production economics to corn and related agricultural inputs suggests that efficiency-driven competitiveness will remain central. Periods of elevated feedstock pricing sharpen the distinction between producers with cost-flexible operations and those with tighter input exposure. Over the forecast period, this is likely to reinforce investment in fermentation efficiency, feedstock management, and geographic placement that reduces exposure to input cost volatility.
The commercial opportunity here lies in linking production efficiency to customer value. Producers that can maintain stable pricing and reliable delivery through input cycles can build stronger long-term contracts and capture share from less resilient competitors. Buyers, in turn, can benefit from supplier partnerships that emphasize transparent cost dynamics and predictable service levels, rather than relying solely on spot-market alternatives.
Demand Diversification and Higher-Value Application Growth
While animal feed will continue to dominate volume, the medium-term growth narrative is likely to be supported by gradual expansion in food, dietary supplement, and pharmaceutical channels, especially where quality and specification requirements create higher barriers to entry. As these segments scale, they can offer differentiated margin opportunities for producers capable of meeting stricter quality demands and providing consistent documentation and technical service.
This trend also creates a segmentation opportunity. Not all lysine demand requires the same grade, certification, or service model. Suppliers that can efficiently manage multiple quality tiers and route product to the most appropriate channels may improve asset utilization and capture more value per unit than those competing strictly on commodity-grade volume. For downstream companies, selecting the right grade and supplier profile for each application becomes a lever for both cost control and performance reliability.
Potential Risks and Uncertainties
The outlook carries several uncertainties that merit careful monitoring. Continued trade policy escalation could further restrict market access or redirect trade flows in ways that alter regional price relationships. Feedstock and freight volatility can compress margins and complicate contract stability. Concentration in supply means that operational disruptions at major facilities can have outsized effects on regional availability and pricing. In addition, demand growth may not always track linearly with livestock production if formulation trends shift, alternative amino acid strategies gain traction, or economic conditions affect meat consumption patterns in key markets.
These risks do not negate the market's growth potential, but they reinforce the need for scenario-aware planning. Companies that build flexibility into sourcing, capacity expectations, and contract structures will be better positioned to manage disruption without losing strategic momentum.
Decision-Maker Action Priorities
For lysine manufacturers and producers, the priority is to strengthen resilience across the full value chain rather than focusing solely on fermentation capacity. That means evaluating feedstock exposure, logistics corridors, and market-specific regulatory risk in parallel with scale expansion. Companies should also consider how product-grade differentiation and application-specific service can support more defensible positioning in a concentrated market. Where export strategies depend on access to jurisdictions with active trade measures, scenario planning around redirection, regional partnerships, and compliance readiness becomes especially important.
For investors, the key is to assess which producers have durable advantages in cost structure, geographic diversification, and ability to navigate trade complexity. Scale alone is insufficient if it comes with concentrated input risk or heavy exposure to duties and border measures in major export markets. Investment theses should weigh the stability of demand channels, the credibility of compliance and documentation capabilities, and the flexibility of production footprints. Companies that can demonstrate consistent execution through input cycles and regulatory shifts are more likely to sustain value creation through the forecast period.
For procurement leaders and downstream buyers, the strategic task is to move beyond single-dimension price optimization. Diversifying approved suppliers, evaluating total landed cost including trade and compliance variables, and aligning grade selection with actual application requirements can reduce exposure to supply interruptions and unexpected cost swings. Building longer-term relationships with suppliers that offer transparent cost dynamics and reliable service can also improve planning stability. Where operations span multiple regions, regional sourcing strategies and inventory buffers should be calibrated to the specific trade and logistics risk profile of each market.
Executing these priorities effectively requires continuous access to detailed market data, supplier-level intelligence, and region-specific trade and cost analysis. The broader lysine market story is clear in its direction, but the actionable specifics—segment-level dynamics, pricing structures, demand shifts by application, and the implications of evolving trade measures—are where strategy becomes executable. Decision-makers who supplement high-level market awareness with deeper, current intelligence are better equipped to time investments, negotiate contracts, and adapt sourcing strategies as conditions change. A comprehensive research report can provide that layer of detail, offering the segmentation depth and customized context needed to translate market trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Lysine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Magnetic Bead Purification Kits Market: Why 6.6% CAGR Reshapes the DNA/RNA Landscape
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Magnetic Bead Purification Kits Market
The magnetic bead purification kits market has evolved from a niche laboratory tool into a critical component of modern molecular diagnostics, pharmaceutical development, and genomic research. At its core, the market enables the isolation of nucleic acids and proteins with greater reproducibility, scalability, and compatibility with automation than traditional column-based methods. This shift is not merely technical; it reflects a broader transformation in how biological samples are processed across clinical, industrial, and academic settings. For decision-makers evaluating long-term positioning in life sciences reagents and consumables, understanding the trajectory of this market requires looking beyond product specifications to the structural forces shaping demand, competition, and innovation cycles.
The global market for magnetic bead purification kits reached an estimated revenue base of 274.0 million in 2025, expanding from approximately 200.0 million in 2020. Growth over this period reflects sustained adoption across research and clinical workflows, with the market projected to advance at a compound annual growth rate of 6.6 percent through 2032, reaching roughly 426.49 million. The expansion is not evenly distributed across product types or end-use segments, but the overall trajectory signals a maturing market where differentiation, regulatory readiness, and workflow integration increasingly determine competitive advantage. Revenue concentration remains notable, with the top three players capturing around half of total market value and the top five holding approximately two-thirds, indicating that scale, brand trust, and established distribution channels still confer meaningful advantages. At the same time, the presence of specialized and regionally strong suppliers suggests that targeted product strategies and application-specific solutions continue to carve out defensible positions.
PW Consulting
Several structural challenges and inflection points define the current environment. First, the market is navigating a transition from broadly applicable research kits toward application-specific, regulatory-compliant solutions for clinical diagnostics and high-throughput testing. Kits that perform reliably in a research laboratory do not automatically meet the reproducibility, traceability, and clearance requirements demanded in molecular diagnostic workflows. This creates a divide between suppliers that have invested in validation, documentation, and regulatory pathways and those that remain primarily focused on research-grade offerings. Second, supply chain sensitivity around high-purity magnetic beads and specialized buffers has become a practical constraint. The performance of purification kits depends heavily on bead chemistry, surface functionalization, and buffer composition, meaning that shortages, quality inconsistencies, or cost volatility in critical inputs can disrupt both product development and customer trust. Third, the rising importance of automated platforms is reshaping purchasing logic. Laboratories and clinical operations increasingly view purification kits not as standalone consumables but as part of integrated workflows that include instrumentation, software, and throughput requirements. Suppliers that cannot align their kits with automated systems risk being bypassed in favor of more compatible solutions, even if their chemistry is competitive on a standalone basis.
The market’s expansion is being propelled by a combination of technological, regulatory, and demand-side forces that reinforce one another. Technological innovation remains the most visible driver. Magnetic bead chemistry continues to advance in ways that directly affect throughput, purity, and applicability to demanding downstream applications. High-molecular-weight DNA extraction, viral nucleic acid purification, and circulating free DNA isolation are examples where bead design and buffer systems determine whether a kit can support long-read sequencing, sensitive diagnostics, or reproducible biomarker workflows. Recent product introductions illustrate this trajectory. The launch of magnetic bead kits optimized for high-molecular-weight DNA extraction and automated workflows reflects a clear alignment between chemistry and the needs of long-read sequencing platforms, where fragment integrity and consistent yield are essential. Similarly, magnetic bead solutions designed for high-throughput viral nucleic acid purification from saliva, respiratory swabs, and wastewater demonstrate how purification kits are increasingly tailored to sample types and testing scenarios rather than generic isolation tasks. These developments matter commercially because they expand the addressable use cases for magnetic bead kits beyond conventional research workflows and into settings where performance specifications are tightly linked to downstream value.
Regulatory and policy environments are shaping the market with increasing force. For clinical applications, magnetic bead-based kits intended for viral and circulating free DNA purification increasingly require in vitro diagnostic clearance, CE marking, or regulatory submissions that document performance and safety. This does not simply add compliance costs; it changes the market’s structure by raising barriers for new entrants and rewarding established suppliers with regulatory experience, quality systems, and validated manufacturing processes. At the same time, regulatory expectations are also influencing product design in subtler ways. Features such as thermal stability, compatibility with sterilization procedures, and consistent lot-to-lot performance are becoming more important as laboratories seek to reduce contamination risk and maintain dependable results across high-volume workflows. Supplier claims around easy autoclave sterilization and thermal stability, for example, are not just technical specifications; they address operational concerns that matter in regulated or high-throughput environments. The practical effect is that regulatory dynamics are pushing the market toward more standardized, validated, and workflow-ready solutions, which favors companies that can provide both the chemistry and the evidentiary support needed for clinical adoption.
Demand-side behavior is also changing the market’s direction. Molecular diagnostics and infectious disease testing continue to drive usage of nucleic acid extraction workflows across clinical laboratories, creating steady demand for purification kits that can be deployed in routine testing and surge scenarios alike. This is not solely a function of outbreak response; it reflects the broader integration of molecular testing into standard diagnostic pathways. Academic and research institutions remain significant users, but the nature of demand is shifting as laboratories prioritize reproducibility, scalability, and compatibility with automated processing. Pharmaceutical and biotechnology companies increasingly rely on purification kits as part of complex development workflows, where consistency and documentation can influence decision-making from early discovery through clinical-stage work. The commercial implication is that demand is becoming more segmented by performance requirements and less driven by price alone. Buyers in diagnostic and industrial settings are often willing to accept premium pricing if a kit reduces variability, integrates with existing instruments, or supports regulatory documentation, while research buyers may remain more price-sensitive but increasingly value workflow efficiency and technical support.
Cost and supply chain structures are influencing competitive positioning in ways that merit close attention. Magnetic bead purification kits depend on specialized raw materials and precise manufacturing controls, which means that material costs, quality assurance, and supply resilience all affect margin stability and customer reliability. High-purity beads and purpose-built buffers are essential for consistent performance in applications such as viral RNA and circulating free DNA isolation, so any disruption in sourcing or production can have outsized consequences. Over time, this dynamic encourages consolidation among suppliers that can secure reliable input streams, standardize manufacturing, and invest in quality systems. It also creates opportunities for companies that can differentiate through manufacturing efficiency, regional supply agility, or kit designs that reduce waste and handling complexity. The broader point is that the market is increasingly rewarding operational excellence as much as product innovation, because performance claims are only valuable if they can be delivered consistently at scale.
The competitive landscape is characterized by a mix of large, diversified life sciences companies and specialized suppliers with strong application focus. Thermo Fisher Scientific maintains a prominent position through magnetic bead-based nucleic acid purification kits and automated extraction workflows, with product lines that emphasize compatibility with high-throughput processing and a range of sample types. Its recent emphasis on high-molecular-weight DNA kits and automated workflow optimization illustrates a strategy centered on aligning chemistry with instrumentation and downstream applications. Qiagen contributes a broad portfolio of magnetic bead kits for nucleic acid and protein purification, including solutions for viral RNA and circulating free DNA isolation. Its positioning reflects deep experience in sample preparation and a focus on validated workflows that can bridge research and diagnostic use. New England Biolabs has strengthened its presence through magnetic bead-based kits designed for high-throughput viral nucleic acid purification, a move that highlights the importance of sample-type specificity and workflow throughput in contemporary product strategy.
Worldwide AAV Purification Kit Market
PerkinElmer’s acquisition of Covaris illustrates a broader consolidation trend in which companies expand their capabilities by combining chemistry, instrumentation, and sample preparation technologies. The integration of magnetic bead-based extraction kits with automated platforms creates a more complete value proposition for customers seeking streamlined workflows, and it signals that competitive advantage increasingly depends on how well a supplier can connect consumables with equipment and software environments. Promega and Revvity both emphasize magnetic bead-based purification across research and diagnostic workflows, with Revvity’s technology highlighting multi-sample-type compatibility and automation readiness. These strategies reflect a shared industry direction: suppliers are seeking to reduce friction for customers by offering kits that work across platforms, sample types, and throughput requirements. Smaller and regionally focused companies such as Norgen Biotek, Bioneer, TIANGEN Biotech, Zymo Research, Geneaid, Omega Bio-tek, RayBiotech, Diagenode, Magbio Genomics, and others remain important participants by serving specialized needs, regional markets, or application niches. Their continued presence suggests that the market is not simply consolidating into a few dominant players; rather, it is stratifying into broad-platform leaders and focused specialists, each competing on different dimensions of performance, support, and accessibility.
The strategic positioning of leading companies reveals several recurring advantages. Scale and brand trust help secure adoption in regulated and high-volume settings, where switching costs and validation burden favor established suppliers. Broad product portfolios and automation compatibility broaden the addressable market and create cross-selling opportunities across kits, instruments, and service offerings. At the same time, differentiated chemistry and application-specific validation allow smaller or focused companies to compete where performance requirements are exacting or where regional support and responsiveness matter. Recent industry moves support this interpretation. Product launches that target high-molecular-weight DNA extraction, viral nucleic acid purification, and compatibility with automated particle processors show how suppliers are aligning their roadmaps with the practical needs of laboratories and diagnostic operations. Acquisitions and platform integrations further suggest that the market is moving toward bundled solutions in which purification kits are evaluated as part of a larger workflow rather than as isolated reagents. The competitive trend, then, is not simply toward larger players but toward more integrated, workflow-aware offerings that reduce operational complexity for end users.
Looking ahead, the market is likely to be shaped by a few interconnected trends over the next several years. One is the continued shift toward automation-compatible, workflow-integrated kits. As laboratories and clinical operations expand high-throughput processing, suppliers that can ensure their kits work seamlessly with common magnetic particle processors and automated extraction systems will capture a growing share of demand. This trend creates commercial opportunities for companies that design kits with automation in mind from the outset, including consistent handling characteristics, compatibility with standard instrumentation, and packaging or format choices that reduce manual intervention. It also raises the stakes for suppliers whose kits are difficult to automate or require extensive protocol adjustment. A second trend is the deepening alignment between purification kits and diagnostic regulation. As molecular testing becomes more embedded in routine clinical workflows, the importance of cleared or certifiable solutions will increase. Products that can support viral and circulating free DNA purification under appropriate regulatory frameworks are likely to benefit from stronger demand in diagnostic settings, while also facing higher development and compliance costs. This trend opens opportunities for suppliers that can provide documentation, validation support, and regulatory readiness, but it also introduces uncertainty for those that rely primarily on research-grade positioning and may face pressure to adapt if clinical adoption expands faster than expected. A third trend is the growing importance of specialized applications such as high-molecular-weight DNA, viral pathogen detection, and circulating free DNA workflows. These areas are driven by sequencing technology advancement, infectious disease testing, and liquid biopsy–related research, all of which place distinct demands on purification performance. The commercial opportunity lies in designing kits that meet the specific yield, purity, and integrity requirements of these applications while also supporting scalable processing.
Magnetic Beads Market
These trends carry both opportunity and risk. The upside is clear: workflow integration, regulatory-aligned products, and application-specific chemistry can expand margins and strengthen customer loyalty in high-value segments. The risks are equally important. Overinvestment in highly specialized kits without sufficient demand depth can leave suppliers exposed if downstream applications shift. Regulatory timelines and requirements can vary across markets, complicating global launches and creating uneven growth. Supply chain fragility for critical inputs can undermine performance claims and reduce trust if quality issues arise. In addition, automation adoption is not uniform; some laboratories continue to rely on manual or semi-automated processes, meaning that the pace of transition to fully integrated workflows may vary by region, institution type, and application. Decision-makers should therefore weigh both the direction of change and the unevenness with which it will be adopted.
For manufacturers, the strategic priority is to build differentiation that survives beyond product specifications. That means aligning chemistry, workflow compatibility, and documentation so that customers can adopt kits with confidence in both research and clinical contexts. Companies should evaluate whether their portfolios are sufficiently connected to automation platforms and whether they can support customers through validation, training, and stable supply. Where specialization is pursued, it should be tied to applications with credible demand depth and clear performance requirements, rather than to incremental variations that do not change customer outcomes. For investors, the market offers interest in companies that combine defensible chemistry with strong workflow integration, regulatory readiness, and reliable manufacturing. Attention should be paid to suppliers that are expanding platform compatibility, improving margin stability through supply chain control, or positioning themselves in higher-value diagnostic and biopharmaceutical workflows. At the same time, investment theses should account for regulatory exposure, input cost sensitivity, and the possibility that automation adoption will reshape the relative attractiveness of manual versus automated kit formats. For procurement and laboratory operations, the emphasis should be on total workflow value rather than unit price alone. This includes assessing how well a kit integrates with existing instrumentation, how consistently it performs across sample types, and whether the supplier can support regulatory or quality documentation when needed. Building relationships with suppliers that can scale with throughput requirements and reduce operational variability is likely to pay off as testing and research workloads become more complex.
The commercial picture that emerges is one of steady growth underpinned by real shifts in how nucleic acid and protein purification are performed across research, clinical, and industrial settings. The market is large enough to reward scale, but it is also segmented enough to reward focus. Successful players will be those that can couple reliable chemistry with automation compatibility, regulatory alignment, and the operational resilience needed to deliver consistent results at volume. For organizations seeking to navigate this landscape with greater precision, detailed segmentation, regional dynamics, and company-specific benchmarking can sharpen strategy further. A comprehensive research report on the Magnetic Bead Purification Kits Market can provide the deeper data and customized analysis needed to translate these strategic trends into concrete decisions.
For detailed analysis of this topic, please visit the official page: Magnetic Bead Purification Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Conference System Market: How Wireless Shift and 7.6% CAGR Reshape Growth
By PW Consulting, 2026-09-21
The Conference System (Microphone) Market: Strategic Trends and Commercial Opportunities Through 2032
The conference system microphone market is entering a period of structural expansion, moving beyond incremental improvements in audio fidelity toward comprehensive integration of digital infrastructure, hybrid meeting capabilities, and intelligent audio processing. With total market revenue projected to grow from approximately 215.0 million USD in 2025 to 358.54 million USD by 2032, the sector is tracking a compound annual growth rate of 7.62 percent across the 2026–2032 forecast window. This trajectory reflects a fundamental shift in how organizations conceptualize meeting spaces: audio capture is no longer a peripheral accessory but a central component of collaboration infrastructure, governance workflows, and enterprise productivity ecosystems.
Historical revenue progression from 2020 through 2025 illustrates steady acceleration, with the market expanding from 163.15 million USD to 215.0 million USD. The post-pandemic normalization of hybrid work patterns, coupled with sustained capital expenditure in corporate real estate modernization and public sector digital transformation initiatives, has created a durable demand baseline. Yet the market’s growth narrative is not simply a function of volume expansion. It is increasingly defined by technology substitution, infrastructure readiness, regulatory alignment, and competitive repositioning among manufacturers that must balance performance differentiation with supply chain economics.
Market Landscape and Core Challenges
The conference microphone market operates at the intersection of professional audio engineering, networked IT infrastructure, and organizational behavior. Revenue expansion is being driven by installations that treat microphone arrays, discussion units, and ceiling-mounted capture systems as integral components of unified meeting environments. However, several structural challenges are shaping how manufacturers, integrators, and end users navigate the next phase of market development.
Infrastructure Alignment and Installation Complexity
Networked conference systems increasingly depend on robust cabling standards and centralized audio processing architectures. Ethernet infrastructure upgrades for simultaneous interpretation in large assembly spaces require Cat 6A cabling to maintain signal integrity and latency thresholds. This infrastructure dependency creates a practical bottleneck: facilities that upgrade meeting rooms often discover that audio hardware deployment cannot outpace network modernization. For manufacturers and solution providers, this means product roadmaps must account for installation environments that vary widely in readiness, from greenfield corporate campuses to retrofitted legacy government buildings.
Cost Structures and Component Sensitivity
Wireless conference microphone designs face material cost pressures that influence pricing strategy and margin management. Polymer housings and rare-earth magnets in wireless conference microphones contribute approximately 18 percent to total unit cost in 2026 supply chains. This cost composition matters because it ties product economics to commodity markets and manufacturing geography. Companies that rely heavily on wireless form factors must navigate input cost volatility while still delivering the mobility and deployment flexibility that enterprise buyers increasingly expect. The result is a market where supply chain optimization is becoming as strategically relevant as acoustic performance.
Regulatory Compliance and Procurement Pathways
Standardization and public procurement dynamics are shaping market access. Digital infrared conference systems must comply with IEC 60914 for electromagnetic compatibility and safety in public meeting spaces. At the same time, conference microphone systems in government facilities are eligible for public procurement funding under digital government modernization programs. These two forces create a dual dynamic: compliance requirements raise the barrier for entrants that cannot meet certification expectations, while modernization funding expands the addressable base in public sector settings. Manufacturers that align product certification and procurement positioning with these frameworks gain a structural advantage in segments where purchasing decisions are less price-sensitive and more specification-driven.
Key Demand Drivers
The market’s expansion is being propelled by a combination of technological, regulatory, behavioral, and supply-side developments. Each driver reinforces the others, creating a landscape where audio capture is becoming more networked, more automated, and more tightly integrated with broader collaboration workflows.
Technology Innovation and Intelligent Audio Processing
One of the most significant shifts is the move from standalone microphone hardware toward integrated audio processing chains. Ceiling and table array microphones, wireless discussion systems, and all-in-one audio bars are increasingly paired with digital signal processing that handles noise suppression, beamforming, automatic mixing, and speaker tracking. This evolution reduces the burden on end users to tune audio environments manually and supports consistent capture quality across varied room configurations. The practical implication is that manufacturers are competing not only on microphone sensitivity or form factor, but on the intelligence embedded in the acoustic pipeline. Companies that can deliver predictable audio performance across hybrid and in-room scenarios are gaining traction with IT and facilities teams that need to manage many meeting spaces without specialized audio engineering support.
Hybrid Meeting Behavior and Coverage Demand
Hybrid meeting adoption has increased demand for wireless conference microphone coverage by 45 percent in enterprise environments since 2024. This behavioral shift reflects a durable change in how organizations operate: meetings are no longer confined to a single room with all participants present. Instead, distributed participation has become routine, and audio capture must serve both in-room clarity and remote intelligibility. Wireless coverage expansion is not simply about adding more devices; it is about ensuring that discussion systems can accommodate mobile participants, flexible seating arrangements, and multi-site integration. For solution providers, this means product portfolios must support rapid redeployment, simplified pairing, and seamless integration with video and collaboration platforms. The enterprise buyer is increasingly evaluating microphones not as isolated audio tools, but as components of a broader hybrid collaboration architecture.
Public Sector Modernization and Formal Gathering Requirements
Government facilities, legislative bodies, and large institutional meeting spaces continue to represent a meaningful demand base for formal conference systems. Digital wired and wireless conference systems, paperless solutions, and hybrid meeting technologies for formal gatherings are particularly relevant where voting, simultaneous interpretation, and recorded proceedings are part of the operational workflow. Public procurement funding tied to digital government modernization programs further supports adoption in these environments. At the same time, compliance expectations around electromagnetic compatibility and safety reinforce the importance of certified, proven systems. This segment rewards manufacturers that can offer durable, specification-aligned solutions with clear support for formal meeting processes rather than purely casual collaboration use cases.
Supply Chain and Cost Architecture Realignment
Beyond component cost sensitivity, the broader supply chain environment is influencing product strategy. Manufacturers are reassessing how much functionality is integrated into a single device versus distributed across networked endpoints. Ethernet-based networked conference systems introduce different cost and deployment considerations compared with standalone infrared or wired discussion units. Meanwhile, raw material exposure in wireless designs encourages engineering teams to explore material efficiency, modular architecture, and manufacturing footprints that can better absorb input cost fluctuations. The practical outcome is a market in which product differentiation is increasingly tied to total cost of deployment rather than unit price alone. Buyers are weighing installation labor, cabling requirements, management overhead, and long-term maintainability alongside acoustic specifications.
Competitive Positioning and Strategic Evolution
The competitive landscape is shaped by manufacturers that have built reputations across professional audio, conference systems, and integrated meeting solutions. The market remains moderately fragmented, with concentration levels indicating room for both specialization and consolidation. This environment rewards companies that can combine product reliability, deployment practicality, and clear alignment with the use cases their customers prioritize.
Differentiation Through Integrated System Design
Several established players have emphasized end-to-end discussion and audio processing ecosystems rather than isolated microphone products. For example, some manufacturers focus on ceiling and table array microphones paired with advanced audio processing for hybrid conference rooms, creating a compelling value proposition for organizations that want consistent capture without complex tuning. Others prioritize digital wired and wireless conference systems with main units and multimedia devices designed for structured meetings, which appeals to customers with formal deliberation, voting, or interpretation requirements. There are also vendors emphasizing all-in-one meeting audio solutions and ceiling microphone arrays that simplify installation in modern collaboration spaces. These approaches illustrate a broader competitive theme: differentiation is increasingly defined by how well a product portfolio addresses the full meeting workflow, from audio capture to processing to integration with room systems.
Worldwide Pro Microphone Market
Regional and Segmental Specialization
Competitive positioning also varies by market orientation. Some manufacturers have strong presence in enterprise collaboration environments where wireless flexibility and hybrid coverage are priorities. Others have built credibility in formal government and institutional settings where wired and infrared systems, certification compliance, and paperless meeting capabilities are central. Asian manufacturers, in particular, have expanded digital conference system offerings with wireless and paperless multimedia solutions, reflecting both scaling capacity and growing emphasis on feature parity with established Western brands. This diversification means that procurement teams often evaluate suppliers not just by brand familiarity, but by how well a vendor’s portfolio matches the operational profile of the facility and the expectations of the meeting participants.
Market Evolution Toward Consolidation and Capability Concentration
The market is likely to see continued pressure toward consolidation among companies that can combine audio hardware, DSP software, and integration support under a coherent portfolio. At the same time, specialized entrants may thrive by targeting narrow requirements such as ceiling array optimization, wireless discussion scalability, or AI-enhanced capture for specific room types. Recent trade show activity underscores this dynamic. VISSONIC exhibited a full line of digital conference systems, ceiling microphones, and paperless multimedia units at ISE 2026 in Barcelona. TAIDEN launched and showcased a fully digital conference main unit, a conference flex dock, and paperless multimedia terminals at the same event, and later presented additional conference solutions at InfoComm China 2026. These moves highlight how manufacturers are using major industry events to reinforce product breadth, demonstrate integration readiness, and signal momentum in both wired and wireless conference categories.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, the market’s trajectory will be shaped by the interaction of technology maturity, facility readiness, and purchasing behavior across enterprise, education, public sector, and large-event environments. Three trends appear especially consequential.
Trend One: From Device Sales to Managed Audio Environments
Meeting audio is increasingly treated as an environment to be managed rather than a device to be purchased. This shift favors solutions that can be centrally configured, monitored, and updated across multiple rooms. Manufacturers and integrators that offer repeatable deployment templates, remote diagnostics, and consistent processing performance will be better positioned to capture multi-site contracts. The commercial opportunity lies in building offerings that reduce operational friction for IT and facilities teams, because those teams are often the real gatekeepers in scaled rollouts.
Trend Two: Wireless Expansion Balanced by Infrastructure and Cost Realities
Wireless microphone coverage demand will continue to grow, especially in enterprise settings where hybrid participation is standard. However, growth will be moderated by cabling constraints, electromagnetic compliance expectations, and material cost exposure in wireless units. The practical implication is that product strategies will need to balance mobility with reliability and total deployment cost. Manufacturers that can offer wireless flexibility without creating hidden installation or maintenance burdens will gain a competitive edge. This is also where supply chain discipline becomes commercially visible: pricing stability, predictable lead times, and component efficiency will matter as much as feature lists.
Trend Three: Formal and Public Sector Demand as a Stabilizing Anchor
Government modernization funding, formal meeting requirements, and compliance-driven procurement will continue to provide a stable demand base. This segment values certification, durability, and workflow support such as voting, interpretation, and paperless operations. The opportunity for manufacturers is to align product certification, documentation, and support models with public procurement expectations while also offering enough flexibility to serve hybrid and multimedia needs. In practice, this means that solutions designed for formal gatherings can benefit from clear differentiation on reliability and procedural support, rather than competing solely on cost.
Risks and Uncertainties
Several factors could temper the market’s growth path. If enterprise real estate investment slows, meeting room upgrades may be deferred, reducing near-term procurement velocity. If wireless component costs rise further, pricing pressure could compress margins or slow adoption in cost-sensitive segments. If compliance or infrastructure requirements become more stringent without corresponding procurement support, installation timelines could lengthen, particularly in large halls and public facilities. Finally, if hybrid meeting practices stabilize into a narrower set of use cases, the demand surge for expanded wireless coverage could moderate. These uncertainties do not negate growth, but they suggest that forecast confidence will depend on how well manufacturers and buyers manage deployment complexity and total cost.
Strategic Guidance for Decision Makers
The market’s expansion creates distinct implications depending on a decision maker’s role. While the following recommendations are general in nature, they highlight where attention is likely to yield the greatest strategic value.
PW Consulting
For Manufacturers and Solution Providers
- Align product roadmaps with total deployment cost, not just unit performance. Ethernet readiness, cabling requirements, and installation labor increasingly shape purchasing decisions, so designs that simplify integration can win even when acoustic specifications are comparable.
- Invest in intelligent audio processing and repeatable room templates. Consistent capture across varied environments reduces the operational burden on end users and strengthens multi-site sales opportunities.
- Manage supply chain exposure in wireless product lines. Given the material cost contribution of polymer housings and rare-earth magnets, manufacturers should evaluate component efficiency, sourcing resilience, and pricing strategies that protect margin without sacrificing mobility features.
For Investors and Corporate Strategists
- Focus on companies that can combine hardware, processing, and integration support into coherent offerings. The market appears to reward portfolios that reduce complexity for buyers rather than those that compete on narrow hardware specs alone.
- Watch public sector modernization and compliance-aligned product positioning as indicators of durable demand. Certification readiness and procurement alignment can create stickier relationships in government and institutional segments.
- Monitor competitive moves around wireless coverage, ceiling array solutions, and paperless meeting capabilities, since these areas reflect where manufacturers are placing bets on future meeting behavior.
For Procurement and Facilities Leaders
- Evaluate conference microphone systems as part of the broader room infrastructure, including network cabling, interpretation requirements, and ongoing management. Total cost and deployment feasibility often matter more than headline device features.
- Prioritize compliance and certification where formal meetings, public spaces, or large halls are involved. Aligning procurement with recognized standards can reduce project risk and support smoother approval processes.
- Consider hybrid meeting behavior explicitly when specifying wireless coverage. Deployment plans should account for flexible seating, multi-site participation, and the practicalities of redeploying devices across spaces.
Closing Perspective
The conference system microphone market is expanding against a backdrop of hybrid work normalization, digital infrastructure upgrades, and growing expectations for consistent audio capture across meeting environments. Growth through 2032 will be shaped not only by demand volume, but by how effectively manufacturers, integrators, and buyers navigate infrastructure dependencies, cost structures, compliance requirements, and the shift toward managed audio environments. Strategic advantage will increasingly belong to those who treat conference microphones as part of an integrated collaboration architecture rather than as isolated components.
Worldwide Audio Conference System Market
For decision makers seeking deeper segmentation detail, company-level comparisons, and customized scenario planning, the full PW Consulting research report provides more granular data and targeted recommendations across region, type, and application dimensions.
For detailed analysis of this topic, please visit the official page: Conference System (Microphone) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Optical Transceivers Market 2026: How 13.5% CAGR Reshapes Data Center Competition
By PW Consulting, 2026-09-21
The Optical Transceivers Market: Strategic Trends and Commercial Opportunities in a High-Speed Era
The global optical transceivers market has entered a phase of accelerated expansion, driven by an unprecedented surge in data traffic and the rapid deployment of high-performance computing infrastructure. From 2020 to 2025, the market experienced a compound annual growth rate that significantly outpaced broader semiconductor sectors, culminating in an estimated annual revenue of USD 13.9 billion for the base year 2025. This trajectory is projected to continue through the forecast period ending 2032, with the market size expected to more than double from its 2025 base. The sustained momentum suggests a CAGR of approximately 13.5 percent over the forecast horizon, indicating that optical connectivity is transitioning from a supporting component to a critical bottleneck and enabler of digital infrastructure.
However, this growth is not linear. The industry stands at a complex inflection point where technological capability, regulatory friction, and supply chain realities intersect. While demand signals from hyperscale data centers and telecommunications providers remain robust, the path to capturing value is fraught with challenges that require strategic navigation rather than passive participation. Understanding these dynamics is essential for executives and investors looking to position themselves advantageously in the coming cycle.
Market Landscape and Core Challenges
The current market environment is characterized by intense demand for higher bandwidth densities, yet this demand is mediated by significant structural constraints. The market size evolution from 2020 to 2032 reflects a compounding effect of data center expansion and network modernization, but the concentration of revenue among top players indicates a mature competitive field. With the top three and top five companies holding an identical market concentration share, the barrier to entry for new competitors remains high, while existing players must defend share through continuous innovation and cost efficiency.
Several key challenges define the current operational landscape. First, the transition to higher data rates such as 400G and 800G has introduced substantial complexity in manufacturing tolerances. Precision photonic components, including laser diodes and photodetectors, require stringent production controls. These technical requirements contribute to elevated unit costs, creating a cost structure that can strain margins if volume scaling does not materialize as expected. High manufacturing costs and component supply chain vulnerabilities result in elevated unit costs for 400G and 800G modules, making price sensitivity a relevant factor despite strong overall demand.
Worldwide Copper Transceivers Market
Second, geopolitical friction is reshaping supply chain strategies. US-China Technology Export Restrictions are disrupting supply chains for key optical components, forcing manufacturers to reconsider sourcing strategies and regional footprints. This regulatory environment introduces uncertainty regarding component availability and potential delays in product rollouts. Simultaneously, the EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, creating divergent regional incentives that complicate global standardization efforts.
Third, the industry must reconcile the pace of technological obsolescence with capital investment cycles. As hyperscale operators push for next-generation interconnects to support AI workloads, the window for profitable deployment of specific transceiver generations narrows. Companies must balance the risk of investing in standards that may evolve rapidly against the risk of falling behind in performance capabilities required by key customers. The industry must navigate the tension between performance leadership and manufacturing readiness, particularly as specifications move toward 1.6T and beyond.
Key Drivers of Market Evolution
The expansion of the optical transceivers market is underpinned by a convergence of technological, regulatory, and demand-side factors. Understanding the interplay between these drivers provides a clearer picture of where growth will originate and how value will be captured over the next several years.
Technological Innovation and Breakthroughs
The primary engine of growth remains the relentless push for higher data throughput per lane. The industry is shifting from 100G and 200G per lane architectures toward 400G and 800G standards, with early developments pointing toward 1.6T capabilities. This shift is not merely an incremental upgrade; it requires fundamental changes in transceiver design, including the adoption of advanced modulation formats, silicon photonics integration, and co-packaged optics.
Recent developments illustrate the pace of this innovation. In April 2025, Coherent Corp. demonstrated its 1.6T-SR8 optical transceiver based on advanced 200G VCSELs at OFC 2025. This demonstration highlights the industry's focus on pushing the limits of vertical-cavity surface-emitting laser technology to achieve higher densities without compromising power efficiency. Such advancements are critical for hyperscale AI data centers, where power and space constraints are as binding as bandwidth requirements.
Concurrently, the move toward co-packaged optics represents a structural shift in how optical interfaces are integrated with switching silicon. By moving the optical engine closer to the ASIC, vendors can reduce electrical interconnect losses and improve energy efficiency. Broadcom Inc. announced the shipment of its industry's first 102.4 Tbps co-packaged optics Ethernet switch with 200 Gbps per channel performance in October 2025. This milestone signals that co-packaged optics are moving from conceptual demonstrations to commercial shipments, opening new design paradigms for AI infrastructure. These technological breakthroughs directly influence market composition by creating demand for specialized transceiver modules and integrated optical engines that differ from traditional pluggable form factors.
Policy and Regulatory Environment
Regulatory frameworks are increasingly shaping market dynamics, influencing both supply chains and demand patterns. On one hand, trade restrictions and export controls are fragmenting the global supply base. The disruption of supply chains for key optical components creates divergence between regions that can access advanced manufacturing capabilities and those that face constraints. This environment incentivizes regionalization of production, as companies seek to mitigate risk by establishing local manufacturing hubs or securing supply from allied jurisdictions.
On the other hand, policy initiatives aimed at digital infrastructure development are stimulating demand. The EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, while harmonized regulation under the European Electronic Communications Code is streamlining spectrum allocation and infrastructure deployment approvals. These regulatory improvements reduce friction for network operators deploying new capacity, indirectly boosting the addressable market for transceivers in European telecommunications and enterprise networks. Additionally, national strategies in Asia and North America continue to prioritize data center expansion and broadband connectivity, providing a stable policy backdrop for long-term infrastructure investment.
Demand-Side Dynamics
Demand for optical transceivers is driven by distinct but complementary applications. Data centers remain the largest application segment, fueled by the exponential growth of AI model training, cloud services, and content delivery networks. The concentration of revenue in this segment reflects the capital intensity of hyperscale facilities and their need for high-speed interconnects to manage massive datasets and distributed computing workloads.
Telecommunications networks form a significant secondary driver, as operators upgrade backbone and access networks to support 5G densification, fixed wireless access, and growing enterprise connectivity requirements. The need for coherent transceivers in long-haul and metro networks is sustained by the requirement to maximize capacity over existing fiber assets while preparing for future bandwidth demands. Enterprise networks also contribute to demand, particularly as organizations modernize LAN and WAN infrastructures to support hybrid work models, IoT deployments, and security requirements that demand higher throughput and lower latency.
Across all segments, the common thread is the expectation of sustained bandwidth growth. Users and enterprises are increasingly data-hungry, and applications such as high-definition video, real-time collaboration, and AI-driven services continue to push traffic volumes upward. This demand-side resilience provides a buffer against short-term cyclical fluctuations, ensuring that the underlying driver for optical connectivity remains strong.
Supply Chain and Cost Structure Changes
The supply chain for optical transceivers is undergoing structural adjustments in response to demand signals and geopolitical pressures. Manufacturers are investing in capacity expansion and geographic diversification to secure supply and reduce dependency on single-source regions. For example, Applied Optoelectronics, Inc. is expanding U.S. manufacturing capacity to meet high-volume demand for 800G and 1.6T datacom transceivers, reflecting a broader trend toward nearshoring or friend-shoring critical optical component production.
Cost structures are also evolving as technologies mature and volumes increase. While initial units for new generations like 1.6T carry premium pricing due to low yields and complex assembly, continued investment in automated manufacturing and photonic integration is expected to drive down per-bit costs over time. Companies that can achieve superior yield rates and scalable production processes will gain a competitive advantage in pricing power and margin retention. However, the need for stringent manufacturing tolerances and high-quality precision photonic components means that cost reduction cannot come at the expense of performance reliability, creating a narrow operational window for suppliers.
Competitive Landscape and Leading Strategies
The competitive environment in the optical transceivers market is defined by a mix of established multinational players, specialized optical component manufacturers, and region-specific challengers. Market concentration remains high, indicating that scale, technological leadership, and ecosystem relationships are critical determinants of success. Companies are pursuing differentiated strategies to capture value across various segments of the market.
Strategic Positioning of Key Players
Several companies illustrate the range of strategic approaches currently in play. Coherent Corp. has focused on vertically integrated silicon photonics, VCSEL arrays, and coherent transceivers, including 1.6T-DR8 modules for hyperscale AI data centers and enterprise interconnects. Their strategy emphasizes deep technological integration and the ability to deliver high-performance solutions that address the specific needs of AI-driven workloads. By demonstrating advanced 200G VCSEL-based transceivers, Coherent is positioning itself at the forefront of next-generation lane speeds.
Broadcom Inc. is pursuing a co-packaged optics platform strategy, developing optical I/O engines for AI infrastructure with direct chip-to-chip integration. Their announcement of a 102.4 Tbps co-packaged optics Ethernet switch underscores a commitment to rearchitecting the interconnect layer for future AI clusters. This approach targets the highest end of the market where performance and energy efficiency are paramount, potentially reshaping the form factor and integration model of optical transceivers over time.
Cisco Systems, Inc. continues to leverage its comprehensive portfolio of pluggable transceivers supporting 100G to 800G+ Ethernet in data center and metro networks. The acquisition of CoreOptics in March 2025 expanded its optical networking engineering teams in Europe and Asia, signaling a strategy of strengthening internal capabilities and geographic reach. Cisco's approach relies on breadth of product offerings and strong customer relationships across enterprise and service provider segments.
Lumentum Holdings Inc. focuses on 800G and 1.6T OSFP and coherent transceivers with hybrid photonic integrated circuits for data center interconnects. Their emphasis on hybrid integration reflects an effort to combine the benefits of different photonic technologies to achieve performance and manufacturability goals. Meanwhile, Accelink Technology Co., Ltd. and Eoptolink Technology Inc. are emerging as significant forces in the Asia-Pacific region, offering 800G and 1.6T silicon photonics OSFP transceivers and active optical cables for AI and data center networks. Their growth highlights the increasing capability and competitiveness of regional manufacturers.
Huawei Technologies Co., Ltd. offers the StarryLink series of 400G and 800G pluggable optical modules for intelligent computing and data center interconnect scenarios. Their strategy is closely tied to the broader ecosystem of intelligent computing platforms, which can provide integrated solutions for customers building large-scale compute clusters. Sumitomo Electric Industries, Ltd. emphasizes low-power, compact designs for optical transceiver modules, targeting applications where energy efficiency and form factor are critical constraints.
High Speed Optical Transceiver Market
Other notable players include Source Photonics, Inc., which provides 200G-per-lane 1.6T and 800G PAM4 transceiver families for telecommunications and data connectivity, and Infinera Corporation, known for intelligent coherent pluggable transceivers in the ICE series for long-haul and metro optical networks. NeoPhotonics Corporation focuses on photonic integrated circuit-based transceivers for high-performance networking applications. These companies illustrate the diversity of technological approaches and application focuses within the market. Credo Technology Group Holding Ltd entered the space with its ZeroFlap optical transceiver line in November 2025, delivering secure high-speed connectivity for 400G, 800G, and 1.6T network speeds, indicating that security features are becoming a differentiator in certain segments. Jabil Inc. launched 1.6T transceivers in April 2025 for AI/ML, HPC, and high-speed data center interconnects, demonstrating that large-scale manufacturing services firms are also entering the market with high-speed solutions.
Evolving Market Dynamics
The competitive landscape is likely to evolve along several axes. First, consolidation may continue as larger players acquire specialized technologies or talent to fill gaps in their portfolios, as seen with Cisco's acquisition of CoreOptics. Such moves can accelerate capability development but also intensify competition for key intellectual property and engineering resources.
Second, the market may see divergence between highly integrated solutions for AI hyperscale customers and more standardized pluggable modules for broader enterprise and telecom use. Companies that can serve both ends of the spectrum or choose a focused niche will need to align their R&D and manufacturing strategies accordingly. The rise of co-packaged optics and chip-to-chip integration suggests that the boundary between transceivers and switching silicon may blur, creating opportunities for players with expertise in both optical and electronic integration.
Third, regional dynamics will play an increasing role. Manufacturers in China are expanding their capabilities in high-speed silicon photonics and transceiver modules, potentially capturing significant share in regional data center and telecom markets. At the same time, regulatory pressures and the push for local manufacturing in regions like Europe and North America may lead to a more fragmented supply base, with local content requirements influencing procurement decisions. Companies that can navigate these regional nuances while maintaining global quality and performance standards will be better positioned to scale.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape the optical transceivers market and create distinct commercial opportunities. Anticipating these trends allows decision-makers to align investments, product roadmaps, and partnership strategies with the direction of market evolution.
Acceleration of High-Speed Lane Rates and Form Factor Evolution
The transition toward 1.6T and potentially higher lane rates will accelerate as AI workloads continue to demand greater interconnect bandwidth. This trend will drive demand for transceiver modules that can support 200G per lane and beyond, while also pushing the industry to develop new form factors that balance density, power, and thermal management. Commercial opportunities lie in developing transceivers that offer superior energy efficiency per bit, as power consumption becomes an increasingly critical constraint in dense data center environments. Vendors that can demonstrate meaningful improvements in watts per gigabit will find strong demand from hyperscale operators seeking to manage total cost of ownership.
Additionally, the proliferation of co-packaged optics may create opportunities for suppliers of optical engines and integrated photonic modules that differ from traditional pluggable formats. Companies that can deliver reliable, scalable co-packaged solutions with strong integration support will be well-positioned to participate in next-generation switch architectures. However, this transition also introduces risk, as the adoption rate of co-packaged optics may vary across customer segments, and standards maturity could influence deployment timelines.
Regionalization and Supply Chain Resilience
The trend toward regionalization of manufacturing and supply chains is expected to continue, driven by both regulatory pressures and customer preferences for resilient sourcing. This creates opportunities for manufacturers that invest in local production capabilities or secure partnerships within target regions. Companies that can offer transparency, flexibility, and compliance with regional content requirements may gain preferential access to key accounts in government, telecommunications, and enterprise sectors. Conversely, suppliers heavily reliant on single-geography supply chains may face increasing challenges in serving global markets, necessitating strategic adjustments in sourcing, distribution, and partnerships.
For investors, this trend suggests that companies with diversified manufacturing footprints or strong alignment with regional digital infrastructure initiatives may offer more resilient growth profiles. The ability to navigate export controls and trade restrictions while maintaining product availability will be a valuable competitive attribute. Companies that can demonstrate robust supply chain management and compliance frameworks will differentiate themselves in an environment where geopolitical risk is a material consideration.
Integration of Advanced Features: Security, Intelligence, and Modulation Flexibility
As networks become more complex and security requirements intensify, transceivers that incorporate advanced features beyond raw bandwidth will gain relevance. The launch of secure high-speed connectivity solutions indicates that authentication, encryption, and tamper resistance are emerging as value-added attributes for certain customer segments. Commercial opportunities exist for vendors that can embed security features without significant penalties in power, cost, or performance. Similarly, transceivers with flexible modulation capabilities or software-defined configurations may appeal to operators seeking to optimize network resources dynamically across different traffic patterns and service requirements.
Intelligent transceivers that provide telemetry, diagnostics, and proactive maintenance capabilities may also find demand in large-scale networks where operational efficiency is paramount. The ability to monitor performance parameters in real time and predict failures can reduce downtime and optimize capacity planning, creating value for network operators managing diverse infrastructure. Vendors that integrate these capabilities into their product offerings can differentiate beyond price and performance specifications.
Potential Risks and Uncertainties
Despite the positive growth outlook, several risks warrant attention. The pace of adoption for next-generation standards such as 1.6T may be influenced by the readiness of host devices, switch ecosystems, and fiber plant capabilities. If the broader infrastructure does not evolve in lockstep, demand for ultra-high-speed transceivers could be delayed or concentrated in a narrower set of applications. Additionally, macroeconomic conditions affecting capital expenditure cycles could alter the timing of deployments, particularly in enterprise and telecom segments that are more sensitive to budget constraints than hyperscale data centers.
Technological risk remains significant, as rapid innovation can render current product generations obsolete faster than anticipated. Companies must balance the cost of R&D and capacity investment against the uncertainty of standards evolution and customer adoption. Overinvestment in a specific technology path that loses out to an alternative approach could lead to stranded assets. Finally, the regulatory environment remains fluid, with potential for further trade restrictions, changes in spectrum policy, or shifts in digital sovereignty initiatives that could impact supply chains and market access. Navigating these uncertainties requires continuous monitoring, scenario planning, and agile strategic responses.
PW Consulting
Strategic Guidance for Decision-Makers
The optical transceivers market offers substantial opportunities for those who can align their strategies with the underlying drivers of demand, technological change, and regulatory evolution. The following actions provide a starting point for manufacturers, investors, and procurement organizations seeking to capitalize on this dynamic environment.
For Manufacturers and Technology Providers
Invest in scalable manufacturing capabilities that can support high-speed lane rates while maintaining stringent quality and yield targets. Modular architectures that allow for flexibility across form factors and speeds may provide a hedge against standards volatility. Strengthen supply chain resilience by diversifying sourcing, exploring regional production options, and developing contingency plans for component availability. Differentiate through value-added features such as security, power efficiency, and integration support, particularly for customers building AI and high-performance computing infrastructure. Monitor co-packaged optics and silicon photonics developments closely, as these technologies may reshape the competitive landscape and create opportunities for new product categories.
For Investors and Financial Stakeholders
Evaluate companies based on their ability to execute on high-growth segments such as 800G and 1.6T transceivers, their manufacturing scalability, and their exposure to resilient demand applications like AI data centers. Consider the geographic diversification of their supply chains and their alignment with regional digital infrastructure initiatives as indicators of long-term sustainability. Assess R&D pipelines and partnerships that provide access to next-generation technologies, as technological leadership will be a key determinant of market share in a concentrated industry. Recognize that the market may see periods of volatility as standards mature and adoption cycles vary, requiring a balanced view of near-term execution and long-term positioning.
For Procurement and Network Operators
Develop a multi-vendor strategy that balances performance requirements with supply chain risk mitigation. Engage early with suppliers on roadmap alignment, particularly for high-speed transceivers that may impact system design and thermal management. Evaluate total cost of ownership, including power consumption and operational efficiency, rather than focusing solely on unit price, as energy costs and density constraints become increasingly important in high-density deployments. Stay informed about evolving standards and regulatory developments that could affect component availability, compliance requirements, and regional sourcing options. Building relationships with suppliers that offer transparency, flexibility, and advanced feature sets can provide strategic advantages in managing network evolution.
Navigating the Opportunity Horizon
The optical transceivers market is at a pivotal moment where sustained demand growth intersects with rapid technological advancement and shifting geopolitical dynamics. The projected market expansion through the end of the decade underscores the strategic importance of optical connectivity in the broader digital infrastructure ecosystem. However, realizing value in this environment requires more than recognizing the growth trajectory; it demands a nuanced understanding of the competitive landscape, supply chain realities, and the specific technological and regulatory factors that will shape outcomes.
For stakeholders seeking to deepen their understanding of market segments, regional nuances, company-specific profiles, and detailed forecasts, accessing comprehensive research reports can provide the granular data and customized insights needed to refine strategies. Detailed segmentation data, competitive benchmarking, and scenario analysis can help translate high-level trends into actionable plans tailored to specific business contexts. Engaging with specialized market intelligence allows decision-makers to move from general awareness to precise execution, ensuring that investments and initiatives are aligned with the most relevant opportunities and risks in the optical transceivers market.
For detailed analysis of this topic, please visit the official page: Optical Transceivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


