



Polyphenylene Sulfide Fibers Market: How 4.7% CAGR and Filtration Demand Reshape 2032
By PW Consulting, 2026-09-21
The Polyphenylene Sulfide Fibers Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
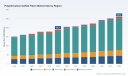
The global market for polyphenylene sulfide fibers has entered a phase of steady, value-driven expansion. Valued at approximately 151.2 million USD in 2020 and reaching roughly 189.6 million USD by 2025, the market is projected to grow to around 259.8 million USD by 2032, reflecting a compound annual growth rate of 4.7 percent over the forecast period. This trajectory signals a mature yet resilient industry where demand is increasingly tied to high-performance applications rather than volume-led commoditization. For executives, investors, and procurement leaders, the question is no longer whether PPS fibers will grow, but how the competitive landscape, cost structure, and regulatory environment will reshape who captures value in the next cycle.
Despite the consistent growth profile, the market is navigating several structural inflection points. First, margin compression is becoming a reality as energy-intensive production collides with tightening environmental controls and rising utility costs. Second, geopolitical and trade dynamics are introducing uncertainty around cross-border sourcing, particularly as major economies reassess anti-dumping frameworks and regional supply dependencies. Third, demand is shifting from generic filtration uses toward more specialized, specification-driven applications that reward technical differentiation and consistent quality. These forces are redefining the baseline for competitive performance and forcing companies to rethink scale, innovation, and supply chain architecture.
Innovation at the Fiber Level: Performance Trumps Volume
Technical advancement remains the most powerful growth lever in this market. The industry is moving beyond baseline heat and chemical resistance toward engineered fiber architectures that solve specific operational pain points. Trilobal cross-section designs, for example, have demonstrated measurable improvements in dust collection efficiency for filtration systems, while new flame-retardant grades are opening pathways into high-voltage electrical insulation where safety margins are non-negotiable. Simultaneously, bio-based feedstock initiatives are beginning to reshape the sustainability narrative, offering a credible route for buyers under pressure to reduce embodied carbon without sacrificing performance. These innovations are not incremental tweaks; they are creating application-specific value pools that command pricing resilience and longer-term customer lock-in.
Regulatory Realignment and the Trade Policy Variable
Policy and regulatory shifts are becoming a decisive factor in sourcing strategy. Environmental controls in key production regions have already influenced raw material pricing, with p-dichlorobenzene costs rising sharply in 2024 as tightened standards constrained supply. At the same time, trade policy dynamics are entering a new phase. The initiation of a sunset review investigation into anti-dumping measures on imports of polyphenylene sulfide from Japan and other countries signals that tariff and duty environments may be recalibrated in the near term. For multinational buyers and producers alike, this creates a dual challenge: maintaining supply continuity while preparing for potential cost volatility and redirected logistics. Companies that treat compliance and trade exposure as strategic variables rather than administrative hurdles will be better positioned to navigate procurement disruptions.
Demand-Side Transformation: From Filtration Dominance to High-Performance Diversification
End-use demand continues to be anchored by filtration applications, which remain the largest consumption segment. Bag filters in industrial dust collection and emission control systems represent a core demand driver, supported by stricter air quality standards and the need for durable, high-temperature-resistant media. However, the most notable shift is the growing interest in insulation materials and engineering applications where PPS fibers are being evaluated for thermal stability, chemical resistance, and long service life. Procurement behavior is also evolving: buyers are increasingly specification-driven, evaluating total cost of ownership rather than unit price alone. This change rewards suppliers that can demonstrate consistent grade quality, technical support, and application engineering capability. It also creates an opening for fiber producers to expand into adjacent high-performance segments where differentiation is achievable.
Cost Structure and Supply Chain Pressure
The economics of PPS fiber production are increasingly sensitive to energy intensity and raw material availability. Producing one metric ton of PPS requires approximately 3,200 kWh of electricity, which places a premium on regional energy tariffs and grid reliability. In markets with high or volatile electricity costs, this translates directly into margin pressure and can influence plant location decisions, capacity timing, and pricing strategies. At the same time, the supply chain is experiencing selective consolidation and regional rebalancing. Capacity expansions and targeted acquisitions are being used to strengthen local market access and reduce exposure to long logistics chains. These moves reflect a broader industry recognition that resilience and proximity to key end markets are becoming as important as scale alone.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players accounting for roughly 35.8 percent of share and the top five reaching approximately 42.6 percent. This concentration suggests a landscape where scale and brand recognition matter, yet enough fragmentation remains to allow differentiated entrants to compete on technical performance, regional presence, or application specialization. Leadership in this market is increasingly defined by how effectively a company aligns product architecture, capacity strategy, and regional access with the evolving needs of specification-driven buyers.
Japanese and European Incumbents: Engineering Heritage and Application Depth
Several established manufacturers have built strong positions by emphasizing application-specific fiber grades and long-standing technical credibility. Leading PPS fiber producers have focused on high-temperature and chemical-resistant grades tailored for bag filters and insulation, reinforcing their relevance in industrial filtration and demanding engineering environments. Other major players offer PPS fiber variants with superior heat, chemical, and hydrolysis resistance across yarn, fabric, and non-woven formats, broadening their reach into both filtration and high-performance industrial uses. A notable differentiator in the market has been the development of trilobal cross-section fibers designed specifically to improve dust collection efficiency, a clear example of structural innovation translating into measurable performance gains. European suppliers have also maintained a presence with fiber grades suitable for monofilament and multifilament extrusion in high-performance engineering applications, positioning themselves in niches where precision and consistency are critical.
Phosphorus Pentasulfide Market
Regional Expansion and Capacity Strategy
Capacity and supply chain strategy are becoming central to competitive positioning. Recent activity includes the completion of an acquisition of a regional PPS fiber manufacturing plant in Southeast Asia, a move aimed at strengthening supply chain resilience and improving market access. In parallel, capacity expansions by major producers in China are signaling a continued push to serve both industrial and automotive-adjacent demand more efficiently. These developments point to a market that is not only growing but also reconfiguring its geographic footprint. For buyers and investors, regional capacity additions can reduce lead times and logistics risk, but they also intensify local competition and may pressure margins in oversupplied segments.
Product Innovation as a Competitive Moat
Recent product launches illustrate how innovation is being used to defend and extend market position. One major Japanese manufacturer introduced a new flame-retardant PPS fiber grade specifically designed for high-voltage electrical insulation, targeting an application space where reliability and safety certification create strong barriers to entry. Meanwhile, a European supplier announced an eco-friendly PPS fiber line using bio-based feedstocks, aligning product development with sustainability goals in markets where procurement teams face increasing pressure to document lifecycle impacts. In a related high-performance direction, a partnership between a global chemical company and an aerospace OEM has focused on co-developing ultra-high-performance nanocomposite PPS fibers, suggesting that the upper end of the market is moving toward tailored, application-engineered materials rather than standardized grades.
PPS Resin Market
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The competitive trajectory appears to be moving toward a hybrid structure. On one side, consolidation and capacity acquisitions are strengthening the scale and regional reach of incumbents. On the other, product differentiation and application specialization are enabling companies to compete without relying solely on volume. New and expanding entrants, particularly in China, are increasing production capacity for filtration and industrial uses, which broadens available supply but also raises the importance of quality consistency and technical support. Over the next few years, the market is likely to reward players that can combine reliable scale with clear application advantages, while those competing primarily on price in commoditized segments may face intensifying pressure.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of growth will be shaped by the interaction of technical differentiation, cost resilience, and regulatory uncertainty. Three trends stand out as particularly consequential for commercial strategy.
PW Consulting
Trend 1: Application-Specific Value Pools Will Outperform Generic Segments
As buyers increasingly prioritize total cost of ownership and performance reliability, specification-driven applications are expected to capture a disproportionate share of margin growth. High-voltage insulation, advanced filtration media, and engineered industrial textiles are likely to see stronger demand for premium grades that solve clear operational problems. This trend favors producers with strong application engineering capabilities and consistent grade control, and it creates opportunities for companies that can demonstrate measurable performance advantages in targeted use cases. The broader implication is that growth will be less about expanding volume across all segments and more about winning in high-value niches where customers are willing to pay for proven performance.
Trend 2: Cost and Energy Dynamics Will Drive Regional Strategy Decisions
Given the electricity intensity of PPS production and ongoing raw material price volatility, regional cost structures will increasingly influence where capacity is added, how production is scheduled, and which suppliers are preferred in tender processes. Producers in regions with stable, cost-competitive energy and efficient logistics may gain a structural advantage, while high-energy-cost regions could see margin pressure unless offset by premium product positioning or local demand strength. For downstream buyers, this trend underscores the importance of multi-region sourcing strategies and scenario planning for energy and input cost fluctuations. It also suggests that near-market capacity expansions could become a differentiator for suppliers seeking to reduce lead times and improve supply assurance.
Trend 3: Sustainability and Regulatory Compliance Will Become Commercial Inputs
Sustainability is transitioning from a reputational consideration to a procurement requirement in several end markets. Bio-based feedstock development and other eco-aligned product initiatives are likely to gain traction among buyers who need to document environmental performance across their supply chains. At the same time, trade and regulatory reviews will continue to shape cross-border sourcing, potentially altering duty exposure and supply routes. The commercial implication is clear: sustainability claims and regulatory readiness will increasingly influence supplier selection, especially in sectors where compliance, safety, and lifecycle documentation carry operational weight. Companies that can provide credible, verifiable product attributes and maintain agile sourcing options will be better positioned to retain and expand share.
Risks and Uncertainties to Monitor
Despite the constructive growth outlook, several risks warrant attention. Continued raw material price volatility, especially for key precursors, could compress margins if not managed through pricing strategy or supply contracts. Energy cost escalation in certain regions may affect production economics and plant utilization decisions. Trade policy reviews and potential duty adjustments could introduce short-term sourcing disruption and pricing uncertainty. Finally, the risk of overcapacity in specific regional segments could intensify price competition, particularly in more commoditized filtration applications. Navigating these risks will require a combination of technical differentiation, flexible sourcing, and disciplined capacity planning.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with the applications that command the strongest performance requirements and willingness to pay. Investing in grade consistency, application-specific fiber architectures, and credible sustainability attributes can create meaningful differentiation. At the same time, capacity and energy strategy should be evaluated in the context of regional cost structures and customer proximity, rather than scale alone. Companies that can combine reliable supply with clear technical advantage will be best placed to defend pricing and expand into higher-value segments.
For investors, the market offers a profile of steady growth with pockets of higher-margin opportunity in specialized applications. Due diligence should focus on the durability of product differentiation, the exposure of production costs to energy and raw materials, and the ability of target companies to navigate trade and regulatory shifts. Regional capacity moves and acquisitions may improve supply chain resilience, but they also require scrutiny around utilization, local competition, and end-market demand quality. Selective exposure to engineered fiber segments and application-led growth appears more attractive than undifferentiated volume plays.
For procurement and supply chain leaders, the strategic task is to reduce exposure to single-source dependency and price-only purchasing logic. Evaluating suppliers on the basis of grade consistency, technical support, energy and regulatory resilience, and sustainability documentation can lower total risk and improve long-term cost stability. Building multi-region sourcing options and maintaining visibility into trade policy developments will help mitigate disruption if duty environments or input costs shift. In practice, procurement strategies that treat PPS fibers as a performance-critical input rather than a commodity are more likely to secure reliable supply and better commercial outcomes.
The market is entering a period where technical value, cost resilience, and regulatory readiness will separate durable participants from price-takers. For decision-makers seeking a deeper, segment-level view of demand dynamics, competitive positioning, and scenario-based planning parameters, a more detailed research compendium can provide the granularity needed to translate these strategic trends into specific operational choices.
For detailed analysis of this topic, please visit the official page: Polyphenylene Sulfide Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surgical Blades & Scalpels Market 2026: Why 5.2% CAGR and Disposable Blades Reshape Strategy
By PW Consulting, 2026-09-21
The Surgical Blades & Scalpels Market: Strategic Trends and Commercial Opportunities Through 2032
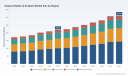
The global market for surgical blades and scalpels has entered a phase of steady, structurally supported expansion. Valued at approximately $172.5 million in 2020, the market reached $219.8 million in 2025 and is projected to climb to $312.3 million by 2032, reflecting a compound annual growth rate of 5.2 percent. This trajectory mirrors broader shifts in surgical practice, infection control standards, and procurement economics. While the product category itself is mature, the competitive and operational dynamics beneath the surface are evolving quickly. For executives, investors, and procurement leaders, the market presents a paradox: top-line growth is predictable, yet margin structures, channel control, and innovation pathways are being reshaped by regulation, safety mandates, and regional supply chain reconfiguration.
The market is heavily concentrated. The top three players account for roughly 60 percent of revenue, and the top five capture about 72 percent. This concentration signals scale advantages in manufacturing, sterilization, distribution, and compliance management. Yet the remaining share is fragmented across regional manufacturers, specialty blade producers, and safety-focused innovators, creating both pressure and opportunity depending on a company's positioning. The following analysis examines the core challenges, demand and supply drivers, competitive strategies, and forward-looking opportunities that will shape decision-making through the end of the decade.
Market Landscape and Core Challenges
A Mature Category Operating Under Structural Efficiency Pressure
The surgical blades and scalpels market is not experiencing explosive growth, but it is benefiting from persistent procedural volume expansion, a shift toward single-use sterile disposables, and tightening safety standards. The overall revenue path from 2020 through 2032 shows consistent year-over-year gains, with the steepest incremental increases expected in the latter half of the forecast period. This pattern is consistent with a category where volume growth, product mix shifts, and regional procurement changes compound rather than spike.
One of the most pressing challenges is the tension between cost containment and safety compliance. Hospitals and surgical centers are under sustained pressure to reduce indirect costs, yet regulatory and occupational safety expectations continue to favor single-use sterile blades and safety scalpels. The result is a procurement environment where price sensitivity exists alongside mandatory or strongly encouraged adoption of safety-engineered products. Manufacturers that can deliver standardized, compliant, and competitively priced disposable blades are better positioned than those relying on premium differentiation alone.
PW Consulting
A second challenge lies in the regulatory asymmetry across regions. In the United States, scalpel blades and scalpels are generally classified as Class I exempt devices, meaning most models do not require a premarket submission, but establishments must still register and list with the appropriate authorities. Manufacturing facilities are expected to meet ISO 13485 quality management expectations, and EU markets impose stricter single-use validation protocols under the Medical Device Regulation framework. This duality creates a compliance burden for companies selling across multiple jurisdictions, especially when validation documentation, sterilization records, and traceability requirements differ. The cost of maintaining multi-region compliance can erode margins for smaller producers while reinforcing the position of established players with mature quality systems.
A third challenge is the absence of dedicated reimbursement codes for blades and scalpels. Costs are typically embedded within global surgical procedure fees rather than billed as standalone items. This structure pushes procurement decisions toward total cost of procedure rather than device-level price comparisons, and it places a premium on reliability, inventory turnover, and integration with broader perioperative workflows. Suppliers that can demonstrate predictable availability, reduced sharps injury risk, and compatibility with existing surgical workflows gain leverage in a reimbursement environment that does not isolate blade economics.
Key Demand and Supply Drivers
Safety Standards and the Shift Toward Single-Use Sterile Disposables
A major driver of market evolution is the continued migration from reusable blades to single-use sterile disposables. This shift is reinforced by occupational safety mandates and international standards for safety scalpels, which aim to reduce sharps injuries among surgical staff. Facilities are increasingly standardizing on disposable sterile blades not only for clinical reasons but also to streamline infection control protocols and minimize reprocessing costs. The practical effect is a product mix that tilts toward disposable blades in many general surgery settings, while reusable blades retain relevance in specific use cases where reprocessing infrastructure and cost equations remain favorable.
Double Edges Blades Market
The commercial implication is clear: manufacturing capacity, sterilization capability, and distribution reliability for disposable blades are becoming strategic assets. Companies that can scale sterile disposable production while maintaining tight dimensional tolerances and consistent sharpness profiles are better positioned to capture share in a market where safety standards are accelerating adoption. At the same time, safety scalpel designs and retractable or shielded options are gaining attention in procurement specifications, giving an edge to suppliers with differentiated safety portfolios.
Regulatory Classification and Quality System Expectations
Regulatory classification shapes both entry barriers and operating economics. The Class I exempt status of most scalpel blades and scalpels in the United States lowers the premarket submission burden for many models, but it does not remove the need for establishment registration, listing, and robust quality management. ISO 13485 certification is effectively a baseline expectation for manufacturing facilities, and EU requirements add further validation rigor for single-use devices. These conditions favor manufacturers with mature quality infrastructure and disciplined documentation practices.
Worldwide Surgical Saw Blades Market
This environment also affects innovation incentives. Since many conventional blade models face a lighter regulatory pathway, competition often centers on manufacturing consistency, packaging, sterilization reliability, and supply continuity rather than dramatic product redefinition. By contrast, safety-engineered scalpels and specialty micro blades can involve more complex design validation, creating a higher barrier but also a stronger differentiation opportunity for companies that can demonstrate clinical and operational value.
Procurement Economics and the Embedded Cost Reality
Because blades and scalpels are generally absorbed into broader surgical procedure costs rather than reimbursed under dedicated codes, procurement decisions are influenced by total procedure economics. Surgical teams and purchasing departments evaluate availability, standardization, waste reduction, and injury prevention alongside unit price. This creates an environment where bundling compatibility, inventory management support, and safety alignment can be as important as the blade itself.
Demand-side behavior reflects this embedded cost reality. Hospitals seek to minimize variation across surgical service lines, which encourages standardization on a limited set of blade and handle configurations. At the same time, specialty procedures and microsurgical applications sustain demand for precision blades and ophthalmic knives. The net effect is a market where volume flow favors standardized disposable products, while higher-value niches reward precision engineering and application-specific design.
Manufacturing Scale, Regional Sourcing, and Cost Structure Dynamics
Cost structure remains a decisive competitive lever. Blade manufacturing requires precise metallurgy, controlled edge geometry, reliable sterilization, and consistent packaging. Companies with integrated production and quality systems can manage unit costs more effectively, while smaller or regionally focused producers must compete on flexibility, local service, or niche applications. Regional sourcing strategies are gaining importance as procurement teams look to reduce logistics risk, improve lead-time predictability, and align with local compliance expectations.
Recent distribution developments illustrate how channel strategy is evolving. For example, in early 2025, a Canadian distribution agreement expanded exclusive coverage for a major blade and scalpel portfolio, signaling a push to strengthen regional availability and service reliability. Moves like this reflect a broader pattern: established manufacturers are investing in distribution density and localized support to protect share in regulated, service-intensive markets, while emerging producers pursue export growth and selective partnerships to enter new regions.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines long-established multinational manufacturers, precision-focused producers, and regional exporters with growing scale. The leading companies differentiate along several axes: product range breadth, safety portfolio depth, metallurgical precision, sterilization and sterile packaging capability, and integration into broader perioperative or specialty workflows.
Several strategic profiles are visible across the market. One group emphasizes heritage, broad blade and handle ranges, and comprehensive sterile disposable offerings. These players often compete on consistency, distribution reach, and the ability to serve General Surgery and multiple specialty segments with standardized products. Another group focuses on precision manufacturing and high-sharpness stainless steel products, with particular attention to safety scalpel lines and micro blade options. This positioning appeals to surgical specialties that require fine edge control and reliable performance in delicate procedures.
A third profile is built around regional export strength and cost-competitive sterile disposable manufacturing. These companies have expanded their footprint by offering full lines of carbon steel and stainless steel blades and scalpels, targeting price-sensitive procurement environments while meeting international quality expectations. A fourth profile lies in specialty focus, where ophthalmic surgical knives, micro blades, and dental-oriented scalpel systems create differentiated value in narrower but higher-specification applications. Finally, some broader perioperative solution providers incorporate scalpel blades and handles into integrated surgical workflows, using device availability and service continuity as part of a larger institutional relationship.
Market Structure Evolution: Consolidation Pressure and Targeted Expansion
The high concentration at the top of the market indicates that scale, compliance, and distribution maturity matter. Larger players benefit from the ability to standardize quality systems, manage sterilization at volume, and maintain inventory across multiple regions. At the same time, the long tail of smaller and regional manufacturers remains active, particularly where localized service, flexible order sizes, or specialty products create room for differentiation.
The evolution of the landscape is likely to continue along two tracks. First, established manufacturers will keep strengthening distribution partnerships and regional coverage to protect share and improve service levels. Second, targeted expansion by efficient regional producers and specialty innovators will pressure incumbents in specific segments, especially where disposable adoption is rising and procurement is open to alternative suppliers that can meet compliance requirements at competitive cost. M&A and rebranding activity also reshape the landscape indirectly, as companies reposition portfolios to emphasize safety, specialty precision, or perioperative integration.
Given the embedded cost structure and safety-driven adoption trends, competitive advantage increasingly comes from the ability to deliver standardized sterile disposables with reliable lead times, consistent quality, and safety-aligned design features. In specialty niches, the advantage shifts toward precision, application fit, and clinical trust. Companies that can operate effectively across both tracks—scale-driven standard products and higher-specification specialty offerings—are best placed to defend and expand their positions.
Forward Trends and Commercial Opportunities Through 2032
Continued Mix Shift Toward Sterile Disposable and Safety-Aligned Products
Over the next three to five years, the product mix is expected to keep moving toward single-use sterile disposables and safety-oriented scalpels where protocols and procurement specifications allow. This trend is supported by safety standards, infection control expectations, and the operational simplicity of disposables in high-volume surgical environments. For suppliers, the opportunity lies in scaling sterile disposable capacity, improving packaging and traceability, and aligning product lines with the safety expectations that hospitals are increasingly embedding into purchasing criteria.
A related opportunity is the expansion of safety scalpel adoption in settings that have historically relied on conventional blades. Education, workflow integration, and cost acceptance will influence the pace of adoption, but the direction of travel favors designs that reduce handling risk and support standardized disposal procedures.
Regional Growth and Supply Chain Localization
Regional dynamics will continue to shape growth patterns. North America remains the largest market, supported by established surgical volumes, safety adoption, and mature distribution. Europe follows with substantial demand and stricter validation expectations that reinforce quality and traceability requirements. Asia Pacific represents a meaningful growth path, driven by expanding surgical capacity, increasing procurement professionalism, and growing export competitiveness among efficient manufacturers. Latin America and the Middle East and Africa remain smaller in absolute terms but offer incremental opportunities where access, service, and compliance alignment improve.
Commercially, this points to a strategy of regional reinforcement rather than uniform global rollout. Companies that invest in localized distribution, predictable lead times, and documentation readiness for multiple regulatory environments can capture share more effectively than those relying solely on product price. For investors, regional scalability and channel control are likely to be critical indicators of long-term resilience.
Precision, Specialty, and Workflow-Integrated Positioning
While standardized disposables drive volume, specialty applications sustain higher-margin opportunities. Ophthalmic knives, micro blades, and application-specific scalpel systems require tighter tolerances and greater clinical confidence, which can support differentiated pricing when performance and reliability are demonstrable. At the same time, broader perioperative providers can create value by integrating blade and scalpel availability into larger surgical workflow solutions, making supply reliability and service continuity part of the value proposition.
This bifurcation suggests a practical strategic path: maintain a strong core in standardized sterile disposables to capture volume and safety-driven adoption, while building or strengthening specialty lines that serve precision procedures and specialized surgical workflows. The risk is spreading too thin across unrelated segments; the opportunity is to align precision and workflow integration with genuine clinical need rather than broad but shallow expansion.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory and validation expectations may tighten further in certain markets, raising compliance costs and slowing the pace at which new entrants can scale. Procurement pressure could intensify if hospitals prioritize cost over safety features in specific budget cycles, temporarily dampening the shift toward premium safety designs. Supply chain disruptions, raw material cost volatility, and sterilization capacity constraints could also affect margin stability and service levels. Finally, because reimbursement does not isolate blade costs, demand can be indirectly affected by changes in surgical procedure volumes, service line economics, and broader healthcare spending patterns.
Strategic Implications for Decision Makers
For Manufacturers
Prioritize the operational foundations that convert market growth into defensible share. That means investing in sterile disposable capacity, quality system maturity, and distribution reliability, while maintaining enough precision capability to serve specialty segments. Standardize core blade and handle configurations where hospital procurement favors consistency, but preserve differentiated safety and micro blade options where clinical value supports them. Build regional channel strength through partnerships or localized service capacity, especially in markets where lead time and documentation readiness influence purchasing decisions.
For Investors
Evaluate businesses on their ability to manage compliance, scale sterile production, and control distribution across regions. Concentration in the market indicates that scale and quality infrastructure matter, but growth opportunities also exist for efficient producers and specialty innovators that can meet safety expectations at competitive cost. When assessing potential investments or partnerships, look for evidence of ISO 13485-aligned quality systems, reliable sterilization and traceability processes, and channel strategies that reduce reliance on a single geography or customer type. Also consider exposure to procedural volume cycles, since blade demand is tied to surgical activity even though reimbursement does not itemize the device separately.
For Procurement and Supply Chain Leaders
Treat blade and scalpel selection as part of total procedure economics rather than an isolated unit-price exercise. Standardize where clinical workflows allow, but preserve access to safety-aligned disposables and precision options for specialties that require them. Evaluate suppliers on consistency, injury-prevention design, inventory reliability, and documentation readiness as much as on price. Where possible, align purchasing specifications with occupational safety standards and infection control goals to reduce downstream operational risk.
Closing Perspective
The surgical blades and scalpels market is moving through a period where growth is steady, safety expectations are rising, and competitive advantage depends on execution quality as much as product design. The mix shift toward sterile disposables, the regulatory and validation environment, and the embedded cost structure of surgical procedures all point in the same direction: future success will belong to organizations that can combine scale, compliance discipline, and targeted precision where it matters most. For leaders navigating this landscape, the most valuable next step is to ground strategy in detailed, segment-level intelligence—covering regional demand patterns, product mix economics, channel dynamics, and competitor positioning—so that decisions on capacity, portfolio focus, and market entry are calibrated to the opportunities and risks that lie ahead.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Agarose Market 2032: Why the 6.98% CAGR Trajectory Signals Strategic Shifts in Life Sciences
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Agarose Market
Market Overview and Core Challenges
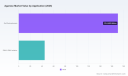
The global agarose market has demonstrated consistent expansion over the past half-decade, establishing itself as a critical component within the broader life sciences and bioprocessing supply chain. Starting from a valuation of approximately 153.44 million USD in 2020, the market has grown steadily to reach an estimated 215.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.98 percent, with projections indicating continued expansion through 2032. By the end of the forecast period, the market is expected to surpass 344 million USD, signaling sustained demand across research and industrial applications.
This growth is not merely a function of population or academic output increases; it represents a structural shift in how biological materials are processed and analyzed. The market has moved from a niche consumable model toward a more integrated industrial supply dynamic. However, this expansion faces headwinds that strategic planners must account for. The period from 2025 to 2032 will not be defined solely by volume growth but by how players navigate supply chain fragility and regulatory divergence.
Three critical challenges define the current inflection point for industry stakeholders. First, raw material security remains a persistent vulnerability. Agarose is primarily derived from seaweed, linking market stability directly to marine agriculture and geopolitical trade flows. Recent data indicates that geopolitical tensions between major seaweed-producing nations and key import markets like the European Union and the United States have triggered higher import/export tariffs. These barriers have increased operational costs for producers, squeezing margins on standard grades while complicating long-term capacity planning.
Second, regulatory uncertainty in key regions is altering demand patterns. In 2024, China introduced classification rules for bio-stimulant products such as seaweed extracts that created inspection delays and price fluctuations. While this specifically impacts biostimulants, it signals a broader trend of tighter oversight on seaweed-derived materials that can spill over into industrial and laboratory-grade agarose supply chains. Additionally, the new French national roadmap launched in March 2025 aims to triple domestic seaweed production by 2027. While this enhances sector resilience in Europe, it also shifts regional supply dynamics and may alter competitive advantages for producers reliant on specific geographic sources.
Third, the market is experiencing a bifurcation in demand quality. Standard agarose continues to drive volume, but high-performance variants such as low melting point agarose are gaining strategic importance in specialized applications. This divergence forces manufacturers to choose between competing on cost efficiency in commoditized segments or investing in differentiation for high-value niches. Companies that fail to align their product portfolios with this shift risk exposure to margin compression as standard-grade pricing comes under pressure from rising input costs.
For executives and investors, these challenges underscore the need to look beyond top-line growth figures. The market size trajectory is positive, but the underlying economics are tightening. Success in the next cycle will depend on supply chain agility, regulatory foresight, and the ability to capture value in differentiated segments rather than competing solely on volume.
Gracilaria Agarose and Gelidium Agarose Market
Key Growth Drivers
Understanding the forces propelling the agarose market requires examining the intersection of technological advancement, regulatory evolution, demand-side shifts, and cost structures. Each driver influences not only the pace of growth but also where value is created within the market ecosystem.
Technological Innovation and Performance Breakthroughs
Innovation in agarose chemistry and manufacturing processes is reshaping application boundaries. Advances in purification and gel characterization have enabled products that deliver higher resolution and reproducibility for nucleic acid analysis. More importantly, the development of specialized resins for bioprocessing has opened new commercial pathways. Manufacturers are increasingly engineering agarose-based matrices tailored for affinity purification and monoclonal antibody processing, where performance consistency directly impacts downstream therapeutic production.
Recent market activity illustrates this trajectory. In February 2024, Purolite, part of Ecolab, commercially launched Praesto CH1, a 70-micron agarose-based affinity resin developed in partnership with Repligen for specialized monoclonal antibody purification. This launch highlights how agarose is moving beyond traditional laboratory electrophoresis into high-value bioprocessing workflows. Such developments expand the addressable market and create pricing power for suppliers capable of meeting stringent performance and regulatory standards for biological drug manufacturing.
Policy and Regulatory Environment
Regulatory frameworks are acting as both constraints and catalysts. On one hand, trade policies and tariffs are raising input costs and complicating cross-border sourcing. On the other, government initiatives aimed at strengthening domestic production capacity are creating new opportunities. The French national roadmap to triple seaweed production by 2027 exemplifies this dual dynamic. By supporting local cultivation, the policy reduces dependency on imported raw materials and enhances supply chain resilience for European processors.
At the same time, regulatory clarity around product classification remains uneven. The 2024 Chinese regulatory adjustments for seaweed-derived biostimulants caused temporary market disruptions, demonstrating how policy ambiguity can ripple through related supply chains. For agarose producers, this signals the importance of monitoring regulatory developments in bothsource and destination markets. Proactive engagement with policy trends can help companies anticipate sourcing shifts and position their product lines to comply with evolving standards for laboratory and industrial-grade materials.
Demand-Side Shifts in Research and Biomanufacturing
End-user behavior is evolving as laboratory workflows become more automated and throughput requirements increase. In academic and clinical research settings, the demand for reliable DNA and RNA isolation and gel electrophoresis remains foundational. However, the scale and standardization expectations are rising. Laboratories are increasingly seeking precast solutions and certified powders that reduce variability and preparation time. This shift favors suppliers who can offer consistent quality and integrated product systems rather than bulk commodity powders alone.
Simultaneously, the biopharmaceutical sector's expansion is driving demand for agarose-based chromatography media. As monoclonal antibody therapies and advanced biologics continue to scale, manufacturers require purification resins that can handle larger volumes while maintaining binding capacity and flow properties. This demand is less price-sensitive than routine research applications and more focused on performance validation and supply reliability. Companies that can demonstrate batch-to-batch consistency and offer technical support for process integration are capturing a growing share of this higher-value demand segment.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping competitive positioning across the value chain. Rising fuel prices and trade barriers since 2024 have increased the cost of seaweed extract biostimulants and related upstream resources used in agarose production. These input cost increases affect both raw material procurement and logistics. Producers with diversified sourcing strategies or localized supply networks are better positioned to absorb these shocks compared to those relying on single-source or long-distance procurement models.
At the same time, the cost structure is encouraging consolidation and specialization. Smaller players may struggle to invest in the capacity expansions or quality systems required to meet bioscience-grade standards, while larger entities can leverage scale and integration to maintain margins. This dynamic is pushing the market toward a structure where competitive advantage is increasingly tied to supply chain robustness, technical service capabilities, and the ability to offer graded product portfolios that match distinct end-user requirements.
Competitive Landscape and Leading Strategies
The agarose market is characterized by a mix of specialized manufacturers and broader life sciences companies, each pursuing distinct strategic positions. Market concentration data shows that the top three companies hold approximately 35 percent of the market, while the top five account for around 48 percent. This moderate concentration suggests a landscape where established leaders maintain meaningful share but room remains for niche players and regional specialists to compete on differentiation.
Thermo Fisher Scientific and Bio-Rad Laboratories represent the large-cap life sciences segment, offering certified agarose powders and precast gel systems optimized for routine and high-throughput nucleic acid analysis. Thermo Fisher's UltraPure powders and E-Gel precast systems cater to laboratories seeking consistency and workflow efficiency, while Bio-Rad's certified molecular biology powders and precast gels serve similar demand with a strong reputation in research and teaching environments. Their strategic advantage lies in brand trust, distribution scale, and integrated product ecosystems that reduce user variability.
Lonza occupies a specialized position with products such as SeaKem and NuSieve grades tailored for nucleic acid gel electrophoresis. Its focus on high-clarity and specialized gel formulations addresses applications where resolution and reproducibility are paramount. By maintaining a dedicated product architecture for electrophoresis, Lonza competes on technical performance rather than volume pricing, appealing to users with demanding analytical requirements.
Agarose Bead Technologies (ABT) and Purolite represent the bioprocessing-oriented flank of the market. ABT, based in Spain, specializes in high-performance custom agarose resins for bioprocessing applications including monoclonal antibody purification and advanced therapies. Its strategy emphasizes customization and capacity investment. In October 2024, ABT completed a 1,000 square meter addition to its Burgos facility, increasing agarose resin production capacity to 100,000 liters annually. This expansion signals a commitment to scaling supply for bioprocessing demand. ABT's participation in Analytica 2026 in Munich further underscores its focus on showcasing agarose-based resins and custom chromatography solutions to a global bioprocessing audience.
Purolite, operating across the UK and US under Ecolab, leverages patented jetting technology for agarose-based chromatography resins used in bioprocessing and affinity purification. Its partnership-driven approach, exemplified by the Praesto CH1 launch in collaboration with Repligen, illustrates how resin suppliers are building ecosystems around specific therapeutic manufacturing needs. This model allows Purolite to align product development with customer process requirements and capture value in the antibody purification workflow.
Worldwide Agar Resin Market
The competitive landscape is evolving along two axes: integration and specialization. Larger life sciences companies are expanding their agarose offerings through brand extension and precast system integration, competing on workflow convenience and global reach. Specialized manufacturers are deepening their technical focus on custom resins, high-performance grades, and bioprocessing applications, competing on performance, customization, and supply reliability for advanced therapies. New entrants are most likely to succeed by targeting underserved niches, such as regional supply optimization, tailored resin specifications, or cost-efficient production of standard grades with consistent quality. Mergers and partnerships may increase as companies seek to combine upstream raw material access with downstream application expertise.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the 2026 to 2032 period, several trends are likely to shape market direction and create distinct commercial opportunities. These trends are grounded in current data trajectories and recent industry developments, offering a basis for strategic planning.
Trend 1: Premiumization and Workflow-Integrated Solutions
The market is likely to see continued growth in high-performance and low melting point agarose variants as laboratories and bioprocessors prioritize reproducibility, speed, and integration. Demand for precast gels, certified powders, and resins with validated performance characteristics will expand as users seek to reduce preparation variability and accelerate throughput. This trend favors suppliers that can offer complete workflow solutions, technical documentation, and application support. Commercial opportunities lie in bundling products with service offerings, developing application-specific grades, and building partnerships with equipment and automation providers to embed agarose solutions into standardized workflows.
Trend 2: Regional Supply Restructuring and Sourcing Diversification
Policy initiatives such as France's push to triple domestic seaweed production and ongoing trade tensions affecting import/export tariffs will encourage regional supply chain restructuring. Producers and buyers alike will increasingly value diversified sourcing strategies and localized processing capabilities to mitigate tariff risks and input cost volatility. Over the next few years, expect more investment in regional cultivation partnerships, alternative sourcing routes, and capacity located closer to key demand centers. Companies that secure resilient raw material access and can offer transparent sourcing will gain a competitive edge, particularly in Europe and North America where supply security is becoming a strategic priority.
Trend 3: Convergence of Research and Bioprocessing Demand
As biomanufacturing scales and research workflows become more standardized, the boundary between laboratory-grade and bioprocessing-grade agarose applications may continue to blur in certain segments. Advanced therapies and biologics production require high-purity, consistent resins, while research labs increasingly adopt precast and certified products that mirror industrial quality expectations. This convergence creates opportunities for suppliers that can span both domains with appropriate quality tiers and regulatory documentation. It also raises the bar for quality systems, traceability, and technical support, rewarding companies that can bridge research and production requirements without compromising cost efficiency.
Potential risks and uncertainties accompany these trends. Regulatory ambiguity in key seaweed-producing and consuming markets could resurface, causing supply disruptions or reclassification of products that affect demand. Geopolitical tensions and fuel price volatility may continue to pressure input costs, particularly if trade barriers persist or intensify. Additionally, oversaturation in standard-grade segments could intensify price competition, eroding margins unless companies successfully differentiate through quality, service, or application-specific value. Strategic planners should stress-test their assumptions around sourcing stability, regulatory clarity, and pricing power in commoditized segments.
Actionable Insights for Decision Makers
For manufacturers, the priority is to align product portfolios with the shift toward differentiation and workflow integration. Investing in high-performance grades, precast systems, and custom resin capabilities can protect margins and capture higher-value demand. At the same time, strengthening supply chain resilience through diversified sourcing, regional partnerships, or localized processing can reduce exposure to tariffs and input cost volatility. Manufacturers should also evaluate whether capacity expansion aligns with demand concentration in bioprocessing or whether a regional strategy better serves market needs. Technical service capabilities and application support should be treated as core competitive assets rather than ancillary functions, as end-users increasingly value validation, consistency, and process integration.
For investors, the market offers attractive structural growth supported by a steady CAGR and expanding demand across research and bioprocessing. However, due diligence should focus on supply chain robustness, regulatory exposure, and product mix. Companies with diversified sourcing, clear quality systems, and a balanced portfolio of standard and premium products are better positioned to navigate input cost pressures and regulatory uncertainty. Interest in specialized bioprocessing resins and custom chromatography solutions is likely to remain a value-creation driver, particularly as monoclonal antibody and advanced therapy production scales. Evaluating capacity expansion plans against realistic demand trajectories and regional policy developments can help identify companies with sustainable competitive positioning.
For procurement and supply chain leaders, securing reliable supply while managing cost volatility requires proactive supplier engagement and sourcing diversification. Qualifying multiple suppliers across regions, establishing clear quality and documentation requirements, and exploring partnerships with manufacturers that offer transparent sourcing and capacity visibility can reduce risk. Buyers should also assess the total cost of ownership beyond unit price, considering workflow efficiency, reproducibility, and technical support, especially for critical applications where variability can impact results or production timelines. Monitoring regulatory developments in source and destination markets enables earlier adjustments to sourcing strategies and reduces the likelihood of disruption from classification changes or trade policy shifts.
Accessing detailed segmentation data, regional demand patterns, and customized strategic recommendations can sharpen decision-making in this evolving landscape. Comprehensive market intelligence that breaks down growth trajectories by application, product type, and region, along with scenario analysis for regulatory and supply chain variables, provides the granularity needed to turn high-level trends into actionable plans. For organizations seeking to optimize sourcing, prioritize product development, or evaluate investment and partnership opportunities, a deeper data-backed view of the agarose market is an essential input to strategic planning.
For detailed analysis of this topic, please visit the official page: Agarose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lab Glassware Market 2026: The 4.7% CAGR Trajectory and What It Reveals
By PW Consulting, 2026-09-21
Navigating the Laboratory Glassware Market: Strategic Trends and Commercial Imperatives
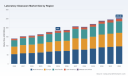
The laboratory glassware market is entering a phase of structural transformation, driven by technological refinement, evolving regulatory expectations, and shifting procurement behaviors across end-user segments. Valued at approximately USD 185.0 million in 2025, the market has expanded from USD 140.5 million in 2020, reflecting steady compounding growth over the post-pandemic period. Forward projections indicate a trajectory toward USD 253.28 million by 2032, with a compound annual growth rate of 4.7 percent across the forecast horizon. This expansion is not merely incremental; it reflects a market responding to heightened precision requirements, supply chain recalibration, and the integration of traceability and standardization into routine laboratory operations. For executives, investors, and procurement leaders, the window to align product portfolios, capital allocation, and sourcing strategies with these underlying shifts is opening now.
Market Snapshot: Growth Trajectory and Structural Realities
The market’s historical performance from 2020 through 2025 demonstrates a consistent upward curve, with annual revenue crossing the USD 160 million threshold in 2022 and accelerating into the USD 170–185 million range by mid-decade. The forecast period from 2026 to 2032 projects continued expansion, though the growth path is not uniform. The transition from USD 185.0 million in 2025 to the projected USD 253.28 million in 2032 implies that demand generation will increasingly depend on application-specific precision, regulatory compliance, and regional capacity dynamics rather than broad volume expansion alone.
At the structural level, the market operates with moderate concentration. The top three participants collectively command roughly 45 percent of total revenue, while the top five extend that share to approximately 60 percent. This concentration pattern indicates that established manufacturers retain meaningful pricing power and distribution leverage, yet the remaining 40 percent of the market remains fragmented across regional players, specialty suppliers, and cost-focused producers. Such a landscape creates both defensive moats for incumbents and entry points for well-positioned challengers, particularly where customization, compliance documentation, or supply chain reliability becomes a differentiating factor rather than a baseline expectation.
The market is also characterized by a clear hierarchy of product and application relevance. Volumetric measurement tools and general containment vessels continue to anchor demand, while pipettes and precision dispensing instruments represent a growing precision segment. In application terms, pharmaceutical and biotechnology workflows consume the largest share of glassware volumes, followed by academic and research environments, clinical diagnostic settings, and ancillary use cases. This distribution indicates that demand is increasingly tied to regulated, high-throughput, or quality-sensitive environments where measurement accuracy, material consistency, and documentation traceability carry direct operational and compliance implications.
Defining Challenges and Inflection Points
Despite the favorable growth baseline, the industry faces several interconnected challenges that will shape competitive outcomes over the next three to five years.
Precision Standards and Calibration Expectations
The laboratory glassware sector is moving toward tighter standardization for measurement-critical items, particularly in one-mark volumetric instruments. Updated international requirements are reinforcing calibration consistency, marking accuracy, and manufacturing repeatability. For producers, this translates into higher compliance costs, more rigorous quality control protocols, and the need to align product specifications with evolving normative references. Laboratories and procurement teams, in turn, are placing greater weight on certification documentation and conformance assurance, raising the barrier for sellers that cannot demonstrate consistent specification integrity across batches.
Material Consistency and Thermal Performance Requirements
Borosilicate glass remains the dominant material foundation because of its thermal shock resistance and chemical durability. While this dominance provides stability, it also constrains rapid material substitution and heightens sensitivity to raw material quality, melting consistency, and forming precision. Variability in feedstock composition or furnace control can affect wall thickness uniformity, dimensional tolerance, and long-term reliability in temperature-cycling applications. Manufacturers that treat material consistency as a core process capability rather than a commodity input will be better positioned to capture demand from environments where thermal stress and chemical exposure are routine.
Traceability, Documentation, and Procurement Digitalization
A quiet but consequential shift is underway in how laboratories track, verify, and manage glassware inventory. The introduction of QR-coded product items, enhanced batch traceability, and digital catalog integration reflects growing demand for item-level identification and audit-ready documentation. This trend is especially relevant in regulated environments where lot traceability, usage history, and replacement scheduling influence both operational efficiency and compliance reviews. Suppliers that enable faster verification, clearer product identification, and smoother integration with laboratory inventory systems can reduce friction in the procurement cycle while strengthening supplier-of-choice positioning.
Core Drivers Reshaping the Market
Regulatory Alignment and Standardization Momentum
The push toward harmonized international standards is one of the most consequential forces in the market. Updated normative references for one-mark volumetric flasks are establishing clearer expectations for dimensional accuracy, marking, and conformity testing. Rather than treating standards as static compliance checkboxes, leading manufacturers are using them as product development anchors, aligning tooling, inspection routines, and documentation with anticipated certification expectations. For buyers, the practical implication is that specification sheets and conformity evidence are becoming more comparable across suppliers, which can compress differentiation based solely on branding and shift attention toward reliability, lead-time consistency, and technical support.
Innovation in Safety and Durability Features
Product-level innovation is increasingly focused on reducing breakage risk, improving handling safety, and extending service life in demanding workflows. Coated laboratory bottles with enhanced shatter protection illustrate this direction, addressing both workplace safety and total cost of ownership concerns. In settings where glassware is handled frequently, moved across benches, or used in environments with vibration, temperature variation, or incidental impact, safety-oriented design features can differentiate a product line and influence purchasing decisions beyond base price comparisons. Innovation is also extending to interchangeability, filtration-compatible configurations, and specialized vessel geometries that reduce workflow adaptation time.
Demand-Side Shifts in Regulated and Research Workflows
End-user behavior is evolving as laboratory workflows become more standardized, auditable, and throughput-sensitive. Pharmaceutical and biotechnology environments continue to absorb the largest share of demand because measurement precision, contamination control, and reproducibility carry direct implications for development timelines and quality outcomes. Academic and research institutions remain a substantial demand base, but their procurement patterns are increasingly influenced by budget cycles, shared instrumentation models, and the need for broad compatibility across teaching and research labs. Clinical diagnostic settings add another layer of complexity, where glassware usage is tied to laboratory service delivery and reimbursement frameworks that do not always map cleanly onto individual product codes. This fragmentation in reimbursement and procurement pathways means that suppliers must navigate both technical specifications and institutional purchasing logic.
Supply Chain and Cost Structure Pressures
Cost dynamics in the market are influenced by raw material availability, energy intensity in glass melting and forming, and logistics complexity across regions. Borosilicate glass production requires controlled high-temperature processing, which makes energy pricing and furnace utilization relevant to cost structure. At the same time, regional demand patterns are reshaping sourcing strategies. North American and European markets maintain substantial demand bases, while Asia Pacific represents a growing volume center supported by expanding research infrastructure, manufacturing capacity, and domestic consumption. The result is a supply environment in which regional presence, export capability, and inventory positioning increasingly matter for competitive responsiveness. Companies that can combine consistent production output with dependable distribution and clear compliance documentation are gaining an advantage in tenders and recurring procurement programs.
Competitive Landscape and Strategic Positioning
The competitive environment blends incumbent scale, regional manufacturing strength, and niche specialization. Companies with established brand portfolios and broad product ranges are using brand trust, specification consistency, and application coverage to defend share. At the same time, regional manufacturers are gaining relevance by offering competitive cost profiles, adaptable production runs, and growing conformity to local certification expectations. This dual dynamic creates a market where scale and reputation matter, but they no longer guarantee automatic preference if a competitor can match specifications and improve traceability, lead time, or safety features.
Differentiation Patterns Among Leading Players
Several strategic positioning patterns are evident across the competitive set.
-
Brand-led premium positioning: Multi-brand manufacturers leverage well-known product lines and long-standing laboratory recognition to anchor trust in precision measurement and material quality. Their differentiation often rests on specification consistency, broad application coverage, and established distribution relationships.
-
Customization and specialty systems: Some suppliers emphasize custom configurations, reaction systems, and application-specific geometries. This approach is particularly relevant for research environments that require non-standard vessel dimensions, specialized port configurations, or integrated handling solutions.
-
Standards-aligned volume manufacturing: Regional producers focus on USP, ASTM, and local certification alignment, offering general laboratory glassware and consumables at competitive cost points. Their relevance grows where procurement teams prioritize specification compliance, batch consistency, and pricing predictability.
Glassware Market -
Traceability and catalog modernization: Suppliers introducing QR-coded items, updated catalogs, and improved identification systems are reducing friction in inventory verification and lot tracking. This is becoming a practical value-add, especially for repeat purchasers managing large SKU counts or regulated usage environments.
-
Safety-enhanced product extensions: Manufacturers introducing shatter-protection coatings, coated bottles, and handling-safety features are targeting total cost of ownership and workplace risk reduction. This positioning resonates in environments where breakage-related disruptions, cleanup, and replacement frequency influence operating costs.
PW Consulting
Evolution of the Competitive Structure
The market is unlikely to consolidate into a single dominant configuration over the near term. Instead, the structure appears to be evolving through selective integration, regional capacity expansion, and specialization by workflow. Incumbents are defending core positions by strengthening product reliability, demonstration value at major industry events, and application-aligned product launches. Regional producers are expanding relevance by combining cost efficiency with growing conformity to certification and standards expectations. At the same time, new entrants and expanders can gain traction by addressing unmet needs in traceability, safety, specialized geometries, or regional service responsiveness. The practical outcome is a landscape where competitive advantage is increasingly defined by the intersection of specification integrity, documentation readiness, and operational convenience rather than by brand alone.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Standards-Driven Harmonization of Precision Glassware
Over the next several years, the emphasis on harmonized requirements for measurement-critical items is likely to intensify. One-mark volumetric instruments will continue to serve as a focal point for calibration discipline, and suppliers that proactively align manufacturing controls, inspection protocols, and documentation with evolving normative expectations will face fewer friction points in regulated procurement. The commercial implication is that quality documentation and specification consistency will become more central to supplier selection, and companies that treat conformance as a design and process priority rather than an after-the-fact certification activity will be better positioned for repeat business in quality-sensitive environments.
Trend 2: Safety, Durability, and Total-Cost-of-Ownership Framing
Demand for safety-enhanced and durability-oriented products is expected to grow as laboratories and procurement teams evaluate glassware not only by unit price but by handling risk, breakage frequency, replacement cycles, and workflow interruption. Coated bottles, protective designs, and improved handling characteristics can shift purchasing conversations toward operational outcomes. This trend creates opportunity for manufacturers that can demonstrate measurable benefits in safety and lifecycle performance, especially where laboratory staffing constraints, training variability, or high-throughput handling increase exposure to breakage and handling errors.
Trend 3: Digital Traceability and Procurement System Integration
QR-enabled identification, updated product catalogs, and improved traceability are early indicators of a broader move toward inventory digitization and audit-readiness. As laboratories seek faster verification, clearer lot history, and easier integration with procurement and inventory systems, suppliers that provide machine-readable identification and well-structured product data will reduce administrative burden and improve buyer confidence. This trend is particularly relevant for recurring procurement programs, multi-site institutions, and regulated settings where documentation continuity matters. The opportunity lies not only in labeling, but in supporting buyers with data consistency, clear product hierarchy, and compatibility with modern procurement workflows.
Risks and Uncertainties to Monitor
Several risks could temper or redirect these trends. Regulatory and standards implementation can vary by region and by procurement cycle, creating uneven adoption timelines. Raw material and energy cost volatility may pressure margins, particularly for producers with limited pricing flexibility or high exposure to energy-intensive forming processes. Reimbursement and procurement structures in diagnostic and clinical service settings remain complex, which can obscure demand signals and slow purchasing decisions. In addition, the fragmented portion of the market can intensify price competition, especially where differentiation is limited to specification parity and brand recognition. Companies that fail to strengthen traceability, documentation, and safety value propositions may find themselves competing primarily on price in an increasingly demanding specifications environment.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Owners
Strengthen the link between product design and compliance readiness. Where measurement-critical items are concerned, investment in process control, inspection discipline, and conformity documentation can reduce friction in regulated procurement and improve repeat-order reliability. Equally important is the differentiation path beyond base specifications: safety coatings, handling improvements, traceability features, and application-specific geometries can shift purchasing conversations toward operational value. Manufacturers should also evaluate regional certification expectations and determine where local compliance, service responsiveness, or cost-positioning can open access to growing demand centers. Participation in major industry exhibitions and consistent product demonstration can reinforce visibility, but the durable advantage will come from repeatable conformance, clear documentation, and the ability to reduce buyer risk across the ordering and use cycle.
For Investors and Strategic Allocators
Evaluate exposure through the lens of specification integrity, regional capacity, and value-added differentiation rather than aggregate volume alone. Segments tied to precision measurement, safety-enhanced products, and traceability-enabled catalog systems are likely to see stronger demand resilience because they address compliance, handling risk, and procurement efficiency. It is also important to assess the regional balance of demand and production capacity, since energy intensity, raw material access, and logistics can shape margin durability. Companies that combine stable production quality with clear documentation and differentiated product features may offer more defensible positioning than those reliant on undifferentiated commodity supply. In addition, investors should monitor how reimbursement and procurement structures evolve in diagnostic-linked settings, since those frameworks influence demand timing even when the product itself is not directly coded.
For Procurement Leaders and Laboratory Operators
Expand evaluation criteria beyond unit price to include specification conformance, documentation completeness, handling safety, and traceability support. In precision-sensitive workflows, the cost of measurement uncertainty, replacement delays, and compliance friction can outweigh small differences in list price. Suppliers that provide clearer product identification, reliable conformity evidence, and efficient replenishment processes can reduce administrative burden and improve continuity. Procurement teams should also consider total cost of ownership when breakage, handling risk, and replacement frequency are material, since safety-enhanced options may lower downstream disruptions even if upfront pricing differs. Where multi-site or regulated environments are involved, standardized product data and traceable lot management can simplify audit preparation and inventory control.
From Insight to Execution
The laboratory glassware market is moving from a period of steady expansion to one where differentiation is increasingly determined by precision discipline, safety enhancement, traceability readiness, and regional execution. The baseline growth trajectory remains constructive, but the more valuable question for decision-makers is not whether the market will continue to grow, but which capabilities will earn preference as specifications tighten and procurement becomes more documentation-driven. Manufacturers that align product development with standards expectations, reinforce material and process consistency, and reduce operational friction for buyers can convert market-wide growth into share gains. Investors and procurement leaders, meanwhile, can use these signals to prioritize exposure, negotiate with clearer evaluation criteria, and reduce hidden cost risks in precision-sensitive workflows.
Worldwide Laboratory Glass Container Market
For organizations that need a granular view of regional demand splits, product-type dynamics, application-level consumption patterns, and company-specific competitive positioning, a more detailed research view can help translate these high-level trends into segment-specific strategy. Access to the full breakdown supports scenario planning, sourcing decisions, and portfolio prioritization with finer granularity than is possible in a market overview alone.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LPO Market at 22.91% CAGR: What’s Really Driving the $125.85B Surge to 2032
By PW Consulting, 2026-09-21
The Legal Process Outsourcing Market: Strategic Shifts and Growth Horizons (2025–2032)
The legal process outsourcing (LPO) sector has transitioned from a cost-arbitrage experiment into a core operational function for corporations, law firms, and compliance teams worldwide. Over the past five years, the market has demonstrated consistent expansion, with revenues climbing from approximately 11.0 billion USD in 2020 to nearly 30 billion USD by 2025. The trajectory continues upward, with annual growth momentum expected to push the sector past 125 billion USD by 2032. At a compound annual growth rate of roughly 22.9 percent across the 2026–2032 forecast window, LPO is outpacing many adjacent professional services categories, reflecting a structural recalibration of how legal work is sourced, managed, and delivered.
This growth is not merely a function of volume expansion. It reflects a deeper transformation in how organizations approach legal capacity, regulatory complexity, and technology integration. For executives, investors, and procurement leaders, the LPO landscape now offers a mix of established scale players, specialized capability providers, and emerging technology-driven models. Navigating this environment requires a clear understanding of where value is being created, where operational friction persists, and which strategic moves are separating consistent performers from the rest of the field.
Healthcare BPO Market
Market Realities and Core Challenges
The LPO market has reached a scale where traditional outsourcing playbooks no longer apply uniformly. Organizations today are leveraging external legal operations for everything from high-volume document review to regulatory monitoring, contract lifecycle management, and specialized intellectual property support. The breadth of services has expanded significantly, and the revenue base now spans multiple service categories with varying maturity levels. Litigation support and e-discovery workflows remain a substantial portion of the service mix, while contract management, regulatory and compliance services, and legal research functions have grown in strategic importance as internal legal teams face increasing workloads and tighter budgets.
Despite the strong growth profile, the industry faces several structural challenges that will shape its next phase of development.
- Quality and consistency at scale. As volumes increase and service delivery crosses multiple jurisdictions, maintaining consistent quality standards becomes more difficult. Legal work is inherently high-stakes, and errors in contract review, compliance monitoring, or discovery processes can carry significant financial and reputational consequences. Vendors must balance speed and cost efficiency with rigorous quality controls, which often requires layered review processes, specialized training, and robust performance metrics.
- Data security, privacy, and cross-jurisdictional compliance. Legal outsourcing frequently involves transferring sensitive information across borders, which introduces regulatory complexity. Data protection requirements, industry-specific confidentiality obligations, and evolving cross-border data transfer rules create operational hurdles for providers and clients alike. Delivery models must be designed with security architecture, access controls, and compliance monitoring built in from the start rather than treated as add-ons.
- Talent availability and capability gaps. The LPO sector depends on a blend of legal knowledge, process discipline, and increasingly technical skills. Demand for professionals who can operate across legal workflows, data analytics, and AI-assisted tools is rising, but supply remains uneven across regions. Provider organizations that can develop, retain, and continuously upskill talent gain a meaningful advantage, while those relying on purely labor-cost arbitrage face growing pressure as automation absorbs more routine tasks.
These challenges are not static barriers; they are becoming strategic differentiators. Providers that design their operating models around quality assurance, secure data handling, and talent development are better positioned to capture higher-value work, while those that compete primarily on price are likely to face margin compression and client churn as buyers become more sophisticated.
Core Drivers Reshaping the Market
The expansion of the LPO sector is being driven by a combination of technological, regulatory, demand-side, and cost-structure forces. These drivers interact with one another, creating feedback loops that accelerate adoption in certain segments while reshaping competitive expectations across the broader market.
Technology Innovation as a Core Enabler
Artificial intelligence and automation are no longer peripheral tools in legal operations; they are increasingly embedded in how work is scoped, executed, and reviewed. Machine-assisted document review, contract analysis, legal research, and compliance monitoring are reducing turnaround times and allowing provider teams to focus on higher-judgment tasks. The shift is not simply about replacing manual effort. It is about re-architecting workflows so that technology handles the repetitive, high-volume components while human expertise is applied where nuance, interpretation, and client-specific context matter most.
Recent industry activity illustrates how seriously providers are investing in this direction. Several leading firms have moved to strengthen their AI-enabled service lines and data capabilities, integrating legal operations support with more advanced analytics, contract management platforms, and compliance workflows. In parallel, partnerships aimed at deploying end-to-end platforms with stronger security and compliance controls are becoming more common, particularly where cross-border data handling is involved. These moves signal that technology is now a competitive baseline rather than a differentiator reserved for a few early adopters.
Regulatory Complexity and Monitoring Demands
The regulatory environment for large corporations and regulated industries continues to become more demanding. Environmental, social, and governance expectations, data privacy regimes, sector-specific compliance obligations, and cross-border operational requirements have all increased the volume and urgency of legal and compliance work. This is pushing organizations to seek external support not only for episodic litigation or transaction work, but also for ongoing monitoring, reporting, and risk management.
A notable example is the introduction of managed services focused on ESG compliance, including real-time regulatory monitoring and reporting. Such offerings reflect a broader trend: clients increasingly want continuous, structured support rather than ad hoc project-based assistance. As regulatory expectations become more dynamic, providers that can combine legal knowledge with operational monitoring and reporting capabilities are well placed to capture recurring revenue streams.
Demand-Side Shifts in Legal Capacity and Procurement
Internal legal departments are under growing pressure to manage expanding workloads with constrained headcount and budgets. At the same time, corporate procurement and legal operations teams are becoming more deliberate about how they source external support. The conversation has evolved from simple cost reduction to total value, including speed, quality, predictability, security, and the ability to scale up or down as needs change. This has encouraged a shift toward managed services and longer-term partnerships rather than one-off engagements.
The result is a more diverse buyer profile. Some organizations are building hybrid models in which internal teams oversee strategy and high-judgment work while external providers handle volume-driven processes. Others are using LPO providers to fill capability gaps in specialized areas, such as multilingual litigation support, intellectual property analytics, or jurisdiction-specific compliance. In both cases, the common theme is flexibility: buyers want providers who can adapt to changing caseloads, regulatory demands, and internal priorities without sacrificing control or consistency.
Cost Structure and Delivery Model Evolution
Cost remains a foundational driver, but the way cost advantage is achieved is changing. Pure labor-cost arbitrage is increasingly insufficient in segments where quality, turnaround speed, and technology integration matter most. Providers are restructuring delivery around a blend of onshore, nearshore, and offshore locations, with secure facilities and specialized centers supporting specific legal domains or jurisdictional requirements. This geographic diversification helps manage cost while also addressing data residency, language, and legal system familiarity.
At the same time, operational efficiency is being improved through process standardization, workflow automation, and better portfolio management. Organizations that treat legal outsourcing as a managed operation—complete with governance, performance tracking, and continuous improvement—are more likely to realize durable savings and service reliability than those that rely on transactional, project-by-project purchasing.
Competitive Landscape and Leading Strategies
The LPO market remains moderately fragmented, with the top three providers accounting for a combined share in the high twenties and the top five reaching just over a third of total market revenue. This structure implies that while scale players have meaningful presence, there is still substantial room for specialization, regional strength, and capability-based differentiation. The competitive dynamic is less about a single dominant model and more about how providers combine scale, technology, domain expertise, and delivery footprint.
Strategic Positioning Among Key Players
Several established providers illustrate different pathways to competitive advantage.
- Integreon Managed Solutions has focused on AI-powered legal operations support spanning contract management, document review, legal research, and compliance services. Its recent strategic collaboration with PwC for legal managed services in the EMEA region, along with the opening of a new secure delivery center in Cape Town to support offshore outsourcing with an emphasis on English common law jurisdictions, reflects a strategy centered on both geographic expansion and partnership-driven scale.
- Elevate Services has positioned itself around AI-powered legal services that include litigation support, contract management, legal operations consulting, and managed services. Its acquisition of a specialist in Chinese, Japanese, and Korean language support for litigation, together with a legal data and AI consulting company, demonstrates a push to deepen multilingual capability and data/AI advisory strength in a single move.
- QuisLex has built its offering on managed services for document review, contract management, compliance, litigation support, and legal spend optimization. Its launch of a managed service focused on ESG compliance with real-time regulatory monitoring and reporting shows an effort to move beyond traditional litigation-support work into recurring, compliance-driven engagements.
- Epiq Global continues to emphasize technology-enabled legal and compliance services, including e-discovery, class actions, bankruptcy, and outsourcing for law firms and corporations. Its profile reflects the importance of scale infrastructure and specialized case-type expertise in high-volume, process-intensive work.
- Axiom Law has carved out a position around on-demand legal talent, secondments, and AI-enabled services supporting in-house legal teams and complex projects. This model highlights the value of flexible talent deployment and close integration with internal legal functions, especially for organizations that want external support without fully handing off operational control.
- UnitedLex has focused on data-driven legal and litigation support services, including e-discovery, patent analytics, and case management. Its strategic partnership with a major cloud provider to deploy an advanced end-to-end e-discovery platform with enhanced data security and cross-border compliance capabilities underscores the increasing importance of secure technology infrastructure in competitive positioning.
How the Landscape Is Evolving
Three patterns are evident in the current competitive environment.
- Capability-driven consolidation. M&A and strategic partnerships are being used to add multilingual capacity, data and AI consulting, and broader managed-service portfolios. This suggests a market in which buyers increasingly want integrated solutions rather than narrow point services.
- Geographic and jurisdictional specialization. Providers are expanding or refining delivery centers to align with common law frameworks, language requirements, and regional compliance expectations. This reflects a recognition that legal outsourcing is not a uniform global service; jurisdictional familiarity and data handling rules shape where and how work can be performed.
- Platform and security as competitive foundations. Partnerships and platform investments focused on secure, end-to-end processing are becoming more prominent, particularly for e-discovery and other data-sensitive workflows. In a market where information security and regulatory compliance are central concerns, technology infrastructure is increasingly part of the value proposition rather than a back-office utility.
For new entrants, the bar is rising. Pure cost-based entry is harder to sustain as automation reduces the advantage of low-cost labor alone, and buyers are more capable of evaluating quality, security, and service design. New players that can bring specialized domain expertise, strong technology integration, or a clear regional and jurisdictional fit have a more credible path than those offering only generalized volume services.
Forward Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape how the LPO market develops and where commercial opportunities emerge.
AI-Embedded Legal Operations Become Standard Configuration
The integration of AI and automation into legal workflows is expected to deepen, moving from selected use cases to broader operational baselines. Document review, contract abstraction, legal research, compliance monitoring, and matter management are all candidates for increased automation, with human reviewers focusing on exception handling, strategic judgment, and client-specific interpretation. For providers, this trend creates opportunities to redesign service offerings around technology-assisted efficiency, predictable turnaround times, and measurable quality outcomes. For buyers, it opens the possibility of scaling legal support without proportionally increasing headcount, provided vendor selection emphasizes workflow design and governance rather than tool presence alone.
Compliance and ESG-Linked Services Grow as Recurring Revenue Engines
As regulatory expectations continue to expand, managed services tied to regulatory monitoring, compliance reporting, and ESG-related obligations are likely to become more prominent. Unlike episodic litigation or transaction support, these engagements can create more predictable, recurring demand. Providers that can combine real-time monitoring, structured reporting, and cross-functional coordination with legal and compliance teams are well positioned to capture this demand. For enterprises, the opportunity lies in moving from reactive compliance support to continuous operational oversight, reducing the risk of late responses to regulatory changes and improving internal accountability.
Regional Rebalancing and Jurisdiction-Focused Delivery Models
The geographic distribution of LPO activity is expected to remain dynamic. While some regions already account for a substantial share of market activity, others are positioned for faster growth during the forecast period as legal demand, regulatory complexity, and delivery infrastructure evolve. Western Europe, for example, is widely expected to emerge as one of the fastest-growing regions during the forecast window, reflecting expanding compliance needs and increasing adoption of external legal operations support. At the same time, Asia Pacific continues to hold a leading share, underscoring the region’s established role in global legal service delivery. For providers, this environment favors deliberate investment in regional capabilities, language coverage, and jurisdiction-specific expertise. For buyers, it creates options for aligning delivery location with legal framework familiarity, data residency requirements, and cost considerations.
Legal Practice Management Software Market
Risks and Uncertainties to Monitor
Despite the strong growth outlook, several uncertainties could affect the pace and shape of market development. Regulatory changes around data transfer, privacy, and cross-border operations may increase compliance costs and slow certain delivery models if requirements become more restrictive. Security incidents or quality failures in high-stakes legal work could also shift buyer caution and raise due-diligence requirements. In addition, rapid automation could compress margins for providers that have not reinvested in workflow redesign, talent development, or higher-value service capabilities. Finally, macroeconomic fluctuations may influence how aggressively organizations expand external legal support, even if the underlying structural drivers remain intact.
Implications for Decision-Makers
The current LPO environment rewards deliberate strategy over reactive purchasing. Executives, investors, and procurement leaders each face a distinct set of priorities, but all benefit from a clearer view of where the market is heading and how to position accordingly.
For Corporations and Legal Operations Leaders
- Move from project-based buying to managed service design. Where possible, structure engagements around governance, service-level expectations, quality metrics, and continuous improvement. This reduces variability and makes it easier to scale support as workload fluctuates.
- Define security and compliance requirements before sourcing. Data handling, jurisdiction, access controls, and reporting expectations should be part of the initial scoping process, not negotiated after the fact. Providers with built-in secure infrastructure and cross-border compliance capabilities will be easier to integrate into sensitive workflows.
- Use external support to build capability, not just capacity. The most valuable engagements often combine volume handling with knowledge transfer, process improvement, and access to specialized expertise. This helps internal teams evolve while maintaining strategic control over high-judgment work.
For Investors and Strategic Allocators
- Focus on models with durable differentiation. Sustainable advantage is increasingly tied to technology integration, quality systems, multilingual and jurisdiction-specific capability, and recurring compliance-oriented services rather than labor-cost advantage alone.
- Watch consolidation and partnership activity as signals. Acquisitions and collaborations that add language coverage, data and AI advisory strength, or platform security capabilities often indicate where the market is heading and which capability gaps are being closed.
- Evaluate exposure to regulatory-driven demand. Segments tied to ongoing compliance monitoring, ESG reporting, and data-sensitive discovery workflows may offer more predictable demand profiles, though they also carry higher expectations for security, accuracy, and operational discipline.
For Procurement and Sourcing Professionals
- Evaluate total value, not just unit cost. Speed, quality, security, scalability, and the ability to manage changing requirements can matter as much as price, especially in complex or high-volume legal work.
- Build vendor portfolios by capability, not by brand alone. Different providers are stronger in different areas, such as litigation support, contract management, IP analytics, or compliance monitoring. A diversified sourcing approach can match work types to the most suitable providers.
- Embed performance management into ongoing relationships. Regular review of quality, turnaround, cost predictability, and security compliance helps maintain alignment and reduces the risk of service drift over time.
Conclusion
The legal process outsourcing market is entering a phase defined by greater technological integration, more demanding compliance expectations, and a growing preference for managed, scalable service models. Growth momentum remains strong, but the competitive edge is shifting toward providers that can combine secure infrastructure, quality assurance, jurisdictional awareness, and AI-enabled workflows with the ability to support recurring legal and compliance needs. For organizations seeking to use LPO strategically, the priority is no longer simply finding lower-cost support. It is selecting partners and service designs that improve speed, control, and resilience while allowing internal teams to focus on the work that most requires judgment and accountability.
PW Consulting
For decision-makers needing a more detailed view of service-line dynamics, regional trajectories, competitive positioning, and custom sourcing implications, the full research report provides a deeper breakdown of market segments, company-level developments, and forward scenarios. It is designed to support more granular planning, from service portfolio design and vendor evaluation to investment prioritization and risk assessment.
For detailed analysis of this topic, please visit the official page: Legal Process Outsourcing (LPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fresh Meat Packaging Market: How 5.12% CAGR and Plastic Dominance Are Redefining the $5.79B Landscape
By PW Consulting, 2026-09-21
The Fresh Meat Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Defining Challenges
The global fresh meat packaging market has evolved from a commoditized segment into a strategically contested arena where material science, regulatory compliance, and supply chain resilience intersect. Historical trajectory from 2020 through 2025 demonstrates consistent expansion, anchored by steady volume growth in developed retail channels and accelerating modernization in emerging distribution networks. The baseline year value reached approximately 4.09 billion USD, representing a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast horizon. This trajectory projects revenue climbing toward 5.79 billion USD by 2032, signaling a market that is expanding at a measured but structurally significant pace.
Several structural headwinds define the current inflection point. First, the gap between conventional plastic-dependent formats and rapidly evolving recyclability mandates creates a compliance-cost squeeze. Processors and converters must balance shelf-life performance with design-for-recyclability requirements that increasingly dictate fee structures and market access. Second, raw material volatility has shifted from a cyclical nuisance to a persistent margin pressure. Limited availability of key polymer resins has elevated input costs for trays and films, pushing converters and brand owners to evaluate alternative material pathways that can maintain barrier properties while improving end-of-life outcomes. Third, retail and foodservice procurement models are fragmenting. Case-ready and centralized packaging specifications vary significantly across geographies and retailer tiers, forcing suppliers to navigate a maze of performance, sustainability, and footprint requirements simultaneously.
Vacuum Skin Packaging Market
These challenges are not isolated. They interact to reshape cost structures, dictate formulation and tooling investments, and influence where competitive advantage can be sustained. Companies that treat packaging as a performance and compliance layer rather than a disposable cost center are better positioned to navigate the transition ahead.
Core Drivers Reshaping the Market
Material and design innovation remains the primary engine of differentiation. Mono-material architectures and recyclable polymer structures are advancing rapidly, driven by the need to maintain oxygen and moisture barriers while simplifying downstream sorting and recycling streams. Vacuum skin packaging continues to evolve with tighter film tolerances and integrated equipment logic, enabling retailers to standardize display readiness while extending case life. The shift toward paper-based and fiber-reinforced formats is gaining commercial traction where fresh meat applications demand reduced plastic load and clearer recyclability claims. Innovations in heat-sealable membranes, die-cut lids, and preformed trays are narrowing the historical performance gap between conventional and sustainable formats, creating more options for processors seeking to balance cost, protection, and compliance.
Regulatory momentum is accelerating the pace of change. Extended producer responsibility frameworks are expanding across multiple jurisdictions, with several U.S. states now embedding recycled content and recyclability-based fee schedules that directly affect packaging economics. In parallel, European requirements are reinforcing design-for-recyclability expectations and minimum recycled content thresholds for plastic packaging. These mandates are not static footnotes; they alter the total cost of ownership for packaging portfolios and create financial incentives for early adopters of compliant materials and designs. Producer fees tied to recyclability performance are increasingly influencing sourcing decisions, particularly for high-volume formats such as trays and films used in beef, poultry, and seafood categories.
Pet Food Packaging Market
Demand-side behavior is reinforcing the material transition. Consumers continue to prioritize freshness visibility, portion clarity, and label legibility, while retailers are under growing pressure to demonstrate shelf-level sustainability credentials without compromising product integrity. Processors are responding by standardizing case-ready formats that reduce handling and improve throughput, while also aligning packaging specifications with retailer sustainability scorecards. The result is a more demanding specification environment where protection, presentation, and post-consumer outcomes must be optimized together rather than in sequence.
Cost and supply chain dynamics are reshaping sourcing strategies. Resin availability constraints have elevated film and tray costs, accelerating evaluation of recycled content and alternative materials. At the same time, processing-side efficiency opportunities are attracting attention; adjustments to slaughter line speeds and throughput logistics can unlock meaningful cost savings for meat operations over multi-year horizons, indirectly influencing the packaging specification conversation by altering the cost context in which packaging decisions are made. Companies are increasingly weighing packaging investments against broader operational levers, recognizing that packaging performance and processing efficiency are linked in total landed cost and service reliability.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leaders differentiating through material portfolios, equipment integration, and regional manufacturing footprints. Amcor has built a position around responsible and recyclable flexible and rigid solutions, emphasizing mono-material films and trays tailored to fresh meat applications. Sealed Air maintains a strong presence through specialized vacuum skin packaging, preformed trays, and integrated automation that supports case-ready workflows for beef, pork, lamb, and poultry. Berry Global pursues next-generation vacuum skin and sustainable flexible solutions, focusing on shelf-life extension and improved recyclability profiles.
Regional and fiber-oriented players are expanding the strategic options available to buyers. Pactiv Evergreen continues to serve processors and retailers with foam trays, films, and case-ready solutions that prioritize display readiness and throughput. Huhtamaki emphasizes sustainable fiber-based and flexible packaging, aligning fresh meat applications with evolving recyclability expectations. Mondi has moved aggressively in paper-based mono-material and pulp solutions, pairing tray and film innovations with targeted partnerships and acquisitions that expand production capacity in key regions. Winpak rounds out the flexible segment with heat-sealable membranes, die-cut lids, and processing-focused flexible formats. Sonoco contributes paperboard trays, tubes, and composite packaging, while Coveris has expanded its portfolio across paper-based and flexible sustainable solutions, including dedicated fresh meat ranges and new vacuum skin packaging capacity. Edelmann rounds out the landscape with high-performance packaging solutions and facilities oriented toward fresh meat products.
Recent moves highlight how incumbents are translating strategy into capability. Mondi partnered with Scan Sverige to advance recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to compliance and performance. In parallel, Mondi completed the acquisition of a pulp mill in Alberta to strengthen sustainable paper-based packaging capacity for North America, illustrating how vertical capacity can be used to secure supply and regional relevance. Coveris introduced a fully recyclable paper-based flexible packaging range for fresh meat and expanded a vacuum skin packaging facility in the UK, reflecting coordinated investment in both material innovation and manufacturing scale. These actions suggest a market where differentiation is increasingly built on material architecture, regional capacity, and the ability to deliver compliant solutions without sacrificing barrier or presentation performance.
The landscape is evolving through both consolidation and specialization. Large converters are broadening portfolios to capture cross-category volume and compliance advantages, while focused players are carving out niches around fiber-based solutions, advanced vacuum skin systems, and regional case-ready formats. New entrants are likely to appear where material innovation intersects with recycling infrastructure readiness, but scale, tooling, and qualification timelines continue to favor established players with proven supply reliability and retail relationships. Concentration among the top firms remains notable, yet the diversity of material pathways and regional demand patterns creates room for differentiated positioning rather than pure price competition.
Forward-looking Trends to 2030 and Beyond
The first trend is the broadening commercial viability of mono-material and recyclable structures for fresh meat. As design-for-recyclability expectations become embedded in procurement and compliance frameworks, formats that simplify sorting and improve recovery outcomes will gain preference in high-volume channels. This favors suppliers that can deliver barrier performance in mono-material architectures, supported by film and tray designs that meet both protection and circularity criteria. The commercial opportunity lies in standardizing these formats across retail ready lines and processor specifications, reducing complexity while improving compliance economics.
A second trend is the growing role of fiber-based and paper-forward solutions in select applications where plastic reduction and recyclability communication provide commercial value. These formats are advancing in areas where presentation, protection, and end-of-life messaging align with retailer and consumer expectations. The opportunity is not universal replacement; it is targeted deployment where fiber-based trays, films, and flexible ranges can meet performance thresholds and simplify sustainability narratives without compromising shelf life or handling efficiency. Success will depend on matching format to application, ensuring that barrier and structural requirements are met while leveraging recyclability positioning where it truly matters.
A third trend is the tightening linkage between packaging strategy and regional compliance economics. Producer responsibility fees, recycled content mandates, and recyclability rules are increasingly shaping total cost profiles and market access. Companies that anticipate these shifts and align material choices with local regulatory trajectories can reduce future rework, avoid fee exposure, and secure preferential positioning with sustainability-conscious buyers. The risk is regulatory fragmentation, where differing requirements across regions complicate portfolio standardization and increase qualification overhead. Firms that manage this tension through modular material platforms and region-specific compliance mapping will navigate the transition more efficiently.
PW Consulting
Potential uncertainties include raw material availability, which can shift the economics of polymer-based versus alternative formats faster than expected, and processing-side changes that alter the cost context of packaging decisions. If resin constraints persist or intensify, the pace of migration toward paper and recycled content could accelerate, while in a more benign supply environment the transition may unfold more gradually. Retail specification volatility and regional recycling infrastructure readiness also remain variables, meaning that the timing and scale of adoption will differ by market and application.
Implications and Action Points for Decision Makers
For packaging manufacturers and converters, the priority is to build material and format flexibility that can absorb regulatory and cost shifts without disrupting supply. Invest in mono-material and recyclable film and tray architectures that maintain barrier performance, and develop modular designs that can be tuned to regional recyclability rules and retailer specifications. Strengthen regional production or sourcing options where compliance economics and resin availability are likely to diverge, and align equipment and lines with formats that reduce qualification friction for case-ready and retail-ready workflows. Validate performance claims with rigorous shelf-life, sealing, and handling data so that sustainability positioning is credible and defensible.
For investors and corporate strategists, the market rewards exposure to companies with clear material-transition roadmaps, credible compliance positioning, and the capacity to execute across regions. Assess portfolios for diversification across plastic, paper-based, and flexible formats, and evaluate the quality of recent partnerships and capacity investments that secure supply and regional relevance. Weigh concentration dynamics against the opportunity set created by material innovation and regional compliance divergence. Focus on players that demonstrate both technical performance and the operational discipline to scale compliant formats without sacrificing service reliability.
For procurement leaders and retail or foodservice buyers, the strategic task is to align specifications with total cost, compliance exposure, and shelf impact rather than unit price alone. Standardize where possible to reduce complexity, but maintain application-specific flexibility for formats where protection and presentation requirements differ. Incorporate recyclability and recycled content expectations into sourcing criteria early, and map those expectations to supplier capability and regional infrastructure readiness. Communicate specifications clearly to reduce rework and qualification delays, and coordinate with suppliers on pilot programs that validate performance and compliance before broad rollout.
The trajectory of the fresh meat packaging market will be shaped by how effectively companies integrate material innovation, compliance strategy, and supply chain resilience. Detailed segmentation, regional dynamics, and scenario-level cost modeling can sharpen these decisions further, and the full PW Consulting research report provides the granular data and tailored analysis needed to translate these trends into concrete plans for specific business contexts.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Denim Jeans Market 2026: 5.8% CAGR and Strategic Shifts Reshaping Global Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Denim Jeans Market: A 2025–2032 Outlook
The global denim jeans market continues to demonstrate measured resilience, growing from 131.0 million USD in 2020 to an estimated 170.0 million USD in 2025. Over the historical period from 2020 to 2025, the category navigated pandemic-era disruptions, inventory corrections, and shifting consumer preferences, ultimately stabilizing at a pace that reflects both the durability of denim as a wardrobe staple and the structural adjustments taking place across sourcing and manufacturing. Looking toward the 2026–2032 forecast window, the market is projected to expand at a CAGR of 5.8 percent, reaching 252.0 million USD by 2032. This trajectory is not merely a function of population growth or rising disposable incomes; it reflects deeper changes in how denim is designed, produced, regulated, and valued by end users. For executives and investors, the central question is no longer whether denim will grow, but where value will crystallize in a market that is increasingly shaped by raw material volatility, regulatory scrutiny, and divergent consumer expectations across regions.
Market Snapshot and Core Challenges
The current market size reflects a category that has moved past the acute volatility of the early 2020s and is now operating in a more normalized but still complex environment. Revenue growth has been underpinned by steady end-use demand in casual wear, where denim remains a default choice for consumers seeking versatility, durability, and relative affordability. At the same time, the segment has seen gradual expansion in more structured applications and specialized fits, indicating that denim is no longer confined to a single occasion or silhouette. The 2025 baseline of 170.0 million USD sets the stage for a forecast period in which growth will increasingly depend on the ability of companies to manage cost pressures, navigate trade policy shifts, and respond to sustainability expectations without eroding margin or brand equity.
Three challenges stand out as particularly consequential for commercial planning. First, raw material dynamics are introducing renewed cost uncertainty. Each kilogram of cotton is projected to cost up to 1.75 USD in 2026, a 2.9 percent increase from prior forecasts, against a backdrop of a global cotton production contraction of up to 2 percent during the 2025–2026 season. This tightening supply environment pressures both fabric suppliers and finished-goods manufacturers, particularly those with thin pricing flexibility or limited access to alternative fibers. Second, trade policy and enforcement are reshaping sourcing calculus. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, creating a landscape where incremental cost adjustments can quickly alter the economics of established supply chains. Third, compliance risk is becoming a material commercial factor rather than a back-office concern. U.S. Customs and Border Protection issued a Withhold Release Order against Firemount Group Ltd. in November 2025, directing detention of denim jeans and apparel produced in Mauritius due to indicators of forced labor. This action, along with broader enforcement trends, signals that sourcing visibility and documented labor practices are now integral to market access, especially for companies selling into high-value Western markets.
Denim Market
Key Drivers Reshaping the Category
Technical innovation and product differentiation
Product-level innovation is moving from a peripheral creative exercise to a core commercial lever. The introduction of heavier, selvedge-inspired denim and customizable fits reflects a broader shift toward premiumization, where consumers are willing to pay for construction quality, longevity, and a more deliberate sense of style. In November 2025, Levi Strauss & Co. expanded availability of its Blue Tab premium line, featuring Japanese selvedge-inspired heavier denim jeans, to more stores for fall 2026. This move illustrates how established brands are using product architecture to protect margin and reinforce brand distinctiveness in a category that can easily slip into commodity competition. Alongside signature fits and heavier constructions, innovation is also occurring in fabric technology, where stretch formulations, regenerative inputs, and lower-impact processing are becoming differentiated selling points rather than niche add-ons.
At the fabric and materials level, circularity and regenerative approaches are increasingly embedded in commercially available offerings. Candiani Denim has built its positioning around high-end denim fabrics and jeans with a focus on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while maintaining supply chain relationships for fashion brands. In September 2025, Alberto Candiani x Velasca launched a new made-in-Italy denim capsule collection with customizable Millesimo fits, showing how premium Italian fabric competence can be paired with consumer-facing customization. Meanwhile, MUD Jeans specializes in premium circular denim jeans produced from post-consumer recycled jeans and emphasizes lower-impact production for men and women. These examples suggest that sustainability in denim is no longer a single message but a set of product and process choices that can be tailored to different price points, regions, and brand identities.
Regulatory and policy environment
Policy dynamics are exerting a direct influence on sourcing decisions, cost structures, and market access. The Withhold Release Order against Firemount Group Ltd. demonstrates how enforcement actions can alter the viability of specific suppliers and geographies in a short period. For vertically integrated manufacturers and importers alike, the implication is that documented supply chain transparency is becoming a commercial prerequisite, not just a reputational preference. This is reinforced by the broader regulatory environment around import duties. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, meaning that sourcing diversification and tariff-aware inventory planning are now central to operational resilience.
These regulatory pressures are interacting with the structural reality that many leading players already operate distributed, contract-based manufacturing models. Gap Inc. sources and offers denim jeans under Gap and Old Navy brands while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. H&M Group operates as an outsourced manufacturer of denim jeans for H&M and other brands, maintaining quarterly-updated supplier lists across 969 tier-1 factories primarily in Asia. In this context, regulatory exposure is not uniform across the industry; it varies by geography, tier of supplier, and the level of visibility a company has into its upstream operations. The practical effect is that policy risk is increasingly a selection criterion, influencing which partners are viable over a multi-year horizon.
Demand-side behavior and category evolution
Consumer demand in denim is bifurcating along two overlapping axes: value-driven volume and premiumized differentiation. Casual wear remains the dominant application, absorbing a large share of category revenue and providing a stable base for everyday fits, durable construction, and accessible pricing. Yet demand is also expanding in more formal and specialized applications, where denim is being repositioned for smarter occasions, structured silhouettes, and premium finishes. This is visible in the growth of formal wear applications and the increasing relevance of tailored denim within broader menswear and womenswear assortments. The commercial takeaway is that denim is no longer a monolithic segment; it is a set of sub-categories with different frequency patterns, margin profiles, and innovation requirements.
A second demand-side dynamic is the growing importance of transparency as a purchasing heuristic. Consumers and retail partners are increasingly attentive to where and how denim is made, particularly as sustainability claims become more scrutinized and as regulatory enforcement raises the stakes of opaque sourcing. This is not simply a matter of marketing language; it affects product design, material selection, factory relationships, and even the cadence of supplier disclosure. Companies that can credibly connect product attributes to process choices are better positioned to command price integrity and reduce the risk of reputational friction.
Supply chain and cost structure shifts
The cost environment is being reshaped by the combination of raw material projections, tariff exposure, and labor-related enforcement. With cotton projected to reach up to 1.75 USD per kilogram in 2026 amid a contraction in global production, fabric procurement will likely place upward pressure on input costs unless offset by efficiency gains, blend strategies, or alternative fiber adoption. At the same time, tariff conditions on key sourcing countries create a need for dynamic scenario planning. A 46 percent baseline scenario for Vietnamese imports and a 10 percent scenario for Turkish imports are not trivial adjustments; they can reallocate cost competitiveness across regions and alter the relative attractiveness of nearshore, offshore, and multi-country sourcing models.
Supply chain structure itself is also a strategic variable. Vertically integrated manufacturers such as Firemount Group Ltd. have historically offered the advantage of integrated control over production and logistics, with documented supply chain details supporting operational coordination. However, vertical integration does not insulate a company from enforcement actions or policy risk, as the November 2025 Withhold Release Order against Firemount Group Ltd. illustrates. For importers and distributors such as Denim and Beyond LLC, which handles U.S. distribution and import logistics for lines including Levi Strauss and Banana Republic, the challenge is to manage flow, visibility, and compliance without over-concentrating exposure in any single geography or supplier. The broader trend is toward more deliberate sourcing architectures, where redundancy, documentation, and trade-aware planning are treated as value drivers rather than overhead.
Competitive Landscape and Leading Strategies
The competitive structure of the denim jeans market remains relatively fragmented at the top, with no single company dominating total category revenue. The CR3 and CR5 concentration levels indicate that while large global players are influential, the market still accommodates a wide range of models, from premium brands and fabric specialists to vertically integrated manufacturers and circular denim specialists. This fragmentation is important because it suggests that leadership will be defined less by scale alone and more by the ability to combine product differentiation, supply chain resilience, and credible sustainability positioning.
Levi Strauss & Co. exemplifies a brand-led strategy built around design, marketing, and global sourcing, with contract manufacturers operating across more than 32 countries and supply chain transparency supported by an interactive supplier map. Its recent move to expand the Blue Tab premium line for fall 2026 underscores a strategy of using signature product tiers to reinforce brand equity and price integrity. Gap Inc. competes through brand portfolio breadth, using Gap and Old Navy to address a wide consumer base while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. This diversification is strategically meaningful because it provides flexibility in cost and geography, though it also requires disciplined supplier oversight. H&M Group operates at scale through outsourced manufacturing, maintaining quarterly-updated supplier lists across a large base of tier-1 factories primarily in Asia, which allows agility in assortment and production but also places a premium on continuous compliance monitoring.
Denim Fabric Market
A different set of strategies is emerging among specialists. MUD Jeans focuses on premium circular denim jeans produced from post-consumer recycled jeans, emphasizing lower-impact production for men and women. Candiani Denim has positioned itself at the fabric and premium jeans level, with emphasis on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while supplying fashion brands through its fabric capability. Firemount Group Ltd. has pursued a vertically integrated model with production in Mauritius and documented supply chain details, a structure that can support coordination and quality control but also concentrates regulatory exposure. Denim and Beyond LLC operates on the distribution and import side, handling U.S. logistics for established denim lines, which makes it sensitive to tariff and enforcement dynamics but less directly exposed to production-level sourcing decisions.
PW Consulting
These profiles point to a market that is simultaneously consolidating around scale and brand power while also fragmenting around specialization. New and specialist entrants can compete by owning a clear point of differentiation, whether that is circularity, premium fabric quality, customizable fits, or specific regional production advantages. At the same time, larger players are using product architecture, supplier diversification, and transparency tools to defend share and manage cost and policy risk. The most consequential evolution is not a single wave of consolidation, but a broadening of what “competitive advantage” means in denim: product credibility, sourcing visibility, tariff-aware cost design, and the ability to translate sustainability into tangible product attributes.
A practical illustration of the innovation ecosystem is the Denim Show, which returned to Pragati Maidan in New Delhi, India, offering a platform for denim brands to launch new products and explore innovation trends. Events of this kind matter because they concentrate fabric innovation, product launches, and supplier connections in one place, accelerating the spread of new fits, finishes, and process ideas across a globally connected supply base. For companies seeking to stay ahead of product cycles, these nodes of industry interaction are increasingly important complements to internal R&D and supplier development.
Outlook for the Next Three to Five Years
The first major trend is continued premiumization paired with fit and construction specialization. Heavier denim, customizable fits, and signature construction details are likely to become more important as brands search for ways to differentiate beyond price. This trend favors companies that can control quality, manage longer production runs of specialty items, and communicate product value in a way that resonates with consumers who view denim as an investment garment rather than a disposable commodity. The commercial opportunity lies in building product hierarchies that protect entry-level volume while creating higher-margin tiers with fewer direct comparability points.
The second trend is the institutionalization of circularity and lower-impact production as commercial norms rather than niche initiatives. As post-consumer recycled denim, regenerative cotton, and biodegradable stretch options become more available through suppliers such as Candiani Denim and MUD Jeans, brands will have more options to align product claims with demonstrable process choices. The opportunity here is twofold: brands can use material and process transparency to support price integrity, and fabric and mill specialists can become preferred partners for brands seeking credible differentiation. The risk is that consumer skepticism and regulatory scrutiny will increase alongside the number of sustainability claims, making verification, traceability, and consistent disclosure essential rather than optional.
The third trend is a more complex sourcing and compliance environment driven by tariff uncertainty and enforcement actions. Import duty dynamics affecting Vietnam and Turkey, together with enforcement measures such as the Withhold Release Order against Firemount Group Ltd., suggest that companies will need to treat trade and compliance planning as a continuous operational discipline. Over the next three to five years, sourcing portfolios that balance cost, geography, and documentation are likely to outperform those optimized primarily for unit cost. The associated opportunity is for suppliers and service providers that can help brands manage multi-country sourcing, audit readiness, and import logistics with greater predictability. The primary risk is that rapid policy shifts or enforcement actions can disrupt established supply paths faster than a company can replan, especially if visibility into tier-1 and upstream suppliers is incomplete.
A broader uncertainty to monitor is raw material supply. With cotton projected at up to 1.75 USD per kilogram in 2026 and global production contraction of up to 2 percent during the 2025–2026 season, the denim market could face periodic cost pressure that tests margin discipline and accelerates the adoption of blends, recycled content, or alternative sourcing strategies. The direction of this pressure will depend on weather, harvest outcomes, and broader commodity dynamics, but the prudent planning assumption is that input volatility will remain a recurring factor rather than a one-time event.
Actionable Priorities for Decision-Makers
For manufacturers and fabric producers, the immediate priority is to strengthen the link between product innovation and cost resilience. This means investing in specialty fits, premium constructions, and lower-impact material options while also building flexibility into sourcing and production planning. Companies that can offer regenerative cotton, recycled denim, or biodegradable stretch options with verifiable documentation will be better positioned to serve brands under pressure to demonstrate credible sustainability. Equally important is scenario planning for cotton costs and tariff exposure, so that pricing and capacity decisions are not made on the assumption of a stable input environment.
For investors, the opportunity is to evaluate denim businesses on the basis of differentiation quality, sourcing resilience, and compliance readiness rather than revenue scale alone. Brands and manufacturers with clear premium product tiers, documented supplier visibility, and diversified sourcing footprints are better equipped to navigate enforcement actions and tariff volatility. Specialist players with defensible circular or regenerative positioning can also offer attractive exposure to the growing demand for lower-impact denim, provided their claims are operationalized through product, process, and disclosure. The risk to watch is over-concentration in any single geography or supplier model without the documentation and contingency planning needed to respond to enforcement or trade changes.
For procurement and sourcing leaders, the priority is to treat transparency and geographic diversification as value-protecting disciplines. Tariff scenarios affecting Vietnam and Turkey, along with enforcement actions such as the Withhold Release Order against Firemount Group Ltd., make it prudent to map exposure, strengthen supplier documentation, and maintain alternatives across regions. Procurement teams should also align fabric and product decisions with consumer-facing claims, because the commercial value of sustainability positioning will increasingly depend on the credibility of the underlying process and supply chain evidence. In practical terms, this means more disciplined supplier audits, clearer traceability, and closer coordination between merchandising, compliance, and logistics functions.
For organizations seeking a deeper operational view, the full research report provides additional segmentation detail, company-level sourcing profiles, and scenario analysis that can support more precise planning. The market trajectory is clear enough to justify strategic action now, but the value of that action will depend on how well it is calibrated to product strategy, sourcing architecture, and regulatory exposure. Denim is entering a phase in which durable growth will belong to companies that can combine product credibility, resilient sourcing, and verifiable sustainability with disciplined cost management.
For detailed analysis of this topic, please visit the official page: Denim Jeans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polymer Capacitor Market at 8.2% CAGR: What 2032 Growth and Consumer Electronics Demand Really Signal
By PW Consulting, 2026-09-21
The Polymer Capacitor Market: Strategic Trends and Commercial Opportunities Through 2032
The global polymer capacitor market stands at a pivotal inflection point. From 2020 to 2025, total market revenue expanded from approximately 163.15 million to 215.0 million, reflecting steady growth across multiple end-use sectors. Looking ahead, the trajectory accelerates, with the market projected to reach 344.8 million by 2032, delivering a compound annual growth rate of 8.2 percent over the 2026 to 2032 forecast period. These numbers signal more than incremental expansion; they reflect a structural shift in how electronics manufacturers, automotive system designers, and industrial equipment engineers approach power management and signal integrity.
Beneath the headline figures lies a fragmented yet increasingly strategic competitive arena. The top three players collectively account for 24.6 percent of market revenue, while the top five capture 26.2 percent. This moderate concentration suggests room for differentiation, regional specialization, and technology-led positioning rather than pure scale dominance. For executives and investors evaluating the space, the question is no longer whether polymer capacitors will grow, but which sub-segments, applications, and supply chain strategies will capture disproportionate value as the market matures.
Market Dynamics and Structural Challenges
The polymer capacitor sector operates within a broader passive component ecosystem that is simultaneously experiencing demand surges, material constraints, and tightening qualification standards. Three interconnected challenges define the current landscape and will shape competitive outcomes over the next several years.
Balancing Miniaturization With Reliability Expectations
Design engineers across consumer electronics, automotive, and industrial applications continue pushing for smaller form factors while demanding higher ripple current tolerance, lower ESR, and extended operational lifespans. Polymer capacitors inherently address many of these requirements through conductive polymer electrolyte technology, but the pressure to reduce profile dimensions without compromising thermal stability or moisture resistance creates genuine engineering tension. Manufacturers that can deliver low-profile solutions while maintaining certification-ready performance metrics gain a clear advantage in qualification cycles and design-in opportunities.
PW Consulting Information & Electronics Research Center
Material Cost Volatility and Pricing Pressures
Cost structures across the passive component supply chain have faced sustained upward pressure, particularly in tantalum-based polymer lines. Industry pricing adjustments took effect in mid-2024 as manufacturers cited rising material input costs, and those dynamics have persisted into subsequent quarters. For product planners and procurement teams, this translates into longer hedging windows, tighter inventory buffers, and increased sensitivity to raw material availability. Suppliers with vertically integrated material strategies or diversified polymer formulations are better positioned to manage margin erosion while maintaining competitive pricing.
Qualification Rigor and Customer-Specific Validation Cycles
Automotive and high-reliability industrial applications now require stricter validation protocols. Compliance with AEC-Q200 qualification remains a baseline expectation for automotive polymer capacitors, ensuring consistent performance in electric vehicle power systems and related subsystems. Beyond automotive, industrial-grade polymer products increasingly face moisture-resistance benchmarking at elevated temperature and humidity conditions over extended durations. These qualification thresholds extend time-to-market for new part numbers and raise the barrier for generic commodity players. Companies that invest early in robust qualification dossiers and maintain transparent reliability data shorten customer design cycles and strengthen long-term supply agreements.
Supply chain timing further complicates planning. Across all capacitor technologies, average lead times have hovered around 19 weeks as of late 2025, reinforcing the importance of stable production scheduling and proactive capacity alignment. For buyers, this means demand forecasting and supplier diversification are no longer optional procurement best practices; they are operational necessities.
Core Drivers Shaping Market Trajectory
Several overlapping forces explain why polymer capacitors are capturing growing share across multiple end markets. Understanding these drivers helps decision-makers distinguish structural growth from cyclical demand swings.
Technology Innovation and Form-Factor Engineering
The most visible product-level evolution centers on profile reduction, thermal endurance, and ripple current performance. Recent commercial introductions illustrate how manufacturers are aligning advanced materials with application-specific constraints. In late 2025, Panasonic Industry began commercial production of conductive polymer tantalum solid capacitors with an industry-leading 3 mm profile, targeting USB Type-C power delivery architectures where space and current handling are equally critical. Around the same period, Taiyo Yuden commercialized hybrid aluminum electrolytic capacitor series engineered for higher rated ripple current and reduced profile, specifically addressing automotive ADAS and power steering applications. These launches reflect a broader pattern: manufacturers are not simply scaling existing designs, they are engineering product families around real-world system constraints such as board space, thermal environment, and power delivery topology.
Nichicon’s recent activity reinforces this trend from a thermal-reliability angle. The company introduced a highly heat-resistant conductive polymer hybrid aluminum electrolytic series capable of sustaining 4000 hours at 135°C, alongside automotive-rated hybrid capacitor series distributed across EMEA channels. High-temperature endurance directly supports automotive under-hood and near-power-electronics placements, where long-term degradation profiles determine component selection. Similarly, Nichicon’s broader portfolio emphasis on conductive polymer hybrid aluminum electrolytic and solid capacitors with elevated temperature ratings signals a strategy centered on reliability differentiation rather than cost-only competition.
Application-Side Demand Transformation
Consumer electronics remain the largest application anchor for polymer capacitors, driven by compact power systems, wireless charging, high-density motherboard designs, and ever-increasing power conversion requirements in portable devices. However, the most strategically significant demand shift is occurring in automotive electrification and advanced driver-assistance architectures. As vehicle power systems become more complex and electronics content per platform rises, polymer capacitors are increasingly integrated into DC-DC conversion stages, noise filtering networks, and decoupling arrangements that must tolerate fluctuating thermal and vibration environments.
Industrial automation, renewable energy inverters, and high-reliability infrastructure equipment also contribute to demand diversification. These sectors prioritize long service life, stability under continuous load, and qualification documentation over lowest-unit-cost sourcing. The result is a demand landscape that rewards suppliers capable of matching application-specific performance profiles, not merely volume capacity.
Regulatory, Qualification, and Standardization Pressure
Qualification frameworks and environmental reliability benchmarks increasingly shape purchasing decisions. AEC-Q200 continues to serve as the foundational reliability standard for automotive-grade polymer capacitors, while industrial product expectations have evolved toward stricter moisture and thermal endurance testing. These standards create a two-tier market dynamic: commodity-grade applications tolerate broader performance variance, while automotive and industrial buyers reward proven qualification records and traceable reliability data.
Standardization also influences supply chain behavior. When qualification requirements become more uniform across tier customers, manufacturers with established validation infrastructure gain efficiencies in documentation, testing throughput, and customer onboarding. Those without dedicated qualification capabilities face longer approval timelines and higher rejection risk, particularly in safety-related or mission-critical subsystems.
Supply Chain Resilience and Material Strategy
Recent pricing actions across tantalum-based polymer capacitors underscore the importance of material resilience. Rising input costs have prompted manufacturers to reassess sourcing strategies, formulation alternatives, and inventory positioning. At the same time, lead time elongation across capacitor technologies has reinforced the value of multi-source arrangements and forecast-aligned production planning.
For incumbent suppliers, the response has included hybrid capacitor architectures that combine conductive polymer benefits with aluminum electrolytic structural familiarity, offering a balance of performance and manufacturability. For buyers, this environment emphasizes the need to evaluate not only unit price but also manufacturing continuity, qualification coverage, and the supplier’s ability to sustain availability through cost cycles.
Competitive Landscape and Strategic Positioning
The polymer capacitor market features a mix of established Japanese manufacturers, U.S.-based specialty players, European component specialists, and Taiwan-based producers with regional manufacturing advantages. Despite moderate top-tier concentration, competitive differentiation is increasingly driven by product architecture, application targeting, and qualification readiness rather than broad commoditization.
KYOCERA AVX Components Corporation has positioned itself around conductive polymer solid electrolytic capacitors with notable attention to automotive and high-reliability segments. Its portfolio includes TCO and TCQ automotive series, high-reliability hermetically sealed polymers, and COTS+ military-grade tantalum polymer lines. This mix suggests a strategy that leans into reliability-grade differentiation and application-specific series development rather than volume-only competition.
Panasonic Industry Co., Ltd. maintains a broad polymer capacitor portfolio spanning conductive polymer aluminum electrolytic, tantalum solid, aluminum solid, and hybrid aluminum electrolytic capacitors. Its recent product activity emphasizes profile reduction for power delivery applications, aligning with consumer and computing trends that prize compact form factors without sacrificing current-handling capability.
Murata Manufacturing Co., Ltd. continues to leverage its broader passive component ecosystem, offering conductive polymer aluminum electrolytic and solid capacitors for automotive, industrial, and high-reliability applications. The company’s positioning benefits from integration with adjacent component categories and a strong design-in support structure across multiple end markets.
Nippon Chemi-Con Corporation has expanded its polymer capacitor emphasis through high-voltage series, liquid immersion cooling-oriented series, and hybrid models. The inclusion of high-voltage and cooling-specific product lines indicates attention to power electronics and industrial applications where voltage stress and thermal management are key selection criteria.
Nichicon Corporation has pursued a reliability-led strategy, highlighting conductive polymer hybrid aluminum electrolytic and solid capacitors with high-temperature ratings. Its recent automotive-rated series and heat-resistant product introductions reinforce a focus on application-grade durability, particularly relevant for automotive and industrial environments with sustained thermal exposure.
Rubycon Corporation and Lelon Electronics Corp. provide conductive polymer aluminum electrolytic solutions for general and automotive use. Their market roles illustrate how regional and mid-tier manufacturers compete by combining cost-competitiveness with targeted application support, rather than attempting to match the broadest portfolio breadth of larger incumbents.
Vishay Intertechnology, Inc. extends its presence through polymer tantalum and aluminum solid electrolytic capacitors for industrial, automotive, and aerospace applications. Its positioning reflects the demands of sectors where qualification rigor, material traceability, and reliability documentation carry significant commercial weight.
Würth Elektronik GmbH & Co. KG competes with aluminum polymer electrolytic capacitors and radial series, aligning with the broader European component distribution and design ecosystem. ROHM Co., Ltd. rounds out the competitive field with polymer tantalum and aluminum solid electrolytic capacitors following integration of related business assets, indicating continued consolidation and portfolio rationalization across the sector.
Several competitive themes emerge from this landscape. First, differentiation is shifting from generic capacitance ranges toward application-optimized families with defined thermal, profile, and ripple current characteristics. Second, hybrid architectures are gaining prominence because they combine polymer-level ESR and ripple performance with structural and manufacturing familiarity. Third, the market is unlikely to consolidate rapidly into a single dominant structure; instead, it will likely evolve into a tiered ecosystem where automotive and high-reliability applications favor qualified incumbents, while consumer and general-purpose segments remain more price-sensitive and accessible to multiple suppliers.
Recent product introductions also suggest that regional channel strategies matter. Automotive-rated series launched across EMEA channels highlight the importance of localized qualification support, distribution partnerships, and application engineering availability. Suppliers that can demonstrate consistent technical support across geographies are better positioned to secure design wins in regions where automotive and industrial sourcing decisions are highly relationship and qualification driven.
Forward Outlook: Trends and Opportunities Through 2032
Extrapolating current growth dynamics, qualification momentum, and product innovation patterns points to several interrelated trends that will shape commercial opportunities over the next three to five years.
Trend 1: Application-Specific Polymer Capacitor Families Will Displace One-Size-Fits-All Sourcing
As system designers face tighter thermal envelopes, higher power densities, and more demanding reliability thresholds, generic capacitor specifications will become less persuasive. Buyers will increasingly evaluate parts against application-level benchmarks such as thermal endurance, ripple current capability, profile constraints, and qualification documentation. Suppliers that publish clear application 매핑 and maintain robust reliability data will capture more design-ins, particularly in automotive and industrial segments where failure cost is high.
Commercial opportunity: Companies that invest in application engineering, reference designs, and qualification-ready documentation can shorten customer evaluation cycles and build longer-term supply relationships. This creates a defensible position even in a moderately concentrated market.
Trend 2: Hybrid and Advanced Polymer Formulations Will Broaden Performance Windows
Hybrid aluminum electrolytic structures and advanced conductive polymer formulations will continue to expand the balance between ESR reduction, temperature stability, and manufacturability. These architectures are particularly relevant where designers need polymer-level electrical performance without abandoning aluminum-based mechanical or cost advantages. The ongoing appearance of hybrid-oriented product launches supports the view that this direction is not a niche experiment but a mainstream performance strategy.
Commercial opportunity: Product planners should monitor hybrid and advanced polymer lines as potential candidates for next-generation power delivery, noise filtering, and decoupling designs. Early engagement with suppliers offering these architectures can provide first-mover advantages in demanding applications.
Trend 3: Automotive Electrification and High-Reliability Industrial Demand Will Drive Sustained Volume Growth, With Qualification as the Gatekeeper
Conductive Polymer Aluminum Solid Capacitors Market
The 8.2 percent CAGR projected through 2032 reflects more than cyclical replacement demand; it reflects a structural increase in electronics content across vehicles, industrial equipment, and energy-related infrastructure. Automotive platforms in particular will continue placing higher capacitor content per vehicle as power management architectures grow more decentralized and more performance-critical. At the same time, qualification requirements will remain the commercial gatekeeper, meaning that volume growth will disproportionately flow to suppliers with credible reliability records and efficient validation processes.
Commercial opportunity: Suppliers that build automotive and industrial qualification capabilities early can secure longer design cycles and multi-program visibility. For buyers, prioritizing qualification readiness and supply continuity over short-term unit cost can reduce downstream risk in safety-related or mission-critical designs.
Vacuum Capacitor Market
Risk and Uncertainty Considerations
Several uncertainties could alter this trajectory. Material cost volatility may persist, affecting tantalum-based and other polymer lines unevenly. Lead time normalization is not guaranteed; supply disruptions, capacity constraints, or sudden demand shifts could reintroduce planning friction. Qualification expectations may continue to tighten, compressing timelines for new entrants and rewarding incumbents with established testing infrastructure. Finally, competitive overcapacity in certain commodity-grade segments could pressure pricing, even as qualified automotive and industrial segments remain more resilient. Decision-makers should therefore treat the polymer capacitor market as a portfolio of differentiated sub-segments rather than a single homogeneous opportunity.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities in this environment. The following actions are designed to translate market dynamics into executable planning.
For Manufacturers and Component Suppliers
- Prioritize application-specific product families that address profile, thermal endurance, and ripple current requirements simultaneously rather than competing solely on capacitance range or unit cost.
- Strengthen qualification documentation and reliability data packages, especially for automotive and industrial customers where AEC-Q200 and extended environmental testing are baseline expectations.
- Evaluate hybrid and advanced polymer formulations as a way to expand performance differentiation while maintaining manufacturability and cost discipline.
- Align production planning and inventory strategy with current lead-time realities, and consider multi-source options where qualification and performance allow.
For Investors and Strategic Allocators
- Focus due diligence on suppliers with credible automotive and high-reliability qualification footprints, because those segments are likely to capture disproportionate value even in a moderately concentrated market.
- Assess exposure to material cost sensitivity and pricing actions across tantalum and aluminum polymer lines, and weigh vertical integration or formulation diversification as risk-mitigation indicators.
- Watch for portfolio consolidation and asset integration activity that may reshape competitive positioning, especially where adjacent business assets are combined to strengthen polymer capacitor capabilities.
For Procurement, Engineering, and Supply Chain Leaders
- Treat qualification status, thermal performance, profile constraints, and supply continuity as core evaluation criteria alongside price, particularly for automotive and industrial designs.
- Diversify approved sources where application requirements permit, while maintaining clear qualification thresholds to avoid fragmented validation burden.
- Engage suppliers early in the design phase to align on reliability testing, documentation, and lead-time expectations, reducing the risk of late-stage redesign or sourcing disruption.
The polymer capacitor market is expanding with clarity in direction but complexity in execution. Growth will continue toward 344.8 million by 2032, but the value capture will depend on how well companies align product engineering, qualification readiness, and supply resilience with the application needs that matter most. For organizations seeking deeper segmentation data, regional positioning detail, and tailored strategy recommendations, the full PW Consulting research report provides the granular breakdown and scenario analysis needed to convert these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


