



Fine Surface Oriented Strand Board FOSB Market: Why 5.85% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Fine Surface Oriented Strand Board (FOSB) Market: Navigating Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The Fine Surface Oriented Strand Board (FOSB) market has established itself as a significant segment within the broader wood-based panels industry, bridging the performance characteristics of traditional Oriented Strand Board (OSB) with the aesthetic and surface quality requirements of finer applications. Over the historical period from 2020 to 2025, the market demonstrated resilient growth, reflecting steady commercialization and increasing adoption across multiple downstream sectors. With the value expanding from approximately 939.85 million USD to 1250.0 Million in 2025, the sector has transitioned from a niche product to a recognized alternative to plywood, medium-density fiberboard (MDF), and particleboard in specific use cases. Projections for the forecast period 2026 through 2032 indicate sustained expansion, driven by broader structural demand for engineered wood products and the material's favorable strength-to-weight properties.
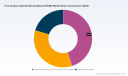
At the macroeconomic level, the market is characterized by a moderate consolidated structure. The top three firms hold a combined share of roughly 28.5 percent, while the top five account for about 39.2 percent of total revenue. This concentration suggests that while global capacity is distributed across multiple geographies, specialized FOSB production is still dominated by a limited number of players with the technical capability to produce fine surface layers at commercial scale. The forecast compound annual growth rate of approximately 5.85 percent through 2032 points to steady but not explosive expansion, implying that value creation will increasingly depend on differentiation, cost efficiency, and alignment with downstream application trends rather than pure volume scaling.
Despite the positive trajectory, the industry currently faces several structural challenges that are shaping competitive positioning. First, raw material security and adhesive cost exposure remain persistent concerns. FOSB production relies on specific feedstock profiles, often fast-growing eucalyptus or selected softwood strands, combined with resin systems that meet stringent surface and emission requirements. Fluctuations in wood supply dynamics and the cost of adhesives, which are influenced by petrochemical feedstock movements, introduce margin variability that producers cannot entirely pass through to downstream buyers.
Second, the market sits at a technical crossover point. FOSB must continuously justify its position against established substitutes such as MDF and high-grade particleboard, particularly in furniture manufacturing and interior finishing, where surface finish, machining behavior, and total installed cost are tightly evaluated. While FOSB offers structural advantages and surface quality improvements over standard OSB, the value proposition must be clearly articulated to specifiers and fabricators who are accustomed to traditional materials.
Third, regulatory and environmental expectations are becoming more granular across major end markets. Low formaldehyde emission classifications and other indoor air quality considerations are increasingly treated as baseline requirements rather than differentiators, especially in furniture and interior construction applications. Compliance is necessary, but it also compresses the space for premium pricing unless accompanied by genuine performance or process advantages.
Key Drivers Shaping the FOSB Market
The growth and evolution of the FOSB market are being shaped by a convergence of technological, regulatory, demand-side, and cost-structure developments. Understanding how these forces interact is essential for identifying where durable advantages can be built.
Technology and process capability remain the most distinctive driver. FOSB is not simply OSB with a cosmetic overlay; it typically integrates an OSB core with fine surface layers engineered for superior finish and structural properties. Producers investing in advanced continuous press technology and precision surface treatment are better positioned to deliver consistent panel quality, reduced variability, and surface characteristics that can compete with more traditionally processed boards. The move toward low-formaldehyde or formaldehyde-free adhesive solutions in selected product lines further illustrates how process innovation can simultaneously address performance, regulatory, and branding objectives. Where these technologies are deployed effectively, they enable FOSB to enter applications that previously favored MDF or laminated particleboard.
On the policy and regulatory side, emission standards and interior-use specifications are acting as both a constraint and an enabler. Low formaldehyde emission grades, such as E0 and E1 classifications, have become standard expectations in major markets for FOSB used in furniture and interior applications. Rather than being treated as optional premium features, these requirements are increasingly embedded in procurement specifications and building practices. This regulatory trajectory favors producers that have already integrated cleaner adhesive systems and quality control processes into their operations, while creating a barrier for capacity that cannot reliably meet tighter emission profiles at scale.
Demand-side dynamics are equally important and are shifting the center of gravity for FOSB adoption. Furniture manufacturing continues to represent a large end-use segment, where surface appearance, stability, and finish compatibility influence material selection. At the same time, construction and renovation activity sustains demand for panels that combine structural performance with improved surface qualities for exposed or semi-exposed applications. A smaller but meaningful portion of demand also comes from packaging and industrial uses, where board consistency and mechanical properties matter. What ties these segments together is a broader move toward engineered wood solutions that can reduce weight, improve dimensional stability, or offer more predictable machining behavior than conventional alternatives.
Cost structure and supply chain factors complete the picture. Wood-based panel economics are sensitive to feedstock availability, log and fiber pricing, energy costs, and resin markets. For FOSB, the use of fast-growing eucalyptus or selected softwood strands and the incorporation of specialized adhesives mean that procurement strategy is tightly linked to product positioning. Recent price signals for OSB and FOSB in key supply regions indicate a market where cost discipline matters, but where differentiation in surface quality and adhesive profile can still support value-based positioning. Producers that manage feedstock mix, press efficiency, and resin usage with greater precision are better insulated against input volatility and more capable of competing on quality rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in FOSB is defined by a mix of established OSB producers, regional specialists, and manufacturers actively expanding fine-surface capability. The strategic positioning of leading firms reflects different combinations of technology access, feedstock strategy, geographic presence, and application focus.
Strategic Positioning Among Core Players
PW Consulting Health Care Research Center
Fletcher Building is advancing a focused FOSB strategy that emphasizes the material's superiority over particleboard and MDF in targeted applications. Its planned CEBRO Fine OSB production at the Laminex Taupo site, supported by Dieffenbacher technology, signals an intent to move beyond conventional OSB into higher-value surface panels. The timeline for commissioning of the finishing line, followed by initial board production activity in 2026, indicates a deliberate ramp-up rather than an immediate volume play, consistent with a strategy centered on qualification, application development, and downstream acceptance.
In China, Luli Group represents a scale-oriented approach, with multiple fine OSB lines operational and expanded FOSB capacity coming online through additional fine-OSB lines. The company's emphasis on low-formaldehyde formulations and advanced continuous press technology reflects an alignment with furniture and construction requirements in domestic and export markets. This positions Luli as a player that can address volume demand while maintaining attention to surface and emission specifications.
GuangXi Dekek Group adopts a more specialized premium positioning. Its use of Dieffenbacher equipment, MDI adhesive options, and eucalyptus feedstock points to a product focus on fine surface panels for furniture and decorative uses. By concentrating on premium fine surface panels, Dekek illustrates how feedstock and adhesive choices can be combined with process technology to serve higher-specification end segments rather than competing primarily on commodity board characteristics.
West Fraser and Louisiana-Pacific contribute a different competitive logic. As large North American OSB manufacturers with broad structural and specialty panel portfolios, they bring extensive capacity, supply chain scale, and market access. Their relevance to FOSB lies partly in the structural OSB base that can support fine surface applications and engineered wood product development, offering the potential to leverage existing operational strengths while expanding into higher-value panel grades where requirements permit.
In Europe, Kronospan and Egger bring established wood-based panel expertise and broad construction and furniture market reach. Kronospan's capabilities in OSB with fine surface variants and Egger's wood-based material portfolio indicate that European producers are not merely following North American or Asian FOSB developments but are shaping their own product strategies around regional application needs, emission expectations, and finish requirements.
Market Evolution and Competitive Dynamics
The overall market structure suggests a landscape in transition. With the top five firms accounting for under 40 percent of revenue, there is room for both consolidation and specialist differentiation. New capacity additions in key producing regions indicate that growth is being pursued not only by incumbents expanding within existing footprints but also by producers building dedicated fine surface lines to capture specific application demand. This points toward a market that is likely to remain somewhat fragmented at the global level while becoming more concentrated within premium FOSB niches where technology, feedstock, and qualification matter most.
Competitive advantage is increasingly likely to come from three intertwined elements: the ability to deliver consistent fine surface quality at scale, the capacity to meet low-emission expectations without compromising cost, and the strength of application-specific relationships with furniture manufacturers, construction specifiers, and industrial buyers. Firms that treat FOSB as a distinct product category with its own technical and commercial requirements are better positioned than those that view it simply as a subset of general OSB production.
OSB Sheathing Market
Future Outlook: Trends and Opportunities
Looking ahead to the 2026-2032 period, several interconnected trends are likely to shape the FOSB market and define where commercial value accrues.
The first trend is the gradual narrowing of FOSB's application footprint around segments where its combination of surface quality and structural performance delivers a clear advantage. Rather than displacing all competing boards, FOSB is likely to gain traction in furniture parts, interior fit-out components, and certain construction applications where surface finish, stability, and machining behavior are critical. This selective adoption will reward producers that invest in application development and specifiers' education rather than relying solely on board-level marketing.
The second trend is the growing importance of adhesive technology and emission performance as baseline expectations. As low-formaldehyde and formaldehyde-free options become more common in premium FOSB lines, producers that can control resin usage, achieve consistent bonding, and document emission performance will be better equipped to serve regulated interior markets. This trend also creates opportunities for differentiation through product documentation, testing, and specification support, especially in markets where compliance is expected but implementation quality varies.
Oriented Strand Board (OSB) Market
The third trend concerns supply chain and cost management. With wood and adhesive inputs remaining sensitive to broader commodity dynamics, producers that optimize feedstock mix, press efficiency, and surface layer application are likely to manage margins more effectively. In parallel, regional pricing conditions will continue to influence competitive attractiveness across geographies, meaning that market entry and expansion decisions will need to account for local feedstock availability, logistics, and downstream pricing power.
These trends translate into tangible commercial opportunities. For producers, the opportunity lies in converting technological capability into recognized application fit, particularly in furniture and interior construction, where surface and emission attributes can support value-based positioning. For investors, the opportunity is to distinguish between capacity that is aimed at commodity substitution and capacity that is designed to serve premium fine surface demand with defensible technical and supply chain advantages. For procurement and specification teams, the opportunity is to use FOSB selectively where it reduces downstream processing cost, improves finished-product quality, or enables design choices that are harder to achieve with traditional boards.
Potential risks and uncertainties should not be overlooked. Substitution pressure from MDF, particleboard, and improved OSB grades remains real, particularly where FOSB does not offer a sufficiently compelling cost or performance advantage. Feedstock and adhesive cost volatility can compress margins if not managed proactively. In addition, regulatory expectations may continue to rise, shifting the baseline for what qualifies as acceptable performance and increasing the cost of non-compliance. These factors suggest that confidence in long-term FOSB growth should be paired with disciplined application targeting and cost control.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to define FOSB as a distinct product platform rather than a generic panel. This means aligning technology investment, feedstock strategy, and adhesive selection with specific end-use requirements, and building qualification and specification support that helps buyers understand where FOSB adds value. Producers that can demonstrate consistent surface quality, predictable emission performance, and reliable supply are better positioned to secure long-term relationships in furniture and interior construction segments.
For investors, due diligence should focus on the fit between capacity strategy and application reality. The most attractive opportunities are likely to be found where new lines are tied to clear downstream demand, supported by appropriate press and surface technology, and managed with cost structures that can withstand input volatility. Broader OSB capacity expansions should be evaluated separately from dedicated FOSB projects, since the commercial logic and risk profile differ meaningfully.
For procurement and specification teams, the practical path is to evaluate FOSB on a segment-by-segment basis, comparing total installed cost, finish compatibility, machining behavior, and compliance attributes against entrenched alternatives. Where FOSB offers a genuine combination of surface quality, structural performance, and supply reliability, it can be a constructive option; where it does not, traditional boards may remain the better choice.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, and company-level positioning, the full PW Consulting report provides structured detail and customized interpretation to support internal planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Fine Surface Oriented Strand Board (FOSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Nb Alloys Market: Why 7.03% CAGR and Asia Pacific's Rise Redefine Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Nb Alloys Market
The global niobium alloys market has demonstrated robust expansion over the past five years, driven by sustained demand from high-performance industrial sectors and critical infrastructure applications. Valued at approximately $530 million in 2020, the market reached $740 million by 2025, reflecting a compound annual growth rate that positions the sector for continued momentum through the end of the decade. Projections indicate that revenue will surpass $1.19 billion by 2032, underpinned by a steady growth trajectory of 7.03 percent annually. This expansion is not merely a function of macroeconomic recovery but stems from structural shifts in how advanced materials are specified, sourced, and integrated into next-generation engineering solutions.
At the heart of this growth lies a concentration dynamic that shapes both opportunity and vulnerability. The top three players control roughly 78.5 percent of market revenue, while the top five entities account for 86.2 percent, indicating a highly consolidated landscape where strategic positioning carries disproportionate weight. Such concentration reflects the capital-intensive nature of niobium extraction, refining, and alloy production, as well as the specialized technical expertise required to meet demanding application standards. For decision-makers, this means that supply security, qualification pathways, and long-term supplier relationships are not operational details but strategic imperatives.
Despite the favorable growth outlook, the industry stands at a critical juncture shaped by three interconnected challenges. First, raw material cost volatility has introduced margin pressure across the value chain. Ferroniobium pricing hovered around $42,500 per metric ton in 2023, driven largely by concurrent steel alloy demand, creating upstream cost fluctuations that cascade into downstream alloy formulations. Second, regulatory and compliance frameworks are tightening at a pace that requires proactive adaptation. Environmental and safety standards, particularly around mining operations and material purity thresholds, are reshaping permissible supply routes and adding complexity to qualification processes. Third, logistics disruptions have exposed fragility in export corridors. Port surcharges and routing inefficiencies have added 5-7 percent to export costs in certain periods, directly impacting landed costs for internationally sourced alloy feedstocks. Together, these forces demand that market participants move beyond passive procurement models toward more resilient, transparent, and strategically aligned sourcing architectures.
Key Drivers Shaping Market Trajectory
Technical Innovation and Material Performance Breakthroughs
The most compelling growth catalyst in the niobium alloys sector stems from continuous material science advancement. Niobium-titanium and niobium-zirconium systems remain foundational for superconducting applications, but recent engineering iterations have expanded their operational envelopes. The introduction of certified alloy variants tailored for high-field magnetic resonance imaging magnets exemplifies how incremental compositional optimization can unlock immediate commercial demand. When a supplier launches a formulation that meets stringent superconducting performance criteria while maintaining manufacturability, it does not merely add a product line; it opens a new procurement pathway for medical equipment manufacturers who require predictable electromagnetic properties at scale.
Beyond superconductivity, high-temperature stability and corrosion resistance continue to drive alloy development for extreme-environment applications. Sintered niobium composites and vacuum-remelted microstructures are increasingly specified for furnace components, sputtering targets, and chemical processing equipment where failure tolerance is non-negotiable. These technical improvements translate directly into longer service life, reduced maintenance cycles, and lower total cost of ownership for end users, which in turn reinforces repeat procurement and specification lock-in. The implication for commercial strategy is clear: differentiation is increasingly tied to validated performance data, certification readiness, and the ability to support engineering teams during material selection phases.
Policy and Regulatory Evolution
Regulatory dynamics are no longer peripheral considerations; they actively shape sourcing feasibility and market access. Environmental oversight of mining operations has intensified, with regulatory bodies mandating stricter tailings dam safety protocols following post-2022 audit cycles. While these measures improve long-term operational sustainability, they also compress short-term supply flexibility and elevate compliance costs for producers operating in affected jurisdictions. Simultaneously, chemical regulatory frameworks such as EU REACH impose material purity thresholds that restrict the use of niobium alloys containing certain impurity levels in consumer-facing applications. Such mandates do not shrink the market; rather, they redirect it toward certified, traceable, and technically compliant supply streams.
This regulatory tightening creates a bifurcation effect. Suppliers that invest early in documentation, purity control, and certification infrastructure gain preferential access to regulated markets, while those relying on ad hoc compliance face increasing friction. For procurement leaders, this means that supplier qualification cannot be reduced to price and lead time alone. Material traceability, regulatory alignment, and the ability to provide evidence of compliance are becoming table stakes in competitive bidding environments, particularly for medical, nuclear, and aerospace-grade applications.
Demand-Side Shifts in Critical Sectors
Demand growth is being shaped less by broad-based industrial expansion and more by concentrated, high-value application clusters. Aerospace and defense continue to represent the largest application share, reflecting the material's role in structural and propulsion components where weight-to-strength ratios and thermal performance are decisive. However, equally significant is the rising specification of niobium alloys in medical devices and superconductivity infrastructure, where precision, biocompatibility, and magnetic performance drive procurement decisions. Chemical processing and nuclear energy applications further contribute to demand stability, albeit at more niche volumes, by requiring alloys that withstand corrosive environments and radiation exposure without degradation.
What distinguishes the current demand cycle is the shift toward qualification-driven procurement. Engineering teams are increasingly reluctant to qualify new materials unless the supplier can demonstrate consistent microstructure control, reproducible mechanical properties, and robust quality management systems. This behavior does not slow demand; it concentrates it among suppliers that can offer verifiable technical endorsements. The commercial consequence is that market share expansion is becoming less about volume pricing and more about engineering trust, repeat qualification, and strategic co-development relationships.
Supply Chain and Cost Structure Dynamics
The niobium supply chain remains geographically concentrated, with Brazil accounting for the overwhelming majority of global mine production. This geographic concentration provides scale advantages but also introduces structural dependency on a limited set of mining and processing hubs. When coupled with export logistics friction, such as port surcharges and route disruptions, the result is a supply environment where cost predictability requires active risk management rather than passive contracting. Logistics exposure is not merely a transportation issue; it influences inventory strategy, regional buffer stocking, and the economics of local versus imported alloy forms.
Cost structures are also being reshaped by the interplay between ferroniobium feedstock pricing and downstream alloy conversion. Because a significant share of mined niobium flows into steel alloy applications, primary material pricing often reflects broader metallurgy demand rather than specialty alloy requirements alone. This dynamic means that specialty alloy producers must navigate upstream cost signals that are partially decoupled from their own demand cycles. Companies that secure long-term feedstock arrangements, optimize conversion yields, or integrate vertically where feasible are better positioned to maintain margin stability through price cycles.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation Pillars
The market's concentrated structure has produced a set of incumbents whose strategies reflect distinct differentiation paths. The largest producer operates from a scale and feedstock dominance perspective, maintaining a near-ubiquitous position in ferroniobium supply for steel and superalloy applications. This positioning is reinforced by recent capacity expansions that increase oxide production volumes, ensuring feedstock availability for downstream alloy manufacturers. Scale leadership here is not just about tonnage; it is about supply reliability, pricing influence, and the ability to absorb demand fluctuations without disrupting customer schedules.
In contrast, specialized metallurgical groups differentiate through application-grade alloy expertise. Their vacuum arc remelting capabilities and targeted product launches for superconducting and aerospace use cases illustrate a strategy centered on technical precision rather than volume dominance. By introducing certified variants that meet specific magnet and structural requirements, these players convert technical capability into procurement preference. Their growth narrative is built on reproducibility, certification readiness, and the ability to serve demanding engineering specifications that generic feedstock suppliers cannot easily replicate.
Other significant players pursue diversification within the niobium value chain. Some focus on sintered alloys and sputtering targets for high-temperature industrial use, while others emphasize ingot, powder, and implant-grade supply chains for electronics and medical applications. A further cluster of producers ties expansion to mining-linked feedstock integration, leveraging resource access to stabilize input costs and support alloy output. Meanwhile, niche suppliers specializing in vacuum-melted alloys for nuclear and chemical processing equipment differentiate through application-specific material grades and long-standing qualification relationships. Each strategy is viable, but durability depends on execution consistency and the ability to align product development with procurement cycles in target end markets.
PW Consulting
Strategic Evolution of the Landscape
The competitive environment is evolving along three observable trajectories. First, capacity and capability expansion among incumbents signals a push to protect feedstock positioning and capture incremental demand without ceding technical differentiation to smaller rivals. Second, product-level innovation continues to fragment the market at the application layer, with certified medical-grade alloys and specialized superconducting variants creating sub-markets where qualification leadership translates into pricing power and stickier customer relationships. Third, regulatory and logistics pressures are encouraging more deliberate supplier selection, which benefits established players with documented compliance records and penalizes those lacking traceability or certification depth.
Integration and partnership dynamics are also gaining prominence. Where vertical integration is feasible, it provides cost and supply certainty; where it is not, long-term offtake agreements and technical co-development arrangements serve as alternatives to secure feedstock and align product roadmaps with downstream requirements. For new entrants, the barrier is less about conceptual feasibility than about qualification time, certification burden, and the trust required to displace incumbents in engineered applications. As a result, market evolution is likely to remain consolidation-heavy at the top while allowing targeted differentiation at the application and grade level.
Forward Outlook: Trends and Commercial Implications
Trend One: Qualification-Led Demand Concentration
Over the next three to five years, procurement behavior in high-value applications will continue to reward suppliers with established qualification footprints. As engineering teams face tighter project timelines and higher performance expectations, the cost of material re-qualification becomes a deterrent to supplier switching. This will reinforce demand concentration among incumbents and well-documented specialists, while creating entry opportunities only where new materials solve demonstrable performance gaps or cost-performance tradeoffs. The commercial opportunity lies in positioning product development around validated performance claims, certification readiness, and engineering support services that accelerate customer adoption.
Trend Two: Compliance as a Competitive Filter
Regulatory and purity requirements will increasingly function as competitive filters rather than mere compliance exercises. Suppliers that proactively align with tailings safety expectations, export compliance, and impurity thresholds will secure preferential access to regulated regions and applications. Conversely, those treating compliance as retrospective will face longer qualification cycles and growing procurement friction. Businesses that invest in traceable supply chains, documented purity control, and forward-looking regulatory monitoring will be better positioned to win tenders in medical, nuclear, and consumer-adjacent markets where material specifications are becoming more stringent.
High Performance Alloys Market
Trend Three: Feedstock Security and Margin Resilience
Cost and supply resilience will remain central to profitability, particularly as ferroniobium feedstock pricing continues to reflect broad metallurgy demand cycles. Organizations that secure stable feedstock access, optimize conversion efficiency, or align procurement geography with logistics realities will be better equipped to protect margins through volatility. At the same time, regional sourcing diversification and inventory buffering strategies will gain importance as export cost variability persists. The strategic implication is that resilience is not a back-office function but a competitive differentiator that influences pricing confidence, delivery reliability, and customer retention.
These trends carry inherent uncertainty. Geopolitical logistics disruptions, regulatory shifts, and raw material price swings can alter cost structures and demand timing unexpectedly. Market participants should therefore treat forecasts as directional guides rather than fixed trajectories, and build flexibility into sourcing, inventory, and product roadmaps accordingly.
Strategic Recommendations for Decision-Makers
For Manufacturers and Alloy Producers
Prioritize qualification depth and technical documentation as commercial assets. Invest in reproducibility, certification readiness, and engineering support that reduces adoption friction for demanding applications. Where feasible, secure feedstock arrangements or conversion optimizations that insulate margins from upstream pricing volatility, and align product development with the performance priorities of aerospace, medical, superconducting, and nuclear end users rather than competing solely on volume pricing.
For Investors and Capital Allocators
Evaluate opportunities through the lens of supply resilience, regulatory alignment, and application-specific differentiation rather than broad market growth narratives alone. Companies with credible compliance records, traceable supply chains, and targeted product certifications are better positioned to capture premium demand and sustain margins. Monitor capacity expansion signals, feedstock access strategies, and logistics exposure, as these factors will increasingly determine which players can convert market growth into durable profitability.
For Procurement and Supply Chain Leaders
Treat supplier selection as a multidimensional risk and performance decision. Price and lead time remain important, but traceability, certification status, purity control, and logistics resilience are increasingly decisive in strategic sourcing. Diversify supply geography where practical, maintain buffer strategies for critical alloy grades, and require evidence of compliance readiness from suppliers serving regulated applications. Proactive supplier qualification now reduces disruption and cost volatility later.
Superalloy Market
For organizations seeking deeper segmentation, regional supply dynamics, and tailored strategic scenarios, a full market research report provides the granular data and structured analysis needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Nb Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global E-Government Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide e-government market has entered a phase of accelerated transformation, driven by sustained public sector investment in digital infrastructure and shifting citizen expectations. Between 2020 and 2025, the market expanded from approximately $15.2 billion to $26.5 billion, reflecting a compound annual growth rate of 11.5 percent. Projections indicate this momentum will continue through 2032, with revenues climbing toward $56.8 billion by the end of the forecast period. This trajectory underscores a structural shift in how governments procure, deploy, and manage digital services, moving beyond isolated IT modernization projects toward integrated ecosystems that span identity management, service delivery, and data governance.
eDiscovery Market
Regional dynamics reveal a market that is both broad and uneven. North America maintains a leading position, supported by mature digital procurement frameworks and high public sector IT budgets. Europe follows closely, shaped by cross-border interoperability mandates and strong regulatory alignment. Asia Pacific represents a rapidly scaling region, where population size, urban digitization, and varying stages of administrative modernization create diverse demand patterns. Latin America and the Middle East and Africa, while smaller in absolute terms, are experiencing incremental adoption driven by targeted modernization initiatives and international development partnerships.
Despite this growth trajectory, the sector faces several structural challenges that determine which initiatives scale and which stall. First, legacy system integration remains a persistent barrier. Many agencies operate decades-old platforms that were never designed for cloud interoperability, API-based service chaining, or real-time data exchange. Upgrading these environments requires not only technology replacement but also process redesign, workforce reskilling, and careful data migration strategies. Second, cybersecurity and data sovereignty requirements are intensifying. Governments increasingly treat citizen data as a protected national asset, which means vendors must demonstrate robust encryption, identity verification, and compliance with local data residency rules. Third, digital inclusion and service accessibility remain uneven. High online service adoption in advanced economies contrasts with regions where connectivity gaps, language diversity, and varying digital literacy levels limit effective service reach. These challenges are not merely operational; they shape procurement decisions, vendor selection criteria, and the pace at which new platforms can be deployed at scale.
Key Drivers Shaping Market Evolution
Technology innovation continues to be the most visible catalyst for change. Cloud adoption has shifted from a cost optimization discussion to a foundational architecture choice for public sector digital services. In manyOECD countries, cloud infrastructure now represents a substantial share of e-government ICT budgets, reflecting the need for elastic compute, centralized data management, and faster service deployment. Alongside this shift, artificial intelligence and automation are being embedded into citizen-facing workflows. Predictive analytics are improving case routing and service personalization, while generative tools are being tested for document drafting, policy summarization, and internal productivity. However, the real differentiator is not the presence of AI alone but the ability to govern it responsibly. Public sector buyers are prioritizing platforms that offer transparency, auditability, and compliance controls, which is why governance-oriented AI tooling has gained attention among agencies seeking to balance innovation with accountability.
Policy and regulatory environments are equally influential. Governments are no longer treating digital transformation as a discretionary modernization effort; it is increasingly tied to national competitiveness, service resilience, and citizen trust. Regulatory frameworks are pushing vendors and agencies toward stricter security postures. For example, the US federal zero-trust strategy sets a clear direction for cybersecurity architecture, requiring agencies to adopt identity-centric access controls and continuous verification across e-government systems. In Europe, the Digital Services Act has introduced broader transparency and risk management expectations that affect online intermediaries and platforms supporting public service delivery. Meanwhile, data localization requirements in certain markets add complexity for multinational providers, forcing them to adapt deployment models, data storage arrangements, and compliance documentation to meet jurisdiction-specific rules. These policy shifts raise the bar for entry, but they also reward vendors that can demonstrate verifiable compliance and secure architecture at scale.
Demand-side behavior is changing as well. Citizens and businesses increasingly expect government services to match the responsiveness and usability of private-sector digital experiences. Mobile-first portals, self-service transaction flows, and personalized service journeys are becoming baseline expectations rather than differentiators. At the same time, workforce expectations inside government are evolving. Public sector teams want tools that reduce manual processing, improve inter-agency coordination, and provide clearer visibility into service performance. This demand pressure is encouraging agencies to move away from fragmented point solutions toward platforms that connect identity, case management, payments, and engagement tools in a more unified way.
Cost structures and procurement models are also being reshaped by the shift toward cloud and subscription-based delivery. Traditional on-premises deployments still play a role, particularly in contexts with strict data control requirements or existing infrastructure commitments, but cloud-based models are gaining share because they reduce upfront capital burden and allow agencies to scale services as demand fluctuates. This transition changes how vendors compete. Instead of winning large one-time license deals, providers are increasingly evaluated on long-term operational value, integration capability, security assurance, and total cost of ownership across the service lifecycle. The result is a market where differentiation comes less from feature count and more from reliability, compliance readiness, and the ability to support sustained digital service delivery.
Competitive Landscape and Leading Strategies
The competitive field is dominated by providers with strong public sector credentials, cloud infrastructure advantage, and the ability to connect digital services to broader transformation programs. Large platform companies have focused on offering secure government cloud environments, identity and data management tools, and application layers that support citizen portals and administrative workflows. Their strategic advantage lies in scale, global delivery capacity, and the ability to embed security, compliance, and analytics into a common architecture. This makes them particularly relevant for agencies seeking to modernize broad portfolios of services rather than isolated functions.
PW Consulting
Differentiation among leading players increasingly centers on how well they address government-specific requirements. Some vendors emphasize sovereign or government-dedicated cloud regions that support data residency and compliance obligations. Others focus on analytics and AI-enabled decision support, targeting the operational needs of agencies that want better insight into service demand, case handling, and citizen engagement. Specialist providers occupy an important position as well, particularly where deep domain expertise in permitting, licensing, payments, or civic engagement creates a stronger fit for specific agencies and local government contexts. These players often compete by offering purpose-built workflows, rapid deployment models, and long-standing relationships with public sector customers.
Recent market activity reflects a landscape that is both consolidating around platform plays and fragmenting through specialized solutions. Product and platform updates have focused on strengthening secure data processing, improving predictive capabilities for citizen services, and expanding governance tooling for public sector AI use. At the same time, contract awards and implementation wins show that demand is shifting toward cloud-based permitting, licensing, and service delivery platforms that can be scaled across multiple jurisdictions. International benchmarks also matter. High-performing e-government ecosystems tend to combine strong online service delivery with reliable digital identity and infrastructure, which reinforces the competitive importance of integrated offerings rather than standalone tools.
Looking ahead, the competitive environment will likely continue to evolve along three lines. First, larger platform providers will push further into verticalized government solutions, using their cloud and data foundations to deliver end-to-end service experiences. Second, specialized vendors will seek to defend their position by deepening domain depth, improving interoperability with larger platforms, and building implementation credibility across repeated public sector deployments. Third, services-led integrators will remain critical because many e-government programs depend on process redesign, change management, data migration, and cross-agency coordination, not just software installation. In this environment, the most successful players will be those that can combine technology with public-sector delivery discipline, compliance assurance, and measurable service outcomes.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the maturation of digital identity as a core component of e-government architecture. As online services expand, secure and convenient identity verification will become the gateway to citizen access, benefit distribution, tax processing, and regulatory engagement. This creates opportunities for providers that can offer strong authentication, privacy-conscious design, and interoperability across agencies and, in some cases, across borders. Identity is not just a security function; it is an enabler of service efficiency and trust.
A second trend is the growing emphasis on AI-enabled service operations with explicit governance controls. Governments are likely to adopt AI in targeted areas first, such as case triage, document handling, internal knowledge retrieval, and service demand forecasting. The commercial opportunity lies in solutions that integrate AI into existing public sector workflows while offering audit trails, policy controls, and human-in-the-loop oversight. Providers that can demonstrate responsible use, compliance readiness, and operational reliability will be better positioned than those competing primarily on novelty.
A third trend is the continued shift toward integrated citizen engagement and service delivery platforms. Agencies are under pressure to reduce friction across channels, improve transparency, and make services more accessible. This favors platforms that connect identity, case management, communications, payments, and performance analytics in a cohesive manner. Commercial value will accrue to vendors that can help agencies move from siloed digital tools to service journeys that are easier for citizens to navigate and easier for governments to manage.
These trends carry risks. Implementation complexity can delay value realization, especially when programs require legacy modernization and cross-agency coordination. Regulatory change may alter data handling requirements or security expectations faster than procurement cycles can adapt. Cybersecurity threats remain persistent, and any high-profile failure in public service reliability can undermine confidence in digital transformation efforts. In addition, uneven digital access can create adoption gaps that limit the impact of otherwise well-designed platforms. Companies entering or expanding in this market should plan for long sales cycles, multi-stakeholder evaluation processes, and the need to prove outcomes beyond technical capability.
Worldwide Information Technology Market
Strategic Implications for Decision-Makers
For technology and solution providers, the priority is to align offerings with government procurement realities and compliance expectations. Products that combine secure cloud deployment, identity and access capabilities, and clear governance features will have an advantage in markets where agencies are balancing innovation with risk management. Equally important is delivery capability: public sector buyers continue to value proven implementation approaches, interoperability with existing systems, and support for workforce transition. Companies that can articulate measurable service improvements, not just technical specifications, will differentiate more effectively.
For investors, the market signals a preference for businesses with defensible public sector relationships, recurring revenue models, and the ability to operate across complex regulatory environments. Interest is likely to concentrate on platforms and integrators that can sustain long-term engagements through cloud migration, digital identity, service modernization, and AI-enabled operations. Due diligence should pay close attention to compliance readiness, data handling practices, and the quality of government clientele, since these factors often determine whether a provider can scale beyond initial pilot deployments.
For government agencies and public sector buyers, the most effective path is to prioritize architectural coherence over fragmented tool accumulation. Investments that strengthen identity, security, data interoperability, and citizen engagement foundations tend to create more durable value than isolated feature upgrades. Procurement teams should evaluate vendors on total lifecycle cost, integration capacity, security posture, and the ability to support inclusive service delivery. In fast-moving areas such as AI and cloud transformation, starting with well-scoped use cases and clear governance rules can reduce risk while building organizational capability for broader rollout.
Given the speed of policy change, regulatory divergence, and platform evolution, decision-makers benefit from continuous market intelligence that tracks vendor moves, compliance shifts, and regional adoption patterns in detail. A broader research view can help organizations validate assumptions, compare subsegments, and refine entry or investment strategies with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide E-Government Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind Bismuth Ingot Market's 5.45% CAGR Trajectory to 2032
By PW Consulting, 2026-09-18
Strategic Trends & Commercial Opportunities in the Worldwide Bismuth Ingot Market
Market Snapshot: Growth Dynamics and Structural Constraints
The global bismuth ingot market has entered a phase of sustained expansion, driven by resilient demand across specialty alloys, pharmaceuticals, and high-purity industrial applications. With a compound annual growth rate of 5.45% projected through 2032, the sector is transitioning from a niche minor-metal segment to a strategically significant component of advanced manufacturing supply chains. This trajectory reflects not only incremental volume growth but also an upward recalibration of value, as producers capture premiums for higher purity grades and more consistent metal specification.
Despite the optimistic forward curve, the industry operates under structural constraints that define both its near-term volatility and its long-term evolution. One of the most defining characteristics of the market is its byproduct dependency. Bismuth is overwhelmingly recovered from lead, copper, tungsten, or zinc processing streams rather than from primary extraction dedicated solely to bismuth. This means supply responsiveness is inherently lagged and partially decoupled from downstream demand signals. Producers cannot simply commission new capacity to chase price rallies; additional volumes must align with broader smelting economics and base-metal market conditions.
A second structural challenge lies in geographic concentration and regulatory friction. Production is heavily clustered in regions where lead and nonferrous smelting infrastructure is mature, and where the mineral endowment supports integrated metal recovery. Recent policy actions in key producing jurisdictions have added a new layer of complexity. Export controls and licensing requirements on bismuth metal and related products have tightened global availability, contributed to price volatility, and forced downstream buyers to rethink procurement logic. The combination of concentrated supply, policy-driven disruption, and byproduct-linked production creates an environment where inventory management, qualification cycles, and substitution readiness become critical operational disciplines.
A third challenge is the widening gap between standard and high-purity supply. Demand for controlled-purity bismuth ingots is accelerating in electronics, semiconductor-adjacent processes, and specialty catalysts, yet the metallurgy to reach and validate elevated purity grades is not uniformly available across smelters and refiners. This creates a bifurcated market. Lower-specification ingots may move through commodity-oriented channels, while high-purity material often requires traceability, process validation, and long-term offtake alignment. The result is a market where commercial success is increasingly tied to technical capability and qualification infrastructure rather than volume alone.
Key Drivers Reshaping the Bismuth Ingot Landscape
Technological Innovation in Refining and Purity Control
Metallurgical progress is one of the clearest value-creation vectors in the bismuth ingot market. Test work and process optimization efforts have demonstrated that concentrated leachates can be transformed into high-purity ingots through integrated leaching, cementation, and pyrometallurgical refining pathways such as liquation, sulphuration, and chlorination. These process refinements matter commercially because they can improve yield consistency, reduce equipment footprint, and lower the unit cost of reaching target purity.
For downstream users, this translates into a more reliable pathway to 4N-grade and above material without relying solely on legacy refining operations that were designed around older product specifications. In high-value applications, small improvements in purity control can be the difference between qualification approval and procurement rejection. The broader implication is that refining competence is becoming a strategic asset. Producers that can demonstrate repeatable purity outcomes, supported by metallurgical validation and controlled process parameters, are better positioned to serve electronics, pharmaceutical-adjacent users, and specialty alloy makers that require specification integrity rather than occasional bulk availability.
Policy, Trade Controls, and the Reorientation of Procurement
Regulatory developments have shifted bismuth from a relatively stable minor metal into a material with explicit strategic trade sensitivity. Export controls on bismuth metal and products, introduced in response to broader tariff dynamics, have influenced global supply tightness and price behavior. In parallel, defense-related procurement activity has surfaced as a notable demand signal, with government agencies issuing tenders for high-purity bismuth in slab or ingot form for stockpile purposes.
These developments do more than move prices. They change the incentives for supply chain design. Buyers that previously treated bismuth as a readily available minor commodity are now factoring in geographic diversification, supplier qualification, and contractual flexibility. At the same time, the concentration of refinery production in one dominant producing region amplifies the effects of policy shifts. When a major share of global refined material flows from a limited set of countries, trade frictions can quickly propagate into lead times, price discovery, and inventory strategy.
For executives, the strategic takeaway is that regulatory risk has become a procurement variable, not just a compliance concern. Flexible sourcing, dual-supplier strategies, and reserves planning are increasingly relevant, especially for applications where substitution is technically constrained or where qualification cycles are long.
Demand-Side Shifts in Specialty Alloys, Pharmaceuticals, and Electronics
Demand growth is being pushed by a cluster of application trends rather than a single volume driver. In fusible alloys and solders, bismuth continues to serve as a functional substitute in formulations where lower melting points, density characteristics, or environmental constraints matter. In pharmaceuticals and related chemical applications, bismuth-based compounds and metal inputs remain embedded in product lines that depend on controlled specifications and consistent supply. In pigments, electronics, and specialty metallurgical uses, the need for purity assurance is intensifying as downstream processes become more sensitive to impurity profiles.
What makes this demand environment distinctive is that it rewards reliability and specification control more than it rewards cheap availability. A pharmaceutical or high-purity electronics supply chain does not respond in the same way as a generic alloy market. Qualification lead times, documentation, lot consistency, and technical support all influence purchasing decisions. As a result, application growth in higher-value segments is strengthening the commercial logic of dedicated high-purity production and long-term customer relationships, even when total tonnage remains comparatively modest relative to base metals.
Supply Chain Structure and Cost Dynamics
Cost and availability in the bismuth ingot market are shaped less by standalone mining economics than by the health and configuration of base-metal smelting. Because bismuth is primarily a byproduct, its supply is tied to the operational intensity of lead, copper, tungsten, and zinc circuits. This has two practical effects. First, bismuth availability can expand or contract depending on smelting throughput and concentrate processing decisions that are made for reasons unrelated to bismuth alone. Second, cost structures are influenced by the complexity of separation and refining, especially when higher purity grades are required.
Price behavior has also reflected this structural reality. Recent annual price levels have reached historically elevated averages, and warehouse pricing in key hubs has shown sharp intermittent peaks. Such movements indicate that the market is not only reacting to demand but also absorbing the effects of supply concentration, policy disruption, and the premium attached to specification-sensitive material. For producers, this creates an opportunity to capture value through purity differentiation and service reliability. For buyers, it underscores the importance of visibility into refining capacity, inventory positions, and the metallurgical route used to produce the ingots they purchase.
Competitive Landscape and Leadership Strategies
The competitive field in the bismuth ingot market is defined by a mix of integrated smelters, specialty refiners, and distributors with strong technical and application orientation. Concentration is meaningful, with a relatively small group of players accounting for a substantial share of market activity. This structure favors companies that combine production competence with application knowledge, purity control, and the ability to serve complex procurement requirements.
A clear pattern in the landscape is the divergence between byproduct-oriented smelting operations and more specialized minor-metal producers. Companies that recover bismuth from lead smelting or from battery-related recycling streams can benefit from existing infrastructure and scale, particularly when bismuth is packaged for alloys, industrial uses, and pharmaceutical-adjacent applications. Their strategic advantage often lies in established processing routes and the ability to supply material that aligns with ingot form requirements at commercial scale.
At the same time, high-purity specialists are positioning around purity assurance, traceability, and application-specific service. These producers focus on controlled grade architecture, working with customers in electronics, thin-film deposition, specialty alloys, and catalytic applications where specification integrity is paramount. Their differentiation typically comes from process discipline, lot documentation, custom formulations, and the capacity to bridge laboratory demand with bulk supply.
Another important evolution is the emergence of project-stage producers aiming for vertically integrated operations. One notable direction is the development of projects intended to produce high-purity bismuth ingots alongside cobalt, gold, and copper-related outputs. Recent milestones in these initiatives have included metallurgical test work validating 4N bismuth ingot production and progress on site control for hydrometallurgical processing. If such projects advance through construction decisions, they could add supply diversification and reinforce the strategic relevance of non-China refining outside traditional byproduct channels. For the market overall, these developments matter because they could introduce new sourcing geographies, new purity pathways, and additional optionality for buyers seeking to reduce concentration risk.
The competitive trend to watch is therefore not simply consolidation, but functional specialization. Some players will continue to compete on volume and integrated smelting economics. Others will compete on purity, qualification support, and reliability for high-specification buyers. The most strategically resilient firms are likely to be those that can navigate both worlds: producing material at meaningful scale while maintaining the technical credibility to serve demanding end-use segments.
Indium Market
Forward Outlook: Three Trends Shaping the Next 3-5 Years
The first likely trend is widening premium differentiation by purity and application readiness. As more customers in electronics, pharmaceuticals, catalysts, and specialty materials require documented purity and lot consistency, the market will increasingly separate standard commercial ingots from validated high-purity supply. This creates commercial opportunities for producers that can formalize quality systems, support qualification processes, and maintain stable grade control. It also raises the cost of entry for new suppliers targeting higher-value segments, since metallurgical competence and customer validation will be decisive.
Solar Ingot Wafer Market
The second trend is continued supply-side reconfiguration driven by policy and byproduct economics. Because bismuth availability is linked both to smelting dynamics and to trade policy, buyers should expect periodic tightening and price volatility rather than smooth, linear supply growth. At the same time, interest in refining diversification and project-stage development may gradually broaden geographic supply. The commercial implication is that procurement strategies will need to incorporate redundancy, qualification lead times, and scenario planning for regulatory change, especially where bismuth has no easy substitute.
The third trend is the growing strategic relevance of bismuth in resilience-focused procurement. Strong price signals and stockpiling interest point to recognition of bismuth as a material with both industrial and strategic value. For commercial players, this can mean stronger negotiating leverage for qualified producers, but also higher inventory expectations from some buyers. The uncertainty lies in the pace and direction of policy evolution, the timing of new project capacity, and whether base-metal smelting conditions remain favorable for consistent byproduct recovery. These variables will shape whether the market remains tight and premium-driven or opens up as new supply matures.
PW Consulting
Actionable Recommendations for Decision-Makers
For manufacturers and application developers, the priority is to treat purity specification and supplier qualification as core business variables rather than administrative requirements. Where applications depend on tight impurity control, building longer qualification cycles into planning, requesting documented metallurgical routes, and securing multi-source options can reduce exposure to supply shock and quality variability. Aligning product design with available purity grades can also unlock more stable sourcing and reduce substitution friction.
For investors and corporate development teams, the strategic opportunity lies in identifying where value is being created along the bismuth value chain. Premium capture is increasingly tied to refining capability, purity assurance, and access to demand segments that tolerate less substitution. Projects and producers that can demonstrate validated high-purity output, diversified supply logic, or strong application-oriented service may offer more durable positioning than volume-only plays in a market shaped by byproduct constraints and trade sensitivity.
For procurement and supply chain leaders, the recommendation is to move from transactional buying to structured resilience planning. That means mapping exposure to concentrated supply, evaluating inventory and stockpiling options where substitution is limited, and negotiating contracts that account for purity variability and lead-time risk. In a market where prices can react sharply to policy shifts and refining constraints, visibility into the supply base becomes a competitive advantage in its own right.
Detailed segment-level sizing, purity-grade dynamics, regional exposure, and company-specific operating profiles can materially sharpen these decisions. For teams that need deeper granularity on demand composition, refining pathways, and competitive positioning, the full market research report provides the dissection required to translate these trends into company-specific action.
For detailed analysis of this topic, please visit the official page: Worldwide Bismuth Ingot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide LED Tube Covers Market: What 5.5% CAGR Reveals About Commercial Lighting Dynamics
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global LED Tube Covers Market
Market Overview and Core Challenges
The global market for LED tube covers has demonstrated consistent expansion over the past half-decade, evolving from a niche component segment into a critical element of the broader linear lighting supply chain. Valued at approximately 915.2 million USD in 2020, the market reached 1204.08 million USD by 2025, reflecting a compound annual growth rate of 5.5 percent through the forecast period extending to 2032. This trajectory underscores a structural shift in how lighting manufacturers approach tube assembly, where protective and diffusive covers are no longer treated as commodity afterthoughts but as engineered components that directly influence light quality, thermal management, and regulatory compliance.
Despite the positive growth signals, the industry currently navigates several interconnected challenges that will define competitive dynamics in the near term. The first challenge revolves around material cost volatility and geographic price dispersion. Polycarbonate, which dominates the material mix for LED tube covers, has experienced notable price fluctuations across major production hubs. In early 2026, polycarbonate prices in Northeast Asia were recorded at 1.92 USD per kilogram, while European buyers faced rates of 3.38 USD per kilogram, with Southeast Asia and North America positioned at intermediate levels. These regional discrepancies create uneven input cost structures for manufacturers operating across multiple supply chains, forcing difficult decisions around sourcing localization, inventory buffering, and final pricing strategies.
A second challenge lies in the accelerating regulatory push toward phasing out legacy fluorescent technologies. The European Union's RoHS Directive restrictions on mercury have effectively driven bans on common linear fluorescent tubes, creating a rapid conversion cycle toward LED alternatives that rely heavily on polycarbonate or compatible housing solutions. Simultaneously, several U.S. states, including California, Colorado, and Maryland, have implemented or scheduled bans on linear fluorescent lamps between 2024 and 2026, further compressing the remaining replacement market and shifting procurement cycles toward full LED system adoption. While this regulatory momentum fuels demand, it also compresses the timeline for manufacturers to scale compliant designs, source certified materials, and align distribution channels with accelerated retrofit schedules.
The third challenge emerges from shifting trade policies and their ripple effects on component assembly costs. Recent increases in U.S. tariffs on steel and aluminum imports during 2025 have directly impacted the cost structure of aluminum bases paired with polycarbonate covers in LED tube assemblies. For manufacturers that rely on integrated metal-and-polymer designs, this tariff environment introduces margin pressure and complicates regional sourcing strategies, particularly for companies balancing domestic production against imported component dependencies. Collectively, these challenges signal a market that is growing but increasingly stratified, where cost discipline, regulatory foresight, and supply chain agility will separate resilient players from those reliant on legacy pricing models.
Key Growth Drivers
The momentum behind LED tube covers is anchored in a convergence of technological, regulatory, and demand-side forces that are reshaping both product design priorities and procurement behaviors across commercial, industrial, and residential applications.
Technological Innovation and Material Performance
Advancements in polycarbonate extrusion and surface treatment technologies have elevated the functional role of LED tube covers beyond simple optical diffusion. Modern covers are increasingly engineered to balance light uniformity, impact resistance, and thermal dissipation, enabling manufacturers to offer retrofit solutions that closely match or exceed the performance characteristics of legacy fluorescent fixtures. The availability of fire-retardant polycarbonate extrusions tailored for high-voltage markets has become particularly relevant for North American applications, where compliance with UL standards and safe operation across 110V-120V systems are non-negotiable requirements. Guidance released by leading component suppliers in late 2025 and early 2026 has emphasized the importance of matching cover material specifications with aluminum profile designs to ensure structural integrity, thermal stability, and regulatory alignment. This growing emphasis on engineered compatibility reflects a broader industry shift toward integrated component thinking, where covers, housings, and bases are co-optimized rather than sourced as independent commodities.
PW Consulting
Surface finish innovation also continues to drive differentiation. Frosted and diffused finishes remain the most widely adopted option for general lighting applications, offering predictable light distribution and glare reduction across broad installation footprints. Clear and transparent variants serve niche requirements where maximum light output or visual inspection of internal components is prioritized, while prismatic and striated designs are gaining traction in settings that demand controlled beam patterns or architectural lighting effects. The ability to offer a spectrum of surface finishes from a single production line has become a competitive lever for manufacturers aiming to serve multiple end-use segments without fragmenting operational efficiency.
Policy and Regulatory Catalysts
Regulatory pressure on mercury-containing fluorescent lighting has emerged as one of the most powerful accelerators for LED tube cover demand. At the European level, RoHS-driven restrictions have effectively curtailed the availability of common linear fluorescent tubes, forcing facility managers and electrical contractors to transition toward LED retrofit assemblies that incorporate durable polycarbonate or compatible housing solutions. The same dynamic is unfolding across multiple U.S. states, where legislative actions and scheduled phase-out dates have created a fragmented but accelerating compliance landscape. These regulatory shifts do more than simply replace one light source with another; they fundamentally alter procurement cycles, technical specification requirements, and the speed at which distributors and installers must adapt their inventory and skill sets.
For manufacturers and suppliers, the regulatory environment presents both a demand tailwind and a compliance burden. Products destined for regulated markets must meet increasingly stringent performance, safety, and environmental criteria, which in turn raises the value of covers and housings that contribute to overall system certification. Companies that proactively align their material sourcing, testing protocols, and documentation with regional requirements are better positioned to capture conversion-driven demand, while those that treat regulatory compliance as a reactive exercise risk delays, rework, and margin erosion.
Demand-Side Shifts and Retrofit Economics
On the demand side, the economic case for LED tube retrofits continues to strengthen as energy prices fluctuate and sustainability targets become embedded in corporate and municipal procurement policies. Commercial lighting remains the largest application segment for LED tube covers, driven by offices, warehouses, retail spaces, and institutional facilities that prioritize long-term operating cost reduction and minimal disruption during fixture upgrades. Industrial facilities represent a rapidly growing demand pool, particularly in environments where robust cover materials must withstand dust, moderate impact, and thermal stress while maintaining consistent illumination quality. Residential adoption, while smaller in absolute terms, is expanding as homeowners and multifamily property managers replace aging fluorescent fixtures with LED solutions that offer improved aesthetics, lower maintenance, and compatibility with smart lighting ecosystems.
A notable behavioral shift is the growing preference for integrated LED tube solutions that bundle covers, housings, and bases into cohesive product packages. Electrical contractors and facility managers increasingly favor supply chains that reduce assembly complexity, minimize compatibility risk, and provide clear warranty and support pathways. This preference rewards manufacturers that design covers as part of a complete system rather than as standalone components, while challenging suppliers that rely on fragmented, multi-vendor procurement models.
Supply Chain and Cost Structure Dynamics
The cost structure of LED tube covers is being reshaped by regional material pricing, trade policy adjustments, and evolving manufacturing footprints. Polycarbonate pricing divergence across Asia, Europe, and North America requires manufacturers to make strategic choices about where to source raw materials, how much inventory buffer to maintain, and whether to localize production to reduce exposure to freight volatility and tariff barriers. The 2025 increase in U.S. tariffs on steel and aluminum imports has added a layer of complexity for assemblies that combine aluminum bases with polycarbonate covers, prompting some manufacturers to reevaluate bill-of-materials composition, explore alternative metal sourcing, or adjust finished product pricing to preserve margins.
At the same time, economies of scale in polycarbonate extrusion and surface finishing are gradually improving cost predictability for high-volume producers, particularly those that have invested in dedicated lines for LED tube cover profiles. The combination of scale benefits, material innovation, and more disciplined procurement practices is enabling a subset of manufacturers to offer competitive pricing without sacrificing compliance or performance quality. This dynamic is likely to intensify as the market matures and buyers become more sophisticated in comparing total cost of ownership rather than unit price alone.
Competitive Landscape and Leading Strategies
The competitive environment for LED tube covers is characterized by a wide spectrum of participants, from specialized component manufacturers focused on polycarbonate extrusions and aluminum profiles to integrated lighting brands that offer complete T8 and T5 tube systems with compatible covers and housings. Market concentration remains relatively moderate, with the top three players accounting for approximately 18.5 percent of total revenue and the top five representing around 28.35 percent, indicating ample room for specializedplayers and regional specialists to compete on performance, compliance, and service differentiation rather than scale alone.
Several strategic positioning patterns have emerged among the leading participants. Companies such as JE Led Profile, Dachang Plastic Hardware Processing Factory, Shenzhen AOD Plastic Products, TOPPO LED Lighting, Farwise Technology, Shenzhen Syhdee, and Xiamen PVTECH illustrate the depth of China-based manufacturing capability in polycarbonate covers, aluminum-based assemblies, and custom extrusion profiles. These manufacturers often compete by offering a broad range of finish options, flexible customization for tube dimensions and surface treatments, and close alignment with domestic LED tube factories as well as international distributors. Their value proposition typically centers on production agility, material availability, and the ability to match cover specifications with aluminum profiles or integrated tube designs across multiple voltage and compliance requirements.
On the integrated lighting side, companies such as TCP Lighting, LEDVANCE, and Signify demonstrate a different strategic orientation. These firms position LED tube covers and compatible housings as part of broader professional lighting portfolios, emphasizing system-level performance, regulatory certification, and application-specific design guidance. Signify's professional trade lighting catalogues, for example, have highlighted LEDtube ranges with PC housing and cover options tailored to diverse installation contexts, while TCP's Select Series has incorporated glass and PC-compatible housings for commercial retrofit scenarios. LEDVANCE has similarly emphasized high-performance tube designs suitable for various covers and external systems. This integrated approach allows these companies to capture value not only from component sales but also from the specification, branding, and service relationships that accompany complete lighting solutions.
Recent industry developments underscore the growing importance of intellectual property, technical guidance, and compliance alignment as competitive differentiators. In early 2026, PVTECH filed a patent infringement lawsuit against Super Lighting concerning ten U.S. patents related to T8 LED tube designs, spanning housing and cover technologies. This legal action signals a broader trend in which component and system designs are becoming more heavily protected, and where the boundaries between cover extrusion, housing engineering, and tube assembly are increasingly subject to proprietary claims. Simultaneously, JE Led Profile's release of guidance on selecting PC covers and aluminum profiles for 2026 emphasized fire-retardant polycarbonate extrusions for U.S. 110V-120V markets meeting UL standards, highlighting how technical specification support is becoming a strategic tool for capturing compliance-driven demand. Signify's publication of its professional trade lighting catalogue further illustrates how leading brands are using documented product ranges and application guidance to shape procurement decisions in commercial and industrial segments.
Looking ahead, the competitive landscape is likely to evolve along two parallel tracks. The first involves consolidation and partnership activity as larger integrated lighting brands seek to secure reliable cover and housing supply, potentially through long-term contracts, joint development agreements, or selective acquisitions of specialized extrusion and assembly capabilities. The second involves continued fragmentation at the component level, where regional manufacturers differentiate through surface finish expertise, material certification, voltage-specific design support, and rapid response to local retrofit demand spikes. New entrants will find opportunities in niche finish technologies, application-specific cover designs, and supply chain models that reduce compliance risk for distributors and installers, while generic commodity players will face increasing pressure from both material cost volatility and the growing premium attached to certified, system-compatible cover solutions.
Future Trends and Commercial Implications
Over the next three to five years, several interconnected trends are likely to shape the LED tube covers market and create actionable commercial opportunities for manufacturers, distributors, and investors who align their strategies with evolving demand patterns and compliance requirements.
The first trend is the deepening integration of cover design with system-level performance and certification. As regulatory bans on fluorescent tubes continue to expand and facility managers accelerate retrofit programs, buyers will increasingly evaluate covers and housings as part of a certified, warranty-backed lighting system rather than as interchangeable parts. This shift will reward manufacturers that can document material specifications, demonstrate compliance with regional safety and environmental standards, and provide clear guidance on compatibility with aluminum bases, driver configurations, and installation conditions. Companies that invest in application-specific cover designs and maintain robust testing and documentation practices will be well positioned to capture premium segments of the retrofit market.
The second trend is the continued regional divergence in material costs and trade conditions, which will drive more localized sourcing and assembly strategies. Polycarbonate price dispersion across Northeast Asia, Europe, Southeast Asia, and North America, combined with evolving tariff structures on metals and related inputs, will encourage manufacturers to align production footprints with end-market demand clusters. This localization trend will create opportunities for regional suppliers that can offer consistent material availability, predictable pricing, and faster response times, while also challenging companies that rely on highly centralized sourcing models to absorb logistics and tariff exposure. Investors and strategic buyers should anticipate a market in which supply chain resilience and regional compliance capability become as important as unit cost competitiveness.
The third trend is the gradual expansion of cover functionality beyond diffusion and protection into areas such as enhanced thermal management, improved impact resistance, and tighter integration with smart lighting ecosystems. As LED tube installations become more common in environments that demand durable, low-maintenance solutions, covers that contribute to longer system life, reduced failure rates, and easier integration with sensors or connected controls will gain incremental value. This creates opportunities for product development teams to explore material formulations and surface architectures that support these broader performance goals, particularly in commercial and industrial segments where total cost of ownership considerations drive procurement decisions.
Potential risks and uncertainties include the pace and geographic fragmentation of regulatory implementation, which could accelerate demand in some markets while delaying it in others. Material price volatility remains a persistent threat, especially if supply disruptions or demand spikes in adjacent industries affect polycarbonate availability. Tariff and trade policy uncertainty could also reshape cost structures unexpectedly, particularly for assemblies that depend on cross-border metal and polymer components. Companies that treat these variables as static will face margin and planning challenges, while those that build flexible sourcing, pricing, and compliance strategies will be better equipped to navigate an evolving landscape.
Actionable Guidance for Decision Makers
For manufacturers, the immediate priority is to strengthen the alignment between cover material specifications, housing designs, and regional compliance requirements. Investing in fire-retardant polycarbonate options, voltage-specific guidance, and clear documentation of compatibility with aluminum bases and existing tube formats can help capture compliance-driven retrofit demand while reducing the risk of rejected specifications or delayed installations. Manufacturers should also evaluate whether to deepen relationships with regional distributors and integrated lighting brands that can accelerate market access, particularly in territories where fluorescent phase-outs are advancing most rapidly.
LED Glass Market
For investors, the opportunity lies in identifying companies that combine material supply reliability with system-level design capability and demonstrated regulatory readiness. Businesses that have developed proprietary extrusion lines, secured consistent polycarbonate sourcing, or built application-specific cover portfolios for commercial and industrial segments are better positioned to benefit from sustained retrofit momentum. Conversely, exposure to purely commodity-oriented models without clear differentiation in finish technology, certification support, or regional sourcing resilience may face margin compression as the market matures and buyers prioritize total cost of ownership over initial price.
For procurement teams and facility operators, the focus should be on reducing integration risk and long-term operating cost rather than selecting covers on unit price alone. Specifying covers and housings that are designed for compatibility with chosen LED tube formats, that meet relevant safety and environmental standards, and that are supported by clear warranty and technical guidance can simplify installation, reduce failure rates, and improve lifecycle economics. As regulatory deadlines tighten and retrofit timelines accelerate, securing reliable supply of compliant cover solutions will become a critical component of project planning and asset management.
Tonneau Covers Market
Given the pace of regulatory change, material price movement, and competitive differentiation across regions and applications, decision makers seeking to act with precision will benefit from access to more granular segmentation data, company-level profiling, and customized scenario analysis. Detailed market intelligence can help translate broad trends into specific sourcing, pricing, and product development decisions, enabling stakeholders to anticipate demand shifts, identify supply chain vulnerabilities, and prioritize investments where they are most likely to generate durable returns.
For detailed analysis of this topic, please visit the official page: Worldwide LED Tube Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Life Simulation Game Market CAGR 7.52: The Logic Behind 5.7B Global Scale
By PW Consulting, 2026-09-18
Navigating the Worldwide Life Simulation Game Market: Strategies, Shifts, and Commercial Opportunities
The worldwide life simulation game market has firmly established itself as a resilient and culturally influential segment of the interactive entertainment industry. Characterized by immersive environments, character-driven progression, and sandbox-style freedom, these titles span everything from relationship and community management to procedural survival and daily-life roleplay. Over the past five years, developers have successfully expanded the definition of life simulation beyond traditional domestic or social settings, integrating ecosystems, base-building, and even mortality mechanics into player experiences.
The market’s trajectory reflects steady expansion rather than speculative spikes. From a base of approximately $2.2 billion in 2020, industry revenue has progressed through consecutive growth years, reaching roughly $3.45 billion in 2025. Forward projections indicate continued expansion through 2032, with the sector expected to surpass $5.7 billion by the end of the forecast window. The compound annual growth rate sits at 7.52 percent, signaling a middle-ground pace: faster than legacy console-anchored genres in some mature markets, but tempered by rising production costs and platform fragmentation. Revenue remains denominated in USD, with the largest share generated through premium releases, digital expansions, and recurring seasonal monetization tied to long-lived franchises.
Behind the headline figures, the market is navigating several pivotal inflection points. First, development economics are tightening as labor cost structures shift. In the United States, average salaries for game developers working on life simulation titles approach $110,000 annually, and these compensation costs now represent roughly 60 percent of production budgets per title. Teams can no longer rely on sheer headcount growth to deliver richer experiences; efficiency, tooling, and procedural content generation have become strategic priorities.
Second, platform distribution has fragmented the audience in ways that complicate portfolio planning. Mobile and PC remain the two dominant access points, each carrying distinct design expectations, monetization logics, and audience turnover patterns. Console remains meaningful but narrower in reach for this particular genre. The result is a market where publishers must reconcile cross-platform ambition with platform-specific polish, community management, and backend infrastructure.
Third, regulatory and compliance requirements are becoming more assertive. Content rating and age-appropriateness enforcement, especially for titles distributed through app stores and regulated digital marketplaces, now impose operational friction that earlier cohorts of developers did not face. Industry participants are adapting rating workflows, localization practices, and community-moderation standards to meet these expectations without disrupting creative cycles.
Taken together, these dynamics point to a market that is still expanding but demanding greater precision. Growth is no longer a simple function of launching another large-scale simulation title. It depends on balancing audience expectations, development efficiency, platform strategy, and regulatory readiness while preserving the emotional immersion that makes life simulation games compelling.
Key Drivers Shaping Market Momentum
The continued expansion of life simulation gaming is not the product of a single force. It reflects intersecting shifts in technology, consumer behavior, platform economics, and production constraints. The most consequential drivers can be grouped into four areas, each shaping how studios build, publish, and sustain these titles.
AI-Enabled Interaction and Dynamic Social Systems
Artificial intelligence has become a defining lever for life simulation design. Rather than relying entirely on scripted dialogue trees and static routines, studios are increasingly experimenting with AI-driven non-player characters that can adapt behavior based on context, previous interactions, and environmental cues. Generative AI integration is now present in roughly one out of four new titles, a proportion that reflects both technical feasibility and player appetite for more responsive social worlds.
This trend matters commercially because it extends content longevity. Titles with reactive companions, shifting community dynamics, or emergent social routines can maintain engagement beyond the early launch period. They also change the development equation: teams are investing in behavior systems and moderation safeguards rather than only in handcrafted narrative content. The payoff is a more persistent sense of agency for players, which aligns closely with the emotional core of the life simulation experience.
Audience Demographics and Engagement Patterns
Demand-side behavior has stabilized around a recognizable profile. A majority of life simulation players fall within the 18-to-34 age range, and engagement on mobile and PC is highly habitual. A significant portion of this audience spends close to two hours per session on a daily basis. That pattern is not accidental. Life simulation games offer routine, progression, and social texture that fit naturally into daily leisure windows.
For commercial strategy, this means retention mechanics and session pacing matter as much as launch performance. Titles that encourage regular check-ins, community participation, or incremental life-stage progression tend to generate sustained revenue and word-of-mouth visibility. At the same time, the expectation of daily engagement raises the stakes for live operations, content cadence, and cross-session continuity. Developers that fail to support habitual play often lose momentum faster than the market’s growth curve would suggest.
Recent Content Expansions Reinforcing Franchise Longevity
Several high-profile releases and updates in the last year illustrate how established studios are deepening life simulation appeal without abandoning core identity. Electronic Arts expanded The Sims 4 with new mechanics around mortality, legacy, and family systems, demonstrating that even mature franchises can reinvent emotional stakes and replay incentives. Around the same time, the Stardew Valley franchise received a major update adding festivals, pets, and broader relationship systems, reinforcing the value of community-driven, multi-year support for simulation titles with strong player attachment. In the survival-angle of the genre, Sons of the Forest reached full release with enhanced multiplayer, base-building, and survival dynamics, reflecting demand for cooperative life simulation that blends routine progression with challenge-based systems.
These developments are strategically important because they validate a central commercial principle: life simulation franchises can remain relevant through iterative emotional and mechanical expansion. Rather than resetting into entirely new intellectual properties, publishers are extending lifecycles by refining social systems, adding new life-stage content, and supporting cooperative or community-oriented modes.
Cost Structures and Production Efficiency
On the supply side, rising labor costs and production complexity are reshaping development strategies. When developer compensation accounts for a large share of per-title budgets, teams need to make deliberate trade-offs between scope, polish, and release cadence. This has accelerated interest in procedural generation, modular asset pipelines, reusable interaction systems, and smarter testing tools. Efficiency is no longer just an engineering concern; it is a commercial differentiator.
Studios that can maintain high perceived quality while controlling production overhead gain more room to experiment, support live services, and sustain franchise momentum. Conversely, teams that treat every release as a bespoke handcrafted experience without reusable systems face greater risk when development budgets rise and audience expectations remain unchanged. The market is gradually rewarding studios that find a productive balance between creative ambition and operational discipline.
Competitive Positioning and Strategic Differentiation
The life simulation landscape is defined less by uniform competition and more by divergent strategic postures. A handful of established players anchor different corners of the market, each leveraging distinct design philosophies, audience relationships, and franchise ecosystems.
Leading Studio Archetypes
Maxis remains the most recognizable reference point for mainstream life simulation. Its franchise positioning centers on life management, home building, and social interaction, supported by an ecosystem of expansion packs and recurring updates. Its advantage lies in a deeply established audience relationship and a play pattern that is easy to understand, iterate upon, and extend across demographic segments. The recent expansion around life stages, legacy, and mortality reinforces a broader strategic direction: using emotional narrative systems to sustain engagement beyond cosmetic or building-based motivations.
Worldwide Simulation Game Market
ConcernedApe occupies a different position, built around a farming life simulation that blends daily routines, relationships, and seasonal progression across PC, console, and mobile. Its differentiation stems from player trust, stylized accessibility, and long-term community support. The recent update cycle focused on social content, festivals, and pets shows a commitment to expanding relational depth without fracturing the core loop that made the title attractive in the first place. This approach demonstrates how a single-developer-originated title can compete with larger publishing structures through sustained iteration and strong community alignment.
PW Consulting
Klei Entertainment and Curve Games represent the survival-adjacent side of life simulation. Don’t Starve and The Forest series emphasize resource management, lifecycle constraints, and open-world bases, but they still deliver life simulation value through progression, survival routines, and social dynamics in persistent environments. Their strategic advantage lies in offering tension and agency alongside simulation, attracting players who want routine-based progression within more challenging conditions. The full release of Sons of the Forest, with expanded multiplayer and base-building, illustrates how this niche can mature into a larger player base by strengthening cooperative play and environmental depth.
Hello Games and Giant Squid illustrate exploration-centered life simulation approaches. By emphasizing ecosystem interaction, procedural environments, and serene or expansive world dynamics, these studios frame life simulation as participation in a living environment rather than only domestic or social management. Their positioning is narrower in mainstream reach but valuable in expanding the genre’s expressive range, especially for players interested in discovery, base management, and environmental immersion.
Colony Wing represents a more recent entry point with AI-driven life stage simulation and quirky behavioral mechanics. Its profile suggests a growing area of experimentation: using AI behaviors and generational progression to create more individualized, emergent life narratives. Even when such titles remain smaller in scale, they contribute to the genre’s evolution by testing new simulation logic that larger franchises may later adapt.
How the Competitive Landscape Is Changing
The market is moving toward a dual pattern of consolidation and niche divergence. Larger, well-capitalized franchises continue to extend their reach through expansions, live content, and multi-platform support. These titles benefit from recognizable brands, established communities, and infrastructure for recurring monetization. At the same time, independent and mid-tier studios continue to carve out distinct identities by leaning into specialization: survival simulation, exploration-focused life systems, relationship-rich farming loops, or AI-driven life stages.
This divergence matters because it reduces the likelihood that a single design formula will dominate the category. Instead, the market increasingly rewards franchise stamina, cross-platform execution, and simulation-specific player retention. New entrants are most likely to succeed by targeting underserved simulation moods or mechanics rather than attempting to replicate mainstream household names outright. The result is a healthier, more varied ecosystem, but also one where execution discipline is essential. A strong concept alone is insufficient if the studio cannot support ongoing engagement, manage platform-specific distribution expectations, and stay within cost constraints.
Forward Outlook: Three Trends to Watch
The next three to five years are likely to be shaped by the interaction between technology adoption, audience habits, and production realities. Three directional trends stand out.
First, AI-driven social and behavioral systems will become more mainstream in life simulation design. As more titles integrate generative AI for NPC interaction, dynamic routines, and emergent storytelling, the genre’s value proposition will increasingly hinge on reactivity and personalization. Studios that can deliver meaningful social variation without compromising coherence or moderation will have an advantage. The commercial opportunity here lies in higher retention, broader replay appeal, and stronger emotional attachment. The risk is that poorly governed AI behavior can undermine trust, especially when players expect predictable fairness and respectful interaction in daily-life contexts.
Second, cross-platform lifecycle management will become a baseline expectation for commercially ambitious titles. Players in this category are not tied to a single device ecosystem; they migrate between mobile and PC depending on context, and some extend to console. That means successful products must be designed with synchronized progression, platform-appropriate interaction, and coherent live operations. The opportunity is to capture habitual engagement across devices rather than treating each platform as a separate release window. The uncertainty lies in fragmentation of investment: if teams spread resources too thin across platforms, quality can suffer and audience expectations can decline.
Third, the genre will continue to diversify around simulation mood rather than a single core experience. Some players will gravitate toward serene routines, relationship building, and community rhythm; others will want survival tension, generational progression, or exploration-centered ecosystems. Publishers that understand which emotional mode their audience values can design differentiated roadmaps instead of trying to serve every possibility at once. The upside is stronger franchise identity and more efficient marketing. The downside is that over-indexing on one mood can limit audience breadth and make franchises more vulnerable if engagement habits shift.
Strategic Implications for Decision Makers
For publishers and developers, the practical takeaway is to treat life simulation as a lifecycle business rather than a launch event. Teams should prioritize reusable simulation systems, clear session loops, and content plans that reinforce habitual engagement. Where AI tools are adopted, they should be integrated with strong behavioral design and moderation safeguards so that responsiveness enhances rather than destabilizes the experience. Cross-platform planning should be explicit from the outset, with platform-specific interaction logic mapped to a shared progression backbone.
For investors, the most relevant signal is that growth is real but quality-sensitive. The category is expanding at a moderate CAGR, yet budget pressures and audience expectations make execution risk substantial. Capital is better directed toward studios with proven retention logic, sustainable production pipelines, and franchise roadmaps that extend emotional depth rather than relying on novelty alone. Portfolios should favor projects that can support ongoing live operations or have a clear path to community-led longevity.
For acquisition and partnership teams, the market presents opportunities in specialized simulation mechanics, cross-platform lifecycle support, and AI-assisted social systems. Rather than seeking only the largest brands, partnership strategies can focus on studios with distinctive simulation moods, efficient content pipelines, or strong player attachment that can be scaled through publishing, tooling, or distribution support.
The market’s continued expansion does not guarantee success for every entrant, but it does create a strong case for sharper strategic intelligence. Detailed segmentation, platform-level revenue dynamics, regional diffusion patterns, and company-specific benchmarking can clarify where investment, development, and partnership decisions are likely to yield the strongest returns. Readers seeking a fuller breakdown of revenue segments, platform shifts, competitive benchmarks, and forward scenarios can find that level of detail in the complete research report, where the underlying numbers and company-level implications are mapped out in greater depth.
Worldwide Simulation Business Mobile Game Market
For detailed analysis of this topic, please visit the official page: Worldwide Life Simulation Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LFP Cathode Material Market: Why 19.24% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Worldwide Lithium Iron Phosphate Cathode Material Market: Strategic Trends and Commercial Opportunities
Market Overview: Scale, Momentum, and Critical Inflection Points
The worldwide lithium iron phosphate (LFP) cathode material market has transitioned from a regional specialty to a central pillar of the global battery supply chain. Valued at approximately 3,480 million USD in 2020, the market expanded to 26,850 million USD by 2025, reflecting an aggressive compound annual growth rate of 19.24% through 2032. By the end of the forecast window, total revenue is projected to approach 92,022 million USD, reshaping how automakers, energy developers, and industrial manufacturers approach cost structures, performance trade-offs, and sourcing strategies.
This trajectory is not merely a reflection of broader battery demand. It signals a structural shift in chemistry preference, where LFP has captured meaningful share from nickel-cobalt-based alternatives in applications that prioritize cycle life, thermal stability, and manufacturing economics over raw gravimetric energy density. The market’s expansion has been broad-based across segments, with commercial momentum concentrated in regions that host integrated battery manufacturing, rapid EV deployment, and large-scale stationary storage projects.
Despite the clear growth narrative, the industry sits at a strategic inflection point defined by three overlapping challenges. First, suppliers must navigate a volatile raw material environment. Lithium carbonate prices, which languished near 59,000 CNY/ton in mid-2025, rebounded sharply and surpassed 130,000 CNY/ton by year-end, directly pressuring cathode input costs and squeezing margins where long-term pricing agreements lag spot market movement. Second, geographic policy asymmetry is fragmenting supply chains. Export controls introduced in late 2025 on high-density, high-capacity LFP cathode materials and associated production technologies have tightened the movement of advanced manufacturing know-how, encouraging parallel development efforts outside China and altering previously efficient cross-border flows. Third, pricing pressure in key destination markets is intensifying. In the United States, LFP cathode material pricing reached roughly 12,799 USD/MT in the third quarter of 2025 before softening, as cell makers prioritized output and lithium salt dynamics shifted. For cathode producers, the implication is clear: volume growth alone will not protect profitability. Competitive advantage will increasingly depend on cost discipline, process efficiency, and the ability to align product specifications with regional regulatory and performance requirements.
Key Drivers Reshaping Demand, Supply, and Competitive Advantage
Technology innovation remains the most potent catalyst for LFP cathode market expansion. The standard LFP chemistry has matured into a highly reliable baseline, but the real strategic action now centers on lithium manganese iron phosphate (LMFP) and process engineering that pushes compacted density and gram capacity higher. These advancements matter because they allow manufacturers to retain LFP’s cost and safety benefits while improving energy density for mobility applications and reducing material intensity per kilowatt-hour. Companies actively refining one-pot synthesis routes, continuous production workflows, and more consistent particle engineering are building a measurable edge in throughput quality and capital efficiency. The broader trend is toward cathode architectures that align more closely with cell-level design optimization rather than treating cathode material as a commoditized input.
Policy and regulatory dynamics are simultaneously restructuring where capacity is built and how trade flows. Chinese export restrictions on high-density LFP and LMFP cathode production technologies have elevated the strategic importance of non-Chinese manufacturing capabilities. At the same time, tariff exposure on Chinese LFP cells in the United States has reinforced the case for re-shoring cathode active material production, especially as battery energy storage system demand accelerates. These policy shifts are not simply barriers; they are allocation mechanisms. They create incentives for localized supply, technology transfer partnerships, and regional qualification cycles that can become durable sources of advantage for producers who move early. In effect, the market is moving from a globally integrated model to a more multi-node architecture, where regional compliance, customer proximity, and certification readiness carry increasing commercial weight.
Demand-side behavior is another critical driver. Electric vehicles continue to anchor the largest share of LFP cathode consumption, but the growth profile is broadening. Energy storage systems are becoming an increasingly strategic volume pool because stationary applications tolerate LFP’s heavier pack weight while rewarding long service life, safety, and total cost of ownership. In consumer electronics and industrial use cases, LFP adoption remains more selective, yet it offers manufacturers a predictable, lower-volatility chemistry for specific performance envelopes. More importantly, procurement behavior is changing. Buyers are less willing to accept undifferentiated supply at volatile spot prices. They are seeking qualified suppliers with stable quality, reliable delivery, and transparent cost structures. This shift tilts bargaining power toward producers who can demonstrate process consistency, capacity credibility, and regional responsiveness.
Worldwide Cathode and Precursor Materials Market
Finally, cost structure and supply chain strategy are being redefined together. LFP cathode economics are closely tied to lithium feedstock exposure, precursor availability, and manufacturing yield. When lithium prices spike, margin resilience depends on how efficiently a producer can convert inputs, manage inventory cycles, and negotiate customer contracts. This environment rewards manufacturers with scale, backward integration options, or process technologies that reduce waste and energy intensity. It also elevates the importance of partnerships across the value chain, including cathode producers, cell manufacturers, and end-market customers who are willing to coordinate product roadmaps. In this setting, cost leadership is no longer purely about input price timing; it is about structural efficiency and supply chain coordination.
Competitive Landscape: Positioning, Differentiation, and Structuring Shifts
The competitive landscape is defined by a concentration of established producers, a growing set of technology-focused entrants, and an expanding group of regional players seeking to capture policy-driven localization opportunities. Several large-scale manufacturers in the Asia-Pacific region have built strong positions through high-volume output, extensive customer networks, and deep familiarity with battery cell qualification cycles. Their strategic value lies in proven scale, repeatability, and the ability to support EV and energy storage programs with consistent supply. For global battery manufacturers, these producers often serve as core-volume partners, which gives them leverage in customer relationships but also exposes them to cyclical pricing pressure and geopolitical trade dynamics.
Differentiation is increasingly visible along three dimensions: process innovation, regional footprint, and application specialization. Technology-oriented producers are pursuing proprietary synthesis routes and continuous manufacturing models that promise better control over particle morphology, energy consumption, and quality consistency. Where these approaches translate into lower cost per useful ton or superior electrochemical consistency, they become meaningful differentiators rather than marketing claims. At the same time, regional diversification is emerging as a distinct strategic posture. Stakeholders outside China are building capacity not only to serve domestic markets but also to reduce exposure to cross-border constraints and align with customer requirements tied to local content, certification, and logistics resilience.
Recent developments illustrate how these strategies are being executed. One Canadian producer has advanced detailed engineering and equipment procurement for an 800 tpa LFP cathode capacity expansion in Quebec, signaling a focus on scaling proprietary process technology in North America. In South Korea, POSCO Future M moved decisively by approving investment in an LFP cathode plant with up to 50,000 tons of annual capacity and converting selected existing Pohang lines to begin LFP supply in the second half of 2026. The same effort expanded through a joint venture with CNGR and FINO to build a 50,000-ton facility in Pohang, with site construction scheduled for 2026. These moves highlight a broader pattern: incumbents with existing chemical or materials expertise are using brownfield conversion, partnerships, and targeted greenfield capacity to enter or scale LFP offerings with lower timing risk than fully organic standalone builds.
The market is therefore evolving through a blend of consolidation, differentiation, and new entry. On one side, scale players are likely to continue consolidating volume positions and tightening relationships with major cell customers. On the other, chemically adjacent companies, regional materials suppliers, and technology specialists are entering with narrower but higher-value propositions. The result is a market that is not simply fragmenting into many small competitors, but rather stratifying by value proposition: high-volume cost leaders, technology-differentiated producers, and regionally anchored suppliers positioned for policy and customer proximity advantages. Over the next several years, competitive success will depend less on the sheer announcement of capacity and more on execution quality, qualification speed, and the ability to align product specifications with regional demand realities.
Forward Outlook: Three Trends Defining the Next Three to Five Years
The first trend is the continued regionalization of LFP cathode supply. As export controls, tariff exposure, and customer localization preferences shape procurement decisions, production capacity is expected to become more geographically distributed. This does not eliminate global trade, but it increases the value of regionally qualified supply bases. For businesses, that means sourcing strategies will need to account for certification timelines, technical support proximity, and the risk of policy shifts that can disrupt previously efficient flows.
The second trend is the progressive refinement of LFP and LMFP product portfolios. Demand will increasingly reward cathodes that offer an optimized balance of energy density, cycle durability, and manufacturing practicality. Standard LFP will remain essential for cost-driven applications, but LMFP and higher-performance LFP variants are likely to capture growing attention in automotive and storage use cases where incremental energy gains and specification flexibility improve total system economics. Companies that can produce differentiated grades with consistent quality will be better positioned to command pricing and stickier customer relationships.
The third trend is cost structure competitiveness becoming a strategic moat rather than a temporary advantage. Lithium feedstock volatility and evolving manufacturing economics will continue to test margins. The producers most likely to sustain profitability will be those that combine scale, efficient process design, inventory and contract management, and the flexibility to serve both high-volume baseline demand and specialty-grade needs. At the same time, risk remains. Policy uncertainty, technology export constraints, demand pacing in certain EV segments, and commodity price swings can all alter the speed and distribution of value capture. Planning will need to treat these variables as structural inputs, not temporary noise.
Strategic Actions for Decision-Makers
For cathode and battery materials manufacturers, the priority is to convert capacity plans into execution credibility. That means aligning process choices with customer qualification requirements, securing feedstock resilience, and building product lines that span both cost-sensitive baseline demand and higher-specification opportunities. Suppliers that can demonstrate stable quality, regional responsiveness, and transparent cost logic will be better placed to win long-term contracts in a more fragmented trade environment.
Lithium Hexafluorophosphate Market
For investors, the key is to distinguish announced capacity from commercially viable capacity. The most valuable opportunities are likely tied to producers with credible technology differentiation, disciplined cost structures, and clear regional positioning that matches policy incentives and customer demand. Capital allocation should weigh not only tonnage targets but also process maturity, qualification readiness, and exposure to lithium input volatility and trade constraints.
PW Consulting
For procurement and sourcing leaders, resilience should take precedence over short-term spot optimization. Diversifying qualified suppliers across regions, securing visibility into production roadmaps, and aligning specifications with application needs can reduce vulnerability to pricing spikes and policy-driven supply disruptions. As LFP cathode markets mature, purchasing advantage will increasingly come from strategic supplier relationships and forward visibility rather than transactional bargaining alone.
For organizations seeking deeper segment data, regional breakdowns, cost-model scenarios, and company-level benchmarking, the full PW Consulting research report provides a more detailed analytical framework to support planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Lithium Iron Phosphate Cathode Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Luxury Cosmetics Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide luxury cosmetics packaging market has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately USD 5.8 billion in 2020, the market reached USD 7.45 billion by 2025, reflecting a compound annual growth rate of 5.18 percent through the forecast horizon extending to 2032. This trajectory translates to a projected valuation exceeding USD 10.6 billion by the end of the forecast period. The growth pattern reveals consistent upward momentum, with notable acceleration expected from 2029 onward as regulatory frameworks mature and consumer preferences continue to shift toward premiumized, sustainability-aligned offerings.
At the macro level, the market structure remains moderately fragmented, with the top three players holding an 18.4 percent share and the top five collectively commanding 27.15 percent. This concentration level indicates a competitive landscape where no single entity dominates outright, allowing specialized manufacturers to thrive alongside broad-line suppliers. The moderate fragmentation creates both pressure and opportunity: established players must continuously differentiate through design, material innovation, and service capabilities, while agile newcomers can capture niches by addressing unmet needs in specific application categories or regional markets.
Several structural challenges currently define the industry's inflection point. First, the regulatory environment is undergoing its most significant transformation in decades, particularly in Europe, where the Packaging and Packaging Waste Regulation entered into force in early 2025 and will apply from mid-2026. This framework introduces mandatory recyclability criteria, minimum post-consumer recycled content thresholds for certain plastic formats, and extended producer responsibility schemes with fees modulated by recyclability performance. For luxury cosmetics packaging, these requirements create a complex compliance landscape that demands proactive design-for-recycling strategies rather than reactive adjustments.
Second, raw material dynamics are introducing cost volatility and sourcing complexities. Glass continues to serve as a cornerstone material for high-end packaging due to its barrier properties, aesthetic versatility, and recyclability profile, with the broader cosmetic glass packaging segment reflecting substantial value concentration. Simultaneously, premium plastics and metal formats face mounting pressure from both regulatory cost mechanisms and consumer expectations around sustainability. Italy's planned plastic tax, scheduled for implementation in 2026, exemplifies the national-level fiscal measures that are reshaping material economics across the value chain.
Third, the tension between luxury brand aesthetics and sustainable material performance remains a persistent challenge. Premium positioning historically relied on visual and tactile cues—weight, transparency, metallic finishes, intricate molding—that can conflict with lightweighting, mono-material conversion, or PCR integration mandates. Brands and packaging suppliers must navigate this balance carefully, as compromising perceived quality can undermine the premium value proposition that drives margin premiums in the first place.
Key Drivers Reshaping the Market
Technological Innovation and Material Science Breakthroughs
Material science and dispensing technology are driving the most consequential product-level changes in the market. Airless packaging systems have evolved significantly, offering improved product preservation, reduced contamination risk, and enhanced consumer dosing precision—attributes that resonate strongly with high-end skincare and fragrance applications. Several leading suppliers have expanded their airless portfolios with lines specifically engineered for recyclability and premium performance, targeting the 15 to 50 milliliter range that dominates prestige skincare formats.
Parallel advances in mono-material design and post-consumer recycled content integration are enabling brands to meet sustainability targets without abandoning premium aesthetics. Mono-material structures simplify end-of-life recycling streams and align with design-for-recycling criteria, while PCR incorporation allows manufacturers to communicate tangible sustainability credentials. The challenge lies in maintaining visual and tactile quality: advanced coatings, textured substrates, and refined molding techniques are increasingly deployed to preserve the sensory experience that luxury consumers expect. Specialty label providers have also contributed by introducing textured substrates and sustainable material options that enhance brand differentiation on primary and secondary packaging surfaces.
Regulatory Pressure and Compliance-Driven Redesign
Regulatory momentum represents both a constraint and a catalyst for innovation. The EU Packaging and Packaging Waste Regulation establishes a comprehensive framework that will influence packaging formulations, labeling, and end-of-life management well into the 2030s. Extended producer responsibility obligations with fee modulation tied to recyclability grades create a direct financial incentive for designers to prioritize recyclable architectures from the outset. Standardized labeling requirements further push toward transparency and consumer education, which can become a brand advantage when executed thoughtfully.
Cosmetics Brushes Market
National-level measures add additional layers of complexity. Plastic packaging taxes and modulated EPR fees are being implemented or considered across multiple jurisdictions, altering the cost calculus for plastic-intensive formats. These measures disproportionately affect non-recyclable or multi-material constructions, accelerating the shift toward mono-material solutions and higher PCR content. For market participants, the strategic implication is clear: regulatory compliance is no longer a checkbox exercise but a core design parameter that influences material selection, supplier partnerships, and total cost of ownership.
Demand-Side Evolution: Consumers and Brand Strategies
Consumer expectations continue to drive premiumization, but the definition of luxury is expanding. High-income consumers increasingly evaluate sustainability credentials alongside craftsmanship, heritage, and sensory appeal. The rise of refillable and reusable formats reflects this shift: consumers are willing to accept slightly different usage mechanics if the design communicates environmental responsibility without sacrificing perceived quality. Refillable architectures also create recurring engagement opportunities, strengthening brand loyalty and enabling lifetime value expansion.
PW Consulting
Brand strategies are adapting accordingly. Prestige houses are investing more heavily in packaging that tells a coherent sustainability story, recognizing that packaging serves as a tangible touchpoint for brand values. This dynamic elevates the importance of packaging suppliers that can deliver customizable, high-end solutions with verified material credentials and transparent lifecycle narratives. The demand for bespoke designs remains strong, particularly in fragrance and color cosmetics, where packaging function as brand signature.
Supply Chain Reconfiguration and Cost Structure Shifts
Supply chain dynamics are undergoing recalibration as manufacturers balance cost efficiency with resilience and compliance. Regional concentration patterns show Europe and Asia Pacific as the largest value pools, followed by North America, with Middle East and Africa and Latin America representing smaller but growing contributions. This geographic distribution encourages suppliers to develop regional production and sourcing strategies that reduce logistics exposure while meeting local regulatory expectations.
Cost structures are being reshaped by material taxes, recycled content premiums, and the capital investment required for recycling-compatible manufacturing processes. At the same time, consolidation activity is intensifying as larger players acquire specialized capabilities to expand their premium portfolios. A notable acquisition saw a packaging group strengthen its folding carton offerings for perfumery and cosmetics, illustrating how inorganic growth is being used to secure high-end presentation capabilities. These moves signal a market where integrated capabilities—from primary packaging to secondary presentation—are increasingly valued.
Competitive Landscape and Leading Strategies
Incumbent Strengths and Differentiation Pathways
The competitive field features a diverse mix of multinational suppliers and regional specialists, each pursuing distinct differentiation strategies. AptarGroup has built a strong position around dispensing systems, airless packaging, pumps, and closures designed for premium skincare, fragrance, and color cosmetics. The company's emphasis on sustainable and customizable high-end solutions aligns with the dual imperatives of performance and compliance, and recent portfolio expansions in Latin America reflect a deliberate push to capture growth in emerging premium segments.
Albéa Group stands out as a global leader in cosmetic tubes, compacts, lipsticks, and jars, with a particularly strong footprint in luxury and prestige beauty packaging. Its focus on mono-material structures, PCR integration, and refillable designs positions it well for the regulatory and consumer trends reshaping the market. Gerresheimer AG leverages its heritage in high-quality glass and plastic packaging to serve luxury cosmetics and skincare, offering premium jars, bottles, and vials that capitalize on glass's enduring appeal for high-end formulations. Amcor plc brings a broad capability set spanning flexible and rigid packaging with premium finishes, emphasizing sustainable materials and high-barrier properties that suit luxury cosmetics applications.
Specialist players are carving out niches through focused expertise. Silgan Holdings supplies metal and plastic containers, closures, and dispensing systems suitable for luxury personal care, while HCP Packaging concentrates on luxury color cosmetics packaging including compacts, lipsticks, jars, and brushes for high-end global brands. Quadpack emphasizes sustainable and premium packaging for beauty, including airless systems, jars, and bottles for luxury skincare and makeup. Regional specialists such as Lumson and Baralan in Italy provide premium dispensing systems, airless packaging, and glass and plastic solutions that leverage the country's strong design heritage. Meanwhile, U.S.-based players like World Wide Packaging, FusionPKG, and Cosmopak serve prestige brands with innovative and custom luxury packaging components, focusing on stock and bespoke solutions for high-end applications.
Market Evolution: Consolidation, Differentiation, and New Entrants
The market is evolving along three parallel tracks. Consolidation is accelerating as larger suppliers acquire specialized assets to deepen their premium capabilities, expand geographic reach, or strengthen material and format portfolios. These acquisitions tend to target companies with proven design expertise, proprietary dispensing technologies, or strong relationships with prestige brands. The result is a landscape where integrated suppliers increasingly offer end-to-end solutions spanning primary packaging, dispensing mechanisms, closures, and secondary presentation elements.
Differentiation is intensifying around sustainability credentials, customization depth, and application-specific engineering. Suppliers that can demonstrate verifiable recyclability, PCR content, mono-material architectures, or refillable systems gain a competitive edge, particularly when paired with the design sophistication that luxury brands demand. Customization remains a key battleground: bespoke molds, exclusive finishes, and tailored dispensing experiences allow brands to create distinctive packaging signatures that reinforce premium positioning.
New entrants and regional specialists continue to find opportunities by addressing underserved niches or geographies. The moderate market concentration leaves space for agile players that can deliver high-quality, design-forward solutions with shorter lead times or specialized material expertise. At the same time, the regulatory environment raises the barrier to entry for low-cost, non-compliant offerings, effectively filtering the market toward participants that can invest in compliant design and material innovation.
Future Trends: 2026 to 2032 Outlook
Sustainability as a Design Baseline, Not a Differentiator
Over the next three to five years, sustainability will transition from a competitive differentiator to a baseline requirement. The cascading effect of EU regulations, national plastic taxes, EPR fee modulation, and PCR content mandates will make recyclable, mono-material, and recycled-content packaging the default expectation for luxury cosmetics. Brands and suppliers that treat sustainability as an afterthought will face rising compliance costs and potential market access limitations. Those that integrate these requirements into core design processes will unlock efficiencies in material sourcing, waste management, and brand messaging. Commercial opportunities will emerge for suppliers offering verified PCR content, design-for-recycling consultation, and refillable system architectures that balance convenience with environmental performance.
Premiumization Through Intelligent and Refined Formats
Luxury consumers will continue to reward packaging that enhances the product experience through refined engineering rather than sheer material volume. Airless systems, precision dispensing mechanisms, and packaging that preserves product integrity will gain prominence, especially in skincare and fragrance categories. Intelligent features—such as tamper evidence, dosage control, and interactive elements that communicate usage guidance or brand stories—may become more prevalent as brands seek to justify premium price points through functional value. The opportunity lies in integrating these features without compromising recyclability or inflating material costs unnecessarily. Suppliers that can deliver sophisticated dispensing and preservation performance within recyclable or mono-material frameworks will capture increasing share.
Luxury Packaging Market
Regional Growth Divergence and Supply Chain Localization
Regional growth patterns will diverge as local regulatory regimes, consumer income trends, and brand distribution strategies shape demand. Europe's regulatory leadership will continue to influence global design standards, while Asia Pacific's expanding premium beauty market will drive volume growth and encourage localized packaging solutions. Latin America and Middle East and Africa represent smaller but increasingly relevant opportunities, particularly as international prestige brands expand their footprints and local consumers adopt premium consumption patterns. Supply chain localization will become more pronounced as manufacturers seek to reduce logistics exposure, respond faster to regional regulatory changes, and align material sourcing with local recycling infrastructure. This trend favors suppliers with multi-region production capabilities and the flexibility to adapt material specifications to regional compliance environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory implementation timelines and enforcement intensity may vary across jurisdictions, creating compliance complexity for globally distributed brands. Material cost volatility, particularly for recycled content and specialty glass, could pressure margins if supply does not keep pace with demand. Consumer willingness to accept material substitutions or refillable formats may diverge from stated preferences, requiring careful testing and brand communication. Finally, rapid technological change in recycling infrastructure and waste management could shift what counts as "recyclable" in practice, requiring ongoing design adaptation.
Strategic Recommendations for Decision-Makers
For Manufacturers and Packaging Suppliers
Embed design-for-recycling and PCR integration into product development cycles now, rather than treating them as retrofit requirements. Invest in mono-material architectures and airless or dispensing technologies that meet both performance and compliance standards. Build verifiable material credentialing and transparent lifecycle narratives that luxury brands can use in consumer communication. Monitor regulatory developments closely, particularly around PCR thresholds and recyclability grading, and align product roadmaps with the 2030 horizon when several mandates will take full effect.
For Investors
Evaluate targets based on their ability to deliver premium aesthetics alongside sustainable material performance, as this dual capability will command pricing power and customer loyalty. Prioritize companies with strong relationships in skincare and fragrance segments, where airless systems and glass formats drive value, and those with proven customization and bespoke design capabilities. Assess geographic balance: suppliers with exposure to Europe's regulatory-driven redesign and Asia Pacific's premium growth offer complementary risk-return profiles. Watch for consolidation opportunities where specialized design or dispensing technologies can be integrated into broader portfolios.
For Procurement and Brand Teams
Treat packaging suppliers as strategic partners rather than transactional vendors. Develop joint roadmaps that align material selection, dispensing technology, and sustainability credentials with brand positioning and regulatory timelines. Prioritize suppliers that can provide transparent material data, recyclability documentation, and flexible customization without compromising lead times. Explore refillable and reuse formats where brand architecture and consumer behavior support recurring engagement, and pilot these formats in controlled segments before scaling. Ensure packaging decisions reflect total cost of ownership, including compliance risk, recyclability fees, and brand perception impact, not just unit price.
Navigating this market successfully requires detailed, segment-specific intelligence that connects macro trends to actionable decisions across materials, applications, regions, and company strategies. Comprehensive analysis with granular data on market sizing, competitive positioning, regulatory timelines, and material dynamics can help decision-makers prioritize investments and mitigate risk with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Cosmetics Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


