



M.2 SSD Market: Why NVMe PCIe and 17% CAGR Redefine the 2032 Growth Trajectory
By PW Consulting, 2026-09-18
The M.2 Interface SSD Market at an Inflection Point: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
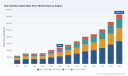
The worldwide M.2 interface solid-state drive market has entered a phase of aggressive expansion, fueled by the convergence of high-performance computing, AI-driven workloads, and rapidly evolving endpoint devices. Over the historical period from 2020 to 2025, the sector demonstrated remarkable resilience and growth, with revenues climbing from roughly 24.15 billion USD in 2020 to an estimated 48.65 billion USD in 2025. This trajectory positions the market to sustain a compound annual growth rate of approximately 17.02 percent through the forecast horizon ending in 2032, reaching a projected revenue scale that underscores the M.2 form factor's dominance across consumer, enterprise, and specialized computing applications.
Such rapid expansion is not without structural friction. The first critical challenge lies in the severe tightness of NAND flash supply. Contract pricing for memory components has experienced dramatic swings, with late 2025 and early 2026 reports documenting increases ranging from over 50 percent to nearly 246 percent compared to early 2025 baselines. Major suppliers have indicated that 2026 production capacity is fully committed, extending lead times and pressuring the bill of materials for M.2 SSDs. This supply-demand imbalance forces manufacturers and OEMs to navigate volatile input costs while maintaining competitive pricing and margin structures.
A second pivotal challenge stems from the intensifying geopolitical and regulatory landscape. Ongoing export controls on advanced semiconductors and related manufacturing equipment continue to reshape global supply chains for memory components. Concurrently, geopolitical tensions and associated tariffs create additional layers of complexity for sourcing NAND flash and finished SSD components across regions. These dynamics elevate the strategic importance of supply chain resilience, regional diversification, and inventory planning, particularly for organizations that rely on tightly coupled component ecosystems.
The third challenge centers on the rapid pace of protocol and form factor evolution. As PCIe Gen5 technology matures and moves into mainstream and ultra-compact applications, the market faces a transitional period where legacy SATA-based M.2 deployments must be carefully managed alongside next-generation NVMe solutions. The coexistence of multiple generations, varying endurance requirements across client, enterprise, and industrial segments, and the emergence of highly specialized compact form factors creates a complex engineering and product strategy environment. Companies that fail to align their roadmaps with these technological inflection points risk losing relevance in increasingly performance- and efficiency-driven segments.
Key Drivers of Market Evolution
Technological Innovation and Architectural Breakthroughs
The most potent catalyst for M.2 SSD growth is the rapid advancement of NAND flash density, controller efficiency, and interface bandwidth. The transition to PCIe Gen5 represents a fundamental shift in performance ceilings, enabling dramatically higher sequential and random throughput that directly benefits AI inference at the edge, content creation workstations, and high-density client computing. Manufacturers are pushing these capabilities into increasingly compact footprints. For example, Samsung showcased the PM9E1, recognized as the world's first 4TB PCIe Gen5 SSD in a compact M.2 2242 form factor, specifically optimized for AI workloads and compact systems. Such innovations demonstrate that high capacity and top-tier performance can be delivered in space-constrained environments, opening new design possibilities for OEMs and system integrators targeting both mainstream and specialized applications.
Worldwide SSD Memory Card Market
Equally significant is the democratization of advanced NAND technologies for broader market reach. Micron's launch of the 3610 NVMe SSD, the industry's first PCIe Gen5 G9 QLC client SSD for mainstream computing, brought single-sided M.2 2230, 2242, and 2280 form factors with capacities up to 4TB to the forefront of general-purpose laptop and ultra-thin designs. Kioxia followed with the BG8 series, introducing PCIe Gen5 to mainstream PC systems across 2230, 2242, and 2280 form factors with 512GB to 2TB capacities, with sampling to OEM partners leading to expected system availability in the second quarter of 2026. These moves signal that cutting-edge performance is no longer confined to premium niche products; it is being systematically embedded into volume platforms, expanding the addressable market and raising the baseline expectations for consumer and business computing devices.
Demand-Side Shifts Across Endpoint Segments
Demand-side dynamics are being reshaped by the proliferation of AI-enabled workflows, data-intensive professional applications, and the continuous evolution of client and embedded computing. Enterprise and client environments are increasingly requiring storage solutions that can sustain high I/O concurrency, low latency, and robust endurance under sustained workloads. At the same time, the industrial and embedded sectors are developing specialized requirements that call for secure boot capabilities, ruggedized designs, and compliance with ecosystem standards. Virtium's announcement of the StorFly-HS OCP S.A.F.E.-certified industrial M.2 2242 PCIe Gen4 NVMe boot SSD highlights this trend, delivering the first such certified solution for secure boot in OCP ecosystems with mass production and qualification samples available. The expansion of Greenliant's PrimeDrive SX Series economical NVMe M.2 2280 SSDs, with volume shipping beginning in late 2025, further illustrates how industrial and embedded applications are accessing cost-optimized NVMe performance while meeting stringent deployment needs.
On the brand and market positioning side, Western Digital unveiled SANDISK Optimus as the new branding for its internal NVMe SSD portfolio, consolidating previously separated lines and signaling updated product rollouts expected at retailers during the first half of 2026. This rebranding reflects a broader industry pattern: as performance tiers and use cases become more granular, companies are refining their go-to-market narratives to better align with creator, gaming, professional, and mainstream segments. The cumulative effect is a market where demand is not only growing in volume but also becoming more segment-aware, requiring tailored performance, reliability, and value propositions.
Supply Chain Dynamics and Cost Structure Pressures
The cost structure of M.2 SSDs is being redefined by raw material dynamics and the strategic behavior of vertically integrated assemblers. NAND flash constitutes the majority of the SSD bill of materials, meaning that contract price movements directly translate into OEM and end-product pricing shifts. Industry commentary in late 2025 emphasized that SSD prices faced significant upward pressure as NAND contract increases were passed through to downstream customers. Combined with reports that major suppliers had fully allocated 2026 production, this environment creates an acute tension between volume growth and margin preservation.
Vertically integrated participants are positioned to navigate this tension with greater flexibility, as they control critical stages from memory fabrication through controller integration and final assembly. This structure offers leverage in prioritizing high-margin applications, managing allocation during tight cycles, and accelerating time-to-market for next-generation platforms. Meanwhile, controller specialists and solution providers continue to play a vital enabling role, supplying controllers and complete M.2 SSD designs across PCIe Gen4 and Gen5 drives to multiple NAND vendors and brands. The interplay between memory suppliers, controller designers, and system-level assemblers is becoming increasingly strategic, with collaboration and co-engineering accelerating the arrival of differentiated products in a constrained environment.
Competitive Landscape and Leading Strategies
The competitive architecture of the M.2 SSD market is defined by a concentrated group of dominant players alongside a diverse set of specialists and enablers. Market concentration remains high, with the top three firms holding a combined share exceeding half of total revenue and the top five capturing more than four-fifths. This concentration reflects the structural advantages of scale, vertical integration, and deep relationships with OEM and enterprise customers. Yet the landscape is not static; differentiation is increasingly determined by how companies balance performance leadership, capacity innovation, form factor versatility, and ecosystem alignment.
Samsung and SK hynix stand out as vertically integrated Korean manufacturers with broad exposure across consumer and enterprise segments. Samsung leverages proprietary V-NAND technology and a comprehensive portfolio spanning high-performance consumer drives and enterprise PCIe Gen5 M.2 solutions, including compact form factors tailored for AI applications. SK hynix, including its Solidigm brand, supplies M.2 SSDs across multiple use cases, with Solidigm placing particular emphasis on high-capacity client and data center M.2 NVMe drives that target enterprise-grade requirements. Both firms benefit from end-to-end control over key components, enabling them to optimize cost, performance, and supply continuity in a market where input constraints are acute.
Micron and Kingston reinforce the competitive depth of the segment with strong U.S. footprints and broad M.2 NVMe portfolios. Micron's Vertically integrated approach and the rollout of the 3610 series demonstrate a strategy of pushing advanced Gen5 QLC technology into mainstream and ultra-thin laptop segments across single-sided M.2 form factors. Kingston maintains a wide-reaching consumer and enterprise M.2 NVMe portfolio, active in high-capacity and performance solutions that serve diverse deployment scenarios. These players highlight the importance of aligning product breadth with segment-specific performance and endurance requirements.
PW Consulting
Regional strength and specialization further enrich the competitive spectrum. Kioxia and TEAMGROUP bring Japanese and Taiwanese expertise to bear, with Kioxia targeting mainstream PC OEMs through BG8 series client M.2 SSDs in multiple form factors and TEAMGROUP offering high-performance PCIe 5.0 NVMe options such as the NV10000 series. Western Digital, through its WD Black and SanDisk branding and the 2026 SANDISK Optimus rebrand, provides an extensive M.2 NVMe lineup covering gaming, creator, and professional applications. Phison operates as a leading controller designer and SSD solution provider, supplying controllers and complete M.2 SSD designs to multiple NAND vendors and brands, thereby acting as a critical enabler across the value chain. Virtium and Greenliant address the industrial and embedded niche with certified, ruggedized, and economical M.2 NVMe solutions, reflecting the growing demand for application-specific storage.
The market is evolving through a blend of consolidation at the top and differentiation at the edges. Incumbents are strengthening their moats via vertical integration, brand restructuring, and targeted form factor innovation for AI and compact systems. At the same time, opportunities are emerging for specialists who can deliver certified security features, cost-optimized embedded solutions, and controller-level expertise that de-risks customer development cycles. New entrants and sub-segment challengers are unlikely to dislodge the leaders through scale alone; instead, success will depend on precise alignment with supply chain realities, protocol transitions, and the rising demand for application-tailored performance and reliability.
Forward Trends and Strategic Horizons
Looking ahead over the next three to five years, the M.2 SSD market will likely be shaped by the continued mainstreaming of PCIe Gen5 and the concurrent refinement of form factor strategies. High-performance protocols will migrate from premium and enterprise-centric deployments into volume client platforms and compact edge devices, expanding the base of systems that demand next-generation throughput and low latency. This shift will reward manufacturers that can deliver competitive performance across a range of M.2 sizes without compromising thermal efficiency or cost viability. The emergence of multi-capacity, single-sided solutions in 2230, 2242, and 2280 formats indicates a trajectory toward more flexible design envelopes that accommodate thin-and-light laptops, handhelds, and AI-capable compact systems.
A second trend is the deepening segmentation between client, enterprise, and industrial/embedded storage requirements. As workloads diverge, one-size-fits-all propositions will lose traction. Enterprise and data center adjacent applications will prioritize sustained endurance, predictable latency, and ecosystem certifications, while client segments will balance performance, capacity, and price sensitivity. Industrial and embedded deployments will increasingly seek secure boot, ruggedness, and supply reliability, creating space for certified, application-specific drives. Organizations that design portfolios with clear segment logic and corresponding go-to-market narratives will be better positioned to capture margin and customer loyalty.
A third trend concerns the interplay of supply constraints, pricing volatility, and geopolitical complexity. If NAND availability remains tight and contract pricing elevated, the market will likely see sustained upward pressure on component costs and extended lead times, with implications for OEM planning and end-product pricing. At the same time, export controls and trade friction will continue to influence sourcing strategies, encouraging regional diversification, multi-supplier risk management, and inventory buffering for critical programs. Potential risks include sudden shifts in demand intensity as AI capital expenditure cycles adjust, technology transitions that outpace customer qualification timelines, and margin erosion if pricing power does not keep pace with input cost escalation. Navigating this environment will require disciplined roadmap planning, scenario-aware inventory strategies, and close coordination across the memory, controller, and system integration layers.
Strategic Actions for Decision-Makers
For manufacturers and solution providers, the immediate priority is to align product roadmaps with protocol transitions and form factor flexibility while safeguarding supply continuity. Investing in controller and SSD design collaborations, securing early allocations for next-generation NAND, and developing clear segment-specific value propositions can help convert market momentum into defensible market share. Companies should also evaluate platform-level co-engineering opportunities with OEM and enterprise customers to shorten qualification cycles and lock in design wins ahead of volume ramps.
For investors, the market offers attractive growth signals but demands rigorous evaluation of vertical integration, allocation resilience, and segment exposure. Favor companies that demonstrate control over critical components, diversified customer bases, and differentiated positioning in high-growth subsegments such as AI-adjacent compact storage and certified industrial/embedded solutions. Monitor margin trajectories, lead time trends, and branding or portfolio restructuring as leading indicators of how well firms are adapting to pricing volatility and demand shifts.
Solid State Drive (SSD) Market
For procurement and supply chain leaders, the emphasis should be on scenario planning and supplier diversification. Establishing multi-region sourcing options, qualifying alternative controllers and form factors where feasible, and building buffer strategies for mission-critical programs can reduce exposure to sudden price spikes and extended lead times. Engaging with suppliers early to align on capacity commitments and roadmap timing will improve visibility and enable more predictable program execution. For stakeholders seeking detailed, segment-level data and customized strategic recommendations, the full research report provides the granular breakdowns and forward-looking models needed to translate these dynamics into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide M.2 Interface Solid State Drive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Technical Grade Salicylic Acid Market: A 6.28% CAGR Outlook to 2032
By PW Consulting, 2026-09-18
Global Technical Grade Salicylic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
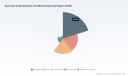
The global market for technical grade salicylic acid has demonstrated steady, resilient growth over the past half-decade, expanding from approximately USD 382.5 million in 2020 to an estimated USD 516.6 million in 2025. Projections indicate continued expansion at a compound annual growth rate of 6.28 percent through 2032, with the market expected to surpass USD 790 million by the end of the forecast window. This trajectory reflects a sector that has moved beyond cyclical volatility to establish a more structurally robust demand foundation, driven by its critical role as a building block in industrial chemistry, cosmetics formulation, and polymer synthesis.
Despite this positive momentum, the industry is navigating a set of interconnected challenges that are reshaping competitive dynamics and investment calculus. The first major pressure point is cost volatility tied to upstream feedstock dependencies. Technical-grade salicylic acid is synthesized primarily through the Kolbe-Schmitt reaction, which relies heavily on phenol and carbon dioxide as core inputs. Phenol pricing, in turn, tracks closely with benzene markets and broader crude oil fluctuations. Recent price movements illustrate this sensitivity: in Northeast Asia, salicylic acid prices dipped to USD 1.68 per kilogram in early 2026, driven by lower phenol input costs and regional oversupply, while European markets experienced the opposite pressure, with prices reaching USD 5.38 per kilogram following elevated phenol and energy costs throughout late 2025. This regional divergence creates uneven margin landscapes and complicates global sourcing strategies for downstream buyers.
The second critical challenge revolves around regulatory compliance and environmental standards. Stringent frameworks such as EU REACH have raised the operational bar for chemical manufacturing facilities, requiring significant capital allocation toward waste treatment infrastructure, emission controls, and process modifications. For producers operating in or exporting to regulated markets, these requirements are no longer optional overhead but foundational cost components. Facilities that cannot absorb or pass through these compliance costs risk margin compression, while those that proactively upgrade processes can leverage regulatory readiness as a competitive differentiator.
A third structural tension lies in market concentration and capacity alignment. The industry exhibits moderate concentration, with the top three players accounting for roughly 44.5 percent of revenue and the top five capturing approximately 61.2 percent. While this level of consolidation provides some pricing stability, it also means that supply disruptions at a handful of major facilities can ripple through global availability. At the same time, demand patterns are shifting across application verticals, with industrial intermediates and personal care formulations absorbing growing shares of production output. Manufacturers must balance capacity allocation across competing end-use segments while maintaining grade purity and consistency that meet increasingly specific customer requirements.
Key Demand Drivers and Structural Shifts
Innovation in Manufacturing Processes and Product Grade Optimization
Process innovation has emerged as a primary catalyst for market evolution, particularly as manufacturers seek to differentiate technical grade offerings in a commodity-adjacent space. Recent industry activity highlights a clear pivot toward capacity optimization and grade specialization. In early 2026, a leading European producer executed a strategic internal restructuring and asset integration initiative designed to expand global salicylic acid production capacity across both pharmaceutical and industrial technical grades. This consolidation signals a broader industry recognition that scale, process efficiency, and grade flexibility are increasingly intertwined competitive advantages. Around the same period, multiple manufacturers advanced capacity expansion projects and process innovations specifically targeting industrial-grade and technical-grade supply, indicating that the segment is attracting focused investment rather than serving as a residual output of pharma-grade operations.
These process advancements translate directly into commercial value. Improved yield rates, reduced waste streams, and tighter control over impurity profiles allow producers to offer technical grade material that meets increasingly stringent specifications from downstream formulators. For applications such as dyes, pigments, rubber auxiliaries, and organic synthesis intermediates, batch-to-batch consistency and purity thresholds directly impact end-product performance. Manufacturers that can reliably deliver high-purity technical grades with lower processing costs are capturing preferential supplier status and building longer-term supply agreements.
Regulatory Evolution and the Compliance Premium
Regulatory dynamics are reshaping the competitive landscape by creating a compliance premium that separates established producers from marginal capacity. Environmental mandates and chemical safety regulations have elevated the cost of market participation, particularly in Europe and other highly regulated jurisdictions. Facilities that have already invested in advanced waste treatment systems, closed-loop processing, and documented quality management frameworks are positioning compliance as a value proposition rather than a burden. This is especially relevant for buyers in cosmetics, personal care, and industrial applications who face their own downstream scrutiny and require suppliers with verifiable environmental and quality credentials.
The regulatory environment also influences geographic sourcing patterns. As compliance costs rise in certain regions, buyers are reassessing supply chain configurations, weighing the trade-offs between proximity, logistics costs, and regulatory assurance. Producers with established certifications, transparent audit trails, and documented process controls are gaining leverage in negotiations, while those without clear compliance positioning face increasing friction in accessing premium markets.
Worldwide Sodium Salicylate Market
Shifting Demand Patterns Across End-Use Verticals
Demand-side behavior is evolving as formulation trends, industrial manufacturing needs, and consumer preferences reshape application priorities. Technical grade salicylic acid serves as a versatile intermediate across multiple sectors, and its growth is being pulled by several distinct demand streams. In personal care and cosmetics, the compound continues to play a foundational role in exfoliating formulations, acne treatments, and skin-conditioning products. Consumer preferences for effective, scientifically backed skincare ingredients have sustained demand for high-quality salicylic acid, while formulators increasingly require materials that meet both performance and regulatory standards.
Industrial and chemical synthesis applications represent another powerful demand engine. Technical grade material is widely used in the production of dyes, pigments, preservatives, resins, and rubber auxiliaries. Growth in specialty chemicals, advanced materials, and performance coatings has increased the need for reliable, specification-grade intermediates that can be integrated into complex manufacturing workflows. Additionally, the pharmaceutical intermediates segment continues to absorb a significant portion of production, with technical grade output often serving as a cost-effective feedstock for further refinement or for applications where ultra-high purity is not the primary requirement.
Feedstock Economics and Supply Chain Realignment
The economics of salicylic acid production are fundamentally tied to phenol availability and pricing, which themselves depend on benzene markets and crude oil dynamics. This upstream linkage means that feedstock cost fluctuations can rapidly alter production economics, influencing capacity utilization decisions, pricing strategies, and regional competitiveness. Recent market conditions have underscored this relationship, with price divergence between Northeast Asia and Europe reflecting localized differences in feedstock costs, energy inputs, and supply-demand balances.
Supply chain realignment is also being driven by logistics considerations, regional trade dynamics, and the desire to reduce exposure to single-source dependencies. Buyers are increasingly evaluating multi-regional sourcing strategies, balancing cost advantages from lower-price regions against the reliability and compliance assurance offered by established suppliers in other markets. For producers, this environment rewards operational flexibility, transparent pricing mechanisms, and the ability to maintain consistent supply across fluctuating input cost cycles.
Competitive Landscape and Leading Strategies
The competitive structure of the technical grade salicylic acid market features a mix of vertically integrated European producers, established Indian manufacturers with strong export orientation, and a growing cohort of Chinese suppliers serving both domestic and global industrial markets. This geographic and strategic diversity creates a dynamic environment where differentiation is achieved through process expertise, grade specialization, regulatory readiness, and supply reliability rather than price alone.
Seqens Group (Novacyl) stands out as the sole European producer of salicylic acid, leveraging a vertically integrated model and a proprietary single-step process that converts phenol directly into both pharmaceutical and technical grades. This integration provides control over key process stages and enables the company to supply high-purity material for industrial intermediates, dyes, and resins while maintaining the flexibility to shift output across grade categories based on demand signals. The company's recent capacity consolidation and asset integration efforts reinforce its focus on scaling production capabilities to support both pharma and industrial technical grade requirements, positioning it as a strategic supplier for customers seeking European-sourced material with established process credibility.
Indian manufacturers represent a significant and growing presence in the technical grade segment, with companies such as Siddharth Carbochem Products Ltd., Alta Laboratories Ltd. (Lona Industries), and Muby Chemicals (Mubychem Group) focusing on industrial applications including dyes, resins, rubber auxiliaries, and chemical synthesis. These producers benefit from competitive cost structures and established export channels, while also investing in product grade consistency and application-specific capabilities. Their ability to supply reagent and technical grades for a range of non-pharma industrial uses makes them important partners for downstream buyers seeking reliable, cost-effective material for bulk and intermediate applications.
Chinese producers, including JQC (Huayin) Pharmaceutical Co., Ltd., Hebei Jingye Medical Technology, Zhenjiang Gaopeng Pharmaceutical Co., Ltd., and Achilles Chemical, have expanded their footprint by offering technical, pharmaceutical, and cosmetic grades with varying degrees of compliance documentation and international certification. Achilles Chemical, for example, emphasizes REACH and ISO9001 compliance to support access to global industrial markets, while other Chinese manufacturers have built supply portfolios that span dyes, preservatives, organic synthesis, and rubber auxiliaries. The scale of Chinese production capacity, combined with growing attention to grade differentiation and compliance, has made these suppliers increasingly relevant for buyers looking to diversify sourcing or access competitive pricing without sacrificing specification reliability.
Worldwide Toluicacid Market
The market is showing signs of both consolidation and differentiation. Capacity expansion and process innovation activity has concentrated among manufacturers that are investing specifically in technical and industrial grade supply, suggesting that the segment is moving from a byproduct mindset to a strategic focus. At the same time, regulatory requirements, feedstock cost pressures, and application-specific quality demands are creating barriers that favor established players with documented process control, compliance infrastructure, and supplier relationships. New entrants face the challenge of matching not only price but also grade consistency, certification readiness, and supply reliability, which means that competitive advantage is increasingly earned through operational capability rather than capacity alone.
Future Trends and Commercial Implications
Looking ahead to the 2027 through 2030 period, several trends are likely to shape the technical grade salicylic acid market and create distinct commercial opportunities. First, grade specialization and specification-driven sourcing will intensify. As downstream formulators in cosmetics, industrial coatings, dyes, and chemical synthesis demand tighter impurity controls and more consistent batch profiles, producers that can offer clearly differentiated technical grades with documented quality parameters will command stronger positioning. This creates an opportunity for manufacturers to move up the value chain within the technical grade segment itself, capturing margin by aligning product specifications with application requirements rather than competing solely on volume and price.
Second, regional supply chain rebalancing will continue as buyers respond to feedstock cost divergence, regulatory differences, and logistics considerations. The price gap observed between Northeast Asia and Europe in early 2026 is indicative of a broader pattern where regional cost structures and supply-demand balances influence sourcing decisions. Companies that can offer transparent pricing, flexible supply arrangements, and multi-region fulfillment options will be better positioned to serve global customers navigating these variations. For producers, this environment rewards operational agility and the ability to maintain reliable output across fluctuating input cost cycles.
Third, regulatory compliance and environmental process investment will increasingly function as strategic differentiators rather than pure cost centers. As environmental standards tighten and downstream industries face greater scrutiny over their supply chains, suppliers with robust waste treatment, energy efficiency, and quality management systems will gain preference in qualification processes. This trend opens opportunities for producers that have already invested in compliance infrastructure, while raising the stakes for those that have not. Buyers, in turn, will place greater weight on documented compliance and process transparency when evaluating supplier portfolios.
Potential risks and uncertainties remain. Feedstock price volatility linked to crude oil and benzene markets can disrupt production economics and compress margins if not managed through hedging, pass-through mechanisms, or process efficiency gains. Regulatory changes in key markets could require additional capital investment or alter the cost competitiveness of certain production sites. Additionally, if regional oversupply emerges in specific markets, price pressure could intensify, testing the ability of producers to maintain differentiation and protect margins. Navigating these uncertainties will require proactive monitoring of feedstock trends, regulatory developments, and application-level demand shifts.
Strategic Recommendations for Decision Makers
For manufacturers and producers, the priority should be to strengthen grade differentiation and process reliability as competitive anchors. Investing in process control, impurity profiling, and compliance documentation enables technical grade offerings to be positioned as specification-matched solutions rather than undifferentiated commodities. Capacity decisions should account for the ability to serve multiple application verticals without compromising consistency, and supply chain strategies should incorporate feedstock cost monitoring and scenarios for regional price divergence.
For investors and strategic stakeholders, the market's 6.28 percent CAGR trajectory and the ongoing capacity and process innovation activity suggest that technical grade salicylic acid remains an attractive segment for targeted investment, particularly in operations that combine scale with grade flexibility and regulatory readiness. Due diligence should evaluate feedstock exposure, compliance infrastructure, application diversification, and the supplier's ability to maintain consistent output across input cost cycles. Companies that have already consolidated capacity or advanced process improvements are likely to capture disproportionate share in a market where reliability and specification control are increasingly decisive.
For procurement and sourcing leaders, the current environment rewards a structured evaluation of supplier capabilities beyond unit price. Qualification processes should weigh grade consistency, compliance certifications, supply reliability across regions, and the supplier's track record in managing feedstock and energy cost volatility. Building a diversified supplier base that includes both cost-competitive regional sources and compliance-assured strategic partners can reduce exposure to regional price shocks while maintaining access to material that meets application-specific requirements.
Given the pace of capacity consolidation, process innovation, and regulatory evolution, decision makers benefit from access to detailed segmentation data, regional price dynamics, and company-level capability profiles to inform sourcing, investment, and production strategy. Comprehensive market research that maps grade specifications, application demand shifts, and competitive positioning can provide the granularity needed to translate broad trends into actionable business decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Technical Grade Salicylic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Stainless Steel Bailers Market: Why 6.82% CAGR and Groundwater Demand Redefine Growth
By PW Consulting, 2026-09-18
Navigating the Stainless Steel Bailers Market: Strategic Shifts and Commercial Frontiers (2025–2032)
Market Overview and Core Challenges
The global stainless steel bailers market has matured into a specialized yet steadily expanding segment, characterized by consistent demand from environmental monitoring, industrial remediation, and materials processing applications. Between 2020 and 2025, the sector demonstrated resilient growth, settling into an estimated revenue trajectory that extends through 2032. Current market sizing places the industry at approximately USD 54.6 million in 2025, with projections indicating a compound annual growth rate of 6.82 percent through the forecast horizon. By 2032, total market revenue is expected to surpass USD 86.5 million, reflecting sustained institutional procurement cycles and gradual substitution of legacy sampling equipment with corrosion-resistant alternatives.
This growth trajectory is neither uniform nor guaranteed. The market operates within a fragmented ecosystem where three leading manufacturers collectively account for roughly a third of total revenue, while the top five players capture just under half. Such concentration suggests that scale advantages exist, yet the remaining share is distributed across regional specialists, niche fabricators, and emerging equipment assemblers. This structural dispersion creates both operational friction and strategic opening. Companies that rely on standardized product lines without adapting to regional compliance requirements or material specifications frequently encounter margin compression and slower order conversion. Conversely, firms that align manufacturing capabilities with localized sampling protocols and decontamination standards are capturing repeat contracts and longer equipment lifecycles.
Three intersecting challenges currently define the market’s inflection point. First, material cost volatility and geographic price divergence are reshaping cost structures. Stainless steel pricing has shown meaningful variation across major sourcing corridors, forcing manufacturers to recalibrate procurement strategies, hedge inventory exposure, or shift production footprints to maintain competitive pricing without sacrificing metallurgical integrity. Second, regulatory expectations around contamination control and sampling integrity are accelerating design evolution. Buyers increasingly require equipment that eliminates cross-sample interference, supports rapid decontamination, and avoids legacy sealing materials that compromise analytical accuracy. Third, the convergence of corrosion-resistant sampling tools with broader industrial compaction and recycling equipment is blurring traditional category boundaries. Organizations that previously sourced bailers and balers from entirely separate supply chains are now evaluating integrated procurement frameworks, which pressures incumbent suppliers to clarify product positioning and avoid internal cannibalization.
These dynamics do not merely represent operational headwinds; they function as signal filters for market entry, product investment, and partnership strategy. Firms that treat the current period as a static demand environment risk misallocating engineering resources and missing procurement consolidation windows. Those that recognize the overlap between material science, compliance timing, and procurement behavior can position themselves ahead of specification shifts and contract renewal cycles.
Key Drivers Reshaping the Market
Technological innovation is reshaping how stainless steel bailers are specified, manufactured, and deployed in the field. Advances in forming precision, weld integrity, and surface finishing have moved crevice-free and mirror-polished configurations from premium custom orders toward standard expectations for high-integrity sampling. Equipment engineered with fully welded seams, controlled internal geometries, and removable top and bottom assemblies reduces residual contamination risk and shortens decontamination cycles. These design attributes directly translate into fewer sampling errors, faster site turnaround, and lower long-term replacement frequency, which procurement teams increasingly value when comparing total cost of ownership rather than upfront unit price alone.
Stainless Steel Sink Market
Regulatory and compliance environments are exerting parallel pressure on product architecture. Environmental sampling standards continue to tighten around PFAS-related concerns and analytical purity, prompting manufacturers to introduce sealing and component configurations that avoid contamination pathways. Equipment supplied with PFAS-free O-ring options and fluoropolymer check mechanisms is gaining preference in groundwater monitoring programs where regulatory bodies and laboratory partners demand verifiable sample integrity. At the same time, safety and hygiene certification requirements are influencing broader stainless steel equipment categories, including compaction and recycling machinery used in sensitive operational environments. Compliance with recognized safety standards and material traceability documentation is becoming a procurement prerequisite rather than an optional differentiator.
Worldwide Stainless Steel Fermenter Market
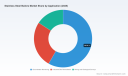
Demand-side behavior is shifting as end users consolidate sampling programs and prioritize equipment durability over short-cycle replacement. Groundwater monitoring remains the dominant application driver, supported by ongoing environmental assessment, site characterization, and regulatory compliance activities. Industrial site remediation and mining or geological survey work contribute additional demand, particularly where repeated borehole access, composite sample collection, and field decontamination efficiency matter. Procurement teams in these segments are increasingly favoring reusable stainless steel configurations that withstand repeated cleaning, resist pitting and stress corrosion in demanding media, and support standardized attachment or retrieval systems across multiple well diameters.
Supply chain and cost structure changes are reinforcing these demand trends. The broader stainless steel market continues to expand on the back of industrial equipment demand, yet regional price differentials require deliberate sourcing strategies. Manufacturers operating with transparent material grade documentation and consistent finish specifications can command stronger positioning in procurement evaluations, especially when buyers need to verify material provenance for compliance records. Meanwhile, the cost of non-compliance is rising. Equipment that fails to support adequate decontamination, introduces particulate or chemical interference, or requires excessive maintenance adds hidden operational expense that outweighs initial savings. This reality is pushing buyers toward suppliers that can demonstrate repeatable quality control, consistent metallurgical specifications, and service-ready component designs.
Taken together, these drivers suggest that the market’s growth will be defined less by volume expansion alone and more by specification upgrading, compliance alignment, and procurement rationalization. Companies that integrate material traceability, contamination-reducing design, and service-friendly construction into their product roadmaps are better positioned to capture share in contracts where sample integrity and operational efficiency carry significant weight.
Competitive Landscape and Leading Strategies
The competitive field reflects a mix of established environmental sampling specialists, regional fabricators, and broader industrial equipment manufacturers whose stainless steel product lines touch overlapping customer needs. Several firms have anchored their positioning around durability, material grade consistency, and decontamination efficiency. Manufacturers offering 304 and 316 stainless steel configurations with removable ends, tapered profiles, or fully welded and crevice-free interiors are emphasizing ease of cleaning, material compatibility, and long service life in sampling contexts. These design choices are not merely technical preferences; they function as commercial signals that align with buyer priorities around repeat use, sample protection, and reduced field downtime.
Differentiation is increasingly expressed through compliance readiness and application-specific fit rather than generic durability claims. Some suppliers have focused on groundwater sampling specifications that support composite collection, well retrieval, and rapid decontamination, with material and sealing configurations chosen to meet environmental testing expectations. Others have extended stainless steel bailer and baler capabilities into hygiene-sensitive or heavy-duty environments, where certification documentation, surface finish quality, and corrosion-resistant construction support procurement requirements in food-adjacent, recycling, or industrial processing settings. This divergence in focus illustrates how the market is splitting into application-driven sub-positions, even as the underlying material and manufacturing technologies overlap.
The landscape is evolving along three observable directions. First, consolidation remains selective rather than sweeping. Larger players with established distribution channels and recognized product lines are gaining incremental advantage through repeat procurement relationships and specification familiarity, but the market still accommodates specialized manufacturers that can respond faster to regional compliance nuances or custom size requirements. Second, segmentation is sharpening. Procurement teams are distinguishing between bailers intended for high-integrity environmental sampling and balers or compactors used in scrap handling and recycling workflows. Suppliers that clearly articulate these boundaries, while retaining shared manufacturing efficiencies where possible, are less exposed to comparison confusion and margin erosion. Third, new entrants and re-entering competitors are leveraging trade platforms and regional supply networks to validate technology relevance and sourcing connectivity. Industry gatherings and supplier exhibitions continue to function as alignment points where component suppliers, fabricators, and end users compare material options, finish standards, and integration requirements. The resulting visibility can accelerate adoption of newer specifications, particularly when they address contamination control, material traceability, or cleaning efficiency.
Strategic advantage in this environment belongs to organizations that combine consistent metallurgical control with clear application positioning. Firms that invest in repeat-use durability, rapid decontamination design, and documented material conformity can compete on reliability rather than price alone. At the same time, those that maintain responsive production for diameter variations, sealing options, and region-specific compliance documentation are better equipped to capture procurement cycles where buyers evaluate total operational impact rather than unit economics in isolation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The market’s next phase will likely be defined by specification upgrades, procurement consolidation, and continued convergence between sampling integrity and broader industrial stainless steel equipment requirements. One central trend is the deepening preference for contamination-minimizing construction and sealing configurations. As sampling programs face more stringent analytical expectations and laboratory partnership requirements, equipment that supports crevice-free geometries, controlled finishes, and alternative sealing materials will become harder to replace with lower-specification alternatives. This trend favors suppliers that can standardize such features without sacrificing production efficiency or inflating lead times.
A second trend is the increasing alignment of procurement decisions with total lifecycle value. Buyers are paying closer attention to decontamination speed, corrosion behavior under repeated use, and component accessibility for cleaning and inspection. This shift rewards manufacturers that design for serviceability and repeated field use, and it pressures those that compete primarily on initial price to justify hidden maintenance or replacement costs. Over the next several years, contract renewals and multi-unit procurement agreements are likely to reflect these lifecycle considerations more explicitly, creating opportunities for suppliers with demonstrable durability records and consistent quality control.
A third trend involves regional sourcing strategy adaptation in response to material cost divergence and compliance documentation expectations. As buyers verify material grades, certification traceability, and finish consistency, suppliers that can provide clear documentation and stable specification control will gain an edge in evaluation processes. At the same time, regional price variation will continue to push manufacturers toward more deliberate procurement routing, inventory planning, and production allocation. Companies that treat material cost fluctuation as a design and sourcing variable rather than a passive input are more likely to preserve margins while meeting specification demands.
These trends carry commercial opportunity, but also risk. Demand for higher-specification equipment may intensify competition among capable manufacturers, compressing differentiation if multiple suppliers converge on similar construction standards. Regulatory language around contamination and sampling integrity may also evolve, requiring product updates or documentation adjustments that are not always predictable in timing. Additionally, if downstream sampling programs reduce activity levels or shift toward alternative collection methods in certain regions, revenue growth could become uneven across applications. Firms that monitor specification changes, procurement behavior, and material cost movement will be better placed to adjust product emphasis and contract strategy before cycles turn.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize specification clarity and design-for-cleaning as core commercial levers. Where product lines span multiple applications, maintaining clear distinctions between environmental sampling configurations and industrial compaction or recycling equipment reduces comparison confusion and protects positioning. Engineering effort is best directed toward repeatable weld quality, accessible decontamination design, and documented material conformity, since these attributes increasingly influence procurement evaluation beyond initial pricing.
Investors and strategic partners should evaluate exposure to specification-driven demand rather than volume assumptions alone. Companies with strong documentation practices, consistent metallurgical control, and application-specific positioning are more likely to retain purchase cycles in environments where sample integrity and compliance requirements carry weight. Monitoring procurement consolidation, regional price dynamics, and certification expectations provides early signals about which product categories will face margin pressure and which will command stronger retention.
Procurement teams and end users should structure evaluations around total operating impact. Variables such as decontamination time, residual contamination risk, corrosion behavior under repeated use, and material traceability can materially affect program reliability and long-term cost. Requesting consistent specification documentation and comparing lifecycle implications across diameter options, sealing configurations, and finish standards supports more resilient sourcing decisions, especially when equipment is deployed across multiple sites or monitoring campaigns.
For decision-makers seeking a deeper mapping of segment dynamics, competitive positioning, and procurement trends across regions and applications, the full PW Consulting market analysis provides expanded segmentation detail, scenario-based projections, and customization options tailored to internal planning needs.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Bailers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bio-based Ethylene Glycol Market: Why 8.25% CAGR and Asia Pacific Leadership Change Everything
By PW Consulting, 2026-09-18
The Strategic Inflection Point: Worldwide Bio-based Ethylene Glycol Market Trends and Commercial Opportunities
1. Market Reality: Navigating Scale, Sustainability Mandates, and Feedstock Complexity
The global market for bio-based ethylene glycol has crossed a structural threshold. In 2025, worldwide revenue reached approximately USD 1,250 million, reflecting a compound annual growth rate of 8.25 percent projected through 2032. The trajectory since 2020 reveals a market that has matured beyond early experimentation into a phase of disciplined scaling, with values moving from USD 890.5 million in 2020 to USD 1,194.92 million in 2024 before stabilizing at the current baseline. This growth pattern is not linear; it reflects the interplay of capacity ramp-ups, feedstock availability, and the pace at which downstream customers are willing to integrate renewable building blocks into established supply chains.
Three structural tensions define the current operating environment. First, feedstock economics remain the primary variable in cost competitiveness. Sugarcane ethanol, molasses-derived bio-ethanol, and corn-based dextrose each carry distinct agricultural, logistical, and carbon-intensity profiles, creating regional asymmetries in both supply reliability and margin structure. Producers must navigate commodity volatility while maintaining sustainability credentials that downstream buyers increasingly demand.
Second, certification and traceability have shifted from optional compliance to commercial prerequisites. The adoption of frameworks such as ISCC Plus in European markets underscores a broader reality: sustainability claims now require verifiable chain-of-custody documentation. This raises the operational bar for producers and introduces administrative complexity that smaller or regionally confined players must absorb to remain viable in premium channels.
Third, the market exhibits a moderate degree of concentration, with the top three players holding approximately 42.5 percent of revenue and the top five capturing 61.2 percent. This concentration signals that scale, feedstock integration, and established commercial relationships still confer meaningful advantages. At the same time, it leaves room for specialized entrants and joint ventures that can bring differentiated technology or regional feedstock access, particularly as lignocellulosic pathways move from pilot validation toward commercial deployment.
2. Core Drivers Reshaping the Market Trajectory
Technological Innovation and Feedstock Diversification
The most consequential shift in the bio-based ethylene glycol landscape is the parallel advancement of first-generation and second-generation feedstock pathways. Sugarcane ethanol remains the commercially mature and cost-competitive anchor, particularly in regions with established agricultural ethanol infrastructure. Corn-based dextrose has gained traction where corn processing capacity and dextrose economics align with industrial-scale conversion. Meanwhile, second-generation lignocellulosic feedstocks, including corn stover, wheat straw, and bagasse, are increasingly viewed as a strategic lever to reduce reliance on food-grade sugars and lower feedstock costs by an estimated 25 to 35 percent over the medium term.
PW Consulting
This diversification is not merely an academic improvement; it directly affects capacity planning and geographic positioning. Recent developments illustrate the trend: UPM has progressed toward introducing wood-sourced bio-based monoethylene glycol at its Leuna biorefinery in Germany, targeting around 220,000 tons of lignocellulosic-based output. In parallel, a Chinese pilot plant technology using corn stalks and straw sugars has achieved approximately 1,000 metric tonnes of annual capacity, supported by over 40 patents that point to potential scale-up. These signals suggest that feedstock flexibility will increasingly determine where production can be economically located and which customer segments can be reached without compromising carbon or cost targets.
Policy, Regulation, and Certification Dynamics
Regulatory and certification frameworks are acting as both a catalyst and a gatekeeper. European markets, in particular, are reinforcing traceability expectations through mechanisms such as ISCC Plus certification, which enables documented sustainability claims for bio-based and bio-circular hydrocarbons. This dynamic raises the bar for market entry in premium segments, but it also rewards producers who can embed verification into their operating model rather than treating it as an afterthought.
The implication is twofold. For established players, certification-ready supply chains can become a commercial moat, enabling access to customers who need defensible sustainability narratives. For new entrants, the cost and complexity of certification increase the importance of early alignment with recognized standards, especially when targeting European packaging and textile customers. Policy expectations are also accelerating the value of bio-based content in applications where brands are under pressure to reduce fossil-derived inputs, which in turn strengthens demand-side pull for renewable glycol feedstocks.
Demand-Side Shifts Across Packaging, Textiles, and Industrial Applications
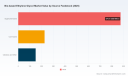
Demand is being reshaped by downstream customer priorities more than by any single regulatory mandate. Packaging and bottles represent the largest application segment, driven by brand-level commitments to renewable content, recyclable packaging systems, and consumer-facing sustainability messaging. Textiles and fibers form a second major demand base, where polyester producers and fiber manufacturers are increasingly seeking bio-based building blocks to differentiate in highly competitive markets. Industrial and coolant applications, while smaller in scale, provide steady demand that can help stabilize utilization rates during periods of feedstock or pricing volatility.
The commercial pattern emerging here is one of selective adoption rather than blanket replacement. Downstream customers are not uniformly switching to bio-based ethylene glycol; they are prioritizing applications where the sustainability narrative translates into tangible brand value or regulatory alignment. This creates a premium corridor for producers who can deliver consistent quality, traceability, and reliable volume, while also leaving room for conventional or blended solutions in cost-sensitive segments.
Supply Chain Configuration and Cost Structure Evolution
Cost structures are being redefined by geography, feedstock logistics, and the economics of scale. Brazil’s access to sugarcane ethanol, India’s molasses-based bio-ethanol ecosystem, and North America’s corn-based dextrose infrastructure create distinct cost baselines that influence where bio-based ethylene glycol can be produced most efficiently. At the same time, second-generation feedstocks are broadening the opportunity set by enabling utilization of agricultural residues that may offer lower input costs and reduced exposure to food-commodity volatility.
Recent commercial activity reflects this reconfiguration. Braskem continues to evaluate a joint venture for biobased ethylene glycol production from corn dextrose in Indiana as part of its renewable chemicals portfolio, while its Sustainea joint venture with Sojitz is advancing a planned USD 400 million facility in Lafayette, Indiana to convert corn-based dextrose into monoethylene glycol at commercial scale, with startup targeted from 2028. These moves indicate that North America is becoming an increasingly relevant arena for corn-based renewable glycol, complementing established sugarcane and molasses routes elsewhere.
3. Competitive Landscape and Leadership Strategies
Established Leaders and Differentiated Positioning
The competitive field includes players with distinct feedstock access, technology routes, and geographic advantages. India Glycols Limited operates as one of the largest commercial producers of bio-based monoethylene glycol from molasses-based bio-ethanol, with long-standing industrial-scale production supplying PET, polyester, and related applications. Its scale and established customer relationships provide a durable base in segments where reliability and volume matter. Braskem and the Sustainea joint venture are strengthening the corn-based and sugarcane-ethanol pathways, leveraging existing bio-ethanol platforms and partnerships to advance renewable monoethylene glycol for packaging and textiles.
Avantium is pursuing a technology-led differentiation through its PlantMEG offering, developed via proprietary Ray Technology from renewable sugars, with an emphasis on plant-based monoethylene glycol for sustainable PET and polyester applications. UPM is positioning around lignocellulosic feedstock, using wood-sourced material at its Leuna biorefinery to target packaging and fiber markets with a lower food-grade-sugar dependency. Together, these players illustrate a market that is not converging on a single winning route, but rather segmenting by feedstock, technology, and end-use positioning.
Bio Methanol Market
Strategic Themes Among Leaders
Several patterns stand out in how leading participants are positioning themselves:
- Feedstock integration as a strategic asset. Companies with access to sugarcane ethanol, molasses-based bio-ethanol, or corn-based dextrose can better manage input risk and anchor cost structures, especially where agricultural-platform synergies exist.
- Commercial readiness over pilot novelty. Scale-up decisions are increasingly driven by the ability to deliver consistent volume and certification-ready supply, not simply by technical feasibility. The planned Sustainea facility and UPM’s Leuna preparation reflect a focus on commercial execution timelines.
- Application-aligned messaging. Successful positioning tends to connect bio-based glycol to specific downstream value, whether in packaging sustainability, polyester differentiation, or industrial reliability, rather than presenting the product as a generic renewable substitute.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The landscape is evolving along multiple axes. Concentration at the top suggests that scale and established distribution relationships remain important, particularly for large-volume contracts. At the same time, technology differentiation and regional feedstock opportunities are enabling specialized entrants to compete in defined niches. The rise of lignocellulosic pathways and regional corn-based dextrose projects adds further fragmentation potential, especially if cost and carbon-intensity advantages translate into commercial advantage at scale.
A plausible trajectory is selective consolidation in volume-driven segments paired with continued differentiation in technology-led or application-focused segments. New entrants will need either a credible feedstock advantage, a defensible conversion technology, or strong downstream partnerships to avoid being squeezed between established scale players and premium sustainability positioning.
4. Forward Outlook: Where the Market Is Heading
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, lignocellulosic and residue-based feedstocks will move from proof-of-concept toward early commercial relevance. If cost reduction targets in the 25 to 35 percent range are realized at scale, these pathways could broaden geographic options and reduce exposure to food-grade sugar volatility. This would create opportunities for producers and partners who can secure reliable residue supply and operate conversion assets efficiently.
Second, certification and traceability will increasingly function as commercial infrastructure rather than a compliance layer. Customers in Europe and other regulated or brand-sensitive markets will continue to reward documented sustainability claims, which means the ability to provide chain-of-custody assurance may become as important as price and volume. This favors organizations that build traceability into procurement, production, and logistics from the outset.
Third, regional supply chains will become more distinct. Sugarcane-linked routes will remain strong where ethanol infrastructure is mature, corn-based dextrose routes will expand in North America, and lignocellulosic projects will test the viability of non-food feedstocks in new locations. The result will be a more geographically diversified market, with regional cost and carbon profiles influencing where bio-based ethylene glycol is produced and purchased.
These trends create commercial opportunity, but also uncertainty. Feedstock availability can shift with agricultural cycles and competing demand from fuels and other bio-based chemicals. Scale-up risk remains real, particularly for second-generation pathways that must prove reliability at commercial volumes. Pricing dynamics may also pressure margins if conventional glycol costs move favorably or if multiple capacity additions converge faster than downstream adoption. The strategic response is to treat these uncertainties as variables to be actively managed through feedstock diversification, certification readiness, and application-targeted commercial strategy.
5. Decision-Maker Playbook: Actionable Priorities
For Manufacturers and Producers
Prioritize feedstock flexibility and certification readiness as core operational capabilities, not peripheral initiatives. Evaluate whether existing or planned capacity aligns with the most defensible feedstock route in your target geography, and build traceability into production and logistics early so sustainability claims can support commercial positioning. Where possible, structure partnerships or joint ventures that reduce scale-up risk while securing access to either established feedstocks or emerging lignocellulosic supply.
For Investors
Focus on the intersection of feedstock economics, technology readiness, and downstream demand quality. The most attractive opportunities are likely to combine credible feedstock access, a clear path to commercial-scale conversion, and customers who can absorb a sustainability premium or achieve regulatory alignment. Monitor capacity announcements, pilot-to-commercial transitions, and certification developments as indicators of which pathways are moving from potential to execution.
Polyethylene Glycol (PEG) Market
For Procurement and Supply Chain Leaders
Align bio-based ethylene glycol sourcing with application value rather than treating it as a blanket substitution. Identify segments where renewable content strengthens brand positioning, regulatory compliance, or customer relationships, and secure supply from partners who can provide verifiable traceability and consistent quality. Diversify feedstock exposure where feasible to reduce vulnerability to regional commodity swings or certification gaps.
For organizations seeking a deeper, segment-level view of regional dynamics, feedstock pathways, application mixes, and company-level strategic positioning, the full research report provides more granular data and tailored recommendations to support planning across these rapidly evolving market conditions.
For detailed analysis of this topic, please visit the official page: Worldwide Bio-based Ethylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharma Grade Calcium Hydroxide Market: Beyond the 5.36% CAGR, Unpacking Regional and Form Splits
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Market Overview and Core Challenges
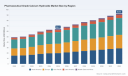
The global market for pharmaceutical grade calcium hydroxide has demonstrated steady expansion over the past half-decade, reflecting the compound's critical role in drug formulation, dental procedures, and specialized manufacturing processes. Valued at approximately 49.3 million USD in 2020, the market reached 64.2 million USD by 2025, and current projections indicate a trajectory toward 92.55 million USD by 2032. This growth path corresponds to a compound annual growth rate of 5.36 percent, signaling a mature yet consistently expanding sector where incremental gains compound over time.
Pharmaceutical Grade Sodium Chloride Market
The revenue base is distributed across multiple forms and applications, with powder formats capturing the largest share of commercial activity. Liquid and suspension variants represent a meaningful secondary segment, particularly in applications requiring uniform dispersion or handling flexibility. From an application standpoint, endodontic and dental filling procedures constitute the most significant demand driver, underscoring the material's established utility in clinical settings. Secondary demand streams include active pharmaceutical ingredient synthesis coupled with pH regulation workflows, as well as the use of calcium hydroxide as an excipient or calcium supplement in nutritional medicines. Geographically, demand is broadly distributed, with Asia Pacific, North America, and Europe each representing substantial portions of total volume. Emerging regions in Latin America and the Middle East and Africa contribute smaller but growing shares, reflecting gradual healthcare infrastructure development and localized manufacturing capacity.
Concentrated market dynamics shape the current landscape. The top three participants command roughly 38.4 percent of total revenue, while the five largest firms account for approximately 52.15 percent. This level of concentration suggests established relationships, entrenched quality certifications, and meaningful barriers to entry for new manufacturers seeking to compete on purity, regulatory compliance, or supply reliability.
Key Challenges at the Inflection Point
Despite the favorable growth narrative, several structural challenges are reshaping how companies plan capacity, pricing, and compliance investments.
-
Raw material cost volatility and environmental compliance pressure. Calcium hydroxide is produced through the hydration of quicklime, itself derived from calcination of high-calcium limestone. Recent data from Northeast Asia shows prices reaching 0.14 USD per kilogram in December 2025, a 12.7 percent increase from September of that year. The surge stems from rising upstream quicklime and energy costs, compounded by supply constraints linked to environmental compliance. These input pressures are not isolated; they reflect a broader pattern where production cost bases are increasingly sensitive to energy markets and regulatory-driven operating conditions.
-
Evolving emissions standards for lime manufacturing. Regulatory authorities in the United States finalized amendments to National Emission Standards for Hazardous Air Pollutants targeting lime manufacturing plants, addressing previously unregulated hazardous air pollutant emissions from lime kilns. In parallel, broader expectations around hazardous air pollutant and potential greenhouse gas emission standards are increasing scrutiny of kiln operations. For calcium-based compound producers, these developments can translate into higher capital expenditure requirements, operational adjustments, and cost structure changes that affect competitiveness.
PW Consulting -
Purity expectations and cross-application regulatory complexity. The material is simultaneously used in pharmaceutical manufacturing, food-grade formulations, and laboratory processes. U.S. FDA regulations explicitly list calcium hydroxide USP as an approved alkali for color additives exempt from certification, including caramel production for food use. This dual-use reality requires manufacturers to maintain rigorous documentation, lot traceability, and grade-specific production controls. Companies that struggle to separate or certify distinct purity tiers face higher compliance costs and greater risk of customer disqualification.
Key Drivers Shaping Market Evolution
The sustained expansion of pharmaceutical grade calcium hydroxide is not merely a function of incremental demand. It is shaped by a convergence of technological, regulatory, demand-side, and supply-side dynamics that are altering competitive requirements and opening differentiated opportunities for firms that respond proactively.
Technological Innovation and Purity Differentiation
Technical differentiation is becoming a decisive competitive lever. Leading producers are emphasizing ultra-low impurity profiles, targeting reductions in aluminum, iron, and manganese content that can interfere with pharmaceutical synthesis, nutritional formulations, or sensitive endodontic applications. High-purity calcium hydroxide meeting FCC, USP, and BP specifications is increasingly expected rather than treated as a premium add-on. Manufacturers that invest in controlled calcination conditions, advanced hydration processes, and rigorous analytical testing can command stronger customer loyalty and improve pricing resilience.
The practical impact of this trend is that technical capability now functions as a barrier to entry and a retention mechanism. Buyers in API synthesis and pH adjustment workflows select suppliers based on impurity thresholds, batch consistency, and documented certificates of analysis. In dental and endodontic applications, consistency and biocompatibility expectations further reward suppliers with mature quality management systems. Over time, these requirements are likely to compress the viable supplier base toward firms that can demonstrate repeatable purity performance rather than simply meet baseline specifications.
Regulatory Environment and Compliance Costs
The regulatory environment is shaping both demand and supply. On the demand side, explicitly approved usage pathways expand the addressable market. For example, the inclusion of calcium hydroxide USP in FDA regulations for color additives exempt from certification validates its role in food-related manufacturing, which can indirectly benefit producers with multi-grade capabilities. On the supply side, emissions-related amendments for lime manufacturing facilities introduce new compliance obligations. National emission standards targeting hazardous air pollutants from lime kilns, along with broader environmental performance expectations, increase the cost of maintaining operating permits and upgrading combustion or filtration systems.
This dual pressure creates a clear strategic implication: regulatory expertise is becoming a source of competitive advantage. Suppliers that anticipate emissions rule implementation, incorporate environmental compliance into capacity planning, and communicate transparently about product grade integrity will be better positioned to retain pharmaceutical and laboratory customers. Conversely, firms that treat compliance as a retrospective cost rather than a forward-looking operational design parameter may face margin compression and customer attrition.
Demand-Side Shifts in Healthcare and Manufacturing Practices
Demand patterns are evolving as healthcare procedures and pharmaceutical manufacturing practices mature. The prominence of endodontic and dental filling applications reflects the sustained clinical use of calcium hydroxide in pulp capping, disinfection, and related procedures. As dental care access expands in developing markets and as clinical protocols continue to favor established materials with predictable performance, demand for high-quality medical-grade material remains robust. Simultaneously, the role of calcium hydroxide in API synthesis and pH adjustment is supported by broader pharmaceutical production activity, where precise pH control and alkali selection influence yield, purity, and downstream processing efficiency.
Another demand-side driver is the use of calcium hydroxide within excipients and calcium supplements, where formulation reliability and mineral quality are central to product acceptance. Across these segments, procurement behavior is increasingly risk-averse: buyers favor suppliers with validated quality systems, consistent lead times, and clear regulatory documentation. This shift encourages longer-term supply relationships and rewards manufacturers that can provide not just a chemical product, but a documented, auditable supply solution.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by energy costs, upstream lime availability, and regional production constraints. As noted in recent market data, regional price movements can be pronounced when energy costs rise or when compliance-driven constraints tighten supply. These fluctuations affect downstream procurement strategies, prompting buyers to consider regional sourcing, inventory buffers, and multi-supplier frameworks rather than relying on single-source procurement.
At the same time, large distributors and diversified chemical suppliers are extending their reach by offering pharmaceutical-grade calcium hydroxide alongside other specialty materials. This distribution model can improve availability, simplify procurement for smaller manufacturers, and create value through logistics and technical support. However, it also intensifies pressure on niche producers to differentiate through purity, technical service, or regional responsiveness. The net effect is a market where cost structures are increasingly tied to energy, compliance, and logistics, and where value capture depends on the ability to manage these elements while maintaining grade integrity.
Competitive Landscape and Leading Strategies
The competitive field includes manufacturers and distributors spanning North America, Europe, and Asia, with notably strong activity among Indian producers and Western suppliers serving pharmaceutical, laboratory, and food-related end markets. The current landscape is characterized by distinct strategic positions rather than a single unified approach.
Strategic Positioning of Leading Players
Several companies illustrate the range of viable strategies in this market. One U.S.-based producer specializes in high-purity calcium hydroxide with FCC/USP grades and ultra-low impurities, including low aluminum, iron, and manganese, targeting pharmaceutical synthesis and nutritional formulations. This profile reflects a purity-centric strategy where technical specifications and traceability are the primary differentiators. Another U.S. supplier provides pharmaceutical-grade material meeting USP standards for laboratory and manufacturing use, emphasizing consistent availability and compliance-aligned documentation for research and production environments.
Indian manufacturers represent a significant and differentiated cohort. Firms based in Maharashtra, Uttarakhand, and Gujarat produce calcium hydroxide in BP/USP/FCC/ACS grades, often with ISO-9001-2015 and GMP certifications. Their value proposition combines pharmaceutical and food-grade capabilities with regional cost advantages, enabling them to compete on price while maintaining accredited quality systems. Some Indian producers also pursue national standard participation, including involvement in drafting standards for food-additive calcium hydroxide, which can strengthen downstream acceptance and create reputational advantages in regulated markets.
European participants add further diversity. One German firm offers high-purity mineral salts including pharmaceutical-grade calcium hydroxide, while a major global distributor supplies calcium hydroxide across pharmaceutical and industrial applications. The distributor model emphasizes breadth, logistics, and technical support, often serving customers who prefer consolidated sourcing or who require flexible regional fulfillment. Another U.S. company provides calcium hydroxide suitable for food and pharmaceutical applications, reinforcing the multi-grade strategy that allows a single producer to serve overlapping demand streams.
Differentiation and Market Evolution
Across these profiles, differentiation is concentrated in a few recurring themes. Purity and impurity control remain central, especially for buyers in API synthesis and sensitive formulations. Certifications and audit-ready documentation are increasingly treated as baseline expectations. Regional availability and lead-time reliability influence purchasing decisions, particularly for dental and laboratory customers with tight production schedules. Multi-grade capability, allowing a supplier to serve pharmaceutical, food, and laboratory needs from related production assets, can broaden revenue opportunities and improve asset utilization.
Market evolution is likely to proceed through both consolidation and selective fragmentation. Concentration data indicates that a limited number of participants already command a meaningful share of revenue, and this pattern may persist as larger or better-capitalized firms invest in compliance, technical service, and supply reliability. At the same time, specialized producers with strong purity credentials or regional certifications can sustain defensible positions by serving high-value segments where specification control and documentation outweigh price alone. New entrants will face meaningful hurdles, not because the chemistry is complex, but because pharmaceutical customers require proven quality systems, consistent supply, and regulatory alignment that take time to build.
The role of distributors is also likely to expand as procurement teams seek flexibility. Distributors can aggregate supply from multiple producers, reduce administrative burden, and provide technical logistics support. However, their growth depends on the willingness of manufacturers to maintain consistent grade integrity and on buyers' confidence that distributor-supplied material meets the same specifications as direct procurement.
Future Trends and Commercial Implications
Looking ahead to the 2026-2032 period, three trends are likely to shape market behavior and commercial outcomes.
1. Compliance-Linked Cost Structures Will Become a Strategic Variable
Emissions-related standards for lime manufacturing and broader environmental expectations will continue to influence production economics. As facilities adapt kiln operations, filtration, and monitoring processes, cost structures will evolve. Suppliers that plan for compliance as part of capacity design, rather than reacting after rule implementation, will be better able to preserve margins and maintain supply continuity. Buyers should anticipate periodic cost pressure and build procurement strategies that incorporate resilience, such as qualified alternate sources and contract structures that account for input volatility.
2. Purity and Documentation Will Drive Segment Winners
As pharmaceutical, dental, and laboratory buyers increasingly prioritize impurity control and traceable documentation, firms that can consistently deliver USP/FCC/BP-grade material with low contamination profiles will capture disproportionate value. This trend favors producers with strong analytical capabilities, disciplined batch control, and transparent certification practices. It also suggests that multi-grade producers with clear internal segregation between pharmaceutical and food grades may gain advantage by reducing cross-contamination risk and simplifying audits.
3. Regional Demand Growth and Distribution Models Will Redefine Access
Demand growth is expected to remain broad-based, with Asia Pacific, North America, and Europe continuing to anchor volume, while Latin America and the Middle East and Africa contribute incremental expansion as healthcare and manufacturing capacity develop. distributors and regional suppliers are likely to play a larger role in connecting producers with end users, especially where localized availability, technical support, and flexible logistics are valued. For manufacturers, this creates opportunities to expand reach without necessarily building extensive direct sales infrastructure, provided product quality and documentation remain dependable.
Potential risks include sharper-than-expected energy price swings, tightening environmental requirements that accelerate cost escalation, and the possibility that procurement teams shift toward alternative alkalis or formulation approaches in specific applications. These uncertainties do not undermine the overall growth trajectory, but they do emphasize the need for flexible sourcing and continuous monitoring of regulatory and input-cost developments.
Actionable Guidance for Decision-Makers
The evolving market environment rewards proactive positioning. Different stakeholders can derive distinct value from a focused response.
For Manufacturers
-
Invest in purity assurance and analytical documentation as core capabilities rather than support functions. Ultra-low impurity profiles and audit-ready certificates can improve retention in pharmaceutical and dental segments.
-
Incorporate environmental compliance into capacity and operational planning. Anticipating emissions standards and energy cost exposure can reduce surprise margin compression and protect supply reliability.
-
Evaluate multi-grade production strategies carefully. Clear segregation between pharmaceutical and food-grade output can reduce risk while enabling broader customer coverage.
For Investors
-
Assess companies based on their ability to manage compliance-linked cost structures, maintain grade integrity, and serve stable demand segments such as endodontics, API synthesis, and excipient use.
-
Look for suppliers and distributors with diversified geographic exposure and credible certifications, since these attributes support resilience amid input volatility and regulatory change.
-
Monitor consolidation potential among smaller producers and the strategic role of distributors, as both can reshape competitive dynamics over the forecast period.
Magnesium Hydroxide Market
For Procurement and Supply Chain Leaders
-
Diversify sourcing where feasible, balancing price with purity credentials, lead-time reliability, and documentation quality. Single-source dependence can increase exposure to regional price spikes or compliance disruptions.
-
Align supplier selection with application sensitivity. Dental and API synthesis uses may warrant stronger emphasis on impurity control and traceability, while less sensitive uses may allow broader sourcing flexibility.
-
Track regulatory developments affecting lime manufacturing and downstream material availability. Early awareness can support contract planning and inventory decisions.
Given the interplay of purity requirements, regulatory shifts, energy-linked cost dynamics, and regional demand growth, timely access to detailed segment data and customized strategic assessment is essential for effective decision-making. For deeper visibility into regional breakdowns, application-level demand patterns, pricing trajectories, and competitor-specific positioning, the full PW Consulting market report provides expanded data coverage and tailored implications across manufacturing, investment, and procurement scenarios.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Oblong Container Market: Beyond the 4.28% CAGR and Hidden Regional Shifts
By PW Consulting, 2026-09-18
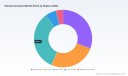
Strategic Trends and Commercial Opportunities in the Worldwide Oblong Container Market
Market Overview and Core Challenges
The worldwide oblong container market has evolved into a structurally significant segment within the broader rigid packaging industry, driven by consistent demand across consumer goods, industrial applications, and pharmaceuticals. With a total market valuation reaching approximately 1,251 million USD in 2025 and projected to advance toward 1,678 million USD by 2032, the segment reflects a compound annual growth trajectory of roughly 4.28 percent. This growth is not a simple continuation of historical expansion but rather a response to converging pressures in material economics, regulatory mandates, and application-specific performance requirements. The market has demonstrated measured resilience through cyclical demand shifts, with notable valuation stability between 2021 and 2023 before a reacceleration in recent years.
Despite this favorable trajectory, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, rising resin and metal input volatility is compressing margins for mid-tier producers and forcing earlier design-phase decisions around material substitution. Second, fragmented regulatory frameworks across major economies are accelerating the need for standardized sustainability attributes, creating compliance complexity for companies operating across multiple jurisdictions. Third, application differentiation is intensifying as end-use sectors demand containers that balance ergonomics, dispensing precision, chemical compatibility, and recyclability, narrowing the window for generic, low-differentiation product offerings. These pressures are not merely operational hurdles; they are redefining entry barriers and rewarding firms that can integrate material science, regulatory foresight, and application engineering into a single value proposition.
Worldwide Oblong Jar Market
Key Drivers Reshaping the Market
Technological innovation is no longer a peripheral advantage in this segment; it is becoming a core determinant of market share. Advances in blow molding precision, multi-layer coextrusion, and dispensing integration are enabling oblong containers that meet stricter performance criteria without proportionally increasing material weight. For manufacturers targeting personal care, household, and pharmaceutical applications, this translates into containers that can support airless mechanisms, controlled dosing, and improved barrier properties while maintaining the familiar oblong footprint preferred for shelf presence and user handling. The ability to embed functionality directly into container architecture reduces secondary packaging needs and aligns with broader sustainability objectives, creating a compounding benefit for brands seeking to meet both performance and environmental targets.
Regulatory pressure is simultaneously accelerating material transition timelines. In Europe, packaging regulations are establishing recycled content thresholds for plastic packaging that will effectively require redesigned oblong formats by the end of the decade. Parallel requirements in parts of the United States are mandating post-consumer recycled material adoption for rigid plastic containers, while extended producer responsibility frameworks in several states are shifting financial responsibility for end-of-life recovery toward producers. These developments are not isolated compliance events; they are restructuring the economics of container procurement. Companies that adopt recyclability-by-design principles and secure reliable recycled resin streams early are positioned to reduce future reformulation risk and avoid rushed transitions that often accompany late-stage regulatory deadlines.
Demand-side behavior is also shifting the competitive center of gravity. Consumer brands and industrial buyers increasingly evaluate packaging decisions through a combined lens of sustainability performance, supply reliability, and application compatibility. In the chemicals and solvents space, oblong containers must deliver chemical resistance, secure closure systems, and compatibility with industrial handling. In automotive and lubricant applications, containers are expected to support branding durability, safe transport, and efficient dispensing. Food and beverage, personal care, and pharmaceutical buyers are prioritizing material consistency, contamination control, and dispensing precision. This diversification of requirements is increasing the premium on engineered container solutions rather than commodity-style supply, pushing market value toward suppliers that can demonstrate application-specific competency.
Supply chain and cost structure dynamics complete the driver set. The cost of primary materials such as HDPE and PET has experienced measurable volatility, with HDPE resin averaging around 1,450 USD per metric ton in late 2025 and PET resin prices moving upward by roughly 8 percent year-over-year due to supply chain constraints. These fluctuations affect not only direct material costs but also the relative attractiveness of alternative material pathways and regional sourcing models. At the same time, production footprint decisions are being influenced by proximity to end markets, energy costs, and logistics resilience. Suppliers that can balance regional responsiveness with scale efficiency are gaining leverage, especially as buyers prioritize continuity of supply in addition to price competitiveness.
- Material innovation is moving from optional differentiation to baseline expectation, particularly where recycled content, lightweighting, and dispensing integration converge.
- Regulatory mandates are shifting procurement cycles toward longer planning horizons, rewarding early compliance and transparent material traceability.
- Application-specific requirements are raising the value of engineered oblong containers, reducing the share of purely commodity-oriented supply.
- Input cost volatility is reshaping sourcing strategies, increasing the importance of regional supply resilience and resin mix flexibility.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated structure in which a limited group of established players accounts for a substantial share of revenue, while regional specialists and application-focused suppliers compete on differentiation rather than scale alone. Leading companies are pursuing distinct strategic positions that reflect their material competencies, end-use focus, and integration depth. Berry Global has reinforced its presence in oblong HDPE and PET containers for personal care, household, and pharmaceutical packaging, with recent product introductions emphasizing recycled content integration for personal care applications. Amcor has focused on custom oblong plastic bottles and jars for beauty, food, and healthcare use, showcasing recyclable designs optimized for hot-fill processes at major industry events. These moves reflect a broader emphasis on recyclability and application engineering rather than volume-only competition.
AptarGroup has built advantage around dispensing and closure integration, supplying oblong dispensing containers and pumps that work with rigid packaging for cosmetics and pharmaceuticals. This positioning allows the company to participate in value creation beyond the container body itself, where dispensing functionality, user experience, and dosing precision directly influence brand preference. Gerresheimer has concentrated on oblong glass and plastic primary packaging for pharmaceuticals, including vials and bottles, an area where regulatory compliance, material purity, and dimensional consistency are especially critical. Silgan has extended its portfolio across oblong metal and plastic containers through its plastics operations, targeting personal care and household products where durability and shelf-ready presentation matter. Albea has carved out a recognizable role in skincare and cosmetics packaging by supplying oblong airless and pump-enabled plastic containers, an approach that ties container geometry to product protection and dispensing performance.
What distinguishes these leaders is not simply product breadth but the alignment of capability with regulatory and demand trends. Companies that combine material expertise, dispensing or closure integration, and application-specific validation are better positioned to support customer transitions toward recycled content, recyclable formats, and enhanced end-use functionality. This alignment is also shaping competitive dynamics: larger players are expanding integration across container bodies, closures, and dispensing systems, while application specialists are seeking partnerships or niche scale to serve sectors with stringent performance requirements. New entrants face meaningful hurdles in raw material access, process engineering, and compliance readiness, but targeted entry remains possible in high-value subsegments where dispensability, barrier properties, or pharmaceutical-grade consistency create defensible positioning. Consolidation is likely where overlapping capabilities and regional footprints create cost or capability synergies, while fragmentation will persist where end-use customization demands small-batch engineering and close customer collaboration.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the oblong container market will likely be shaped by three interconnected trends. The first is the mainstreaming of recycled content and recyclability as procurement prerequisites. As recycled content expectations rise and regional rules tighten, oblong container designs that can accommodate post-consumer resin without compromising strength, clarity, or dispensing performance will gain preference. Commercial opportunity will accrue to suppliers that can provide validated material blends, transparent traceability, and consistent lot-to-lot quality, especially in personal care, household, and pharmaceutical applications where aesthetics and functional reliability are both important.
The second trend is the continued convergence of container geometry with dispensing and closure systems. Oblong formats are well suited to ergonomics and shelf presentation, but their value will increasingly depend on how effectively they integrate pumps, airless mechanisms, and closure technologies. This will favor suppliers that can offer coordinated container-plus-dispensing solutions rather than standalone vessels. For brands, this integration can reduce development risk, improve user experience, and support premium positioning in categories such as skincare, cosmetics, and specialty chemicals. The commercial opportunity lies in co-developed solutions that shorten time to market while meeting sustainability and performance targets simultaneously.
The third trend is regional supply realignment driven by material economics, regulatory geography, and logistics considerations. As resin pricing fluctuates and producer responsibility frameworks expand, buyers will place greater emphasis on supply continuity, regional manufacturing proximity, and compliance readiness. Suppliers with diversified production footprints and flexible material portfolios will be better equipped to manage cost shocks and meet jurisdiction-specific requirements. At the same time, consolidation may accelerate among players with overlapping capabilities, while application-specific niches remain open to focused specialists. The main risk is that rapid regulatory or input-cost changes could outpace product development cycles, forcing reactive redesigns and temporary margin pressure for companies with less flexible architectures.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product portfolios with the direction of regulation and demand. This means investing in designs that can accommodate recycled content, ensuring compatibility with recyclable formats, and strengthening dispensing or closure integration where end-use applications justify it. Companies should also evaluate resin mix flexibility and regional sourcing options to reduce exposure to input volatility, while prioritizing application validation that supports customer adoption in higher-value segments.
PW Consulting
For investors, the most relevant signal is the widening gap between commodity-oriented container supply and engineered, application-integrated solutions. Capital allocation should favor businesses that demonstrate measurable progress in recycled content readiness, regulatory compliance, and functional integration, especially where those capabilities are tied to defensible end-use relationships. Monitoring M&A activity and capacity realignment will also help identify where scale synergies are being created versus where niche differentiation remains the stronger value driver.
For procurement and sourcing leaders, the imperative is to treat container selection as a multi-year strategic decision rather than a transactional purchase. Evaluating suppliers on recycled content capability, regulatory preparedness, dispensing integration, and supply resilience will reduce exposure to future reformulation and compliance risk. Longer-term partnerships with suppliers that can support coordinated design, material traceability, and application testing will typically deliver more stable outcomes than short-cycle price optimization alone.
For decision makers seeking deeper segmentation data, regional detail, and tailored scenario planning, the complete research report provides expanded breakdowns across material pathways, application categories, and competitive positioning. It also includes structured guidance for assessing investment timing, procurement strategy, and product development priorities in relation to evolving regulatory and cost dynamics.
Worldwide Bulk box Market
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cosmetic Grade Urolithin A Market: Why 18.05% CAGR And 98% Purity Catalysts Change Everything
By PW Consulting, 2026-09-18
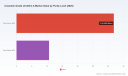
The Cosmetic Grade Urolithin A Market: Strategic Trends and Commercial Opportunities in Cellular Skincare
The global market for cosmetic grade Urolithin A has entered a phase of rapid expansion, driven by a convergence of biotechnology breakthroughs, shifting consumer preferences toward cellular-level skincare, and incremental regulatory clarity in key markets. With a compound annual growth rate of approximately 18% through 2032, the category is transitioning from an emerging scientific concept to a commercially viable active ingredient portfolio. Revenue projections indicate a sustained upward trajectory, positioning Urolithin A alongside established mitochondrial-supporting compounds and next-generation peptide technologies. This growth is not merely a function of pricing dynamics or temporary marketing cycles; it reflects a structural shift in how formulators and brands approach skin longevity, barrier resilience, and topical bioactivity.
Worldwide Cosmetic Grade Retinol Market
At its core, Urolithin A represents a metabolite derived from ellagitannins and ellagic acid, naturally processed through gut microbiota metabolism. In cosmetic applications, it is valued for its potential to support mitochondrial function, cellular energy renewal, and anti-aging pathways when delivered in topical formats. The market's macroeconomic momentum is underpinned by consistent investment in synthesis and purification capabilities, alongside growing clinical and preclinical interest in mitochondrial health as a lever for skin rejuvenation. However, the category is not without friction. As a relatively new cosmetic active, manufacturers and brand owners must navigate evolving regulatory pathways, particularly around ingredient notification, safety substantiation, and claims language. The absence of a fully harmonized global framework means that regional divergence in approval timelines, documentation requirements, and local market access strategies continues to shape go-to-market planning.
PW Consulting Chemical & Energy Research Center
A second challenge lies in the technical complexities of purity and formulation stability. Cosmetic grade Urolithin A must meet stringent specifications for active content, impurity profiles, and compatibility with emulsified or anhydrous systems. Achieving and maintaining high-purity grades through scalable synthesis or extraction pathways remains a differentiator, especially as premium product architectures demand actives that can be integrated without compromising sensory performance or shelf stability. Third, the category is still building consumer-facing science narratives. Unlike well-known antioxidants or retinoid derivatives, Urolithin A operates in a conceptually sophisticated space that requires clear, credible messaging around cellular renewal, mitochondrial support, and measurable skin benefits. Brands that can translate biochemical mechanisms into tangible product outcomes are better positioned to capture premium pricing and loyalty, while those relying on vague longevity claims risk consumer skepticism and regulatory scrutiny.
Food Grade Urolithin A Market
These dynamics set the stage for a market that is growing quickly but remains selective in how value is created and captured. Success will depend on the ability to combine technical rigor, regulatory fluency, and product storytelling in ways that resonate with both formulators and end consumers.
Key Drivers Shaping the Market Trajectory
Biotechnology Innovation and Purity Advancement
One of the most consequential drivers is the ongoing advancement in synthesis, fermentation, and purification technologies. High-purity cosmetic grade Urolithin A lowers barriers for premium formulations, where active consistency and impurity control are critical to safety assessments and performance claims. As manufacturing processes mature, suppliers are increasingly able to offer grades tailored to specific application needs, from stable emulsions to concentrated serums and mask formats. This technical maturation also supports broader adoption by reducing variability across batches and enabling formulators to design products with predictable sensory and stability profiles. In parallel, research into delivery mechanisms and topical bioavailability continues to refine how Urolithin A can be integrated into skin-facing architectures without compromising integrity, which strengthens its appeal for anti-aging and skin protection formulations.
Regulatory Milestones and Ingredient Recognition
Regulatory progress in key markets is another pivotal driver, particularly where new cosmetic ingredient frameworks enable structured market entry. In China, recent approvals and filings have provided clearer pathways for Urolithin A as a cosmetic active, including recognition for skin protection and anti-aging applications. These milestones reduce ambiguity for manufacturers seeking to incorporate the ingredient into commercially distributed products and encourage local and international brands to evaluate Urolithin A within their pipelines. Meanwhile, in other major cosmetic markets, the absence of restrictive prohibitions has allowed Urolithin A to be positioned as an innovative anti-aging ingredient with topical clinical interest. The net effect is a more predictable environment for product development, though companies still need to maintain robust documentation, safety data, and region-specific compliance strategies to scale efficiently.
Consumer Demand for Longevity-Oriented Skincare
Demand-side momentum is increasingly shaped by a broader cultural and consumer shift toward longevity, wellness, and proactive skin health. Skincare consumers are moving beyond reactive correction toward products that frame aging as a biological process that can be supported through targeted actives. This mindset aligns closely with the narrative potential of Urolithin A, which connects mitochondrial function and cellular renewal to visible skin concerns such as firmness, texture, and resilience. Brand owners are responding by developing product architectures that emphasize scientific credibility, transparency, and demonstrable benefits, often pairing advanced actives with well-established delivery systems. As a result, Urolithin A is finding traction in premium anti-aging creams, serums, and rejuvenation masks where formulation sophistication and ingredient storytelling can command higher value perception.
Supply Chain Maturation and Competitive Manufacturing Capacity
The supply side is evolving as multiple manufacturers expand production capabilities and diversify sourcing strategies. Competition among suppliers is encouraging improvements in scale, quality control, and application support, which benefits formulators seeking reliable access to cosmetic-grade material. At the same time, supply chain resilience has become a strategic priority, with buyers placing greater emphasis on vendor qualification, consistency, and the ability to support launch timelines. Manufacturers that can combine high-purity output with GMP-aligned production practices and responsive technical service are increasingly preferred partners, particularly for larger brand programs that require dependable volumes and regulatory-grade documentation. This supply-side maturation is helping transform Urolithin A from a niche ingredient into a more accessible building block for contemporary skincare portfolios.
Competitive Landscape and Leading Strategies
The competitive field for cosmetic grade Urolithin A reflects a blend of proprietary ingredient developers, precision manufacturers, and bulk suppliers serving both cosmetic and adjacent personal care applications. Companies with differentiated positioning tend to emphasize either clinical-grade purity, application-specific formulation expertise, or regulatory readiness in priority markets. Rather than competing solely on price, leading players are building value through active branding, scientific backing, and the ability to support downstream product development with technical documentation and stability insights.
A notable strategic divergence is emerging between proprietary active platforms and broader supply-oriented manufacturers. Proprietary approaches often center on branded Urolithin A ingredients that are integrated into specific skincare lines and supported by targeted communication around mitochondrial renewal and skin anti-aging. This model enables closer collaboration with brand partners and supports premium positioning through ingredient recognition and formulation ecosystems. In contrast, supply-oriented producers focus on scalable output, purity consistency, and flexible grading to meet varied formulation needs. This pathway is particularly relevant for manufacturers and private-label brands that seek dependable raw material access without necessarily requiring a proprietary active narrative. Both models have merit, and the market is increasingly accommodating multiple entry points depending on brand strategy, price architecture, and technical requirements.
Regulatory fluency is becoming a defining capability. Companies that have secured or are actively progressing ingredient notifications in major markets gain a meaningful advantage in speed-to-market and brand confidence. Approvals and filings that recognize Urolithin A for skin protection and anti-aging use not only validate the ingredient's cosmetic relevance but also reduce ambiguity for downstream users. This is especially important in regions where cosmetic ingredient governance is tightening and documentation expectations are rising. Firms that proactively maintain compliance readiness, including safety data packages, usage parameters, and region-specific labeling considerations, are better positioned to support brand partners through launch and scaling.
Market structure is also evolving through consolidation and specialization. Larger brand collaborations and high-profile product launches can accelerate category visibility and create demand spikes that influence supplier prioritization. At the same time, the proliferation of manufacturers indicates room for continued new entry, particularly where quality, cost efficiency, and application support are clearly demonstrated. Over time, the landscape is likely to differentiate further: premium branded actives will compete on science, positioning, and partnership ecosystems, while volume-oriented suppliers will compete on reliability, scale, and cost-competitiveness. For buyers, this means that supplier selection will increasingly hinge on alignment between ingredient strategy, regulatory pathway, and formulation objectives rather than on commodity benchmarks alone.
A practical implication is that competitive advantage will depend on the ability to connect ingredient quality with credible product outcomes. Companies that can demonstrate consistent purity, provide formulation guidance, and align with regional compliance expectations will have stronger positioning than those competing on price in isolation. As visibility grows, the market is likely to reward players who can convert scientific promise into repeatable commercial execution.
Forward-Looking Trends for the Next Three to Five Years
One of the clearest forward trends is the continued elevation of Urolithin A within premium anti-aging and cellular skincare categories. As formulators gain more experience integrating the ingredient across creams, serums, masks, and targeted treatments, product architectures will likely become more refined and application-specific. This should support a move toward differentiated claims and more precise product positioning, particularly where brands can pair Urolithin A with complementary actives and delivery systems that reinforce visible skin benefits. The strategic opportunity here is not simply to include the ingredient, but to design complete formulations that make its mechanism understandable and perceptible to consumers.
A second trend is the growing importance of regulatory and documentation maturity as a market-access prerequisite. As awareness of cosmetic-grade Urolithin A expands, buyers and regulators will likely place greater emphasis on traceability, quality consistency, claims substantiation, and region-specific filing status. Companies that invest early in robust technical packages and compliance readiness will be better equipped to enter new geographies, support larger brand programs, and reduce launch risk. This trend also implies that ingredient suppliers with strong regulatory orientation will increasingly serve as strategic partners rather than transactional vendors.
A third trend concerns the potential for broader application development beyond initial anti-aging use cases. Sun care and repair products, eye care formulations, and rejuvenation masks represent areas where Urolithin A's biological narrative may be extended into more specialized routines. The commercial opportunity lies in tailoring messaging and formulation choices to distinct consumer needs while maintaining scientific integrity. At the same time, uncertainty remains around the pace of consumer education, the consistency of premium demand, and the degree to which regulatory frameworks will converge or remain fragmented. Over the next few years, market participants will need to balance optimism with disciplined validation, ensuring that product claims, supply commitments, and expansion plans are grounded in realistic execution capacity.
Strategic Implications for Decision Makers
For manufacturers and ingredient suppliers, the priority is to strengthen the link between production quality and commercial credibility. Consistent purity, clear application guidance, and compliance readiness can become durable differentiators, especially as brand partners seek to reduce formulation risk and accelerate time-to-market. Companies that invest in technical service, stability support, and region-specific documentation will be better positioned to secure long-term partnerships rather than one-off transactions.
For investors and strategic planners, the market's growth trajectory suggests meaningful opportunity, but success will depend on segmentation discipline. Not all Urolithin A supply is equivalent, and value creation will likely concentrate among players that can combine scalable production with ingredient branding, regulatory fluency, and viable formulation ecosystems. Evaluating a company's ability to navigate approvals, maintain quality at scale, and support downstream product narratives will be central to assessing durability of advantage.
For brand owners and procurement teams, the practical imperative is to treat Urolithin A as a strategically selected active rather than a commodity addition. Supplier qualification should include purity consistency, documentation completeness, application compatibility, and the ability to support claims responsibly. Building internal understanding of how mitochondrial-focused narratives translate into consumer-facing benefits can also improve product positioning and reduce the risk of overpromising. In a category that is expanding quickly but still maturing, access to detailed segmentation, regional compliance status, and supplier benchmarking can materially improve sourcing and launch decisions. More comprehensive data and customized scenario analysis are available in the full PW Consulting research report for teams that need deeper commercial planning support.
For detailed analysis of this topic, please visit the official page: Cosmetic Grade Urolithin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soft Tissue Repair Mesh Market: 5 Strategic Shifts Reshaping Growth to $6.68B by 2032
By PW Consulting, 2026-09-18
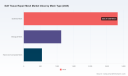
Strategic Trends and Commercial Opportunities in the Global Soft Tissue Repair Mesh Market
Market Landscape and Core Challenges
The global soft tissue repair mesh market has demonstrated resilient expansion over the past five years, establishing itself as a critical component within the broader surgical devices sector. Valued at approximately 4.5 billion USD in 2025, the market has recovered from a period of stagnation and litigation-driven caution that characterized the early 2020s. Historical trajectories indicate a steady climb from roughly 3.37 billion USD in 2020, reflecting an industry that has successfully navigated regulatory headwinds to return to a growth trajectory. Looking ahead, the market is projected to expand at a compound annual growth rate of 5.81 percent through 2032, suggesting a mature yet evolving landscape where value creation depends on innovation rather than volume alone.
Despite this positive outlook, the industry stands at a significant inflection point defined by heightened scrutiny and shifting clinical preferences. One of the primary challenges involves the complex regulatory environment surrounding product safety and transparency. While mesh products for hernia repair generally maintain Class II classification, specific applications such as transvaginal pelvic organ prolapse have faced severe restrictions due to long-term safety concerns. This dichotomy creates a fragmented market where manufacturers must differentiate rigorously between product categories to avoid reputational spill-over effects. The increased demand for transparency is reshaping how products are labeled and marketed, forcing companies to provide more clinically relevant mechanical data on packaging to facilitate safe use.
Furthermore, the market concentration remains high, with the top few players commanding a significant share of total revenue. This consolidation poses barriers to entry for smaller innovators while simultaneously pressuring incumbent leaders to maintain portfolios that satisfy diverse surgical needs. A second critical challenge lies in the reimbursement landscape. Payment rates for procedures involving mesh implantation vary widely based on complexity and setting, creating economic pressure on healthcare providers. These reimbursement constraints influence procurement decisions, often favoring cost-effective synthetic options over premium biological alternatives unless clinical outcomes clearly justify the added expense. Consequently, manufacturers face the dual challenge of proving superior clinical efficacy while navigating tight hospital budgets.
Finally, the supply chain for raw materials and manufacturing capacity remains a point of vulnerability. As demand shifts toward specialized composite and hybrid meshes, the ability to scale production without compromising quality becomes a strategic differentiator. These challenges collectively suggest that future growth will not be uniform across all segments but will instead favor companies that can balance regulatory compliance, clinical evidence, and economic efficiency.
Key Drivers of Market Change
Several fundamental factors are propelling the soft tissue repair mesh market forward, transforming it from a commodity-driven space into one defined by technological differentiation. The most prominent driver is technological innovation in material science. There is a marked shift away from traditional heavyweight synthetics toward lightweight, composite, and bioresorbable options. Manufacturers are increasingly developing meshes that integrate with host tissue more effectively, reducing foreign body responses and chronic pain. For instance, the recent regulatory clearance for electrospun fiber matrices highlights the industry's movement toward advanced structures that mimic natural tissue properties. This innovation is not merely about material composition but also about structural design, such as macroporous configurations that allow for better tissue ingrowth while maintaining mechanical strength.
Regulatory dynamics are simultaneously acting as both a constraint and a catalyst. While the FDA has tightened oversight on specific high-risk applications, the pathway for hernia repair meshes remains well-defined under the 510(k) clearance process. However, the recent draft guidance recommending standardized package labeling indicates a push toward greater transparency. This regulatory evolution forces companies to invest more heavily in clinical data generation and labeling compliance. Rather than hindering growth, this environment tends to favor larger, well-resourced organizations that can absorb the costs of compliance and clinical trials. It effectively raises the barrier to entry, consolidating the market around players who can demonstrate robust safety profiles and provide clear usage guidelines.
On the demand side, the aging global population and the rising prevalence of conditions requiring soft tissue reconstruction are driving volume. Hernia repair remains the dominant application, supported by consistent surgical rates across developed and developing regions. However, there is growing interest in pelvic organ prolapse and breast reconstruction, provided safety concerns are adequately addressed through improved product design. Surgeons are increasingly seeking solutions that reduce recurrence rates and minimize complications, which drives demand for higher-performance meshes. This shift in surgeon preference influences procurement policies, pushing hospitals to adopt products that offer long-term cost savings through reduced revision surgeries, even if the upfront device cost is higher.
Supply chain and cost structures also play a pivotal role. The pressure to reduce healthcare costs globally encourages the adoption of efficient manufacturing processes and cost-effective synthetic materials. Yet, the rise of biological and hybrid meshes suggests a premium segment is emerging for complex cases where synthetic options are contraindicated. Companies are responding by optimizing their supply chains to support diverse product lines, ranging from mass-market synthetics to specialized biologics. This dual approach allows manufacturers to capture volume in standard procedures while maintaining margins in specialized applications. The interplay between reimbursement rates and device pricing continues to shape adoption patterns, with economic factors often determining the speed at which new technologies penetrate the market.
Worldwide Hernia Mesh Devices Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large diversified medical device conglomerates and specialized niche players. The market concentration is significant, with the top three companies holding a substantial portion of total revenue. This structure implies that competitive advantage is often derived from portfolio breadth and global distribution networks rather than single-product superiority. Leading players such as Johnson & Johnson and Medtronic leverage their extensive surgical portfolios to offer comprehensive solutions, integrating meshes with fixation devices and surgical tools. Their strategy focuses on maintaining market leadership through continuous product iteration and strong relationships with surgical communities. For these giants, the ability to offer a range of options—from synthetic to composite—allows them to address various clinical scenarios while mitigating risk associated with any single product line.
Specialized manufacturers employ different strategic maneuvers. Companies like BD, formerly associated with Bard, focus on expanding portfolios that include bioresorbable options like Phasix, catering to surgeons seeking long-term safety without permanent implantation. Recent commercial launches of absorbable hernia patches highlight a strategy centered on innovation in material absorption rates and handling characteristics. Similarly, companies like TELA Bio and Organogenesis focus on regenerative medicine and reinforced tissue matrices. Their value proposition lies in providing alternatives for patients where synthetic meshes pose higher risks, thereby capturing a premium segment willing to pay for biologic properties. These players often invest heavily in clinical evidence to support reimbursement claims and differentiate themselves from standard synthetic offerings.
The landscape is also evolving through strategic partnerships and acquisitions. Larger entities often acquire innovative smaller firms to gain access to novel technologies or specific market segments without developing them internally. This trend accelerates the integration of new materials like electrospun fibers into established product lines. Meanwhile, the regulatory environment acts as a filter. Recent FDA actions regarding pelvic organ prolapse meshes have reshaped the competitive field, removing certain products from the market and redirecting demand toward safer alternatives. This dynamic benefits companies with strong compliance records and diversified portfolios that are not overly exposed to high-risk applications. The result is a market where stability and trust are becoming as valuable as technological features.
PW Consulting
New entrants face a challenging path. While the 510(k) pathway provides a mechanism for market access, the reputational risks associated with mesh products require careful positioning. Success for new players often depends on identifying underserved niches, such as specific anatomical repairs or regions with growing surgical volumes. The presence of established global players means that pricing pressure is inevitable, pushing innovators to demonstrate clear clinical advantages that command premium pricing. Overall, the competitive dynamics suggest a market moving toward consolidation among top players while allowing room for specialized innovators who can navigate regulatory complexity and prove distinct clinical value.
Future Trends and Commercial Implications
Looking toward the next three to five years, several trends are likely to define the trajectory of the soft tissue repair mesh market. First, the differentiation between synthetic and biological meshes will become more nuanced. Rather than a binary choice, hybrid and composite meshes are expected to gain prominence, offering a balance of mechanical strength and biocompatibility. This trend creates opportunities for manufacturers who can successfully engineer materials that degrade at controlled rates while providing sufficient support during the healing phase. The commercial implication is a shift in R&D focus toward material science that can justify premium pricing through reduced long-term complications.
Second, regulatory transparency will continue to intensify. The move toward standardized labeling and clearer communication of mechanical properties suggests that future market access will depend heavily on how well a product's performance is documented and communicated. Companies that proactively align with these regulatory shifts will gain trust among surgeons and procurement teams. This environment may slow the adoption of unproven innovations but will strengthen the position of established products with robust data packs. For investors, this signals a preference for assets with clear regulatory pathways and strong intellectual property protection around material composition and labeling data.
Third, regional dynamics will play an increasingly important role. While mature markets drive revenue through high-value products, emerging regions offer volume growth driven by increasing surgical access. However, reimbursement constraints in developed markets may push cost-sensitive innovations toward emerging economies. A potential risk lies in the variability of regulatory standards across regions, which can complicate global launches. Companies must balance the need for standardized products with the flexibility to adapt to local reimbursement and clinical preferences. The uncertainty surrounding long-term safety data for certain applications remains a persistent risk, potentially impacting adoption rates if new safety signals emerge. Success in this environment requires agility in product positioning and a deep understanding of local market nuances.
Worldwide Inguinal Hernia Repair Mesh Market
Strategic Actions for Decision Makers
For manufacturers, the priority should be to strengthen clinical evidence packages that support both safety and cost-effectiveness. Investing in data that demonstrates reduced revision rates or faster recovery times can justify premium positioning and align with value-based care initiatives. Companies should also monitor regulatory guidance closely to ensure labeling and marketing materials meet evolving transparency standards, reducing the risk of compliance issues.
Investors evaluating opportunities in this sector should focus on companies with diversified portfolios that are not overly reliant on high-risk applications. Technologies that offer unique material properties or clear pathways to reimbursement are more likely to sustain growth. Due diligence should include a thorough assessment of regulatory clearance status and the strength of intellectual property surrounding material innovations.
Procurement leaders and healthcare providers need to balance cost considerations with long-term patient outcomes. Selecting meshes that offer proven safety profiles and align with reimbursement structures can optimize procedure costs over time. Engaging with suppliers who provide comprehensive training and data support can also improve surgical consistency and outcomes. Access to detailed segmentation data and customized market intelligence is essential for navigating these complex decisions effectively.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Tissue Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


