



PW Consulting Report: Compressor Blades Market Hits $12.5 Billion in 2025, Forecasts 5.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Phase of Growth: Strategic Intelligence for the Compressor Blades Market
In an era defined by rapid technological evolution and stringent regulatory oversight, the compressor blades sector stands at a critical inflection point. As propulsion systems demand higher efficiency, lighter weight, and enhanced durability, manufacturers and investors must move beyond surface-level trends to grasp the underlying structural drivers shaping the industry. This article outlines the strategic value of our latest market research, offering a preview of the comprehensive intelligence designed to support confident decision-making throughout the forecast horizon.
The global compressor blades market has demonstrated consistent expansion over the past half-decade, reflecting steady demand across aerospace and industrial energy sectors. Drawing on a robust historical dataset spanning 2020 through 2025 and extending forward to 2032, our analysis establishes a clear trajectory of sustained growth. The market has evolved from a baseline of 9.57 billion USD in 2020 to an estimated 12.5 billion USD in 2025, with projected revenues reaching 17.82 billion USD by 2032. This expansion corresponds to a compound annual growth rate of 5.2 percent across the forecast period, underscoring a mature yet dynamically evolving industry landscape.
Worldwide Gas Turbine Turbine Blades Market
Such macroeconomic momentum is not uniform; it is propelled by intersecting technological, regulatory, and operational forces that require nuanced strategic interpretation. Our research dissects these drivers to reveal where capital allocation, supply chain optimization, and product development efforts will yield the highest marginal returns. Rather than presenting static figures, the report contextualizes growth within real-world operational constraints, procurement cycles, and engineering imperatives that define competitive advantage.
Decoding Market Architecture Through Actionable Segmentation
To translate broad market trajectories into executable strategy, our report constructs a multidimensional segmentation framework that isolates the structural components of demand. The analysis examines compressor blade categories differentiated by operational pressure profiles, highlighting how high-pressure variants and low-pressure alternatives serve distinct engineering requirements and procurement cycles. Each category carries unique material specifications, manufacturing tolerances, and lifecycle considerations that influence pricing dynamics, lead times, and aftermarket opportunities.
Similarly, the application landscape is dissected across aviation engines, industrial gas turbines, and turbocharger systems. These segments operate under divergent performance benchmarks, regulatory environments, and replacement cadences. By mapping demand intensity, technological readiness, and procurement predictability across these applications, the report equips strategists with the clarity needed to prioritize product roadmaps and market entry initiatives without relying on oversimplified generalizations.
Regional dynamics are explored with equal rigor, examining how established aerospace hubs, emerging manufacturing corridors, and defense procurement centers contribute to overall market momentum. The geographic breakdown illuminates disparities in supply chain maturity, local content requirements, and infrastructure readiness, enabling organizations to calibrate their operational footprint and risk exposure accordingly. Throughout this analysis, the report deliberately reserves granular percentage splits and region-specific revenue figures for the full dataset, ensuring that strategy teams engage with the complete intelligence package before committing to allocation decisions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The compressor blades industry exhibits a moderately consolidated structure, with the top three players commanding approximately 45.6 percent of market revenue and the top five collectively controlling 62.3 percent. This concentration reflects the high barriers to entry inherent in precision aerospace manufacturing, including advanced metallurgy capabilities, certified quality management systems, and long-cycle customer relationships. Yet beneath this consolidated core lies a diverse ecosystem of specialized manufacturers, repair providers, and component integrators that compete on precision, lead time, and niche engineering expertise.
Our competitive analysis profiles a broad spectrum of incumbent leaders and specialized operators, mapping their strategic positioning across commercial aviation, military propulsion, and industrial applications. Organizations such as GKN Aerospace, Rolls-Royce Holdings, and Safran S.A. anchor the high-end aerospace segment, leveraging advanced composites, titanium alloy production, and integrated gas turbine designs to sustain performance leadership. RTX Corporation and Pratt & Whitney reinforce their positions through engine program integration, spanning commercial platforms and military series such as the F100 family, while MTU Aero Engines and IHI Corporation extend their reach across both aircraft and industrial gas turbine applications.
The competitive field also includes precision manufacturers and supply chain specialists that enable agility and cost efficiency across a range of platforms. Howmet Aerospace, Chromalloy, Hi-Tek Manufacturing, TURBOCAM International, Moeller Aerospace, Doncasters Group, Farinia Group, Stork B.V., Blades Technology, Pacific Sky Supply, and Collins Aerospace each contribute distinct capabilities, from titanium alloy precision machining to aftermarket repair and component substitution services. Mitsubishi Heavy Industries rounds out the landscape with dual-use aero and industrial competence. By evaluating these players through lenses of technology ownership, vertical integration, geographic reach, and aftermarket competency, the report reveals where consolidation pressure may intensify, where partnership opportunities are most viable, and where new entrants could capture niche share.
Importantly, the report does not merely catalog competitors; it assesses the strategic implications of their product architectures, procurement dependencies, and capacity utilization patterns. This enables executives to benchmark their own positioning, identify vulnerability in single-source dependencies, and evaluate potential consolidation or joint development scenarios with a clear understanding of market concentration dynamics.
Regulatory Pressures and Operational Dynamics Reshaping Demand
Beyond structural segmentation and competitive positioning, the compressor blades market is increasingly shaped by regulatory mandates, sustainment contracts, and in-service durability considerations. Recent regulatory activity illustrates how safety-driven interventions can rapidly alter demand patterns and procurement timelines. In November 2025, the FAA announced plans to mandate the replacement of specific V2500 high-pressure compressor stage 3 rotor blades to address durability issues identified in operational service. This enforcement trajectory highlights the direct link between airworthiness oversight and replacement demand, reinforcing the importance of aftermarket readiness, traceability, and rapid response manufacturing capabilities.
Parallel defense procurement activity further illustrates the interplay between regulatory programming and component demand. In August 2025, the Defense Logistics Agency Aviation issued contract SPRTA1-25-R-0356, requiring procurement of compressor blade sets for F100-229 engines with delivery scheduled by May 31, 2026. Shortly thereafter, in January 2026, the Air Force Sustainment Center solicited support for TF33 first-stage compressor blade repair, with a due date in early February 2026. These actions underscore the persistent demand generated by military sustainment cycles, engine modernization programs, and the operational necessity of maintaining readiness across legacy and current-generation platforms.
These developments are integrated into the report’s market dynamics section, where regulatory trajectories, procurement calendars, and durability-driven replacement cycles are analyzed as strategic levers rather than isolated events. Organizations that internalize these patterns can better align production scheduling, inventory positioning, and repair network investments with the rhythm of mandated replacements and defense procurements. The research deliberately abstracts away from exposing specific contract values or segment-level percentages, preserving the analytical edge of the full report while demonstrating its relevance to near-term operational planning.
What the Full Study Delivers: A Practical Toolkit for Decision-Makers
While this overview signals the strategic scope of the research, the complete study provides an operational toolkit designed for cross-functional deployment. The report integrates historical performance analysis with forward-looking scenario modeling, enabling teams to test assumptions around capacity expansion, material sourcing, and aftermarket service growth. Decision-makers gain access to a structured examination of manufacturing technologies, including precision machining, titanium alloy processing, and composite integration, alongside an evaluation of how these capabilities influence cost structures, cycle times, and qualification pathways.
The study also maps supply chain architecture across raw material inputs, subcomponent fabrication, assembly, and repair ecosystems. By illuminating concentration risks, lead-time variability, and regional sourcing constraints, the report helps organizations design more resilient procurement strategies and evaluate vertical integration or supplier diversification options. In addition, the analysis includes an assessment of aftermarket dynamics, where replacement cycles, repairability thresholds, and airworthiness compliance converge to shape recurring revenue opportunities and service-level commitments.
Strategists will also find dedicated attention to product development implications. The report evaluates how performance requirements across aviation engines, industrial gas turbines, and turbocharger applications influence airfoil design, cooling architectures, and material selection, translating engineering priorities into commercially relevant investment guidance. Throughout, the research maintains a disciplined focus on actionable insight, ensuring that every analytical module connects to a decision context—whether that involves capacity planning, market entry, partnership evaluation, or risk mitigation.
To preserve the integrity of this intelligence and encourage rigorous strategic application, certain granular data points are reserved for the full report. This includes segment-specific revenue contributions, regional value splits, detailed company-level capability matrices, and proprietary scenario outputs. The intent is not to withhold value, but to ensure that the depth of analysis is experienced in its complete form, allowing executives and analysts to draw conclusions with full context rather than fragmented snapshots.
Compressor Blades Market
Strategic Imperatives for 2026 and Beyond
As organizations enter the 2026 planning cycle, the compressor blades market presents a landscape where disciplined intelligence can differentiate resilient strategies from reactive maneuvers. The convergence of steady top-line growth, concentrated competition, regulatory-driven replacement demand, and sustainment procurement creates a multi-layered environment that rewards analytical precision. Companies that align their product portfolios with durability mandates, fortify their supply chains against regional and material constraints, and calibrate their aftermarket capabilities to replacement cycles will be best positioned to capture value across the forecast window.
This research is designed to support that alignment. By combining macro trajectory analysis with segment-level architecture, competitive dynamics, regulatory context, and operational supply chain evaluation, the report delivers a comprehensive vantage point for strategy formulation. The 5.2 percent compound annual growth pathway to 2032 is not merely a headline figure; it is a signal of sustained demand intensity that must be interpreted through the lenses of application specificity, pressure-class differentiation, and geographic readiness.
For leadership teams seeking to translate market momentum into concrete plans, the full study offers the structured evidence base required to reduce uncertainty and accelerate decision velocity. We invite executives, strategy directors, and industry analysts to engage with the complete dataset, where the detailed segmentation splits, proprietary competitive assessments, and forward scenario tools are available in their entirety. In a market where precision, compliance, and timing determine outcomes, comprehensive intelligence is not an optional enhancement—it is the foundation of durable competitive strategy.
For detailed analysis of this topic, please visit the official page: Compressor Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Magnesium Die Casting Hits $2.72B in 2025, 5.6% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Automotive Parts Magnesium Die Casting Market: A 2026 Outlook
The automotive industry stands at a critical inflection point where lightweighting mandates intersect with stringent emission regulations. For stakeholders monitoring the Automotive Parts Magnesium Die Casting Market, the convergence of technological capability and regulatory pressure is reshaping competitive positioning. Our latest market research provides a comprehensive analysis designed to guide executive decision-making throughout the 2026 to 2032 forecast horizon. This report serves as a foundational intelligence asset, translating complex industry dynamics into actionable strategic roadmaps for OEMs, Tier suppliers, and investment groups.
Operationalizing Market Intelligence for Executive Teams
Understanding the trajectory of magnesium die casting requires more than surface-level observation. It demands a rigorous examination of production capabilities, alloy innovations, and downstream integration. The automotive sector is increasingly relying on magnesium alloys to achieve fuel efficiency standards and reduce greenhouse gas emissions. As manufacturers pivot toward electrified and lightweight platforms, the demand for high-pressure and vacuum die casting processes is intensifying. Our research framework captures these nuances, offering a granular view of how pressure die casting and vacuum die casting serve as primary processes due to their superior precision and repeatability. This operational focus ensures that leadership can evaluate supplier capabilities with confidence.
The market intelligence encapsulated in this study extends beyond aggregate figures. It dissects the mechanisms driving growth, including the integration of magnesium components into body panels, engine parts, and transmission components. By analyzing the interplay between structural integrity requirements and weight savings, the report equips strategists with the context needed to assess risk and opportunity. Whether evaluating new capacity investments or negotiating supply contracts, having access to verified industry data is paramount. The following sections outline the core pillars of our analysis, demonstrating why this report is an essential tool for navigating the coming years.
Market Landscape and Growth Trajectory
The economic landscape for automotive magnesium die casting has demonstrated robust expansion over the recent historical period. Our analysis tracks market revenue trends from 2020 through the base year of 2025, establishing a validated baseline for future projections. The data indicates a consistent upward movement, reflecting the automotive industry's commitment to material optimization. As we extend the forecast period to 2032, the study projects sustained momentum, underpinned by a Compound Annual Growth Rate that underscores the strategic importance of this material segment.
Worldwide Automotive Magnesium Alloy Wheel Market
This growth is not merely a function of volume but is deeply tied to value creation through engineering innovation. The report highlights how the market valuation evolves as manufacturers scale production of integrated magnesium components. From the initial baseline years to the projected peak in the early 2030s, the trajectory suggests a maturing market where efficiency and scale converge. For decision-makers, understanding the magnitude of this expansion is crucial for capital allocation. The research details the revenue pathways without exposing the granular segmentation tables, ensuring that subscribers gain a holistic view of the economic environment before diving into specific regional or application-based calculations available in the full document.
Dynamics Driving Industry Participation
Several key dynamics are fueling the widespread adoption of magnesium die casting in automotive applications. Foremost among these is the imperative for weight reduction. Magnesium die casting enables significant weight reduction in automotive components, directly supporting fuel efficiency standards and greenhouse gas emission regulations. This regulatory tailwind is a persistent force, compelling manufacturers to seek solutions that do not compromise performance. Furthermore, high-pressure die casting of magnesium alloys complies with automotive safety standards for structural integrity in body and powertrain applications. This dual benefit of lightness and strength is a powerful value proposition that the report analyzes in depth.
Infrastructure and process technology also play a pivotal role. The industry relies heavily on pressure die casting and vacuum die casting as primary processes used for automotive magnesium die casting due to superior precision and repeatability. These technical specifications determine the quality of output in engine parts, transmission components, and body panels. Our research examines how these processes are optimized across different manufacturing environments. By mapping the technological landscape, we provide insights into which production methods are gaining traction and how they align with the demands of modern vehicle architectures. This section of the report is critical for assessing the technical readiness of potential partners or internal production lines.
Competitive Landscape and Key Incumbents
The market structure is characterized by a mix of established global players and specialized firms focusing on lightweighting solutions. Our analysis identifies key companies that are shaping the competitive environment. Leaders such as GF Casting Solutions and Nemak are prominent for their focus on high-pressure die-cast components and lightweighting solutions, respectively. GF Casting Solutions operates with a focus on high-pressure die-cast aluminum and magnesium components for global automotive OEMs, including powertrain and structural parts. Similarly, Nemak focuses on lightweighting solutions with magnesium die casting components for the global automotive industry, showcasing innovations such as cross car beams and oil sumps with significant weight reduction properties.
Automotive Parts Magnesium Die Casting Market
Regional specialization is evident among other key participants. In North America, firms like Shiloh Industries, Pace Industries, Meridian Lightweight Technologies, Kinetic Die Casting Company, and ZD Metal Products contribute to a diverse ecosystem. Shiloh Industries focuses on high-pressure and high-vacuum structural die castings, while Pace Industries offers full-service magnesium die casting for automotive parts, ranging from prototypes to long-term production. Meridian Lightweight Technologies concentrates on innovative die cast magnesium solutions and assemblies, and Kinetic Die Casting Company targets magnesium die casting for lightweight automotive parts. ZD Metal Products rounds out this group with a focus on high-performance magnesium die castings for automotive Tier I and Tier II suppliers.
In Asia, Haitian Die Casting stands out as a major force. Headquartered in Ningbo, China, the company focuses on high-pressure magnesium alloy forming technology and integrated magnesium die-cast components for automotive mass production. The report provides a detailed competitive profiling of these entities, examining their strategic moves, technological deployments, and market positioning. Understanding the scope of operations for these incumbents allows stakeholders to benchmark their own strategies and identify gaps in the supply chain.
Recent Strategic Developments and Innovation
The competitive landscape is dynamic, with recent events highlighting the pace of innovation. Our research integrates recent developments to show how key players are executing their strategies. In 2025, Haitian Die Casting was active with multiple milestones. They debuted magnesium alloy forming technology at the 5th China Foundry Association Die Casting CEO Annual Meeting and Nonferrous Casting Lightweight Forum. Shortly thereafter, they powered the mass production of the world's largest integrated magnesium rear body for SERES vehicles. Additionally, Haitian signed a strategic partnership with Guangdong Hongte Technology Co., Ltd. for comprehensive collaboration in magnesium die casting and showcased aluminum and magnesium forming solutions at automotive industry forums in Wuhan and Hefei.
Moving into 2026, Nemak continued this trend of showcasing advanced components. At the 2026 China Die Casting Congress in Wuhan, they showcased an HPDC Magnesium Cross Car Beam with 53% weight reduction and an HPDC Magnesium Oil Sump with 24% weight reduction and creep resistance. These examples illustrate the tangible progress being made in component engineering. The report contextualizes these developments within the broader industry narrative, helping readers understand how specific technological breakthroughs translate into market share and capability expansion. By tracking these events, the study offers a real-time perspective on where the industry is heading.
Market Concentration and Industry Structure
An understanding of market concentration is vital for assessing competitive intensity and barriers to entry. Our research provides data on the concentration levels within the industry, indicating the share held by leading firms. The analysis reveals a landscape where a significant portion of market revenue is captured by top-tier players, yet ample space remains for specialized innovators. This structure suggests that while scale is important, technological differentiation and service integration are equally critical for success. The report elaborates on these concentration metrics to help stakeholders evaluate the risk of supplier dependency and the potential for consolidation.
This structural insight is complemented by a review of supply chain dynamics. The interplay between major suppliers and automotive manufacturers is complex, influenced by quality requirements, delivery timelines, and cost pressures. By mapping the relationships and dependencies within the value chain, the report supports better vendor selection and risk management strategies. The concentration data serves as a benchmark for understanding the balance of power in the market and informs decisions regarding partnership or acquisition opportunities.
Conclusion: Value for Decision-Makers
The Automotive Parts Magnesium Die Casting Market represents a sector where strategic foresight can yield significant competitive advantage. As regulations tighten and vehicle architectures evolve, the ability to anticipate market shifts is invaluable. This report delivers the depth of analysis required to navigate these complexities. From the macroeconomic growth drivers to the micro-level innovations showcased by key companies, every section is designed to support informed decision-making. The integration of historical data with forward-looking projections ensures that stakeholders have a reliable compass for the forecast period.
For executives seeking to understand the full scope of opportunities and risks, the detailed segmentation analysis offers the necessary granularity. The complete study unpacks regional variations, application-specific demands, and type-based market splits, providing the precise data points needed for detailed planning. We invite industry leaders to leverage this comprehensive intelligence to refine their strategies. Accessing the full report will unlock the specific breakdowns and strategic recommendations that underpin this executive overview, enabling a data-driven approach to growth in the automotive magnesium die casting sector.
For detailed analysis of this topic, please visit the official page: Automotive Parts Magnesium Die Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BIM Market Hits $113M in 2025, Projected 13.05% CAGR to $267.4M by 2032
By PW Consulting, 2026-09-16
The Digital Backbone of Construction: Unlocking Strategic Value in the 2026 BIM Market
The construction industry stands at a critical inflection point, where digital transformation is no longer optional but existential. Building Information Modeling (BIM) has evolved from a niche technological advantage into the central nervous system of modern infrastructure development. As we navigate through 2026, understanding the trajectory of this market is vital for stakeholders ranging from civil engineering firms to software investors. Our latest comprehensive market research provides a granular look at this ecosystem, offering the intelligence required to navigate the next cycle of growth.
Recent historical data underscores the resilience and accelerating momentum of the sector. The market has demonstrated consistent expansion over the past half-decade, moving from a valuation of 60.0 million USD in 2020 to approximately 113.0 million USD in 2025. This historical trajectory sets the stage for a forecast period defined by robust acceleration. Projections indicate that the market will reach 128.71 million USD by the end of 2026, eventually climbing toward 267.4 million USD by 2032. This growth pattern corresponds to a compound annual growth rate of 13.05 percent during the forecast horizon, signaling a high-confidence environment for capital allocation and strategic planning.
However, top-line numbers only tell a fraction of the story. The true value for enterprise decision-makers lies in understanding the underlying mechanics driving this expansion. Our report dissects the ecosystem to reveal where value is being created, which geographies are leading the charge, and how the competitive landscape is consolidating. This article serves as a strategic preview of those findings, highlighting the critical dynamics that will define success in 2026 and beyond.
Market Trajectory and Growth Drivers
The forecast period from 2026 to 2032 is expected to be characterized by a shift from adoption to optimization. While the initial push for BIM was driven by regulatory compliance and basic digitalization, the current phase is fueled by efficiency mandates and integrate data workflows. The steady increase from 146.71 million USD in 2027 to 208.68 million USD in 2030 suggests that demand is becoming less sensitive to economic fluctuations, embedding itself deeper into operational budgets.
Our analysis identifies several key catalysts propelling this growth. The industry is moving beyond static 3D modeling toward dynamic information management. This shift is not merely technological but procedural, requiring firms to rethink how data is handled from preconstruction through postconstruction phases. The research highlights that while certain phases traditionally dominate revenue share, the growth rate is accelerating in areas related to lifecycle management and digital twin integration. Understanding these shifts is crucial for vendors positioning their solutions and for firms selecting partners to ensure long-term compatibility.
Furthermore, the revenue unit analysis indicates a significant reliance on specific type segments. The market remains heavily weighted toward software solutions compared to services, reflecting a preference for scalable digital tools over manual consultancy. Yet, the services segment continues to play a pivotal role in implementation and customization, ensuring that organizations can actually derive value from the software licenses they purchase. This balance between software and services is a key consideration for investors assessing recurring revenue models versus one-off service engagements.
Regional Dominance and Emerging Hubs
Geographic distribution remains a critical component of market strategy. Current analyses point to a mature landscape in developed economies, yet the potential for expansion in emerging regions is substantial. North America continues to command a significant share of the global revenue, reflecting early adoption rates and a high density of large-scale infrastructure projects. Europe follows as a strong second, driven by stringent regulatory frameworks and public sector mandates for digital delivery.
Asia Pacific represents a dynamic growth engine, with rapid urbanization and increasing investment in smart infrastructure fueling demand. While the share values vary, the momentum in this region often outpaces mature markets in terms of percentage growth. Latin America and the Middle East and Africa, while currently representing smaller portions of the total revenue, are identified as areas where strategic entry could yield high long-term returns. Our report provides a detailed breakdown of these regional nuances, helping entities identify where to focus sales efforts or where to seek partnership opportunities.
It is essential for decision-makers to recognize that regional preferences are not static. Local regulations, labor costs, and technological infrastructure influence how BIM is deployed. For instance, markets with higher labor costs may prioritize automation and clash detection tools to reduce rework, whereas developing regions might focus on basic coordination and documentation capabilities. The research delves into these behavioral differences to provide a localized view of global trends.
Building Management System Market
Competitive Landscape and Key Players
The BIM market is defined by a mix of established giants and specialized innovators. Market concentration metrics indicate a moderately fragmented environment, with the top three players capturing a combined share of approximately 25.5 percent and the top five holding around 30.2 percent. This suggests that while there are dominant forces, there is still ample room for niche players or specialized solutions to thrive, particularly in vertical-specific applications.
Autodesk remains a cornerstone of the ecosystem, headquartered in San Francisco. Their portfolio, including Autodesk Revit for parametric 3D modeling and Autodesk Forma, continues to set industry standards. Recent updates in 2026 have focused on enhancing modeling workflows and cloud-based cost management. The company has also expanded its API ecosystem to drive third-party integration, reinforcing its platform strategy and recurring revenue potential. Their continuous updates, such as the Revit 2026 launch with accelerated graphics and the BIM 360 Cost Management update, demonstrate a commitment to maintaining technological leadership.
Bentley Systems , based in Exton, Pennsylvania, maintains a strong focus on infrastructure and digital delivery. Their offerings like ProjectWise for data governance and SYNCHRO for 4D planning are integral to large-scale engineering projects. The emphasis on digital twins through iTwin positions them uniquely for lifecycle management beyond the construction phase. As the industry moves toward information-centric standards, Bentley's focus on data governance aligns well with emerging regulatory requirements.
Nemetschek Group in Munich operates as a powerful conglomerate with diverse holdings including ALLPLAN. Their recent 2026 updates for ALLPLAN emphasize multilayer finishes modeling and BIM-compliant detailing, reflecting a push toward granular construction accuracy. Additionally, the transition of subsidiary Graphisoft away from perpetual licenses toward subscription models signals a broader industry shift toward recurring revenue streams, changing how customers access and pay for architectural tools like Archicad.
Graphisoft , headquartered in Vienna, continues to innovate in the architectural space. The release of Archicad 29 in late 2025 introduced AI Assistant features and enhanced MEP Designer toolkits. However, their decision to terminate perpetual licenses by the end of 2026 forces a market-wide transition to subscription licensing. This move impacts cash flow planning for many firms and underscores the industry's pivot toward cloud-based, continuously updated software environments.
Dassault Systèmes brings a different dimension with their 3DEXPERIENCE platform. Based in France, they focus on integrating BIM with broader digital twin capabilities across the AEC industry. Their use of CATIA for integrated BIM suggests a strong orientation toward complex manufacturing and high-precision building requirements, appealing to clients who need deep engineering integration.
Regulatory Shifts and Operational Dynamics
The regulatory environment is undergoing a significant transformation that directly impacts market dynamics. The release of the ISO 19650:2026 Draft International Standard marks a pivotal shift from model-centric to information-centric lifecycle management. This revision emphasizes information management over traditional BIM terminology, introducing new requirements for data validation, exchange, and lifecycle maintenance. For organizations, this means compliance is no longer just about producing a model but about ensuring the integrity and usability of data throughout the asset's life.
Simultaneously, cloud hosting and data privacy rules are reshaping workflows. New rules effective February 2026 regarding Revit Cloud Model downloads require updates to workflows for unpublished linked files. Compliance in cloud-based BIM environments is now more complex, necessitating careful attention to data governance. Additionally, Autodesk's platform consolidation using Forge APIs aims to drive third-party integration, which benefits the ecosystem but also increases dependency on specific cloud architectures. These technical and regulatory shifts create barriers to entry but also solidify the moats for platforms that can ensure seamless compliance.
Report Scope and Strategic Utility
To fully capitalize on these opportunities, stakeholders need more than high-level trends. Our comprehensive report offers a deep dive into the operational specifics that drive decision-making. The study is structured to provide actionable intelligence across multiple dimensions, ensuring that readers can translate data into strategy.
- Historical and Forecast Analysis: Detailed year-over-year data from 2020 through 2032, allowing for trend extrapolation and budget forecasting.
- Segmentation Deep Dives: Comprehensive breakdowns by application, type, and region, revealing where growth is concentrated without relying on surface-level aggregates.
- Company Profiling: In-depth profiles of key market participants, including their strategic positioning, recent product launches, and technological focus.
- Regulatory Impact Assessment: Analysis of how new standards like ISO 19650:2026 and cloud compliance rules affect operational workflows and vendor selection.
- Growth Drivers and Restraints: Identification of the specific factors accelerating adoption versus those posing challenges, such as labor shortages or integration complexity.
This research is designed for chief strategy officers, market analysts, and investment managers who require precision. Whether you are evaluating market entry, assessing competitor moves, or planning long-term R&D investments, the granularity provided in the full report is essential. We have intentionally omitted specific percentage splits and exact revenue figures for segments in this overview to preserve the proprietary value of the full dataset.
Conclusion: The Path Forward
The BIM market in 2026 is defined by convergence—of data, regulations, and platforms. The growth from 113.0 million USD to a projected 267.4 million USD by 2032 is not just a number; it represents a fundamental restructuring of how the built environment is designed, constructed, and managed. Success in this environment requires a clear understanding of where the market is heading and who is leading the way.
Building Information Modeling (BIM) Market
Our full market research report provides the detailed compass needed to navigate this landscape. By securing access to the complete intelligence package, your organization can move beyond speculation and make decisions grounded in rigorous data. We invite you to explore the full findings to unlock the specific insights required to drive your strategic agenda in this evolving digital construction era.
For detailed analysis of this topic, please visit the official page: Building Information Modeling (BIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Hypochlorite Generator Market to Hit USD 239M by 2032, 8.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Sodium Hypochlorite Generator Market: Strategic Intelligence for 2026 Decision-Makers
As global industries accelerate the transition toward decentralized and sustainable water treatment solutions, the sodium hypochlorite generator market has emerged as a critical battleground for infrastructure investment, public health modernization, and operational resilience. For executives, municipal planners, and industrial operators navigating the 2026 landscape, understanding the trajectory of on-site chemical generation is no longer a technical exercise—it is a strategic imperative. PW Consulting’s latest market intelligence study dissects the forces shaping this sector, offering a rigorous, data-backed framework to align capital allocation, supply chain strategy, and regulatory compliance with the decade ahead.
The market has already demonstrated remarkable momentum over the past half-decade. Valued at approximately 90.6 million USD in 2020, it has consistently expanded through successive years, crossing the 116.5 million USD threshold by 2023 and climbing to an estimated 134.0 million USD in 2025. This historical trajectory underscores a structural shift rather than a cyclical fluctuation. Looking forward, our forecast model projects sustained expansion through the end of the decade, with revenue expected to approach 239.0 million USD by 2032. The implied compound annual growth rate of 8.7 percent reflects deepening adoption across water utilities, industrial facilities, and commercial operations that are actively seeking to mitigate supply chain vulnerabilities, reduce reliance on bulk chemical transport, and improve on-site disinfection reliability. These macro figures, while compelling, represent only the surface of a highly nuanced landscape. The true strategic advantage lies in understanding how regional deployment patterns, capacity tiering, application-specific demand, and shifting compliance requirements intersect to create asymmetric opportunities for early movers.
The 2026 Decision Matrix: Why Traditional Procurement Models Are Falling Short
For years, water disinfection procurement followed a familiar playbook: order bulk sodium hypochlorite, manage storage and handling risks, and absorb the volatility of chemical shipping and seasonal supply bottlenecks. The 2026 operating environment has rendered that model increasingly fragile. Infrastructure modernization initiatives are accelerating, and public and private operators alike are recognizing that on-site electrolysis systems offer a compelling alternative to centralized chemical logistics. The strategic calculus has shifted from simple cost-per-gallon comparisons to total lifecycle value, encompassing regulatory compliance, worker safety, environmental footprint, and resilience against transport disruptions.
Utilities and industrial facilities are now evaluating generator deployments through a multi-dimensional lens. Municipal operators must weigh NSF/ANSI/CAN 61 certification pathways for drinking water applications against evolving state-level procurement standards, while industrial managers must align system capacities with fluctuating production schedules and brine feedstock availability. Meanwhile, commercial and recreational operators are exploring compact generation units that can deliver consistent disinfection without the logistical overhead of chemical delivery. The procurement cycle has lengthened, the technical evaluation criteria have multiplied, and the competitive field has matured. Organizations that approach this transition with fragmented vendor comparisons or outdated cost models risk overcommitting to suboptimal configurations. The market demands a structured, forward-looking evaluation framework—and that is precisely what our research delivers.
Decoding the Competitive Arena
The sodium hypochlorite generator market is characterized by a concentrated yet strategically active competitive landscape. CR3 firms account for approximately 35 percent of market revenue, while the top five players collectively command around 45 percent. This concentration reflects the technological barriers to entry, the capital intensity of electrolytic system development, and the lengthy qualification cycles required to secure municipal and industrial contracts. Yet the market remains dynamic, with established players continuously refining system architectures, expanding application portfolios, and responding to emerging compliance mandates.
Among the most prominent participants, De Nora, headquartered in Milan, Italy, has built a recognized portfolio around its ClorTec® on-site low-strength sodium hypochlorite generators, alongside the CECHLO-MS high-strength systems that leverage electrolytic brine electrolysis for demanding disinfection environments. The company’s dual focus on low-strength and high-strength architectures positions it to serve both routine municipal water treatment and specialized industrial applications where concentration precision matters.
Xylem Inc., based in Chicago, Illinois, has established a strong presence through its OSEC® branded on-site hypochlorite generation systems, including the B-Plus, B-Pak, and L series. These platforms are engineered for municipal, aquatics, and industrial water disinfection, and their electrolytic process design aligns with utilities seeking to transition away from bulk chemical handling. Xylem’s integration of generation technology within broader water infrastructure offerings gives it a distinctive value proposition for operators pursuing end-to-end system optimization.
Sodium Hypochlorite Generator Market
Ecolab Inc., headquartered in St. Paul, Minnesota, brings a different dimension to the market through its eChlorine® electrolytic sodium hypochlorite generation systems. Designed for on-site production at the point of use, these systems have found particular traction in healthcare and hospitality environments where localized disinfection control, safety, and operational flexibility are paramount. Ecolab’s service-oriented model and cross-sector expertise allow it to address compliance and hygiene requirements that extend beyond traditional water treatment boundaries.
Electrolytic Technologies, operating in the United States, rounds out the competitive core with its Klorigen™ systems, which generate high-strength sodium hypochlorite in the 10 to 15 percent range alongside chlorine gas for municipal water and wastewater disinfection as well as industrial applications. This dual-output capability reflects a differentiated engineering approach that appeals to facilities seeking integrated disinfection chemistry rather than isolated hypochlorite production.
The competitive field is not static. Recent procurement activity and industry engagement signal where demand is crystallizing and where regulatory attention is intensifying. In March 2026, the City of Westminster issued a request for proposals for the purchase and delivery of two on-site sodium hypochlorite generation systems, illustrating how mid-sized municipal operators are moving from evaluation to execution. In November 2025, the City of Tampa’s Water Department completed construction of a new on-site sodium hypochlorite generation facility to produce liquid bleach on-site for disinfection, underscoring the growing momentum behind utility-scale deployments. Meanwhile, the Chlorine Institute scheduled its 2026 Annual Meeting with a focused agenda on sodium hypochlorite manufacturers and on-site chemical generator compliance, signaling that industry standardization and regulatory alignment will remain central themes throughout the forecast period.
Sodium Hypochlorite Market
Regulatory Realities and Infrastructure Tailwinds
No strategic assessment of this market can be separated from the regulatory and infrastructure context that shapes procurement decisions. On-site generation is not merely a technology substitution; it is an operational model change that intersects with drinking water certification, environmental verification, and standards development. The NSF/ANSI/CAN 61 certification framework applies to on-site generated sodium hypochlorite systems used in drinking water treatment, and compliance with these requirements has become a baseline expectation for municipal procurement teams evaluating system reliability and public health protection.
Parallel to certification requirements, the EPA Environmental Technology Verification program has confirmed the performance of on-site hypochlorite generation systems for primary and residual disinfection, reinforcing the technical credibility of electrolytic approaches in environments where consistent disinfection efficacy must be demonstrated. These verification pathways are increasingly referenced in procurement documentation and technical evaluation scores, making them a practical consideration rather than an abstract regulatory footnote.
Beyond drinking water, evolving standards and compliance expectations are shaping adjacent markets. The EN 18087:2026 standard sets requirements for in-situ chlorine dioxide generation from sodium chlorite, reflecting broader momentum toward on-site chemical generation and stricter controls over disinfection chemistry handling. While this standard addresses a different chemical pathway, it illustrates the regulatory trajectory: authorities are formalizing performance, safety, and operational expectations for decentralized generation systems, and manufacturers able to align their architectures with emerging standards will gain a distinct advantage in qualification processes.
Infrastructure dynamics further reinforce demand. Utility infrastructure upgrades are driving demand for on-site generators as operators seek to replace bulk chemical deliveries with more resilient, locally controlled production. This trend is reinforced by the practical realities of brine electrolysis systems, which use diluted salt solution as the primary electrolyte feedstock. The relative availability and logistical simplicity of salt-based feedstocks, combined with the reduction in hazardous chemical transport, make on-site generation an increasingly attractive option for facilities reevaluating their supply chains. These dynamics do not operate in isolation; they interact with regional procurement cycles, utility capital planning horizons, and industrial production requirements, creating a complex but navigable landscape for organizations that have access to granular, forward-looking intelligence.
Inside the PW Consulting Research Framework
Our study is structured to convert market complexity into actionable decision support. Rather than presenting abstract trends, the report maps the operational, financial, and competitive parameters that executives and technical leaders must evaluate before committing to on-site generation investments. The analysis covers the full forecast window from 2026 through 2032, anchored in a verified historical base that traces market development from 2020 onward. This temporal span allows readers to distinguish between short-term procurement cycles and longer structural shifts, ensuring that investment theses are calibrated to realistic adoption timelines.
The report examines capacity segmentation patterns, differentiating between lower-capacity systems designed for localized or intermittent disinfection needs and higher-capacity architectures suited to continuous utility-scale or large industrial operations. These capacity tiers are not merely technical specifications; they determine footprint requirements, brine handling logistics, maintenance cadences, and the economics of scale that vary significantly across deployment contexts. Our analysis unpacks how these capacity splits influence procurement strategy, vendor selection criteria, and total cost of ownership across different operational profiles.
Application-level demand is similarly dissected. Municipal water and wastewater disinfection remains a foundational driver, but the market also encompasses industrial process disinfection, food industry hygiene applications, and swimming pool and recreational water treatment. Each application segment carries distinct compliance expectations, 화학 concentration requirements, and operational rhythms. By mapping these application dynamics without oversimplifying them, the report equips decision-makers to identify where their organization’s operational profile aligns with the strongest demand signals and where cross-segment learning can accelerate evaluation timelines.
Regional deployment patterns are analyzed with attention to market maturity, procurement pacing, and infrastructure readiness. Rather than reducing regional variation to static share percentages, the research contextualizes how North American, European, Asia Pacific, Latin American, and Middle East and Africa markets differ in terms of utility modernization cadence, regulatory emphasis, and the pace at which bulk chemical delivery models are being supplemented or replaced by on-site production. This regional framing is critical because the same generator architecture may present very different risk-return profiles depending on the local procurement environment and infrastructure context.
Competitive positioning is evaluated through a combination of technology architecture, application coverage, geographic reach, and recent procurement momentum. The report does not stop at company descriptions; it examines how incumbent players are leveraging their system portfolios, service networks, and compliance credentials to shape procurement outcomes, and where gaps in application coverage or regional presence may create openings for new entrants or strategic partnerships. Recent project completions, RFP activity, and industry meetings are integrated into this analysis to connect high-level competitive positioning with real-world procurement behavior.
How to Translate This Intelligence Into 2026 Action
The strategic value of this research lies in its applicability to concrete decision points. For capital planners, the forecast trajectory and segmentation framework support scenario-based budgeting, helping organizations align procurement timing with capacity availability and financing cycles. For technical evaluation teams, the report’s treatment of certification pathways, brine electrolysis feedstock considerations, and performance verification provides a structured basis for vendor qualification and specification development. For commercial and corporate strategy leaders, the competitive concentration data, company profiles, and recent procurement signals offer a lens for assessing partnership opportunities, differentiation potential, and market entry timing.
Organizations that treat on-site sodium hypochlorite generation as a commodity procurement decision risk underestimating the operational and compliance nuances that determine long-term success. Those that approach it as a strategic infrastructure investment, grounded in robust market intelligence, are better positioned to select the right system architecture, align procurement with regional readiness, and anticipate the regulatory developments that will shape qualification standards in the years ahead.
The complete PW Consulting market research study delivers the detailed segmentation data, regional deployment context, application-level demand mapping, and competitive intelligence required to build a decisive 2026 strategy. We invite executives, procurement leaders, and technical decision-makers to access the full report, where the macro trajectory outlined here is expanded into the granular, actionable intelligence necessary to navigate this market with confidence.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Purity IPA Market to Reach $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Imperative in High-Purity Isopropyl Alcohol: Navigating the 2026 Market Landscape
In the rapidly evolving landscape of advanced materials, High-purity Isopropyl Alcohol (IPA) stands as a critical enabler for two of the most transformative sectors of the 21st century: semiconductor manufacturing and pharmaceutical production. As industries push toward nanometer-scale precision and stringent regulatory compliance, the demand for solvents with ultra-high purity specifications has never been more acute. PW Consulting is pleased to introduce our latest comprehensive market intelligence report, designed to equip strategic decision-makers with the foresight required for 2026 and beyond. This analysis delves into the complex interplay of technological advancement, supply chain resilience, and shifting regional dynamics that define the high-purity IPA market.
Our research provides a granular examination of the market from 2020 through 2025, establishing a baseline of historical performance, before projecting trends across the forecast period from 2026 to 2032. For corporate strategists, investors, and procurement leaders, the ability to distinguish between transient fluctuations and structural shifts is vital. This report offers more than just top-line figures; it delivers a diagnostic of the competitive environment, regulatory currents, and raw material volatilities that will dictate margin structures and supply security over the coming years. The strategic value of this intelligence lies in its capacity to transform raw data into actionable roadmaps, enabling stakeholders to anticipate demand surges, evaluate supplier viability, and optimize cost structures in an increasingly competitive global arena.
Market Trajectory: Resilience and Acceleration
The macroeconomic environment for high-purity IPA has demonstrated remarkable resilience over the past half-decade, characterized by a steady upward trajectory in revenue. From a base of 163.15 million USD in 2020, the market has navigated various challenges, including pandemic-induced disruptions and logistics bottlenecks, to reach a valuation of 215.0 million USD by 2025. This historical progression underscores the inelastic nature of demand in core application areas, particularly where high-purity solvents are non-substitutable inputs for critical processes.
Looking ahead to the forecast period, the market is poised for accelerated expansion. Starting from 235.07 million USD in 2026, the revenue landscape is projected to climb consistently, reaching 344.8 million USD by 2032. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent, reflecting sustained investment in advanced electronics, clean energy technologies, and life sciences. The forecast is not merely a linear extrapolation; it accounts for the varying maturation rates of market segments and the impact of capacity expansions by key industry participants. Stakeholders analyzing these figures must look beyond the aggregate numbers to understand the divergent growth vectors within the market. The report dissects these nuances, offering scenario-based insights that help organizations prepare for both baseline expectations and high-growth contingencies.
Segmentation Drives Strategic Differentiation
While the overall market growth is impressive, the true strategic opportunity lies in the segmentation of demand. The high-purity IPA market is not monolithic; it is defined by distinct purity thresholds and application specificities that command different pricing dynamics and supply chain requirements. By purity, the market spans from standard high-purity grades to ultra-high-purity electronic grades that meet rigorous parts-per-billion impurity limits. The report evaluates the competitive positioning of grades such as the 99.9% to 99.99% high-purity range, which caters to broad industrial needs, against the premium Electronic Grade (>99.99%) segment, which is essential for semiconductor wafer fabrication and advanced packaging. Additionally, the "Other Grades" category, including pharmaceutical and specialty variants, represents a vital niche where regulatory compliance and certification become key differentiators.
The application landscape further illustrates the market's bifurcation. Semiconductor wafer cleaning remains the dominant driver of value, fueled by the relentless scaling of logic and memory chips, the rise of advanced packaging techniques, and the need for defect-free surface preparation. However, the Pharmaceutical and Cosmetics sector, as well as Electronics Assembly and Cleaning, contribute significant and growing demand streams. Each application vertical imposes unique specifications regarding water content, acidity, and organic impurities. For instance, the report details how semiconductor manufacturers are imposing increasingly stringent requirements, such as keeping C7-12 acetal impurities below 100 parts per billion per USP/EP monographs to support 2nm node cleaning processes. Similarly, pharmaceutical-grade IPA must meet strict FDA cGMP standards, including maximum 0.5% water content and acidity under 0.002%. These technical barriers create moats for suppliers capable of consistent quality assurance, influencing sourcing strategies and vendor selection criteria.
Recovered Isopropyl Alcohol Market
Regional dynamics add another layer of complexity. The market analysis examines consumption patterns across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The Asia Pacific region, home to a dense concentration of semiconductor fabs and pharmaceutical manufacturers, exhibits distinct demand characteristics and supply chain interdependencies. Europe and North America maintain strong positions driven by established industrial bases and robust regulatory frameworks. Emerging regions present both opportunities for expansion and risks related to infrastructure maturity. Our segmentation analysis provides the framework to assess regional exposure, identify arbitrage opportunities, and align supply networks with demand centers without oversimplifying the geopolitical and logistical realities on the ground.
Competitive Landscape and Capacity Evolution
The competitive environment for high-purity IPA is characterized by a mix of global chemical majors, specialized electronics material suppliers, and regional players. With a CR3 of 24.6 percent and CR5 of 26.2 percent, the market remains relatively fragmented, allowing for active competition and innovation, yet concentration is gradually increasing in high-value segments. Key players such as ExxonMobil Chemical, Eastman Chemical Company, LyondellBasell Industries, Dow Inc., Mitsubishi Chemical Corporation, LCY Chemical Corporation, Tokuyama Corporation, LG Chem Ltd., Shell Chemicals, BASF SE, INEOS Group, and GJ Chemical are actively shaping the market through capacity expansions, product innovation, and strategic partnerships.
Recent developments highlight the strategic importance of ultra-high-purity capabilities. For example, ExxonMobil Chemical announced a significant USD 100 million investment in March 2025 to upgrade its Baton Rouge plant, targeting the production of 99.999% ultra-high-purity IPA starting in 2027 to support semiconductor chip manufacturing. This move reflects a broader industry trend where integrated supply chains and plant upgrades are prioritized to secure the "EastaPure-equivalent" grades demanded by leading fabs. Similarly, Eastman Chemical Company has reinforced its position by introducing its EastaPure™ ultrahigh-purity IPA (4N grade) in its active catalog, specifically targeting semiconductor wafer fabrication wet cleaning and drying applications. These product launches underscore the race to capture market share in the premium electronic grade segment.
Capacity expansions are not limited to the United States. LyondellBasell Industries expanded its Texas facility IPA production by 25 percent in November 2025 to meet growing North American demand, underscoring the region's strategic focus on domestic supply security. In Asia, LCY Chemical Corporation launched its LCY Advanced Formulations portfolio in September 2025, including electronic-grade high-purity IPA for advanced packaging and wafer cleaning, while Tokuyama Corporation continues to supply ultra-high-purity grades essential for 2nm semiconductor cleaning processes. Other players like Mitsubishi Chemical, LG Chem, and Deepak Fertilisers are also upgrading facilities to enable full-scale production and export of high-grade pharma-certified IPA, signaling a global alignment of supply capabilities with end-market needs. The report provides a deep-dive company profile for each major participant, analyzing their product portfolios, geographic footprint, recent investments, and competitive differentiators, offering readers the intelligence needed to benchmark suppliers and anticipate shifts in market power.
Market Dynamics: Raw Materials and Regulatory Pressures
A sophisticated market analysis must address the underlying forces that influence pricing, availability, and risk. Raw material dynamics play a pivotal role in the economics of high-purity IPA, given its chemical derivation from acetone via hydrogenation. Acetone price volatility can propagate through the value chain, affecting production costs and margin stability. Our research integrates current market intelligence on acetone pricing, noting that CIF acetone prices in North America have observed significant levels, with Northeast Asia FOB prices showing distinct regional differentials. Furthermore, geopolitical events have impacted supply flows; disruptions linked to the US-Iran conflict in 2025 tightened Middle East acetone supply, which in turn elevated European CIF acetone prices. These fluctuations highlight the importance of monitoring upstream commodity markets and securing diversified sourcing strategies. The report explores how suppliers manage these cost pressures through long-term contracts, integration, and hedging, and how these strategies affect the pricing power of high-purity grades.
Regulatory compliance constitutes another formidable driver of market structure. The transition to advanced technology nodes in semiconductors has necessitated tighter control over impurities, with industry standards increasingly referencing USP/EP monographs and ISO 9001 certifications. The requirement for <100 ppb C7-12 acetal impurities in high-purity IPA for 2nm node cleaning exemplifies the technical chasm between standard grades and electronic grades. In the pharmaceutical sector, adherence to FDA cGMP regulations, including limits on water content and acidity, is not optional but a license to operate. These regulatory frameworks create high entry barriers, rewarding suppliers with robust quality management systems and advanced purification technologies. BASF SE, for instance, supplies high-purity IPA grades for pharmaceutical and electronic applications leveraging advanced purification tech, while INEOS Group produces high-purity IPA including bio-based variants to meet evolving sustainability and performance metrics in EU and global markets. The report analyzes how these regulatory and technological demands shape supplier selection, contract negotiation, and the overall cost of quality.
Unlocking the Full Intelligence: Why This Report Matters for 2026
As we move deeper into 2026, the margin for error in strategic planning is shrinking. The high-purity IPA market is influenced by a confluence of factors: rapid technological advancement in semiconductors, evolving regulatory landscapes, volatile raw material inputs, and shifting geopolitical trade patterns. Decision-makers cannot afford to rely on outdated benchmarks or generalized industry narratives. PW Consulting's High-purity Isopropyl Alcohol Market report is engineered to provide the depth, accuracy, and actionable insights required to navigate this complexity.
This report offers a comprehensive toolkit for strategic analysis. It includes detailed market sizing and forecasts that isolate growth drivers by purity and application, enabling precise demand modeling. It profiles the key companies, detailing their recent developments, capacity strategies, and product innovations, allowing you to assess competitive threats and partnership opportunities. It maps the regulatory environment, identifying compliance risks and standards that will impact your supply chain eligibility. It examines raw material dynamics, providing context on cost structures and price volatility drivers. And it analyzes regional dynamics, helping you optimize your geographic exposure and logistics strategy.
Crucially, the report does not merely present data; it interprets it. The segmentation splits, historical performance, and forecast trajectories are woven into a narrative that highlights strategic implications. You will gain an understanding of which purity grades are seeing the most aggressive capacity investment, which applications are driving the highest value growth, and how regulatory shifts are redefining quality benchmarks. You will see where market concentration is building and where fragmentation offers agility. You will understand the interplay between acetone pricing, geopolitical supply disruptions, and the premium pricing of electronic-grade materials.
However, the full strategic value of this intelligence is realized only through access to the complete dataset, scenario analyses, and detailed regional and segment-level forecasts. The overview provided here is a preview of the analytical rigor and strategic relevance embedded in the full report. To secure your competitive advantage in 2026 and build a resilient, forward-looking strategy, we invite you to access the complete PW Consulting High-purity Isopropyl Alcohol Market report. The detailed intelligence within will empower your organization to make informed decisions on procurement, capacity planning, supplier qualification, and market entry, ensuring you are not just reacting to market changes, but anticipating and shaping them.
The high-purity IPA market is at a pivotal juncture. The convergence of semiconductor scaling, pharmaceutical innovation, and supply chain recalibration creates a landscape rich with opportunity for those equipped with the right intelligence. PW Consulting stands ready to provide the clarity and depth you need to lead in this dynamic market. Explore the full report to unlock the actionable insights that will drive your success.
High-purity Isopropyl Alcohol (IPA) Market
For detailed analysis of this topic, please visit the official page: High-purity Isopropyl Alcohol (IPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Trailer Refrigeration Market Hits $544.07 Million in 2025, Projected 5.67% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Cold Chain: Strategic Imperatives in the Trailer Refrigeration System Market (2026–2032)
The global supply chain stands at a critical inflection point. As logistics networks strive for greater resilience, efficiency, and environmental compliance, the trailer refrigeration system market has emerged as a vital enabler of modern cold chain integrity. From temperature-sensitive pharmaceuticals to perishable food shipments crossing continents, the reliability of transport refrigeration directly influences product safety, regulatory adherence, and commercial viability. PW Consulting's latest in-depth market analysis, Trailer Refrigeration System Market: Global Industry Outlook 2026–2032 , offers a comprehensive strategic roadmap for executives, investors, and supply chain leaders seeking to navigate this rapidly evolving landscape.
Trailer Refrigeration System Market
This report is engineered not merely as a statistical compendium, but as a decision-support instrument. Drawing on rigorous primary research, proprietary modeling, and granular competitive intelligence, the study quantifies market trajectories, dissects segment-level value drivers, and evaluates the operational and regulatory forces reshaping the industry. For organizations operating in 2026, when capital allocation, product roadmapping, and compliance strategy demand precision, this analysis delivers the contextual clarity needed to move beyond reactive tactics and toward sustained competitive advantage.
Market Trajectory: A Decade of Measured Expansion
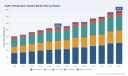
The historical trajectory of the trailer refrigeration system market reflects a sector characterized by steady organic growth, punctuated by technological modernization and regulatory evolution. Between 2020 and 2025, global revenue expanded from approximately 406.5 million USD to 544.1 million USD, demonstrating consistent demand absorption across developed and emerging logistics corridors. This upward momentum is projected to continue through the 2026–2032 forecast horizon, with the market expected to surpass 789.7 million USD by the close of the decade.
At the core of this expansion lies a compound annual growth rate of 5.67 percent, a figure that signals more than nominal market scaling. It indicates structural demand amplification driven by cold chain formalization, e-commerce fulfillment requirements, and the ongoing transition toward temperature-controlled freight solutions. For industry participants, this growth profile carries strategic weight: it suggests a market that is neither saturated nor speculative, but rather one where disciplined investment, product differentiation, and regional execution discipline can yield meaningful returns.
The forecast period also reveals nuanced dynamics that warrant executive attention. Growth is not uniform; it is being reshaped by shifting equipment preferences, ambient performance expectations, and the accelerating adoption of connected refrigeration platforms. Organizations that align their strategy with these underlying currents will be better positioned to capture share in a market where incremental operational efficiencies translate directly into margin preservation and customer retention.
Strategic Segmentation: Where Value Is Created and Captured
The report's segmentation framework is designed to illuminate how revenue flows through distinct equipment configurations, application verticals, and geographic corridors. Rather than treating the market as a monolith, the analysis isolates the structural factors that determine unit economics, competitive positioning, and long-term growth potential.
- Equipment Architecture: The market continues to be shaped by a diversified mix of power architectures, including electric, diesel, and hybrid configurations. Each pathway presents distinct trade-offs in total cost of ownership, emissions performance, grid dependency, and operational range. The analysis examines how fleet operators weigh these variables against deployment environments, regulatory exposure, and sustainability commitments, offering insight into where capital is naturally gravitating as infrastructure and policy conditions mature.
- Application End-Market Demand: Food and beverage logistics remain the dominant commercial driver, reflecting the scale and frequency of perishable goods movement. Simultaneously, pharmaceuticals and chemicals represent a high-value, compliance-intensive segment where temperature excursion risk carries disproportionate financial and reputational consequences. The report evaluates how these verticals differ in procurement behavior, service expectations, and receptivity to advanced monitoring and electric platform adoption.
- Regional Demand Patterns: Geographic distribution of demand is influenced by freight volume concentration, cold chain maturity, regulatory intensity, and local manufacturing or assembly ecosystems. The analysis maps how these factors intersect to create uneven but predictable growth pockets, helping stakeholders prioritize market-entry sequencing, service-network design, and partnership strategies without relying on blunt regional generalizations.
By contextualizing segmentation through an operational lens, the study equips readers to identify which sub-markets offer the most favorable risk-adjusted opportunities, where product specifications must evolve to meet segment-specific requirements, and how pricing architecture should adapt to preserve value across heterogeneous customer bases.
Road Transport Refrigeration Equipment Market
Competitive Dynamics: Incumbents, Innovation, and Consolidation Signals
Market structure analysis reveals a moderately concentrated landscape, with the top three participants collectively accounting for nearly half of total industry revenue and the leading five firms representing over 71 percent of market value. This concentration underscores the competitive advantage held by established players with scaled manufacturing capacity, broad service networks, and deep engineering heritage. Yet concentration alone does not dictate competitive outcomes; it intensifies the premium on differentiation, compliance readiness, and ecosystem integration.
Several core participants define the current competitive baseline. Carrier Transicold, headquartered in Charlotte, North Carolina, maintains a comprehensive portfolio spanning single-temperature and multi-temperature trailer refrigeration units, electric and stationary configurations, and heating platforms, reinforced by its ecoForward sustainability technologies. Thermo King, based in Woodridge, Illinois, competes with its Precedent trailer solutions, T-90 Series architecture, ConnectedSuite telematics capabilities, and TriPac auxiliary power units, while expanding its all-electric and e-reefer offerings with an emphasis on emissions-compliant performance. Polar King Mobile, operating from Fort Wayne, Indiana, has carved a distinct position with all-electric compact refrigerated trailers engineered for modular deployment, E-Track readiness, and NATM compliance, utilizing refrigeration systems capable of maintaining precise temperature bands across demanding transit conditions.
The competitive narrative is further shaped by recent product and regulatory milestones that illustrate how the market is evolving in real time. In early 2026, Utility Trailer Manufacturing Company and Cargobull North America introduced next-generation hybrid transport refrigeration units designed for enhanced cooling performance and efficiency within their 3000R refrigerated trailer lineup. Around the same period, Polar King previewed fresh trailer innovations at a major industry expo, signaling continued product iteration in the compact electric segment. These developments unfold against a backdrop of tightening regulatory architecture, including updated cold appliance emissions standards and refrigerant guidance that increasingly steer procurement decisions toward lower-global-warming-potential solutions and zero-emission transition pathways.
For corporate strategists, the implication is clear: competitive advantage in this market is increasingly determined by how effectively firms integrate regulatory foresight into product design, align service and telematics capabilities with fleet customer expectations, and communicate verifiable sustainability performance without sacrificing operational reliability.
Regulatory and Technological Currents Reshaping the Market
No strategic assessment of the trailer refrigeration system market is complete without a rigorous examination of the regulatory environment. Compliance is no longer a peripheral concern; it is becoming a primary determinant of equipment eligibility, total cost of ownership, and long-term asset viability. Over the past several years, regulators have steadily tightened emissions expectations for transport refrigeration units, with particular emphasis on refrigerant global warming potential thresholds, particulate emission controls, and registration and reporting obligations for owners and large facilities.
These regulatory pressures are compounded by evolving refrigerant chemistry and component standards. The industry's shift toward lower-GWP refrigerant blends reflects a broader transition toward systems that can meet compliance mandates without compromising cooling capacity or serviceability. At the same time, telematics and connected monitoring are transitioning from value-added features to operational necessities, enabling fleet managers to track temperature excursions, optimize preventive maintenance, and demonstrate compliance documentation with greater precision.
The interaction between regulation and technology creates a distinctive strategic environment. Equipment that meets current compliance thresholds may still face retrofit risk or shortened service life if future amendments tighten standards further. Conversely, platforms designed with forward-looking architecture can reduce transition costs, preserve resale value, and strengthen supplier credibility with compliance-sensitive customers. The report evaluates these dynamics in detail, helping organizations distinguish between compliance-driven costs and strategic investments that build durable market positioning.
What This Report Delivers for 2026 Decision-Makers
PW Consulting's market study is structured to convert complex industry data into actionable strategic intelligence. The analysis extends beyond high-level sizing to address the operational and commercial questions that executives face when allocating resources, evaluating competitive threats, and planning product or service expansion. Key deliverables include:
- Market sizing and forecast architecture that provides a transparent view of historical performance and projected growth pathways, enabling scenario planning around demand sensitivity, adoption pacing, and external shocks.
- Segment-level evaluation that isolates the structural drivers behind equipment type preferences, application-specific procurement patterns, and regional demand concentration, supporting more precise go-to-market and investment decisions.
- Competitive profiling that maps the strategic positioning, product offerings, and recent activity of leading participants, with context on how innovation, service capability, and compliance readiness influence share dynamics.
- Regulatory and technology impact assessment that connects emissions standards, refrigerant transitions, telematics adoption, and enforcement trends to practical procurement, design, and service implications.
- Strategic recommendation frameworks tailored to manufacturers, component suppliers, fleet operators, and investors, helping each audience translate market signals into prioritized actions for capacity planning, R&D focus, partnership strategy, and risk mitigation.
By integrating quantitative forecasts with qualitative market intelligence, the report enables readers to stress-test assumptions, identify where consensus expectations may understate or overstate opportunity, and build strategies that remain robust across a range of plausible futures.
Conclusion: Turning Market Intelligence into Strategic Action
The trailer refrigeration system market in 2026 is defined by a convergence of forces: durable cold chain demand, accelerating sustainability mandates, technological differentiation in electric and hybrid platforms, and a competitive field where scale and service quality remain powerful advantages. Growth projections indicate that the sector will continue expanding toward the high-700-million-USD range by 2032, but the more consequential question for decision-makers is not simply how large the market will become, but how value will be distributed across segments, regions, and competitive tiers.
Organizations that treat this market as a purely mechanical equipment category risk overlooking the strategic levers that determine long-term performance: compliance architecture, telematics-enabled service differentiation, segment-specific product customization, and disciplined regional execution. Those that approach it as a strategically layered ecosystem will be better positioned to protect margins, win compliance-sensitive contracts, and build defensible relationships with fleet customers who increasingly evaluate suppliers on total value rather than unit price alone.
This report provides the depth, structure, and forward-looking context required to make those judgments with confidence. To access the full dataset, detailed segmentation analysis, competitive benchmarking, and scenario-based strategic guidance, we invite executives and research buyers to visit the source page for the complete PW Consulting market intelligence package.
For detailed analysis of this topic, please visit the official page: Trailer Refrigeration System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beauty Devices Market to Hit $176.36M by 2032, 11.54% CAGR Drives 2026-2032 Forecast
By PW Consulting, 2026-09-16
Navigating the Inflection Point: Strategic Intelligence for the 2026 Beauty Devices Market
The global beauty devices market stands at a decisive inflection point. After a period of contraction that tested supply chains, compressed margins, and forced a hard reset in consumer expectations, the industry is now preparing for a sustained, technology-led expansion. For executives, investors, and product leaders operating in 2026, the question is no longer whether the category will rebound, but how to position across the right segments, geographies, and regulatory pathways before the next wave of competition compresses differentiation.
This introduction frames the strategic rationale behind our latest Beauty Devices Market research. The full study is designed to convert macroeconomic signals into executable decision frameworks. What follows is a preview of the analytical architecture, the competitive terrain we map, and the market dynamics that will shape portfolio strategy in the years ahead.
The Trajectory: A Contraction That Forged Discipline, and a Forecast Built for Scale
The historical record tells a story of correction. Between 2020 and 2025, the market navigated a demanding cycle, with revenue compressing through the post-pandemic recalibration period before stabilizing into a new baseline. That contraction was not merely a temporary dip; it functioned as a market-wide stress test. It separated durable innovation from short-lived novelty, exposed fragile channel strategies, and reshaped how consumers evaluate efficacy, safety, and long-term value in at-home and professional treatment devices.
From that reset, the forward outlook is notably constructive. The market is projected to grow from an estimated 88.56 million USD in 2026 to approximately 176.36 million USD by 2032, supported by a forecasted compound annual growth rate of 11.54 percent across the 2026 to 2032 period. This trajectory reflects more than top-line recovery. It signals structural momentum driven by converging forces: the maturation of home-use aesthetics, escalating demand for non-invasive and minimally invasive modalities, and the steady integration of intelligent diagnostics into both consumer and professional devices.
Beauty Devices Market
For leadership teams, the strategic implication is clear. Planning in 2026 cannot rely on category-level optimism alone. It requires a granular understanding of which subsegments are absorbing investment, which use cases are expanding fastest, and where regional adoption curves are diverging. The full report is built to provide that clarity without forcing executives to extrapolate from surface-level headlines.
What the Study Delivers: Operational Intelligence Over Generic Narrative
A market overview can confirm direction. It cannot, on its own, guide capital allocation, channel construction, or product roadmap choices. Our research is structured to bridge that gap. The study moves beyond high-level trend commentary to deliver a decision-ready architecture that organizations can plug directly into strategy sessions, board discussions, and annual planning cycles.
The report combines macro market modeling with segmentation frameworks that dissect the landscape across device categories, end-use environments, and geographic markets. Rather than presenting static snapshots, the analysis is designed to help leaders pressure-test assumptions. It connects historical volatility to forward-looking scenarios, allowing readers to evaluate how shifts in consumer behavior, clinical adoption, and distribution models could alter growth outcomes across the forecast horizon.
Equally important, the study treats the beauty devices ecosystem as a competitive system rather than a collection of isolated product lines. It examines how technology roadmaps, brand positioning, and regulatory milestones interact to shape market access. The intent is to give executives a working map of where differentiation is still achievable, where consolidation pressure is building, and where emerging standards may redefine what counts as a defensible product proposition.
Competitive Architecture: Incumbents, Specialists, and the Reconfiguration of Advantage
The competitive field in beauty devices is defined by a blend of global personal care and electronics incumbents, focused aesthetic technology specialists, and a growing set of clinically oriented entrants pursuing regulatory validation as a moat. Market concentration remains moderately distributed, with the top three players accounting for roughly 24.6 percent of market share and the top five reaching approximately 32.0 percent. That concentration profile matters strategically: it suggests the category is large enough to support multiple viable positions, but competitive enough that differentiation must be engineered deliberately rather than assumed.
Several established names illustrate the diverse strategic postures now competing for share. L'Oréal S.A., based in Clichy, France, has extended its portfolio into AI-driven skin analysis and nano-resurfacing through devices such as Perso, Lumea, and Cell BioPrint. Philips, headquartered in Amsterdam, Netherlands, has built recognition around adaptive tone recognition within its hair removal and skincare device lines. FOREO, from Stockholm, Sweden, has advanced its Luna series of microcurrent and LED facial devices while pairing product development with AI-powered skin analysis and circular economy programs.
Alongside these consumer-facing ecosystems, a parallel competitive dynamic is unfolding in professional and hybrid aesthetic platforms. InMode Ltd., in Irvine, California, develops radiofrequency-based aesthetic platforms for facial and body treatments. Sofwave Medical, based in San Clemente, California, supplies SUPERB ultrasound devices for non-invasive skin lifting and toning. Cutera, Inc., in Brisbane, California, produces laser and RF systems spanning skin rejuvenation, hair removal, and vascular treatments. NuFACE, part of the Carol Cole Company in Vista, California, focuses on microcurrent facial toning devices for non-invasive anti-aging applications. CLASSYS Inc., in Seoul, South Korea, offers radiofrequency-based medical aesthetic platforms such as Volnewmer, including CE MDR certification. Dermalogica, Alma Lasers, Accure Acne, Inc., and SkinHealth Systems further widen the competitive spectrum, each pursuing a distinct blend of clinical credibility, treatment specificity, and channel alignment.
This is not a market where scale alone guarantees advantage. The strategic edge increasingly comes from how well a company connects device performance, user experience, evidence generation, and regulatory readiness. The full report evaluates these players through that operational lens, tracing how their technology choices, launch cadence, and certification activity position them relative to the next generation of entrants and the shifting expectations of both professional and home users.
Aesthetic Devices Market
Regulatory Momentum and Technology Signals as Strategic Variables
One of the most consequential dynamics for 2026 planning is the accelerating cadence of regulatory and technology milestones. In this category, clearance and certification activity is not simply a compliance event; it often functions as a market-access trigger, a credibility signal, and at times a competitive barrier. The study tracks these developments as strategic inputs rather than background news.
Recent regulatory progress illustrates the point. Accure Acne, Inc. secured FDA clearance for its laser system for the long-term treatment of mild to severe inflammatory acne vulgaris. CLASSYS received CE MDR approval for its Volnewmer radiofrequency-based anti-aging system, a notable milestone as the first radiofrequency aesthetic device to achieve that designation in Europe. Ultherapy PRIME obtained FDA clearance for use on the abdomen and arms with real-time visualization across face, neck, décolleté, and body applications. Cutera's truFlex clearance expanded into rehabilitation and therapy applications. In parallel, Dermalogica's PRO Pen microneedling system secured FDA clearance, with launch planned in the US in 2026.
These events are not isolated. They reflect a broader pattern in which regulatory validation, device precision, and treatment specificity are increasingly intertwined. For companies operating in or entering the market, this creates a dual strategic question: how to build products that meet clinical and consumer expectations, and how to navigate a landscape where approvals, certifications, and evidence standards can alter the pace of adoption in specific segments. The report integrates these dynamics into its forward analysis so that leadership teams can better anticipate where access, messaging, and investment priority should shift.
Why This Research Matters for 2026 Decision-Making
The beauty devices market in 2026 rewards disciplined strategy over broad positioning. Organizations that succeed will be those able to align product development with validated demand, construct channel strategies that reflect regional and application-level realities, and interpret regulatory signals as part of competitive planning rather than as a separate compliance track.
This study is designed to support exactly that kind of decision-making. It provides the structural context needed to evaluate where growth is likely to concentrate, how the competitive field is rearranging itself, and which strategic levers will matter most as the forecast period unfolds. By connecting historical volatility to a forward CAGR of 11.54 percent and a projected 2032 revenue trajectory of roughly 176.36 million USD, the research frames the market as both a recovery story and a reallocation story. In other words, the real strategic task is not simply to capture growth, but to capture the right growth.
The full report goes further. It delivers the segmentation detail, company-level analysis, and market-structure insight necessary to translate high-level momentum into actionable plans. For executives evaluating expansion, product roadmap priorities, partnership strategy, or market-entry timing, the complete analysis is built to reduce uncertainty and sharpen judgment.
Conclusion: From Category Outlook to Executable Strategy
The beauty devices sector is entering a phase in which insight quality will separate durable players from reactive ones. The market's path from contraction to expansion is now backed by a credible growth trajectory, but realizing that opportunity will depend on how precisely organizations can read the subsegments, competitive moves, and regulatory developments shaping the landscape. This research begins with that premise and is structured to help leaders act on it.
To access the complete segmentation framework, competitive assessment, and forward-looking scenario analysis, we invite you to explore the full Beauty Devices Market research. The detailed intelligence within is intended to serve as a working resource for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Beauty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Blade Fuse Market to Reach $1.96B by 2032, CAGR 5.8%
By PW Consulting, 2026-09-16
Navigating the Automotive Blade Fuse Market: Strategic Intelligence for 2026 Decision-Making
The automotive electrical ecosystem is undergoing a structural transformation driven by electrification, advanced driver-assistance systems, and increasingly complex in-vehicle power architectures. At the foundation of these circuits lies a critical yet often overlooked component: the automotive blade fuse. As vehicle manufacturers and aftermarket suppliers navigate tightening reliability standards, fluctuating raw material costs, and shifting regional demand patterns, the need for precise, forward-looking market intelligence has never been more acute. Our latest Automotive Blade Fuse Market research delivers exactly that, translating historical trajectories and multi-year projections into actionable strategic frameworks for 2026 and beyond.
This analysis is designed specifically for executives, procurement leaders, product planners, and competitive intelligence teams who require more than headline figures. The study anchors its methodology in verified historical data spanning 2020 through 2025, then extends the analytical lens across a forecast period from 2026 to 2032. Over the historical window, the market demonstrated steady expansion, moving from approximately 0.99 billion USD in 2020 to 1.31 billion USD by 2025. The trajectory continues into the forecast horizon, with 2026 projections reaching 1.43 billion USD and sustained growth anticipated through 2032, when the market is expected to approach 1.96 billion USD. These figures reflect a compound annual growth rate of 5.8 percent, a pace that signals consistent demand expansion rather than speculative volatility.
Such macro-level momentum creates both opportunity and complexity. Growth is not uniformly distributed across product categories, application segments, or geographic corridors. Manufacturers must understand how pricing dynamics, regulatory compliance, supply chain localization, and vehicle architecture shifts interact to shape revenue pools. Our report dissects these intersections without overwhelming readers with fragmented statistics, instead presenting a structured narrative that clarifies where strategic focus will yield the highest return on investment.
What the Research Delivers: Operational Intelligence for Product, Pricing, and Portfolio Strategy
A market study is only as valuable as its applicability to real-world decision cycles. This report is built around operational utility. It moves beyond generic industry commentary to provide structured assessments that can be integrated directly into annual planning, sourcing evaluations, and competitive positioning exercises. Readers will encounter detailed evaluations of product architecture trends, including the continued dominance of blade-style configurations in contemporary vehicle electrical designs, alongside comparative insights into glass tube and other specialized fuse formats. The analysis examines how form factor preferences align with OEM specifications, aftermarket replacement cycles, and regional certification requirements.
The research also maps the evolution of application-driven demand. Passenger vehicle platforms remain the primary consumption base, reflecting high production volumes and extensive electrical component integration. Commercial vehicle segments introduce distinct load profiles, environmental durability expectations, and maintenance intervals that influence fuse selection and procurement frequency. Other application corridors, including specialty mobility platforms and emerging aftermarket service networks, are evaluated for their incremental contribution to overall market expansion. By contextualizing these segments within broader vehicle production forecasts and fleet turnover cycles, the study enables stakeholders to anticipate demand shifts rather than react to them.
Pricing architecture and value chain dynamics receive equal attention. The report explores how automotive-grade manufacturing standards, testing protocols, and certification pathways influence cost structures and competitive positioning. It examines the interplay between volume-driven OEM supply agreements and the margin characteristics of aftermarket distribution, highlighting how players optimize portfolio mix to balance volume stability with profitability. Supply chain considerations are addressed through the lens of component sourcing, production capacity allocation, and the increasing importance of regional supply resilience.
Forecasting methodology is transparent and grounded in observable industry indicators. Projections integrate historical growth patterns, vehicle production outlooks, electrification roadmaps, and regulatory trajectories to construct a multi-scenario view of market development. This approach allows decision-makers to stress-test internal assumptions against external baselines, reducing exposure to overconfidence or missed inflection points.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market structure plays a decisive role in pricing power, innovation pacing, and customer access. The automotive blade fuse sector exhibits meaningful concentration, with a compact group of established manufacturers capturing a substantial share of global demand. The report profiles the companies that define this landscape, analyzing their geographic footprints, product specializations, certification capabilities, and go-to-market strategies.
Littelfuse, Inc., headquartered in Rosemont, Illinois, operates as a broad-line manufacturer of automotive blade fuses and related circuit protection products, serving both OEM and aftermarket channels with a focus on standardized reliability and integrated protection solutions. Eaton Corporation, based in Cleveland, Ohio, leverages its Bussmann series to deliver blade fuse offerings tailored for automotive and marine overcurrent protection, combining engineering heritage with extensive distribution networks. Mersen S.A., headquartered in Courbevoie, France, supplies automotive fuses including blade types, positioning itself within electrical protection portfolios that emphasize material performance and application-specific engineering.
Beyond North America and Western Europe, the competitive field includes highly specialized manufacturers with strong regional anchors and global supply relationships. Pacific Engineering Corporation (PEC), located in Ogaki, Gifu, Japan, manufactures automotive blade fuses supplied to global vehicle makers, underscoring the importance of precision manufacturing and long-term OEM collaboration. MTA SpA, based in Codogno, Italy, produces certified automotive blade fuses and power distribution components, aligning product quality with rigorous automotive certification expectations. Conquer Electronics Co., Ltd., in New Taipei City, Taiwan, operates as a designer and manufacturer of automotive and other fuses including blade types, reflecting the role of flexible manufacturing and export-oriented production in the broader supply ecosystem.
European specialist producers further diversify the landscape. ESKA Erich Schweizer GmbH, headquartered in Kassel, Germany, produces miniature and automotive fuses including blade designs, emphasizing compact form factors and application-sensitive engineering. SIBA, based in Lünen, Germany, manufactures high-quality fuses for automotive and industrial applications, reinforcing the market's emphasis on durability and compliance. AEM Components (USA), Inc., located in San Diego, California, supplies automotive-grade surface mount and blade fuses, addressing niche requirements that span conventional and advanced electrical architectures.
Thermal Fuse Market
The report evaluates how these players compete across dimensions that matter most to procurement and strategy teams: certification breadth, production scalability, OEM relationship depth, aftermarket penetration, and responsiveness to regional specification variations. It also examines the structural implications of market concentration, where a limited number of large suppliers shape baseline pricing expectations and technology adoption rhythms. Understanding this concentration is essential for identifying negotiation leverage, assessing entry barriers, and evaluating partnership or sourcing diversification strategies.
Industry Dynamics Shaping 2026 and the Forecast Horizon
No market develops in isolation. The automotive blade fuse sector is influenced by overlapping forces that alter demand timing, product requirements, and supplier competitiveness. Vehicle electrification continues to redefine electrical load characteristics, increasing the importance of reliable circuit protection across hybrid, battery-electric, and conventionally powered platforms. At the same time, the proliferation of electronic control units, connectivity modules, and advanced sensors expands the number of protected circuits within a single vehicle, changing fuse density requirements and replacement patterns.
Regulatory and safety expectations further tighten the operational environment. Automotive-grade certification, thermal performance validation, and environmental durability standards influence both product design and supplier qualification processes. These requirements create meaningful differentiation between general-purpose and certified automotive offerings, affecting how manufacturers structure their portfolios and how buyers evaluate total cost of ownership.
Supply chain configuration is another critical dynamic. Regional production footprints, logistics resilience, and material availability shape lead times and cost predictability. As manufacturers and Tier-1 suppliers increasingly prioritize supply security, the ability to source from trusted, certified producers with stable capacity becomes a strategic advantage rather than a tactical preference. The report places these dynamics in context, showing how they interact with demand growth to influence market outcomes over the 2026 to 2032 window.
Automotive Blade Fuse Market
Aftermarket behavior also remains a steady demand engine. Vehicle fleet aging, service interval patterns, and the replacement of legacy electrical components sustain consumption even as new vehicle architectures evolve. The interplay between OEM volume cycles and aftermarket replacement demand creates a multi-layered market rhythm that rewards companies capable of balancing both channels effectively.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert market complexity into structured decision support. For product planning teams, it clarifies where blade fuse demand is most likely to intensify and how application requirements are shifting. For procurement and sourcing leaders, it provides context on concentration, certification, and supply chain resilience that can inform supplier evaluation and contract negotiation. For competitive strategy groups, it outlines how established players position themselves and where differentiation opportunities may emerge.
Most importantly, the report is designed to prevent strategic overreach. Market growth at a 5.8 percent CAGR is meaningful, but it does not eliminate risk. Regional variation, application segmentation, and competitive concentration mean that aggregate growth can mask divergence at the segment level. Companies that rely on headline numbers alone may misallocate resources or underestimate the operational requirements needed to capture demand in specific corridors. By integrating historical performance, forward-looking projections, and competitive context, this research equips stakeholders to make calibrated decisions rather than assumptions.
The complete study expands on every dimension introduced here, offering detailed market sizing across historical and forecast periods, segmentation analysis that identifies where growth concentrates, competitive profiling that maps supplier strengths and positioning, and strategic implications tailored to product, pricing, and sourcing decisions. It is built for teams that require a rigorous baseline before committing capital, capacity, or commercial strategy.
For executives planning 2026 initiatives, the strategic question is no longer whether the automotive blade fuse market is expanding, but how to position within that expansion with precision. This report provides the analytical foundation to answer that question with confidence, while the full dataset and segment-level intelligence remain available for teams that need to ground strategy in complete, validated market intelligence.
For detailed analysis of this topic, please visit the official page: Automotive Blade Fuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


