



PW Consulting: Industrial Butt Fusion Machines Market to Hit $0.29B by 2032, 4.32% CAGR
By PW Consulting, 2026-09-16
Industrial Butt Fusion Machines Market: Strategic Intelligence for 2026 Decision-Making
Navigating a Consolidated Landscape Defined by Precision, Digital Integration, and Material Dynamics
As industrial infrastructure demands continue to prioritize leak-free, high-integrity piping systems, the Industrial Butt Fusion Machines Market remains a critical enabler across utility, energy, and chemical sectors. Our latest market research delivers a comprehensive, forward-looking assessment of this specialized equipment arena, calibrated to guide corporate strategy through 2026 and beyond. The study is structured not merely as a historical retrospective but as a decision architecture that aligns procurement planning, product development, competitive positioning, and geographic expansion with verifiable market mechanics. By synthesizing multi-year historical tracking with a disciplined forecast window through 2032, the report equips executives with the contextual clarity needed to allocate capital, differentiate offerings, and respond to evolving technical standards.
The market’s trajectory reflects a broader industrial shift toward automation, traceable weld documentation, and diameter-flexible machine architectures. Over the historical review period spanning 2020 through 2025, the sector navigated an environment characterized by fluctuating raw material pricing, varying municipal procurement cycles, and the gradual adoption of digitally enabled fusion equipment. This period laid the foundation for a measured, yet structurally positive, growth path. The research captures these dynamics and translates them into actionable frameworks, allowing stakeholders to distinguish between cyclical pricing noise and durable demand shifts.
Macro Trajectory and Forecast Architecture: What 2026 Executes for Long-Range Planning
A core value of this research lies in its disciplined forecast architecture. The study establishes a forecast horizon from 2026 through 2032, anchored against a recent reference year and supported by a consistent historical dataset. Across the projection window, the market is positioned for a compound annual growth rate of 4.32%, signaling a steady and calculable expansion rather than a speculative surge. This level of growth implies that operators, investors, and suppliers must plan with precision: incremental volume gains will depend on successful deployment of advanced machine classes, alignment with regional infrastructure programs, and the ability to navigate raw material cost variability.
The revenue trajectory across the forecast horizon points toward gradual but compounding market scaling, with total industry revenue progressing into a higher range by the close of the decade. For leadership teams, the strategic implication is that timing matters as much as scale. Early positioning in semi-automated and fully automated platforms, along with service and data-recording ecosystems, becomes a differentiator when growth is distributed across a broad equipment continuum rather than concentrated in a single product breakthrough. The report maps this progression in a manner that supports scenario planning, allowing executives to test sensitivity around pricing, adoption pace, and application-led demand without relying on superficial indicators.
Electrofusion Fittings Market
Segmentation Architecture: Understanding Where Value and Volume Converge
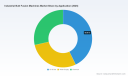
A defining feature of the Industrial Butt Fusion Machines Market is its segmentation across multiple operational dimensions. Rather than presenting isolated percentages, the report contextualizes each segment through its functional relevance to buyers and manufacturers. By machine type, the market distinguishes among automatic, semi-automatic, and manual butt fusion equipment. This classification is not simply descriptive; it signals how various end users balance throughput requirements, labor availability, and site conditions. Automatic platforms tend to anchor high-volume industrial deployments where repeatability and weld-record traceability are paramount. Semi-automatic variants address mid-range projects with a need for flexibility and operator oversight, while manual configurations remain relevant for specialized or constrained installations where portability and lower upfront cost dominate purchasing logic.
By application, the research examines how core end-use environments shape equipment requirements and purchasing cycles. Oil and gas operations continue to demand robust fusion solutions for pressure-critical piping, often favoring machines capable of handling larger diameters and ensuring rigorous documentation. Water supply networks depend on reliable fusion for municipal and regional distribution infrastructure, where consistency across long pipeline runs and field serviceability are decisive. Chemical applications place emphasis on material compatibility and welded joint integrity across corrosive or high-purity service conditions. The report details how these application streams influence machine specification, maintenance expectations, and aftermarket service demand, giving suppliers a clearer picture of where operational value is created over the equipment lifecycle.
On the regional front, the study evaluates how geographic demand clusters and infrastructure priorities create distinct market environments. Instead of reducing each territory to a single numeric share, the report analyzes regional demand drivers, competitive intensity, import and distribution patterns, and the role of localized service support. This approach allows readers to understand where equipment demand is likely to be volume-led, where technical customization dominates, and where export-oriented manufacturing strategies may create pricing pressure. In practice, this means stakeholders can better align product portfolios, distribution partnerships, and service footprints with the realities of each region’s procurement culture and infrastructure agenda.
Industrial Butt Fusion Machines Market
Competitive Dynamics: A Focused Field of Specialized Manufacturers
The competitive environment is characterized by a modest level of concentration, reflecting a market where specialized engineering capability, measurement precision, and application-specific reliability remain decisive advantages. The research examines the landscape through the lens of established manufacturers that have built reputations on machine performance, weld documentation, and breadth of pipe material compatibility. These firms span North America, Europe, Asia, and other regions, each competing through differentiated machine architectures, digital integration, and service ecosystems.
Key competitors evaluated in the study include firms such as McElroy Manufacturing, Inc., recognized for premium automatic and semi-automatic butt fusion machines designed for HDPE and PE piping, with digital weld recording capabilities and track-mounted platforms suited for demanding field conditions. Georg Fischer Piping Systems Ltd. is assessed for its automated and portable fusion equipment supporting pressure piping systems across water, gas, and industrial contexts. Ritmo S.p.A. is examined for its emphasis on high-productivity track-mounted and workshop-based machines covering HDPE, PP, and other thermoplastics. Fusion Group Limited contributes to the analysis as a supplier of precision butt fusion equipment for PE pipe and fittings in industrial and municipal projects. Rothenberger USA LLC and Hurner Welding Technology GmbH are reviewed for their manual, semi-automatic, and automatic machine offerings and workshop or on-site solutions for thermoplastics up to large diameters. WIDOS Wilhelm Dommer Söhne GmbH and KraussMaffei Technologies GmbH round out the evaluation as manufacturers of plastic welding machinery and butt fusion systems oriented toward pressure pipe applications. Additional players, including Wuxi Baoda Plastic Pipe Welding Equipment Co., Ltd., SWT Plastic Welding, Leister Technologies AG, Plasson Ltd., Worldpoly Pty Ltd, and Nupi Americas, Inc., are assessed for their contributions to multi-angle, portable, and industrial-grade fusion equipment portfolios. This competitive mapping is designed to provide relative positioning insight, not just product lists, enabling strategic benchmarking around automation levels, diameter coverage, documentation technology, and regional service reach.
Recent Developments and Operational Signals Shaping 2026 Strategy
Market momentum is not driven by forecasts alone; it is continuously reshaped by product launches, trade-channel activity, material cost behavior, and equipment pricing signals. The report integrates recent operational developments to give decision-makers a current picture of how the competitive field is moving. In mid-to-late 2025, new product catalog releases and showcase activity brought renewed attention to hydraulic butt fusion machines for water, gas, mining, and petrochemical applications. Trade show participation and technical demonstrations further illustrate how manufacturers are communicating advanced thermoplastic welding solutions and buyer guidance, reinforcing the importance of visibility and specification support in procurement cycles.
On the materials side, polyethylene pricing behavior remains a relevant variable for machine utilization, project budgeting, and pipe procurement. Recent price movements have reflected shifts in regional supply dynamics and import competition, with European HDPE markets experiencing steady softening in late 2025 due to competitive imports from Asia and the Middle East. These material fluctuations do not change the fundamental demand for fusion equipment, but they do influence project economics and the pace at which operators invest in higher-capacity or higher-automation machines. The report contextualizes such input-cost behavior so that market participants can separate short-term commodity movements from durable equipment demand.
At the equipment level, recent industry signals underscore how pricing ranges and product innovation interact. For example, automatic butt fusion machines in the 315 mm to 630 mm size range were observed at average selling price levels ranging broadly in 2025, reflecting the premium associated with larger-diameter, higher-throughput platforms. This matters because price dispersion across machine classes shapes buyer expectations, financing decisions, and competitive differentiation. Simultaneously, the introduction of independently powered track-mounted machines for large-diameter oil and gas applications demonstrates how manufacturers are expanding machine capability to serve more technically demanding installation environments. The report connects these developments to purchasing logic, showing how feature sets and power architecture affect total cost of ownership and site deployment efficiency.
Report Structure and Practical Content for Executive Use
Beyond high-level market orientation, this research is designed as an operational reference. The report introduces a structured view of segmentation logic, historical performance patterns, and forecast assumptions, allowing readers to interrogate demand drivers rather than simply accept summary figures. It includes detailed discussion of how machine type, application, and regional context interact in real purchasing environments, enabling more precise go-to-market planning and product positioning. The analysis also addresses competitive behavior, including how dominant firms maintain relevance through automation, documentation tools, and service coverage, and where smaller or regionally focused manufacturers can compete on specialization, lead time, or application-specific configuration.
In addition, the study incorporates market concentration indicators to provide a realistic view of competitive structure. With a moderately concentrated field, the research explains the strategic significance of scale, technical reputation, and the ability to support large-diameter or digitally integrated platforms. This is especially useful for companies evaluating partnership opportunities, acquisition targets, import pathways, or regional expansion, because it clarifies where market influence is distributed and where entry barriers remain tied to technical credibility and service reliability. The report’s practical orientation extends to purchase considerations, operational deployment factors, and the ways in which weld-record data and machine control architectures are becoming part of the broader value proposition in industrial piping projects.
Why This Research Matters for 2026 Decisions
The strategic value of this report comes from its ability to convert complex market mechanics into decision-ready intelligence. For manufacturers, it supports product roadmap choices by clarifying where automation, portability, and documentation features are most valued. For distributors and service providers, it highlights where regional demand patterns and machine-class preferences create opportunities for targeted inventory, training, and field support. For investors and corporate planners, it offers a forecast-consistent view of how the market is likely to expand and where competitive advantage will be earned through differentiation rather than volume alone.
By maintaining a disciplined balance between macro trajectory and operational detail, the study helps stakeholders avoid overreliance on fragmented indicators and instead base decisions on a connected understanding of type, application, region, and competitive behavior. It also prepares readers to interpret raw material movements, equipment pricing dispersion, and product launch activity as part of a larger market system rather than isolated events.
Accessing the Full Strategic Intelligence
This introduction outlines the scope and analytical direction of the research, but the complete dataset, scenario framing, and detailed segmentation discussion reside in the full report. To obtain the comprehensive market intelligence needed for precise 2026 planning across equipment strategy, regional deployment, competitive benchmarking, and demand forecasting, readers are encouraged to access the complete report directly through the source page. The full version delivers the depth required to convert market awareness into executable corporate strategy.
For detailed analysis of this topic, please visit the official page: Industrial Butt Fusion Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Family Entertainment Market Hits $182.3M in 2025, 5.45% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Future of Family and Indoor Entertainment: Navigating the 2026 Landscape
The global Family/Indoor Entertainment Centres market stands at a pivotal inflection point as we move through 2026. Against a backdrop of shifting consumer priorities, rising operational costs, and aggressive physical expansion by market leaders, strategic clarity is no longer optional. This newly released market research report delivers a comprehensive, data-driven foundation for decision-makers operating in or adjacent to the family entertainment ecosystem. By synthesizing historical performance, forward-looking projections, competitive intelligence, and operational benchmarks, the study equips executives, investors, and site-selection teams with the analytical rigor required to allocate capital, design experiential offerings, and defend market share in an increasingly crowded arena.
The sector has demonstrated remarkable resilience over the past half-decade. Drawing on verified historical records and carefully modeled trajectories, the market has evolved from a baseline of approximately $145.35 million in 2020 to a projected $182.3 million in 2025. The forward window extends through 2032, with revenue forecasts charting a steady climb toward $262.7 million by the terminal year. This expansion is underpinned by a compound annual growth rate of 5.45 percent across the forecast horizon, a figure that reflects sustained demand for structured, family-oriented leisure experiences even as discretionary spending patterns continue to recalibrate. The trajectory underscores a fundamental truth: experiential entertainment is transitioning from a discretionary luxury to a normalized component of household recreation budgets.
Macro Market Trajectory and Growth Architecture
Understanding the shape of this growth requires more than headline numbers. The report dissects the revenue curve across multiple temporal layers, beginning with the historical reconstruction from 2020 through 2025 and extending into a granular forecast spanning 2026 to 2032. Each year is contextualized within broader economic signals, seasonal visitation patterns, and capital deployment cycles. The analysis reveals that momentum is not evenly distributed; rather, it concentrates around specific operational models, geographic clusters, and experiential formats that consistently outperform peer configurations. By isolating the structural drivers behind the 5.45 percent CAGR, the study enables stakeholders to distinguish between temporary cyclical strength and durable secular expansion.
Revenue projections are anchored to realistic assumptions about foot traffic, per-visit spend, and operational scalability. Internal benchmarks indicate that families typically allocate between $12 and $22 at individual location-based entertainment venues, with an average spend nearing $25 when admission, gaming, food and beverage, retail, and equipment rentals are combined. This per-transaction economics framework is critical because it exposes the leverage points where design, pricing, and ancillary monetization converge. The report maps these dynamics across the forecast period, allowing operators to model sensitivity scenarios around ticket pricing, promotional cadence, and ancillary attach rates without relying on broad industry averages that obscure site-level reality.
Consumer Experience Drivers and Behavioral Segmentation
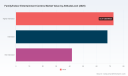
The heart of the family indoor entertainment proposition lies in how guests experience the venue. The research categorizes consumer engagement through experience intensity, revealing a clear hierarchy in how different guest profiles translate into revenue and loyalty. Full-experience environments, which integrate multi-attraction layouts, sustained dwell time, and comprehensive dining or retail components, command the largest share of market value. Half-experience configurations, which balance active play with selective amenities, represent a substantial secondary tier, while no-experience or entry-level formats capture a smaller but strategically relevant segment of the market.
Parallel to experience depth, the report examines attitude-driven demand. Consumer sentiment clusters into highly interested, interested, and not interested cohorts, each requiring distinct site design, marketing messaging, and operational pacing. The highly interested segment drives repeat visitation and word-of-mouth amplification, while the moderately interested group responds strongly to seasonal programming, group bookings, and value-added passes. By aligning venue architecture and promotional calendars with these behavioral strata, operators can avoid the common pitfall of designing for an undifferentiated mass audience and instead engineer experiences that convert interest into recurring revenue.
Regional demand patterns further shape the opportunity set. Market value is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each geography presenting distinct visitation frequency norms, labor cost structures, and competitive density. The analysis does not treat these regions as monolithic blocks; instead, it examines how local consumption habits, real estate economics, and regulatory environments interact with the core entertainment model. For instance, North American households tend to visit family entertainment centers three to five times per year, prioritizing shared experiential leisure over material goods. This frequency baseline becomes a critical input for staffing models, inventory planning, and loyalty program design.
Competitive Landscape and Strategic Positioning
The competitive architecture of the sector is defined by a mix of highly scaled incumbents and regionally focused challengers, all competing on experience density, brand recognition, and operational efficiency. Dave & Buster's, headquartered in Coppell, Texas, has built a formidable presence through large-scale indoor entertainment centers that combine extensive arcade gaming, full-service dining, sports bar environments, and family-oriented attractions across North America. Its recent expansion cadence, including a major new location in King of Prussia, Pennsylvania, opened in May 2026 with over 100 arcade games, integrated dining, and the creation of 150 new jobs, signals a deliberate strategy of market deepening and brand reinforcement in high-traffic suburban corridors.
Urban Air Adventure Parks, based in Bedford, Texas, pursues a distinctly active-play orientation. Its indoor adventure parks center on climbing walls, trampoline networks, inflatable features, and structured active play zones designed to attract families seeking physical engagement rather than passive entertainment. The company's continued footprint growth, including a newly signed lease for an Owings Mills, Maryland facility expected to open in early 2027, reflects confidence in the durability of motion-centric family experiences and the willingness of consumers to pay for structured activity-based leisure.
Chuck E. Cheese, also headquartered in Irving, Texas, maintains its status as an iconic family entertainment brand by fusing arcade gaming, pizza dining, and birthday party venues into a tightly integrated experience model. Its May 2026 product launch introduced ten new arcade games alongside a 2026 Summer Fun Pass offering unlimited visits, a move that underscores the brand's focus on repeat engagement, seasonal campaign alignment, and family-centric programming. Main Event Entertainment, located in Coppell, Texas, competes through multi-activity indoor centers that layer bowling, laser tag, arcade games, and team-building experiences into a single destination. Its expansion pipeline, including a new Huntsville location unveiled in May 2026, a Brownsville center planned for July 2026, and a Greensboro grand opening, illustrates a methodical approach to geographic penetration and multi-attraction differentiation.
Scene75 Entertainment Centers, operating from Dayton, Ohio, rounds out the competitive field with large indoor venues that combine go-karts, laser tag, arcade gaming, bouncing areas, and full dining under one roof. This breadth of offering positions Scene75 as a destination-style player that competes on variety and dwell time. Collectively, these companies illustrate the spectrum of operational philosophies currently shaping the market, from arcade-and-dining dominance to active-play specialization and multi-activity integration.
Market Concentration and Structural Efficiency
A critical dimension of strategic planning is understanding how concentrated the market truly is and what that implies for new entrants, site acquisition, and competitive response. The report quantifies concentration through standard industry metrics, revealing that the top three players account for approximately 26.5 percent of market revenue, while the top five capture roughly 34.2 percent. This moderate concentration indicates a fragmented landscape with room for regional leaders and well-executed niche concepts, but it also signals that scaled operators retain meaningful advantages in purchasing power, brand recognition, and multi-site operational learnings.
The concentration profile has direct implications for capital deployment. Operators evaluating expansion must weigh the benefits of scale-driven cost efficiencies against the risks of market saturation in established corridors. The study provides a framework for assessing whether a given submarket is dominated by a single experiential format or remains open to differentiated concepts. By mapping concentration patterns alongside regional demand intensity, the report helps decision-makers identify corridors where competitive white space still exists and where brand positioning can be established before saturation intensifies.
Family/Indoor Entertainment Centres Market
Operational Economics and Profitability Levers
Operational discipline separates sustainable operators from those that chase foot traffic without securing margin. Industry benchmark data continues to show that employee payroll represents the largest expense category for family entertainment centers, making labor scheduling, cross-training, and peak-hour staffing efficiency central to profitability. The report integrates these cost realities into its strategic analysis, demonstrating how venue layout, attraction mix, and service design directly influence labor intensity per guest hour. Venues that optimize throughput without sacrificing experience quality consistently outperform peers on margin, even when facing similar revenue levels.
Profitability benchmarks further contextualize the operating environment. Approximately one-third of facilities report revenue exceeding $1 million, with an average profit margin of 14.8 percent across the sector. These figures are not aspirational; they are achievable outcomes of disciplined site selection, pricing architecture, and operational orchestration. The research breaks down how ancillary revenue streams, group bookings, birthday party packages, and seasonal promotions contribute to margin expansion, enabling operators to move beyond top-line growth and focus on value capture. By aligning labor models with visitation patterns and designing pricing structures that protect attach rates, operators can convert per-visit spend into durable profitability.
Party Costumes Market
What the Full Research Delivers
This report is engineered for execution, not observation. It provides a structured intelligence package that translates market dynamics into actionable planning inputs across strategy, operations, finance, and expansion functions. The full document includes:
- A complete historical reconstruction and forward forecast with year-by-year revenue trajectories, enabling scenario modeling under multiple demand and cost assumptions.
- Experience-level and attitude-level segmentation analysis that maps guest engagement intensity to revenue contribution, visitation frequency, and operational design requirements.
- Regional demand distribution and competitive density profiling that supports site selection, market entry timing, and format localization decisions.
- Competitive profiling of leading operators, including business model differentiation, recent expansion and product-launch activity, and strategic positioning cues.
- Operational benchmark integration covering labor cost structures, revenue thresholds, profit margin ranges, and per-visit spend dynamics that inform pricing, staffing, and ancillary monetization strategies.
- Market concentration metrics and structural readouts that clarify scale advantages, fragmentation risk, and the conditions under which new concepts can achieve defensible positioning.
- Actionable strategic recommendations for capital allocation, experiential design, promotional cadence, and geographic expansion sequencing through the 2032 horizon.
Each section is designed to feed directly into planning cycles. The historical reconstruction anchors expectations, the forecast window supports budgeting and expansion scheduling, the segmentation analysis guides venue architecture and marketing targeting, and the competitive and concentration readouts inform positioning and risk assessment. Together, these components create a decision-ready intelligence platform rather than a passive market summary.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment demands more than intuition. Consumer habits continue to favor shared experiential leisure, but families are also more deliberate about where they allocate limited discretionary budgets. Operators that succeed will be those that design for repeat engagement, manage labor intensity intelligently, and position their offerings against clearly defined competitive alternatives rather than against an abstract market average. The report's combination of macro trajectory, segmentation depth, competitive tracking, and operational benchmarking provides the evidentiary base required to make those choices with confidence.
For executives, the study functions as a strategic compass. It clarifies where growth is structurally supported, which experiential formats align with high-intent guest segments, how labor and ancillary revenue interact to shape margin, and where competitive concentration leaves space for differentiated concepts. For investors and corporate development teams, it offers a disciplined framework for evaluating expansion timing, site economics, and brand positioning in a market that rewards operational precision as much as creative concepting.
Conclusion
The Family/Indoor Entertainment Centres market is expanding along a measurable, multi-year trajectory, but the opportunity is not uniformly accessible. Success in 2026 and beyond will belong to organizations that translate market data into operational design, pricing strategy, staffing models, and expansion sequencing. This research report exposes the underlying architecture of that opportunity, from historical performance and forward forecasts to experience segmentation, competitive behavior, and concentration dynamics. It is built to support real decisions: where to invest, how to design, whom to target, and how to sustain margin in a competitive, labor-sensitive environment.
The complete analysis, including the full dataset, segmentation breakdowns, regional profiles, competitive tracking, and strategic recommendations, is available through the full report download. Stakeholders seeking to align their 2026 planning with a rigorous, forward-looking market view are encouraged to access the complete intelligence package and integrate its findings into capital allocation, site strategy, and experiential design decisions.
For detailed analysis of this topic, please visit the official page: Family/Indoor Entertainment Centres Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Building Market Hits $111B in 2025, Projected to Reach $298.3B by 2032 at 15.2% CAGR
By PW Consulting, 2026-09-16
Unlocking the 2032 Horizon: Strategic Intelligence for the Smart Building Revolution
The trajectory of the global commercial real estate and infrastructure sectors has fundamentally shifted. As we move through 2026, the smart building market is no longer a niche segment of facility management but a central pillar of corporate sustainability, operational efficiency, and tenant experience strategies. For C-suite executives, investors, and industry stakeholders, understanding the velocity and direction of this transformation is critical for capitalizing on emerging opportunities and mitigating regulatory risks.
PW Consulting has synthesized extensive primary and secondary research to deliver a comprehensive Smart Building Market study, covering the historical performance from 2020 through 2025 and providing a robust revenue forecast from 2026 to 2032. This article serves as a strategic overview of the intelligence contained within our latest report, demonstrating why this analysis is an indispensable tool for navigating the next seven years of market evolution.
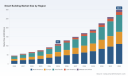
The numbers tell a compelling story of rapid acceleration. From a market size of US 46.0 Billion in 2020, the industry has expanded dramatically to reach an estimated US 111.0 Billion in 2025. This growth underscores the pent-up demand and the urgent adoption of automation technologies following the global shifts in work patterns and energy consciousness over the past few years. As we look forward, the momentum shows no signs of slowing. The total market revenue is projected to cross the US 130.12 Billion mark in 2026, continuing its ascent toward a transformative milestone of nearly US 298.3 Billion by 2032.
Driving this expansion is a compound annual growth rate (CAGR) of 15.2 percent over the forecast period. For strategy teams, this metric signals that smart building technologies are entering a phase of mainstream maturity where scale becomes as important as innovation. However, raw market size and growth rates are only the starting point. The true value of the PW Consulting study lies in decoding the underlying dynamics, competitive pressures, and technological standards that will determine which players thrive and which are left behind in this hyper-competitive environment.
The Anatomy of Market Acceleration
The surge from 2020 to 2025 was characterized by a rapid digitalization of building operations, driven by the need for remote monitoring, energy cost volatility, and heightened occupant health expectations. The jump from US 76.01 Billion in 2023 to US 91.93 Billion in 2024, followed by the breakout to US 111.0 Billion in 2025, reflects a decisive market shift. Organizations are moving beyond pilot projects to enterprise-wide deployments.
Looking ahead to the 2026-2032 forecast horizon, the growth trajectory suggests a market that is consolidating around integrated platforms. The revenue jump from US 130.12 Billion in 2026 to US 149.86 Billion in 2027, and the subsequent climb to US 224.76 Billion by 2030, indicates that adoption will deepen across diverse building portfolios. By 2032, when the market is anticipated to reach US 298.3 Billion, the definition of a smart building will have expanded to encompass fully autonomous energy management, predictive maintenance ecosystems, and seamless occupant interaction layers. Our analysis deconstructs these phases to identify the inflection points where investment yields the highest return.
Segmentation Insights and Strategic Allocation
While the aggregate market figures provide the macro context, the allocation of revenue across different dimensions reveals where the battle for market share is being fought. Our research dissects the market into key components, building types, and geographic regions to highlight concentration and opportunity.
A significant majority of current market activity is concentrated within the Solutions segment, accounting for the lion's share of revenue generation compared to Services. This dominance indicates that the market is prioritizing software platforms, automation engines, and integrated control systems over standalone consulting or maintenance services. The value is shifting toward intellectual property and scalable digital products. However, our report also provides a granular look at how the services component is evolving, particularly in areas such as integration support and lifecycle management, which remain essential for successful deployment.
In terms of building typologies, the market is no longer solely dominated by one sector. Commercial properties continue to drive substantial volume, reflecting the high density of enterprise deployments. Yet, residential and industrial applications are emerging as high-growth vectors. The residential segment is seeing a wave of upgrades driven by consumer demand for energy efficiency and home automation, while the industrial sector is leveraging smart building controls for safety, compliance, and operational resilience. Our study quantifies the interplay between these segments, helping clients identify cross-sector synergies and market gaps.
Building Management System Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains a powerhouse of adoption, fueled by mature infrastructure and strong enterprise investment. Europe is undergoing a regulatory-led transformation, while Asia Pacific presents rapid urbanization and digital leapfrogging opportunities. Latin America and the Middle East and Africa represent emerging frontiers with distinct growth drivers. The report avoids superficial generalizations, offering a nuanced view of regional maturity levels, investment climates, and specific adoption barriers that vary by location. By understanding these regional weights, multinational corporations can tailor their market entry or expansion strategies with precision.
Competitive Landscape: Titans and Disruptors
The smart building ecosystem is populated by a mix of established industrial giants, technology enablers, and specialized innovators. Market concentration data reveals that a core group of players holds significant sway, with the top three competitors collectively commanding more than half of the market revenue, while the top five extend their influence further. This level of concentration suggests that while barriers to entry exist, competitive intensity remains high as incumbents vie for dominance in platform ecosystems.
At the forefront of this landscape are companies that have built comprehensive portfolios spanning hardware, software, and analytics. Siemens AG continues to leverage its integrated building automation capabilities, utilizing platforms like Desigo CC and Building X to unify HVAC, lighting, security, and fire systems. Their focus on energy optimization and remote control positions them as a critical partner for large-scale infrastructure projects. Similarly, Johnson Controls International plc has reinforced its leadership through the OpenBlue smart building platform and Metasys building management system, integrating AI-driven analytics and cloud services to drive portfolio optimization and enhance occupant experience.
Schneider Electric SE contributes to the competitive fray with its EcoStruxure Building Operation platform, offering integrated control across HVAC, power, lighting, and access for commercial and campus buildings, backed by BACnet certification to ensure interoperability. ABB Ltd. counters with its ABB Cylon and i-bus KNX platforms, focusing on building automation, energy management, and HVAC controls, while also exploring integration opportunities within broader smart ecosystems such as SmartThings.
The landscape also includes major technology and industrial players adapting their core competencies to the built environment. Honeywell International Inc. is deploying AI and IoT solutions for predictive maintenance, security, and energy optimization, adding a layer of intelligence to traditional building controls. Cisco Systems, Inc. provides the foundational networking infrastructure and cybersecurity solutions necessary to support connected smart building systems and the proliferation of IoT devices, recognizing that connectivity is the backbone of the smart building. IBM Corporation brings its strength in cloud computing, AI, and analytics to building management, offering predictive insights that transform raw data into actionable strategy.
Regional and specialized players are also making their mark. Hitachi, Ltd. focuses on automation and control systems tailored for energy management and environmental monitoring, addressing the growing need for sustainability in Asian and global markets. Legrand SA rounds out the competitive field with its expertise in electrical installation and smart building solutions, delivering value through lighting, access, and automation technologies that enhance both functionality and user experience.
Recent developments illustrate how these companies are competing for mindshare and wallet share. In April 2025, Johnson Controls released a commissioned Forrester study quantifying up to 155 percent ROI and 10 percent energy savings from its OpenBlue platform across a composite customer model. This type of evidence-based marketing underscores the industry's shift toward demonstrating tangible financial returns to justify capital expenditures. Our report analyzes such developments to help clients benchmark vendor claims against market realities.
Regulatory Tailwinds and Industry Standards
The smart building market is operating within a dynamic regulatory environment that acts as both a catalyst and a constraint. In Europe, the revised Energy Performance of Buildings Directive (EU/2024/1275) entered into force on 28 May 2024, with a transposition deadline of 29 May 2026 for EU countries. This directive mandates significant improvements in building energy efficiency and promotes the deployment of building automation and control systems (BACS). Furthermore, EU countries are required to submit draft national building renovation plans by 31 December 2025 and final plans by 31 December 2026. The European Commission's adoption of a support package offering practical guidance to EU countries for transposing these requirements, including specific BACS mandates, signals a tightening regulatory framework that will drive demand for compliant solutions.
The industry is also responding to the need for harmonization and interoperability. Standardization efforts such as CEN/TR 18081:2024 specify the requirements of hardware and functions for products and systems for the control and management of HVAC in smart building automation. This standard, alongside the development of open international standards like KNX, LonWorks, and BACnet for BACS, is crucial for ensuring interoperability in smart building systems. As noted in recent academic research, these standards mitigate the risk of vendor lock-in and facilitate the integration of multi-vendor environments. Our study evaluates the impact of these regulatory and standardization trends on market growth, procurement cycles, and technology selection criteria.
Why This Study Matters for 2026 Decision-Making
In an era of information overload, clarity and actionable intelligence are the ultimate competitive advantages. The PW Consulting Smart Building Market report is designed for decision-makers who require more than high-level estimates. It provides a detailed map of the market landscape, enabling stakeholders to:
- Identify high-growth segments and geographic regions where investment can yield superior returns.
- Understand the competitive positioning of key players and anticipate shifts in market share.
- Align product development and go-to-market strategies with regulatory timelines, such as the EU building renovation plan deadlines and BACS requirements.
- Evaluate the financial impact of technologies by referencing independent studies and industry benchmarks.
- Navigate the complexities of interoperability and integration by leveraging insights on standards like KNX, BACnet, and CEN/TR 18081.
Our forecast model is built on a rigorous methodology that accounts for historical performance, current market indicators, and forward-looking variables. The revenue projections from 2026 to 2032 are not merely extrapolated trends but reflect a deep understanding of the drivers, restraints, and opportunities that will shape the industry. For investors, this means a clearer view of valuation metrics and risk factors. For technology vendors, it means validated demand signals for R&D prioritization. For facility owners and operators, it means a roadmap for phased modernization that aligns with budget cycles and compliance mandates.
The market concentration data, showing significant revenue held by leading players, also highlights the importance of differentiation. New entrants and established players alike must find unique value propositions, whether through superior analytics, niche application focus, or unbeatable integration capabilities. Our report includes profiling of key companies, detailing their core offerings, strategic moves, and areas of focus, providing a reference point for competitive analysis and partnership opportunities.
Smart Building Market
Conclusion: Your Gateway to Market Mastery
The smart building market stands at the intersection of technology, sustainability, and urban development. With projections pointing to a near tripling of market size by 2032, the decisions made in 2026 will have lasting implications for portfolio performance, operational resilience, and brand reputation. The PW Consulting Smart Building Market study offers the comprehensive intelligence needed to navigate this complex terrain with confidence.
We invite you to explore the full depth of our research. The complete report contains detailed segmentation data, competitive benchmarking matrices, regional analysis, and strategic recommendations that go beyond the scope of this overview. Don't rely on fragmented insights; equip your organization with the authoritative data and strategic context required to lead in the smart building era. Access the full report to unlock the detailed intelligence that will define your success over the next seven years.
For detailed analysis of this topic, please visit the official page: Smart Building Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Pruning Shears Market Hits $215M in 2025, Poised for 5.2% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Green Cut: Strategic Imperatives in the Global Electric Pruning Shears Market Through 2032
The agricultural and landscaping equipment sectors are undergoing a profound transformation, driven by the urgent need for operational efficiency, labor optimization, and sustainability compliance. At the forefront of this shift is the Electric Pruning Shears Market, a segment that has evolved from a niche innovation to a critical component of modern horticultural management. Our latest market intelligence report offers a comprehensive roadmap for stakeholders aiming to capitalize on the projected growth trajectory spanning from 2026 to 2032. As enterprises allocate capital for the upcoming fiscal year, understanding the nuanced dynamics of this market is no longer optional—it is a strategic necessity.
Market Trajectory and Growth Outlook
The financial footprint of the electric pruning shears market has demonstrated consistent resilience and expansion over the past half-decade. Our analysis tracks the market journey from a robust baseline in 2025, with readings hitting approximately 215.0 Million USD in base year revenue. This establishes a solid foundation for the forecast period extending through 2032, where the market is anticipated to reach significantly higher valuation milestones, crossing the 340 Million USD threshold by the end of the forecast window.
This upward trajectory is underpinned by a Compound Annual Growth Rate (CAGR) estimated at 5.2% over the forecast horizon. Such growth signals more than just incremental improvement; it indicates a structural shift in how pruning tasks are executed across both commercial and residential sectors. For enterprise leaders, this 5.2% CAGR represents a stable yet dynamic environment where early movers can secure significant market share before saturation occurs in mature segments. The historical data from 2020 to 2025 reveals a pattern of steady acceleration, suggesting that the drivers of demand are systemic rather than cyclical, rooted in technological adoption and regulatory pressure.
Key Growth Catalysts
Several intrinsic factors are fueling this expansion. First, the rigorous labor constraints in agriculture and landscaping have made efficiency a priority, pushing operators toward high-performance electric solutions that offer precision and reduced physical strain. Second, the push toward sustainability and organic farming practices aligns perfectly with the low-impact nature of electric pruning tools, which often complement broader environmental compliance strategies. Third, advancements in battery technology and motor efficiency have addressed earlier concerns regarding runtime and power, making these tools viable for extended professional use. These converging trends create a fertile ground for sustained investment and product development.
Detailed Segmentation Analysis and Market Drivers
Our report dissects the market into critical dimensions that influence purchasing decisions and product development roadmaps. By categorizing the market through type, application, and geography, we provide clients with the granularity needed to refine their strategic positioning without exposing every tactical detail in the summary view. The segmentation data reveals distinct preferences that vary by use case, highlighting where value is being generated and where competitive intensity is highest.
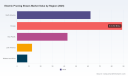
In terms of product type, the market shows a clear divergence between cordless and corded options. Cordless electric pruning shears currently command a significant portion of the market, reflecting the industry's strong preference for mobility, reduced noise, and ease of use in diverse terrains. Corded models remain relevant in specific stationary or high-power applications, but the momentum clearly favors wireless convenience. This shift is not merely about convenience; it is about enabling workflows that were previously impractical with tethered equipment. The adoption of brushless motor technology has further enhanced the appeal of cordless units, offering longer life and higher efficiency.
When examining applications, the data underscores the dominance of high-value agricultural sectors. Vineyards and orchards represent the primary demand centers, where precision cutting is essential for yield optimization and plant health. These sectors demand tools capable of handling substantial branch diameters while maintaining ergonomic standards for prolonged use. Landscaping follows as a significant secondary application, driven by residential and commercial grounds maintenance needs. Each segment presents unique requirements regarding cut capacity, battery life, and durability, and our analysis maps these requirements against available product offerings to identify gaps and opportunities.
Geographically, market distribution reflects the varying stages of technological adoption and economic activity across regions. Certain established markets demonstrate higher penetration rates, while emerging regions exhibit rapid growth potential as infrastructure and awareness improve. Understanding these regional nuances is vital for companies planning export strategies or localized manufacturing. The report provides context on how regulatory environments, labor costs, and agricultural practices differ by region, influencing the rate of adoption for electric pruning tools.
Technology and Product Advancement Trends
The competitive landscape is being reshaped by continuous innovation in core technologies. Lithium-ion battery advancements have been a game-changer, extending runtime to six to ten hours per charge in professional models while keeping tool weights under 800 grams. This improvement directly addresses one of the historical barriers to adoption: battery anxiety and user fatigue. Furthermore, the integration of smart features is beginning to emerge, with some manufacturers exploring connectivity options that allow for performance monitoring, battery health tracking, and user customization via mobile applications. These technological leaps are raising the bar for what constitutes a competitive product, pushing the entire market toward higher standards of performance and user experience.
Competitive Landscape and Strategic Initiatives
The market features a diverse array of players, from specialized Swiss precision manufacturers to global power tool giants and value-oriented brands. Our report delves deep into the profiles, capabilities, and strategic moves of key competitors, including Felco SA, STIHL Group, Makita Corporation, Worx, DeWalt, RYOBI, Craftsman, and Pellenc SA. Understanding the positioning of these entities is critical for assessing threat levels, identifying partnership opportunities, and benchmarking product development efforts.
Felco SA continues to lead in the niche of high-precision electric pruning shears, leveraging its heritage of iconic designs. The company recently unveiled the FELCO 2e electric successor to its legendary model, featuring patented CUT SHIELD technology and enhanced battery efficiency. This release reinforces Felco's commitment to precision and durability, targeting users who demand the highest standards of cutting performance and reliability. Similarly, STIHL Group has maintained its aggressive posture in the cordless battery pruning segment. At CES 2026, the company launched the GTA 30 battery-powered pruner, boasting 400W cutting power tailored for residential and DIY applications. This launch expands STIHL's reach beyond professional arborists into the consumer and light commercial markets, demonstrating a strategy of capturing demand across multiple user tiers.
Makita Corporation has also made significant strides with its 18V LXT brushless cordless pruning shears. The introduction of the DUP181Z brushless pruning shear in the 18V LXT line underscores Makita's focus on high-efficiency precision cutting, appealing to professionals who require seamless integration with existing battery ecosystems. This ecosystem lock-in strategy is a common theme among major tool manufacturers, and our analysis examines how it influences customer retention and competitive dynamics. On the value side, brands like Worx and RYOBI are competing with lightweight, affordable options. Worx focuses on its 20V PowerShare brushless pruning shears, emphasizing ergonomic, one-handed operation for branch trimming. RYOBI leverages its 18V ONE+ HP brushless line for quick, trigger-powered cutting of light pruning tasks, targeting users who prioritize ease and versatility.
DeWalt and Craftsman round out the competitive field with robust offerings designed for durability and high capacity. DeWalt's 20V MAX cordless pruning shears, such as the DCPR320 series, advertise high cut counts per charge, positioning the brand for shrub trimming and branch clipping applications. Craftsman's V20 cordless pruning shears offer substantial cut capacity and reliable performance, appealing to general contractors and serious DIY enthusiasts. The presence of these well-funded brands introduces intense price and feature competition, pressuring smaller players to differentiate through specialization or superior service. Additionally, specialized players like Pellenc SA have commercialized advanced series, such as the C3X series with integrated batteries and NFC connectivity, signaling a trend toward smart, connected tools in the professional segment.
Regulatory and market alerts also shape the competitive environment. Recent product safety alerts, such as the recall issued for Moore Electric Pruning Shears, highlight the importance of quality control and compliance. For market participants, these events serve as reminders of the risks associated with supply chain vulnerabilities and the necessity of rigorous testing. Companies that can maintain high safety standards and avoid such pitfalls can leverage compliance as a competitive advantage, building trust with institutional buyers and risk-averse procurement teams.
Regulatory Tailwinds and Macro-Economic Factors
Beyond product and competitive factors, the market is heavily influenced by regulatory frameworks and macro-economic conditions that are reshaping demand. In Europe, the EU Farm to Fork Strategy targets 25% organic farming by 2030, a policy directive that drives the adoption of precision, low-impact tools like electric pruning shears in major agricultural nations including France, Germany, Spain, and Italy. This regulatory push encourages farmers to invest in equipment that aligns with organic and sustainable practices, creating a sustained demand stream for compliant tools.
Furthermore, there is a growing regulatory focus on reducing occupational musculoskeletal disorders among agricultural and landscaping workers. This has accelerated the procurement of ergonomic electric pruning shears, as employers seek to mitigate health risks and improve worker retention. The EU Common Agricultural Policy 2023-2027 includes horticultural equipment subsidies that support technology adoption for electric pruning shears, effectively lowering the barrier to entry for many operators. These subsidies not only boost sales volumes but also encourage the transition from manual or gas-powered tools to electric alternatives.
Worldwide Power Shears Market
On the operational side, electric pruning shears are delivering tangible labor savings in commercial orchards and vineyards. Professional models now enable up to 2000+ cuts per charge, significantly reducing the manpower required for pruning tasks and allowing for faster completion of seasonal work. This labor reduction is particularly valuable in regions facing labor shortages or rising wage costs. The combination of subsidy support and demonstrated ROI through labor savings creates a compelling business case for adoption, ensuring that demand is driven by both compliance and economic rationality.
Strategic Conclusion and Recommendations for 2026
As enterprises evaluate their strategic priorities for 2026 and beyond, the Electric Pruning Shears Market presents a landscape rich with opportunity but demanding of careful navigation. The projected growth, anchored by a solid CAGR and supported by favorable regulatory and technological trends, suggests that the market will continue to expand and evolve. However, success will depend on more than just participating; it will require a nuanced understanding of segment-specific needs, competitive differentiation, and the ability to anticipate shifts in consumer and institutional behavior.
For manufacturers, the emphasis should be on balancing innovation with reliability. The market is rewarding products that offer extended battery life, ergonomic design, and sufficient cut capacity, but it is also sensitive to quality and safety standards. Investment in R&D should focus on maintaining competitive edges in battery efficiency, motor performance, and user interface, while ensuring that supply chains remain robust and compliant. For distributors and retailers, understanding the varying needs of application segments—from high-end vineyards to residential landscaping—is essential for inventory optimization and targeted marketing. Partnerships with brands that have strong ecosystem compatibility or unique value propositions may yield strategic advantages.
For agricultural and landscaping businesses, the procurement decision should extend beyond unit price to total cost of ownership, including labor savings, maintenance, and lifecycle durability. The availability of subsidies and the potential for improved worker health outcomes should be factored into the investment rationale. As the market matures, differentiation will increasingly come from service, support, and the ability to integrate tools into broader operational workflows.
This market intelligence report serves as a foundational resource for making informed decisions in this dynamic environment. By providing deep insights into market size, segmentation nuances, competitive dynamics, and regulatory influences, the study equips stakeholders with the knowledge necessary to identify high-potential avenues and mitigate risks. We invite you to explore the full report for a comprehensive analysis, including detailed data tables, forecasting models, and strategic recommendations tailored to specific business objectives. The future of pruning is electric, and those who act with foresight will define the next era of horticultural efficiency.
Electric Pruning Shears Market
For detailed analysis of this topic, please visit the official page: Electric Pruning Shears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: English Language Learning Market to Hit $344.8M by 2032, 6.98% CAGR from $215M in 2025
By PW Consulting, 2026-09-16
Strategic Intelligence for the ELT Sector: Why the 2026 Language Learning Market Report Is Essential for Executive Decision-Making
The English Language Learning market is undergoing a structural transformation that few organizations are equipped to navigate with confidence. Between historical fluctuations and compound growth trajectories, the sector has moved from fragmented experimentation to consolidated demand patterns. For corporate leaders, investors, and institutional strategists operating in 2026, surface-level market headlines are no longer sufficient. What matters is a disciplined reading of how technology adoption, regulatory shifts, learner behavior, and competitive positioning intersect to shape revenue pipelines, product roadmaps, and regional expansion strategies.
PW Consulting has prepared a comprehensive research study designed specifically for decision-makers who require actionable intelligence rather than generic market summaries. This article outlines the strategic architecture of that research, demonstrates how macro-level market dynamics inform 2026 planning cycles, and explains why the granular segmentation, competitive profiling, and scenario-based analysis contained in the full report are critical for organizations seeking durable advantage in a rapidly evolving sector.
The 2026 Market Context: Growth With Complexity
Over the past half-decade, the English Language Learning sector has progressed from a post-pandemic recovery phase into a more mature expansion cycle. The market reached an estimated 205.57 million USD in 2024, advanced to 215.0 million USD in 2025, and is projected to continue its upward path through the 2026-2032 forecast window. This trajectory reflects sustained demand across professional upskilling, academic preparation, migration-driven language acquisition, and enterprise training programs. Yet the headline trajectory alone masks the strategic tensions that matter most to executives.
A compound annual growth rate of 6.98 percent during the forecast period signals healthy expansion, but growth at this pace rarely distributes evenly across products, geographies, or buyer segments. The real strategic question for 2026 is not whether the market is growing, but where value is concentrating, which distribution channels are capturing disproportionate share, and how the mix between institutional procurement and individual self-directed spending is reshaping customer acquisition economics. Organizations that treat the market as monolithic risk misallocating capital toward channels or product formats that may be structurally disadvantaged in the next cycle.
The full research study breaks down these dynamics with a level of segmentation precision that allows leadership teams to distinguish between broad sector tailwinds and specific commercial opportunities. Rather than relying on generalized growth narratives, the report maps how structural demand drivers interact with format preferences, regional purchasing environments, and application-type adoption patterns, giving strategists a practical framework for prioritizing investments and adjusting go-to-market assumptions.
What the Research Delivers: Operational Content for Decision-Makers
This study is constructed as a decision-support instrument, not an academic survey. Its architecture is designed to help executives, product leaders, and market-entry teams answer concrete questions about positioning, resource allocation, and competitive exposure. The report integrates both historical reconstruction and forward-looking scenario analysis so that readers can test strategic assumptions against a range of plausible market outcomes.
The core content areas include:
- A detailed market sizing and trajectory analysis that reconstructs past performance and extends the outlook across the full forecast horizon, enabling leaders to benchmark internal expectations against sector-wide momentum.
- A multi-dimensional segmentation framework that separates the market by region, product type, and end-user application, allowing teams to evaluate where demand is most structurally supported and where growth may be more volatile or contingent on external factors.
- A competitive landscape assessment that profiles major participants, examines their strategic orientations, and identifies how differing business models—digital-first platforms, blended academy models, assessment-driven offerings, and enterprise-focused programs—compete for the same learner pools.
- An analysis of market concentration and consolidation signals, helping stakeholders assess whether the sector is fragmenting toward niche specialization or consolidating around platforms that can combine content, technology, and distribution at scale.
- A regulatory and policy environment review that places recent institutional changes within the broader context of language education governance, student support frameworks, and multilingual service guidance, all of which can influence procurement behavior, compliance requirements, and program design assumptions.
In addition to these structural analyses, the report incorporates recent industry developments that directly affect planning assumptions. Signals ranging from federal administrative adjustments to regional program guidance are evaluated for their potential impact on institutional funding flows, learner demand patterns, and the operating environment for service providers. This contextual layer is essential for organizations that need to anticipate how policy recalibration may alter demand concentration or shift purchasing authority within education and enterprise channels.
The full document is organized to support rapid executive consumption as well as deeper cross-functional alignment. Strategists can use it to pressure-test market-entry theses, product leaders can use it to assess whether existing feature sets align with emerging buyer expectations, and finance teams can use the segmentation structure to refine revenue forecasts with more defensible assumptions about where growth is most likely to materialize.
Competitive Landscape: How Strategic Positioning Is Evolving
The English Language Learning market is contested by a diverse set of players whose strategic postures differ not only in scale but in underlying value propositions. The research evaluates the competitive environment through the lens of commercial model, distribution reach, learner engagement strategy, and institutional vs. individual orientation. This approach matters because competition in the sector is increasingly defined by how effectively companies integrate content quality, technology-enabled personalization, assessment infrastructure, and brand trust across distinct buyer segments.
Several large, established organizations anchor the market with multi-layered offerings that span curriculum, assessment, and proficiency certification. Pearson, based in London, competes through a broad suite of English Language Teaching courseware, assessment services, and proficiency testing solutions that address institutions, governments, and individual learners. Its positioning reflects an orientation toward structured institutional procurement and credibility-driven evaluation tools, making it a relevant benchmark for organizations assessing how assessment and credentialing capabilities influence purchasing decisions.
English Language Learning Market
International immersion and cultural-exchange-focused operators occupy a different strategic space. EF Education First, headquartered in Baar, Switzerland, has built its identity around immersive English programs and cross-cultural learning experiences. Berlitz, operating from the United States, emphasizes immersive instruction built around its signature teaching method, serving individuals, businesses, and government clients. These companies illustrate how experiential and instructor-mediated models continue to compete against purely digital approaches, particularly in segments where outcomes depend heavily on speaking confidence, cultural familiarity, or enterprise credibility.
The digital learning frontier is represented by a cluster of platform-driven companies with distinct user acquisition and engagement strategies. Duolingo, based in Pittsburgh, has popularized mobile and web-based bite-sized lessons that lower the barrier to habitual practice for English and other languages. Rosetta Stone, headquartered in Harrisonburg, Virginia, focuses on immersive computer-assisted learning with speech recognition capabilities that aim to strengthen pronunciation and listening proficiency. Babbel, based in Germany, pursues online subscription-based lessons structured around scientific learning methods for English. Wall Street English, with its base in Italy, differentiates through guaranteed-results course models supported by coaches and teachers, blending digital convenience with human accountability.
In parallel, network-based and infrastructure-oriented providers shape the operational environment for institutions and training centers. inlingua International, headquartered in Switzerland, operates through blended and online language training centers, while Sanako Corporation, based in Finland, focuses on language lab software and hardware that support classroom pronunciation and speaking-skill development. These offerings matter because they influence the technical backbone available to institutions seeking to standardize instruction, track learner progress, and scale language practice in structured settings.
Taken together, these competitive profiles reveal a market in which advantage is increasingly tied to the ability to combine scalable technology with credible outcomes signaling. The research explores how different players are attempting to capture value across the Learner journey—acquisition, practice, assessment, certification, and institutional adoption—and where overlaps in target segments create pressure on pricing, retention, and differentiation. The complete report provides deeper comparisons of business-model resilience, channel dependencies, and the strategic implications of recent product and market developments, without reducing the analysis to simple market-share statements.
Why This Report Matters for 2026 Strategy
Strategic decisions made in 2026 will be judged not by whether they aligned with last year’s assumptions, but by whether they anticipated how the market is reorganizing itself around format preferences, buyer motivation, and regulatory reality. A growth environment of this nature rewards organizations that can distinguish durable demand from temporary hype, and that can identify which customer segments are expanding their willingness to pay for structured learning, assessment, or enterprise-language solutions.
The report is designed to support that kind of judgment. It enables leadership teams to evaluate whether current expansion plans reflect genuine segment traction or simply broad sector optimism. It helps product and operations leaders assess whether their offerings are aligned with the channels and application types that are capturing the most sustainable demand. It also provides investors and corporate strategy teams with a structured way to think about concentration risk, competitive response patterns, and the likelihood that certain subsegments may consolidate faster than others.
Equally important, the research places recent policy and institutional developments in context so that executives can incorporate regulatory uncertainty into scenario planning rather than treating it as an external distraction. Shifts in federal administrative structures, changes in language-access guidance, and state-level adjustments to English learner program frameworks can all influence demand visibility, procurement timelines, and program-design constraints. Organizations that integrate these variables into strategic planning are better positioned to manage risk and identify emerging opportunities before competitors do.
Online Language Learning Market
The full study goes further than the overview presented here. It supplies the segmentation detail, company-level profiling, and forward-looking analysis needed to convert market awareness into concrete action. For teams that require defensible assumptions about where growth is concentrated, which business models are most exposed, and how the competitive field is likely to evolve, the complete research package provides the depth necessary to support board-level discussion, investment committee review, and cross-functional planning cycles.
Conclusion: Moving From Market Awareness to Strategic Precision
The English Language Learning market in 2026 is not simply expanding; it is reconfiguring. Demand continues to grow, but the strategic value of that growth depends on how precisely organizations can interpret segmentation signals, competitive behavior, and policy-driven changes in the operating environment. PW Consulting’s English Language Learning Market research is built to help executives make that interpretation with confidence, offering a structured, evidence-based foundation for decisions that will shape growth, positioning, and resilience over the coming years.
Organizations that want to move beyond high-level market narratives and into the detail that supports concrete strategy should review the complete report. The full analysis provides the segmentation clarity, competitor context, and forward-looking assessment needed to turn market movement into informed strategic action.
For detailed analysis of this topic, please visit the official page: English Language Learning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UPVC Window And Door Market Hits $28.4B In 2025, Projected 6.4% CAGR To $43.61B By 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the UPVC Window and Door Market in 2026 and Beyond
Executive Overview
The global construction and renovation landscape is undergoing a significant transformation, driven by stringent energy efficiency regulations, urbanization trends, and a growing emphasis on sustainable building materials. Within this evolving ecosystem, Unplasticized Polyvinyl Chloride (UPVC) windows and doors have emerged as a cornerstone solution for manufacturers, contractors, and homeowners alike. Our latest market intelligence report offers a comprehensive deep dive into this sector, providing the strategic clarity necessary for informed decision-making throughout the 2026-2032 forecast period.
This analysis serves as a strategic preview of our full market research publication. While we highlight the macro-economic trajectories and competitive forces shaping the industry, the complete dataset—including granular segmentation splits, precise regional revenue shares, and detailed financial modeling—remains an exclusive resource for our clients. Understanding the broad contours of the market is the first step; mastering the specific data points is where competitive advantage is forged.
Market Trajectory and Macro Economic Indicators
The UPVC window and door market has demonstrated robust resilience and growth over the past five years. Historical data from 2020 through 2025 indicates a consistent upward trend, reflecting the material's increasing adoption in both replacement markets and new construction projects. The market valuation, expressed in USD billions, has progressed steadily, signaling strong underlying demand fundamentals.
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion phase. Industry analysts anticipate a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely linear but is influenced by shifting demographic patterns, infrastructure spending, and regulatory pushes toward energy conservation. The trajectory suggests that by the early 2030s, the market will reach significantly higher valuation thresholds, presenting substantial opportunities for stakeholders who position themselves correctly during the current cycle.
Key macro indicators suggest that the industry is moving past a phase of volatility into a period of structured growth. However, realizing the full potential of this growth requires more than just observing top-line numbers. It demands an understanding of how different product types, application sectors, and geographic regions contribute to the aggregate figure. Our full report dissects these layers, providing the specificity needed to allocate capital efficiently and identify high-yield segments.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global players and agile regional specialists. Concentration metrics indicate a moderately consolidated environment where top-tier manufacturers hold significant influence. The CR3 and CR5 ratios suggest that while a few key players dominate the landscape, there remains ample room for differentiation through technology, design, and regional presence.
UPVC Window and Door Market
Leading manufacturers are actively maneuvering to secure their positions through capacity expansion, strategic partnerships, and innovation in profile systems. Major entities such as VEKA Group, Rehau, aluplast, and Deceuninck continue to set benchmarks in PVC profile systems and energy-efficient solutions. These companies are not merely competing on price but are engaging in sophisticated value-chain integrations. For instance, recent collaborations have focused on sustainability initiatives, such as partnerships aimed at promoting green construction practices and enhancing the lifecycle efficiency of window systems.
Regional dynamics also play a crucial role in competitive strategy. In North America, companies like United Window & Door are expanding production capacities to meet local demand, reducing reliance on imported profiles and strengthening supply chain resilience. Simultaneously, in Asia Pacific, manufacturers like Fenesta and LG Hausys are leveraging local manufacturing advantages to cater to booming residential and commercial sectors. TWR Group in the UK and other fabricators are also adapting their offerings to meet specific trade and commercial requirements.
Recent developments highlight the pace of change. Facility expansions involving significant capital investment have been announced to accommodate growing order books. Product launches introducing new systems, such as tilt-turn solutions and triple-track patio doors, indicate a focus on diversifying portfolios to capture niche demands. Furthermore, partnerships regarding finishes and materials suggest an industry-wide push toward aesthetic customization and performance enhancement. Understanding the specific timing and impact of these moves is critical for benchmarking one's own strategy against the market leaders.
Industry Dynamics: Cost Structures and Regulatory Pressures
One of the most critical factors influencing margin stability and pricing strategies is the cost of raw materials. UPVC profile costs account for a substantial portion of manufacturing expenses, making resin price fluctuations a key risk variable. Recent market intelligence indicates divergent trends across major regions. In Europe, PVC resin prices have seen upward pressure, impacting cost structures for profile manufacturers. Conversely, in markets like India, price adjustments have followed global supply chain realignments, presenting a different cost environment. These disparities create complex challenges for multinational strategists who must navigate varying input costs while maintaining competitive pricing.
Regulatory frameworks are equally influential. Government initiatives aimed at affordable housing and energy efficiency are acting as primary demand drivers. In the European Union, plans emphasizing renovation-first approaches and stringent energy efficiency standards are accelerating the replacement of old fenestration systems with high-performance UPVC alternatives. Industry associations have welcomed these developments, recognizing the potential for increased market volume. However, regulatory shifts also bring compliance complexities. For example, changes in logistics schemes regarding PVC window profile transport pallets require operational adjustments.
In emerging markets, protectionist measures are gaining traction. Industry bodies in regions like India have appealed for import controls on uPVC profiles to safeguard domestic manufacturing interests. Such policy developments can alter competitive dynamics overnight, favoring local producers while potentially restricting supply options for assembled goods. Monitoring these regulatory signals is essential for risk mitigation. Our detailed report provides a nuanced analysis of how these dynamics vary across sectors and regions, offering actionable insights on navigating the regulatory maze.
Segmentation and Application Opportunities
The market is multifaceted, segmented by window and door types, applications, and geography. While the aggregate market size provides a high-level view, the real strategic value lies in understanding the performance of specific segments. Product diversity ranges from casement and sliding systems to tilt and turn configurations and French doors. Each type serves different functional and aesthetic needs, commanding different market shares and growth rates. For example, energy-efficient tilt-turn systems are gaining traction in markets with strict thermal performance codes, while sliding systems remain popular in space-constrained residential settings.
Application-wise, the residential sector typically constitutes the largest share of demand, driven by housing starts and renovation activities. Commercial applications follow, fueled by office complexes, hospitality projects, and institutional buildings. Industrial applications, while smaller in volume, offer specialized requirements regarding durability and security. The interplay between these segments determines the overall health of the market. A slowdown in residential construction might be offset by a surge in commercial retrofitting, depending on economic conditions.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Developed markets may focus on replacement cycles and energy upgrades, while developing markets might see higher volume from new infrastructure projects. Our complete analysis breaks down these regional nuances without relying on broad generalizations, providing the specific intelligence needed to tailor go-to-market strategies.
Strategic Value for 2026 Decision Making
For executives and strategists, the ability to anticipate market shifts is paramount. The 2026 landscape offers both risks and rewards. On one hand, rising raw material costs and regulatory changes pose challenges to margin management and compliance. On the other hand, government incentives for energy efficiency and housing create clear demand pull. Navigating this environment requires more than intuition; it requires data-backed precision.
PVC Window Profile Market
Our market research report is designed to equip leaders with the tools necessary to make decisive moves. Whether it is evaluating potential mergers and acquisitions, planning capacity expansions, or refining product portfolios, the data provided serves as a foundational asset. The report goes beyond static numbers to offer context on how competitive moves, such as new facility openings or strategic partnerships, are reshaping the battlefield.
Furthermore, understanding the concentration of market power helps in assessing barriers to entry and the viability of niche strategies. Companies can identify gaps where innovation can disrupt incumbent players or where consolidation might be beneficial. The insights into recent developments—such as specific product launches and investment rounds—provide a real-time view of where competitors are placing their bets. This intelligence allows organizations to align their own roadmaps with emerging trends rather than reacting to them after the fact.
The forecast period through 2032 offers a long-term horizon for planning. Stakeholders can model various scenarios based on the projected CAGR and market valuation trends. This long-view perspective is crucial for capital-intensive decisions in manufacturing and distribution. By integrating macro trends with segment-specific data, organizations can build robust strategies that are resilient to short-term volatility while capitalizing on long-term growth vectors.
Conclusion
The UPVC window and door market stands at a pivotal juncture. The convergence of economic recovery, regulatory support for energy efficiency, and technological innovation in profile systems creates a fertile ground for growth. However, realizing this potential requires a sophisticated understanding of the market's inner workings.
This article has provided a high-level overview of the market's trajectory, competitive forces, and dynamic pressures. To access the complete landscape of intelligence discussed herein—including precise segmentation data, detailed regional breakdowns, and exhaustive company profiles—we invite you to explore our full market research report. The detailed intelligence contained within is designed to transform uncertainty into strategic clarity, empowering your organization to lead rather than follow in the years ahead.
For detailed analysis of this topic, please visit the official page: UPVC Window and Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ursodeoxycholic Acid Market to Reach $1.1B by 2032 with 10.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Ursodeoxycholic Acid Drug Product Market: Strategic Intelligence for 2026 and Beyond
The global landscape for hepatology therapeutics is undergoing a period of significant recalibration, driven by evolving regulatory frameworks, patent expirations, and a growing prevalence of chronic liver conditions. At the center of this shift stands Ursodeoxycholic Acid (UDCA), a compound that has long maintained its position as a foundational therapy. For pharmaceutical executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional; it is a critical component of portfolio optimization and competitive positioning. Our latest comprehensive market research report offers a granular examination of the UDCA drug product landscape, designed specifically to equip decision-makers with the actionable intelligence required to navigate the complexities of 2026 and the subsequent forecast period through 2032.
A Market on a Defined Growth Trajectory
The macroeconomic signals for the UDCA drug product market are unmistakable. Drawing on historical data spanning from 2020 through 2025, our analysis tracks a consistent upward arc in global revenue, measured in millions of US dollars. The baseline established in recent years reflects a compound annual growth rate that underscores sustained demand across multiple therapeutic areas. As we pivot into the forecast window of 2026 to 2032, the projection indicates a robust expansion that will reshape revenue pools and alter the calculus for market entry, capacity planning, and partnership strategies.
This growth is not merely a function of population expansion or generic substitution. It is being propelled by a confluence of factors: the chronic nature of primary biliary cholangitis, which demands long-term patient adherence and stable reimbursement pathways, and the ongoing utilization of UDCA as a first-line intervention under established FDA guidelines. Furthermore, the anticipated dominance of the generics segment, expected to command a substantial share of the market in 2026 following a wave of patent expirations, introduces a new dynamic of price pressure and volume-driven economics. Understanding how these forces interact requires more than top-line figures; it demands a dissection of the underlying structural drivers that our report meticulously maps out.
What Is Inside: A Blueprint for Operational and Strategic Execution
Our market research is structured to move beyond abstract trends and deliver concrete, operational utility. The report provides a multi-dimensional view of the UDCA drug product ecosystem, encompassing historical performance, forward-looking projections, and a detailed breakdown of the competitive and regulatory environment. Below is a preview of the core components that will enable your organization to translate market intelligence into decisive action.
- Historical and Forecast Revenue Analysis: A year-by-year examination of global revenue performance from 2020 through 2032, highlighting inflection points, growth acceleration, and the projected scale of the market as it approaches the end of the decade. Readers will gain clarity on the magnitude of the opportunity and the temporal windows most relevant to investment and capacity decisions.
- Segmentation Dynamics: A deep dive into the primary axes that define the market: dosage form, therapeutic application, and geographic distribution. The report evaluates how tablets and capsules compete for share, how indications such as gallstones and primary biliary cholangitis drive distinct demand profiles, and how regional markets are evolving in response to local regulatory, reimbursement, and supply chain conditions.
- Competitive Landscape and Corporate Profiles: An in-depth assessment of the leading integrated producers, generic suppliers, and specialized manufacturers shaping the market. Each profile includes geographic footprint, product positioning, and strategic implications for partnership, acquisition, or competitive defense.
- Recent Developments and Regulatory Intelligence: A curated timeline of pivotal events, including accelerated approvals for combination therapies targeting primary biliary cholangitis, new generic product launches, and updates to reimbursement and standard-of-care guidance. These developments are analyzed for their near-term and medium-term impact on market dynamics.
- Industry Context and Structural Forces: An examination of the reconcentration metrics that reveal the degree of market consolidation, alongside an assessment of supply chain considerations, raw material dynamics, and the reimbursement environment that underpins long-term patient access.
The Competitive Arena: Key Players and Strategic Positioning
The UDCA drug product market is characterized by a mix of established integrated manufacturers, global generic giants, and regional specialists. Our report provides detailed profiles of the companies that are actively shaping supply, pricing, and innovation within this space, offering a framework for evaluating competitive threats and partnership opportunities.
Among the most prominent participants is ICE Pharma, an Italy-based integrated producer that has built a significant presence in UDCA bile acid derivatives. With manufacturing capabilities spanning Europe, Latin America, Asia, and Oceania, and a distribution network that reaches over fifty countries, ICE Pharma exemplifies the globalized, vertically integrated model that can command respect in both branded and generic segments. For organizations evaluating supply chain resilience or seeking regional market access, ICE Pharma's footprint offers a case study in scale and geographic diversification.
Teva Pharmaceuticals, headquartered in Israel, represents a major force in the generic UDCA space, with an active supply of USP tablets and capsules. As one of the world's largest generic pharmaceutical companies, Teva's involvement signals both the maturity of the UDCA market and the ongoing relevance of high-volume, cost-competitive manufacturing. Similarly, Sun Pharmaceutical Industries Ltd, a leading Indian generic supplier, has reinforced its commitment to the market through recent product launches, underscoring the strategic importance of India as a production hub and the intensifying competition among generic manufacturers.
Daewoong Pharmaceutical, based in South Korea, adds another dimension to the competitive landscape as a supplier of UDCA drug products, including once-daily formulations. Formulation innovation and patient-centric dosing regimens are increasingly important differentiators, and Daewoong's presence highlights the potential for regional manufacturers to compete on convenience and adherence. In India, Mankind Pharma and Octavius Pharma Pvt. Ltd continue to be active manufacturers and suppliers of UDCA tablets, capsules, and API, reflecting the dense and competitive Indian manufacturing ecosystem that plays a critical role in global supply. Meanwhile, in the United States, Willow Birch Pharma and Lannett Company serve as active suppliers and manufacturers of generic UDCA products, catering to domestic demand and navigating the nuances of the US regulatory and reimbursement environment.
Ursodeoxycholic Acid Drug Product Market
Our report goes beyond company descriptions to analyze how these players interact within a market that, based on our concentration metrics, exhibits a moderate level of consolidation. With a focused analysis of market share distribution and the strategic implications of competitive density, decision-makers can better assess barriers to entry, the feasibility of niche positioning, and the potential for consolidation or partnership-driven growth.
Market Dynamics: Regulation, Reimbursement, and Supply Chain Forces
The structural underpinnings of the UDCA market are defined by a set of regulatory and reimbursement realities that create both stability and pressure. UDCA remains the standard first-line therapy for primary biliary cholangitis under FDA guidance, with no substantive changes reported through 2025. This continuity reinforces the compound's central role in treatment protocols and supports predictable demand over the long term. At the same time, the chronic nature of the disease drives sustained patient adherence, which in turn bolsters the case for consistent reimbursement coverage. For market participants, this dynamic translates into a durable revenue base, but also into heightened scrutiny of pricing, access, and the value proposition relative to emerging adjunct therapies.
On the supply side, the generics segment is anticipated to hold a significant majority share of the market in 2026, a shift driven by patent expirations on branded products and the resulting price pressure. This transition has profound implications for manufacturing strategy, margin expectations, and competitive differentiation. Companies that can optimize production efficiency, secure reliable API sourcing, and navigate regulatory compliance with agility will be best positioned to capture volume in a increasingly price-sensitive environment. Our report explores these supply chain and raw material dynamics in detail, offering insights into the operational levers that can determine success as the market tilts further toward generics.
Recent regulatory and commercial developments add further texture to the landscape. In 2024, the FDA granted accelerated approval for elafibranor for primary biliary cholangitis in combination with ursodeoxycholic acid, and shortly thereafter, accelerated approval for seladelpar in combination with ursodeoxycholic acid. These milestones, achieved by major pharmaceutical companies, signal a growing emphasis on combination and adjunct treatment paradigms for primary biliary cholangitis. While UDCA remains the foundational therapy, the emergence of combination approaches could reshape treatment pathways, create new co-marketing opportunities, and influence the competitive positioning of standalone UDCA products over time. Additionally, the recent launch of generic UDCA drug products by Sun Pharmaceutical Industries Ltd in late 2024 illustrates the ongoing pace of generic entry and the need for continuous monitoring of product availability, pricing shifts, and geographic rollout strategies.
Strategic Implications for 2026 Decision-Making
As organizations prepare for 2026, the UDCA drug product market presents a blend of opportunity and complexity that demands a disciplined strategic approach. The forecast period through 2032 suggests a market that will continue to expand materially, but the distribution of that growth across dosage forms, indications, and regions will not be uniform. Companies that rely on aggregate market figures alone risk missing the granular shifts that determine whether a product, a market entry, or a partnership will succeed or underperform.
Ursodeoxycholic Acid Market
For manufacturers, the anticipated dominance of the generics segment in 2026 underscores the importance of cost leadership, supply chain robustness, and regulatory agility. For branded and specialized players, the opportunity may lie in formulation differentiation, patient support programs, combination strategies, or targeted regional expansion where competitive density is lower. For investors and strategic advisors, the concentration metrics and competitive profiles provide a lens through which to evaluate market access, barriers to entry, and the potential for consolidation or vertical integration.
Reimbursement dynamics and the chronic disease context further emphasize the need for a long-term perspective. Patient adherence and sustained coverage create a relatively stable demand floor, but they also heighten the importance of demonstrating value, managing pricing expectations, and aligning with payer and provider priorities. The introduction of combination therapies and the evolving treatment landscape for primary biliary cholangitis add another layer of strategic consideration, as organizations must anticipate how new regimens may complement, compete with, or redefine the role of UDCA in standard care.
Why Comprehensive Intelligence Matters
The decisions that will shape your organization's position in the UDCA drug product market over the next several years depend on a clear, evidence-based understanding of the forces at play. Aggregate trends provide direction, but they do not replace the need for detailed segmentation, competitive profiling, regulatory tracking, and scenario analysis. Our full market research report delivers that depth, equipping stakeholders with the data and context required to make informed choices about capacity, product strategy, geographic focus, partnership structures, and competitive responses.
We invite you to access the complete report to explore the full scope of our analysis, including the specific regional and application-level insights, detailed company assessments, and forward-looking projections that will support your strategic planning for 2026 and beyond. In a market defined by both continuity and change, the organizations that thrive will be those that invest in the intelligence needed to act with precision, anticipate shifts before they become disruptive, and align their capabilities with the most promising avenues for growth.
For detailed analysis of this topic, please visit the official page: Ursodeoxycholic Acid Drug Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: VLM Market Hits $1.6B in 2025, Surges to $2.6B by 2032 at 9.25% CAGR
By PW Consulting, 2026-09-16
Strategic Vertical Lift Module Market Assessment 2026: Capitalizing on Automation Momentum
The operational landscape for automated storage and retrieval systems is undergoing a definitive structural shift. As supply chain resilience becomes a board-level priority, the Vertical Lift Module Market is emerging as a critical lever for enterprise efficiency. Our latest research publication, Vertical Lift Module Market 2026, provides a comprehensive strategic roadmap for navigating this high-growth sector. This analysis is designed to equip decision-makers with the intelligence required to optimize capital allocation, mitigate supply chain risks, and capitalize on the accelerating adoption of high-density automated storage solutions.
Vertical Lift Module (VLM) Market
Based on rigorous historical analysis and forward-looking modeling, the global market for Vertical Lift Modules has demonstrated robust expansion over the past five years. Historical revenue figures from 2020 through 2025 show a consistent upward trajectory, culminating in a strong baseline entering the forecast period. Projections for the forecast window extending to 2032 indicate sustained momentum, driven by the urgent need for space optimization and labor efficiency in modern logistics and manufacturing environments. The market is expected to grow from a substantial 2025 baseline to a significantly larger valuation by the end of the forecast period, underpinned by a compound annual growth rate reflecting high single-digit expansion. This growth trajectory signals that demand for automated vertical storage is not cyclical but structural, influenced by long-term operational imperatives rather than short-term fluctuations.
Operational Imperatives Driving Market Expansion
The fundamental drivers of this market growth are deeply rooted in the operational constraints facing modern enterprises. As urbanization increases and industrial real estate costs escalate, the economic pressure to maximize cubic space utilization has intensified. Vertical Lift Modules offer a compelling solution by reclaiming significant floor space and leveraging ceiling height for storage density. Industry analysis highlights that these systems support broader sustainability initiatives by reducing energy waste through efficient vertical space utilization in warehouse operations. Furthermore, the economic case for adoption is strengthening. Automated VLM systems deliver a compelling return on investment within a relatively short timeframe through labor savings derived from increased picking efficiency. With modern systems capable of delivering picking rates exceeding several hundred picks per hour, the labor productivity gains are substantial, directly impacting bottom-line performance in sectors facing chronic labor shortages.
Competitive Dynamics and Strategic Positioning
The competitive landscape for the Vertical Lift Module Market is characterized by a moderate level of concentration, with established players leveraging technological differentiation and regional manufacturing footprints to secure market share. Our research provides detailed profiles of key market participants, analyzing their specific value propositions, geographic strengths, and technological focus areas.
Leading Market Participants:
- Modula (Casalgrande, Reggio Emilia Province, Italy): A recognized leader in automated vertical storage, focusing on their specific offering for the Vertical Lift Module Market with Modula Lift and Modula Slim fully automated vertical storage systems. Their solutions are engineered to reclaim up to 90% floor space by utilizing ceiling height, offering a distinct advantage in space-constrained environments. Their recent product developments highlight a focus on specialized configurations; in October 2025, Modula released a comparison highlighting differences between traditional Vertical Lift Modules and their Modula Flexibox specialized bin-based configuration for high-volume picking, underscoring their strategy to address diverse throughput requirements.
- White Systems (Hamilton, Ohio, USA): White Systems emphasizes robust, US-manufactured enclosed automated storage and retrieval systems, including the PowerColumn 3 and Compact Lift models. These heavy-duty and compact solutions are engineered for demanding applications, offering up to 99% picking accuracy. A significant strategic development occurred in February 2026, when SencorpWhite, the parent company of White Systems, established a new US headquarters in Hamilton, Ohio. This move is designed to support continued investment in American-made VLM manufacturing, signaling a commitment to localized supply chains and potentially influencing regional market dynamics and lead times for North American clients.
- Kardex (Switzerland): Kardex brings a global footprint with a focus on tray-based enclosed automated storage systems, specifically the Kardex Shuttle. Their strategy centers on the Total Intelligence Concept control system, designed for operator-centric picking, enhancing usability and integration with broader warehouse workflows. In January 2025, Kardex introduced an upgraded Kardex Shuttle Vertical Lift Module with the Total Intelligence Concept control system featuring an intuitive user interface, demonstrating a continuous investment in user experience and control system sophistication to maintain competitiveness.
- Vidir Solutions (Arborg, Manitoba, Canada): Vidir Solutions provides high-density automated vertical storage systems tailored for industrial and healthcare applications. Their VLM and VLM Mini solutions are focused on reclaiming up to 85% floor space, positioning them as a key player in sectors where space efficiency and hygiene or safety standards are paramount. Their emphasis on industrial and healthcare applications suggests a strategic niche focus within the broader VLM ecosystem.
The concentration of the market remains notable, with leading entities commanding a significant share of global revenue. This concentration fosters an environment where technological innovation and specialized application focus are key differentiators. Our research dissects these competitive interactions, providing insights into how incumbents are defending their positions and where new entrants might find opportunity gaps.
Macro-Economic Variables and Regulatory Considerations
Strategic planning in this sector requires a nuanced understanding of macro-economic variables and regulatory frameworks that influence both supply and demand. Our report integrates critical external factors that impact project feasibility and total cost of ownership.
Supply Chain and Raw Material Dynamics
Cost structures for VLM manufacturing are sensitive to raw material fluctuations. For instance, hot-rolled coil steel prices have shown variability, averaging approximately $1,109 per ton as of June 2026, with upward trending futures into mid-2026. These commodity price movements directly affect the cost of construction for steel-intensive automated storage units. Decision-makers must account for these input cost trends when evaluating procurement strategies and long-term contracts, as price volatility can impact project timelines and budget allocations.
Intelligent Automatic Warehouse And Logistic Equipment Market
Regulatory Compliance and Certification
Compliance requirements add a layer of complexity to market entry and product deployment, particularly in regulated regions. VLM units require CE certification to meet strict European safety, efficiency, and compliance guidelines for automated storage systems. Adherence to these standards is not merely a legal formality but a critical enabler for market access and customer trust in Europe. Our analysis examines how regulatory landscapes shape product specifications and the competitive advantages derived from early compliance and certification readiness.
Deep Dive into Research Methodology and Content Architecture
The Vertical Lift Module Market 2026 report is structured to provide actionable intelligence at multiple levels of strategic planning. The research leverages a multi-tiered analytical framework, synthesizing historical performance data with forward-looking indicators to construct a reliable outlook through 2032.
- Market Sizing and Trajectory Analysis: The report provides detailed revenue valuations for the historical period and the forecast horizon. By analyzing year-over-year growth patterns from 2020 to 2025, the study establishes a robust baseline that accounts for market corrections and acceleration phases. The forecast period projections isolate key drivers to estimate market size evolution, offering a clear view of the total addressable market and growth velocity.
- Segmentation Insights: Understanding the heterogeneity of demand is essential for targeted strategy development. The research segments the market based on key dimensions, allowing stakeholders to identify high-growth niches and volume drivers. While specific regional and application splits are detailed within the full report, the analysis highlights how different segments are evolving in response to industry-specific needs. For example, the dominance of certain material types and application areas points to where technological standardization and scale economies are most pronounced, while other segments may represent emerging opportunities requiring tailored approaches.
- Competitive Intelligence: Beyond company profiles, the report examines strategic moves, product launches, and expansion activities. Recent developments, such as Kardex's control system upgrade, Modula's configuration differentiation, and White Systems' manufacturing footprint expansion, are analyzed not just as isolated events but as indicators of broader competitive strategies. These developments reveal how companies are responding to market pressures, whether through enhanced functionality, supply chain localization, or product versatility.
- Market Concentration and Power Dynamics: The research quantifies market concentration levels, providing context for negotiation leverage and partnership opportunities. A moderately concentrated market suggests that while key players hold significant influence, there remains room for specialized integrators and regional service providers to capture value. Understanding these power dynamics is crucial for vendors seeking distribution partnerships and for end-users evaluating supplier stability and support capabilities.
Strategic Implications for 2026 Decision-Makers
As organizations evaluate automation investments in 2026, the Vertical Lift Module Market presents both opportunities and complexities. The convergence of labor economics, real estate constraints, and technological maturity creates a favorable environment for VLM adoption. However, the diversity of available solutions and the influence of external factors such as raw material costs and regulatory requirements demand a disciplined evaluation process.
Our research serves as a decision-support tool to navigate this environment. It enables stakeholders to benchmark potential solutions against market standards, assess the viability of deployment in specific operational contexts, and anticipate competitive responses. For investors and analysts, the detailed market sizing and segmentation offer a foundation for valuation and risk assessment. For manufacturers and system integrators, the competitive landscape analysis provides insights into positioning, differentiation, and potential areas for strategic collaboration or innovation.
The forecast period through 2032 suggests that the current growth trajectory will persist, though the rate and composition of growth may shift as technology matures and new applications emerge. Early movers who align their strategies with the structural drivers identified in this research are likely to secure competitive advantages in efficiency and market share. Conversely, organizations that overlook the nuances of this market risk suboptimal capital deployment and missed opportunities to enhance operational resilience.
Conclusion and Access to Full Intelligence
The Vertical Lift Module Market is poised for sustained expansion, driven by the imperatives of space optimization, labor efficiency, and automation integration. The strategic value of this market extends beyond immediate productivity gains, touching on broader themes of supply chain agility and sustainability. Our comprehensive research report, Vertical Lift Module Market 2026, delivers the depth of analysis required to make informed decisions in this dynamic environment.
To fully leverage these insights, we invite stakeholders to access the complete report. The full publication contains detailed regional and application breakdowns, granular competitor benchmarking, and extensive data tables that support precise scenario planning. By exploring the complete dataset, decision-makers can uncover the specific growth vectors and competitive signals that are most relevant to their strategic objectives. Visit our source page to download the full market intelligence and equip your organization with the knowledge needed to lead in the automated storage sector.
For detailed analysis of this topic, please visit the official page: Vertical Lift Module (VLM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


