

Blogs
Global Stainless Steel Bailers Market: Why 6.82% CAGR and Groundwater Demand Redefine Growth
By PW Consulting, 2026-09-18
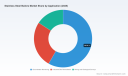
Navigating the Stainless Steel Bailers Market: Strategic Shifts and Commercial Frontiers (2025–2032)
Market Overview and Core Challenges
The global stainless steel bailers market has matured into a specialized yet steadily expanding segment, characterized by consistent demand from environmental monitoring, industrial remediation, and materials processing applications. Between 2020 and 2025, the sector demonstrated resilient growth, settling into an estimated revenue trajectory that extends through 2032. Current market sizing places the industry at approximately USD 54.6 million in 2025, with projections indicating a compound annual growth rate of 6.82 percent through the forecast horizon. By 2032, total market revenue is expected to surpass USD 86.5 million, reflecting sustained institutional procurement cycles and gradual substitution of legacy sampling equipment with corrosion-resistant alternatives.
This growth trajectory is neither uniform nor guaranteed. The market operates within a fragmented ecosystem where three leading manufacturers collectively account for roughly a third of total revenue, while the top five players capture just under half. Such concentration suggests that scale advantages exist, yet the remaining share is distributed across regional specialists, niche fabricators, and emerging equipment assemblers. This structural dispersion creates both operational friction and strategic opening. Companies that rely on standardized product lines without adapting to regional compliance requirements or material specifications frequently encounter margin compression and slower order conversion. Conversely, firms that align manufacturing capabilities with localized sampling protocols and decontamination standards are capturing repeat contracts and longer equipment lifecycles.
Three intersecting challenges currently define the market’s inflection point. First, material cost volatility and geographic price divergence are reshaping cost structures. Stainless steel pricing has shown meaningful variation across major sourcing corridors, forcing manufacturers to recalibrate procurement strategies, hedge inventory exposure, or shift production footprints to maintain competitive pricing without sacrificing metallurgical integrity. Second, regulatory expectations around contamination control and sampling integrity are accelerating design evolution. Buyers increasingly require equipment that eliminates cross-sample interference, supports rapid decontamination, and avoids legacy sealing materials that compromise analytical accuracy. Third, the convergence of corrosion-resistant sampling tools with broader industrial compaction and recycling equipment is blurring traditional category boundaries. Organizations that previously sourced bailers and balers from entirely separate supply chains are now evaluating integrated procurement frameworks, which pressures incumbent suppliers to clarify product positioning and avoid internal cannibalization.
These dynamics do not merely represent operational headwinds; they function as signal filters for market entry, product investment, and partnership strategy. Firms that treat the current period as a static demand environment risk misallocating engineering resources and missing procurement consolidation windows. Those that recognize the overlap between material science, compliance timing, and procurement behavior can position themselves ahead of specification shifts and contract renewal cycles.
Key Drivers Reshaping the Market
Technological innovation is reshaping how stainless steel bailers are specified, manufactured, and deployed in the field. Advances in forming precision, weld integrity, and surface finishing have moved crevice-free and mirror-polished configurations from premium custom orders toward standard expectations for high-integrity sampling. Equipment engineered with fully welded seams, controlled internal geometries, and removable top and bottom assemblies reduces residual contamination risk and shortens decontamination cycles. These design attributes directly translate into fewer sampling errors, faster site turnaround, and lower long-term replacement frequency, which procurement teams increasingly value when comparing total cost of ownership rather than upfront unit price alone.
Stainless Steel Sink Market
Regulatory and compliance environments are exerting parallel pressure on product architecture. Environmental sampling standards continue to tighten around PFAS-related concerns and analytical purity, prompting manufacturers to introduce sealing and component configurations that avoid contamination pathways. Equipment supplied with PFAS-free O-ring options and fluoropolymer check mechanisms is gaining preference in groundwater monitoring programs where regulatory bodies and laboratory partners demand verifiable sample integrity. At the same time, safety and hygiene certification requirements are influencing broader stainless steel equipment categories, including compaction and recycling machinery used in sensitive operational environments. Compliance with recognized safety standards and material traceability documentation is becoming a procurement prerequisite rather than an optional differentiator.
Worldwide Stainless Steel Fermenter Market
Demand-side behavior is shifting as end users consolidate sampling programs and prioritize equipment durability over short-cycle replacement. Groundwater monitoring remains the dominant application driver, supported by ongoing environmental assessment, site characterization, and regulatory compliance activities. Industrial site remediation and mining or geological survey work contribute additional demand, particularly where repeated borehole access, composite sample collection, and field decontamination efficiency matter. Procurement teams in these segments are increasingly favoring reusable stainless steel configurations that withstand repeated cleaning, resist pitting and stress corrosion in demanding media, and support standardized attachment or retrieval systems across multiple well diameters.
Supply chain and cost structure changes are reinforcing these demand trends. The broader stainless steel market continues to expand on the back of industrial equipment demand, yet regional price differentials require deliberate sourcing strategies. Manufacturers operating with transparent material grade documentation and consistent finish specifications can command stronger positioning in procurement evaluations, especially when buyers need to verify material provenance for compliance records. Meanwhile, the cost of non-compliance is rising. Equipment that fails to support adequate decontamination, introduces particulate or chemical interference, or requires excessive maintenance adds hidden operational expense that outweighs initial savings. This reality is pushing buyers toward suppliers that can demonstrate repeatable quality control, consistent metallurgical specifications, and service-ready component designs.
Taken together, these drivers suggest that the market’s growth will be defined less by volume expansion alone and more by specification upgrading, compliance alignment, and procurement rationalization. Companies that integrate material traceability, contamination-reducing design, and service-friendly construction into their product roadmaps are better positioned to capture share in contracts where sample integrity and operational efficiency carry significant weight.
Competitive Landscape and Leading Strategies
The competitive field reflects a mix of established environmental sampling specialists, regional fabricators, and broader industrial equipment manufacturers whose stainless steel product lines touch overlapping customer needs. Several firms have anchored their positioning around durability, material grade consistency, and decontamination efficiency. Manufacturers offering 304 and 316 stainless steel configurations with removable ends, tapered profiles, or fully welded and crevice-free interiors are emphasizing ease of cleaning, material compatibility, and long service life in sampling contexts. These design choices are not merely technical preferences; they function as commercial signals that align with buyer priorities around repeat use, sample protection, and reduced field downtime.
Differentiation is increasingly expressed through compliance readiness and application-specific fit rather than generic durability claims. Some suppliers have focused on groundwater sampling specifications that support composite collection, well retrieval, and rapid decontamination, with material and sealing configurations chosen to meet environmental testing expectations. Others have extended stainless steel bailer and baler capabilities into hygiene-sensitive or heavy-duty environments, where certification documentation, surface finish quality, and corrosion-resistant construction support procurement requirements in food-adjacent, recycling, or industrial processing settings. This divergence in focus illustrates how the market is splitting into application-driven sub-positions, even as the underlying material and manufacturing technologies overlap.
The landscape is evolving along three observable directions. First, consolidation remains selective rather than sweeping. Larger players with established distribution channels and recognized product lines are gaining incremental advantage through repeat procurement relationships and specification familiarity, but the market still accommodates specialized manufacturers that can respond faster to regional compliance nuances or custom size requirements. Second, segmentation is sharpening. Procurement teams are distinguishing between bailers intended for high-integrity environmental sampling and balers or compactors used in scrap handling and recycling workflows. Suppliers that clearly articulate these boundaries, while retaining shared manufacturing efficiencies where possible, are less exposed to comparison confusion and margin erosion. Third, new entrants and re-entering competitors are leveraging trade platforms and regional supply networks to validate technology relevance and sourcing connectivity. Industry gatherings and supplier exhibitions continue to function as alignment points where component suppliers, fabricators, and end users compare material options, finish standards, and integration requirements. The resulting visibility can accelerate adoption of newer specifications, particularly when they address contamination control, material traceability, or cleaning efficiency.
Strategic advantage in this environment belongs to organizations that combine consistent metallurgical control with clear application positioning. Firms that invest in repeat-use durability, rapid decontamination design, and documented material conformity can compete on reliability rather than price alone. At the same time, those that maintain responsive production for diameter variations, sealing options, and region-specific compliance documentation are better equipped to capture procurement cycles where buyers evaluate total operational impact rather than unit economics in isolation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The market’s next phase will likely be defined by specification upgrades, procurement consolidation, and continued convergence between sampling integrity and broader industrial stainless steel equipment requirements. One central trend is the deepening preference for contamination-minimizing construction and sealing configurations. As sampling programs face more stringent analytical expectations and laboratory partnership requirements, equipment that supports crevice-free geometries, controlled finishes, and alternative sealing materials will become harder to replace with lower-specification alternatives. This trend favors suppliers that can standardize such features without sacrificing production efficiency or inflating lead times.
A second trend is the increasing alignment of procurement decisions with total lifecycle value. Buyers are paying closer attention to decontamination speed, corrosion behavior under repeated use, and component accessibility for cleaning and inspection. This shift rewards manufacturers that design for serviceability and repeated field use, and it pressures those that compete primarily on initial price to justify hidden maintenance or replacement costs. Over the next several years, contract renewals and multi-unit procurement agreements are likely to reflect these lifecycle considerations more explicitly, creating opportunities for suppliers with demonstrable durability records and consistent quality control.
A third trend involves regional sourcing strategy adaptation in response to material cost divergence and compliance documentation expectations. As buyers verify material grades, certification traceability, and finish consistency, suppliers that can provide clear documentation and stable specification control will gain an edge in evaluation processes. At the same time, regional price variation will continue to push manufacturers toward more deliberate procurement routing, inventory planning, and production allocation. Companies that treat material cost fluctuation as a design and sourcing variable rather than a passive input are more likely to preserve margins while meeting specification demands.
These trends carry commercial opportunity, but also risk. Demand for higher-specification equipment may intensify competition among capable manufacturers, compressing differentiation if multiple suppliers converge on similar construction standards. Regulatory language around contamination and sampling integrity may also evolve, requiring product updates or documentation adjustments that are not always predictable in timing. Additionally, if downstream sampling programs reduce activity levels or shift toward alternative collection methods in certain regions, revenue growth could become uneven across applications. Firms that monitor specification changes, procurement behavior, and material cost movement will be better placed to adjust product emphasis and contract strategy before cycles turn.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize specification clarity and design-for-cleaning as core commercial levers. Where product lines span multiple applications, maintaining clear distinctions between environmental sampling configurations and industrial compaction or recycling equipment reduces comparison confusion and protects positioning. Engineering effort is best directed toward repeatable weld quality, accessible decontamination design, and documented material conformity, since these attributes increasingly influence procurement evaluation beyond initial pricing.
Investors and strategic partners should evaluate exposure to specification-driven demand rather than volume assumptions alone. Companies with strong documentation practices, consistent metallurgical control, and application-specific positioning are more likely to retain purchase cycles in environments where sample integrity and compliance requirements carry weight. Monitoring procurement consolidation, regional price dynamics, and certification expectations provides early signals about which product categories will face margin pressure and which will command stronger retention.
Procurement teams and end users should structure evaluations around total operating impact. Variables such as decontamination time, residual contamination risk, corrosion behavior under repeated use, and material traceability can materially affect program reliability and long-term cost. Requesting consistent specification documentation and comparing lifecycle implications across diameter options, sealing configurations, and finish standards supports more resilient sourcing decisions, especially when equipment is deployed across multiple sites or monitoring campaigns.
For decision-makers seeking a deeper mapping of segment dynamics, competitive positioning, and procurement trends across regions and applications, the full PW Consulting market analysis provides expanded segmentation detail, scenario-based projections, and customization options tailored to internal planning needs.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Bailers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bio-based Ethylene Glycol Market: Why 8.25% CAGR and Asia Pacific Leadership Change Everything
By PW Consulting, 2026-09-18
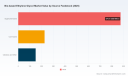
The Strategic Inflection Point: Worldwide Bio-based Ethylene Glycol Market Trends and Commercial Opportunities
1. Market Reality: Navigating Scale, Sustainability Mandates, and Feedstock Complexity
The global market for bio-based ethylene glycol has crossed a structural threshold. In 2025, worldwide revenue reached approximately USD 1,250 million, reflecting a compound annual growth rate of 8.25 percent projected through 2032. The trajectory since 2020 reveals a market that has matured beyond early experimentation into a phase of disciplined scaling, with values moving from USD 890.5 million in 2020 to USD 1,194.92 million in 2024 before stabilizing at the current baseline. This growth pattern is not linear; it reflects the interplay of capacity ramp-ups, feedstock availability, and the pace at which downstream customers are willing to integrate renewable building blocks into established supply chains.
Three structural tensions define the current operating environment. First, feedstock economics remain the primary variable in cost competitiveness. Sugarcane ethanol, molasses-derived bio-ethanol, and corn-based dextrose each carry distinct agricultural, logistical, and carbon-intensity profiles, creating regional asymmetries in both supply reliability and margin structure. Producers must navigate commodity volatility while maintaining sustainability credentials that downstream buyers increasingly demand.
Second, certification and traceability have shifted from optional compliance to commercial prerequisites. The adoption of frameworks such as ISCC Plus in European markets underscores a broader reality: sustainability claims now require verifiable chain-of-custody documentation. This raises the operational bar for producers and introduces administrative complexity that smaller or regionally confined players must absorb to remain viable in premium channels.
Third, the market exhibits a moderate degree of concentration, with the top three players holding approximately 42.5 percent of revenue and the top five capturing 61.2 percent. This concentration signals that scale, feedstock integration, and established commercial relationships still confer meaningful advantages. At the same time, it leaves room for specialized entrants and joint ventures that can bring differentiated technology or regional feedstock access, particularly as lignocellulosic pathways move from pilot validation toward commercial deployment.
2. Core Drivers Reshaping the Market Trajectory
Technological Innovation and Feedstock Diversification
The most consequential shift in the bio-based ethylene glycol landscape is the parallel advancement of first-generation and second-generation feedstock pathways. Sugarcane ethanol remains the commercially mature and cost-competitive anchor, particularly in regions with established agricultural ethanol infrastructure. Corn-based dextrose has gained traction where corn processing capacity and dextrose economics align with industrial-scale conversion. Meanwhile, second-generation lignocellulosic feedstocks, including corn stover, wheat straw, and bagasse, are increasingly viewed as a strategic lever to reduce reliance on food-grade sugars and lower feedstock costs by an estimated 25 to 35 percent over the medium term.
PW Consulting
This diversification is not merely an academic improvement; it directly affects capacity planning and geographic positioning. Recent developments illustrate the trend: UPM has progressed toward introducing wood-sourced bio-based monoethylene glycol at its Leuna biorefinery in Germany, targeting around 220,000 tons of lignocellulosic-based output. In parallel, a Chinese pilot plant technology using corn stalks and straw sugars has achieved approximately 1,000 metric tonnes of annual capacity, supported by over 40 patents that point to potential scale-up. These signals suggest that feedstock flexibility will increasingly determine where production can be economically located and which customer segments can be reached without compromising carbon or cost targets.
Policy, Regulation, and Certification Dynamics
Regulatory and certification frameworks are acting as both a catalyst and a gatekeeper. European markets, in particular, are reinforcing traceability expectations through mechanisms such as ISCC Plus certification, which enables documented sustainability claims for bio-based and bio-circular hydrocarbons. This dynamic raises the bar for market entry in premium segments, but it also rewards producers who can embed verification into their operating model rather than treating it as an afterthought.
The implication is twofold. For established players, certification-ready supply chains can become a commercial moat, enabling access to customers who need defensible sustainability narratives. For new entrants, the cost and complexity of certification increase the importance of early alignment with recognized standards, especially when targeting European packaging and textile customers. Policy expectations are also accelerating the value of bio-based content in applications where brands are under pressure to reduce fossil-derived inputs, which in turn strengthens demand-side pull for renewable glycol feedstocks.
Demand-Side Shifts Across Packaging, Textiles, and Industrial Applications
Demand is being reshaped by downstream customer priorities more than by any single regulatory mandate. Packaging and bottles represent the largest application segment, driven by brand-level commitments to renewable content, recyclable packaging systems, and consumer-facing sustainability messaging. Textiles and fibers form a second major demand base, where polyester producers and fiber manufacturers are increasingly seeking bio-based building blocks to differentiate in highly competitive markets. Industrial and coolant applications, while smaller in scale, provide steady demand that can help stabilize utilization rates during periods of feedstock or pricing volatility.
The commercial pattern emerging here is one of selective adoption rather than blanket replacement. Downstream customers are not uniformly switching to bio-based ethylene glycol; they are prioritizing applications where the sustainability narrative translates into tangible brand value or regulatory alignment. This creates a premium corridor for producers who can deliver consistent quality, traceability, and reliable volume, while also leaving room for conventional or blended solutions in cost-sensitive segments.
Supply Chain Configuration and Cost Structure Evolution
Cost structures are being redefined by geography, feedstock logistics, and the economics of scale. Brazil’s access to sugarcane ethanol, India’s molasses-based bio-ethanol ecosystem, and North America’s corn-based dextrose infrastructure create distinct cost baselines that influence where bio-based ethylene glycol can be produced most efficiently. At the same time, second-generation feedstocks are broadening the opportunity set by enabling utilization of agricultural residues that may offer lower input costs and reduced exposure to food-commodity volatility.
Recent commercial activity reflects this reconfiguration. Braskem continues to evaluate a joint venture for biobased ethylene glycol production from corn dextrose in Indiana as part of its renewable chemicals portfolio, while its Sustainea joint venture with Sojitz is advancing a planned USD 400 million facility in Lafayette, Indiana to convert corn-based dextrose into monoethylene glycol at commercial scale, with startup targeted from 2028. These moves indicate that North America is becoming an increasingly relevant arena for corn-based renewable glycol, complementing established sugarcane and molasses routes elsewhere.
3. Competitive Landscape and Leadership Strategies
Established Leaders and Differentiated Positioning
The competitive field includes players with distinct feedstock access, technology routes, and geographic advantages. India Glycols Limited operates as one of the largest commercial producers of bio-based monoethylene glycol from molasses-based bio-ethanol, with long-standing industrial-scale production supplying PET, polyester, and related applications. Its scale and established customer relationships provide a durable base in segments where reliability and volume matter. Braskem and the Sustainea joint venture are strengthening the corn-based and sugarcane-ethanol pathways, leveraging existing bio-ethanol platforms and partnerships to advance renewable monoethylene glycol for packaging and textiles.
Avantium is pursuing a technology-led differentiation through its PlantMEG offering, developed via proprietary Ray Technology from renewable sugars, with an emphasis on plant-based monoethylene glycol for sustainable PET and polyester applications. UPM is positioning around lignocellulosic feedstock, using wood-sourced material at its Leuna biorefinery to target packaging and fiber markets with a lower food-grade-sugar dependency. Together, these players illustrate a market that is not converging on a single winning route, but rather segmenting by feedstock, technology, and end-use positioning.
Bio Methanol Market
Strategic Themes Among Leaders
Several patterns stand out in how leading participants are positioning themselves:
- Feedstock integration as a strategic asset. Companies with access to sugarcane ethanol, molasses-based bio-ethanol, or corn-based dextrose can better manage input risk and anchor cost structures, especially where agricultural-platform synergies exist.
- Commercial readiness over pilot novelty. Scale-up decisions are increasingly driven by the ability to deliver consistent volume and certification-ready supply, not simply by technical feasibility. The planned Sustainea facility and UPM’s Leuna preparation reflect a focus on commercial execution timelines.
- Application-aligned messaging. Successful positioning tends to connect bio-based glycol to specific downstream value, whether in packaging sustainability, polyester differentiation, or industrial reliability, rather than presenting the product as a generic renewable substitute.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The landscape is evolving along multiple axes. Concentration at the top suggests that scale and established distribution relationships remain important, particularly for large-volume contracts. At the same time, technology differentiation and regional feedstock opportunities are enabling specialized entrants to compete in defined niches. The rise of lignocellulosic pathways and regional corn-based dextrose projects adds further fragmentation potential, especially if cost and carbon-intensity advantages translate into commercial advantage at scale.
A plausible trajectory is selective consolidation in volume-driven segments paired with continued differentiation in technology-led or application-focused segments. New entrants will need either a credible feedstock advantage, a defensible conversion technology, or strong downstream partnerships to avoid being squeezed between established scale players and premium sustainability positioning.
4. Forward Outlook: Where the Market Is Heading
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, lignocellulosic and residue-based feedstocks will move from proof-of-concept toward early commercial relevance. If cost reduction targets in the 25 to 35 percent range are realized at scale, these pathways could broaden geographic options and reduce exposure to food-grade sugar volatility. This would create opportunities for producers and partners who can secure reliable residue supply and operate conversion assets efficiently.
Second, certification and traceability will increasingly function as commercial infrastructure rather than a compliance layer. Customers in Europe and other regulated or brand-sensitive markets will continue to reward documented sustainability claims, which means the ability to provide chain-of-custody assurance may become as important as price and volume. This favors organizations that build traceability into procurement, production, and logistics from the outset.
Third, regional supply chains will become more distinct. Sugarcane-linked routes will remain strong where ethanol infrastructure is mature, corn-based dextrose routes will expand in North America, and lignocellulosic projects will test the viability of non-food feedstocks in new locations. The result will be a more geographically diversified market, with regional cost and carbon profiles influencing where bio-based ethylene glycol is produced and purchased.
These trends create commercial opportunity, but also uncertainty. Feedstock availability can shift with agricultural cycles and competing demand from fuels and other bio-based chemicals. Scale-up risk remains real, particularly for second-generation pathways that must prove reliability at commercial volumes. Pricing dynamics may also pressure margins if conventional glycol costs move favorably or if multiple capacity additions converge faster than downstream adoption. The strategic response is to treat these uncertainties as variables to be actively managed through feedstock diversification, certification readiness, and application-targeted commercial strategy.
5. Decision-Maker Playbook: Actionable Priorities
For Manufacturers and Producers
Prioritize feedstock flexibility and certification readiness as core operational capabilities, not peripheral initiatives. Evaluate whether existing or planned capacity aligns with the most defensible feedstock route in your target geography, and build traceability into production and logistics early so sustainability claims can support commercial positioning. Where possible, structure partnerships or joint ventures that reduce scale-up risk while securing access to either established feedstocks or emerging lignocellulosic supply.
For Investors
Focus on the intersection of feedstock economics, technology readiness, and downstream demand quality. The most attractive opportunities are likely to combine credible feedstock access, a clear path to commercial-scale conversion, and customers who can absorb a sustainability premium or achieve regulatory alignment. Monitor capacity announcements, pilot-to-commercial transitions, and certification developments as indicators of which pathways are moving from potential to execution.
Polyethylene Glycol (PEG) Market
For Procurement and Supply Chain Leaders
Align bio-based ethylene glycol sourcing with application value rather than treating it as a blanket substitution. Identify segments where renewable content strengthens brand positioning, regulatory compliance, or customer relationships, and secure supply from partners who can provide verifiable traceability and consistent quality. Diversify feedstock exposure where feasible to reduce vulnerability to regional commodity swings or certification gaps.
For organizations seeking a deeper, segment-level view of regional dynamics, feedstock pathways, application mixes, and company-level strategic positioning, the full research report provides more granular data and tailored recommendations to support planning across these rapidly evolving market conditions.
For detailed analysis of this topic, please visit the official page: Worldwide Bio-based Ethylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharma Grade Calcium Hydroxide Market: Beyond the 5.36% CAGR, Unpacking Regional and Form Splits
By PW Consulting, 2026-09-18
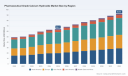
Strategic Trends and Commercial Opportunities in the Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Market Overview and Core Challenges
The global market for pharmaceutical grade calcium hydroxide has demonstrated steady expansion over the past half-decade, reflecting the compound's critical role in drug formulation, dental procedures, and specialized manufacturing processes. Valued at approximately 49.3 million USD in 2020, the market reached 64.2 million USD by 2025, and current projections indicate a trajectory toward 92.55 million USD by 2032. This growth path corresponds to a compound annual growth rate of 5.36 percent, signaling a mature yet consistently expanding sector where incremental gains compound over time.
Pharmaceutical Grade Sodium Chloride Market
The revenue base is distributed across multiple forms and applications, with powder formats capturing the largest share of commercial activity. Liquid and suspension variants represent a meaningful secondary segment, particularly in applications requiring uniform dispersion or handling flexibility. From an application standpoint, endodontic and dental filling procedures constitute the most significant demand driver, underscoring the material's established utility in clinical settings. Secondary demand streams include active pharmaceutical ingredient synthesis coupled with pH regulation workflows, as well as the use of calcium hydroxide as an excipient or calcium supplement in nutritional medicines. Geographically, demand is broadly distributed, with Asia Pacific, North America, and Europe each representing substantial portions of total volume. Emerging regions in Latin America and the Middle East and Africa contribute smaller but growing shares, reflecting gradual healthcare infrastructure development and localized manufacturing capacity.
Concentrated market dynamics shape the current landscape. The top three participants command roughly 38.4 percent of total revenue, while the five largest firms account for approximately 52.15 percent. This level of concentration suggests established relationships, entrenched quality certifications, and meaningful barriers to entry for new manufacturers seeking to compete on purity, regulatory compliance, or supply reliability.
Key Challenges at the Inflection Point
Despite the favorable growth narrative, several structural challenges are reshaping how companies plan capacity, pricing, and compliance investments.
-
Raw material cost volatility and environmental compliance pressure. Calcium hydroxide is produced through the hydration of quicklime, itself derived from calcination of high-calcium limestone. Recent data from Northeast Asia shows prices reaching 0.14 USD per kilogram in December 2025, a 12.7 percent increase from September of that year. The surge stems from rising upstream quicklime and energy costs, compounded by supply constraints linked to environmental compliance. These input pressures are not isolated; they reflect a broader pattern where production cost bases are increasingly sensitive to energy markets and regulatory-driven operating conditions.
-
Evolving emissions standards for lime manufacturing. Regulatory authorities in the United States finalized amendments to National Emission Standards for Hazardous Air Pollutants targeting lime manufacturing plants, addressing previously unregulated hazardous air pollutant emissions from lime kilns. In parallel, broader expectations around hazardous air pollutant and potential greenhouse gas emission standards are increasing scrutiny of kiln operations. For calcium-based compound producers, these developments can translate into higher capital expenditure requirements, operational adjustments, and cost structure changes that affect competitiveness.
PW Consulting -
Purity expectations and cross-application regulatory complexity. The material is simultaneously used in pharmaceutical manufacturing, food-grade formulations, and laboratory processes. U.S. FDA regulations explicitly list calcium hydroxide USP as an approved alkali for color additives exempt from certification, including caramel production for food use. This dual-use reality requires manufacturers to maintain rigorous documentation, lot traceability, and grade-specific production controls. Companies that struggle to separate or certify distinct purity tiers face higher compliance costs and greater risk of customer disqualification.
Key Drivers Shaping Market Evolution
The sustained expansion of pharmaceutical grade calcium hydroxide is not merely a function of incremental demand. It is shaped by a convergence of technological, regulatory, demand-side, and supply-side dynamics that are altering competitive requirements and opening differentiated opportunities for firms that respond proactively.
Technological Innovation and Purity Differentiation
Technical differentiation is becoming a decisive competitive lever. Leading producers are emphasizing ultra-low impurity profiles, targeting reductions in aluminum, iron, and manganese content that can interfere with pharmaceutical synthesis, nutritional formulations, or sensitive endodontic applications. High-purity calcium hydroxide meeting FCC, USP, and BP specifications is increasingly expected rather than treated as a premium add-on. Manufacturers that invest in controlled calcination conditions, advanced hydration processes, and rigorous analytical testing can command stronger customer loyalty and improve pricing resilience.
The practical impact of this trend is that technical capability now functions as a barrier to entry and a retention mechanism. Buyers in API synthesis and pH adjustment workflows select suppliers based on impurity thresholds, batch consistency, and documented certificates of analysis. In dental and endodontic applications, consistency and biocompatibility expectations further reward suppliers with mature quality management systems. Over time, these requirements are likely to compress the viable supplier base toward firms that can demonstrate repeatable purity performance rather than simply meet baseline specifications.
Regulatory Environment and Compliance Costs
The regulatory environment is shaping both demand and supply. On the demand side, explicitly approved usage pathways expand the addressable market. For example, the inclusion of calcium hydroxide USP in FDA regulations for color additives exempt from certification validates its role in food-related manufacturing, which can indirectly benefit producers with multi-grade capabilities. On the supply side, emissions-related amendments for lime manufacturing facilities introduce new compliance obligations. National emission standards targeting hazardous air pollutants from lime kilns, along with broader environmental performance expectations, increase the cost of maintaining operating permits and upgrading combustion or filtration systems.
This dual pressure creates a clear strategic implication: regulatory expertise is becoming a source of competitive advantage. Suppliers that anticipate emissions rule implementation, incorporate environmental compliance into capacity planning, and communicate transparently about product grade integrity will be better positioned to retain pharmaceutical and laboratory customers. Conversely, firms that treat compliance as a retrospective cost rather than a forward-looking operational design parameter may face margin compression and customer attrition.
Demand-Side Shifts in Healthcare and Manufacturing Practices
Demand patterns are evolving as healthcare procedures and pharmaceutical manufacturing practices mature. The prominence of endodontic and dental filling applications reflects the sustained clinical use of calcium hydroxide in pulp capping, disinfection, and related procedures. As dental care access expands in developing markets and as clinical protocols continue to favor established materials with predictable performance, demand for high-quality medical-grade material remains robust. Simultaneously, the role of calcium hydroxide in API synthesis and pH adjustment is supported by broader pharmaceutical production activity, where precise pH control and alkali selection influence yield, purity, and downstream processing efficiency.
Another demand-side driver is the use of calcium hydroxide within excipients and calcium supplements, where formulation reliability and mineral quality are central to product acceptance. Across these segments, procurement behavior is increasingly risk-averse: buyers favor suppliers with validated quality systems, consistent lead times, and clear regulatory documentation. This shift encourages longer-term supply relationships and rewards manufacturers that can provide not just a chemical product, but a documented, auditable supply solution.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by energy costs, upstream lime availability, and regional production constraints. As noted in recent market data, regional price movements can be pronounced when energy costs rise or when compliance-driven constraints tighten supply. These fluctuations affect downstream procurement strategies, prompting buyers to consider regional sourcing, inventory buffers, and multi-supplier frameworks rather than relying on single-source procurement.
At the same time, large distributors and diversified chemical suppliers are extending their reach by offering pharmaceutical-grade calcium hydroxide alongside other specialty materials. This distribution model can improve availability, simplify procurement for smaller manufacturers, and create value through logistics and technical support. However, it also intensifies pressure on niche producers to differentiate through purity, technical service, or regional responsiveness. The net effect is a market where cost structures are increasingly tied to energy, compliance, and logistics, and where value capture depends on the ability to manage these elements while maintaining grade integrity.
Competitive Landscape and Leading Strategies
The competitive field includes manufacturers and distributors spanning North America, Europe, and Asia, with notably strong activity among Indian producers and Western suppliers serving pharmaceutical, laboratory, and food-related end markets. The current landscape is characterized by distinct strategic positions rather than a single unified approach.
Strategic Positioning of Leading Players
Several companies illustrate the range of viable strategies in this market. One U.S.-based producer specializes in high-purity calcium hydroxide with FCC/USP grades and ultra-low impurities, including low aluminum, iron, and manganese, targeting pharmaceutical synthesis and nutritional formulations. This profile reflects a purity-centric strategy where technical specifications and traceability are the primary differentiators. Another U.S. supplier provides pharmaceutical-grade material meeting USP standards for laboratory and manufacturing use, emphasizing consistent availability and compliance-aligned documentation for research and production environments.
Indian manufacturers represent a significant and differentiated cohort. Firms based in Maharashtra, Uttarakhand, and Gujarat produce calcium hydroxide in BP/USP/FCC/ACS grades, often with ISO-9001-2015 and GMP certifications. Their value proposition combines pharmaceutical and food-grade capabilities with regional cost advantages, enabling them to compete on price while maintaining accredited quality systems. Some Indian producers also pursue national standard participation, including involvement in drafting standards for food-additive calcium hydroxide, which can strengthen downstream acceptance and create reputational advantages in regulated markets.
European participants add further diversity. One German firm offers high-purity mineral salts including pharmaceutical-grade calcium hydroxide, while a major global distributor supplies calcium hydroxide across pharmaceutical and industrial applications. The distributor model emphasizes breadth, logistics, and technical support, often serving customers who prefer consolidated sourcing or who require flexible regional fulfillment. Another U.S. company provides calcium hydroxide suitable for food and pharmaceutical applications, reinforcing the multi-grade strategy that allows a single producer to serve overlapping demand streams.
Differentiation and Market Evolution
Across these profiles, differentiation is concentrated in a few recurring themes. Purity and impurity control remain central, especially for buyers in API synthesis and sensitive formulations. Certifications and audit-ready documentation are increasingly treated as baseline expectations. Regional availability and lead-time reliability influence purchasing decisions, particularly for dental and laboratory customers with tight production schedules. Multi-grade capability, allowing a supplier to serve pharmaceutical, food, and laboratory needs from related production assets, can broaden revenue opportunities and improve asset utilization.
Market evolution is likely to proceed through both consolidation and selective fragmentation. Concentration data indicates that a limited number of participants already command a meaningful share of revenue, and this pattern may persist as larger or better-capitalized firms invest in compliance, technical service, and supply reliability. At the same time, specialized producers with strong purity credentials or regional certifications can sustain defensible positions by serving high-value segments where specification control and documentation outweigh price alone. New entrants will face meaningful hurdles, not because the chemistry is complex, but because pharmaceutical customers require proven quality systems, consistent supply, and regulatory alignment that take time to build.
The role of distributors is also likely to expand as procurement teams seek flexibility. Distributors can aggregate supply from multiple producers, reduce administrative burden, and provide technical logistics support. However, their growth depends on the willingness of manufacturers to maintain consistent grade integrity and on buyers' confidence that distributor-supplied material meets the same specifications as direct procurement.
Future Trends and Commercial Implications
Looking ahead to the 2026-2032 period, three trends are likely to shape market behavior and commercial outcomes.
1. Compliance-Linked Cost Structures Will Become a Strategic Variable
Emissions-related standards for lime manufacturing and broader environmental expectations will continue to influence production economics. As facilities adapt kiln operations, filtration, and monitoring processes, cost structures will evolve. Suppliers that plan for compliance as part of capacity design, rather than reacting after rule implementation, will be better able to preserve margins and maintain supply continuity. Buyers should anticipate periodic cost pressure and build procurement strategies that incorporate resilience, such as qualified alternate sources and contract structures that account for input volatility.
2. Purity and Documentation Will Drive Segment Winners
As pharmaceutical, dental, and laboratory buyers increasingly prioritize impurity control and traceable documentation, firms that can consistently deliver USP/FCC/BP-grade material with low contamination profiles will capture disproportionate value. This trend favors producers with strong analytical capabilities, disciplined batch control, and transparent certification practices. It also suggests that multi-grade producers with clear internal segregation between pharmaceutical and food grades may gain advantage by reducing cross-contamination risk and simplifying audits.
3. Regional Demand Growth and Distribution Models Will Redefine Access
Demand growth is expected to remain broad-based, with Asia Pacific, North America, and Europe continuing to anchor volume, while Latin America and the Middle East and Africa contribute incremental expansion as healthcare and manufacturing capacity develop. distributors and regional suppliers are likely to play a larger role in connecting producers with end users, especially where localized availability, technical support, and flexible logistics are valued. For manufacturers, this creates opportunities to expand reach without necessarily building extensive direct sales infrastructure, provided product quality and documentation remain dependable.
Potential risks include sharper-than-expected energy price swings, tightening environmental requirements that accelerate cost escalation, and the possibility that procurement teams shift toward alternative alkalis or formulation approaches in specific applications. These uncertainties do not undermine the overall growth trajectory, but they do emphasize the need for flexible sourcing and continuous monitoring of regulatory and input-cost developments.
Actionable Guidance for Decision-Makers
The evolving market environment rewards proactive positioning. Different stakeholders can derive distinct value from a focused response.
For Manufacturers
-
Invest in purity assurance and analytical documentation as core capabilities rather than support functions. Ultra-low impurity profiles and audit-ready certificates can improve retention in pharmaceutical and dental segments.
-
Incorporate environmental compliance into capacity and operational planning. Anticipating emissions standards and energy cost exposure can reduce surprise margin compression and protect supply reliability.
-
Evaluate multi-grade production strategies carefully. Clear segregation between pharmaceutical and food-grade output can reduce risk while enabling broader customer coverage.
For Investors
-
Assess companies based on their ability to manage compliance-linked cost structures, maintain grade integrity, and serve stable demand segments such as endodontics, API synthesis, and excipient use.
-
Look for suppliers and distributors with diversified geographic exposure and credible certifications, since these attributes support resilience amid input volatility and regulatory change.
-
Monitor consolidation potential among smaller producers and the strategic role of distributors, as both can reshape competitive dynamics over the forecast period.
Magnesium Hydroxide Market
For Procurement and Supply Chain Leaders
-
Diversify sourcing where feasible, balancing price with purity credentials, lead-time reliability, and documentation quality. Single-source dependence can increase exposure to regional price spikes or compliance disruptions.
-
Align supplier selection with application sensitivity. Dental and API synthesis uses may warrant stronger emphasis on impurity control and traceability, while less sensitive uses may allow broader sourcing flexibility.
-
Track regulatory developments affecting lime manufacturing and downstream material availability. Early awareness can support contract planning and inventory decisions.
Given the interplay of purity requirements, regulatory shifts, energy-linked cost dynamics, and regional demand growth, timely access to detailed segment data and customized strategic assessment is essential for effective decision-making. For deeper visibility into regional breakdowns, application-level demand patterns, pricing trajectories, and competitor-specific positioning, the full PW Consulting market report provides expanded data coverage and tailored implications across manufacturing, investment, and procurement scenarios.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cosmetic Grade Urolithin A Market: Why 18.05% CAGR And 98% Purity Catalysts Change Everything
By PW Consulting, 2026-09-18
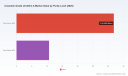
The Cosmetic Grade Urolithin A Market: Strategic Trends and Commercial Opportunities in Cellular Skincare
The global market for cosmetic grade Urolithin A has entered a phase of rapid expansion, driven by a convergence of biotechnology breakthroughs, shifting consumer preferences toward cellular-level skincare, and incremental regulatory clarity in key markets. With a compound annual growth rate of approximately 18% through 2032, the category is transitioning from an emerging scientific concept to a commercially viable active ingredient portfolio. Revenue projections indicate a sustained upward trajectory, positioning Urolithin A alongside established mitochondrial-supporting compounds and next-generation peptide technologies. This growth is not merely a function of pricing dynamics or temporary marketing cycles; it reflects a structural shift in how formulators and brands approach skin longevity, barrier resilience, and topical bioactivity.
Worldwide Cosmetic Grade Retinol Market
At its core, Urolithin A represents a metabolite derived from ellagitannins and ellagic acid, naturally processed through gut microbiota metabolism. In cosmetic applications, it is valued for its potential to support mitochondrial function, cellular energy renewal, and anti-aging pathways when delivered in topical formats. The market's macroeconomic momentum is underpinned by consistent investment in synthesis and purification capabilities, alongside growing clinical and preclinical interest in mitochondrial health as a lever for skin rejuvenation. However, the category is not without friction. As a relatively new cosmetic active, manufacturers and brand owners must navigate evolving regulatory pathways, particularly around ingredient notification, safety substantiation, and claims language. The absence of a fully harmonized global framework means that regional divergence in approval timelines, documentation requirements, and local market access strategies continues to shape go-to-market planning.
PW Consulting Chemical & Energy Research Center
A second challenge lies in the technical complexities of purity and formulation stability. Cosmetic grade Urolithin A must meet stringent specifications for active content, impurity profiles, and compatibility with emulsified or anhydrous systems. Achieving and maintaining high-purity grades through scalable synthesis or extraction pathways remains a differentiator, especially as premium product architectures demand actives that can be integrated without compromising sensory performance or shelf stability. Third, the category is still building consumer-facing science narratives. Unlike well-known antioxidants or retinoid derivatives, Urolithin A operates in a conceptually sophisticated space that requires clear, credible messaging around cellular renewal, mitochondrial support, and measurable skin benefits. Brands that can translate biochemical mechanisms into tangible product outcomes are better positioned to capture premium pricing and loyalty, while those relying on vague longevity claims risk consumer skepticism and regulatory scrutiny.
Food Grade Urolithin A Market
These dynamics set the stage for a market that is growing quickly but remains selective in how value is created and captured. Success will depend on the ability to combine technical rigor, regulatory fluency, and product storytelling in ways that resonate with both formulators and end consumers.
Key Drivers Shaping the Market Trajectory
Biotechnology Innovation and Purity Advancement
One of the most consequential drivers is the ongoing advancement in synthesis, fermentation, and purification technologies. High-purity cosmetic grade Urolithin A lowers barriers for premium formulations, where active consistency and impurity control are critical to safety assessments and performance claims. As manufacturing processes mature, suppliers are increasingly able to offer grades tailored to specific application needs, from stable emulsions to concentrated serums and mask formats. This technical maturation also supports broader adoption by reducing variability across batches and enabling formulators to design products with predictable sensory and stability profiles. In parallel, research into delivery mechanisms and topical bioavailability continues to refine how Urolithin A can be integrated into skin-facing architectures without compromising integrity, which strengthens its appeal for anti-aging and skin protection formulations.
Regulatory Milestones and Ingredient Recognition
Regulatory progress in key markets is another pivotal driver, particularly where new cosmetic ingredient frameworks enable structured market entry. In China, recent approvals and filings have provided clearer pathways for Urolithin A as a cosmetic active, including recognition for skin protection and anti-aging applications. These milestones reduce ambiguity for manufacturers seeking to incorporate the ingredient into commercially distributed products and encourage local and international brands to evaluate Urolithin A within their pipelines. Meanwhile, in other major cosmetic markets, the absence of restrictive prohibitions has allowed Urolithin A to be positioned as an innovative anti-aging ingredient with topical clinical interest. The net effect is a more predictable environment for product development, though companies still need to maintain robust documentation, safety data, and region-specific compliance strategies to scale efficiently.
Consumer Demand for Longevity-Oriented Skincare
Demand-side momentum is increasingly shaped by a broader cultural and consumer shift toward longevity, wellness, and proactive skin health. Skincare consumers are moving beyond reactive correction toward products that frame aging as a biological process that can be supported through targeted actives. This mindset aligns closely with the narrative potential of Urolithin A, which connects mitochondrial function and cellular renewal to visible skin concerns such as firmness, texture, and resilience. Brand owners are responding by developing product architectures that emphasize scientific credibility, transparency, and demonstrable benefits, often pairing advanced actives with well-established delivery systems. As a result, Urolithin A is finding traction in premium anti-aging creams, serums, and rejuvenation masks where formulation sophistication and ingredient storytelling can command higher value perception.
Supply Chain Maturation and Competitive Manufacturing Capacity
The supply side is evolving as multiple manufacturers expand production capabilities and diversify sourcing strategies. Competition among suppliers is encouraging improvements in scale, quality control, and application support, which benefits formulators seeking reliable access to cosmetic-grade material. At the same time, supply chain resilience has become a strategic priority, with buyers placing greater emphasis on vendor qualification, consistency, and the ability to support launch timelines. Manufacturers that can combine high-purity output with GMP-aligned production practices and responsive technical service are increasingly preferred partners, particularly for larger brand programs that require dependable volumes and regulatory-grade documentation. This supply-side maturation is helping transform Urolithin A from a niche ingredient into a more accessible building block for contemporary skincare portfolios.
Competitive Landscape and Leading Strategies
The competitive field for cosmetic grade Urolithin A reflects a blend of proprietary ingredient developers, precision manufacturers, and bulk suppliers serving both cosmetic and adjacent personal care applications. Companies with differentiated positioning tend to emphasize either clinical-grade purity, application-specific formulation expertise, or regulatory readiness in priority markets. Rather than competing solely on price, leading players are building value through active branding, scientific backing, and the ability to support downstream product development with technical documentation and stability insights.
A notable strategic divergence is emerging between proprietary active platforms and broader supply-oriented manufacturers. Proprietary approaches often center on branded Urolithin A ingredients that are integrated into specific skincare lines and supported by targeted communication around mitochondrial renewal and skin anti-aging. This model enables closer collaboration with brand partners and supports premium positioning through ingredient recognition and formulation ecosystems. In contrast, supply-oriented producers focus on scalable output, purity consistency, and flexible grading to meet varied formulation needs. This pathway is particularly relevant for manufacturers and private-label brands that seek dependable raw material access without necessarily requiring a proprietary active narrative. Both models have merit, and the market is increasingly accommodating multiple entry points depending on brand strategy, price architecture, and technical requirements.
Regulatory fluency is becoming a defining capability. Companies that have secured or are actively progressing ingredient notifications in major markets gain a meaningful advantage in speed-to-market and brand confidence. Approvals and filings that recognize Urolithin A for skin protection and anti-aging use not only validate the ingredient's cosmetic relevance but also reduce ambiguity for downstream users. This is especially important in regions where cosmetic ingredient governance is tightening and documentation expectations are rising. Firms that proactively maintain compliance readiness, including safety data packages, usage parameters, and region-specific labeling considerations, are better positioned to support brand partners through launch and scaling.
Market structure is also evolving through consolidation and specialization. Larger brand collaborations and high-profile product launches can accelerate category visibility and create demand spikes that influence supplier prioritization. At the same time, the proliferation of manufacturers indicates room for continued new entry, particularly where quality, cost efficiency, and application support are clearly demonstrated. Over time, the landscape is likely to differentiate further: premium branded actives will compete on science, positioning, and partnership ecosystems, while volume-oriented suppliers will compete on reliability, scale, and cost-competitiveness. For buyers, this means that supplier selection will increasingly hinge on alignment between ingredient strategy, regulatory pathway, and formulation objectives rather than on commodity benchmarks alone.
A practical implication is that competitive advantage will depend on the ability to connect ingredient quality with credible product outcomes. Companies that can demonstrate consistent purity, provide formulation guidance, and align with regional compliance expectations will have stronger positioning than those competing on price in isolation. As visibility grows, the market is likely to reward players who can convert scientific promise into repeatable commercial execution.
Forward-Looking Trends for the Next Three to Five Years
One of the clearest forward trends is the continued elevation of Urolithin A within premium anti-aging and cellular skincare categories. As formulators gain more experience integrating the ingredient across creams, serums, masks, and targeted treatments, product architectures will likely become more refined and application-specific. This should support a move toward differentiated claims and more precise product positioning, particularly where brands can pair Urolithin A with complementary actives and delivery systems that reinforce visible skin benefits. The strategic opportunity here is not simply to include the ingredient, but to design complete formulations that make its mechanism understandable and perceptible to consumers.
A second trend is the growing importance of regulatory and documentation maturity as a market-access prerequisite. As awareness of cosmetic-grade Urolithin A expands, buyers and regulators will likely place greater emphasis on traceability, quality consistency, claims substantiation, and region-specific filing status. Companies that invest early in robust technical packages and compliance readiness will be better equipped to enter new geographies, support larger brand programs, and reduce launch risk. This trend also implies that ingredient suppliers with strong regulatory orientation will increasingly serve as strategic partners rather than transactional vendors.
A third trend concerns the potential for broader application development beyond initial anti-aging use cases. Sun care and repair products, eye care formulations, and rejuvenation masks represent areas where Urolithin A's biological narrative may be extended into more specialized routines. The commercial opportunity lies in tailoring messaging and formulation choices to distinct consumer needs while maintaining scientific integrity. At the same time, uncertainty remains around the pace of consumer education, the consistency of premium demand, and the degree to which regulatory frameworks will converge or remain fragmented. Over the next few years, market participants will need to balance optimism with disciplined validation, ensuring that product claims, supply commitments, and expansion plans are grounded in realistic execution capacity.
Strategic Implications for Decision Makers
For manufacturers and ingredient suppliers, the priority is to strengthen the link between production quality and commercial credibility. Consistent purity, clear application guidance, and compliance readiness can become durable differentiators, especially as brand partners seek to reduce formulation risk and accelerate time-to-market. Companies that invest in technical service, stability support, and region-specific documentation will be better positioned to secure long-term partnerships rather than one-off transactions.
For investors and strategic planners, the market's growth trajectory suggests meaningful opportunity, but success will depend on segmentation discipline. Not all Urolithin A supply is equivalent, and value creation will likely concentrate among players that can combine scalable production with ingredient branding, regulatory fluency, and viable formulation ecosystems. Evaluating a company's ability to navigate approvals, maintain quality at scale, and support downstream product narratives will be central to assessing durability of advantage.
For brand owners and procurement teams, the practical imperative is to treat Urolithin A as a strategically selected active rather than a commodity addition. Supplier qualification should include purity consistency, documentation completeness, application compatibility, and the ability to support claims responsibly. Building internal understanding of how mitochondrial-focused narratives translate into consumer-facing benefits can also improve product positioning and reduce the risk of overpromising. In a category that is expanding quickly but still maturing, access to detailed segmentation, regional compliance status, and supplier benchmarking can materially improve sourcing and launch decisions. More comprehensive data and customized scenario analysis are available in the full PW Consulting research report for teams that need deeper commercial planning support.
For detailed analysis of this topic, please visit the official page: Cosmetic Grade Urolithin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Oblong Container Market: Beyond the 4.28% CAGR and Hidden Regional Shifts
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Oblong Container Market
Market Overview and Core Challenges
The worldwide oblong container market has evolved into a structurally significant segment within the broader rigid packaging industry, driven by consistent demand across consumer goods, industrial applications, and pharmaceuticals. With a total market valuation reaching approximately 1,251 million USD in 2025 and projected to advance toward 1,678 million USD by 2032, the segment reflects a compound annual growth trajectory of roughly 4.28 percent. This growth is not a simple continuation of historical expansion but rather a response to converging pressures in material economics, regulatory mandates, and application-specific performance requirements. The market has demonstrated measured resilience through cyclical demand shifts, with notable valuation stability between 2021 and 2023 before a reacceleration in recent years.
Despite this favorable trajectory, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, rising resin and metal input volatility is compressing margins for mid-tier producers and forcing earlier design-phase decisions around material substitution. Second, fragmented regulatory frameworks across major economies are accelerating the need for standardized sustainability attributes, creating compliance complexity for companies operating across multiple jurisdictions. Third, application differentiation is intensifying as end-use sectors demand containers that balance ergonomics, dispensing precision, chemical compatibility, and recyclability, narrowing the window for generic, low-differentiation product offerings. These pressures are not merely operational hurdles; they are redefining entry barriers and rewarding firms that can integrate material science, regulatory foresight, and application engineering into a single value proposition.
Worldwide Oblong Jar Market
Key Drivers Reshaping the Market
Technological innovation is no longer a peripheral advantage in this segment; it is becoming a core determinant of market share. Advances in blow molding precision, multi-layer coextrusion, and dispensing integration are enabling oblong containers that meet stricter performance criteria without proportionally increasing material weight. For manufacturers targeting personal care, household, and pharmaceutical applications, this translates into containers that can support airless mechanisms, controlled dosing, and improved barrier properties while maintaining the familiar oblong footprint preferred for shelf presence and user handling. The ability to embed functionality directly into container architecture reduces secondary packaging needs and aligns with broader sustainability objectives, creating a compounding benefit for brands seeking to meet both performance and environmental targets.
Regulatory pressure is simultaneously accelerating material transition timelines. In Europe, packaging regulations are establishing recycled content thresholds for plastic packaging that will effectively require redesigned oblong formats by the end of the decade. Parallel requirements in parts of the United States are mandating post-consumer recycled material adoption for rigid plastic containers, while extended producer responsibility frameworks in several states are shifting financial responsibility for end-of-life recovery toward producers. These developments are not isolated compliance events; they are restructuring the economics of container procurement. Companies that adopt recyclability-by-design principles and secure reliable recycled resin streams early are positioned to reduce future reformulation risk and avoid rushed transitions that often accompany late-stage regulatory deadlines.
Demand-side behavior is also shifting the competitive center of gravity. Consumer brands and industrial buyers increasingly evaluate packaging decisions through a combined lens of sustainability performance, supply reliability, and application compatibility. In the chemicals and solvents space, oblong containers must deliver chemical resistance, secure closure systems, and compatibility with industrial handling. In automotive and lubricant applications, containers are expected to support branding durability, safe transport, and efficient dispensing. Food and beverage, personal care, and pharmaceutical buyers are prioritizing material consistency, contamination control, and dispensing precision. This diversification of requirements is increasing the premium on engineered container solutions rather than commodity-style supply, pushing market value toward suppliers that can demonstrate application-specific competency.
Supply chain and cost structure dynamics complete the driver set. The cost of primary materials such as HDPE and PET has experienced measurable volatility, with HDPE resin averaging around 1,450 USD per metric ton in late 2025 and PET resin prices moving upward by roughly 8 percent year-over-year due to supply chain constraints. These fluctuations affect not only direct material costs but also the relative attractiveness of alternative material pathways and regional sourcing models. At the same time, production footprint decisions are being influenced by proximity to end markets, energy costs, and logistics resilience. Suppliers that can balance regional responsiveness with scale efficiency are gaining leverage, especially as buyers prioritize continuity of supply in addition to price competitiveness.
- Material innovation is moving from optional differentiation to baseline expectation, particularly where recycled content, lightweighting, and dispensing integration converge.
- Regulatory mandates are shifting procurement cycles toward longer planning horizons, rewarding early compliance and transparent material traceability.
- Application-specific requirements are raising the value of engineered oblong containers, reducing the share of purely commodity-oriented supply.
- Input cost volatility is reshaping sourcing strategies, increasing the importance of regional supply resilience and resin mix flexibility.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated structure in which a limited group of established players accounts for a substantial share of revenue, while regional specialists and application-focused suppliers compete on differentiation rather than scale alone. Leading companies are pursuing distinct strategic positions that reflect their material competencies, end-use focus, and integration depth. Berry Global has reinforced its presence in oblong HDPE and PET containers for personal care, household, and pharmaceutical packaging, with recent product introductions emphasizing recycled content integration for personal care applications. Amcor has focused on custom oblong plastic bottles and jars for beauty, food, and healthcare use, showcasing recyclable designs optimized for hot-fill processes at major industry events. These moves reflect a broader emphasis on recyclability and application engineering rather than volume-only competition.
AptarGroup has built advantage around dispensing and closure integration, supplying oblong dispensing containers and pumps that work with rigid packaging for cosmetics and pharmaceuticals. This positioning allows the company to participate in value creation beyond the container body itself, where dispensing functionality, user experience, and dosing precision directly influence brand preference. Gerresheimer has concentrated on oblong glass and plastic primary packaging for pharmaceuticals, including vials and bottles, an area where regulatory compliance, material purity, and dimensional consistency are especially critical. Silgan has extended its portfolio across oblong metal and plastic containers through its plastics operations, targeting personal care and household products where durability and shelf-ready presentation matter. Albea has carved out a recognizable role in skincare and cosmetics packaging by supplying oblong airless and pump-enabled plastic containers, an approach that ties container geometry to product protection and dispensing performance.
What distinguishes these leaders is not simply product breadth but the alignment of capability with regulatory and demand trends. Companies that combine material expertise, dispensing or closure integration, and application-specific validation are better positioned to support customer transitions toward recycled content, recyclable formats, and enhanced end-use functionality. This alignment is also shaping competitive dynamics: larger players are expanding integration across container bodies, closures, and dispensing systems, while application specialists are seeking partnerships or niche scale to serve sectors with stringent performance requirements. New entrants face meaningful hurdles in raw material access, process engineering, and compliance readiness, but targeted entry remains possible in high-value subsegments where dispensability, barrier properties, or pharmaceutical-grade consistency create defensible positioning. Consolidation is likely where overlapping capabilities and regional footprints create cost or capability synergies, while fragmentation will persist where end-use customization demands small-batch engineering and close customer collaboration.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the oblong container market will likely be shaped by three interconnected trends. The first is the mainstreaming of recycled content and recyclability as procurement prerequisites. As recycled content expectations rise and regional rules tighten, oblong container designs that can accommodate post-consumer resin without compromising strength, clarity, or dispensing performance will gain preference. Commercial opportunity will accrue to suppliers that can provide validated material blends, transparent traceability, and consistent lot-to-lot quality, especially in personal care, household, and pharmaceutical applications where aesthetics and functional reliability are both important.
The second trend is the continued convergence of container geometry with dispensing and closure systems. Oblong formats are well suited to ergonomics and shelf presentation, but their value will increasingly depend on how effectively they integrate pumps, airless mechanisms, and closure technologies. This will favor suppliers that can offer coordinated container-plus-dispensing solutions rather than standalone vessels. For brands, this integration can reduce development risk, improve user experience, and support premium positioning in categories such as skincare, cosmetics, and specialty chemicals. The commercial opportunity lies in co-developed solutions that shorten time to market while meeting sustainability and performance targets simultaneously.
The third trend is regional supply realignment driven by material economics, regulatory geography, and logistics considerations. As resin pricing fluctuates and producer responsibility frameworks expand, buyers will place greater emphasis on supply continuity, regional manufacturing proximity, and compliance readiness. Suppliers with diversified production footprints and flexible material portfolios will be better equipped to manage cost shocks and meet jurisdiction-specific requirements. At the same time, consolidation may accelerate among players with overlapping capabilities, while application-specific niches remain open to focused specialists. The main risk is that rapid regulatory or input-cost changes could outpace product development cycles, forcing reactive redesigns and temporary margin pressure for companies with less flexible architectures.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product portfolios with the direction of regulation and demand. This means investing in designs that can accommodate recycled content, ensuring compatibility with recyclable formats, and strengthening dispensing or closure integration where end-use applications justify it. Companies should also evaluate resin mix flexibility and regional sourcing options to reduce exposure to input volatility, while prioritizing application validation that supports customer adoption in higher-value segments.
PW Consulting
For investors, the most relevant signal is the widening gap between commodity-oriented container supply and engineered, application-integrated solutions. Capital allocation should favor businesses that demonstrate measurable progress in recycled content readiness, regulatory compliance, and functional integration, especially where those capabilities are tied to defensible end-use relationships. Monitoring M&A activity and capacity realignment will also help identify where scale synergies are being created versus where niche differentiation remains the stronger value driver.
For procurement and sourcing leaders, the imperative is to treat container selection as a multi-year strategic decision rather than a transactional purchase. Evaluating suppliers on recycled content capability, regulatory preparedness, dispensing integration, and supply resilience will reduce exposure to future reformulation and compliance risk. Longer-term partnerships with suppliers that can support coordinated design, material traceability, and application testing will typically deliver more stable outcomes than short-cycle price optimization alone.
For decision makers seeking deeper segmentation data, regional detail, and tailored scenario planning, the complete research report provides expanded breakdowns across material pathways, application categories, and competitive positioning. It also includes structured guidance for assessing investment timing, procurement strategy, and product development priorities in relation to evolving regulatory and cost dynamics.
Worldwide Bulk box Market
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soft Tissue Repair Mesh Market: 5 Strategic Shifts Reshaping Growth to $6.68B by 2032
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Soft Tissue Repair Mesh Market
Market Landscape and Core Challenges
The global soft tissue repair mesh market has demonstrated resilient expansion over the past five years, establishing itself as a critical component within the broader surgical devices sector. Valued at approximately 4.5 billion USD in 2025, the market has recovered from a period of stagnation and litigation-driven caution that characterized the early 2020s. Historical trajectories indicate a steady climb from roughly 3.37 billion USD in 2020, reflecting an industry that has successfully navigated regulatory headwinds to return to a growth trajectory. Looking ahead, the market is projected to expand at a compound annual growth rate of 5.81 percent through 2032, suggesting a mature yet evolving landscape where value creation depends on innovation rather than volume alone.
Despite this positive outlook, the industry stands at a significant inflection point defined by heightened scrutiny and shifting clinical preferences. One of the primary challenges involves the complex regulatory environment surrounding product safety and transparency. While mesh products for hernia repair generally maintain Class II classification, specific applications such as transvaginal pelvic organ prolapse have faced severe restrictions due to long-term safety concerns. This dichotomy creates a fragmented market where manufacturers must differentiate rigorously between product categories to avoid reputational spill-over effects. The increased demand for transparency is reshaping how products are labeled and marketed, forcing companies to provide more clinically relevant mechanical data on packaging to facilitate safe use.
Furthermore, the market concentration remains high, with the top few players commanding a significant share of total revenue. This consolidation poses barriers to entry for smaller innovators while simultaneously pressuring incumbent leaders to maintain portfolios that satisfy diverse surgical needs. A second critical challenge lies in the reimbursement landscape. Payment rates for procedures involving mesh implantation vary widely based on complexity and setting, creating economic pressure on healthcare providers. These reimbursement constraints influence procurement decisions, often favoring cost-effective synthetic options over premium biological alternatives unless clinical outcomes clearly justify the added expense. Consequently, manufacturers face the dual challenge of proving superior clinical efficacy while navigating tight hospital budgets.
Finally, the supply chain for raw materials and manufacturing capacity remains a point of vulnerability. As demand shifts toward specialized composite and hybrid meshes, the ability to scale production without compromising quality becomes a strategic differentiator. These challenges collectively suggest that future growth will not be uniform across all segments but will instead favor companies that can balance regulatory compliance, clinical evidence, and economic efficiency.
Key Drivers of Market Change
Several fundamental factors are propelling the soft tissue repair mesh market forward, transforming it from a commodity-driven space into one defined by technological differentiation. The most prominent driver is technological innovation in material science. There is a marked shift away from traditional heavyweight synthetics toward lightweight, composite, and bioresorbable options. Manufacturers are increasingly developing meshes that integrate with host tissue more effectively, reducing foreign body responses and chronic pain. For instance, the recent regulatory clearance for electrospun fiber matrices highlights the industry's movement toward advanced structures that mimic natural tissue properties. This innovation is not merely about material composition but also about structural design, such as macroporous configurations that allow for better tissue ingrowth while maintaining mechanical strength.
Regulatory dynamics are simultaneously acting as both a constraint and a catalyst. While the FDA has tightened oversight on specific high-risk applications, the pathway for hernia repair meshes remains well-defined under the 510(k) clearance process. However, the recent draft guidance recommending standardized package labeling indicates a push toward greater transparency. This regulatory evolution forces companies to invest more heavily in clinical data generation and labeling compliance. Rather than hindering growth, this environment tends to favor larger, well-resourced organizations that can absorb the costs of compliance and clinical trials. It effectively raises the barrier to entry, consolidating the market around players who can demonstrate robust safety profiles and provide clear usage guidelines.
On the demand side, the aging global population and the rising prevalence of conditions requiring soft tissue reconstruction are driving volume. Hernia repair remains the dominant application, supported by consistent surgical rates across developed and developing regions. However, there is growing interest in pelvic organ prolapse and breast reconstruction, provided safety concerns are adequately addressed through improved product design. Surgeons are increasingly seeking solutions that reduce recurrence rates and minimize complications, which drives demand for higher-performance meshes. This shift in surgeon preference influences procurement policies, pushing hospitals to adopt products that offer long-term cost savings through reduced revision surgeries, even if the upfront device cost is higher.
Supply chain and cost structures also play a pivotal role. The pressure to reduce healthcare costs globally encourages the adoption of efficient manufacturing processes and cost-effective synthetic materials. Yet, the rise of biological and hybrid meshes suggests a premium segment is emerging for complex cases where synthetic options are contraindicated. Companies are responding by optimizing their supply chains to support diverse product lines, ranging from mass-market synthetics to specialized biologics. This dual approach allows manufacturers to capture volume in standard procedures while maintaining margins in specialized applications. The interplay between reimbursement rates and device pricing continues to shape adoption patterns, with economic factors often determining the speed at which new technologies penetrate the market.
Worldwide Hernia Mesh Devices Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large diversified medical device conglomerates and specialized niche players. The market concentration is significant, with the top three companies holding a substantial portion of total revenue. This structure implies that competitive advantage is often derived from portfolio breadth and global distribution networks rather than single-product superiority. Leading players such as Johnson & Johnson and Medtronic leverage their extensive surgical portfolios to offer comprehensive solutions, integrating meshes with fixation devices and surgical tools. Their strategy focuses on maintaining market leadership through continuous product iteration and strong relationships with surgical communities. For these giants, the ability to offer a range of options—from synthetic to composite—allows them to address various clinical scenarios while mitigating risk associated with any single product line.
Specialized manufacturers employ different strategic maneuvers. Companies like BD, formerly associated with Bard, focus on expanding portfolios that include bioresorbable options like Phasix, catering to surgeons seeking long-term safety without permanent implantation. Recent commercial launches of absorbable hernia patches highlight a strategy centered on innovation in material absorption rates and handling characteristics. Similarly, companies like TELA Bio and Organogenesis focus on regenerative medicine and reinforced tissue matrices. Their value proposition lies in providing alternatives for patients where synthetic meshes pose higher risks, thereby capturing a premium segment willing to pay for biologic properties. These players often invest heavily in clinical evidence to support reimbursement claims and differentiate themselves from standard synthetic offerings.
The landscape is also evolving through strategic partnerships and acquisitions. Larger entities often acquire innovative smaller firms to gain access to novel technologies or specific market segments without developing them internally. This trend accelerates the integration of new materials like electrospun fibers into established product lines. Meanwhile, the regulatory environment acts as a filter. Recent FDA actions regarding pelvic organ prolapse meshes have reshaped the competitive field, removing certain products from the market and redirecting demand toward safer alternatives. This dynamic benefits companies with strong compliance records and diversified portfolios that are not overly exposed to high-risk applications. The result is a market where stability and trust are becoming as valuable as technological features.
PW Consulting
New entrants face a challenging path. While the 510(k) pathway provides a mechanism for market access, the reputational risks associated with mesh products require careful positioning. Success for new players often depends on identifying underserved niches, such as specific anatomical repairs or regions with growing surgical volumes. The presence of established global players means that pricing pressure is inevitable, pushing innovators to demonstrate clear clinical advantages that command premium pricing. Overall, the competitive dynamics suggest a market moving toward consolidation among top players while allowing room for specialized innovators who can navigate regulatory complexity and prove distinct clinical value.
Future Trends and Commercial Implications
Looking toward the next three to five years, several trends are likely to define the trajectory of the soft tissue repair mesh market. First, the differentiation between synthetic and biological meshes will become more nuanced. Rather than a binary choice, hybrid and composite meshes are expected to gain prominence, offering a balance of mechanical strength and biocompatibility. This trend creates opportunities for manufacturers who can successfully engineer materials that degrade at controlled rates while providing sufficient support during the healing phase. The commercial implication is a shift in R&D focus toward material science that can justify premium pricing through reduced long-term complications.
Second, regulatory transparency will continue to intensify. The move toward standardized labeling and clearer communication of mechanical properties suggests that future market access will depend heavily on how well a product's performance is documented and communicated. Companies that proactively align with these regulatory shifts will gain trust among surgeons and procurement teams. This environment may slow the adoption of unproven innovations but will strengthen the position of established products with robust data packs. For investors, this signals a preference for assets with clear regulatory pathways and strong intellectual property protection around material composition and labeling data.
Third, regional dynamics will play an increasingly important role. While mature markets drive revenue through high-value products, emerging regions offer volume growth driven by increasing surgical access. However, reimbursement constraints in developed markets may push cost-sensitive innovations toward emerging economies. A potential risk lies in the variability of regulatory standards across regions, which can complicate global launches. Companies must balance the need for standardized products with the flexibility to adapt to local reimbursement and clinical preferences. The uncertainty surrounding long-term safety data for certain applications remains a persistent risk, potentially impacting adoption rates if new safety signals emerge. Success in this environment requires agility in product positioning and a deep understanding of local market nuances.
Worldwide Inguinal Hernia Repair Mesh Market
Strategic Actions for Decision Makers
For manufacturers, the priority should be to strengthen clinical evidence packages that support both safety and cost-effectiveness. Investing in data that demonstrates reduced revision rates or faster recovery times can justify premium positioning and align with value-based care initiatives. Companies should also monitor regulatory guidance closely to ensure labeling and marketing materials meet evolving transparency standards, reducing the risk of compliance issues.
Investors evaluating opportunities in this sector should focus on companies with diversified portfolios that are not overly reliant on high-risk applications. Technologies that offer unique material properties or clear pathways to reimbursement are more likely to sustain growth. Due diligence should include a thorough assessment of regulatory clearance status and the strength of intellectual property surrounding material innovations.
Procurement leaders and healthcare providers need to balance cost considerations with long-term patient outcomes. Selecting meshes that offer proven safety profiles and align with reimbursement structures can optimize procedure costs over time. Engaging with suppliers who provide comprehensive training and data support can also improve surgical consistency and outcomes. Access to detailed segmentation data and customized market intelligence is essential for navigating these complex decisions effectively.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Tissue Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Low Vision Devices Market: Home Care Leads the $1.1B Growth Trajectory
By PW Consulting, 2026-09-18
Navigating the Global Low Vision Devices Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The worldwide market for low vision devices has entered a phase of sustained expansion, driven by demographic shifts and rapid advancements in assistive technology. Valued at approximately 685.5 million USD in 2025, the market has demonstrated consistent growth over the past five years and is projected to reach 1,115.2 million USD by 2032, reflecting a compound annual growth rate of 7.2 percent. This trajectory signals more than incremental demand; it indicates a structural transformation in how vision impairment is managed across clinical, home, and rehabilitation settings. As the global population ages and chronic conditions affecting visual acuity become more prevalent, the commercial relevance of low vision solutions continues to rise across both developed and emerging economies.
Despite this favorable headline trajectory, the industry operates within a landscape of persistent structural challenges. The first challenge lies in reconciling clinical prescription pathways with real-world adoption barriers. Many low vision devices meaningfully improve daily functioning, yet end users often face fragmented access to specialized fitting, training, and follow-up care. The second challenge centers on reimbursement architecture. Public and private health programs frequently cover rehabilitation services and assistive technology instruction, but direct device procurement remains inconsistently covered. This mismatch can slow purchase cycles, shift cost burden toward patients, and complicate forecasting for manufacturers. The third challenge is fragmentation within the product ecosystem. Optical aids, electronic video magnifiers, software-driven applications, and wearable systems serve overlapping clinical needs, yet user experience, compatibility, and service expectations vary significantly across categories and channels.
The market is also undergoing a credibility test as technology claims accelerate faster than reimbursement structures and clinical integration models. Devices that deliver clearer performance benefits are entering the field, but adoption depends on more than hardware capability. It requires clinician confidence, caregiver education, and durable support ecosystems. For commercial stakeholders, the implication is clear: success will depend less on isolated product launches and more on how effectively companies reduce friction across prescription, training, reimbursement navigation, and long-term usability.
Key Demand Drivers Shaping the Market
Technological innovation is the most visible force reshaping the low vision market. Electronic video magnifiers and AI-enabled wearables are no longer competing solely on magnification strength; they are increasingly differentiating through contrast optimization, text recognition, voice interaction, and portability. Head-mounted and handheld systems are closing the gap between clinical functionality and everyday convenience, allowing users to move beyond stationary reading tasks into navigation, workplace use, and independent living. The rise of software and application-based support has also broadened the addressable use case set, enabling integration with mobile platforms, remote configuration, and personalized visual profiles. In practical terms, this means device value propositions are shifting from magnification alone to functional independence, which expands adoption potential beyond traditional eye care channels.
Policy and regulatory dynamics are shaping the pace and confidence of innovation. Device classifications under medical device frameworks create structured pathways for many electronic and optical aids, while certain lower-risk optical magnifiers remain exempt from premarket notification requirements. This regulatory stratification matters commercially because it influences time-to-market, documentation burden, and the ability to scale across jurisdictions. At the same time, growing attention to accessibility standards and vision rehabilitation support is reinforcing the legitimacy of low vision technology as a healthcare priority rather than a niche assistive category. The increasing visibility of breakthrough designations and clinical trial activity for advanced visual restoration and augmentation approaches further underscores how seriously the innovation pipeline is being taken by regulators and investors.
Demand-side behavior is evolving as clinical awareness and user expectations change simultaneously. Eye care professionals are increasingly prescribing low vision technology alongside rehabilitation services, particularly when patients face progressive conditions or functional limitations that affect reading, mobility, and work. At the same time, end users are seeking devices that fit seamlessly into daily routines rather than requiring specialized setups or constant assistance. Home healthcare environments are playing a growing role in this shift, as patients and caregivers prioritize tools that can be used independently, maintained easily, and adapted to changing visual needs. This behavioral change favors solutions that combine ease of use with demonstrable functional gains, especially when supported by training and follow-up guidance.
Supply chain and cost structure factors are introducing both pressure and strategic differentiation. Components supporting high-resolution displays, sensing, battery efficiency, and AI processing have become more central to product performance, which increases sensitivity to sourcing stability, quality control, and manufacturing complexity. At the same time, the cost of delivering device-supported rehabilitation has become a critical commercial variable. When device pricing, service expectations, and reimbursement uncertainty combine, manufacturers that offer stronger service models, clearer clinical value narratives, and adaptable product tiers can gain an advantage in procurement discussions. In this environment, cost efficiency is not simply a margin issue; it is a market-access issue.
Competitive Landscape and Leading Strategies
The competitive field in low vision devices is broad, active, and increasingly differentiated by technology orientation and go-to-market style. HumanWare has built a strong reputation around electronic video magnifiers and portable assistive devices designed for reading and daily independence, reflecting a focus on practical usability and sustained user support. Eschenbach Optik GmbH represents the high-precision optical tradition, emphasizing magnifiers, telescopic devices, and illuminated hand and stand magnifiers for professional and everyday use. Vispero, through its VFO Group, offers a broader low vision portfolio that includes CCTV and video magnifiers alongside a range of optical and electronic aids, an approach that allows it to address multiple use cases within a single ecosystem. Enhanced Vision concentrates on electronic video magnifiers with features such as text-to-speech and high-contrast imaging, positioning itself around rehabilitation-oriented functionality. Optelec develops portable and desktop video magnifiers and electronic aids, supporting both low vision and broader vision support applications.
The landscape also includes companies advancing more immersive or intelligent device forms. OrCam Technologies has pushed into AI-powered wearable devices that convert visual information into audio feedback, giving users real-time text reading and object and face recognition capabilities. This direction reflects a broader shift from passive magnification toward active visual assistance. eSight Corp. has focused on electronic eyewear and head-mounted systems that enhance functional vision through advanced imaging, appealing to users seeking hands-free and mobility-friendly solutions. Zoomax Technology produces a range of portable, handheld, and desktop video magnifiers with AI integration and tablet-based systems, illustrating how regional manufacturing strength can align with feature-rich product development. Other contributors, including LVI Low Vision International, Aumed Group Corp., Ocutech, Inc., ZEISS, IrisVision Global, and HIMS Inc., extend the competitive base across optical specialization, bioptic and telescopic design, filter and contrast-control optics, headset-based magnification with voice and OCR capabilities, and broader assistive technology offerings.
Across this set of players, strategic differentiation is emerging around four dimensions. The first is product architecture, where manufacturers choose between optical precision, electronic magnification, wearable augmentation, or software-enabled support. The second is user experience, where portability, intuitive controls, training requirements, and real-world task coverage increasingly influence purchase decisions. The third is regulatory and reimbursement positioning, where companies that proactively align with classification pathways and prescription workflows can reduce friction in clinical adoption. The fourth is ecosystem readiness, where service, fitting support, and follow-up usability become competitive assets rather than secondary operations.
Night Vision Devices Market
The market structure is evolving along two complementary paths. Consolidation is becoming more attractive for players seeking broader portfolios, stronger distribution, and improved ability to serve end users across care settings. Simultaneously, the field remains open to new entrants that bring fresh technology approaches, particularly in wearable AI, intelligent image processing, and integrated digital support. This combination of consolidation pressure and innovation-driven entry suggests that competitive advantage will increasingly depend on how well companies combine technical capability with practical clinical and consumer adoption strategies.
Future Trends and Strategic Outlook
Over the next three to five years, one of the clearest trends will be the continued migration from standalone magnification hardware toward integrated, intelligent assistance. Devices will likely become more adaptive, more connected, and more capable of supporting daily functions beyond reading, including object identification, orientation support, and digital workflow interaction. This trend expands the commercial opportunity beyond traditional low vision segments into broader accessibility-oriented use cases, especially where usability and independence are prioritized.
A second trend will be increasing pressure on reimbursement and access pathways to catch up with product innovation. As devices become more clinically meaningful and more technologically advanced, stakeholders will likely push harder for clearer coverage logic, stronger rehabilitation integration, and better alignment between prescribed services and device purchase models. Companies that invest early in evidence generation, clinician education, and reimbursement navigation will be better positioned to convert innovation into durable demand.
A third trend will be portfolio and channel convergence. The line between optical aids, electronic magnifiers, software support, and wearable systems will continue to blur as users seek flexible solutions that adapt to changing vision levels and living environments. This creates opportunities for manufacturers to design modular product strategies, cross-sell across care settings, and build offerings that support both clinical use and home-based independence.
Still, uncertainty remains. Regulatory pathways can affect launch timing and documentation requirements. Reimbursement inconsistency can slow volume growth, especially in segments where device cost is highly visible. In addition, rapid feature escalation can raise expectations and complicate clinical integration if support, training, and interoperability are not addressed with equal seriousness. The market’s upside is significant, but it will be captured by organizations that can translate technology leadership into practical adoption.
Strategic Actions for Decision Makers
For device manufacturers, the priority should be aligning product roadmaps with adoption friction rather than feature count alone. That means investing in usability, training support, clinician-facing evidence, and reimbursement-friendly positioning as core commercial capabilities. Differentiating through ecosystem strength: fitting, service, compatibility, and long-term user engagement can be as important as the next technical enhancement.
PW Consulting
For investors, the most compelling opportunities are likely to sit at the intersection of intelligent assistance, wearable form factors, and rehabilitation integration. Due diligence should focus not only on technical novelty, but also on regulatory readiness, reimbursement exposure, channel access, and the ability to scale support infrastructure. Companies that can demonstrate real-world functional value and clear access pathways are better positioned for sustained traction.
Assistive Technologies for Visual Impairment Market
For procurement and care-program leaders, the practical opportunity is to treat low vision devices as part of a broader rehabilitation strategy rather than isolated purchases. Selecting solutions with stronger training support, clearer outcome expectations, and compatibility with home healthcare or clinic-based workflows can improve adoption consistency and long-term value. Structured evaluation across clinical benefit, usability, service model, and reimbursement fit will reduce downstream implementation risk.
Detailed segmentation data, company-level positioning, and region-specific commercial dynamics can sharpen these decisions further, especially for teams evaluating product entry, partnership structures, or investment theses in a market that is expanding quickly but remains operationally complex.
For detailed analysis of this topic, please visit the official page: Worldwide Low Vision Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Heavy-Duty Wear Protection Materials Market: Asia Pacific Dominance and 5.85% Growth Redefining 2032
By PW Consulting, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Global Heavy-Duty Wear Protection Materials Market
Market Status and Core Challenges
The global heavy-duty wear protection materials market has demonstrated resilient growth over the past five years, expanding from approximately $1.38 billion in 2020 to an estimated $1.85 billion in 2025. This trajectory reflects a compound annual growth rate of 5.85 percent through 2032, with revenue projections reaching $2.75 billion by the end of the forecast horizon. Such expansion underscores a structural shift: wear protection is no longer treated as a routine maintenance commodity but as a strategic operational lever that directly impacts asset longevity, downtime reduction, and total cost of ownership across heavy industries.
Beneath these headline figures, several structural tensions are reshaping how organizations evaluate and deploy wear-resistant solutions. First, the market is experiencing a pronounced performance-versus-cost optimization challenge. Operators in mining, cement, and power generation face mounting pressure to extend maintenance intervals while avoiding excessive upfront capital expenditure. This has accelerated demand for engineered hybrid materials that balance abrasion resistance, impact tolerance, and installability, forcing procurement teams to evaluate lifecycle economics rather than unit pricing alone.
Wear Resistant Steel Market
Second, raw material volatility and supply chain fragmentation continue to test margin stability. Advanced ceramics, high-alloy steels, and engineered polymers rely on energy-intensive processing and geographically concentrated feedstock networks. Fluctuations in energy costs, logistics bottlenecks, and regional manufacturing capacity constraints have introduced unpredictability into lead times and pricing structures. Companies that depend on single-source sourcing or rigid specification frameworks are encountering disproportionate exposure to these disruptions.
Third, the regulatory and sustainability agenda is altering material selection criteria. Environmental evaluations of cast wear protection alloys increasingly compare traditional cobalt-, nickel-, and iron-based formulations against lower-impact iron aluminide and alternative composite approaches. While performance requirements in extreme abrasion and high-temperature environments remain non-negotiable, procurement specifications are gradually incorporating lifecycle carbon considerations, recycling pathways, and compliance documentation into vendor qualification processes. These converging pressures are pushing the market past a transition point where incremental material upgrades are being replaced by systematic engineering and sourcing redesigns.
Key Drivers Shaping Market Dynamics
Technological innovation remains the most visible catalyst for market evolution. Material science advancements have shifted the performance ceiling for abrasion-resistant solutions, particularly in ceramic and composite segments. Alumina and silicon carbide continue to serve as primary feedstocks for advanced ceramics deployed in heavy-duty linings, delivering exceptional hardness and thermal stability in high-wear environments. Simultaneously, engineered polymer systems, including polyurethane-based liners and ceramic-filled epoxy coatings, have expanded the solution envelope for applications where spray-applied repair, conformability, and rapid reinstatement are critical. The result is a broader toolkit that enables engineers to match material architecture to specific wear mechanisms rather than applying uniform protective layers across dissimilar operating conditions.
PW Consulting
Policy and regulatory developments are reinforcing this technical diversification. Environmental scrutiny around alloy composition, energy-intensive manufacturing, and end-of-life material handling is influencing both product design and procurement standards. Industry evaluations increasingly compare conventional hardfacing alloys with sustainable iron aluminide alternatives, especially where regulatory reporting, emissions tracking, and responsible sourcing requirements are tightening. This does not eliminate high-performance alloys from consideration, but it encourages specification teams to document environmental impact alongside mechanical performance, gradually shifting vendor selection toward suppliers with transparent material credentials and validated sustainability pathways.
Demand-side behavior is changing as well. Operators are prioritizing predictive maintenance and condition-based replacement strategies over reactive repairs. In mining and mineral processing, cement and construction, and power generation, equipment downtime carries steep production penalties, making wear protection a direct contributor to operational continuity. This mindset favors materials and installation methods that reduce intervention frequency, simplify field repair, and integrate with monitoring programs. Companies are also demanding more consistent performance data, accelerated testing results, and application-specific validation rather than relying solely on generic laboratory benchmarks.
Supply chain and cost structure shifts are amplifying these demand-side expectations. Regionalization of manufacturing, nearshoring of service capabilities, and greater emphasis on inventory resilience are reshaping how wear protection products reach end users. Lead-time reliability, localized technical support, and adaptable product formats are becoming competitive differentiators alongside raw material pricing. At the same time, the need to maintain high wear resistance in steel, cement, and power plant environments has sustained strong demand for materials that can withstand severe abrasion without frequent replacement. Organizations that can combine material performance with responsive supply and installation support are capturing disproportionate share in applications where downtime costs dominate procurement decisions.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a concentration of specialized material suppliers and industrial solution providers, with the top three players accounting for roughly a third of total market revenue and the top five representing just under half. This structure reflects a market where technical credibility, application-specific engineering, and installed-base relationships matter as much as scale. Leading organizations are competing on differentiated value propositions rather than on product commoditization alone.
Several strategic archetypes are emerging among incumbent players. One group emphasizes advanced ceramic and refractory expertise, positioning high-hardness alumina, silicon carbide, and zirconia-toughened formulations as the default choice for extreme abrasion and thermal stress. These suppliers typically focus on engineered linings, custom shapes, and stringent quality control to serve demanding sectors such as mining, cement, and power generation. Their advantage lies in material science depth, repeatable performance in severe environments, and the ability to tailor formulations to specific wear profiles.
A second archetype centers on composite, coating, and hardfacing solutions designed for repair, retrofit, and rapid field application. Polyurethane liners, chrome carbide overlay plates, ceramic-filled epoxy systems, and hardfacing alloys address applications where installability, impact resistance, and on-site reinstatement are prioritized over monolithic ceramic performance. Companies in this segment often compete through application engineering, field service coverage, and the ability to extend equipment life without full component replacement. Their differentiation comes from bridging the gap between laboratory-grade material performance and practical operational deployment.
A third strategic orientation integrates wear protection into broader equipment ecosystems. The strongest players combine proprietary liner technologies with equipment design, wear monitoring guidance, and maintenance planning. By embedding wear solutions into chutes, hoppers, mills, and conveying systems, they create switching costs and long-term service relationships. This model is particularly effective in mining and mineral processing, where wear patterns are predictable enough to support engineered upgrades that reduce recurring replacement cycles.
Wear Plate Market
Market evolution is moving toward selective consolidation and capability expansion. Larger industrial suppliers are acquiring or partnering with specialized material formulators to broaden their application coverage and geographic reach. At the same time, smaller firms with niche formulations, regional service footprints, or proprietary installation methods continue to compete by serving high-value applications where customization outweighs scale advantages. New entrants are most likely to succeed where they bring genuine material innovation, validated field data, or digitally enabled service models that shorten diagnostic and replacement cycles. The overall trend is fragmentation at the application level combined with consolidation at the strategic level, as buyers increasingly prefer partners who can deliver consistent performance across multiple assets and sites.
Future Trend Forecasts
Over the next three to five years, one defining trend will be the acceleration of hybrid and engineered composite wear systems. Monolithic solutions will remain necessary for the most extreme environments, but many applications will shift toward layered or blended architectures that combine ceramic hardness, polymer toughness, and steel reinforcement where appropriate. This approach enables more precise matching to abrasion, impact, and thermal conditions while reducing installation complexity and enabling partial repairs rather than full component swaps. Commercial opportunity lies with suppliers that can standardize modular system designs, provide clear performance comparison frameworks, and support faster field reinstatement.
A second trend will be the growing integration of wear protection decisions into lifecycle and sustainability planning. Procurement and engineering teams are expected to weigh material composition, manufacturing energy intensity, repairability, and end-of-life handling alongside traditional performance metrics. This creates openings for vendors that can supply lower-impact alloy alternatives, recyclable composite formats, or coatings that extend service life with reduced material input. The risk is that sustainability requirements may outpace standardized testing and reporting norms, creating uneven compliance burdens for suppliers operating across multiple jurisdictions. Companies that move early to document environmental performance and align specifications with operational realities will be better positioned to navigate evolving expectations.
A third trend is the shift toward predictive wear management and service-integrated offerings. As condition monitoring, sensor data, and maintenance analytics become more accessible, wear protection will increasingly be specified as part of a broader uptime strategy rather than as a standalone material purchase. Suppliers that combine durable materials with installation expertise, replacement forecasting, and site-specific wear mapping will capture stronger customer retention. The principal uncertainty is the pace at which smaller operators adopt data-driven maintenance practices and whether labor constraints and skill gaps limit the speed of more advanced wear management deployments.
Strategic Recommendations for Decision Makers
Manufacturers and material suppliers should prioritize application-specific validation and lifecycle-oriented messaging. Investing in field data, comparative performance documentation, and modular system designs will help differentiate offerings in a market where buyers are scrutinizing total cost of ownership rather than unit price. Expanding regional service capability and technical support can also reduce exposure to supply chain volatility while strengthening customer retention.
Investors should look for participants with defensible technical positioning, diversified end-use exposure, and the ability to integrate material performance with service or equipment ecosystems. Companies that can navigate raw material constraints, incorporate lower-impact material options without compromising performance, and capture recurring maintenance demand are likely to deliver more resilient growth than those competing solely on commodity pricing.
Procurement and operations leaders should evaluate wear protection suppliers based on installed performance, repairability, and responsiveness rather than catalog specifications alone. Establishing clear wear mechanism profiles for critical assets, standardizing qualification criteria that include environmental and maintenance considerations, and building relationships with suppliers capable of supporting predictive replacement cycles can materially reduce unplanned downtime. For organizations seeking deeper segmentation data, regional demand patterns, competitive benchmarking, and tailored sourcing or investment scenarios, accessing a comprehensive market study provides the granularity needed to convert these strategic themes into executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy-Duty Wear Protection Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Container Vans Market: Why 4.35% CAGR and Asia Pacific Growth Redefine Future Returns
By PW Consulting, 2026-09-18
The Worldwide Container Vans Market: Navigating Growth, Geopolitics, and Industrial Transformation Through 2032
The global container vans market has evolved from a cyclical, commodity-driven sector into a strategically critical component of international trade and logistics infrastructure. Over the past five years, the market has demonstrated resilience amid shifting trade patterns, supply chain reconfiguration, and tightening environmental standards. Measured in USD across the baseline year of 2025 and extending through the forecast horizon to 2032, the industry reflects a steady, structurally anchored trajectory. Revenue figures spanning the historical period from 2020 through 2025 reveal a market that absorbed the turbulence of pandemic-era disruptions, rebound in global freight volumes, and gradually stabilized into a more predictable growth environment. Entering the forecast window, the market is expanding at a compound annual growth rate of approximately 4.35 percent, with total revenue values projected to cross the mid-point of the next decade at a scale that underscores the enduring role of standardized containerized transport in global commerce.
This expansion is not merely a function of increased freight tonnage. It reflects deeper structural shifts in how goods move across maritime routes, inland corridors, and multimodal gateways. The container van has become the foundational unit of intermodal efficiency, enabling seamless transfers between ocean carriers, rail networks, and trucking fleets. Yet, beneath the headline growth trajectory, the industry is navigating a period of pronounced transition. Capacity utilization patterns, regional trade realignments, and the economics of manufacturing consolidation are reshaping competitive dynamics. Stakeholders across the value chain are confronting a landscape where scale, cost discipline, and specification differentiation increasingly determine long-term positioning.
Several interrelated challenges define the current inflection point. First, the sector operates under intense cost pressure tied to the volatility of core input materials. The economics of container production remain tightly coupled to steel pricing, and fluctuations in metallurgical markets transmit directly into manufacturing margins, pricing strategies, and order book planning. Second, the industry must reconcile sustained demand growth with evolving compliance and safety requirements that govern structural performance, load ratings, and international approval standards. Containers that fail to meet recognized testing protocols or safety certifications face exclusion from global service networks, making regulatory alignment a non-negotiable operational baseline. Third, the market is experiencing a gradual divergence in demand profiles across application areas. The core volume driver remains firmly anchored in maritime shipping, where standardized units enable high-throughput port operations and dense vessel utilization. At the same time, land transport corridors are generating incremental demand for durable, road-compliant units that support inland distribution and cross-border logistics, while storage and modular construction applications create niche but meaningful utilization pathways for surplus and repurposed inventory. These overlapping pressures require operators to balance volume ambitions with cost control, compliance rigor, and application-specific engineering.
Key Forces Propelling Market Evolution
The trajectory of the container vans market is being shaped by a set of reinforcing drivers that extend well beyond simple freight volume growth. Understanding these forces is essential for decision-makers seeking to align capacity planning, procurement strategy, and investment priorities with where the market is actually heading.
Technological innovation and manufacturing precision have become central to competitive differentiation. While the fundamental design of the container van remains anchored in ISO-compliant geometry, advances in fabrication workflows, material utilization, and quality assurance are reshaping cost structures and product consistency. High-volume producers have progressively integrated more controlled welding processes, automated inspection routines, and tighter tolerance management to reduce structural variability and improve durability under repeated loading cycles. These improvements matter because container vans are subject to harsh operational environments, including salt exposure, stacking pressure, and repeated handling across congested terminal operations. Manufacturers that can deliver more consistent structural performance while containing unit costs are better positioned to secure long-term supply agreements with shipping lines and freight forwarders that prioritize reliability and reduced maintenance downtime.
Policy and regulatory frameworks continue to impose discipline on the market, but they also function as a filter that rewards operational maturity. International standards governing testing, structural integrity, and load ratings establish a common technical language for container performance, enabling interoperability across global shipping networks. Safety approval regimes administered through national authorities reinforce this baseline by ensuring that units in international service meet defined structural and handling requirements. For manufacturers and operators alike, compliance is not a peripheral activity; it is an integral part of market access. The implication is that regulatory alignment increasingly rewards scale producers with established certification pipelines and repeatable quality systems, while raising the barrier for entrants that lack the institutional capacity to manage documentation, testing, and audit traceability efficiently.
Demand-side behavior is shifting in ways that extend beyond headline trade growth. The continued expansion of e-commerce and complex multinational supply chains has reinforced the need for standardized, rugged, and easily transferable container units that support rapid modal switching. Buyers are increasingly attentive not only to acquisition cost but also to lifecycle performance, including resistance to corrosion, structural fatigue, and handling wear. At the same time, shipping lines and logistics providers are evaluating container fleets through a broader operational lens, weighing factors such as stackability, space optimization on vessel cells, and the ability to maintain service reliability under variable port conditions. These preferences gradually elevate the importance of specification quality and consistency over pure price competition, particularly in segments where operational downtime or cargo integrity carries high financial risk.
Supply chain and cost structure dynamics represent the most immediate pressure point. Steel remains the dominant raw material in container van production, and the economics of manufacturing are closely linked to steel price behavior and regional availability. In the recent operating environment, steel pricing in major industrial markets has reflected the combined influence of infrastructure demand, energy input costs, and trade flow patterns, sustaining moderate volatility into the near term. Because new production costs track these material inputs closely, manufacturers face a continuous challenge in managing margin stability while preserving competitive pricing for volume customers. This dynamic is magnified by the concentration of manufacturing capacity in key production regions, which can amplify the impact of localized demand swings, logistics bottlenecks, or input scarcity. The resulting environment favors operators with disciplined procurement strategies, diversified sourcing options, and the ability to pass through or absorb cost fluctuations without disrupting order fulfillment.
Competitive Landscape and Strategic Positioning
The competitive architecture of the container vans market is characterized by a high degree of concentration among established manufacturers with broad production scale, global distribution reach, and strong integration with shipping and logistics networks. This concentration is not accidental; it reflects the capital intensity of container manufacturing, the importance of certification and compliance infrastructure, and the value that large buyers place on dependable supply and uniform specification quality.
Several major producers illustrate the dominant strategic models in the market. Large-scale manufacturers headquartered in China have built global leadership by emphasizing high-volume output of ISO-compliant dry van and specialized units, supported by multiple production facilities designed to serve international intermodal demand. Their advantage lies in the ability to combine scale, breadth of product range, and efficient cost structures while maintaining close links to port infrastructure and shipping line procurement cycles. Other significant players have pursued similar strategies with varying degrees of specialization, expanding their offerings across dry freight, special-purpose, and container van products to capture demand across both standard and differentiated applications. Meanwhile, select European-linked producers have positioned around higher-specification and refrigerated container vans, emphasizing quality, durability, and integration with broader logistics operations. This specialization matters because reefer and high-performance units typically command different procurement logic, with greater emphasis on thermal performance, equipment reliability, and lifecycle service support.
PW Consulting
Differentiation in this market is increasingly defined by three overlapping dimensions. The first is scale and supply reliability. Large buyers prioritize manufacturers who can meet sustained order volumes without disruption, particularly when fleet replacement cycles and network expansion plans require predictable delivery schedules. The second is specification performance and compliance maturity. Operators that can demonstrate consistent structural integrity, standardized testing alignment, and robust safety approval processes gain an advantage in segments where service continuity and cargo protection are critical. The third is application-specific engineering and product breadth. As demand evolves across maritime shipping, land transport, and storage or modular construction use cases, manufacturers with the ability to tailor unit configurations while preserving core standardization can capture value beyond undifferentiated volume competition.
The market structure also shows signs of gradual evolution. Consolidation pressures remain relevant where scale economies, certification overhead, and global distribution requirements favor larger, well-capitalized producers. At the same time, segmentation continues to create space for focused players that serve specific application niches or regional demand pockets. New entry remains challenging due to the combination of material cost exposure, compliance burden, and the importance of entrenched buyer relationships, but it is not impossible for producers that bring clear cost advantages, specialized engineering capabilities, or strategic alignment with emerging logistics corridors. The overall direction points toward a landscape where competitive advantage is less about isolated unit pricing and more about the integration of manufacturing discipline, product reliability, and customer-specific service model alignment.
Forward Outlook: Three Trends Shaping the Next Era
The next three to five years are likely to be shaped by a combination of demand momentum, cost discipline, and operational specialization. Several trends stand out as particularly consequential for strategic planning.
Steady growth anchored in intermodal standardization. Global trade activity and e-commerce-driven logistics complexity are expected to continue supporting demand for standardized container vans that enable efficient movement across sea, rail, and road. The market’s projected compound growth trajectory reflects this foundational role rather than speculative expansion. The opportunity here lies not simply in volume but in capturing demand from corridors and customer segments where reliability, turnaround speed, and fleet consistency deliver measurable operating advantages.
Cost volatility as a permanent management challenge. Because production economics remain closely linked to steel pricing and manufacturing concentration patterns, material cost volatility is likely to persist as a central operational concern. The strategic response will increasingly involve procurement diversification, inventory and order timing optimization, and pricing frameworks that protect margin without eroding customer relationships. Companies that treat input cost management as a core capability rather than a periodic reaction will be better positioned to navigate fluctuations without sacrificing competitiveness.
Specification and application differentiation gaining relative importance. As maritime shipping continues to anchor the largest share of demand, growth opportunities will also emerge from land transport intensifications and storage or modular construction utilization. These segments create incremental value for units with specific durability characteristics, handling resilience, or configuration flexibility. Over time, the market is likely to reward manufacturers and buyers who can match product attributes to application requirements rather than relying on uniform, lowest-common-denominator procurement. This shift creates opportunities for targeted product development, more precise fleet planning, and stronger supplier-customer alignment around operational objectives.
Worldwide Container Dumper Market
These trends carry embedded uncertainty. Trade policy shifts, port congestion dynamics, energy and input cost shocks, and the pace of logistics network modernization can all alter regional demand patterns and procurement timing. Similarly, any acceleration in regulatory expectations around safety, testing, or lifecycle performance would raise the operational bar for market participation. Decision-makers should therefore treat the medium-term outlook as directional rather than deterministic, using scenario planning to evaluate how shifts in trade flows, material costs, and compliance requirements might affect capacity deployment and sourcing choices.
Container Leasing Market
Strategic Implications for Key Stakeholders
For manufacturers and producers, the priority is to reinforce the strategic value of scale, compliance maturity, and specification consistency. Investing in process control, quality traceability, and application-aligned product breadth can strengthen positioning with buyers who increasingly assess total operational value rather than unit price alone. Proactive management of material cost exposure and delivery reliability should be treated as central competitive capabilities, especially in an environment where input volatility and concentration amplify margin risk.
For investors and capital allocators, the market presents a profile of steady structural demand combined with concentration and cost sensitivity. Opportunities are most compelling where operators demonstrate durable manufacturing efficiency, broad product capability, and the ability to serve high-value segments such as refrigerated or higher-specification container vans. At the same time, exposure to raw material volatility and regional demand cyclicality warrants disciplined due diligence on cost management, customer concentration, and the resilience of order pipelines across different trade environments.
For procurement leaders and logistics operators, the strategic emphasis should shift from transactional price comparison toward fleet performance, service continuity, and specification fit. Aligning container procurement with actual operational requirements across maritime, land, and storage or modular use cases can reduce downstream risk and improve total cost outcomes. Building stronger visibility into supplier production capacity, certification standing, and material sourcing strategy can also improve resilience when demand spikes or input markets become unsettled.
For executives seeking to act on these dynamics with precision, detailed segmentation data, pricing context, regional demand patterns, and company-level benchmarks provide the kind of granular intelligence that supports targeted capital allocation, sourcing strategy, and product planning. A comprehensive market report can help translate the broad structural trends outlined here into decision-ready detail tailored to specific segments and operational priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Container Vans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Uncooled Infrared Detector Housing Market: Why 8.11% CAGR Reshapes Competition
By PW Consulting, 2026-09-18
Navigating the Global Uncooled Infrared Detector Housing Market: Strategic Shifts and Commercial Pathways
Market Landscape and Core Challenges
The worldwide market for uncooled infrared detector housings has entered a phase of sustained expansion, driven by the broader adoption of thermal imaging across defense, industrial, and commercial sectors. Revenue has grown consistently from the early 2020s through the base year of 2025, with the trajectory pointing toward a robust forecast window extending to 2032. At the heart of this growth is the continuous reduction in size, weight, power, and cost (SWaP-C) requirements, which has made uncooled microbolometer technology viable for an expanding range of applications. The sector's compound annual growth rate reflects both organic demand pull and structural improvements in packaging and integration methodologies, positioning housings not merely as protective enclosures but as critical enablers of performance, reliability, and miniaturization.
Worldwide Microbolometer Infrared Detector Market
Despite the positive momentum, the industry confronts a set of interconnected challenges that will shape competitive outcomes over the next several years. The first revolves around the tension between performance thresholds and supply chain accessibility. As applications demand lower noise-equivalent temperature difference (NETD) values and higher resolution formats, packaging architectures must preserve thermal stability, mechanical resilience, and signal integrity while accommodating tighter dimensional constraints. This creates a technical bottleneck for manufacturers that cannot simultaneously optimize vacuum integrity, material compatibility, and high-volume yield. The second challenge stems from regulatory and export control dynamics. Performance-based restrictions on certain detector classes have introduced additional qualification cycles and constrained the flow of advanced components across borders, forcing suppliers to navigate divergent compliance regimes depending on end-use and destination markets. The third challenge is the pressure on cost structures amid intensifying competition. As wafer-level and ceramic packaging approaches mature, incumbents and new entrants alike must reconcile the economics of high-precision manufacturing with the expectation of lower unit costs, particularly in price-sensitive commercial and consumer-adjacent segments.
These pressures are not merely operational; they redefine how value is captured in the housing segment. Suppliers that treat packaging as a commodity risk margin erosion, while those that integrate housings with detector design, thermal management, and application-specific qualification can command premium positioning. The market's concentration among leading players underscores the importance of scale, technical know-how, and long-term qualification relationships. Yet the same concentration also signals opportunity for differentiated entrants that can address regional demand nuances, leverage localized production, or offer packaging solutions that reduce integration friction for system integrators. For decision-makers, the central question is no longer whether the market is growing, but which packaging pathways, qualification strategies, and geographic footprints will determine competitiveness in an environment where performance, cost, and compliance must be balanced simultaneously.
Key Drivers Reshaping the Market
Technology Innovation and Packaging Architecture Evolution
The most consequential driver is the ongoing evolution of packaging technologies that directly determine detector performance, durability, and integration cost. Ceramic packaging has emerged as a preferred pathway for many uncooled infrared detectors because it combines mechanical robustness with design flexibility, enabling miniaturization without sacrificing reliability. Optimized ceramic structures have demonstrated the ability to reduce material volume and overall footprint while preserving mechanical integrity under demanding vibration and shock conditions, making them suitable for mobile, airborne, and field-deployed systems. At the same time, wafer-level vacuum packaging is gaining traction for high-volume production of entry-level and mid-tier thermal imaging modules. By moving vacuum encapsulation closer to the wafer process, suppliers can significantly lower assembly complexity and integration cost, supporting mass deployment in applications where SWaP-C is the dominant selection criterion. The coexistence of ceramic and wafer-level approaches reflects a broader segmentation logic: high-performance and mission-critical use cases continue to favor robust ceramic carriers, while volume-driven commercial applications increasingly adopt wafer-level formats to achieve cost thresholds that unlock new market pockets.
Policy, Export Controls, and Compliance as Strategic Variables
Regulatory and export control environments are increasingly shaping technology roadmaps and supply chain decisions. Performance-based thresholds on detector sensitivity and related specifications have introduced compliance considerations into packaging qualification, influencing which architectures can be supplied to specific end-use markets and geographies. For manufacturers, this means that packaging strategies must account not only for technical performance but also for the documentation, traceability, and qualification pathways required in defense, homeland security, and certain industrial deployments. These dynamics can lengthen qualification cycles and narrow the pool of eligible suppliers for advanced applications, reinforcing the value of established relationships and proven reliability records. At the same time, the evolving policy landscape encourages regional diversification, as system integrators seek to de-risk supply by qualifying multiple packaging sources and maintaining flexibility across different compliance regimes.
Demand-Side Shifts Across Application Verticals
Demand is expanding beyond traditional defense and security applications into industrial thermography, advanced driver-assistance systems, and a growing set of commercial imaging solutions. Automotive ADAS is a particularly influential driver, as thermal imaging is increasingly evaluated for low-visibility detection and pedestrian recognition in safety-critical contexts. This application trajectory pushes packaging requirements toward compact form factors, thermal stability under vehicular conditions, and cost profiles compatible with volume production. Industrial and thermography applications, meanwhile, reward housings that support consistent performance across varied environmental conditions and that can be integrated into portable or fixed inspection systems with minimal re-engineering. In security and surveillance, the trend favors smaller, lower-power modules that can be embedded into networked camera platforms, drones, and mobile monitoring solutions. Together, these demand shifts are broadening the base of end-users and forcing packaging suppliers to develop application-tailored variants rather than relying on a single standardized offering.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are intensifying as multiple manufacturing hubs expand capabilities in metal, ceramic, and wafer-level packaging. In Asia-Pacific, domestic production lines for vanadium oxide-based uncooled detectors across multiple packaging formats have supported more competitive pricing and shorter lead times for regional system integrators. This localization trend is reinforced by the desire to reduce exposure to cross-border constraints and to align supply with regional demand growth. However, cost competitiveness must be balanced against reliability and qualification expectations, particularly where applications require proven mechanical and thermal performance. Suppliers that can demonstrate high-yield manufacturing, consistent vacuum integrity, and robust test protocols are better positioned to protect margins even as unit prices face downward pressure. The broader effect is a market in which scale, process control, and application-specific validation are becoming the primary levers for commercial success, rather than packaging alone as a discrete component sale.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established defense-linked suppliers, regional specialists, and packaging-focused manufacturers that serve the broader uncooled detector ecosystem. Leonardo DRS stands out for its work in leadless chip carrier and wafer-level vacuum packaging for uncooled vanadium oxide long-wave infrared microbolometers, supporting high-resolution formats for both defense and commercial thermal imaging. Its strategic positioning emphasizes proven packaging reliability and the ability to scale sophisticated architectures for demanding applications, including ongoing development toward higher-resolution focal plane arrays. This approach reflects a broader pattern among top-tier suppliers: differentiation comes from integrating packaging expertise with detector performance roadmaps and from maintaining qualification depth in mission-critical use cases.
Global Sensor Technology, associated with Wuhan Guide Infrared, illustrates a volume-and-flexibility strategy. By offering metal, ceramic, and wafer-level packages across multiple resolutions, the company targets high-volume production with an emphasis on SWaP-C optimization and integration into thermal modules. Its recent introduction of ceramic-packaged uncooled infrared detectors using mainstream technology highlights a push toward improved reliability and cost performance, reinforcing the idea that packaging choices are increasingly tied to application economics. For commercial and industrial customers, this type of multi-format capability can reduce integration risk and provide a path to cost-down without abandoning performance requirements.
European and Israeli suppliers contribute additional differentiation through high-performance formats and compact pixel pitch technologies. Lynred has expanded its uncooled microbolometer portfolio with ceramic packaging options for aerospace, defense, and industrial applications, and its move toward smaller pixel pitch architectures signals a focus on resolution and portability for advanced thermal imaging. SCD complements this landscape with low SWaP-C ceramic-packaged detectors aimed at military, homeland security, and industrial deployments, emphasizing form factors and performance attributes suited to specialized end-use scenarios. These players illustrate how regional technology strengths and application histories shape packaging strategies, with a shared emphasis on reliability, performance consistency, and the ability to support higher-resolution or smaller-format trends.
In South Korea, i3system manufactures uncooled infrared detectors for commercial and military thermal imaging, including formats designed for security, surveillance, and night vision systems. Its footprint demonstrates how regional champions can serve both domestic demand and export markets by aligning packaging and detector capabilities with application-driven requirements. Meanwhile, specialized packaging suppliers such as Hebei Sinopack and Hefei Shengda focus on ceramic and electronic packaging components tailored to uncooled infrared focal plane detectors, supporting night vision, security, and monitoring applications. Their role highlights an important structural dynamic: the housing and packaging segment is not served only by detector manufacturers, but also by suppliers whose core competency lies in precision packaging, thermal management, and mechanical integration. Kyocera adds another dimension with ceramic packages and lids for optical and infrared sensors, including surface-mount designs that replace traditional can-style packages. Its emphasis on miniaturization and thermal management reflects an industry-wide shift toward form factors that simplify integration and support higher packaging density.
Taken together, the competitive landscape is evolving along three axes. First, consolidation of capability is occurring among suppliers that can combine detector know-how, vacuum packaging expertise, and qualification depth, especially for higher-resolution and defense-adjacent applications. Second, segmentation is intensifying as ceramic, wafer-level, and metal packaging each find distinct footholds depending on performance, volume, and cost priorities. Third, new entry opportunities exist for companies that can deliver packaging solutions reducing integration friction, supporting regional supply resilience, or enabling cost thresholds for emerging commercial applications. For system integrators and end-product manufacturers, the implication is clear: supplier selection is increasingly a strategic decision that affects not only component cost, but also qualification timelines, application fit, and long-term flexibility across performance tiers and geographies.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most important trends will be the continued migration toward smaller pixel pitches and higher-resolution formats in uncooled microbolometer families. As packaging architectures adapt to these tighter geometries, housings will need to preserve thermal stability, vacuum integrity, and mechanical resilience at reduced scales. This trend creates commercial opportunity for suppliers that can deliver compact, high-reliability packages suitable for portable and high-resolution thermal imaging, where size and performance are jointly decisive. It also raises the bar for process control, because yield and consistency become more sensitive as formats shrink and packing density increases.
A second trend is the widening of volume-driven commercial applications, particularly where SWaP-C thresholds open new adoption pathways. Wafer-level vacuum packaging and optimized ceramic designs are well positioned to support high-volume production and lower integration costs, making thermal imaging more accessible for security, industrial, and certain consumer-adjacent use cases. The commercial opportunity here lies in packaging solutions that standardize interfaces, simplify module integration, and reduce qualification burden for platform manufacturers seeking to deploy thermal imaging at scale. Suppliers that can provide repeatable, cost-effective housings with predictable performance will be better positioned to capture demand in these expanding segments.
A third trend is the growing importance of regional supply resilience and compliance-aware sourcing. As export controls and performance-based restrictions influence which components can be supplied to specific markets, system integrators and OEMs will increasingly pursue multi-source strategies and regional qualification pathways. This creates opportunity for packaging suppliers with localized production, flexible compliance documentation, and the ability to support different end-use regimes. At the same time, uncertainty remains. Regulatory shifts, raw material and process cost volatility, and the risk of quality or yield challenges in advanced packaging formats can all affect timing and margin. The companies that navigate this environment most effectively will be those that treat packaging not as a static enclosure, but as a strategic interface between detector performance, application economics, and supply chain risk management.
Strategic Recommendations for Decision-Makers
For packaging and detector manufacturers, the priority is to align packaging roadmaps with the performance-versus-cost curve that different applications demand. This means investing in process maturity for both ceramic and wafer-level pathways, strengthening vacuum integrity and mechanical validation, and developing application-specific variants that reduce integration effort for system builders. Companies should also evaluate where miniaturization, pixel pitch reductions, and higher-resolution formats create openings for differentiated housings, and where volume economics require a more standardized, cost-optimized approach. Building qualification depth and documentation rigor will be especially valuable where compliance cycles and performance thresholds shape purchasing decisions.
Infrared Detector Market
For investors, the most promising signals lie in suppliers that combine scalable manufacturing with clear application focus and compliance-aware supply strategies. Attention should be paid to firms that can demonstrate yield consistency, multi-format capability, and the ability to serve both specialized and volume markets without compromising reliability. Regional production momentum, particularly where domestic lines support cost-competitive supply while maintaining qualification relevance, is another important indicator of resilience. In a market where concentration is meaningful but segmentation is deepening, capital allocation should favor businesses with defensible process expertise and clear pathways to integration into high-growth application verticals.
For procurement and strategic planning teams, supplier selection should extend beyond unit price to include integration complexity, qualification timelines, mechanical and thermal reliability, and the ability to support future format changes. Diversifying across packaging types and geographies can reduce exposure to regulatory and supply disruptions, while standardizing interfaces where possible can lower total system cost. Engaging early with packaging suppliers on application requirements, test protocols, and anticipated resolution or form-factor evolution can shorten integration cycles and improve long-term flexibility. For organizations that need detailed segmentation data, regional revenue splits, and tailored sourcing or investment scenarios, the full market research report provides the deeper quantitative foundation and customized context required to translate these strategic directions into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Uncooled Infrared Detector Housing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com