

Blogs
The Acoustic Edge: Strategic Trends and Commercial Opportunities in the Gunshot Detection Systems Market
Urban safety architecture is undergoing a fundamental reassessment. As municipal authorities, critical infrastructure operators, and defense contractors confront escalating security threats, the market for gunshot detection systems has transitioned from a niche public safety tool to a core component of integrated security ecosystems. Valued at approximately USD 1.04 billion in 2025, the sector is projected to expand to USD 2.25 billion by 2032, reflecting a compound annual growth rate of 11.8 percent over the forecast period. This trajectory is not merely a function of rising threat perception; it represents a structural shift in how organizations approach real-time threat identification, response automation, and cross-platform interoperability. For executives navigating capital allocation, technology roadmaps, or procurement strategies, understanding the underlying dynamics of this market is no longer optional.
The growth pattern reveals a market maturing beyond initial adoption cycles. Historical data from 2020 through 2025 shows consistent year-over-year expansion, with the 2025 valuation marking a notable inflection point where commercial and institutional deployments began scaling in parallel with military and homeland security applications. Looking ahead to 2032, the revenue curve suggests sustained momentum rather than a temporary surge. This outlook is underpinned by converging technological advancements, evolving regulatory frameworks, and a clear demand-side pivot toward systems that deliver actionable intelligence rather than passive alerting. Yet growth alone does not guarantee strategic advantage. The market carries structural complexities, technological trade-offs, and competitive pressures that demand careful navigation.
Market Landscape and Core Challenges
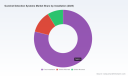
The gunshot detection sector operates at the intersection of acoustic engineering, sensor fusion, and emergency response logistics. Revenue distribution across installation types reflects a clear preference for permanent, infrastructure-integrated deployments, which continue to dominate commercial and municipal contracts. Vehicle-mounted and soldier-mounted configurations maintain a strong presence in defense and tactical mobility applications, while the split between indoor and outdoor use cases highlights a persistent operational reality: outdoor environments account for the majority of deployment volume due to their coverage requirements and public safety mandates, yet indoor installations carry disproportionately high value in critical facilities where response time precision is non-negotiable.
Worldwide Automatic Noise Monitoring System Market
Challenge 1: False Positive Management and Environmental Interference
No metric captures the operational friction of this market more accurately than false positive rates. Acoustic sensors operating in dense urban environments, industrial zones, or high-traffic transit hubs must continuously differentiate between genuine ballistic events and environmental noise—construction equipment, vehicle backfires, fireworks, and even structural resonance. The consequence of misclassification extends beyond alert fatigue; it erodes trust in automated response protocols and can trigger costly emergency mobilization. Recent product iterations have leaned heavily on multi-sensor fusion and machine learning refinement to address this gap, but environmental variability remains a persistent engineering constraint.
Challenge 2: Certification Bottlenecks and Procurement Complexity
Deployment at scale increasingly hinges on regulatory alignment rather than raw sensor performance. In the United States, DHS SAFETY Act certification has become a functional prerequisite for suppliers targeting government agencies and critical infrastructure operators. Without this designation, manufacturers face restricted access to federal contracts and limited eligibility for institutional procurement channels. In the United Kingdom, the National Police Chiefs' Council has reinforced similar expectations through the NPSA Technical Guidance, requiring all deployed systems to appear in the Catalogue of Security Equipment with documented performance metrics. These frameworks elevate accountability but also compress time-to-market for vendors lacking established compliance pathways.
PW Consulting
Challenge 3: Integration Friction Across Legacy Security Stacks
A standalone detection sensor offers limited strategic value if it cannot communicate seamlessly with access control systems, video management platforms, and automated lockdown protocols. Many organizations still operate fragmented security architectures where alert data arrives too late or in incompatible formats to trigger coordinated responses. The market's next growth frontier lies less in improving standalone detection accuracy and more in reducing integration complexity, standardizing data exchange, and ensuring that detection outputs translate directly into executable emergency procedures.
Key Drivers Accelerating Market Evolution
Technological Innovation and Sensor Fusion
The most consequential shift in this market is the move from single-modality acoustic detection to multi-sensor architectures that combine acoustic, infrared, and energy-based inputs. By cross-validating signals across modalities, systems can isolate ballistic signatures with greater confidence and reduce reliance on post-event manual verification. Machine learning layers are now being embedded directly into sensor firmware, enabling continuous adaptation to localized acoustic profiles rather than depending on static threshold settings. This evolution is particularly visible in recent outdoor detection releases, where multi-mode configurations have demonstrated improved discrimination in open environments with higher ambient noise variability.
Military-grade sensing technology is also migrating into civilian and commercial applications at an accelerating pace. Acoustic and energy-based detection platforms originally designed for battlefield situational awareness are being re-engineered for schools, transit hubs, corporate campuses, and industrial sites. This transfer of capability lowers the performance barrier for high-confidence detection while expanding the addressable use-case portfolio. Vendors that can adapt military-proven architectures to civilian installation constraints—without sacrificing durability, calibration stability, or maintenance efficiency—are capturing disproportionate attention from procurement teams.
Policy and Funding Mechanisms as Growth Accelerators
Regulatory and fiscal environments are actively shaping deployment velocity. Federal funding channels, particularly grants administered through the Bureau of Justice Assistance, have made implementation and evaluation resources available for high-crime areas, reducing the financial friction that historically slowed municipal adoption. These programs do not merely subsidize hardware purchases; they incentivize evidence-based deployment models that require measurable outcomes, thereby rewarding vendors that can supply performance data, audit trails, and post-deployment evaluation frameworks.
At the same time, certification regimes are functioning as market filters. DHS SAFETY Act approval and comparable international standards are effectively separating suppliers that can integrate into government and critical infrastructure procurement pipelines from those confined to ad-hoc or private-sector deals. For manufacturers, compliance is no longer a bureaucratic afterthought; it is a strategic capability that determines contract eligibility, pricing leverage, and long-term contract durability.
Worldwide Audio Sensors Market
Demand-Side Shifts Toward Automated Response and Situational Awareness
End-user expectations have evolved beyond immediate alert generation. Security operators now demand systems that classify threat location, estimate trajectory context, and feed structured data into broader emergency management workflows. This shift is driven by the recognition that detection without coordinated response creates operational gaps. Educational institutions, for example, have prioritized indoor detection solutions engineered specifically to minimize false positives in environments where routine noise—sports events, maintenance work, or student activity—can overwhelm conventional acoustic thresholds. The emphasis has moved toward systems that support institutional response plans rather than simply notifying security personnel after an event has occurred.
Supply Chain and Cost Structure Dynamics
Sensor manufacturing, edge processing hardware, and calibration services are experiencing incremental cost optimization as production scales and component standardization improves. At the same time, the cost of deployment is increasingly tied to integration effort, ongoing maintenance, and data management rather than raw hardware expense. Vendors that bundle detection hardware with integration support, remote calibration tools, and performance monitoring dashboards are positioning themselves to capture recurring revenue streams while reducing the total cost of ownership for buyers. This structural change is nudging the market toward service-oriented commercial models rather than one-time equipment transactions.
Competitive Landscape and Strategic Positioning
The market exhibits moderate to high concentration, with a limited group of established players commanding the majority of revenue share. This concentration reflects the capital intensity of sensor development, the importance of certification track records, and the long validation cycles required to earn trust in public safety and defense procurement environments. Yet the competitive field is not static. Differentiation is increasingly defined by architectural approach, integration readiness, and the ability to demonstrate measurable performance in specific deployment contexts.
Company Positioning and Differentiation
- ACOEM Group has anchored its strategy around acoustic threat detection engineered for critical infrastructure and public safety use cases. Its recent system iterations emphasize high-attribute acoustic intelligence engines capable of single-sensor gunshot identification while improving situational awareness. The company's positioning reflects a focus on precision detection with reduced dependency on multi-node sensor arrays, which can lower installation complexity in certain environments.
- EAGL Technology, Inc. differentiates through energy-based detection combined with adaptive response protocols. Its integration capabilities span access control, video systems, and automated emergency workflows, creating a more closed-loop security architecture. DHS SAFETY Act approval further strengthens its eligibility for U.S. government and critical infrastructure contracts, giving it a clear procurement advantage in regulated channels.
- Hyperion Technology Group, Inc. has built its reputation on infrasound-based detection sensors designed for military, homeland security, and industrial applications. Its field-proven deployments and continued R&D emphasis position it as a specialist in environments where conventional acoustic sensing faces physical or operational limitations.
- QinetiQ has extended its EARS family of gunshot localization systems into both soldier-mounted and military police applications. With thousands of portable units shipped and combat-tested validation, the company leans on operational credibility and scalability in tactical mobility contexts. Its SWATS model illustrates how portable localization can complement fixed infrastructure in layered defense strategies.
- Raytheon Company maintains a strong footprint in vehicle-mounted detection, with continued model upgrades targeting faster threat response and improved battlefield situational awareness. Its positioning reflects the broader trend of adapting mobile detection platforms for both defense operations and high-security mobile units.
- Shooter Detection Systems (SDS) has expanded its portfolio across indoor and outdoor environments, combining acoustic and infrared modalities with machine learning refinement. Its recent outdoor system commercialization and institutional indoor deployments highlight a strategy centered on multi-mode accuracy, false-positive reduction, and recognized performance validation through industry awards and safety certifications.
- SoundThinking, Inc. remains a prominent name in acoustic detection for law enforcement, with wide city-level deployments and an expanded AI engine that emphasizes real-time alert processing. Its scale in municipal deployments provides a strong reference base, though the company continues to navigate the broader market shift toward integrated response ecosystems rather than standalone alerting.
- Safety Dynamics, Inc. maintains a focused presence in public safety and law enforcement applications, reinforcing the market's continued reliance on specialized vendors that understand operational policing and emergency response requirements.
Competitive Evolution: Consolidation, Specialization, and New Entrants
The market is exhibiting a dual trajectory. On one side, established players are deepening integration capabilities, expanding certification coverage, and broadening product lines across indoor, outdoor, fixed, and mobile installation types. On the other, specialization is intensifying as vendors carve out defensible positions in infrasound sensing, energy-based detection, portable military localization, or institution-specific false-positive mitigation. New entrants face a high barrier to credibility, particularly when procurement decisions rely on certification status, deployment track records, and interoperability with existing security stacks. Nevertheless, the ongoing migration of military sensing technology into civilian contexts creates openings for companies that can translate advanced sensing capabilities into practical, compliance-ready commercial solutions. Integration partnerships are also reshaping competitive dynamics, as detection suppliers align with video management, access control, and emergency communications providers to offer more complete response architectures.
Future Trends and Commercial Implications
Trend 1: Multi-Modal Detection as the Baseline Standard
The market is moving toward multi-sensor fusion as a default expectation rather than a premium feature. Systems that rely on a single detection modality will increasingly face scrutiny in environments where environmental noise, structural echo, or weather conditions complicate acoustic-only identification. Commercial opportunity lies in architectures that combine acoustic, infrared, and energy-based inputs with on-device machine learning capable of continuous calibration. Vendors that can demonstrate measurable false-positive reduction across varied deployment settings will command pricing leverage and longer contract tenure.
Trend 2: Response Automation and Cross-Platform Interoperability
Detection is becoming only one layer of a broader automated response chain. The next phase of value creation will come from systems that not only identify and locate threats but also trigger access control lockdowns, redirect camera coverage, notify first responders with structured data packets, and log event timelines for post-incident analysis. Procurement teams are likely to prioritize solutions that minimize integration effort and support open data exchange with existing security infrastructure. This creates commercial upside for vendors that invest in API compatibility, standardized alert formats, and pre-built integration modules for common security platforms.
Trend 3: Funding-Linked Deployment Models and Evidence-Based Procurement
Federal and institutional funding mechanisms will continue to influence deployment patterns, particularly in municipal and high-crime area initiatives. Buyers will increasingly require vendors to support grant-aligned implementation models, including performance evaluation, auditability, and documented outcomes. This trend favors suppliers that can provide deployment analytics, maintenance transparency, and post-installation assessment frameworks. At the same time, certification requirements will remain a gating factor for government and critical infrastructure contracts, reinforcing the strategic importance of compliance readiness.
Risks and Uncertainties
Despite the favorable growth trajectory, several uncertainties warrant attention. Environmental and operational variability will continue to challenge detection accuracy in edge cases, particularly in dense urban or industrial settings where ambient noise profiles shift unpredictably. Regulatory frameworks may tighten or diverge across regions, increasing compliance costs and complicating international expansion. Procurement cycles in public safety and defense can be prolonged, with budget approvals and certification timelines creating revenue timing risk. Additionally, as integration becomes more central to system value, vendors that fail to align with prevailing security architectures may face margin pressure or displacement by bundled solution providers.
Strategic Recommendations for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize multi-modal architectures and on-device machine learning that reduce false positives without requiring excessive sensor density. Calibration stability and environmental adaptability should be treated as core product attributes, not secondary engineering tasks.
- Treat certification and compliance as strategic capabilities. Align product development with DHS SAFETY Act requirements and equivalent international standards early in the design cycle to avoid late-stage procurement disqualification.
- Expand integration readiness. Invest in open data interfaces, pre-built connectors for common video and access control platforms, and clear documentation that reduces deployment friction for procurement teams and system integrators.
For Investors and Strategic Capital Allocators
- Evaluate companies based on recurring revenue potential, integration capability, and certification coverage rather than hardware unit sales alone. The market's value migration is tilting toward solutions that support ongoing performance monitoring, maintenance, and automated response workflows.
- Watch for consolidation signals in the integration layer. Vendors that can bundle detection with emergency protocol automation, data analytics, and compliance reporting are positioned to capture higher contract value and longer customer retention.
- Assess exposure to funding-dependent deployment channels. Municipal and grant-aligned contracts can accelerate volume, but they also introduce procurement timing risk and evaluation requirements that may affect cash flow predictability.
For Procurement Leaders and End-User Organizations
- Define operational requirements around response integration before evaluating detection accuracy in isolation. A system that delivers fast, precise alerts but cannot feed structured data into lockdown, video redirection, or first-responder notification workflows will underdeliver relative to total cost.
- Weight certification status and documented performance metrics heavily in vendor selection. Compliance readiness directly affects contract eligibility, especially for government and critical infrastructure deployments.
- Request deployment-specific false-positive data and environmental profiling support. Vendors that can tailor calibration to site conditions and provide ongoing performance transparency will reduce operational risk over the system lifecycle.
The gunshot detection systems market is expanding on the back of technological convergence, regulatory alignment, and a clear demand shift toward actionable response rather than passive alerting. Yet the winners in this environment will be determined less by headline growth figures and more by the ability to deliver accurate detection, seamless integration, and compliance-ready deployment in real-world conditions. Organizations that need granular segment data, regional deployment patterns, pricing architecture breakdowns, or tailored competitive benchmarking will benefit from access to the full research report, which provides the detailed segmentation, company-level financials, and customized strategic recommendations required to convert market awareness into executable decision-making.
For detailed analysis of this topic, please visit the official page: Gunshot Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DSL Chipset Market 2026: Understanding the [5.94%] CAGR Beyond Reported Figures
By PW Consulting, 2026-09-21
DSL Chipsets Market: Strategic Trends and Commercial Opportunities
The DSL chipsets market has entered a period of measured but steady expansion, driven by the continuing need for high-speed broadband access in regions where fiber deployment remains incomplete or economically challenging. Valued at approximately USD 215.0 million in 2025, the market is projected to reach USD 322.0 million by 2032, reflecting a compound annual growth rate of 5.94 percent. This trajectory indicates a mature segment that is not experiencing explosive growth, but rather a sustained, technology-driven evolution shaped by infrastructure realities, competitive dynamics, and shifting demand patterns. For executives and investors operating in broadband hardware, semiconductor supply chains, or telecommunications infrastructure, understanding the forces shaping this market is essential to positioning for the next cycle of investment and product development.
The historical trajectory from 2020 through 2025 reveals a market that has recovered from pandemic-era supply disruptions and stabilized around a baseline of consistent demand. Growth has been supported by incremental upgrades to existing copper-based access networks, particularly in residential and commercial environments where last-mile connectivity continues to rely on xDSL technologies. The forecast period through 2032 suggests that DSL chipsets will maintain relevance, though the pace of expansion will be moderated by the gradual migration toward fiber and wireless alternatives in certain geographies. The market's resilience lies not in volume breakthroughs, but in the ability of chipset vendors to deliver higher throughput, improved power efficiency, and more flexible architectures that extend the useful life of copper infrastructure while accommodating next-generation access requirements.
Market Overview: Positioning in a Mature but Evolving Segment
The DSL chipsets market operates at the intersection of legacy infrastructure and modern broadband expectations. Copper-based networks remain deployed across large portions of the global access landscape, particularly in areas where fiber rollout has been delayed by terrain, cost, or regulatory hurdles. In these environments, DSL chipsets continue to serve as the enabling technology for delivering broadband services that meet contemporary speed and reliability standards. The market's size and growth profile reflect a balance between ongoing replacement cycles, incremental upgrades, and the introduction of higher-performance variants such as VDSL2 and G.fast, which have gained traction in dense urban and suburban deployments where copper vectoring can deliver meaningful throughput improvements.
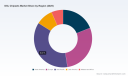
Several structural features define the current market environment. Demand is distributed across residential, commercial, and industrial applications, with residential connectivity representing the largest share of end-use volume. Regional demand patterns vary considerably, with Asia Pacific representing the largest market by value, followed by Europe and North America. Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by infrastructure expansion programs and emerging broadband adoption. The market is characterized by moderate concentration, with the top three players accounting for roughly a quarter of total revenue and the top five holding approximately a third. This fragmentation indicates that no single vendor dominates the landscape, creating room for specialized players, regional competitors, and technology-focused entrants to compete on performance, cost, and support capabilities.
The competitive environment is further shaped by the coexistence of established semiconductor manufacturers and specialized DSL technology providers. Broadcom, MaxLinear, Texas Instruments, Intel's Lantiq division, Qualcomm's Ikanos portfolio, STMicroelectronics, Marvell, Realtek, Sckipio, and Hitron Technologies each occupy distinct positions in the value chain, with product portfolios spanning ADSL, VDSL, and G.fast solutions. The presence of multiple well-resourced incumbents alongside niche specialists suggests a market where differentiation is driven by architecture, power management, signal processing capability, and the ability to support high-density deployment scenarios. This diversity also implies that pricing pressure and technology migration risks are distributed unevenly across vendors, depending on their product focus and geographic exposure.
Key Challenges and Inflection Points
Despite the market's steady growth profile, several challenges and transition points warrant attention. The first is the ongoing tension between copper-based access and fiber migration. While DSL chipsets continue to serve a meaningful role in existing networks, the long-term trajectory of broadband infrastructure favors fiber in many developed markets. This does not eliminate demand for DSL solutions, but it does require vendors and buyers to assess where copper upgrades remain economically viable and where fiber investment will eventually render DSL chipsets obsolete in specific service areas. The inflection point lies in determining the pace of fiber rollout and the extent to which G.fast and VDSL2 can sustain service quality in the interim.
PW Consulting
A second challenge is supply chain concentration risk. Advanced G.fast and VDSL2 chipsets are increasingly manufactured on leading-edge CMOS nodes at a limited set of foundries, including TSMC and Samsung. This concentration creates potential production vulnerability, particularly in the event of geopolitical disruptions or capacity constraints. For manufacturers and buyers who rely on these advanced nodes, the risk is not merely theoretical; it affects lead times, cost stability, and the ability to scale production in response to demand fluctuations. The implication is that supply chain resilience is becoming a strategic consideration, not just an operational one.
A third challenge comes from pricing dynamics in volume-sensitive segments. In ADSL customer premises equipment markets, particularly in Asia and emerging economies, Chinese semiconductor vendors have developed competitive domestic alternatives that exert downward pressure on average selling prices. This pricing pressure complicates margin expectations for incumbents and raises the bar for differentiation. At the same time, geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, creating a bifurcated competitive landscape where regional accessibility and trade policy influence market share as much as product performance.
Together, these challenges point to a market that is not standing still. Vendors and buyers must navigate the intersection of technology lifecycle, supply chain exposure, and regional competitive dynamics. The companies that succeed will be those that can align product roadmaps with realistic infrastructure timelines, manage sourcing risk, and maintain differentiation in the face of pricing pressure.
Key Growth Drivers
Technology Innovation and Signal Processing Advances
Technology development remains a central driver of market activity. Chipset vendors have increasingly focused on improving throughput, reducing noise, and enhancing power efficiency within the constraints of copper-based transmission. Intel's Lantiq division, for example, has emphasized AI-enhanced DSP algorithms for DSL applications, targeting throughput improvements in the 20 to 30 percent range. Such advances are significant because they extend the capability of existing copper infrastructure without requiring immediate fiber replacement, allowing service providers to improve customer experience while managing capital expenditure. Similarly, Broadcom's BCM65x00 family and BCM65550 G.fast vector processor chipsets support high-density multi-DSL and vectoring applications across ADSL2+, VDSL2, and G.fast standards, reflecting a focus on central office and access equipment that can handle multiple line types in a single platform.
MaxLinear's recent product activity illustrates another dimension of technological progress. The company's announcement of an intelligent modular power management solution for next-generation broadband SoCs, supporting DSL, fiber, cable, and fixed wireless access gateways, highlights a shift toward integrated architectures that address power, thermal, and modularity requirements across multiple access technologies. This kind of cross-platform competence is valuable because it allows equipment manufacturers to streamline design cycles and reduce component complexity, even as they support diverse access standards.
Policy and Regulatory Environment
Policy and regulatory developments also shape market dynamics. In the United States, the CHIPS Act incentives have enhanced domestic semiconductor processing capacity, with new facilities expected to create approximately 2,000 jobs by 2029. While the CHIPS Act is broader than DSL chipsets, its impact on domestic manufacturing capacity and supply chain diversification is relevant to any semiconductor segment that depends on advanced nodes and stable production environments. Improved domestic capacity can reduce exposure to geopolitical risk and support more predictable sourcing for vendors and buyers who prioritize supply assurance.
At the same time, regulatory and trade dynamics continue to influence regional market access. Geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, even as those vendors maintain strong deployments in China and other regions. This divergence creates a fragmented competitive landscape where product availability is shaped not only by technical merit, but also by trade policy and national security considerations. For multinational equipment manufacturers, this means that chipset selection cannot be evaluated in isolation from sourcing geography and regulatory risk.
Demand-Side Shifts and Infrastructure Realities
Demand-side behavior continues to support DSL chipset relevance in specific contexts. Residential broadband remains a primary application, with consumers and households expecting reliable connectivity for streaming, remote work, education, and smart home services. In areas where fiber is not yet available, copper-based solutions continue to meet these needs, and upgrades to VDSL2 or G.fast can deliver meaningful improvements in speed and stability. Commercial and industrial applications also contribute to demand, though at lower volume shares, as businesses and facilities rely on broadband access for operations, monitoring, and connectivity in environments where fiber deployment may be delayed or impractical.
The broader demand picture is influenced by the pace of infrastructure investment and the economic calculus of upgrading versus replacing. In many markets, extending the life of copper networks through higher-performance chipsets is a cost-effective strategy, particularly when paired with vectoring and other throughput-enhancing techniques. This demand dynamic supports continued chipset sales, but it also requires vendors to justify the value of DSL solutions against the backdrop of fiber migration plans and wireless alternatives.
Supply Chain and Cost Structure Considerations
Cost structure and supply chain strategy are increasingly important drivers of competitive outcomes. The concentration of advanced node manufacturing among a limited number of foundries means that cost volatility and supply risk are not evenly distributed. Vendors that can secure reliable access to leading-edge production, or that can architect chipsets to operate effectively on more accessible process nodes, may gain an advantage in cost predictability and delivery assurance. At the same time, pricing pressure in ADSL CPE segments from competitive domestic alternatives in China underscores the importance of managing bill-of-materials costs and offering value that goes beyond raw chipset performance.
The cost dynamic also intersects with product architecture. Integrated power management, modular designs, and support for multiple access standards can reduce system-level costs for equipment manufacturers, creating value that is not captured by chipset pricing alone. In this sense, the commercial opportunity is not only in selling chipsets, but in enabling lower total cost of ownership and simpler integration for the broader access ecosystem.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a mix of broad-line semiconductor companies and DSL-focused specialists. Broadcom and Intel's Lantiq division occupy positions that emphasize vector processing, high-density support, and algorithm-driven throughput improvements. Broadcom's BCM65x00 family and BCM65550 G.fast vector processor address central office and multi-DSL scenarios, while Intel's Lantiq division leverages AI-enhanced DSP to target measurable throughput gains. These strategies reflect a focus on performance and integration in environments where dense line handling and advanced signal processing are critical.
MaxLinear differentiates through broadband SoC power management and modular architectures that span DSL, fiber, cable, and FWA gateways. This approach positions the company as a supplier capable of supporting next-generation access equipment with integrated power and control solutions, rather than offering DSL chipsets in isolation. Texas Instruments contributes analog components and integrated circuits optimized for DSL applications, including low-noise pre-amps and ADC-capable components, supporting the signal chain requirements of DSL systems. Qualcomm's Ikanos Communications portfolio provides ADSL, VDSL, and G.fast chipset options for broadband applications, while STMicroelectronics supplies semiconductor solutions and components for xDSL standards in access network equipment. Marvell offers DSL chipset solutions for broadband access and CPE applications, with support for VDSL and G.fast technologies.
Realtek focuses on cost-effective DSL chipsets primarily for ADSL CPE segments in Asia and emerging markets, reflecting a strategy centered on volume and affordability. Sckipio specializes in G.fast chipset solutions for high-density DSL deployments, targeting environments where advanced copper vectoring is a priority. Hitron Technologies develops DSL chipsets and gateways for CPE and broadband access platforms, combining chipset and endpoint capabilities in certain segments. This diversity of focus illustrates a market where differentiation is achieved through product scope, regional emphasis, technology specialization, and system-level integration.
The market is evolving through a combination of consolidation pressure and niche specialization. Larger players with broad portfolios can leverage cross-platform competence and supply chain scale, while specialized vendors can compete on G.fast performance, power efficiency, or regional cost leadership. At the same time, the influence of Chinese domestic alternatives in volume-sensitive ADSL segments and the constrained access of certain vendors in Western markets suggest that competitive outcomes will increasingly depend on geographic strategy, regulatory alignment, and the ability to deliver differentiated value beyond price alone. The trend is not toward a single dominant architecture, but toward a multi-vector landscape where incumbents, specialists, and regional competitors each pursue distinct advantages.
Power Over Ethernet Poe Chipset Market
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued optimization of copper-based access through higher-performance chipsets and vectoring techniques. G.fast and VDSL2 will remain relevant in dense urban and suburban environments where fiber rollout is gradual, and chipset improvements that deliver higher throughput and better noise resilience will sustain demand. The commercial opportunity lies in enabling service providers to extract more value from existing copper assets while planning for eventual fiber migration, creating a bridge technology that supports revenue and customer retention.
The second trend is the increasing importance of power management and modular architectures. As access equipment becomes more integrated and energy-aware, chipsets that contribute to lower power consumption, simpler thermal management, and flexible platform design will be more attractive to equipment manufacturers. MaxLinear's modular power management approach for broadband SoCs is one example of this direction. The opportunity here is not limited to chipset performance; it extends to system-level cost reduction and design simplification, which can be decisive in competitive CPE and access equipment markets.
Wi-Fi Chipsets Market
The third trend is supply chain resilience and regional diversification. Given the concentration of advanced node production and the influence of geopolitical and trade dynamics, vendors and buyers will place greater weight on sourcing security, domestic capacity, and supplier diversification. The CHIPS Act-driven expansion of U.S. semiconductor processing capacity is one indicator of this shift. For companies that can demonstrate reliable supply, flexible architecture, and alignment with regional regulatory expectations, this trend creates an opportunity to build trust and secure long-term design wins, particularly in markets where supply assurance is a priority.
These trends are not without risk. Fiber migration could accelerate in certain regions, reducing the addressable market for DSL chipsets faster than anticipated. Supply chain concentration may continue to expose advanced node-dependent products to disruption. Pricing pressure could intensify in volume segments, compressing margins for vendors that cannot differentiate effectively. And regulatory or trade shifts could alter the competitive balance in specific geographies. The commercial opportunity is real, but it requires a clear-eyed assessment of where copper-based DSL solutions remain viable, how supply risk is managed, and what value proposition justifies adoption in a changing infrastructure landscape.
Strategic Recommendations for Decision Makers
For manufacturers and chipset vendors, the priority is to align product roadmaps with realistic infrastructure timelines and to invest in differentiation that goes beyond raw speed. Power management, modular architectures, and support for high-density deployments can create value that resonates with equipment makers seeking lower system cost and simpler integration. Securing reliable access to advanced nodes, or designing for process flexibility where possible, should be treated as a strategic capability rather than a sourcing detail. In volume-sensitive segments, cost leadership must be paired with defensible differentiation to avoid margin erosion from competitive domestic alternatives.
For investors, the market offers exposure to a mature but resilient segment with steady growth and clear technology-driven demand drivers. The key is to evaluate vendors based on their ability to manage supply chain concentration, navigate regional competitive dynamics, and deliver differentiated architectures that support multi-standard access equipment. Companies with strong positions in G.fast and VDSL2, effective power management solutions, and diversified sourcing strategies are better positioned to sustain value as the market evolves. Investors should also monitor the pace of fiber migration and the impact of trade policy on regional market access, as these factors can influence demand trajectories and competitive outcomes.
For procurement and network planning teams, chipset selection should be evaluated in the context of total cost of ownership, supply assurance, and alignment with infrastructure roadmaps. Where copper-based solutions are part of a longer-term access strategy, prioritizing chipsets that support higher throughput, efficient power use, and flexible integration can reduce lifecycle cost and improve service quality. Where supply risk is a concern, diversifying sourcing and considering vendors with stronger regional manufacturing alignment may provide additional assurance. Procurement decisions should also account for the competitive and regulatory environment in each geography, as market access and pricing dynamics can vary significantly across regions.
For executives and planners seeking a deeper understanding of segmentation dynamics, regional demand patterns, pricing structures, and vendor-specific positioning, a more detailed research report can provide the granular data and tailored analysis needed to support precise decisions. Comprehensive segmentation breakdowns, competitive benchmarking, and scenario-based forecasts can help translate the strategic themes discussed here into actionable plans for product development, investment, and procurement.
For detailed analysis of this topic, please visit the official page: DSL Chipsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CVT Market 2026-2032: Decoding the 4.5% CAGR Surge and Key Segment Dynamics
By PW Consulting, 2026-09-21
Navigating the Continuously Variable Transmission Market: Strategic Shifts and Commercial Opportunities
The global automotive transmission landscape is undergoing a quiet but consequential transformation. Continuously Variable Transmissions (CVTs) have moved from a niche alternative to a mainstream powertrain choice, driven by endurance efficiency mandates, shifting consumer expectations, and relentless refinement in mechanical design. The market has steadily expanded from approximately $15.6 billion in 2020 to $18.65 billion in 2025, settling into a forecasted compound annual growth rate of 4.5 percent through 2032, when it is projected to reach $25.65 billion. This trajectory is not linear, nor is it guaranteed. It reflects a sector balancing mechanical optimization against electrochemical disruption, regulatory pressure against supply chain fragility, and established dominance against emerging competitive architectures. Understanding where the CVT market stands today, what forces are bending its trajectory, and how incumbents are positioning themselves offers practical guidance for executives, investors, and procurement leaders navigating the next cycle of powertrain strategy.
Worldwide Hydrostatic Transmission Market
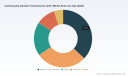
The current market structure reveals both maturity and vulnerability. CVT technology now accounts for a meaningful share of light vehicle powertrains, with belt-driven systems commanding the largest typology share, chain-driven variants holding a substantial secondary position, and toroidal and hydrostatic configurations serving specialized niches. Passenger cars remain the dominant application, while light and heavy commercial vehicles contribute incremental but strategically important volumes. Geographically, the market is distributed across mature and emerging regions, with North America and the Asia Pacific region anchoring the largest revenue pools, Europe maintaining steady demand, and Latin America and the Middle East and Africa representing smaller but growing footprints. This broad distribution masks a highly concentrated competitive environment. The top three players control more than half of market revenue, and the top five extend that share past sixty percent, underscoring the advantage of scale, proprietary manufacturing experience, and long-term procurement relationships. Concentration is not merely a statistical observation; it shapes pricing power, innovation pacing, and the barriers that new entrants must clear.
Concentrated Leadership and Structural Fragility
The market operates under a dual reality. On one side, scale players benefit from accumulated learning curves, volume-driven component sourcing, and deep integration with vehicle manufacturers who value predictable pricing and validated reliability. On the other side, the sector remains exposed to component-specific supply constraints, manufacturing cost sensitivity, and the ever-present question of whether internal combustion efficiency improvements will ultimately be overtaken by electrification trajectories. These forces do not cancel each other out; they interact. A firm that has mastered belt-pulley dynamics and launch-gear integration can extract better fuel economy and smoother acceleration, but if the global supply chain for specialized steel push-belts and precision-machined pulleys experiences disruption, production schedules slip and unit costs rise. The result is a market that rewards disciplined operational execution as much as mechanical ingenuity.
Key Challenges and Inflection Points
Three challenges dominate strategic discussions. The first is cost and reliability perception. While modern CVT designs have improved markedly, earlier generations left a residual impression among some consumers and fleet operators. Addressing that perception requires sustained refinement in durability, thermal management, and packaging efficiency, all of which translate directly into warranty exposure and brand trust. The second challenge is regulatory uncertainty intertwined with compliance economics. Regulatory bodies continue to model transmission cost and efficiency at a granular level, and CVT manufacturing cost estimates have been adjusted through learning curve factors in recent compliance demonstrations. Simultaneously, earlier planning scenarios projected minimal CVT penetration under certain compliance pathways, highlighting how regulatory modeling can influence OEM architecture choices. The third challenge is the tension between incremental internal combustion optimization and the broader shift toward electrification. CVTs can improve fuel economy and help automakers meet Corporate Average Fuel Economy standards and emissions targets, but their long-term role must be evaluated against hybrid, plug-in hybrid, and battery electric architectures. This tension is not a binary conflict; it is a strategic calibration problem that requires understanding where CVTs deliver the greatest marginal benefit and where alternative solutions will outcompete them.
The Resilience-And-Recalibration Paradox
The practical implication for decision makers is that the CVT market is not a single trend line but a portfolio of outcomes. Passenger car adoption continues to benefit from smoothness and fuel economy, commercial applications are expanding where torque delivery and efficiency matter, and specialty architectures remain important for specific duty cycles. Yet all of these segments must contend with component availability, cost discipline, and the credibility of the underlying mechanical design. Companies that manage these trade-offs well are not simply selling transmissions; they are selling validated reliability, predictable total cost of ownership, and regulatory alignment. That is the real competitive currency in this market.
Key Drivers Shaping Market Trajectory
Market growth is not speculative; it is being pulled by identifiable forces that interact across technology, regulation, demand, and supply. The strongest drivers are not isolated innovations but layered dynamics that reinforce one another, making the market more attractive to scale players while simultaneously raising the bar for new entrants.
Technical Refinement as a Competitive Multiplier
Continuous improvement in CVT architecture has shifted the conversation from basic functionality to refined performance. Launch gears, wider ratio ranges, reduced friction losses, and enhanced thermal durability have addressed historical concerns about acceleration response and reliability. These refinements matter because they convert a transmission technology into a brand-level asset. A CVT that delivers seamless operation and strong fuel efficiency becomes a selling point in passenger car lineups, while a robust, torque-tolerant design supports commercial vehicle applications where uptime and operating cost are paramount. The mechanical evolution also has a learning curve effect. As cumulative production volumes rise, manufacturing knowledge deepens, tolerances tighten, and unit economics improve. This is precisely why regulatory and industry analyses continue to apply learning curve factors to cost estimates; the trajectory of cost reduction is tied to output and experience, not to static assumptions. The strategic implication is clear: companies with sustained volume and disciplined process control can lower costs faster and pass through competitive pricing or reinvest in further refinement, creating a virtuous cycle that is difficult for low-volume players to replicate.
Regulatory Pressure and Emissions Strategy
Fuel economy standards and emissions targets remain a powerful structural driver. CVTs contribute directly to compliance strategies by enabling engines to operate closer to optimal efficiency across a wider range of vehicle speeds and loads. This makes them relevant not only for consumer perception but for fleet-average compliance economics. At the same time, regulatory documentation continues to provide granular insights into transmission cost, market penetration assumptions, and compliance scenarios. These documents are not mere paperwork; they influence how automakers model portfolio trade-offs, how suppliers anticipate volume commitments, and how investors assess the durability of transmission demand under different compliance regimes. A market participant that understands the interplay between efficiency mandates, compliance cost modeling, and vehicle architecture choices gains an early-warning advantage when regulatory expectations shift or when specific scenarios reweight the attractiveness of CVTs relative to alternative transmissions.
Demand-Side Behavior and Commercial Uptake
Consumer and commercial demand is moving along two tracks. In passenger vehicles, drivers value smoothness, quiet operation, and fuel economy, and manufacturers have leaned into these attributes in widely sold models. In commercial segments, the calculation is more functional: torque delivery, durability, serviceability, and total cost of ownership drive adoption. The commercial track is especially important because it tends to be less fashion-driven and more performance-driven, making it a stabilizing demand base when consumer taste cycles fluctuate. Additionally, commercial adoption often benefits from fleet-scale procurement and longer lifecycle evaluations, which means winners in this segment can secure recurring volume and deeper integration with operating economics. The broader demand signal is therefore dual-polarized: consumer-facing value propositions build volume and brand relevance, while commercial applications build revenue stability and engineering credibility.
Supply Chain Realities and Cost Structure
No discussion of demand and regulation is complete without addressing the physical supply chain. CVT systems depend on specialized global sourcing for steel push-belts, pulleys, and precision components. This dependence creates both leverage and vulnerability. When supply is stable and scale is high, manufacturers can achieve competitive pricing and dependable delivery. When disruptions occur, production schedules are affected and costs rise, sometimes with cascading effects on OEM build plans. Cost structure, therefore, is not just a function of design efficiency; it is also a function of supply continuity, logistics resilience, and multi-sourcing strategy. Companies that treat the supply chain as a strategic asset rather than a transactional input are better positioned to absorb shocks and preserve margin. This is a practical differentiator that often matters more in day-to-day competitiveness than marginal improvements in marketing position.
Competitive Landscape and Leader Strategies
The CVT market is defined by a concentration of capability among a small group of manufacturers and vehicle makers who have built long-standing technical and contractual relationships. The competitive story is less about scattered experimentation and more about deepening expertise, expanding application breadth, and defending reliability perceptions through sustained product refinement.
Japanese Leadership and Differentiated Positioning
Japanese firms continue to anchor the sector. One transmission specialist has built a leading global market share in CVT technology, with product lines such as CVT-X, CVT-XS, and CVT-S for front-wheel-drive vehicles, and a business model centered on design, development, manufacture, and sale of CVT systems. Its strategic advantage lies in vertical focus and a broad application portfolio that can serve multiple OEM platforms. Another major supplier develops and supplies advanced CVT systems for passenger cars, including models equipped with launch gear to improve fuel efficiency and acceleration response. Its differentiation is engineering integration, especially where launch performance and efficiency must coexist. On the automaker side, several large Japanese brands have embedded CVTs deeply into their lineups. One producer offers its Xtronic CVT across models such as Rogue, Sentra, and Altima, and has continued refining reliability and performance through successive generations. Another incorporates CVTs in widely recognized models for seamless operation and fuel efficiency. A third utilizes its Lineartronic CVT across models such as Forester, Crosstrek, and Outback for efficient power delivery and drivability. The common strategic thread is not mere adoption but sustained optimization: each brand uses the CVT as part of a broader value proposition that ties efficiency, ride quality, and model-specific tuning together.
Worldwide Hybrid Dual-Clutch Transmission Market
Evolution of the Field: Consolidation Depth and Niche Expansion
The competitive field is evolving along two tracks. The first is deepening consolidation among scale players who can amortize engineering, tooling, and supply chain commitments over large volumes. High market concentration means that incumbents already control much of the learning curve, supplier relationships, and customer qualification process. New entrants face not just a technical hurdle but an institutional one: OEMs prefer proven durability, predictable supply, and validated warranty performance. The second track is differentiation within specialized applications and architectures. Toroidal, hydrostatic, and other configurations remain smaller in volume, but they matter where specific torque, speed, or duty-cycle requirements make belt-driven or chain-driven designs less suitable. The opportunity here is not to challenge the dominant architectures head-on, but to own a credible position in segments where mechanical requirements or operating conditions reward alternative designs. This is a classic concentration-plus-niche dynamic: scale players defend the mainstream, while specialists preserve optionality and option value in targeted applications.
Recent Market Signal: Confidence Through Refined Reliability Messaging
A telling recent signal is the emphasis on decades of refinement and improved reliability in updated model-year content. In mid-2025, one major automaker released refreshed messaging highlighting twenty years of CVT improvements and the enhanced reliability of its CVT across 2025 and 2026 models such as the Rogue. This kind of communication is strategically meaningful. It does more than promote a product; it attempts to reset a reliability narrative that has lingered in consumer and fleet perception, and it ties mechanical refinement to model-year continuity. From a competitive standpoint, it signals that leading players understand the market is won as much on trust and durability as on efficiency claims. It also suggests that incumbents are actively managing the perception gap as a core part of their go-to-market strategy, not leaving it to dealer networks or word of mouth.
What This Means for Positioning and Entry
For existing leaders, the priority is to protect scale advantages while continuing to improve launch performance, thermal durability, and packaging flexibility. For suppliers, the priority is to integrate more tightly with OEM calibration and vehicle-level efficiency goals, because CVTs are increasingly evaluated within the full powertrain system rather than as standalone components. For potential new entrants, the realistic path is not to commoditize the mainstream but to address underserved niches, alternative architectures, or regional supply gaps where specificity and responsiveness can outweigh scale. The market does not reward generic entry; it rewards credible specialization backed by engineering discipline and supply reliability.
PW Consulting Automotive & Machinery Research Center
Future Trends and Commercial Opportunities
Predicting the next three to five years of the CVT market requires reading the interaction of technical momentum, regulatory direction, supply resilience, and the broader electrification debate. The trends that matter are not isolated forecasts; they are conditions that reshape where value is created.
Efficiency-as-Standard, Reliability-as-Differentiator
The first trend is the normalization of efficiency and the elevation of reliability into a competitive differentiator. As consumers and fleets become more familiar with CVTs, the baseline expectation will shift from novelty to dependability. Companies that can consistently deliver smooth operation, low noise, and durable performance will capture disproportionate trust and repeat adoption. This trend opens commercial opportunities in warranty-optimized design, improved thermal management, and better service diagnostics, all of which can reduce total cost of ownership and strengthen brand confidence. It also suggests that communications around reliability will remain a strategic lever, especially as new model years refresh the narrative and older concerns fade.
Commercial and Specialty Applications as Growth Anchors
The second trend is the incremental but strategically significant expansion of commercial and specialty applications. While passenger cars will continue to drive volume, commercial vehicles and niche architectures offer stability and higher willingness to pay for functional performance. This is where CVTs can build recurring demand that is less sensitive to consumer taste cycles and more aligned with operational economics. The opportunity lies in tailoring designs to specific duty cycles, improving torque handling and serviceability, and positioning CVTs as part of a broader commercial vehicle efficiency strategy. Companies that treat these applications as afterthoughts will miss a valuable anchor; those that invest in application-specific engineering can create defensible positions and longer contract cycles.
Regulatory Modeling and Portfolio Calibration
The third trend is the growing importance of regulatory modeling in portfolio decisions. Compliance documentation continues to provide detailed estimates of transmission cost, penetration assumptions, and scenario-based outcomes. These documents influence how automakers plan architectures and how suppliers anticipate commitment levels. The commercial opportunity here is foresight: firms that can interpret regulatory trajectories, translate them into volume and cost expectations, and align their product roadmaps accordingly will be better positioned to capture demand when scenarios shift in favor of CVTs, and to protect margins when alternative architectures gain relative weight. This is not about betting on a single future; it is about building optionality and responding quickly to changes in compliance expectations.
Risks and Uncertainties to Watch
No forecast is complete without identifying where the model could break. The most immediate risk is supply chain disruption in specialized components, which can affect production continuity and unit cost. A second risk is the ongoing recalibration of electrification strategies, which could alter the relative attractiveness of internal combustion optimization in certain segments. A third risk is perception persistence: if reliability concerns resurface in high-mileage or extreme-duty conditions, brand trust can erode quickly, reversing some of the gains made through product refinement. A fourth risk is regulatory assumption shifts, where modeling scenarios change how CVT penetration is projected under different compliance pathways. Each of these risks is manageable, but only if firms monitor the signals early and build flexibility into sourcing, product design, and portfolio planning.
Strategic Playbook for Decision Makers
The CVT market rewards participants who combine technical credibility with operational discipline and regulatory awareness. The most useful actions are not generic; they are tailored to the role each organization plays in the value chain.
For Manufacturers and Suppliers
- Double down on reliability as a marketable asset. Invest in durability validation, thermal management, and launch performance, and align product messaging with model-year continuity to strengthen consumer and fleet trust.
- Treat the supply chain as a strategic moat. Develop multi-source strategies for critical components, maintain buffer capacity for specialized steel push-belts and pulleys, and coordinate logistics resilience with OEMs to reduce exposure to disruption.
- Expand application-specific engineering where it pays. Focus development on commercial and specialty segments that value torque, duty-cycle performance, and serviceability, and use these segments to stabilize volume and reinforce engineering credibility.
For Investors
- Assess scale and learning curve advantages rather than headline growth alone. Concentration, cumulative production experience, and supplier integration often determine who can sustain cost improvement and margin stability.
- Monitor compliance modeling signals closely. Changes in regulatory assumptions, cost estimates, and penetration scenarios can shift portfolio preferences more quickly than product trends, and early interpretation can create timing advantages.
- Look for durable demand anchors in commercial and specialty applications, where functional value and total cost of ownership can support recurring volume even as consumer preferences fluctuate.
For Procurement and Fleet Decision Makers
- Evaluate CVTs within the full operating context, not just on efficiency claims. Consider warranty performance, serviceability, supplier continuity, and total cost of ownership across the expected vehicle lifecycle.
- Request evidence of durability and reliability improvements, especially for higher-mileage or commercial use, and align procurement criteria with the reliability narrative that manufacturers are actively reinforcing in current model years.
- Build procurement flexibility around specialized components and delivery continuity to reduce exposure to supply disruptions that can affect uptime and operating cost.
The strategic takeaway is that the CVT market is advancing through disciplined refinement, regulatory alignment, and selective application expansion, not through indiscriminate growth. The companies that will capture the most value are those that understand this nuance and act on it: improving reliability, protecting the supply chain, and positioning CVTs where they deliver the strongest marginal benefit. For leaders who need to go beyond directional trends and make precise decisions on segment allocation, cost modeling, supplier selection, or product roadmaps, detailed segmentation data and customized analysis are available in the complete PW Consulting report on the Continuously Variable Transmission market.
For detailed analysis of this topic, please visit the official page: Continuously Variable Transmissions (CVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Computer Cart Market 2026: Why 6.98% CAGR and Mobility Trends Reshape Healthcare IT Infrastructure
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Medical Computer Cart Market
The medical computer cart market has moved from a niche peripheral category to a foundational component of point-of-care infrastructure. Between 2020 and 2025, the sector grew from approximately $163.15 million to $215.0 million in annual revenue, reflecting an accelerated adoption curve driven by digital Records, bedside workflows, and hybrid care models. Looking ahead through 2032, the market is projected to expand at a compound annual growth rate of 6.98%, reaching $344.8 million by the end of the forecast period. This trajectory reflects more than incremental device replacement; it captures a structural re-architecture of how clinical teams interact with technology at the bedside, in imaging suites, and during virtual encounters.
For executives and investors, the outline signals a maturing but still expanding category with concentrated leadership, clear compliance guardrails, and evolving clinical demands. The growth is not uniform across all use cases or geographies. Rather, it is being shaped by the convergence of workflow digitization, safety certification requirements, and the operational need for mobile, battery-enabled computing stations that can move seamlessly across care environments. The market is large enough to attract specialized entrants, yet concentrated enough that established players with strong certification footprints and integration-ready designs continue to set the pace.
Market Snapshot and Core Challenges
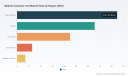
The revenue path through 2032 indicates steady expansion with a notable inflection in the mid-2020s, when the market crossed the $200 million threshold and sustained momentum into the late 2020s. By 2032, total revenue is expected to approach $345 million, a level that underscores the category’s transition from optional mobility accessories to integral clinical workflow platforms. This growth is underpinned by recurring institutional procurement cycles, the need to replace aging carts with smarter, safer alternatives, and the broader digitization of bedside documentation, medication administration, and tele-consultation workflows.
Several structural challenges and inflection points are shaping the market’s next phase.
- Regulatory and certification compliance as a market gatekeeper. Electrical safety standards such as UL/EN/IEC 60601-1 and quality management frameworks like ISO 13485:2016 have become baseline expectations for active manufacturers. Products that integrate powered systems or diagnostic accessories increasingly require 510(k) clearance, adding time and cost to development cycles. Compliance is no longer a differentiator; it is the price of entry, which elevates the importance of proven engineering and documentation capabilities.
- Reimbursement ambiguity and procurement cycles. While mobile carts are often covered under durable medical equipment and physician fee schedule categories, there are no specific new CPT or DRG updates that directly target the cart category beyond standard electronic health record infrastructure billing. This means purchase decisions are typically tied to broader hospital IT modernization budgets and workflow efficiency narratives, making adoption sensitive to capital planning cycles and internal ROI framing.
- Workflow integration versus device proliferation. As hospitals deploy more mobile computing stations, the challenge shifts from acquiring hardware to integrating it into clinical workflows without adding friction. Carts that are not optimized for battery management, ergonomic adjustment, antimicrobial protection, or seamless mounting of imaging and telehealth peripherals can become underutilized assets. Procurement teams increasingly evaluate carts as workflow platforms rather than standalone terminals, pressuring manufacturers to deliver systems that reduce cart replacement frequency and align with infection control protocols.
These dynamics create a market where technical readiness, compliance documentation, and real-world usability converge as decision criteria. The result is a category that rewards manufacturers with integrated power systems, proven safety certifications, and designs that adapt to varied clinical settings, while filtering out less differentiated offerings.
Key Drivers of Market Evolution
The market’s growth is being propelled by a combination of technological breakthroughs, regulatory shaping, demand-side behavior changes, and supply-side cost dynamics. Each driver reinforces the others, creating a compounding effect on adoption and product sophistication.
Technological Innovation and Workflow Enablement
The most visible driver is the shift from passive computer stands to intelligent mobile workstations that combine battery management, height adjustability, integrated power systems, and mounting flexibility for cameras, tablets, and imaging peripherals. Recent product movements illustrate this trajectory. In early 2024, a leading telehealth cart platform was updated with integrated camera positioning and device mounting capabilities designed for remote consultations, reflecting the broader expansion of virtual care into bedside and clinic workflows. Around the same time, upgraded workstation carts with integrated battery management systems were introduced to support bedside digital documentation, addressing a persistent pain point around uptime and mobility during long shifts. By early 2025, broader exhibitions of mobile mounts, power systems, and medical carts at major health IT conferences signaled that the category is increasingly presented alongside complementary infrastructure rather than as isolated hardware.
Metabolic Cart Market
These innovations matter because they reduce the operational burden on clinical teams. Battery systems that provide clear charge indicators and reliable runtime diminish downtime and cart swapping. Height-adjustable designs improve ergonomics for both clinicians and patients across varied tasks. Antimicrobial coatings and robust power architectures support infection control and safety requirements. In combination, these features turn the cart from a simple mount into a workflow enabler that can host electronic prescribing, medication administration, and point-of-care documentation without disrupting movement through rooms, bays, and imaging areas.
Policy, Regulation, and Certification as Market Architects
Regulatory and certification requirements are shaping product design and competitive entry. Electrical safety standards for powered systems, quality management expectations for healthcare manufacturing, and, where relevant, premarket notification for diagnostic accessories or powered patient-care configurations create a compliance environment that favors established engineering processes. This environment is reinforcing a market where manufacturers that maintain ISO 9001:2015 and ISO 13485:2016 certifications across design, manufacturing, and service are better positioned to win institutional trust and multi-year contracts.
At the same time, reimbursement structures remain tied to broader electronic health record infrastructure billing rather than to the cart category itself. This does not constrain demand, but it does influence procurement logic: purchasing decisions are more likely to be justified through operational efficiency, error reduction, and bedside documentation improvements than through direct device-level reimbursement. As a result, the policy environment rewards vendors that can articulate clear workflow benefits, demonstrate compliance readiness, and support standardized integration with existing clinical systems.
Demand-Side Shifts in Clinical and Care Delivery Models
Clinical demand is evolving as hospitals and ambulatory providers expand hybrid care, mobile documentation, and bedside digital workflows. Workstations on wheels are increasingly used for medication management, bedside documentation, and virtual consultations, while also supporting imaging workflows that require adjustable ergonomics and reliable power. The rise of remote consultations and point-of-care electronic records has made mobile computing stations more than convenience items; they are becoming essential for care teams that must move between rooms while maintaining continuous access to patient information and communication tools.
This demand shift is also visible in the prominence of hospital and clinic settings as primary application areas, alongside ambulatory surgical centers and other care environments. Facilities are looking for carts that can adapt to varied clinical contexts, from acute care and imaging to outpatient procedures and telehealth. The result is a demand profile that values versatility, durability, and integration potential over narrowly specialized form factors.
Medical Panel PC Market
Supply Chain and Cost Structure Dynamics
Supply-side conditions are influencing both product design and commercial strategy. Lead times, component availability, and the cost of certification and compliance activities affect development cycles and pricing. Manufacturers that can offer multi-year warranties, consistent power system performance, and clear service support are better equipped to manage total cost of ownership arguments with procurement teams. Meanwhile, the emphasis on antimicrobial coatings, integrated power, and ergonomic adjustments adds value but also requires disciplined manufacturing and quality processes, which tends to favor companies with established quality management systems and repeatable production practices.
Cost structures are also being shaped by the growing importance of interoperability and mounting ecosystems. As carts are deployed alongside mobile monitors, tablets, and peripherals, the ability to standardize mounting and power across devices reduces integration friction and can lower total deployment costs. This is pushing manufacturers toward modular designs and robust accessory ecosystems that support varied clinical configurations without sacrificing safety or compliance.
Competitive Landscape and Leading Strategies
The market’s competitive structure remains concentrated, with leading players capturing a significant share of revenue while a broader set of specialized manufacturers competes on workflow fit, certification readiness, and regional service capabilities. The strategic positioning of incumbents reflects a blend of product breadth, compliance documentation, ergonomic design, and integration-ready ecosystems.
Several companies illustrate the range of strategic approaches shaping the category:
- Capsa Healthcare emphasizes mobile computing workstations and telehealth platforms designed for point-of-care electronic records, medication management, and virtual consultations. Its recent updates to telehealth cart platforms with integrated camera positioning and device mounting reflect a focus on enabling remote patient consultations within bedside and clinic workflows.
- Ergotron focuses on medical carts with integrated power systems, height-adjustable designs, and full electrical safety certifications tailored to acute care and imaging contexts. This positioning underscores the importance of compliance-ready engineering and ergonomic flexibility in high-acuity environments.
- RDP Health Ltd offers custom workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and phlebotomy, with features such as 360-degree battery indicators and extended warranties aimed at public health system procurement. This approach highlights regional workflow customization and long-term service reliability.
- Lund Industries (DataCart) provides custom powered and non-powered healthcare computer carts with antimicrobial coatings, sit/stand height adjustment, and multi-year warranties. Its emphasis on customization and durability reflects a strategy centered on adapting to varied clinical configurations while supporting infection control requirements.
- Advantech contributes computerized medical carts and tablets for mobile medication administration, point-of-care documentation, and telehealth in hospitals, positioning its offerings around mobility, documentation efficiency, and broad clinical deployment.
- Parity Medical supplies UK-designed and assembled workstations on wheels for electronic patient records, electronic prescribing and medicines administration, and bedside clinical applications, illustrating the role of regional design and assembly in meeting local procurement expectations and service requirements.
These players are competing on a combination of product features, certification readiness, regional customization, and ecosystem compatibility. The result is a landscape where differentiation is increasingly tied to workflow fit and compliance documentation rather than to hardware novelty alone. Companies that can deliver reliable battery management, clear safety certifications, ergonomic flexibility, and mounting ecosystems that support monitors, tablets, and telehealth peripherals are better positioned to win multi-year contracts and repeat procurement cycles.
Recent market activity reinforces these strategic directions. An advanced medical cart received FDA listing for hospital use in mid-2024, highlighting the regulatory pathway for products that integrate powered systems or diagnostic accessories. Upgraded workstation carts with integrated battery management systems entered the market around the same period, addressing bedside documentation needs with improved uptime and charge visibility. Updated telehealth cart platforms with camera positioning and device mounting expanded remote consultation capabilities, while broader exhibition of mobile mounts, power systems, and medical carts at major health IT events signaled growing integration between carts and surrounding infrastructure. Together, these developments suggest a category that is moving toward more standardized safety expectations, smarter power management, and tighter alignment with virtual care and point-of-care documentation workflows.
Looking ahead, the competitive landscape appears likely to evolve along three lines. First, consolidation pressure may build as larger technology and medical device ecosystems seek to offer more complete mobile computing solutions that combine carts, power, mounting, and software integration. Second, segmentation may continue between general-purpose mobile workstations and more specialized configurations for imaging, medication management, and telehealth, with differentiation driven by certification, ergonomics, and workflow integration. Third, new entrants may find opportunities in niche regions, custom configurations, and service-led models that emphasize long warranties, battery transparency, and local support, particularly where public-sector procurement values compliance documentation and predictable lifecycle costs.
Forward Outlook: Trends and Commercial Opportunities
Based on current growth dynamics and the trajectory of product and regulatory developments, several trends are likely to shape the market over the next three to five years.
Trend One: Workflow-Integrated Mobility Becomes the Baseline. Mobile computing stations will increasingly be evaluated as integrated workflow platforms rather than as standalone hardware. Buyers will expect reliable battery management, clear charge indicators, height adjustability, antimicrobial protection, and mounting options that support cameras, tablets, and monitors. Vendors that design for interoperability with existing clinical systems and accessory ecosystems will capture more procurement interest, while devices that create integration friction will face greater resistance. The commercial opportunity lies in bundling compatible power systems, mounting solutions, and service terms that reduce total cost of ownership and simplify deployment across departments.
PW Consulting
Trend Two: Compliance and Safety Readiness Move from Advantage to Requirement. As electrical safety standards and quality management expectations become more firmly embedded in purchasing criteria, certification readiness will function as a market requirement rather than a differentiator. This will favor manufacturers with disciplined design controls, documented safety testing, and consistent service processes. For buyers, this trend creates an opportunity to streamline procurement by prioritizing vendors with verifiable compliance footprints and multi-year support commitments, reducing the risk of integration delays and lifecycle service gaps.
Trend Three: Hybrid Care and Point-of-Care Digitalization Expand Use Cases. The continued expansion of remote consultations, bedside documentation, and mobile medication workflows will broaden the application profile of medical computer carts. Telehealth-ready configurations, integrated camera positioning, and flexible device mounting will become more important, while carts used in imaging and acute care will need robust power, ergonomic adjustment, and safety certifications. The commercial opportunity is in designing and positioning products that can serve multiple clinical contexts without sacrificing specialization, enabling facilities to standardize on fewer platforms while meeting varied workflow needs.
These trends are accompanied by risks and uncertainties. Reimbursement frameworks remain tied to broader electronic health record infrastructure billing rather than to the cart category, so procurement momentum can be sensitive to capital budget cycles and internal ROI framing. Regulatory pathways for powered systems and diagnostic accessories can add development time and cost, particularly for new entrants or highly specialized configurations. Supply chain variability, component availability, and certification timelines may affect product launches and pricing. Finally, if workflow integration is under-prioritized, organizations risk accumulating underutilized carts that do not deliver expected efficiency gains, undermining the business case for broader adoption.
Strategic Recommendations for Decision Makers
The market’s direction suggests practical priorities for different stakeholder groups. The following guidance translates current dynamics into actionable focus areas.
- For manufacturers: Prioritize workflow integration and compliance readiness as core product attributes. Build battery management systems with transparent charge indicators, support height adjustability and ergonomic flexibility, and maintain documented safety certifications that align with recognized electrical and quality standards. Develop mounting and power ecosystems that accommodate monitors, tablets, and telehealth peripherals, and structure service terms around multi-year warranties and clear lifecycle support. Differentiation will increasingly come from reliability, integration ease, and certification documentation rather than from hardware novelty alone.
- For investors: Evaluate companies on their ability to deliver compliant, integration-ready mobile workstations with defensible service and warranty models. Focus on manufacturers that demonstrate consistent quality management, clear safety certification status, and product lines that serve multiple clinical contexts without fragmenting the portfolio. Watch for consolidation opportunities among specialized players, and consider the commercial value of ecosystems that combine carts, power, mounting, and service support into repeatable deployment packages. Be mindful of regulatory pathway complexity and reimbursement framing, which can influence procurement timing and margin profiles.
- For procurement and clinical operations leaders: Treat medical computer carts as workflow infrastructure investments rather than commodity hardware. Standardize on configurations that meet electrical safety and quality management expectations, and prioritize battery transparency, ergonomic adjustability, and mounting compatibility with existing devices. Build procurement narratives around bedside documentation efficiency, medication management support, and virtual consultation enablement, and align purchasing cycles with broader IT modernization plans to strengthen justification. Evaluate total cost of ownership including service, warranty, and integration effort, and select vendors that can demonstrate consistent compliance documentation and reliable lifecycle support.
As the market approaches the late 2020s, the most successful commercial outcomes will belong to organizations that can connect product capabilities to real clinical workflows, maintain rigorous compliance readiness, and deliver predictable service over multi-year cycles. For executives and investors seeking detailed segmentation data, regional dynamics, application-level revenue splits, and custom scenario analysis, a comprehensive research report can provide the deeper breakdown needed to support procurement planning, portfolio strategy, and investment decisions. The broader market signals are clear; the next step is translating them into precise, actionable plans with the right level of detail.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Composite Insulators Market: Why 6.98% CAGR Redefines 2032 Revenue Trajectory
By PW Consulting, 2026-09-21
Composite Insulators Market: Strategic Trends and Commercial Opportunities Through 2032
The composite insulators market has transitioned from a niche alternative to a mainstream component in high-voltage infrastructure, reflecting a structural shift in how utilities and OEMs approach reliability, weight, and maintenance economics. Valued at approximately 215.0 million USD in 2025 and projected to reach 344.8 million USD by 2032, the market follows a compound annual growth rate of 6.98 percent across the 2026–2032 forecast window. Growth from 163.15 million USD in 2020 to 215.0 million USD in 2025 illustrates a steady expansion trajectory, with momentum accelerating through the end of the decade. This trajectory is not simply volume-driven; it signals a maturing value proposition where polymer-based designs are increasingly selected for their durability in harsh environments, reduced creepage requirements, and compatibility with modular grid architectures.
Behind the headline numbers lies a market that is gaining confidence but not without friction. The sector is navigating raw material volatility, evolving certification expectations, and a competitive landscape that is consolidating around firms with differentiated manufacturing depth. For executives and investors, the question is no longer whether composite insulators will capture additional share, but where the highest-margin segments will form, which capabilities will separate winners from commoditized producers, and how supply chain and regulatory dynamics will shape returns over the next five years.
A Market at an Inflection Point
The current landscape is defined by three intersecting pressures that are reshaping strategy across the value chain. First, cost structures are increasingly sensitive to input price swings, particularly in resin and fiberglass, which directly influence pultrusion economics and margin stability. Second, international standards are tightening, raising the bar for sheath integrity, interface quality, and long-term performance validation. Third, the supplier base is undergoing selective consolidation, with larger multinational groups acquiring specialized production assets to secure technology, capacity, and certification portfolios. These forces are not isolated; together they are increasing the importance of process integration, quality assurance, and regional compliance readiness.
For market participants, the practical implication is that scale alone is no longer a sufficient advantage. Competitors that can control core manufacturing steps, align product designs with updated standards, and demonstrate consistent performance in demanding applications are better positioned to defend pricing and win long-term utility contracts. Firms that remain dependent on fragmented sourcing or minimal differentiation face greater exposure to price competition and specification-driven disqualification.
Core Drivers Reshaping Demand and Supply
Several structural drivers are underpinning the market’s expansion, and each carries distinct implications for product strategy and commercial positioning.
Technological innovation continues to broaden the applicability of composite insulators. Advances in silicone rubber formulations and hollow-core engineering are enabling lighter, more hydrophobic solutions that perform well in polluted or high-humidity environments. The release of new high-consistency silicone rubber for composite insulator production illustrates how material innovation is opening design space for manufacturers, especially where traditional porcelain or glass solutions carry weight, breakage, or maintenance penalties. At the same time, process technologies that improve interface quality and sheath uniformity are becoming more important as standards raise minimum performance thresholds.
Policy and regulatory evolution is sharpening the focus on compliance and interoperability. Updated frameworks such as IEC 61109 Edition 3.0 and EN IEC 62217:2025 are reinforcing expectations around sheath thickness, interface quality, and defined performance classes for polymeric high-voltage insulators. These revisions do more than set technical baselines; they reduce ambiguity for specifiers and create a more uniform path for manufacturers seeking to serve multiple regions. In practice, this is encouraging producers to invest in certification readiness and to design families of products that can be validated across transmission, substation, and distribution contexts.
Demand-side behavior is also changing. Utilities and industrial operators increasingly favor solutions that reduce footprint, simplify installation, and lower long-term maintenance burden. Composite insulators are gaining traction where their mechanical resilience and corrosion resistance translate into lower lifecycle risk, especially in remote corridors, coastal settings, or regions with aggressive atmospheric contamination. At the same time, the broader push toward grid modernization and expanded transmission capacity is lifting volumes across both overhead lines and substation equipment, broadening the addressable base beyond traditional replacement cycles.
PW Consulting Chemical & Energy Research Center
Supply chain and cost dynamics remain a critical variable. Pultruded fiberglass profiles for composite insulator cores generally cost between 5 and 15 USD per linear foot, or roughly 2 to 10 USD per pound depending on resin selection and customization. This range underscores how sensitive production economics are to glass fiber and resin pricing, and why manufacturers with integrated processes or disciplined procurement strategies can achieve more stable margins. When raw material prices fluctuate, the impact is not limited to input cost; it ripples through lead times, quotation reliability, and the ability to scale capacity without eroding unit economics.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of technologically specialized manufacturers, regionally concentrated producers, and multinational groups pursuing targeted expansion. Market concentration remains moderate, with the top three firms holding approximately 24.6 percent and the top five about 26.2 percent of the market. This fragmentation suggests room for both differentiation and consolidation, depending on the segment and geography.
Worldwide Low Voltage Insulators Market
Leading players are pursuing distinct strategic positions. Some manufacturers emphasize full vertical integration in hollow composite insulator production, building end-to-end control over core fabrication, housing, and final assembly. This model is particularly valuable where OEMs and utilities prioritize traceability, repeatability, and the ability to offer alternative gas or insulation options. Others compete on breadth of product families, covering suspension, line post, pin, tension, and bushing types across transmission, substation, and distribution networks. That breadth can be a strong commercial advantage when specifiers want a single source for multiple asset classes, especially in large-scale grid build-outs.
A third strategic theme is technology-led specialization. Certain producers focus on epoxy-resin glass fiber cylinders and high-temperature injection or advanced molding technologies that target substation and line applications requiring precise mechanical and electrical performance. These capabilities can support premium positioning when paired with rigorous qualification data and strong service networks. In parallel, manufacturers active in Asia and India continue to expand capacity and export reach, often competing on combination of cost, scale, and growing technical credibility. Their growth reflects both domestic demand and the broader international search for reliable supply alternatives.
Recent industry developments offer a clear window into how the landscape is evolving. The introduction of new silicone rubber materials for composite insulator production highlights the ongoing push to improve material consistency and processing efficiency. Meanwhile, corporate moves such as the acquisition of composite insulator production facilities by a larger group, including machinery and intellectual property, point to a strategy of securing specialized manufacturing assets and expanding capacity in established industrial regions. This kind of transaction suggests that controls over core processes, proprietary know-how, and certified production lines are becoming strategic assets rather than mere operational inputs.
Trade show participation and regional exhibition activity also indicate where companies are concentrating commercial effort. Exhibiting advanced high-voltage composite insulators at international grid equipment events and utility-focused conferences signals a continued emphasis on face-to-face specification engagement, particularly in markets where project pipelines are active and relationships with utilities, contractors, and system integrators matter.
Taken together, the competitive picture suggests three unfolding dynamics. First, differentiation is shifting toward process depth, materials expertise, and certification readiness rather than catalog breadth alone. Second, consolidation is likely to continue in pockets where complementary technologies, regional access, or specialized production assets create clear value. Third, new entrants and expanding regional manufacturers will keep pressure on pricing in commodity-adjacent segments, while more engineered applications remain open to firms with strong technical validation and application support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the intersection of materials progress, standards-driven specification clarity, and selective consolidation. The first trend is the continued migration of composite insulators into higher-value applications where performance under stress, weight reduction, and maintenance savings justify the choice over traditional alternatives. This shift will not be uniform; it will concentrate in environments where contamination, humidity, vibration, or access limitations make polymer-based designs especially advantageous.
Composite Insulated Panels Market
The second trend is the growing importance of compliance as a commercial differentiator. As updated standards raise expectations for sheath quality, interface integrity, and consistent high-voltage performance, manufacturers that can demonstrate robust qualification processes and repeatable production control will gain an advantage in tender evaluations and OEM supply agreements. Certification readiness is becoming less of a back-office function and more of a market-access requirement, particularly for suppliers targeting multiple regions or working with large multinational buyers.
The third trend is the continued realignment of manufacturing capacity and ownership. Strategic acquisitions and capacity expansions in established production hubs indicate that scale, technology control, and localized capability will matter more as customers seek reliable supply and shorter qualification cycles. At the same time, raw material sensitivity will keep cost discipline and formulation flexibility in focus, especially where resin and fiberglass pricing can compress margins or disrupt quoting.
These trends create concrete commercial opportunities. There is room for product strategies that pair material consistency with application-specific design, enabling suppliers to serve both transmission and substation segments without diluting manufacturing focus. There is also opportunity in regional expansion where grid investment is accelerating and where localized support, certification alignment, and service responsiveness can outweigh pure price competition. For buyers, the opportunity lies in reducing lifecycle risk through more predictable performance and in consolidating the supplier base where quality assurance and technical support can be managed more efficiently.
Risks and uncertainties remain. Raw material volatility can quickly alter cost assumptions and erode the economics of capacity expansions if not managed with hedging, formulation options, or process efficiencies. Regulatory updates, while beneficial in the long run, can impose rework, retesting, or redesign costs if product families are not aligned early. In addition, intensified competition in volume-oriented segments may pressure margins even as premium segments expand, creating a bifurcated market where profitability depends heavily on positioning and execution.
Strategic Implications for Decision Makers
Manufacturers should prioritize capabilities that convert technical advantage into commercial advantage. That means investing in process integration where it strengthens quality, consistency, and traceability; aligning product families with updated standards before specification cycles lock in; and building formulation and procurement flexibility to absorb raw material swings. Where possible, firms should also consider targeted expansion of engineered product lines rather than undifferentiated catalog growth, since higher-value applications are likely to reward proven performance and application support more than breadth alone.
Investors should evaluate exposure not just to market growth but to the underlying drivers of margin durability. Capacity expansions, technology acquisitions, and regional entry decisions all look more attractive when paired with certification readiness, material expertise, and a clear route to utility or OEM demand. The most resilient opportunities are likely to emerge where operators can demonstrate control over critical production steps and where the customer base values reliability and lifecycle performance enough to support disciplined pricing.
Procurement and specification teams should treat composite insulator selection as a lifecycle decision rather than a unit-price comparison. Evaluating sheath quality, interface design, material consistency, certification status, and supplier process control can reduce installation risk and long-term maintenance exposure. Consolidating suppliers where supported by strong technical documentation and consistent qualification data may also improve procurement efficiency, especially across transmission, substation, and distribution programs with overlapping performance requirements.
Closing Perspective
The composite insulators market is entering a phase where growth is increasingly tied to technical credibility, standards alignment, and strategic control of manufacturing depth. The pathway from 215.0 million USD in 2025 to 344.8 million USD by 2032 will not be evenly distributed across every supplier or segment. Instead, value will accrue to participants that can combine material innovation, compliance readiness, and operational discipline with a clear focus on the applications where composite designs deliver the strongest economic and technical case. For organizations operating in or adjacent to this market, the most valuable next step is to map these shifts against specific product portfolios, regional pipelines, and procurement strategies, and to update assumptions as standards, materials, and ownership structures continue to evolve.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pomegranate Market 2026-2032: Why 6.8% CAGR Growth Redefines Future Strategy
By PW Consulting, 2026-09-21
The Pomegranate Market: Strategic Trends and Commercial Opportunities Through 2032
The global pomegranate market has transitioned from a niche seasonal offering to a mainstream, multi-segment commercial category. Total market revenue crossed the 215 million USD threshold in the base year, reflecting consistent expansion across production geographies and value-added formats. The sector has demonstrated a compound annual growth rate of 6.8 percent across the forecast horizon, a pace that positions pomegranates ahead of many legacy fruit categories but still requires deliberate portfolio strategy to capture. Revenue figures across the historical and projected periods illustrate a trajectory that moved from 163.15 million USD in 2020 to 341.83 million USD by 2032, with particularly pronounced expansions occurring after 2023. Such progression is not simply a function of acreage expansion; it reflects structural shifts in how fruit is processed, formulated, and positioned across food, wellness, and personal care applications.
For executives evaluating exposure to this category, the takeaway is that pomegranate is no longer a single-commodity story. The market now operates as an ecosystem where fresh fruit distribution, juice and concentrate processing, and ingredient-level applications for supplements and cosmetics interact with each other. This interconnected structure means that shifts in one segment can rapidly alter demand, pricing, and margin profiles across the broader chain. Understanding the interplay between volume growth, product-form diversification, and regional production patterns is essential before committing capital or reformulating supply strategies.
Key Structural Challenges and Inflection Points
Three pressures are reshaping how participants compete and where profitability is likely to concentrate. First, water intensity and irrigation discipline are becoming strategic variables rather than operational details. Recent scoping work in Western Cape orchards and commercial field trials have demonstrated that optimized irrigation scheduling can improve yield, fruit quality, and water use efficiency at the same time, which indicates that water management is a direct lever on quality consistency and cost structure rather than a compliance cost alone.
Second, labor exposure in high-touch orchard systems continues to pressure margins. Pruning and multi-stage harvesting can account for a substantial share of annual operational expenses in established European orchards, alongside significant upfront investment per hectare. This cost reality means that differentiation increasingly depends on agronomic efficiency, mechanization readiness, and yield consistency, not simply access to premium labeling or origin prestige.
Third, the category is being reshaped by the dominance of a few high-volume production centers alongside scattered but growing cultivation in newer regions. The structural imbalance between large-scale sourcing geographies and fragmented downstream processors creates both sourcing advantages and concentration risk, particularly for companies that rely on a narrow band of origin points or single processing formats. The practical implication is that resilience planning must account for agronomic variability, logistics continuity, and the ability to pivot across fresh and processed channels when weather, labor, or regulatory conditions shift.
Key Drivers Shaping the Pomegranate Market
The growth path is being generated by several reinforcing forces that operate across technology, regulation, consumer behavior, and cost structure. These drivers do not simply lift volume; they change which business models are likely to outperform.
Technological and Agronomic Innovation
Precision orchard management is becoming a core competitive advantage. Field evidence from commercial monitoring indicates that adjusting irrigation to a carefully managed fraction of evapotranspiration can improve fruit quality and yield while reducing cost and certain quality defects such as sun cracking. Equally important, the findings underline that evapotranspiration levels can vary widely across seasons and sites, so standardized irrigation assumptions are increasingly inadequate. For processors and brand owners, the strategic implication is that fruit quality consistency is becoming more dependent on upstream production discipline and traceability than on downstream blending or formulation alone.
Policy and Regulatory Context
Regulatory and environmental pressures are reinforcing the shift toward water-smart cultivation and documentation-intensive supply chains. In markets where water availability is tightening or where agricultural resource management is being scrutinized more closely, orchard-level efficiency is increasingly tied to license to operate. At the same time, cultivation expansion in newer regions is often supported by targeted investment in high-density systems and structured production programs. The broader lesson is that regulatory trends are not only creating constraints; they are also shaping where and how expansion is economically viable, particularly in regions where water productivity can be measured and improved.
Demand-Side Transformation
Consumer and corporate purchasing behavior is moving pomegranate further into wellness-oriented and convenience-driven use cases. Fresh fruit remains a foundation, but demand from food and beverage applications continues to be the largest consumption channel, reflecting both traditional culinary use and broader incorporation into beverages and formulated products. At the same time, nutraceutical and supplement use, along with cosmetics and pharmaceutical applications, adds a higher-value demand layer that rewards standardized extracts, stable concentrates, and ingredient-grade consistency. For commercial strategy, this means the same raw crop can support multiple value pathways, but each pathway requires different quality thresholds, formulation controls, and positioning.
Supply Chain and Cost Structure Evolution
Cost structure is being redefined by the interaction of labor intensity, capital investment per hectare, and the economics of processing form. Orchards that rely heavily on manual pruning and repeated harvesting face structurally higher operating costs, while growers adopting denser plantings and more controlled inputs can improve unit economics if they can sustain quality and yield. On the processing side, the economics of juice, concentrate, and other processed forms depend on fractionation efficiency, shelf-life management, and the ability to serve both bulk ingredient buyers and branded consumer channels. The combined effect is that margin leadership is increasingly determined by integrated efficiency from orchard to finished product, rather than by any single step in isolation.
Competitive Landscape and Leading Strategies
The competitive environment includes vertically integrated growers, branded fruit and juice operators, organic-focused processors, and international ingredient exporters. The market remains moderately fragmented at the top, with concentration levels indicating room for consolidation but also for differentiated niches. That combination matters because it means scale is not the only path to leadership; consistency, origin storytelling, certification, and format specialization can all support premium positioning.
Strategic Positioning of Key Players
Vertically integrated operators that control both growing and processing have a structural advantage in managing quality, timing, and channel mix. By managing cultivation alongside juice and value-added products, these companies can reduce dependency on third-party sourcing and create tighter feedback loops between orchard outcomes and finished product specifications. Their differentiation often rests on branded narrative, consistent supply, and the ability to offer multiple formats from a single origin. These are powerful advantages in consumer-facing channels, but they also require disciplined execution across agronomy, cold chain, and product development.
Organic and family-oriented processors compete through provenance, minimal-processing positioning, and consumer trust. In categories where label simplicity and clean formulation matter, these players can command attention even without the broadest distribution footprint. Their challenge is scaling while preserving the operational discipline and certification standards that support their positioning. For ingredient buyers, such producers can be attractive where traceability and organic integrity are procurement priorities.
PW Consulting Health Care Research Center
International ingredient exporters, particularly from major production geographies, play a different role: they supply bulk fruit products, pulps, concentrates, pastes, and fresh fruit for broader distribution networks. These companies are important to the market because they provide volume flexibility and geographic reach, especially for processors and formulators that need consistent input supply across seasons. Their competitive edge typically comes from sourcing scale, processing capability, export logistics, and the ability to match specifications for both food service and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and fragmentation depending on the segment. In branded consumer channels, scale and marketing intensity favor players who can sustain shelf presence and brand recognition. In ingredient and processed forms, the trend is more fragmented, with regional and origin-specific suppliers competing on cost, quality consistency, and service reliability. At the same time, newer cultivation regions are expanding, which introduces additional sourcing diversity and can reduce dependence on a narrow set of origins over time.
Another important shift is the growing relevance of supply-side innovation as a competitive differentiator. Where water productivity, irrigation scheduling, and yield optimization are measurable and improved, suppliers can offer better quality and more predictable delivery. This is gradually turning agronomic performance into a commercial asset rather than a private operational matter. Companies that can document efficiency, quality stability, and responsible resource use are better positioned to enter higher-value contracts and withstand volatility in labor or weather conditions.
Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend One: Water-Smart Production as a Purchasing Criterion
Water productivity is moving from an operational concern to a procurement differentiator. Evidence from orchard monitoring and irrigation studies indicates that optimized water use can support both quality and cost performance, which suggests that buyers will increasingly favor suppliers who can demonstrate responsible irrigation management and consistent output under variable conditions. The commercial opportunity lies in tying sourcing decisions to measurable production efficiency, not only to price or origin. Suppliers able to provide verifiable efficiency data, stable quality, and documented yield improvement are likely to gain preference in higher-value contracts and long-term supply arrangements.
The uncertainty here is that water conditions, regulatory expectations, and climate variability differ significantly by region. Strategies that work where evapotranspiration is highly variable may need adjustment in other contexts, and over-reliance on a single improvement model could leave some operators exposed if local conditions change.
Trend Two: Format Diversification Will Outpace Single-Channel Growth
The market will continue to reward companies that can move fluidly across fresh fruit, juice and concentrate, and other processed forms. This diversification matters because different formats absorb seasonality and price volatility differently, and because downstream demand is spread across food and beverage, nutraceuticals, supplements, and cosmetics or pharmaceutical uses. Companies that can align product-form capability with the quality requirements of each channel are better positioned to capture multiple revenue streams from the same crop base.
The strategic opportunity is to treat product form as a portfolio decision rather than an operational afterthought. Where a company can efficiently fractionate fruit into fresh, juice, concentrate, or ingredient-grade outputs, it can better serve both consumer-facing and industrial buyers. The risk is that format expansion can dilute focus or strain quality control if processing lines, specification management, and customer support are not designed to handle varied applications.
Trend Three: Origin Expansion and Sourcing Reconfiguration
Cultivation is expanding in regions that have historically been smaller players, supported by investment in production systems and targeted development programs. This trajectory introduces new sourcing options and gradually broadens the geographic base of supply. For buyers, the opportunity is greater flexibility, potential cost arbitrage, and reduced concentration risk. For growers and processors, it is a chance to enter supply chains that value differentiated origin, consistent quality, and documented efficiency.
Garnet Market
The uncertainty is execution. Newer production regions often face startup costs, learning-curve effects, and logistics complexity. The most attractive opportunities will not automatically go to regions with expansion potential; they will go to those that can combine growth with quality reliability, export readiness, and credible performance data.
Actionable Guidance for Decision-Makers
For Manufacturers and Consumer-Facing Brands
Treat pomegranate as a multi-format portfolio rather than a single ingredient. Build flexibility into sourcing and processing so that fresh, juice, concentrate, and value-added forms can be balanced according to demand and margin. Where possible, align product development with applications that reward consistency and documentation, since those uses are likely to grow alongside wellness and personal care demand. Prioritize suppliers whose agronomic discipline and quality traceability are visible and verifiable, as those attributes are increasingly tied to commercial reliability.
For Investors
Evaluate exposure across the value chain rather than assuming that volume growth alone translates into returns. The most resilient opportunities are likely to be found where operational efficiency, format diversification, and measurable sustainability performance reinforce one another. Look closely at companies that can demonstrate water productivity improvements, controlled labor exposure, and the capability to serve more than one demand channel. Equally important, assess concentration risk in sourcing regions and the readiness of supply bases to adapt to weather, labor, and regulatory shifts.
Avocado Market
For Procurement and Supply Chain Leaders
Diversify origin exposure while maintaining specification rigor. Multi-origin strategies can reduce vulnerability to localized weather, labor, or logistics disruption, but they only work if quality standards and documentation are consistently applied across suppliers. Consider sourcing criteria that include irrigation efficiency, yield stability, and the ability to provide evidence of production discipline. Where possible, structure relationships that allow flexibility across processed forms so that supply continuity can be maintained when fresh-market conditions or processing availability shift.
Closing Perspective
The pomegranate market is entering a phase where commercial success depends less on simple category growth than on structural clarity: how fruit is produced, how it is processed into different forms, and how well participants can demonstrate value beyond price. The combination of water-smart production, format diversification, and broadening origin geography is expanding the strategic surface area of the category. That expansion rewards companies that can align quality, efficiency, and application fit across multiple channels. It also raises the cost of passive sourcing, since buyers and investors alike are increasingly exposed to agronomic variability, labor intensity, and concentration risk. In that environment, the most valuable next step is to move from broad category confidence to precise, segment-level intelligence that supports sourcing, product, and investment choices with greater certainty.
For detailed analysis of this topic, please visit the official page: Pomegranate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fiber Coloring Rewinding Machines Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Fiber Coloring Rewinding Machines Market
Overview
The Fiber Coloring Rewinding Machines Market encompasses equipment designed for the precise coloring and rewinding of fiber materials. These machines are essential in ensuring consistent dye application, high-quality finishes, and efficient processing of fibers used across textiles, automotive, and industrial sectors. Their core functionalities include automated dyeing, tension control, and seamless rewinding, supporting the production of vibrant, uniform fiber products.
This market plays a vital role in modern manufacturing by enabling scalable, cost-effective fiber processing solutions. The Fiber Coloring Rewinding Machines Market helps industries meet stringent quality standards and sustainability goals, particularly as demand for customized and eco-friendly fiber products grows. Its significance is especially pronounced as industries seek advanced automation and precision in fiber treatment processes.
Market Size and Growth
The current market value for the Fiber Coloring Rewinding Machines Market is estimated at around USD 1.2 billion. Over the next decade, it is projected to reach approximately USD 2.3 billion, reflecting a compound annual growth rate (CAGR) of about 8%. Factors driving this growth include rising demand for high-performance fibers, technological innovations, and increasing automation in manufacturing.
Advancements in dyeing techniques and the expansion of fiber-based industries are key growth catalysts. Additionally, the push for sustainable processing methods and stricter regulatory standards further stimulate market expansion. As industries prioritize efficiency and quality, the demand for specialized rewinding machinery continues to rise.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2006
Key Drivers
- Growing demand for high-quality, color-accurate fibers
- Increasing automation in fiber processing industries
- Rising adoption of eco-friendly dyeing technologies
- Expansion of textile and composite markets
- Technological innovations in machine efficiency
Restraints
- High initial capital investment in advanced machinery
- Technical complexity limiting ease of operation
- Stringent regulatory compliance costs
- Limited availability of skilled operators
- Operational challenges in integrating new systems
Segmentation
• By Type: Manual, Semi-automatic, Fully automatic
• By Deployment: Factory-based, Mobile units
• By Enterprise Size: Small, Medium, Large enterprises
• By End User: Textile manufacturers, Automotive industry, Industrial fibers, Others
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits steady growth driven by technological adoption and sustainability initiatives. Europe’s demand is fueled by stringent quality standards and innovations in eco-friendly dyeing. In Asia-Pacific, rapid industrialization and expanding textile sectors lead to high demand for fiber rewinding solutions. Latin America shows emerging opportunities, while Middle East & Africa are gradually adopting advanced fiber processing technologies.
Opportunities
- Expansion in emerging Asian markets
- Integration of IoT and automation technologies
- Development of energy-efficient, eco-friendly machines
- Adoption in high-growth textile and composite industries
- Innovation in modular and scalable rewinding solutions
Key Companies
Barmag, Rieter, Oerlikon, SSM Schärer Schweiter Mettler AG, Karl Mayer, Murata Machinery, Yamato, Texpa, DiloGroup, Lohia Corp, Kusters Engineering
Conclusion
The Fiber Coloring Rewinding Machines Market holds significant long-term growth potential as industries demand higher quality, automation, and sustainability. Its strategic importance is underscored by ongoing technological advancements and expanding application areas. Overall, the market is poised for steady expansion, driven by innovation and increasing industry adoption, making it a crucial component of modern fiber processing infrastructure.
Related Reports
Portable Odor Scanner Market , Size Share and Analysis | Report 2033
Agitator Impellers Market , Size Share and Analysis | Report 2033
Weight Dosing Dispenser Market , Size Share and Analysis | Report 2033
Altitude Pressure Experiment Cabin Market , Size Share and Analysis | Report 2033
Insulating Oil Volume Resistivity Tester Market , Size Share and Analysis | Report 2033
Automatic Powder Coating Line Market , Size Share and Analysis | Report 2033
Built In Fireplace Market , Size Share and Analysis | Report 2033
Electric Winding Machine Market , Size Share and Analysis | Report 2033
Automatic Hull Cleaning Robot Market , Size Share and Analysis | Report 2033
Engineering Rammer Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Particle Size Analyzers Market: Why 6.5% CAGR and Healthcare Demand Shift Strategy Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Particle Size Analyzers Market: A PW Consulting Outlook
Market Landscape and Core Challenges
The particle size analyzers market has entered a phase of accelerated expansion, driven by tightening quality control requirements across regulated industries and the growing demand for precise material characterization in pharmaceutical, chemical, and advanced manufacturing applications. Measured in millions of USD, the sector moved from approximately 350.0 in 2020 to an estimated 512.0 in 2025, with a projected compound annual growth rate of 6.5 percent through 2032, when revenue is expected to approach 800. The trajectory reflects a market that has transitioned from steady instrumentation replacement cycles to a broader adoption environment shaped by regulatory scrutiny, miniaturization of analytical workflows, and cross-industry quality standards.
At the macro level, regional demand shows a clear concentration in established industrial and research hubs, with mature pharmaceutical and chemical markets driving consistent procurement volumes. Technology segments remain anchored by laser diffraction as the dominant measurement principle, while complementary methods such as dynamic light scattering, imaging, and nanoparticle tracking analysis continue to expand the addressable use cases in sub-micron and nano-range characterization. End-user demand is similarly structured around sectors where particle attributes directly influence product performance, stability, dissolution behavior, and process efficiency. Healthcare applications represent the largest share of demand, followed by academia, chemicals, and a diversified set of manufacturing sectors including food, cosmetics, and mining. The market remains moderately consolidated, with the top three players accounting for roughly 38 percent of revenue and the top five reaching about 42 percent, indicating that while scale and brand recognition matter, the competitive field still accommodates specialized and regional entrants.
Despite the favorable growth outlook, the market faces three structural challenges that are reshaping commercial strategies:
- Intense capital expenditure scrutiny in healthcare and public-sector laboratories: Particle size analyzers are treated as laboratory capital equipment rather than revenue-generating diagnostic tools. Hospitals and clinical laboratories operate under tight budget envelopes and reimbursement constraints, which prolong procurement cycles and increase competition for available CapEx. This dynamic places pressure on vendors to justify total cost of ownership, service reliability, and workflow integration rather than relying solely on technical performance.
- Standardization, compliance, and costly component requirements: Laser diffraction remains governed by established measurement standards that ensure traceable and repeatable results, but high-end instruments increasingly rely on precision optics and electronics that must meet certified, medical-grade component expectations in regulated pharma and clinical settings. Maintaining ISO certifications, CE marking, and audit-ready documentation adds operational complexity and restricts cost-down strategies, especially for manufacturers serving dual-use markets.
- Competition between performance differentiation and cost-efficient alternatives: The market is not homogeneous. While premium vendors compete on reproducibility, automation, and application-specific support, cost-effective alternatives have expanded reach in laboratory and industrial segments. Buyers in price-sensitive environments are increasingly weighing functional adequacy against brand prestige, forcing incumbents to demonstrate measurable advantages in throughput, operator ease, and integration with broader quality systems.
Key Drivers Shaping Market Dynamics
The growth of the particle size analyzers market is not simply a function of incremental instrument replacement. It is being reshaped by converging forces across technology, regulation, user behavior, and supply economics. Understanding these drivers is essential for assessing where demand will intensify and which commercial models will hold up under scrutiny.
Technology innovation and measurement versatility
Instrument development is moving beyond basic size distribution outputs toward integrated workflows that combine repeatability, automation, and easier interpretation for non-specialist operators. Laser diffraction systems continue to lead because they cover broad size ranges with fast measurement cycles, but the market is also expanding where sub-micron, nanoparticle, and morphological characterization matter. Dynamic light scattering and nanoparticle tracking analysis are gaining relevance for nanoformulations and dispersed systems, while imaging-based methods support morphology and shape factors that size-only outputs cannot capture. These capabilities matter because particle attributes increasingly affect formulation behavior, processing consistency, and downstream performance in complex materials.
PW Consulting
For vendors, the strategic implication is that performance leadership now depends on more than optical precision alone. Automation, sample handling flexibility, software usability, and seamless data traceability are becoming differentiators that influence purchasing decisions, especially where laboratory throughput and compliance documentation are critical. Instruments that reduce operator variability and simplify validation packages can command stronger adoption in regulated settings, even when upfront pricing is higher.
BET Surface Area Analyzer Market
Regulatory expectations and compliance-driven procurement
Regulatory and standardization dynamics play an outsized role in purchase timing, specification requirements, and vendor selection. Laser diffraction measurement practices are anchored by long-standing standards that support traceable and repeatable results, which makes them well suited to pharmaceutical and clinical applications where data integrity is essential. In parallel, major manufacturers maintain CE marking and relevant certifications for instruments used in regulated medical device and pharmaceutical particle characterization. This compliance posture is not a minor detail; it is a procurement prerequisite in many quality-sensitive environments.
At the same time, reimbursement and budgeting realities shape adoption. Particle size analyzers are capital equipment items without dedicated procedural billing codes, so purchasing decisions are strongly influenced by laboratory budget cycles and institutional cost control. The result is a dual dynamic: regulated applications can create durable demand because particle characterization supports quality and process validation, but procurement timing can be delayed or compressed depending on institutional CapEx availability. Vendors that can align their value proposition with audit readiness, documentation support, and predictable service coverage are better positioned to convert technical strength into commercial wins.
Demand-side shifts in formulation, manufacturing, and research
User demand is changing because the importance of particle attributes is rising across multiple end-use sectors. In healthcare and pharmaceutical environments, particle size and distribution can influence dissolution, bioavailability, and consistency of drug products, which reinforces the need for reliable characterization during development and quality control. Academic and research institutions continue to drive demand through fundamental material science, nanomaterial studies, and interdisciplinary programs that require precise sizing across different measurement ranges.
In industrial settings, the motivation is often operational rather than regulatory. Chemical, food, cosmetic, and mineral-processing operations use particle size data to optimize mixing, dispersion, reactivity, flow behavior, and end-product consistency. As manufacturers seek greater process control and reduced variability, the analyzer shifts from a periodic measurement device to a more integral quality assurance tool. This shift expands the value proposition beyond the instrument itself and toward workflow integration, repeat measurement confidence, and support for process decisions.
Supply-side and cost structure pressures
Cost structures in the high-end segment are increasingly shaped by component requirements. Precision optics and electronics in advanced laser diffraction systems often depend on certified, medical-grade components when instruments are deployed in pharma or clinical environments. These requirements constrain aggressive cost reduction and can affect lead times, sourcing flexibility, and service scalability. Meanwhile, in the broader market, regional manufacturers and cost-efficient models are expanding choice for laboratory and industrial users who prioritize functionality and price over premium brand positioning.
This divergence creates an important strategic tension. On one side, compliance and performance requirements support premium pricing and more defensible margins for vendors with strong documentation, service networks, and application support. On the other, price sensitivity in less regulated or more volume-driven segments pressures incumbents to compete on throughput, ease of use, and total cost of ownership. Supply-side strategy therefore matters as much as product performance: sourcing resilience, service coverage, and scalable calibration support can determine whether a product succeeds commercially across regions and customer segments.
Competitive Landscape and Leading Strategies
The market is led by a set of established multinational players with distinct technology portfolios, application focus areas, and geographic strengths. Their strategies reveal how vendors are navigating the tension between premium performance, compliance, and broader accessibility.
Amino Acid Analyzers Market
Malvern Panalytical remains a prominent force in laser diffraction, with a recognized presence in pharmaceutical applications where particle characterization supports drug dissolution and bioavailability studies. Its positioning reflects the broader value of strong brand recognition, application depth, and alignment with regulated workflows. Danaher, through its life sciences portfolio, combines Coulter Principle and laser diffraction systems that serve clinical laboratory and pharmaceutical particle characterization, giving it a strong fit in environments where clinical and quality control demands intersect. HORIBA Scientific offers laser diffraction systems covering sub-micron to larger particle ranges, emphasizing broad measurement versatility for laboratory and scientific use. Anton Paar focuses on laser diffraction analyzers with automation features designed to improve precision and repeatability, an approach that addresses the need for reduced operator variability in controlled environments.
A second layer of competitors illustrates the market's expanding accessibility. Bettersize Instruments, based in China, specializes in cost-effective laser diffraction and dynamic light scattering systems for laboratory and industrial applications, targeting users who require solid measurement capability without premium pricing. Microtrac provides laser diffraction, DLS, and image analysis options for fluid and dry materials, supporting customers who need multi-mode characterization flexibility. Sympatec develops laser diffraction systems oriented toward powders, granules, suspensions, and process monitoring, aligning closely with manufacturing and inline or process-adjacent use cases. Shimadzu supplies particle characterization instruments for laboratory powders and liquids, benefiting from broad scientific instrumentation credibility. Fritsch integrates particle sizing within a wider milling and sizing portfolio, which can be attractive for customers linking sample preparation and analysis. Mettler Toledo incorporates particle size analyzers into automated characterization offerings for laboratory and process use, reinforcing a workflow-oriented value proposition. Scitek Global, also from China, offers lab and medical equipment including particle size analyzers with ISO 13485 certification, a compliance signal that can matter in regulated procurement environments.
These profiles show a market where differentiation is no longer defined solely by measurement method. Leading positions are increasingly tied to application support, software usability, compliance documentation, service reach, and the ability to serve both development and quality control needs. Vendors that can bridge laboratory characterization and process-relevant insights gain an advantage in sectors where particle data must inform operational decisions, not just generate reports.
The competitive landscape is evolving along three trajectories:
- Consolidation pressure among mid-tier and regional players: As buyers demand broader support, calibration, and service coverage, smaller vendors face mounting pressure to scale service infrastructure or partner for distribution. This favors larger players with existing institutional relationships and multi-channel support, while creating opportunities for acquisitions that add geographic coverage or complementary technologies.
- Differentiation through workflow integration and software: Hardware performance remains essential, but commercial advantage is shifting toward automation, data handling, and traceability features that reduce burden in regulated environments. Systems that simplify validation, reporting, and multi-user operation are better positioned to withstand procurement scrutiny.
- New entry and niche expansion in specific measurement ranges and applications: Demand for nano-range characterization, dispersed systems, and specialized sample types continues to create openings for focused entrants. Rather than challenging leaders across the full instrument spectrum, new players often compete by targeting specific size ranges, sample formats, or regional price points with credible certification and application support.
Future Trends and Strategic Opportunities (2026–2032)
The next several years are likely to be shaped by how the market balances performance, compliance, cost, and workflow value. Three trends stand out as particularly consequential for commercial planning.
1. Wider adoption of automated, workflow-oriented analyzers in regulated environments
As laboratories face staffing constraints and greater documentation demands, instruments that reduce operator dependence and improve measurement repeatability will gain traction. Automation in sampling, cleaning, data export, and reporting can lower total cost of ownership by improving throughput and reducing error-related rework. This trend is especially relevant in pharmaceutical and clinical-adjacent settings, where compliance-ready documentation and consistent results support validation and audit processes. Commercial opportunity lies not only in instrument sales but in bundled offerings that include service, training, software updates, and compliance support. The risk is that automation claims must be backed by demonstrable reliability and service coverage; otherwise, perceived complexity can slow adoption.
2. Growing demand for multi-method and application-specific characterization solutions
Particle characterization needs are becoming more diverse as materials and formulations grow more complex. Some applications require broad dynamic range, others need nano-scale sensitivity, and still others benefit from shape or morphology information. This is likely to increase demand for vendors that can offer method flexibility or integrate complementary techniques within a coherent workflow. For end users, the appeal is faster method selection, fewer handoffs between instruments, and more interpretable results for specific applications. For vendors, the opportunity is to position instruments as part of an application solution rather than as standalone measurement boxes. The uncertainty is that cross-method integration can raise cost and support complexity, so success will depend on clear use-case targeting rather than broad but shallow capability claims.
3. Intensifying competition between premium performance and cost-efficient access
Market growth is likely to broaden access to particle characterization in emerging industrial and regional markets, where cost sensitivity and practical usability may outweigh premium brand value. At the same time, regulated and performance-critical applications will continue to reward vendors with strong compliance credentials, service depth, and demonstrated reproducibility. This bifurcation creates a strategic choice for companies: compete premium or compete broadly. The more profitable path may be a segmented strategy that protects high-margin regulated positions while using targeted cost-efficient models to capture volume in less regulated sectors. A key risk is brand erosion if premium positioning is diluted without clear differentiation, or if cost-focused models cannot sustain service and calibration quality over time.
Actionable Guidance for Decision-Makers
The commercial implications of these trends vary by role, but a common theme is that purchasing and competitive decisions increasingly hinge on total workflow value, compliance readiness, and service sustainability rather than on measurement capability alone.
For manufacturers and technology providers
- Prioritize differentiation through automation, software usability, and documentation support that reduces burden in regulated settings. Technical excellence matters, but repeatable workflows and audit-ready outputs often decide procurement outcomes.
- Segment the portfolio deliberately. Use premium, compliance-oriented offerings for pharmaceutical and clinical-adjacent demand, while developing credible cost-efficient options for broader laboratory and industrial segments without compromising support quality.
- Strengthen service, calibration, and regional coverage. In a market where CapEx approval is cyclical and compliance expectations are high, long-term customer value depends heavily on post-sale support and sourcing resilience for precision components.
For investors and strategic planners
- Focus on business models that combine instrument revenue with recurring service, software, and application support, since these elements can improve resilience through budget-constrained procurement cycles.
- Watch for consolidation signals among regional and mid-tier players, especially where scale in service distribution, certification coverage, or application breadth becomes a competitive requirement.
- Evaluate exposure to regulated end-use demand carefully. While pharmaceutical and healthcare applications can sustain premium positioning, purchasing timing may be sensitive to hospital and laboratory budget cycles, which can affect short-term revenue visibility even when long-term demand remains strong.
For procurement leaders and laboratory operators
- Evaluate total cost of ownership, not just purchase price. Consider measurement repeatability, operator training burden, service response time, and documentation support, especially where compliance and throughput matter.
- Define application requirements clearly before sourcing. The “best” instrument depends on sample type, size range, throughput needs, and regulatory context, and over-specifying or under-specifying can create unnecessary cost or performance gaps.
- Request evidence of workflow fit and support capability. References, validation support, and service coverage may be as important as performance specifications when procurement must justify capital allocation within institutional budget constraints.
The strategic picture is clear: the particle size analyzers market is expanding under the influence of regulatory expectations, workflow automation, and broader application demand, but it is also becoming more segmented and more service-dependent. Companies that understand where compliance, cost, and performance intersect will be best positioned to capture durable demand, while buyers who evaluate instruments as part of a broader quality workflow will make more resilient procurement decisions. For decision-makers seeking detailed segmentation data, regional demand patterns, and customized competitive scenarios across technologies and end users, a full research report can provide the deeper quantitative context needed to translate these trends into precise commercial planning.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Color Coated Steel Market: How 4.86% CAGR and Asia Pacific's Lead Redefine Revenue Paths
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Color Coated Steel Market
The color coated steel market is navigating a period of structural transition. Between 2020 and 2025, global revenue grew from $183.0 million to $238.0 million, reflecting steady demand across construction, manufacturing, and consumer applications. The trajectory points toward $330.71 million by 2032, implying a compound annual growth rate of 4.86 percent. This expansion is neither uniform nor frictionless. Regional imbalances, regulatory reconfiguration, and material cost volatility are reshaping how value is created and captured across the value chain. For executives and investors, the opportunity lies not in chasing aggregate growth, but in positioning operations and portfolios around the structural forces that will determine competitive advantage over the next five years.
The market remains moderately concentrated, with three firms accounting for roughly 55 percent of revenue and five firms controlling approximately 62 percent. This concentration masks significant fragmentation at the regional and application levels, particularly among processors and fabricators who serve localized construction and industrial demand. The operating environment is also being redefined by policy shifts and material economics that differ sharply across jurisdictions. The following analysis examines the core challenges, demand drivers, competitive dynamics, and emerging trends that will shape strategic decisions in the color coated steel sector.
Market Landscape and Critical Inflection Points
The period from 2020 through 2025 demonstrates resilient demand, but the growth path is uneven. Revenue crossed the $220 million threshold in 2023 before a slight contraction in 2024, followed by recovery in 2025. This pattern reflects the sensitivity of coated steel demand to construction cycles, import policy volatility, and the timing of large project pipelines. The forecast horizon through 2032 indicates that growth will increasingly be driven by application diversification, coating technology upgrades, and regional supply realignment rather than by uniform volume expansion.
Steel Roofing Market
Several structural challenges are converging at once.
- Policy and trade friction are compressing arbitrage opportunities. Tariff escalations and anti-dumping actions are narrowing the traditional cost advantages of cross-border sourcing. Import-dependent supply chains face higher landed costs and greater planning uncertainty, while domestic producers confront both protection and the pressure to justify scale investments.
- Material cost volatility is reshaping margin structures. The zinc galvanizing layer that provides the essential corrosion barrier accounts for approximately 8 to 12 percent of total production cost, with pricing influenced by global commodity exchanges. Fluctuations in zinc and substrate costs directly affect coating economics, especially for producers operating on thin service-center margins.
- Regulatory mandates are accelerating formulation change. Environmental requirements around chromate-free and ultra-low-VOC coating systems are moving from optional best practice to compliance baseline in key markets. This shifts the competitive conversation from price-per-ton to performance durability, compliance documentation, and downstream certification readiness.
These forces are not isolated. Trade policy influences where capacity is built, material costs determine which coating chemistries remain economically viable, and environmental regulations raise the bar for product qualification. The net effect is a market that rewards operators with flexible production systems, transparent compliance records, and the ability to serve application-specific performance requirements rather than generic commodity volumes.
Key Demand Drivers Reshaping the Market
Growth is being pulled by a combination of technology, policy, demand-side behavior, and supply chain economics. Each driver reinforces the others, creating a landscape where differentiation is increasingly tied to capability depth rather than scale alone.
Coating technology and performance differentiation. Advances in resin systems and surface engineering are expanding the addressable use cases for color coated steel. Polyester-based formulations continue to anchor high-volume construction and consumer applications due to cost efficiency and adequate durability. At the same time, higher-performance chemistries are gaining traction where exposure conditions, aesthetic requirements, and service life expectations justify premium pricing. The practical impact is a market that is segmenting by performance tier rather than by commodity classification. Producers who can demonstrate measurable improvements in weather resistance, color retention, and formability are capturing share in application segments where failure costs are high.
Policy and regulatory reconfiguration. Trade and environmental policy are becoming central to competitive positioning. The United States increased Section 232 tariffs on steel from 25 percent to 50 percent in mid-2025, a move intended to reduce import dependence and stimulate domestic capacity investment. In parallel, the European Union's carbon border adjustment mechanism for iron and steel became fully operational at the end of 2025, imposing carbon-related costs on imported products. Brazil's foreign trade authority also announced definitive anti-dumping tariffs in early 2026 on pre-painted steel from India and China, with rates spanning a wide per-tonne range. These measures alter the economics of inter-regional trade and push buyers and suppliers to reconsider sourcing geography, inventory strategy, and contract structures.
Demand-side behavior and application expansion. Construction remains the largest demand anchor, but the character of demand is evolving. Residential and commercial building activity, infrastructure renewal, and retrofit programs continue to support volume, while specification requirements increasingly emphasize durability, corrosion protection, and environmental compliance. Beyond construction, consumer goods and automotive applications provide additional demand layers that value consistent finish quality, weight efficiency, and formability. The presence of multiple application streams reduces dependence on any single cycle and creates opportunities for suppliers who can align coating systems with specific end-use performance criteria.
Supply chain structure and cost dynamics. The cost stack for color coated steel is sensitive to substrate availability, coating raw materials, and energy intensity. The zinc layer, which serves as the critical anti-corrosion component, introduces commodity-linked cost variability. At the same time, regional production footprints are being reassessed in response to tariff and carbon policy. Some operators are prioritizing closer-to-market coil processing and finishing to reduce exposure to trade friction, while others are investing in integrated capabilities to protect margin and improve qualification speed. Supply chain resilience is becoming a commercial differentiator, particularly for buyers who require consistent lead times and documented compliance across multiple SKUs.
Competitive Landscape and Strategic Positioning
The competitive field spans manufacturers, processors, and traders across North America, India, and South Korea, with distinct strategic postures emerging by region and business model. Companies are not competing solely on price; they are competing on qualification breadth, coating system versatility, compliance readiness, and the ability to support downstream fabrication and assembly requirements.
In North America, a group of active manufacturers and processors has built positions around pre-painted and color coated steel coils for construction, building panels, garage doors, and service canopy applications. Several of these firms emphasize specific resin platforms, including PVDF-based systems and weather-resistant polyester coatings, to align with architectural and industrial specification requirements. The regional focus reflects both the tariff environment and the importance of responsive service, short lead times, and localized technical support for fabricators and building product manufacturers.
India hosts a dense set of manufacturers and exporters with varying capacities and coating portfolios. Some operators focus on large-scale production and broad geographic reach, exporting across multiple continents. Others differentiate by offering a wide range of colors, embossed patterns, and coating systems such as RMP, SMP, PU, and PVDF to serve roofing, cladding, and industrial applications. The combination of domestic demand growth and export orientation creates a competitive environment where scale, standard compliance, and coating versatility are key advantages.
South Korean participants include integrated manufacturers and traders offering pre-painted coils and sheets across multiple coating types, including silicon polyester, PVDF, and high-polymer systems. Several firms maintain substantial annual production capacity and emphasize product standards compliance and appliance-grade finish quality. Their positioning reflects the region's strength in process precision and the importance of meeting specification requirements for downstream manufacturers in construction and consumer durable segments.
Across these regions, several strategic patterns are evident.
- Differentiation through coating systems and compliance. Leading participants are building reputations around specific resin platforms, color consistency, and adherence to international standards. This matters because downstream buyers increasingly require documented performance, VOC compliance, and corrosion resistance data as part of procurement decisions.
- Regionalization of supply as a risk management tool. Tariff and carbon policy are encouraging closer alignment between production, processing, and end markets. Operators with flexible regional footprints can reduce exposure to trade volatility and respond faster to specification changes.
- Capacity and qualification as barriers. In segments where reliability, certification, and throughput matter, capacity scale and process control create meaningful barriers. At the same time, niche processors can compete effectively by specializing in high-specification applications or by offering rapid customization for local fabricators.
The market structure suggests continued divergence. Large integrated players will continue to compete on scale, standard compliance, and export reach, while regional processors and specialists will compete on service speed, coating flexibility, and application-specific performance. Consolidation is possible where scale and compliance costs favor larger operators, but fragmentation can persist where localized service and specification support remain critical to winning business.
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026 through 2032 horizon, three trends are likely to shape where value concentrates and where risk accumulates.
Coil Coatings Market
Trade and carbon economics will continue to rewire sourcing maps. The combination of higher steel tariffs in certain markets, operational carbon border mechanisms in others, and targeted anti-dumping actions will keep inter-regional arbitrage under pressure. Over the next few years, buyers and suppliers will likely place greater weight on nearby processing capacity, inventory buffering, and contract structures that can absorb policy variability. For producers, this environment rewards transparency around carbon intensity and the ability to offer compliance-ready documentation alongside product quality. The commercial opportunity lies in serving buyers who need predictable sourcing under changing policy conditions.
Performance-tier segmentation will intensify. As formulators advance chromate-free and ultra-low-VOC systems and as end markets raise durability expectations, the market will increasingly separate into performance tiers. Commodity-grade volumes will remain important, but growth and margin will be more concentrated in applications that demand long service life, high weather resistance, and strict environmental compliance. Suppliers with validated coating systems, clear test data, and application engineering support will have an advantage in specification-driven segments such as architectural cladding, infrastructure, and corrosion-sensitive industrial uses.
Material cost management will become a strategic capability rather than an operational detail. With zinc-linked costs representing a meaningful share of the production cost base, effective raw material procurement, coating formulation optimization, and waste reduction will directly influence profitability. Operators that can align coating selection with application requirements while controlling input costs will be better positioned to maintain margins through commodity cycles. This is particularly relevant for processors serving price-sensitive construction and consumer segments, where small cost advantages can translate into competitive share gains.
PW Consulting
These trends carry risk. Policy directions can shift faster than capacity decisions, and carbon compliance costs may rise as mechanisms mature. Formulation mandates can increase production complexity and require reformulation investment. Demand in construction-linked applications remains sensitive to interest rates, project finance conditions, and regional economic cycles. Participants who overestimate the stability of current trade and demand patterns risk building capacity or sourcing commitments that become suboptimal if conditions change.
Actionable Guidance for Decision Makers
Different roles in the value chain face different priorities, but several strategic moves are broadly relevant.
For manufacturers and processors. Prioritize coating flexibility and compliance documentation as core capabilities. The ability to offer multiple resin systems, demonstrate VOC and chromate compliance, and provide clear performance data will increasingly determine access to specification-driven demand. Where possible, align production and finishing capacity with the markets you serve most frequently to reduce exposure to trade and logistics volatility. In parallel, treat raw material cost management as a strategic lever, integrating supplier relationships, formulation optimization, and yield improvement into a single margin-protection plan.
For investors. Focus on operators with differentiated positioning rather than undifferentiated volume exposure. Companies with strong certification records, application-specific coating expertise, and regional supply alignment are better placed to navigate policy and cost volatility. Assess exposure to carbon-related costs, tariff sensitivity, and the proportion of revenue tied to performance-tier applications versus commodity-grade volume. In markets where consolidation is plausible, look for signs of scale advantage in compliance, process control, and export readiness; in more fragmented settings, look for specialists with durable local relationships and technical service depth.
For procurement and specification teams. Build sourcing strategies that assume continued policy and cost variability. Diversify between domestic and regional supply options where feasible, validate compliance documentation before award, and include coating performance and environmental requirements explicitly in specifications. Where lead time and availability matter, consider the trade-offs between lowest landed cost and supply resilience, especially for applications where re-specification or replacement carries high downstream cost.
The color coated steel market is moving from a phase where aggregate volume growth was the primary narrative to one where policy, performance, and cost structure determine who wins share and where margin is earned. Navigating this environment requires granular understanding of regional dynamics, coating system capabilities, and the evolving requirements of downstream applications. Detailed segmentation data, company-level benchmarks, and scenario-based sourcing analysis can sharpen these decisions significantly. For decision makers who need to move beyond high-level trends into market-specific sizing, competitive mapping, and tailored strategy options, the full research report provides the deeper dataset and structured analysis necessary to support investment, capacity, and procurement choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Color Coated Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Constant Temperature Metal Bath Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Overview
The Constant Temperature Metal Bath Market encompasses specialized equipment designed to maintain precise and stable thermal conditions for metal samples, components, or processes. These baths are essential in laboratories, manufacturing, and quality control settings where consistent temperature regulation is critical for metallurgical testing, calibration, and research activities. Their core functionalities include accurate temperature control, uniform heat distribution, and reliable operational stability, supporting modern industries such as aerospace, automotive, and electronics.
The market for constant temperature metal baths is vital for ensuring process consistency and safety in high-precision manufacturing. As industries demand tighter quality standards and advanced testing protocols, the importance of these systems continues to grow. The Constant Temperature Metal Bath Market plays a crucial role in facilitating technological development, enabling precise material analysis, and ensuring compliance with industry regulations.
Market Size and Growth
The current market value for the Constant Temperature Metal Bath Market is estimated at approximately USD 250 million. Over the next decade, this figure is projected to reach around USD 400 million, reflecting a compound annual growth rate (CAGR) of roughly 6%. Growth is driven by increasing adoption in research laboratories, expanding manufacturing sectors, and technological advancements in thermal regulation systems. Rising demand for high-quality materials and stringent testing standards further bolster market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1972
Key Drivers
• Increasing automation and precision in manufacturing processes
• Rising investments in R&D across industries
• Growing adoption in quality assurance and testing labs
• Technological innovations improving temperature stability and control
• Expansion of electronics and aerospace sectors globally
Restraints
• High initial capital expenditure for advanced systems
• Technical complexity requiring specialized maintenance
• Stringent regulatory standards increasing compliance costs
• Limited availability of customizable solutions for niche applications
Segmentation
• By Type
- Standard models
- Customizable models
• By Deployment
- Benchtop systems
- Floor-standing systems
• By Enterprise Size
- Small and medium enterprises
- Large corporations
• By End User
- Research laboratories
- Manufacturing facilities
- Academic institutions
- Quality control labs
• By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Insights
North America exhibits strong demand driven by advanced research institutions and strict quality standards, particularly in the U.S. and Canada. Europe’s focus on precision manufacturing and regulatory compliance supports steady growth, especially within Germany and the UK. In Asia-Pacific, rapid industrialization, a burgeoning electronics sector, and expanding research infrastructure present significant opportunities. Latin America’s growth is mainly fueled by developing manufacturing and research capabilities, while Middle East & Africa show emerging interest in technological upgrades for industrial applications.
Opportunities
• Expansion in emerging markets such as India and Southeast Asia
• Integration with Industry 4.0 and smart manufacturing initiatives
• Development of energy-efficient and environmentally friendly systems
• Adoption in additive manufacturing and advanced materials testing
• Growing demand from biotech and pharmaceutical sectors
Key Companies
Julabo GmbH
HAAKE (Thermo Fisher Scientific)
Julabo GmbH
PolyScience
Memmert GmbH + Co. KG
Lauda-Brinkmann
Grant Instruments
Buchi Labortechnik AG
VWR International
Hirschmann Engineering
Hirschmann Engineering
Esco Micro Pte Ltd
Conclusion
The overall outlook for the Constant Temperature Metal Bath Market remains positive, with long-term growth driven by technological innovation and expanding industrial applications. As industries seek higher precision and quality standards, the strategic importance of reliable thermal regulation solutions will continue to rise. The market offers substantial growth potential, emphasizing its critical role in supporting modern manufacturing, research, and testing environments.
Related Reports
Automatic Printing And Binding Machine Market , Size Share and Analysis | Report 2033
Wireless Document Transmitters Market , Size Share and Analysis | Report 2033
Cinema Self Service Ticket Machines Market , Size Share and Analysis | Report 2033
Protable Ordering Machines Market , Size Share and Analysis | Report 2033
Unmanned Self Service Food Ordering Machines Market , Size Share and Analysis | Report 2033
All In One Food Order And Settlement Machines Market , Size Share and Analysis | Report 2033
Intelligent Interactive Electronic Whiteboards Market , Size Share and Analysis | Report 2033
Projection Interactive Electronic Whiteboards Market , Size Share and Analysis | Report 2033
Interactive Teaching Electronic Whiteboards Market , Size Share and Analysis | Report 2033
E Invoice Self Service Printers Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher