

Blogs
Heat Exchanger Market: How 5.5% CAGR and Asia Pacific's 6.9B Size Redefine Growth
By PW Consulting, 2026-09-21
The Heat Exchanger Market: Strategic Shifts and Commercial Opportunities in a Transforming Industrial Landscape
The global heat exchanger market has entered a phase of steady, structurally driven expansion. Between 2020 and 2025, revenue climbed from approximately $14.5 billion to $20.01 billion, reflecting an environment where thermal management has become inseparable from industrial efficiency, energy transition goals, and operational resilience. The forward trajectory points to continued growth through 2032, with a compound annual growth rate of 5.5 percent and projected revenue reaching nearly $29.5 billion by the end of the forecast period. This expansion is not merely cyclical. It is being shaped by overlapping forces: stricter energy and emissions regulations, the electrification of process heat, the cooling demands of digital infrastructure, and a recalibration of supply chains after years of disruption.
For executives and investors, the market presents a familiar paradox. Demand is broad and durable, yet the profitability and competitive positioning of individual players depend heavily on product specialization, regional supply dependencies, and the ability to navigate certification and materials constraints. Understanding where value is created—and where margin pressure is intensifying—requires looking beyond top-line growth and examining the structural dynamics that will separate resilient operators from those exposed to cost volatility and substitution risk.
Market Status and Core Challenges
The current market structure reflects a mature but still evolving industry. Revenue is distributed across multiple product configurations, end-use sectors, and geographic regions, with no single segment dominating to the point of rendering others irrelevant. That dispersion is both a strength and a source of strategic complexity. Manufacturers must balance standardized high-volume offerings with engineered solutions that command higher margins but require deeper customer integration. At the same time, the industry is operating under heightened scrutiny on safety, performance verification, and traceability, which raises the barrier to entry for undifferentiated competitors but also increases compliance burdens for established players.
Heat Transfer Equipment Market
Several challenges stand out as true inflection points.
- Materials cost escalation is reshaping economics. The cost of metallic heat exchanger equipment has risen from less than $100 per kilowatt thermal to a range between $500 and $1,000 per kilowatt thermal. This shift directly affects project economics, particularly for large industrial and power-generation installations where thermal capacity is a primary cost driver. Manufacturers and buyers are now forced to weigh material selection, design optimization, and lifecycle performance more carefully than in the past.
- Regulatory and certification frameworks are tightening the operational baseline. Pressure vessel and heat exchanger fabrication increasingly depends on recognized stamps and certification programs that verify design integrity and performance. Compliance with established mechanical codes and industry certification schemes is no longer optional; it is a precondition for supplying critical industrial, HVAC, and refrigeration applications. These requirements improve safety and interoperability, but they also lengthen qualification cycles and constrain the speed at which new entrants can scale.
- Trade and import dynamics are altering supply reliability. Projections indicate substantial increases in U.S. imports of heat exchange units within specific tariff classifications through 2025. This pattern points to a market that is becoming more internationally interdependent, with sourcing strategies shifting in response to capacity constraints, regional manufacturing investments, and the need to secure consistent supply for downstream projects.
Together, these forces create a market where growth is achievable, but only for participants who can align product strategy with cost discipline, certification readiness, and supply-chain certainty. The days of competing primarily on price are giving way to competition on verified performance, delivery reliability, and application-specific engineering.
Core Drivers of Market Change
Technology Innovation and Product Differentiation
Product innovation is moving along two complementary paths: performance enhancement in established designs and targeted development for emerging cooling and thermal-management needs. In industrial applications, the emphasis remains on improving heat-transfer efficiency, reducing footprint, and extending service life under harsher operating conditions. In parallel, new product introductions are increasingly oriented toward sectors where thermal control is becoming a bottleneck, such as data center cooling and district energy systems.
Recent product activity illustrates this shift. New brazed plate heat exchanger models have been introduced specifically for data center cooling and district energy applications, signaling that manufacturers are tailoring designs to high-density thermal loads and integrated energy networks rather than treating these as generic secondary markets. At the same time, the continued expansion of large-scale plate heat exchanger manufacturing capacity in the United States reflects a strategic bet on domestic production for a product category where throughput, lead time, and proximity to customers can be decisive advantages.
For businesses, the implication is clear: technology leadership is increasingly defined by application fit rather than generic product breadth. Companies that can match thermal performance to specific operating environments—while maintaining manufacturability and serviceability—are better positioned to defend margins and capture premium projects.
Policy and Regulatory Environment
Policy and standards are not background conditions; they are actively shaping demand patterns and competitive eligibility. Mechanical design and fabrication standards for shell and tube units, certification programs for brazed and fusion-bonded plate heat exchangers, and pressure vessel stamping requirements all create a shared technical language across buyers, engineers, and suppliers. That commonality reduces transaction risk in complex projects, but it also means that compliance competence has become a core capability rather than a back-office function.
The regulatory environment also interacts with broader energy and sustainability agendas. As industries face pressure to reduce energy consumption and emissions, thermal recovery and heat integration become more valuable. Heat exchangers that enable waste-heat recovery, efficient process heating, and lower refrigeration loads are increasingly evaluated against energy-performance criteria that extend beyond initial capital cost. In practical terms, this favors suppliers that can document efficiency gains, support lifecycle assessments, and align product specifications with project-level compliance requirements.
Demand-Side Shifts in Key Sectors
Demand is being reshaped by changes in how companies use energy, how facilities are designed, and how critical infrastructure is cooled. Industrial operators are looking for equipment that supports continuous operation with fewer interruptions and lower operating expense. Commercial and infrastructure projects are placing greater emphasis on thermal systems that can scale with load variability and integrate into broader energy strategies. These shifts are not uniform across sectors, but they share a common theme: thermal management is moving from a supporting utility to a strategic performance variable.
PW Consulting
This demand evolution is visible in the localization of manufacturing and the diversification of application-focused product lines. Facility expansions in North America are intended to improve supply reliability for regional customers, while new models designed for data centers and district energy reflect an understanding that future growth will be tied to specific high-value use cases. For buyers, this means that procurement decisions are increasingly influenced by operational continuity, lead-time predictability, and the ability to match equipment to changing load profiles.
Supply Chain and Cost Structure Transformation
The cost structure of heat exchanger production is being re-evaluated in response to materials inflation, fabrication complexity, and the need for dependable delivery. The sharp increase in metallic equipment costs per unit of thermal capacity is a clear signal that design choices and procurement strategies must be recalibrated. Suppliers that rely on rigid material specifications without exploring optimization opportunities may face margin compression, while those that integrate material efficiency, standardized yet customizable platforms, and robust fabrication processes can better absorb input-cost volatility.
At the same time, trade flows and import projections suggest that sourcing strategies are becoming more dynamic. Companies are balancing domestic production with international supply to manage risk, cost, and capacity. This balancing act is especially important in segments where project timelines are tight and certification or quality documentation must be maintained across the supply chain. The organizations that succeed will be those that treat supply chain design as part of product strategy, not as a separate logistics function.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized manufacturers, broad thermal-system providers, and service-oriented firms that support installation, repair, and maintenance. This diversity is one of the market’s defining features. Some companies compete through large-scale shell and tube solutions for industrial and power generation applications. Others focus on plate and frame, brazed plate, or dry cooling systems for HVAC, refrigeration, and process industries. A further group builds its position on custom fabrication, ASME-aligned pressure vessel work, or aftermarket services that extend asset life and reduce downtime.
Graphite Heat Exchanger Market
Several strategic patterns are evident among the more prominent players.
- Application anchoring. Leading manufacturers tend to differentiate by anchoring their offerings in specific end-use environments. Some build their identity around industrial and power applications, others around refrigeration and cooling, and others around engineered systems for refining and process sectors. This focus allows them to develop deeper technical credibility and repeatable project references in their chosen domains.
- Certification and standards as competitive infrastructure. Companies that operate confidently within recognized mechanical and performance standards are better positioned to win bids in regulated or safety-critical environments. Stamping readiness, documented quality systems, and alignment with widely accepted design standards reduce friction in project approval and procurement.
- Capacity and supply localization. Recent facility investments in the United States and Mexico highlight a strategic emphasis on regional production capability. Expanding domestic or nearshore manufacturing can improve delivery speed, reduce exposure to long-distance logistics risk, and strengthen relationships with customers who prioritize supply reliability.
- Aftermarket and service differentiation. Firms that provide repair, maintenance, and heat recovery services create additional value streams while reinforcing customer relationships. In asset-intensive industries, the ability to keep existing equipment operating efficiently can be as strategically important as selling new units.
The market is not consolidating into a single dominant model, and that is deliberate. The diversity of applications, sizes, materials, and certification requirements makes full horizontal consolidation difficult. Instead, the landscape is evolving through a combination of specialization, selective capacity expansion, and targeted product launches. New entrants face a meaningful hurdle because they must establish trust in performance, compliance, and delivery before they can compete for large projects. Meanwhile, established players are expanding where demand is strongest and where manufacturing scale or technical specialization gives them an advantage.
International activity also remains important. Large exhibitions and technology gatherings in Asia continue to draw hundreds of companies showcasing new equipment, materials, and process technologies. This global exchange of innovation matters because it influences product roadmaps, material choices, and competitive benchmarks across regions. Companies that monitor these developments closely can identify emerging design directions and supply-chain shifts before they become mainstream.
Future Trends and Commercial Opportunities
Trend One: Application-Specific Thermal Solutions Will Command Greater Value
Over the next three to five years, the market is likely to reward manufacturers that move from generic product catalogs to solution-oriented portfolios tailored to high-priority applications. Data centers, district energy, industrial heat recovery, and specialized refrigeration systems are all areas where thermal performance has direct operational and economic consequences. Equipment that is designed for these contexts—rather than adapted after the fact—will increasingly be preferred in procurement decisions.
The commercial opportunity lies in combining technical customization with repeatable engineering platforms. If a company can standardize core design elements while varying capacity, materials, and integration features for specific applications, it can achieve both efficiency in production and relevance in the market. The risk is that over-customization can erode the cost advantages of scale, so the balance between flexibility and standardization will be a critical managerial challenge.
Trend Two: Cost and Materials Strategy Will Become a Competitive Weapon
Given the significant increase in metallic equipment costs per unit of thermal capacity, cost management will move up the strategic agenda. Companies that succeed will not simply pass through higher input costs; they will actively redesign for material efficiency, evaluate alternative configurations where appropriate, and work with customers to optimize total cost of ownership rather than initial price. Procurement teams, in turn, will increasingly seek evidence that installed equipment will perform efficiently over time, reducing operating expense and exposure to future materials volatility.
This trend creates opportunities for suppliers that can offer transparent performance data, lifecycle cost modeling, and design choices that align material use with actual thermal requirements. It also raises the stakes for buyers, who must weigh short-term price against long-term reliability and efficiency. Misaligned purchasing decisions could lead to higher operating costs or premature replacement cycles, especially in demanding service environments.
Trend Three: Supply Reliability and Regional Manufacturing Will Shape Market Access
As import patterns shift and major manufacturers invest in North American production capacity, supply reliability is becoming a competitive differentiator. Projects that depend on tight installation schedules or operate in environments where downtime is costly will naturally favor suppliers that can demonstrate consistent delivery and strong regional support. This does not mean international supply will disappear, but it does suggest that regional manufacturing and service presence will be valued more highly than in the past.
The opportunity here is for manufacturers to align capacity investments with the customer segments most sensitive to lead time and service response. For investors, the relevant question is whether capacity expansion is attached to durable demand or merely to short-term pricing conditions. Overbuilding without clear application demand can create pressure on utilization and pricing, while targeted expansion in growing segments can strengthen market position and improve margins over time.
Uncertainty and Risk Considerations
Several uncertainties should temper overly optimistic planning. Materials cost trajectories remain volatile, and any further escalation could pressure project economics and delay capital decisions. Regulatory and certification requirements may become more demanding in certain jurisdictions, increasing qualification time and reducing flexibility in sourcing. Trade dynamics could also shift if tariff structures, import patterns, or domestic content expectations change. Finally, demand growth may be uneven across sectors, with some applications expanding rapidly while others remain constrained by broader industrial activity or capital spending cycles.
These risks do not undermine the market’s long-term direction, but they do reinforce the need for scenario-based planning. Companies that treat demand, cost, and supply assumptions as fixed are more exposed to disruption than those that prepare for a range of outcomes.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between product strategy and application demand. That means identifying the segments where thermal performance, certification readiness, and delivery reliability matter most, and then concentrating engineering and manufacturing investment there. It also means reviewing material and fabrication choices with a clear eye on cost exposure, exploring where standardization can protect margins without sacrificing application fit. Companies that can offer verified performance, predictable lead times, and strong service support will be better positioned to win and retain high-value projects.
For investors, the key is to distinguish between capacity that is tied to structural demand and expansion that is primarily reactive. Look for evidence that growth is anchored in application-driven need, supported by clear operational advantages, and aligned with compliance and supply reliability. Companies with diversified but focused portfolios, strong certification capabilities, and a credible aftermarket or service presence often have more resilient business models than those relying on undifferentiated volume alone. Monitoring regional manufacturing investments and product launches in emerging applications can also provide early signals about where competitive advantages are being built.
For procurement and operations leaders, the focus should shift from transactional price comparison to total value assessment. That includes evaluating equipment against lifecycle efficiency, serviceability, delivery risk, and compliance documentation. In environments where downtime, energy cost, or regulatory exposure is significant, the cheapest initial option may not be the most economical over the life of the asset. Building procurement criteria that reflect operational reality can reduce vulnerability to supply delays, performance shortfalls, and avoidable operating expenses.
Because the market is evolving across technology, regulation, cost structure, and regional supply simultaneously, the full picture is difficult to capture from headlines or isolated announcements alone. Detailed segmentation data, company-level positioning, and scenario analysis are needed to convert these broad dynamics into concrete decisions about product investment, sourcing, and market entry. For organizations that want to move faster and with more confidence, a comprehensive research perspective can help identify where growth is most durable, where margin pressure is most likely, and which strategic choices will matter most over the next several years.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Grinding Wheels Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Landscape and Core Challenges
The global grinding wheels market has demonstrated steady expansion over the past five years, moving from a valuation of approximately USD 5,450 million in 2020 to an estimated USD 6,665 million in 2025. Looking ahead, the market is projected to reach USD 8,770 million by 2032, representing a compound annual growth rate of 4.1 percent across the 2026–2032 forecast period. This trajectory reflects a mature but resilient market that is increasingly shaped by shifting industrial priorities rather than raw volume growth alone.
While the top-line figures suggest continuity, the underlying structure tells a more nuanced story. Market concentration remains moderate, with the top three players accounting for roughly 28.5 percent of industry revenue and the top five reaching 35.2 percent. This fragmentation indicates that value is not solely captured by scale; differentiation in product performance, regional service capabilities, and application-specific engineering are becoming decisive competitive factors. The market is large enough to accommodate specialized players, yet consolidating around firms that can integrate abrasives knowledge with machine-tool compatibility and end-user process expertise.
Key Structural Challenges
Several intersecting pressures are redefining how grinding wheels businesses compete and plan for the near term.
- Performance-pressure vs. cost trade-offs. End users are increasingly unwilling to accept incremental wear rates or inconsistent surface finishes in exchange for lower unit prices. Grinding wheels are now evaluated as part of total cost-per-part equations, where dressing frequency, wheel life, and machine downtime carry as much weight as purchase price. This shifts competitive advantage toward suppliers who can demonstrate measurable productivity gains rather than competing purely on commodity pricing.
- Regulatory complexity and standardization. Revised safety and marking frameworks are raising the compliance bar for both wheels and the machines they run on. Updated standards have clarified arbor hole dimensions and anti-overspeed requirements, while newer machine classification schemes require risk-based safety measures, including burst guard strength calculations. At the same time, labeling obligations now extend to maximum operating speed, shelf life or expiry date, dimensions, usage restrictions, traceable manufacturing numbers, mounting instructions, and ISO-type markings. These requirements elevate quality assurance and documentation costs, particularly for cross-border trade and multi-market portfolios.
- Raw material and input volatility. The abrasive grain base remains heavily weighted toward aluminum oxide, which continues to command a substantial share of the broader abrasive grains market. Any disruption to grain supply, binder systems, or additive availability can ripple through wheel pricing and formulation stability. Suppliers that lack diversified sourcing or formulation flexibility face margin exposure when input costs move unexpectedly.
The practical implication is that the grinding wheels market is entering a phase where operational and regulatory excellence are as commercially significant as product performance. Companies that treat compliance, consistency, and process integration as strategic capabilities are better positioned to protect margins and secure long-term contracts.
2. Key Drivers Shaping the Market
Market momentum is being directed by a combination of technological, regulatory, demand-side, and supply-chain forces. Rather than operating in isolation, these drivers are reinforcing one another and reshaping what buyers expect from grinding wheel suppliers.
Technology Innovation and Breakthroughs
Precision-shaped grain technology and advanced bonding approaches are changing the performance envelope of conventional grinding wheels. Products built on controlled grain geometry can deliver more consistent cutting action and predictable wear behavior, which matters increasingly in high-value metalworking, automotive, and aerospace applications. At the same time, developments in diamond and CBN abrasives are extending the role of superabrasive solutions beyond niche operations into more mainstream grinding processes, especially where component tolerances, surface integrity, and throughput are critical.
Recent industry activity underscores this direction. During 2026 trade events, multiple participants showcased grinding-related technologies that blur the line between wheel design and machine-process compatibility. Diamond and CBN abrasives applicable to grinding wheels were highlighted as part of broader precision grinding solutions, while large-format double disc grinding wheels for face and fine grinding demonstrated continued investment in high-productivity processes. Grinding machine providers also presented equipment compatible with electroplated and dressable CBN grinding wheels, reflecting a growing emphasis on process-integrated performance rather than standalone consumable supply. In parallel, resin-bonded grinding wheel offerings continued to appear at hardware-focused exhibitions, signaling sustained interest in flexible bonding solutions for a wide range of workshop and industrial applications.
Policy and Regulatory Environment
Regulations are increasingly shaping both product design and commercial readiness. Updated standards for grinding wheels and accessories have tightened requirements around dimensional consistency and speed safety, making specification accuracy and manufacturing control more important. Machine-related classifications that assign risk levels and mandate appropriate safety measures, including burst guard strength calculations, are also influencing how wheels are selected, validated, and deployed in industrial settings.
For suppliers, these developments raise the value of robust documentation, traceable production, and consistent marking practices. For buyers, they create a stronger expectation that wheel suppliers can support compliance as part of the product proposition. The broader effect is a market where higher safety and quality standards are becoming a competitive filter rather than a back-office obligation.
Demand-Side Shifts in Transport and Steel Industries
Demand for grinding wheels remains closely tied to industrial sectors where precision metal removal, surface conditioning, and tooling support are essential. The transport industry and steel industry continue to represent significant application anchors, reflecting the ongoing need for grinding solutions across component manufacturing, maintenance, and fabrication workflows. Beyond these sectors, the wider application base remains substantial, underscoring the market's diversification across general industrial metalworking, toolmaking, and precision grinding tasks.
What is changing is not simply the volume of activity, but the performance criteria attached to it. Transport and steel-related production environments are placing greater emphasis on consistency, reduced rework, and process reliability. As a result, buyers are more inclined to evaluate grinding wheels based on how effectively they support downstream quality and machine utilization. This demand-side evolution favors suppliers that can align product recommendations with specific process conditions, machine types, and finishing objectives.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures across the grinding wheels value chain are being influenced by input availability, formulation complexity, and the cost of maintaining consistent quality at scale. Since a large share of abrasive grain demand is tied to aluminum oxide, grain pricing and supply reliability can have an outsized impact on margin planning. Binder systems, additives, and manufacturing precision add further layers of variability, particularly for products that must meet application-specific performance targets.
At the same time, logistics and regional demand patterns are reshaping how suppliers think about inventory positioning and production footprints. Markets with strong industrial activity are placing a premium on responsiveness, technical support, and local specification expertise. Suppliers that can balance formulation consistency with regional service capability are gaining an advantage in segments where downtime and specification errors carry significant operational costs.
3. Competitive Landscape and Leading Strategies
The competitive field in grinding wheels is broad and varied, combining large multinational abrasive businesses with focused regional producers and specialized technology providers. The market's moderate concentration suggests room for differentiation, but also intensifying competition for customers who increasingly prioritize performance reliability, application fit, and compliance support.
Worldwide Floor Grinding Tools Market
Strategic Positioning of Core Players
Several established companies illustrate the different ways value is being pursued in this market.
- Saint-Gobain Abrasives leverages its Norton Abrasives brand to serve industrial metalworking, automotive, and aerospace applications with vitrified, resin-bonded, and CBN grinding wheels. Its positioning reflects a focus on broad application coverage and a portfolio that spans conventional and superabrasive solutions.
- Norton Abrasives continues to emphasize its established manufacturing footprint in conventional aluminum oxide, silicon carbide, and superabrasive grinding wheels. Its relevance lies in the combination of product familiarity and the ability to address a wide range of standard and demanding grinding tasks.
- 3M Abrasives differentiates through precision-shaped grain technology in products such as its Cubitron II and silver series depressed-center and cut-off grinding wheels. The emphasis on controlled grain geometry highlights a strategy centered on performance consistency and process efficiency rather than commodity substitution.
- Tyrolit Group specializes in metal and precision grinding wheels, including vitrified and superabrasive products for automotive, aerospace, and toolmaking. Its profile suggests a strategy rooted in application-specific engineering and precision grinding expertise.
- Klingspor produces abrasive discs, cut-off wheels, and bonded grinding wheels, reflecting a practical, broad-based offering for workshop and industrial users. Its strength lies in versatility and coverage across common abrasive product categories.
- Camel Grinding Wheels manufactures resin-bonded and vitrified grinding wheels, cut-off wheels, and coated abrasives, positioning itself across a mix of bonded and coated solutions that serve both general and specialized applications.
- Carborundum Universal Limited operates as a leading abrasives producer for industrial applications in India and globally. Its relevance in the broader market highlights the importance of regional strength, cost-competitive production, and expanding international reach.
Taken together, these profiles show two ongoing patterns. One is the continued importance of portfolio breadth and application coverage among larger players. The other is the growing relevance of technology-led differentiation, especially where grain design, superabrasive compatibility, and process-specific recommendations can justify preferential selection.
Market Evolution and Strategic Trends
The competitive landscape appears to be moving along several recognizable paths.
- Technology-led segmentation. Suppliers are increasingly competing on process-enabling features such as grain geometry, wheel dressing compatibility, and performance stability under specific operating conditions. This creates subtle but commercially meaningful differentiation even within broadly similar product categories.
- Application and sector alignment. Companies with clearer alignment to high-value end markets, including automotive, aerospace, and precision toolmaking, are better placed to command attention from buyers who value consistency and technical support over lowest-cost supply.
- Regional presence and responsiveness. Strong local service, specification assistance, and supply reliability remain critical, especially in active industrial regions where downtime and process mismatches are expensive. This continues to support the relevance of regional leaders alongside global portfolios.
- Integration with grinding process ecosystems. The growing visibility of machine-compatible wheel solutions, including electroplated and dressable CBN options and large-format grinding formats, indicates a widening competitive field where wheel suppliers are increasingly evaluated in the context of overall grinding performance.
The market is not necessarily trending toward rapid consolidation into a single dominant model. Instead, it is becoming more layered: global portfolios provide scale and breadth, regional specialists offer responsiveness and local expertise, and technology-focused players compete on measurable process advantages. For buyers and investors alike, the most relevant question is not only who sells grinding wheels, but who can most reliably translate product characteristics into reduced total cost and improved process outcomes.
4. Future Trends to Watch (2026–2032)
Based on current market direction, regulatory development, and product activity, several trends are likely to shape commercial decision-making over the next three to five years.
Trend 1: Performance Differentiation Will Matter More Than Category Growth
With a projected CAGR of 4.1 percent through 2032, market expansion will provide a supportive backdrop, but growth alone will not determine competitive success. The more decisive battleground will be performance differentiation: wheel life consistency, surface finish quality, dressing behavior, and the ability to reduce total cost per part. Suppliers that can validate these outcomes with practical evidence will have stronger positioning in demanding metalworking, transport, and steel-related applications.
The commercial opportunity lies in moving the conversation from specification matching to process improvement. This includes helping buyers select wheels based on machine type, material removal requirements, and quality targets rather than defaulting to habitual choices. The risk is that companies relying on undifferentiated product lines may face margin pressure as buyers compare solutions more rigorously.
Trend 2: Safety, Traceability, and Compliance Will Become Commercial Levers
Updated standards for wheel marking, dimensional requirements, and anti-overspeed provisions, together with machine risk classification and burst guard considerations, are reinforcing the importance of documentation and manufacturing control. Over time, these requirements are likely to become embedded in procurement expectations, particularly in environments where safety, auditability, and supply consistency are heavily scrutinized.
This creates opportunity for suppliers that can package compliance as part of a dependable supply proposition. Traceable manufacturing numbers, clear usage restrictions, shelf life or expiry information, and complete dimensional and speed markings are increasingly part of the credibility equation. The uncertainty lies in how quickly different regions and customer types adopt consistent procurement practices around these requirements, which could create uneven implementation burdens.
Trend 3: Superabrasive and Process-Integrated Solutions Will Expand Their Reach
The continued visibility of diamond and CBN abrasives in grinding-related applications, alongside machine solutions designed for electroplated and dressable CBN wheels, points toward broader adoption of advanced grinding approaches in selected high-value processes. Large-format grinding wheels and precision-focused formats also indicate that specific high-productivity applications will continue to drive specialized demand.
For suppliers, the opportunity is to develop credible offerings where superabrasive or precision formats deliver clear advantages in tolerance, surface integrity, or throughput. For buyers, the strategic value depends on identifying the applications where these solutions justify their cost through measurable process gains. The risk is over-extension: superabrasive solutions are not universally advantageous, and misaligned adoption can erode return on investment if process conditions are not properly matched.
Grinding Media Market
5. Strategic Actions for Decision Makers
The grinding wheels market is evolving in a way that rewards preparation, evidence, and process-oriented thinking. The following actions can help different stakeholder groups respond effectively.
For Manufacturers and Product Leaders
- Prioritize differentiation through measurable performance attributes such as consistent wear behavior, predictable dressing response, and compatibility with precision grinding processes.
- Strengthen documentation and marking practices to align with evolving safety and traceability expectations, reducing friction in regulated or audit-sensitive procurement environments.
- Invest in application-specific support where transport, steel, and precision metalworking demand clearer guidance on wheel selection and process integration.
For Investors and Strategic Planners
- Assess exposure not only to overall market growth, but to segments where performance differentiation, compliance readiness, and region-specific service can sustain pricing power.
- Watch for signals of technology-led competition, including precision grain designs and superabrasive process compatibility, as indicators of where value may shift over the forecast period.
- Consider supply-chain resilience in abrasive grains and binder inputs as a strategic factor, especially in portfolios sensitive to formulation consistency and input cost volatility.
For Procurement and Operations Leaders
- Evaluate grinding wheels within total cost-per-part frameworks, incorporating wheel life, dressing frequency, rework reduction, and machine utilization rather than unit price alone.
- Verify that suppliers can meet updated marking, speed, and traceability expectations, especially where operational safety and compliance documentation are increasingly important.
- Align specifications with actual process conditions and machine compatibility, including where electroplated or dressable CBN solutions may be justified by precision and throughput requirements.
The market's trajectory suggests that the most consequential decisions will come from understanding where grinding wheels create process value, not just where they fit into a consumables budget. Detailed segmentation data, region-specific demand patterns, application-level performance profiles, and company-level competitive positioning can sharpen these decisions considerably. For readers seeking deeper, segment-level data and tailored interpretation for specific business situations, the full market research report provides a more granular view of the categories, regions, and competitive dynamics shaping the grinding wheels market through 2032.
For detailed analysis of this topic, please visit the official page: Grinding Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BMP-2 Market Set to Hit $347 Million: 5 Shifts Reshaping Bone Healing Through 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Bone Morphogenetic Protein 2 Market Through 2032
The bone morphogenetic protein 2 (BMP-2) market has entered a phase of measured expansion characterized by steady clinical adoption, evolving regulatory frameworks, and shifting reimbursement dynamics. After reaching approximately $238.12 million in 2025, the market is projected to scale toward $346.71 million by 2032, reflecting a compound annual growth rate of 5.5 percent over the forecast horizon. This trajectory signals a mature but still growing sector where incremental innovation, 신중한 임상 적용, and healthcare payment 정책调整 will determine competitive positioning rather than explosive volume expansion. For executives and investors evaluating orthobiologics, understanding the structural forces behind this growth curve is essential for allocating capital, shaping R&D priorities, and anticipating procurement shifts.
Market Landscape and Core Challenges
The BMP-2 segment operates within a concentrated competitive environment. The top three players collectively command over half of total revenue, while the five largest firms account for nearly three-quarters of market share. This concentration reflects the high barriers to clinical validation, regulatory clearance, and surgeon familiarity that shield established products from rapid displacement. At the same time, the distribution of volume across geographies and clinical applications reveals where growth is accumulating and where friction persists.
Several structural challenges define the current inflection point for BMP-2 stakeholders:
- Clinical adoption boundaries and safety perception. While recombinant BMP-2 has demonstrated efficacy in specific fusion and trauma indications, historical concerns around ectopic bone formation, inflammatory responses, and dosing limitations continue to influence prescribing behavior. Surgeons and hospital committees increasingly weigh off-the-shelf osteoinductive agents against alternative graft strategies, requiring manufacturers to reinforce indication-specific evidence and refine delivery systems.
- Reimbursement complexity and procedural coding evolution. The trajectory of BMP-2 utilization is closely tied to how procedural codes and payment rules recognize osteobiologic adjuncts. Recent clarifications from the Centers for Medicare & Medicaid Services maintained recognition of multiple FDA-approved indications beyond primary anterior lumbar interbody fusion, including acute open tibial shaft fractures, sinus augmentation, and localized alveolar ridge augmentations. Such policy continuity reduces uncertainty for specific use cases, yet broader reimbursement variability across payers and institutional formularies still creates uneven demand patterns.
- Supply chain resilience and cost structure pressures. Recombinant protein manufacturing demands controlled bioprocessing, stringent quality assurance, and reliable delivery vehicle production. Any disruption in raw material sourcing, fill-finish capacity, or cold-chain logistics can affect product availability and pricing stability. Simultaneously, healthcare systems under margin pressure are scrutinizing the cost-per-fusion or cost-per-procedure calculus, pushing suppliers to justify value through outcomes data and total episode cost considerations.
These challenges are not insurmountable, but they reshape the commercial playbook. Market participants that treat clinical evidence, coding alignment, and manufacturing reliability as integrated strategic priorities are better positioned to convert steady demand into durable share gains.
Key Drivers Shaping Market Trajectory
The expansion path of BMP-2 through the late 2020s and into the early 2030s is being pulled by a handful of interlocking forces. Each driver carries distinct implications for product design, commercial access, and partnership strategy.
Technological Innovation and Delivery Engineering
Innovation in BMP-2 is less about discovering new protein variants and more about improving how the molecule is presented, localized, and released at the surgical site. Advanced absorbable carriers, tunable resorption profiles, and combination approaches that pair osteoinductive signals with structural scaffolds are reducing variability in bone formation while addressing safety concerns associated with high initial doses. Incremental formulation and device integration are enabling surgeons to deploy recombinant BMP-2 in a broader set of anatomies with greater confidence. For manufacturers, these refinements create differentiation beyond the molecule itself, turning delivery performance into a commercial moat.
Demineralized Bone Matrix (DBM) Market
Regulatory Frameworks and Coding Clarity
Regulatory and coding environments act as gatekeepers for reimbursement and, by extension, for routine clinical use. The 2026 ICD-10-PCS updates affirmed ongoing FDA-approved indications for recombinant BMP-2 products, including new codes for introduction of recombinant BMP-2 into joints and retention of indications for acute open tibial shaft fractures, sinus augmentation, and localized alveolar ridge augmentations. Such clarifications reduce ambiguity for specific procedural contexts, making it easier for hospitals to justify use within established pathways. At the same time, the broader regulatory landscape continues to emphasize post-market evidence, indication-specific labeling, and appropriate use criteria. Companies that proactively align clinical data packages with procedural coding realities and payer expectations can accelerate adoption in eligible segments while limiting off-label exposure.
Demand-Side Shifts in Surgical Practice and Patient Populations
Demand for bone graft substitutes is influenced by demographic trends, surgical volume patterns, and evolving preferences among spine, trauma, and craniofacial surgeons. An aging population and the rising prevalence of degenerative spinal conditions support continued procedural volume in fusion and reconstruction settings. In parallel, minimally invasive and lateral approaches are expanding the range of cases where locally applied osteoinductive agents can add value. Surgeons increasingly look for products that integrate smoothly into their preferred techniques, simplify operative workflow, and provide predictable outcomes. This behavior favors suppliers that invest in surgeon education, procedural compatibility, and real-world evidence generation tailored to specific clinical narratives.
PW Consulting
Cost Structure and Value-Based Procurement
Hospital procurement is moving toward total cost-of-care thinking rather than isolated device pricing. In fusion and trauma cases, the economic argument for BMP-2 hinges on reducing revision rates, accelerating fusion or healing, and streamlining recovery pathways. When suppliers can demonstrate that their product contributes to fewer complications or shorter downstream resource utilization, the conversation shifts from unit price to episode value. At the same time, manufacturers must manage input costs, scale production efficiently, and maintain margin discipline. The tension between value demonstration and cost control creates an opening for organizations that can translate clinical performance into economic language that procurement teams and value analysis committees understand.
Competitive Landscape and Leading Strategies
The competitive structure of the BMP-2 market reflects the advantages of first-mover clinical recognition, robust manufacturing capability, and deep surgeon relationships. Medtronic stands out as a central player, with its INFUSE Bone Graft platform built around recombinant human BMP-2 delivered on an absorbable collagen sponge. The product’s established footprint in anterior lumbar interbody fusion, oblique lateral interbody fusion, posterolateral fusion, and acute open tibial shaft fractures gives the company a strong reference base and procedural familiarity advantage. The recent CMS coding updates that sustain multiple FDA-approved indications reinforce the commercial viability of these use cases and support continuity in surgical adoption where evidence and technique align.
Strategic positioning among leading participants tends to converge on several differentiating levers:
- Indication anchoring and evidence depth. Companies that maintain rigorous, indication-specific clinical data and update labeling in step with regulatory expectations can defend their core territories and expand within approved boundaries. This reduces reliance on off-label usage and strengthens payer and hospital committee confidence.
- Delivery system integration. Differentiating through carrier technology, handling characteristics, and compatibility with emerging surgical approaches allows suppliers to compete on more than molecule identity. Integration with instruments, sleeves, or minimally invasive delivery workflows can improve adoption by reducing operative friction.
- Commercial engagement and education. Surgeon training, case-based education, and support for value analysis committees help convert product attributes into real-world utilization. In a market where procedural familiarity matters, sustained engagement can protect share even as alternatives evolve.
- Manufacturing reliability and supply assurance. Consistent production quality and predictable availability are critical in orthobiologics. Any lapse can disrupt surgical scheduling and erode trust quickly. Leading firms invest in process robustness, capacity planning, and quality systems to minimize these risks.
Looking forward, the market is likely to experience selective consolidation, strategic partnerships, and cautious new entry rather than a flood of disruptors. High clinical and regulatory hurdles favor incumbents, but opportunities remain for companies that bring differentiated delivery technologies, targeted indications, or region-specific commercialization capabilities. New entrants may focus on underserved anatomical sites, alternative carrier platforms, or localized market access strategies where incumbent coverage is thinner. The overall pattern points to a competitive environment where defensible niches, evidence leadership, and execution reliability determine outcomes more than broad-based price competition.
Future Trends and Commercial Implications for 2027–2032
Several trends will shape how the BMP-2 market evolves through the end of the decade. Each trend carries clear commercial consequences for manufacturers, investors, and healthcare buyers.
Refinement of Indication-Specific Use and Procedural Alignment
Over the next several years, BMP-2 utilization is expected to become more precisely aligned with procedural contexts where the evidence base and delivery approach are strongest. Rather than broad diffusion, growth will likely concentrate in applications such as spinal fusion, selected trauma scenarios, reconstruction, and oral maxillofacial procedures where osteoinductive adjuncts address specific biological gaps. This trend creates value for suppliers that can map product attributes to surgical workflows, support appropriate-use guidance, and generate real-world data that resonate with hospital committees. The commercial opportunity lies in helping customers match the right formulation and delivery approach to the right case, improving both outcomes and reimbursement capture.
Carrier and Combination Technology as a Differentiator
The next wave of competitive advantage will increasingly come from how BMP-2 is delivered and combined with structural or resorbable materials. Innovations in controlled release, scaffold integration, and handling characteristics can improve localization, reduce dose variability, and expand compatibility with newer surgical approaches. Companies that lead in carrier engineering and device integration may command stronger positioning in high-value procedural segments, while also creating switching costs through workflow familiarity. For investors, technology-led differentiation in delivery platforms can offer a more durable growth narrative than volume alone.
Reimbursement Harmonization and Regional Expansion
Reimbursement dynamics will remain a swing factor. Where procedural coding and payer policies converge with clinical indications, adoption can stabilize and grow; where they diverge, demand will remain fragmented. The recent maintenance of multiple FDA-approved indications through ICD-10-PCS updates illustrates how coding clarity can reinforce commercial viability in defined use cases. At the same time, regional variation in surgical volumes, healthcare financing, and access to advanced osteobiologics will influence growth rates across geographies. The trend suggests that commercial success will depend on localized reimbursement strategy, surgeon engagement, and supply readiness tailored to each market’s payment environment. Risk surfaces when reliance on a narrow set of indications or a single geographic concentration leaves the business exposed to policy shifts or volume slowdowns.
Strategic Actions for Decision Makers
Different stakeholders face distinct imperatives as the BMP-2 market moves toward 2032. The following actions are designed to translate market dynamics into practical decisions.
Angiopoietin 2 Market
For Manufacturers and Commercial Leaders
- Anchor product strategy in indication-specific evidence and procedural compatibility. Align clinical data, labeling, and education with the fusion, trauma, reconstruction, and oral maxillofacial contexts where surgeons are most likely to deploy recombinant BMP-2.
- Invest in delivery system differentiation and workflow integration. Enhance carrier performance, handling, and compatibility with preferred surgical approaches to create practical value beyond molecule identity.
- Build reimbursement readiness into the commercial plan. Monitor coding updates, payer policies, and institutional value analysis criteria, and prepare economic narratives that connect clinical performance to episode-level value.
For Investors and Strategic Capital Allocators
- Prioritize companies with defensible evidence positions, reliable manufacturing, and clear delivery differentiation. In a concentrated market, execution quality and clinical trust are often the real barriers to entry and the basis for durable share.
- Focus on value drivers rather than headline volume. Evaluate how candidates translate outcomes, workflow benefits, and reimbursement alignment into sustainable economics, especially under increasing procurement scrutiny.
- Watch for selective consolidation and niche entry. opportunities may arise from targeted indications, regional access plays, or platform technologies that improve localization and safety profiles without requiring broad molecule replacement.
For Procurement and Clinical Operations Leaders
- Evaluate BMP-2 products through total episode value rather than unit price alone. Consider impact on fusion success, revision risk, recovery pathways, and downstream resource use when comparing alternatives.
- Align product selection with procedural planning and coding realities. Ensure that chosen products fit the surgical approaches, indications, and documentation requirements that support reimbursement in your setting.
- Establish clear criteria for supplier reliability and evidence maturity. Consistent supply, quality assurance, and up-to-date clinical support reduce operational risk and help standardize appropriate use across service lines.
The BMP-2 market is moving through a period where incremental innovation, regulatory clarity, and value-based procurement will determine who captures growth and who merely defends share. For organizations seeking to navigate this environment with precision, detailed segmentation data, competitive benchmarking, and region-specific reimbursement insights can materially sharpen strategy. The full research report provides deeper breakdowns across type, application, and geographic dynamics, along with expanded competitor tracking and scenario analysis, offering a practical foundation for product planning, investment decisions, and procurement prioritization.
For detailed analysis of this topic, please visit the official page: Bone Morphogenetic Protein (BMP) 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
7 Strategic Shifts Driving the Electronic Components Market to $717.6B by 2032
By PW Consulting, 2026-09-21
The Electronic Components Market: Strategic Trends and Commercial Opportunities Through 2032
The electronic components sector has transitioned from a commodity-driven business into a technology-intensive, strategically critical industry. Over the historical period from 2020 through 2025, global revenue climbed from approximately $300 billion to over $438 billion, reflecting an average compound annual growth rate of 7.36 percent across the full forecast horizon extending to 2032, when the market is projected to exceed $717 billion. This trajectory is not merely a recovery from supply disruptions of the early 2020s; it reflects a structural realignment driven by electrification, connectivity mandates, industrial automation, and a reconfiguration of global manufacturing footprints. The current landscape presents a paradox for decision makers: demand volumes are robust and accelerating, yet availability, cost structures, and competitive positioning are being reshaped by forces that do not always move in tandem.
Understanding where value will concentrate, which capabilities will command premiums, and how supply-chain architecture will evolve requires looking beyond headline volumes. The segmentation of the market by component type reveals a hierarchy of strategic relevance that is not always intuitive. Active components continue to anchor the largest share of revenue, reflecting their centrality to integrated circuits, analog and power management, and embedded control functions. Passive components represent a substantial and often underestimated revenue pool, driven by demand for capacitors, inductors, resistors, and RF modules that scale directly with the complexity of electronic assemblies. Electromechanical components, while smaller in relative terms, serve as critical enablers for connectors, switches, and sensors that bridge electrical and mechanical systems. By application, consumer electronics remains the largest end-use driver, followed by telecommunications, industrial, medical, automotive, and a diversified remainder that spans aerospace, test and measurement, and specialized instrumentation. Regionally, Asia Pacific leads in volume, with North America and Europe maintaining meaningful shares supported by design activity, high-value manufacturing, and policy-driven incentives.
Any realistic strategy must be built on these structural realities. The market's growth is not uniform across products or geographies; it is uneven, with pockets of intense competition, long lead times, and pricing volatility coexisting alongside segments where differentiation and reliability command durable margins. For executives and investors, the task is to map their exposure to the segments where the economics are most favorable, and to anticipate the inflection points that will separate winners from laggards.
Market Context: Baseline Dynamics and Critical Junctures
A Growth Profile That Rewards Timing and Positioning
The market's expansion from 2020 to 2025 was propelled by a confluence of restocking after pandemic-era shortages, the acceleration of automotive electrification, the proliferation of connected devices, and sustained capital expenditure in industrial and infrastructure electronics. The forward trajectory through 2032 reflects continued momentum, but with a widening dispersion of opportunity. The overall growth rate of 7.36 percent over the forecast period is meaningful, yet it conceals divergent sub-trends: components tied to high-growth applications will outpace the average, while mature commodity categories may experience pricing pressure and cyclical volatility. The implication is that aggregate market size is a useful sanity check, but it is insufficient for tactical planning. Companies need to align their portfolios with the application and technology vectors that are expanding faster than the baseline.
Three Junctures Redefining the Playing Field
First, supply-chain resilience has moved from an operational concern to a strategic lever. Lead-time variability remains a practical challenge for certain categories, particularly automotive-grade microcontrollers and specialized discrete devices, where procurement teams report extended delivery windows for select product lines. This is not a transient inconvenience; it is a structural feature of a market where qualified production capacity for high-reliability parts does not always scale in lockstep with demand. Organizations that treat sourcing strategy as a core competency, rather than a transactional function, can convert lead-time risk into negotiating leverage and preferential access.
Second, the regulatory and sustainability agenda is reshaping cost structures and competitive dynamics. Carbon-related mechanisms, including the EU Carbon Border Adjustment Mechanism, have begun publishing certificate pricing data, signaling that environmental compliance will be increasingly priced into cross-border trade. For component manufacturers and distributors, this creates both operational complexity and differentiation potential: firms that can demonstrate transparent, lower-carbon supply chains and efficient material utilization will be better positioned for markets where procurement criteria are expanding beyond performance and price.
Third, the balance between integration and fragmentation is shifting. Large incumbents continue to consolidate capabilities across analog, power, microcontrollers, and sensing to serve high-value applications, while independent distributors and niche specialists gain relevance by offering speed, accessibility, and hard-to-source inventory. At the same time, new manufacturing initiatives and partnerships are being deployed to stabilize supply in discrete and power categories, indicating that regional diversification and capacity partnerships are becoming permanent features of the landscape rather than one-off remedies.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most consequential technology trends are converging around power semiconductors, analog and precision ICs, and the integration of sensing with processing. Wide-bandgap devices based on silicon carbide and gallium nitride are expanding the addressable range for higher-efficiency power conversion, a theme especially relevant for electric vehicles, industrial drives, and renewable-energy systems. Companies with strong positions in power semiconductors and discrete devices are investing in manufacturing and product roadmaps that target these applications, while also extending into intelligent sensing and connectivity solutions that bridge functional domains. In parallel, the push toward physically aware and secure architectures is prompting collaboration around hardware anchored in AI edge platforms, with security and reliability increasingly treated as core product attributes rather than add-ons. These advancements are not abstract; they translate into higher value per unit, longer lifecycle relevance, and greater switching costs for customers who standardize on qualified solutions.
Policy and Regulatory Environment
Policy is now an active force in shaping where production occurs, what qualifies as a compliant component, and how trade flows are priced. Incentive programs and local-content expectations have encouraged investment in new fabrication and assembly capacity across multiple regions, reducing over-concentration risk while simultaneously complicating multi-site qualification. Regulatory instruments tied to carbon intensity are becoming operational realities, with certificate pricing now visible to market participants. This trend elevates the strategic importance of supply-chain transparency, material efficiency, and energy-aware manufacturing. For buyers, it introduces a new dimension to supplier evaluation; for manufacturers, it rewards those who can quantify and reduce the footprints associated with their products. Policy is no longer a background condition. It is a variable in cost, access, and go-to-market strategy.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, two patterns stand out. Consumer electronics continues to anchor a large share of total volume, fueled by the ongoing refresh cycles of smartphones, wearables, home appliances, and connected accessories, each of which places incremental demands on passive components, RF modules, and power management. Simultaneously, enterprise demand is being reshaped by automation, data infrastructure, and the electrification of mobility and industrial equipment. Automotive and industrial applications are increasingly value-dense, with requirements that span high-reliability microcontrollers, power devices, secure connectivity, and long lifecycle support. Medical electronics is another segment where precision analog, sensing, and power management converge to support diagnostic, monitoring, and treatment devices. The practical takeaway is that demand is not only growing, it is becoming more application-specific, more certification-intensive, and more loyal to qualified suppliers, which raises the value of domain expertise.
Supply-Chain Architecture and Cost Structures
Capital intensity, lead-time discipline, and component availability are interacting to redefine cost structures. In memory-related ecosystems, production capacity has lagged rapidly growing demand, an imbalance visible in export flows from major manufacturing centers and a symptom of how quickly demand can outpace supply in certain technology nodes. In the automotive and industrial arenas, extended lead times for specific microcontroller series illustrate that even mature categories can experience bottlenecks when qualified capacity and demand are misaligned. At the same time, new partnerships in power discrete manufacturing, the opening of additional fabrication and assembly sites, and the expansion of distribution catalogs are all aimed at smoothing availability. The net effect is a market where cost is increasingly a function of reliability, qualification status, and supply assurance, not just unit price. Companies that manage inventory intelligently, qualify alternate sources prudently, and maintain visibility into production pipelines will be better positioned to absorb volatility and protect margins.
Competitive Landscape and Leading Strategies
Incumbents Anchored in Technology Gravity
The competitive field is anchored by firms with deep portfolios and established design-ins across analog, power, microcontrollers, precise sensing, and discrete devices. Several large players have built their advantage around a combination of technical breadth, application familiarity, and long-term customer relationships in automotive, industrial, and medical markets. Analog-focused companies emphasize precision and signal integrity for demanding environments. Power-semiconductor leaders are extending their relevance through wide-bandgap platforms and secure, intelligent solutions for edge and mobility applications. Microcontroller specialists serve automotive and industrial customers with architectures optimized for reliability and integration. Passive component manufacturers and connector specialists, meanwhile, compete on miniaturization, electrical performance, and the ability to scale volume with consistent quality. These positions are not easily replicated because they depend on sustained R&D investment, qualification history, and the trust that arises when components are embedded in safety-critical or high-value systems.
Strategic Moves That Are Reshaping the Landscape
Recent activity shows a market in motion. A power MOSFET manufacturing partnership was formed to strengthen supply stability, illustrating how discrete and power markets are addressing availability through collaboration and expanded fabrication reach. New manufacturing capacity has come online, including a power module plant in Southeast Asia, underscoring the multi-region footprint that major producers are building to serve global demand more flexibly. On the distribution side, catalog expansion and targeted campaigns are improving access to new parts and highlighting application areas such as industrial automation. Participation in major industry events has been used to advance hardware security and edge-compute solutions, signaling that safeguarding and intelligent processing are extensions of core component strategy. Taken together, these moves reflect a landscape where incumbents are reinforcing technology leadership and supply assurance, while distributors and specialists differentiate through breadth, speed, and application focus.
Integration, Differentiation, and the Rise of Niche Strengths
The market is not consolidating into a single mold. Instead, it is bifurcating in a productive way. Some segments reward scale, integrated portfolios, and the ability to support long-lifecycle applications with stable supply. Others reward specialization, speed to market, and the ability to source or rapidly introduce parts that are difficult to obtain. Independent distribution continues to play a meaningful role by connecting customers with new products and hard-to-find inventory, and by offering supply-chain services that go beyond transaction processing. This dual structure means that competitive advantage is context-specific: a manufacturer competing for automotive-grade design wins will pursue a different playbook than a distributor competing for rapid availability and broad catalog depth. The most resilient organizations are those that understand where they sit in this spectrum and invest accordingly.
Looking Ahead: Three Trends to Watch Through 2032
1. Power and Wide-Bandgap Economics Will Keep Improving, but Qualification Will Be the Gatekeeper
As efficiency requirements intensify across automotive, industrial, and energy applications, the addressable market for advanced power semiconductors and supporting components will expand. Yet growth will be uneven because adoption depends on qualification, system integration, and total-cost-of-ownership evidence. Organizations that can shorten qualification cycles, provide application support, and demonstrate reliability across lifecycle conditions will capture more design wins. The risk is that expectations for rapid adoption outrun the practical pace of validation, particularly in automotive and medical applications where certification timelines are long and unforgiving. Strategy should therefore pair technology roadmaps with customer-facing qualification and support capabilities.
2. Sustainability Metrics Will Be Priced Into Procurement and Product Design
With carbon-related mechanisms becoming operational and certificate pricing now visible, environmental performance is transitioning from a compliance topic to a procurement variable. Expect more purchasing decisions to incorporate supply-chain transparency, material sourcing, and energy intensity as evaluation criteria. This trend creates opportunity for manufacturers and distributors that can document and improve their footprints, and it raises the cost of opacity. The uncertainty lies in how quickly and uniformly these criteria will be applied across regions and customers. Firms that treat sustainability as a measurable, certifiable attribute rather than a narrative will have an advantage in negotiations and market access.
Electronics Market
3. Supply Assurance Will Become a Differentiated Value, Not Just a Cost Center
The combination of lead-time variability in select categories, capacity investments across multiple regions, and the strategic use of partnerships points toward supply assurance as a core competitive element. Buyers will increasingly value partners that can provide visibility, inventory flexibility, and qualification-ready alternatives. Manufacturers and distributors that invest in pipeline visibility, multi-site production options, and responsive catalog management will be able to command loyalty in segments where availability is a deciding factor. The downside risk is geopolitical and operational: the continued importance of advanced semiconductor manufacturing hubs means that regional disruptions can have disproportionate effects. Resilience planning, rather than assumption of continuity, will be a necessary discipline.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps with the applications and technologies where value density is rising, especially power management, precision analog, sensing, secure connectivity, and reliable microcontrollers for automotive and industrial use. Prioritize qualification and lifecycle support as core capabilities, because design-in decisions in high-stakes applications are often driven by risk reduction as much as by performance. Use regional capacity and partnership options to improve supply assurance without overcommitting to a single geography. Treat sustainability data as a product attribute that can support customer requirements and mitigate future trade friction. Finally, resist the temptation to chase every volume opportunity; concentrate resources where differentiation, certification, and application expertise create durable returns.
PW Consulting
For Investors and Strategic Planners
Assess exposure to sub-segments with the most favorable growth and margin dynamics rather than relying on aggregate market size alone. Favor business models that combine technology leadership with supply assurance, because these two attributes together tend to protect share and pricing. Watch for consolidation among players seeking to broaden portfolios and shorten customer time-to-integration, and monitor the role of independent distribution as a source of market intelligence and rapid introduction capability. Be mindful of policy risk and raw-material dynamics, and model scenarios that reflect extended lead times in certain categories and the possibility of pricing volatility in commodity-like segments. The most resilient investments are those that account for both upside from electrification and connectivity and the operational complexity that accompanies them.
Worldwide Rail Components Market
For Procurement, Supply-Chain, and Sourcing Leaders
Build sourcing strategies that incorporate qualification readiness, lead-time transparency, and alternate-source planning, especially for automotive-grade and industrial parts where delivery windows can be extended. Treat distributor relationships as strategic channels for new product access and hard-to-source inventory, not merely as transactional routes. Incorporate environmental and supply-chain transparency criteria into supplier evaluations, since these are increasingly part of purchasing decisions. Maintain a disciplined approach to inventory and pipeline visibility, balancing the cost of holding buffer stock against the cost of interrupted production. Where feasible, negotiate for improved visibility, regional delivery options, and design-in support, because these capabilities can reduce risk more effectively than price concessions alone.
Closing Perspective
The electronic components market is large, growing, and structurally complex. The aggregate trajectory points toward sustained expansion, but the real opportunities are distributed unevenly across technologies, applications, and geographies. Companies that map their activities to the segments where demand is intensifying, qualification matters, and supply assurance is valued will be best positioned to convert growth into durable advantage. For leaders seeking to move from broad trends to specific, actionable insight, the full research report provides detailed segment-level data and tailored recommendations to support portfolio, investment, and sourcing decisions with greater precision.
For detailed analysis of this topic, please visit the official page: Electronic Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DNS Security Software Market: Why 8.9% CAGR and Cloud Shift Change Everything
By PW Consulting, 2026-09-21
DNS Security Software Market: Strategic Shifts and Commercial Opportunities in a Reshaping Domain Defense Landscape
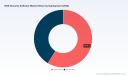
The DNS Security Software market is entering a period of accelerated structural transformation, driven by converging pressures in cloud migration, regulatory mandates, and increasingly sophisticated DNS-layer attacks. Market estimates place total revenue at approximately $170.0 million in 2025, with historical growth from 2020 through 2025 reflecting a steady acceleration as organizations progressively re-architect their security perimeters around identity and traffic visibility. Forecasts project the market to reach $310.0 million by 2032, representing a compound annual growth rate of 8.9% over the 2026–2032 period. This trajectory signals more than incremental demand growth; it reflects a fundamental reorientation of how organizations treat DNS—not as a passive directory service, but as an active security control point that must be continuously monitored, encrypted, and secured against both volumetric and application-layer threats.
For executives and strategy teams, the commercial implication is clear: DNS security is no longer a niche add-on within broader network protection portfolios. It is becoming a core component of zero-trust architectures, hybrid-cloud resilience programs, and compliance-driven security budgets. Yet the market is also navigating several inflection points that will separate winners from laggards over the next five years. Understanding where momentum is building—and where friction remains—provides a foundation for portfolio decisions, vendor selection, and investment timing.
Market Landscape and Core Challenges
The current market environment is characterized by rising deployment volumes, expanding regulatory expectations, and a persistent mismatch between organizational maturity and the operational complexity of DNS protection. Demand has been sustained by the expansion of cloud-hosted workloads, the proliferation of remote and hybrid work patterns, and an increase in DNS abuse vectors ranging from cache poisoning and tunneling to DDoS amplification. At the same time, buyers are confronted with a fragmented vendor landscape in which capabilities vary widely across threat intelligence integration, posture management, encryption support, and operational simplicity.
Inflection Point 1: DNS as a Security Control, Not Just Infrastructure
Historically, DNS management and DNS security were often treated separately, with networking teams handling resolution reliability and security teams focusing on perimeter and endpoint controls. That division is breaking down. Modern threat campaigns exploit the DNS layer to exfiltrate data, command compromised hosts, and bypass traditional inspection points. As a result, organizations are reassessing DNS security as a first-line control that must be integrated into broader security operations. This shift creates both opportunity and execution risk: organizations that succeed are those that can unify visibility, automate response, and embed DNS protections into existing workflows, while organizations that treat DNS tools as standalone point solutions risk operational silos and coverage gaps.
Inflection Point 2: Regulatory Acceleration and Procurement Mandates
Policy pressure is rapidly reshaping purchasing criteria. In the United States, executive guidance now requires support for encrypted DNS protocols as a procurement requirement for products acting as DNS resolvers for federal agencies, effectively tilting demand toward solutions that natively support encrypted resolution paths and demonstrate compliance readiness. Concurrently, CISA guidance emphasizes enterprise investment in AI-enabled DNS capabilities to address attacks targeting critical infrastructure, pushing buyer expectations toward analytics and automated detection functions. In Japan, national cybersecurity strategy documents are reinforcing the adoption of AI-enabled threat detection within DNS protection programs. These directives do not merely raise awareness; they create procurement momentum, especially among public-sector buyers and regulated industries, where compliance considerations increasingly influence vendor shortlists.
Inflection Point 3: Operational Complexity in Hybrid and Multi-Cloud Environments
As organizations distribute workloads across on-premises environments, multiple cloud providers, and edge deployments, DNS assets become dispersed and harder to inventory, monitor, and secure consistently. The operational burden includes managing authoritative and recursive resolvers, ensuring consistent policy enforcement, and detecting misconfigurations that can expose services to hijacking or denial-of-service conditions. This complexity is a central barrier to adoption for many mid-sized organizations, where staffing constraints limit the ability to operate advanced DNS security tools without agentless, automated, or managed approaches.
Key Drivers Shaping Market Momentum
Technology Innovation: Cloud-Native Resolution, Encrypted Protocols, and AI-Enabled Detection
Technological evolution is one of the strongest catalysts for market expansion. Cloud-native DNS architectures are increasingly favored for their scalability, centralized policy management, and integration with broader security ecosystems. Encrypted DNS protocols are no longer optional enhancements in many procurement contexts; they are becoming baseline expectations for privacy, tamper resistance, and compliance. Equally important, AI-enabled detection and analytics are moving from experimental features to operational requirements, particularly for identifying anomalous query patterns, detecting domain generation algorithms, and reducing response time during active incidents. Vendors that can combine reliable resolution, encrypted transport, and actionable threat intelligence are positioned to capture demand from organizations seeking to consolidate tools and improve security outcomes.
Policy and Regulatory Environment: Mandates as Adoption Accelerators
Regulatory developments are functioning as adoption accelerators rather than abstract compliance checkboxes. Encrypted DNS requirements in federal procurement create downstream pressure on suppliers serving government accounts and the broader supply chain. Sector-specific guidance that calls for AI-enabled DNS protections signals an expectation that critical infrastructure and high-risk industries will invest in more advanced detection and response capabilities. For vendors, this environment rewards clear compliance narratives, documented control mappings, and demonstrable integration with security operations workflows. For buyers, it introduces a practical urgency to evaluate whether existing DNS protections meet evolving expectations for encryption, visibility, and automated detection.
Demand-Side Change: Larger Attack Surfaces and Rising Business Risk
Demand is expanding because the cost of DNS abuse is becoming more visible and more consequential. Phishing, malware command-and-control, data exfiltration, and service disruption are all enabled or amplified by DNS manipulation, and these outcomes carry direct operational, financial, and reputational consequences. Enterprise buyers are increasingly linking DNS security to resilience objectives: ensuring that external-facing services remain reachable, that internal resolution is trustworthy, and that anomalous traffic can be identified before it escalates. This risk-based framing supports budget allocation even in cost-conscious planning cycles, because DNS-layer protections are often positioned as relatively low-friction controls with high preventive value.
Supply-Side and Cost-Structure Dynamics: Integration, Automation, and Service Models
On the supply side, market dynamics are shaped by the push toward integrated platforms, automation, and flexible deployment models. Cloud-based delivery continues to attract interest because it reduces the operational overhead associated with maintaining and updating on-premises resolver infrastructure, while also simplifying expansion across distributed locations. At the same time, on-premises deployments remain relevant in scenarios where data residency, latency sensitivity, or existing network architectures favor local control. The broader cost-structure trend is toward solutions that lower ongoing staffing demands through agentless visibility, automated remediation, and managed services options. This evolution is particularly important for smaller and mid-sized organizations that need enterprise-grade protections without proportional increases in specialized personnel.
Domain Name System Tools Market
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of incumbent infrastructure vendors, cloud and networking specialists, and providers with strong DNS heritage. Market concentration remains moderate, with the top three firms collectively representing roughly 25% of revenue and the top five reaching approximately 38%. This level of concentration suggests a market that is still fragmented enough for differentiation to matter, while also indicating that scale, ecosystem reach, and integrated portfolios provide meaningful advantages.
Differentiation Through Integration, Intelligence, and Resilience
Leading players are pursuing distinct strategic positions. Cisco Systems emphasizes cloud-delivered DNS-layer protection integrated with threat intelligence, aiming to block malware, phishing, and related threats before connections are established. Infoblox focuses on protective DNS and threat defense designed to safeguard DNS infrastructure against hijacking, cache poisoning, and DDoS attacks, appealing to organizations that prioritize DNS integrity as a core operational requirement. Cloudflare builds on its resolver and DNS firewall offerings by embedding DDoS mitigation, DNSSEC, and malware blocking for both enterprise and consumer contexts, leveraging its broader network presence to position DNS protection as part of a wider edge security model. Akamai Technologies emphasizes DDoS-resilient DNS delivery and posture management for hybrid cloud security, targeting organizations that need robust availability and visibility across complex environments. F5 Networks positions its DNS offerings around advanced security, load balancing, and protection against DNS attacks in hybrid settings, which resonates with enterprises seeking to align traffic management and security controls. Verisign and Neustar draw on established DNS infrastructure expertise, offering threat intelligence, DDoS protection, and managed DNS services that support enterprises and critical infrastructure scenarios.
PW Consulting Information & Electronics Research Center
The differentiating factors that matter most in this landscape are not limited to feature checklists. Buyers increasingly evaluate the breadth of threat intelligence integration, the quality of visibility across hybrid environments, the practicality of automated response, and the ability to meet procurement requirements for encrypted DNS. Providers that can connect DNS security to broader security operations, cloud governance, and compliance workflows are better positioned to win multi-year commitments.
Recent Developments and Evolving Market Structure
Recent product and partnership activity illustrates how vendors are closing capability gaps and expanding distribution. In June 2025, Akamai introduced DNS Posture Management, an agentless solution designed to provide unified multicloud visibility over DNS assets for real-time monitoring and remediation. This type of offering reflects a broader trend toward visibility and configuration governance as prerequisites for reliable DNS protection, especially where environments span multiple cloud providers. In September 2024, IGIT partnered with NS1 and Cisco to deliver agile DNS security application deployments targeting the EMEA region, demonstrating how channel and technology partnerships can accelerate regional reach and deployment flexibility.
These moves point to a market in which differentiation is increasingly tied to visibility, automation, and ecosystem enablement rather than standalone DNS features alone. The competitive trend is not simply toward consolidation; it is toward layered value propositions in which DNS security becomes embedded in multicloud operations, edge security, and compliance programs. New entrants and specialist providers can still compete by addressing niche requirements—such as specific compliance frames, high-scale DDoS resilience, or verticalized threat detection—while larger vendors compete on breadth, integration, and operational scale.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
Trend 1: Encryption and AI-Enabled Detection Become Baseline Expectations
Over the next several years, the combination of encrypted DNS and AI-enabled detection is likely to shift from differentiated capability to baseline expectation, especially in regulated and publicly exposed environments. Encrypted resolution paths will increasingly be required not only for privacy but also for procurement alignment and tamper resistance. AI-driven analytics will be expected to support faster triage, anomaly detection, and policy refinement. The commercial opportunity for vendors lies in delivering these capabilities in ways that are operationally practical: integrated into existing security tools, explainable to analysts, and measurable in terms of detection and response improvements. The risk for buyers is assuming that advanced features automatically translate into reduced operational overhead; without integration and governance, AI-enabled tools can add complexity rather than remove it.
Trend 2: DNS Posture Management and Multicloud Visibility Gain Strategic Importance
As multicloud adoption deepens, DNS posture management and unified visibility will become more central to security programs. Organizations will need to inventory DNS assets across environments, detect misconfigurations, and enforce consistent policies without relying entirely on manual audits or highly specialized staff. Agentless and automated approaches are likely to gain traction because they reduce the friction of expanding coverage across new workloads and locations. The commercial opportunity here extends beyond detection to remediation and governance: solutions that help teams maintain DNS hygiene, validate configuration changes, and respond quickly to deviations are well positioned to become part of ongoing operational budgets rather than one-time project spend.
Trend 3: Verticalized Demand and Compliance-Linked Procurement Intensify
Demand is likely to become more verticalized as industry-specific risk profiles and regulatory expectations diverge. BFSI, healthcare, government, and critical-infrastructure-adjacent sectors are already among the more pronounced areas of adoption interest, and further guidance or procurement requirements could intensify focus on DNS protections in these domains. This trend favors providers that can articulate clear control mappings, demonstrate sector-relevant threat coverage, and provide deployment flexibility for environments with distinct privacy, residency, or availability constraints. The uncertainty lies in the pace and consistency of regulatory evolution: while some jurisdictions are advancing clear directives, others may Lag, creating uneven demand patterns across regions and industries.
Strategic Recommendations for Decision Makers
For vendor and product leaders, the strategic imperative is to move beyond DNS security as a feature narrative and toward integrated outcomes. Solutions that combine reliable resolution, encrypted protocols, threat intelligence, and automated posture management will be better positioned to compete in procurement environments where buyers seek consolidation and operational simplicity. Differentiation should be expressed in terms of deployment flexibility across cloud and on-premises contexts, the practicality of integration with security operations, and the clarity of compliance support. Partnerships, particularly those that expand regional reach or enable faster deployment in complex environments, can be decisive in shortening sales cycles and broadening addressable segments.
For investors, the market’s growth trajectory and moderate concentration suggest that value creation will come from both scale advantages and targeted differentiation. Due diligence should examine not only revenue momentum but also the defensibility of threat intelligence pipelines, the operational burden of the deployed architecture, and the extent to which offerings are aligned with procurement requirements for encrypted DNS and AI-enabled detection. Capital allocation decisions should weigh the potential for platform consolidation against the persistence of specialist niches, particularly in DDoS resilience, critical infrastructure support, and verticalized compliance contexts.
For enterprise buyers and procurement teams, the priority is to treat DNS security as a continuum rather than a single purchase decision. Evaluations should consider encrypted protocol support, visibility across hybrid and multicloud assets, integration with existing security tooling, and the operational model required to keep protections current. Organizations should also assess whether they have sufficient internal capability to manage posture, respond to anomalies, and maintain configuration hygiene, or whether managed services, automation, or agentless approaches are needed to close gaps. Because requirements are evolving quickly, access to detailed segmentation insights, vendor benchmarking, and deployment-pattern data can materially improve buying and planning decisions.
Application Security Software Market
Detailed market segmentation, vendor-level benchmarking, and region- and industry-specific deployment dynamics remain essential for firms that need to act with precision rather than rely on aggregated trends alone. For leaders seeking deeper coverage of demand patterns, competitive positioning, and tailored recommendations across sectors and deployment contexts, the full PW Consulting research report provides the granular data and scenario analysis needed to translate market momentum into concrete strategy.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Footwear Market 2026: Beyond the 4.7% CAGR Story and What's Really Driving Growth
By PW Consulting, 2026-09-21
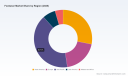
The Strategic Agenda for the Footwear Market: Navigating Growth, Tariffs, and Sustainability Through 2032
1. Market Overview and Core Challenges
The global footwear market has demonstrated resilient expansion over the past five years, growing from approximately $389.5 billion in 2020 to an estimated $483.0 billion in 2025. This trajectory reflects a compound annual growth rate of 4.7% over the historical period, driven by consistent consumer demand, evolving product categories, and geographic shifts in consumption patterns. Looking ahead to the forecast horizon of 2026 through 2032, the market is projected to reach $663.9 billion by the end of the period, with year-on-year increments reflecting both baseline growth and the compounding effect of structural changes across the value chain.
Several converging forces now place the industry at a strategic inflection point. First, tariff architectures and trade policy volatility have reshaped cost structures and sourcing logic. In the United States, average footwear tariffs stand at roughly 23.6%, with certain categories exposed to duties of 48% or higher, and importers paid an estimated $6.221 billion in duties during 2025. This environment compels brands and distributors to rethink landed cost, inventory positioning, and supplier diversification with greater urgency than in prior cycles. Second, regulatory momentum around sustainability and product traceability is accelerating. The EU Ecodesign for Sustainable Products Regulation requires Digital Product Passports for footwear by 2027, raising the bar for transparency, material disclosure, and lifecycle accountability across markets that interact with European supply chains and consumers. Third, the competitive field remains concentrated yet dynamic, with the top three firms capturing roughly 52% of market share and the top five approximately 58%, leaving meaningful room for specialized players, regional champions, and new entrants that can differentiate on performance, comfort, or sustainability claims.
These dynamics create a dual mandate for leadership teams: protect near-term margin and supply continuity while building optionality for regulatory compliance and shifting consumer preferences. The firms that treat these pressures as isolated compliance tasks risk forfeiting share to competitors who embed them into product roadmaps, sourcing strategies, and channel planning.
2. Key Drivers Shaping Market Trajectory
Technology and material innovation continue to redefine product value propositions across athletic, casual, and specialized segments. Advances in midsole geometries, lightweight foams, knit uppers, and comfort-focused constructions have expanded the performance envelope of everyday footwear, while sustainability-oriented materials and processes are increasingly tied to both consumer appeal and compliance readiness. Recent expositions underscore this direction: the Footwear Show New York Expo in June 2026 highlighted sustainable innovations, sculptural heels, and minimalist sneakers as focal points for buyers, signaling that aesthetic experimentation and eco-conscious design are moving in tandem rather than in competition.
Policy and standards environments are exerting an equally powerful pull on decision-making. Beyond tariff exposure, the impending Digital Product Passport requirement in the EU is prompting manufacturers and brand owners to build traceability infrastructure, consolidate material data, and align design choices with recyclability and durability targets. This is not solely a European concern; global suppliers serving multinational accounts are increasingly asked to provide standardized data packages that travel with products across jurisdictions, raising the baseline for documentation and process discipline throughout the supply chain.
Demand-side behavior is evolving around comfort, versatility, and occasion-blurring usage. Footwear and accessories led outdoor retail sales growth in 2024, with a modest rebound continuing into 2025, illustrating how health-oriented activity, leisure travel, and hybrid lifestyles are sustaining demand beyond core athletic use cases. At the same time, consumers are scrutinizing durability, comfort, and authenticity claims more closely, rewarding brands that can credibly connect product performance with responsible sourcing. This creates openings for comfort-led casual lines, performance-oriented running offerings, and specialized work or outdoor boots that serve distinct functional needs while adhering to higher design standards.
Supply chain and cost structures are being reconfigured in response to trade frictions and capacity considerations. Global footwear brands and suppliers have adapted sourcing footprints under U.S. tariff pressures, and acquisitions increased in 2025 as companies sought to offset cost impacts and secure capabilities. This shift is visible not only in brand-level M&A but also in the strengthening of domestic and allied production capacity for specialized categories, including military and tactical footwear, where compliance requirements and national sourcing priorities intersect. Collectively, these supply-side responses are recalibrating lead times, inventory risk, and the economics of made-to-order versus forecast-driven production.
Industry forecasts anticipate low single-digit growth for the broader fashion sector in 2026, with footwear positioned as a key subsector affected by tariff uncertainties and consumer caution. This outlook reinforces the need to prioritize productivity, assortment discipline, and differentiated value over volume-driven expansion in the near term.
3. Competitive Landscape and Strategic Positioning
The market features a broad set of established players spanning athletic and lifestyle performance, comfort-led casual lines, outdoor and work footwear, and specialized tactical or safety boots. Companies such as Nike, adidas America, ASICS America, Puma, New Balance, Crocs, Skechers, and Brooks Running anchor the athletic and lifestyle segments, each emphasizing distinct blends of performance, style, and mass-market accessibility. Nike and adidas continue to leverage global brand equity and broad category coverage across athletic and lifestyle footwear, while ASICS and Brooks Running concentrate on performance-oriented running and training offerings that serve dedicated user bases. Puma complements this field with athletic and lifestyle positioning that bridges sport and culture, and New Balance has strengthened its dual identity across performance running and casual footwear.
In the comfort and casual space, Crocs, Skechers, Clarks, ECCO, Geox, and Rieker illustrate the breadth of consumer appeal around ease, fit, and everyday wearability. Crocs focuses on casual, comfortable, and lifestyle footwear with recognizable design signatures, while Skechers emphasizes comfort-driven casual styles. Clarks, ECCO, Geox, and Rieker each bring differentiated perspectives on comfort, breathability, and orthopedic-friendly design, appealing to segments that prioritize long-wear comfort and functional materials. Premium casual and lifestyle positioning is further reinforced by ECCO’s design-led approach and Geox’s specialization in breathable comfort footwear, giving consumers multiple entry points into the casual category.
Outdoor, work, and safety footwear represents a distinct strategic layer, with firms such as Timberland, Wolverine World Wide, Red Wing Shoe Company, Danner, Belleville Boot Company, McRae Industries, Made Plus, and Steinberg Systems addressing durability, protection, and specialized compliance needs. Timberland offers outdoor, work, and lifestyle footwear that bridges function and style, while Wolverine World Wide’s brand portfolio spans work, outdoor, and broader footwear segments. Red Wing and Danner emphasize work, outdoor, and safety-oriented boots, with Red Wing also extending into casual boot offerings. Belleville Boot Company and McRae Industries serve military and tactical requirements, with McRae noted for Berry Amendment-compliant combat boots and Belleville for military and tactical footwear. Made Plus has entered the conversation with next-generation performance footwear that combines performance and sustainability focus, while Steinberg Systems contributes to the work and safety footwear manufacturing base.
Sports Footwear Market
Recent developments indicate a market in which membership, capacity, and trade events are reinforcing supply-side alignment and product innovation. McRae Industries was welcomed as the newest USFMA manufacturer member in May 2026, underscoring its legacy in Berry Amendment-compliant military combat boots. YKK Americas joined the association in April 2026, expanding national capacity for military boot production following its acquisition of Collt’s Manufacturing. In February 2026, USFMA added Gusbi, Autec Automation, and Robot System Automation as Italian footwear machinery leaders to enhance U.S. production capacity for domestic manufacturers. On the commercial side, the Footwear Show New York Expo in June 2026 showcased sustainable innovations, sculptural heels, and minimalist sneakers to buyers, and the 26th International Shoes & Leather Exhibition in Ho Chi Minh City was scheduled for July 2026 to promote new machinery, materials, and sustainable footwear initiatives. These events and membership moves reflect a broader tendency to strengthen production capabilities, align on compliance and traceability, and surface product directions that blend sustainability with design differentiation.
Strategically, the landscape is evolving through both consolidation and fragmentation. Concentration among leading firms remains significant, yet the breadth of specialized players indicates that differentiation by function, comfort, compliance, and materials can support durable positions even in a concentrated market. New entrants and established niche players can gain traction by solving specific problems—whether that is performance-per-wear in running, all-day comfort in casual settings, or regulated compliance in defense and industrial applications—while larger incumbents pursue scale, brand breadth, and channel leverage. The net effect is a market in which leadership is increasingly defined not only by volume but by the ability to align product, supply, and compliance narratives with the priorities of distinct customer groups.
4. Future Trends and Commercial Opportunities (2026–2031)
One defining trend for the next several years is the integration of compliance and traceability into product design and sourcing decisions. As Digital Product Passport requirements take effect and sustainability expectations rise, footwear that can demonstrate material provenance, durability, and end-of-life considerations will gain advantages in regulated channels and among informed consumers. This creates commercial opportunities for manufacturers and brand owners that invest early in data collection, material standardization, and design-for-circularity, turning compliance from a cost center into a trust signal that supports premium positioning and retailer relationships.
A second trend is the continued recalibration of supply chains around cost, resilience, and category-specific needs. Tariff exposure and acquisition activity through 2025 have accelerated shifts in sourcing geography, supplier consolidation, and the selective development of domestic or allied capacity for specialized products. Over the forecast period, firms are likely to pursue more flexible manufacturing arrangements, closer coordination between brands and tier-one suppliers, and greater use of automation and machinery partnerships to improve responsiveness. The expansion of production capacity for military and tactical footwear, supported by machinery and membership developments, illustrates how category-specific requirements can drive targeted capacity investments that differentiate suppliers in regulated segments.
A third trend is the broadening of usage occasions and the corresponding rise of hybrid product strategies. Footwear and accessories have led outdoor retail sales growth, and the modest rebound into 2025 suggests sustained appetite for products that support active leisure, travel, and everyday wear. This environment favors lines that balance performance, comfort, and style, such as minimalist sneakers, sculptural heel designs, and comfort-focused casual footwear. Brands that can bridge athletic-derived technologies with lifestyle aesthetics, or that can offer durable outdoor and work products with consumer-facing design appeal, are well positioned to capture spend across overlapping occasions.
PW Consulting
These trends carry both opportunity and uncertainty. Growth is expected to continue, but low single-digit industry growth in 2026 and ongoing tariff uncertainties mean that volume-led expansion will be less reliable than disciplined assortment planning, cost control, and differentiated value creation. Additionally, regulatory timelines, consumer receptivity to sustainability claims, and the pace of supply chain restructuring will vary by region and category, requiring scenario-based planning rather than single-point forecasts. Firms that prepare for multiple pathways—by building traceability readiness, diversifying sourcing options, and maintaining agile product development cycles—will be better placed to capture upside while limiting exposure to shocks.
5. Actionable Recommendations for Decision-Makers
For manufacturers and brand owners, the priority is to align product roadmaps with compliance and consumer value at the same time. This means embedding traceability and material disclosure considerations into design phases, prioritizing constructions and materials that support both performance and sustainability narratives, and evaluating sourcing options against tariff exposure and lead-time reliability. Companies should also assess where specialized capacity—such as regulated military or safety footwear, comfort-led casual lines, or performance running—can be strengthened through equipment partnerships, selective acquisitions, or closer supplier integration, particularly as machinery and membership developments continue to expand production capabilities.
Military Footwear Market
For investors, the strategic question is where differentiation is durable enough to support margin and share gains in a concentrated yet diverse market. Opportunities are likely to be found in segments where function, comfort, and compliance intersect, in suppliers that can provide traceability and data infrastructure, and in brands that combine athletic-derived technology with lifestyle appeal. Due diligence should weigh tariff sensitivity, regulatory readiness, assortment discipline, and the credibility of sustainability claims, while monitoring consolidation activity and capacity investments that may reshape competitive dynamics. A selective approach that favors defensible niches and operationally resilient business models is better suited to a low single-digit growth environment than broad-based volume bets.
For procurement and distribution leaders, the imperative is to manage landed cost and assortment risk without sacrificing the product variety that drives demand. Diversifying sourcing where feasible, negotiating with visibility into tariff exposure, and prioritizing suppliers that can deliver consistent data packages for compliance will reduce friction as Digital Product Passport requirements and retailer expectations intensify. Procurement teams should also align category strategies with usage trends, ensuring that comfort, outdoor-adjacent, and lifestyle-led lines are represented in ways that reflect actual consumer behavior rather than legacy category boundaries. Building supplier relationships that emphasize transparency, responsiveness, and proven compliance readiness will become a structural advantage in negotiations and assortment planning.
Across these audiences, timely access to detailed market intelligence supports better decisions. Detailed segmentation data, competitor benchmarking, and scenario analysis can clarify where growth is most attainable, which compliance investments matter earliest, and how sourcing shifts affect cost and service levels. For decision-makers who need granular breakdowns, supplier-level insight, and tailored recommendations, the full research report provides the depth required to translate these strategic trends into concrete plans.
For detailed analysis of this topic, please visit the official page: Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PAPR Market Set for 8.3% CAGR Growth: Unpacking the Forces Behind 2032’s $5.38 Billion Outlook
By PW Consulting, 2026-09-21
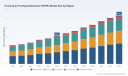
Powered Air Purifying Respirator Market: Strategic Trends and Commercial Opportunities, 2025–2032
The Powered Air Purifying Respirator market has transitioned from a specialized niche into a strategic infrastructure investment across healthcare, industrial manufacturing, energy, and construction. Since 2020, annual revenue has expanded from approximately 2.07 billion to 3.08 billion, reflecting a compound annual growth rate of 8.3 percent through 2032. By the end of the forecast window, total market value is projected to reach 5.38 billion. This trajectory is not merely a function of incremental demand; it signals a structural shift in how organizations approach respiratory protection, occupational safety compliance, and workplace readiness.
Regional leadership remains firmly anchored in North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa collectively represent emerging demand corridors. The product landscape is dominated by half mask configurations, which account for the largest share of total revenue, with full face mask and hood variants serving specialized use cases where field of view, comfort, or contamination control requirements differ. In application terms, healthcare and manufacturing represent the two largest demand pools, with oil and gas, construction, and ancillary sectors providing complementary growth vectors.
Despite the favorable growth outlook, the market operates under a moderate concentration profile. The three largest players control roughly 54.5 percent of total revenue, and the top five firms account for approximately 65.0 percent. This concentration shapes pricing discipline, channel access, and the pace at which innovation diffuses across the industry. At the same time, it leaves meaningful room for differentiated entrants, particularly in product formats, regional distribution, and application-specific engineering.
Executives evaluating exposure to this market should view it as a convergence point between regulatory evolution, engineering upgrades, and changing workplace risk profiles. The growth numbers provide directionality, but the strategic value lies in understanding where demand is becoming more repeatable, where compliance friction is easing, and where battery, filtration, and ergonomics are redefining product competitiveness.
Key Challenges and Inflection Points
The market's expansion is real, but it is not frictionless. Three challenges currently define the strategic inflection point for suppliers, buyers, and investors.
The first is the tension between regulatory streamlining and quality assurance. Recent draft guidance from the U.S. Food and Drug Administration and proposed updates from the Occupational Safety and Health Administration signal a clear intent to reduce premarket and medical clearance burdens for certain respiratory protection categories, including NIOSH-approved powered air-purifying respirators used in healthcare and public health settings. While these adjustments can accelerate procurement and broaden adoption, they also introduce a different type of risk: organizations must maintain rigorous internal validation and post-market surveillance when external clearance requirements loosen. The same guidance cycle has also referenced a Class 2 device recall involving 528 units tied to potential mis-assembly of elastic headband rivets to the face shield. That incident underscores a broader point—regulatory flexibility does not eliminate the need for robust design control, assembly consistency, and field reliability.
The second challenge centers on total cost of ownership rather than unit price. Battery systems, particularly lithium-ion and nickel-metal hydride chemistries, represent a primary material expense in powered respirator architectures. Equally important are the labor and administrative costs tied to fit-testing, maintenance protocols, filter replacement, and hospital or plant-level respiratory protection programs. For buyers, the economic question is shifting from “What is the purchase price?” to “What does a dependable protection program cost across its lifecycle?” For manufacturers, this reorients innovation toward battery endurance, serviceability, consumable logistics, and ease of inspection.
The third challenge relates to reimbursement and procurement categorization in healthcare. Current coding and reimbursement structures do not reflect a dedicated, updated framework for powered air-purifying respirator consumables and program costs. Hospitals and health systems continue to classify these items under existing procedures, which can create budgetary friction when scaling protection programs. The absence of specific reimbursement revisions means that adoption in healthcare is being driven less by incremental reimbursement incentives and more by institutional risk management, infection control priorities, and internal compliance mandates. That dynamic favors suppliers who can demonstrate program-level value rather than product-level savings alone.
Together, these challenges point to a market that is maturing but still uneven. Growth will increasingly favor organizations that can align product design, service model, and regulatory navigation with how buyers actually budget and operate.
Core Demand Drivers
Technology Innovation and Product Architecture
Engineering progress is reshaping the value proposition of powered respirators. Recent product activity illustrates how manufacturers are competing on usability, runtime, and filtration performance rather than basic protection alone. In early 2025, Bullard introduced a third-generation system with an improved battery architecture, higher filter efficiency, and streamlined maintenance protocols. These changes matter because they reduce the operational burden on end users and simplify inventory and service planning for safety teams.
At the same time, form factor diversification continues to expand the addressable use cases. Half mask systems remain the volume leader because they offer a pragmatic balance of protection, compatibility, and cost. Full face mask designs serve environments where face and eye protection integration is critical. Hood configurations address scenarios where loose-fitting comfort, extended wear time, and minimization of fit-testing dependency are priorities. The practical implication is that product strategy is less about a single winning configuration and more about matching architecture to workflow, environment, and compliance profile.
Particulate Respirators Market
Battery performance remains a central technical battleground. Runtime, charging logistics, thermal stability, and replacement cycles directly influence field adoption, particularly in healthcare settings where continuity of care and shift-based usage are critical, and in industrial environments where maintenance windows are tightly constrained. Innovations that improve effective runtime or reduce downtime can create meaningful competitive advantage, especially when paired with better diagnostic indicators and predictable consumable schedules.
Regulatory and Compliance Environment
The regulatory trajectory is a powerful demand catalyst, but its effects are nuanced. The April 2026 draft guidance from the U.S. Food and Drug Administration proposes an enforcement discretion compliance policy for NIOSH-approved powered air-purifying respirators and other non-surgical respirators, aimed at reducing premarket requirements for healthcare and public health usage. This type of guidance tends to shorten procurement cycles and lower administrative barriers, which can stimulate demand in health systems and public-sector buyers.
In parallel, the July 2025 proposed amendments from the U.S. Occupational Safety and Health Administration target medical evaluation requirements, removing clearance mandates for users of filtering facepiece respirators and loose-fitting powered air-purifying respirators. The rationale cited in the proposed rule rests on insufficient evidence that such clearance materially reduces impairment in the covered populations. If finalized, this shift would lower a persistent administrative obstacle, particularly for organizations that deploy loose-fitting systems at scale and have struggled with medical evaluation throughput.
Worldwide Medical Powered Air Purifying Respirators Market
These developments should not be interpreted as a blanket deregulation of respiratory safety. Instead, they reflect a targeted recalibration: the regulatory burden is being adjusted where evidence suggests limited marginal benefit, while foundational protection standards remain in force. For the market, the result is likely to be faster adoption in specific channels, greater emphasis on post-market quality, and a growing premium on manufacturers who can provide clear documentation, validated performance, and traceable quality systems.
Demand-Side Behavior and Workplace Risk Perception
Demand is being shaped by a durable change in how organizations think about airborne exposure. In healthcare, respiratory protection programs have moved from episodic compliance to a more continuous readiness mindset. The use of powered air-purifying respirators in clinical and decontamination contexts is increasingly influenced by the need to protect staff during airborne pathogen exposure risk, aerosol-generating procedures, and environmental cleaning operations. Even where reimbursement codes remain unchanged, institutional decision-making is driven by staff safety, operational continuity, and the desire to reduce fit-test dependency for certain loose-fitting deployments.
In industrial environments, demand is tied to both compliance and productivity. Manufacturing and oil and gas operations use powered respirators where particulate exposure, chemical environments, or extended task duration make passive protection less practical. Construction and related trades use them in scenarios where dust, abrasive materials, or mixed-exposure conditions create recurring protection needs. A notable channel development is the expansion of welding-focused solutions through distribution partnerships, which broadens access to specialized air-purifying configurations in fabrication and metalworking settings.
A subtle but important demand shift is the growing preference for solutions that reduce operational friction. Buyers are increasingly attentive to battery swap convenience, filter life clarity, cleaning procedures, and the time burden imposed on safety coordinators. This does not make price irrelevant, but it does mean that competitive differentiation is increasingly derived from program convenience and reliability as much as from protection specifications alone.
Supply Chain, Cost Structure, and Procurement Dynamics
Cost structures in this market are influenced by more than raw material prices. Battery chemistry costs, filter media, housing components, and assembly labor all feed into final pricing, while fit-testing, maintenance labor, and consumable replacement shape the recurring cost profile for end users. In hospital and industrial settings, these operational costs can dominate the economics of a protection program, particularly when deployment scales across multiple sites or shifts.
Supply chain stability matters because respiratory protection is both safety-critical and usage-sensitive. Intermittent availability of filters, batteries, or replacement components can undermine program confidence even when the base equipment is sound. As a result, suppliers that can offer predictable consumable availability, clear service intervals, and localized support often gain an advantage that is not fully captured by headline product specifications.
For procurement teams, this environment rewards a more programmatic purchasing approach. Rather than evaluating individual units in isolation, buyers are increasingly assessing how equipment, consumables, training, and maintenance fit together across a season of use. That shift creates opportunities for suppliers to bundle service elements, provide usage forecasting, and reduce the administrative load on safety teams.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a small group of well-positioned manufacturers with distinct engineering legacies, channel strengths, and application focus areas. The market’s moderate concentration gives established players meaningful scale advantages, while still leaving space for differentiated positioning.
Dräger occupies a strong position in industrial and decontamination-oriented powered respirator systems, with helmet and facepiece architectures designed for demanding environments. Its strategic value lies in integration, durability, and the credibility of a safety-focused brand in heavy-duty applications. For buyers in industrial and specialized decontamination settings, Dräger’s appeal often centers on perceived reliability and alignment with stringent operational requirements.
3M maintains a broad industrial footprint with powered air-purifying respirator systems built for heavy industrial and hazardous location use. Its advantage is scale, distribution reach, and the ability to position respiratory protection within a wider ecosystem of safety and industrial products. In markets where procurement relies on consolidated vendor relationships and multi-product support, that breadth can be a decisive factor.
MSA Safety combines its own powered respirator portfolio with targeted distribution partnerships, including the introduction of welding and industrial-focused air-purifying systems through an exclusive North American partnership. This hybrid approach is strategically significant. It allows MSA to expand its application coverage without building every solution internally, while leveraging existing channel relationships to reach welding, fabrication, and general industrial users more efficiently.
Bullard’s recent product refresh highlights a different competitive angle: iterative improvement in battery system design, filter efficiency, and maintenance simplicity. In a market where operational friction often determines adoption, Bullard’s focus on usability and upkeep can resonate with buyers seeking to reduce training burden and service complexity. The company’s positioning is especially relevant where industrial protective equipment programs value straightforward maintenance and predictable consumable management.
AirBoss Defense Group brings a compact, lightweight design philosophy to the market, with configurations that emphasize portability and particulate protection, including NIOSH-approved options. Its relevance lies in use cases where weight, mobility, and streamlined form factors matter, particularly for teams that need protection without the burden of bulkier systems.
Taken together, the competitive landscape is evolving along three paths. One is consolidation of capability, where larger players use portfolio breadth and distribution to capture cross-application demand. Another is application specialization, where firms deepen their relevance in healthcare, welding, decontamination, or heavy industry through product tuning and channel focus. The third is selective partnership and distribution, which accelerates market access for specialized systems without requiring full vertical build-out. New entrants and smaller firms are most likely to succeed where they solve a specific operational pain point, serve an underserved geography, or offer a form factor that better matches a particular workflow.
Forward Outlook: Three Trends to Watch
Trend One: Faster Adoption in Healthcare and Public Health Settings Through Regulatory and Workflow Alignment
The combination of draft FDA guidance and proposed OSHA amendments is likely to lower administrative barriers for selected powered respirator deployments. If these developments move toward final implementation, healthcare and public health buyers may accelerate evaluation and procurement, especially where programs are designed around loose-fitting options and reduced medical clearance friction. The strategic opportunity here is not simply more units sold; it is the emergence of more standardized procurement pathways, more repeat demand, and greater interest in systems that integrate cleanly into infection control and staff protection workflows.
The associated risk is uneven adoption. Institutions will still differ in how they interpret guidance, manage internal validation, and budget for consumables. Suppliers that over-index on regulatory optimism without supporting program-level usability and service may find adoption slower than the headline environment suggests.
Trend Two: Continued Competition Around Battery, Filtration, and Maintenance Experience
Over the next several years, competitive advantage will increasingly hinge on runtime, charging convenience, filter life clarity, and maintenance simplicity. Buyers are likely to favor systems that reduce downtime, make consumable management predictable, and minimize the training burden for frontline users and safety coordinators. Manufacturers that can pair solid protection performance with a better operational experience should be able to command preference even in a market where multiple products meet baseline requirements.
The risk on this front is that battery and filtration innovation can be copied incrementally, and price competition can intensify once a category matures. Durable advantage will depend on execution quality, support infrastructure, and the ability to demonstrate measurable reductions in program friction, not just specification upgrades.
Trend Three: Program-Level Purchasing and Service Differentiation
As total cost of ownership becomes more central, procurement is likely to shift further toward program-oriented evaluation. That means greater weight on filter supply reliability, battery replacement logistics, maintenance protocols, fit-testing strategy where applicable, and vendor support responsiveness. Suppliers that help buyers plan and manage these elements—rather than only deliver hardware—will be better positioned in competitive bids and multi-year deployments.
The uncertainty here lies in how consistently different buyer segments will adopt program-level thinking. Industrial procurement may move faster in environments with strict compliance cycles and high usage, while other segments may continue to prioritize unit economics and approval simplicity. Companies that can tailor their commercial model to the buying habits of each segment will be more resilient.
Action Considerations for Decision Makers
For manufacturers and product leaders, the priority is to align engineering roadmaps with where buyers feel friction most acutely. Battery lifecycle, filter service clarity, cleaning and maintenance simplicity, and form factor fit for specific applications should be treated as core value drivers, not secondary features. Equally important is the quality system behind the product. Recent regulatory and recall signals indicate that documentation, assembly consistency, and post-market reliability will remain central to market access and customer trust. Firms should also consider where partnerships or targeted distribution agreements can expand application coverage more efficiently than internal expansion alone.
For investors, the market offers a constructive demand backdrop, but selection matters. The most resilient opportunities are likely in companies with defensible application positioning, credible quality and compliance processes, and commercial models that address recurring consumables and support rather than one-time hardware sales alone. Monitoring the trajectory of FDA and OSHA actions will be important, but the more durable signals will come from product adoption patterns, channel execution, and the ability to reduce operational burden for end users. Investors should also watch for consolidation activity, especially where larger players seek to fill application gaps or strengthen regional distribution.
For procurement and safety leaders, the practical move is to evaluate powered air-purifying respirators as part of a protection program rather than as stand-alone purchases. That evaluation should include battery and filter logistics, maintenance workload, training requirements, and support responsiveness alongside protection performance. Where loose-fitting systems are appropriate, the evolving regulatory environment may reduce certain administrative steps, but internal validation and quality verification remain essential. Buyers should also clarify how consumables will be sourced over time, because program confidence depends heavily on predictable availability and clear replacement intervals.
For organizations seeking a sharper view of segment-level demand, regional variation, product configuration economics, and competitive positioning across specific application niches, a more detailed research deep dive can help translate these market-wide trends into segment-specific decisions. The broad trajectory of the powered air purifying respirator market is clear; the strategic advantage comes from understanding where within that trajectory the most actionable opportunities and risks sit for your particular operating context.
PW Consulting
For detailed analysis of this topic, please visit the official page: Powered Air Purifying Respirator (PAPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Prefab Bathroom Pods Market: Why 9.4% CAGR and Commercial Demand Change Everything
By PW Consulting, 2026-09-21
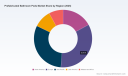
The Prefabricated Bathroom Pods Market: Strategic Shifts and Commercial Opportunities Through 2032
The prefabricated bathroom pods market has moved from a niche construction alternative to a mainstream operational lever for developers, contractors, and facility operators. Valued at approximately USD 6.7 billion in 2025 and projected to expand at a compound annual growth rate of 9.4% through 2032, reaching a revenue base near USD 12.59 billion by the end of the forecast period, the sector reflects a structural recalibration of how built-environment programs are delivered. The trajectory from 2020 through 2025 alone—moving from 4.32 billion to 6.7 billion—demonstrates that the shift is not cyclical but cumulative, driven by persistent labor constraints, schedule compression, and the maturation of offsite manufacturing capabilities.
For decision-makers, this market now sits at an inflection point where technology, regulation, and procurement behavior are reinforcing one another. The opportunity is no longer simply about buying a prefabricated unit; it is about integrating factory-built bathrooms into broader project delivery models, managing supply chain dependencies, and aligning product specifications with evolving compliance and sustainability expectations. The following analysis maps the current state of the market, the forces reshaping it, the competitive positioning of leading manufacturers, and the strategic implications for executives navigating the next three to five years.
Market Status and Core Challenges
The scale of the prefabricated bathroom pods market signals broad adoption, but scale alone does not guarantee smooth execution. The market's growth path from 2020 to 2025—expanding from 4.32 billion to 6.7 billion—has been supported by repeatable factory processes, standardized connection systems, and a growing pipeline of residential, commercial, and institutional projects that prioritize speed and predictability. The forecast band from 2026 through 2032, moving toward 12.59 billion, suggests continued deployment across multiple building types, with commercial and institutional programs likely to remain the primary volume drivers while residential applications gain share as production costs stabilize and design libraries mature.
Despite the positive revenue curve, three challenges define the current operating environment and will shape who captures value in the next phase of growth.
1. Quality Standardization Versus Design Flexibility
Factory production favors repetition, yet end-user expectations increasingly demand customized finishes, layouts, and accessibility configurations. The tension between manufacturing efficiency and project-specific variation is intensifying as pods move from standardized hotel rooms and student housing into healthcare environments, defense facilities, and higher-spec residential programs. Manufacturers that can modularize variation—through configurable framing, interchangeable finish panels, and digital specification workflows—gain a meaningful advantage, while those locked into rigid product lines face margin pressure or limited addressable demand.
2. Compliance Complexity Across Jurisdictions
Prefabricated bathroom pods must satisfy a layered set of requirements that vary by region and building type. International Building Code (IBC) and IRC provisions, local plumbing regulations, and fire-retardant packaging standards such as Loss Prevention Standards LPS 1207 create a compliance landscape that can slow deployment if not addressed upstream. The practical implication is that factory readiness does not automatically translate into site readiness; manufacturers and buyers need aligned inspection pathways, documentation protocols, and transport safeguards to avoid rework or delays during final on-site approval.
3. Supply Chain Concentration and Material Volatility
The market remains moderately concentrated, with leading manufacturers holding a meaningful share of capacity and project flow. Concentration can improve quality consistency and scale economies, but it also raises dependency risks when raw material availability, freight constraints, or production bottlenecks emerge. Steel, composite materials, and lightweight concrete inputs each carry distinct cost and performance profiles, and shifts in one material stream can ripple through lead times and pricing. Buyers and competitors alike are increasingly evaluating dual-sourcing strategies, regional production footprints, and buffer inventory approaches to reduce exposure.
Key Drivers Shaping Market Evolution
Market expansion is not accidental; it is being pulled by a convergence of technical, regulatory, demand-side, and cost-driven forces. The most consequential drivers are not isolated trends but interacting dynamics that change how projects are planned, priced, and delivered.
Technological Innovation and Manufacturing Maturation
Factory-built bathroom pods are benefiting from more disciplined production environments, digital design integration, and material optimization. Advanced composite and steel-frame production lines, BIM-aligned specification workflows, and lean manufacturing practices are reducing defect rates, improving dimensional accuracy, and shortening assembly sequences. Lightweight concrete and patented galvanized steel frame solutions have expanded the structural envelope available for multi-story and higher-load applications, while GRP-based pods are increasingly preferred for their corrosion resistance, reduced maintenance burden, and ease of handling. These material and process improvements are not merely incremental; they broaden the range of projects where pods can be deployed without compromising performance or schedule.
Recent product activity reinforces this trajectory. In February 2026, Offsite Solutions introduced a next-generation steel-framed bathroom pod line with modular design elements that allow customization of layouts and finishes while preserving manufacturing efficiency. That kind of development matters because it addresses a core market tension: buyers want flexibility, but manufacturers need repeatable throughput. Solutions that standardize the underlying frame and connection system while enabling finish and layout variation create a more scalable value proposition.
Policy and Regulatory Environment
Regulatory expectations are becoming both a constraint and a differentiator. Manufacturers are increasingly designing pods to align with local building codes, plumbing regulations, and inspection pathways so that units arrive at the site with a higher degree of factory readiness. At the same time, loss prevention and transport standards are shaping packaging, storage, and handling requirements, particularly for temporary coverings and protective materials used during movement and staging. Compliance is no longer a back-office concern; it is a commercial specification. Projects that integrate code alignment, documentation, and transport safeguards earlier in the procurement cycle reduce the likelihood of delayed approvals or on-site corrections.
This regulatory pull is most visible in programs where inspection risk is high or where multiple jurisdictions are involved. In those settings, manufacturers with established compliance frameworks and predictable quality control processes can shorten decision cycles and lower project risk. The broader effect is a market in which credibility around code conformance and inspection readiness becomes part of the product itself.
Demand-Side Behavior and Procurement Priorities
Buyers are increasingly treating bathrooms as a delivery bottleneck rather than a downstream trade. Onsite bathroom assembly can consume disproportionate labor, extend schedule risk, and create coordination challenges across plumbing, finishes, and inspections. Prefabricated pods accelerate project timelines by roughly 40-50% and reduce on-site workforce needs compared with traditional construction methods, which makes them attractive in labor-constrained markets and in programs where speed-to-occupancy is a financial priority.
Demand is also shifting in response to program type. Commercial and institutional projects—hotels, student accommodation, healthcare facilities, and social housing—continue to be strong adopters because they value repeatable units, predictable quality, and faster fit-out. At the same time, residential applications are gaining momentum as developers and contractors look for ways to compress schedules and control finish quality. The result is a broadening demand base that rewards manufacturers capable of serving multiple sectors without sacrificing production discipline.
Worldwide Bathroom Product Market
Cost Structure and Labor Dynamics
Labor availability and cost remain a structural driver. Where skilled trades are scarce or wage pressure is high, offsite production offers a practical route to reduce on-site labor intensity and improve schedule certainty. Factory settings also enable better material yield, more controlled quality checks, and fewer Weather-related delays, all of which contribute to a more predictable cost profile. This does not mean prefabrication eliminates cost risk; transportation, staging, crane logistics, and interface coordination with the primary structure still matter. But the cost conversation is moving from unit price alone toward total program efficiency, including time savings, rework reduction, and workforce allocation.
Project activity in 2026 illustrates how demand and delivery models are converging. In March 2026, BAUDET secured contracts for multiple hotel modernizations and student residence projects, including Kyriad Hotels Modernization for Louvre Hotels Group in Paris, along with student residence projects in Saint-Étienne and Caen. These wins point to a repeatable commercial pattern: modernization programs and high-volume residential/hospitality pipelines where consistent finishes, predictable lead times, and reduced on-site disruption are decisive. Later, in April 2026, Southwest Solutions Group participated in modular construction and restroom solutions events showcasing code-compliant prefabricated bathroom pods for fast deployment, reflecting a wider industry emphasis on compliance-ready, rapidly deployable units.
Competitive Landscape and Leading Strategies
The competitive environment is defined by manufacturers that have built reputation around production scale, material specialization, and sector focus. The market's concentration suggests that established players hold substantial influence over pricing, specification norms, and buyer confidence, but it also leaves room for regional specialists and new entrants that can differentiate through customization, compliance readiness, or logistics advantage.
Several strategic positions are emerging among leading companies. Walker Modular, based in Hull, United Kingdom, operates as a leading manufacturer of high-quality prefabricated bathroom pods with advanced composite and steel frame production lines, serving UK developers, hotels, healthcare facilities, and student accommodation projects. Its positioning reflects a broad-sector approach anchored in production quality and repeat supply relationships. Offsite Solutions, located in Highbridge, Somerset, specializes in GRP composite and steel-framed pods and utility units, delivering over 10,000 units annually for main contractors and developers. Its scale and material breadth suggest a focus on throughput, consistency, and contractor-facing reliability.
Bathsystem S.p.A., headquartered in Calcinato, Italy, produces lightweight concrete and patented SUPERLIGHT galvanized steel frame solutions in controlled facilities, with annual capacity exceeding 12,000 units. Its strategy leans on proprietary frame technology and controlled production to support both bathroom pods and kitchen units, appealing to buyers who value structural efficiency and repeatable manufacturing. Interpod, based in Berkeley Vale, New South Wales, Australia, focuses on bespoke modular pods for residential, hospitality, healthcare, and defence applications, operating a dedicated factory with custom design and quality finishes. Its differentiation lies in tailored specification and finish quality for programs that require a higher degree of project-specific adaptation.
Prefabricated Security Booth Market
In North America, SurePods, headquartered in Orlando, Florida, has established itself as a factory-built pod supplier for healthcare, hospitality, and residential projects, using BIM and lean manufacturing with expanding facilities and ISO-compliant quality control. Its orientation toward digital specification and quality systems aligns with buyers seeking predictable interfaces and inspection-ready units. B&T Manufacturing, in Rapid City, South Dakota, uses FRAMECAD light-gauge steel technology to produce steel modular pods for hotels, healthcare, and commercial projects, emphasizing plug-and-play units with customizable layouts. Its approach highlights the role of light-gauge steel systems in balancing structural strength with layout flexibility.
European and emerging-market players add further variety. BAUDET, based in Mouchamps, France, has manufactured ready-to-install bathroom pods with full interior finish since 1992, supplying turnkey units for hotels, student residences, and social housing. Hydrodiseño, in Spain, produces prefabricated modular bathroom and kitchen pods with patented designs, targeting efficient, high-quality units for large-scale construction projects. Durapods, in the United States, offers offsite production through PDM Constructors, focusing on simplified logistics and faster delivery across residential and commercial markets. Loom Crafts, in India, produces custom prefabricated bathroom pods for hospitality, healthcare, and housing clients, reflecting growing regional manufacturing capacity and customization demand.
Strategic Positioning and Differentiation
Across these players, several recurring differentiation themes appear. Material expertise is one: some manufacturers emphasize GRP composites for corrosion resistance and low maintenance, while others lean on steel framing for structural strength and multi-story suitability. Production discipline is another: companies that can combine high annual throughput with controlled quality environments tend to win repeat contractor and developer relationships. Sector specialization also matters; firms aligned to hospitality, healthcare, student accommodation, or defence can tailor finishes, accessibility features, and compliance documentation to the expectations of those programs. Finally, interface readiness—BIM-aligned specifications, code documentation, and transport protection—increasingly separates suppliers that merely deliver units from those that reduce project risk.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is likely to evolve along three paths simultaneously. First, consolidation pressure may intensify among mid-tier producers as scale, compliance documentation, and logistics capability become harder to sustain independently. Second, differentiation will deepen around material systems, finish flexibility, and sector-specific compliance, making product category less homogeneous than it once appeared. Third, new entry remains possible in regions where construction demand is expanding and where local production can reduce transport cost and lead-time risk, especially if entrants can combine customization with repeatable framing and quality systems.
Competition will not be won on unit price alone. Buyers are increasingly weighing total program impact: installation speed, inspection readiness, transport resilience, finish consistency, and the ability to adapt layouts without disrupting production. Suppliers that can demonstrate those attributes in repeatable ways are better positioned to secure long-term specification relationships rather than one-off project wins.
Forward Outlook: Trends and Commercial Implications
Looking across the current market trajectory and the forces shaping production, procurement, and regulation, three trends are likely to define the next three to five years.
1. Modular Variation as a Standard Capability
The next phase of growth will favor manufacturers that can offer configurable layouts, interchangeable finish options, and accessibility adaptations without sacrificing throughput. As pods move further into healthcare, defence, and higher-spec residential programs, the ability to vary the visible and functional elements of a unit—while keeping the underlying frame, connection logic, and quality process stable—will become a core selling point. The commercial implication is clear: product lines that enable specification flexibility within a controlled manufacturing regime will capture more diverse demand and reduce the risk of being undercut by lower-cost standardized alternatives.
2. Compliance and Inspection Readiness as a Procurement Criterion
Regulatory alignment will become increasingly embedded in buying decisions. Pods that are designed for code conformance, backed by clear documentation, and protected during transport and storage will face fewer site-level obstacles. Standards related to fire-retardant packaging and temporary protective materials, along with building and plumbing code expectations, will not only influence manufacturing practices but also shape supplier selection. Buyers will look for manufacturers that can reduce inspection friction and demonstrate repeatable compliance, especially in multi-jurisdiction or high-risk programs.
3. Program-Level Integration Over Component Purchasing
The market will increasingly reward suppliers and buyers who think in terms of total program delivery rather than isolated bathroom units. That means closer coordination on sequencing, interface points with the primary structure, crane and staging logistics, and finish schedules. It also means that partnerships between manufacturers, main contractors, and developers may become more structured, with earlier involvement in design and procurement to lock in compatibility and reduce change orders. The commercial opportunity lies in moving from transactional supply to specification-level influence, where the pod becomes part of a broader schedule and cost strategy.
PW Consulting
These trends carry risks. Material cost volatility and supply concentration can affect pricing and availability. Customization can erode the efficiency gains that make prefabrication attractive if variation is poorly managed. Compliance expectations can differ across regions and project types, creating hidden integration costs. And rapid growth can tempt less disciplined entrants to overpromise on lead times or finish quality, creating reputational and execution risk for buyers who do not vet suppliers carefully. The net effect is that the market rewards operational maturity as much as product capability.
Strategic Actions for Decision-Makers
For executives evaluating the prefabricated bathroom pods market, the priority is to convert market momentum into defensible operating choices. The following actions are most relevant depending on role and exposure.
For Manufacturers and Producers
- Invest in configurable product architectures that separate stable structural systems from variable finishes and layouts, preserving throughput while expanding addressable demand.
- Strengthen compliance documentation and inspection readiness as part of the core offering, including transport and storage protection aligned with relevant loss prevention and code expectations.
- Align production capacity and geographic footprint to the programs you want to win, weighing the trade-off between scale concentration and regional responsiveness.
For Investors and Capital Allocators
- Assess suppliers on total program value rather than unit pricing alone, focusing on throughput stability, quality control systems, sector alignment, and the ability to reduce schedule risk.
- Monitor material and logistics exposure, especially where steel, composite, or lightweight concrete inputs are central to a company's value proposition.
- Look for signs of repeatable specification relationships and multi-project pipelines, which tend to indicate stronger commercial moats than one-off wins.
For Procurement, Development, and Construction Leaders
- Engage manufacturers earlier in the design and procurement cycle to align specifications, code documentation, and interface requirements, reducing the likelihood of late-stage rework.
- Evaluate pods against total program metrics—schedule compression, on-site labor reduction, inspection friction, and logistics complexity—rather than isolating initial purchase cost.
- Build qualification criteria that include compliance readiness, finish consistency, transport protection, and the supplier's ability to support variation without disrupting production.
The pace of change in this market makes detailed, current intelligence valuable. Segment-level dynamics, regional demand patterns, material shifts, and competitive moves can alter both opportunity and risk quickly, especially for programs that depend on predictable lead times and compliant delivery. A fuller examination of these dimensions—supported by granular segmentation data, company-level activity, and scenario-based demand views—can help decision-makers pressure-test assumptions before committing to specifications, capacity decisions, or investment theses. Readers seeking deeper segmentation detail and tailored strategic guidance can access the complete PW Consulting research report for a more comprehensive view of the market landscape and its commercial implications.
For detailed analysis of this topic, please visit the official page: Prefabricated Bathroom Pods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BAW Filters Market: Why 7.32% CAGR and Stratification Redefine 2032 Revenue to $5.5B
By PW Consulting, 2026-09-21
Beyond the Noise: Strategic Trends and Commercial Opportunities in the BAW Filters Market
The BAW (Bulk Acoustic Wave) filters market has entered a phase of sustained, structurally driven expansion that rewards firms able to translate technological advancement into reliable supply and differentiated performance. Over the 2020-2025 historical window, the market grew from approximately 2,286.78 million to 3,361.14 million, reflecting a compound trajectory that accelerated through the mid-2020s as mobile device complexity and connectivity infrastructure converged. Looking ahead to the 2026-2032 forecast period, the market is projected to expand at a CAGR of 7.32%, reaching an estimated 5,512.51 million by 2032. This is not merely incremental growth; it reflects a fundamental recalibration of RF front-end design priorities as spectrum utilization, device form factors, and performance requirements continue to tighten.
For executives and investors, the headline figures convey scale, but the strategic signal lies in the dynamics beneath the surface. The market has moved past the early adoption curve for 5G and is now navigating a more nuanced environment shaped by competing filter technologies, intensifying spectrum congestion, and a concentration of capability among a small group of established players. At the same time, the demand base is broadening beyond smartphones into automotive connectivity, industrial IoT, and wireless infrastructure. Understanding where value is created—and where margins and market share are at risk—requires a clear read on the forces shaping this landscape.
Paint Filters Market
Market Landscape and Core Challenges
The current market size sits around 3,361.14 million as of the base year, and the forward projection of 5,512.51 million by 2032 reflects sustained demand across mobile, connectivity, and industrial applications. This trajectory is underpinned by rising RF content per device, the proliferation of multi-band and wideband designs, and the rollout of next-generation Wi-Fi and cellular standards that place greater stress on filtering performance. In this environment, BAW filters continue to command attention because of their ability to deliver high rejection, temperature stability, and compact integration in frequency ranges where SAW-based alternatives are increasingly strained.
Beneath these favorable dynamics, three challenges stand out as strategic inflection points.
1. Technology Choice and Coexistence Pressure
The filtering landscape is not a single-technology story. Film Bulk Acoustic Resonator (FBAR) and Solidly Mounted Resonator (SMR) approaches each present distinct trade-offs in performance, packaging, and manufacturing complexity. FBAR solutions have historically been associated with superior rejection curves and broad applicability in mobile and infrastructure settings, while SMR variants offer a different cost and integration profile. As device architectures demand more bands, more bandwidth, and tighter rejection, design teams must decide where to deploy each technology across bands and platforms. This decision is increasingly tied to total cost of ownership, not just unit performance, and the wrong allocation can create efficiency losses in both bill of materials and system-level gain.
2. Spectrum Reallocation and Filter Performance Requirements
The opening of substantial spectrum in the 6 GHz band for unlicensed use has accelerated the development of Wi-Fi 6E and Wi-Fi 7 products, which depend heavily on high-frequency, high-selectivity filters. This shift expands the addressable opportunity but also raises the performance bar. Higher frequency operation, wider channel plans, and greater spectral density mean that filters must maintain selectivity and stability under more demanding conditions. The result is a moving target for manufacturers: designs must be optimized not just for today’s network architecture but for the broader spectrum ecosystem that regulators and standards bodies continue to reshape.
3. Supply Security, Concentration, and Scale Economics
The market exhibits meaningful concentration, with a relatively small group of participants accounting for a large share of revenue. This concentration reflects the realities of technology maturity, packaging expertise, and the capital intensity of scaling high-performance RF components. For downstream customers, this creates a tension between sourcing reliability and competitive pressure. Qualifying new suppliers or alternative technologies involves engineering validation, production ramp risk, and long-term supply commitments. In such an environment, supply resilience becomes as important as unit cost, and multi-source strategies are gaining relevance for programs where downtime or component shortages carry significant system-level consequences.
Key Drivers Shaping the Market
Growth in the BAW filters market is not accidental. It is being propelled by a convergence of technology, regulation, demand behavior, and cost structure shifts that reinforce one another. The most consequential drivers are the following.
Technological Innovation and Performance Migration
The strongest driver is the ongoing migration of performance expectations across frequency ranges and use cases. High-performance platforms for mobile and connectivity devices are increasingly integrating BAW solutions to support wider bandwidths, more bands, and higher signal integrity requirements. Parallel innovation in packaging and integration—such as wafer-level packaging where applicable—supports miniaturization while preserving electrical performance. The push toward ultra-compact designs with improved efficiency and reduced footprint is especially relevant for next-generation smartphones and wireless devices, where board space and thermal constraints are unforgiving. In parallel, new high-frequency filter technologies are emerging that target lower insertion loss and improved signal efficiency for 5G, Wi-Fi 7, and early 6G scenarios, intensifying competition at the high end of the performance curve.
PW Consulting
Policy and Spectrum Regulation as Demand Catalysts
Regulatory and spectrum policy decisions are shaping demand with unusual clarity. The FCC’s decision to make 1200 MHz of spectrum in the 6 GHz band available for unlicensed use created a direct catalyst for products that require high-selectivity filtering at higher frequencies. In Europe, the steady rollout of 5G across major economies, combined with a strong industrial base and automotive sector, provides a stable demand backdrop that supports both consumer device growth and infrastructure-related RF content. At the same time, increasing emphasis on energy efficiency, electromagnetic compatibility, and compliance with stringent ETSI standards is reinforcing the value of high-quality filtering in both consumer and professional equipment. Regulatory pressure does more than create compliance obligations; it raises the baseline expectation for RF performance and reduces the tolerance for inferior solutions.
Demand-Side Shifts Across Devices and Verticals
On the demand side, the most notable change is the broadening of RF complexity beyond flagship smartphones. Devices are carrying more bands and more connectivity options, and the absolute RF content per device is rising across mobile, IoT, automotive, and infrastructure categories. Automotive and infrastructure applications, in particular, are expanding as connected vehicle features, telematics, and roadside infrastructure add new filtering requirements. The C-V2X domain illustrates this trend clearly, with new filter solutions being developed for 5.9 GHz operation and band 47 to support advanced automotive and infrastructure use cases. In the same way, Wi-Fi and IoT device growth is pushing demand toward filters that can handle higher frequencies while maintaining selectivity and reliability in dense deployment environments.
Cost Structure and Manufacturing Strategy
Cost dynamics are shifting as manufacturers pursue tighter integration, higher yield, and more efficient packaging. For high-volume mobile and connectivity applications, the ability to deliver strong RF performance within a smaller footprint is becoming a competitive differentiator, not simply a technical achievement. This favors participants who can combine product performance with disciplined manufacturing scale and consistent quality. At the same time, demand across industrial, aerospace, defense, and communications applications introduces additional complexity: customized solutions and reliable wafer-level packaging for specific frequency ranges can command premium positioning, but they also require specialized process control and customer-specific qualification. The net effect is that cost leadership and value leadership are increasingly defined by the ability to match technology choices to application requirements without sacrificing reliability or ramp capability.
Competitive Landscape and Leading Strategies
The competitive field in the BAW filters market is defined by a handful of companies with deep RF expertise, differentiated product portfolios, and strategies that emphasize either breadth, specialization, or manufacturing control. Rather than competing on price alone, leaders are building advantage through frequency range coverage, packaging capability, performance stability, and integration with next-generation standards.
Strategic Positioning Among Leading Participants
Several incumbents are shaping the market through distinct positioning. One established leader continues to emphasize BAW filtering solutions for mobile products, radar, and communications systems, with a focus on ultra-stable temperature performance and wafer-level packaging across frequencies in the 1.5-9 GHz range. This profile reflects a mobile- and radar-oriented strategy built on performance consistency and broad band coverage. Another participant has pursued a broader high-frequency and ultra-wideband angle, developing RF filters aimed at high-power and wideband scenarios across 5G/6G, Wi-Fi, automotive, defense, IoT, and Satcom markets. This approach signals an intent to capture demand where performance extremes matter and where filter requirements diverge from mainstream mobile designs.
A third participant has positioned itself around custom BAW RF filters with wafer-level packaging for specific frequency ranges in industrial, aerospace, defense, and communications applications. This specialization points toward a strategy that values tailored solutions and application-specific qualification over mass-market volume alone. A fourth company offers BAW filters integrated into high-performance platforms for mobile and connectivity devices, leveraging internal manufacturing for next-generation 5G and Wi-Fi standards. Integration of design and manufacturing can improve responsiveness and quality control, and may be especially valuable as standards evolve quickly and customers seek sustained supply alignment. A fifth player has emphasized FBAR-based BAW filters with strong rejection characteristics for 5G, Wi-Fi, and wireless infrastructure, reflecting a technology-specific focus that plays to the strengths of film-based acoustic resonance in demanding RF environments.
Recent product activity reinforces how competitive differentiation is evolving. In early 2026, one participant began sampling a C-V2X filter solution designed for 5.9 GHz operation, including band 47, targeting advanced automotive and infrastructure applications. This move illustrates how filter suppliers are expanding into connectivity domains where timing, reliability, and standards alignment are critical. Shortly afterward, another participant introduced ultra-compact BAW filter technology aimed at 5G and Wi-Fi 7 devices, emphasizing improved RF performance, higher efficiency, and reduced footprint for next-generation smartphone and wireless applications. These announcements are not isolated product updates; they are indicators of where competitive energy is being directed: higher frequency, smaller form factor, tighter integration, and new verticals.
Market Structure Evolution
The market is not simply consolidating around a single formula. Instead, it is showing signs of both concentration and selective divergence. Concentration remains meaningful, reflecting the advantages of scale, process maturity, and long-term customer qualification. At the same time, differentiation is increasing as suppliers target distinct frequency ranges, application verticals, and packaging philosophies. New entrants and technology alternatives can still find room where they address unmet needs in high-power, ultra-wideband, or specialized industrial and defense scenarios, but the bar to meaningful share gains is high. For incumbents, the strategic priority is to maintain performance leadership while expanding into adjacent demand areas such as automotive connectivity and infrastructure. For customers, the practical implication is that supplier selection is increasingly a multi-dimensional decision involving performance, supply resilience, standards alignment, and long-term roadmap compatibility.
Future Trends and Commercial Implications
Based on the current trajectory and the forces already in motion, two to three trends are likely to shape the next three to five years.
Higher-Frequency, Multi-Standard Filter Architectures Will Become the Norm
As 5G matures, Wi-Fi 6E and Wi-Fi 7 expand, and early 6G exploration advances, RF front ends will need to support wider frequency coverage and more simultaneous standards. Filters will be expected to perform not just in a single band but across broader, more complex spectral environments. This creates commercial opportunities for suppliers that can deliver high-selectivity solutions with stable temperature behavior, low insertion loss, and packaging that supports denser integration. It also raises the importance of design flexibility, because device manufacturers will want platforms that can adapt to evolving band plans and channel allocations without sacrificing performance.
Bypass Filter Market
Automotive, Infrastructure, and Industrial Demand Will Grow in Strategic Importance
Automotive and infrastructure applications are becoming more prominent in the demand mix, driven by connected vehicle features, C-V2X expansion, and the broader rollout of wireless infrastructure. These segments often emphasize reliability, temperature resilience, and long program lifecycles, which can reward suppliers with disciplined qualification processes and consistent continuity. For companies able to align product roadmaps with automotive and infrastructure timing, the opportunity is not just additional volume but a more diversified revenue base that can partially offset cyclicality in consumer device cycles.
Supply Strategy and Multi-Source Qualification Will Matter as Much as Performance
As concentration remains high and standards evolve quickly, downstream customers will place greater weight on supply resilience, ramp support, and the ability to qualify alternative sources where appropriate. This does not mean uniformity; different applications may continue to require different solutions. But it does mean that companies with flexible sourcing strategies, robust validation capabilities, and transparent roadmap communication will have an advantage in critical programs. The commercial implication is that value will increasingly accrue to participants who can reduce total risk for their customers, not only deliver a strong unit specification.
Risks and Uncertainties
These trends carry meaningful uncertainty. Technology competition between FBAR, SMR, and emerging alternatives could shift cost-performance trade-offs faster than expected, particularly if new high-frequency filter approaches improve efficiency or reduce insertion loss in commercially meaningful ways. Regulatory and spectrum decisions may accelerate demand in some bands while constraining others, creating uneven growth across applications. Standard cycles and device adoption timing can also affect the pace of content increases, especially if device roadmaps shift or if integration strategies change. Finally, the capital intensity and process sensitivity of high-performance filter manufacturing mean that execution risk remains a real factor; ramp delays, yield issues, or qualification challenges can have outsized consequences in a concentrated market.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the direction of spectrum use, device complexity, and vertical expansion. That means investing in higher-frequency and wideband capabilities, continuing to sharpen packaging and integration for compact high-performance platforms, and preparing for demand growth in automotive and infrastructure as well as mobile and connectivity. Equally important is disciplined qualification and supply continuity, since customer trust in RF components is built on consistency as much as on specification performance.
For investors, the strategic question is not whether the BAW filters market will continue to expand, but where durable advantages are being created. The most attractive positions are likely to be those that combine technology leadership with the ability to scale reliably, support next-generation standards, and address a diversified set of applications. Attention should be paid to participants that are extending into automotive, infrastructure, and specialist high-frequency domains, as well as those with integrated design-and-manufacturing strategies that can respond quickly to changing requirements. At the same time, it is worth monitoring technology alternatives and supply-side execution, since shifts in either can alter competitive positioning.
For procurement and sourcing leaders, the most prudent approach is to treat filtering as a system-critical decision rather than a commodity purchase. That includes evaluating not just unit cost and baseline performance, but also temperature stability, rejection characteristics, packaging fit, standards alignment, and the supplier’s ability to support long program lifecycles or rapid platform evolution. Where feasible, developing qualified alternatives for critical bands can reduce exposure to concentration risk, especially in applications where downtime or performance shortfalls carry significant consequences.
The strategic picture is clear enough to act on, but the details matter. Fine-grained segmentation, frequency-specific demand profiles, technology-specific cost structures, and company-level roadmap mapping can materially change sourcing and investment judgments. For readers seeking a more detailed breakdown of market size by segment, competitive positioning across frequency ranges and applications, and customized implications for a specific product portfolio or sourcing strategy, a comprehensive research report can provide the level of detail needed to support more precise decision-making.
For detailed analysis of this topic, please visit the official page: BAW Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Advanced CO2 Sensors Market: Why 7.1% CAGR and $1.1B Scale Change Everything
By PW Consulting, 2026-09-21
Advanced CO2 Sensors: Navigating Convergence, Compliance, and Commercial Opportunity
The advanced CO2 sensor market occupies a pivotal position where environmental regulation, building decarbonization, and precision measurement intersect. Market estimates point to a total revenue trajectory moving from approximately $690.0 million in 2025 toward $1,115.26 million by 2032, reflecting a compound annual growth rate of 7.1% across the forecast horizon. This expansion is not purely incremental; it is being reshaped by compliance mandates that elevate measurement accuracy from a desirable feature to a mandatory requirement, by product architectures that compress form factors while preserving performance, and by a supply environment where miniaturization and power efficiency dictate competitive differentiation. The sector’s structure remains moderately concentrated, with the top three players capturing roughly 55% of revenue and the top five accounting for about 68%, yet the composition of leadership continues to shift as incumbents navigate product roadmaps, regulatory alignment, and downstream integration with building management systems.
For decision-makers, the core question is no longer whether CO2 sensing will grow, but how the convergence of standards, product form factors, and application-specific performance requirements will reshape value capture across the value chain. The following analysis examines the current market backdrop, the forces propelling change, the competitive logic among leading suppliers, and the strategic implications for manufacturers, investors, and procurement organizations.
Market Snapshot and Structural Pressure Points
The market has matured through a period of steady expansion, driven by broader adoption of indoor air quality monitoring, demand-controlled ventilation in commercial buildings, and industrial process control. The current revenue base is anchored by established end-use demand, but the rhythm of growth is increasingly governed by regulatory cycles and product upgrades rather than by first-time deployments alone. The market’s growth curve suggests that incremental volume gains will be supplemented by higher-value deployments where accuracy, calibration stability, and integration readiness become the primary purchasing criteria.
Challenge 1: Compliance Becomes a Product Requirement, Not a Feature
A defining shift in the market is the elevation of measurement accuracy and repeatability to the center of procurement specifications. Standards such as ANSI/ASHRAE 62.1-2022 Addendum d place precise CO2 measurement at the heart of demand-controlled ventilation performance, aligning sensor capability directly with energy-efficiency objectives. In Europe, the Energy Performance of Buildings Directive sets zero-emission expectations for new buildings by 2030, reinforcing the link between ventilation control, air quality, and compliance documentation. As these requirements cascade into procurement specifications, sensor suppliers must demonstrate not only functionality but verifiable alignment with building standards, including IAQ frameworks such as RESET Grade B and WELL Building Standard v2 in relevant deployments.
The implication is structural: compliance becomes a gatekeeper for market access in higher-value segments. Sensors that cannot meet accuracy thresholds, calibration expectations, or documentation rigor face increasing friction in specification-driven purchasing processes. This elevates the importance of product validation, test data, and support materials that translate technical performance into compliance readiness.
PW Consulting Information & Electronics Research Center
Challenge 2: Miniaturization, Power, and Integration Are Redefining Winning Form Factors
The market is moving toward smaller, lower-power devices that can be embedded across HVAC controls, smart building nodes, and battery-operated IoT installations. This trend pressures suppliers to balance size reduction with accuracy and environmental robustness. Product roadmaps increasingly emphasize solderability, compact packaging, and low power draw, especially where continuous monitoring must fit within constrained energy budgets or tight mechanical envelopes. In parallel, integration with building management platforms and environmental sensing ecosystems is becoming a differentiator, because end users favor solutions that reduce installation complexity and streamline commissioning.
This miniaturization-and-integration trajectory creates a double-edged challenge. It opens room for higher unit volumes in distributed monitoring, yet it also compresses margins if products compete primarily on size alone. The winners are likely to be those that combine small footprints with validated performance and integration support, not just packaging efficiency.
Challenge 3: Concentrated Leadership Meets Application-Specific Competition
Market share concentration indicates that a limited group of suppliers holds substantial influence over product direction and customer relationships. At the same time, application requirements differ enough that leadership in one segment does not automatically translate into leadership across all segments. Accuracy-intensive building and healthcare deployments may favor different characteristics than industrial process monitoring or automotive-adjacent applications. As a result, competitive positioning is becoming more application-aware, with suppliers emphasizing specific feature sets, compliance alignment, and platform integration instead of competing broadly on sensor category alone.
This dynamic creates room for targeted differentiation, but it also raises the stakes for portfolio coherence. Suppliers must manage trade-offs between breadth and depth, ensuring that product lines are credible in the segments they choose to serve, with the documentation and support to match.
Core Drivers Reshaping Demand and Product Strategy
Technological Innovation: Smaller Sensors with Higher Accuracy and Lower Power
Product launches in recent periods illustrate how technology roadmaps are converging around accuracy, size, and energy efficiency. One example is the introduction of ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and surface-mount integration, with a substantially smaller footprint than previous generations and compliance positioning aligned with ASHRAE 62.1-2022 Addendum d. Mass production timing and sample distribution activity indicate that these designs are moving from demonstration to deployment readiness, with relevance for smart buildings, IAQ monitoring, and compact environmental sensing. Another example is a photoacoustic NDIR CO2 sensor positioned as a drop-in upgrade pathway for an existing platform, with best-in-class accuracy and building-standard alignment. Together, these developments reflect an industry trend in which accuracy improvements are being packaged into more compact, easier-to-integrate modules.
Air Quality Sensor Market
For manufacturers, this trend changes the equation between performance and form factor. Historically, users may have accepted trade-offs between size or power and measurement precision. The current direction suggests that multiple product tiers can deliver high accuracy within compact formats, which expands the addressable design space for OEMs and system integrators.
Policy and Regulatory Environment: Standards as Adoption Accelerators
Regulatory and standards-based pressure is one of the strongest demand accelerators in the market. The shift toward more rigorous ventilation control requirements is effectively converting CO2 measurement from an optional monitoring parameter into a compliance-critical input for energy-efficient building operation. In both North America and Europe, building codes and directives are reinforcing expectations for precise environmental sensing and low-emission building performance. This does not merely increase total demand; it changes the composition of demand toward applications where specification, validation, and documentation matter more than price alone.
This regulatory overlay has strategic consequences. Suppliers with products already positioned for relevant standards can benefit from shorter specification cycles and faster customer confidence. Conversely, suppliers without clear alignment may face more intensive evaluation, particularly in projects where building certification, energy performance, or IAQ documentation is part of the procurement scope.
Demand-Side Shifts: Building Operators, Healthcare, and Industrial Users Are Prioritizing Air Quality and Efficiency Together
Demand is increasingly driven by an overlap of operational objectives rather than by a single use case. Building operators are linking indoor air quality with energy optimization, making demand-controlled ventilation and continuous monitoring more attractive where both occupant comfort and compliance are in play. Healthcare environments continue to place a premium on environmental monitoring, where measurement stability and reliability can influence operational confidence. Industrial users remain focused on process control and safety-adjacent sensing, but with growing interest in compact, low-power devices that can be integrated into broader monitoring architectures.
This demand evolution is notable because it tilts purchasing behavior toward total solution value. Buyers are less likely to evaluate sensors in isolation and more likely to consider how a device fits into commissioning, calibration, maintenance, and system-level reporting. The practical implication is that sensor products compete not only on measurement performance, but also on how easily they support operational workflows.
Supply-Side and Cost Structure Dynamics: Integration and Miniaturization Influence Margin Logic
The supply environment is being shaped by the same miniaturization and integration pressures that influence product design. Smaller sensors with SMD compatibility, low-power operation, and multi-function environmental sensing capabilities can enable broader deployment, but they also invite closer scrutiny of production efficiency, calibration processes, and support economics. Where volume grows through distributed installations, cost-to-serve and after-sales support become increasingly relevant to profitability.
At the same time, suppliers that can combine compact hardware with strong compliance documentation and integration support may be able to defend pricing better than those competing primarily on unit cost. In this sense, supply-side advantage is shifting from scale alone toward the ability to deliver validated, easily deployable solutions at scale.
Competitive Landscape and Where Leadership Is Being Built
The competitive field includes a mix of specialized sensor developers and broader industrial or building-technology players. Senseair, based in Sweden, is associated with ultra-compact NDIR CO2 sensors for demand-controlled ventilation and smart building integration, with recent activity emphasizing smaller form factors, SMD solderability, and compliance alignment for IAQ monitoring and DCV systems. Sensirion AG, based in Switzerland, is notable for photoacoustic NDIR CO2 sensors positioned around high accuracy and building-standard compliance, with a product trajectory that includes drop-in upgrade capability for an existing platform. Gas Sensing Solutions, based in the UK, has focused on solid-state NDIR CO2 sensors optimized for ultra-low-power IoT and battery-powered applications, with integrated environmental sensing functionality. Vaisala Oyj, based in Finland, is linked to advanced NDIR CO2 sensors using optical technology for precision applications in building management, industrial settings, and data-center-related monitoring.
Larger ecosystem players also play distinct roles. Amphenol Advanced Sensors, based in the USA, supplies compact, low-power CO2 sensors with emphasis on miniaturization and high accuracy across HVAC, IoT, and environmental monitoring. Siemens AG, based in Germany, integrates NDIR CO2 sensor modules into building management systems with portfolios directed at HVAC and air quality control. Honeywell International Inc., based in the USA, offers chemical and infrared CO2 sensors for safety, IAQ, and industrial applications, including low-power draw options.
Strategic Positioning and Differentiation
Differentiation in this market is increasingly multidimensional. Some suppliers compete primarily on accuracy and measurement physics, especially where standards compliance and repeatability are critical. Others emphasize form factor, power consumption, and ease of integration, particularly for IoT and battery-limited deployments. A third group focuses on system-level integration, where sensor modules are embedded within broader building management or environmental monitoring platforms. These paths are not mutually exclusive, but they shape how each supplier is likely to win in specific segments.
Worldwide Carbon Dioxide Detector Market
A notable pattern is the alignment between product releases and compliance targets. Where new sensors are introduced with explicit positioning against ventilation standards, IAQ frameworks, and building certification requirements, they are effectively reducing the evaluation burden for specification-driven buyers. This suggests that regulatory alignment is becoming a competitive asset, not just a technical specification.
Evolution of the Market Structure
The market structure appears to be moving along two parallel tracks. One is consolidation of leadership among established players that can combine technical credibility, standards alignment, and broad application reach. The other is continued differentiation in niche requirements, where low-power IoT sensing, compact SMD integration, or application-specific robustness create space for focused competition. New entrants and platform players are likely to test the market where installation simplicity, integration readiness, or compliance documentation provide a distinct advantage.
Over time, this points to a landscape in which broad market share remains important, but segment relevance and solution readiness become more decisive. Suppliers that can bridge the gap between a sensor component and a spec-ready, integration-friendly solution are better positioned to capture value as procurement processes become more standards-driven and application-specific.
Forward View: Three Trends Shaping the Next Three to Five Years
Trend 1: Compliance-Linked Specifications Will Drive More Discriminating Purchasing
As building codes, ventilation standards, and IAQ frameworks continue to tighten, procurement will likely place greater weight on verifiable performance and compliance alignment. This should shift demand toward sensors that can demonstrate accuracy, calibration stability, and documentation suitable for specification and certification requirements. The commercial opportunity lies in products and support packages that reduce the friction of evaluation, commissioning, and ongoing compliance evidence. The risk is that suppliers with products not clearly aligned to evolving standards may face slower adoption in higher-value deployments, even if unit costs are attractive.
Trend 2: Compact, Low-Power, Integrated Sensing Will Expand Deployment Surface Area
Continued miniaturization and lower power draw should enable wider dispersal of sensing into smart buildings, distributed HVAC controls, and battery-operated monitoring nodes. This trend expands the potential installation base and encourages integration with broader environmental sensing and building management platforms. The commercial opportunity is in designs that make continuous monitoring practical at scale, especially where installation constraints or energy budgets have historically limited coverage. A key uncertainty is whether competition on size and power will intensify to the point of compressing differentiation, unless suppliers can pair compact designs with strong accuracy and integration support.
Trend 3: Platform Integration and Ecosystem Positioning Will Matter as Much as Sensor Performance
As end users increasingly seek streamlined commissioning and system-level reporting, the value of a sensor will be shaped not only by its measurement capability but also by how well it fits into building management, HVAC control, or IoT platforms. Suppliers that offer modules, integration guidance, and compatibility with common system architectures can strengthen their position beyond the component level. The commercial opportunity lies in becoming easier to specify and easier to deploy. The risk is that fragmented compatibility or weak integration support can slow adoption even when sensor performance is competitive.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
Product roadmaps should be evaluated against the standards and deployment realities that are shaping purchasing decisions, not just against sensor category benchmarks. Where accuracy, compliance alignment, and compact integration are increasingly decisive, investment in validation, documentation, and integration support can be as important as hardware development. At the same time, product differentiation should be anchored in clearly defined application value, because broad claims compete less effectively than segment-specific strengths in a market where specification-driven purchasing is gaining ground.
For Investors and Strategic Allocators
The market’s growth trajectory is supported by regulation-led demand and product innovation, but returns will likely depend on which suppliers can combine credible accuracy with scalable deployment and standards alignment. Attention should be given to companies that are moving products from sample activity into mass production with clear compliance positioning, as well as to those with integration-rich portfolios that reduce customer friction. Concentration in the market also suggests that competitive advantage may be unevenly distributed across applications, so segment-level adoption and support economics deserve careful scrutiny.
For Procurement and Operations Leaders
Specifying CO2 sensing increasingly means specifying compliance readiness, integration fit, and operational support, not just a measurement device. Evaluation processes should account for accuracy claims, calibration stability, commissioning requirements, and compatibility with existing building or monitoring platforms. A sensor that is marginally cheaper upfront may carry higher total cost if it complicates documentation, installation, or ongoing verification. In practice, procurement decisions will be stronger when sensor selection is treated as part of a broader air quality and ventilation control strategy.
Closing Perspective
The advanced CO2 sensor market is entering a phase in which growth is increasingly shaped by the interaction of standards, product form factors, and solution readiness. The revenue path toward the 2032 horizon reflects more than incremental adoption; it reflects a shift in how sensing is specified, integrated, and valued across buildings, healthcare, industrial, and related applications. In that environment, the most consequential questions are not only about measurement capability, but about whether a sensor can be validated for compliance, deployed efficiently, and supported within the operational workflows that customers actually use.
For organizations seeking to move from market awareness to precise segment-level planning, the additional detail in the full research report can help narrow priorities around end-use demand, regional variation, product category splits, and competitive positioning. Detailed segmentation data and customized scenario analysis are available for teams that need to translate these trends into actionable procurement, product, or investment decisions.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com