

Blogs
Modified Starch Market Outlook: Why 3.5% CAGR and Food Demand Reshape Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Modified Starch Market: A 2025 Perspective
Market Current State and Core Challenges
The modified starch market has established itself as a foundational ingredient segment across multiple industrial and consumer-facing sectors. Over the historical period from 2020 to 2025, the market expanded from approximately 10.5 billion USD to 13.7 billion USD, reflecting steady demand across food processing, paper manufacturing, textiles, and animal feed applications. Forward-looking projections through 2032 indicate continued growth, with revenue expected to reach 17.17 billion USD. The compound annual growth rate over the forecast horizon of 2026 to 2032 stands at 3.5 percent, a trajectory that signals resilience but also underscores the importance of strategic positioning in a maturing landscape.
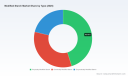
Market structure reveals a moderately concentrated environment, with the top three players accounting for 35 percent of revenue and the top five capturing 45 percent. This concentration pattern suggests that incumbents enjoy meaningful scale advantages in sourcing, formulation expertise, and distribution networks, yet sufficient fragmentation remains to allow specialized or regional players to compete on functionality, price, or supply reliability. The regional distribution of revenue reflects a globally dispersed supply-demand matrix, with Asia Pacific contributing the largest share, followed by North America and Europe. Such geographic spread creates both opportunities for localized production strategies and vulnerabilities to regional supply disruptions.
Key Challenges and Inflection Points
The current market environment presents several structural challenges that demand strategic attention. First, raw material price volatility has intensified, particularly for tapioca starch, where continuous upward pricing trends and tightening supply were observed toward the end of 2025 and into early 2026, reaching 490 USD per ton. This dynamic pressures cost structures across applications that rely on tapioca-based modification and forces manufacturers to reconsider sourcing diversification and contract structures.
Second, regulatory evolution is reshaping formulation strategies. In the European Union, HS Code 35051090 for modified starches has been subject to CN refinements and duty adjustments effective in 2025, altering trade cost calculations for cross-border transactions. Simultaneously, 2025 updates to FDA labeling guidelines have increased demand for label-friendly modified starches that do not require an E-number or complex chemical name, pushing formulators toward cleaner ingredient narratives. Additionally, 2025 US tariffs on modified starch products have had a direct price impact on imports, creating cost asymmetries that favor domestic production or alternative sourcing corridors.
Corn Starch Market
Third, the market is approaching an inflection point in application mix. While food and beverages remain the dominant end-use category, industrial and non-food applications such as paper, textiles, and adhesives continue to absorb a significant share of modified starch volumes. The strategic question for participants is whether to deepen specialization in high-margin food-grade functionality or to build resilient industrial-grade supply chains that benefit from broader demand diversification.
Key Drivers of Market Change
Technological Innovation and Formulation Breakthroughs
Innovation in modification techniques continues to expand the functional envelope of starch-based ingredients. Physical, chemical, and enzymatic modification pathways each offer distinct performance profiles, with physically modified starch currently commanding the largest share of the type segmentation, followed by chemically modified and enzymatically modified variants. Enzymatic approaches are gaining attention for their ability to produce cleaner ingredient profiles and more tailored functional outcomes, aligning with cleaner-label expectations in food applications.
Recent product-level developments illustrate the pace of innovation. In March 2025, Cargill highlighted a first-of-its-kind dent-corn modified starch designed to improve sauce color and texture, alongside a pectin replacer. This launch underscores a broader trend toward multifunctional ingredients that can replace more expensive or less label-friendly alternatives while preserving or enhancing sensory performance. For manufacturers, such innovations reduce formulation complexity and open opportunities to respond to consumer preferences for simpler ingredient lists without sacrificing product quality.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. The EU CN refinements for modified starches influence duty structures and administrative compliance for exporters and importers, requiring closer attention to classification accuracy and trade documentation. In parallel, FDA labeling updates have elevated the importance of ingredient nomenclature, encouraging suppliers to develop modified starches that can be presented in a label-friendly manner. These regulatory shifts are not merely compliance issues; they affect product positioning, customer education, and the relative attractiveness of modified starches versus alternative thickeners, stabilizers, and texturizers.
Trade policy further complicates the landscape. Tariff actions on modified starch products have impacted import pricing, creating localized cost advantages for domestic producers and prompting re-evaluation of supply chain geography. Companies that can align sourcing, manufacturing, and distribution with the prevailing regulatory and tariff environment will be better positioned to manage margin pressure and maintain competitive pricing.
PW Consulting Health Care Research Center
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, food and beverage manufacturers continue to drive the largest portion of modified starch consumption, reflecting the ingredient's versatility in thickening, stabilizing, and texturizing applications. Consumer preferences for cleaner labels, plant-based formulations, and improved texture have reinforced the relevance of modified starches as functional solutions that can meet multiple objectives simultaneously. In industrial contexts, paper and textile manufacturers rely on modified starches for binding, coating, and finishing functions, where performance consistency and cost efficiency remain decisive.
Trade show activity in late 2025 highlighted the intensity of demand-side engagement. SMS Corporation unveiled high-performance modified starch solutions at Fi Europe 2025 and, in November 2025, presented modified tapioca starch innovations while winning Plant-Based Manufacturing of the Year at Gulfood Manufacturing 2025. These developments indicate that suppliers are actively aligning product portfolios with plant-based and performance-driven demand, while also using industry events to validate innovation and build commercial relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by raw material price movements and regional supply tightness. The tapioca starch price trajectory toward 490 USD per ton illustrates how concentrated supply conditions can rapidly alter input economics for modification producers. In parallel, U.S. potato starch export prices in 2025 ranged from 0.40 USD per kg to 5.74 USD per kg, reflecting wide variability tied to quality, grade, and destination market conditions. Such variability rewards suppliers with diversified feedstock portfolios and flexible formulation capabilities that can shift between corn, wheat, potato, tapioca, and pea sources depending on availability and economics.
The supply chain implications extend beyond raw material procurement. Logistics, trade compliance, and regional production footprints are increasingly important determinants of total delivered cost. Companies that invest in supply chain transparency, multi-source sourcing, and regional manufacturing capacity can mitigate exposure to single-commodity shocks and tariff-driven price distortions, while also improving responsiveness to customer demand cycles.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field includes a mix of global ingredient corporations and specialized regional producers. Cargill, headquartered in Minneapolis, produces and supplies modified starches for personal care, food and beverage, and industrial applications, emphasizing grades with stable viscosity and functional benefits. Ingredion Incorporated, based in Westchester, Illinois, manufactures modified food starches and industrial starches for texturizing, thickening, and stabilizing across food, beverage, and non-food applications. Roquette Frères, located in Lestrem, France, is a global producer of native and modified starches from multiple sources including corn, wheat, potatoes, tapioca, and peas, offering over 300 modified starch variants. Tate & Lyle PLC, headquartered in London, supplies modified starches and starch derivatives for food and beverage, with clean-label and specialty portfolios. These global players derive competitive advantage from broad feedstock access, application laboratories, and established customer relationships across multiple sectors.
Regional and specialized manufacturers add important diversity to the landscape. Premier Starch, based in Bengaluru, India, manufactures modified starches, dextrins, and corrugation adhesives for packaging, paper, paints, abrasives, and mining industries. Angel Starch & Food Pvt. Ltd., also in India, produces modified starches for textile binders, thickeners, emulsifiers, stabilizers, and functional food ingredients. Jay Dinesh Chemicals, with over 50 years of experience in chemical modification processes, manufactures and exports modified starch from India. Vinayak Ingredients provides modified starches derived from maize, cassava, or potato for food additives and industrial use. SMS Corporation Company Limited, headquartered in Thailand, is a global manufacturer and distributor of premium modified tapioca starch for food, pharmaceutical, nutraceutical, paper, adhesive, construction, and textile applications. Grain Processing Corporation, located in Muscatine, Iowa, produces modified starches including acid-modified, oxidized, pregelatinized, and cationic types for industrial and food applications. AEBE U.A., based in the Netherlands, manufactures modified starches for food and industrial sectors. Global Bio-Chem Technology Group Company Limited, a Chinese producer, supplies modified starch products for food and industrial use. SPAC Starch Products India Private Limited manufactures advanced modified starches from maize, corn, and tapioca sources for industrial applications.
Strategic Differentiation and Competitive Evolution
Leading strategies in this market tend to cluster around three pillars: feedstock flexibility, application-specific functionality, and regulatory-aware formulation. Global incumbents leverage multi-source starch portfolios to balance cost and performance across regions, while also maintaining dedicated food-grade and industrial-grade lines. Specialist producers often compete by deepening expertise in particular applications or modification types, offering tailored solutions that address specific processing conditions, label requirements, or regional price dynamics.
The market is simultaneously experiencing consolidation pressures and fragmentation opportunities. Concentration among the largest players reflects the advantages of scale in R&D, quality systems, and global distribution, yet the continued presence of numerous regional manufacturers indicates that local responsiveness, niche functionality, and price competitiveness remain viable differentiation paths. New entrants and expanding regional players can gain traction by focusing on underserved applications, developing cleaner-label modification profiles, or building reliable supply in regions where imported modified starches face tariff or logistics headwinds.
Recent activity among leading companies confirms the emphasis on innovation and market engagement. SMS Corporation's trade show participation in late 2025, including the unveiling of high-performance modified starch solutions at Fi Europe 2025 and the recognition at Gulfood Manufacturing 2025, illustrates how suppliers use visible innovation and industry recognition to strengthen positioning in food and industrial segments. Cargill's March 2025 product innovation further demonstrates the ongoing push toward differentiated functionality that supports label-friendly reformulation and sensory improvement.
Potato Starch Market
Future Trends and Commercial Opportunities
Trend 1: Cleaner-Label and Functionally Efficient Modified Starches
Over the next three to five years, demand for label-friendly modified starches is likely to intensify, driven by labeling guideline updates and consumer expectations for simpler ingredient statements. Commercial opportunities will arise for suppliers that can deliver stable viscosity, thickening, and texturizing performance without relying on nomenclature that complicates label readability. Formulations that can replace pectin, gum, or other more expensive or less desirable ingredients while maintaining sensory quality will be particularly valuable in food and beverage applications. The risk here lies in balancing clean-label positioning with performance consistency; manufacturers must ensure that cleaner ingredient narratives do not erode the functional reliability that customers depend on.
Trend 2: Regional Sourcing and Supply Chain Reconfiguration
Tariff impacts, raw material price volatility, and regional supply tightness are expected to accelerate reconfiguration of supply chains. Companies may increasingly favor regional production footprints, diversified feedstock sourcing, and long-term supply agreements that reduce exposure to single-commodity shocks. Opportunities exist for producers that can offer reliable delivery, transparent cost structures, and flexibility across starch sources such as corn, potato, tapioca, wheat, and peas. The key uncertainty is the trajectory of trade policy and commodity markets; shifts in tariff regimes or unexpected supply disruptions could alter the economics of regional versus cross-border supply strategies.
Trend 3: Industrial and Non-Food Diversification with Performance Focus
While food and beverages remain the largest application segment, industrial uses in paper, textiles, adhesives, and related sectors provide demand diversification and volume stability. Over the forecast period, opportunities will likely emerge for modified starches that deliver consistent binding, coating, and finishing performance at competitive cost, especially where manufacturers seek alternatives to more expensive synthetic additives. The risk is that industrial demand can be sensitive to macroeconomic cycles and substitution pressures; suppliers will need to manage capacity and pricing dynamically to preserve margins during demand fluctuations.
Actionable Guidance for Decision-Makers
For Manufacturers and Ingredient Suppliers
- Strengthen feedstock diversification and formulation flexibility to respond to raw material price volatility and regional supply tightness, particularly for tapioca and potato-based inputs.
- Invest in label-friendly and multifunctional modification profiles that align with evolving FDA and EU expectations, enabling customers to simplify ingredient statements while maintaining performance.
- Use application-level expertise and visible innovation, including trade show engagement and targeted product launches, to differentiate from both global incumbents and regional competitors.
For Investors
- Evaluate exposure to regulatory and tariff dynamics across key regions, recognizing that classification refinements, duty adjustments, and import tariffs can materially affect cost structures and competitive positioning.
- Prioritize companies with diversified feedstock access, application breadth, and the ability to shift between physical, chemical, and enzymatic modification pathways as customer requirements evolve.
- Monitor concentration trends and consolidation potential; while the market remains moderately concentrated, specialized players with strong application niches or regional supply advantages may present attractive value creation pathways.
For Procurement and Supply Chain Leaders
- Build multi-source sourcing strategies that reduce dependence on single starch types or single-origin suppliers, improving resilience against price spikes and supply tightness.
- Align supplier selection with regulatory-aware ingredient profiles, ensuring that modified starch choices support label objectives and trade compliance requirements in target markets.
- Incorporate total delivered cost, including logistics and tariff implications, into sourcing decisions rather than relying solely on ex-works pricing, especially when cross-border trade is involved.
Conclusion
The modified starch market is entering a phase where steady growth coexists with meaningful structural change. Raw material volatility, regulatory updates, and trade policy shifts are reshaping cost and compliance dynamics, while innovation in functionality and cleaner-label formulation is opening new commercial pathways. Companies that combine feedstock flexibility, application-specific expertise, and supply chain resilience are best positioned to convert these dynamics into durable advantage. For decision-makers seeking deeper segmentation data, regional cost modeling, and customized strategic recommendations, the full research report provides the detailed analysis needed to translate these market signals into actionable plans.
For detailed analysis of this topic, please visit the official page: Modified Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GF and GFRP Composites Market: Why 4.16% CAGR and 51.43 Billion Demand Signals a Strategic Shift
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global GF and GFRP Composites Market
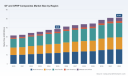
The global glass fiber (GF) and glass fiber reinforced polymer (GFRP) composites industry is navigating a period of structural transformation. From 2020 through 2025, the market expanded from roughly 31.5 billion to 38.6 billion in annualized revenue, reflecting steady adoption across high-performance engineering sectors. Looking ahead to 2032, the trajectory points toward a market size approaching 51.4 billion, underpinned by a compound annual growth rate of 4.16 percent. This growth is neither uniform nor speculative. It is concentrated in application verticals where weight reduction, corrosion resistance, and lifecycle durability deliver measurable economic and operational returns.
The scale of this expansion matters because it signals a shift from niche substitution to mainstream material selection. GFRP is no longer competing solely on cost parity; it is gaining ground where total cost of ownership, maintenance intervals, and regulatory compliance favor advanced polymer-matrix systems. Yet the same dynamics that drive adoption also create friction. Raw material volatility, regional capacity imbalances, and evolving performance standards are reshaping how producers, fabricators, and end-users evaluate risk and return.
For decision-makers, the immediate question is not whether GFRP continues to gain share, but where value will accumulate and which capabilities will separate durable competitors from marginal players. The answer depends on how companies interpret the interplay between fiber types, application-specific performance requirements, and the regulatory frameworks governing structural and industrial use.
Market Context and Structural Challenges
The market's expansion since 2020 has been supported by broad-based demand rather than a single sector tailwind. Revenue growth over the historical period reflects incremental penetration in construction, energy, transportation, and industrial fabrication. By mid-decade, the composition of demand began to favor higher-specification fiber grades and longer-life composite systems, particularly where exposure to moisture, chemicals, or cyclic loading erodes conventional alternatives.
Glass Fiber Composites Market
Several structural challenges now define the industry's inflection points.
Raw Material Volatility and Capacity Constraints
Glass fiber pricing has faced repeated upward pressure as producers manage furnace maintenance cycles and respond to sustained demand from wind energy and automotive applications. When major manufacturers run cold repairs or adjust throughput, the ripple effect reaches resin compounders, pultruders, and fabricators within weeks. This sensitivity is structural, not cyclical. As high-performance GFRP applications scale, any disruption in fiber availability or grade availability translates directly into margin compression for downstream players who lack diversified sourcing or inventory buffers.
Regulatory Fragmentation and Certification Pathways
The expansion of GFRP into structural and load-bearing roles has triggered more rigorous standards alignment. Building codes, emissions controls, and product specification frameworks are converging, but at different speeds across jurisdictions. Facilities producing reinforced plastic composites must navigate emissions standards for hazardous air pollutants, while structural applications increasingly require compliance with recognized code guidelines and consensus specifications. For manufacturers, this is both a barrier and a differentiator. Companies that invest early in code-aligned qualification processes can unlock premium project pipelines, while those that treat certification as an afterthought face longer sales cycles and higher rework risk.
PW Consulting Chemical & Energy Research Center
Performance Expectations and Lifecycle Validation
As GFRP moves beyond corrosion-resistant replacement parts into primary structural roles, end-users are demanding longer service life validation, predictable fatigue behavior, and demonstrable sustainability attributes. This shifts the competitive conversation from price-per-kilogram to verified performance over decades of use. Suppliers that cannot provide application-specific testing data, environmental resistance documentation, or consistent lot-to-lot quality will lose ground to competitors who can when the cost of failure is high.
Key Drivers Reshaping the Market
Three overlapping forces are driving the next phase of market evolution: technological innovation in fiber and resin systems, regulatory and standards alignment, and demand-side shifts in industrial and infrastructure behavior. A fourth factor, supply chain reorientation, is amplifying the impact of the first three.
Technology Innovation and Material Performance
Advancements in E-glass formulations, high-modulus fiber variants, and resin compatibility are expanding the feasible design space for GFRP components. Manufacturers are increasingly selecting fiber grades based on stiffness-to-weight ratios, surface treatments for improved interfacial bonding, and resin systems that reduce cure time without sacrificing mechanical properties. These improvements are especially relevant in wind energy and automotive applications, where component geometry, production throughput, and long-term durability must be balanced simultaneously.
A useful indicator of this shift is the introduction of advanced GFRP reinforcement products designed for infrastructure use. Enhanced-durability rebar concepts, for example, reflect a broader push to extend composite performance in concrete environments where corrosion avoidance and maintenance reduction justify higher upfront cost. When such products reach commercial readiness, they do more than open a new application; they reset buyer expectations for what glass-fiber reinforcement can deliver over a structure's service life.
Policy, Standards, and Compliance Momentum
Regulatory and standards activity is increasingly shaping procurement decisions. Emissions frameworks for composite production facilities continue to define operational requirements, while structural code guidance and product specifications provide the technical language that engineers and contractors need to specify GFRP with confidence. The presence of recognized standards for panels, structural bars, and composite fabrication processes lowers adoption risk for large projects. It also creates a competitive filter: suppliers whose products are already aligned with prevailing specifications can quote faster, win more technically complex work, and reduce liability exposure.
This is particularly important in regions where code adoption is accelerating. As structural concrete reinforcement standards and panel specifications gain traction, the market transitions from ad hoc substitution to engineered specification. That transition favors companies that can provide not only material supply but also technical support, testing documentation, and application engineering.
Demand-Side Shifts in Infrastructure, Energy, and Mobility
Demand is being pulled by sectors where durability and weight optimization translate directly into operational savings. In wind energy, larger rotor architectures and continuous deployment pipelines keep fiberglass demand firm. In automotive and transportation, the pressure to reduce mass while maintaining stiffness supports GFRP in selective structural and semi-structural components. In construction and infrastructure, the appeal of non-corroding reinforcement is gaining attention in environments where steel maintenance costs or exposure conditions are especially severe.
Equally important is the change in buyer behavior. Procurement teams are increasingly evaluating composite solutions through lifecycle lenses rather than initial purchase price. This makes a difference in tender evaluations, because the lowest material cost does not always produce the lowest installed cost once fabrication complexity, connection details, corrosion protection, and maintenance intervals are included. Companies that can help customers model total cost implications are better positioned to defend price and secure longer-term supply relationships.
Supply Chain Reorientation and Cost Structure
The geographic distribution of fiber production is shifting the economics of regional supply. Additional manufacturing capacity in proximity to European and Middle Eastern demand centers illustrates how producers are responding to logistics costs, delivery reliability, and local content expectations. At the same time, price adjustments across key product lines signal tighter supply conditions for certain high-demand grades. For buyers, this creates a trade-off between spot availability and long-term supply continuity. For producers, it rewards capacity strategies that are aligned with regional demand clusters rather than purely centralized output.
Cost structure is also being redefined by the interaction of energy input costs, furnace utilization, and fiber grade mix. Higher-value T-glass and specialty reinforcements command different pricing dynamics than commodity E-glass, and the balance between them influences margin stability across the value chain. Organizations that manage grade mix strategically can cushion volatility, while those dependent on a narrow commodity slate are more exposed to price swings and demand surges.
Competitive Landscape and Leading Strategies
The industry is characterized by a high degree of concentration among established producers of glass fiber and reinforced materials. With the top three firms holding a substantial share of revenue and the top five capturing an even larger proportion, scale, consistency, and technical capability remain powerful advantages. Concentration does not eliminate competition, but it does shape it. Smaller fabricators and regional suppliers often compete by specializing in application-specific solutions, localized service, or niche product configurations, while larger players compete on volume reliability, grade breadth, and global distribution.
Strategic Positioning Across Leading Producers
Several patterns distinguish the most effective competitors.
- Capacity scale and regional proximity are being used to secure supply continuity. One of the world's largest glass fiber producers recently completed an expansion in Egypt, adding significant annual output to support European and Middle Eastern GFRP markets. This type of move is less about sheer volume than about shortening supply lines, improving delivery reliability, and embedding capacity closer to demand hotspots.
- Pricing discipline is being deployed in response to grade-specific demand and supply tightness. A notable price increase across glass fiber product lines highlighted how T-glass demand growth and supply constraints can translate into recalibrated pricing. The strategic implication is that companies with differentiated grades can protect margins more effectively than those competing purely on commodity terms.
- Application-aligned product development is becoming a growth lever. New GFRP rebar products with enhanced durability and sustainability features show how composite suppliers are targeting infrastructure use cases where corrosion resistance and long service life justify premium positioning. This approach relies less on broad product proliferation and more on solving specific engineering problems.
- Technical support and code alignment are increasingly part of the value proposition. Suppliers that can contribute to specification development, provide testing data, and support fabricators with application engineering are better positioned to win structural and industrial work where qualification risk matters.
Market Evolution: Consolidation, Specialization, and Entry Points
The competitive field is evolving along multiple paths. Consolidation remains attractive for producers seeking scale efficiencies, integrated grade portfolios, and broader geographic coverage. At the same time, specialization is creating durable niches for companies focused on pultruded profiles, continuous fiber for molding, structural reinforcement, or industrial panel products. These players often win by understanding a narrower set of applications in greater depth and by building repeat relationships with fabricators and engineering teams.
New entry is possible, but the barriers are practical rather than theoretical. Access to reliable fiber supply, consistent reinforcement quality, and application-qualified processing capability determines whether a newcomer can move beyond pilot projects into commercial volume. In practice, the most credible entrants are those that link material supply with proven fabrication know-how, or those that bring a differentiated product concept validated by performance data and standards alignment.
A further evolution is occurring in the relationship between fiber producers and composite fabricators. As demand becomes more application-specific, upstream suppliers are increasingly expected to offer grade selection guidance, surface treatment options, and consistent dimensional quality. Downstream fabricators, in turn, are investing in process control and quality documentation to meet stricter specification requirements. This tighter coupling rewards collaboration and punishes fragmentation in both quality and technical support.
Forward Outlook: Trends and Commercial Implications
Based on the current trajectory of demand, capacity actions, and standards activity, three trends are likely to shape the market over the next three to five years.
Trend 1: Application-Led Specification Will Become the Norm in High-Value Sectors
As GFRP enters more structural and semi-structural roles, procurement will increasingly follow engineered specification rather than generic substitution. That means engineers and contractors will select fiber types, resin systems, and fabrication methods based on performance requirements, environmental exposure, and code alignment. Commercial opportunity lies in offering application-specific grade recommendations, verified testing packages, and fabrication guidance that reduce specification risk. The risk is that suppliers unable to support specification-level conversations will be relegated to commodity replacement transactions with thinner margins and higher churn.
Trend 2: Regional Supply Alignment Will Matter More Than Global Volume Alone
Demand clusters in wind energy, automotive, construction, and industrial fabrication will continue to reward producers and fabricators that can deliver the right grades near the right markets. Capacity expansions positioned to serve regional demand, combined with reliable logistics and stock management, will be a competitive advantage. For buyers, this creates a stronger case for dual sourcing and regional partnerships. For producers, it raises the importance of capacity utilization discipline and grade mix optimization. A key uncertainty is how quickly regional capacity additions can absorb demand surges without creating localized oversupply in lower-value grades.
Trend 3: Standards Maturity Will Open Doors but Raise the Bar for Entry
As building codes, product specifications, and consensus standards continue to mature for structural and panel applications, the addressable market for engineered GFRP solutions should expand. At the same time, compliance and documentation requirements will become more central to vendor selection. Companies that invest early in qualification, testing, and specification support will be better positioned to capture project pipelines. Those that delay may find themselves excluded from bids where code alignment and traceability are prerequisites. The uncertainty here lies in the uneven pace of code adoption across regions and project types, which can create short-term demand variability even as the long-term trend strengthens.
Implications for Decision-Makers
Different roles in the value chain should prioritize different actions, but all share a common need: clearer visibility into grade-level demand, regional supply dynamics, and the standards pathways that govern specification.
Glass Fiber Prepreg Market
For Manufacturers and Fabricators
- Align capacity and grade mix with the applications that generate the strongest lifecycle value, not just the highest volume. Wind energy, automotive, and structural infrastructure each reward different fiber and resin combinations, and strategy should reflect that.
- Build application engineering capability as a margin defense. When customers evaluate total cost, the ability to advise on connection details, cure optimization, and environmental resistance can justify premium positioning and reduce rejection risk.
- Strengthen qualification documentation now. Code-aligned specifications and consensus standards are increasingly part of procurement filters, and preparedness will shorten sales cycles in structurally sensitive projects.
For Investors and Strategic Planners
- Focus on segments where specification momentum and durability advantages reinforce each other. Applications with high maintenance costs, corrosion exposure, or weight sensitivity are the most likely to sustain durable demand for GFRP solutions.
- Evaluate suppliers on regional supply resilience and grade differentiation, not just declared capacity. Price adjustments and capacity expansions reveal where demand is strongest and where supply tightness is most likely to persist.
- Watch for consolidation that improves grade breadth and distribution reach, as well as specialization that deepens application expertise. Both models can create value, but they require different evaluation criteria and risk tolerances.
For Procurement and Supply Chain Leaders
- Move beyond spot pricing when sourcing critical grades. Dual sourcing, regional partnerships, and forward visibility into furnace maintenance cycles can reduce the chance of disruption during demand spikes.
- Incorporate lifecycle cost and specification support into supplier evaluation. The lowest initial price can be offset by fabrication complexity, rework, or qualification delays if the supplier cannot support engineered applications.
- Track standards and code developments as part of sourcing strategy. Products that already align with prevailing specifications can reduce project risk and accelerate approval processes.
The market for GF and GFRP composites is moving from broad adoption to more purposeful, specification-driven growth. That shift rewards organizations that can combine material capability with application understanding, regional supply reliability, and standards readiness. It also raises the cost of staying passive, because the companies defining specifications today are shaping procurement preferences for the next cycle of infrastructure, energy, and mobility projects.
For teams that need a deeper breakdown of segment dynamics, regional demand patterns, and company-level positioning across the competitive field, the full PW Consulting research report provides detailed data and tailored strategic guidance to support planning decisions.
For detailed analysis of this topic, please visit the official page: GF and GFRP Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Prostaglandin Market: Why 6.5% CAGR and Clinical Shifts Change Everything
By PW Consulting, 2026-09-21
Navigating the Prostaglandin Market: Strategic Trends and Commercial Opportunities in a Transforming Landscape
The prostaglandin market is entering a phase of structural transformation. Over the historical period from 2020 through 2025, global revenue expanded from approximately $3.3 billion to $4.47 billion, reflecting steady demand growth across therapeutic categories and geographic markets. Looking ahead to the 2026–2032 forecast window, the market is projected to continue its upward trajectory, reaching an estimated $6.9 billion by 2032 with a compound annual growth rate of 6.5 percent. This growth rate places prostaglandins above many traditional generic pharmaceutical segments and signals sustained commercial relevance for manufacturers, buyers, and investors alike.
Beneath these headline figures lies a market defined by concentration, regulatory friction, and rapid innovation in formulation and delivery. The top three competitors currently capture roughly 58.5 percent of total revenue, while the top five account for about 68.2 percent. Such concentration indicates that scale, supply reliability, and regulatory expertise remain powerful moats, yet it also suggests that targeted entrants with differentiated capabilities can still carve out meaningful positions. The next several years will reward organizations that can read the shifting demand signals, navigate cost pressures, and align product strategies with evolving clinical and reimbursement realities.
Market Context: What the Numbers Reveal and What They Conceal
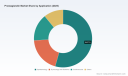
The size and trajectory of the prostaglandin market reflect more than incremental volume growth. The steady expansion from 2020 to 2025 was underpinned by consistent utilization in ophthalmology, ongoing demand in gynecology and obstetrics, and a mature but resilient cardiovascular segment. The projected climb toward 2032 indicates that the market is not merely catching up from a temporary slowdown but is benefiting from durable therapeutic relevance and incremental innovation in delivery formats.
At the same time, the concentration profile tells a story of distributed value chains. A relatively small group of large-scale players commands the majority of revenue, yet the broader ecosystem includes specialized API producers, formulation-focused companies, catalyst and intermediate suppliers, and reagent distributors. This structure creates both stability and vulnerability. Buyers benefit from multiple sourcing options, but the reliance on a concentrated set of suppliers for critical inputs introduces risk when regulatory, geopolitical, or operational disruptions occur.
Key Challenges and Inflection Points
Three challenges stand out as particularly consequential for market participants.
- Supply chain concentration and tariff exposure. A substantial share of global API production for prostaglandin analogs is concentrated in India and China, making Western manufacturers and distributors dependent on these sources. Recent tariff actions on Chinese pharmaceutical imports have raised landed costs and introduced new uncertainty around sourcing economics. Organizations that have not diversified or reconfigured their supply chains face margin pressure and continuity risk.
- Regulatory divergence across applications. Regulatory scrutiny is intensifying in specific use cases, particularly where prostaglandin analogs intersect with consumer-facing or semi-consumer products. A recent European Chemicals Agency opinion raised safety concerns around reproductive toxicity for cosmetic lash serums, creating reformulation requirements and channel-specific disruption. This illustrates how a single regulatory signal can cascade across supply chains, even when the core pharmaceutical indications remain unaffected.
- Reimbursement and access dynamics in high-value procedures. The introduction of new reimbursement pathways for certain intravitreal and intracameral delivery procedures demonstrates that payment policy can accelerate or delay adoption of advanced formulation technologies. While positive reimbursement updates can unlock volume, the timing and scope of coverage vary by market, creating uneven commercialization opportunities across regions.
Core Drivers Shaping the Market
The prostaglandin market is being reshaped by four interlocking drivers. Together, they determine which companies gain share, which supply chains remain resilient, and where the most attractive commercial opportunities emerge.
1. Technological Innovation in Production and Delivery
Innovation is advancing on two fronts: how prostaglandins are made and how they are delivered to patients. On the production side, recent scientific progress has demonstrated improved de novo synthesis of prostaglandin F2α from glucose using engineered microbial strains. This type of bioscience-driven manufacturing has the potential to complement traditional chemical synthesis, offering greater efficiency, reduced dependency on complex intermediate steps, and new options for scale. Even where fermentation-based routes are not yet the dominant commercial standard, the direction of travel is clear: manufacturability is increasingly tied to biological and process engineering capabilities.
On the delivery side, the most visible commercial momentum is coming from sustained-release and intracameral technologies in ophthalmology. Recent regulatory approvals supporting re-administration of intracameral implants, alongside new fixed-dose combination eye drops that pair prostaglandin analogs with beta-blockers, reflect a broader push toward convenience, adherence, and differentiated therapeutic positioning. These formats do more than add product variants; they redefine the value proposition by extending duration of action and simplifying treatment regimens. For manufacturers, the opportunity lies not only in active ingredient supply but in enabling technologies, formulation expertise, and compatible delivery systems.
2. Policy and Regulatory Environment
Regulatory policy is simultaneously a constraint and a catalyst. Tariff expansions on certain pharmaceutical imports have increased cost pressure on API sourcing, prompting manufacturers to reassess exposure to specific geographies and to evaluate alternative supply routes. At the same time, regulatory decisions in adjacent application areas can reshape demand quickly. The European Chemicals Agency’s position on cosmetic lash serums, for example, underscores that prostaglandin-related molecules are subject to broader scrutiny when used outside strictly controlled pharmaceutical contexts. Companies that treat regulatory risk as narrowly confined to approved drug indications may miss upstream and downstream consequences that affect raw material sourcing, labeling, distribution channels, and product strategy.
On the positive side, reimbursement developments can create meaningful access advantages. Updated payment policies for certain procedural codes associated with intracameral implants have supported the economics of advanced delivery approaches in specific settings. Such changes can improve adoption trajectories and make novel formulations more commercially viable, especially when aligned with favorable clinical outcomes and clear administration protocols.
3. Demand-Side Changes in Clinical and Commercial Behavior
Demand for prostaglandins continues to be driven by established therapeutic needs, but the nature of that demand is evolving. In ophthalmology, clinicians are increasingly focused on adherence, tolerability, and long-term management, which favors products that reduce dosing frequency or simplify combination therapy. In gynecology and obstetrics, prostaglandin utilization remains tied to well-defined procedural and therapeutic protocols, with demand influenced by clinical guidelines, training, and hospital procurement patterns. Across cardiovascular applications, the market reflects mature usage with ongoing reliance on prostaglandins in specific acute and specialized settings.
A broader demand-side shift is also visible in the way end users evaluate products. Buyers increasingly weigh supply resilience, regulatory clarity, and formulation differentiation alongside price. This is especially true in segments where procurement teams are managing multiple risk layers at once, from API availability to product-specific regulatory status. The practical implication is that value propositions are expanding beyond cost per unit to include reliability, documentation, and the ability to support downstream compliance and patient access.
4. Supply Chain and Cost Structure Transformation
Cost structures are being reshaped by geography, input availability, and the economics of advanced manufacturing. Because a large proportion of API production is clustered in India and China, global markets are exposed to both pricing advantages and concentration risk. Tariff actions have further complicated the cost equation for importers, making it more important to model landed costs realistically and to consider where value can be captured through process efficiency, vertical integration, or alternative sourcing.
At the same time, the cost frontier is shifting through innovation. Improved fermentation routes, catalyst optimization, and better intermediate management can alter unit economics over time, especially for high-volume or high-purity requirements. Companies that can integrate production steps more effectively, or that can secure dependable access to critical intermediates and catalysts, may be able to offset external cost pressures and improve margin stability. In a market where several players compete on similar active ingredients, cost structure and supply reliability can become decisive differentiators.
Competitive Landscape: Positioning, Differentiation, and Evolution
The prostaglandin market features a layered competitive structure. Large multinational pharmaceutical organizations participate through API manufacturing and formulation capabilities, while specialized producers focus on prostaglandin synthesis, analogs, APIs, and related intermediates or reagents. This mix creates multiple pathways to value, but it also means that competitive advantage depends heavily on the specific segment a company serves and the customer problems it solves.
Strategic Positioning Across the Value Chain
Several patterns emerge when looking at how leading participants position themselves.
PW Consulting
- Integrated API and formulation players tend to derive advantage from scale, quality systems, and the ability to support both human and veterinary applications. Companies with established manufacturing infrastructure can compete on reliability and breadth of capability, which is particularly valuable when buyers are seeking to consolidate suppliers or reduce qualification burden.
- Specialized synthesis and fine chemical producers compete on technical precision, purity, and the ability to serve demanding pharmaceutical and research requirements. For these firms, differentiation often comes from process know-how, consistent batch quality, and responsiveness to custom specifications.
- Catalyst and intermediate suppliers occupy a critical enabling role. While they may not be visible to end customers in the same way as API or formulated-product manufacturers, they influence cost, yield, and supply continuity across the value chain. Strong positions in this layer can create indirect competitive leverage.
- Regional and emerging-market manufacturers are increasingly relevant because of capacity, cost positioning, and growing technical competence. Their strategic importance is magnified by the concentration of global API production and by the need for diversified sourcing.
- Research and reagent suppliers serve a different but important demand pool, supporting R&D, quality testing, and preclinical work. This segment may be smaller in revenue terms, but it can shape downstream product development and reinforce technical ecosystems around prostaglandin use.
How the Landscape Is Evolving
Three forces are shaping the evolution of the competitive field. First, supply chain reconfiguration is encouraging a pragmatic mix of consolidation and diversification. Some buyers are seeking to reduce exposure to concentrated sourcing by qualifying additional suppliers or shifting portions of demand to alternative regions. Others are moving in the opposite direction by deepening relationships with suppliers that can demonstrate robust reliability and regulatory readiness. The net effect is a more selective market in which trust, documentation, and operational track record matter as much as price.
Second, product differentiation is becoming more important as the market matures. Fixed-dose combinations, sustained-release implants, and analog-based formulations illustrate how innovation can create space for competitive distinction even when the underlying molecule class is well established. Companies that can combine API or synthesis competence with formulation insight, delivery compatibility, and clinical-commercial alignment are better positioned to capture premium value.
Third, the entry and expansion dynamics are being influenced by cost pressures and capability gaps. New entrants and expanding players are likely to focus on niches where they can offer a clear advantage: specialized synthesis, cost-competitive API supply, unique intermediates, or targeted formulation support. Broad-based competition remains intense among established players, but the most attractive openings increasingly require a focused value proposition rather than undifferentiated capacity.
Worldwide Prostaglandins and Related Drugs Market
Looking Ahead: Three Trends to Watch Over the Next 3–5 Years
Based on current market dynamics, the following trends are likely to shape commercial outcomes through the end of the decade and into the early 2030s.
Trend 1: Supply Chain Realignment and Multi-Sourcing as Baseline Strategy
The combination of geographic concentration and tariff-related cost pressure is accelerating a shift toward deliberate multi-sourcing and regional diversification. Over the next few years, organizations are likely to treat supply resilience as a core commercial requirement rather than a contingency plan. This will favor suppliers that can demonstrate consistent quality, transparent sourcing, and the capacity to support qualified alternative routes. It may also encourage more regional manufacturing investment, or at least stronger contractual and operational integration with key upstream partners.
Commercial implication: supply reliability and regulatory readiness will increasingly be priced into relationships. Companies unable to support credible diversification will face growing procurement friction, while those that can document resilience and scale will gain negotiating leverage.
Trend 2: Formulation and Delivery Innovation as the Primary Growth Lever in Key Segments
While volume growth in mature indications provides a stable base, the most visible upside is coming from differentiated delivery and combination therapies, especially in ophthalmology. Sustained-release implants, intracameral approaches, and combination drops are examples of formats that can improve adherence and clinical convenience while creating new commercial entry points. As these formats become more widely adopted, demand for compatible APIs, formulation support, and delivery-enabling technologies will increase.
Worldwide Dienogest Market
Commercial implication: companies that remain focused solely on commodity-style active ingredient supply may see margin and differentiation erode. Those that can align with advanced delivery strategies—through synthesis quality, scale, formulation partnerships, or integrated offerings—will be better positioned to capture value from format-driven growth.
Trend 3: Regulatory Scrutiny Expanding Beyond Core Pharmaceutical Indications
The prostaglandin opportunity set is not confined to approved drug products, and regulatory attention is already extending into adjacent categories. Cosmetic and semi-consumer applications represent one visible area of scrutiny, but the broader lesson is that product classification, intended use, and supply chain labeling can affect market access and risk exposure. Over the next several years, this may lead to more conservative positioning in borderline applications, more rigorous documentation requirements, and greater emphasis on end-use clarity across the value chain.
Commercial implication: organizations operating across multiple application channels need to separate pharmaceutical and non-pharmaceutical strategies carefully, anticipate reformulation or channel restrictions, and avoid assumptions that regulatory outcomes in one segment will remain isolated from others.
Strategic Implications by Stakeholder Type
The prostaglandin market offers distinct strategic priorities depending on a company’s role in the value chain.
For Manufacturers and Suppliers
- Evaluate supply chain exposure honestly, especially where dependence on concentrated API sources or tariff-sensitive import routes creates cost and continuity risk. Model alternatives, qualify candidates, and stress-test continuity scenarios.
- Invest in process and formulation capabilities that support advanced delivery formats. Even when the core molecule is familiar, the ability to meet the quality, purity, and compatibility requirements of sustained-release or combination products can open higher-value positions.
- Clarify application-channel strategy. Where a company serves both pharmaceutical and adjacent categories, ensure that regulatory positioning, documentation, and end-use claims are aligned with evolving scrutiny and do not create unintended exposure.
For Investors
- Focus on companies with defensible cost structures and credible diversification strategies. In a market where external cost shocks and sourcing concentration create volatility, resilience is a meaningful indicator of long-term performance potential.
- Look for exposure to formulation and delivery innovation rather than assuming growth will come only from volume expansion in mature indications. Businesses connected to advanced delivery technologies and combination approaches may capture more durable value.
- Assess regulatory and reimbursement alignment as part of the investment thesis. Positive payment policy developments can accelerate adoption, while adverse regulatory signals in adjacent channels can affect demand and restructuring costs.
For Procurement and Commercial Buyers
- Prioritize supplier qualification on the basis of reliability, regulatory readiness, and the ability to support alternative sourcing if needed. In a concentrated but dynamically shifting market, the cheapest option is not always the lowest-risk option.
- Build transparency into specifications and end-use requirements. Clear documentation of intended use and quality expectations helps reduce downstream compliance risk and supports more predictable supplier relationships.
- Monitor reimbursement and clinical adoption signals in high-value segments. Changes in procedure-based payment policies and adoption of new delivery formats can materially affect volume trajectories and supplier demand patterns.
Why Now Is the Moment for Deeper Intelligence
The prostaglandin market is not simply expanding; it is reconfiguring around supply chain geography, regulatory pressure, and delivery-format innovation. That combination means the most valuable decisions are increasingly specific: which supplier relationships to deepen, which application channels to prioritize, how to position against tariff and sourcing risk, and where to invest in capabilities that support advanced formulations. Broad market sizing alone does not answer those questions.
Detailed segment-level data, supplier benchmarking, regional cost modeling, and scenario analysis can materially improve strategic planning in this environment. Organizations that rely on high-level aggregates risk missing the operational and regulatory nuances that determine margin, continuity, and competitive positioning. A more granular view also helps identify where concentration risk is manageable and where it is structural, as well as where emerging technologies and reimbursement changes are likely to alter demand faster than the base forecast implies.
For executives, strategists, and investors seeking to move from general market awareness to actionable planning, the next step is to connect these trends with company-specific exposure and opportunity. A comprehensive research report can provide the detailed segmentation, competitive profiling, and forward-looking scenarios needed to support procurement strategy, investment prioritization, and product-roadmap decisions. Given the pace of regulatory and supply chain change, the value of current, granular intelligence is highest before major sourcing or investment commitments are locked in.
For detailed analysis of this topic, please visit the official page: Prostaglandin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Enzymes Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot: Scale, Trajectory, and the Current Inflection Point
The global industrial enzymes market has firmly entered a phase of sustained expansion, reflecting a broader structural shift toward biological catalysis across manufacturing, processing, and treatment applications. Measured in USD Millions, the sector moved from a base above 5.3 billion in 2020 to an estimated 7.4 billion in 2025, and the forward trajectory points to continued upward momentum through 2032, when the market is projected to approach the 12 billion threshold. The implied compound annual growth rate of 6.4 percent over the forecast window signals that demand is not merely recovering from cyclical softness but accelerating along a secular growth path. This pace matters because it compresses planning horizons for capacity, R&D, and commercialization, rewarding organizations that can align product roadmaps with the timing of regulatory clearances, feedstock availability, and application adoption.
Enzyme for Pulp & Paper Market
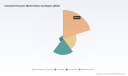
Regionally, the market is anchored by mature industrial ecosystems in North America and Europe, while Asia Pacific represents a large and structurally rising share shaped by expanding food processing, biofuels infrastructure, and animal nutrition demand. The geographic distribution underscores that enzyme demand does not travel in isolation; it follows local processing capacity, agriculture-linked feedstock flows, and consumer-driven formulation trends. In practical terms, the same enzyme capability can face very different commercialization pacing depending on where it is introduced, which makes regional regulatory calendars and sourcing strategies decisive variables in go-to-market execution.
At the current stage, the industry sits at a rare intersection of scale, innovation, and policy influence. Applications across food and beverages, biofuels, animal feed, detergents, paper and pulp, wastewater treatment, and textiles are collectively pulling demand forward, but the growth is uneven in character._value_differences_ between sectors are becoming less about raw volume and more about the economic value enzymes create in specific process steps, tolerance profiles, and purification requirements. That shift is changing how suppliers are evaluated, from broad product availability to application-specific performance, consistency, and integration support.
Three challenges are shaping the industry's next chapter. First, the market remains highly concentrated, with a small group of large players holding a dominant share of revenue and customer relationships. This concentration creates an elevated bar for new entrants and mid-sized suppliers that must differentiate on technology, niche application delivery, or cost structure rather than competing head-on on scale alone. Second, macromaterial inputs, regulatory timelines, and tariff dynamics are introducing new variability into the supply chain, affecting sourcing decisions, pricing stability, and the pace at which localized production becomes economically attractive. Third, the rate of adoption in several end-use sectors now depends less on whether enzymes exist and more on whether they can be integrated into existing process architectures without adding operational friction. In that environment, the winners are increasingly those who can make enzymes work within real-world manufacturing constraints, not just demonstrate laboratory performance.
Key Drivers: What Is Actually Moving the Market
The market is being reshaped by several reinforcing forces. Technological progress is the most visible, but the commercial impact depends on how quickly breakthroughs translate into cost-effective, scalable production and application-ready formulations. Innovation in enzyme engineering, strain development, and high-throughput screening is extending the range of reactions that enzymes can perform efficiently and the conditions under which they remain stable. This matters because industrial environments often demand activity under elevated temperature, pH variability, or challenging substrate matrices. Companies that can deliver robust biocatalysts for starch saccharification, grain processing, oil and fat processing, protein modification, or high-temperature industrial processes are gaining credibility in applications where consistency and operational simplicity determine repeat usage.
Equally important is the policy and regulatory environment. Government approvals for new enzymes continue to create openings across multiple applications, and the approval pathway itself has become a strategic variable. A new enzyme that clears regulatory scrutiny can unlock incremental demand in food processing, animal nutrition, detergents, or technical applications, but delays or divergent regional requirements can slow commercial deployment. As a result, suppliers are paying closer attention to the sequence of evaluations across jurisdictions, to labeling and compliance considerations, and to how regulatory status affects downstream customer adoption. The market is increasingly shaped not only by technical performance, but by the speed at which performance can be made commercially permissible and operationally accepted.
PW Consulting
On the demand side, consumption patterns and corporate behavior are shifting in ways that reinforce enzyme utility. Food and beverage manufacturers are under pressure to improve efficiency, manage ingredient costs, and accommodate cleaner-label or novel processing needs. Biofuels and bioindustrial applications are drawing renewed interest where renewable fuel demand and enzyme approvals intersect, creating a demand loop that rewards suppliers capable of supporting substrate conversion and process reliability. In animal feed and nutrition, enzymes are increasingly viewed as tools for optimizing digestibility and resource use, particularly where feed formulation flexibility is tied to cost control and supply resilience. These demand-side changes are not uniform, yet they share a common thread: organizations seek inputs that can reduce waste, improve yield, or enable formulation changes without sacrificing throughput.
Supply chain and cost structure dynamics are adding a further layer of strategic pressure. Enzyme production relies heavily on microbial fermentation using plant-based feedstocks, meaning that feedstock availability, fermentation economics, and process scale directly influence cost competitiveness. At the same time, cumulative tariff developments through 2025 have begun to reshape sourcing, pricing, and localization strategies across the value chain. For many industry participants, this is prompting a reassessment of where to manufacture, how to buffer input exposure, and whether regional production or localized supply agreements can reduce volatility. The practical implication is that enzymes are no longer evaluated only on performance or price per unit; they are increasingly evaluated on the resilience and predictability of the supply chain that delivers them.
Enzymes For Fuel Ethanol Market
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is defined by a blend of global incumbents with broad fermentation and formulation capabilities and specialized players that compete on application depth or technology specificity. Novonesis has built a strong position around enzymes and biosolutions for industrial bioprocessing, starch saccharification, grain processing, and high-performance biocatalysts for food and beverage, biofuels, and detergent applications. Its profile reflects a strategy oriented toward broad process coverage and the ability to serve multiple high-volume industrial segments with integrated biocatalytic solutions. dsm-firmenich has emphasized enzymes and solutions for processing ingredients including oils and fats, fermentation, fruit and vegetable processing, and starch saccharification, highlighting a focus on ingredient- and process-level value rather than commodity enzyme supply alone. BASF SE has positioned around high-performance industrial enzymes and solutions for grain processing, bio-ethanol production, animal nutrition, and detergents, leveraging scale, process integration, and a presence in both food-adjacent and industrial applications.
A second layer of competition comes from suppliers that differentiate through application-specific portfolios or specialized production expertise. Kerry Group emphasizes enzymes for food and beverage processing, dairy, and plant-based applications, aligning closely with formulation trends and ingredient innovation in modern food systems. AB Enzymes focuses on formulated enzyme preparations for food, feed, technical uses, pulp and paper, baking, and plant-based food processing, where product formulation and application consistency are central to customer value. Amano Enzyme has developed a specialty industrial enzyme presence around plant-based beverages, protein isolates, and non-dairy applications, an area where processing nuances and customer formulation needs can create defensible niches. Enzyme Development Corporation contributes plant-based enzyme options including papain, ficin, thistle rennet, cellulases, and hemicellulases for food, beverage, and industrial uses, illustrating the continued relevance of botanical and specialty enzyme sources alongside fermentation-based platforms. Dyadic International is notable for recombinant enzymes and biocatalysts for biofuels, pulp and paper, brewing, specialty chemicals, and high-temperature industrial processes, with a technology orientation that can extend into difficult process conditions and non-animal production routes. Advanced Enzyme Technologies serves grain processing, brewing, dairy, oil and fat, and non-food applications, reflecting a diversified portfolio model that spans both food-linked and industrial segments.
Recent developments show how competitive advantages are being built in real time. In late 2025, Lubrizol announced a $10 million investment to expand fermentation production capacity by five times at its Center of Skin Care Excellence in Gavà, Spain, signaling that fermentation capacity expansion remains a strategic lever even in more specialized biotech-leaning applications. In early 2026, Dyadic Applied BioSolutions and Inzymes ApS announced plans to commercialize recombinant non-animal bovine chymosin for cheese and dairy processing after reaching a development milestone, an example of how recombinant technology can open product opportunities that address non-animal sourcing preferences and supply-chain alternatives. In December 2025, Dyadic and Fermbox Bio expanded their collaboration on commercializing animal-free proteins and enzymes across life science, food and nutrition, and bio-industrial markets, underscoring the growing importance of partnerships that combine production platforms, application expertise, and commercialization pathways.
The structural trend across the landscape is not simply consolidation; it is selective integration paired with targeted fragmentation. Large players continue to compete on breadth, fermentation scale, application coverage, and customer integration, while smaller or focused firms compete by occupying specific application niches, offering distinct enzyme sources, or advancing recombinant and specialty biocatalyst capabilities. New entrants tend to succeed when they bring a clear technical edge or a commercially compelling route to an underserved use case rather than attempting to replicate broad incumbent portfolios. Over time, the most durable differentiation is likely to come from the combination of application reliability, regulatory readiness, and supply resilience, because customers in industrial environments increasingly want performance that is verifiable under process conditions and supply that is traceable and dependable.
Future Outlook: Three Trends Shaping the Next Three to Five Years
The first trend is the continued integration of enzyme-enabled process improvements into mainstream industrial operations. As enzyme approvals expand and fermentation-based production matures, more manufacturers are likely to treat enzymes as core process inputs rather than specialty additives. This creates commercial opportunities for suppliers that can document consistent performance, reduce process variability, and support scale-up. It also raises the stakes for companies that cannot demonstrate operational reliability, because adoption in demanding environments depends on outcomes at commercial scale, not only on technical capability.
The second trend is the growing strategic importance of application-specific and source-specific enzyme solutions. In food and beverage, plant-based and non-dairy applications, non-animal rennet alternatives, and other formulation-sensitive areas, the value proposition is increasingly tied to specificity, compatibility, and consumer-facing positioning. This is reinforcing demand for recombinant routes, specialty plant-based enzymes, and tailored formulations that address narrow but commercially valuable needs. For suppliers, the opportunity lies in building application expertise and customer integration capabilities, not just product catalogs. For buyers, the opportunity is to use such solutions to streamline formulation, reduce reliance on constrained inputs, or align product positioning with market preferences.
The third trend is supply chain localization and cost-structure redesign in response to feedstock and trade dynamics. Tariff developments and feedstock dependencies are prompting a more deliberate approach to where enzymes are manufactured, how fermentation capacity is scaled, and how customer supply commitments are structured. Over the next few years, organizations that invest early in regional capacity, feedstock resilience, or flexible sourcing models may gain pricing and service advantages when volatility intensifies. At the same time, there is a risk that excessive localization could raise unit costs if not matched by sufficient demand density or process efficiency. The strategic balance will be between resilience and competitiveness, and firms that over-index on one side may lose ground to those that can manage both.
These trends carry inherent uncertainties. Demand in biofuels and bioindustrial applications can fluctuate with policy signals and commodity economics. Regulatory clearance timelines can differ across regions, affecting the pace at which new enzyme solutions reach market. Feedstock availability, fermentation yields, and process scale can shift cost structures quickly enough to alter competitive dynamics. In addition, the concentration of the market means that a few large players can shape pricing, capacity allocation, and partnership patterns in ways that smaller companies must anticipate carefully. The overall outlook is positive, but the path is conditional on execution, regulatory timing, and supply resilience.
Strategic Moves for Decision-Makers
For manufacturers and product suppliers, the clearest imperative is to align enzyme strategy with application reliability and supply continuity. That means prioritizing capability in the processes that matter most to customers, documenting performance under realistic operating conditions, and building the fermentation or formulation infrastructure needed to support repeatable delivery. Companies should also assess where regulatory approvals, feedstock exposure, and trade dynamics intersect with their commercial plans, because timing and sourcing can determine whether a technically strong solution reaches the market with commercial momentum.
For investors, the market offers value in companies that combine differentiated technology with a credible path to commercialization in specific applications. The most informative signals are not simply revenue scale but product maturity, regulatory readiness, application validation, partnership footprint, and capacity expansion logic. Investors should pay particular attention to firms that can translate innovation into cost-effective production and that have clear positioning in high-value segments such as food processing, biofuels, animal nutrition, detergents, or specialty technical uses. Portfolio decisions are likely to be more durable when they reflect both growth potential and the operational constraints that shape industrial adoption.
For procurement and sourcing leaders, enzyme selection should be treated as a strategic input decision rather than a routine specification. That involves evaluating not only performance characteristics but also supplier resilience, regional sourcing options, lead-time stability, and the degree to which a supplier can support integration and process changes. Where feasible, multi-supplier strategies, localized supply arrangements, or partnerships that reduce exposure to single points of failure can improve continuity. Procurement teams that understand the link between feedstock economics, fermentation scale, and regulatory status will be better positioned to anticipate price behavior and manage long-term supply agreements.
Timely access to detailed market segmentation, regional dynamics, regulatory trackers, and company-level assessments can materially strengthen planning in this environment. Detailed intelligence supports more precise prioritization of applications, capacity investments, partnership opportunities, and risk mitigation measures. The industrial enzymes market is large enough and diverse enough that broad directional insight only goes so far; actionable advantage comes from knowing where demand is forming fastest, which applications are opening through approvals or formulation shifts, and how suppliers are positioning their production and commercialization strategies. Readers seeking a structured, data-backed view of these dimensions can access the full research report for deeper dives into market splits, competitive profiles, and forward scenarios tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Industrial Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aqua Feed Market Hits $21.5B in 2025: Why 6.98% CAGR Reshapes Competition
By PW Consulting, 2026-09-21
The Aqua Feed Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global aquaculture industry has crossed a structural threshold. As marine capture fisheries approach their biological and economic limits, farmed seafood is no longer a supplementary protein source but a primary pillar of global food security. Feed represents the single largest operating cost in aquaculture, typically accounting for 50 to 70 percent of total production expenses. The trajectory of the aqua feed sector, therefore, functions as a leading indicator for the entire seafood value chain. Macro data from 2020 through the current cycle show a market that has grown from approximately 16.3 billion USD to over 21.5 billion USD at the base year, with the momentum carrying forward into a forecast period extending to 2032. The projected compound annual growth rate of 6.98 percent points to an expansion toward 34.48 billion USD by the end of the decade. This is not merely incremental growth. It reflects a recalibration of how protein is sourced, formulated, and delivered across emerging and mature markets alike.
Behind these aggregate figures lies a more complex operational reality. The sector is confronting simultaneous pressures on input costs, regulatory compliance, and biological performance. Manufacturers and buyers who treat feed as a commoditized expense are increasingly exposed to margin compression and supply volatility. Those who approach aqua nutrition as a strategic lever, integrating formulation science, supply chain resilience, and sustainability compliance, are positioning themselves to capture disproportionate value as the market matures.
Market Landscape and Core Challenges
The current size and growth profile of the aqua feed market mask significant underlying friction. The industry is operating in an environment where demand expansion is healthy, yet the cost and complexity of delivering consistent, compliant, and biologically effective feed are rising across multiple fronts.
PW Consulting
Feed Cost Volatility and Ingredient Supply Constraints
The tight linkage between aqua feed economics and marine ingredient markets has become a persistent stress test for producers. Fishmeal and fish oil supplies have experienced notable price swings, with fishmeal prices climbing by nearly 16 percent during supply shortages observed in 2025. These fluctuations are not isolated events. They are structural signals of constrained wild catch volumes, shifting allocation priorities, and the growing competition between direct human consumption and industrial feed applications.
For feed manufacturers, this volatility translates into formulation instability and margin unpredictability. For aquaculture operators, it creates uncertainty in breakeven thresholds and contract pricing. In response, the industry is accelerating the shift toward alternative protein sources, including soy derivatives, single-cell proteins, insect meals, and algae-based oils. Yet the transition is not frictionless. Nutritional equivalence, palatability, regulatory acceptance, and consistent batch quality remain practical hurdles that limit how quickly substitution can occur without compromising growth rates or feed conversion ratios.
Regulatory Pressure and Sustainability Mandates
Regulatory frameworks are progressively reshaping what it means to operate a feed mill or procure aqua nutrition. The ASC Feed Standard V1.2, released in December 2025 with mandatory effect for certified feed mills from February 2026, exemplifies the tightening trajectory. The revised standard places stronger emphasis on sustainable ingredient sourcing, traceability, and environmental impact accountability. Compliance is no longer a niche expectation tied to premium certification; it is becoming a baseline requirement for market access, export eligibility, and buyer confidence.
Beyond certification standards, national regulations are introducing specific operational constraints. Norway's 2024 Aquaculture Act limits phosphorus discharge to 45 kilograms per metric ton of fish produced, a threshold that directly pressures feed mills to increase phytase enzyme usage and adopt low-phosphorus formulations. These regulatory moves do not merely raise compliance costs. They alter formulation architecture, require process adaptation, and favor operators with technical capabilities and data infrastructure to demonstrate compliance consistently.
Biological Performance and Species-Specific Demands
Feed performance is no longer reducible to crude protein percentage and energy density alone. The industry is navigating increasingly complex biological demands as production intensifies. Shrimp and salmon operations face distinct challenges related to disease pressure, gut health, environmental stress, and growth efficiency. The margin between a formulation that merely sustains and one that actively enhances resilience can dictate whether an operation remains economically viable in high-intensity cycles.
Producers and feed suppliers are therefore under pressure to deliver functional nutrition that addresses immunity, pathogen resistance, and stress tolerance while maintaining cost competitiveness. This is particularly acute in regions where water quality variability, disease outbreaks, or rapid production scaling have historically disrupted output consistency. The challenge for the market is to balance precision nutrition with scalability, ensuring that advanced formulations can be deployed across diverse production environments without prohibitive cost premiums.
Key Drivers Shaping the Sector
Several converging forces are reshaping demand, formulation strategy, and competitive positioning across the aqua feed landscape. These drivers are not independent. They interact, creating compounding effects that reward operators with integrated capabilities and penalize those relying on static approaches.
Technological Innovation in Formulation and Functional Nutrition
Advances in enzymatic technology, functional additives, and precision supplementation are increasingly central to product differentiation. The integration of EDGEOS PhytoComplexes into next-generation shrimp feeds, as demonstrated by recent launches from Skretting, illustrates a broader shift toward formulations aimed at improving health, resilience, and sustainability rather than focusing solely on growth metrics. Similarly, BioMar's introduction of functional seabass feed solutions targeting bacterial infection resilience reflects the growing expectation that feed must contribute to disease management in high-risk production environments.
From an industry perspective, these developments signal that the next wave of value creation will be tied to biological efficacy and measurable outcomes. Enzymes that improve phosphorus availability, functional complexes that support gut integrity, and species-specific nutrient profiling are becoming competitive differentiators rather than optional enhancements. Operators who invest in formulation R&D, clinical or farm-level validation, and data-driven performance feedback loops are better positioned to command premium positioning and secure long-term buyer commitment.
Policy, Standards, and Export-Driven Compliance
Policy developments and certification standards are functioning as both constraints and catalysts. The mandatory implementation of updated feed standards, combined with nutrient discharge limits and regional environmental regulations, is compressing the timeline for compliance across producing regions. This dynamic is particularly pronounced for exporters and integrated producers who must satisfy multiple regulatory regimes simultaneously.
At the same time, policy trends are accelerating investment in traceability, ingredient transparency, and sustainable sourcing programs. The Bühler Group's partnership with Nissui to develop sustainable tuna feed for economically viable farming in Japan highlights how technology providers and producers are collaborating to align economic viability with environmental responsibility. For the broader market, this trend means that regulatory pressure is not purely a cost center. It is increasingly a gatekeeping mechanism that rewards operators who can demonstrate verifiable sustainability performance and supply chain integrity.
Demand-Side Shifts Driven by Protein Consumption and Production Localization
Consumer and corporate demand patterns are reshaping the geographic and species composition of feed consumption. The expansion of aquaculture in Asia, Latin America, and parts of Africa is creating localized feed demand that diverges from the mature salmon-centric demand profiles of Northern Europe and North America. Domestic production growth is increasingly prioritized, driven by food security objectives, import substitution strategies, and the desire to reduce exposure to global logistics volatility.
This localization trend is visible in regional capacity developments. Indonesia's aqua feed production is estimated to rise by approximately 9 percent to 1.6 million metric tons in 2025/26, supported by a recovering shrimp sector following contamination and mitigation measures. Meanwhile, capacity additions in Uganda and Indonesia by De Heus underscore how multinational and regional operators are aligning expansion with local demand growth rather than concentrating exclusively in traditional feed hubs. For the market, the implication is clear: demand is becoming more geographically dispersed and more species-diverse, requiring formulation adaptability and regional supply chain 설계가 rather than uniform global product architectures.
Cost Structure Reconfiguration and Supply Chain Adaptation
The cost structure of aqua feed is undergoing reconfiguration as ingredient substitution, logistics complexity, and regional capacity investment interact. Rising reliance on alternative proteins and the associated processing requirements can introduce new cost layers even as traditional marine ingredient exposure is reduced. At the same time, localized production can reduce freight costs and improve supply reliability, but it also demands more distributed manufacturing footprints, quality control systems, and market-specific formulation adjustments.
The net effect is that competitive advantage is increasingly determined by how efficiently an operator can manage a multi-source ingredient portfolio, maintain formulation consistency, and navigate regional cost differentials. Vertical integration in certain parts of the value chain, strategic supplier relationships, and inventory management against volatile input cycles are becoming central to margin defense. Feed manufacturers and aquaculture operators that treat supply chain design as part of their strategic architecture, rather than a back-office function, are better positioned to absorb shocks and capture availability premiums during constrained periods.
Competitive Landscape and Leading Strategies
The competitive structure of the aqua feed market reflects a blend of global scale players, specialized high-value formulators, and regionally anchored producers. Concentration is moderate, with the top three firms representing approximately 24.6 percent of market revenue and the top five accounting for about 26.2 percent. This dispersion indicates that while scale matters, category specialization, geographic presence, and formulation capability remain significant sources of differentiation.
Scale, Integration, and Portfolio Breadth
Large global suppliers have built competitive advantage through extensive manufacturing footprints, multi-species formulation capabilities, and integration across the nutrition value chain. Cargill operates approximately 20 dedicated mills and offers salmon, shrimp, and other species feeds under established brands, leveraging its broader animal nutrition platform to support scaling and distribution. Nutreco, through its Skretting brand, maintains a leading position in aquaculture feed with ongoing capacity expansions and specialized shrimp and species formulations. Within the broader Cargill portfolio, Purina Animal Nutrition LLC contributes specialized aqua feed lines that reinforce reach across species segments.
ADM approaches the market from an ingredient and formulation perspective, supporting aquaculture production with supply capabilities that tie into broader agricultural and nutrition operations. Alltech differentiates through sustainability-focused nutrition solutions, aligning product positioning with the growing buyer emphasis on environmental accountability. These scale-oriented players benefit from purchasing power, diversified species exposure, and the ability to invest across R&D and manufacturing. Their strategic challenge is maintaining agility across regions where local demand dynamics, regulatory expectations, and species-specific requirements diverge from global averages.
Specialization in High-Value and Species-Focused Segments
Beyond scale, several players compete through specialization. BioMar ranks among the top three globally in the high-value segment, with formulations tailored to salmon and shrimp and capacity growth initiatives spanning 2024 and 2025. Aller Aqua focuses on fish feeds and nutrition solutions for trout, tilapia, catfish, and shrimp, pursuing species-specific positioning rather than broad commodity coverage. Mowi illustrates an integrated producer model, running dedicated feed mills that supply more than 95 percent of its farmed salmon feed requirements, thereby aligning feed procurement tightly with production strategy and quality control.
This specialization pattern matters for market dynamics. High-value formulators can command stronger positioning where biological performance, traceability, and premium species requirements justify differentiated products. Integrated producers can reduce dependency on external suppliers and internalize formulation feedback from their own farms, accelerating performance optimization. The strategic risk for specialized players is exposure to species-specific downturns or regional production disruptions; for integrated producers, the risk is capital intensity and reduced flexibility if production plans shift.
Regional Expansion and Emerging Market Presence
A second competitive dimension is the growth of regionally focused manufacturers and multinationals extending capacity into high-growth geographies. In India, a cluster of producers including Avanti Feeds, Growel Feeds, IFB Agro Industries, Godrej Agrovet, and others serves marine and freshwater species with increasing species-specific formulation focus and sustainability orientation. Thai Union Feedmill concentrates on shrimp feed, with profit growth driven by sales momentum even as input costs pressure margins. Haid Group operates as a tier-one Chinese producer with annual aquafeed sales exceeding 5 million tonnes, demonstrating the scale that domestic demand can support.
De Heus provides a clear example of how regional expansion is being executed. The company opened a new state-of-the-art fish feed factory in Njeru, Uganda, with capacity up to 100,000 metric tons per year to support local aquaculture growth, and later inaugurated a fifth production site in Purwodadi, Central Java, Indonesia, adding significant aquafeed capacity. Ridley Corporation continues to supply aqua feeds, additives, and premixes across global markets, while Dibaq Aquaculture manufactures products for fish and shrimp in its home region. These moves highlight a competitive dynamic in which market share gains are increasingly tied to localized capacity, responsiveness to regional species demand, and the ability to support local industry development.
Strategic Trends in Competitive Evolution
Three patterns are shaping how the competitive landscape is likely to evolve. First, consolidation and partnership activity is expected to continue as scale players seek geographic reach and specialized players seek distribution strength or ingredient access. Second, differentiation is moving toward functional nutrition, sustainability credentials, and measurable performance rather than price alone. Third, new entrants and regional expansions are fragmenting demand capture in growth markets, increasing the importance of local formulation capability and service infrastructure.
For buyers and investors, this landscape suggests that supplier selection should weigh not only price and availability but also formulation adaptability, compliance readiness, and the ability to support species-specific performance. For manufacturers, the strategic question is whether to compete on breadth, depth, or regional proximity, and whether to invest in proprietary formulation assets or in scalable platform capabilities that can be adapted across species and markets.
Forward Outlook: Trends for the Next Three to Five Years
Looking ahead, several trends are likely to define the strategic contour of the aqua feed market through the middle of the next decade.
Functional nutrition and resilience-focused formulations will become more mainstream. As disease pressure, environmental variability, and intensification increase, feed products that support immunity, gut health, and pathogen resistance will move from premium niches to expected features in key species segments. Companies that can validate performance outcomes and communicate them credibly to producers will gain share in high-value categories.
Sustainable sourcing and compliance verification will increasingly determine market access. Updated feed standards, nutrient discharge limits, and buyer-driven sustainability requirements are converging into a practical baseline. Operators that invest early in traceability, alternative ingredient qualification, and low-impact formulation architectures will reduce the cost and disruption of later compliance shifts. Those that treat sustainability as an afterthought will face rising barriers to export markets and premium buyer relationships.
Geographic and species diversification of demand will accelerate, supported by localized production investment. Demand growth is not concentrated in a single region or species. Feed manufacturers that build flexible, regionally adaptable production and formulation capabilities will be better positioned to capture emerging demand, while those locked into narrow geographies or species portfolios may encounter growth ceilings or vulnerability to localized disruptions.
Insect Feed Market
These trends are accompanied by notable uncertainties. Input market volatility can persist as marine ingredient supply remains constrained and alternative protein supply chains are still scaling. Regulatory pace and scope may vary by jurisdiction, creating uneven compliance burdens and opportunities. Biological performance claims require robust validation, and the market is likely to discipline exaggerated or poorly substantiated product promises over time. Climate-related effects on raw material availability and water conditions add an additional layer of unpredictability that will test supply chain adaptability and formulation robustness.
Strategic Implications for Decision-Makers
For executives, planners, and investors operating in or adjacent to the aqua feed market, the current environment rewards proactive positioning over reactive adjustment. Several practical actions stand out.
Manufacturers and feed suppliers should prioritize formulation platforms that can incorporate alternative ingredients, functional additives, and compliance-driven adjustments without losing consistency or cost control. Investment in validation capabilities, whether through farm partnerships, trial programs, or data collection on performance outcomes, will strengthen commercial positioning in an increasingly evidence-driven buyer environment. Equally important is the design of manufacturing and sourcing networks that can flex across regions and ingredient cycles, reducing exposure to single-source volatility while maintaining quality standards.
Investors evaluating exposure to the sector should look beyond headline growth and assess differentiation durability, compliance readiness, and geographic concentration risk. Companies with credible functional nutrition assets, verifiable sourcing and sustainability programs, and a clear strategy for regional demand expansion are better equipped to sustain margins through input cycles and regulatory transitions. Portfolio attention should also be paid to species exposure, since shrimp, salmon, tilapia, and other categories face distinct biological and market dynamics that shape revenue resilience.
Aquaculture operators and procurement teams should approach feed as a strategic variable rather than a fixed cost line. Supplier selection should incorporate formulation adaptability, performance track record, and compliance alignment alongside price. Long-term supply arrangements, transparent ingredient sourcing expectations, and close feedback loops on farm-level performance can reduce risk and improve outcomes. Building internal capability to evaluate nutritional claims and align feed strategy with species goals and environmental constraints will strengthen negotiating position and operational reliability.
For all of these stakeholders, the depth and granularity of market intelligence determines how quickly and effectively they can act. Strategic decisions around capacity expansion, supplier qualification, ingredient substitution, and regional entry depend on detailed segmentation data, competitive benchmarks, and forward indicators that go well beyond top-line market size. Access to more comprehensive research can sharpen prioritization, reduce blind spots, and support more confident allocation of capital and operational resources. For those seeking a deeper, data-rich view of segment dynamics, company positioning, regional trajectories, and tailored strategic recommendations, the full PW Consulting report provides the level of detail required to translate market direction into concrete business action.
Feed + Aquafeed Market
For detailed analysis of this topic, please visit the official page: Aqua Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insurance Market 2026: How 6.8% CAGR Growth to $91.4B Redefines Regional Competition
By PW Consulting, 2026-09-21
Insurance Market Strategic Trends & Commercial Opportunities: Navigating Disruption in a Structurally Expanding Sector
1. Market Structure and Critical Crossroads
The global insurance market has demonstrated pronounced structural resilience through recent macroeconomic volatility, with total market value progressing from $47.5 billion in 2020 to $58.4 billion in 2025. The sector is now projected to compound at a steady 6.8 percent CAGR across the 2026 to 2032 forecast horizon, ultimately reaching a scale of $91.4 billion by the endpoint year. This trajectory reflects more than cyclical recovery; it signals a fundamental rewiring of how risk is quantified, priced, and distributed across commercial and personal lines.
Within this expansion, several operational and strategic challenges are actively reshaping competitive dynamics. The first centers on pricing volatility and risk reassessment in property exposures. Climate frequency, inflationary repair costs, and supply chain disruptions have forced underwriters to recalibrate actuarial assumptions at a pace that traditional core systems struggle to absorb. Carriers are confronting margin compression precisely when policyholder demand for comprehensive coverage is intensifying. The second challenge lies in technological legacy drag. Many established insurers and managing general agents still operate on fragmented policy administration and claims architectures that were designed for stable risk environments rather than dynamic, API-driven distribution. Upgrading these foundations requires meaningful capital allocation, organizational readiness, and careful vendor selection, yet delaying modernization constrains responsiveness to emerging product models. The third crosscurrent reflects regulatory scrutiny intersecting with artificial intelligence deployment. Supervisory bodies are advancing structured frameworks to evaluate algorithmic decision-making, model governance, and consumer protection in underwriting and claims triage. While these initiatives promote accountability, they also introduce compliance complexity that firms must absorb without slowing time-to-market for new coverages or digital engagement channels.
Together, these forces create a market environment where growth potential and operational risk coexist. Firms that treat pricing agility, core modernization, and responsible AI adoption as interconnected priorities rather than isolated initiatives are positioned to capture disproportionate share in the next cycle.
2. Core Drivers Reshaping the Insurance Landscape
Technological Innovation and Intelligent Core Platforms
Platform architecture has become a decisive competitive variable. Modern cloud-native and API-first policy administration solutions are replacing monolithic legacy back ends, enabling carriers and MGAs to launch products faster, integrate third-party data streams, and adjust rating logic without extensive custom development. The shift toward intelligent core platforms is evident in recent product and ecosystem movements. In late 2025, Guidewire Software released an updated platform version that incorporated enhanced underwriting and pricing capabilities, signaling a continued emphasis on equipping carriers with more granular risk evaluation modules. Around the same period, the company expanded its solution ecosystem by onboarding hundreds of partner-developed integrations, reinforcing the direction toward composable insurance technology stacks. In parallel, cloud-native providers are pushing deeper into configurable policy and claims workflows. Duck Creek Technologies used its 2026 user conference to showcase advancements in its intelligent core environment, illustrating how policy, claims, and analytics are increasingly packaged as integrated capabilities rather than standalone functions. No-code and low-code product configuration layers are also gaining traction as a mechanism to shorten launch cycles. One Denver-based platform provider has focused on enabling insurers and MGAs to assemble new product specifications without heavy engineering reliance, a model that becomes especially valuable when risk conditions shift and coverage terms must be iterated rapidly.
For decision-makers, the strategic implication is clear: technology selection is no longer a back-office procurement decision. The chosen platform determines how quickly a carrier can respond to emerging exposures, integrate alternative data for pricing, and maintain consistent customer experiences across digital channels.
Policy and Regulatory Evolution
The supervisory environment is becoming more structured and more demanding at the same time. In mid-2025, the International Association of Insurance Supervisors published an application paper on the supervision of artificial intelligence, with supervisory question banks under development to address AI use cases in insurance. This trajectory signals a move from abstract principles toward operational expectations for model governance, transparency, and risk controls in automated decision processes. At the national level, regulatory attention is also sharpening around affordability and market stability. A U.S. Treasury roundtable convened in early 2025 brought together insurance sector representatives to address homeowners insurance cost and availability challenges, highlighting how public policy pressure can influence underwriting appetite and pricing communication. Simultaneously, the National Association of Insurance Commissioners implemented a principles-based bond classification framework effective at the start of 2025, which altered risk-based capital charges for insurers and reframed how fixed-income holdings are evaluated within solvency calculations. In the terrorism insurance domain, federal register guidance set the aggregate retention amount for the 2025 marketplace at $53.366 billion, reinforcing the importance of predictable reinsurance and government backstop parameters for large-scale risk programs.
These developments do not merely create compliance tasks; they reshape product economics and operating standards. Carriers and agents that anticipate supervisory direction, particularly around AI usage and capital treatment, can avoid retrofitted compliance work and instead design processes that are auditable and adaptive from the outset.
Demand-Side Behavior and Risk Expectations
Behavioral shifts on both the commercial and consumer sides are altering how insurance is purchased and valued. Organizations are increasingly seeking coverage structures that flex with operational reality rather than static annual renewals. In health-related coverage, employer survey data for 2025 shows that 44 percent of workers at small firms with 10 to 49 employees were enrolled in self-funded or level-funded arrangements, a response to premium pressures that underscores a broader appetite for funding models with greater cost transparency and control. This pattern reflects a wider market tendency: buyers want solutions that align coverage with measurable risk profiles, provide clearer claims pathways, and integrate with broader enterprise digital workflows. At the same time, professional intermediaries are embedding AI-enabled decision support into advisory processes. Marsh introduced an AI-powered risk companion suite in 2026 designed to strengthen risk decision-making in underwriting contexts, illustrating how broker-side tools are becoming more analytical and more closely tied to client exposure conversations.
Demand momentum is therefore moving toward personalization, speed, and demonstrable value. Insurers that can present tailored coverage structures, explain pricing rationale clearly, and deliver consistent service across touchpoints are better positioned to defend retention and expand share in competitive segments.
Cost Structure and Platform Economics
Cost dynamics are influencing both carriers and service providers. Inflationary pressure on claims costs, combined with higher reinvestment and technology operating costs, is pushing firms to reexamine operating leverage. Cloud-hosted platforms, modular architectures, and ecosystem marketplaces are helping some organizations reduce bespoke integration burdens and shift spending toward configurable capabilities. Expansion of partner solution marketplaces, such as the broad integration catalog added to Guidewire’s ecosystem in mid-2025, reflects an industry-wide preference for reusable components rather than custom-built point solutions. The economic logic is straightforward: when risk volatility increases, the ability to reconfigure products, pricing, and service flows without extensive redevelopment becomes a cost-control mechanism as much as an agility advantage.
For executives, the practical takeaway is that platform economics should be evaluated over a multi-year horizon. Initial licensing or implementation cost matters, but the more decisive variable is total cost of adaptation when product lines, data sources, or regulatory expectations change.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Core Platform Providers
The competitive field is defined by a set of established platform providers, each pursuing a distinct value proposition around core administration, digital transformation, and ecosystem reach. Guidewire Software, based in San Mateo, California, continues to anchor its strategy on a comprehensive property and casualty software platform spanning policy, claims, and underwriting functions for large carriers. Its recent product and marketplace activity illustrates a dual focus: upgrading core underwriting and pricing instruments while broadening partner connectivity to extend platform utility. Duck Creek Technologies, headquartered in Boston, emphasizes an intelligent core approach for property, casualty, and general insurance with cloud-native delivery and integrated analytics, suggesting a strategic preference for unified workflows and data-informed operations. Majesco, originally based in New York, has moved to deepen its core insurance software footprint through acquisition, including the purchase of Vitech Systems Group in late 2025, a move that expanded its portfolio across policy, billing, and claims domains for property, life, and annuity carriers. Sapiens International, operating from Tel Aviv, focuses on intelligent insurance software covering policy administration, claims, and underwriting for global carriers, positioning itself as a provider for organizations that require broad functional coverage with international deployment considerations. EIS Group, located in Denver, promotes a Coretech insurance platform approach for property, life, and group insurers with an emphasis on digital transformation and high-volume operations, aligning closely with carriers seeking to modernize at scale. Applied Systems and Vertafore, both U.S.-based, concentrate on agency management and insurance platform solutions, targeting efficiency for agencies and distribution partners rather than direct carrier core administration. Socotra, based in San Francisco, emphasizes a cloud-native, API-first policy administration model oriented toward carriers, MGAs, and insurtech startups, appealing to organizations that value rapid integration and modular product construction. Instanda, also headquartered in Denver, centers its offering on no-code insurance product configuration, targeting faster product launches through visual configuration rather than heavy engineering cycles.
These positions reveal a landscape where differentiation is increasingly expressed through delivery model, ecosystem breadth, and time-to-product flexibility rather than functional coverage alone.
PW Consulting
Leadership Patterns and Differentiation
A few patterns distinguish the more assertive players. First, platform extensibility is becoming a signature capability. Providers that cultivate partner ecosystems, prebuilt integrations, and marketplace catalogs reduce the burden on individual carriers to assemble every capability in-house. Second, underwriting and pricing instrumentation is moving to the foreground. Enhancements in underwriting and pricing modules reflect a broader industry need to evaluate risk more dynamically and to support pricing decisions with richer data inputs. Third, acquisition and portfolio expansion are being used to consolidate capability across policy, billing, claims, and adjacent domains. Majesco’s acquisition of Vitech illustrates how firms are seeking broader functional reach to serve multi-line carriers and reduce fragmentation across vendor relationships. Fourth, cloud and API-first design philosophies are increasingly treated as baseline expectations rather than differentiators, with true differentiation emerging from how quickly new products can be configured, how cleanly external data can be ingested, and how effectively insights can be operationalized in workflows.
Worldwide Real Estate Insurance Market
Leaders are therefore not simply offering software; they are shaping the operating model through which insurance products are designed, priced, bound, and serviced.
Market Evolution: Consolidation, Specialization, and New Entrants
The competitive structure appears to be moving along multiple paths simultaneously. Consolidation is evident where established providers acquire complementary capabilities to serve broader carrier portfolios and reduce switching friction across lines of business. Specialization is equally visible, with some vendors concentrating on agency management, others on carrier core administration, and others on insurtech-oriented, API-first deployment patterns. New entrants and mid-tier challengers are carving out space by emphasizing no-code configuration, rapid product launches, and direct integration with modern distribution and MGA models. At the same time, the market remains relatively concentrated at the top, with the largest providers holding meaningful share, but the presence of multiple architectural philosophies suggests that future advantage will depend on fit-for-purpose selection rather than uniform dominance by a single approach. In practice, larger carriers may gravitate toward expansive platforms with strong governance and ecosystem depth, while MGAs, startups, and digitally native carriers may prefer modular, API-first environments that reduce time-to-market and integration overhead.
4. Forward Outlook: Strategic Trends and Commercial Implications
Trend One: Underwriting and Pricing Will Become More Continuous and Data-Rich
Over the next three to five years, underwriting and pricing workflows are likely to become more continuous, more data-intensive, and more tightly integrated with external signals. The direction already visible in recent platform releases and broker-side AI tools suggests that risk evaluation will increasingly rely on composable data inputs, dynamic rating logic, and decision-support layers that assist rather than replace professional judgment. Commercial opportunity here lies in products and services that help carriers ingest, validate, and operationalize alternative data sources; in tools that make rating adjustments transparent and explainable; and in advisor-enabled experiences that translate complex risk profiles into understandable coverage options. The principal uncertainty is supervisory expectation around AI-assisted decisions. Firms that build governance, documentation, and model oversight into their workflows early will be able to scale these capabilities with less friction than those that attempt retrofitting after deployment.
Travel Insurance Market
Trend Two: Core Platform Modernization Will Shift From Project to Operating Discipline
Core modernization is likely to transition from episodic replacement programs to ongoing operating discipline. As risk volatility, product experimentation, and regulatory expectations increase, organizations will need platforms that can be reconfigured without prolonged redevelopment cycles. The rise of cloud-native architectures, API-first designs, marketplace ecosystems, and no-code configuration all point toward an environment where adaptability is a recurring requirement. Commercial opportunity extends across implementation services, integration partnerships, data migration, change management, and ongoing optimization. Firms that can help carriers and MGAs manage transition while maintaining service continuity will find sustained demand. The key risk is execution complexity: integrating modern modules with existing policy, billing, and claims processes can surface data quality issues, process misalignment, and user adoption barriers that must be managed deliberately rather than assumed away.
Trend Three: Distribution and Intermediation Will Blend Digital Efficiency With Advisory Depth
Distribution models are expected to continue blending digital efficiency with deeper advisory engagement. Broker and agent workflows are becoming more analytical, with AI-supported risk companions and enhanced platform tools helping intermediaries structure recommendations and support client conversations. At the same time, buyers continue to expect faster quotes, clearer terms, and smoother service experiences. The commercial opportunity includes tools that improve agent productivity, strengthen risk advisory capabilities, and connect carrier platforms with distribution channels through cleaner data exchange and consistent service flows. A related risk is that digital speed and advisory quality can pull in different directions if platforms are not designed to support both. The most effective systems will be those that enable rapid transactional activity while preserving space for nuanced risk discussion and tailored structuring.
5. Strategic Actions for Decision-Makers
For carrier and MGA executives, the priority is to align platform strategy with risk responsiveness. Selection should be evaluated not only on functional breadth but on how quickly new products can be configured, how easily pricing logic can be adjusted, and how effectively external data and analytics can be embedded into underwriting and claims processes. Modernization roadmaps should treat integration, data quality, and user adoption as first-class concerns rather than afterthoughts, and AI-related initiatives should be paired with governance frameworks that satisfy emerging supervisory expectations.
For investors and strategic partners, the opportunity lies in distinguishing between platform providers that offer genuine extensibility and those that rely on legacy lock-in. Indicators worth monitoring include ecosystem expansion, pace of product and module releases, acquisition strategies that broaden functional reach, and the ability to serve both large carriers and more agile MGAs or insurtech entrants. Business models that depend on reusable components, marketplace connectivity, and configurable product design are better positioned to benefit from ongoing demand for agility.
For procurement and technology leaders, the focus should be on total cost of adaptation rather than initial deployment cost alone. Vendor evaluation should examine API maturity, integration pathways, configuration flexibility, and the practical effort required to onboard new data sources or modify product specifications. Where possible, organizations should favor architectures that reduce bespoke development and enable incremental enhancement, because the cost of change over a multi-year horizon often matters more than the cost of starting.
Given the speed of platform evolution, regulatory refinement, and demand-side shifts, detailed segment-level data and customized recommendations can materially improve planning quality. Readers seeking deeper segmentation detail, competitive benchmarking, and tailored action plans can explore the full PW Consulting research report for expanded figures, scenario analysis, and implementation-oriented guidance.
For detailed analysis of this topic, please visit the official page: Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stevia Extract Market 2026-2032: Why 9.85% CAGR Masks Real Regional Shifts
By PW Consulting, 2026-09-21
The Stevia Extract Market: Navigating Growth, Innovation, and Regulatory Shifts in the Sugar-Reduction Era
The global stevia extract market has evolved from a niche alternative sweetener segment into a mainstream component of the broader sugar-reduction landscape. Valued at approximately USD 215.0 million in 2025, the market expanded from USD 163.15 million in 2020, reflecting a compound annual growth rate of 9.85% projected through 2032, when revenue is expected to reach USD 410.55 million. This trajectory signals more than incremental growth; it points to a structural shift in how food and beverage manufacturers, retailers, and consumers approach sweetness formulation. As governments tighten nutritional labeling standards, health-conscious purchasing accelerates, and ingredient technologies advance, stevia extract has positioned itself at the intersection of regulatory pressure, consumer demand, and industrial innovation. Yet the path forward is not without friction. Supply chain complexities, evolving purity requirements, and taste-flavor balancing remain pivotal variables that will determine which players capture value in the coming years.
Market Landscape: Scale, Structure, and Key Challenges
The stevia extract market operates within a moderately concentrated environment. The top three companies command roughly 58% of market share, while the top five extend that footprint to approximately 72%. This concentration reflects the technical barriers to entry, the capital intensity of extraction and fermentation platforms, and the importance of long-term customer qualification cycles in food and beverage manufacturing. As a result, market expansion is increasingly shaped by established players with the capacity to invest in bioconversion, scale production, and secure regulatory approvals across multiple jurisdictions.
Despite the clear growth momentum, several structural challenges define the current inflection point. First, taste and mouthfeel remain persistent formulation hurdles. Stevia’s natural high-intensity sweetness profile can introduce bitter or licorice-like aftertastes if not carefully balanced. Manufacturers are continually seeking blends, masking technologies, and newer glycoside ratios to achieve sugar-like sensory outcomes without compromising clean-label positioning. Second, regulatory divergence across regions creates compliance overhead. Purity thresholds, labeling nomenclature, and novel food authorizations differ significantly between markets, requiring ingredient suppliers and end-product manufacturers to maintain flexible documentation strategies and region-specific formulations. Third, raw material sourcing and geopolitical tensions continue to influence cost structures and supply continuity. Intermediates, processing methods, and origin tracing can affect both pricing and market access, particularly for buyers with stringent audit requirements.
Taken together, these dynamics suggest that market growth will not simply be a function of demand volume. Instead, value capture will increasingly favor participants who can simultaneously manage sensory performance, regulatory alignment, and supply reliability.
Core Growth Drivers: Technology, Regulation, Demand, and Supply Dynamics
Technological Innovation and Glycoside Specialization
Innovation in stevia extract has shifted beyond generic leaf extraction toward precision glycoside targeting and fermentation-based production. High-purity steviol glycosides such as Reb A and Reb M are increasingly central to formulation strategies because they allow manufacturers to reduce the total amount of stevia needed while improving taste outcomes. Fermentation-derived platforms have gained particular attention for their potential to deliver consistency, scalability, and sourcing flexibility. By decoupling certain production steps from agricultural variability, fermentation routes can help stabilize supply and support higher purity specifications. At the same time, enzyme-based bioconversion approaches are being used to optimize yield and refine flavor profiles, offering a pathway to cleaner taste and better solubility in complex matrices.
For product developers, the practical implication is straightforward: stevia is no longer treated as a single-ingredient swap for sugar. It is increasingly integrated into customized sweetness systems, often combined with other natural ingredients or used in calibrated ratios to achieve target sensory profiles. This evolution expands the addressable opportunity beyond tabletop sweeteners and into beverages, bakery, confectionery, and dairy formats where taste fidelity matters most.
Policy and Regulatory Environment
Regulatory frameworks continue to shape market access and product design. In the United States, FDA Import Alert 45-06, revised in March 2025, detains leaves and crude stevia extracts unless they contain at least 95% steviol glycosides or are labeled as dietary supplements. This directive effectively raises the bar for import eligibility and reinforces the commercial relevance of high-purity extracts. In the European Union, novel food regulations for steviol glycosides impose strict purity and composition requirements, which influence both formulation choices and supplier qualification processes. Canada has also moved toward more specific labeling expectations for steviol glycosides, including the use of synonyms such as Reb M alongside approved names.
These regulatory developments carry two strategic implications. First, they reward suppliers and manufacturers with robust quality systems, traceable sourcing, and clear documentation. Second, they increase the importance of regional readiness. A formulation that performs well in one market may require adjustment elsewhere, not only for taste but also for compliance. Companies that build regulatory adaptability into their ingredient strategy can reduce time-to-market risk while improving their positioning with multinational customers.
Demand-Side Shifts in Consumer and Corporate Behavior
Consumer preference continues to tilt toward reduced-sugar and zero-calorie options, but the nature of that demand has matured. Buyers now expect clean-label ingredients, recognizable sourcing narratives, and reliable taste consistency. At the same time, corporate behavior is being reshaped by public health targets, retailer formulation goals, and internal nutrition strategies. Many food and beverage companies are setting sugar-reduction objectives that require ingredients capable of delivering sweetness without introducing new labeling complications or sacrificing shelf stability.
This environment favors stevia extracts that can be positioned as natural, functional, and compatible with broader reformulation programs. Demand is increasingly shaped by end-product performance rather than ingredient novelty alone. As a result, suppliers that can demonstrate application-level benefits—such as improved solubility, stronger flavor compatibility, or formulary flexibility—are better placed to secure long-term partnerships.
Supply Chain and Cost Structure Considerations
Supply chain resilience is becoming a decisive differentiator. Raw material availability, processing reliability, and logistics continuity all influence final cost structures and customer confidence. Recent enforcement actions related to U.S. Customs and border protections have drawn attention to the importance of ethical sourcing and origin transparency for stevia extracts from certain manufacturing hubs. While such actions affect only specific supply streams, they underscore a broader reality: importers and end-users are increasingly scrutinizing not just price, but the integrity and traceability of the entire supply chain.
In parallel, capacity expansion and platform scaling are reshaping supply dynamics for fermentation-derived and high-purity stevia ingredients. As production scales, suppliers can better support large-volume programs and reduce lead-time variability. However, scaling also introduces execution risk if quality control, process consistency, or customer qualification timelines are not managed carefully. For buyers, the opportunity lies in diversifying sourcing strategies while maintaining rigorous supplier evaluation, particularly when formulating for high-volume or highly regulated categories.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The stevia extract market is shaped by a mix of large ingredient suppliers, specialized producers, and vertically integrated companies. Each brings a distinct strategic orientation to the market, and the strongest players tend to differentiate through technology platforms, application focus, and regulatory readiness rather than price alone.
Strategic Positioning of Leading Players
Cargill has emphasized high-purity steviol glycosides and fermentation-derived stevia solutions, including its EverSweet platform, as part of a broader push into natural sugar-reduction ingredients. Its scale and customer integration capabilities make it well positioned for large-format beverage and food programs that require consistent supply and formulation support. Tate & Lyle has focused on advanced extraction and fermentation technologies, using its TASTEVA Reb M stevia extract to target clean-label natural sweetener applications where taste performance is a primary purchase driver. ADM contributes through its SweetRight stevia portfolio, which emphasizes enhanced taste profiles and sugar-reduction functionality across beverages and food applications, aligning ingredient capabilities with end-product formulation needs.
GC Life Tech has built its positioning around vertical integration, organic and non-GMO options, and seed-to-solution control. This approach appeals to buyers seeking traceability and ingredient integrity within natural or premium formulation strategies. Guilin Layn Natural Ingredients Corp. has focused on enzyme-based bioconversion for Reb M extracts, including SteviUp M2, aiming to improve solubility and deliver cleaner taste in food and beverage applications. Pyure Brands operates with a consumer- and formulation-facing brand lens, offering pure stevia extracts for zero-calorie and organic sweetener use cases, which gives it a distinct presence in segments where brand trust and label simplicity matter. Sunwin Stevia International remains active in high-purity stevia production with global distribution, supporting broad food and beverage applications through manufacturing scale and export capacity.
Recent Moves That Signal Direction
Recent product and capacity developments illustrate how competition is evolving. In June 2025, Guilin Layn introduced SteviUp M2, a Reb M stevia extract developed through enzyme-based bioconversion to improve taste cleanliness and solubility across food and beverage applications. That launch reflects a broader industry emphasis on glycoside selection and processing precision rather than generic extract quality. In May 2025, Cargill continued expanding its EverSweet fermentation-based stevia platform to strengthen supply for natural sugar-reduction solutions. This move highlights the strategic importance of fermentation as a route to scalability and consistency. Also noteworthy is the September 2024 launch by HOWTIAN Group of SoPure Dorado, an unrefined golden stevia extract designed for minimally processed clean-label applications and sugar reduction. That product signals continued interest in differentiated processing approaches that appeal to label-conscious buyers.
Worldwide Tea Tree Extract Market
Market Structure Trends: Integration, Differentiation, and Entry Risks
The market appears to be moving along two parallel tracks. On one hand, scale players are investing in fermentation, bioconversion, and application support to secure positions in high-volume categories. On the other hand, specialized producers continue to pursue differentiation through purity, taste, organic certification, and clean-label positioning. This combination suggests a market that is neither fully commoditized nor uniformly premium. Instead, it is segmenting by use case, regulatory target, and sensory requirement.
New entrants face meaningful hurdles. Qualification cycles in food and beverage manufacturing can be long, and customers often require extensive documentation, pilot testing, and consistency evidence before adopting a new stevia ingredient. Regulatory navigation across multiple markets further raises the barrier. As a result, market share shifts are likely to come less from sudden disruption and more from gradual realignment, driven by technology upgrades, supply reliability, and the ability to solve formulation problems at scale. Consolidation may continue where larger suppliers acquire capabilities that strengthen glycoside portfolios, application expertise, or geographic reach. At the same time, smaller specialized players can remain relevant if they occupy clear niches with strong technical or labeling advantages.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Higher-Purity, Application-Tailored Stevia Systems Will Become the Default
The market is likely to move further toward high-purity glycosides and application-specific sweetness systems. As fermentation and bioconversion technologies mature, suppliers should be able to offer more consistent profiles and broader formulation support. For manufacturers, this means stevia will increasingly be used as part of engineered sweetness solutions rather than as a standalone substitute. The commercial opportunity lies in matching glycoside composition, solubility, and taste behavior to the needs of specific categories such as beverages, dairy, bakery, and confectionery. The uncertainty lies in whether processing advances can consistently deliver sugar-like sensory outcomes across diverse matrices without increasing cost or complexity.
Trend 2: Regulatory Alignment Will Drive Sourcing and Labeling Strategy
Regulatory conditions will continue to influence both ingredient selection and market entry timing. Purity thresholds, labeling nomenclature, and import requirements will reward suppliers and manufacturers with strong compliance infrastructure. Over the next few years, companies that build regional regulatory readiness into their product development process are more likely to avoid reformulation delays and market access bottlenecks. The upside is clearer market access and stronger customer confidence; the risk is that divergent requirements may increase operating complexity for global portfolios, especially for smaller players with limited regulatory support resources.
PW Consulting
Trend 3: Supply Chain Integrity and Resilience Will Become Purchase Criteria
Sourcing transparency, ethical production verification, and continuity assurance are expected to become more prominent in purchasing decisions. Buyers already weigh quality and taste; they are increasingly factoring in traceability, audit readiness, and geopolitical exposure. Companies that can demonstrate robust sourcing governance and diversified production pathways will be better positioned to secure long-term contracts, particularly in high-volume or highly visible categories. The challenge is that stronger compliance and traceability requirements may raise operational costs and narrow the field of eligible suppliers, especially in price-sensitive segments.
Strategic Implications for Decision-Makers
For Food and Beverage Manufacturers
Treat stevia as a formulation system rather than a single ingredient. Prioritize partnerships with suppliers that can provide glycoside-specific options, application support, and consistency data across your target categories. Build flexibility into reformulation roadmaps so that regulatory changes or taste-performance adjustments do not force broad program delays. Where possible, pilot stevia systems in products with clear sugar-reduction goals and consumer-facing positioning, using those launches to learn about sensory thresholds, labeling implications, and customer response.
Stevia Market
For Investors and Strategic Buyers
Focus on durable competitive advantages that are difficult to replicate quickly: fermentation or bioconversion capability, glycoside portfolio breadth, regulatory readiness across key markets, and credible application-level performance. Evaluate supply chain resilience as a core value driver, not just a cost item. In a market where qualification cycles are long and compliance requirements are rising, the most attractive positions are likely those that combine technical differentiation with the operational discipline to scale responsibly. Watch for consolidation opportunities where capability gaps can be closed through acquisition or partnership.
For Procurement and Sourcing Teams
Diversify sourcing where possible while maintaining rigorous quality criteria. Evaluate suppliers not only on price but also on purity consistency, documentation strength, traceability, and capacity reliability. Establish clear specifications for glycoside content, processing method, and labeling compatibility so that sourcing decisions align with both product goals and regulatory expectations. Where supply concentration or origin risk is a concern, develop contingency pathways and validation protocols before dependence becomes a constraint.
Closing Perspective
The stevia extract market is entering a phase in which growth is increasingly tied to precision, compliance, and application performance. The numbers outline a strong demand trajectory, but the operational reality is shaped by taste engineering, regulatory divergence, and supply chain integrity. Participants that can integrate these factors into a coherent strategy will be best positioned to convert market expansion into durable advantage. For decision-makers seeking a deeper, segment-level view of pricing dynamics, regional nuances, formulation trends, and competitive scenarios, the full PW Consulting industry report provides a more granular foundation for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Stevia Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Point-to-Multipoint Microwave Backhaul: The 5.8% CAGR Shift Reshaping Network Strategies
By PW Consulting, 2026-09-21
Navigating the Point-to-Multipoint Microwave Backhaul Systems Market: Strategic Trends and Commercial Opportunities
The global point-to-multipoint microwave backhaul systems market has evolved from a niche connectivity solution into a foundational component of modern telecommunications infrastructure. Valued at approximately $143.0 million in 2020 and projected to reach $277.0 million by 2032, the market is demonstrating a consistent compound annual growth rate of 5.8 percent over the forecast period extending through 2032. This trajectory reflects a structural shift in how network operators, enterprises, and government agencies approach last-mile and middle-mile connectivity, particularly as fiber deployment faces persistent economic and geographic constraints. The market's expansion is not merely a function of incremental demand but rather the result of converging technological capabilities, regulatory recalibration, and evolving service delivery models that collectively position point-to-multipoint microwave architecture as a viable alternative or complement to traditional fixed-line transport.
Understanding this market requires recognizing that growth is unevenly distributed across use cases, frequency bands, and geographic contexts. The revenue trajectory from 2020 through the forecast horizon reveals periods of acceleration followed by recalibration, suggesting that market participants are navigating cycles of investment, technological maturation, and regulatory adjustment. Rather than treating the market as a monolithic opportunity, strategic decision-makers must examine the underlying dynamics that shape where capital will flow, which technical approaches will gain traction, and how competitive positioning is likely to evolve as incumbents and challengers alike seek to capture share in a segment characterized by moderate concentration and meaningful differentiation potential.
Market Context and Structural Realities
The current market landscape is defined by a revenue base that has grown from roughly $147.6 million in 2021 to an estimated $187.0 million in 2025, with forward projections indicating continued expansion toward the $202.01 million mark in 2026 and beyond. This growth pattern reflects a market that is past the early adoption phase and entering a period where deployment scale, operational efficiency, and integration with broader network architectures become the primary differentiators. The concentration of revenue among the top three competitors, estimated at 65.0 percent, and the top five at 78.0 percent, indicates a market where scale players hold meaningful influence, yet the remaining share distribution leaves room for specialized entrants, regional specialists, and technology-focused innovators to compete on performance, cost structure, or deployment flexibility rather than pure volume.
A defining characteristic of the market is the divergence between established licensed-band deployments and emerging higher-frequency approaches that promise greater capacity but introduce new planning, environmental, and interference management requirements. This divergence is not simply a technical choice; it reflects a broader tension between reliability and scalability, between capital efficiency and future-proofing, and between standardized deployment models and customized solutions tailored to specific terrain, density, and service-level requirements. Organizations operating in this space must therefore balance near-term deployment practicality with longer-term bandwidth demands, particularly as 5G densification, fixed wireless access expansion, and enterprise private network initiatives place additional load on backhaul infrastructure that was originally designed for lower-throughput voice and data transport.
Key Challenges and Inflection Points
Several structural challenges are reshaping how participants approach the market and where value is likely to be captured. First, the tension between spectrum availability and deployment density remains a persistent constraint. As demand for higher throughput increases, operators must navigate the trade-offs inherent in lower-frequency bands, which offer broader coverage and better penetration but limited capacity, versus higher-frequency bands that deliver greater bandwidth but require more precise line-of-sight planning, finer site selection, and more rigorous interference management. This tension is not resolving toward a single optimal band; instead, it is driving a more layered approach where different frequency ranges serve distinct roles within the same network architecture, requiring integrated planning capabilities and flexible hardware platforms.
Second, the market is experiencing a shift in total cost of ownership calculations as fiber expansion continues in certain regions while remaining economically unviable in others. Microwave backhaul is no longer evaluated solely as a fallback option; in many scenarios, it is being assessed as a primary transport choice where deployment speed, terrain complexity, or rights-of-way constraints make fiber impractical. However, this shift demands that microwave solutions demonstrate not only competitive bandwidth but also operational reliability, manageability, and integration with packet-switched network architectures. Providers that continue to position microwave backhaul as a legacy or secondary technology risk losing relevance as customers evaluate total network economics rather than per-link cost alone.
Third, the competitive environment is being reshaped by the entry of players with distinct technological pedigrees and by the consolidation of capabilities within larger telecommunications equipment portfolios. Companies with deep roots in microwave transmission are expanding into software-defined management, higher-frequency mmWave platforms, and integrated small-cell backhaul solutions, while telecommunications infrastructure leaders are embedding microwave backhaul into broader 5G transport strategies. This convergence is increasing the bar for differentiation, as customers increasingly expect unified support models, interoperable management interfaces, and solutions that scale across heterogeneous network environments rather than standalone point solutions.
Core Demand Drivers Shaping the Market
The market's trajectory is being propelled by a combination of technological innovation, regulatory evolution, demand-side behavior changes, and supply-side cost dynamics. Each driver interacts with the others, creating a reinforcing cycle that expands the addressable use cases for point-to-multipoint microwave architecture while simultaneously raising the expectations of end users and network integrators.
Technological innovation in radio design, spectrum utilization, and packet-processing architecture is central to the market's expansion. Multi-gigabit point-to-multipoint platforms have moved from concept to commercial deployment, enabling a single hub site to serve multiple remote endpoints with higher aggregate throughput and more efficient spectrum use. These platforms increasingly incorporate adaptive modulation, advanced antenna configurations, and integrated packet optimization features that reduce the operational burden of managing interference, capacity allocation, and service quality across distributed nodes. The emergence of solutions that support simultaneous multi-band transmission from a single antenna represents a notable shift in hub-site design, allowing operators to consolidate equipment, reduce site complexity, and improve capacity utilization without sacrificing flexibility across frequency ranges. Such capabilities are particularly relevant for 5G small-cell backhaul, where the density of connection points demands transport solutions that are both compact and capable of handling heterogeneous traffic patterns.
Worldwide Wireless Communication Systems Market
Regulatory and policy developments are reinforcing the market's growth by creating clearer pathways for licensed spectrum access and by acknowledging the role of point-to-multipoint microwave in both commercial telecom and enterprise networking. In certain markets, regulatory bodies have issued recommendations or established frameworks that explicitly recognize the importance of microwave backhaul for network expansion, setting the stage for more predictable licensing processes and greater deployment confidence. These regulatory signals are particularly impactful in regions where spectrum assignment has historically been fragmented or where enterprises and operators have faced uncertainty about long-term access to appropriate frequency bands. At the same time, standards organizations and regulatory agencies in other regions have advanced approaches that enable dynamic spectrum access and regional licensing models, providing deployment flexibility that aligns with the operational realities of point-to-multipoint architectures. The cumulative effect is a regulatory environment that, in many jurisdictions, is becoming more conducive to investment in microwave backhaul as a legitimate transport layer rather than a temporary workaround.
Demand-side changes are equally significant. Telecom operators are under pressure to expand 5G coverage and capacity while managing capital expenditure, which has renewed interest in microwave backhaul for small-cell densification, rural coverage extension, and rapid network rollout scenarios where fiber timelines are incompatible with service launch targets. Enterprise demand is also evolving, with organizations seeking private network solutions, branch connectivity, and industrial communications that require reliable transport without the lead times and civil works associated with fiber deployment. Government and public-sector applications further broaden the demand base, as agencies deploy surveillance networks, emergency communications infrastructure, and remote operations support that rely on flexible, quickly deployable backhaul. The common thread across these demand segments is the need for transport that balances bandwidth, speed of deployment, and operational manageability, a balance that point-to-multipoint microwave systems are increasingly positioned to deliver.
Supply-side dynamics are shaping the market through evolving cost structures, component availability, and the competitive implications of manufacturing and integration strategies. The cost of deploying microwave backhaul relative to fiber varies significantly by geography, terrain, and density, but the broader trend is one of improving economics for microwave as hardware platforms mature, software optimization reduces operational overhead, and standardized components lower procurement complexity. At the same time, supply chain considerations remain relevant, as equipment manufacturers navigate component sourcing, regional production requirements, and the need to support diverse frequency plans across different regulatory environments. Companies that can offer predictable lead times, regional support, and flexible configuration options are better positioned to capture demand in markets where deployment certainty is as important as technical performance.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established microwave specialists, telecommunications infrastructure leaders, and regional or application-focused players, each pursuing different forms of differentiation. The market's moderate concentration suggests that incumbents hold meaningful share, but it also indicates that the space is not so dominated that new approaches or niche expertise cannot achieve traction. Competitive advantage is increasingly determined by the ability to combine hardware performance with deployment practicality, integration readiness, and support models that match the operational expectations of telecom operators, enterprises, and government customers.
Companies with deep specialization in point-to-multipoint microwave backhaul are emphasizing product families that span licensed and unlicensed spectrum, support both urban and rural deployment scenarios, and align with 5G small-cell and fixed-wireless use cases. These players often compete on the basis of throughput scalability, spectral efficiency, and the ability to serve a wide range of endpoint densities from a single hub architecture. Their strategic positioning tends to center on reliability in diverse environments, flexibility across frequency bands, and practical deployment features that reduce planning complexity. By maintaining portfolios that address both carrier-grade and enterprise-grade requirements, such companies aim to capture demand across multiple segments while leveraging their domain expertise as a barrier to entry for less specialized competitors.
Larger telecommunications equipment vendors are approaching the market from a different angle, integrating microwave backhaul into broader 5G transport portfolios and emphasizing interoperability, network-level manageability, and alignment with their wider infrastructure ecosystems. For these players, point-to-multipoint microwave is often part of a larger narrative about end-to-end network evolution, where backhaul choices must fit within standardized operating models, support automated provisioning, and integrate with core and RAN architectures. Their differentiation frequently comes from the ability to offer a unified support relationship, global deployment experience, and solutions that scale across multiple network generations and geographic markets. In some cases, these vendors have introduced hub-site solutions that consolidate multi-band transmission or emphasize high-capacity licensed-band performance, signaling a focus on scenarios where capacity and operational simplicity are paramount.
Regional and application-focused participants are carving out position by emphasizing specific deployment contexts, such as dense urban mmWave backhaul, rural carrier-grade connectivity, or enterprise and government networks that require modular, quickly deployable systems. These companies often compete on agility, specialized antenna or radio designs, and close alignment with local regulatory and spectrum conditions. Their growth strategies may rely on strong partnerships with system integrators, tailored configuration options, and the ability to adapt to local spectrum assignments and terrain challenges. In markets where local knowledge and rapid deployment matter as much as headline throughput, such positioning can be highly effective, particularly when combined with product families that support both licensed and unlicensed spectrum or offer modular upgrade paths.
Recent developments illustrate how these competitive strategies are being executed in practice. One major vendor introduced a point-to-multipoint solution designed to enable simultaneous multi-band transmission from a single antenna for hub-site 5G backhaul, a move that directly addresses site complexity and capacity flexibility. Another specialist unveiled a new multi-gigabit point-to-multipoint backhaul platform aimed at both urban and rural 5G deployments, reinforcing the industry's focus on scalable throughput across diverse environments. In parallel, a strategic partnership between a major infrastructure vendor and a large African operator highlighted the continued relevance of microwave backhaul network upgrades in support of 5G capacity expansion, underscoring how commercial deployment decisions are being made in real operating contexts rather than in isolation. These events collectively suggest a market where product innovation, partnership-driven deployment, and ecosystem alignment are all contributing to competitive momentum.
PW Consulting
Evolving Market Structure and Entry Dynamics
The market's structure appears likely to continue evolving along multiple axes. Integration is occurring as larger infrastructure providers incorporate microwave backhaul more deeply into their 5G transport narratives, while specialization persists among companies that compete on narrowband flexibility, mmWave performance, or targeted vertical applications. At the same time, the entry of new players or the repositioning of existing ones remains possible, particularly where innovative spectrum utilization, cost-efficient hardware design, or software-centric management creates a compelling value proposition for specific customer segments. The practical outcome is a landscape where no single model dominates; rather, different competitive approaches coexist, and success depends on matching product and go-to-market strategy to the expectations of distinct buyer groups.
Macrocell Baseband Unit Market
For buyers, this means that evaluation criteria are expanding beyond raw throughput to include deployment speed, interference management capabilities, management integration, support availability, and long-term upgrade paths. For vendors, it means that differentiation must be credible across the full lifecycle of a deployment, from initial site planning through ongoing operations and eventual capacity expansion. The companies that navigate this environment most effectively are likely to be those that can articulate a clear technical and operational value proposition, support it with demonstrable deployments, and sustain it through consistent product evolution and regional execution.
Forward-Looking Trends and Strategic Implications
Looking ahead across the next three to five years, several trends are likely to shape how the market develops and where commercial opportunity emerges. First, multi-band and higher-frequency point-to-multipoint architectures will become more mainstream as operators seek to balance coverage, capacity, and site efficiency. The practical implication is that vendors and integrators who can design, provision, and manage heterogeneous frequency deployments within a unified operational framework will be better positioned to capture demand from networks that must serve both dense urban small-cell clusters and broader rural coverage areas. This trend favors platforms that are flexible enough to adapt to different spectrum assignments while maintaining consistent management and service quality across bands.
Second, the integration of microwave backhaul with software-driven network management and automation is likely to accelerate, as operators look to reduce the operational burden of scaling distributed backhaul networks. Expect greater emphasis on centralized provisioning, dynamic capacity allocation, interference monitoring, and integration with broader transport orchestration tools. For commercial players, this creates opportunities to differentiate through operational simplicity and service assurance rather than hardware specifications alone. Organizations that can demonstrate measurable reductions in deployment time, operational overhead, or fault-resolution cycles will have a stronger value proposition in markets where labor, expertise, and operational continuity are significant cost drivers.
Third, regional regulatory clarity and spectrum planning will continue to influence where and how quickly point-to-multipoint microwave deployments scale. Markets that provide predictable licensing pathways, clear frequency assignments, and flexibility for both telecom and enterprise use cases are likely to see faster adoption, while regions with fragmented or uncertain spectrum frameworks may experience slower investment despite strong technical demand. The strategic implication is that market participants should pay close attention to regulatory trajectories in their target geographies, as these trajectories can materially affect addressable demand, deployment economics, and the relative attractiveness of different frequency plans.
These trends also point to potential risks and uncertainties. Spectrum congestion and interference management will remain challenging as more point-to-multipoint systems operate in overlapping or adjacent bands, particularly in dense environments. Economic conditions may influence capital expenditure timing for both telecom operators and enterprises, affecting deployment velocity even when technical demand is strong. Additionally, the ongoing comparison with fiber and emerging alternative transport technologies means that microwave backhaul must continue to demonstrate not only competitive performance but also credible total cost of ownership and integration advantages. Participants that assume static demand or treat microwave as a mature, low-change segment risk underestimating the operational and strategic shifts that are reshaping buyer expectations.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority should be to invest in platform flexibility and operational integration rather than competing solely on headline capacity. This means developing product portfolios that can address multiple frequency ranges and deployment scenarios, supporting software-defined management and automation features that reduce operator burden, and building regional execution capabilities that make deployment predictable across diverse regulatory environments. Differentiation will increasingly come from how easily a solution fits into a customer's broader network operations, how quickly it can be deployed and scaled, and how confidently it can be supported over time. Companies that align their product roadmap with these operational realities are more likely to capture sustained demand across telecom, enterprise, and government segments.
For investors, the opportunity lies in identifying players with credible technical differentiation, clear deployment traction in target regions, and business models that can scale as point-to-multipoint microwave becomes more embedded in 5G and enterprise connectivity strategies. Due diligence should focus on spectrum strategy, regulatory alignment in key markets, the ability to compete across both licensed and unlicensed contexts where relevant, and the strength of partnerships with operators and system integrators. Equally important is assessing whether a company's differentiation is durable in the face of consolidation, standards evolution, and increasing customer expectations around manageability and service assurance. Companies that can demonstrate repeatable deployment models and a clear path to operational value are better positioned to benefit from the market's continued expansion.
For procurement teams and network operators, the strategic emphasis should be on evaluating point-to-multipoint microwave solutions within the context of total network architecture and long-term service requirements rather than as isolated links. This includes assessing how well a solution supports multi-band or higher-frequency expansion paths, how it integrates with existing transport and management systems, and how deployment economics compare not only with fiber but also with the operational costs of scaling and maintaining distributed backhaul over time. Procurement decisions should account for regional spectrum conditions, site planning complexity, and the availability of support and integration expertise, as these factors often determine whether a technically sound solution translates into reliable operational performance. Engaging with detailed market intelligence that maps vendor capabilities, regulatory developments, and regional deployment patterns can help procurement teams make more informed sourcing and architecture decisions.
For organizations seeking a deeper understanding of how these trends translate into specific segment dynamics, vendor benchmarking, and regional opportunity assessment, a more granular view of the market can support more precise planning. Detailed segmentation data, competitive profiling, and scenario-based insights can help decision-makers move from general strategic direction to targeted action, whether that involves prioritizing specific frequency strategies, evaluating regional expansion opportunities, or refining procurement criteria in line with evolving buyer expectations.
The point-to-multipoint microwave backhaul systems market is entering a phase where growth is sustained not by a single driver but by a combination of technological maturation, regulatory support, and expanding demand across telecom, enterprise, and government applications. The organizations that will capture the most value are those that can align product strategy with operational realities, respond to regional spectrum and regulatory conditions, and position their solutions as integral components of modern transport networks rather than as standalone hardware purchases. As deployment patterns continue to evolve, timely and detailed market intelligence will remain an essential input for strategic planning, investment decisions, and procurement execution.
For detailed analysis of this topic, please visit the official page: Point-to-Multipoint Microwave Backhaul Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Battery Separator Films Market
Market Landscape: Navigating Scale and Structural Complexity
The battery separator films market is entering a phase of accelerated maturation, defined by steady revenue expansion and a hardening of competitive dynamics. Over the historical period from 2020 to 2025, industry revenue climbed from roughly $163.15 million to $215.0 million, reflecting a trajectory that survived macroeconomic volatility and supply chain disruptions. The forward outlook reinforces this momentum, with the market projected to reach $344.8 million by 2032, translating to a compound annual growth rate of 6.98 percent across the 2026 to 2032 forecast window. This growth profile signals more than incremental demand expansion; it points to a structural realignment in how energy storage components are manufactured, sourced, and integrated into global electrification strategies.
Within this expansion lies a concentration profile that remains relatively fragmented at the top. The top three players account for 24.6 percent of market revenue, while the top five capture 26.2 percent. Such figures indicate that no single manufacturer commands pricing power sufficient to dictate industry-wide terms, yet the gap between tier-one specialists and regional challengers is widening. This dynamic creates a bifurcated environment: established suppliers are investing heavily in process superiority, geographic diversification, and coating technologies, while smaller participants must either carve out highly specialized niches or risk being squeezed by capacity overhangs and cost compression.
The current market posture reflects several unavoidable inflection points. First, the push toward localized battery production, particularly in North America and select Asian corridors, is reshaping traditional sourcing models. Buyers increasingly prioritize supply assurance and regulatory alignment over lowest unit cost, forcing suppliers to make irreversible capacity commitments. Second, the technical ceiling for conventional polyolefin architectures is approaching in certain high-power and high-safety applications, prompting parallel development tracks for coated membranes, ceramic-reinforced designs, and ultra-thin structures that balance ionic conductivity with mechanical robustness. Third, raw material conditions for polyethylene and polypropylene feedstocks remain exposed to energy price swings and logistics constraints. This volatility complicates margin planning, especially for manufacturers that lack integrated resin supply or long-term hedging agreements.
For decision makers, the implication is straightforward: the separator market is no longer a commodity layer within the battery value chain. It is a strategic component where process technology, geographic positioning, and coating differentiation determine long-term contract viability and margin resilience.
Core Drivers Reshaping Demand and Supply Dynamics
Technology Innovation and Process Differentiation
Technological advancement remains the primary engine of competitive separation in this market. Wet-process and dry-process polyolefin routes each present distinct trade-offs in pore architecture, thickness control, mechanical strength, and throughput economics. Wet-process films typically offer tighter control over micropore structure and uniformity, attributes that matter for consistent electrochemical performance in lithium-ion cells. Dry-process films, in contrast, often provide higher throughput and lower processing complexity, which becomes attractive where scale and cost efficiency dominate procurement criteria.
The industry’s most active design frontier is coating technology. Ceramic-coated and polymer-coated variants improve thermal stability, wettability, and resistance to shrinkage under elevated temperatures, addressing safety concerns that intensify as cell energy densities rise. Ultra-thin coated structures are also gaining attention because they enable energy density gains without proportionate losses in puncture resistance or dimensional integrity. Recent operational developments underscore the momentum behind these directions. In July 2025, Microporous introduced a new ultra-thin coated wet-process polyethylene separator line at its Piney Flats, Tennessee facility, expanding the practical range of thin-film options in North American supply. Similarly, W-SCOPE doubled its lithium-ion separator output capacity in May 2025 through a major Chungju plant expansion, reinforcing the link between process scaling and the availability of coated and microporous membrane options for high-volume applications.
For manufacturers, the strategic takeaway is that innovation is shifting from base film production alone to integrated film-plus-coating value creation. Companies that can coordinate resin selection, pore engineering, and coating consistency on the same line gain an advantage in qualification cycles and customer lock-in.
Policy and Regulatory Pressure on Supply Chain Localization
Policy frameworks are increasingly shaping investment logic rather than simply constraining operations. The United States has emerged as a notable example of how financing and content requirements converge to redirect capacity placement. A $1.2 billion direct loan from the U.S. Department of Energy supported ENTEK’s Terre Haute, Indiana lithium-ion battery separator facility, an intervention designed to strengthen domestic EV supply chains and reduce reliance on imported components. The facility reached full-scale operations in October 2025, marking a concrete step in localized capacity deployment.
Parallel federal and regional incentives tied to Inflation Reduction Act content requirements are reinforcing the localization theme. Procurement teams in automotive and energy storage programs are evaluating component origins with greater scrutiny, and separator sourcing now intersects with broader battery content eligibility calculations. This environment rewards manufacturers that can demonstrate not only product performance but also traceability, domestic or near-shore production, and the ability to scale under regulatory timelines. Sumitomo Chemical’s restructuring of its PERVIO® separator business illustrates a different but related dimension of policy-linked optimization. By ceasing production at its Ohe Works in Japan and consolidating functions at its South Korean SSLM facility by the end of March 2026, the company signaled a move toward higher productivity and a more concentrated regional operating model, showing that regulatory and cost pressures can drive production footprints even among established players.
The commercial implication for buyers and investors is that local supply narrative is becoming a material procurement factor. Capacity located in jurisdictions that align with incentive programs and content rules can secure preferential access to anchor contracts, while foreign-supply-dependent models may face increased qualification friction.
Demand-Side Transformation in Electrification and Storage
Demand growth is no longer solely a function of passenger EV volume. Energy storage systems, commercial electrification, and advanced consumer applications are expanding the addressable base for separator films, and the composition of that demand is changing the technical requirements placed on suppliers. North American manufacturing capacity expansions accelerated in 2025 and 2026 as EV and energy storage system growth drove lithium-ion battery separator demand, reflecting a broader shift toward regionalized production for regionalized demand.
PW Consulting
This demand mix introduces new performance priorities. Higher cycle-life expectations, wider operating temperature ranges, and more demanding safety thresholds are pushing specifications beyond baseline polyolefin performance. Asahi Kasei’s October 2025 strategic agreement with Toyota Tsusho for North American supply of Hipore wet-process lithium-ion battery separators shows how tier-one manufacturers are aligning product lines with regional channel partners to meet localized demand at scale. UBE MAXELL’s planned 50 percent increase in separator base film production capacity at its Sakai Works in Japan, announced in May 2026, reflects a similar bet that sustained EV and energy storage demand will justify expanded base film output.
The operational lesson is that demand growth is increasingly segmented by application intensity. Suppliers that can match film architecture to specific use cases, whether high-power transport, stationary storage, or specialty electronics, will capture more defensible positions than those competing primarily on volume alone.
Cost Structure and Raw Material Sensitivity
Even with strong demand, cost structure remains a decisive factor in margin durability. Polyethylene and polypropylene feedstocks used in battery separator films experienced volatility in 2025 due to oil price fluctuations and supply chain factors. Because polyolefin chemistry sits close to petrochemical feedstock markets, separator producers are exposed to price movements that are only partially controllable through internal procurement tactics.
In this context, cost leadership is less about chasing commodity input prices and more about reducing conversion losses, improving line yield, extending film life in service, and differentiating with coatings that justify premium pricing. Capacity expansions also change the cost equation: as new lines come online and utilization rises, fixed-cost absorption improves, but only if demand can absorb additional volume without triggering aggressive price competition. ENTEK’s completion of its first major U.S. separator production expansion in Terre Haute, Indiana demonstrates how capacity deployment can be timed to align with regional demand growth, but the long-term profitability of such investments depends on sustained offtake and disciplined pricing.
For executives, the practical implication is that raw material sensitivity should be managed through product strategy as much as procurement strategy. Coating differentiation, qualification moats, and application-specific film design can buffer businesses from the full force of resin price swings.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field is anchored by a set of manufacturers with distinct technological heritage, geographic reach, and product architectures. Asahi Kasei Corporation, based in Tokyo, produces Hipore wet-process polyethylene and Celgard dry-process polypropylene battery separator films for lithium-ion batteries, giving it a broad platform across processing routes. Toray Industries, also headquartered in Tokyo, manufactures Setela coated and uncoated polyethylene and polypropylene separator films for EV and energy storage applications, with an emphasis on functional coating in addition to base film. SK Innovation, in Seoul, develops ceramic-coated and non-coated polyolefin separator films with enhanced safety, aligning its product narrative with risk mitigation for lithium-ion systems.
In China, SEM CORP, based in Jiaxing, operates as a global supplier of lithium-ion battery separator films including coated and uncoated polyolefin options, combining scale with multi-format capability. W-SCOPE, headquartered in Chungju, produces microporous and coated lithium-ion battery separator membranes using polymer film technology, and its May 2025 capacity doubling illustrates how regional champions can rapidly expand output to support EV and storage demand. In the United States, ENTEK International, based in Lebanon, Oregon, manufactures wet-process polyethylene and coated lithium-ion separator films for EV and energy storage, while Microporous LLC, in Danville, Virginia, produces ionForce coated wet-process polyethylene separator films, with the July 2025 launch of its ultra-thin coated line in Piney Flats, Tennessee further extending thin-film capability.
European participation remains meaningful. Freudenberg Performance Materials, headquartered in Weinheim, Germany, supplies innovative separator materials for lithium-ion batteries and energy storage systems, bringing material science depth to the field. UBE Corporation, in Tokyo, produces battery separator base films and related polyolefin materials for lithium-ion applications, emphasizing base film supply and upstream material linkage. Ahlstrom Oyj, in Helsinki, develops separator materials including absorbent glass mat and polyolefin films, positioning around materials versatility and specialized substrate engineering.
The strategic positioning emerging from this landscape favors several differentiation paths. One is process leadership in wet-process uniformity and thinner film architectures, where qualification success can create durable customer relationships. Another is coating capability, where thermal stability, safety performance, and wetting behavior become decision criteria beyond base film thickness. A third is geography-aligned supply, where manufacturers that can serve regional content requirements and local production programs gain preferential access to anchor accounts. A fourth is vertical relevance, where base film producers that integrate with polyolefin supply or downstream coating operations reduce exposure to intermediate market inefficiencies.
Market structure appears to be evolving through selective consolidation and capacity realignment rather than uniform concentration. Sumitomo Chemical’s closure of its Ohe Works and consolidation of PERVIO® production at SSLM in South Korea reflects a productivity-focused rationalization. At the same time, the expansion cadence of companies such as W-SCOPE, ENTEK, and UBE MAXELL suggests that new capacity continues to enter where demand visibility is strongest. The result is a competitive environment in which technology and regional supply alignment matter more than sheer scale, and where new entrants must either bring a distinct coating or process advantage or target underserved regional demand with credible execution capability.
Forward Trajectory: Three Directional Shifts and the Opportunities They Create
Over the next three to five years, the separator market is likely to be shaped by three interrelated trends. The first is the widening premium for coated and safety-enhanced architectures. As cell formats evolve and energy density targets rise, buyers will increasingly select membranes that reduce risk under thermal and mechanical stress. This does not eliminate demand for uncoated base films, but it shifts the value mix toward coated variants and makes coating consistency a qualification gate. Commercial opportunity lies with producers that can standardize coating quality at scale and document performance in ways that simplify customer validation.
Lithium-Ion Battery Separator Market
The second trend is regional capacity alignment as a competitive asset. Local production is becoming tied to content eligibility, supply assurance, and logistics resilience, especially in markets where incentive programs and industrial policy reward domestic manufacturing. The opportunity here is dual-edged: established suppliers can lock in multi-year supply relationships by co-locating with customer programs, while regional entrants can build defensible positions if they achieve process reliability and cost discipline quickly enough. The risk is that capacity is brought online ahead of demand absorption, creating localized overcapacity and forcing price concessions.
The third trend is ongoing raw material and energy cost sensitivity, which will keep pressuring conversion economics. Feedstock volatility is unlikely to disappear entirely, and separator manufacturers will continue to face decisions about resin sourcing, hedging, and process efficiency. The strategic opportunity is to design products that earn price resilience through function rather than volume. Ultra-thin films, ceramic-coated variants, and application-tailored membrane designs can offset input cost pressure if they are validated for performance and safety in high-value applications. The risk, by contrast, is that undifferentiated commodity competition intensifies when multiple producers chase the same conventional film specifications.
A further nuance is that qualification cycles and customer switching costs can either accelerate or dampen these trends. In applications where validation timelines are long and failure costs are high, suppliers with established testing records and reproducible process control can maintain share even in a growing market. In more price-sensitive segments, however, rapid capacity entry and cost competition can compress margins and reward only the leanest operators. Understanding which applications fall into each category is essential for realistic forecasting and capital planning.
Strategic Actions for Decision Makers
For manufacturers, the priority is to connect process capability with qualification speed and regional relevance. Investments in coating consistency, thickness control, and line yield should be evaluated not just for cost reduction but for their ability to shorten customer validation and support premium positioning. Where capacity expansion is contemplated, alignment with end-market demand visibility and regulatory or content incentives should be treated as a core part of the investment thesis, not a peripheral consideration. Companies should also assess whether base film production, coating, or both are most defensible in their target segments, because the margin story increasingly depends on integrated capability rather than single-step output.
For investors, the market rewards disciplined capital allocation tied to application intensity and supply localization rather than headline volume growth alone. The strongest opportunities lie where technology differentiation, coating capability, and regional production alignment converge, particularly in jurisdictions where energy storage and EV programs are expanding under incentive frameworks. Due diligence should focus on utilization trajectories, feedstock exposure, qualification pipelines, and the durability of supply agreements. Equally important is the risk of overbuilt regional capacity and the possibility that raw material volatility erodes margins for producers without differentiated product mixes.
For procurement and supply chain leaders, separator sourcing should be treated as a performance-and-assurance decision rather than a commodity purchase. Evaluating suppliers on coated film consistency, thermal and mechanical performance documentation, domestic or near-shore production capability, and the ability to scale under program timelines can reduce downstream risk in cell and pack programs. Diversifying the supplier base between wet-process and dry-process options, and between coated and non-coated variants where appropriate, can also improve resilience against feedstock volatility and capacity constraints. Contract structures that link pricing to validated performance and supply assurance, rather than to spot input conditions alone, may offer more stable economics over multi-year program horizons.
Worldwide Polyolefin Battery Separator Films Market
The range of possible outcomes in this market remains wide, and the margin between success and delay often comes down to the speed and precision of strategic decisions. Detailed segment-level sizing, application-specific demand mapping, regional capacity tracking, and company-level positioning data provide the granularity needed to convert these directional trends into executable plans. Readers seeking that level of detail, including deeper segmentation and customized strategic guidance, can explore the full PW Consulting research report for the Battery Separator Films Market.
For detailed analysis of this topic, please visit the official page: Battery Separator Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Energy Management System Market: Why 8.27% CAGR 2026-2032 Changes Everything
By PW Consulting, 2026-09-21
The Industrial Energy Management System (IEMS) Market: Navigating Growth, Technology Disruption, and Strategic Imperatives
Market Landscape and Structural Challenges
The industrial energy management system (IEMS) market has entered a phase of accelerated maturation, driven by converging pressures around operational efficiency, regulatory compliance, and digital transformation. Over the past five years, the market has expanded from approximately $25.0 billion in 2020 to $35.2 billion in 2025, reflecting a compounded annual growth rate of 8.27% across the 2026-2032 forecast horizon. By the end of the forecast period, revenue is projected to approach $61.85 billion, signaling a structural shift from incremental efficiency upgrades to comprehensive, data-driven energy governance across industrial operations.
This trajectory reflects more than sustained capital expenditure; it indicates a fundamental reorientation of how industrial enterprises conceptualize energy. Historically treated as an overhead cost to be minimized through isolated equipment upgrades, energy is increasingly positioned as a managed asset with real-time visibility, predictive control, and measurable return on investment. The market’s expansion is broad-based across regions and applications, with industrial manufacturing, oil and gas, and petrochemical operations representing the largest deployment bases. Hardware continues to form the largest revenue component, reflecting the ongoing need for metering infrastructure, control systems, and integration layers, while software and service segments are growing faster as organizations seek actionable analytics and ongoing optimization support.
Despite this momentum, the market faces three structural challenges that will shape deployment patterns and vendor positioning over the next several years. First, fragmentation in system architectures and data standards continues to raise integration complexity. Industrial facilities often operate across legacy control environments, distributed utility interfaces, and heterogeneous equipment fleets. Deploying an IEMS that delivers enterprise-wide visibility without disrupting production cycles requires significant engineering effort, change management, and cross-functional alignment.
Second, the value proposition of energy management is increasingly tied to broader operational outcomes rather than energy savings alone. Decision-makers are evaluating IEMS investments against production throughput, asset reliability, emissions compliance, and resilience to volatile power markets. Systems that cannot demonstrate multi-dimensional ROI risk slower adoption, especially in capital-constrained environments or facilities with shorter investment horizons.
Third, the regulatory environment is tightening at both global and regional levels, but compliance requirements are evolving unevenly. Industrial operators must navigate a patchwork of efficiency mandates, reporting obligations, and emissions-related incentives that differ by jurisdiction and sector. While this regulatory pressure expands the addressable market, it also introduces execution risk for organizations that lack internal expertise to translate compliance mandates into operational programs.
These challenges are not barriers to growth; they are filters. They favor deployments that combine robust hardware foundations with flexible software, clear integration pathways, and services that help organizations move from data collection to measurable performance improvement.
Key Drivers Reshaping the Market
Technology Innovation and the Shift Toward Intelligent Energy Control
The most significant technological driver is the convergence of industrial automation, Internet of Things (IoT) connectivity, and advanced analytics. Modern IEMS solutions increasingly rely on high-resolution metering, edge processing, and cloud-based analytics to convert raw consumption data into operational insight. This shift enables real-time monitoring, anomaly detection, load forecasting, and optimization recommendations that were previously impractical in complex industrial environments.
Recent product and organizational moves reflect this trajectory. Emerson’s relocation to a new global headquarters in Clayton, Missouri, in February 2026 underscores a broader emphasis on industrial automation capabilities, including IEMS-linked process optimization and energy efficiency systems. The move signals not only investment in physical infrastructure but also a strategic focus on integrated automation and energy management as complementary domains. Similarly, Rockwell Automation’s energy monitoring and optimization tools within its industrial software portfolio illustrate how energy visibility is being embedded into existing automation ecosystems rather than treated as a standalone initiative.
On the software side, AI-enabled energy management is emerging as a differentiator. Tibo Energy’s €6 million funding round in May 2025 highlights growing investor interest in AI-driven energy optimization for industrial grid congestion and multi-site coordination. This funding dynamic suggests that next-generation IEMS offerings are moving beyond static dashboards toward predictive control, demand response enablement, and cost-reduction logic that can adapt to variable grid conditions and operational constraints. Start-ups and specialized software providers are increasingly competing on algorithmic sophistication, user experience, and deployment speed, pressuring larger incumbents to accelerate their own software-centric roadmaps.
Policy, Standards, and the Compliance-to-Strategy Transition
Policy and standards activity is both expanding demand and reshaping purchase criteria. The EU Energy Efficiency Directive continues to require industrial facilities to implement energy management systems with regular reporting on consumption and efficiency improvements. In parallel, the U.S. Energy Policy Act reinforces energy management practices in industrial settings, aligning efficiency objectives with broader sustainability goals. These frameworks create a compliance floor, but the most strategically advantaged operators are treating them as a starting point for deeper operational transformation.
ISO 50001 remains a widely adopted reference point for systematic energy performance improvement. Its influence extends beyond certification; it encourages organizations to establish measurement architectures, target-setting processes, and continuous improvement cycles that naturally align with IEMS deployments. At the same time, Paris Agreement implementation efforts are intensifying carbon-related taxes and incentives, particularly in manufacturing-intensive sectors. This creates a direct financial linkage between energy management and emissions outcomes, making IEMS solutions relevant not only to facility engineering teams but also to sustainability, finance, and executive leadership.
PW Consulting Chemical & Energy Research Center
Regional building and industrial codes are also contributing to demand. The California Energy Code’s 2025 updates aim to reduce industrial energy costs through mandatory efficiency measures and monitoring, illustrating how subnational policy can accelerate adoption in specific industrial clusters. Collectively, these regulatory and standards-driven dynamics are moving IEMS from optional best practice toward operational necessity in many markets.
Demand-Side Behavior and the Broadening Buyer Profile
A second major driver is the evolution of buyer expectations. Energy managers no longer evaluate IEMS purely on metering accuracy or report generation. Procurement and operations leaders increasingly prioritize interoperability with existing control systems, scalability across sites, and the ability to connect energy data with production scheduling, maintenance, and asset performance management. This broadens the stakeholder base around IEMS purchases and raises the bar for usability and integration.
In oil and gas and petrochemical operations, energy management is increasingly intertwined with process reliability and safety-critical control environments. Manufacturing buyers, meanwhile, are looking for systems that can support demand response participation, load shifting, and cost avoidance under volatile electricity pricing. As industrial organizations adopt more distributed energy resources and explore electrification of processes, the need for dynamic energy management becomes more acute. The result is a market where IEMS is evaluated not only as a compliance or efficiency tool but also as an enabler of operational flexibility.
Supply Chain and Cost Structure Dynamics
Supply chain conditions and cost structures continue to influence deployment economics. Hardware-heavy installations remain sensitive to component availability, procurement lead times, and integration labor. At the same time, the growing emphasis on software and services is shifting some spending toward recurring models, which can improve vendor revenue visibility but also increases buyer expectations for measurable outcomes over time. Organizations that can offer modular deployment pathways, standardized integration frameworks, and clear service-level commitments are better positioned to navigate these cost and supply chain realities.
For end users, the cost equation is increasingly framed around total cost of ownership and operational payback rather than upfront capital. This favors solutions that can be phased in across facilities, demonstrate early wins through focused use cases, and scale without proportional increases in project complexity.
Competitive Landscape and Strategic Positioning
Incumbents Anchoring the Market with Integrated Automation and Power Expertise
The IEMS market remains comparatively concentrated, with a limited number of large players commanding a substantial share of revenue. This concentration reflects the importance of scale, integration credibility, and longstanding relationships in industrial automation and power management.ABB continues to build on its industrial automation and power management heritage, emphasizing energy monitoring, optimization, and efficiency systems suited to manufacturing and heavy industry. Its positioning benefits from the ability to connect energy management with broader electrification and automation portfolios, which is particularly relevant for operators seeking a single vendorarrative across control, distribution, and monitoring functions.
Eaton’s focus on power management and electrical systems gives it a strong foothold in environments where energy optimization must align with electrical infrastructure and industrial power quality requirements. Emerson, through its automation and control capabilities, positions IEMS as part of a wider process optimization agenda, which can be attractive in complex manufacturing and process industries where energy outcomes are tightly linked to production parameters.
Siemens and Schneider Electric represent two of the most visible platforms plays in this space. Siemens leverages its digital industries and automation strengths to offer IoT-based energy optimization platforms that connect plant-level data with broader enterprise analytics. Schneider Electric’s EcoStruxure concept exemplifies an architecture-centric approach that combines energy management, automation, and connected services. Both companies benefit from global reach, broad industrial footprints, and the ability to package IEMS within larger digital transformation narratives.
Honeywell and General Electric also occupy important positions. Honeywell’s building and industrial automation platforms extend into energy efficiency and management for facilities, while GE’s industrial solutions and automation background supports energy management for process and manufacturing industries. Their presence reinforces the market’s emphasis on vendors that can bridge operational technology and energy performance management.
Automation Specialists and the Embedding of Energy Visibility
Rockwell Automation illustrates a strategic path that integrates energy monitoring directly into manufacturing software environments. By offering tools such as real-time energy monitoring and optimization within its factory software ecosystem, Rockwell reduces the friction of adding energy intelligence to existing production workflows. This embedded approach can shorten adoption cycles for manufacturers already standardized on its automation stack.
Building Energy Management System (BEMS) Market
Cisco’s relevance in the IEMS market may appear less obvious at first glance, but its networking and IoT capabilities underpin many industrial data infrastructures. As energy management becomes more data-intensive and distributed, reliable connectivity, edge networking, and secure data transport become critical enablers. Cisco’s positioning therefore reflects an ecosystem play: it supports energy management platforms and analytics by strengthening the underlying data fabric across industrial sites.
Specialists, Software-First Providers, and the Rise of Niche Differentiation
The market also includes a meaningful set of specialists and software-oriented entrants. EnerNOC, now operating under Enel X North America, has historically been associated with demand response and energy management services for commercial and industrial customers. Its service-oriented model highlights the continued importance of managed energy programs, particularly for organizations that prefer outsourced expertise or want to participate in grid-related revenue opportunities.
Worldwide Power Energy Management System (EMS) Market
Yokogawa, Azbil, and Mitsubishi Electric bring strong measurement, control, and automation expertise, particularly relevant in process industries where precise instrumentation and control logic are essential. Azbil’s headquarters relocation to Tokyo’s Marunouchi Park Building in November 2025 reflects a continued organizational focus on industrial automation and energy management offerings, signaling commitment to evolving its portfolio in a competitive environment.
On the software side, providers such as explitia, Tibo Energy, Prescient Technologies, and MRI Software illustrate the diversity of modern IEMS offerings. explitia’s EMS software emphasizes real-time monitoring, cost control, and process optimization in manufacturing. Tibo Energy’s AI-driven EMS targets real-time optimization and grid management for industrial sites. Prescient Technologies’ IIoT-based monitoring and analysis system is oriented toward manufacturing plants, while MRI Software’s energy platform addresses portfolio-wide consumption monitoring, optimization, and compliance. These players often compete on agility, user experience, and specialized analytics capabilities rather than on breadth of hardware portfolios.
How the Competitive Structure Is Evolving
The competitive landscape is not static. Large incumbents continue to strengthen their integration advantages and expand through product consolidation, services, and platform development. At the same time, software-first and specialist companies are gaining traction by addressing specific pain points: faster deployment, more intuitive dashboards, AI-based optimization, or superior multi-site coordination. IEM (Industrial Electric Manufacturing) adds another dimension with custom power distribution systems and energy management solutions tailored to industrial clients, reflecting demand for engineered solutions in specific application contexts.
This dynamic suggests a market that is simultaneously consolidating at the top and fragmenting in niche segments. Buyers benefit from choice, but they also face an increasingly complex evaluation process. Vendors that succeed are likely to be those that can articulate a clear value pathway: whether through deep integration with automation and electrical systems, superior analytics and optimization, strong service models, or rapid deployment in targeted verticals.
Future Outlook: Three Trends That Will Shape the Next 3–5 Years
1. From Monitoring to Autonomous Optimization
The next wave of IEMS adoption will be defined less by the ability to measure energy and more by the ability to act on it automatically. As analytics mature and industrial data environments become more connected, systems will increasingly support closed-loop optimization, predictive load management, and coordinated control across equipment and sites. For operators, this creates opportunities to reduce waste, improve scheduling, and participate more actively in demand-side flexibility. For vendors, competitive advantage will increasingly depend on the quality of algorithms, the reliability of recommendations, and the ease with which operators can trust and operationalize automated decisions.
The commercial opportunity here is substantial, but so is the execution risk. Autonomous optimization requires robust data quality, well-defined operational boundaries, and change management that aligns energy logic with production priorities. Organizations that deploy these capabilities prematurely, without sufficient process discipline or integration depth, may struggle to realize expected returns.
2. Energy Management as a Multisite, Portfolio-Level Discipline
Industrial enterprises are increasingly managing energy across multiple facilities, regions, and operating models. This is driving demand for portfolio-level visibility, standardized reporting, and centralized optimization that still respects local constraints. MRI Software’s focus on portfolio-wide monitoring and optimization reflects this broader shift. As organizations expand their use of IEMS beyond single plants, they will need architectures that can normalize data across sites, accommodate different equipment baselines, and support both strategic benchmarking and local action.
This trend opens opportunities for platforms that can scale without excessive customization. It also introduces complexity around governance, data ownership, and localization of compliance requirements. Multisite deployments will favor vendors that can balance standardization with flexibility, and that can provide services to help operators interpret enterprise-level insights in facility-specific terms.
3. Integration with Decarbonization, Electrification, and Grid Interaction
Energy management is becoming more tightly coupled with decarbonization strategy, electrification roadmaps, and grid interaction. Carbon-related policy pressure, regional efficiency mandates, and the financial implications of emissions performance are pushing industrial operators to treat energy data as a strategic input for sustainability planning. At the same time, the growing presence of distributed energy resources, storage, and electrification of industrial processes will increase the need for real-time coordination between energy consumption, on-site generation, and external grid signals.
This creates a market opportunity around IEMS solutions that can support emissions tracking, scenario analysis, and flexible load management. It also raises the stakes for integration: energy management platforms will need to interface not only with traditional industrial control systems but also with sustainability reporting workflows, electrical asset management, and increasingly dynamic power markets. The principal uncertainty is the pace and shape of policy and market evolution, which may differ significantly across regions and could influence which capabilities become essential first.
Strategic Implications for Decision-Makers
For Industrial Operators and Manufacturers
Energy management should be treated as an operational capability, not a one-time compliance project. The most effective deployments begin with a clear use-case strategy: identify where energy visibility can immediately improve cost control, production scheduling, asset reliability, or emissions reporting. Prioritize integration with existing automation and electrical systems to avoid creating parallel data silos. Where possible, adopt modular rollouts that deliver early value and build organizational confidence before scaling across sites.
Leadership alignment is critical. IEMS investments are more likely to succeed when energy, operations, maintenance, and sustainability teams share a common set of metrics and decisions. Establish a governance model that connects data collection to action, and ensure that optimization recommendations are validated against production and safety constraints.
For Investors and Strategic Partners
The market offers multiple entry points, but not all are equal in risk and reward. Large incumbents provide scale, integration breadth, and established industrial relationships, which can translate into more predictable demand in automation-heavy environments. Software-first and specialist providers may offer faster growth in niche segments, particularly where AI-driven optimization, multisite platforms, or service-based models address clear inefficiencies. When evaluating opportunities, pay close attention to differentiation in data architecture, integration capability, and the ability to convert insights into measurable operational outcomes.
It is also worth monitoring consolidation signals. As the market matures, firms that can combine hardware credibility, software sophistication, and services depth may be better positioned to capture share across the full deployment lifecycle. Conversely, players that remain overly fragmented or limited to narrow functionality may face pressure to partner, specialize further, or exit less competitive segments.
For Procurement and Technology Selection Teams
Evaluation criteria should extend beyond feature checklists. Assess how easily a solution integrates with current control and metering environments, how it handles data quality issues, and whether it supports the specific operational decisions your organization needs to make. Ask how the vendor handles multisite scaling, update cycles, and ongoing services, since these often determine long-term value more than initial deployment speed. Where possible, structure pilots around measurable operational outcomes rather than technical demonstrations alone.
Given the pace of regulatory change and the growing importance of energy optimization in industrial competitiveness, timely access to detailed market intelligence can materially improve decision quality. Segmentation trends, vendor positioning, regional regulation, and technology adoption patterns all influence which solutions are most appropriate for a given operating context. For organizations evaluating market entry, capital allocation, or vendor selection, a deeper review of segment-level data and tailored scenarios can help convert broad market momentum into a focused execution plan.
The IEMS market is moving from a period of broad growth to one of sharper strategic differentiation. The organizations that benefit most will be those that treat energy management as a core operational capability, select partners with clear integration and optimization depth, and build the internal discipline to turn data into action. As deployment models mature and software-driven optimization becomes more central, the gap between basic monitoring and genuinely managed energy performance will widen, creating both risk for laggards and opportunity for those who move with intent.
For detailed analysis of this topic, please visit the official page: Industrial Energy Management System (IEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com