

Blogs
Mercury Analyzer Market: Why 6.58% CAGR and Environmental Monitoring Reshape Growth
By PW Consulting, 2026-09-21
Navigating the Mercury Analyzer Market: Strategic Trends and Commercial Opportunities in an Era of Shifting Compliance
The global mercury analyzer market stands at a critical inflection point. As of 2025, the sector commands a total revenue base of approximately USD 353.78 million, having grown from USD 258.75 million in 2020. The market is projected to reach USD 551.95 million by 2032, reflecting a compound annual growth rate of 6.58 percent over the 2026–2032 forecast horizon. This trajectory signals more than steady demand; it reflects a structural recalibration driven by tightening environmental mandates, evolving pharmaceutical quality standards, and a growing emphasis on real-time trace-element detection across industrial and regulatory workflows.
Behind these headline figures lies a market that is moderately concentrated yet highly fragmented in terms of application needs and technological preferences. The top three players account for roughly 52.3 percent of revenue, while the top five capture 78.5 percent, indicating that scale advantages and established certification footprints matter, but niche specialization and regional compliance alignment continue to create room for focused competitors. The commercial landscape rewards organizations that can pair detection reliability with regulatory readiness, deployment flexibility, and total-cost-of-ownership clarity.
1. Market Landscape and Core Challenges
The mercury analyzer market has evolved from a compliance-driven, laboratory-centric procurement category into a broader instrumentation domain spanning continuous emissions monitoring, food safety screening, petrochemical process control, and pharmaceutical impurity testing. Revenue expansion over the 2020–2025 period was propelled by sustained investment in environmental monitoring networks, incremental replacement of aging analytical systems, and rising adoption of automated sample-handling workflows that reduce operator dependency. The forecast period extends this momentum, but the growth path is no longer uniform across regions or end-use segments.
Three core challenges define the current operating environment and will shape how companies position themselves over the next several years.
- Regulatory divergence creates a two-speed demand environment. While certain jurisdictions are reinforcing mercury emission limits and expanding monitoring requirements for waste incineration and coal-fired facilities, other markets have pulled back or deferred stricter standards. This divergence means that demand growth is increasingly conditional on local policy trajectories rather than global harmonization. Manufacturers and buyers alike must navigate uneven compliance calendars, which complicates capacity planning, product roadmaps, and aftermarket service models.
- Technology trade-offs between sensitivity, portability, and total cost of ownership. End users increasingly weigh detection limits and method robustness against deployment complexity, maintenance burden, and workforce training requirements. Laboratory-grade systems offer high precision and automation, while portable and field-deployable platforms expand reach but can introduce trade-offs in throughput, calibration stability, or consumables usage. The challenge for suppliers is to deliver demonstrable performance without inflating operating costs, and for buyers to match instrument class to actual monitoring frequency and compliance risk.
- Supply chain and consumables dependency in trace analysis. Mercury analysis at trace levels relies on specialized reagents, calibration standards, gold-based trapping components, and tightly controlled sample introduction workflows. Volatility in component availability, reagent pricing, and service-part lead times can affect uptime and operating budgets. In addition, buyers are increasingly scrutinizing vendor lock-in risks, particularly where proprietary sample preparation or consumables are tied to instrument performance claims.
These challenges are not barriers to growth so much as filters that separate reactive suppliers from strategically positioned ones. Organizations that anticipate regulatory variability, design for serviceability, and articulate clear operating economics are better placed to capture share in a market where purchasing decisions are increasingly tied to risk management rather than unit price alone.
2. Key Demand Drivers
Technological Innovation and Breakthroughs
Advances in atomic absorption and fluorescence detection architectures continue to shape purchasing decisions. Cold vapor atomic absorption systems remain the dominant product segment, favored for their combination of sensitivity, automation potential, and cost-effectiveness in routine laboratory and continuous emissions monitoring applications. At the same time, cold vapor atomic fluorescence techniques are gaining attention where ultra-trace detection and reduced interferences are prioritized, particularly in specialized environmental and research settings.
The broader technology story is less about a single breakthrough and more about convergence: improved vaporization control, better background correction, more robust software workflows, and greater integration with sample preparation and data management systems. These improvements reduce manual intervention, support audit-ready records, and make it easier for labs and field teams to standardize methods across sites. For suppliers, differentiation increasingly comes from workflow completeness, not just detector performance.
Moisture Analyzer Market
Policy and Regulatory Environment
Regulatory dynamics remain the most powerful driver of instrument demand, but they are also the most uneven. Tightening global mercury-emission limits under the revised EU Industrial Emissions Directive and China’s GB 13223-2011 standard are accelerating demand for real-time mercury detection in waste incinerators and coal plants. In parallel, Minamata Convention ratification and enforcement in Europe, China, and Japan sustain instrument replacement cycles across regulated facilities, as existing systems age and compliance expectations rise.
At the same time, the US EPA’s 2026 repeal of strengthened Mercury and Air Toxics Standards creates a two-speed growth trajectory, with slowed coal-utility upgrades in North America relative to regions where emission limits continue to tighten. This divergence does not eliminate demand in North America; it rebalances it toward other applications, including environmental monitoring programs, industrial hygiene, and non-coal emission sources. For decision makers, the implication is that regulatory exposure must be mapped at the jurisdiction and facility level rather than assumed from regional averages.
Demand-Side Shifts in Customer Behavior
Demand is broadening beyond traditional environmental laboratories. Pharmaceutical quality-control laboratories face long-term demand signals from ICH Q3D elemental-impurity limits, which require trace mercury analysis as part of broader contamination-control programs. Food industry stakeholders continue to invest in screening and verification workflows for mercury in seafood and other high-risk matrices, driven by both regulatory scrutiny and brand-protection considerations. In the oil, gas, and petrochemical sector, mercury monitoring supports catalyst protection, process integrity, and emissions management, creating demand for both laboratory and process-adjacent measurement solutions.
A notable behavioral shift is the growing preference for solutions that reduce method variability and documentation burden. Procurement teams are increasingly evaluating vendors on certification alignment, method compatibility, and the ability to support multi-site consistency, not solely on instrument price. This shift favors suppliers that can demonstrate regulatory readiness and repeatable performance across diverse sample types.
Supply Chain and Cost Structure Evolution
Cost structures in the mercury analyzer market are being reshaped by the interplay of instrument durability, consumables intensity, and service-model design. Buyers are paying closer attention to total cost of ownership, including calibration frequency, replacement-part availability, reagent consumption, and the cost of downtime during critical compliance windows. Suppliers that offer modular service designs, longer calibration intervals, or more efficient sample-introduction pathways can gain an edge, especially in operations where labor and throughput are constrained.
Recent commercial activity reinforces this focus on practical deployment and user enablement. Lumex Instruments has continued to invest in user-facing engagement, including plans to exhibit at analytica 2026 in Munich and the delivery of a RA-915-Series mercury analyzer technical training course in Chile in late 2025. These moves reflect a broader industry pattern in which manufacturers extend their reach through demonstrations, training, and localized support rather than relying on specification sheets alone. Nippon Instruments Corporation’s September 2025 contract with the US Geological Survey for delivery of a MA-1001 Model MA-2000 Mercury Analyzer also illustrates how public-sector and specialized research procurement can validate platform credibility and create reference-value effects in adjacent markets.
3. Competitive Landscape and Leading Strategies
The competitive field combines established multinational instrument manufacturers with specialized players that have built strong positions around specific detection methods, application segments, or regulatory certifications. The market’s moderate concentration suggests that incumbency matters, but it does not guarantee dominance across all use cases. Instead, competitive advantage tends to emerge from alignment between technology choice, compliance documentation, service reach, and application expertise.
PW Consulting
Several strategic positioning patterns are visible among leading participants.
Water Quality Analyzer Market
- Method-specialized leadership. Companies that concentrate on cold vapor atomic absorption or cold vapor atomic fluorescence platforms often compete on method familiarity, certification alignment, and repeatability across routine analyses. This focus can make it easier for laboratories and monitoring programs to standardize methods and train operators, especially where regulatory methods are well established.
- Portable and field-deployable strength. Portable mercury analyzers and vapor monitors appeal to environmental field teams, industrial hygiene programs, and rapid-screening applications. In this segment, differentiation often comes from ruggedization, battery or transport logistics, ease of calibration, and the ability to deliver defensible results outside controlled laboratory conditions.
- Continuous monitoring and compliance-oriented platforms. Suppliers offering continuous mercury emissions monitoring systems and ultra-trace industrial analyzers target facilities where compliance reporting and process visibility depend on sustained measurement rather than periodic sampling. Here, value is tied to integration with plant data systems, service availability, and the ability to withstand demanding emission environments.
- Broad-platform and ecosystem positioning. Larger scientific-instrument manufacturers can leverage wider analytical portfolios, service networks, and software ecosystems to provide mercury analysis as part of integrated testing programs. This approach can be attractive to organizations that prefer consolidated vendor relationships, standardized data workflows, and cross-application support.
Specific company footprints illustrate these patterns. Lumex Instruments emphasizes Zeeman atomic absorption mercury analyzers such as the RA-915M series and portable Light 915 models, positioning around field and laboratory flexibility. Mercury Instruments GmbH focuses on portable mercury analyzers, vapor monitors, and process instruments for environmental and industrial applications, aligning with on-site monitoring needs. Teledyne Leeman Labs offers laboratory and environmental elemental analysis solutions such as Hydra II and QuickTrace systems, appealing to organizations that require trace metal analysis within broader environmental testing workflows. ENVEA GmbH provides continuous mercury CEMS monitoring and ultra-trace industrial analyzers for emissions compliance, targeting regulated facility operators. Nippon Instruments Corporation supplies direct mercury analyzers and series designed for regulatory compliance applications, including models commonly associated with standardized elemental analysis workflows. Thermo Fisher Scientific Inc. offers stack emissions monitoring solutions for coal-fired and waste incinerator applications, reinforcing a compliance-oriented industrial position. PerkinElmer Inc. integrates mercury analysis systems into atomic spectroscopy and environmental testing platforms, supporting laboratories that value broader spectroscopic ecosystems. Brooks Rand Instruments emphasizes advanced mercury analyzers and speciation systems certified to US EPA methods, an appealing differentiator for customers whose compliance requirements are closely tied to recognized regulatory methods.
How the Landscape Is Evolving
Three evolutionary themes are shaping the market’s trajectory. First, consolidation pressure is likely to persist among suppliers seeking to expand service coverage, strengthen regulatory documentation, or acquire application-specific expertise. Second, differentiation is moving toward application readiness, including method certification support, software integration, and service-level assurance, rather than detector specifications alone. Third, new entrants and niche specialists can still gain footholds by targeting underserved applications, regional compliance needs, or particular sample matrices where existing platforms create friction.
For buyers, this environment rewards structured vendor evaluation. The most attractive suppliers are not necessarily those with the broadest portfolios; they are those that can demonstrate reliable performance in the specific compliance context, sample type, and operating environment that matter most to the buyer. For suppliers, the strategic imperative is to reduce friction in procurement, installation, training, and ongoing compliance support, because these factors increasingly determine repeat business and reference value.
4. Forward Trends and the Opportunities They Create
A More Jurisdiction-Specific Demand Map
Over the next three to five years, demand is likely to become more explicitly mapped to jurisdiction-specific compliance calendars and facility-level risk profiles. In regions where emission limits continue to tighten, continuous monitoring upgrades and replacement cycles should remain robust. In markets where regulatory momentum has slowed, demand may shift toward environmental monitoring programs, pharmaceutical impurity testing, food safety verification, and non-coal industrial sources. This pattern creates an opportunity for organizations that can flex their commercial messaging and deployment models by region and application, rather than relying on a single growth narrative.
The associated risk is that policy reversals or compliance delays can compress near-term demand in specific segments, particularly where capital planning has been tied to anticipated regulatory changes. Companies that depend heavily on a narrow set of regulated end-users may experience more volatile order pipelines than those with diversified application exposure.
Workflow Integration as a Commercial Differentiator
Instrument performance will remain essential, but commercial advantage will increasingly depend on how well mercury analysis fits into broader laboratory or plant workflows. Expectations are rising around method standardization, data traceability, automated reporting, and compatibility with existing quality systems. Solutions that reduce manual steps, simplify audit preparation, and support multi-site consistency will be better positioned to win in procurement environments where total cost of ownership and operational risk are weighed alongside detection limits.
This trend favors suppliers that invest in software usability, service documentation, training, and integration support. It also creates opportunities for partnerships with organizations that can bundle analytical capability with sample handling, data management, or compliance consulting. The risk is that buyers may become more intolerant of platforms that require significant customization or ongoing specialist intervention to produce compliant results.
Expansion of Portable, Field, and Ultra-Trace Use Cases
Demand for portable and field-deployable mercury measurement is likely to continue expanding where rapid screening, incident response, site characterization, and distributed monitoring are priorities. At the same time, ultra-trace analysis will remain important in applications where low detection limits and interference management determine acceptability. The commercial opportunity lies in matching instrument class to use case with clarity, so that buyers avoid over-specifying laboratory systems for field needs or under-specifying field tools for compliance-grade monitoring.
A related opportunity is service-led growth. As installed bases age and regulatory expectations rise, aftermarket support, calibration services, training, and replacement-part availability become more strategic. Suppliers that build credible service models can create recurring revenue streams and deepen customer relationships, particularly in markets where compliance downtime carries meaningful financial or reputational consequences. The main uncertainty is that service expectations are rising faster than some organizations can scale trained personnel and parts logistics, which could create gaps that better-organized competitors are able to exploit.
5. Strategic Actions for Decision Makers
The mercury analyzer market offers genuine growth potential, but the most valuable opportunities will go to organizations that act with clarity about where compliance, technology, and operational reality intersect. The following actions can help different stakeholder groups translate market dynamics into practical decisions.
For Manufacturers and Suppliers
- Align product roadmaps with the applications most likely to see sustained demand, including environmental monitoring, pharmaceutical impurity control, food safety screening, and industrial emissions compliance, rather than betting primarily on a single regulatory storyline.
- Strengthen differentiation through workflow completeness: method documentation, training, service availability, calibration practicality, and integration with customer data systems. These factors increasingly influence repeat purchase and reference adoption.
- Plan for regional variability in compliance momentum by building flexible deployment models, localized support capabilities, and clear messaging for both laboratory and field-use scenarios.
For Investors and Corporate Development Teams
- Evaluate exposure not just by market size, but by end-use mix and regulatory sensitivity. Diversified application portfolios may provide more stable growth than heavy dependence on a narrow set of compliance-driven customers.
- Pay attention to service and consumables economics, as these often determine long-term margin durability and customer retention in trace-analysis instrumentation.
- Look for value creation in companies that combine credible method alignment with strong user enablement, because these attributes can support pricing power and installation momentum in a moderately concentrated market.
For Procurement and Operational Leaders
- Match instrument selection to the actual compliance context, sample matrix, and monitoring frequency rather than to generic performance claims. Over-specification can raise costs without improving compliance outcomes, while under-specification can create audit or operational risk.
- Evaluate total cost of ownership holistically, including calibration demands, consumables, service response times, training burden, and the operational impact of downtime during critical monitoring periods.
- Prioritize vendors that can demonstrate method compatibility, certification alignment, and consistent multi-site performance, especially where standardized reporting and audit readiness are important.
The market’s next phase will reward organizations that treat mercury analysis as part of a broader compliance and operational strategy rather than as a standalone equipment purchase. Detailed segmentation data, application-level demand patterns, and company-specific positioning can materially improve planning quality, particularly when decisions involve multi-year capital allocation, service-model design, or market-entry choices. For teams that need a deeper factual base before committing resources, a full market research report can provide the granular breakdown and structured scenario detail that high-stakes decisions warrant.
For detailed analysis of this topic, please visit the official page: Mercury Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Dental 3D Printer Market’s 6.98% CAGR and Orthodontics Boom Redefine Growth Beyond 2032
By PW Consulting, 2026-09-21
The Dental 3D Printer Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The dental 3D printing market has evolved from a niche prototyping tool into a core component of digital dentistry workflows. Valued at approximately 98.45 million USD in 2020, the sector reached 143.76 million USD by 2025, reflecting a compound annual growth rate of 6.98 percent through 2032. This trajectory is not merely a function of printer adoption; it signals a structural shift in how dental laboratories, clinics, and manufacturing partners approach restorations, surgical planning, and orthodontic appliances. The expansion is broad-based, yet concentrated enough that strategic positioning matters significantly for players navigating the next cycle.
Several inflection points define the current environment. First, the transition from laboratory-centric production to chairside and direct-clinical workflows is accelerating, but infrastructure readiness varies widely. Many practices are still integrating intraoral scanning, design software, and post-processing into cohesive pipelines, creating both friction and whitespace for integrated solutions. Second, material validation and regulatory clearance remain gatekeepers to clinical adoption. Not all resins or printing protocols achieve the mechanical, biocompatibility, or long-term performance thresholds required for permanent or semi-permanent restorations, which means technology adoption is often paced by regulatory milestones rather than hardware availability alone. Third, the industry is grappling with fragmentation in workflow compatibility. Printer manufacturers, material suppliers, design platforms, and milling or post-curing partners do not always align on open standards, creating integration costs that can slow decision-making for laboratories evaluating capital investment.
These challenges are not insurmountable, but they do shape where growth will materialize first. Markets that already support digital restoration reimbursement frameworks are seeing faster uptake, while regions still building clinical and laboratory digital literacy are likely to follow a more stepwise adoption curve. The implication for decision-makers is clear: the market's headline numbers mask uneven readiness across workflows, materials, and geographies, and the winners will be those who reduce integration friction while aligning with regulatory and clinical validation pathways.
Key Drivers Reshaping the Market
Technology Innovation and Material Advancements
Hardware innovation continues to raise the bar on speed, resolution, and repeatability, but the more consequential shifts are occurring in materials and process integration. High-precision stereolithography and digital light processing platforms are becoming more accessible, and the emergence of direct-print aligner systems and jetted denture solutions demonstrates that the industry is moving beyond models and temporary appliances toward permanent and semi-permanent restorative applications. The commercial availability of FDA-cleared resins for flexible removable partial dentures, alongside clearances for multi-material monolithic dentures and fixed hybrid dentures, illustrates how material science is expanding the clinical envelope. For manufacturers, these developments open new use cases; for laboratories and clinics, they reduce the need for multi-step hybrid workflows that combine printing with milling or manual fabrication.
Regulatory and Reimbursement Dynamics
Regulatory clearance is increasingly a bottleneck and a competitive moat. Several resin and system-level clearances in recent years have enabled broader clinical use cases, including temporary crowns, bridges, veneers, surgical guides, and certain denture applications. These approvals do more than validate safety and performance; they shape purchasing confidence and procurement cycles. When a material or workflow carries recognized clearance, laboratories and dental practices face fewer clinical and liability concerns, and procurement teams can justify capital expenditure with clearer clinical rationale. At the same time, reimbursement frameworks in leading markets are beginning to better accommodate digital restorations and appliance production, which strengthens the economic case for in-house or near-site production. The interplay between clearance velocity and reimbursement clarity will influence regional uptake patterns and the pace at which new applications move from pilot to routine use.
Demand-Side Behavioral Changes
Demand is being reshaped by both clinical expectations and operational economics. Patients and providers increasingly expect faster turnaround, improved fit, and more aesthetic outcomes, particularly in orthodontics and restorative cases. At the same time, dental laboratories and group practices are under pressure to manage labor constraints, reduce remake rates, and improve margin stability. Digital workflows that consolidate design, printing, and post-processing can address these pressures by standardizing outputs and reducing dependence on highly variable manual steps. The orthodontic segment, in particular, continues to show strong pull for aligner and appliance production, while implantology and prosthodontics are expanding as surgical guide and restoration workflows become more reproducible. The net effect is a demand environment that rewards speed, consistency, and clinical validation over novelty alone.
Supply Chain and Cost Structure Evolution
Cost structures are shifting as printer reliability improves, material libraries expand, and post-processing becomes more standardized. Lower total cost of ownership is enabling smaller laboratories and group practices to evaluate in-house production that previously made less economic sense. At the same time, supply chain considerations around material availability, resin formulation consistency, and servicing have become more salient. Buyers are increasingly sensitive not just to printer price but to the reliability of material supply, the breadth of validated materials, and the ease of workflow integration. This is tilting competitive advantage toward providers that can offer stable material portfolios, clear validation documentation, and support ecosystems that reduce downtime and rework.
Competitive Landscape and Leading Strategies
The competitive field blends established hardware and materials players with specialized dental-focused providers, each pursuing different angles of differentiation. Some competitors emphasize chairside accessibility and closed workflows tailored to clinical settings, while others focus on laboratory-grade precision, open material ecosystems, or multi-material capabilities for complex restorations. The divergence in strategy is intentional: dental 3D printing is not a single use case, and the companies gaining traction are those aligning their hardware, materials, and workflow support with specific clinical or laboratory priorities.
A notable pattern is the convergence of hardware, material validation, and workflow automation. Providers that can offer FDA-cleared resins for specific applications, paired with printers designed for those workflows, are positioned to reduce adoption friction. Systems that support direct-print aligner production or multi-material denture fabrication are expanding the addressable scope beyond models and temporaries. At the same time, companies with open material libraries are appealing to laboratories that value flexibility and the ability to test multiple formulations across different restoration types. The strategic lesson is that hardware specifications alone no longer define leadership; the combination of clearance readiness, material breadth, workflow integration, and support reliability now determines who can scale adoption in real clinical environments.
PW Consulting
Market concentration remains moderate, with the top three and top five players holding comparatively modest shares, indicating that the landscape is still accessible to focused entrants and that differentiation can be achieved through application-specific solutions rather than scale alone. However, consolidation dynamics are likely to intensify as larger players seek to broaden material portfolios, integrate design and post-processing, and strengthen regional support networks. New entrants that can demonstrate clear clinical value in a narrow application area may still carve out meaningful positions, but sustained advantage will increasingly depend on regulatory readiness, reproducibility, and the ability to fit into existing digital ecosystems.
Recent product launches and clearances underscore how quickly the application frontier is moving. Multi-material monolithic denture solutions and flexible removable partial denture resins have moved from development to commercial availability, signaling that the market is expanding into higher-value restorative and prosthetic use cases. These milestones matter because they change the conversation from "can we print it" to "can we print it with validated performance for a specific clinical indication." For competitors, that raises the stakes on material development, regulatory strategy, and clinical evidence generation.
Future Trends to Watch Over the Next 3 to 5 Years
One defining trend will be the continued expansion of printable, clinically validated applications. As material portfolios grow and more indications secure regulatory clearance, printing is likely to displace portions of workflows that previously relied on subtractive fabrication or manual layering. This expansion will not be uniform; it will concentrate first in applications where reproducibility, turnaround, and labor savings offer clear operational advantages. Manufacturers and laboratories that prepare for multi-application flexibility, rather than optimizing for a single workflow, will be better positioned to capture value as indications diversify.
A second trend is the deepening integration of design, printing, and post-processing into more automated, enterprise-ready workflows. The market is moving toward solutions that reduce hands-on steps, standardize output quality, and provide better traceability for clinical and quality assurance purposes. This is particularly relevant for group practices and larger laboratories seeking consistent outputs across multiple sites. The commercial opportunity lies in bundled workflows, training, and support models that reduce the operational burden of digital adoption, rather than selling hardware as a standalone commodity.
Metal 3D Printer Market
A third trend is regional divergence in adoption pace and reimbursement maturity. Markets with more advanced digital restoration reimbursement frameworks and established clinical digital infrastructure are likely to lead in volume and application breadth, while other regions will adopt more gradually as laboratory capabilities, clinician familiarity, and reimbursement clarity improve. For companies and investors, this means that go-to-market strategies should be calibrated to local workflow readiness and regulatory context rather than assuming a single global rollout curve. The uncertainty lies in how quickly reimbursement and clinical guidelines evolve, and whether material and workflow validation can keep pace with clinical demand in each region.
Dental CBCT Market
These trends intersect with a clear commercial opportunity: the market is transitioning from early adoption of models and temporary appliances toward broader restorative, surgical, and orthodontic production. That transition rewards players who can reduce integration complexity, offer validated materials for specific indications, and support customers through the change-management aspects of digital workflow adoption. The principal risk is over-indexing on hardware capability without sufficient attention to material validation, regulatory timing, and real-world workflow fit, which can slow adoption regardless of technical merit.
Strategic Actions for Decision-Makers
For Manufacturers and Workflow Providers
Focus investment on application-specific validation and workflow integration rather than broad, undifferentiated hardware portfolios. Clear regulatory positioning, robust material documentation, and reliable post-processing pathways will increasingly differentiate suppliers in a market where buyers weigh clinical confidence and operational stability alongside print quality. Consider where open versus closed material strategies create the most value for your target customer base, and build support models that reduce downtime and rework across multiple sites.
For Investors
Evaluate opportunities through the lens of application depth and workflow fit rather than headline printer volumes. Segments with stronger reimbursement alignment, higher labor savings, and clearer regulatory pathways are likely to scale faster. Pay attention to companies that combine material development, clearance strategy, and regional support capabilities, because those Attributes often determine whether a product moves from pilot to routine clinical use. Monitor consolidation signals and partnership activity, as ecosystem alignment is becoming a competitive differentiator.
For Procurement and Clinical Leaders
Approach capital decisions as workflow investments rather than equipment purchases. Assess total cost of ownership across material availability, validation coverage for your target indications, integration with existing design and scanning pipelines, and the reliability of service and training. Prioritize solutions that demonstrate clearance for the specific applications you intend to produce, and request evidence of consistent output quality and post-processing requirements before scaling volume. A phased rollout that validates workflow fit in a limited setting can reduce risk before committing to broader deployment.
The dental 3D printing market is entering a phase where clinical validation, workflow integration, and reimbursement alignment matter as much as print resolution. Decision-makers who align their strategies with these realities will be better positioned to capture the next wave of growth. For a more detailed view of segmentation dynamics, regional readiness, material and application trajectories, and company-level strategic positioning, the full research report provides deeper segmentation data and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Dental 3D Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Leather Goods Market 2026–2032: How 7.2% CAGR and Genuine Leather Lead Demand Shifts
By PW Consulting, 2026-09-21
Leather Goods Market: Strategic Trends and Commercial Opportunities Through 2032
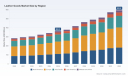
The global leather goods market is navigating a period of structural transformation, shaped by evolving consumer expectations, regulatory pressures, and shifting trade dynamics. Valued at 363.2 million USD in 2025, the sector has expanded steadily from 284.5 million USD in 2020, reflecting a compound annual growth rate of approximately 7.2 percent through 2032. This trajectory signals a market that is no longer driven solely by volume expansion but by fragmentation of demand, material innovation, and intensifying competition across regional and product boundaries. For executives and investors, the question is no longer whether the market will grow, but how value will be captured amid rising costs, compliance complexity, and changing sourcing behaviors.
PW Consulting
Three structural challenges define the current inflection point. First, raw material volatility is compressing margins while forcing reallocation of sourcing strategies. Second, regulatory divergence across major markets is altering compliance costs and product positioning, particularly around material disclosure and end-of-life responsibility. Third, trade policy uncertainty is reshaping export competitiveness for manufacturing hubs that rely on cross-border supply chains. These pressures are not isolated; they interact with consumer preferences and technological adoption, creating a landscape where agility in sourcing, positioning, and compliance will separate resilient operators from those caught in cost or reputation traps.
Within this context, the market concentration profile indicates that scale remains a meaningful advantage, yet differentiation is increasingly achieved through specialization rather than breadth alone. The leading firms are not simply expanding output; they are aligning with distinct demand segments, building provenance narratives, and adapting to material transitions while maintaining quality expectations. The following analysis examines the forces driving this reshaping, the competitive logics emerging among core players, and the strategic implications for manufacturers, investors, and procurement teams.
Market Landscape and Core Challenges
The leather goods sector has demonstrated resilient growth through a recent expansion cycle, with the 2025 base position cementing a path toward sustained double-digit cumulative value creation over the forecast window. This growth is underpinned by durable demand for footwear, bags, and accessories, though the composition of that demand is shifting in ways that matter for strategy. The market is large enough to support multiple business models, but the distribution of opportunity is uneven across regions and product categories, and the benefits of scale are increasingly contingent on operational flexibility and compliance readiness.
The first core challenge is raw material cost pressure. Leather input costs have become a recurring headwind, affecting manufacturers that depend on traditional tanning and slaughter-linked supply chains. This pressure is not merely cyclical; it reflects tightening environmental scrutiny, supply concentration in specific sourcing regions, and the broader cost of managing waste, water, and chemical inputs. For producers, the implication is that cost mitigation can no longer rely on procurement timing alone. It increasingly requires formulation alternatives, yield optimization, and selective material substitution without eroding perceived value.
The second challenge is regulatory fragmentation. Compliance requirements are diverging across jurisdictions, creating a more complex operating environment for brands and manufacturers that sell across borders. Disclosure expectations for imitation and hybrid materials are tightening, while extended producer responsibility considerations are emerging in major consumer markets. These developments raise the stakes for transparency, labeling accuracy, and lifecycle management, particularly for firms that position themselves on authenticity or premium quality. The risk is not only enforcement exposure but also brand trust erosion when material claims and product realities diverge.
The third challenge is trade and tariff uncertainty. Tariff structures affecting leather and allied products have become a persistent factor in export competitiveness, influencing where goods are manufactured, assembled, and shipped. As tariff levels and trade flows remain sensitive to policy shifts, manufacturers with concentrated export exposure face margin variability and sourcing reconfiguration pressure. This environment favors companies that can modularize production, diversify destination markets, or align manufacturing footprints with customer risk tolerance.
Key Drivers Shaping the Market
Material Innovation and Positioning Tension
One of the most consequential drivers is the ongoing tension between genuine leather and faux leather positioning. Genuine leather continues to command the largest share of market value, rooted in durability perceptions, craftsmanship narratives, and the premium associations many consumers attach to animal-derived materials. At the same time, synthetic and alternative materials are gaining ground in segments where price sensitivity, ethical positioning, or weight and maintenance considerations matter more than traditional material prestige.
This is not simply a substitution story. It is a segmentation and communication challenge. Brands that rely on leather as a value signal must manage disclosure expectations and consumer interpretation carefully, especially where products may contain blends or where visual appearance resembles leather. Regulatory guidance requiring disclosure of non-leather content for products that appear leather reinforces the need for clearer material storytelling and more disciplined product claims. For manufacturers, this creates an opportunity to offer verified material grading, traceable sourcing, and coordinated messaging that reduces ambiguity and supports premium pricing where justified.
Regulatory and Compliance Dynamics
Policy and regulatory activity is becoming a strategic variable rather than a background compliance cost. In the United States, tariff levels on leather and allied product manufacturing have averaged above 18 percent, with trade reports indicating potential further adjustments. These levels affect landed cost calculations and influence how brands evaluate make-versus-source decisions across geographies. For export-oriented manufacturers, tariff exposure can determine whether a given sourcing model remains viable for a specific customer base.
In parallel, environmental policy is moving toward lifecycle accountability. A proposed national Extended Producer Responsibility scheme for leather goods in Italy signals a broader direction in which end-of-life responsibility, material recovery, and waste management may become integrated into product economics. Even where such schemes are still in draft or early implementation stages, they shape investment decisions because manufacturers and brands must anticipate compliance costs and consumer expectations around sustainability. The direction of travel suggests that environmental compliance will increasingly interact with brand positioning, especially in premium segments where provenance and responsibility claims are part of the purchase rationale.
Bovine Leather Goods Market
Demand-Side Shifts and Consumer Behavior
Consumer demand is evolving along multiple axes at once. Lifestyle and hobby-related spending patterns are shifting, influencing how discretionary purchases are prioritized across footwear, bags, and accessories. At the same time, product launches in the premium and fashion-forward space continue to emphasize limited editions, collaborative design, and region-specific craftsmanship. Recent product activity illustrates this dynamic: limited-edition leather jackets and handbags developed through brand collaborations, and timeless bag collections designed in one market and manufactured in another to leverage specialized material and production heritage.
The strategic implication is that demand is becoming more occasion-specific and story-driven. Consumers are not simply buying a category; they are buying into a narrative of rarity, design intent, and material authenticity. This favors manufacturers and brands that can coordinate design, sourcing, and limited production runs with credible craftsmanship signals. It also creates pressure on mass-market players to justify value through durability, repairability, or transparent material claims, rather than relying on volume alone.
Supply Chain Reconfiguration and Cost Structure Evolution
Trade uncertainty is reshaping how supply chains are configured for leather goods. Export competitiveness in key manufacturing regions is affected by tariff exposure, logistics variability, and the broader cost of maintaining cross-border production networks. In this environment, some operators are shifting toward regional or near-customer manufacturing, while others are preserving offshore advantages but building more flexible routing and inventory strategies.
Cost structures are also changing through raw material dynamics and compliance expenditures. When input costs rise, manufacturers that can protect yield, reduce waste, and offer consistent quality gain relative advantage. When compliance complexity rises, firms that can standardize disclosure, manage material documentation, and anticipate regulatory change reduce the cost of market access. Together, these factors reward operators that treat supply chain design as a strategic asset rather than a fixed cost base.
Competitive Landscape and Strategic Positioning
The competitive field in leather goods is shaped by contrasting business models that reflect regional advantage, customer type, and material philosophy. Several core companies illustrate how differentiation is being constructed in practice.
TBS Group, based in Vietnam, has built a dedicated handbag division serving major international brands, producing leather handbags, wallets, and accessories for clients that include Coach, Tory Burch, and Skechers. Its positioning reflects the advantages of a manufacturing hub with scaling capacity and brand-facing execution, where the value proposition rests on reliable volume, specification adherence, and the ability to serve global brand programs.
Guangzhou Gionar Leather Co., Ltd. in China emphasizes OEM and ODM capabilities across high-end leather handbags, backpacks, briefcases, wallets, and belts. This model targets brands and buyers that need design support alongside manufacturing, making the company relevant for customers seeking a single partner for development and production. The strategic logic is integration of service depth with category breadth.
Wollsdorf, operating from Austria, focuses on premium leather steering wheel products and leather goods, an example of specialization in a niche but high-perception category. Its positioning depends on quality, fit, and the prestige associated with refined interiors and driver-focused craftsmanship. The company illustrates how narrow category focus can support premium pricing when execution and brand context align.
Keifung-intl, headquartered in Hong Kong, manufactures fashion handbags and small leather goods with private label programs for European and American brands. Its relevance lies in combining manufacturing capability with brand-service orientation, supporting label-driven businesses that need consistent output and commercial flexibility.
Leather Country, based in Italy, operates a B2B wholesale model for leather handbags, belts, wallets, and accessories. Its positioning leverages Italian material heritage and wholesale distribution, serving buyers who value material reputation and assortment breadth. In a market where origin signals matter, this model uses geographic association as part of the offering.
On the luxury and heritage side, Lotuff Leather in the United States produces handmade vegetable-tanned leather handbags and luxury goods with a lifetime guarantee. Frank Clegg Leatherworks, also U.S.-based, focuses on ultra-luxury briefcases, travel gear, and executive leather products. Horween Leather Co. supplies premium American vegetable-tanned leather for custom goods. These firms represent a different axis of competition: durability, repairability, and long-term value claims rather than speed or scale. Their advantage lies in craftsmanship reputation, material philosophy, and customer relationships built around longevity.
The market is evolving along two reinforcing trends. First, consolidation pressures are emerging where scale, compliance capacity, and supply chain resilience provide advantages in serving large brand programs and export markets. Second, fragmentation is strengthening at the premium and specialty end, where differentiation comes from material authenticity, limited production, and narrative-driven design. New entrants and expanding producers are likely to compete not by replicating the same model, but by choosing a clear position: volume and service integration for brand clients, or craftsmanship and provenance for luxury and heritage demand. Trade fair activity across the sector, from footwear and leather goods exhibitions in Europe and Asia to sourcing-focused events in the Middle East, underscores the continued importance of in-person networking, specification alignment, and regional sourcing relationships.
Future Outlook: Trends and Opportunities to 2032
The next three to five years are likely to be defined by three interconnected trends.
The first trend is the intensification of material transparency as a commercial norm. Disclosure expectations and consumer scrutiny will continue to raise the cost of ambiguity. Products that appear to be leather but contain significant non-leather content will face greater scrutiny, and brands will need more rigorous material documentation and labeling discipline. The opportunity here is for manufacturers and suppliers that can offer verified material grades, traceable sourcing, and clear communication frameworks. Transparency, when executed credibly, can become a trust asset rather than a compliance burden.
The second trend is the continuing divergence between mass-market value competition and premium durability positioning. Rising costs and trade uncertainty will pressure margins in volume segments, while premium segments will increasingly reward craftsmanship, repairability, and long-life product claims. This divergence creates distinct commercial opportunities: efficiency-driven sourcing and modular production for scale customers, and limited runs, material heritage, and lifetime service promises for high-value customers. Companies that attempt to occupy both spaces without clear operational separation may struggle to defend either position.
The third trend is supply chain adaptation to regulatory and tariff volatility. Manufacturers and brands will continue to adjust footprints, routing, and sourcing mixes in response to trade policy and compliance evolution. Regional diversification, closer coordination with buyers on landed-cost tolerance, and investment in documentation and compliance processes will become more valuable. The opportunity lies in building supply chain flexibility that can respond to policy shifts without sacrificing quality or delivery reliability.
These trends carry risk. If raw material costs remain elevated and tariff or trade disruptions intensify, margin compression could accelerate in export-dependent models. If regulatory expectations expand faster than compliance capabilities, brands and manufacturers could face both cost and reputation exposure. If consumer preferences shift more quickly toward alternative materials in core categories, traditional leather positioning may need to be recalibrated around performance, provenance, or service rather than material alone.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to choose a defensible positioning and build the operating capabilities that support it. Volume-oriented producers should invest in yield efficiency, compliance documentation, and flexible sourcing to protect margins under tariff and input-cost pressure. Specialty and premium producers should reinforce material credibility, craftsmanship signals, and service commitments such as repair or guarantee structures that support long-term value perception. In both cases, the ability to provide clear material disclosure and consistent quality will increasingly determine market access and pricing power.
Leather Market
For investors, the key is to assess exposure to the structural drivers rather than rely on category-level growth alone. Evaluate whether a company's model is aligned with transparency requirements, whether its supply chain can absorb tariff and trade variability, and whether its positioning is distinct enough to resist commoditization. Businesses that combine regulatory readiness with a clear value proposition, whether in scale service or premium craftsmanship, are better placed to capture value across the forecast period.
For procurement and brand teams, sourcing strategy should account for both cost and narrative alignment. Where leather is used as a value signal, verify material claims, disclosure practices, and supplier documentation. Where price or ethical considerations drive material choices, ensure that alternative materials are positioned with consistent claims and that product appearance does not create misleading consumer expectations. Building supplier relationships that can support traceability, compliance, and design collaboration will reduce risk and improve optionality as demand patterns continue to shift.
The market trajectory through 2032 will reward operators that treat transparency, compliance, and positioning as integral to commercial strategy rather than as downstream considerations. For decision makers seeking more granular segmentation data, regional breakdowns, and tailored sourcing or investment implications, the full PW Consulting research report provides expanded detail across market segments and competitive scenarios.
For detailed analysis of this topic, please visit the official page: Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bromine Market 2026: Why 5.5% CAGR and Asia’s 1.23B Demand Shift the DNA of Global Competition
By PW Consulting, 2026-09-21
Bromine Market Outlook 2026–2032: Strategic Shifts and Commercial Opportunities
Market Overview and Core Challenges
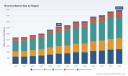
The global bromine market is entering a phase of measured but structurally significant growth. Revenues expanded from approximately $2.2 billion in 2020 to an estimated $3.1 billion in 2025, with forward indicators pointing toward a sustained annual growth rate of roughly 5.5 percent through 2032. By the end of the forecast period, total market value is projected to exceed $4.4 billion. This trajectory reflects more than cyclical recovery; it signals a market being reshaped by diverging regional supply realities, tightening environmental controls, and shifting demand patterns across industrial, energy, and specialty chemical end-use sectors.
Despite the positive top-line momentum, the market faces a set of interconnected challenges that reward strategic foresight rather than passive participation. Three structural pressures stand out as particularly consequential for commercial decision-making.
First, supply concentration and geographic vulnerability continue to define market stability. Bromine extraction relies heavily on natural brine deposits that are inherently localized. Operations tied to a few major basins face disproportionate exposure to regulatory shifts, resource management constraints, and geopolitical friction. When supply from these nodes is interrupted or restricted, downstream manufacturers and formulators experience cost variability and procurement uncertainty that cannot always be smoothed through inventory alone.
Second, environmental and operational regulations are increasingly reshaping production economics. Jurisdictions with significant brine processing capacity have moved to tighten oversight of extraction and handling practices. These measures are necessary from a sustainability and safety standpoint, but they also introduce compliance costs, operational pauses, or capacity reductions that ripple through the supply chain. The result is a market in which price stability is less a function of raw commodity dynamics and more a function of regulatory resilience and operational adaptability.
Third, demand is bifurcating in ways that complicate long-term planning. Traditional applications tied to industrial formulations and energy services remain foundational, yet growth is increasingly concentrated in specialty and pharmaceutical pathways. Companies that depend on a single demand profile are more exposed to substitution pressure, margin compression, or regional policy swings. The market now favors players who can navigate between steady bulk demand and higher-value, specification-sensitive applications.
These challenges do not undermine the market’s growth narrative; they clarify it. The opportunity lies in recognizing that bromine is transitioning from a largely commoditized input to a more strategically managed material where supply security, regulatory readiness, and application-specific differentiation determine competitive advantage.
Key Drivers of Market Change
Innovation and Product Specialization
Technological progress in bromine chemistry is steadily expanding the value that end-users can extract from bromine-based compounds. Rather than competing purely on volume, leading manufacturers are investing in higher-purity grades, controlled derivative portfolios, and application-tailored formulations. This shift matters because downstream sectors increasingly demand consistency, contaminant control, and reproducible performance, especially where bromine acts as a building block in complex synthesis pathways.
The trend is visible in pharmaceutical and fine chemical production, where bromine-derived intermediates support the synthesis of active ingredients used in sedatives, antiseptics, and oncology-related therapies. As drug manufacturing scales in major production hubs, the need for reliable, specification-grade bromine inputs grows in tandem. Companies that can supply with consistent purity and documented quality controls are gaining preference over those competing primarily on base price. In this context, innovation is less about dramatic breakthroughs and more about the cumulative value of precision, reliability, and technical support.
Regulatory and Policy Influence
Policy and regulatory developments are now central drivers of market behavior, not peripheral compliance issues. Environmental oversight of brine operations has intensified in several regions, influencing production continuity and cost structures. At the same time, safety standards and handling requirements affect logistics, storage, and customer qualification processes. These forces create a market where regulatory agility has become a competitive asset.
The commercial implication is straightforward: producers and distributors that can demonstrate robust compliance frameworks, predictable operating practices, and transparent sourcing are better positioned to retain and expand customer relationships during periods of regulatory tightening. Conversely, operations that depend on lenient enforcement environments or have limited flexibility to adjust processes face higher risk of disruption and price instability. Regulatory change is therefore acting as a filter, rewarding disciplined operators and reshaping procurement preferences across the value chain.
Demand-Side Shifts in Energy, Construction, and Healthcare
Demand patterns are evolving on multiple fronts. In oil and gas drilling, bromine-based fluids remain important for well completion and operational performance, sustaining demand from energy service activity. At the same time, the flame retardant segment continues to anchor a substantial share of consumption, driven by ongoing requirements in electrical equipment, building materials, and transportation components. These applications benefit from long-lived infrastructure and equipment cycles, providing a stable baseline for market activity.
Beyond these core uses, healthcare and specialty chemical demand is becoming increasingly influential. Growth in pharmaceutical manufacturing, together with rising interest in bromine-based intermediates for targeted chemical synthesis, is expanding consumption among formulators and producers seeking higher-value output. This does not replace traditional demand, but it alters the composition of growth. Companies that can serve both bulk industrial needs and specification-driven specialty applications are capturing a broader set of revenue opportunities than those locked into a single demand channel.
Supply Chain and Cost Structure Dynamics
Cost structures in the bromine market are increasingly shaped by location-specific factors rather than uniform global benchmarks. Production tied to stable domestic feedstock and favorable operating conditions can offer a meaningful buffer against international price volatility. By contrast, supply dependent on distant or constrained brine sources may be more exposed to energy costs, logistics complexity, and operational interruptions.
This divergence has practical consequences for procurement and production strategy. Buyers in regions with access to steady local supply are often better positioned to manage cost predictability, while those reliant on international flows must account for geopolitical, regulatory, and logistical risk in sourcing decisions. For producers, the implication is that cost leadership is no longer purely a function of scale; it also depends on securing resilient feedstock access, optimizing handling and transport, and maintaining operational continuity under changing environmental and policy conditions.
Competitive Landscape and Leading Strategies
The bromine market is concentrated among a group of well-positioned producers and specialty suppliers, with the top three firms accounting for roughly two-thirds of market share and the top five approaching four-fifths. This concentration reflects the capital intensity of brine-based extraction, the technical requirements of derivative production, and the importance of long-term customer qualification in pharmaceutical and industrial applications. Yet the landscape is not static; it is evolving through investment partnerships, regional specialization, and increasing divergence between bulk suppliers and fine-chemical-focused entrants.
Albemarle Corporation stands out for its scale and breadth across elemental bromine and derivatives serving industrial and pharmaceutical markets. Its positioning benefits from integrated capabilities, established customer relationships, and a presence in regions that can help insulate certain buyers from global price volatility. ICL Group Ltd has built a strong identity around bromine and bromine-based compounds sourced from Dead Sea brines, emphasizing industrial solutions and derivatives. Its operations illustrate both the advantages and the vulnerabilities of geographically concentrated feedstock: strong cost and supply advantages under normal conditions, but heightened sensitivity to environmental and operational disruptions.
LANXESS AG and Tosoh Corporation represent important nodes in the value chain for flame retardants, organobromines, and fine chemical intermediates. Their relevance lies in the ability to connect bromine supply with downstream application requirements, particularly where performance specifications and chemical consistency are critical. Gulf Resources Inc. reflects the importance of regional brine-based production and export capacity, while TETRA Technologies Inc. reinforces the link between bromine supply and energy-sector applications. Tata Chemicals Limited and Hindustan Salts Limited highlight the growing role of Indian producers in serving industrial, technical, and specialty demand.
In parallel, a cluster of firms with stronger fine-chemical and pharmaceutical orientations is gaining relevance. Archean Chemical Industries Ltd. has established a notable position in liquid bromine supply with high-purity offerings for pharmaceutical use. Jordan Bromine Company Ltd. operates as an exclusive regional producer serving industrial and pharmaceutical applications, and its strategic connection with broader regional partners underscores the role of investment alignment in capacity expansion. Chemada Fine Chemicals, Solaris ChemTech Industries Ltd., and Agrocel Industries Pvt. Ltd. illustrate how specialized manufacturers are carving out value in pharmaceutical, agrochemical, and intermediate segments by focusing on precision, customer-specific requirements, and application knowledge rather than competing solely on commodity terms. Honeywell International Inc. further rounds out the landscape as a supplier of bromine-based products and derivatives for industrial chemicals and performance materials, reinforcing the breadth of demand across multiple end markets.
PW Consulting
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Scale remains important, but differentiation is coming from supply reliability, purity and quality assurance, regional reach, and the ability to serve both industrial and specialty pathways. Recent developments reinforce this direction. In January 2025, Arab Potash Company and Albemarle Corporation signed a joint investment agreement to expand bromine production capacity at Jordan Bromine Company, signaling that capacity growth is being pursued through partnership structures that combine regional resource access with established technical and commercial capabilities. Meanwhile, the July 2025 launch of Ipratropium Bromide Nasal Solution by Lupin Limited in the United States illustrates how bromine-based pharmaceutical products continue to enter competitive markets in forms that demand consistent raw material quality and regulatory readiness upstream.
Looking forward, the market is likely to see both consolidation and targeted fragmentation. Consolidation may continue where scale, feedstock access, and integrated derivative capabilities create durable advantages. Fragmentation is equally plausible in fine chemicals and pharmaceutical intermediates, where smaller or more specialized producers can compete on purity, customization, and technical service. New entry will probably remain limited at the raw extraction level due to resource and regulatory barriers, but value-added derivative production and application-specific formulation remain open avenues for disciplined players.
Future Trends and Commercial Implications
Trend 1: Supply Resilience Will Become a Primary Commercial Differentiator
Over the next three to five years, customers are likely to place increasing weight on suppliers that can demonstrate predictable continuity, transparent sourcing, and the ability to absorb or mitigate disruptions. This is not simply a procurement preference; it reflects the reality that brine-based supply is exposed to environmental, operational, and geopolitical variables. Companies that invest in diversified supply relationships, contingency planning, and clear quality documentation will be better positioned to secure long-term contracts and preferred-supplier status.
Lithium Bromide Market
For commercial players, the opportunity lies in building credibility around reliability. This can include strengthening regional supply options, improving inventory and logistics planning, and offering downstream customers clearer visibility into sourcing and handling practices. In a market where disruption risk is a meaningful cost driver, reliability can command preference even when base pricing is not the lowest.
Trend 2: Growth Will Accelerate in Specification-Sensitive and Specialty Applications
The next phase of market expansion is expected to lean increasingly on demand that requires higher purity, tighter controls, and stronger application support. Pharmaceutical synthesis, fine chemicals, and selected specialty industrial uses are natural beneficiaries of this shift, especially as manufacturing activity in major chemical-producing regions continues to expand. This trend favors suppliers and intermediaries that can provide consistent grades, technical collaboration, and responsive service rather than those operating purely as volume sellers.
Commercially, this suggests that revenue growth may be increasingly tied to value-added positioning. Companies that align product portfolios with specification needs, support customer qualification processes, and maintain strong quality systems can capture share in higher-margin segments. The broader implication is that bromine’s commercial relevance will depend not only on how much is produced, but on how effectively it is adapted to demanding downstream requirements.
Trend 3: Regional Divergence Will Shape Pricing, Risk, and Sourcing Strategy
Market participants should expect continued divergence between regions with stable, well-controlled production environments and those facing tighter regulatory or operational constraints. This divergence will influence not only price levels but also risk premiums, contract structures, and sourcing strategies. Buyers who depend on a single geography or a narrow supplier base may face greater exposure to localized disruptions or policy shifts, while those with flexible sourcing and regional alternatives can manage volatility more effectively.
Worldwide Bromobenzene Market
The strategic opportunity here is to treat geography as a risk-management variable rather than a background detail. For procurement teams, that may mean broadening supplier options, qualifying alternate sources, and aligning contract terms with continuity requirements. For producers and distributors, it may mean emphasizing regional stability, operational resilience, and service consistency as part of the commercial proposition.
Risks and Uncertainties to Watch
Several uncertainties could alter the pace or shape of these trends. Regulatory actions affecting brine operations may tighten further, creating additional constraints on production in certain regions. Geopolitical tensions and conflict-related disruptions can affect transport, feedstock access, and operating confidence, particularly where supply is concentrated. Demand could also evolve faster or slower than expected if substitution technologies advance in flame retardants or if energy-sector activity changes materially. Finally, quality and compliance expectations in pharmaceutical and specialty applications may rise, increasing the cost of entry for suppliers that cannot meet stricter requirements. These uncertainties do not cancel the market’s growth outlook; they make strategic preparedness essential.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Position portfolios for both continuity and specialization. Core industrial demand provides a stable base, but long-term advantage will increasingly come from higher-purity grades, reliable derivative supply, and the technical support that specialty customers require. Invest in quality systems, application-facing expertise, and supply contingency planning so that operational resilience becomes part of the commercial offer. Where feasible, pursue partnerships or capacity alignment that strengthen regional feedstock access without over-concentrating risk in a single basin or operating environment.
For Investors and Strategic Capital Players
Focus on resilience and segmentation rather than aggregate volume alone. The market’s growth is real, but the most durable value creation is likely to come from players that can manage supply risk, meet specification-sensitive demand, and operate with disciplined compliance and cost control. Evaluate exposure to region-dependent brine operations, the ability to serve pharmaceutical and fine chemical pathways, and whether a company’s differentiation rests on credible operational and technical advantages. Capacity expansion financed through partnerships may offer a more balanced risk profile than isolated scale bets, particularly where feedstock concentration and regulatory sensitivity are high.
For Procurement and Supply Chain Leaders
Treat bromine sourcing as a continuity and quality strategy, not just a price optimization exercise. Diversify supplier options where possible, qualify alternate supply routes for critical applications, and align contract terms with the need for stable delivery and documented quality. Forspecification-driven use cases, prioritize suppliers with strong traceability, consistent purity, and proven regulatory readiness. Building flexibility into sourcing can reduce exposure to regional disruptions and help stabilize total cost of ownership, especially when international supply is subject to environmental or geopolitical shocks.
The bromine market is moving toward a phase where strategic positioning matters as much as raw market size. Success will depend on how well organizations anticipate supply vulnerability, regulatory evolution, and the shift toward higher-value applications. For decision makers who need more granular segmentation data, regional cost dynamics, and tailored scenario planning, a detailed market study can provide the deeper commercial context required to translate these trends into specific action plans.
For detailed analysis of this topic, please visit the official page: Bromine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bimetallic Bandsaw Blade Market: Why 6.5% CAGR Reshapes Steel Cutting Growth to $860M
By PW Consulting, 2026-09-21
Navigating the Bimetallic Bandsaw Blade Market: Strategic Trends and Commercial Opportunities Through 2032
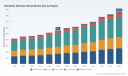
The global market for bimetallic bandsaw blades has entered a sustained growth trajectory, valued at approximately $555 million in 2025 and projected to expand at a compound annual growth rate of 6.5%, reaching nearly $860 million by 2032. This expansion is not merely a function of incremental industrial demand but reflects a structural shift in how manufacturers approach material processing, precision machining, and operational efficiency. Over the past half-decade, revenue climbed from $420.5 million in 2020 to $555.0 million in 2025, with consistent year-over-year gains signaling resilient underlying fundamentals. By 2028, the market is expected to surpass $664 million, and the upward momentum will continue through the end of the decade as automation, energy optimization, and advanced alloy requirements reshape procurement criteria. Understanding the forces converging on this niche but strategically vital segment is essential for executives, investors, and procurement leaders who must align positioning, capital allocation, and supply strategies with where the market is heading.
Two structural inflection points define the current landscape. First, the transition from general-purpose cutting tools to application-specific, high-performance blade architectures is accelerating, driven by tighter tolerances in metal fabrication, increased use of hardened alloys, and the need to minimize downtime in continuous production environments. Second, the industry is experiencing a concentration dynamic where a relatively small group of established manufacturers controls the majority of revenue, creating both a barrier for undifferentiated entrants and an opportunity for companies that can differentiate through tooth geometry, backing material engineering, or integrated service models. These forces do not simply shape pricing and shelf space; they redefine the competitive battlefield, where performance consistency, lifecycle value, and alignment with automated sawing systems increasingly outweigh commodity cost competition.
Key Drivers Shaping Market Trajectory
Technical Innovation and Material Science Breakthroughs
The durability and cutting performance of bimetallic bandsaw blades depend directly on the interaction between the high-speed steel cutting edge and the flexible alloy backing. Recent material developments have reinforced this value proposition. High-speed steel grades rich in molybdenum have advanced at a notable pace, strengthening wear resistance and heat tolerance in demanding metal cutting scenarios. This progression supports longer blade life, more stable cutting parameters, and reduced frequency of blade changes, which in turn lowers total cost of ownership for high-volume operations. Alongside alloy improvements, manufacturers are refining tooth geometry, set patterns, and substrate bonding processes to optimize chip evacuation, reduce vibration, and improve cut finish across varying material thicknesses. The practical implication is clear: blade selection is shifting from a transactional purchase to a performance engineering decision, with procurement teams weighing throughput, scrap rates, and machine compatibility alongside unit price.
Regulatory and Operational Pressures Toward Efficiency
Energy efficiency mandates and broader sustainability expectations in industrial operations are reshaping tooling choices. Metal cutting processes that consume less power per cut, maintain stable performance over extended runtimes, and reduce waste are increasingly favored in facilities subject to efficiency monitoring or carbon accountability frameworks. Bimetallic blades that deliver consistent cutting speeds with lower resistance and fewer remachining cycles align well with these priorities. Beyond energy, labor dynamics are influencing adoption patterns. Shortages of skilled operators in manufacturing environments have accelerated the uptake of automated bandsaw systems that rely on reliable bimetallic blades to sustain unmanned or semi-autonomous production runs. In this context, blade reliability becomes a bottleneck or an enabler of automation ROI, making performance predictability a strategic procurement criterion rather than a secondary specification.
Band Saw Blades Market
Market momentum is also reinforced by application diversity. Steel cutting remains a core demand center, supported by structural fabrication, maintenance, and heavy equipment production. Aluminum cutting continues to draw volume from automotive, aerospace, and general manufacturing workflows, where clean cuts and minimal material deformation are valued. Cast iron cutting serves niche but critical requirements in foundry and machinery remanufacturing contexts, while additional applications span specialized alloys and mixed-material processing. This breadth provides revenue resilience, as demand is not overly dependent on a single vertical, and it encourages blade suppliers to maintain differentiated product lines tailored to material-specific cutting characteristics.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiation Logic
The market features a mix of long-standing Western manufacturers and emerging Asian producers, each pursuing distinct routes to advantage. Companies such as Lenox Tools, M.K. Morse Company, and DoALL Sawing Products have built reputations around application-specific bi-metal blades for metal cutting, with product lines oriented toward high-production environments and general-purpose versatility. L.S. Starrett Company emphasizes advanced tooth geometry and geometry optimization to improve cut quality and blade stability, while Bahco positions around production-focused series designed for sustained cutting operations. German manufacturers bring specialized engineering depth: Wikus offers modified cutting materials and alloyed steel backing for alloyed steel applications, Eberle focuses on duoflex architectures for stainless steel, high-speed steel, and cast iron, and Honsberg targets a broad range of industrial applications with bimetal solutions. Simonds International LLC supports production, general-purpose, and structural steel cutting segments, rounding out a competitive field where brand trust, technical service, and consistent quality are central to customer retention.
On the supply side, Bichamp Cutting Technology Co Ltd represents the expanding presence of Chinese manufacturers focused on high-performance metal cutting, leveraging scale, cost competitiveness, and increasing technical capability to serve both domestic and export markets. This dynamic creates a bifurcated competitive environment: premium segments remain contested by manufacturers emphasizing engineering depth, application-specific performance, and service integration, while value-oriented segments face pressure from producers able to combine acceptable performance with lower procurement costs. The result is a market where differentiation is increasingly tied to measurable outcomes—blade life, cut consistency, compatibility with automated systems, and technical support—rather than brand alone.
Recent Industry Activity and Market Evolution
Company activity over the past year underscores the emphasis on application expansion, customer engagement, and technology visibility. In early 2025, Wikus hosted a targeted industry event focused on innovation for efficient steel processing, signaling a strategic interest in aligning blade performance with demanding production requirements. Later in the year, the company participated in trade shows highlighting bimetal bandsaw blades and sawing solutions for industrial sheet metal processing, and presented a bimetal blade tailored for wood industry applications, illustrating how manufacturers are exploring adjacent end-use contexts to broaden demand pools. These moves reflect a broader trend: leading players are not only refining core metal-cutting offerings but also testing cross-industry applicability, strengthening dealer and user relationships, and using live demonstrations to communicate performance advantages in concrete operating conditions.
PW Consulting
The competitive trajectory points toward modest consolidation in the premium tier, as larger manufacturers seek to broaden application coverage and strengthen regional distribution, while smaller or specialized producers may find growth by focusing on niche applications, custom geometries, or localized service networks. New entrants face a steep climb given the concentration of revenue among established names, but they can still carve positions through rapid customization, cost-efficient manufacturing, or targeted service offerings for underserved geographies and applications. The landscape is therefore evolving along two parallel paths: consolidation and brand elevation in high-value segments, and fragmentation with specialized solutions in niche or price-sensitive contexts.
Forward Outlook: Trends and Commercial Implications
Trend One: Automation-Ready Blades as a Standard Expectation
As automated and semi-autonomous bandsaw systems become more prevalent in response to labor constraints and throughput goals, blade specifications will increasingly be evaluated for compatibility with consistent feed rates, reduced variability, and extended runtime between changes. Manufacturers that design blades with automation in mind—stable cutting behavior, predictable wear patterns, and clear performance envelopes—will be better positioned to capture demand from facilities scaling automated sawing capacity. For suppliers, this creates an opportunity to bundle blades with system integration guidance, application engineering, and maintenance planning, shifting the conversation from unit price to uptime and process reliability.
Trend Two: Material-Specific Engineering as a Value Driver
Demand for differentiated performance across steel, aluminum, cast iron, and other materials will continue to reward suppliers that can deliver application-tuned tooth geometry, set design, and backing material characteristics. As more producers encounter mixed-material workflows or harder alloys, the ability to match blade architecture to material properties will become a decisive purchasing factor. This trend favors companies that invest in application testing, provide clear selection frameworks, and communicate lifecycle performance data. Commercial opportunity lies in developing documented performance benchmarks and helping customers translate material requirements into blade choices that reduce trial-and-error procurement.
Trend Three: Cost Structure Dynamics and Supply Chain Resilience
The interplay between raw material pricing, alloy availability, and manufacturing efficiency will remain central to margin management and pricing strategy. With certain high-speed steel grades trending upward in cost, producers must balance input cost pressures against the value delivered through longer service life and reduced downstream waste. Supply chain resilience—spanning specialty alloy sourcing, bonding process control, and logistics—will differentiate companies that can maintain consistent quality and delivery from those exposed to volatility. The strategic implication is straightforward: competitive advantage will accrue to firms that can stabilize input costs through forward sourcing, optimize manufacturing yield, and articulate total cost of ownership benefits that justify performance premiums where appropriate.
These trends carry both opportunity and uncertainty. On the opportunity side, the convergence of automation, efficiency mandates, and application-specific engineering expands the rationale for premium blade adoption and creates openings for service-led business models. On the risk side, macroeconomic swings in industrial production, fluctuations in alloy availability, and intensifying price competition in value segments could pressure margins and slow adoption in price-sensitive regions. Geopolitical factors affecting trade flows and raw material supply may also influence regional cost structures and availability, requiring flexible sourcing and clear communication of supply continuity plans.
Strategic Takeaways for Decision Makers
For blade manufacturers and tooling suppliers, the priority is to convert technical differentiation into commercially legible value. This means investing in application-specific validation, documenting performance outcomes in terms that procurement and operations teams can use, and aligning product roadmaps with automation compatibility and material-specific needs. Companies should also evaluate where service, technical support, and selection guidance can strengthen customer retention, particularly in markets where blade longevity and cut consistency directly affect production economics. Where cost competition is intense, clear positioning around total cost of ownership, downtime reduction, and application fit can help defend margins without resorting to undifferentiated price competition.
For investors evaluating exposure to this segment, the relevant signals are the durability of demand across multiple applications, the pace of automation-driven adoption, and the ability of leading manufacturers to sustain differentiation through engineering and service rather than volume alone. Concentration in the market suggests that scaled players with strong brand equity and application coverage may capture disproportionate share of incremental growth, while specialized or regionally focused companies can still generate attractive returns if they serve underserved applications or maintain a credible cost-to-performance ratio. Due diligence should assess supply chain exposure to specialty alloys, the credibility of performance claims, and the extent to which product portfolios are aligned with the shift toward automated and efficiency-conscious operations.
For procurement and operations leaders, the practical imperative is to treat blade selection as a process decision rather than a commodity purchase. Evaluating blades against actual material mixes, machine configurations, and throughput targets can reveal where higher-performance options reduce total cost through longer life, fewer cut defects, and better automation compatibility. Establishing clearer selection criteria, testing application-specific options in representative conditions, and engaging suppliers for technical guidance can improve procurement outcomes and reduce variability in sawing performance. In environments where energy efficiency, labor constraints, and production consistency matter, the blade choice can influence more than cutting quality; it can affect overall operating economics.
For organizations seeking a deeper dive into segment-level sizing, regional demand patterns, application split trends, and company-specific positioning, a comprehensive research report provides the granularity needed to translate these strategic themes into concrete plans. Detailed breakdowns by region, application, and type, along with company profiles and recent development tracking, enable more precise market-entry decisions, pricing strategies, and procurement frameworks. Accessing that level of detail allows decision makers to convert broad market direction into targeted actions, whether the goal is to expand product coverage, enter a new geography, refine a procurement specification, or assess investment exposure with greater confidence.
Worldwide Welded Band Saw Blades Market
For detailed analysis of this topic, please visit the official page: Bimetallic Bandsaw Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vector Network Analyzer Market: Why 3.38% CAGR and 67% CR3 Redefine Strategic Outlook
By PW Consulting, 2026-09-21
Vector Network Analyzer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Vector Network Analyzer (VNA) market operates at the intersection of precision measurement and high-frequency engineering, serving as a critical enabler for telecommunications, aerospace engineering, and advanced electronics manufacturing. After a period of steady expansion, the market reached approximately 0.44 billion USD in 2025, building on a trajectory that saw moderate growth through the early 2020s. Over the forecast horizon through 2032, the market is projected to advance at a compound annual growth rate of 3.38 percent, with revenue scaling toward 0.56 billion USD by the end of the period. This growth profile reflects a mature, specialized instrumentation sector where incremental expansion is tied closely to broader technological adoption cycles rather than standalone product demand.
Market concentration remains notably high, with the top three participants commanding roughly two-thirds of total revenue and the top five players accounting for approximately 84 percent. This concentration underscores the technical barriers to entry, the importance of established calibration and certification ecosystems, and the long procurement cycles typical of enterprise and institutional buyers. At the same time, the distribution of revenue across technology classes and end-use sectors reveals where the market’s weight truly sits. Lower-frequency instruments in the 0-to-10 GHz range dominate share, while higher-frequency segments above 50 GHz remain relatively small in absolute terms but strategically important for next-generation applications. Communications continues to represent the largest application bucket, with automotive, electronic manufacturing, and aerospace and defense each contributing meaningful but more modest shares. Regionally, North America leads in revenue contribution, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but emerging pockets of activity.
Worldwide 5G Analyzer Market
Against this backdrop, three core challenges define the current inflection point. First, the cost and complexity of high-frequency development create a persistent barrier. Designing and calibrating VNAs for operation above 15 GHz demands substantial research and development investment, while premium components and high-speed data acquisition systems further increase production expenses. These cost dynamics constrain product accessibility and place pressure on vendors to justify performance premiums in customer conversations. Second, the market must navigate a shifting compliance and standardization environment. As RF testing becomes more tightly integrated into 5G, IoT, and Industry 4.0 deployment requirements, precision and traceability are no longer optional attributes; they are procurement prerequisites. Accredited calibration laboratories and standardized measurement protocols are increasingly baked into purchasing decisions, raising the stakes for both established players and new entrants. Third, the market faces a segmentation tension between broad-coverage, mid-range instruments and specialized high-frequency or portable solutions. Buyers want flexibility, but vendors must balance feature expansion against size, weight, power, and cost constraints. Solving this tension will separate growth-oriented vendors from those stuck in the middle.
Key Drivers Shaping Market Direction
Technological Innovation and Measurement Capability Expansion
Innovation in VNA architectures is expanding what practitioners can measure in the field and in the lab. Recent product moves illustrate this trajectory clearly. In September 2024, Keysight Technologies introduced the NA520xA PNA-X Vector Network Analyzer, configured with four RF sources, two internal combiners, and two low-noise receivers. This configuration reflects a broader push toward multi-dimensional characterization, where faster sweep capability, improved signal-to-noise performance, and integrated test configurations reduce the need for external mixing hardware. For engineering teams, such architectures translate into shorter test cycles and more compact bench setups, which matters as product development timelines tighten across communications and electronic manufacturing.
A complementary innovation thread is the extension of VNA functionality into field-portable instruments. In May 2025, Anritsu added Vector Network Analyzer and Vector Voltmeter measurements to its Site Master field portable instruments. This move blurs the line between bench-grade analysis and on-site troubleshooting, enabling technicians to capture vector-level data outside controlled laboratory environments. The strategic implication is significant: as deployment and maintenance activities move closer to real-world infrastructure, portable precision becomes a differentiator rather than a niche convenience.
Beyond individual product launches, two structural cost and capability dynamics continue to shape innovation incentives. High development and calibration costs for high-frequency operation above 15 GHz require substantial R&D investment, reinforcing the advantage of vendors with deep component expertise and established calibration infrastructure. At the same time, premium components and high-speed data acquisition systems increase production expenses, which keeps price-performance positioning under constant scrutiny. Vendors that can modularize performance, offer tiered configurations, or shift complexity toward software and calibration workflows are better positioned to absorb these cost pressures while preserving margin.
Policy, Regulation, and the Calibration Imperative
Regulatory and standards-driven expectations are increasingly shaping procurement behavior. Precision RF testing is now tightly coupled to compliance requirements in 5G, IoT, and Industry 4.0 applications, making VNAs essential tools for demonstrating that devices meet spectral, impedance, and linearity expectations. This is not merely a technical requirement; it is a commercial one. Buyers in regulated industries and supply chains are more likely to require evidence of traceable measurements, accredited calibration support, and documented measurement integrity.
This environment rewards vendors with recognized calibration ecosystems. For example, calibration laboratories associated with major instrumentation providers have been accredited in accordance with the ISO/IEC 17025 standard, reinforcing the value of standardized, auditable measurement workflows. For enterprise buyers, such accreditation reduces risk in qualification processes and simplifies supplier evaluation. For vendors, it creates a defensible moat: once a calibration and compliance pathway is embedded in a customer’s procurement process, switching costs rise, and relationship durability improves.
Demand-Side Shifts Across Communications, Automotive, and Advanced Manufacturing
Demand growth is being shaped less by any single application surge than by the broadening use of RF characterization across multiple sectors. Communications remains the largest application anchor, driven by continuous network evolution and the need to validate antenna systems, filters, and front-end components. Yet the more strategically interesting story is the diffusion of VNA use into adjacent domains. Automotive electrification and advanced driver-assistance systems increase the need for component and subassembly validation. Electronic manufacturing relies on VNAs for quality assurance and process control as circuit designs become more sensitive to impedance mismatches and parasitic effects. Aerospace and defense continue to represent a steady, requirements-driven demand base where high-reliability measurement and traceability are non-negotiable.
A parallel demand-side shift is the growing preference for deployable measurement solutions. Field technicians, line engineers, and distributed test teams increasingly expect instruments that are lighter, easier to power, and simpler to calibrate in non-ideal environments. This is where smaller-footprint, USB-powered, and calibration-module-supported designs gain relevance. The demand signal is not that every application requires a portable solution, but that a meaningful subset of use cases rewards reduced setup burden and faster time to measurement. Vendors that align product portfolios to this operational reality can open new customer segments without necessarily competing head-to-head in flagship laboratory instruments.
Supply Chain and Cost Structure Dynamics
The VNA market is affected by the same broader considerations that influence precision electronics: component availability, manufacturing complexity, and the cost of maintaining high performance at elevated frequencies. Premium components and high-speed data acquisition systems raise production expenses, while high-frequency calibration and validation compound the cost of bringing products to market. These factors do not necessarily cap growth, but they do shape how growth is captured. Vendors with stronger supply chain leverage, more efficient calibration workflows, and the ability to standardize subsystems across product families can better manage cost inflation and preserve competitive pricing.
At the same time, the market’s concentration pattern suggests that scale advantages matter. With the top five participants representing a substantial majority of revenue, established players can amortize R&D, calibration infrastructure, and support operations across broader installed bases. Newer or smaller vendors must therefore find defensible positions through specialization, portability, ease of use, or targeted application support rather than attempting to out-invest incumbents across the full performance spectrum.
Competitive Landscape and Leading Strategies
Positioning Among the Leading Participants
The market’s leadership group reflects distinct strategic emphases, each aligned to different buyer priorities. Keysight Technologies continues to emphasize high-performance bench architectures, with its NA520xA PNA-X and VectorStar/Streamline families positioning around multi-source flexibility and advanced receiver configurations. The strategic signal here is clear: Keysight is investing in measurement depth and configuration versatility for customers who prioritize characterization speed, signal integrity, and laboratory-grade performance. Its September 2024 introduction of the NA520xA PNA-X, with four RF sources, two internal combiners, and two low-noise receivers, reinforces an emphasis on reducing external hardware dependencies while expanding in-line test capability.
Rohde & Schwarz takes a different posture, focusing on broad frequency coverage and multiport scalability with offerings such as the ZNBT and ZVA families, including multiport VNAs extending up to 1.1 THz. This positions the company strongly in applications where frequency range, port density, and system integration matter more than compact portability. For buyers scaling test systems or requiring high-frequency coverage for advanced materials and component characterization, this breadth becomes a central value proposition.
Copper Mountain Technologies has carved out a pragmatic, accessibility-oriented position with 1-port and 2-port USB-powered VNAs supported by calibration modules. The strategic appeal lies in lower total cost of ownership, simpler deployment, and easier integration into distributed or resource-constrained environments. Rather than competing on extreme frequency or multi-source complexity, this approach targets customers who value fast setup, portability, and straightforward calibration workflows. It is a useful reminder that the market does not reward a single winning formula; it rewards fit-to-use-case.
Worldwide Vector Network Test Instrument Market
Anritsu combines field-portable capability with bench-class measurement expansion. Its VNA Master series and VectorStar/ShockLine families span a range of performance needs, while the May 2025 addition of Vector Network Analyzer and Vector Voltmeter measurements to Site Master field portable instruments illustrates a deliberate push to bring vector-level insight into field environments. This dual orientation gives Anritsu credibility in both installation/commissioning contexts and more detailed component characterization, allowing it to serve customer journeys that span lab and field.
How the Competitive Map Is Evolving
The landscape is not static. Several dynamics are reshaping how competition plays out. One is the continued consolidation of value among established players who can fund high-frequency R&D, sustain calibration infrastructure, and maintain global support networks. With market concentration already high, the Near-term question is less about dramatic market share rebalancing and more about how incumbents defend their positions through product refresh cycles, application-specific packaging, and service-grade differentiation.
A second dynamic is the emergence of sharper segmentation. Portable and field-deployable solutions are gaining visibility, while high-frequency laboratory systems remain essential but demanding. In between, vendors are experimenting with software-defined calibration, modular configurations, and tiered performance bundles. This suggests a market that is gradually moving away from one-size-fits-all positioning toward a portfolio logic where product families are designed around distinct workflows: bench characterization, field troubleshooting, production line verification, and specialized high-frequency research.
PW Consulting
A third dynamic is the role of compliance and certification as a competitive lever. In a market where measurement integrity is directly tied to product acceptance and regulatory alignment, vendors that can offer accredited calibration support and standardized documentation gain an advantage in enterprise and institutional sales cycles. This does not eliminate competition, but it raises the bar for entry and rewards organizations that treat calibration and traceability as strategic assets rather than back-office functions.
Outlook: Three Trends That Will Shape the Next 3 to 5 Years
Trend 1: Precision Testing Becomes Embedded in Broader Technology Deployment Cycles
VNA demand will increasingly be linked to the deployment cadence of 5G-related infrastructure, IoT scale-up, and Industry 4.0 automation. As these environments mature, the need for repeatable, traceable RF characterization will move from project-stage validation to ongoing maintenance and quality assurance. For vendors, this means opportunity lies not only in selling instruments but in enabling recurring workflows: calibration services, software-supported measurement routines, and application content that helps customers integrate VNAs into standard operating procedures. The commercial upside is sticky relationships and broader usage across the product lifecycle. The risk is that buyers may treat measurement as a commodity if differentiation is limited to hardware specifications alone.
Trend 2: Field-Portable and Accessible Form Factors Will Expand the Addressable User Base
Instrumentation that reduces setup burden, power requirements, and calibration complexity will continue to open opportunities beyond traditional laboratory buyers. USB-powered architectures, portable field instruments with vector-level capability, and calibration modules that simplify on-site workflows all point toward broader adoption among technicians, field engineers, and distributed production teams. This trend creates room for growth even in a market with modest overall CAGR, because it expands who can use VNAs and where they can be used. The risk is that ease-of-use offerings must still meet enough performance expectations to be trusted in serious characterization tasks. If portability comes at the expense of measurement credibility, adoption will stall.
Trend 3: High-Frequency and Multi-Port Capabilities Will Remain Strategic, Not Mass-Market
Above-50 GHz measurement and advanced multiport configurations will continue to matter disproportionately for certain applications, even if they represent a smaller share of total market revenue. In aerospace and defense, advanced materials research, and select communications roadmap items, high-frequency performance is a gating requirement. Vendors that can sustain leadership here will protect premium positions and high-value customer relationships. At the same time, the cost and complexity of high-frequency development above 15 GHz will keep this segment concentrated among players with strong R&D capacity and calibration maturity. The strategic opportunity is to use high-frequency leadership as an anchor for credibility while competing in broader segments through more accessible product tiers. The uncertainty is that demand for extreme-frequency instrumentation can be lumpy and dependent on specific program cycles, which makes revenue timing less predictable.
Strategic Implications for Decision Makers
For Instrument Manufacturers and Technology Providers
Product strategy should be guided by a clearer separation of use cases. High-performance laboratory systems, field-portable tools, and accessible mid-range instruments are not interchangeable; they solve different problems and carry different cost structures. Rather than stretching a single platform to cover every requirement, vendors can gain advantage by designing families that align with distinct buyer workflows and then integrating them through software, calibration support, and application documentation. Equally important is treating calibration and compliance support as marketable capabilities. In a market where measurement integrity influences purchasing decisions, accredited calibration pathways and standardized documentation can be as strategically relevant as raw frequency specifications. Finally, managing cost pressures from premium components and high-speed data acquisition will require disciplined modular design, shared subsystems, and efficient calibration processes.
For Investors and Strategic Partners
The VNA market offers stability more than explosive expansion, which makes selection of exposure points especially important. Given high concentration, the most direct path to market participation often runs through established players with strong calibration infrastructure, broad application coverage, and diversified product families. However, the most interesting differentiation may come from enabling layers: portable form factors, field-ready measurement workflows, software-assisted calibration, and application-specific packages that reduce friction for non-specialist users. Investment logic should therefore weigh not only headline revenue trajectory but also how well a company is positioned to capture value from recurring workflows, service attachment, and segmentation-driven expansion. The key uncertainty is that demand in high-frequency and program-driven segments can be uneven, so momentum should be evaluated across multiple application streams rather than a single headline driver.
For Procurement Leaders and Engineering Decision Makers
Purchasing decisions should begin with workflow reality rather than maximum specification. The right VNA choice depends on whether the priority is laboratory characterization depth, field portability, production line throughput, or compliance documentation. Buyers should assess not only instrument performance but also calibration support, accreditation alignment, and the practical burden of setup and maintenance. In regulated or supply-chain-sensitive environments, measurement traceability and standardized documentation can materially affect qualification risk. It is also worth considering total cost of ownership over the instrument lifecycle, including calibration, support, and the operational time required to bring the system into productive use. A slightly less ambitious specification that is easier to deploy and maintain can often deliver better business value than a higher-specification instrument that underutilizes its capabilities.
Closing Perspective
The Vector Network Analyzer market is entering a phase where growth will be shaped less by raw specification escalation than by how effectively vendors connect measurement capability to real-world deployment, compliance, and operational simplicity. The market’s steady expansion through 2032, combined with high concentration and clear segmentation across frequency ranges and applications, suggests a sector where differentiation will come from workflow fit, calibration credibility, and the ability to serve both laboratory and field environments. For manufacturers, the opportunity lies in portfolio logic and service-grade differentiation. For investors, the opportunity lies in identifying exposure to recurring value and accessible adoption pathways. For buyers, the opportunity lies in matching instrument capability to actual use cases while reducing qualification and maintenance risk.
Detailed segmentation data, regional and application-level revenue splits, company-level market share context, and forward scenarios are available in the full PW Consulting research report. That deeper dataset can support more precise sizing, competitor positioning analysis, and customized recommendations tailored to specific product plans, investment theses, or procurement requirements.
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steel Grating Market at $227M: What the 3.61% CAGR Really Means for 2026-2032
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Steel Grating Market
Market Landscape and Structural Challenges
The steel grating market has demonstrated consistent expansion over the past five years, with total market revenue growing from approximately 183.8 million USD in 2020 to 227.0 million USD in 2025. The trajectory continued into 2026, reaching 230.47 million USD, and forward projections indicate a climb to 289.39 million USD by 2032. This represents a compound annual growth rate of 3.61 percent across the forecast horizon. While the absolute growth rate may appear measured, the underlying composition reveals a market undergoing meaningful recalibration. Demand is no longer driven purely by replacement cycles or basic infrastructure spend. Instead, the market is being shaped by shifts in safety compliance, industrial modernization, and regional capacity realignments.
At the same time, the industry is navigating a set of structural challenges that will define competitive positioning over the next several years. One of the most pressing is the tension between raw material price volatility and margin preservation. Steel and aluminum input costs have experienced sharp fluctuations, with carbon steel price hikes placing direct pressure on manufacturing economics. These swings are not isolated events. They compound with rising non-raw material input costs, including labor and freight, which continue to escalate beyond initial commodity-driven increases. Producers that rely on static pricing models or long-term fixed contracts without effective pass-through mechanisms are being squeezed from both sides of the cost structure.
A second challenge lies in the evolving regulatory perimeter. Trade oversight has intensified, particularly regarding imported grating products. The United States International Trade Commission instituted five-year reviews for steel grating from China to assess whether continued dumping or subsidization warrants duty extensions. This development signals that trade policy will remain an active variable rather than a settled backdrop. Companies with heavy exposure to cross-border sourcing or those that have built cost advantages on imported feedstock must now factor in the possibility of renewed duties, supply route adjustments, and administrative review cycles. Regulatory shifts of this nature do not merely alter pricing. They reshape sourcing strategies, lead times, and risk allocation across the value chain.
The third challenge is operational and strategic rather than purely financial. Market concentration data indicates that the top three players hold approximately 35.0 percent of total revenue, while the top five capture around 55.0 percent. This level of consolidation suggests a market where scale, brand equity, and distribution reach matter significantly. Yet concentration also creates friction for mid-tier and regional manufacturers that must differentiate without competing purely on volume. The industry is not fragmented in a way that allows easy entry. It rewards producers that can combine reliable capacity, specification flexibility, and application-specific engineering. Firms that remain positioned as generic commodity suppliers face a narrowing path to sustainable margins.
Key Drivers Reshaping Market Dynamics
Technological Advancement and Material Innovation
Product engineering has moved from a secondary concern to a core competitive lever. Grating manufacturers are increasingly differentiating through fabrication precision, load-specific designs, and surface treatments that extend service life in demanding environments. Pressed and electro-forged gratings, for example, allow tighter tolerances and more consistent anti-slip performance, which matters in walkway and platform applications where safety and durability intersect. Manufacturers that integrate custom fabrication into their core operations are better positioned to serve industrial customers with non-standard dimensions, specialized coatings, or elevated corrosion resistance requirements. This shift toward engineered solutions raises the barrier to entry and rewards capability depth over pure volume production.
In parallel, the industry is seeing gradual adoption of improved surface refinement and finishing processes. Pickling and controlled surface treatment are becoming more relevant for stainless and specialized carbon steel applications where appearance, cleanliness, and long-term corrosion control influence procurement decisions. These technical upgrades are not cosmetic. They translate into lower maintenance intervals, better compliance with hygiene or environmental specifications, and stronger positioning in applications where downtime is costly. The broader implication is that value in the steel grating market is migrating toward specification accuracy, finish quality, and application engineering, rather than remaining anchored solely to base metal weight and standard profiles.
Policy Frameworks and Trade Oversight
Policy and trade dynamics are actively shaping cost structures and sourcing decisions. The May 2026 decision by the United States International Trade Commission to open five-year reviews for Chinese steel grating imports underscores the continued scrutiny of cross-border competition. For domestic producers, this environment can reinforce the case for localized capacity and established supply relationships. For buyers and distributors, it introduces both risk and opportunity, depending on how procurement portfolios are structured. Where reliance on low-cost imports has been a primary margin strategy, renewed duty exposure can compress flexibility and force rapid renegotiation of supply terms.
Environmental regulation is also influencing upstream conditions. The finalization of amendments to National Emission Standards for Hazardous Air Pollutants related to taconite iron ore processing in March 2024 affects the feedstock environment for steel production. While the direct impact reaches further up the value chain, the downstream consequence is a regulatory landscape that can influence iron ore processing economics and, indirectly, the stability of input costs for steel-intensive products. Producers and procurement teams that monitor these regulatory milestones can anticipate shifts in feedstock cost structures earlier and adjust hedging, inventory, or supplier diversification strategies accordingly.
Demand-Side Evolution in Industrial and Infrastructure Applications
Demand patterns are shifting as end users prioritize safety, asset longevity, and functional integration. Walkways remain a significant application area, reflecting ongoing needs in industrial facilities, utilities, and commercial infrastructure where safe pedestrian access must be maintained under heavy use or harsh conditions. Platforms represent another substantial demand center, particularly in processing plants, energy operations, and manufacturing environments where equipment access, inspection routes, and worker safety zones must be structurally reliable. Stair treads continue to draw consistent demand due to their dual role in functionality and code-driven safety requirements.
Beyond these core uses, security fencing, drainage covers, and trench covers illustrate how steel grating is increasingly specified as part of broader infrastructure and site-management solutions. Procurement teams are no longer buying grating simply as an isolated metal component. They are integrating it into facility design, drainage planning, perimeter security, and load-bearing access systems. This application-level thinking increases the importance of product consistency, lead-time reliability, and technical support. Buyers are more likely to consolidate suppliers that can deliver across multiple application needs, which in turn rewards manufacturers with broader catalogs and stronger service capabilities.
Supply Chain Cost Architecture and Operational Pressure
The cost environment is being reshaped by more than commodity price movement alone. Labor costs and freight expenses continue to rise, adding pressure that extends well beyond initial steel price fluctuations. This broader cost architecture means that manufacturers must manage a wider set of margin variables simultaneously. Efficient production scheduling, regional distribution logic, and freight-sensitive order optimization are becoming part of the competitive formula. Producers that can align capacity with demand geography, reduce unnecessary handling, and maintain consistent order fulfillment gain an advantage that is not always visible in raw material benchmarks alone.
At the same time, carbon steel price volatility remains a persistent feature of the landscape. The impact is felt not only in direct input costs but also in the predictability of quoting, contracting, and inventory planning. In a market where customers increasingly value reliability and specification accuracy, the ability to manage price variability without sacrificing responsiveness is a meaningful operational capability. This is one reason why strategic sourcing, forward purchasing discipline, and transparent price communication are becoming central topics in buyer-supplier negotiations.
Competitive Positioning and Market Structure
The competitive landscape is anchored by manufacturers that combine production scale, application breadth, and regional footprint. Nucor Corporation operates steel bar grating through its Vulcraft and Verco divisions, with annual capacity around 50,000 tons and a product range that spans standard, heavy-duty, and custom-fabricated offerings. This positions the company within a broader structural steel ecosystem where grating is integrated with complementary metal products and distributed through established industrial channels. Its scale and divisional integration provide a strong foundation for serving large-volume and specification-driven buyers.
IKG has built a recognized position in pressure-locked bar grating and safety flooring, supported by more than 100 years of expertise across the United States and Mexico. Its full product line includes pressure-locked and anti-slip solutions, which align closely with demand in access infrastructure and safety-critical applications. Ohio Gratings stands out as the largest privately-owned industrial and commercial grating provider in the United States, with specialization in design, manufacturing, and custom fabrication using carbon steel, stainless steel, and aluminum. That combination of private ownership and broad material capability allows a high degree of flexibility in custom work and customer-specific engineering.
AMICO continues to emphasize domestically produced bar grating for industrial applications, expanding its range to include common bar grating items. This focus on U.S.-based production appeals to buyers prioritizing supply continuity, domestic sourcing expectations, and shorter lead times for standard products. On the international side, JK TECHNIC in France manufactures pressed gratings, electro-forged grating, and solutions for stair treads, platforms, and industrial applications, while Meiser in Germany focuses on high-grade products and surface refinement, including pickling, and maintains a U.S. subsidiary through Meiser Gratings Inc. These European manufacturers illustrate how specialized finishing capability and engineered product lines can support cross-border positioning, particularly where surface quality and specification precision are valued.
A defining recent development is the February 2026 acquisition of IKG by a joint venture of Meiser and Dutco from KPS Capital Partners. The transaction is notable because it combines brands and capacity to form what is described as the world's largest grating manufacturer. This kind of consolidation signals a market trajectory toward greater scale integration, shared technical resources, and broader geographic coverage. For the competitive field, it raises the strategic stakes around capacity alignment, brand portfolio strength, and the ability to serve multi-region demand without losing application-specific expertise. Consolidation of this nature can improve purchasing leverage and production efficiency, but it also places pressure on remaining independent players to clarify their differentiation, whether through custom fabrication speed, regional service density, or niche material expertise.
Market evolution is therefore shaped by both integration and specialization. Large-scale combinations can capture efficiencies and widen distribution reach, while privately-held and regionally anchored manufacturers can compete by offering faster custom turnaround, closer customer collaboration, and material-specific proficiency. New entrants face a challenging environment given the concentrated revenue structure and the importance of established production capability. As a result, the most viable path for expansion is often through targeted capability building, strategic partnerships, or acquisition of specialized assets rather than attempting to compete purely on price in standard product categories.
PW Consulting Chemical & Energy Research Center
Forward Outlook and Emerging Opportunities
Consolidation as a Strategic Accelerator
Over the next three to five years, further consolidation is likely to remain a central theme, particularly where combined capacity can strengthen supply reliability and broaden application coverage. The recent move to unite major brands and production resources illustrates how scale can be leveraged not only for cost efficiency but also for a wider product and service footprint. For customers, this can translate into simpler sourcing across multiple grating types and faster access to engineered solutions. For competitors, the strategic response will involve deciding whether to pursue scale through partnership or acquisition, or to double down on differentiation through customization, regional responsiveness, and specialized material performance.
Regulatory Continuity and Sourcing Realignment
Trade oversight and environmental regulation are expected to continue influencing sourcing strategies. The review of duties on Chinese steel grating and the broader regulatory environment around steel production feedstock suggest that supply chain design will remain dynamic. In practical terms, this creates opportunities for producers with stable domestic or near-shore capacity, as well as for procurement teams that build flexibility into supplier portfolios. Companies that preempt regulatory review cycles by diversifying sources, strengthening quality documentation, and aligning lead times with trade uncertainty will be better positioned to maintain continuity when policy conditions shift.
Engineered, Application-Specific Solutions as a Growth Axis
A third forward trend is the increasing premium on application-tailored grating products. As end users integrate grating into safety systems, drainage infrastructure, security setups, and industrial access platforms, the specification process becomes more nuanced. This favors manufacturers that can support custom dimensions, refined surface finishes, anti-slip performance, and consistent load-bearing characteristics. The commercial opportunity lies in moving up the value chain from commodity supply toward solution provision. Suppliers that invest in engineering support, responsive fabrication, and application knowledge can capture higher-margin work and build stickier customer relationships.
Steel Roofing Market
These trends also carry risk. Over-reliance on any single region, feedstock channel, or pricing model can become exposed if trade conditions change, raw material volatility intensifies, or labor and freight costs continue to rise. Additionally, if consolidation proceeds too aggressively without preserving local service quality or customization capacity, some customers may seek alternatives that can offer more direct engagement and faster adaptation to project-specific requirements. The balance between scale and responsiveness will therefore remain a critical strategic tension.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to strengthen the operational and technical foundations that support margin resilience and customer retention. This includes tightening cost pass-through mechanisms, investing in custom fabrication capability, and clarifying material specialization where it creates genuine differentiation. Producers should also evaluate whether their distribution and service models align with application-driven buying behavior. Where customers increasingly seek integrated solutions across walkways, platforms, stair treads, and covers, manufacturers that can respond with consistent quality and specification support will have a stronger competitive position. In an environment shaped by consolidation, clearly defined differentiation is not optional. It is the basis for defending share without engaging in unsustainable price competition.
For investors, the market presents a landscape where scale, integration, and application capability matter more than ever. The recent formation of a combined global-scale manufacturer highlights the value created through strategic consolidation, but it also underscores the need to assess whether scale translates into durable margins, better customer coverage, and operational flexibility. Investment decisions should account for exposure to trade review cycles, raw material volatility, and the extent to which a company's portfolio is tied to standard commodity products versus engineered, specification-sensitive solutions. Companies that can demonstrate both capacity reliability and the ability to serve higher-value application segments are better positioned for long-term relevance.
For procurement and supply chain leaders, the key is to move beyond price-only evaluation and build sourcing strategies that account for regulatory continuity, lead-time stability, and specification performance. Diversifying suppliers across regions and product types can reduce vulnerability to duty reviews or feedstock disruptions. At the same time, developing clearer technical requirements around load capacity, surface treatment, anti-slip performance, and corrosion resistance can improve long-term total cost outcomes by reducing maintenance, downtime, and replacement frequency. Procurement teams that engage earlier with manufacturers on application needs and lead-time planning are more likely to secure consistent supply and avoid reactive purchasing when market conditions tighten.
Structural Steel Market
Across all of these perspectives, the strategic value of detailed, segment-level intelligence is clear. Broad market direction provides context, but the decisions that shape outcomes sit in the specifics: how demand is distributed across applications, which material types are gaining or losing relative share, where regional capacity is expanding or constrained, and how competitive consolidation is altering supply dynamics. A more comprehensive view of these elements supports sharper planning, more disciplined sourcing, and better-timed investment choices. For organizations that need granular segment data, competitive tracking, and tailored scenario analysis, the full research report offers a deeper breakdown of market structure and forward options.
For detailed analysis of this topic, please visit the official page: Steel Grating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fiber Cement Market 2026: Asia Pacific's 9.79B Demand Reshapes Growth Beyond 4.08% CAGR
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Fiber Cement Market: A 2032 Outlook
The global fiber cement market has established itself as a cornerstone of modern construction materials, driven by the demand for durable, fire-resistant, and low-maintenance building envelopes. As of 2025, the market is valued at 22.45 billion USD, reflecting steady growth from 18.17 billion USD in 2020. This trajectory indicates a compound annual growth rate of approximately 4.08% through 2032, signaling a mature yet expanding sector. The forecast period from 2026 to 2032 suggests continued momentum, with projected revenues reaching nearly 29.71 billion USD by the end of the decade. This growth is not uniform; it is shaped by regional dynamics, technological advancements, and shifting regulatory landscapes. For executives and investors, understanding the underlying forces behind these figures is critical to capitalizing on emerging opportunities while mitigating structural risks.
Fiber Cement Board Market
Market Resilience Amidst Structural Headwinds
Despite the positive growth trajectory, the industry faces significant challenges that demand strategic attention. The market is characterized by high concentration, with the top three players commanding 60% of the revenue and the top five holding 70%. Such consolidation creates barriers for new entrants and places pressure on mid-tier manufacturers to differentiate or consolidate. Additionally, the production of fiber cement involves fibrous silicate minerals, which have come under increased regulatory scrutiny. In 2025, the United States Environmental Protection Agency issued instructions on safe use and exposure during manufacturing, while the government of British Columbia proposed additional safety measures for plants handling these materials. These regulatory shifts introduce compliance costs and operational complexities that can erode margins if not managed proactively. Furthermore, raw material price fluctuations for cement and cellulose have raised production costs, compounding the pressure from rising labor expenses in high-cost regions.
The Inflection Point: Compliance vs. Innovation
The industry is currently at an inflection point where regulatory compliance and technological innovation intersect. Manufacturers must navigate the dual challenge of adhering to stricter safety protocols while simultaneously investing in product enhancements that justify premium pricing. The balance between cost efficiency and safety standards is becoming a key differentiator. Companies that treat compliance as a mere obligation risk falling behind, whereas those that integrate safety into their operational ethos can leverage it as a competitive advantage. This dynamic is reshaping the competitive landscape, favoring firms with robust R&D capabilities and agile supply chains.
Cement Boards Market
Key Drivers Shaping Market Evolution
Several core factors are propelling the fiber cement market forward, creating a complex environment where strategic agility is paramount.
Technological Innovation and Product Differentiation
Innovation remains a primary catalyst for growth. Manufacturers are continuously expanding their portfolios to meet diverse architectural and performance needs. For instance, in February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie® products, including Artisan Trim, at the NAHB International Builders' Show. This move highlights the industry's focus on aesthetic versatility and customization, allowing fiber cement to compete more effectively with traditional materials like wood and vinyl. Such product unveilings are not merely incremental; they represent a strategic push to capture higher-margin segments within the siding and trim categories. As consumers and builders increasingly demand materials that offer both durability and design flexibility, companies that lead in product innovation are well-positioned to capture market share.
Regulatory Environment and Standardization
Regulatory developments are fundamentally altering the market's operational framework. In October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in both combustible and noncombustible construction. This standardization effort aims to clarify performance expectations and facilitate broader adoption in construction projects where fire safety is paramount. Simultaneously, environmental regulations regarding fibrous silicate minerals are tightening. The EPA's guidelines on safe use and exposure, along with provincial measures in British Columbia, signal a global trend toward stricter occupational and environmental health standards. While these regulations increase compliance burdens, they also raise the barrier to entry, potentially consolidating the market further around established players with the resources to manage complex regulatory requirements. Standardization can also open new application avenues, particularly in commercial and multi-family residential sectors where code compliance is a critical decision factor.
Demand-Side Shifts and Cost Pressures
On the demand side, the construction industry's preference for low-maintenance and long-lasting materials continues to drive adoption. Fiber cement's resistance to rot, pests, and fire aligns with the growing emphasis on sustainable and resilient building practices. However, cost structures are evolving. Raw material price volatility for cement and cellulose directly impacts production economics, forcing manufacturers to optimize supply chains or pass costs to customers. Concurrently, the cost of living in high-cost states drives up both labor and material costs for fiber cement siding projects, which can dampen demand in price-sensitive segments. This economic pressure is prompting buyers to evaluate total cost of ownership rather than upfront prices, favoring materials that reduce lifecycle maintenance expenses. Manufacturers must therefore communicate value propositions that extend beyond unit price, emphasizing durability and energy efficiency benefits.
Supply Chain Dynamics and Regional Concentration
Supply chain resilience has become a focal point, particularly given the geographic distribution of production and consumption. Asia Pacific represents the largest revenue contributor, reflecting rapid urbanization and infrastructure development in the region. North America follows as a significant market, driven by residential renovation and new construction activity. The concentration of revenue in these regions underscores the importance of localized supply chains and distribution networks. Disruptions in raw material sourcing or logistics can have outsized impacts, making diversification and strategic partnerships essential. Companies are increasingly investing in regional manufacturing capabilities to reduce lead times and mitigate currency or tariff risks. This localization trend also supports faster response to regional building codes and consumer preferences.
Competitive Landscape and Leadership Strategies
The fiber cement market is defined by a mix of global giants and regional specialists, each pursuing distinct strategies to secure their position.
Strategic Positioning of Leading Players
James Hardie Industries PLC, headquartered in Ireland, maintains a strong focus on Hardie® fiber cement siding and backer boards, leveraging its brand recognition and extensive distribution network in North America. The company's recent activities, such as the three-year exclusive agreement with Davidson Homes announced in May 2025, illustrate a strategy of deepening partnerships with key builders to secure volume and market presence. This approach not only guarantees supply volume for Hardie® siding and trim products but also embeds the brand into the builder's product specifications, creating switching costs for competitors.
ETEX Group, based in Belgium, specializes in fiber cement boards and sheets, catering to a broad range of construction applications. Their strategy emphasizes product versatility and technical performance, positioning them as a reliable supplier for both residential and commercial projects. Saint-Gobain, a France-based multinational, offers fiber cement products for construction applications, benefiting from its vast resources and cross-industry synergies. The company's scale allows it to invest in sustainability initiatives and global distribution, appealing to large-scale developers and institutional buyers who prioritize supplier stability and comprehensive product lines.
Nichiha Corporation from Japan focuses on high-performance fiber cement panels and siding, leveraging technological expertise to deliver products with superior durability and aesthetic qualities. This focus on high-performance segments allows them to command premium pricing in markets that value advanced material properties. Cembrit Holding A/S, headquartered in Denmark, provides fiber cement siding and exterior products, with a strong presence in European markets where aesthetic preferences and regulatory standards differ from those in North America.
In the United States, companies like Allura USA and American Fiber Cement Corporation offer fiber cement siding products and boards, competing on regional availability and customer service. Allura USA's focus on fiber cement siding products positions it as a direct competitor in the residential siding segment, where brand loyalty and installer networks play crucial roles. American Fiber Cement Corporation's offering of fiber cement boards and sheets addresses both siding and industrial applications, diversifying its revenue streams.
Elementia Materials from Mexico supplies fiber cement products for construction, capitalizing on its proximity to the North American market and cost advantages. Everest Industries Limited, based in India, produces fiber cement boards, tapping into the growing demand for affordable yet durable building materials in emerging economies. CSR Limited in Australia provides fiber cement products, serving the Asia Pacific region with a focus on local market requirements. Plycem Corporation and Swisspearl Group, both US and Switzerland-based respectively, offer fiber cement siding, boards, and cladding, emphasizing quality and design in their respective markets.
PW Consulting
Competitive Dynamics and Market Evolution
The competitive landscape is evolving through a combination of integration, differentiation, and selective entry. The high market concentration suggests that mergers and acquisitions may continue as larger players seek to expand their geographic reach or product portfolios. However, niche players are finding opportunities by specializing in specific applications, such as high-performance panels or decorative trim, where they can build strong brand identities. New entrants face significant hurdles due to regulatory barriers and the capital intensity of manufacturing, but strategic partnerships or acquisitions of smaller brands can provide a pathway to market. The trend toward exclusive distribution agreements, as seen with James Hardie and Davidson Homes, indicates a shift toward securing dedicated channel partnerships to ensure stable demand and reduce competitive pressure in key accounts.
Future Trends and Commercial Opportunities (2026-2032)
Looking ahead, several trends will shape the fiber cement market, presenting both opportunities and risks for stakeholders.
Trend 1: Consolidation of Standards and Expansion into New Applications
As regulatory bodies like ICC-ES finalize criteria for fibre-cement siding, the market is likely to see a harmonization of standards that facilitates broader adoption in commercial and multi-family construction. This trend opens opportunities for manufacturers to develop products that exceed new performance benchmarks, positioning them as preferred choices for code-compliant projects. The clarification of combustible and noncombustible construction usage can unlock new revenue streams, particularly in regions where fire safety regulations have previously limited material choices. Companies that proactively align their product development with these standards can gain first-mover advantage in emerging application segments.
Trend 2: Supply Chain Localization and Cost Optimization
Continued raw material volatility and labor cost pressures will drive further localization of supply chains. Manufacturers will increasingly invest in regional production facilities to reduce logistics costs and respond faster to local demand fluctuations. This trend favors companies with the capital to expand capacity or form joint ventures with local partners. For investors, regions with growing construction activity and favorable cost structures, such as parts of Asia Pacific and Latin America, may offer higher growth potential. However, localization also requires navigating diverse regulatory environments and building local expertise, which can be resource-intensive. Opportunities exist for firms that can balance global scale with local agility, leveraging regional hubs to serve nearby markets efficiently.
Trend 3: Sustainability and Lifecycle Value as Purchasing Drivers
Sustainability is becoming a more prominent factor in material selection, driven by both regulatory requirements and consumer preference for eco-friendly buildings. Fiber cement's durability and resistance to environmental degradation align with lifecycle assessment criteria, potentially giving it an edge over materials with shorter lifespans or higher maintenance needs. Manufacturers that can provide transparent data on environmental impact, recycling potential, and energy efficiency benefits will be better positioned to capture projects with green building certifications. This trend also creates opportunities for innovation in formulations that reduce the use of regulated materials or improve recyclability. However, the risk lies in greenwashing accusations or failure to substantiate claims, which can damage brand reputation. Stakeholders must ensure that sustainability messaging is backed by verifiable data and third-party certifications.
Actionable Insights for Decision Makers
For executives, investors, and procurement professionals, navigating the fiber cement market requires a clear understanding of where to focus efforts and resources.
For Manufacturers and Producers
Prioritize innovation in product lines that address emerging aesthetic and performance demands, such as specialized trim and high-performance panels. Invest in compliance infrastructure to navigate evolving regulations regarding fibrous silicate minerals and product standards, turning these requirements into a competitive moat. Explore strategic partnerships or exclusive agreements with key builders and distributors to secure demand and reduce channel conflict. Additionally, evaluate supply chain resilience by diversifying raw material sources and considering regional production investments to mitigate cost volatility and logistics risks. Building a robust installer and contractor network can also enhance market penetration, as these groups influence product specification at the project level.
For Investors and Capital Allocators
Focus on companies with strong market positions, high concentration advantages, and the capability to invest in R&D and compliance. The market's growth trajectory suggests steady returns, but selectivity is crucial given the concentration and regulatory risks. Look for firms that demonstrate adaptability to regional demand shifts and have strategies to manage raw material and labor cost pressures. Consider the potential of consolidation plays, where acquiring regional players can accelerate market entry or product diversification. Due diligence should include a thorough assessment of regulatory exposure, supply chain dependencies, and the sustainability of competitive advantages in a market where barriers to entry are rising.
For Procurement and Construction Decision Makers
Evaluate fiber cement products based on total cost of ownership, including durability, maintenance requirements, and compliance with local building codes. Engage with suppliers that offer transparent information on product performance, safety standards, and environmental impact. Consider the reputational and operational risks associated with supply chain disruptions; diversifying suppliers or selecting manufacturers with localized production can mitigate these risks. Stay informed about evolving standards, such as the proposed ICC-ES criteria, to ensure that selected materials meet current and future code requirements. Building relationships with manufacturers that provide technical support and installer training can also reduce installation errors and improve project outcomes.
Accessing Detailed Intelligence for Strategic Advantage
The fiber cement market presents a complex array of opportunities and challenges that require granular data and tailored analysis to navigate effectively. While macroeconomic trends and competitive dynamics provide a high-level view, the specific nuances of regional demand, segment performance, and company-level strategies are essential for making informed decisions. Detailed segmentation data, including breakdowns by region, type, and application, can reveal hidden growth pockets and inform targeted market entry or expansion plans. Furthermore, customized insights into supply chain dynamics, regulatory timelines, and competitor benchmarking can help organizations anticipate shifts and allocate resources with precision. For those seeking to deepen their understanding and refine their strategic planning, accessing comprehensive research reports with granular segmentation and proprietary analysis is a valuable step toward securing a competitive edge in this evolving market.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Toothbrush Market: How the 6.98% CAGR and Asia Pacific Surge Redefine Growth Beyond 2032
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Electric Toothbrush Market
Market Overview and Core Challenges
The global electric toothbrush market has demonstrated consistent expansion over the past half-decade, reaching an estimated 215.0 million USD in 2025. Historical growth from 163.15 million USD in 2020 reflects a sustained shift in consumer oral care preferences, while the projected trajectory through 2032 points toward a market approaching 344.8 million USD. This expansion is underpinned by a compound annual growth rate of approximately 6.98 percent, signaling steady but not explosive momentum. The market structure remains relatively fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding just over a quarter. Such concentration levels indicate that no single entity dominates the value chain, leaving meaningful room for differentiation and strategic positioning.
Electric Dental Handpieces Market
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive outcomes over the next cycle. First, the transition from basic cleaning functionality to connected, data-driven oral care is raising the bar for product differentiation. Consumers increasingly expect seamless app integration, personalized brushing feedback, and durable hardware, which compresses margins for generic manufacturers and rewards companies with robust software ecosystems. Second, regulatory complexity continues to constrain speed-to-market. In the United States, electric toothbrushes are classified as Class II medical devices, requiring 510(k) premarket notification clearance. Compliance with ISO 19452:2022 for performance testing, alongside material and chemical standards tied to FDA 21 CFR Part 177 and biocompatibility requirements, adds layers of validation that smaller entrants must navigate carefully. Third, cost structures are bifurcating. Entry-level units now carry manufacturing costs in the range of 6 to 11 USD, while ultra-premium smart devices can reach 31 to 55 USD per unit. This spread forces companies to make deliberate portfolio choices: compete on volume and accessibility, or invest in premium features and validation that justify higher price points.
Key Drivers of Market Evolution
Technological Innovation and Intelligent Oral Care
The most consequential shift in the electric toothbrush space is the migration from mechanical cleaning to intelligent, feedback-enabled hygiene. Sonic technology continues to lead share of attention, but the real value creation lies in how companies embed sensors, pressure monitoring, and app-based coaching into the user experience. Recent product launches illustrate this direction. In March 2026, Royal Philips N.V. introduced two new Philips Sonicare ranges built around next-generation sonic technology, fluid action cleaning, pressure sensors, and app connectivity, signaling a continued emphasis on clinical-style cleaning paired with digital engagement. Earlier, in February 2026, quip expanded its Ultra family with the Ultra Lite Sonic Electric Toothbrush, featuring EasyClick brush pods, a pressure sensor, and extended battery life. The move highlights how design simplicity and modular replacement systems can lower friction for users migrating from manual brushes. In January 2025, Procter & Gamble Co. launched the Oral-B iO2, an oscillating-rotation model positioned for users making the easiest switch from manual brushing, underscoring the importance of onboarding and ease of use in driving conversion.
These developments point to a broader pattern: hardware excellence is becoming table stakes, while differentiation is increasingly driven by software, data, and user journey design. Companies that can translate brushing data into actionable habits, reduce replacement friction, and maintain clinically credible cleaning claims are better positioned to command loyalty and justify premium pricing.
Regulatory and Standards Environment
Regulatory expectations are tightening around performance validation and material safety. Powered toothbrushes must comply with ISO 19452:2022 for test methods that measure performance, and manufacturers must ensure that brush heads and materials meet FDA regulations for medical devices, including biocompatibility testing and FDA 21 CFR Part 177 for food-contact and medical-grade materials. These requirements do not merely add compliance overhead; they shape product architecture, supplier selection, and time-to-market. Firms that standardize testing protocols early, invest in material qualification, and document validation trails can reduce launch risk and build trust with dental professionals and retail partners. The regulatory backdrop also creates an implicit moat: brands that can demonstrate consistent compliance and clinical-style performance claims gain credibility that generic alternatives struggle to replicate.
Consumer Behavior and Demand-Side Shifts
Demand-side dynamics are being reshaped by three interrelated forces. First, oral care is increasingly viewed through a preventive health lens, with consumers and dental professionals alike emphasizing plaque removal, gum health, and consistent technique. This framing supports repeat purchases of replacement heads and encourages adoption among users who previously relied on manual brushes. Second, subscription and refill models are expanding the commercial relationship beyond the initial hardware sale. Modular pod systems, predictable replacement cycles, and bundled accessories create recurring revenue streams and deepen brand touchpoints. Third, eligibility dynamics are evolving. There is growing industry attention around the potential expansion of FSA/HSA eligibility for oral care products, including electric toothbrushes, which would offer consumers additional tax-advantaged spending options and could lower effective purchase barriers for certain segments. Even before formal changes, the conversation signals that oral care devices are increasingly positioned alongside health-related expenditures, reinforcing premiumization and repeat usage narratives.
Cost Structures and Supply Chain Realities
Manufacturing economics are pressuring both ends of the portfolio. At the entry level, cost discipline is essential to maintain acceptable margins while competing on accessibility. At the premium end, the cost of sensors, batteries, app infrastructure, and certification can escalate quickly, requiring careful feature prioritization. The supply base reflects this tension: a mix of established consumer goods manufacturers, dental-focused innovators, and specialized OEM/ODM partners in Shenzhen and surrounding regions offers customization, ISO 13485 and FDA-aligned certifications, and volume flexibility. This ecosystem enables faster iteration and private-label options, but it also raises quality assurance and brand consistency considerations. Companies that invest in supplier qualification, standardized testing, and clear design-to-manufacturing handoffs can reduce variability and protect brand integrity as they scale.
Competitive Landscape and Leading Strategies
The competitive field combines large consumer goods portfolios, dental-adjacent specialists, and a growing cohort of Chinese OEMs and smart-device innovators. Royal Philips N.V. continues to anchor its position around Philips Sonicare, leveraging next-generation sonic technology, fluid action cleaning, pressure sensing, and app connectivity to frame the category around clinical-style cleaning and guided habits. Procter & Gamble Co. competes through Oral-B's oscillating-rotation heritage, with the iO2 launch emphasizing the easiest transition from manual brushing, a strategic focus on reducing adoption friction. Colgate-Palmolive Company positions its electric toothbrushes around oscillating-rotation technology for plaque and stain removal, aligning with its broader oral care distribution strengths. Water Pik, Inc. differentiates by combining sonic oscillation with water flossing capabilities, appealing to users seeking a more comprehensive hygiene routine in a single device.
Smaller and mid-tier players are carving out niches through design, material choice, and smart features. Foreo emphasizes sonic technology with medical-grade silicone bristles for gentle, effective cleaning, targeting users who prioritize soft-tissue comfort. quip focuses on minimalist design, EasyClick brush pods, pressure sensors, and long battery life, lowering the barriers to consistent use. Oclean Technology Co., Ltd. pursues AI coaching, app connectivity, and high-performance sonic oscillation to deliver professional-level feedback, aligning with the intelligence trend. Broxo S.A. maintains a clinical focus on plaque removal and gum health, while Panasonic Corporation offers user-friendly sonic designs that balance performance and accessibility. On the supply side, a network of Shenzhen- and Ningbo-based manufacturers, including Relish Tech, Auxbon, Shenzhen Libai Technology, and several Ningbo and Yueqing producers, provides OEM/ODM capacity with ISO 13485 and FDA-aligned certifications, enabling global brands to iterate quickly and localize offerings.
The landscape is evolving along two parallel tracks. On one hand, consolidation pressure is building as larger players seek to strengthen digital engagement, repeat-purchase models, and clinical credibility. On the other hand, fragmentation persists at the smart-device and OEM level, where rapid iteration, modular designs, and regional manufacturing flexibility allow new entrants to test differentiated value propositions. The strategic implication is clear: scale alone is insufficient. Winning positions will combine credible cleaning performance, compliant materials and testing, a compelling user journey, and a commercial model that captures recurring value after the initial sale.
Future Trends and Commercial Opportunities
Intelligent, Habit-Forming Oral Care
Over the next three to five years, the market is likely to reward products that translate brushing into measurable, coachable habits. Expect tighter integration between hardware sensors and app-based feedback, more refined pressure and coverage metrics, and design choices that reduce friction in replacement and charging. The commercial opportunity lies in pairing hardware with services: subscription refills, personalized recommendations, and dental-professional-aligned guidance that reinforce consistent use. Brands that can demonstrate credible performance while making good habits effortless will be better positioned to retain users and defend premium pricing. The risk is feature creep without corresponding value; overly complex apps or unreliable sensors can erode trust and increase support costs.
Premiumization Paired with Accessibility Tiers
The market is moving toward a dual-structure portfolio strategy. Premium smart devices will continue to target users willing to pay for connectivity, coaching, and refined materials, while entry-level and mid-tier models will compete on reliability, ease of use, and affordability. This bifurcation creates opportunities for tiered branding, modular feature sets, and channel-specific assortments. Manufacturers can use OEM/ODM partnerships to scale distinct tiers efficiently, provided they maintain quality and compliance discipline across the range. The key uncertainty is how quickly reimbursement and tax-advantaged spending dynamics evolve; if FSA/HSA eligibility broadens, it could accelerate adoption in certain segments and shift price sensitivity, while a slower trajectory would keep volume growth dependent on out-of-pocket conversion.
Compliance and Clinical Credibility as Differentiators
As the category matures, regulatory and standards compliance will increasingly function as a differentiator rather than a hurdle. Manufacturers that standardize ISO 19452:2022 testing, maintain rigorous material and biocompatibility documentation, and align brush head materials with FDA expectations will reduce launch risk and strengthen retailer and professional confidence. The opportunity is to use compliance and validated performance as narrative anchors in marketing, retail merchandising, and dental-channel engagement. The downside risk is complacency: incremental changes in material regulations or testing expectations can disrupt product lines if qualification processes are not proactive and well-documented.
Strategic Implications for Decision-Makers
For Manufacturers and Brand Owners
Build a portfolio that explicitly separates accessibility from intelligence. Use modular hardware and replaceable pod systems to reduce long-term friction, and invest in app and sensor design that delivers consistent, understandable feedback. Prioritize compliance infrastructure early, including ISO 19452:2022 testing and material qualification aligned with FDA expectations, so that performance claims and launch timelines remain credible. Evaluate OEM/ODM partners for quality systems, certification coverage, and design-to-production consistency, and use regional manufacturing flexibility to scale tiers without compromising brand standards.
For Investors
Focus on business models that capture value beyond the initial hardware sale. Recurring revenue from refills, subscription pods, and accessories can improve durability of margins and reduce reliance on cyclical replacement cycles. Assess whether a company's differentiation rests on defensible features—credible cleaning performance, compliant materials, and engaging software—rather than transient marketing claims. Pay attention to regulatory readiness and supplier qualification, as these factors increasingly influence launch speed and retail access. Monitor the reimbursement conversation as a potential catalyst that could shift effective price sensitivity in select markets.
PW Consulting
For Procurement and Channel Partners
Prioritize suppliers with documented compliance trails, standardized performance testing, and clear material specifications. Consistency across batches and regions matters as much as unit cost, particularly for premium SKUs where brand trust and professional recommendation drive repeat purchases. Evaluate replacement-system design and battery life as practical determinants of customer satisfaction and return rates. Where possible, structure contracting to ensure quality assurance, certification continuity, and transparent testing documentation, reducing the risk of downstream compliance or performance issues.
The electric toothbrush market is entering a phase where growth is increasingly defined by how well companies convert hardware capability into sustained user behavior, credible performance, and compliant, repeatable operations. For decision-makers seeking deeper segmentation data, pricing dynamics, and customized go-to-market guidance, the full PW Consulting research report provides the granular detail needed to translate these trends into specific commercial moves.
Power Toothbrush Market
For detailed analysis of this topic, please visit the official page: Electric Toothbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
POE Market CAGR: The 7.6% Growth Story Reshaping Automotive and Packaging Demand
By PW Consulting, 2026-09-21
Polyolefin Elastomers (POE) Market: Strategic Shifts and Profitable Pathways Through 2032
The polyolefin elastomers (POE) sector is entering a phase of accelerated transformation, driven by a convergence of material science breakthroughs, shifting end-use requirements, and deliberate capacity strategies. Market size has expanded from 1,200.0 million USD in 2020 to 1,880.0 million USD in 2025, and the trajectory extends through 2032, reaching 3,112.0 million USD. The compound annual growth rate of 7.6 percent over the 2026–2032 forecast period underscores a market that is no longer growing purely on volume expansion, but increasingly on value capture, application migration, and regional realignment.
PW Consulting
A market expanding at this pace does not simply reward incremental improvements. It rewards organizations that can anticipate how performance requirements, regulatory expectations, and supply chain architecture will evolve together. POE has moved from a niche additive and specialty modifier into a core enabler for lightweighting, flexible barrier systems, durable consumer products, and increasingly, advanced electronics and renewable energy components. The question for executives, planners, and investors is not whether the category will grow, but where margin will concentrate and where competition will intensify.
The current landscape is defined by a high degree of concentration, with the top three players accounting for 65.0 percent of market revenue and the top five reaching 80.0 percent. This concentration suggests that leadership positions are already established, but it also signals that the next wave of growth will likely emerge through application-specific differentiation, capacity timing, and strategic consolidation rather than broad-based market sharing.
Market Snapshot and the Structural Crossroads
Over the 2020–2025 period, the category moved from 1,200.0 million USD to 1,880.0 million USD, reflecting a steady step-up in demand across automotive components, flexible packaging, consumer goods, and other applications. By 2025, the regional distribution indicates strong commercial presence across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with the largest revenue pools clustered in the most industrialized and automotive-intensive markets. On a type basis, polyethylene-based POE leads with 1,412.47 million USD, while polypropylene-based POE contributes 467.53 million USD, reflecting differing property profiles and end-use preferences.
This market is now at a structural crossroads. Growth is no longer a simple function of adding capacity; it depends on aligning resin design with application economics, securing feedstock stability, and navigating an increasingly complex sustainability and compliance environment. Three challenges stand out as particularly consequential.
The first is the tension between volume expansion and differentiation. As new capacity comes online and regional supply grows, commodity pressure can compress pricing for undifferentiated grades. The organizations that protect margin will be those that translate technical properties into measurable cost-in-use advantages, not those that compete solely on price per kilogram.
The second challenge is feedstock and input volatility. POE economics remain tightly linked to ethylene, propylene, catalyst systems, and energy costs. Capacity expansions can be undermined if feedstock arrangements, energy exposure, or plant utilization assumptions do not match the operating environment. Pricing power in the category increasingly depends on integrating supply chain resilience with product design.
The third challenge is the evolving regulatory and customer sustainability agenda. Packaging, automotive, and consumer-product buyers are placing greater weight on recyclability, material efficiency, and lower-carbon production pathways. These expectations are reshaping qualification criteria, not only environmental reporting. Materials that cannot support downstream compliance or circularity goals risk losing specification positions, even if they remain technically adequate.
Key Drivers Reshaping the POE Landscape
The market’s direction is being shaped by four reinforcing forces: material innovation, policy and regulatory momentum, demand-side substitution behavior, and supply chain reconfiguration. Each driver is altering where value is created and how quickly it can be captured.
Technological innovation continues to expand the performance ceiling. POE is increasingly chosen not simply for elasticity, but for its ability to improve toughness, sealing behavior, clarity, processability, and integration with other polymer systems. This is enabling adoption in higher-value applications where conventional elastomers or softer plastomers cannot meet combined mechanical and processing requirements. The trend is especially visible where lightweighting and part consolidation reduce total system cost, or where flexible packaging demands better barrier compatibility and strength without sacrificing seal performance.
Policy and regulatory dynamics are changing the qualification bar. In several regions, decarbonization targets, extended producer responsibility frameworks, and packaging redesign expectations are altering the base assumptions for material selection. POE grades that support downgauging, multi-material compatibility, recyclability pathways, or lower embodied carbon profiles gain a practical advantage in specification decisions. In this context, the regulatory environment is not simply a compliance cost; it is becoming a filter through which certain grades become easier to specify and others become harder to defend.
Demand-side behavior is shifting from cost-first selection to performance-in-use economics. Automotive manufacturers continue to push for weight reduction and component simplification. Packaging converters and brand owners are balancing strength, appearance, and process efficiency with sustainability commitments. Consumer goods producers are looking for materials that can improve durability and aesthetic quality while maintaining manufacturability. Across these segments, the buying logic is increasingly tied to total system outcome, including processing speed, rejection rates, downstream recyclability, and end-product performance. That shift creates room for premium and semi-premium POE grades when they solve a real application problem.
Supply chain and cost structure changes are reshaping competitive positioning. New large-scale capacity additions are expanding regional availability, particularly in Asia, while established producers refine global footprints and application portfolios. The market is also seeing targeted moves around feedstock integration, plant location strategy, and consolidation. A recent example is the preliminary merger review initiated in March 2026 by South Korea’s Ministry of Trade, Industry and Resources and the Korea Fair Trade Commission regarding Lotte Chemical’s proposed merger with Yeochun NCC. The business focus of the combined entity is expected to emphasize high value-added LDPE and POE for medical use. Even at the review stage, this development illustrates a broader strategic theme: players are repositioning capacity and product direction toward higher-margin, application-specific grades rather than generic volume.
Worldwide Propylene Based POE Market
Competitive Landscape and the Logic Behind Leading Strategies
The POE market is led by firms that combine scale, application depth, and brand recognition with increasingly targeted technology and regional strategies. The leading ecosystem includes global producers and regional specialists, each pursuing a distinct route to resilience and margin protection.
The Dow Chemical Company remains a central reference point in the market, with the largest POE production footprint and well-known product families such as ENGAGE™ and AFFINITY™ across automotive, packaging, wire and cable, and specialty applications. Its strategic strength lies in breadth of application coverage and the ability to offer multiple performance tiers that fit different buyer requirements.
ExxonMobil Corporation competes through its Vistamaxx™ line, with large-scale operations including facilities such as Baytown, Texas, and a focus on elastomers for adhesives, medical, and packaging segments. Its advantage is rooted in integrated feedstock access and the ability to scale high-performance grades for demanding use cases where consistency and property control matter.
Mitsui Chemicals, Inc. is a key international producer supplying high-performance elastomers for automotive, wire and cable, and industrial applications. Its relevance in the market comes from a clear orientation toward performance-intensive segments where customers are willing to pay for optimized material behavior.
Borealis AG has built a strong position in Europe through its Queo™ platform, with offerings spanning packaging, automotive, and medical applications. Its strength lies in regional proximity to key European converters and end users, combined with a product strategy that emphasizes innovation in polyolefin elastomer design.
LG Chem Ltd. is expanding capacity and targeting automotive and specialty elastomers for high-value applications. In a rapidly growing market, capacity expansion is strategically meaningful only when paired with grade differentiation and customer qualification. LG Chem’s focus reflects that broader logic.
SABIC, through SABIC SK Nexlene Company, produces POE with special relevance in advanced materials, including FORTIFY™ encapsulant grades for solar. This highlights an important evolution in the market: POE applications are moving beyond traditional polymer uses into areas where encapsulation, protection, and high-performance processing are critical.
Wanhua Chemical Group Co., Ltd. has moved aggressively on capacity, with a new 200,000 t/yr unit operational since 2024 and plans to expand toward 600,000 t/yr. This is a signal of how regional dynamics are shifting: large-scale capacity additions can change local supply balances quickly, but sustained advantage will depend on how effectively the producer converts volume into qualified demand.
LyondellBasell Industries N.V. operates POE production across multiple regions and supplies elastomers for wire and cable and industrial uses. Its multi-region presence helps support supply continuity and market access, an increasingly important attribute as buyers prioritize resilience alongside cost and performance.
Taken together, these players reveal a market that is simultaneously concentrated and strategically divergent. The leaders are not all competing in the same way. Some emphasize application breadth and global reach, others emphasize regional proximity and specialized grade design, and a third group is scaling capacity for high-volume markets while trying to lift value through targeted applications. This divergence is one of the most important features of the current landscape.
Consolidation is emerging as a central theme in the next stage of market evolution. Capacity rationalization, feedstock strategy alignment, and the push toward higher-value applications all favor consolidation in select chains. At the same time, differentiation is intensifying at the grade level, meaning that the market is not simply becoming more uniform; it is becoming more segmented by performance need, regional requirement, and application qualification. New entrants and capacity expansions can influence local supply, but winning position will depend on downstream relationships, technical service, and grade-level competitiveness.
PolyOlefin Elastomer (POE) Synthetic Materials Market
Forward-Looking Trends and Where Value Is Likely to Concentrate
Looking ahead across the 2026–2032 horizon, three trends appear especially likely to shape commercial outcomes.
Trend one is application migration toward higher-value specifications. POE demand will increasingly come from applications where the material is selected for system-level benefits rather than simple softness or elasticity. Automotive components will continue to be a major demand pool, but the growth logic will depend on lightweighting, part integration, and improved toughness in more complex assemblies. Flexible packaging will remain significant, with additional emphasis on strength, seal performance, and compatibility with evolving packaging formats. In parallel, specialty uses such as advanced encapsulants and performance-critical industrial applications will gain relative importance, especially where material reliability affects product lifetime or safety performance.
This trend creates commercial opportunity for producers and converters who can translate resin properties into application outcomes. It also raises the stakes for qualification: as applications become more demanding, switching costs increase, but so does the need for robust technical support and consistent supply.
Trend two is the alignment of capacity growth with value capture rather than volume alone. Capacity additions are part of the market’s growth story, but the more strategic question is where new tonnage will be directed. The most attractive positions will likely be in grades tied to higher-margin applications, feedstock-advantaged production, and regions where demand growth outpaces local supply. At the same time, regions or segments with oversupply risk will pressure undifferentiated pricing. That means capacity announcements should be read carefully: scale matters, but application selection, ramp-up quality, and customer qualification determine whether scale becomes profitable.
Trend three is regulatory and sustainability-driven specification change becoming a durable competitive factor. If packaging redesign, circularity expectations, and decarbonization pressures continue to intensify, POE grades that fit into more recyclable or more efficient material systems will have a structural advantage. This is not simply a compliance issue; it influences customer willingness to adopt, brand owner preferences, and downstream converter economics. Producers that can present credible pathways for material efficiency, recyclability compatibility, and lower-carbon production may gain access to specifications that are otherwise difficult to win.
These trends also carry risk. Feedstock volatility can erode the economics of expansion plans. Regulatory frameworks may diverge by region, creating complexity for global product rollouts. Demand shifts can alter qualification priorities faster than capacity can be adapted. And concentration in the market means that competitive reactions from leading players can quickly change pricing dynamics in key grades and regions.
Strategic Implications for Decision-Makers
For manufacturers, the immediate priority is to align grade development with application economics, not merely polymer properties. The market increasingly rewards materials that solve a downstream problem: lighter components, better seals, improved durability, improved process efficiency, or better compatibility with evolving sustainability requirements. Manufacturers should also evaluate where capacity and feedstock assumptions create durable advantage versus where they merely add volume. In a market where the top five players already account for 80.0 percent of revenue, incremental growth will often come from stealing application share through superior solution fit, not from taking broad commodity share.
For investors, the key task is to separate capacity announcements from value creation potential. Large expansions can reshape regional supply, but investment merit depends on application mix, qualification status, feedstock positioning, and the ability to protect pricing in the face of competition. The most defensible opportunities are likely in grades and applications where performance requirements are rising and switching costs are meaningful. Investors should also watch consolidation signals and regulatory developments as indicators of where the supply base is heading, since those changes can reshape competitive dynamics well before financial results fully reflect them.
For procurement and sourcing leaders, the strategic imperative is to manage total cost and qualification risk rather than focusing only on resin price. POE is increasingly specified in applications where performance inconsistency or supply disruption carries a high downstream cost. Sourcing strategies should therefore account for grade suitability, supplier technical capability, regional supply resilience, and the ability of suppliers to support evolving sustainability or compliance expectations. Where possible, long-term supply partnerships should be evaluated against the backdrop of application migration and regulatory change, since today’s qualification decisions can lock in advantages or constraints for several years.
Across all of these perspectives, timing matters. The POE market is large enough, and moving fast enough, that broad narratives can obscure important differences in grade-level demand, regional supply balance, and application qualification momentum. Decision-makers who treat POE as a single market risk missing where margins are actually being created. Those who focus on application-driven performance, feedstock and capacity strategy, and the regulatory direction of end markets are more likely to identify durable opportunities before they become crowded.
For a fuller picture of segment-level dynamics, regional demand patterns, capacity timing, and company-specific positioning, the complete study offers the deeper breakdown required for operational planning and investment decisions. In a market defined by concentrated leadership and simultaneous application divergence, detailed intelligence is often the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Polyolefin Elastomers (POE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com