

Blogs
Robot Tool Changers Market 2026: The Real Drivers Behind a 13.81% Growth Trajectory
By PW Consulting, 2026-09-21
The Strategic Shift in Robot Tool Changers: Navigating a High-Growth Market
Market Overview: A Sector Accelerating Under Industrial Automation Demand
The global market for robot tool changers has entered a phase of sustained expansion, driven by the broader adoption of industrial automation and the increasing need for flexible manufacturing systems. Valued at approximately 543.55 million USD in 2025, the market has demonstrated consistent growth over the past five years, rising from 284.67 million USD in 2020. This trajectory reflects a compound annual growth rate of 13.81 percent through 2032, signaling that tool changing systems are no longer peripheral components but strategic enablers of production efficiency. The market is projected to reach 1.35 billion USD by 2032, a figure that underscores the compounding effect of automation investments across multiple sectors.
This growth is not uniform across all geographies or applications. Demand is concentrated in regions with mature automation ecosystems and in industries where rapid changeover times directly impact throughput. The current market structure reflects a balance between established industrial robotics hubs and emerging manufacturing centers that are integrating robotic cells at an accelerating pace. While the numbers illustrate a clear upward path, the underlying dynamics reveal a market that is selectively rewarding players who can align product capabilities with shifting operational requirements.
Two structural shifts are reshaping the competitive baseline. First, the transition from fixed, single-purpose end-of-arm tooling toward modular, quickly interchangeable systems is becoming a default expectation rather than a premium feature. Second, the integration of tool changing mechanisms with collaborative robots and light automation cells is expanding the addressable use cases beyond traditional heavy manufacturing. These shifts are forcing suppliers to reconsider design priorities, safety alignment, and deployment speed.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the market faces operational and strategic tensions that will determine which participants capture disproportionate value. Three challenges stand out as particularly consequential for decision-makers evaluating this space.
Safety Standardization as a Compliance and Design Gatekeeper
Updated global safety requirements, including ISO 10218-2:2025 for industrial robot systems and the continued relevance of ANSI/RIA R15.06-2012 Part 2 for completed machinery integration in the United States, are reshaping how tool changers are specified and deployed. These standards are not merely documentation exercises; they influence interface design, fail-safe behavior, detection of unintended contact, and system-level integration. Manufacturers that treat compliance as an afterthought risk costly redesign cycles, slower qualification processes, and reduced appeal to OEMs seeking plug-and-play compatibility. Conversely, suppliers that embed safety alignment into product architecture can shorten customer validation timelines and strengthen positioning in regulated environments such as medical device production, food processing, and automotive assembly.
Cost Pressures and Regional Supply Chain Realignment
Tool changer manufacturers are navigating a cost environment shaped by component pricing volatility and shifting trade dynamics. U.S. tariff policies, for example, are prompting localized supply chain adjustments among major manufacturers of robotic components. This restructuring affects lead times, sourcing strategies, and the economics of cross-border distribution. Companies that rely heavily on single-source components or centralized production footprints may face margin compression or delivery uncertainty. At the same time, customers are increasingly sensitive to total cost of ownership, including maintenance, downtime during changeovers, and the speed with which a new end-effector can be deployed. The market is therefore moving toward an environment where reliability and serviceability are as commercially important as the initial purchase price.
Balancing Automation Gains with Practical Deployment Complexity
A recurring tension in this market is the gap between the promise of faster changeovers and the reality of integration effort. Automatic tool changers can reduce manual intervention and improve cycle consistency, but they also introduce requirements around alignment, actuation reliability, air and electrical pass-throughs, and control coordination. For many mid-sized manufacturers, the decision is not simply whether to adopt automation but how much complexity they are prepared to absorb. This creates a split in demand: some buyers prioritize fully automatic solutions with integrated sensing and robust retention features, while others opt for manual or semi-automatic systems that are easier to retrofit and maintain. Suppliers that can reduce deployment friction, whether through modular configurations, clear compatibility roadmaps, or application-specific guidance, are better positioned to convert interest into installed base growth.
PW Consulting Automotive & Machinery Research Center
Core Drivers of Market Change
The expansion of the robot tool changer market is being propelled by a combination of technological progress, regulatory evolution, demand-side behavior, and supply chain restructuring. Understanding these drivers individually and in combination provides a clearer view of where growth is likely to concentrate.
Technological Innovation and Payload Flexibility
Product development is increasingly focused on broadening payload compatibility, improving retention reliability, and simplifying integration. Automatic systems are being designed with ISO-standard flange compatibility and modular configurations, allowing them to serve a wider range of robot platforms without extensive custom engineering. Pneumatic actuation remains a practical choice for many applications, especially where simplicity and robustness are valued, while sensing and end-effector accessories are increasingly used to support precision tasks and force-sensitive operations. The introduction of automatic tool changer lines aimed at reducing manual changeovers in machine tending automation illustrates how suppliers are targeting the practical pain points of repetitive loading and unloading. These developments matter because they lower the barrier to re-tooling and help manufacturers shift from dedicated single-product cells to more adaptable layouts.
Regulatory and Safety Environment
The regulatory backdrop is both a constraint and a catalyst. As safety requirements become more explicit and harmonized, customers are paying closer attention to certified integration paths and documented performance under failure conditions. This environment favors suppliers that can demonstrate consistent quality, traceable manufacturing practices, and alignment with recognized robot system standards. In practice, safety compliance is becoming part of the commercial argument: it reduces risk for integrators, supports faster approval in regulated industries, and can differentiate products in tenders where system reliability is a priority. The effect is most visible in sectors where uptime and repeatability are closely tied to product quality and audit readiness.
Demand-Side Behavior and Workforce Dynamics
On the demand side, manufacturers are responding to chronic labor shortages, the need for faster changeovers, and the desire to redeploy assets as product mixes change. Tool changers enable robots to switch between tasks without extensive downtime, which is particularly valuable in environments where batch sizes vary or where multiple operations are consolidated into a single cell. Collaborative robot applications are also expanding the user base, since lighter and more flexible tooling solutions can be introduced in spaces where traditional industrial robots would be impractical or overly complex. This demand behavior is widening the market beyond large-scale automotive and electronics operations into chemical processing, medical manufacturing, and food and beverage production, where hygiene, precision, and quick reconfiguration are increasingly important.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are influencing both product strategy and customer purchasing behavior. As manufacturers of robotic components adjust to new tariff and sourcing realities, there is growing interest in regional availability, shorter logistics paths, and locally supported service networks. For tool changer suppliers, this creates an opportunity to compete not only on product features but also on responsiveness and continuity of supply. Customers in turn are weighing the stability of their supplier relationships more heavily, especially when a tool changer is embedded in a production line where downtime has a direct financial impact. The result is a market where service coverage, spare parts availability, and local engineering support can be decisive factors in winning and retaining business.
Competitive Landscape and Strategic Positioning
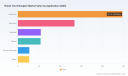
The robot tool changer market is moderately concentrated, with a small group of established players accounting for a significant share of revenue. This concentration reflects the importance of product maturity, application knowledge, and long-term customer relationships in a segment where reliability and compatibility are paramount. At the same time, the landscape is evolving as suppliers differentiate around payload class, actuation method, collaborative robot compatibility, and deployment speed.
Several companies illustrate distinct strategic approaches. Stäubli has positioned its offering around automatic tool changers with defined payload capacity and modular configurations, emphasizing compatibility with industrial robots and standardized flanges. Zimmer Group provides a broader portfolio that spans automatic, manual, pneumatic, and magnetic solutions, aligning its product range with the need for manufacturing flexibility and productivity across different operating environments. SCHUNK continues to emphasize pneumatically actuated automatic tool changers with integrated retention features for air-loss scenarios, alongside quick-change systems that support faster changeovers. These design choices reflect a shared focus on robustness and practical reliability, but they also reveal different priorities in how each company addresses failure modes and integration complexity.
In the collaborative and lighter-automation segment, other players have carved out niches by focusing on ease of deployment and end-of-arm tool compatibility. SMC Corporation manufactures pneumatic tool changers and grippers suited to collaborative robots and broader automation systems, while Destaco develops cobot end-of-arm tools and manual changeovers with pass-through air and electric ports for materials handling and manufacturing tasks. Robot System Products offers a tool changer family tailored to collaborative robots with automated exchange capabilities, and SmartShift Robotics promotes a universal tool changer system designed for fast deployment and redeployment of tools on robots. ATI Industrial Automation rounds out this competitive picture by specializing in robotic tool changers, multi-axis force and torque sensing, and end-effector accessories for industrial applications, highlighting the increasing importance of sensing and precise control in higher-value use cases.
Worldwide Tool Changers Market
The strategic lesson from this landscape is that differentiation is increasingly tied to the intersection of product design and deployment experience. Companies that combine compatible mechanical interfaces with clear guidance on integration, safety alignment, and maintenance are better positioned to win across both large industrial accounts and smaller automation projects. At the same time, the market shows signs of both consolidation and fragmentation. Incumbents with broad portfolios can leverage cross-selling and entrenched relationships, while smaller or more focused players can win in specific applications by addressing changeover speed, collaborative robot fit, or rapid redeployment needs. New entrants and product-line expansions are likely to persist as long as demand continues to grow and as long as manufacturers seek tools that can be adapted quickly to changing production requirements.
Recent Developments as a Signal of Direction
Recent activity in the market reinforces the emphasis on practical changeover reduction and machine tending automation. In May 2025, SCHUNK USA promoted its CPS automatic tool changer line as a solution for manual changeovers in machine tending automation. This type of development is notable because it targets a recurring operational bottleneck rather than a purely niche application. It also signals that automatic changeover systems are being marketed not only as high-end industrial upgrades but as accessible improvements for repetitive machine tending tasks. For competitors and buyers alike, such announcements highlight where commercial attention is moving: toward reliability in routine use, reduced intervention, and solutions that can be integrated without extensive reconfiguration of existing equipment.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, three trends are likely to shape how the robot tool changer market evolves and where commercial opportunities emerge.
Trend 1: Broader Adoption of Automatic Changeover in Mid-Complexity Applications
Automatic tool changers will increasingly move beyond the largest, most heavily engineered installations and into mid-complexity environments where changeover frequency and labor constraints make manual intervention costly. As modular interfaces and standardized compatibility become more common, the effort required to specify and integrate automatic systems should decline. The commercial opportunity here lies in application-specific packages that address machine tending, light assembly, and repetitive load/unload tasks with minimal customization. The risk is that overstating automation benefits without accounting for integration readiness could lead to slower adoption in settings where maintenance capacity or control integration is limited.
Trend 2: Safety and Compliance as a Competitive Filter
Updated safety expectations will continue to act as a filter in procurement decisions, especially in regulated industries and in projects that require integration with completed machinery. Suppliers that proactively align product design with current standards and that can provide clear documentation and integration support will have an advantage in qualification speed and customer confidence. This trend creates opportunity for companies that can package compliance, reliability, and ease of integration into a coherent value proposition. The uncertainty lies in how quickly standards are adopted across regions and customer segments, since uneven uptake may create temporary fragmentation in approval requirements and system specifications.
Automatic Tool Change Spindle Market
Trend 3: Regional Supply Strategies and Service-Led Competition
As manufacturing of robotic components adjusts to tariff and sourcing pressures, regional availability and service continuity will become more important in supplier selection. Tool changer providers that can offer localized support, predictable lead times, and accessible spare parts will be better positioned to retain customers in cost-sensitive or uptime-critical environments. This trend favors businesses that treat after-sales capability as part of the core offering rather than a secondary function. The risk is that supply chain restructuring could temporarily disrupt availability or increase costs during transition periods, which may affect both suppliers and end users that depend on steady component flow.
Strategic Implications for Decision-Makers
For executives, planners, and investors evaluating this market, the most useful question is not whether growth will continue, but where the most defensible value can be created. The following considerations can help translate market dynamics into action.
For Manufacturers and System Integrators
- Prioritize compatibility and standardization in tooling selection. Systems that align with common flanges, actuation methods, and control interfaces reduce integration risk and make future reconfiguration easier.
- Treat safety alignment and documentation as part of product design rather than a final checklist. This can shorten qualification cycles, improve integrator confidence, and support expansion into regulated applications.
- Evaluate total cost of ownership beyond purchase price, including downtime during changeovers, maintenance complexity, and the speed of redeployment when production needs shift.
For Investors and Strategic Planners
- Pay attention to companies that combine product breadth with strong application support and service coverage, since these attributes tend to drive repeat business and reduce switching in a concentrated market.
- Monitor how suppliers are positioning around collaborative robots, machine tending, and quick redeployment, as these areas are expanding the user base beyond traditional heavy industrial automation.
- Assess exposure to regional supply chain shifts and component sourcing strategies, because tariff and logistics responses can influence margins, delivery reliability, and competitive positioning over time.
For Procurement and Operations Leaders
- Define requirements around changeover frequency, payload, failure-mode behavior, and integration constraints before evaluating specific products, so that selection reflects operational realities rather than feature lists alone.
- Consider how easily a tool changer can be maintained, recalibrated, and redeployed, especially if future production programs are expected to vary in scope or volume.
- Validate supplier support capabilities, including spare parts availability and engineering responsiveness, since service continuity can be as important as initial performance in production-critical environments.
Conclusion
The robot tool changer market is expanding in line with the broader shift toward flexible automation, but the real strategic story lies in how that growth is being shaped by safety requirements, deployment complexity, and supply chain adjustments. Over the next several years, value will likely accrue to suppliers and adopters who can combine mechanical reliability with practical integration, compliance readiness, and dependable support. For decision-makers, the most effective approach is to treat tool changing systems as long-term operational assets rather than interchangeable accessories, and to evaluate them against the specific changeover, payload, and integration demands of each application. Continued attention to product evolution, regulatory alignment, and regional supply dynamics will be essential for those seeking to capture the commercial opportunities embedded in this accelerating market. More granular segmentation, competitive benchmarking, and scenario analysis are available in the full market report for teams that need detail beyond the strategic overview.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Contact Image Sensor Market: What the 7.2% CAGR and 2032 $2.5B Trajectory Really Mean
By PW Consulting, 2026-09-21
The Contact Image Sensor Market: Navigating Structural Shifts and Strategic Growth Trajectory Through 2032
Market Landscape and Critical Inflection Points
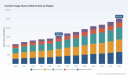
The Contact Image Sensor market has transitioned from a mature, incremental growth phase into a period of strategic redefinition. Revenue crossed the 1.5 billion USD threshold in the 2025 base year, building on a steady upward trajectory from approximately 1.09 billion USD in 2020. The expansion has been broad-based, with consistent year-over-year gains reflecting steady adoption across imaging, document handling, and industrial inspection workflows. Projected forward through 2032, the market is expected to reach roughly 2.52 billion USD, underpinned by a compound annual growth rate of 7.2 percent. This growth profile signals more than legacy replacement cycles; it indicates structural demand formation tied to digitization, automation, and quality control imperatives across multiple verticals.
Within this trajectory, the market exhibits a balanced spatial distribution across developed and emerging economies, with North America, Europe, and Asia Pacific each contributing meaningfully to aggregate demand. Type segmentation shows monochrome and color imaging maintaining substantial and relatively comparable footprints, reflecting a market where application requirements, rather than pure technology preference, dictate adoption. On the application side, scanners and copy machines continue to anchor volume, while surface inspection systems and banknote readers represent higher-value, specification-driven segments. The concentration profile remains notably consolidated, with the top three participants capturing a disproportionate share of revenue and the top five commanding an even larger portion of total market activity. This structure shapes pricing dynamics, innovation pacing, and the strategic options available to both incumbents and new entrants.
Despite the favorable growth math, the industry is passing through a set of inflection points that will determine which participants capture disproportionate value over the next several years.
1. The Shift From Commodity Imaging to High-Specification Inspection
The market is no longer driven primarily by basic document digitization. Instead, a growing portion of demand is migrating toward inspection-grade performance, where resolution, line speed, contrast handling, and dimensional repeatability matter more than unit cost alone. This shift changes the value equation for Contact Image Sensors: devices that once competed on price and availability must now demonstrate imaging fidelity, environmental robustness, and integration readiness. Suppliers that treat the sensor as a commoditized component risk being squeezed into low-margin volume streams, while those that align performance with application-specific tolerances can command stronger positioning.
2. Integration Complexity as a Competitive Moat and Barrier
As end systems become more compact and performance expectations rise, the sensor is increasingly evaluated as part of a broader optical and electrical subsystem rather than as an isolated component. Illumination design, signal processing, module form factors, and OEM integration support are becoming integral to commercial success. This creates a higher bar for market entry and rewards companies that can deliver complete, validated solutions rather than discrete sensor SKUs. At the same time, it places pressure on assembly, calibration, and support capabilities, which can erode differentiation if not managed deliberately.
3. Regulatory and Export Control Sensitivities Emerging in High-Performance Segments
Performance-driven adoption is beginning to intersect with trade and export control considerations. Equipment and sensing technologies capable of sub-micron surface repeatability or high-accuracy measurement are increasingly subject to regulatory scrutiny in select jurisdictions. While this does not constrain the entire Contact Image Sensor market, it introduces a meaningful overlay for high-specification machine vision and inspection applications. Companies operating in these segments must anticipate compliance requirements earlier in product development, rather than treating them as post-design checks.
Key Drivers Shaping Market Trajectory
The 7.2 percent growth path through 2032 is not a uniform expansion. It is being shaped by a combination of technology, regulation, demand behavior, and supply-side economics that reward participants who align their roadmaps with where value is actually forming.
Technology Innovation and Performance Leapfrogging
Innovation in Contact Image Sensors is increasingly centered on resolution, line rate, and dynamic range, particularly for inspection and machine vision use cases. The push toward higher dpi and extended scan lengths is enabling more demanding defect detection, surface characterization, and print-quality verification tasks. Recent product expansion from Teledyne DALSA illustrates this direction clearly: the extension of its AxCIS family with new 1,800 dpi and 1,500 mm models, delivering monochrome line rates up to 80 kHz with HDR capability, reflects a market moving toward faster, higher-fidelity line-scan imaging for semiconductor wafer, battery, and print inspection. This type of advancement does more than add specification points; it expands the addressable set of applications where Contact Image Sensors can compete against alternative imaging architectures.
Equally important is the growing emphasis on customization and color capability. CMOS Sensor Inc’s focus on custom-designed Contact Image Sensors supporting color imaging and diverse application needs underscores a parallel trend: differentiation is increasingly tied to tailoring sensor characteristics to specific workflows. In a consolidated market, the ability to adapt resolution, color response, and integration parameters can be the difference between being specified in a system design or being bypassed by a more flexible alternative.
Regulation, Compliance, and the Redefinition of Eligible Applications
Policy and trade controls are becoming a more visible factor in how high-performance sensing technologies are deployed and sold. Canada’s Export Control List, updated in May 2025, includes sensors and lasers in Category 6 with specific clauses for equipment capable of measuring surfaces with sub-micron repeatability or 0.5 mm accuracy. This does not halt market growth, but it does introduce a segmentation effect: some high-specification inspection applications will require additional compliance consideration, documentation, and channel discipline. For suppliers, the practical implication is that performance leadership must be paired with regulatory literacy, especially where accuracy and repeatability become selling points. For buyers, it means that sourcing strategies need to account for documentation, origin, and end-use classification more carefully than in the past.
Demand-Side Evolution: From Office Imaging to Industrial and Security Workflows
A major driver of sustained demand is the broadening of application contexts beyond traditional document handling. Scanners and copy machines remain substantial demand anchors, but surface inspection systems and banknote readers represent segments where the sensor is tied to operational integrity, security, and quality assurance. In these environments, imaging is not a convenience feature; it is a control function. That shift increases the willingness to invest in sensor performance and reliability, while also raising the cost of failure.
At the same time, large-format document and print workflows continue to create niche but strategically meaningful demand. ColorTrac’s focus on CIS-based large-format scanners for wide-format printing and document handling points to a segment where scan width, document handling, and imaging consistency matter more than aggressive cost reduction. This kind of application specialization often offers steadier margins than high-volume commodity scanning, especially where the sensor is tightly coupled to a defined system architecture.
Supply Chain and Cost Structure Realignment
Cost dynamics are being reshaped by both component-level innovation and broader supply-chain realignment. On one hand, advances in CMOS sensor ICs and illumination integration allow higher performance without necessarily increasing system complexity in a linear fashion. On the other hand, the consolidation of supply around a limited number of capable providers means that continuity, qualification, and long-term availability are becoming strategic purchasing considerations. The market’s concentration profile means that buyers cannot assume frictionless switching between suppliers; qualification cycles, firmware or interface compatibility, and support arrangements can create real sticking points.
A significant structural signal comes from Mitsubishi Electric Corporation, which issued a notice of Contact Image Sensor business transfer to affiliated Miyoshi Electronics Corporation effective April 1, 2028, with production relocation and a long-term customer supply commitment. This type of organizational move matters because it signals how incumbents are restructuring their manufacturing and support footprint to preserve continuity while repositioning operational control. For customers and partners, the key question is not whether supply will continue, but how transition timing, production relocation, and documentation will be managed without disrupting qualification or field performance.
Cmos Image Sensor For Adas Market
Competitive Landscape and Emerging Strategic Postures
The Contact Image Sensor market is defined by a small group of capable players with distinct differentiation strategies. Rather than competing solely on price, leading participants are carving out positions based on performance class, integration support, application specialization, and continuity assurance. This creates a landscape where strategic advantage is less about being the largest sensor vendor and more about being the most reliable solution partner for specific high-value application sets.
Incumbent Performance Leadership and Application Alignment
Mitsubishi Electric Corporation has built its positioning around high-performance Contact Image Sensors with original CMOS sensor ICs and illumination solutions aimed at surface inspection, copy machines, and banknote applications. The emphasis on original ICs and illumination integration indicates a strategy centered on controlling critical subsystems rather than assembling interchangeable parts. This approach aligns well with inspection and security-oriented applications where image consistency and lighting uniformity directly affect system performance. At the same time, the announced business transfer to Miyoshi Electronics Corporation reflects a long-cycle move to reorganize production and supply responsibility while preserving customer commitments. For the market, this suggests continuity in the near term, but also an evolving ownership and operational structure that participants should monitor as the 2028 transition approaches.
High-Speed Line-Scan Focus for Machine Vision
Teledyne DALSA has positioned itself around high-speed, high-resolution integrated line-scan Contact Image Sensors for machine vision inspection, with the AxCIS family targeting semiconductor wafer, battery, and print applications. The company’s recent expansion into 1,800 dpi and 1,500 mm models with 80 kHz monochrome line rates and HDR reinforces a strategy aimed at the upper end of performance requirements. This is a meaningful competitive posture because it ties product leadership directly to inspection scenarios where speed and resolution translate into throughput and defect-detection confidence. In a market where some volumes remain price-sensitive, this focus allows Teledyne DALSA to compete on specification-driven value rather than pure unit economics.
Customization and OEM-Ready Integration as Differentiators
CMOS Sensor Inc and FRAMOS GmbH represent a different but complementary set of strategic angles. CMOS Sensor Inc emphasizes custom-designed Contact Image Sensors with support for color imaging and application-specific customization, positioning flexibility as a commercial advantage where standard SKUs do not fully match system requirements. FRAMOS GmbH focuses on integration of high-quality CIS modules into compact scanning and machine vision systems, including electrical and optical specification support and OEM equipment compatibility. Together, these profiles highlight an important market reality: in a consolidated environment, many wins are decided by integration ease, specification tailoring, and the ability to reduce time-to-deployment for equipment manufacturers.
PW Consulting
Application-Locked Niche Positioning
ColorTrac’s CIS-based large-format scanners for wide-format printing and document handling demonstrate the value of application-locked specialization. In wide-format workflows, scan width, mechanical handling, and imaging consistency can be more decisive than marginal sensor cost differences. This kind of positioning can be resilient because it is tied to a defined use case with limited substitution, although it also depends on continued demand in the underlying printing and document-handling segments.
Market Structure Evolution: Consolidation, Selective Specialization, and Entry Risk
The market’s concentrated revenue distribution implies that broad-based new entry will face meaningful barriers. Qualification cycles, integration support demands, and the established relationships between sensor suppliers and equipment manufacturers all raise the bar for entry. At the same time, the landscape is not static. There is room for selective specialization, especially where a new or expanding participant can match a high-specification requirement, provide better integration support, or offer a more flexible customization model for a defined application set. The more probable structural evolution is not a wholesale reshuffling of leaders, but a continued sorting of the market into performance-driven inspection segments, integration-heavy OEM relationships, and application-specialized niches. Consolidation pressure may intensify where scale, qualification depth, and supply continuity matter most, while differentiation opportunities remain stronger where customization and application alignment are valued over pure volume.
Outlook: Three Strategic Trends for the Next Three to Five Years
Trend 1: Inspection-Grade Imaging Will Become the Core Growth Engine
Over the next several years, the most attractive growth pocket is likely to remain inspection and machine vision applications, where resolution, speed, and dynamic range translate directly into operational value. This trend favors suppliers that can deliver repeatable high-performance modules and the surrounding support needed for industrial integration. The commercial opportunity lies not only in selling sensors, but in enabling end systems that can justify higher specification investment through improved defect detection, throughput, and audit readiness.
The associated risk is performance overreach without application fit. Specifying sensors for the highest available resolution or line rate does not automatically produce better outcomes if illumination, processing, or mechanical constraints are not addressed in tandem. In inspection-driven segments, the winners are likely to be those who can align sensor capability with system-level tolerances and validation requirements.
Trend 2: Long-Cycle Supply Continuity and Organizational Restructuring Will Shape Purchasing Confidence
As production footprints and business structures evolve among major participants, supply continuity will become an increasingly prominent purchasing criterion. The Mitsubishi Electric-to-Miyoshi Electronics transfer is a clear example of how incumbents may reorganize manufacturing responsibility while attempting to preserve long-term supply commitments. For buyers, this creates both reassurance and planning complexity: continuity is intended, but transition timing, engineering support, and documentation will need active management.
Strategically, this trend increases the value of supplier stability, qualified second sources where feasible, and clear roadmap visibility. For participants on the supply side, the opportunity lies in making transitions predictable and minimizing qualification disruption. The uncertainty is that organizational changes can alter support models, response times, and regional availability even when nominal supply continues.
Trend 3: Regulation Will Act as a Segment Filter Rather Than a Market-Wide Constraint
Trade and export-control developments are likely to function as a segmentation mechanism, particularly influencing high-accuracy, sub-micron-class inspection applications. The practical effect is not a blanket slowdown, but a need for earlier compliance consideration in product definition, documentation, and channel strategy. Companies that proactively address classification and end-use considerations will encounter fewer surprises when targeting high-specification projects across multiple regions.
Worldwide 3D Image Sensor Market
The risk here is complacency. As accuracy and repeatability become stronger competitive differentiators, the same attributes can attract regulatory attention. This creates a feedback loop in which performance leadership must be matched by compliance readiness, especially for suppliers and buyers operating in cross-border equipment programs.
Actionable Implications for Decision Makers
For Equipment Manufacturers and Integrators
Treat sensor selection as a system-level decision rather than a discrete component purchase. In inspection and high-specification scanning applications, prioritize suppliers that can support illumination integration, module form factors, electrical and optical specification alignment, and OEM deployment needs. Where applications require color imaging or specialized customization, evaluate flexibility and development support early, because late-stage adaptation can erode time-to-market advantages.
Also, build continuity planning into sourcing strategy. In a concentrated market, switching costs are not just pricing-related; they include qualification, compatibility, and support dependencies. Mapping transition risk, including production relocation or business structure changes, should be part of long-term procurement planning.
For Investors and Strategic Partners
Look beyond headline market size and focus on where specification-driven value is forming. The most compelling exposure is likely in segments where imaging performance directly affects quality, security, or throughput, and where integration support is a meaningful part of the commercial proposition. In those areas, differentiation is less fragile than in commoditized scanning volumes, and competitive position can be more durable when tied to application lock-in and validation requirements.
At the same time, monitor organizational and supply-chain transitions among leading participants. Restructuring can create both opportunity and risk, depending on how smoothly production, support, and documentation are managed. The strategic question is whether a transition strengthens continuity or introduces uncertainty in qualification and service.
For Procurement and Operations Leaders
Strengthen qualification frameworks and documentation expectations, especially for higher-accuracy and inspection-oriented deployments. Where regulatory sensitivity may apply, coordinate early with internal compliance and trade-control functions so that accuracy and repeatability claims do not create unintended classification exposure. Establish clearer criteria for supplier stability, support responsiveness, and long-term availability, since these factors will increasingly determine operational resilience in a concentrated market.
Finally, avoid assuming that specification parity equals substitutability. Two sensors may appear similar on a datasheet while differing substantially in integration effort, support model, or transition risk. Procurement decisions that incorporate total deployment cost and continuity risk are better positioned than decisions based solely on unit price or headline performance.
The Contact Image Sensor market is moving into a phase where growth is increasingly tied to performance specificity, integration readiness, and supply continuity rather than broad volume expansion alone. That shift creates clearer routes to differentiation for participants who align their capabilities with the right application sets, but it also raises the stakes for buyers who must navigate consolidation, transition planning, and emerging regulatory considerations. For decision makers seeking detailed segment splits, regional revenue structures, concentration analysis, and company-level tracking through 2032, a full scope market intelligence report can provide the more granular framework needed to translate these trends into concrete sourcing, investment, and product decisions.
For detailed analysis of this topic, please visit the official page: Contact Image Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Endoscopy Ultrasound Market: Why 7.1% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
The Strategic Horizon of the Endoscopy Ultrasound Market: Growth, Innovation, and Competitive Positioning
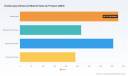
The endoscopy ultrasound (EUS) market stands at a compelling inflection point. Valued at approximately $950 million in 2020, the space has grown to an estimated $1,340 million by 2025, reflecting sustained adoption across diagnostic and interventional gastroenterology. With a forecasted compound annual growth rate of 7.1 percent through 2032, the market is projected to surpass $2,170 million within the decade. This trajectory is not merely a function of clinical demand; it reflects structural shifts in how minimally invasive diagnostics are integrated into care pathways, how imaging hardware evolves, and how reimbursement and regulatory frameworks shape commercial viability. For executives, investors, and procurement leaders, the opportunity lies in recognizing which segments, geographies, and product architectures will compound value over the next five years, and which legacy assumptions are already eroding.
Market Landscape and Core Challenges
A Market Defined by Cross-Sectional Innovation and Procedural Convergence
The EUS ecosystem spans a deliberately integrated product set: echoendoscopes, ultrasound processors, biopsy needles, and specialized probes that together enable high-resolution imaging alongside tissue acquisition and therapeutic intervention. Over the historical period from 2020 to 2025, the market crossed the threshold from niche advanced endoscopy to a more mainstream procedural platform. Growth has been propelled by the convergence of diagnostic clarity and minimally invasive biopsy capabilities, particularly in oncology workups and complex gastroenterology cases. The hardware-software integration model has matured, with processors increasingly serving as the computational backbone that interprets signals from scopes and probes, while needles and accessories define the procedural throughput and clinical yield.
The market’s structure also reveals a concentrated competitive field, with a handful of multinational players holding significant share through established distribution channels, clinical training networks, and proprietary imaging pipelines. This concentration creates both stability and friction: incumbents benefit from installed-base economics and procedural familiarity, while smaller entrants must either differentiate on architecture, cost, or workflow simplification to gain traction.
Three Pressing Challenges Shaping the Near-Term Trajectory
Even as the market expands, several structural challenges are redefining how value is created and captured. The first is the tension between imaging fidelity and procedural efficiency. Clinicians are increasingly unwilling to trade scan time, learning curve, or setup complexity for marginal gains in resolution. The next generation of EUS systems is therefore being judged not only on image quality, but on how seamlessly they integrate into existing endoscopy workflows, how quickly specialists can achieve competency, and how reliably devices can be reprocessed between cases.
PW Consulting Health Care Research Center
The second challenge is the reimbursement and coding environment. EUS procedures rely on standard outpatient coding structures, with payments varying across regions and payer mix. While this provides a baseline pathway for utilization, it also means that adoption is sensitive to procedural coding shifts, outpatient site-of-service economics, and the relative cost burden of disposables versus capital equipment. Vendors and providers alike must navigate the operational reality that revenue generation depends on both clinical value and administrative predictability.
The third challenge lies in regulatory clearance and clinical validation cadence. New devices in this space typically require premarket notifications, and the bar for differentiation increasingly includes not just technical performance but infection-prevention compliance, reprocessing validation, and documented procedural support. This regulatory layer is not a barrier per se, but it does reshape time-to-market dynamics and raises the operational burden for companies introducing novel architectures or accessory ecosystems.
Key Drivers Reshaping the Market
Technology Innovation as the Core Value Multiplier
The most visible driver of market momentum is the continued refinement of imaging and procedural tools. Advanced ultrasound platforms are pushing higher resolution and more structured imaging outputs, while echoendoscopes and linear scopes are being engineered to improve navigation, durability, and image consistency across varied patient anatomies. At the same time, biopsy needles and accessories are evolving toward more reliable tissue acquisition, with designs that emphasize secure sampling and compatibility across procedural use cases. The practical implication is that EUS is increasingly positioned as a single procedural environment where diagnosis, sampling, and in certain cases intervention can be coordinated without disjointed device switching.
Recent product announcements illustrate this trajectory. In May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States through a partnership with Canon, signaling a continued push toward advanced imaging integration and cross-company engineering collaboration. The same period saw Olympus expand its visible EUS solution set at Digestive Disease Week 2026, reinforcing the message that the company is competing on platform breadth as much as individual hardware. Earlier, in September 2025, Fujifilm launched the Arietta 850 EUS processor alongside its 700 Series linear scopes, emphasizing enhanced image clarity for EUS applications. These moves are not isolated product launches; they are indicators of a competitive posture in which imaging clarity, processor capability, and scope architecture are being optimized together rather than in isolation.
Regulatory and Reimbursement Context as Commercial Architecture
Regulation and reimbursement form the structural scaffolding within which EUS adoption scales. On the regulatory side, new EUS devices typically move through FDA 510(k) clearance pathways, as exemplified by recent premarket notifications for systems such as Olympus’s EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and EndoSound’s Vision System. This clearance process is a predictable requirement, but it also means that innovation cycles must accommodate not only engineering milestones but documentation, validation, and post-clearance support. The practical effect is that companies with mature regulatory workflows and established quality systems can convert development progress into commercial availability more reliably than those still building compliance infrastructure.
On the reimbursement side, EUS procedures are generally covered under standard outpatient CPT codes, with Medicare national average payments providing a reference point for site-of-service economics. The nuance is that payment variability across payers and settings can influence how aggressively hospitals and ambulatory surgery centers adopt capital-intensive imaging platforms, especially when disposables such as needles add recurring cost. The business implication is that value propositions increasingly need to account for total procedural economics rather than device performance alone.
Demand-Side Shifts Toward Integrated, Minimally Invasive Workflows
Demand is being reshaped by the broader movement toward outpatient, minimally invasive diagnostics and the growing expectation that advanced imaging should support both detection and tissue acquisition. Oncology-related workups and gastroenterology procedures remain central to utilization, and clinicians are looking for platforms that reduce handoffs, shorten setup, and improve reproducibility across operators. This is a subtle but important shift: the purchase decision is increasingly anchored not just by image quality, but by the predictability of the entire procedural flow from insertion to sampling to reprocessing.
Training and on-site application support have become part of the value equation. The availability of certified clinical application specialists who provide EUS training and procedural optimization support is a differentiator for many institutions, especially as new platforms and accessories enter the workflow. In practice, the ability to shorten learning curves and standardize techniques contributes directly to adoption velocity and long-term utilization rates.
Supply Chain and Material Considerations
Behind the clinical narrative, supply chain and material choices are shaping product durability, cost structure, and differentiation. EUS biopsy needles rely on medical-grade materials such as nitinol with multi-layer sheaths to support secure tissue acquisition, and these material decisions influence both performance and unit economics. At the same time, companies that supply ultrasonic components for EUS probes and accessories occupy an important supporting role in the value chain, contributing to imaging consistency and manufacturing scalability. The broader implication is that competitive advantage is not solely defined by brand or platform; it is also shaped by the reliability of component supply, reprocessing compatibility, and the ability to manage recurring accessory economics.
Ultrasound Market
Competitive Landscape and Leading Strategies
Incumbents Competing on Platform Breadth and Ecosystem Integration
The market’s leadership tier is anchored by large, diversified players with the capacity to offer integrated portfolios spanning processors, echoendoscopes, needles, and accessories. Olympus Corporation remains a prominent reference point, with a comprehensive EUS portfolio that includes processors, echoendoscopes, miniature probes, biopsy needles, and advanced imaging systems. Its recent U.S. introduction of the Aplio i800 EUS Premium Ultrasound System in partnership with Canon, along with expanded EUS visibility at Digestive Disease Week 2026, illustrates a strategy centered on strengthening imaging capability while maintaining broad procedural coverage. For institutions already using Olympus ecosystems, this approach reinforces installed-base continuity and clinical training familiarity.
Fujifilm Holdings Corporation has taken a parallel but distinct path, focusing on processor-image clarity improvements and scope architecture. Its launch of the Arietta 850 EUS processor and 700 Series linear scopes at ACG 2025 reflects a design emphasis on high-resolution imaging and procedural consistency. This positions Fujifilm as a strong alternative for sites prioritizing image performance and processor evolution, particularly where imaging clarity is a decisive clinical or purchasing factor.
Boston Scientific Corporation, Medtronic plc, Pentax Medical, and Cook Medical each bring differentiated strengths to the market. Boston Scientific’s emphasis on EUS-guided biopsy systems, needles, and processors aligns with procedural efficiency and tissue acquisition workflows. Medtronic’s offering of EUS endoscopes, needles, and ultrasound-guided interventional tools builds toward a broader interventional orientation. Pentax Medical contributes echoendoscopes and processors for diagnostic and therapeutic applications, while Cook Medical’s portfolio of EUS endoscopes, needles, and stents supports GI intervention. These companies compete not only on product features but on how well their portfolios map to institutional procedure mixes and clinical priorities.
Specialists, Niche Entrants, and the Value of Workflow Disruption
Beyond the broad-portfolio players, the market includes specialists and newer entrants targeting specific friction points. EndoSound, Inc. has developed a Vision System that converts standard upper GI endoscopes into full EUS capability, a concept that directly addresses capital cost and equipment deployment flexibility. This kind of approach appeals to sites seeking to expand EUS access without committing to a fully new scope fleet, and it highlights a competitive dynamic in which software-assisted conversion and modular capability can challenge traditional hardware-centric purchasing.
Worldwide Ultra HD Endoscope Market
Other participants illustrate the breadth of the supporting ecosystem. ConMed Corporation and CONMED Corporation focus on EUS biopsy needles and accessories, where recurring consumable economics and procedural reliability matter. Medi-Globe Corporation, HUACO HEALTHCARE TECHNOLOGIES CO., LTD, and SonoScape Medical Corp. contribute EUS scopes, ultrasound systems, and accessories, expanding regional and value-tier options. B.Braun, Philips, and Smith & Nephew add further depth across needles, systems, and therapeutic products. Steris plc occupies a critical supporting role through endoscope reprocessing and sterilization, reinforcing the operational requirement that EUS devices must be validated for safe reuse. Downstream and upstream component suppliers such as NIHON DEMPA KOGYO CO., LTD also play a meaningful role in enabling probe and transducer performance. Limaca Medical rounds out the landscape with a precision EUS biopsy device concept, reflecting continued experimentation with tissue acquisition optimization.
Market Structure Dynamics: Concentration, Integration, and Selective Entry
With a substantial share concentrated among a limited set of large players, the market’s evolution is likely to be shaped by a mix of integration, selective acquisition, and targeted differentiation rather than uniform fragmentation. Large incumbents will continue to benefit from distribution scale, training infrastructure, and installed-base momentum. At the same time, the presence of companies pursuing modular or conversion-based architectures suggests that differentiation may increasingly come from reducing capital burden, simplifying scope management, or improving accessory economics. The competitive question for the next few years is whether the market rewards broad platform dominance, or whether workflow-specific innovations can carve out durable niches by solving procurement and operational constraints.
Future Trends and Commercial Opportunities
Trend One: Imaging and Procedural Platforms Will Be Judged as Integrated Systems
Over the next three to five years, EUS purchasing is likely to shift further from evaluating discrete components toward assessing how processors, scopes, needles, and support services function as a single procedural system. The practical opportunity for providers and manufacturers is to align product roadmaps with workflow continuity: faster setup, more consistent imaging across operators, and accessories that integrate cleanly into sampling workflows. Companies that can demonstrate measurable improvements in procedural predictability, training efficiency, and reprocessing compliance will have stronger positioning than those competing only on headline image quality.
A related commercial opportunity lies in total-cost and utilization framing. As sites balance capital equipment decisions against recurring disposable costs, vendors that offer transparent economics, reliable accessory supply, and on-site application support will be better positioned to influence long-term procurement. The risk to watch is over-indexing on advanced features without corresponding gains in ease of use or consumable efficiency, which can slow adoption in cost-sensitive outpatient settings.
Trend Two: Reimbursement Logic and Site-of-Service Economics Will Shape Adoption Patterns
Because EUS procedures are embedded in standard outpatient coding and payment structures, adoption will continue to be sensitive to site-of-service economics and payer mix. As more procedures move to ambulatory and outpatient environments, the relative economics of capital equipment, disposables, and procedural throughput will matter more than ever. This creates an opportunity for vendors and providers to develop more explicit value narratives that connect clinical outcomes with operational efficiency and reimbursement predictability.
The uncertainty here is that coding and payment environments are not static. Shifts in outpatient reimbursement practice, regional payment variation, and the cost profile of needles and accessories can influence how quickly new platforms are deployed or refreshed. Companies and buyers that monitor coding and payment dynamics closely will be better prepared to anticipate adoption cycles and plan capacity accordingly.
Trend Three: New Entrants Will Pressure Legacy Assumptions Around Capital and Access
The emergence of systems that convert standard scopes into EUS-capable platforms, alongside continued experimentation in biopsy device design, suggests that the market will see ongoing pressure to reduce capital intensity and broaden access. This does not eliminate the role of full-featured dedicated systems, but it does introduce more choice for institutions that want to expand EUS capability without full fleet replacement. For innovators, the opportunity is to prove that converted or modular approaches can deliver reliable imaging and sampling performance with predictable reprocessing and support requirements.
The associated risk is that performance, durability, and clinical confidence must be demonstrated consistently. New architectures that appear attractive on cost must still meet regulatory clearance expectations, reprocessing validation standards, and the clinical workgroup expectations that drive sustained utilization. The market will likely reward entrants that combine economic appeal with credible validation and visible procedural support.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
Position product roadmaps around integrated procedural value rather than isolated specifications. That means aligning processor imaging, scope design, and needle/accessory performance with training, reprocessing, and support economics. Where possible, differentiate by shortening the learning curve, improving consistency across operators, and demonstrating total procedural efficiency. For companies with broad portfolios, reinforce installed-base continuity through clear upgrade paths and application support. For smaller or more specialized entrants, focus on a defined point of friction—such as capital reduction, modular capability, or accessory reliability—and build a credible evidence and support package around it.
For Investors and Strategic Allocators
Evaluate companies based on their ability to convert innovation into predictable commercial availability and repeat utilization. Regulatory competence, application support infrastructure, and supply chain reliability for consumables are not secondary details; they are part of the execution equation that determines whether a product gains traction. Pay attention to players that are strengthening imaging partnerships, expanding processor capabilities, or pursuing modular approaches, while also assessing the durability of their reimbursement and reprocessing assumptions. Diversification across the ecosystem—including processors, scopes, needles, and reprocessing support—can provide a more complete view of where value is likely to compound.
For Procurement Leaders and Clinical Administrators
Structure evaluation criteria around total procedural workflow, not just image performance or list price. Consider how a platform affects training timelines, reprocessing compliance, accessory availability, and the economics of recurring disposables. Where capital constraints are significant, assess whether modular or conversion-based solutions can deliver the required clinical capability with lower deployment burden, provided they meet clearance and validation requirements. Ensure that procurement decisions are linked to a clear plan for clinical application support and staff competency development, since adoption velocity often depends on these operational factors as much as hardware selection.
Closing Perspective
The endoscopy ultrasound market is expanding on the back of imaging refinement, procedural integration, and sustained demand for minimally invasive diagnostics, but the most valuable insights for decision makers lie in how these forces interact. Future advantage will belong to organizations that treat EUS as a workflow system, manage reimbursement and reprocessing realities with discipline, and differentiate in ways that are both clinically credible and operationally efficient. For executives and investors seeking deeper segmentation detail, competitive profiling, and customized commercial guidance, the full PW Consulting market report provides the granularity needed to translate these trends into precise, actionable strategy.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Acoustic Panel Market: Beyond the 6.7% CAGR, What's Fueling $13.68B Growth by 2032
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Acoustic Panel Market
The acoustic panel market has evolved from a niche building material segment into a strategically significant component of modern interior design, workplace optimization, and healthcare environment planning. Between 2020 and 2025, the market expanded from $6.34 billion to $8.6 billion, reflecting a compound annual growth rate of 6.7 percent through the forecast horizon ending in 2032. That trajectory signals more than incremental demand growth; it indicates a structural reweighting of how organizations approach indoor environmental quality, occupant well-being, and material compliance.
For executives and strategic planners, the question is no longer whether acoustic treatment will be specified, but how procurement, product design, and supplier partnerships will adapt to changing performance expectations, regulatory scrutiny, and material sourcing realities. The market's direction is being shaped by overlapping forces: greener material standards, stricter indoor air quality benchmarks, hybrid workspace acoustics, and a competitive landscape that remains relatively fragmented while rewarding innovation in sustainability and durability.
Market Snapshot and Core Challenges
The acoustic panel market’s expansion from $6.34 billion in 2020 to $8.6 billion in 2025 reflects steady, broad-based demand rather than a single sector surge. Growth has been supported by renovations in commercial interior spaces, healthcare facility upgrades, and ongoing residential acoustic improvements. Looking ahead, revenues are projected to climb from $9.2 billion in 2026 to $13.68 billion by 2032, with a 6.7 percent CAGR indicating consistent expansion through the end of the decade.
Floor Panel Market
That growth, however, is unfolding against a backdrop of operational and strategic friction. Three challenges are particularly consequential for market participants.
1. Compliance Pressure Is Becoming a Material Differentiator
Indoor air quality and chemical emissions have moved from secondary considerations to procurement gatekeepers in many commercial and institutional projects. Panels that previously competed primarily on cost or aesthetic flexibility now face scrutiny around volatile organic compound emissions, formaldehyde content, and certified low-emitting performance. This shift raises the bar for suppliers: products must demonstrate compliance, and specifiers increasingly request documentation rather than relying on generic material claims.
The practical consequence is a bifurcation in the market. Manufacturers with established certification pathways, transparent material data, and low-emitting formulations are gaining specification advantage, while lower-cost alternatives risk losing ground in projects where health, wellness, and regulatory compliance carry more weight than unit price.
2. Raw Material and Supply Chain Complexity
Acoustic panels draw from a diverse set of input materials, including wood, mineral wool, fiberglass, polyester, felt, and hybrid composites. That diversity is a strength in product design, but it also exposes manufacturers to varying supply risks. Recycled fabric availability, fiber sourcing consistency, and binder chemistry all influence both cost structure and product positioning. Companies that rely on single-source inputs or narrow supplier bases may face volatility in pricing or lead times, particularly when sustainability requirements demand traceable or recycled content.
At the same time, sustainability claims are becoming more prominent in competitive bids. Materials marketed as biodegradable, recycled, carbon-neutral, or Red List Free can command attention, but they also create expectations for verification. Suppliers that can align material innovation with credible documentation are better positioned to convert sustainability messaging into commercial advantage.
3. Specification Fragmentation Across End-Use Segments
Acoustic needs differ sharply by environment. Commercial and corporate spaces often prioritize speech privacy, aesthetic integration, and modularity. Healthcare and medical facilities may emphasize hygienic surfaces, durability, and low-emission performance. Other applications, ranging from education to residential and specialized industrial settings, introduce additional performance requirements.
This fragmentation makes broad product portfolios attractive, but it also complicates standardization. A panel that performs well in an open-plan office may not align with the cleaning protocols of a medical setting or the environmental constraints of a public building project. Organizations that can tailor product lines to distinct performance profiles, rather than pushing one-size-fits-all solutions, are more likely to secure repeat specification in targeted verticals.
Key Drivers Shaping Market Direction
The market’s momentum is not simply a function of construction activity or interior renovation spending. Several structural drivers are reshaping what buyers ask for and what suppliers must deliver.
Technological and Material Innovation
Innovation in acoustic panels is increasingly centered on material chemistry and performance transparency. Formaldehyde-free binders, natural binder systems, and low-emitting formulations are no longer niche features; they are becoming central to competitive positioning. Fabric-wrapped and hybrid panels are also expanding the design envelope, allowing acoustic treatment to blend into architectural interiors rather than serving as purely functional add-ons.
Recent product activity illustrates this shift. In mid-2025, Kinetics Noise Control introduced Econetic Core, described as the industry’s first DECLARE Red List Free fabric-wrapped fiberglass acoustical panels using a natural formaldehyde-free binder. The same product line was noted for compliance with CDPH 01350 VOC testing standards as a fully wrapped product. This type of launch reflects a broader industry move toward verified low-emission materials and cleaner chemistry, particularly in projects where indoor environmental quality is a priority.
On the material side, recycled content and sustainability claims are becoming part of product identity. Lamvin’s Oceanside fabric-wrapped acoustic panels have been described as using 100 percent post-consumer recycled biodegradable fabric with no formaldehyde content. Autex Composition acoustic wall coverings have been presented with 100 percent PET content, including recycled fiber, alongside carbon-neutral product claims. These examples show how material sourcing and environmental positioning are being woven directly into product narratives rather than treated as optional extras.
Composite Panel Market
Policy, Certification, and Regulatory Expectations
While the acoustic panel market is not governed by a single sweeping regulation, procurement environments are increasingly shaped by indoor air quality standards, low-emitting material requirements, and project-level certification programs. Specifications that reference CDPH 01350 or similar low-emitting performance benchmarks are becoming more common in commercial, institutional, and healthcare settings.
USG’s Halcyon Eco Acoustical Panels, for example, have been noted for certification to meet CDPH 01350 v1.2-2017 for low-emitting performance, with certificates of compliance available. This kind of documentation matters because it reduces risk for specifiers and provides a clearer path to approval in sensitive projects. As a result, regulatory and certification dynamics are not merely compliance costs; they are becoming levers for differentiation and specification confidence.
Demand-Side Behavior and Environment Quality Priorities
Demand patterns are being influenced by changing expectations around workplace comfort, healthcare environments, and interior design sensibility. Organizations are paying more attention to speech privacy, noise distraction, and the broader experience of occupied spaces. That attention is especially visible in corporate and commercial interiors, where acoustic treatment is integrated into workplace strategy rather than treated as an afterthought.
At the same time, aesthetic integration is becoming a demand driver in its own right. Acoustic panels are increasingly expected to function as architectural elements, not just hidden performance components. Slat wood panels with felt backing, textured PET-based designs, fabric-wrapped systems, and sculptural configurations all point to a market where acoustic function and visual identity are converging. Barron Designs’ December 2025 acoustic panel collection, featuring slat wood wall panels with felt backing for residential and commercial sound control, reflects this kind of crossover between acoustic performance and interior design appeal.
PW Consulting Chemical & Energy Research Center
Supply-Base Evolution and Competitive Positioning
The supply side is adapting through product diversification, regional specialization, and incremental consolidation of expertise. Several companies are building reputations around specific material families, such as mineral fiber ceiling and wall systems, PET-based panels, felt-based architectural surfaces, or fiberglass solutions for demanding environments. Others are emphasizing sustainability credentials or specialized performance attributes like durability, hygiene, or industrial-grade noise control.
This is a market where scale alone does not guarantee advantage. Instead, the most visible competitive moves involve targeted product development, documentation strength, and the ability to serve distinct project types with credible performance claims. Companies that combine material innovation with specification-ready transparency are better positioned to convert demand growth into durable market share.
Competitive Landscape and Leading Strategies
The acoustic panel market remains relatively fragmented, with concentration levels that leave room for multiple viable players and differentiated strategies. Rather than a small number of dominant incumbents controlling the field, the market is shaped by companies with distinct material strengths, regional footprints, and application expertise.
Distinct Strategic Profiles
Several companies illustrate how competing firms are carving out positioning through product architecture and performance claims.
- Lamvin operates as a manufacturer of premium acoustical products, including Hushwood, Oceanside, Sonic Sound Block, and Hushtone polyester panels, with an emphasis on interiors and custom applications. Its profile suggests a focus on tailored, design-conscious solutions and material differentiation in fabric-wrapped and polyester-based offerings.
- Sound Seal is positioned as a leading manufacturer of architectural and commercial noise control products, including Poly-Coustix polyester acoustical panels and EchoWool sustainable boards. Its strategy appears centered on broad commercial noise control coverage with sustainable board options.
- Kinetics Noise Control provides fabric-wrapped fiberglass acoustical panels, including Econetic Core and HardSide lines, with attention to voice noise management and durability. Its recent Eco-oriented product development underscores a strategic push toward verified low-emission construction.
- USG Corporation supplies mineral fiber acoustical ceiling and wall panels, including Mars, Juno, Radar Education, and Glacier series, with high NRC and ClimaPlus performance. Its scale and product breadth make it relevant in commercial ceiling and wall systems where standardized performance and documentation are important.
- Armstrong World Industries produces mineral fiber and wood-wool acoustical panels, including SOUNSCAPES SHAPES and SUSTAIN portfolio offerings for sculptural and sustainable applications. Its portfolio reflects a blend of aesthetic flexibility and material sustainability messaging.
- Autex Acoustics designs and supplies PET-based acoustic panels, including Mirage textured series and Composition wall coverings, with carbon-neutral claims. Its positioning leans toward design-forward PET solutions and sustainability-oriented product language.
- CSI Creative manufactures architectural felt wall and ceiling acoustic panels, including WoodLite for high-end commercial interiors. Its focus suggests a premium, design-led segment of the market where finish quality and interior presentation matter.
- Rockfon, under the Rockwool Group , provides acoustical ceiling and wall panels for commercial and industrial applications, reinforcing a strong presence in mineral wool-based systems and broader building ecosystem integration.
- IAC Acoustics manufactures industrial and commercial Noise-Foil panels for harsher environments, indicating a more specialized, performance-heavy position in environments where durability and industrial conditions are central.
Differentiation Through Compliance, Material Claims, and Application Fit
The differentiating factors in this market are becoming more specific. In practice, leading strategies tend to combine three elements: credible low-emission or sustainability performance, clear application fit, and specification-ready documentation.
For example, verified compliance with low-emitting standards can be a meaningful advantage in healthcare, education, and corporate projects where indoor quality documentation is requested early in the specification process. Material stories involving recycled fabric, recycled PET, biodegradable content, or formaldehyde-free binders can support distinct positioning, but they are most effective when paired with accessible compliance information. At the same time, product lines that serve a specific environment well, whether fabric-wrapped systems for commercial interiors, mineral fiber systems for ceiling and wall applications, or industrial-grade panels for demanding settings, can build stronger repeat demand than broadly generic offerings.
How the Landscape Is Evolving
The market is not moving toward a single dominant model. Instead, it is evolving along several axes. One is the continued strengthening of sustainability and emissions documentation as commercial requirements, which raises the importance of certification, testing, and transparent product data. Another is the expansion of design-integrated acoustic products, which broadens the market’s appeal beyond purely technical buyers and into architectural and interior design workflows. A third is the persistence of specialized players alongside larger suppliers, allowing the market to serve both standardized commercial projects and highly tailored environments.
New entry and expansion opportunities remain, particularly for companies that can combine material innovation with strong specification support. At the same time, established players are likely to deepen their portfolio coverage, pursue sustainability-aligned product lines, and reinforce documentation capabilities to protect their position in specification-driven procurement.
Forward-Looking Trends for the Next Three to Five Years
Looking ahead, several trends are likely to shape how the acoustic panel market develops through the late 2020s and into the early 2030s.
1. Low-Emission and Verified Sustainable Materials Will Move From Differentiator to Expectation
As indoor environmental quality becomes a more prominent part of project specifications, low-emitting formulations and credible sustainability documentation are likely to become baseline expectations in many commercial and institutional segments. Panels that can demonstrate compliance with recognized low-emitting standards, provide clear material content information, and reduce concerns around formaldehyde or VOC emissions will be better positioned for repeat specification.
The commercial opportunity lies in turning verified performance into a specification advantage. Suppliers that invest early in certification pathways, transparent documentation, and cleaner material chemistry can reduce friction in the approval process and create stronger relationships with specifiers and procurement teams.
2. Acoustic Products Will Continue Blending Performance With Architectural Identity
The market is increasingly rewarding products that function as visible interior elements rather than concealed treatments. Textured surfaces, wood-based configurations, felt-based architectural panels, and sculptural forms are all part of a broader shift toward acoustic solutions that contribute to spatial design. This trend expands the addressable market by aligning acoustic purchase decisions with design-drivenInterior decisions.
Strategically, this creates opportunities for companies that can pair acoustic performance with aesthetic versatility and format flexibility. It also raises the importance of customization, finish options, and the ability to support design intent without sacrificing performance or compliance.
3. Segment-Specific Solutions Will Outperform Generic One-Size-Fits-All Offerings
Because acoustic requirements vary widely across commercial, healthcare, education, residential, and industrial settings, product strategies that align closely with specific end-use needs are likely to gain traction. Healthcare environments may prioritize hygiene and low emissions. Corporate spaces may prioritize speech privacy and design integration. Industrial settings may prioritize durability and harsh-environment performance.
This trend favors suppliers that organize their portfolios around use-case clarity rather than broad, undifferentiated catalogs. It also creates a role for targeted market intelligence: understanding which applications are expanding, which performance criteria are becoming mandatory, and where documentation or material claims matter most can inform product development and sales focus more effectively than broad generalizations.
Risk and Uncertainty
Several uncertainties could alter the pace or shape of market growth. Material costs and availability may shift if recycled content supply, fiber sourcing, or binder inputs become constrained. Certification and compliance expectations could evolve faster than product development cycles, creating transitional pressure for suppliers with less flexible material portfolios. Demand may also vary by region and project type, particularly if commercial interior spending, healthcare facility investment, or residential acoustic upgrades follow uneven trajectories.
In addition, sustainability claims will face increasing scrutiny. Marketing language around recycled content, carbon neutrality, or biodegradability is more powerful when supported by verifiable data and third-party-aligned documentation. Companies that overstate environmental benefits without supporting evidence risk weakening buyer trust, especially in specification-driven markets.
Strategic Implications for Decision-Makers
The acoustic panel market is large enough and dynamic enough that strategy matters at multiple levels. The most effective actions depend on the role a company plays in the value chain.
For Manufacturers and Product Developers
- Prioritize verified low-emission and sustainability attributes, but treat documentation as part of the product, not an accessory. Compliance-ready data can be as important as the material itself in specification environments.
- Develop products with clear application fit. Differentiating by environment, finish, and performance profile can be more effective than competing solely on price or generic feature lists.
- Monitor material sourcing risk. Recycled content, biodegradable fabric, PET-based inputs, and formaldehyde-free binders can strengthen positioning, but supply consistency and cost control remain essential to scalable execution.
For Investors and Strategic Planners
- Focus on companies with credible compliance documentation, recurring specification relationships, and product lines aligned to expanding end-use segments. In a fragmented market, durable advantage often comes from specification trust and repeat demand rather than headline scale alone.
- Watch for consolidation patterns and portfolio expansion in sustainability-aligned product lines. Firms that can combine material differentiation with strong commercial documentation are better positioned to capture higher-value projects.
- Assess exposure to regulatory and certification trends. Shifts in low-emitting expectations or indoor quality requirements can alter competitive dynamics quickly, creating both risk and opportunity depending on product readiness.
For Procurement Teams and Specifiers
- Evaluate acoustic panels using both performance and material transparency. NRC, durability, and installation fit matter, but so do emissions documentation, binder chemistry, recycled content claims, and compliance certificates where relevant.
- Align product selection with the environment’s operational needs. Healthcare, corporate, education, and industrial settings can have materially different priorities, and the right panel choice often depends on more than appearance or unit cost.
- Request specification-ready documentation early. Products that provide clear compliance evidence and consistent material information reduce project risk and speed approval cycles.
Turning Market Intelligence Into Execution
The acoustic panel market is moving on multiple fronts at once: material chemistry, indoor air quality expectations, design integration, and application-specific performance. That combination creates a market where credible differentiation and specification readiness matter more than ever. For organizations making decisions in this space, the most valuable intelligence is not just a top-line size estimate or a generic growth rate, but a clear view of where demand is concentrated, which product attributes are becoming mandatory, and how leading suppliers are positioning themselves for repeat specification.
For readers who need a deeper breakdown of segment dynamics, regional demand patterns, company-by-company positioning, and forward scenarios through 2032, the full Acoustic Panel Market research report provides expanded data and customized strategic context. It is designed for teams that want to move from high-level trend awareness to specific procurement, product, and investment decisions with more precise segmentation and detail.
For detailed analysis of this topic, please visit the official page: Acoustic Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
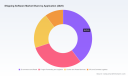
The Shipping Software Market: Strategic Trends and Commercial Opportunities Through 2032
The shipping software market has entered a decisive growth phase, driven by the compounding effects of e-commerce expansion, digital fulfillment mandates, and enterprise modernization programs. Valued at approximately $2.19 billion in 2025, the market has expanded consistently over the past half-decade and is projected to accelerate toward a ~$3.87 billion valuation by 2032, reflecting a compound annual growth rate of 8.5 percent over the 2026–2032 forecast window. This trajectory is not merely a function of volume growth; it signals a structural reorientation in how shippers, logistics providers, and merchant networks orchestrate transportation execution, rate optimization, and customer-facing delivery experiences. The sector is no longer defined by simple label printing or carrier selection. It has evolved into a critical control layer that connects order management, warehouse operations, freight procurement, and post-purchase engagement into a unified operational fabric.
Despite the favorable expansion path, the market is navigating a series of inflection points that will shape competitive outcomes over the next several years. The following analysis examines the forces driving this transformation, maps the strategic positioning of leading participants, and outlines the commercial opportunities and risks that executives and investors should monitor as the landscape matures.
Market Context: Growth Trajectory and Structural Headwinds
The market's expansion over the 2020–2025 period demonstrates resilient demand across multiple buyer segments, with the 2025 valuation establishing a foundation for more aggressive growth in the forecast period. The projected acceleration toward the late 2020s and early 2030s reflects both incremental adoption and deeper enterprise penetration, as organizations move from point solutions to integrated shipping orchestration platforms. Growth is being reinforced by the ongoing shift to cloud-based architectures, which now represent the dominant deployment model, and by sustained demand from commerce-driven fulfillment environments that require rapid carrier selection, automation, and customer visibility.
However, several structural challenges are reshaping how vendors position their offerings and how buyers evaluate procurement decisions. Three dynamics merit particular attention.
Operational Cost Pressure and Infrastructure Economics
Shipping software buyers are increasingly sensitive to total cost of ownership, not only in license or subscription terms but also in the underlying infrastructure and integration costs required to operate at scale. Cloud hosting and infrastructure expenses can range from several hundred to multiple thousands of dollars per month depending on transaction volume and architecture choices, while API usage at scale introduces incremental fee structures that can accumulate quickly as call volumes rise. For enterprises processing high parcel volumes, these operational costs become material line items that influence platform selection, vendor negotiation, and architectural decisions around multi-carrier abstraction layers. The practical implication is that shipping software is no longer evaluated solely on feature breadth; buyers are scrutinizing cost predictability, usage-based pricing transparency, and the efficiency of underlying integration patterns.
Regulatory Shifts and Data Transfer Economics
Changing regulatory frameworks are beginning to influence cloud economics and data handling requirements, with implications for how shipping platforms manage cross-border data flows, carrier integrations, and customer information. Forthcoming requirements such as the EU Data Act, taking effect in early 2027, are expected to affect cloud transfer fees and pricing dynamics for data-intensive workloads. Shipping software that depends on continuous data exchange across carriers, marketplaces, and global fulfillment nodes will need to account for evolving compliance expectations and potential cost shifts tied to data movement. This creates both a compliance burden and a strategic consideration for vendors offering global multi-carrier capabilities, as regulatory alignment increasingly factors into enterprise procurement criteria.
Labor Dynamics, Incident Cost, and Operational Resilience
While shipping software is a technology category, its value proposition is tightly linked to labor efficiency and operational continuity. Workforce spending remains a dominant cost center across logistics-heavy environments, and downtime or incident response can carry significant financial consequences when fulfillment operations are disrupted. Shipping platforms are therefore expected to demonstrate not only automation depth but also reliability, rapid issue resolution, and integration stability. The market is tilting toward solutions that reduce manual intervention, streamline exception handling, and minimize operational friction during peak shipping periods. Resilience is becoming a competitive differentiator.
Core Drivers Reshaping the Shipping Software Landscape
The current growth cycle is being propelled by several interrelated forces. Understanding how these drivers interact provides a clearer view of where value is being created and where competitive advantage is likely to consolidate.
Technology Innovation and API-Centric Architecture
One of the most consequential shifts in the market is the move toward API-first shipping orchestration. Cloud-based shipping APIs now enable rate shopping, label creation, address verification, tracking, and return workflows across hundreds of carriers through standardized integration layers. This architecture reduces development overhead for merchants and platforms that need to connect multiple carriers without building bespoke integrations one by one. It also supports modular adoption, where shipping functionality can be embedded into commerce platforms, order management systems, or fulfillment workflows without requiring a monolithic replacement of existing systems.
The rise of versionless or continuously updated software models further reinforces this trend. Rather than waiting for periodic releases, buyers increasingly expect incremental feature delivery, ongoing carrier rule updates, and dynamic automation capabilities that adapt to changing shipping conditions. At the same time, advanced functionality such as branded tracking, predictive delivery estimates, and returns management is extending the value of shipping software beyond execution into customer experience and post-purchase engagement. This expansion broadens the addressable use case and increases the strategic importance of shipping platforms within the commercial technology stack.
Demand-Side Evolution in Commerce and Fulfillment
buyer behavior is reshaping requirements on multiple fronts. E-commerce and retail fulfillment continue to exert strong demand for scalable shipping automation, multi-carrier rate optimization, and seamless platform integrations with ecosystems such as Shopify, WooCommerce, and other commerce environments. At the same time, freight forwarding, logistics providers, courier and postal services, and third-party logistics operators are seeking more capable multi-carrier execution tools that can handle mixed parcel and LTL workflows, broker rating, and enterprise system integration.
A notable shift is the growing expectation that shipping software should support brand-consistent delivery experiences and flexible fulfillment choices. Shoppers increasingly expect transparent tracking, accurate delivery estimates, and easy returns, while merchants want to manage carrier selection dynamically based on cost, speed, and service levels. This pushes vendors to integrate rate optimization, delivery promise communication, and post-purchase visibility into a single workflow rather than treating them as separate concerns.
Salon Software Market
Supply Chain Complexity and Multilayer Logistics Requirements
Shipping software is also being reshaped by the increasing complexity of supply chain execution. Organizations are managing more intricate fulfillment networks, cross-region shipping obligations, and hybrid parcel/LTL operations. In this environment, the ability to consolidate carrier management, support enterprise integrations with ERP and warehouse systems, and provide multi-carrier abstraction becomes a practical necessity rather than a convenience feature.
This complexity favors platforms that can act as an intermediate control layer between enterprise systems and carrier ecosystems. For large shippers and logistics service providers, the value lies in reducing fragmentation, standardizing rate and label workflows, and enabling centralized decision-making across carrier options. As a result, the market is seeing heightened interest in solutions that combine parcel execution with broader transportation and supply chain management capabilities, as well as in connectors that link shipping software to major enterprise platforms.
Partnerships, Enterprise Integrations, and Ecosystem Expansion
A growing number of partnerships are extending shipping software reach into enterprise environments. Recent integration activity has connected multi-carrier parcel shipping capabilities with major cloud SCM and ERP ecosystems, enabling organizations to embed shipping execution within broader enterprise workflows. These collaborations are strategically important because they lower adoption friction for large buyers and accelerate deployment in environments where standalone shipping tools would otherwise require extensive customization.
PW Consulting
This ecosystem-oriented approach is also visible in product refinements that target operational specificity, such as expanded automation rules for regional address handling, broker rating enhancements, and multi-carrier support improvements. Rather than positioning shipping software as a static utility, leading vendors are investing in capabilities that adapt to changing carrier rules, regional requirements, and enterprise integration needs. The trend suggests that competitive advantage will increasingly belong to platforms that can combine API flexibility, enterprise connectivity, and ongoing operational updates within a manageable cost structure.
Competitive Dynamics and Strategic Positioning
The shipping software market is characterized by a broad set of participants spanning standalone shipping platforms, API-centric providers, enterprise supply chain vendors, and large technology companies with shipping integrations. Market concentration remains moderate, indicating that no single player dominates the entire landscape, but a cluster of established vendors holds meaningful share through product breadth, carrier relationships, and ecosystem reach.
Differentiation Among Leading Participants
Competitive positioning generally falls along a few distinct axes. Some vendors emphasize multi-carrier rate comparison, label automation, and shipment execution for SMB and mid-market commerce users. Others focus on API-first abstraction layers that let platforms and enterprises integrate shipping functionality at scale. A third group anchors its strategy in enterprise-grade supply chain and transportation management, where shipping execution is part of a broader operational suite. A fourth segment extends into post-purchase experience, using branded tracking and delivery communication as a differentiator that supports customer retention and brand consistency.
- Multi-carrier execution and automation remain foundational. Vendors in this space compete on carrier breadth, rate shopping intelligence, and the ability to handle high-volume fulfillment workflows with minimal manual intervention.
- API and platform integration capabilities are increasingly decisive for technology-forward buyers. Providers that offer clean abstraction layers, address verification, and scalable tracking support can embed themselves more easily into commerce and logistics ecosystems.
- Enterprise integration and ERP alignment create stickiness in larger accounts. Shipping solutions that connect cleanly to enterprise resource planning and warehouse systems reduce operational silos and support consolidated procurement and execution.
- Customer-facing shipping experiences are becoming a competitive lever. Branded tracking, estimated delivery communication, and returns management extend the software's role from operational utility to commercial enablement.
Evolution of the Market Structure
The market appears to be moving toward a dual pattern of consolidation and specialization. On one hand, larger enterprise vendors and well-resourced platform providers are strengthening their positions through integration depth, carrier reach, and broader supply chain alignment. On the other hand, specialized players continue to compete by targeting clearly defined buyer needs, such as e-commerce shipping automation, API-centric parcel orchestration, or post-purchase engagement tools.
New entrants and incumbent expansion both remain viable paths, but the bar is rising. Buyers increasingly expect carrier coverage, integration flexibility, automation depth, and predictable operating costs. As a result, pure point solutions must demonstrate a strong niche advantage or a clear path to integration breadth, while broader platforms must prove they can deliver shipping-specific usability and carrier-level accuracy without becoming overly complex. The competitive frontier is shifting toward solutions that can operate as a reliable intermediary across carriers, enterprise systems, and customer-facing workflows while keeping cost structures transparent.
Recent Moves and What They Signal
Recent industry activity underscores the strategic importance of product continuity, leadership focus, and ecosystem integration. Recognition of leading vendors in shipping software reflects the market's heightened attention to operational reliability and solution maturity. Leadership appointments in sending technology and shipping solutions indicate that organizations are investing in focused management attention for core shipping capabilities. Product updates that expand automation rules, regional support, and broker rating functionality show that vendors are tuning their platforms for practical operational complexity rather than merely adding surface-level features.
Partnership activity connecting multi-carrier parcel shipping with major cloud SCM environments is particularly telling. These moves lower the barrier for enterprises to adopt advanced shipping functionality within existing systems and suggest that integration readiness is becoming a competitive necessity. At the same time, feature launches around broker rating and carrier management point to a wider recognition that shipping software must support nuanced procurement decisions, not just execution. Taken together, these developments indicate a market that is maturing rapidly and rewarding vendors that can combine technical agility with operational relevance.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, the shipping software market is likely to be shaped by a small number of high-impact trends. These developments will influence vendor strategy, buyer expectations, and the allocation of investment capital.
Real Estate Software Market
Trend 1: From Execution Tool to Orchestration Platform
Shipping software is increasingly positioned as an orchestration layer rather than a transactional utility. That means broader responsibility for rate optimization, carrier selection logic, exception handling, delivery communication, and returns workflows. Over the next three to five years, platforms that can unify these functions in a configurable, API-accessible architecture will likely capture more enterprise value. The commercial opportunity lies in selling not just shipping labels or rate comparison, but operational control, cost optimization, and customer experience consistency across channels and regions.
The risk here is complexity creep. As platforms broaden their scope, they must preserve usability, carrier accuracy, and deployment speed. Buyers may resist solutions that become too heavy or expensive relative to the value they deliver. The winners will be those that expand capability without sacrificing integration clarity or cost predictability.
Trend 2: Ecosystem Embedding and Enterprise Interoperability
Enterprise adoption will continue to favor shipping software that fits cleanly into broader technology environments. Integration with ERP, cloud SCM, order management, and warehouse systems will be a key enabler of scale, especially for organizations that want centralized governance over carrier selection and fulfillment execution. Partnerships and prebuilt connectors will likely become more important than custom integration work as buyers seek faster time-to-value and lower operational risk.
This creates opportunity for vendors that invest in ecosystem alignment and enterprise-grade reliability. It also raises the stakes for smaller providers that lack integration depth, unless they can win through niche focus, superior developer experience, or distinctive post-purchase capabilities. A practical uncertainty is the pace and consistency of enterprise platform evolution, which can affect integration roadmaps and dependency management.
Trend 3: Cost Transparency, Compliance, and Operational Resilience
As infrastructure and API usage costs become more visible in buyer evaluations, platforms that offer predictable pricing, efficient data handling, and resilient operations will gain an advantage. At the same time, regulatory developments affecting data transfer and cloud economics will require vendors and buyers to plan for evolving compliance obligations. Shipping software that handles cross-border data flows, carrier integrations, and customer information will need to demonstrate both operational efficiency and regulatory awareness.
The commercial implication is that cost structure and compliance readiness will become more differentiated factors in procurement decisions. Buyers will likely favor solutions that make usage economics easier to forecast and that reduce the burden of adapting to new regulatory requirements. The risk side includes potential shifts in cloud transfer costs, API pricing pressure at scale, and the operational impact of downtime or incident response during high-volume periods. Resilience will not be a nice-to-have; it will be part of the value equation.
Strategic Implications for Decision-Makers
The shipping software market offers meaningful opportunities, but the right course of action depends on the role an organization plays in the value chain. The following recommendations are intended to translate market dynamics into practical strategic choices.
For Shipping Software Vendors and Technology Manufacturers
Product strategy should emphasize orchestration breadth without sacrificing integration simplicity. vendors that can combine multi-carrier execution, API accessibility, enterprise interoperability, and customer-facing delivery tools will be better positioned to capture expanding demand across commerce, logistics, and enterprise segments. Equally important is cost structure discipline: usage-based economics, cloud hosting assumptions, and API fee exposure should be modeled clearly so that pricing remains competitive as transaction volumes grow.
Investment in automation depth and operational adaptability also deserves priority. Regional address handling, broker rating, carrier rule changes, and peak-season operational needs are not edge cases; they are central to reliable fulfillment at scale. Vendors that keep pace with these requirements while maintaining a clear developer and administrator experience will strengthen their competitive standing.
For Investors and Strategic Allocators
The market's 8.5 percent CAGR trajectory and expanding enterprise penetration suggest continued demand, but differentiation will matter more over time. Investors should look beyond headline growth and assess whether a company has durable advantages in carrier relationships, integration ecosystems, automation depth, or post-purchase engagement. Concentration dynamics indicate room for both scaled incumbents and specialized challengers, but long-term winners are likely to be those that can defend margins while expanding scope.
It is also prudent to monitor operating cost exposure and compliance readiness as selection criteria that may influence churn, expansion, and competitive displacement. Companies that can articulate a clear path to efficient scale, predictable cost profiles, and resilient operations will generally present stronger investment theses than those relying primarily on feature volume.
For Procurement Leaders and Enterprise Buyers
Buyers should evaluate shipping software as a strategic operational layer, not merely a transactional tool. Key evaluation criteria should include carrier coverage, integration compatibility with existing ERP or cloud SCM environments, automation capabilities for rate selection and fulfillment workflows, and the predictability of ongoing usage costs. Post-purchase functionality such as branded tracking and returns management should be assessed for their contribution to customer experience and operational efficiency, not treated as optional extras.
Given the pace of change in carrier rules, regulatory expectations, and enterprise integration patterns, buyers should also prioritize vendors with a demonstrated ability to update product capabilities and maintain interoperability over time. Selecting a platform that can grow with the organization while keeping cost and complexity under control will reduce the risk of future rework or displacement.
Conclusion
The shipping software market is entering a period in which growth, complexity, and strategic differentiation are converging. Demand is being sustained by commerce expansion, enterprise modernization, and the need for more capable multi-carrier execution and visibility tools. At the same time, buyers are becoming more discriminating about cost transparency, integration readiness, regulatory alignment, and operational resilience. For vendors, the opportunity lies in building platforms that combine API flexibility, enterprise interoperability, and customer-facing delivery value without allowing cost or complexity to erode competitiveness. For investors and buyers, the priority is to identify solutions and partners that can scale efficiently while adapting to a rapidly changing operational and regulatory environment.
Given the breadth of segmentation, regional variation, and evolving enterprise requirements across the shipping software landscape, detailed segmentation data and tailored commercial assessment can help decision-makers move from high-level trends to specific procurement, investment, and product decisions. PW Consulting's full research report provides deeper coverage of market segmentation, competitive positioning, and actionable recommendations designed to support planning across vendor, investor, and buyer perspectives.
For detailed analysis of this topic, please visit the official page: Shipping Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diesel Fuel Injection Systems Market Gains 5.5% CAGR Amid Regional Power Shifts
By PW Consulting, 2026-09-21
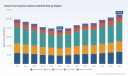
Diesel Fuel Injection Systems Market: Navigating the Tipping Point Toward Sustainable Efficiency
The diesel fuel injection systems market is currently navigating a complex period of structural adjustment. Drawing from historical data spanning 2020 to 2025 and a forecast period extending to 2032, the market exhibits a clear narrative of recent contraction followed by a projected recovery. In 2020, the market revenue stood at approximately $98,208 million. Over the subsequent five years, the sector experienced a steady decline in revenue, reaching a base year valuation of $75,142 million in 2025. This contraction reflects the lingering effects of global supply chain disruptions and the initial phases of regulatory pressure on internal combustion engines.
However, the trajectory shifts markedly from 2026 onward. The market is expected to rebound, growing at a compound annual growth rate (CAGR) of 5.5% through 2032. By the end of the forecast period, revenue is projected to surpass $109,400 million. This growth is not merely a return to pre-pandemic levels but indicates a maturing market where value is derived from higher-performance, precision-engineered systems rather than volume alone. The market remains moderately fragmented, with a top-three concentration ratio of 25.4% and a top-five concentration ratio of 30.5%, suggesting that while dominant players hold significant sway, there is ample room for specialized competitors and niche innovations to capture value.
PW Consulting
These macroeconomic figures provide the backdrop for a deeper investigation into the operational realities facing executives and investors. The following analysis dissects the core challenges, driving forces, and competitive maneuvers defining this sector, offering a strategic lens for decision-making in a transforming landscape.
Market Landscape: The Contraction-Recovery Paradox
The revenue decline observed from 2020 to 2025 masks a critical underlying dynamic: the qualitative evolution of the product mix. While unit volumes may have faced headwinds due to economic fluctuations and the gradual transition toward electrification in light-duty segments, the revenue erosion was partially mitigated by the increasing adoption of high-pressure common rail technologies. As legacy systems are phased out, the average value per unit in the installed base shifts toward more sophisticated injection architectures capable of meeting stringent efficiency and emission targets.
This period of contraction has forced a recalibration of expectations. Market participants who previously relied on steady volume growth are now focusing on margin preservation and technological differentiation. The recovery projected for 2026 and beyond suggests that the market has absorbed the initial shocks of regulatory and economic volatility. The growth phase is driven by the need to retrofit and upgrade existing fleets, the expansion of commercial vehicle markets in high-growth regions, and the continuous push for thermal efficiency in heavy-duty applications where diesel remains the dominant power source.
Key Challenges and Inflection Points
Three critical challenges define the current operational environment and serve as inflection points for strategic planning:
- Regulatory Tightening as a Dual-Edged Sword: Emission standards continue to escalate, requiring precise control over fuel injection timing and quantity. While this drives demand for advanced systems, it also increases the complexity and cost of compliance. Manufacturers must balance the engineering requirements of meeting standards such as EPA and Euro norms with the commercial reality of price-sensitive end markets. Nonconformance penalties further raise the stakes, making reliability and validation paramount.
- Material and Supply Chain Pressures: The trend toward higher operating pressures—exceeding 2,000 bar in many common rail systems—demands components fabricated from high-performance steels and specialized alloys. These materials are subject to price volatility and supply constraints. Any disruption in the availability of critical raw materials can impact production schedules and cost structures, forcing manufacturers to rethink sourcing strategies and inventory management.
- The Electrification Cross-Pressure: The long-term shift toward electrification in passenger cars and light commercial vehicles creates a structural headwind for traditional diesel injection volumes in these segments. Manufacturers must determine how to allocate R&D resources between defending existing diesel markets with incremental improvements and investing in technologies that support alternative fuels or hybrid architectures.
Core Drivers of Market Dynamics
Understanding the recovery trajectory requires a granular look at the forces propelling change. The market is not growing simply due to macroeconomic recovery; it is being reshaped by specific technological, regulatory, and demand-side innovations.
Technological Innovation: The Push for Higher Pressure and Precision
The technical arms race in diesel fuel injection centers on pressure, speed, and control. Leading systems now operate at pressures exceeding 2,500 bar, with some architectures pushing toward 3,000 bar. This is not merely an engineering milestone but a functional necessity. Higher injection pressures improve atomization, leading to more complete combustion, lower particulate emissions, and better fuel economy.
Recent developments highlight this trajectory. For instance, innovations unveiled in 2026 demonstrate a focus on supporting future emissions standards through 500-bar-plus fuel injection capabilities and alternative fuel compatibility. This signals that the industry is preparing for a diversified fuel landscape where diesel injection technology must adapt to new energy carriers while maintaining performance benchmarks. Furthermore, the ability to achieve ultra-fast actuation in injectors allows for multiple injection events per cycle, giving engine control units finer granularity over combustion dynamics. These capabilities are essential for meeting the dual mandates of power output and emission compliance.
Regulatory and Policy Environment: Compliance as a Market Filter
Policy continues to be a primary determinant of market structure. Heavy-duty engines, in particular, are subject to rigorous standards that require optimized fuel injection timing and quantity, often in conjunction with aftertreatment systems. Regulations are not static; they evolve, imposing stricter limits on nitrogen oxides and particulates.
This regulatory environment acts as a filter. It raises the barrier to entry for manufacturers who cannot demonstrate consistent compliance and reliability. At the same time, it creates a sustained demand for upgrade kits and retrofit solutions. The introduction of modular common rail fuel system upgrade kits for legacy engines illustrates how regulators and market needs converge. By converting older high-pressure injection systems with newer components, manufacturers can extend the life of existing assets while achieving efficiency gains, such as the verified 5% improvement noted in recent upgrade initiatives. This trend underscores a market where service and upgrade revenue streams are becoming increasingly relevant alongside new equipment sales.
Diesel Engines Market
Demand-Side Shifts: Commercial Vehicles and Off-Highway Resilience
While passenger car volumes face long-term uncertainty, the demand profile for diesel injection systems is being bolstered by the commercial vehicle and off-highway segments. Heavy-duty trucks, mining equipment, and agricultural machinery rely on the torque, durability, and energy density of diesel power. In these applications, the operational imperative is efficiency and uptime, and advanced injection systems deliver tangible value by reducing fuel consumption and maintenance intervals.
The off-highway sector, in particular, benefits from the ruggedness of modern injection architectures. High-pressure systems designed for extreme operating conditions ensure that engines perform reliably in remote or demanding environments. As global infrastructure projects and mining activities expand, especially in Asia Pacific and other developing regions, the demand for high-performance engines equipped with advanced injection systems remains robust. This demand provides a stable revenue base that cushions the market against volatility in the light-duty segment.
Supply Chain and Cost Structure Evolution
The cost structure of diesel fuel injection systems is undergoing a transformation driven by material science and manufacturing efficiency. The reliance on specialized steels and alloys for components that withstand extreme pressures means that cost management is no longer solely about labor arbitrage. It involves securing resilient supply chains for critical raw materials and investing in advanced manufacturing processes such as precision machining and additive manufacturing for complex geometries.
Diesel Common Rail Injection System Market
Companies are increasingly looking at vertical integration and long-term supplier partnerships to mitigate risk. The ability to control the quality and supply of key components becomes a competitive differentiator. Moreover, as systems grow more complex, the integration of software and sensors adds a new layer to the cost and value equation. The shift from purely mechanical systems to electronically controlled, sensor-rich architectures means that value capture is moving toward intellectual property, calibration expertise, and system-level integration.
Competitive Landscape and Strategic Positioning
The market features a mix of global tier-one suppliers and specialized engine manufacturers with strong fuel system capabilities. The top players have carved out distinct positions based on technology focus, application coverage, and geographic reach.
Bosch remains a dominant force, leveraging its extensive portfolio of common-rail systems with piezo injectors capable of high pressures. Its strength lies in the breadth of coverage across passenger cars, light commercial, and heavy-duty vehicles, supported by a comprehensive fuel supply ecosystem. Bosch's ability to deliver full-system solutions, including pumps and rails, provides a holistic value proposition to OEMs seeking single-source reliability.
Denso Corporation has established itself through its i-ART common rail technology, which integrates advanced control capabilities. Its focus on medium- and large-sized vehicles, with pressures up to 2,500 bar and the integration of SCR and DPF controls, highlights a strategy centered on system-level emissions management. By linking injection performance directly to aftertreatment optimization, Denso offers a solution that addresses the full emission compliance chain.
BorgWarner has expanded its footprint through strategic acquisitions, such as the 2020 acquisition of Delphi Technologies. This move bolstered its portfolio with EUI and DFi7 injectors for heavy-duty and passenger segments, alongside PLD systems. BorgWarner's trajectory reflects a consolidation strategy, using scale to offer a wide array of injection technologies while maintaining the specialized engineering heritage of its acquired units.
PHINIA occupies a strong niche in light- and medium-duty engines, producing injector families and high-pressure pumps that support emissions standards through 3,000 bar operation. Its upcoming focus on 500-bar-plus innovations and alternative fuel support indicates a forward-looking stance, positioning the company to cater to OEMs preparing for evolving regulatory and fuel landscapes.
Cummins Inc. distinguishes itself with deep integration into heavy-duty and mining engines. Its common rail systems, including the Modular Common Rail Fuel System, feature ultra-fast actuated injectors and dual-stage pumps delivering up to 2,600 bar. Cummins emphasizes verified efficiency gains, such as the 5% improvement delivered by its MCRS upgrade kits. This focus on measurable performance outcomes appeals to fleet operators and OEMs in demanding applications where fuel cost and operational efficiency are critical.
Strategies of Leaders and Market Evolution
The strategies of these leaders reveal common themes. First, there is a clear push toward higher pressure and faster actuation, which serves as a technological moat. Second, integration is key; players that can offer injectors, pumps, rails, and control software as a coherent system reduce complexity for customers and lock in value. Third, the ability to support legacy engine upgrades and alternative fuel readiness is becoming a strategic imperative, extending the relevance of diesel injection technology beyond new engine production.
The market is likely to see continued consolidation among smaller players who cannot match the R&D investment requirements of high-pressure systems. At the same time, new entrants may emerge in the form of specialized component suppliers or software-centric firms focusing on injection control algorithms. The moderate concentration ratios suggest that while the leaders hold significant share, the market structure allows for competitive differentiation through niche technologies and regional expertise.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are poised to shape the market and create actionable opportunities.
Trend 1: Retrofit and Upgrade Economy Gains Momentum
As regulations tighten and older fleets face compliance pressures, the market for retrofit solutions will expand. Upgrade kits that convert legacy inline pump systems to modern common rail architectures, increasing injection pressure and accumulator volume, will see growing demand. This trend offers commercial opportunities for manufacturers with strong aftermarket channels and technical support capabilities. It also appeals to operators seeking to extend asset life while meeting emission standards without full vehicle replacement.
Trend 2: Integration of Alternative Fuel Compatibility
Diesel injection systems are not disappearing; they are evolving. The push toward alternative fuels means that injection hardware and control strategies must adapt to different fuel properties. Innovations supporting alternative fuels alongside traditional diesel will become a key differentiator. Companies that develop flexible injection platforms capable of handling multiple fuel types will capture value in a transitioning energy landscape. This trend also opens opportunities for partnerships with fuel producers and alternative energy developers.
Trend 3: Software-Defined Injection and Data Analytics
As electronic control becomes more pervasive, the value of software in optimizing injection timing, quantity, and pressure profiles will grow. Advanced calibration and real-time adaptation based on sensor feedback will drive efficiency gains. This shift creates opportunities for firms that can provide sophisticated control algorithms, diagnostic tools, and data analytics services. The integration of injection data with broader fleet management systems could unlock new value streams, enabling predictive maintenance and performance optimization.
Risks and Uncertainties
Despite the positive outlook, risks remain. The pace of electrification in certain segments could accelerate, eroding long-term demand for diesel systems faster than anticipated. Raw material costs and supply chain disruptions could pressure margins. Regulatory shifts could introduce new compliance requirements that demand rapid redesign cycles. Additionally, geopolitical factors affecting trade and supply routes may impact the availability of critical components. Companies must maintain agility and diversify their technology portfolios to navigate these uncertainties.
Strategic Recommendations for Decision Makers
For executives, investors, and procurement leaders, the current market dynamics call for a proactive and nuanced approach.
For Manufacturers and Technology Developers
- Invest in High-Pressure and Multi-Fuel Platforms: Prioritize R&D in systems that exceed current pressure norms and can accommodate alternative fuels. This ensures relevance as emission standards tighten and energy sources diversify.
- Expand Aftermarket and Upgrade Capabilities: Develop modular upgrade kits and retrofit solutions that allow customers to modernize existing fleets. This creates a recurring revenue stream and strengthens customer relationships beyond the initial sale.
- Strengthen Supply Chain Resilience: Secure long-term agreements for critical materials and explore vertical integration where feasible. Diversify sourcing to mitigate the risk of disruptions in high-performance alloy supply.
For Investors
- Assess Technology Moats and System Integration: Evaluate potential investments based on their ability to deliver high-pressure solutions, integrated system architectures, and software-defined control. Companies with strong IP in piezo actuation or advanced control algorithms are well-positioned for sustained value creation.
- Monitor Retrofit and Commercial Vehicle Exposure: Companies with a strong footprint in commercial vehicles, off-highway applications, and aftermarket upgrade services may offer more stable growth profiles than those heavily reliant on passenger car volumes.
- Watch for Consolidation and Niche Disruptors: The market may see further consolidation among mid-tier players. Simultaneously, look for niche entrants with specialized technologies in areas such as alternative fuel injection or data-driven optimization.
For Procurement and Fleet Operators
- Evaluate Total Cost of Ownership, Not Just Unit Price: Advanced injection systems that offer verified efficiency gains and lower emission compliance costs can deliver significant long-term savings. Consider the impact of fuel savings, maintenance intervals, and regulatory compliance when selecting systems.
- Plan for Fleet Modernization and Retrofits: Assess the compatibility of existing engines with available upgrade kits. Proactive planning for retrofits can help manage compliance timelines and reduce downtime.
- Engage with Suppliers on Long-Term Support: Ensure that suppliers can provide ongoing technical support, calibration services, and parts availability. Strong supplier partnerships are critical for maintaining operational reliability in demanding applications.
As the diesel fuel injection systems market enters a phase of recovery and technological refinement, the landscape offers clear pathways for those who can align their strategies with the driving forces of efficiency, compliance, and adaptability. The interaction between regulatory demands, material science, and system integration continues to reshape value creation in this sector. Decision makers who maintain a close pulse on technology roadmaps, competitive moves, and regional demand shifts will be best positioned to capitalize on the opportunities ahead. For those seeking a comprehensive breakdown of segment trajectories, regional nuances, and granular competitive intelligence, the full suite of detailed research available through PW Consulting provides the depth required to inform precise strategic moves and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Diesel Fuel Injection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
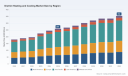
The District Heating and Cooling Market: Strategic Trends and Commercial Opportunities Through 2032
The district heating and cooling (DHC) sector has entered a phase of structural expansion, driven by urban decarbonization mandates, technological maturation, and shifting consumer expectations around energy resilience. Market valuation reached approximately USD 260 billion in 2025, reflecting a compound annual growth rate of 4.5 percent across the 2026-2032 forecast horizon. The trajectory from 2020 onward demonstrates consistent upward momentum, with recent acceleration tied to policy enforcement and capital reallocation toward low-carbon thermal infrastructure. This growth is not merely cyclical; it represents a reconfiguration of how cities and industrial clusters source, distribute, and optimize thermal energy.
At this scale, the market carries meaningful implications for capital allocation, technology roadmapping, and partnership strategy. Understanding where value is created—and where friction persists—requires looking beyond headline figures to the operational, regulatory, and competitive forces shaping deployment decisions. The following analysis examines the current market reality, the forces accelerating change, the competitive dynamics among established players, and the strategic implications for executives navigating the next five years.
Market Reality: Scale, Structure, and Core Challenges
The thermal infrastructure market has grown from roughly USD 180 billion in 2020 to the current USD 260 billion baseline, with forward projections pointing toward USD 354 billion by 2032. This expansion reflects both incremental capacity additions and a structural shift toward integrated heating and cooling networks that serve multi-consumer zones. Geographically, the market is diversified across mature and emerging deployment regions, with Asia Pacific representing the largest demand pool, followed by North America and Europe. Europe and parts of the Middle East have concentrated heavily on cooling infrastructure in high-density urban and commercial environments, while Northern European and select Asian markets have prioritized heating network modernization and renewable integration.
Three challenges define the current inflection point:
- Infrastructure capital intensity and deployment timelines. District networks require extensive piping, substations, valve assemblies, and balancing equipment. Concession-based expansions frequently span tens of kilometers and involve multi-year construction, permitting, and interconnection sequencing. Capital planning must accommodate prolonged payback periods, material procurement risk, and coordination with municipal authorities.
- Decarbonization compliance pressure. Regulatory frameworks are tightening renewable share requirements and performance measurement methodologies for both heating and cooling. Operators and equipment suppliers must demonstrate measurable emissions reductions while maintaining reliability, particularly in markets where fossil-based backup still provides peak-load stability.
- Systems integration and operational complexity. Modern networks increasingly blend multiple heat sources—industrial waste heat, data center exhaust, geothermal, biomass, and large-scale heat pumps—into unified distribution systems. This introduces control coordination challenges, flow balancing complexity, and the need for advanced monitoring and predictive maintenance to protect efficiency targets.
These challenges are not blockers; they are the organizing constraints that determine which business models scale and which stall. Companies that treat thermal infrastructure as a systems problem—spanning source generation, distribution, control hardware, and consumer-side efficiency—gain a meaningful advantage in winning concessions, securing supply contracts, and delivering performance guarantees.
PW Consulting
Key Drivers Accelerating Market Transformation
Multiple forces are converging to reshape demand patterns, investment priorities, and technology adoption curves. The following drivers explain why growth is accelerating and where competitive advantage is being formed.
Technology Innovation and System-Level Breakthroughs
Thermal networks are transitioning from single-source, linear distribution models to multi-source, digitally coordinated systems. Heat pumps, advanced substations, motorized control valves, and heat exchangers now enable finer temperature control, better load-matching, and higher renewable penetration. Waste heat recovery has emerged as a particularly valuable capability. Large data center operators and industrial facilities are increasingly viewed as thermal asset owners rather than pure electricity consumers, with excess heat routed into neighboring district networks. This shift changes the economics of thermal supply: low-marginal-cost heat becomes available where population and commercial density intersect with suitable infrastructure corridors.
Practical examples illustrate how this is unfolding. Operator activity in Espoo has demonstrated the commencement of large-scale heat pump plants utilizing excess heat from major data center operations, producing substantial district heating output and covering a significant share of local demand. Such deployments show that data-center-adjacent thermal integration is moving from feasibility studies into operating reality. At the same time, equipment manufacturers continue to refine skid-mounted substation solutions and valve assemblies that reduce on-site integration friction, helping network builders standardize components across expansions.
Policy and Regulatory Momentum
Policy has become a central determinant of deployment economics. In the European Union, binding national targets now require increasing the share of renewables in district heating and cooling, supported by revised methodologies for counting renewable cooling performance. The EU Heating and Cooling Strategy, expected in the second quarter of 2026, is positioned to accelerate decarbonization implementation and clarify compliance pathways. These policy signals matter because they influence concession award criteria, public funding eligibility, and long-term off-take certainty.
Funding mechanisms are reinforcing the regulatory direction. Calls such as LIFE-2025-CET-DHC provide support at up to 95 percent for proposals focused on efficient district heating and cooling networks that integrate renewable energy and waste heat. For project developers and equipment providers, this creates a pathway to reduce capital exposure on pilot and early-scale deployments, particularly in regions where municipal balance sheets are constrained. Meanwhile, national and municipal authorities continue to structure concessions that tie network expansion to decarbonization outcomes, as shown in recent green heating network agreements that add tens of kilometers of distribution capacity and serve tens of thousands of households through biomass and recovered energy.
Demand-Side Shifts in Urban, Industrial, and Commercial Settings
Demand is no longer driven solely by legacy residential heating contracts. Industrial clusters remain a major consumer segment, but the composition of demand is broadening. Commercial complexes, education campuses, healthcare facilities, and mixed-use urban districts are increasingly evaluated through the lens of thermal efficiency, continuity of supply, and emissions performance. Cooling demand in hot climates and densely built environments is also accelerating the case for centralized chilled water systems, particularly where peak electricity pricing and grid constraints make decentralized cooling less attractive.
Partnership structures reflect this broadening demand base. Recent expansions of district cooling systems serving education group buildings demonstrate how institutional clients are being integrated into larger sustainability programs, with completion timelines aligned to academic and operational cycles. Large-scale cooling plant inaugurations with significant refrigeration tonnage further indicate that high-capacity centralized cooling is becoming a standard asset class in regions where cooling is a dominant load. These demand-side shifts create opportunities for operators to secure long-term service relationships and for equipment suppliers to tailor control and heat exchange solutions to multi-building portfolios.
Supply Chain and Cost Structure Dynamics
The cost structure of district networks is being reshaped by material intensity, component standardization, and financing availability. Piping, substations, valves, and heat exchangers remain essential physical inputs, and large concession-driven expansions highlight how material procurement and installation logistics influence project pace. At the same time, standardization of skid-based substation packages and advanced control hardware can reduce customization cost and accelerate commissioning. Financing innovation also matters: where public grants, climate funds, and long-term concession revenue streams exist, the cost of capital becomes a decisive factor in who can pursue expansion aggressively.
A nuanced risk in the cost picture is the tension between rapid expansion and performance assurance. Faster network growth can strain quality control, balancing, and maintenance planning if supply chains are not aligned to technical specifications. Operators and manufacturers that invest in repeatable engineering processes and remote monitoring capabilities can protect margins while scaling, whereas fragmented procurement approaches may create operational inefficiencies that erode the value of expansion.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment combines global operators, regional specialists, and equipment manufacturers, each competing on a different axis of value creation. The structure is moderately concentrated, but the variation in business models means that direct comparison requires attention to whether a company competes as a network operator, a technology supplier, or both.
Danfoss operates from an equipment and control standpoint, providing advanced control valves, motorized control valves, ball valves, heat exchangers, and complete substation or skid solutions for district heating and cooling networks and building applications. Its differentiation lies in component-level precision and integration support, positioning it as a critical supplier for operators seeking to standardize control architectures and improve balancing across networks. For DHC projects, Danfoss-type solutions can reduce engineering complexity and improve the reliability of temperature and flow regulation across varied load conditions.
Veolia competes as an operator and developer, with a strong orientation toward fifth-generation systems that use geothermal and waste heat, and a clear decarbonization focus. Its advantage is the ability to bundle development, operation, and low-carbon sourcing into a single value proposition, which is appealing to municipalities and institutional clients that want emissions reduction outcomes without managing multiple vendor relationships. Veolia’s positioning suggests a strategy centered on asset development and long-term service contracts tied to sustainability performance.
Fortum illustrates the operator-as-system-integrator model, running heating and cooling networks while capturing waste heat from data centers and targeting carbon-neutral supply by 2030. The recent start of operations at large-scale heat pump plants that draw on data center excess heat demonstrates a strategy of turning adjacent industrial heat into a competitive supply advantage. By combining operational scale with innovative sourcing, Fortum shows how a regional operator can build differentiation through source diversification and decarbonization commitments.
ENGIE operates a broad international footprint, with hundreds of heating networks and a substantial number of cooling networks across multiple countries, alongside significant heat and cooling production capacity. Its strategy appears oriented toward scale, international replication, and strategic partnerships that extend network reach into institutional and commercial demand pools. Recent concession activity securing long-term rights for green district heating network expansion and partnership expansions for sustainable cooling delivery indicate a focus on securing multi-year growth pipelines through public-sector and institutional collaboration.
Emicool represents a regionally concentrated but strategically important cooling operator, with large-scale plant assets and an emphasis on energy-efficient cooling supply. In high-cooling-load environments, operators like Emicool compete on plant efficiency, reliability, and the ability to serve dense commercial and residential zones with centralized chilled water infrastructure. Its relevance highlights the importance of regional specialization: in markets where cooling dominates thermal demand, expertise in plant design, load management, and operational efficiency becomes the core competitive battleground.
The broader market trajectory suggests continued evolution along three lines:
- Integration and consolidation. Larger operators are likely to pursue network acquisitions, concession portfolios, and partnership expansions to secure growth corridors and diversify heat and cooling sources.
- Specialization and regional depth. Regional specialists will continue to win in high-demand cooling markets and in niche heating segments where local regulatory, climatic, or industrial conditions create durable advantages.
- Technology supplier relevance. Manufacturers of control hardware, heat exchangers, and substation skids will gain importance as networks become more complex and operators seek standardized, monitorable, and efficient component ecosystems.
New entrants are most likely to appear where data center heat recovery, geothermal integration, or grant-funded renewable network development create viable project structures. However, successful entry typically requires access to land-use coordination, financing, and operational expertise, not merely technology capability.
Future Trends and Commercial Opportunities for the Next 3-5 Years
Several trends are likely to define the medium-term market, each carrying distinct commercial implications.
Underfloor Heating Market
Trend 1: Multi-source thermal integration becomes standard. Networks will increasingly combine waste heat from industrial and data center operations, geothermal, biomass, and large-scale heat pumps within unified control frameworks. This trend creates opportunities for operators that can secure heat supply agreements, for technology providers that enable source-agnostic control and balancing, and for financiers that structure projects around diversified thermal supply contracts. A practical commercial pathway is to align heat sourcing with urban and industrial land-use planning, ensuring that new heat loads are identified before network expansions are finalized.
Trend 2: Policy-driven decarbonization expands public funding and concession availability. Continued regulatory tightening and dedicated funding instruments will support projects that demonstrate renewable share growth and measurable emissions reductions. The commercial opportunity is not only in capturing grants but in designing projects that qualify for sustained support and that can be replicated across multiple municipalities. Developers that standardize project templates—combining proven sourcing, standardized substation and valve assemblies, and measurable performance reporting—can reduce delivery risk and improve scalability.
Trend 3: Cooling infrastructure scales as a strategic asset class. In high-temperature and high-density environments, district cooling will increasingly be treated as critical infrastructure rather than an optional convenience. Large-capacity plants and campus-linked cooling expansions indicate a pipeline of demand that favors operators with strong plant efficiency, reliable chilled water distribution, and the ability to integrate with building-level efficiency programs. Suppliers that support optimized heat exchange, cold storage integration, and load forecasting can differentiate within this pipeline.
Risk considerations. Deployment timelines can slip if permitting, material availability, or interconnection sequencing become constrained. Performance claims tied to renewable share or emissions reduction may face scrutiny if measurement methodologies evolve or if supply conditions change. In addition, rapid expansion without strong operational control can create balancing issues that undermine efficiency and customer satisfaction. Commercial planning should therefore incorporate contingency thinking around permitting, component standardization, and post-commissioning maintenance capacity.
Strategic Actions for Decision-Makers
Different stakeholders face different priorities, but all benefit from a clear view of where value is created in the thermal infrastructure value chain. The following actions are most relevant in the current environment.
Heat Cost Allocator Market
For Equipment Manufacturers and Technology Providers
Prioritize standardization and integration support. Substation skids, control valves, and heat exchangers that can be deployed repeatedly across multiple networks reduce engineering friction and improve project predictability. Emphasize coordination capabilities that help operators manage multi-source inputs, variable loads, and balancing requirements. Where possible, align product roadmaps with the growing relevance of waste heat recovery and renewable integration, since those themes are shaping both concession criteria and funding eligibility.
For Investors and Developers
Focus on corridors with aligned policy incentives, identifiable waste-heat sources, and credible long-term demand. Data center-adjacent heating, geothermal-enabled networks, and institutional cooling portfolios represent areas where project structures can combine revenue visibility with decarbonization goals. Evaluate not only technical feasibility but also the availability of grants, concession stability, and the operational capability required to run complex multi-source networks. Projects that can demonstrate repeatable deployment templates will generally attract more favorable capital terms and partnership interest.
For operators and procurement teams, the priority is performance assurance and supply resilience. Select components and partners that support long-term balancing, monitoring, and maintenance rather than lowest-first-cost procurement alone. In cooling-heavy markets, prioritize plant efficiency, redundancy, and load-forecasting capability. In heating markets, emphasize source diversification and control hardware that can accommodate future renewable and waste-heat integration without major redesign.
Across all roles, the strategic value of granular market intelligence is high. Macro trends indicate direction, but concession timelines, funding eligibility details, regional cooling and heating demand patterns, and component-level deployment preferences determine execution success. Decision-makers who can map these details to their own project pipelines, procurement plans, or investment theses are better positioned to move quickly when opportunities appear.
The district heating and cooling market is expanding on the back of policy pressure, multi-source heat integration, and growing recognition of thermal networks as decarbonization infrastructure. Growth will not be uniform; it will concentrate where regulatory support, demand density, and source availability align. For executives and investors, the practical task is to identify where those conditions overlap and to build capabilities—technical, operational, and commercial—that allow participation at the right scale. For those seeking deeper segmentation detail, competitive benchmarking, and tailored strategic recommendations, the full PW Consulting research report provides the supporting data and analysis needed to translate these market signals into concrete action.
For detailed analysis of this topic, please visit the official page: District Heating and Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
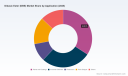
Dibasic Ester Market: Strategic Trends & Commercial Opportunities Through 2032
The dibasic ester (DBE) market has transitioned from a niche solvent portfolio to a strategically relevant segment within specialty chemicals, driven by tightening environmental regulations and evolving application requirements. Over the historical period from 2020 to 2025, the market demonstrated resilient expansion, reaching a base-year valuation of approximately 162.0 million USD in 2025. Forward projections indicate a compound annual growth rate of 6.5 percent across the 2026 to 2032 forecast horizon, with revenue scaled in millions of USD. This trajectory reflects a market that has moved past early-adoption friction and is now embedding DBE formulations into mainstream industrial, coating, and cleaning applications where performance, regulatory compliance, and sustainability must align.
The structural expansion is not uniform across all regions and end-use categories, but the overall momentum is clear. Asia Pacific continues to scale rapidly as manufacturing hubs reconfigure solvent portfolios, North America and Europe anchor demand through regulatory-driven reformulation, and emerging regions are gradually capturing share as cost-effective DBE grades become more accessible. Market concentration remains moderate, with the top three participants holding roughly 35 percent of industry revenue and the top five reaching approximately 45 percent. This fragmented-yet-concentrated structure signals room for both consolidation and differentiated positioning, depending on how companies navigate product quality, feedstock sourcing, and regional compliance requirements.
Worldwide Dibutyl Maleate (DBM) Market
Market Landscape And Core Challenges
The current DBE landscape is defined by a need to balance performance consistency with environmental compliance, while simultaneously managing feedstock volatility and regional specification fragmentation. Two to three structural challenges stand out as critical inflection points for operators and buyers alike.
First, regulatory pressure across major markets is accelerating solvent reformulation, but compliance pathways are not harmonized. Manufacturers and formulators must navigate differingVOC thresholds, hazardous air pollutant restrictions, and regional certification timelines. This creates adaptation costs and can delay product commercialization, especially for companies serving multiple jurisdictions with a single formulation strategy. Second, feedstock economics and supply chain resilience remain sensitive. Even as bio-based routes mature, parity with petrochemical equivalents fluctuates with agricultural commodity prices, fermentation scale-up timelines, and logistics constraints. Operators that rely on single-source raw materials or narrow regional procurement face margin pressure during periods of input cost instability. Third, application-specific performance expectations are rising. Paints and coatings, industrial cleaners, plasticizers, paint strippers, and other specialty uses each impose distinct solvency, evaporation, and safety profiles. Delivering consistent quality across these segments without compromising cost structure requires tighter process control and more advanced quality assurance capabilities.
Together, these challenges are reshaping how participants design production footprints, manage formulation partnerships, and prioritize product grades. They also create a clear divergence between suppliers that can offer compliant, traceable, and performance-validated solutions and those competing primarily on price in commoditized niches.
Key Drivers Shaping Market Dynamics
The expansion of the DBE market is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, making DBE increasingly attractive as a multifunctional solvent and intermediate across industrial applications.
Technological innovation and process breakthroughs are expanding the value proposition of DBE beyond conventional solvent replacement. Purification advances, fractionation techniques, and custom blending capabilities have improved consistency, odor profiles, and application compatibility. This has enabled higher-performance use cases where formulators need predictable evaporation rates, low residue, and compatibility with resin systems. Companies with proprietary fractionation and blending know-how are increasingly differentiating through specification-grade products rather than generic solvent volumes.
Policy and regulatory environments are acting as a powerful catalyst. Ongoing reviews of legacy solvents and evolving emission standards are pushing formulators toward alternatives with lower VOC profiles and reduced hazardous air pollutant exposure. In parallel, broader sustainability frameworks are encouraging substitution away from chlorinated and high-VOC solvents, particularly in European markets and other regions with strict environmental enforcement. The cumulative effect is a reformulation pipeline where DBE is prioritized as a practical, performance-aligned alternative.
Demand-side behavior is also shifting. Industrial buyers are increasingly treating solvent selection as a risk-management decision rather than a purely cost-driven purchase. Procurement teams prioritize compliance documentation, biodegradability profiles, and supply reliability, especially in coatings, pharmaceutical-adjacent applications, and electronics-related cleaning processes. This change in buying logic favors suppliers that can provide transparent product attributes, consistent lot-to-lot quality, and application support.
PW Consulting
Supply chain and cost structure dynamics are evolving alongside these demand shifts. Bio-based feedstock routes have progressed toward commercial viability, with certain fermentation-derived intermediates reaching cost levels that are within a reasonable range of conventional petrochemical equivalents. This progress reduces the premium historically associated with greener solvent pathways and opens the door to broader adoption, provided that scale, production reliability, and integration with existing DBE manufacturing lines can be sustained. At the same time, partnerships between specialty fermentation players and established DBE producers are laying the groundwork for commercial-scale bio-succinate-related projects, which could further strengthen the sustainability narrative and expand the feedstock base over the next several years.
Competitive Landscape And Leading Strategies
The DBE competitive field is a mix of global specialty chemical players, regional manufacturers, and application-focused producers. Their strategic positioning varies by geography, product purity requirements, feedstock strategy, and end-use specialization, but several competitive themes are visible across the market.
Some leading participants emphasize recycled-content and biodegradable solvent solutions, positioning their DBE offerings as compliant, performance-tested options for coatings, polyurethane polyols, recycling solvents, and soil stabilization. Others differentiate through high-performance solvent grades derived from mixed acid streams and fractionation expertise, targeting coatings, resins, and industrial applications where clarity, low odor, and processing ease matter. European-based manufacturers leverage regional production and specialty distribution channels to serve industrial solvents and performance materials, while multinational portfolios maintain breadth across geographies and application categories. Certain players focus on high-purity grades for pharmaceutical, personal care, and electronics-adjacent markets, where exacting quality standards become a barrier to entry and a source of margin resilience. In Asia, large-scale production capacity and growing specification-grade capabilities are enabling regional suppliers to capture demand from paint, coating, printing ink, and dispersant applications while progressively upgrading quality for more demanding contracts.
These different strategic postures are producing a market that is both consolidating and fragmenting at the same time. Consolidation is likely where scale, feedstock integration, and regulatory compliance create advantages for larger portfolios and well-capitalized producers. Fragmentation persists where regional formulation needs, purity specifications, and application-specific service requirements reward localized expertise and narrower specialization. New entrants and capacity expansions tend to succeed when they bring a clear position—whether in bio-based content, ultra-high purity, cost-efficient large-volume production, or application-tailored blends—rather than attempting to compete across all segments without differentiation.
Recent corporate activity underscores the strategic importance of this positioning. Investments in bio-based DBE production facilities signal a long-term commitment to sustainability-linked demand and feedstock diversification. Product launches targeting low-VOC formulations for automotive applications illustrate how regulatory and performance requirements can converge into commercially viable specialty grades. These moves are not isolated announcements; they indicate how participants are aligning R&D, regulatory preparation, and application development to capture reformulation demand in specific end markets.
Forward Outlook: Trends And Commercial Opportunities
Looking ahead across the 2026 to 2032 window, several trends are likely to shape how the DBE market evolves and where commercial opportunities emerge.
One major trend is the continued acceleration of solvent reformulation as regulatory review and emission standards tighten further. This creates opportunities for suppliers that can offer compliant, application-validated DBE grades with strong documentation and technical support. Companies that proactively align product portfolios with regional compliance expectations will be better positioned to secure long-term formulation partnerships, especially in coatings and industrial cleaning segments where reformulation cycles can be lengthy and switching costs are meaningful.
A second trend is the greater commercial maturity of bio-based and fermentation-derived intermediates for DBE-related product families. As production scales and cost gaps narrow, sustainability credentials become more commercially actionable rather than purely aspirational. This opens opportunities for differentiation through lower-carbon sourcing, recycled content integration, and tailored bio-based blends. It also raises the strategic importance of feedstock contracts, fermentation partnerships, and production reliability, since buyers will increasingly evaluate not only performance but also supply continuity and traceability.
A third trend is the growing premium on specification-grade quality and application-specific service. As DBE moves deeper into demanding markets—including pharmaceutical-adjacent, electronics, and advanced coatings—the ability to deliver consistent purity, predictable behavior, and technical problem-solving becomes a competitive advantage. This favors producers that invest in quality control, custom blending, and application engineering, and it creates room for segmented pricing rather than undifferentiated commodity competition.
These trends carry commercial opportunities, but they also contain risks. Regulatory timelines can shift, and regional enforcement intensity may vary, affecting the pace of substitution. Feedstock availability and cost parity may be influenced by agricultural market dynamics, energy prices, and logistics disruptions. Capacity additions could intensify competition in certain regions or grades, particularly where differentiation is limited. Finally, application migration is not automatic; performance validation, customer testing, and formulation compatibility can slow adoption even when regulatory and sustainability incentives are strong. Participants that monitor these uncertainties and build flexible sourcing, product, and service strategies will be better prepared to capture upside while managing downside exposure.
Divinylbenzene (DVB) Market
Strategic Actions For Decision-Makers
For manufacturers, the priority is to define a clear DBE positioning that matches both market demand and internal capability. Companies should evaluate whether they can win through scale and cost efficiency, through high-purity specialty grades, through bio-based or recycled-content differentiation, or through application-specific formulation support. Investments in fractionation, blending, quality assurance, and technical service often matter as much as raw capacity, because buyers increasingly choose suppliers that reduce reformulation risk and improve process reliability. Feedstock strategy also deserves close attention, especially where bio-based routes and partnerships can strengthen long-term resilience and align with customer sustainability expectations.
For investors, the market calls for discipline in distinguishing durable advantage from short-term capacity expansion. The most attractive opportunities are likely to sit with participants that combine regulatory readiness, consistent quality, and credible sustainability pathways with a defensible application focus. Capacity announcements alone do not guarantee differentiation; the key questions are whether a company can protect margins through specification leadership, secure reliable feedstock supply, and sustain customer relationships in reformulation-intensive segments. Monitoring partnerships, product launches, and regional compliance shifts can provide early signals about where share and value creation are consolidating.
For procurement and sourcing leaders, DBE should be evaluated as part of a broader solvent strategy rather than as a simple price comparison. Factors such as compliance documentation, biodegradability and VOC characteristics, lot consistency, technical support, and supply continuity can have a material impact on formulation risk and operational reliability. Building relationships with suppliers that can support multiple regional requirements and provide transparent product information may reduce exposure to reformulation delays and quality variability. Where possible, securing longer-term supply arrangements for critical grades can help manage volatility in both feedstock costs and regional availability.
As the DBE market continues to evolve, the companies and buyers that act early on regulatory alignment, feedstock strategy, and specification-grade differentiation will be best positioned to translate market momentum into commercial advantage. For decision-makers seeking more granular segmentation data, regional demand patterns, and tailored strategic recommendations, the full research report provides a deeper view of the market structure and the operational choices that will determine competitive outcomes through 2032.
For detailed analysis of this topic, please visit the official page: Dibasic Ester (DBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Consumer Pressure Washers: 4.8% CAGR Growth and Where the Market Is Moving
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Consumer Pressure Washers Market
The consumer pressure washers market has demonstrated resilient growth over the past half-decade, transitioning from a mature, cyclical segment to one characterized by technological differentiation and evolving regulatory pressures. Market valuation reached approximately 215 million USD in 2025, expanding from roughly 163 million USD at the start of the historical review period in 2020. The trajectory suggests a steady advance toward 345 million USD by 2032, underpinned by a compound annual growth rate of 4.8 percent across the forecast window. This expansion is not merely a function of population growth or disposable income trends; it reflects a structural recalibration in how consumers and light commercial operators approach surface maintenance, driven by convenience expectations, sustainability mandates, and rapid iteration in motor and battery architecture.
Despite the positive top-line momentum, the sector confronts several inflection points that will separate agile operators from those constrained by legacy product architectures or static distribution assumptions. First, regulatory tightening at the municipal and national levels is beginning to reshape allowable use cases, particularly where water consumption, runoff management, or electrical safety standards intersect with consumer-grade equipment. Second, the cost and availability dynamics of core components—particularly lithium-ion cells, rare-earth motors, and polymer composites—are pressuring margin structures and forcing manufacturers to reconsider bill-of-materials strategies. Third, competitive intensity at the consumer end of the spectrum is elevating customer acquisition costs while compressing the window for product lifecycle differentiation, as feature parity spreads across mainstream retail channels. These forces collectively demand a more granular approach to product positioning, regional go-to-market planning, and risk mitigation.
Electricity, Autonomy, and the Redefinition of Consumer Utility
Technological innovation remains the primary engine of market evolution, with the most consequential advances unfolding in electric powertrain design and battery integration. Gas-powered units continue to hold meaningful share, particularly among users who prioritize high continuous output and portability in off-grid settings, but electric architectures are capturing incremental share among urban and suburban consumers who value quieter operation, lower maintenance burdens, and indoor storage compatibility. The broader trend is not a simple substitution of power sources; rather, it reflects a segmentation of use cases. High-cycle residential cleaning tasks, such as driveway and siding maintenance, increasingly favor electric platforms that can be deployed without fuel handling or combustion-related ventilation concerns. Meanwhile, battery-powered models are expanding the boundary of convenience by eliminating cord constraints, though their adoption remains tied to runtime improvements, charge-cycle durability, and price thresholds that make premium battery packs accessible to mainstream buyers.
Within this context, manufacturers are investing in horizontal series architectures and modular accessories that simplify assembly, reduce service friction, and create cross-sell pathways. Companies that have emphasized compact electric lines for home and garden applications are aligning product roadmaps with the expectation that consumers will favor equipment that is easy to store, quick to start, and straightforward to maintain. This shift is also reshaping purchasing behavior: buyers are increasingly comparing total cost of ownership rather than sticker price alone, weighing factors such as filter replacement intervals, pump life, and the availability of replacement nozzles or hoses. The practical implication is that innovation is no longer measured solely by pressure output or flow rate; it is increasingly defined by ecosystem completeness and the degree to which a unit integrates with the user’s existing cleaning routines.
PW Consulting
Regulatory Signals and the Rebalancing of Adoption Pathways
Policy and regulatory developments are introducing both constraints and catalysts. In several jurisdictions, water conservation rules are narrowing the permissible frequency or scope of aesthetic pressure washing, which can dampen repeat purchases for non-essential cleaning while simultaneously elevating demand for high-efficiency nozzle designs, flow-restriction features, and equipment that performs effectively at lower water volumes. These constraints are prompting manufacturers and retailers to rethink product messaging, shifting emphasis from raw power toward precision, water management, and compliance-friendly operation. Where local ordinances increasingly target runoff or noise, equipment that can satisfy municipal expectations while maintaining perceived effectiveness gains a structural advantage in retail placement and consumer trust.
Safety regulation is simultaneously sharpening the focus on electrical integrity and component certification. Recalls tied to missing ground-fault protection or inadequate insulation have underscored the importance of rigorous design validation, particularly for corded electric models that operate in wet environments. These events reinforce a broader truth for the category: consumer confidence in electric pressure washers depends heavily on perceived reliability and clear safeguards. Manufacturers that standardize on integral protection mechanisms, transparent labeling, and traceable quality controls are better positioned to insulate their brands from reputational and liability exposure. In practice, regulatory risk is becoming a design input rather than a post-market afterthought, and companies that embed compliance into product architecture early are likely to face lower retrofitting costs and fewer market interruptions.
Demand-Side Evolution and the New Purchasing Calculus
On the demand side, the market is being reshaped by a blend of practical maintenance needs and discretionary cleaning behavior. Home exterior cleaning remains the largest application context, driven by the visibility of surface wear, seasonal grime accumulation, and the growing preference for DIY approaches that avoid service-call expenses. Car washing and garden or patio maintenance form the next tier of demand, with consumer preferences increasingly influenced by time savings, storage limitations, and the desire for equipment that can transition between tasks without extensive reconfiguration. This multi-purpose expectation is encouraging manufacturers to optimize for quick accessory swaps, adjustable pressure settings, and ergonomic handling, since a single unit that can address multiple surfaces expands its perceived value within the household.
High Pressure Washers Market
Behavioral shifts are also evident in how consumers evaluate and purchase equipment. Retail visibility, digital research, and post-purchase service access increasingly influence brand choice as much as baseline specifications. Buyers are comparing warranty terms, parts availability, and online tutorial support alongside motor type and pressure rating. In this environment, the ability to provide clear guidance on safe operation, appropriate chemical use, and routine upkeep becomes a competitive lever. The commercial opportunity lies in packaging equipment with educational content, maintenance kits, and accessible replacement parts, thereby transforming a transactional sale into a longer-term relationship that reduces premature abandonment of the product and supports repeat purchases of consumables and accessories.
Supply Chain and Cost Structure Pressures
Cost structures across the value chain are being recalibrated by component availability, freight variability, and the capital intensity of battery technology. Electric and battery-powered models are particularly sensitive to cell pricing and electronics supply, which can create uneven margin profiles across product tiers. In response, manufacturers are pursuing design simplification, supplier consolidation, and regional assembly strategies that reduce exposure to single-source dependencies. There is also a growing emphasis on standardizing pumps, motors, and hose interfaces across multiple product lines, which allows firms to aggregate procurement volume and streamline inventory management. The strategic implication is clear: cost competitiveness in this market is increasingly derived from platform discipline and supply chain flexibility rather than from marginal negotiation on individual parts.
At the same time, logistics and after-sales service networks are gaining strategic importance. Because pressure washers are used infrequently but critically, consumers expect timely access to replacement components and practical troubleshooting support. Distributors and retailers that can offer efficient parts fulfillment and knowledgeable service guidance are better positioned to defend margin and foster loyalty. This dynamic is nudging the market toward tighter coordination between manufacturers, channel partners, and service providers, particularly in regions where residential ownership is concentrated and seasonal demand spikes place pressure on inventory and support capacity.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with leading players commanding a combined share that leaves ample room for differentiated challengers and regional specialists. Headquartered in Germany, Alfred Kärcher SE & Co. KG has built recognition around compact electric lines for home and garden use, emphasizing accessibility in entry-level series and an expanding family of horizontal-format models that appeal to storage-conscious consumers. The company’s approach illustrates how a brand can anchor its consumer offering in ease of use, familiar design cues, and a product ladder that bridges routine household cleaning with light hobbyist applications. By maintaining a clear focus on the residential use case, the firm reinforces a reputation for practical reliability and broad retail availability.
Greenworks Tools, based in North Carolina, has strengthened its presence by leaning into battery-powered and electric pressure washers distributed through major retail channels. The company’s strategy highlights the value of aligning product design with the purchasing habits of DIY consumers who expect cordless flexibility, straightforward assembly, and compatibility with broader outdoor power equipment ecosystems. This orientation supports cross-category brand exposure and gives retailers a cohesive narrative around backyard maintenance. In practice, the company’s positioning demonstrates how battery platform consistency and retail accessibility can translate into a recognizable consumer identity, especially among buyers who prefer a unified tool ecosystem over standalone appliances.
FNA Group, operating under Simpson Cleaning in Wisconsin, has carved out a premium residential and commercial electric pressure washer offering that emphasizes durability and a higher-performance perception. The brand’s presence in both consumer and light commercial contexts allows it to borrow credibility from professional-grade expectations while still addressing the home market. This dual orientation is strategically useful because it supports a tiered narrative: entry-level electric units capture convenience-driven buyers, while premium electric models provide a pathway for users who anticipate heavier use or demand more robust construction. The result is a portfolio that can span multiple price points without diluting the core promise of electric reliability.
Mi-T-M Corporation, headquartered in Iowa, has focused on residential and commercial pressure washers that include hot water options and a broader equipment ecosystem. By incorporating temperature control into select offerings, the company addresses use cases where grease removal or Winter-related cleaning tasks benefit from heated flow, differentiating its lineup from standard cold-water consumer units. This specialization illustrates how a manufacturer can expand perceived utility by targeting specific cleaning challenges, thereby creating a reason for consumers and light business operators to choose a more capable machine even at a higher price point.
The landscape is evolving through a combination of consolidation, specialization, and channel-driven new entry. Larger players are expanding their reach by standardizing platforms and acquiring complementary brand equity, while smaller firms are competing through niche features, regional distribution depth, and specialized service arrangements. Trade activity continues to serve as a visible pulse point for the category. Major outdoor product demonstrations and new product showcases, such as the POWERCLEAN® 2026 event scheduled for late 2026, provide a recurring forum where manufacturers introduce refinements in nozzle technology, pump assemblies, and cordless platforms. Similarly, appearances at events like the PPC Pro Show allow suppliers to test market reaction to equipment variations and gauge interest from both retail and light commercial buyers. These gatherings are not merely promotional; they function as timing markers for product launches, channel negotiations, and competitive benchmarking.
Differentiation is increasingly determined by the integration of product design, regulatory readiness, and channel experience. Brands that can offer clear safety certifications, intuitive controls, efficient water usage, and easy parts access are better equipped to command shelf space and sustain consumer confidence. At the same time, the market is not consolidating uniformly; regional preferences, purchasing channels, and use-case priorities create pockets where specialized offerings can thrive. For new entrants, the most viable path is often to identify an underserved combination of power source, accessory ecosystem, or service promise rather than to race directly into the most crowded price segments.
Future Trends and Commercial Implications
Over the next three to five years, one dominant trend will be the continued rebalancing between gas, electric, and battery-powered architectures, shaped less by total displacement than by use-case segmentation. Electric models will strengthen their foothold in semi-urban and suburban households where storage constraints, noise sensitivity, and maintenance simplicity matter, while gas units retain relevance for longer-duration tasks and locations with limited electrical access. Battery-powered lines will expand as runtime and charge-cycle performance improve, but their growth will depend on the ability to lower effective ownership cost through standardized packs, interchangeable batteries across product families, and retail programs that make premium battery hardware accessible. The commercial opportunity lies in designing product families that let consumers upgrade from entry-level electric to battery-capable configurations without replacing the entire system.
A second trend will be the normalization of compliance-oriented feature design. As water conservation rules and electrical safety standards become more visible in local markets, equipment that demonstrates efficient flow, integral protection mechanisms, and clear usage guidance will gain a reputational and practical edge. This creates an opportunity for manufacturers and channel partners to lead with transparency: product materials that explain appropriate use cases, maintenance expectations, and local regulatory compatibility can reduce returns, limit liability exposure, and strengthen retail trust. In markets where aesthetic pressure washing is being restricted, compliant efficiency becomes a selling point rather than a concession.
A third trend will be the shift toward multi-purpose household cleaning systems. Consumers increasingly prefer units that can move between home exteriors, vehicles, and patio or garden surfaces with minimal setup change. This favors designs with quick-connect accessories, adjustable pressure regulation, and accessories that address a range of soils and surfaces. The strategic reward for companies that solve this versatility challenge is higher basket value, stronger repeat purchase potential for attachments and consumables, and reduced competitive vulnerability to single-feature rivals. The uncertainty to watch is the risk of over-engineering: adding features that complicate storage, increase weight, or obscure the core cleaning task can erode the convenience advantage that drives consumer adoption in the first place.
Strategic Guidance for Decision Makers
Manufacturers should prioritize platform discipline and compliance integration as part of the core product roadmap rather than treating them as downstream adjustments. Standardizing pumps, motors, and accessory interfaces across a coherent family of electric and battery-capable models can reduce procurement fragmentation, improve inventory turnover, and make after-sales support more efficient. At the same time, embedding safety and water-efficiency considerations early in the design process can limit retrofit cycles and create a clearer value proposition in regulated markets. Companies that align product messaging with real household use cases—storage footprint, quick setup, maintenance simplicity, and multi-surface versatility—will be better positioned to capture share from generic commodity competition.
Investors evaluating exposure to this market should focus on the companies and segments that demonstrate platform leverage, retail channel strength, and a credible response to regulatory and safety dynamics. Battery platform compatibility, parts accessibility, and the ability to cross-sell accessories are indicators of durable consumer relationships, while reliance on a narrow feature set or a single distribution chute increases vulnerability to competitive pressure and regulatory shifts. Due diligence should also examine how a company manages component cost volatility and whether its product roadmap reflects a realistic balance between performance, safety, and user convenience. Opportunities are likely to accrue to firms that can articulate a differentiated use-case story and execute on service and parts fulfillment as part of the brand experience.
Pressure Washers Market
Procurement and channel leaders should approach sourcing and assortment decisions with an eye toward total cost of ownership and compliance readiness. Evaluating suppliers on the basis of electrical safety design, ease of maintenance, availability of replacement components, and clarity of operating guidance can reduce downstream friction and improve customer satisfaction. Where local water-use restrictions or safety recalls have altered purchasing expectations, assortment plans that emphasize efficient, well-documented equipment can strengthen retailer credibility and reduce exposure to non-compliant products. Building relationships with manufacturers that provide transparent documentation and reliable parts supply will pay dividends during seasonal demand peaks and in post-purchase support scenarios.
The convergence of technology, regulation, and consumer behavior means that the most actionable intelligence is highly segmented and forward-looking. Detailed product-level data, regional demand profiles, and scenario-based forecasts are essential for translating these broad dynamics into specific sourcing, launch, and investment decisions. PW Consulting’s Consumer Pressure Washers Market research report provides that deeper layer of granularity, including segment performance, regional breakdowns, and competitive benchmarking tailored to decision-critical questions. For executives, planning teams, and investors seeking to move beyond market-level overviews into actionable strategy, the full report offers the detailed structure needed to align product, channel, and capital decisions with the trajectory of the market.
For detailed analysis of this topic, please visit the official page: Consumer Pressure Washers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Car Care Products Market 2032: What Really Fuels the 4.5% CAGR Growth Beyond 15.4×10³ Million
By PW Consulting, 2026-09-21
The Car Care Products Market: Strategic Trends and Commercial Opportunities Through 2032
The global car care products market is navigating a period of structural transformation. With total revenue reaching approximately USD 11,500 million in 2025 and projected to expand at a compound annual growth rate of 4.5% through 2032, the sector is moving beyond cyclical demand patterns toward a more innovation-driven and regulation-shaped landscape. The market has demonstrated steady recovery from the volatility of the early decade, with revenue climbing from USD 9,500 million in 2020 to a base of USD 11,500 million in 2025. Forecasts indicate continued growth, with revenue expected to reach USD 15,400 million by 2032, though the trajectory will not be uniform. Mid-period fluctuations, such as the slight contraction projected in 2028 before accelerating again toward 2032, signal that pricing dynamics, regulatory shifts, and innovation cycles will create uneven growth pockets rather than a straight-line expansion.
For executives, strategists, and investors, the size of the market is only the starting point. The strategic question is how value is redistributed across product categories, application channels, and geographic demand centers, and which capabilities will determine market share in the next cycle. The concentration structure of the industry, with the top three players accounting for roughly 42% of revenue and the top five capturing about 55%, indicates a moderately consolidated landscape. This creates room for both competitive pressure from established multinationals and meaningful disruption from specialized entrants that can command premium positioning through performance differentiation or format innovation.
Market Landscape and Core Challenges
The car care products market operates at the intersection of consumer discretionary spending, professional detailing services, and increasingly, regulatory and trade dynamics that reshape cost structures. The sector's revenue base has grown at a moderate but persistent pace, reflecting a combination of vehicle parc expansion, renewed emphasis on vehicle appearance as a value-preservation behavior, and the gradual formalization of care routines among both retail and commercial users. However, the headline growth rate masks underlying tensions that decision-makers must address when positioning product portfolios, pricing strategies, and geographic exposure.
One of the most consequential challenges is the rising impact of trade and tariff policy on input costs and competitive positioning. Recent policy actions have adjusted import conditions for automobiles and automobile parts, with duties that extend indirectly into the broader automotive ecosystem. For car care manufacturers and formulators, these measures matter because they influence the cost of imported raw materials, packaging components, and specialized chemical inputs, as well as the competitive balance between domestically produced and imported finished goods. In a market where ingredient quality, coating performance, and formulation consistency are central to brand trust, even modest cost pressure can compress margins unless companies can pass through changes without eroding volume.
A second challenge lies in the shifting balance between do-it-yourself and do-it-for-me application channels. While both segments remain significant, the relative growth trajectories of each are being reshaped by workforce availability in professional detailing, consumer time constraints, and the growing sophistication of products that are designed to be effective with less user expertise. Companies that rely heavily on one channel face exposure if user behavior or service economics move in an unanticipated direction. The practical implication is that product design, packaging format, and go-to-market strategy must increasingly accommodate hybrid usage models rather than treating consumer and commercial applications as separate silos.
A third challenge is the premiumization paradox. Consumer and commercial buyers are demonstrating willingness to pay more for products that promise longer-lasting protection, easier application, or enhanced aesthetic results. At the same time, inflationary sensitivity and the availability of value-oriented alternatives restrict how much premiumization can be counted on as a standalone growth engine. The result is a market where superior performance must be evidenced not just through claims but through demonstrable results, repeat usage, and integration with broader care routines. Brands that can translate product superiority into clear consumer-facing or service-facing value propositions are better positioned to defend margin, while those competing primarily on price face a narrowing path to sustainable differentiation.
Key Demand Drivers and Structural Forces
Technology Innovation and Formulation Breakthroughs
Product performance is increasingly defined by advances in protective coatings, quick-application finishes, and formulations that reduce the effort required to achieve professional-grade results. The segment focused on glaze and coating products, while smaller in absolute terms than wax and cleaning categories, plays an outsized role in shaping the premium narrative of the market because it directly addresses durability, gloss retention, and surface protection. Innovation in this space is not only about chemistry; it is also about usability. Products that combine protective performance with shorter curing times, reduced sensitivity to application conditions, or compatibility with a broader range of substrates can unlock faster adoption among both retail users and commercial detailers.
Recent product launches illustrate how companies are using new formulations and catalog expansion to reinforce positioning. In early 2025, Luminous introduced a new catalog of premium car care products emphasizing advanced detailing and protection formulas, signaling a continued push toward differentiated performance claims in the higher-end segment. Later in the year, Stinger Chemicals announced plans to launch its Quantum Car Care Line at a major industry event, targeting commercial users with specialized retail products. These moves reflect a broader pattern: innovation is being deployed both to elevate the performance ceiling in premium categories and to create purpose-built offerings for professional and retail channels that demand consistency, throughput, and specialized protection characteristics.
Car Care Cosmetics for Petrol Channel Market
Policy and Regulatory Environment
Regulatory and trade policy is becoming a more prominent force in the market's cost and competitive dynamics. Adjustments to import duties on automobiles and parts have direct and indirect implications for the automotive aftermarket ecosystem, including the suppliers of care products that serve vehicle owners, service providers, and fleet operators. While car care products are not always the primary target of such measures, the broader policy environment influences the cost of inputs, the relative attractiveness of domestic versus imported manufacturing, and the strategic calculus of supply chain design.
Car Wax Market
The practical significance for market participants is that regulatory volatility is no longer a peripheral risk. Companies with flexible sourcing strategies, regional manufacturing footprints, and the ability to reformulate around input availability are better equipped to manage sudden cost shifts. At the same time, the regulatory environment can create opportunity for firms that can demonstrate compliance, consistency, and transparency as competitive advantages. In segments where trust and performance claims matter, the ability to navigate policy shifts without disrupting product availability or quality becomes part of the brand promise itself.
Demand-Side Shifts in Consumer and Commercial Behavior
Demand patterns are being reshaped by evolving attitudes toward vehicle ownership, maintenance, and appearance. Vehicles are increasingly viewed not only as transportation assets but also as personal spaces and, for many owners, as items whose condition has tangible economic and emotional value. This has supported demand for products that preserve interior surfaces, protect exterior finishes, and simplify routine maintenance. At the same time, professional detailing and commercial fleet care continue to drive demand for higher-volume, repeatable, and operationally efficient products.
The interior segment represents a meaningful portion of market value, reflecting sustained attention to surfaces, materials, and cleanliness inside the cabin. Exterior care remains the largest body-part category, consistent with the visibility and protection benefits that drive purchase decisions. In application terms, both DIY and DIFM channels contribute substantially, but their relative importance varies by region, customer segment, and product type. Companies that understand where convenience, performance, and service support matter most can tailor product formats, instruction design, and distribution to the channel in which they compete, rather than treating all demand as interchangeable.
Supply Chain and Cost Structure Dynamics
The cost environment for car care products is influenced by raw material availability, chemical input pricing, packaging costs, and logistics complexity. As with many consumer and industrial goods, the ability to manage these pressures depends on formulation flexibility, supplier diversification, and packaging efficiency. Products that rely heavily on specialized imported inputs may face greater exposure to tariff-related and logistics-related cost fluctuations, while those with more standardized ingredient profiles or regional supply options can adapt more readily.
In addition, the market's moderate concentration means that larger players often have advantages in procurement scale, distribution breadth, and brand investment capacity. Smaller or more specialized firms, however, can compete by focusing on performance niches, channel-specific needs, and faster product iteration. The strategic implication is that cost management and innovation are not separate agendas; they are increasingly intertwined. A formulation decision that reduces sensitivity to volatile inputs, or a packaging change that improves shelf efficiency and user experience, can have a direct impact on competitiveness in a market where differentiation is often subtle and repetition of purchase depends on consistent satisfaction.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a group of established manufacturers and specialists, each with a distinct positioning strategy. Turtle Wax operates as a broad-based manufacturer of washes, waxes, coatings, and detailing supplies, giving it a wide touchpoint across consumer and professional needs. Meguiar's maintains a strong identity around high-quality chemicals, polishes, waxes, and interior and exterior appearance products, with an emphasis on performance credibility in appearance care. SONAX positions itself in the premium automotive chemical segment, focusing on vehicle maintenance and detailing products that appeal to users seeking higher-end results. Stinger Chemicals develops both retail and commercial product lines for detailing and protection, giving it a dual-channel orientation that can adapt to different purchasing and usage contexts.
Beyond these specialists, larger diversified manufacturers also participate in the market. 3M contributes abrasives, cleaners, polishes, waxes, and detailing compounds, leveraging its broader materials science capabilities and distribution reach. Calumet's role as a manufacturer of specialty solvents, waxes, and petrolatums used in consumer car care formulation illustrates the importance of upstream ingredient and input suppliers in shaping what is ultimately possible at the finished-product level. Together, these companies reflect a market in which competitive advantage comes from a combination of brand trust, formulation expertise, channel relationships, and the ability to align product claims with real-world performance.
Several strategic patterns are visible among the leaders. One is segmentation discipline: companies are increasingly differentiating not just by brand but by intended user, application context, and performance promise. Another is the use of product-line expansion to capture adjacent demand without diluting core positioning. Catalog launches and specialized line introductions, such as those seen in 2025, are examples of how firms attempt to broaden relevance while maintaining a credible performance narrative. A third pattern is the growing importance of channel-specific product design. Commercial users often prioritize consistency, coverage, and operational efficiency, while retail buyers may weigh ease of use, visible results, and perceived value. Companies that design for these differences rather than offering a uniform portfolio across all channels are better placed to defend share and pricing.
PW Consulting Health Care Research Center
The market structure also suggests ongoing evolution rather than static competition. With a moderately concentrated base, there is room for consolidation among players seeking scale in procurement, distribution, or brand investment. At the same time, new entrants and niche specialists can gain traction by focusing on underserved use cases, premium protection claims, or specific regional demand patterns. The most successful players are likely to be those that can combine a clear positioning with operational flexibility, allowing them to adapt product offerings and supply strategies as demand and policy conditions shift.
Forward Outlook: Three Strategic Trends for 2026 to 2032
The next several years are likely to be defined by a combination of product performance competition, channel rebalancing, and continued sensitivity to cost and regulatory pressures. Three trends stand out as particularly relevant for commercial planning.
The first trend is the continued premiumization of protection and finish products, especially in categories associated with longer-lasting results and easier application. As users become more discerning and more aware of the link between surface care and vehicle appearance, demand for products that deliver durable gloss, resistance to environmental wear, and simplified application is expected to remain strong. The commercial opportunity lies in creating credible, repeatable performance stories that support higher price points without depending solely on marketing claims. Products that can demonstrate measurable differences in durability, ease, or finish quality are more likely to command loyalty and reduce price sensitivity over time.
The second trend is the ongoing realignment between DIY and DIFM demand, influenced by labor availability, consumer time use, and the increasing sophistication of user-friendly formulations. Even within the DIY segment, products that reduce effort and increase consistency can blur the line between consumer and professional outcomes. For commercial users, the opportunity is in products that improve throughput, reduce variability, and support service quality across multiple locations or fleets. For manufacturers and distributors, the strategic priority is to ensure that product design, instructional support, and packaging are aligned with the practical realities of how each channel actually uses the product.
The third trend is the increasing importance of supply-side resilience and regulatory adaptability. Tariff adjustments and import policy shifts can influence input costs, sourcing decisions, and competitive positioning, particularly for products that depend on specialized imported components. Companies that build redundancy into sourcing, maintain formulation flexibility, and can communicate reliability to customers will be better positioned to manage disruption. Conversely, firms that are heavily dependent on a single supply route or a narrow set of inputs may face more volatile margin performance. This creates an opportunity for players to differentiate not only through product performance but also through operational dependability and transparent compliance practices.
These trends are not without risk. Premiumization depends on sustained consumer and commercial willingness to invest in appearance care, which can weaken if macroeconomic pressure intensifies. Channel shifts may not unfold uniformly across regions, making geographic assumptions risky if treated as universal. Regulatory and trade policy can change quickly, altering cost structures and competitive dynamics in ways that are difficult to predict far in advance. The market's growth path also includes intermittent deceleration points, as reflected in the mid-period forecast pattern, which suggests that short-term momentum should not be mistaken for a guaranteed straight-line trajectory. Companies that plan for variability, rather than assuming constant acceleration, will be better prepared to allocate resources and adjust strategies as conditions evolve.
Actionable Priorities for Decision Makers
For manufacturers, the priority is to align product innovation with the performance and usability expectations that actually drive repeat purchase. This means investing in formulations and formats that deliver visible, durable results while reducing the risk of user error or inconsistent outcomes. It also means evaluating where portfolio breadth adds value and where focus sharpens competitive positioning. Companies should assess channel-specific needs carefully, since the same product may need different packaging, instructions, or performance emphasis depending on whether it is sold into retail, professional detailing, or fleet contexts.
For investors, the emphasis should be on identifying companies with credible differentiation, resilient supply strategies, and the ability to convert product superiority into measurable customer retention. Market size and growth rate provide a useful backdrop, but the more important questions are whether a company can defend margin in a moderately concentrated market, whether its innovation pipeline addresses real user pain points, and whether its cost and sourcing structure can withstand regulatory or input-price shocks. Businesses that combine strong positioning with operational flexibility are more likely to sustain advantage through uneven growth cycles.
For procurement and commercial buyers, the priority is to balance performance requirements with total cost of ownership, taking into account not only unit price but also consistency, application efficiency, and the downstream impact on service quality or customer satisfaction. In professional and fleet environments, variability in results can create hidden costs through rework, customer complaints, or inconsistent presentation. Evaluating product options against practical usage conditions, rather than against label claims alone, can help buyers select solutions that support both operational reliability and end-user perception.
Across all these perspectives, one consistent theme is that the market is becoming more demanding in terms of proof, not just promise. As product performance expectations rise and cost and regulatory pressures intensify, the ability to access detailed segment-level intelligence, competitive benchmarks, and scenario-based planning assumptions becomes increasingly valuable. Organizations that can ground strategic choices in granular data on product categories, application channels, regional demand patterns, and supplier dynamics will be better equipped to anticipate shifts and act before they become obvious to the broader market.
The car care products market is moving toward a phase in which durable differentiation will depend on the intersection of formulation quality, channel alignment, and operational resilience. Growth to 2032 is supported by steady demand and continued product innovation, but the value created will accrue disproportionately to companies that can convert broad market momentum into focused, defensible positioning. For executives and investors seeking a deeper, segment-level view of these dynamics, a more detailed research assessment can provide the kind of customized insight needed to sharpen portfolio strategy, evaluate competitive exposure, and prioritize the opportunities most relevant to a specific business context.
For detailed analysis of this topic, please visit the official page: Car Care Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com