



Category: IT & Electronics
IC Substrate Market: Why 6.63% CAGR and Asia Pacific Dominance Reshape 2026 Strategy
By PW Consulting, 2026-09-21
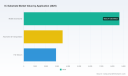
Navigating the IC-Substrate Market: Strategic Trends and Commercial Opportunities Through 2032
The integrated circuit (IC) substrate market has entered a decisive growth phase, driven by structural shifts in semiconductor packaging, escalating compute demands, and regional industrial policies. With the market valued at approximately USD 10 billion in 2025 and projected to expand at a 6.63 percent compound annual growth rate (CAGR) through 2032, the sector is no longer merely a supporting component in the electronics value chain. It has become a strategic bottleneck and a competitive differentiator for high-performance computing, automotive electrification, and next-generation mobile architectures. The trajectory from 2020 through 2032 reveals a market that has more than doubled in scale, but growth alone does not guarantee profitability or supply stability. Decision-makers must understand where value is concentrating, which constraints are structural versus cyclical, and how leading players are repositioning their capabilities to capture premium segments.
Market Landscape and Core Challenges
The IC-substrate industry is characterized by a concentrated competitive structure and a clear shift toward advanced packaging formats. The top three players control a majority of revenue, and the top five collectively account for a significant share, indicating high barriers to entry and capital-intensive scaling requirements. This concentration reflects the technical complexity of advanced substrates, the long qualification cycles with semiconductor manufacturers, and the need for sustained investment in specialized production lines. While regional demand patterns show Asia Pacific as the dominant volume center, other regions are actively building localized capacity to reduce supply chain dependencies and align with policy incentives. The type mix increasingly favors flip-chip ball grid array (FC-BGA) and flip-chip chip scale package (FC-CSP) configurations, reflecting the industry's migration toward higher interconnect density, shorter signal paths, and thermal efficiency. Application demand is equally diversified, with mobile and consumer electronics sustaining baseline volume, while automotive and IT/telecom segments accelerate their pull for higher-performing substrate solutions.
Despite strong top-line growth, the market faces several structural challenges that will shape competitive outcomes over the next five years.
1. Raw material constraints are reshaping cost structures and supply reliability. Fiberglass and base resin shortages have persisted into 2026, creating upward pressure on ABF substrate film pricing and tightening availability for AI-related production. Ajinomoto Fine-Techno raised ABF substrate film prices by approximately 30 percent due to critical base resin supply constraints, signaling that input cost pressures are not transient. For substrate manufacturers, this translates into margin compression risk, pricing renegotiation complexity, and the need to secure long-term material agreements. For downstream customers, it means qualification lead times and supply continuity must be managed with greater urgency.
2. Capacity expansion is racing against demand elasticity and qualification timelines. Multiple leading manufacturers are executing large-scale capital programs to expand advanced substrate capacity, yet ramp-up schedules, yield stabilization, and customer qualification processes can delay the realization of revenue. The market is effectively in a phase where supply additions are necessary but not instantly absorbable at premium economics. Companies that expand without aligned demand visibility or without differentiated technology risk underutilization, while those that can secure early design wins and long-term supply agreements are positioned to monetize new capacity more effectively.
3. Technology transitions are creating segmentation between commodity and premium tiers. The industry is moving toward glass-core substrates, multifunctional core technologies, and low-loss organic laminates for high-frequency and advanced thermal requirements. This transition is not uniform across all product categories. Some segments will continue to compete on cost and volume, while others will increasingly be defined by performance, reliability, and integration complexity. Manufacturers that cannot navigate this bifurcation may find themselves trapped in price-sensitive segments with limited differentiation, while those that advance into higher-value technology tiers can capture stronger pricing power and tighter customer relationships.
Key Demand Drivers and Structural Shifts
The IC-substrate market is being reshaped by interconnected technology, policy, demand-side, and supply chain forces. Understanding how these drivers interact is essential for anticipating where growth will be most durable and where vulnerabilities may emerge.
Technology innovation is elevating substrates from passive interposers to performance-defining components. Advanced packaging requirements for AI servers and high-performance computing are pushing substrate design toward higher layer counts, finer pitch routing, and improved electrical and thermal performance. Glass-core substrates and advanced ABF variants are moving from research and development into industrial deployment, enabling better signal integrity and thermal management for next-generation chips. This shift increases the strategic importance of substrate engineering capabilities, as material selection, dielectric properties, and mechanical stability now directly influence system-level performance. Companies investing in proprietary core technologies, low-loss laminates, and integrated multifunctional designs are building moats that are difficult for followers to replicate quickly.
Policy and regulatory environments are accelerating regional capacity build-out. Industrial policy is no longer a background factor; it is actively shaping where capacity is added and who can access funding. Support mechanisms have enabled major substrate projects in multiple regions, including flip-chip substrate fabs in the United States and significant expansions in Europe. These initiatives are intended to strengthen supply chain resilience and reduce concentration risk, but they also create a more fragmented geographic footprint. For manufacturers, policy-aligned investments can lower capital barriers and improve long-term demand visibility. For buyers, this may increase sourcing options over time, but near-term supply will still depend heavily on the pace of fab commissioning and qualification.
Demand-side behavior is shifting from volume-driven consumption to performance- and reliability-driven selection. End-market adoption patterns are reinforcing the need for higher-performing substrates. AI server deployments are creating demand that is outstripping existing production limits in certain high-end categories, while automotive and transportation applications require substrates that can meet stringent reliability, thermal, and longevity requirements. Mobile and consumer segments remain important volume drivers, but they increasingly demand compact form factors and efficient thermal solutions rather than simple cost optimization. The broader implication is that demand is becoming more segmented: some volumes remain price-sensitive, while strategic applications are willing to pay for performance assurance, supply stability, and long-term partnership alignment.
Supply chain and cost structure dynamics are reinforcing the premiumization trend. Persistent raw material constraints, combined with the capital intensity of advanced substrate production, are altering the economics of the market. Fiberglass shortages and base resin supply limitations are tightening ABF substrate availability, prompting price adjustments for premium products. At the same time, capacity expansions are concentrated among players with the financial and operational capacity to commit to multi-year investment programs. This dynamic favors companies that can secure material supply, manage yield during ramp-up, and align production with qualified high-value programs. It also increases the importance of vertical coordination, supplier diversification, and strategic inventory planning across the value chain.
Competitive Landscape and Leading Strategies
The competitive environment in the IC-substrate market is defined by a small group of established players pursuing differentiated technology strategies, regional expansion, and selective pricing actions to protect margins in premium segments. Rather than competing purely on volume, leading firms are positioning around performance categories, customer qualification depth, and capacity alignment with high-growth applications.
Several companies illustrate the strategic directions now shaping the market. Japanese and Korean producers are expanding high-performance IC package substrate capacity to serve AI server and automotive demand, often with multi-year capital programs and site-specific ramp plans. Taiwan-based manufacturers are advancing advanced flip-chip substrates, including ABF and glass-core variants, while adjusting pricing in premium categories to reflect material costs and constrained supply. European players are pushing glass-core and multifunctional core technologies into industrial deployment for AI, high-performance computing, and photonics applications, supported by regional expansion plans. Across these profiles, a common theme is the pursuit of technology leadership in advanced substrate formats combined with capacity investments that target confirmed or highly probable demand pipelines.
The strategic positioning of leading players can be understood through several differentiating dimensions:
- Technology specificity. Some leaders focus on high-end server and AI packaging substrates, including ABF variants and glass-core designs, while others emphasize low-loss organic laminates for high-frequency and automotive applications. This specialization allows firms to align their process capabilities with the most demanding requirements and to reduce direct head-to-head competition in commodity segments.
- Capacity timing and scale. Large capital commitments are being deployed to expand production for FC-BGA and advanced flip-chip substrates. The differentiator is not simply building capacity, but aligning it with confirmed demand, managing ramp-up risk, and securing the material inputs needed to sustain output.
- Customer integration and qualification depth. Advanced substrates require close collaboration with semiconductor and system manufacturers. Companies that can manage long qualification cycles, support design-in decisions early, and maintain reliability across volume production are more likely to secure multi-year supply relationships.
- Margin defense in constrained markets. In environments where raw material availability is tight, some leaders are adjusting pricing for premium substrates to offset cost pressure and capacity limitations. This reflects a shift toward value-based pricing in segments where performance and supply continuity carry strategic importance.
Recent developments highlight how these strategies are being executed in practice. One major Japanese substrate producer approved a substantial multi-year capital investment to expand high-performance IC package substrates at plants in Gifu Prefecture, with mass production ramping from fiscal 2027 to meet AI server demand. In the United States, support from CHIPS Act funding enabled a flip-chip substrate fab targeting significant monthly panel output by late 2027, illustrating how policy alignment can accelerate regional capacity deployment. A European manufacturer advanced glass-core substrate technology from research to industrial deployment for AI, high-performance computing, and photonics, while also expanding capacity in China and Europe to serve high-end IC substrate demand. Another leading Asian producer approved capital expenditure exceeding KRW 1 trillion for high-end FC-BGA manufacturing after AI server substrate demand exceeded production limits by more than 50 percent, underscoring the intensity of demand pull in advanced categories. Meanwhile, a Taiwan-based supplier raised prices for premium ABF substrates to offset raw material costs and capacity constraints amid fiberglass shortages, reflecting the market's shift toward pricing discipline in high-value segments.
Ceramic Substrate Market
The competitive landscape is evolving along several trajectories. Consolidation is likely to continue among players that can finance advanced capacity and sustain technology development, while smaller or less differentiated entrants may struggle to secure qualified positions in premium segments. At the same time, regional capacity additions are creating a more diversified geographic supply base, which may reduce single-point dependencies over time. New entry remains difficult because of the combination of capital requirements, qualification lead times, and material supply complexity, but targeted partnerships, technology licensing, and policy-supported projects could enable selective expansion by well-positioned participants. The broader trend is not simply toward concentration or fragmentation, but toward a layered market in which premium technology tiers are tightly held by a few capable suppliers, while lower-tier segments remain more competitive and cost-driven.
PW Consulting Information & Electronics Research Center
Future Outlook: Key Trends and Commercial Implications
Looking ahead to the 2026-2032 period, several trends are likely to define the IC-substrate market's evolution and shape commercial opportunities for stakeholders across the value chain.
Advanced substrate technologies will become mainstream requirements rather than niche differentiators. Glass-core substrates, multifunctional core designs, and low-loss laminates are expected to move from early deployment into broader production as AI, high-performance computing, and high-frequency applications scale. This transition will increase the importance of material science expertise, process control, and thermal-electrical co-optimization. For manufacturers, the opportunity lies in capturing design-ins early and building repeatable processes that can support volume production without compromising performance. For downstream innovators, advanced substrates will enable tighter integration, higher compute density, and improved reliability, but only if supply can be secured with sufficient lead time and consistent quality.
Capacity expansion will remain a defining strategic variable, but utilization and demand alignment will separate winners from casualties. The next several years will see continued investment in high-end substrate lines, particularly for FC-BGA and advanced flip-chip formats. However, the commercial outcome will depend on whether new capacity is matched to qualified demand, stabilized quickly, and supported by reliable material inputs. Overbuilding in segments with uncertain demand could lead to pricing pressure and underutilization, while tightly coordinated expansion tied to long-term supply agreements can reinforce pricing power and customer lock-in. This dynamic favors stakeholders that treat capacity planning as a demand-signal discipline rather than a standalone capital decision.
Regionalization and policy-driven supply chains will reshape sourcing strategies. Industrial policy support is encouraging substrate production in multiple regions, which may improve resilience and create new sourcing options over time. Yet near-term supply will still be constrained by ramp-up schedules and qualification requirements. Buyers will need to balance the benefits of regional diversification against the realities of limited immediate capacity and the technical constraints of qualifying alternative suppliers. For manufacturers, policy-aligned programs can provide capital support and demand visibility, but they also require disciplined execution to convert funding and announcements into commercially viable production.
These trends carry embedded risks and uncertainties. Material shortages may persist or ease depending on upstream capacity and resin supply dynamics, making cost planning and supply continuity highly sensitive to external conditions. Demand for advanced substrates could evolve faster than expected in some application areas, while other segments may moderate if end-market cycles shift. Technology transitions may also create temporary supply gaps as manufacturers retool or qualify new processes. Stakeholders should therefore plan for both upside demand scenarios and disruption scenarios, rather than assuming linear growth.
IC Substrate Market
Strategic Implications for Decision-Makers
The IC-substrate market offers clear opportunities, but capturing them requires precise positioning, disciplined supply planning, and early engagement with technology roadmaps. The following recommendations are designed to help different stakeholder groups translate market dynamics into actionable strategy.
For Substrate Manufacturers and Capacity Planners
Prioritize technology differentiation in premium segments where performance, reliability, and supply continuity justify stronger pricing. Expand capacity with explicit demand alignment, securing material supply agreements and qualification pathways before scaling output. Where raw material constraints are structural, diversify input sources, lock in long-term contracts, and build buffer strategies for critical materials. Avoid undifferentiated capacity additions in price-sensitive tiers unless supported by clear cost advantages or regional policy benefits. The most resilient strategies will combine technology leadership with disciplined execution and close customer collaboration.
For Investors and Strategic Capital Allocators
Focus on players with credible pathways to high-value segments, demonstrated ability to manage material and capacity constraints, and visible demand anchors in AI, automotive, or high-performance computing. Evaluate not only announced capacity but also ramp readiness, qualification momentum, and material supply resilience. The market's concentration and technology intensity mean that financial strength alone is insufficient; operational execution and customer integration are equally important. Investors should also monitor regional policy-supported projects for execution risk, since funding announcements do not automatically translate into timely, profitable production.
For Procurement Leaders and End-Market Buyers
Treat advanced substrates as strategic procurement categories rather than commoditized inputs. Early design-in engagement, multi-source qualification where feasible, and long-term supply coordination can reduce exposure to material shortages and capacity bottlenecks. Where performance requirements are high, consider the trade-offs between cost optimization and supply assurance, especially in AI server, automotive, and high-frequency applications. Building transparency into supplier roadmaps, material availability, and ramp timelines will help align internal product planning with realistic supply expectations.
The IC-substrate market is entering a phase where technology, policy, material constraints, and demand dynamics intersect in ways that reward foresight and disciplined execution. Stakeholders that understand where value is concentrating, how premium segments are being redefined, and which supply risks are structural will be better positioned to act before competitive positioning solidifies.
This analysis is intended as a strategic overview of market direction and commercial logic. For decision-makers who need deeper segmentation detail, scenario-based demand modeling, company-level benchmarking, and tailored recommendations aligned to specific product categories or regional sourcing strategies, a more comprehensive research package can provide the granularity required for execution planning. Access to full segmentation data, capacity ramp timelines, and competitive tracking can help translate these market-level insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DNS Security Software Market: Why 8.9% CAGR and Cloud Shift Change Everything
By PW Consulting, 2026-09-21
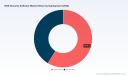
DNS Security Software Market: Strategic Shifts and Commercial Opportunities in a Reshaping Domain Defense Landscape
The DNS Security Software market is entering a period of accelerated structural transformation, driven by converging pressures in cloud migration, regulatory mandates, and increasingly sophisticated DNS-layer attacks. Market estimates place total revenue at approximately $170.0 million in 2025, with historical growth from 2020 through 2025 reflecting a steady acceleration as organizations progressively re-architect their security perimeters around identity and traffic visibility. Forecasts project the market to reach $310.0 million by 2032, representing a compound annual growth rate of 8.9% over the 2026–2032 period. This trajectory signals more than incremental demand growth; it reflects a fundamental reorientation of how organizations treat DNS—not as a passive directory service, but as an active security control point that must be continuously monitored, encrypted, and secured against both volumetric and application-layer threats.
For executives and strategy teams, the commercial implication is clear: DNS security is no longer a niche add-on within broader network protection portfolios. It is becoming a core component of zero-trust architectures, hybrid-cloud resilience programs, and compliance-driven security budgets. Yet the market is also navigating several inflection points that will separate winners from laggards over the next five years. Understanding where momentum is building—and where friction remains—provides a foundation for portfolio decisions, vendor selection, and investment timing.
Market Landscape and Core Challenges
The current market environment is characterized by rising deployment volumes, expanding regulatory expectations, and a persistent mismatch between organizational maturity and the operational complexity of DNS protection. Demand has been sustained by the expansion of cloud-hosted workloads, the proliferation of remote and hybrid work patterns, and an increase in DNS abuse vectors ranging from cache poisoning and tunneling to DDoS amplification. At the same time, buyers are confronted with a fragmented vendor landscape in which capabilities vary widely across threat intelligence integration, posture management, encryption support, and operational simplicity.
Inflection Point 1: DNS as a Security Control, Not Just Infrastructure
Historically, DNS management and DNS security were often treated separately, with networking teams handling resolution reliability and security teams focusing on perimeter and endpoint controls. That division is breaking down. Modern threat campaigns exploit the DNS layer to exfiltrate data, command compromised hosts, and bypass traditional inspection points. As a result, organizations are reassessing DNS security as a first-line control that must be integrated into broader security operations. This shift creates both opportunity and execution risk: organizations that succeed are those that can unify visibility, automate response, and embed DNS protections into existing workflows, while organizations that treat DNS tools as standalone point solutions risk operational silos and coverage gaps.
Inflection Point 2: Regulatory Acceleration and Procurement Mandates
Policy pressure is rapidly reshaping purchasing criteria. In the United States, executive guidance now requires support for encrypted DNS protocols as a procurement requirement for products acting as DNS resolvers for federal agencies, effectively tilting demand toward solutions that natively support encrypted resolution paths and demonstrate compliance readiness. Concurrently, CISA guidance emphasizes enterprise investment in AI-enabled DNS capabilities to address attacks targeting critical infrastructure, pushing buyer expectations toward analytics and automated detection functions. In Japan, national cybersecurity strategy documents are reinforcing the adoption of AI-enabled threat detection within DNS protection programs. These directives do not merely raise awareness; they create procurement momentum, especially among public-sector buyers and regulated industries, where compliance considerations increasingly influence vendor shortlists.
Inflection Point 3: Operational Complexity in Hybrid and Multi-Cloud Environments
As organizations distribute workloads across on-premises environments, multiple cloud providers, and edge deployments, DNS assets become dispersed and harder to inventory, monitor, and secure consistently. The operational burden includes managing authoritative and recursive resolvers, ensuring consistent policy enforcement, and detecting misconfigurations that can expose services to hijacking or denial-of-service conditions. This complexity is a central barrier to adoption for many mid-sized organizations, where staffing constraints limit the ability to operate advanced DNS security tools without agentless, automated, or managed approaches.
Key Drivers Shaping Market Momentum
Technology Innovation: Cloud-Native Resolution, Encrypted Protocols, and AI-Enabled Detection
Technological evolution is one of the strongest catalysts for market expansion. Cloud-native DNS architectures are increasingly favored for their scalability, centralized policy management, and integration with broader security ecosystems. Encrypted DNS protocols are no longer optional enhancements in many procurement contexts; they are becoming baseline expectations for privacy, tamper resistance, and compliance. Equally important, AI-enabled detection and analytics are moving from experimental features to operational requirements, particularly for identifying anomalous query patterns, detecting domain generation algorithms, and reducing response time during active incidents. Vendors that can combine reliable resolution, encrypted transport, and actionable threat intelligence are positioned to capture demand from organizations seeking to consolidate tools and improve security outcomes.
Policy and Regulatory Environment: Mandates as Adoption Accelerators
Regulatory developments are functioning as adoption accelerators rather than abstract compliance checkboxes. Encrypted DNS requirements in federal procurement create downstream pressure on suppliers serving government accounts and the broader supply chain. Sector-specific guidance that calls for AI-enabled DNS protections signals an expectation that critical infrastructure and high-risk industries will invest in more advanced detection and response capabilities. For vendors, this environment rewards clear compliance narratives, documented control mappings, and demonstrable integration with security operations workflows. For buyers, it introduces a practical urgency to evaluate whether existing DNS protections meet evolving expectations for encryption, visibility, and automated detection.
Demand-Side Change: Larger Attack Surfaces and Rising Business Risk
Demand is expanding because the cost of DNS abuse is becoming more visible and more consequential. Phishing, malware command-and-control, data exfiltration, and service disruption are all enabled or amplified by DNS manipulation, and these outcomes carry direct operational, financial, and reputational consequences. Enterprise buyers are increasingly linking DNS security to resilience objectives: ensuring that external-facing services remain reachable, that internal resolution is trustworthy, and that anomalous traffic can be identified before it escalates. This risk-based framing supports budget allocation even in cost-conscious planning cycles, because DNS-layer protections are often positioned as relatively low-friction controls with high preventive value.
Supply-Side and Cost-Structure Dynamics: Integration, Automation, and Service Models
On the supply side, market dynamics are shaped by the push toward integrated platforms, automation, and flexible deployment models. Cloud-based delivery continues to attract interest because it reduces the operational overhead associated with maintaining and updating on-premises resolver infrastructure, while also simplifying expansion across distributed locations. At the same time, on-premises deployments remain relevant in scenarios where data residency, latency sensitivity, or existing network architectures favor local control. The broader cost-structure trend is toward solutions that lower ongoing staffing demands through agentless visibility, automated remediation, and managed services options. This evolution is particularly important for smaller and mid-sized organizations that need enterprise-grade protections without proportional increases in specialized personnel.
Domain Name System Tools Market
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of incumbent infrastructure vendors, cloud and networking specialists, and providers with strong DNS heritage. Market concentration remains moderate, with the top three firms collectively representing roughly 25% of revenue and the top five reaching approximately 38%. This level of concentration suggests a market that is still fragmented enough for differentiation to matter, while also indicating that scale, ecosystem reach, and integrated portfolios provide meaningful advantages.
Differentiation Through Integration, Intelligence, and Resilience
Leading players are pursuing distinct strategic positions. Cisco Systems emphasizes cloud-delivered DNS-layer protection integrated with threat intelligence, aiming to block malware, phishing, and related threats before connections are established. Infoblox focuses on protective DNS and threat defense designed to safeguard DNS infrastructure against hijacking, cache poisoning, and DDoS attacks, appealing to organizations that prioritize DNS integrity as a core operational requirement. Cloudflare builds on its resolver and DNS firewall offerings by embedding DDoS mitigation, DNSSEC, and malware blocking for both enterprise and consumer contexts, leveraging its broader network presence to position DNS protection as part of a wider edge security model. Akamai Technologies emphasizes DDoS-resilient DNS delivery and posture management for hybrid cloud security, targeting organizations that need robust availability and visibility across complex environments. F5 Networks positions its DNS offerings around advanced security, load balancing, and protection against DNS attacks in hybrid settings, which resonates with enterprises seeking to align traffic management and security controls. Verisign and Neustar draw on established DNS infrastructure expertise, offering threat intelligence, DDoS protection, and managed DNS services that support enterprises and critical infrastructure scenarios.
PW Consulting Information & Electronics Research Center
The differentiating factors that matter most in this landscape are not limited to feature checklists. Buyers increasingly evaluate the breadth of threat intelligence integration, the quality of visibility across hybrid environments, the practicality of automated response, and the ability to meet procurement requirements for encrypted DNS. Providers that can connect DNS security to broader security operations, cloud governance, and compliance workflows are better positioned to win multi-year commitments.
Recent Developments and Evolving Market Structure
Recent product and partnership activity illustrates how vendors are closing capability gaps and expanding distribution. In June 2025, Akamai introduced DNS Posture Management, an agentless solution designed to provide unified multicloud visibility over DNS assets for real-time monitoring and remediation. This type of offering reflects a broader trend toward visibility and configuration governance as prerequisites for reliable DNS protection, especially where environments span multiple cloud providers. In September 2024, IGIT partnered with NS1 and Cisco to deliver agile DNS security application deployments targeting the EMEA region, demonstrating how channel and technology partnerships can accelerate regional reach and deployment flexibility.
These moves point to a market in which differentiation is increasingly tied to visibility, automation, and ecosystem enablement rather than standalone DNS features alone. The competitive trend is not simply toward consolidation; it is toward layered value propositions in which DNS security becomes embedded in multicloud operations, edge security, and compliance programs. New entrants and specialist providers can still compete by addressing niche requirements—such as specific compliance frames, high-scale DDoS resilience, or verticalized threat detection—while larger vendors compete on breadth, integration, and operational scale.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
Trend 1: Encryption and AI-Enabled Detection Become Baseline Expectations
Over the next several years, the combination of encrypted DNS and AI-enabled detection is likely to shift from differentiated capability to baseline expectation, especially in regulated and publicly exposed environments. Encrypted resolution paths will increasingly be required not only for privacy but also for procurement alignment and tamper resistance. AI-driven analytics will be expected to support faster triage, anomaly detection, and policy refinement. The commercial opportunity for vendors lies in delivering these capabilities in ways that are operationally practical: integrated into existing security tools, explainable to analysts, and measurable in terms of detection and response improvements. The risk for buyers is assuming that advanced features automatically translate into reduced operational overhead; without integration and governance, AI-enabled tools can add complexity rather than remove it.
Trend 2: DNS Posture Management and Multicloud Visibility Gain Strategic Importance
As multicloud adoption deepens, DNS posture management and unified visibility will become more central to security programs. Organizations will need to inventory DNS assets across environments, detect misconfigurations, and enforce consistent policies without relying entirely on manual audits or highly specialized staff. Agentless and automated approaches are likely to gain traction because they reduce the friction of expanding coverage across new workloads and locations. The commercial opportunity here extends beyond detection to remediation and governance: solutions that help teams maintain DNS hygiene, validate configuration changes, and respond quickly to deviations are well positioned to become part of ongoing operational budgets rather than one-time project spend.
Trend 3: Verticalized Demand and Compliance-Linked Procurement Intensify
Demand is likely to become more verticalized as industry-specific risk profiles and regulatory expectations diverge. BFSI, healthcare, government, and critical-infrastructure-adjacent sectors are already among the more pronounced areas of adoption interest, and further guidance or procurement requirements could intensify focus on DNS protections in these domains. This trend favors providers that can articulate clear control mappings, demonstrate sector-relevant threat coverage, and provide deployment flexibility for environments with distinct privacy, residency, or availability constraints. The uncertainty lies in the pace and consistency of regulatory evolution: while some jurisdictions are advancing clear directives, others may Lag, creating uneven demand patterns across regions and industries.
Strategic Recommendations for Decision Makers
For vendor and product leaders, the strategic imperative is to move beyond DNS security as a feature narrative and toward integrated outcomes. Solutions that combine reliable resolution, encrypted protocols, threat intelligence, and automated posture management will be better positioned to compete in procurement environments where buyers seek consolidation and operational simplicity. Differentiation should be expressed in terms of deployment flexibility across cloud and on-premises contexts, the practicality of integration with security operations, and the clarity of compliance support. Partnerships, particularly those that expand regional reach or enable faster deployment in complex environments, can be decisive in shortening sales cycles and broadening addressable segments.
For investors, the market’s growth trajectory and moderate concentration suggest that value creation will come from both scale advantages and targeted differentiation. Due diligence should examine not only revenue momentum but also the defensibility of threat intelligence pipelines, the operational burden of the deployed architecture, and the extent to which offerings are aligned with procurement requirements for encrypted DNS and AI-enabled detection. Capital allocation decisions should weigh the potential for platform consolidation against the persistence of specialist niches, particularly in DDoS resilience, critical infrastructure support, and verticalized compliance contexts.
For enterprise buyers and procurement teams, the priority is to treat DNS security as a continuum rather than a single purchase decision. Evaluations should consider encrypted protocol support, visibility across hybrid and multicloud assets, integration with existing security tooling, and the operational model required to keep protections current. Organizations should also assess whether they have sufficient internal capability to manage posture, respond to anomalies, and maintain configuration hygiene, or whether managed services, automation, or agentless approaches are needed to close gaps. Because requirements are evolving quickly, access to detailed segmentation insights, vendor benchmarking, and deployment-pattern data can materially improve buying and planning decisions.
Application Security Software Market
Detailed market segmentation, vendor-level benchmarking, and region- and industry-specific deployment dynamics remain essential for firms that need to act with precision rather than rely on aggregated trends alone. For leaders seeking deeper coverage of demand patterns, competitive positioning, and tailored recommendations across sectors and deployment contexts, the full PW Consulting research report provides the granular data and scenario analysis needed to translate market momentum into concrete strategy.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Advanced CO2 Sensors Market: Why 7.1% CAGR and $1.1B Scale Change Everything
By PW Consulting, 2026-09-21
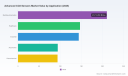
Advanced CO2 Sensors: Navigating Convergence, Compliance, and Commercial Opportunity
The advanced CO2 sensor market occupies a pivotal position where environmental regulation, building decarbonization, and precision measurement intersect. Market estimates point to a total revenue trajectory moving from approximately $690.0 million in 2025 toward $1,115.26 million by 2032, reflecting a compound annual growth rate of 7.1% across the forecast horizon. This expansion is not purely incremental; it is being reshaped by compliance mandates that elevate measurement accuracy from a desirable feature to a mandatory requirement, by product architectures that compress form factors while preserving performance, and by a supply environment where miniaturization and power efficiency dictate competitive differentiation. The sector’s structure remains moderately concentrated, with the top three players capturing roughly 55% of revenue and the top five accounting for about 68%, yet the composition of leadership continues to shift as incumbents navigate product roadmaps, regulatory alignment, and downstream integration with building management systems.
For decision-makers, the core question is no longer whether CO2 sensing will grow, but how the convergence of standards, product form factors, and application-specific performance requirements will reshape value capture across the value chain. The following analysis examines the current market backdrop, the forces propelling change, the competitive logic among leading suppliers, and the strategic implications for manufacturers, investors, and procurement organizations.
Market Snapshot and Structural Pressure Points
The market has matured through a period of steady expansion, driven by broader adoption of indoor air quality monitoring, demand-controlled ventilation in commercial buildings, and industrial process control. The current revenue base is anchored by established end-use demand, but the rhythm of growth is increasingly governed by regulatory cycles and product upgrades rather than by first-time deployments alone. The market’s growth curve suggests that incremental volume gains will be supplemented by higher-value deployments where accuracy, calibration stability, and integration readiness become the primary purchasing criteria.
Challenge 1: Compliance Becomes a Product Requirement, Not a Feature
A defining shift in the market is the elevation of measurement accuracy and repeatability to the center of procurement specifications. Standards such as ANSI/ASHRAE 62.1-2022 Addendum d place precise CO2 measurement at the heart of demand-controlled ventilation performance, aligning sensor capability directly with energy-efficiency objectives. In Europe, the Energy Performance of Buildings Directive sets zero-emission expectations for new buildings by 2030, reinforcing the link between ventilation control, air quality, and compliance documentation. As these requirements cascade into procurement specifications, sensor suppliers must demonstrate not only functionality but verifiable alignment with building standards, including IAQ frameworks such as RESET Grade B and WELL Building Standard v2 in relevant deployments.
The implication is structural: compliance becomes a gatekeeper for market access in higher-value segments. Sensors that cannot meet accuracy thresholds, calibration expectations, or documentation rigor face increasing friction in specification-driven purchasing processes. This elevates the importance of product validation, test data, and support materials that translate technical performance into compliance readiness.
PW Consulting Information & Electronics Research Center
Challenge 2: Miniaturization, Power, and Integration Are Redefining Winning Form Factors
The market is moving toward smaller, lower-power devices that can be embedded across HVAC controls, smart building nodes, and battery-operated IoT installations. This trend pressures suppliers to balance size reduction with accuracy and environmental robustness. Product roadmaps increasingly emphasize solderability, compact packaging, and low power draw, especially where continuous monitoring must fit within constrained energy budgets or tight mechanical envelopes. In parallel, integration with building management platforms and environmental sensing ecosystems is becoming a differentiator, because end users favor solutions that reduce installation complexity and streamline commissioning.
This miniaturization-and-integration trajectory creates a double-edged challenge. It opens room for higher unit volumes in distributed monitoring, yet it also compresses margins if products compete primarily on size alone. The winners are likely to be those that combine small footprints with validated performance and integration support, not just packaging efficiency.
Challenge 3: Concentrated Leadership Meets Application-Specific Competition
Market share concentration indicates that a limited group of suppliers holds substantial influence over product direction and customer relationships. At the same time, application requirements differ enough that leadership in one segment does not automatically translate into leadership across all segments. Accuracy-intensive building and healthcare deployments may favor different characteristics than industrial process monitoring or automotive-adjacent applications. As a result, competitive positioning is becoming more application-aware, with suppliers emphasizing specific feature sets, compliance alignment, and platform integration instead of competing broadly on sensor category alone.
This dynamic creates room for targeted differentiation, but it also raises the stakes for portfolio coherence. Suppliers must manage trade-offs between breadth and depth, ensuring that product lines are credible in the segments they choose to serve, with the documentation and support to match.
Core Drivers Reshaping Demand and Product Strategy
Technological Innovation: Smaller Sensors with Higher Accuracy and Lower Power
Product launches in recent periods illustrate how technology roadmaps are converging around accuracy, size, and energy efficiency. One example is the introduction of ultra-compact NDIR CO2 sensors designed for demand-controlled ventilation and surface-mount integration, with a substantially smaller footprint than previous generations and compliance positioning aligned with ASHRAE 62.1-2022 Addendum d. Mass production timing and sample distribution activity indicate that these designs are moving from demonstration to deployment readiness, with relevance for smart buildings, IAQ monitoring, and compact environmental sensing. Another example is a photoacoustic NDIR CO2 sensor positioned as a drop-in upgrade pathway for an existing platform, with best-in-class accuracy and building-standard alignment. Together, these developments reflect an industry trend in which accuracy improvements are being packaged into more compact, easier-to-integrate modules.
Air Quality Sensor Market
For manufacturers, this trend changes the equation between performance and form factor. Historically, users may have accepted trade-offs between size or power and measurement precision. The current direction suggests that multiple product tiers can deliver high accuracy within compact formats, which expands the addressable design space for OEMs and system integrators.
Policy and Regulatory Environment: Standards as Adoption Accelerators
Regulatory and standards-based pressure is one of the strongest demand accelerators in the market. The shift toward more rigorous ventilation control requirements is effectively converting CO2 measurement from an optional monitoring parameter into a compliance-critical input for energy-efficient building operation. In both North America and Europe, building codes and directives are reinforcing expectations for precise environmental sensing and low-emission building performance. This does not merely increase total demand; it changes the composition of demand toward applications where specification, validation, and documentation matter more than price alone.
This regulatory overlay has strategic consequences. Suppliers with products already positioned for relevant standards can benefit from shorter specification cycles and faster customer confidence. Conversely, suppliers without clear alignment may face more intensive evaluation, particularly in projects where building certification, energy performance, or IAQ documentation is part of the procurement scope.
Demand-Side Shifts: Building Operators, Healthcare, and Industrial Users Are Prioritizing Air Quality and Efficiency Together
Demand is increasingly driven by an overlap of operational objectives rather than by a single use case. Building operators are linking indoor air quality with energy optimization, making demand-controlled ventilation and continuous monitoring more attractive where both occupant comfort and compliance are in play. Healthcare environments continue to place a premium on environmental monitoring, where measurement stability and reliability can influence operational confidence. Industrial users remain focused on process control and safety-adjacent sensing, but with growing interest in compact, low-power devices that can be integrated into broader monitoring architectures.
This demand evolution is notable because it tilts purchasing behavior toward total solution value. Buyers are less likely to evaluate sensors in isolation and more likely to consider how a device fits into commissioning, calibration, maintenance, and system-level reporting. The practical implication is that sensor products compete not only on measurement performance, but also on how easily they support operational workflows.
Supply-Side and Cost Structure Dynamics: Integration and Miniaturization Influence Margin Logic
The supply environment is being shaped by the same miniaturization and integration pressures that influence product design. Smaller sensors with SMD compatibility, low-power operation, and multi-function environmental sensing capabilities can enable broader deployment, but they also invite closer scrutiny of production efficiency, calibration processes, and support economics. Where volume grows through distributed installations, cost-to-serve and after-sales support become increasingly relevant to profitability.
At the same time, suppliers that can combine compact hardware with strong compliance documentation and integration support may be able to defend pricing better than those competing primarily on unit cost. In this sense, supply-side advantage is shifting from scale alone toward the ability to deliver validated, easily deployable solutions at scale.
Competitive Landscape and Where Leadership Is Being Built
The competitive field includes a mix of specialized sensor developers and broader industrial or building-technology players. Senseair, based in Sweden, is associated with ultra-compact NDIR CO2 sensors for demand-controlled ventilation and smart building integration, with recent activity emphasizing smaller form factors, SMD solderability, and compliance alignment for IAQ monitoring and DCV systems. Sensirion AG, based in Switzerland, is notable for photoacoustic NDIR CO2 sensors positioned around high accuracy and building-standard compliance, with a product trajectory that includes drop-in upgrade capability for an existing platform. Gas Sensing Solutions, based in the UK, has focused on solid-state NDIR CO2 sensors optimized for ultra-low-power IoT and battery-powered applications, with integrated environmental sensing functionality. Vaisala Oyj, based in Finland, is linked to advanced NDIR CO2 sensors using optical technology for precision applications in building management, industrial settings, and data-center-related monitoring.
Larger ecosystem players also play distinct roles. Amphenol Advanced Sensors, based in the USA, supplies compact, low-power CO2 sensors with emphasis on miniaturization and high accuracy across HVAC, IoT, and environmental monitoring. Siemens AG, based in Germany, integrates NDIR CO2 sensor modules into building management systems with portfolios directed at HVAC and air quality control. Honeywell International Inc., based in the USA, offers chemical and infrared CO2 sensors for safety, IAQ, and industrial applications, including low-power draw options.
Strategic Positioning and Differentiation
Differentiation in this market is increasingly multidimensional. Some suppliers compete primarily on accuracy and measurement physics, especially where standards compliance and repeatability are critical. Others emphasize form factor, power consumption, and ease of integration, particularly for IoT and battery-limited deployments. A third group focuses on system-level integration, where sensor modules are embedded within broader building management or environmental monitoring platforms. These paths are not mutually exclusive, but they shape how each supplier is likely to win in specific segments.
Worldwide Carbon Dioxide Detector Market
A notable pattern is the alignment between product releases and compliance targets. Where new sensors are introduced with explicit positioning against ventilation standards, IAQ frameworks, and building certification requirements, they are effectively reducing the evaluation burden for specification-driven buyers. This suggests that regulatory alignment is becoming a competitive asset, not just a technical specification.
Evolution of the Market Structure
The market structure appears to be moving along two parallel tracks. One is consolidation of leadership among established players that can combine technical credibility, standards alignment, and broad application reach. The other is continued differentiation in niche requirements, where low-power IoT sensing, compact SMD integration, or application-specific robustness create space for focused competition. New entrants and platform players are likely to test the market where installation simplicity, integration readiness, or compliance documentation provide a distinct advantage.
Over time, this points to a landscape in which broad market share remains important, but segment relevance and solution readiness become more decisive. Suppliers that can bridge the gap between a sensor component and a spec-ready, integration-friendly solution are better positioned to capture value as procurement processes become more standards-driven and application-specific.
Forward View: Three Trends Shaping the Next Three to Five Years
Trend 1: Compliance-Linked Specifications Will Drive More Discriminating Purchasing
As building codes, ventilation standards, and IAQ frameworks continue to tighten, procurement will likely place greater weight on verifiable performance and compliance alignment. This should shift demand toward sensors that can demonstrate accuracy, calibration stability, and documentation suitable for specification and certification requirements. The commercial opportunity lies in products and support packages that reduce the friction of evaluation, commissioning, and ongoing compliance evidence. The risk is that suppliers with products not clearly aligned to evolving standards may face slower adoption in higher-value deployments, even if unit costs are attractive.
Trend 2: Compact, Low-Power, Integrated Sensing Will Expand Deployment Surface Area
Continued miniaturization and lower power draw should enable wider dispersal of sensing into smart buildings, distributed HVAC controls, and battery-operated monitoring nodes. This trend expands the potential installation base and encourages integration with broader environmental sensing and building management platforms. The commercial opportunity is in designs that make continuous monitoring practical at scale, especially where installation constraints or energy budgets have historically limited coverage. A key uncertainty is whether competition on size and power will intensify to the point of compressing differentiation, unless suppliers can pair compact designs with strong accuracy and integration support.
Trend 3: Platform Integration and Ecosystem Positioning Will Matter as Much as Sensor Performance
As end users increasingly seek streamlined commissioning and system-level reporting, the value of a sensor will be shaped not only by its measurement capability but also by how well it fits into building management, HVAC control, or IoT platforms. Suppliers that offer modules, integration guidance, and compatibility with common system architectures can strengthen their position beyond the component level. The commercial opportunity lies in becoming easier to specify and easier to deploy. The risk is that fragmented compatibility or weak integration support can slow adoption even when sensor performance is competitive.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
Product roadmaps should be evaluated against the standards and deployment realities that are shaping purchasing decisions, not just against sensor category benchmarks. Where accuracy, compliance alignment, and compact integration are increasingly decisive, investment in validation, documentation, and integration support can be as important as hardware development. At the same time, product differentiation should be anchored in clearly defined application value, because broad claims compete less effectively than segment-specific strengths in a market where specification-driven purchasing is gaining ground.
For Investors and Strategic Allocators
The market’s growth trajectory is supported by regulation-led demand and product innovation, but returns will likely depend on which suppliers can combine credible accuracy with scalable deployment and standards alignment. Attention should be given to companies that are moving products from sample activity into mass production with clear compliance positioning, as well as to those with integration-rich portfolios that reduce customer friction. Concentration in the market also suggests that competitive advantage may be unevenly distributed across applications, so segment-level adoption and support economics deserve careful scrutiny.
For Procurement and Operations Leaders
Specifying CO2 sensing increasingly means specifying compliance readiness, integration fit, and operational support, not just a measurement device. Evaluation processes should account for accuracy claims, calibration stability, commissioning requirements, and compatibility with existing building or monitoring platforms. A sensor that is marginally cheaper upfront may carry higher total cost if it complicates documentation, installation, or ongoing verification. In practice, procurement decisions will be stronger when sensor selection is treated as part of a broader air quality and ventilation control strategy.
Closing Perspective
The advanced CO2 sensor market is entering a phase in which growth is increasingly shaped by the interaction of standards, product form factors, and solution readiness. The revenue path toward the 2032 horizon reflects more than incremental adoption; it reflects a shift in how sensing is specified, integrated, and valued across buildings, healthcare, industrial, and related applications. In that environment, the most consequential questions are not only about measurement capability, but about whether a sensor can be validated for compliance, deployed efficiently, and supported within the operational workflows that customers actually use.
For organizations seeking to move from market awareness to precise segment-level planning, the additional detail in the full research report can help narrow priorities around end-use demand, regional variation, product category splits, and competitive positioning. Detailed segmentation data and customized scenario analysis are available for teams that need to translate these trends into actionable procurement, product, or investment decisions.
For detailed analysis of this topic, please visit the official page: Advanced CO2 Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tank Cleaning Service Market: Why 6.5% CAGR and Asia Pacific's Lead Reshape Strategy
By PW Consulting, 2026-09-21
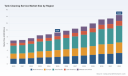
The Tank Cleaning Service Market: Navigating Growth, Regulation, and Technological Transformation (2025–2032)
1. Market Context and Structural Challenges
The global tank cleaning service industry has entered a phase of steady expansion, valued at approximately $9.28 billion in 2025. Over the 2020–2025 period, the market demonstrated consistent year-over-year growth, reflecting the sector's fundamental role in maintaining operational efficiency, regulatory compliance, and asset integrity across energy, chemical, and industrial sectors. Current projections indicate the market will reach $14.44 billion by 2032, reflecting a compound annual growth rate of 6.5 percent from 2026 through 2032. This trajectory signals a market that is not merely expanding in absolute terms but is also undergoing a structural shift in how cleaning operations are delivered, regulated, and integrated into broader industrial workflows.
At first glance, the growth story appears straightforward: aging storage infrastructure, rising throughput volumes, and stringent environmental mandates all demand more frequent and more thorough cleaning cycles. Yet beneath the headline numbers lie several structural bottlenecks that will determine which operators capture value and which face margin compression or operational disruption.
The first critical challenge centers on the tension between labor availability and operational safety. Tank cleaning has historically been a high-touch, entry-intensive process requiring specialized crews to navigate confined spaces, manage hazardous residues, and adhere to rigorous atmospheric testing protocols. Recent enforcement actions by occupational safety regulators underscore the reality that noncompliance carries severe financial and reputational consequences. A notable case involved a proposed penalty exceeding $800,000 against a service provider for failing to conduct required atmospheric testing before worker entry, following a prior incident that resulted in dual fatalities. This episode is not an outlier; it illustrates a broader industry reality where safety protocols, permit administration, exposure limits for hydrocarbon vapors and oxygen concentrations, and confined space entry requirements are becoming non-negotiable operational prerequisites. For service providers, the implication is clear: scaling capacity without scaling safety infrastructure and compliance expertise is no longer viable.
The second challenge involves the uneven pace of technological adoption. While automated and robotic cleaning systems have demonstrated measurable improvements in throughput, residue recovery, and worker exposure reduction, their deployment remains uneven across geographies and customer segments. Facilities with high-value throughput, complex sludge profiles, or strict environmental reporting requirements are increasingly willing to invest in or contract automated solutions. However, many mid-tier and regionally focused operators continue to rely on manual or semi-automated processes, constrained by upfront capital considerations, workforce familiarity, and the perceived complexity of integrating new equipment into existing maintenance cycles. This divergence creates a two-speed market where service quality, cost structures, and compliance postures increasingly diverge between early adopters and laggards.
The third challenge relates to margin stability in an environment of rising input costs and evolving waste-handling requirements. Cleaning operations do not end when tanks are emptied; they extend into sludge processing, residue disposal, and, in many cases, advanced contaminant management. As regulatory expectations around hazardous waste classification, transport logistics, and specialized treatment pathways tighten, operators must absorb higher downstream costs or pass them through to customers in a market where procurement teams are increasingly scrutinizing service-level agreements and total cost-of-ownership metrics. The result is a market where pricing power increasingly belongs to providers who can demonstrate integrated service capabilities rather than isolated cleaning transactions.
These challenges are not debilitating; they are shaping the market's next phase. They create differentiation opportunities for operators who can align safety compliance, technology deployment, and end-to-end waste management into coherent service offerings. They also define the boundaries of competitive advantage: scale alone is insufficient without operational discipline, and technology alone is insufficient without integration into customer workflows.
PW Consulting Information & Electronics Research Center
2. Core Drivers Reshaping the Market
The market's growth trajectory is being propelled by a set of interconnected drivers that extend beyond incremental demand increases. Understanding these drivers is essential for decision-makers evaluating capacity investments, service portfolio adjustments, or partnership strategies.
Technological Innovation and the Automation Imbalance
Automated cleaning systems, robotic entry platforms, and online desludging technologies are transitioning from niche capabilities to commercially viable differentiators. The value proposition is multifaceted: reduced worker exposure to hazardous atmospheres, higher consistency in cleaning outcomes, faster turnaround times, and improved recovery of residual hydrocarbons and 슬러드 materials. Recent commercial activity reflects this shift. In 2025, a major service provider announced a nationwide rollout of upgraded robotic crude oil tank cleaning services, integrating advanced robotic systems, online desludging technologies, and enhanced oil sludge recovery solutions. This type of deployment signals a broader industry movement where automation is no longer framed solely as a cost-reduction tool but as a compliance and risk-management enabler.
For operators and investors, the strategic implication is that technology adoption is becoming a marker of service quality and operational maturity. Facilities evaluating service partners are increasingly weighting automation capabilities alongside safety records, geographic coverage, and waste-handling integration. Providers that can demonstrate repeatable automated cleaning protocols, validated residue recovery rates, and seamless handoff to downstream treatment processes are positioning themselves for preferential contracting in high-value segments. Conversely, operators that treat automation as a peripheral upgrade rather than a core capability risk being relegated to price-competitive, lower-margin segments where differentiation is difficult to sustain.
Regulatory Pressure and Compliance as a Service Differentiator
Regulation continues to be a primary catalyst for service demand, but its influence is evolving from blanket compliance requirements to more granular, risk-based expectations. Confined space entry protocols, atmospheric testing mandates, personal protective equipment standards, and exposure limits for hydrocarbon vapors and gases are now embedded in operational guidance that supervisors and entry teams must administer and implement consistently. These requirements do not merely add procedural steps; they reshape the economics of tank cleaning by elevating the importance of trained personnel, documented procedures, and auditable compliance trails.
Regulatory dynamics also extend beyond the cleaning act itself. The broader waste management landscape is seeing heightened scrutiny around contaminant management, including emerging expectations around complex substances such as PFAS. These expectations are pushing service providers to expand their capabilities beyond cleaning into treatment, storage, disposal, and advanced contaminant handling. The market response has been visible in recent corporate activity, with major environmental services players pursuing acquisitions that substantially expand their hazardous waste footprint and treatment infrastructure. One such transaction, completed in 2026, nearly doubled a leading provider's U.S. hazardous waste footprint and strengthened capabilities across treatment, storage, disposal, and advanced contaminant management. This move illustrates how regulatory and compliance pressures are reshaping industry structure by rewarding operators that can offer integrated, end-to-end solutions rather than fragmented services.
For procurement teams and facility operators, the takeaway is that compliance risk is increasingly transmitted through service provider selection. Vendors with robust safety governance, documented permitting processes, and integrated waste-handling pathways reduce the operational and regulatory burden on the customer. In this environment, compliance capability is not a back-office function; it is a commercial attribute that directly influences contracting decisions.
Demand-Side Shifts Across Industrial and Energy value Chains
Demand for tank cleaning services is being shaped by changes in how industrial and energy operators manage storage, throughput, and product transitions. In the oil and gas sector, fluctuating throughput patterns, shifts in crude quality, and the need to maintain tank integrity across varying product slates increase the frequency and complexity of cleaning cycles. Chemical sector demand is driven by product changeovers, residue management requirements, and the need to prevent cross-contamination in multi-use storage systems. Water and wastewater treatment operations, while representing a smaller share of overall demand, are influenced by sludge removal cycles, regulatory reporting, and infrastructure maintenance schedules. Food and beverage applications, though more modest in scale, require strict hygiene and contamination-control protocols that elevate cleaning standards and documentation requirements.
What ties these segments together is a common theme: tank cleaning is no longer a reactive maintenance activity but a scheduled, compliance-linked component of operational planning. Customers are increasingly seeking providers who can align cleaning cycles with production schedules, minimize downtime, and deliver consistent outcomes that support downstream quality and environmental reporting. This shift favors service providers that can offer predictable scheduling, transparent performance metrics, and flexible engagement models tailored to specific facility constraints.
Supply Chain and Cost Structure Dynamics
Cost structures in the tank cleaning market are being reshaped by labor dynamics, equipment procurement, waste disposal pathways, and geographic variability in regulatory and logistics costs. Labor remains a central cost driver, and the safety and training requirements associated with confined space entry and hazardous residue handling mean that workforce quality directly affects both cost and risk. At the same time, the growing availability of automated and robotic systems is creating a pathway to reduce labor intensity for suitable cleaning scenarios, though the economics depend on tank configuration, residue profile, and utilization rates.
Waste handling and disposal costs add another layer of complexity. As downstream treatment requirements become more specialized, providers must either develop in-house capabilities, secure long-term partnerships with treatment facilities, or structure service offerings that clearly delineate cleaning from waste management responsibilities. The cost implications are significant: operators that can internalize or tightly coordinate waste handling gain cost predictability and service integration advantages, while those that rely on fragmented external arrangements face greater exposure to price volatility and compliance gaps.
Worldwide Industrial Cleaning Services Market
Overall, the cost structure trend favors integrated service models that combine cleaning, recovery, and waste management within a coordinated operational framework. This integration reduces handoff friction, improves cost visibility, and strengthens the value proposition for customers seeking to simplify vendor management and reduce compliance risk.
Underwater Hull Cleaning Service Market
3. Competitive Landscape and Emerging Strategic Positions
The market's competitive structure reflects a mix of established environmental services players, specialized tank cleaning providers, and regional operators with strong local footprints. Concentration metrics indicate that the top three providers account for roughly 46.8 percent of market revenue, while the top five capture approximately 58.2 percent. This level of concentration suggests that scale, brand recognition, and integrated service capabilities confer meaningful advantages, but it also leaves substantial room for specialized and regionally focused players that can compete on service quality, responsiveness, and niche technical capabilities.
Strategic Positioning Among Leading Providers
Several patterns emerge when examining how leading providers position themselves within the market. Large environmental services companies are increasingly leveraging acquisitions and capability expansion to build end-to-end portfolios that span cleaning, treatment, storage, disposal, and advanced contaminant management. This strategy is designed to capture value across the full service lifecycle, reduce customer fragmentation, and strengthen compliance-related value propositions. By broadening their hazardous waste and treatment footprint, these providers can offer customers a more unified operational relationship and greater assurance around downstream waste handling.
Specialized tank cleaning providers, by contrast, often compete on technical depth, regional coverage, and service responsiveness. Their differentiation frequently rests on demonstrable safety performance, experienced field crews, flexible scheduling, and the ability to tailor cleaning protocols to specific tank configurations and residue types. In markets where customers prioritize rapid turnaround, localized service, or specialized sludge recovery, these providers can maintain strong positions even as larger players expand their footprints.
Technology-focused entrants and expanding incumbents are also carving out positions centered on automation and robotic cleaning. Their appeal lies in reduced worker exposure, consistent cleaning outcomes, and the ability to handle complex sludge profiles with minimal manual intervention. As these capabilities mature, they are increasingly being incorporated into broader service portfolios rather than sold as standalone innovations, reflecting a market trend toward integrated, capability-rich offerings.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three parallel tracks. The first is consolidation, driven by the desire to expand geographic coverage, integrate waste management capabilities, and achieve economies of scale in safety infrastructure, equipment deployment, and regulatory compliance. Recent acquisition activity in the broader environmental services space illustrates this trend, with major players seeking to strengthen their U.S. hazardous waste footprint and expand treatment and contaminant management capabilities. For the tank cleaning segment, consolidation can raise the bar for integrated service quality while also increasing the resource intensity required to compete at scale.
The second track is differentiation through technology and service design. Providers that invest in robotic systems, online desludging, enhanced residue recovery, and digital scheduling or performance tracking are creating identifiable value propositions that distinguish them from more traditional manual-service models. This differentiation is particularly relevant for customers in high-throughput or high-compliance environments where cleaning consistency, safety, and downtime reduction are prioritized.
The third track involves new entrants and regional specialists that compete by addressing localized demand patterns, niche tank types, or specific industry requirements. In fragmented geographies or specialized application areas, these players can sustain competitive positions by offering tailored service levels, strong customer relationships, and agile operational responses. The long-term challenge for such players is to scale capabilities without diluting the service quality and safety standards that underpin their reputations.
Taken together, the competitive evolution suggests that the market will increasingly reward providers that can combine operational safety, technological capability, and integrated waste-handling or treatment pathways. Pure price competition in undifferentiated service segments is likely to remain intense, but value creation will increasingly concentrate in offerings that reduce customer risk, improve throughput predictability, and align cleaning with broader operational and compliance objectives.
4. Forward Outlook: Key Trends Shaping 2027–2032
Based on current growth trajectories, regulatory direction, and recent commercial activity, several trends are likely to define the market over the next three to five years.
Automation Moves from Differentiator to Baseline Expectation in Select Segments
Robotic and automated cleaning systems will become increasingly common in applications where tank geometry, residue characteristics, and throughput economics support their deployment. As equipment costs moderate, utilization models improve, and customer familiarity grows, automation is expected to transition from a premium offering to a standard consideration in many high-value service engagements. The commercial opportunity lies not only in equipment deployment but in packaging automation with validated performance metrics, recovery outcomes, and integration into customer maintenance schedules. Providers that can demonstrate repeatable results and measurable downtime reduction will be best positioned to capture preference in segments where operational efficiency and safety are jointly prioritized.
Integrated Service Models Gain Commercial Weight
The market is likely to see continued movement toward bundled or tightly coordinated service models that combine cleaning, residue recovery, waste handling, and, where relevant, advanced contaminant management. This trend is reinforced by regulatory expectations, customer desire for simplified vendor management, and the cost advantages of coordinating downstream processes. For providers, the strategic task is to build or secure the capabilities needed to offer credible end-to-end pathways without overextending into areas where operational complexity or capital requirements outweigh the returns. For customers, integrated models can reduce compliance friction and improve cost predictability, but they also require careful evaluation of provider capabilities across the full service chain.
Safety and Compliance Capability Become Procurement-Critical Attributes
Safety performance, documented permitting processes, atmospheric testing protocols, and exposure management are expected to remain central to service selection, with increasing emphasis on auditable compliance trails and consistent field execution. Recent enforcement actions and regulatory guidance reinforce the message that compliance failures carry substantial financial and operational consequences. As a result, procurement teams are likely to place greater weight on safety records, training rigor, and procedural discipline when evaluating providers. This shift creates an opportunity for operators that can institutionalize safety and compliance as visible, verifiable components of their service offering rather than treating them as internal operational concerns.
Potential Risks and Uncertainties
Several factors could alter the trajectory of these trends. Regulatory requirements may evolve unevenly across regions, creating compliance complexity for multi-geography operators and potentially raising the cost of standardized service delivery. Technology adoption may progress more slowly than anticipated in segments where tank configurations, residue variability, or capital constraints limit automation feasibility. Labor market conditions could continue to pressure cost structures and workforce availability, particularly in markets where specialized training and safety certification are required. Finally, waste handling and disposal pathways may face their own regulatory or capacity constraints, affecting the economics of integrated service models and the ability to deliver consistent downstream outcomes. Decision-makers should monitor these variables closely, as they can influence both service costs and the feasibility of specific operational strategies.
5. Strategic Considerations for Decision-Makers
For executives, planners, and investors evaluating the tank cleaning service market, the current environment offers both clear opportunities and distinct execution risks. The following considerations can help frame next steps across common stakeholder perspectives.
For Service Providers and Operators
- Align automation investments with application suitability rather than pursuing broad deployment. Prioritize tank types, residue profiles, and throughput scenarios where robotic or automated systems can deliver measurable improvements in safety, turnaround time, and residue recovery.
- Strengthen safety governance and compliance documentation as visible commercial assets. Ensure atmospheric testing, permit administration, exposure management, and confined space entry procedures are consistently executed and auditable, reducing both operational risk and customer procurement concern.
- Evaluate integration opportunities across cleaning, recovery, and waste handling. Where feasible, coordinate downstream processes to improve cost predictability, reduce handoff friction, and strengthen the value proposition for customers seeking simplified vendor relationships.
For Investors and Corporate Strategists
- Assess consolidation potential in segments where integrated hazardous waste, treatment, and contaminant management capabilities create meaningful competitive advantage. Recent transaction activity suggests that expanding end-to-end footprints can strengthen market position, particularly where regulatory expectations are rising.
- Distinguish between technology novelty and commercially scalable capability. Investment theses should account for utilization rates, equipment deployment economics, customer adoption curves, and the extent to which automation is bundled into differentiated service offerings rather than sold as a standalone feature.
- Monitor regional demand dynamics and regulatory divergence. Growth opportunities may vary significantly by geography, and multi-market strategies should account for differences in compliance requirements, waste handling pathways, and labor market conditions.
For Procurement Teams and Facility Operators
- Incorporate safety performance, compliance documentation, and waste-handling integration into vendor evaluation criteria alongside pricing and scheduling flexibility. Total cost-of-ownership considerations increasingly include risk reduction, downtime predictability, and downstream treatment coordination.
- Request clear performance metrics for cleaning consistency, residue recovery, and turnaround time. Transparent, verifiable outcomes support better contracting decisions and reduce ambiguity in service-level expectations.
- Assess provider capability across the full service chain rather than evaluating cleaning in isolation. Providers that can demonstrate coordinated processes from cleaning through recovery and disposal may offer greater operational simplicity and compliance assurance.
The tank cleaning service market is entering a period where growth is increasingly tied to how well operators manage safety, technology, and integration. The providers and customers that succeed will be those who treat these elements not as separate operational concerns but as interconnected components of a commercially valuable service model. For decision-makers seeking detailed segmentation data, regional breakdowns, and tailored scenario analysis across the 2026–2032 forecast horizon, a comprehensive research report can provide the granular context needed to translate these market-level trends into specific commercial actions.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Cords & Extension Cords Market: 6.2% CAGR Trajectory Changes Everything
By PW Consulting, 2026-09-21
The Power Cords & Extension Cords Market: Strategic Shifts and Commercial Opportunities (2026–2032)
The global market for power cords and extension cords has matured into a sector defined by steady value accumulation, structural segmentation, and incremental but consequential regulatory change. Over the 2020–2025 period, revenue expanded from roughly $3.26 billion to $4.4 billion, establishing a trajectory that carries forward into the 2026–2032 forecast window. The extended outlook points to a compound annual growth rate of 6.2%, lifting projected revenue to approximately $6.68 billion by 2032. This pace is neither explosive nor stagnant; it reflects a market where demand fundamentals are broad-based, yet growth is increasingly tied to differentiation in safety, performance, and application-specific engineering.
Regional activity illustrates a market that is geographically diversified but unevenly developed. North America and Asia Pacific together anchor the largest revenue pools, reflecting mature commercial construction patterns, dense electronics ecosystems, and sustained household demand. Europe remains a substantial contributor, shaped by localized certification regimes and building practices. Latin America and the Middle East/Africa represent smaller but expanding bases, often driven by infrastructure investment, urbanization, and gradual formalization of electrical supply chains. Rather than signaling saturation, the geographic spread highlights where product configuration, voltage standards, and certification pathways must be managed with precision.
The market is structurally split across indoor, outdoor, and heavy-duty product families. Indoor configurations hold the largest share, supported by continuous deployment in homes, offices, and light commercial environments. Outdoor solutions form a smaller but resilient segment tied to construction, outdoor equipment, temporary power setups, and seasonal demand cycles. Heavy-duty cords occupy a distinct position, serving industrial use, medical-adjacent environments, and settings where thermal stress, abrasion resistance, and mechanical durability are non-negotiable. Application-side demand also divides across residential, commercial, and industrial channels. Residential remains the largest demand base, commercial contributes a meaningful mid-tier volume, and industrial represents a specialized segment that rewards higher engineering rigor and compliance confidence.
Key Challenges and Inflection Points
A market growing at a consistent mid-single-digit rate can still feel pressure at the margin. Three challenges stand out as current inflection points. First, raw material volatility is reshaping cost expectations. Price movements in PVC and related polymer inputs have introduced variability in production economics, especially for manufacturers balancing export competitiveness with domestic cost structures. The gap between regional input prices has become more than a procurement issue; it now influences margin planning, inventory strategy, and the timing of price adjustments to downstream customers.
Second, safety and certification requirements are tightening in ways that alter product design and time-to-market. Recent revisions to the UL 817 standard for cord sets and power-supply cords, including new provisions for heater-use power-supply cords, reflect a broader push toward clearer performance expectations in higher-load and thermally sensitive applications. For manufacturers, this is not merely a compliance update. It changes testing protocols, documentation practices, and the engineering margin needed to remain acceptable across North American and internationally harmonized channels.
Third, the market faces an identity challenge around commoditization versus specialization. Many product forms are still viewed as interchangeable, especially in price-sensitive consumer channels. Yet the highest-value opportunities increasingly reside in application-specific performance, traceability, and certification clarity. Companies that compete primarily on generic specifications risk margin compression, while those building defensible positions around medical-grade, industrial-grade, or custom cord sets are better positioned to protect pricing and customer retention.
Key Drivers Reshaping Market Trajectory
The 6.2% CAGR over the forecast horizon is not simply a continuation of past momentum. It reflects structural drivers that interact with one another: technology, regulation, demand-side behavior, and cost architecture. Understanding how these forces converge is essential for deciding where to invest, where to build capability, and where to exercise caution.
Innovation in Materials, Plug Geometry, and Application-Specific Design
One of the more durable drivers is incremental engineering innovation. Power cord and extension cord demand is not only increasing in volume; it is becoming more exacting in specification. This includes better insulation and jacket formulations that balance flexibility, flame resistance, and thermal endurance. It also includes design improvements in connector geometry, strain relief, and cord organization, which matter in both residential convenience and commercial durability. In data center-adjacent and hospital-adjacent settings, where cord integrity is tied to uptime and safety, even modest improvements in strain management, labeling, and configuration consistency can influence procurement decisions.
A second innovation theme is the broadening of purpose-built product families. Heavy-duty and outdoor configurations continue to gain relevance in applications where exposure, repeated flexing, and mechanical stress are routine. Medical-grade and hospital-grade cord sets represent a narrower but higher-stakes segment where performance documentation and certifiable consistency can become competitive differentiators. Custom wiring harnesses and OEM-tailored solutions extend the market beyond standardized retail SKUs into value-added configurations that are less vulnerable to direct price comparison.
Regulatory and Certification Dynamics
Regulatory expectations are becoming a more explicit part of market strategy. Certification is already central to many channels, but recent standard revisions are adding precision around higher-risk use cases. The July 30, 2025 revision of UL 817 introduced new requirements for heater-use power-supply cords, signaling that regulators are paying closer attention to load conditions where thermal management becomes critical. This matters because heater-related applications often operate near the upper bounds of common cord capabilities, where small specification gaps can become safety or reliability concerns.
For companies with North American exposure, UL alignment is a market-access prerequisite in many cases and a competitive trust signal in others. For internationally oriented manufacturers, the challenge is maintaining certification readiness across multiple regulatory regimes while keeping product families efficient enough to avoid over-fragmentation. The practical effect is that compliance is no longer a back-office function; it is increasingly part of product strategy, marketing credibility, and channel access.
Demand-Side Shifts in Residential, Commercial, and Industrial Use
Demand behavior is evolving on both the consumer and enterprise sides. In residential settings, the growth of home offices, entertainment setups, and smart-home devices continues to support accessory demand. Extension cords and power strips are no longer treated solely as temporary utilities; they are being chosen for cord length, barrier compatibility, aesthetic integration, and perceived safety. In commercial environments, demand is shaped by office refurbishment, retail upgrades, hospitality turnover, and the ongoing need for flexible power distribution during fit-outs and reconfigurations.
Industrial demand plays a different role. It is less about volume expansion and more about reliability, specification discipline, and supply assurance. Factories, maintenance operations, and facilities teams often prioritize cords and cord sets that can withstand repeated use, environmental exposure, and inspection regimes. As industrial procurement becomes more selective, the value shifts toward documentation, consistency, and the ability to match cord sets to specific equipment and site conditions.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal driver because it influences both competitiveness and product strategy. Recent pricing movements in PVC illustrate how material economics can diverge by region. In April 2026, China PVC prices were reported near $735.45 per metric ton, while U.S. PVC prices were reported at $822.45 per metric ton. That spread matters for manufacturers operating across export and domestic channels, because it affects landed cost, relative pricing power, and the attractiveness of localization versus import-based supply.
Beyond raw materials, the supply chain is also being shaped by the need for resilience. Procurement teams increasingly value supplier stability, lead-time predictability, and the ability to support custom configurations without excessive turnaround penalty. As a result, some buyers are willing to accept differentiated pricing if it is paired with dependable certification support, batch consistency, and timely delivery. This is gradually shifting the market from pure cost competition toward a more balanced evaluation of cost, risk, and performance assurance.
Competitive Landscape and Leading Strategies
The competitive field is broad, with participants spanning large North American and European manufacturers, Indian electricals players, and specialized Asian cord-set producers. What distinguishes the more successful players is not simply scale, but the ability to align product families with the market’s growing emphasis on safety, application specificity, and configuration flexibility.
Southwire Company LLC occupies a strong position in building wire and cable, including extension cords used in utility, industrial, and commercial applications. Its profile reflects a broad distribution footprint and familiarity with the requirements of installation, infrastructure, and commercial construction markets. For Southwire, the strategic advantage lies in combining product breadth with the credibility needed to serve demanding channel requirements.
Volex plc represents a more globally integrated model, manufacturing power cords, plugs, connectors, and custom wiring harnesses for consumer, industrial, and data center-related uses. Its broad configuration capability supports customers that need standardized solutions and tailored assemblies alike. The strategic implication is that cord-set suppliers with harness and connector expertise can capture additional value by addressing OEM and facility needs beyond simple off-the-shelf cords.
Havells Ltd and Goldmedal Electricals both illustrate the strength of electricals-focused manufacturers in India, with product lines spanning home electricals, extension cords, flexible cables, switches, and power accessories. Their relevance comes from serving both residential and commercial channels with products that balance affordability and practical reliability. In these markets, scale in distribution, brand recognition, and breadth across electrical accessories can be as important as cord-specific engineering.
In China, Ningbo Biaoda Electric Co., Ltd., Jiaxing Hongzhou Cable Co., Ltd., and similar specialized manufacturers reinforce the region’s role as a production base for power cords, power boards, extension cords, and power strips. Their competitive strength typically lies in manufacturing efficiency, configuration variety, and export readiness. The challenge for these players is converting cost and volume advantages into durable positioning, particularly as buyers pay closer attention to certification, traceability, and application suitability.
Taiwan-based YFC-Boneagle Electric Co., Ltd. adds a further dimension through global exports of power cords, cord sets, LAN cables, and networking accessories. Its export-oriented profile underscores how regional manufacturers can compete internationally by aligning with end-market requirements in connectivity and power distribution.
On the U.S. and specialty side, Kord King, Electri-Cord Manufacturing, Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate a different competitive logic. Kord King’s emphasis on premium cords, medical-grade, heavy-duty, and construction-grade cord sets shows how a manufacturer can pursue higher-margin positioning by aligning with demanding use cases. Electri-Cord Manufacturing’s focus on domestic, international, and hospital-grade cords reinforces the same theme: specialty certification and application specificity can create defensible niches. Webber Electronics combines international, North American, hospital-grade, and GFCI power cords across medical, industrial, dental, and commercial markets, reflecting the importance of multi-standard readiness and sector-targeted product lines. Z-Tronix and Quail Electronics extend this pattern with OEM, industrial, commercial, and international configuration capabilities, including custom power cords and cord sets. Their presence suggests that serving both standard and custom requirements can be a practical way to diversify demand while maintaining deeper customer relationships.
PW Consulting Information & Electronics Research Center
Strategic Positioning and Differentiation
Across these companies, several strategic patterns are emerging. One is the move toward application-specific credibility. Manufacturers that can demonstrate consistent performance in medical, industrial, or higher-load contexts are better positioned to escape pure price competition. Another is the blending of standardization with customization. Companies offering both standard cord sets and tailored configurations can capture broader demand while preserving relationships with customers who need tailored specifications. A third pattern is certification readiness as a competitive asset, especially where UL and other standard alignments affect purchasing confidence and channel access.
Market Structure and Evolution
Market concentration remains moderate. A collective concentration reading shows that the top three participants account for roughly 28.5% of the market, while the top five reach about 39.2%. This suggests a field that is not dominated by a small number of incumbents, but still features meaningful leadership positions. The structure leaves room for both consolidation and specialized entry.
Consolidation is plausible in segments where distribution scale, certification infrastructure, and cost discipline matter increasingly. New or expanding entrants can still find openings by focusing on underserved configurations, niche certification needs, or regional demand that is not fully served by larger players. At the same time, the low-concentration structure means that brand trust, product reliability, and compliance documentation can be decisive in purchasing decisions, particularly when buyers compare otherwise similar offerings.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, the market’s direction is unlikely to be driven by a single breakthrough. More likely, it will be shaped by the compounding effect of specification tightening, demand fragmentation, and cost-aware procurement. Three trends are especially relevant for decision-makers.
First, application-specific certification and documentation will become more central to product competitiveness. As revisions such as the UL 817 update for heater-use power-supply cords take effect, buyers in higher-load or higher-risk environments will likely increase scrutiny on whether cords are explicitly appropriate for the intended use. This favors manufacturers that can provide clear guidance, consistent batch quality, and reliable conformity evidence.
Second, cost and material volatility will continue to reward supply chain discipline. With regional PVC pricing divergence and broader input variability, companies that can manage inventory, hedging, sourcing mix, and localized production more effectively will have an advantage in protecting margins without sacrificing service levels. This may also encourage more regionalized production or supplier diversification in response to regional cost differentials.
Wireless Chargers & Power Cords and Portable or Wearable Charging Cable Market
Third, demand will continue to fragment across more specialized use cases, increasing the importance of configuration capability. Residential convenience products will persist at scale, but commercial and industrial buyers will increasingly value solutions tailored to equipment, environment, and installation constraints. That creates opportunities for cord-set suppliers that combine standard SKUs with custom engineering, especially where connectors, cord length, jacket type, and certifying marks must be aligned to specific procurement standards.
Risks and Uncertainties
These opportunities are not risk-free. Regulatory evolution can accelerate and vary by region, imposing additional testing and documentation burdens that disrupt product rollouts if compliance systems are not prepared. Raw material price swings may compress margins more quickly than pricing adjustments can recover them, particularly for manufacturers with limited flexibility in sourcing or product mix. There is also the persistent risk that certain consumer-facing categories remain commoditized for longer than anticipated, making volume growth dependent on distribution strength and promotional intensity rather than value-based differentiation.
Another uncertainty lies in the pace of channel consolidation among buyers. If procurement becomes more centralized and specification-driven, smaller suppliers may face higher barriers to entry unless they can demonstrate clear technical or certification advantages. Conversely, if buyers continue to value flexibility and responsiveness, specialized suppliers may retain a strong position even in a moderately concentrated market.
Actionable Recommendations for Decision-Makers
For manufacturers, the central question is whether product strategy is built around interchangeable volume or defensible specialization. The more durable path is to align at least part of the portfolio with higher-trust applications and clearer certification requirements. That could mean investing in medical-grade or industrial-grade offerings, strengthening documentation for heater-use and other higher-load applications, and ensuring that connector and cord configurations are developed with end-use conditions in mind rather than generic specifications alone. It also means checking whether cost structures can absorb regional material volatility without forcing reactive price moves that erode customer trust.
Appliance Power Cord Market
For investors, the market offers a mix of steady growth and selective upside. Broad exposure may be attractive for its consistency, but the most meaningful value creation is likely to come from companies that demonstrate certification readiness, application specificity, and the ability to serve custom or higher-specification demand. Due diligence should pay attention to whether a company’s product mix is concentrated in price-sensitive commodity segments or balanced with segments that justify stronger pricing and longer customer retention. Supply-chain resilience and regional cost positioning should also be evaluated, given the divergence in raw material pricing and its effects on competitiveness.
For procurement and supply chain leaders, the priority is to treat cord and cord-set purchasing as a specification and risk decision, not solely a unit-cost decision. Evaluations should include suitability for the intended application, certification alignment, traceability, and the supplier’s ability to support standard and custom configurations without unacceptable lead-time penalties. Where operations involve higher loads, medical contexts, or industrial conditions, the cost of qualification errors can exceed the apparent savings from choosing the lowest-priced option. Supplier stability and documentation quality are therefore part of the value equation, not optional extras.
The broader takeaway is that the power cords and extension cords market is changing in ways that reward preparedness. The growth path is solid, but the competitive winners will be those who interpret regulation, cost volatility, and demand fragmentation as strategic signals rather than background noise. For organizations that need detailed segmentation, regional cost dynamics, and application-level demand patterns to refine their plans, deeper commercial intelligence can shorten the gap between high-level strategy and executable action.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PhotoMOS Optically Isolated Relay Market: Why 7.5% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Navigating the PhotoMOS Optically Isolated Relay Market: Strategic Trends and Commercial Opportunities
Market Landscape and Defining Challenges
The PhotoMOS optically isolated relay sector has demonstrated consistent expansion over the past five years, with total market revenue climbing from approximately $320 million in 2020 to an estimated $463.5 million by 2025. The forward trajectory points toward sustained growth, with projections indicating a rise to roughly $766 million by 2032, translating to a compound annual growth rate of 7.5 percent. This expansion reflects the technology’s entrenched role in signal and power switching where galvanic isolation, low leakage, and high-frequency performance are non-negotiable. Unlike electromechanical counterparts, optically isolated MOSFET relays eliminate moving parts, reduce contact wear, and enable faster switching cycles, making them increasingly attractive in environments where reliability and footprint constraints dominate design decisions.
Despite the favorable growth trajectory, the industry is navigating a series of structural pressures that are reshaping how value is created and captured. First, raw material dynamics have tightened margins across the supply chain. Substrate costs tied to gallium arsenide and silicon-based components rose sharply in 2024, contributing to a measurable increase in manufacturing complexity. Energy and labor expenses in the sector followed a similar upward path, compounding the challenge for producers operating on thin conversion economics. Second, the competitive field remains moderately concentrated, with the top three players commanding roughly half of total revenue and the top five firms accounting for approximately 65 percent. This concentration provides scale advantages to established players but leaves smaller manufacturers exposed to pricing pressure and input volatility, with nearly 30 percent of smaller producers reporting direct exposure to component cost fluctuations.
A third challenge lies in application-specific qualification and thermal ruggedization. Automotive and high-temperature industrial deployments increasingly demand devices that can operate reliably at elevated temperatures without compromising isolation integrity or switching consistency. Meeting these thresholds requires tighter process control, advanced packaging, and more rigorous validation cycles, which in turn extend time-to-market and raise development costs. Together, these dynamics create a market that is growing steadily but not uniformly; profitability and competitive positioning now depend on how well firms can absorb input cost variability, accelerate qualified product introductions, and align portfolio breadth with high-growth application pockets.
Key Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
The core appeal of PhotoMOS relays continues to be refined through device-level engineering. Recent product iterations emphasize lower on-resistance variability, reduced leakage under idle conditions, and packaging formats that support higher power density without sacrificing isolation margins. Optical semiconductor architectures that combine LED inputs, photodiode detection arrays, and MOSFET outputs have matured to the point where non-contact switching can rival or surpass electromechanical performance in many signal and power routing tasks. These improvements matter commercially because they allow designers to replace multiple discrete components with a single isolated switching element, simplifying board layouts, reducing assembly complexity, and improving long-term reliability in cycling applications.
A concrete example of this trajectory is the introduction of voltage-driven photorelays in compact package formats with elevated temperature ratings. Newly launched devices targeting semiconductor testers, electric vehicles, and high-temperature industrial equipment demonstrate how manufacturers are pushing the envelope on thermal endurance and form factor simultaneously. By shipping voltage-driven models rated for operation at 135°C in small S-VSON4T packages, suppliers are directly addressing the qualification needs of automotive and heavy-duty industrial users who must maintain performance under harsher thermal cycles. The immediate start of volume shipments signals that these enhanced specifications are moving from prototype interest to production demand.
Policy and Regulatory Environment
Regulatory expectations around safety isolation, electromagnetic compatibility, and automotive qualification frameworks continue to shape product roadmaps. Markets that serve medical devices, automotive systems, and telecommunications infrastructure are governed by standards that reward demonstrateable isolation reliability, temperature stability, and long-term drift characteristics. In practice, this means that a relay’s datasheet performance is only part of the commercial equation; documented qualification pathways, traceability, and certifiable manufacturing processes increasingly influence procurement decisions. The regulatory tilt favors suppliers that can provide not only performance metrics but also the documentation and process consistency that downstream integrators require to clear their own validation hurdles.
PW Consulting Information & Electronics Research Center
At the same time, energy efficiency expectations in industrial automation and telecom equipment are nudging designers toward solutions that minimize standby losses and reduce wasted power in switching nodes. Optically isolated relays with stable on-resistance and low leakage align well with these efficiency goals, creating a policy-adjacent tailwind that reinforces demand beyond pure performance considerations.
Demand-Side Shifts Across End Use Segments
Demand patterns are being reshaped by the electrification and automation of core industrial and mobility systems. The push toward smarter factories, responsive motor control, and modular automation architectures is expanding the set of points in a design where isolated switching is useful. Telecommunications infrastructure, particularly where power distribution and signal routing must remain robust under continuous operation, continues to represent a substantial demand base. Medical device developers also rely on isolation for safety-critical circuits, and the trend toward more compact, portable, and battery-aware equipment is reinforcing interest in relay solutions that combine isolation with minimal footprint. Automotive and electric vehicle applications form a faster-growing but more exacting demand pocket, where temperature tolerance, vibration resilience, and high-frequency switching capability determine commercial relevance.
Supply Chain and Cost Structure Evolution
Cost structure remains a pivotal driver of competitive outcomes. The rise in GaAs and silicon substrate costs, coupled with higher energy and labor expenses, has raised the baseline cost of production and increased the importance of yield optimization, packaging efficiency, and supply continuity planning. Smaller manufacturers have been disproportionately affected, with a notable share reporting exposure to component cost volatility and a measurable increase in production energy usage across the sector. This environment rewards firms that can manage bill-of-material variability, secure stable substrate supply, and design around cost-effective package options without compromising qualification readiness.
Strategic sourcing is becoming more important as a differentiator. Producers that build relationships with qualified substrate suppliers, maintain disciplined inventory planning, and design families of parts that share common internal architectures can reduce per-unit complexity and improve margin resilience. In this sense, the cost story is not only about reacting to price increases; it is about engineering the product portfolio and manufacturing flow to tolerate volatility while preserving performance integrity.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of established electronics and components manufacturers with distinct positioning strategies. Panasonic Corporation has built a broad offering around its proprietary PhotoMOS MOSFET-based optically isolated semiconductor relays, with a wide variant range designed to cover automation, automotive, and high-frequency switching needs. Its emphasis on low leakage and stable on-resistance reflects a focus on predictable switching behavior across diverse application conditions. The breadth of variants supports integrators who need multiple specification points within a consistent family, reducing design fragmentation and simplifying substitution decisions.
PhotoMos Relays Market
OMRON Corporation positions its MOSFET relay line around optical semiconductor technology that combines LED input, photodiode array detection, and MOSFET output for non-contact signal and power switching. This framing emphasizes the isolation mechanism and the resulting contactless operation, appealing to applications where switching reliability and isolation clarity are central to the design rationale. OMRON’s strategy appears to lean on integration ease and application breadth, providing engineers with drop-in options that align with established industrial and instrumentation workflows.
Toshiba Electronic Devices & Storage Corporation has focused on photorelays with MOSFET output, including voltage-driven models and high-temperature variants tailored for semiconductor testers, electric vehicles, and high-frequency applications. Its recent push into small packages with elevated temperature ratings illustrates a clear strategic move toward thermally demanding and space-constrained deployments. By targeting automotive and industrial equipment with devices that can withstand higher operating temperatures, Toshiba is positioning itself in segments where qualification durability and package efficiency translate directly into commercial advantage.
Littelfuse, Inc. brings an optically isolated MOSFET power relay portfolio aimed at DC switching in motors, medical systems, robotics, and vehicles, with emphasis on high isolation and current handling. This positioning underscores the power-handling side of the market, where the value proposition extends beyond signal switching to scenarios requiring robust current transfer under isolated conditions. Littelfuse’s focus on power-centric applications complements the broader signal-switching emphasis seen elsewhere, indicating that competition is not monolithic but segmented by performance emphasis and end-use fit.
Strategic Positioning and Differentiation
Across these leaders, differentiation is emerging along three axes: portfolio breadth, application qualification readiness, and packaging efficiency. Broad variant families reduce customer integration effort and create switching costs that favor incumbents. High-temperature and voltage-driven models address the exacting requirements of automotive and industrial users, turning thermal endurance into a competitive moat. Compact packaging that preserves isolation and current capability supports density-sensitive designs, which is increasingly important as equipment footprints shrink and thermal management becomes more constrained.
Commercial success in this environment depends on aligning these attributes with real procurement drivers. Engineers do not select relays on datasheet elegance alone; they choose components that clear qualification gates, fit existing layouts, and can be sourced reliably over the product lifecycle. Suppliers that can demonstrate consistent performance across lot variations, provide clear documentation for safety and isolation requirements, and offer practical mechanical compatibility are better placed to convert technical appeal into sustained design wins.
Market Structure Evolution
The market is likely to see a mix of consolidation and targeted specialization. Incumbents with scale advantages will continue to invest in variant breadth, thermal ruggedization, and qualification support, reinforcing their hold on high-volume application areas. At the same time, smaller manufacturers may find the most viable path through niche focus, such as specialized packaging, custom voltage-driven configurations, or application-specific isolation profiles. New entrants typically face steep qualification and documentation hurdles, but targeted innovation in package form factors or substrate efficiency could create entry points where performance-per-cost improves enough to attract design attention. Overall, the concentration profile suggests that scale matters, yet differentiation in qualified performance and supply stability will determine who captures incremental share in faster-growing application pockets.
Future Trends and Commercial Opportunities
Trend 1: Thermal-Ruggedized, Voltage-Driven Devices in Automotive and Heavy-Duty Industrial Use
The demand for relays that can sustain performance at elevated temperatures is expected to strengthen as automotive and industrial equipment designs push into harsher operating envelopes. Voltage-driven photorelays in compact packages with high temperature ratings are well aligned with this direction, and volume adoption is likely to increase as validation cycles mature and supply stabilizes. The commercial opportunity here lies in securing qualified supply, offering design-in support that shortens customer validation time, and building variant coverage that matches the exact voltage and package needs of target platforms. Firms that can pair thermal robustness with reliable volume availability will be positioned to convert specification leadership into design wins.
The risk side of this trend includes qualification lag. Even when devices are technically capable, automotive and heavy-duty industrial programs require extended validation, and any supply inconsistency or lot variation can slow adoption. Thermal claims must be backed by repeatable manufacturing control; otherwise, the promise of high-temperature operation becomes a marketing point rather than a dependable design advantage.
Trend 2: Consolidation Around Supply Stability and Qualification Support
As input costs and energy expenses remain elevated, buyers will increasingly favor suppliers that reduce risk across the procurement lifecycle. This points toward a trend where the winners are not only those with strong datasheet performance but also those with demonstrated supply continuity, clear qualification documentation, and responsive engineering support. Integrating these capabilities into a coherent value proposition will become a central competitive battleground. The opportunity is to reframe the product offering from a component to a reliability package: part selection assistance, documentation readiness, lot consistency, and lifecycle availability.
The uncertainty here is that consolidation pressure can squeeze smaller players who lack scale in substrate sourcing or packaging efficiency. If smaller manufacturers cannot manage cost volatility or demonstrate qualification readiness, they may lose relevance in volume-driven segments even if their technical performance is competitive. The market may therefore prune the long tail of suppliers, leaving a mix of broad-line incumbents and a smaller set of specialized niche players.
Worldwide Opto-Isolators Market
Trend 3: Higher Switching Density and Application-Leveraged Portfolios
Because optically isolated relays reduce mechanical wear and support faster cycling, they are well suited to designs that need more switching points in less space. As automation, telecom power distribution, and medical equipment continue to increase functional density, demand is likely to grow for relay families that are optimized around specific voltage ranges, isolation requirements, and mechanical footprints. The opportunity is to build application-leveraged portfolios: groups of parts that share internal architecture but cover the voltage, current, and package variations that a given application class requires. This reduces customer integration effort and increases the likelihood of multiple design wins within the same end-use segment.
The risk is that over-broad variant proliferation can dilute manufacturing focus and raise complexity costs. The strategic answer is disciplined portfolio design: cover the most commercially relevant specification points with efficient shared architectures, and avoid spreading resources across low-demand variants that add complexity without proportional revenue potential.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize thermal-ruggedized and voltage-driven variants where automotive and heavy-duty industrial demand is expanding, and align package strategy with the compact form factors that density-sensitive designs require.
- Manage substrate and energy cost exposure through disciplined sourcing, yield improvement, and shared architectures that lower per-unit complexity without sacrificing qualification readiness.
- Invest in qualification documentation and application support as part of the product offering, since selection decisions are increasingly influenced by validation ease and supply reliability as much as by raw performance.
For Investors and Strategic Allocators
- Focus on suppliers that combine variant breadth with credible high-temperature and compact packaging roadmaps, because these attributes are most likely to capture demand in faster-growing automotive, industrial automation, and medical device segments.
- Evaluate exposure to input cost volatility and the company’s ability to sustain margins through sourcing discipline, packaging efficiency, and portfolio concentration on commercially relevant specification points.
- Watch for consolidation signals and niche specialization patterns; the market is likely to reward firms that can demonstrate supply continuity and qualification support, while marginal players without these capabilities may face share erosion.
For Procurement and Design-In Teams
- Evaluate optically isolated relays not only on datasheet metrics but also on qualification pathways, lot consistency, documentation readiness, and lifecycle availability, since these factors influence long-term program risk.
- Assess package and voltage compatibility against existing layouts and future density goals, and favor families that reduce the need for multiple discrete parts across similar switching functions.
- Plan for cost-structure variability by engaging suppliers that can provide transparent sourcing strategies and stable volume commitments, particularly for programs with elevated temperature or high-cycle requirements.
The PhotoMOS optically isolated relay market is expanding along a clear trajectory, but the most important competitive questions are no longer about whether the technology is useful. They are about which suppliers can deliver qualified performance reliably, manage cost volatility without eroding margins, and align portfolio design with the application segments that are growing fastest. For decision-makers navigating this landscape, the edge will come from detailed visibility into segment-level demand patterns, regional intensity, qualification requirements, and the specific product roadmaps that incumbents and specialists are advancing.
To map these dynamics at the granularity required for program planning, vendor selection, and investment allocation, a closer look at segmented demand estimates, regional distribution, and company-by-company positioning is essential. A full research report can provide the detailed breakdown needed to translate these strategic themes into specific sourcing decisions, portfolio priorities, and risk assessments.
For detailed analysis of this topic, please visit the official page: PhotoMOS Optically Isolated Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Employee Scheduling Software Market 2026: Why 11.2% CAGR Redefines Growth Strategy
By PW Consulting, 2026-09-21
The Employee Scheduling Software Market: Navigating Growth, Fragmentation, and the AI Inflection Point
The employee scheduling software market has transitioned from a tactical admin utility to a strategic operational layer that directly shapes labor costs, compliance exposure, and service continuity. Revenue across the sector expanded from approximately USD 148.5 million in 2020 to an estimated USD 225.0 million by 2025, reflecting a compound annual growth rate of 11.2% over the 2020–2025 period. Forward projections indicate the market will reach roughly USD 250.7 million in 2026 and continue expanding toward USD 367.0 million by 2032, sustained by the same structural tailwinds that drove the earlier acceleration. This trajectory signals more than incremental software adoption; it reflects a fundamental rethinking of how organizations translate demand volatility into shift coverage while controlling overtime, reducing compliance risk, and preserving employee experience.
The growth curve is not uniform. Cloud-based deployment continues to dominate new implementations, while on-premises footprints are shrinking as organizations migrate toward integrated platforms that connect scheduling with payroll, time tracking, and workforce analytics. Mid-size enterprises and small businesses together account for the largest share of adoption volume, driven by the need for affordable, mobile-first tools that can scale without dedicated HRIT teams. Large enterprises are pursuing fewer but deeper deployments, prioritizing forecasting accuracy, multi-site orchestration, and integration with broader HCM ecosystems. Geography also matters: North America remains the largest revenue center, Europe follows with strong compliance-led demand, and Asia Pacific is emerging as the fastest-expanding region as service-sector digitization and flexible staffing models accelerate.
Defining the Current Inflection Points
Despite the expansion, the market sits at a series of crossroads. First, legacy schedulers that rely on static templates and manual overrides are increasingly misaligned with demand patterns characterized by seasonal spikes, last-minute absenteeism, and customer-facing fluctuations. Organizations that continue to manage shifts through spreadsheets or siloed tools face mounting labor mismatches that translate directly into overtime leakage, understaffed service windows, and scheduling friction for employees. Second, compliance complexity is intensifying. Meal-and-rest mandates, overtime thresholds, union rules, and region-specific labor regulations are proliferating, making manual enforcement error-prone and legally risky. Platforms that cannot automate policy enforcement and audit trails are losing relevance in regulated environments. Third, integration expectations are rising. Buyers now assume that a scheduling tool will connect with time and attendance, payroll, demand signals, and workforce analytics without custom middleware. Vendors that remain point solutions risk being bypassed in favor of platforms that can reduce integration debt and administrative fragmentation.
Key Drivers Reshaping the Market
Three to four forces are converging to redefine the value proposition of employee scheduling software, shifting it from convenience to operational leverage.
Technology Innovation and the AI Forecasting Shift
Artificial intelligence has moved from a feature promise to a core differentiator. Modern platforms combine historical attendance, demand signals, seasonality, and employee availability to generate shift forecasts and coverage recommendations that adjust in real time. This matters because scheduling accuracy directly affects labor cost and service quality. Organizations using AI-driven planning and real-time analytics report meaningful reductions in overstaffing and overtime, with customer-reported outcomes pointing to an average 21% decrease in labor costs. At the same time, automated shift planning paired with mobile self-service has been associated with roughly 30% higher shift coverage and 23% lower overtime costs in typical deployments. The strategic implication is clear: scheduling software is increasingly a cost-control and continuity tool, not merely a shift calendar. The vendors winning attention are those that translate forecasting into actionable coverage plans, flag compliance conflicts early, and let employees swap or pick shifts without creating coverage gaps.
Policy and Regulatory Pressure as a Catalyst for Automation
Labor regulation is no longer a static backdrop; it is becoming one of the most powerful adoption drivers. Platforms increasingly embed rules for meal breaks, rest periods, overtime limits, union requirements, and state-specific mandates so that schedule generation and adjustments automatically respect policy boundaries. This reduces legal exposure and administrative burden while giving managers a defensible scheduling process. In parallel, data privacy expectations have hardened, especially for cloud-based tools serving European and regulated markets. Maintaining GDPR and SOC 2 compliance is now table stakes for enterprise buyers, and platforms that can demonstrate consistent controls around data handling, access, and auditability enjoy a shorter sales cycle in sensitive environments. The practical outcome is that compliance automation and privacy assurance are becoming competitive moats, particularly for vendors serving multi-jurisdiction workforces.
Demand-Side Change: Frontline Work Patterns and Employee Expectations
The shape of hourly and frontline work continues to evolve. Service sectors, retail, logistics, healthcare support, and hospitality face demand that fluctuates with weather, seasons, local events, and consumer behavior. Employees, meanwhile, expect greater visibility and control over their schedules, faster shift confirmation, and simpler swap mechanisms. This dual pressure pushes organizations toward scheduling tools that are mobile-first, self-service enabled, and capable of balancing business coverage needs with employee preferences. Mobile clock-in, shift templates, real-time notifications, and team communication features are increasingly expected rather than optional. Companies that ignore the employee experience dimension tend to see higher attrition and last-minute coverage gaps, which in turn inflate labor costs and degrade service consistency.
Worldwide Field Service Software Market
Cost Structure and SaaS Economics Favoring Cloud Deployment
The cost equation favors cloud-based delivery, especially for small and mid-size organizations that lack large internal IT footprints. Subscription economics reduce upfront capital barriers, accelerate deployment, and make it easier to add locations, users, and modules as needs evolve. For larger enterprises, the cloud transition is less about affordability and more about integration and analytics. Centralized data from scheduling, time tracking, and payroll creates visibility into labor cost trends, coverage efficiency, and overtime patterns, enabling more informed workforce planning. This dynamic reinforces the dominance of cloud models in new revenue and explains why on-premises installations are increasingly limited to specialized or legacy environments with strict data residency or operational constraints.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three providers holding roughly 24.6% of revenue and the top five near 26.2%. That leaves substantial room for specialization, regional strength, and segment-focused differentiation. The field spans global HCM-scale platforms, workforce-management specialists, and SMB-oriented mobile tools, each pursuing distinct strategic positions.
Strategic Positioning Among Leading Providers
ADP has built a broad workforce management footprint with ADP Workforce Now, integrating scheduling, time tracking, shift optimization, and compliance tools aimed at hourly and frontline workers. Its strength lies in scale, payroll linkage, and the ability to serve a wide range of organization sizes with a single platform. UKG has pushed enterprise-grade capabilities through UKG Pro and Kronos Workforce Central, emphasizing AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management. The recent expansion of UKG’s integration ecosystem underscores a platform strategy: in March 2026, it introduced 15 Workforce Management APIs to streamline connections with scheduling and time-tracking platforms, reflecting a recognition that interoperability now shapes buying decisions. Ceridian Dayforce positions around a unified platform for global enterprises, combining scheduling, shift assignment, workforce analytics, and automated compliance within a single system, appealing to organizations that want consistency across regions and functions.
Rippling targets growing businesses with an integrated HR and workforce management suite that links scheduling, AI demand forecasting, shift planning, and payroll, reducing the friction of juggling separate tools. Deputy remains focused on shift-based industries with AI labor forecasting, mobile apps, and compliance automation, a model that resonates in retail, hospitality, and light industrial settings. Connecteam and Homebase emphasize SMB usability through app-based scheduling, shift swapping, mobile clock-in, labor cost tracking, and compliance alerts, competing on ease of adoption and day-to-day usability. Paychex Flex and Paycor extend mid-market reach by tying scheduling to payroll and HCM dashboards, providing labor cost visibility and shift management within broader HR processes. When I Work emphasizes employee self-scheduling and real-time reporting, a straightforward value proposition for teams that want flexibility without administrative overhead. Workday brings enterprise HCM depth with advanced scheduling, demand forecasting, and compliance-driven workforce planning for large organizations. Finally, TCP Software and Shiftboard highlight highly operational niches: automated forecasting, mobile management, fatigue management, contingent labor tools, and labor cost reduction for mission-critical environments, where coverage assurance and risk control outweigh convenience alone.
Nurse Scheduling Software Market
How the Landscape Is Evolving
Three trends are reshaping the competitive structure. Integration is becoming a default expectation rather than a differentiator, pushing vendors to offer APIs, prebuilt connectors, and data flows that tie scheduling into payroll, analytics, and demand systems. At the same time, specialization is intensifying in high-stakes segments such as healthcare support, logistics, manufacturing, and other environments where fatigue management, compliance enforcement, and contingent labor coordination carry direct operational and safety implications. A third dynamic is the steady arrival of well-funded new entrants that lean into mobile-first design, AI forecasting, and SMB affordability, expanding choice but also fragmenting attention for buyers. The net result is a market that rewards clear positioning: platforms that can demonstrate measurable coverage improvements, labor cost control, and compliance automation within a buyer’s existing technology stack are gaining traction, while undifferentiated schedulers are facing longer evaluation cycles and stricter comparison criteria.
Forward-Looking Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to determine where value accrues and where new opportunities emerge.
AI-First Scheduling Becomes the Operational Standard
Forecasting and real-time adjustment will become embedded baseline capabilities rather than premium add-ons. As models improve with richer attendance history, demand signals, and policy constraints, organizations will expect scheduling systems to anticipate coverage gaps, recommend shift fills, and flag labor cost risks before shifts are published. The commercial opportunity lies in solutions that connect forecasting with execution: auto-suggested shifts, mobile acceptance flows, and manager dashboards that make actionable decisions fast. Vendors that can show defensible improvements in coverage and overtime—with clear measurement frameworks—will find it easier to justify expansion and renewals.
Compliance Automation as a Core Buying Criterion
The regulatory environment will continue to reward platforms that can encode rules, enforce them at schedule creation, produce audit-ready documentation, and adapt quickly to changing requirements. This is particularly relevant for multi-state, multi-jurisdiction, and unionized workforces. The opportunity for providers is to package policy guidance, rule templates, and document support as part of the workflow rather than as separate services. Organizations that treat compliance automation as a design principle—rather than a retroactive fix—will reduce legal exposure and administrative effort while strengthening employee trust in the scheduling process.
Integration Ecosystems and Workforce Data Platforms
The future value chain is increasingly interoperable. Scheduling will connect more tightly with time and attendance, payroll, labor analytics, and demand planning, creating a more complete view of workforce costs and coverage. Buyers will favor solutions that minimize custom integration work and enable data to move cleanly between functions. This opens opportunities for platforms that act as orchestration layers, standardize data models, and provide APIs that accelerate deployments and reduce total cost of ownership. For enterprises, the prize is workforce visibility that supports planning beyond individual shifts: staffing models, labor budgets, and service-level commitments aligned with realistic demand.
These trends carry uncertainty. AI adoption depends on data quality and change management; inaccurate inputs or poorly governed models can erode trust and limit realized savings. Compliance expectations can shift quickly, requiring vendors and buyers alike to keep pace with new rules and interpretations. Integration depth can also become a double-edged sword: over-engineaging ecosystems may complicate deployments, while under-integrated tools may fail to meet enterprise expectations. Finally, pricing pressure is likely to intensify as more competitors offer AI features at competitive price points, making it essential for providers to differentiate on outcomes, not just feature lists.
Strategic Actions for Decision-Makers
The market’s direction suggests several practical moves, tailored to different roles in the value chain.
PW Consulting Information & Electronics Research Center
-
For enterprise and mid-market buyers evaluating scheduling software: prioritize platforms that link scheduling with payroll and time tracking, enforce compliance rules automatically, and provide measurable coverage and labor-cost outcomes. Run pilots that test forecasting accuracy under real demand variability, not just idealized scenarios. Confirm that the solution supports mobile self-service, shift swaps, and rapid manager overrides without creating policy violations. Assess integration effort early, because hidden middleware and data cleanup can turn a low-cost tool into a high-friction deployment.
-
For investors and strategic partners: focus on providers with credible AI forecasting, strong compliance automation, and clear integration roadmaps, especially those demonstrating repeatable labor-cost reductions and coverage improvements in target verticals. The highest-conviction opportunities are likely in platforms that can serve shift-based and mission-critical environments at scale while maintaining data-privacy assurance for regulated markets. Watch for consolidation signals, since interoperability demands and integration fatigue may drive buyers toward platforms that can unify functions and reduce vendor count.
- For vendors and product leaders: invest in measurable outcome claims, not just feature breadth. Make compliance automation, auditability, and privacy controls visible and easy to validate. Build integration pathways that reduce deployment time and data fragmentation, and design mobile self-service experiences that improve employee adoption while protecting coverage integrity. Differentiation will increasingly come from how well a platform reduces overtime leakage, improves shift coverage, and keeps schedules within policy boundaries without adding manager workload.
The employee scheduling software market is moving from incremental digitization to a more outcome-driven phase in which forecasting accuracy, compliance automation, and integration maturity determine competitive strength. For organizations navigating shifting labor patterns and rising regulatory complexity, the question is no longer whether to adopt scheduling software, but which platform can convert schedule planning into lower labor costs, fewer compliance risks, and more reliable coverage. Detailed segmentation data, vendor-by-vendor benchmarks, and customized adoption roadmaps can sharpen those decisions further; PW Consulting’s full research report provides that deeper breakdown for teams preparing investment, procurement, or product strategy choices in this space.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polymer Capacitor Market at 8.2% CAGR: What 2032 Growth and Consumer Electronics Demand Really Signal
By PW Consulting, 2026-09-21
The Polymer Capacitor Market: Strategic Trends and Commercial Opportunities Through 2032
The global polymer capacitor market stands at a pivotal inflection point. From 2020 to 2025, total market revenue expanded from approximately 163.15 million to 215.0 million, reflecting steady growth across multiple end-use sectors. Looking ahead, the trajectory accelerates, with the market projected to reach 344.8 million by 2032, delivering a compound annual growth rate of 8.2 percent over the 2026 to 2032 forecast period. These numbers signal more than incremental expansion; they reflect a structural shift in how electronics manufacturers, automotive system designers, and industrial equipment engineers approach power management and signal integrity.
Beneath the headline figures lies a fragmented yet increasingly strategic competitive arena. The top three players collectively account for 24.6 percent of market revenue, while the top five capture 26.2 percent. This moderate concentration suggests room for differentiation, regional specialization, and technology-led positioning rather than pure scale dominance. For executives and investors evaluating the space, the question is no longer whether polymer capacitors will grow, but which sub-segments, applications, and supply chain strategies will capture disproportionate value as the market matures.
Market Dynamics and Structural Challenges
The polymer capacitor sector operates within a broader passive component ecosystem that is simultaneously experiencing demand surges, material constraints, and tightening qualification standards. Three interconnected challenges define the current landscape and will shape competitive outcomes over the next several years.
Balancing Miniaturization With Reliability Expectations
Design engineers across consumer electronics, automotive, and industrial applications continue pushing for smaller form factors while demanding higher ripple current tolerance, lower ESR, and extended operational lifespans. Polymer capacitors inherently address many of these requirements through conductive polymer electrolyte technology, but the pressure to reduce profile dimensions without compromising thermal stability or moisture resistance creates genuine engineering tension. Manufacturers that can deliver low-profile solutions while maintaining certification-ready performance metrics gain a clear advantage in qualification cycles and design-in opportunities.
PW Consulting Information & Electronics Research Center
Material Cost Volatility and Pricing Pressures
Cost structures across the passive component supply chain have faced sustained upward pressure, particularly in tantalum-based polymer lines. Industry pricing adjustments took effect in mid-2024 as manufacturers cited rising material input costs, and those dynamics have persisted into subsequent quarters. For product planners and procurement teams, this translates into longer hedging windows, tighter inventory buffers, and increased sensitivity to raw material availability. Suppliers with vertically integrated material strategies or diversified polymer formulations are better positioned to manage margin erosion while maintaining competitive pricing.
Qualification Rigor and Customer-Specific Validation Cycles
Automotive and high-reliability industrial applications now require stricter validation protocols. Compliance with AEC-Q200 qualification remains a baseline expectation for automotive polymer capacitors, ensuring consistent performance in electric vehicle power systems and related subsystems. Beyond automotive, industrial-grade polymer products increasingly face moisture-resistance benchmarking at elevated temperature and humidity conditions over extended durations. These qualification thresholds extend time-to-market for new part numbers and raise the barrier for generic commodity players. Companies that invest early in robust qualification dossiers and maintain transparent reliability data shorten customer design cycles and strengthen long-term supply agreements.
Supply chain timing further complicates planning. Across all capacitor technologies, average lead times have hovered around 19 weeks as of late 2025, reinforcing the importance of stable production scheduling and proactive capacity alignment. For buyers, this means demand forecasting and supplier diversification are no longer optional procurement best practices; they are operational necessities.
Core Drivers Shaping Market Trajectory
Several overlapping forces explain why polymer capacitors are capturing growing share across multiple end markets. Understanding these drivers helps decision-makers distinguish structural growth from cyclical demand swings.
Technology Innovation and Form-Factor Engineering
The most visible product-level evolution centers on profile reduction, thermal endurance, and ripple current performance. Recent commercial introductions illustrate how manufacturers are aligning advanced materials with application-specific constraints. In late 2025, Panasonic Industry began commercial production of conductive polymer tantalum solid capacitors with an industry-leading 3 mm profile, targeting USB Type-C power delivery architectures where space and current handling are equally critical. Around the same period, Taiyo Yuden commercialized hybrid aluminum electrolytic capacitor series engineered for higher rated ripple current and reduced profile, specifically addressing automotive ADAS and power steering applications. These launches reflect a broader pattern: manufacturers are not simply scaling existing designs, they are engineering product families around real-world system constraints such as board space, thermal environment, and power delivery topology.
Nichicon’s recent activity reinforces this trend from a thermal-reliability angle. The company introduced a highly heat-resistant conductive polymer hybrid aluminum electrolytic series capable of sustaining 4000 hours at 135°C, alongside automotive-rated hybrid capacitor series distributed across EMEA channels. High-temperature endurance directly supports automotive under-hood and near-power-electronics placements, where long-term degradation profiles determine component selection. Similarly, Nichicon’s broader portfolio emphasis on conductive polymer hybrid aluminum electrolytic and solid capacitors with elevated temperature ratings signals a strategy centered on reliability differentiation rather than cost-only competition.
Application-Side Demand Transformation
Consumer electronics remain the largest application anchor for polymer capacitors, driven by compact power systems, wireless charging, high-density motherboard designs, and ever-increasing power conversion requirements in portable devices. However, the most strategically significant demand shift is occurring in automotive electrification and advanced driver-assistance architectures. As vehicle power systems become more complex and electronics content per platform rises, polymer capacitors are increasingly integrated into DC-DC conversion stages, noise filtering networks, and decoupling arrangements that must tolerate fluctuating thermal and vibration environments.
Industrial automation, renewable energy inverters, and high-reliability infrastructure equipment also contribute to demand diversification. These sectors prioritize long service life, stability under continuous load, and qualification documentation over lowest-unit-cost sourcing. The result is a demand landscape that rewards suppliers capable of matching application-specific performance profiles, not merely volume capacity.
Regulatory, Qualification, and Standardization Pressure
Qualification frameworks and environmental reliability benchmarks increasingly shape purchasing decisions. AEC-Q200 continues to serve as the foundational reliability standard for automotive-grade polymer capacitors, while industrial product expectations have evolved toward stricter moisture and thermal endurance testing. These standards create a two-tier market dynamic: commodity-grade applications tolerate broader performance variance, while automotive and industrial buyers reward proven qualification records and traceable reliability data.
Standardization also influences supply chain behavior. When qualification requirements become more uniform across tier customers, manufacturers with established validation infrastructure gain efficiencies in documentation, testing throughput, and customer onboarding. Those without dedicated qualification capabilities face longer approval timelines and higher rejection risk, particularly in safety-related or mission-critical subsystems.
Supply Chain Resilience and Material Strategy
Recent pricing actions across tantalum-based polymer capacitors underscore the importance of material resilience. Rising input costs have prompted manufacturers to reassess sourcing strategies, formulation alternatives, and inventory positioning. At the same time, lead time elongation across capacitor technologies has reinforced the value of multi-source arrangements and forecast-aligned production planning.
For incumbent suppliers, the response has included hybrid capacitor architectures that combine conductive polymer benefits with aluminum electrolytic structural familiarity, offering a balance of performance and manufacturability. For buyers, this environment emphasizes the need to evaluate not only unit price but also manufacturing continuity, qualification coverage, and the supplier’s ability to sustain availability through cost cycles.
Competitive Landscape and Strategic Positioning
The polymer capacitor market features a mix of established Japanese manufacturers, U.S.-based specialty players, European component specialists, and Taiwan-based producers with regional manufacturing advantages. Despite moderate top-tier concentration, competitive differentiation is increasingly driven by product architecture, application targeting, and qualification readiness rather than broad commoditization.
KYOCERA AVX Components Corporation has positioned itself around conductive polymer solid electrolytic capacitors with notable attention to automotive and high-reliability segments. Its portfolio includes TCO and TCQ automotive series, high-reliability hermetically sealed polymers, and COTS+ military-grade tantalum polymer lines. This mix suggests a strategy that leans into reliability-grade differentiation and application-specific series development rather than volume-only competition.
Panasonic Industry Co., Ltd. maintains a broad polymer capacitor portfolio spanning conductive polymer aluminum electrolytic, tantalum solid, aluminum solid, and hybrid aluminum electrolytic capacitors. Its recent product activity emphasizes profile reduction for power delivery applications, aligning with consumer and computing trends that prize compact form factors without sacrificing current-handling capability.
Murata Manufacturing Co., Ltd. continues to leverage its broader passive component ecosystem, offering conductive polymer aluminum electrolytic and solid capacitors for automotive, industrial, and high-reliability applications. The company’s positioning benefits from integration with adjacent component categories and a strong design-in support structure across multiple end markets.
Nippon Chemi-Con Corporation has expanded its polymer capacitor emphasis through high-voltage series, liquid immersion cooling-oriented series, and hybrid models. The inclusion of high-voltage and cooling-specific product lines indicates attention to power electronics and industrial applications where voltage stress and thermal management are key selection criteria.
Nichicon Corporation has pursued a reliability-led strategy, highlighting conductive polymer hybrid aluminum electrolytic and solid capacitors with high-temperature ratings. Its recent automotive-rated series and heat-resistant product introductions reinforce a focus on application-grade durability, particularly relevant for automotive and industrial environments with sustained thermal exposure.
Rubycon Corporation and Lelon Electronics Corp. provide conductive polymer aluminum electrolytic solutions for general and automotive use. Their market roles illustrate how regional and mid-tier manufacturers compete by combining cost-competitiveness with targeted application support, rather than attempting to match the broadest portfolio breadth of larger incumbents.
Vishay Intertechnology, Inc. extends its presence through polymer tantalum and aluminum solid electrolytic capacitors for industrial, automotive, and aerospace applications. Its positioning reflects the demands of sectors where qualification rigor, material traceability, and reliability documentation carry significant commercial weight.
Würth Elektronik GmbH & Co. KG competes with aluminum polymer electrolytic capacitors and radial series, aligning with the broader European component distribution and design ecosystem. ROHM Co., Ltd. rounds out the competitive field with polymer tantalum and aluminum solid electrolytic capacitors following integration of related business assets, indicating continued consolidation and portfolio rationalization across the sector.
Several competitive themes emerge from this landscape. First, differentiation is shifting from generic capacitance ranges toward application-optimized families with defined thermal, profile, and ripple current characteristics. Second, hybrid architectures are gaining prominence because they combine polymer-level ESR and ripple performance with structural and manufacturing familiarity. Third, the market is unlikely to consolidate rapidly into a single dominant structure; instead, it will likely evolve into a tiered ecosystem where automotive and high-reliability applications favor qualified incumbents, while consumer and general-purpose segments remain more price-sensitive and accessible to multiple suppliers.
Recent product introductions also suggest that regional channel strategies matter. Automotive-rated series launched across EMEA channels highlight the importance of localized qualification support, distribution partnerships, and application engineering availability. Suppliers that can demonstrate consistent technical support across geographies are better positioned to secure design wins in regions where automotive and industrial sourcing decisions are highly relationship and qualification driven.
Forward Outlook: Trends and Opportunities Through 2032
Extrapolating current growth dynamics, qualification momentum, and product innovation patterns points to several interrelated trends that will shape commercial opportunities over the next three to five years.
Trend 1: Application-Specific Polymer Capacitor Families Will Displace One-Size-Fits-All Sourcing
As system designers face tighter thermal envelopes, higher power densities, and more demanding reliability thresholds, generic capacitor specifications will become less persuasive. Buyers will increasingly evaluate parts against application-level benchmarks such as thermal endurance, ripple current capability, profile constraints, and qualification documentation. Suppliers that publish clear application 매핑 and maintain robust reliability data will capture more design-ins, particularly in automotive and industrial segments where failure cost is high.
Commercial opportunity: Companies that invest in application engineering, reference designs, and qualification-ready documentation can shorten customer evaluation cycles and build longer-term supply relationships. This creates a defensible position even in a moderately concentrated market.
Trend 2: Hybrid and Advanced Polymer Formulations Will Broaden Performance Windows
Hybrid aluminum electrolytic structures and advanced conductive polymer formulations will continue to expand the balance between ESR reduction, temperature stability, and manufacturability. These architectures are particularly relevant where designers need polymer-level electrical performance without abandoning aluminum-based mechanical or cost advantages. The ongoing appearance of hybrid-oriented product launches supports the view that this direction is not a niche experiment but a mainstream performance strategy.
Commercial opportunity: Product planners should monitor hybrid and advanced polymer lines as potential candidates for next-generation power delivery, noise filtering, and decoupling designs. Early engagement with suppliers offering these architectures can provide first-mover advantages in demanding applications.
Trend 3: Automotive Electrification and High-Reliability Industrial Demand Will Drive Sustained Volume Growth, With Qualification as the Gatekeeper
Conductive Polymer Aluminum Solid Capacitors Market
The 8.2 percent CAGR projected through 2032 reflects more than cyclical replacement demand; it reflects a structural increase in electronics content across vehicles, industrial equipment, and energy-related infrastructure. Automotive platforms in particular will continue placing higher capacitor content per vehicle as power management architectures grow more decentralized and more performance-critical. At the same time, qualification requirements will remain the commercial gatekeeper, meaning that volume growth will disproportionately flow to suppliers with credible reliability records and efficient validation processes.
Commercial opportunity: Suppliers that build automotive and industrial qualification capabilities early can secure longer design cycles and multi-program visibility. For buyers, prioritizing qualification readiness and supply continuity over short-term unit cost can reduce downstream risk in safety-related or mission-critical designs.
Vacuum Capacitor Market
Risk and Uncertainty Considerations
Several uncertainties could alter this trajectory. Material cost volatility may persist, affecting tantalum-based and other polymer lines unevenly. Lead time normalization is not guaranteed; supply disruptions, capacity constraints, or sudden demand shifts could reintroduce planning friction. Qualification expectations may continue to tighten, compressing timelines for new entrants and rewarding incumbents with established testing infrastructure. Finally, competitive overcapacity in certain commodity-grade segments could pressure pricing, even as qualified automotive and industrial segments remain more resilient. Decision-makers should therefore treat the polymer capacitor market as a portfolio of differentiated sub-segments rather than a single homogeneous opportunity.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities in this environment. The following actions are designed to translate market dynamics into executable planning.
For Manufacturers and Component Suppliers
- Prioritize application-specific product families that address profile, thermal endurance, and ripple current requirements simultaneously rather than competing solely on capacitance range or unit cost.
- Strengthen qualification documentation and reliability data packages, especially for automotive and industrial customers where AEC-Q200 and extended environmental testing are baseline expectations.
- Evaluate hybrid and advanced polymer formulations as a way to expand performance differentiation while maintaining manufacturability and cost discipline.
- Align production planning and inventory strategy with current lead-time realities, and consider multi-source options where qualification and performance allow.
For Investors and Strategic Allocators
- Focus due diligence on suppliers with credible automotive and high-reliability qualification footprints, because those segments are likely to capture disproportionate value even in a moderately concentrated market.
- Assess exposure to material cost sensitivity and pricing actions across tantalum and aluminum polymer lines, and weigh vertical integration or formulation diversification as risk-mitigation indicators.
- Watch for portfolio consolidation and asset integration activity that may reshape competitive positioning, especially where adjacent business assets are combined to strengthen polymer capacitor capabilities.
For Procurement, Engineering, and Supply Chain Leaders
- Treat qualification status, thermal performance, profile constraints, and supply continuity as core evaluation criteria alongside price, particularly for automotive and industrial designs.
- Diversify approved sources where application requirements permit, while maintaining clear qualification thresholds to avoid fragmented validation burden.
- Engage suppliers early in the design phase to align on reliability testing, documentation, and lead-time expectations, reducing the risk of late-stage redesign or sourcing disruption.
The polymer capacitor market is expanding with clarity in direction but complexity in execution. Growth will continue toward 344.8 million by 2032, but the value capture will depend on how well companies align product engineering, qualification readiness, and supply resilience with the application needs that matter most. For organizations seeking deeper segmentation data, regional positioning detail, and tailored strategy recommendations, the full PW Consulting research report provides the granular breakdown and scenario analysis needed to convert these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Textile Chemicals Market 2026: Beyond the 4.8% CAGR and Asia Pacific’s $15.4B Pull
By PW Consulting, 2026-09-21
The Textile Chemicals Market: Strategic Shifts and Commercial Opportunities Through 2032
The textile chemicals sector has entered a phase of structural recalibration. After a decade of steady volume growth underpinned by expanding apparel production and industrial fabric consumption, the market is now being reshaped by tighter environmental mandates, evolving consumer expectations, and technological breakthroughs that are redefining how fibers are treated, dyed, and finished. For executives, investors, and procurement leaders, the central question is no longer whether demand will grow, but where value will concentrate and which capabilities will separate winners from laggards in the coming years.
The global market for textile chemicals has reached a valuation of approximately 30 billion USD in 2025, representing a measured acceleration from roughly 21.5 billion USD in 2020. Over the 2020 to 2025 period, revenue expanded at a compound trajectory that reflects both post-pandemic recovery and the steady integration of chemical solutions across garment, home textile, and technical fabric supply chains. Looking ahead to 2032, the market is projected to surpass 41 billion USD, driven by a compound annual growth rate averaging 4.8 percent. While this growth rate signals resilience, it also indicates that the era of unconstrained volume expansion is giving way to a more selective, regulation-aware, and performance-driven landscape. Value creation will increasingly depend on how effectively companies navigate compliance complexity, capture premium segments, and align product portfolios with sustainability and circularity mandates.
Market Reality and Critical Inflection Points
The headline growth figures mask underlying tensions that are already reshaping competitive dynamics. Three interlocking challenges define the current inflection point for the sector.
First, regulatory intensity is shifting from voluntary best practices to enforceable, auditable standards. Chemical input approval criteria, substance restriction lists, and wastewater discharge targets are no longer confined to niche certifications. They are cascading through procurement contracts, brand compliance programs, and regional market access requirements. Companies that treat compliance as a retrospective documentation exercise are finding themselves locked out of premium accounts or forced into costly reformulation cycles. The regulatory wave is compressing margins for undifferentiated products while rewarding firms that have built formulation transparency and substitution capability into their R&D workflows.
Second, the cost and availability of conventional chemical building blocks remain structurally uncertain. Feedstock volatility, energy price swings, and shifting trade flows have disrupted the predictability that many formulators relied on for cost planning. At the same time, the transition toward lower-impact and bio-based alternatives introduces new input economics that can be higher in the short term. The practical consequence is that pricing strategies based solely on historical material costs are increasingly brittle. Businesses that succeed are those that combine multi-source sourcing, formulation flexibility, and service-level agreements that share risk more intelligently across the value chain.
Textile Dyes Market
Third, customer expectations are bifurcating the market. Mass-market segments continue to pressure suppliers for cost efficiency and reliable delivery, while premium and performance-oriented segments demand demonstrable environmental attributes, functional performance in demanding applications, and traceability. This polarization makes portfolio strategy decisive. Suppliers that attempt to serve all segments with a uniform offering risk being commoditized in the low end while failing to capture the margin in the high end. Those that can clearly segment their value proposition, back claims with verified data, and align service models accordingly are better positioned to defend pricing and deepen customer relationships.
Key Drivers Reshaping the Landscape
Understanding where growth and margin will concentrate requires looking past top-line volume to the forces that are changing how textile chemicals are developed, approved, and deployed.
Technological innovation and formulation breakthroughs. Advances in low-temperature dyeing, enzyme-assisted pretreatment, waterless or reduced-water finishing, and digital color matching are steadily reducing resource intensity while improving reproducibility. Digital tools are also enabling faster formula optimization and more precise dosing, which directly lowers wastewater load and chemical waste. These innovations matter commercially because they translate environmental performance into operational savings that customers can verify. Suppliers that embed these capabilities into ready-to-adopt process packages, rather than offering only raw ingredients, are building stickier relationships and gaining pricing power.
Policy and regulatory environment. The regulatory framework is tightening across multiple jurisdictions, with substance restrictions, organic textile chemical criteria, and endocrine disruptor limits all moving toward stricter thresholds and broader coverage. Recent updates to major standards have introduced lower limits for certain substances, expanded the list of regulated compounds, and added mandatory due diligence expectations for chemicals used in organic fiber production. In parallel, regional legislation targeting specific chemical families in textiles, clothing, footwear, and waterproofing agents has moved into force or toward implementation, with exemptions limited to specific recycled or industrial use cases. For suppliers, the strategic implication is clear: product stewardship is now a market-access requirement. Formulation roadmaps must anticipate substitution needs, documentation must meet audit expectations, and technical support must help customers navigate compliance without disrupting production.
Demand-side behavior. Brands and manufacturers are increasingly tying procurement decisions to measurable sustainability outcomes and risk reduction. Consumer-facing claims are being scrutinized more closely, which pushes upstream suppliers to provide credible, standardized evidence rather than marketing narratives. At the same time, the rise of technical textiles and high-performance applications is expanding demand for chemicals that deliver specific functionalities such as durability, moisture management, antimicrobial action, or flame resistance, often with tighter environmental profiles. This dual pressure rewards suppliers that can combine performance with verifiable attributes and that can support customers in meeting both internal targets and external claims.
Supply chain and cost structure realignment. Geographic concentration of production, logistics bottlenecks, and evolving trade dynamics have encouraged buyers to diversify sources and favor suppliers with regional presence or strong distribution networks. Distributors and integrated suppliers that can guarantee continuity, offer technical troubleshooting, and consolidate multiple chemical needs into a single interface are gaining importance, particularly for smaller and mid-sized processors. The cost structure is also being reshaped by the premium attached to compliant, lower-impact chemistries and by the operational savings that come from more efficient application processes. Businesses that can articulate total cost of ownership rather than unit price are better equipped to navigate these shifts.
The Competitive Field: Positioning, Differentiation, and Evolution
The market remains moderately concentrated, with the largest players holding a meaningful share of total revenue while significant space remains for specialized and regional players. This structure favors a dual strategy: scale players compete on broad portfolios, global reach, and technical service infrastructure, while specialists compete on deep application knowledge, niche performance attributes, and agility in formulation.
Fine Chemicals Market
Archroma occupies a prominent position as a global provider of sustainable dyes, colorants, and performance chemicals tailored to dyeing, finishing, and printing applications. Its differentiation rests on a strong sustainability narrative backed by product development focused on reduced environmental impact and process efficiency, combined with the ability to serve large, multi-site customers with consistent standards.
Huntsman Textile Effects, with operations spanning Switzerland and Germany, focuses on functional dyes, finishing chemicals, and performance solutions. Its strength lies in blending application expertise with high-performance outcomes, allowing it to address demanding end-use requirements while supporting customers in meeting quality and compliance expectations.
CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing. Its positioning emphasizes depth in application know-how and a focused specialty portfolio, which enables close collaboration with processors seeking tailored solutions rather than broad commodity offerings.
Azelis operates as a distributor and integrated supplier across dyes, bleaching agents, pretreatment chemicals, and finishing solutions. Its competitive advantage comes from network reach, inventory continuity, and the ability to bundle technical support with supply reliability, an increasingly valuable proposition for customers managing complex compliance and sourcing requirements.
On the Asia-centric side, NICCA Chemical stands as Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, leveraging strong process expertise and a reputation for quality and reliability. Sarex Chemicals and Fineotex Chemical, both based in India, contribute specialist coverage across auxiliaries, pretreatment, dyeing, printing, and finishing. Their relevance lies in serving full value-chain needs with regional cost structures, local technical presence, and the ability to support high-volume production environments that demand consistent availability and practical process support.
The competitive landscape is evolving along three trajectories. Consolidation continues to favor larger players that can integrate R&D, compliance documentation, and global service delivery, particularly as customers seek fewer, more accountable partners. At the same time, fragmentation remains viable for specialists that can dominate specific application niches, offer differentiated performance, or provide rapid regional responsiveness. A third dynamic is the growing role of events and platforms that concentrate the industry's attention on chemicals and dyes. The launch of a dedicated Textile Chemicals and Dyes product segment at a major international trade fair, featuring more than 30 exhibitors across dyes, auxiliaries, functional finishes, and polymer technologies, signals that chemical solutions are being elevated from supporting inputs to strategic showcase categories. Early booking windows and confirmed participation from established players further indicate that the segment is becoming a focal point for partnership formation, product launches, and market signaling. Regional expos centered on textile chemicals and auxiliaries continue to reinforce the importance of Asia as both a manufacturing base and a sourcing hub, where proximity, cost, and technical support intersect.
Forward Outlook: Three Trends Shaping 2026 to 2032
The combination of regulation, technology, and demand evolution points to a set of trends that will define commercial opportunities over the next several years.
Compliance-driven reformulation will become a recurring revenue stream rather than a one-time project. As substance restrictions tighten, due diligence expectations expand, and wastewater guidelines grow more prescriptive, processors will need ongoing support to maintain market access. This creates sustained demand for alternative chemistries, testing support, documentation services, and process adjustments. The commercial opportunity lies not only in new molecules but in service architectures that help customers stay ahead of change. Suppliers that anticipate regulatory trajectories and pre-develop substitute portfolios will capture switching demand before competitors react. The risk is that compliance becomes a reactive cost center if firms lack foresight, leading to rushed substitutions, production disruptions, and eroded trust.
Performance and sustainability will increasingly converge in premium segments. Functional finishes, durable properties, and reduced-impact processing are moving from separate considerations to combined requirements. Customers want chemicals that deliver specific end-use performance without undermining environmental targets, and they expect evidence that can satisfy both internal procurement criteria and external claims. This convergence favors suppliers that can bundle functional chemistry with application engineering and verified attribute data. The upside is margin expansion in segments where differentiation is defensible. The uncertainty is that verification standards and claim scrutiny will continue to rise, which raises the bar for substantiation and can slow adoption if proof points are weak.
Regional service models and distribution strength will matter as much as product formulations. As procurement teams diversify sourcing and tighten continuity requirements, the ability to deliver reliably, troubleshoot locally, and consolidate multiple needs into a coherent package becomes a differentiator. Distributors and integrated suppliers with strong regional footprints can reduce risk for processors that cannot manage complex multi-supplier relationships across borders. This trend supports growth for players that invest in local technical presence, inventory resilience, and responsive service. The downside is that building and maintaining such networks requires capital and operational discipline, and players that over-extend geographically without adequate support infrastructure may struggle to convert reach into profitable relationships.
Strategic Imperatives for Decision-Makers
The choices made over the next twelve to twenty-four months will shape competitiveness through the end of the decade. The following actions are most relevant across the main stakeholder groups.
PW Consulting Information & Electronics Research Center
For manufacturers and formulators. Build a reformulation pipeline that maps current product portfolios against anticipated regulatory thresholds and customer sustainability expectations. Prioritize formulations that lower water, energy, and waste intensity while maintaining or improving performance, because these solutions convert environmental goals into operational savings that customers can measure. Strengthen documentation, testing, and traceability so that claims can withstand audit scrutiny. Segment the portfolio clearly between cost-competitive essentials and premium performance or sustainability-led offerings, and align sales and technical service teams accordingly so that each segment is supported with the right value narrative and service model.
For investors. Favor business models with defensible differentiation: proprietary formulations paired with verified attributes, strong compliance capability, and regional service reach. Assess exposure to regulatory risk by examining how dependent revenue is on substances likely to face tighter limits, and evaluate whether the company has substitution roadmaps and credible alternatives. Look for evidence that environmental performance is being integrated into product design rather than treated as a separate initiative, since this integration increasingly determines access to premium accounts. Monitor distribution partnerships and technical service capacity, because continuity and support can be the deciding factor in procurement decisions for processors facing compliance and sourcing complexity.
For procurement and buying organizations. Treat chemical selection as a risk-management and total-cost decision rather than a unit-price exercise. Evaluate suppliers on formulation transparency, compliance readiness, substitution capability, and the ability to support process efficiency improvements that reduce resource use and waste. Encourage multi-year collaboration with key suppliers so that reformulation, testing, and documentation can be planned in advance rather than triggered by emergency compliance events. Prioritize suppliers that can provide standardized evidence packages aligned with the certifications and standards relevant to your markets, because this reduces downstream verification friction and strengthens your own claims.
Timely, granular intelligence is essential for executing these actions with precision. Market-level growth rates and segment sizes provide useful context, but the decisions that determine competitive advantage depend on how specific regulations will affect product lines, where substitution demand is emerging earliest, which applications are capturing premium margins, and how distribution and service models are shifting in key regions. A complete research report offers the detailed segmentation, company benchmarking, regulatory mapping, and scenario-based forecasts needed to translate these dynamics into concrete plans. It also provides the granular data and customized recommendations that allow decision-makers to prioritize initiatives, assess risk exposure, and identify the most actionable opportunities for their specific portfolio and geography.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wireless Communication Intelligent Module Market: Why 13.5% CAGR Reshapes Strategy
By PW Consulting, 2026-09-18
The Wireless Communication Intelligent Module Market: Navigating the Next Wave of Connectivity Growth
1. Market Landscape and Core Challenges
The wireless communication intelligent module market has entered a phase of sustained, high-velocity expansion. From 2020 through 2025, the sector compounded at a steady pace, crossing the twenty-five billion dollar threshold in the base year before accelerating into the forecast window. The growth trajectory points toward a double-digit compound annual growth rate through 2032, with revenue projections approaching sixty-two billion dollars by the end of the decade. This expansion reflects a structural shift rather than a cyclical upturn: intelligent modules are transitioning from peripheral connectivity components to core architectural elements in connected products across multiple verticals.
Geographic distribution of revenue reveals a market that is simultaneously mature in developed economies and rapidly scaling in emerging regions. Asia Pacific continues to generate the largest share of global revenue, driven by manufacturing density, consumer electronics demand, and accelerated industrial automation. North America and Europe maintain substantial, stable contributions, supported by automotive adoption, enterprise IoT deployments, and regulated connectivity standards. Latin America and the Middle East and Africa, while smaller in absolute terms, are expanding as infrastructure investment and digital transformation initiatives create new monetization pathways for wireless intelligent modules.
Technology segmentation further illustrates where value is concentrating. Cellular IoT dominates the technology mix, reflecting the broad applicability of licensed-band connectivity for mission-critical, mobility-heavy, and long-range deployments. Wi-Fi and Bluetooth remain essential for short-range, high-throughput, and cost-sensitive applications, particularly in consumer and enterprise environments. Low-power wide-area networks and satellite or ultra-wideband technologies occupy smaller but strategically important positions, enabling niche use cases in remote monitoring, asset tracking, and specialized positioning scenarios. On the application side, automotive and transportation represent the largest demand pool, followed by industrial IoT and consumer electronics. Smart city and utilities, along with healthcare, contribute meaningful but comparatively narrower revenue streams, each with distinct regulatory, reliability, and integration requirements.
Several structural challenges are shaping the market's inflection points. First, the competitive landscape is moderately concentrated, with a small group of established players accounting for the majority of global revenue. This concentration creates both pricing discipline and barriers for newcomers, while also intensifying pressure on incumbents to differentiate through performance, certification breadth, and application-specific optimization. Second, the industry is navigating a transition from volume-driven growth to value-driven design. Customers increasingly demand modules that integrate processing capability, edge intelligence, security features, and multi-standard interoperability rather than standalone connectivity silicon. This shift requires deeper engineering collaboration, longer qualification cycles, and more sophisticated lifecycle management. Third, supply chain and infrastructure dynamics are introducing new cost and timing variables. Rising material and deployment costs in adjacent infrastructure segments, including fiber and broadband construction, indirectly influence the economics of network-dependent modules by shaping rollout timelines and total cost of ownership for end customers.
These pressures do not diminish the market's growth potential; rather, they redefine where competitive advantage will be earned. Companies that align product roadmaps with regulatory momentum, application-specific reliability needs, and cost-aware design will be better positioned to capture share as the market matures. Understanding these inflection points is essential for any organization evaluating product strategy, procurement planning, or investment allocation in the wireless intelligent module space.
2. Key Drivers Shaping Market Trajectory
The market's expansion is not being pulled by a single force. Instead, several interlocking drivers are reinforcing each other, creating a compounding effect on demand, product evolution, and competitive behavior.
PW Consulting Information & Electronics Research Center
Technical innovation remains the most visible driver. Intelligent modules are increasingly defined by their ability to combine connectivity with on-device processing, improved power efficiency, and multi-protocol support. The emergence of reduced-capability cellular variants, such as RedCap, illustrates how the industry is expanding the addressable design space between full-featured 5G modules and low-bandwidth alternatives. These intermediate solutions enable manufacturers to deploy richer sensing, telemetry, and edge-computing functions without the cost and power profiles of flagship cellular platforms. Similarly, the integration of positioning, short-range radios, and cellular capabilities into unified intelligent module architectures is reducing integration complexity for OEMs and system integrators. The practical effect is faster time to market for connected products and a broader set of applications that can justify wireless connectivity in previously cost-sensitive or power-constrained contexts.
Regulatory and spectrum policy dynamics are another powerful catalyst. Authorities in key markets are altering the operating environment in ways that directly affect module demand and design choices. Recent rule changes aimed at easing technology transitions from legacy networks to IP-based infrastructure are reducing friction for operators and enterprises preparing for next-generation connectivity. Parallel efforts to expand the commercial spectrum pipeline create longer-term optimism around capacity, coverage, and new service models that can rely on wireless intelligent modules as enabling hardware. In specific regions, certification pathways and regulatory approvals are also becoming more structured, which helps module suppliers plan product lifecycles and gives end customers greater confidence in long-term support. At the same time, ongoing work to modernize spectrum sharing and allocate mid-band spectrum for advanced wireless services is shaping which standards and frequency bands module developers prioritize in their roadmaps.
Demand-side behavior is evolving as enterprises and consumers reassess what connected products must deliver. Purchasing decisions are increasingly influenced by total cost of ownership, reliability under real operating conditions, and the ability to support future feature upgrades without hardware replacement. In automotive and transportation, connectivity is no longer limited to infotainment or basic telemetry; it is becoming integral to fleet optimization, safety-related communications, and infrastructure interaction. In industrial IoT, the emphasis is shifting toward modules that can withstand harsh environments, maintain secure and deterministic communication, and support integration with analytics and automation workflows. Consumer electronics demand continues to reward compact, energy-efficient, and multi-standard solutions that can serve diverse usage scenarios without fragmenting bill-of-materials complexity. These preferences are pushing module suppliers to offer more application-tailored configurations, reference designs, and certification packages rather than generic connectivity components.
Supply chain and cost structure changes are adding both friction and opportunity. On one hand, input cost volatility and infrastructure deployment pressures in adjacent segments can complicate planning for network-dependent products. Rising material and labor costs in broadband and fiber deployment, for example, can influence rollout pace and indirectly affect the timing of demand for certain connectivity modules. On the other hand, these pressures are encouraging more disciplined design practices, including greater use of standardized form factors, platform-based development, and supplier partnerships that can share qualification risk. Companies that can stabilize lead times, manage component sourcing across regions, and provide clear migration paths between technology generations are gaining trust in segments where downtime or redesign cost is unacceptable.
Taken together, these drivers point to a market in which product excellence, regulatory awareness, and application-specific value creation matter as much as raw connectivity performance. Players that treat intelligent modules as part of a broader system solution, rather than as commoditized radio components, are likely to capture disproportionate value as demand broadens and matures.
3. Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of global specialists, region-rooted scale players, and operator-affiliated or diversified technology firms. The leading companies share a common strategic imperative: build credible application coverage while differentiating on reliability, certification depth, platform integration, and lifecycle support.
Worldwide Wireless Communication Systems Market
Several established players have anchored their positions through broad cellular IoT portfolios and extensive certification footprints. These companies typically compete on the strength of their product breadth across 5G, LTE, low-power wide-area, and positioning technologies, as well as their ability to support automotive, industrial, and enterprise use cases with pre-validated designs. Their advantage often lies in offering customers a predictable migration path across generations, reducing qualification risk, and maintaining long-term availability for deployed systems. In practice, this means leading module suppliers are investing not only in silicon selection but also in firmware support, security frameworks, and regional compliance packages that make it easier for OEMs to scale across markets.
Other strong competitors have built differentiation through specialization. Some focus on high-reliability and security-oriented modules for industries where failure is not an option, emphasizing robust architectures, traceability, and certification for demanding environments. Others concentrate on cost-effective cellular and wireless solutions that address price-sensitive IoT, machine-to-machine, and smart applications, using lean product structures and efficient manufacturing to compete on value. A further group emphasizes embedded wireless modules for consumer electronics, industrial equipment, and automotive applications, leveraging integration expertise and compact form factors to serve design-constrained products. Operator-affiliated providers add yet another angle, drawing on network relationships and shipment scale in cellular IoT to support integrated connectivity solutions.
Recent product and market activity underscores how competition is evolving from catalog expansion to targeted, application-driven launches. In early 2026, multiple companies introduced or expanded 5G-capable modules and platform integrations designed for specific deployment contexts. New 5G NR sub-6 module series with platform-based architectures and railway-ready variants signaled growing attention to mobility, public-transport, and specialized communication standards. Parallel expansions in reduced-capability 5G portfolios reflected efforts to capture mid-tier use cases that need more capability than legacy low-power options but do not require full flagship performance. At the same time, flagship fixed-wireless and CPE-oriented solutions combining advanced 5G modules with high-performance processor platforms showed how module suppliers are increasingly positioning themselves within broader system-level solutions rather than selling connectivity in isolation.
Certification and market-access moves are equally important. Securing regional approvals for LTE Cat 1 bis and similar efficiency-focused modules illustrates how suppliers are building out addressable markets in geographies where cost, power, and coverage trade-offs favor leaner cellular options. Trade show showcases featuring next-generation IoT modules, AI-oriented platforms, and advanced 5G connectivity further highlight the industry's emphasis on embedding intelligence and future-proofing designs for evolving workloads. Collectively, these developments suggest a market where competitive advantage is being earned through a combination of technical readiness, regional compliance, and the ability to align module capabilities with application roadmaps.
Looking at the broader structure, the market appears to be moving toward selective consolidation in certain segments and continued fragmentation in others. In high-volume, standardized segments, scale, cost efficiency, and certification breadth will reward larger, well-resourced players. In specialized or vertically demanding applications, differentiation through reliability, integration, and domain expertise can sustain smaller or more focused competitors. New entrants face a real barrier in certification lead times, supply chain credibility, and the need to demonstrate long-term support, but targeted opportunities remain in emerging applications, region-specific requirements, and architectures that combine connectivity with edge intelligence in novel ways. The most resilient strategies are likely those that balance scale with specialization, allowing companies to serve broad demand while retaining the flexibility to win in higher-value niches.
4. Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market will likely be shaped by three interlocking trends. First, intelligent modules will increasingly be evaluated as integrated system enablers rather than radio components. Buyers will expect stronger combinations of connectivity, processing efficiency, security, and application-specific certification in a single design path. This trend favors suppliers that can offer cohesive platforms and reference architectures, and it raises the importance of firmware, lifecycle management, and migration planning.
Second, the spectrum and regulatory environment will continue to influence product priorities. Policy moves that ease network modernization and expand commercial spectrum access should support long-term demand for advanced wireless modules, while regional certification and sharing rules will keep shaping which standards and bands receive the most engineering focus. Companies that monitor regulatory timelines and align product roadmaps accordingly will be better positioned to capture emerging opportunities without costly redesigns.
Third, application demand will keep diversifying in ways that reward tailored solutions. Automotive and transportation, industrial IoT, and consumer electronics will remain core growth engines, but the most interesting margin opportunities may come from specialized deployments where reliability, power constraints, or integration complexity create room for higher-value module designs. Smart city, utilities, and healthcare will contribute incremental but strategically meaningful demand, especially where secure, dependable connectivity is non-negotiable.
These trends carry both opportunity and risk. On the opportunity side, broader intelligent module adoption opens the door to platform-based revenue models, longer customer relationships, and cross-selling into security, positioning, and edge-processing add-ons. On the risk side, input cost volatility, infrastructure deployment delays, certification bottlenecks, and the ongoing concentration of share among leading players can compress margins and raise entry barriers. Organizations that plan for these dynamics by diversifying supply, prioritizing application-relevant differentiation, and investing in regulatory readiness will be better prepared to convert market growth into durable commercial advantage.
5. Strategic Implications for Decision-Makers
For manufacturers and product leaders, the near-term priority is to align module selection with application realities rather than treating connectivity as a commodity input. The most effective strategies typically combine platform-based development, proactive certification planning, and clear migration paths across technology generations. Where possible, companies should evaluate suppliers not only on unit cost but also on qualification support, regional compliance coverage, power-performance balance, and the ability to support future feature upgrades without full hardware redesign.
For investors, the market offers a nuanced picture. Growth is robust, but value creation is increasingly concentrated in players that can combine scale with application-specific differentiation and disciplined lifecycle management. Due diligence should focus on product roadmaps, certification momentum, supply chain resilience, and exposure to both high-volume standards and specialized high-reliability segments. Companies that can demonstrate repeatable wins in demanding applications while maintaining cost competitiveness are likely to command more durable positioning than those competing primarily on price in commoditizing segments.
WiFi Modules Market
For procurement and procurement-led organizations, the strategic task is to balance cost, availability, and long-term support risk. Multi-source strategies, clear technical requirements for security and reliability, and early engagement with suppliers on regional certifications can reduce exposure to lead-time shocks and redesign costs. Establishing performance and compliance criteria before specification freezes helps ensure that module choices support both immediate deployment goals and future scalability.
Given the pace of product launches, regulatory activity, and application expansion, staying current with detailed segment data, competitive moves, and region-specific requirements is increasingly important. Deeper analysis of subsegments, technology transitions, and supplier-by-supplier positioning can help decision-makers refine product roadmaps, investment theses, and sourcing strategies with greater precision. For those seeking a fuller picture of market sizing by segment, competitive dynamics, and scenario-based guidance, the complete PW Consulting report provides the structured detail needed to support more granular planning decisions.
For detailed analysis of this topic, please visit the official page: Wireless Communication Intelligent Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


