



Category: Machinery & Automotive
PW Consulting: Building Dedicated Outdoor Air System Market to Reach USD 8.86 Billion by 2032, Driven by a 7.85% CAGR
By PW Consulting, 2026-07-06
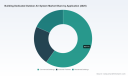
Building Dedicated Outdoor Air System Market: Strategic Insights for 2026 Decisions
Executive summary
As organizations finalize capital plans for 2026, Dedicated Outdoor Air Systems (DOAS) have moved from niche specifications to central elements of building decarbonization, indoor air quality (IAQ) strategies, and compliance programs. PW Consulting’s latest market study—anchored on a 2025 base year and forecasting through 2032—finds the global DOAS market to be a multi-billion-dollar opportunity. After steady expansion during 2020–2025, the market recorded a measured increase to USD 5,214.5 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.85% through our 2026–2032 forecast window, reaching roughly USD 8.9 billion by 2032.
Building Dedicated Outdoor Air System Market
Why this matters for 2026 decision-makers
Three concurrent dynamics make 2026 a pivotal year for commercial real estate owners, HVAC OEMs, utilities, and large contractors:
Building Dedicated Outdoor Air System Market
- Regulatory pressure is increasing around system-level energy performance and moisture removal metrics, elevating DOAS from optional ventilation devices to compliance-driving equipment.
- Electrification and heat-pump integration are reshaping product roadmaps and procurement specifications, creating winners and laggards among manufacturers.
- Market structure remains moderately consolidated—while leading suppliers command meaningful scale, a large long tail of specialists sustains intense innovation and price competition.
For executives planning capital allocations, product roadmaps, or M&A activity in 2026, timely, sector-specific intelligence on these fronts is essential. PW Consulting’s report is designed to convert that intelligence into executable priorities over the coming 12–18 months.
Building Dedicated Outdoor Air System Market
Market outlook: what the headline numbers hide and reveal
The headline trajectory—mid-single-digit to high-single-digit growth culminating in a near-doubling of revenue by 2032—highlights a market driven by retrofit demand, new construction ventilation codes, and technology upgrades (dehumidification, energy recovery, and integrated heat pumps). However, beneath that top-line expansion are differentiated pockets of margin improvement, supply-chain vulnerability, and specification-led procurement dynamics. Our analysis explains where to deploy capital to capture the higher-margin segments, how to hedge material inputs, and which go-to-market models accelerate adoption without eroding ASPs.
Competitive dynamics: players, positioning, and recent moves
The competitive landscape mixes large multinational OEMs with specialized manufacturers. Our report profiles the capabilities, strategic priorities, and product architectures of the market’s most influential participants—evaluating not only product portfolios but also service models and channel strategies.
- Greenheck Fan Corporation: Known for a broad line of pre-engineered rooftop DOAS units, Greenheck expanded capacity and electrified offerings in 2025–2026—most notably by increasing large-capacity rooftop models and adding air-source heat pump options to selected product lines. This dual move accelerates their appeal for both compliance-driven projects and clients seeking electrification-ready solutions.
- Trane Technologies: With DOAS offerings that emphasize humidity control and energy efficiency, Trane is aligning product development with DOE efficiency expectations and large-portfolio building owners seeking harmonized energy strategies.
- AAON, Carrier, Johnson Controls (YORK): These large OEMs combine scale manufacturing with configurable architectures to serve institutional and large commercial clients. Their investments are concentrated on performance, integrated controls, and meeting emerging energy standards.
- Specialists—Addison HVAC, Desert Aire, United CoolAir, XeteX, and others: These firms focus on niche applications (precision dehumidification, retrofit packages, fully-custom DOAS) and provide the innovation and customization that many projects require.
Our competitive chapter maps product breadth, channel reach, typical deal sizes, and aftermarket revenue potential for each named player, and identifies strategic adjacencies for partnership or bolt-on acquisition.
Regulation, standards, and supply-chain dynamics shaping 2026
Regulatory shifts in 2025–2026 tightened minimum efficiency expectations and standardized performance metrics for DX-DOAS units—changes that directly affect product eligibility in publicly-funded projects and many corporate procurement frameworks. Standards such as AHRI 920 have become de facto performance baselines, and recent rulemaking enforces them in procurement and code compliance contexts. Our analysis covers:
- How new DOE efficiency requirements change total cost of ownership (TCO) calculations for DX-DOAS versus heat-pump-based DOAS.
- Spec-writing strategies to ensure competitive bidding while preserving long-term energy savings.
- Supply risk from raw material exposure—particularly copper—and strategies to mitigate input-cost volatility through design, hedging, and supplier diversification.
What the report delivers: operational modules for 2026 execution
Rather than just describing market direction, the report is structured as a practical playbook for teams executing in 2026. Core deliverables include:
- Commercial playbooks: standard spec templates, bid evaluation matrices, and retrofit priority checklists calibrated to different asset classes.
- Financial tools: TCO and NPV models adjusted for energy price scenarios, tax incentives, and anticipated maintenance costs—ready to be adapted to client portfolios.
- Procurement and sourcing frameworks: supplier scorecards, total delivered-cost assumptions, and sourcing timelines that reflect lead-time inflation and material risk.
- Product roadmaps: feature-prioritization matrices juxtaposing DOE compliance, electrification pathways (heat pumps), and energy-recovery integration to inform R&D and partnership choices.
- M&A and partnership playbook: acquisition target profiling, synergy quantification, and integration checklists for strategic buyers seeking scale or technical gaps.
Strategic recommendations for 2026 (actionable priorities)
Our advisory guidance is purpose-built for near-term decision windows. Recommendations are prioritized and sequenced for organizations with different objectives—OEMs, building owners/operators, EPCs, and investors:
- For OEMs: accelerate modular electrified DOAS variants that comply with current efficiency metrics; bundle controls and commissioning services to protect margins as unit prices compress.
- For building owners/operators: adopt a staged retrofit approach—prioritize spaces with high latent loads and occupant density for early DOAS deployment to maximize IAQ benefits and near-term energy savings.
- For EPCs and integrators: develop fixed-scope retrofit packages with clear performance guarantees and a streamlined commissioning protocol to reduce deployment risk and shorten payback timelines.
- For investors and private equity: target niche specialists with strong aftermarket service streams or OEMs with scalable modular platforms—these offer asymmetric value creation through consolidation and cross-selling.
Risk matrix and KPIs to monitor in 2026
The report includes a prioritized risk matrix and recommended KPIs to track throughout 2026 to inform course corrections:
- Regulatory compliance risk: certification timelines and product requalification status under current performance standards.
- Supply-chain cost pressure: copper and refrigerant availability and cost trajectories, and their impact on BOM.
- Market adoption risk: retrofit uptake velocity, driven by capital availability and competing decarbonization priorities.
- Operational KPIs: installed cost per cfm, commissioning time per installation, warranty claim rate, and aftermarket revenue per unit.
How PW Consulting’s report supports immediate 2026 actions
PW Consulting’s Building DOAS Market report is intentionally tactical: it translates macro forecasts (including the market’s 2025 baseline and the 7.85% CAGR outlook) into concrete steps for procurement, product development, and M&A prioritization. The report’s templates, models, and vendor evaluations are set up to be used directly in RFPs, board-level investment memos, and engineering specifications—helping teams move from strategic intent to implemented projects within months.
Conclusion and next steps
DOAS is now central to the narrative on indoor air quality, energy efficiency, and building electrification. As the marketplace expands—from the multi-billion-dollar baseline in 2025 into a nearly USD 9 billion market by the early 2030s—organizations that adopt a disciplined, data-driven approach in 2026 will capture outsized returns.
PW Consulting’s full report contains the granular regional, application, and product splits, detailed competitor benchmarking, and downloadable operational tools referenced above. For teams preparing 2026 budgets, product roadmaps, or acquisition pipelines, the full intelligence set provides the validated inputs necessary for confident execution.
For detailed analysis of this topic, please visit the official page: Building Dedicated Outdoor Air System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aviation Oxygen Systems Market to Expand from USD 5,685.5 Million in 2025 to USD 9,010.1 Million by 2032 at a 6.8% CAGR — North America Leads with USD 2,126.2M
By PW Consulting, 2026-07-06
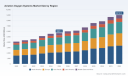
Aviation Oxygen Systems Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest market intelligence on the Aviation Oxygen Systems market synthesizes five years of observed dynamics (2020–2025) and projects industry evolution across a seven-year forecast window (2026–2032). The global market—measured in USD Million—has expanded steadily through the base year 2025 and PW’s forecasting model anticipates continued compound growth at a 6.8% CAGR through 2032. This release is intended as an executive briefing: it highlights the strategic inflection points that matter to OEMs, airlines, MROs, defense planners, and investors in 2026, while preserving the granular split data and proprietary scenario outputs for readers who access the full report.
Aviation Oxygen Systems Market
Headline market trajectory
After a recovery and growth phase during 2020–2025, the Aviation Oxygen Systems market reached a substantial global volume by the 2025 base year. PW’s scenario-driven forecast shows the market expanding further through the late 2020s and into the early 2030s, reflecting a combination of fleet growth, retrofits, regulatory tightening, and aftermarket expansion. The trajectory underscores a durable expansion opportunity for companies that can couple certified product portfolios with resilient MRO and supply-chain strategies.
Aviation Oxygen Systems Market
Why this matters for 2026 strategic decisions
- Investment timing: With a multi-year recovery firmly established by 2025, 2026 is a pivotal year to commit capex to production scale-up, certification pathways, or MRO capacity. Waiting risks misspent cycles as parts of the market move from retrofit to integrated-system demand.
- Regulatory tailwinds and constraints: Recent airworthiness directives and tightening compliance for portable breathing equipment and onboard systems create replacement and upgrade demand—unpredictable in timing but certain in magnitude. Firms without rapid certification or replacement supply chains will face procurement constraints and contract exposure.
- Aftermarket premium: The economics of oxygen systems increasingly favor aftermarket services—MRO, spare parts, inspection cycles, and cylinder hydrostatic testing—creating annuity-like revenue streams that materially affect valuation models in 2026.
Key demand and technology drivers
- Regulatory compliance and safety standards: Regulatory frameworks (notably FAA rules on supplemental oxygen thresholds, cylinder hydrostatic testing, and purity/contamination standards) continue to be primary demand levers. Compliance-driven replacements and mandated maintenance cycles create predictable windows of opportunity.
- Fleet modernization and interior retrofits: Commercial and business aviation operators are incorporating passenger-centric systems and integrated PSUs as part of broader cabin upgrade programs, increasing demand for integrated oxygen delivery and monitoring solutions.
- Military and specialized applications: Defense procurements for OBOGS, compact regulators, and high-altitude solutions remain technologically differentiated, driving R&D investment among a handful of established suppliers.
- Product innovation: Advancements in pulse-demand delivery, lighter composite cylinders, digital monitoring of oxygen consumption, and modular portable systems are reshaping total cost of ownership and maintenance patterns.
Competitive landscape and concentration
The market displays a moderate-to-high level of concentration among established system integrators and specialized manufacturers. The combined market share of the top three and top five suppliers indicates that lead players exert substantial influence over certification standards, aftermarket ecosystems, and OEM supply chains. For 2026, competitive advantage will be determined less by single-product innovation and more by integrated propositions—certified product portfolios, fast-turn MRO capability, and deep OEM/airframe partnerships.
Aviation Oxygen Systems Market
- Aerox Aviation Oxygen Systems (Bonita Springs, FL, USA) – A leading provider spanning portable and installed systems, noteworthy for expanding its MRO footprint through recent acquisitions and FAA-certified repair capabilities.
- Safran Aerosystems Oxygen (AVOX Systems) (Lancaster, NY, USA) – Offers comprehensive passenger and crew oxygen solutions; recent airworthiness directives affecting portable breathing equipment have direct operational consequences for units in service.
- Collins Aerospace (RTX) (Charlotte, NC, USA) – Focuses on integrated oxygen and passenger service unit systems for both commercial and military platforms; strength lies in systems integration with larger avionics and cabin architectures.
- Precise Flight, Inc. (Bend, OR, USA) – Specialist in GA systems with a reputation for durable, PMA/OEM-compatible equipment and long product warranties that favor owner-operators and FBOs.
- Mountain High Equipment & Supply Co. (Redmond, OR, USA) – Known for pulse-demand delivery technology and a portfolio that spans portable to built-in systems.
- Meggitt (now part of Parker Hannifin) (UK) – Strong in military and high-altitude portable systems, with modular AMOS offerings for tactical platforms.
- Honeywell Aerospace (Charlotte, NC, USA) – Provides OBOGS and life support systems with a focus on fighter and transport platforms where reliability and integration with avionics are critical.
Recent strategic moves and implications
- Aerox’s acquisition of an FAA-certified repair station (early 2025) demonstrates an aggressive move to capture aftermarket and MRO margin pools. For competitors, this signals that vertical integration into maintenance and certification services will be a competitive imperative.
- Regulatory activity around portable breathing equipment—adopted ADs and EASA operational directives—creates immediate replacement demand and constrains installation options for certain legacy units. Market entrants without rapid replacement product approvals may encounter limited market access.
- Consolidation among component suppliers and OEMs is likely to accelerate as firms seek to control certification, reduce lead times for critical components (valves, regulators, certified cylinders), and protect aftermarket revenue.
Operational and supply-chain considerations for 2026
Across procurement, manufacturing, and service networks, executives must prioritize three operational questions this year:
- Certification velocity: How quickly can new product variants and retrofit kits achieve TSO/PMA and operator acceptance across jurisdictions?
- Aftermarket capacity: Do current MRO infrastructures align with forecasted hydrostatic testing cycles, AD-related replacements, and increased retrofit activity?
- Supply resilience: Are critical components—composite cylinders, precision regulators, electronic sensors—sourced from single vendors or dual-sourced to mitigate disruption risk?
Strategic playbook: recommended moves for core stakeholders
PW Consulting’s analysis distills pragmatic actions tailored to organizational roles and risk profiles. For 2026 decision-makers, we recommend the following prioritized moves:
- Airlines and fleet operators: Commission a gap analysis of installed oxygen systems against emergent ADs and regulatory guidance; prioritize pre-emptive retrofits where downtime can be scheduled during maintenance checks to avoid operational disruptions.
- OEMs and system integrators: Accelerate modular-certified offerings that reduce install time and interface risk with cabin and avionics systems; invest in field-demonstration programs with key operators to shorten acceptance cycles.
- MRO providers and independent repair stations: Expand hydrostatic testing throughput and develop bundled service packages (inspection + replacement + data reporting) to capture recurring revenue from rising compliance cycles.
- Investors and corporate development teams: Look for targets offering either aftermarket scale (MRO footprint, long-term service contracts) or differentiated tech (OBOGS, pulse-demand efficiency, digital monitoring) rather than pure-play hardware suppliers without service plays.
Report contents — what PW Consulting provides
The full PW Consulting report is designed as an actionable decision-support tool. Key deliverables include:
- A validated market-sizing model (historical 2020–2025 and forecast 2026–2032) with scenario toggles for regulatory shock, defense procurement acceleration, and fuel-price driven fleet utilization changes.
- Competitive positioning maps, supplier scorecards (certification status, aftermarket reach, OEM relationships), and an MRO capability heatmap to prioritize partnership targets.
- Regulatory impact analyses that translate airworthiness directives and FAA/EASA guidance into serviceable demand curves and compliance cost estimates.
- Investment cases and forward-looking business-model scenarios including subscription/MRO bundling, retrofit-as-a-service, and integrated cabin system partnerships.
- Implementation playbooks for 12-month, 24-month, and 36-month horizons tailored to OEMs, airlines, and MROs with recommended KPIs and go/no-go criteria.
What we are not disclosing here—and why it matters
To preserve the report’s value as a strategic research product and to respect client confidentiality where applicable, this briefing intentionally omits granular regional and application-level split figures and specific revenue assignments to subsegments. Those granular tables, supplier revenue breakdowns, and the full scenario outputs are included in the purchasable report and are essential for transactional diligence, bid preparation, and valuation modeling. The high-level insights provided here are sufficient to prioritize strategic investments and to detect where deeper analysis will yield the greatest ROI in 2026 planning cycles.
Conclusion: the 2026 strategic horizon
For executives setting strategy in 2026, the Aviation Oxygen Systems market presents a combination of steady organic growth and episodic upside driven by regulation and defense procurement. The 6.8% CAGR embedded in PW’s base forecast signals attractive expansion, but capturing value will require alignment across certification, aftermarket capability, and supply-chain resilience. Market leaders will be those who transform regulatory compliance into recurring service revenue and who integrate safety-critical equipment into broader cabin and avionics ecosystems.
PW Consulting stands ready to support board-level strategy sessions, due-diligence processes, and operational playbook rollouts. Access the full report or contact our aviation practice to obtain the complete data tables, supplier scorecards, and the scenario model that operationalizes these insights for your 2026 plans.
For detailed analysis of this topic, please visit the official page: Aviation Oxygen Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Aircraft Stainless Steel Market Tops USD 2,734.08 Million in 2025, Signaling Strong Upside
By PW Consulting, 2026-07-06
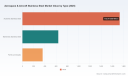
PW Consulting Releases Strategic Brief: Aerospace Aircraft Stainless Steel Market — A 2026 Decision-Maker’s Playbook
As aerospace supply chains enter a new phase of structural transformation, PW Consulting today publishes an executive-grade industry briefing derived from our full "Aerospace Aircraft Stainless Steel Market" research. Built on a base year of 2025 and delivering forward-looking analysis across 2026–2032, this briefing translates market-scale dynamics into executable guidance for procurement chiefs, materials engineers, and corporate strategists preparing decisions in 2026.
Aerospace Aircraft Stainless Steel Market
Why this report matters for 2026
The global aerospace stainless steel market reached a substantive scale in 2025 (base year) and is on a sustained growth trajectory through the forecast window. Our topline modelling foresees steady expansion driven by fleet renewal, rising defense spending in select markets, and substitution dynamics where stainless grades compete with advanced alloys and composites. The 2026–2032 compound annual growth rate (CAGR) underpinning our scenarios is 5.45%, reinforcing the thesis that materials strategy will remain a core enabler of competitive aircraft programs.
Aerospace Aircraft Stainless Steel Market
For executives making sourcing, product development, or M&A decisions in 2026, three simple facts emerge from the numbers: the market is sizable and growing; cost volatility and regulation will be primary drivers of near-term margin pressure; and supplier selection will materially affect program risk and time-to-market.
Aerospace Aircraft Stainless Steel Market
What the full report delivers (practical, decision-ready content)
- Actionable executive summary mapping immediate 12–18 month strategic choices to medium-term portfolio outcomes.
- Topline market sizing and scenario modelling that translates macro drivers into spend trajectories and sensitivity runs for commodity price shocks.
- Supply-side heatmaps: capacity, lead-time risk, and single-source exposure across stainless grades used in aircraft applications.
- Procurement playbook: hedging options, contractual clauses for alloy price pass-through, collaborative product development templates with suppliers, and inventory strategies tuned to aerospace lead times.
- Engineering-cost workstreams: cost-to-manufacture breakdowns by stainless family, alloy substitution matrices, and guidance on qualification paths to accelerate new-material adoption.
- Regulatory and carbon-impact modelling that quantifies the profit-and-cost implications of emerging regimes (including EU carbon mechanisms and U.S. trade measures).
- Competitive supplier scorecards and an M&A watchlist focused on strategic tuck-ins, capacity expansion targets, and value-accretive vertical plays.
- Scenario-based risk register and mitigation playbooks for supply-disruption, raw-material shock, and policy shifts affecting cross-border flows.
Competitive landscape — who matters and why
The aerospace stainless steel value chain is shaped by a mix of global producers, specialist distributors, and precision fabricators. Our analysis highlights several players whose strategic decisions and investments are likely to shape market structure over the coming 24 months:
- Outokumpu (Helsinki, Finland) — https://www.outokumpu.com A global stainless producer with tailored alloys that meet the stringency of aerospace certifications. Their material technology and scale make them a partner of choice for OEMs seeking high-temperature and corrosion-resistant solutions.
- Service Steel Aerospace (Fife, WA, USA) — https://www.ssa-corp.com A leading aerospace-focused distributor with an expanding footprint; recent capacity investments enhance regional fulfillment and reduce lead-time exposure for U.S.-based programs.
- Universal Stainless (Bridgeville, PA, USA) — https://www.univstainless.com Specializes in aircraft-grade stainless and nickel alloys used in structural and engine applications; their production footprint supports qualification timelines critical to OEM programs.
- Carpenter Technology (Reading, PA, USA) — https://www.carpentertechnology.com Known for high-performance specialty alloys tailored for extreme operational envelopes—an important supplier where substitution away from titanium or nickel-based alloys is considered.
- BUTTING (Knesebeck, Germany) — https://www.butting.com A precision manufacturer of tubes and assemblies; its capability to deliver ready-to-install components reduces downstream integration risk for airframe suppliers.
- Continental Steel & Tube Co. (Fort Lauderdale, FL, USA) — https://www.continentalsteel.com Distributor with a broad product slate supporting diverse aircraft applications, valuable for buyers prioritizing logistics agility.
- Future Metals (Tamarac, FL, USA) — https://futuremetals.com Provides industry-standard forms and custom blanks; their supply chain flexibility is relevant to tier-2/3 fabricators pursuing rapid turn prototypes or low-volume production runs.
Our competitive mapping combines publicly available corporate disclosures, recent facility investments, and proprietary supplier assessments to score each firm across capability, geographic reach, certification depth, and supply-risk exposure. The full report includes anonymized benchmarking templates you can deploy immediately with incumbent suppliers.
Recent developments and why they matter for 2026 strategy
- Service Steel Aerospace completed a notable facility expansion in late 2025, increasing distribution capacity and improving regional responsiveness—an example of tactical capacity investments that materially shorten procurement cycles for U.S.-based programs.
- Industry trade-show activity in late 2025 signalled renewed supplier focus on aerospace-grade stainless solutions, with several vendors showcasing process and finishing capabilities that reduce downstream qualification pain.
- New production and advanced manufacturing center builds for stainless and alloy components will create pockets of incremental capacity — an opportunity for buyers to secure long-term offtake at favorable terms if negotiations begin in 2026.
Policy, commodity, and supply risks that will shape 2026
Material procurement in 2026 cannot be considered in isolation from policy and raw-material swings. Key inputs to our risk models include:
- Carbon regulation: The entry into the payment phase of the EU Carbon Border Adjustment Mechanism (CBAM) in 2026 introduces an added cost vector for imported stainless components, changing landed-cost calculus for European buyers and their global suppliers.
- Tariff environment: U.S. Section 232 measures remain in place as of April 2026, maintaining elevated trade frictions that continue to favor localized supply or tariff-mitigation strategies such as bonded inventories and tariff engineering.
- Raw material pressure: Stainless pricing in North America has experienced upward pressure (price points observed in early 2026), driven by rises in nickel, chromium, and ferroalloys. Notably, nickel can constitute up to 70% of the variable cost input for certain austenitic stainless productions — a dominant cost sensitivity captured in our stress-testing.
- Geopolitical industrial policy: National strategies—such as China’s emphasis on high-tech and aerospace in 2026—will support domestic demand for special stainless grades and could redirect regional flows of precision alloys.
Strategic priorities for executives in 2026
Based on scenario analyses and supplier scoring, PW Consulting recommends that decision-makers prioritize the following initiatives before mid-2026 to preserve optionality and reduce program risk:
- Embed carbon and tariff scenario clauses into supplier contracts. Short window to negotiate terms tied to CBAM pass-through and Section 232 exposure will differentiate cost outcomes over the next 18 months.
- Adopt a layered sourcing strategy: combine long-term strategic partnerships with flexible regional distributors to manage lead-time and compliance risk without inflating inventory carrying costs.
- Invest in alloy substitution pilots where feasible. Engineering-validation roadmaps in the report show where stainless subtypes can replace higher-cost alloys at acceptable lifecycle trade-offs.
- Accelerate supplier qualification and shared R&D agreements. Co-funded trials can significantly shorten qualification timelines for alternative stainless grades and finishing processes that improve fatigue life or weight efficiency.
- Use targeted M&A and capacity-as-a-service plays to secure critical upstream supply — particularly where certification and metallurgy knowledge creates effective barriers to entry.
- Lock-in price-hedging instruments for nickel-linked exposure and implement transparent pass-through mechanisms to protect program margins.
How PW Consulting’s deliverables translate into boardroom action
The full report is designed not as an academic exercise but as a direct inputs-to-decision system: each chapter concludes with a short set of board-level choices, estimated impact ranges under three scenarios, and recommended KPIs to include in quarterly supplier reviews. For procurement teams, we provide templates for negotiation, a supplier scorecard, and a six-month supplier engagement roadmap. For engineering and program leads, actionable route-maps outline test, qualification, and certification timelines tailored to the typical aerospace program cadence.
Accessing the full intelligence
This release is a strategic preview intended to demonstrate the depth and applicability of PW Consulting’s analysis while preserving the full granularity for subscribers. To unlock the complete dataset, segmentation tables, supplier scorecards, and downloadable tools (including the scenario model and negotiation templates), visit our report landing page or contact our industry practice. The complete study includes the granular splits by region, type, and application that underpin the strategies summarized here — essential inputs for any team preparing capital allocation and sourcing decisions in 2026.
PW Consulting remains available for bespoke briefings, supplier due-diligence engagements, and rapid-market-entry workshops tailored to aerospace OEMs, tier suppliers, and private-equity investors assessing opportunities in the stainless steel value chain.
For detailed analysis of this topic, please visit the official page: Aerospace Aircraft Stainless Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Commercial Aircraft In‑Seat Power Market to Grow from USD 164.78 Million in 2025 to USD 229.62 Million by 2032 at a 4.85% CAGR
By PW Consulting, 2026-07-06
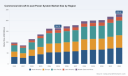
Commercial Aircraft In-Seat Power Systems Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting today publishes an executive briefing accompanying our full Commercial Aircraft In-Seat Power System Market report (base year 2025). The companion analysis synthesizes market sizing, supplier dynamics, regulatory drivers and actionable decision frameworks that procurement, product and fleet-planning teams need to make defensible investments in 2026. Our macro findings: the global in-seat power market reached approximately USD 164.8 Million in 2025 and is forecast to grow at a 4.85% CAGR through our 2026–2032 projection horizon, reaching roughly USD 229.6 Million by 2032. These headline metrics frame the commercial logic; the full report provides the granular scenarios, competitive scorecards and supplier playbooks required to convert intent into outcomes.
Commercial Aircraft In Seat Power System Market
Why this intelligence matters in 2026
-
Time-sensitive procurement windows — With OEMs and retrofit cycles aligning to narrowbody and widebody refreshes in many fleets, procurement teams face trade-offs between linefit upgrades versus staged retrofits. Selecting the wrong migration path can lock operators into suboptimal weight, power and certification profiles for an entire fleet sector.
Commercial Aircraft In Seat Power System Market -
Regulatory inflection points — The industry is coalescing around universal USB‑C standards and higher wattage delivery to support 60–100W device charging. Decisions made now will determine compliance costs, certification timelines and long-term passenger experience differentiation.
Commercial Aircraft In Seat Power System Market -
Supply chain and design constraints — Raw material dynamics and fuel-efficiency mandates are reshaping engineering choices. Constraints on high-grade copper and mandates for slimmer, lighter power converters mean hardware choices now affect wiring architecture, aircraft weight and cabin space for years to come.
-
Competitive concentration — Market structure is moderately concentrated: the leading three suppliers command a substantial share of installed bases, and the top five firms capture an even larger portion of market activity. This concentration affects negotiation leverage, aftermarket support options and the pace of technology diffusion.
What the PW Consulting report delivers — practical content mapped to execution
-
Market sizing and scenario modeling: A defensible baseline market size (base year 2025) and three forecast scenarios through 2032 that stress-test assumptions about device power demand, retrofit rates and new-build penetration.
-
Procurement playbook: Step-by-step sourcing templates for RFIs/RFPs, evaluation matrices that weight certification risk, TCO, modularity and support contracts, and negotiation levers we’ve validated with airline and OEM partners.
-
Retrofit vs. linefit decision framework: A practical decision tree incorporating downtime costs, installation labor profiles, electrical rework scopes and passenger experience uplift modeling to justify capital allocation.
-
Supplier benchmarking and scorecards: Comparative assessments of product families across key dimensions — power density, certification status, modularity, mean-time-between-failure, and aftermarket service footprints — without disclosing proprietary vendor revenue breakdowns.
-
Certification and regulatory checklist: Task-level guidance for meeting evolving USB‑C standards, EMI/EMC constraints and lightweight design mandates — including likely certification timelines and critical path items.
-
Supply chain risk assessment: Scenario-based mitigation plans for raw-material shortages and single-source dependencies, and engineering responses such as adoption of higher-voltage distribution networks that reduce conductive-material usage.
-
Commercial models and TCO templates: CapEx/Opex modeling templates for fleet planners and finance teams to evaluate payback windows under multiple charging-usage profiles and maintenance cost assumptions.
Competitive landscape: who to watch and how to align
The in-seat power ecosystem blends established avionics suppliers, specialized enablers and vertically integrated cabin-systems players. Our report profiles core suppliers and synthesizes their strategic posture as of 2026, helping buyers judge which partners best fit a chosen route-to-market — whether linefit integration with OEMs, aftermarket retrofits or bundled IFE + power offerings.
-
Astronics Corporation (East Aurora, NY) — A market leader with a broad installed base and mature EmPower product family. Recent product launches reinforce a focus on high-power USB‑C outlets and dual-port options designed for both retrofit and linefit. Astronics’ combination of certified hardware and award-winning product iterations makes it a default consideration for operators prioritizing proven reliability and certification readiness.
-
KID-Systeme GmbH (Buxtehude, Germany) — A specialist with strengths in cabin electronics and system integration for passenger and corporate aircraft. Their value proposition centers on innovation in seat-level integration and adaptability for differentiated cabin architectures.
-
Collins Aerospace (RTX, Charlotte, NC) — Integrates power and data ports within broader seating and IFE ecosystems. Collins positions itself as a systems integrator that can streamline supplier interfaces for OEMs and airlines seeking turnkey cabin solutions.
-
Burrana Pty Ltd (Cannon Hill, QLD) — Leverages its RISE cabin technology to position in-seat power as part of a broader cabin modernization play, targeting narrowbody refurbishments where integrated digital-cabin architectures deliver higher passenger perceived value.
-
IFPL Group Ltd (Isle of Wight, UK) — A high-volume supplier of in-seat power modules and interfaces with deep aftermarket reach. IFPL’s long history and extensive unit shipments make it a strong candidate for operators prioritizing supply continuity and unit-level cost advantages.
-
Mid-Continent Instrument Co. / True Blue Power (Wichita, KS) — Focused on certified USB power systems and chargers, offering TSO-certified solutions attractive to operators focused on rigorous compliance and cockpit/cabin safety standards.
-
Panasonic Avionics (Lake Forest, CA) — Bundles high-power USB‑C delivery within its Astrova IFE platform; operators aiming for an integrated passenger entertainment and power experience should evaluate the trade-offs between bundled systems and best-of-breed component selection.
-
Astrodyne TDI (Hackettstown, NJ) — Supplies custom power modules and EMI filters that increasingly matter as operators pursue lighter, higher-density power architectures.
Notable recent developments underline the market’s technological momentum: Astronics launched a dual USB‑C outlet in 2026; Burrana elevated its RISE in-seat offering at AIX 2026; IFPL celebrated three decades and showcased new modules; and Panasonic’s Astrova deployments with high-wattage USB‑C entered commercial service. These product and market moves accelerate standardization and increase pressure on lagging suppliers to update portfolios or partner to remain competitive.
Regulatory and technical dynamics shaping strategy
-
USB‑C standardization is not merely convenience — it is a sourcing and certification pivot. Operators must decide whether to mandate universal USB‑C across new-builds and retrofits now, or to accept a phased conversion with increased spares complexity and customer inconsistency.
-
Raw-material constraints (notably on high-grade copper) are driving system architects toward higher-voltage distribution topologies that reduce conductor mass by an estimated margin. That shift has implications for converter placement, thermal management and certification effort.
-
BYOD consumer behavior has made basic seat power an operational baseline rather than a premium amenity. Suppliers and airlines must therefore separate “table stakes” power delivery from premium differentiated services (e.g., guaranteed 60–100W ports, managed power allocation, or subscription-based fast-charging access).
-
Fuel efficiency and slimline design mandates require power converters and modules to occupy less cavity space and weigh less — design constraints that favor suppliers investing in high power-density, low-profile architectures.
How to use this report in 90 days
-
Procurement teams: Adapt our RFP template, run a short-list evaluation against the supplier scorecard, and secure a trial installation on a pre-selected aircraft within 60–90 days to validate integration assumptions.
-
Engineering leads: Use the TCO and wiring-architecture scenarios to determine whether a high-voltage distribution migration yields net weight and cost benefits across the fleet within a 5–7 year horizon.
-
Commercial leaders: Quantify passenger experience uplift versus incremental cost and decide on a uniform USB‑C policy for new-builds versus selective retrofit rollouts to optimize ancillary revenue and NPS impact.
Conclusion — strategic value proposition
For executives and practitioners planning capital allocation, vendor selection or cabin modernization roadmaps in 2026, the PW Consulting Commercial Aircraft In-Seat Power System Market report delivers the synthesis required to act with confidence. It pairs headline market sizing and a validated CAGR with operationally focused tools — procurement templates, certification checklists, supplier scorecards and risk-mitigation playbooks — so that decisions made in 2026 align to the technology, regulatory and supply-chain realities that will define fleet competitiveness through 2032.
To access the complete dataset, vendor scorecards and downloadable decision-support templates that underpin this briefing, please consult the full report on our website. The headline intelligence above is intended to orient your 2026 strategy; the full report contains the granular analyses that will convert strategy into executable programs.
For detailed analysis of this topic, please visit the official page: Commercial Aircraft In Seat Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Target Drones Market Set to Soar at an 8.12% CAGR, Transforming Combat Training and Weapon Testing
By PW Consulting, 2026-07-06
Aerial Target Drones Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As defence budgets refocus on realistic, high-intensity training and weapons integration in the face of evolving aerial and unmanned threats, the aerial target drones market is entering a strategic inflection point. PW Consulting’s new market study (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) synthesizes commercial, programmatic and supply-chain intelligence into an actionable playbook for 2026 decision-makers. The headline: the global market stood at approximately USD 6,250 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 8.12% to reach roughly USD 10,790 Million by 2032. This preview outlines why that trajectory matters, what is driving risk and opportunity, how the competitive field is evolving, and the specific strategic moves procurement, program and corporate leaders should prioritize this year.
Aerial Target Drones Market
Why 2026 is a Strategic Pivot Year
-
Convergence of demand drivers: The market’s growth is being driven by an intensifying requirement set — from live-fire air defence training through to realistic threat replication for integrated air and missile defence. Service-level training demand is converging with R&D and weapons-testing cycles, creating durable recurring procurement streams.
Aerial Target Drones Market -
Policy and procurement velocity: Recent policy signals — including US export-control adjustments and domestic-sourcing provisions — are reshaping supplier selection, industrial partnerships and contracting timelines. These regulatory vectors accelerate demand for compliant, allied-sourced solutions while increasing the complexity of cross-border programs.
Aerial Target Drones Market -
Supply-chain fragility as a strategic variable: Concentrated supply chokepoints in magnets, cells and semiconductors amplify program risk and are actively influencing supplier selection, total cost of ownership models and stockpile strategies.
Market Dynamics — Drivers, Constraints and Structural Features
Our analysis identifies four structural dynamics that will determine winners and losers through the forecast window:
-
Capability complexity and modularity: Buyers demand targets that reproduce signature, kinematic and countermeasure behavior across a spectrum of threats. Systems that combine modular payloads, scalable signature management and reusable design elements command price premiums and generate higher lifecycle revenue.
-
Program longevity and fleet sustainment: Governments favour suppliers who can demonstrate production scalability, long-term sustainment and spare-part resiliency. That preference is reinforcing incumbent advantage but also opening the door to specialised subsystem suppliers with compelling non-recurring engineering (NRE) economics.
-
Regulatory bifurcation: Two concurrent regulatory trends are shaping trade and sourcing. On one hand, streamlined export provisions for certain UAV categories into allied markets are lowering friction for allied cooperation; on the other, national procurement rules and defence industrial policies are tightening the acceptable origin profile for components and subsystems.
-
Supply-chain concentration: A handful of upstream inputs remain dominated by single-country production footprints, creating strategic fragility. This is shifting sourcing strategies toward dual-sourcing, alternative chemistries and domestic industrial incentives.
Competitive Landscape — Who Matters and Why
The market exhibits a moderate level of concentration: the top three suppliers account for a meaningful plurality of sales, and the top five possess a majority share — dynamics that create both high barriers to entry and clear acquisition/opportunity corridors for new entrants with specialized capabilities. Our report examines each of the major players and their positioning across product architecture, program access and international footprint.
-
Kratos Defense & Security Solutions (San Diego, CA, USA — https://www.kratosdefense.com). A market leader in high-performance subscale targets, Kratos combines production-scale manufacturing with program-level integration. Recent program wins and collaborative work with allied indigenous manufacturers have reinforced its role as a principal supplier for high-end target systems.
-
QinetiQ (Farnborough, UK — https://www.qinetiq.com). QinetiQ’s Banshee family and related systems are positioned for broad live-fire training and test ranges globally. Their sustained programme support contracts demonstrate the durability of platform-service models in this segment.
-
Griffon Aerospace (Madison, AL, USA — https://www.griffonaerospace.com). Known for subscale tactical target platforms, Griffon’s solutions are widely used in integrated air-defence training and continue to be selected where repeatable, cost-effective target sorties are a priority.
-
Boeing (Arlington, VA, USA — https://www.boeing.com). Boeing’s conversion of retired fighters into full-scale aerial targets is a strategic differentiator where authentic radar and kinematic fidelity is required for weapons testing and systems integration.
-
AeroTargets International (ATI) (USA — http://www.aerotargets.com). ATI is a supplier of a range of target drones and has positioned itself for theatre-level air-defence and counter-UAS training requirements.
-
Air Affairs Australia (QinetiQ) (Nowra, NSW, Australia — https://www.airaffairs.com.au). Offering high-performance jet targets, this group is strategically important for regional allied trials and capability demonstration programmes.
-
Northrop Grumman (Falls Church, VA, USA — https://www.northropgrumman.com) and Lockheed Martin (Bethesda, MD, USA — https://www.lockheedmartin.com). Both primes maintain programmes and technology portfolios that intersect target systems through broader unmanned and weapons testing capabilities, often providing systems integration and lifecycle logistics at scale.
Recent industry events underline the strategic momentum: major suppliers have secured follow-on production and sustainment work, primes are deepening partnerships to meet national sourcing expectations, and cross-border collaborations are being used to accelerate interoperability and local industrial participation. These developments demonstrate how program awards and partnerships, more than single-platform features, are defining market advantage.
Supply-Chain and Regulatory Imperatives
-
Export controls and allied access: An interim export-control adjustment in early 2026 has lowered some friction for moving certain civil and commercial UAV capabilities to allied nations; however, national defense procurement rules continue to mandate restricted component sourcing in many jurisdictions. Navigating this duality requires granular compliance frameworks tied to design decisions.
-
Component chokepoints: Concentration in rare-earth magnet production, battery cells and specialised semiconductors remains a live program risk. Companies and defence customers will need prioritized investment plans for alternative sourcing, inventory buffers and domestic substitution incentives.
-
Industrial policy alignment: Public procurement is increasingly a tool of industrial policy. Suppliers with demonstrable local industrial participation, transfer-of-technology pathways and secure supply arrangements are being favoured where governments emphasize defence sovereignty.
What PW Consulting’s Report Delivers — Practical, Transactional and Programmatic Tools
Our full report is structured as an operational manual for 2026 decision-makers. Highlights include:
-
High-resolution market model — top-line market sizing and validated demand scenarios across the 2026–2032 forecast window, with sensitivity analyses and upside/downside casework keyed to procurement cycles and policy shifts.
-
Supplier capability atlases — supplier-by-supplier matrices mapping platform architectures, signature management options, reusable vs expendable economics and sustainment footprints.
-
Regulatory and compliance matrix — an actionable toolkit for export control navigation, component provenance mapping and contract clause recommendations to reconcile allied access with domestic sourcing rules.
-
Supply-chain risk heatmaps and mitigation playbooks — identification of single-source chokepoints, recommended dual-sourcing strategies, strategic stockpile criteria and NRE prioritization guidance for alternative materials and components.
-
Procurement playbook — tender evaluation scorecards, TCO comparators, contract structures (fixed-price vs. DPS-style), and clauses to manage obsolescence and sustainment risk.
-
M&A and partnership screening — screening criteria for strategic acquisitions, JV frameworks for rapid industrial access, and a short-list of target profiles that deliver capability or capacity inflection.
-
Scenario-based training and testing roadmaps — programmes of record options aligned with capability objectives, sortie throughput planning, and cost-per-sortie benchmarking.
2026 Strategic Imperatives — Five Priority Moves
-
Adopt a supply-first procurement lens: Prioritise suppliers who can demonstrate secure, compliant input sourcing and deliverable sustainment pipelines. Where possible, include conditional award language that phases payment against verified supplier supply-chain remediation milestones.
-
Design contracts for lifecycle, not just hardware: Shift award criteria toward integrated service models that price sustainment, flight-hour availability and signature fidelity — converting one-off procurements into durable fleet-support contracts.
-
Hedge component risk aggressively: Implement targeted dual-sourcing initiatives for magnets, cells and key electronics; fund prototype efforts for alternative chemistries and domestic fabrication where strategic risk is unacceptable.
-
Leverage allied industrial partnerships: Use programme-level collaboration to satisfy domestic sourcing rules while capitalising on both production scale and interoperability gains. Local industrial participation, not just final assembly, will increasingly be required.
-
Pursue capability adjacencies: If you are a prime or subsystem supplier, evaluate acquisitions or partnerships that add signature management, reusable airframes, or logistics-as-a-service competencies — features that materially increase lifecycle revenue.
Conclusion — The Strategic Payoff for 2026 Decisions
For defense programme managers, procurement leads and corporate strategists, 2026 is the year to align industrial policy realities with operational needs. The aerial target drones market’s projected expansion — reflected in our top-line market model and an 8.12% CAGR across the forecast window — creates multiple levers for value capture: scale and sustainment, modular capability, and supply-chain assurance. But the same growth amplifies second-order risks from component concentration and an increasingly complex regulatory landscape.
PW Consulting’s full report translates this complexity into executable choices: procurement scorecards, supplier atlases, regulatory compliance matrices and scenario-driven financials designed to be used at the contract-negotiation table. This preview demonstrates the strategic contours; the full intelligence package contains the granular segmentation, unit economics and supplier-level data required to operationalise these recommendations.
For access to the complete dataset, supplier profiles, and the procurement playbook that supports 2026 programme decisions, visit our report page or contact PW Consulting’s Aerospace & Defence practice lead. Equip your team to convert market growth into durable program advantage — with supply-chain resilience, regulatory compliance and lifecycle economics front and centre.
For detailed analysis of this topic, please visit the official page: Aerial Target Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chromatography Cartridges Market Poised for 7.85% CAGR in 2026–2032 Forecast, Signaling Strong Global Expansion
By PW Consulting, 2026-07-06
Chromatography Cartridges Market: Strategic Briefing for 2026 — A PW Consulting Insight
As life sciences, environmental testing, and industrial quality assurance accelerate investment in separation technologies, the global chromatography cartridges market is entering a phase of sustained expansion. PW Consulting’s new market study — with a 2025 base year and a 2026–2032 forecast horizon — shows the market at roughly USD 925 million in 2025 and growing at a compound annual growth rate (CAGR) of 7.85% through 2032. By the end of the forecast period the market approaches the mid‑billion dollar range, reflecting durable demand across analytical, preparative, and process applications.
Chromatography Cartridges Market
Why this report matters for 2026 decision-makers
-
Timing against capital allocation cycles: The report aligns market projections with typical 1–3 year product development and procurement horizons, enabling companies to prioritize investments in cartridge platforms, consumable supply, and automation that will meaningfully affect 2026 budgets and 2027 roadmaps.
Chromatography Cartridges Market -
Risk-aware growth planning: We translate broad growth into practical scenarios — base, accelerated, and downside — helping procurement, R&D, and commercial leaders stress-test expansion plans against upstream raw material volatility and regulatory tightening.
Chromatography Cartridges Market -
M&A and partnership scouting: With market concentration materially favoring established vendors, the analysis surfaces where bolt-on acquisitions, exclusive supply agreements, or co‑development deals will unlock scale benefits or technological differentiation.
-
Supply chain and manufacturing footprint decisions: The report’s supplier maps and cost-driver model identify where localized manufacturing or dual-sourcing materially reduces lead-time risk for high-value customers, important for 2026 contract negotiations.
-
Commercial optimization: We provide pricing-sensitivity frameworks and channel-mix levers that sales leaders can deploy to protect gross margins as commoditization pressures increase in certain cartridge categories.
Market snapshot — what the macro numbers tell us
PW Consulting’s topline estimate places the global market at approximately USD 925 million in 2025. Under the baseline forecast, the market grows at 7.85% CAGR through 2032 to reach a substantially larger market size by the end of the period. This pace reflects several converging dynamics: continued expansion of biopharma analytics and downstream processing; rising regulatory scrutiny and documentation requirements that favor validated cartridge suppliers; and ongoing adoption of prepacked, single‑use formats in laboratories and industrial processes.
Importantly, concentration metrics indicate a market where a small set of incumbents command a significant share of revenue, yet there is meaningful room for specialist entrants and regional manufacturers to capture niche segments. This structure creates distinct strategic pathways depending on scale and capability: defend and deepen for large incumbents; specialize and partner for mid-sized players; and localize and automate for regionally focused suppliers.
What’s in the PW Consulting report — practical, executable content
-
Methodology and transparent data model: We document our approach for historical reconstruction (2020–2025) and forecasting (2026–2032), including demand drivers, price inflation assumptions, and scenario sensitivity to raw material and regulatory risks.
-
Commercial playbooks: Segment-specific GTM templates covering value proposition, channel economics, distribution agreements, and specimen RFP language for procurement teams.
-
Buy‑side intelligence: A supplier risk matrix and lead-time benchmarking tool for procurement to quantify inventory and dual‑sourcing needs for 2026 contract cycles.
-
Innovation heatmaps: Technology and application prioritization for R&D investments — from guard cartridge inertness and superficially porous phases to monolithic and membrane‑based process cartridges for large molecule purifications.
-
M&A screening and valuation checklist: A shortlist of capability-based acquisition archetypes, integration risk factors, and quick valuation heuristics tailored to the cartridges market.
-
Regulatory and quality roadmap: GMP, traceability, and documentation templates aimed at bioprocess cartridge suppliers targeting process-scale biopharma customers.
-
Commercial pricing simulator: A tool that models margin outcomes by product category, volume tiers, and channel discounts to guide 2026 pricing strategies.
Competitive landscape — strategic positioning of key suppliers
The market is shaped by a mixture of specialized cartridge manufacturers and broad-based analytical instrument and consumables players. Several vendors exemplify different winning approaches:
-
BUCHI Labortechnik (Flawil, Switzerland) — plays to strength in prefilled flash cartridges optimized for purification performance across loading ranges. Its FlashPure series emphasizes application‑driven cartridge sizing and backpressure management, making it a go‑to for labs focused on preparative workflows.
-
Biotage (Uppsala, Sweden) — leverages a portfolio that spans normal and reversed-phase prepacked flash cartridges tailored for drug discovery and research scales. Its product breadth and historical ties to medicinal chemistry workflows provide strong channel credibility.
-
Restek Corporation (Bellefonte, PA, USA) — differentiates through inert guard and protection cartridges designed for metal‑sensitive chemistries; recent product introductions underscore the importance of column protection as a value stream for analytical customers.
-
Sartorius AG (Göttingen, Germany) — targets process-scale bioprocessing with monolithic and CIMmultus cartridges, addressing large molecule purification and the regulatory demands of GMP manufacturing.
-
Agilent Technologies (Santa Clara, CA, USA) and Waters Corporation (Milford, MA, USA) — these legacy analytical leaders combine cartridge and column technology with deep applications support for biotherapeutics, peptides, and oligonucleotide analysis, positioning them well for the high‑value, regulated segments.
-
Thermo Fisher Scientific (Waltham, MA, USA) — offers comprehensive cartridges across analytical and preparative scales, capitalizing on integrated instrument‑consumable relationships and global distribution reach.
-
Orochem Technologies (Naperville, IL, USA) — operates in the flash and HPLC domain with a focus on scalable separations, serving customers seeking customizable solutions across analytical and preparative needs.
Recent product activity reinforces these strategic themes. Notable launches in 2025 include new inert guard cartridges and ultra‑inert HPLC column series optimized for biotherapeutics and metal-sensitive compounds, signaling supplier focus on two adjacent opportunities: protecting expensive analytical hardware and serving highly regulated biopharma workflows.
Industry dynamics and near-term headwinds
-
Raw material and technology choices: Silica gel remains the foundational stationary phase across many cartridge types, with spherical silica favored for reproducibility and resolution in flash and HPLC applications. Suppliers oriented around advanced silica processing or alternative stationary phases can extract premium pricing where performance matters.
-
Regulatory pressure in bioprocessing: Process-scale cartridges for biologics must satisfy stringent GMP and traceability requirements. This raises entry barriers but also creates differentiation for vendors able to demonstrate validated supply chains and high‑quality documentation.
-
Commercial fragmentation versus consolidation: The market exhibits a dual dynamic — consolidation among high-value, regulated segments and continued fragmentation in commoditized consumables. Strategic choices in 2026 will hinge on whether companies pursue scale in regulated niches or focus on agile, regional supply models.
-
Price and performance tension: As prepacked and single‑use formats become standard, pricing pressure increases for commodity cartridges, while specialized chemistries and protection technologies (e.g., inert phases for metal‑sensitive analyses) retain margin resilience.
Actionable recommendations for leadership teams in 2026
-
Align portfolio investments to where performance and regulation create differentiated value (e.g., process‑scale cartridges and inert protection cartridges) rather than broadening into low‑margin commodity SKUs.
-
Negotiate multi‑year supply agreements with key raw material suppliers and consider dual‑sourcing or vertical integration for critical silica supplies to protect margins and lead times.
-
Pursue selective partnerships with instrument OEMs and contract development/manufacturing organizations (CDMOs) to embed cartridges into validated workflows and lock in recurring demand.
-
Deploy the report’s pricing simulator and channel playbooks during 2026 commercial planning cycles to quantify margin sensitivities and prioritize high‑return customer segments.
-
For private equity and corporate development teams: use the M&A screening templates to identify tuck‑ins that add regulatory depth, geographic reach, or differentiated phases/functionalization capabilities.
Next steps — how PW Consulting accelerates your 2026 strategy
This briefing is a strategic condensate designed to surface the critical decisions stakeholders must make in 2026. The full PW Consulting Chromatography Cartridges Market Report contains the proprietary datasets, granular regional and application breakdowns, product‑level unit economics, and supplier scorecards that operational teams and investors need to execute on the recommendations above. To convert the directional insights herein into executable plans — including downloadable models and workshop‑ready slides — request the complete report and our custom advisory offering tailored to your role in the value chain.
For detailed analysis of this topic, please visit the official page: Chromatography Cartridges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Wireless POS Market Valued at USD 7,425.3 Million in 2025, Poised to Grow at 9.25% CAGR Through 2032
By PW Consulting, 2026-07-06
Smart Wireless POS Terminal Device Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new market study on Smart Wireless POS Terminal Devices delivers a practical, strategy-first view of a fast-evolving hardware-plus-software ecosystem. Drawing on a robust historical analysis (2020–2025), an actionable base year (2025), and a forward-looking forecast window (2026–2032), the report translates macro trajectories into executive-grade playbooks for procurement, product strategy, partnerships, and risk management.
Smart Wireless Pos Terminal Device Market
Why this study matters for 2026
The market for smart wireless POS terminals has moved beyond episodic hardware refresh cycles and into a phase where integration, software extensibility, and field mobility determine winners. Our analysis shows the global market more than doubled in scale over the last five years and, with a compound annual growth rate of 9.25% across the forecast period, remains a high-conviction opportunity for vendors, integrators, and enterprise adopters alike. For CFOs, CTOs, and business unit leaders planning 2026 budgets, the report provides the evidence base and decision frameworks needed to prioritize initiatives that deliver near-term ROI while preserving strategic optionality through 2032.
Smart Wireless Pos Terminal Device Market
What the report contains — practical, decision-oriented deliverables
-
Macro-to-Micro Market Architecture — A clear mapping of demand drivers (mobility, contactless payments, SME digitization), technology enablers (Android SmartPOS platforms, 4G/5G, Wi‑Fi, Bluetooth), and constraint vectors (security certifications, device lifecycle management). This section contextualizes the overall market scale and growth trajectory so you can align capital allocation to realistic opportunity windows.
Smart Wireless Pos Terminal Device Market -
Vendor Positioning Frameworks — Proprietary scorecards that compare incumbent and emerging suppliers across product breadth, software ecosystem, go-to-market channels, certification status, and aftermarket services. These are calibrated for procurement teams to shorten vendor selection cycles without sacrificing due diligence.
-
Go-to-Market Playbooks — Playbooks for three common enterprise strategies: (a) Device-as-a-Service (DaaS) for distributed retail fleets; (b) Integrated POS + Vertical SaaS for hospitality and restaurants; (c) Mobile-first mPOS rollouts for field operations. Each playbook includes recommended partner archetypes, commercial terms to negotiate, and KPIs tied to TCO and replacement cadence.
-
Security & Compliance Checklist — A practical, prioritized checklist centered on industry requirements (including PCI PTS 7.x) and mobile-specific attack vectors. The checklist bridges product selection and deployment controls to reduce certification and insurance friction.
-
Adoption Scenarios & Sensitivity Models — Three scenarios (conservative, base, accelerated) showing how adoption, pricing pressure, and software monetization interact to affect vendor revenues and buyer economics through 2032. These models are delivered in spreadsheet form so teams can input their own assumptions.
-
M&A and Partnership Radar — Tactical guidance on targets for bolt-on acquisitions, joint-venture structures, and partnership ecosystems that accelerate time-to-market for Android SmartPOS bundles, managed services, and vertical integrations.
Core market signals to inform 2026 strategy
-
Momentum behind Android SmartPOS: Our research validates that Android-based platforms have crossed into mainstream adoption, accounting for a substantial share of devices in recent years. The platform advantages—app ecosystems, faster feature iteration, and developer familiarity—make Android a de facto standard for vendors seeking rapid vertical integration.
-
Security and certification are non-negotiable: PCI PTS 7.x and EMV/NFC compatibility are table stakes for global deployments. Certifications materially affect time-to-revenue and insurance costs; firms must budget certification pathways into roadmaps and vendor contracts.
-
Concentration and consolidation dynamics: The market’s competitive structure shows a middle-to-high level of concentration among a limited set of global tier-1 suppliers, while a large number of regional and niche players compete on form factor, price, or vertical specialization. This creates multiple strategic options—partner with incumbents for scale, or target cloud-native niches where integration and service matter more than device margins.
-
Software monetization is the strategic lever: Hardware remains the entry point, but long-term value accrues to companies that capture recurring revenue—through software subscriptions, payment routing, value-added apps, and managed services. Winning strategies separate device economics from platform economics.
Competitive landscape — what leading players signal for 2026
Our competitive analysis profiles global and regional leaders and synthesizes recent product moves to reveal strategic intent rather than raw market shares. Highlights:
-
Ingenico (Paris): Continues to invest in versatile portable devices that blend cellular and Wi‑Fi connectivity, targeting field services and retail mobility. Their product roadmaps emphasize security and integration with payment processors—key for enterprise customers seeking low-friction rollouts.
-
Verifone (San Jose): Maintains a broad product stack across fixed, portable, and mobile form factors. Verifone’s focus is on scale and channel reach, aiming to serve large retailers and hospitality chains that require global support footprints.
-
PAX Technology (Shenzhen / North America HQ: Jacksonville): Aggressively pushing Android SmartPOS into hospitality and restaurant verticals. Their trade-show presence and restaurant-focused demonstrations in early 2026 indicate a strategy to bundle hardware with vertical capabilities and services.
-
Newland Payment Technology (Fuzhou): Focuses on certified, export-ready devices and competes where global compliance and localization matter. Their emphasis is on secure Android-based devices for cross-border customers.
-
Castles Technology and NEXGO (Taipei, Shenzhen): Compete on compactness, durability, and price-performance—appealing to SMEs and mobile-first use-cases. NEXGO’s recent N6 Pro launch reflects ongoing product iteration in the mini POS segment.
-
Worldline (Bezons): Shifting toward integrated SmartPOS solutions for SMEs in Europe, rolling out Android terminals aimed at unifying payments and business apps—evidence of software-centric revenue ambitions.
-
Platform-native entrants (Square/Block, Toast, NCR Voyix): These players convert deep software/customer relationships into specialized hardware offerings tailored to SMBs and restaurants. Their strength lies in ecosystem lock-in and vertical-tailored workflows rather than raw hardware breadth.
Recent product launches and trade-show activity (e.g., Worldline’s Android SmartPOS introductions, NEXGO’s N6 Pro release, and PAX’s NRA 2026 restaurant exhibits) point to a competitive rhythm centered on verticalized devices, certification milestones, and tighter software/hardware integration.
Implications and recommended actions for 2026 planning
-
Procurement: Shift from one-off CAPEX buys to flexible models—DaaS and bundled SW subscriptions—to reduce replacement risk and accelerate deployments. Include certification exit-criteria (PCI PTS 7.x, EMV/NFC) in RFPs and tie pricing to software feature tiers.
-
Product Roadmaps: Prioritize Android compatibility, modular OS update strategies, and secure element support. Plan for OTA update pipelines and partner with MDM providers early to manage device fleets at scale.
-
Partnership Strategy: For vendors, two routes are viable—(a) scale via channel partnerships with payment processors and value-added resellers; or (b) vertical depth by integrating with industry SaaS (restaurant management, retail ERP, healthcare workflows). Choose one as primary and the other as secondary to avoid execution dilution.
-
M&A and Investment: Prioritize acquisitions that accelerate software capabilities (payments orchestration, loyalty, analytics) over mere hardware volume. Small tuck-ins that fill capability gaps will often deliver higher multiples than bolt-on hardware factories.
-
Risk & Compliance: Budget multi-year certificate renewal and incident response programs into operational spend. Security lapses in payment hardware attract regulatory and reputational penalties that far exceed incremental product development costs.
How PW Consulting supports execution
Beyond analysis, our service package converts insight into outcomes: vendor selection facilitation, commercial negotiation playbooks, pilot design and metrics, and integration blueprints for connecting SmartPOS fleets to enterprise back-ends and cloud services. We also provide a customized scenario model that lets corporate teams stress-test investment decisions under alternate pricing and adoption curves.
Next steps — where to get the full intelligence
This briefing is a condensed preview of the full report, designed to orient 2026 strategy and highlight where near-term investments will compound into long-term advantage. The complete market study contains the full segmentation analysis, the vendor scorecards, downloadable financial sensitivity models, and executable playbooks required to operationalize these recommendations. Access the full report to obtain the granular data and procurement-ready tools that PW Consulting provides to enterprise clients and strategic partners.
Contact PW Consulting to request the report package, schedule a strategic briefing, or commission a tailored implementation roadmap aligned with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Smart Wireless Pos Terminal Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.0% CAGR for Hybrid Cross Car Beam Market Through 2032
By PW Consulting, 2026-07-06
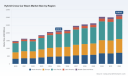
Hybrid Cross Car Beam Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
The hybrid cross car beam market has moved from engineering niche to strategic priority for vehicle OEMs and tier‑1 suppliers. Our 2025 base‑year assessment shows the global market reached USD 2,127.8 Million, and, under a range of realistic adoption and technology pathways, we forecast a 6.0% CAGR through 2032, reaching roughly USD 3,199.4 Million by the end of the forecast window. This trajectory captures a confluence of forces—electrification, regulatory pressure on tailpipe and lifecycle CO₂, material innovation, and integration of multiple vehicle functions into fewer, lighter structural components.
Hybrid Cross Car Beam Market
Why this report matters for 2026 decision cycles
-
Capital allocation and platform planning: OEMs finalizing platform investments in 2026 need a clear view of structural-material tradeoffs that affect mass targets, NVH, safety certification timelines, and supplier selection. Our analysis translates market-scale forecasts into practical scenarios for production ramp and break‑even of hybrid beam adoption under conservative and aggressive electrification roadmaps.
Hybrid Cross Car Beam Market -
Procurement and supplier strategy: With market concentration indicating a moderately consolidated supplier base (CR3 ~48.5%; CR5 ~62.3%), sourcing strategies must balance partnership depth with capacity risk. The report provides frameworks for multi‑tier contracting, qualification roadmaps, and scorecards to evaluate materials, co‑engineering capability, and sustainability credentials.
Hybrid Cross Car Beam Market -
R&D prioritization: Engineering leaders deciding between incremental steel optimizations, aluminum hybrids, or advanced thermoplastic/composite solutions will benefit from our comparative assessments of weight‑to‑cost, manufacturability, and integration potential — all benchmarked against real program outcomes and awards in the sector.
-
Regulatory and sustainability planning: As low‑carbon mandates and LCA reporting tighten, cross car beam choices increasingly influence lifecycle CO₂ accounting. The report quantifies how material and design choices contribute to OEM decarbonization targets and where regulatory risk can become a competitive advantage.
What the report delivers (practical table of contents)
-
Market sizing & forecast: Base year 2025 market estimate and 2026–2032 scenarios with sensitivity analysis tuned to EV penetration, material costs, and regulatory shocks.
-
Technology & materials playbook: Comparative lifecycle and cost modeling for steel hybrids, aluminum hybrids, and thermoplastic/composite hybrids; manufacturability constraints; tooling and cycle‑time implications; and state‑of‑the‑art material suppliers.
-
Supply chain stress tests: End‑to‑end risk mapping (raw materials, recycled feedstocks, processing capacity), supplier concentration analysis, and contingency sourcing strategies for 12–36 month horizons.
-
Competitive landscape & capability mapping: Strategic profiles of leading technology and supply players, M&A watchlist, and go‑to‑market archetypes for OEM partnerships.
-
Commercial & procurement playbook: Negotiation levers, cost‑plus vs. value‑sharing contract templates, pilot program sequencing, and supplier KPIs to de‑risk qualification cycles.
-
Program case studies & implementation roadmaps: Real‑world program timelines, certification milestones, and practical checklists for plant readiness, demolding, joining, and secondary operations.
-
Scenario planning & strategic options: Five plausible market futures (from slow adoption to rapid hybridization), with clear implications for CapEx, sourcing, and product design choices for 2026 decision-makers.
Market dynamics: what is actually driving adoption
-
Lightweighting as a systemic lever: Hybrid cross car beams are now evaluated not simply for component weight reduction but for their ability to consolidate functions (airbag supports, HVAC integration, cable management), which yields system‑level mass and cost benefits that OEM architects find compelling.
-
Material innovation: Thermoplastics reinforced with strategic fibers (including recycled carbon fiber compounds), and advanced polyamides such as PA6‑GF and PA66 grades, are delivering step‑change reductions in mass versus traditional steel while enabling injection molding economies and part consolidation.
-
Regulatory pressure and lifecycle accounting: Manufacturers are increasingly held accountable for upstream carbon and end‑of‑life impacts. High‑visibility programs highlight that replacing high‑carbon metals (e.g., magnesium in certain architectures) with fiber‑reinforced plastics plus local metal inserts can deliver substantial CO₂ savings at scale.
-
System integration and cost parity: The move to hybrid solutions is accelerated where suppliers can demonstrate integrated assemblies that cut secondary fasteners, reduce assembly steps, and lower TCO — not just per‑part mass.
Competitive landscape: who matters and why
The competitive map blends traditional metal formers with polymer specialists and materials innovators. Key players to watch combine deep platform experience, materials IP, and the ability to execute large program launches:
-
Röchling Automotive (Germany): Strength lies in metal‑plastic integration and functional integration (mount points, ducts), making them a natural partner where OEMs seek localized integration and weight reduction without wholesale redesign.
-
ElringKlinger (Germany): Notable for thermoplastic injection with local metal reinforcement — a technology profile that maps well to e‑mobility programs seeking low mass and robust manufacturing repeatability.
-
FORVIA / Faurecia (France): Brings modular system thinking and platform standardization to bear; their component modularity can shorten time‑to‑market for OEMs pursuing cockpit customization across multiple platforms.
-
Materials specialists (Envalior, AKRO‑PLASTIC): These firms supply the high‑performance polymers and reinforced compounds that enable 20–30% mass savings versus conventional steel solutions in validated programs — a critical enabler of wider hybrid adoption.
-
Large system suppliers (Magna, Gestamp, Benteler): These incumbents combine global manufacturing scale with integration into electrified vehicle supply chains; they are the logical partners for OEMs requiring supply reliability during high‑volume ramp.
Our competitive analysis highlights three actionable supplier archetypes for OEMs in 2026: (1) materials/IP leaders, (2) integrators capable of system delivery at scale, and (3) nimble innovators for premium or niche programs. Strategic sourcing should balance these archetypes against capacity and localization needs.
Recent industry signals you cannot ignore
-
Program awards and recognition: High‑profile wins and industry awards validate manufacturing readiness and crashworthiness credentials for thermoplastic composite beams, accelerating OEM confidence in adoption.
-
OEM decarbonization moves: Leading OEM design launches demonstrating substantial CO₂ reductions by replacing carbon‑intensive metals signal that regulatory and investor scrutiny will continue to favor lifecycle‑efficient material choices.
-
Material performance claims: Suppliers are now publicly quantifying weight savings and recycled content percentages, making sustainability a more transparent procurement criterion — but verifying those claims through third‑party LCA remains essential.
How to use this report to shape 2026 actions — practical next steps
-
Immediate (0–6 months): Run a focused pilot with one OEM program: select one hybrid beam architecture, execute a supplier qualification sprint, and lock a procurement framework aligned to volume triggers.
-
Near term (6–18 months): Decide between in‑house capability versus strategic partnership. If scale is moderate and program differentiation matters, prioritize co‑development with a materials leader; if scale is high, secure capacity with an integrator.
-
Medium term (18–36 months): Harden manufacturing and logistics playbooks, including recycling and end‑of‑life streams to meet evolving regulatory requirements and to extract value from secondary markets.
What we intentionally withhold here — and why you should read the full report
This briefing presents the strategic contours and practical implications you need to act in 2026. To preserve the "trailer" value of this release and to respect the commercial sensitivity of program-level intelligence, we have withheld proprietary segmentation matrices and granular region/application revenue splits, as well as the detailed supplier scorecards, cost build‑ups, and forecasting model drivers. The full PW Consulting report contains these elements, including downloadable scenario models you can adapt to your own product and procurement assumptions.
Closing recommendation
For executives facing make‑or‑buy decisions, program prioritization, or sustainability commitments in 2026, the hybrid cross car beam is not an incremental engineering choice — it is a strategic lever that affects platform economics, brand carbon targets, and supplier ecosystems. Use this briefing as the strategic north star and consult the full PW Consulting report for the granular inputs and executable playbooks required to convert insight into advantage.
To access the complete report and interactive models, contact PW Consulting or visit our Hybrid Cross Car Beam market page.
For detailed analysis of this topic, please visit the official page: Hybrid Cross Car Beam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Aircraft Stainless Steel Market to Expand at 5.45% CAGR During 2026–2032, 2025 Report Reveals
By PW Consulting, 2026-07-06
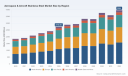
Aerospace Aircraft Stainless Steel Market: Strategic Intelligence for 2026 Decision-Makers
Executive Snapshot
PW Consulting is pleased to publish an actionable intelligence brief drawn from our comprehensive Aerospace Aircraft Stainless Steel Market study. Built on a base year of 2025 and projecting through 2032, the report synthesizes market-sizing, cost dynamics, regulatory pressures, supplier capabilities, and near-term demand scenarios that will shape procurement, production, and M&A decisions in 2026 and beyond.
Aerospace Aircraft Stainless Steel Market
Key macro takeaways: the market has expanded steadily from recent historical levels and, with a compound annual growth rate (CAGR) of 5.45% over the forecast window, is set to continue its recovery and structural growth. Using revenue measured in USD Million, the industry’s trajectory from 2020 through our forecast to 2032 demonstrates both cyclical inflection points and enduring secular drivers that matter to C-suite and strategy teams planning for 2026.
Aerospace Aircraft Stainless Steel Market
Why this report matters for 2026 strategy
-
Timing and precision: 2026 is a pivot year—new regulatory regimes, commodity volatility, and sovereign industrial policy are converging to create asymmetric risks and opportunities across aerospace stainless steel supply chains.
Aerospace Aircraft Stainless Steel Market -
Tactical clarity: buyers, fabricators, and investors need near-term tools to translate price signals and regulatory impacts into sourcing, hedging, and capital allocation decisions. Our report provides those tools in operational form.
-
Portfolio reshaping: the combination of steady market growth and concentrated supplier positions means selective vertical integration, partnership, or bolt-on M&A can create outsized value; the report surfaces where those opportunities are most likely to materialize without exposing confidential segment-level payoffs in this summary.
Market trajectory: what the numbers tell us
The dataset anchoring the report tracks total market revenue (USD Million) through the historical period and out to 2032. From a post-pandemic recovery start in 2020, the market reaches an approximate midpoint in 2025 and is forecast to continue rising to materially higher levels by 2032. This pattern—steady annual expansion reflected in a 5.45% CAGR across the forecast horizon—signals robust demand fundamentals but with episodic volatility tied to commodity cycles and regulatory shocks. The report decomposes that macro trajectory into demand scenarios and supply-side reactions, enabling executives to stress-test plans under alternative 2026 market conditions.
Drivers, risks and structural dynamics
-
Commodity and input-cost pressure: North American stainless steel pricing data from March 2026 points to price levels that reflect significant upstream inflation; nickel remains a dominant driver of variable production cost—accounting for a very large share of the cost base in common austenitic formulations. This means small nickel price movements can materially change margins for processors and component manufacturers.
-
Policy and trade: The European Union’s Carbon Border Adjustment Mechanism (CBAM) entering its payment phase in early 2026 and the continued existence of U.S. Section 232 tariffs on steel and aluminum as of April 2026 introduce both cost and compliance layers that reshape cross-border sourcing economics, favor near-shore strategies, and alter supplier selection criteria.
-
Industrial strategy: National-level efforts—most notably policy signals from China emphasizing high-tech sectors including aerospace—add asymmetric demand upside for specialty stainless grades and advanced processing capabilities in targeted jurisdictions.
-
Market concentration: The competitive field exhibits measurable concentration at the top end; leading suppliers account for a substantial portion of supply, creating supplier power and signaling the potential for strategic partnerships or supplier risk should capacity shifts occur.
What PW Consulting’s report delivers (practical, decision-grade content)
This study was intentionally designed as a toolkit for executives who must make real-world decisions in 2026. Highlights include:
-
Market sizing and validated forecast models calibrated to 2025 base-year data, with scenario variants that isolate regulatory, commodity, and demand shocks.
-
End-to-end supply chain maps for aerospace stainless steel, showing where value concentrates, where single points of failure exist, and how material flows respond to trade and tariff shifts.
-
Cost-curve analysis that quantifies the sensitivity of tiered producers and distributors to nickel and ferroalloy movements, plus an embedded TCO (total cost of ownership) calculator to compare sourcing alternatives under CBAM and tariff regimes.
-
Proprietary supplier scorecards and a five-factor stress-test matrix for assessing continuity risk, carbon-intensity exposure, and scale economics across potential partners.
-
Procurement playbooks—covering hedging, contract structures, dual-sourcing arrangements, and inventory strategies—tailored to OEMs, tier suppliers, and distributors operating in the aerospace segment.
-
Capex and expansion decision frameworks for downstream fabricators: build vs. buy scenarios, greenfield vs. brownfield assumptions, and payback profiles under multiple price and demand paths.
-
M&A and JV prioritization guidance that aligns strategic intent with integration complexity and regulatory horizons—enabling acquirers to size deals and prioritize targets without exposing proprietary subsegment valuations in this summary.
Competitive landscape: profiles and strategic implications
The report includes a focused review of incumbent and emerging players whose strategic moves will define supply capacity, service quality, and product innovation over the next three years. Notable firms examined include:
-
Outokumpu (Helsinki, Finland) — A global stainless solutions leader whose technical portfolio and high-temperature/corrosion-resistant grades position it as a natural partner for advanced aerospace applications. The firm’s scale and R&D footprint make it a bellwether for pricing and specification shifts.
-
Service Steel Aerospace (Fife, WA, USA) — A major distributor focused on aerospace-quality stainless and alloys. Recent capacity additions in North America underline a strategy that pairs distribution scale with quick-turn service to OEMs and cross-border fabricators.
-
Universal Stainless (Bridgeville, PA, USA) — Specialty producer of aircraft-grade stainless and nickel alloys that plays a critical role in supplying structural and engine-related billets and forgings; its product mix makes it sensitive to nickel and alloy premia.
-
Carpenter Technology (Reading, PA, USA) — Serves extreme-performance niches with high-end alloys and tailored metallurgy for engine and high-stress applications; its portfolio is strategic for OEMs pursuing weight and life improvements.
-
BUTTING (Knesebeck, Germany) — Known for precision tubes and ready-to-install assemblies, an important supplier in regions prioritizing integrated component supply and near-net-shape manufacturing.
-
Continental Steel & Tube Co., Future Metals and other specialized distributors — Collectively, these channel players underpin speed-to-market, small-batch capability, and aftermarket responsiveness.
Recent industry developments—facility expansions by distribution firms, new manufacturing hubs aimed at defense and aerospace customers, and concentrated showing at regional trade exhibitions—reinforce the strategic value of combining scale, geographic reach, and certification depth. PW Consulting’s report provides decision-makers with a comparative matrix that captures capability, lead-time risk, and carbon exposure for each major supplier.
Actionable recommendations for 2026
-
Hedge and stress-test: Implement commodity hedges and run three-tier scenario stress tests (base, tariff-adverse, carbon-compliant) using the report’s models to understand margin corridors and working-capital needs.
-
Rebalance sourcing: Prioritize a mix of near-shore and certified global suppliers to hedge against tariff and CBAM shocks while preserving cost competitiveness.
-
Negotiate outcome-linked contracts: Use performance-based pricing and indexation mechanisms tied to key input price indices to share upside and downside with strategic suppliers.
-
Invest in low-carbon pathways: Start capex planning for decarbonization investments (recycling, electrification, green energy procurement) and engage with suppliers on shared carbon-intensity roadmaps to avoid CBAM penalties and to access green-premium markets.
-
Targeted M&A: Pursue bolt-on assets that deliver immediate capacity, certification, or geographic diversification—using the report’s acquisition screening framework to prioritize targets that improve resilience while keeping integration risk manageable.
Access and next steps
This announcement intentionally outlines the strategic contours and actionable takeaways from PW Consulting’s Aerospace Aircraft Stainless Steel Market report while reserving the full, granular datasets, supplier-level valuation models, and downloadable tools for subscribers. For teams deploying 2026 operating plans, the report offers the necessary modeling artifacts, negotiation templates, and scenario outputs to convert insight into execution.
Executives seeking to operationalize the analysis can request a tailored briefing, license the embedded calculators, or commission a bespoke deep-dive focused on their supply chain cluster. Our research supports integration into ERP/planning systems and provides client workshops to translate scenarios into 90–180 day tactical roadmaps.
Conclusion
As the aerospace sector recalibrates for a new regime of regulation, commodity volatility, and sovereign industrial strategy, decision-makers cannot rely on static benchmarks. PW Consulting’s market study provides a dynamic, implementable intelligence layer—combining validated market sizing (USD Million base-year 2025), a 5.45% CAGR forecast window, supplier concentration analysis, and operational toolkits—to guide procurement, capital, and M&A decisions in 2026. For the complete dataset, supplier scorecards, and interactive tools that underpin these recommendations, please consult the full report via our release portal.
For detailed analysis of this topic, please visit the official page: Aerospace Aircraft Stainless Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Building Dedicated Outdoor Air System Market Poised to Grow at a 7.85% CAGR, Signaling Robust 2026–2032 Upside
By PW Consulting, 2026-07-06
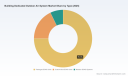
Building Dedicated Outdoor Air System Market — Strategic Insight for 2026 Decision-Makers
Executive summary
As building owners, HVAC manufacturers, and systems integrators prepare for the next planning cycle, PW Consulting's new Building Dedicated Outdoor Air System (DOAS) Market report provides a forward-looking playbook for 2026 decisions. Anchored on a 2025 base year and a 2026–2032 forecast window, the market is projected to expand at a compound annual growth rate (CAGR) of 7.85%. Our proprietary modeling shows the market moving from roughly USD 3,125 million in 2020 to an estimated USD 5,214.5 million in 2025, with an anticipated rise to approximately USD 5,579.8 million in 2026 and reaching about USD 8,856.8 million by 2032. These macro trajectories underscore robust demand dynamics driven by electrification, indoor air quality (IAQ) regulation, and retrofit momentum — factors that will materially shape capital allocation and product roadmaps in 2026.
Building Dedicated Outdoor Air System Market
Why this report matters for 2026 strategic planning
-
Actionable timing: 2026 is the first full planning year post-implementation of new efficiency rules and early commercial rollouts of electrification options; our report decodes the near-term windows for product launches, pricing strategy, and channel investment.
Building Dedicated Outdoor Air System Market -
Regulatory clarity: The U.S. Department of Energy's minimum efficiency standards for DX-DOAS units (effective May 7, 2025) and AHRI Standard 920's performance metrics create both compliance obligations and differentiating opportunities. We translate those requirements into commercial thresholds that affect product development, certification strategy, and capital budgeting.
Building Dedicated Outdoor Air System Market -
Competitive positioning: With market concentration measured at a moderate level — CR3 ~28.5% and CR5 ~41.8% — incumbents and challengers alike can still materially improve share through targeted innovation, channel partnerships, and retrofit-focused offerings. The fragmented structure rewards focused execution.
Market trajectory and structural drivers
The DOAS market is moving from niche ventilation-centric applications toward mainstream building systems architecture. Several structural forces are converging:
-
Electrification and decarbonization: The rapid maturation of air-source heat pump (ASHP) modules and the push to reduce on-site fossil heating are increasing demand for electrically driven, heat-pump-capable DOAS platforms. Manufacturers extending ASHP options on DOAS product lines will find earlier access to electrification budgets in commercial retrofit projects.
-
Stronger IAQ mandates and design practice shifts: After the pandemic-era emphasis on ventilation, building codes and owner specifications increasingly prioritize dedicated ventilation streams with precise humidity control and energy recovery — elevating DOAS from optional to strategic in many new builds and major retrofits.
-
Compliance and efficiency standardization: DOE and AHRI frameworks are raising the bar for certification and rating methods; compliance is now a licensing gate for certain market segments. Companies that align product testing and labelling early will avoid market access friction and improve tender competitiveness.
-
Supply chain sensitivity: DOAS production remains exposed to commodity swings (notably copper for coils and refrigerant piping), and to lead times for certain refrigeration components. Procurement strategies that hedge copper exposure and diversify refrigerant sourcing will materially improve margin resilience.
Practical contents of the report — what executives will use immediately
PW Consulting’s report is deliberately operational. It is not just high-level forecasting; it is a toolkit for 2026 decision cycles. Core deliverables include:
-
Validated market sizing and growth scenarios (base year 2025; forecast 2026–2032), with sensitivity runs that isolate the effects of electrification rate, retrofit intensity, and regional code tightening.
-
A regulatory playbook translating DOE and AHRI requirements into product-level compliance checklists and time-to-market implications.
-
Procurement guidance for OEMs and contractors, including bill-of-material cost drivers, supplier risk scoring, and commodity hedging strategies.
-
Channel and go-to-market blueprints for launching packaged, modular, and custom-built DOAS platforms across new construction and retrofit cohorts.
-
A decision matrix for CAPEX prioritization that ranks product investments by payback horizon, incremental margin potential, and strategic fit under three rollout scenarios.
-
Executive-ready slides and custom-ready models that buyers can integrate into board and investor presentations to justify 2026 budget requests.
Competitive landscape — implications for 2026 plays
The competitive field blends large global HVAC platforms with focused specialists. Key strategic observations:
-
Greenheck Fan Corporation — strength in rooftop, pre-engineered solutions: Greenheck’s expanded RV series and newly added RV-220 (2025) plus the introduction of ASHP options (early 2026) reflect a playbook that targets packaged rooftop DOAS demand and electrification-ready roofs. For rivals, the lesson is clear: speed-to-market with electrified rooftop SKUs is a differentiator for large-volume commercial retrofits.
-
Trane Technologies — systems integration and efficiency branding: Trane’s Horizon and DOAS offerings emphasize humidity control and compliance with energy efficiency standards. Their scale in services and controls means they can sell system-level value (performance warranties, controls integration) — a model that smaller OEMs should emulate through partnerships.
-
AAON, Carrier, Johnson Controls (YORK) — configurable high-capacity options: These incumbents combine modularity with configurable performance, appealing to large commercial and industrial projects. Their advantage is manufacturing scale and channel reach; challengers should target niche performance claims (e.g., superior dehumidification, low-global-warming-potential refrigerants) to carve space.
-
Desert Aire, United CoolAir, XeteX, Addison HVAC — specialty and retrofit-focused players: These companies compete on precise humidity control, DX-DOAS expertise, and retrofit integration. For 2026, their strongest avenue is partnering with distributors and commissioning firms to win mid-market retrofit projects where specification flexibility and speed of installation matter.
-
Strategic M&A and alliances: Given the market’s moderate fragmentation, 2026 will be fertile for tuck-ins that add controls expertise, heat pump modules, or modular manufacturing capacity. Buyers seeking scale should prioritize targets that enhance performance differentiation rather than only adding volume.
Recommended 2026 strategic moves — prioritized, pragmatic steps
-
Product roadmap acceleration: Commit to electrified DOAS variants and certify to AHRI 920/DOE-aligned metrics before the next procurement cycle. Early certification reduces bid friction and signals compliance competence to large customers.
-
Retrofit-focused go-to-market: Allocate dedicated commercial teams to identify low-to-medium complexity retrofit opportunities where DOAS yields rapid IAQ and energy wins. Standardized modular solutions and pre-packaged control sequences shorten installation windows and lower O&M risk.
-
Supply chain hedging: Lock multi-year copper and compressor contracts, and develop dual-sourcing strategies for refrigerants and controls electronics. Consider vertical inventory buffers for high-lead-time components to protect project delivery timelines.
-
Service and digital monetization: Build commissioning-as-a-service and performance monitoring offerings that bundle hardware with SaaS controls. This increases recurring revenue and differentiates commoditized hardware.
-
Channel partnerships for code-driven opportunities: Partner with engineering firms and code consultants to be first-in-line for projects that will pivot to DOAS due to stricter ventilation or energy codes.
Risks, sensitivity, and mitigation
-
Commodity price volatility: Copper exposure can erode margins quickly. Recommended mitigation includes indexed procurement contracts, alternative materials where possible, and design optimizations that reduce copper content without sacrificing performance.
-
Regulatory uncertainty and certification lag: Compliance windows for DOE/AHRI alignment create short-term market access risk for non-certified SKUs. Prioritize testing and certification pipelines to avoid losing tenders on compliance grounds.
-
Competitive price pressure: The fragmented market and modular supply chains may lead to aggressive pricing in retrofit segments. Protect margins by bundling services and offering differentiated warranties and performance guarantees.
What PW Consulting’s clients will gain
Subscribers to this report receive both the strategic narrative and the tactical instruments needed for 2026 resource allocation: timing maps for product launches, procurement playbooks to protect margin, partner scorecards for distribution and retrofit channels, and compliance checklists that translate standards into engineering milestones. Importantly, while this executive summary highlights the macro trajectory and competitive posture, the full report contains granular regional, product-type, and application-level breakdowns — including downloadable models and scenario tools — that are essential for precise budgeting and investment planning.
Next steps and how to access full intelligence
PW Consulting’s Building Dedicated Outdoor Air System Market report is constructed to be immediately actionable for board-level and operating leaders planning 2026 initiatives. To review the detailed segment-level tables, supplier scorecards, and downloadable scenario models that underpin the recommendations in this release, visit our report page or contact our industry team for a bespoke briefing. The bigger strategic point is clear: with a forecast market expansion and shifting regulatory landscape, organizations that align product certification, supply-chain resilience, and retrofit go-to-market capabilities in 2026 will secure outsized share and margin gains through the forecast horizon.
For detailed analysis of this topic, please visit the official page: Building Dedicated Outdoor Air System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


