



Category: market research
Eddy Current Sensor Market: How $1.86B Scale and 6.5% CAGR Redefine 2026 Growth
By PW Consulting, 2026-09-21
Navigating the Eddy Current Sensor Market: Strategic Trends and Commercial Opportunities Through 2032
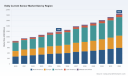
The eddy current sensor market has evolved from a niche instrumentation segment into a critical enabler of precision monitoring, non-destructive testing, and automated control across heavy industry, advanced manufacturing, and critical infrastructure. Tracking the revenue trajectory from 2020 through 2032 reveals a market that has consistently expanded, crossing the 1.1 billion threshold by 2025 and moving toward approaching 1.9 billion by the end of the forecast horizon. The compound annual growth rate sits at approximately 6.5 percent, a rate that signals steady, technology-led expansion rather than cyclical volatility. This growth is not uniform across all segments; it reflects a reallocation of capital toward high-reliability displacement and condition monitoring applications, alongside a steady uptake of advanced inspection probes in asset-intensive sectors.
For executives and investors, the headline numbers matter less than the structural shifts underneath them. The market is maturing in ways that reward suppliers who can pair submicron measurement accuracy with ruggedized packaging, certified reliability, and integration-ready interfaces. At the same time, procurement teams and system integrators face a landscape where raw material volatility, certification requirements, and shifting trade policies are reshaping cost structures and lead times. Understanding these dynamics is essential for positioning product portfolios, negotiating supplier relationships, and anticipating where value will accrue over the next several years.
Market Snapshot and Core Challenges
The revenue path from 2020 to 2032 illustrates a market that has grown through steady adoption rather than sudden spurts. After moving from roughly 850 million in 2020 to approximately 1.195 billion in 2025, the trajectory continues upward with incremental but compounding gains each year, reaching an estimated 1.856 billion by 2032. This pattern points to a market where recurring replacement cycles, expanding end-use monitoring requirements, and the gradual penetration of advanced sensor types are driving volume. The consistency of the growth curve also suggests that demand is becoming more predictable, which benefits suppliers that can plan capacity and service networks with greater confidence.
Despite the positive trajectory, the industry faces a set of challenges that will define competitive outcomes. Three stand out as especially consequential for strategy and operations.
Precision-to-Ruggedness Trade-offs in Harsh Environments
As deployment shifts from controlled laboratory and clean manufacturing settings into turbines, petrochemical plants, and outdoor automation cells, the tolerance for environmental stress has increased sharply. Sensors must now deliver submicron accuracy while surviving high temperatures, moisture, chemical exposure, and mechanical shock. The push for ingress-protected designs, such as IP69K-rated housings, is no longer optional for many industrial buyers. This creates a design tension: protecting the sensing element and electronics without compromising thermal stability, signal integrity, or mounting flexibility. Suppliers that solve this engineering puzzle with purpose-built mechanical designs and validated sealing approaches gain a meaningful advantage in bids where reliability is weighted heavily against price.
Certification, Qualification, and Personnel Requirements
Non-destructive testing and condition monitoring applications increasingly require adherence to recognized standards for both equipment and personnel. For eddy current testing, qualification frameworks for inspectors and the alignment of sensor performance with accepted procedures are becoming table stakes in regulated sectors. This raises the barrier to entry for generic instrumentation and favors suppliers that can document traceability, provide application guidance, and support certification workflows. For buyers, the challenge is not only evaluating sensor accuracy but also ensuring that the entire measurement chain—from probe selection to data interpretation—meets auditable standards. This dynamic is shifting purchasing decisions toward bundled solutions that include training, documentation, and service support, rather than standalone hardware.
Cost Structure Pressure from Materials and Trade Policy
The bill of materials for eddy current probes and instruments is increasingly exposed to commodity and trade dynamics. Copper wire coils, essential to many sensor designs, are subject to price swings tied to broader commodity volatility. At the same time, magnet assemblies used in high-frequency sensors depend on materials that face export constraints in key sourcing regions. Layered on top of this are tariffs and trade measures that affect the landed cost of sensors originating in certain countries, particularly for North American manufacturers. These pressures do not invalidate the market's growth but they do compress margins for suppliers that rely on undifferentiated component sourcing and pass through cost shocks without engineering countermeasures. Forward-looking players are responding with material substitution where feasible, dual-sourcing strategies, and design choices that reduce sensitivity to any single input.
Key Drivers Shaping the Market
Growth in this market is being propelled by a combination of technological advancement, regulatory and standards activity, evolving demand-side behavior, and supply-side restructuring. Each driver reinforces the others, creating a multi-year pull that extends beyond simple capacity expansion.
Technology Innovation: Submicron Accuracy Meets Industrial Hardening
Recent product introductions show a clear emphasis on improving measurement fidelity while extending environmental durability. The launch of new eddy current displacement sensor series with submicron accuracy and high ingress protection ratings reflects a deliberate push to serve applications where even minor measurement drift can affect process quality or equipment safety. In turbomachinery and other rotating equipment, updated sensor specifications for radial and axial displacement are enabling more precise vibration and shaft monitoring, which supports predictive maintenance and reduces unplanned downtime. For non-destructive testing, the continued refinement of eddy current array probes and associated instrumentation is expanding inspection coverage and reducing scan time on complex geometries. These innovations matter because they convert sensors from passive measurement devices into integral parts of reliability and quality programs, increasing their value proposition and sticking power in customer operations.
Policy and Standards Environment: Compliance as a Competitive Moat
Regulatory and standards activity is shaping both procurement and product development. Personnel qualification requirements for eddy current testing reinforce the importance of instruments that produce repeatable, interpretable results and that can be supported with documented procedures. In parallel, equipment-level protection standards are becoming reference points in industrial procurement, with IP-rated sensors increasingly specified where washdown, chemical exposure, or outdoor deployment is expected. This environment rewards suppliers that invest in compliance documentation, application notes, and service frameworks that reduce the administrative burden on end users. It also raises the cost of disintermediation: once a sensor family is integrated into a certified maintenance or inspection workflow, switching costs rise, creating longer contract horizons and more predictable revenue for incumbents.
Eddy Current NDT Equipment Market
Demand-Side Shifts: Predictive Maintenance and Automation Integration
On the demand side, the most important behavioral change is the accelerating move from reactive repair to condition-based and predictive maintenance. Industrial operators are deploying displacement, vibration, and proximity monitoring earlier in asset lifecycles and integrating sensor data into broader digital maintenance strategies. In factory automation, the push for more reliable presence detection, positioning, and displacement feedback is driving adoption in high-cycle environments where contactless measurement offers clear advantages in wear reduction and throughput. In energy and heavy process industries, turbines, generators, and rotating shafts are being monitored with greater rigor to protect availability and extend service intervals. This demand shift is significant because it expands the addressable use cases for eddy current sensors beyond inspection alone, pulling them into continuous monitoring and control loops where recurring value is created.
Supply Chain and Cost Structure: Regional Realignment and Collaboration
Supply-side dynamics are being reshaped by both cost pressures and strategic collaboration. Tariffs and trade measures affecting certain sensor origins are prompting North American and European manufacturers to reconsider sourcing and assembly footprints, with some shifting toward regional integration or diversified supplier bases to manage landed cost and lead time risk. At the same time, partnerships aimed at joint development of advanced displacement sensors for factory automation signal a move toward co-engineering and scaled deployment, where shared roadmaps and large installation targets reduce per-unit risk and accelerate field validation. These developments indicate that the market is moving beyond fragmented, transactional sales toward more structured ecosystems in which partners align on performance targets, qualification paths, and deployment scale. For suppliers, this means that supply chain resilience and partnership strategy are now as important as sensor performance in winning multi-year programs.
Competitive Landscape and Leading Strategies
The market is characterized by a meaningful but not immovable concentration, with the top three competitors accounting for roughly 48 percent of revenue and the top five approaching 58 percent. This structure suggests that established players hold strong positions in high-value applications and regional channels, while there is still room for specialized entrants and regional challengers to capture share in focused segments. The competitive game is increasingly defined by application mastery, environmental robustness, certification support, and the ability to embed sensors into broader automation or inspection solutions rather than selling components in isolation.
Magnetic Field Sensors Market
Differentiation Themes Among Leading Players
Several companies illustrate the breadth of strategic positioning in the market. One German manufacturer has built a reputation around high-precision non-contact displacement measurement, with product lines designed for applications that demand stable accuracy and clean signal performance. Its recent introduction of a new displacement sensor series with submicron accuracy and IP69K protection underscores a strategy of pairing measurement precision with ruggedization for harsh industrial settings. A United States-based specialist focuses on linear encoders and displacement sensors that emphasize reliable linear measurement for automation and machine building, positioning itself around repeatable feedback in production environments. A Canadian company has carved out a differentiated role in non-destructive testing through eddy current array probes and instruments, where inspection coverage and data quality are the primary value drivers. A German test equipment maker emphasizes crack detection and material sorting through its eddy current test instruments and probes, serving qualification-heavy environments where procedural reliability matters as much as hardware performance. A major United States industrial player contributes a different dimension with sensors designed for turbomachinery displacement and vibration monitoring, linking sensor performance to rotating equipment reliability programs.
Additional participants broaden the competitive field. A Japanese manufacturer offers eddy current sensors and measuring systems for displacement, rotation, and vibration, reflecting a strategy that spans multiple measurement modalities within a unified portfolio. A Chinese manufacturer targets non-destructive testing applications with eddy current detectors and testing systems, competing on accessibility and application breadth in inspection workflows. A United States precision instruments company supplies eddy current proximity probes for displacement and vibration measurement, reinforcing the importance of established probe families in condition monitoring. A Japanese measurement systems leader integrates eddy current displacement sensors into broader measurement platforms, illustrating a strategy that leverages platform ecosystems and customer relationships to expand sensor attachment rates. Together, these players show that success is not monolithic: some win on precision and ruggedness, others on inspection coverage, some on platform integration, and others on cost-accessible testing solutions.
Strategic Moves and What They Signal
Recent developments provide a window into how competitors are shaping the next phase of the market. The introduction of a new displacement sensor series with submicron accuracy and high ingress protection indicates that incremental performance gains continue to be a viable growth lever, especially where environmental resilience is becoming a procurement requirement. A partnership between a large automation supplier and a sensor specialist to jointly develop advanced displacement sensors for factory automation, with a target of over 18,000 installations, signals the increasing importance of scaled co-development and deployment-oriented roadmaps. This kind of collaboration reduces risk for both sides and creates a pathway to embedded adoption in standardized automation cells, where sensor selection is influenced by integration readiness and service support as much as by raw specification.
On the instrumentation side, an updated specification sheet for a 5mm eddy current sensor for radial and axial shaft displacement in turbomachinery highlights the continued refinement of rotating equipment monitoring products, where small specification improvements can unlock broader acceptance in reliability programs. More dramatically, the acquisition of a leading eddy current array and NDNondestructive Testing solutions provider by a large industrial corporation demonstrates that consolidation is actively reshaping the landscape. This transaction enhances the acquirer's portfolio in eddy current array and inspection solutions, adding capability that can be leveraged across a broader customer base and combined with adjacent technologies. The implication for the market is that capability concentration is increasing at the high end of non-destructive testing, while displacement and proximity sensing remain competitive across a wider set of specialists and platform players.
Market Evolution: Consolidation, Differentiation, and Selective Entry
The competitive trajectory appears to be moving along three parallel paths. Consolidation is strengthening the offerings of larger players in inspection and condition monitoring, particularly where array-based testing and rotating equipment monitoring can be bundled with broader service and platform capabilities. Differentiation is deepening around environmental robustness, submicron accuracy, certification support, and integration readiness, making product selection more application-specific and reducing the relevance of price-only comparisons in high-stakes deployments. Selective entry remains possible in regional or application-focused niches, especially where suppliers can offer cost-effective testing systems, strong local support, or specialized probe geometries for particular inspection challenges. For buyers, this means that the supplier landscape is increasingly stratified: a handful of broad-capability leaders, a set of application-dominant specialists, and a tail of regional or price-competitive providers. Navigating this landscape successfully requires matching the supplier's strengths to the application's criticality, compliance needs, and integration requirements.
Future Outlook: Trends and Commercial Opportunities
Looking ahead three to five years, the market's direction is likely to be shaped by the convergence of measurement performance, environmental hardening, and integration depth. Three trends stand out as particularly consequential for strategy and investment.
Trend One: Embedded Monitoring Becomes the Default in Critical Assets
Edy current sensors are increasingly being specified earlier in asset design and integrated into continuous monitoring architectures for turbines, generators, rotating shafts, and high-cycle automation equipment. This trend is driven by the availability of ruggedized, high-accuracy sensors and by the economic logic of predictive maintenance: avoiding downtime and extending service intervals creates value that justifies higher sensor performance and more thorough installation. The commercial opportunity here lies in moving from component sales to solution-oriented engagement, where suppliers help define mounting, calibration, data paths, and maintenance procedures. Suppliers that can document reliability in service, simplify integration, and support data workflows will capture more of the lifecycle value than those that stop at the point of hardware sale.
Trend Two: Inspection Coverage and Speed Improvements Expand NDT Use
In non-destructive testing, eddy current array probes and associated instrumentation continue to improve inspection coverage and reduce scan time on complex components. As certification and qualification expectations rise, the ability to produce repeatable, well-documented results becomes a stronger differentiator. The opportunity for technology providers is to align probe designs and instrument features with the practical needs of inspectors and quality teams, including intuitive operation, clear data presentation, and support for standardized procedures. For operators, the upside is faster throughput and broader inspection coverage without sacrificing compliance, which can translate into lower inspection cost per unit and better asset availability. The risk is that procurement may treat inspection sensors as commoditized unless suppliers invest in documentation, training, and application engineering that reinforces the link between equipment performance and inspection quality.
Trend Three: Supply Chain Resilience and Regional Strategy Become Pricing and Margin Determinants
Material volatility in copper and constraints on certain magnet materials, combined with tariffs and trade measures affecting specific origins, are making supply chain strategy a direct determinant of competitiveness. Over the next several years, suppliers that diversify sourcing, qualify alternative materials where performance allows, and structure assembly and logistics to reduce landed-cost exposure will be better positioned to hold margin while remaining responsive to customers. There is also an opportunity for partnerships and co-development models that spread risk across larger installation targets and shared roadmaps, particularly in factory automation where standardized deployments can amortize engineering cost. The uncertainty here lies in the trajectory of trade policy and commodity markets; both can shift quickly, and suppliers that have not built flexibility into their cost structures may find themselves reacting rather than shaping commercial terms.
Strategic Guidance for Decision-Makers
The market's trajectory creates different implications for manufacturers, investors, and procurement organizations. In each case, the key is to align strategy with where value is consolidating and where flexibility is most needed.
For Manufacturers and Product Leaders
- Prioritize ruggedized precision as a combined design objective. Submicron accuracy is increasingly expected, but industrial bids are increasingly won by products that pair accuracy with verified ingress protection, thermal stability, and mounting practicality. Treat environmental robustness as a core specification, not a secondary feature.
- Invest in integration readiness and documentation. Suppliers that provide clear mounting guidance, calibration support, and compliance-relevant documentation reduce the friction of adoption in certified maintenance and inspection workflows. This lengthens contract horizons and raises switching costs in the customer's favor.
- Build supply chain optionality. Where copper and magnet dependencies create exposure, explore qualified alternatives, dual sources, and design adjustments that reduce sensitivity to any single input. Pair this with regional sourcing or assembly considerations where trade policy affects landed cost.
For Investors and Corporate Development Teams
- Focus on application depth over broad component exposure. Value is accruing to players with strong positioning in rotating equipment monitoring, factory automation displacement feedback, and advanced array-based inspection, where performance, certification, and integration create defensible positions. Evaluate targets and partners through the lens of application mastery and service attach rates rather than unit volume alone.
- Watch consolidation in non-destructive testing and the co-development model in automation. Acquisitions that add array and inspection capability can create cross-selling and platform leverage, while partnerships aimed at large installation targets can accelerate deployment and reduce per-unit risk. Both structures can improve competitive durability if they are paired with strong field support and qualification alignment.
- Assess exposure to trade and material dynamics in cost models. Investments that assume stable input costs or single-origin supply may face margin pressure if commodity volatility or tariff structures shift. Portfolios with diversified sourcing and regional flexibility are better positioned to preserve returns through cycles.
For Procurement and Operations Leaders
- Evaluate the full measurement chain, not just the sensor. In regulated or high-availability contexts, total value includes qualification support, repeatability documentation, ingress protection, and the supplier's ability to support installation and service. A marginally cheaper sensor that creates compliance friction or integration rework can carry higher total cost than a better-documented alternative.
- Specify environmental and protection requirements explicitly. Where washdown, chemical exposure, temperature extremes, or outdoor deployment are expected, treat ingress protection and ruggedization as primary selection criteria. This reduces the risk of field failures and rework and aligns procurement with the realities of the operating environment.
- Negotiate with supply continuity in mind. Given volatility in key materials and trade-related cost impacts, consider sourcing strategies that include qualified alternatives, regional supply options, and clear lead-time commitments. Contracts that account for material and logistics realities are more resilient than those based on static pricing assumptions.
The eddy current sensor market is moving from a phase defined by incremental specification gains to one shaped by application integration, environmental robustness, compliance alignment, and supply chain strategy. Growth at a steady mid-single-digit pace through the end of the forecast period provides a constructive backdrop, but the commercial winners will be those who convert that growth into durable positions in critical monitoring and inspection applications. For decision-makers who need segment-level sizing, regional deployment patterns, competitive benchmarking, and tailored scenario planning, a detailed research report can provide the deeper data and structured frameworks required to translate these trends into concrete portfolio, sourcing, and investment decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Eddy Current Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Print Quality Inspection System Market: Why 5.8% CAGR and $300M Expansion Reshape Production
By PW Consulting, 2026-09-21
The Print Quality Inspection System Market: Navigating Strategic Shifts and Commercial Opportunities
The global landscape for print quality inspection systems is undergoing a structural transformation. What was once a niche segment focused on routine defect detection has evolved into a critical infrastructure layer for manufacturing industries where visual fidelity, regulatory compliance, and production efficiency intersect. The market has demonstrated steady expansion over the past half-decade, with revenue climbing from approximately USD 148.5 million in 2020 to USD 201.5 million in 2025. Projections through 2032 indicate continued growth, reaching an estimated USD 300.0 million by the end of the forecast period, supported by a compound annual growth rate of 5.8 percent. This trajectory reflects more than incremental demand; it signals a fundamental reassessment of how manufacturers approach quality assurance in an era defined by tighter regulatory frameworks, rising labor costs, and accelerating automation adoption.
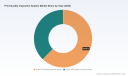
Yet the growth narrative is not uniform across all segments or regions. The market remains moderately fragmented, with the top three players capturing roughly 24.6 percent of total revenue and the top five accounting for approximately 26.2 percent. Such concentration levels suggest a competitive environment where established incumbents hold meaningful advantages in brand recognition, installed base, and technical maturity, but where room exists for differentiated newcomers and niche specialists to carve out defensible positions. The following sections dissect the forces shaping this market, the competitive dynamics at play, and the strategic implications for executives navigating procurement decisions, investment allocations, and product development roadmaps.
Market Structure and the Current Growth Trajectory
The print quality inspection system market has expanded consistently since 2020, with each year underscoring a broader industrial shift toward automated visual verification. Revenue growth between 2023 and 2024, for instance, reflected a notable step change as manufacturers accelerated deployment of inspection hardware on high-speed production lines. By 2025, the market had surpassed the USD 200 million threshold, and forward estimates suggest that annual revenue will continue climbing at a pace that outstrips general manufacturing equipment growth rates. This expansion is not merely a function of unit sales; it is increasingly tied to the value of integrated software, cloud-enabled workflows, and AI-driven defect classification, which together elevate the total cost of ownership and lifetime value of each installation.
Geographically, the market exhibits a multi-polar distribution rather than reliance on a single dominant region. North America, Europe, and Asia Pacific each represent substantial revenue pools, reflecting the widespread adoption of inspection systems across packaging, pharmaceutical labeling, and consumer goods manufacturing. Emerging regions such as Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by localized packaging investments and the gradual modernization of legacy production lines. The geographic spread indicates that demand is not confined to mature industrial economies; rather, it is spreading as manufacturing capabilities and regulatory expectations mature across diverse markets.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the market faces several friction points that will determine which participants capture disproportionate value over the next five to seven years.
First, the transition from traditional rule-based inspection to AI-enhanced defect recognition remains uneven. While the technology promise is clear, manufacturers must weigh the upfront integration complexity against incremental yield improvements. Legacy systems often rely on fixed thresholds and manual calibration, which limits adaptability to shifting substrates, ink formulations, or packaging designs. Upgrading to systems capable of learning from production variability requires not only hardware refresh but also data infrastructure, operator training, and sustained model maintenance. This creates a barrier for mid-sized producers who may lack the internal engineering capacity to manage algorithmic lifecycle management.
Second, regulatory pressure is intensifying the stakes for inspection accuracy, particularly in sectors where visual defects carry compliance or safety implications. In pharmaceutical and medical packaging, print quality is not merely a cosmetic concern; it is tied to traceability, dosage clarity, and patient safety. Recent regulatory updates, including the Quality Management System Regulation that took effect in early 2026 and incorporated ISO 13485:2016 principles, have tightened quality management expectations for device manufacturers. These changes increase the value of inspection systems that can provide auditable records, consistent defect classification, and integration with broader quality management workflows. At the same time, they raise the compliance burden for suppliers who must demonstrate that their inspection solutions meet evolving standards across multiple jurisdictions.
Third, capital intensity and infrastructure requirements constrain adoption in certain deployment contexts. High-speed line scan imaging modules, specialized illumination, and integration with existing web or sheet-fed lines represent significant investment. For some producers, the decision to deploy a comprehensive inspection system competes with other capital priorities, especially when labor shortages are not yet acute enough to force automation. Industry data points to rising labor constraints in manufacturing as a broader catalyst for inspection adoption, but the translation of labor pressure into procurement decisions varies by region, sector, and company size. This creates a bifurcated market where large, efficiency-focused operators move quickly while smaller or margin-constrained players lag.
Core Drivers Shaping the Market
The sustained expansion of the print quality inspection system market is propelled by a convergence of technological, regulatory, and operational forces. Understanding these drivers in isolation is useful; understanding their interaction is essential for strategic planning.
Technological Innovation and the AI Transition
The most consequential shift in the market is the integration of machine vision and AI-based defect detection into inspection workflows. Vendors are increasingly offering systems that combine high-resolution imaging with algorithmic classification, enabling real-time identification of misregistration, color deviation, foreign material, and substrate defects. This evolution addresses a long-standing limitation of earlier inspection approaches: the reliance on static defect libraries that struggle to adapt to new packaging formats or variable production conditions. AI-enhanced systems can reduce false rejects, improve line throughput, and provide richer data outputs that feed into downstream quality analytics.
Product launches and software releases over recent years illustrate how vendors are translating this technological trajectory into commercial offerings. One notable example is the introduction of an AI-powered inspection platform designed for high-speed printing and packaging environments, which emphasizes automated visual quality control and defect detection at production speeds. Another significant development is the release of cloud-based prepress inspection software that operates independently of specific hardware configurations, reflecting a broader industry move toward software-centric value addition. These releases signal that competitive differentiation is increasingly determined by software ecosystems, data portability, and the ability to integrate with prepress, production, and quality management systems rather than by imaging hardware alone.
Regulatory and Compliance Pressures
Regulatory expectations are reinforcing demand for inspection systems that deliver consistency, traceability, and audit readiness. Quality management standards such as ISO 9001:2015 serve as foundational references for inspection workflows across global manufacturing, while sector-specific requirements add further layers of complexity. In pharmaceutical and medical packaging, inspection systems must align with standards enforced by regulatory bodies such as the FDA and EMA, ensuring that print quality supports broader compliance obligations. The recent amendment of device current good manufacturing practice requirements through the Quality Management System Regulation exemplifies how regulatory updates can directly influence procurement priorities by raising the bar for documented quality control and process verification.
For manufacturers operating in regulated environments, the commercial case for advanced inspection systems is strengthened by the potential to reduce compliance risk, streamline audit preparation, and standardize defect documentation across lines and sites. This dynamic is particularly relevant for multinational producers who must maintain consistent quality standards across diverse regulatory regimes. Inspection systems that offer configurable rule sets, robust data logging, and integration with quality management platforms are better positioned to meet these demands than standalone defect detection tools.
Demand-Side Shifts in Packaging and Labeling
Consumer expectations and retail dynamics are reshaping the packaging and labeling sector in ways that indirectly elevate the importance of print quality inspection. Brands are increasingly reliant on packaging as a primary engagement channel, which raises the visibility of print defects and the reputational cost of quality failures. At the same time, the proliferation of short-run packaging, variable data printing, and customized labeling increases production variability, making manual inspection less scalable and more error-prone. In food and beverage, consumer goods, and medical packaging, the combination of higher quality expectations and more heterogeneous production runs drives demand for inspection systems that can maintain accuracy across frequent changeovers.
Worldwide Thermal Warpage Inspection System Market
This demand-side evolution also intersects with operational efficiency goals. As manufacturers seek to minimize waste, reduce rework, and improve first-pass yield, inspection systems function as both a quality gate and a productivity enabler. Real-time defect detection allows operators to intervene before defective material proceeds further down the line, reducing material loss and downstream sorting costs. In high-volume environments, even small improvements in defect capture rates can translate into meaningful savings over time, strengthening the return case for inspection investments.
Supply Chain and Cost Structure Considerations
The cost structure surrounding print quality inspection systems is influenced by component availability, integration complexity, and the broader economics of high-speed imaging hardware. Capital equipment costs and infrastructure investments for advanced line scan modules represent a notable deployment barrier, particularly for producers upgrading from legacy systems or introducing inspection on previously unmonitored lines. At the same time, the supply chain for vision components, illumination systems, and processing hardware continues to evolve, with vendors seeking to balance performance with total cost of ownership.
Rising labor costs and workforce constraints in manufacturing are also reshaping the cost-benefit calculus for inspection adoption. In environments where skilled operators are difficult to recruit or retain, automated inspection offers a pathway to stabilize quality output while reducing reliance on manual inspection labor. This dynamic does not uniformly apply across all markets, but it is increasingly relevant in regions and sectors where labor availability is tightening. The interaction between labor economics and inspection investment helps explain why adoption rates can diverge even among producers with similar product portfolios.
Competitive Landscape and Strategic Positioning
The competitive environment in the print quality inspection system market is characterized by a mix of specialized inspection vendors, broader machine vision providers, and prepress solution companies. This diversity reflects the multidisciplinary nature of the market, which draws on expertise in imaging, color measurement, web monitoring, packaging workflows, and quality management software. The presence of both established European and North American players and rapidly evolving Asian manufacturers adds further complexity, as differing regional strengths shape product focus, pricing approaches, and go-to-market strategies.
Differentiation Strategies Among Leading Players
Leading participants are pursuing differentiation along several axes, with the most successful strategies combining technical capability with workflow integration and sector-specific relevance.
- Some vendors position themselves around AI-powered inspection for packaging and printed products, emphasizing defect detection and prepress verification across dedicated hardware and software series. Their approach targets customers who prioritize integrated solutions with established brand recognition in print inspection.
- Other companies focus on label and flexible packaging applications, offering real-time defect detection and color measurement tools designed to reduce waste and support high-speed production environments. This specialization allows them to align closely with the operational priorities of label converters and flexible packaging manufacturers.
- A separate group develops vision-based inspection systems for printing and packaging that emphasize automated visual quality control at high speeds, often leveraging AI to improve defect classification and adaptability across substrates.
- Web monitoring and inspection specialists serve the pulp, paper, and printing industries with surface defect detection solutions, reflecting a distinct application focus that differs from packaging-centric vendors.
- Providers of integrated web inspection and tension control systems combine print quality solutions with broader process control capabilities, appealing to customers who value unified monitoring across multiple production parameters.
- Machine vision and vision system companies offer automated inspection and verification tools for packaging and labeling, drawing on broader portfolio strength in industrial vision to address print quality as part of a larger automation strategy.
- Prepress and artwork verification vendors concentrate on upstream quality control, enabling automated artwork and packaging verification before production, which complements downstream inspection and can reduce defect propagation.
These positioning differences matter because they shape which customers view a given vendor as a natural fit. A label converter prioritizing real-time waste reduction will evaluate vendors differently than a pharmaceutical packaging producer focused on compliance documentation and audit readiness. Similarly, a printing operation seeking to upgrade both prepress and in-line inspection may prefer a vendor with capabilities spanning both domains, while another may value best-of-breed specialization.
Recent Market Movements and Their Strategic Signals
Recent corporate and product developments provide useful signals about where competitive pressure is intensifying and how vendors are attempting to capture value. One significant move involved the acquisition and restructuring of a prominent inspection company into an independent entity, enabling a dedicated focus on print quality inspection solutions. Such a transformation typically reflects a strategic decision to sharpen product focus, reallocate resources, and respond more agilely to market demands without the constraints of a broader corporate structure. For customers, this can translate into more specialized support and roadmap clarity; for competitors, it may intensify pressure in segments where the newly independent company has strong installed bases.
On the product side, the launch of a next-generation AI inspection system at a major industry event highlighted the continuing emphasis on AI-driven visual quality control for printing applications. Concurrently, another vendor introduced cloud-based prepress inspection software designed to operate independently of specific hardware, underscoring a shift toward software-defined inspection workflows that can reduce dependency on proprietary hardware ecosystems. The visibility of these solutions at major trade events further illustrates how vendors are using industry platforms to demonstrate defect detection capabilities and align product messaging with current production challenges.
Taken together, these developments suggest a market in which hardware capability remains important, but software flexibility, AI maturity, and workflow integration are increasingly decisive in competitive battles. Vendors that can offer modular, upgradeable solutions and clear data pathways between prepress, production, and quality management systems are better positioned to retain customers through technology refresh cycles.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The moderate concentration levels in the market indicate that fragmentation persists, but the trajectory points toward gradual consolidation in certain segments. Larger machine vision and industrial automation companies may seek to expand their footprint by leveraging existing customer relationships and broader automation portfolios, while specialized inspection vendors may pursue partnerships, selective acquisitions, or geographic expansion to strengthen their positions. At the same time, new entrants—particularly those bringing novel AI capabilities or cost-competitive imaging architectures—can gain traction in segments where incumbents are slow to adapt or where price sensitivity is elevated.
The evolution of the market will likely be shaped by the relative success of three dynamics. First, consolidation may accelerate where installed base advantages and service networks create meaningful switching costs, allowing larger players to capture share through bundling and cross-selling. Second, specialization may remain attractive in high-value verticals such as pharmaceutical packaging, where compliance expertise and sector-specific workflows command premium positioning. Third, new entrants may disrupt segments where traditional inspection approaches are perceived as overly rigid or too costly relative to emerging AI-based alternatives. The interplay among these dynamics will determine which companies build durable advantages and which face pressure to differentiate more sharply or reposition.
X-ray Inspection Systems Market
Forward Outlook: Three Trends to Watch
Looking ahead, the print quality inspection system market is likely to be shaped by several interconnected trends over the next three to five years.
AI Maturity and the Shift from Detection to Classification and Prediction
The next phase of AI adoption in inspection systems is expected to move beyond basic defect detection toward more sophisticated classification, root-cause suggestion, and predictive quality analytics. As algorithms become more robust and training data more abundant, inspection systems can increasingly distinguish between defect types, prioritize issues by severity, and feed insights back into process control. This evolution enhances the value of inspection not only as a gate but as an intelligence source that supports continuous improvement. Commercial opportunity lies in systems that can integrate defect data with production parameters, enabling operators to correlate visual defects with substrate changes, ink variability, or machine settings. The primary risk is that AI capabilities may outpace customers’ ability to operationalize them, creating a gap between feature availability and practical benefit realization.
Software-Defined Inspection and Interoperability as Competitive Battlegrounds
The introduction of hardware-independent, cloud-enabled inspection software reflects a broader movement toward interoperability and software-centric value. As manufacturers seek to avoid lock-in and integrate inspection data across prepress, production, and enterprise quality systems, the ability to exchange data seamlessly and configure inspection workflows without hardware constraints will become more important. Vendors that invest in open architectures, standardized data outputs, and flexible deployment models are likely to gain an advantage in environments where multi-vendor equipment and evolving IT strategies are the norm. The risk for the market is that interoperability expectations may pressure margins for vendors reliant on proprietary hardware ecosystems, while also raising the bar for software development and integration support.
PW Consulting
Regulatory Tightening and Sector-Specific Premiumization
As regulatory frameworks continue to evolve, particularly in pharmaceutical, medical, and food-related packaging, the premium on inspection systems that support compliance documentation, audit readiness, and consistent defect classification is likely to increase. This creates a segmentation dynamic in which regulated sectors may adopt higher-specification solutions and accept stronger compliance-related value propositions, while less regulated segments may compete more intensely on price and throughput. Commercial opportunity exists for vendors that can clearly articulate compliance benefits, provide configurable rule sets aligned with sector requirements, and offer data integrity features that support audit trails. The uncertainty lies in the pace and variability of regulatory change across jurisdictions, which can complicate product planning and require ongoing adaptation.
Strategic Guidance for Decision Makers
The trajectory of the print quality inspection system market suggests that decision makers should evaluate opportunities and risks through a lens that goes beyond unit pricing and specification sheets. In practice, three strategic considerations stand out.
For manufacturers and producers considering inspection deployment, the priority should be to align system selection with the broader quality and operational roadmap rather than treating inspection as an isolated procurement. This means evaluating how well a solution integrates with prepress workflows, production line control, and quality management systems, and whether it can scale as defect classification, data analytics, and regulatory documentation needs evolve. It also means assessing total cost of ownership in the context of labor constraints, waste reduction potential, and compliance risk, rather than focusing solely on initial capital expenditure. Where possible, manufacturers should favor solutions that offer modular upgrade paths, configurable inspection rules, and clear data portability, reducing the risk of obsolescence as requirements change.
For investors and strategic partners, the market presents a nuanced opportunity set shaped by the balance between hardware-driven deployments and software-defined value creation. Companies that can demonstrate AI capability, interoperability, and sector-specific relevance are better positioned to capture share than those competing primarily on imaging hardware alone. Investment theses should consider the durability of installed base advantages, the potential for consolidation in segments with high switching costs, and the risk that new entrants with novel AI or cost architectures could challenge incumbents in price-sensitive segments. Due diligence should also account for regulatory exposure, particularly in verticals where compliance dynamics directly influence procurement decisions and solution requirements.
For procurement and quality leaders, the immediate focus should be on building an inspection strategy that balances near-term defect reduction with long-term data utilization. This includes defining clear acceptance criteria for defect classification accuracy, false reject rates, and integration requirements; ensuring that inspection data can feed into broader quality analytics; and evaluating vendor support for changeovers, substrate variability, and evolving regulatory expectations. Procurement decisions made without a clear view of data integration, compliance alignment, and upgrade flexibility may deliver short-term savings but create downstream bottlenecks as quality programs mature. Access to detailed segmentation data, vendor benchmarking, and customized deployment scenarios can materially improve the quality of these decisions, particularly when evaluating multi-vendor shortlists or planning multi-site rollouts.
For executives seeking a more granular understanding of regional demand patterns, application-specific growth differentials, and vendor-level positioning across sub-segments, a deeper dive into the full research dataset can provide the scaffolding needed to translate these market-level insights into actionable plans. Detailed breakdowns of segmentation dynamics, competitive benchmarks, and scenario-based procurement considerations can help clarify where to prioritize investment, which vendor profiles warrant closer evaluation, and how to structure quality inspection roadmaps in line with operational and regulatory realities.
For detailed analysis of this topic, please visit the official page: Print Quality Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Micro-Lens Arrays Market: Strategic Trends and Commercial Opportunities Beyond 2030
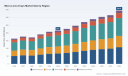
The global micro-lens array (MLA) market has matured into a strategically vital component of modern optical systems, driven by the convergence of photonics innovation, automotive electrification, and high-bandwidth data infrastructure. From 2020 through 2025, the sector expanded from approximately USD 163 million to an estimated USD 215 million, reflecting a compound annual growth rate (CAGR) of 6.49% across the forecast horizon extending to 2032. This trajectory is not merely a function of incremental demand; it signals a structural shift in how precision optics are integrated across telecommunications, advanced driver-assistance systems, medical imaging, and next-generation energy modules. As the market approaches a projected valuation exceeding USD 340 million by 2032, executives and investors must navigate a landscape where technological differentiation, supply chain resilience, and regulatory volatility intersect.
PW Consulting
Market Snapshot: Scale, Structure, and Hidden Pressures
The MLA ecosystem has transitioned from a niche photonics supplier to a foundational enabler of high-value optical architectures. Historical revenue patterns reveal a market that experienced a brief contraction in 2022, followed by a robust rebound and sustained expansion through 2025. This correction was temporary but instructive: it exposed the fragility of highly optimized, geographically concentrated supply chains when confronted with raw material constraints and sudden trade policy shifts. By 2025, the market's recovery and upward momentum underscore a broader reality—demand for micro-optical components is no longer cyclical; it is structurally embedded in multiple high-growth verticals.
Worldwide Microdisplay Spatial Light Modulators Market
Several structural pressures are reshaping how manufacturers, buyers, and capital allocators approach the space. First, precision fabrication requirements have tightened tolerances across pitch accuracy, surface quality, and coupling efficiency, elevating process control costs and extending lead times. Second, raw material dynamics have introduced periodic volatility, particularly for specialty optical glasses doped with rare-earth elements, where sourcing bottlenecks can quickly translate into pricing adjustments. Third, regulatory interventions in major consumer markets have recalibrated procurement strategies, compelling buyers and producers alike to reconsider geographic sourcing, inventory buffering, and localized production pathways. These pressures are not isolated disruptions; they are becoming baseline considerations in strategic planning.
Key Drivers Reshaping the Micro-Lens Arrays Landscape
Technological Innovation and Process Maturation
The acceleration of co-packaged optics (CPO), silicon photonics integration, and high-density fiber coupling has elevated MLAs from passive optical elements to active performance determinants. Fabricators are increasingly deploying wafer-level imprint lithography, two-photon polymerization, and hybrid glass-composite molding to achieve freeform, aspherical, and sub-micron pitch architectures. These process advances enable tighter beam shaping, improved homogenization, and higher coupling efficiency in telecom and datacom environments. At the same time, additive microfabrication techniques are unlocking complex geometries that were previously cost-prohibitive, expanding the design space for machine vision, laser systems, and compact medical optics. The commercial implication is clear: vendors that can translate fabrication agility into repeatable, high-yield production gain a measurable edge in qualification cycles and customer retention.
Policy and Regulatory Realignment
Trade policy adjustments in the United States during 2025 introduced additional duties on imported fused silica substrates and finished microlens arrays, directly altering cost structures and procurement timelines. Rather than treating these measures as transient friction, leading organizations are recalibrating sourcing architectures to reduce exposure to single-point customs risk. This has spurred incremental investments in localized manufacturing, dual-sourcing arrangements, and qualification of alternative substrate materials. Regulatory shifts of this nature typically accelerate supplier consolidation among entities with established compliance infrastructure, while simultaneously opening opportunities for regional producers capable of meeting technical specifications without compromising lead times.
Demand-Side Evolution in End-Use Verticals
Demand momentum is increasingly dictated by application adoption curves rather than broad macroeconomic indicators. In telecommunications and IT infrastructure, the push toward higher bandwidth, lower latency, and integrated optical interconnects continues to drive MLA utilization in fiber coupling and light management. Automotive applications are expanding as advanced lighting architectures, sensing modules, and in-vehicle optical systems require compact, reliable micro-optics that can withstand harsh environmental conditions and meet stringent quality standards. Medical imaging, diagnostic devices, and specialized laser systems contribute a steady, high-value demand stream where precision and repeatability outweigh cost sensitivity. Concurrently, solar module optimization and auxiliary optical applications provide incremental volume that supports capacity utilization. For commercial leaders, the strategic takeaway is to align product roadmaps with the qualification rhythms and technical thresholds of these verticals, rather than competing solely on price in commoditized segments.
Supply Chain and Cost Structure Realities
Precision manufacturing of MLAs remains labor- and process-intensive. High-precision polishing, alignment, and metrology contribute to elevated unit economics, particularly as volumes scale and tolerance requirements tighten. Material supply concentration in select regions for high-grade optical glass introduces vulnerability to geopolitical friction, export control expansions, and localized disruptions. These structural characteristics mean that lead-time reliability, quality consistency, and technical support often carry as much commercial weight as baseline pricing. Organizations that invest in process stabilization, qualification transparency, and resilient material sourcing are better positioned to convert technical capability into sustained contract wins and reduced negotiation friction.
Competitive Landscape: Positioning, Differentiation, and Evolution
The MLA market remains moderately concentrated, with the top three participants collectively accounting for just under a quarter of total revenue and the top five holding a slightly larger share. This fragmentation reflects a market where technical specialization, application-specific qualification, and regional servicing capabilities often matter more than scale alone. Several established players illustrate distinct strategic archetypes that define current competitive dynamics.
Glass-focused fabricators have built reputations around high-precision glass microfabrication, molding, and composite technologies, targeting applications such as CPO, digital imaging, high-brightness LEDs, and OLED architectures. Their differentiation typically hinges on material consistency, yield stability, and deep process know-how in glass-based optics. Custom photonics specialists, by contrast, emphasize design flexibility and rapid iteration, offering dedicated engineering services that help customers translate optical concepts into manufacturable MLA devices. This service-led model supports next-generation photonics development and positions the supplier as a design partner rather than a pure component vendor.
Wafer-scale manufacturers operating on 150mm and 150mm-class platforms serve telecom, datacom, automotive, and consumer segments with a focus on pitch accuracy and coupling efficiency. Their competitive strength lies in standardized substrate handling, repeatable wafer-level processes, and qualification pathways aligned with automotive and semiconductor expectations. Meanwhile, additive microfabrication providers leverage two-photon polymerization to deliver freeform and hybrid micro-optics on fibers and chips, targeting complex geometries and rapid prototyping cycles that conventional lithography cannot easily accommodate. Imprint lithography specialists contribute wafer-level MLAs suited for automotive lighting, fiber coupling, photonic integrated circuits, and semiconductor applications, with quality systems aligned to automotive production standards.
Other participants differentiate through material selection and application focus. Some offer high-grade fused silica arrays with spheric, aspheric, or freeform profiles tailored for fiber coupling, while others emphasize precision polishing and alignment for machine vision, laser systems, and optical sensing. PMMA-based arrays remain relevant for light homogenization and shaping in research, instrumentation, and industrial settings where cost and ease of integration are prioritized. Across these profiles, the common thread is application alignment: vendors that embed their technical strengths within the qualification and performance requirements of specific use cases tend to secure more durable demand.
The competitive trajectory is moving toward selective consolidation and parallel specialization. Larger optical and materials groups are exploring targeted acquisitions or partnerships to broaden substrate capabilities, strengthen regional service coverage, and accelerate qualification in regulated verticals. At the same time, new entrants with advanced fabrication methods or niche design expertise continue to fragment the market at the high-value end, particularly where freeform design, hybrid materials, or custom photonics services create Defensible differentiation. The net effect is a landscape where broad commoditization is limited; value accrues to organizations that can combine technical precision, application understanding, and supply chain reliability.
Optical Lenses Market
Commercial Implications of the Competitive Shift
- Technical service and design engagement are becoming as important as component pricing, especially for customers developing next-generation optical architectures.
- Regional qualification and compliance readiness increasingly influence sourcing decisions, particularly in automotive and telecom environments.
- Substrate availability and material continuity are emerging as deal-critical factors, elevating the strategic importance of diversified sourcing and inventory planning.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Integration-Driven Demand in High-Bandwidth Optical Architectures
As co-packaged optics and photonic integration gain traction in datacom and telecom deployments, MLAs will be evaluated less as standalone components and more as integrated elements within broader optical subsystems. This shift favors suppliers who can support system-level design considerations, including alignment tolerances, thermal stability, and coupling efficiency under realistic operating conditions. The opportunity lies in offering qualified, repeatable MLAs that reduce integration risk for system designers, while the risk is that pricing pressure intensifies if specifications become standardized across multiple vendors.
Trend 2: Regionalization of Sourcing and Manufacturing Capability
tariff measures and raw material concentration risks are accelerating a broader move toward localized production, dual sourcing, and qualification of alternative supply bases. Over the next several years, this is likely to produce a more geographically diversified supplier base for fused silica and specialty glass MLAs, with regional hubs emerging to serve nearby automotive, medical, and industrial customers. The upside is improved lead-time predictability and reduced customs exposure; the downside is that firms without capital to invest in localized capacity or qualification infrastructure may face margin compression or exclusion from preferred supplier lists.
Trend 3: Advanced Fabrication Methods Opening High-Value Niches
Additive microfabrication, imprint lithography, and hybrid molding are expanding the feasible design space for freeform, hybrid, and complex micro-optics. These methods create openings in custom photonics, compact sensing, and specialized imaging applications where performance requirements cannot be met by conventional arrays. The commercial benefit is access to higher-margin, application-specific work; the risk is that process scalability and cost control remain challenging, potentially limiting volume growth if demand stays fragmented across many small programs.
Associated Risks and Uncertainties
- Raw material availability for rare-earth-doped optical glasses may continue to create periodic cost and lead-time volatility during demand spikes.
- Regulatory frameworks can shift quickly, altering the relative attractiveness of different sourcing routes and requiring continuous supply chain reassessment.
- Labor intensity in high-precision polishing and alignment may sustain elevated unit economics, limiting the pace at which cost reductions can be passed through to customers.
- Geopolitical disruptions or export control expansions could disproportionately affect supply chains with concentrated production in a small number of regions.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Prioritize process stabilization and qualification transparency in the segments where you intend to compete. In automotive and telecom environments, documentation, repeatability, and compliance readiness often determine supplier selection as much as baseline performance. Evaluate whether to deepen specialization in a high-value niche—such as custom photonics design, freeform micro-optics, or wafer-level automotive lighting—or to expand substrate and material options to reduce concentration risk. Where feasible, develop dual-sourcing strategies for critical raw materials and consider regional capacity or partnerships that shorten lead times for nearby customer bases.
For Investors and Capital Allocators
Focus diligence on differentiation durability rather than headline growth alone. The most resilient opportunities typically combine technical moats, application-specific qualification, and supply chain resilience. Assess whether target companies have clear pathways to scale without sacrificing quality, whether their customer base is diversified across multiple verticals or overly dependent on a single program cycle, and whether they have responded to recent trade and material dynamics with actionable sourcing or capacity strategies. In a moderately concentrated market, value creation often comes from firms that can convert specialized capability into recurring, qualified demand rather than from broad-based volume plays.
For Procurement and Engineering Leaders
Treat MLA sourcing as a systems-integration decision rather than a commodity purchase. Align specifications with actual performance needs, qualify alternative substrates and suppliers where feasible, and build buffer strategies for materials with known concentration risk. Engage suppliers early on design-for-manufacturability and qualification timelines to reduce downstream rework and schedule risk. Where application requirements permit, balance precision requirements against cost by selecting the simplest architecture that meets system performance targets, reserving high-complexity freeform or hybrid designs for cases where they deliver measurable system-level benefits.
The micro-lens arrays market is entering a phase where technical capability, supply chain resilience, and application alignment determine commercial outcomes more than volume alone. Decision makers who map their strategies to these structural dynamics will be better positioned to capture high-value demand while navigating material, regulatory, and process uncertainties. For organizations seeking detailed segmentation data, regional demand patterns, and tailored recommendations aligned to specific product portfolios or investment theses, the full PW Consulting research report provides the deeper quantitative and qualitative detail needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Micro-Lens Arrays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bovine Lactoferrin Market 2026: How the 4.3% CAGR and Asia Pacific’s 325.41M Surge Redefine Growth
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Bovine Lactoferrin Market
Market Snapshot and the Structural Inflection Point
The bovine lactoferrin market has moved from a niche specialty ingredient to a strategically significant component of the global nutrition and health ecosystem. Valued at approximately 378.0 million USD in 2020, the market expanded to 565.08 million USD by 2025, reflecting a compound annual growth rate of 4.3 percent over the 2026-2032 forecast period. Annual revenue is projected to progress from 591.33 million USD in 2026 toward 747.35 million USD by 2032, signaling sustained demand expansion rather than a temporary cyclical uptick.
This trajectory is not uniform across segments or geographies. The market is fragmenting along functional, regulatory, and sourcing lines, creating pockets of high-value growth alongside commodity-like pressure in commoditized supply chains. For executives and investors, the headline growth rate obscures a more nuanced reality: value migration is occurring toward producers who can guarantee purity, traceability, functional consistency, and regulatory clearance across multiple jurisdictions simultaneously.
Several structural challenges and inflection points are reshaping how participants position themselves:
- Functional consistency versus scale tension . Manufacturers face mounting pressure to deliver batch-to-batch consistency in iron-binding capacity, protein integrity, and microbiological profile while scaling output. As demand concentrates in infant nutrition and premium dietary supplements, buyers increasingly treat lactoferrin as a functional active rather than a bulk dairy by-product, raising the cost of quality failures.
- Regulatory divergence as a market filter . Jurisdictional differences in ingredient classification, novel food assessment, and safety notifications are creating asymmetric market access. Companies that can navigate multiple regulatory pathways simultaneously are gaining disproportionate commercial leverage, while those dependent on a single region face constrained expansion options.
- Feedstock volatility and margin sensitivity . High-quality bovine milk feedstock exhibits price volatility tied to seasonal variations, feed costs, and broader dairy market fluctuations. This introduces margin unpredictability for producers and complicates long-term pricing commitments for formulators, particularly in categories where lactoferrin represents a meaningful share of raw material cost.
These dynamics are not merely operational headaches; they are strategic filters. They determine which players can credibly serve premium segments, which can secure multi-year supply agreements, and which are relegated to price-competitive commodity positions.
Key Drivers Reshaping the Market
Precision fermentation and bioprocessing breakthroughs
A defining shift in the market is the emergence of precision-fermented bovine lactoferrin as a commercially viable alternative to milk-derived extraction. In May 2025, TurtleTree received the first FDA no-questions GRAS letter for precision-fermented bovine lactoferrin, enabling broader use in food and supplement applications. Around the same time, the FDA issued a no-questions GRAS letter for recombinant bovine lactoferrin isolate produced by Komagataella phaffii M020. These regulatory milestones matter because they open a supply pathway that is less tethered to dairy feedstock volatility and potentially more scalable for high-purity applications.
The strategic implication is twofold. First, fermentation-based supply expands the addressable market by reducing dependency on milk supply constraints and offering a potentially more controlled production environment. Second, it introduces a new competitive axis: producers of milk-derived lactoferrin must differentiate on native protein attributes, organic certification, and established regulatory status, while fermentation players compete on scalability, purity, and pricing predictability. This does not eliminate dairy-derived lactoferrin; rather, it segments the market into performance- and credential-driven tiers.
Regulatory acceleration and market access realignment
Regulatory developments are simultaneously opening and structuring demand. China eliminated import tariffs on dairy-based formula foods for special medical purposes, effective in late 2023 and continuing into 2025, creating a more favorable environment for specialized nutrition imports. In parallel, the European Union assessed bovine lactoferrin as a food ingredient in 2025 under Novel Food regulation for uses in infant formula, supplements, and sports nutrition. These processes are not just compliance exercises; they redefine which applications can scale and which regions can serve as growth platforms.
Bovine Colostrum Market
For commercial planners, the key insight is that regulatory clarity often precedes demand formalization. Once an ingredient is cleared for specific categories, formulators can invest in product development, claim substantiation, and distribution with reduced regulatory risk. The uneven pace of approvals across regions means that early movers in cleared markets can build brand and supply relationships before competition intensifies.
Demand-side evolution toward functional and clinical nutrition
Consumer and enterprise demand is increasingly shaped by functional outcomes rather than generic protein supplementation. Infant formula remains a central application area, driven by the perceived nutritional and immune-support benefits of lactoferrin for early-life development. Dietary supplements continue to absorb meaningful volume as well, particularly where lactoferrin is positioned around immune health and active wellness. At the same time, interest is expanding into sports nutrition, medical nutrition, and functional food and beverage formats, where lactoferrin's iron-binding and bioactive properties are being repurposed for differentiated product claims.
This demand evolution raises the stakes for ingredient suppliers. Formulators want documentation, stability data, application compatibility, and regulatory support, not just price and bulk availability. The winners are increasingly those who function as application partners, helping customers integrate lactoferrin into complex matrices while maintaining label-claim integrity and sensory acceptance.
Supply chain reconfiguration and capacity investments
Capacity expansion is a visible signal of strategic confidence in the category. Beston Global Food Company Ltd expanded lactoferrin production capacity at its Jervois dairy factory in Australia to up to 25 MT of 95% pure lactoferrin per year. More broadly, the U.S. Department of Energy invested $9.7 million in alternative protein projects, including lactoferrin, to support decarbonization of the food sector in 2025, reinforcing the policy tailwinds behind alternative and lower-impact production routes.
These investments reflect a broader realignment in supply chain thinking. Participants are increasingly weighing feedstock security, geographic diversification, and processing efficiency alongside traditional metrics such as throughput and unit cost. For buyers, this means supply is becoming more modular and regionally distributed, which can improve resilience but also increases the importance of qualification, vendor auditing, and multi-source strategies.
Competitive Landscape and the Emerging Strategic Playbook
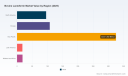
The bovine lactoferrin market remains moderately concentrated, with CR3 at 34.2 percent and CR5 at 41.5 percent. This concentration level suggests a landscape where leading players hold meaningful share but no single entity dominates the category outright. The result is a market in which differentiation, application expertise, and regulatory positioning matter as much as sheer scale.
Worldwide 2'-Fucosyllactose (2'-FL) Market
Several patterns distinguish the more strategically advantaged participants:
- Vertical integration from dairy processing to high-value ingredients . Companies rooted in dairy processing are leveraging existing milk supply, quality systems, and co-product economics to produce lactoferrin alongside broader ingredient portfolios. This model can lower effective feedstock risk and provide operational leverage, particularly when lactoferrin is positioned within a wider nutritional ingredients offering rather than as a standalone commodity.
- Specialization in organic and native-grade positioning . A subset of manufacturers is building reputation around native bovine lactoferrin with specific certification profiles, including organic grade for infant nutrition and dry-mix applications. This approach targets premium segments where purity credentials, traceability, and application-specific documentation command higher margins and deeper customer stickiness.
- Process technology ownership and scale leadership . Long-standing technology relationships and proprietary processing approaches remain a durable advantage. One of the largest-volume producers uses Morinaga process technology, illustrating how established production know-how can underpin scale leadership and consistent output. In a category where functional performance depends heavily on processing integrity, technology lineage is a meaningful moat.
- Regional branding and traceability narratives . Some producers emphasize origin-specific attributes, such as Australian whey sourcing or Swiss production, to differentiate in premium markets. These narratives can support pricing power when they are paired with verifiable quality systems and strong documentation, especially in categories where safety and provenance are closely scrutinized.
Strategic developments in 2024 and 2025 point to an accelerating evolution in the competitive map:
- Joint ventures and commercialization partnerships . In December 2025, All G and Armor Protéines formed a joint venture to scale production and commercialization of human and bovine lactoferrin, with All G's first bovine lactoferrin powder product launching in late 2025. This reflects a broader trend in which companies combine complementary capabilities—one partner may bring production or process strengths, while the other contributes market access or application expertise—to reduce time to scale and de-risk commercialization.
- Capital reinforcement for first-mover positioning . In January 2025, All G raised over A$10 million to support commercial-scale production of its first bovine lactoferrin product, with launch targeted for Q1 2026. Capital inflows of this type often signal investor conviction that scale, purity, and timing can translate into defensible market positions, particularly when paired with clear application roadmaps.
- Regulatory milestones enabling category expansion . TurtleTree's FDA GRAS notice and related regulatory activity are lowering barriers for precision-fermented lactoferrin in food and supplement channels. This expands the competitive field by enabling new entrants to pursue applications that previously depended on milk-derived supply and more complex compliance pathways.
- Capacity and purity upgrades among established producers . Beston Global Food Company Ltd's capacity expansion and emphasis on up to 95% purity illustrate how incumbents are responding to premiumization by improving both volume and grade. This is a competitive response to buyers who increasingly evaluate lactoferrin on functional performance and specification consistency rather than price alone.
The market is therefore not simply consolidating or fragmenting; it is stratifying. At one end, price-competitive volume players compete on supply efficiency and broad availability. At the other, capabilities-driven participants compete on regulatory clearance, application support, purity, and brand credibility. Between these poles, partnerships and joint ventures are becoming a practical mechanism for bridging production scale with commercialization reach.
A critical trend to watch is the rise of hybrid supply strategies. As fermentation-based and dairy-derived routes both advance, some downstream buyers will seek multi-source portfolios to balance cost, resilience, and functional requirements. That, in turn, may push ingredient suppliers to develop clearer product-line segmentation, with distinct specifications and value propositions for different end-use categories rather than offering a single undifferentiated lactoferrin product.
Outlook for the Next Three to Five Years
Precision-fermented lactoferrin will move from regulatory novelty to commercial optionality
The 2025 regulatory progress for precision-fermented bovine lactoferrin is likely to translate into a growing set of commercial pilots and selective scale-up over the next few years. The near-term opportunity lies in applications where controlled purity, supply consistency, and reduced dairy feedstock exposure provide tangible value, such as specialized supplements and certain functional food formats. Over time, fermentation routes could pressure margins in commoditizing segments while also expanding total addressable demand by making high-purity lactoferrin more broadly available.
The commercial risk is that fermentation-based supply initially enters at a cost or scale disadvantage in some applications, or faces its own regulatory and consumer-acceptance hurdles in specific markets. Companies will need to track not just approval status, but actual adoption curves, labeling outcomes, and procurement economics before treating fermentation as a full substitute for milk-derived supply.
Demand will increasingly center on documented functionality and application fit
Over the next three to five years, procurement decisions are likely to place greater weight on functional documentation, stability performance, and compatibility with target matrices. Infant nutrition and premium dietary supplements will remain anchor categories, but the growth conversation will also include sports nutrition, medical nutrition, and functional food and beverage formats where lactoferrin is used for differentiated benefits. Suppliers that can provide robust technical support and category-specific solutions will be better positioned to capture value than those competing primarily on volume and price.
Regulatory and geopolitical asymmetry will shape geographic expansion
PW Consulting
Because regulatory pathways and trade conditions are not moving in lockstep, geographic expansion will increasingly require localized regulatory strategy rather than uniform global positioning. Tariff changes, novel food assessments, and import conditions can open or constrain markets with little warning. Participants that build regional regulatory intelligence into their product and supply planning will gain faster market entry and fewer stalled launches. At the same time, feedstock cost volatility and dairy market swings will continue to require pricing and sourcing strategies that can absorb short-term disruption without undermining long-term contract credibility.
Strategic Actions for Decision Makers
For manufacturers and ingredient suppliers
- Define clear product-tier strategies that separate premium, application-specific offerings from volume-oriented supply. Purity, certification, documentation, and application support should be explicitly mapped to the segments where they generate pricing power and customer retention.
- Invest in regulatory and market-access capabilities as a core commercial function. Track GRAS and novel food developments, tariff shifts, and category-specific clearance status in target markets so that product roadmaps are aligned with where demand can realistically scale.
- Evaluate partnerships and joint ventures where complementary strengths accelerate scale or market entry. In a moderately concentrated market, combining process technology, supply access, or application expertise can be more efficient than building every capability internally.
For investors and corporate development teams
- Assess lactoferrin exposure in the context of application mix and supply route resilience rather than top-line growth alone. Value creation will likely accrue to businesses that can protect margins through differentiation, multi-source options, or regulatory positioning, not simply to those with the largest volume footprint.
- Monitor fermentation-based entrants as both competitors and potential partnership candidates. The strategic question is not whether alternative production will matter, but where it will be economically superior and which applications it will unlock first.
- Watch for consolidation signals around capacity, purity upgrades, and commercialization agreements. Joint ventures and targeted capital raises may indicate where the market is moving from early validation toward scaled commercialization.
For procurement and supply chain leaders
- Diversify sourcing strategies across dairy-derived and emerging supply routes where specifications and compliance profiles align with product requirements. Multi-source portfolios can improve resilience against feedstock volatility and regional supply disruptions, provided qualification and documentation are managed rigorously.
- Standardize technical and regulatory evaluation criteria for lactoferrin ingredients. Batch consistency, purity specifications, stability data, and application compatibility should be assessed with the same discipline as cost, especially when lactoferrin supports claim-sensitive formulations.
- Build forward-looking sourcing plans around expected regulatory and capacity changes. As new capacity comes online and regulatory clearances expand, early qualification of alternative suppliers can reduce launch risk and preserve negotiating leverage.
The bovine lactoferrin market is entering a phase in which commercial success is increasingly determined by specificity: specificity of application, of regulatory readiness, of supply strategy, and of value proposition. Broad market growth provides opportunity, but durable advantage will depend on which organizations can translate that growth into differentiated, defensible positions across increasingly segmented demand and supply environments. Detailed segmentation data, company-level capability assessments, and scenario-based market outlooks can sharpen these decisions further, especially for teams weighing entry timing, capacity commitments, and multi-market rollout strategies.
For detailed analysis of this topic, please visit the official page: Bovine Lactoferrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pad Printing Supplies Market: Why 5.65% CAGR Reshapes Industry Dynamics
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Global Pad Printing Supplies Market
The pad printing supplies market has evolved from a niche decorating technique into a critical enabler of mass customization, product identification, and industrial marking across multiple manufacturing verticals. Over the 2020-2025 period, the sector demonstrated steady expansion, reaching a valuation of 182.0 million USD in 2025. Forward projections indicate the market will scale to 267.3 million USD by 2032, supported by a compound annual growth rate of 5.65 percent through the forecast horizon. This trajectory reflects a maturing yet still dynamic landscape where incremental technological improvements, regulatory tightening, and shifting end-user expectations are reshaping competitive priorities. For executives and investors, the market no longer rewards pure volume play; it rewards precision in formulation, compliance readiness, and the ability to integrate consumable supply with automated production workflows.
The growth pattern is not uniform across all segments. Historical momentum has been anchored by established industrial applications, but the forward curve is increasingly influenced by regions and use cases that demand higher durability, stricter chemical compliance, and faster turnaround. The market structure remains moderately fragmented, with the top three players capturing roughly a third of total revenue and the top five accounting for just under half. This concentration level signals a space where scale advantages exist but are not insurmountable, and where differentiated value propositions can still secure meaningful share. The following analysis examines the structural challenges, demand drivers, competitive positioning, and forward trends that will determine which organizations capture the next wave of value.
Market Landscape and Core Challenges
The pad printing supplies market has built its recent growth on a foundation of recurring industrial demand, but the operating environment is being reshaped by three overlapping pressures that decision-makers cannot treat as background noise. The first is the compliance burden surrounding ink chemistry and material safety. Formulators and converters are no longer competing only on adhesion, color fidelity, or drying speed. They are increasingly evaluated against a widening set of regulatory expectations that govern volatile organic compound emissions, restricted substances, and end-use safety. Products intended for toys, consumer electronics, packaging decoration, or medical-adjacent components must pass through certification and documentation requirements that vary by jurisdiction. This raises the cost of entry for new formulations and forces suppliers to treat compliance as a core product attribute rather than a post-launch add-on.
The second challenge is the tension between automation throughput and consumable consistency. As pad printing moves from manual or semi-manual cells to integrated automated lines, the tolerance for variation shrinks. Pad wear, cliché durability, ink viscosity stability, and cup performance become process reliability issues rather than simple replenishments. Manufacturers that upgrade equipment often discover that the limiting factor is not the machine itself but the consistency of the consumables feeding it. This creates a structural demand for higher-grade pads, more stable ink systems, and tighter technical support, while also exposing suppliers that rely on commodity-grade inputs to quality and claim risks.
The third challenge is cost volatility in raw materials and logistics, layered with a shift in buyer behavior toward total cost of ownership. Price-per-liter comparisons are losing relevance in many procurement cycles because they ignore waste reduction, line downtime, rework, and compliance risk. Buyers are increasingly scrutinizing whether a marginally cheaper ink generates higher hidden costs through slower curing, more frequent pad changes, or failed audits. Suppliers that compete primarily on unit price face margin compression, while those that can demonstrate measurable process efficiency and reduced compliance exposure are better positioned to defend their positioning. Together, these challenges reframe the market from a transactional supplies business into a performance and risk-management partnership.
Key Drivers of Market Evolution
Technological Innovation and Formulation Advances
Technology is reshaping the pad printing supplies market along two reinforcing paths: ink performance and process integration. On the ink side, the industry is moving toward systems that balance print quality with environmental and safety constraints. Solvent-based formulations continue to hold a strong position where adhesion and metering stability are critical, but the innovation frontier is increasingly defined by how cleanly those systems can operate and how easily they fit into controlled production environments. UV-curable options have gained relevance where rapid hardening, reduced handling, and energy-efficient processing are priorities, especially in high-speed decorative and marking applications. Ceramic-based inks remain essential for products that must withstand elevated temperatures and harsh surface conditions, maintaining their role in demanding industrial and household contexts. The broader trend is not replacement of one chemistry by another, but the expansion of application-specific toolkits that let manufacturers match consumables to substrate, curing method, and end-use exposure.
Worldwide Specialty Ink Market
Beyond chemistry, the integration of consumables with automation is becoming a differentiator. Suppliers that support custom mixing, automated ink delivery, pad replacement schedules, and cliché management reduce the operational friction that often slows line optimization. When consumables are treated as part of a controlled process rather than as standalone purchases, manufacturers achieve more predictable output and fewer interruptions. This shift is particularly visible in high-volume environments where even small improvements in metering consistency or pad life translate into meaningful throughput gains. The strategic implication is that value is migrating from the mere supply of materials toward the supply of repeatable, documented process performance.
Regulatory and Compliance Pressure as a Market Filter
Regulatory expectations are increasingly functioning as a market filter, shaping both product design and customer selection. Standards and directives associated with chemical safety, restricted substances, and end-use certification are no longer isolated concerns for specific niches. They influence purchasing decisions across packaging decoration, electronics marking, and consumer goods. In practice, this means that documentation, substance control, and test evidence have become commercial assets. Ink systems that can demonstrate alignment with major compliance frameworks reduce the burden on downstream manufacturers and lower the risk of downstream audit failures or product holds.
Recent market activity illustrates this shift clearly. One major supplier introduced a solvent-based and sustainable pad printing ink system designed to support recycling of recovered packaging materials while maintaining durability for toys, electronics, automotive components, and promotional items. The same offering was positioned as free from phthalates and BPA and suitable for printing on the non-food contact side of packaging, with conformance claims tied to multiple regulatory frameworks. Separately, another supplier achieved certification for a group of eco-focused pad printing inks, emphasizing freedom from naphtha, PAH, and cyclohexanone, with compliance references to REACH, RoHS, and EN 71-3. These moves are not isolated product launches; they signal a broader market dynamic in which environmental and safety credentials are becoming decision-critical, especially where procurement teams must justify material choices to internal stakeholders and external auditors alike.
Digital Textile Printing Ink Market
Demand-Side Shifts in Manufacturing and Branding
Demand is being shaped by a combination of industrialization, product complexity, and brand expectations. Manufacturers are printing more than logos; they are applying identification marks, functional labels, safety information, and decorative finishes that must survive handling, cleaning, and time. The growth of short-run customization and rapid product variation also increases the value of flexible pad printing supplies that can adapt to frequent changeovers without sacrificing quality. In electronics, smaller components and tighter tolerances increase the need for precise deposition and stable ink behavior. In glass and plastic products, surface diversity demands inks and pads that can maintain adhesion across varying textures and finish types. In ceramic and porcelain applications, the need for durability under heat and moisture keeps specialty ink systems relevant.
At the same time, downstream brands and contract manufacturers are placing greater weight on process reliability and material documentation. Procurement is increasingly influenced by the need to reduce variability across shifts, minimize rework, and avoid supply-chain surprises caused by reformulation or compliance gaps. This makes supply consistency, technical support, and change-management capability more valuable than ever. Buyers are not simply purchasing pads, inks, and plates; they are purchasing predictability.
Supply Chain and Cost Structure Realignment
Cost structure is being rethought around durability, waste, and support rather than headline price. Volatile input costs and logistics uncertainty have made it harder for suppliers to compete on discount alone, while buyers are more willing to pay for solutions that reduce line waste or improve uptime. The result is a gradual realignment toward value-based positioning, where suppliers justify their pricing through measurable operational benefits. This also favors companies with stronger technical service models, more controlled formulation pipelines, and the ability to provide custom mixes or region-specific compliance support. For customers, the supply chain is becoming a source of process advantage rather than just a procurement function.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by a mix of established ink and consumables specialists, regional machine-and-consumable integrators, and suppliers that combine equipment, tooling, and consumables under one roof. The distinct strategic advantage in this market is rarely derived from a single product feature. It is built from the combination of formulation capability, compliance readiness, automation support, and service responsiveness. Companies that treat pad printing supplies as a system rather than a commodity are better positioned to retain customers through line upgrades, regulation changes, and application expansion.
On the ink and consumables side, several players are competing on specialized chemistry and certification strength. One German-based supplier maintains a broad portfolio covering inks, clichés, printing pads, ink and doctoring cups, auxiliary materials, and laser cliché production, positioning itself as a full-line provider for pad printing operations. Another German formulates a wide range of solvent-based and UV-curable inks oriented toward industrial decoration, marking, and identification, emphasizing breadth across application types. In the United States, a major international supplier has pushed eco-oriented formulations, including solvent-based and UV pad printing inks designed without phthalates or BPA for packaging and product decoration, appealing to buyers who need both performance and cleaner substance profiles. A separate U.S. consumables specialist has emphasized eco-certified formulations, with a portion of its SB Eco Series inks achieving GOTS certification and aligning with REACH, RoHS, and EN 71-3 requirements. This certification-driven positioning is strategically important because it converts compliance into a marketable advantage rather than a hidden cost.
A second competitive cluster revolves around integration with equipment and automation. One U.S. supplier focuses on custom pad printing machines, tooling, fixtures, and consumables for high-volume automated applications, effectively combining hardware and consumables to reduce sourcing complexity. Another U.S. player offers a wide range of pad printing machines, fixtures, inks, pads, printing plates, and operates a large North American ink warehouse, leveraging distribution scale and inventory depth as a service advantage. A silicone and consumables-focused supplier produces in-house silicone pads, inks, plates, fixtures, and accessories, giving it tighter control over the pad supply chain and a direct route to custom specifications. Yet another U.S. company emphasizes custom-mixed inks, printing pads, cliché plates, and full automation support, highlighting the importance of flexibility in demanding production environments.
The competitive pattern suggests two parallel value routes. The first is depth in formulation and compliance, where differentiation comes from certification, substance control, and application-specific ink performance. The second is breadth and integration, where differentiation comes from equipment compatibility, inventory availability, custom mixing, and process support. Companies that can bridge both routes, even partially, gain a stronger hold on customers because they reduce the number of separate sourcing decisions and make it easier to standardize across multiple lines or sites.
Market structure is likely to evolve through selective consolidation and targeted specialization rather than across-the-board merger activity. Larger players with distribution scale and compliance infrastructure can absorb smaller regional suppliers or geographic distributors, especially where customers value single-source reliability. At the same time, niche specialists can prosper by owning a specific application, chemistry, or certification niche that larger generalists cannot serve as precisely. New entrants face a meaningful barrier in formulation know-how, certification timelines, and established technical service relationships, but they can still gain traction by addressing underserved compliance needs or automation-centric consumable packages. The most durable strategy appears to be building defensible positioning through either regulatory readiness and documented performance, or integrated automation support and customizability, while avoiding reliance on price alone.
Forward Trends and Commercial Implications
Compliance and Eco-Aligned Formulations Will Become Baseline Expectations
Over the next three to five years, the market is likely to see compliance-friendly and lower-impact formulations move from premium differentiators to baseline requirements in many application areas. Buyers serving consumer-facing, electronics, and packaging-adjacent markets will increasingly expect substance control, test evidence, and documentation as standard deliverables. This trend favors suppliers with established certification pathways and formulation discipline, while raising the risk for those that treat compliance as reactive. The commercial opportunity lies in building repeatable compliance narratives that simplify customer purchasing and reduce audit friction. The uncertainty is that regulatory expectations can diverge by region and application, creating a moving target for global suppliers and requiring localized documentation strategies.
Automation-Ready Consumables and Process-Locked Partnerships
As more production lines adopt higher levels of automation, consumables will be evaluated for their behavior inside controlled systems rather than in isolation. This should increase demand for inks and pads that support consistent metering, stable curing or drying, predictable wear, and easier integration with auto-ink delivery or changeover workflows. Suppliers that provide custom mixing, process tuning, and technical support will be better positioned to lock in long-term relationships, because the value they deliver is tied to line performance rather than unit transactions. The opportunity is to design consumables and service packages that reduce downtime and variability. The risk is that automation increases the stakes of inconsistency; a single recurring failure mode can erode trust quickly and push buyers toward more controlled supply alternatives.
Application Expansion and Regional Rebalancing
Forward growth is likely to be supported by continued application expansion across glass and plastic products, ceramic and porcelain items, electronic components, and other industrial uses, with regional demand patterns shifting as manufacturing footprints and export channels evolve. Regions with expanding industrial output, packaging activity, and consumer goods production will create incremental demand for marking, decoration, and identification supplies. The commercial opportunity is to align product portfolios and service coverage with the applications and geographies that are scaling fastest, rather than assuming legacy demand patterns will persist unchanged. The downside is that regional expansion can expose suppliers to new compliance regimes, logistics constraints, and competitive responses, making localized positioning and supply resilience more important than generic global messaging.
Actionable Implications for Decision-Makers
For manufacturing and operations leaders, the priority is to treat pad printing supplies as a process variable with measurable business impact. Procurement should evaluate ink systems, pads, and cliché solutions against line throughput, waste, changeover time, and compliance exposure, not just purchase price. Where production is moving toward higher automation or stricter end-use requirements, teams should prioritize suppliers that can provide documented performance, stable formulation pipelines, and responsiveness to custom specifications. Establishing clear acceptance criteria for consistency and certification documentation can reduce the risk of downstream failures and make supplier comparisons more objective.
For investors and corporate development teams, the market presents opportunities in players with credible compliance positioning, formulation depth, and integration with automation-focused customers. Businesses that have built certification readiness, custom-mixing capability, or strong regional distribution and inventory support are better placed to defend margins and capture share from purely transactional competitors. At the same time, due diligence should account for regulatory variability, raw-material exposure, and the durability of customer relationships beyond single projects. The most attractive profiles typically combine technical differentiation with recurring consumable demand and clear alignment to end-use compliance needs.
PW Consulting
For procurement and sourcing professionals, the strategic task is to move from transactional purchasing to supplier partnership models that reduce total operating risk. That includes evaluating eco-oriented and certified formulations where relevant, aligning consumable selection with equipment and line requirements, and ensuring that documentation and compliance claims are part of the sourcing decision. Where multiple sites or product families are involved, standardization on a smaller set of validated consumables can improve consistency and simplify audits, provided the selected options remain flexible enough for application-specific needs. In markets where compliance expectations are rising, sourcing decisions made without adequate documentation can create hidden cost and operational risk.
For organizations seeking deeper segmentation data, company-level positioning, and scenario-based guidance across regions and applications, the full PW Consulting market research report provides a more detailed breakdown of revenue splits, competitive profiles, and forecast assumptions. The report supports more precise planning by extending the core market view into actionable detail for procurement strategy, investment screening, and long-range capacity or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Pad Printing Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Drive Shaft Market 2026: Beyond The 5.2% CAGR—Strategic Shifts Reshaping Growth
By PW Consulting, 2026-09-21
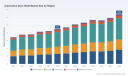
Strategic Trends and Commercial Opportunities in the Automotive Drive Shaft Market
The automotive drivetrain is undergoing one of its most significant structural transformations in decades. As propulsion architectures diversify and vehicle platforms evolve, the drive shaft has shifted from a standardized mechanical component to a strategically differentiated element of vehicle performance, efficiency, and packaging. Market tracking indicates that the global automotive drive shaft sector has grown from approximately $6.9 billion in 2020 to an estimated $9.03 billion in 2025, with a projected compound annual growth rate of 5.2 percent across the 2026–2032 horizon. The trajectory points toward a market surpassing $12.8 billion by the end of the forecast period, reflecting both volume expansion and a steady shift toward higher-performance, lightweight, and application-specific designs.
Beneath the headline growth figures lies a more nuanced reality. The sector is no longer driven solely by total vehicle production; it is increasingly shaped by propulsion mix, regional platform strategies, material substitution, and the consolidation of driveline technology portfolios. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where value is being created, which capabilities are becoming non-negotiable, and how prevailing cost and regulatory pressures will reshape competitive dynamics over the next five years.
Market Landscape and Core Challenges
The current market structure reflects a maturing but directionally shifting ecosystem. Growth over the historical period was supported by steady passenger vehicle demand, incremental content gains in vehicle platforms, and early-stage electrification programs that required rethinking torque delivery and packaging constraints. The commercial vehicle segment continues to provide meaningful volume stability, while the passenger car segment anchors the majority of revenue. Within product categories, hollow shaft designs dominate the revenue split, driven by their weight advantages, torsional efficiency, and broader adoption in modern front-wheel and all-wheel-drive architectures. Solid shafts retain a strong presence where durability, load capacity, and cost predictability remain paramount, particularly in heavier commercial applications and certain rear-drive configurations.
Worldwide Intermediate Shaft for Vehicle Market
Against this backdrop, three core challenges are reshaping how suppliers, OEMs, and investors should read the market.
- Propulsion-mode fragmentation. The transition from conventional internal combustion architectures to hybrid and electric platforms is not a 1:1 replacement of existing driveline content. Electric and hybrid vehicles alter torque characteristics, packaging envelopes, and NVH requirements, forcing suppliers to redesign joint interfaces, support structures, and shaft geometries. This creates short-term engineering complexity and lengthens validation cycles, even as it opens longer-term opportunities for propulsion-agnostic driveline systems.
- Material cost volatility and sourcing pressure. Steel continues to serve as the foundational material for many drive shaft applications because of its balance of strength, toughness, and supply chain maturity. At the same time, aluminum and composite solutions are gaining ground where weight reduction and efficiency targets are most stringent. The practical challenge is that raw material price swings for steel, aluminum, and composites can push component costs upward by as much as 15 percent in a single year, complicating quotation stability, margin planning, and long-term program commitments.
- Competitive concentration with room for differentiation. The market remains relatively fragmented at the top, with the leading three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration signals a sector where scale, customer relationships, and engineering breadth matter, but also where differentiation is still possible through application-specific engineering, regional manufacturing footprints, and value-added design services. In practical terms, market share alone does not guarantee resilience unless it is paired with program wins in higher-growth configurations and cost-competitive execution.
Key Demand Drivers
Technology Innovation and Design Breakpoints
The most consequential driver of near-term market change is the engineering redefinition of what a drive shaft must accomplish. Lightweight aluminum and carbon fiber composites are increasingly specified by EV manufacturers as standard options to meet efficiency and emissions requirements, signaling a structural shift in component specifications rather than a temporary trend. This push toward weight reduction intersects with higher torque density in electrified powertrains, which places new demands on joint durability, balance, and vibration damping. Suppliers that can deliver hollow shaft designs with tighter tolerances, optimized wall profiles, and advanced joint integration are better positioned to capture content in vehicles where every kilogram and every decibel of NVH performance matters.
Technically, the opportunity is not limited to material substitution. The growth of high-angle CV joints, telescopic solutions, and integrated driveline architectures reflects a broader demand for packaging flexibility in crossovers, EVs, and premium passenger vehicles. Product launches in this space are increasingly framed around supporting multiple propulsion types within a single platform strategy, which suggests that future winning components will be judged as much on adaptability as on baseline performance.
Policy and Regulatory Environment
Regulatory expectations continue to influence design choices indirectly but powerfully. Efficiency mandates, emissions targets, and durability standards create incentives for weight reduction, friction reduction, and longer service life. In electric vehicle programs, these requirements can translate into more aggressive use of aluminum and composites, as well as tighter specifications for rotating components. The regulatory environment also affects commercial vehicle demand, where emissions and payload considerations shape axle and driveline selection. While policy does not prescribe a single drivetrain architecture, it consistently raises the cost of inefficiency, which benefits suppliers capable of delivering lighter, more integrated, and more reliable driveline solutions.
Demand-Side Shifts in Consumer and OEM Behavior
On the demand side, the expansion of SUVs, crossovers, and premium passenger vehicles has increased the relevance of driveline systems that can accommodate varied packaging constraints and higher performance expectations. Passenger cars continue to represent the dominant revenue base, but the composition of that demand is changing. OEMs are prioritizing platforms that can be reused across propulsion types, which favors suppliers with modular, propulsion-agnostic capabilities. At the same time, commercial vehicle demand remains a critical anchor for solid shaft and heavy-duty applications, particularly where strength, load capacity, and total cost of ownership outweigh the emphasis on minimal weight.
The commercial-vehicle side also introduces a different purchasing logic. Fleet operators and commercial OEMs focus heavily on lifecycle cost, serviceability, and reliability under sustained load. That creates a dual-track market: one track oriented toward efficiency and lightweight integration in passenger vehicles, another oriented toward robustness and cost predictability in commercial applications. Suppliers that can manage both tracks without diluting engineering focus tend to be more resilient across cycles.
Supply Chain and Cost Structure Dynamics
Cost structure is becoming a strategic battleground. Established steel supply chains provide reliability and scale, but they are exposed to price volatility and regional availability constraints. Aluminum and composites can improve performance and packaging, yet they introduce additional complexity in sourcing, processing, and validation. The practical consequence is that cost competitiveness is increasingly determined not just by material choice, but by supplier integration, manufacturing efficiency, and the ability to manage mix shifts without sacrificing delivery reliability. Programs that require rapid transitions between material grades or joint configurations amplify the importance of flexible production and strong supplier relationships.
This environment favors suppliers that can combine engineering support with disciplined cost execution. In practice, the winners are those who can help OEMs navigate the trade-offs between weight, strength, NVH, and cost while keeping programs on schedule. That is especially true as recent industry developments show major players investing in driveline technologies that span EVs and conventional platforms, indicating that breadth of capability is becoming a commercial advantage.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a set of established driveline specialists, each with a distinct strategic posture. GKN Automotive remains focused on sideshafts, CV joints, and propeller shafts across ICE, hybrid, and electric vehicles, emphasizing propulsion-agnostic drive systems. That positioning reflects an effort to stay relevant across propulsion transitions rather than betting on a single powertrain future. Nexteer Automotive has built a reputation around premium telescopic drive shafts and high-angle CV joints for OEM applications, with a recent emphasis on driveline technologies designed to support both EVs and premium driving experiences across propulsion types. In the first quarter context, Dana Incorporated reported strong results alongside new business wins in drivetrain solutions, illustrating how program-level victories can reinforce commercial momentum even as broader market conditions remain mixed.
The competitive picture also includes major driveline and metal-forming players such as American Axle & Manufacturing, which supplies front and rear axles and driveshafts for global OEMs, and Hyundai WIA Corporation, which produces driveline systems and drive shafts for both passenger and commercial applications. Neapco Holdings rounds out the landscape with driveline components including driveshafts and CV joints for OEM and aftermarket use. Together, these companies highlight a market where scale, geographic reach, and application coverage matter, but differentiation increasingly depends on engineering integration and program execution.
Recent corporate and product activity underscores how the landscape is evolving. The announcement of a combination involving Dauch Corporation and Dowlais Group, integrating GKN Automotive driveline technologies, signals a consolidation path aimed at broadening technical portfolios and strengthening competitive scale. At the same time, product-level moves such as Nexteer’s introduction of three driveline technologies for EVs and premium applications show that innovation remains a central competitive lever. The pattern suggests a market that is neither fully consolidated nor static; rather, it is being shaped by selective integration, technology broadening, and continued investment in next-generation driveline architectures.
Strategic differentiation is emerging along several axes. One is propulsion-agnostic engineering: the ability to support multiple powertrain types with shared platform logic reduces OEM complexity and increases the value of suppliers that can deliver flexible component families. Another is material and design leadership, especially where lightweight solutions can be adopted without compromising durability or cost targets. A third is regional manufacturing and customer proximity, which supports faster response times, lower logistics exposure, and better alignment with local content expectations. In this environment, scale alone is inadequate; competitive advantage is increasingly tied to technical breadth, portfolio coherence, and the capacity to convert innovation into repeatable program wins.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Propulsion-Agnostic Driveline Architectures Will Become a Standard Expectation
Over the next three to five years, OEMs are likely to continue prioritizing platforms that can accommodate multiple propulsion modes. That dynamic favors drive shaft and driveline solutions that can be adapted across ICE, hybrid, and electric applications without sacrificing performance or packaging efficiency. The commercial opportunity lies in offering modular component families, joint configurations, and integration support that reduce redesign effort and accelerate time-to-production. Suppliers that can demonstrate flexibility without compromising quality or cost structure will be better positioned to secure multi-program relationships.
The associated risk is execution complexity. Supporting diverse propulsion modes increases engineering workload, validation requirements, and inventory complexity. Companies that overextend across too many configurations without disciplined platform logic may face margin erosion and operational strain.
Trend 2: Lightweight Materials Will Expand, but Steel Will Remain Foundational
Industry direction points toward broader adoption of aluminum and composite solutions in applications where efficiency targets and packaging constraints are most demanding. At the same time, steel’s strength, toughness, and established supply chain will keep it central to many drive shaft applications, particularly where cost, durability, and volume manufacturing reliability matter most. The commercial opportunity here is not a simple swap from one material to another; it is the ability to offer the right material choice for each application while managing volatility in raw material costs. Suppliers with strong sourcing strategies, material expertise, and cost-forecasting discipline can convert material transitions into differentiated value rather than margin risk.
A key uncertainty is the pace and consistency of material adoption. If lightweight material specifications become more standardized across EV platforms, adoption could accelerate quickly and reward early movers with strong process capability. If volatility in raw material pricing persists, OEMs may adopt a more cautious stance, prioritizing total cost of ownership over absolute weight reduction in certain segments.
Trend 3: Consolidation and Portfolio Broadening Will Reshape Competitive Access
The market is likely to continue experiencing selective consolidation and portfolio integration as companies seek broader driveline capabilities, greater scale, and stronger positions across propulsion types. This creates two related opportunities. For larger players, integration can expand technical coverage and improve competitive positioning in high-value programs. For smaller or more specialized suppliers, the opportunity lies in focusing on niches where application knowledge, speed, or regional proximity creates defensible value. Investors and executives should watch for combinations that deepen technology portfolios, as well as for supplier strategies that emphasize end-to-end driveline integration rather than single-component competition.
The risk is that consolidation can also raise customer concentration concerns and reduce flexibility in some procurement relationships. Buyers may need to balance the benefits of integrated supply against the desire for multi-source resilience, especially in programs where supply continuity is critical.
PW Consulting
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Focus engineering investment on propulsion-agnostic designs and lightweight material capabilities, but pair that investment with disciplined cost management. The market is rewarding suppliers that can support multiple propulsion types while maintaining stable quotations and reliable delivery. Strengthen program-management and validation capacity so that new product introductions do not become bottlenecks. Where possible, build modular component strategies that reduce redesign risk and enable faster response to OEM platform decisions.
For Investors
Evaluate exposure not just by market size, but by technology breadth, application mix, and sensitivity to material cost volatility. Companies with strong positions in high-growth configurations, diversified propulsion coverage, and credible integration strategies are better placed to capture the next phase of growth. Monitor corporate consolidation activity closely, since combinations that broaden driveline portfolios may change competitive intensity and margin dynamics. Be mindful that revenue growth can mask uneven profitability if material volatility or program mix shifts are not managed effectively.
For Procurement and OEM Sourcing Leaders
Treat supplier selection as a multi-factor decision that includes technical flexibility, material strategy, and regional execution capability, not only unit price. Given raw material volatility, consider sourcing frameworks that provide visibility into cost drivers and allow for structured adjustments without destabilizing program economics. Where lightweight materials are specified for efficiency or emissions reasons, ensure that suppliers have validated processes and sufficient capacity to support scale-up. Diversifying across propulsion-capable suppliers can reduce program risk, especially when platform strategies span multiple powertrain types.
Closing Perspective
The automotive drive shaft market is moving from a period of steady volume-driven growth into a phase where technology choice, propulsion mix, material economics, and supplier integration matter as much as overall demand. The sector’s expansion toward the $12.8 billion range by 2032 is meaningful, but the more important story is how value is being redistributed across product types, applications, and competitive positions. Companies that can align engineering flexibility with cost discipline, while navigating material volatility and shifting propulsion requirements, are the ones most likely to convert market growth into durable advantage.
For decision-makers seeking a sharper read on regional dynamics, application-level demand patterns, material segment shifts, and company-specific positioning, a more detailed research asset can provide the granularity needed to translate these trends into procurement, investment, and product strategy. A full market report offers deeper segmentation detail, competitive benchmarking, and scenario-based guidance tailored to specific business decisions, making it a practical next step for teams that need to move from strategic direction to execution.
Cardan Shaft Market
For detailed analysis of this topic, please visit the official page: Automotive Drive Shaft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Methyl Methacrylate Market
The global methyl methacrylate (MMA) market has entered a period of structural transformation, driven by shifting capacity dynamics, evolving sustainability mandates, and expanding downstream applications. Valued at approximately 162.5 million USD in 2025, the market reflects steady expansion from 113.25 million USD in 2020, with a projected compound annual growth rate of 7.9 percent through 2032. This trajectory signals robust underlying demand, yet the growth path is neither uniform nor frictionless. Industry participants must navigate supply chain reconfigurations, regional price volatility, and intensifying competitive pressures while aligning product portfolios with emerging end-use requirements. Understanding the interplay between technological advancement, regulatory shifts, and demand-side evolution is essential for capturing value in the coming years.
The market concentration remains notably high, with the top three players holding roughly 65 percent of global capacity and the top five accounting for an estimated 85 percent. Such concentration shapes pricing dynamics, influences capacity expansion decisions, and creates both barriers and opportunities for new entrants. While the monomer remains the dominant form consumed across applications, the broader methacrylate ecosystem encompasses a range of derivatives that extend value creation beyond raw monomer supply. Companies that successfully integrate upstream efficiency with downstream formulation expertise are positioned to command stronger margins and deeper customer relationships.
Market Scale and Growth Trajectory
The historical expansion of the MMA market demonstrates consistent growth punctuated by cyclical supply disruptions and regional demand fluctuations. The transition from 2020 through 2025 saw incremental gains as downstream sectors resumed activity following global disruptions, while the forecast period through 2032 points toward accelerated expansion fueled by infrastructure investment, electrified mobility adoption, and electronics miniaturization. Growth is not evenly distributed across regions or applications, but the aggregate trajectory reflects a market that is repricing itself around sustainability premiums, supply reliability, and application-specific performance requirements.
Revenue projections indicate that the market will surpass 180 million USD by 2026 and continue climbing toward 272.5 million USD by 2032. This expansion reflects both volume growth and structural shifts in product mix, as high-performance grades and sustainably produced variants capture a larger share of downstream spending. The pace of growth will depend on how quickly capacity transitions align with demand signals, how regulatory frameworks shape production economics, and how quickly end-use industries adopt next-generation materials.
Key Challenges and Inflection Points
Several structural challenges are redefining the MMA market landscape. First, the transition from traditional C3-based production pathways to alternative feedstock routes introduces both operational complexity and capital intensity. Companies investing in newer production technologies must manage ramp-up risk, supply chain adaptation, and customer qualification timelines, all while maintaining competitive pricing in a market sensitive to raw material spreads.
Second, regional capacity realignment is reshaping supply reliability and pricing architecture. Strategic plant closures, capacity transfers, and geographic shifts in production footprint have altered regional supply balances, creating short-term volatility and forcing downstream buyers to recalibrate sourcing strategies. The interplay between legacy capacity retirement and new facility commissioning has produced uneven supply conditions that reward agile procurement and penalize rigid long-term contracting.
Third, sustainability compliance and carbon footprint differentiation are emerging as decisive commercial factors. End-use industries increasingly demand materials with lower lifecycle emissions, verified recycling integration, and transparent environmental reporting. Producers that cannot demonstrate credible sustainability performance risk losing share to competitors with lower-carbon production pathways or stronger ESG credentials. This dynamic is particularly pronounced in construction, automotive, and electronics, where regulatory pressure and corporate sustainability targets are accelerating material substitution decisions.
Key Drivers Reshaping the Market
Technological Innovation and Production Pathways
Technological advancement remains a primary catalyst for market evolution. Alternative production routes that utilize different feedstock inputs are gaining traction, offering potential advantages in carbon intensity, feedstock flexibility, and integration with circular material flows. One notable development involves the commercialization of a C2-based production pathway that integrates chemical recycling for closed-loop operations, reducing the carbon footprint associated with traditional MMA synthesis. The successful ramp-up of full industrial-scale operation at a major North American facility signals a shift toward lower-emission production models, provided that feedstock availability, operational reliability, and cost competitiveness can be sustained.
Such innovations are not merely technical achievements; they alter competitive positioning by enabling producers to differentiate on sustainability credentials, supply reliability, and long-term cost structure. Companies that can validate performance at scale, secure feedstock partnerships, and communicate environmental benefits to downstream customers are likely to capture premium positioning. Conversely, reliance on legacy production methods without parallel sustainability investments may expose suppliers to margin compression as buyers prioritize lower-carbon alternatives.
Policy and Regulatory Environment
Regulatory frameworks and policy signals are exerting growing influence on capacity planning, feedstock selection, and regional investment decisions. Environmental compliance requirements, emissions reporting mandates, and sustainability-related procurement standards are reshaping the cost calculus for both producers and downstream users. In some cases, regulatory uncertainty has prompted reassessment of large-scale capacity projects, with firms pausing or redirecting investments as they evaluate long-term policy trajectories and market demand alignment.
At the same time, sustainability-driven regulations are creating incentives for process innovation and material efficiency. Producers that proactively align operations with emerging compliance expectations can reduce future retrofit risk and position themselves as preferred suppliers for customers facing their own sustainability mandates. The regulatory landscape is therefore not simply a constraint; it is a filter that rewards operational agility and penalizes complacency.
Demand-Side Evolution and Application Expansion
Downstream demand patterns are shifting as end-use industries pursue performance, lightweighting, and durability improvements. The automotive sector continues to drive volume through applications that require transparent, weather-resistant, and impact-tolerant materials, with electric vehicle platforms creating additional demand for specialized acrylic components and interior trim solutions. Construction activity, supported by infrastructure renewal and modernization initiatives, sustains demand for signage, glazing, and durable surface materials that benefit from MMA-derived performance characteristics.
Electronics and medical applications represent additional growth vectors. Electronics manufacturers are increasingly relying on high-purity acrylic materials for components that demand dimensional stability, optical clarity, and thermal resistance. Medical device and healthcare applications are expanding as biocompatible and sterilizable acrylic materials gain acceptance in diagnostic, procedural, and consumer health products. These application segments are not only adding volume; they are also elevating the value of specialized grades, which command stronger margins and require closer technical collaboration between suppliers and end users.
Supply Chain Dynamics and Cost Structure
Supply chain conditions and raw material cost movements are directly influencing pricing stability and margin outcomes. Global MMA prices experienced upward pressure in early 2026, with momentum intensifying toward the end of the quarter as supply tightened and production costs increased. Such price dynamics highlight the sensitivity of the market to feedstock availability, energy costs, and production utilization rates. Companies that manage feedstock sourcing, energy efficiency, and inventory positioning effectively are better equipped to navigate price volatility and protect margins.
PW Consulting
Capacity realignment across key regions has further complicated supply reliability. Strategic decisions to close certain legacy facilities while commissioning newer, more efficient plants have altered regional supply balances, creating temporary dislocations and forcing downstream buyers to adapt sourcing strategies. In parallel, some producers have adjusted product offerings and geographic sales strategies to optimize portfolio performance, reflecting a broader trend toward disciplined capacity management and targeted market participation.
Competitive Landscape and Leading Strategies
The MMA market is characterized by a concentrated set of global producers, each pursuing distinct strategic priorities to defend or expand their market position. Leading players are differentiating through a combination of production technology, geographic footprint, sustainability commitments, and application-specific product development. The competitive environment rewards scale, operational excellence, and the ability to align supply capabilities with evolving downstream requirements.
Strategic Positioning of Major Players
Major producers are pursuing multiple levers to strengthen competitive advantage. One prominent global producer has focused on expanding its methacrylate leadership through large-scale capacity investments and technology differentiation, maintaining a dominant position in global methacrylate production. Another key player has advanced sustainability-oriented production approaches, emphasizing lower-carbon pathways and closed-loop operations to appeal to customers with stringent environmental targets. Integrated producers supplying monomer and derivatives for coatings, adhesives, and polymer applications are leveraging vertical integration and technical service capabilities to deepen customer relationships and stabilize demand.
Regional presence and supply chain resilience are also central to competitive positioning. Producers with North American operations have invested in capacity expansions and facility modernizations to strengthen regional supply reliability, while Asian-focused manufacturers have adjusted pricing and product strategies in response to regional market conditions. Companies with dedicated division structures for MMA and acrylic resins are increasingly emphasizing high-performance grades for electronics, automotive, and optical applications, reflecting a strategic shift toward value-added segments rather than commodity volume competition.
Specialist producers focusing on methacrylate derivatives and sustainable PMMA solutions are carving out niches by combining application expertise with environmental credentials. Their strategy often centers on technical customization, supply consistency, and sustainability reporting that resonates with downstream customers facing procurement mandates. Meanwhile, global distributors and suppliers of methacrylate-based systems for coatings, adhesives, and polyurethane applications are expanding their geographic reach and product portfolios to capture demand across diverse end-use markets.
Poly Methyl Methacrylate (PMMA) Market
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. Consolidation and capacity optimization are enabling established players to streamline operations, retire less efficient assets, and redirect capital toward higher-return projects. At the same time, the emergence of alternative production technologies and sustainability-focused differentiation is creating space for companies that can operationalize new pathways at scale. New entrants face meaningful barriers due to capital intensity, feedstock logistics, customer qualification requirements, and the prominence of incumbent technical service networks, but targeted entry into specialty grades or regional supply gaps remains plausible for well-positioned organizations.
Pricing power and margin resilience are increasingly tied to sustainability credentials, supply reliability, and application-specific expertise. Producers that can demonstrate consistent performance, lower lifecycle emissions, and responsive technical support are better positioned to negotiate favorable commercial terms and retain customers during supply disruptions. The market is therefore moving toward a more value-driven competition model, where volume alone is insufficient to secure long-term advantage.
Future Outlook and Emerging Opportunities
Trend 1: Sustainability as a Structural Differentiator
Lower-carbon production and circular material integration are set to become central competitive dimensions over the next three to five years. Producers that successfully scale alternative feedstock routes, chemical recycling integration, and verified emissions reductions will gain preferential access to customers with sustainability procurement mandates. This trend creates opportunities for suppliers to command premiums for certified low-carbon grades, secure long-term commitments from environmentally focused end users, and differentiate from competitors reliant on higher-emission pathways. The risk lies in greenwashing exposure and the need for credible verification, as downstream buyers increasingly scrutinize sustainability claims and demand transparent reporting.
Trend 2: Regional Supply Rebalancing and Sourcing Strategy Shifts
The ongoing realignment of production capacity across regions will continue to influence pricing, availability, and contract structures. As legacy facilities are retired and newer plants reach full operational scale, regional supply balances will evolve, creating both disruption and opportunity. Buyers that diversify sourcing, develop contingency supply arrangements, and align contract terms with capacity transition timelines will be better insulated from volatility. Producers that can offer reliable regional supply, flexible delivery models, and transparent capacity reporting will strengthen their negotiating position and customer retention.
Trend 3: Application Specialization and High-Performance Grade Expansion
Demand for specialized acrylic materials in automotive, electronics, medical, and advanced construction applications is expected to grow as performance requirements become more stringent. This trend favors producers with strong formulation capabilities, technical service infrastructure, and the ability to co-develop solutions with end users. Opportunities exist for suppliers to capture higher margins through grade customization, application-specific certification, and integrated product systems that address multiple performance criteria. The risk is that overinvestment in unproven application segments or inadequate technical support could limit returns, particularly if downstream adoption timelines extend or substitution alternatives emerge.
Methacrylic Acid (MAA) (CAS 79-41-4) Market
Actionable Insights for Decision Makers
The evolving MMA market environment requires proactive strategy adjustments across the value chain. Decision makers should align sourcing, investment, and product development plans with the structural trends shaping supply, pricing, and sustainability expectations.
- For manufacturers and producers, priority should be placed on operationalizing lower-carbon production pathways, securing feedstock and energy cost advantages, and building technical service capabilities that support application-specific sales. Investing in scale where it delivers cost and sustainability benefits, while maintaining disciplined capacity management, can strengthen margin resilience and customer retention.
- For investors, attention should focus on companies with credible sustainability roadmaps, visible capacity transition plans, and exposure to higher-growth application segments such as automotive electrification, electronics miniaturization, and medical devices. Assessing feedstock flexibility, regional supply positioning, and ESG verification readiness can help identify businesses positioned for durable value creation.
- For procurement and sourcing leaders, diversifying supplier bases, developing scenario-based contracting, and incorporating sustainability criteria into supplier selection can reduce exposure to regional disruptions and price volatility. Establishing clear performance and compliance requirements, while maintaining flexibility for capacity transition periods, will support supply continuity and cost control.
Detailed segmentation data, capacity flow analysis, pricing trajectory modeling, and company-level assessments can provide the precision needed to convert these strategic directions into execution plans. Organizations seeking to deepen their market intelligence and align decisions with granular demand, supply, and competitive signals will benefit from comprehensive research that maps the full landscape and isolates actionable opportunities.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cat Litter Market 2026: Why 5.5% CAGR and Clay Dominance Signal a Strategic Shift
By PW Consulting, 2026-09-21
Strategic Shifts Defining the Global Cat Litter Market (2025–2032)
The global cat litter market has evolved from a low-differentiation commodity category into a strategically contested space shaped by material science, consumer expectations, and tightening operational standards. With the market reaching an estimated USD 11.81 billion in 2025 and expanding at a compound annual growth rate of approximately 5.5 percent through 2032, the category’s trajectory reflects broader shifts in pet care, sustainability, and retail consolidation. Growth is not uniform, and the value creation path is increasingly segmented by formulation performance, supply chain resilience, and brand trust. For executives and investors, the opportunity lies less in chasing volume and more in aligning product portfolios, manufacturing capabilities, and distribution strategies with structural demand changes.
Several factors sharpen the strategic stakes. Household penetration of cats continues to rise in mature markets, while emerging markets are building foundational pet care consumption patterns. At the same time, raw material dynamics, formulation innovation, and regulatory scrutiny of manufacturing hygiene are reshaping competitive benchmarks. The sector’s concentration, with a small group of players holding the majority of industry revenue, suggests that scale, distribution relationships, and brand equity remain powerful moats. Yet the appearance of rapid product experimentation, especially around biodegradable and silica-based formats, indicates that incumbents cannot rely solely on legacy formulations or traditional retail placements.
Three friction points define the current transition. First, raw material price volatility and supply geography create margin exposure for both traditional clay-based and silica-based lines, forcing manufacturers to balance cost control with performance consistency. Second, consumer preference is bifurcating: one segment prioritizes low-cost, high-clumping mineral products, while another increasingly demands natural, low-dust, or flush-friendly alternatives. Third, operational integrity is becoming a strategic differentiator after a high-profile contamination incident involving a widely distributed litter brand, which triggered regulatory review and heightened retailer vigilance. These dynamics do not merely create risk; they establish the criteria by which leading players will be judged over the next several years.
Key Demand and Supply Drivers Reshaping the Category
Technological and formulation innovation is shifting from incremental improvements toward targeted performance solutions. The most notable advances cluster around rapid clumping, odor neutralization, low-dust engineering, and compatibility with automated cleaning systems. Recent product introductions have emphasized fast absorption, instant clumping behavior, and suitability for self-cleaning litter boxes, signaling that convenience is becoming a performance specification rather than a marketing phrase. Alongside this, odor-control strategies are incorporating activated carbon and mineral blends that address the household cleanliness expectations of urban consumers and multi-pet households. The practical implication is that product leadership increasingly depends on formulation precision and repeatability rather than on broad distribution alone.
Worldwide Prescription Cat Food Market
Regulatory and quality standards are also exerting a more direct influence on market behavior. Following a voluntary recall tied to rodent and avian contamination and insanitary storage conditions affecting Tidy Cats products distributed by Gold Star Distribution, Inc., the FDA elevated the recall classification for certain pet products to Class II after reviewing contamination hazards. This sequence matters beyond the immediate compliance event. It demonstrates that hygiene, traceability, and storage controls are becoming procurement concerns for retailers and distributors, especially in markets where consumer trust can shift quickly after a publicized safety issue. For manufacturers, the strategic response is not simply to meet baseline requirements but to embed operational hygiene into product handling, packaging integrity, and distribution protocols as a visible competitive attribute.
Demand-side behavior is changing through a combination of premiumization and value sensitivity. Cat owners are not a monolithic group: some remain highly price-conscious and gravitate toward familiar mineral-based options, while others willingly pay for natural, plant-based, or starch-derived formulations that align with environmental expectations and low-dust preferences. This split is reinforced by the growth of subscription and direct-to-consumer models in certain regions, which reward consistency, packaging convenience, and reliable replenishment. The result is a market where brand trust and usage experience can justify premium positioning even as mainstream segments continue to compete on cost-per-use and retail availability.
Worldwide Natural Cat Litter Products Market
Supply chain and cost structure dynamics add another layer of complexity. Clay remains the dominant raw material base, which means pricing exposure is tied to extraction, processing, freight, and energy costs. Silica-based options face different economics, including synthesis and material intensity considerations. At the same time, natural and biodegradable inputs depend on agricultural and processing supply chains that can vary in consistency, seasonality, and regional availability. Companies that can manage formulation flexibility, lock in dependable sourcing, and minimize waste in conversion processes are better positioned to protect margins through cycles of input inflation. For buyers and distributors, this reinforces the importance of supplier diversification and specification clarity when evaluating long-term contracts.
Competitive Positioning and the Emerging Landscape
The competitive field is anchored by a concentrated group of manufacturers with strong mineral-based capabilities and well-known retail brands, alongside a widening set of regional and formulation-focused producers. TOLSA SA and Laviosa Chimica Mineraria SpA represent established bentonite and mineral-based production profiles with international reach. Oil DRI Corporation of America specializes in absorbent material formulations, while InterSand operates as a North American bentonite and cat litter producer and exporter. On the branded side, The Clorox Company and its Fresh Step portfolio maintain broad retail distribution, and Dr. Elsey's competes in the premium clumping and natural segments. These players benefit from scale, shelf relationships, and formulation familiarity, but their strategic challenge is to sustain relevance as product experimentation and retail assortment complexity increase.
A parallel competitive track is emerging around natural, biodegradable, and plant-based options. Brands such as Naturally Fresh, World's Best Cat Litter, and Kent Corporation illustrate the positioning of pine and plant-based formulations, while manufacturers like Shandong Aiyu Pet Products, Changzhou Sanmei Pet Products, and Anhui Hengjie Group reflect a broader Asian production base spanning cassava, tofu, zeolite, and mixed formats. Several of these companies have expanded visibility through trade activity and product catalog updates. For example, recent exhibition presentations highlighted pure tofu cat litter with natural soybean residue, strong clumping, odor locking with activated carbon, and low dust, while other launches emphasized rapid absorption, instant clumping, and suitability for automatic litter boxes. This activity signals that Asia-based producers are not only competing on cost but increasingly on specification performance and OEM customization capability.
The strategic differentiation among leaders is becoming less about category ownership and more about segmentation mastery. Incumbents with strong mineral-based positions can defend share through consistent performance, packaging innovation, and retail execution. Premium natural brands can build loyalty through perceived safety, environmental alignment, and user experience. Meanwhile, OEM-oriented manufacturers with flexible formulation capabilities can serve private-label programs, regional distributors, and product-development partners seeking to move quickly into biodegradable or mixed-material formats. This creates a landscape where M&A, joint supply arrangements, and brand acquisitions are plausible tools for players seeking to fill portfolio gaps or enter new geographic channels.
Market structure is likely to evolve through both consolidation and fragmentation. Consolidation may occur as larger consumer goods and distribution players acquire regional brands or integrate upstream sourcing to secure input stability. Fragmentation may continue as new entrants target specialized needs, including low-dust formulations, flush-compatible options, and automatic litter box compatibility. The Company is also likely to see increased importance of brand trust and retail compliance, especially after recent contamination-related scrutiny. In practice, this means that competitive advantage will be determined by a combination of formulation consistency, operational discipline, distribution access, and the ability to communicate product benefits in ways that resonate with increasingly discerning buyers.
PW Consulting
Forward-Looking Trends and Commercial Implications
One of the most important forward-looking trends is the growing role of performance-specific formulations in product selection. Not all litter is evaluated primarily on price anymore; automatic cleaning devices, odor sensitivity, dust exposure, and tracking behavior increasingly influence purchase decisions. Over the next three to five years, this should drive further refinement in clumping speed, absorption capacity, and low-dust manufacturing controls. The commercial implication is that product specifications will become more consequential in procurement decisions, and successful players will need to validate performance claims with repeatable production quality rather than relying on broad category messaging.
A second trend is the continued expansion of natural and biodegradable alternatives as a meaningful, though still minority, share of activity. As plant-based, starch-based, and tofu-derived options gain visibility, the strategic question is not whether they will replace conventional mineral products, but where they will hold strongest appeal and how they can be produced consistently at scale. Distribution will matter as much as formulation, because eco-oriented products often require clearer consumer education, distinct shelf positioning, and reliable replenishment cycles. Companies that can stabilize input supply, maintain clumping and odor-control performance, and communicate environmental benefits without sacrificing usability are likely to capture the most durable demand within this segment.
A third trend concerns supply chain integrity and regulatory responsiveness becoming more visible in brand credibility. The recent recall and subsequent FDA classification update have reinforced that hygiene, storage, and distribution conditions are not back-office concerns; they are customer-facing trust signals. Over the coming years, this is likely to translate into tighter audit expectations, stronger quality assurance requirements from retailers, and greater emphasis on traceability in sourcing and logistics. The upside is that disciplined operators can use compliance and safety assurances as differentiators, especially in markets where consumers and retailers are especially sensitive to product cleanliness and brand reliability.
These trends carry both opportunity and uncertainty. On the opportunity side, there is room for manufacturers to capture value through formulation leadership, private-label partnerships, premiumization, and regional expansion into channels that reward consistency and freshness of product design. There is also scope for investors to identify companies with defensible sourcing, scalable OEM capabilities, or brands positioned in high-trust segments. On the risk side, raw material volatility, consumer skepticism after safety incidents, and fragmentation of retail channels could pressure margins and slow share shifts. Demand may also evolve unevenly across regions, meaning that growth assumptions need to be tested against local pet ownership patterns, retail structure, and price sensitivity.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with the ways consumers now evaluate performance. This means investing in clumping reliability, odor control, dust reduction, and compatibility with automated litter systems, while also building supply flexibility across mineral, silica, and natural inputs. Equally important is operational hygiene and traceability, which should be treated as brand assets rather than minimum compliance steps. Companies that can combine specification leadership with dependable production quality will be better positioned to defend premium pricing and secure retailer confidence.
For investors, the most useful discipline is to evaluate competitive positions through the lens of margin resilience and channel access rather than headline category growth alone. Opportunities are likely strongest where companies demonstrate scalable sourcing, formulation versatility, or brand strength in premium or eco-oriented segments. At the same time, diligence should account for input exposure, regulatory sensitivity, and the risk that safety incidents can quickly alter retail placement and consumer trust. Portfolio selection should favor operators that can sustain product consistency and adapt to shifting material economics.
For procurement and distribution leaders, the strategic focus should be on supplier qualification, specification clarity, and contingency planning. Diversifying across mineral and natural-based sources can reduce exposure to single-material volatility, while explicit performance requirements can reduce the risk of assortment inconsistencies. Given the elevated attention to storage and contamination risks, procurement teams should also strengthen audit expectations and handling standards across the distribution chain. In practice, this means treating litter procurement as a quality and reliability decision as much as a cost decision.
For decision-makers seeking to move from directional insight to actionable planning, the market’s segmentation details, regional demand patterns, formulation economics, and competitive moves warrant closer examination. Many of the richest strategic choices—whether in product development, channel expansion, supplier selection, or capital allocation—depend on granular data that cannot be fully captured in a high-level review. Access to a more detailed market study can help translate these trends into specific scenarios, segment-level demand estimates, and tailored recommendations aligned with each organization’s position.
For detailed analysis of this topic, please visit the official page: Cat Litter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roadmarking Paints Market 5.8% CAGR: Strategic Shifts Behind the $10.6B 2032 Trajectory
By PW Consulting, 2026-09-21
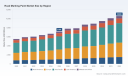
Strategic Trends and Commercial Opportunities in the Roadmarking Paints Market
The global roadmarking paints market has entered a phase of mature expansion, characterized by steady demand recovery across infrastructure sectors and a gradual shift in material preferences. With a market valuation of 7.18 billion USD in 2025, the sector has demonstrated consistent revenue growth from 5.52 billion USD in 2020, reflecting a compound annual growth rate of 5.8 percent through the forecast period extending to 2032. This trajectory suggests that the industry is moving beyond post-pandemic normalization into a structure defined by regulatory evolution, material innovation, and geographic demand divergence. At first glance, the numbers indicate a reliable growth engine for coatings and infrastructure suppliers. A closer look reveals a market navigating cost volatility, tightening environmental specifications, and intensifying competition among established players and emerging regional suppliers.
The current landscape is shaped by three interconnected dynamics that decision-makers cannot afford to overlook. First, the transition toward low-emission and waterborne coating systems is accelerating, but the pace of adoption remains uneven across regions and project types. Second, raw material price fluctuations, particularly in thermoplastic compounds, specialty resins, and optical glass components, are compressing margins and forcing procurement strategies to become more flexible. Third, infrastructure spending is increasingly being directed toward high-visibility, safety-critical applications, which elevates the standard for durability and reflectivity but also raises the bar for supplier qualification. These forces create a market that is expanding in aggregate yet becoming more selective in how value is captured.
Navigating the Current Inflection Points
The market’s growth narrative is not uniform. While overall demand continues to climb, several structural pressures are reshaping how manufacturers, contractors, and public agencies evaluate roadmarking solutions. The expansion of urban and interurban road networks, combined with periodic resurfacing programs, sustains baseline demand. However, the composition of that demand is shifting. Projects are increasingly scrutinized for lifecycle cost, environmental footprint, and compliance with updated technical specifications. This means that suppliers offering conventional solvent-based products without clear pathways to compliant alternatives face growing friction in specification lists and bidding processes.
At the same time, the industry is witnessing a quiet recalibration of cost expectations. Budget-constrained infrastructure programs are more sensitive to upfront material pricing, which can slow the uptake of premium thermoplastic and specialized cold plastic systems. The tension between performance requirements and cost containment is not simply a procurement inconvenience; it is a strategic variable that determines which product categories gain traction in different project environments. Suppliers that can balance performance, compliance, and total cost of ownership are positioned to secure more consistent wins, while those locked into single-format portfolios may encounter narrowing windows of opportunity.
A third inflection point lies in the standardization and enforcement of roadmarking specifications. Updated technical benchmarks for ready-mixed paints and related marking materials are raising the minimum threshold for adhesion, durability, and reflectivity. These updates are not merely administrative; they influence which formulations are acceptable for public works, how frequently markings must be renewed, and what documentation suppliers must provide. For companies operating across multiple markets, alignment with evolving specifications is becoming a competitive differentiator rather than a baseline requirement.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Material Evolution
Material science is quietly redefining what roadmarking paints can do. Waterborne formulations have advanced significantly in terms of drying time, abrasion resistance, and wet-edge performance, making them increasingly viable for high-traffic corridors where downtime is costly. At the same time, thermoplastic and cold plastic systems continue to be valued for their durability and reflective performance in demanding applications, but their deployment is increasingly tied to project economics and supply availability. The practical outcome is a market where performance claims must be substantiated by application-specific evidence, not just laboratory benchmarks.
Innovation is also extending beyond the paint itself. Improvements in optical glass quality, bead shape consistency, and bond strength are influencing the longevity of marked lines, which in turn affects maintenance cycles and total project cost. Suppliers that integrate material formulation with application technology, including spray equipment compatibility and line-width precision, are delivering more predictable outcomes for contractors and road authorities. This convergence of formulation and application engineering is reducing variability in the field, which is increasingly important as agencies compare bids on the basis of lifecycle performance rather than unit price alone.
Policy and Regulatory Pressures
Regulatory expectations are becoming a central force in product selection. Concerns over volatile organic compound emissions and broader environmental impact are prompting many procurement entities to favor lower-emission alternatives. This does not automatically eliminate solvent-based systems from the market, but it does raise the importance of documentation, emission profiles, and regional compliance pathways. In practice, regulation is acting as both a constraint and a catalyst: it limits the unconstrained use of older chemistries while creating demand for suppliers who can demonstrate credible low-emission performance without sacrificing durability.
Technical specifications are also evolving. Updated standards for ready-mixed road marking paints and related systems are tightening expectations around consistency, application conditions, and performance verification. For manufacturers, this means that product development cycles must account for specification alignment in key markets. For distributors and contractors, it means that stocking decisions and bidding strategies need to reflect the likely direction of regulatory enforcement. The companies that treat specification updates as early signals rather than late obstacles are better positioned to maintain preferred status on project shortlists.
Demand-Side Shifts in Infrastructure and User Behavior
Demand is being influenced by more than road construction volume. Public safety priorities, traffic growth, and the operational needs of airports and commercial parking facilities are all contributing to more frequent marking cycles and higher visibility requirements. Roads and highways remain the dominant application context, but the strategic importance of parking areas and airport tarmacs should not be underestimated. These environments often require specialized markings that can withstand different stress factors, from heavy vehicle turning loads to aircraft pavement conditions, and they tend to be less price-sensitive when reliability is at stake.
There is also a behavioral shift on the part of procurement teams. Buyers are increasingly comparing solutions on a total-cost basis that includes application efficiency, drying time, weather tolerance, and expected service life. This is changing the conversation from “which paint is cheapest per liter” to “which system delivers the best outcome over the project cycle.” Suppliers that can articulate these trade-offs clearly, and back them with field-relevant performance data, are gaining influence in specification decisions.
Supply Chain and Cost Structure Realignment
Cost structures in the roadmarking paints market are under pressure from multiple directions. Volatility in raw material pricing, especially for thermoplastic compounds and specialty glass components, creates uncertainty for both manufacturers and buyers. The challenge is compounded by differences in sourcing availability across resin suppliers and regional supply networks, which can affect lead times and price consistency. For companies relying on fixed-price contracts or tight bidding windows, this volatility can quickly translate into margin compression or project risk.
In response, supply chain resilience is becoming a strategic priority. Some suppliers are diversifying input sources, renegotiating terms with material partners, or adjusting product portfolios to reduce exposure to the most volatile components. Others are investing in formulation efficiency to stretch high-cost inputs while maintaining performance. The broader implication is that cost advantage in this market is increasingly determined by procurement agility and formulation discipline, not simply by scale. Firms that can manage input variability while preserving product consistency will be better equipped to offer stable pricing and reliable fulfillment, which are increasingly valued in competitive procurement environments.
Competitive Landscape and Strategic Positioning
The market is characterized by a concentrated core of established coatings and infrastructure material providers alongside a broader base of regional and specialized players. This structure creates a competitive environment where scale, product breadth, and technical service capability matter, but so does local specification knowledge and adaptability to regional procurement practices. The presence of major global names reflects the importance of cross-market reach, integrated product portfolios, and the ability to support large infrastructure programs with consistent supply and technical documentation.
Several leading companies illustrate the different ways to compete. PPG Industries has built recognition around waterborne and solvent-based traffic paint systems, emphasizing formulation families designed for road marking applications. Its positioning reflects a broader strategy of offering choices that align with varying regulatory and performance requirements while maintaining a consistent technical backbone. Swarco, with operations spanning multiple regions, provides a mix of solvent-based, waterborne, and two-component systems, which allows it to match products to project-specific conditions and specification environments. This breadth supports flexibility in bidding and application scenarios.
Meon Ltd has carved out a role focused on line marking paints and cold plastic systems for roads, parking lots, and airports, highlighting the value of serving multiple application contexts with a coherent product set. Axalta Coating Systems contributes a portfolio that includes spirit-soluble and modified alkyd formulations, showing continued relevance for markets where established chemistries still fit within accepted specifications. Cloverdale Paint Inc underscores another competitive angle: regional specification alignment. Its waterborne traffic paint formulations approved for Canadian infrastructure specifications illustrate how regulatory fit and local qualification can be decisive in securing market access.
Differentiation Beyond Product Catalog Breadth
In a market where many players offer overlapping product categories, differentiation is increasingly determined by how well a supplier can reduce risk and uncertainty for the buyer. Technical support, specification readiness, application guidance, and consistent quality control are becoming part of the core value proposition. Companies that can help contractors and public agencies navigate formulation choices, meet updated standards, and manage application conditions are building a defensible position that is harder to replicate than price alone.
This also means that the competitive battleground is shifting from pure product features to service-integrated solutions. Suppliers that combine reliable product performance with practical field support, clear compliance documentation, and predictable supply are better positioned to win repeat business and preferred supplier status. In contrast, competitors that rely primarily on catalog breadth without strong technical and service integration may find themselves vulnerable when buyers compare total project risk and lifecycle outcomes.
Portfolio Evolution and Market Structure Trends
The competitive landscape is likely to continue evolving through a combination of consolidation, portfolio specialization, and selective entry by regional players. Larger firms may pursue broader coverage through acquisitions or geographic expansion, aiming to strengthen supply continuity and specification reach. Smaller and mid-sized suppliers may compete by focusing on niche applications, regional specifications, or specialized material systems that larger players deprioritize. At the same time, new entrants with differentiated formulations or application-focused technologies could gain traction in segments where durability, drying speed, or environmental compliance are especially valued.
One important trend is the growing importance of portfolio coherence. Buyers are less interested in isolated product lines and more interested in suppliers that can address a range of marking needs across roads, parking areas, and airports with consistent quality and clear technical guidance. This favors companies that can offer a structured portfolio rather than fragmented offerings, while still retaining the flexibility to serve project-specific requirements. Another trend is the increasing relevance of regional compliance knowledge. As specifications become more localized and more stringent, suppliers with strong familiarity with local standards and procurement practices are gaining an edge in winning formal qualifications and specification inclusions.
Forward Outlook: Trends Shaping the Next 3 to 5 Years
Over the next several years, the roadmarking paints market is likely to be shaped by three reinforcing trends. The first is the continued migration toward lower-emission and more durable marking systems, driven by regulatory expectations, safety priorities, and total-cost considerations. This will not result in a single dominant chemistry across all contexts. Instead, it will produce a more segmented market in which waterborne, thermoplastic, and cold plastic solutions coexist, each anchored to specific application profiles and specification regimes.
Traffic Marking Paints Market
The second trend is the growing emphasis on supply chain stability and cost predictability. As raw material volatility and specification updates continue to influence procurement decisions, suppliers that can manage input risk, maintain consistent quality, and offer transparent pricing logic will be rewarded with stronger customer relationships and more resilient order flow. This trend favors organizations that treat supply chain management as a strategic capability rather than an operational back-office function.
The third trend is the increasing role of performance verification and lifecycle thinking in specification and bidding processes. Buyers are likely to place greater weight on demonstrated durability, reflectivity retention, application efficiency, and compliance readiness. This creates opportunities for suppliers that can provide credible evidence of field performance and support buyers in evaluating total project outcomes. It also introduces risk for companies that depend on price-based competition without a clear performance narrative or specification alignment.
These trends open commercial opportunities in several areas. Suppliers with strong waterborne or low-emission portfolios can benefit from specification shifts in markets where emission constraints are tightening. Companies with robust thermoplastic and cold plastic capabilities can focus on high-durability applications where performance justifies premium positioning, especially if they can manage cost exposure effectively. There is also room for service-led differentiation, where technical support, application guidance, and specification expertise become the basis for preference rather than product features alone. At the same time, uncertainty remains. Raw material cost swings, uneven regulatory enforcement, and project budget constraints can all slow adoption or shift demand between product categories. Firms that monitor these variables closely and adjust portfolios and procurement strategies accordingly will be better prepared to capture upside while limiting downside.
Strategic Implications for Decision-Makers
For Manufacturers and Material Formulators
Portfolio strategy should be guided by the need to balance compliance, durability, and cost control. Rather than treating product lines as static offerings, manufacturers can benefit from aligning formulations with the specification trajectories of key markets and identifying where performance claims can be credibly extended. Investment in application-relevant testing, clear documentation, and supply chain flexibility can strengthen competitive positioning more reliably than incremental catalog expansion alone. Companies should also consider where they can reduce exposure to volatile inputs without compromising field performance, since cost stability is increasingly part of the value proposition.
PW Consulting
For Investors and Strategic Buyers
The market offers exposure to steady infrastructure-linked demand, but value creation will likely come from companies that can manage regulatory transitions, supply variability, and application performance in an integrated way. Due diligence should pay attention to specification alignment, regional qualification strength, and the ability to serve multiple application environments with coherent product and service offerings. Businesses that rely heavily on single-format dependency or on price competition in volatile input conditions may face narrower margins for error. Strategic acquisitions or partnerships that expand compliance coverage, regional reach, or service capability can create advantages in a market where buyer preferences are shifting toward reliability and lifecycle value.
For Procurement Teams and Infrastructure Buyers
Evaluating roadmarking solutions with a total-cost perspective can reduce project risk and improve long-term outcomes. This means accounting for application speed, drying behavior, weather tolerance, expected service life, and compliance readiness alongside unit pricing. Early engagement with suppliers on specification alignment and performance expectations can help avoid mismatches during bidding and execution. Procurement teams can also benefit from tracking specification updates and material availability trends, since these often signal which product categories will become easier or harder to source at competitive terms in upcoming project cycles.
Paint Market
For all of these audiences, the value of detailed market intelligence lies in its ability to connect broad trends to specific decisions. Segment-level demand patterns, regional specification trajectories, raw material exposure by product category, and competitive positioning by application context all influence how the market will evolve beyond the headline growth narrative. A more granular view helps manufacturers prioritize formulation and portfolio choices, helps investors identify where durable advantage is being built, and helps procurement teams structure sourcing strategies that are resilient to both regulatory and cost-side uncertainty.
The roadmarking paints market is not simply expanding; it is restructuring around performance expectations, environmental mandates, and supply chain realities. Companies that interpret these signals early and align their strategies accordingly are more likely to convert market growth into sustained commercial advantage. For decision-makers seeking a deeper, segment-level view of demand splits, regional specification trends, raw material exposure, and competitive positioning across product types and application contexts, the full PW Consulting market report provides the additional granularity needed to support planning, procurement, and investment decisions with greater confidence.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Heat Exchanger Market: How 5.5% CAGR and Asia Pacific's 6.9B Size Redefine Growth
By PW Consulting, 2026-09-21
The Heat Exchanger Market: Strategic Shifts and Commercial Opportunities in a Transforming Industrial Landscape
The global heat exchanger market has entered a phase of steady, structurally driven expansion. Between 2020 and 2025, revenue climbed from approximately $14.5 billion to $20.01 billion, reflecting an environment where thermal management has become inseparable from industrial efficiency, energy transition goals, and operational resilience. The forward trajectory points to continued growth through 2032, with a compound annual growth rate of 5.5 percent and projected revenue reaching nearly $29.5 billion by the end of the forecast period. This expansion is not merely cyclical. It is being shaped by overlapping forces: stricter energy and emissions regulations, the electrification of process heat, the cooling demands of digital infrastructure, and a recalibration of supply chains after years of disruption.
For executives and investors, the market presents a familiar paradox. Demand is broad and durable, yet the profitability and competitive positioning of individual players depend heavily on product specialization, regional supply dependencies, and the ability to navigate certification and materials constraints. Understanding where value is created—and where margin pressure is intensifying—requires looking beyond top-line growth and examining the structural dynamics that will separate resilient operators from those exposed to cost volatility and substitution risk.
Market Status and Core Challenges
The current market structure reflects a mature but still evolving industry. Revenue is distributed across multiple product configurations, end-use sectors, and geographic regions, with no single segment dominating to the point of rendering others irrelevant. That dispersion is both a strength and a source of strategic complexity. Manufacturers must balance standardized high-volume offerings with engineered solutions that command higher margins but require deeper customer integration. At the same time, the industry is operating under heightened scrutiny on safety, performance verification, and traceability, which raises the barrier to entry for undifferentiated competitors but also increases compliance burdens for established players.
Heat Transfer Equipment Market
Several challenges stand out as true inflection points.
- Materials cost escalation is reshaping economics. The cost of metallic heat exchanger equipment has risen from less than $100 per kilowatt thermal to a range between $500 and $1,000 per kilowatt thermal. This shift directly affects project economics, particularly for large industrial and power-generation installations where thermal capacity is a primary cost driver. Manufacturers and buyers are now forced to weigh material selection, design optimization, and lifecycle performance more carefully than in the past.
- Regulatory and certification frameworks are tightening the operational baseline. Pressure vessel and heat exchanger fabrication increasingly depends on recognized stamps and certification programs that verify design integrity and performance. Compliance with established mechanical codes and industry certification schemes is no longer optional; it is a precondition for supplying critical industrial, HVAC, and refrigeration applications. These requirements improve safety and interoperability, but they also lengthen qualification cycles and constrain the speed at which new entrants can scale.
- Trade and import dynamics are altering supply reliability. Projections indicate substantial increases in U.S. imports of heat exchange units within specific tariff classifications through 2025. This pattern points to a market that is becoming more internationally interdependent, with sourcing strategies shifting in response to capacity constraints, regional manufacturing investments, and the need to secure consistent supply for downstream projects.
Together, these forces create a market where growth is achievable, but only for participants who can align product strategy with cost discipline, certification readiness, and supply-chain certainty. The days of competing primarily on price are giving way to competition on verified performance, delivery reliability, and application-specific engineering.
Core Drivers of Market Change
Technology Innovation and Product Differentiation
Product innovation is moving along two complementary paths: performance enhancement in established designs and targeted development for emerging cooling and thermal-management needs. In industrial applications, the emphasis remains on improving heat-transfer efficiency, reducing footprint, and extending service life under harsher operating conditions. In parallel, new product introductions are increasingly oriented toward sectors where thermal control is becoming a bottleneck, such as data center cooling and district energy systems.
Recent product activity illustrates this shift. New brazed plate heat exchanger models have been introduced specifically for data center cooling and district energy applications, signaling that manufacturers are tailoring designs to high-density thermal loads and integrated energy networks rather than treating these as generic secondary markets. At the same time, the continued expansion of large-scale plate heat exchanger manufacturing capacity in the United States reflects a strategic bet on domestic production for a product category where throughput, lead time, and proximity to customers can be decisive advantages.
For businesses, the implication is clear: technology leadership is increasingly defined by application fit rather than generic product breadth. Companies that can match thermal performance to specific operating environments—while maintaining manufacturability and serviceability—are better positioned to defend margins and capture premium projects.
Policy and Regulatory Environment
Policy and standards are not background conditions; they are actively shaping demand patterns and competitive eligibility. Mechanical design and fabrication standards for shell and tube units, certification programs for brazed and fusion-bonded plate heat exchangers, and pressure vessel stamping requirements all create a shared technical language across buyers, engineers, and suppliers. That commonality reduces transaction risk in complex projects, but it also means that compliance competence has become a core capability rather than a back-office function.
The regulatory environment also interacts with broader energy and sustainability agendas. As industries face pressure to reduce energy consumption and emissions, thermal recovery and heat integration become more valuable. Heat exchangers that enable waste-heat recovery, efficient process heating, and lower refrigeration loads are increasingly evaluated against energy-performance criteria that extend beyond initial capital cost. In practical terms, this favors suppliers that can document efficiency gains, support lifecycle assessments, and align product specifications with project-level compliance requirements.
Demand-Side Shifts in Key Sectors
Demand is being reshaped by changes in how companies use energy, how facilities are designed, and how critical infrastructure is cooled. Industrial operators are looking for equipment that supports continuous operation with fewer interruptions and lower operating expense. Commercial and infrastructure projects are placing greater emphasis on thermal systems that can scale with load variability and integrate into broader energy strategies. These shifts are not uniform across sectors, but they share a common theme: thermal management is moving from a supporting utility to a strategic performance variable.
PW Consulting
This demand evolution is visible in the localization of manufacturing and the diversification of application-focused product lines. Facility expansions in North America are intended to improve supply reliability for regional customers, while new models designed for data centers and district energy reflect an understanding that future growth will be tied to specific high-value use cases. For buyers, this means that procurement decisions are increasingly influenced by operational continuity, lead-time predictability, and the ability to match equipment to changing load profiles.
Supply Chain and Cost Structure Transformation
The cost structure of heat exchanger production is being re-evaluated in response to materials inflation, fabrication complexity, and the need for dependable delivery. The sharp increase in metallic equipment costs per unit of thermal capacity is a clear signal that design choices and procurement strategies must be recalibrated. Suppliers that rely on rigid material specifications without exploring optimization opportunities may face margin compression, while those that integrate material efficiency, standardized yet customizable platforms, and robust fabrication processes can better absorb input-cost volatility.
At the same time, trade flows and import projections suggest that sourcing strategies are becoming more dynamic. Companies are balancing domestic production with international supply to manage risk, cost, and capacity. This balancing act is especially important in segments where project timelines are tight and certification or quality documentation must be maintained across the supply chain. The organizations that succeed will be those that treat supply chain design as part of product strategy, not as a separate logistics function.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized manufacturers, broad thermal-system providers, and service-oriented firms that support installation, repair, and maintenance. This diversity is one of the market’s defining features. Some companies compete through large-scale shell and tube solutions for industrial and power generation applications. Others focus on plate and frame, brazed plate, or dry cooling systems for HVAC, refrigeration, and process industries. A further group builds its position on custom fabrication, ASME-aligned pressure vessel work, or aftermarket services that extend asset life and reduce downtime.
Graphite Heat Exchanger Market
Several strategic patterns are evident among the more prominent players.
- Application anchoring. Leading manufacturers tend to differentiate by anchoring their offerings in specific end-use environments. Some build their identity around industrial and power applications, others around refrigeration and cooling, and others around engineered systems for refining and process sectors. This focus allows them to develop deeper technical credibility and repeatable project references in their chosen domains.
- Certification and standards as competitive infrastructure. Companies that operate confidently within recognized mechanical and performance standards are better positioned to win bids in regulated or safety-critical environments. Stamping readiness, documented quality systems, and alignment with widely accepted design standards reduce friction in project approval and procurement.
- Capacity and supply localization. Recent facility investments in the United States and Mexico highlight a strategic emphasis on regional production capability. Expanding domestic or nearshore manufacturing can improve delivery speed, reduce exposure to long-distance logistics risk, and strengthen relationships with customers who prioritize supply reliability.
- Aftermarket and service differentiation. Firms that provide repair, maintenance, and heat recovery services create additional value streams while reinforcing customer relationships. In asset-intensive industries, the ability to keep existing equipment operating efficiently can be as strategically important as selling new units.
The market is not consolidating into a single dominant model, and that is deliberate. The diversity of applications, sizes, materials, and certification requirements makes full horizontal consolidation difficult. Instead, the landscape is evolving through a combination of specialization, selective capacity expansion, and targeted product launches. New entrants face a meaningful hurdle because they must establish trust in performance, compliance, and delivery before they can compete for large projects. Meanwhile, established players are expanding where demand is strongest and where manufacturing scale or technical specialization gives them an advantage.
International activity also remains important. Large exhibitions and technology gatherings in Asia continue to draw hundreds of companies showcasing new equipment, materials, and process technologies. This global exchange of innovation matters because it influences product roadmaps, material choices, and competitive benchmarks across regions. Companies that monitor these developments closely can identify emerging design directions and supply-chain shifts before they become mainstream.
Future Trends and Commercial Opportunities
Trend One: Application-Specific Thermal Solutions Will Command Greater Value
Over the next three to five years, the market is likely to reward manufacturers that move from generic product catalogs to solution-oriented portfolios tailored to high-priority applications. Data centers, district energy, industrial heat recovery, and specialized refrigeration systems are all areas where thermal performance has direct operational and economic consequences. Equipment that is designed for these contexts—rather than adapted after the fact—will increasingly be preferred in procurement decisions.
The commercial opportunity lies in combining technical customization with repeatable engineering platforms. If a company can standardize core design elements while varying capacity, materials, and integration features for specific applications, it can achieve both efficiency in production and relevance in the market. The risk is that over-customization can erode the cost advantages of scale, so the balance between flexibility and standardization will be a critical managerial challenge.
Trend Two: Cost and Materials Strategy Will Become a Competitive Weapon
Given the significant increase in metallic equipment costs per unit of thermal capacity, cost management will move up the strategic agenda. Companies that succeed will not simply pass through higher input costs; they will actively redesign for material efficiency, evaluate alternative configurations where appropriate, and work with customers to optimize total cost of ownership rather than initial price. Procurement teams, in turn, will increasingly seek evidence that installed equipment will perform efficiently over time, reducing operating expense and exposure to future materials volatility.
This trend creates opportunities for suppliers that can offer transparent performance data, lifecycle cost modeling, and design choices that align material use with actual thermal requirements. It also raises the stakes for buyers, who must weigh short-term price against long-term reliability and efficiency. Misaligned purchasing decisions could lead to higher operating costs or premature replacement cycles, especially in demanding service environments.
Trend Three: Supply Reliability and Regional Manufacturing Will Shape Market Access
As import patterns shift and major manufacturers invest in North American production capacity, supply reliability is becoming a competitive differentiator. Projects that depend on tight installation schedules or operate in environments where downtime is costly will naturally favor suppliers that can demonstrate consistent delivery and strong regional support. This does not mean international supply will disappear, but it does suggest that regional manufacturing and service presence will be valued more highly than in the past.
The opportunity here is for manufacturers to align capacity investments with the customer segments most sensitive to lead time and service response. For investors, the relevant question is whether capacity expansion is attached to durable demand or merely to short-term pricing conditions. Overbuilding without clear application demand can create pressure on utilization and pricing, while targeted expansion in growing segments can strengthen market position and improve margins over time.
Uncertainty and Risk Considerations
Several uncertainties should temper overly optimistic planning. Materials cost trajectories remain volatile, and any further escalation could pressure project economics and delay capital decisions. Regulatory and certification requirements may become more demanding in certain jurisdictions, increasing qualification time and reducing flexibility in sourcing. Trade dynamics could also shift if tariff structures, import patterns, or domestic content expectations change. Finally, demand growth may be uneven across sectors, with some applications expanding rapidly while others remain constrained by broader industrial activity or capital spending cycles.
These risks do not undermine the market’s long-term direction, but they do reinforce the need for scenario-based planning. Companies that treat demand, cost, and supply assumptions as fixed are more exposed to disruption than those that prepare for a range of outcomes.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between product strategy and application demand. That means identifying the segments where thermal performance, certification readiness, and delivery reliability matter most, and then concentrating engineering and manufacturing investment there. It also means reviewing material and fabrication choices with a clear eye on cost exposure, exploring where standardization can protect margins without sacrificing application fit. Companies that can offer verified performance, predictable lead times, and strong service support will be better positioned to win and retain high-value projects.
For investors, the key is to distinguish between capacity that is tied to structural demand and expansion that is primarily reactive. Look for evidence that growth is anchored in application-driven need, supported by clear operational advantages, and aligned with compliance and supply reliability. Companies with diversified but focused portfolios, strong certification capabilities, and a credible aftermarket or service presence often have more resilient business models than those relying on undifferentiated volume alone. Monitoring regional manufacturing investments and product launches in emerging applications can also provide early signals about where competitive advantages are being built.
For procurement and operations leaders, the focus should shift from transactional price comparison to total value assessment. That includes evaluating equipment against lifecycle efficiency, serviceability, delivery risk, and compliance documentation. In environments where downtime, energy cost, or regulatory exposure is significant, the cheapest initial option may not be the most economical over the life of the asset. Building procurement criteria that reflect operational reality can reduce vulnerability to supply delays, performance shortfalls, and avoidable operating expenses.
Because the market is evolving across technology, regulation, cost structure, and regional supply simultaneously, the full picture is difficult to capture from headlines or isolated announcements alone. Detailed segmentation data, company-level positioning, and scenario analysis are needed to convert these broad dynamics into concrete decisions about product investment, sourcing, and market entry. For organizations that want to move faster and with more confidence, a comprehensive research perspective can help identify where growth is most durable, where margin pressure is most likely, and which strategic choices will matter most over the next several years.
For detailed analysis of this topic, please visit the official page: Heat Exchanger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


