



Category: market research
PAPR Market Set for 8.3% CAGR Growth: Unpacking the Forces Behind 2032’s $5.38 Billion Outlook
By PW Consulting, 2026-09-21
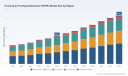
Powered Air Purifying Respirator Market: Strategic Trends and Commercial Opportunities, 2025–2032
The Powered Air Purifying Respirator market has transitioned from a specialized niche into a strategic infrastructure investment across healthcare, industrial manufacturing, energy, and construction. Since 2020, annual revenue has expanded from approximately 2.07 billion to 3.08 billion, reflecting a compound annual growth rate of 8.3 percent through 2032. By the end of the forecast window, total market value is projected to reach 5.38 billion. This trajectory is not merely a function of incremental demand; it signals a structural shift in how organizations approach respiratory protection, occupational safety compliance, and workplace readiness.
Regional leadership remains firmly anchored in North America, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa collectively represent emerging demand corridors. The product landscape is dominated by half mask configurations, which account for the largest share of total revenue, with full face mask and hood variants serving specialized use cases where field of view, comfort, or contamination control requirements differ. In application terms, healthcare and manufacturing represent the two largest demand pools, with oil and gas, construction, and ancillary sectors providing complementary growth vectors.
Despite the favorable growth outlook, the market operates under a moderate concentration profile. The three largest players control roughly 54.5 percent of total revenue, and the top five firms account for approximately 65.0 percent. This concentration shapes pricing discipline, channel access, and the pace at which innovation diffuses across the industry. At the same time, it leaves meaningful room for differentiated entrants, particularly in product formats, regional distribution, and application-specific engineering.
Executives evaluating exposure to this market should view it as a convergence point between regulatory evolution, engineering upgrades, and changing workplace risk profiles. The growth numbers provide directionality, but the strategic value lies in understanding where demand is becoming more repeatable, where compliance friction is easing, and where battery, filtration, and ergonomics are redefining product competitiveness.
Key Challenges and Inflection Points
The market's expansion is real, but it is not frictionless. Three challenges currently define the strategic inflection point for suppliers, buyers, and investors.
The first is the tension between regulatory streamlining and quality assurance. Recent draft guidance from the U.S. Food and Drug Administration and proposed updates from the Occupational Safety and Health Administration signal a clear intent to reduce premarket and medical clearance burdens for certain respiratory protection categories, including NIOSH-approved powered air-purifying respirators used in healthcare and public health settings. While these adjustments can accelerate procurement and broaden adoption, they also introduce a different type of risk: organizations must maintain rigorous internal validation and post-market surveillance when external clearance requirements loosen. The same guidance cycle has also referenced a Class 2 device recall involving 528 units tied to potential mis-assembly of elastic headband rivets to the face shield. That incident underscores a broader point—regulatory flexibility does not eliminate the need for robust design control, assembly consistency, and field reliability.
The second challenge centers on total cost of ownership rather than unit price. Battery systems, particularly lithium-ion and nickel-metal hydride chemistries, represent a primary material expense in powered respirator architectures. Equally important are the labor and administrative costs tied to fit-testing, maintenance protocols, filter replacement, and hospital or plant-level respiratory protection programs. For buyers, the economic question is shifting from “What is the purchase price?” to “What does a dependable protection program cost across its lifecycle?” For manufacturers, this reorients innovation toward battery endurance, serviceability, consumable logistics, and ease of inspection.
The third challenge relates to reimbursement and procurement categorization in healthcare. Current coding and reimbursement structures do not reflect a dedicated, updated framework for powered air-purifying respirator consumables and program costs. Hospitals and health systems continue to classify these items under existing procedures, which can create budgetary friction when scaling protection programs. The absence of specific reimbursement revisions means that adoption in healthcare is being driven less by incremental reimbursement incentives and more by institutional risk management, infection control priorities, and internal compliance mandates. That dynamic favors suppliers who can demonstrate program-level value rather than product-level savings alone.
Together, these challenges point to a market that is maturing but still uneven. Growth will increasingly favor organizations that can align product design, service model, and regulatory navigation with how buyers actually budget and operate.
Core Demand Drivers
Technology Innovation and Product Architecture
Engineering progress is reshaping the value proposition of powered respirators. Recent product activity illustrates how manufacturers are competing on usability, runtime, and filtration performance rather than basic protection alone. In early 2025, Bullard introduced a third-generation system with an improved battery architecture, higher filter efficiency, and streamlined maintenance protocols. These changes matter because they reduce the operational burden on end users and simplify inventory and service planning for safety teams.
At the same time, form factor diversification continues to expand the addressable use cases. Half mask systems remain the volume leader because they offer a pragmatic balance of protection, compatibility, and cost. Full face mask designs serve environments where face and eye protection integration is critical. Hood configurations address scenarios where loose-fitting comfort, extended wear time, and minimization of fit-testing dependency are priorities. The practical implication is that product strategy is less about a single winning configuration and more about matching architecture to workflow, environment, and compliance profile.
Particulate Respirators Market
Battery performance remains a central technical battleground. Runtime, charging logistics, thermal stability, and replacement cycles directly influence field adoption, particularly in healthcare settings where continuity of care and shift-based usage are critical, and in industrial environments where maintenance windows are tightly constrained. Innovations that improve effective runtime or reduce downtime can create meaningful competitive advantage, especially when paired with better diagnostic indicators and predictable consumable schedules.
Regulatory and Compliance Environment
The regulatory trajectory is a powerful demand catalyst, but its effects are nuanced. The April 2026 draft guidance from the U.S. Food and Drug Administration proposes an enforcement discretion compliance policy for NIOSH-approved powered air-purifying respirators and other non-surgical respirators, aimed at reducing premarket requirements for healthcare and public health usage. This type of guidance tends to shorten procurement cycles and lower administrative barriers, which can stimulate demand in health systems and public-sector buyers.
In parallel, the July 2025 proposed amendments from the U.S. Occupational Safety and Health Administration target medical evaluation requirements, removing clearance mandates for users of filtering facepiece respirators and loose-fitting powered air-purifying respirators. The rationale cited in the proposed rule rests on insufficient evidence that such clearance materially reduces impairment in the covered populations. If finalized, this shift would lower a persistent administrative obstacle, particularly for organizations that deploy loose-fitting systems at scale and have struggled with medical evaluation throughput.
Worldwide Medical Powered Air Purifying Respirators Market
These developments should not be interpreted as a blanket deregulation of respiratory safety. Instead, they reflect a targeted recalibration: the regulatory burden is being adjusted where evidence suggests limited marginal benefit, while foundational protection standards remain in force. For the market, the result is likely to be faster adoption in specific channels, greater emphasis on post-market quality, and a growing premium on manufacturers who can provide clear documentation, validated performance, and traceable quality systems.
Demand-Side Behavior and Workplace Risk Perception
Demand is being shaped by a durable change in how organizations think about airborne exposure. In healthcare, respiratory protection programs have moved from episodic compliance to a more continuous readiness mindset. The use of powered air-purifying respirators in clinical and decontamination contexts is increasingly influenced by the need to protect staff during airborne pathogen exposure risk, aerosol-generating procedures, and environmental cleaning operations. Even where reimbursement codes remain unchanged, institutional decision-making is driven by staff safety, operational continuity, and the desire to reduce fit-test dependency for certain loose-fitting deployments.
In industrial environments, demand is tied to both compliance and productivity. Manufacturing and oil and gas operations use powered respirators where particulate exposure, chemical environments, or extended task duration make passive protection less practical. Construction and related trades use them in scenarios where dust, abrasive materials, or mixed-exposure conditions create recurring protection needs. A notable channel development is the expansion of welding-focused solutions through distribution partnerships, which broadens access to specialized air-purifying configurations in fabrication and metalworking settings.
A subtle but important demand shift is the growing preference for solutions that reduce operational friction. Buyers are increasingly attentive to battery swap convenience, filter life clarity, cleaning procedures, and the time burden imposed on safety coordinators. This does not make price irrelevant, but it does mean that competitive differentiation is increasingly derived from program convenience and reliability as much as from protection specifications alone.
Supply Chain, Cost Structure, and Procurement Dynamics
Cost structures in this market are influenced by more than raw material prices. Battery chemistry costs, filter media, housing components, and assembly labor all feed into final pricing, while fit-testing, maintenance labor, and consumable replacement shape the recurring cost profile for end users. In hospital and industrial settings, these operational costs can dominate the economics of a protection program, particularly when deployment scales across multiple sites or shifts.
Supply chain stability matters because respiratory protection is both safety-critical and usage-sensitive. Intermittent availability of filters, batteries, or replacement components can undermine program confidence even when the base equipment is sound. As a result, suppliers that can offer predictable consumable availability, clear service intervals, and localized support often gain an advantage that is not fully captured by headline product specifications.
For procurement teams, this environment rewards a more programmatic purchasing approach. Rather than evaluating individual units in isolation, buyers are increasingly assessing how equipment, consumables, training, and maintenance fit together across a season of use. That shift creates opportunities for suppliers to bundle service elements, provide usage forecasting, and reduce the administrative load on safety teams.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a small group of well-positioned manufacturers with distinct engineering legacies, channel strengths, and application focus areas. The market’s moderate concentration gives established players meaningful scale advantages, while still leaving space for differentiated positioning.
Dräger occupies a strong position in industrial and decontamination-oriented powered respirator systems, with helmet and facepiece architectures designed for demanding environments. Its strategic value lies in integration, durability, and the credibility of a safety-focused brand in heavy-duty applications. For buyers in industrial and specialized decontamination settings, Dräger’s appeal often centers on perceived reliability and alignment with stringent operational requirements.
3M maintains a broad industrial footprint with powered air-purifying respirator systems built for heavy industrial and hazardous location use. Its advantage is scale, distribution reach, and the ability to position respiratory protection within a wider ecosystem of safety and industrial products. In markets where procurement relies on consolidated vendor relationships and multi-product support, that breadth can be a decisive factor.
MSA Safety combines its own powered respirator portfolio with targeted distribution partnerships, including the introduction of welding and industrial-focused air-purifying systems through an exclusive North American partnership. This hybrid approach is strategically significant. It allows MSA to expand its application coverage without building every solution internally, while leveraging existing channel relationships to reach welding, fabrication, and general industrial users more efficiently.
Bullard’s recent product refresh highlights a different competitive angle: iterative improvement in battery system design, filter efficiency, and maintenance simplicity. In a market where operational friction often determines adoption, Bullard’s focus on usability and upkeep can resonate with buyers seeking to reduce training burden and service complexity. The company’s positioning is especially relevant where industrial protective equipment programs value straightforward maintenance and predictable consumable management.
AirBoss Defense Group brings a compact, lightweight design philosophy to the market, with configurations that emphasize portability and particulate protection, including NIOSH-approved options. Its relevance lies in use cases where weight, mobility, and streamlined form factors matter, particularly for teams that need protection without the burden of bulkier systems.
Taken together, the competitive landscape is evolving along three paths. One is consolidation of capability, where larger players use portfolio breadth and distribution to capture cross-application demand. Another is application specialization, where firms deepen their relevance in healthcare, welding, decontamination, or heavy industry through product tuning and channel focus. The third is selective partnership and distribution, which accelerates market access for specialized systems without requiring full vertical build-out. New entrants and smaller firms are most likely to succeed where they solve a specific operational pain point, serve an underserved geography, or offer a form factor that better matches a particular workflow.
Forward Outlook: Three Trends to Watch
Trend One: Faster Adoption in Healthcare and Public Health Settings Through Regulatory and Workflow Alignment
The combination of draft FDA guidance and proposed OSHA amendments is likely to lower administrative barriers for selected powered respirator deployments. If these developments move toward final implementation, healthcare and public health buyers may accelerate evaluation and procurement, especially where programs are designed around loose-fitting options and reduced medical clearance friction. The strategic opportunity here is not simply more units sold; it is the emergence of more standardized procurement pathways, more repeat demand, and greater interest in systems that integrate cleanly into infection control and staff protection workflows.
The associated risk is uneven adoption. Institutions will still differ in how they interpret guidance, manage internal validation, and budget for consumables. Suppliers that over-index on regulatory optimism without supporting program-level usability and service may find adoption slower than the headline environment suggests.
Trend Two: Continued Competition Around Battery, Filtration, and Maintenance Experience
Over the next several years, competitive advantage will increasingly hinge on runtime, charging convenience, filter life clarity, and maintenance simplicity. Buyers are likely to favor systems that reduce downtime, make consumable management predictable, and minimize the training burden for frontline users and safety coordinators. Manufacturers that can pair solid protection performance with a better operational experience should be able to command preference even in a market where multiple products meet baseline requirements.
The risk on this front is that battery and filtration innovation can be copied incrementally, and price competition can intensify once a category matures. Durable advantage will depend on execution quality, support infrastructure, and the ability to demonstrate measurable reductions in program friction, not just specification upgrades.
Trend Three: Program-Level Purchasing and Service Differentiation
As total cost of ownership becomes more central, procurement is likely to shift further toward program-oriented evaluation. That means greater weight on filter supply reliability, battery replacement logistics, maintenance protocols, fit-testing strategy where applicable, and vendor support responsiveness. Suppliers that help buyers plan and manage these elements—rather than only deliver hardware—will be better positioned in competitive bids and multi-year deployments.
The uncertainty here lies in how consistently different buyer segments will adopt program-level thinking. Industrial procurement may move faster in environments with strict compliance cycles and high usage, while other segments may continue to prioritize unit economics and approval simplicity. Companies that can tailor their commercial model to the buying habits of each segment will be more resilient.
Action Considerations for Decision Makers
For manufacturers and product leaders, the priority is to align engineering roadmaps with where buyers feel friction most acutely. Battery lifecycle, filter service clarity, cleaning and maintenance simplicity, and form factor fit for specific applications should be treated as core value drivers, not secondary features. Equally important is the quality system behind the product. Recent regulatory and recall signals indicate that documentation, assembly consistency, and post-market reliability will remain central to market access and customer trust. Firms should also consider where partnerships or targeted distribution agreements can expand application coverage more efficiently than internal expansion alone.
For investors, the market offers a constructive demand backdrop, but selection matters. The most resilient opportunities are likely in companies with defensible application positioning, credible quality and compliance processes, and commercial models that address recurring consumables and support rather than one-time hardware sales alone. Monitoring the trajectory of FDA and OSHA actions will be important, but the more durable signals will come from product adoption patterns, channel execution, and the ability to reduce operational burden for end users. Investors should also watch for consolidation activity, especially where larger players seek to fill application gaps or strengthen regional distribution.
For procurement and safety leaders, the practical move is to evaluate powered air-purifying respirators as part of a protection program rather than as stand-alone purchases. That evaluation should include battery and filter logistics, maintenance workload, training requirements, and support responsiveness alongside protection performance. Where loose-fitting systems are appropriate, the evolving regulatory environment may reduce certain administrative steps, but internal validation and quality verification remain essential. Buyers should also clarify how consumables will be sourced over time, because program confidence depends heavily on predictable availability and clear replacement intervals.
For organizations seeking a sharper view of segment-level demand, regional variation, product configuration economics, and competitive positioning across specific application niches, a more detailed research deep dive can help translate these market-wide trends into segment-specific decisions. The broad trajectory of the powered air purifying respirator market is clear; the strategic advantage comes from understanding where within that trajectory the most actionable opportunities and risks sit for your particular operating context.
PW Consulting
For detailed analysis of this topic, please visit the official page: Powered Air Purifying Respirator (PAPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Prefab Bathroom Pods Market: Why 9.4% CAGR and Commercial Demand Change Everything
By PW Consulting, 2026-09-21
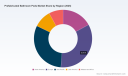
The Prefabricated Bathroom Pods Market: Strategic Shifts and Commercial Opportunities Through 2032
The prefabricated bathroom pods market has moved from a niche construction alternative to a mainstream operational lever for developers, contractors, and facility operators. Valued at approximately USD 6.7 billion in 2025 and projected to expand at a compound annual growth rate of 9.4% through 2032, reaching a revenue base near USD 12.59 billion by the end of the forecast period, the sector reflects a structural recalibration of how built-environment programs are delivered. The trajectory from 2020 through 2025 alone—moving from 4.32 billion to 6.7 billion—demonstrates that the shift is not cyclical but cumulative, driven by persistent labor constraints, schedule compression, and the maturation of offsite manufacturing capabilities.
For decision-makers, this market now sits at an inflection point where technology, regulation, and procurement behavior are reinforcing one another. The opportunity is no longer simply about buying a prefabricated unit; it is about integrating factory-built bathrooms into broader project delivery models, managing supply chain dependencies, and aligning product specifications with evolving compliance and sustainability expectations. The following analysis maps the current state of the market, the forces reshaping it, the competitive positioning of leading manufacturers, and the strategic implications for executives navigating the next three to five years.
Market Status and Core Challenges
The scale of the prefabricated bathroom pods market signals broad adoption, but scale alone does not guarantee smooth execution. The market's growth path from 2020 to 2025—expanding from 4.32 billion to 6.7 billion—has been supported by repeatable factory processes, standardized connection systems, and a growing pipeline of residential, commercial, and institutional projects that prioritize speed and predictability. The forecast band from 2026 through 2032, moving toward 12.59 billion, suggests continued deployment across multiple building types, with commercial and institutional programs likely to remain the primary volume drivers while residential applications gain share as production costs stabilize and design libraries mature.
Despite the positive revenue curve, three challenges define the current operating environment and will shape who captures value in the next phase of growth.
1. Quality Standardization Versus Design Flexibility
Factory production favors repetition, yet end-user expectations increasingly demand customized finishes, layouts, and accessibility configurations. The tension between manufacturing efficiency and project-specific variation is intensifying as pods move from standardized hotel rooms and student housing into healthcare environments, defense facilities, and higher-spec residential programs. Manufacturers that can modularize variation—through configurable framing, interchangeable finish panels, and digital specification workflows—gain a meaningful advantage, while those locked into rigid product lines face margin pressure or limited addressable demand.
2. Compliance Complexity Across Jurisdictions
Prefabricated bathroom pods must satisfy a layered set of requirements that vary by region and building type. International Building Code (IBC) and IRC provisions, local plumbing regulations, and fire-retardant packaging standards such as Loss Prevention Standards LPS 1207 create a compliance landscape that can slow deployment if not addressed upstream. The practical implication is that factory readiness does not automatically translate into site readiness; manufacturers and buyers need aligned inspection pathways, documentation protocols, and transport safeguards to avoid rework or delays during final on-site approval.
3. Supply Chain Concentration and Material Volatility
The market remains moderately concentrated, with leading manufacturers holding a meaningful share of capacity and project flow. Concentration can improve quality consistency and scale economies, but it also raises dependency risks when raw material availability, freight constraints, or production bottlenecks emerge. Steel, composite materials, and lightweight concrete inputs each carry distinct cost and performance profiles, and shifts in one material stream can ripple through lead times and pricing. Buyers and competitors alike are increasingly evaluating dual-sourcing strategies, regional production footprints, and buffer inventory approaches to reduce exposure.
Key Drivers Shaping Market Evolution
Market expansion is not accidental; it is being pulled by a convergence of technical, regulatory, demand-side, and cost-driven forces. The most consequential drivers are not isolated trends but interacting dynamics that change how projects are planned, priced, and delivered.
Technological Innovation and Manufacturing Maturation
Factory-built bathroom pods are benefiting from more disciplined production environments, digital design integration, and material optimization. Advanced composite and steel-frame production lines, BIM-aligned specification workflows, and lean manufacturing practices are reducing defect rates, improving dimensional accuracy, and shortening assembly sequences. Lightweight concrete and patented galvanized steel frame solutions have expanded the structural envelope available for multi-story and higher-load applications, while GRP-based pods are increasingly preferred for their corrosion resistance, reduced maintenance burden, and ease of handling. These material and process improvements are not merely incremental; they broaden the range of projects where pods can be deployed without compromising performance or schedule.
Recent product activity reinforces this trajectory. In February 2026, Offsite Solutions introduced a next-generation steel-framed bathroom pod line with modular design elements that allow customization of layouts and finishes while preserving manufacturing efficiency. That kind of development matters because it addresses a core market tension: buyers want flexibility, but manufacturers need repeatable throughput. Solutions that standardize the underlying frame and connection system while enabling finish and layout variation create a more scalable value proposition.
Policy and Regulatory Environment
Regulatory expectations are becoming both a constraint and a differentiator. Manufacturers are increasingly designing pods to align with local building codes, plumbing regulations, and inspection pathways so that units arrive at the site with a higher degree of factory readiness. At the same time, loss prevention and transport standards are shaping packaging, storage, and handling requirements, particularly for temporary coverings and protective materials used during movement and staging. Compliance is no longer a back-office concern; it is a commercial specification. Projects that integrate code alignment, documentation, and transport safeguards earlier in the procurement cycle reduce the likelihood of delayed approvals or on-site corrections.
This regulatory pull is most visible in programs where inspection risk is high or where multiple jurisdictions are involved. In those settings, manufacturers with established compliance frameworks and predictable quality control processes can shorten decision cycles and lower project risk. The broader effect is a market in which credibility around code conformance and inspection readiness becomes part of the product itself.
Demand-Side Behavior and Procurement Priorities
Buyers are increasingly treating bathrooms as a delivery bottleneck rather than a downstream trade. Onsite bathroom assembly can consume disproportionate labor, extend schedule risk, and create coordination challenges across plumbing, finishes, and inspections. Prefabricated pods accelerate project timelines by roughly 40-50% and reduce on-site workforce needs compared with traditional construction methods, which makes them attractive in labor-constrained markets and in programs where speed-to-occupancy is a financial priority.
Demand is also shifting in response to program type. Commercial and institutional projects—hotels, student accommodation, healthcare facilities, and social housing—continue to be strong adopters because they value repeatable units, predictable quality, and faster fit-out. At the same time, residential applications are gaining momentum as developers and contractors look for ways to compress schedules and control finish quality. The result is a broadening demand base that rewards manufacturers capable of serving multiple sectors without sacrificing production discipline.
Worldwide Bathroom Product Market
Cost Structure and Labor Dynamics
Labor availability and cost remain a structural driver. Where skilled trades are scarce or wage pressure is high, offsite production offers a practical route to reduce on-site labor intensity and improve schedule certainty. Factory settings also enable better material yield, more controlled quality checks, and fewer Weather-related delays, all of which contribute to a more predictable cost profile. This does not mean prefabrication eliminates cost risk; transportation, staging, crane logistics, and interface coordination with the primary structure still matter. But the cost conversation is moving from unit price alone toward total program efficiency, including time savings, rework reduction, and workforce allocation.
Project activity in 2026 illustrates how demand and delivery models are converging. In March 2026, BAUDET secured contracts for multiple hotel modernizations and student residence projects, including Kyriad Hotels Modernization for Louvre Hotels Group in Paris, along with student residence projects in Saint-Étienne and Caen. These wins point to a repeatable commercial pattern: modernization programs and high-volume residential/hospitality pipelines where consistent finishes, predictable lead times, and reduced on-site disruption are decisive. Later, in April 2026, Southwest Solutions Group participated in modular construction and restroom solutions events showcasing code-compliant prefabricated bathroom pods for fast deployment, reflecting a wider industry emphasis on compliance-ready, rapidly deployable units.
Competitive Landscape and Leading Strategies
The competitive environment is defined by manufacturers that have built reputation around production scale, material specialization, and sector focus. The market's concentration suggests that established players hold substantial influence over pricing, specification norms, and buyer confidence, but it also leaves room for regional specialists and new entrants that can differentiate through customization, compliance readiness, or logistics advantage.
Several strategic positions are emerging among leading companies. Walker Modular, based in Hull, United Kingdom, operates as a leading manufacturer of high-quality prefabricated bathroom pods with advanced composite and steel frame production lines, serving UK developers, hotels, healthcare facilities, and student accommodation projects. Its positioning reflects a broad-sector approach anchored in production quality and repeat supply relationships. Offsite Solutions, located in Highbridge, Somerset, specializes in GRP composite and steel-framed pods and utility units, delivering over 10,000 units annually for main contractors and developers. Its scale and material breadth suggest a focus on throughput, consistency, and contractor-facing reliability.
Bathsystem S.p.A., headquartered in Calcinato, Italy, produces lightweight concrete and patented SUPERLIGHT galvanized steel frame solutions in controlled facilities, with annual capacity exceeding 12,000 units. Its strategy leans on proprietary frame technology and controlled production to support both bathroom pods and kitchen units, appealing to buyers who value structural efficiency and repeatable manufacturing. Interpod, based in Berkeley Vale, New South Wales, Australia, focuses on bespoke modular pods for residential, hospitality, healthcare, and defence applications, operating a dedicated factory with custom design and quality finishes. Its differentiation lies in tailored specification and finish quality for programs that require a higher degree of project-specific adaptation.
Prefabricated Security Booth Market
In North America, SurePods, headquartered in Orlando, Florida, has established itself as a factory-built pod supplier for healthcare, hospitality, and residential projects, using BIM and lean manufacturing with expanding facilities and ISO-compliant quality control. Its orientation toward digital specification and quality systems aligns with buyers seeking predictable interfaces and inspection-ready units. B&T Manufacturing, in Rapid City, South Dakota, uses FRAMECAD light-gauge steel technology to produce steel modular pods for hotels, healthcare, and commercial projects, emphasizing plug-and-play units with customizable layouts. Its approach highlights the role of light-gauge steel systems in balancing structural strength with layout flexibility.
European and emerging-market players add further variety. BAUDET, based in Mouchamps, France, has manufactured ready-to-install bathroom pods with full interior finish since 1992, supplying turnkey units for hotels, student residences, and social housing. Hydrodiseño, in Spain, produces prefabricated modular bathroom and kitchen pods with patented designs, targeting efficient, high-quality units for large-scale construction projects. Durapods, in the United States, offers offsite production through PDM Constructors, focusing on simplified logistics and faster delivery across residential and commercial markets. Loom Crafts, in India, produces custom prefabricated bathroom pods for hospitality, healthcare, and housing clients, reflecting growing regional manufacturing capacity and customization demand.
Strategic Positioning and Differentiation
Across these players, several recurring differentiation themes appear. Material expertise is one: some manufacturers emphasize GRP composites for corrosion resistance and low maintenance, while others lean on steel framing for structural strength and multi-story suitability. Production discipline is another: companies that can combine high annual throughput with controlled quality environments tend to win repeat contractor and developer relationships. Sector specialization also matters; firms aligned to hospitality, healthcare, student accommodation, or defence can tailor finishes, accessibility features, and compliance documentation to the expectations of those programs. Finally, interface readiness—BIM-aligned specifications, code documentation, and transport protection—increasingly separates suppliers that merely deliver units from those that reduce project risk.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is likely to evolve along three paths simultaneously. First, consolidation pressure may intensify among mid-tier producers as scale, compliance documentation, and logistics capability become harder to sustain independently. Second, differentiation will deepen around material systems, finish flexibility, and sector-specific compliance, making product category less homogeneous than it once appeared. Third, new entry remains possible in regions where construction demand is expanding and where local production can reduce transport cost and lead-time risk, especially if entrants can combine customization with repeatable framing and quality systems.
Competition will not be won on unit price alone. Buyers are increasingly weighing total program impact: installation speed, inspection readiness, transport resilience, finish consistency, and the ability to adapt layouts without disrupting production. Suppliers that can demonstrate those attributes in repeatable ways are better positioned to secure long-term specification relationships rather than one-off project wins.
Forward Outlook: Trends and Commercial Implications
Looking across the current market trajectory and the forces shaping production, procurement, and regulation, three trends are likely to define the next three to five years.
1. Modular Variation as a Standard Capability
The next phase of growth will favor manufacturers that can offer configurable layouts, interchangeable finish options, and accessibility adaptations without sacrificing throughput. As pods move further into healthcare, defence, and higher-spec residential programs, the ability to vary the visible and functional elements of a unit—while keeping the underlying frame, connection logic, and quality process stable—will become a core selling point. The commercial implication is clear: product lines that enable specification flexibility within a controlled manufacturing regime will capture more diverse demand and reduce the risk of being undercut by lower-cost standardized alternatives.
2. Compliance and Inspection Readiness as a Procurement Criterion
Regulatory alignment will become increasingly embedded in buying decisions. Pods that are designed for code conformance, backed by clear documentation, and protected during transport and storage will face fewer site-level obstacles. Standards related to fire-retardant packaging and temporary protective materials, along with building and plumbing code expectations, will not only influence manufacturing practices but also shape supplier selection. Buyers will look for manufacturers that can reduce inspection friction and demonstrate repeatable compliance, especially in multi-jurisdiction or high-risk programs.
3. Program-Level Integration Over Component Purchasing
The market will increasingly reward suppliers and buyers who think in terms of total program delivery rather than isolated bathroom units. That means closer coordination on sequencing, interface points with the primary structure, crane and staging logistics, and finish schedules. It also means that partnerships between manufacturers, main contractors, and developers may become more structured, with earlier involvement in design and procurement to lock in compatibility and reduce change orders. The commercial opportunity lies in moving from transactional supply to specification-level influence, where the pod becomes part of a broader schedule and cost strategy.
PW Consulting
These trends carry risks. Material cost volatility and supply concentration can affect pricing and availability. Customization can erode the efficiency gains that make prefabrication attractive if variation is poorly managed. Compliance expectations can differ across regions and project types, creating hidden integration costs. And rapid growth can tempt less disciplined entrants to overpromise on lead times or finish quality, creating reputational and execution risk for buyers who do not vet suppliers carefully. The net effect is that the market rewards operational maturity as much as product capability.
Strategic Actions for Decision-Makers
For executives evaluating the prefabricated bathroom pods market, the priority is to convert market momentum into defensible operating choices. The following actions are most relevant depending on role and exposure.
For Manufacturers and Producers
- Invest in configurable product architectures that separate stable structural systems from variable finishes and layouts, preserving throughput while expanding addressable demand.
- Strengthen compliance documentation and inspection readiness as part of the core offering, including transport and storage protection aligned with relevant loss prevention and code expectations.
- Align production capacity and geographic footprint to the programs you want to win, weighing the trade-off between scale concentration and regional responsiveness.
For Investors and Capital Allocators
- Assess suppliers on total program value rather than unit pricing alone, focusing on throughput stability, quality control systems, sector alignment, and the ability to reduce schedule risk.
- Monitor material and logistics exposure, especially where steel, composite, or lightweight concrete inputs are central to a company's value proposition.
- Look for signs of repeatable specification relationships and multi-project pipelines, which tend to indicate stronger commercial moats than one-off wins.
For Procurement, Development, and Construction Leaders
- Engage manufacturers earlier in the design and procurement cycle to align specifications, code documentation, and interface requirements, reducing the likelihood of late-stage rework.
- Evaluate pods against total program metrics—schedule compression, on-site labor reduction, inspection friction, and logistics complexity—rather than isolating initial purchase cost.
- Build qualification criteria that include compliance readiness, finish consistency, transport protection, and the supplier's ability to support variation without disrupting production.
The pace of change in this market makes detailed, current intelligence valuable. Segment-level dynamics, regional demand patterns, material shifts, and competitive moves can alter both opportunity and risk quickly, especially for programs that depend on predictable lead times and compliant delivery. A fuller examination of these dimensions—supported by granular segmentation data, company-level activity, and scenario-based demand views—can help decision-makers pressure-test assumptions before committing to specifications, capacity decisions, or investment theses. Readers seeking deeper segmentation detail and tailored strategic guidance can access the complete PW Consulting research report for a more comprehensive view of the market landscape and its commercial implications.
For detailed analysis of this topic, please visit the official page: Prefabricated Bathroom Pods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BAW Filters Market: Why 7.32% CAGR and Stratification Redefine 2032 Revenue to $5.5B
By PW Consulting, 2026-09-21
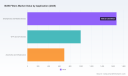
Beyond the Noise: Strategic Trends and Commercial Opportunities in the BAW Filters Market
The BAW (Bulk Acoustic Wave) filters market has entered a phase of sustained, structurally driven expansion that rewards firms able to translate technological advancement into reliable supply and differentiated performance. Over the 2020-2025 historical window, the market grew from approximately 2,286.78 million to 3,361.14 million, reflecting a compound trajectory that accelerated through the mid-2020s as mobile device complexity and connectivity infrastructure converged. Looking ahead to the 2026-2032 forecast period, the market is projected to expand at a CAGR of 7.32%, reaching an estimated 5,512.51 million by 2032. This is not merely incremental growth; it reflects a fundamental recalibration of RF front-end design priorities as spectrum utilization, device form factors, and performance requirements continue to tighten.
For executives and investors, the headline figures convey scale, but the strategic signal lies in the dynamics beneath the surface. The market has moved past the early adoption curve for 5G and is now navigating a more nuanced environment shaped by competing filter technologies, intensifying spectrum congestion, and a concentration of capability among a small group of established players. At the same time, the demand base is broadening beyond smartphones into automotive connectivity, industrial IoT, and wireless infrastructure. Understanding where value is created—and where margins and market share are at risk—requires a clear read on the forces shaping this landscape.
Paint Filters Market
Market Landscape and Core Challenges
The current market size sits around 3,361.14 million as of the base year, and the forward projection of 5,512.51 million by 2032 reflects sustained demand across mobile, connectivity, and industrial applications. This trajectory is underpinned by rising RF content per device, the proliferation of multi-band and wideband designs, and the rollout of next-generation Wi-Fi and cellular standards that place greater stress on filtering performance. In this environment, BAW filters continue to command attention because of their ability to deliver high rejection, temperature stability, and compact integration in frequency ranges where SAW-based alternatives are increasingly strained.
Beneath these favorable dynamics, three challenges stand out as strategic inflection points.
1. Technology Choice and Coexistence Pressure
The filtering landscape is not a single-technology story. Film Bulk Acoustic Resonator (FBAR) and Solidly Mounted Resonator (SMR) approaches each present distinct trade-offs in performance, packaging, and manufacturing complexity. FBAR solutions have historically been associated with superior rejection curves and broad applicability in mobile and infrastructure settings, while SMR variants offer a different cost and integration profile. As device architectures demand more bands, more bandwidth, and tighter rejection, design teams must decide where to deploy each technology across bands and platforms. This decision is increasingly tied to total cost of ownership, not just unit performance, and the wrong allocation can create efficiency losses in both bill of materials and system-level gain.
2. Spectrum Reallocation and Filter Performance Requirements
The opening of substantial spectrum in the 6 GHz band for unlicensed use has accelerated the development of Wi-Fi 6E and Wi-Fi 7 products, which depend heavily on high-frequency, high-selectivity filters. This shift expands the addressable opportunity but also raises the performance bar. Higher frequency operation, wider channel plans, and greater spectral density mean that filters must maintain selectivity and stability under more demanding conditions. The result is a moving target for manufacturers: designs must be optimized not just for today’s network architecture but for the broader spectrum ecosystem that regulators and standards bodies continue to reshape.
3. Supply Security, Concentration, and Scale Economics
The market exhibits meaningful concentration, with a relatively small group of participants accounting for a large share of revenue. This concentration reflects the realities of technology maturity, packaging expertise, and the capital intensity of scaling high-performance RF components. For downstream customers, this creates a tension between sourcing reliability and competitive pressure. Qualifying new suppliers or alternative technologies involves engineering validation, production ramp risk, and long-term supply commitments. In such an environment, supply resilience becomes as important as unit cost, and multi-source strategies are gaining relevance for programs where downtime or component shortages carry significant system-level consequences.
Key Drivers Shaping the Market
Growth in the BAW filters market is not accidental. It is being propelled by a convergence of technology, regulation, demand behavior, and cost structure shifts that reinforce one another. The most consequential drivers are the following.
Technological Innovation and Performance Migration
The strongest driver is the ongoing migration of performance expectations across frequency ranges and use cases. High-performance platforms for mobile and connectivity devices are increasingly integrating BAW solutions to support wider bandwidths, more bands, and higher signal integrity requirements. Parallel innovation in packaging and integration—such as wafer-level packaging where applicable—supports miniaturization while preserving electrical performance. The push toward ultra-compact designs with improved efficiency and reduced footprint is especially relevant for next-generation smartphones and wireless devices, where board space and thermal constraints are unforgiving. In parallel, new high-frequency filter technologies are emerging that target lower insertion loss and improved signal efficiency for 5G, Wi-Fi 7, and early 6G scenarios, intensifying competition at the high end of the performance curve.
PW Consulting
Policy and Spectrum Regulation as Demand Catalysts
Regulatory and spectrum policy decisions are shaping demand with unusual clarity. The FCC’s decision to make 1200 MHz of spectrum in the 6 GHz band available for unlicensed use created a direct catalyst for products that require high-selectivity filtering at higher frequencies. In Europe, the steady rollout of 5G across major economies, combined with a strong industrial base and automotive sector, provides a stable demand backdrop that supports both consumer device growth and infrastructure-related RF content. At the same time, increasing emphasis on energy efficiency, electromagnetic compatibility, and compliance with stringent ETSI standards is reinforcing the value of high-quality filtering in both consumer and professional equipment. Regulatory pressure does more than create compliance obligations; it raises the baseline expectation for RF performance and reduces the tolerance for inferior solutions.
Demand-Side Shifts Across Devices and Verticals
On the demand side, the most notable change is the broadening of RF complexity beyond flagship smartphones. Devices are carrying more bands and more connectivity options, and the absolute RF content per device is rising across mobile, IoT, automotive, and infrastructure categories. Automotive and infrastructure applications, in particular, are expanding as connected vehicle features, telematics, and roadside infrastructure add new filtering requirements. The C-V2X domain illustrates this trend clearly, with new filter solutions being developed for 5.9 GHz operation and band 47 to support advanced automotive and infrastructure use cases. In the same way, Wi-Fi and IoT device growth is pushing demand toward filters that can handle higher frequencies while maintaining selectivity and reliability in dense deployment environments.
Cost Structure and Manufacturing Strategy
Cost dynamics are shifting as manufacturers pursue tighter integration, higher yield, and more efficient packaging. For high-volume mobile and connectivity applications, the ability to deliver strong RF performance within a smaller footprint is becoming a competitive differentiator, not simply a technical achievement. This favors participants who can combine product performance with disciplined manufacturing scale and consistent quality. At the same time, demand across industrial, aerospace, defense, and communications applications introduces additional complexity: customized solutions and reliable wafer-level packaging for specific frequency ranges can command premium positioning, but they also require specialized process control and customer-specific qualification. The net effect is that cost leadership and value leadership are increasingly defined by the ability to match technology choices to application requirements without sacrificing reliability or ramp capability.
Competitive Landscape and Leading Strategies
The competitive field in the BAW filters market is defined by a handful of companies with deep RF expertise, differentiated product portfolios, and strategies that emphasize either breadth, specialization, or manufacturing control. Rather than competing on price alone, leaders are building advantage through frequency range coverage, packaging capability, performance stability, and integration with next-generation standards.
Strategic Positioning Among Leading Participants
Several incumbents are shaping the market through distinct positioning. One established leader continues to emphasize BAW filtering solutions for mobile products, radar, and communications systems, with a focus on ultra-stable temperature performance and wafer-level packaging across frequencies in the 1.5-9 GHz range. This profile reflects a mobile- and radar-oriented strategy built on performance consistency and broad band coverage. Another participant has pursued a broader high-frequency and ultra-wideband angle, developing RF filters aimed at high-power and wideband scenarios across 5G/6G, Wi-Fi, automotive, defense, IoT, and Satcom markets. This approach signals an intent to capture demand where performance extremes matter and where filter requirements diverge from mainstream mobile designs.
A third participant has positioned itself around custom BAW RF filters with wafer-level packaging for specific frequency ranges in industrial, aerospace, defense, and communications applications. This specialization points toward a strategy that values tailored solutions and application-specific qualification over mass-market volume alone. A fourth company offers BAW filters integrated into high-performance platforms for mobile and connectivity devices, leveraging internal manufacturing for next-generation 5G and Wi-Fi standards. Integration of design and manufacturing can improve responsiveness and quality control, and may be especially valuable as standards evolve quickly and customers seek sustained supply alignment. A fifth player has emphasized FBAR-based BAW filters with strong rejection characteristics for 5G, Wi-Fi, and wireless infrastructure, reflecting a technology-specific focus that plays to the strengths of film-based acoustic resonance in demanding RF environments.
Recent product activity reinforces how competitive differentiation is evolving. In early 2026, one participant began sampling a C-V2X filter solution designed for 5.9 GHz operation, including band 47, targeting advanced automotive and infrastructure applications. This move illustrates how filter suppliers are expanding into connectivity domains where timing, reliability, and standards alignment are critical. Shortly afterward, another participant introduced ultra-compact BAW filter technology aimed at 5G and Wi-Fi 7 devices, emphasizing improved RF performance, higher efficiency, and reduced footprint for next-generation smartphone and wireless applications. These announcements are not isolated product updates; they are indicators of where competitive energy is being directed: higher frequency, smaller form factor, tighter integration, and new verticals.
Market Structure Evolution
The market is not simply consolidating around a single formula. Instead, it is showing signs of both concentration and selective divergence. Concentration remains meaningful, reflecting the advantages of scale, process maturity, and long-term customer qualification. At the same time, differentiation is increasing as suppliers target distinct frequency ranges, application verticals, and packaging philosophies. New entrants and technology alternatives can still find room where they address unmet needs in high-power, ultra-wideband, or specialized industrial and defense scenarios, but the bar to meaningful share gains is high. For incumbents, the strategic priority is to maintain performance leadership while expanding into adjacent demand areas such as automotive connectivity and infrastructure. For customers, the practical implication is that supplier selection is increasingly a multi-dimensional decision involving performance, supply resilience, standards alignment, and long-term roadmap compatibility.
Future Trends and Commercial Implications
Based on the current trajectory and the forces already in motion, two to three trends are likely to shape the next three to five years.
Higher-Frequency, Multi-Standard Filter Architectures Will Become the Norm
As 5G matures, Wi-Fi 6E and Wi-Fi 7 expand, and early 6G exploration advances, RF front ends will need to support wider frequency coverage and more simultaneous standards. Filters will be expected to perform not just in a single band but across broader, more complex spectral environments. This creates commercial opportunities for suppliers that can deliver high-selectivity solutions with stable temperature behavior, low insertion loss, and packaging that supports denser integration. It also raises the importance of design flexibility, because device manufacturers will want platforms that can adapt to evolving band plans and channel allocations without sacrificing performance.
Bypass Filter Market
Automotive, Infrastructure, and Industrial Demand Will Grow in Strategic Importance
Automotive and infrastructure applications are becoming more prominent in the demand mix, driven by connected vehicle features, C-V2X expansion, and the broader rollout of wireless infrastructure. These segments often emphasize reliability, temperature resilience, and long program lifecycles, which can reward suppliers with disciplined qualification processes and consistent continuity. For companies able to align product roadmaps with automotive and infrastructure timing, the opportunity is not just additional volume but a more diversified revenue base that can partially offset cyclicality in consumer device cycles.
Supply Strategy and Multi-Source Qualification Will Matter as Much as Performance
As concentration remains high and standards evolve quickly, downstream customers will place greater weight on supply resilience, ramp support, and the ability to qualify alternative sources where appropriate. This does not mean uniformity; different applications may continue to require different solutions. But it does mean that companies with flexible sourcing strategies, robust validation capabilities, and transparent roadmap communication will have an advantage in critical programs. The commercial implication is that value will increasingly accrue to participants who can reduce total risk for their customers, not only deliver a strong unit specification.
Risks and Uncertainties
These trends carry meaningful uncertainty. Technology competition between FBAR, SMR, and emerging alternatives could shift cost-performance trade-offs faster than expected, particularly if new high-frequency filter approaches improve efficiency or reduce insertion loss in commercially meaningful ways. Regulatory and spectrum decisions may accelerate demand in some bands while constraining others, creating uneven growth across applications. Standard cycles and device adoption timing can also affect the pace of content increases, especially if device roadmaps shift or if integration strategies change. Finally, the capital intensity and process sensitivity of high-performance filter manufacturing mean that execution risk remains a real factor; ramp delays, yield issues, or qualification challenges can have outsized consequences in a concentrated market.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the direction of spectrum use, device complexity, and vertical expansion. That means investing in higher-frequency and wideband capabilities, continuing to sharpen packaging and integration for compact high-performance platforms, and preparing for demand growth in automotive and infrastructure as well as mobile and connectivity. Equally important is disciplined qualification and supply continuity, since customer trust in RF components is built on consistency as much as on specification performance.
For investors, the strategic question is not whether the BAW filters market will continue to expand, but where durable advantages are being created. The most attractive positions are likely to be those that combine technology leadership with the ability to scale reliably, support next-generation standards, and address a diversified set of applications. Attention should be paid to participants that are extending into automotive, infrastructure, and specialist high-frequency domains, as well as those with integrated design-and-manufacturing strategies that can respond quickly to changing requirements. At the same time, it is worth monitoring technology alternatives and supply-side execution, since shifts in either can alter competitive positioning.
For procurement and sourcing leaders, the most prudent approach is to treat filtering as a system-critical decision rather than a commodity purchase. That includes evaluating not just unit cost and baseline performance, but also temperature stability, rejection characteristics, packaging fit, standards alignment, and the supplier’s ability to support long program lifecycles or rapid platform evolution. Where feasible, developing qualified alternatives for critical bands can reduce exposure to concentration risk, especially in applications where downtime or performance shortfalls carry significant consequences.
The strategic picture is clear enough to act on, but the details matter. Fine-grained segmentation, frequency-specific demand profiles, technology-specific cost structures, and company-level roadmap mapping can materially change sourcing and investment judgments. For readers seeking a more detailed breakdown of market size by segment, competitive positioning across frequency ranges and applications, and customized implications for a specific product portfolio or sourcing strategy, a comprehensive research report can provide the level of detail needed to support more precise decision-making.
For detailed analysis of this topic, please visit the official page: BAW Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Massage Chair Market: Why the 6.98% CAGR Trajectory Signals More Than Just Growth
By PW Consulting, 2026-09-21
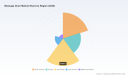
The Massage Chair Market: Strategic Trends and Commercial Opportunities
The global massage chair market has transitioned from a niche wellness accessory to a strategically significant segment within the broader health and home comfort ecosystem. Over a five-year historical window, the market demonstrated steady expansion, with annual revenue growing from approximately $163.15 million in 2020 to an estimated $215.0 million in 2025. Looking ahead to the forecast horizon ending in 2032, the sector is projected to reach $344.8 million, reflecting a compound annual growth rate of 6.98 percent. This trajectory signals more than incremental demand growth; it indicates a structural shift in how households, wellness providers, and commercial operators view massage chairs as integrated health infrastructure rather than discretionary furniture.
For executives and strategic planners, the numbers alone do not capture the full story. The market’s evolution is being shaped by converging forces: advanced robotics, AI-driven personalization, shifting consumer health behaviors, and a regulatory and cost environment that rewards speed to market and engineering differentiation. Understanding where the market is heading requires looking beyond headline revenue figures and examining the underlying dynamics that will determine which companies capture margin, which regions scale fastest, and which product categories become commoditized.
Market Landscape and Core Challenges
The market’s current footprint reflects a maturing but still rapidly evolving category. Revenue growth has accelerated as consumer acceptance broadens and product sophistication improves, with the 2025 estimate of $215.0 million serving as a clear inflection point. The forecast period through 2032 projects continued expansion toward $344.8 million, but the pace and composition of that growth will be uneven across segments and geographies. The category is no longer defined solely by basic mechanical rollers and basic air pressure systems; it is increasingly shaped by intelligent tracking, adaptive pressure mapping, and wellness-program integration that blur the line between consumer electronics and therapeutic devices.
Despite the favorable growth outlook, the industry faces several structural challenges that will test competitive positioning in the coming years.
First, the market is navigating a technology inflection point where differentiation is becoming harder to sustain. Early robotic and AI-integrated features created meaningful premium pricing power, but as core sensing, motor control, and body-mapping technologies mature, the risk of feature parity increases. Companies that rely on incremental additions without underlying engineering depth will face margin compression as buyers increasingly compare specifications and total cost of ownership rather than brand narrative alone.
Second, the regulatory and safety environment is adding complexity to product design and market entry. In North America, massage chairs must comply with Consumer Product Safety Commission standards and Federal Trade Commission advertising guidelines for electrical products. These requirements are not static; they evolve as product functionalities become more interactive and health-adjacent. Compliance is not merely a legal checkbox but a design constraint that influences component selection, user interface architecture, and claims language. Companies with mature quality systems and proactive regulatory engagement will have an advantage in scaling across channels without facing costly redesigns or marketing restrictions.
Third, cost structures and trade dynamics are reshaping margin calculations. Import controls and tariff environments have introduced uncertainty around sourcing strategies, particularly for Chinese-origin units. Sector analysis indicates that tariffs in the 15 to 20 percent range on certain Chinese-origin massage chairs have resulted in limited consumer price increases, largely because manufacturers and distributors have adapted supply chains through sourcing shifts, regional assembly, and value engineering. This suggests that tariff exposure is manageable but requires active supply chain design rather than passive pass-through. At the same time, labor and engineering costs in premium manufacturing markets influence pricing architecture, with Japanese manufacturers sustaining premium positioning through advanced engineering and patent portfolios in high-margin wellness models.
For decision makers, these challenges point to a clear conclusion: the market rewards companies that treat compliance, supply chain flexibility, and engineering depth as strategic inputs rather than operational afterthoughts.
Key Drivers of Market Change
Several interconnected drivers are accelerating the market’s evolution and creating distinct opportunities for operators that can align product strategy with emerging demand patterns.
Technological innovation remains the most visible and impactful driver. The category is moving from fixed-program massage routines toward adaptive systems that interpret user posture, tension patterns, and preferred intensity in real time. Body-scan programs, AI health detection, and multi-dimensional roller mechanisms are becoming central to premium offerings. Recent product unveilings illustrate this shift in practice. At CES 2026, Body Friend Co., Ltd. introduced the 733 massage chair and the Pharaoh Q AI massage chair, emphasizing advanced AI health solutions and robotic massage technology. Around the same period, Human Touch showcased the Novo XT and Super Novo X, highlighting whole-body massage innovations and teardrop doors designed to improve accessibility and user experience. KoziSense also presented a latest 4D massage chair lineup at CES 2026, including ergonomic high-end models with intelligent massage technology. These launches reflect a broader industry direction: the value proposition is shifting from mechanical repetition to personalized, context-aware wellness intervention.
Policy and regulatory dynamics are shaping both market access and consumer trust. Safety and advertising compliance influence how products are positioned, especially when marketing language approaches health or therapeutic claims. In parallel, reimbursement-adjacent mechanisms are expanding the practical affordability of select models. Certain Human Touch and OSIM models are eligible under HSA/FSA frameworks, allowing tax-advantaged wellness purchases that can lower effective consumer cost and broaden the addressable market. This does not transform massage chairs into insured medical devices, but it does create a purchasing pathway that can accelerate adoption among health-conscious households and corporate wellness programs that already use flexible spending accounts.
Demand-side behavior is changing as consumers increasingly view wellness expenditure as preventive and habitual rather than occasional. Residential use remains a dominant application context, but commercial deployment is also gaining relevance in settings such as hotels, spas, clinics, and corporate relaxation spaces. The commercial segment benefits from recurring visibility and shared-use economics, but it also demands durability, hygiene considerations, and serviceability that differ from residential expectations. This divergence is encouraging manufacturers to think in terms of product families rather than single SKUs, with variations in robustness, interface complexity, and service support tailored to each use case. Osaki’s recent exhibition activity reinforces this commercial-residential balance: at the Las Vegas Furniture Market 2026, the company exhibited premium models including the Platinum Escape Duo 4D and OS-Pro 4D+3D, signaling continued attention to both high-end home formats and commercial-adjacent placement opportunities.
Supply chain and cost-structure changes are redistributing where value is created. As demand grows, manufacturers are under pressure to balance engineering ambition with manufacturability, component availability, and logistics resilience. The ability to localize certain assembly steps, diversify component sourcing, and manage warranty and service costs is becoming a competitive lever in its own right. Industry market data projects North American premium segment growth at 5 to 7 percent CAGR driven by AI-integrated wellness features, suggesting that premiumization is not merely a pricing strategy but a demand-led trend that rewards products capable of delivering perceptible differentiation in user experience and health-adjacent functionality.
Together, these drivers indicate that the market’s next phase will favor companies that integrate technology, compliance, distribution, and consumer financing into a coherent value proposition rather than optimizing each in isolation.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leading players occupying distinct strategic positions based on engineering heritage, patent portfolios, regional origin, and targeted use cases. Market concentration data indicates that the top three firms account for roughly 48.5 percent of revenue, while the top five reach approximately 57.8 percent. This level of concentration suggests a market where scale, brand trust, and product portfolios matter, but where specialized differentiation can still support strong niche positioning.
Lift Chair Market
Human Touch, headquartered in Long Beach, California, competes with a focus on state-of-the-art robotic massage chairs, zero-gravity recliners, and wellness solutions built around patented technologies such as CirQlation and HT Flex. Its strategic positioning leans toward accessible premium wellness, with product design that emphasizes circulation-focused mechanisms and user-friendly recliner formats. The company’s HSA/FSA-eligible models also indicate an understanding of financing pathways as part of the purchase decision.
Osaki, based in Japan, positions itself around premium 4D and 5D full-body massage chairs with AI health detection, SL Flex track mechanisms, and automated body-scan programs. Its strength lies in combining advanced track geometry with intelligent sensing, appealing to buyers who want a more data-informed and adaptive massage experience. Osaki’s recent Las Vegas Furniture Market 2026 presence, including the Platinum Escape Duo 4D and OS-Pro 4D+3D, underscores its commitment to maintaining visibility in both premium home and commercial-adjacent channels.
OSIM, headquartered in Singapore, competes with full-body shiatsu and zero-gravity massage chairs supported by 250 or more patented technologies, including V-Hand™ and Tui-Na gliding, and endorsements such as recognition by the American Chiropractic Association. This profile suggests a strategy rooted in clinical-adjacent credibility and broad patent coverage, which can support both consumer trust and retailer confidence in product claims.
Body Friend Co., Ltd., based in South Korea, offers 4D full-body massage chairs with patented walking-leg technology, zero-gravity design, heat, airbags, and foot rollers. Its CES 2026 reveals, including the 733 and Pharaoh Q AI models, highlight a focus on combining mechanical innovation with AI health solutions, reinforcing a forward-looking product roadmap.
FAMILY INADA, located in Osaka, Japan, competes in high-performance shiatsu massage chairs and is recognized for originating the first automatic shiatsu chair along with specialized wellness therapy solutions. Its positioning reflects heritage and specialization in shiatsu-style mechanics, which can appeal to buyers seeking authentic technique differentiation rather than generalized relaxation features.
Ceragem, also based in South Korea, focuses on luxury zero-gravity massage chairs with SPINE-Tech™ spinal therapy, Pro Dual Engine, and custom automatic modes. Its strategy centers on spinal-focused therapy claims and premium build, targeting consumers who prioritize targeted spinal support and high-end comfort in a single platform.
Ogawa, headquartered in Switzerland, competes with luxury massage chairs and zero-gravity recliners that emphasize advanced wellness features for both home and professional use. Its Swiss positioning supports a premium perception and broad use-case framing, which can be advantageous in markets where design credibility and cross-context versatility matter.
PW Consulting
The strategic patterns emerging across these players are instructive. Some compete on patent depth and clinical-adjacent credibility; others on AI-driven adaptability and ergonomic innovation; still others on premium design and use-case flexibility. What separates the leaders is not a single feature but the ability to connect engineering, brand trust, channel strategy, and financing accessibility into a coherent offering. Recent trade show activity in early 2026 demonstrates that product messaging is increasingly tied to intelligent personalization, accessibility improvements, and multi-dimensional massage quality, rather than simple roller count or basic air compression.
Looking at the broader market evolution, three dynamics are likely to shape competitive outcomes. First, consolidation pressure may increase as larger players seek to broaden portfolios through acquisition or expanded distribution, particularly in regions where retail trust and service networks are decisive. Second, segmentation will likely deepen, with clearer separation between mass-premium comfort products and high-end AI-integrated wellness systems, each requiring distinct supply chain, marketing, and service models. Third, new entrants may find opportunity not by competing head-to-head in established premium segments, but by targeting underserved use cases, regional price points, or hybrid commercial-residential designs that better match specific buyer economics.
Forward Outlook: Trends and Opportunities
Based on current data and industry dynamics, three trends are likely to define the market over the next three to five years.
The first trend is the continued premiumization of AI-integrated wellness features. As body mapping, adaptive pressure control, and health-oriented user interfaces become more refined, premium products will increasingly serve as platforms for personalized wellness routines rather than static massage devices. This creates opportunity for manufacturers that can translate sensor and software capabilities into measurable user benefits, and for retailers that can communicate those benefits without overstating therapeutic claims. The risk is that feature complexity outpaces reliability or usability, leading to buyer fatigue if intelligent features are perceived as gimmicks rather than meaningful improvements.
The second trend is the expansion of commercial and semi-commercial deployment models. Hotels, wellness centers, corporate facilities, and medical-adjacent environments are likely to increase adoption where durability, serviceability, and shared-use ergonomics can be proven. This opens opportunities for products designed with higher cycle durability, easier maintenance, and hygiene-oriented materials, as well as for service partners who can support installation and ongoing maintenance at scale. The uncertainty lies in standardization: commercial buyers will demand consistent performance and clear total cost of ownership data, which may pressure manufacturers to provide more transparent service and warranty economics.
The third trend is supply chain and pricing adaptation in response to trade and cost pressures. As tariff environments and component costs continue to vary by origin and configuration, successful players will likely diversify sourcing, consider regional assembly or finishing options, and engineer product architectures that allow modular cost management without degrading perceived quality. This creates opportunity for companies that can maintain premium positioning while managing landed cost strategically. The risk is that aggressive cost reduction erodes the engineering and safety attributes that justify premium pricing in the first place.
Across all three trends, the commercial opportunity is clearest for organizations that can align product innovation with channel readiness, compliance discipline, and clear communication of user value. Markets that treat these as integrated choices are more likely to convert growth into durable margin than those that chase features or price points in isolation.
Luxury Massage Chair Market
Implications for Decision Makers
For manufacturers, the priority is to build differentiation that is difficult to replicate through specification matching alone. That means investing in track geometry, sensing accuracy, user interface clarity, and reliability data that support premium positioning, while ensuring compliance and claims language are aligned with actual product capabilities. Product roadmaps should also anticipate commercial and residential divergence, with distinct durability, service, and hygiene considerations where relevant. Speed to market matters, but not at the expense of safety and consistency; in a category where CPSC and FTC expectations shape both design and marketing, disciplined launch processes can be a competitive advantage.
For investors, the market offers growth but requires selective exposure. The most resilient opportunities are likely in companies with defensible engineering or patent assets, clear premium-segment traction, and flexible supply chain strategies that can absorb trade and cost variability. Interest in AI-integrated wellness features is real, but returns will depend on whether those features translate into repeat purchase, stronger brand trust, and improved channel economics rather than short-lived novelty. Monitoring product launches, trade show presence, and compliance-related messaging can provide early signals about which players are building durable positions versus those relying on promotional momentum.
For procurement and channel buyers, the focus should be on total value rather than sticker price alone. Evaluation criteria should include body-scan accuracy, adaptive pressure control, durability in intended use settings, serviceability, warranty structure, and financing eligibility where applicable. For commercial deployments, additional weight should be given to hygiene, maintenance access, and expected service cycles. Given the pace of product iteration and the variability in claims and specifications across the category, access to current, granular market intelligence can materially improve sourcing and assortment decisions.
The market is moving quickly enough that static assumptions about features, pricing, and regional opportunity can become outdated within a product cycle. Detailed segmentation data, track-level competitive benchmarking, and scenario-based cost and demand analysis can help decision makers separate durable trends from temporary noise. For those evaluating market entry, portfolio expansion, or sourcing strategy, deeper research provides the granularity needed to calibrate investment and reduce exposure to misaligned assumptions. A complete research report offers expanded segmentation detail, company-level profiling, and customizable scenario analysis for organizations that need to move from strategic direction to operational planning.
For detailed analysis of this topic, please visit the official page: Massage Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microbial Air Samplers Market Surpasses $158M: 5 Shifts Reshaping 2032 Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Microbial Air Samplers Market
Market Overview: Navigating a Maturing Landscape
The global market for microbial air samplers has demonstrated steady, measured expansion over the past half-decade, evolving from a niche compliance tool into a core component of environmental quality management. Between 2020 and 2025, the sector moved from a base of approximately 127 million USD to nearly 159 million USD, reflecting annual revenue growth that has stabilized around a low-to-mid single-digit pace. Looking ahead through the early 2030s, the trajectory suggests a continuation of this measured expansion, with the market expected to approach the 220 million USD mark by 2032. This progression is not explosive, but it is structurally meaningful: it signals a transition from reactive, post-event sampling to systematic, real-time contamination control embedded within manufacturing and healthcare workflows.
PW Consulting
The revenue distribution across equipment categories further illustrates how the market has matured. Portable units command the largest share of the equipment mix, underscoring the enduring demand for flexibility, mobile verification, and rapid deployment across multi-line or multi-site facilities. Desktop and isokinetic configurations together represent a substantial secondary layer, catering to fixed monitoring stations and environments where airflow accuracy matters. Single-stage and multi-stage systems occupy a smaller but increasingly specialized niche, particularly where cascade impaction or size-fractionated sampling is required for detailed microbial characterization. The diversity of form factors is not a symptom of fragmentation; it reflects a market responding to heterogeneous operational requirements, from grade A aseptic suites to routine environmental verification across food processing or hospital spaces.
As the sector approaches its next growth phase, several structural realities define the commercial landscape. Demand is no longer driven solely by regulatory minimums; it is increasingly shaped by operational risk tolerance, productivity targets, and the economics of quality failures. At the same time, the supplier base remains modestly concentrated, leaving room for differentiation through engineering, service, and data integration rather than pure volume. For decision-makers, this creates a market where performance credibility, regulatory alignment, and total cost of ownership matter more than upfront sticker price alone.
Air Sampling Pumps Market
Core Challenges and Inflection Points
Regulatory Pluralism and the Cost of Compliance Misalignment
One of the most pressing operational challenges in this market is the absence of a single, globally uniform compliance framework. Cleanroom and critical-environment monitoring must align with overlapping expectations, including EU-GMP Annex 1, ISO 14698, EN 17141, FDA aseptic guidance, and USP standards. While this layered regulatory environment strengthens patient and product safety, it also introduces complexity for equipment selection, validation, and ongoing qualification. Manufacturers and end users alike must ensure that sampling heads, flow paths, and data outputs satisfy not just one standard but the entire stack of requirements relevant to their jurisdiction and production type. When a device is optimized for one framework but fails to accommodate another cleanly, the consequence is often rework, revalidation cycles, or delayed qualification, all of which erode the commercial value of otherwise capable instruments.
Sterilization, Contamination Control, and Lifecycle Management
A second challenge lies in the interplay between sampling performance and decontamination practicality. In high-risk environments, sampling heads and internal flow paths must be fully compatible with vaporized hydrogen peroxide and other decontamination methods, while surfaces must resist particulate retention and secondary contamination. Electropolished stainless steel and VHP-compatible materials have become essential rather than optional features in many Grade A and B settings. At the same time, consumable components such as membrane filters must balance retention efficiency, shelf stability, and sterility assurance. Filters with long shelf life and high spore retention can reduce waste and logistics complexity, but they also raise procurement costs and inventory management questions. The market is therefore shifting from a focus on sampling alone toward a broader consideration of the entire monitoring lifecycle, including preparation, execution, decontamination, documentation, and consumable management.
The Data Integrity Premium
A third inflection point is the growing emphasis on data integrity and electronic recordkeeping. Modern cleanroom operations increasingly require auditable, tamper-resistant data streams that satisfy requirements such as 21 CFR Part 11. This elevates the importance of remote and connected sampling solutions that can support continuous monitoring, time-stamped records, and robust user-access controls. The challenge for suppliers is not simply to add connectivity, but to design instruments where data generation, storage, and retrieval are integrated in a way that reduces manual handling and human error. For buyers, the lesson is that a sampler with strong physical performance can still fail commercially if its documentation and data architecture do not align with enterprise quality systems.
Key Drivers Shaping the Market
Technological Innovation: From Sampling Devices to Smart Monitoring Nodes
The most visible driver of change is the shift toward smart, integrated sampling systems. Recent product developments have highlighted a move beyond mechanical reliability alone toward instruments that combine process safety, minimal secondary contamination risk, and higher assurance of data integrity. In this context, features such as magnetic perforated lids, smart functional controls, and enhanced usability are not cosmetic; they are engineering responses to real operational pain points. By reducing handling variability and improving repeatability, these innovations help operators achieve more consistent environmental verification and lower the risk of false signals caused by sample contamination or user error.
At the same time, connected and remote sampling options are gaining traction because they address the need for continuous observation without constant manual intervention. In pharmaceutical and semiconductor cleanrooms, where interruptions can carry significant operational and compliance costs, remote samplers can support ongoing monitoring regimens while preserving documentation rigor. This trend is expanding the market’s value proposition: samplers are increasingly judged not only on capture efficiency but also on how seamlessly they fit into broader quality and digital ecosystems.
Regulatory and Standards Evolution as a Catalyst for Upgrade Cycles
Regulatory and guidance evolution continues to act as a structural catalyst for equipment refreshes. As expectations around Grade A and B environments tighten, and as standards for viable air monitoring become more explicit, facilities often re-evaluate legacy equipment against updated requirements. The result is a recurring upgrade cycle driven by compliance modernization, especially in sectors where environmental monitoring is integral to product release and audit readiness. Importantly, this dynamic does not depend on regulatory shocks; it is sustained by incremental clarification, harmonization efforts, and the broader industry drift toward proactive contamination control. Suppliers that can demonstrate clear alignment with current expectations and foreseeable updates are better positioned to participate in these refresh cycles.
Demand-Side Shifts: Risk Management Beyond Pharma
Demand is also broadening as organizations in adjacent sectors recognize the value of routine viable air monitoring. Pharmaceutical and biopharmaceutical production remains the dominant application context, but hospital and healthcare environments are increasingly integrating air monitoring into infection-prevention strategies. Reducing healthcare-associated infections is a systemic priority, and environmental verification can contribute to that objective when conducted consistently and interpreted correctly. Similarly, food and beverage production, research laboratories, and cleanroom monitoring functions are cultivating a more preventive mindset. In these settings, air sampling is less about passing an audit and more about understanding environmental variability, supporting root-cause investigations, and reducing the probability of costly quality events.
Active Air Sampler Market
Supply Chain and Cost Structure Considerations
Underlying all of these demand shifts is the reality of cost and supply dynamics. High-performance materials, sterilization-compatible components, and durable consumables influence both purchase price and ongoing operational expense. A filter or sampling head that offers strong retention and long shelf life can lower replacement frequency and support inventory stability, but it must be balanced against procurement budgets and sterilization workflows. Meanwhile, the ability to standardize on fewer device families can reduce validation burden, training requirements, and service complexity across sites. In practice, cost competitiveness in this market is increasingly defined by total lifecycle economics rather than unit price alone. Buyers are looking for instruments that lower validation friction, reduce consumable waste, and simplify training, because those factors translate directly into lower cost of ownership over time.
Competitive Landscape and Leading Strategies
The supplier landscape is shaped by a mix of specialized manufacturers and broader life-science players, with activity centered on cleanroom and critical-environment monitoring. Several firms have established recognizable positions by combining instrument design, application expertise, and service models that match the risk profile of regulated environments.
One recurring strategic theme is specialization with regulatory clarity. Companies that focus on microbial air sampling for cleanrooms tend to differentiate through designs that support compliance-intensive use cases. This includes devices marketed for pharmaceutical-grade environments, with emphasis on Grade A and B suitability, decontamination compatibility, and documentation support. Where these suppliers succeed, it is often because their instruments are presented as part of a monitoring solution rather than as isolated tools, with attention to sampling accuracy, contamination control, and the practical needs of validation teams.
Another theme is distribution leverage and ecosystem reach. Some players compete not only through their own device portfolios but also by acting as global distributors for established sampling platforms. This expands access to customers across pharmaceutical, biopharmaceutical, food, and medical device segments, while reducing the barrier to adoption in regions where local service and support networks matter. Distribution-oriented strategies can be particularly effective when paired with strong application support, because regulated buyers often choose suppliers based on confidence in installation, qualification, and post-deployment assistance.
A third differentiator is application breadth across sectors. While pharmaceutical production remains the most demanding and highest-profile use case, several suppliers have expanded their positioning to cover food, hospital, and medical device environments. This diversification can stabilize demand against sector-specific cycles, but it also requires the ability to tailor value propositions. A device that excels in aseptic manufacturing may need different communication and support when sold to a hospital or food facility, where the priorities are operational continuity and infection control rather than product release assurance.
Recent product activity reinforces these strategic directions. Newer iterations of portable sampling platforms have introduced features designed to reduce secondary contamination and improve process safety, reflecting the market’s sensitivity to sample integrity and operator workflow. Updated product catalogs and continued refinement of established series indicate that incumbents are focusing on incremental innovation, reliability, and compliance alignment rather than dramatic category disruption. At the same time, remote and active sampling concepts are gaining visibility because they respond to the demand for continuous monitoring and data integrity support.
Looking at the broader competitive evolution, the market appears to be moving toward selective consolidation of value rather than a race to the bottom on price. Buyers are likely to favor suppliers that can demonstrate clear regulatory fit, robust data handling, and dependable service. This environment favors incumbents with mature portfolios and application credibility, while leaving room for new entrants that can solve a specific pain point exceptionally well, such as portability with uncompromised accuracy, or connectivity that genuinely integrates with quality systems. The presence of both manufacturers and distributors also complicates direct comparison, because commercial advantage may come from either device design or market access, depending on the buyer’s procurement model.
Future Trends and Commercial Opportunities
Trend One: Connected Monitoring as a Standard Expectation
Over the next three to five years, the market is likely to treat connected, auditable monitoring as a baseline expectation rather than a premium feature. As quality systems become more digitized and audit scrutiny intensifies, devices that can support continuous or semi-continuous monitoring with reliable recordkeeping will gain preference. The commercial opportunity here is not simply in selling more connected units, but in helping buyers reduce manual documentation burden, improve trend detection, and strengthen deviation management. Suppliers that can show how instrumentation fits into broader data workflows, rather than functioning as an isolated endpoint, will be better positioned to command value.
Trend Two: Lifecycle-Driven Procurement and Standardization
Another likely trend is a shift toward procurement decisions that weigh the full monitoring lifecycle. Facilities are expected to place greater weight on decontamination compatibility, consumable stability, training simplicity, and cross-site standardization. This creates an opportunity for suppliers to articulate total cost of ownership more convincingly, especially in multi-plant or multi-site operations where device homogeneity can reduce validation and service complexity. It also creates an opening for consumables strategies that lower logistical friction while preserving sterility and retention performance. In practice, the winning offerings will be those that make ongoing monitoring easier to sustain at scale.
Trend Three: Broadening Adoption with Sector-Specific Value Narratives
Adoption is likely to broaden beyond the most traditional pharmaceutical settings, but with an important caveat: growth will be strongest where suppliers can express value in sector-specific terms. In healthcare, the narrative will center on infection-prevention support and environmental control. In food and beverage, it will focus on process hygiene and contamination prevention. In research and cleanroom monitoring, it will emphasize reproducibility, data quality, and risk reduction. The commercial opportunity lies in tailoring messaging and support packages so that the same underlying monitoring discipline can be positioned appropriately for each audience. A generic “compliance tool” narrative will be less effective than an application-specific story that connects sampling outcomes to real operational decisions.
These trends carry risks as well. If regulatory expectations diverge further across regions, procurement teams may face longer qualification timelines and more complex documentation. If connectivity features are added without clear integration benefits, buyers may perceive them as overhead rather than value. And if consumables or sterilization demands become more costly without offsetting operational savings, adoption could slow in price-sensitive segments. The market’s trajectory will depend on whether suppliers can convert technical sophistication into measurable ease, compliance confidence, and economic efficiency.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority should be to reinforce credibility in the areas that regulated buyers weigh most heavily: validation alignment, decontamination compatibility, and data integrity support. Rather than competing only on feature count, companies can create advantage by reducing friction in qualification and use. That means designing instruments and consumables with lifecycle economics in mind, documenting performance in ways that facilitate audit readiness, and offering service models that match the operational tempo of critical environments. Differentiation is increasingly likely to come from how well a product simplifies compliance and daily operation, not from how many functions it can claim.
For investors, the market’s appeal lies less in rapid headline growth and more in its resilience and structural upgrade potential. Demand is anchored by ongoing cleanroom use, regulatory modernization, and expanding environmental monitoring practices across healthcare and adjacent industries. The most attractive opportunities are likely to be found where value is tied to reliability, service access, and compliance fit, because those attributes support retention and reduce the volatility associated with price-driven competition. Investors should also pay attention to where connected monitoring, consumables strategy, and application diversification intersect, since those intersections often define the next step in commercial differentiation.
For procurement and quality leaders, the strategic question is not simply which device performs best in isolation, but which solution will reduce risk and effort across the entire monitoring process. Procurement decisions should assess decontamination compatibility, documentation architecture, consumable logistics, training burden, and service responsiveness alongside sampling performance. Standardization may offer real advantages in multi-site contexts by lowering validation and maintenance complexity. At the same time, end users should resist the temptation to over-index on a single feature without considering how it affects qualification, recurring costs, and day-to-day workflow. The strongest buying decisions are those that align instrument choice with long-term operating reality rather than immediate procurement convenience.
Conclusion
The microbial air samplers market is entering a phase where growth is increasingly defined by how well products integrate with compliance discipline, operational reliability, and data-driven quality management. The sector’s steady expansion reflects durable demand, but the more important story is the shift in what buyers value: confidence in measurement, assurance in decontamination and sample integrity, and support for scalable, auditable monitoring practices. Suppliers and investors who understand these priorities will be better positioned to capture the market’s next wave of opportunity, while procurement leaders who evaluate total lifecycle economics will be better equipped to reduce risk and cost over time. The commercial winners in this space will be those who treat microbial air sampling not as a standalone instrument purchase, but as part of a broader quality-control strategy that must perform consistently under real-world conditions.
For detailed analysis of this topic, please visit the official page: Microbial Air Samplers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ultrafiltration Membrane Filtration Market: How 7.45% CAGR and Key Applications Redefine Growth
By PW Consulting, 2026-09-21
Navigating the Ultrafiltration Membrane Filtration Market: Strategic Trends and Commercial Opportunities Through 2032
The ultrafiltration membrane filtration market has entered a phase of steady, structurally supported expansion. Valued at approximately 195.4 million USD in 2025 and projected to reach 321.45 million USD by 2032, the sector is tracking a compound annual growth rate of 7.45 percent across the 2026–2032 horizon. This trajectory is underpinned by measurable historical momentum, with revenue climbing from 152.3 million USD in 2020 through successive annual increments to the current baseline. The market’s evolution reflects a convergence of tightening water quality standards, industrial process optimization demands, and technological maturation in membrane materials and module architectures. For executives and investors, the critical question is no longer whether the market will grow, but how growth will be distributed across regions, applications, and technology platforms, and where competitive positioning can be deliberately shaped rather than passively inherited.
Market Context and Core Challenges
The current market landscape is characterized by broad-based adoption across water and wastewater treatment, food and beverage processing, pharmaceutical and biotechnology operations, and chemical industry applications. Revenue concentration remains relatively fragmented, with the top three players accounting for roughly 18.75 percent of total market value and the top five reaching 25.6 percent. This dispersion signals a field where scale advantages exist but have not yet consolidated into dominant pricing power or exclusive technology gates. At the same time, the market is passing through a set of structural inflection points that will determine which participants capture disproportionate value over the next several years.
One of the most pressing challenges is the tension between performance durability and operational cost. Ultrafiltration systems are increasingly deployed in environments with high fouling potential, variable feed water quality, and stringent effluent requirements. Membrane biofouling, scaling, and mechanical degradation continue to drive energy consumption, chemical cleaning frequency, and replacement cycles. Participants that can demonstrably extend service life, reduce cleaning intensity, or lower footprint without compromising rejection rates are beginning to separate themselves from commoditized offerings. The challenge is not merely technical; it is commercial. Operators evaluate total cost of ownership over multi-year horizons, meaning that marginal improvements in flux stability or chemical resistance must translate into verifiable operational savings to justify premium positioning.
A second challenge lies in the uneven pace of regulatory and infrastructure modernization across geographies. In mature markets, existing water infrastructure is aging, and replacement cycles create steady demand for upgrade-grade filtration solutions. In emerging industrial corridors, rapid capacity expansion is colliding with tightening discharge norms and water reuse mandates. The result is a bifurcated demand environment: some segments move toward standardization and price sensitivity, while others prioritize reliability, compliance assurance, and integration with downstream processes. Suppliers that cannot adapt their commercial models, technical support, and application engineering to these differing buying contexts risk being trapped in low-margin volume competition.
A third challenge is the shifting economics of materials and manufacturing. Membrane fabrication depends on polymers, specialized coatings, and precision module assembly, all of which are sensitive to raw material volatility, energy costs, and supply chain continuity. At the same time, customers are increasingly scrutinizing lifecycle impacts, including chemical usage, water recovery rates, and end-of-life handling. Companies that rely on rigid product portfolios or single-source material dependencies face margin pressure and responsiveness gaps. The market is therefore rewarding participants that combine material science flexibility with scalable, regionally balanced production and service networks.
Key Drivers Shaping Market Direction
Technological Innovation and Module Architecture Evolution
Innovation in ultrafiltration is increasingly centered on module design, pore size control, and fouling mitigation rather than incremental polymer substitutions alone. Recent product movements illustrate a clear direction: integrated pre-filtration approaches that combine coarse screening with ultrafiltration in a single module are being positioned to reduce footprint and capital expenditure for drinking water and seawater applications. Alongside this, next-generation hollow-fiber modules with notably small nominal pore sizes are entering commercial rollout, targeting lower biofouling propensity and higher removal consistency. These developments matter because they shift the value proposition from standalone membrane performance to system-level efficiency. When pre-filtration and ultrafiltration are co-optimized, operators can reduce piping complexity, lower headloss, and simplify installation, which directly influences procurement decisions in space-constrained or cost-sensitive projects.
PW Consulting
Material differentiation remains important, particularly where chemical resistance, temperature tolerance, or위생 compatibility are decisive. Polysulfone, polyethersulfone, polyvinylidene fluoride, and ceramic-based platforms each occupy distinct niches defined by feed characteristics and operating conditions. The strategic signal is that no single material is universally dominant; rather, the opportunity lies in matching material architecture to application profiles while reducing the operational burden of cleaning and replacement. Companies that can offer configurable module formats, predictable performance envelopes, and documented longevity are better positioned to win in segments where downtime and compliance risk are unacceptable.
Membrane Filtration Market
Policy, Regulatory, and Standards Environment
Regulatory pressure continues to be a durable demand catalyst. Stricter limits on particulate matter, pathogen indicators, and industrial effluents are expanding the addressable base for ultrafiltration in both municipal and industrial settings. Equally important is the growing emphasis on water reuse and resilience, which pushes ultrafiltration into pretreatment and polishing roles that were historically handled by alternative technologies. In sectors such as semiconductor manufacturing and advanced industrial processing, water quality consistency is not merely an environmental concern but a process requirement, which elevates ultrafiltration from a cost center to a reliability enabler.
This regulatory and operational convergence is visible in recent contract and certification activity. High-value, long-duration operational contracts for complex water treatment facilities are being secured alongside public demonstrations of resilient wastewater treatment technologies at industry events. These moves indicate that leading participants are not only selling equipment but also embedding themselves into multi-year service and performance arrangements. For the market, this signals a shift toward outcome-based positioning, where technology selection is increasingly tied to guaranteed operational behavior, compliance documentation, and integration with broader treatment trains.
Ultrafiltration Membrane Market
Demand-Side Shifts in Industrial and Municipal Buying Behavior
Buyers are behaving differently than in prior cycles. In municipal and utility contexts, capital constraints and workforce limitations are favoring solutions that reduce installation complexity, simplify operation, and lower long-term maintenance burdens. In industrial settings, procurement is increasingly influenced by process continuity, footprint constraints, and the need to integrate filtration with downstream units such as reverse osmosis, membrane distillation, or specialty separation steps. The food and beverage sector adds another dimension: consistency, flavor preservation, and sanitary design can be as important as nominal filtration performance.
These demand-side shifts create a strategic implication: product specifications alone no longer win deals. Application engineering, pilot validation, and post-installation support have become decisive differentiators. Suppliers that can demonstrate how an ultrafiltration module behaves in a specific feed context, how it interacts with pretreatment chemistry, and how it affects total operating expense are gaining traction over suppliers that compete primarily on unit pricing. The market is therefore moving toward segment-specific value narratives rather than generic performance claims.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by material availability, manufacturing scalability, and the economics of service delivery. Companies with diversified material platforms and flexible module formats can better absorb input cost fluctuations and tailor supply to regional demand patterns. At the same time, logistics, installation support, and local technical service are becoming more influential in winning and retaining contracts, particularly where project timelines are tight or where operators lack specialized filtration expertise.
This environment favors participants that view the supply chain as a commercial asset rather than a back-office function. Regional production presence, application testing capabilities, and responsive spare-part networks can translate into shorter delivery cycles, lower risk for buyers, and stronger customer lock-in. Conversely, suppliers dependent on centralized production and limited service footprints may find themselves disadvantaged in markets where responsiveness and localization are increasingly weighted in procurement decisions.
Competitive Landscape and Strategic Positioning
The competitive field includes large diversified material and membrane manufacturers, water technology integrators, and specialized membrane producers with deep application focus. This mix creates a layered competitive dynamic. Larger players benefit from broad R&D resources, global distribution, and the ability to bundle membranes with systems, controls, and service. Smaller or regionally anchored specialists compete through material specificity, customization, and close engagement with niche applications such as high-throughput industrial processing, bioprocess filtration, or specialty food and beverage clarification.
Several strategic positions are evident. One is the module-integration advantage, where combined pre-filtration and ultrafiltration architectures are used to reduce footprint and capital cost while simplifying installation. A second is fouling-resistance and pore-size differentiation, where smaller nominal pore sizes and lower-biofouling designs are positioned for environments that demand higher removal consistency and reduced cleaning intensity. A third is application-centric specialization, where ceramic-based or custom flat-sheet and spiral-wound formats are tailored to demanding industrial feeds, sanitary processing, or laboratory and bioprocess requirements. A fourth is market-entry expansion through localized manufacturing and commercial presence, which enables faster response to regional demand and reduces reliance on distant supply chains.
The market is also showing signs of evolving through selective consolidation and targeted expansion rather than across-the-board merger activity. Large players are strengthening system-level offers and securing long-duration operational roles in complex facilities, while specialized manufacturers are widening their reach through trade presence, technical presentations, and application-specific demonstrations. New entrants and regional manufacturers are gaining ground where local cost structures, feed-specific expertise, or first-mover status in domestic production provide a foothold. The overall direction suggests that competitive advantage will increasingly depend on the ability to combine material and module innovation with regional responsiveness, application engineering, and service integration.
Forward Outlook: Three Trends to Watch Through 2032
The first trend is the continued shift toward integrated and footprint-optimized filtration solutions. As installation space, capital budgets, and operational simplicity become more prominent decision factors, modules and systems that reduce component count, lower piping complexity, and combine pre-filtration with ultrafiltration will see growing interest. Commercial opportunity lies in offering validated, application-ready configurations that shorten project cycles and reduce total installed cost, especially in municipal upgrades and space-constrained industrial facilities.
The second trend is the widening role of ultrafiltration as a resilience and reuse enabler. Water scarcity, discharge tightening, and process-water reliability requirements are pushing ultrafiltration into more pretreatment, polishing, and reuse positions across municipal, industrial, and specialized manufacturing contexts. The opportunity here is not simply volume growth but value-tier expansion: participants that can document recovery performance, chemical robustness, and integration compatibility with downstream processes are better positioned to capture higher-margin roles rather than competing solely as commodity membrane suppliers.
The third trend is the growing importance of lifecycle economics and service-embedded offerings. Buyers are increasingly weighing cleaning frequency, membrane lifespan, energy behavior, and support responsiveness alongside initial purchase price. This opens the door to performance-based service models, predictive maintenance support, and region-specific technical engagement. The risk is that companies with rigid product portfolios or weak local support may be squeezed as operators prioritize predictable operation over lowest upfront cost. Uncertainty remains in the pace of regulatory adoption, the volatility of material inputs, and the degree to which large-scale infrastructure programs translate into discrete filtration procurement opportunities. Participants should therefore treat macro growth as an enabling condition rather than a guarantee, and build flexibility into product, pricing, and service strategies.
Strategic Recommendations for Decision-Makers
For membrane and module manufacturers, the priority is to move beyond specification competition toward application-validated value propositions. This means investing in feed-specific performance data, configurable module formats, and demonstrable reductions in cleaning intensity or footprint. Manufacturers that align material choices with clear operating envelopes and back them with regional technical support will be better positioned to defend margins and win complex projects. It also means evaluating supply chain resilience as a strategic lever, including material diversification and localized production where demand growth and service expectations justify the investment.
For investors, the most relevant signal is that growth is real but uneven across segments and geographies. Capital allocation should favor participants with durable application ties, module or system integration capabilities, and credible service economics rather than those competing primarily on volume pricing. The market’s moderate concentration and ongoing product launches suggest continued room for differentiators, but also the risk of margin erosion where technology gaps narrow. Due diligence should therefore weigh total cost of ownership narratives, pipeline visibility in reuse and industrial treatment, and the ability to convert product launches into commercial traction across target regions.
For procurement leaders and operations executives, the practical imperative is to evaluate ultrafiltration choices within the full treatment context rather than as isolated components. Pilot validation, cleaning and replacement cost modeling, and integration compatibility with downstream processes should carry as much weight as nominal pore size or material label. Where projects are space- or capital-constrained, integrated module approaches and footprint-optimized designs merit close scrutiny. Where process reliability is paramount, documented fouling behavior and service responsiveness should be treated as primary selection criteria. Strategic sourcing decisions made with this broader lens are more likely to deliver durable operational savings and lower compliance risk.
The ultrafiltration membrane filtration market is moving from broad-based expansion toward more differentiated, application-led competition. The participants that will capture disproportionate value are those that can combine material and module innovation with system-level efficiency, regional responsiveness, and credible lifecycle economics. Understanding where these advantages are forming, and how procurement and investment decisions are shifting in response, is essential for shaping strategy through 2032. The broader market trajectory is clear; the real leverage lies in the details of segmentation, material and module positioning, regional demand patterns, and competitive move sequencing. For decision-makers seeking to translate these dynamics into concrete plans, a detailed examination of segmented market sizing, application-specific growth paths, regional nuances, and company-level strategic plays provides the necessary foundation for sharper capital allocation, product roadmap decisions, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Ultrafiltration Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Headless Compression Screws Market: 4.1% CAGR Trajectory Redefining Orthopedic Demand
By PW Consulting, 2026-09-21
The Headless Compression Screws Market: Strategic Trends and Commercial Opportunities Through 2032
Market Trajectory: Resilience Amid Structural Shifts
The global headless compression screws market has demonstrated steady expansion over the past half-decade, establishing a baseline of approximately 312.8 million USD by 2025. Growth from 2020 to 2025 reflects a compound trajectory shaped by incremental surgical adoption, material standardization, and expanding indications for small-bone and joint-preserving fixation. Looking ahead to 2032, the market is projected to advance toward 414.4 million USD, supported by a five-year CAGR of 4.1 percent. This pace indicates a mature but still expanding segment, where incremental gains are increasingly tied to product differentiation, surgical workflow optimization, and access channel evolution rather than volume-driven expansion alone.
The market structure is moderately concentrated, with the top three players accounting for roughly 57 percent of revenue and the top five approaching 65 percent. This concentration suggests that scale advantages in R&D, regulatory compliance, and distribution infrastructure remain meaningful barriers, yet it also leaves room for specialized manufacturers and regional entrants that can compete on tailored indications, pricing flexibility, or service intensity. The balance between incumbency and niche positioning is likely to define competitive outcomes over the forecast horizon.
Core Challenges and Inflection Points
Despite the broadly favorable trajectory, the market is navigating several interrelated challenges that are reshaping how manufacturers, hospitals, and investors evaluate opportunity.
Regulatory and quality discipline is intensifying. Recent device recalls underscore that even established product families are subject to heightened scrutiny when performance, labeling, or manufacturing consistency falls short. For headless compression screws, which rely on precise pitch geometry and secure fixation mechanics, any deviation in production tolerances or clinical instructions can translate into reputational and compliance exposure. Manufacturers are consequently investing more heavily in process validation, post-market surveillance, and surgical technique support to protect market access.
Raw material cost volatility is reshaping margin architecture. Titanium remains the dominant material for many headless compression systems, and pricing dispersion across grades and forms has introduced uncertainty into cost planning. Commercially pure titanium grades have traded in a comparatively accessible band, while aerospace-grade Ti-6Al-4V alloy has commanded substantially higher prices. Even titanium scrap has its own market dynamics, creating a layered procurement environment. The implication is not simply higher input costs, but a need to rethink design-for-manufacturability, inventory strategy, and value-based pricing in ways that preserve competitiveness without compromising mechanical performance.
Clinical adoption is being redefined by workflow and access preferences. Surgeons and care providers increasingly weigh implant performance alongside operative efficiency, instrumentation simplicity, and compatibility with ambulatory or outpatient settings. This shift is pushing manufacturers to consider not only the screw itself, but also the surrounding procedural ecosystem, including instrumentation, training, and distribution reach. Competitors that can reduce surgical friction and support faster case throughput are gaining an edge in contexts where reimbursement pressure and site-of-care migration are accelerating.
PW Consulting
Key Drivers Shaping Market Direction
Technological Innovation and Design Differentiation
The central value proposition of headless compression screws lies in their ability to provide stable fixation while minimizing soft-tissue irritation and preserving joint surfaces. Innovation has therefore concentrated on thread geometry, variable or differential pitch designs, cannulation for guidewire use, and material selection that balances strength with biocompatibility. Recent product expansions illustrate this trajectory, with manufacturers introducing finer diameter options, extended length ranges, and updated surgical technique guides to support broader clinical use.
This emphasis on design refinement matters commercially because it directly affects surgeon preference and repeat usage. In small-bone applications particularly, where anatomy varies significantly and space is constrained, incremental improvements in screw performance can translate into meaningful competitive advantage. The trend is moving toward systems that integrate the implant with purpose-built instrumentation and procedural guidance, rather than treating the screw as a standalone commodity.
Regulatory Environment and Standards Alignment
Regulatory expectations continue to shape both market entry and incumbent resilience. For established devices, active approval and licensing frameworks can reinforce clinical credibility and support sustained adoption. In this context, alignment with recognized standards and technique validation has become a strategic asset, helping manufacturers demonstrate consistency, safety, and clinical support. At the same time, the visibility of recall activity across the broader orthopedic device space has increased attention to post-market controls, lot traceability, and surgeon communication.
For companies operating in this market, regulatory capability is not merely a compliance function. It is part of the value proposition to hospitals and surgeons who are themselves under pressure to minimize risk and standardize practices. Firms that can combine robust quality systems with clear clinical documentation and prompt field action are better positioned to retain trust and defend share when disruptions occur.
Demand-Side Evolution and Site-of-Care Shifts
Demand for headless compression screws is being influenced by broader changes in orthopedic practice patterns. Joint-preserving fixation, minimally invasive techniques, and the management of fractures and osteotomies in hand, wrist, foot, ankle, and other small-bone applications continue to drive utilization. At the same time, the migration of suitable procedures toward ambulatory surgery centers and outpatient environments is changing purchasing dynamics and service expectations.
Cannulated Compression Headless Screws Market
One notable development in this direction is the expansion of distribution partnerships aimed at reaching ambulatory settings more effectively. Such arrangements reflect a strategic recognition that access is increasingly tied to channel specialization, not just product capability. For manufacturers, this means that commercial models must adapt to the operating-room realities of different care settings, including volume variability, inventory constraints, and the need for responsive local support.
Supply Chain Economics and Material Strategy
The titanium supply environment has introduced both pressure and opportunity. With pricing varying substantially by grade and form, manufacturers face decisions about material sourcing, design optimization, and cost pass-through. Some are likely to pursue hybrid strategies that reserve higher-cost alloys for applications where their mechanical properties deliver the greatest clinical value, while using more economical material grades where suitable. Others may focus on reducing waste, improving machining efficiency, and standardizing configurations to lower total cost of ownership.
This environment also creates a potential opening for suppliers that can offer consistent material quality, transparent pricing, and flexible lot sizing. In a market where many participants compete on similar clinical claims, supply chain reliability and cost discipline can become differentiating factors, especially when hospitals are scrutinizing total procedural cost and manufacturers are protecting margins.
Biodegradable Micro Screws Market
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field is anchored by a group of established orthopedic players, each with distinct strategic emphases. DePuy Synthes has maintained a broad footprint with titanium and stainless variants across multiple diameters, leveraging scale, surgeon familiarity, and integration into wider trauma and fixation portfolios. Acumed has concentrated on small-bone and precision applications, with system updates that extend diameter and length options and reinforce surgical technique support. Zimmer Biomet has emphasized cannulated solutions and targeted application focus, while also pursuing access expansion through partnerships that extend reach into ambulatory settings.
Arthrex has built a strong identity around compression-focused screw systems for foot, ankle, hand, and wrist applications, often linking implant design with procedure-specific instrumentation. In Europe, Rita Leibinger has pursued a specialized position with cannulated titanium systems used in corrective osteotomies and fracture scenarios where controlled compression is important. Stryker’s support of headless compression approaches through related procedural systems illustrates another pathway: competing not only through proprietary screws, but also through integrated tooling and platform ecosystems.
Smaller or more specialized participants, including Trax Surgical, TriMed, TST Orthopedics, and Bonetech Precision, contribute additional variety to the market. Their strategies often center on particular size ranges, material choices, or regional service models. This diversity matters because it signals that the market is not fully homogeneous; there are still openings for firms that can serve specific anatomical segments, cost tiers, or procedural niches with credible clinical support.
Strategic Themes Among Leaders
Several common strategic themes emerge across the leading players:
- Product-line extension and precision expansion. Companies are broadening size ranges and refining thread and cannulation designs to address more anatomical scenarios and surgeon preferences.
- Access and channel diversification. Partnerships and distribution strategies are increasingly designed to align with site-of-care migration and the needs of different surgical environments.
- Technique and education as competitive tools. Surgical technique guides, training, and procedural support are becoming integral to adoption, especially where new sizes or expanded indications require updated surgeon confidence.
- Quality and recall responsiveness. Recent recall activity has reinforced the importance of manufacturing consistency and rapid communication, making operational discipline part of brand trust.
Together, these themes suggest a market in which product capability remains necessary but no longer sufficient. Winning increasingly depends on how well a company integrates implant design, surgical support, distribution reach, and quality assurance into a coherent offering.
Market Evolution: Consolidation Pressure and Niche Entry
Given the current concentration levels and the investment required to maintain regulatory, clinical, and distribution capabilities, continued consolidation pressure is plausible, especially among mid-tier players seeking scale or geographic expansion. At the same time, the diversity of anatomical applications and the continued emergence of smaller specialists indicate that differentiation remains viable. New entrants are most likely to succeed by targeting underserved configuration needs, offering compelling value in specific regions, or providing superior service and instrumentation around a focused product line.
The long-term structure may therefore evolve into a dual pattern: concentrated leadership at the top of the market, with sustained activity from specialized firms that compete on precision, cost, or local access. For strategic planners, this implies that competitive intelligence must be paired with a clear view of where a given company sits on the spectrum between scale-based positioning and niche specialization.
Future Trends and Commercial Opportunities
Trend One: Design-to-Cost and Material Optimization
As titanium pricing remains uneven across grades and forms, a clear trend is likely to be more deliberate material strategy. Manufacturers may increasingly design for cost by matching material grade to clinical requirement, standardizing common sizes, and reducing complexity in inventory and machining. This does not imply compromise on performance; rather, it reflects a more disciplined alignment between material selection, surgical need, and margin management.
The commercial opportunity lies in achieving a stronger cost position without losing clinical credibility. Companies that can demonstrate consistent quality, transparent sourcing, and efficient production may be able to compete more effectively on total value, particularly in price-sensitive procurement environments. There is also potential for suppliers and manufacturers to collaborate more closely on material availability and scrap recycling, turning raw material dynamics into a managed advantage rather than a recurring disruption.
Trend Two: Ambulatory Access and Procedural Ecosystem Competition
As more procedures migrate toward outpatient and ambulatory environments, competition will increasingly extend beyond the implant itself to the surrounding procedural ecosystem. This includes instrumentation that streamlines setup, technique support that reduces learning curves, and distribution models that can serve lower-volume or higher-turnover surgical sites. Partnerships aimed at broadening access in ambulatory settings are an early signal of this direction.
For manufacturers, the opportunity is to position headless compression screws as part of a workflow solution rather than an isolated device. That may mean bundling instruments, offering flexible pack configurations, or strengthening local support to match the operational cadence of ambulatory centers. For investors and strategic planners, the relevant question is which companies are building durable access routes and service capabilities, not just product portfolios.
Trend Three: Confidence, Standards, and Post-Market Reputation
The combination of active standards engagement and visible recall events is likely to heighten the importance of post-market reputation management. Over the next few years, surgeons and procurement teams may place greater weight on manufacturers with strong quality records, clear technique documentation, and responsive handling of field issues. This trend favors incumbents with established clinical support infrastructure, but it also creates risk for any player that underestimates the reputational impact of quality disruptions.
The commercial implication is that trust is becoming a more explicit competitive variable. Companies that invest in transparent communication, surgical education, and proactive quality processes can convert regulatory and operational discipline into long-term preference. Conversely, short-term cost actions that weaken quality assurance or surgeon support may carry disproportionate downstream consequences.
Strategic Implications for Decision-Makers
For Manufacturers
Companies competing in headless compression screws should treat product design, material strategy, and access model as an integrated system. Priorities include:
- Aligning screw geometry, size range, and material selection with the clinical scenarios that generate the strongest surgeon loyalty, while guarding against unnecessary complexity that raises cost and inventory risk.
- Building supply chain resilience around titanium sourcing, with planning that accounts for grade variation, lead-time uncertainty, and the potential value of standardization.
- Strengthening technique support, training, and field responsiveness as tools for both adoption and risk mitigation, especially where expanded sizes or new procedural contexts are involved.
- Evaluating distribution and partnership models that reflect site-of-care migration, ensuring that service levels and pack configurations match the needs of different surgical settings.
For Investors
Investment decisions in this space should account for both steady market growth and the increasing importance of execution quality. Useful lenses include:
- Assessing whether a company’s differentiation is anchored in defensible clinical and workflow value, or primarily in pricing and generic specification overlap.
- Tracking channel strategy and access expansion, since reach into ambulatory and specialized surgery environments may become a more important driver of commercial momentum.
- Monitoring quality, recall exposure, and post-market responsiveness as indicators of durability, because trust and regulatory discipline increasingly influence purchasing decisions.
- Considering raw material exposure and design-for-manufacturability as part of margin resilience, especially given ongoing titanium price dispersion.
For Procurement and Clinical Leaders
Hospital and surgery-center buyers can use the evolving market structure to strengthen value without sacrificing clinical reliability:
- Evaluate total procedural value rather than implant price alone, including instrumentation, case support, availability, and the manufacturer’s track record in quality and technique support.
- Consider standardized configurations where clinically appropriate to improve inventory efficiency and reduce variability across sites.
- Require clear documentation, lot traceability, and responsive communication processes, given that post-market discipline is becoming a more prominent element of supplier selection.
- Monitor supplier strategies for ambulatory and outpatient compatibility, since these may better match future site-of-care plans and operating-room economics.
Why Deeper Intelligence Matters
The headless compression screws market is moving through a phase where broad growth is visible, but the real strategic differences are hidden in segmentation, design choices, access models, and competitive execution. Revenue direction alone does not reveal which anatomical segments are gaining share, which size ranges are most contested, how material economics affect margins across suppliers, or which distribution moves are likely to reshape regional access. It also does not fully untangle the interplay between recall risk, standards alignment, and surgeon preference at the product level.
For executives and investors seeking to act rather than merely observe, the value lies in segment-level precision and scenario-based interpretation. Detailed breakdowns by type, application, and region, combined with company-specific assessments and material-cost context, can support more targeted product planning, pricing decisions, partnership evaluation, and investment allocation. In a mature but still evolving market, the winners are likely to be those who translate macro trends into specific operational choices.
Further detail on these dynamics—including segment structures, competitive positioning, and material and regulatory developments—is available in the full market research report. That broader analysis is intended to support decision-making with the granularity needed to move from strategic direction to executable planning.
For detailed analysis of this topic, please visit the official page: Headless Compression Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
IP Cameras Market 2032: Why 13% CAGR and $32B Value Are Only Half the Story
By PW Consulting, 2026-09-21
The IP Cameras Market: Strategic Trends and Commercial Opportunities Through 2032
The IP cameras market is entering a phase of accelerated expansion, driven by a convergence of technological maturation, regulatory shifts, and evolving end-user expectations. By 2025, the global market has reached a valuation of approximately $13.72 billion, reflecting sustained momentum from the $8.15 billion recorded in 2020. The trajectory points toward a robust compound annual growth rate of 13.0 percent through the 2026–2032 forecast period, with projected revenues climbing to $32.22 billion by 2032. This growth roadmap signals more than incremental hardware sales; it underscores a structural transformation in how surveillance, safety, and operational intelligence are deployed across commercial, residential, and public infrastructure environments. For executives and investors, the market offers meaningful expansion potential, but success will hinge on navigating fragmentation, compliance mandates, and the rapid integration of intelligence into imaging hardware.
PTZ Camera Market
Market Landscape and Core Challenges
The IP cameras ecosystem has matured beyond simple video capture. Modern deployments function as distributed sensing nodes that feed into broader security, analytics, and facility management architectures. The market’s expansion reflects widespread adoption across multiple verticals, with commercial facilities, residential estates, and government or public safety installations each contributing substantial revenue streams. Fixed cameras continue to hold significant share, reflecting their cost-effectiveness and reliability in standardized monitoring scenarios. Pan-tilt-zoom units address the need for flexible, remotely directed surveillance, while infrared-capable devices cater to low-light and perimeter applications. This diversified product mix allows end users to piece together solutions that balance coverage, resolution, and budget constraints.
Behind the positive growth signals, several structural challenges are reshaping how companies compete and how buyers evaluate procurement decisions. One of the most pressing issues is regulatory compliance, which increasingly functions as both a market gatekeeper and a competitive differentiator. Procurement rules now restrict the use of certain non-compliant devices in sensitive deployments, creating clear boundaries around eligible suppliers. At the same time, data privacy expectations are becoming more stringent across healthcare, commercial, and public-sector environments, forcing manufacturers and integrators to embed privacy-preserving features directly into platforms rather than treating them as afterthoughts.
A second challenge lies in budget dynamics and capital allocation. While the demand for AI-enabled analytics and advanced imaging capabilities continues to rise, many organizations face constraints in funding large-scale upgrades. Hospitals, municipal authorities, and commercial operators frequently weigh the upfront investment in intelligent camera systems against operational budgets that must also cover staffing, maintenance, and core infrastructure. This tension creates an environment where value is measured not only by image quality or feature lists, but by measurable improvements in safety, workflow efficiency, and risk reduction.
A third challenge is the evolving infrastructure of deployment itself. Fixed dome configurations have become particularly prominent in sensitive indoor environments due to their discreet appearance, resistance to vandalism, and consistent coverage in corridors and waiting areas. This preference shapes product design priorities and installation practices, pushing manufacturers to refine form factors, mounting flexibility, and environmental durability. Meanwhile, enterprises are increasingly expecting seamless integration with existing facility systems, access control, and centralized management platforms, which raises the bar for interoperability and long-term support.
PW Consulting
Core Drivers of Market Change
Technological Innovation and Intelligence Integration
Progress in imaging sensors, edge computing, and on-device analytics is redefining what IP cameras can deliver. Modern devices are no longer passive recording endpoints; they increasingly support real-time detection, behavioral alerting, and metadata generation that feeds downstream systems. This shift is especially apparent in healthcare-adjacent deployments, where camera platforms are being positioned to support patient safety monitoring, fall detection, and privacy-compliant installations. Suppliers that can pair high-quality imaging with integrated analytics, secure access controls, and privacy mechanisms such as face blurring are gaining traction among organizations that need both protection and compliance.
The technology trajectory also favors platforms that reduce dependency on heavy backend processing. By moving more intelligence to the edge, deployments can lower bandwidth demands, improve responsiveness, and enhance resilience in environments where connectivity may be intermittent. For commercial operators and public safety agencies, this translates into more reliable monitoring and quicker decision-making without requiring massive centralized infrastructure upgrades.
Regulatory and Compliance Environments
Compliance has moved from a procurement footnote to a strategic constraint. In the United States, federal buyers are increasingly required to select NDAA-compliant cameras from approved suppliers, a development that directly shapes the competitive field in government and public safety applications. In parallel, privacy-related obligations continue to influence product design and deployment models, particularly where cameras may capture patient-related or personally identifiable information. Enterprise-grade platforms are increasingly expected to provide configurable privacy features, secure authentication, and auditable access management as standard capabilities.
Regulatory momentum is also expanding geographically. For example, standards requiring essential compliance for CCTV and IP cameras have become mandatory in certain markets for healthcare facility deployments, with enforcement timelines that compel early preparation. Organizations evaluating multi-country rollouts must now account for divergent certification requirements, local testing frameworks, and region-specific procurement rules. This compliance layer is becoming a major factor in vendor selection, implementation timelines, and total cost of ownership.
Demand-Side Shifts in End-User Behavior
End-user expectations are shifting from surveillance as a reactive measure to monitoring as part of a broader operational and safety strategy. In healthcare settings, the emphasis is increasingly on patient safety, facility flow, and clinical workflow support rather than purely on external perimeter defense. In commercial environments, organizations are seeking systems that can support occupancy insights, access coordination, and incident response without fragmenting their technology stack. Residential users, meanwhile, are responding to greater availability of connected, cloud-managed options that emphasize ease of use and remote access.
This demand evolution is also changing the buying conversation. Decision-makers increasingly compare solutions based on integration readiness, lifecycle support, and the ability to adapt to future analytics needs. The most compelling propositions combine reliable core imaging with extensible software capabilities, ensuring that a deployment can evolve without requiring full hardware replacement. Consequently, vendors that can articulate clear operating value, not just technical specifications, are gaining advantage in competitive evaluations.
Supply Chain and Cost Structure Dynamics
Cost structures across the IP cameras market are being shaped by both material innovation and product lifecycle strategy. Manufacturers are exploring environmentally sustainable design choices, including the use of recycled materials in new product lines, which signals a broader shift toward responsible sourcing and corporate accountability. While sustainability does not automatically reduce unit costs, it can influence purchasing decisions in organizations with formalized ESG targets and procurement policies.
At the same time, competitive pressure continues to push the market toward greater efficiency in manufacturing, logistics, and support. The balance between premium feature sets and affordability remains delicate, especially where budgets are constrained and buyers must justify capital expenditure. Companies that can manage cost while maintaining compliance readiness, durability, and platform extensibility are better positioned to defend margins and scale across multiple end markets.
Competitive Landscape and Leading Strategies
The market is marked by meaningful concentration at the top, with a small group of established players accounting for a substantial share of revenue. This concentration reflects the importance of brand trust, long-term deployment support, compliance readiness, and the ability to serve regulated verticals with specialized configurations. Yet the landscape is not static. Different leaders are pursuing distinct strategic positions, and the gap between hardware-centric suppliers and platform-oriented entrants is widening in terms of customer expectations.
Axis Communications has maintained a strong identity around purpose-built network IP cameras, with particular emphasis on healthcare surveillance, patient monitoring, and privacy-compliant installations. Its approach highlights the value of specialized use-case positioning, where product architecture is aligned with the operational and regulatory needs of sensitive environments. Hanwha Vision has pursued a similar vertical focus by supporting AI-enabled IP cameras and modular systems integrated into clinical environments, targeting hospital safety, fall detection, and workflow enhancement. This combination of imaging and application-level integration illustrates a broader trend: winning in regulated settings increasingly depends on demonstrating how a camera system fits into daily operations rather than simply offering higher resolution.
Dahua Technology and Hikvision continue to play significant roles in the broader ecosystem, offering video-centric AIoT IP cameras and network IP camera solutions aimed at facility operations and security. Their scale and breadth of product portfolios give them reach across multiple deployment contexts. Bosch Security Systems contributes a strong engineering reputation with IP camera systems designed for healthcare security monitoring and integration with hospital infrastructure, reinforcing the importance of infrastructure compatibility. Pelco has carved out a recognizable niche with IP camera series engineered for hospital patient safety monitoring and regulatory-compliant applications, while Honeywell International Inc. serves secure healthcare environments and facility upgrades with performance-oriented and explosion-proof options. Arecont Vision remains relevant for high-quality megapixel coverage in hospital video surveillance upgrades, where image fidelity is a primary requirement.
One of the more notable competitive shifts is the rise of cloud-managed platforms that bundle compliance and privacy features into the operating model. Verkada, for example, has positioned a cloud-managed IP camera platform with built-in HIPAA-relevant compliance and privacy features for hospital and healthcare facility security. This model appeals to organizations seeking simplified management, centralized visibility, and reduced reliance on fragmented on-premises administration. It also reflects a broader market movement toward subscription-friendly, software-forward service models that can lower operational friction for end users.
Recent product developments illustrate how competitive positioning is evolving in practice. In September 2025, Axis launched a new line of environmentally sustainable IP cameras utilizing recycled materials. This move signals that differentiation is expanding beyond imaging and analytics into materials, lifecycle impact, and procurement alignment with organizational sustainability commitments. In a market where multiple vendors can offer strong technical performance, such initiatives can influence buying decisions among customers with explicit environmental or procurement goals.
The competitive trajectory points toward both consolidation and differentiation. Larger players with strong compliance credentials, vertical expertise, and platform breadth are well placed to capture regulated and enterprise demand. At the same time, new entrants and regional specialists can still compete by targeting specific installation types, offering favorable integration economics, or delivering cloud-managed experiences that reduce deployment complexity. The most likely evolution is a market in which broad-scale vendors coexist with focused specialists, each winning on different combinations of compliance, integration, service model, and total cost of ownership.
Future Trends and Commercial Opportunities
Intelligence Becoming Standard Rather Than Optional
Over the next three to five years, AI-enabled capabilities are expected to move from premium add-ons to baseline expectations in many deployment categories. As edge processing becomes more efficient and analytics become easier to configure, organizations will increasingly expect cameras to contribute to detection, alerting, and workflow support without demanding heavy external infrastructure. The commercial opportunity lies in solutions that make these capabilities usable, not merely available. Suppliers that simplify configuration, improve false-positive management, and connect camera-generated insights to practical operational actions will have stronger competitive positioning. The risk is that feature competition alone will erode margins unless vendors can demonstrate tangible value in safety, efficiency, or compliance outcomes.
Compliance as a Market Filter and Growth Enabler
Regulatory requirements are likely to continue tightening the boundaries of eligible suppliers and deployment models. Rather than simply limiting competition, this trend can create growth opportunities for vendors that proactively align with compliance frameworks and communicate that alignment clearly. In healthcare and public-sector contexts, the ability to provide privacy controls, secure access management, and recognized certification readiness may become as important as image quality. Organizations that invest early in compliant architectures and integrate them into broader facility operations may benefit from faster procurement cycles and reduced redesign risk. The uncertainty lies in the pace and fragmentation of regulatory change across regions, which can complicate planning for multinational or multi-site rollouts.
Platform Models and Managed Services Reshaping Ownership
The market is gradually shifting toward models in which the camera is part of a managed platform rather than a standalone purchase. Cloud-managed visibility, centralized administration, and subscription-oriented service options can reduce operational burden for end users while creating recurring value streams for suppliers and integrators. This shift opens opportunities for companies that can combine reliable hardware with strong software experience, data security, and scalable support. At the same time, it raises expectations for long-term reliability, cybersecurity posture, and vendor continuity. Buyers will increasingly weigh how easily a system can be maintained, updated, and integrated over time, not just how it performs on day one.
Strategic Guidance for Decision-Makers
For manufacturers and technology providers, the priority is to connect product capabilities to operational outcomes that regulated and budget-conscious buyers can justify. Differentiation will increasingly come from compliance readiness, privacy-aware design, integration with existing infrastructure, and platform extensibility. Companies should evaluate where they can lead in specialized verticals such as healthcare-adjacent safety and monitoring, while ensuring that sustainability and supply chain credibility support broader procurement appeal. In practical terms, this means articulating not only what a camera can capture, but how it helps an organization reduce risk, improve workflow, and meet compliance requirements without inflating total cost of ownership.
For investors, the market offers expansion potential, but the most durable opportunities will likely belong to players that combine scale with vertical relevance and platform-oriented business models. The key is to distinguish between short-term hardware demand and longer-term value creation through software, services, and compliance-aligned positioning. Investments that support integration ecosystems, secure cloud-managed experiences, and analytics that are demonstrably useful in operational settings may offer stronger resilience as the market matures. Attention should also be paid to regulatory evolution, since compliance shifts can rapidly change which suppliers and deployment models are viable in important end markets.
For procurement leaders and end-user organizations, the strategic task is to move beyond feature comparison and evaluate total deployment value. This includes assessing NDAA compliance or equivalent regulatory alignment where applicable, confirming privacy and data protection capabilities, and verifying that the selected platform can integrate with existing security, access, and facility systems. Organizations should also weigh the operational model they prefer, whether that is locally managed infrastructure, cloud-managed visibility, or a hybrid approach, and ensure that staffing, maintenance, and lifecycle support are factored into the decision. Early planning for certification requirements and compliance timelines can prevent costly redesigns and speed up deployment.
Given the speed of change across technology, regulation, and end-user expectations, detailed segmentation data, region-specific compliance maps, and vendor-level positioning analysis can make a meaningful difference in strategic planning. The broader market direction is clear, but the practical choices around product architecture, procurement eligibility, and commercial model depend on granular intelligence that reflects local requirements and vertical realities. For decision-makers seeking to act with confidence in this environment, deeper research can help translate the overall growth narrative into targeted entry points, risk mitigations, and execution priorities.
Industrial Cameras Market
For detailed analysis of this topic, please visit the official page: IP Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminator Market 2026: Why 7.25% CAGR Forecasts a New Growth Trajectory
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Laminator Market
The laminator market has evolved from a niche machinery segment into a critical enabler of packaging integrity, print durability, and industrial surface protection. With the market valued at 347.0 million USD in 2020 and reaching 489.0 million USD in 2025, the sector demonstrates steady expansion driven by structural demand across packaging, printing, and commercial environments. The projected trajectory from 2026 through 2032 points toward sustained growth, with revenues scaling toward approximately 800 million USD by the end of the forecast period. A compound annual growth rate near 7.25 percent reflects a mature but still expanding equipment ecosystem, where incremental efficiency gains, format flexibility, and compliance requirements reshape procurement priorities. Understanding how this landscape is shifting matters for equipment manufacturers, converters, investors, and procurement leaders who must align capacity planning with demand signals rather than historical inertia.
Market Snapshot and Core Challenges
The laminator market spans a diverse range of machine architectures, from office-grade thermal pouch systems to high-throughput industrial and roll-to-roll units used in flexible packaging and graphic arts. Growth has been supported by the ongoing need for durable surface finishes, moisture resistance, and brand protection across consumer goods, medical packaging, and point-of-sale materials. At the same time, the market faces structural friction points that determine which operators will capture margin expansion and which will face margin compression.
One of the most consequential challenges is raw material volatility. Laminating films based on polypropylene and polyester, along with adhesive formulations tied to oil-derived inputs, create pricing uncertainty that directly influences machine utilization, conversion costs, and product positioning. When input costs swing sharply, manufacturers and converters must decide whether to absorb costs, pass them through, or redesign processes to reduce consumption. This dynamic pressures both equipment suppliers and end users, especially in packaging applications where thin-film optimization and material efficiency are becoming strategic levers.
A second challenge centers on safety and compliance scrutiny. Recent regulatory attention on thermal laminators highlights how product safety incidents can reshape procurement standards, especially in education, office, and small commercial environments. Recalls and hazard assessments trigger compliance reviews that affect purchasing cycles, after-sales expectations, and supplier qualification processes. For machine builders, the implication is clear: reliability, thermal management, and transparent safety documentation are no longer optional features but market-entry prerequisites.
A third challenge is the uneven cost environment for advanced lamination technologies. High manufacturing costs, combined with fluctuating film and adhesive pricing, can slow adoption of thermal lamination films in certain applications and constrain expansion where converters are already operating on narrow margins. This creates a divide between operators who can justify investment in automation and multi-function platforms, and those that remain tied to labor-intensive or fragmented workflows.
Core Demand Drivers Shaping the Market
The market’s direction is being shaped by several interconnected drivers, each pulling equipment requirements in different directions and rewarding manufacturers that can balance throughput, flexibility, and compliance.
Technological Innovation and Process Flexibility
A defining trend is the push toward machines that can handle multiple formats, curing methods, and finishing options within a single platform. The industry is seeing growing interest in systems that combine lamination with digital foil, UV and UV LED curing, embossing, and integrated slitting. This convergence reduces changeover time and broadens the value proposition for printing and packaging service providers who need to run shorter runs without sacrificing finish quality. Recent product unveilings at trade shows demonstrate that manufacturers are actively positioning versatility as a competitive differentiator, especially for converters seeking to serve both conventional and digitally enabled workflows.
Innovation is also visible in automation and process control. Automatic thermal film and roll-to-roll laminating systems with multi-function capabilities are increasingly associated with certifications and standardization that support international deployment. In a market where buyers compare total cost of ownership rather than initial price alone, equipment that improves repeatability, reduces waste, and simplifies operator training gains traction faster than machines that solve only one process step.
Policy, Safety, and Compliance Expectations
Regulatory and safety dynamics are becoming more influential in purchasing decisions, particularly where equipment affects end-user safety and brand risk. The recall of a widely recognized thermal laminator model due to overheating hazards illustrates how quickly compliance concerns can alter the commercial environment. Even when incidents are limited in scope, they prompt broader reviews of thermal management, electrical safety, and product documentation across categories.
BT Laminate Market
For industry participants, this environment rewards transparency and consistency. Companies that maintain recognizable safety certifications, clear usage guidelines, and traceable quality processes are better positioned to navigate procurement audits and institutional purchasing requirements. In commercial and office segments, compliance has become part of the value proposition, not just a legal checkbox.
Demand-Side Shifts in Packaging and Print
Demand behavior is shifting as brands and converters prioritize durable packaging, surface protection, and enhanced print presentation. Packaging continues to represent a substantial application base for lamination equipment, where lamination contributes to barrier performance, handling durability, and aesthetic finish. At the same time, printing and graphic arts applications rely on lamination for color enhancement, abrasion resistance, and shelf appeal.
A notable demand-side change is the increasing expectation for shorter runs, faster turnaround, and broader finish variation. This favors equipment that can move between tasks with minimal reconfiguration and supports hybrid production models where digital and conventional processes coexist. For converters, the commercial opportunity lies in expanding service offerings without proportionally expanding floor space or labor, which makes flexible laminator platforms strategically attractive.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal force in market behavior. Volatile raw material costs for laminating films and adhesives create uncertainty in budgeting and can slow adoption where conversion margins are tight. These pressures do not simply affect consumables; they influence machine design priorities, since more efficient film handling, reduced waste, and better tension control can materially change operating economics.
At the same time, the supply chain environment is encouraging regional and application-specific specialization. Equipment providers that can deliver machines aligned with local production needs, certification requirements, and consumable availability often gain an advantage in markets where lead times, service access, and parts availability matter as much as equipment performance. This has contributed to a landscape where some players compete on global reach while others compete on localized process fit.
Competitive Landscape and Leading Strategies
The laminator market is characterized by a broad supplier base spanning office and print-shop equipment, commercial printing systems, and industrial packaging lines. Market concentration remains moderate, with the top three players holding roughly 26.5 percent and the top five near 30.1 percent, indicating room for differentiated positioning rather than domination by a small group of universal incumbents. This fragmentation creates both competition and opportunity, especially for companies that can claim distinct application strengths or technology leadership.
Laminating Machine Market
Strategic Positioning Across Market Segments
Several patterns emerge when comparing leading companies. In office and small commercial production, established players maintain strong recognition through thermal pouch and roll laminators designed for schools, offices, and light commercial use. Their advantage often rests on brand familiarity, distribution reach, and product ranges that address straightforward laminating needs with predictable operation. In this segment, sustained relevance depends on balancing ease of use, reliability, and service support.
In commercial printing and graphics protection, suppliers tend to emphasize print enhancement, film encapsulation, and reel-to-reel or reel-to-sheet systems. These companies compete on finish quality, format handling, and the ability to protect or elevate printed materials for demanding applications. Their differentiation typically comes from machine versatility, film compatibility, and the precision required for consistent high-end output.
In packaging and industrial applications, the competitive emphasis shifts toward roll-to-roll and solventless lamination, multi-technology coating and laminating, and integrated line solutions. Leading equipment suppliers in this space focus on flexible packaging, food and pharma-relevant processing, and high-throughput configurations that can be incorporated into broader converting lines. Their strategic edge often lies in combining lamination with slitting, gravure integration, or solventless adhesive compatibility, allowing operators to streamline production and reduce process complexity.
A parallel dynamic is emerging among machinery manufacturers that pursue international deployment through standardized certifications and patented automation features. Companies with explicit ISO and CE alignment, along with multi-function automatic thermal lamination designs, are positioned to serve buyers who require documented compliance and repeatable performance across multiple installations. This is particularly relevant for exporters and converters scaling operations across regions where qualification standards differ.
Market Evolution: Integration, Differentiation, and New Entry
The competitive landscape is evolving along several paths. One is consolidation through capability expansion, where existing players add curing, foil, embossing, or line-integration features to deepen their relevance in targeted verticals. Another is differentiation by format and application, with some manufacturers concentrating on packaging, others on commercial printing, and others on office and light commercial use. This specialization allows companies to build recognised expertise but also raises the risk of overlap when customer requirements cross traditional segment boundaries.
PW Consulting
New entrants and regional manufacturers continue to play an important role, especially where cost efficiency, rapid model updates, and application-tailored configurations are valued. Trade show activity suggests that live demonstrations and hands-on machine comparisons are increasingly central to procurement decisions, giving newer players a channel to establish credibility through visibility and performance proof. As a result, the market is not simply becoming more concentrated; it is becoming more competitive on the basis of demonstrated capability, compliance readiness, and production flexibility.
Future Trends and Commercial Implications
Looking ahead, several trends are likely to define the market’s next phase and shape where commercial value is created.
First, multi-function and hybrid laminator platforms will become more important as converters seek to manage shorter runs, varied finishes, and faster changeovers. Machines that can combine lamination with curing, foil application, or integrated slitting will appeal to operators trying to consolidate steps and reduce downtime. The commercial opportunity here is not only in selling equipment, but in enabling higher mix production with lower operational friction.
Second, safety, compliance, and documentation will increasingly influence procurement. Product incidents and regulatory scrutiny will continue to encourage buyers to evaluate thermal management, electrical safety, and quality assurance more carefully. Suppliers that can provide clear certification alignment and consistent product reliability will gain trust in segments where institutional purchasing and risk management are prominent.
Third, material and adhesive cost volatility will keep efficiency and waste reduction at the center of buying decisions. Equipment that optimizes film usage, improves tension control, or supports thinner or more cost-effective material setups will be especially valuable in packaging and flexible converting environments. In practice, this means machine choice will be judged not only by speed or throughput, but by how effectively it helps stabilize operating costs under variable input pricing.
These trends carry risk as well. Adoption of advanced platforms may slow if buyers face capex constraints or if raw material instability disrupts project economics. Regulatory attention may also raise compliance burdens that affect time-to-market for new equipment variants. In addition, regional differences in certification expectations and service infrastructure can limit how quickly a successful product in one market translates into another. Operators and investors should therefore treat flexibility and compliance readiness as core risk mitigants, not optional enhancements.
Actionable Guidance for Decision-Makers
For equipment manufacturers and converters, the priority is to align product and process strategy with where demand is becoming more complex. This means investing in platforms that reduce changeover time, support multiple curing or finishing options where relevant, and provide documented safety and quality credentials that simplify buyer qualification. Companies should also evaluate how machine design affects consumable efficiency, since film and adhesive cost volatility will continue to shape total operating economics. In markets where integrated packaging lines are gaining interest, positioning lamination as part of a broader process solution can strengthen commercial relevance.
For investors and strategic planners, the market’s moderate concentration and diverse application base suggest that value will be created through differentiated capability rather than uniform scale. Segments tied to packaging, commercial printing, and compliance-sensitive office use each present distinct growth logic, but they also require different product, service, and distribution approaches. Tracking trade show launches, product certifications, and application-focused positioning can provide early signals about where competitive advantage is forming. Given the pace of change in hybrid machine features and compliance expectations, detailed segmentation data becomes valuable when it is tied to real procurement drivers rather than broad category averages.
For procurement and operations leaders, purchasing decisions should weigh more than throughput or list price. Total cost of ownership considerations should include film and adhesive efficiency, service access, spare parts availability, safety documentation, and the machine’s ability to handle anticipated format variation. Where production environments require frequent changeovers or mixed finishing options, versatility and process stability may deliver more commercial value than raw speed alone. Evaluating suppliers against compliance readiness and operational support can reduce downstream risk, especially when safety or quality scrutiny is elevated.
The laminator market is entering a phase where growth is less about uniform expansion and more about matching equipment capability to shifting production realities. Machines that combine flexibility, efficiency, and compliance credibility will be better positioned to capture demand across packaging, printing, and commercial environments. For readers seeking deeper segmentation detail, regional application dynamics, and tailored strategic scenarios, the full PW Consulting Laminator Market report provides a more granular view of the opportunities and tradeoffs shaping this landscape.
For detailed analysis of this topic, please visit the official page: Laminator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Boilers Market: Why 4.2% CAGR and Condensing Tech Shift Strategy
By PW Consulting, 2026-09-21
The Commercial Boilers Market at an Inflection Point: Strategy for a High-Efficiency, Decarbonizing Future
The commercial boilers sector is navigating a structural transition. After reaching approximately 10,029.1 million USD in the base year, the market expands with a measured CAGR of 4.2 percent through the end of the forecast period, surpassing 13,000 million USD by the final projected year. The trajectory reflects steady demand for dependable heating infrastructure, but the composition of that demand is shifting. Efficiency mandates, fuel substitution, and digitalization are redefining what buyers expect from a core building systems component. For manufacturers, investors, and procurement leaders, the imperative is not simply to capture volume growth, but to align product roadmaps, capital allocation, and sourcing strategies with a market where performance, compliance, and operational flexibility increasingly determine competitive outcomes.
The Current Landscape and Core Challenges
The market size and growth rate signal a mature but evolving category. Historical expansion through the late 2020s and into the early 2030s demonstrates consistent investment in commercial heating capacity. Yet the headline numbers mask three pressure points that shape today’s decision-making environment.
PW Consulting
First, efficiency expectations have moved from desirable to mandatory. Condensing technology now accounts for a substantial share of the technology split and continues to gain ground as operators seek lower fuel consumption and tighter emissions compliance. This shift compresses margins for legacy non-condensing designs and raises the bar for manufacturers that must fund combustion optimization, heat recovery engineering, and validation testing while competing on a narrower performance delta.
Second, fuel transition is uneven but undeniable. Natural gas continues to dominate the fuel mix and anchors the revenue base, yet rising scrutiny on carbon footprint, local air quality rules, and long-run fuel price volatility is accelerating experimentation with biomass, hybrid configurations, and electrified alternatives in niche applications. The practical challenge for commercial operators is that switching fuels often requires capital changes beyond the boiler itself—venting, storage, control systems, and utility coordination—which slows adoption and introduces project risk.
Third, operating economics and labor dynamics are reshaping total cost of ownership. Inspection fees, compliance verification, and service labor are becoming more visible line items in fleet management decisions. Recent regulatory updates in certain U.S. jurisdictions have adjusted inspection and pressure vessel fees, while energy programs increasingly require post-installation performance verification and combustion efficiency checks. Combined with skilled technician shortages, these factors push commercial buyers toward equipment that is easier to commission, simpler to maintain, and better integrated with remote monitoring.
Key Drivers Reshaping the Market
The commercial boilers market is being steered by four reinforcing forces. Understanding how they interact clarifies where value will be created over the next several years.
Technology Innovation and Breakthroughs. Efficiency gains are increasingly delivered through integrated systems rather than isolated hardware. Condensing boilers and high-efficiency water heating solutions continue to set the benchmark for fuel utilization in commercial applications. At the same time, modular and low-emission designs are expanding into process-intensive settings where steam and hot water demand must be met with fast response and minimal standby losses. The Danish dairy sector illustrates this convergence in practice. A whey processing facility introduced a 16 MW electric boiler to replace gas-fired units, enabling 72-hour unsupervised operation and demonstrating that electrified thermal assets can be integrated into continuous industrial processes when paired with robust controls. Alongside such electrification pilots, biomass projects are proving economically attractive in regions with favorable feedstock economics and support structures; a Danish dairy installation secured a subsidy and achieved rapid payback by displacing natural gas with a 2 MW biomass boiler. These examples underscore that technology leadership now spans combustion efficiency, emissions control, modularity, and the ability to partner with operators on hybrid or alternative-fuel architectures.
Policy and Regulatory Environment. Regulation is no longer a compliance checkbox; it is a design constraint and a demand catalyst. Emissions limits, inspection regimes, and incentive programs influence both equipment selection and the pace of replacement cycles. In the United States, updates to boiler and pressure vessel inspection rules have shifted cost assumptions for owners and service providers. Elsewhere, efficiency programs and utility-sponsored initiatives are embedding performance checks into installed bases—requiring combustion efficiency verification and post-tune-up reviews for certain greenhouse and commercial installations. For manufacturers and specifiers, this environment rewards designs that simplify compliance, document performance, and reduce the risk of failed inspections. For end users, it makes future-proofing a procurement criterion, especially in jurisdictions where rules are tightening on cadence.
Steam Boiler System Market
Demand-Side Behavior. Commercial operators are increasingly making heating decisions through a total cost lens that combines energy cost, maintenance burden, uptime requirements, and sustainability targets. Hospitals, offices, educational institutions, lodging, and food processing facilities each have distinct load profiles and reliability needs, but a common thread is the desire for systems that reduce unplanned downtime and simplify oversight. Dairy and other processing environments, for example, require commercial-grade hot water capacity with predictable operating costs; energy program technical manuals now reflect incremental cost assumptions that guide retrofit decisions. As building owners and facility managers weigh modernization against deferred maintenance, the value proposition shifts toward solutions that deliver measurable efficiency gains, faster commissioning, and clearer service interfaces.
Worldwide Water Tube Industrial Boilers Market
Supply Chain and Cost Structure. The commercial boilers market operates within broader input cost and logistics dynamics that affect lead times, pricing, and the economics of service networks. Raw material movements, component availability, and freight costs influence manufacturer margins and the timing of delivery commitments. On the demand side, the cost of inspections, compliance documentation, and skilled labor adds to the operating burden, making low-maintenance designs and remote diagnostics increasingly attractive. Companies that can stabilize cost structures, localize service capacity, and reduce the friction of installation and verification are better positioned to protect margins while competing on reliability and performance.
Competitive Landscape and Winning Strategies
The competitive field features a mix of established manufacturers with broad commercial portfolios and specialists oriented toward specific heat transfer or emission-control niches. Market concentration is moderate, and the structure creates room for differentiation through application expertise, integrated offering, and service depth rather than price alone.
Cleaver-Brooks positions around complete boiler room solutions, including firetube boilers and integrated systems tailored for commercial and industrial applications such as food processing and dairy. The strategic advantage here is system-level thinking: by spanning equipment, controls, and installation support, the company reduces integration risk for operators running continuous processes. Fulton Companies competes with high-efficiency steam and hydronic boilers, thermal fluid heaters, and custom heat transfer systems, leaning into application-specific engineering for commercial users that require precise temperature and pressure control. Hurst Boiler and Welding Co. broadens the fuel conversation with gas, oil, biomass, and hybrid steam and hot water boilers, an offering that aligns with operators exploring fuel flexibility or biomass substitution in regions with supportive economics.
On the efficiency and comfort side, Lochinvar and AERCO, a Watts brand, emphasize high-efficiency condensing boilers and water heating solutions for commercial settings. Their positioning reflects the broader market tilt toward condensing technology and the demand for water heating systems that perform reliably in continuous-use environments. Miura Boiler adds a distinct angle with modular low NOx steam boilers suited to commercial food processing and industrial uses, targeting sites where emissions limits and space constraints favor compact, quick-response units. Burnham Commercial Boilers and Laars Heating Systems round out the landscape with commercial-grade boilers and water heaters designed for HVAC and process heating applications, reinforcing the breadth of options available to specifiers across building types and load ranges.
The strategic patterns among leading players are converging on three themes. First, differentiation is shifting from unit efficiency alone to integrated value, including controls, commissioning support, and serviceability. Second, application specialization is becoming a moat; companies that understand the operating rhythms of food processing, healthcare, education, lodging, and office environments can tailor solutions that reduce downtime and simplify compliance. Third, flexibility in fuel and form factor is increasingly important as operators hedge against fuel price risk and regulatory change. The market is not consolidating rapidly enough to eliminate fragmentation, but it is rewarding companies that can bridge product capability with deployment and service realities. New entrants and niche specialists continue to find openings in modular, low-emission, and electrified thermal niches, while incumbents extend their advantage through installed base relationships and service networks.
Forward-Looking Trends for the Next 3–5 Years
The next several years will be defined by how quickly the market converts efficiency potential into deployed reality. Three trends stand out.
Efficiency as a baseline, integration as the differentiator. Condensing and high-efficiency designs will continue to expand their share, but the commercial opportunity will increasingly favor manufacturers that embed controls, diagnostics, and service-ready architecture into the product. Remote monitoring, predictive maintenance cues, and simplified verification of combustion performance will become selling points because they address labor constraints and compliance overhead simultaneously. Companies that make it easier to prove and sustain efficiency after installation will capture a disproportionate share of replacement and retrofit demand.
Fuel and thermal flexibility as risk management. While natural gas remains the dominant fuel, commercial operators will pursue options that reduce exposure to price volatility and evolving emissions expectations. Biomass, hybrid systems, and targeted electrification will grow where local conditions—feedstock cost, utility rates, incentives, and facility constraints—make the economics work. The strategic implication is that boiler offerings will need to support fuel transition pathways rather than single-fuel assumptions, and manufacturers will benefit from partnerships that extend to controls, venting, and commissioning for alternative configurations.
Serviceable, verified performance becoming part of the product promise. Inspection fee adjustments, program-driven performance checks, and the cost of skilled labor are elevating the importance of designs that are straightforward to inspect, tune, and sustain. Buyers will increasingly prioritize equipment that reduces ambiguity in compliance and minimizes the need for specialized intervention. This creates an opportunity for manufacturers and service providers to package equipment with clear documentation, verifiable efficiency targets, and support models that reduce lifecycle friction. The associated risk is that regulatory pace and program design vary by region, which can accelerate demand in some markets while slowing it in others, creating uneven near-term growth even as the long-term direction remains clear.
Strategic Moves for Decision-Makers
For manufacturers, the priority is to align product development with lifecycle value rather than initial specification. Invest in combustion and heat recovery refinements that hold efficiency in real-world operation, not just rated conditions. Build modularity and service access into designs, and equip sales and engineering teams to address fuel-flexible and hybrid scenarios where local economics justify them. Strengthen the link between equipment, controls, and documentation so that compliance verification and post-installation checks become easier for customers to manage. Where possible, pair hardware with service models that reduce the burden of inspection, tuning, and remote oversight, turning operational reliability into a competitive moat.
For investors, the signal is to look beyond top-line growth and assess which capabilities will command premium positioning as efficiency and compliance become default expectations. Evaluate exposure to condensing and high-efficiency segments, application specialization in process-intensive verticals, and the strength of installed-base service relationships. Consider the defensibility of manufacturers that can navigate fuel transition without fragmenting their portfolio, and favor players that translate regulatory and labor headwinds into product and service advantages. Watch regional variation closely: incentive structures, inspection regimes, and utility programs will create pockets of accelerated demand, and portfolio concentration in those pockets can materially affect growth trajectories.
For procurement and facility leaders, the practical move is to evaluate heating investments against a broader set of outcomes: efficiency sustainability over time, emissions compliance risk, service complexity, and integration with existing controls. Favor solutions that simplify verification and reduce dependence on scarce specialized labor, and model fuel transition scenarios where local incentives, feedstock, or utility economics make alternatives viable. Include inspection and compliance cost trends in total cost analysis, and treat documentation, commissioning support, and remote diagnostics as purchase criteria rather than optional extras.
The commercial boilers market is large enough to reward scale, but its future belongs to those who anticipate how efficiency, regulation, and operating economics will reshape purchasing criteria. Detailed segmentation data, regional dynamics, and company-level benchmarks are essential to translating these directional insights into actionable plans. For decision-makers seeking precise sizing across segments, competitive positioning detail, and tailored recommendations aligned to specific applications and geographies, the full research report provides the depth required to convert strategic direction into execution.
For detailed analysis of this topic, please visit the official page: Commercial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


