



Category: market research
PW Consulting: Tractor Market Set to Expand at a 5.8% CAGR Through 2032
By PW Consulting, 2026-07-12
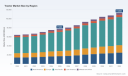
Tractor Market 2026 Strategic Outlook — Why PW Consulting’s Research Is Mission-Critical for Your Next Move
The tractor industry stands at a strategic inflection point. After a steady recovery through the early 2020s, the global tractor market reached an estimated USD 77,200 million in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 5.8% across our 2026–2032 forecast window, reaching roughly USD 112,800 million by 2032. Those headline numbers tell a simple story of scale and momentum; the real strategic value for executives lies in the granular dynamics — demand shocks, input-cost pressure, regulatory shifts, and technology adoption curves — that will determine who captures tomorrow’s value.
Tractor Market
Why this study matters for decisions made in 2026
-
Capital allocation under uncertainty — The report translates high-level growth into investment priorities. We map product-level returns across propulsion mixes (diesel, electric, hybrid), horsepower tiers, and use cases, allowing capital planners to compare near-term ROI versus strategic positioning for 2030+ demand profiles.
Tractor Market -
Go-to-market and network optimization — Dealers, distributors and OEMs will need to rebalance inventory, service capability and training for electrified and high-horsepower lines. The study provides playbooks to right-size dealer footprints and service-skill matrices aligned to regional demand patterns.
Tractor Market -
Supply-chain resilience and sourcing strategy — With raw-material and tariff volatility persisting, procurement leaders can use our scenario-based cost models to stress-test supplier contracts, hedge strategies and nearshoring options that preserve gross margins without sacrificing time-to-market.
-
M&A and partnership targeting — For strategic buyers and PE sponsors, the study surfaces the capability gaps that justify bolt-on versus transformational deals, and prioritizes target archetypes by strategic fit and valuation sensitivity.
-
Regulatory and trade compliance planning — OEMs face tightening emission standards and evolving testing codes. The research converts regulatory trajectories into product compliance roadmaps and market-entry constraints, which are essential to plan certification timelines and capex.
What’s inside the report — practical, useable modules
-
Transparent market sizing and forecast methodology — Historical series (2020–2025), a clearly articulated base year (2025) and scenario-based forecasts to 2032. We disclose model assumptions, sensitivity levers and confidence intervals so users can re-run outcomes under alternative macroeconomic or commodity inputs.
-
Demand-driver analysis and scenarios — Deep dives on drivers such as mechanization trends, commodity prices, farm consolidation, infrastructure investment and climate adaptation. Each driver is scored for directional impact and timing to support strategic timing decisions.
-
Granular segmentation — Multi-dimensional segmentation across region, application, horsepower bands, drive-type and propulsion. Note: this summary highlights structure and trends; the full report contains the proprietary segmentation tables and time-series datasets necessary for transaction and operating decisions.
-
Competitive playbooks and company scorecards — Benchmarked operating models, product roadmaps, R&D pipelines, go-to-market strengths and weaknesses for leading OEMs. Proprietary scoring weights strategic importance to help identify where competitors are vulnerable or dominant.
-
Supply-chain mapping and margin impact analysis — Bill-of-material concentration, supplier risk heatmaps, and tariff/commodity sensitivity models tailored to tractor manufacturing footprints.
-
Regulation & standards intelligence — A practical guide to emission requirements, testing certification and trade compliance implications for export strategies and product homologation schedules.
-
Commercial playbooks — Pricing strategy under cost-pressure, service-led revenue models, fleet-leasing and subscription frameworks that improve lifetime customer economics.
-
Financial toolkits — Discounted cash flow templates, valuation comparables and M&A due-diligence checklists calibrated to tractor-specific dynamics.
Competitive landscape — what the largest OEMs are placing their bets on
-
John Deere (Moline, IL) — Continues to push the envelope on high-horsepower capability and integrated precision systems. Recent product activity has reinforced their leadership posture in advanced powertrain and high-horsepower segments. The brand’s scale and integrated services create both margin advantage and higher R&D amortization, but exposure to commodity and tariff-driven input-costs remains a material operating risk.
-
CNH Industrial (Amsterdam) — CNH’s Case IH and New Holland portfolios emphasize operator comfort and efficiency. Recent model introductions underscore a strategy of steady platform evolution and dealer experience upgrades to protect share in mature markets.
-
AGCO Corporation (Atlanta, GA) — AGCO is accelerating electrification efforts while leveraging established brands (including Fendt) to commercialize battery-powered solutions. Early mover activity in compact electric tracors signals a dual-track approach: defend traditional powertrains while incubating low-emission offerings.
-
Kubota Corporation (Osaka) — Market-leading in compact and utility segments, Kubota’s advantage lies in small-farm optimization and high-density dealer networks. Their product mixes are engineered for precision-agriculture integration on smaller acreage footprints.
-
Mahindra & Mahindra (Mumbai) — Mahindra’s global reach and lightweight 4WD models are tailored to both domestic and export demand. Competitive pricing and localized supply chains underpin their volume-oriented strategy in price-sensitive markets.
-
Escorts Kubota (Gurgaon) — Focused on compact utility applications with product features tuned to local implement compatibility. Their strategy emphasizes local engineering, aftermarket integration and cost-competitive production.
Collectively, the market shows notable concentration among the top OEMs (top-three and top-five concentration metrics point to a market where a small set of global incumbents capture a majority of revenue), but sizeable opportunity pockets remain for niche players and new entrants that can deliver differentiated technology or localized value propositions.
Key industry dynamics to watch in 2026
-
Input-cost volatility and tariff impacts — Elevated steel and aluminum cost exposure and trade-policy instruments are increasing manufacturing cost baselines. Manufacturers and suppliers must assume partial cost pass-through to end-users while exploring material substitution and supply-chain reconfiguration.
-
Regulatory acceleration toward low-emission powertrains — Tightening emission standards for off-road engines and more stringent state-level requirements are shortening the window for transition, driving capital into electrification and aftertreatment technologies.
-
Standards and export compliance — International testing codes and homologation requirements are raising the bar for cross-border product sales; firms must budget time and certification spend into product launch timelines.
-
Electrification and autonomy trajectories — Two parallel trends dominate: electrification of low- and mid-power segments (driven by regulation and operational cost advantages) and increased automation/integration across horsepower tiers to support labor-constrained farming regions.
How executives should translate the report into action in 2026
-
Prioritize product investments by expected margin uplift and regulatory urgency. Use our scenario outputs to sequence electrification and high-horsepower investments to optimize payback periods.
-
Rework procurement strategies now. Hedge material exposure, accelerate dual-sourcing for critical inputs and evaluate nearshoring for high-risk components to contain lead-time and cost shocks.
-
Reconfigure dealer and service networks to support new powertrains and telematics-enabled service models. Training and spare-parts strategies will define aftermarket economics as EV fleets grow.
-
Treat regulation as a product-development input. Advance certification timelines, and organize cross-functional squads to translate emission and safety standards into requirements for engineering, QA and supply chain.
-
Adopt a portfolio approach to M&A: protect market share through bolt-ons that expand service and digital capabilities, but consider transformational buys where internal development is too slow or capital intensive.
Concluding note — what this “trailer” reveals and what it withholds
This executive briefing highlights why the tractor market’s growth trajectory and structural shifts make 2026 a pivotal year for strategic repositioning. We have surfaced the growth baseline, the fundamental forces at work, and a tactical menu of responses that leaders must consider this year. To preserve the tactical advantage for our clients, detailed segmentation tables, time-series datasets, company scorecards with granular KPIs, and our proprietary financial models are reserved for the full report and accompanying data deliverables.
To access the complete market models, downloadable datasets and the actionable playbooks that underpin these conclusions, please visit the PW Consulting Tractor Market report page or contact your PW Consulting representative. Senior teams using the full suite will gain the specific directional inputs and ready-to-run tools required to convert market growth into sustainable competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Tractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beauty Tools Market to Hit USD 345.3 Million by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-12
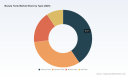
Beauty Tools Market: Strategic Outlook for 2026 Decision-Making
Executive summary
As the beauty tools market enters a decisive phase, 2026 will be the year when portfolio choices, channel plays and supply-chain architecture determine winners and laggards. Our PW Consulting Beauty Tools Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro trajectories, regulatory and hygiene dynamics, and operator-level moves into a compact playbook for senior leaders. At the market level, the industry continues to grow at a steady mid-single-digit pace (CAGR 6.8% across the forecast window), with the total global market evolving from a 2025 baseline to a substantially larger opportunity by the end of the forecast period. This research is constructed to support 2026 capital allocation, GTM prioritization, and M&A screening—while preserving the deeper segmentation tables and modeled scenarios behind our paywall to protect high-value insights.
Beauty Tools Market
Market trajectory: what the headline numbers tell you
The market’s near-term momentum is robust. After a period of recovery and re-normalization through 2020–2025, 2026 marks the next inflection where secular demand drivers—personal grooming habits, professional salon spending, and the rise of at-home beauty rituals—translate into consistent revenue expansion. The study’s forecast (2026–2032) applies a 6.8% compound annual growth rate, projecting a meaningful uplift in total market revenues by the end of the period. For executives, this trajectory validates both organic growth investments and selective inorganic strategies: the market is large enough to justify scale plays, but sufficiently fragmented to reward targeted differentiation.
Beauty Tools Market
Key demand and supply dynamics shaping 2026 choices
-
Hygiene and safety as purchase drivers. Hygiene standards for beauty tools have moved from a compliance checkbox to a competitive differentiator—particularly in professional channels. New evidence on contamination risks and buyer sensitivity has elevated sterilization, single-use disposables, and easily sanitizable designs as premium features. Brands that build validated hygiene protocols into product innovation will unlock pricing power with salons, spas and health-conscious consumers.
Beauty Tools Market -
Sustainability and “clean” credentials. Industry awards and certification programs are beginning to evaluate beauty tools alongside finished cosmetics. Sustainable materials, circular packaging, and transparent supply chains are no longer marketing embellishments but procurement requirements for many retail and professional buyers. Expect procurement teams across retailers and professional distributors to increasingly demand documented sustainability pathways in 2026.
-
Channel bifurcation—personal vs. professional consumption. Consumer adoption of at-home tools continues to grow, while professional demand remains differentiated by hygiene standards, bulk procurement and private label needs. This bifurcation requires dual GTM models: DTC and retail for consumer-led innovation; distributor and B2B solutions for professional-grade lines.
-
Operational resilience and regional footprint. Manufacturers with flexible production footprints and private-label capabilities are better positioned to capture abrupt shifts between regional demand patterns. Streamlining operations and regionalizing supply chains (as some incumbents have recently done) are pragmatic responses to logistic volatility and rising input costs.
Competitive landscape: who to watch and why
The market structure remains moderately fragmented: the top three suppliers account for roughly one-third of the market, and the top five capture just over two-fifths—an environment that favors both established suppliers and nimble private-label specialists. In this context, a small set of companies stand out because of scale, specialization, or vertical integration, and each offers a different playbook for incumbents and new entrants evaluating partnerships or acquisition targets.
-
Qosmedix (Ronkonkoma, NY) — A wholesale supplier with a broad catalog across makeup brushes, applicators, disposables and spa tools. Recent repositioning (new tagline and expanded sustainable range) signals a strategic emphasis on becoming a one-stop, sustainability-conscious source for professional buyers and manufacturers.
-
Anisa International (Atlanta, GA) — A designer-manufacturer with vertically integrated facilities and cruelty-free positioning. Their vertical model is a compelling case for brands seeking control over quality and traceability, especially where hygiene certification and sustainability claims are pivotal.
-
Green Brush (Cangzhou, China) — A premium, handcrafted brush maker that supports global private-label customers with artisanal techniques. Their model emphasizes differentiation through craftsmanship and positioned quality—an attractive alternative to mass-produced commodity lines.
-
Taiki Cosmetics (Boulogne-Billancourt, France) — A private-label manufacturer serving European and Americas customers. Recent operational streamlining demonstrates an effort to balance global portfolio breadth with regional responsiveness—important for buyers seeking consistent quality across markets.
-
Pennelli Faro (Casalmaggiore, Italy) — A fully Italian production house expanding into applicators and packaging components. Their recent capacity expansion highlights demand for integrated product+packaging solutions for premium beauty customers.
Recent vendor moves—new sustainable lines, operational consolidation, and factory expansions—underscore two strategic facts: first, incumbents are investing behind sustainability and hygiene as differentiators; second, private-label and component-integration capabilities are becoming more attractive to retailers and brands wanting faster product development cycles.
What the PW Consulting report contains (practical, decision-ready modules)
Our study is structured to convert market intelligence into boardroom decisions. Key deliverables include:
- Macro market model and forecasts (2026–2032) with scenario pathways that stress-test demand under variable hygiene, regulation and channel-shift assumptions.
- Strategic frameworks for portfolio prioritization—how to determine whether to build, buy, or partner across haircare, skincare, makeup and nail tool categories.
- Operational playbooks for supply-chain resilience: capacity planning templates, regionalization checklists and supplier scorecards emphasizing hygiene and sustainability KPIs.
- Channel and commercialization strategies for 2026: DTC vs retail vs professional distribution heuristics and margin bridge analyses.
- Tactical M&A and JV screening tools, including quick-hit valuation multiples calibrated to market concentration and margin profiles in the beauty tools space.
- Competitive dossiers and case studies on leading suppliers—detailing capabilities, recent strategic moves and partnership fit for different buyer archetypes.
Note: To preserve commercial value and adhere to our “trailer” approach, the public summary intentionally omits granular segmentation tables and numerical splits by region, application and sub-type. Subscribers to the full report receive the complete quantitative matrix and downloadable models.
2026 playbook: recommended strategic moves for executives
The coming year is about translating the forecast into prioritized initiatives. Below are high-impact actions that senior teams should consider for 2026:
-
Prioritize hygiene and traceability investments. Build validated cleaning/sterilization claims into product roadmaps, or acquire partners who can provide hygienic single-use solutions. This is a low-risk, high-return differentiator in professional channels.
-
Segment the portfolio by demand archetype, not just product type. Separate mass-consumer, premium DTC and professional/procurement-led offerings and adopt tailored pricing, materials and go-to-market models for each.
-
Use private-label partnerships to accelerate shelf breadth. For retailers and distributors, private-label alliances—especially with vertically integrated manufacturers—can compress time-to-market and secure margin uplift without heavy capex.
-
Invest in sustainable materials and supply-chain transparency. Certification and documented sustainability pathways will increasingly serve as gating criteria for large retail and professional buyers; plan CAPEX and supplier development accordingly.
-
Rationalize production footprints for agility. Consider a hybrid model that combines a regionalized, nimble production layer with centralized capabilities for complex/specialty manufacturing. Recent operator moves illustrate this trade-off between scale and responsiveness.
-
Apply the “fast-follower” M&A lens. Given moderate market concentration, bolt-on acquisitions in niche high-value segments (e.g., hygienic disposables, premium handcrafted brushes, integrated packaging-applicator systems) can meaningfully lift margins and market access.
Risk considerations and monitoring signals for 2026
-
Regulatory tightening and award-driven standards. Industry awards and evolving certification frameworks are shaping product claims—monitor both formal regulation and key industry award criteria that influence buyer perception.
-
Contamination risk and consumer sentiment. Scientific findings on bacterial contamination highlight an ongoing reputational risk; rapid response protocols and transparent consumer education will be required if incidents occur.
-
Supply input volatility. Raw material and logistics cost swings can compress margins; hedging and supplier diversification remain practical mitigants.
How PW Consulting’s study informs board-level decisions in 2026
This study is built for executives who need to convert market direction into investment and operational priorities within a 12–24 month decision window. The combination of a macro forecast, scenario stress-tests, competitor dossiers, and actionable operational templates enables three immediate outcomes:
- Faster, evidence-based portfolio pruning and resource reallocation to high-return SKUs and channels.
- Clearer M&A and partnership screening criteria that align with hygiene, sustainability and scale objectives.
- Operational blueprints to improve time-to-market and procurement resilience—reducing execution risk while pursuing growth.
Next steps
If your 2026 plan hinges on winning in beauty tools—through organic growth, acquisition, or category launch—our report provides the executable intelligence you need. The public preview above is intentionally selective; the full report contains the granular segmentation matrices, regional demand models, and downloadable financial scenarios necessary for underwriting investments and guiding operational implementation. Reach out to PW Consulting to schedule a briefing and receive the subscriber-only data pack and decision-support tools.
For detailed analysis of this topic, please visit the official page: Beauty Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
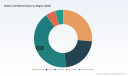
Button Cell Market 2026: Strategic Preview for Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Button Cell Market research — a practical intelligence brief crafted for executives who must make high‑stakes decisions in 2026. This preview synthesizes the macro trajectory, structural dynamics, regulatory inflection points, and competitor archetypes that will shape supplier strategies, procurement plans, and M&A activity over the coming cycle. It intentionally showcases analytical depth while preserving the granular segment tables and model outputs for subscribers — think of this as the trailer that proves the film is worth seeing.
Button Cell Market
Why this market matters in 2026
The global button cell market is no longer a niche industrial input — it is a foundational component for a wide range of miniaturized electronics across medical, consumer, industrial and automotive applications. Between the start of the historical baseline (2020) and our base year (2025), the market expanded steadily, rising from approximately USD 3.4 billion to about USD 4.55 billion. From 2026 through 2032 we model a continued compound annual growth rate (CAGR) of 6.5%, culminating in a market value that reaches roughly USD 7.0 billion by 2032. That pace of growth, combined with concentrated supply chains and regulatory pressures, creates both opportunity and operational risk for manufacturers, OEMs and investors.
Button Cell Market
Key demand drivers and structural dynamics
- Miniaturization and functionality creep: As devices demand more features per unit volume (sensors, connectivity, secure elements), button cells are increasingly viewed as enablers for product differentiation. This is especially true in medical wearables and certain consumer IoT endpoints.
- Medical and safety‑critical adoption: Growing use in implantables, monitoring devices and hearing aids raises the bar for reliability, certification and traceability. Buyers are paying a premium for validated supply chains and documented qualification processes.
- Portfolio bifurcation: The market is bifurcating between commoditized commodity formats and engineered, application‑specific variants that command margins and locked‑in design wins. Strategy choices here determine whether a firm competes on cost or on integrated solutions.
- Supply chain tightness and lead times: Our sector analysis shows lead times for standard lithium coin cell formats can range between 8 and 16 weeks, with raw material cost volatility — particularly lithium and manganese dioxide — impacting procurement cycles and hedging strategies.
Regulatory and logistics inflection points
- Transport classifications and handling: The IATA 2026 Battery Guidance Document introduced updated classification pathways for lithium and sodium‑ion batteries, including button cell types. Manufacturers and shippers must revisit their logistics playbooks to avoid delays and compliance failures.
- Safety and product standards: Enforcement of ANSI/UL 4200A‑2023 for button cell and coin battery systems (effective enforcement since March 19, 2024) is already reshaping product verification protocols. For 2026 purchasers and product managers, proof of compliance will increasingly become a prerequisite for qualification.
- Operational implications: Certification timelines, test lab capacity and documentation requirements now feature in time‑to‑market calculations. Firms that internalize these non‑negotiables into R&D and procurement roadmaps reduce program risk and preserve launch windows.
Supply side and competitive archetypes
The competitive field comprises long‑established global brands, regionally strong manufacturers, and agile private players that specialize in niche medical or military segments. Market concentration metrics indicate material clustering at the top end of the market: the top three firms account for roughly a third of global supply, and the top five for under half — enough concentration to influence pricing dynamics, but not so consolidated that new entrants or scale‑fast followers cannot disrupt.
Button Cell Market
- Major multinational incumbents: Firms such as Energizer, Duracell, Panasonic Energy, Sony, and Renata deploy global channels, deep R&D reservoirs and broad brand equity. Their strength is in scale, regulatory capability, and end‑market relationships (e.g., watch, automotive key‑fob, consumer electronics OEMs).
- Japanese precision specialists: Seiko Instruments, Toshiba Battery, Maxell (recently the recipient of a transferred micro battery business), and others compete on high‑reliability, small‑form‑factor cells for timing, medical and precision applications. They bring very high product and process discipline, which is attractive for regulated medical designs.
- Chinese manufacturers and OEM suppliers: EVE Energy, PKCELL, Omnergy, Vtery, Great Power Energy and peers combine cost competitiveness with rapid scale‑up capabilities. Several also target design wins in consumer electronics and lab equipment where speed and price matter most.
- Specialists and solutions providers: ZEUS Battery Products (US) and a number of smaller US and European outfits emphasize customization — tailored chemistries, packaging and qualification for military, medical and industrial customers. Their go‑to‑market is built around co‑engineering and performance guarantees.
Notably, the March 2026 transfer of a major Japanese micro battery business changes supplier maps for specific medical and hearing‑aid niches. Buyers and investors should evaluate how this reallocation of IP and production capacity alters qualification roadmaps and competitive dynamics in those subsegments.
Risk map: what to watch in 2026
- Certification bottlenecks: Growing demand for UL and sector‑specific approvals is colliding with finite third‑party test capacity; programs that ignore this timing risk face delayed launches.
- Raw material swings: Lithium and manganese dioxide price and availability remain the foremost near‑term cost variables; procurement teams must add layered hedges and dual‑sourcing where practicable.
- Logistics compliance risk: Updated IATA classification and packaging requirements mean cross‑border shipments require more documentation and pre‑approval — unexpected noncompliance disrupts product flows.
- Concentration leverage: With top suppliers holding meaningful share, strategic buyers should evaluate lock‑in risk and design for supply flexibility (alternative formats, redesign windows, or multi‑vendor sourcing).
Strategic implications for 2026 decision‑makers
For executives calibrating 2026 strategy, four practical implications should guide choices:
- Prioritize qualification lead time as a KPI: When choosing a supplier or planning product launches, the calendar for certification and logistical approvals must be treated as a hard constraint equal to unit cost.
- Differentiate between commodity and engineered plays: Decide whether your firm competes on unit economics (price, scale) or on integrated solutions (custom chemistries, extended life, safety traceability). Each path requires different capex, R&D focus and channel strategies.
- Design for supply redundancy: Given lead‑time volatility and material swings, modularizing designs to accept multiple coin cell formats or alternative chemistries reduces program fragility.
- Use M&A and partnerships tactically: Small, targeted acquisitions (IP, niche manufacturing assets, or test labs) can accelerate time to compliance and protect margin in medical and safety‑critical segments.
What our full report delivers (operationally focused)
The full PW Consulting Button Cell Market report is designed to be immediately actionable for procurement, product and corporate strategy teams. Highlights include:
- Forward‑looking market model (2026–2032) with scenario toggles and sensitivity analysis so you can stress test volume, price and raw material paths;
- Detailed supplier scorecards and a procurement playbook that ranks vendors on quality systems, regulatory readiness, geographic risk and scalability;
- Regulatory compliance matrix with timelines and a practical gap‑remediation checklist for ANSI/UL and IATA updates;
- Cost build‑up templates and margin desks for different chemistries and cell formats, enabling competitive pricing benchmarks;
- Market concentration and competitive positioning maps, plus a prioritized M&A heatmap and integration checklists;
- Supply chain resilience toolkit: dual‑sourcing strategies, inventory policy simulations, and lead‑time hedging frameworks;
- Executive decision aids: board‑ready one‑page strategy briefs, supplier negotiation playbooks, and a capital allocation decision matrix.
We intentionally withhold core subsegment tables and granular region‑by‑application breakdowns from this preview. Those granular splits are embedded in the interactive model included in the full report and are essential for investment memos, supplier scorecards and product‑level margin planning.
How to use this intelligence in 2026
- If you are a product manager launching a regulated device in 2026 — incorporate UL compliance and transport classification milestones into your Gantt, and lock supplier audits early.
- If you lead procurement — focus immediately on establishing parallel supply options for critical cell formats and negotiate clauses for raw material pass‑through and lead‑time commitments.
- If you are an investor or corporate development leader — target tuck‑ins that provide regulatory test capacity, niche medical production lines, or IP that accelerates certification.
Next steps
PW Consulting’s full Button Cell Market study provides the granular segmentation, revenue tables, vendor profiles and the Excel model needed to operationalize the strategies outlined here. If your 2026 decisions hinge on supplier selection, product timing, or capital commitments in this space, request the full report and model to move from strategic intent to executable plans.
For direct access to the report, data exports and a tailored briefing that maps the findings to your portfolio, contact PW Consulting’s market intelligence desk. The macro signals are clear; the local operating decisions will determine who captures the margin premium as the market scales toward 2032.
For detailed analysis of this topic, please visit the official page: Button Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Bread Flour Market to Reach USD 253.1M by 2032 at 6.96% CAGR
By PW Consulting, 2026-07-12
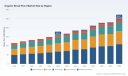
Organic Bread Flour Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a strategic preview of the Organic Bread Flour market designed specifically to inform high-stakes decisions in 2026. Our full study, anchored on a 2025 base year and projecting through 2032, shows the market expanding at a compound annual growth rate of 6.96%. To ground the narrative: the market progressed from approximately USD 115.4 Million in 2020 to USD 159.2 Million in 2025, and is forecast to reach roughly USD 253.1 Million by 2032, with an interim projected size of about USD 167.5 Million in 2026. These macro dynamics frame a market that is both maturing and offering distinct windows for differentiation, scale, and consolidation.
Organic Bread Flour Market
Why this matters for 2026 strategy
2026 is the inflection year when supply-chain constraints, regulatory shifts, and consumer premiumization coalesce into actionable risks and opportunities. For executives and investors, the central strategic question is not whether the organic segment will grow—our topline forecast confirms it will—but how you capture value within a market that commands pricing premiums, requires supply-chain transparency, and remains fragmented in supplier power.
Organic Bread Flour Market
- Premium dynamics: Organic flours carry a meaningful premium versus conventional equivalents due to certification and production costs. This premium creates margin upside but also raises expectations for quality, traceability, and branding investments.
- Supply elasticity and raw-material risk: Certified-organic wheat availability is improving—North American certified acreage expanded materially in recent years—but remains supply-constrained versus conventional wheat. Policy moves and trade frictions can quickly reroute flows and compress margins.
- Regulatory and trade volatility: Emerging trade measures and evolving organic rules will alter cross-border sourcing economics. Executives must model these variables into procurement, capacity, and channel strategies starting in 2026.
Market dynamics and structural drivers
Demand drivers are multi-dimensional. Health and sustainability narratives continue to underpin consumer willingness to pay, while artisanal and in-home baking trends sustain steady volume from specialty and retail channels. At the same time, commercial bakery demand for consistent, high-performance organic bread flour is rising as industrial bakers retrofit formulations to meet retailer and foodservice callouts.
Organic Bread Flour Market
On the supply side, there has been meaningful growth in certified-organic farm supply in key producing markets over the past half-decade, improving raw-material availability but not yet eliminating volatility. Packaging and labeling also play a direct role: organic products typically command a 30–40% price premium over conventional equivalents, which places additional emphasis on premium packaging and certification claims that can justify that spread.
Overlaying these fundamentals are two regulatory developments that will materially affect 2026 planning. First, in March 2025 Canada implemented retaliatory tariffs covering selected agricultural goods, including certain wheat and flour products—an active trade-policy headwind that has already altered short-term regional sourcing economics. Second, the European Commission moved in late 2025 to simplify labelling and organic certification for third-country imports; this has implications for exporters and market-entry strategies and should be modeled into compliance and go-to-market timelines.
Competitive landscape: profiles and strategic implications
The Organic Bread Flour market shows low to moderate concentration: the three-largest firms account for a minority share of the market and the top five still capture less than a third overall—an indicator of fragmentation and opportunity for scale plays or differentiated positioning.
- Ardent Mills (Denver, CO) — Ardent Mills has signaled its strategic intent through capacity expansion investments in 2025 to meet growing organic demand. Their strength is scale-based supply programs, grower networks, and the ability to offer USDA-certified organic lines to both commercial bakers and ingredient customers. For incumbents, Ardent’s moves raise the bar on logistics and private-label supply capability.
- King Arthur Baking Company (Vermont, USA) — Positioned as the artisanal benchmark, King Arthur focuses on product performance and brand trust. Their organic bread flours are tailored to artisan bakers, a segment where differentiation is quality-driven rather than price-driven. Competitive defensive strategies must consider King Arthur’s strong retail and direct-to-consumer channels.
- Bob’s Red Mill Natural Foods (Oregon, USA) — With a product launch in early 2025 emphasizing stone-ground organic flours optimized for home bakers, Bob’s Red Mill is reinforcing its specialty-baking credentials. Their approach highlights the importance of formulation and consumer-facing innovation in protecting premium margins.
- Fairhaven Mill (Washington State, USA) — As a regional, community-focused miller with a long heritage in certified organic production, Fairhaven underscores the strategic value of local sourcing, provenance storytelling, and niche quality segments.
- Great River Milling (Minnesota, USA) — Strong on traceability and supporting both artisan and commercial customers, Great River is illustrative of mid-sized players that bridge the gap between local authenticity and commercial reliability.
- General Mills (Minneapolis, MN) — As a diversified food company, General Mills leverages integrated organic wheat sourcing programs and broad retail reach. Their presence illustrates how corporate buyers can move the market through integrated procurement and retailer partnerships.
New entrants and adjacent-category players are also active—most notably a U.S. retail entrant into the organic flour category in late 2024—signaling low barriers to brand entry so long as credible supply and certification are secured.
What PW Consulting’s full report provides (practical, operational content)
To support immediate 2026 action plans, our full study contains a suite of decision-grade, executable deliverables. Highlights include:
- Top-down market sizing and validated forecasts (2020–2032) with sensitivity lanes tied to tariff scenarios and organic acreage expansion assumptions.
- Demand-shift matrices by channel and buyer persona, with elasticities calibrated for premium pricing and promotional tactics.
- Supply-side maps: supplier & mill capability matrices, grower network overlays, and a traceability maturity model for organic flour sourcing.
- Pricing and margin models that factor certification costs, packaging premiums, and shipping differentials under multiple trade-policy scenarios.
- Regulatory-impact playbook that translates specific policy moves—such as tariff events and EU organic-labeling amendments—into operational checklists for procurement, QC, and export compliance.
- Packaging and go-to-market toolkits that convert the 30–40% premium opportunity into SKU, pack-size, and channel recommendations with ROI timelines.
- M&A and partnership screen for 2026–2028 including target qualification criteria and accretion/dilution modeling under varying integration costs.
- Risk matrices and scenario-running tools: price shocks, crop yield variance, and certification disruptions with mitigation playbooks.
Note: core segmentation tables and granular supplier or region-level shares are intentionally omitted from this preview to preserve the proprietary value of our datasets. Subscribers to the full report gain access to those tables and the underlying models.
Priority strategic moves for 2026 decision-makers
Our analysis points to a set of prioritized actions that can be implemented rapidly in 2026 to capture upside while containing downside risk:
- Secure multi-year contracts with certified-organic growers or enter into revenue-sharing grower programs to lock-in volumes and improve margin predictability.
- Invest in batch-level traceability and documentation; buyers will pay premiums for provenance, and traceability reduces compliance risk under emerging EU and North American rules.
- Re-examine the SKU portfolio to shift toward premium, higher-margin bread-flour SKUs while optimizing pack sizes for both commercial and retail channels.
- Adopt a hedged sourcing strategy that blends local/regional supply with vetted third-country sources to insulate from tariff-induced dislocations.
- Accelerate packaging and labeling upgrades that communicate organic credentials and sustainability—these convert the 30–40% price premium into repeat purchase behavior.
- Consider selective capacity expansion or tolling partnerships (including with larger millers expanding organic capacity) rather than full-scale greenfield builds to limit CapEx while scaling quickly.
- Pursue bolt-on M&A targets that provide traceability, regional sourcing, or formulation IP rather than large-market-share acquisitions—this preserves agility in a fragmented landscape.
Closing: how PW Consulting helps you translate the preview into a 2026 roadmap
The Organic Bread Flour market is moving from niche to mainstream premium: growth is steady, margins are attractive, and structural changes—policy shifts, packaging premiums, and supply evolution—create a narrow window in 2026 to secure advantaged positions. Our full report supplies the transactional and operational playbooks executives will need to mobilize investment committees, supply-chain teams, and commercial organizations.
For competitive intelligence, actionable scenario models, and the proprietary segmentation matrices referenced in this preview, visit the PW Consulting report page to access the complete study and downloadable tools. The preview above outlines the strategic contours; the full report equips you to act.
For detailed analysis of this topic, please visit the official page: Organic Bread Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luncheon Meat Market to Reach USD 276.5M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-12
Luncheon Meat Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive introduction to our Luncheon Meat Market study — a decision-grade intelligence product crafted to inform 2026 corporate strategy, portfolio prioritization, and M&A screening. The research uses 2025 as its base year, traces historical performance across 2020–2025, and projects the market through a seven‑year forecast window (2026–2032). The headline: the global luncheon meat market is a resilient, mid-growth category with a compound annual growth rate (CAGR) of 5.8% across our forecast horizon (USD, Revenue unit: Million). Our analysis is deliberately deep in causation and implication; core subsegment figures and granular splits are reserved for the full report to preserve competitive value and to invite a targeted read of the source study.
Luncheon Meat Market
Why this study matters for 2026 decision-makers
-
Macro predictability with tactical volatility: While the market trajectory shows steady expansion from the mid‑six‑figure range in 2025 into higher levels through 2032 under a 5.8% CAGR, short‑term operating conditions in 2026 will be shaped by input cost swings, safety events, and evolving consumer preferences. Executives who align near‑term operations to the longer‑term demand envelope will preserve margins and optionality.
Luncheon Meat Market -
Margin and volume playbooks diverge: Large-scale producers and retailers can exploit scale to manage raw‑material cycles and ensure distribution, while agile premium and niche players can extract margin via formulation, provenance, and convenience innovations. Our study maps strategic choices against quantified outcomes to inform channel and SKU rationalization decisions.
Luncheon Meat Market -
Regulatory and food‑safety events materially change risk profiles: The market’s concentrated core (CR3 ~45%, CR5 ~56%) means that recalls or alerts involving any sizable supplier can propagate to category demand and trading dynamics. Our risk scenarios model the financial and operational impact of such events and the mitigants that buy time and credibility.
Market trajectory and structural context
Our topline sizing shows the category’s recovery and expansion path through the base year and into the forecast window. The market expanded consistently between 2020 and 2025 and, under steady demand and product innovation, is projected to continue growing across 2026–2032 under a 5.8% CAGR. This pace reflects a balance between persistent consumer demand for convenience proteins and headwinds from higher‑value protein competition, cost pressure on raw materials, and intermittent food‑safety episodes that periodically reset shopper behavior.
From a structural perspective, the category is neither a commodity pure play nor a niche artisanal market. It is a hybrid: scale favors lower‑cost producers and private‑label suppliers, while premiumization and health‑oriented product innovation create profitable niches. The concentration metrics (CR3 and CR5) confirm that several global players exert significant influence on pricing, retail negotiations, and supply security — a dynamic that informs both defensive playbooks (inventory and supply redundancy) and offensive options (brand differentiation and exclusive formats).
Key demand and supply drivers in 2026
-
Consumer trends: Convenience, snacking occasions, and format innovation continue to drive demand. Health and label clarity (reduced sodium, “no nitrates added,” clean‑label recipes) are critical for new product acceptance. Premium deli positioning and limited‑edition flavors generate disproportionate attention and trial.
-
Raw‑material cycles: USDA data through early 2026 indicate divergent supply signals for primary inputs — pork production is forecast higher in 2026 relative to prior year, putting mild downward pressure on hog prices, whereas beef production is forecast lower, supporting elevated cattle prices. These divergent trajectories require differentiated hedging and category pricing strategies per protein type.
-
Food safety and regulation: Recent recalls and public health alerts highlight downside tail risk from contamination or mislabeling. Even isolated events can reshape retailer stocking decisions and consumer trust for a category, particularly in regions with strong cold‑chain dependence.
-
Channel dynamics: Brick‑and‑mortar channels remain primary volume drivers, but online and direct‑to‑consumer formats are accelerating innovation in packaging, multipack formats, and subscription models. Retailer assortment optimization (fewer SKUs, higher rotation) favors SKUs that deliver higher sales velocity or margin per square foot.
Competitive landscape: strategic positions and near‑term plays
Our competitive synthesis concentrates on the firms that shape pricing, innovation cadence, and distribution. Below, I summarize strategic posture and implications for competitors, customers, and potential entrants. Full competitive scorecards, capability matrices, and scenario models are contained in the full report.
-
Hormel Foods Corporation — Strength: iconic heritage brands and a broad pork‑led portfolio that includes lower‑sodium and lite variants. Strategic implication: Hormel leverages brand equity and scale to pursue incremental premiumization while defending core value segments. For competitors, the counterplay is targeted differentiation on provenance and health attributes where scale is less decisive.
-
Tyson Foods, Inc. — Strength: diversified protein supply chains and rapid NPD cadence in sandwich‑style lunch meats. Recent flavor launches (e.g., bold sandwich style variants) illustrate a playbook focused on occasion expansion and flavor innovation to drive frequency. Retail partners should evaluate co‑development opportunities to accelerate exclusivity and shelf differentiation.
-
JBS USA Holdings, LLC — Strength: end‑to‑end scale across beef, pork, and poultry. Strategic implication: JBS’s scale underpins competitive pricing and private‑label wins; challengers must focus on agility, product story, and channel intimacy to compete effectively.
-
Cargill, Incorporated — Strength: supply‑chain integration and bulk/pre‑sliced solutions for retail and foodservice. Strategic implication: Cargill is a counterparty of choice for retailers seeking supply continuity and custom formulations; branded players must invest in consumer marketing to defend shelf space.
-
Boar’s Head Provisions Co. — Strength: premium deli positioning and craftsmanship narrative. Strategic implication: premium players can extend margin by leveraging foodservice partnerships and premium retail placements; the challenge is scaling without diluting brand authenticity.
-
Kraft Heinz Company — Strength: powerful legacy brands and broad distribution through Oscar Mayer and related lines. Strategic implication: brand reach supports rapid new‑product rollouts; smaller competitors can win niche loyalty through sharper positioning on health and provenance.
-
Deli Brands of America & Farmland Foods — Strength: specialized product portfolios and retailer relationships focused on traditional sliced deli and lunch meats. Strategic implication: these firms excel in meeting retailer assortment needs; broader competitors must balance SKU rationalization against localized consumer tastes.
Recent events that recalibrate 2026 strategy
-
Product innovation continues to be a high‑impact lever: flavor innovation and sandwich‑ready formats (notably launches in 2025–2026 by major brands) are proving effective at increasing basket penetration and frequency.
-
Food safety and labeling incidents remain an acute operational risk: recalls and public health alerts in the recent period underscore the need for rigorous supplier governance, traceability, and rapid crisis‑communications playbooks. Retailers and manufacturers with transparent traceability systems have a measurable brand‑value advantage in post‑event recovery.
-
Input volatility requires active risk management: USDA forecasts for 2026 show asymmetric supply movements across pork and beef that will alter input cost curves. Firms should update procurement hedging, contract structures, and pricing cadence in light of the new supply outlook.
What the PW Consulting report delivers (operational highlights)
The full Luncheon Meat Market study is intentionally structured to move leaders from insight to action. Key deliverables include:
-
A validated market model: topline historicals (2020–2025) and a scenario‑based forecast (2026–2032) with sensitivity levers tied to raw‑material price bands and structural demand shifts.
-
Commercial playbooks: SKU rationalization templates, retail assortment decision trees, and pricing elasticity matrices to quantify the profit impact of format and label changes.
-
Competitive scorecards: capability assessments, product mapping, and go‑to‑market gap analyses for the leading global players — enabling rapid benchmarking and partner selection.
-
Supply‑chain & risk toolkit: supplier risk heatmaps, recall preparedness checklists, and traceability investment ROIs that help prioritize capital allocation for resilience.
-
M&A and portfolio scenarios: thematic targets, concentration safeguards, and accretion/dilution modeling for roll‑up and capability acquisition strategies.
-
Implementation roadmap: 90‑, 180‑, and 365‑day action plans aligned to capability gaps, with measurable KPIs that link operational changes to margin and volume outcomes.
How to use this intelligence in 2026
-
Prioritize quick wins that reduce exposure to input swings (e.g., targeted hedges, alternate protein mixes, and contractual indexation) while investing in the consumer propositions that sustain premium margins.
-
Accelerate product and channel experiments (limited‑edition flavors, sandwich‑ready formats, DTC pilots) with rapid learning loops; our playbooks show which experiments scale and which dilute margins.
-
Strengthen supplier governance and traceability now — the cost of inaction after a recall is disproportionately higher than proactive investment in cold‑chain audits and labeling assurance.
-
Use concentration dynamics to your advantage — scale actors should lock distribution and capacity, while mid‑sized and niche players should carve defensible positions around brand authenticity, health claims, and retail partnerships.
PW Consulting’s Luncheon Meat Market study is crafted to support CEO, CFO, and Head of Commercial decisions for 2026 and beyond. The executive summary and methodological notes are public; proprietary segment matrices, company scorecards, and downloadable datasets are available in the full report. For access to the complete dataset, scenario models, and a tailored briefing aligned to your strategic questions, please visit the full report page or contact PW Consulting directly.
For detailed analysis of this topic, please visit the official page: Luncheon Meat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
3D Automated Optical Inspection (AOI) Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As manufacturers and equipment investors reset capital plans for 2026, 3D Automated Optical Inspection (AOI) has moved from a productivity enabler to a strategic linchpin for electronics and semiconductor assembly. PW Consulting’s latest market study — base year 2025, forecasting through 2032 — quantifies a market that expanded from below one billion USD in 2020 to approximately USD 1.506 billion in 2025, and that is on a sustained growth trajectory (compound annual growth rate of 9.8%). Under our central forecast, the global 3D AOI market more than doubles by the end of the forecast window.
3D Automated Optical Inspection (AOI) Market
Why this preview matters for 2026 strategy
-
Capital allocation: Buyers and OEMs face a narrow window to align automation CAPEX with product life cycles. The market’s near‑term momentum implies that decisions taken in 2026 will lock-in inspection architectures for the next five to seven years.
3D Automated Optical Inspection (AOI) Market -
Technology selection: The choice between inline and offline AOI, sensor modalities, and AI-enabled analytics is no longer purely a cost-performance tradeoff. It is also a supply‑chain and compliance decision — affecting time‑to‑volume and geopolitical resilience.
3D Automated Optical Inspection (AOI) Market -
M&A and partnerships: With a moderate level of market concentration among incumbents, there are strategic opportunities for vertical integration, niche consolidation, and software-enabled differentiation that can materially change competitive positioning.
-
Regulatory and procurement risk: New export-controls and component‑level licensing introduced in recent years materially affect sensor sourcing and program timelines — making procurement strategy a first‑order business risk in 2026.
What PW Consulting’s full study delivers (practical, action‑oriented)
-
Robust market sizing and trajectory models — base year 2025 with historical context (2020–2025) and scenario forecasts through 2032. These models are built for sensitivity analysis and direct integration into capex planning tools.
-
Driver and restraint mapping that links end‑market dynamics (consumer electronics, automotive electrification, advanced packaging, medical devices, aerospace) to AOI demand by inspection mode and deployment pattern.
-
Supply‑chain heatmaps and lead‑time matrices for critical subsystems (high‑speed imaging, laser modules, optics, and processing electronics), including trade‑control and sourcing risk overlays.
-
Competitive intelligence dossiers on leading OEMs, with comparative capability matrices covering sensor technology, throughput, AI/ML analytics, inline integration, and post‑sales support models.
-
Commercial benchmarking and procurement playbooks — RFP templates, TCO (total cost of ownership) models, and criteria checklists for pilot to volume ramp decisions.
-
Strategic playbook for OEMs and integrators, including three prioritized growth strategies: product leadership (sensor/AI differentiation), solution leadership (line‑level integration and analytics), and footprint leadership (regional manufacturing & service hubs).
-
Regulatory impact scenarios and mitigation options — mapping export‑control permutations and supplier diversion strategies that materially change program timelines and costs.
Competitive landscape — who matters and why
The 3D AOI vendor universe blends established capital‑equipment leaders, specialist imaging firms, and assembly‑equipment OEMs. Market concentration is meaningful but not prohibitive: the top three players account for a significant share of revenue, and the top five together represent about half of the market — a structure that supports both scale economies and targeted disruption.
-
KLA Corporation — brings advanced substrate and IC‑level 3D inspection pedigree to AOI through high‑resolution metrology and AI‑enhanced defect detection. Their portfolio has been extended to address complex substrate formats and high‑density interconnect inspection needs.
-
Omron Corporation — differentiates with multi‑angle imaging and AI workflows tailored for high‑mix PCB and automotive electronics lines. Recent product enhancements emphasize pre/post‑reflow solder and component inspection for demanding manufacturing environments.
-
CyberOptics Corporation and Nordson — both leveraging advanced sensor technologies (including MRS®-style suppression methods) to deliver high‑resolution SMT inspection and, increasingly, multifunction platforms that combine AOI with SPI and inline metrology.
-
Test Research, Inc., Viscom AG, Koh Young, Saki, Mirtec, Mycronic, GÖPEL electronic, and JUKI — each occupies a distinct niche: ultra‑high resolution for advanced packaging, precision coplanarity and height metrology, phase‑shift 3D sensing, high‑speed dense‑PCB inspection, integration expertise for high‑mix assembly, AR‑augmented inspection workflows, and SMT line integration respectively. Buyers evaluate these vendors not only on headline throughput but on how their systems integrate into existing MES/line control and analytics stacks.
Recent industry developments and their strategic implications
-
Product refresh cycles among major vendors accelerated in 2025–2026, with new catalogs and trade‑show debuts emphasizing higher resolution, AI‑driven analytics, and multifunction consolidation. For buyers, this raises the question: buy now and retrofit later, or plan for next‑generation platforms that deliver step‑change capability?
-
Export controls and component licensing have tightened for high‑speed imaging sensors and laser modules. The US Bureau of Industry and Security and other jurisdictions have expanded review scopes, and some supplier nations have introduced countermeasures — extending procurement cycles. Strategic implication: procurement teams must vet alternate sources and build longer lead‑time buffers into production ramp plans.
-
Reshoring and CHIPS‑era incentives have redirected demand toward new inline inspection investments in target manufacturing regions. This is creating regional pockets of accelerated demand — an opportunity for service‑oriented players and for OEMs that localize assembly and service footprints.
Practical strategic recommendations for 2026
-
Adopt a two‑track procurement strategy: secure capacity now for existing line requirements while reserving allocation for next‑generation systems. This reduces risk from both supplier lead‑time volatility and imminent product upgrades.
-
Prioritize sensor‑level due diligence. Given regulatory and component supply risk, assess suppliers’ vertical exposure (e.g., reliance on specific imaging sensors or lasers), their compliance posture, and their contingency plans for sourcing constrained components.
-
Invest in AI and analytics integration early. The long‑term value of AOI is increasingly realized through data — closed‑loop defect analytics, adaptive process control, and predictive maintenance. Build integration requirements into RFPs and require demonstrable API and data‑model compatibility during pilots.
-
Pursue partnerships for service and localization. Suppliers that can establish regional service hubs, spare‑parts pools, and rapid calibration turnarounds will win share in markets driven by near‑shoring and high‑uptime SLAs.
-
Use scenario planning for trade‑control permutations. Our report includes playbooks that quantify P&L and schedule impact under alternative regulatory outcomes — necessary inputs for board‑level risk conversations and contingency budgeting.
-
Consider strategic M&A or alliance moves to obtain sensor technologies, AI stacks, or in‑country service capabilities — particularly in markets where local presence materially lowers procurement friction and time‑to‑volume.
How PW Consulting’s report supports fast, defensible decisions in 2026
This study is built to be executable. Beyond headline forecasts (the market reached approximately USD 1.506 billion in 2025 and is growing at an estimated 9.8% CAGR), the deliverables are designed as board‑level and operational toolkits: downloadable forecast models that plug into CAPEX pipelines, vendor scorecards you can use during RFP evaluations, and supply‑chain risk heatmaps you can present to procurement committees.
We intentionally keep this preview high‑level — showcasing the framework, the strategic levers, and the vendor landscape — while preserving the detailed segmentation, regional breakdowns, and interactive forecast tables for subscribers. Those granular datasets power drill‑down analysis (by inspection mode, application end‑market, and region) that are essential when dollars and factory lines are on the table.
Next steps
-
For equipment buyers and manufacturing leaders: request the interactive model to map AOI investments against your product roadmaps and ramp schedules.
-
For OEMs and component suppliers: use our vendor benchmarking to identify capability gaps and partnership targets for 2026 execution.
-
For investors and corporate development teams: schedule a briefing with PW Consulting to review M&A opportunity maps and regulatory‑scenario stress tests.
PW Consulting’s full 3D AOI market study provides the empirical backbone and the decision templates that executives need to navigate a market that is growing rapidly and being reshaped by technology, geopolitics, and policy. For access to the segmented forecasts, vendor scorecards, and the downloadable scenario models referenced in this preview, please visit our report page or contact our research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: 3D Automated Optical Inspection (AOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hindered Amine Light Stabilizers Market to hit USD 2,479M by 2032 (6.98% CAGR)
By PW Consulting, 2026-07-12
Hindered Amine Light Stabilizers (HALS) Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this concise strategic briefing drawn from our full Hindered Amine Light Stabilizers Market study (base year 2025; historical 2020–2025; forecast 2026–2032). The intent is to equip senior leaders — procurement chiefs, R&D heads, commercial strategists and M&A teams — with the high-level, decision-useful insights they need for 2026, while reserving the granular segment-level tables and supplier scorecards for subscribers to the full report.
Hindered Amine Light Stabilizers Market
Executive snapshot: Where the market stands
- The HALS market is on a structurally healthy growth path, supported by expanding polymer demand, tougher longevity requirements across coatings and plastics, and ongoing adoption in packaging and specialty applications. Our model shows a sustained compound annual growth rate (CAGR) of 6.98% through the 2026–2032 forecast window.
- Measured in USD (Million), total market value expanded materially through the early-2020s and reached a robust base in 2025. The market is forecast to continue expanding through 2032, reflecting both volume growth and higher unit realizations driven by input-cost pass-throughs and premium product uptake.
- Market concentration remains significant: the top three suppliers account for a clear majority of market share, while the top five solidify a high-concentration oligopolistic structure. This creates strategic dynamics around pricing power, capacity coordination and innovation leadership.
Why this matters for 2026 decision-making
2026 will be a year of tactical choices with long-term consequences. The combination of (a) steady end-market expansion, (b) input-price volatility, and (c) a concentrated supplier base means that choices made in procurement, product development and commercial policy this year will materially influence margin resilience and competitive position over the next five to seven years.
Hindered Amine Light Stabilizers Market
- Procurement and supply security: With producers showing the ability to execute large, market-wide price adjustments, buyers must reassess contracting strategies. Short-term spot purchasing exposes converters to swings; long-term indexed contracts or joint hedging arrangements become strategic tools.
- R&D and product roadmap: The market rewards HALS formulations that deliver enhanced UV protection with lower additive loading and improved processing compatibility. Investments focused on NOR-HALS and next-generation polymer-tailored stabilizers will accelerate time-to-value.
- Commercial and pricing playbook: Given concentration among incumbent suppliers, manufacturers of compounds and finished goods should model plausible supplier-led price escalations and prepare transparent pass-through strategies to customers. Differentiation via performance claims and validated durability testing will enable premium pricing.
- M&A and partnerships: Consolidation among mid-tier producers and specialized formulators is a likely outcome. Acquirers should prioritize inorganic moves that add complementary chemistries, regional footholds, or backward integration into critical intermediates.
Market trajectory — selective, high-level data from our model
- Historical momentum (2020–2025) established the market foundation, with steady annual expansion driven by coatings, automotive, packaging and construction demand.
- Near-term (2026) modeling shows continuing growth as manufacturers recover post supply-chain dislocations and as end-users shift toward higher-performance stabilization solutions.
- By the end of our forecast horizon (2032) the market size is materially larger relative to 2025, reflecting compounded volume gains, formulation upgrades, and inflationary pressure in raw materials and logistics.
Competitive landscape — what to watch in 2026
The HALS competitive map blends global chemical majors with specialist additives firms. Leading players maintain broad portfolios and global distribution; regional specialists and distributors provide tactical access and local technical support. Key firms featured in our coverage include global majors with flagship HALS product lines and recognized specialty producers active in targeted segments.
Hindered Amine Light Stabilizers Market
- Large incumbents maintain strong R&D pipelines and branded HALS products designed for coatings and polymer stability — positioning them to lead on new standardized test validation and global certification.
- Specialist producers and regional manufacturers focus on cost-competitive supply, close technical service to converters, and rapid product customization — attractive to customers seeking local responsiveness.
- Distributor-manufacturer hybrids extend reach by combining branded chemistries with local inventory and sales models, intensifying competition in price-sensitive applications.
Recent industry moves underscore competitive tensions: one major producer announced a significant global price increase in early 2026 across antioxidants, process stabilizers and light stabilizers, citing raw material, energy and logistics pressures. Earlier, the same company launched a next-generation NOR-HALS product at a global polymer trade event, signaling parallel strategies of revenue protection via pricing and value creation via differentiated chemistry.
Regulatory and raw-material context — immediate risks and mitigants
- Regulation: HALS preparations are subject to major regulatory regimes, including REACH in Europe and food-contact rules (e.g., FDA statutes) where HALS may be used in packaging. Compliance timelines and testing requirements can materially affect time-to-market and formulation choices.
- Raw-materials: Primary feedstocks (specialty amines, acetone and related organic intermediates) are petrochemical derivatives exposed to feedstock price swings. Feedstock risk translates rapidly into additive pricing and margin compression when not actively hedged.
- Supply-chain disruption: Logistics cost inflation and regional capacity imbalances have become a standing risk. Strategies such as diversified sourcing, buffer inventory and co-located blending can mitigate production interruptions.
What our full report provides (practical, actionable tools)
To support 2026 implementation, the full PW Consulting HALS report combines forward-looking intelligence with executable tools:
- A demand model (by end-use and region) with scenario toggles to test alternative assumptions on growth, substitution, and price elasticity.
- Supplier scorecards and a competitive positioning matrix that rank providers by product breadth, technical support, geographic reach, and pricing behavior.
- Pricing-impact scenarios that translate supplier price moves and feedstock shocks into converter-level margin outcomes and recommended pass-through strategies.
- A regulatory compliance matrix that maps REACH, FDA and other jurisdictional requirements to product development timelines and test portfolios.
- An M&A playbook and target short-list methodology — focused on strategic fit, integration risk, and likely valuation multiples — to support inorganic growth planning.
- Implementation checklists for procurement, R&D, and sales that distill the top 10 operational moves to protect margins and capture share in 2026.
Note: while the full report contains detailed segmentation tables and revenue splits by type, application, and region, this briefing intentionally omits those granular figures to preserve the commercial value of our proprietary models.
Actionable recommendations for calendar-year 2026
- Procurement: Move from tactical buying to a hybrid approach — secure core supply through formula-linked contracts, use limited spot exposure for innovation-grade grades, and negotiate supply continuity clauses tied to feedstock pass-through mechanisms.
- Commercial: Validate premium claims with third-party durability testing and structure tiered pricing aligned to validated performance outcomes; prepare customer communications for potential supplier-led price increases.
- R&D and product portfolio: Prioritize NOR-HALS and other next-generation stabilizers that enable lower loading and maintain processing reliability. Accelerate co-development pilots with key converters in high-growth verticals.
- M&A / partnerships: Identify targets offering either backward integration (intermediate amines) or route-to-market advantages in emerging regional hubs; prioritize bolt-on deals that shorten lead times for strategic customers.
- Risk management: Establish a cross-functional raw-material monitoring cell; implement early-warning KPIs for feedstock price inflection and logistics bottlenecks and run quarterly “stress-test” simulations against supplier pricing scenarios.
Conclusion — how PW Consulting helps you convert insight into advantage
2026 is a pivot year for HALS market participants. Structural demand growth and technological differentiation create opportunity, but concentrated supplier power and feedstock-driven price shocks raise execution risk for manufacturers and converters. PW Consulting’s full HALS study combines rigorous demand modelling, supplier intelligence, regulatory mapping and executable playbooks to help you prioritize capex, insulate margins and capture premium segments.
For decision-makers seeking immediate, practical steps for 2026 — from procurement contracts to R&D prioritization and M&A screening — our report is designed as an operational toolbox. To access the complete datasets, supplier scorecards and scenario models referenced here, please visit the report landing page or contact PW Consulting directly for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Hindered Amine Light Stabilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Media-Based Water Filters Market to Hit USD 27.2B by 2032 (6.69% CAGR)
By PW Consulting, 2026-07-12
Media-Based Water Filters Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concentrated strategic preview of our new Media Based Water Filters Market study — designed to orient executive decision-making for 2026 and beyond. This briefing synthesizes the market’s macro trajectory, regulatory and input-cost headwinds, and competitive posture, while preserving the granular segmentation intelligence within the full report to drive demand for the complete dataset and operational playbooks.
Media Based Water Filters Market
Market at a Glance: Growth Trajectory and Structural Signals
The media-based water filters market has shown persistent expansion through the 2020–2025 base period and is positioned for continued growth across our 2026–2032 forecast horizon. On a total-market basis (USD, denominated in billions), the market climbed materially during the historical window and is projected to continue expanding at a steady compound annual growth rate (CAGR) of 6.69% over the forecast period. The dataset underpinning our analysis provides annualized totals from the 2020 baseline through 2032, enabling scenario modeling for CAPEX planning, procurement cycles, and channel investments.
Media Based Water Filters Market
Two high-level implications follow. First, the predictable mid-single-digit CAGR gives procurement and product teams time to phase investments in media technologies and supply chains rather than forcing binary, near-term strategic bets. Second, steady expansion amplifies the value of incremental share gains: given the market breadth, marginal improvements in product differentiation, certification, or service models can compound into meaningful revenue uplifts over multi-year horizons.
Media Based Water Filters Market
Why This Study Matters for 2026 Decisions
- Timing of Investments: With a clear forward growth path, 2026 is the pivot year for converting exploratory R&D and pilot programs into scaled deployments. The study isolates the tactical entry points — product-configurations, certification sequences, and go-to-market models — that minimize time-to-revenue while containing regulatory exposure.
- Risk Calibration: Regulatory and disposal constraints materially affect lifecycle costs and project timelines. Our analysis translates regulatory enforcement vectors and end-of-life obligations into scenario-specific cost multipliers and compliance timelines to inform procurement and capital approval processes.
- Supplier & Contract Strategy: The market’s structure is moderately fragmented (top-three and top-five concentration metrics indicate limited dominance by a handful of players). That fragmentation creates room for incumbents to defend margins via service differentiation and for new entrants to carve niches through specialized media or certification-led propositions.
- Operational Playbooks: The report supplies actionable operational tools — including replacement-interval modeling, backwash scheduling benchmarks, and media disposal routing templates — that facilities operators can apply immediately to reduce OPEX and extend asset uptime.
Key Market Dynamics — What Will Drive Wins and Losses in 2026
- Regulatory Tightening and Certification as a Market Gatekeeper: Standards and guidance such as longstanding FDA controls for water purification components in clinical applications, and evolving certification expectations for drinking-water treatment units, elevate certified product offerings to a premium position. For companies targeting regulated end-markets (healthcare, municipal, and certain commercial verticals), certification timelines and audit-readiness are now strategic bottlenecks.
- Input Cost and Waste Management Pressures: Granular activated carbon (GAC) and other media face both price volatility and regulated disposal regimes. Replacement and disposal costs — along with hazardous-waste permitting in some jurisdictions — should be built into multi-year TCO models rather than treated as one-off line items. Firms that optimize media life, offer take-back or regeneration services, or develop lower-cost recyclable media will realize competitive cost advantages.
- Service & Lifecycle Economics: Typical maintenance rhythms (e.g., periodic backwashing cycles and scheduled media replacement) create recurring-revenue and aftermarket opportunities. Service-led business models — especially those bundling monitoring, predictive maintenance, and consumables — have outsized potential to increase lifetime customer value compared with one-time equipment sales.
- Technology Convergence and Product Differentiation: Advances in redox media, multi-media beds, and hybrid systems that combine adsorption and biological control are closing performance gaps across applications. However, meaningful differentiation increasingly comes from integrated systems thinking — combining media selection, control logic, and maintenance protocols — rather than from single-media claims alone.
Competitive Landscape: Strategic Profiles and Implications
The market is served by a mixture of specialized media manufacturers, systems integrators, and distributors. While the market concentration metrics show the top players do not fully dominate, a small set of firms exerts clear influence through technology ownership, established distribution, and certification pedigrees. The study provides a close look at core firms that exemplify current strategic archetypes:
- Kymera International (United States): A technology-led player whose KDF® redox media underpin water-treatment applications where oxidative control complements adsorption. Their strength is specialized media IP and formulations that address specific contaminant removal challenges.
- Crystal Quest (United States): A portfolio player focused on media and resin manufacturing. Their vertical integration across media production and consumer-facing systems provides flexibility in tailoring product mixes for both aftermarket and OEM channels.
- Pure Aqua (United States): A supplier of multimedia filter systems and packaged media solutions; positioned as a systems integrator across commercial and industrial segments that require turnkey delivery and performance certifications.
- Pentek, Inc. (United States): A manufacturer historically focused on filter media for commercial and industrial applications; their product breadth supports customers that prioritize standardized cartridges and scalable filtration assemblies.
- Pure Water Products, LLC (United States): A regional distributor and specialist in backwashing filter media; plays a critical role in supply continuity, aftermarket resupply, and installation support for service providers.
Strategic takeaways for market participants: incumbents must balance certification investments with targeted technology bets; challengers can attack by bundling lifecycle services and lower-TCO media replacements; and distributors that can offer fast-channel logistics and regulatory-compliant disposal solutions will gain share, especially in fragmented end-markets.
Report Contents — What Practitioners Will Find Inside
The full PW Consulting report is structured to be operationally useful to strategy teams, product managers, procurement leaders, and business development executives. Highlights include:
- Market sizing and trend analysis with annual totals from the historical base through the forecast horizon, enabling scenario-based revenue and unit planning.
- Regulatory and standards matrix mapping relevant controls (clinical-grade water, drinking-water certification, and regional disposal/handling rules), with impact scoring for each end-market and adoption pathway guidance.
- Technology and media taxonomy that organizes media types, performance attributes, lifecycle profiles, and procurement implications without exposing client-specific or sensitive segment shares.
- Operational playbooks: replacement-interval modeling, backwash optimization templates, and vendor selection checklists that translate market intelligence into immediate cost and reliability improvements.
- Competitive profiles and go-to-market archetypes, illustrating where to compete on price, certification, service, or proprietary media blends, and the trade-offs each choice implies for margin and scale.
- Commercial scenarios and risk matrices that combine input-cost volatility, regulatory timelines, and adoption curves to inform three investment confidence levels (conservative, base, and accelerated).
Strategic Recommendations for 2026
- Prioritize Certification Roadmaps: Allocate budget and cross-functional resources to achieve relevant certifications early. For regulated end-markets, certification unlocks premium pricing and preferred-vendor status.
- Design for Lifecycle Advantage: Embed aftermarket service, media regeneration, or recovery programs into your commercial offering. Lifecycle revenue streams stabilize cash flow and create defensibility against purely price-led competition.
- Hedge Input-Price Risk: Negotiate mixed supply contracts, explore media blends that reduce cost-per-cycle, and evaluate circular strategies (regeneration, reclamation) to contain disposal liabilities.
- Segment Go-to-Market by Value Driver: Use a two-track approach: defend margin in high-compliance, high-service verticals; scale volume in lower-compliance, cost-sensitive channels through efficient manufacturing and distribution partnerships.
- Invest in Data-Enabled Reliability: Deploy monitoring and predictive maintenance capabilities that reduce unplanned downtime and increase the value proposition for service contracts.
Data Integrity, Coverage and How to Use the Model
The study uses a bottom-up revenue-construction methodology aligned with industry shipment data, supplier financials, certification records, and validated end-user maintenance cycles. The base year is 2025, with historical series covering 2020–2025 and forecasts through 2032. We deliberately modeled multiple uptake curves for emerging media technologies and regulatory-driven adoption to produce conservative and upside scenarios that feed into the strategic playbooks.
Note: this preview refrains from publishing detailed regional, type, or application splits contained in the full report. That granularity is intentionally reserved for subscribers and buyers because the segmentation tables and channel-level elasticity matrices are the operative intelligence used for commercial execution.
Conclusion — Where to Focus in 2026
Media-based water filtration is a structurally growing market with a measured CAGR, regulatory tailwinds in safety-sensitive applications, and operational levers that convert market activity into recurring revenue. For firms positioning for 2026, the imperative is clear: combine certification-led access, lifecycle service models, and input-cost mitigation to capture disproportionate returns in a market that rewards steady, differentiated execution.
PW Consulting’s full Media Based Water Filters Market report contains the actionable segmentation, supplier scorecards, and implementation templates required to translate this strategic direction into a 90–180 day operational plan. For access to the complete dataset, scenario models, and executive briefing materials, please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Media Based Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Enteral Feeding Devices Market to Reach USD 643.2M by 2032, Growing at 5.5% CAGR
By PW Consulting, 2026-07-12
Enteral Feeding Devices Market 2026: Strategic Imperatives from PW Consulting’s Preview
As healthcare systems recalibrate in the post-pandemic era and long-term care models evolve, enteral feeding devices have shifted from a narrow clinical niche to a strategic component of nutritional care pathways. PW Consulting’s forthcoming Enteral Feeding Devices Market study synthesizes five years of historical performance (2020–2025) with a rigorous forecast (2026–2032). At the top level, the market is expected to expand from the 2025 base into a materially larger opportunity by 2032, growing at a steady compound annual growth rate (CAGR) of 5.5%. For corporate leaders planning resource allocation, R&D prioritization, or M&A activity in 2026, the implications are clear: this is a stable, moderate-growth market where execution and regulatory competence will determine winners.
Enteral Feeding Devices Market
Why this study matters for 2026 decision-making
-
Investment Timing: With a predictable mid-single-digit CAGR and a clear multi-year revenue runway, the market supports both organic expansions and targeted acquisitions. Our models translate the macro CAGR into horizon-specific revenue expectations and payback timelines that are immediately actionable for capital planning committees.
Enteral Feeding Devices Market -
Portfolio Prioritization: Device manufacturers and healthcare suppliers must choose where to concentrate development spend — connectivity and smart pumps, disposables and low-cost tubes, or integrated nutrition-device offerings. The report provides the demand, reimbursement, and margin context required to rank those options for FY2026.
Enteral Feeding Devices Market -
Regulatory & Quality Risk Management: Enforcement activity and connector standardization have real commercial consequences. Our risk matrices quantify the probability and P&L impact of regulatory actions, helping procurement and compliance teams prioritize remediation investments.
-
Supply Chain Resilience: Volatility in medical-grade plastics and concentrated manufacturing footprints in parts of East Asia create procurement risk. The study offers scenario-based stress tests and sourcing playbooks tailored for 2026 supplier negotiations.
Data-driven synopsis (high level)
Using 2025 as the base year, PW Consulting’s topline forecast projects meaningful expansion through 2032 driven by an aging population, broader use of enteral nutrition in chronic disease management, and rising adoption of ambulatory and home-care feeding solutions. The model balances unit-driven growth, product mix shifts (toward connected pumps and disposables), and pricing dynamics under varying reimbursement pressures. While we disclose headline figures such as the 5.5% CAGR and the 2025 base, detailed regional, type, and application-level breakouts remain proprietary and are presented in the full study.
What the report contains — practical deliverables
-
Comprehensive market sizing and a seven-year forecast (2026–2032) including scenario and sensitivity analyses tailored for strategic planning.
-
Granular segmentation (by product type, application, and region) with proprietary unit and revenue models — presented as interactive dashboards and downloadable Excel workbooks for CFOs and commercial leads.
-
Competitive landscape maps and benchmark dashboards with CR metrics, pricing bands, and go-to-market evaluations for incumbent and challenger players.
-
Regulatory and reimbursement tracker, including a quantified impact assessment of recent FDA actions and CMS reporting updates.
-
Supply chain risk assessment with mitigation options, dual-sourcing strategies, and a checklist for onshore/nearshore manufacturing evaluations.
-
Technology and innovation briefings covering connectivity, wearable/portable devices, elastomeric solutions, and disposable materials science implications.
-
Actionable playbooks — market-entry, partnership, pricing, and M&A frameworks — prioritized by expected return, time-to-market, and regulatory complexity.
Competitive landscape — what to watch in 2026
The market remains moderately concentrated, with the top-three vendors accounting for a majority share and the top-five further extending that dominance (our concentration metrics show CR3 at ~55% and CR5 at ~64%). That structure generates strategic dynamics worth noting for 2026 planning:
-
Incumbent strength and distribution depth: Firms with broad global distribution networks and integrated nutrition portfolios will continue to defend share through bundled offerings and service contracts. Established players emphasize reliability, regulatory compliance, and hospital-level contracting advantages.
-
Platform differentiation: Leaders investing in connectivity and clinical integration — those who can link pump telemetry to EMRs and nutrition analytics — will command premium pricing and stickier accounts. Expect product roadmaps that prioritize data integrity, remote monitoring, and patient mobility features.
-
Challenger innovation: Smaller, agile entrants and medtech innovators are proving that differentiation can be achieved via wearable, electricity-free delivery systems, and portable connected pumps that focus on home and ambulatory care. These are the vectors most likely to disrupt specific subsegments rather than the entire market.
-
M&A and consolidation prospects: Given the market concentration, mid-sized firms with compelling IP or regional strength are logical acquisition targets for larger players aiming to broaden portfolios or accelerate entry into ambulatory spaces.
Leading companies profiled in the report include multinational integrators with broad portfolios and distribution (whose strengths include global reach and clinical partnerships), specialist device makers with focused product platforms (notably for pumps, tubes, and disposables), and nutrition companies that are building integrated solutions. Each profile includes capability maps, regulatory track records, and a five-point strategic scorecard assessing R&D pipeline, manufacturing footprint, reimbursement expertise, commercial coverage, and recent strategic moves.
Regulatory and reimbursement dynamics — immediate implications
-
Enforcement & quality: Recent enforcement actions and recalls highlight that quality-system robustness is a competitive moat. Companies must accelerate audit readiness and supplier oversight to avoid costly market interruptions and reputational damage.
-
Connector standardization: Ongoing updates to connector guidance and ENFit adoption remain central to device design and labeling strategies. Compliance timelines should be integrated into 2026 product launches to avoid market barriers.
-
Reimbursement complexity: Changes in reporting and improper payment rates mean that suppliers and providers need tightened documentation and billing support services. The report quantifies how reimbursement shifts can compress near-term revenue and offers tactics to protect margins via contracting and bundled services.
Supply chain and materials — risk to margin and delivery
Medical-grade thermoplastics supply constraints originating in East Asia have magnified lead times and input cost volatility. Our procurement scenarios model the financial impact of single-source vs. diversified sourcing, identify candidate geographies for nearshoring, and list capex vs. opex trade-offs for reshoring manufacturing. For 2026, clients should prioritize dual-sourcing contracts for high-risk components and evaluate long-term supplier partnerships that include quality-assurance covenants.
Technology and innovation signals to monitor
-
Connected pumps and telemetry: Expect healthcare providers to demand integration with EMRs and nutrition analytics. Vendors that demonstrate secure data pathways and actionable clinical alerts will increase share of wallet.
-
Wearable and silent solutions: The market is seeing validated approvals for silent, electricity-free wearable systems that enable outpatient mobility — a clear growth vector for home-care use cases.
-
Disposable innovation: Materials science advances in low-cost, biocompatible disposables can alter unit economics. However, regulatory scrutiny on manufacturing controls and traceability will increase for such innovations.
Strategic recommendations for 2026 (executive checklist)
-
Prioritize regulatory hardening: Invest in quality systems, supplier audits, and traceability now to avoid disruptive corrective actions.
-
Accelerate digital integration: Allocate R&D and partnership budgets to connectivity features that lower total cost of care for customers.
-
De-risk supply chains: Implement dual-sourcing for plastics and critical components; evaluate nearshoring options and inventory hedging strategies for 2026 contract negotiations.
-
Choose M&A targets defensibly: Seek bolt-on assets that fill product gaps (e.g., ambulatory pumps, wearable solutions, disposable innovations) and bring complementary commercial networks.
-
Align commercial models with reimbursement realities: Build contracting playbooks that reflect updated CMS rules and local payer idiosyncrasies to preserve gross margins.
What we are intentionally withholding (and why)
Pursuant to our “trailer” approach, this article presents headline market sizing and the strategic takeaways necessary to orient 2026 planning. To preserve the value of our proprietary work and encourage direct engagement, we are not publishing the report’s detailed subsegment revenue tables, regional percentage splits, unit-sales forecasts, or vendor market shares in this preview. These elements are available in the full report and the accompanying datasets which include interactive regional dashboards, product-type rollups, and detailed company benchmarking.
Closing — how PW Consulting helps your 2026 plan
PW Consulting’s Enteral Feeding Devices Market study combines quantitative rigor with practical playbooks aimed at near-term execution. For 2026, leaders who integrate our forecasts, regulatory risk matrices, and sourcing strategies into their planning processes will be best positioned to convert predictable market growth into durable competitive advantage. To access the full dataset, detailed segmentation, and tailored advisory services (including bespoke scenario runs for your product portfolio), consult the full report and our strategic advisory team.
For detailed analysis of this topic, please visit the official page: Enteral Feeding Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bike Locks Market Poised for 5.5% CAGR Through 2026-2032
By PW Consulting, 2026-07-12
Bike Locks Market 2026: Strategic Intelligence Briefing — PW Consulting
Executive snapshot
This briefing introduces PW Consulting’s comprehensive Bike Locks Market study (base year: 2025). It synthesizes five core strategic takeaways that should shape boardroom and product decisions in 2026. The global market has demonstrated steady recovery and expansion, growing from roughly USD 1.3 billion in 2020 to about USD 1.695 billion in 2025, and is projected to continue at a compound annual growth rate (CAGR) of approximately 5.5% through the 2026–2032 forecast window — reaching an estimated USD 2.46 billion by 2032. These macro dynamics create both runway and pressure: growth provides room to invest, while the pace and character of that growth require disciplined choices across R&D, manufacturing, and channel strategies.
Bike Locks Market
Why this study matters for 2026 corporate decisions
- Resource allocation under measured growth: With mid-single-digit CAGR expectations, organizations must prioritize bets that compound margin and defensibility rather than pursue broad-based expansion. Capital should favor technologies and programs that increase lock effectiveness, reduce warranty and return costs, and open higher-margin aftermarket channels.
- Certification and trust as market access: Third-party security ratings and programmatic customer protections increasingly determine shelf-space and e-commerce conversion. Certification compliance and certified testing footprints are now de facto prerequisites for entering premium retail channels in key markets.
- Product differentiation vs. commoditization: The market is bifurcating — incumbents reinforce security credentials and service guarantees, while challengers pursue material innovation, wearable convenience, or digital features. 2026 is the inflection point to choose a clear product strategy and invest behind it.
- Supply chain and quality risk management: Recent product fixes and recalls highlight the operational risk in hardware manufacturing. Companies should re-evaluate their quality-control regimes, supplier audits, and contingency manufacturing plans to reduce reputational and warranty exposure.
- M&A and partnership timing: Market concentration metrics indicate meaningful scale among top players, but there remains room for bolt-on acquisitions that deliver complementary technology (e.g., biometrics, app connectivity) or regional distribution reach.
Market dynamics shaping near-term strategy
Several intersecting forces are shaping the market environment in 2026:
Bike Locks Market
- Urban mobility and micromobility growth: Continued urbanization and bike adoption sustain steady demand for reliable anti-theft solutions. Lock designs that address commuter behaviour and parking infrastructure are achieving higher conversion in urban retail channels.
- Smartification and electronics integration: App-based access, alarms, and biometric features are migrating from novelty to mainstream in select product tiers, changing the cost base and aftersales model for lockmakers.
- Materials and methods innovation: New composite and textile-based solutions, as well as foldable formats, are expanding design choices for manufacturers seeking a balance between weight, packability, and cut resistance.
- Certification and testing regimes: Sold Secure and similar third-party testing houses continue to codify buyer expectations. In particular, United Kingdom market practices demonstrate Sold Secure ratings as standard gatekeepers for premium channels.
- Quality remediation and reputational risk: Industry actors have recently addressed product-level manufacturing defects and design issues; these events emphasize the need for transparent post-market surveillance and rapid design iteration to maintain brand trust.
Competitive landscape — positioning and implications
The competitive map reflects a mix of established global brands, specialized regional players, and technologically focused challengers. Market concentration measures indicate that the top three firms account for slightly more than half of industry sales, while the top five capture roughly seven in ten dollars — a structure that supports both scale advantages and targeted disruption.
Bike Locks Market
- Kryptonite (Canton, MA, USA): A legacy brand known for U-locks, chains, and integrated anti-theft programs that include registered coverage. Strengths: brand recognition, established retail partnerships, and programmatic customer assurance. Strategic focus: protect core credibility while selectively integrating smarter features that do not compromise mechanical reliability.
- ABUS (Wetter, Germany): Renowned for folding and U-lock designs with a strong emphasis on certification (Sold Secure) and hardware innovation. Recent product catalog updates and design fixes underline an ongoing commitment to addressing field failures proactively. Strategic focus: maintain premium positioning through rigorous R&D and certified claims.
- Litelok (Swansea, UK): Differentiated by lightweight, high-security U-lock variants manufactured in a solar-powered domestic facility. Strengths: sustainability narrative plus design-led value. Strategic focus: scale production while preserving brand authenticity.
- Hiplok (Leamington Spa, UK): Specialist in wearable and anti-angle-grinder locks with a lifestyle and commuter orientation. Strategic focus: deepen apparel-tech channels and partnership with micromobility fleets.
- Black X (Sharon, MA, USA): Emerging player pushing a Titan Smart Bike Lock lineup combining angle-grinder resistance with app-based access. Recent product release activity signals a push into connected high-value segments. Strategic focus: convert smart lock early adopters while solidifying mechanical resilience claims.
- Altor Locks (Virginia, USA): Niche maker of hand-assembled folding and APEX locks with a premium, craft-focused positioning. Strategic focus: defend margin through limited-volume, high-quality production and direct channels.
- ULAC (Taiwan): Innovator in biometric, alarm, and RFID-enabled bicycle locks. Strategic focus: partner with OEMs and e-bike makers where integrated access solutions can be co-developed.
- texlock (Leipzig, Germany): Developer of textile-based flexible locks, offering weight and flexibility advantages for urban riders. Strategic focus: target cyclists prioritizing portability, while validating cut-resistance claims under third-party testing.
Recent market moves are informative. Black X’s March 2026 Titan release and ABUS’s 2026 catalog refresh both illustrate active product cycles where incumbents and challengers aim to capture evolving consumer preferences. Parallel to these innovations, industry authorities — including the Master Locksmiths Association and Sold Secure — continue to set testing and certification expectations that materially affect channel acceptance.
What the PW Consulting report delivers (practical, action-oriented)
Our full study is built for commercial teams, investors, and product leaders who need executable insights — not just descriptive statistics. The report contains:
- Validated top-line historical and forecast market sizing (base year 2025) and a transparent methodology annex.
- Scenario-driven forecasts and sensitivity analyses that quantify outcomes under alternative adoption and pricing paths.
- Competitive benchmarking, including product-positioning maps, patent and IP heatmaps, and recent development timelines.
- Channel and route-to-market playbooks for premium retail, e-commerce, and OEM partnerships.
- Practical templates: Go-to-market plan, price-sensitivity thresholds, cost-plus and value-based pricing models, and an M&A diligence checklist tuned to lock technology and manufacturing risks.
- Supply-chain resilience framework with supplier-risk scoring and nearshoring/dual-sourcing scenarios.
- Certification and compliance roadmaps keyed to Sold Secure and other regional test houses, including recommended budgets and test sequencing to speed market entry.
Note: Detailed segment-level revenue tables (regional splits, type and application breakdowns) and granular company financials are purposefully reserved for the full report to protect source value and to enable interactive scenario work in our client portal.
Prioritized recommendations for 2026
- Immediate (0–6 months): Harden quality assurance and post-market surveillance; institute a rapid-response engineering team for field issues; validate suppliers against a tightened quality checklist. Begin Sold Secure or equivalent certification processes for high-tier SKUs intended for premium channels.
- Near-term (6–18 months): Pilot a connected-lock SKU with robust mechanical fundamentals and a minimal viable app, targeting fleet partners or premium commuters. Pursue retail partnerships that require certification and offer programmatic coverage to reduce buyer risk.
- Medium-term (18–36 months): Evaluate bolt-on acquisitions in imaging/biometrics or textile-composite material providers to accelerate product differentiation. Expand manufacturing flexibility via select nearshoring to reduce lead times for high-margin SKUs.
- Portfolio governance: Rationalize low-margin commodity SKUs unless they serve strategic channels; concentrate R&D and marketing spend on two to three differentiating pillars (e.g., certified high security, smart integration, or lightweight portability).
- Risk management: Embed certification testing early in the design cycle, and build insured registered-coverage offers where feasible to convert price-sensitive buyers into loyal customers.
How to use this briefing — and next steps
This briefing outlines why 2026 is a pivotal year: steady growth gives firms the latitude to invest, but market structure and certification regimes reward focused, high-quality execution. For practical deployment, we recommend that leadership teams schedule three deliverables in Q1–Q2 2026: a product roadmap tied to certification milestones, a supplier-quality rapid audit, and a three-scenario commercial plan (conservative, base, accelerated) built on the forecast assumptions in our study.
To access the detailed segmental forecasts, regional revenue tables, vendor scorecards, and interactive scenario tools that underpin these recommendations, consult the full PW Consulting Bike Locks Market report and client portal.
For detailed analysis of this topic, please visit the official page: Bike Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


