



Category: market research
PW Consulting: Electrofusion Fittings Market to grow 6.99% CAGR to USD 2,182.4M by 2032
By PW Consulting, 2026-07-12
Electrofusion Fittings Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
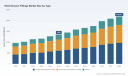
PW Consulting’s new Electrofusion Fittings Market study is designed as an operational playbook for companies making strategic choices in 2026. Built on a 2025 base year and a detailed 2020–2025 historical reconstruction, the report projects the market through 2032. At the macro level, the market has expanded from under USD 1 billion in 2020 to roughly USD 1.36 billion in 2025 and, under our central assumptions, is forecast to exceed USD 2.18 billion by 2032 — a compound annual growth rate of approximately 6.99% across the 2026–2032 forecast window. That trajectory reflects persistent infrastructure investment, accelerating adoption in new applications, and steady product and process innovation.
Electrofusion Fittings Market
Why this matters for 2026 strategy
- Timing of investment: The market growth profile and forecasted CAGR identify 2026 as a pivotal year to move from pilot investments to scale deployment of product variants, automation, or channel expansion.
- Unit economics focus: As raw material volatility and labour constraints compress margins, firms must refresh sourcing strategies and productivity benchmarks now to sustain returns across the forecast period.
- Regulatory and standards alignment: Recent standard-setting activity and procedural updates are shifting procurement and installation specifications — creating both compliance risk and differentiation opportunities for early adopters.
Market trajectory: what the numbers imply (without giving away the granular map)
The topline expansion visible in the historical series and forecast underscores three structural dynamics. First, core utility renewal and new-build programs continue to underpin steady baseline demand. Second, engineering and process innovations are shortening cycle times and enabling electrofusion solutions to compete more broadly against mechanical and welded alternatives. Third, the net effect of raw material cost swings and labour challenges is to widen dispersion in profitability across participants — favoring firms that can control feedstock exposure or achieve higher field productivity.
Electrofusion Fittings Market
For executives, the headline CAGR provides a frame for portfolio sizing and long‑term capacity planning. But our research goes beyond the headline: it quantifies sensitivity to resin price shocks, models labour availability scenarios, and maps product‑level operating margins under different adoption curves. These are the inputs that turn a growth percentage into executable capex, procurement, and go‑to‑market decisions.
Electrofusion Fittings Market
Competitive landscape — what the report will enable you to do
Our competitive analysis combines primary interviews, product audits, and recent corporate announcements to create vendor scorecards that are decision-ready. Highlights:
- Plasson Ltd. (Israel): Strong catalogue management and tooling support; recent catalog releases reinforce focus on product continuity and installer enablement. The report evaluates how this approach translates into channel resilience and specification wins.
- Georg Fischer Central Plastics Company (United States): Institutional strength in standards‑compliant fittings and training materials; recognized for automatic parameter-setting features. We analyze how compliance-led differentiation affects specification selection by large utilities.
- Integrity Fusion Products (United States): Depth in large-diameter, pressure-rated couplers under the IntegriFuse brand. Our assessment models the economics of scaling large-diameter production versus subcontracting strategies.
- Radius Systems Limited (United Kingdom): Integrated offering of fittings and welding equipment for municipal customers. The report quantifies cross-sell advantages when equipment and consumables are bundled.
- Pipelife International (Finland): Product innovation focused on reduced-cycle fittings and demonstrated deployment scale in Europe. We interrogate the time-to-profitability trade-offs of cycle-time reductions versus higher unit pricing.
- Agru Kunststofftechnik GmbH (Austria), Egeplast (Turkey), Strongbridge Inc. (United States), Kimplas/NORMA Group (India): Each profile covers manufacturing depth, regional go‑to‑market models, and niche strengths (e.g., high-pressure classes, large-diameter capability, or mass deployment experience). The report also flags likely partnership, M&A, and distribution plays for each.
Recent market developments and operational implications
- MAB-1 (Third Edition, November 2025) — Municipal Advisory Board: The approval of a uniform electrofusion field-joining procedure materially raises the bar for installer qualifications and auditability. Our operational playbook includes a gap analysis for contractors and vendors to meet the updated procedural controls.
- ISO 12176‑2:2025: New performance requirements for electrofusion control units mean procurement specs must be updated to avoid obsolescence. The report supplies a compliance matrix and a supplier assessment checklist to streamline RFPs.
- Labour availability: In 2025 a significant majority of utility contractors reported difficulty sourcing qualified electrofusion technicians, driving project delays. We provide labor productivity benchmarks and a staffing optimization model that quantifies training and automation investments required to protect schedule and margin.
- Raw material volatility: Polyethylene resin prices have shown large swings, with manufacturers citing significant volatility. Our sensitivity scenarios translate feedstock price movements into unit-cost impacts and suggest hedging and sourcing strategies appropriate to different firm sizes.
- New application signals: Events such as industry exhibitions and targeted product launches indicate growing interest in hydrogen distribution and transition couplings. The report contains a practical assessment of hydrogen compatibility and the R&D or certification steps required to enter that segment.
What’s inside the report — actionable, not academic
We designed the study for immediate use by strategy, product, operations, and commercial teams. Key operational deliverables include:
- Market sizing and forward-looking demand curves (2026–2032) with scenario variants reflecting high/low infrastructure spend, labour constraints, and feedstock volatility.
- Vendor scorecards and a procurement decision matrix that tie product features (e.g., cycle time, pressure class, diameter range) to utility specs and installer economics.
- Installation productivity benchmarks and a field quality checklist aligned to MAB‑1 and ISO guidance, enabling contractors to reduce rework and inspection time.
- Raw-material sensitivity dashboards and recommended hedging/contract strategies by firm archetype.
- Go‑to‑market playbooks for incumbent manufacturers and new entrants — channel selection, pricing levers, and partnership mapping.
- M&A and alliance screening: diagnostic criteria for target selection and commercial due diligence templates tailored to the electrofusion value chain.
Key uncertainties and trigger events to monitor in 2026
- Standards and procedure rollouts: Wider adoption of MAB‑1 and national uptake of ISO 12176‑2 could reshape procurement specs within months, not years.
- Labour market shifts: Any material easing or tightening in trained appliance availability will alter the economics of design-for-installation investments.
- Feedstock shocks: Large polyethylene price moves remain a primary margin risk; monitoring resin contract windows and inventory strategies is essential.
- New end-use markets: Early movers into hydrogen or other specialty gases can gain specification advantages, but must validate material compatibility and regulatory approvals first.
How executives should use this study in 2026
Use the report as a decision engine rather than a desk reference. Recommended actions include:
- Run the contained sensitivity models against your P&L to identify the minimum productivity or price improvement needed to hit margin targets under adverse feedstock or labour scenarios.
- Update procurement specifications to align with ISO 12176‑2 and MAB‑1 where applicable; use our supplier assessment templates during Q2 vendor reviews.
- Pilot reduced-cycle-time fittings and track end-to-end installed cost per joint; the report includes a template for a 90‑day pilot that isolates installation time, inspection cost, and failure rates.
- Map potential partners in regions where you lack scale; our competitive profiles and distribution maps provide shortlists and negotiation levers.
What we intentionally leave out here — and why you’ll want the full study
In this executive preview we surface strategic conclusions, vendor positioning, standards impacts, and operational playbooks — but we deliberately omit the detailed segment-by-segment revenue breakdowns, regional and application-level percentage splits, and granular company market-share tables that constitute the core intelligence asset in the full report. Those datasets are the proprietary drivers of Go/No-Go capital allocations, tender bid modeling, and territory planning; they are provided in the full deliverable to paying subscribers and enterprise clients only.
Next steps
If your 2026 roadmap includes capacity investments, product launches, or major procurement re‑specifications, PW Consulting’s full Electrofusion Fittings Market report will convert the strategic direction above into executable plans — including downloadable models, RFP templates, and supplier scorecards. Contact our industry team to request the full dataset, tailored briefings for your executive leadership, or a workshop to run the sensitivity and procurement exercises with your finance and operations teams.
For detailed analysis of this topic, please visit the official page: Electrofusion Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air & Water Pollution Control Market to Reach USD 209.3M by 2032 (5.5% CAGR)
By PW Consulting, 2026-07-12
Air & Water Pollution Control Equipment Market — Strategic Outlook for 2026 Decision-Making
Executive summary
As organizations finalize capital allocation and product roadmaps for 2026, the Air & Water Pollution Control Equipment market is entering a period of steady, investment‑grade growth underpinned by steady regulatory pressure, aging installed bases, and technology-driven replacement cycles. Our PW Consulting model — built on primary interviews, supplier financials, and installed‑base analytics — estimates the market at approximately USD 143.5 Million in the base year (2025) and projects growth to roughly USD 209.3 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.5% over the forecast horizon. Historical momentum from 2020–2025 shows consistent expansion driven by retrofit demand and municipal infrastructure renewal; the 2026 planning year is pivotal for firms seeking to translate this trajectory into defensible revenue and margin gains.
Air & Water Pollution Control Equipment Market
Why this study matters for 2026 decisions
- Allocation of scarce CAPEX: Our analysis helps prioritize retrofit versus green‑field projects based on total cost of ownership, permitting timelines, and expected payback under near‑term regulatory scenarios.
- M&A and portfolio pruning: With market concentration measured at CR3 = 28.5% and CR5 = 35.2%, the competitive field is fragmented — presenting targeted bolt‑on acquisition opportunities for medium‑sized incumbents and private equity.
- Product and service strategy: The market is bifurcated between equipment suppliers and aftermarket/service providers; success in 2026 will depend on moving up the lifecycle curve into long‑term service contracts and digital monitoring.
- Supply chain and input risk management: Raw material volatility (notably polymer and resin inputs affected by shipping disruptions) requires procurement hedges and alternate sourcing strategies.
- Regulatory compliance planning: Even as broad national emissions inventories show multi‑decadal declines, station‑specific and sectoral rules continue to create pockets of urgent retrofit demand — our regulatory scenario mapping turns those pockets into actionable sales pipelines.
Market dynamics and near‑term catalysts
Three forces will shape decisions in 2026:
Air & Water Pollution Control Equipment Market
- Regulatory evolution and enforcement concentration: Long‑term reductions in criteria pollutant totals (as recorded in recent U.S. EPA inventories) coexist with tighter local and sectoral limits for industrial VOCs, SOx/NOx and particulate matter. This creates persistent demand for both air and water treatment equipment across specific stationary sources even when national totals trend down.
- Technology maturation and modularization: Vendors are increasingly offering modular, skid‑mounted systems and digital monitoring to reduce installation lead times and enable performance‑guarantee contracts. Buyers in 2026 must weigh modular capex vs. bespoke engineering for lifetime economics.
- Input cost and logistics volatility: The May 2026 resin price shock — traced to shipping disruptions — is a timely reminder that polymer‑based components (filters, gaskets, lining materials) can materially affect BOM inflation and project scheduling. Scenario planning for raw material spikes is now a core procurement requirement.
Competitive landscape — what to watch
The space remains populated by a mix of specialized air equipment manufacturers, water technology leaders, and multi‑domain suppliers. Key players profiled in the study include CECO Environmental, Ducon Environmental Systems, Airnord, Thermax, KC Cottrell, Pentair, and HUBER Group. Our strategic read of these firms yields the following implications for 2026 positioning:
Air & Water Pollution Control Equipment Market
- CECO Environmental (Addison, TX) — Strength: diversified filtration and emissions control portfolio (scrubbers, cyclones, biofiltration, thermal oxidizers) combined with aftermarket capabilities. Strategic emphasis should be on converting project wins into longer‑term service streams and on cross‑selling to adjacent end‑markets.
- Ducon Environmental Systems (Farmingdale, NY) — Strength: wet electrostatic precipitators, baghouses and activated carbon systems for industrial stacks. 2026 opportunity: leverage deep application expertise to expand turnkey delivery for refining and petrochemical clients seeking single‑vendor accountability.
- Airnord (Copenhagen) — Background: emerged from a divestment transaction (FLSmidth’s Air Pollution Control business) and retains established tech and customer relationships. Strategic focus: stabilize after transition and exploit European retrofit pipelines where emissions enforcement is most active.
- Thermax (Pune) — Strength: strong presence in industrial air pollution control in high‑growth Asian markets. Competitive pathway: bundle finance and long‑term service agreements to overcome price competition on equipment.
- KC Cottrell (Seoul) — Strength: power‑sector‑grade ESPs, fabric filters, FGD and DeNOx systems. For 2026: target utilities with aging units that face near‑term tightening of emission limits and a need for phased upgrades.
- Pentair (London) — Strength: broad water and wastewater treatment platform with global aftermarket reach. Strategic lever: integrate digital water monitoring and remote service into pricing models to convert municipal and industrial customers to subscription‑like revenue.
- HUBER Group (Berching) — Strength: mechanical and process equipment for municipal/industrial water and sludge treatment. 2026 opportunity: scale into emerging markets with packaged treatment plants that reduce engineering complexity and tender risk.
Recent industry signals — such as demonstrator activity at IE Expo China and forum appearances by Anguil at SESHA — confirm that trade shows remain high‑value deal origination venues. The divestment and rebranding of legacy portfolios are creating windows for agile players to capture market share.
Report contents — practical chapters and tools
PW Consulting’s full report is designed as an operational playbook for executives and includes:
- A comprehensive market model (2020–2025 historical, 2026–2032 forecast) with scenario toggles for regulatory tightening, raw material shocks, and slower capex cycles.
- Segment and regional demand drivers, with end‑user behaviors modeled at the plant‑level (note: detailed segment tables and granular splits are included in the full report and intentionally withheld from this summary).
- Competitive benchmarking: product matrix, installed‑base analysis, win/loss patterns, and aftermarket exposure for the leading vendors profiled above.
- M&A and partnership playbook: valuation multiples observed, integration risk checklists, and a shortlist of acquisition targets by strategic fit.
- Procurement and supply‑chain risk tools: raw material sensitivity analyses, alternative supplier maps, and contracting templates to hedge resin and specialty chemical exposure.
- Practical commercial templates: RFP scorecards, test & commissioning checklists, and KPI frameworks for O&M and performance guarantees.
Strategic implications and recommended actions for 2026
- Implement modular-first product strategies for quick wins: prioritize skid-based systems where permitting and schedule pressure dominate.
- Lock in long‑term service and remote-monitoring contracts to convert one‑time equipment revenue into recurring streams; align incentives through availability-based SLAs.
- Hedge raw material risk: secure secondary polymer sources and include indexation clauses in long‑lead supplier contracts to mitigate sudden resin price moves.
- Pursue targeted bolt‑on M&A where service capability or regional presence can be rapidly combined to improve CR margins; use the CR3/CR5 concentration data to identify consolidation gaps.
- Adopt regulatory scenario planning: build three regulatory tracks (status quo, moderate tightening, aggressive tightening) to stress test procurement and sales pipelines.
- Invest in demonstration projects and local certifications in priority markets to lower vendor switching costs for prospective customers.
- Leverage trade shows and technical workshops — these remain high‑impact channels for lead generation and for shaping procurement specification language.
How PW Consulting can support your 2026 plan
Our consulting engagement is structured to move from insight to execution in 90–120 days: baseline diagnostic (installed‑base, customers, and supplier map), scenario modelling workshops with executive stakeholders, and delivery of transaction‑grade diligence packs or a commercial playbook. For teams preparing capital cycles in 2026, our work translates market forecasts and supplier intelligence into specific project prioritization and a defensible investment thesis.
Next steps — where to get the full data
This article highlights the strategic implications and capabilities contained in PW Consulting’s full research. For the granular market tables, segmented forecasts by region/type/application, supplier financial matrices, and downloadable procurement templates, please consult the full Air & Water Pollution Control Equipment Market report. The executive access version includes the complete datasets and interactive scenario tools that are deliberately withheld from this summary to preserve the actionable value of the primary research.
For detailed analysis of this topic, please visit the official page: Air & Water Pollution Control Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Mixers Market at USD 6.2B in 2025, Poised for 4.5% CAGR to 2032
By PW Consulting, 2026-07-12
Concrete Mixers Market — Strategic Briefing for 2026 Decision-Making
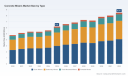
As PW Consulting’s lead industry analyst, I present an executive introduction to our new Concrete Mixers Market study — a forward-looking, decision-oriented intelligence product built to inform capital allocation, R&D prioritization, fleet strategy, and M&A activity through the pivotal year of 2026 and beyond. Grounded in a 2020–2025 historical reconstruction and a 2026–2032 forecast horizon, the study translates raw market movement into operational choices. Our base-year framework (2025) and modeled trajectories capture a market that grew from a global size of approximately USD 4.78 Billion in 2020 to an estimated USD 6.20 Billion in 2025, with projections pointing to roughly USD 8.51 Billion by 2032 at a compound annual growth rate of 4.5% (USD, Billion).
Concrete Mixers Market
Why this study matters in 2026
-
Timing: 2026 is a turning point. Post-pandemic construction rebound, shifting infrastructure priorities, and early electrification pilots are conflating to reshape demand and fleet composition. Decisions made in 2026 will lock in fleets and supplier relationships that shape operational costs for the rest of the decade.
Concrete Mixers Market -
Margin pressure & input volatility: Volatile steel and commodity prices are raising production costs for drums, chassis and batching systems. Procurement and design choices taken now — from material substitution strategies to supplier risk-sharing — will protect margins as volumes normalize.
Concrete Mixers Market -
Technology acceleration: Real-time monitoring, telematics and hybrid powertrains have moved from pilots to commercially visible launches. Early adopters can harvest productivity gains and new service revenues in maintenance and data-driven route optimization.
-
Regulatory and ESG vectors: While full zero-emission concrete mixer trucks are not yet commercially available in some leading markets as of 2026, regulatory focus on emissions and job-site pollution is increasing capital and operating constraints for fleet operators and OEMs.
What PW Consulting’s Concrete Mixers Market report delivers
-
Market sizing and forecasts: A transparent, bottom-up market model covering 2020–2025 historical performance and a 2026–2032 forecast (CAGR 4.5%). We provide scenario runs that stress-test demand against three adoption curves for electrification and volumetric solutions.
-
Segmentation analysis: Discrete breakdowns by product type, application and region to reveal where margin pools and growth pockets reside (note: this executive brief omits detailed subsegment tables; the full report contains the granular splits and proprietary market-share mapping).
-
Competitive landscaping and vendor benchmarking: Strategic profiles, capability matrices, and a partner/competitor heatmap covering OEMs and niche innovators across continuous, volumetric, stationary and truck-mounted mix solutions.
-
Technology and product roadmaps: Assessment of electrification, hybridization, telematics, in-drum monitoring and mobile batching innovations — with lifecycle and TCO implications for fleet operators.
-
Supply chain, cost modeling and procurement playbooks: Practical mitigations for raw-material volatility (steel, hydraulic components) and guidance on contractual arrangements to lock in capacity and cost certainty.
-
Commercial and service strategies: Aftermarket revenue levers, digital subscription models for monitoring systems, and dealer network optimization to increase uptime and lifetime value.
-
M&A/partnership screens: A prioritized list of strategic acquisition and JV targets informed by capability gaps, market concentration (CR3 ~45%, CR5 ~60%) and regional footprint objectives.
Key market dynamics and strategic implications
-
Demand composition and resilience: The market’s recovery path through 2020–2025 demonstrates resilient underlying demand from residential, commercial and infrastructure projects. Growth to 2032 is steady but non-linear — episodic public infrastructure spend and localized construction booms create concentrated windows of high utilization.
-
Product strategy: Manufacturers of continuous and volumetric systems are diverging on go-to-market paths. Volumetric mixers emphasize just-in-time, on-site blending flexibility and reduced waste, while drum and truck-mounted solutions prioritize payload efficiency and scale. OEMs should map product roadmaps to customer segments that value flexibility versus scale.
-
Electrification and hybridization: 2026 has seen the first commercialized hybrid mixers and greater in-drum intelligence. These developments lower operating emissions and improve asset utilization. However, full battery-electric heavy mixers remain constrained by energy density, charging infrastructure and regulatory timelines—meaning pragmatic transition strategies (hybrid pilots, retrofit programs) will win the near term.
-
Telematics and data-as-service: Real-time in-drum monitoring and integrated telematics are maturing into monetizable services — enabling route optimization, quality assurance and SLA-based maintenance. Early adopters can convert telemetry into recurring revenue while differentiating on uptime guarantees.
-
Supply-side fragility: Component concentration and material price swings necessitate multi-sourcing, long-term contracts and design tolerances for alternative materials to preserve margins.
Competitive landscape — who matters and why
-
Established global OEMs: Players with integrated batching, truck-mounted and truck-chassis capabilities continue to dominate on large infrastructure projects due to scale, service networks and product breadth. These firms compete on durability, payload optimization and dealer reach.
-
Volumetric and mobile innovators: Companies focused on volumetric and portable solutions appeal to contractors seeking flexibility, lower waste and minimal dependence on central ready-mix plants. This segment is fertile ground for partnerships with regional contractors and rental chains.
-
Niche disruptors and digital leaders: Startups and specialist manufacturers are differentiating on electrification, lightweight designs, and embedded sensors for asset management. Their ability to iterate quickly and pilot novel business models (e.g., telemetry subscriptions) presents an acquisition or white-label opportunity for larger OEMs.
Representative company positioning captured in our report (illustrative, not exhaustive): Graco with continuous in-plant systems; Zimmerman and ProAll in volumetric/on-site delivery; Vince Hagan and Columbia Machine serving mobile batching and ready-mix producers; Schwing, Putzmeister, CIFA and SANY shaping heavy-duty truck-mounted and batching solutions; Mack and International offering vocational truck platforms; MudMixer, Mix Right and other portable specialists enabling site-level flexibility; Revolution, Chaney and a handful of innovators pushing electrification and in-drum monitoring. Recent 2026 activity validates these dynamics: Chaney’s production-proven hybrid mixer launch (April 2026), Revolution’s in-drum xBOLT™ temperature monitoring integrated with INSIGHT™ (May 2026), Mack Trucks’ expanded concrete mixer lineup showcased at World of Concrete 2026 (January 2026) and ProAll’s new lightweight volumetric L20R (May 2026).
Methodology and scenarios underpinning our forecasts
-
Data foundations: The market model combines public financials, OEM shipment data, dealer inventories, tender pipelines, and primary interviews with fleet operators and construction contractors across the 2020–2025 historical window. Base-year normalization is anchored in 2025.
-
Forecast approach: We apply a blended demand model decomposing volume growth, replacement cycles and equipment intensity per application and region. Forecast sensitivity focuses on three levers: infrastructure spend variance, steel/commodity cost shocks, and pace of electrification adoption.
-
Concentration and competition: Market concentration metrics (CR3 ~45%, CR5 ~60%) inform competitive dynamics — indicating a moderately consolidated market in which large OEMs set technical and commercial standards while smaller specialists maintain pockets of influence.
Actionable recommendations for 2026
-
Refine fleet mix decisions: Run a TCO vs. flexibility assessment to determine the optimal ratio of drum, volumetric and portable assets by project type. Prioritize volumetric pilots where labor scarcity and waste reduction are critical.
-
Pilot hybrid and telemetry programs: Initiate limited fleet trials of hybrid drivetrains and in-drum monitoring to quantify fuel savings, emissions reduction and quality control benefits before scaling.
-
Hedge input risk: Negotiate multi-year agreements with key component suppliers, consider inventory buffers for critical items (drums, hydraulic parts), and review design alternatives to reduce steel dependency where feasible.
-
Build aftermarket revenue: Commercialize telematics, predictive maintenance and performance guarantees as recurring-revenue products. These services materially improve unit economics and customer stickiness.
-
Pursue targeted M&A and partnerships: Use our M&A screens to identify bolt-on acquisitions that close capability gaps (e.g., telematics, volumetric designs) or extend regional distribution.
Next steps and how to access the full intelligence
This brief highlights the strategic frame and core implications from PW Consulting’s Concrete Mixers Market report. The full study contains proprietary subsegment tables, granular regional and application splits, vendor market shares, price curves, and executable playbooks (procurement templates, integration checklists and an M&A target prioritization matrix). If your 2026 planning depends on accurate fleet sizing, supplier selection, technology investment sequencing or M&A screening, the complete report provides the operational detail and datasets required to convert insight into action.
For executives calibrating strategy in 2026: treat this market as structurally steady but tactically volatile. Growth to 2032 is positive, but value capture will be decided by those who manage supply risk, adopt the right mix of electrification and telematics, and convert product differentiation into service-based revenue. PW Consulting’s full-market dossier contains the playbooks you need to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Concrete Mixers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Tubing Set Market to Reach USD 1,370.0M by 2032 at 4.12% CAGR
By PW Consulting, 2026-07-12
Blood Tubing Set Market — Strategic Preview for 2026 Decision-Makers
As healthcare providers, device manufacturers, and investors prepare plans for 2026, the Blood Tubing Set market is entering a phase where modest compound growth masks structurally important shifts in concentration, regulation, and procurement behavior. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — identifies the commercially actionable inflection points that will determine winners and laggards over the coming investment cycle. Our high-level findings: the market expanded from a steady baseline in the early 2020s to exceed USD 1 billion in the 2025 base year and is projected to approach roughly USD 1.37 billion by 2032 under a 4.12% compound annual growth trajectory. That trajectory coexists with a high degree of supplier concentration, making strategic partner selection and operational resilience central to 2026 planning.
Blood Tubing Set Market
Why this analysis matters in 2026
- Decision clarity for capital allocation: The market is growing steadily but not explosively. Firms deciding whether to invest in new manufacturing capacity, automation, or M&A need forward-looking margin and volume scenarios — not just historical growth rates.
- Regulatory and reimbursement alignment: Blood tubing sets remain Class II devices under FDA 510(k) pathways and are embedded in dialysis reimbursement regimes. Regulatory readiness and coding strategy materially affect time-to-revenue and capture rates in tendered contracts.
- Supplier and product risk management: High market concentration raises counterparty risk; a single device correction or supply shock can ripple through procurement networks and contracts.
- Commercial segmentation playbooks: Differences between procurement in dialysis centers vs. hospital systems, product compatibility across dialysis machines, and single-use sterilization logistics create pathways for premium positioning or cost competition.
Report composition — what you get (practical and deployable)
- Concise executive summary with strategic imperatives tailored for manufacturers, contract manufacturers, large buyers (dialysis networks), and private equity.
- Validated market sizing and a transparent forecast model (2026–2032) with scenario and sensitivity modules you can run for alternate price, volume, and raw material scenarios.
- Demand-side analysis covering clinical drivers (CKD prevalence, modality mix), procurement cycles, and pricing dynamics across care settings.
- Supply-side diagnostics: capacity maps, technology footprints (materials, connector systems, airless/low-volume designs), and a supplier risk heatmap.
- Regulatory and reimbursement dossier: FDA pathways, ISO biocompatibility expectations, sterilization validation protocols, and implications for market access timelines and cost-of-goods.
- Competitive intelligence: company profiles, go-to-market archetypes, contract structures, and a playbook to win tenders and long-term supply agreements.
- Actionable commercial plans: pricing levers, tender strategies, cross-sell opportunities, and sample contracting clauses to de-risk supply continuity.
- Strategic M&A and partnership targets, plus diligence checklists focused on manufacturing quality, sterile supply chain, and regulatory histories.
Macro takeaways and near-term dynamics
The forecasted CAGR of approximately 4.12% conceals heterogeneity that matters. Growth is underpinned by stable demand from hemodialysis programs coupled with incremental value capture from product innovation (e.g., airless systems, low-volume tubing, and machine-specific bundles). At the same time, the market exhibits high concentration among a handful of global suppliers, producing clear advantages for incumbent manufacturers but also exposing buyers to supplier-side disruptions. Our concentration analysis shows that the top three suppliers command a substantial share of the market, with the top five even more dominant — a structural fact that tightens competition for smaller players and elevates consolidation as an effective route to scale.
Blood Tubing Set Market
Cost dynamics are pragmatic: manufacturing economics are driven by medical-grade polymer supply and customization levels (connector types, lengths, and machine compatibility). Material unit economics are modest at the per-set level, but they compound across volume and customization complexity; even small changes in raw-material pricing, sterilization method selection, or yield can swing margins materially. All blood tubing sets in the market are single-use and require validated sterilization prior to release (gamma irradiation and ethylene oxide are the mainstream methods), and biocompatibility testing consistent with ISO 10993 is a gating requirement for market entry.
Blood Tubing Set Market
Regulatory and reimbursement context
- FDA: Hemodialysis blood tubing sets are regulated as Class II devices requiring 510(k) submissions demonstrating substantial equivalence. Post-market vigilance and labeling accuracy are increasingly scrutinized.
- ISO: Compliance with ISO 10993 biocompatibility standards is essential for blood-contacting devices; sterilization validation and leachables testing create non-trivial time and cost hurdles.
- Reimbursement: Dialysis procedures are reimbursed under established outpatient codes in major markets. Manufacturers should align pricing models to procedure-level economics and bundle strategies where possible.
Competitive landscape — profiles and strategic implications
- Nipro Corporation (Osaka, Japan) — Nipro offers machine-specific blood tubing solutions designed for close integration with hemodialysis platforms. Their strategy emphasizes component validation and machine compatibility, which supports long-term OEM relationships and replacement part sales. For incumbents and challengers alike, Nipro’s approach underlines the commercial value of device compatibility and OEM certification pathways. ( https://www.nipro-group.com/en)
- B. Braun Melsungen AG (Melsungen, Germany) — B. Braun’s Streamline Airless System and DiaStream product families highlight differentiation through safety and handling features. However, recent events require careful monitoring: in April 2026, an Urgent Medical Device Correction was issued for certain Streamline Airless System and Low Volume bloodlines due to potential microbubble and leakage risks, illustrating how product quality events can create immediate reputational and supply disruptions. ( https://www.bbraun.com)
- Fresenius Medical Care AG (Bad Homburg, Germany) — Fresenius groups product and service strategies, offering integrated blood tubing solutions like the CombiSet SMARTECH, and often bundles disposables with machine sales and service agreements. Their playbook demonstrates how vertical integration and service contracts can create stickiness in buyer relationships. ( https://freseniusmedicalcare.com/en)
Implications: product differentiation (safety, air elimination, low priming volume), machine interoperability, and field support are decisive commercial levers. Quality incidents — even when resolved quickly — can shift procurement toward alternate suppliers or longer qualification processes, amplifying the importance of robust post-market surveillance and rapid field corrective action capability.
Strategic playbook for 2026
- Supply resilience and cost control: Diversify polymer and connector sources, qualify secondary sterilization partners, and build safety stock for critical SKUs. Use the forecast model to stress-test gross margin under raw-material shocks and sterilization pricing changes.
- Regulatory-first product development: Prioritize designs that reduce microbubble risk, ease of priming, and simplified labeling to shorten 510(k) cycles. Invest early in biocompatibility and sterilization validation to avoid costly post-market actions.
- Commercial packaging and contracting: Design bundled offers that tie bloodline sales to service, warranties, or training for dialysis staff — emphasizing total cost-of-use rather than per-set price alone.
- Tender and regional go-to-market: Tailor contract terms by buyer type (chain dialysis centers vs. independent hospitals) and incorporate supply assurance clauses and rapid field-replacement commitments into bids.
- M&A and partnerships: Target niche technology providers (e.g., microbubble mitigation, smart sensors), regional CMOs with validated sterile capacity, or distributors with deep access to dialysis clinic networks.
- Quality and communications: Strengthen post-market surveillance and communications protocols. The April 2026 corrective action by a major supplier underscores how quickly public trust and procurement patterns can pivot following a safety advisory.
How PW Consulting helps execute
Our deliverable is more than a slide deck. We provide an integrated toolkit: an editable financial model with baseline and alternate scenarios; a supplier map with qualification checklists; tender-play templates; a regulatory timeline with required testing and documentation; and a prioritized action matrix for immediate (0–6 months), medium (6–18 months), and strategic (18–36 months) initiatives. All findings are backed by primary interviews with procurement leads, OEM engineers, and sterilization specialists, cross-checked against regulatory filings and publicly available alerts.
Closing — the strategic choice for 2026
For executives planning resource allocation in 2026, the choice is not binary between cost leadership and product innovation. In a market with modest topline growth, concentrated supplier dynamics, and strict regulatory gates, winning strategies will blend disciplined cost engineering with clear, verifiable safety differentiation and supply resilience. PW Consulting’s full Blood Tubing Set Market report provides the granular segmentation, contract templates, supplier risk scores, and model outputs that enable those strategic choices. We have intentionally withheld the detailed segment-by-region and application-level breakdowns from this preview; those granular insights and the downloadable forecast workbook are available in the full report on our portal.
To move from competitive awareness to operational readiness in 2026, stakeholders need a playbook that connects regulatory timelines, procurement cycles, and manufacturing levers — exactly what our study delivers. Contact PW Consulting or visit the full report page to access the complete dataset, scenario models, and supplier diligence materials.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogenated DLC Market to Hit USD 217.9M by 2032 at 5.85% CAGR
By PW Consulting, 2026-07-12
Hydrogenated Diamond-Like Carbon (DLC) Coatings: Strategic Imperatives for 2026
As a strategic advisor at PW Consulting, I present an executive primer that frames our full Hydrogenated Diamond-Like Carbon (DLC) Coating Market study—designed to inform high-stakes decisions in 2026. This piece highlights the report’s analytical depth, synthesizes the market’s macro trajectory, and outlines the pragmatic use-cases that should drive board-level conversations. Per our “trailer” approach, we demonstrate methodological rigor and actionable perspective while intentionally reserving detailed subsegment figures for the full report.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Macro snapshot and trajectory (why numbers matter)
Our analysis uses 2025 as the base year and covers historical performance from 2020–2025 with forward-looking forecasts through 2032. The hydrogenated DLC market shows a resilient growth profile with an underlying compound annual growth rate (CAGR) of 5.85% across the forecast horizon. After a period of volatility in the early 2020s, the market recovered and entered a structural expansion phase driven by multiple secular forces—lightweighting and efficiency demands in mobility, tougher wear performance requirements in industrial tooling, and rising clinical and precision-device applications.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
From a planning perspective for 2026, the headline figures matter because they translate strategic choices into tangible outcomes: a market base in 2025 that supports immediate investment decisions; a mid-single-digit CAGR that justifies staged capacity expansion rather than aggressive overbuild; and a 2032 market endpoint that signals significant, but not explosive, upside—requiring focused, differentiated plays rather than broad market bets.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
What this report delivers — operational and strategic content
- Transparent market sizing and dynamic scenario modelling: calibrated bottom‑up and top‑down approaches with sensitivity analysis for raw-material shocks, production scale, and demand elasticity.
- Actionable segmentation logic: commercial, industrial, and medical use-cases mapped to purchase drivers and adoption hurdles—presented with decision-ready filters (note: detailed subsegment figures are included in the full study).
- Technology and performance roadmap: process comparison (PACVD vs. PVD variants), coating chemistries, deposition economics, and real-world lifecycle testing outcomes that affect TCO and Total Cost of Ownership calculations.
- Supply-chain and manufacturing playbook: vendor evaluation frameworks, capital- and asset-light manufacturing models, and sourcing strategies under different demand scenarios.
- Competitive benchmarking and M&A playbook: scorecards, transaction comparators, and due-diligence templates to accelerate target screening or divestiture planning.
- Regulatory and standards landscape: compliance pathways, testing protocols, and certification timelines relevant to automotive, defense, and medical device buyers.
- Practical tools: downloadable financial model in USD Million, NPV templates, supplier scorecards, and risk matrices ready for board review.
Competitive landscape: positioning the key players
The industry exhibits a balance between global coating specialists and regional applied-surface players. Market concentration is moderate: the three largest players account for roughly 28.5% of market capacity, while the top five represent about 42.1%, signaling a competitive field where technical differentiation and customer relationships are decisive.
- Oerlikon Balzers (Liechtenstein): A leading PACVD player with deep OEM relationships in automotive and aerospace. Their strength lies in scale, robust process control, and a broad global service footprint.
- IHI Group / Ionbond (Switzerland / Japan): Combines coating technology breadth with a strong presence in tooling and precision components. Their portfolio spans both hydrogenated and non-hydrogenated solutions—useful for clients seeking multi-process suppliers.
- Calico Coatings (United States): A specialist focused on hydrogenated a-C:H lines for industrial applications, known for agile customer support and application engineering for mid-market manufacturers.
- IBC Coatings Technologies (United States): Differentiates through testing rigor and military-grade qualifications—an attractive partner for defense and high-reliability industrial segments.
- Acree Technologies (United States): Targets automotive, industrial, and medical niches with applied surface treatments—an option for co-development and localized service models.
- Miba Group / Teer Coatings (Austria): Strong in powertrain and engine component coatings, combining material science with deep OEM integration in mobility powertrain systems.
- CemeCon (Germany): Known for high-performance coatings for toolmaking and wear-critical applications, with a focus on advanced DLC variants and hybrid solutions.
For 2026 execution plans, the critical takeaway is that supplier selection must be made against a matrix of technical fit, capacity responsiveness, geographic service capability, and co-development willingness—rather than purely on headline brand presence.
Strategic recommendations for 2026 decision-makers
Executives evaluating exposure to the hydrogenated DLC opportunity should prioritize the following actions over a 6–36 month horizon.
- Near-term (0–12 months): Run targeted pilot programs with two contrasting supplier archetypes (a global integrator and a nimble specialist) to validate performance claims and quantify unit economics under real operating conditions. Use the report’s pilot checklist and test-protocol templates to accelerate execution.
- Medium-term (12–24 months): Commit to selective capacity or supply agreements only after validated pilots. Structure contracts with performance milestones and shared IP clauses to de-risk capex while preserving upside.
- Mid-to-long-term (24–36 months): Build strategic partnerships for joint development in adjacent coatings (hybrid DLC solutions, multilayer stacks) that target differentiated price-performance for EV powertrains and high-speed tooling segments.
- Cross-cutting actions: integrate the report’s scenario outputs into capex planning, update supplier scorecards quarterly, and institute an IP watch and standards-compliance calendar to anticipate regulatory drift.
Risk matrix and decision levers
Key risks that should influence 2026 decisions are concentration of critical equipment suppliers, potential shifts in raw-material prices, standardization of testing protocols across regions, and the pace of adoption in core end markets (notably automotive powertrain and precision medical devices). The full report provides quantified downside scenarios and mitigation levers—ranging from dual-sourcing strategies to licensing arrangements and flexible manufacturing partnerships.
How to use this report to accelerate value capture
PW Consulting’s Hydrogenated DLC study is built to be operational: boards and strategy teams can use the included financial model to translate adoption scenarios into P&L and cash-flow impacts, use vendor scorecards to accelerate procurement cycles, and apply our M&A playbook to screen targets within days rather than months. The report is particularly useful for executives who must reconcile incremental performance benefits of DLC coatings with capital allocation, supplier risk, and time-to-market constraints.
We designed the public primer to show the analytical frame and strategic implications while preserving the detailed subsegment economics and supplier-level metrics for report subscribers. That deeper intelligence is necessary when you are sizing pilots, negotiating supply agreements, or preparing investment memoranda.
Next steps
- Download the full market model and vendor benchmarks to run custom scenarios for your product lines.
- Request a tailored briefing with our industry analysts to map opportunities specific to your supply chain, product portfolio, and risk profile.
- Use the included pilot checklist and test protocols immediately to de-risk first deployments and capture early learning.
For 2026, the strategic imperative is clear: treat hydrogenated DLC coatings as a performance enabler that requires careful, evidence-based scaling. The PW Consulting study equips decision-makers with the frameworks, data, and tactical tools needed to convert technical advantage into commercial value—while the detailed segment-level intelligence available in the full report supports transactional and operational execution.
For detailed analysis of this topic, please visit the official page: Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Pipes for Oil & Gas Market Set to Reach USD 2,292M by 2032; 6.5% CAGR
By PW Consulting, 2026-07-12
Flexible Pipes for Oil & Gas: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
As the global energy industry transitions into a more complex mix of conventional and low‑carbon strategies, flexible pipes retain an outsized strategic role. PW Consulting’s latest market study — anchored on a 2025 base year and validated across a 2020–2025 historical window — shows the industry growing at a compound annual growth rate (CAGR) of 6.5% through our 2026–2032 forecast. The total addressable market expanded materially in the first half of the decade and is projected to reach approximately USD 2.3 billion (Million-USD unit) by 2032. This brief distils the study’s executive takeaways and explains how the full analysis should inform capital allocations, supplier strategies, and technology bets in 2026.
Flexible Pipes for Oil and Gas Market
Why this study matters for 2026 decisions
- Timing of investment: The market’s steady mid‑single-digit CAGR and the uneven distribution of project awards mean that 2026 will be a decisive year for de‑risking supply and capacity commitments. Early movers who align procurement with validated demand scenarios will capture outsized share while preserving margin.
- Supplier selection & resilience: Consolidation dynamics and capacity constraints have concentrated market power among a few global vendors (our analysis shows the top three players capture a substantive share of market revenue, with the five largest firms controlling a clear majority). Procurement teams must balance performance, certification pedigree, and strategic optionality when selecting partners.
- Material & cost exposure: Polymer feedstock pricing — driven by petroleum derivatives — is a primary margin lever. Firms that adopt active raw‑material hedging, multi‑material qualification, and localized sourcing will protect margins through 2026’s procurement cycles.
- Regulatory and technical gating factors: Compliance with ISO 13628 series and API 17J remains non‑negotiable for unbonded flexible systems. Buyers and technology developers should prioritise certification roadmaps as milestones in R&D and delivery schedules.
What PW Consulting’s full study delivers (practical, actionable)
- Proprietary market sizing and validated historical series (2020–2025) plus scenario‑based forecasts to 2032, with transparent methodology and sensitivity parameters for price, CapEx cycles, and offshore activity.
- Supply‑chain and capacity maps highlighting manufacturing bottlenecks, lead‑time drivers, and logistics choke points for subsea and onshore deployments.
- Cost models down to raw‑material exposure (polymer cost curves), manufacturing overheads, and freight/installation imprints — delivered as downloadable Excel workbooks for quick internal modelling.
- Regulatory matrix and certification playbook outlining timelines and resource implications for ISO 13628 and API 17J compliance, including test‑matrix prioritisation for new materials.
- Vendor benchmarking and capability heatmaps covering technology stack, manufacturing footprint, project track record, and commercial playbooks (bid tactics, warranty structures, and liability exposure).
- M&A and partnership intelligence: target screens, valuation perimeter templates, and integration checklists tuned to flexible‑pipe technologies and composite alternatives.
- Commercial templates and negotiation levers for long‑lead equipment, including recommended contract clauses that protect buyers against polymer price and supply volatility.
- Scenario playbooks: stress‑tested plans for accelerated deepwater build‑out, CO2‑rich field development, and a slower demand path tied to energy transition outcomes.
Competitive landscape — who matters and why
The market is anchored by a set of global system integrators and specialised composite suppliers. Our competitive assessment combines technical capability, commercial footprint, and recent go‑to‑market moves to create an actionable picture for 2026 planning.
Flexible Pipes for Oil and Gas Market
- TechnipFMC (UK): A world leader in flexible-pipe design and supply for subsea risers and flowlines. Recent large contract awards for gas injection risers and combined riser/flowline packages underscore its continued strength on large, integrated offshore projects. For buyers, TechnipFMC represents a low‑execution‑risk partner for complex, deepwater scopes.
- National Oilwell Varco (NOV, USA): NOV has been aggressive on product development, launching high‑pressure flexible pipe lines and entering pre‑commercial agreements for CO2‑resistant solutions with major operators. NOV’s moves make it a technology‑centric option for fields with elevated CO2 or high‑pressure service requirements.
- Baker Hughes (USA): As an established supplier of risers, flowlines, and jumpers, Baker Hughes remains visible in trade shows and industry fora, signalling continued emphasis on system completeness and aftermarket services — a key differentiator for operators seeking single‑vendor accountability.
- Specialist composite players (Strohm, SoluForce, Magma): These firms are advancing bonded thermoplastic and carbon‑fibre composite alternatives. Their offerings are increasingly relevant for projects that prioritise weight reduction, fatigue performance, or aggressive chemical environments. Expect selective partnerships with majors on early‑adopter field trials.
- Established diversified suppliers (ContiTech, Shawcor, Prysmian): These vendors provide industrial‑scale manufacturing and broad product portfolios. They are often competitive on price and logistics for high‑volume onshore and nearshore applications.
Collectively, the top three players capture a significant slice of the market, while the top five widen that concentration further — a structure that shapes competitive dynamics, pricing, and procurement leverage.
Flexible Pipes for Oil and Gas Market
Key market dynamics and risks to monitor in 2026
- Material volatility: High‑density polyethylene remains the dominant raw material platform for flexible systems; material price swings directly alter production economics. Companies should model polymer price scenarios as a first‑order sensitivity in capex and pricing strategies.
- Deepwater acceleration and steel substitution: Continued deepwater developments and a preference for polymer/composite replacements for certain steel components are meaningful demand drivers, but they require demonstrable life‑cycle performance and qualification evidence.
- Standards and certification: ISO and API standards are gating factors for acceptance on many projects. Late or under‑resourced certification programs are a common cause of project slippage and cost overruns.
- CO2 and aggressive chemistries: Fields with high CO2 concentrations are catalysing innovation in CO2‑resistant flexible solutions. Early movers in material qualification will secure first‑mover advantage on niche but high‑value projects.
- Supply and capacity risks: Lead times for specialised manufacturing, coupled with concentrated fabrication capacity, create upside risk in a rapid demand cycle; conversely, a demand pause exposes high‑fixed‑cost producers to margin compression.
How executive teams should use the report in 2026
- Investment prioritisation: Use our scenario outputs to identify which project portfolios warrant bespoke flexible‑pipe investment, and which are better served by contracted supply or composite trials.
- Sourcing & contracting: Adopt our contract templates and supplier scorecards to lock down multi‑year supply with price‑adjustment mechanisms tied to polymer indices and milestone‑based acceptance tests.
- Technology strategy: Prioritise R&D spend on qualification areas with fastest path to commercial acceptance (CO2 resistance, fatigue life, and third‑party certification).
- M&A and partnerships: Leverage our target screens and integration playbooks to identify bolt‑on acquisitions that fill capability gaps (e.g., composite fabrication, testing labs, or regional spool capacity).
- Risk management: Integrate the report’s stress cases into CapEx approval processes and board reporting to ensure that downside scenarios are modeled in funding and contract structures.
What we intentionally withhold here — and why
To preserve actionable value for decision makers, this executive brief demonstrates the study’s methodological rigor and strategic implications while intentionally refraining from publishing granular regional and application‑level splits or core segment dollar amounts. Those detailed breakdowns — including regional market allocations, type/application perfor‑mance, vendor scorecards with quantitative rankings, and the downloadable modelling workbooks — are contained in the full PW Consulting report and interactive dashboard. This “teaser” approach is designed to give you clear insight into the study’s conclusions and to protect the ready‑to‑use intelligence that will inform bidding, sourcing, and M&A activity.
Next steps — making the study work for your 2026 plan
- Request the full report and the accompanying Excel models to run company‑level scenario tests against our base, upside, and downside forecasts.
- Schedule a tailored workshop with our market and technical teams to align vendor strategies, certification roadmaps, and procurement timelines to your project milestones.
- Use our vendor benchmarking to short‑list partners for pilot programmes on CO2‑exposed or deepwater fields where material and fatigue performance are critical.
PW Consulting’s Flexible Pipes for Oil & Gas Market study is structured to be immediately operational for 2026 decision cycles — translating market forecasts, standards compliance, vendor positioning, and material economics into executable procurement, investment, and R&D choices. To access the full datasets, vendor scorecards, and downloadable modelling tools, please visit the PW Consulting report portal or contact our industry team to arrange a private briefing.
For detailed analysis of this topic, please visit the official page: Flexible Pipes for Oil and Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Electronic Power Steering Market — Strategic Primer for 2026 Decision-Makers
By PW Consulting — Senior Strategy & Industry Analysis
Automotive Electronic Power Steering Market
Executive preview
The transition to electric, software-defined, and safety-integrated steering architectures is no longer a distant industry storyline — it is the operating context for 2026 planning cycles. Our Automotive Electronic Power Steering (EPS) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, supplier strategy, regulatory dynamics, technology inflection points and procurement playbooks into an actionable roadmap for OEMs, Tier‑1 suppliers, investors and policy teams. The market grew from approximately USD 198.0 Million in 2020 to USD 273.7 Million in 2025 and is forecast to expand to USD 286.6 Million in 2026 and reach roughly USD 397.0 Million by 2032, implying a compound annual growth rate (CAGR) of about 5.57% over the forecast horizon. Market concentration remains high: the top three firms control an estimated 78% of reported revenues, while the leading five account for around 90% — a structural characteristic that shapes negotiating power, innovation diffusion, and M&A dynamics.
Automotive Electronic Power Steering Market
Why this study matters for 2026 strategy
Two planning realities define urgency in 2026. First, regulatory and safety mandates are accelerating EPS adoption and functional complexity, converting what was a mechanical cost‑center into a strategic chassis and software development area. Second, architectural convergence (EPS + ADAS + steer‑by‑wire readiness) is creating winner-take-disproportionate returns for suppliers who can deliver integrated, validated systems at scale. Our research translates those realities into three pragmatic decision levers for 2026:
Automotive Electronic Power Steering Market
- Resource allocation: whether to build, buy, or partner for steer‑by‑wire and torque‑overlay capabilities;
- Supplier strategy: how to structure long‑term contracts, local footprint and co‑development terms to secure supply and update cycles; and
- Product and IP planning: where to invest in sensor fusion, solid‑state sensing, and software safety stacks to protect up‑front engineering spend and post‑launch margins.
Market trajectory and implications
The EPS market has demonstrated resilient expansion through 2020–2025, accelerated by electrification and CO2 compliance drivers. The modest but steady CAGR of 5.57% forecast for 2026–2032 masks important structural shifts: unit growth is being compounded by rising electronic content per vehicle, higher validation costs for safety-rated torque overlay, and the premium commanded by steer‑by‑wire subsystems. For 2026 boardrooms, the implication is clear — growth is not simply about volume; it is about value capture within the system stack (mechanical, electromechanical, power electronics, and software).
Regulatory and standards tailwinds
Recent regulatory moves materially reshape product roadmaps and procurement criteria. Notable policy inflection points include tightened CO2/efficiency regimes and new safety assessment protocols that implicitly favor electronic steering solutions over hydraulic systems. Additionally, vehicle safety rating bodies now treat lane‑keeping assistance functionality as a rated feature, which creates technical prerequisites (such as EPS torque overlay and redundancy) for OEMs seeking premium safety scores. These regulatory constraints convert product reliability and software determinism into commercial differentiators.
Technology convergence and supply‑chain effects
Material advances (higher‑strength gear materials, precision manufacturing) and sensor evolution (solid‑state and sensor‑fusion approaches) are simplifying architectures while improving NVH and durability. At the same time, steer‑by‑wire development is transitioning from lab demonstrations to series production — an inflection that carries new supplier roles (actuator integrators, backup power architects, safety‑certified software houses). This convergence amplifies two operational realities for 2026:
- Up‑front validation budgets and functional safety certification timelines will constitute a larger share of program CAPEX, necessitating earlier alignment between OEM system architects and chosen Tier‑1 partners;
- Sourcing strategies must incorporate software SLAs, cybersecurity roadmaps, and hardware redundancy plans in addition to traditional mechanical supply metrics.
Competitive landscape — what the leading players signal
The EPS supplier base shows a dual structure: a small group of global incumbents with system breadth and validation depth, and a broader tier of regional specialists focusing on cost and volume. Key global players include established system integrators and component specialists that are actively competing on system performance, ADAS integration and steer‑by‑wire readiness. Recent industry movements underline who is closest to commercialization and how competition is evolving:
- Nexteer Automotive: expanding its product suite for heavier vehicles and moving to series production for steer‑by‑wire programs — an indicator that full drive‑by‑wire is pushing into mainstream OEM platforms.
- Robert Bosch GmbH and ZF Friedrichshafen AG: continuing to iterate on integrated EPS+ADAS solutions and leveraging their systems know‑how to anchor OEM relationships across vehicle segments.
- Japanese incumbents (NSK, JTEKT, Denso): emphasise precision, force‑feedback and backup power solutions, with validated subsystems already embedded in premium BEV and PHEV programs.
- Asia‑Pacific suppliers (Mando, Hyundai Mobis, China Automotive Systems): pursuing aggressive volume and localization plays, evidenced by recent volume shipments and regional contract awards.
These dynamics produce a two‑track competitive field. Track one: system integrators that compete on validated steer‑by‑wire platforms and safety‑certified software ecosystems. Track two: high‑volume suppliers that deliver cost‑optimized EPS iterations for mainstream platforms but must now invest to remain relevant as content per vehicle rises.
Recent developments — what they reveal about timing and risk
Concrete examples from 2025–2026 reveal the timing of commercialization and the nature of contract opportunity windows:
- A leading supplier’s series production launch of a steer‑by‑wire system in 2026 signals that certification and OEM validation cycles are moving from multi‑year pilot phases into production ramps; procurement teams should expect new qualification gates on supply contracts.
- Product portfolio expansions and OEM validations in 2025–2026 show that suppliers are layering high‑output and backup solutions into existing product families, compressing the time between prototype and production readiness.
- Volume shipment contracts between regional suppliers and global OEMs demonstrate that localization and scale are win conditions in certain geographies — and that cost pressures remain front and center despite added electronic content.
Taken together, these moves indicate that 2026 is an inflection year where early movers will capture platform positions and late movers face elongated, more expensive catch‑up investments.
Actionable intelligence contained in the full study
The report provides operational tools designed to shorten decision cycles and de‑risk investments:
- Proprietary market sizing and scenario model (USD, revenue unit: Million) that allows users to run sensitivity analyses across regulatory, material cost, and pace‑of‑adoption assumptions for 2026–2032;
- Supplier scorecards and supplier SWOTs focused on systems delivery, functional safety track record, software capability and global footprint;
- Program playbooks covering build vs. buy thresholds, qualification milestones, and sample contract terms for tiering and co‑development;
- Risk heatmaps and mitigation blueprints for supply chain, IP, and regulatory compliance; and
- Financial impact snapshots for OEMs and suppliers showing margin implications of increased ESW (electronic steering weight) and validation overhead.
The full deliverables include an interactive Excel model, a procurement checklist for 2026 programs, and a buyer’s guide to structuring partnerships around steer‑by‑wire and torque‑overlay requirements.
Strategic recommendations for 2026 planning
Based on the synthesis of market growth, competitive positioning and regulatory pressures, PW Consulting advises stakeholders to prioritize the following actions this year:
- Establish a clear systems roadmap that aligns EPS hardware and software milestones with ADAS development timelines — treating steering as a joint mechanical‑software program rather than a discrete hardware procurement.
- Secure at least two qualified suppliers for critical EPS subsystems to mitigate single‑point risks, and negotiate staged IP/royalty sharing to balance upfront engineering costs with long‑term licensing exposure.
- Invest selectively in solid‑state sensing and actuator reliability testing facilities or partner with test houses to shorten validation cycles and improve time‑to‑market.
- For investors and M&A teams: prioritize targets that combine software safety stacks with scalable actuator manufacturing; for OEMs: favor suppliers with demonstrated series production capability for steer‑by‑wire if premium safety and autonomy packages are strategic priorities.
- Embed regulatory monitoring into project gating. With emission and safety protocols now directly influencing steering architecture decisions, early regulatory alignment avoids late redesigns and resale impact.
Closing — the strategic value of this research
The EPS ecosystem is evolving from a component market to a systems battleground. For 2026, decisions about engineering investment, supplier structure and platform differentiation will determine whether organizations capture the increased electronic content value, or become price takers in a concentrated supplier market. Our study offers a pragmatic, scenario‑based foundation for those decisions: robust market sizing (USD, revenue unit: Million), competitor diagnostics, regulatory impact mapping, and a practical set of procurement and engineering playbooks. This briefing demonstrates the depth of analysis you can expect; the full report contains the confidential, segment‑level data and interactive models necessary to operationalize strategy. Visit our source page to access the complete study and the supporting analytical toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Portable Toilets Market to Hit USD 327.72M by 2032 at 7.94% CAGR
By PW Consulting, 2026-07-12
Portable Toilets Market 2026: Strategic Insights for Action — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our full Portable Toilets Market study — an evidence‑based roadmap intended to shape high‑confidence commercial decisions in 2026. This preview conveys the report’s core takeaways, the decision levers executives must prioritize, and why immediate action will materially affect revenue, cost and risk profiles over the next planning cycle. To preserve the tactical advantage embedded in our proprietary segmentation and scenario models, the granular sub‑segment matrices and vendor scorecards are reserved for the full report.
Portable Toilets Market
Why this market matters in 2026
The portable toilets market is transitioning from a largely transactional rental industry to a technology‑enabled, sustainability‑driven ecosystem. After a steady recovery period in the early 2020s, the market reached a meaningful scale in our base year (2025) and is now on a structurally higher growth trajectory. Our topline model shows the global market moving from the 2025 base through the forecast period (2026–2032) at a compound annual growth rate (CAGR) of 7.94%. Under our central forecast, that trajectory drives the market toward roughly USD 327.7 million by 2032.
Portable Toilets Market
Two structural shifts underpin this growth: first, the professionalization and consolidation of rental and servicing models; second, accelerated product innovation around vacuum systems, luxury sanitation, ADA compliance, and circular manufacturing. Together these forces increase average revenue per unit, create higher aftermarket revenue streams (consumables, deodorants, servicing subscriptions), and raise barriers to entry for low‑cost incumbents.
Portable Toilets Market
What the full study delivers: pragmatic, transaction‑ready intelligence
PW Consulting designed this study to be directly actionable for C‑suite, corporate development, procurement, and field operations teams. The full report contains:
- Topline market sizing and a seven‑year forecast with scenario sensitivity (base, upside, downside) and clear assumptions tied to construction activity, live events recovery, and regulatory pacing.
- Unit economics models for rental fleets (capex, opex, utilization) and ROI breakeven timelines by equipment class.
- Segmentation matrices across product type, application, and region — with elasticities on price, service frequency, and maintenance intensity. (Note: detailed segment share tables are available in the full report.)
- Competitive landscaping and a ranked M&A target list with valuation heuristics, integration risks, and synergies (cost, route density, cross‑sell potential).
- Procurement playbooks — supplier scorecards, sourcing strategies for recycled polymer inputs, and mitigation steps for raw‑material volatility.
- Regulatory and tender tracker covering municipal bid behavior, tax treatments, ADA compliance trends, and environmental permitting that materially affect service obligations.
- Operational blueprints for digitalization: telematics, fill‑level sensing, predictive routing and staffing models that reduce empty miles and service costs.
- Risk matrices covering supply chain, labor, environmental fines, and reputational risk — with mitigation playbooks tailored to rental operators, manufacturers, and event planners.
Competitive landscape: consolidation runway and capability gaps
The market remains moderately fragmented: concentration metrics show that the top three firms account for under one‑quarter of global share, with the top five still well below one‑third of the market. This dispersion creates both acquisition runway for scale‑seeking players and white‑space for differentiated product and service plays.
- PolyJohn (Whiting, Indiana) — A manufacturing stalwart known for portable toilets, sinks, and accessories. Its February 2026 acquisition of EcoFab signals a deliberate expansion into advanced vacuum toilet systems, accelerating its product roadmap and creating a technology arbitrage opportunity for customers seeking lower water usage and improved odor control.
- Satellite Industries (United States) — The largest manufacturer with a broad portfolio spanning restroom trailers, septic trucks, modular solutions and consumables. Satellite’s scale in both hardware and aftermarket supplies positions it as a one‑stop provider for large event and municipal contracts.
- United Site Services (USS) (United States) — The nation’s leading rental provider; strong in standard and ADA‑compliant offerings. USS’s route density and national footprint deliver operational advantages for time‑sensitive tenders but leave opportunity to increase per‑unit profitability through tech‑enabled services.
- Rumpke (Cincinnati, Ohio) — A provider leveraging recycled plastic in unit manufacture and offering VIP trailers and ADA units. Rumpke’s focus on circular inputs aligns with corporate sustainability mandates and creates differentiation where green procurement criteria influence public and private tenders.
- WM (United States) — The broader environmental services firm provides portable sanitation as part of an integrated waste services portfolio. WM’s bundled selling approach is especially effective in construction and long‑duration municipal engagements.
- Stallion Infrastructure Services (United States) — A niche provider of premium and high‑rise solutions and luxury trailers. Stallion illustrates a viable premiumization path that captures higher margins in event and hospitality verticals.
Together, these players illustrate three playbooks that will shape M&A and competitive strategy in 2026: scale consolidation (roll‑ups to capture route density), technology plays (vacuum systems and telematics), and premium/sustainability verticalization (luxury units, recycled materials, and compliance solutions).
Market dynamics that will dictate near‑term strategic moves
- Sustainability and circular manufacturing: Manufacturers increasingly use blow‑molding with recycled plastics for unit bodies. This is not only a marketing differentiator but a procurement lever — clients with ESG targets will prefer vendors with demonstrable recycled content and end‑of‑life recovery programs.
- Regulatory and municipal procurement: Several US municipalities issued tenders for portable toilet rental and servicing for 2026 (including county and municipal bids). In some jurisdictions, rental services receive tax treatment that materially affects contract economics. Firms should map local tax and tender cycles into their go‑to‑market calendars.
- Product innovation and performance: Vacuum toilet systems and luxury flushing units are moving from pilot projects to commercial deployments. These technologies change utilization patterns (longer productive life, different cleaning cadence) and create aftermarket service opportunities.
- Digital operations: Telematics (fill‑level sensors, route optimization) are proven ROI drivers. Early adopters cut empty‑mile costs substantially and improve responsiveness in event deployments.
Strategic implications and recommended 2026 priorities
For executive teams planning 2026 initiatives, our study prioritizes the following actions — each paired with practical KPIs that appear in the full report:
- Adopt a differentiated fleet strategy: Segregate assets into cost‑efficient standard units and higher‑margin premium or vacuum units. Track utilization, maintenance cost per service, and PPE & consumable attachment rates. Run pilots to quantify margin differentials before large‑scale fleet transitions.
- Make targeted technology investments: Invest in telematics across a representative fleet cohort to validate savings in routing and servicing. Shortlist vacuum and advanced flushing systems for high‑value contracts where water scarcity or hygiene standards are non‑negotiable.
- Pursue consolidation where route density creates synergy: Use the full report’s M&A heatmap to identify targets with complementary geographies, under‑utilized fleets, or strong public tender pipelines. Expected outcomes include faster route density improvements and cross‑sell into events and construction segments.
- Embed circular procurement and recycling economics: Negotiate recycled polymer supply contracts and secure takeback agreements. Incorporate lifecycle emission metrics into bids to win ESG‑weighted tenders.
- Revise commercial models for municipal and large event contracts: Account explicitly for local tax treatments, compliance obligations, and service frequency requirements. Structure multi‑year pricing with CPI or input‑price collars.
- Develop aftermarket and consumables revenue streams: Bundled servicing, deodorant subscriptions, and preventive maintenance plans increase ARPU and create more predictable revenue.
How to use this preview — and the next step
This preview is intended to align leadership around the strategic tradeoffs and near‑term priorities we see as essential in 2026. The full PW Consulting Portable Toilets Market report provides the playbooks, models, and deal scoring required to execute these moves with confidence — including:
- Detailed segment economics and pricing sensitivity tables;
- Vendor scorecards and M&A target dossiers with integration checklists;
- Operational templates for telematics deployment and route optimization pilots;
- Regulatory tender calendars and a matrix showing tax and compliance impacts by jurisdiction.
Leaders preparing budgets or pursuing M&A in 2026 should treat this study as prescriptive: the difference between incremental improvement and meaningful market capture will come from combining fleet modernization, targeted acquisitions, and service innovation — executed with a clear, data‑driven plan. For organizations that want to convert these insights into a 100‑day plan, PW Consulting offers tailored workshops and scenario modeling to operationalize the findings.
Closing perspective
The portable toilets sector is no longer a low‑margin, commoditized corner of services. It is evolving into a modular, capital‑efficient market where technology, sustainability and tender‑savvy operators will earn a disproportionate share of growth. With the market growing at an expected 7.94% CAGR through 2032 and compelling opportunities for differentiation across product, service and geographic plays, 2026 represents a critical inflection year. PW Consulting’s full report equips decision‑makers with the actionable intelligence required to convert that inflection into durable competitive advantage.
For access to the full dataset, proprietary segment breakdowns, and the operational playbooks referenced here, please contact PW Consulting. The detailed annexes and vendor scorecards are provided exclusively with the full research package.
For detailed analysis of this topic, please visit the official page: Portable Toilets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrafast Lasers Market to hit USD 6,887 Million by 2032 (16.62% CAGR)
By PW Consulting, 2026-07-12
Ultrafast Lasers Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this strategic preview of our Ultrafast Lasers Market study to help executive teams, corporate development units, and R&D leaders prioritize decisions in 2026. The objective here is to surface the high-fidelity signals that matter—market trajectory, competitive positioning, structural risks, and where actionable value can be captured—while reserving the full segmented detail for the primary report. Think of this as a briefing trailer: rigorous, directional, and designed to accelerate a decision to obtain the full playbook.
Ultrafast Lasers Market
Market trajectory and what it means for 2026
Ultrafast lasers are in a clear growth phase. Using 2025 as the study base year, the global market expanded materially through the first half of this decade, and the outlook from 2026–2032 is robust. Our model (USD, revenue unit: Million) shows the market crossing the multi-billion-dollar threshold in the late 2020s and accelerating toward several billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate of approximately 16.6%, reflecting sustained demand across materials processing, medical & healthcare, scientific research, and advanced electronics.
Ultrafast Lasers Market
Why this matters for 2026 decisions:
Ultrafast Lasers Market
- Capital allocation windows are open now. A double-digit CAGR means earlier movers can secure development, capacity, and contracts at terms that will be harder to obtain later as demand concentrates.
- Product roadmaps that hit market readiness in the 2026–2028 window are positioned to capture disproportionate share as adoption curves steepen.
- Supply chain and regulatory constraints (detailed below) create optionality value for firms that can build resilient sourcing and compliance capabilities in 2026.
Competitive landscape — who matters and why
The ultrafast lasers market exhibits moderate concentration: the top three firms account for a majority share of industrial revenue, and the top five together hold an even larger portion. This concentration creates two strategic realities—market leaders can shape price, standards, and channel structures, while mid-tier and niche players can capture value by specializing in adjacent segments or by offering integrated solutions that reduce customer switching costs.
Principal companies we track (representative profiles):
- Coherent Corp (United States) — Offers a complete range of ultrafast scientific oscillators and amplifiers across research, OEM, and industrial channels ( https://www.coherent.com).
- TRUMPF (Germany) — Strong in industrial materials processing and precision manufacturing solutions, with deep machine-integration expertise ( https://www.trumpf.com).
- IPG Photonics (United States) — Known for compact, cost-effective ultrafast fiber lasers optimized for microprocessing and industrial usage ( https://www.ipgphotonics.com).
- Amplitude Systèmes (France) — Femtosecond systems leader focused on micromachining and medical device applications ( https://amplitude-laser.com).
- Ekspla (Lithuania), NKT Photonics (Denmark), Light Conversion (Lithuania), Menlo Systems (Germany), IMRA America (United States), Clark-MXR (United States), Thorlabs (United States) — each brings specialized product, systems, or OEM engineering capabilities relevant to targeted use cases (see full profiles in the report).
Recent competitive moves highlight evolving battlegrounds:
- IPG Photonics showcased ultrafast innovations at Laser World of Photonics in mid-2025 and won a major SPIE award in May 2026 for a high-power compact source—signaling continued R&D and branding momentum in high-power fiber solutions.
- NKT Photonics has moved from product delivery into strategic partnerships, notably delivering subsystems to a quantum computing supplier—an example of lasers enabling adjacent high-value ecosystems.
- IMRA America’s 2026 Foreign-Trade Zone production notification in Michigan signals onshoring of femtosecond fiber manufacturing capacity within the U.S., with implications for lead times, compliance, and U.S. supply resilience.
Structural headwinds and operational risks (and practical mitigations)
Several non-market forces will shape winners and losers in 2026. Our study integrates these "industry context" factors and provides playbooks to mitigate them.
- Regulatory constraints: Certain optical sources and components fall under defense-related export controls (e.g., items identified on the U.S. Munitions List), raising ITAR/ export compliance costs and limiting go-to-market pathways for some advanced products. Strategic recommendation: establish a compliance-first product taxonomy and segregate export-controlled product lines from those that can scale globally without restrictions. The report includes a compliance checklist and decision tree for product development and partnership selection.
- Labor and skills gap: Skilled labor shortages for precision assembly and optical engineering constrain scaling. Tactical moves: partner with regional universities for apprenticeship programs, invest in automation of repeatable assembly stages, and design modular subsystems that reduce manual integration time. We quantify the trade-off between automation CAPEX and shortened time-to-revenue in our financial models.
- Raw material and supplier constraints: Lead times for specialty components (nonlinear crystals, gain media, precision optics) remain extended. Mitigations include strategic inventory hedging, dual-sourcing programs, and selective vertical integration for “bottle-neck” components. The report maps supplier concentration and recommends which components are priority candidates for in-house production versus long-term contracts.
- Supply chain fragility: Low-volume, high-risk commodity supply chains require collaborative risk sharing. Recommended approaches: develop supplier scorecards tied to performance SLAs, invest in supplier development, and use geographically diversified sourcing to minimize single-point failures.
Commercial and product strategy recommendations for 2026
Based on scenario modelling, customer interviews, and technology assessments, firms should prioritize the following:
- Define a two-track product strategy: (1) defend and extend core modules for established industrial customers (service contracts, integrated laser-heads, system-level guarantees), and (2) accelerate a “disruptor” line aimed at high-growth pockets (consumer electronics microprocessing, advanced medical device manufacturing, and quantum subsystem suppliers). The full report provides a timeline-driven roadmap and R&D milestones for each track.
- Negotiate supplier financing and forward-purchase contracts in 2026 to lock down critical optics and pump diodes; include clauses for demand-growth scalability. Our procurement playbook includes model contracts and sensitivity analyses for price and lead-time volatility.
- Leverage partnerships with OEM integrators and system houses to provide bundled solutions that reduce customer integration risk; value-capture models in the report quantify margin uplift from systems sales versus component sales.
- Pursue targeted M&A or strategic JV plays focused on thin but critical capabilities—nonlinear crystals, compact amplifier modules, or real-time beam-monitoring electronics—rather than broad, horizontal consolidation. The report ranks acquisition targets by strategic fit and integration complexity.
What PW Consulting’s full study delivers (practical, executable content)
This preview highlights themes; the full Ultrafast Lasers Market report contains the operational tools that senior teams will use to act in 2026:
- Detailed market-sizing and validated demand scenarios (historical 2020–2025 base, forecast 2026–2032, revenue unit: USD Million) and sensitivity runs tied to adoption curves.
- Go-to-market playbooks for product, pricing, and channel strategies across industrial, medical, scientific, and electronics end-markets.
- Supplier and component maps with recommended sourcing strategies, dual-sourcing candidates, and suggested inventory policies to manage lead-time risk.
- Regulatory and compliance roadmaps (including ITAR/export-control decision trees) and an implementation checklist for product development and international sales.
- Commercial models—TCO, pricing elasticity, and ROI calculators—designed to evaluate leasing vs. outright sale, service tiering, and spare-parts strategies.
- Competitor dossiers with capability matrices, recent strategic moves, and M&A targets, plus stakeholder matrices to support diligence and negotiations.
- Operational playbooks for workforce upskilling, automation deployment, and quality-management practices specific to ultrafast laser assembly and testing.
How to use this preview in your 2026 planning cycle
If you are budgeting, negotiating supplier contracts, or refining your product roadmap for 2026, use this preview to:
- Accelerate capital allocation decisions for R&D and capacity by referencing the market’s growth trajectory and the timing of opportunity windows in the next 24 months.
- Prioritize compliance and supply-chain programs now; regulatory and sourcing lead times will materially affect your time-to-market.
- Prepare tactical M&A playbooks focused on capability fills rather than market share grabs—our scenarios show higher near-term ROI from bolt-on capabilities that shorten customer integration cycles.
Next steps — how PW Consulting can help
For teams ready to act in 2026, PW Consulting offers tailored briefings, acquisition diligence support, supplier negotiation workshops, and integration planning built from the full study. The complete report contains the granular segmented data, exact regional and application breakdowns, and financial schedules you’ll need to finalize investments and contracts. Use this preview to align executive priorities—then commission a customized deep-dive to convert strategy into executable programs.
In short: the ultrafast lasers sector is entering a phase where technological leadership, supply-chain resilience, and regulatory-savvy commercialization will define value creation. The market’s growth dynamics make early 2026 the decisive moment to set the terms of competition for the latter half of this decade.
For detailed analysis of this topic, please visit the official page: Ultrafast Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zener Diodes Market to Reach USD 1,063.11 Million by 2032 at 4.2% CAGR
By PW Consulting, 2026-07-12
Zener Diodes Market 2026: Strategic Imperatives for Decision Makers
Market snapshot
The Zener diodes market has moved from a compact specialty segment into a core building block of modern power-management and protection architectures. Our baseline analysis (base year 2025) shows the market expanding from roughly USD 654 million in 2020 to USD 797 million in 2025, and, under our central forecast, progressing to approximately USD 1,063 million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 4.2% across the 2026–2032 projection window. That steady, mid-single-digit expansion masks important inflection points—miniaturization, automotive qualification, and transient-protection demand driven by large-scale compute and communications deployments—that will define competitive advantage in 2026 and beyond.
Zener Diodes Market
Why this research matters for 2026 decisions
- Strategic clarity in a fragmented market: With the market exhibiting modest overall growth and a relatively low top-player concentration (CR3 ~25.4%, CR5 ~33.0%), there is room for both incumbents and focused challengers to expand share. However, scale alone is insufficient; product differentiation and go-to-market agility matter more than ever.
- Design-to-supply alignment: 2026 will be the year many OEMs consolidate system-level design choices (power islands, transient suppression strategies, and packaging standards). Choosing a Zener strategy now determines qualification timelines, inventory commitments, and total cost of ownership through 2028.
- Risk calibration against structural shocks: Supply-chain disruptions and demand spikes (notably from AI server motherboard procurement cycles) have and will continue to create asymmetric lead-time and pricing pressures. Buyers who align sourcing and design-in strategies with resilient suppliers will sustain lower product-development friction.
Macro dynamics shaping vendor and buyer strategies
- Miniaturization and packaging technology: Leadless and sidewall-plated packages such as DFN variants are becoming standard in designs where board real estate is constrained. Suppliers introducing robust, miniaturized packages gain preferential design-ins for portable and space-constrained applications.
- Automotive and reliability qualification: AEC-Q101 and PPAP capability are now de facto requirements for suppliers targeting automotive and certain industrial segments. Products with explicit automotive qualification reduce customer lead time to production and unlock higher-margin segments.
- Precision and low-noise variants: Tight-tolerance devices (±1%–±2%) and low-bias-current series are moving from niche to mainstream as sensor interfaces and high-speed digital front ends demand cleaner, more predictable clamping and regulation behavior.
- Supply chain pressure points: Recent industry data indicate dramatic lead-time inflation for certain suppliers—where single-digit-week leads stretched into the 48–52+ week band—while pricing rose materially (noted increases around 20% in affected lines). This dynamic is concentrated in components servicing AI compute and similar high-velocity markets, but the spillover affects broader supply availability and commercial terms.
- Process control and manufacturability: Suppliers demonstrating high maturity (for example, validated Cpk metrics in qualification runs) materially reduce qualification risk and offer a faster ramp to production. This is a decisive selection criterion for large OEMs.
Competitive landscape — what to watch in 2026
The competitive field mixes global diversified semiconductor houses with focused discrete specialists. Across the leading players we track, several capability tiers and strategic postures have emerged:
Zener Diodes Market
- Broad portfolio and systems play: Companies such as Texas Instruments and Microchip position Zener diodes within a broader protection and power-management portfolio. Their recent product introductions and data-sheet promotions in early 2026 underscore an integrated protection strategy that speaks to system architects seeking single-vendor simplicity.
- Form-factor and precision differentiation: Vishay and Diodes Incorporated are leveraging packaging and process improvements—leadless DFN packages, sidewall plating, and ion-implanted epitaxial processes—to offer smaller, tighter-tolerance devices. These moves address miniaturization and precision demands in consumer, industrial, and automotive segments.
- Automotive and reliability-focused specialists: Toshiba and Nexperia are pushing AEC-Q101-qualified lines, ±1% tolerance families, and low-bias/low-noise variants explicitly aimed at automotive and high-reliability industrial applications. Their product roadmaps shorten qualification cycles for customers that require PPAP-capable supply.
- Discrete and transient protection specialists: onsemi and other discrete-focused vendors continue to compete on transient robustness, multi-device configurations (e.g., dual common-cathode), and portfolio depth for power-management customers.
Recent product and portfolio moves bear attention: Texas Instruments’ 2026 introduction of Zener devices as part of an expanded protection lineup, Toshiba’s November 2025 CMZBxxA series for surge and switching protection, Vishay’s October 2025 DFN1006-2A package expansion, and Diodes Incorporated’s December 2025 tight-tolerance surface-mount updates all signal where customer demand and R&D investment are converging.
Zener Diodes Market
Strategic implications and recommended actions for 2026
- Supplier portfolio optimization: Blend a small set of high-capability, automotive-qualified suppliers with a flexible second-tier network to balance qualification speed and price leverage. Prioritize suppliers demonstrating mature process control metrics and who communicate lead-time transparency.
- Design-for-availability: Standardize on a limited set of package families and tolerance classes across platforms to ease cross-platform inventory pooling and allow rapid substitution if a supplier experiences capacity constraints.
- Qualification acceleration: Invest in concurrent qualification tracks (parallel lab, reliability and in-system testing) to reduce time-to-production. When suppliers offer AEC-Q101 or PPAP-capable parts, fast-track those options for automotive/industrial programs.
- Value-based pricing and cost-to-serve: For manufacturers, capture margin by offering differentiated variants (e.g., ±1% tolerance, low-noise lines, automotive-grade) at premium price points. For OEM buyers, conduct lifecycle TCO assessments—factoring yield improvements and MTBF benefits from higher-grade Zener solutions—rather than accepting unit-price as the sole procurement metric.
- M&A and partnership focus areas: Target capabilities that accelerate miniaturized packaging, advanced process technologies (ion implantation, planar silicon), or capacity for automotive-qualified runs. Strategic partnerships with wafer-foundries or packaging specialists can shorten lead-time volatility exposure.
- Scenario planning for compute-driven demand shocks: Model inventory and contractual terms around plausible AI/data-center procurement spikes. Hedging strategies, capacity pre-booking, and dual-sourcing are practical mitigants against the demonstrated risk of price and lead-time shocks.
What PW Consulting’s Zener Diodes Market report contains (practical, execution-focused)
This study is built for 2026 decision-makers who need both a strategic view and executable detail. The report combines:
- Market sizing and trend analysis across a 2020–2032 horizon with scenario variants calibrated to demand shocks and adoption accelerators.
- Supply-chain risk maps and mitigation playbooks (lead-time stress testing, contractual levers, inventory optimization heuristics).
- Product and technology roadmaps highlighting packaging, process, and tolerance innovations and their likely adoption timelines.
- Vendor benchmarking and heat maps (capability, qualification, vertical focus, and commercial behavior) with raw vendor data and contactable profiles for procurement teams.
- Actionable go-to-market modules: a buyer’s checklist for qualification, a supplier scorecard template, and a sample RFP language set tailored for automotive and high-reliability programs.
- Commercial scenarios and pricing elasticity models to support negotiation and sourcing strategies under volatile demand conditions.
Note: this article intentionally omits the granular regional, type, and application splits and the full numerical segmentation tables that are included in the report. Those detailed breakdowns are critical for SKU-level sourcing and program planning and are available in the full report materials.
How to use these insights in 2026
- CEOs and business-unit leaders: Use the market trajectory and concentration metrics to set portfolio priorities—scale up investment where differentiation yields premium positioning, and de-emphasize commoditized low-margin offerings.
- Procurement and supply-chain leaders: Implement lead-time and price-stress scenarios drawn from the report to define contract terms, safety-stock levels, and dual-sourcing triggers.
- R&D and product teams: Prioritize development on tight-tolerance, low-noise, and automotive-qualified variants and choose packages aligned with customer roadmaps for miniaturization.
- M&A teams: Leverage the report’s gap analysis to identify acquisition targets that fill capability or capacity shortfalls—especially in packaging, process technology, or automotive qualification lanes.
Conclusion — an executive roadmap for 2026
The Zener diodes market in 2026 is characterized by steady growth, pockets of rapid demand-driven stress, and clear technical vectors—miniaturization, automotive qualification, and precision variants—that separate winners from the rest. With a market base approaching USD 800 million in 2025 and an expected climb to about USD 1.06 billion by 2032 at a 4.2% CAGR, companies must choose between chasing scale in a fragmented space or establishing defensible differentiation through qualification, packaging, and process excellence.
PW Consulting’s full Zener Diodes Market report provides the granular segmentation, supplier-level data, and scenario modeling necessary to operationalize these strategic choices. For teams that must convert insight into procurement tactics, product roadmaps, or M&A targets in 2026, the complete dataset and templates in the report are designed to accelerate decision velocity while de-risking execution.
Next step
To access the detailed segmentation tables, supplier scorecards, and executable playbooks referenced here, please consult the full report materials available on our publication page.
For detailed analysis of this topic, please visit the official page: Zener Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


