



Category: market research
Mobile App Development Platform Market: Why 22.5% CAGR Redefines Growth by 2032
By PW Consulting, 2026-09-18
Global Mobile Application Development Platform Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for mobile application development platforms has entered a period of rapid expansion. From a valuation of approximately $10.2 billion in 2020, the sector grew to around $28.5 billion by 2025, reflecting a compound annual growth rate of 22.5 percent over the historical period. Projections indicate that the market will continue its upward trajectory, reaching roughly $117.9 billion by 2032. This acceleration is not merely a byproduct of broader digital adoption; it reflects a fundamental shift in how organizations conceive, build, and deploy mobile experiences. The pace of growth suggests that development platforms are evolving from tactical tools into strategic infrastructure components that determine how quickly enterprises can respond to changing customer expectations and operational demands.
Geographically, the market demonstrates a broad but uneven distribution. North America continues to represent the largest single regional bloc, while Asia Pacific and Europe each command substantial shares of total revenue. Latin America and the Middle East and Africa, though smaller in absolute terms, are growing faster than mature markets as organizations in those regions modernize legacy systems and expand digital service offerings. Deployment models are similarly tilted toward cloud-based solutions, which now account for the majority of platform revenue, though on-premise deployments retain a meaningful presence among organizations with strict security, compliance, or latency requirements. In terms of development approach, cross-platform solutions lead in overall market share, reflecting the broad appeal of unified codebases and faster time-to-market, while native development maintains a solid position in sectors where performance, platform-specific features, and deep ecosystem integration remain decisive.
The market is moderately concentrated. The three largest players collectively hold roughly 41.8 percent of total revenue, and the top five account for approximately 56.4 percent. This concentration indicates that leading platforms have achieved scale advantages in distribution, ecosystem depth, and enterprise trust. Yet the presence of a long tail of specialized and emerging vendors suggests that differentiation is increasingly driven by vertical expertise, workflow-specific capabilities, and integration quality rather than by generic low-code features alone. For decision-makers, this means that platform selection is less about picking the largest name and more about aligning platform strengths with the organization's operating model, compliance posture, and speed-to-value requirements.
IoT Platforms Market
Several structural challenges and inflection points shape the current environment. First, platform Evaluation fatigue is rising as the number of viable options expands and feature overlap increases. Buyers face growing difficulty in assessing which platforms will genuinely accelerate delivery versus those that simply promise flexibility but create hidden integration and maintenance burdens. Second, the cost and reliability of underlying infrastructure are becoming more material. As AI-enabled development assistants, continuous integration pipelines, and cloud-hosted testing environments become standard, demand for compute and storage is intensifying, and organizations must factor rising infrastructure costs into total cost of ownership assessments. Third, regulatory complexity is accelerating. Data sovereignty requirements, consumer privacy laws, and the impending full implementation of the EU AI Act are redefining what constitutes a compliant mobile application, especially for platforms that embed AI-assisted generation, personalization, or automated decisioning. Together, these forces are turning platform procurement into a multi-dimensional decision that balances speed, governance, and long-term operational risk.
Key Drivers of Market Change
The expansion of mobile application development platforms is being propelled by a convergence of technological, regulatory, demand-side, and cost-structure forces. Each of these drivers is reshaping the value proposition of platforms and redefining what buyers expect from their development tooling.
Technological innovation remains the most visible driver. AI-assisted development, model-driven design, and low-code/no-code interfaces are compressing delivery timelines for both enterprise and mid-market teams. Platforms are increasingly embedding generative capabilities that help developers scaffold interfaces, generate business logic, and automate repetitive tasks, while still providing governance hooks for controlled deployment. A notable example is Appian Corporation's version 25.1 release in February 2025, which introduced an AI-powered data fabric that significantly improved document processing speed for enterprise applications. This kind of capability illustrates how platforms are moving beyond simple UI builders to become orchestration layers that handle complex data workflows, document intake, and process acceleration. For organizations, the implication is clear: platforms that combine rapid development with AI-enhanced productivity can shorten project cycles and reduce the reliance on scarce specialized engineering resources.
Regulatory and policy shifts are also reshaping platform design and procurement. As of January 2026, twenty U.S. states had comprehensive consumer privacy laws in effect, requiring mobile applications to address data collection, consent, and processing practices in a consistent and auditable manner. Meanwhile, data sovereignty and localization rules continue to tighten in the EU under GDPR, across parts of Asia-Pacific, and in the Middle East, mandating where user data must be stored and processed. These requirements are pushing platforms to offer stronger controls around data residency, consent management, and audit trails. They are also encouraging enterprises to favor platforms that provide transparent governance and the ability to configure regional data handling without sacrificing speed. For vendors, compliance is no longer a secondary feature; it is a competitive differentiator that can determine win rates in regulated industries and multinational deployments.
PW Consulting
On the demand side, enterprise behavior is shifting toward faster, more continuous delivery of mobile experiences. Companies are increasingly treating mobile applications as living touchpoints rather than static product releases, requiring platforms that support iterative updates, offline-first usage patterns, and tight integration with back-end systems such as CRM, ERP, and data clouds. Salesforce's completion of its Informatica acquisition in May 2025 highlights this trend: by strengthening data and AI capabilities across its Lightning Platform, the company signaled a broader industry move toward unifying application development with deeper data integration and AI-driven insights. For buyers, this convergence means that platform decisions increasingly affect not just development velocity but also the ability to derive actionable insights from the data that mobile applications generate.
Cost and supply-side dynamics are adding both pressure and opportunity. The infrastructure underpinning cloud-based development and deployment is experiencing significant demand growth. U.S. data centers' total electricity demand is projected to nearly double from roughly 80 GW in 2025 to about 150 GW in 2028, driven by AI and cloud workloads that support mobile application development and deployment. This infrastructure strain is likely to translate into higher compute and storage costs over time, particularly for platforms that rely heavily on AI-assisted services and continuous cloud-based testing. At the same time, the shift toward cloud-based deployment is helping many organizations reduce on-premise overhead and gain elasticity. The net effect is that cost optimization is becoming a more sophisticated exercise: enterprises must weigh the savings from cloud elasticity against the risk of rising infrastructure pricing and the need for resilient, well-governed architecture.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a handful of scaled platform providers, a strong presence of ecosystem-led players, and a persistent set of native tooling champions. Each cluster pursues a distinct strategic logic, and understanding these differences is essential for assessing where value is being created and how the landscape may evolve.
Microsoft Corporation has anchored its offering around Power Apps, a low-code mobile application development platform integrated with Microsoft 365, Azure, and Dataverse. Its strategy emphasizes rapid enterprise mobile and web app creation with strong governance and AI capabilities, positioning the platform as a natural fit for organizations already invested in the Microsoft ecosystem. OutSystems, Inc. takes a different approach, offering a full-stack low-code platform specialized in complex, mission-critical mobile and web applications. Its differentiation rests on AI-assisted development, one-click deployment, and enterprise-grade security and scalability, making it attractive to organizations that need to build sophisticated applications without sacrificing control or performance. Mendix, now part of Siemens, focuses on collaborative, model-driven development with strong support for offline-first mobile apps and industrial and enterprise use cases. Its positioning reflects an emphasis on teamwork, model-based design, and scenarios where mobile apps must operate reliably in environments with intermittent connectivity or in close integration with industrial systems.
Appian Corporation supplies a low-code automation platform that combines mobile application development with process management, case management, and AI-powered decision-making for complex enterprise workflows. Its strategic emphasis is on workflow orchestration and decision support, appealing to organizations that view mobile applications as part of broader operational processes rather than isolated digital products. Salesforce, Inc. offers the Lightning Platform and related tools for building custom mobile applications deeply integrated with CRM, data cloud, and AI capabilities. Its strength lies in extending the CRM ecosystem into custom mobile experiences, particularly for enterprise customers that want development to stay closely aligned with customer data and sales/service workflows. Google LLC provides AppSheet as a no-code/low-code platform for building mobile apps directly from data sources such as Google Sheets or databases, with strong integration into Google Workspace and cloud services. This approach targets rapid, data-driven app creation for teams that want to move quickly without heavy engineering investment.
Apple Inc. remains the primary native development anchor through Xcode and associated SDKs for iOS, iPadOS, and related ecosystems. While not a low-code player in the traditional sense, Apple's tooling defines the standard for platform-specific performance, user experience fidelity, and access to device capabilities, and it continues to influence how cross-platform and low-code tools must evolve to meet native expectations. IBM Corporation provides IBM Mobile Foundation as an enterprise mobile application development platform supporting secure mobile app management, backend integration, and hybrid development, which appeals to organizations that need a balance of mobile delivery and enterprise security. Oracle Corporation delivers APEX and related cloud tools as low-code platforms for building mobile-ready enterprise applications integrated with Oracle databases and cloud infrastructure, targeting environments where database-centric development and Oracle ecosystem alignment are strategic priorities. SAP SE offers SAP Mobile Services and low-code capabilities within its Business Technology Platform for developing mobile applications integrated with SAP ERP and enterprise systems, positioning mobile development as part of a broader enterprise transformation strategy.
Several strategic patterns emerge from this landscape. First, ecosystem integration is a powerful differentiator. Platforms that align closely with widely adopted productivity, CRM, ERP, or cloud ecosystems benefit from shorter adoption cycles, familiar governance models, and clearer value narratives for business buyers. Second, AI-assisted development is becoming a central battleground. As platforms embed AI for scaffolding, documentation, testing, and process automation, the winners are likely to be those that balance speed with governance, ensuring that AI-generated outputs remain auditable and controllable. Third, the market is showing signs of both consolidation and specialization. Large players are expanding through acquisitions and capability broadening, as seen with Salesforce's data and AI-focused moves, while specialized vendors compete on vertical depth, workflow complexity, and industrial or regulated-use scenarios. New entrants and niche providers continue to appear, often targeting underserved segments or specific development pain points. The net effect is a market in which scale confers advantages, but differentiation increasingly depends on the ability to solve specific workflow, compliance, and integration problems rather than on generic low-code promises.
Future Trends and Strategic Implications
Looking ahead to the next three to five years, several trends are likely to shape the market's trajectory and create distinct commercial opportunities. These trends are grounded in current data patterns and the regulatory, technological, and cost dynamics already in motion.
One major trend is the shift from generic low-code platforms toward workflow- and industry-aware development environments. As enterprises demand more than simple form builders and UI scaffolds, platforms that embed domain-specific templates, process orchestration, offline-first design, and AI-assisted decisioning will gain preference in complex environments such as healthcare, manufacturing, financial services, and field operations. This creates an opportunity for vendors that can combine rapid development with deep workflow intelligence, and for buyers who can reduce long-term maintenance burdens by choosing platforms aligned with their operational realities rather than generic development needs.
A second trend is the growing importance of governance, compliance, and data handling as core platform selection criteria. With the EU AI Act reaching full implementation in August 2026 and imposing requirements on high-risk AI systems used in mobile application development platforms, and with consumer privacy and data sovereignty rules continuing to tighten, platforms will need to offer transparent controls, auditable AI usage, and configurable data residency. For enterprises, this means that platform evaluations should increasingly include compliance stress-testing, especially for applications handling sensitive data or supporting automated decisions. Vendors that can demonstrate robust governance without sacrificing speed will be well positioned to win in regulated and multinational contexts.
Messaging Platform Market
A third trend is the rising influence of infrastructure economics on platform strategy. As AI workloads and cloud-based development pipelines intensify demand on data center capacity, costs associated with compute, storage, and AI services are likely to become more prominent in total cost of ownership calculations. This may encourage platforms to optimize resource usage, offer more efficient AI assistance modes, or provide hybrid deployment options for cost-sensitive scenarios. For buyers, it suggests that platform comparisons should extend beyond license or subscription pricing to include the likely trajectory of infrastructure and AI service costs over the planning horizon.
These trends carry both opportunity and uncertainty. The outlook is favorable for platforms that can deliver speed, governance, and ecosystem integration in a coherent package, and for enterprises that use development platforms to accelerate digital initiatives while maintaining control over compliance and cost. However, uncertainty remains around the pace of AI regulation, the trajectory of infrastructure pricing, and the degree to which cross-platform tools can continue to narrow the gap with native experiences in performance-critical scenarios. Organizations that monitor these variables closely will be better prepared to adapt their platform strategies as conditions evolve.
Recommendations for Decision-Makers
For platform vendors and product manufacturers, the priority is to reinforce differentiation through depth rather than breadth alone. Investing in workflow-specific capabilities, strong governance and compliance controls, and seamless integration with widely used enterprise systems can create defensibility even in a crowded market. Vendors should also consider how AI-assisted features are packaged and governed, since buyers are increasingly evaluating not just how fast a platform can build an app, but how safely and auditably it can do so.
For investors, the strategic value lies in distinguishing between platforms with genuine enterprise traction and those riding generic low-code narratives. Attention should be paid to governance capabilities, ecosystem integration, vertical specialization, and the ability to manage infrastructure cost pressures. Companies that can demonstrate measurable reductions in development cycle time while maintaining compliance and operational reliability are likely to command stronger positioning as the market matures.
For procurement and technology leadership teams, platform decisions should be approached as multi-year strategic choices rather than short-term productivity purchases. Evaluations should weigh development speed, integration complexity, data handling and compliance posture, offline and field-use requirements, and the likely evolution of AI-related infrastructure costs. Given the pace of change in regulation and platform capabilities, ongoing market intelligence is essential for keeping procurement criteria aligned with shifting risk and value drivers.
For readers seeking a more detailed breakdown of segmentation dynamics, regional nuances, competitive benchmarking, and customized strategic recommendations, the full PW Consulting research report provides a deeper evidence base and structured scenarios to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Application Development Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Nail Care Packaging Market Shaped by 5.5% CAGR and Glass Lead
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Nail Care Packaging Market
Market Snapshot and Core Challenges
The global nail care packaging market has demonstrated resilient expansion over the past half-decade, reaching an estimated valuation of $1,532.65 million in 2025. This growth trajectory reflects a compound annual growth rate of 5.48 percent projected through 2032, signaling steady demand despite broader macroeconomic volatility. The sector's foundation rests on a specialized ecosystem where material choices, regional production hubs, and product form factors dictate competitive positioning. Glass continues to dominate material preferences due to its premium aesthetics and barrier properties, while plastic formulations capture significant volume through cost efficiency and design flexibility. Product architecture remains heavily skewed toward bottles, which serve as the primary delivery mechanism, though caps, brushes, tubes, and jars collectively represent a substantial secondary segment that shapes user experience and brand differentiation.
Several structural headwinds are reshaping how manufacturers and brand owners approach capacity planning, material sourcing, and product development. The first challenge stems from escalating raw material volatility, particularly in resin markets where producer price indices have climbed sharply amid energy cost pressures and constrained supply chains. This inflation directly impacts plastic component pricing, forcing converters to navigate margin compression while maintaining competitive retail pricing. The second challenge emerges from an accelerating regulatory environment that demands fundamental redesigns of packaging architectures. Extended producer responsibility frameworks are gaining momentum across multiple jurisdictions, compelling manufacturers to internalize end-of-life management costs and adjust commercial models accordingly. The third challenge lies in balancing sustainability mandates with performance requirements. Nail care products demand precise dispensing mechanisms, chemical compatibility, and tamper evidence, which historically limited material substitution options. Companies now face the complex task of meeting recycled content targets and design-for-recycling criteria without compromising functionality or aesthetic appeal.
These intersecting pressures create a market at an inflection point. Stakeholders must reconcile cost discipline with compliance readiness, while simultaneously responding to evolving consumer expectations around sustainability and premiumization. The companies that successfully navigate this transition will be those that treat regulatory and material shifts not as isolated constraints but as catalysts for structural innovation across their packaging portfolios.
Key Drivers Reshaping the Market
Technological innovation continues to serve as a primary catalyst for market evolution, particularly in the realm of dispensing systems, closure mechanisms, and material engineering. Advanced brush geometries, precision dropper assemblies, and ergonomically optimized caps are redefining application consistency and user satisfaction. Suppliers are increasingly integrating smart manufacturing techniques, including precision molding and automated quality verification, to reduce defect rates and improve batch uniformity. These advancements matter because nail care products rely heavily on tactile and visual cues during application; even minor improvements in flow control or bristle alignment can translate into measurable brand loyalty gains. The trend toward hybrid formulations, including products that blend traditional color delivery with added functional benefits, further reinforces the need for packaging that supports stable ingredient interactions while maintaining clarity and structural integrity.
Policy and regulatory developments are simultaneously restructuring competitive dynamics by imposing new design and compliance obligations. Extended producer responsibility frameworks in several U.S. states are moving from legislative intent to operational requirements, with recycling rate disclosures and fee structures increasingly tied to material choice and packaging complexity. In parallel, the European Union's packaging and packaging waste regulation trajectory is steering manufacturers toward design-for-recycling standards and recycled content thresholds that directly affect cosmetic and nail care containers. These policy shifts are not merely compliance exercises; they influence upstream sourcing strategies, mold investment timelines, and collaboration models between brand owners and packaging suppliers. Companies that anticipate these requirements and build modular design capabilities into their development pipelines are better positioned to avoid retrofitting costs and supply disruptions later in the product lifecycle.
Nail Polish Market
Demand-side behavior is also undergoing a meaningful transformation, driven by a combination of premiumization, sustainability sensibility, and the expansion of professional and at-home nail care usage. Consumers increasingly associate packaging quality with product efficacy and brand credibility, which elevates the strategic importance of bottle clarity, labelability, and closure reliability. At the same time, the rise of hybrid care categories encourages manufacturers to consider packaging that communicates added benefits without complicating the user journey. On the supply chain side, cost structures are being recalibrated by resin price fluctuations, energy inputs, and logistics constraints. These pressures are prompting sourcing diversification, closer coordination between converters and raw material producers, and renewed evaluation of glass-versus-plastic trade-offs based on total cost of ownership rather than unit price alone. Recent trade activity and product introductions illustrate how these forces are converging, with suppliers showcasing material alternatives, refill-compatible configurations, and specialized dispensing components that respond to both performance and regulatory expectations.
Competitive Landscape and Leading Strategies
The market's competitive architecture is characterized by a mix of incumbent packaging specialists, global container manufacturers, and regional suppliers with focused nail care expertise. Concentration levels remain moderate, indicating that no single entity controls the majority of supply and that differentiation is largely achieved through design capability, material specialization, and service integration rather than sheer scale alone. Leading players have positioned themselves along distinct strategic axes, balancing premium aesthetics, sustainability readiness, dispensing innovation, and regional manufacturing proximity. This diversification allows brand owners to select partners based on product positioning, compliance requirements, and speed-to-market considerations.
Worldwide Nail Strips Market
Several companies illustrate the breadth of current strategic approaches. Global cosmetic packaging providers with strong glass and hybrid container capabilities emphasize complete solution offerings, combining bottle design, finish options, and compatibility testing to reduce development friction for nail care brands. European design-driven suppliers focus on customizable, eco-oriented constructions that align with regional regulatory expectations while maintaining premium visual appeal. Specialized glass and plastic container manufacturers prioritize safety, clarity, and aesthetic consistency, appealing to brands where product presentation and chemical stability are paramount. Suppliers centered on dispensing systems, closures, and brushes contribute differentiated value by improving application precision and user experience rather than competing solely on container volume. Meanwhile, manufacturers offering turnkey or private-label capabilities integrate formulation and packaging workflows, creating efficiencies for brands seeking streamlined go-to-market pathways.
The landscape is evolving through a combination of capability consolidation and niche specialization. Larger players are expanding their nail care portfolios through targeted investments in dispensing technology, sustainable material options, and regional production footprints that shorten lead times. At the same time, smaller and mid-sized suppliers are carving out positions by offering highly customizable glass solutions, specialized brush assemblies, or region-specific compliance support. New entrants and adjacent players are also testing the market by leveraging flexible manufacturing and design services to serve emerging brands that prioritize speed, distinctiveness, and sustainability credentials. This dynamic suggests that competition will increasingly hinge on the ability to deliver integrated solutions rather than standalone components, with success measured by how effectively a supplier can align material performance, regulatory readiness, and brand storytelling within a single packaging system.
PW Consulting
Future Outlook and Emerging Opportunities
Over the next three to five years, the market is likely to be shaped by the convergence of regulatory-driven design changes, material innovation, and continued premiumization. One prominent trend will be the broader adoption of recyclable and refill-compatible packaging architectures as extended producer responsibility obligations mature and recycled content expectations become more enforceable. This shift will create opportunities for suppliers that can standardize modular components, simplify material sorting, and demonstrate verifiable end-of-life pathways without sacrificing dispensing accuracy or product protection. Brands that proactively align their packaging roadmaps with these requirements will reduce future reformulation risk and strengthen shelf positioning in markets where sustainability claims are scrutinized.
A second trend will involve the acceleration of functional integration within packaging, including closures and brushes designed to support hybrid product types, precision dosing, and improved application control. As nail care categories expand beyond traditional color cosmetics into care-oriented and hybrid formulations, packaging will need to signal functionality while maintaining the tactile and visual attributes consumers associate with quality. Suppliers that invest in application-specific engineering and user testing will be better equipped to capture premium segments and support brand differentiation. A third trend relates to supply chain reconfiguration, as manufacturers seek to mitigate raw material volatility and compliance complexity through diversified sourcing, regional production, and closer collaboration with converters and resin suppliers. This reconfiguration may favor partners that offer transparency, flexible order structures, and predictable lead times.
These opportunities are not without risk. Material substitution can introduce compatibility challenges, especially when formulations evolve faster than packaging validation cycles. Regulatory timelines may diverge across regions, creating uneven compliance burdens and complicating global product rollouts. Additionally, if resin price pressures persist or recycling infrastructure lags behind policy goals, the economics of sustainable packaging transitions could tighten, rewarding only those players with strong cost control and technical validation capabilities. Strategic foresight will therefore matter as much as execution.
Strategic Implications for Decision-Makers
For packaging manufacturers and converters, the priority is to build modular design capability that can accommodate recycled content, design-for-recycling standards, and changing dispensing requirements without requiring complete toolchain overhauls. Investing in application testing, closure optimization, and glass-plastic integration strategies will help protect margins while meeting evolving brand demands. For investors, the most attractive exposure lies in suppliers that combine regulatory readiness with differentiated dispensing or material solutions, especially those serving premium and hybrid nail care segments where performance and aesthetics command pricing power. For procurement teams and brand owners, the focus should be on supplier partnerships that offer compliance transparency, stable material sourcing, and design flexibility, since these attributes reduce launch risk and support consistent product experience across markets.
Given the pace of regulatory change, material volatility, and product innovation, decision-makers benefit from access to detailed segmentation data, regional compliance mapping, and supplier capability assessments that go beyond high-level market sizing. Deeper Intelligence on volume splits, material transitions, competitive positioning, and scenario-based forecasts can sharpen capacity planning, sourcing decisions, and portfolio prioritization. For organizations seeking a comprehensive view of market structure, company strategies, and forward-looking dynamics, the full PW Consulting research report provides expanded segmentation detail and tailored analysis to support sector-specific planning.
For detailed analysis of this topic, please visit the official page: Worldwide Nail Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Screening Services Market: Why 8.12% CAGR and $11B Forecast Change Everything
By PW Consulting, 2026-09-18
The Worldwide Job Screening Services Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global job screening services market has demonstrated sustained expansion over the past half decade, moving from an estimated $4.45 billion in 2020 to $6.39 billion in 2025. This trajectory reflects a compound annual growth rate of 8.12 percent, with revenue projections scaling toward $11.03 billion by 2032. The growth is not merely a function of headline hiring volumes; it signals a structural recalibration of how organizations approach talent acquisition, risk management, and regulatory compliance. As hiring cycles accelerate and workforce models grow more distributed, screening has shifted from a periodic administrative check to a continuous, data-intensive function embedded in the employee lifecycle.
Beneath the aggregate figures, three interconnected challenges are reshaping how market participants operate and compete. First, regulatory fragmentation continues to complicate compliance at scale. Fair chance and ban-the-box legislation has expanded across additional states and municipalities, requiring employers to postpone criminal history inquiries until after a conditional offer and mandating precise written disclosures for adverse actions. Simultaneously, new state-level provisions, such as the automatic sealing of certain misdemeanors and older convictions, narrow the scope of information available in standard employment background checks. Organizations must now navigate a mosaic of jurisdictional rules while maintaining consistent hiring standards, a balance that strains both internal HR teams and external screening vendors.
Second, cost pressures on verification infrastructure are intensifying. Third-party vendor fees for court records, employment and education verifications, and supplemental services have continued to rise through 2025 and into 2026, elevating operational costs for both screening providers and their clients. These increases are not uniform across data sources or geographies, creating uneven margin dynamics and prompting renegotiation of service-level expectations. Companies that rely on fragmented, manual procurement of verification data are finding it harder to predict total cost of ownership, while providers must decide whether to absorb cost increases, pass them through, or restructure service bundles to preserve value.
Third, the regulatory environment around automated decision-making and data privacy is adding a new layer of scrutiny. California’s CCPA regulations, effective January 1, 2026, require privacy risk assessments for automated decision-making technology used in employment contexts that present significant privacy risks. This development pushes employers and vendors alike to document how algorithms influence candidate outcomes, how data is retained, and how individuals can challenge automated results. The broader implication is clear: screening is no longer evaluated solely on speed and coverage, but also on explainability, consent management, and audit readiness. Organizations that treat these requirements as afterthoughts face mounting exposure, while those that build compliance into their workflows gain a durable advantage in regulated industries and multi-jurisdiction deployments.
Key Drivers Shaping Market Dynamics
Technology innovation is redefining the speed, granularity, and continuity of screening. API-first architectures and automated adjudication have become baseline expectations for high-volume hiring, particularly in sectors where candidate throughput must align with rapid operational scaling. Real-time and continuous monitoring solutions are extending screening beyond the point of hire, enabling organizations to track changes in criminal records, licensure status, and identity signals over time. The acquisition of a provider of AI-driven real-time screening and continuous monitoring by a private equity sponsor highlights how capital is flowing toward platforms that can reduce manual review, improve consistency, and support ongoing risk assessment rather than one-time checks. These capabilities are especially valuable where hiring is distributed across multiple locations or where roles involve recurring access to sensitive systems and data.
Policy and regulatory evolution is simultaneously acting as both a constraint and a catalyst. The CFPB’s interpretive rule clarifying that the FCRA generally preempts conflicting state laws in matters addressed by the statute introduces a degree of federal clarity into a historically fragmented compliance landscape. For employers and vendors, this reduces the risk of contradictory state obligations in areas already governed by the FCRA, though it does not eliminate the need to manage state-specific fair chance requirements, consent processes, and adverse action procedures. Industry guidance published in late 2025 emphasized the importance of revisiting screening policies for 2026, covering ban-the-box expansions, consent requirements, adverse action workflows, and continuous monitoring practices. Compliance is increasingly treated as a design question: systems must capture appropriate authorizations, sequence checks in the correct order, and produce auditable records that withstand regulatory review.
Demand-side behavior is shifting as organizations connect screening more tightly to quality of hire, retention, and enterprise risk. The IT and telecom sector, alongside BFSI and healthcare, continues to represent a substantial share of screening activity, reflecting the sensitivity of roles in these verticals and the pace at which they hire. In technology and gig-economy contexts, volume, speed, and integration with applicant tracking systems are paramount, while in regulated industries, depth of verification and defensible adjudication take precedence. Employers are also increasingly viewing screening as part of a broader trust-and-safety strategy rather than a standalone HR task. This mindset supports demand for bundled services that combine identity verification, criminal checks, education and employment verification, and health or drug screening where relevant, reducing the friction of coordinating multiple vendors and improving the candidate experience through unified workflows.
Cost structure and supply chain dynamics are pushing the market toward integration and automation. As court record and verification fees rise, providers and clients are reassessing how to consolidate touchpoints, reduce manual handoffs, and standardize data ingestion. Unified ordering models that pair background checks with occupational health services, along with deeper ATS integrations and candidate workflow optimizations, are gaining traction because they lower administrative burden and improve completion rates. At the same time, the labor and data economics of verification are prompting a focus on selectivity: not every role requires the same depth of check, and tiered or risk-based approaches can align scope with actual exposure. The practical effect is a market that is moving from uniform, one-size-fits-all packages toward configurable, role-sensitive screening programs that balance coverage, cost, and compliance.
Security Screening Market
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established providers and a dynamic perimeter of technology-forward entrants and specialized firms. Concentration among the largest participants remains meaningful, with the top three holding roughly 41.5 percent and the top five approaching 54.2 percent of market revenue. This structure reflects the advantages of scale in global data access, compliance infrastructure, and enterprise sales, while also leaving room for differentiation through product design, integration depth, and vertical focus. The leading incumbents compete on breadth of coverage, regulatory expertise, and the ability to serve large, multi-national workforces with consistent standards across jurisdictions.
First Advantage and HireRight illustrate two complementary formulations of scale-led strategy. First Advantage emphasizes comprehensive global employment screening across 200-plus countries, combining criminal background checks, identity verification, drug screening, and verifications with advanced risk scoring and compliance tooling for large enterprises. Its recent compliance-focused analysis addressed 2026 FCRA trends, identity fraud mitigation, and CFPB interpretive rules on preemption, signaling a strategy that ties product capability to forward-looking regulatory interpretation. HireRight similarly operates with extensive international coverage and a strong orientation toward regulated industries, offering employment and education verifications alongside compliance solutions for enterprise clients. Its acquisition of ClearChecks expanded its reach to small and medium-sized businesses with technology-based screening services, illustrating a move to capture segments that require lighter-touch, automated offerings while preserving enterprise-grade capabilities for larger accounts.
Worldwide Job Search Recruitment Services Market
The technology-driven segment is shaping competition on speed, integration, and user experience. Checkr has built a reputation around API-first, high-volume screening with automated adjudication and strong alignment to tech, gig-economy, and retail use cases. GoodHire, now part of Checkr, targets small to mid-sized businesses with a user-friendly, FCRA-compliant platform and customizable packages, showing how brand and usability can differentiate even within a consolidated market. Accurate Background combines background screening with drug testing and occupational health services, while expanding international coverage in Asia Pacific and Europe, a reminder that service bundling and geographic extension remain viable ways to create value. Universal Background Screening has reinforced its position through ATS integrations, unified ordering with occupational health, and compliance-focused workflows, reflecting a broader industry push to reduce friction in candidate and HR workflows.
Compliance and governance specialists are carving out a distinct competitive lane. Cisive emphasizes compliance, policy support, social media screening guidelines, and FCRA-aligned processes, and its late-2025 policy guidance on reviewing screening policies for 2026 underscores the importance of proactive governance. Mitratech’s AssureHire platform serves mid-market and enterprise clients with deep compliance, audit trails, and continuous screening capabilities, appealing to organizations that need traceability and ongoing monitoring rather than point-in-time checks. DISA Global Solutions focuses on background screening, drug testing, and compliance services, with explicit attention to AI risks in HR screening, a topic that is gaining prominence as automated tools become more prevalent. Meanwhile, Sterling Check and Cisisive continue to reinforce identity, pre-hire, and post-hire monitoring capabilities within broader service portfolios.
The competitive landscape is evolving along three vectors. Consolidation is accelerating as larger platforms acquire technology and customer bases to broaden segment coverage and strengthen automation capabilities. Differentiation is intensifying around integration quality, regulatory interpretation, and the ability to tailor screening depth to role-specific risk. New entrants and private capital are drawn to continuous monitoring, identity fraud detection, and decision intelligence, areas where software margins and recurring engagement models can complement traditional verification economics. The net result is a market in which scale provides reach and compliance depth, but product design, integration, and governance discipline increasingly determine who wins in specific verticals and customer segments.
PW Consulting
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be defined by the maturation of continuous and risk-based screening. Point-in-time checks will remain essential, but organizations will increasingly pair them with ongoing monitoring for roles that carry elevated access or responsibility. This shift creates commercial opportunities for platforms that can deliver timely alerts, prioritized case management, and clear escalation paths without overwhelming HR and security teams with noise. Providers that can calibrate monitoring frequency and scope to actual risk, while maintaining defensible audit trails, will be well positioned to capture recurring engagement and expand share of wallet within existing accounts.
A second trend is the convergence of compliance, privacy, and decision intelligence. As automated decision-making tools become more embedded in screening workflows, employers and vendors will need to demonstrate how decisions are made, how data is used, and how candidates can contest outcomes. The requirement for privacy risk assessments in employment-related automated decision-making, together with evolving fair chance rules and interpretive guidance on federal preemption, will raise the bar for documentation and process design. Commercially, this favors organizations that invest early in explainable workflows, consent management, and policy engines that can adapt to jurisdictional changes without requiring wholesale rebuilds. It also creates advisory and enablement opportunities for partners that can help clients translate regulatory complexity into operational practice.
A third trend is the continued pressure on verification costs and the corresponding push toward integration and selectivity. Rising third-party fees for court records and verifications will encourage more consolidated procurement, deeper ATS and HRIS integrations, and tiered screening models that align scope with role risk. Bundled offerings that unite background checks with occupational health, identity verification, and drug screening where applicable will likely gain share by reducing vendor fragmentation and improving completion rates. At the same time, uncertainty remains. Regulatory direction can shift at the state and municipal level faster than platform roadmaps, and automated tools introduce new governance and bias considerations that require careful validation. Organizations that treat these uncertainties as design constraints rather than exceptional risks will be better prepared to scale confidently.
Strategic Recommendations for Decision Makers
For enterprise employers and HR leaders, the priority is to move from reactive, one-off screening to a governed, risk-tiered program. This means mapping role types to appropriate screening depth, standardizing consent and adverse action workflows, and embedding continuous monitoring where the risk profile justifies it. Integrating screening with applicant tracking and HR systems reduces administrative drag and improves candidate completion, while documented policy reviews help align practices with evolving fair chance and privacy requirements. Treat compliance and explainability as product features, not add-ons, and ensure that any automated adjudication is auditable and contestable.
For investors and strategic buyers, the most compelling value creation levers are automation, continuous monitoring, and international expansion in high-growth regions. Platforms that can demonstrate measurable reductions in manual review, faster time to decision, and defensible compliance records are better positioned to command premium valuations and cross-sell across segments. Due diligence should focus on data sourcing economics, jurisdictional coverage, integration depth, and the operational maturity of privacy and AI governance, because these factors will increasingly differentiate scalable platforms from point solutions as regulation tightens and cost pressures persist.
For procurement teams and mid-market buyers, the practical goal is to consolidate vendors without sacrificing flexibility or compliance rigor. Seek providers that offer configurable packages, clear audit trails, and integration with existing systems, and evaluate total cost of ownership across verification fees, workflow efficiency, and candidate experience rather than headline price alone. Continuous monitoring and occupational health bundling can be valuable where they fit the use case, but they should be assessed against actual risk exposure and operational capacity.
Given the pace of regulatory change, cost dynamics, and product consolidation, detailed segment-level intelligence is essential for timing decisions and prioritizing investments. More granular data on regional trajectories, service-type demand, vertical adoption patterns, and provider-level positioning can sharpen strategy and reduce execution risk. The complete analysis, including deeper segmentation and customized recommendations, is available in the full PW Consulting report on the Worldwide Job Screening Services Market.
For detailed analysis of this topic, please visit the official page: Worldwide Job Screening Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Signature Capture Pad Market: Beyond the 6.25% CAGR—Key Drivers to $328.66M by 2032
By PW Consulting, 2026-09-18
The Worldwide Signature Capture Pad Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global signature capture pad market has entered a phase of steady, structurally driven expansion, with total revenue projected to grow from approximately $215.0 million in 2025 to $328.7 million by 2032, representing a compound annual growth rate of 6.25 percent. This trajectory reflects a mature yet still evolving hardware category that is increasingly integrated into broader digital transaction and compliance ecosystems. The market's expansion over the historical period from 2020 to 2025 has been uneven but directional, with noticeable acceleration in application-specific deployments and a gradual shift toward higher-functionality devices. While the broader market continues to consolidate around established players, the revenue distribution across end-use environments and geographic corridors reveals a landscape where institutional procurement cycles, regulatory alignment, and workflow digitization are acting as primary growth multipliers.
One of the most pronounced challenges shaping the current market is the tension between hardware commoditization and the demand for compliance-grade functionality. As signature capture devices become commonplace in routine administrative processes, price sensitivity increases in commoditized segments, yet regulated environments continue to prioritize security certifications, audit trail integrity, and interoperability with existing enterprise infrastructure. This bifurcation forces manufacturers to decide between competing on cost in volume-driven segments or investing in specialized build quality, firmware reliability, and regulatory alignment for higher-margin deployments. The result is a market where generic price competition is increasingly unsustainable without compromising long-term customer retention in regulated verticals.
A second structural challenge lies in integrating signature capture hardware into increasingly software-centric workflows. Organizations are no longer purchasing signature pads as standalone tools; they are embedding them into electronic health record systems, point-of-sale platforms, logistics digitization initiatives, and document management architectures. This integration requirement raises the barrier to entry for smaller manufacturers and places pressure on all suppliers to provide clear API support, stable driver ecosystems, and predictable firmware update cycles. Hardware that cannot be seamlessly paired with modern software stacks risks rapid obsolescence, even if the capture quality and build durability remain strong.
A third challenge concerns supply chain and material cost volatility. The transition toward medical-grade and enterprise-grade enclosures, enhanced sensor components, and more durable connectivity modules has changed the underlying cost structure of signature capture devices. Even when unit pricing appears stable at the shelf, internal manufacturing economics can shift as material specifications rise and production volumes fluctuate. Manufacturers that rely on generic components or positioning reliant on low-cost assembly are finding that margin compression is no longer offset by volume growth alone. In this environment, the ability to forecast component availability, manage enclosure specifications efficiently, and align cost structures with the intended deployment context has become a strategic differentiator rather than an operational detail.
Key Growth Drivers
Technological Innovation and Functional Differentiation
The signature capture pad market is being reshaped less by raw hardware novelty and more by the convergence of sensing precision, connectivity, and security features. Devices are increasingly expected to deliver consistent signature fidelity across varied surface conditions, while also supporting faster handshake processes, reduced driver dependency, and more resilient performance in mobile or semi-mobile environments. In healthcare-related deployments, for example, the integration of biometric verification capabilities has emerged as a meaningful enhancement to patient consent workflows, while in retail and logistics settings, simplified connectivity and faster deployment characteristics are reducing implementation friction. These incremental but cumulative improvements are changing the value proposition of signature capture hardware from a basic input accessory into a functionally targeted component of compliance and transaction workflows.
Recent product activity illustrates this pattern clearly. In mid-2025, Topaz Systems introduced a signature pad with biometric verification designed for heightened medical security, reinforcing the trend toward devices that address both signature acquisition and identity assurance in regulated contexts. That same year, Wacom secured an updated HIPAA compliance certification for its STU-540 model to support electronic medical record integration, underscoring how certification alignment can become a commercial enabler rather than a simple regulatory checkbox. Earlier, in late 2024, ePADlink expanded its healthcare catalog with an updated model emphasizing improved battery life for mobile clinical use, reflecting the growing importance of portability and operational continuity in environments where fixed workstations are not always practical. Collectively, these developments point to a market in which innovation is increasingly measured by workflow fit, certification readiness, and reliability in targeted deployment scenarios.
Policy, Compliance, and Regulatory Alignment
Regulatory expectations continue to function as a powerful demand-side driver, particularly in sectors where electronic signatures interact with protected information or formally governed processes. In the United States, signature capture devices used in healthcare must align with HIPAA Security Rule expectations when handling protected health information, a requirement that shapes not only product design but also procurement criteria and vendor evaluation. Compliance is no longer treated as a backend legal concern; it has become a purchasing priority for organizations that need to demonstrate secure handling of patient consent forms, prescriptions, and related documentation.
At the same time, reimbursement and billing frameworks are influencing adoption indirectly by increasing the value of digitally captured signatures when linked with electronic health record systems. For instance, electronic signature workflows integrated with EHR platforms can support chronic care management billing processes under relevant CPT coding practices, giving healthcare providers an operational incentive to standardize capture devices that behave predictably within certified workflows. The commercial implication is significant: devices that are demonstrably compatible with compliance requirements and clinical documentation systems gain an advantage in procurement decisions, especially where administrative integrity, auditability, and reimbursement readiness are all under consideration.
Demand-Side Shifts in Enterprise and Consumer Behavior
The broader digitization of signed transactions is changing how organizations think about signature capture hardware. In banking and finance, signed authentication remains embedded in account openings, loan documentation, and consent-based transactions, but the emphasis is increasingly on streamlined experiences that reduce processing time without weakening audit integrity. Retail environments continue to rely on signatures in contexts where payment verification, return authorization, or service acknowledgment is required, yet the device expectations are shifting toward integration with point-of-sale platforms and cleaner end-customer interactions. Logistics operations, meanwhile, are adopting capture devices to accelerate proof-of-delivery and shipment acknowledgment processes, particularly where mobile workflows demand simpler deployment and faster turnaround.
Across these settings, a common theme is the growing preference for devices that reduce friction rather than merely replicate ink-on-paper signatures in digital form. Procurement teams are asking whether a signature pad will simplify intake, speed up authorization, and lower the administrative burden of reconciling paper and digital records. When the answer is yes, adoption accelerates. When the device introduces complexity, driver issues, or inconsistent behavior across operating environments, adoption stalls regardless of the hardware's baseline performance. This demand-side shift is pushing manufacturers to prioritize real-world usability, support consistency, and software compatibility alongside sensor quality.
Supply Chain and Cost Structure Evolution
The economics of signature capture hardware are being recalibrated as material specifications and production expectations change. Medical-grade polycarbonate enclosures, for example, carry meaningful per-unit cost implications when produced at scale, and manufacturers must weigh that expense against the intended deployment environment. In segments where durability, cleaning compatibility, and a cleaner clinical or enterprise appearance are essential, higher enclosure costs can be justified. In more price-sensitive environments, the same specification may be difficult to absorb without sacrificing competitiveness. This tension is prompting more deliberate product segmentation, with some manufacturers designing variants that align cost structures with the expectations of specific workflows rather than attempting a single universal platform.
On the production side, the discontinuation of certain legacy devices in non-EMR healthcare contexts has highlighted how connectivity limitations can erase the commercial viability of otherwise functional hardware. Devices that lack modern wireless support, for instance, can become obstacles in mobile clinical workflows, even if they remain technically capable of capturing signatures. This dynamic encourages both incumbents and new entrants to design for future-proof connectivity, battery behavior where needed, and a clearer match between device capabilities and real-world deployment conditions. The cost of not doing so is increasingly visible in shortened product lifecycles and reduced procurement relevance.
Competitive Landscape and Leading Strategies
The signature capture market remains moderately concentrated, with the top three players accounting for roughly 35.5 percent of revenue and the top five representing approximately 48.2 percent. This structure indicates a landscape where scale, brand trust, and vertical alignment still matter, but where specialized positioning can also create durable demand. The leading companies are not simply competing on capture quality; they are carving out relevance through regulatory alignment, vertical-specific product narratives, connectivity choices, and ecosystem compatibility.
Topaz Systems has positioned itself as a strong player in medical consent and patient check-in environments, with signature capture solutions designed to meet privacy and compliance expectations in clinical administrative workflows. Its recent emphasis on biometric verification for medical security reflects a strategy oriented toward higher-assurance use cases where the signature pad contributes not just to document capture but also to identity confidence. Wacom continues to leverage its broader reputation for input precision, extending it into secure digital signing for healthcare and EMR-linked environments, where certification updates and integration readiness serve as important trust signals. ePADlink has focused more narrowly on medical documentation and prescription workflows, with an emphasis on connectivity options and practical mobile usability, including battery life considerations for clinicians moving between locations.
On the transaction and point-of-sale side, NCR Voyix, Ingenico Group, and Verifone each bring different strengths, linking signature capture with payment processing, retail healthcare environments, and consent capture scenarios. Their relevance lies in combining signature functionality with devices and platforms that already operate within payment and retail workflows, reducing the need for organizations to stitch together unrelated systems. This approach illustrates a broader competitive pattern: in application contexts where signature capture is part of a larger transaction or service process, integration advantage can matter as much as hardware performance.
Signature Pad Market
Strategically, the market is evolving through both consolidation and targeted differentiation. Larger players benefit from brand recognition, broader support infrastructure, and the ability to invest in certification and compatibility initiatives that smaller competitors may find difficult to sustain. At the same time, specialized manufacturers can win in niches by delivering products that align closely with workflow realities, whether that means wireless readiness for clinical mobility, healthcare compliance emphasis, or simplified deployment in retail and logistics operations. The presence of discontinued legacy models in certain non-EMR healthcare settings further reinforces the idea that narrow feature gaps, especially around connectivity and integration, can quickly erode competitiveness. New entrants face a steep climb unless they bring a clearly defined deployment advantage, a defensible compliance or integration story, or a cost structure suited to a segment that larger players are underserving.
For decision-makers evaluating the competitive field, the key question is not which manufacturer has the largest catalog, but which vendor's trajectory aligns with the intended operating environment. Devices that are positioned for secure healthcare documentation demand different strengths than devices aimed at high-volume retail transactions or mobile logistics capture. The most resilient companies are those that can articulate where their hardware fits, maintain that positioning through certification and integration efforts, and avoid diluting their value by competing indiscriminately across unrelated segments.
Future Trends and Strategic Outlook
Over the next three to five years, one of the clearest trends will be the continued shift from generic signature capture devices toward workflow-specific hardware. Procurement will increasingly be shaped by the environment in which the device will be used, with healthcare, finance, retail, and logistics each placing different weight on security, portability, integration, and operating cost. This suggests a market in which success will depend less on offering a single universally acceptable product and more on building credible variants that correspond to distinct compliance and operational requirements.
A second trend will be deeper integration between signature capture hardware and software ecosystems. As organizations reduce dependence on paper-based processes, they will expect capture devices to behave as dependable components within digital workflows rather than as isolated peripherals. That expectation will favor vendors that maintain stable driver support, clear compatibility pathways, and firmware management that keeps pace with broader system updates. Devices that cannot keep up with software-centric procurement expectations will face diminishing relevance, even if their capture quality remains acceptable.
PW Consulting
A third trend is likely to be the growing commercial importance of security-enabled signing in regulated settings. Biometric verification, compliance certification, and auditable consent workflows will continue to create value in environments where identity assurance and document integrity are critical. At the same time, this trend introduces uncertainty: regulatory expectations can evolve, integration requirements can become more demanding, and reimbursement or billing frameworks may shift in ways that alter adoption incentives. Material costs and component availability will also remain sources of variability, meaning that forecasting and product planning need to account for both performance goals and cost resilience.
Taken together, these trends suggest that the most attractive opportunities will lie in segments where signature capture hardware solves a concrete workflow problem, aligns with compliance expectations, and integrates cleanly into the surrounding digital environment. Organizations that treat the device as part of a process will be better positioned than those that treat it as a commodity input.
Decision-Maker Action Points
For Manufacturers
Focus product development on clearly defined deployment contexts rather than attempting to serve every workflow with a single platform. Where healthcare or other regulated environments are the target, prioritize certification alignment, integration reliability, and features that directly support auditable consent or documentation workflows. Where mobility matters, design for practical battery behavior, wireless readiness, and durable enclosures without over-engineering for segments that do not require it. Segmentation executed with discipline can protect margins and improve procurement relevance.
For Investors
Evaluate exposure to signature capture hardware in the context of vertical adoption rather than device volume alone. The stronger growth cases are likely to emerge where capture pads are tied to compliance-driven workflows, digital documentation integration, and transaction environments that still rely on signed authorization. Pay attention to companies that can demonstrate recurring relevance through certification, compatibility, and vertical-specific product roadmaps, since these characteristics tend to support longer commercial lifecycles.
Biometric Signature Pads Market
For Procurement and IT Leaders
Treat signature capture devices as workflow components, not standalone peripherals. Clarify whether the primary need is compliance assurance, mobility, integration simplicity, or volume cost, and then evaluate vendors against those priorities. Ask how the device will behave within the actual software environment, how updates will be managed, and what happens if connectivity or driver requirements change over time. Selecting for fit and long-term support can reduce operational disruption and avoid premature replacement cycles.
For organizations that need deeper segmentation data, competitive benchmarks, and procurement scenarios tailored to specific deployment contexts, a full market research report can provide the additional detail required to move from strategic direction to operational decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Signature Capture Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Consumer Electronics Accessories Market: Why 6.57% CAGR Reshapes Growth Through 2032
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Consumer Electronic Accessories Market
Market Overview and Core Challenges
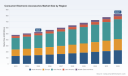
The worldwide consumer electronic accessories market has demonstrated resilient growth, expanding from 482.17 billion USD in 2023 to approximately 530.5 billion USD in 2025. This trajectory reflects a compound annual growth rate of 6.57 percent through 2032, positioning the sector to reach 828.27 billion USD by the end of the forecast period. Such expansion is not merely a function of population growth or rising disposable income; it is structurally tied to the deepening integration of accessories into primary device ecosystems. As smartphones, tablets, laptops, and personal audio devices become longer-lived capital investments, consumers and enterprises increasingly allocate spend toward protection, power management, connectivity, and audio enhancement. The sheer scale of demand, however, masks underlying friction points that will define competitive outcomes over the next several years.
One foundational challenge lies in the shifting balance between ecosystem lock-in and cross-platform compatibility. Accessories have historically benefited from brand-specific optimization, where proprietary connectors, magnetic alignment systems, and software-tuned audio profiles create repeat purchase behavior. At the same time, regulatory pressure and consumer fatigue around walled gardens are accelerating interoperability mandates and universal charging standards. Companies that rely exclusively on closed-loop accessory strategies face margin compression as third-party alternatives mature in performance and aesthetics, while those that invest in certified compatibility, adapter ecosystems, and software-adjacent features are finding new room to differentiate. The market is thus entering a phase where technical parity is increasingly common, and the real contest shifts to trust, lifecycle durability, and ecosystem integration.
A second challenge is the reconfiguration of supply chain geography and its impact on cost predictability. For years, concentrated manufacturing hubs provided scale efficiencies, but tariff adjustments, compliance complexity, and geopolitical risk have prompted importers to diversify sourcing. This diversification improves resilience but also fragments volume commitments, raises coordination costs, and temporarily disrupts the price advantage that low-cost manufacturing once delivered. Forward-looking operators are responding by blending regional assembly, qualifying alternative component suppliers, and redesigning accessories for modular sourcing rather than single-origin fabrication. Those that treat supply chain flexibility as a design parameter, rather than a back-office procurement issue, are better positioned to stabilize pricing and protect gross margins.
Worldwide E-commerce of Consumer Electronics Products Market
A third challenge is intensifying compliance and sustainability reporting. Electronic accessories are increasingly subject to product safety certification updates, substance restrictions, and material traceability expectations. The operational burden is no longer limited to final assembly; it extends into component documentation, eFiling processes, and product-level transparency. Firms that treat compliance as a reactive checkpoint often encounter shipment delays and re-certification costs, whereas those that embed documentation workflows and material data collection into product development cycles reduce time-to-market risk and create a defensible compliance posture. In this environment, the ability to evidence conformity and sustainability claims is becoming a commercial asset, not just a regulatory requirement.
Key Drivers of Market Change
Several interconnected forces are shaping the direction of the market. The most immediate is the rapid maturation of charging and power management technology. Gallium nitride and related wide-bandgap semiconductor materials have enabled chargers and power banks that are smaller, run cooler, and support higher wattage outputs without a proportional increase in size or heat. This shift is changing consumer expectations: portable power is no longer an afterthought but a primary purchase criterion for travelers, remote workers, and mobile-first users. The growth of fast-charging protocols and the gradual alignment of interoperability standards are also reducing the penalty of using non-proprietary accessories, which expands the addressable market for multi-brand compatible solutions while raising the performance bar for entrants.
Policy and regulatory dynamics are exerting a second, equally powerful influence. Product safety certification processes are becoming more digitized and stringent, with mandatory electronic filing of compliance certificates for consumer products including electronic accessories. These changes increase the administrative precision required from importers and manufacturers, especially those selling across multiple jurisdictions. At the same time, regional sustainability frameworks are advancing material-level transparency requirements that will affect electronics accessories, prompting companies to track substances, recovery pathways, and lifecycle information with greater rigor. For market participants, this means compliance capability is increasingly part of the product strategy, influencing component selection, supplier qualification, and packaging decisions well before launch.
PW Consulting
Consumer behavior is evolving in ways that reinforce accessory spend even as primary device upgrade cycles lengthen. Users are retaining phones and tablets for longer periods, which paradoxically increases demand for protective cases, screen protection, battery support, and audio upgrades that restore or extend the experience of aging hardware. There is also a pronounced preference shift toward products that combine durability with aesthetics; rugged protection is no longer sufficient on its own when consumers expect slim profiles, refined finishes, and brand-compatible design cues. In entertainment and gaming contexts, audio accessories are becoming more specialized, with users seeking improved comfort, directional sound characteristics, and microphone performance that supports both leisure and communication use cases. These behavioral trends reward companies that can deliver accessory solutions tuned to specific usage scenarios rather than generic, one-size product lines.
Supply chain and cost structure changes are reshaping where and how accessories are produced. Regional sourcing patterns have shifted markedly, with certain Southeast Asian manufacturing centers now supplying a larger share of U.S. consumer electronics imports by value than traditional sources. This transition reflects a blend of cost optimization, diversification strategy, and proximity considerations for specific components and assembly steps. At the same time, tariff adjustments on selected electronic inputs and continuing trade policy variability have increased landed cost uncertainty for some categories. The practical effect is that companies with diversified sourcing, multi-region assembly capability, and clear visibility into component-level cost exposure are gaining an operational advantage. Accessory design that anticipates component substitution and regional manufacturing flexibility is becoming a competitive differentiator as much as a cost strategy.
Competitive Landscape and Leading Strategies
The competitive field is wide and increasingly layered, ranging from ecosystem-anchored brands to specialized third-party players and value-oriented multi-brand suppliers. Apple exemplifies ecosystem integration, with accessories designed to align tightly with proprietary charging, magnetic alignment, and device-specific compatibility. This approach creates strong brand affinity and repeat purchase behavior among users already committed to the platform, and it allows the company to bundle accessory value into the broader device experience. The strategic implication is clear: ecosystem alignment can command premium positioning, but it also concentrates risk if consumer adoption of third-party alternatives accelerates under interoperability pressure.
Samsung and Sony illustrate complementary approaches within large device ecosystems. Samsung extends its device relationship through audio, protective cases, power banks, and fast-charging accessories that are optimized for its smartphone and tablet lineup, reinforcing ecosystem retention while maintaining broad retail visibility. Sony focuses more narrowly on premium audio accessories, leveraging brand strength in sound and consumer electronics to compete on performance perception and user experience rather than ecosystem bundling. Both strategies show that scale and brand recognition can be leveraged either broadly across categories or deeply within a specialty segment, depending on where the company wants to own the value proposition.
Charging and power specialists such as Anker and UGREEN highlight the potency of multi-brand compatibility combined with performance and design leadership. By focusing on chargers, cables, power banks, hubs, and docking solutions that work across major device brands, these companies address the growing consumer desire for versatile, travel-friendly power solutions without being tied to a single device maker. Their recent product introductions around high-capacity fast-charging models and expanding hub and cable portfolios reflect a broader industry move toward compact, high-output power products that serve hybrid work, travel, and multi-device environments. Their strategic advantage lies in solving a universal pain point—power access across devices—while maintaining flexibility to adapt to changing connector standards and protocol requirements.
Protective and lifestyle-oriented accessory brands, including Belkin, Spigen, OtterBox, and Baseus, demonstrate the importance of positioning around specific consumer expectations. Belkin emphasizes compatibility with widely adopted charging and connectivity standards and maintains strong retail and accessory categories that pair protection with charging solutions. Spigen and OtterBox compete on durability, fit, and visual style, targeting users who prioritize physical protection without sacrificing design appeal. Baseus broadens reach through value-oriented accessories that emphasize compatibility and affordability across a wide device base. The common thread among these players is that protection and daily-use accessories are increasingly judged on a combination of reliability, aesthetics, and compatibility rather than on ruggedness alone.
The market is evolving along two simultaneous tracks. On one track, larger device and audio brands continue to use accessories as retention and experience-enhancement tools, reinforcing integrated ecosystems and cross-selling opportunities. On the other, specialized third-party players are gaining share by offering cross-compatible performance, faster innovation cycles, and category depth in charging, audio, and protection. This dynamic is encouraging both consolidation among retailers and distributors seeking broader assortment efficiency and fragmentation at the product level, where niche use cases create room for focused innovation. New entrants that can demonstrate superior materials, clearer compatibility, or stronger user-experience design are finding pathways into the market, especially where legacy offerings lag in compactness, heat management, or multi-device utility.
Future Trends to Watch
Over the next three to five years, the market is likely to be shaped by three converging trends. The first is the continued normalization of compact high-performance power solutions as a baseline expectation rather than a premium feature. As faster charging, improved thermal management, and multi-port utility become more common, consumers will increasingly expect power accessories that are both travel-ready and capable of supporting multiple device types. Commercial opportunities will accrue to companies that can deliver these capabilities in slim form factors while maintaining reliability and safety documentation that meets evolving import requirements.
The second trend is deeper compatibility and interoperability, supported by consumer demand and regulatory direction. Accessories that rely on universal charging approaches, adaptable mounting or alignment systems, and clear cross-device performance will gain relevance as users reduce their tolerance for fragmented standards. This creates opportunities for brands and private-label suppliers to build portfolios around compatibility, modular adapters, and product lines that can pivot more easily when connector or protocol preferences shift. The risk for product strategies that assume long-lived proprietary advantage is rising, especially where compliance and interoperability expectations continue to tighten.
Power Tool Accessories Market
The third trend is sustainability and traceability becoming part of the purchasing and sourcing calculus. Material-level reporting, certification digitization, and growing buyer sensitivity to end-of-life and component transparency are likely to influence assortment decisions and supplier selection. Companies that can substantiate material claims, manage documentation efficiently, and design for easier recovery or component substitution will be better positioned to navigate compliance and to meet procurement requirements in more demanding channels. The uncertainty here lies in the pace and scope of regulatory implementation across regions, which may require flexible reporting and material data capabilities rather than one-time certification efforts.
Actionable Guidance for Decision-Makers
For manufacturers and product developers, the priority is to design accessory portfolios around compatibility, thermal and size performance, and supply chain modularity. Treating compliance documentation, material traceability, and alternative sourcing as integral to product architecture reduces launch risk and supports faster adaptation to standard changes. Teams should also assess which accessory categories are best positioned for ecosystem-aligned premium offerings versus cross-brand compatible volume plays, and allocate innovation resources accordingly.
For investors and strategic planners, the clearest value creation is likely to come from companies that combine multi-device compatibility with credible performance in power, protection, or audio, and that demonstrate disciplined compliance and sourcing exposure management. Observers should track category-level momentum in compact fast-charging products, audio specialization, and durability-plus-design protective accessories, while monitoring how import compliance and tariff variability influence margin structures and sourcing shifts. Diversification of revenue across compatible accessories and ecosystem-linked categories can reduce dependency on any single device cycle.
For procurement and channel leaders, the focus should be on supplier resilience, clear compatibility claims, and documented compliance readiness. Supplier selection criteria that include regional sourcing flexibility, eFiling and certification process maturity, and product-level transparency will help minimize disruption and protect assortment continuity. Evaluating accessory partnerships through the lens of lifecycle durability, documentation capability, and multi-device utility will support more durable category performance.
For detailed segmentation data, regional dynamics, and tailored scenario analysis, readers may refer to the full PW Consulting research report on the worldwide consumer electronic accessories market, which expands on the trends and strategic considerations outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Electronic Accessories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Ice-phobic Coating Market Surging Past 13% CAGR: Key Demand Shifts by 2032
By PW Consulting, 2026-09-18
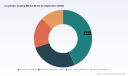
Navigating the Global Ice-Phobic Coating Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global ice-phobic coating market has undergone substantial transformation over the past five years, expanding from approximately USD 98.45 million in 2020 to USD 168.22 million in 2025. This trajectory reflects a compound annual growth rate of 13.38 percent, with projections indicating the market will reach USD 405.46 million by 2032. Such sustained expansion underscores a broader industrial shift toward passive ice protection solutions that reduce reliance on energy-intensive de-icing systems and mitigate operational disruptions caused by ice accumulation across critical infrastructure.
Behind these headline figures lies a market characterized by uneven maturity levels across application verticals and geographic regions. Aerospace and defense applications continue to command the largest revenue share, driven by stringent safety requirements, harsh operating environments, and the high cost of operational downtime. Renewable energy, particularly wind turbine blade protection, represents the fastest-growing application segment as operators seek to maintain power output and blade integrity in cold climates. Power lines and infrastructure, alongside marine and automotive use cases, demonstrate steady but more fragmented adoption patterns shaped by localized weather risks and varying regulatory mandates.
Several structural challenges define the current inflection point for industry participants. First, durability and environmental degradation remain persistent technical hurdles. Ice-phobic coatings must withstand UV exposure, thermal cycling, abrasion, and chemical exposure while maintaining low ice adhesion over multi-year service intervals. Coatings that degrade prematurely force costly reapplication cycles, eroding the total cost-of-ownership advantage that drives procurement decisions. Second, the regulatory landscape is tightening around fluorinated chemistries. Many traditional low-surface-energy formulations rely on perfluorinated compounds, and growing scrutiny of persistent chemicals is pushing developers toward PFAS-free or fluorocarbon-free alternatives without sacrificing performance. This transition introduces formulation complexity, re-validation costs, and in some cases, trade-offs between repellency and mechanical durability. Third, certification pathways for aviation and critical infrastructure applications remain lengthy and capital-intensive. Validating ice adhesion reduction, wear resistance, and performance under operational thermal conditions requires extensive laboratory and field testing, creating barriers that favor established players with existing qualification relationships while slowing the commercialization cadence of newer entrants.
These dynamics create both pressure and opportunity. Companies that can deliver durable, certifiable, and environmentally compliant formulations at scale are positioned to capture premium market segments, while those dependent on legacy chemistries or lacking validation infrastructure face erosion in competitive positioning. The market is not merely growing; it is re-segmenting around performance reliability, regulatory alignment, and application-specific engineering.
Key Drivers Shaping Market Trajectory
Several interconnected forces are accelerating adoption and reshaping competitive priorities across the ice-phobic coating landscape. Understanding these drivers is essential for anticipating where demand will concentrate and which capabilities will differentiate winners.
Technological Innovation and Performance Breakthroughs
Advances in material science are expanding the performance envelope of ice-phobic coatings beyond simple hydrophobicity. Nanocomposite formulations incorporating silica nanoparticles, silicone-based matrices, and hybrid organic-inorganic architectures are delivering improved ice adhesion reduction alongside enhanced resistance to erosion, corrosion, and UV degradation. One-part and moisture-cured systems are gaining traction because they simplify application on complex geometries such as wind turbine blades, aircraft leading edges, and power line components. At the same time, slippery liquid-infused porous surface technologies are pushing the boundaries of ultra-low ice adhesion, offering self-healing characteristics and repellency across a broader range of environmental conditions. These innovations are shifting the value proposition from basic ice shedding to multifunctional surface engineering that also addresses fouling, soiling, and signal interference.
Anti-Fog Coatings Market
Regulatory and Environmental Pressures
Environmental compliance is emerging as a decisive market force. The industry trend toward PFAS-free and fluorocarbon-free formulations reflects both regulatory momentum and customer ESG requirements, particularly in aerospace, defense, and publicly regulated infrastructure. Formulators are responding with solvent-based hybrid systems, epoxy-based composites, and surface treatments that maintain low surface energy without relying on long-chain fluorinated compounds. However, regulatory transitions are not uniform across regions or applications, and aviation coatings must still satisfy rigorous certification regimes that validate durability, adhesion, and thermal performance. This regulatory complexity increases development costs but also creates a protective moat for manufacturers that can navigate qualification processes efficiently.
Demand-Side Shifts in Critical Infrastructure and Energy
Operational resilience is driving procurement behavior across multiple sectors. Wind turbine operators in cold-climate regions are increasingly prioritizing passive ice protection to sustain energy yield, reduce blade fatigue, and defer mechanical de-icing capital expenditure. In aerospace, operators seek coatings that reduce ice accumulation on wings, propellers, sensors, and engine components while minimizing weight and maintenance burden. Utility and infrastructure managers face growing pressure to mitigate ice loading on transmission lines and critical assets during extreme weather events. These demand-side shifts are not cyclical; they reflect long-term exposure to colder operating environments, higher availability expectations, and the rising cost of unplanned downtime. As a result, procurement decisions are increasingly evaluated on total lifecycle value rather than upfront coating cost alone.
Supply Chain and Cost Structure Evolution
Raw material selection and application logistics are reshaping cost structures. Common feedstocks such as fluoropolymers, polydimethylsiloxane, silica nanoparticles, and perfluorinated or alkoxysilane precursors influence both formulation performance and supply risk. Manufacturers are balancing the performance benefits of fluorinated chemistries against supply volatility and regulatory exposure, while exploring alternative architectures that can be applied by brush, spray, or wipe without specialized equipment. Application certification programs and scalable production methods are becoming differentiators, particularly for wind turbine and infrastructure markets where field application consistency directly affects performance outcomes. Companies that streamline application workflows and secure reliable feedstock pipelines are better positioned to scale without compromising quality or margin.
Competitive Landscape and Leading Strategies
The market features a mix of specialized materials developers, application-focused coating suppliers, and research-driven innovators. Competitive positioning is increasingly defined by formulation architecture, certification track record, application scalability, and environmental compliance rather than price alone.
Strategic Positioning Among Leading Participants
Several companies illustrate the breadth of strategic approaches shaping the market. NEI Corporation has built a commercial presence around nanocomposite anti-ice coatings that combine reduced ice adhesion with hydrophobic properties and UV protection, targeting aerospace, wind, power line, and marine applications across multiple substrate types. The emphasis on one-part formulations and flexible application methods reflects a strategy centered on ease of deployment and broad substrate compatibility.
Aerospace & Advanced Composites GmbH represents a strong focus on fluorocarbon-free and PFAS-free systems, offering solvent-based and hybrid SLIPS formulations designed for extreme cold, heat, and moisture conditions. Its product architecture targets ultra-low ice adhesion while maintaining hydrophobic and easy-clean characteristics, appealing to industrial and aerospace customers seeking to align performance with environmental standards.
NanoSonic, Inc. emphasizes durability in harsh operational settings, with hybrid nanocomposite coatings validated for corrosion, erosion, abrasion, and UV resistance. Targeted at naval superstructures, military drones, and similar extreme environments, the company's single-component moisture-cured formulations highlight a strategy built around robustness and application simplicity for defense and marine use cases.
Cytonix LLC continues to develop fluorochemical-based ice-repellent and superhydrophobic coatings for antennas, radomes, marine, and general surface protection. Its smooth, low-surface-energy formulations are oriented toward signal preservation and operational reliability in adverse weather, reflecting a niche where functional performance in telecommunications and marine settings creates a distinct value proposition.
Super Hydrophobic Nano Coating Market
Elemental Coatings has concentrated on durable anti-icing and anti-scaling solutions for aerospace, transportation, energy, marine, and consumer applications, with an emphasis on low ice adhesion and scalability for large surfaces. Public funding relationships for aircraft-related applications illustrate how endorsement and validation can accelerate credibility in high-assurance sectors.
PW Consulting
Adaptive Surface Technologies has commercialized SLIPS-based platforms for icephobic, foul-release, and repellent applications across aviation, marine, industrial, and medical markets. Its focus on ultra-low ice adhesion and self-healing properties, along with public funding support for aircraft anti-icing, underscores a technology-led strategy aimed at high-performance use cases where repellency and resilience are critical.
Aculon, Inc. develops nanoscale hydrophobic and oleophobic surface treatments with icephobic relevance across optics, electronics, metals, and industrial substrates. Its thin, durable, PFAS-free options reflect a strategy oriented toward precision applications where surface finish and chemical compliance intersect.
Phazebreak Coatings has built a notable commercial footprint in wind turbine blade protection, with its icephobic coating installed on a substantial number of blades globally since its launch. The company's focus on passive ice protection, applicator certification programs, and variants tailored to warmer climates demonstrates a market-specific strategy that prioritizes field validation, application quality control, and climate-adapted product segmentation.
Market Structure Evolution
The competitive landscape is evolving along multiple axes. On one hand, consolidation potential exists as larger materials and coatings players seek to acquire specialized ice-phobic capabilities to broaden their surface engineering portfolios. On the other hand, market fragmentation persists because application requirements vary dramatically across substrates, climates, and certification environments, making single-formulation dominance difficult. New entrants continue to emerge from academic and national laboratory research pipelines, bringing advanced architectures such as dynamic epoxy-based composites, nanostructured surfaces, and photothermal approaches into commercialization pathways. Public funding mechanisms and small business innovation programs are playing a meaningful role in bridging early-stage development and field validation, particularly in aerospace and defense.
The practical implication is that competitive advantage will increasingly depend on three capabilities: the ability to deliver certifiable, durable performance in target applications; the capacity to formulate compliant chemistries without sacrificing repellency; and the operational competence to ensure consistent field application at scale. Companies that integrate product development with application training, qualification support, and climate-specific product variants are likely to capture greater share in high-value segments.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define market direction and shape commercial opportunity.
Accelerated Adoption in Renewable Energy and Infrastructure
Wind turbine blade protection and power line infrastructure are expected to drive a disproportionate share of incremental growth. As cold-climate wind deployment expands and operators seek to protect asset longevity and revenue consistency, demand for field-validated, scalable ice-phobic solutions will intensify. Commercial opportunity will center on coatings that balance ice adhesion reduction with erosion resistance, enable reliable field application, and integrate with existing maintenance workflows. Variants tailored to different climate bands will become more important as manufacturers serve geographically diverse fleets.
Regulatory-Driven Chemistry Transitions
The shift toward PFAS-free and fluorocarbon-free formulations will move from a compliance exercise to a competitive requirement in many segments, particularly where public procurement, environmental permitting, or customer ESG expectations influence purchasing. This transition will reward formulators that can demonstrate comparable durability and ice repellency without relying on regulated chemistries. At the same time, it may create short-term friction in applications where fluorinated materials have historically delivered the best balance of performance and robustness. Organizations that invest early in alternative chemistries and validation will be better positioned to capture procurement cycles as standards tighten.
Certification as a Strategic Bottleneck and Moat
Certification and field validation will remain both a barrier and a competitive advantage. Aviation and critical infrastructure applications require demonstration of durability under thermal cycling, wear, and operational stress. The organizations that can efficiently manage testing, documentation, and qualification relationships will gain a structural edge in high-assurance markets. Commercial opportunity lies not only in coating performance but in the surrounding service model: application protocols, operator training, quality assurance, and post-application monitoring. In this context, certification-capable suppliers may command premium positioning even when alternative products are technically feasible.
Risks and uncertainties remain. Durability gaps in demanding environments could lead to reapplication costs that weaken economic justification. Regulatory timelines and substance restrictions may evolve unevenly across jurisdictions, complicating global product strategies. Supply chain volatility for specialty nanoparticles and silane precursors could affect formulation consistency and margin. Finally, overpromotion of performance claims without robust field validation may erode buyer trust and slow adoption in risk-averse procurement environments. Companies that manage these uncertainties through disciplined testing, transparent performance data, and conservative commercialization pacing will be better positioned to sustain growth.
Strategic Implications for Decision Makers
The evolving ice-phobic coating market presents distinct implications depending on organizational role and strategic objective.
For coating manufacturers and materials developers, the priority is to align formulation roadmaps with the twin demands of performance durability and environmental compliance. Investing in PFAS-free or fluorocarbon-free systems, validating long-term adhesion and erosion resistance under realistic thermal and mechanical conditions, and building application protocols that ensure field consistency will separate credible suppliers from commodity competitors. Where relevant, pursuing qualification pathways and public funding mechanisms can accelerate credibility in high-assurance sectors such as aerospace and defense. Diversification into climate-specific variants and multi-substrate compatibility can broaden addressable markets without diluting core technical strengths.
For investors, the most attractive opportunities lie where adoption drivers are structural rather than cyclical. Renewable energy ice protection, aviation anti-icing, and infrastructure resilience all reflect long-term exposure to operational risk, availability expectations, and extreme weather frequency. Due diligence should focus on durability validation, certification readiness, feedstock supply resilience, and the company's ability to scale application processes rather than on marketing claims alone. Companies with defensible qualification relationships, clear compliance strategies, and demonstrated field deployments are more likely to sustain premium positioning as the market matures.
For procurement and asset operators, the decision framework should move beyond unit price toward total cost of ownership and risk reduction. Evaluating ice adhesion performance under relevant environmental conditions, expected service life, reapplication frequency, application complexity, and certification status provides a more accurate basis for supplier selection. Where operational downtime is costly or safety-critical, partnering with suppliers that offer application certification, quality control support, and climate-adapted product variants can materially improve outcome reliability. Procurement teams should also monitor regulatory trends that may affect chemical compliance over the service life of coated assets.
For organizations seeking a structured assessment of segmentation dynamics, regional demand patterns, competitive positioning, and tailored commercial recommendations, the full market research report provides the detailed data and scenario analysis needed to translate these trends into actionable strategy. The complete study examines revenue trajectories, application-specific adoption drivers, regional nuances, and company-level benchmarks in greater depth, supporting more precise planning across product development, investment allocation, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Ice-phobic Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mechanical Chucks Market: Why 4.4% CAGR and Packaging Demand Redefine Growth
By PW Consulting, 2026-09-18
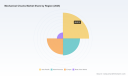
Mechanical Chucks Market: Strategic Trends and Commercial Opportunities Through 2032
The global mechanical chucks market has demonstrated consistent expansion over the past half-decade, with valuations climbing from approximately 601.12 million USD in 2020 to 742.5 million USD in 2025. Looking ahead, the sector is projected to reach the 1 billion USD threshold by 2032, supported by a compound annual growth rate of 4.4 percent across the 2026 to 2032 forecast period. This trajectory reflects sustained capital expenditure in precision manufacturing, steady replacement cycles for aging workholding equipment, and incremental but meaningful technology migration across industrial workshops worldwide. The market remains moderately fragmented, with the top five suppliers accounting for roughly 27.12 percent of revenue and the top three holding approximately 18.45 percent. This concentration profile indicates that while scale players command meaningful share, substantial value remains distributed among specialized and regional manufacturers capable of delivering application-specific solutions.
Beneath the headline growth figures, the industry is navigating a series of transition points that will define competitive outcomes over the next several years. First, the pricing and availability of structural raw materials have introduced renewed margin pressure. Steel continues to serve as the dominant input for mechanical chucks used in machine tool workholding, with United States prices stabilizing in the low-to-mid 800 dollars per short ton range into early 2026 amid moderate volatility. Tool steels such as D2 and H13, critical for high-precision chuck components, command elevated relative pricing due to the stringent performance demands of demanding machining applications. Manufacturers must balance input cost resilience with the need to preserve competitive pricing in cost-sensitive segments. Second, trade policy has become a more prominent cost variable. Elevated Section 232 steel tariffs, increased to 50 percent in 2025 for certain imports, have affected the landed cost of imported machine tool components including chucks, reshaping sourcing strategies for distributors and end-users in tariff-exposed markets. Third, the demand environment is shifting from volume-driven replacement toward performance-driven specification. Increasing demand for automation and precision in manufacturing is driving adoption of advanced mechanical chucks featuring equalising jaws, high gripping strength, and integrated coolant delivery. This shift rewards suppliers that can demonstrate measurable gains in workpiece security, cycle stability, and setup flexibility rather than those competing primarily on unit price.
These dynamics converge on a central reality: the mechanical chucks market is moving from a mature, commodity-leaning category toward a more specification-led, value-differentiated segment. Companies that can align product engineering with regional cost structures, navigate trade-related input pressures, and articulate clear productivity benefits will be best positioned to capture share as the market scales toward the next billion-dollar milestone.
Key Drivers Reshaping Demand and Competitive Value
Technological Innovation and Precision Workholding
Advances in chuck design are redefining what manufacturers expect from workholding. Equalising master jaws, high-gripping strength mechanisms, and integrated coolant pathways have moved from niche features to baseline expectations in many machining environments. These capabilities reduce workpiece deflection, improve surface finish consistency, and enable secure clamping of large rough castings and forgings that previously required multiple setup adjustments. The broader trend toward automation and precision in manufacturing is accelerating this transition, as producers seek chucks that integrate cleanly with programmed workflows and reduce operator-dependent variability. Suppliers that engineer for repeatability, rigidity, and ease of changeover are gaining preference in segments where setup time and clamping reliability directly influence throughput.
Mechanical Presses Market
Policy and Trade Environment: Cost, Sourcing, and Regionalization
Trade policy has become a structural factor in chuck procurement and production planning. The increase in Section 232 steel tariffs to 50 percent in 2025 for certain imports has raised the cost base for imported machine tool components, prompting decisive shifts in sourcing footprints. Some end-users and machine tool builders are reweighting procurement toward domestic or tariff-advantaged supply, while others are recalibrating bill-of-materials choices to offset higher input costs. At the same time, regional export strength from Taiwan and Japan in high-precision power and mechanical chucks has remained robust, with manufacturers actively showcasing solutions at major industry events. This combination of tariff pressure and established export capabilities is encouraging a more geographically diversified supply base, with procurement teams weighing total cost of ownership, lead-time reliability, and specification fit rather than relying on a single sourcing lane.
Demand-Side Shifts in Packaging, Metalworking, and Web Processing
End-use demand is evolving across multiple verticals, creating differentiated growth pockets. Packaging and converting continues to anchor a substantial share of chuck demand, driven by high-speed line requirements, core handling precision, and rolls handling safety. Metalworking and machine tools remain a core application base, with turning and milling operations seeking workholding that supports tighter tolerances and heavier cuts. In parallel, printing and textiles, along with paper and pulp manufacturing, sustain steady demand for core chucks and roll-handling solutions that emphasize safe unwind, rewinding, and shaft-less core management. Across these applications, the common thread is a move toward equipment that reduces downtime, improves operator safety, and maintains grip integrity under variable load conditions. Manufacturers that tailor mechanical solutions to the operational rhythms of each vertical are finding stronger retention and more favorable specification positioning.
Supply Chain and Cost Structure Considerations
Input volatility and logistics complexity continue to shape how chuck manufacturers structure their cost bases. Steel price stabilization in the low-to-mid 800 dollars per short ton range has provided some predictability, yet tool steel premiums and periodic swings still require active inventory and hedging discipline. Beyond raw materials, the cost equation increasingly includes compliance with evolving safety expectations, engineering for energy efficiency, and the operational expense of serving custom and standard product lines simultaneously. Companies that streamline design-for-manufacturing, standardize common interfaces across product families, and maintain selective vertical integration for critical components are better able to protect margins while remaining responsive to custom specification requests.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is anchored by a mix of precision-focused European manufacturers, high-capability Asian exporters, and specialized North American and European workholding specialists. This diversity is a defining strength of the market, as it allows end-users to select suppliers based on application fit, regional service proximity, and the balance between standard and custom offerings. Leadership in this environment is less about sheer scale and more about the ability to deliver repeatable precision, engineering responsiveness, and reliable integration with broader machine tool and production systems.
Several incumbent groups illustrate the strategic paths that are currently shaping the market. Global leaders in clamping devices have built reputations around comprehensive mechanical lathe chuck and drill chuck portfolios, pairing broad application coverage with high-precision standards for machine tools. Their advantage lies in catalogue depth, consistent quality, and the ability to serve a wide range of standard and semi-custom requirements across multiple regions. In turning applications for demanding machining environments, long-established specialists emphasize decades of experience and rugged mechanical and power chuck solutions designed for stability under heavy cutting loads. These firms differentiate through application know-how, robust component engineering, and service networks that reduce downtime for operators running high-utilization workflows.
On the heavy-machining side, manufacturers offering power and mechanical chucks with equalising capabilities are expanding their addressable scope for large rough castings and forgings. Recent product extensions, including new models with equalising master jaws engineered for secure gripping of large workpieces, illustrate how incumbents are pushing into higher-value applications that reward clamping security and setup flexibility. Taiwanese and Japanese suppliers continue to strengthen their export positions in high-precision power and mechanical chucks, leveraging active participation in major trade events and a focus on features such as ultra-thin rotary cylinders, large compound chucks for vertical lathes, and custom jaw solutions that emphasize energy efficiency and operator safety. These companies are competing not only on price but on engineering specifics that matter to machine tool builders and end-users seeking to optimize footprint, cycle time, and handling safety.
Regional specialists add further texture to the landscape. In the United States and Europe, workholding-focused manufacturers provide custom and standard mechanical chucks designed for milling, CNC, and industrial applications, often emphasizing gripping strength, rigidity, and coolant delivery for demanding use cases. Precision scroll and independent mechanical chuck producers serve metalworking customers that value manual and power options with reliable, time-tested geometries. In web processing, mechanical core chuck specialists deliver solutions for roll handling, unwinding, and rewinding, focusing on safety and precision for shaft-less unwinders and rewinders as well as air-assisted and mechanical core chucks for winding systems. The presence of these application-oriented players indicates that the market is unlikely to consolidate into a single dominant model; rather, differentiation by application, region, and service model will remain the primary axes of competition.
Looking at structural evolution, the market is likely to see continued specialization alongside selective consolidation. Larger players may pursue targeted acquisitions to broaden application coverage or strengthen regional service capabilities, while smaller specialists will compete by deepening domain expertise and offering tailored solutions that generalist catalogues cannot easily replicate. New entrants are most likely to succeed by focusing on underserved application niches, improving integration with automation workflows, or delivering cost-competitive precision through disciplined manufacturing and design standardization. Trade dynamics and input cost conditions will continue to influence where production and sourcing are located, reinforcing the value of a flexible, multi-node supply strategy.
PW Consulting
Forward Outlook: Three Trajectories Shaping the Next Three to Five Years
The first trajectory is the continued migration toward specification-led purchasing. As manufacturers pursue automation and precision gains, mechanical chucks with equalising jaws, high gripping strength, and application-specific features will see stronger adoption in metalworking, heavy machining, and high-speed converting environments. The commercial implication is clear: suppliers that can quantify the productivity impact of advanced clamping features will gain preference in bids where setup reliability and workpiece security are decisive. This trend favors engineering transparency, application benchmarking, and close collaboration with machine tool builders and line designers.
The second trajectory is a more deliberate regionalization of supply and sourcing. Trade policy effects and input cost variability are encouraging procurement teams to diversify supply bases, nearshore where feasible, and prioritize total cost of ownership over lowest unit price. For chuck manufacturers, this means that regional service capacity, inventory positioning, and the ability to offer tariff-advantaged configurations will increasingly influence purchasing decisions. Companies that can support local lead times without sacrificing precision standards are likely to capture incremental share from single-source dependency models.
The third trajectory is the widening role of safety, energy efficiency, and operator-centric design. Recent industry showcases have highlighted features such as ultra-thin rotary cylinders, large compound chucks for vertical lathes, and custom jaw solutions that reduce handling risk and improve energy efficiency. As workforce availability and operating cost pressures intensify, these attributes will move from differentiators to requirements in many purchasing decisions. The opportunity lies in packaging these features into standard families that simplify specification while preserving the flexibility needed for custom applications. Potential risks include continued raw material volatility, tariff escalation on specific import categories, and uneven demand recovery across regions and verticals, which could pressure margins for suppliers with limited cost flexibility or over-reliance on a single application channel.
Strategic Actions for Decision-Makers
For manufacturers and machine tool builders, the priority is to align product and sourcing strategies with the transition toward precision-led specifications and tariff-aware procurement. This includes evaluating design standardization opportunities that lower cost while preserving performance, securing input supply for critical tool steels and steel grades, and building regional service and inventory capabilities that reduce lead-time risk. Suppliers should also invest in demonstrating measurable productivity outcomes from advanced clamping features, since specification decisions are increasingly tied to setup stability, cycle consistency, and operator safety.
For investors, the market’s moderate concentration and diversified application base suggest value in companies with clear engineering differentiation, disciplined cost management, and exposure to resilient demand channels such as packaging and converting, metalworking machine tools, and web processing. Due diligence should weigh not only revenue growth but also margin resilience under raw material and trade-policy variability, the breadth of standard-versus-custom product mix, and the strength of regional service and export capabilities. Companies that can scale precision solutions into higher-value applications while maintaining cost discipline are best positioned to translate market growth into durable profitability.
For procurement and operations leaders, the practical imperative is to evaluate chuck suppliers on total cost of ownership, specification fit, and reliability under real production conditions rather than on headline price alone. This means prioritizing clamping security, ease of changeover, and safety features that reduce downtime and handling risk, while also mapping supply continuity against tariff exposure and lead-time volatility. Engaging suppliers early in machine design or line configuration can unlock more efficient workholding architectures and avoid costly retrofits later. In a market that is growing steadily but changing in how value is created and captured, timely access to detailed segmentation data, regional pricing dynamics, and supplier benchmarking will be essential to sharpen sourcing decisions and investment prioritization. For those seeking a deeper look at segment-level dynamics, regional nuances, and tailored scenario planning, the full PW Consulting market research report provides the granular data and structured recommendations needed to act with confidence.
Electrostatic Chucks for Wafer Market
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Chucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Balloon Forming Machine Market: Why 6.51% CAGR Changes Everything
By PW Consulting, 2026-09-18
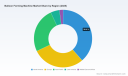
Navigating the Worldwide Balloon Forming Machine Market: Strategic Trends and Commercial Opportunities (2026–2032)
市场现状与核心挑战
The global balloon forming machine market is undergoing a period of steady but structurally significant expansion. Valued at approximately USD 212.55 million in 2025, the market has demonstrated consistent year-over-year growth since 2020, when it stood at around USD 155.12 million. The compound annual growth rate of 6.51 percent across the 2026–2032 forecast horizon projects the market to reach USD 330.52 million by 2032, with incremental acceleration expected in the latter half of the decade. This trajectory reflects a maturing industrial ecosystem that is increasingly aligned with the broader shift toward minimally invasive medical interventions, yet it also reveals structural tensions that will shape competitive dynamics and investment priorities in the years ahead.
At this scale and growth rate, the market operates in a moderately concentrated environment. A handful of established equipment suppliers command a disproportionate share of revenue, while a broader tier of regional and specialized manufacturers competes on cost, customization, or niche application coverage. This concentration creates a dual dynamic: it stabilizes pricing and technology standards in the high-precision segment, but it also raises barriers for new entrants seeking to compete on engineering complexity alone. For equipment buyers and device manufacturers, the landscape offers proven solutions with documented performance records, but it also demands careful evaluation of total cost of ownership, upgrade pathways, and regional service availability.
Several structural challenges and inflection points define the current moment. First, the industry is navigating a transition from standardized balloon geometries toward increasingly complex, high-pressure, and multi-lumen designs. As interventional procedures target harder-to-reach anatomies and longer-duration therapies, forming equipment must accommodate tighter tolerances, variable material behavior, and more aggressive thermal and pressure profiles. Machines that cannot reliably replicate these conditions face obsolescence pressure, while those that can command premium positioning and longer deployment lifecycles.
Second, raw material volatility and sourcing complexity are reshaping cost structures across the supply chain. Medical balloons are formed from specialized polymers whose availability, pricing, and consistency directly influence machine throughput, mold design, and process stability. Fluctuations in polymer pricing, combined with shifting trade and tariff dynamics, introduce variability into manufacturing economics and can compress margins for producers operating on tight cost models. Equipment vendors that offer better temperature uniformity, faster cycle times, or flexible material compatibility gain a practical advantage in this environment, but the broader ecosystem must manage input-cost unpredictability as a persistent operational reality.
Third, the regulatory and quality-assurance backdrop continues to elevate the importance of process documentation and repeatability. In medical device production, equipment that supports certified production environments and consistent output is not merely a technical preference; it is a compliance and commercial necessity. Suppliers that embed traceability, validation support, and stable process control into their platforms reduce integration friction for device manufacturers, while those that treat certification as an afterthought risk slower adoption cycles and more procurement scrutiny. Together, these challenges point to a market where incremental capability improvements, supply-chain resilience, and compliance-aligned design are becoming as important as raw throughput.
关键驱动因素分析
The growth trajectory of the balloon forming machine market is not the result of a single force. It is being pulled forward by a convergence of technological, regulatory, demand-side, and supply-chain developments that reinforce one another and create pockets of accelerated adoption.
Technological innovation and breakthrough capability
At the core of market momentum is a clear technological shift toward faster, more uniform, and more versatile forming systems. Induction heating, advanced resistance heating, and rapid heat-and-cool mold technologies are reducing cycle times and improving temperature consistency across complex geometries. These improvements matter because balloon performance is highly sensitive to thermal history, material expansion, and mold contact uniformity. Machines that shorten cycle times while maintaining dimensional fidelity increase effective throughput without requiring proportional increases in floor space or labor, which makes them attractive in cost-conscious and capacity-constrained production environments.
Recent product activity illustrates this trajectory. High-force forming platforms have been introduced to support structural heart applications and thick-walled, high-pressure balloons, extending the operational envelope beyond traditional coronary and peripheral designs. Split-mold and rapid thermal-cycling configurations have also gained visibility, with demonstrable reductions in cycle time that directly affect unit economics. Equally important, the technology conversation is expanding beyond forming alone. Equipment portfolios increasingly encompass related catheter production tools such as pre-stretching, folding, and specialized mold sets, enabling more integrated workflows and reducing changeover complexity.
Policy and regulatory environment
Regulatory expectations continue to shape both equipment design and procurement behavior. For medical device manufacturers, the ability to run validated, documented, and repeatable processes is a baseline requirement rather than a differentiator. This environment favors equipment suppliers that are already aligned with quality management expectations and that can provide clear support for installation qualification, operational qualification, and process validation activities. When forming equipment contributes to a compliant production environment, procurement decisions become less about absolute lowest price and more about risk reduction, consistency, and lifecycle support.
In practice, this means that features such as controlled heating profiles, reproducible cooling behavior, and clear process data capture are increasingly valued by buyers who must demonstrate control over critical manufacturing steps. Regulatory momentum also interacts with material selection, because approved balloon materials must be processed in ways that preserve their mechanical integrity and surface characteristics. As a result, machine platforms that can accommodate common medical-grade polymers while maintaining tight process control are better positioned for sustained adoption.
Demand-side change in medical procedures and device strategy
On the demand side, the most persistent driver is the ongoing expansion of minimally invasive procedures, particularly in cardiovascular, neurovascular, urological, and gastrointestinal applications. As interventional teams pursue more complex lesions, higher-pressure dilatations, and structurally demanding implants, the specifications for balloons become more demanding. Thicker walls, higher burst pressures, and more precise tapering or shaping requirements translate into greater need for forming equipment that can handle high-force conditions and deliver consistent outcomes across smaller batches or more variable designs.
Worldwide Burrito Forming Machine Market
This demand shift also affects production planning. Device manufacturers are not simply scaling volume; they are increasingly managing product families with varied specifications, material grades, and mold configurations. Equipment that can switch between configurations efficiently, maintain stability across different polymers, and support shorter commissioning cycles becomes strategically important. The result is a market where versatility and reliability often compete with pure cost efficiency as decisive purchase criteria.
Supply chain and cost-structure dynamics
Supply chain conditions are a quieter but highly influential driver. Medical balloon production depends on specialized polymers, and the broader medical polymer market remains large and sensitive to industrial demand patterns. At the same time, localized price movements in commodity and specialty resins can affect the economics of balloon manufacturing, especially when import tariffs or logistics disruptions alter input costs. Even modest price changes can influence mold design choices, forming parameters, and the financial case for upgrading equipment.
This environment increases the value of machines that offer robust temperature control, efficient cooling, and material flexibility. Faster cycle times help compensate for cost pressure by improving output per shift, while better thermal uniformity reduces scrap and rework. Supply-side uncertainty also favors suppliers that can provide dependable service, replacement part availability, and regional support, because downtime in a precision process can be disproportionately expensive. In this sense, cost structure is not only about equipment price; it is about the stability and responsiveness of the entire production environment.
竞争格局与领先策略
The competitive landscape in balloon forming equipment is defined by a mix of specialized engineering firms, multi-brand distributors, and a growing set of manufacturers focused on cost-competitive or application-targeted solutions. The market does not yet resemble a commodity segment; instead, it rewards companies that combine process expertise, material knowledge, and dependable support with clear product differentiation.
Leading European and North American players have built their positions around precision, engineering depth, and product breadth. These firms typically offer a range of forming configurations spanning single-up to multi-up vertical machines, induction or resistance heating options, and specialized platforms for high-force or high-cycle applications. Their differentiation often lies in the ability to address demanding medical balloon requirements with documented process stability, broad mold compatibility, and established relationships within catheter and interventional device manufacturing networks. Presence at major industry exhibitions and consistent product updates signal an emphasis on visibility, customer engagement, and continuous refinement rather than static product lines.
A notable strategic theme among advanced suppliers is the pursuit of cycle-time reduction and thermal control as core value propositions. Split-mold designs with rapid heat and cool capabilities, high-force forming platforms for structural heart and thick-wall balloons, and induction-based systems for temperature uniformity all reflect a shared recognition that throughput and quality are increasingly inseparable. In this context, advantage is gained not simply by offering another forming machine, but by targeting specific pain points: production speed, material versatility, improved yield, or support for the next class of balloon designs.
The market also includes a meaningful presence of manufacturers oriented toward entry-level and mid-range solutions, often with vertical forming architectures, rapid mold cooling features, and broad material compatibility across nylon, PEBAX, polyurethane, and related polymers. These offerings play an important role in expanding access to forming capability, particularly for smaller producers or regional device manufacturers. Their strategic positioning typically emphasizes accessibility, practical feature sets, and integrated tooling ecosystems that support related catheter production steps. This creates a segmented field in which premium, application-intensive platforms coexist with more accessible solutions that lower the barrier to scaled production.
Distribution and support networks are becoming an important axis of competition as well. Some companies extend their reach by distributing and servicing equipment from complementary manufacturers, effectively building broader solution portfolios around precision, yield, and local support. This approach can shorten procurement cycles and simplify equipment sourcing for buyers who prefer fewer integration points and clearer accountability. It also reflects a wider industry trend in which value is created not only through original equipment design but through installation, training, service responsiveness, and spare-part reliability.
Looking at market evolution, three patterns stand out. First, consolidation at the service and distribution layer is likely to continue, as buyers prefer integrated relationships that cover equipment, molds, training, and ongoing support. Second, differentiation will increasingly center on application-specific capability, especially for structural heart, high-pressure, and complex geometry balloons, where performance requirements are rising fastest. Third, new entrants will need to decide whether to compete on cost and accessibility or on engineering specialization and compliance-aligned process control. Attempts to occupy both positions without clear focus tend to struggle in a market where buyers are increasingly sophisticated about trade-offs between price, consistency, and lifecycle support.
PW Consulting
未来趋势预测
Over the next three to five years, the balloon forming machine market is likely to diverge along capability, integration, and regional service lines rather than moving toward a uniform global standard. The following trends are the most consequential for strategic planning.
- Advanced high-force and rapid-cycle platforms will become a larger share of incremental demand.
As structural heart interventions and complex high-pressure balloon applications expand, equipment that can reliably process thicker walls and more demanding geometries will gain prominence. This trend favors suppliers that can demonstrate controlled heating, robust pressure handling, and consistent cooling behavior. The commercial opportunity lies in serving devices that are harder to manufacture consistently, where yield improvement and process stability create measurable value beyond raw machine price.
- Integrated tooling and workflow ecosystems will matter more than standalone forming units.
Buyers are increasingly looking beyond the forming step to the surrounding process, including molds, pre-stretching, folding, and related catheter production tools. Equipment that reduces changeover time, supports multiple configurations, and fits into a coherent production flow will be preferred, especially by manufacturers managing diverse product families. This creates opportunities for vendors that can package forming capability with complementary tooling and process support, rather than selling isolated machines.
- Regional service, compliance alignment, and supply resilience will become decisive procurement factors.
Because polymer input conditions and trade dynamics can shift costs and availability, manufacturers will place greater weight on equipment suppliers that offer dependable support, predictable uptime, and compatibility with validated production environments. This trend strengthens the position of companies that invest in documentation, service responsiveness, and regional reach. The risk is that buyers may consolidate around a smaller set of trusted partners, making it harder for newer or less-supported entrants to gain traction without a clear differentiation strategy.
决策者行动建议
For equipment manufacturers and suppliers, the priority is to sharpen differentiation around the operational problems that buyers now care about most: cycle-time reduction, temperature uniformity, high-force capability, and compliance-aligned process support. Product roadmaps should anticipate not only current balloon specifications but also the next wave of thicker-wall, high-pressure, and more complex geometries. Equally important, service, training, and regional support should be treated as core competitive assets rather than overhead, because uptime and consistency increasingly determine total cost of ownership.
For investors and strategic partners, the opportunity is to distinguish between volume-driven segments and capability-driven segments. High-growth demand is likely to concentrate where forming equipment enables higher-yield production of more demanding balloons, and where suppliers can combine technology with dependable support. Capital allocation and partnership decisions should account for the fact that pricing pressure alone is a weak indicator of long-term value; differentiation, application fit, and service reliability will be stronger signals of durable positioning.
Thermoforming Machines Market
For device manufacturers and procurement teams, the practical imperative is to evaluate forming equipment as part of a broader process strategy. Selection criteria should include thermal control quality, cycle-time performance, material compatibility, changeover efficiency, and the supplier's ability to support validation and ongoing production stability. Where possible, buyers should pressure-test total cost of ownership rather than initial price, and consider how equipment choices will affect scalability if product portfolios expand into more complex balloon types. In a market that is growing steadily but changing in structure, timely access to segmented demand data, competitive benchmarks, and application-specific procurement insight can materially improve planning and reduce adoption risk.
For detailed analysis of this topic, please visit the official page: Worldwide Balloon Forming Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Auto-fill Humidification Chamber Market: The 6.45% CAGR and Hospital Demand Shift
By PW Consulting, 2026-09-18
Global Auto-fill Humidification Chamber Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Overview and Core Challenges
The global market for auto-fill humidification chambers has entered a phase of steady, structurally driven expansion. Valued at approximately 641.93 million USD in 2025, the sector has demonstrated consistent compounding since 2020, with a long-term compound annual growth rate projected at 6.45 percent through 2032. This trajectory reflects a transition from routine respiratory support accessories to precision-engineered components that directly impact clinical outcomes, ventilation efficiency, and infection control protocols. The market's scale underscores a fundamental shift in how respiratory therapies are delivered across acute care, outpatient, and residential environments, positioning humidification hardware as a critical node in the broader respiratory care ecosystem.
Despite the favorable growth trajectory, the industry faces several structural challenges that will shape competitive positioning in the coming years. First, regulatory standardization continues to evolve across major markets. Devices intended for continuous respiratory gas humidification are classified as Class II medical devices in the United States, requiring documented 510(k) clearance before commercialization. While established manufacturers navigate this pathway efficiently, the requirement creates barriers for new entrants and mandates continuous post-market compliance across regions with differing sterilization, labeling, and clinical validation requirements. This regulatory complexity increases time-to-market for novel designs and heightens the cost of maintaining global product portfolios.
Second, the single-patient-use paradigm fundamentally shapes both procurement economics and supply chain strategy. Auto-fill humidification chambers are typically manufactured from clear polycarbonate and supplied as disposable units, often with sterile packaging options to align with hospital infection control mandates. This disposable design eliminates cross-contamination risks and reduces reprocessing overhead, but it also ties revenue streams to continuous replacement cycles. Procurement teams increasingly scrutinize per-procedure cost, sterilization logistics, and waste management implications, forcing manufacturers to balance clinical safety with economic efficiency. The tension between infection control standards and cost containment will remain a persistent pressure point, particularly in public healthcare systems and high-volume critical care networks.
Third, supply chain resilience and material sourcing present ongoing operational considerations. Polycarbonate production, precision molding, and sterile packaging rely on specialized manufacturing capabilities and consistent raw material availability. Geopolitical shifts, logistics disruptions, and fluctuations in medical-grade polymer pricing can compress margins or delay product launches. Companies that have diversified supplier bases, localized critical manufacturing steps, or invested in standardized component architectures are better positioned to absorb these shocks. Conversely, firms dependent on single-source supply chains face elevated risk exposure. These overlapping challenges define the current inflection point: growth is robust, but capturing value requires disciplined navigation of regulatory pathways, cost structures, and supply chain volatility.
Key Growth Drivers
Technological Innovation and Clinical Performance Optimization
The most significant catalyst for market expansion lies in the continuous refinement of auto-fill mechanisms and their integration with modern ventilation workflows. Leading chamber designs now employ dual-float or multi-valve architectures that regulate automatic water replenishment while preventing overfilling. These mechanisms maintain consistent compressible volume, a critical parameter for patients undergoing high-frequency ventilation, non-invasive respiratory support, or conventional mechanical ventilation. By stabilizing humidity delivery without requiring clinician intervention, these designs reduce workflow interruptions and support more predictable therapeutic outcomes. The clinical benefit is clear: stable humidity levels minimize airway drying, reduce mucus viscosity complications, and support patient comfort during extended ventilation sessions.
Recent product clearances and submissions illustrate how manufacturers are translating these engineering advances into market-ready solutions. Regulatory documentation from mid-2023 highlighted submission activity for next-generation dual-chamber systems designed to improve thermal consistency and streamline compatibility with existing heated humidifier platforms. Earlier clearances had already established pathways for auto-fill chambers integrated into non-invasive ventilation and nasal high-flow circuit kits, signaling a deliberate push toward broader clinical applicability. These filings demonstrate an industry-wide focus on reducing setup complexity while expanding the range of ventilation modes that can be supported reliably. For manufacturers, the emphasis is shifting from basic humidification functionality toward integrated performance characteristics that align with modern respiratory care bundles.
Regulatory Pathways and Compliance as Market Filters
Regulatory frameworks are simultaneously constraining and shaping market dynamics. The classification of auto-fill humidification chambers as Class II devices under respiratory gas humidifier provisions means that manufacturers must demonstrate substantial equivalence to legally marketed predicates through structured 510(k) pathways. This requirement creates a natural filter: companies with established regulatory infrastructure, active quality management systems, and experience in respiratory device submissions gain a competitive advantage. The process also encourages iterative product improvement, as design modifications often require updated testing documentation or new clearance submissions when compatibility claims or performance parameters change.
Beyond the United States, variation in regional regulatory expectations adds complexity to global commercialization. Differences in sterilization validation requirements, labeling standards, and clinical documentation expectations mean that a single chamber design may require region-specific adaptations before launch. This fragmentation raises the operational bar for international expansion but also rewards manufacturers that invest in harmonized design architectures and proactive regulatory planning. The result is a market where compliance capability is itself a competitive asset, and where firms that treat regulatory engagement as a continuous engineering function rather than a periodic submission exercise are better equipped to scale across geographies.
Demand-Side Shifts in Respiratory Care Delivery
Clinical utilization patterns are evolving in ways that directly expand the addressable market for auto-fill humidification chambers. Critical care environments continue to represent the largest demand concentration, driven by sustained ICU admissions, the need for precise humidity control during invasive and non-invasive ventilation, and the integration of humidification into standardized airway management protocols. However, growth is increasingly distributed across additional care settings. Home healthcare utilization has expanded as patients require ongoing respiratory support outside acute facilities, and specialty clinics have adopted heated humidification for a broader range of procedures and therapy regimens. These shifts extend the product lifecycle beyond episodic acute care and create recurring demand in decentralized care environments.
Patient demographic trends further reinforce this broadening demand base. Adult patient populations continue to account for the majority of utilization, reflecting higher prevalence of chronic respiratory conditions, post-surgical ventilation needs, and age-related pulmonary complications. At the same time, pediatric and neonatal applications sustain meaningful demand, particularly in units requiring precise compressible volume management and gentle humidity delivery for sensitive airways. The dual demand profile supports a diversified product strategy, where manufacturers can maintain broad-compatible platforms while offering configurations tailored to specific patient cohorts. This segmentation does not necessarily require entirely separate product lines, but it does demand engineering flexibility and clear clinical differentiation in marketing and distribution.
PW Consulting
Supply Chain Architecture and Cost Structure Dynamics
Cost structures in the auto-fill humidification chamber market are shaped by material selection, manufacturing precision, sterilization requirements, and distribution logistics. The prevailing disposable, single-patient-use model simplifies infection control but introduces continuous procurement cycles. Healthcare providers evaluate these products not only on clinical performance but also on total cost of ownership, which includes inventory management, waste handling, and compatibility with existing humidifier and breathing system ecosystems. Manufacturers that can offer reliable compatibility across major heated humidifier platforms reduce procurement friction and increase stickiness with institutional buyers.
Simultaneously, the cost of maintaining sterile packaging and meeting infection control specifications adds a layer of operational overhead. Sterile configurations require validated packaging processes, environmental controls, and cold-chain or controlled-storage considerations depending on regional distribution networks. These requirements elevate baseline costs but also create differentiation opportunities. Suppliers that can deliver sterile, ready-to-use chambers with consistent fill reliability and minimal setup time align closely with hospital priorities around workflow efficiency and patient safety. On the supply side, companies that standardize component designs, consolidate mold families, and regionalize manufacturing reduce exposure to logistics volatility and improve margin predictability. The companies that thrive will be those that treat supply chain design as an integral part of product strategy rather than a downstream execution concern.
Respiratory Humidifying Equipment Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentrated group of established manufacturers alongside regional and specialty suppliers that compete on compatibility, configuration breadth, and clinical support. The market exhibits notable concentration, with a small number of players capturing a substantial share of global demand. This structure reflects the importance of regulatory experience, existing humidifier ecosystem relationships, and manufacturing scale, all of which create meaningful barriers to rapid displacement. Yet the landscape is not static. Product differentiation, regional licensing strategies, and targeted portfolio expansions continue to reshape positioning within the leading cohort.
Fisher & Paykel Healthcare has built a strong position through a clearly defined product architecture centered on its MR290 series. The lineup includes multiple configurations designed to accommodate adult, pediatric, and high-frequency ventilation use while maintaining consistent compressible volume. The dual-float mechanism addresses two persistent clinical concerns: automatic refilling without flow interruption and overfill prevention. By aligning chamber design with the broader myAirvo and MR-series humidifier ecosystem, the company reinforces platform compatibility and simplifies procurement for facilities already standardized on its humidification infrastructure. Recent regulatory clearances for circuit kits incorporating these chambers further demonstrate a strategy of bundling chamber technology with integrated respiratory therapy solutions rather than selling components in isolation.
Intersurgical maintains a differentiated focus on dual-float auto-fill chambers offered in both standard and sterile configurations, with fill sets designed for compatibility with common heated humidifiers used across CPAP to full mechanical ventilation, including high-frequency oscillation. The emphasis on constant water level maintenance reflects a direct response to the clinical need for stable compressible volume across neonatal to adult populations. This positioning supports use in ICU environments where ventilation modes vary widely within a single unit, allowing a single chamber platform to serve multiple patient scenarios without compromising performance consistency.
Flexicare competes by expanding configuration options, including sterile versions and double-valve variants tailored for Bi-PAP applications. The use of primary and secondary floats for overfill protection, combined with designs optimized for reduced warm-up time through lower water volume, points to a strategy focused on operational efficiency and compatibility with heated wire breathing systems. By targeting specific ventilation modes and emphasizing setup speed, Flexicare addresses practical pain points in busy respiratory care environments where time-to-therapy and compatibility with existing airway circuits influence purchasing decisions.
In the Asia-Pacific region, GaleMed Corporation and Vadi Medical Technology illustrate a different competitive approach centered on sensitivity of the auto-filling mechanism and broad brand compatibility. GaleMed’s auto-feeding designs emphasize uninterrupted ventilation during sterile water refill, a feature particularly relevant for neonatal and adult applications where continuity of therapy is paramount. Vadi’s offering extends this logic with reusable and auto-feed versions designed to work across major humidifier brands, appealing to procurement teams seeking flexibility in mixed-equipment environments. These manufacturers demonstrate that regional players can compete effectively by prioritizing compatibility breadth and mechanism responsiveness rather than relying solely on global brand recognition.
Yaxin Medical adds another layer to the competitive mix with disposable auto-fill chambers engineered for compatibility with ICU ventilators and generic humidifiers, incorporating standardized connectors to simplify integration. This approach reflects a cost-conscious, compatibility-first strategy that targets high-throughput environments where standardization and ease of integration reduce training and setup burden. Vyaire Medical, through its AirLife product line, reinforces the importance of established respiratory care distribution channels and regulatory familiarity. Recent submission activity referencing prior autofill chamber technology indicates ongoing iteration within an existing platform framework, suggesting a strategy of incremental refinement rather than radical redesign.
The overall competitive trajectory points toward selective convergence around a few strategic themes. First, compatibility across major humidifier platforms remains a primary battleground, as institutions prefer fewer integration variables and simpler replacement workflows. Second, sterile single-use configurations are becoming a baseline expectation in hospital settings, making sterile packaging capability a table-stakes feature rather than a differentiator. Third, the market is experiencing incremental consolidation pressure as larger respiratory care suppliers seek to expand their humidification ecosystems, while smaller or regional manufacturers pursue niche positioning through specialized ventilation modes, regional distribution strength, or cost-optimized disposable formats. New entrants will likely need to navigate the regulatory pathway efficiently while offering a clear clinical or procurement advantage, whether through improved fill reliability, broader compatibility, faster warm-up, or streamlined supply arrangements.
Future Trends and Commercial Implications (2026–2032)
Over the next several years, the auto-fill humidification chamber market is likely to be shaped by three interlocking trends. The first is the continued expansion of heated humidification into decentralized care settings. As respiratory support increasingly extends beyond traditional ICU environments into home-based and ambulatory care pathways, demand for reliable, easy-to-deploy humidification components will grow. This trend favors products that combine clinical consistency with straightforward setup and clear patient-use guidance. Commercial opportunities will emerge for suppliers that can support both institutional and decentralized procurement models without compromising sterility, compatibility, or documentation standards.
The second trend is the gradual tightening of performance expectations around compressible volume stability and workflow integration. Clinicians and procurement teams are increasingly aware that humidification performance directly affects ventilation efficiency and patient comfort. Chambers that maintain stable water levels across varying ventilation modes, reduce warm-up time, and integrate cleanly with heated wire circuits will be preferred in competitive evaluations. This creates opportunities for manufacturers that invest in mechanism precision, standardized connector architectures, and compatibility validation across widely used humidifier platforms. The practical implication is that product leadership will be measured less by presence in the market and more by demonstrable consistency across real-world ventilation scenarios.
The third trend involves ongoing regulatory and reimbursement scrutiny that will influence purchasing behavior and product design. As healthcare systems continue to optimize cost structures, the classification and billing pathways for humidification supplies will remain relevant to procurement decisions. Devices that fit cleanly into existing reimbursement frameworks and demonstrate clear clinical utility are more likely to retain favorable purchasing status. However, regulatory expectations around single-patient-use labeling, sterilization validation, and post-market surveillance will continue to evolve, creating compliance overhead that rewards organizations with mature quality systems and proactive documentation practices. The principal risk lies in supply chain disruption, material cost volatility, and the potential for regional regulatory divergence to slow international rollouts. Additionally, any shift toward reprocessing debates or alternative materials could pressure the disposable model, though current infection control priorities strongly reinforce single-use adoption. Companies that monitor these dynamics early and build adaptable manufacturing and compliance frameworks will be better positioned to convert market growth into sustainable margin expansion.
Strategic Recommendations for Decision-Makers
Manufacturers should prioritize platform compatibility and configuration flexibility as core growth levers. Investing in chamber designs that maintain consistent performance across major humidifier ecosystems reduces procurement friction and strengthens retention in institutional accounts. Where possible, standardizing connector geometries, float mechanisms, and sterile packaging workflows will lower operational complexity while expanding addressable use cases across adult, pediatric, and neonatal settings. Regulatory planning should be treated as a continuous engineering function, with early alignment to submission pathways for new configurations or compatibility claims.
Investors evaluating exposure to this market should focus on companies that demonstrate durable regulatory capability, diversified supply chains, and clear positioning in high-utilization care settings. The market’s steady growth trajectory is attractive, but value capture depends on execution in manufacturing consistency, sterile packaging reliability, and global compliance management. Portfolio strength in ICU and respiratory care distribution channels, combined with evidence of iterative product refinement, is a meaningful indicator of resilience against competitive and supply chain disruption.
Walk In Humidity Chambers Market
Healthcare procurement and clinical operations leaders should prioritize total cost of ownership analyses that account for setup time, compatibility breadth, infection control compliance, and replacement cycle predictability. Standardizing on chambers that integrate cleanly with existing humidifier platforms can reduce training overhead and inventory complexity, while sterile single-use configurations help align with institutional infection control mandates. As utilization continues to expand across care settings, maintaining visibility into supplier reliability, regulatory status, and product iteration pipelines will support more informed sourcing decisions. For organizations seeking deeper segmentation data, regional demand patterns, and customized procurement or investment guidance, the full PW Consulting research report provides a more granular view of market dynamics and actionable next steps.
For detailed analysis of this topic, please visit the official page: Worldwide Auto-fill humidification chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
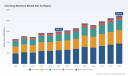
Strategic Shifts and Commercial Opportunities in the Global Clinching Machines Market: A 2025 Outlook
Market Snapshot and Critical Inflection Points
The global market for clinching machines has demonstrated robust momentum over the past half-decade, transitioning from a niche mechanical joining solution to a strategically relevant alternative in sheet metal assembly. Valued at approximately USD 1,145.2 million in 2020, the sector expanded to an estimated USD 1,502.41 million by 2025, reflecting sustained demand across heavy industrial and precision manufacturing verticals. Forward-looking projections indicate the revenue base will reach USD 2,232.35 million by 2032, supported by a compound annual growth rate of 5.82 percent through the forecast period. This trajectory underscores a market that is no longer defined solely by traditional fabricators but is increasingly embedded in high-volume, automation-driven production ecosystems.
Despite the positive growth narrative, operators and investors must navigate three structural challenges that are reshaping competitive dynamics. First, the shift toward lighter-weight materials and dissimilar material combinations—such as aluminum-to-steel or coated composite hybrids—places tighter tolerances on tool design and joint integrity, forcing manufacturers to balance cold-forming precision with cycle time efficiency. Second, capital expenditure sensitivity in cyclically exposed sectors like construction and general engineering creates demand volatility, compelling suppliers to offer more flexible fleet configurations, modular tooling, and service-oriented pricing models. Third, the growing expectation for seamless integration with automated work cells raises the technical barrier to entry; standalone manual or semi-automated units face margin pressure as end-users prioritize robotic compatibility, electrical efficiency, and consistent repeatability over simple equipment acquisition.
These inflection points are not deterrents but signals of market maturation. Companies that treat clinching as a standalone hardware transaction are losing ground to those positioning it as part of a broader process solution encompassing tooling management, integration architecture, and operational performance guarantees.
Core Demand Drivers Reshaping the Landscape
Several converging forces are accelerating adoption and redefining value creation within the clinching ecosystem. Technical innovation stands at the forefront, with servo-driven electric presses and precision-controlled punch-die geometries enabling cold-forming joints to be completed in milliseconds while maintaining fatigue resistance and airtight seals. The mechanical process eliminates the need for supplementary fasteners or adhesives, reducing material overhead and simplifying downstream disassembly or recycling workflows. Concurrently, electrical and hybrid press architectures are gaining traction as manufacturers seek to lower energy intensity relative to thermal joining alternatives, aligning equipment specifications with corporate sustainability mandates and total cost of ownership frameworks.
Regulatory and policy environments are exerting a quieter but equally powerful influence. Environmental compliance expectations around emissions, energy consumption, and circular material usage are pushing assembly lines toward low-heat, fastener-free joining methods. In sectors where structural safety standards intersect with material efficiency targets, clinching offers a viable pathway to join multi-layer sheets and dissimilar alloys without introducing thermal distortion or chemical residues. This regulatory tailwind is particularly visible in automotive lightweighting programs and appliance manufacturing, where weight reduction and component consistency are tied directly to performance certifications and consumer expectations.
Demand-side behavior is shifting as well. Original equipment manufacturers and tier suppliers are increasingly prioritizing process standardization and line simplification. The elimination of fastener inventory, reduced tooling changeover complexity, and the ability to maintain consistent joint quality across coated and galvanized substrates are driving procurement decisions toward integrated clinching solutions. Moreover, labor constraints in several industrial markets are accelerating interest in automated work cells, where robotic handling and servo-controlled actuation reduce dependency on skilled manual operators while improving throughput consistency.
Cold Heading Machine Market
On the supply side, cost structure dynamics are evolving. Tooling longevity, maintenance predictability, and modular machine configurations are becoming as commercially significant as base equipment pricing. Suppliers that provide clear lifecycle costing, standardized replacement tooling, and rapid service response are differentiating themselves in a competitive landscape where initial sticker price is no longer the decisive factor. Recent corporate communications from established players highlight this strategic emphasis: one veteran manufacturer refreshed its catalog and digital presence in late 2025 to reinforce its flagship machine families and underscore three decades of field validation for global sheet metal fabricators. Another automated assembly specialist announced preparations for a major industry exhibition in late 2025, signaling its intent to showcase integrated clinching modules within broader automation platforms. These moves reflect a broader industry pivot from equipment-only selling to solution-level engagement.
PW Consulting
Competitive Positioning and Evolving Dynamics
The competitive field is anchored by a mix of technology originators, specialized machine builders, and automation integrators. In Europe, firms with deep press and cold-forming heritage have built strong positions around proprietary joint geometries and modular press platforms, offering pneumatic, hydraulic, and electric variants tailored to steel, stainless, aluminum, and multi-layer assemblies. Their differentiation rests on process reliability, broad material compatibility, and extensive application engineering support across automotive, railway, energy, and appliance segments. In North America, a leading clinching technology provider has historically shaped the market through its patented sealed clinch system and comprehensive portfolio spanning manual, automated, and robotic equipment, positioning itself as a reference point for joint integrity and full-line integration. Canadian and U.S.-based specialists contribute niche strength in precision machines for HVAC, roofing, architectural, and pool applications, competing on ease of use, fast no-heat joining, and targeted industry fit.
In Asia and emerging industrial corridors, manufacturers are expanding capacity and targeting high-volume automotive, electronics, and appliance production with performance-oriented machines designed for throughput and material versatility. Meanwhile, system integrators and tooling specialists are increasingly partnering with press manufacturers to deliver turnkey assembly cells, combining clinching modules with robotic handling and line synchronization. This division of labor reflects a market that is stratifying along two axes: core press and tooling expertise on one side, and automated integration and application engineering on the other.
Several strategic patterns define the current landscape. First, differentiation is shifting from machine specifications alone to ecosystem value: joint consistency across material grades, compatibility with robotic work cells, energy-efficient actuation, and modular scalability. Second, concentration among top players remains moderate, with leading firms commanding a combined share that signals room for specialist entrants and regional champions, but also creates pressure on smaller assemblers to articulate clear technical or service advantages. Third, the market is experiencing both consolidation tendencies and fragmentation in niches. Larger groups pursue broader application coverage and integrated automation platforms, while focused manufacturers retain advantage in specialized industries or regional service networks. New entrants are most likely to succeed by targeting underserved material combinations, lightweighting requirements, or compact automation footprints rather than competing head-on in mature general-purpose segments.
For decision-makers evaluating suppliers, the practical implication is straightforward: assess not only the press family and tooling range but also the provider's integration track record, service response model, and ability to support material transitions without requalifying entire production lines. In a market where process reliability and line flexibility increasingly outweigh hardware novelty, the strongest positions belong to organizations that can demonstrate repeatable performance across diverse assemblies and adapt quickly to changing material and automation requirements.
Linear Friction Welding Machines Market
Forward Outlook: Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape commercial outcomes over the next three to five years. The first is the deepening integration of clinching into robotic and servo-controlled work cells. As assembly strategies prioritize precision, repeatability, and reduced energy intensity, electromechanical drives and automated cell architectures will become standard in high-volume automotive and appliance production. This trend expands the addressable market for robotic clinching systems and creates secondary demand for compatible end-of-arm tooling, cell synchronization software, and service agreements that maintain uptime and joint quality.
The second trend is material diversification and the rise of dissimilar and coated substrate joining. Lightweighting mandates, corrosion-resistant specifications, and multi-material component designs will require tools and press parameters that accommodate aluminum, galvanized, stainless, and coated steels without compromising joint integrity. Suppliers that invest in adaptive tooling, flexible punch-die configurations, and validated process windows for mixed-material assemblies will capture premium positioning and longer-term customer stickiness. This also creates an opportunity for application-led sales models, where joint qualification support and material testing become part of the commercial package rather than afterthoughts.
The third trend is the growing emphasis on total cost of ownership and lifecycle performance. As buyers compare clinching against alternative joining methods, the evaluation criteria are expanding beyond cycle time to include energy consumption, fastener and adhesive elimination, tooling replacement cadence, and maintenance predictability. Companies that can quantify operational savings, reduce consumable dependency, and offer modular upgrades will be better positioned to defend margins and compete against both thermal processes and lower-cost equipment imports. At the same time, uncertainty remains around macroeconomic cycles in construction and general engineering, potential volatility in coated and aluminum supply, and the risk that a subset of smaller fabricators may delay automation investments during periods of capital constraints. These factors suggest that growth will be durable but uneven, with leading positions accruing to organizations that can align product flexibility with customer financing and service models.
Strategic Recommendations for Decision-Makers
For manufacturers and production leaders, the priority is to align joining technology selection with long-term material and automation roadmaps rather than short-term equipment cost. Investing in clinching solutions that support dissimilar materials, robotic integration, and modular tooling can reduce line complexity and future-proof assembly processes against lightweighting and compliance shifts. Process validation, operator training, and service availability should be evaluated with the same rigor as press specifications.
For investors and corporate development teams, attention should focus on companies that combine press expertise with integration capability, application engineering, and service-driven revenue streams. The most resilient profiles are those that can expand across multiple end-use sectors, sustain differentiation through proprietary joint designs or electric actuation platforms, and capture value beyond hardware sales through tooling, upgrades, and maintenance contracts. Monitoring regional capacity additions, partnership activity with automation integrators, and movement into underserved material or application niches can provide early signals of competitive repositioning.
For procurement and supply chain leaders, the commercial case increasingly rests on total operating impact. Evaluations should incorporate energy efficiency, fastener and adhesive elimination, changeover simplicity, and lifecycle tooling economics, alongside conventional price comparisons. Supplier selection should weigh integration readiness and responsiveness, especially where production lines are transitioning toward higher automation or mixed-material assemblies. Detailed segmentation data, company-level capability assessments, and scenario-based volume projections can sharpen these decisions and reduce implementation risk. For teams seeking a deeper dive into regional dynamics, application-specific demand patterns, and competitive positioning across machine types, a comprehensive research report offers the structured detail needed to translate these strategic directions into actionable planning.
For detailed analysis of this topic, please visit the official page: Worldwide Clinching Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


