



Category: market research
Worldwide School Assessment Tools Market: Why 13.65% CAGR Changes Everything
By PW Consulting, 2026-09-18
Worldwide School Assessment Tools Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
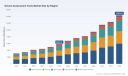
The global market for school assessment tools has entered a phase of accelerated expansion, driven by a fundamental shift in how educational institutions measure student progress, allocate resources, and personalize instruction. From 2020 to 2025, the sector moved from a baseline of approximately $3.1 billion to roughly $5.9 billion, reflecting a compound annual growth rate of 13.65 percent. Projections through 2032 indicate sustained momentum, with the market expected to surpass $14.3 billion in the final forecast year. This trajectory is not merely a function of enrollment growth or regulatory compliance; it represents a structural reorientation of assessment from a periodic, end-of-cycle event to an ongoing, data-rich feedback mechanism embedded in daily instruction. The scale of adoption, combined with broadening use cases across K-12 and early higher education segments, has turned assessment platforms into critical infrastructure for school networks, district administrations, and curriculum publishers alike.
Despite the favorable growth backdrop, the market is navigating several structural tensions that will shape competitive outcomes over the next decade. First, data privacy and regulatory compliance have become non-negotiable design constraints rather than peripheral legal considerations. In the United States, more than 121 state laws now extend student privacy protections beyond federal FERPA requirements, with California's SOPIPA imposing explicit restrictions on how EdTech vendors collect, use, and share student data. In parallel, COPPA violations for platforms serving children under 13 can trigger penalties reaching $51,744 per affected child, compelling vendors to embed strict data minimization, consent workflows, and retention controls into their product architecture. In the European Union, GDPR mandates explicit consent for most processing of children's data and requires data protection impact assessments for platforms serving EU students or international schools. These frameworks are fragmenting compliance requirements across jurisdictions, raising the cost of market entry, and forcing vendors to build privacy-by-design capabilities that smaller or less-resourced competitors cannot easily replicate.
Second, the market is experiencing a tension between customization and standardization. Schools increasingly demand assessments that align tightly with local curricula, multilingual populations, and differentiated instructional models, yet large-scale comparability, accountability reporting, and cross-district benchmarking still require standardized measurement frameworks. This divergence pressures vendors to offer modular, configurable assessment engines that can accommodate local pedagogical needs without sacrificing psychometric rigor or reporting consistency. The operational burden of maintaining multiple assessment variants, scoring rubrics, and data pipelines is substantial, and the firms that can balance flexibility with reliability will capture disproportionate share.
PW Consulting
Third, cost structures and deployment economics are shifting as cloud adoption matures. While cloud-based delivery has become the dominant model, the economics of large-scale educational software deployments remain sensitive to compute, storage, and data egress costs. Typical cloud waste rates in the 27 to 32 percent range mean that even mature operations can face margin pressure if FinOps discipline and architecture optimization are not embedded early. Vendors and district procurement teams alike are scrutinizing total cost of ownership more closely, favoring platforms that demonstrate measurable efficiency gains, predictable scaling, and clear alignment between assessment data and instructional action. These dynamics are compressing the window for undifferentiated point solutions and rewarding platforms that integrate assessment, analytics, and curriculum delivery into coherent workflows.
Key Drivers of Market Change
Technology Innovation and Adaptive Assessment Capabilities
Technology advancement is the most visible catalyst reshaping the assessment landscape. Computer-adaptive testing, once confined to specialized interim and large-scale programs, is increasingly embedded in formative and diagnostic workflows, allowing schools to measure student knowledge with greater precision while reducing testing time and fatigue. The shift toward digitally based assessment is not limited to multiple-choice formats; it increasingly incorporates interactive tasks, scenario-based performance items, and real-world applications that capture higher-order skills such as reasoning, problem-solving, and application. Recent initiatives by the National Center for Education Statistics advancing digitally based assessment for NAEP illustrate how even federal-level measurement programs are moving toward tasks that simulate authentic contexts, signaling a broader expectation that modern assessments should evaluate what students can do, not just what they can recall.
Assessment Services Market
Under the hood, the infrastructure enabling these capabilities is becoming more sophisticated and more accessible. Scalable assessment authoring and delivery platforms allow publishers, school networks, and third-party developers to build, deploy, and analyze assessments without reconstructing the underlying technology stack for every program. This democratization of assessment technology lowers the barrier for new content and assessment formats, while simultaneously raising expectations for interoperability, data quality, and analytics. The practical implication is that assessment is no longer a standalone product category; it is increasingly a data layer that feeds instructional decision-making, resource allocation, and personalized learning pathways. Vendors that can connect assessment outputs to actionable insights, and that can integrate those insights with existing instructional ecosystems, are gaining a durable advantage.
Policy, Accountability, and the Regulatory Environment
Policy dynamics continue to shape demand, but the nature of that influence is evolving. Accountability frameworks have historically driven demand for standardized, summative assessments, yet many education systems are rethinking how assessment data is used to balance accountability with instructional support. The result is a broader portfolio of assessment types gaining traction, including formative tools that guide day-to-day teaching, diagnostic instruments that identify learning gaps early, and interim measures that track progress between major accountability cycles. This diversification is expanding the addressable use cases for assessment vendors beyond compliance-driven procurement, creating opportunities for products that demonstrate clear instructional value rather than mere reporting capability.
At the same time, the regulatory environment is becoming more rigorous and more fragmented. FERPA permits schools to disclose education records to service providers under the school official exception when there is legitimate educational interest, but it requires oversight through contracts that specify data use limitations. This means procurement processes increasingly hinge on the strength of data governance agreements, transparency around data handling, and the vendor's ability to demonstrate compliant architecture. In parallel, state-level privacy laws and international data protection regimes are layering additional obligations onto vendors operating across multiple markets. For providers, this is not merely a legal exercise; it is a competitive differentiator. Organizations that can offer clear consent management, localized data handling options, and auditable compliance documentation are better positioned to win enterprise-level district contracts and cross-border deployments.
Demand-Side Shifts in School Behavior and Procurement
Schools and districts are reevaluating what they expect from assessment tools. The longstanding model of purchasing disconnected testing products is giving way to expectations for integrated ecosystems where assessment data flows directly into curriculum planning, intervention targeting, and progress monitoring. Educators want tools that reduce administrative burden, provide timely feedback, and support differentiation without requiring extensive manual data reconciliation. This demand is especially acute in reading and mathematics, where diagnostic precision and ongoing progress monitoring are central to closing learning gaps and meeting instructional goals. Platforms that combine assessment with aligned instructional pathways, or that integrate seamlessly with widely used core curriculum systems, are therefore capturing stronger adoption momentum.
Procurement behavior is also shifting toward ecosystem fit and total value rather than isolated feature comparisons. District decision-makers are increasingly evaluating whether assessment platforms can interoperate with existing learning management systems, curriculum delivery tools, and data warehouses. Integration partnerships are becoming a strategic lever, because they reduce implementation friction, accelerate time-to-value, and create stickier workflows for teachers and administrators. At the same time, schools are more sensitive to implementation complexity and professional development requirements, favoring solutions that are intuitive, well-supported, and demonstrably linked to improved instructional outcomes. This environment rewards vendors that invest in user experience, integration breadth, and evidence of impact, while challenging those that rely on legacy feature sets without meaningful workflow integration.
Cost Structure Evolution and Cloud Economics
The economics of delivering assessment at scale are changing as cloud infrastructure becomes the default and as vendors and customers alike become more disciplined about utilization. Cloud-based deployment dominates current delivery models, reflecting the advantages of scalability, faster updates, and broader access across device types and geographies. However, scale introduces cost 관리의 complexity. Compute and storage pricing for educational software environments remains relatively granular, and without careful architecture and FinOps practices, organizations can absorb significant inefficiency. This reality is pushing vendors to optimize data pipelines, assessment delivery engines, and reporting workloads to keep marginal costs aligned with growth. It is also pushing district procurement teams to evaluate pricing models that reflect real usage patterns rather than flat, undifferentiated licensing structures.
For vendors, the strategic implication is that cloud economics are no longer a back-office concern; they are a product and pricing design issue. Assessment platforms that can handle spikes in testing demand efficiently, store and process data without unnecessary redundancy, and offer transparent scaling models are better positioned to maintain margin integrity while competing on price and value. For customers, the opportunity lies in selecting platforms that demonstrate operational efficiency and predictable cost behavior, especially as assessment programs expand in frequency and scope. The firms that treat cost efficiency as a product attribute, rather than an afterthought, will have more room to invest in innovation and customer success.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with a handful of large, well-established players holding meaningful share and a broader set of specialized providers competing on differentiation, integration, and regional reach. The market structure favors firms that can combine psychometric credibility, scalable technology, and strong ecosystem positioning. Rather than competing solely on assessment content, leading companies are increasingly competing on data utility, workflow integration, and the ability to connect assessment signals to concrete instructional actions. This is a meaningful shift because it expands the basis of competition beyond test quality into the broader value chain of teaching, learning, and decision support.
Renaissance Learning illustrates the integration strategy clearly. Its Star Assessments are positioned as adaptive, data-rich tools that support K-12 instruction, but the company's recent moves emphasize connectivity with core curriculum providers rather than standing alone as a testing product. The rollout of Star assessment data integration with Great Minds' Eureka Math Squared curriculum, along with an earlier core curriculum integration with the Savvas Realize platform, signals a deliberate effort to embed assessment insights directly into the instructional materials that teachers already use. In parallel, McGraw Hill's integration of Pearson's PRoPL assessment tool into its core curriculum products reflects a similar logic: assessment becomes more valuable when it is tied to curriculum delivery and classroom workflows. Pearson itself continues to offer a broad portfolio, including digital testing platforms and large-scale K-12 assessments, positioning itself as a provider that can span both instructional and measurement needs.
Curriculum Associates has built a strong position around diagnostic and progress monitoring in reading and mathematics through its i-Ready platform, an approach that aligns closely with the demand-side shift toward early identification and ongoing monitoring. NWEA's MAP Growth and other computer-adaptive interim assessment tools have become widely used in U.S. and international schools, benefiting from a reputation for comparability and growth measurement that supports both instructional decision-making and accountability contexts. Educational Testing Service brings deep assessment development expertise and scoring services, which supports custom program development and large-scale testing needs. These players demonstrate that credibility in measurement, combined with strong product execution, remains a foundational requirement, even as integration and data utility become decisive differentiators.
A second competitive dynamic is the rise of platforms and technology providers that enable assessment ecosystems rather than delivering end-to-end branded assessment programs. Instructure offers Mastery and Canvas-based assessment solutions spanning formative, interim, and predictive use cases across K-12 and higher education, leveraging its learning platform footprint to embed assessment into broader teaching workflows. Kahoot! uses game-based formative assessment and quiz tools to drive engagement and real-time feedback, expanding the definition of assessment into more interactive, low-stakes classroom experiences. Edmentum provides online assessment and instructional tools, including Study Island and Exact Path, with a focus on personalized learning pathways. Learnosity supplies scalable assessment authoring and delivery technology that powers many school and publisher assessment platforms, representing a critical infrastructure role in the market. Open Assessment Technologies offers the TAO open-source assessment platform for customizable school and large-scale testing, appealing to organizations that want flexibility and control over their assessment environment.
The strategic implications of this landscape are clear. First, integration and interoperability are becoming decisive. Vendors that can connect assessment data to curriculum platforms, learning management systems, and analytics environments reduce friction for schools and increase the practical value of their tools. Second, there is room for both integration and specialization, but the specialization must be meaningful. Niche providers can thrive by dominating a specific assessment type, subject area, or regional market, but they increasingly need to articulate how their solution fits into broader data and instructional workflows. Third, the market is likely to see continued consolidation pressure, as larger players acquire or partner to expand integration breadth, content coverage, and analytics capability, while nimble specialists compete by serving unmet needs in adaptive diagnostics, multilingual assessment, and scenario-based performance measurement. New entrants with strong technology execution can still gain traction, but only if they solve a clearly defined workflow problem and demonstrate compliance, scalability, and measurable instructional value from the outset.
Future Trends and Strategic Implications
Over the next three to five years, several trends are likely to shape the market's direction and the distribution of commercial opportunity. One major trend is the continued expansion of adaptive and digitally based assessment into everyday instruction, rather than reserving adaptive technology for periodic interim or large-scale tests. As assessment engines become more embedded in formative routines, the value proposition shifts from measurement accuracy alone to speed, usability, and the ability to translate results into immediate instructional adjustments. This creates opportunities for tools that support teachers with clear, actionable recommendations, and for vendors that can demonstrate measurable improvements in teaching efficiency and student progress.
A second trend is the growth of interoperable assessment ecosystems. Schools are unlikely to standardize on a single isolated testing product; they are more likely to assemble stacks that include assessment tools, curriculum platforms, learning management systems, and data analytics layers. This favors vendors that invest in open integration, standards-based data exchange, and flexible deployment models. It also favors technology providers that power assessment authoring, delivery, and analytics for multiple brands and programs, because the underlying infrastructure becomes a strategic bottleneck and a long-term moat. Companies that can serve as reliable assessment technology partners across multiple customers and content providers are positioned to benefit from ecosystem growth even if they do not own the end-user brand.
A third trend is the tightening link between assessment, privacy compliance, and trust. As regulatory expectations rise and procurement processes become more rigorous, compliance capability will increasingly function as a market access condition and a differentiator. Vendors that can offer clear data governance, consent management, regional data handling options, and strong auditability will be better positioned for district-wide and cross-border deployments. The opportunity here is not just risk avoidance; it is the ability to win confidence in environments where data sensitivity is high and the consequences of missteps are severe. At the same time, this trend introduces uncertainty. Regulatory fragmentation can slow cross-market scaling, and overly rigid compliance postures can constrain product innovation if not managed carefully. Firms will need to balance protective design with usable, efficient assessment experiences.
A fourth trend worth noting is the rising importance of evidence and impact. As procurement teams become more sophisticated and budgets face scrutiny, tools that can show a credible connection between assessment use and improved instructional outcomes will gain advantage. This does not require every vendor to produce academic-grade impact studies, but it does favor organizations that can articulate clear usage models, provide transparent reporting, and support implementation in ways that make results observable. The commercial risk for vendors that cannot demonstrate value beyond feature checklists is growing, especially as alternatives multiply and integration expectations rise.
Actionable Guidance for Decision-Makers
For assessment and curriculum providers, the priority is to strengthen integration capacity and data utility while maintaining psychometric and compliance rigor. Product roadmaps should treat interoperability, privacy-by-design, and workflow fit as core features rather than optional enhancements. Partnerships with curriculum platforms, learning management systems, and assessment technology providers can accelerate adoption and increase the practical value of assessment data. Pricing and packaging should reflect real usage patterns and total cost of ownership, because procurement teams are increasingly sensitive to efficiency and predictable scaling. Differentiation will come less from adding more test formats and more from making assessment data immediately useful within existing instructional environments.
Education Software Market
For investors, the market's growth trajectory is attractive, but the dispersion of outcomes will widen. Capital should favor companies with scalable technology architecture, credible measurement expertise, and a clear integration or ecosystem strategy. Interest in infrastructure-oriented providers that power multiple assessment programs, as well as in specialists with strong positioning in adaptive diagnostics or high-demand subject areas, is likely to remain justified. At the same time, due diligence should scrutinize compliance readiness, cloud cost discipline, implementation complexity, and the strength of evidence linking product use to instructional value. Growth alone is not enough; the winners will be those who convert adoption into durable workflow dependency and efficient operations.
For school administrators and procurement teams, selection criteria should expand beyond assessment content to include integration fit, data governance, implementation support, and the clarity of actionable reporting. The most effective platforms are those that reduce burden, connect to existing systems, and help teachers act on results without extensive manual work. Even so, many decisions will benefit from deeper, segmented intelligence on adoption patterns, pricing dynamics, regional compliance requirements, and the relative strengths of competing platforms in specific use cases. Access to more granular market data and customized scenario analysis can substantially improve procurement strategy, partnership choices, and long-term technology planning.
For detailed analysis of this topic, please visit the official page: Worldwide School Assessment Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Probiotic Ingredients for Animal Use: The Real Drivers Behind the 8.2% CAGR to 2032
By PW Consulting, 2026-09-18
Global Probiotic Ingredients for Animal Use Market: Strategic Trends and Commercial Opportunities
Market Overview and Critical Challenges
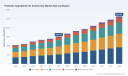
The worldwide market for probiotic ingredients designed for animal applications has entered a sustained growth trajectory, reflecting a fundamental shift in how livestock producers approach animal health and performance. Between 2020 and 2025, the market expanded from approximately $1.05 billion to $1.52 billion, establishing a compound annual growth rate of 8.21 percent through the forecast period extending to 2032. By the end of the projection window, revenue is expected to surpass $2.63 billion. This expansion is not merely a function of volume increases but represents a structural reallocation of spending within animal nutrition portfolios, as producers replace traditional input models with microbiome-focused interventions.
Market distribution reveals clear regional and application patterns. The Asia Pacific region commands the largest revenue share, followed by Europe and North America, highlighting how intensive production systems in densely populated agricultural economies drive early adoption of gut health solutions. The poultry segment consistently leads consumption, with swine and ruminants forming substantial secondary demand pools, while aquaculture and companion animal applications represent smaller but rapidly expanding niches. In terms of formulation, bacteria-based probiotics dominate the ingredient mix, with yeast and fungi-based alternatives occupying a meaningful secondary position. Industry concentration metrics indicate that the top three participants capture just under 39 percent of total revenue, while the top five command slightly more than half, suggesting a moderately consolidated landscape with meaningful room for specialized and regional players.
Despite the clear growth momentum, three structural challenges define the current market inflection point. First, the regulatory environment for feed additives increasingly demands strain-specific safety and efficacy validation. Manufacturers must now produce detailed dossiers that demonstrate performance under commercial production conditions rather than controlled laboratory settings. This requirement raises barriers to market entry and rewards companies with robust clinical data and established regulatory relationships.
Second, technical performance during feed manufacturing remains a persistent constraint. Probiotic viability through steam pelleting, high-temperature conditioning, and extended storage continues to differentiate products in the field. Not all strains survive processing equally, and the gap between laboratory stability and real-world shelf life has become a decisive commercial factor. Spore-forming organisms have gained advantage in this context, but delivery formats, microencapsulation, and postbiotics are actively reshaping how formulators think about survivability.
PW Consulting
Third, antibiotic growth promoter restrictions continue to reshape demand, but the transition is uneven. In some jurisdictions, the removal of in-feed antibiotics has accelerated probiotic adoption; in others, lingering regulatory ambiguity or economic pressures have slowed substitution. The net effect is that demand is real and durable, but pricing power and volume growth depend heavily on local policy clarity and on whether probiotic solutions can demonstrate measurable returns in feed conversion, mortality reduction, or veterinary cost savings.
Key Drivers of Market Change
Technological Innovation and Strain Performance
The competitive center of gravity in this market has shifted from generic microbial suspensions to strain-engineered, application-specific solutions. Bacteria-based probiotics remain the dominant category because of their broad use across poultry, swine, and aquaculture, but leadership increasingly belongs to companies that can articulate strain-level benefits and deliver consistent performance under real production conditions. Spore-forming Bacillus strains, for example, have gained traction in poultry, swine, and aquaculture because their natural stability supports pathogen mitigation and gut microbial balance in environments where storage and feed processing impose stress on more fragile organisms. This technical reality has pushed formulators and producers to evaluate probiotics not just by genus or species, but by survivability, onset speed, and interaction with existing feed programs.
Recent product activity illustrates this direction. In November 2025, Evonik Industries AG showcased an enhanced version of its Ecobiol probiotic with an optimized outgrowth profile designed to support a faster onset of activity in poultry production. Earlier in the year, in August 2025, International Flavors and Fragrances Inc. introduced Enviva DUO, a direct-fed microbial solution combining two bacterial strains to support poultry gut health during challenging conditions. These moves are not isolated product updates; they reflect a strategic pivot toward faster activity, dual-strain synergy, and condition-specific formulations. For commercial buyers, this means the evaluation criteria are expanding beyond price per kilogram to include time-to-effect, resilience under disease pressure, and compatibility with feed processing and water delivery systems.
Policy and Regulatory Environment
Regulatory momentum continues to be one of the most durable demand catalysts for probiotic ingredients in animal use. Restrictions on antibiotic growth promoters have accelerated interest in natural alternatives that support gut health and performance without relying on antimicrobial mechanisms. This policy-driven shift is especially relevant in regions where resistance concerns, consumer expectations, and export market requirements are all pushing producers toward non-antibiotic strategies.
At the same time, the regulatory bar for market access is rising. Strain-specific approvals and efficacy dossiers are becoming standard expectations for entry into major regional markets. In 2025, the European Food Safety Authority evaluated the safety and efficacy of multiple Lactobacillus and Bifidobacterium strains as feed additives for various animal species, reinforcing the broader trend toward evidence-based approvals. This pattern matters commercially because it rewards companies that already maintain validated performance data, established strain libraries, and the capability to navigate multi-jurisdiction registration. It also means that supply commitments and commercial partnerships increasingly depend on documented regulatory status, not just the availability of microbial cultures.
Demand-Side Behavioral Change
Demand is being shaped by more than regulation. Producers are under sustained pressure to improve feed efficiency, reduce mortality, and limit veterinary interventions while maintaining animal welfare standards. In poultry and swine operations particularly, the gut is increasingly treated as a performance interface: a system where microbial balance, nutrient absorption, and pathogen resistance directly affect margin. This mindset encourages procurement teams to view probiotics as functional inputs rather than optional additives.
At the same time, downstream consumers and retail channels are exerting indirect influence. Product claims around reduced antibiotic use, improved animal health, and more sustainable production methods create commercial incentives for producers to adopt gut-health solutions that can be credibly supported. This pressure does not always translate into immediate premium pricing, but it does strengthen the willingness to invest in solutions that have a defensible performance narrative. Yeast and fungi-based probiotics and postbiotic innovations are finding traction in this context, especially where producers want alternatives or complements to bacterial strains, or where specific applications benefit from the functional properties of non-bacterial microorganisms.
Supply Chain and Cost Structure
Cost dynamics are becoming a more important part of the probiotic sourcing conversation. Feed ingredient volatility, processing energy costs, and the economics of specialized fermentation and stabilization all affect the final landed price of probiotic ingredients. Equally important is the cost of technical support. In a market where strain selection, dosing strategy, and integration with feed formulation matter, the total cost of adoption includes service, technical validation, and consistency of supply.
This environment favors suppliers that can offer not only viable microorganisms but also technical reliability across batches and geographies. It also encourages consolidation of capabilities around strain development, industrial-scale fermentation, stability engineering, and application support. For buyers, the practical implication is that procurement decisions are increasingly tied to supply continuity and technical competence rather than short-term price movements. Companies that can maintain performance consistency through pelleting, storage, and on-farm use are better positioned to sustain relationships in a cost-conscious environment.
Competitive Landscape and Leading Strategies
The competitive field in global probiotic ingredients for animal use is defined by a mix of large, diversified nutrition and biosolutions companies, specialized microbial experts, and regional suppliers with strong local application knowledge. The top five participants together account for a modest majority of revenue, but the relatively fragmented structure below that tier creates opportunity for differentiation based on strain portfolio, formulation technology, and segment focus.
A useful way to understand the landscape is through strategic positioning. Some leaders compete on breadth and integration. Firms such as ADM, Cargill, and dsm-firmenich sit within broader animal nutrition and specialty feed additive ecosystems, allowing them to bundle probiotic solutions with other gut health, performance, and nutrition inputs. This integration can be attractive to large producers seeking streamlined sourcing and consolidated technical support. Their advantage lies in the ability to align probiotics with overall feed strategy, offer multi-species portfolios, and leverage existing commercial infrastructure.
Other incumbents compete on microbial specialization and documented strain performance. Novonesis, Kemin Industries, Kerry Group, Church and Dwight Co., and Huvepharma each emphasize particular strengths, whether that is a recognized Bacillus-based program, direct-fed microbial products with pathogen control intent, or strain-specific offerings that target gut morphology, intestinal flora balance, and performance outcomes. Lallemand and Lesaffre extend this specialization into yeast and bacterial solutions, giving them flexibility across animal nutrition and feed applications. Alltech and Phibro Animal Health Corporation maintain strong positioning around natural gut health messaging and direct-fed microbial products, including options that serve specific certification or market-access needs. Life Products Inc. represents a longer-tenured, application-focused profile, with probiotic and microbial feed additive experience across dairy, poultry, swine, cattle, and aquaculture.
What separates stronger competitors from the rest is increasingly not the organism itself in isolation, but the surrounding system: strain selection logic, stability through processing, delivery format, and application support. In poultry, for instance, some companies emphasize Bacillus-based spore-forming stability and pathogen mitigation, while others build differentiation around multi-strain blends or condition-specific formulations. In aquaculture and ruminants, the value proposition often depends on survivability, handling practicality, and the ability to deliver consistent outcomes in more variable production settings. The technical reality that certain Bacillus strains demonstrate superior survival compared with Lactobacillus during steam pelleting is not a minor detail; it shapes product design, sales claims, and ultimately customer adoption.
The market structure appears to be evolving along two paths at once. One is gradual consolidation among participants seeking scale in fermentation, regulatory capacity, and global distribution. Another is continued differentiation among specialists targeting high-value niches such as aquaculture, companion animals, or strain-specific programs with strong clinical backing. New entrants are likely to succeed most readily when they bring a clear technical advantage, such as faster onset, improved viability, dual-strain synergy, or a delivery format that solves a known processing or storage problem, rather than attempting to compete on commodity pricing alone. The recent activity from Evonik and IFF reinforces this point: the most visible product moves center on performance optimization and challenge-specific support, not broad-market commoditization.
Forward Outlook: Trends shaping the next three to five years
Several trends are likely to define the coming half-decade for probiotic ingredients in animal use. The first is the continued shift from generic probiotic inputs toward strain-specific, application-validated solutions. As regulatory expectations and commercial proof requirements rise, products that can document performance in target species and production systems will capture disproportionate attention. The implication for commercial opportunity is that value will concentrate around organizations that can connect strain science to on-farm results and communicate that linkage credibly to procurement and technical teams.
Worldwide Aquaculture Probiotic Clarifier Market
The second trend is the widening of the solution set beyond conventional bacterial probiotics. Postbiotics, yeast and fungi-based probiotics, and blended direct-fed microbial programs are expected to gain relevance where buyers want complementary mechanisms, improved stability, or solutions tailored to specific stress conditions. This diversification will create opportunities for suppliers with strong formulation and stability capabilities, and it will give buyers more options for fitting probiotics into existing feed programs without disrupting processing or performance.
The third trend is increasing technical scrutiny of delivery and survivability. Steam pelleting, storage conditions, and on-farm handling will continue to determine whether a product performs as promised. As a result, differentiation around microencapsulation, spore-forming stability, water-soluble formats, and faster activity onset is likely to become more commercially important than simple organism naming. The risk side is equally clear: where efficacy claims outpace documentation, adoption will stall. In addition, regulatory timing, regional policy divergence, and feed cost volatility can all slow or reshape demand, creating uneven growth across geographies and species segments.
For businesses evaluating this space, the commercial opportunity lies in aligning product capabilities with the where and why of procurement decisions. Poultry and swine will likely remain the largest demand centers, but higher-margin growth may emerge from segments where performance improvement is harder to achieve and where technical service adds disproportionate value, such as aquaculture, ruminants, and companion animals. Companies that can demonstrate repeatable outcomes, maintain supply consistency, and support customers through integration will be better positioned to convert demand into durable share.
Strategic Actions for Decision-Makers
For manufacturers and ingredient suppliers, the priority is to strengthen strain-level differentiation and make performance claims defensible. Investment in stability through processing, faster-onset formulations, and blended or condition-specific programs can create meaningful separation in a market where organism names alone are increasingly insufficient. Equally important is the ability to support customers with technical validation, dosing guidance, and supply reliability across geographies.
Animal Feed Ingredients Market
For investors, the market offers growth supported by durable demand drivers, but value capture will depend on execution quality. Preference should be given to participants with documented efficacy, credible regulatory positioning, and a clear route to species or application specialization. Broad commodity exposure is less attractive than focused capabilities in strain development, stabilization, and application support, especially as customer expectations shift toward proven outcomes and consistent delivery.
For procurement and operations leaders in animal production, the practical task is to evaluate probiotics as system inputs rather than catalog items. Selection should account for survivability through feed processing, compatibility with delivery methods, compatibility with existing nutrition programs, and the quality of technical support behind the product. Where possible, decisions should be grounded in species-specific performance evidence and in the supplier's ability to maintain consistency across batches and seasons.
Given the pace of product evolution, regulatory activity, and regional demand variation, organizations that want to act with confidence should seek detailed segment-level intelligence before committing to long-term sourcing or investment plans. A fuller research report can provide the deeper segmentation, company positioning detail, and regional pathway analysis needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Probiotic Ingredients for Animal Use Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Indian Curry Paste Market: Why 6.85% CAGR Dynamics Reshape Growth
By PW Consulting, 2026-09-18
Navigating the Global Indian Curry Paste Market: Strategic Insights for Decision-Makers
Market Snapshot and Critical Crossroads
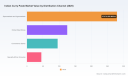
The worldwide Indian curry paste market has evolved from a niche ethnic food segment into a structured global consumer category, driven by sustained demand for convenient, authentic Indian flavors. Measured in USD millions, the market has demonstrated consistent expansion over the past half-decade, with a clear upward trajectory extending through the forecast horizon. Base-year positioning reflects a mature but still-growing revenue base, and the projected compound annual growth rate of 6.85% signals durable momentum rather than a temporary consumption spike. This growth profile is notable because it persists across economic cycles and geographic regions, indicating that Indian curry pastes are transitioning from discretionary gourmet purchases to routine pantry staples in multiple consumer markets.
At a strategic level, the market is defined by concentrated leadership alongside broad fragmentation in specialty and regional niches. A relatively small group of established players commands a meaningful share of total revenue, while a long tail of regional manufacturers, diaspora-focused brands, and private-label operations competes on authenticity, price, or distribution access. This structure matters for decision-makers because it shapes negotiation dynamics with suppliers, influences shelf-space competition, and determines how quickly new entrants can scale. The presence of strong incumbents with established foodservice and retail relationships raises the barrier to entry for pure-play startups, but it also creates clear acquisition and partnership pathways for companies seeking faster market access.
PW Consulting
Several structural challenges now define the industry's next phase. First, quality assurance and food safety risk have moved to the forefront following recent product recall events involving potential foreign-material contamination in widely distributed curry paste lots. These incidents highlight the operational complexity of scaling production across multiple facilities, maintaining consistent metal-detection and sieving controls, and managing lot traceability across long supply chains. For buyers and brand owners, the implication is clear: safety and quality credentials are no longer a baseline expectation but a competitive differentiator that affects retailer trust, import clearance speed, and consumer repurchase behavior.
Second, input cost volatility is reshaping margin planning. Key spices, particularly turmeric and allied ingredients used in curry paste formulations, have experienced significant price swings tied to production conditions, export dynamics, and seasonal availability. This volatility complicates recipe cost modeling, inventory timing, and long-term pricing commitments. Companies that rely on fixed-price contracts or single-origin sourcing are especially exposed, while those with diversified sourcing strategies and flexible procurement frameworks are better positioned to protect profitability without alienating price-sensitive consumers.
Third, distribution pathways are fragmenting more rapidly than many traditional manufacturers anticipated. Consumers increasingly blend offline grocery trips with online replenishment, while foodservice operators balance consistency, labor savings, and menu differentiation. This dual-channel reality requires brands to maintain distinct packaging, format, and communication strategies for retail shelves and professional kitchen environments, rather than assuming a single go-to-market approach will carry both segments efficiently.
Key Drivers Powering Market Change
Technology and formulation innovation are reshaping what curry paste can be and how quickly it can reach diverse consumers. Advances in spice blending, moisture management, and preservation techniques allow manufacturers to deliver consistent flavor profiles across larger batches while supporting cleaner ingredient narratives. This matters because global consumers and foodservice chefs are increasingly seeking products that combine authentic taste with predictable performance, longer shelf stability, and reduced reliance on artificial additives. Companies investing in process control and sensory consistency are gaining an advantage in both retail and HoReCa channels, where repeat usage depends on dependable results during preparation.
Regulatory and compliance conditions are also becoming a more active force in market expansion. Cross-border trade in value-added spice products now intersects with stricter food safety oversight, import documentation expectations, and recall-management requirements. Recent enforcement actions have underscored how quickly a single quality issue can affect multi-state distribution and brand reputation. At the same time, regulatory alignment and clearer compliance pathways can unlock faster market entry for exporters who invest early in documentation, testing, and traceability. The companies most effectively navigating this environment treat compliance as part of their product architecture rather than a back-office checkpoint.
On the demand side, consumer and operator behavior is shifting toward convenience without sacrificing perceived authenticity. In household and retail settings, shoppers want ready-to-use curry pastes that reduce prep time while still feeling rooted in recognizable Indian flavor traditions. In foodservice and HoReCa environments, operators value paste-based solutions that standardize seasoning, reduce variability across kitchen shifts, and support menu innovation with lower labor intensity. This demand pattern is expanding the addressable market beyond traditional ethnic grocery shoppers and into mainstream retail shelves, convenience channels, and international casual dining formats.
Supply chain and cost structure dynamics are reinforcing the urgency of strategic sourcing. India continues to play a central role as both an ingredient source and an export hub for spice-based prepared products, and the broader export momentum of value-added spice offerings reflects the growing global appetite for Indian culinary inputs. However, raw-material price movement remains sensitive to seasonal production shifts and broader agricultural conditions. Turmeric, in particular, has shown significant price variability, which directly affects formulation economics for many curry paste categories. Firms that manage this risk through forward contracting, blended sourcing, and ingredient substitution flexibility are better equipped to maintain pricing stability and protect consumer value perception.
These drivers interact with one another. Innovation makes it easier to meet consumer expectations; regulatory readiness determines whether those products can move across borders efficiently; demand growth pulls volume through retail and foodservice channels; and sourcing discipline governs whether margin can be sustained during periods of input-price stress. For strategists, the practical takeaway is that success in this market increasingly depends on connecting product development, compliance, and procurement in a single operating logic rather than managing them in isolation.
Competitive Landscape and Leading Strategies
The competitive field combines globally active brands with strong Indian manufacturing footprints and regional successors that have built distribution through ethnic grocery networks and export channels. Companies such as Patak's have long anchored their positioning around a broad portfolio of familiar curry paste and sauce varieties, appealing to both retail consumers and foodservice users who want consistent, recognizable flavor families. Other established manufacturers, including MTR Foods, Haldiram's, Dabur India, Tasty Bite Eatables, Kitchens of India, ITC Limited, and Priya Foods, leverage deep domestic production capabilities, brand recognition in India, and growing international distribution to compete across packaged curry paste and related meal solutions.
Pasta Sauce Market
In North America and similar export markets, Indian-origin brands such as Rani Brand and Sukhi's Gourmet Indian Foods have built presence by focusing on convenience formats and direct access to ethnic retail shelves. Specialty manufacturers like Aachi Masala and Desai Foods, along with export-oriented suppliers such as G.A. Foods India, reflect the broader reality that many players compete not by national scale alone but by category focus, regional recipe strength, and channel-specific relationships. This mix creates a market where leadership is measured not just by volume but by the ability to maintain flavor authenticity, shelf availability, and trust across multiple geographic and channel contexts.
Several recent developments illustrate how competitive strategy is evolving. A partnership between Dabur India and Grace Foods for co-development and distribution of Indian curry pastes in North America and the Caribbean signals a growing preference for collaboration over standalone expansion when entering complex Western retail environments. Co-development can accelerate localization, improve format fit for regional taste expectations, and share the commercial risk of new market entry. At the same time, Kitchens of India's introduction of a premium chef-inspired curry paste range shows that there is still room for differentiation through higher-tier positioning, especially where consumers and operators are willing to pay for perceived culinary craftsmanship.
The market is also being shaped by quality and compliance events. A voluntary Class II recall involving Sukhi's Classic Curry Paste and related sauces, triggered by potential metal fragment contamination and affecting multiple lots distributed across numerous U.S. states, serves as a practical reminder that scale, availability, and flavor alone do not protect a brand if quality control fails. For competitors, this reinforces the value of transparent safety processes, robust lot control, and proactive retailer communication. For buyers, it highlights the importance of supplier due diligence that goes beyond price and extends into quality systems, testing frequency, and incident responsiveness.
Looking at market structure, the landscape appears to be moving toward selective consolidation at the top while remaining highly fragmented in specialty segments. Larger players are expanding portfolios, strengthening export logistics, and using partnerships to gain faster access to new channels. Smaller manufacturers continue to thrive by focusing on regional authenticity, niche flavor varieties, and strong relationships with ethnic grocers and diaspora communities. New entrants face a realistic challenge: they must either bring a clearly differentiated product story, such as clean-label positioning, chef-driven formulation, or innovative packaging, or secure distribution through acquisition, licensing, or partnership rather than attempting to compete broadly from launch.
Forward Outlook: Where the Market Is Heading
One clear direction for the next three to five years is the continued mainstreaming of Indian curry paste in non-ethnic retail and foodservice channels. As consumers become more familiar with Indian flavor profiles and operators seek efficient ways to expand global menu offerings, curry paste is likely to gain shelf space beyond specialty groceries. This broadening creates opportunities for brands that can translate authentic flavor into formats suited to mainstream packaging, labeling, and consumption habits while preserving taste credibility.
A second trend will be greater emphasis on formulation transparency and safety assurance as competitive levers. In the wake of recent recall activity and heightened consumer scrutiny, brands that can demonstrate disciplined quality control, traceable sourcing, and consistent production standards will be better positioned to secure retail listings, maintain import momentum, and build repeat usage. This is likely to elevate safety and documentation from operational hygiene to a visible brand asset.
A third trend is the growing importance of channel-specific product architecture. Retail consumers and professional kitchens increasingly demand different value propositions: convenience, portion size, and shelf visibility in retail; batch consistency, speed, and integration into prep workflows in foodservice. Companies that design separate go-to-market strategies for these segments, rather than treating the market as uniform, will be better able to capture value across both worlds.
These trends carry opportunity, but also risk. Raw-material price volatility may pressure margins if sourcing strategies remain rigid. Regulatory scrutiny may slow market entry for companies without mature compliance frameworks. And brand trust can erode quickly if quality incidents are not managed decisively. The most resilient strategies will treat flexibility, compliance readiness, and consumer trust as core strategic assets rather than operational afterthoughts.
Decision-Maker Actions for the Next Planning Cycle
For manufacturers and brand owners, the priority is to align product development with channel reality and sourcing resilience. That means building distinct retail and foodservice offerings, reinforcing quality and traceability systems, and creating procurement flexibility around key ingredients so that price swings do not force reactive pricing decisions. Partnerships should be evaluated not only for immediate distribution access but also for their ability to improve localization, compliance readiness, and long-term brand credibility in target markets.
For investors, due diligence should focus on the durability of a company's distribution relationships, the strength of its quality infrastructure, and its exposure to input-cost volatility. Market growth is attractive, but revenue expansion is most valuable when supported by repeatable quality, defensible channel access, and the ability to manage recall or compliance risk without major brand damage. Companies with clear differentiation and disciplined operational controls are better positioned to convert market growth into sustainable returns.
For procurement teams and retail or foodservice buyers, supplier selection should extend beyond unit price to include safety systems, lot traceability, recall responsiveness, and flexibility during raw-material volatility. A supplier that can demonstrate consistent quality and adaptive sourcing will likely create fewer downstream disruptions and support more stable cost planning over time. In a market where trust and consistency drive repeat usage, procurement decisions increasingly influence brand performance as much as product features do.
Copper Paste Market
For decision-makers who need a deeper, segment-level view of revenue splits, regional dynamics, distribution-channel behavior, and competitive positioning, the full PW Consulting market analysis provides more granular data and tailored scenario support. The detailed study is designed to help teams move from market awareness to specific planning decisions with clearer visibility into where volume, margin, and risk are most likely to concentrate in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Indian Curry Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Hydrogel Bioink Market: 13.5% CAGR and Strategic Shifts Reshaping Growth
By PW Consulting, 2026-09-18
Navigating the Global Hydrogel Bioink Market: Strategic Trends and Commercial Opportunities Through 2032
1. Market Landscape and Core Challenges
The worldwide hydrogel bioink market has transitioned from an experimental niche to a structurally significant component of the broader bioprinting and 3D cell culture ecosystem. Over the historical period from 2020 to 2025, the sector expanded from approximately USD 65.0 million to USD 120.0 million, reflecting a compound trajectory that accelerated as academic laboratories, contract research organizations, and early-stage biomanufacturing firms moved beyond proof-of-concept printing toward standardized, reproducible tissue models. The forecast window extending through 2032 indicates sustained momentum, with projected revenue climbing toward the USD 290 million threshold by the end of the period. This growth is underpinned by an anticipated CAGR of 13.5 percent, signaling that hydrogel bioinks are no longer dependent on grant-funded experimentation alone but are increasingly embedded in commercial workflows for drug discovery, disease modeling, and regenerative medicine research.
Despite this expansion, the market is navigating a series of structural friction points that will define competitive positioning over the next several years. The first challenge revolves around material standardization and batch-to-batch reproducibility. As demand shifts from small-scale academic procurement to multi-site R&D programs and preclinical pipelines, buyers are demanding tighter specifications around viscosity, crosslinking kinetics, and cell viability retention. Suppliers that rely on manually formulated or loosely controlled natural polymer blends face mounting pressure to implement robust quality management systems, while manufacturers investing in defined synthetic or hybrid architectures are gaining a credibility advantage in regulated or semi-regulated environments.
PW Consulting
A second critical inflection point lies in the evolving regulatory and compliance landscape. Authorities have begun clarifying how hydrogel-based materials should be classified when they move closer to clinical or therapeutic applications, introducing new documentation, biocompatibility verification, and traceability requirements. These shifts create a divide between products positioned strictly for exploratory research and those engineered to meet higher safety thresholds. Companies that proactively align their formulations, manufacturing controls, and labeling practices with emerging expectations are better placed to retain long-term customers who plan to transition from benchtop research to translational studies.
A third challenge stems from input cost volatility and logistical complexity. Certain foundational biomaterials have experienced price movements linked to harvest variability, regional supply interruptions, and shifting demand from adjacent industries. At the same time, temperature-sensitive bioink shipments increasingly face additional freight surcharges and handling constraints as they cross major trade corridors. These pressures compress margins for undifferentiated products and reward suppliers that can secure stable raw material channels, optimize formulation efficiency, or redesign kits to reduce cold-chain dependency where feasible.
Taken together, the current landscape suggests a market that is simultaneously scaling and maturing. Growth is no longer a simple function of expanding print volumes; it increasingly depends on how effectively suppliers manage reproducibility, compliance readiness, and supply resilience while meeting the performance expectations of professional R&D buyers.
Medical Grade Hydrogel Market
2. Key Drivers Reshaping Market Trajectory
Technological Innovation and Material Performance
Material science advancements remain the most visible driver of commercial adoption. Hydrogel bioinks have progressed from basic alginate or collagen suspensions toward engineered systems with tunable mechanical properties, controlled degradation profiles, and improved cell interaction cues. Recent product updates illustrate how vendors are refining crosslinking mechanisms to support more demanding printing protocols and sensitive cell populations. Improved print fidelity, faster stabilization, and formulations optimized for stem cell handling are reducing the iterative trial-and-error that previously slowed tissue and organoid model development. These innovations are not merely incremental; they expand the practical scope of bioprinting workflows by enabling more consistent vascular-like structures, multi-material deposition, and longer culture durations. As performance gaps narrow, laboratories are more willing to standardize on specific bioink families, which strengthens repeat purchasing and creates switching costs for users who have validated their protocols around particular material characteristics.
Regulatory and Reimbursement Context
The regulatory environment is reshaping how bioinks are positioned across the value chain. Authorities have begun applying clearer device-classification frameworks to hydrogel materials intended for clinical research use, and guidance documents increasingly emphasize biocompatibility documentation and process control. This does not slow the entire market but does accelerate segmentation. Formulations developed and documented with higher compliance rigor are becoming more attractive to customers who anticipate future translational use or who operate within quality-sensitive organizations. At the same time, standards discussions around ancillary materials and research-grade limitations are prompting end users to distinguish between exploratory tools and materials that can be carried forward into more advanced workflows. Suppliers that anticipate these requirements and provide transparent testing data, material traceability, and application support are differentiating themselves from competitors selling primarily on price or convenience.
Demand-Side Shifts Toward Higher-Value Applications
Demand patterns are moving beyond general 3D cell culture toward higher-complexity applications that place tougher requirements on bioink performance. Tissue engineering remains a central use case, driven by the need for scaffolds and printed constructs that support cell organization, nutrient diffusion, and eventual functional maturation. Drug screening and development pipelines are also increasingly incorporating printed models to improve physiological relevance and reduce reliance on traditional two-dimensional assays. In parallel, academic and clinical research programs continue to consume significant volumes, but even there, the emphasis is shifting toward reproducibility, multi-lab comparability, and compatibility with imaging or downstream analytics. This demand evolution favors bioinks that can deliver predictable behavior across varied printing modalities and that support more ambitious experimental designs without sacrificing cell health or structural integrity.
Worldwide Photocuring Biological 3D Printer Market
Supply Chain, Cost Structure, and Operational Constraints
Cost structures and logistics are exerting a quieter but increasingly material influence on purchasing decisions. Selected natural polymer inputs have experienced price increases tied to harvest disruptions and regional sourcing constraints, altering the economics of bioink formulations that rely heavily on those feedstocks. Simultaneously, temperature-sensitive shipments of live-cell or cell-compatible bioinks are encountering additional air-freight surcharges for controlled transit, especially across major transatlantic routes. These pressures do not necessarily stall adoption, but they do encourage buyers to evaluate total cost of ownership more carefully, including storage requirements, shelf life, formulation stability, and sensitivity to shipping interruptions. Suppliers that can mitigate exposure through broader sourcing strategies, higher-concentration formats, stabilized kits, or clearer handling guidance are better positioned to retain price-sensitive customers without sacrificing performance perception.
3. Competitive Landscape and Leading Strategies
The hydrogel bioink field is populated by a mix of specialized material companies, bioprinting-adjacent vendors, and firms extending into bioink portfolios from adjacent biomaterials expertise. Rather than a single dominant model, the market is shaped by several distinct strategic positions. Some players focus on established hydrogel families such as GelMA, alginate, and hyaluronic acid derivatives, building recognition around printability, compatibility with extrusion and light-based methods, and broad application support. Others emphasize engineered crosslinking systems or recombinant protein-based formulations, seeking differentiation through cell encapsulation precision, mechanical tunability, or improved biocompatibility narratives. This diversity means that competitive advantage increasingly comes from the intersection of material performance, documentation quality, and workflow support rather than from brand visibility alone.
Differentiation Through Formulation and Application Focus
Leading suppliers are carving out positions by aligning their formulations with specific printing technologies and end-use requirements. For example, companies offering GelMA and related methacryloyl-based hydrogels have emphasized crosslinking control and compatibility with high-resolution printing, appealing to users who prioritize shape fidelity and cell-laden construct stability. Firms with collagen-derived or recombinant collagen bioinks have pursued a different angle, positioning their materials as biologically familiar options with potential advantages for tissue engineering applications. Meanwhile, vendors offering thiol-ene or other precisely crosslinkable synthetic systems have targeted users who need controlled gelation behavior and reliable cell encapsulation outcomes. The practical effect is a market where customers select materials less on generic claims and more on how well a formulation matches their printing method, cell type, and downstream assay needs.
Strategic Positioning Through Certifications, Launches, and Ecosystem Support
Recent developments highlight how commercial positioning is being reinforced through quality milestones and targeted product introductions. Certification achievements for biocompatibility are becoming important signals for buyers evaluating materials for extended research or preclinical-adjacent use, because they reduce uncertainty around biological safety and support internal compliance reviews. New product launches that improve printability for vascular tissue models or strengthen crosslinking for stem cell bioprinting show how vendors are moving from broad catalogs toward application-oriented refinements. These releases matter because they reduce the burden on end users to re-engineer protocols, making switching to a new supplier more attractive when the performance and support claims are credible. In a market where R&D timelines are costly, time-to-results is a meaningful purchase criterion.
Market Evolution: Consolidation Pressure, Specialization, and New Entrants
Looking at structural trends, the market displays both consolidation pressure and continued room for specialization. Moderate concentration among leading suppliers indicates that established players have secured meaningful share, but the field has not reached a point where new entrants are automatically blocked. Instead, newcomers tend to succeed by targeting under-served niches, such as bioinks for specific imaging-compatibility requirements, particular cell lineages, or defined bioprinting platforms. At the same time, broader bioprinting and biomaterials companies are likely to keep evaluating portfolio additions that strengthen their ability to offer end-to-end solutions. This dynamic suggests a landscape in which incumbents will compete on ecosystem breadth, technical service, and reliability, while challengers compete on focused performance advantages, faster customization, or specialized regulatory-readiness narratives. Buyers, in turn, benefit from having multiple credible options but also face increasing complexity in comparing products that are optimized for different workflows.
4. Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be the continued professionalization of bioink procurement. As more organizations move from pilot projects to recurring bioprinting programs, purchasing decisions will rely less on anecdotal performance and more on standardized evaluation criteria, including viability outcomes, mechanical stability, lot consistency, and compatibility with established hardware and assay pipelines. This shift creates opportunities for suppliers that can provide robust technical documentation, application notes, and support services, because procurement teams will increasingly prefer materials that reduce validation burden and variability across users or sites.
A second trend is the widening gap between research-grade materials and formulations built with higher compliance expectations. As regulatory expectations around safety documentation, biocompatibility, and manufacturing controls become more visible, customers planning to transition materials toward translational or clinical-adjacent work will gravitate toward suppliers that can demonstrate a credible path through those requirements. That creates commercial upside for companies investing early in quality systems, testing transparency, and clear labeling strategies, while leaving purely convenience-driven products exposed to commoditization in lower-value segments.
A third trend concerns supply resilience and logistics optimization. With selected raw material costs under pressure and temperature-sensitive shipments subject to additional freight costs, the competitive edge may increasingly belong to suppliers that can maintain stable input channels, offer formulations with reduced handling sensitivity, or structure kits to minimize waste and cold-chain exposure. For commercial buyers, this means total cost and operational reliability will matter as much as baseline print performance. At the same time, uncertainty remains: regulatory interpretations may continue to evolve, raw material markets can shift with harvesting conditions and trade dynamics, and customer adoption may vary by region and application maturity. Companies that plan for these uncertainties—by diversifying sourcing, stress-testing logistics, and expanding technical support—will be better positioned to convert market growth into durable revenue rather than one-off sales.
5. Strategic Recommendations for Decision-Makers
For Bioink and Bioprocessing Manufacturers
- Prioritize reproducibility and documentation as core commercial assets, not just technical metrics. Develop lot-to-lot controls, application-specific validation data, and clear compatibility guidance that help customers reduce protocol risk.
- Evaluate formulation strategies against both performance and supply resilience. Where feasible, reduce dependence on volatile inputs or design kit formats that improve stability, storage practicality, and shipping efficiency.
- Build differentiated application support around the workflows that matter most to your target customers, such as specific printing modalities, stem cell handling, or vascularized model development, rather than competing solely on catalog breadth.
For Investors and Strategic Partners
- Assess bioink opportunities through the lens of workflow integration and compliance readiness. Assets that combine material performance with credible quality documentation and application support are better positioned to retain customers as programs mature.
- Watch for consolidation and portfolio-extension activity, particularly where bioprinting hardware, cell culture, or biomaterials capabilities can be combined into more complete solutions that reduce friction for end users.
- Track regulatory and reimbursement signals closely, because shifts in classification, biocompatibility expectations, and research-to-clinical transition requirements can rapidly change the relative attractiveness of different product tiers.
For Procurement and R&D Leaders
- Move beyond price-driven comparisons by standardizing internal evaluation criteria that capture viability, mechanical behavior, reproducibility, and cold-chain or storage burden across candidate materials.
- Align material selection with your anticipated timeline and use case. Research-only programs and workflows that may later move toward more regulated or translational contexts have different needs, and purchasing decisions should reflect that trajectory.
- Request transparent technical and compliance information early in the evaluation process, including handling guidance, shelf-life considerations, and any relevant certifications or standards alignment that support internal review.
For teams that need deeper segmentation data, company-level benchmarking, regional dynamics, and customized scenario planning, a more detailed market assessment can help translate these strategic themes into actionable plans. Readers seeking that level of granularity are encouraged to explore the full report suite for further breakdowns tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrogel Bioink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solvent-based Organoclay Market: Why Asia Pacific's 308.8M Lead Matters
By PW Consulting, 2026-09-18
Global Solvent-based Organoclay Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide solvent-based organoclay market has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 595.2 million USD in 2020 to an estimated 737.56 million USD in 2025. The trajectory reflects a compound annual growth rate of 4.75 percent between 2026 and 2032, with revenue projected to surpass 1 billion USD by the end of the forecast window. This growth is not merely a function of incremental demand but rather the result of sustained industrial reliance on rheology control in non-aqueous systems. Organophilic clays remain indispensable for managing viscosity, suspension stability, and anti-settling behavior across formulations where water cannot be used as a carrier medium.
Despite the favorable top-line outlook, the industry operates against a backdrop of structural friction. One critical challenge lies in raw material dependency and price volatility. Solvent-based organoclay is produced by modifying montmorillonite, typically sourced from bentonite deposits, with quaternary ammonium salts to render the clay organophilic. The performance and cost profile of the final additive are tightly coupled to the purity of the starting mineral and the chemistry of the surface treatment. Producers operating without vertically integrated supply chains face margin pressure when clay sourcing costs fluctuate or when regulatory-compliant amine chemistries become more expensive. Pricing indications for rheological additives in this category have historically ranged between 1,600 and 2,700 USD per metric ton FOB, depending on grade granularity and polarity optimization, making cost predictability a persistent concern for downstream formulators.
A second inflection point involves the regulatory environment. Organoclay grades must align with REACH directives and EPA guidelines, which has accelerated product development toward optimized alkyl quaternary ammonium surface treatments that improve dispersion while maintaining compliance within solvent systems. The regulatory trajectory is not a barrier per se, but it imposes a higher bar for formulation validation, product stewardship documentation, and continuous reformulation to keep pace with evolving chemical restrictions. Suppliers that treat compliance as an afterthought risk losing procurement preference in markets where environmental and safety disclosures carry increasing weight.
A third challenge is the uneven pace of demand growth across end-use verticals. While paints and coatings, oil-based drilling fluids, lubricating greases, inks and adhesives, and other industrial applications all consume solvent-based organoclay, their growth dynamics differ substantially. Volume expansion in coatings and inks is tied to regional industrialization, construction activity, and packaging trends, whereas drilling fluid demand is more sensitive to upstream oil and gas capital expenditure cycles. This divergence forces suppliers to manage multiple demand rhythms simultaneously and to avoid overconcentration in any single application segment that could be vulnerable to cyclical downturns.
Hectorite Clays Market
For business leaders, the implication is clear. The solvent-based organoclay market is large enough to support profitable participation, but success depends on navigating raw material exposure, regulatory compliance, and application-specific demand variability rather than simply selling a commodity thickener.
Key Demand Drivers and Structural Shifts
Innovation in Product Chemistry and Dispersion Performance
The most visible driver of market evolution is continued advancement in product chemistry. Manufacturers are engineering organoclay grades optimized for low, medium, and high polarity solvent systems, allowing formulators to achieve thixotropic and anti-settling performance with reduced additive loading or fewer secondary rheology modifiers. Easy-dispersible grades have gained commercial prominence because they reduce mixing energy, shorten dispersion time, and lower the risk of agglomeration in high-speed coating production or ink manufacturing. Conventional pre-gel grades remain relevant for applications requiring higher viscosity build-up or specific gel structures, particularly in lubricating greases and certain oil-based drilling fluids. The shift toward grades that perform reliably across a broader polarity range helps formulators simplify supply chains while maintaining performance consistency.
Montmorillonite Clay (Bentonites) Market
Regulatory and Compliance Pressures Shaping Product Design
Regulatory expectations are acting as a design constraint and an opportunity in equal measure. Compliance with REACH and EPA frameworks has pushed producers to refine alkyl quaternary ammonium surface treatments, aiming for formulations that deliver the desired rheological response while minimizing handling concerns and supporting downstream customer documentation requirements. This dynamic favors suppliers that can articulate clear compliance positioning, provide consistent batch-to-batch quality, and support customers with technical data that eases integration into regulated formulations. In practical terms, compliance has become a competitive differentiator rather than a baseline requirement, especially in European and North American applications where procurement teams scrutinize chemical documentation before qualification.
Demand-Side Behavior and Application Broadening
Demand behavior is being reshaped by end-user preference for high-performance, low-maintenance formulations. In paints and coatings, manufacturers increasingly seek rheology additives that support sag resistance, pigment suspension, and shelf stability without compromising application properties. In inks and adhesives, dispersion efficiency and gloss retention are primary considerations. In lubricating greases, organoclays contribute to structure stability and resistance to softening under shear. In oil-based drilling fluids, effective rheology control is essential for carrying cuttings and maintaining wellbore stability. Across these applications, the common theme is a willingness to pay for performance predictability and processing efficiency. This creates room for suppliers offering tailored grades, application-specific technical support, and consistent availability, especially where procurement teams are trying to reduce variation in final product quality.
Supply Chain Configuration and Cost Structure
Cost structure and supply chain configuration are increasingly decisive. Organoclay manufacturing relies on high-purity montmorillonite from dedicated bentonite mines, and producers that control both mineral sourcing and chemical modification gain leverage in cost management, quality control, and supply assurance. Vertical integration helps reduce dependency on external clay suppliers, improves the consistency of the base mineral, and supports a more stable cost base for finished grades. At the same time, logistics, energy costs, and chemical input pricing influence the landed cost of organoclays in different regions. Buyers are therefore paying closer attention to total cost of ownership, not just unit price, because dispersion efficiency, dosage optimization, and performance reliability can offset apparent price differences between suppliers. In a market where pricing spans a meaningful range by grade and polarity optimization, the commercial winner is often the supplier that can demonstrate the best balance between cost, performance, and supply reliability.
Taken together, these drivers suggest that the market is moving away from undifferentiated product sales toward value-added solutions. Formulators are looking for partners who can help them meet performance targets, manage compliance, and stabilize input costs, while suppliers are investing in grade optimization, application support, and supply chain resilience to capture that preference.
Competitive Landscape and Strategic Positioning
The competitive field in solvent-based organoclay includes a mix of established specialty players and regional manufacturers with strong bentonite access. Elementis plc, with its BENTONE series, is recognized for solvent-based organoclay rheological additives including hectorite and bentonite-based grades such as BENTONE 34 and 38. Its positioning emphasizes thixotropic and anti-settling performance for coatings, greases, and industrial applications, supported by a global specialties footprint that spans operations in Europe and the United States. This global reach gives Elementis an advantage in multi-region customer support and technical service, particularly where formulators require consistent performance across markets and regulatory contexts.
Bentonite Performance Minerals operates with a strong focus on vertically integrated production of organically modified bentonite, primarily for oil and gas drilling fluids. Its product range includes powder and granular forms using quaternary amine chemistry designed to address contaminant targeting and rheology control in demanding drilling environments. This application-centric specialization allows BPM to build deep domain expertise and long-term supplier relationships in drilling fluid formulation, where performance under downhole conditions and resistance to electrolyte contamination are critical.
Minerals Technologies Inc. contributes a global perspective as a provider of organoclay rheological additives and specialty minerals for solvent-based systems in paints, coatings, and industrial applications. Its scale and breadth of mineral expertise enable it to serve a wide range of formulators and to maintain supply consistency across major end-use markets. The company’s positioning benefits from its ability to combine mineral sourcing capability with additive product knowledge, which supports both performance and supply assurance for large-volume industrial customers.
A notable cluster of competitive activity sits in Asia, where manufacturers have expanded capacity, emphasized vertical integration, and built export-oriented supply chains. Zhejiang Camp Shinning New Material Co., Ltd. is a leading manufacturer specializing in solvent-based organoclay rheological additives for paints, coatings, inks, grease, and oil drilling fluids. Its product strategy centers on multiple grades optimized for low, medium, and high polarity solvent systems, supported by ownership of its own bentonite mine and ISO certification. This combination of mine-to-finished-product control and grade customization supports cost competitiveness and quality consistency. Hangzhou Jingyi Chemical Co., Ltd., part of a large Asian organoclay manufacturing group with operations dating back to 1984, is another major producer of rheological additives for solvent-based systems. Its annual capacity supports paints, inks, sealants, and lubricants, and its long operating history contributes to established production know-how and export experience.
Indian manufacturers such as Suraiya Private Limited and Bentec Organoclays have carved out roles as experienced producers and exporters of solvent-borne organoclays and rheological additives. Suraiya positions its Smectone organoclays as import substitutes for thickening, gelling, and anti-settling in solvent-based systems, oils, and organic liquids, appealing to formulators looking to diversify supply sources or reduce import dependence. Bentec Organoclays offers various grades of rheological additive organoclays for industrial applications including solvent-based formulations, supporting regional demand and export channels. Weifang Huawei Bentonite Group, another China-based producer, serves rheological needs in solvent-based coatings, drilling, and related sectors, contributing to the broader supply base that continues to expand across Asia.
PW Consulting
The market structure reflects meaningful concentration, with the top three firms holding roughly 48.5 percent and the top five firms holding about 62.3 percent of market share. This concentration indicates that established players retain substantial influence, but it also leaves room for regional specialists and niche manufacturers to compete on grade customization, pricing, and application support. The competitive trend is not purely consolidation or fragmentation; it is a blend of both. Larger players strengthen their position through product breadth, global service networks, and compliance credentials, while regional manufacturers compete by offering tailored grades, responsive technical service, and vertically integrated cost advantages. New entrants and expanding regional suppliers add pressure on pricing and availability, which benefits buyers but raises the bar for differentiation among incumbents.
For strategic planners, the key insight is that supplier selection increasingly hinges on more than price. Performance reliability across polarity ranges, compliance documentation, supply continuity, and application-specific technical support are becoming the decisive variables. Companies that treat organoclay procurement as a pure commodity purchase risk exposing their formulations to variability, while those that engage with suppliers around grade optimization and supply strategy can convert rheological performance into tangible processing and quality advantages.
Future Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, one dominant trend is the continued emphasis on easy-dispersible and polarity-flexible grades. As coating and ink producers seek to reduce processing time, limit agglomeration risk, and simplify formulation architecture, organoclay products that disperse quickly and deliver consistent rheology across a wider solvent spectrum will likely capture additional preference. This creates an opportunity for suppliers that can demonstrate measurable dispersion improvements, lower shear requirements, and stable performance in solvent systems with varying polarity. It also raises expectations for technical support, because formulation gains depend on matching grade selection to specific solvent and pigment/polymer systems rather than using a generic thickener.
A second trend is the tightening alignment between product chemistry and regulatory readiness. As compliance expectations become more embedded in procurement decisions, organoclay grades with cleaner documentation, optimized surface treatments, and consistent batch quality will gain an edge. Suppliers that proactively support customer compliance requirements may see preferential qualification in European and North American accounts, while those with less transparent product stewardship could face longer qualification cycles or displacement by alternatives that reduce regulatory friction. This trend favors organizations that can integrate regulatory readiness into product development rather than treating it as a separate administrative task.
A third trend concerns supply chain localization and diversification. Demand growth in Asia Pacific is significant, and regional production capacity continues to expand, supported by bentonite access and export-oriented manufacturing. At the same time, buyers in other regions are increasingly interested in supply diversification to reduce dependency on single-source suppliers and to improve resilience against logistics disruptions. The combination of regional capacity growth and buyer appetite for alternative sourcing creates an environment where both incumbents and expanding regional players can gain ground if they can deliver consistent quality and dependable lead times.
These trends intersect with commercial opportunity, but they also carry uncertainty. Oil and gas capital expenditure cycles can affect drilling fluid demand, regulatory interpretations can shift product qualification requirements, and raw material availability can alter cost structures. In addition, the market may see substitution pressure in specific applications if alternative rheology technologies improve their performance or cost position. Participants should therefore treat growth as attainable but conditional on product relevance, supply reliability, and the ability to respond to changing compliance and application requirements.
Strategic Implications for Decision Makers
Manufacturers and formulators should treat organoclay selection as a performance-and-risk decision rather than a price-only purchase. Prioritizing grades that match the polarity profile and processing conditions of the target system can improve dispersion, reduce additive loading, and stabilize final product quality. Where possible, qualification programs should include dispersion efficiency, sag resistance, shelf-life behavior, and compliance documentation, not just viscosity build-up. Building relationships with suppliers that can offer multiple grades and application-specific guidance can reduce formulation risk and shorten troubleshooting cycles when solvent systems or raw material inputs change.
Investors evaluating exposure to this market should focus on structural advantages that support durable margins. Vertical integration from bentonite sourcing to finished organoclay production, broad grade coverage across polarity ranges, and a credible compliance narrative are indicators of competitive resilience. It is also important to assess exposure to cyclical end-use segments such as drilling fluids alongside steadier demand in coatings, inks, and greases, because segment mix influences revenue stability. Companies that can combine cost control, product differentiation, and multi-region supply capability are better positioned to navigate both demand growth and competitive pressure.
Procurement and supply chain leaders should seek to lower total cost by balancing price with performance reliability and supply assurance. Multi-supplier qualification can provide leverage and contingency, but it should be paired with clear technical criteria so that alternative grades do not introduce variability in application behavior. Where regional supply diversification is feasible, it can reduce exposure to logistics shocks and import dependency, provided consistent quality and documentation are maintained.
For organizations that need deeper segmentation, pricing nuance, and tailored recommendations across regions and applications, a full market study can provide the granularity required to convert these trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Solvent-based Organoclay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide Container Twistlock Market
Market Landscape and Core Challenges
The global container twistlock market has established itself as a critical component of international trade infrastructure, enabling the secure stacking and transport of intermodal freight containers across maritime, rail, and road networks. Valued at approximately 585.4 million USD in 2025, the market reflects steady growth from its 2020 baseline of 451.3 million USD, driven by expanding global trade volumes and the ongoing modernization of logistics infrastructure. With a projected compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast period, the market is expected to reach roughly 830.34 million USD by 2032. This trajectory underscores the essential role of twistlock technology in maintaining the efficiency and safety of containerized cargo movement worldwide.
Despite this positive momentum, the industry is navigating several structural challenges that will define competitive dynamics in the coming years. One prominent tension lies in the coexistence of legacy manual systems alongside emerging automated alternatives. While manual and semi-automatic twistlocks continue to dominate procurement spending due to lower upfront costs and established supply chains, the accelerating electrification and automation of port operations are reshaping deployment priorities. Terminal operators and shipping lines are increasingly evaluating equipment that reduces manual intervention, minimizes occupational safety risks, and integrates with digital cargo management systems. This transition creates a bifurcation in procurement behavior, where cost-conscious operators in developing regions prioritize affordability, while advanced hubs invest in higher-capacity and remotely controlled solutions.
A second challenge centers on standardization and regulatory alignment across diverse operating environments. Function, dimensions, strength requirements, and testing protocols for twistlocks are governed by international specifications such as ISO 3874, which defines performance expectations for securing series 1 freight containers, and ISO 1161, which standardizes corner fittings geometry to ensure compatibility. Compliance with these standards is necessary but not sufficient for market access in specialized segments. Marine applications demand class society approvals from organizations such as ABS, DNV-GL, and CCS, while rail intermodal transport often requires AAR certification. The multiplicity of certification pathways complicates product development cycles, raises compliance costs, and creates barriers for smaller manufacturers seeking to expand into regulated segments. Companies that streamline certification strategies and align product portfolios with multiple standards gain a distinct advantage in penetrating high-value applications.
Supply chain and cost structure pressures represent a third critical juncture. Container twistlocks are primarily manufactured from high-strength forged or cast steel, making the category sensitive to fluctuations in metallurgical raw material pricing. With steel rebar futures trading at approximately 3103 CNY per ton in early 2026, manufacturers face ongoing input cost volatility that compresses margins and influences pricing strategies. At the same time, concentrated customer bases and long replacement cycles in maritime shipping mean that demand elasticity is relatively low in core segments. This dynamic forces producers to balance cost pass-through mechanisms with volume retention, particularly as logistics operators optimize total cost of ownership rather than focusing solely on unit price. The interaction between raw material economics, certification costs, and procurement cycles creates a complex environment where operational efficiency and product differentiation become decisive competitive levers.
Key Drivers Shaping Market Evolution
Technology innovation and the shift toward operational automation are restructuring how twistlocks are designed, deployed, and integrated into broader cargo handling ecosystems. The move toward electrification and remote control in twistlock systems reflects a broader industry ambition to reduce manual intervention, improve consistency in container securing, and enhance worker safety in demanding terminal environments. Recent product advancements illustrate this trajectory clearly. In November 2025, LOX Container Technology introduced its Road Gen 2 electrified fully retractable automatic clamping twistlock, which has been adopted in autonomous vehicle projects across Europe, North America, and Asia. This development signals that automatic twistlock technology is no longer confined to specialized pilot programs; it is entering operational use cases where interoperability with automated transport systems and reduced reliance on human handling are central requirements.
For manufacturers and equipment suppliers, this technological shift carries strategic implications. Fully automatic and semi-automatic solutions are gaining relevance not only in high-throughput container terminals but also in contexts where safety regulations, labor constraints, and throughput targets converge. The capability to offer remotely controlled, fully retractable designs that align with autonomous project specifications opens pathways to differentiated positioning. At the same time, the maturity of manual and semi-automatic product lines remains commercially significant, particularly where capital expenditure limits or operational models favor proven, lower-complexity equipment. The strategic opportunity lies in developing modular product architectures that allow customers to upgrade or adapt securing systems as automation adoption accelerates, rather than forcing a binary choice between legacy and advanced configurations.
Container Leasing Market
Policy and regulatory environments continue to shape market demand with direct consequences for product design and market access. ISO 3874 remains the foundational specification for function, dimensions, strength requirements, and testing of twistlocks, latchlocks, stacking fittings, and lashing systems used in securing series 1 freight containers. Complementing this, ISO 1161 standardizes corner fittings geometry, ensuring that twistlocks maintain compatibility across container fleets. These standards reduce fragmentation and create a baseline for interoperability, which benefits large-scale logistics operators seeking predictable performance across multiple ports and transport modes. However, the regulatory landscape extends beyond baseline compatibility. Marine applications require class society approvals, and railroad intermodal use often depends on AAR-certified components. These layered certification demands reward manufacturers that invest early in compliance infrastructure and maintain transparent documentation for end users and regulators.
Recent compliance-driven activity also indicates that standards are not static reference documents; they influence product refreshes and catalog positioning. In September 2025, various manufacturers maintained ongoing availability of ISO 3874-compliant manual, semi-automatic, and automatic twistlocks with updated strength requirements for container securing. This sustained alignment with recognized specifications suggests that compliance is becoming a market expectation rather than a differentiating feature alone. For market participants, the implication is clear: regulatory adherence must be embedded into engineering and quality processes, while differentiation is increasingly achieved through performance under load, durability, ease of maintenance, and compatibility with automated handling workflows.
Demand-side behavior is evolving as logistics operators reconsider total cost of ownership, safety performance, and throughput reliability. Containerized trade remains the backbone of global commerce, and the requirement to secure containers during stacking, vessel loading, and intermodal transfers generates consistent demand across maritime shipping, road and rail transport, and port terminals and storage. Yet procurement priorities are shifting. Terminal operators and fleet managers are placing greater weight on equipment that reduces manual handling risks and supports consistent securing performance across high-volume cycles. This preference is especially pronounced in segments where labor availability, training costs, and occupational safety considerations add operational pressure. Semi-automatic and fully automatic twistlocks address these concerns by standardizing engagement and disengagement processes, reducing variability introduced by manual operation, and supporting integration with digital tracking and monitoring systems.
Simultaneously, the market is witnessing demand segmentation based on application intensity and operating environment. High-cycle maritime shipping applications prioritize strength, reliability, and class society compliance, while road and rail transport segments focus on compatibility with chassis and inter-box connectors, alongside capacity ratings suited to specific load profiles. Port terminals and storage environments, meanwhile, value equipment that supports efficient stacking, quick turnaround, and safe handling in congested yard operations. This segmentation encourages manufacturers to refine product messaging and specification packages for distinct use cases rather than offering uniform solutions. Companies that map product capabilities to application-specific requirements and communicate the operational benefits clearly are better positioned to capture demand in targeted segments.
Supply chain and cost structure dynamics add another layer of complexity to market growth. Because twistlocks are manufactured primarily from high-strength forged or cast steel, input cost movements directly influence production economics. With steel rebar futures around 3103 CNY per ton in early 2026, manufacturers must navigate a cost environment where pricing discipline and efficiency in material utilization become critical. This is not solely a margin issue; it also affects product development decisions, inventory planning, and the commercial feasibility of specialized variants. In response, some producers are emphasizing yield optimization, forging and casting process improvements, and configuration strategies that balance performance with material intensity.
Hitch Lock Market
Beyond raw material considerations, supply chain resilience is increasingly valued by procurement teams. Global delivery expectations, strategic stocking locations, and the ability to support both loose and fixed lashing equipment requirements influence supplier selection. Logistics operators prefer partners that can maintain availability across key regions, reduce lead time variability, and support urgent replacement needs without compromising certification or quality standards. This environment rewards manufacturers and distributors that invest in multi-node inventory strategies and maintain transparent supply chain communication. It also creates differentiation opportunities for companies that can combine regional proximity with consistent compliance and technical support.
Competitive Landscape and Leading Strategies
The market features a diverse mix of established marine equipment manufacturers, regional producers, and specialists focused on automated or certified twistlock solutions. This diversity reflects the broad application base of the category, spanning maritime shipping, road and rail transport, and port terminals and storage. Rather than a single dominant model, competitive success depends on how effectively companies align product portfolios with certification needs, application intensity, regional availability, and increasingly, automation readiness.
PW Consulting
Several leading players demonstrate distinct strategic positioning. Pacific Marine & Industrial, based in California, offers manual, semi-automatic, and automatic container twistlocks, including AAR-approved railroad inter-box connectors and class society approved models for marine deck cargo securing. This breadth of certification coverage enables the company to address multiple regulated applications through a unified product strategy. Container Technics NV, headquartered in Antwerp, supplies certified twistlocks and stackers for container vessels and ConRo ships, with strategic stock positioned in Antwerp, Dubai, Houston, and Shanghai for worldwide delivery of loose and fixed lashing equipment. Its regional inventory footprint supports responsiveness and reduces delivery friction for global customers.
General Lashing System Co., Ltd. in Ningbo manufactures twistlocks designed for deck and hatch cover installation, including semi-automatic models with large seat variants for marine shipping cargo securing. This application-oriented specialization illustrates how design focus on specific installation contexts can create a defensible position in marine securing segments. Shanghai Metal Corporation produces a broad range of twistlocks, including semi-automatic, fully automatic, dovetail, and manual types for shipping applications, reflecting a portfolio approach that targets varied customer preferences and budget profiles. Zava Marine Corporation supplies durable manual twistlocks meeting stringent safety standards for shipbuilders, shipowners, and offshore operators, emphasizing reliability and compliance in demanding marine environments.
Additional participants illustrate further strategic angles. SEC Ship's Equipment Centre Bremen GmbH & Co. KG is a leading manufacturer of container lashing equipment, including twistlocks, serving global ports and reinforcing the importance of established distribution and service reach. TEC Container operates as an OEM supplier of container lashing gear and handling equipment, including twistlocks, highlighting the relevance of manufacturing partnerships and integrated equipment offerings. Delta Mark, based in the USA, supplies semi-automatic and manual shipping container twistlocks, including AAR-approved models with up to 50-ton capacity for rail, ships, and trucks, demonstrating how capacity ratings and rail certification can support position in intermodal transport.
Automation-focused differentiation is also increasingly visible. LOX Container Technology, with a Europe-focused automation orientation and global reach, specializes in remotely controlled, electrified, fully retractable automatic twistlocks for autonomous vehicle projects and container securing, reducing manual handling. This focus points to a strategic direction in which technological integration and automation compatibility become core value propositions rather than optional features. In India, International Trailer & Parts manufactures retractable, non-retractable, screw, handle, casted, welded, and forged twistlocks and spare parts for trailer container chassis, reflecting a broad component and parts orientation that supports regional fleet and trailer ecosystems. NDRAGOLD in Jalandhar produces high-quality twistlocks with compact design for export markets, while Karma Steels manufactures forged container spreader twistlocks and guide assemblies, showing how specialized forging capabilities can support specific handling configurations. CIE Manufacturing provides twistlocks as part of intermodal chassis technology for secure container transport across modes, emphasizing integration within broader transport equipment rather than standalone component sales. ILS in Belgium supplies left and right-handed longitudinal U-frame twistlocks with high BLS ratings for container vessels, and MacGregor, part of the Cargotec group in Sweden, offers integrated cargo handling systems including advanced twistlocks with emphasis on safety and efficiency for marine applications, reinforcing the value of system-level solutions and maritime engineering credibility.
The competitive landscape is evolving through a combination of differentiation and selective consolidation pressure. On one side, product differentiation is intensifying around certification breadth, material and manufacturing quality, capacity ratings, automation readiness, and regional service availability. Companies that can demonstrate compliance with ISO 3874 and ISO 1161, secure class society or AAR approvals where required, and support automated or electrified deployment models are better positioned to command preference in higher-value segments. On the other side, the market structure encourages consolidation of supply chain value in certain channels, particularly where customers prioritize vendor reliability, multi-region stock availability, and integrated lashing solutions over purely price-based sourcing.
New entry and expansion dynamics are also shaping the field. Lower-cost manufacturing bases continue to support competitive offerings in manual and semi-automatic categories, especially where export-oriented design, compact form factors, and quality consistency meet international expectations. At the same time, automation-linked innovation is raising the barrier for entry in advanced segments, where engineering complexity, certification timelines, and integration with autonomous or electrified systems require sustained investment. This creates a market environment in which incumbents with strong certification records, established distribution networks, and clear automation roadmaps can strengthen their position, while nimble regional players can thrive by focusing on specific applications, parts supply, or cost-efficient product lines.
Future Outlook and Emerging Opportunities
Over the next three to five years, the market is likely to be shaped by three interconnected trends. First, automation and remote-controlled twistlock systems will move from selective deployment to broader operational relevance, particularly in terminals and logistics projects that prioritize safety, throughput consistency, and reduced manual handling. Electrified, fully retractable designs suitable for autonomous vehicle projects and automated securing workflows are expected to gain incremental adoption where capital investment and infrastructure readiness align. This trend opens opportunities for manufacturers that can deliver reliable automatic solutions, support integration with terminal control systems, and demonstrate measurable operational benefits.
Second, certification and standards alignment will remain central to market access, but the commercial emphasis will increasingly shift toward demonstrating performance under real operating conditions. As ISO 3874 and ISO 1161 continue to provide the baseline for function, dimensions, strength requirements, and testing, companies that combine compliance with strong load retention, durability, and ease of maintenance will stand out. Class society approvals and AAR certification will continue to gate participation in marine and rail intermodal segments, making early and efficient certification strategy a competitive asset rather than a back-office task.
Third, cost pressure from steel raw materials and the need for supply chain resilience will reinforce the value of efficient manufacturing, strategic inventory positioning, and transparent sourcing. With input costs influenced by prices such as the approximately 3103 CNY per ton steel rebar futures level observed in early 2026, producers will continue to optimize material usage, forging and casting processes, and product configurations that balance performance with cost. Customers will increasingly favor suppliers that can maintain availability across regions, support urgent replacement needs, and reduce total cost of ownership through reliability and service responsiveness.
These trends create commercial opportunities for manufacturers that can bridge traditional robustness with automation readiness, for investors evaluating companies with strong certification portfolios and regional distribution advantages, and for procurement teams seeking suppliers that reduce operational risk while meeting evolving technical requirements. At the same time, uncertainty remains. Adoption of fully automatic systems may proceed more slowly in cost-sensitive regions, certification requirements may evolve as operating practices change, and raw material volatility can disrupt margin planning and pricing stability. Companies that treat these uncertainties as design constraints rather than external noise will be better prepared to capture value as the market matures.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to align product development with both compliance rigor and automation trajectory. This means maintaining clear adherence to ISO 3874 and ISO 1161, pursuing class society and AAR approvals where relevant, and developing product variants that support remote control, electrification, and integration with automated securing workflows. Equally important is building regional availability and aftermarket support, since responsiveness and parts supply often influence repeat procurement as much as initial price.
For investors, the most compelling signals are certification breadth, application-specific engineering strength, regional distribution capability, and credible roadmaps for semi-automatic and fully automatic solutions. Businesses that combine these attributes with disciplined material cost management and multi-region stock positioning are better equipped to navigate segmented demand and regulatory complexity. Investment diligence should therefore weigh not only unit economics but also the ability to serve marine, rail, and terminal applications reliably under varying operating conditions.
For procurement and logistics operators, the strategic focus should be on total cost of ownership, safety performance, and compatibility with current and near-term handling requirements. Evaluating suppliers on certification coverage, capacity ratings, maintenance burden, and availability across key locations can reduce operational risk and support smoother integration with automated or semi-automated processes. As deployment scenarios mature, access to detailed segment-level data and customized guidance can help refine specification choices and sourcing strategies. For those seeking a more granular view of regional splits, application demand patterns, type-level dynamics, and company-level positioning, the full PW Consulting market study offers expanded segmentation detail and tailored strategic recommendations to support planning decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Container Twistlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Concentrated Tomatoes Market: Why 5.6% CAGR and 34% Europe Share Redefine 2032 Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Concentrated Tomatoes Market
Market Overview: Scale, Trajectory, and Critical Inflection Points
The global concentrated tomatoes market has established itself as a foundational pillar of modern food processing and retail supply chains, driven by the dual demands of convenience, shelf stability, and consistent flavor delivery. With a revenue trajectory that reflects steady expansion through the early 2020s and into the mid-2020s, the sector demonstrates resilience amid shifting agricultural conditions and evolving industrial procurement patterns. The market crossed the nine-billion-dollar threshold in the base year and is projected to maintain a compound annual growth rate of 5.6 percent through the early 2030s, signaling a broadening of application channels, sustained industrial demand, and gradual geographic diversification. This growth trajectory suggests that concentrated tomato products are transitioning from commodity-style bulk inputs toward strategically positioned ingredients where quality, traceability, and processing consistency increasingly dictate purchasing decisions.
Beneath the headline expansion, the industry is navigating several structural inflection points that will redefine competitive positioning over the next five years. Climate volatility has begun to exert measurable pressure on processing-grade tomato yields and harvest windows, particularly in traditional production zones where water availability and temperature extremes are constraining grower output. At the same time, the cost structure of raw material procurement remains a central pressure point for processors seeking to stabilize margins without compromising product specifications. These agricultural and cost variables are intersecting with a broader operational shift: manufacturers are re-evaluating sourcing dependencies, inventory models, and ingredient-formulation strategies to safeguard volume consistency while responding to tighter commercial timelines from food-service and industrial buyers. The confluence of supply-side uncertainty and demand-side expectation escalation means that the market is no longer driven purely by volume expansion, but increasingly by reliability, quality differentiation, and compliance readiness.
Another defining feature of the current landscape is the growing complexity of regional trade dynamics and sourcing arithmetic. Trade measures, tariff structures, and compliance requirements have introduced new considerations for buyers evaluating cross-border supply, while producers juggle capacity allocation decisions between domestic industrial channels and export markets. This environment favors suppliers that can demonstrate transparent sourcing documentation, consistent batch profiles, and operational flexibility. The market is also witnessing a subtle re-rating of ingredient specifications: as food manufacturers seek to streamline formulations and reduce supply-chain variability, concentrated tomato products are being positioned not merely as cost-effective bulk inputs, but as stabilized ingredient platforms that can support cleaner labels, reduced processing steps, and more predictable flavor profiles. These intersecting pressures mark a transition period where operational efficiency, sourcing resilience, and specification leadership will increasingly determine which participants capture disproportionate value as the market advances toward the end of the decade.
Coffee Concentrates Market
Key Drivers Reshaping Market Dynamics
Technological innovation continues to serve as a powerful lever for competitive differentiation across the concentrated tomatoes sector. Processing operations are increasingly integrating precision sorting, controlled concentration techniques, and aseptic preservation technologies that improve consistency while reducing dependency on extensive post-processing intervention. Beyond equipment-level upgrades, there is growing adoption of digital agronomy and supply-chain visibility tools that enable producers to align crop intake with factory throughput, improve yield utilization, and minimize variability between harvest batches. These enhancements are especially valuable for manufacturers supplying industrial food processors, where specification stability and repeatable viscosity, color, and flavor profiles directly influence downstream production efficiency. Innovation is also extending into product design: concentrated derivatives with tailored solids content, reduced sodium intensity, and cleaner processing footprints are gaining relevance as formulators search for ingredient systems that can simplify label declarations while preserving organoleptic performance.
The regulatory environment is simultaneously reshaping sourcing strategies, documentation requirements, and trade flows. Compliance expectations are intensifying around supply-chain traceability and environmental due diligence, with obligations such as the EU Deforestation Regulation requiring structured oversight of agricultural supply chains beginning in late 2025. For concentrated tomato suppliers, this translates into a need to strengthen provenance data, map supplier networks more systematically, and prepare documentation that can withstand scrutiny across multiple jurisdictions. Regulatory initiatives are not confined to environmental compliance. Food safety oversight remains a persistent operational priority, as allergen control, contamination prevention, and recall readiness continue to influence procurement standards across food service, retail, and industrial channels. In practice, regulatory pressure is accelerating a shift toward suppliers that can provide verifiable sourcing narratives and consistent quality assurance systems, because non-compliance risks increasingly carry commercial consequences beyond the immediate cost of a disruption.
On the demand side, purchasing behavior is being reshaped by both end-consumer expectations and corporate procurement priorities. Food manufacturers and food-service operators are prioritizing consistency, convenience, and formulation flexibility, which sustains demand for concentrated formats that deliver reliable performance with fewer processing steps. At the same time, premiumization is gaining traction among retailers and consumer-facing brands seeking differentiation through regional origin, varietal character, and processing intensity. This dual trajectory creates a market where volume-driven industrial applications coexist with specification-sensitive premium demand, each rewarding different sourcing and production models. The household and retail channel, while smaller in scale than industrial processing, is becoming an important arena for brand-led positioning, where packaging, origin storytelling, and perceived quality can justify differentiated price points and support repeat purchase behavior. These demand-side shifts encourage suppliers to think beyond bulk volume and invest in ingredient-grade positioning, batch traceability, and application-specific product design.
Supply-chain and cost structure dynamics complete the picture by reinforcing the importance of sourcing resilience and capacity strategy. Raw material pricing for processing tomatoes has reflected the realities of regional growing conditions, labor availability, and seasonal output variability, making procurement planning more complex for processors that rely on concentrated supply. In major producing regions, total crush volumes and grower pricing trends serve as leading indicators of how tightly supply will match industrial requirements in a given season. At the same time, cross-border trade measures, including antidumping duties affecting select origins, have altered the cost competitiveness of certain import pathways and encouraged buyers to diversify sourcing footprints or renegotiate allocation structures. These dynamics increase the value of suppliers that can offer dependable volume commitments, flexible contract terms, and transparent pricing logic. Where producers can combine agronomic planning, logistical reliability, and processing adaptability, they are better positioned to sustain margin stability even as input-cost volatility and trade friction persist.
Competitive Landscape and Leading Strategies
The competitive structure of the concentrated tomatoes market is defined by a mix of large-scale processors, premium-positioned producers, and regionally focused exporters, each pursuing distinct strategies to protect relevance in a market that rewards both scale efficiency and specification clarity. Leading participants are generally competing on three fronts: supply reliability, product-grade differentiation, and geographic reach. Companies with substantial processing capacity and established relationships with industrial buyers tend to emphasize volume consistency, contract stability, and the ability to serve high-volume food-processing requirements with predictable specification profiles. At the same time, other strong players differentiate through varietal selection, regional sourcing narratives, and premium presentation, positioning concentrated tomato products as ingredients that contribute not only functional performance but also brand value for end users seeking quality and origin authenticity.
Strategic positioning varies significantly by operational model. Large independent producers focused on processing tomatoes typically build advantage through integrated handling of crop intake, concentration efficiency, and logistics coordination, allowing them to serve broad industrial demand while managing seasonal supply fluctuations. Their differentiation often rests on scale, factory throughput, and the ability to offer multiple concentrate grades suited to industrial formulation needs. By contrast, producers associated with premium Italian tomato traditions emphasize varietal character, controlled processing methods, and origin-linked quality narratives. These companies often target retail, food service, and premium industrial applications where label distinctiveness and taste consistency support higher-value positioning. Cooperative structures and regional manufacturers also play an important role by combining local grower relationships with export capability, enabling them to connect regional production bases with international demand while maintaining closer oversight of raw material sourcing.
The market landscape is gradually evolving through a combination of consolidation pressure and segmentation intensification. On one side, scale advantages remain meaningful for participants handling large volumes, meeting industrial service requirements, and absorbing the fixed costs associated with compliance documentation, quality assurance, and supply-chain traceability. On the other side, segmentation is becoming more pronounced, with increasing separation between industrial commodity-style procurement and specification-sensitive premium demand. This divergence encourages some suppliers to specialize, either by reinforcing their industrial supply credentials or by investing in premium-grade product development and brand-facing positioning. New and expanding entrants are also reshaping regional supply patterns, particularly where domestic production growth or export-oriented capacity creation enables alternative sourcing routes. At the same time, trade measures and tariff structures introduce friction that can limit certain cross-border flows and reinforce regional sourcing preferences in specific markets, indirectly supporting suppliers with local or tariff-advantaged supply positions.
Recent operational and market signals further illustrate the emphasis on resilience and compliance readiness across the competitive field. As sourcing documentation expectations rise and trade pathways are reshaped by tariff and regulatory conditions, competitive advantage increasingly depends on the ability to demonstrate transparent supply chains, maintain consistent processing quality, and adapt capacity allocation across domestic and export channels. Suppliers that can combine operational discipline with product differentiation are better positioned to navigate both cost pressure and specification expectations. Over time, the market appears headed toward a structure in which scale, compliance maturity, and grade-specific value proposition will collectively determine competitive strength rather than volume leadership alone.
Future Outlook: Three Trends That Will Shape the Next Phase
Looking ahead to the next three to five years, one central trend will be the continued alignment of concentrated tomato supply with traceability and compliance expectations. As due-diligence requirements expand and food safety standards continue to influence procurement decisions, suppliers that invest early in documentation systems, supplier mapping, and quality verification will gain a structural advantage in buyer selection. This shift will likely elevate the importance of transparency as a commercial asset, making provenance and process discipline part of the value proposition rather than a back-office function. For buyers, this trend means that sourcing decisions will increasingly weigh compliance readiness alongside price and volume reliability.
Worldwide Citrus Concentrate Market
A second trend will be the growing differentiation between industrial-grade volume channels and premium specification channels. Industrial food processing will remain a major demand base, but the premium end of the market is expected to strengthen as brands and food service operators seek ingredient positioning that supports cleaner labels, origin storytelling, and taste consistency. This divergence will reward producers capable of operating both ends effectively, or those that commit strategically to one lane with clear product architecture. Opportunities will emerge for suppliers that can offer application-tailored concentrate profiles, adaptable solids levels, and consistent sensory performance, especially where food manufacturers want to reduce processing complexity without sacrificing quality.
A third trend will be the reconfiguration of sourcing geography and supply-chain buffers in response to climate variability, trade measures, and cost volatility. Buyers are likely to place greater emphasis on multi-origin sourcing, contractual flexibility, and visibility into seasonal supply status. Suppliers with strong agronomic planning, diversified intake channels, and responsive logistics will be better equipped to secure dependable volume allocation. The main risk in this environment is that climate-driven yield variability, combined with trade friction in specific corridors, could create periods of tight supply or uneven pricing. Participants that treat sourcing resilience as a strategic capability rather than a procurement tactic will be better positioned to manage those disruptions while preserving commercial relationships.
Actionable Insights for Decision Makers
For manufacturers and processors, the most immediate priority is to align product architecture with the dual reality of industrial volume demand and premium specification expectations. That means evaluating whether concentrate grades, solids ranges, and processing methods are adequately matched to key end-use segments, while also strengthening quality consistency and documentation capabilities. Investment in traceability infrastructure, batch-level control, and application-specific product development can help protect margin stability and improve the ability to serve buyers who increasingly require verifiable sourcing and predictable ingredient performance. Capacity planning should also account for seasonal supply variability, because operational agility will matter as much as scale when harvest outcomes and input costs fluctuate.
PW Consulting
For investors, the opportunity lies in identifying participants that combine sourcing discipline with clear positioning in high-growth value segments. Companies with demonstrable compliance readiness, resilient raw-material relationships, and the ability to serve either industrial or premium channels with consistency are likely to benefit disproportionately as the market rewards reliability and specification leadership. Due diligence should examine not only revenue trajectory and capacity, but also the strength of supply-chain documentation, exposure to trade friction, and the degree to which product differentiation supports pricing flexibility. In a market expanding at a steady mid-single-digit pace, long-term value creation will depend on whether a company can convert operational maturity into competitive insulation from cost volatility and compliance pressure.
For procurement and supply-chain leaders, the practical imperative is to treat sourcing resilience as a strategic variable rather than a transactional one. Diversifying supply bases, clarifying specification requirements early, and establishing procurement terms that account for seasonal variability and documentation needs can reduce exposure to disruption. At the same time, procurement teams should engage suppliers with a clearer view of compliance expectations and quality consistency, since these factors are becoming integral to supplier selection. In this environment, detailed segment intelligence, regional sourcing assessments, and tailored scenario planning can provide a meaningful advantage in negotiating allocation, evaluating alternative origins, and anticipating cost shifts before they affect production schedules.
The concentrated tomatoes market is moving into a phase where scale alone is no longer sufficient to secure durable advantage. The next layer of competition will be defined by traceability maturity, specification relevance, and the ability to maintain dependable supply under changing agronomic and trade conditions. Decision makers who build strategies around these priorities will be better positioned to capture the commercial opportunities embedded in the market’s ongoing expansion. For organizations seeking deeper segmentation data, competitive benchmarking, and region-specific sourcing scenarios, a fuller research assessment can provide the level of detail needed to translate these strategic themes into operational decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Concentrated Tomatoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Nervous System Medications Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global nervous system medications market has entered a phase of sustained expansion, with total revenue projected to climb from approximately $137.6 billion in 2025 to over $222 billion by 2032, reflecting a compound annual growth rate of 7.12 percent. This trajectory underscores a structural shift in how neurological and psychiatric conditions are diagnosed, treated, and managed across healthcare systems worldwide. The growth is not merely incremental; it signals deepening clinical reliance on targeted pharmacotherapies, expanding indication coverage, and increasing integration of nervous system treatments into broader chronic care pathways. As healthcare providers confront growing caseloads of neurodegenerative, psychiatric, and pain-related conditions, pharmaceutical stakeholders are recalibrating portfolios to capture value across both established and emerging therapeutic areas.
Despite the favorable macro trajectory, the sector faces several pivotal challenges that will shape competitive outcomes over the next decade. First, the tension between innovation and patent cliffs remains acute. Recent exclusivity losses on widely prescribed anti-epileptic and psychiatric agents have accelerated generic infiltration, compressing margins for originator manufacturers while simultaneously expanding affordable access for patients and payers. Second, reimbursement architectures are undergoing recalibration. Payers are increasingly scrutinizing real-world effectiveness, pharmacoeconomic outcomes, and differentiated clinical value, particularly for high-cost neurology therapies and specialty injectables. This environment rewards manufacturers that can demonstrate measurable health economic benefits rather than relying solely on clinical efficacy narratives. Third, supply chain dependencies continue to introduce volatility. The concentration of active pharmaceutical ingredient sourcing, particularly for complex nervous system compounds, across select contract manufacturing ecosystems has highlighted the need for geographic diversification, inventory resilience, and robust quality oversight. These dynamics collectively demand a more agile, data-informed approach to portfolio strategy, pricing, and market access.
PW Consulting
Key Drivers Shaping Market Evolution
Technological and scientific breakthroughs are redefining the therapeutic ceiling for nervous system disorders. The emergence of first-in-class mechanisms that target peripheral pain pathways without engaging opioid receptors illustrates a broader industry pivot toward safer, mechanism-driven interventions. Concurrently, advances in monoclonal antibody platforms and neurodegenerative disease modulation are expanding the treatment frontier for conditions historically considered difficult to modify pharmacologically. These scientific strides are enabling developers to pursue earlier intervention, more precise patient stratification, and formulations that improve adherence through reduced dosing frequency or alternative delivery routes. For commercial teams, the implication is clear: therapeutic differentiation increasingly hinges on mechanism novelty, convenience, and aligned diagnostic ecosystems rather than incremental efficacy gains alone.
Worldwide Sedative-Hypnotic Drug Market
Regulatory environments are simultaneously reshaping market entry and lifecycle management. Regulators have maintained a relatively active approval cadence, with notable clearances spanning acute pain management, advanced Parkinson’s motor fluctuation therapies, and expanded indications for neuroimmunological conditions. At the same time, agencies are embedding more nuanced post-market requirements, including genetic or biomarker-based testing considerations, pediatric expansion pathways, and real-world evidence expectations. These regulatory nuances create both opportunity and complexity. Companies that proactively design development programs with regulatory and market access requirements in mind are gaining faster, more defensible commercial launches, while those that treat approval as an endpoint rather than a commercial starting point risk under-monetizing valuable assets.
On the demand side, patient and provider behavior is evolving in ways that favor targeted CNS therapeutics. Growing awareness of mental health conditions, broader screening initiatives, and destigmatization efforts are expanding treatment-seeking behavior across psychiatric indications. In neurology, clinicians are increasingly prioritizing therapies that reduce caregiver burden, minimize administration friction, and support long-term disease management. This demand shift is particularly pronounced in outpatient and community care settings, where ease of use, tolerability, and predictable supply are decisive adoption factors. At the same time, healthcare systems are under pressure to control total cost of care, driving preference for treatments that can reduce hospitalizations, emergency interventions, or downstream complications.
Cost structure and supply dynamics complete the driver quartet. Nervous system product portfolios remain sensitive to raw material availability, specialty formulation requirements, and manufacturing scale-up timelines. Regional concentration in active ingredient production has created pockets of exposure, prompting manufacturers to reassess dual-sourcing strategies, technology transfer readiness, and inventory buffers. At the same time, the interplay between branded innovation and generic entry is restructuring profitability across drug classes. Market participants are increasingly balancing portfolio mix between protected innovation, lifecycle management, and generic or biosimilar positioning to sustain revenue resilience through competitive transitions.
Competitive Landscape and Leading Strategies
The competitive field in nervous system medications is characterized by a mix of large diversified pharmaceutical companies, focused neurology and psychiatry specialists, and generic manufacturers with substantial distribution reach. This structure creates a fragmented yet strategically layered environment where value capture depends on therapeutic focus, patent positioning, and market access execution. Leading players are not competing on the same axis; instead, they are differentiating through portfolio concentration, mechanism leadership, and lifecycle management agility.
Worldwide Central Nervous System (CNS) Stimulants Market
Several strategic patterns stand out among top competitors. Large diversified companies are leveraging neuroscience pipelines alongside broad commercial infrastructures to cross-sell into adjacent therapeutic areas and maintain payer relationships across multiple categories. Their advantage lies in scale, regulatory experience, and the ability to fund long-cycle neurodegenerative and neuroimmunological programs. Focused neurology and psychiatric specialists, by contrast, are pursuing sharper differentiation through niche indications, specialized delivery formats, and concentrated medical affairs engagement. These companies often move faster in targeted disease areas and build deep clinical credibility that supports premium positioning in specific segments. Generic and broad portfolio manufacturers continue to play a critical role in expanding access and managing cost pressure, particularly as exclusivity windows close on established products. Their strategic emphasis typically centers on supply reliability, formulation breadth, and competitive pricing across retail and institutional channels.
Recent commercial and regulatory activity illustrates how these strategies are unfolding in practice. The approval of a first-in-class non-opioid peripheral pain mechanism reflects the industry’s push to reduce opioid reliance while addressing acute pain with a differentiated pharmacological approach. In advanced Parkinson’s disease, new subcutaneous therapy options demonstrate continued investment in improving motor fluctuation management and patient convenience. Expanded indications in neuroimmunology and early symptomatic Alzheimer’s therapies highlight how incumbents are extending franchise value through lifecycle refinement and geographically staggered regulatory launches. At the same time, exclusivity changes affecting certain anti-epileptic and psychiatric agents are reshaping competitive intensity in those categories, forcing originators to plan for volume transitions and generic entrants to compete on distribution strength and cost efficiency.
The market structure is evolving along three interlocking trends. Consolidation remains relevant for players seeking scale in commercialization, supply chain control, or pipeline breadth, especially where therapeutic areas require sustained investment and multi-market execution. Differentiation is intensifying as mechanism innovation, delivery innovation, and diagnostic alignment become more central to market access conversations. New and emerging entrants are finding room in specialized indications, novel pain pathways, and psychiatric formulations where focused development can outperform broad but diffuse strategies. The result is a market in which strategic positioning matters as much as scientific merit: companies that clearly define the patient population, value proposition, and reimbursement narrative they are pursuing are better equipped to convert clinical progress into durable commercial outcomes.
Forward Outlook: Trends Defining the Next 3 to 5 Years
Looking ahead, one of the most consequential trends will be the continued shift toward mechanism-specific and non-opioid pain management strategies. As clinical and regulatory momentum builds around peripheral-targeted interventions, the acute and chronic pain segments are likely to experience a gradual but meaningful rebalancing away from traditional opioid-centric prescribing. Commercial winners in this space will be those that can pair differentiated pharmacology with clear safety positioning, practical dosing, and integration into surgical and emergency care pathways. A second major trend will be the broader adoption of neurodegenerative and neuroimmunological therapies as disease-management staples rather than niche options. With approvals and indication expansions advancing in conditions such as early symptomatic Alzheimer’s disease and generalized myasthenia gravis, neurological care is increasingly moving toward earlier diagnosis, biomarker-informed treatment selection, and longer-duration therapy management. This shift creates opportunities for manufacturers and service providers that can support diagnostic workflows, adherence infrastructure, and specialty distribution.
A third trend will be increasing segmentation within psychiatric and neurological prescribing driven by tolerability, administration preference, and health economic considerations. As payers and providers compare alternatives more rigorously, value will accrue to therapies that offer measurable advantages in adherence, side-effect profiles, or total cost-of-care impact. This environment favors portfolio strategies that are explicit about which clinical and economic problems they solve, rather than competing solely on broad category presence. At the same time, uncertainty persists. Patent expirations will continue to redraw competitive boundaries, reimbursement pressure may accelerate pricing negotiation and value-based contracting, and supply chain vulnerabilities could disrupt product availability if not proactively managed. Market participants should therefore treat resilience, evidence generation, and access strategy as core commercial capabilities rather than supporting functions.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to sharpen therapeutic positioning around clearly defined patient outcomes and access-enabling evidence. Investments in differentiated mechanisms, convenient delivery, and robust real-world data generation are likely to yield stronger launch momentum and more defensible pricing positions, especially in categories where generic competition and reimbursement scrutiny are intensifying. For investors, the most attractive opportunities will be found where scientific differentiation, regulatory timing, and market access readiness converge. Due diligence should focus not only on clinical promise but also on exclusivity windows, lifecycle planning, supply chain exposure, and the likelihood of reimbursement alignment in target markets. For procurement and supply chain leaders, the emphasis should shift toward multi-source readiness, demand forecasting for specialty nervous system products, and supplier diversification that reduces concentration risk without sacrificing quality or continuity.
Across all roles, the strategic value of granular market intelligence is rising. Broad category growth signals are useful for direction, but durable decisions depend on segment-level dynamics, competitive timing, regional access conditions, and product-level lifecycle trajectories. Stakeholders seeking to translate these trends into actionable portfolio, investment, or procurement decisions can benefit from deeper segmentation detail, competitive scenario mapping, and tailored market access analysis that aligns with specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Nervous System Medications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Shifts and Commercial Opportunities in the Global Dairy Logistics Market
Market Status and Core Challenges
The worldwide dairy logistics market continues its steady expansion, with revenue moving from approximately $21.4 billion in 2023 to a projected $24.5 billion in 2025, and forecast to approach $39.9 billion by 2032. This trajectory reflects a compound annual growth rate of 7.2% across the 2026–2032 forecast period, signaling sustained investment in temperature-controlled movement, storage, and value-added handling of dairy products. Growth is not uniform across activity types or end products, but the overall direction remains clear: dairy supply chains are becoming longer, more regulated, and more dependent on precise thermal management as consumption habits and sourcing footprints diversify.
Several structural challenges are testing the sector’s resilience. First, temperature integrity across multimodal journeys remains a persistent operational friction point. Dairy shipments frequently traverse refrigerated trucking, cold storage nodes, and ocean or air freight legs, and any deviation can trigger rapid quality degradation, retail rejection, or regulatory non-compliance. The operational burden is amplified when shipments cross jurisdictions with different monitoring and documentation expectations, forcing logistics providers to standardize validation protocols while maintaining flexibility at regional nodes. In practice, this means cold chain performance is increasingly tied to data continuity, equipment reliability, and handler training, not merely to the presence of refrigeration assets.
Second, packaging and transport equipment costs are introducing new volatility into dairy logistics planning. Dairy transport relies heavily on specialized containers, intermediate bulk containers, and pallets engineered to withstand repeated cold cycles while meeting hygiene standards. When resin pricing and manufacturing capacity shift, operators face cost adjustments that are difficult to pass through quickly, especially in contract-heavy lanes. Procurement teams are therefore being pushed to evaluate packaging durability, reuse cycles, and material sourcing as part of logistics cost management rather than treating them as static inputs.
Third, workforce availability and labor economics are reshaping service design. Long-haul refrigerated routes, particularly those carrying dairy across extended distances, depend on skilled drivers and disciplined handling procedures. Wage pressure in reefer segments has become a meaningful component of operating cost, encouraging carriers and logistics managers to rethink route consolidation, asset utilization, and automation where feasible. The challenge is not simply finding labor; it is aligning service frequency, transit windows, and handling complexity with sustainable cost structures. These pressures are not stopping growth, but they are raising the bar for execution quality and forcing operators to demonstrate measurable cold chain reliability rather than simply capacity availability.
Pharmaceutical Logistics Market
Key Growth Drivers
Technological innovation in temperature control and shipment visibility is becoming a central driver of dairy logistics performance. Real-time monitoring hardware, smarter reefer container controls, and integrated telemetry are reducing the risk window during long-distance transport and storage. For dairy products, where temperature excursions can rapidly alter texture, shelf life, and safety parameters, the value of continuous data is no longer theoretical. Recent expansions in reefer capacity paired with live monitoring for dairy exports between Europe and Asia illustrate how carriers are bundling physical capacity with digital assurance. Similarly, the introduction of traceability-oriented reefer platforms indicates a broader shift: shippers are looking for logistics partners that can provide auditable temperature records alongside movement updates, especially when products cross multiple regulatory zones or feed into retail and food-service channels with strict freshness expectations.
Policy and regulatory environments are also reshaping cold chain requirements. Dairy logistics is increasingly governed by mandates that formalize temperature recording, storage practices, and packaging standards. In Europe, refrigerated transport of dairy products above certain temperature thresholds must now be supported by compliant recording devices, turning temperature documentation into a baseline expectation rather than a premium service. At the same time, packaging-related legislation in key markets is nudging operators toward recycled and lower-impact materials for dairy transport packaging. These rules raise the compliance floor, but they also reward operators that can standardize monitoring practices across lanes and proactively adapt packaging strategies. For shippers, the practical implication is that regulatory readiness is now part of logistics suitability: a provider that cannot demonstrate consistent documentation or packaging alignment may face friction in regulated markets regardless of transit speed.
Worldwide Agricultural Logistics Market
Demand-side shifts are altering how dairy is sourced, stored, and moved. Consumer preferences increasingly favor fresh, chilled, and specialty dairy formats, while food-service and retail channels continue to demand dependable availability across broader geographic footprints. This has contributed to longer supply chains and greater reliance on controlled cold storage and transport for categories such as milk, cheese, yogurt, and cream-based products. At the same time, manufacturers are diversifying sourcing footprints, which increases the need for cross-border and inter-regional refrigerated movement. Growth is therefore not only about moving more volume; it is about moving a wider mix of dairy products with different temperature tolerances, shelf-life profiles, and handling requirements. Logistics providers that can manage product differentiation at scale gain a clear advantage because they can support both routine bulk movement and higher-touch specialty dairy flows within a coherent network.
Supply chain structure and cost dynamics are acting as a second-order driver, pushing organizations to optimize asset use and reduce waste. Cold storage capacity remains a strategic constraint in several regions, particularly where demand for chilled dairy inputs is rising faster than facility development. That constraint encourages investment in automated storage, higher-density layouts, and better throughput management. On the transportation side, cost variables such as reefer-specific freight rates, driver economics, and packaging input pricing all influence lane decisions. The result is a market in which efficiency is becoming inseparable from service quality. Operators are increasingly evaluated on whether they can reduce dwell time, improve load consolidation, limit temperature-related losses, and stabilize total landed cost, rather than simply offering a refrigerated slot or a warehouse location.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is anchored by large logistics and cold chain organizations with the scale to design integrated dairy networks rather than isolated refrigerated services. Maersk has positioned itself around refrigerated container shipping and cold chain solutions for dairy products including milk, cheese, and butter, leveraging global ocean connectivity and increasingly digital reefer capabilities. DB Schenker focuses on temperature-controlled logistics and multimodal transport, using specialized reefer trucks and warehousing to support dairy supply chains across complex routing scenarios. Kuehne+Nagel has built a reputation around end-to-end cold chain management, combining sea freight in reefer containers with air cargo options for perishable dairy goods, which helps shippers handle urgent or high-value movements without breaking the cold chain. DHL Supply Chain adds depth in temperature-monitored trucking, warehousing, and distribution networks spanning Europe, the Americas, and Asia, positioning itself as a multi-region execution partner for dairy operators.
In cold storage, Americold and Lineage Logistics bring different but complementary forms of scale. Americold operates one of the largest cold storage networks globally, with precise temperature control that supports dairy storage and downstream logistics. Lineage Logistics has expanded its footprint as a global leader in temperature-controlled logistics, combining warehousing, transport, and traceability for dairy supply chains. Nichirei Logistics plays a distinct role in Asia-Pacific markets, providing refrigerated transport and cold storage for dairy imports and distribution, where growing demand and import dependence create specialized regional needs.
What separates the leaders is not only asset scale, but the ability to connect physical infrastructure with technology, compliance, and service design. Recent activity reflects this orientation. Maersk expanded reefer capacity for dairy exports from Europe to Asia while adding real-time temperature monitoring, effectively pairing capacity growth with visibility. Lineage Logistics opened an automated cold storage facility in the Netherlands dedicated to dairy logistics serving EU markets, strengthening its position in a region where regulated cold chain expectations and proximity to demand matter. Kuehne+Nagel introduced a reefer platform with blockchain traceability for dairy shipments, reinforcing the move toward documentation and shipment integrity as competitive differentiators rather than optional features. These moves suggest a market in which differentiation is increasingly expressed through data assurance, automation, and regional specialization.
The broader competitive trend is one of selective consolidation alongside targeted specialization. Large players are strengthening integrated networks that span transport, storage, and monitoring, while regional specialists continue to compete on local market knowledge, import/export handling, and tailored compliance execution. At the same time, new entrants and niche operators can find room where specific product categories, lanes, or compliance requirements are underserved. The result is a landscape that is not simply consolidating into a few dominant incumbents, but one where the practical battleground is shifting toward reliability, traceability, and the ability to handle dairy’s varied temperature and packaging demands across multiple trade lanes. Market participants that can combine scale with product-level precision are best positioned to capture value, while those relying on commoditized refrigerated capacity alone face growing exposure to price and performance pressure.
Future Trends
Over the next three to five years, one of the clearest trends will be the continued elevation of cold chain visibility from a supporting function to a core commercial requirement. Dairy buyers, manufacturers, and retail partners are likely to place greater weight on temperature documentation, exception handling, and audit-ready records when selecting logistics partners. This will favor operators that can deliver consistent monitoring across transport and storage, integrate data from different legs of the journey, and translate that data into actionable service commitments. The commercial opportunity lies in turning visibility into differentiated service levels, where shippers can align product category, risk tolerance, and routing choices with measurable cold chain performance.
A second trend will be the deepening integration of automation and smarter cold storage design. As demand for chilled dairy products grows and labor economics remain tight, facilities that improve throughput, reduce handling errors, and support more consistent temperature control will gain strategic value. Automation is unlikely to replace the full breadth of cold chain work, but it can materially improve the consistency of high-volume dairy storage and dispatch, especially in regions where capacity is strained. The opportunity here is not simply building more space; it is improving how space is used, how inventory moves through it, and how product integrity is preserved during transitions between storage, transport, and distribution.
A third trend is the increasing influence of regulatory and packaging requirements on logistics operating models. Rules around temperature recording and packaging content are expanding the baseline expectations for dairy movement, and these expectations will likely become more granular over time. Logistics providers and dairy operators that proactively align their equipment, documentation, and material choices with evolving standards will face fewer disruption points, while late adapters may incur rework, delays, or renegotiation costs. The associated risk is that compliance costs and packaging transitions can compress margins if they are treated as isolated procurement issues rather than integrated logistics decisions. Climate-related disruptions, energy volatility, and geopolitical shifts in trade routes also remain external uncertainties that could pressure transit times, facility operations, and cost planning.
Actionable Guidance for Decision Makers
For dairy manufacturers and processors, the priority is to treat cold chain performance as a product-level design parameter rather than a downstream service choice. Selecting logistics partners should involve aligning temperature tolerance, shelf-life expectations, and packaging choices with the capabilities of the transport and storage network, especially for categories that move across longer distances or multiple regulatory environments. Building visibility requirements into contracts and service agreements can help reduce quality risk and improve responsiveness when deviations occur. For investors, the most durable opportunities are likely to be tied to operators that combine scale with technology-enabled reliability, automation-ready cold storage, and compliance-ready service architectures. Capital allocation should favor businesses that can demonstrate measurable improvements in temperature integrity, throughput efficiency, and documentation consistency, since these attributes are increasingly tied to competitive positioning.
For procurement and supply chain leaders, the practical focus should be on total landed cost and risk reduction rather than unit transport price alone. That means evaluating carrier and warehouse partners on performance indicators relevant to dairy: temperature excursion handling, dwell time, load consolidation, and packaging alignment with evolving content requirements. Procurement strategies that incorporate packaging durability, reuse potential, and regulatory trajectory can help reduce future disruption and cost shock. For organizations seeking a sharper segment view, detailed breakdowns by region, service type, and application can help pinpoint where to prioritize capacity, renegotiate contracts, or invest in technology and compliance readiness. A full market report with deeper segmentation, competitive benchmarks, and scenario-based insight can support more targeted planning across those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Perfumes Market: How 5.85% CAGR and Luxury Shifts Redefine Growth
By PW Consulting, 2026-09-18
Worldwide Perfumes Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global perfumes market has demonstrated steady expansion, moving from an estimated valuation of USD 54.5 billion in 2023 to USD 58.5 billion in 2025. Projections indicate continued growth through the forecast period, with revenues expected to reach USD 61.92 billion in 2026 and climb toward USD 87.11 billion by 2032. This trajectory reflects a compound annual growth rate of 5.85 percent over the 2026–2032 forecast period, signaling a market that is maturing yet retaining robust growth potential. The expansion is not merely a function of population growth or rising disposable incomes; it reflects deeper structural shifts in consumer preferences, distribution channels, and product positioning.
Despite this positive momentum, the industry faces several structural challenges that will shape competitive outcomes over the next decade. First, regulatory tightening continues to reshape formulation practices and cost structures. The fragrance industry operates under an evolving framework of safety standards and ingredient restrictions that require manufacturers to continuously reformulate products. Compliance with emerging restrictions on certain fragrance ingredients and essential oils has forced brands to reformulate existing creations, introducing both cost implications and potential delays in product launches. This regulatory environment favors larger companies with dedicated compliance resources while placing pressure on smaller niche players that may lack the technical infrastructure to navigate complex ingredient regulations efficiently.
Second, the market is undergoing a significant transformation in distribution and consumer engagement models. The shift toward direct-to-consumer channels, e-commerce expansion, and experiential retail has altered how fragrances are discovered, sampled, and purchased. Travel retail, historically a high-margin channel for prestige fragrances, has experienced volatility due to geopolitical tensions and shifting travel patterns, creating revenue variability for brands that historically relied on airport and duty-free locations. Companies must now balance traditional wholesale relationships with owned digital storefronts and experiential touchpoints, requiring investment in omnichannel capabilities that many mid-tier players struggle to finance.
Third, raw material volatility and sustainability expectations are converging to create a new cost and positioning paradigm. The market for natural fragrance ingredients has been valued at USD 17.1 billion as of 2022, underscoring the sustained demand for natural and sustainable perfume formulations. However, sourcing consistent-quality botanical materials while maintaining price stability remains challenging, particularly as climate variability, land-use competition, and certification requirements add complexity to supply chains. Brands that cannot secure reliable access to preferred natural ingredients or demonstrate credible sustainability claims risk losing share to competitors who can.
These challenges are not insurmountable, but they demand strategic attention. Companies that treat regulatory compliance, channel evolution, and raw material strategy as isolated operational issues will find themselves reacting rather than leading. Those that integrate these factors into a coherent market strategy will be better positioned to capture growth while managing exposure.
AI Perfume Generator Market
Key Drivers of Market Change
Technological Innovation and Formulation Advances
Innovation in fragrance creation and delivery technologies is reshaping what perfumes can achieve and how they reach consumers. Advances in olfactory science, molecular design, and encapsulation technologies are enabling brands to develop longer-lasting scents, more nuanced fragrance profiles, and products that can be tailored to specific consumer preferences. The expansion of dedicated fragrance zones at major industry events reflects the growing emphasis on new ingredients, technologies, and scent trends, with exhibits showcasing innovations from ingredient suppliers and formulation houses. These platforms serve as critical nodes where technical breakthroughs translate into commercial opportunities, allowing brands to source differentiated scent solutions and stay ahead of consumer expectations for novelty and quality.
Beyond formulation, digital tools are transforming how fragrances are developed, tested, and marketed. Data-driven consumer insights, predictive analytics, and virtual sampling technologies are reducing the friction between product creation and market validation. Brands that invest in these capabilities can iterate more quickly, respond to emerging taste shifts, and personalize offerings at a level that was previously impractical. The integration of technology into fragrance development is not merely an operational efficiency play; it is becoming a differentiator that influences brand perception and consumer loyalty in an increasingly crowded market.
Regulatory and Compliance Landscape
The regulatory environment continues to be a defining force in the perfumes market, with implications that extend beyond compliance into product strategy and brand positioning. International fragrance associations have published updated transparency lists detailing thousands of ingredients used across the industry, providing greater visibility into the composition of fragrance products. At the same time, amendments to usage restrictions have required full compliance for existing creations within specific timelines, forcing reformulation of products containing restricted substances. These developments create both operational burdens and strategic opportunities.
For large multinational brands, regulatory change is absorbed as part of a broader compliance infrastructure, often integrated with sustainability and safety messaging that resonates with conscious consumers. For smaller brands, the cost and complexity of reformulation can be a barrier, but it can also serve as a filter that benefits those with strong technical partnerships and agile development processes. The transparency trend also aligns with broader consumer demand for ingredient clarity, suggesting that regulatory compliance and marketing communication around ingredient safety and sourcing will become increasingly intertwined in the years ahead.
Demand-Side Shifts in Consumer Behavior
Consumer behavior is evolving in ways that directly influence fragrance purchasing patterns. There is a growing appetite for personalization, self-expression, and emotional connection through scent, driving demand for products that feel distinct and meaningful rather than generic. This has fueled interest in unisex fragrances, niche and artisanal offerings, and fragrances that align with individual identity and lifestyle values. At the same time, the luxury segment continues to command a significant share of market value, reflecting the enduring appeal of prestige branding, heritage, and aspirational positioning. Luxury perfumes represent a substantial portion of overall market revenue, highlighting the importance of premium positioning even as mass-market options remain relevant for broader consumer segments.
Gender-based segmentation is also evolving. Women's fragrances continue to represent the largest consumer group, but men's fragrances and unisex options are gaining traction as traditional gender boundaries in beauty and personal care blur. This shift creates opportunities for brands to develop inclusive scent narratives and expand their addressable market. Consumers are also increasingly influenced by social media, influencer culture, and experiential marketing, making discovery and endorsement dynamics more fluid and fast-moving than in previous eras. Brands that can leverage these channels authentically while maintaining product quality and brand integrity are better positioned to capture attention and convert it into sustained purchase behavior.
Supply Chain and Cost Structure Dynamics
Supply chain pressures and cost structures are reshaping how fragrance companies manage production, sourcing, and pricing. The post-pandemic recovery brought initial normalization, but subsequent geopolitical tensions and logistical disruptions have introduced renewed variability. Travel retail slowdowns linked to regional instability have impacted sales for several major fragrance players, with estimates indicating a measurable negative effect on group sales during recent quarters. These disruptions highlight the vulnerability of channel-dependent revenue streams and the importance of diversification across geographies and distribution models.
Raw material costs remain a critical factor, particularly for brands that emphasize natural ingredients or premium botanical components. Price volatility in essential oils and other natural materials can compress margins if not managed through forward contracting, supplier diversification, and formulation flexibility. At the same time, the rising cost of compliance, packaging, and sustainability certification adds to the overall cost base. Companies that build resilient supply chains, invest in ingredient substitution strategies, and maintain transparency with consumers about sourcing and pricing are better equipped to protect margins without sacrificing brand value.
Competitive Landscape and Leading Strategies
The competitive structure of the worldwide perfumes market is characterized by a mix of large diversified beauty and luxury conglomerates, specialized fragrance houses, and ingredient suppliers that play a critical role in enabling product innovation. Market concentration data indicates that the top three companies hold approximately 28.5 percent of total market revenue, while the top five account for roughly 41.2 percent. This level of concentration suggests a market where scale, brand portfolio breadth, and distribution capabilities confer advantages, but it also leaves meaningful space for specialized players and regional leaders to compete on differentiation, agility, and niche positioning.
L'Oréal Groupe stands as a global leader in beauty with an extensive fine fragrance portfolio spanning brands such as Lancôme, Yves Saint Laurent, and Giorgio Armani perfumes. Its strength lies in the ability to operate across both mass and prestige segments worldwide, leveraging broad distribution networks, consumer data, and marketing scale. The Estée Lauder Companies Inc. maintains a major presence in prestige fragrances through brands including Estée Lauder, Tom Ford, Jo Malone London, and Le Labo, with a strong focus on luxury perfume offerings that emphasize brand heritage, craftsmanship, and premium positioning. Coty Inc. operates a large portfolio of licensed and owned fragrances, including Gucci, Calvin Klein, Marc Jacobs, and Burberry, giving it significant presence in both mass and prestige segments and enabling it to capture demand across multiple price points and consumer segments.
LVMH Moët Hennessy Louis Vuitton reinforces the luxury fragrance landscape through iconic perfume houses under Parfums Christian Dior, Givenchy, and Kenzo, with active involvement in high-end fragrance creation and distribution. Puig, a family-owned group specializing in fashion and fragrance, competes with brands such as Carolina Herrera, Paco Rabanne, Jean Paul Gaultier, and Byredo, maintaining a strong force in global perfumes through a blend of licensed and owned brands. Shiseido Company Ltd. offers premium fragrances through its own brand and subsidiaries, with active participation in Asian and international markets. Chanel S.A. remains an iconic luxury house with flagship perfumes including Chanel No. 5 and other high-end fragrance lines, benefiting from an unparalleled brand legacy and consistent demand for its prestige offerings.
Beyond brand owners, the ingredient and creation side of the market is dominated by firms that supply the fragrance industry with specialized capabilities. Givaudan operates as a leading fragrance ingredient and creation house, focusing on fine fragrance development and innovation for major brands worldwide. International Flavors & Fragrances (IFF) serves as a global supplier of fragrances and scents, creating perfumes for numerous consumer brands and holding a significant share in fine fragrance compounding. DSM-Firmenich, following its merger, has become a major player in fragrance creation, supplying luxury and mass-market perfume houses with innovative scent solutions. Symrise provides fragrances and flavor solutions to the perfume industry, with an active focus on sustainable and fine fragrance development. These suppliers are not merely cost providers; they are innovation partners whose capabilities influence product differentiation, speed to market, and sustainability outcomes.
Recent industry developments illustrate how the competitive landscape is evolving. In early 2026, Puig and The Estée Lauder Companies confirmed discussions regarding a potential business combination that could create a major luxury beauty group with a strengthened position in the global fragrance market. Such consolidation would reflect a broader trend toward scale and portfolio strength in the prestige segment, as companies seek to combine brand equity, distribution reach, and creative capabilities. At the same time, new entrants and brand extensions continue to test the market, as demonstrated by the debut of a first prestige fragrance from a fashion brand entering the high-end perfume segment, signaling that luxury fragrance remains an attractive adjacency for established names in adjacent categories.
The competitive dynamics suggest several strategic imperatives. Large players are pursuing integration and portfolio optimization to strengthen their position across segments and geographies, while also investing in innovation pipelines that keep brands relevant. Mid-tier and niche brands are competing through storytelling, ingredient differentiation, direct consumer relationships, and channel specialization. Ingredient suppliers are increasingly important strategic partners, offering not only raw materials but also formulation expertise, sustainability credentials, and speed to market. The market is likely to continue evolving through a combination of consolidation among established players, entry of new brand names from fashion and lifestyle sectors, and growing importance of supplier collaboration in driving differentiation.
Perfume Market
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the worldwide perfumes market and create distinct commercial opportunities. The first is the continued premiumization and personalization of fragrance offerings. As consumers seek products that reflect individual identity and emotional resonance, brands that can deliver customized or semi-customized scent experiences, supported by digital tools and data insights, will be well placed to capture higher-margin demand. This trend favors companies with strong creative capabilities, agile development processes, and direct consumer engagement channels that enable feedback loops between product development and market response.
The second trend is the deepening integration of sustainability and transparency into brand strategy and product design. Consumers and regulators alike are pushing for clearer ingredient disclosure, responsible sourcing, and credible environmental claims. Brands that can demonstrate authentic sustainability practices, whether through natural ingredient sourcing, reduced environmental footprint, or ethical supply chain management, will differentiate themselves in a market where green claims are increasingly scrutinized. This creates opportunities for ingredient suppliers and formulation houses that can provide verified sustainable solutions, as well as for brand owners that can communicate these attributes effectively without overstating their impact.
The third trend is the ongoing reconfiguration of distribution and channel strategy. E-commerce, direct-to-consumer models, and experiential retail are expected to grow in importance, while traditional wholesale and travel retail may remain subject to volatility. Brands that build flexible, omnichannel capabilities and can shift sales mix toward higher-margin owned channels will be more resilient to external shocks and better positioned to capture consumer attention across touchpoints. At the same time, companies must manage the complexity of channel conflict, inventory allocation, and brand experience consistency as they expand their digital and physical presence.
These trends carry both opportunities and risks. Premiumization and personalization can drive margin expansion, but they also require investment in technology, talent, and consumer insight capabilities that may be challenging for smaller players. Sustainability and transparency can enhance brand equity, but they demand rigorous execution and credible evidence to avoid backlash from skeptical consumers and regulators. Channel reconfiguration can improve resilience and profitability, but it introduces operational complexity and may require renegotiation of existing wholesale relationships. Companies that approach these trends with a clear strategic framework and timely access to market intelligence will be better equipped to navigate uncertainty and capture growth.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to strengthen innovation pipelines and formulation agility while embedding sustainability and compliance into product development from the outset. Investing in partnerships with ingredient suppliers that offer both creative and technical capabilities can accelerate time to market and improve differentiation. At the same time, diversifying distribution channels and building direct consumer relationships can reduce dependence on volatile channels and create richer data for product refinement and marketing.
For investors, the market presents opportunities in companies with strong brand equity, scalable distribution, and credible sustainability positioning, as well as in suppliers that provide differentiated ingredient and formulation capabilities. Due diligence should focus on the ability to navigate regulatory change, manage raw material volatility, and execute channel transformation, rather than relying solely on historical revenue trajectories. Consolidation activity may create value through portfolio synergies, but integration risk and brand preservation should be weighed carefully.
PW Consulting
For procurement and sourcing teams, securing resilient supply chains for natural and sustainable ingredients is essential to protect both cost structures and brand promises. Diversifying suppliers, exploring alternative materials where appropriate, and establishing clear quality and compliance benchmarks can reduce exposure to volatility while supporting product positioning. Close coordination with formulation and regulatory teams will be critical to balancing cost, performance, and compliance objectives.
Timely access to detailed market intelligence remains a critical enabler for all these actions. The perfumes market is evolving rapidly across regulation, consumer behavior, channel dynamics, and competitive structure, and decisions made without current, granular data carry higher risk. For those seeking deeper segmentation data, regional breakdowns, and customized strategic guidance, PW Consulting's comprehensive research report on the worldwide perfumes market provides the detailed analysis needed to inform investment, product, and sourcing decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Perfumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


