



Category: market research
PW Consulting: VCI Anti-Rust Paper Market to Reach USD 136.7M by 2032 at 4.8% CAGR
By PW Consulting, 2026-07-09
VCI Anti‑Rust Paper Market: Strategic Briefing for 2026 Decisions
Executive snapshot
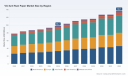
The global VCI (volatile corrosion inhibitor) anti‑rust paper market reached an influential inflection point in 2025 (base year). Our research shows steady expansion through the 2020–2025 historical window and a continued upward trajectory across the 2026–2032 forecast period, underpinned by a compound annual growth rate (CAGR) of 4.8%. Measured in USD (Revenue unit: Million), the market scale in the base year and its projected endpoint by 2032 demonstrate a market that is mature yet still receptive to product innovation, regulatory adaptation, and supply‑chain re‑engineering. Market concentration is meaningful: the top three suppliers account for a dominant share, with the top five nearing four‑fifths of industry revenues — a structure that shapes competitive dynamics, margin discipline, and consolidation potential.
VCI Anti Rust Paper Market
Why this report matters to executives in 2026
- Board and investment committees need a concise, evidence‑based view on whether to invest in VCI capability expansion, enter via M&A, or accept a procurement partnership strategy.
- Procurement and operations teams must translate tightening environmental regulation and rising raw‑material cost into contract clauses, hedging strategies, and alternative‑chemistry roadmaps.
- Product and R&D leaders require clarity on the commercial viability of nitrite‑free, low‑VOC, and biodegradable VCI chemistries versus incumbent formulations.
- Sales and distribution heads are preparing channel plays for 2026 — prioritizing aftermarket services, extended storage protection, and value‑added packaging systems that extend beyond commodity paper rolls.
What the market signals tell us (dynamics)
Three convergent forces are shaping strategic choices in 2026: regulation, chemistry substitution, and operational economics. Regulatory regimes in major markets are increasingly restrictive toward legacy amine‑based chemistries and certain plasticizers, while air‑emission standards place new compliance burdens on manufacturers and converters. These trends accelerate the transition to nitrite‑free and biodegradable inhibitor systems and raise the commercial premium for compliant formulations.
VCI Anti Rust Paper Market
On the cost side, inflation across specialty chemical inputs and logistics has compressed margin structures for commodity VCI papers, forcing suppliers to pursue formulation efficiencies, scale advantages, or product differentiation through multi‑functional substrates (VCI + cushioning, VCI + barrier coatings). Finally, customer demand is bifurcating: OEMs and tier‑1 suppliers buying for critical long‑term storage are willing to pay for demonstrable vapor‑phase protection and recyclability, while high‑volume commodity users remain highly price sensitive.
VCI Anti Rust Paper Market
Competitive landscape: strategic profiles and implications
The market’s incumbent set displays a mix of technical depth, channel access, and product differentiation. Below are directional strategic takeaways from the principal competitors tracked in our study.
- Cortec Corporation (St. Paul, Minnesota) — Cortec’s CorShield® VpCI® coated kraft papers emphasize renewable, recyclable, and fully repulpable chemistries aimed at ferrous and non‑ferrous protection for storage and shipping. Strategically, Cortec positions itself on sustainability credentials and solvent‑free chemistries, attracting customers where end‑of‑life recyclability and indoor air quality matter.
- Daubert Cromwell (Alsip, Illinois) — Known for nitrite‑free formulations and military‑grade offerings, Daubert Cromwell leverages specification‑driven demand (including legacy MIL standards) and multi‑metal protection. For buyers, this supplier is a logical fit when compliance, long shelf life and specification conformance dominate procurement criteria.
- ZERUST Solutions / NTIC (Beachwood, Ohio) — With its ICT® series and reinforced/poly‑coated variants, ZERUST exploits vapor‑phase protection expertise and reinforced substrates for heavier duty applications. Their approach is oriented to higher value use‑cases (longer storage horizons, higher value assets), and they demonstrate how product layering (coatings + VCI) commands a premium.
- Intertape Polymer Group (IPG, Charlotte, North Carolina) — IPG’s VCI2000 series speaks to a manufacturing playbook focused on scalable, nitrite‑free saturated kraft papers with clear multi‑metal claims and extended protection periods. IPG’s scale and conversion capabilities make them a pivotal partner for high‑volume industrial users.
- Armor Protective Packaging (Howell, Michigan) — Armor’s recent innovations blend cushioning with VCI nanotechnology on renewable kraft substrates. Their product roadmap highlights defensive moves into engineered packaging systems that reduce secondary packaging needs and address handling damage along with corrosion protection.
- Rust‑X (USA) — Rust‑X focuses on mechanically robust, laminated VCI papers with superior tear and puncture resistance for parts handling. For operations susceptible to mechanical damage in transit, such materials reduce scrap and warranty exposure.
Notably, product launches in 2026 — exemplified by a high‑profile cushioning + VCI paper introduced in May 2026 — illustrate the industry pivot toward integrated protection systems. Suppliers are increasingly competing on formulation compliance, substrate engineering and demonstrable end‑use performance rather than price alone.
What the full PW Consulting report contains (practical/livable guidance)
- Market sizing and forecast models (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario outputs under alternative regulatory and raw‑material trajectories.
- Regulatory and standards heatmap (REACH, RoHS, CARB and regional emission regimes) tied to actionable reformulation checklists and compliance timelines.
- Supplier scorecards and insourcing/outsourcing decision trees that translate technical attributes (repulpability, nitrite status, VOC footprint, multi‑metal claims, mechanical robustness) into procurement KPIs.
- Commercial playbooks for OEMs, distributors and converters: negotiation levers, contract templates, performance‑based acceptance criteria and inventory hedging strategies.
- Cost‑to‑serve and margin sensitivity models that quantify the impact of key input inflation and logistical disruption scenarios on product profitability.
- M&A and partnership screening framework (fit‑for‑scale, IP defensibility, channel reach) calibrated to a market where the top five players represent the majority of revenues.
- Practical pilots, trial designs and measurement protocols for validating promised protection life (lab + in‑field), including sample size guidance and acceptance thresholds.
- Ready‑to‑use Excel models and executive slides for board briefings, investor teasers and procurement RFPs that preserve commercial confidentiality while enabling immediate decision making.
2026 decision‑maker playbook — prioritized actions
- Run an immediate compliance audit of your VCI supply chain: map formulations against REACH/RoHS/CARB triggers and identify near‑term reformulation risk.
- Segment your usage by criticality (strategic long‑term storage vs. transactional transit protection) and align supplier tiers and contract terms accordingly.
- Initiate supplier performance audits focused on repulpability, VOC emissions, and documented protection durations – make sustainability verifications contractual.
- Negotiate price adjustment clauses tied to defined chemical index baskets or logistics indices to manage raw‑material volatility.
- Pilot integrated packaging systems (e.g., cushioning + VCI) where handling damage and corrosion coexist; measure total cost of ownership rather than unit price.
- Screen potential M&A targets using concentration metrics and capability gaps — prioritize targets that accelerate compliant chemistries, conversion capacity or channel access.
Risks, opportunities and the strategic horizon
The primary near‑term risk is regulatory acceleration that outpaces supplier reformulation cadence, producing specification bottlenecks or temporary supply squeezes. Secondary risks include raw‑material inflation and logistics shocks that compress margins and drive supplier consolidation. Counterbalancing these risks are measurable opportunities: premium pricing for compliant, recyclable, and demonstrably effective VCI papers; productization of packaging systems (VCI + handling protection); and aftermarket services such as certified reconditioning and life‑cycle documentation.
For 2026, winning strategies will be those that integrate compliance and product development with commercial contracting and supply‑chain engineering — not just marketing claims. Firms that move first to lock in compliant supply, validate performance via rigorous pilots, and re‑price to reflect true total cost will defend margins and capture growth as the market expands.
How to use this intelligence
This briefing is designed as a strategic linchpin for 2026 planning cycles. The full PW Consulting VCI Anti‑Rust Paper Market report provides the underlying models, supplier due diligence templates, and scenario workbooks you need to convert the insights above into executable programs. If your 2026 agenda includes procurement rationalization, product reformulation, M&A screening or channel redefinition, the detailed datasets and supplier matrices in the full study are essential.
To access the complete analysis, modelling files and supplier scorecards that support board‑level or investment decisions, request the full VCI Anti‑Rust Paper Market report from PW Consulting — the only resource combining market economics, regulatory roadmaps and hands‑on commercial playbooks tailored for the 2026 operating year.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Equipment Maintenance Market to Reach USD 57.0 Billion in 2025
By PW Consulting, 2026-07-09
Medical Equipment Maintenance Market — Strategic Imperatives for 2026 (PW Consulting)
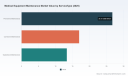
PW Consulting’s latest market study on Medical Equipment Maintenance uses a 2025 base year and a 2026–2032 forecast window to translate an accelerating service economy into executable strategy. At the macro level the market has expanded materially over the past five years and is set to nearly double through the forecast horizon, tracking a compound annual growth rate of 9.9%. These topline dynamics reflect reinvestment across installed equipment fleets, rising regulatory scrutiny, and rapid adoption of digital service models — all of which combine to make maintenance strategy a revenue and risk agenda for healthcare enterprises and investors alike.
Medical Equipment Maintenance Market
Why this study matters for 2026 decision-making
-
From a risk perspective, 2026 is a hinge year. New and clarified regulatory requirements (including the FDA’s updated Quality Management System provisions and consolidated accreditation expectations from major certifying bodies) fundamentally change the compliance baseline for both device manufacturers and organizations performing servicing. Decision-makers must reconcile operating models with explicit QMS expectations to avoid latent liabilities and continuity risk.
Medical Equipment Maintenance Market -
From a value-capture perspective, the service layer is shifting from break/fix and preventive routines toward continuous, software-enabled asset performance management. Recent regulatory guidance on AI/ML lifecycle management and the distinction between remanufacturing and servicing create both barriers and opportunities: vendors that embed compliant update pathways and transparent post-market change control will command premium contract terms.
Medical Equipment Maintenance Market -
From a portfolio-management perspective, the services market is concentrated: incumbents and high-capability platform providers account for a large share of enterprise service revenue, creating a two-speed market where global OEMs, specialised national providers, and health-system-owned HTM hubs coexist. Understanding where to compete or partner within that structure is critical for 2026 capital allocation.
What the PW Consulting report gives you — practical, implementable outputs
This study is designed as an executive-to-operational playbook. It moves beyond descriptive market sizing to provide the templates and decision-support tools leaders will use in 2026:
-
Scenario-based market sizing and growth drivers, with sensitivity models to stress-test capex and utilization assumptions against macro healthcare spending scenarios.
-
Service-economics and pricing frameworks: margin drivers for preventive vs corrective vs operational maintenance, and the profit implications of digital service monetisation.
-
Procurement and contracting playbooks for health systems: templated SLA language, performance metrics, and risk allocation matrices suited to AI-enabled and software-driven device fleets.
-
Vendor benchmarking and due-diligence checklists that evaluate technology stacks, regulatory readiness, and field-service capacity — calibrated for both OEMs and third-party providers.
-
M&A and partnership playbook: valuation levers, integration risk assessments, and an acquisition checklist focused on software assets, remote-monitoring capabilities, and spare-parts logistics.
-
Regulatory impact matrix that maps new QMS, PCCP and accreditation changes to operational gaps, staff certification needs, and documentation requirements.
-
Operational templates: predictive-maintenance pilot designs, HTM centre-of-excellence blueprints, talent & certification roadmaps, and sample financial models (TCO, OPEX vs CAPEX scenarios).
Competitive landscape — capabilities, moves and what they mean
The industry’s competitive topology is dominated by a set of global platform players complemented by specialised service firms and health-system-centered engineering organisations. Our analysis profiles the leading providers and recent strategic moves that illustrate the direction of travel:
-
GE HealthCare (Chicago) — has reinforced a platform-plus-services strategy by acquiring software assets and entering long-term care alliances. Recent M&A and multi-year care alliances underscore a playbook of bundling hardware, enterprise software, and predictive-service contracts to lock in recurring revenue.
-
Siemens Healthineers (Erlangen) — continues to emphasize integrated diagnostic and lab maintenance with remote monitoring capabilities, positioning itself to sell end-to-end uptime guarantees to large hospital systems.
-
Koninklijke Philips (Amsterdam) — is leveraging advanced informatics and FDA-cleared predictive features to move service offerings up the value chain toward outcome-linked contracts.
-
Medtronic (Dublin) and B. Braun (Melsungen) — exemplify OEM-led lifecycle management for implantables and therapy-centric devices, where servicing is tightly coupled to clinical pathways and supplier risk management.
-
STERIS, Agiliti, TriMedx and specialist operators — provide infection-prevention, large-scale HTM, and clinical-engineering services that are becoming strategic partners for health systems seeking centralized, high-quality, cost-effective maintenance solutions.
These provider moves are more than headlines; they represent strategic playbooks investors and operators must evaluate: consolidate service portfolios through targeted acquisitions, invest in software and remote monitoring to convert episodic revenue into predictable streams, and secure regulatory compliance as a market-entry barrier.
Recent developments you should factor into 2026 plans
-
Consolidation and strategic partnerships among OEMs and enterprise service providers are accelerating — examples include significant acquisitions and multi-year alliance agreements that combine imaging software with service delivery networks.
-
Regulatory shifts in 2024–2026 clarified servicing vs remanufacturing, formalized AI/ML update pathways and tightened QMS expectations. Organizations that delay alignment expose themselves to increased inspection risk and contractual noncompliance.
-
Providers are scaling centralized HTM infrastructure — new facilities and lab-focused HTM hubs show demand for high-throughput, standardized maintenance workflows that reduce mean-time-to-repair and spare-part inventories.
Strategic playbook — recommended moves by stakeholder
-
OEMs: Accelerate investment in service SaaS platforms and PCCP-aligned architectures. Pursue tuck-ins that bring telemetry, scheduling automation, and spare-parts optimisation. Structure contracts to shift a portion of revenue into recurring service streams while preserving lifecycle compliance evidence.
-
Health systems: Execute a rapid compliance and capability audit this quarter. Use TCO models to compare in-house HTM expansion vs outsourcing to a platform provider; prioritize pilots for predictive maintenance on high-value imaging and life-support fleets to validate savings and safety metrics.
-
Third-party service providers: Differentiate through regulatory certification, rapid-response field networks, and outcomes-based SLAs. Consider vertical specialisation (e.g., imaging, dialysis, infusion) to counterbalance scale advantages of OEMs.
-
Private equity and strategic investors: Target software-enabled service platforms and bolt-on HTM assets with stable recurring cashflows. Look for businesses that have proven ability to scale remote monitoring and to comply with tightened QMS expectations.
From insight to action — a 90-day operational checklist
-
Conduct a regulatory-gap diagnostic against the new QMS and accreditation standards.
-
Run a rapid inventory and risk-prioritization of critical assets; identify three high-impact pilots for predictive maintenance.
-
Renegotiate or reframe service contracts to include transparent performance metrics and audit-ready documentation flows.
-
Initiate vendor diligence on service platform vendors; evaluate software maturity, PCCP readiness and spare-parts logistics.
-
Assess the strategic fit of potential M&A targets: software IP, field-service footprint, and regulatory-compliance posture should be primary filters.
Conclusion — why previewing this analysis matters
As capital deployment decisions are made in 2026, the medical equipment maintenance market will be a decisive battleground for both revenue growth and operational resilience. The macro opportunity is unambiguous — robust growth and accelerating monetization of digital services — but the competitive and regulatory terrain has become more complex. PW Consulting’s full report equips leaders with the scenario-tested models, regulatory mappings, vendor scorecards and operational tools needed to convert market momentum into defensible advantage.
Note: this executive preview highlights study scope, strategic implications and actionable playbooks but omits the granular segmentation tables and device- and region-level models that are essential for transaction-level decisions. For the full data appendices, device- and service-level breakouts, company profiles and downloadable financial models, please visit the report page on PW Consulting.
For detailed analysis of this topic, please visit the official page: Medical Equipment Maintenance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tracheostomy Market - From USD 215M (2025) to USD 344.8M by 2032 at 5.67% CAGR
By PW Consulting, 2026-07-09
Tracheostomy Market — 2026 Strategic Preview
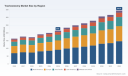
As PW Consulting’s Lead Industry Analyst, I present this strategic preview of our full Tracheostomy Market study to orient executive decisions entering 2026. The global market for tracheostomy products has moved from a stabilizing post‑pandemic baseline into a predictable growth trajectory driven by ICU care patterns, procedural shifts, device innovation and supply‑chain resilience. Using 2025 as the study’s base year, our market model projects steady expansion at a mid‑single‑digit compound annual growth rate (CAGR of 5.67%) through 2032, with overall market value crossing multiple important inflection points during the forecast window. This preview highlights the report’s operational insights, competitive implications and the concrete strategic levers senior leaders should prioritize in 2026 — while preserving the detailed segment-level analytics that are available in the full report.
Tracheostomy Market
Why this study matters for 2026 corporate strategy
- Decision clarity in an incremental market: With the overall market expanding year‑over‑year, near-term investments (product R&D, manufacturing capacity, M&A) will compound over the 2026–2032 horizon. Understanding the timing and durability of growth is essential to avoid over- or under-investing in capacity and commercialization.
- Regulatory and reimbursement tailwinds and risks: Device approvals, standards compliance and modality‑level reimbursement dynamics will directly shape unit economics and go‑to‑market approaches in 2026.
- Fragmentation creates arbitrage: The market remains comparatively unconsolidated, creating acquisition and roll‑up opportunities for organizations that combine operational scale with clinical differentiation.
- Operational execution matters: Margins will be determined as much by sterilization, materials sourcing, and clinical support services as by device features. Tactical supply‑chain actions taken in 2026 will affect P&L for years to come.
What the full report delivers — practical, actionable content
Our study is designed for executives who need immediately actionable intelligence. Key deliverables include:
Tracheostomy Market
- Robust market sizing and forecasting model (base year 2025; predictive horizon 2026–2032) with scenario and sensitivity capabilities to test demand shocks, regulatory changes and price erosion scenarios.
- Epidemiology and procedure‑level demand drivers mapped to device consumption and consumable lifecycles, enabling SKU‑level revenue forecasting for commercialization teams.
- Regulatory compendium and compliance tracker: ISO norms, material‑spec updates and a timeline of recent clearances and adverse‑event reporting that affect product risk registers.
- Reimbursement playbook and procedural economics maps to help pricing, contracting and hospital sales functions optimize capture.
- Competitive benchmarking including capability maps (product breadth, manufacturing, regulatory footprint, and service offerings) and strategic profiles of leading and fast‑growing players.
- Supplier and raw‑material risk assessment with mitigation options for medical‑grade polymers, sterilization pathways and capacity constraints.
- Commercialization templates and a 90/180/360‑day tactical roadmap for market entry, product refresh or acquisition integration.
- M&A target screens and valuation guidance using earnings and margin improvement levers specific to tracheostomy product lines.
Key market dynamics shaping 2026 strategy
The report synthesizes primary research and proprietary models to isolate the following dynamics that will determine winners and losers in 2026:
Tracheostomy Market
- Stable, predictable growth: Our base scenario anticipates a continuation of mid‑single‑digit annual growth from 2026 onward. The overall market value grows noticeably between the base year and the mid‑2030s, offering a favorable backdrop for measured expansion.
- Procedure mix matters: Shifts between percutaneous and surgical approaches, and the increasing use of percutaneous techniques in many settings, alter accessory and disposables demand patterns. Companies that align product portfolios and training programs to procedural trends will capture outsized share.
- Materials and manufacturing evolution: The market continues to migrate toward medical‑grade polymers (PVC, silicone, polyurethane) and modern plasticizers to meet biocompatibility and regulatory expectations. EO and gamma sterilization pathways remain dominant and are a critical cost and quality axis.
- Regulatory and post‑market vigilance: Recent clearances for enhanced product variants and ongoing adverse‑event reporting underscore the dual importance of proactive regulatory strategy and robust post‑market surveillance to protect market access and brand value.
- Fragmented supplier landscape: Market concentration is low compared with many medtech categories, leaving room for consolidation and for nimble regional manufacturers to compete on cost and service.
- Reimbursement sensitivity: Procedural and device reimbursement structures materially affect hospital purchasing decisions and bundle economics. Aligning value propositions to these reimbursement realities is a precondition for volume penetration in 2026.
Competitive landscape — how incumbent and challenger strategies are shaping up
The competitive environment is heterogeneous, spanning global OEMs with extensive clinical relationships to regionally focused manufacturers and cost‑efficient contract producers. Key strategic archetypes we identify are:
- Global platform leaders: Large medtech companies that pair deep hospital relationships with broad product portfolios, differentiated cuff and inner‑cannula designs, and extensive regulatory dossiers. These players are selectively launching upgraded variants and pursuing indications that lock hospitals into platform buying.
- Specialist innovators: Firms focusing on design features (e.g., flexible cannulas, taper‑cuff technologies, disposable inner cannulas) and procedural kits that increase clinician preference and procedure efficiency.
- Regional cost players: Manufacturers with strong low‑cost production bases and aggressive global distribution strategies, competing on price and basic functionality while investing in regulatory harmonization to access new markets.
- Service‑oriented competitors: Organizations bundling devices with clinician training, tracheostomy care kits and post‑acute support to differentiate on total cost of care.
Recent market events in late 2024–2025 exemplify these dynamics: major suppliers have secured regulatory clearances for upgraded tube variants, while isolated adverse‑event reports underscore the reputational and regulatory risks that can accrue quickly. These signals reiterate the need for comprehensive regulatory and post‑market programs as part of any 2026 strategic plan.
Strategic plays to prioritize in 2026
Based on our analysis, companies should consider the following prioritized plays, tailored by scale and ambition:
- For global incumbents: Double down on differentiated product upgrades that target procedural efficiency and clinician safety, while using M&A to acquire regional manufacturing capacity and shorten time‑to‑reimbursement alignment. Invest in bundled care solutions to capture a larger share of lifetime patient economics.
- For mid‑sized companies: Focus on niche product differentiation (accessories, introducer sets, specialized cannulas) and build clinical evidence that supports premium pricing. Strengthen quality systems and adverse‑event monitoring to defend against regulatory headwinds.
- For new entrants and contract manufacturers: Target underserved geographies and service models that reduce hospital total cost of ownership. Prioritize regulatory readiness and clinical validation to accelerate adoption over price‑only competition.
- For investors and PE sponsors: Consider roll‑up strategies to consolidate manufacturing, rationalize SKUs and extract operational synergies in this fragmented market — high single‑digit CAGR and predictable procedural demand support disciplined buy‑and‑build value creation.
Translating insight into a 90/180/360‑day plan
- 90 days: Run a rapid portfolio fit assessment against our market model, validate top 3 product bets and initiate regulatory gap analysis for priority markets.
- 180 days: Execute clinical evidence generation plans, finalize supplier risk mitigations for polymer supply and sterilization, and pilot bundled service offerings with 1–2 hospital systems.
- 360 days: Launch revised commercialization strategy, integrate any targeted bolt‑on acquisitions, and begin scale‑up of manufacturing or contract production aligned to forecasted demand.
How PW Consulting supports execution
Our full report combines proprietary forecasting, primary interviews with procurement and clinical stakeholders, and supplier due‑diligence templates to convert insight into executable plans. We model multiple adoption and pricing scenarios and provide an M&A target list prioritized by integration ease and margin upside. For teams preparing 2026 budgets, the study delivers the market context and tactical playbook that align investment to expected return timelines.
To preserve the strategic value of the study as a decision‑support tool, this preview omits several granular segmentation tables and SKU‑level forecasts that are available in the complete deliverable. If you are preparing product investments, acquisition screenings, or commercialization plans for 2026, accessing the full report will provide the detailed segmentation, regional modelling, unit economics and scenario outputs you need to execute with confidence.
Contact PW Consulting to request the full Tracheostomy Market report and accompanying models, or to commission a tailored executive workshop that translates the forecast and competitive analysis into a 2026 action plan specific to your organization.
For detailed analysis of this topic, please visit the official page: Tracheostomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hexanoic Acid Market to Reach USD 396.32 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-09
Hexanoic Acid Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s senior industry analyst, I present a high-level strategic briefing designed to orient executives, investors, and procurement leaders preparing for decisive actions in 2026. This article synthesizes the research foundation and forward-looking implications from our full Hexanoic Acid Market study (base year 2025), showing where value will be created and where risks will concentrate over the 2026–2032 forecast horizon. Think of this as the trailer: we demonstrate the analytical depth and strategic line-of-sight that underpins our recommendations, while intentionally withholding the granular segment tables that are available in the full report.
Hexanoic Acid Market
Market trajectory and what it means for strategy
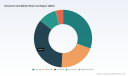
The hexanoic acid market has moved from a niche specialty chemical into a reliably growing industrial segment. Our consolidated market model—built on five years of historical data (2020–2025) and bottom-up supply-demand mapping—pegs the global market at roughly USD 255 million in 2025, rising to approximately USD 396 million by 2032 under the central case. The forecasted compound annual growth rate (CAGR) for the 2026–2032 period is 6.5%.
Hexanoic Acid Market
Two strategic implications flow directly from this trajectory:
Hexanoic Acid Market
- Scale and premiumization matter. A market growing at mid-single digits offers enough room for volume plays, but true margin expansion comes from premium, higher-purity grades and value-added derivatives targeted to regulated end-markets (food, personal care, pharmaceuticals).
- Timing of capacity and commercial moves is critical. Given the growth profile, late 2025–early 2026 is the window to commit to capacity expansion, offtake agreements or M&A to capture the high-probability value pools identified in our demand scenarios.
Supply-side pressure points
Hexanoic acid production economics are tightly coupled to oleochemical feedstocks, primarily palm kernel oil and coconut oil. These feedstocks drive a majority of operating costs for conventional production routes, making feedstock exposure the single largest controllable risk on producer margins. Our scenario analysis evaluates short-term price shocks and structural supply shifts; the key takeaway is that companies with integrated oleochemical chains or diversified feedstock options will sustain superior margin resilience.
Regulatory dynamics also shape supply-side strategy. European chemical regulation has accelerated adoption of higher-purity grades in certain end-markets, and bio-based supply chains face heightened documentation and certification demands. Producers planning to expand capacity or pivot to food- or pharma-grade supply must bake compliance and traceability costs into their planning from day one.
Demand-side opportunities and segmentation strategy (conceptual)
Demand is expanding across multiple end-markets: flavor and fragrance, personal care, pharmaceuticals, and industrial chemicals. But the economics and go-to-market playbooks differ by application. Our segmentation framework in the full study maps margin pools, customer willingness-to-pay for purity and traceability, and supplier-switching costs for each application cluster.
- Premium food and pharma channels reward certified, traceable bio-based supply and high-purity manufacturing; entry requires investment in quality systems and regulatory dossiers.
- Personal care and fragrance markets value consistent sensory characteristics and supplier reliability; co-development and collaborative R&D with formulators unlock differentiation.
- Industrial chemical uses are price-sensitive and favor scale and integrated supply; here, Verbund-style integration or long-term feedstock contracts are decisive.
We deliberately do not disclose application-by-application revenue splits in this briefing. The full report contains the granular segmentation and routable worksheets you will need to quantify addressable opportunity by customer cohort.
Competitive landscape: who matters and why
The hexanoic acid ecosystem blends global integrated majors, regional specialists, and oleochemical producers. Market concentration is moderate: the top-tier players do not fully dominate, creating room for regional challengers and specialty entrants. This dispersion produces both consolidation opportunities and niche entry points depending on your strategic objectives.
- Perstorp (Sweden): A leading specialty carboxylic acid producer with a clear strategic focus on premium pharmaceutical and personal care segments. Recent moves include targeted capacity expansion in the UK and a global price action in 2026—both signals that Perstorp is defending margin and premium positioning.
- Eastman Chemical (United States): Broad-based carboxylic acid and derivative capabilities, combined with downstream formulation know-how. Eastman’s playbook leverages application integration to move up value chains.
- OXEA (Germany) and BASF (Germany): European specialists with access to regional industrial and food ingredient markets. Integrated production networks and regulatory experience make these firms natural partners for clients needing EU-compliant supply chains.
- Tokyo Chemical Industry (TCI): A global supplier of high-purity organics serving research and flavor/fragrance markets—valuable for businesses seeking small-batch, high-purity supply and rapid technical support.
- KLK OLEO and IOI OLEO (Malaysia): Oleochemical producers that control palm kernel- and coconut-based feedstock channels. Their cost structures and proximity to feedstock supply can be an advantage for volume-oriented contracts.
Our competitive playbook in the full study profiles these suppliers on capacity, quality certifications, feedstock exposure, and commercial positioning—information that supports buy-side tender strategies, JV assessment, and acquisition screening.
Regulatory and quality signals that will matter in 2026
Several regulatory touchpoints will shape capital allocation and commercial strategy:
- European regulatory pressure has accelerated the uptake of higher-purity grades for certain applications; compliance readiness is a de facto market barrier.
- In the United States, hexanoic acid’s GRAS recognition for flavoring use provides a stable legal footing for food manufacturers, but brand owners increasingly demand chain-of-custody and origin documentation for bio-based variants.
- Food-grade bio-based supply chains are subject to stricter documentation and certification when shipped into the EU; these are non-trivial costs that affect margin profiles and customer pricing.
Companies that anticipate and proactively manage these regulatory and quality requirements will enjoy shorter commercial ramp-up times and lower surrendering rates during audits.
Price dynamics and procurement playbook
Price volatility in feedstocks translates quickly into finished-product volatility. Our pricing model—built from producer supply curves, inventory dynamics, and historical pass-through rates—identifies statistically robust lead-lag relationships between feedstock indices and hexanoic acid prices. For procurement teams, that translates into four actionable moves we prioritize for 2026:
- Shift from spot-heavy buying to a blended strategy with hedged feedstock exposure or fixed-price collars for predictable volumes.
- Pursue dual-sourcing with at least one supplier offering bio-based certified material and another offering scale-based cost advantage.
- Negotiate value-sharing mechanisms (indexation plus quality premia) rather than fixed-price contracts that can quickly become uncompetitive in a rising-cost environment.
- Invest in a contractual right-to-inspect and audit provisions for origin and purity documentation for food- and pharma-grade purchases.
M&A, CapEx and strategic partnerships: where to focus
Given the market’s moderate concentration and differentiated end-markets, the most value-accretive plays in 2026 are:
- Buyers seeking scale: acquire regional oleochemical capacity or tie up long-term feedstock contracts to secure cost advantage.
- Specialists seeking margin uplift: invest in high-purity finishing, certification processes, and formulation co-development to capture premium channels.
- Strategic partnerships: joint ventures with oleochemical producers or contract manufacturing agreements that provide capped-cost feedstock access while sharing regulatory-compliance investment.
The full report contains a CapEx tracker, vendor scorecards, and an M&A heat map with indicative valuation ranges and integration checklists to support transaction planning.
Risk matrix and scenario playbooks
Our risk framework lays out six high-probability scenarios (feedstock shock, rapid regulatory tightening, premium-demand acceleration, technological synthesis breakthrough, trade barrier escalation, and consolidation wave). For each scenario we provide tactical playbooks—timing triggers, KPIs to monitor, and decision thresholds for stop/go capital commitments. These are operationally prescriptive tools: they translate market signals into board-level decision points and procurement triggers.
What the full PW Consulting study provides
The full Hexanoic Acid Market study is built for practitioners. It includes:
- A detailed market model (2020–2032) with transparent assumptions and downloadable worksheets;
- Segment-level demand forecasts by application and region, with sensitivity testing;
- Supplier profiles, capacity maps, and a five-year capital expenditure tracker;
- Price and margin models, plus procurement templates and contract language examples;
- Regulatory and certification playbooks including compliance cost estimates and audit checklists;
- M&A heat maps, integration checklists, and scenario-based strategic playbooks tailored for CEOs, CFOs, and heads of supply chain.
We intentionally withhold detailed segmentation tables and revenue-by-segment figures in this briefing to preserve the value of the full dataset and models, which are provided with the licensed report.
Recommended first moves for 2026
- Run a rapid supplier risk assessment focused on feedstock exposure and certification readiness; prioritize counterparties that can supply both certified bio-based and high-purity grades.
- Model a blended procurement contract that protects margins during feedstock volatility while providing suppliers a pathway to recoup certification costs.
- Initiate targeted CapEx or JV discussions if your strategy is to capture premium food/pharma margins—delay increases the cost and time-to-market.
- Embed regulatory scenario triggers in commercial KPIs so pricing and product allocation decisions can be made in weeks, not months.
Final note
Hexanoic acid is no longer a peripheral commodity; it is a strategically significant feedstock and specialty chemical with differentiated commercial pathways. The 6.5% CAGR and the projected near-double market size over the forecast horizon create choice-rich opportunities for firms that align supply, compliance, and product strategy. PW Consulting’s full report equips your team with the numbers, supplier intelligence, risk scenarios, and executable playbooks to turn those opportunities into realized value in 2026 and beyond.
Contact PW Consulting to access the complete dataset, supplier scorecards, and the executable 90-day action plan tailored to your role—procurement, manufacturing, or corporate development.
For detailed analysis of this topic, please visit the official page: Hexanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Biopsy Market to Reach USD 8,610M by 2032 at 14.85% CAGR
By PW Consulting, 2026-07-09
Liquid Biopsy Products Market — Strategic Outlook for 2026 Decision-Makers
The liquid biopsy market is entering a decisive phase. As companies, investors, and health systems plan their 2026 moves, they must interpret a rapidly expanding total market while navigating technological plurality, regulatory inflection points, and shifting commercial models. This briefing—an executive introduction to PW Consulting’s full Liquid Biopsy Products Market study—summarizes the strategic insights that matter most to C-suite leaders and corporate strategy teams preparing for near-term action. It intentionally signals depth and practical utility while reserving granular subsegment figures for the full report.
Liquid Biopsy Products Market
Why 2026 Is a Pivotal Year
Liquid biopsy has moved from high-potential science into scalable clinical deployment. Our base-year framing (2025) and the forecast window (2026–2032) show a clear trajectory: from a market measured in the low thousands of USD million in 2025 to a multi-billion market by the early 2030s, underpinned by a compound annual growth rate of 14.85%. That pace reflects accelerating adoption across clinical applications, expanding use of NGS and digital PCR platforms, and the rise of multi-cancer early detection programs.
Liquid Biopsy Products Market
For strategy teams, the consequence is straightforward: near-term investments and partnerships made in 2026 will disproportionately determine market position across the next funding cycle. The market’s growth profile creates a runway for rapid scale—but competitive advantages are becoming harder to establish and easier to erode without clear playbooks addressing regulation, reimbursement, and integration into clinical pathways.
Liquid Biopsy Products Market
Macro Drivers and Strategic Implications
-
Clinical validation moving to commercial scale: Increasingly robust evidence linking liquid biopsy readouts to clinical decision-making is driving adoption beyond research centers. Organizations that can shorten the evidence-to-adoption timeline—through pragmatic trials, payer pilots, or co-developed protocols—will capture disproportionate share early.
-
Technology differentiation vs. platform convergence: Next-generation sequencing, digital PCR, and algorithmic analytics each offer tradeoffs in sensitivity, cost, and throughput. Expect continued specialization (e.g., highly sensitive ctDNA panels for minimal residual disease) alongside bundling strategies that combine instrumentation, kits, and analysis software. Strategy: choose whether to compete on platform excellence or on integrated solutions that lock customers into ecosystems.
-
Regulatory and reimbursement inflection points: 2025–2026 activity indicates accelerating regulatory submissions and public-private deployments. Commercial strategies must now include regulatory pathway mapping and payer engagement roadmaps early in product development. Companies that neglect reimbursement evidence at pilot stages risk stalled uptake despite strong technical performance.
-
Consolidation vs. fragmentation: The market shows measurable concentration among leading vendors, but technological fragmentation persists. This hybrid state favors strategic alliances, targeted M&A, and channel partnerships that provide complementary capabilities rather than broad vertical integration alone.
What PW Consulting’s Full Report Delivers (Practical, Actionable)
-
Robust market-sizing and scenario models covering 2020–2032, including a transparent methodology, sensitivity testing, and revenue forecasts tied to clinical adoption curves and regulatory timelines.
-
Strategy playbooks for five enterprise archetypes (instrument OEMs, reagent/Kits specialists, clinical service providers, payers/health systems, and platform/software players) with prioritized growth initiatives for 2026.
-
Commercial diligence templates: unit economics, pricing levers, channel cost models, and deployment scenarios for decentralized vs. centralized testing.
-
Technology readiness and differentiation matrix that evaluates sensitivity/specificity tradeoffs, workflow integration, and scaling constraints across common liquid biopsy modalities.
-
Regulatory and reimbursement playbooks, including milestone maps for approvals, recommended evidence generation strategies tailored by market, and payer engagement timelines.
-
Competitive intelligence dossiers for the leading vendors, a deal-activity heatmap, and an M&A stress-test framework to support valuations and integration planning.
Competitive Landscape — Who’s Moving the Market
The market is shaped by a mix of specialist diagnostics companies, instrument manufacturers, and reagent suppliers. Each of the core players is pursuing a distinct route to scale:
-
Guardant Health is focused on comprehensive clinical services and expanding public-private partnerships to deploy on-site testing in major health systems. Its moves show the strategic value of aligning clinical evidence generation with revenue-bearing services.
-
Illumina remains a key platform enabler for NGS-based liquid biopsy applications. Their leverage derives from broad sequencing infrastructure and partnerships across clinical labs and assay developers.
-
Established diagnostics incumbents (e.g., Roche) continue to translate assay-level credibility into clinician-facing solutions, emphasizing regulatory-compliant diagnostics for oncology.
-
Suppliers such as QIAGEN and Bio-Rad focus on the essential sample-prep and reagent layer—components that determine both assay sensitivity and supplier stickiness.
-
Platform players like Thermo Fisher and SOPHiA GENETICS are combining instrument capability with analytics to offer end-to-end propositions that appeal to networked laboratory groups.
-
Multi-cancer early detection/testing players (e.g., Myriad, Exact Sciences) are commercializing population-level screening concepts, forcing incumbents and new entrants to clarify clinical utility and scale economics.
Recent developments through early 2026 underscore market momentum and shifting focal points. New product launches that extend platform capabilities, expanded in‑hospital services, and regulatory progress for multi-cancer tests all shift competitive dynamics and accelerate commercialization opportunities. Each event matters because it changes the evidence, cost, or access equation that payers and providers use to decide.
Strategic Priorities and 90‑ to 180‑Day Actions for 2026
-
Prioritize payer pilots and evidence collectives: Launch targeted payer pilots now, using a limited set of high-impact clinical pathways (e.g., adjuvant monitoring, therapy selection). Structure agreements to accelerate coverage decisions and collect health-economic data.
-
Optimize go-to-market segmentation: Decide whether to emphasize centralized lab services, decentralized point-of-care models, or hybrid partnerships; align commercial resources accordingly and validate via two rapid pilots.
-
Lock in strategic partnerships for critical supply chain components: Secure reagent supply and instrument service agreements to avoid capacity bottlenecks as demand scales in 2026–2027.
-
Invest selectively in clinical evidence generation that maps to reimbursement endpoints: Design trials that demonstrate real-world utility, not only analytic performance.
-
Run an M&A readiness assessment: Identify target capabilities (analytics, assay IP, channel access) and prepare integration plans and valuation guardrails in anticipation of consolidation windows.
Indicators to Watch — Decision Triggers for Course Correction
-
Regulatory milestones for early-detection tests and large payer coverage announcements—signals to accelerate commercialization investments.
-
Price erosion across commoditized reagent segments—prompt to shift to value-based contracts or to refocus on proprietary assays.
-
Rapid adoption by major health systems or national screening initiatives—trigger to scale manufacturing and logistics capabilities.
-
Key competitor moves such as vertical integration or exclusive distribution partnerships—signal to strengthen partner networks or pursue counter‑M&A.
Conclusion — How to Use This Briefing in 2026 Planning
PW Consulting’s full Liquid Biopsy Products Market study is designed to be an operational asset for 2026 planning cycles: it translates market momentum (base‑year 2025 benchmarks and a forecast horizon through 2032) and a 14.85% CAGR into concrete commercial and R&D choices. The difference between a good and a great 2026 is not access to headline growth numbers but the ability to map those numbers into prioritized bets—partnerships, evidence generation, regulatory sequencing, and channel design—that deliver defensible economics as the market scales.
If your team is building 2026 budgets, preparing investor materials, evaluating targets, or designing payer evidence, the full report contains the detailed subsegment-level forecasts, competitive market shares, and scenario models required to make high-confidence decisions. Use this briefing to set the strategic frame; consult the full study to execute with precision.
To access the complete dataset, proprietary segmentation, and the executable playbooks referenced here, please follow the link to PW Consulting’s Liquid Biopsy Products Market report.
For detailed analysis of this topic, please visit the official page: Liquid Biopsy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Licorice Extract Market to Reach USD 300.6M by 2032 at 5.4% CAGR
By PW Consulting, 2026-07-09
Licorice Extract Market 2026: Strategic Preview for Decision-Makers
Executive preview
As global ingredient markets tighten and regulatory scrutiny intensifies, licorice extract has emerged as a high-value botanical with multi-sector applications across food & beverage, pharmaceuticals, cosmetics, and nutraceuticals. PW Consulting’s forthcoming Licorice Extract Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical behavior with an actionable forward-looking view. At a macro level the market has expanded from the low hundreds of million USD in 2020 to approximately USD 208.2 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of about 5.4% through the 2026–2032 forecast window, reaching roughly USD 300.6 Million by 2032. This briefing highlights the strategic value of the full study for 2026 corporate planning while deliberately withholding granular segment tables—our aim is to demonstrate the analytical depth that underpins the study and motivate direct engagement for the full dataset and implementation tools.
Licorice Extract Market
Why this study matters for 2026 decisions
-
Timing and capital allocation: With a stable mid-single-digit CAGR and periodic price volatility in raw roots, licensors, manufacturers and ingredient buyers need a clear investment timing strategy. The report quantifies near-term supply risk and identifies windows where margin recovery or cost-containment measures are most effective.
Licorice Extract Market -
Regulatory-led product design: Recent regulatory clarifications in major jurisdictions create both constraints and opportunities for formulators. The study translates statutory language into product-level design rules and commercialization guardrails so R&D and compliance teams can act with confidence.
Licorice Extract Market -
Competitive positioning and M&A screening: The market concentration profile reveals a moderately consolidated industry with room for strategic aggregation. The report provides a pragmatic M&A screen and value-upgrade playbook to convert scale or capability acquisitions into predictable revenue lifts.
Market trajectory and what the numbers mean
Understanding the headline trajectory is straightforward: a multi-year expansion that accelerates under select demand scenarios. The data series underpinning our projections show a steady increase in total market value through 2025, a continuation of growth into 2026, and a forecast path that culminates in the high two-to-three hundreds of million USD range by 2032 under the central-case assumptions. Within that picture, short-term dislocations—driven by raw material price swings and regulatory advisories—can create tactical windows for margin improvement or contract renegotiation. Our modeling deliberately incorporates stochastic scenarios for input cost, regulatory shocks, and novel product approvals to stress-test business plans for 2026 board cycles.
Key growth drivers and downside risks
-
Demand-side catalysts: Reformulation in F&B to natural flavours, new functional food approvals, and expanding cosmetic ingredient lists are driving steady demand. Notable entrants and product launches in the first half of 2026 have already begun to validate premium claims in functional health segments.
-
Supply-side constraints: Licorice root sourcing remains concentrated regionally and subject to agricultural and trade volatility. In 2025, raw root import prices experienced marked volatility, exerting upward pressure on production costs and compressing spot margins. Buyers need flexible sourcing and hedging strategies in their procurement playbook.
-
Regulatory regime risks: Recent agency updates offer clearer pathways for food and beverage use in certain markets, but labeling thresholds and glycyrrhizin caps impose formulation limits that can materially affect product claims and permissible dosage. The report converts these legal thresholds into practical product design matrices for R&D prioritization.
-
Innovation and substitution: Synthetic sweeteners, botanical blends, and alternative liquorice-like ingredients introduce substitution risk. Our analysis assesses where licorice extract retains defensible advantages (e.g., targeted pharma functionalities, patented cosmetic actives) and where it is most exposed to displacement.
Competitive landscape — who matters and why
The market structure is characterized by a mix of specialized botanical suppliers, vertically integrated producers, and a handful of players with global reach. Market concentration indicates meaningful leadership by a small group of firms, which creates both scale-driven advantages and attractive niches for differentiated players.
-
Norevo GmbH (Germany) — A specialized supplier with a broad confectionery and food-oriented portfolio; recent product literature emphasizes multiple physical formats tailored for production lines.
-
MAFCO Worldwide LLC (United States) — A global heavyweight supplying pure derivatives and extracts across food, beverage and personal care, with depth in raw-material sourcing and global supply chains.
-
F&C Licorice Ltd. (Israel) — A major producer with strong positions in tobacco, confectionery and pharma ingredient markets, offering multiple concentrate formats for industrial customers.
-
Regional specialists — Companies in Iran, China, India, Japan and the UK supply differentiated products such as powder, paste, block and liquid extracts and are critical to regional supply balances and formulation innovation.
Recent notable developments underscore the market’s dynamics: several suppliers refreshed their product literature in early 2026 to emphasize low-dust powder grades and tailor formulations for confectionery processing lines, while a leading Japanese firm launched a proprietary licorice-derived functional ingredient in 2026 that is positioned for body-fat management claims in its home market—an example of how product innovation can create new demand pockets. The competitive chapter in the full report includes supplier scorecards, capability maps, and a CR3/CR5 breakdown to support strategic sourcing and partnership decisions.
Regulatory and trade context
Regulation is a defining force for 2026 strategies. Major jurisdictions have clarified pathways: certain food flavoring listings now provide a pragmatic route to market in the U.S., while EU labeling thresholds for glycyrrhizin require explicit on-pack statements at defined levels and carry hypertension warnings—an operational constraint for high-dose formats. The study synthesizes these legal touchpoints into a compliance matrix that links formulation options to allowable claims and labeling requirements. Trade flows and reported global trade values indicate a modest year-on-year increase in cross-border commerce, reinforcing the necessity of integrated trade-risk planning in procurement strategies.
What the full report delivers (practical, implementable content)
-
Decision-grade forecasts: Base, upside and downside scenarios that drive five-to-seven-year revenue and margin planning—built for CFOs and corporate strategists.
-
Supplier scorecards: Comparative analysis of production footprint, quality certifications, format capabilities and risk exposure—mapped to procurement levers and contingency plans.
-
Regulatory playbooks: Jurisdiction-by-jurisdiction interpretive guidance on labeling, glycyrrhizin limits, and functional claims, with ready-to-use checklists for product launches.
-
Cost & margin models: Granular cost-of-goods models that incorporate root-price volatility, processing yield variability and utility inputs to quantify margin sensitivity.
-
Commercial motion templates: Channel strategies for food, pharma and cosmetic customers; pricing architectures; and negotiation playbooks for long-term contracts.
-
M&A and partnership screen: Criteria-driven shortlists and valuation heuristics tailored to strategic buyers and private equity sponsors seeking roll-up or capability expansion plays.
Each module is accompanied by implementation checklists and an executive-ready slide set to accelerate board-level decision-making in 2026.
How to use this preview in your 2026 planning
-
Procurement teams should prioritize scenario-based hedging and supplier diversification plans now—our models show that even short-lived price spikes can erode thin-margin formulations.
-
R&D and regulatory functions must collaborate to align product pipelines with allowable dosing and labeling regimes; several high-value opportunities require compliance-enabled claims that the full study maps explicitly.
-
Corporate development teams can use the report’s M&A screen to identify acquisition targets that provide either scale in processing or rare functional actives—these targets typically deliver rapid synergies when integrated with a defined commercialization roadmap.
Methodology, data integrity and what’s intentionally withheld
The analysis integrates primary supplier interviews, trade data, regulatory texts and longitudinal price series across 2020–2025, with scenario-based Monte Carlo forecasting for 2026–2032. To respect the “trailer” principle and preserve the incentive to access the full study, this preview intentionally omits the granular regional and application-level percentage splits, as well as line-by-line revenue tables. The full subscription report contains those segment tables, format-level volumes and client-ready Excel models required to execute the strategies summarized above.
Next steps
For procurement, R&D, corporate development, or regulatory teams preparing 2026 budgets, the full PW Consulting Licorice Extract Market study offers the decision-grade analysis and operational toolset required to convert insight into measurable outcomes. Visit our report page to download the executive deck, purchase the full dataset, or arrange a tailored briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Licorice Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sucker Rod Market to Reach USD 3.07 Billion by 2032 at 5.5% CAGR
By PW Consulting, 2026-07-09
PW Consulting Strategic Brief: Sucker Rod Market (Base Year 2025) — A 2026 Decision-Maker’s Preview
As capital allocation committees, procurement leads, and corporate strategy teams prepare 2026 plans, the sucker rod market presents a mix of steady expansion, technological inflection points, and regulatory pressure that will materially affect supplier selection, product development, and M&A options. This brief previews the full PW Consulting market research on the Sucker Rod Market (base year 2025; historical period 2020–2025; forecast period 2026–2032) and highlights the strategic choices we expect organizations to face in the coming 12–18 months. Currency: USD; revenue unit: Billion.
Sucker Rod Market
Executive summary
Between 2020 and 2025 the global sucker rod market scaled from roughly USD 1.55 Billion to USD 2.10 Billion. Our forecast through 2032 projects continued expansion to approximately USD 3.07 Billion under a compound annual growth rate (CAGR) of about 5.5% over the 2026–2032 period. This trajectory reflects a combination of stable demand from traditional onshore pumping systems, rising adoption of engineered composite solutions in selective offshore and challenging-well environments, and incremental aftermarket and remanufacturing activity.
Sucker Rod Market
Importantly, market concentration is moderate: the top three and top five suppliers account for a meaningful but not overwhelming share of revenue, leaving room for regional specialists, remanufacturers, and specialty alloy providers to capture niche value. The market should be viewed as a balanced arena where scale matters, but targeted capabilities — corrosion resistance, fatigue performance, monitoring integration, and remanufacturing economics — can unlock outsized returns.
Sucker Rod Market
Why this research matters for 2026 planning
- Allocation of capital. Forecasted mid-single-digit growth combined with rising complexity in product specifications requires disciplined capital allocation: incremental production capacity should be balanced against technology investments (FRP, hollow rods, coatings) and digital integration.
- Supplier strategy. Price volatility in steel and a regulatory landscape that varies by jurisdiction make supplier diversification and near-shore sourcing strategies essential to manage risk and lead times in 2026.
- Product roadmap prioritization. The fastest value accrual for many producers will come from higher-margin differentiated components (advanced couplings, specialty alloys, integrated monitoring) rather than increasing commodity rod volumes.
- M&A and partnerships. Moderate market concentration combined with specialized capabilities among small-to-medium vendors creates attractive bolt-on targets for companies seeking to expand technical breadth or regional presence.
Market trajectory & key metrics
Our topline market model (2020–2032) indicates a clear path of recovery and steady growth: from USD 1.55 Billion in 2020 to USD 2.10 Billion in 2025, driven by restored upstream activity and efficiency upgrades, and reaching roughly USD 3.07 Billion by 2032 under a 5.5% CAGR across the forecast window. These numbers are derived from a bottom-up synthesis of rig counts, pumping unit fleets, rod life-cycle replacement rates, and aftermarket service intensity, adjusted for material price pass-through and regional compliance constraints.
While this growth profile is robust enough to justify selective capacity expansions, it does not support indiscriminate greenfield investment in commodity rod production — especially where steel price volatility and potential tariff or licensing restrictions create margin risk.
Dynamics: regulation, raw materials, and operational drivers
- Standards and compliance. API 11B remains the core specification governing rod manufacturing, and vendors continue to reference updated product data sheets and best-practice guidelines. Industry workshops through 2025 reinforced adoption of standardized testing and installation practices.
- Import and trade controls. Import regulation and licensing regimes in some markets (notably certain North American jurisdictions) continue to influence sourcing decisions and create competitive advantages for local or regionally licensed manufacturers.
- Environmental and permitting timelines. Extensions and adjustments to performance deadlines by environmental authorities in mid‑2025 alter the compliance horizon for upstream operators, with knock-on implications for artificial lift retrofit cycles.
- Raw material pressure. Steel price volatility is a persistent factor — Q2 2025 average US steel pricing and the prospect of higher galvanized processing costs tied to iron ore and zinc movements materially affect producers’ cost of goods sold and pricing decisions. Hedging and supply contracts are no longer tactical but strategic necessities.
Competitive landscape — who matters and why
The market is populated by a spectrum of players: established global OEMs, specialized domestic manufacturers, remanufacturers, materials specialists, and cost-competitive regional producers. The following high-level strategic profiles capture the relevant positioning of notable firms covered in our research.
- US Rod Manufacturing (Nappanee, IN). The only US-based privately owned full-service domestic manufacturer — a strategic partner for operators prioritizing domestic supply chains, short lead-times, and API-grade steel product continuity.
- Weatherford International (Houston). Focused on engineered high-strength steel and fiberglass rods with surface treatments and induction case-hardening; recent product showcases and fiber rod announcements underline an offshore and challenging-well playbook emphasizing fatigue and corrosion performance.
- Tenaris (Luxembourg). Global scale and API 11B compliance; strong for operators seeking integrated supply commitments across multiple geographies and premium-grade rod specifications.
- Chinese OEM cluster. A number of manufacturers with cost-focused models and breadth of product lines serve global commodity demand — attractive to price-sensitive operators but subject to licensing, compliance, and trade friction in certain jurisdictions.
- TRC Services (Midland, TX). Represents the remanufacturing and value-recovery model: reprocessing used rods to extend field life, offering an economically compelling alternative in mature basins.
- Materion Corporation & ChampionX. Material science and corrosion-resistant coupling providers that enable operators to extend run-life and reduce intervention frequency — an increasingly important source of differentiation and price-inelastic revenue.
- Regional specialists and integrators (e.g., Q2, Liberty Lift). Provide bundled artificial lift solutions, integration with pumps, and regional aftermarket support — ideal partners for operators seeking consolidated service contracts.
Recent industry moves — product showcases of high-hardness models, collaborations to integrate monitoring systems into rods, and announcements of fiberglass rod lines for offshore services — indicate vendor strategies are converging on three value paths: higher-performing materials, diagnostic-enabled products, and cost-reduction through remanufacturing and regional sourcing.
What PW Consulting’s full report delivers (practical contents)
The full report is built for executable decisions and includes:
- Top-down and bottom-up market sizing (historical 2020–2025; forecast 2026–2032) with sensitivity cases that isolate demand drivers and price scenarios.
- Segment intelligence across region, type (steel, FRP, hollow), and application (onshore/offshore) with anonymized trend matrices to support commercial prioritization (note: granular segment tables are reserved for the full report).
- Supply chain mapping and a raw-materials stress test that quantifies margin exposure to steel, galvanization, and alloy inputs.
- Competitive benchmarking and capability heatmaps for the major suppliers, plus a short-list of due-diligence questions for M&A or strategic partnerships.
- Go-to-market playbooks for three archetypes: global OEM, regional low-cost manufacturer, and engineered-component specialist — each with product, sales, and channel KPIs for 12–36 month horizons.
- Regulatory and trade impact assessment (API standards, licensing, import controls) with recommended compliance pathways.
- Financial model templates, unit-economics calculators, and an investment decision checklist tailored for 2026 capital planning cycles.
Strategic implications and prioritized actions for 2026
For executive teams planning budgets and initiatives for 2026, we recommend the following prioritized actions.
- Lock in strategic supply agreements with price collars. Given steel volatility, negotiate multi-year contracts with indexed pricing and galvanized-processing cost-sharing clauses to preserve margins and predictability.
- Invest selectively in differentiated components. Prioritize R&D and commercial roll-out for high-margin elements (advanced couplings, specialty alloys, coated rods) where vendors can command premium pricing and reduce intervention frequency for customers.
- Accelerate remanufacturing and circular strategies. In mature basins, remanufacturing can reduce total cost-of-ownership; consider partnerships or minority stakes in remanufacturers to secure feedstock and service capacity.
- Pilot integrated monitoring on high-value wells. Partner with control-system vendors or collaborators (see recent monitoring collaborations) to pilot condition-based rod monitoring that can reduce downtime and create data-driven upsell pathways.
- Prioritize regulatory coverage and licensing diligence. For market expansion, ensure products meet API 11B requirements and pre-clear imports where applicable; regulatory friction can nullify low-cost advantages.
- Refine M&A scorecards. Target bolt-ons that fill capability gaps (composite rod expertise, specialty couplings, regional service networks) rather than commodity capacity increases alone.
KPIs to monitor through 2026
- Rod run-life (average months between interventions)
- Average selling price per rod length, adjusted for material surcharge
- Share of sales from engineered/aftermarket components
- Percentage of capacity under long-term contract
- Inventory days and lead-time-to-customer
- Compliance incidents and licensing exposure by market
Final note — why PW Consulting’s research is the operational advantage
This preview is designed to show the connective tissue between market dynamics and the decisions 2026 leaders must make. The full PW Consulting Sucker Rod Market report contains the granular datasets, scenario models, supplier scorecards, and contractual templates that translate the market’s 5.5% CAGR and forecasted USD 3.07 Billion runway into actionable, finance-backed choices. We have deliberately withheld granular split tables in this public briefing to preserve the report’s utility as a decisive planning tool; clients who require the detailed segment breakouts, region-by-region demand curves, and supplier-level revenue estimates will find them in the complete dataset and model package.
To convert the market trajectory into competitive advantage in 2026 — reduce exposure to raw-material shocks, prioritize high-margin engineered offerings, and secure supply through targeted partnerships — organizations need not only good information but executable options. PW Consulting’s full report is structured to deliver both.
For detailed analysis of this topic, please visit the official page: Sucker Rod Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cytokines Market to Hit USD 137.91M by 2032 at 7.08% CAGR
By PW Consulting, 2026-07-09
Cytokines Market — 2026 Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a concise, executive-focused preview of our comprehensive Cytokines Market study. Grounded in quantitative rigor and practical playbooks, this preview highlights the strategic value of the full report for decisions you will make in 2026 — from portfolio prioritization and manufacturing partnerships to M&A screening and regulatory planning. We deliberately surface high-level, data-driven conclusions while reserving detailed segment-level breakdowns for the full report to protect proprietary modelling and to drive targeted follow-up.
Cytokines Market
Market at a glance — the macro view you need now
The cytokines market has shown sustained growth through the first half of this decade, reflecting stronger clinical momentum in immuno-oncology, cell and gene therapies, and an expanding set of autoimmune and inflammatory indications. Using 2025 as our base year, the market is quantified at a mid-double digit figure (USD, Million) and is forecast to expand to an estimated market size approaching USD 138 Million by 2032, implying a compound annual growth rate of 7.08% over the 2026–2032 forecast window. Historical trend analysis (2020–2025) confirms an accelerating uptake that underpins both near-term commercial opportunities and medium-term capacity needs for GMP-grade cytokines and related services.
Cytokines Market
Why this study matters for 2026 corporate strategy
- Timing matters: 2026 is a year when multiple clinical programs and manufacturing investments will alter competitive advantage. Recent clinical updates and presentations (notably at ASCO 2026) and manufacturing capacity announcements mean the landscape your organization faces this year will be materially different by Q4.
- Regulatory dynamics are favorable but fragmented: As regulators increasingly accept cytokine-targeted therapies and expedited pathways for high-priority biologics, companies that align regulatory strategy early can shave months off development timelines. FDA activity—including approvals and pilot expedited filings in recent years—creates practical precedents to inform 2026 regulatory plans.
- Supply chain and capacity are a bottleneck and an opportunity: The market’s growth trajectory is already driving GMP manufacturing expansion; facility announcements and commercial scale-ups by major suppliers are signals for early sourcing and partnership decisions.
- Ancillary markets matter: The majority of cell and gene therapy potency and ancillary assay work now uses GMP-grade cytokines; industry data indicate such use is widespread, reinforcing the premium on reliable supply and quality certification.
What the full PW Consulting report delivers — practical, decision-ready content
Designed for senior leaders, BD teams, and investors, the full report blends rigorous market modelling with executable tools. Highlights include:
Cytokines Market
- Transparent market sizing & methodology: Base year 2025 calibration, historical reconstruction (2020–2025), and a detailed model covering 2026–2032 with scenario and sensitivity options.
- Demand-driver mapping and scenario analysis: Clinical pipeline milestones, reimbursement triggers, and adoption inflection points translated into quantitative scenarios you can apply to your portfolio.
- Go-to-market playbooks: Commercial launch templates for cytokine-enabled therapeutics and GMP cytokine supplies, including channel strategies, pricing levers and contracting models for CDMOs and OEM customers.
- Supplier & CDMO scorecards: Operational, regulatory and business-risk assessments of manufacturing partners, with negotiation playbooks and contingency pathways for capacity shortfalls.
- M&A and partnership screening tools: A transaction-ready shortlist methodology, standardized valuation drivers for cytokine assets, and integration risk checklists.
- Regulatory & reimbursement compendium: Use-cases and precedent files for accelerated filings and label extensions, including recent examples of expedited submissions and evolving payer responses.
- Financial templates and dashboards: Ready-to-use Excel models and board-ready slides that let you stress-test acquisition targets, partnership deals and internal investment cases under multiple CAGR scenarios.
Note: This preview intentionally omits the detailed region-, type- and application-level splits and unit-price matrices — those confidential tables and interactive models are presented in the full report and are essential inputs for transaction diligence and commercial launch planning.
Competitive landscape — strategic takeaways (high-level)
The competitive map in cytokines reflects two overlapping universes: novel therapeutic developers and GMP-grade supply/manufacturing providers. Understanding where each player sits on the risk-return spectrum is essential for partnership and investment strategy.
- Next-generation cytokine therapeutics: Firms developing engineered, selective, or locally anchored cytokines are advancing rapidly. Companies pursuing IL-2 partial agonists, IL-12 tumor-anchored constructs, and CD8-selective cytokine modalities are moving through clinical milestones that will determine commercial differentiation. Recent clinical updates and ASCO presentations in 2026 are validating several approaches and will create near-term licensing and co-development opportunities.
- Precision immune-modulation and antibody-enabled approaches: Early innovators targeting inflammatory cell subsets and novel cytokine axes are positioning for label expansion in autoimmunity and fibrotic disease; their success will re-shape demand across therapeutic and diagnostic uses of cytokines.
- GMP cytokine and ancillary suppliers: Established life-science suppliers and CDMOs are scaling manufacturing capacity and expanding product portfolios to serve both clinical and commercial demand. Recent facility expansions and capacity announcements demonstrate the strategic importance of reliable GMP supply for cell and gene therapy manufacturers.
Collectively, the competitive dynamics point to an ecosystem where biotech innovators will increasingly rely on deep supplier partnerships, and commercial-scale incumbents will compete on integrated solutions (supply + regulatory support + technical services).
Recent industry signals you must factor into 2026 plans
- Clinical presentations at ASCO 2026 showcased progress for anchored IL-12 approaches and CD8-targeted cytokine programs — readouts that will influence partnering appetite and licensing valuations.
- Major suppliers announced capacity expansions in early 2026, underscoring the need to secure supply agreements now to avoid later bottlenecks.
- Clinical-stage updates for IL-2 partial agonists and similar next-gen constructs indicate that mono- and combination-therapy trial design choices made in 2026 will affect reimbursement narratives and launch sequencing.
- Regulatory precedents in 2025 and 2026 — including priority filings and label extensions — provide practical templates for accelerated pathways in the U.S.
- Operational metrics from industry leaders show GMP-grade protein revenues and ancillary product demand growing at materially higher-than-industry average rates, reinforcing the commercial runway for quality suppliers.
Priority actions for executives in 2026
- Lock in supply and qualify secondary vendors: Negotiate multi-year supply agreements with capacity release clauses and audited quality metrics. Include contingency sourcing from vetted smaller manufacturers to mitigate single-source exposure.
- Advance regulatory strategy alongside clinical design: Align pivotal trial endpoints with regulatory and payer expectations early; consider adaptive designs and accelerated filing tactics where precedent exists.
- Prioritize partnering over greenfield manufacturing: For most mid-sized players, strategic alliances or revenue-share manufacturing agreements will be faster to market than new-build facilities in 2026.
- Use scenario modelling in every board discussion: Run downside and upside cases around the market’s 7.08% baseline CAGR and stress-test price, penetration and time-to-reimbursement variables.
- Screen M&A for capability gaps: Target acquisitions that offer either differentiated cytokine modalities or secured GMP capacity with transferable quality documentation.
- Commercial readiness: Build cross-functional launch teams now — market access, medical affairs, and manufacturing supply chain — to compress the time between approval and revenue realization.
How to use this preview and next steps
This document is a strategic trailer: it frames the investment, regulatory, and operational imperatives you must confront in 2026, and it identifies the decision levers that will most materially affect outcomes. The full PW Consulting Cytokines Market report contains the granular, transaction-ready data and modelling — including the detailed region/type/application splits, supplier pricing curves, and downloadable financial models — that corporate development, commercial, and supply chain teams require for execution.
To convert these high-level insights into actionable deals and operational plans, request the full report and the accompanying model package. Our team can also undertake customized deep dives: supplier due diligence, target valuation, scenario customizations, or a half-day executive workshop to align 2026 tactical priorities.
Contact PW Consulting to access the full dataset, proprietary segment models, and tailored advisory support that will convert 2026 opportunities into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Cytokines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MVR Compressor Market to reach USD 1,512.06M by 2032 at 5.6% CAGR
By PW Consulting, 2026-07-09
MVR Compressor Market — Strategic Outlook for 2026 Decisions
Executive teaser — why leaders must read this in 2026
As energy-efficiency regulations tighten and industrial decarbonization projects accelerate, mechanical vapor recompression (MVR) compressors are moving from a niche efficiency play to a core process-optimization lever across chemicals, food, pharma and emerging carbon-management projects. Our PW Consulting MVR Compressor Market study synthesizes seven years of historical performance and a forward-looking 2026–2032 forecast to show where value will be created — and where competitive advantage will erode — through 2032. This introduction previews strategic implications and competitive dynamics while withholding granular segment allocations to invite a deeper, subscription-based read of the full study.
MVR Compressor Market
High-level market trajectory (what the numbers imply)
Using 2025 as the study’s base year, the MVR compressor market has demonstrated steady expansion from a roughly USD 821 million footprint in 2020 to just over USD 1.02 billion in 2025. We forecast continuation of this growth pathway into 2026 and beyond, with the market progressing to an estimated USD 1.08 billion in 2026 and reaching approximately USD 1.51 billion by 2032, implying a compound annual growth rate of about 5.6% across the forecast window. These figures reflect a market sizable enough to justify targeted capital allocation, but not so large as to remove the advantage from focused, technology-led entrants and incumbents that execute disciplined differentiation strategies.
MVR Compressor Market
Why this matters for 2026 corporate strategy
- Investment Prioritization: The mid-single-digit CAGR requires companies to choose between expanding core product portfolios, pursuing adjacency wins (e.g., integrated evaporator+compressor systems), or concentrating on aftermarket and service-led revenue to improve ROI.
- Technology and Product Roadmap: Efficiency claims and material innovation materially affect lifecycle economics — decision-makers must prioritize impeller and sealing innovations to secure lifetime cost advantages.
- Market Entry & Partnerships: New project pipelines (including CCUS and large-scale continuous processes) present win-win opportunities for OEMs and engineering firms to bundle MVR systems with process equipment.
- Supply-Chain Resilience: Specialized alloys and precision machining mean procurement strategy is as critical as product strategy in 2026.
Key dynamics shaping the market
- Energy re-use as a regulatory and commercial lever — MVR’s fundamental value proposition is reusing latent heat from process vapors to reduce external energy demand. As industrial decarbonization policies and energy-cost volatility persist, MVR systems move from desirable to essential (source: official product information from major technology providers, 2026).
- Materials and manufacturing constraints — High-speed impellers are increasingly fabricated from ductile alloy plates or specialty stainless and nickel alloys (examples include X3CrNi13-4/1.4313, titanium alloys, Inconel 625, Hastelloy C22). These materials improve durability but create sourcing and fabrication complexity that provokes CAPEX and lead-time risk (source: OEM documentation and product literature, 2026).
- System-level integration — Buyers increasingly prefer integrated evaporator/compressor/crystallizer packages that reduce engineering friction and commissioning risk. Suppliers able to deliver turnkey solutions capture price and timeline premium.
- Service and performance contracting — With efficiency claims becoming table stakes, after-sales services (performance monitoring, retrofit upgrades, guaranteed steam savings contracts) are a primary route to recurring revenue.
Competitive landscape — capability map and tactical implications
The competitive field blends long-established European engineering specialists, global OEMs with alloy and materials expertise, and regionally strong manufacturers that excel in local project delivery and customization. Below is a concise, strategic reading of the firms we track closely.
MVR Compressor Market
- PILLER Blowers & Compressors GmbH (Moringen, Germany)
Strengths: Deep mechanical engineering pedigree and a field-proven VapoLine® platform that emphasizes high thermodynamic efficiency and reliability. A substantial installed base and demonstrable field performance give PILLER a credible advantage when bidding for efficiency-critical retrofits and brownfield upgrades.
Strategic posture for 2026: PILLER should monetize its installed base via performance contracts and focus R&D on lower lifecycle-cost solutions to defend margins against price-led entrants.
- Chart Industries — Howden brand (Ball Ground, Georgia, USA)
Strengths: Materials engineering competency and the capacity to offer impellers in stainless steel, titanium and specialty alloys position the company well where corrosive service or high-speed operation is required. This technical differentiation is meaningful to buyers focused on long-run lifecycle costs.
Strategic posture for 2026: Protect margin through materials-led differentiation, and invest in supply chain partnerships for alloy sourcing to reduce lead-time exposure.
- GEA Wiegand GmbH (Ettlingen, Germany)
Strengths: Proven ability to supply integrated MVR systems (meVap®) with evaporators and crystallizers included. This system-level focus helps reduce buyer procurement complexity and shortens project delivery timelines.
Strategic posture for 2026: Prioritize platform modularity and digital monitoring features to convert integrated system advantages into service revenues.
- Hanwha Power Systems (South Korea)
Strengths: Rapidly moving into CO₂-focused MVR applications and active in CCUS project supply chains, as demonstrated by a recent European supply contract for CO₂ MVR compressors in a combined-cycle power plant (Hanwha press release, September 2025).
Strategic posture for 2026: Use momentum in decarbonization projects to develop a project-delivery and financing capability that can compete for large CAPEX plays.
- Thermosag (India) & LeHeng Evaporator (China)
Strengths: Regional manufacturing scale, local customization, and cost-competitive execution for domestic and regional projects. These vendors are often preferred partners for large process plant builders in Asia due to responsiveness and localized after-sales support.
Strategic posture for 2026: Expect these players to expand selectively into adjacent export markets by leveraging turnkey offerings and attractive TCO propositions.
Risks and friction points executives must plan for
- Alloy and machining bottlenecks — specialized materials push lead times and capital intensity higher; failure to secure supplier agreements will delay project delivery.
- Technological obsolescence — incremental efficiency improvements can be rapidly commoditized; protect IP around system integration and digital services.
- Consolidation pressure — the market is not fragmented enough to prevent scale players from consolidating share; smaller suppliers must choose defensible niches.
- Project execution complexity — retrofits in operating plants carry operational risk; owners prefer vendors that can guarantee downtime and performance outcomes.
Actionable strategic playbook for 2026
- Secure critical-material suppliers: negotiate multi-year supply agreements for specialty alloys and invest in dual-sourcing where possible to reduce single-point failure risk.
- Prioritize integrated solutions: where feasible, bundle compressors with evaporators/crystallizers and offer performance-based contracts to capture higher-margin, recurring revenue.
- Invest in service and digital-monitoring: roll out remote-condition monitoring and predictive-maintenance offerings to increase customer stickiness and generate annuity revenues.
- Target CCUS and decarbonization projects: develop tailored CO₂-ready compressor packages and finance-capability partnerships to win large, multi-year infrastructure contracts.
- Consider bolt-on M&A or JV to close capability gaps: identify regional OEMs with installed bases or specialist metallurgy firms to accelerate time-to-market.
- Design flexible CapEx options: offer leasing, performance guarantees or energy savings agreements to lower buyer hurdle rates and accelerate adoption.
- Run scenario-based portfolio reviews: use our forecast scenarios to stress-test CAPEX plans under energy-price volatility, regulatory tightening, and material-cost shocks.
What the PW Consulting MVR Compressor Market study delivers
This study is built for commercial leaders, strategy teams, and engineering procurement executives who must translate market signals into investment decisions in 2026. At a high level, the deliverables include:
- Market sizing and a 2020–2032 forecast with scenario variants and sensitivity analysis (base year: 2025).
- Competitive profiles and capability benchmarking for global and regional OEMs, including go-to-market and service strategies.
- Technology, materials and manufacturing deep-dive: metallurgy, impeller design trade-offs, reliability drivers and cost-to-serve implications.
- Commercial playbooks: procurement strategies, performance contracting templates, and aftermarket monetization models.
- Supply-chain risk map and mitigation options for high-cost inputs and precision machining dependencies.
- Financial modelling tools and case studies to test retrofit vs greenfield economics under various energy-price scenarios.
Note: this briefing purposefully omits the detailed regional, type and application splits and the full company-by-company market shares to preserve the study’s role as a subscription-grade source of proprietary intelligence. Those granular disclosures, along with downloadable models and negotiation playbooks, are available in the full report and the secured client portal.
Next steps
If you are preparing capital plans, supplier rationalization, or M&A screening for 2026 and beyond, the study provides the operational analysis and market intelligence required to act with conviction. Contact PW Consulting to receive the comprehensive dataset, model files and tailored advisory support to convert the market trajectory into measurable shareholder value.
For detailed analysis of this topic, please visit the official page: MVR Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zinc Borate Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-09
Zinc Borate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Market snapshot
As businesses plan capex, procurement and product strategies for 2026, zinc borate merits renewed strategic attention. Our PW Consulting baseline shows the zinc borate market growing from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025 (base year), accelerating to USD 234.17 Million in 2026 and projecting to USD 344.8 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 6.98% over the forecast window (2026–2032).
Zinc Borate Market
Those headline figures mask important non-linear dynamics: a strong recovery and premiumization of demand into mid-decade, momentary pressure points linked to feedstock and regulatory shocks, and pockets of persistent premium growth where high-purity and specialty grades command value. For decision-makers in 2026, the combination of mid-single-digit CAGR and episodic supply-side disruption spells both risk and strategic optionality.
Zinc Borate Market
Why this matters for 2026 decisions
-
Procurement and supply security — Boric acid, the primary feedstock for zinc borate, has shown price volatility and supply concentration. Buyers who finalize 2026 sourcing strategies without a robust hedging and dual-sourcing framework risk sudden cost spikes and lead-time extension.
Zinc Borate Market -
Regulatory and product positioning — Recent regulatory moves (notably updated restrictions and risk-management scopes for boric acid in certain jurisdictions) change use-cases and market access. Firms that act early to reformulate, certify alternative applications, or secure compliance documentation will preserve market access and pricing power.
-
Premium segmentation is accelerating — Demand for high-purity and REACH/region-compliant grades (for electronics, automotive, and high-end coatings) is growing faster than standard industrial volumes. 2026 is a year where R&D alignment and targeted commercial investments can unlock higher-margin channels.
-
Geopolitical and trade signals — Tariff actions and strategic expansions (including recent capacity projects in Turkey and new facilities online in 2026) are reshaping landed-cost equations and sourcing maps for 2026 purchasing cycles.
Market dynamics driving near-term outcomes
-
Feedstock concentration and price transmission — The boron value chain remains geographically concentrated. Supply interruptions or export policy shifts have historically transmitted quickly into zinc borate pricing and availability. In 2026, buyers should expect episodic price uplifts tied to feedstock tightness unless long-term contracts or tolling arrangements are negotiated.
-
Regulatory tightening in use-cases — Regulatory developments in 2024–2025 expanded scrutiny on boric acid and related substances in consumer and industrial applications. This influences formulation choices (e.g., substitution in cosmetics and sensitive consumer segments) and increases demand for compliant grades in industrial polymers and electrical applications.
-
Product differentiation — Manufacturers are differentiating on hydration state, particle size control, and low-impurity, high-purity grades for electronics and automotive. Technical service (formulation support, regulatory documentation) is becoming as important as price in certain accounts.
-
Supply-side evolution — New capacity coming online and expansions in strategically located facilities (notably new phase starts in 2026) relieve some near-term tightness, but uneven global footprint means local price and lead-time dislocations persist.
Competitive landscape — what to watch
The market retains a fragmented profile: market concentration metrics indicate the top three producers account for roughly a quarter of the market (CR3 ~24.6%), and the top five only slightly more (CR5 ~26.2%). That fragmentation produces distinct strategic postures across the supplier base:
-
Large integrated suppliers — Established players with vertically integrated access to boron feedstocks and legacy product lines are focusing on premium anhydrous and performance grades for polymers, wire & cable, and construction. Their strengths include scale, product breadth and global distribution networks.
-
Regional specialists and high-purity houses — Certain European and Turkish suppliers emphasize REACH-compliant, high-purity grades targeted at automotive and electronics. These firms compete on regulatory dossiers, tight impurity specifications and supply reliability for sensitive end markets.
-
Cost-focused producers — Several producers in price-competitive regions serve domestic and price-sensitive export markets with standard grades and high-volume throughput. Their play is cost leadership and short lead-times to nearby processors.
-
Service-led players — A set of specialized providers offers formulation advisory, regulatory support and certification packages — valuable for compounders facing regulatory headwinds or high-performance requirements.
Notable company dynamics to monitor in 2026 include announced capacity additions that are already influencing regional flows, product-grade positioning (e.g., anhydrous vs. hydrated grades), and the extent to which suppliers can back technical support with robust compliance documentation for regulated markets. These firms exemplify the commercial strategies in play: integrated feedstock security, geographical coverage, premium-grade focus, and regulatory documentation as a differentiator.
What our full report delivers (practical, transaction-ready outputs)
- Validated market sizing and growth scenarios (base year 2025; forecast 2026–2032) with modular sensitivity tables you can plug into financial models.
- Supplier scorecards covering capacity, technical capability, regulatory readiness and commercial terms — formatted for procurement negotiation playbooks.
- Supply-chain risk matrix and mitigation playbook (tactical options: dual-sourcing, inventory optimization, toll manufacturing, and feedstock hedging strategies).
- Regulatory tracker mapping jurisdictional risk to commercial impact across end markets, plus product reformulation decision trees for affected applications.
- Competitive landscaping with strategic profiles (strengths, weakness, likely moves) and an M&A screening tool to identify consolidation targets aligned to four acquisition theses.
- Price and margin bridge scenarios that reconcile feedstock volatility, tariffs, and premiumization strategies so commercial teams can stress-test 2026 price lists.
- Go-to-market playbooks for premiumization: technical validation checklists, certification roadmaps, and channel strategies for electronics, automotive and construction compounders.
Strategic recommendations for 2026 (what to do now)
-
Lock supply optionality early: Negotiate layered contracts that combine short-term spot capacity with medium-term supply agreements. Include clauses for feedstock-driven price pass-throughs and defined escalation caps.
-
Prioritize regulatory-proof product lines: If you sell into consumer-sensitive or regulated geographies, move to certify and document grades today. The cost of late certification in 2026 will be higher than the near-term investment.
-
Defend margins via product segmentation: Invest in R&D to create performance-differentiated grades commanding premium pricing in electronics and automotive. Pair technical support with sales to lock-in strategic accounts.
-
Screen acquisition and alliance targets: Use the report’s M&A screening tool to identify regional mills or tech-enabled specialists that deliver either feedstock security or premium-grade capability.
-
Hedge feedstock and logistics risk: Evaluate multi-sourced boric acid contracts, and consider tolling agreements or nearshoring to manage landed cost volatility amplified by tariffs and freight cycles.
-
Implement a regulatory monitoring cadence: Assign cross-functional ownership (R&D, legal, regulatory affairs) to track changes and pre-authorize reformulation budgets if jurisdictional risk rises.
Conclusion — the strategic view for 2026
Zinc borate is no longer a commodity-only story. The market’s mid-single-digit CAGR masks a bifurcation: standard industrial demand remains volume-driven and price-sensitive, while high-purity and compliance-backed grades are premium engines. Fragmentation in supplier shares creates opportunities for disciplined players to secure supply, capture premium segments, and pursue consolidation where it boosts scale or technical capability.
For any organization executing 2026 commercial, procurement or M&A plans, the critical success factors will be feedstock risk management, regulatory foresight, product differentiation, and an adaptive sourcing footprint. Our full PW Consulting report delivers the granular inputs, supplier assessments and executable playbooks required to turn this strategic view into 2026-ready decisions.
Next step
Access the complete report for the full dataset, segmented demand analysis, supplier scorecards and transaction-ready frameworks that we intentionally exclude from this preview. PW Consulting’s zinc borate study is designed to convert insight into action — and to protect your 2026 strategy from surprise shocks in feedstock, regulation and trade.
For detailed analysis of this topic, please visit the official page: Zinc Borate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


