



Category: market research
PW Consulting: Global Slaked Lime Market to Reach $9B by 2032, Driven by 4.25% CAGR
By PW Consulting, 2026-09-17
Navigating the Slaked Lime Sector in 2026: Strategic Imperatives from PW Consulting's Global Outlook
The global slaked lime market stands at a critical intersection of regulatory pressure, infrastructure renewal, and energy-driven cost volatility. As industrial operators and municipal authorities alike confront tightening emissions standards and aging water treatment networks, the demand for high-purity calcium hydroxide has evolved from a commodity consideration into a strategic supply chain priority. PW Consulting's latest Worldwide Slaked Lime Market report offers decision-makers a comprehensive, data-grounded lens into this transformation, mapping historical trajectories, projecting medium-term growth, and dissecting the competitive and operational forces that will define profitability through 2032.
For executives operating in construction, environmental services, chemical manufacturing, or public utilities, the 2026–2032 forecast period demands more than incremental planning. It requires a clear understanding of where value is concentrating, how feedstock economics are reshaping margin structures, and which regional demand centers will absorb capacity expansion. This overview distills the analytical architecture of the full study, illustrating how the report translates macro trends into actionable intelligence while preserving detailed quantitative breakdowns for subscribers who require precision in their strategic modeling.
The Macro Trajectory: Growth, Volatility, and Structural Shifts
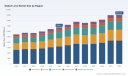
The global slaked lime market has demonstrated resilient expansion over the past half-decade, progressing from approximately USD 5,450.2 million in 2020 to an estimated USD 6,745.5 million in 2025. This historical arc reflects a compound trajectory shaped by post-pandemic infrastructure stimulus, sustained environmental compliance spending, and the gradual recovery of industrial processing volumes across multiple regions. Our baseline projection extends this momentum into a forecast window running through 2032, with the market advancing toward the USD 9 billion threshold as construction cycles mature, water and wastewater treatment mandates intensify, and flue gas desulfurization programs scale in high-emission economies.
The projected compound annual growth rate of 4.25 percent through 2032 may appear measured at first glance, but it understates the operational complexity beneath the headline figure. Medium-term growth is neither uniform nor automatic; it is being filtered through energy pricing dynamics, freight cost variability, and divergent regulatory timelines across jurisdictions. Forecasts for individual years between 2026 and 2032 reveal periods of acceleration followed by modest contractions, underscoring how capacity timing, feedstock availability, and demand-side project pipelines interact to create a non-linear revenue path. The full report unpacks these year-by-year inflection points, enabling planners to align procurement calendars, capex commitments, and product mix decisions with realistic volume expectations rather than smoothed averages.
Understanding the absolute revenue scale of the market is essential, but so is recognizing where concentration lies and where fragmentation persists. The total addressable opportunity across all forms, applications, and regions continues to expand, yet the distribution of that opportunity is highly uneven. Decision-makers who rely on aggregate growth rates without understanding the underlying structural drivers risk misallocating resources toward segments with limited margin expansion or constrained capacity absorption.
Regulatory Tailwinds and Supply-Side Constraints
Environmental regulation remains the most persistent catalyst for slaked lime demand. Stringent pollution control requirements across the United States, China, and India continue to drive procurement for hydrated lime in flue gas treatment and water and wastewater applications. As industrial emitters face tighter sulfur oxide, particulate, and heavy metal discharge limits, the consumption of high-purity slaked lime in desulfurization scrubbing systems and neutralization processes has become a compliance necessity rather than an optional upgrade. This regulatory floor provides a degree of demand certainty that insulates the market from cyclical downturns in discretionary construction or industrial processing.
Yet the supply side of the equation has grown increasingly complex. Lime kilns are inherently energy-intensive, requiring between 4.5 and 10 megajoules of fuel per kilogram of quicklime produced. Surges in natural gas and fuel oil prices accordingly translate directly into higher calcination costs, compressing margins for producers who cannot pass through cost increases or who operate with inflexible contract structures. In early 2026, quicklime feedstock pricing reflected significant geographic divergence, with benchmarks reported at approximately USD 156 per metric ton in China, USD 170 per metric ton in the Netherlands, and USD 128 per metric ton in the United States. These differentials influence downstream slaked lime economics, shaping regional competitiveness, import-export dynamics, and the viability of localized versus centralized production models.
Compounding these cost pressures, geopolitical tensions in early 2026 disrupted energy flows and logistics corridors, pushing freight rates higher by roughly 15 to 25 percent and adding surcharges to lime-related products. For buyers and sellers alike, the result has been a market where delivery reliability, regional inventory positioning, and contract hedging have become as strategically important as unit pricing. The report examines how these energy, logistics, and regulatory layers interact, providing a framework for evaluating risk exposure across procurement geographies and supply routes.
Regional and Application Dynamics: Where Demand Converges
Demand for slaked lime is distributed across a diverse set of end-use environments, each with distinct volume drivers, specification requirements, and procurement cycles. At a high level, the market's application footprint spans water and wastewater treatment, environmental protection through flue gas desulfurization, construction and infrastructure, chemical and industrial processing, and agriculture or soil treatment. The relative weight of these segments reflects broader economic and policy priorities: environmental compliance and municipal water security consistently anchor baseline demand, while construction activity and industrial processing volumes introduce cyclical sensitivity.
Regionally, the market's footprint is anchored by the Asia Pacific region, followed by Europe and North America, with Latin America and the Middle East and Africa representing additional but comparatively smaller demand pools. This distribution is not static. Shifts in municipal infrastructure investment, industrial relocation patterns, and the pace of environmental regulation implementation are gradually reweighting demand geography. Capacity additions in one region can alter trade flows, while localized feedstock availability and energy cost structures determine which production hubs remain competitive over time.
The full report provides granular segmentation that maps these regional and application dynamics in detail, allowing readers to assess which end-use categories are expanding most rapidly, how form preferences vary by region, and where regulatory or infrastructure projects are likely to generate near-term procurement spikes. Access to this level of segmentation is essential for companies evaluating market entry, capacity allocation, or product specialization strategies.
The Competitive Landscape: Scale, Focus, and Recent Moves
The slaked lime sector features a mix of globally integrated producers and regionally focused manufacturers, with consolidated players commanding significant but not overwhelming market share. The top three competitors account for approximately 18.4 percent of total market revenue, while the top five reach roughly 26.15 percent. This concentration profile indicates a market where scale matters for cost efficiency and distribution reach, yet where regional specialists and niche-grade producers retain meaningful positioning through localized service, product customization, and specialized application expertise.
Several established players illustrate the strategic directions shaping the competitive field. Carmeuse, headquartered in Belgium, operates as a global leader in lime products spanning high-calcium and dolomitic hydrated lime for steelmaking, environmental, construction, and chemical applications, with production facilities distributed across North America, Europe, and Asia. Lhoist Group, also based in Belgium, operates in more than 25 countries and supplies high-purity grades for water treatment, flue gas desulfurization, construction, and industrial uses, maintaining significant global production volumes. Graymont Limited, headquartered in Canada, has reinforced its North American and Asia-Pacific presence by focusing on construction, environmental, and industrial markets while pursuing capacity additions through acquisitions.
In the United States, Mississippi Lime Company stands as a key manufacturer of high-calcium quicklime and hydrated lime for chemical, industrial, environmental, and construction sectors, operating multiple plants with an emphasis on high-purity and specialty grades. United States Lime & Minerals, Inc. produces quicklime and hydrated lime from limestone quarries for construction, metals, environmental, oil and gas, and agriculture applications across multiple states. Complementary producers such as Nordkalk in Finland, Linwood Mining & Minerals Corporation, Cheney Lime & Cement Company, Pete Lien & Sons, Inc., Cape Lime in South Africa, Sigma Minerals Ltd in India, Valley Minerals LLC, Cornish Lime in the United Kingdom, Brookville Manufacturing in Canada, and Minerals Technologies Inc. in the United States further enrich the competitive fabric, each contributing regional depth, specialized grades, or application-specific capabilities.
Recent corporate activity underscores how companies are positioning for the 2026–2032 cycle. In February 2026, Lhoist Group commissioned an expanded hydrated lime production facility in North America to support growing demand from water treatment and flue gas desulfurization markets. Earlier, in January 2026, Graymont Limited announced a strategic partnership with a leading municipal water authority for the long-term supply of high-purity hydrated lime supporting water treatment plant upgrades, following its September 2025 acquisition of a lime processing facility in Malaysia that added significant quicklime and hydrated lime production capacity. In January 2025, Mississippi Lime Company committed to constructing a state-of-the-art sustainable kiln at its Bonne Terre, Missouri facility, signaling the industry's increasing attention to energy efficiency and environmental performance as competitive differentiators.
Worldwide Slaked Lime Market
These developments reflect a broader pattern: producers are aligning capacity investments and partnership structures with demand visibility in water and environmental applications, while simultaneously pursuing operational efficiencies that mitigate energy cost exposure. The report analyzes these moves not as isolated announcements but as indicators of how competitive advantage is being redefined through regional capacity timing, feedstock integration, and application specialization.
What the Full Report Delivers
PW Consulting's Worldwide Slaked Lime Market study is structured to support multiple layers of strategic decision-making. Beyond the macro revenue trajectory and forecast horizon, the report provides a detailed segmentation architecture covering product forms, end-use applications, and geographic markets. This structure enables readers to evaluate not just how large the market is, but how value is distributed across powdered slaked lime, slurry or milk of lime, and granular slaked lime; across environmental, construction, water treatment, chemical, and agricultural applications; and across the regional demand centers that shape procurement and logistics strategies.
The competitive analysis extends beyond corporate profiles to assess positioning, capacity footprints, and strategic timing. Readers gain insight into how leading producers are balancing scale with specialization, how recent facility expansions and acquisitions alter regional supply dynamics, and where fragmentation still creates opportunities for focused entrants or niche-grade suppliers. The inclusion of recent industry developments, from commissioning events to partnership announcements and sustainable production commitments, anchors the competitive assessment in real-time operational realities rather than static positioning maps.
Equally important, the study integrates supply-side dynamics that directly affect commercial planning. Energy intensity, feedstock pricing divergence, freight cost volatility, and regulatory implementation timelines are examined as interconnected variables rather than isolated headwinds. This integrated perspective helps procurement leaders, production planners, and market strategists evaluate where cost pressure is structural versus cyclical, where contractual flexibility can protect margins, and where capacity timing can create temporary windows of advantage or risk.
Worldwide Hydrated Lime Market
The full report also includes historical data spanning 2020 through the base year of 2025, providing a calibrated baseline against which forecasts can be tested. This historical context is essential for validating trend assumptions, understanding the magnitude of post-stimulus recoveries, and identifying whether current growth patterns reflect durable demand expansion or temporary cyclical rebounds.
Strategic Takeaways for 2026 Decision-Makers
For executives navigating the slaked lime sector in 2026 and beyond, several strategic imperatives emerge from the study's analytical framework:
- Recognize that regulatory-driven demand provides a durable baseline but does not eliminate volatility in construction, industrial processing, and freight-exposed segments.
- Model procurement and production decisions against year-by-year forecast variation rather than relying on smoothed long-term growth rates, especially where energy and logistics costs can shift margin profiles quickly.
- Assess regional competitiveness through the combined lens of feedstock pricing, energy cost structures, and freight exposure, since these variables increasingly determine which production hubs can compete on total delivered cost.
- Evaluate partnership and capacity strategies against visible demand pipelines in water treatment, flue gas desulfurization, and infrastructure projects, where multi-year procurement visibility can justify targeted capacity investments or long-term supply agreements.
- Monitor competitive moves not only by announced capacity additions but by the timing of commissioning, the specificity of application focus, and the operational efficiency investments that will determine cost leadership over the forecast period.
The slaked lime market is no longer a straightforward commodity play. It is a sector where regulatory mandates, energy economics, logistics constraints, and regional infrastructure priorities converge to shape both demand and competitive positioning. PW Consulting's Worldwide Slaked Lime Market report equips stakeholders with the analytical depth required to navigate that complexity, translating broad market trajectories into segment-level insights, competitive intelligence, and supply-side context that can be directly incorporated into commercial and operational planning.
For organizations that require precise segmentation data, region-specific demand breakdowns, form-level revenue splits, and detailed competitor benchmarking, the complete study provides the full quantitative architecture behind these strategic observations. Access to the complete dataset and analysis ensures that planning assumptions are grounded in validated market structure rather than aggregated approximations, enabling sharper execution across procurement, capacity, and market development decisions throughout the 2026–2032 forecast window.
For detailed analysis of this topic, please visit the official page: Worldwide Slaked Lime Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Towed Array Sonar Market to Hit $1.83B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-17
Global Undercurrents: Strategic Insights into the Towed Array Sonar Market Through 2032
The undersea domain has become the defining theater of modern naval competition. As quiet submarines grow more sophisticated and unmanned underwater vehicles proliferate, navies worldwide are re-evaluating their anti-submarine warfare capabilities. At the heart of this shift lies towed array sonar technology, a critical sensor suite that extends acoustic detection ranges far beyond the hull of a ship or submarine. For defense contractors, procurement officers, and investors, understanding where this market is heading is no longer optional. PW Consulting presents our comprehensive Worldwide Towed Array Sonar System Market analysis, designed to equip decision-makers with the intelligence needed to navigate a rapidly evolving landscape from 2026 through 2032.
This introduction provides a strategic preview of the findings contained within our full report. It outlines the trajectory of the global market, the competitive forces shaping supply, and the geopolitical and industrial dynamics driving procurement. Our goal is to demonstrate the depth of analysis available while highlighting why detailed segmentation and forward-looking modeling are essential for capitalizing on emerging opportunities.
Market Trajectory and Growth Outlook
The global towed array sonar market has demonstrated resilient growth over the past half-decade, evolving from a specialized naval requirement into a broader strategic asset class. Our analysis covers historical performance from 2020 through 2025, with a detailed forecast extending to 2032. In 2025, the market established a baseline of 1,280 million USD, reflecting sustained investment in anti-submarine warfare modernization programs across major naval powers.
Looking ahead, the forecast period reveals an accelerating expansion trajectory. Revenue is projected to reach 1,336.9 million USD in 2026, moderating slightly before climbing steadily through the end of the decade. By 2032, the market is anticipated to reach 1,825.23 million USD. This growth translates to a compound annual growth rate of 5.2 percent over the forecast window, driven by a combination of fleet renewal cycles, technological upgrades, and escalating undersea threats.
The historical data underscores a pattern of organic expansion punctuated by procurement spikes. Growth from 2020 to 2025 reflects the post-pandemic recovery of defense budgets and the prioritization of undersea surveillance assets. Notably, revenue growth is expected to gain momentum after 2027, suggesting that program approvals and major contract awards initiated in the mid-2020s will begin materializing in reported revenues toward the end of the decade. Decision-makers evaluating entry points or expansion strategies must account for this lag between procurement announcements and realized market revenue.
Strategic Segmentation and Application Realities
Effective market strategy requires a clear understanding of how demand is distributed across technology types, platforms, and geographic theaters. Our report dissects the market into granular segments that reveal where the highest-value opportunities reside.
Technology Types and Platform Integration
The market is bifurcated primarily by sensor architecture, with passive towed arrays commanding a larger revenue share than active systems. Passive arrays remain the cornerstone of long-range detection, favored for their ability to listen without revealing the host platform's position. Active towed arrays, while smaller in current revenue terms, are gaining traction in scenarios requiring precise target localization and tracking in high-clutter environments. Both technologies are increasingly integrated into multi-function suites that combine variable depth capabilities with advanced signal processing.
Platform adoption follows a distinct hierarchy. Surface warships represent the largest application segment, driven by the broad deployment of frigate, destroyer, and cruiser fleets equipped with variable-depth and towed array systems for open-ocean anti-submarine warfare. Submarines constitute the second-largest application, with towed arrays serving as essential complements to hull-mounted sonars on attack and ballistic missile submarines. A third, rapidly emerging segment is unmanned underwater vehicles. Though currently the smallest in revenue terms, this segment reflects a strategic pivot toward distributed sensing networks and autonomous reconnaissance, areas where lightweight towed array adaptations are beginning to appear in prototype and early-production configurations.
Geographic Demand Distribution
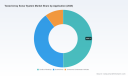
Demand is not uniformly distributed across global theaters. North America remains the largest regional market, reflecting the United States Navy's extensive modernization programs and the deep integration of towed array systems across submarine and surface combatant fleets. Europe follows as a significant market, shaped by NATO interoperability requirements and the procurement cycles of major naval powers. The Asia Pacific region represents a substantial and growing share of demand, fueled by security dynamics in key maritime corridors and the region's accelerating naval procurement. The Rest of World segment, while smaller in absolute terms, includes strategic procurements by allied nations seeking to enhance their anti-submarine capabilities in coordination with major defense partners.
For prospective suppliers and investors, the geographic breakdown is not merely a snapshot of current revenue. It reflects where procurement pipelines are deepest, where upgrade cycles are most active, and where export opportunities are constrained or enabled by regional policy frameworks. Our full report maps these dynamics in detail, providing the regional intelligence necessary to align sales strategies with actual demand centers.
Worldwide Towed Array Sonar System Market
Competitive Landscape: Leaders, Dynamics, and Strategic Positioning
The towed array sonar market is characterized by a concentrated supplier base, with a handful of established defense primes and specialized maritime technology firms commanding the majority of revenue. Our analysis indicates a heavily consolidated landscape, with the top three players accounting for 64.5 percent of market revenue and the top five representing 82.2 percent. This concentration reflects the high barriers to entry created by complex integration requirements, long certification timelines, and the necessity of deep relationships with naval procurement authorities.
Worldwide Towed Sonar Market
Several firms define the competitive frontier. L3Harris Technologies, based in Melbourne, Florida, has reinforced its position through the integration of advanced towed array suites such as the AN/SQQ-89 and thin-line arrays like the TB-29 and TB-37 for US Navy submarines and surface ships. In October 2025, the company secured a US Department of Defense contract for TB-37 Multi-Function Towed Array upgrades, signaling continued investment in next-generation signal processing and sensor capability. Thales Group, headquartered in Paris, supplies the CAPTAS variable depth sonar and towed array systems such as SLASM for anti-submarine warfare on frigates and destroyers. Its June 2025 delivery of the CAPTAS-4 towed array sonar to the Royal Canadian Navy for Halifax-class frigate upgrades demonstrates the company's ability to support both new construction and life-extension programs across allied fleets.
Lockheed Martin Corporation, based in Bethesda, Maryland, continues to develop and integrate towed array sonars including the AN/BQQ-10 for Virginia-class submarines and SURTASS/Low Frequency Active systems. A key integration milestone was achieved in November 2024 with the completion of AN/BQQ-10 towed array integration on a Block V Virginia-class submarine, underscoring the company's role in next-generation submarine sensor suites. Atlas Elektronik, part of ThyssenKrupp Marine Systems and headquartered in Bremen, Germany, manufactures low-frequency towed array sonars and systems tailored for Type 212 submarines, maintaining a strong European supply footprint. Leonardo S.p.A., based in Rome, offers towered array systems such as BlackHole and W-ASS for Italian Navy frigates and international export markets, while Ultra Maritime, headquartered in Dartmouth, UK, produces the Sea Spear towed array sonar and has supported Type 23 frigate upgrades to bolster Royal Navy anti-submarine warfare capabilities.
The competitive dynamics extend beyond product portfolios. Recent contract awards, delivery milestones, and integration achievements reveal which firms are successfully translating development work into fielded systems. Our report evaluates each competitor's strategic positioning, including their strength in specific technology segments, geographic reach, and the durability of their contractual relationships with major naval customers. For organizations considering partnerships, acquisitions, or competitive entry, this competitor intelligence is critical to understanding where market share is being won and lost.
Industry Dynamics: Supply Constraints, Regulation, and Geopolitical Forces
Market growth does not occur in a vacuum. Several structural forces are reshaping the supply environment, cost structures, and the pace at which new systems can be fielded.
Material Constraints and Cost Pressures
The production of sonar transducers relies heavily on PZT-based piezoelectric ceramics, which serve as the core sensing elements in towed array systems. Recent supply-side developments have introduced cost pressures. Rare earth supply constraints linked to Chinese export restrictions have driven an 8 percent price increase in PZT-based piezoelectric ceramics, according to mineral commodity data from January 2026. This escalation affects not only raw material costs but also the broader economics of sonar system production, particularly for manufacturers operating on fixed-price contracts or seeking to maintain competitive pricing in export markets. Understanding how suppliers are mitigating these cost pressures through material substitution, inventory strategies, or supplier diversification is essential for evaluating long-term profitability and contract risk.
Export Controls and Technology Transfer Restrictions
The transfer of towed array sonar technology is heavily influenced by regulatory frameworks governing defense trade. ITAR and the Wassenaar Arrangement impose strict export controls on sonar technologies, limiting technology transfers to non-NATO allies and complicating cross-border collaboration on development programs. These restrictions shape who can buy, who can build, and under what conditions systems can be integrated across allied supply chains. For commercial players, this means that market access is often determined as much by regulatory alignment as by technical capability. Our report examines how these controls affect regional market dynamics and where exceptions or allied cooperation frameworks create viable pathways for technology sharing and joint development.
Geopolitical Drivers and Alliance Frameworks
Geopolitical tensions are among the most powerful accelerants of demand. The AUKUS Pillar 2 agreement, announced in September 2024, has accelerated shared development of advanced anti-submarine warfare sonar technologies among the United States, United Kingdom, and Australia. This trilateral framework is fostering collaborative research, interoperability standards, and procurement alignment that benefit suppliers positioned to participate in joint programs. Simultaneously, security tensions in the South China Sea have driven Indo-Pacific nations to procure towed array sonars for anti-submarine warfare fleet upgrades, according to arms transfer data from December 2025. These regional pressures are expanding the addressable market beyond traditional NATO procurement cycles and creating new demand centers in Asia.
Integration with Unmanned and Distributed Systems
Beyond traditional platform integration, the market is witnessing a strategic shift toward distributed sensing. Towed array technology is being adapted and miniaturized for use with unmanned underwater vehicles, expanding the scope of where and how acoustic sensing can be deployed. This transition introduces new requirements around weight, power consumption, autonomous deployment, and data fusion, creating both challenges and opportunities for suppliers. Firms that can deliver compatible, scalable solutions for unmanned platforms will be positioned to capture growth in an application segment that, while currently small, is expected to expand as navy doctrines increasingly embrace autonomous reconnaissance networks.
Strategic Value for 2026 Decision-Making
For executives, procurement leaders, and investors evaluating the towed array sonar sector in 2026, the decisions made today will determine competitive positioning for the remainder of the decade. The market is entering a phase where growth is no longer linear but shaped by intersecting factors: fleet modernization timelines, material cost volatility, export control frameworks, alliance-driven R&D collaboration, and the emergence of unmanned platforms. A superficial understanding of market size and growth rate is insufficient to guide strategy. What is needed is detailed segmentation that reveals where revenue is concentrated, which applications are expanding fastest, which regions present the most viable export or partnership opportunities, and which competitors are securing the contracts that will define market share through 2032.
Our full Worldwide Towed Array Sonar System Market report delivers this depth. It combines macro-level trend analysis with actionable segmentation, competitor profiling, regulatory and supply chain mapping, and forward-looking scenario modeling. The report is designed to support concrete decisions: where to allocate sales and marketing resources, which technology segments to prioritize for R&D or acquisition, how to assess competitor moves in real time, and how to structure bids in a market where cost pressures and regulatory barriers can erode margins if not properly accounted for.
The preview provided here captures the structure and analytical rigor of the full study, but the complete picture requires access to the detailed data, segment breakdowns, regional demand models, and competitive intelligence compiled across hundreds of sources and validated through primary research. PW Consulting's analysis is built to serve as a strategic asset for organizations that need more than general market awareness. It is designed to provide the precision needed to act with confidence in a market where the difference between informed positioning and reactive decision-making can define long-term success.
For those committed to understanding the full scope of opportunity and risk in the towed array sonar market, the complete report offers the granularity and forward-looking insight necessary to translate market dynamics into strategic advantage. We invite you to explore the full study, where every segment, competitor profile, and dynamic driver is unpacked to support the decisions that will shape your position in the market through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Towed Array Sonar System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Baby Monitors Market Hits $1.85B in 2025, 8.12% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Multifunction Baby Monitors Market
The global landscape for infant care technology is shifting from simple surveillance to comprehensive health and wellness ecosystems. As parents increasingly demand devices that offer more than just video feeds, the multifunction baby monitor sector has emerged as a critical battleground for consumer electronics firms, health tech startups, and established legacy brands. At PW Consulting, we have synthesized extensive primary and secondary research to produce our latest Worldwide Multifunction Baby Monitors Market study. This document serves as a strategic overview for executives, investors, and product leaders who need to navigate the complexities of the 2026-2032 forecast period with confidence.
Understanding the trajectory of this market requires more than just observing current sales figures. It demands a nuanced grasp of how technological convergence, regulatory pressures, and supply chain dynamics interact to shape revenue potential. Our latest research provides the framework necessary to make informed decisions in an environment characterized by rapid innovation and volatile component costs. This article outlines the strategic value of our findings, highlighting the macro-economic currents and competitive pressures that will define the industry over the next seven years.
Macro-Economic Trajectory and Growth Fundamentals
The financial scale of the multifunction baby monitors market underscores its significance as a high-growth vertical within the broader consumer electronics and health tech sectors. Our analysis establishes a robust baseline rooted in historical performance data spanning from 2020 through 2025. During this historical window, the market demonstrated consistent resilience and expansion, evolving from a valuation of approximately 1,260.4 million USD in 2020 to an estimated 1,850.25 million USD by 2025. This historical growth pattern reflects a steady adoption curve driven by increasing disposable incomes in key regions and a heightened parental focus on infant safety and sleep quality.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with evolving drivers. The market is projected to reach a valuation of roughly 1,991.97 million USD in 2026, climbing steadily to exceed 3,195.75 million USD by 2032. This expansion corresponds to a Compound Annual Growth Rate (CAGR) of 8.12 percent over the forecast horizon. Such growth rates indicate that the sector is outpacing many traditional consumer electronics categories, fueled by the integration of artificial intelligence, advanced sensor technology, and connectivity features that transform passive monitors into active health management tools.
However, revenue projections are only one piece of the puzzle. The strategic value for decision-makers lies in understanding the volume and value dynamics behind these figures. Our research dissects the factors contributing to this upward trajectory, including the premiumization of hardware, the subscription potential of accompanying apps, and the replacement cycles of older non-connected devices. By analyzing these underlying drivers, stakeholders can better anticipate shifts in consumer willingness to pay for advanced features such as breathing tracking, temperature sensing, and AI-enabled alerts.
Product Convergence and Technological Differentiation
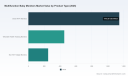
The definition of a baby monitor has fundamentally changed. The market is no longer segmented simply by video versus audio; it is now defined by the depth of functionality integrated into a single unit. Our report categorizes the landscape into distinct product archetypes that reflect this convergence. Smart Wi-Fi Monitors represent the largest share of value generation, leveraging connectivity to offer remote viewing, cloud storage, and seamless integration with smart home ecosystems. These devices are increasingly becoming the hub for nursery monitoring, incorporating features that extend beyond basic observation.
Parallel to the smart video category is the growing prominence of Wearable Health Tracking Monitors. This segment has gained traction due to advancements in sensor miniaturization and battery life, allowing for contactless or minimal-contact health monitoring such as heart rate and oxygen level tracking. The convergence of video and wearable capabilities is particularly notable in high-end offerings where parents seek redundancy and comprehensive data. Meanwhile, Non-Wi-Fi Digital Monitors maintain a presence in the market, appealing to consumers with specific privacy concerns or those in regions with inconsistent internet infrastructure, though their growth trajectory differs significantly from the connected counterparts.
Technological differentiation is becoming the primary lever for competition. Features such as computer vision for breathing motion tracking, AI-driven alerts for rollover or face-covering risks, and environmental sensing for temperature and humidity are moving from niche innovations to expected standards in the premium tier. Our study details how these features impact unit economics, production complexity, and perceived value. For product managers, understanding the cost-benefit analysis of integrating these technologies is essential for positioning devices against competitors who may offer similar specs at different price points.
Regional Dynamics and Consumer Behavior
Geographical performance varies significantly across the global landscape, influenced by local purchasing power, regulatory environments, and the maturity of e-commerce channels. Our analysis covers key regions including North America, Europe, Asia Pacific, and the Rest of World. Each region presents a unique set of opportunities and challenges. In developed markets, demand is often driven by premiumization and the adoption of smart home ecosystems, whereas emerging markets may focus on entry-level digital solutions or affordability-driven smart options as connectivity improves.
Distribution channels also play a pivotal role in shaping market access and consumer reach. The shift towards Online Retail has accelerated, reflecting broader consumer behavior changes regarding electronics purchasing. Specialty Stores remain relevant for brands that rely on hands-on demonstration and expert advice, while Supermarkets and Hypermarkets offer volume opportunities for established, trusted brands. Our research evaluates the effectiveness of these channels in different regions, providing insights into where product visibility and conversion rates are highest. This granular understanding helps supply chain and sales teams optimize their distribution strategies to maximize market penetration without diluting brand equity.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of specialized health-tech innovators, large consumer electronics conglomerates, and agile entrants leveraging global supply chains. Market concentration indicates a moderately fragmented landscape, with the top three firms holding a combined share that leaves substantial room for disruption and consolidation. The top five players account for a significant portion of revenue, suggesting that scale and brand recognition are critical assets, yet mid-tier competitors continue to carve out niches through innovation.
Several key players define the current strategic context. Companies like Nanit and Owlet have positioned themselves at the intersection of video monitoring and health analytics. Nanit utilizes computer vision for breathing motion tracking and sleep insights, while Owlet has expanded into AI-enabled camera features paired with FDA-cleared wearable elements like the Dream Sock. These firms exemplify the trend towards multifunctionality where video, audio, and analytics are bundled to provide a holistic view of infant well-being.
Legacy and diversified electronics manufacturers also maintain a strong presence. VTech Communications offers video monitors with HD video, audio, and temperature monitoring, leveraging brand trust and distribution reach. Motorola's baby division provides connected options like the PIP1710 CONNECT, emphasizing reliability and connectivity. Meanwhile, brands like eufy and Cubo AI focus on smart features, with Cubo AI delivering AI rollover and face-cover alerts alongside environmental sensing. The presence of entities like Philips Avent highlights the interest of major healthcare-adjacent corporations in connected care portfolios, suggesting potential future convergence between consumer electronics and medical-grade monitoring concepts.
Other notable participants include Infant Optics, known for long-range transmission and interchangeable lenses; Momcozy and HelloBaby, which target value-conscious segments with 1080p video and multifunction features; and Miku, which emphasizes contactless breathing tracking. The list extends to companies like Angelcare, Dorel Industries through brands like Safety 1st, iBaby Labs, Lollipop, and even adaptable security hardware providers like Wyze Labs. This diverse array of competitors underscores the importance of clear value propositions. Our report provides detailed company profiles and strategic assessments of these players, analyzing their product roadmaps, geographical focus, and recent strategic moves.
Baby Monitoring System Market
Industry Dynamics: Regulatory, Supply Chain, and Operational Risks
Strategic planning in this sector must account for external forces that can materially impact operations and market access. Regulatory scrutiny is intensifying, particularly regarding safety standards for electronic devices used around infants. A notable example occurred in February 2026, when a significant recall was issued for approximately 81,800 units of a specific baby monitor model due to overheating and sparking hazards during charging. This event serves as a critical reminder of the reputational and financial risks associated with product safety failures. Our study incorporates these dynamics, offering guidance on compliance frameworks and quality assurance protocols necessary to mitigate such risks.
Supply chain stability remains another focal point. The market for camera modules, essential components for video-enabled multifunction monitors, was valued in the tens of billions of USD during the 2025-2026 period, with demand driven by consumer electronics including security and monitoring devices. This high demand can influence lead times and availability. Furthermore, component costs for microcontrollers and sensors have experienced upward pressure in early 2026, attributed to AI-driven demand and raw material fluctuations. Procurement teams need to be aware of these cost drivers as they impact margin structures and pricing strategies.
Geopolitical factors also introduce complexity. Export controls on advanced semiconductors and related manufacturing equipment continue to affect supply chains for chips used in smart Wi-Fi-enabled devices. Additionally, recent adjustments regarding imports of processed critical minerals and derivative products highlight national security concerns related to supply chain vulnerabilities. These macro-level developments can alter the cost and availability of critical components. Our research analyzes how these geopolitical and regulatory currents influence the manufacturing and distribution landscapes, helping stakeholders build more resilient supply chain strategies.
Real-Time Intelligence and Recent Market Developments
To remain actionable, market intelligence must be current. Our 2026 research incorporates the latest developments that signal shifting priorities and capabilities among key market participants. For instance, recent earnings and product updates from companies like Owlet highlight the rollout of AI-enabled camera features paired with wearable tracking, emphasizing enhanced multifunction monitoring beyond basic video. Such moves indicate a strategic pivot towards deeper data integration and health analytics.
Conversely, recent product recalls, such as the February 2026 action involving specific models sold through major retail channels, underscore the importance of rigorous safety testing and post-market surveillance. These events are not isolated incidents but part of a broader regulatory landscape that demands vigilance. Additionally, editorial reviews and testing updates, such as the inclusion of new multifunction options in expert comparisons, reflect the rapid pace of product iteration. Our report contextualizes these developments within long-term trends, distinguishing between short-term noise and structural shifts that should influence investment and product development decisions.
The Strategic Value of Comprehensive Market Intelligence
In a market growing at over 8 percent annually with evolving technological and regulatory requirements, generalized data is insufficient for high-stakes decision-making. PW Consulting's Worldwide Multifunction Baby Monitors Market report offers the depth and precision required to navigate this environment. We provide detailed segmentation analysis that goes beyond high-level totals, exploring the interplay between product types, distribution channels, and regional nuances. By accessing the full report, stakeholders gain visibility into specific market sizes, growth rates within segments, and competitive share dynamics that are not publicly disclosed.
The report is designed to support a range of strategic objectives. For investors, it provides validated market sizing and growth forecasts to assess opportunity size and risk. For manufacturers and brand managers, it offers competitive benchmarking and feature trend analysis to guide product roadmaps. For supply chain and procurement leaders, it highlights component market dynamics and regional supply considerations. The inclusion of detailed company profiles allows for direct comparison of strategies among key players, while the analysis of recent developments ensures that strategic plans are grounded in the current reality of the market.
Worldwide Multifunction Baby Monitors Market
Furthermore, our research addresses the operational implications of market entry or expansion. Understanding distribution channel efficacy, consumer preferences in different regions, and the regulatory hurdles specific to infant electronics is crucial for successful execution. The report synthesizes these elements into actionable insights, reducing the uncertainty associated with strategic planning. We invite executives and analysts to leverage this intelligence to secure a competitive advantage. The full dataset, including granular segmentation splits, detailed company assessments, and forward-looking scenario analyses, is available through our comprehensive publication. Accessing this complete intelligence will empower your organization to anticipate market shifts, optimize product offerings, and capture value in the evolving landscape of worldwide multifunction baby monitors.
For detailed analysis of this topic, please visit the official page: Worldwide Multifunction Baby Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NF3 and F2 Market Hits $1.52B in 2025, Projected 7.15% CAGR to $2.46B by 2032
By PW Consulting, 2026-09-17
Strategic Imperatives in the Global Nitrogen Trifluoride and Fluorine Gas Market Through 2032
In an era defined by relentless semiconductor scaling, accelerating solar photovoltaic deployment, and increasingly stringent environmental compliance frameworks, specialty fluorine chemistry has transitioned from a niche industrial input to a critical strategic enabler. Nitrogen trifluoride (NF3) and fluorine gas (F2) now sit at the intersection of advanced electronics manufacturing, clean energy infrastructure, and high-value chemical synthesis. Understanding where this market is headed, which participants will capture disproportionate value, and how regulatory and supply chain pressures will reshape procurement strategies has never been more urgent for corporate planners, procurement leaders, and capital allocators.
This comprehensive market intelligence study, anchored in a 2025 baseline and projecting through 2032, delivers the analytical rigor required to navigate one of the most capital-intensive and technically demanding specialty chemical segments in the global economy. Drawing on multi-year historical tracking, forward-looking modeling, and primary industry validation, the research translates macro growth trajectories into actionable decision frameworks for organizations operating across semiconductor fabrication, display manufacturing, solar cell production, and advanced fluorination applications.
Mapping the Macro Trajectory: From Historical Consolidation to Forecasted Expansion
The global NF3 and F2 market has demonstrated consistent upward momentum across the 2020 to 2025 historical window, expanding from approximately 1.08 billion USD in 2020 to an estimated 1.52 billion USD by 2025. This trajectory reflects sustained capital investment in advanced node semiconductor capacity, rapid scaling of next-generation display fabrication lines, and growing utilization of high-purity fluorination agents in specialty chemical workflows. The compounding effect of these demand drivers has established a durable growth foundation that extends well beyond the baseline year.
Projecting forward through the 2026 to 2032 forecast horizon, the market is expected to continue its expansion at a compound annual growth rate of 7.15 percent. Under this trajectory, total market revenue advances steadily from the mid-1.6 billion USD range in 2026 toward nearly 2.46 billion USD by 2032. This growth pace is neither speculative nor reliant on isolated technology breakthroughs; rather, it is grounded in multi-year capacity build-outs, sustained electronics output expansion, and the gradual substitution of lower-efficiency cleaning and etching chemistries with high-performance NF3 and F2 grades.
Fluorine Gas (F2) Market
Importantly, the forecast architecture reflects scenario-aware modeling that accounts for supply chain volatility, raw material price fluctuations, and evolving regulatory reporting requirements. Rather than presenting a single deterministic line, the analysis incorporates sensitivity bands around key demand drivers, allowing readers to stress-test procurement plans, capacity allocation decisions, and geographic sourcing strategies against plausible market shifts. This approach ensures that the intelligence delivered is not merely descriptive but operationally deployable for budgeting, inventory planning, and long-term supplier negotiation.
Structural Composition: How Product Types and Applications Shape Market Behavior
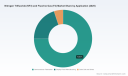
The market's internal architecture is defined by a clear divergence in scale and functionality between its two principal product categories. Nitrogen trifluoride dominates the overall revenue base, driven by its entrenched role in plasma-enhanced cleaning and etching processes within advanced semiconductor fabrication. Its high fluorine content, stability under controlled delivery conditions, and compatibility with ultra-high-purity handling requirements have cemented NF3 as a non-substitutable input for leading-edge wafer processing and flat-panel display manufacturing. Fluorine gas, while representing a smaller share of total revenue, occupies a strategically distinct position. Its aggressive reactivity profile supports specialized fluorination reactions in pharmaceutical synthesis, specialty chemical production, and select nuclear-related applications, creating a demand profile that is less cyclical but highly sensitive to purity grading, delivery safety protocols, and regulatory oversight.
On the application side, the demand landscape is concentrated around high-technology manufacturing ecosystems. Semiconductor fabrication represents the largest consumption channel, reflecting the continuous push toward smaller node geometries, higher wafer throughput, and increasingly complex multi-patterning and high-aspect-ratio etching requirements. Display panel manufacturing constitutes the second major demand pillar, with NF3 serving critical cleaning functions across LCD and advanced display production lines. A smaller but strategically important application segment encompasses solar cell manufacturing and ancillary industrial uses, where fluorine-based chemistries support surface treatment, cleaning, and specialty synthesis workflows.
Regional distribution of market activity further illustrates the concentration of demand within advanced electronics manufacturing corridors. Asia Pacific accounts for the substantial majority of total market revenue, reflecting the dense clustering of semiconductor fabs, display production facilities, and solar manufacturing capacity across the region. North America and Europe maintain meaningful but comparatively smaller shares, supported by domestic semiconductor investments, specialty chemical synthesis demand, and regional regulatory frameworks that shape procurement and compliance strategies. The rest of the world represents a modest but gradually developing footprint, with emerging semiconductor and electronics initiatives contributing incremental demand over the forecast period.
Complementing this structural overview, the report provides granular segmentation breakdowns that map historical consumption patterns, forecast evolution, and competitive positioning across each product type, application vertical, and geographic corridor. Readers gain access to demand elasticity considerations, purity-grade differentiation dynamics, and application-specific substitution risk assessments that are essential for building resilient sourcing strategies and identifying high-margin service opportunities.
Competitive Architecture and Strategic Positioning
The NF3 and F2 market is characterized by a moderately concentrated competitive landscape, where scale advantages, purity certification capabilities, and geographic proximity to end-user manufacturing clusters heavily influence market share distribution. The top three participants collectively command a significant portion of total market revenue, while the leading five firms extend their combined footprint to an even larger share, underscoring the importance of established supply chain reliability, technical service capabilities, and long-term supply agreements in capturing premium positioning.
Solvay has embedded itself as a leading global producer of NF3 for semiconductor cleaning and F2 for chemical synthesis, maintaining production infrastructure across Europe and Asia that enables flexible regional servicing and rapid response to purity specification changes. Air Products operates as a major supplier of high-purity NF3 for the electronics industry alongside F2 serving uranium enrichment and pharmaceutical workflows, with operational facilities in the United States, China, and Taiwan that position the company at the center of key electronics and specialty chemistry corridors. Linde, leveraging its legacy capabilities in industrial gases and advanced process chemicals, provides NF3 for plasma etching in semiconductor environments and F2 for broader fluorination processes, supported by a global supply chain that includes plants in the United States and South Korea.
In the Asian electronics supply chain, Kanto Denka Kogyo has carved out a specialized role by focusing on ultra-high purity NF3 tailored for LCD and semiconductor manufacturing, with production capabilities in Japan that align closely with regional electronics demand patterns. Hyundai Steel's green gas operations contribute NF3 for flat panel display cleaning and F2 derivatives, utilizing South Korean facilities to supply regional semiconductor and display firms with integrated, geographically proximate delivery models. Pelchem, operating within the Peltzer Group, stands as a key African producer of F2 and NF3 for specialty chemicals and nuclear applications, with an export-oriented business model that extends its reach into global specialty and regulated markets. Morita Chemical Industries rounds out the competitive field by manufacturing NF3 for semiconductor and solar panel production, emphasizing high-purity grades designed for Japanese and global market requirements.
Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
The competitive dynamics among these players are shaped not only by capacity and pricing but also by recent strategic initiatives that signal long-term positioning. Air Products announced a capacity expansion at its Hsinchu, Taiwan facility in late 2024 to meet escalating semiconductor demand, reflecting a direct response to regional fab growth trajectories. Solvay introduced an upgraded high-purity F2 grade in mid-2024 aimed at advanced fluorination workflows in pharmaceutical synthesis, highlighting the ongoing premiumization of specialty fluorine products. Linde achieved ISO 45001 certification for NF3 and F2 handling at its Dalian, China plant in late 2023, reinforcing the growing importance of occupational safety and process safety certification as competitive differentiators in high-risk chemical handling environments.
The full competitive analysis within the report extends well beyond corporate profiles. It includes market share estimation frameworks, capacity expansion tracking, purity-grade portfolio mapping, regional servicing capabilities, supply agreement structures, and strategic M&A or partnership activity where relevant. Readers will gain a nuanced view of how incumbents defend share, how regional specialists capture premium niches, and where pocket opportunities may emerge for new entrants or existing players seeking to reposition their portfolios.
Market Dynamics: Raw Materials, Regulation, Trade Controls, and Logistics Friction
No strategic assessment of the NF3 and F2 market can be separated from the external dynamics that continuously reshape cost structures, delivery reliability, and compliance obligations. Raw material pricing volatility remains a persistent pressure point. Anhydrous hydrogen fluoride, a foundational input for fluorine chemistry production, experienced a 15 percent price increase to approximately 2,500 USD per metric ton in the fourth quarter of 2024, driven by supply disruptions originating in China. This movement illustrates how regional feedstock constraints can rapidly transmit into broader cost structures, affecting margin planning, contract pricing negotiations, and inventory risk management across the value chain.
Regulatory evolution adds another layer of strategic complexity. The European Union's REACH framework tightened NF3 emissions reporting requirements for semiconductor manufacturers effective January 2025, placing greater emphasis on traceability, abatement effectiveness, and environmental disclosure. For producers and end-users alike, these requirements elevate the importance of certified handling protocols, emissions tracking systems, and compliance documentation that can withstand regulatory scrutiny while supporting customer sustainability commitments.
Trade policy interventions have also begun to alter regional flow patterns. United States export controls on F2 shipments to China expanded under Bureau of Industry and Security rules in October 2024, affecting a meaningful share of cross-border deliveries and prompting reassessment of sourcing redundancy, alternative routing, and regional inventory buffering strategies. For organizations with exposure to China-linked semiconductor, display, or specialty chemical supply chains, these controls introduce both compliance risk and strategic planning complexity, particularly where F2 demand depends on cross-border material movement or where dual-use considerations intersect with industrial applications.
Logistics friction further compounds the operational challenge. The UN 1045 classification for fluorine gas mandates specialized cryogenic tanker handling, adding an estimated 10 to 15 percent to global logistics costs. This requirement influences delivery economics, regional servicing feasibility, and the relative attractiveness of localized production versus centralized distribution models. In markets where purity preservation, safety compliance, and timely delivery are non-negotiable, logistics architecture becomes a strategic variable rather than a mere operational detail.
The report integrates these dynamic factors into a cohesive analytical framework that connects raw material price sensitivity, regulatory chronology, trade control evolution, and logistics cost structures to practical decision guidance. Readers will find scenario-based cost modeling, compliance timeline mapping, and supply chain resilience recommendations that translate external volatility into structured mitigation pathways.
Why This Research Matters for 2026 Strategic Decision-Making
As organizations enter the 2026 planning cycle, the NF3 and F2 market presents a landscape where informed foresight separates resilient strategies from reactive adjustments. Procurement teams must navigate purity-grade differentiation, regional supply concentration, and rising compliance documentation demands while preserving cost competitiveness. Capital planners evaluating capacity investments or long-term supplier partnerships require forward-looking demand visibility that accounts for semiconductor node transitions, display technology evolution, solar manufacturing scaling, and specialty chemical application growth. Executives overseeing risk management need integrated understanding of raw material exposure, trade control implications, regulatory reporting obligations, and logistics cost trajectories to build strategies that hold under multiple future scenarios.
This research is designed to meet those needs by combining macro market sizing, multi-segment growth analysis, competitive positioning assessment, and dynamic external factor integration into a single, decision-ready intelligence package. It provides the structural clarity required to prioritize sourcing regions, evaluate supplier capability claims, forecast procurement cost trends, and identify where premium purity grades or localized delivery capabilities may generate margin advantage. Just as importantly, it deliberately preserves analytical depth on sensitive segmentation data, proprietary forecast models, and granular competitive measurements to ensure that readers who commit to the full study gain access to information that cannot be reconstructed from public summaries or fragmented industry commentary.
For organizations that treat specialty fluorine chemistry as a strategic input rather than a commodity purchase, the difference between adequate planning and optimized positioning lies in the quality of the underlying intelligence. This study delivers that foundation. To access the complete segmentation breakdowns, regional demand evolution, competitive share analysis, scenario-based cost and compliance modeling, and forward forecast detail across the 2026 to 2032 horizon, please visit the full report page and secure the comprehensive intelligence required to guide your 2026 and beyond strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pipe Flanges Market Hits $5.34B in 2025, Projects $7.03B by 2032 at 4.01% CAGR
By PW Consulting, 2026-09-17
Navigating the 2026 Industrial Landscape: Why the Pipe Flanges Market Demands Strategic Foresight
In the complex ecosystem of industrial infrastructure, few components hold as much critical importance as the humble pipe flange. Serving as the vital connective tissue in piping systems, flanges ensure safety, pressure integrity, and modularity across sectors ranging from energy extraction to municipal water management. Yet, as we move deeper into 2026, the market for these essential components is undergoing a subtle but profound transformation. Static supply chains are giving way to dynamic networks influenced by regulatory shifts, raw material volatility, and regional industrial pivots. For executives, procurement leaders, and investors, understanding the trajectory of the worldwide pipe flanges market is no longer optional; it is a strategic imperative.
Worldwide Pipe Flanges Market
Our latest market research, spanning historical data from 2020 through the forecast period extending to 2032, offers a comprehensive lens into this evolution. This report is not merely a collection of statistics; it is a decision-support tool designed to help organizations navigate uncertainty. By analyzing revenue trends, competitive maneuvers, and regulatory frameworks, we provide the intelligence necessary to secure supply lines, optimize capital expenditure, and identify high-growth opportunities in a market projected to expand significantly over the coming years.
The Macro Trajectory: Growth Amidst Volatility
The global pipe flanges market has demonstrated resilience in the face of recent economic headwinds. Based on our analysis, the market revenue stood at approximately 5,342 million USD in the base year of 2025. Looking forward, the forecast period from 2026 to 2032 suggests a steady upward trajectory, with the market expected to reach over 7,000 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.01 percent.
While these top-line figures provide a snapshot of health, the true value lies in understanding the drivers behind the numbers. The period from 2020 to 2025 revealed patterns of recovery and adjustment, with revenue figures fluctuating as industries adapted to post-pandemic operational realities and shifting energy demands. The transition from 2025 into 2026 marks a critical inflection point. The modest growth observed in the immediate year suggests a market stabilizing after previous adjustments, setting the stage for more robust expansion in the latter half of the decade. For stakeholders, this implies that while immediate spikes may be tempered, the long-term fundamentals remain strong, driven by ongoing industrialization and infrastructure renewal projects globally.
Structural Dynamics: Segmentation and Demand Drivers
To truly leverage this market intelligence, one must look beyond aggregate revenue and understand the structural composition of demand. The market is differentiated by several key dimensions, including material composition, product type, end-user industry, and geographic region. Each of these segments presents distinct risk profiles and opportunity sets.
Material and Manufacturing Considerations
The choice of material remains a primary determinant of value within the supply chain. Carbon steel continues to hold a dominant position due to its cost-effectiveness and widespread application in standard industrial piping. However, the demand for stainless steel and alloy steel flanges is gaining momentum, driven by sectors requiring higher corrosion resistance and pressure tolerance. This shift is not merely technical; it is economic. Recent fluctuations in raw material costs have placed pressure on manufacturing margins. For instance, recent data indicates that U.S. Producer Price Index values for stainless steel have hovered significantly above historical baselines, reflecting ongoing cost volatility. Simultaneously, global steel prices in the U.S. market have shown stabilization in the low-to-mid 800s per short ton following previous fluctuations. These input cost dynamics directly influence the pricing strategies and production planning of manufacturers specializing in carbon and alloy steel flanges.
Application End-User Trends
Demand is heavily concentrated in specific industrial verticals. The oil and gas sector remains a cornerstone of consumption, leveraging flanges for upstream, midstream, and downstream infrastructure. Closely following are the petrochemical and chemical industries, which require high-integrity fittings for complex processing networks. Power generation also represents a substantial portion of the market, as utilities upgrade aging grids and explore new energy frameworks. Water and waste management sectors contribute a steady stream of demand, often driven by municipal infrastructure investments. Each of these end-users faces unique regulatory and operational pressures that dictate their procurement cycles and specification requirements.
Regional Perspectives
Geographically, the market is distributed across major economic zones. Asia Pacific represents a significant volume of activity, reflecting rapid industrialization and massive infrastructure projects in the region. North America and Europe maintain strong market positions, supported by mature industrial bases and ongoing maintenance replacements. Emerging regions in Latin America and the Middle East and Africa also contribute to the global total, often linked to energy exploration and development projects. Understanding the regional balance is crucial for companies looking to optimize their logistics networks or target specific export markets.
Regulatory Shifts Reshaping Compliance and Specifications
One of the most critical developments for market participants in 2026 is the regulatory landscape. Standards governing pipe flanges are not static; they evolve to address safety concerns and technological advancements. A major milestone occurred with the release of the ASME B16.5-2025 standard for Pipe Flanges and Flanged Fittings. This update, which covers nominal pipe sizes from 1/2 through 24, introduces revised pressure-temperature ratings based on updated ceiling values.
For manufacturers and engineers, compliance with the ASME B16.5-2025 edition is paramount. The standard introduces new definitions for key operational terms and adds additional ASTM materials for consideration. Furthermore, it includes a new appendix addressing minimum temperature limits and revises variables that impact design calculations. Pipe flanges must now comply with updated requirements for materials, dimensions, tolerances, marking, and testing to ensure pressure integrity in industrial piping systems. These changes ripple through the supply chain, affecting inventory planning, certification processes, and product development. Companies that fail to align their offerings with these updated specifications risk disqualification from bids or, worse, liability issues in the field. Our report details how these regulatory shifts are influencing manufacturer strategies and procurement timelines.
Competitive Landscape: Consolidations and Capabilities
The market structure is characterized by a mix of specialized manufacturers and large diversified conglomerates. Our analysis indicates a moderate level of market concentration, with the top three companies holding a combined share of approximately 16.4 percent and the top five holding around 22.85 percent. This fragmentation suggests that while there are key leaders, there is still ample room for niche players and regional specialists to thrive.
Several key companies define the current competitive arena. In the United States, Texas Flange and Federal Flange, both headquartered in Houston, remain prominent. Texas Flange specializes in ANSI, API, and AWWA pipe flanges in carbon steel, stainless steel, and alloys, catering to petrochemical, process, and waterworks industries with both standard and custom solutions. Federal Flange distinguishes itself as a leading manufacturer of ANSI and API 6A pipe flanges and fittings, with a strong emphasis on fast-turnaround capabilities and large diameter solutions. Similarly, Federal Flange and Allied International Group, with operations spanning Houston and Italy, operate as global producers and distributors of fittings, flanges, pipes, and PVF products through multiple manufacturing divisions.
On the technology and precision front, Swagelok Company supplies precision pipe flanges and fluid system components for critical applications, while Nippon Steel Corporation leverages advanced forging technology to offer precision pipe flanges for global industrial use. European and Asian players also exert significant influence. Metalfar S.p.A. in Italy and Flanschenwerk Bebitz GmbH in Germany produce high-performance steel pipe flanges and fittings for international markets. In China, Longan Flange manufactures a comprehensive range of steel flanges, including weld neck, blind, and orifice types, while Hebei Shengtian Pipe-Fitting Group Co., Ltd. stands as a major manufacturer of carbon steel pipe fittings and flanges.
Recent activity highlights the proactive nature of these competitors. In April 2026, Allied International Group participated as a major player in fittings, flanges, and pipes at TUBE Düsseldorf 2026. Similarly, Arrow Pipes participated as a Platinum partner at the same trade fair, the leading event for the tube and pipe industry. These engagements underscore the importance of face-to-face networking and product demonstration in a market where specifications and quality assurances are paramount. Additionally, the release of the ASME standard in May 2025 saw industry-wide responses, with companies adjusting their catalogs and compliance documentation to meet the new criteria.
Strategic Implications for 2026 Decision Makers
For business leaders, the insights contained in this report translate into actionable strategic directives. First, supply chain resilience must be prioritized. Given the fluctuations in raw material costs and the geographic dispersion of manufacturing hubs, relying on single-source suppliers exposes organizations to significant risk. Diversifying sourcing strategies across regions with different cost structures and regulatory environments can mitigate these vulnerabilities.
Second, compliance agility is a competitive advantage. With the ASME B16.5-2025 standard now in effect, companies that can rapidly certify their products and communicate compliance to customers will capture market share from slower-moving competitors. This requires investment in quality assurance teams and updated testing protocols.
Third, innovation in custom solutions offers higher margin opportunities. As seen with companies like Texas Flange and Federal Flange, the ability to provide custom-engineered connectors and large diameter capabilities allows manufacturers to serve specialized projects that standard off-the-shelf products cannot address. Understanding the specific needs of end-users in oil and gas or power generation can reveal gaps in the current market offerings.
Conclusion: Access the Full Intelligence
The worldwide pipe flanges market is at a junction where historical stability meets future complexity. The projection of growth to over 7,000 million USD by 2032 offers promise, but realizing value in this environment requires more than passive observation. It demands a granular understanding of material costs, regulatory updates, regional demand shifts, and competitive maneuvers.
This article has only scratched the surface of the available intelligence. To fully equip your organization for the decisions ahead, we invite you to access the complete Worldwide Pipe Flanges Market research report. Inside, you will find detailed segmentation analysis, comprehensive company profiles, deep dives into regulatory impacts, and scenario-based forecasting that goes beyond the high-level trends discussed here. Do not navigate the 2026 industrial landscape with incomplete data. Secure the full report today and turn market insight into strategic advantage.
Stainless Steel Flanges Market
For detailed analysis of this topic, please visit the official page: Worldwide Pipe Flanges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global PCB Epoxy Resin Market to Reach $4.9 Billion by 2032, Growing at 5.88% CAGR
By PW Consulting, 2026-09-17
Strategic Imperatives in the Worldwide Epoxy Resin for PCB Market: Navigating Growth, Volatility, and Trade Friction Through 2032
The printed circuit board (PCB) industry is currently navigating a transformation defined by the simultaneous pull of three powerful forces: the insatiable demand for high-performance electronics, the tightening grip of global trade defenses, and the relentless pressure of raw material cost volatility. Epoxy resin remains the cornerstone material for modern PCBs, dictating everything from thermal stability and dielectric performance to environmental compliance and manufacturing yield. For executives, procurement leaders, and investors, understanding the trajectory of this essential material is not merely an exercise in supply chain management; it is a prerequisite for securing competitive advantage in sectors ranging from consumer electronics to aerospace and defense.
In this context, PW Consulting has released a comprehensive new market study focused on the Worldwide Epoxy Resin for PCB Market. This strategic intelligence report provides the depth and rigor required to make informed decisions through the end of the decade and beyond. By integrating historical performance data with forward-looking scenario modeling, the study offers a clear roadmap for navigating one of the most technically demanding and geopolitically sensitive segments of the electronic materials supply chain.
Market Trajectory and the Case for Long-Term Planning
The scale of the global epoxy resin market for PCBs underscores its critical role in the broader electronics ecosystem. Recent historical data and baseline projections reveal a market that has consistently expanded, driven by the proliferation of advanced computing, automotive electrification, and the relentless miniaturization of electronic components. From a base exceeding $3,280 million in 2025, the market is projected to follow a robust upward trajectory, reaching a total revenue value of nearly $4,900 million by 2032. This expansion reflects a compound annual growth rate of approximately 5.88 percent over the forecast period, signaling a market that is growing steadily rather than experiencing erratic, cyclical swings.
However, the headline figures only tell part of the story. For strategic planners, the more telling narrative lies in the divergence between growth rates in mature regions versus high-velocity markets, and in the shifting balance of demand across application verticals. The interplay between volume expansion and value dynamics becomes particularly pronounced when analyzing how specific end-use sectors, such as communications and networking or automotive electronics, are modulating their material requirements in response to technological roadmaps and regulatory pressures.
The Technical Divergence Driving Demand Shifts
Demand for epoxy resin in PCBs is no longer uniform. As electronic devices push the boundaries of speed, density, and reliability, the material specifications required by PCB manufacturers are fragmenting into highly specialized formulations. The market is increasingly bifurcating between standard grades that serve high-volume, cost-sensitive applications and premium grades engineered for extreme performance. This bifurcation is most visible in the tension between brominated epoxy resins, which have long dominated due to their cost-effectiveness and flame retardancy, and halogen-free alternatives, which are gaining traction as environmental regulations and corporate sustainability mandates tighten globally.
Simultaneously, the push toward high-frequency, high-speed signal integrity in 5G infrastructure, advanced server base stations, and high-layer packaging substrates is accelerating the adoption of high-Tg (glass transition temperature) and specialized epoxy systems. These formulations, while typically commanding higher unit economics, are becoming indispensable for applications where thermal management, dimensional stability, and low dielectric loss are non-negotiable. The competitive dynamics within this landscape are heavily influenced by players who have vertically integrated their capabilities, from raw monomer production to finished copper-clad laminates and PCB inks.
Competitive Landscape: Vertically Integrated Giants and Regional Power Players
The competitive architecture of the global epoxy resin for PCB market is shaped by a mix of established multinational chemical corporations, regional specialists, and aggressively expanding Asian manufacturers. Market concentration remains a defining characteristic, with the top five firms accounting for a significant share of global revenue and the top three wielding a commanding portion of the market. This concentration amplifies the strategic importance of understanding not just who the players are, but how their distinct technological portfolios, geographic footprints, and capital allocation decisions are reshaping the supply-demand equilibrium.
Technology Moats and Regional Specialization
Japanese and Korean chemical giants continue to anchor the high-performance end of the spectrum. Companies such as DIC Corporation, Mitsubishi Gas Chemical Company, and Resonac Corporation have built formidable reputations around low-dielectric-loss formulations, high thermal resistance, and advanced novolac and BT resin systems tailored for multilayer PCBs, IC package substrates, and high-layer printed wiring boards. Their focus on materials for server, base station, and high-frequency applications positions them at the forefront of the technology curve, where performance premiums justify higher price points.
Epoxy Resins for Casting and Lamination Market
In tandem, Taiwanese and mainland Chinese manufacturers are executing aggressive capacity expansion strategies designed to capture volume growth and climb the value chain. Nan Ya Plastics Corporation, a vertically integrated producer of bisphenol-A based liquid and solid epoxy resins, exemplifies this approach, supplying high-Tg FR-4 materials and electronic-grade formulations with excellent electrical, mechanical, and dimensional stability for multilayer PCBs. Meanwhile, Chinese players such as Hongchang Electronics and Shengyi Technology are scaling up production of electronic-grade functional resins, halogen-free compositions, and high-Tg liquid systems, often with explicit targets in copper-clad laminates and high-end electronic materials.
Recent Strategic Shifts and Competitive Realignments
The competitive landscape has been further reshaped by a series of high-impact developments over the past year. In mid-2025, Zhuhai Hongchang commenced production on its Phase II project, adding 140,000 tons of annual capacity for liquid epoxy resin and reducing unit costs by an estimated 15 percent, thereby strengthening its cost competitiveness in the electronics and electrical sectors. By the end of 2025, the company disclosed an action plan for a Phase III project targeting an additional 80,000 tons per year of electronic-grade functional epoxy resin, alongside a high-end copper-clad laminate project, signaling a clear intent to deepen its footprint in advanced electronic materials.
Geopolitical and trade dynamics have introduced an equally potent layer of complexity. In May 2025, the U.S. International Trade Commission issued a final affirmative determination of material injury to the domestic industry from subsidized and dumped imports of epoxy resins from South Korea, Taiwan, and Thailand, effectively clearing the path for antidumping and countervailing duties. This ruling, which noted negligible imports from China and India, has immediate implications for cross-border supply chain configurations and pricing strategies. Across the Atlantic, the European Union imposed definitive anti-dumping duties on epoxy resin imports from China, South Korea, Taiwan, and Thailand in July 2025, while India followed suit in November 2025 with a five-year anti-dumping duty regime on liquid epoxy resin imports from a broad set of exporting nations.
On the commercial front, cost pressures are reverberating through the value chain. In April 2026, Mitsubishi Gas Chemical announced a 30 percent across-the-board price increase for products within its electronic materials division, including copper-clad laminates and related epoxy-based substrates, citing rising costs for copper foil, electronic cloth, and special epoxy resins. This move underscores the challenge manufacturers face in balancing input cost inflation with margin preservation, and highlights the growing importance of raw material forecasting in procurement planning.
Supply Chain Volatility and the Raw Material Matrix
No strategic assessment of the epoxy resin for PCB market is complete without a granular examination of the raw material environment. Bisphenol A, the key feedstock for most epoxy resin production, has exhibited notable price volatility, with downward pressure emerging in North America during the final quarter of 2025 as Asian offers intensified and downstream demand softened across polycarbonate and epoxy applications. Concurrently, epoxy resin prices across Asia followed a weak to bearish trend in the second half of 2025, characterized by ample supply, elevated inventories, and limited cost support from stable pricing in both bisphenol A and epichlorohydrin.
This macroeconomic backdrop creates a complex environment for procurement and production planning. On one hand, fading raw material costs can provide temporary relief and improve margin potential for resin producers and PCB fabricators. On the other hand, the protective trade measures enacted by the United States, the European Union, and India are artificially constraining supply flows in certain corridors, potentially decoupling regional price dynamics and creating arbitrage opportunities or, conversely, supply bottlenecks. Companies that fail to model these dual forces, commodity price cycles and trade policy interventions, risk suboptimal inventory positioning and unanticipated cost exposures.
Report Architecture: The Operational Intelligence Inside the Study
The Worldwide Epoxy Resin for PCB Market study is engineered to serve as a decision-making toolkit rather than a static data summary. The full report delivers a multi-layered analysis that bridges macroeconomic trends, granular segmentation, competitive profiling, and actionable supply chain intelligence. Key components of the study include:
- A detailed historical and forecast revenue analysis spanning the base year through the end of the forecast window, allowing readers to benchmark current performance against long-term trajectories and identify inflection points in the growth cycle.
- Segment-level breakdowns that dissect market size and growth dynamics across resin types, including brominated, halogen-free, and high-Tg specialized formulations, alongside application-driven analysis spanning consumer electronics, automotive electronics, communications and networking, industrial and medical equipment, and aerospace and defense sectors.
- A comprehensive regional assessment that quantifies the relative weight of key geographies and explores the structural drivers, including manufacturing footprints, end-user demand profiles, and regulatory environments, shaping market performance in each territory.
- Deep-dive company profiles covering the leading global and regional players, with a focus on their technological capabilities, product portfolios, strategic positioning, and recent operational or financial developments that influence competitive dynamics.
- An integrated regulatory and trade analysis that maps the impact of antidumping and countervailing duty proceedings, environmental compliance mandates, and raw material feedstock trends, providing a holistic view of the forces that will shape pricing, sourcing, and market access over the forecast horizon.
- Scenario-based strategic implications designed to help stakeholders stress-test their planning assumptions against plausible shifts in demand, input costs, trade policy, and technological adoption rates.
By consolidating these dimensions into a single, rigorously sourced reference, the report enables executives to move beyond reactive management and toward proactive, evidence-based strategy formulation. Whether the objective is to evaluate capacity investment timing, optimize global sourcing architectures, benchmark against incumbent competitors, or assess the viability of entry into high-growth application segments, the study provides the granularity required to reduce uncertainty and accelerate decision velocity.
Why This Study Matters for 2026 Decision-Making
The decisions made in 2026 will set the tone for the entire forecast period. As the industry absorbs the effects of newly imposed trade remedies, responds to aggressive capacity additions in Asia, and adapts to fluctuating raw material economics, the margin for error is shrinking. Companies that continue to rely on fragmented data sources, outdated market assumptions, or generalized forecasts will face compounding strategic disadvantages. The epoxy resin for PCB market is entering a phase where differentiation will be earned through precision, not just scale.
Worldwide Epoxy Resin for PCB Market
Access to the complete market study offers a tangible advantage. It equips stakeholders with the contextual depth to interpret headline trends, the segmentation clarity to identify where growth is genuinely materializing, and the competitive intelligence to anticipate how rivals are positioning themselves. More importantly, it provides the connective tissue between seemingly disparate developments, linking a capacity expansion announcement in one region to a trade ruling in another, and connecting a raw material price dip in the third quarter to a major price increase announcement in the first quarter of the following year.
For organizations committed to capturing value in this market, the full report is not an optional reference; it is a strategic asset. The complete dataset, competitive benchmarks, and forward-looking scenario analysis are available in the full Worldwide Epoxy Resin for PCB Market study, accessible now on the PW Consulting website. Readers are invited to explore the full publication to obtain the detailed segment breakdowns, precise regional valuations, and actionable recommendations required to navigate the market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resin for PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Rail AC Market Hits $14.05B in 2025, Forecast 6.55% CAGR Through 2032
By PW Consulting, 2026-09-17
Worldwide Rail Air Conditioning Market: Strategic Intelligence for 2026 Decision-Making
As global rail networks accelerate modernization and passenger expectations for comfort and reliability intensify, the rail air conditioning market has emerged as a critical nexus of engineering innovation, regulatory compliance, and commercial opportunity. PW Consulting’s latest industry research delivers a comprehensive, data-driven assessment of this sector, providing executives, procurement leaders, and strategic planners with the actionable intelligence required to navigate a complex 2026 landscape. This study is not a static snapshot; it is a forward-looking strategic compass designed to align capital allocation, product portfolio planning, and competitive positioning with the market’s most consequential trajectories.
Worldwide Rail Air Conditioning Market
The research is anchored in rigorous historical analysis spanning 2020 through 2025, with a detailed forecast extending to 2032. Over this period, the market has demonstrated consistent expansion, transitioning from a total revenue baseline of approximately 10.8 billion USD in 2020 to an estimated 14.05 billion USD in 2025. The projected trajectory indicates sustained momentum, with the market expected to approach 14.77 billion USD in 2026 and continue scaling toward nearly 22 billion USD by the end of the forecast window. A compound annual growth rate of 6.55 percent underscores the sector’s structural resilience, driven by fleet renewal programs, urban transit expansion, and the integration of next-generation thermal management systems across diverse rail platforms. These figures represent more than aggregate movement; they reflect a fundamental shift in how rail operators conceptualize climate control, energy efficiency, and passenger experience as interdependent operational priorities.
Rail Market
Report Architecture and Operational Utility
PW Consulting’s methodology prioritizes translational insight over raw data compilation. The study is structured to support real-world planning cycles, offering decision-makers a clear pathway from macro trends to tactical execution. The report delivers an integrated examination of market sizing, segmentation dynamics, competitive positioning, and regulatory-technological inflection points, all calibrated to the practical needs of industry stakeholders.
Core Analytical Dimensions
The research dissects the market across multiple structural axes, enabling precise alignment with corporate strategy and operational planning:
- Comprehensive historical tracking and forward-looking revenue modeling that contextualizes growth within broader rail infrastructure investment cycles and fleet modernization timelines
- Analysis of product architecture evolution, including roof-mounted, split, and under-floor configurations, with attention to integration complexity, maintenance profiles, and application-specific performance requirements
- Evaluation of deployment environments spanning passenger cars and metros, high-speed trains, and locomotives, highlighting how thermal load profiles, duty cycles, and operational constraints shape procurement preferences
- Geographic revenue mapping that identifies regional demand intensity, infrastructure maturity, and procurement pathway variations without oversimplifying local market nuances
- Assessment of material supply pressures, including copper price volatility for HVAC heat exchangers and skilled labor cost trajectories, with implications for manufacturing economics and margin management
Strategic Application for 2026 Planning
For executives confronting 2026 budgeting, capacity planning, and technology roadmap decisions, the report functions as an operational bridge between market intelligence and executable strategy. Procurement teams can leverage the segmentation analysis to validate supplier shortlists against application-specific performance thresholds and lifecycle cost expectations. Product development groups gain insight into technological adoption patterns, including inverter-driven compressor architectures, brushless DC motor integration, and low-global-warming-potential refrigerant transitions, enabling prioritization of R&D investments that align with near-term regulatory and operational mandates. Corporate strategy and business development functions benefit from competitive landscape mapping that clarifies positioning, partnership opportunities, and white-space identification across mature and emerging demand centers.
Competitive Landscape and Strategic Positioning
The rail air conditioning sector is characterized by a concentrated yet dynamically competitive environment, where established industrial manufacturers, specialized HVAC integrators, and regional equipment suppliers compete on engineering differentiation, compliance robustness, and global service reach. PW Consulting’s analysis maps this landscape with attention to both market structure and recent corporate activity, providing a realistic view of how leading players are shaping demand and defending share.
Market Concentration and Structural Dynamics
The market exhibits meaningful concentration among top-tier suppliers, with the top three firms collectively representing approximately 42.5 percent of revenue and the top five capturing roughly 58.3 percent. This structure reflects the technical barriers inherent in rail HVAC design, the importance of certified reliability, and the value of long-term operator relationships across multi-year rolling stock programs. At the same time, regional specialization and application-focused expertise continue to create room for nimble suppliers that can deliver tailored solutions for metro networks, high-speed corridors, and locomotive fleets. The competitive environment rewards companies that can combine thermal engineering precision with scalable manufacturing, regulatory compliance, and localized support infrastructure.
Leading Participants and Strategic Differentiation
Several companies define the current competitive rhythm through product innovation, contract execution, and certification readiness:
- Knorr-Bremse maintains a strong position through its HVAC division, supplying roof-mounted and under-floor units for passenger trains worldwide, and recently advanced its portfolio with a next-generation rail HVAC system targeting meaningful energy savings for European metro applications
- Faiveley Transport, operating under Wabtec Corporation, emphasizes modular air conditioning architectures with global installation experience across locomotives, coaches, and urban transit, and has been positioned as a primary HVAC supplier for major Indian Railways train expansions
- Toshiba Carrier Corporation focuses on advanced rail air conditioning units leveraging inverter technology for Japanese Shinkansen and international export projects, with an emphasis on lightweight and low-power designs
- Hitachi delivers integrated rail HVAC systems for high-speed trains and metros, incorporating energy recovery features, and has progressed validation testing for eco-friendly units tied to major high-speed infrastructure programs
- Bombardier Transportation, now part of Alstom, provides custom air conditioning packages for passenger rolling stock with an emphasis on reliability and compliance with EN 14750 standards, reinforced by recent major trainset supply awards in Europe
- Siemens Mobility offers climate control systems for rail applications, including platforms such as Mireo and Desiro, with a clear focus on sustainable cooling technologies and energy-conscious compressor innovation
- Mitsubishi Electric manufactures rail air conditioning equipment with variable refrigerant flow for metro and commuter trains, maintaining active global participation and updated certification coverage for its rail lineup
- Aqua Group produces HVAC systems for railcars, including distributed and centralized unit configurations, serving European and Asian operators with application-flexible designs
- STULZ Air Technology Systems supplies precision air conditioning for rail control rooms and passenger compartments, utilizing modular designs that support integration efficiency and serviceability
- Guangzhou Metro AC Equipment Co., Ltd. stands as a key Chinese supplier of air conditioning systems for urban rail transit, supporting domestic high-speed and metro projects with regionally attuned engineering and manufacturing execution
Recent Commercial and Technological Activity
The competitive picture is further illuminated by recent developments that signal where the market is heading in 2025 and 2026. Product launches emphasizing energy efficiency, contract awards tied to next-generation high-speed fleets, testing validation for environmentally aligned systems, supplier nominations for large-scale national rail programs, and updated compliance certifications all point to a sector in active transition. These events are not isolated milestones; they are indicators of how leading firms are recalibrating portfolios around efficiency, regulatory readiness, and regional program participation. The research synthesizes these moves into a coherent competitive narrative, helping stakeholders interpret which capabilities are likely to command premium positioning in upcoming procurement cycles.
Regulatory, Material, and Technological Forces Shaping 2026
Market trajectory in rail air conditioning is increasingly determined by intersecting external forces. Regulation, raw material economics, and technology substitution are no longer background variables; they are active determinants of cost structure, product design, and supplier selection. The report integrates these dynamics into a unified view of market risk and opportunity.
Compliance and Refrigerant Transition
Rail HVAC systems operate under strict performance expectations, including compliance with EN 14750, which governs air conditioning systems in rail vehicles and mandates reliable performance under extreme temperature conditions ranging from -25°C to +50°C. Beyond baseline performance, the refrigerant landscape is shifting. EU Stage V emission standards for refrigerants require low-GWP alternatives such as R1234yf in new rail HVAC systems from 2025, compelling manufacturers and operators to align product selection with environmental mandates while managing transition complexity. These requirements influence not only design engineering but also sourcing 전략, certification timelines, and lifecycle service planning.
Input Cost Pressures and Manufacturing Economics
Material and labor economics add another layer of strategic consideration. Copper prices for HVAC heat exchangers have risen 15 percent year-over-year to approximately 9,500 USD per tonne, directly affecting production costs for heat exchanger-intensive rail AC configurations. At the same time, skilled HVAC assembly labor costs in Europe averaged 45 EUR per hour in 2025, increasing 8 percent due to workforce shortages. These pressures interact with product architecture decisions, sourcing strategies, and regional manufacturing footprints, making cost resilience and supply chain flexibility critical competitive attributes in 2026 planning.
Technology Substitution and Efficiency Gains
Technological evolution continues to reshape performance expectations. The shift to brushless DC motors in rail AC compressors has been shown to reduce energy use by roughly 25 percent compared with traditional units, offering a clear pathway to operational savings and emissions-aligned performance. Inverter-driven architectures, energy recovery features, and modular integration approaches further expand the design space for manufacturers seeking to differentiate on efficiency without compromising reliability. The research evaluates how these technology trends interact with application requirements, certification frameworks, and operator priorities, enabling stakeholders to anticipate which solutions are likely to gain traction in upcoming procurement and fleet renewal cycles.
Translating Market Intelligence into Strategic Action
PW Consulting’s Worldwide Rail Air Conditioning Market research is designed to support decisive action under uncertainty. The study does not merely describe market size and segmentation; it contextualizes growth within the forces that will shape bidding outcomes, supplier negotiations, technology roadmaps, and regional expansion choices in 2026 and beyond. Executives who engage with the full analysis gain access to detailed segmentation insights, competitive benchmarking, procurement pathway considerations, and forward-looking indicators that connect market scale to strategic execution.
The report’s value lies in its ability to clarify where demand is forming, which technical and regulatory requirements are becoming non-negotiable, how leading suppliers are positioning themselves, and what cost dynamics may influence margin and pricing strategies. By integrating historical performance, forecast trajectory, and current industry developments into a single analytical framework, the research equips stakeholders with the perspective needed to prioritize investments, structure supplier relationships, and align product or procurement strategies with the market’s most durable trends.
For organizations preparing for 2026 planning cycles, the complete dataset, segmentation detail, competitive profiles, and regulatory-technological assessments provide the depth required to move from intuition to evidence-based strategy. PW Consulting’s full market research offers the comprehensive intelligence necessary to inform capital deployment, product planning, and competitive positioning with confidence. Readers seeking the complete segmentation breakdown, company-level analysis, and actionable recommendations are encouraged to access the source report directly, where the full scope of market intelligence is available for strategic review and decision support.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Air Conditioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Foam Market Hits $78.5M in 2025, Projects 17.84% CAGR to $247.74M by 2032
By PW Consulting, 2026-09-17
Navigating the Green Shift: Strategic Insights from the Worldwide Wood Foam Market Research 2026
The global materials landscape is undergoing a seismic transformation. As industries grapple with the dual pressures of regulatory compliance and sustainability mandates, wood foam has emerged from a niche innovation to a critical component in the supply chain of major sectors ranging from packaging to construction. At PW Consulting, we recognize that understanding this trajectory is not merely an academic exercise but a commercial imperative. Our latest comprehensive study, the Worldwide Wood Foam Market research, offers a granular look at this evolving sector, providing the intelligence necessary for stakeholders to navigate the complexities of 2026 and beyond.
This article serves as a strategic preview of our findings. It outlines the macroeconomic forces driving growth, the competitive dynamics reshaping the supply base, and the specific operational insights contained within the full report. Our goal is to equip decision-makers with the context needed to evaluate opportunities in this high-growth market, while highlighting why detailed data access is crucial for precise planning.
Market Trajectory: From Niche to Mainstream
The wood foam market has demonstrated remarkable resilience and acceleration over the past half-decade. Based on historical analysis spanning 2020 through 2025, the sector has moved steadily away from its experimental roots toward established commercial viability. The total revenue generated by the market has seen a consistent upward trend, reflecting a broader industrial shift toward bio-based materials. By the base year of 2025, the market had solidified its position, setting the stage for the forecast period extending to 2032.
Our analysis indicates that the momentum is not slowing down. The forecast period from 2026 to 2032 predicts a robust compound annual growth rate (CAGR) of 17.84%. This growth trajectory suggests that wood foam will capture significant market share from traditional petroleum-based foams. The total market size is projected to expand substantially by the end of the forecast window, signaling a mature acceptance of wood fiber-based solutions in high-volume applications. For investors and corporate strategists, this growth curve represents more than just volume; it indicates a structural change in how materials are sourced, processed, and disposed of globally.
Worldwide Wood Foam Market
The acceleration is driven by a confluence of factors that go beyond simple cost competition. It is rooted in a fundamental reassessment of material lifecycle. As companies face increasing scrutiny regarding their carbon footprints, the appeal of a material derived from sustainably managed forests becomes a strategic asset. The market data underscores that this is not a temporary trend but a long-term reallocation of capital and resources toward renewable feedstocks.
Melamine Foam Market
Regulatory Tailwinds and Raw Material Realities
One of the most critical drivers identified in our research is the regulatory environment. Governments worldwide are tightening restrictions on single-use plastics and non-recyclable packaging materials. In Europe, the Packaging and Packaging Waste Regulation (PPWR) stands out as a pivotal force. This regulation drives demand for fiber-based alternatives like wood foam to replace single-use plastics in packaging. For manufacturers operating in or exporting to the European Union, compliance is no longer optional, and wood foam offers a compliant pathway that aligns with circular economy goals.
Beyond compliance, there is a technical advantage regarding end-of-life scenarios. Wood foam materials are designed for kerbside recyclability in existing paper and cardboard streams, supporting circular economy compliance. This feature differentiates wood foam from many biodegradable plastics that require industrial composting facilities. The ability to integrate into existing waste infrastructure reduces liability for downstream customers and simplifies the value proposition for procurement teams.
On the supply side, the reliance on sustainably sourced Nordic wood fibers from managed forests as the primary renewable feedstock ensures a stable raw material base. Unlike petrochemical feedstocks, which are subject to volatile oil prices and geopolitical instability, wood fiber supplies are managed through established forestry protocols. Furthermore, advanced processes start with wood fibers and water suspension foamed without petrochemical additives, resulting in 100% renewable resource composition. This purity profile is increasingly valuable as brands seek to eliminate hidden plastics from their product portfolios.
Segmentation Dynamics: Where the Opportunity Lies
While our full report delves into precise volumetric and valuation splits, the strategic narrative points to clear dominance in specific areas. The segmentation analysis reveals that certain types of wood foam are outpacing others in adoption rates. Flexible variants are capturing a significant portion of the market attention, driven largely by their versatility in cushioning and protective roles. Rigid variants also hold a substantial position, particularly where structural insulation and lightweight construction are priorities.
Application-wise, the building and construction sector represents a major consumption center. The need for thermal insulation and sustainable building materials aligns perfectly with the properties of wood foam. However, the protective packaging sector is rapidly emerging as a critical growth engine. As e-commerce continues to expand and consumers demand eco-friendly unboxing experiences, the demand for cushioning materials that do not compromise on sustainability is surging. Automotive and transportation applications also contribute to the mix, leveraging the lightweight nature of the material to improve fuel efficiency and reduce vehicle weight.
It is important for strategists to note that regional demand varies significantly based on local regulations and industrial maturity. Europe currently holds a leading position in terms of market share, reflecting its early adoption of sustainability mandates. North America and Asia Pacific are following closely, with distinct growth drivers in each region. North America is seeing growth driven by consumer brand commitments to sustainability, while Asia Pacific is leveraging manufacturing scale and growing domestic demand for green materials. The Rest of the World segment, while smaller currently, presents potential for future expansion as regulatory frameworks evolve globally.
Competitive Landscape: Innovation and Collaboration
The competitive environment in the wood foam market is characterized by a mix of established material giants, specialized research institutes, and niche distributors. Our report provides detailed profiles and strategic assessments of key companies shaping the industry. Leading the charge is Stora Enso, headquartered in Helsinki, Finland. As a primary global producer of Fibrease and Papira wood foam, Stora Enso is setting the benchmark for cellulose and wood fiber-based foam. Their focus on bio-based, recyclable alternatives to polymer foams with cushioning and insulating properties has made them a central figure in the transition away from plastics.
Collaboration is a key theme in this landscape. Nature-Pack serves as an exclusive North American distributor and partner for Stora Enso Fibrease, providing sustainable, recyclable packaging foam solutions as a low-carbon substitute for traditional polymer foams. Similarly, NOVAPOR supplies Stora Enso Fibrease wood foam as sheets, cuttings, punched parts, and finished packaging solutions for protective, insulating, and cushioning applications. This ecosystem approach allows technology developers to focus on production while partners handle regional distribution and customization.
Research and development remain vital. Fraunhofer WKI, based in Braunschweig, Germany, is a research institute developing 100% wood-based foam from wood particles and fibers for thermal insulation, packaging, and lightweight construction applications. Their focus on scalable production processes for rigid boards and flexible mats ensures that the technology remains viable for industrial-scale adoption. On the commercial side, Nefab collaborated on early commercialization of wood foam for eco-friendly fibre-based recyclable packaging, offering fibre-based foam solutions for industrial packaging.
The market concentration indicates a somewhat consolidated environment, with the top firms holding a significant share of revenue. This consolidation suggests that barriers to entry may be high regarding proprietary technology and supply chain integration. However, there are active manufacturers such as Reilly Foam Corporation and JB Polymers, both based in the United States, who are listed as active in the wood foam sector. Their involvement signals that the technology is accessible enough for broader manufacturing participation, provided the right capabilities are in place. Recent developments, such as the continued commercial supply and development of Fibrease and Papira wood foam lines by Stora Enso in early 2025, validate the scalability for plastic phase-out in protective applications. Additionally, capacity expansions in related foam sectors, such as the investment by American Excelsior Company to triple molded urethane production capacity, indicate a broader industry readiness to meet growing demand in foam-based applications.
Inside the Report: Actionable Intelligence for 2026
The Worldwide Wood Foam Market research report is designed to be a practical tool for strategic planning. It goes beyond high-level trends to offer specific data points that can inform budgeting, sourcing, and expansion decisions. The report covers the historical period from 2020 to 2025, providing a solid baseline for understanding how the market reacted to recent economic shocks and policy changes. It then extends the forecast through 2032, allowing for long-term capacity planning.
Readers will find detailed segmentation analysis that breaks down the market by Region, Type, and Application. While we cannot disclose the full granularity here, the report quantifies the revenue contributions of each segment in USD Million. This allows clients to identify which niches offer the highest margin potential or the fastest growth rates. For example, understanding the precise split between flexible and rigid foam helps manufacturers decide whether to invest in flexible mat production lines or rigid board presses.
The report also includes a comprehensive competitive landscape section. We analyze the market concentration, noting that the top three players account for a significant portion of the market revenue. This insight helps new entrants understand the competitive intensity and helps existing players benchmark their position. We also track recent developments and company profiles, ensuring that stakeholders know who is partnering with whom and where capacity is being added.
Furthermore, the research integrates industry context noise into the analysis. This includes specific facts about raw material sourcing, such as the use of sustainably sourced Nordic wood fibers, and regulatory impacts like the EU PPWR. By contextualizing the data within these operational realities, the report helps users assess risks related to supply chain continuity and regulatory compliance. Whether you are looking to invest in production technology, switch materials for packaging, or identify acquisition targets, the data provided is structured to support those specific use cases.
Strategic Imperatives for Decision Makers
As we look toward 2026, the message from the data is clear: wood foam is transitioning from an alternative material to a mainstream solution. The CAGR of 17.84% is not just a number; it represents a window of opportunity for companies that act decisively. For material suppliers, the imperative is to secure supply chains and scale production to meet the anticipated demand surge. For users of foam materials, such as packaging firms and construction companies, the strategic move is to pilot wood foam solutions now to stay ahead of regulatory curves and consumer expectations.
Risk management is also a key component of the strategy. While the growth outlook is positive, reliance on specific feedstocks and regulatory stability requires careful monitoring. The report provides the frameworks to assess these risks. Understanding the market concentration helps in evaluating supplier dependency. Knowing the application splits helps in diversifying revenue streams. The integration of raw material facts and regulatory updates ensures that strategies are built on a foundation of reality rather than speculation.
Ultimately, the Worldwide Wood Foam Market research is an investment in clarity. In a market defined by rapid change and complex sustainability criteria, having access to verified, detailed data is the difference between guessing and strategizing. We invite stakeholders to explore the full report to access the specific regional valuations, application splits, and competitive metrics that will define their success in this evolving landscape.
The transition to sustainable materials is inevitable. The question for industry leaders is no longer if they should adapt, but how quickly they can integrate solutions like wood foam into their operations. With the insights provided in our comprehensive study, PW Consulting aims to be the partner that accelerates that transition, turning market data into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High Voltage System Market to Hit $247B by 2032, Growing at 18.64% CAGR
By PW Consulting, 2026-09-17
Unlocking the Currents of Growth: Strategic Intelligence for the Global High Voltage System Market (2026-2032)
The global energy infrastructure is undergoing a paradigm shift. As nations race to decarbonize grids and accommodate the surging power demands of artificial intelligence data centers and electric mobility, the high voltage system market stands at the forefront of this transformation. At PW Consulting, we recognize that navigating this landscape requires more than general industry knowledge; it demands precise, data-backed strategic intelligence. Our latest report, Worldwide High Voltage System Market, offers a comprehensive roadmap for stakeholders aiming to capitalize on the opportunities defining the next decade.
This market research is not merely a collection of statistics. It is a strategic instrument designed to inform capital allocation, risk assessment, and competitive positioning in 2026 and beyond. With a projected Compound Annual Growth Rate (CAGR) of 18.64% from 2026 to 2032, the sector is experiencing exponential expansion. The total market revenue, valued at approximately 74,550.0 Million USD in the base year 2025, is forecasted to surge toward 247,030.12 Million USD by 2032. This trajectory underscores a critical reality: the window to secure supply chains, forge partnerships, and enter key territories is narrowing. Decision-makers need to understand the magnitude of this expansion without getting lost in the noise of fragmented data sources.
Macro Trends Driving the 18.64% CAGR
The velocity of growth in the high voltage sector is fueled by converging macro trends. Historically, the market has demonstrated resilience and acceleration. From 2020 to 2025, revenue climbed from roughly 22,450.12 Million USD to the aforementioned 74,550.0 Million USD. This five-year historical performance sets the stage for the forecast period, where the compounding effect of renewable integration, grid modernization, and cross-border energy trade will drive figures even higher. By 2028, the market size is expected to breach 136,430.59 Million USD, and by the end of the decade in 2030, it will approach 196,261.41 Million USD.
Several underlying dynamics are propelling this surge. Firstly, the transition to high voltage direct current (HVDC) technologies is becoming standard for long-distance bulk power transfer and offshore wind integration. Traditional alternating current (AC) systems are increasingly unable to handle the efficiency requirements of modern renewable energy corridors. Secondly, the electrification of transport and industry is placing unprecedented load on transmission networks, necessitating upgrades to high voltage infrastructure. Thirdly, geopolitical energy security concerns are driving nations to invest in independent, robust grid capabilities, further stimulating demand for high voltage components and systems.
However, these opportunities are tempered by supply chain complexities. Industry data indicates that lead times for critical components, such as large power transformers, have extended significantly. Prices for these units have risen approximately 77% since 2019, driven by raw material costs including steel and copper. Understanding how these cost pressures impact overall market revenue and project viability is essential for financial planning. Our research dissects these cost drivers to help organizations anticipate budgeting needs and negotiate better terms with suppliers.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of established global giants and specialized regional players. Concentration ratios indicate a moderately consolidated environment where strategic alliances and technological superiority determine market share. The CR3 stands at 38.5%, while the CR5 reaches 52.1%, suggesting that while there are dominant forces, there remains ample room for niche players and regional specialists to flourish.
Key enterprise players are actively shaping the market through capacity expansion and landmark contract wins. Hitachi Energy, headquartered in Zurich, continues to strengthen its manufacturing footprint, including a significant investment exceeding 1 billion USD in U.S. manufacturing expansion announced in September 2025. This move targets high voltage grid infrastructure needs, including those for AI data centers. Similarly, GE Vernova, based in Cambridge, Massachusetts, has secured major contracts, such as the consortium award with Seatrium for the BalWin5 2.2 GW offshore HVDC grid connection in the German North Sea in December 2025. These moves highlight the strategic importance of offshore wind transmission.
In the Asia-Pacific region, companies like TBEA Co., Ltd. and NR Electric Co., Ltd. are expanding their influence with HVDC converter equipment and control systems. Meanwhile, European cable specialists such as Prysmian Group, Nexans, and NKT A/S are critical to the submarine and land interconnection segments. NKT, for instance, secured 2 billion Euro contracts with SSEN Transmission in January 2026 for 525 kV HVDC transmission links in Scotland. Sumitomo Electric Industries and Toshiba Energy Systems & Solutions Corporation are also prominent in providing cables and transformers for bulk power applications.
High Voltage Cables Market
Our report provides detailed profiles on these entities, analyzing their strategic moves, technological portfolios, and regional strengths. However, the specific revenue contributions, exact market shares, and proprietary partnership networks are detailed within the full study. Access to this granular competitive intelligence allows clients to identify potential collaborators, assess competitor vulnerabilities, and refine their own go-to-market strategies.
Segmentation Insights: Components, Voltage, and Geography
Understanding where value is generated within the high voltage system market is crucial for targeted investment. The market is segmented by component, voltage level, and region, each presenting unique growth vectors. Among components, traction inverters and battery management systems represent significant portions of the revenue stream, reflecting the electrification trend in transport and energy storage. On-board chargers, DC-DC converters, and high voltage connectors and cabling also constitute vital parts of the ecosystem.
Voltage level segmentation reveals a bifurcation between standard 400V to 600V systems and the emerging above 600V (800V architecture) systems. While the former currently holds a larger share of the market revenue, the latter is poised for accelerated adoption as efficiency standards tighten and power demands increase. The shift toward higher voltage architectures is particularly relevant for automotive and industrial applications where energy density and transmission efficiency are paramount.
Geographically, the market exhibits varied growth patterns. Asia Pacific remains a dominant region in terms of market value, driven by rapid industrialization and renewable energy installations. Europe and North America follow, with strong regulatory pushes for grid modernization and decarbonization. The Rest of the World segment also presents emerging opportunities as developing nations upgrade their transmission infrastructure. While the aggregate regional values are substantial, the specific percentage contributions and localized growth rates are reserved for the full report to ensure clients rely on our comprehensive analysis rather than partial data points.
Our segmentation analysis goes beyond top-line numbers. We explore the inter dependencies between components and voltage levels, identifying which combinations offer the highest margin potential and fastest deployment cycles. This granular view is essential for component manufacturers and system integrators looking to optimize their product portfolios.
Regulatory and Operational Dynamics Shaping 2026
Policy and regulation are as influential as technology in the high voltage sector. Governments are increasingly intervening to streamline project development and fund innovation. For instance, the U.S. Department of Energy selected four projects totaling 11 million USD under the IDEAL HVDC program in November 2024 to develop high-performance, low-cost HVDC converters. Such initiatives signal a long-term commitment to reducing the cost barrier of high voltage transmission.
Operational milestones are also accelerating. The New England Clean Energy Connect 1,200 MW high-voltage direct current transmission line from Hydro-Quebec began commercial operations on January 16, 2026. This event marks a significant step in cross-border renewable energy integration. Furthermore, regulatory bodies are adapting to infrastructure needs; Colorado enacted legislation allowing co-location of high voltage transmission lines within state highway rights-of-way to streamline development. These regulatory shifts reduce development timelines and lower soft costs, directly impacting project economics.
Grid operators are also planning aggressively. TenneT's Onshore and Offshore Grid Investment Plans 2026 outline multiple high voltage grid expansion projects, though they note longer realization times for new substations and connections. This tension between ambitious investment plans and execution realities creates a complex environment for suppliers. Understanding the timing and scale of these grid plans is vital for aligning production capacity and sales forecasts. Our report integrates these regulatory and operational updates to provide a realistic view of market accessibility and risk.
Why This Report is Indispensable for 2026 Decision-Making
In a market growing at nearly 19% annually, hindsight is insufficient. Leaders need foresight. The Worldwide High Voltage System Market report is designed to provide that foresight. It combines historical data integrity with forward-looking forecasts that account for technological shifts, regulatory changes, and competitive maneuvers.
For investors, the report offers clarity on where capital is most likely to yield returns, highlighting high-growth segments and regions. For manufacturers and suppliers, it provides actionable intelligence on demand forecasting, supply chain vulnerabilities, and customer expectations. For policymakers and grid operators, it offers a benchmark against global trends to validate domestic strategies.
Worldwide High Voltage System Market
The depth of analysis covers over 15 key companies, detailed segmentation across components and voltage levels, and a thorough examination of market dynamics including raw material constraints and regulatory frameworks. While the summary provides a sense of the scale—highlighting the jump from 74,550.0 Million USD in 2025 to a projected 247,030.12 Million USD by 2032—the specific strategic recommendations, normalized data tables, and executable insights require the full document.
We invite industry leaders, investors, and strategy teams to access the complete Worldwide High Voltage System Market research. In an era where energy infrastructure defines economic resilience, having the right data at the right time is the ultimate competitive advantage. PW Consulting delivers the intelligence necessary to navigate the high voltage currents of the future.
For detailed analysis of this topic, please visit the official page: Worldwide High Voltage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trichomonas Rapid Testing Market to Hit $1.05B by 2032, 6.3% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Half-Decade: Inside the Worldwide Trichomonas Rapid Testing Market
The landscape of infectious disease diagnostics is undergoing a structural shift, driven by the convergence of rapid molecular innovations, evolving regulatory frameworks, and a heightened global focus on sexual health. For stakeholders navigating the Trichomonas vaginalis testing sector, understanding the trajectory of this market is no longer optional—it is a critical component of strategic planning. PW Consulting's latest comprehensive study, the Worldwide Trichomonas Rapid Testing Market report, offers a definitive roadmap for the period spanning 2026 through 2032. This article serves as a strategic briefing, outlining the macro-environmental drivers, competitive undercurrents, and the actionable intelligence embedded within our full analysis, designed to empower executive decision-making in 2026 and beyond.
A Market Poised for Sustained Expansion
Historical performance provides the baseline for any robust forecast. The global revenue for Trichomonas rapid testing demonstrated consistent growth between 2020 and 2025, reflecting the steady adoption of point-of-care solutions and the increasing prevalence of screening initiatives. As the market moves into the forecast window starting in 2026, the revenue trajectory indicates a continuation of this upward momentum, with significant valuation milestones expected to be reached by the end of the decade.
Our analysis projects that the market will expand to reach a substantial valuation by 2032, underpinned by a compound annual growth rate (CAGR) of 6.3 percent over the forecast period. This growth rate is not merely a statistical projection; it reflects the compounding effect of technological maturation, expanded test indications, and the integration of trichomoniasis screening into broader sexual health protocols. For 2026, the year serves as a pivotal inflection point, bridging the established baseline of 2025 with the accelerated growth phases anticipated through 2032. The revenue expansion from the 2025 baseline underscores the momentum that market participants must capitalize on immediately to secure competitive positioning for the remainder of the decade.
Navigating the Segmentation Architecture
Understanding the "where" and "how" of market value is essential for resource allocation and product strategy. The market is delineated across multiple dimensions, each presenting distinct opportunities and challenges for manufacturers, distributors, and service providers.
Geographic Value Distribution
The global market is geographically dispersed, with distinct regional growth profiles shaped by healthcare infrastructure, reimbursement policies, and disease prevalence. North America continues to represent a significant portion of the global revenue, driven by advanced diagnostic adoption and established clinical guidelines. Europe follows as a major contributor, characterized by robust public health frameworks and increasing awareness campaigns. Asia Pacific presents a dynamic growth corridor, where expanding healthcare access and rising diagnostic demands are creating new avenues for market penetration. Latin America and the Middle East and Africa, while currently representing smaller shares of the global total, harbor latent demand that is gradually being unlocked by improved distribution networks and targeted public health interventions. Our detailed regional analysis in the full report dissects these dynamics, revealing the specific growth vectors and infrastructure dependencies that define each territory. Stakeholders seeking to expand their footprint will find granular insights into the regulatory and economic factors influencing adoption rates across these diverse markets.
Rapid Influenza Diagnostic Test (RIDT) Market
Technological Paradigms: Antigen vs. Molecular
The test type segmentation reveals a competitive interplay between rapid antigen kits and rapid nucleic acid amplification tests (NAATs). Rapid antigen kits dominate the volume and revenue landscape, favored for their speed, ease of use, and suitability for point-of-care and resource-limited settings. These assays provide qualitative detection of Trichomonas vaginalis antigens from vaginal specimens, delivering actionable results within minutes. On the other hand, rapid NAATs are carving out a high-value niche, particularly in settings demanding superior sensitivity and specificity, or where molecular confirmation is required. The evolution from traditional lateral flow formats to isothermal molecular platforms is reshaping the technical requirements of end-users. The full report provides a deep dive into the performance characteristics, market acceptance, and pricing dynamics of each technology class, enabling clients to assess the strategic fit of their product portfolios against the evolving technical preferences of the diagnostic community.
End-User Ecosystems and Adoption Channels
Where testing occurs fundamentally influences product design, procurement strategies, and market access. Diagnostic laboratories remain a core pillar of demand, leveraging high-throughput capabilities and specialized expertise to process large volumes of specimens. Hospitals and clinics represent another critical channel, where rapid turnaround times directly impact patient management and treatment initiation. Notably, the segment encompassing home care and self-testing is gaining prominence, reflecting a broader trend toward patient empowerment and decentralized care. The rise of self-collection and at-home diagnostic options is altering the traditional provider-centric model, introducing new considerations for product usability, regulatory clearance, and consumer education. Our market study maps the revenue contributions and growth trajectories of these end-user categories, offering strategic guidance on channel mix optimization and partnership opportunities that align with the shifting patterns of healthcare delivery.
Competitive Dynamics and Key Player Profiles
The competitive environment is defined by a concentrated group of specialized players, each leveraging unique technological advantages and market positions. Our report provides in-depth profiles of the key companies shaping the industry, analyzing their product portfolios, strategic moves, and competitive strengths.
- Sekisui Diagnostics, based in Burlington, MA, and formerly associated with Genzyme, holds a differentiated position with the OSOM Trichomonas Rapid Test. This assay is recognized as the only CLIA-waived lateral flow antigen detection test for Trichomonas vaginalis from vaginal swabs, delivering results in approximately 10 minutes with high agreement rates compared to culture and wet mount methods. The CLIA-waived status is a strategic asset, broadening the scope of testing sites and facilitating integration into diverse clinical workflows. Additionally, the test is associated with Medicare reimbursement under relevant procedure codes for infectious agent antigen detection, a factor that significantly influences adoption in the US healthcare system.
- Liming Bio, headquartered in China, manufactures the StrongStep Trichomonas Vaginalis Antigen Rapid Test, focusing on the qualitative detection of antigens from vaginal specimens. As a manufacturer in a key manufacturing hub, Liming Bio contributes to the global supply of affordable rapid testing solutions, catering to markets where cost-effectiveness and accessibility are paramount.
- Vitrosens Biotechnology, operating from Turkey, provides the RapidFor Trichomonas Vaginalis Rapid Test Kit as part of its broader suite of rapid diagnostic solutions. The company represents the growing capabilities of the Turkish diagnostic sector, offering products that address the need for reliable and rapid detection in various healthcare settings.
- QuidelOrtho, based in San Diego, CA, offers the Solana Trichomonas Assay, an isothermal molecular test, and previously the AmpliVue Trichomonas assay. These solutions target the detection of Trichomonas vaginalis nucleic acids from vaginal and urine specimens in women, positioning QuidelOrtho at the intersection of rapid turnaround and molecular accuracy.
- Cepheid, headquartered in Sunnyvale, CA, markets the GeneXpert TV assay, a moderately complex rapid molecular test capable of detecting Trichomonas vaginalis from a wide range of specimen types, including vaginal swabs, endocervical swabs, urine from both female and male patients, with results available in less than an hour. The GeneXpert platform's versatility and widespread installation base provide Cepheid with a strong foothold in hospital and reference laboratory settings, particularly where multiplex testing and high specificity are required. The assay is FDA-cleared for detection in female urine, endocervical swabs, patient-collected or clinician-collected vaginal specimens, and male urine specimens, aligning with comprehensive CDC STI treatment guidelines.
Beyond individual company profiles, the full report analyzes the broader competitive structure, noting that the top three players account for over half of the market revenue, while the top five collectively represent more than 72 percent. This concentration highlights the dominance of established entities with specialized product clearances and strong distribution networks, while also signaling opportunities for emerging players who can introduce disruptive technologies or expand into underpenetrated geographic segments.
Industry Dynamics: Regulation, Reimbursement, and Clinical Validation
The market's evolution is heavily influenced by regulatory milestones and clinical evidence that shape adoption patterns. Recent developments underscore the pace of innovation and the tightening of evidentiary standards. In March 2025, Visby Medical received FDA clearance for its Sexual Health Test, a significant event that granted marketing authorization for an at-home diagnostic test for STIs, including Trichomonas vaginalis, in women with or without symptoms. This clearance also included a CLIA waiver for point-of-care PCR testing, signaling a potential paradigm shift toward highly accurate molecular testing accessible outside traditional laboratory settings. Such regulatory breakthroughs lower barriers to entry for decentralized testing and expand the addressable market for companies aligned with these technological capabilities.
Clinical validation continues to reinforce the utility of rapid testing modalities. A meta-analysis published in July 2025 in the Journal of Lower Genital Tract Disease evaluated rapid antigen tests for trichomoniasis, reporting a pooled sensitivity of 87.0 percent and specificity of 98.3 percent across 5,884 samples. These performance metrics provide robust support for the use of antigen-based rapid tests in screening and diagnostic algorithms, balancing the need for speed with acceptable accuracy. For product developers and market strategists, such data points are critical for substantiating claims, guiding healthcare provider education, and influencing procurement decisions.
Regulatory and reimbursement landscapes further complicate the strategic picture. The distinction between CLIA-waived and moderately complex tests affects where and how assays can be deployed, influencing the total addressable market for each product. Reimbursement pathways, including associations with Medicare procedure codes for infectious agent antigen detection, directly impact the financial viability of testing programs and the willingness of providers to adopt specific solutions. Our report dissects these dynamics, providing clients with a clear understanding of the regulatory hurdles, reimbursement opportunities, and compliance requirements that will define market access in the coming years.
Strategic Imperatives for 2026 Decision-Makers
The insights contained within the Worldwide Trichomonas Rapid Testing Market report are designed to translate complex market data into actionable intelligence for 2026. As the industry moves past the 2025 baseline, several strategic imperatives emerge for stakeholders aiming to maximize their position in the growing market.
For manufacturers, the divergence between antigen and molecular technologies presents a critical portfolio strategy question. The sustained demand for rapid, CLIA-waived antigen tests suggests continued relevance for lateral flow solutions, particularly in decentralized and resource-constrained settings. Simultaneously, the growth of molecular assays and the emergence of at-home PCR testing indicate that investment in nucleic acid detection platforms may offer higher-margin opportunities and alignment with the trend toward higher diagnostic accuracy. Companies must evaluate their R&D pipelines, manufacturing capabilities, and regulatory strategies against these dual tracks to ensure they capture value across the spectrum of testing needs.
For distributors and service providers, understanding the geographic and end-user segmentation is vital for targeting go-to-market efforts. The concentration of revenue in North America and Europe requires sustained commitment to these mature markets, where competition is fierce and differentiation depends on service quality, reimbursement support, and clinical evidence. Conversely, the growth potential in Asia Pacific and other emerging regions demands a nuanced approach that accounts for local healthcare infrastructure, pricing sensitivities, and regulatory environments. Tailoring distribution partnerships and product offerings to the specific needs of diagnostic laboratories, hospitals, clinics, and the burgeoning self-testing segment can unlock incremental growth.
Investors and financial analysts will find value in the market concentration data and growth projections, which highlight the stability provided by leading players while also identifying the potential for disruption. The high market share held by the top firms suggests barriers to entry, but recent regulatory clearances for innovative at-home and point-of-care molecular tests demonstrate that new entrants can gain traction by addressing unmet needs in convenience and accessibility. Monitoring the clinical evidence base, such as the sensitivity and specificity data from recent meta-analyses, is essential for assessing the long-term viability of different testing technologies and the competitive moats of incumbent suppliers.
Worldwide Trichomonas Rapid Testing Market
Conclusion: Unlocking the Full Strategic Picture
The Worldwide Trichomonas Rapid Testing Market is at a juncture where historical growth, technological innovation, and regulatory evolution converge to create a dynamic environment for the next seven years. The projected revenue expansion to over 1 billion USD by 2032, supported by a 6.3 percent CAGR, signals a market with substantial opportunities for those equipped with the right intelligence. However, capturing these opportunities requires more than a high-level overview; it demands a granular understanding of segmentation flows, competitive vulnerabilities, regulatory nuances, and the specific dynamics that will drive adoption across regions and end-user groups.
PW Consulting's full market study provides the depth and precision required for confident strategic planning. The report delivers comprehensive segmentation analysis, detailed company profiles, an assessment of market concentration, and an exploration of the key dynamics shaping the industry. It equips executives, product leaders, and investors with the data necessary to forecast demand, optimize portfolios, identify partnership opportunities, and navigate the complexities of the global diagnostic landscape. To access the complete dataset, regional breakdowns, and the full suite of strategic analyses that will inform your 2026 decisions and beyond, we invite you to explore the full report on our website. The complete intelligence is available to guide your strategy with clarity and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Trichomonas Rapid Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


