



Category: market research
PW Consulting: LNG Market to Expand at a 4.09% CAGR, New Market Insights Report Finds
By PW Consulting, 2026-07-02
PW Consulting Releases Strategic LNG Market Briefing: Navigating 2026 with a Data-Driven Playbook
PW Consulting today announces the release of its flagship LNG Market research briefing — a focused, decision-grade analysis built to inform executive choices in 2026 and beyond. The report synthesizes an exhaustive historical view (2020–2025) with forward-looking scenarios for 2026–2032, delivering a consolidated market baseline (USD denominated, revenue unit: Billion) and a forecast path that reflects a compound annual growth rate (CAGR) of 4.09% through 2032. With the global market at an estimated USD 135.0 Billion in 2025 and evolving to a materially larger footprint through our forecast horizon, this briefing translates macro trends into immediate strategic imperatives for producers, midstream players, traders, investors and policy teams.
LNG Market
Why this briefing matters for 2026 decision-making
-
Translate macro momentum into tactical plans — Our baseline and scenario outputs convert headline growth (CAGR 4.09%) into actionable risk-return profiles for new liquefaction capacity, offtake arrangements, and trading exposures.
LNG Market -
Bridge near-term volatility with medium-term strategy — We show how short-term price signals and permit dynamics interact with multi-year project economics, enabling more resilient CAPEX and contracting choices.
LNG Market -
Prioritize where optionality matters most — The briefing highlights where optionality (financial, technical, and contractual) delivers the highest value in an environment of regulatory shifts and evolving trade flows.
Key market dynamics shaping 2026 strategies
-
Commodity-price environment: Henry Hub spot prices averaged approximately $3.50/MMBtu in 2026 — a contextual anchor for cost-of-gas modelling, project sanction thresholds, and trading strategies. Our models show how this level affects margin volatility across different commercialization structures.
-
Permitting and regulatory shifts: The United States’ decision to lift the pause on LNG export permits for non‑free trade agreement countries (Jan 2025) materially changes export optionality for U.S. projects and recalibrates destination-flexibility economics.
-
Policy and fiscal environment: National-level policy changes enacted in 2025 have reshaped incentives for clean-tech manufacturing and energy projects. These shifts change the relative attractiveness of domestic value-add versus export-oriented strategies.
-
Project milestones and commercial activity: Recent milestones — from first production at new projects to multi-year offtake agreements — are creating pockets of incremental supply that will be decisive at the margin for price formation and contract structures in 2026.
Competitive landscape — who matters (and why)
The LNG value chain remains concentrated by incumbent scale players, with a top-three concentration that signals material market power and a top-five concentration that underscores a clustered supplier base. That configuration presents both entry barriers and strategic openings for agile challengers and new project models.
-
Cheniere Energy, Inc. — As an operator of major U.S. liquefaction and export terminals, Cheniere’s scale and cargo cadence set benchmarks for export logistics and contract flexibility. Recent production records underscore its operational leverage and the implications for spot-versus-contract dynamics.
-
Venture Global LNG — The company’s project-development trailblazing in the U.S. demonstrates faster-cycle, modular approaches to capacity build-out. This model pressures traditional capex timelines and provides alternative partnership frameworks for buyers seeking flexible supply.
-
Petronas — With integrated production and export capabilities across multiple geographies, Petronas exemplifies a sovereign-backed producer strategy that blends long-term portfolio optimization with regasification and downstream positioning.
-
International majors (ExxonMobil, Shell, Chevron, BP, TotalEnergies) — These firms combine project development, trading sophistication and integrated marketing. Their balance-sheet strength and trading book capabilities are decisive for short‑term price management and long‑term portfolio optimization.
Our briefing assesses these players not as static incumbents but as vectors of strategic behavior: where they invest, how they price optionality, what offtake structures they prefer, and where partnerships or divestments are most likely. We provide a strategic scorecard that ranks players on execution risk, market influence and strategic flexibility — enough signal to inform competitive playbooks without disclosing proprietary positioning metrics.
Recent developments with material strategic implications
-
Project entry: First production at a major U.S. project in early 2026 adds near‑term export tonnage and changes the effective marginal supplier in Atlantic Basin markets.
-
Long-term offtake agreements: Multi‑decade offtake deals announced in 2026 illustrate continued buyer appetite for anchored supply, but our analysis shows these deals increasingly include price‑linkage and destination flexibility clauses that shift commercial dynamics.
-
Operational performance: Leading exporters reported record cargoes in 2025, tightening the lens on operational uptime, ship scheduling and liquefaction reliability as determinants of short‑term market outcomes.
-
Portfolio evolution: Major national and oil‑major players released updated activity outlooks in early 2026, highlighting regasification and downstream upgrades alongside continued LNG portfolio development.
What’s inside the PW Consulting LNG Market briefing
-
Integrated market model (2020–2032) — reconciled historicals, 2026 baseline and scenario branches with price‑supply sensitivity. The model is delivered in a format that supports immediate plug‑and‑play for bespoke risk analysis.
-
Scenario library — three calibrated scenarios (Central, Upside, Downside) that stress-test commodity, permit, and demand assumptions to reveal tipping points for sanction decisions.
-
Project-level impact templates — a standardized spreadsheet and scoring tool that evaluates new-build and brownfield options across execution risk, netback economics, and financing sensitivity.
-
Contracting playbook — practical negotiation levers for offtake structures, price indexation blends, destination clauses and flexibility premiums that are most likely to preserve value under volatility.
-
Regulatory risk matrix — mapping of critical policy levers (permits, trade policy, subsidy changes) with geographic sensitivity and remediation strategies for market participants.
-
Trading and logistics operational checklist — freight and ship scheduling sensitivity, chartering considerations, and operational KPIs that materially affect near-term P&L.
-
M&A and JV playbook — prioritized acquisition and partnership targets by strategic rationale: capacity growth, market access, trading capability, or technological lift.
How executives should apply the briefing in 2026
-
Producers evaluating sanction decisions — use the scenario outputs to identify the minimum price-path and permit environment required to preserve required IRR under alternative capex phasing.
-
Midstream and terminal operators — employ our project-level scoring to prioritize brownfield upgrades and where to invest in operational resilience to capture premium cargoes.
-
Traders and offtakers — adopt the report’s contracting playbook to incorporate destination flexibility, seasonal shaping, and price-linkage constructs that reduce basis risk.
-
Investors and portfolio managers — align asset allocation with scenario-driven probabilities and use the regulatory risk matrix to stress-test sovereign and corporate exposures.
Methodology and data integrity
The briefing is built from a triangulation of primary and secondary sources: audited company reports, public project trackers, shipping and cargo databases, commodity pricing series (including Henry Hub), regulatory filings and targeted expert interviews. The report uses 2025 as its base year, validates historicals for 2020–2025 and projects through 2032 using a combination of bottom‑up project schedules and top‑down demand forecasting. Our scenario framework explicitly models permit timing, price regimes and policy shocks to reflect the most relevant strategic inflection points for 2026 decisions.
Next steps: where to get full access
This release is a strategic synopsis designed to communicate the evidence-based choices available to executives in 2026. It purposefully presents the narrative and decision logic while reserving detailed segment-level schedules, transaction-grade valuations, and granular regional splits for the full report and underlying dataset. Those who need the complete data tables, the downloadable model, and the extended strategic annex (including our project-by-project universe and negotiation templates) may access the full report via PW Consulting’s report page.
Contact your PW Consulting account lead for an institutional briefing, model walkthrough, or a customized workshop designed to embed these insights into your 2026 planning cycles. Our analysts stand ready to translate the report’s strategic imperatives into a bespoke action plan tailored to your organization’s risk appetite and growth objectives.
For detailed analysis of this topic, please visit the official page: LNG Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cucurbituril Market to Rise from USD 62.36 Million in 2025 to USD 127.86 Million by 2032 at a 10.8% CAGR, Fueled by Drug‑Delivery Demand
By PW Consulting, 2026-07-02
Cucurbituril Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Preview
As organizations position for growth in specialty supramolecular chemistries, our new Cucurbituril Market study offers a focused, actionable line of sight into where value will crystallize between 2026 and 2032. The global cucurbituril market — having expanded from a modest research commodity into a commercially meaningful industrial chemistry platform — reached an estimated USD 62.36 Million in 2025 and is forecast to move to roughly USD 69.8 Million in 2026, before accelerating at a projected compound annual growth rate (CAGR) of 10.8% through the 2026–2032 forecast window. This preview outlines the report’s strategic value for enterprise decision-makers while withholding detailed segment-level tables to encourage full-report access for transaction- and project-level intelligence.
Cucurbituril Market
Why cucurbiturils matter in 2026
Cucurbiturils have migrated from predominantly academic interest into targeted industrial adoption. Advances in kilogram-scale manufacturing, functional substitution chemistries, and commercialization of encapsulation technologies mean cucurbiturils are now enabling commercial propositions across drug delivery, chemical sensing, catalysis, and emerging environmental applications. For executives, 2026 is a pivotal year: product development cycles initiated in 2023–2025 are reaching scale-readiness, and procurement, regulatory, and partnership decisions made this year will determine market access and margins for the remainder of the decade.
Cucurbituril Market
What the PW Consulting report delivers (practical, transaction-ready outputs)
- Market sizing and trajectory — validated historical time series (2020–2025), a 2026 baseline, and forward-looking forecast through 2032 (with scenario bands and sensitivity analyses tied to feedstock volatility and commercialization pace).
- Supply-chain intelligence — mapping of raw material flows (including glycoluril as the principal upstream feedstock), cost pools, bottlenecks, and supplier qualification frameworks for industrial purchasing and risk mitigation.
- Technology and product profiles — synthesis routes, functional-derivative classes, scale-up challenges, and performance trade-offs (water solubility, cross-linking capacity, inclusion-compound stability) that inform R&D prioritization and specification writing.
- Go-to-market playbooks — practical strategies for B2B and B2C adoption across targeted end uses (pharmaceutical formulations, VOC/odour control, sensing devices, catalytic systems), including partner archetypes and commercialization timelines.
- Competitive and sourcing due diligence — supplier scorecards, certifications and compliance checklists, contract templates, and integration pathways for verticalization or toll-manufacturing.
- Regulatory and IP landscape — a focused review of safety, registration, and intellectual property hotspots that affect launch timelines and exclusivity strategies.
- M&A and investment thesis — acquisition targets, valuation levers, and integration risks for private equity and strategic buyers looking to consolidate capacity, technology, or market access.
High-level market dynamics (what the numbers imply)
The market’s trajectory reflects a dual dynamic: accelerating demand as commercial applications move beyond niche laboratory use, and continued maturation of supply capabilities that reduce unit costs and enable larger-volume use cases. The jump from roughly USD 38.5 Million in 2020 to USD 62.4 Million in 2025 underscores rapid commercialization catalyzed by both consumer-product encapsulation solutions and pharma/science-led applications. The projected 10.8% CAGR from 2026 to 2032 signals material expansion, but it is not evenly distributed — growth will be concentrated where functionalized materials and validated end-market use cases coalesce.
Cucurbituril Market
For procurement and corporate strategy teams, the practical takeaway is clear: securing reliable, quality-assured supply now reduces exposure to premium spot prices and capacity constraints later. For R&D and product teams, the window to convert laboratory promise into scalable differentiated products is narrow but definable.
Competitive landscape: who to watch and why
Our market mapping highlights a heterogeneous supplier ecosystem comprised of specialist industrial manufacturers, research-grade chemical houses, and application-focused technology companies. Key players include:
- Cucurbituril Family Biomaterial Technology Co., Ltd (China) — a leader in bulk and kilogram-scale production and the industrialization of both standard and substituted cucurbiturils. Their breadth of product forms — from hydroxyl-substituted homologues to open-loop and functional derivatives — makes them a preferred partner for customers requiring customized, production-ready materials.
- Strem Chemicals, Inc. (Newburyport, MA, USA) — a trusted supplier of high-purity research-grade cucurbiturils and a recent expander of kit offerings supporting supramolecular chemistry research; relevant for early-stage R&D and fine-chemical applications.
- Aqdot Ltd (Cambridge, UK) — a commercializer of a patented cucurbituril-based encapsulation platform (AqFresh™) that is already production-validated for odour and VOC removal in consumer and indoor-air products — an important example of a route-to-market beyond pure chemistry supply.
- Merck KGaA / Sigma-Aldrich (Germany) — continues to supply research-grade cucurbiturils and plays an influential role in standards-setting and early supply for new laboratory-to-market workflows.
- Regional Chinese manufacturers and traders (multiple firms) — several firms now provide kilogram- and drum-scale product options, with differing degrees of quality certification (ISO, REACH) and vertical integration; they are central to cost dynamics and supply availability for industrial customers.
- Specialty service suppliers — firms that provide application engineering, encapsulation formulation support, and toll-manufacture to bridge laboratory formulations to industrial production.
Our competitive assessment examines each company across four dimensions: scale and capability, product breadth and differentiation, regulatory/compliance posture, and customer/industry focus. Readers of the full report receive anonymized supplier scorecards and negotiation playbooks tailored to upstream purchasing, co-development partnerships, and acquisition screening.
Supply chain realities: a pragmatic lens
Glycoluril serves as the primary upstream feedstock for cucurbituril synthesis via classic acid-catalyzed condensation with formaldehyde. This upstream linkage introduces two practical constraints worth acting on in 2026:
- Feedstock security: Any supply disruption or price volatility in glycoluril or formaldehyde disproportionately affects margin and lead time for cucurbituril producers. Companies with long-term feedstock agreements or backward integration will have a structural advantage.
- Process optimization: Scale-up risk is not purely a matter of capacity — yield improvements and impurity control in synthesis directly influence the economics of differentiated derivatives. Capital investment in process chemistry and quality systems delivers outsized returns.
Strategic actions for 2026 — recommended priorities
Based on our scenario modeling and supplier engagement analysis, we advise companies to pursue a prioritized set of actions this year:
- Secure tiered supply arrangements: negotiate a mix of long-term offtake and validated spot capacity to balance cost and flexibility. Include quality and change-control clauses to manage specification drift as functional derivatives are introduced.
- Partner for application validation: engage with technology-commercialization players (e.g., encapsulation specialists and formulation houses) to derisk go-to-market pathways, particularly in consumer and pharma channels.
- Invest selectively in downstream capability: target pilot-scale co-manufacturing or tolling agreements rather than immediate full vertical integration unless your core strategy is control of IP and manufacturing economics.
- Prioritize regulatory and IP diligence: map registration timelines, safety testing needs, and patent landscapes to avoid launch delays and to protect margin-preserving differentiation.
- Design modular product portfolios: align R&D roadmaps to capture both premium niche uses (e.g., targeted drug-delivery systems) and volume-led industrial applications (e.g., sensing, wastewater treatment) without overcommitting to a single commercialization model.
Use cases and commercial timing
Our report provides a time-to-value matrix for core application clusters — identifying which end markets are near-term revenue drivers versus longer-horizon strategic plays. For example, validated consumer/OA (odour and VOC) solutions can be commercialized rapidly via formulations and private-label partnerships; conversely, pharmaceutical and specialized catalysis applications typically require longer development and regulatory timelines but deliver higher margins for differentiated intellectual property.
How to use this preview and next steps
This article is a strategic primer designed to orient executives to the opportunities and decision-relevant risks in 2026. The full PW Consulting Cucurbituril Market report contains the complete set of quantitative segmentations, supplier scorecards, price modeling, and downloadable negotiation templates that commercial and investment teams need to operationalize the guidance summarized here. To move from strategic intent to execution, our recommended next steps are:
- Acquire the full report for transaction-grade tables and supplier analytics;
- Schedule a briefings workshop with our industry team to map your specific portfolio and procurement options against our scenarios;
- Commission a targeted supplier due diligence or pilot partnership assessment if you plan capital deployment or M&A in the next 6–12 months.
Closing perspective
The cucurbituril market in 2026 sits at an inflection point: broader application adoption is beginning to meet industrial-scale supply capability. For companies that move decisively — securing supply, aligning R&D to validated commercial pathways, and protecting differentiation — the next two to three years will deliver disproportionate advantage. PW Consulting’s full study offers the empirical foundation and execution playbooks to make those decisions with confidence. For stakeholders evaluating entry, expansion, or consolidation in the cucurbituril value chain, 2026 is the year to turn strategic intent into measurable action.
To access the complete report, supplier scorecards, and bespoke advisory services, please visit the PW Consulting insights portal (full report access and licensing details available there).
For detailed analysis of this topic, please visit the official page: Cucurbituril Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roadmarking Paints Market to Grow at a 5.8% CAGR, Reaching USD 10,600 Million by 2032
By PW Consulting, 2026-07-02
Roadmarking Paints Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As infrastructure programs accelerate and sustainability requirements tighten, the global roadmarking paints market is entering a phase of measured expansion and fragmentation. PW Consulting’s upcoming Roadmarking Paints Market report — based on a 2025 base year and a detailed 2020–2025 historical analysis — projects steady growth through the 2026–2032 forecast window, with a compound annual growth rate (CAGR) of 5.8%. Our proprietary modelling anticipates that the market, which crossed a notable milestone in 2025, will continue to expand through 2032 as governments and private owners prioritize safety, lifecycle cost reductions, and lower environmental impact.
Roadmarking Paints Market
Why this matters for 2026 corporate decision-making
- Timing of investment: With predictable mid-single-digit growth, 2026 becomes an inflection year for capital allocation — a point at which market leaders must choose between scale-driven consolidation and targeted differentiation.
- Regulatory alignment: An evolving suite of standards and VOC-focused environmental regulations is reshaping product portfolios; firms that align R&D and compliance efforts now will avoid costly retrofits later in the decade.
- Margin resilience: Raw material volatility — notably in specialty resins, thermoplastic compounds, and reflective glass beads — is creating intermittent margin pressure. Procurement strategies implemented in 2026 will materially affect profitability through 2028.
Key macro indicators from our analysis
- Recent historical performance shows clear recovery and acceleration post-2020 structural disruptions, supporting the 2026 growth baseline.
- Forecast trajectory into 2032 indicates steady expansion — a window that favors companies with multi-year product roadmaps and disciplined supply-chain risk management.
- Market concentration analysis reveals a moderate-to-high level of aggregation among leading suppliers, implying both barriers to entry for scale-dependent segments and meaningful opportunities for specialist challengers.
What the report contains — practical, decision-ready assets
PW Consulting has structured the report to serve as a working toolkit for executives, procurement leads, and strategy teams. Highlights include:
Roadmarking Paints Market
- Executive dashboard: A one-page strategic view tying market trajectory, regulatory events, and raw-material risk to likely margin outcomes under alternative scenarios.
- Scenario modelling: Three plausible market pathways (conservative, base-case, accelerated adoption) that quantify revenue and margin impacts through 2032 and identify timing triggers for strategic moves.
- Supplier scorecards: Comparative assessments across technology, regulatory readiness, pricing power, and aftermarket support — designed for sourcing decisions and partnership screening.
- Cost-sensitivity toolkit: A modular model isolating the impact of feedstock price swings (e.g., resins and glass beads), labor, and logistics on product-level margins.
- Regulatory compliance blueprints: Roadmaps to align formulations with the latest VOC and product-spec standards, including practical steps to certify products against updated national specifications.
- Go-to-market playbooks: Channel strategies for contractors, municipalities, and airports, including tender tactics, bundled service offers, and digital monitoring tie-ins to lock recurring revenues.
- M&A and partnership map: Identification of target profiles for bolt-on acquisitions versus JV candidates, supported by valuation sensitivities and operational integration checklists.
Dynamics shaping the market in 2026
Several structural forces converge in 2026 to define winners and laggards:
Roadmarking Paints Market
- Raw material volatility: Price swings across specialty chemicals and reflective media are unevenly distributed across suppliers. This volatility constrains adoption of higher-cost technologies in budget-sensitive infrastructure programs and amplifies the value of multi-source procurement and hedging instruments.
- Regulatory tightening: Updated national specifications and increasingly stringent VOC limits are accelerating demand for low-emission waterborne and two-component systems. Compliance is not optional — it is a market-access requirement in many procurement pipelines.
- Product innovation pressure: Durable, fast-curing formulations and enhanced retroreflectivity are moving from R&D into early commercialisation. Firms able to scale these formulations without compromising margins will command premium contracts.
- Serviceization and digital monitoring: Asset-management platforms that tie pavement markings to maintenance schedules and IoT-based condition monitoring are emerging as differentiators for contractors and municipalities seeking lifecycle cost reductions.
Competitive landscape — what to watch in 2026
The market exhibits a mix of global coating majors, specialized line-marking manufacturers, and regional players with strong local approvals and distribution. Leading firms balance product breadth with regulatory credentials and channel relationships.
- PPG Industries (ENNIS-FLINT by PPG) : A legacy player with a wide portfolio of waterborne and solvent-based traffic paints. Strengths include global manufacturing footprint and established relationships with large contractors; near-term imperatives include accelerating low-VOC product rollouts and optimizing glass-bead supply to reduce exposure to fluctuating raw-material costs.
- Swarco : Known for a diversified offering spanning solvent-based, waterborne, and two-component systems. Swarco’s engineering-led approach positions it well for bundled infrastructure solutions; success in 2026 will hinge on converting system-level advantages into scalable service contracts.
- Meon Ltd : A specialist in line marking paints and cold plastic systems with strong acceptance in specific markets. As demand for longer-lasting cold plastic increases in targeted segments, Meon’s agility and niche expertise can capture premium tenders, provided it secures upstream supply consistency.
- Axalta Coating Systems : Offers traditional spirit-soluble and modified alkyd formulations with heritage relationships in industrial sectors. The company’s challenge is to pivot rapidly enough toward low-VOC formulations while preserving competitive cost structures for price-sensitive projects.
- Cloverdale Paint Inc : A regionally-focused contender whose waterborne traffic paints carry local approvals. Its strength lies in certified specifications and localized service; scaling beyond regional barriers will require selective partnerships or licensing strategies.
Our competitive assessment reiterates that scale and regulatory readiness matter, but so do focused technical capabilities and local approvals — especially where specification updates demand certified formulations.
Strategic recommendations for 2026
- Implement a raw-material hedging and supplier diversification program. Given observed volatility in specialty glass beads and thermoplastic resins, allocate procurement effort to multi-year supply agreements and qualifying secondary suppliers now.
- Prioritise low-VOC and performance-certified formulations. Regulatory momentum is not a short-term blip; aligning R&D priorities to current and anticipated standards will protect access to public tenders and airport contracts.
- Adopt service-led commercial models. Transitioning from one-off product sales to performance guarantees and condition-based maintenance contracts can smooth revenue streams and improve customer retention.
- Pursue selective M&A to plug capability gaps. For firms lacking either specialized polymers or local certification footprints, targeted acquisitions or licensing can be faster and less risky than greenfield expansion.
- Invest in digital and monitoring capabilities. Pair formulations with simple condition-assessment tools to demonstrate lifecycle value to procurement authorities — a selling point that increasingly decides tenders.
- Design flexible pricing mechanisms. Build indexed clauses into public-contract bids to mitigate margin erosion from feedstock price spikes.
Implications of market concentration
With a moderate-to-high concentration among the leading suppliers, competition will be shaped by scale economics in commoditized product classes and by technical differentiation in premium segments. For challengers, the path to growth is often through niche differentiation, certified formulations, or service bundles. For incumbents, 2026 should be used to solidify distribution, secure long-term feedstock access, and make disciplined plays to consolidate capability gaps.
Conclusion — the strategic window in 2026
PW Consulting’s analysis shows that 2026 represents a strategic decision point: firms that shore up supply resilience, align product portfolios with tightening regulations, and innovate around service-led offers will capture outsized value over the remainder of the forecast period. Conversely, those that rely solely on legacy formulations or single-source procurement risk margin compression and restricted market access.
The full Roadmarking Paints Market report delivers the granular, transaction-ready data and models you need to make these 2026 choices with confidence — including scenario outputs, supplier-level scorecards, regulatory timelines, and a detailed playbook for procurement and go-to-market execution. For access to the complete dataset, interactive models, and the step-by-step implementation guide, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2,5‑Dimethyl‑2,4‑Hexadiene Market Poised for 4.51% CAGR Through 2026–2032
By PW Consulting, 2026-07-01
PW Consulting: Strategic Insights — 2,5‑Dimethyl‑2,4‑Hexadiene Market (2026 Strategic Edition)
PW Consulting’s newest market study on 2,5‑Dimethyl‑2,4‑Hexadiene provides a compact, action‑oriented intelligence package designed for executive teams preparing budgets, procurement strategies, and M&A roadmaps in 2026. Built on a comprehensive historical base (2020–2025) with 2025 as the reference year and extending through a seven‑year forecast window (2026–2032), the report frames the market in monetary terms (USD, revenue unit: Million) and models growth under multiple scenarios. At the macro level, the market demonstrated steady expansion from the early 2020s and reached approximately USD 42.5 Million in 2025, with projections showing continued growth at a compound annual growth rate (CAGR) of c. 4.51% across the 2026–2032 forecast period.
2,5-Dimethyl-2,4-Hexadiene Market
Why this report matters for 2026 decision‑makers
- Procurement predictability: A measured CAGR and modeled near‑term uplift provide the scaffolding procurement teams need to negotiate multi‑year supply agreements without relying solely on spot market volatility.
- Risk‑aware sourcing: The market’s structure signals concentrated supply dynamics; where 3–5 incumbent suppliers capture a dominant share, sourcing teams must balance cost with continuity and compliance.
- Product and purity choices: Differential purity tiers (laboratory reagents vs industrial/bulk grades) create distinct pricing, qualification, and regulatory pathways—critical for product development and quality assurance.
- Strategic M&A and partnerships: Mid‑market players and specialized reagents distributors present asymmetric opportunities for vertical integration or bolt‑on acquisitions to secure feedstock-to-finished‑product margins.
Market dynamics: drivers, supply chain realities, and raw material constraints
The demand base for 2,5‑Dimethyl‑2,4‑Hexadiene is shaped by several durable industrial vectors: synthesis of pyrethroid insecticides, applications as intermediates in flavors & fragrances, and use in specialty organic syntheses. Upstream, the molecule’s production routes remain linked to C4 hydrocarbon chemistry. Historic and still‑referenced synthesis routes employ acid‑catalyzed condensations using isobutylene (or tert‑butanol) and isobutyraldehyde—feedstocks that originate in refinery and petrochemical C4 streams. This technical dependency creates two structural exposures:
2,5-Dimethyl-2,4-Hexadiene Market
- Feedstock cyclicality: Volatility in C4 streams (driven by refinery throughputs and olefin cracks) transmits to intermediate pricing and availability.
- Processing risk profile: Legacy acid‑catalyzed chemistries are well‑understood but sensitive to material impurity profiles and require robust QA‑QC regimes for industrial scale‑ups.
On the demand side, substitution dynamics are modest in the near term because the molecule serves specific synthetic roles that are not easily replaced without re‑engineering downstream formulations. That said, incremental shifts in agrochemical formulation trends and fragrance industry preferences can change mix and pricing over a multi‑year horizon.
2,5-Dimethyl-2,4-Hexadiene Market
Competitive landscape — who matters and what to watch
The competitive set is a blend of established fine‑chemical distributors, reagent houses, and regionally focused manufacturers/traders. Key commercially visible firms include Tokyo Chemical Industry (TCI) and Sigma‑Aldrich (Merck) — organizations that position product offerings for laboratory, R&D and small‑scale synthesis with standardized packaging and purity controls. On the other end of the spectrum, a cohort of China‑based manufacturers and traders provide higher‑purity grades and bulk packaging options oriented to industrial customers.
- Laboratory/reagent suppliers (e.g., TCI, Sigma‑Aldrich): Emphasize certified purity claims, small‑pack consistency, and global distribution channels. They are the default choice for R&D and regulated environments where traceability is a purchasing criterion.
- Industrial/bulk suppliers and traders: Offer higher‑purity bulk volumes and flexible packaging, often with cost advantages for scale users. These suppliers are operationally critical for formulators and manufacturers that require larger throughputs.
- Distributor hybrids and specialty chemical houses: Bridge the gap between small‑pack reagent markets and industrial needs by offering quality documentation, multi‑tiered capacity and regional warehousing.
For strategic planners, supplier selection should be predicated on three interlocking factors: purity specification and analytical traceability; guaranteed availability and logistics resilience; and the supplier’s compliance posture and quality certification. The market’s concentration profile—where a modest number of players account for the majority of supply—amplifies the consequences of single‑supplier dependencies and underlines the need for dual‑sourcing, inventory buffers, and contractual protections.
Operational playbook: five tactical moves for 2026
- Segment purchasing by use‑case: Separate R&D/lab reagent purchases (prioritizing certified small‑pack vendors) from production purchases (targeting bulk suppliers with QA systems and consistent lot tracking).
- Lock partial volumes on formula‑linked contracts: Negotiate hybrid contracts with indexation to upstream C4 feedstock proxies, fixing a portion of volumes at stable terms while retaining optionality for spot buys.
- Qualify second‑source suppliers ahead of need: Pre‑qualify at least one alternative supplier per major production site with audit protocols, analytics comparison, and pilot‑scale deliveries to avoid time‑to‑switch delays.
- Invest in analytical capabilities: Bolster in‑house GC/MS and impurity profiling to reduce lot rejection risk and shorten supplier qualification cycles.
- Scenario planning and hedging: Use the report’s scenario models to stress‑test procurement budgets against feedstock shocks, regulatory turn, or sudden demand changes in end‑markets like agrochemicals.
Regulatory, quality and sustainability implications
While the molecule itself is primarily an industrial intermediate, adjacent compliance areas matter. Quality systems (ISO, GMP where relevant), export controls on precursor chemicals, and environmental permit constraints tied to upstream feedstock handling impact suppliers and customers alike. Sustainability conversations are nascent but increasing as downstream formulators seek traceability and carbon visibility across petrochemical inputs. Buyers should include supplier greenhouse‑gas disclosures and feedstock sourcing transparency in 2026 RFPs to anticipate future customer and regulatory requirements.
What the PW Consulting report delivers (practical contents)
This research package combines quantitative market sizing and forecasting (USD Million, 2020–2032 horizon) with qualitative and operational tools that executives can use immediately:
- Base‑case, upside and downside forecast scenarios and sensitivity matrices driven by feedstock and demand levers.
- Supply chain maps and capacity overlays, highlighting strategic chokepoints and lead‑time implications.
- Supplier dossiers and a comparative playbook covering purity tiers, package formats, and qualification criteria.
- Pricing and cost‑pass through frameworks with build‑ups tied to C4 hydrocarbon proxies.
- Regulatory and sustainability risk matrices with mitigation pathways and contract language examples.
- M&A and partnership opportunity screen with acquisition yardsticks and integration risk checklists.
- Actionable procurement templates: RFP language, audit checklists, and contingency stock calculation tools.
How to incorporate this intelligence into your 2026 planning cycle
Use the report to align three planning horizons:
- Near‑term (0–12 months): Operationalize supplier audits, finalize inventory strategies, and implement dual‑sourcing where feasible.
- Medium term (12–36 months): Embed contracted volumes into financial forecasts, pursue targeted partnerships or tolling arrangements, and add analytical capability to reduce qualification timelines.
- Strategic (36+ months): Evaluate vertical integration, selective bolt‑on acquisitions, or long‑term offtake agreements to secure feedstock‑to‑product margins and resilience against upstream shocks.
Closing perspective and next steps
2026 will be a year in which informed positioning—rather than opportunistic buying—creates sustainable competitive advantage in the 2,5‑Dimethyl‑2,4‑Hexadiene value chain. PW Consulting’s study converts market noise into structured decision levers: calibrated forecasts (2026–2032), supplier and purity segmentation, and operational playbooks that reduce execution risk. The study reveals where margin capture is most plausible, how to harden supply chains against feedstock cyclicality, and which supplier archetypes to partner with depending on your use case.
For procurement leaders, R&D heads, and corporate development teams preparing 2026 plans, the full report contains the data tables, supplier scorecards, and scenario models needed to move from strategy to contract. Access the full dossier and interactive dashboards through our official report page to retrieve the underlying charts, supplier rankings, and downloadable procurement templates.
For detailed analysis of this topic, please visit the official page: 2,5-Dimethyl-2,4-Hexadiene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Waste Paper Reuse Market Poised for 5.2% CAGR in 2026–2032, Signaling Strong Upswing in Recycling Sector
By PW Consulting, 2026-07-01
Waste Paper Reuse Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
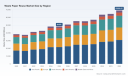
PW Consulting’s latest Waste Paper Reuse Market report — base year 2025, forecast period 2026–2032 — frames a turning point for companies operating across the recovered-fiber value chain. The global waste paper reuse market reached USD 48,458 Million in 2025 and, under the central case, is projected to expand at a 5.2% CAGR through the forecast window. By 2032 the market is expected to approach the USD 69 billion range, driven by policy acceleration, packaging demand dynamics, and structural shifts in trade and processing capacity.
Waste Paper Reuse Market
Why this report matters for 2026 corporate decision-making
-
Timing: 2026 is the inflection year when regulatory tightening, capital investments and a recovering demand base converge. Companies that align procurement, processing capability and commercial contracts in 2026 will lock in margin and supply advantages for the rest of the decade.
Waste Paper Reuse Market -
Practicality: The report goes beyond high-level forecasts — it contains executable playbooks, ROI models and scenario toolkits that translate the macro trajectory (5.2% CAGR) into boardroom-ready investment decisions and operational KPIs.
Waste Paper Reuse Market -
Risk-to-opportunity mapping: With the market expanding but remaining relatively fragmented (CR3 ≈ 18.5%, CR5 ≈ 24.2%), there is room for consolidators and service innovators. The strategic choices are therefore clear: scale selectively, pursue vertical integration where feedstock security matters, or specialize in premium recycled grades and value-added services.
Market dynamics shaping 2026 strategies
Three structural forces create the near-term playbook for 2026:
-
Policy acceleration and materials stewardship — Extended Producer Responsibility (EPR) rules are being implemented across major jurisdictions; several U.S. states phased in fee obligations and reporting requirements in 2025–2026, while European recycling systems continue to deliver high collection rates. These regulatory shifts reallocate costs along the value chain and elevate supply-chain transparency requirements. Companies must redesign commercial terms and data systems to internalize EPR liabilities and exploit compliance-driven demand for audited recycled content.
-
Trade and feedstock quality constraints — Import restrictions and contamination thresholds in many Asian markets are permanently reshaping global recovered paper flows. Procurers and converters must now optimize for onshore processing and invest in upstream sorting/cleaning to maintain consistent fiber quality, rather than rely on low-cost cross-border arbitrage.
-
Capacity realignment and pricing gravity — 2024–2026 saw meaningful capacity additions and plant modernizations in recycling and containerboard processing, with several large-scale facility projects commissioned or announced. These supply-side investments are gradually absorbing incremental recovered fiber demand, producing an environment where price swings are more closely linked to operational uptime and feedstock quality than to simple supply/demand imbalances.
Operational levers for 2026
Executives and procurement leads should prioritize the following actions immediately:
-
Secure feedstock through diversified channels: blend long-term offtakes with local procurement and strategic partnerships with collection networks to mitigate contamination and logistics risk.
-
Invest in quality capture: incremental CapEx in sorting/optical systems, contamination screening, and baling standards can yield outsized improvements in mill yield and pricing power.
-
Negotiate EPR-aware contracts: renegotiate supplier and customer contracts to crystallize who bears EPR fees, documentation costs, and liability for non-compliant material streams.
-
Adopt agile pricing mechanisms: incorporate quality, tonnage bands and index-linked adjustments to protect margins amid feedstock PPI volatility.
Competitive landscape — what the majors are doing (and why it matters)
The market remains fragmented but strategically active. Several established players are executing clear, differentiated strategies that set reference points for 2026 planning.
-
Integrated paper and packaging leaders such as International Paper, Smurfit Westrock, DS Smith, Mondi, UPM and Stora Enso are leveraging scale in recovered-fiber procurement to secure containerboard and packaging feedstock. Their models emphasize vertical integration, procurement control, and closed-loop partnerships with brand owners seeking recycled content assurances.
-
Waste-to-material specialists — Waste Management, Republic Services, Veolia and Sonoco have doubled down on MRF capacity and downstream sorting to supply mills with cleaner bales. Recent plant openings and upgrades indicate a push to capture higher-margin secondary material flows, partnering directly with mills and converters.
-
Regional champions and 100% recycled players — Companies such as Nine Dragons, Pratt Industries, Cascades and Sappi demonstrate that regional sourcing footprints and dedicated recycled-fiber mills continue to be a viable route to scale. Their operations show how proximity, trade-adaptive strategies and tailored product mixes mitigate contamination and trade restriction risks.
-
Innovation signals — Firms are investing in process automation, advanced sorting sensors, and fibre-restoration techniques to raise the value of lower-grade streams. These tech investments are a competitive differentiator for converters targeting premium recycled-content applications.
Recent public moves underscore these trends — large recycling network expansions, multi-million-pound facility launches, and industry statistics pointing to robust recycled consumption all indicate an industry in structured growth and operational upgrade. PW Consulting’s report synthesizes these company-level actions into strategic options for buyers, processors and investors.
What’s inside the PW Consulting report (practical deliverables)
This is a working intelligence product, built to convert market foresight into executable change across 2026 programs:
-
Scenario models (fast/medium/slow adoption) with sensitivity to policy, trade disruption and feedstock price shocks — each scenario includes P&L impact, balance-sheet sensitivity and decision triggers for capex or M&A.
-
Supply chain maps and feedstock flow visualizations — granular network views highlighting choke points, logistics cost pools and onshore processing opportunities (interactive maps available in the full report).
-
Operational playbooks — step-by-step guidance for MRF upgrades, bale specification standards, contamination mitigation, and yield improvement programs with expected payback periods.
-
Commercial templates and EPR compliance checklists — contract language, fee allocation models and reporting frameworks aligned with emerging EPR regimes to reduce legal and cost uncertainty.
-
Investment assessment tools — CapEx calculators, ROI models and post-merger integration checklists tailored to recycling and secondary-fiber assets.
-
Market intelligence appendices — time-series market size by year (2020–2025 historical, 2026–2032 forecast), price indices and a vendor matrix with capabilities assessment (note: detailed segmentation tables are available in the full report portal).
Implications by stakeholder
-
Paper and packaging converters: Redefine procurement around quality-adjusted cost-per-ton rather than headline price. Invest selectively in upstream sorting partnerships to protect production continuity and recycled-content claims.
-
Waste management and MRF operators: Pursue strategic alliances with mills and converters; prioritize automation and certify bale quality to capture greater downstream share.
-
Brand owners and retailers: Use EPR timelines to lock recycled-content procurement, consider shared investment in collection infrastructure, and align packaging design to maximize recyclability and post-consumer reclamation.
-
Investors and private equity: Look for consolidation targets that unlock scale synergies in feedstock procurement and offer immediate yield improvements via operational upgrades.
Near-term watchlist for boards and CEOs (2026 priorities)
-
Finalize EPR exposure analyses and update commercial terms by Q2–Q3 2026.
-
Allocate capital to purification and sorting (optical sorters, deinking, contamination removal) in markets constrained by import quality limits.
-
Pursue targeted partnerships with waste collectors and MRFs to secure quality streams and reduce logistics cost per recoverable ton.
-
Run a one-quarter sprint to certify bale specifications and traceability to support premium recycled-content contracts.
Conclusion — the 2026 strategic moment
2026 is not merely another year of growth for the waste paper reuse market; it is the year in which policy, processing capacity and commercial frameworks crystallize into durable structural advantages for first movers. With the market base at roughly USD 48.5 billion in 2025 and a forecast CAGR of 5.2% to 2032, firms that convert insight into operational certainty — by securing feedstock, investing in quality capture, and renegotiating commercial models for EPR — will outperform peers.
PW Consulting’s Waste Paper Reuse Market report equips leaders with the models, playbooks and scenario-tested recommendations required to act decisively in 2026. For detailed segmentation, interactive models, company scorecards, and downloadable Excel toolkits, access the full report on our portal — the data and executable templates behind this brief are available to subscribers and corporate clients.
For detailed analysis of this topic, please visit the official page: Waste Paper Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Steering-Wheel Adjustment Motor Market to Rise from USD 1,385.45 Million in 2025 to USD 2,110.88 Million by 2032 (6.19% CAGR) as Asia Pacific Leads with USD 574.23 Million
By PW Consulting, 2026-07-01
Automotive Steering Wheel Adjustment Motor Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
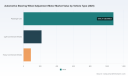
PW Consulting’s new Automotive Steering Wheel Adjustment Motor Market study (base year 2025; historical review 2020–2025; forecast 2026–2032) equips executives with the evidence and frameworks they need to shape profitable, resilient strategies in 2026. At the market level, PW’s topline model places global revenues at USD 1,385.45 Million in 2025 and anticipates growth at a compound annual growth rate (CAGR) of 6.19% over the 2026–2032 forecast window — culminating in a market size of approximately USD 2,110.88 Million by 2032 (USD Million, unless stated otherwise). Market concentration is meaningful: the top three suppliers account for 48.5% of market share, while the top five capture 62.3% — signaling an industry that is neither fully consolidated nor fragmented, and one that rewards targeted capability building.
Automotive Steering Wheel Adjustment Motor Market
Why this report matters for decisions in 2026
-
Actionable sizing and scenario planning: The report provides repeatable top-down and bottom-up sizing approaches that let procurement and product strategy teams stress-test 2026 programs under multiple EV, ADAS and regulatory scenarios.
Automotive Steering Wheel Adjustment Motor Market -
Supply-chain and cost risk quantification: Detailed supplier mapping and raw-material sensitivity models quantify exposure to rare-earth magnet dynamics and logistics disruptions — allowing purchasing leaders to prioritize hedging, localization, or technical substitution.
Automotive Steering Wheel Adjustment Motor Market -
Technology-to-commercial playbooks: For product and R&D leaders, the study lays out motor-architecture trade-offs, integration roadmaps (including steer-by-wire readiness), NVH and crash-safety requirements, and go-to-market approaches tailored to OEM and aftermarket adoption curves.
-
Competitive intelligence for M&A and partnerships: Investor-grade profiles and a scoring matrix for Tier‑1/2 suppliers and sub‑system specialists help corporate development teams identify bolt-on targets and strategic partners that move the revenue and capability needle.
What’s inside — practical deliverables
-
Top-line market model (2020–2032) with deterministic and probabilistic scenarios for EV penetration, steer-by-wire adoption, and premiumization trends.
-
Supplier scorecards and capability maps, combining engineering competency, manufacturing footprint, cost base, and platform exposure.
-
Raw-material exposure analysis — including NdPr dependency curves, price-sensitivity dashboards, and domestication/insourcing scenario impacts on unit economics.
-
Technology decision frameworks comparing brushed vs brushless motor trade-offs across torque density, control complexity, NVH, and lifetime cost-of-ownership.
-
Regulatory and standards playbook: compliance pathways and test matrices tied to emergent standards (e.g., steer-by-wire system safety guidance) and homologation timelines.
-
Commercial templates: tender evaluation criteria, transition plans for incumbent suppliers, and pricing strategies for suppliers entering OEM platforms.
Market dynamics shaping 2026 strategic choices
The industry is being reshaped by three concurrent forces that accelerate or constrain demand for steering wheel adjustment motors, and therefore should be central to 2026 planning:
-
Vehicle architecture evolution: Increased electrification, higher-spec cabins, and nascent steer-by-wire implementations shift spec envelopes toward compact, high-torque actuators with deterministic control and safety mechanisms.
-
Raw‑material and magnet sourcing pressure: The compact high-performance motors characteristic of modern adjusters are magnet‑intensive. Recent supply steps — including domestic qualification of NdPr oxide processing and new supply agreements for neodymium magnets — reduce strategic dependence on traditional import channels but introduce new cost variability and sourcing choices for OEMs and Tier‑1s.
-
Standards and safety expectations: Emerging international guidance for steer-by-wire systems is changing validation requirements for hand‑wheel actuators and adjustment mechanisms — increasing up‑front engineering effort and creating premium for suppliers with demonstrated compliance capability.
Competitive landscape — how the leaders are positioned
PW Consulting’s competitive analysis synthesizes public disclosures, product portfolios and technical differentiators to profile incumbent strengths and strategic levers. Selected company insights:
-
Johnson Electric (Hong Kong) — Focused products for steering wheel adjustment, including column adjuster motors with automatic linear and height adjustment and smart‑cabin-friendly modes. Strengths: established actuator depth and portfolio synergies for EV interior convenience features.
-
Bosch Mobility (Germany) — Broad drive systems with electric adjustment drives (hollow‑shaft and spindle variants) emphasizing low noise, memory functions, and crash robustness. Strengths: scale, system integration, and multi‑voltage compatibility.
-
NSK (Japan) — Tilt and telescopic columns with plastic‑reinforced impact absorption and position memory. Strengths: materials engineering and integration into column assemblies.
-
thyssenkrupp (Germany) — Variable electrical height/length adjustment aimed at luxury segments, using lightweight materials and high crash‑safety engineering. Strengths: premium positioning and structural expertise.
-
Brose (Germany) — Active in motorized column adjusters within its electric motors and drives portfolio; credible candidate for system‑level partnerships.
-
Nexteer Automotive (United States) — Offers steering columns and intermediate shafts designed to integrate steer‑by‑wire and stowable column technologies, enabling new interior packaging options.
-
JTEKT (Japan) — Steering systems expertise that includes electronic power steering and adjustment‑related components with tuning capability for vehicle dynamics.
Strategic takeaways: incumbents combine mechanical, materials and electrical competencies. New entrants and adjacent players must either partner with these capabilities or differentiate through cost, software integration, or localized supply of critical components (magnets, control electronics).
Recent industry developments and implications
-
Series production of steer‑by‑wire systems (e.g., recent launches) validates production readiness for architectures that decouple steering effort from mechanical linkages — opening interior design and automation opportunities that increase the addressable market for advanced adjustment actuators.
-
Automakers and domestic magnet suppliers advancing multi‑year supply agreements and qualification of local NdPr feedstock reduce strategic geopolitical risk but introduce a new layer of cost negotiation and qualification timelines for motor manufacturers and OEM purchasing teams.
-
Price volatility in rare‑earths and rising demand for NdFeB grades suitable for automotive actuators are elevating material management from a procurement line‑item to a strategic capability. Firms that secure predictable access or create magnet‑light motor architectures will improve margin resilience.
Strategic recommendations for 2026
-
For OEMs: Treat steering adjustment as a systems decision. Specify adjuster performance in tandem with cabin E/E architecture and steer‑by‑wire roadmaps to avoid costly re‑engineering during platform transitions.
-
For Tier‑1 suppliers: Prioritize modular, software‑enabled actuator platforms that can be retuned across vehicle lines and certified against emerging steer‑by‑wire system safety requirements. Build or secure magnet supply partnerships to protect margin.
-
For component specialists and new entrants: Focus on niche differentiation — e.g., ultra‑compact high‑torque solutions, crash‑absorbing polymer housings, or integrated memory and comfort features for premium interiors — and target non‑core integration opportunities in retrofit/aftermarket channels.
-
For investors and M&A teams: The sector’s mid‑level concentration implies prime targets for consolidation. Consider vertical plays into magnet processing, power electronics, or software stacks that accelerate product adoption by OEMs.
How PW Consulting quantifies risk and opportunity
Our report includes dynamic scenario matrices that quantify the impact of three principal uncertainties on 2026–2032 revenue trajectories: EV adoption variance, steer‑by‑wire penetration rates, and rare‑earth price shocks. Each scenario ties back to product‑level economics so commercial teams can see how unit price, BOM composition and warranty exposure shift under alternative market conditions.
Next steps — where to get the full intelligence
This Preview demonstrates the depth of PW Consulting’s market model, strategic frameworks and practitioner tools designed for 2026 decision-making. The full report contains the granular segment-level breakouts, country and application demand curves, supplier scorecards, and downloadable financial models that decision-makers need to operationalize the recommendations outlined here. To obtain the complete study, including the detailed appendices and proprietary calculators, please visit PW Consulting’s report page or contact your account representative to arrange access.
Conclusion
The steering wheel adjustment motor market presents a pragmatic growth opportunity for suppliers and OEMs that align product development, sourcing and commercial strategies with evolving vehicle architectures and material realities. With a 6.19% CAGR underpinning medium-term topline growth and a market projected to exceed USD 2.1 billion by 2032, the question for 2026 is not whether demand exists, but who captures the value. PW Consulting’s report equips leaders to make those capture decisions with clarity, speed and confidence.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Adjustment Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Performance Fibers for Defense Market Valued at USD 2,056.35 Million in 2025, Poised for Robust Growth
By PW Consulting, 2026-07-01
High Performance Fibers For Defense Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting today publishes an executive briefing drawn from our forthcoming market research report, High Performance Fibers For Defense Market (base year 2025; forecast 2026–2032). This briefing highlights why the market’s medium‑term trajectory and structural dynamics should be a central consideration for C‑suite strategy, procurement, and R&D roadmaps through 2026. We present actionable, decision‑grade perspectives while preserving the report’s proprietary segmented intelligence — the granular tables, region/application splits and supplier scorecards remain available in full through our report portal.
High Performance Fibers For Defense Market
Executive snapshot: a market expanding under sustained strategic demand
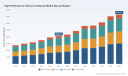
After a steady recovery and expansion during 2020–2025, the global market for high performance fibers for defense rose from approximately USD 1.39 billion in 2020 to an estimated USD 2.06 billion in 2025. Our forecast anticipates continued growth, with the market reaching roughly USD 2.17 billion in 2026 and expanding to an estimated USD 3.64 billion by 2032. That trajectory reflects a compound annual growth rate (CAGR) of approximately 8.52% across the 2026–2032 forecast period — a rate driven by accelerating defense modernisation programs, lightweighting priorities in aerospace and platforms, and sustained demand for personal protection systems.
High Performance Fibers For Defense Market
Why 2026 is a strategic inflection point
-
Qualification timelines compressing: Defense procurement cycles and fielding windows are tightening. Qualification and certification for new fiber systems still commonly require multi‑year ballistic testing and supplier audits, so choices made in 2026 will often determine program supply chains through the early 2030s.
High Performance Fibers For Defense Market -
Supply chain resilience vs. cost pressure: Producers face dual pressures — raw material volatility (notably petrochemical precursors for para‑aramid and capital‑intensive gel‑spinning for UHMWPE) and the need to insure supply against export controls and trade restrictions. Strategic sourcing decisions and localised capacity investments initiated in 2026 can materially alter lifecycle cost and availability for prime contractors.
-
Technology convergence driving premium capture: Advances in carbon fiber grades, new aramid variants, and UHMWPE processing are creating displacement opportunities across vehicle armor, aircraft structures, and personal protective equipment. Early adopters of next‑generation fiber grades can capture weight and performance premiums while increasing barriers to entry for competitors.
What the PW Consulting report delivers (practical, executable content)
Our research is designed for executives who need to convert market insight into executable strategy. The full report package includes:
-
Macro market model (2020–2032) with downloadable time series and scenario options that allow you to run your own revenue and margin sensitivities under differing demand, price, and trade‑policy assumptions.
-
Supplier scorecards that assess technical capability, qualification footprint, production capacity elasticity, and supply‑chain risk for the leading producers.
-
Qualification timeline playbooks that map testing/regulatory gates, average timelines, and mitigation strategies for accelerating supplier approval.
-
Raw‑material exposure matrices that quantify cost sensitivity to petrochemical and solvent price swings and outline hedging and vertical integration levers.
-
Commercial frameworks for negotiating long‑term supply agreements, offtake structures, and shared investment in localized processing (e.g., solvent recovery units for UHMWPE gel‑spinning).
-
Target lists and M&A screening filters identifying mid‑market assets that accelerate market entry, add qualification credentials, or provide complementary processing capabilities.
Competitive landscape: positioning and recent moves
The industry remains moderately concentrated: our competitive analysis finds the top three producers account for nearly half of market revenue, while the five largest players approach just over sixty percent market share — a structure that supports strategic collaboration while leaving room for challengers with focused technical or geographic strengths.
Key incumbent profiles and strategic implications:
-
DuPont de Nemours, Inc. (Wilmington, Delaware, USA) — a global leader in para‑aramid fibers with a well‑established Kevlar franchise. DuPont’s expanded portfolio and ongoing qualification activity signal continued emphasis on ballistic protection for personal and vehicle armor. For customers, DuPont represents a de‑risked, broadly qualified supply source; for competitors, it sets benchmark performance and compliance standards.
-
Teijin Limited (Tokyo, Japan) — major para‑aramid and carbon fiber producer with a balanced defense offering. Teijin’s mix of ballistic and composite capabilities makes it an attractive partner for integrators seeking integrated material solutions for both protection and structural applications.
-
Honeywell International Inc. (Charlotte, North Carolina, USA) — with UHMWPE fibers (Spectra) and ballistic systems (Spectra Shield), Honeywell plays to the lightweight, high‑stopping‑power segment. Its strength is in consolidated ballistic systems rather than raw fiber commoditization, making it a preferred supplier for turnkey armor solutions.
-
Toray Industries, Inc. (Tokyo, Japan) — dominant in high‑performance carbon fibers; recent supply agreements and new grades (e.g., TORAYCA M46X) sharpen its edge for weight‑sensitive aerospace and defense platforms. Strategic customers should monitor Toray’s capacity allocations as its Decatur, Alabama presence grows.
-
Avient Corporation (formerly DSM Dyneema, Cleveland, Ohio, USA) — UHMWPE specialty producer with strengths in high‑strength, ultra‑light fibers. Dyneema‑derived solutions are central for applications where weight and mobility confer tactical advantage.
-
Regional and specialist players — Kolon, Hyosung Advanced Materials, Hexcel, Mitsubishi Chemical, and SGL Carbon each occupy important niches: aramid variants, advanced yarns, carbon fiber prepregs and composites, and semi‑finished components. These firms often act as strategic partners for localized manufacturing and systems integration.
Recent industry developments to watch
-
Supply agreements and capacity reinforcement (e.g., Toray’s multi‑year contracts and facility emphasis) indicate OEMs are seeking supply certainty for defense programs with extended life cycles.
-
New product introductions (e.g., Hexcel’s HexTow IM9 grade and Toray’s high‑modulus TORAYCA lines) are raising the technical bar for weight‑critical composite components — offering designers options to trade cost for dramatic weight savings.
-
Portfolio expansions among legacy aramid and UHMWPE vendors reflect ongoing efforts to shorten qualification cycles and bundle material + systems offerings for defense primes.
Market dynamics that will drive supplier and buyer behavior
-
Raw material volatility: Para‑aramid production depends on petrochemical precursors (PPD, TPC) whose pricing follows benzene/xylene derivatives; UHMWPE manufacture relies on capital‑intensive gel‑spinning and solvent recovery. These inputs create earnings cyclicality and favour suppliers with scale or vertical integration.
-
Trade and export controls: High‑performance fibers for defense remain sensitive to export regulation. Buyers should model geopolitical scenarios when selecting global versus local suppliers and consider qualification paths that mitigate cross‑border risk.
-
Qualification friction: Expect 2–5 year qualification windows for many military systems. Program managers must couple procurement timing with supplier selection early to avoid retrofit costs and program delays.
Strategic imperatives for 2026
Our analysis yields seven imperatives for organizations that need to translate market dynamics into competitive advantage:
-
Embed supply qualification into program schedules — start supplier testing and regulatory engagement early to avoid downstream schedule slippage.
-
Diversify material exposure — evaluate a blended material strategy (aramid, UHMWPE, carbon fibers) as a hedge against raw‑material and policy shocks while preserving platform performance objectives.
-
Invest in localised processing where strategic — co‑investments in solvent recovery or prepreg capacity can reduce lifecycle costs and improve qualification speed for priority programs.
-
Use long‑term commercial structures — offtake, price‑volume collars, and shared capex agreements can align incentives between primes and fiber producers and reduce cost volatility.
-
Pursue selective M&A or JVs — target assets that deliver immediate qualification credentials or fill capability gaps versus building capability organically under constrained timelines.
-
Monitor emerging grades and material substitution risk — track carbon fiber modulus/strength improvements and next‑generation aramid/UHMWPE variants to capture structural or weight‑savings opportunities early.
-
Prioritise compliance and export strategy — build a regulatory playbook and verify alternate sourcing routes for critical programs.
How PW Consulting can accelerate your 2026 planning
This briefing is a preview of our full report, which contains the complete datasets, supplier granularities, and executable playbooks referenced above. For procurement teams, program managers, investors, and R&D leaders, the report functions as both a market map and a tactical toolkit: it prescribes when to lock supply, where to invest in qualification, and how to structure commercial arrangements that protect programs against material and policy shocks.
Contact PW Consulting to request the full report package, access the interactive market model, or commission a tailored decision workshop that applies these findings directly to your program portfolio. The full intelligence suite contains the detailed regional and application segmentation, supplier scorecards, and scenario models that many organizations require to make binding 2026 commitments.
For detailed analysis of this topic, please visit the official page: High Performance Fibers For Defense Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paper Laminates Market to Reach USD 23,934.05 Million by 2032, Growing at a 5.48% CAGR
By PW Consulting, 2026-07-01
Paper Laminates Market: Strategic Preview for 2026 — What's at Stake and What Your Board Needs to Decide
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our full Paper Laminates Market report (base year 2025, forecast 2026–2032). This briefing synthesizes macro trends, regulatory inflection points, raw-material pressure, and competitive moves that will shape strategic choices in 2026. Our aim is to give executives the line-of-sight required to set priorities, while directing tactical teams to the full report for granular segmentation and action plans.
Paper Laminates Market
Executive snapshot
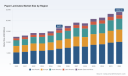
The paper laminates market completed 2025 as a mature but dynamic sector, with an estimated market size approaching USD 16.5 billion and a compound annual growth rate (CAGR) of approximately 5.48% through the 2026–2032 forecast window. Market concentration remains moderate: the top three firms account for roughly 22% of the market, and the top five for about 32.4% — a structure that favors nimble innovation and targeted scale plays rather than outright monopoly strategies.
Paper Laminates Market
Why 2026 is a pivotal year
- Regulatory acceleration: Binding mandates and producer responsibility schemes that take effect or ramp up in 2025–2030 are converting sustainability preferences into commercial requirements.
- Raw material volatility: Pulp and polymer price swings are compressing margin cushions and forcing reengineering of laminate formulations and sourcing strategies.
- Product differentiation: Advances in recyclable and mass-balanced laminates are creating new shelf and supply-chain value that commands premium contracts.
Market dynamics that will guide corporate choices
Four converging forces will dominate boardroom debates in 2026:
Paper Laminates Market
- Regulatory push for recyclability and recycled content. Legislations such as an EU-level packaging waste reform that mandates minimum recycled content, and state-level extended producer responsibility (EPR) programs, are moving paper laminates from optional sustainability narratives to compliance line-items. These rules will influence material specs, supplier selection, and end-of-life cost allocation.
- Cost signals from pulp and polymers. Bleached hardwood kraft pulp and lamination-grade polyolefin prices continue to oscillate at levels that materially affect product economics. Recent indices show pulp averaging in the high hundreds of USD per metric ton late in 2025 and LDPE at elevated levels in early 2026, warranting immediate procurement hedging and substitution assessments.
- Customer preference and brand risk. Retailers and CPG brands are accelerating sourcing policies that prioritize recyclability and lower-carbon feedstocks; suppliers unable to demonstrate credible pathways to recyclability or recycled-content will face margin pressure or disqualification from tenders.
- Consolidation and capability plays. With moderate market concentration, strategic M&A (bolt-on capacity for barrier coatings, extrusion-lamination capabilities, or recycling feedstock) remains an efficient route for capability scaling without the cost of greenfield builds.
What this means for strategic planning in 2026
Executives must translate macro pressure into three core imperatives for 2026 action plans:
- Fix supply-side economics now. Implement multi-year offtake and raw-material contracts, explore co-located compounding/lamination to reduce freight and conversion cost, and evaluate alternative barrier technologies to reduce reliance on volatile polymers.
- De-risk regulatory compliance. Build an explicit roadmap for recycled-content certification and EPR cost pass-through — including pilot programs with customers to validate collection and recycling loops that preserve margin.
- Invest in differentiating capabilities. Prioritize investments in recyclable and mass-balanced laminates, digital quality assurance, and barrier performance improvements that preserve shelf-life without sacrificing recyclability.
Competitive landscape — who’s setting the agenda
The market is shaped by a mix of global paper and packaging integrators and specialized laminate developers. Our analysis focuses on firms that matter to sourcing, benchmarking, and potential partnership/M&A strategies:
- Mondi Group (Vienna, Austria): A global leader in paper-based packaging, Mondi has recently launched a PEEL & SEAL paper-based laminate positioned for recyclable flexible packaging. The product launch signals a use-case-first approach to replacing conventional multilayer films.
- WestRock Company (Atlanta, USA): Known for folding cartons and extrusion-coating capabilities, WestRock’s recent exhibition of fiber-based laminates with high barrier performance highlights an effort to reconcile barrier requirements with fiber-based recyclability.
- Smurfit Kappa Group (Dublin, Ireland): Certification wins for recycled content indicate the company is advancing upstream feedstock credibility — a differentiator in tenders requiring documented recycled inputs.
- International Paper Company (Memphis, USA): With emphasis on corrugated packaging and specialty laminates, International Paper remains relevant for industrial and institutional packaging formats where durability and barrier properties are essential.
- DS Smith plc (London, UK): DS Smith’s focus on sustainable e-commerce and food-sector laminates underscores the growing intersection of logistics performance and recyclability.
- Tetra Laval (Tetra Pak) (Pully, Switzerland): As the leading aseptic carton supplier, Tetra Pak continues to push multi-layer laminate innovations — balancing aluminum/foil and polymer elements for sterilization and shelf stability.
- Stora Enso Oyj (Helsinki, Finland): Investment in mass-balanced paper laminates and commercial-scale production lines reflects a strategic bet on renewable barriers as plastic alternatives.
Recent corporate moves — product launches, trade show showcases, certification achievements, and new production lines — reveal two tactical truths: incumbents are betting on both technology and claims verification (certifications); and first movers on credible recyclable laminates can secure preferential positioning with brand customers.
Report scope and practical outputs (what’s inside the full PW Consulting report)
The full report is structured to support operational and strategic decisions, and includes:
- Market sizing (historical 2020–2025 and detailed forecasts 2026–2032) and a calibrated CAGR assumption to stress-test planning scenarios.
- Scenario-based forecasts that quantify upside/downside outcomes under alternative regulatory and raw-material trajectories.
- Commercial playbooks for procurement (hedging and supplier contracts), R&D prioritization (barrier vs. recyclability trade-offs), and go-to-market (value-selling to brand owners and converters).
- Competitor profiles and capability matrices that benchmark barrier technologies, certification status, and geographic manufacturing footprints.
- Practical checklists for compliance with EPR schemes and recycled-content reporting, plus a vendor shortlist for pilot partnerships.
- Financial sensitivities (margin-at-risk analysis) linked to pulp and polymer price bands and to potential compliance cost pass-throughs.
Examples of board-level questions the report helps answer
- Should we accelerate capital allocation to retrofit lamination lines for recyclable structures, or buy capability via acquisition?
- How do varying pulp and LDPE price scenarios affect our product mix profitability through 2028?
- What is the optimal commercial model to recover EPR costs without losing share to less transparent competitors?
- Which strategic partnerships — fillers, recyclers, certification bodies — deliver the fastest path to demonstrable compliance?
Recommended 90-day playbook for 2026
- Operational: Run a procurement stress-test on pulp and LDPE exposure; secure staggered supplier contracts to smooth cost volatility.
- Regulatory/compliance: Complete a gap analysis against regional recycled-content and EPR mandates; initiate certification pilots where shortfalls exist.
- Commercial: Launch two customer pilots that co-develop recyclable laminate SKUs with anchor CPG partners to secure early wins and reference cases.
- Strategic: Shortlist two capability targets for potential bolt-on M&A (coating expertise; recycling feedstock access) and begin nondisclosure discussions.
Why our granular segmentation is deliberately withheld here
This communication follows a “trailer” approach: our goal is to establish confidence in the report’s strategic value while preserving restricted, high-action segmentation and contract-level insights for subscribers. The full report contains the detailed regional, type and application splits, supplier share movements, and contract-level pricing intelligence necessary to execute or defend market positions — information we withhold here to ensure competitive integrity and to invite stakeholders to the full analysis.
Final perspective
As the paper laminates market transitions from optional sustainability to regulatory imperative, the 2026 planning cycle will reward firms that translate compliance into product premium — and penalize those that view recyclability as a marketing exercise. PW Consulting’s full report equips executives with the data, scenarios, and tactical playbooks needed to preserve margin, capture growth, and reduce regulatory and raw-material exposure. For boards and strategy teams, this is not an incremental planning exercise; it is a portfolio re-underwriting moment.
Next steps
- Access the full report to obtain the detailed regional and application segmentation, contract-level pricing models, and supplier scorecards needed to operationalize the recommendations above.
- Contact PW Consulting to schedule a bespoke executive briefing and a 90-day implementation workshop aligned to your footprint and risk profile.
PW Consulting — translating market complexity into actionable advantage for the paper laminates value chain.
For detailed analysis of this topic, please visit the official page: Paper Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 24‑Hour Emergency Roadside Assistance Market Poised for Steady Expansion with 5.12% CAGR, New 2026–2032 Forecast Reveals
By PW Consulting, 2026-07-01
24 Hour Emergency Roadside Assistance Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting's latest 24 Hour Emergency Roadside Assistance Market study delivers a focused playbook for leadership teams making critical investment, partnership and operational decisions in 2026. Built on a comprehensive historical series (2020–2025) and a detailed forecast window (2026–2032), the report synthesizes market-size trajectories, competitive positioning, regulatory inflection points and executable go-to-market options that materially affect near- and medium-term returns.
24 Hour Emergency Roadside Assistance Market
Executive snapshot
The market is expanding steadily. Our base-year assessment (2025) values the global 24-hour emergency roadside assistance market at roughly USD 31.9 billion and projects that it will reach just over USD 45.2 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 5.12% across the forecast horizon. This trajectory reflects a mix of persistent core-service demand (towing, battery and tire interventions, lockouts and fuel services), plus incremental growth drivers tied to fleet telematics, OEM bundled service programs and technology-led dispatch efficiencies.
24 Hour Emergency Roadside Assistance Market
Why this report matters for 2026 decision-making
- Actionable foresight: The combination of near-term market sizing and scenario-tested forecasts enables boards and commercial teams to stress-test capex and outsourcing decisions against plausible demand and cost environments in 2026–2028.
- Regulatory and operational risk mapping: We identify jurisdictional regulatory shifts that will change unit economics (notably for EV incident handling and vehicle storage), enabling pre-emptive contract and pricing redesigns.
- Competitive posture diagnostics: The study benchmarks incumbent strengths — from membership models to white-label OEM platforms and AI-driven on-demand providers — allowing executive teams to calibrate M&A, JV and partner-selection strategies without overpaying for redundant capabilities.
What the report contains (practical, executable deliverables)
- Clear market sizing and trend narratives for 2020–2025 with modelled forecasts through 2032, plus sensitivity scenarios under alternative EV adoption and macro-inflation assumptions.
- Provider capability maps, technology maturity assessments and a vendor short-list framework that ranks suppliers on operational coverage, SLA performance, telematics integration and claims integration readiness.
- Commercial playbooks for insurers, OEMs and fleet operators that translate forecast implications into pricing levers, bundling options and contract language templates to protect margins and uptime KPIs.
- Regulatory compliance checklists and a priority matrix for jurisdictions where near-term rule changes will affect storage, salvage handling and liability — including modeled P&L impact ranges for likely policy outcomes.
- An M&A and partnership decision tree that identifies where bolt-on consolidation, white-label partnerships or regional network investments will produce the highest IRR in a 24–36 month horizon.
- Operational templates for scaling patrols, training programs for EV incident response, and technology roadmaps for upgrading dispatch and ETA communications.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the leading three providers account for a meaningful share of demand, while the top five capture a clear majority of market revenue — a structure that creates room for both regional specialists and national-scale integrators to capture value. Key provider archetypes we analyze include legacy motor clubs with deep membership economics, insurer add-on programs, OEM-partnered white-label providers, independent on-demand operators and digital disruptors focused on intelligent dispatch.
24 Hour Emergency Roadside Assistance Market
- Legacy membership clubs (e.g., AAA, ADAC, RAC, AA): These organizations leverage trusted brand equity, broad patrol networks and multi-decade operating experience to retain high-margin members. Their strength lies in retention economics and scale logistics.
- White-label integrators (e.g., Agero): These firms deliver platform-based dispatch, claims integration and OEM-grade SLAs. Their commercial value is in bundling services for insurers and manufacturers, enabling rapid market entry without capex-heavy network builds.
- Insurance and OEM programs (Allianz Partners, OEM-linked arrangements): These models tie roadside as a service into product warranties and policy suites, deepening customer lifetime value while shifting operational risk to service partners.
- Digital-first on-demand players (e.g., Urgently): AI-enabled dispatch and marketplace models are compressing response times and enabling margin improvements through dynamic pricing and improved asset utilization.
- Regional specialists and network operators (Falck, ARC Europe, Viking Assistance, SOS): These providers are critical for cross-border continuity and local regulatory navigation.
Our competitive chapter includes company-level capability matrices, partner-fit scoring and a scenario analysis of how recent moves — such as extended OEM contracts, platform consolidations and organizational integrations — alter competitive advantage into 2026.
Recent market developments to watch
- Major OEM and insurer partnerships have continued to proliferate, with multi-market agreements extending standardized roadside offerings across additional countries — accelerating the trend toward harmonized, cross-border service levels.
- Integration of fleet service teams under larger corporate umbrellas is consolidating capability and creating one-stop-shop offerings for larger fleet customers, enabling scale benefits but also increasing competitive pressure on independent operators.
- Digital providers are securing placements with dealerships and fleet managers on the strength of AI-enabled dispatch and real-time ETA improvements, forcing incumbents to elevate their technology investments to defend retention.
Regulatory and operational dynamics shaping 2026
Regulation and localized operational rules are among the highest-impact uncertainties in our analysis. Three trends demand immediate executive attention:
- EV incident handling and storage rules: Emerging statutes in some jurisdictions (for example, mandates on safe storage and separation requirements for damaged electric vehicles) change the cost profile of accident handling and salvage — influencing tow-provider reimbursement, storage fees and liability allocations.
- Regulatory gaps in vendor oversight: At least one U.S. state lacks distinct regulation for roadside assistance providers, creating material risks around vetting, training and equipment standards when insurers or apps contract third-party operators. This gap creates liability exposure that boards should model into contract terms and insurance costs.
- Operational variability in roadside vehicle safety practices: Inconsistent rules for warning lights and roadside vehicle operations across states/countries raise operational complexity and compliance costs for firms operating across multiple jurisdictions.
Operational demand patterns are also shifting: non-traditional call types — from pothole-related breakdown surges to EV-related service requests (which currently remain a small share of overall volume) — are changing the skill mix and equipment requirements of patrol fleets. Our field surveys and operator interviews document doubled pothole-related attendances in a recent quarter for a major patrol operator, an indicator of how infrastructure and seasonal patterns create episodic cost and demand spikes.
Strategic implications for leaders in 2026
Executives should treat 2026 as a decision window where investments or strategic shifts will determine who benefits from the projected 5.12% CAGR over the coming decade. Key implications include:
- Re-price and re-contract for EV economics: Expect higher direct handling costs and potential new storage fees to be passed through or contracted differently; update contract templates and SLA definitions now to avoid margin erosion.
- Prioritize telematics and AI-enabled dispatch: Improved ETA accuracy and dynamic resource allocation produce measurable margin improvements and customer satisfaction gains; early adopters will raise the bar for service-level expectations.
- Use regulatory engagement as a competitive moat: Firms that invest in compliance, participate in standard-setting and build demonstrable training and equipment protocols will secure larger insurer and OEM contracts.
- Evaluate consolidation selectively: With the market's moderate concentration, targeted acquisitions or strategic alliances that add geographic coverage, specialized EV-capable assets or proprietary dispatch technology offer attractive IRRs versus greenfield expansion.
- Redesign pricing and bundling: Work with actuarial and claims teams to design roadside bundles that mitigate predictability risks while capturing higher lifetime value through OEM and membership tie-ins.
Recommended near-term actions (90–365 days)
- Audit current roadside contracts for EV incident clauses, storage liabilities and pass-through fee triggers; insert contingency pricing where absent.
- Run a technology gap assessment focused on dispatch latency, ETA accuracy and telematics integration; prioritize quick wins with measurable cost-to-serve reductions.
- Perform a targeted provider due-diligence sweep in regions where regulatory gaps or new storage rules are emerging; tighten vetting and insurance requirements accordingly.
- Open exploratory dialogues with white-label integrators and digital dispatch providers to test pilot integrations for fleet and dealer channels.
Medium-term choices (12–36 months)
- Decide on build vs. buy for EV-capable roadside assets informed by a break-even analysis tied to regional EV penetration scenarios.
- Pursue one strategic M&A or JV to extend coverage or acquire differentiated technology if internal capability gaps exceed acceptable time-to-market thresholds.
- Develop a regulatory advocacy plan to harmonize safety standards for roadside operations and vehicle storage in high-risk jurisdictions.
Conclusion — the strategic value of this report
For boards, commercial leaders and operations executives, PW Consulting's 24 Hour Emergency Roadside Assistance Market report converts macro growth projections and fragmented competitive dynamics into a clear set of prioritized actions for 2026. With the market expected to grow from roughly USD 31.9 billion in 2025 to USD 45.2 billion by 2032 at a 5.12% CAGR, the opportunity is substantial — but timing, regulatory readiness and technology choices will determine who captures disproportionate value.
To preserve the report's utility as a strategic decision tool, we present this brief as an executive trailer: it surfaces essential insights and strategic recommendations while reserving the full regional, service-type and provider-level segmentation tables, detailed financial models and the complete methodology for the full study. For the complete dataset, downloadable models, company scorecards and procurement templates, please visit the official PW Consulting report page.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Residential Solar Power Solutions to Expand at a 14.02% CAGR Through 2032
By PW Consulting, 2026-07-01
Residential Solar Power Solution Market: Strategic Imperatives for 2026
PW Consulting’s latest market study, Residential Solar Power Solution Market (base year 2025; forecast 2026–2032), synthesizes primary research, proprietary modeling and on-the-ground interviews to deliver a pragmatic playbook for corporate leaders planning 2026 actions. Our headline finding is unambiguous: the global residential solar market has moved from early-scale adoption to a structurally larger, more strategic industry. After growing from roughly USD 61.4 billion in 2020 to USD 128.19 billion in 2025, the market is projected to expand at a 14.02% CAGR through the forecast window and is expected to reach approximately USD 320.88 billion by 2032. 2026 stands as a critical year in which sourcing, product strategy, and policy responses will determine winners and losers over the rest of the decade.
Residential Solar Power Solution Market
Why 2026 Is A Strategic Inflection Point
-
Policy discontinuities and trade actions are changing the playing field. The termination of the U.S. Residential Clean Energy Credit (Section 25D) for systems placed in service after December 31, 2025 alters homeowner economics in the U.S. and shifts the incentive calculus for developers, financiers and manufacturers targeting North American demand.
Residential Solar Power Solution Market -
Trade enforcement and quotas are creating short-term supply distortions. Recent CBP quota and duty regimes on crystalline silicon products and preliminary antidumping determinations for imports from certain geographies introduce margin volatility and regional sourcing risk that require adaptive procurement strategies.
Residential Solar Power Solution Market -
Input-cost dynamics remain non-trivial. Polysilicon spot prices rose materially in early 2025; while raw-material cycles are familiar to the sector, the timing of price normalization and pass-through to downstream system pricing will affect product strategy and inventory decisions.
-
Installer economics and household-level affordability metrics are tightening. Publicly available benchmarking shows U.S. residential system pricing in H1 2025 operating in a mid-single-digit $/Wdc range; small absolute shifts in component cost or subsidy availability therefore have outsized effects on payback and financing product suitability.
What the PW Consulting Report Delivers
This study is designed as a decision-support toolkit for executives, investment committees, product teams and channel leaders. Key practical deliverables include:
-
Robust market sizing and top-down forecasts with sensitivity scenarios—illustrating baseline, upside and downside trajectories through 2032 and the implications of policy and commodity shocks.
-
Supply-chain heatmaps and vulnerability analysis—identifying concentration points across ingot-to-system layers, and offering mitigation playbooks (dual sourcing, nearshoring, contractual hedges).
-
Commercial models for rooftop deployments—downloadable models for LCOE, payback, tariff-sensitive IRR and consumer financing constructs that can be adapted to local pricing and incentive regimes.
-
Competitive vendor profiles and procurement scorecards—benchmarks on manufacturing footprint, technology differentiation, vertical integration and channel strategy (note: granular segment-level market shares and region-by-region revenue splits are summarized in the full report).
-
Operational playbooks for installers and distributors—standardized cost templates, workforce planning scenarios, and digital adoption frameworks for sales, permitting and asset management.
-
M&A and partnership diagnostic—valuation drivers for asset and platform deals, integration risk checklists and prioritization criteria for technology partnerships (e.g., storage + EMS).
-
Regulatory and tariff tracker—rolling timeline of major actions, anticipated policy windows and decision points for 2026 capital planning.
Competitive Landscape: Reading the Field in 2026
The industry shows a mix of consolidation and product-level competition. Top-tier module manufacturers continue to invest in high-efficiency monocrystalline technologies and vertical integration from wafers to modules. At the same time, power electronics and energy management providers are tightening the value chain by offering integrated solar+storage systems with software-enabled energy services.
-
Large module players are competing on scale, margin control and technological steps such as N-type architectures and bifacial designs. Their global shipment capacity and distribution networks remain core competitive levers for rooftop supply.
-
Inverters and balance-of-system innovators are differentiating via optimization technologies—microinverters and module-level power electronics are increasingly paired with storage to offer superior performance in complex roof topologies and behind-the-meter use cases.
-
Storage and integrated-solution vendors are pushing downstream: bundled propositions that simplify installation and O&M, and that provide home energy management capabilities, are gaining traction with homeowner segments focused on resilience and bill hedging.
-
Market concentration metrics indicate a moderate level of concentration among leading suppliers, while independent rankings show the top manufacturers controlling a sizable share of global shipments—this dual reality favors large-scale producers but leaves niches for differentiated, higher-margin products.
For corporate strategists, the competitive interpretation is clear: scale and vertical integration remain defensive advantages, but product differentiation (efficiency, integrated storage, software) and channel excellence can create sustainable premium positions.
2026 Strategic Playbook: Five Priority Moves
-
Hedge procurement and secure optionality. Lock in multi-origin supply contracts and modular inventory strategies to weather tariff windows and input-cost volatility.
-
Prioritize integrated solutions for homeowner segments valuing resilience. Upsell pathways combining PV, storage and energy management increase average deal size and reduce cost-to-serve over the customer lifecycle.
-
Reassess go-to-market economics in incentive-dependent markets. Build alternative consumer financing solutions and tailor product bundles for post-incentive scenarios where tax credits are reduced or removed.
-
Invest in installer enablement and digital workflows. A smaller installed-cost window depends on permitting automation, workforce certification and remote commissioning capabilities.
-
Execute targeted M&A or JV plays to close capability gaps—whether in storage chemistry, EMS software, or regional distribution—and ensure rigorous integration plans to capture synergies.
Scenario Briefs: How Outcomes Could Diverge
-
High-adoption scenario: rapid cost declines and supportive policy in major markets accelerate homeowner uptake, favoring vertically integrated suppliers who can scale production economically.
-
Protectionist scenario: prolonged trade measures and antidumping actions fragment supply chains and reset regional sourcing priorities—this benefits suppliers with diversified, localized manufacturing.
-
Stagnation scenario: policy pullback or prolonged commodity inflation compresses margins and slows installer growth, rewarding companies with strong financing platforms and aftermarket revenue models.
How to Use This Report in 2026 Decision Cycles
PW Consulting’s report is built for immediate use in boardrooms and strategy sessions. It includes dashboards and downloadable models designed for 2026 budget cycles: supplier risk matrices that plug into procurement frameworks, channel profitability templates for sales leadership, and investment case bundles for corporate development teams. Executive summaries and sector briefings are optimized for rapid assimilation; appendices house the detailed assumptions and primary-data citations necessary for compliance and audit.
We deliberately structure the public summary to convey directionality and strategic options while reserving the full suite of granular regional splits, segment-by-segment revenue forecasts and unit-level economics for licensed report holders. This approach protects actionable intelligence and ensures clients who need depth can operationalize recommendations without ambiguity.
Conclusion
The residential solar market is entering a phase where macro growth meets micro complexity. With the global market roughly doubling over the last five years and projected to more than double again by the end of the decade under our baseline, the opportunity is substantial—but so are the execution risks. For firms deciding 2026 capital allocation, go-to-market moves or M&A targets, the imperative is to combine supply resilience, product differentiation and channel efficiency. PW Consulting’s Residential Solar Power Solution Market report equips leaders with the forward-looking evidence and tools to act decisively. For the complete data, scenario models and supplier scorecards that underlie these conclusions, access the full report and interactive resources on our website.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


