



Category: market research
PW Consulting Report: Road Crash Attenuator Market to Grow at 6.09% CAGR, Reaching USD 977.02 Million by 2032
By PW Consulting, 2026-07-01
Road Crash Attenuator Market 2026: Strategic Imperatives for Resilient Growth — PW Consulting Insight
Executive summary
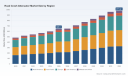
PW Consulting’s latest Road Crash Attenuator Market report synthesizes five years of historical performance and a seven-year forward view to equip executive teams with the evidence base needed for decisive 2026 strategy. The market has demonstrated steady expansion, rising from approximately USD 485.2 Million in 2020 to USD 645.5 Million in 2025. Our model projects continued growth through 2032, with a compound annual growth rate of 6.09% across the 2026–2032 forecast window and an expected market approaching USD 1.0 Billion by 2032.
Road Crash Attenuator Market
This release presents the strategic highlights from that research: a concise interpretation of demand drivers, supply-side pressures, competitive positioning, regulatory implications, and the practical playbook PW Consulting recommends for product, procurement, and M&A agendas in 2026. Detailed segment tables and granular regional/application breakdowns are intentionally held back to preserve the “trailer” principle of this announcement—full segmentation and company-level benchmarking are available in the full report on our website.
Road Crash Attenuator Market
Why this matters for 2026 decision-making
2026 will be a hinge year for road safety infrastructure suppliers and buyers. Governments and contractors face increased pressure to improve work-zone safety, reduce highway fatalities, and meet stricter procurement rules. At the same time, rising raw material costs and concentrated vendor dynamics are reshaping commercial and operational levers. The figures above mask a complex mix of structural demand and episodic procurement cycles; leaders that align product portfolios, capital allocation, and supply chain hedges to these dynamics will capture disproportionate share of the next growth wave.
Road Crash Attenuator Market
Key market dynamics
-
Demand momentum: Public infrastructure programs and renewed focus on work-zone safety undergird the medium-term uplift. Adoption of higher-performance attenuators and increased use of truck-mounted attenuators in temporary works are primary market drivers.
-
Supply-side pressure: Steel — specifically hot-rolled coil (HRC) — remains a cost vector to monitor. Early-2026 HRC price indications in the U.S. were around USD 1,002–1,118 per short ton; such ranges materially affect manufacturing margins, inventory strategy, and contract pricing for larger fabricators.
-
Regulatory gating: Compliance requirements continue to be a market fulcrum. In the U.S., federal-aid eligibility pivots on AASHTO MASH or legacy NCHRP 350 TL-3 approvals as validated by FHWA processes. In Europe, EN 1317 testing and CE marking, supplemented by ASI classifications, define product eligibility and procurement preference.
-
Market concentration: The sector shows moderate concentration at the top; our CR3 and CR5 metrics register at approximately 42.5% and 58.8% respectively — a structural environment that supports both competitive scale plays and targeted consolidation.
Competitive landscape — who’s shaping product and go-to-market
Our competitive profiling identifies a set of established incumbents and technology leaders who together shape product expectations, performance benchmarks, and procurement specifications:
-
Lindsay Corporation (Omaha, Nebraska) — Continues to expand its TAU technology line and truck-mounted offerings. Recent launches include a next-generation Road Runner TMA (early 2026) emphasizing rapid deploy/stow and vertical storage, and the TAU-M Wide 72-inch cushion (late 2025) that underscores a dual focus on enhanced protection and maintainability.
-
TrafFix Devices (San Clemente, California) — Maintains strong positioning with MASH-tested redirective systems and the Scorpion II family of TMAs; their engineering focus on full-width protection and short deployment length sets deployment efficiency benchmarks for contractors.
-
Hill & Smith (Columbus, Ohio / Hill & Smith Holdings) — Offers speed-dependent, self-restoring attenuators that optimize deceleration behavior across vehicle weight and speed profiles, reflecting a trend toward technology differentiation through adaptive resistance characteristics.
-
Valtir LLC (formerly Trinity Highway) — Broad portfolio across crash cushions and TMAs, including systems designed for both permanent and temporary applications; their multi-technology approach supports diverse procurement specifications.
-
Saferoad (Europe) — Emphasizes European compliance and high-performance ASI A certification for high-speed contexts; modular designs supporting rapid installation and repair are gaining traction in continental procurement frameworks.
-
Energy Absorption Systems — Known for compact, deployable TMA innovations; their product features underscore the value of logistical efficiency for contractor fleets.
Strategic implications by capability
-
Product development: Capitalize on value migration toward modularity, maintainability, and rapid deployment. Differentiation via speed-dependent energy management and reduced repair-cycle designs will command premium positioning in tenders that internalize life-cycle cost, not just capex.
-
Manufacturing and cost strategy: Lock in raw-material exposure through hedging, long-term supplier agreements, or material substitution where standards permit. Facility footprint decisions should weigh proximity to key public-works clusters to reduce logistic costs and accelerate response times for repairable systems.
-
Commercial and aftermarket: Build recurring revenue models around maintenance, rapid-repair modules, and rental fleets for TMAs. Competitive advantage accrues to firms that couple product sales with guaranteed service-level response times for work-zone redeployments.
-
M&A and partnerships: Given the sector’s moderate top-end concentration, selective M&A can accelerate entry into complementary segments (e.g., rental fleet providers, repair-service specialists, or regional installers). Joint development agreements with materials innovators (composites, energy-absorbing polymers) can shorten the product roadmap for lighter-weight attenuators.
-
Regulatory and tendering strategy: Invest in regulatory-compliance capability early. Products that are pre-qualified to MASH and EN 1317/ASI regimes unlock the broadest procurement pools. Anticipate evolving test protocols and embed testing timelines in the product development lifecycle to avoid go-to-market delays.
Actionable 90‑day playbook for executives
-
Conduct a rapid supply-cost audit: quantify direct exposure to HRC costs and identify immediate vendor hedging or inventory strategies to smooth margin volatility.
-
Prioritize product backlog by procurement impact: map each SKU against MASH/EN eligibility and expected tender windows over the next 12–18 months.
-
Initiate rental and service pilots in two high-density corridor markets to validate aftermarket revenue potential and improve asset utilization.
-
Target one bolt-on acquisition or strategic JV that adds either geographic reach or service capability within a six- to nine-month window, using a valuation framework that accounts for recurring service cashflows.
Methodology and confidence envelope
Our findings are derived from a multi-source methodology combining supplier financials, product registers, procurement tender analysis, primary interviews with public-works buyers and contractor fleets, and a bottoms-up installations model covering the historical window (2020–2025) and projecting through 2032. Sensitivity scenarios incorporate low/high infrastructure spend assumptions and a commodities shock case reflecting ±20% variance in HRC price paths. While the headline CAGR of 6.09% represents our central forecast for 2026–2032, our scenario analysis equips decision makers to stress-test investment plans against downside and upside macroeconomic outcomes.
What’s in the full report (practical deliverables)
The complete PW Consulting Road Crash Attenuator Market report includes:
-
Comprehensive market sizing and forecast tables (by region, application, and product type) with build-up methodology and source references.
-
Detailed supplier dossiers and benchmarking matrices covering product specs, regulatory certifications, installed base estimates, and go-to-market models.
-
Contract pricing compendia and a total-cost-of-ownership model to support procurement negotiations and lifecycle budgeting.
-
Supply-chain risk map with mitigations for commodity exposure, logistics choke points, and single-source dependencies.
-
Investment screening tool for M&A and JV evaluation, plus a 12–36 month execution roadmap for integration and value capture.
Final recommendation
For senior leaders preparing 2026 plans: treat the road crash attenuator market as a consolidating but innovation-driven sector where scale, regulatory certification, and service capability will determine winners. Prioritize actions that lock in material cost exposure, accelerate certification pipelines, and build recurring-service models. Companies that align product engineering with procurement realities — while remaining opportunistic on strategic partnerships — will be best placed to convert the sector’s steady top-line growth into durable margins and higher enterprise value.
To access the full segmentation dataset, company-level benchmarking, and our downloadable financial models, consult the PW Consulting report landing page. The detailed analyses and appendices provide the operative intelligence required to operationalize the strategic pathways summarized above.
For detailed analysis of this topic, please visit the official page: Road Crash Attenuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PAG Compressor Oil Market to Reach USD 1.46 Billion by 2032 with a 6.51% CAGR — Automotive A/C and End‑Capped PAG Fuel Growth
By PW Consulting, 2026-07-01
Pag Compressor Oil Market: A 2026 Strategic Playbook for Industry Leaders
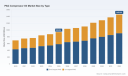
As companies set budgets and strategic priorities for 2026, the Pag (polyalkylene glycol) compressor oil market is at an inflection point. PW Consulting’s latest Pag Compressor Oil Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—delivers the market context and decision-grade analytics that executives and commercial teams need to navigate accelerating regulatory shifts, raw-material volatility, and technology-driven demand changes. The market’s multi-year compound annual growth rate (CAGR) of 6.51% underpins a trajectory that moves the sector into a different competitive posture by late-decade; this analysis translates that macro momentum into concrete strategic options without disclosing the granular splits reserved for the full report.
Pag Compressor Oil Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a planning inflection—capital allocation cycles, OEM specification updates, and refrigerant transitions aligned with regulatory timetables converge this year. Companies that use 2026 as the year to set new supplier, product, and R&D strategies will capture disproportionate upside.
Pag Compressor Oil Market -
Regulatory pressure: Global low‑GWP refrigerant adoption and regional regulatory actions accelerate demand for PAG chemistries compatible with next‑generation refrigerants. The resulting specification changes create both technical barriers to entry and premium pricing opportunities for compliant formulations.
Pag Compressor Oil Market -
Cost and margin volatility: Upstream feedstocks for PAG synthesis experienced measurable cost pressure in late 2025 and into 2026, creating near-term margin compression unless firms adopt hedging, backward-integration, or dynamic pricing strategies.
-
Product evolution: Longer-life formulations, low-ash and dielectric-optimized oils for electrified compressors, and cross‑OEM approvals are reshaping procurement criteria—buyers are prioritizing total cost of ownership and performance under higher discharge temperatures.
What the report delivers: operational depth, built for use
The report is engineered as an operational playbook, not just a market narrative. Key practical deliverables include:
- Market sizing and scenario forecasts built from 2020–2025 historicals and modeled forward across multiple demand and regulatory scenarios for 2026–2032.
- Demand-driver diagnostics linking refrigerant transitions, OEM electrification timetables, and industrial equipment replacement cycles to near- and mid‑term PAG demand.
- Supply-chain and cost modelling that quantifies the impact of feedstock price swings and CPI/PPI trends on cost structures and gross margins.
- Commercial playbooks for pricing, channel segmentation (OEM vs aftermarket vs industrial), and contract design to protect margin under price volatility.
- Supplier and technology scorecards assessing base‑stock producers, additive specialists, and formulators on supply security, technical approvals, and scale-readiness.
- M&A and partnership analytics setting out target profiles, valuation sensitivities, and integration checklists for buyers seeking scale or capability gaps.
- Regulatory heatmaps and compliance roadmaps aligned to the EU F‑Gas timeline, Kigali Amendment implications, and other jurisdictional drivers affecting refrigerant-compatible lubricants.
Competitive landscape: what leading players reveal about industry direction
Market leadership today is defined by three capabilities: approved formulation breadth (multiple refrigerant and compressor types), secure supply of PAG base stocks, and channel penetration across OEM, industrial, and aftermarket sales. The report examines how strategic positions are evolving among the sector’s core participants.
- ExxonMobil —leverages OEM approvals and high-performance synthetic formulations to compete on specification and reliability for industrial and refrigeration applications.
- Shell —positions PAG offerings around fire-resistance and efficiency, with branded lines that emphasize performance in demanding compressor environments.
- Chevron —focuses on reciprocating compressor segments and has pursued scale via strategic transactions to broaden its industrial lubricants footprint.
- Phillips 66 —markets premium synthetic PAGs across a wide set of compressor types, emphasizing versatility and approval breadth.
- BASF —a critical upstream player supplying PAG base stocks; its backward integration and raw materials capability are a supply-security differentiator for formulators.
- TotalEnergies and Idemitsu —both offer formulations tailored for automotive AC and refrigeration use-cases, with attention to compatibility across refrigerant families.
- Specialists and niche players —FUCHS, Klüber, AMSOIL, Castrol (BP), Shrieve, Cargill, Next Lubricants, and Matrix—continue to innovate on additive packages, dielectric properties, and application-specific solutions, competing through technical differentiation rather than scale.
Recent moves underscore two concurrent dynamics: consolidation at scale and rapid product innovation at the edges. Recent product launches for electric and hybrid vehicle HVAC, extended-life air compressor oils, and strategic acquisitions highlight a bifurcation—larger players are securing supply and distribution scale while nimble innovators push technical boundaries that will influence OEM specs.
Supply-chain and raw-material dynamics shaping 2026 strategies
Polyalkylene glycol feedstocks remain the most immediate source of cost and supply risk. Late-2025 inflation and producer price upticks have translated into higher PAG production costs and more volatile procurement windows. Ethylene oxide and propylene oxide price movements are the primary drivers; their volatility forces manufacturers to adopt more flexible sourcing, active hedging, or closer integration with base‑stock suppliers.
For 2026 planning, firms should stress-test procurement strategies against three scenarios: stable feedstock prices, a sustained up‑cycle driven by upstream capacity tightness, and sporadic spikes from feedstock disruptions. Each scenario has distinct implications on pricing strategy, inventory policy, and customer contract terms.
Strategic recommendations for 2026 (executive priorities)
- Prioritize refrigerant compatibility as a product design principle: Update R&D roadmaps to ensure formulations meet low‑GWP refrigerant compatibility and dielectric requirements for electrified compressors—this will unlock OEM approvals and premium pricing.
- Lock in supply through diversified sourcing and strategic partnerships: Negotiate multi-tier agreements with base‑stock suppliers and consider minority investments or offtake arrangements to stabilize input costs.
- Adopt dynamic pricing frameworks: Move away from fixed multi-year pricing where possible; deploy index-linked clauses tied to feedstock cost drivers to preserve margins.
- Segment commercial models by TCO, not price alone: Market extended-life and high-temperature-tolerant oils on lifecycle cost savings to OEMs and industrial customers to capture value beyond commodity pricing.
- Identify M&A and JV targets now: Use 2026 to close capability gaps—whether in additive R&D, specialty formulations for EV HVAC, or geographic distribution—before regulatory and technology transitions accelerate consolidation.
- Invest in compliance and certification pipelines: Fast-track testing and approvals for new refrigerant compatibility and advertise validated approvals as a differentiation tool in procurement cycles.
- Deploy scenario-based capital allocation: Maintain a capital buffer for rapid capacity or capability investment should feedstock or regulatory scenarios require accelerated response.
Decision-support assets you can deploy immediately
Beyond narrative, the report contains actionable templates for 2026 execution: supplier scorecards that map technical and delivery risk; a cost-to-serve matrix for channel optimization; a procurement playbook with negotiation levers tied to feedstock scenarios; and an M&A diligence checklist tailored to lubricant and base-stock assets. These assets are designed to be operationalized within 60–120 days to influence 2026 procurement cycles and partnership negotiations.
How to use this intelligence
Executives should treat the report as a decision-support system: run a three-scenario workshop with commercial, procurement, and R&D leads; prioritize shortlists for supplier and M&A targets; and lock in 2026 procurement terms aligned with the scenario most likely for your cost and margin tolerance. Marketing and product teams should use the regulatory heatmap to accelerate product approvals that will unlock premium segments.
PW Consulting’s Pag Compressor Oil Market report balances strategic narrative and executable detail. It demonstrates why the market’s underlying growth (as captured in our 2026–2032 forecast and the underlying CAGR) creates both opportunity and risk, and it supplies the practical instruments companies require to convert that macro trajectory into winning 2026 actions.
Next steps
-
For full regional and application splits, granular company scorecards, downloadable models, and the regulatory-compliance appendices that inform 2026 decisions, please consult the full report and supporting datasets available from PW Consulting.
-
If you would like a tailored briefing—scenario modeling for your portfolio, supplier stress-testing, or a rapid M&A screen—contact PW Consulting to set up a strategy workshop focused on executable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Pag Compressor Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rainwater Tanks Market Hits USD 1,950.0 Million in 2025, Poised to Grow at a 4.95% CAGR to USD 2,734.71 Million by 2032
By PW Consulting, 2026-07-01
Rainwater Tanks Market 2026: Strategic Imperatives for Resilient Growth — PW Consulting Spotlight
As climate variability, urbanization and resource-efficiency mandates accelerate, rainwater tank deployment has moved from niche sustainability projects into strategic water-security portfolios for farms, municipalities and commercial real estate. PW Consulting’s new Rainwater Tanks Market report (base year 2025, historical 2020–2025, forecast 2026–2032) equips senior executives and investment committees with the forward-looking intelligence required to make high-consequence decisions in 2026. The global market reached approximately USD 1.95 billion in 2025 and, under our central scenario, expands at a compound annual growth rate of 4.95% through 2032, approaching roughly USD 2.73 billion by the end of the forecast window.
Rainwater Tanks Market
Why this report matters for 2026 decision cycles
-
Capital allocation: identify which product forms, channel models and geographies will deliver defendable margins as raw-material and regulatory volatility intensify.
Rainwater Tanks Market -
Product and certification roadmaps: prioritize investments in potable-water certification, bunded solutions and flood-resilient design to preempt regulatory shifts and buyer expectations.
Rainwater Tanks Market -
Supply-chain resilience: quantify exposure to resin price shocks and supplier concentration; build hedging or nearshoring strategies that preserve gross margins.
-
M&A and partnership screening: spot attractive targets—regional champions, specialty fabricators or service integrators—that accelerate route-to-market without overstretching balance sheets.
-
Commercial execution: convert incentive programs and agricultural rebates into high-conversion sales plays through tailored channel incentives and installer partnerships.
What’s inside the report — practical, transaction-ready content
-
Proprietary market sizing and 2026–2032 forecasts anchored to a 2020–2025 historical baseline and stress-tested against three downside/upside scenarios.
-
Segmental frameworks (by region, material, installation type and end-use) with demand drivers and elasticities mapped to price, regulation and climate variables. Note: detailed segment tables and downloadable datapacks are reserved for report subscribers.
-
Regulatory and incentives map covering major jurisdictions—identifying mandates, compliance timelines and rebate programs that materially affect payback calculations.
-
Raw-material sensitivity model that quantifies margin exposure to polyethylene resin and steel price swings and provides hedging and sourcing playbooks.
-
Competitive benchmarking toolkit: product-position matrices, capability heatmaps, channel footprints and M&A fit scoring models built from primary interviews and company filings.
-
Commercial playbooks for OEMs and installers: GTM sequences, installer training templates, rebate-to-sale conversion funnels and digital lead-generation scripts tested in multiple markets.
-
Investor-focused appendices: valuation multiples observed in recent transactions, typical EBITDA ranges by product/material, and due-diligence checklists for strategic acquisitions.
-
Implementation roadmaps and sample KPIs for 6-, 18- and 36-month horizons to move from pilot projects to scaled deployments.
Methodology and data provenance
-
Quantitative modeling combines bottom-up supply-side build-ups, installer/utility channel sales data, and top-down demand assumptions tied to precipitation, construction starts and agricultural acreage trends.
-
Primary research: >120 interviews across manufacturers, distributors, installers, standards bodies and public agencies conducted in 2024–2026 to validate adoption constraints and product preferences.
-
Triangulation: pricing intelligence is reconciled with transactional data and public filings; scenario forecasts are stress-tested for material-price shocks and regulatory accelerations.
-
Base year 2025 data and forecast period 2026–2032 are provided to enable capital planning cycles and three-year strategic reviews commonly used by corporate finance teams.
Key market dynamics shaping 2026 moves
-
Regulatory acceleration: policymakers are increasingly mandating rainwater harvesting in new agricultural and commercial construction. For example, recent European and Australian regulatory actions mean manufacturers and specifiers must be prepared for faster adoption curves and higher compliance requirements.
-
Incentive-driven demand: domestic subsidy programs and agricultural rebates (notably recent US programs that offset installation costs) are converting marginal projects into bankable propositions for smallholders and land managers.
-
Materials pressure: polyethylene resin experienced a notable price uptick in 2025, driven by supply-chain disruptions—this alters unit economics, shortens windows for price promotions and elevates the importance of procurement strategies.
-
Standards and certification: potable-water and lead-free certifications are increasingly table stakes where tanks are used for human or food-agriculture applications; manufacturers who secure these credentials gain access to premium channels.
-
Climate extremes: flood-resilient designs and underground storage options are being evaluated not only for water capture but for stormwater management, broadening the use-case set for tanks beyond simple collection.
Competitive landscape: who’s shaping supply and innovation
The market is characterized by strong regional players and a competitive field of specialized manufacturers. PW Consulting’s strategic review spotlights several entrants whose moves in 2024–2025 exemplify the directions incumbents and challengers are taking:
-
Tank Depot (Florida, USA) — A prominent U.S. polyethylene manufacturer focused on a broad residential and commercial SKU set. Their depth in small-to-medium SKUs and national distribution channels make them a go-to partner for retail and online channels.
-
Norwesco (Oklahoma, USA) — A rotational-molding specialist whose recent potable-water certification expands addressable markets into agricultural reuse and municipal procurement—an example of how certification can unlock premium demand.
-
JoJo Tanks (Cape Town, South Africa) — A regional champion whose new high-capacity slimline product targets arid agricultural regions; representative of growth driven by product adaptation to environment-specific constraints.
-
Clark Tanks & Polyworld (Australia) — Both firms are pushing capacity and design innovation for rural and flood-mitigation applications, illustrating the premium placed on context-specific engineering.
-
Hibernia Tanks (Ireland) — Specialist in bunded solutions and EU-compliant products, signaling the premium value that compliance-driven segments can command in construction and commercial tendering.
-
Sintex Industries (India) — An example of scale in emerging markets where cost-competitive roto-molded products support rapid rural and rooftop adoption.
Recent product launches, certification gains and prototype showcases across this set underscore two strategic themes: (1) certification and design differentiation are pathways to enter and protect higher-margin end uses; (2) regional champions retain advantages through local channel relationships and compliance familiarity. PW Consulting regards the market as commercially diverse—national champions coexist with specialized suppliers—creating both consolidation opportunities and niche plays.
Top strategic moves for 2026 — prioritized
-
Secure certification early: allocate budget and engineering resources to secure potable and lead-free certifications where relevant—this is the single fastest route to premium channel access.
-
Hedge raw-material exposure: implement multi-sourcing, lock in term contracts and evaluate alternative materials or blended formulations to protect gross margins.
-
Build installer economics: create margin-backed installer programs combined with micro-finance or rebate passthroughs to accelerate conversions in agricultural and rural segments.
-
Pilot differentiated products: field-test flood-resistant and underground solutions with municipal partners to build case studies and shorten procurement cycles.
-
Deploy data-enabled services: pair tanks with simple telemetry for level monitoring and maintenance alerts—subscription services increase lifetime customer value and create cross-sell opportunities.
-
Target M&A selectively: prioritize acquisitions that add certification, proprietary design, or distribution in high-growth agro-urban corridors rather than commoditized, price-sensitive SKUs.
How executives should use this intelligence
-
Board-level planning: incorporate the report’s scenario outputs into budget cycles and capital-allocation deliberations to stress-test portfolio investments against the projected 4.95% CAGR baseline and downside shocks.
-
Country and channel prioritization: use the regulatory and incentive mapping to sequence market entry and resource deployment, turning rebate windows into first-mover advantage.
-
Commercial KPI alignment: adopt the report’s recommended installer economics and payback thresholds to standardize sales compensation and project finance approvals.
Next steps & access to the full intelligence pack
This briefing is designed as a strategic preview: it highlights the macro trajectory, competitive dynamics and practical levers executives must consider in 2026. To convert these insights into executable plans, PW Consulting’s full Rainwater Tanks Market report contains the granular segmentation tables, downloadable datapacks, proprietary pricing models and implementation templates required to act with confidence. Organizations preparing 2026 budgets, M&A pipelines or product roadmaps will find the full report’s datasets and scenario models indispensable.
For access to the complete dataset, segmented forecasts and the operational playbooks referenced here, please consult the PW Consulting Rainwater Tanks Market report landing page and request the enterprise datapack and advisory workshop tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Rainwater Tanks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydroelectric Generator Repair Market to Reach USD 7,317.12 Million by 2032, Driven by a 5.22% CAGR
By PW Consulting, 2026-07-01
Hydroelectric Generator Repair Market 2026: Strategic Imperatives from PW Consulting’s Latest Study
PW Consulting’s new Hydroelectric Generator Repair Market report delivers actionable intelligence for executive teams preparing capital, operational, and M&A decisions in 2026. Drawing on an integrated analysis of historical trends (2020–2025), market forecasts (2026–2032), supply‑chain dynamics, and primary interviews with operators and OEMs, the study maps where repair demand will emerge, how cost pressures will reshape procurement choices, and which capabilities will determine winner‑take‑advantage outcomes in the next investment cycle.
Hydroelectric Generator Repair Market
Why 2026 Is a Decisive Year for Repair Investment
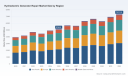
Hydropower operators and service providers are converging on a narrow window to upgrade existing assets and capture value from flexibility and resilience requirements. Our base‑year assessment (2025) places the global hydroelectric generator repair market at USD 5,124.5 Million, with modelled demand jumping to USD 5,685.7 Million in 2026 and continuing on a path to roughly USD 7,317.1 Million by 2032 under a compound annual growth rate of 5.22% for the forecast period. These macro figures reflect both cyclical project timing coming out of pandemic‑era delays and structural drivers — an aging fleet, electrification‑driven metals demand, and renewed policy incentives for refurbishment.
Hydroelectric Generator Repair Market
For corporate leaders, the implication is straightforward: 2026 is not a routine maintenance year. It is a strategic inflection point to accelerate modernization programs, optimize spare‑parts sourcing, and capture premium pricing for fast, reliable outage execution.
Hydroelectric Generator Repair Market
Key Market Dynamics Shaping Repair Strategy
-
Aging fleet and deferred modernization: Nearly two in five hydropower units globally are beyond four decades of service life, creating an outsized cohort of major generator rewinds, rotor refurbishments, and bearing replacements. These are capital‑intensive, technically complex interventions that favor suppliers with integrated engineering, field capabilities, and project management systems.
-
Raw material volatility and lead‑time risk: Copper and steel remain central to generator repairs. Recent industry data shows marked increases in copper prices and producer price indices for copper/brass mill shapes, which elevate repair bill uncertainty and extend procurement timelines for custom components. Long lead times for specialized forgings and machined parts make early procurement planning a competitive advantage.
-
Policy tailwinds and financing levers: Incentive programs and infrastructure funding in major markets have begun to lower the hurdle rate for refurbishment projects. Capital support that targets efficiency upgrades and environmental mitigation is expanding owner willingness to undertake beyond‑routine repairs that also enhance flexibility for grid services.
-
Digitization and performance engineering: Recent refits that couple mechanical overhaul with digital monitoring — for example, turbine‑generator overhauls that include condition monitoring and analytics — are creating new service tiers and recurring revenue streams. Digitally enabled refurbishments reduce unplanned downtime and allow performance‑based contracting models that align OEM incentives with owner outcomes.
What the Report Provides: Practical Tools for 2026 Decisions
PW Consulting designed this study as an operational playbook for in‑year decision making. Highlights include:
-
Investment prioritization framework — A validated scoring matrix to sequence units for repair based on technical urgency, grid value, regulatory eligibility for incentives, and supply‑chain exposure.
-
CapEx phasing and cash‑flow modelling templates — Scenario models that map repair timing to cash‑flow impacts and illustrate the sensitivity of project economics to metal price swings and lead‑time delays.
-
Vendor selection and contracting playbook — Procurement checklists, technical acceptance criteria, and contract clauses that mitigate warranty, logistics, and aftermarket spare‑parts risks.
-
Supply‑chain risk heatmap — Country and supplier risk profiles for long‑lead components, plus recommended hedging and dual‑sourcing strategies to protect schedules.
-
Technology assessment guide — Decision trees for when to pursue component replacement versus in‑situ repair, and conditions under which digitization or minor retrofits deliver disproportionate value.
-
Practical case studies — Detailed anonymized examples of recent overhauls showing timelines, cost drivers, supplier coordination challenges, and measurable post‑refurbishment performance gains.
Competitive Landscape: Capabilities That Win
The repair ecosystem combines global OEMs, specialized service houses, and regional field providers. Market concentration is moderate: the top three suppliers account for roughly 28.4% of identifiable market engagement, and the top five aggregate closer to the low‑forties percent range — a structure that rewards both scale and niche technical capability.
Key competitors profiled in the study include:
-
ANDRITZ HYDRO (Austria) — Offers end‑to‑end rehabilitation, modernization and maintenance services with substantial installed generator capacity worldwide. Their integrated delivery model is advantageous for multi‑unit refit programs requiring single‑contract accountability.
-
Voith Hydro (Germany) — Strong in full electromechanical solutions and modernization projects; competitive on turnkey refurbishments that bundle turbine and generator scopes under unified engineering management.
-
GE Vernova (United States) — Brings rotor repair expertise and manufacturing scale for new rotors; well positioned where owners value OEM‑level parts traceability and factory warranties.
-
RESA Power, HECO, Jenkins Electric, H&N Electric (United States) — These specialist players provide high‑touch maintenance, rewinds, and testing services that are frequently contracted for fast turnaround emergency work and planned rewinds.
-
Goltens and Metalock Engineering — Deliver in‑situ machining and advanced repair techniques that reduce disassembly and shorten outage duration — a critical capability for operators prioritizing availability.
-
Nidec ASI and Ansaldo Energia — Focus on generator upgrades and partial replacements where modernization aims to extend operating envelopes and integrate new control/excitation systems.
-
Regional and specialist firms (e.g., TurbinePROs, Advanced Hydro Solutions) — Often preferred for local knowledge, rapid mobilization, and specific OEM legacy equipment expertise.
Our competitive analysis goes beyond static profiles: the report rates firms across delivery metrics (turnkey capability, field engineering depth, spare parts ecosystem, digital services, and contract flexibility) and identifies which supplier archetypes are best suited to different owner strategies — from minimal‑capex life extension to full modernization that supports grid‑firming revenue streams.
Recent Signals: Projects and Policy That Matter
-
Operational modernization with digitization: A major North American overhaul recently combined mechanical refurbishment with digital upgrades to improve low‑cost clean generation — a blueprint for high ROI refurbishments that reduce forced outages.
-
Large public solicitations: High‑profile solicitations for turbine replacements and generator rewinds signal continued public investment in critical dam infrastructure, which tends to catalyze regional service demand and supplier mobilization.
-
Penstock and civil support: Ongoing penstock refurbishments in long‑running fleets highlight cross‑discipline project risk: generator repairs are frequently coupled with civil and hydraulic scopes, necessitating integrated project delivery capabilities.
-
Data consolidation at policy level: Updated national reports emphasize incremental capacity gains through refurbishments and support more aggressive refurbishment pipelines in regulated markets.
Strategic Recommendations for 2026
-
Adopt a prioritized, staged approach to overhauls: Use a scoring framework to sequence units for intervention — prioritize projects that unlock ancillary revenue or reduce high‑probability failure risk.
-
Hedge raw‑material exposure and de‑risk long‑lead items: Negotiate supplier commitments for critical copper and steel components early, and build conditional contracts that allow schedule flexibility while protecting price risk.
-
Leverage digital retrofits to defray capex: Where full mechanical replacement is not immediately necessary, deploy condition monitoring and analytics to extend life while creating a data‑backed path to future modernization.
-
Choose contracting models to align incentives: Performance‑based contracts that tie supplier payments to availability and efficiency gains can transfer execution risk and improve lifecycle outcomes.
-
Invest in multi‑discipline supplier relationships: Integrated projects that include civil, mechanical, and electrical scopes favor suppliers capable of cross‑scope coordination — owners should evaluate supplier ecosystems, not just unit prices.
How This Report Helps Executives Make Better 2026 Calls
Executives face three concurrent uncertainties in 2026: the timing of project cash flows, material cost volatility, and supplier capacity constraints. PW Consulting’s report converts these uncertainties into decision levers. By combining a transparent market forecast (with base‑year sizing and a clear CAGR trajectory), scenario modelling templates, and a supplier capability matrix, the study lets leaders align capital allocation with operational risk tolerance and strategic objectives — whether that objective is maximizing generation availability, extending asset life at low cost, or positioning assets for new grid‑service revenue.
Importantly, the report acts as a “decision accelerator.” It provides not only the diagnostic — where risk and opportunity are concentrated at the market level — but also the prescriptive playbooks, procurement language, and case examples that enable faster, lower‑risk execution during the 2026 contracting season.
Next Steps
For executives preparing 2026 budgets and procurement plans, the report offers immediate value: actionable frameworks, validated market forecasts, and tactical guidance to reduce outage duration and materially improve project economics. PW Consulting invites operators, investors, and supplier executives to engage with the full study for proprietary segmentation, supplier scoring, and downloadable modelling tools that support rapid prioritization and contracting execution.
For detailed analysis of this topic, please visit the official page: Hydroelectric Generator Repair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Combustion Control Equipment Market Poised to Grow at 5.02% CAGR Through 2032
By PW Consulting, 2026-07-01
Combustion Control Equipment Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s latest market study on Combustion Control Equipment establishes a clear, actionable foundation for corporate decision-making in 2026. After recovering from cyclical pressures in the early 2020s, the global market reached an estimated USD 21,505.9 Million in the base year 2025. Our forecast shows continued expansion at a 5.02% compound annual growth rate (CAGR) through the 2026–2032 horizon, driving the market toward roughly USD 30,261.0 Million by 2032. These headline dynamics create both strategic risk and commercial opportunity for equipment OEMs, systems integrators, aftermarket specialists and energy-intensive end users.
Combustion Control Equipment Market
Why this report matters for 2026 decision cycles
- Timing: 2026 is the inflection year — regulatory enforcement, energy-efficiency programs and capital replacement cycles align to make near-term moves disproportionately impactful.
- Scale: With the market expanding from ~USD 16.85 billion in 2020 to ~USD 21.51 billion in 2025, incumbents must convert topline momentum into sustainable margin expansion and recurring service revenue.
- Concentration: The market exhibits moderate concentration (CR3 ~32.4%, CR5 ~48.15%), leaving strategic room for targeted consolidation, differentiated product plays and service-led growth.
- Decision support: The report translates macro trajectories into prioritized action plans — from product roadmaps to M&A screening — tailored to 12–18 month execution windows.
Market trajectory: read the signals, not the noise
The combustion control equipment market has moved beyond a simple recovery story; it is entering a structural phase driven by decarbonization targets, tighter emissions rules and the digitization of process assets. PW Consulting’s forecast shows steady growth across the 2026–2032 period (5.02% CAGR). The growth is underpinned by three persistent forces:
Combustion Control Equipment Market
- Regulatory tightening — e.g., low-NOx mandates and updated safeguards — which push replacement and retrofit cycles.
- Operational efficiency programs — industry initiatives targeting multi‑percent combustion performance gains to meet corporate net‑zero trajectories.
- Technology convergence — IIoT-enabled controllers, advanced flame monitoring and integration with process DCS now deliver measurable fuel savings and emissions reductions, making investments easier to justify to CFOs.
Dynamics that will shape capital allocation in 2026
Four observable market pressures will determine where firms should allocate capital in 2026:
Combustion Control Equipment Market
- Compliance-driven capex: Standards and directives are moving from guidance to enforced thresholds. Companies that pre-position SIL-certified safety modules and low‑NOx control solutions will avoid rushed, high-cost retrofits.
- Raw material and labor cost inflation: Supply-chain hiccups and input cost increases (for example, stainless-steel price volatility) combined with rising skilled technician wages increase installed costs and compress margins on low-value transactions.
- Service and outcome monetization: Operators are seeking guaranteed performance models (fuel savings / NOx limits). OEMs that can wrap hardware with digital monitoring and performance contracts will win higher-margin, recurring revenue streams.
- Digital and systems integration: Integration of combustion controls into modern DCS and cloud analytics stacks is a differentiator; investments in software and open APIs will accelerate wins for companies that currently rely purely on electro-mechanical differentiation.
Competitive landscape — what the leaders are doing
The report provides a granular, actionable mapping of incumbent and challenger positioning. Highlights include:
- Honeywell International Inc. (Charlotte, NC) — entrenched in burner management systems, flame safeguards and control panels for industrial boilers and furnaces; strong channel relationships in large-scale industrial accounts.
- Emerson Electric Co. (St. Louis, MO) — combines distributed control systems with burner management; recent product introductions (e.g., the Movimentum combustion controller) emphasize boiler efficiency and retrofit friendliness.
- ABB Ltd. (Zurich, Switzerland) — expanding safety and automation credentials through SIL-certified combustion safety modules and integrated control platforms, enabling turnkey safety-compliant upgrades.
- Siemens AG (Munich, Germany) — leverages process control platforms for seamless combustion optimization; recent showcases underline tighter interoperability between burner controls and modern PCS architectures.
- Woodward, Eclipse (Sterling/Eclipse brands), Fives/Maxon, Weishaupt, Oilon and Baltur — each occupies specialized niches across engines, burners, valves and control boxes, offering deep product expertise and aftermarket channels.
Recent industry moves reflect strategic intent: Siemens demoed advanced combustion controls integrated with its PCS neo platform at Hannover Messe (April 2025), Emerson launched a combustion controller aimed at improved boiler efficiency (June 2025), and ABB secured SIL 3 certification for key safety modules (October 2024). These events signal that the frontier of competition is now software-enabled performance, safety certification and systems integration rather than hardware alone.
What’s inside the PW Consulting report (practical, execution-ready content)
The published study is built as an executable playbook for commercial leaders and strategy teams. Key components include:
- Market sizing and validated forecasts (historical 2020–2025, base year 2025 and granular 2026–2032 projections), with scenario sensitivity and upside/downside stress tests.
- Regulatory and standards impact matrix detailing timelines, enforcement risk and compliance cost buckets for major jurisdictions.
- Technology and product taxonomy: control systems, burners, boilers, monitoring systems and their interoperability layers — with deployment pathways for retrofit and greenfield projects.
- Buyer economics and TCO models that convert combustion efficiency gains into ROI for plant owners under different fuel and carbon-cost assumptions.
- Supplier benchmarking and scorecards — performance, certification, digital capability and aftermarket strength (confidential scorecards available in the full report).
- M&A screening framework and candidate scoring methodology to identify attractive tuck‑ins and capability buys aligned to 2026 strategic priorities.
Note: this press summary intentionally omits granular regional and end‑user percentage splits to preserve our subscribers’ competitive advantage. The full report contains the detailed segmentation tables, downloadable models and supplier-level metrics.
Actionable strategic recommendations for 2026
For executive teams planning capital and commercial strategies this year, we recommend prioritizing six actions:
- Shift from product to outcome selling. Bundle sensors, controllers and analytics into performance‑guarantee contracts (fuel savings / emission ceilings) to capture recurring revenue and deepen account penetration.
- Invest selectively in SIL‑certified safety and open‑API digital layers. Safety certification is table stakes for large industrial adopters; interoperability with major DCS platforms accelerates adoption.
- Prioritize retrofit solutions with low installation time and reduced commissioning risk. Given supply‑chain and labor cost pressures, solutions that minimize downtime will command premium pricing.
- Diversify input sourcing and adopt hedging for key materials. Tactical contracts for critical components (e.g., sensor housings) reduce margin volatility and protect project economics.
- Accelerate service and remote monitoring capabilities. Upskilling technician pools and investing in remote diagnostics reduce total cost of ownership for customers and raise aftermarket margins.
- Use M&A to buy capabilities, not just revenue. Look for targets with digital platform elements, installed-base service contracts and local certifications that lower entry barriers in strategic markets.
Implications by function — quick checklist for 90/180/360 day plans
- Commercial: Reprice retrofit offerings to reflect higher labor and material costs; pilot outcome-based contracts with two anchor clients within 90 days.
- Product: Deliver an interoperability roadmap to integrate burner controls with at least one major DCS partner within 180 days; fast-track SIL certification where applicable.
- Supply chain: Secure rolling agreements for critical materials, and establish second-source options for key components within 180–360 days.
- HR / Operations: Launch a technician upskilling program tied to new digital diagnostic tools; reduce field rework rates and improve first-time fix metrics within 360 days.
How to use this report in boardroom and investor conversations
The PW Consulting study is structured to support high-stakes conversations with boards, investors and strategic partners. Use the market scenarios to stress-test capital allocation alternatives, the buyer economics models to justify price premia for performance contracts, and the supplier scorecards to inform build vs. buy decisions. For private equity and strategic acquirers, our M&A framework prioritizes targets that accelerate a shift from one-time hardware sales to annuity-style service streams.
Conclusion — the 2026 strategic playbook
In 2026, the combustion control equipment market is both mature and transformable. Market growth at a mid-single-digit CAGR masks substantial heterogeneity — where regulation, digital integration and service economics create pockets of high-margin opportunity. Leaders will be those who combine certified safety and interoperability with outcome-based commercial models, supply-chain resilience and a focused M&A program to plug capability gaps. PW Consulting’s report equips management teams with the quantitative forecasts, competitive intelligence and the tactical playbooks needed to convert 2026’s inflection into sustainable advantage.
Next steps
For full access to the granular regional, product and end‑user breakdowns, detailed company scorecards, downloadable financial models and bespoke advisory options, visit PW Consulting’s Combustion Control Equipment Market page or contact our research team to schedule a briefing. The public summary is a trailer; the full report contains the data and executable tools that will materially change your 2026 planning assumptions.
For detailed analysis of this topic, please visit the official page: Combustion Control Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Halide Light Tower Market Tops USD 1,470 Million in 2025, Poised for a 2.81% CAGR Through 2032
By PW Consulting, 2026-07-01
Metal Halide Light Tower Market — PW Consulting Executive Preview (2026): Strategic Guidance for CapEx, Procurement and Competitive Positioning
PW Consulting today releases an executive preview of our Metal Halide Light Tower Market report, a practical intelligence product designed to support capital and operational decisions in 2026. Drawing on a five‑year historical analysis and a seven‑year forecast horizon, the study places the global metal halide light tower market in clear strategic context: from a measured recovery over 2020–2025 to a stable, slower‑growth trajectory through 2032. The market registered a level of approximately USD 1,470.0 million in 2025 and, at a 2026–2032 CAGR of 2.81%, is projected to finish the forecast period materially higher while remaining a niche, mission‑critical segment for certain heavy‑industry and rental customers.
Metal Halide Light Tower Market
Why this report matters for 2026 decision‑makers
-
Actionable intelligence for procurement: precise supplier diagnostics, risk scores and a procurement playbook tailored to high‑intensity illumination applications where uptime and luminous performance, not pure energy efficiency, drive buying decisions.
Metal Halide Light Tower Market -
CapEx vs. rental modelling: side‑by‑side TCO frameworks and scenario outputs that quantify trade‑offs across purchase, lease and rental strategies for corporate fleets and rental houses facing variable utilization.
Metal Halide Light Tower Market -
Regulatory and emissions roadmaps: compliance trajectories for diesel‑powered units (including Tier‑4 Final implications in key jurisdictions), plus retrofit and replacement thresholds that tie regulatory timing to equipment replacement cycles.
-
Supply‑chain resilience playbook: mapping of critical lamp and component dependencies, supplier single‑point‑of‑failure diagnostics, and practical mitigation options—from dual sourcing to strategic stocking and near‑shoring considerations.
What the PW Consulting report contains — practical deliverables
-
Market sizing and trend analysis (2020–2025 historical, 2026–2032 forecast) with scenario sensitivity to macro growth, commodity pressure and emissions policy changes.
-
Demand archetypes and buyer personas for construction, heavy industrial, rental and emergency‑response users—translated into procurement decision trees and maintenance schedules.
-
Supplier benchmarking and scorecards covering product robustness, mast and fixture architectures, service networks, spare‑parts support, and rental readiness.
-
CapEx/Opex modelling templates that allow CFOs and fleet managers to stress test fleet renewal cycles versus LED migration and emissions compliance costs.
-
Risk matrix and playbooks for raw‑material volatility (notably lamp and arc‑tube supply), logistics disruption, and regulatory shocks affecting field operations.
-
M&A and partnership watchlist—actionable flags for acquirers and strategic partners based on capability gaps and aftermarket potential.
Market dynamics shaping 2026 choices
Two structural drivers define the market’s strategic profile. First, metal halide light towers continue to serve applications where high lumen output and large‑area coverage are non‑negotiable—mining, oil & gas turnarounds, and specific heavy construction use cases. In these contexts, operators prioritize luminous intensity, penetration, and temporary large‑area coverage over absolute energy efficiency, preserving demand for metal halide technology even as LED alternatives proliferate.
Second, the regulatory and emissions environment is increasingly influential. For diesel‑powered mobile units, compliance with stringent emissions standards in key markets has raised the bar for engine selection and aftertreatment strategies, influencing total ownership costs and replacement timing. On the supply side, metal halide lamps rely on specialized materials—metal halide salts and quartz arc‑tube components—and operate within a lamp market ecosystem that itself demonstrates meaningful scale (industry estimates put the lamp market in the low single‑billion USD range in 2025). These two facts together create a landscape in which manufacturers, rental companies and large end users must balance procurement, inventory and lifecycle decisions against component availability and emissions compliance timing.
Competitive landscape — who to watch and why
The market remains characterized by a set of well‑established industrial OEMs and niche specialists. Competing strategies fall into a few distinct patterns: industrial robustness and rental‑friendliness; vertical mast and compact designs for urban construction; ultra‑large mast and fixture counts for heavy industrial coverage; and custom offerings for project specialists. Highlights from the competitive set include:
-
Atlas Copco (Stockholm, Sweden — https://www.atlascopco.com): positions products around ruggedness and rental suitability, with canopy and structural features designed for harsh quarry and rental environments. Their product messaging emphasizes durability, which is a core procurement criterion for rental houses and contractors aiming to minimize downtime and service costs.
-
Generac Mobile (Magnum) (Waukesha, Wisconsin, USA — https://www.generac.com): emphasizes compact, serviceable vertical‑mast designs that suit congested construction sites. Generac’s product portfolio is built to balance portability with the high lumen output demanded by contractors, making it a common choice for mixed fleet strategies.
-
Wacker Neuson (Munich, Germany — https://www.wackerneuson.com): competes with jobsite‑focused towers that integrate into broader equipment fleets and service infrastructures; differentiation is based on system interoperability and global service reach.
-
Grandwatt Electric Corp (USA/China operations — https://www.grandwatt.com): operates across custom and standard segments, serving clients requiring tailored solutions for unique project needs—an important niche for large‑scale, irregular projects.
-
Boss LTG (BossLTR) (Baton Rouge, Louisiana, USA — https://bossltr.com): focuses on trailer‑mounted high‑output models aimed at construction and mining applications; their positioning reflects a strategy built on high lumen per unit and heavy‑duty trailering.
-
DMI Light Towers (Greenwell Springs, Louisiana, USA — https://dmilighttowers.com): known for very large portable configurations with extended mast heights and high fixture counts, targeting expansive industrial sites where coverage area matters more than portability.
-
Trime USA (part of Trime Group — https://trimeusa.com): offers mobile light towers tuned to contractor and rental needs, blending ease of transport with field reliability.
-
Larson Electronics (Kemp, Texas, USA — https://www.larsonelectronics.com): supplies high‑lumen solutions for hazardous and industrial environments, often competing on niche configurations and rapid delivery for service outages and emergency deployments.
Across this set, competitive differentiation increasingly hinges on aftersales, digital enablement (remote monitoring, telematics for utilization and maintenance), and flexible rental or service models. For buyers, supplier selection is as much about network and spare‑parts agility as it is about lamp and mast specifications.
Strategic recommendations for executives in 2026
-
Revisit fleet renewal timelines with regulatory milestones in mind. Align engine and emissions investments to regulatory windows so replacement and retrofit cycles minimize stranded assets.
-
Adopt a hybrid acquisition strategy: retain ownership where utilization is predictable and serviceable centrally; favor rental for episodic, large‑area projects and peak‑season surges.
-
Insist on supplier scorecards that weigh service network depth and spare‑parts lead times as heavily as initial unit price—downtime cost can exceed purchase savings in heavy‑duty applications.
-
Build a strategic inventory of critical lamp components or establish contractual safeguards with lamp suppliers; material specialization and concentrated supplier capacity can create single‑source risk.
-
Pursue aftermarket monetization: extended warranties, predictive maintenance services enabled by telematics, and rapid‑response field teams unlock recurring revenue and reduce total fleet cost.
How to use the full PW Consulting report
The full report contains the granular tables, regional and application segmentation, and vendor‑level scorecards that underpin the executive recommendations summarized here. Subscribers receive dynamic modelling files, procurement templates and a regulatory compliance roadmap specific to major jurisdictions. For teams building 2026 capital budgets, the forecast scenarios and TCO calculators included in the full study will materially reduce uncertainty when comparing purchase, lease and rental strategies.
To protect strategic value for paying clients while demonstrating the depth of our work, this executive preview highlights direction and implications without publishing the detailed regional, application and type splits. Those granular tables, time‑series datasets and supplier quantitative comparisons are available on the report landing page.
Conclusion
For companies making 2026 capital and operational choices, metal halide light towers remain a distinct category where product performance, regulatory timing and supply‑chain fragility intersect. PW Consulting’s Metal Halide Light Tower Market report equips executives with the scenario‑tested analytics, supplier playbooks, and procurement templates required to optimize fleet decisions, mitigate supply risk, and capture aftermarket value. For access to the full dataset, downloadable modelling tools, and supplier scorecards, please visit our report page to review the comprehensive findings and purchase options.
— PW Consulting, Strategic Advisory and Industry Analysis
For detailed analysis of this topic, please visit the official page: Metal Halide Light Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: 4‑Ethylnitrobenzene Reagent Market Poised to Reach USD 78.8 Million by 2032 at a 4.35% CAGR, Led by Asia‑Pacific
By PW Consulting, 2026-07-01
PW Consulting: Strategic Brief — 4‑Ethylnitrobenzene Reagent Market Outlook and Decision Playbook for 2026
PW Consulting’s newly released market study on the 4‑Ethylnitrobenzene reagent (base year 2025, forecast 2026–2032) delivers a compact, actionable intelligence package intended to shape supplier, buyer and investor decisions in 2026. The market is sized at USD 58.5 Million in 2025 and is projected to expand to approximately USD 62.9 Million in 2026, following a compounded annual growth rate (CAGR) of c. 4.35% through the 2026–2032 horizon — reaching an estimated USD 78.8 Million by 2032. This brief distills the report’s strategic value while preserving the report’s exclusive segment-level datasets to encourage direct engagement with the full study.
4 Ethylnitrobenzene Reagent Market
Why this report matters to 2026 decision-makers
-
Timing: Buyers and producers operate in an environment of raw‑material volatility and changing downstream demand. The 2026 planning cycle is the inflection point for procurement, capex and commercial strategies that will determine competitive positioning through 2032.
4 Ethylnitrobenzene Reagent Market -
Practical intelligence: The report combines primary-market interviews, transaction-level pricing models and a proprietary scenario engine to convert macro trends into executable steps for procurement, commercial and M&A teams.
4 Ethylnitrobenzene Reagent Market -
Risk‑adjusted guidance: Rather than generic forecasting, the study provides stress‑tested recommendations tied to price, volume and regulatory shocks to help operators prioritize scarce resources in 2026.
Macro dynamics and raw‑material realities
Two upstream facts dominate 4‑Ethylnitrobenzene economics: it is a derivative of nitration chemistry (nitrobenzene synthesis from benzene and nitric acid), and alkylbenzene feedstocks (notably ethylbenzene/related streams) influence cost and availability. PW Consulting’s analysis integrates observed feedstock moves into forward pricing curves and supply scenarios.
-
Recent price signals: Nitrobenzene pricing in Northeast Asia moved up to approximately USD 1.18/kg in March 2026, reflecting tightening feedstock availability and regional refinery dynamics. By contrast, US nitrobenzene prices experienced a softening episode in late 2025 amid weaker upstream and downstream demand. Such regional divergences create arbitrage and logistics opportunities for firms with global sourcing flexibility.
-
Feedstock volatility: Ethylbenzene and benzene price swings (reported intra‑quarter variation up to double‑digit percentages in recent quarters) have a non‑linear impact on producer margins for specialty derivatives. The report models pass‑through rates and identifies threshold price points where commercial rebalancing is required.
Market structure and concentration — implications for strategy
Overall market structure is characterized by a moderate level of concentration: the largest three producers account for roughly one third of global supply, while the top five approach half of the market. This balance yields both stability (through scale players) and opportunity (for agile specialists). For 2026 planning, that mixed structure implies that:
-
Large suppliers will compete on scale, regulatory compliance and global distribution, making them attractive partners for large pharma and agrochemical clients seeking reliability.
-
Smaller, technically‑oriented players can win share by offering tailored pack sizes, higher‑purity grades and flexible lead times for R&D and specialty synthesis customers.
Competitive landscape — profiles and strategic reads
The market comprises established laboratory reagent brands, specialty fine‑chemical distributors and regional suppliers. Key firms covered in the report include:
-
Tokyo Chemical Industry Co., Ltd. (TCI), Tokyo, Japan — known for research‑grade supply with GC‑verified purities above 99% in a range of pack sizes, servicing academic and industry R&D channels. ( https://www.tcichemicals.com)
-
Sigma‑Aldrich (Merck KGaA), Darmstadt, Germany — global catalog supplier with broad discovery and laboratory product lines, servicing early discovery and institutional customers. ( https://www.sigmaaldrich.com)
-
Thermo Scientific (Acros Organics), Waltham, MA, United States — supplies high‑purity catalog items under a major laboratory brand, optimized for small‑volume research uses. ( https://www.thermofisher.com)
-
Biosynth, Staad, Switzerland — positions for R&D and pharmaceutical testing with catalogue SKUs and regulatory documentation for testing use cases. ( https://www.biosynth.com)
-
Santa Cruz Biotechnology, Dallas, TX, United States — targets biochemical and proteomics research markets with reagent listings. ( https://www.scbt.com)
-
Combi‑Blocks, San Diego, CA, United States — distributes building blocks and bespoke synthesis materials for organic chemists and small molecule programs. ( https://www.combi-blocks.com)
-
Pharmaffiliates, India — supplies high‑purity grades tailored to analytical and research workflows in emerging market contexts. ( https://www.pharmaffiliates.com)
-
Matrix Scientific, Columbia, SC, United States — services both small and bulk demand for fine‑chemical research. ( https://www.matrixscientific.com)
-
Oakwood Chemical, United States — catalog supplier addressing laboratory requirements. ( https://www.oakwoodchemical.com)
Strategic read: the supplier landscape bifurcates into (a) brand catalog players who compete on traceability, documentation and multi‑channel distribution, and (b) fine‑chemical specialists who win on custom synthesis, packaging flexibility and cost‑competitive bulk supply. The report’s competitor scorecards assess capability gaps and highlight likely M&A and partnership targets for 2026.
What the full report contains — practical, execution‑oriented modules
PWC (PW Consulting) designed the report as a toolkit for commercial and procurement teams. The study includes:
-
Market sizing and validated historical time series (2020–2025) plus bottom‑up and top‑down forecasts to 2032 with sensitivity bands.
-
Price modelling for key intermediates with feedstock pass‑through matrices and regional arbitrage scenarios.
-
Supply chain mapping: producer capacities, lead times, logistical choke points, and regulatory/transport considerations for hazardous intermediates.
-
Vendor scorecards and procurement playbook: negotiation levers, contract templates, and hedging strategies tailored to different buyer archetypes.
-
Commercial growth playbook: go‑to‑market templates for expanding into laboratory, pharma‑intermediate and specialty synth markets.
-
M&A and partnership heatmap: accretive bolt‑on targets, integration risks and valuation assumptions under alternative scenarios.
-
Operational dashboards and Excel models: KPI tracker, inventory vs. service level trade‑offs, and a scenario engine to stress test 2026 decisions.
To preserve competitive value, the public summary highlights directionality and methodology; the full study contains the granular segmentation, regional splits and company‑level revenue estimates required to execute on these modules.
Actionable strategic recommendations for 2026
-
Adopt a dual‑track procurement approach: combine short‑term spot exposure for flexibility with medium‑term contracts that include indexation clauses tied to upstream feedstock indices. The report provides templated contract language and break‑points based on our pricing model.
-
De‑risk supply through geographical and supplier diversification, but prioritize partners that can document chain‑of‑custody and regulatory compliance for pharma and agrochemical applications.
-
Expand value by offering differentiated pack sizes and certified high‑purity grades for R&D customers — small product and packaging changes can unlock margin uplift with minimal capex.
-
Invest selectively in process upgrades that reduce feedstock sensitivity (yield improvements, consumption efficiency) where payback falls within a 24–36 month window under our mid‑case scenario.
-
Prepare for regulatory and sustainability pressures: map emissions and waste streams from nitration chemistry and prioritize cleaner process options or certified waste handlers to preserve market access with multinational buyers.
Risks to monitor and KPIs to track in 2026
Key risks include feedstock price shocks, regulatory tightening on nitration intermediates, logistics disruptions and rapid shifts in downstream demand in pharma or agrochemical pockets. Recommended KPIs (included in the report dashboard) focus on:
-
Real‑time feedstock price variance and cost‑per‑kg impact
-
Contract coverage ratio and percent of sourced volume under indexed vs fixed pricing
-
Inventory days versus target service level
-
Customer concentration and fill‑rate by customer segment
-
Average realized price by grade and pack size
How to use this intelligence in your 2026 planning cycle
Procurement, commercial and corporate development teams should treat the report as a living playbook: extract the vendor scorecards to shape Q2–Q3 sourcing rounds, run the Excel scenario engine to set budget ranges for 2026, and use the M&A heatmap to prioritize targets for due diligence. The combination of transactional pricing models and operational checklists is crafted to reduce time‑to‑decision and to sharpen negotiation outcomes in a market where small cost and lead‑time advantages compound rapidly.
Next steps — where to get the full study
This release is an executive preview designed to convey the strategic value of the full PW Consulting study while protecting the report’s proprietary segmentation and company revenue estimates. The complete report contains the granular regional and application splits, detailed company scorecards, and the downloadable scenario models required to operationalize the recommendations above. For access to the full dataset, model files and consultancy support options for 2026 implementation, please visit the PW Consulting website or contact our industry team directly.
Prepared by: Senior Strategy Advisor & Chief Industry Analyst, PW Consulting — delivering market intelligence and decision frameworks to help you convert chemical market trends into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: 4 Ethylnitrobenzene Reagent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tristrimethylsilylamine Market Poised to Reach USD 47.2 Million by 2032 at a 5.5% CAGR; Asia‑Pacific Leads with USD 16.56M in 2025
By PW Consulting, 2026-07-01
Tris(trimethylsilyl)amine Market Outlook 2026: Strategic Intelligence for Action
Executive summary
PW Consulting’s latest market brief on Tris(trimethylsilyl)amine (commonly referred to as tris(trimethylsilyl)amine or TMS–NH) synthesizes operational intelligence proven to accelerate strategic decision-making in 2026. The market has exhibited steady expansion through the early 2020s and, based on our base-year analysis (2025) and validated forecasting, is set to continue growing through 2032 at a compound annual growth rate of approximately 5.5%. In numeric terms, the market expanded materially between 2020 and 2025 and our scenario set projects continued upward momentum into the early 2030s.
Tristrimethylsilylamine Market
This release serves as a strategic “trailer”: it demonstrates the depth and applicability of our findings while reserving proprietary segmentation matrices and granular forecasts for report subscribers. The intent is to equip procurement leads, R&D heads, corporate development teams and plant managers with a clear view of the strategic levers they should prioritize in 2026 without displacing the need for the full dataset and playbooks contained in the report.
Tristrimethylsilylamine Market
Market trajectory and what it means for 2026 decisions
Tris(trimethylsilyl)amine is positioned at the intersection of specialty reagents and high-value advanced materials workflows. Our benchmarked time series shows a clear recovery and growth profile from 2020 through 2025, and a robust forecast into 2032. This combination of near-term resilience and medium-term expansion supports a pragmatic, phased approach to capacity, sourcing, and partnership decisions in 2026:
Tristrimethylsilylamine Market
- Near-term (12–18 months): focus on supply security, quality gating, and contract standardization to mitigate lead-time and purity variability risks across R&D and pilot-scale use cases.
- Medium-term (18–36 months): evaluate selective capacity buildouts and toll-manufacturing arrangements aligned with validated demand corridors; prioritize flexibility over fixed capex where possible.
- Strategic (36+ months): consider M&A or exclusive supply partnerships in target segments where higher value-add integrations (e.g., advanced electronic-grade inputs) promise margin capture.
Demand drivers — where buyers and innovators should focus
Demand is being shaped by a mix of technology-driven applications and conventional synthetic chemistry. Key demand enablers include:
- Thin-film and surface engineering techniques that require high-purity silicon-nitrogen precursors for atomic layer and chemical vapor deposition processes.
- Specialty organic synthesis use cases in pharma and agrochemical R&D where TMS-based reagents serve as selective silylating agents and intermediates.
- Materials-science applications where surface modification and silicon-containing building blocks create differential value (e.g., dielectric layers, passivation chemistry).
For 2026, procurement and R&D leaders must reconcile two realities: the accelerating demand from advanced materials workflows and the historically conservative adoption curves of regulated industries. Early-mover R&D investments that secure validated supply streams will often translate into disproportionate first-mover advantages when applications scale.
Supply-side dynamics and competitive landscape
The supplier base for Tris(trimethylsilyl)amine is composed of established specialty chemical houses and niche silicon-chemistry specialists. The market is moderately concentrated — our concentration metrics place the top three and top five players as significant influencers of availability and terms. This clustering produces both risk and opportunity:
- Risk: Supply interruptions at a major supplier can quickly propagate to lead-time spikes for research and pilot programs given limited second-source capacity for specific grades.
- Opportunity: Strategic offtake agreements, collaborative tolling, and quality-focused partnerships can yield preferential access to electronic-grade materials and co-development pathways.
Representative participants operating in this space include global life-science and analytical suppliers, specialist silicon-chemistry manufacturers and regional distributors. These players differ by scale, grade focus (e.g., electronic vs. industrial/research grades), product presentation (bulk vs. lab packs), and channel strength. Notably, many suppliers explicitly position products as research-use-only in their documentation, a factor that has implications for commercialization timelines and regulatory due diligence.
Regulation and operational compliance
Regulatory context matters for 2026 planning. Tris(trimethylsilyl)amine is captured under existing chemical registration frameworks in major jurisdictions, with full substance dossiers available in relevant registries. For companies planning scale-up or cross-border sourcing, three action items rise to the top:
- Confirm registration and use-case compatibility under applicable chemical regulations prior to committing to commercial-scale procurement.
- Standardize quality specifications (including acceptable impurity profiles) across internal R&D and manufacturing handoffs, and codify them into supplier contracts.
- Design an incident-response and documentation package that anticipates regulatory audits and customer inquiries related to use restrictions (e.g., research-only labeling implications).
What the PW Consulting report delivers (practical, operational content)
Our full report is structured to be immediately actionable for decision-makers preparing 2026 budgets and roadmaps. Highlights include:
- Supply-risk and resilience matrices that map supplier profiles by grade, scale, and geographic exposure.
- Scalable procurement templates (term-sheet language, quality release testing checklists, and delivery KPIs) tailored to specialty reagents.
- Scenario-based demand models with sensitivity testing across adoption curves for advanced deposition and surface-modification workflows.
- CapEx vs. outsourcing decision frameworks supporting go/no-go gating for pilot plants and toll-manufacturing arrangements.
- Regulatory and compliance playbooks specific to cross-border trade in specialized silane and silylamine chemistries.
- Competitive diagnostic dossiers on incumbent suppliers — benchmarking product specs, packaging strategy, and distribution approaches — to underpin negotiation strategies.
Each deliverable is integrated with an executable roadmap: prioritized next steps, accountable roles, and 90/180/360-day milestone plans that clients can adapt to their operating model.
Competitive implications for acquirers and incumbents
For corporate development teams evaluating M&A or partnership plays, the mid-level market concentration suggests selective consolidation can be accretive if it secures differentiated product grades or proprietary process know-how. Incumbent suppliers should anticipate greater buyer sophistication in 2026—customers will seek validated quality gates, dual-sourcing options, and predictable lot-to-lot consistency. Tactical considerations include:
- Pursue bolt-on capabilities that strengthen supply-chain resiliency (e.g., glassware handling, nitrogen-purging facilities, specialized QC labs).
- Invest in documented grade upgrades and traceability to capture premium pricing in electronic-grade use cases.
- Develop collaborative innovation agreements with key end-user segments to lock in multi-year demand while sharing development risk.
How to use this intelligence in 2026
We recommend three immediate actions for firms that want to convert this market intelligence into operational advantage next year:
- Run a six-week internal sprint to harmonize compound specifications across R&D, analytical, and procurement teams; this will reduce downstream friction when scaling from grams to kilograms.
- Execute supplier stress-tests: simulate extended lead times and impurity excursions to understand the operational and P&L impact under adverse scenarios.
- Pilot a strategic sourcing trial with tiered commitments: a short-term spot allocation, a medium-term tolling agreement, and a conditional long-term offtake tied to validated process milestones.
Conclusion and next steps
Tris(trimethylsilyl)amine occupies a niche but strategically important position in the chemical value chain. The market’s steady growth profile — together with concentration dynamics and application-led demand — creates a window in 2026 for purchasers, manufacturers, and investors to implement high-leverage moves that do not necessarily require large upfront capital but do require disciplined commercial and technical execution.
PW Consulting’s full Tris(trimethylsilyl)amine Market Report offers the detailed segmentation, supplier scorecards, and downloadable templates that teams need to move from strategy to execution. For teams preparing budgets and strategic roadmaps in 2026, this intelligence reduces uncertainty and accelerates confident decision-making.
About PW Consulting
PW Consulting combines industry-grade market analysis with practitioner-tested playbooks to help chemical and materials companies convert insight into profitable action. Our analyst team blends technical chemistry knowledge with strategic transaction and procurement experience to deliver reports that are both rigorous and operationally useful.
For detailed analysis of this topic, please visit the official page: Tristrimethylsilylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Pulmonary Embolism Therapeutics Market Poised to Grow at an 8.15% CAGR Through 2032
By PW Consulting, 2026-07-01
Pulmonary Embolism Therapeutics Market 2026: Strategic Imperatives for Life Sciences and MedTech Leaders
As the global healthcare community contends with rising thromboembolic disease burden and accelerating innovation across pharmaceuticals and interventional devices, PW Consulting’s latest Pulmonary Embolism Therapeutics Market report equips executives with the strategic intelligence required to make high‑stakes decisions in 2026. The market has expanded meaningfully in recent years and is on a sustained growth trajectory: as of the 2025 base year the market stands at approximately USD 2.19 billion (revenue, million USD basis), and our model projects an 8.15% compound annual growth rate through the 2026–2032 forecast window, culminating in a market size approaching USD 3.78 billion by 2032. These headline benchmarks frame a dynamic competitive environment where clinical evidence, regulatory inflection points and reimbursement positioning will decide winners and laggards.
Pulmonary Embolism Therapeutics Market
Why this report matters for 2026 decision-making
-
Actionable foresight: We translate macro growth into decision-ready scenarios for market entry, lifecycle management and M&A, calibrated to 2026 strategic planning cycles.
Pulmonary Embolism Therapeutics Market -
Evidence-to-commercial translation: The report links clinical trial outcomes and device clearances to expected adoption curves in hospital systems, ambulatory care and novel care pathways.
Pulmonary Embolism Therapeutics Market -
Risk-adjusted modeling: Our financial and operational models stress‑test pricing shocks, generic entry timing and supply chain disruptions to quantify downside and upside for company portfolios.
-
Market access playbooks: We deliver payer segmentation, coding and reimbursement levers, and practical tactics to accelerate uptake for both drugs and devices.
What’s inside: pragmatic deliverables for executives
-
A proprietary forecast model (2026–2032) with scenario toggles for clinical adoption, pricing erosion, and device reimbursement—all exportable for board-level presentations.
-
Competitive intelligence dossiers for branded anticoagulants, thrombolytics and thrombectomy platforms, covering clinical positioning, patent cliffs, and likely generics dynamics.
-
Go‑to‑market templates for launch readiness: target hospital profiles, key opinion leader (KOL) mapping, contracting negotiation playbooks and center-of-excellence implementation checklists.
-
Supply chain risk matrix highlighting API vulnerability, raw material concentration, and mitigation strategies for manufacturers and contract partners.
-
Regulatory and reimbursement trackers that map near-term patent expiries, exclusivity windows, and payer policy changes most likely to impact 2026 commercialization plans.
Competitive landscape: incumbents, challengers and tactical implications
The market reflects a balanced mix of established pharmaceutical leaders and highly focused interventional device specialists. Our concentration analysis indicates a market where the top three firms capture a clear majority of the value pool and the top five control roughly three‑quarters—creating an environment in which scale matters for distribution, contracting and evidence generation.
-
Bayer AG: With a direct oral anticoagulant positioned for both acute treatment and prevention, Bayer remains a high‑visibility incumbent. Strategy for 2026: double down on differentiated clinical messaging and consider expanded service offerings to defend hospital formularies against rapid generic substitution.
-
Bristol‑Myers Squibb / Pfizer (Eliquis): Jointly marketed DOACs occupy a central role in outpatient secondary prevention strategies. A near‑term patent event creates a material timing consideration for pricing and contracting teams; companies must be prepared to deploy lifecycle levers and to pre‑negotiate managed‑care agreements to protect realized value.
-
Boehringer Ingelheim and Daiichi Sankyo: Both maintain strategic positions with alternative oral agents and have opportunities to exploit niche clinical segments and guideline‑driven transitions from parenteral to oral regimens.
-
Genentech (Roche): The thrombolytic franchise continues to be clinically indispensable for massive PE with hemodynamic compromise. Payers and providers are tightening criteria for use; market participants need tailored evidence-based reimbursement dossiers to preserve access for eligible patients.
-
Inari Medical and Penumbra: Device innovators have accelerated adoption by coupling robust trial evidence with workflow‑oriented product evolution. Notably, a randomized trial demonstrating device superiority versus anticoagulation in an intermediate‑high risk cohort is a potential watershed event for interventional adoption paradigms and hospital investment decisions.
-
Boston Scientific: Focused on adjunctive technologies, firms with ultrasound‑facilitated thrombolysis and other hybrid solutions will need to justify value through patient‑level outcomes and total cost of care analyses to achieve scale.
Regulatory and reimbursement inflection points that will shape 2026
-
Patent and exclusivity timelines are concentrated in the immediate horizon. Anticipate accelerated price erosion post‑patent cliffs and build contingency plans for launch sequencing, tender participation and market share defense.
-
Reimbursement policy for mechanical thrombectomy and device‑based interventions is maturing; hospitals evaluating capital and procedural investments will increasingly require evidence of both clinical and economic superiority versus conservative pathways.
-
Supply chain fragility—particularly for critical APIs—has raised costs and created procurement pressure. Manufacturers should prioritize dual sourcing, strategic inventory and supplier collaborations to avoid episode‑of‑care disruptions.
-
Clinical guideline nuance constrains off‑label utilization of thrombolytics in many markets; manufacturers and hospitals must align real‑world evidence programs with guideline committees to protect reimbursement pathways.
Strategic priorities by stakeholder
-
Pharmaceutical executives: Reassess portfolio prioritization in light of impending generic dynamics; accelerate lifecycle programs that add clinical differentiation (e.g., pediatric data, formulation advances) and lock in preferred status through outcomes‑based contracts.
-
Device companies: Evidence generation remains the accelerant for adoption—invest in randomized studies, center‑level health economics analyses, and peri‑procedural tools that reduce total blood loss and OR time. Reimbursement teams should push for robust coding and coverage strategies ahead of scale‑up.
-
Health systems and providers: Optimize triage pathways to match therapy intensity to risk; invest in training and cross‑disciplinary care models that enable safe expansion of device‑based care where evidence supports improved outcomes.
-
Investors and M&A teams: Target companies that either de‑risk adoption through strong real‑world datasets or that offer modular technologies with clear plug‑and‑play economics for hospitals.
Where the report intentionally draws the line (and why)
In keeping with the strategic “trailer” approach, this article highlights the market’s macro trajectory, the competitive dynamics and the decision levers most relevant to 2026 planning. To preserve the consultative value of the full deliverable, detailed regional and application‑level splits, granular pricing matrices, and exact revenue shares by segment are available only within the comprehensive report package. Executives seeking to convert these insights into executable plans will need access to the full dataset, scenario models and tailored consulting add‑ons.
How PW Consulting helps implement the insight
-
Tailored advisory sprints (4–12 weeks) to translate market scenarios into board‑ready investment cases.
-
Commercialization accelerators that include KOL engagement playbooks, payer negotiation simulations and launch‑to‑scale operational plans.
-
Transaction support—diligence, valuation stress tests and post‑close integration roadmaps focused on product‑level synergies in PE therapeutics.
Conclusion: positioning for 2026
For strategic leaders setting priorities in 2026, the pulmonary embolism therapeutics landscape presents both disruption and opportunity. The market’s growth trajectory underscores expanding patient needs and investment potential, but patent expiries, evolving reimbursement, and supply pressures demand proactive, evidence‑driven responses. Companies that combine rigorous clinical programs with pragmatic market access strategies and resilient supply chains will be best positioned to capture value as the market scales toward 2032.
For access to the full PW Consulting Pulmonary Embolism Therapeutics Market report—including the downloadable forecast model, segment‑level breakouts and proprietary commercial templates—visit our report page or contact PW Consulting’s strategy team to request a briefing and customized scenario analysis tailored to your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Pulmonary Embolism Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Yoghurt and Sour Milk Drinks Market to Expand at a 5.3% CAGR
By PW Consulting, 2026-07-01
PW Consulting Releases Strategic Brief: Yoghurt And Sour Milk Drinks Market — A Tactical Guide for 2026 Decision-Making
Executive summary
PW Consulting today publishes a strategic industry brief derived from our comprehensive Yoghurt And Sour Milk Drinks Market report (base year: 2025; forecast period: 2026–2032). The global market, measured in USD million, has demonstrated steady expansion across the 2020–2025 historical window and is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of 5.3%. Our analysis translates these macro trends into operationally useful guidance for executives preparing investment, portfolio and commercial decisions in 2026.
Yoghurt And Sour Milk Drinks Market
Why this briefing matters for 2026
-
Macro momentum: After a recovery phase in the early 2020s, the sector reached an estimated market size of approximately USD 134,250.5 million in 2025, and our forecast shows sustained growth to an estimated USD 192,714.6 million by 2032. That trajectory underscores sizeable absolute opportunity for incumbents and new entrants over the next six years.
Yoghurt And Sour Milk Drinks Market -
Strategic inflection points: 2026 will be a year when pricing pressure from raw material volatility, platform shifts in retailing, and tightening nutrition regulation converge — forcing rapid portfolio and pricing choices that will determine share shifts through 2028.
Yoghurt And Sour Milk Drinks Market -
Actionability: PW Consulting’s report is structured as a decision toolkit — it moves beyond descriptive market sizing to provide playbooks for product innovation, channel prioritization, cost pass-through strategies, and M&A screening calibrated to multiple demand scenarios.
Market trajectory at a glance
Our topline tracking shows the market expanding from the 2020 base through 2025 and into the forecast window. The estimated 2025 market size of USD 134,250.5 million serves as the report’s reference point. With a forecast CAGR of 5.3% for 2026–2032, the market is projected to advance materially by 2032, indicating that companies that align product portfolios, price architecture, and channel strategies to capture premiumization and health-driven demand will realize disproportionate gains.
What the full report contains (practical, non-academic deliverables)
-
Integrated market model: Scenario-based forecasts (conservative / base / aggressive) with sensitivity levers for raw material costs, price elasticity and channel mix — enabling finance teams to stress-test revenue and margin outcomes.
-
Go-to-market playbooks: Granular, executable guidance for launching drinkable formats vs. spoonable SKUs, retailer promotional tactics, and bundling strategies for omnichannel rollouts.
-
Commercial levers & pricing playbook: Step-by-step frameworks to assess cost pass-through, promotional ROI thresholds, and trade-off matrices for private-label competition versus brand-led premiumization.
-
Supply chain & procurement playbook: Risk matrices and hedging tactics for dairy powder exposure, co-manufacturing decision frameworks, and capex prioritization for regional production footprint shifts.
-
M&A and partnership scorecards: A decision tree and financial checklist for acquiring capability (e.g., probiotic R&D, plant-based formulations, or direct-to-consumer infrastructure) and for JVs in high-growth emerging markets.
-
Regulatory and quality playbook: Compliance checklists mapped to recent labeling and safety developments to reduce recall and rework risk in targeted markets.
-
Retail & shopper analytics: Channel-specific shopper journeys and assortment optimization guidance for supermarkets, convenience, online, and specialty channels.
Competitive landscape — who matters and why
The sector remains a mix of global platform players, strong regional cooperatives, challenger brands, and private-label competition. Market concentration is moderate: the combined share of the top three players sits in the low 30s (CR3 ≈ 32.4%), with the top five approaching the low 40s (CR5 ≈ 41.8%). This structure creates room for national champions and specialist innovators to outmaneuver larger incumbents through speed and niche focus.
-
Danone (Paris): Global scale in branded probiotic and mainstream yoghurt portfolios. Recent product launches emphasize gut health — a core premiumization vector.
-
Lactalis (Laval): Strength in mass-market and private-label manufacturing; defensive moves on sugar reduction exemplify how large producers defend shelf-space.
-
Chobani (New York): Innovator in protein-led and drinkable formats; recent launches show how value-added nutrition can drive sell-through in developed markets.
-
Yakult Honsha (Tokyo): Probiotic-specialist with deep distribution expertise in key Asian markets; production expansions in South Asia signal geographic focus for probiotic penetration.
-
Fage, Nestlé, Arla, General Mills and others: Each brings distinct strengths — from authentic regional recipes to scale in global retail relationships and plant-based innovation.
-
Smaller challengers (e.g., Siggi’s, Forager Project, Stonyfield): These brands lead on clean-label, organic and plant-based propositions that command margin premiums in select channels.
Recent industry signals that should shape 2026 strategy
-
Raw material volatility: Milk powder costs have risen in early 2026, reflecting supply constraints. Procurement strategies and cost-to-serve re-optimization are immediate priorities for commercial teams.
-
Labeling and nutrition regulation: The EU’s mandatory front-of-pack Nutri-Score and updated US Nutrition Facts rules are shifting on-pack messaging and formulation priorities; anticipating these requirements reduces go-to-market friction.
-
Trade and tariff dynamics: Recent import tariff changes in key markets underscore the need to reassess sourcing and production footprints for export-dependent strategies.
-
Quality and safety vigilance: High-profile recalls in recent years highlight the operational and reputational downside of lapses; the report includes mitigation playbooks for QA, traceability and crisis communications.
Strategic implications & recommended priorities for 2026
Based on the convergence of demand trajectories, regulatory shifts, and supply dynamics, PW Consulting recommends executives focus on three pragmatic priorities in 2026:
-
Portfolio rebalancing toward health-first and convenience formats. Allocate R&D and commercial investment to probiotic, high-protein and low-sugar formulations while rationalizing underperforming SKUs.
-
Channel-led margin optimization. Use channel-specific margin models to reprice, repackage and re-promote SKUs for online and convenience channels where shopper behavior and willingness-to-pay differ materially from traditional supermarket dynamics.
-
Supply resilience and cost-to-serve. Implement tactical hedges, diversify milk powder sourcing, and evaluate co-manufacturing or nearshoring options to blunt tariff and freight risk.
Risk scenarios and mitigation
Our scenario analysis models three plausible 2026 risk vectors — elevated raw material inflation, accelerated private-label penetration, and regulatory tightness on nutrition claims. For each we provide an actionable mitigation menu: pricing cadence design, trade spend reallocation, SKU decommissioning protocols, and targeted promotional elasticity tests to preserve margin without sacrificing volume.
How to use this report in practice
-
CMOs can extract SKU-level go-to-market playbooks to prioritize launches for the next two seasonal windows.
-
CFOs can use the embedded forecast model to run downside stress tests and to underpin working capital plans tied to inventory and trade spend.
-
Heads of Supply Chain can apply the procurement and production decision tree to reconfigure sourcing ahead of potential tariff or freight shocks.
-
M&A teams can leverage the report’s target scorecards to vet bolt-on acquisitions or strategic JV partners in high-growth subsegments.
About the analysis and data transparency
PW Consulting’s market model synthesizes proprietary primary interviews, retailer assortments, company filings and trade data. The public brief intentionally omits detailed subsegment tables and granular regional splits to preserve the executive insights that form the core of our subscription offering. Clients and subscribers receive the full dataset, scenario models, and ready-to-use dashboards suitable for board-level presentations.
Next steps — access and engagement
Executives preparing 2026 budgets and three-year plans should treat this brief as both an early warning system and an operational playbook. To access the full dataset, subsegment forecasts, and tailored advisory workshops, please consult the PW Consulting report page for the Yoghurt And Sour Milk Drinks Market. Our advisory team is available to run a 90-minute executive briefing that translates the model outputs into a prioritized action plan bespoke to your portfolio and regions of interest.
Closing note
The yoghurt and sour milk drinks sector is entering a period where incremental product and channel decisions will compound into meaningful share shifts. With a clear forecast trajectory and the pragmatic tools provided in our report, leaders who align product, pricing and supply choices in 2026 will be best positioned to capture the market’s upside through 2032.
For detailed analysis of this topic, please visit the official page: Yoghurt And Sour Milk Drinks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


