



Category: market research
PW Consulting: Protein Expression Market Valued at USD 4,250 Million in 2025, Projected to Grow at a 9.2% CAGR Through 2032
By PW Consulting, 2026-07-01
Protein Expression Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
As biopharma and biotech enter a phase of accelerated biologics development and manufacturing scale-up, PW Consulting releases a forward-looking strategic briefing that translates the Protein Expression Market’s macro trajectory into executable choices for 2026 executives. Our analysis frames the market’s opportunity and risk architecture around key industry dynamics, competitive moves, supply-chain constraints and regulatory guardrails—while reserving the granular segment matrices and proprietary scenario outputs for the full report.
Protein Expression Market
Market snapshot: sizeable, resilient, and accelerating
Our market model indicates the global Protein Expression Market reached approximately USD 4,250.0 Million in 2025 (base year) and is expected to expand at a compound annual growth rate (CAGR) of 9.2% over the forecast period to approach roughly USD 7,871 Million by 2032. This trajectory reflects sustained demand from therapeutic biologics, increasing research throughput, and growing industrial biomanufacturing adoption.
Protein Expression Market
Two structural features are particularly salient for 2026 decision-making. First, the market’s growth is broad‑based across expression platforms and buyer segments, creating multiple routes to scale. Second, market concentration is moderate: the top three vendors control approximately 42.5% of reported revenues, while the top five capture close to 58.8%—a profile that enables both incumbent leverage and targeted disruption by niche specialists and service integrators.
Protein Expression Market
What the report delivers: operationally relevant intelligence
- Quantitative market-sizing and validated growth scenarios (historical 2020–2025; forecast 2026–2032; base year 2025)
- Decision-ready go/no-go frameworks for build vs. buy across transient, stable, and cell-free production strategies
- Commercial heatmaps and partner archetypes to simplify sourcing, outsourcing and M&A targeting
- Regulatory readiness checklists mapped to ICH and GMP requirements relevant to therapeutic manufacturing
- Cost-to-serve models that isolate raw-material, labor, and capital drivers for new facility or service offerings
- Technology roadmaps highlighting near-term performance inflection points for mammalian, microbial, insect, yeast and cell‑free platforms
- Risk matrices and mitigation playbooks covering supply-chain fragility, IP exposure, and talent scarcity
Note: the full report contains the detailed subsegment breakouts, regional dynamics and financial models that underpin these deliverables. We intentionally withhold those granular tables in this briefing to concentrate on strategic synthesis; the complete intelligence suite is available at our source webpage.
Regulatory and input-cost dynamics shaping strategy
Regulation and input economics are decisive variables for 2026 planning. Therapeutic protein manufacturing remains tightly governed: programs destined for GMP production must align with ICH Q5A on viral safety and Q5D on host cell proteins, which imposes upstream choices with downstream compliance implications. For executives, this means early alignment of process development with regulatory expectations to avoid costly rework during scale-up.
On the cost side, several structural pressures bear close watching. Research- and GMP-grade plasmid DNA prices differ materially and are a recurring cost driver in expression workflows—placing a premium on supplier partnerships or captive plasmid capability. Skilled bioprocess technicians command salary bands that make labor a significant component of operational expenditure; in many developed markets, experienced technicians account for 15–20% of opex in expression operations. Together, these inputs create margin sensitivity to yield improvements and automation interventions.
Competitive landscape: incumbents, challengers and the service layer
The competitive map combines platform technology vendors, component suppliers, and vertically integrated service providers. Key market players profiled in our analysis include Thermo Fisher Scientific, Merck KGaA (MilliporeSigma), Lonza, Sino Biological, Abcam (part of Danaher), QIAGEN, Promega, Takara Bio, GenScript, and Creative Biolabs. Each brings distinct strengths:
- Thermo Fisher Scientific leverages a comprehensive portfolio spanning reagents, expression systems and service-enabling platforms—recently launching high-performance transfection reagents optimized for CHO cell transient expression that push achievable titers significantly higher.
- Merck KGaA focuses on high-yield transient mammalian solutions and transfection chemistries, having refreshed its ExpiCHO line with improved titers tailored to therapeutic applications.
- Lonza continues to solidify its position in CHO-based stable cell-line development and integrated scale-up services; its collaborations to automate scale-up workflows underscore CDMO-style vertical integration as a competitive axis.
- Sino Biological and other catalog-centric players have expanded breadth—rapid catalog growth for viral and oncology targets enables fast time-to-reagent for customers, especially in research and preclinical use cases.
- Specialist vendors (e.g., QIAGEN, Promega, Takara) sustain the market with niche, high-value systems—bacterial, yeast and cell-free offerings that serve both research and manufacturing feeders.
- Service-first providers (GenScript, Creative Biolabs) offer turnkey expression across systems, creating a market for outsourced R&D and preclinical supply that accelerates clients’ timelines while often commanding premium pricing.
Recent vendor moves illustrate the competitive tempo: by 2025 many leaders pushed performance enhancements and platform integrations—high-titer transfection reagents, next-gen transient expression systems, and automation partnerships—sharpening the product-service boundary and increasing customer lock-in opportunities.
Strategic implications for 2026 decisions
Executives should view 2026 as a window for structural positioning rather than short-term playmaking. We recommend five priority actions:
- Prioritize yield and throughput upgrades that produce step-change economics. Small percentage improvements in titer or expression time translate to outsized margin gains given current input-cost structures.
- Lock down plasmid and critical-reagent supply lines with tiered contracts or partial in-sourcing. Price and availability volatility for GMP-grade materials can derail timelines and margins.
- Select platform and partner strategies informed by regulatory end-state. If the target is therapeutic GMP, favor suppliers and CDMOs with documented ICH-aligned processes and viral safety pedigrees.
- Invest selectively in automation and process analytics. Labor cost sensitivity coupled with scarcity of experienced technicians makes automation a durable ROI lever.
- Use M&A and partnerships to close capability gaps. Given the moderate concentration profile, bolt-on acquisitions or technology alliances can rapidly scale capability without contending with entrenched incumbents on all fronts.
Where the opportunities lie—and where to be cautious
High-growth pockets exist across the value chain: therapeutics development (monoclonal antibodies, fusion proteins), expanding research throughput, and nascent industrial biotech applications. However, price compression in commoditized reagents and increasing demands for GMP-readiness create margin traps for undifferentiated players. Firms that combine technology differentiation, regulatory know-how and flexible commercial models (e.g., hybrid product + service bundles) are best-positioned to capture disproportionate value.
Methodology and confidence bounds
PW Consulting’s estimates are built on a triangulated methodology combining supplier disclosures, company financials, proprietary surveys, and bottom-up demand modelling for 2020–2025, with scenario-driven forecasts for 2026–2032. The base year is 2025. Our central case assumes steady adoption of higher-yield transient systems and incremental outsourcing to CDMOs; alternative scenarios in the full report stress-test outcomes under accelerated automation or supply-chain disruption.
Conclusion: the 2026 strategic checklist
The Protein Expression Market presents a clear growth runway, but 2026 will reward disciplined strategic moves more than opportunistic expansion. Companies must concurrently optimize yield, secure supply, meet regulatory barometers and choose partners with demonstrated scale-up credentials. PW Consulting’s full report translates these imperatives into tactical playbooks—financial models, supplier matrices and M&A targets—that operationalize strategy for 2026 boardrooms and investor committees.
For practitioners seeking the granular subsegment tables, regional splits, product-level growth forecasts and our proprietary scenario outputs, the complete Protein Expression Market report and interactive dashboards are available on our website. PW Consulting’s analysts stand ready to customize the models to your company’s asset base and strategic objectives.
For detailed analysis of this topic, please visit the official page: Protein Expression Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts PTFE Release Agent Market to Expand at a 5.2% CAGR Through 2032
By PW Consulting, 2026-07-01
PTFE Release Agent Market 2026 Outlook: Strategic Imperatives for Manufacturers, Buyers, and Investors
As PTFE-based release agents move from niche enablers to strategic inputs across molding, extrusion, and high-value industrial processing, 2026 will be a decision year for companies positioning themselves for the next growth cycle. PW Consulting’s forthcoming Ptfe Release Agent Market report (base year 2025) synthesizes five years of historical performance and a 2026–2032 forecast to provide the action-oriented intelligence executives need to make resilient choices. This briefing highlights the report’s strategic value while preserving the granular segmentation and model outputs exclusively for report subscribers.
Ptfe Release Agent Market
Market snapshot — direction, scale, and trajectory
Our consolidated market model values the global PTFE release agent industry at approximately USD 420 million in 2025. After a steady recovery from 2020, the market is forecast to expand at a compound annual growth rate (CAGR) of roughly 5.2% through the 2026–2032 horizon, reaching the high hundreds of millions by 2032 under the central-case scenario. This trajectory reflects durable demand in core industrial end‑uses and ongoing substitution dynamics where PTFE systems offer performance advantages in release, low friction, and process yield.
Ptfe Release Agent Market
For 2026 planning, the practical implication is clear: the market is neither a hyper‑growth play nor fully commoditized. Instead, it sits in a “value consolidation” phase where performance differentiation, supply‑chain resilience, and regulatory alignment will drive winners and losers.
Ptfe Release Agent Market
Why 2026 is the pivotal year
- Regulatory inflection: Ongoing regulatory developments—most notably broad PFAS restriction proposals and hazardous‑substance designations affecting certain PFAS precursors—are already influencing formulation choices, supplier approvals, and capital planning. Companies must align product roadmaps with emerging compliance realities to avoid downstream disruption.
- Supply‑side stress points: Feedstock concentration and pricing volatility in 2023–2024 exposed structural supply risks. Hydrofluoric acid and fluorspar price and availability swings materially change unit economics for PTFE producers and downstream formulators.
- Technology and application migration: Improved dispersion technologies and semi‑permanent release systems are prompting OEMs and compounders to revisit total cost of ownership analyses—creating opportunities for value capture beyond pound‑for‑pound price competition.
Market dynamics: what’s moving the industry
Three cross‑cutting dynamics define the near‑term operating environment:
- Input concentration and pricing pressure: A high share of certain feedstocks is produced in a limited set of geographies, creating vulnerability to trade disruptions and localized policy shifts. Recent commodity and intermediate price moves—reflected in hydrofluoric acid spikes and elevated fluorspar import valuations—have already driven margin compression cycles and pushed buyers to re‑tool procurement strategies.
- Regulatory and ESG acceleration: Momentum behind comprehensive PFAS policies and hazardous‑substance listings is reshaping acceptable chemistries and disclosure requirements. This is accelerating investments in alternative formulations, lifecycle risk assessments, and chain‑of‑custody traceability for fluoropolymers used in release agents.
- Product innovation and service models: Manufacturers are differentiating via dispersion quality, semi‑permanent release chemistries, and aerosol/dry‑film product platforms. Meanwhile, high‑value customers increasingly demand application engineering, sampling programs, and performance guarantees rather than commodity supply alone.
Competitive landscape — who matters and why
The PTFE release agent market displays moderate concentration, with the top tier of global fluoropolymer and specialty chemical producers holding meaningful share while a diverse set of formulators and regional specialists populate the mid‑market. The competitive map is characterized by producers that combine raw PTFE capability with application engineering and channel reach.
- Chemours (Wilmington, DE, USA): A recognized leader in PTFE resins and dispersions with recent capacity expansion initiatives and sustainability certifications that sharpen its value proposition for industrial release applications.
- Daikin Industries (Osaka, Japan): Offers high‑quality PTFE powders and dispersions used across rubber, plastics, and composite molding—an entrenched supplier to multinational compounders.
- Syensqo (Brussels, Belgium): Brings specialized dispersions tailored to food‑processing and tire markets, reflecting a strategy of application‑focused differentiation.
- 3M (St. Paul, MN, USA): Competes with fine PTFE micropowders and coating systems targeting dry film release and high‑precision extrusion use cases.
- Gujarat Fluorochemicals (GFL) (Noida, India): An expanding capacity player with strategic investments to support rising industrial demand and regional supply diversification.
- AGC Chemicals (Tokyo, Japan), McLube (McGee) (Doylestown, PA), Axel Plastics Research (Woodside, NY), and Miller‑Stephenson (Danbury, CT): These companies demonstrate the market’s breadth—mixing technology, specialty formulations, and channel intimacy with industrial end users.
Recent strategic moves—capacity additions, sustainability certification, and targeted plant investments—underscore how incumbents are converting technical advantage into go‑to‑market momentum. For potential new entrants, these moves raise the bar on both scale and compliance readiness.
What PW Consulting’s report delivers — operational, decision‑grade intelligence
Our full report is built as a playbook for executives who need to translate market intelligence into 12–36 month choices. Key deliverables include:
- Proprietary market sizing and three‑scenario forecasts (base, upside, downside) for 2026–2032 with sensitivity models tied to commodity inputs and regulatory scenarios.
- Supply‑chain maps highlighting single‑sourced intermediates, logistics chokepoints, and alternative feedstock pathways to support resilience planning.
- Competitive benchmarking with capability heatmaps, technology differentiation matrices, and M&A / partnership archetypes tailored to both upstream (PTFE production) and downstream (formulators, OEM integrators) players.
- Regulatory impact assessment and compliance readiness checklists—spanning EU PFAS proposals, North American hazardous‑substance listings, and major Asian regulatory trends—translating policy into operational triggers and capital planning considerations.
- Practical procurement playbooks: vendor evaluation scorecards, cost‑to‑serve models, and hedging/stockpiling decision trees keyed to real price‑shock scenarios.
- R&D and product roadmaps with adoption case studies illustrating how dispersion tech, semi‑permanent systems, and low‑PFAS formulations affect total cost of ownership and cycle time in target applications.
To respect competitive discretion and to preserve client value, the report reserves granular segmentation tables, regional/application-level percentage splits, and unit‑price curves for subscribers.
Strategic playbook for 2026 — six prioritized actions
- Stress-test supply chains now: Run at least two stress scenarios that tie fluorspar and hydrofluoric acid price/availability to margin sensitivity. Prioritize dual‑sourcing or secured off‑take agreements for critical intermediates.
- Accelerate compliance‑first reformulation: Invest in low‑risk alternatives and lifecycle assessments before regulatory enforcement tightens. Early movers will gain qualification advantages with OEMs.
- Shift procurement toward value outcomes: Move from spot procurement to performance‑based contracts that include application engineering, on‑site support, and KPIs tied to yield improvements.
- Pursue bolt‑on capability where it matters: For chemical producers, targeted acquisitions of formulators or dispersion technology specialists can compress time‑to‑market for compliant products and secure channel access.
- Embed product‑service bundles: Develop semi‑permanent and maintenance‑reducing systems with aftermarket service agreements that lock in higher lifetime value.
- Monitor regulatory pipelines closely: Establish a cross‑functional regulatory early‑warning function that converts evolving PFAS policy into product acceptance and capital expenditure triggers.
Who benefits most from this intelligence
The report is tailored for three decision audiences in 2026:
- Producers of PTFE and fluoropolymers seeking to prioritize capacity investments and customer segments that maximize margin per ton while minimizing regulatory exposure.
- Formulators and compounders evaluating partnership, licensing, or acquisition options to secure premium dispersions and semi‑permanent technologies.
- Buyers, OEMs, and private equity investors conducting due diligence on supplier resilience, regulatory risk, and long‑tail operational exposure across manufacturing footprints.
Conclusion — a 2026 playbook, not just a forecast
As companies plan capital and product roadmaps for 2026, the intersection of moderate market growth, concentrated feedstock supply, and accelerating regulatory change makes actionable intelligence essential. PW Consulting’s Ptfe Release Agent Market report provides forecast rigor, executional playbooks, and supplier‑level insights designed to turn uncertainty into competitive advantage. We intentionally limit public disclosure of core segmentation tables and unit economics to report subscribers—because the commercial value is created at the intersection of data and execution.
For boards, procurement leaders, and R&D heads preparing 2026 budgets and strategic priorities, this report distills the choices that matter and the timing for them. To access the complete analysis, segmentation data, and downloadable scenario models, visit PW Consulting’s report page and request the full Ptfe Release Agent Market report.
For detailed analysis of this topic, please visit the official page: Ptfe Release Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Thermoplastic Conductive Additives Market to Reach USD 4,732.36 Million by 2032, Expanding at a 9.42% CAGR
By PW Consulting, 2026-07-01
Thermoplastic Conductive Additives Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market study on Thermoplastic Conductive Additives is released at a pivotal moment for plastics, electronics, and mobility value chains. The report synthesizes longitudinal market sizing, technology trajectories, supply-chain stressors, and competitor positioning into a single decision-useful playbook for executives planning through 2026 and beyond. Below we summarize the report’s strategic value, highlight high-level market dynamics, and preview the operational frameworks that will help corporate leaders convert uncertainty into advantage. For access to the full segmented data, scenario models, and supplier scorecards, please visit the PW Consulting report page.
Thermoplastic Conductive Additives Market
A concise market trajectory that informs allocation decisions
The conductive additives market embedded in thermoplastics is no longer a niche; it has evolved into a growth market with clear investment signal strength. Our base-year analysis (2025) captures an industry that expanded from approximately USD 1.65 billion in 2020 to USD 2.52 billion in 2025, reflecting accelerating demand from electrification, miniaturized electronics, and antistatic packaging. Under our central forecast, the market continues to scale to roughly USD 2.73 billion in 2026 and reaches an estimated USD 4.73 billion by 2032. The compound annual growth rate (CAGR) across the forecast window is 9.42%, a tempo that justifies active strategic planning across procurement, product development, and M&A agendas.
Thermoplastic Conductive Additives Market
Why 2026 is a strategic inflection point
- Convergence of demand vectors: Thermal management for high-power electronics, EMI/ESD shielding in ever-denser PCBs, and static-dissipative requirements in advanced packaging are converging on conductive thermoplastics as an enabling solution. This creates a multi-industry pull that accelerates adoption curves.
- Technology mix matters: Multiple additive classes—traditional carbon blacks, carbon nanotubes (CNTs), graphene derivatives, metal fibers and flakes, and inherently conductive polymers—are competing on performance, cost-in-use, and regulatory footprint. Product roadmaps and supplier selection must be matched to the right additive technology for the target functional threshold (e.g., dissipative vs. shielding vs. thermal path).
- Supply-side evolution: Capacity expansions and compounding partnerships announced in 2025–2026 indicate a maturing upstream-to-compounder pipeline. These moves reduce single-point supply risk but also invite pricing and specification competition.
Market dynamics and near-term headwinds
- Raw material pressure and feedstock competition: Conductive additive sourcing is increasingly correlated with commodity cycles and the broader carbon black/graphite markets. Availability and feedstock allocation decisions—particularly where tire and reinforcement markets dominate—are a practical procurement risk for formulators and compounders.
- Nanomaterials ramping but with scaling complexity: Carbon nanotubes and graphene enable low-loading solutions with superior conductivity and lower mechanical trade-offs, but industrial-scale integration requires proven dispersion technology and validated process windows. Capacity investments and compounding programs are reducing this barrier, yet material qualification cycles remain a gating factor for OEM adoption.
- Regulatory and ESG scrutiny: Policymakers are focusing more on particulate and lifecycle aspects of carbonaceous additives. Planned product evaluations in major jurisdictions create a demand for compliance roadmaps and alternative formulations.
- Concentration and competitive dynamics: The market exhibits a measured level of concentration—three leading groups account for a meaningful share of supply with the top five firms further increasing cluster influence. This concentration affects negotiating leverage, access to proprietary formulations, and timelines for new-product commercialization.
Competitive landscape—positioning and tactical recommendations
The supplier map combines global materials majors, specialist nanotube/graphene providers, and compounders with custom-formulation capability. Understanding the capabilities and vectors of differentiation among incumbent and emergent players is a priority for procurement and product teams.
Thermoplastic Conductive Additives Market
- Materials majors (e.g., carbon black and graphite incumbents): Established chemical players bring scale, quality control, and broad distribution. They are the default partners for high-volume, cost-sensitive applications. Strategy: secure long-term offtake terms with performance clauses and collaborate on application-specific trials to lock early-design wins.
- Formulators and compounders (e.g., engineering-thermoplastic specialists): Compounders that combine conductive additives with tailored resin systems reduce integration risk for OEMs by delivering process-ready pellets. Strategy: prioritize partners with local production footprints and in-line testing to shorten validation cycles.
- Nanomaterials specialists (CNT/graphene-centric firms): These suppliers offer high-performance pathways at low loadings, delivering smaller mechanical penalties and thinner cross-sections. Strategy: adopt staged commercialization—pilot with CNT/graphene in high-value applications while maintaining fallback routes to carbon blacks for cost-sensitive products.
- Hybrid and downstream integrators: Companies that combine fibers, metal fillers, and advanced dispersion technology enable bespoke thermal/EMI profiles. Strategy: co-develop IP and joint testing programs to capture unique performance trade-offs that are hard to replicate.
Representative companies profiled in the report include global majors and specialists who collectively shape technology and go-to-market dynamics. Our firm-level analysis covers capabilities, regional manufacturing footprints, product families, and partnership openness—delivering a map of prospective suppliers and likely strategic allies for 2026 initiatives.
Operational playbook for executives
The PW Consulting report is designed as an executable playbook rather than a passive market summary. Key operational actions we recommend for 2026 are:
- Procurement hedging plus qualification lanes: Establish dual-sourcing for high-volume feedstocks and create qualification lanes that run in parallel—one for cost-optimized carbon-based solutions and another for low-loading nanomaterials. This reduces single-point failure risk and compresses time-to-market for differentiated products.
- R&D staging and material-agnostic design: Shift early product architecture to be material-agnostic where feasible; define electrical and thermal performance by function rather than by additive type to preserve optionality in supplier selection.
- Partnerships with compounders: Co-invest in pilot lines and jointly funded qualification programs with compounders near key OEM plants to reduce logistical complexity and speed up validation.
- M&A and minority investments: Target bolt-on assets that provide novel dispersion technologies, low-cost scale for graphene/CNT processing, or regional compounding capacity. Smaller equity positions with option rights can secure capacity without full acquisitions.
- Regulatory and sustainability roadmap: Preempt compliance risk by mapping potential evaluation timelines and implementing exposure-reduction strategies (e.g., enclosed processing, product stewardship documentation, and lifecycle assessments).
What the PW Consulting report delivers
Our full study is structured to convert analysis into action. Highlights include:
- Validated market sizing and forecast models with scenario sensitivities across 2026–2032, including downside (supply shock) and upside (rapid EV adoption) cases.
- Technology deep dives that compare additive classes on conductivity per loading, mechanical trade-offs, processability, cost-in-use modeling, and qualification timelines.
- Supplier intelligence dossiers that profile strategic intent, proprietary technologies, regional manufacturing nodes, and partnership openness for leading players.
- Procurement and sourcing playbooks with negotiable contract templates, indexation strategies, and supply diversification checklists.
- Go-to-market frameworks for formulators and OEMs, including value-capture levers, certification pathways, and go/no-go decision trees for new additive adoption.
- Risk dashboards covering feedstock volatility, regulatory timelines, and technology obsolescence triggers, with recommended mitigation actions.
Case examples and near-real-time updates
The report contextualizes the opportunities with real corporate moves and industry signals—recent capacity additions and compounding partner programs reduce dispersion risk for nanomaterials, while new plant announcements among compounders in key regions change the latency of supply. Our monitoring continuously captures such developments and factors them into rolling forecasts so that subscribers maintain an operationally ready view for supplier negotiations and product roadmaps.
How to use this intelligence in 90/180/365-day plans
- 90 days: Complete supplier audits, initiate parallel qualification lanes, and secure short-term inventory buffers for critical components.
- 180 days: Launch co-development projects with one nanomaterial provider and one high-volume carbon-based supplier; execute pilot production runs to validate processing windows and cycle times.
- 365 days: Finalize long-term offtake agreements with capacity guarantees, roll out validated materials into select product families, and evaluate M&A/strategic investments to secure mid-term capacity.
Final note — why your 2026 playbook needs this report
At a time when conductive thermoplastic additives are transitioning from specialty to mainstream, the cost of delayed decisions is rising. Executives who can align sourcing strategy, technology adoption, and regulatory preparedness will capture the bulk of near-term margin upside and avoid interruption. PW Consulting’s Thermoplastic Conductive Additives Market report combines verified market sizing, competitor analysis, and prescriptive playbooks to enable those decisions. To unlock the full dataset—including granular segmentation, supplier scorecards, and downloadable scenario models—please access the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Thermoplastic Conductive Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ribbed Smoked Sheet Rubber Market Set to Reach USD 7,168.03 Million by 2032, New Report Reveals
By PW Consulting, 2026-07-01
Ribbed Smoked Sheet (RSS) Rubber Market Outlook 2026: Strategic Imperatives for Buyers, Producers and Investors
PW Consulting’s latest Ribbed Smoked Sheet (RSS) Market report positions 2026 as a pivotal year for commercial strategy in natural rubber. Our analysis synthesizes macro volumes, price dynamics, regulatory shocks and supplier behaviours to deliver an actionable playbook for procurement leads, industrial buyers, producers and private equity evaluating exposure to RSS. The market’s recovery and forward trajectory are clear: after a multi-year oscillation, total RSS market revenues reached USD 5,320.5 Million in our base year (2025) and are forecast to expand to USD 7,168.03 Million by 2032, reflecting a compound annual growth rate of 4.35% across the 2026–2032 horizon. These headline metrics underpin the strategic choices companies must make next year—choices our report is explicitly designed to inform.
Ribbed Smoked Sheet Rubber Rss Market
What the report delivers — practical, decision-ready intelligence
- Multi-year market model (2020–2025 historical; 2026–2032 forecast) with scenario overlays to stress-test demand, pricing and supply disruptions.
- Regulatory and trade-impact module: EUDR traceability compliance pathways, tariff scenario mapping and playbooks for compliance and mitigation.
- Supplier and capability benchmarking templates, including an adjustable supplier scorecard for commercial tendering and SRM (Supplier Relationship Management).
- Cost and margin decompositions that translate latex and processing cost swings into finished-RSS unit cost—and into implications for downstream product pricing.
- Strategic options matrix for corporates: from procurement hedging and contract design to vertical integration and selective capacity investments.
- M&A and partnership heatmap identifying where scale, traceability credentials and processing sophistication create value.
Why 2026 is a strategic inflection point
The near-term market dynamic is defined by three interlocking pressures that materially affect sourcing, pricing and compliance risk in RSS: raw material volatility, evolving regulatory requirements, and a concentrated supplier landscape.
Ribbed Smoked Sheet Rubber Rss Market
- Raw material volatility: Natural rubber latex prices rose materially into late 2024—pressures that flow through to RSS production costs. Additionally, aggregate natural rubber output declined in 2024 due to leaf disease in Southeast Asia, elevating the probability of episodic supply constraints. Procurement strategies that ignore these supply-side shocks will face margin compression or product shortages.
- Regulatory pressure: The EU Deforestation Regulation (EUDR) now requires full traceability from plantations for RSS imports, effective from 2025 onward; geolocation and chain-of-custody data have become non-negotiable. Parallelly, destination market requirements (e.g., updated Thai industrial standards) and higher tariffs in key markets add layers of complexity for exporters and importers alike.
- Market concentration: The RSS market shows a mid-to-high concentration among leading producers. While this concentration supports scale and supply reliability in normal conditions, it elevates exposure to policy measures, certification access and operational incidents at major suppliers.
Competitive landscape — what the leading players are doing
The market’s top producers and exporters present differentiated strategic postures—each offering lessons for partners and rivals.
Ribbed Smoked Sheet Rubber Rss Market
- Sri Trang Agro-Industry (Hat Yai, Thailand): A clear market anchor with large-scale capacity. Recent ISCC certification across Thai facilities signals a prioritized route to premium, certified supply chains. For buyers, Sri Trang represents a low-friction option for companies that must rapidly prove sustainability credentials.
- Von Bundit (Trang, Thailand): Notable for plantation ownership and export orientation. Vertical control of raw material supply delivers quality consistency and cost visibility; however, dependence on geographic clusters increases susceptibility to regional agro-climatic events and regulatory frictions.
- Southland Rubber Supply (Hat Yai, Thailand): Integrated processing capabilities focused on tire- and industrial-grade sheets. Their model underscores the value of processing depth for customers seeking technical specification fidelity and just-in-time supply.
- Vietnam-based players (Halo International, Phuoc Hoa, Tongking Rubber Group): These firms are scaling exports and downstream integration, increasingly supplying higher-grade sheets to Europe and North America. State-linked entities and vertically integrated firms offer reliability—which matters in an era of traceability scrutiny—but can be sensitive to policy shifts.
- Rubber Board Malaysia via licensed mills and Indian exporters (e.g., AVT Natural Products): These participants help diversify sourcing options for buyers seeking mitigation of Thailand-centric trade risk. Licensed mill frameworks illustrate how national governance can be leveraged to certify compliance at scale.
Recent market developments reinforce these themes: global RSS production estimates and country shares reported by industry bodies, certification moves by leading producers, and episodic price spikes driven by supply constraints. Together they create both risk and opportunity for buyers and investors prepared with the right strategies.
Strategic playbook for 2026 — five priority moves
- Operationalize traceability now. Implement geolocation-based traceability pilots with tier-1 suppliers to meet EUDR and major buyer requirements. The report includes an implementation checklist and technology vendor scoring guide that de-risks roll-out timelines.
- Design procurement contracts for cost pass-through and flexibility. Combine shorter price-review windows with limited fixed-volume commitments to handle latex price volatility without forfeiting supply security. We provide model contract clauses tuned for RSS markets.
- Build sourcing resilience through selective diversification. Add non-Thai suppliers and licensed-mill channels to your roster to hedge tariff and country-specific supply risk, while prioritizing certified suppliers to preserve market access in regulated jurisdictions.
- Invest in downstream capability selectively. For midstream players, adding modest processing capacity or forming JV partnerships to upgrade lower grades into application-specific sheets can capture margin and reduce exposure to raw latex swings.
- Adopt a scenario-driven investment lens. Use our three-tier scenario framework (Base, Supply-Shock, Accelerated-Regulation) to evaluate capex and M&A choices. The framework quantifies revenue and margin outcomes under each scenario to inform 2026 capital allocations.
What buyers and investors will value most in our report
Executives tell us they need two things from market intelligence: rapid clarity on downside risks, and concrete steps to convert regulatory or supply disruption into competitive advantage. PW Consulting’s RSS report delivers both. It combines a robust market model—capturing the path from USD 4,250 Million in 2020 through USD 5,320.5 Million in 2025 to a USD 7,168.03 Million projected market in 2032 at a 4.35% CAGR—with playbooks and templates that can be operationalised inside 90–120 days.
Importantly, while we present high-level regional and application trends, the report intentionally withholds detailed segment-by-segment allocations in this release to preserve client value and encourage direct engagement. Subscribers to the full report will receive granular regional and application splits, supplier-level benchmark tables and downloadable scenario models.
How PW Consulting supports execution
- Fast-track advisory: 8–12 week execution sprints to implement traceability and supplier scorecards.
- Quantitative support: bespoke scenario modeling and cost-to-serve analyses calibrated to corporates’ specific grade mix.
- M&A diligence: financial and operational due diligence focused on processing assets, certification status and traceability readiness.
For companies making procurement, manufacturing or investment decisions in 2026, the window to act is clear. The RSS market’s steady long-term growth masks an immediate need for new compliance workflows, diversified sourcing and pragmatic contract designs. Firms that treat traceability and supplier resilience as strategic capabilities—rather than compliance obligations—will unlock preferential access to regulated markets and better withstand the episodic shocks that characterized 2024–2025.
To access the full PW Consulting Ribbed Smoked Sheet (RSS) Market report, including the granular segmentation, supplier scorecards and downloadable scenario models, visit our report page or contact our industry team for a briefing. Our advisors are available to translate the report’s insights into a tailored 100-day implementation plan for your organization.
For detailed analysis of this topic, please visit the official page: Ribbed Smoked Sheet Rubber Rss Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nickel Boride Alloy Market Set to Expand at a 5.48% CAGR Through 2026–2032
By PW Consulting, 2026-07-01
Nickel Boride Alloy Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive overview
Our latest Nickel Boride Alloy Market research positions industry leaders and strategic investors to make high-confidence decisions in 2026. The global market has moved from a modest base in the early 2020s to deutlich expansion: total market revenue increased from approximately USD 111 million in 2020 to about USD 145 million in the 2025 base year, and our forecast projects continued expansion through 2032, with the market approaching the low‑to‑mid‑hundreds of millions by the end of the period. This trajectory reflects a compound annual growth rate (CAGR) of roughly 5.48% across the forecast window of 2026–2032.
Nickel Boride Alloy Market
That topline growth belies a more nuanced landscape: cyclical raw-material pressures, evolving downstream specifications (from catalysts to wear‑resistant coatings and semiconductor‑grade materials), and a competitive mix of global specialty players and regional producers. For corporate leaders, these dynamics create both risk and strategic optionality — the very reason this report is designed as an operational playbook rather than a descriptive summary.
Nickel Boride Alloy Market
Why this report matters for 2026 decision-makers
- Procurement and cost control: Rising nickel markets and volatility have moved procurement from a tactical to a strategic lever; companies without robust hedging, indexation, or vertical sourcing plans face margin compression.
- CapEx and plant positioning: Choosing whether to add conversion capacity, or to invest in higher‑value product forms (e.g., engineered powders, sputtering targets), is dependent on forward demand assumptions and capital intensity — this report links demand scenarios to CAPEX decision thresholds.
- M&A and partnership targeting: Fragmentation in specialty segments presents roll‑up and capability acquisition opportunities; we map realistic targets and valuation sensitivities under multiple pricing regimes.
- Go‑to‑market strategy: For suppliers and new entrants, understanding which downstream specifications drive premium pricing (and which are commoditized) is the difference between sustained margins and margin erosion.
- Regulatory and supply‑risk planning: Export controls and ore export restrictions are reshaping regional supply chains; companies must weigh relocation, alternative sourcing, or product reformulation options.
Report contents — practical, actionable modules
We designed the study to be immediately useful to strategy, procurement, and business‑development teams. Key components include:
Nickel Boride Alloy Market
- Top‑down and bottom‑up market sizing, with sensitivity testing across three demand scenarios and explicit modelling of price pass‑through to end markets.
- Detailed supply‑chain maps that trace material flows from raw nickel feedstocks through master alloys and powders to application grade products, highlighting choke‑points and long‑lead suppliers.
- Cost‑build models for representative product forms that allow in‑house teams to run what‑if analyses under variable nickel price cases.
- Commercial playbooks: customer segmentation, pricing strategies, channel choices, and contract templates tailored to catalyst, thermal‑spray, brazing, and semiconductor customers.
- M&A and partnership scorecards identifying high‑value targets by capability, geography, and integration fit, plus worked examples of accretion/dilution under different financing options.
- Regulatory scenario planning that translates export controls and ore‑export policies into quantifiable supply‑risk indices and mitigation pathways.
Competitive landscape — read‑between‑the‑lines analysis
The market structure combines a handful of established specialty alloy houses with a broader cohort of OEM‑facing and regional manufacturers. Our concentration metrics indicate that the top three suppliers account for a material share of market supply, with the top five firms representing a clear majority — a dynamic that shapes pricing power, technology investment, and access to high‑value channels.
Key players profiled in the report (selected examples):
- American Elements (United States) — a diversified supplier of high‑purity nickel boride variants and specialty forms for research and advanced applications ( https://www.americanelements.com).
- Stanford Advanced Materials (SAM) (United States) — supplier of nickel boride powders and evaporation materials serving high‑performance applications ( https://www.samaterials.com).
- KBM Affilips (Netherlands) — European master‑alloy producer with capabilities in nickel‑boron master alloys used for deoxidation and performance enhancement of Ni‑based superalloys ( https://www.kbmaffilips.com).
- Westbrook Resources (United Kingdom) — specialist supplier focused on master alloys for hard‑facing and superalloy production ( https://www.wbrl.co.uk).
- Luoyang Golden Egret Geotools , Huarui Metal , and Xinglu Chemical (China) — regional manufacturers supplying powder portfolios that feed thermal spray and industrial markets (respective sites: https://www.xtc-thermalspray.com, https://www.hruimetal.com, https://www.xingluchemical.com).
- ESPI Metals and PTG Advanced Catalysts (United States and China) — niche suppliers focused on specialized grades for catalysts and lab‑scale applications ( https://www.espimetals.com, https://www.ptgchemical.com).
Our analysis emphasizes capability differences rather than headline market share alone: purity and particle size control, consistency in master alloy chemistry, and trace‑element management determine which suppliers win high‑margin contracts. Regional logistics and certifications (e.g., semiconductor cleanroom standards) further segment supplier attractiveness.
Supply‑chain dynamics and raw‑material pressures
Two structural themes are driving near‑term risk: raw‑material price pressure and strategic resource policy. Nickel prices have experienced a meaningful upswing into 2026, reflecting competing industrial demand and constrained upstream capacity — a trend that materially affects cost structures for nickel‑containing alloys. Price volatility remains a core planning challenge; our report provides hedging matrices and supplier contract constructs that can protect margin through rolling hedges, indexation clauses, and physical offtake arrangements.
On the policy front, export rules and upstream restrictions are reshaping availability. Long‑standing ore export restrictions in certain producing countries, combined with targeted export controls on specific alloy families from major producing economies, mean companies must reassess sourcing footprints. The practical implications are threefold: higher working capital needs to pre‑position feedstock, a premium for onshore downstream processing, and accelerated interest in substitute chemistries where feasible.
Market concentration and strategic implications
The market’s moderate concentration offers distinct pathways depending on an organization’s position. Incumbent leaders benefit from scale economies and established quality credentials, enabling them to invest in R&D and capture premium applications. Mid‑tier suppliers and new entrants succeed by focusing on differentiated capabilities — ultra‑tight particle distributions, proprietary formulations for catalytic selectivity, or rapid custom‑blend response times.
For buyers, the concentration profile suggests a balance between leveraging supplier relationships for innovation and maintaining optionality through dual‑sourcing. For private equity and strategic acquirers, the fragmentation in certain product forms creates roll‑up opportunities, while the presence of certified, high‑barrier niches (for example, semiconductor‑grade products) demands a different valuation lens.
Strategic playbook for 2026
- Producers: Prioritize product premiumization (application‑specific formulations), invest in quality certifications for semiconductor and catalyst customers, and develop flexible pricing mechanisms tied to nickel indices.
- Buyers/Downstream users: Implement dual‑track sourcing (global + regional), build safety stocks strategically tied to lead times, and negotiate dynamic price‑adjustment mechanisms to limit input cost volatility.
- New entrants: Target narrow, high‑margin niches where quality barriers deter mass competition; partner with certified toll‑processors rather than deploying full greenfield capacity initially.
- Investors: Look for assets with demonstrable technical IP, customer contracts in high‑barrier applications, and supply‑chain control that mitigates nickel price exposure.
How PW Consulting’s analysis de‑risks your 2026 decisions
This report converts market intelligence into executable plans: from granular cost models and supplier scorecards to M&A playbooks and regional risk matrices. Crucially, it provides a framework for scenario‑based planning — enabling executives to stress‑test capital investments, negotiate durable commercial terms, and define tactical sourcing responses as macro conditions evolve.
Next steps — access full intelligence
The summary above highlights the strategic contours you need to know now. Our published report contains the full dataset, scenario models, supplier scorecards, and downloadable financial templates that enable immediate implementation. In accordance with our “trailer” approach, we have intentionally omitted detailed segment breakouts and proprietary subsegment figures from this release to preserve the report’s commercial value and to encourage direct access to the source materials.
For procurement leaders, R&D heads, corporate strategy teams, and investors preparing 2026 plans, the report provides the empirical backbone and pragmatic guidance required to convert uncertainty into competitive advantage. To obtain the full report and the accompanying scenario models and templates, please visit the PW Consulting website and request access to the Nickel Boride Alloy Market report.
For detailed analysis of this topic, please visit the official page: Nickel Boride Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oxindole Market Tops USD 85.5 Million in 2025, Poised for Continued Expansion
By PW Consulting, 2026-07-01
Oxindole Market Outlook 2026: Strategic Imperatives for Chemical, Pharma and Specialty Producers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Oxindole Market report — an evidence-based toolkit designed to influence executive decisions in 2026. This advisory distills market dynamics, competitive pressures and actionable plays derived from a structured analysis of historical performance (2020–2025) and a seven-year forecast (2026–2032). The objective: equip leadership teams with the context and strategic levers necessary to convert nascent demand signals into durable commercial advantage.
Oxindole Market
Executive snapshot — what the numbers tell us
Oxindole has moved from a niche research chemical toward a more diversified specialty intermediate over the past half-decade. On a consolidated basis, the market expanded from USD 67.84 Million in 2020 to USD 85.5 Million in the base year 2025, reflecting both steady end-market adoption and periodic supply-side adjustments. Our forecast models — incorporating demand-side adoption curves, purity-driven pricing dynamics and capacity movements — project the market to grow to approximately USD 86.63 Million in 2026 and to USD 118.72 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 4.81% through the forecast horizon.
Oxindole Market
Concentration metrics indicate a moderately consolidated vendor landscape: the top three players account for over 40% of market share while the top five approach six-tenths of the market. This structure enables scale players to influence pricing and quality standards, while leaving room for focused specialists and regional producers to capture pockets of value through niche differentiation.
Oxindole Market
Why this matters for 2026 strategic planning
-
Timing investments to the demand inflection: With the market projected to grow at ~4.8% CAGR, 2026 is a year for calibrated action rather than wholesale expansion. Companies should prioritize flexible capacity options — tolling agreements, modular reactors and contract manufacturing — over large greenfield investments unless they have secured long-term offtake or a clear technical differentiation (e.g., GMP capability, ultrahigh purity manufacturing).
-
Purity and specification as pricing levers: Purity segmentation and end-use requirements drive value far more than raw volume. Investing in analytical capabilities, validated supply chains for critical raw materials, and documented quality systems creates outsized returns when selling into pharmaceuticals or regulated intermediates. Conversely, commodity-oriented players should refine cost-to-serve and logistics to remain competitive in lower-purity streams.
-
Supply resilience and geographic strategy: The market’s supply base spans incumbent Western lab suppliers, Asian bulk producers and specialty European distributors. Buyers increasingly demand traceability, lead-time certainty and GMP-compliant documentation. For sellers, 2026 should be used to shore up dual-sourcing options and diversify manufacturing footprints to mitigate regional bottlenecks.
-
M&A and partnership playbook: Given the market concentration profile, targeted acquisitions (capability fills rather than broad scale plays), minority investments in innovation-stage producers, or strategic alliances around tolling and supply agreements can accelerate market entry or upgrade product mix without excessive capital outlay.
-
Regulatory and quality readiness: Pharmaceutical demand is a primary driver of high-purity and GMP-segment growth. Companies that proactively align facilities to pharma-grade quality systems, and that articulate clear product dossiers for regulatory audits, will command premiums and shorten qualification cycles in 2026.
Competitive landscape — players to watch
Our competitive mapping assessed global catalog suppliers, specialty distributors, and bulk manufacturers across capability, scale, channel reach and regulatory readiness. Core participants include major lab-supply houses and regionally strong manufacturers. The market dynamic is a continuum from research-scale catalog suppliers to GMP-capable bulk producers; each cluster pursues distinct commercial strategies.
-
MilliporeSigma (Sigma-Aldrich) — Burlington, MA: Positioned as a research-grade incumbent, Sigma-Aldrich supplies oxindole at research purities and benefits from integrated distribution channels into pharma R&D. Its strengths are brand trust, catalog breadth and rapid global logistics; its challenge is translating R&D relationships into higher-purity, regulated supply contracts without significant CAPEX.
-
TCI Chemicals — Tokyo, Japan: TCI has a reputation for high-quality reagents and tight analytical characterization. It competes effectively in discovery and materials science segments, where technical datasheets and lot-to-lot consistency are decision factors. Strategic moves to watch: pricing discipline on premium grades and potential expansion of bespoke synthesis services.
-
Thermo Fisher Scientific (Alfa Aesar) — Waltham, MA: Alfa Aesar combines global reach with a familiar catalog interface for researchers. Its advantage lies in penetrating academic and early-stage industrial R&D; the path to higher-margin, regulated supply is contingent on facility certification and strategic partnerships with licensed manufacturers.
-
Combi-Blocks — San Diego, CA & Apollo Scientific — Stockport, UK: These catalog and specialty distributors focus on gram-to-kilogram sales for medicinal chemistry and heterocycle synthesis. Their commercial edge is responsiveness and custom packaging; scale limitations constrain participation in larger industrial flows.
-
Oakwood Chemical — Estill, SC; Hairui Fine Chemicals & Capot Chemical — China: These manufacturers represent the bulk-production cohort. They are critical to industrial supply, offering larger lot sizes and competitive cost structures. The strategic differentiators for these players are GMP capability, supply chain transparency and the ability to rapidly shift capacity between grades.
Collectively, these players form a layered market: catalog suppliers dominate the R&D funnel, while regional producers and specialty manufacturers capture scale-driven industrial demand. For 2026, successful players will be those who manage channel transitions — converting catalog customers into qualified, higher-value purchasers when projects scale.
What the PW Consulting Oxindole report contains (operationally focused)
Our full report is structured to help commercial, technical and M&A teams act quickly and confidently. Highlights include:
-
Robust demand model: A bottom-up forecast through 2032, integrating end-market adoption curves, purity mix scenarios and elasticity assumptions to stress-test multiple growth narratives.
-
Supplier and capability atlas: A matrix mapping global suppliers by scale, geographies, regulatory posture (including GMP readiness), and typical lot sizes — enabling rapid partner selection and contingency planning.
-
Price and margin benchmarking: Scenario-based analysis showing margin sensitivity to purity, lot size and service level commitments — designed to inform commercial negotiations and product strategy.
-
Risk heatmap and mitigation playbooks: Concentration, raw-material exposure, regulatory and logistics risks quantified with prescriptive responses for procurement, operations and commercial leaders.
-
Go-to-market and commercialization templates: Channel strategies, sample SOPs for qualification, and account penetration plans to convert R&D customers into long-term buyers.
-
M&A screening and partnership playbooks: Criteria-driven target screening and integration checklists for capabilitiy-infill acquisitions and tolling partnerships.
Privacy by design: why this release withholds granular splits
In line with our “trailer” approach, this briefing surfaces the actionable strategic insights while intentionally withholding certain granular segmentation data (detailed regional shares, application-by-application percentages and some proprietary pricing points). Those segmented datapoints are central to competitive decision-making and are available in full through the report’s data appendices. The abbreviated public view is calibrated to inform executive strategy without disclosing the proprietary, transaction-critical inputs our clients rely on.
Practical next steps for executives in 2026
-
Immediate (0–3 months): Run a supplier stress-test using the report’s supplier atlas. Verify dual-source viability for critical projects and prioritize contracts with transparent quality documentation.
-
Near term (3–9 months): Pilot a quality upgrade program for at least one product family where higher purity unlocks access to pharmaceutical or regulated industrial demand. Use modular capacity options to avoid long lead-time capital exposure.
-
Medium term (9–24 months): Evaluate bolt-on acquisitions or strategic alliances that fill capability gaps — GMP certification, analytical lab expansion, or logistics hubs close to key demand centers.
-
Continuous: Monitor purity-driven margin profiles and adapt commercial contracts to include escalation and volume-based incentives that reflect the structural growth projected in our CAGR analysis.
Closing perspective
Oxindole’s evolution from a research chemical into a more strategically relevant intermediate creates a nuanced competitive landscape in 2026. The market’s steady growth trajectory through 2032 — underpinned by a ~4.81% CAGR — rewards companies that combine technical excellence with operational flexibility and targeted commercial execution. Scale matters, but so does specialization: premium returns will accrue to players who can certify quality, shorten qualification cycles and align channel economics to the buyer’s commercial life-cycle.
For executives preparing budgets, negotiating supply agreements, or evaluating M&A in 2026, our Oxindole Market report provides the quantitative foundation and the operational roadmaps to convert aspiration into measurable outcomes. To access the full dataset, granular segmentation, supplier scorecards and executable playbooks, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Oxindole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Fiber Online Monitoring Systems for Power Equipment Forecast to Expand at 9.41% CAGR Through 2032
By PW Consulting, 2026-07-01
Optical Fiber Online Monitoring System for Power Equipment: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive snapshot
As power grids worldwide confront accelerated electrification, aging assets, and tighter reliability mandates, optical fiber–based online monitoring is shifting from niche experimentation to mainstream asset management. Our latest market study — covering historical performance through 2025 and a detailed forecast for 2026–2032 — finds that the total global market has expanded materially from the low hundreds of millions in 2020 to roughly three-quarters of a billion USD by 2025, and is projected to nearly double by the end of the forecast window. The modeled compound annual growth rate for the forecast period is approximately 9.4% — a pace that transforms monitoring from a cost center into a strategic enabler of grid resilience and utilization optimization.
Optical Fiber Online Monitoring System For Power Equipment Market
Why this matters to executives in 2026
-
Capital allocation: The transition from pilot projects to fleet-wide rollouts requires a different capital planning lens. A near-term focus on platforms that support multi-asset, multi-physics sensing (temperature, strain, acoustic) will maximize the return on limited capex while shortening time-to-value.
Optical Fiber Online Monitoring System For Power Equipment Market -
Vendor strategy: Market concentration metrics in our study indicate a mid-tier competitive structure where a handful of players hold meaningful shares but leave considerable whitespace for specialized entrants and system integrators. That dynamic favors strategic partnerships, selective procurement, and staged sourcing approaches.
Optical Fiber Online Monitoring System For Power Equipment Market -
Regulatory alignment: Real-time, continuous monitoring capabilities align directly with regulatory priorities around reliability and asset security. Utilities that accelerate deployment can both mitigate outage risk and create measurable compliance and forensic capabilities.
-
Operational transformation: Long service-life characteristics of fiber sensors and low maintenance profiles enable new O&M models — moving from reactive repairs to condition-based, predictive maintenance programs that materially reduce failure rates and lifecycle costs.
What the PW Consulting report delivers (practical, decision-ready content)
-
Executive playbooks: Pragmatic decision trees for procurement, pilot design, and scale-up, tailored to different utility profiles (urban distribution, long-haul transmission, underground and submarine corridors).
-
Technology mapping: Comparative assessments of sensing modalities (distributed temperature sensing, distributed acoustic sensing, fiber Bragg gratings and hybrid approaches), matching performance characteristics to common power-equipment failure modes.
-
Implementation checklists: Step-by-step guidance for field integration, from fiber routing and splice management to data harmonization with SCADA/ADMS and cyber-hardened telemetry practices.
-
Commercial models: Procurement templates, pricing benchmarks, and total cost of ownership scenarios that account for lifecycle maintenance, warranties, and expected longevity of fiber-based sensors.
-
Vendor evaluation framework: A multi-dimensional scorecard that synthesizes technical capability, deployment experience, support footprint, and partnership openness to help shortlist and negotiate with suppliers.
-
Risk & mitigation matrix: Regulatory, supply-chain, and environmental risk assessments, with mitigation strategies mapped to procurement timelines and contract clauses.
Market trajectory and macro signals
The market has demonstrated consistent year-on-year expansion over the historical window to 2025, with momentum driven by utility modernization programs, increased adoption of live-line monitoring for capacity optimization, and a growing appetite for asset health intelligence that oil-and-gas style monitoring systems have long provided. Our forecast projects sustained growth through 2032 as distributed sensing moves from isolated deployments to integrated grid observability stacks. The combination of equipment durability and expanding use cases — from transmission line thermal management to transformer and switchgear hotspot detection — underwrites the forecasted near-double market size over the forecast period.
Competitive landscape — who matters and why
-
AP Sensing GmbH (Böblingen, Germany): A leader in distributed temperature sensing (DTS) systems tailored to power cable monitoring and high-voltage asset profiling. AP Sensing’s strength lies in deep domain alignment with utilities and a product set designed for continuous, railable temperature profiling.
-
VIAVI Solutions Inc. (Chandler, Arizona, USA): Offers an array of fiber sensing and remote monitoring products, combining temperature and strain sensing with mature remote test and monitoring systems. VIAVI’s global support network and test-to-monitor product evolution make it a pragmatic partner for utilities seeking convergence between commissioning test and permanent monitoring.
-
Luna Innovations (Roanoke, Virginia, USA): With EN.SURE and related long-range DSTS offerings, Luna emphasizes monitoring over extended distances — a critical capability for underground T&D cable networks and long overhead runs.
-
Sumitomo Electric Industries (Osaka, Japan): Brings integrated cable and sensing solutions that embed distributed temperature sensing capabilities into cable systems, offering a productized pathway to real-time cable asset management.
-
Prisma Photonics (Israel, with U.S. deployments): Converts existing fiber infrastructure into distributed sensor networks that add temperature, vibration, and event detection to overhead lines. Recent real-world deployments underscore rapid time-to-value where OPGW or existing fiber is available.
-
Bandweaver (UK, global), OSENSA Innovations (Canada), Yokogawa Electric (Japan), EXFO (Canada): Each brings complementary strengths — from DTS platforms and switchgear-focused temperature sensing to OTDR-based fiber monitoring — enabling layered vendor strategies depending on the utility’s asset mix and deployment constraints.
Recent industry developments to watch (implications for 2026 strategy)
-
Partnerships that combine sensing with analytics and dynamic capacity tools are gaining traction. For example, alliances that pair distributed sensing with dynamic line rating (DLR) services can unlock immediate asset utilization benefits and delay costly reconductoring projects.
-
Deployments that leverage existing fiber infrastructure demonstrate the lowest friction pathways to scale. Recent grid projects converting legacy fiber into live sensing fabrics show how operational barriers — largely logistical and contractual —, rather than purely technical ones, determine pace of adoption.
-
Regulatory recognition of continuous monitoring as an accepted reliability practice is beginning to crystallize procurement rationales. Where regulators incentivize outage reduction or penalize reliability lapses, the business case for monitoring capex improves markedly.
Technology dynamics and deployment patterns
Three technical realities should inform strategy in 2026. First, DTS platforms excel at continuous thermal profiling and have proven use cases for underground and subsea cables where early hotspot detection prevents catastrophic failure. Second, distributed acoustic sensing (DAS) and strain sensing add operational event detection — such as third-party interference or mechanical stress — which is critical for overhead line situational awareness. Third, Fiber Bragg Grating (FBG) approaches provide a compact, long-lived sensing element that integrates well in constrained installations like switchgear or transformer windings. Pragmatic deployments often combine modalities to balance cost, coverage, and diagnostic specificity.
Adoption barriers and risk management
-
Integration friction: Data formats, sampling rates, and telemetry capacity vary across vendors; early planning for SCADA/ADMS integration is vital to avoid stranded insights.
-
Procurement fragmentation: Multi-vendor environments can increase integration and SLA complexity — a source of project delay unless governed through clear system integrator roles or platform-based contracting.
-
Operational skill gaps: Effective condition-based maintenance requires analytics and process changes; investments in workforce enablement are as important as the hardware.
-
Supply chain & lifecycle planning: Long service life of fiber sensors reduces some maintenance burdens, but careful lifecycle supply agreements and spares provisioning remain necessary for mission-critical assets.
Practical next steps: A 90-day executive agenda
-
Inventory and opportunity sizing: Map fiber footprints and high-risk assets to identify “low-friction” pilots (e.g., assets with existing OPGW or accessible fiber).
-
Vendor shortlisting: Use a two-phase procurement — technical pilots followed by scale awards — to hedge technology risk while preserving negotiating leverage.
-
Integration pilots: Prioritize end-to-end pilots that include SCADA/ADMS ingestion, alarm rationalization, and field maintenance workflows to prove operational tangibility.
-
Regulatory engagement: Present monitoring pilots to regulators as verifiable reliability improvements to secure potential rate treatment or pilot funding support.
-
Workforce readiness: Initiate a cross-functional training track that pairs field crews with analytics teams to accelerate the translation of sensor outputs into operational actions.
Conclusion — the strategic value proposition
For corporations making 2026 investment decisions, optical fiber online monitoring represents a practical lever to improve reliability, defer capital-intensive upgrades, and create new operational efficiencies. The market’s growth trajectory and vendor landscape point to a window of opportunity where early, disciplined deployments will yield outsized operational returns and strategic optionality. PW Consulting’s full report combines the macro market model, vendor benchmarking, and hands-on implementation roadmaps that utility and industrial buyers need to convert sensing investments into measurable business outcomes.
Access full insights
This brief outlines the high-level strategic implications and practical guidance contained in our full market report. For granular segmentation, vendor scorecards, and downloadable procurement templates, visit the official report page to obtain the comprehensive dataset, appendices, and the actionable playbooks your team will use to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Optical Fiber Online Monitoring System For Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: N Methoxymethyl N Trimethylsilylmethylbenzylamine Market Forecast to Expand at 7.32% CAGR — 2025 Report
By PW Consulting, 2026-07-01
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Lead Industry Analyst, I present a focused strategic briefing derived from our newly released market research on N-(Methoxymethyl)-N-(Trimethylsilylmethyl)benzylamine. This specialty organosilicon amine occupies a narrow but strategically important niche in modern organic synthesis. For executives planning R&D investment, procurement, or M&A in 2026, the report delivers decision-grade intelligence: a clear view of demand momentum, supplier economics, competitive positioning, and the operational levers that translate a small molecule market into measurable strategic advantage.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
Why this compound matters now
The compound is a high-value research reagent and building block used predominantly for the generation of non‑stabilized azomethine ylides and related [3+2] cycloaddition chemistries, which underpin pyrrolidine synthesis and other heterocycle strategies in medicinal chemistry. Its role as a specialist reagent rather than a commodity raw material creates a set of distinct commercial dynamics: low absolute volumes, high technical specificity, and procurement patterns driven by lab-scale demand cycles rather than industrial bulk flows.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
Our market model shows persistent growth from the mid‑2020s baseline through the end of the decade, underpinned by sustained activity in small molecule discovery and process development. The market compound annual growth rate (CAGR) for the forecast window reflects robust, single‑digit expansion — a tailwind that merits serious strategic attention from companies that interface with discovery chemistry, custom synthesis, and supply chain services.
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
High-level market trajectory (what executives need to know)
- Steady structural growth: The market moved from the low‑double‑digit million level in the early 2020s to a noticeably larger base by the mid‑2020s, and our scenario work projects continued expansion through the early 2030s. This growth reflects ongoing demand from pharmaceutical synthesis, laboratory research, and select agrochemical applications.
- Market concentration profile: The market is not highly consolidated. The top three suppliers capture a meaningful minority of share, and the top five extend that position but do not create a tight oligopoly. This concentration profile creates opportunities for nimble entrants and for incumbent distributors to strengthen partnership economics with differentiated service models.
- Supply posture: Production is focused on research‑scale and kilogram‑scale packaging rather than commodity manufacturing. There are no reported large‑volume capacity expansions, which means availability and responsiveness—rather than price alone—drive supplier selection in many procurement decisions.
What the full report contains (practical, actionable chapters)
- Comprehensive market sizing and forecast model with scenario adjustments calibrated to R&D cycle indicators, pharma small‑molecule pipelines, and laboratory reagent purchasing trends.
- Supplier benchmarking toolkit: validated supplier profiles, capability heatmaps (including catalog purity ranges, packaging scales, cold‑chain options, and geographic service footprints), and an RFP template tailored to specialty reagent procurement.
- Commercial risk matrix: supplier concentration, lead‑time sensitivity, upstream feedstock exposure (notably dependencies on trimethylsilylmethyl derivatives and benzylamine precursors), and customs/regulatory friction points across sourcing corridors.
- Strategic playbook for buyers and service providers: procurement negotiation levers, inventory policies for low‑turnover reagents, co‑development and exclusive supply model options, and tactical sourcing routes for crisis response.
- Regulatory and restrictions map that clarifies permitted end‑uses and labeling/handling expectations for a reagent that is sold for research and synthesis purposes only.
- Go‑to‑market and M&A screening framework that helps acquirers and investors evaluate targets on technical capability, customer stickiness, and scalability potential.
Competitive landscape — how to read supplier signals
The supplier ecosystem blends global life‑science distributors, specialized chemical houses, and regional manufacturers. Each archetype plays a distinct role in buyer decision trees:
- Global distributors: Established names in the life‑science supply chain offer catalog availability, predictable logistics, and brand assurance. Their strengths are breadth of reach, standardized quality control, and integrated customer service. For buyers prioritizing regulatory traceability and swift global delivery, these suppliers often form the backbone of supply strategies.
- Specialty reagent houses and building‑block providers: Firms that focus on reagent design and synthesis deliver technical depth—formulations, tailored purity options, and bespoke packaging. These providers are frequently the originators of novel synthetic methodologies and can offer co‑development pathways that accelerate lab adoption.
- Regional manufacturers and traders: Local producers and distributors in key geographies provide competitive pricing and flexible order sizes. They are especially relevant where lead times, import constraints, or localized regulatory handling make domestic sourcing preferable. Their presence contributes to a market environment in which buyers can trade off cost, risk, and responsiveness.
Representative supplier roles identified in our analysis include: large life‑science players supplying research‑grade product lines through catalog channels; specialist building‑block firms offering the compound as a reagent for azomethine ylide chemistry; bulk suppliers able to provide larger pack sizes for process chemistry; and regional manufacturers covering local demand. The mix of these supplier types is a strategic variable: companies that optimize the supplier mix reduce both operational risk and total landed cost for research programs.
Market dynamics and risk considerations
- End‑use restriction: The compound is commercially supplied strictly for research and chemical synthesis uses. Suppliers explicitly exclude medical, therapeutic, or household applications from their intended use statements. This limitation shapes contracting language, liability profiles, and insurance considerations for buyers and distributors.
- Upstream feedstock sensitivity: Production flows are exposed to availability and price movements in specific organosilicon intermediates and benzylamine derivatives. Given the small‑scale nature of production, short supply disruptions can materially impact delivery times and force buyers to adjust experimental timelines.
- Scale and capacity constraints: This is not a commodity market. Production and inventory strategies must be designed around low‑volume, high‑value flows, with consequences for minimum order quantities, storage requirements, and shelf‑life management.
- Technical service as differentiation: Value accrues to suppliers that pair product supply with technical guidance—application notes, impurity profiles, and reaction optimization support. Buyers consistently rank this bundled expertise as a primary driver of supplier loyalty.
Strategic implications for 2026 planning
For corporate strategy and procurement teams, the 2026 planning cycle should prioritize actions across three horizons:
- Immediate (0–6 months): Lock in primary supplier relationships with clear SLAs for lead time, quality, and contingency shipping. Establish inventory buffers aligned to R&D project pipelines rather than relying on just‑in‑time purchasing. Include explicit clauses around permitted end‑uses and technical support.
- Near term (6–18 months): Develop dual‑sourcing strategies that balance global distributor reliability with specialist supplier technical depth. Pilot supplier co‑development agreements for any proprietary workflows that could deliver future cost or timeline advantages.
- Strategic (18+ months): For organizations seeking to vertically integrate or differentiate in service offerings, evaluate acquisition or partnership opportunities with regional manufacturers or specialty reagent houses that bring complementary capabilities (e.g., custom packaging, cold‑chain logistics, or process‑scale optimization). Use the report’s M&A screening framework to assess synergies and integration risk.
Why PW Consulting’s analysis is decision‑useful
This briefing distills headline insights; the full PW Consulting report contains the underlying models, supplier scorecards, procurement templates, and scenario analyses that operational teams require to act. We deliberately withhold granular segmentation tables and proprietary datasets from this preview: those elements are central to the actionable recommendations and are accessible through the full report and data portal. The “trailer” approach ensures executives can evaluate strategic fit quickly while preserving the analytic assets that power procurement playbooks and M&A diligence.
Call to action
PW Consulting’s full report is designed for teams that need to convert a small but strategically significant molecule market into measurable operational outcomes. Subscribers and report licensees receive the complete dataset, interactive forecast model, supplier RFP templates, and a bespoke briefing workshop to translate insights into 2026‑ready plans.
Contact PW Consulting to request access to the full market study, data export, and a tailored workshop that aligns the report’s findings with your organization’s R&D, procurement, and corporate development objectives.
For detailed analysis of this topic, please visit the official page: N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Satellite Manufacturing and Launch Systems Market to Grow from USD 35,450 Million in 2025 to USD 61,780 Million by 2032 at an 8.26% CAGR
By PW Consulting, 2026-07-01
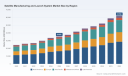
Satellite Manufacturing and Launch System Market: Strategic Guidance for 2026 Decisions
PW Consulting today publishes a forward-looking industry briefing drawn from our comprehensive Satellite Manufacturing And Launch System Market report (base year 2025, forecast 2026–2032). The report synthesizes five years of historical tracking and seven-year forecasts to equip boards, investors, and executive teams with the decision-grade intelligence required for 2026 strategy cycles. At a macro level, the worldwide market expands from approximately USD 35,450 Million in 2025 to an anticipated USD 61,780 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.26% across the forecast window.
Satellite Manufacturing And Launch System Market
Why this report matters for 2026 planning
-
Timing capital allocation: The market’s mid-to-high single-digit CAGR and the accelerating commercial launch cadence create windows for both growth investments and strategic consolidation. Our report shows where near-term capital delivers the highest optionality and which bets carry doubling-time risk in a 24–36 month horizon.
Satellite Manufacturing And Launch System Market -
Portfolio prioritization: Satellite manufacturing and launch services are intertwined but follow different commercial rhythms. We provide prescriptive frameworks to prioritize product lines, manufacturing capacity, and launch procurement over the next 12–18 months.
Satellite Manufacturing And Launch System Market -
Regulatory and supply-chain readiness: Recent regulatory updates and raw-material constraints materially change program risk profiles. Proactive compliance and diversified sourcing become competitive differentiators in 2026.
-
M&A and partnership playbook: With market concentration leaning toward a mid-sized group of dominant players (CR3 ~48.2%; CR5 ~61.5%), the report outlines tactical M&A windows, JV structures, and non-equity partnerships to secure capability quickly without overpaying for scale.
Core market dynamics shaping 2026 strategy
-
Commercial scale meets incumbent specialization: Demand is being driven by both mega-constellation programs and traditional GEO/MEO payloads. Manufacturing volume and launch cadence are rising in parallel, but the operational requirements for mass-produced smallsats differ sharply from traditional, bespoke GEO satellites.
-
Regulatory tightening: Spectrum allocation changes (notably FCC updates in 2025) and ITU enforcement of debris mitigation (including deorbit timelines) are increasing program compliance costs and altering lifecycle planning for constellations. Operators will need interference-mitigation and end-of-life strategies baked into procurement contracts.
-
Critical materials constraints: Export restrictions and supply concentration for high-purity gallium and germanium are affecting solar cell and IR detector availability—components found in a large share of contemporary satellites. Sourcing risk will influence supplier selection, inventory policy, and potential vertical integration discussions in 2026.
-
Manufacturing infrastructure scarcity: High-grade assembly environments (e.g., ISO 5 cleanrooms with vibration isolation) remain limited globally. Capacity constraints create lead-time premiums and favor firms with owned or long-term access to controlled facilities.
Competitive landscape: who matters and why
The market exhibits a mix of vertically integrated incumbents and high-growth niche challengers. The competitive map is nuanced: some firms compete primarily on manufacturing scale and satellite platforms, others on launch reliability and cadence, and an emerging group on smallsat end-to-end solutions.
-
SpaceX — A high-volume manufacturer-launcher hybrid. Its large-scale satellite production and proven Falcon family create commercial advantages in pricing and cadence. Recent constellation deployments underline the company’s ability to compress timelines for vertically integrated operators.
-
Boeing and Lockheed Martin — Incumbent systems integrators with deep heritage in GEO, military, and national programs. Their value remains strong where mission assurance and legacy-system integration are non-negotiable.
-
Airbus Defence and Space, Thales Alenia Space — European platform specialists focused on telecom and high-throughput payloads, leveraging partnerships with commercial launch providers.
-
Rocket Lab and smaller launch specialists — Competitive in the smallsat segment with rapid, responsive launch services and turnkey spacecraft solutions. Their operational model is attractive for distributed architectures and on-orbit experimentation.
-
Blue Origin, ULA, Arianespace — Heavy and medium-lift launcher providers essential to large GEO missions and growing constellation deployments as they ramp newer vehicles to commercial availability.
-
Specialists (Maxar, Ball Aerospace, OHB, SSTL, ISRO, CASC) — Focused on imaging, EO, and government programs; their strengths include high-resolution payloads, regional access, and cost-competitive options for specific mission classes.
Recent industry developments through 2025—commercial launches by SpaceX, Rocket Lab’s in-orbit manufacturing payload deployment, Ariane 6’s ongoing flights, ULA’s Vulcan missions, and Blue Origin’s production funding—underscore the tempo shift from development to sustained operations for launch and manufacturing capacity. For 2026, expect competition to center on launch cadence, contract flexibility, and supplier risk mitigation rather than raw technological novelty alone.
Practical, actionable content inside the report
Our report is constructed to be directly usable by executives during 2026 planning cycles. Highlights include:
-
An investment-timing model that maps revenue and unit-cost inflection points against capital deployment windows.
-
A launch procurement playbook with contract templates and decision criteria for fixed-price versus incentive-based launches.
-
A manufacturing-footprint decision tree that evaluates build-vs-buy, cleanroom access strategies, and co-location benefits for launch-integration.
-
A supply-chain risk matrix addressing critical minerals, key component single-sourcing, and alternative technology pathways to reduce exposure to export restrictions.
-
A regulatory compliance checklist covering FCC/ITU changes and export-control scenarios (including ITAR considerations) to accelerate licensing and offset program delays.
-
Company benchmarking dashboards and a prioritized M&A/partnership target list based on capability adjacency, integration risk, and market reach.
Risks you must account for in 2026 — and how to mitigate them
-
Material access risk: Hedge supply by qualifying multiple vendors, invest in substitutes or recycling programs, and structure payment terms to secure long-lead components.
-
Regulatory risk: Build compliance roadmaps into product lifecycles, fund independent spectrum and debris-risk assessments, and prioritize interoperability testing to reduce post-launch rework.
-
Capacity and scheduling risk: Secure cleanroom and test-facility slots through long-term leases or partnerships, and stagger program phases to avoid bottlenecks.
-
Concentration risk: Given the market’s moderate concentration (CR3 and CR5 figures noted above), avoid single-provider dependencies for critical services. Diversify launch providers where contractual flexibility allows.
-
Insurance and liability risk: Reassess launch and on-orbit insurance structures in light of increased debris liability and constellation scale; consider pooled underwriting for program-level coverage.
How C-suite teams should use this intelligence in 2026
-
CEOs and Boards: Use the report’s scenario maps to validate capital deployment timelines and to set measurable go/no-go gates for large program commitments.
-
CFOs: Leverage our cost curves and investment timing model to align financing instruments with milestone-driven capital needs and to evaluate lease vs. purchase of manufacturing infrastructure.
-
CTOs and Program Leads: Adopt the supplier-qualification and regulatory checklists to de-risk early design choices and to accelerate integration testing windows.
-
Corporate Development: Utilize our M&A screen and partnership scoring to prioritize targets that fill capability gaps or provide strategic access to launch capacity and manufacturing floor space.
Next steps and where to find the full intelligence
This release outlines the strategic contours we expect to shape decision-making in 2026. The full Satellite Manufacturing And Launch System Market report contains the granular, actionable data that underpins these conclusions, including regional and segment breakdowns, company-level revenue models, downloadable financial workbooks, and deal-by-deal benchmarking. To access the complete dataset, segmentation analysis, and proprietary modelling tools, visit PW Consulting’s report page or contact our industry practice for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Satellite Manufacturing And Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Collision Avoidance System Market to Grow at 6.5% CAGR, Reaching USD 25.09 Billion by 2032 as TCAS II/ACAS‑X Takes Lead
By PW Consulting, 2026-07-01
Aircraft Collision Avoidance System Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting today publishes a strategic preview of our forthcoming Aircraft Collision Avoidance System Market report. Built on a base year of 2025 and a seven-year forecast horizon to 2032, our analysis quantifies a market that reached approximately USD 16,149 Million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 6.5% through 2032, when our central-case projection approaches USD 25,095 Million. This preview outlines why the 2026 planning cycle is a critical inflection point for operators, OEMs, Tier‑1 suppliers, MROs, and investors navigating a complex regulatory and technological transition.
Aircraft Collision Avoidance System Market
Why this report matters for 2026 decision-making
-
Regulatory inflection: 2025–2026 marks a visible shift in certification pathways and airworthiness expectations. The FAA’s recent TSO release enabling ACAS Xu certification for unmanned aircraft systems (March 2026) and ongoing ACAS Xa/Xo transition processes require procurement teams and program managers to re-evaluate retrofit timetables, certification budgets, and fleet integration plans.
Aircraft Collision Avoidance System Market -
Technology transition: ACAS X family developments (Xa for larger transport, Xu and sXu for unmanned systems) are moving from research to operational demonstration. This reduces nuisance alerts and supports mixed manned–unmanned operations, but it also introduces software‑centric certification and multi-sensor fusion challenges that stretch traditional avionics roadmaps.
Aircraft Collision Avoidance System Market -
Commercial imperative: With a mid-term market expansion driven by retrofit activity, new-platform integration, and the maturation of detect-and-avoid architectures, 2026 is the year to decide whether to lead, follow, or niche-invest in collision-avoidance capabilities. Those choices will materially affect product roadmaps, aftermarket revenues, and MRO capacity allocation across the forecast period.
What the report delivers — operational, actionable intelligence
-
Proven market model: A transparent, reproducible financial model calibrated to historical performance (2020–2025) and scenario-tested across conservative, central, and aggressive adoption curves for ACAS X variants.
-
Regulatory timelines and impact mapping: A staged analysis of FAA, EASA, and ICAO drivers, including certification windows, retrofit trigger points, and enforcement risk—translated into procurement decision calendars for OEMs and operators.
-
Technology and integration playbooks: Practical guidance for system selection (TCAS II vs ACAS X pathways), sensor-fusion architectures, software update strategies, and avionics‑bus integration that minimize downtime and certification exposure.
-
Vendor benchmarking and negotiation levers: A competitive framework that compares product portfolios, upgradeability, software lifecycle approaches, support footprints, and aftermarket pricing levers—designed for sourcing, legal and program teams to use in RFPs and contract negotiations.
-
Supply‑chain and MRO capacity stress-tests: Identification of bottlenecks—components, test resources, and skilled labor—that could elongate retrofit cycles, with mitigation options and contingency sourcing recommendations.
-
Scenario-based risk analysis: Quantified downside cases tied to certification delays, adverse safety recommendations, and accelerated regulatory mandates; and upside cases driven by faster-than-expected unmanned integration or aggressive retrofits following safety advisories.
Market dynamics: Drivers, friction points, and concentration
The collision avoidance market is expanding on multiple fronts: legacy retrofit demand, fleet modernization programs, and the emergent need for robust detect‑and‑avoid solutions for unmanned aircraft. These drivers are producing steady revenue growth and creating new product adjacencies—particularly for suppliers capable of delivering software-defined, upgradeable platforms.
At the same time, market concentration is non-trivial: our analysis indicates that the top three suppliers capture a meaningful share of the market, and the top five account for a clear majority of market revenues. This concentration shapes competitive dynamics, pricing power, certification pathway control, and aftermarket economics—factors that every buyer and investor should weigh when making 2026 commitments.
Competitive landscape — positioning and strategic moves
-
Honeywell International Inc. — A dominant incumbent in TCAS II systems with a strong installed base across commercial and business aviation. Honeywell’s focus on certified traffic computers and continuity in support positions it as a preferred partner for large transport retrofit programs.
-
Collins Aerospace (RTX) — Offers a broad TCAS product line with upgradeable software pathways. Collins’ depth in avionics integration and OEM relationships makes it a natural supplier for platform-level retrofit strategies and new-production installations.
-
ACSS / Thales consortium — Through joint ventures, ACSS and Thales combine heritage TCAS installations with an increasing focus on integrated solutions (TCAS + TAWS + Mode S). Their global install base creates network effects for support and upgrade monetization.
-
Garmin Ltd. — A key competitor in the general and business aviation segments, integrating TCAS-class solutions into modern flight decks. Garmin’s strength is rapid integration cycles and favorable cost-of-entry for GA operators.
-
L3Harris Technologies — Offers surveillance and collision avoidance capabilities, leveraging defense and avionics expertise. Their portfolio supports both legacy systems and newer surveillance architectures suited to mixed airspace operations.
-
Sagetech Avionics — A leader in lightweight ACAS X implementations for crewed and uncrewed platforms. Sagetech’s ACAS Xu/sXu work and active flight research in multi‑sensor fusion make it a strategic partner for BVLOS drone operators and integrators.
-
Avidyne Corporation — Focused on next-generation cockpit integration for GA and business aviation, Avidyne is notable for its glass‑cockpit integrations and approachable upgrade pathways for smaller fleets.
These vendors occupy overlapping but distinct strategic spaces: incumbents with large transport footprints, avionics integrators targeting fleet-scale retrofits, and agile newcomers specializing in low‑SWaP ACAS X solutions for unmanned systems. The result is an ecosystem where partnerships, software roadmaps, and aftermarket services determine future share more than hardware alone.
Recent industry developments shaping near-term choices
-
FAA TSO release for ACAS Xu (March 2026): Opens a formal certification route for detect‑and‑avoid equipment on UAS, accelerating procurement decisions for operators pursuing BVLOS operations.
-
NTSB safety recommendation after a 2025 mid‑air collision (public follow-up March 2026): Creates reputational and regulatory pressure that could precipitate targeted retrofit programs or expanded ACAS X adoption in certain fleet segments.
-
Industry R&D collaborations: Examples include Sagetech’s flight research into layered ACAS X + multi‑sensor fusion for drones—indicative of practical pathways to address mixed-traffic airspace challenges.
-
FAA transition dynamics: While ACAS Xa/Xo advancement continues, full replacement of all TCAS II mandates remains a work in progress in certain jurisdictions. This hybrid regulatory state requires parallel planning: compliance with existing TCAS II obligations and readiness for ACAS X opportunities.
Strategic playbook — prioritized recommendations for 2026
-
Operators (airlines, cargo, large fleets): Initiate a two-track procurement strategy—maintain compliance with current TCAS II mandates while allocating a capital reserve and technical workstream for ACAS Xa retrofit pilots. Accelerate fleet‑level readiness assessments in Q1–Q2 2026 to lock favorable MRO windows.
-
OEMs and Tier‑1 suppliers: Prioritize software modularity and certificatable update pipelines. Establish cross‑licensing and integration agreements now to shorten delivery cycles for customers seeking ACAS X migration paths.
-
MRO and aftermarket providers: Invest in test benches and skilled certification teams for ACAS X variants and multi‑sensor fusion diagnostics. Capacity investments in 2026 will pay back as retrofit demand converges.
-
UAS operators and system integrators: Leverage the FAA’s ACAS Xu TSO to accelerate BVLOS deployments, focusing first on validated flight corridors and partner ecosystems where detect‑and‑avoid demonstrators already exist.
-
Investors and strategic acquirers: Target companies with software upgrade pathways, strong service revenue streams, and niche ACAS X capabilities—especially those that can bridge crewed and uncrewed markets.
-
Regulators and safety bodies: Use phased mandates and incentivized retrofit programs to reduce sudden aftermarket shocks; publish harmonized certification guidance for ACAS X family elements to reduce commercial uncertainty.
Next steps and how to use the full report
This preview synthesizes the strategic contours of a market in transition. The full PW Consulting Aircraft Collision Avoidance System Market report contains the detailed datasets, region‑ and platform-level scenarios, vendor scorecards, and our full financial model that underpin the insights summarized here. To preserve the integrity of client-grade modelling and to support actionable contracting and investment decisions, we publish granular tables and proprietary segmentation only in the paid report.
For senior leaders preparing 2026 budgets and multi-year-tech roadmaps, the decision window is short. Our report equips teams to quantify retrofit versus new‑build tradeoffs, evaluate supplier negotiation strategies, and stress-test certification/timing risk against revenue and safety objectives. PW Consulting’s structured scenario outputs and implementation playbooks are designed explicitly to convert macro market trends into executable 12–36 month plans.
Contact PW Consulting for a briefing and to access the complete report, datasets, and our interactive decision-support model tailored to your fleet or investment thesis. The next 12 months will define winners and followers in a market where software‑defined avionics and cross-domain integration are reshaping competitive advantage.
For detailed analysis of this topic, please visit the official page: Aircraft Collision Avoidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


