



Category: market research
PW Consulting: Material Handling Robotics Market Poised for 15.01% CAGR During 2026–2032 Forecast
By PW Consulting, 2026-07-01
Material Handling Robotics 2026: Strategic Imperatives from PW Consulting’s Market Research
PW Consulting’s latest Material Handling Robotics Market Research report—anchored on a 2025 base year and a 2026–2032 forecast horizon—translates rapidly evolving technology, supply-chain pressure points, and shifting business models into concrete decision-making guidance for enterprise leaders. Our aim in this briefing is to surface the strategic value of the study for 2026 planning cycles: where the market is headed, which forces will determine winners and losers, how incumbent and emerging suppliers are positioning, and the practical, executable plays that unlock ROI from automation investments. This article showcases the depth of our work while preserving core, proprietary segment tables and pricing intelligence for report subscribers.
Material Handling Robotics Market Research
Market Trajectory: Clear, Rapid, Actionable
Material handling robotics is no longer a niche improvement project—it's a capital strategy. Our bottom-up model shows the global market expanding from roughly USD 25.12 billion in 2020 to USD 48.50 billion in 2025. Under conservative technology adoption and supply assumptions, the market accelerates further: PW Consulting forecasts the market to reach approximately USD 56.58 billion in 2026 and to grow to about USD 129.12 billion by 2032, reflecting a compound annual growth rate (CAGR) of 15.01% over the 2026–2032 forecast period.
Material Handling Robotics Market Research
What this trajectory means for 2026 decision-makers:
Material Handling Robotics Market Research
- Investment timing matters. Organizations that plan for phased automation rollouts in 2026 lock in lower integration costs and earlier productivity gains.
- Scale economies are material. Vendors and integrators will consolidate capability stacks (robotic platforms, fleet orchestration, safety-certified software), accelerating vendor lock-in for late adopters.
- Capital allocation should prioritize modular architectures—systems that permit incremental upgrades and multiple use cases—maximizing utilization across peak and off-peak demand cycles.
Market Structure and Competitive Dynamics
The material handling robotics market sits in a moderately concentrated competitive profile: the top three suppliers account for roughly 38% of the market and the top five about 52%. That balance creates opportunity. There is room for large incumbents to scale integrated solutions and for focused specialists to win by delivering superior total cost of ownership (TCO) or faster time-to-production in targeted verticals.
Key vendors we benchmark across product maturity, go-to-market models, integration capability, and service economics include (representative summaries):
- FANUC Corporation (Japan) — Established leader in articulated robots and specialized palletizing, picking, and automated transfer systems for manufacturing and logistics. Strong OEM channel relationships and service networks.
- ABB Robotics (Switzerland) — Delivers industrial robots and integrated material handling systems; emphasis on flexible automation and intralogistics solutions that support rapid changeovers.
- KUKA AG (Germany) — Supplies robotic arms and AMRs along with complete material handling automation; notable for vehicle-mounted and KMP internal-transport platforms.
- Yaskawa Electric (Motoman) (Japan) — High-speed industrial robots optimized for palletizing, depalletizing, and rapid-transfer applications.
- Kawasaki Heavy Industries (Japan) — Known for heavy-payload systems for palletizing and automated loading/unloading operations.
- Daifuku Co., Ltd. (Japan) — Integrator of AGVs, AMRs, conveyors, and robotics for warehouses and production systems.
- SSI SCHAEFER (Germany) — Provides integrated solutions for picking, sorting, and storage automation combined with robotics.
- Dematic (KION Group) (Germany/USA) — Comprehensive automation provider with strong AS/RS, AGV/AMR and robotic material handling offerings.
- Stäubli (Switzerland) — Specializes in high-precision robots for cleanroom and specialized industrial environments.
- Jungheinrich AG (Germany) — Bridges traditional forklift systems with automated guided vehicles and AMRs.
- Honeywell Intelligrated (USA) — Integrated material handling systems provider with strong presence in distribution center automation.
- Toyota Material Handling (Japan) — Combines AGV and robotic systems with a large installed base of industrial vehicles.
- Geek+ (China) — Rapidly scaling AMR and goods-to-person solutions for warehousing and sorting.
- OTTO Motors / Clearpath Robotics (Canada) — Focused on robust industrial AMRs for production logistics.
- Seegrid Corporation (USA) — Vision-guided AMRs for infrastructure-light deployments in manufacturing and warehousing.
Our vendor benchmarking examines more than headline features. PW Consulting’s analysis compares lifecycle service economics, software openness (APIs and middleware), fleet orchestration maturity, safety certification breadth, and proven vertical use cases—criteria that materially affect implementation risk and TCO.
Forces Driving Adoption and Risk Factors
The report dissects four cross-cutting dynamics that will shape 2026 decisions:
- Labor Cost and Availability — Persistent skilled labor shortages in manufacturing and warehousing are increasing the ROI window for automation. Organizations must model the interplay between wage inflation, attrition risk, and automation scale to justify CAPEX decisions.
- Regulatory and Standards Momentum — Industry 4.0 policies and harmonizing safety/interoperability standards are lowering barriers for multi-vendor deployments and enabling cloud-enabled orchestration across facilities.
- Raw Material and Component Pressure — The cost composition for robotic platforms remains influenced by high-grade steel and advanced polymers, which account for a material share of production cost. Procurement strategies and supplier diversification matter to avoid margin erosion during commodity cycles.
- E-commerce and Fulfillment Growth — Ongoing expansion of fulfillment networks continues to be the single biggest demand tailwind for AMRs, goods-to-person systems, and automation that compresses order cycle times.
Each of these drivers is modeled in scenario runs in the report, and we provide stress-tested investment cases that reflect different combinations of wage inflation, fulfillment demand shock, and component-cost volatility.
What PW Consulting’s Report Contains (Practical, Executable Content)
Subscribers receive a combination of strategic and operational artifacts designed for use by C-suite, site operations, procurement, and automation teams, including:
- Market sizing and forecast model (2020–2032) with downloadable assumptions and sensitivity toggles for wage inflation, robotics lead times, and e-commerce growth inputs.
- Vendor scorecards and quadrant mapping across product maturity, integration capability, and service economics—designed for shortlisting partners in RFPs.
- Technology evolution roadmap covering AMRs, articulated manipulators, cobots, and integrated fleet orchestration software—with practical decision trees for selecting architectures by throughput and SKU-profile.
- Use-case playbooks with implementation timelines, cost templates, and staffing overlays for common deployments: cross-dock, parcel sortation, palletizing, goods-to-person, and production line feeding.
- TCO and ROI calculators that factor CAPEX, OPEX, operator substitution curves, maintenance regimes, and productivity gains at SKU-level pick times.
- Integration playbook and risk register covering safety certification, IT/OT connectivity, cyber-hygiene, and change management for frontline teams.
- M&A and partnership landscape assessment highlighting capability gaps where strategic acquisitions or JV models can accelerate market entry.
To preserve competitive value for subscribers, the report intentionally withholds certain granular segment datapoints from public communications; subscribers receive full segmentation tables, vendor pricing archetypes, and client-ready slide decks.
Recent Signals and Tactical Timing
Recent industry activity reinforces our 2026 strategic guidance. Notable market signals include product feature rollouts by AMR and AGV vendors and concentrated participation by major robotics OEMs at MODEX 2026—indicating accelerated go-to-market programs for North American and global customers. These developments underscore vendor readiness for scaled deployments and the emergence of cross-vendor orchestration as a differentiator.
Our advice to procurement and operations leaders preparing 2026 programs:
- Prioritize pilots that are replicable across facilities. A single successful, templated deployment will dramatically lower the curve for subsequent roll-outs.
- Insist on explicit integration SLAs and open APIs when contracting. Openness reduces lifecycle lock-in and enables phased technology refreshes.
- Build internal capabilities early—create a small center of excellence that combines process engineering, IT/OT, and supplier management to shorten deployment cycles and reduce third-party dependency.
Strategic Plays for 2026
Based on our cross-industry interviews and client work, PW Consulting recommends three high-probability plays for organizations entering or scaling material handling automation in 2026:
- Modular Fleet + Shared Services: Standardize on modular hardware and a common orchestration layer across sites to maximize fleet utilization and simplify maintenance.
- Use-Case Prioritization by Throughput Impact: Target high-frequency, low-variance workflows (e.g., palletizing, high-density picking) for early automation to capture predictable productivity gains.
- Supplier Ecosystem Contracts: Negotiate outcome-based service contracts (uptime, throughput guarantees) and include options to purchase/refinance as-as-a-service models evolve.
Conclusion — Why This Report Matters for 2026
For executives making 2026 capital and operational plans, the decision to accelerate, delay, or stage robotic automation has material implications for cost, service levels, and competitive positioning. PW Consulting’s Material Handling Robotics Market Research translates market momentum—illustrated by a robust CAGR of 15.01% over the forecast window and a market that is projected to more than double from its 2025 scale—into operational playbooks, vendor shortlists, and financial models that reduce implementation risk and maximize ROI.
This article outlines the strategic architecture of our analysis. For organizations seeking the complete dataset, segment-level intelligence, vendor pricing archetypes, and client-ready deployment templates, access to the full report and the interactive model is available on PW Consulting’s Material Handling Robotics Market Research page. The full study contains the proprietary segmentation tables and decision-support assets necessary to convert 2026 automation intent into measurable performance outcomes.
For detailed analysis of this topic, please visit the official page: Material Handling Robotics Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DC Permanent Magnet Motor Market at USD 41,869.04 Million in 2025, Poised to Reach USD 65,063.92 Million by 2032 at a 6.5% CAGR
By PW Consulting, 2026-07-01
DC Permanent Magnet Motor Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s Dc Permanent Magnet Motor Market report frames 2026 as a decisive planning horizon for OEMs, tier suppliers, and strategic investors. The global market, measured at a base year of 2025, is projected to expand steadily through our 2026–2032 forecast window at a compound annual growth rate of 6.5%. By 2032 the market is expected to exceed USD 65 billion (Million, USD unit), creating a widening opportunity set but also exposing firms to intensifying material, regulatory and competitive pressures. This briefing highlights the report’s strategic value for corporate decision-makers in 2026, summarizing why action is needed now and how the full report equips leaders to translate insight into measurable plans.
Dc Permanent Magnet Motor Market
Why 2026 is a turning point
-
Commodity and supply risk is elevated. Rare-earth inputs used in high-performance NdFeB magnets are trading at materially higher levels; for example, market reporting shows benchmark neodymium prices remaining significantly elevated in early 2026, and NdPr price forecasts for China in 2026 point to continued pressure. Those dynamics materially change component cost curves and supplier bargaining power.
Dc Permanent Magnet Motor Market -
Regulatory timelines compress product roadmaps. Energy efficiency standards adopted by the U.S. Department of Energy for expanded-scope electric motors introduce new compliance milestones that begin to bind product development and inventory decisions from mid-2027 onward, with further standards taking effect in 2029. That compressed runway requires manufacturers to validate compliance pathways now.
Dc Permanent Magnet Motor Market -
Competitive positioning is reshaping. While the market remains fragmented relative to some industrial segments, concentration among the largest suppliers has increased enough that CR3 and CR5 dynamics require careful strategic response — from selective partnerships to targeted M&A — to protect margins and secure access to advanced motor platforms.
What the PW Consulting report delivers — practical, transaction-ready content
Our goal with this study is not academic description but operational utility. The report combines rigorously modeled top-down and bottom-up sizing with pragmatic tools that executives can apply immediately in 2026 planning cycles. Highlights include:
- Market sizing and high-level forecast (base year 2025; forecast window 2026–2032) that quantify the overall opportunity and show sensitivity to key assumptions such as commodity cost pathways and regulatory adoption rates.
- Scenario analyses with breakpoints for rare-earth price shocks, regional export control scenarios and accelerated efficiency standard compliance — each tied to P&L and ROIC simulations that let you stress-test product lines.
- Supply-chain heatmaps and supplier scorecards that prioritize counterparties by technology competence, geographic exposure and substitution risk — enabling shortlists for hedging and strategic sourcing.
- Product and portfolio playbooks: go-to-market and product roadmap templates that link technical choices (e.g., brushless vs. brushed architectures, magnet materials) to margin and compliance outcomes.
- M&A and partnership lenses: prioritized target archetypes, valuation heuristics and integration checklists tailored to the motor space.
- Regulatory readiness checklists and a compliance calendar to align engineering, certification and inventory procurements with emerging energy efficiency deadlines.
- Commercial levers and pricing models that incorporate material escalation clauses, total cost of ownership framing for customers, and aftermarket service strategies.
Supply-chain and raw-material dynamics to watch
-
Rare-earth concentration and export policies: Recent policy actions and export controls in major rare-earth producing jurisdictions are increasing the complexity of procurement. Firms without active mitigation plans face margin compression and delivery risk.
-
Price sensitivity analysis: Our modelling demonstrates that persistent high levels in rare-earth prices materially change the economics of high-energy-density magnet solutions. Clients should prioritize scenario planning that includes longer-tail price elevations and supplier-side shocks.
-
Design substitution and technology pivots: Reducing exposure can be achieved through selective design changes (e.g., magnet material optimization, reduced magnet mass, or advanced topologies). The report quantifies trade-offs between energy efficiency, torque density and bill-of-materials cost for those options.
Competition: who matters and where power sits
Corporate strategy in 2026 must be informed by the competitive map. Our analysis shows a market where several global OEMs and specialized motion firms shape technology direction and customer expectations. Overall market concentration metrics indicate that the top three players account for a meaningful—but not dominant—share of revenue, while the top five collectively strengthen market leadership and channel control. This leaves substantial runway for both incumbent growth and targeted consolidation.
- Nidec Corporation (Kyoto, Japan) — Broad permanent magnet DC solutions across industrial, automotive and consumer segments, with deep manufacturing scale.
- ABB Ltd. (Zurich, Switzerland) — Industrial drives and energy-efficient motor offerings that integrate DC PM technologies into automation platforms.
- Siemens AG (Munich, Germany) — Industrial motor portfolio that incorporates permanent-magnet DC architectures for motion control and process industries.
- WEG S.A. (Jaraguá do Sul, Brazil) — Global supplier of PM motor lines tailored for industrial and special applications.
- Johnson Electric (Hong Kong) — Volume motion-systems specialist with PMDC offerings for automotive and consumer markets.
- Maxon Motor AG (Sachseln, Switzerland) — High-precision PMDC and brush DC motors for medical, robotics and aerospace niches.
- Portescap (Altra Industrial Motion, USA), Kollmorgen (USA), Parvalux (UK), MET Motors (USA), ElectroCraft (USA), Twirl Motor (China), Mabuchi Motor (Japan) and several regional specialists — each occupies differentiated positions in precision, miniature, ruggedized, and value markets.
Recent industry activity — from trade-show debuts to catalog updates and certification refreshes — underscores supplier efforts to secure design wins and regulatory alignment ahead of tightening standards.
Strategic priorities for executives in 2026
Based on the synthesis of market sizing, supply-side dynamics and competitive positioning, PW Consulting recommends executives treat 2026 as a planning inflection point with specific, time-bound actions:
- Lock in medium-term raw-material coverage: Negotiate multi-year contracts or financial hedges for magnet-critical inputs and prioritize relationships with downstream magnet processors to reduce price volatility exposure.
- Accelerate compliance programs: Map current product families to forthcoming efficiency standards and begin certification cycles and engineering changes now to avoid revenue interruptions in 2027–2029 windows.
- Prioritize product rationalization: Focus R&D and capex on architectures that combine market demand, margin resilience and lower material risk — including higher-efficiency brushless platforms and selective investments in magnet-minimizing topologies.
- Localize and diversify manufacturing: Add regional capacity or strategic partnerships in low-risk jurisdictions to reduce freight and tariff exposure while supporting lead-time-sensitive customers.
- Pursue targeted M&A: Use bolt-on acquisitions to secure differentiated IP (precision, magnet-processing), fill gaps in high-value verticals (medical, aerospace), or gain scale in markets where top suppliers are consolidating.
- Embed scenario-based pricing: Implement contract terms that share material-cost volatility with customers while preserving competitiveness in procurement cycles.
- Invest in aftermarket and services: Expand retrofit and service offerings to capture recurring revenue and deepen customer relationships that are less sensitive to upfront commodity swings.
How the report supports decision-making in 2026
Leaders will find the report immediately useful for:
- Portfolio and capex prioritization meetings — by quantifying market and margin outcomes across scenarios.
- Procurement negotiations — by providing supplier rankings and cost-to-serve models to support bid evaluation.
- Regulatory-compliance roadmaps — with milestone checklists and cost estimates for certification and redesign.
- M&A screening and integration planning — with target archetypes, valuation ranges and synergy templates specific to motor technologies.
- Sales and pricing strategy — by aligning product value propositions to customer TCO thresholds under different raw-material trajectories.
Next steps and how to access the full intelligence
This briefing is designed as a strategic trailer: it demonstrates the depth of analysis and the practical tools contained in our full Dc Permanent Magnet Motor Market report while intentionally withholding granular regional and application-level splits that are transformative for commercial negotiations and M&A diligence.
Companies preparing 2026 budgets, supply-chain negotiations or M&A pipelines should consult the full report to access:
- Detailed segmentation models by region, type and application with downloadable data tables and scenario toggles.
- Supplier scorecards and contract-risk matrices with contactable supplier dossiers.
- Excel-based financial models and sensitivity dashboards you can repurpose in board-ready presentations.
Contact PW Consulting to arrange a briefing with our industry leads and to obtain the complete study and modelling toolkit. The full report converts the headline growth trajectory and industry signals presented here into transaction-ready intelligence you can use across procurement, engineering, and corporate development functions in 2026.
For detailed analysis of this topic, please visit the official page: Dc Permanent Magnet Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ablation Systems Market to Climb from USD 7.15B in 2025 to USD 13.28B by 2032 at a 9.25% CAGR — North America Leading with USD 2.84B Share
By PW Consulting, 2026-07-01
Ablation Systems Market: Strategic Imperatives from PW Consulting’s 2026 Market Research
PW Consulting today releases a forward-looking industry perspective drawn from our new Ablation Systems Market Research report — a decision-grade briefing designed to orient executive teams, investors, health systems, and technology partners as they set strategy for 2026 and beyond. Our analysis traces market evolution from a USD 4.5 billion base in 2020 to USD 7.15 billion in 2025 and models a multi-channel expansion through 2032, with the market projected to approach roughly USD 13.3 billion by 2032. The compound annual growth rate during the 2026–2032 forecast window is 9.25% — a pace that rewards timely strategic choices in product, regulatory, and reimbursement execution.
Ablation Systems Market Research
Why 2026 Is an Inflection Point
Several converging forces make 2026 the first practical decision year for companies seeking to accelerate commercialization or defend share in ablation technologies:
Ablation Systems Market Research
- Regulatory momentum: Recent approvals and clearances for pulsed field ablation (PFA), cryoablation, and device-centric robotics have materially altered clinical pathways and hospital adoption scenarios. Notable milestones include late-2024 and 2025 approvals for next‑generation mapping/ablation platforms, multiple 2025 510(k)/marketing authorizations for prostate and breast-local therapies, and a January 2026 clearance enabling robotic-mag‑navigation ablation in select congenital indications. These events compress time-to-adoption for well-positioned technologies.
- Reimbursement architecture shifts: U.S. reimbursement updates — including a finalized concomitant MS‑DRG for certain left atrial appendage closure and ablation procedures and FY2026 IPPS adjustments — change hospital economics for combined procedures and inpatient ablation workflows. These moves alter the incremental revenue and cost calculus for devices that change procedural duration, length-of-stay, or readmission risk.
- Portfolio differentiation across modalities: The market is experiencing parallel advancement across PFA, RF, cryo, microwave, ultrasound, irreversible electroporation, and high‑intensity focused ultrasound (HIFU). Clinical and economic evidence is now the primary gating factor for scaling beyond early adopter centers.
What Our Report Delivers — Practically Actionable, Not Just Academic
PW Consulting’s study is intentionally built to inform executable strategy rather than only describe the market. Core deliverables include:
Ablation Systems Market Research
- Top‑line market sizing and a detailed, reproducible forecasting model (historical 2020–2025, base year 2025, forecast 2026–2032) using a mix of bottom‑up device adoption curves and macro scenario overlays.
- Technology roadmaps that map clinical evidence timelines against regulatory and reimbursement inflection points, enabling prioritization of R&D investments and launch sequencing.
- Go‑to‑market playbooks for hospital and ambulatory settings, including purchase economics, capital planning implications, and bundle pricing recommendations informed by recent IPPS/MS‑DRG changes.
- Clinical evidence and HTA gap analysis to support payer submissions, including comparator frameworks and target endpoints most likely to drive coverage and favorable payment.
- Competitive landscaping with detailed company profiles, new product impact assessments, and a supplier scoring system for capability and execution risk.
- Zones of opportunity: identified niche segments and underserved clinical indications that are attractive for bolt‑on M&A or JV strategies.
- Scenario models and sensitivity analyses (optimistic / base / conservative) that quantify the revenue and margin impacts of alternate technology adoption curves, regulatory timelines, and reimbursement outcomes.
Note: In keeping with our “trailer” approach to this executive summary, we highlight frameworks and directionally indicative numbers here while withholding granular regional, technology-application, and company‑level revenue splits. The full dataset and supporting models are available in the complete report.
Competitive Landscape — Who’s Shaping the Next Phase
The ablation market occupies a middle ground between fragmentary innovation and emerging consolidation. Concentration metrics indicate a market with meaningful leader scale but substantial room for disruption — the top three vendors account for a sizable but not dominant share of market value, and the top five capture less than two-thirds of the market. This dynamic creates both defensive priorities for incumbents and attack vectors for challengers.
- Medtronic — A broad cardiac ablation portfolio that spans cryo and dual‑energy PF/RF approaches positions Medtronic to compete across persistent and paroxysmal atrial fibrillation (AF) segments and in procedure suites that value integrated mapping-to-ablation workflows.
- Boston Scientific — With a PFA system and ongoing investment in RF tumor ablation, Boston Scientific is pursuing a strategy that blends electrophysiology leadership with cross‑therapy oncology opportunities.
- Abbott — Volt PFA and electrophysiology catheter lines make Abbott a direct competitor in the fast‑evolving PFA battlefield focused on AF ablation adoption and scale.
- Johnson & Johnson MedTech (Biosense Webster) — Integration of PFA into mapping platforms exemplifies a high‑value bundling approach that raises switching costs in EP labs.
- AtriCure, AngioDynamics, IceCure, Francis Medical — These and other specialists play crucial roles in surgical AF, oncology (including irreversible electroporation and cryo), and urology/prostate thermal therapies, representing acquisition targets and strategic partners for larger medtechs seeking niche innovation.
- Stereotaxis — Robotic navigation approvals create a pathway for procedural standardization in complex arrhythmia cases — a capability that could reshape high‑mix centers of excellence.
- Platform and specialty players such as CONMED, Olympus, Stryker, Hologic, Terumo, Merit, Biotronik, Avanos, Kardium, and EDAP each anchor specific clinical workflows, from pain management and gynecology to HIFU‑based oncology — collectively expanding the competitive topology beyond EP-focused firms.
Key Strategic Implications for 2026 Decision‑Makers
Our market simulations and stakeholder interviews translate into practical priorities for different constituencies:
- Medtech executives: Accelerate investments in PFA and hybrid-energy platforms where clinical evidence suggests superior safety/efficacy tradeoffs; prioritize regulatory pathways and post‑market evidence generation to capture early-referral centers.
- Investors and M&A teams: Seek differentiated assets in niche ablation modalities (e.g., IRE, HIFU, water‑vapor transurethral systems, cryo for outpatient oncology) where the incumbent concentration is lower and upside from clinical validation is clearer.
- Hospital procurement and clinical leaders: Re‑evaluate capital allocation models in light of MS‑DRG and IPPS changes; focus on devices that demonstrably reduce procedure time, length of stay, or downstream admissions.
- Payers and HTA bodies: Use evidence‑based coverage with conditional reimbursement pathways (coverage with evidence development) to accelerate access while limiting upfront financial exposure.
- Startups and innovators: Design clinical programs that align timing of pivotal evidence with reimbursement windows; evaluate partnering with incumbents for scale and distribution rather than solo commercialization in highly consolidated subsegments.
Methodology & Credibility
PW Consulting’s Ablation Systems study synthesizes primary interviews with clinicians, procurement officers, and payers, triangulated against a proprietary device deployment database and regulatory/reimbursement trackers. The report uses a 2025 base year, covers historical trends from 2020–2025, and provides granular forecasting through 2032 (USD, millions). Our competitive scoring, scenario models, and go‑to‑market playbooks are calibrated with contemporaneous regulatory events and reimbursement code changes to ensure tactical relevance for 2026 planning cycles.
Conclusion — How to Use This Intelligence in 2026
For executives and investors, the central conclusion is straightforward: ablation is moving from modality proliferation to selective consolidation driven by evidence, regulatory timing, and payer economics. The winners in 2026 will be those that align product roadmaps with payer and hospital incentives, accelerate the collection of pragmatic evidence, and choose the right commercial partners or M&A targets. PW Consulting’s Ablation Systems Market Research report converts these pressures into executable options and quantified outcomes — enabling your team to make informed decisions in the coming budget and regulatory cycles.
To access the full dataset, granular segment and regional breakdowns, company revenue estimates, and the downloadable forecasting model, request PW Consulting’s complete Ablation Systems Market Research report through our client portal.
For detailed analysis of this topic, please visit the official page: Ablation Systems Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solid State Lighting Market to Expand at a 7.25% CAGR from 2026–2032
By PW Consulting, 2026-07-01
Solid State Lighting Market 2026 Strategic Preview — PW Consulting
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a focused preview of our new Solid State Lighting (SSL) Market research report — designed to equip C-suite leaders, product strategists, and M&A teams with the actionable insight they need to make decisive moves in 2026. This briefing synthesizes our macro forecast, competitive dynamics, technology inflection points, and practical playbooks. It intentionally showcases analytical depth while preserving the detailed segment-level tables for report subscribers.
Solid State Lighting Market
Executive snapshot
The SSL market is transitioning from component-led commoditization to solution-led differentiation. On a macro basis, the market expands from an estimated USD 48,500 Million in 2025 to roughly USD 52,346 Million in 2026, and is projected to grow at a compound annual growth rate (CAGR) of 7.25% through 2032, reaching approximately USD 79,163 Million. This trajectory reflects accelerating uptake of higher-efficacy light sources, increasing integration of connectivity and controls, and steady replacement cycles across commercial and industrial building portfolios.
Solid State Lighting Market
Why this matters for 2026 decision cycles
- Investment timing: The growth runway and technology maturity create a narrow window to scale capabilities (manufacturing, channel partnerships, software) before competition compresses margins further.
- Portfolio prioritization: Companies must decide whether to double-down on high-efficacy LED platforms, pursue OLED/laser niche plays, or climb the value stack into connected lighting systems and services.
- M&A and partnerships: Moderate market concentration (CR3 ~34.2%, CR5 ~42.5%) indicates leaders retain meaningful share but leaves room for strategic bolt-ons — particularly in controls, thermal management, and specialty optics.
Key market dynamics shaping 2026 strategies
Our analysis identifies four compounding dynamics that will determine winners and losers next year:
Solid State Lighting Market
- Efficacy and standards-driven adoption: Regulatory and voluntary performance thresholds (for example, ENERGY STAR updates requiring higher luminaire efficacy) are accelerating product refresh cycles. Products meeting newer efficacy thresholds capture specification-led procurement ahead of competitors.
- System-level value creation: Pure component suppliers face margin pressure as lighting purchasers reward integrated solutions that combine fixture, sensor, controls, and analytics. Software- and services-enabled models open recurring revenue pathways.
- Raw-material and manufacturing economics: High-brightness LED production remains sensitive to GaN substrate costs — a meaningful share of epitaxial cost. Firms that can vertically capture or secure differentiated epi supply will sustain cost leadership.
- Channel evolution and retrofit momentum: Utility rebate schemes and large-scale retrofit programs continue to stimulate demand, but long-term value is being shifted to providers able to deliver turnkey digital lighting services.
Technology and product themes to prioritize
- Ultra-high efficacy platforms: Efficacy milestones — now routinely crossing the 100+ lm/W threshold for luminaires — are table stakes. Roadmaps should prioritize lumen-per-watt gains while managing color quality and thermal budgets.
- Thermal & optical systems engineering: Incremental chip improvements are necessary but insufficient; thermal management and advanced optics deliver the system-level performance purchasers demand for street, industrial, and architectural applications.
- Connected lighting and standards convergence: Interoperability (Matter, Thread, and other IoT frameworks) is moving from marketing promise to procurement requirement. Early adopters of certified, open-protocol solutions gain specification advantage.
- Specialty niche plays: Automotive, horticulture, and specialized backlighting continue to offer higher-margin opportunities for firms that combine domain expertise with optimized optical and spectral solutions.
Competitive landscape — what to watch in 2026
The marketplace is a blend of chip specialists, packaging/module leaders, and fixture-and-controls OEMs. Below are strategic postures of core players and the implications we draw for market entrants and incumbents.
- Nichia Corporation (Anan, Japan) — A technology leader in high-brightness blue LEDs and phosphors. Nichia’s recent product push into 150 lm/W-class white LEDs underlines its continued emphasis on efficacy breakthroughs. For competitors, Nichia’s strength in chip and phosphor supply means securing alternate supply lines or differentiated system-level IP is critical.
- Osram Opto Semiconductors (Regensburg, Germany) — Offers LED chips, packages, and modules across general lighting and automotive segments. Its refreshed product catalogs with improved thermal management demonstrate a pragmatic focus on system reliability for outdoor and industrial markets. Partnerships around thermal and optical sub-systems will be a logical path for firms seeking to accelerate time-to-market.
- Cree (Wolfspeed) (Durham, NC, USA) — Known for high-performance SiC-based devices and XLamp components. Wolfspeed’s differentiated material approach positions it for specialized high-power use cases. Strategic options for others include licensing agreements or co-development for high-heat, high-current applications.
- Lumileds (Amsterdam, Netherlands) — LUXEON product series targeted at indoor/outdoor and specialty lighting; recent certification work underscores commercialization maturity. Lumileds’ channel relationships make it an attractive partner for fixture makers seeking validated components.
- Seoul Semiconductor (Seongnam, South Korea) — Focuses on cost-effective WICOP and ACrich technologies for residential and commercial segments. Cost-competitive platforms remain relevant where upfront capex sensitivity is acute — an important consideration for rollouts in emerging markets.
- Philips Lighting (Signify) (Eindhoven, Netherlands) — A leader in system solutions (luminaires, connected lighting, Hue ecosystem). Signify’s commercial introduction of IoT-enabled lighting with Matter certification signals that open, certified ecosystems are now commercial propositions, not speculative investments.
- Acuity Brands (Atlanta, GA, USA) & Eaton (Cooper Lighting) (Beachwood, OH, USA) — These fixtures-and-controls incumbents combine distribution scale, specification relationships, and controls portfolios. Their ongoing evolution towards data-enabled lighting services increases barriers for component-only players aiming to own customer relationships.
Recent industry signals (select examples)
- Nichia’s October 2025 launch of higher-efficacy white LEDs — a direct response to specification-driven demand for more efficient luminaires.
- Signify’s September 2025 roll-out of Matter-certified Interact systems — accelerating procurement confidence in interoperable IoT lighting solutions.
- Osram’s mid-2025 catalog refresh emphasizing thermal management — reflecting the industry’s growing focus on system reliability under higher flux densities.
- Lumileds’ certification updates in early 2025 — demonstrating the ongoing importance of independent validation across market channels.
Actionable strategic playbook for 2026
Based on our scenario modeling and supplier mapping, firms should consider the following prioritized actions for 2026:
- Secure differentiated supply: Negotiate multi-year epi or wafer agreements, or invest selectively in vertical integration where GaN supply economics materially affect gross margins.
- Invest in system engineering: Allocate R&D to thermal, optics, and driver integration to convert raw chip improvements into measurable luminaires performance advantages.
- Pursue standards-first connectivity: Bring Matter-certified, interoperable lighting offerings to market quickly to capture specification-led procurement and municipal smart-city programs.
- Evaluate bolt-on acquisitions: Target small-to-mid tuck-ins in controls software, sensor fusion, or application-specific optics to accelerate route-to-market and extend lifetime revenue.
- Design for regulatory compliance: Align product roadmaps with ENERGY STAR and IEC test methods, plus regional directives such as RoHS, to avoid go-to-market delays.
- Commercialize services: Pilot lighting-as-a-service models with select channel partners and utilities to move beyond one-time hardware sales.
What PW Consulting’s full report delivers (practical contents)
Our complete market study provides operational tools for 2026 planning, including:
- Scenario-based revenue forecasts (2026–2032) with sensitivity to efficacy gains, retrofit program rollouts, and supply constraints.
- A competitive playbook mapping chip-to-fixture positions, partnership pathways, and likely M&A targets based on capability gaps.
- Technology roadmaps that prioritize R&D investments across epitaxy, packaging, thermal systems, optics, and embedded controls.
- Procurement templates for negotiating wafer/epi agreements and recommended hedging approaches for critical materials.
- Validation checklists to meet ENERGY STAR, IEC, and regional compliance requirements, reducing time-to-specification in public tenders.
- Market-entry and go-to-market guides tailored to different corporate archetypes (component supplier, fixture OEM, systems integrator, service provider).
How to use the report in boardroom decision-making
Bring the report to three pivotal 2026 conversations:
- Capital allocation: Use our scenario returns to prioritize manufacturing expansion versus R&D and M&A spend.
- Portfolio strategy: Leverage product roadmaps and channel analysis to decide whether to pursue integrated offerings or double-down on component specialization.
- Commercial execution: Align sales compensation, distributor incentives, and specification outreach with the segments and geographies showing the fastest net-new demand growth (detailed segmentation is provided in the full dataset).
Conclusion — the strategic imperative for 2026
The SSL market in 2026 is not a single bet on chip economics; it is a portfolio of bets across efficacy, systems integration, supply-chain resilience, and software-enabled services. Our base-case market projection shows sustained mid-single-digit CAGR growth and significant opportunity for firms that convert technical advancements into system-level value and recurring revenue. The coming year is a differentiation moment: organizations that execute on supply, systems, standards, and services will capture disproportionate upside.
PW Consulting’s full report contains the granular tables, regional and application splits, and company-level benchmarking that underpin the scenarios summarized above. For the complete dataset, downloadable segment models, and a tailored briefing for your executive team, please visit PW Consulting’s report page or contact our advisory desk to schedule a private walkthrough.
For detailed analysis of this topic, please visit the official page: Solid State Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: IT Spending on Clinical Analytics Market to Expand at 13.45% CAGR, Reaching USD 54,426.95 Million by 2032
By PW Consulting, 2026-07-01
It Spending On Clinical Analytics Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, It Spending On Clinical Analytics Market (base year 2025), arrives at a pivotal moment for health systems, payers, life‑sciences organizations and technology vendors. Our research finds that the global clinical analytics IT market has entered a sustained growth phase, with the 2025 market estimated at USD 22,500 Million and a compound annual growth rate (CAGR) of 13.45% across the 2026–2032 forecast window. By 2032 the market is projected to more than double from the 2025 baseline, underscoring that investments made this year will materially shape organizational competitiveness through the next decade.
It Spending On Clinical Analytics Market
Why 2026 is a Strategic Inflection Point
Several converging forces elevate 2026 from planning year to action year. First, rapid adoption of AI and predictive analytics is moving from pilot-to-scale in provider and payer settings, shifting budget lines from experimental R&D to core IT and clinical operations. Second, macro infrastructure trends — notably a surge in AI infrastructure investment and emerging data‑center cost and regulatory pressures — are reshaping total cost of ownership (TCO) assumptions for cloud-first architectures. Third, regulatory and national security measures around cross‑border data flows are forcing re-evaluation of global data strategies.
It Spending On Clinical Analytics Market
- Market momentum: The market’s mid‑double digit CAGR signals a durable demand curve for analytics capabilities across the care continuum, from clinical decision support to quality improvement and population health use cases.
- Concentration and competition: Our concentration analysis shows the market remains moderately fragmented (CR3 ~28.4%; CR5 ~36.2%), leaving strategic room for both incumbents and specialized entrants to capture share through differentiated offerings and vertical integration.
- Cost & regulatory headwinds: New legislation and cost allocation requirements for data centers, coupled with national restrictions on bulk health data transfers, create operational and compliance risks that can negate expected efficiency gains if not managed proactively.
What PW Consulting’s Report Delivers — Practical, Transactional Intelligence
This study is built for executives who need to translate market direction into concrete programs, investments and deals in 2026. We avoid high‑level platitudes and instead provide a layered, use‑case driven toolkit that guides procurement, architecture, clinical operations and M&A teams through implementation realities.
It Spending On Clinical Analytics Market
- End‑to‑end market sizing and forecast model (2020–2032) with sensitivity scenarios reflecting variations in AI adoption rates, cloud migration speeds, and regulatory shocks.
- Buyer personas and procurement playbooks for health systems, payers, life sciences firms and ambulatory networks — mapping decision drivers, procurement cycles and typical contract terms.
- Vendor landscaping and matchup frameworks that score vendors across data assets, analytics IP, deployment flexibility, regulatory compliance posture, and partnership ecosystems.
- Implementation roadmaps and TCO models that explicitly account for infrastructure externalities (energy & grid costs), anticipated data center legislation, and the hidden life‑cycle costs of large model deployments.
- Regulatory risk matrix and data residency playbook aligned to recent policy changes affecting health data transfers and cross‑border collaborations.
- M&A and partnership playbooks tailored to buyers and sellers aiming to scale analytics capabilities quickly while managing integration risk.
Competitive Landscape: Who Matters and Why
The competitive terrain blends enterprise IT giants, healthcare‑native analytics firms and specialized data players. Leading incumbents maintain advantages in installed base, clinical data access, and integration capabilities, while challengers focus on high‑value niches, cloud‑native architectures and advanced modeling.
- Optum (UnitedHealth Group) — Leverages one of the largest combined clinical and claims datasets; its scale supports population health optimization and risk stratification at enterprise scope. Strategic implication: buyers seeking rapid population‑level insights may trade off openness for the advantages of pre‑integrated data and managed services.
- Oracle Health (formerly Cerner) — Recent platform expansions reinforce Oracle Health’s push to unify EHR and analytics. Strategic implication: expect continued emphasis on enterprise‑grade EHR‑adjacent analytics and integrated workflows that reduce clinician friction.
- Epic Systems — Embedded analytics within a dominant EHR footprint continue to position Epic as a primary option for care coordination and real‑world evidence generation. Strategic implication: interoperability and extensibility are critical when deploying third‑party analytic modules.
- IQVIA — Strong in life‑sciences and real‑world evidence; their strengths align to outcomes research and commercial evidence generation. Strategic implication: life sciences buyers should evaluate vendors’ clinical and claims data pedigrees in tandem with analytics tooling.
- SAS Institute & Health Catalyst — Both provide advanced analytics platforms with complementary strengths: SAS in statistical modeling and enterprise analytics, Health Catalyst in clinical, financial and operational data integration. Strategic implication: platform selection should be driven by analytical depth needs versus ease of operational integration.
- GE HealthCare & Siemens Healthineers — Integration of diagnostic imaging and monitoring data with analytics yields differentiated diagnostic and workflow value. Strategic implication: organizations prioritizing imaging‑heavy pathways or hybrid device‑to‑analytics solutions find strategic value in these vendors’ portfolios.
- Merative, Philips, Veradigm, McKesson — Each brings focused capabilities across population health, connected care, ambulatory analytics and supply‑chain analytics. Strategic implication: niche strengths and partnerships often unlock quicker ROI in constrained budgets.
Recent market moves — for example, GE HealthCare’s acquisition activity to expand cloud imaging analytics and industry publications citing C‑suite prioritization of AI — signal an acceleration of consolidation around cloud and AI capabilities. These dynamics favor vendors that can demonstrate both domain accuracy and enterprise operational resilience.
Risk & Dynamics: Infrastructure, Regulation, and the Hidden Costs
Our analysis layers recent regulatory and macro trends onto traditional vendor and buyer decision criteria. Three dynamics stand out:
- Infrastructure externalities: Recent analysis highlights multi‑billion dollar annual hidden costs tied to data center operations and AI workloads, including health and environmental damages. For buyers, this means internal TCO models that ignore energy, grid upgrade, and carbon liabilities materially understate long‑term costs.
- State and federal policy shifts: Several U.S. states have advanced or enacted legislation reallocating energy and grid upgrade costs to large data center operators. These policy changes, combined with DOJ restrictions on bulk transfers of sensitive health data, force reappraisal of cloud strategies, particularly for multinational data flows and centralized model training.
- AI infrastructure boom: With industry estimates pointing to hundreds of billions in AI infrastructure investment in 2026, competition for compute and data center capacity will intensify. Procurement teams must balance latency‑ and residency‑driven choices against escalating cloud services pricing and capacity constraints.
For strategy teams, the implication is clear: technology selection decisions cannot be disentangled from energy, regulatory, and geopolitical risk assessments. Our report embeds scenario analyses that quantify the sensitivity of TCO and deployment timelines to these factors.
How Buyers Should Act in 2026 — A Playbook
Based on the study’s integrated analysis, PW Consulting recommends the following priority actions for organizations allocating 2026 budgets:
- Adopt a two‑tier investment strategy: stabilize clinical core analytics (quality, safety, CDS) while selectively funding high‑value AI pilots with clear governance and ROI thresholds.
- Rebuild TCO models to include infrastructure externalities and policy‑driven cost shifts; require vendors to disclose projected energy consumption and data‑transfer footprints for proposed solutions.
- Prioritize vendors with flexible deployment models and clear data residency controls; demand contractual SLAs that address not just uptime but compliance and data portability obligations.
- Use vendor scorecards that weigh domain data assets and model explainability as heavily as feature parity; for mission‑critical clinical use cases, prioritize clinical validation and clinician workflow fit over headline AI capabilities.
- For acquirers: target bolt‑on acquisitions that extend data assets or specialized analytics capabilities rather than repeatable engineering spend; for sellers: emphasize recurring revenue and validated clinical outcomes to maximize valuation.
What the Full Report Contains (and Why You Need It)
This press briefing is intentionally strategic and directional. The full PW Consulting It Spending On Clinical Analytics Market report contains the granular segmentation, vendor scorecards, financial models and executable playbooks that in‑house strategy, procurement and digital transformation teams require to make high‑confidence 2026 decisions. Key deliverables include:
- Detailed segmentation across components, deployment modes, applications and geographies, with downloadable financial models and sensitivity toggles (note: detailed segment tables are available only in the full report).
- Comparative vendor profiling and a decision matrix to map vendor capabilities to buyer personas and desired outcomes.
- Procurement RFP templates, contract clauses and due‑diligence checklists tailored to energy, compliance and data residency risks.
- Implementation timelines and clinical validation checklists that reduce adoption risk and accelerate time to value.
Final Word
Clinical analytics is no longer an exploratory IT line item — it is a core lever for care quality, operational resilience and commercial growth. The market’s strong growth trajectory and persistent fragmentation create an environment rich in opportunity for buyers that act decisively and for vendors that can couple clinical credibility with disciplined operational economics. PW Consulting’s full report provides the forensic detail and executable tools necessary to convert 2026 spending into sustained competitive advantage.
To access the full analytics, vendor scorecards, and downloadable financial models, visit our report page and request the comprehensive dataset and executive briefing.
For detailed analysis of this topic, please visit the official page: It Spending On Clinical Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Anti-Fingerprint Coatings Market Poised to Grow at a 6.45% CAGR Through 2032
By PW Consulting, 2026-07-01
Anti Fingerprint Coatings Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on Anti Fingerprint (AFP) Coatings delivers a focused, actionable briefing designed to inform executive choices in 2026. The global AFP coatings market has moved from roughly USD 841.2 Million in 2020 to approximately USD 1,152.4 Million in 2025, and our modeling indicates continued expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.45%, reaching an estimated USD 1,790.8 Million by 2032. These headline figures reflect an industry that has matured in baseline demand while entering a new phase of technology substitution, regulatory-driven reformulation, and selective consolidation. This release sketches the strategic contours of that transition — enough to inform near-term strategy, but intentionally withholding complete segment tables to encourage direct engagement with our full report.
Anti Fingerprint Coatings Market
Why this matters for 2026 strategic choices
-
Regulatory momentum is a strategic pivot: The phase-out of PFAS under regimes such as REACH has shifted R&D priorities and supplier roadmaps. Firms that treat PFAS restrictions as a compliance exercise alone will lag those that reframe reformulation as a product-differentiation opportunity.
Anti Fingerprint Coatings Market -
Demand is steady but selective: Macro demand growth is supported by large-volume industries (consumer electronics, displays, and automotive interiors) and by premium segments that prioritize appearance and tactile quality. The sustainable edge — PFAS-free, fluorine-free formulations — is becoming a market access criterion in many procurement processes.
Anti Fingerprint Coatings Market -
Market structure favors specialist leaders and adaptable OEM partners: Market concentration metrics show a mid-tier of dominant suppliers alongside a fragmented long tail of niche formulators and finishers. This creates an environment ripe for strategic partnerships, licensing, and targeted M&A to fill capability gaps.
What the full PW Consulting report delivers (practical, executable content)
-
Robust market architecture and forecast engine — Our report includes a reproducible bottom-up model covering the 2020–2032 window, with scenario outputs (base, regulatory-accelerated, and technology-disruption cases) that quantify upside and downside pathways for revenue and volume. We translate those scenarios into playbooks for suppliers, OEMs, and investors.
-
Technology decision framework — We map core AFP chemistries and deposition methods (including vacuum PVD, sol-gel processing, and sprayable solutions), their benefits and trade-offs across substrate types (glass, metals, plastics), and production implications (throughput, capital intensity, and inline integration). The report explains when to favor thin-film PVD over liquid-applied siloxane/silicone or sol-gel systems, guided by lifecycle cost and durability criteria.
-
Regulatory-risk heatmap and reformulation playbook — Detailed analysis of PFAS restrictions and downstream compliance obligations, plus supplier transition plans for PFAS-free chemistries, supplier selection checklists, and third-party validation pathways to accelerate qualification in regulated geographies.
-
Supplier & competitive assessment — A verified supplier matrix combining technology fit, scale, geographical presence, and innovation capacity. Each supplier profile is scored against go-to-market vectors (OEM relationships, service capabilities, and formulation IP) and includes tactical recommendations for sourcing, co-development, or strategic investment.
-
Commercialization accelerators — Time-and-cost roadmaps for pilot-to-production transitions, recommended sample-qualification protocols for OEMs, and a prescriptive GTM (go-to-market) playbook that aligns product positioning, channel strategy, and pricing controls.
-
Investment and M&A intelligence — Target prioritization (capability vs. market access), valuation sensitivities tied to regulatory scenarios, and integration risk checklists to preserve IP and customer continuity post-deal.
Competitive landscape — strategic implications
The AFP coatings market exhibits a mixed structure: a handful of established players with vertically integrated capabilities, several specialist formulators with strong IP in niche chemistries, and a multitude of local service providers focused on finishing and retrofit applications. Concentration metrics indicate that the top three providers hold a meaningful share of the market, while the top five broaden that grip further — a dynamic that simultaneously raises barriers for new mass-market entrants and creates openings for differentiated challengers.
-
Aculon (San Diego) — Positioning as a nimble innovator in liquid-applied nano coatings makes Aculon an attractive co-development partner for OEMs seeking rapid PFAS-free alternatives. Strengths: ease-of-application and substrate versatility. Considerations: scale-up and long-term durability benchmarking relative to fluorinated incumbents.
-
Ionbond (Olten, IHI Group) — With a PVD-centric offering and an emphasis on PFAS-free hard coatings, Ionbond is strategically placed where durability and design aesthetics converge (appliances, devices). For OEMs, Ionbond’s model is compelling when surface endurance and high-throughput deposition are primary constraints.
-
Momentive (Waterford) — Sprayable, PFAS-free hydrophobic/oleophobic chemistries offer a balance between retrofit applicability and regulatory alignment. Momentive’s portfolio is particularly relevant for formulators and contract coaters that prioritize application flexibility across plastics and glass.
-
Henkel (Düsseldorf) — A major industrial player with newly launched silicone-based AF products (e.g., Loctite AF 8810/AF 8812) demonstrates the scale and reach that incumbents can bring to accelerate market adoption of PFAS-free alternatives, especially in automotive displays.
-
PPG Industries, Daikin Industries, AGC Inc., Rimex Metals, Diamond Coatings — These incumbents collectively represent capability breadth (fluoropolymer expertise, substrate-specific finishes, and global channel access). Their strategic choices will influence standards for durability, qualification timelines, and commercial terms across OEM procurement cycles.
Macro dynamics and supply-side signals
-
Raw material transitions — Legacy reliance on fluoropolymers and PFPEs is being replaced (or supplemented) by silane, silica, silicone, and new fluorine-free resins. This creates short- to medium-term supplier displacement risk but also opens margins for firms that can secure alternative chemistries and validate lifetime performance.
-
Manufacturing readiness — Choice of deposition technology materially affects capex, yield, and total landed cost. PVD delivers thin, durable films but requires higher capital; liquid-applied chemistries enable retrofit and lower entry thresholds but face durability scrutiny in certain applications.
-
Procurement dynamics — OEMs increasingly require documented environmental compliance and lifecycle impact reporting as part of supplier qualification. Suppliers without accreditation or clear reformulation roadmaps risk exclusion from tier-one opportunities.
Five strategic recommendations for 2026
-
Accelerate PFAS-free validation programs now — Prioritize independent, standardized durability testing and regulatory documentation to shorten OEM qualification cycles. Begin co-development pilots that validate performance under both operational and accelerated-aging conditions.
-
Choose technology by use-case, not by headline chemistry — Adopt a decision framework that maps deposition method to substrate, production volume, and cost-per-unit requirements. Hybrid approaches (e.g., PVD for premium surfaces, spray/sol-gel for retrofit or cost-sensitive segments) will win share.
-
Use M&A and partnerships strategically — Small-to-mid M&A can secure IP or market access cheaply relative to greenfield development. For incumbent suppliers, targeted acquisitions of niche formulators or contract coaters provide rapid route-to-market for PFAS-free offerings.
-
Operationalize sustainability as a differentiator — Embed lifecycle impact and end-of-life planning into product specs. Early adoption of PFAS-free chemistries paired with transparent supply chains will reduce friction in global rollouts.
-
Invest in qualification speed — Reducing sample-to-qualification time is as valuable as product performance. Focus teams on reproducible process parameters, tighter quality control, and streamlined on-site verification with key OEMs.
Who should read the full PW Consulting report
-
CEOs and corporate strategy teams at coatings and materials firms looking to prioritize 2026 R&D and M&A.
-
R&D and product managers at OEMs in consumer electronics, automotive interiors, and architectural finishes assessing supplier roadmaps.
-
Corporate development and private-equity teams screening targets or building a diligence thesis in specialty coatings.
-
Procurement and quality organizations that must embed regulatory and life-cycle criteria into supplier qualification processes.
Final note — what is withheld here and how to access it
This briefing is intentionally a “trailer”: it presents the strategic insights, opportunities, and recommended actions you need to make confident 2026 decisions while withholding granular segment-level tables and per-region/application dollar breakdowns that form the core of our commercial dataset. The full PW Consulting Anti Fingerprint Coatings Market report contains detailed segmentation dashboards, downloadable datasets, supplier scorecards, and step-by-step implementation worksheets designed for rapid operationalization. For purchase or to arrange a bespoke briefing tailored to your company’s positioning, please contact PW Consulting or visit our report page.
For detailed analysis of this topic, please visit the official page: Anti Fingerprint Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Interactive Therapy Robot Market Poised to Grow from USD 1.59B in 2025 to USD 5.23B by 2032 at an 18.5% CAGR
By PW Consulting, 2026-07-01
Interactive Therapy Robot Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
The interactive therapy robot market has entered a structural growth phase that warrants immediate attention from healthcare providers, device manufacturers, payers and strategic investors. Drawing on a comprehensive evidence base covering historical performance (2020–2025) and forward-looking scenarios for 2026–2032, our analysis shows the market expanding at a sustained double‑digit clip — a compound annual growth rate of 18.5% — moving from a mid‑2020s market measured in the low‑billions of USD (base year 2025) toward multi‑billion valuations by the early 2030s. This trajectory is driven by converging trends: aging populations, workforce constraints in therapy delivery, validated clinical benefits of human‑robot interaction, and a maturing regulatory and reimbursement environment that increasingly recognizes device‑enabled therapeutic interventions.
Interactive Therapy Robot Market
Why this matters for 2026 strategic planning
-
Timing is critical. 2026 marks the inflection where pilot outcomes, reimbursement code updates and first‑wave commercial deployments create an environment in which scale matters. Executives who crystallize platform, clinical and payer strategies in 2026 will capture disproportionate share in the next growth window.
Interactive Therapy Robot Market -
Revenue trajectories are large and rapid. The market’s scale expansion in our central forecast amplifies total addressable opportunity for integrated product‑service models, recurring software revenues and managed‑care partnerships. This elevates valuation multiples for companies with defensible clinical data and repeatable deployment models.
Interactive Therapy Robot Market -
Competitive positioning will be decided on three vectors — clinical validation, regulatory clarity, and reimbursement alignment — rather than hardware novelty alone. Firms that can demonstrate measurable patient outcomes, a clear device classification pathway, and a reimbursement playbook will outcompete hardware‑only entrants.
Market dynamics shaping 2026 decisions
-
Regulatory clarity is improving but still nuanced. Interactive therapy robots intended for therapeutic benefit must align with medical device frameworks in major jurisdictions. A notable precedent is PARO’s classification as a Class II medical device in the United States, which illustrates a credible pathway for emotionally assistive devices that also serves as a model for clinical trial design and labeling strategy.
-
Reimbursement is shifting from theoretical to actionable. The 2026 updates to therapy‑related billing codes — including new categories applicable to remote therapeutic monitoring and device data transmission — create concrete levers for commercial models that bundle robotics, analytics and clinician oversight. Understanding the operational requirements tied to those codes is now a core commercial capability.
-
Adoption signals are accelerating. Recent hospital and long‑term care deployments — exemplified by scaled pilots of AI‑driven therapy robots in pediatrics and geriatrics — are producing early evidence of reduced staff burden and improved engagement metrics. These deployments are shortening procurement cycles for health systems willing to pilot with outcome‑based contracting.
-
Market structure is moderately concentrated. A meaningful share of value is already captured by a handful of focused incumbents and established robotics firms, but the field remains open to challengers that can combine clinical evidence with scalable service delivery.
Competitive landscape — what to watch in 2026
The vendor map is a mix of specialized therapeutic robotics firms, generalist consumer/hospital robotics vendors, and AI startups repurposing companion‑robot designs for clinical use. Key archetypes include:
-
Therapeutic incumbents with clinical heritage: Companies that built reputations in emotionally assistive robotics and secured medical classifications have a first‑mover advantage in institutional channels. Their commercial playbook focuses on clinical validation, scientific publications, and pathway development with regulators and large health systems.
-
AI-native companionship platforms: Firms offering conversational, engagement‑focused robots tailored to home use are leveraging cloud AI stacks and telemetry to deliver personalization at scale. Their strengths lie in user experience and remote monitoring, but they must bolster clinical evidence to win institutional budgets.
-
Multi‑purpose humanoid platforms: Legacy robotics companies are adapting generalist platforms (humanoid or social robots) into therapy workflows through software modules and partnerships with clinical content providers. Their advantage is hardware availability and distribution networks; their challenge is clinical positioning.
From a competitive perspective, the most consequential moves for 2026 will be cross‑sector partnerships (health systems, payers, content developers), completion of clinical trials that meet payers’ evidence thresholds, and early demonstrations of interoperability with electronic health records and remote monitoring ecosystems.
Company vignettes — strategic implications
-
PARO Robots (AIST / U.S.) — A blueprint for device classification and institutional adoption. PARO’s established medical device classification suggests a replicable regulatory and clinical evidence pathway for emotionally assistive robots seeking institutional acceptance.
-
Intuition Robotics — A home‑first AI companion model addressing loneliness and medication adherence. Their strength in conversational engagement positions them for payer interest in preventive and chronic‑care programs, provided they can map engagement metrics to clinical outcomes.
-
Expper Technologies — Signals of rapid institutional traction. Reported hospital and nursing‑home deployments demonstrate how a focused clinical use case (pediatrics/geriatrics engagement) can reduce staff burden and accelerate procurement decisions; this is the kind of go‑to‑market proof point investors and health systems will look for in 2026.
-
SoftBank Robotics, Blue Frog Robotics, LuxAI and Hanson Robotics — Each brings scale, brand and hardware IP. Their strategic questions are whether to pursue deep clinical validation or to partner/sell platforms to clinical specialists. Expect consolidation activity or commercial partnerships as market stakes rise.
What our report delivers — operational, decision‑grade intelligence
PW Consulting’s Interactive Therapy Robot Market report is designed for executives who need to move from concept to commercial execution in 2026. The report includes:
-
Market sizing and scenario forecasts (historical 2020–2025, base year 2025, forecast 2026–2032) with revenue trajectories under conservative, central and aggressive adoption pathways.
-
Regulatory pathway maps for the U.S. and EU, including decision trees for device classification and recommended clinical endpoints aligned with payer evidence requirements.
-
Reimbursement playbook that translates recent CPT/RTM updates into operational requirements for billing, documentation and clinician oversight.
-
Vendor scorecards and build vs. buy matrices that triangulate technology readiness, clinical validation, IP position and commercial reach.
-
Go‑to‑market blueprints for three commercialization archetypes — institutional clinical deployments, managed home programs, and direct‑to‑consumer subscription models — with pilot templates, KPI dashboards and contracting checklist.
-
Deal‑maker guidance including valuation benchmarks, typical partnership structures, and M&A triggers specific to therapeutic robotics.
Note: To preserve strategic confidentiality and encourage direct engagement, the report’s public summary intentionally omits granular sub‑segment tables and regional/application splits that drive pricing and investment decisions. These are available in the full report and accompanying data appendices.
Practical 2026 playbook — five actions for leaders
-
Prioritize evidence generation: Fund or partner on randomized and real‑world studies that measure utilization, functional outcomes and cost offsets. Payer conversations in 2026 will be evidence, not aspiration, driven.
-
Map regulatory and reimbursement milestones into product roadmaps: Build regulatory strategy and CPT/RTM alignment into product development timelines to avoid commercialization delays.
-
Design integrated commercial offers: Combine device, SaaS analytics and clinical services to create defensible recurring revenue and align incentives with health systems and payers.
-
Secure deployment partnerships early: Target a mix of flagship institutional pilots and managed home programs to generate diverse outcome evidence and operational learnings.
-
Evaluate M&A and alliance criteria now: Define the clinical, data and distribution assets that would make an acquisition or partnership accretive to your 2028 revenue and margin goals.
Concluding guidance
Interactive therapy robots are shifting from niche pilots to enterprise‑grade therapeutic assets. For boards and C‑level teams preparing 2026 budgets, the decision is less about “if” and more about “how” to participate: are you building clinical capabilities, licensing proven platforms, or partnering with incumbents that already hold institutional trust? PW Consulting’s full Interactive Therapy Robot Market report translates macro forecasts and market structure into executable plans — from clinical trial design to payer contracting templates. For teams that intend to lead in 2027 and beyond, the time to operationalize is 2026.
For detailed analysis of this topic, please visit the official page: Interactive Therapy Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global Medical Device Calibration Services Market to Expand at a Robust 9.25% CAGR Through 2032
By PW Consulting, 2026-07-01
Medical Device Calibration Service Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s new market research brief on the Medical Device Calibration Service market delivers a focused strategic lens for decision-makers preparing plans in 2026. Built on a rigorous base year of 2025, the study synthesizes five years of historical data (2020–2025) and an actionable forecast (2026–2032), projecting a compound annual growth rate (CAGR) of 9.25% through the forecast window. The market value in 2025 stood at USD 2,156.16 Million (Revenue unit: Million, USD); our model anticipates sustained expansion to just over USD 4,005 Million by 2032. This trajectory reflects accelerating compliance demands, equipment complexity, and a shift to managed service models in clinical and manufacturing environments.
Medical Device Calibration Service Market
Why this brief matters for 2026 corporate decisions
-
Timing matters. The market is transitioning from routine piece-rate calibrations toward integrated service offerings that combine on-site response, accredited lab traceability, digital evidence chains, and outcome-based SLAs. 2026 is the year many buyers will convert pilot programs into procurement standards; suppliers who set the commercial terms now will capture durable margins.
Medical Device Calibration Service Market -
Regulatory tailwinds are driving demand for accredited, traceable calibration. ISO/IEC 17025 accreditation, ISO 13485-aligned systems, and evolving FDA expectations (including ASCA pathways and requirements around 21 CFR Part 820.72) are shifting procurement criteria from price-only to competence, traceability, and defensible data management.
Medical Device Calibration Service Market -
Fragmented competitive dynamics create opportunity windows. Despite the presence of global incumbents, market concentration remains low (CR3 ~18.45%; CR5 ~26.8%), signaling substantial room for regional consolidators, niche specialists, and technology-enabled entrants to scale rapidly.
Headline market signals — what the numbers reveal (and what we intentionally reserve)
-
Historical momentum: the market expanded materially between 2020 and 2025, reflecting increased device volumes, replacement cycles, and stricter compliance checks in healthcare delivery and device manufacturing.
-
Near-term outlook: our forecast shows a steady acceleration beginning in 2026 as national quality infrastructures and mobile calibration capabilities mature in key growth markets.
-
Note on disclosure: to preserve the integrity of commercial insights and to drive direct engagement, this release highlights macro scale and dynamics while withholding granular regional, service-type, and device-type revenue splits. The full report contains the segment-level intelligence buyers and investors need to act decisively.
What the report contains — practical, transaction-focused deliverables
-
Market model and scenario frameworks: transparent bottom-up and top-down models reconciling historical datapoints with 2026–2032 scenarios (base, upside, downside) and sensitivity to regulatory and macroeconomic inflections.
-
Buyer personas and procurement playbooks: decision-tree templates for hospitals, OEMs, contract testing labs, and device manufacturers that transform compliance requirements into vendor selection criteria and SLA negotiation levers.
-
Service line economics: relative margin profiles across third-party lab services, OEM calibration offers, and in-house calibration operations; guidance on pricing architecture, attach-rate levers, and service bundling strategies.
-
M&A and partnership blueprint: valuation heuristics, integration checklists, and a prioritized target list by capability gap—designed to accelerate bolt-on and capability-driven acquisitions without exposing our premium segment-level tables in this summary.
-
Operational risk matrix and compliance checklist: end-to-end operational KPIs, traceability controls aligned to ISO/IEC 17025:2017 and ISO 13485, and recommended audit bench-marks for defending regulatory submissions (including ASCA considerations).
Competitive landscape — strategic implications from company profiles
The market displays a mix of multinational specialists, regionally focused service providers, and equipment manufacturers offering calibration as a complementary service. Our competitive layer analysis identifies four archetypes: global accredited networks, OEM-led service arms, regional niche specialists, and emerging technology-integrated disruptors.
-
Trescal (France) — A prototypical global accredited network offering ISO 17025-traceable services, capable of on-site and laboratory calibrations. Trescal’s model is instructive for companies seeking scale with compliance as a selling point: deep accreditation, cross-border logistics, and multi-standard support (ISO 13485, GMP/GLP, QSR, FDA) enable premium positioning in regulated accounts.
-
Transcat, Inc. (United States) — Demonstrates the inorganic growth path. Recent acquisitions of regional calibration laboratories have strengthened local presence and expanded capacity in healthcare and life sciences. For buyers, Transcat’s playbook highlights the efficiency of acquiring accreditation and customer relationships versus building greenfield capabilities.
-
Tektronix and Fluke Biomedical (United States) — Represent OEM/service hybrids. Their advantage is multi-brand expertise, instrument-level know-how, and the ability to cross-sell test equipment with service contracts—an attractive model for healthcare systems that prefer bundled capital and service solutions to minimize equipment downtime.
-
Regional specialists (e.g., JM Test Systems, Biomedical Technologies Inc./ISS Solutions, NS Medical Systems, Calyx Met, and a cohort of smaller players) — These firms illustrate the competitive depth of local, accredited providers. They often win on responsiveness, domain specialization (e.g., imaging or ultrasonic), and relationships with hospital biomedical engineering teams.
Strategic reading: established global players provide scale and standardization; OEMs offer lifecycle alignment; and regional specialists dominate speed-of-service. For 2026, we expect more M&A and partnership activity as global players seek density while regional firms monetize platform value.
Regulatory and infrastructure dynamics reshaping demand
-
Accreditation as a commercial differentiator — ISO/IEC 17025:2017 is increasingly treated as a baseline for market access. Additionally, the FDA’s ASCA program and statutory obligations (e.g., 21 CFR Part 820.72) are prompting buyers to accept only providers who can produce defensible, traceable calibration records.
-
National quality infrastructure investments — Public and academic initiatives are expanding capacity. Recent examples include mobile calibration facilities and apex-level national labs that will reduce turnaround times in underserved regions and increase local demand for accredited services.
-
Technology uplift — Digital calibration records, remote verification tooling, and connected test instruments are enabling new service propositions: predictive calibration scheduling, asset-health scoring, and performance-as-a-service contracts. These capabilities change margin mechanics and customer stickiness.
Recent industry moves that change the competitive map
-
Strategic acquisitions: notable roll-ups and add-on acquisitions have concentrated capabilities in specific geographies and have served as catalyst events for consolidation of laboratory footprints and client lists.
-
Public-sector capacity building: launches of mobile calibration facilities and national-level labs are creating new demand corridors and shortening calibration lead times in regions that previously relied on imports or long-distance shipments.
-
OEM service expansion and partnerships: equipment manufacturers are continuing to bundle calibration and maintenance into asset lifecycle agreements, putting pressure on independent providers to demonstrate higher-value analytics and faster service response.
Actionable recommendations for executive teams in 2026
-
For suppliers: prioritize accreditation investments and digital evidence chains. Winning proposals will couple ISO/IEC 17025 traceability with encrypted, tamper-evident calibration records and standardized reporting templates compatible with regulatory submissions.
-
For acquirers: focus on targets that deliver immediate accreditation uplift, regional density, or specialty device expertise. Avoid paying for geographic overlap without clear operational synergies—our report’s integration checklist helps quantify those synergies.
-
For buyers (hospitals and OEMs): restructure procurement toward outcome-based SLAs that measure asset uptime, compliance readiness, and total cost of service, not just per-calibration pricing. The procurement playbook in the full report contains contract language templates and KPIs.
-
For technology investors: seek opportunities in SaaS and instrumentation that enable predictive calibration, remote verification, and secure digital traceability—these are the enablers that will reconfigure supplier-buyer economics over the next three years.
How to use this brief and where to go next
This industry brief is a strategic primer intended to inform 2026 planning cycles. It articulates the macro scale, competitive archetypes, regulatory inflections, and practical steps executives should consider now. For teams preparing business plans, RFPs, M&A decks, or compliance investments, the full PW Consulting report provides the segment-level revenue tables, regional and device-type breakdowns, vendor scorecards, and playbooks necessary to move from strategy to execution.
Accessing the complete dataset and our customized advisory services will provide the specific segmentation and toolkits referenced here. PW Consulting stands ready to translate the research into a bespoke road map—whether that is a go-to-market plan for a calibration provider, an integration playbook for an acquirer, or a procurement transformation for a large healthcare system.
For licensing, bespoke briefings, or to request the full report with its granular tables and model files, please contact PW Consulting’s Industry Practice. Our team will tailor the insight package to your role—supplier, buyer, investor, or regulator—and provide the actionable deliverables to accelerate decision quality in 2026.
For detailed analysis of this topic, please visit the official page: Medical Device Calibration Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Cooling Synchronous Condenser Market to Reach USD 573.78 Million by 2032, Expanding at a 5.86% CAGR
By PW Consulting, 2026-07-01
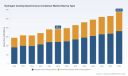
Hydrogen-Cooled Synchronous Condenser Market — A 2026 Strategic Preview for Decision-Makers
As utilities and grid operators accelerate the transition away from conventional synchronous thermal generation, hydrogen-cooled synchronous condensers are emerging as a tactical solution for large-scale inertia, short-circuit strength, and dynamic reactive-power support. PW Consulting’s latest market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — projects the global market will expand at a compound annual growth rate of 5.86% through 2032, reflecting a steady rise in demand from utility, transmission, and industrial buyers. Our modelling shows the market moving from approximately USD 385.4 Million in 2025 toward a materially larger opportunity by the end of the forecast window, underscoring why 2026 is the year organizations should convert strategy into procurement and partnership action.
Hydrogen Cooling Synchronous Condenser Market
Why 2026 is an inflection point
-
System-strength needs are shifting from short-term pilot projects to portfolio-level planning. As large synchronous plants retire, grid operators are increasingly issuing tenders and building Renewable Energy Zone (REZ)-style programs that require engineered solutions for inertia and voltage control at gigawatt scale.
Hydrogen Cooling Synchronous Condenser Market -
Hydrogen cooling has resurfaced as the preferred thermal management approach for high-capacity rotating machinery in utility contexts because of its superior thermal conductivity and low density — characteristics that enable higher continuous ratings and improved electrical efficiency versus air-cooled alternatives. That technical edge is material when sizing assets that must deliver sustained reactive power and inertia to renewables-heavy grids.
Hydrogen Cooling Synchronous Condenser Market -
Procurement and project pipelines have begun to converge into real contracts and EPC awards. Recent vendor wins and consortia activity demonstrate an active market where execution capability, local presence, and hydrogen-handling expertise are decisive procurement filters.
What PW Consulting’s report delivers — practical outputs for 2026 decisions
Our report is structured to be immediately operational for corporate strategy, procurement, and project teams evaluating synchronous condenser options in 2026. Key actionable components include:
-
Market sizing and scenarios: a transparent methodology covering historical trends (2020–2025) and a detailed forecast (2026–2032) with scenario stress-testing to evaluate demand under different renewable rollout, retirement, and policy pathways.
-
Vendor benchmarking and capability maps: qualitative and quantitative scores for OEMs, EPCs, and integrators across technology maturity, hydrogen-cooling experience, modularity, digital diagnostics, and local content.
-
Procurement playbook and contract templates: recommended commercial terms, performance guarantees, acceptance tests, and hydrogen-specific clauses (purity, leak-rate warranties, safety training, and maintenance obligations).
-
Total cost-of-ownership models: capex/opex comparison tools that capture cooling-system trade-offs (hydrogen-only, combined hydrogen-water, air/TEWAC variants), lifecycle maintenance, spare-parts logistics, and reliability assumptions — model variants remain interactive to support buyer-specific inputs.
-
Site-integration and O&M guidance: engineering checklists for hydrogen handling, sealing systems, gas-management, port and transport constraints, and maintenance regimes tailored to different climate and regulatory environments.
-
Deal flow and contract database: curated summaries of recent awards, EPC arrangements, consortiums, and project timelines to help procurement teams benchmark lead times and negotiation points.
To preserve commercial value for report subscribers — and to comply with the “trailer” principle of this press release — we present the analytical depth and practical use cases above while withholding granular segment and regional figures here. The full dataset and interactive models are available in the complete report.
Competitive landscape — who matters in 2026
The market exhibits meaningful concentration at the top. The three largest suppliers control a notable majority of deployed capacity, with the top five firms collectively holding an even larger share — a structural reality that shapes pricing power, lead times, and technology diffusion. For buyers and investors this concentration translates into a small set of preferred partners capable of meeting the largest utility-scale, hydrogen-cooled requirements.
Key vendor archetypes and strategic positioning:
-
Legacy rotating-machinery incumbents with deep hydrogen experience and global service networks (e.g., historic hydrogen-cooled generator developers). These firms excel in high-rating machines, long-term O&M contracts, and white-space leverage into synchronous condenser configurations.
-
Electrification and grid-systems specialists that package advanced control systems, high-inertia options, and turnkey offerings for REZs and transmission-scale retrofits. Their strengths lie in systems integration and proven project delivery across challenging regulatory regimes.
-
Regional players and new entrants that compete on local manufacturing, competitive pricing, and flexibility in tender responses — critical where localization rules or rapid deployment windows dominate procurement criteria.
Recent contract activity signals how these archetypes are translating capability into backlog. Highlights include major awards covering multi-unit supplies to transmission networks and REZ projects, consortium-driven EPC contracts in large interconnection zones, and targeted single-unit deployments to shore up system strength in regions undergoing rapid coal-to-renewables transitions. These developments confirm two immediate lessons: (1) buyers value end-to-end execution capability that spans hydrogen handling, commissioning, and long-term service, and (2) first-mover procurement decisions in 2026 will shape local supply chains and aftermarket economics for years.
Technical and operational preconditions for hydrogen-cooled success
-
Hydrogen handling and purity controls: hydrogen’s flammability and diffusion characteristics require specialized sealing systems, purity regimes, and leak-detection infrastructures. These are not add-ons — they materially affect lifecycle risk profiles and maintenance scheduling.
-
Safety, regulation, and site planning: project teams must coordinate early with local authorities on safety cases, training, and emergency response capability. Tender specifications that ignore these upstream costs materially underprice true lifecycle obligations.
-
Digitalization and remote diagnostics: real-time monitoring of shaft vibration, hydrogen pressure, and cooling-system thermal profiles reduces forced outages and optimizes maintenance windows — a differentiator in vendor selection.
-
Maintenance and spare-parts strategies: long-lead components for hydrogen systems and high-capacity rotors necessitate a strategic spares plan or guaranteed availability clauses in supplier contracts.
Policy, procurement and supply risks to watch in 2026
-
Regulatory direction on grid codes and resource adequacy will continue to drive demand, but tender specifications remain mixed: some transmission operators favor hydrogen-cooled solutions for large ratings, while others explicitly specify non-hydrogen options to reduce operational complexity. Procurement teams must therefore align technical specs with the regulatory appetite in target grids.
-
Hydrogen supply-chain and component market dynamics: while hydrogen consumption within synchronous condensers is modest by energy-system standards, the requirement for certified gas-handling equipment, seals, and testing capacity creates supply concentration risks that can extend lead times.
-
Commodity and logistics volatility: large rotating machinery is sensitive to lead-time inflation and port/logistics constraints. Early contracting and clear acceptance criteria materially reduce schedule risk.
How to act in 2026 — tactical recommendations for executives
-
Integrate synchronous condenser strategy into capital-planning cycles now. Use multi-scenario procurement timelines that account for manufacturer lead times, site readiness, and grid-code updates.
-
Prioritize vendors with documented hydrogen-cooled experience and validated service offers. Where local content requirements matter, evaluate tiered contracting approaches that combine global OEM capability with regional manufacturing partners.
-
Insist on transparent lifecycle modelling from bidders. Ask for sensitivity analyses on hydrogen-management costs, seal-replacement schedules, and digital monitoring guarantees.
-
Embed safety and regulatory deliverables within commercial milestones. Early regulatory engagement is often the single largest determinant of on-time commissioning.
-
Consider strategic partnerships or minority investments to secure preferential design and supply queue positions if your 2026–2028 project pipeline depends on highly rated hydrogen-cooled machines.
Conclusion — a pragmatic outpost in an evolving market
Hydrogen-cooled synchronous condensers are not a generic plug-in; they are a specialist choice that unlocks higher continuous ratings, efficiency, and grid-strength capabilities for large renewable integration projects. With market momentum, a clear set of incumbent suppliers, and a forecasted multi-year expansion at a mid-single-digit CAGR, 2026 is the year to convert strategy into binding procurement choices or strategic partnerships. PW Consulting’s full market study provides the confidential segment-level data, vendor scorecards, financial models, and contract templates you need to execute with confidence.
About PW Consulting
PW Consulting advises utilities, OEMs, investors, and government agencies on decarbonization technologies and grid modernization. Our Hydrogen-Cooled Synchronous Condenser Market report combines project-level intelligence, vendor due diligence, engineering constraints, and commercial playbooks to support capital decisions in 2026 and beyond. For the full dataset, interactive models, and procurement templates, access the complete report via PW Consulting’s official channels.
For detailed analysis of this topic, please visit the official page: Hydrogen Cooling Synchronous Condenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antirusting (Anti‑Rust) Agents Market to Expand at 5.28% CAGR, Reaching USD 7.83 Billion by 2032 — Asia Pacific Leads with USD 2.18 Billion
By PW Consulting, 2026-07-01
Antirusting (Anti‑Rust) Agents Market: Strategic Imperatives for 2026
PW Consulting’s latest Antirusting Anti Rust Agents Market report (base year 2025) provides executive teams with a compact, decision‑ready view into a market poised for steady expansion. The global market was estimated at USD 5,460.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.28% over 2026–2032, reaching an expected USD 7,827.32 Million by 2032. These headline metrics frame a market that is large enough to attract continued participation from specialty chemical majors yet fragmented enough to reward focused technical differentiation and nimble commercial moves.
Antirusting Anti Rust Agents Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 will be a pivot year for many players. With regulatory timelines, raw material repricing, and electrification/weight‑reduction programs in adjacent industries converging, firms must align R&D investments and go‑to‑market plans now to realize 2027–2029 opportunities.
Antirusting Anti Rust Agents Market -
Clarity without overload: We synthesize macro trajectories with supplier‑level intelligence, giving leaders the bottom‑line implications (margin pressure, product gap, M&A windows) without burying them in granular tables—enough insight to act and a clear path to the complete datasets if deeper modeling is required.
Antirusting Anti Rust Agents Market -
Competitive posture: Our analysis converts market dynamics into concrete strategic options—portfolio rationalization, regional footprint shifts, and technology partnerships—that can be evaluated and executed within a 12–18 month program timeline.
What the report delivers (practical, executable content)
-
Market sizing and trajectory: A verified market base for 2020–2025 and a segmented forecast through 2032, enabling revenue‑planning and scenario stress tests anchored to the 2025 base year.
-
Commercial playbooks: Product positioning templates for water‑based, solvent‑based, oil‑based, VCI and wax/grease solutions—structured to support sales enablement, specification wins, and distributor incentives.
-
Supply‑chain cost models: Bottom‑up impact analysis for key feedstocks (including sensitivity to oil and TEA movements), plus hedging and procurement levers to protect gross margins.
-
Regulatory impact mapping: Actionable compliance pathways and reformulation timelines tied to major regulatory triggers, with prioritized remediation steps for affected SKUs.
-
Competitive landscaping and supplier scorecards: Qualitative and quantitative assessment of incumbent and emerging vendors, including capability gaps and likely strategic moves.
-
M&A and partnership pipeline: Identification of target archetypes, valuation multipliers, and integration risk checklists tailored to buy‑and‑build scenarios.
-
Market entry and expansion checklists: Go‑to‑market templates for new regions and applications (e.g., packaging VCI, industrial lubricants, and marine formulations) that reduce time‑to‑revenue.
Dynamics shaping the sector in 2026
-
Price and feedstock volatility: Petroleum‑linked feedstocks remain an input risk—Brent crude averaged approximately USD 81.13/bbl in 2024—and fluctuations transmit through to oil‑soluble inhibitor costs. Triethanolamine (TEA), a common co‑raw material, recorded a notable year‑on‑year price rise into Q4 2024, underlining the need for agile cost modelling and alternative inputs.
-
Regulatory pressure and compliance costs: Chemical regulation is a material strategic variable. Notable recent actions include restrictions such as those under EU REACH Annex XVII that constrain certain phosphate‑based substances and U.S. EPA reporting requirements for PFAS in fluorinated inhibitors. These changes raise reformulation and testing costs and create product gaps for vendors slow to adapt.
-
Trade policy and supply resilience: Trade measures, including U.S. tariffs on certain Chinese‑origin organics, create localized sourcing cost differentials. Firms should evaluate nearshoring and diversified supplier strategies to reduce tariff exposure and lead‑time risk.
-
Product innovation and sustainability: The market is seeing a distinct premium for low‑VOC and reduced‑PFAS formulations. Recent product launches and commercialization efforts have emphasized water‑based VpCI and eco‑oriented chemistries—moves that both reduce regulatory risk and address end‑user sustainability mandates.
-
Market structure: Concentration is moderate—our CR3 and CR5 assessments indicate that the three largest players account for just under one‑third of market sales, while the top five capture close to 40%—leaving significant white space for differentiated entrants and consolidation plays.
Competitive landscape: what the leading firms are doing
Established specialty chemical and lubricant companies are pursuing a two‑track approach: (a) defend incumbent industrial accounts through integrated fluids and coatings bundles, and (b) invest in next‑generation chemistries (water‑based, VpCI) and low‑VOC variants to capture specification upgrades. Key players profiled in the report include global majors and specialized independents, each with distinct go‑to‑market strengths:
-
BASF SE (Ludwigshafen, Germany) — broad corrosion‑inhibitor portfolio focused on industrial process protection and coatings additives.
-
Henkel AG & Co. KGaA (Düsseldorf, Germany) — strong manufacturing channel presence and recent trade‑show activity highlighting low‑VOC offerings.
-
Akzo Nobel N.V. (Amsterdam, Netherlands) — coatings and primer expertise applied to anti‑corrosive solutions for marine and industrial end‑markets.
-
The Lubrizol Corporation (Ohio, USA) — lubricant and additive‑centric strategies that embed rust inhibitors in metalworking fluids.
-
Clariant AG (Switzerland) — synthetic and oil‑based rust preventives geared to machining and storage applications.
-
Cortec Corporation (Minnesota, USA) — specialist in vapor‑phase corrosion inhibition (VpCI) with recent water‑based packaging innovations.
-
Quaker Houghton (Pennsylvania, USA) — integrated process fluid offerings and ongoing certification and compliance updates.
-
McGean, Daubert Chemical, Petrofer AG, Evonik and Lanxess — regional specialists and technology niche players with focused product lines and channel relationships that fill targeted application needs.
Recent market actions underscore these trends: Henkel showcased expanded low‑VOC Bonderite products at FABTECH 2024; Cortec introduced a water‑based VpCI solution targeting packaging applications; and several suppliers have updated certifications relevant to industrial customers. These moves typify the blend of formulation innovation and commercial positioning that will determine winners in 2026–2028.
Strategic playbook for 2026 (practical moves for leadership)
-
Prioritize reformulation and certification cadence: Accelerate low‑VOC and PFAS‑free variants of core SKUs, and align test planning with anticipated regulatory milestones. Shorten validation cycles by investing in shared laboratory partnerships or co‑funded pilot trials with key OEM customers.
-
Hedge feedstock exposure and broaden sourcing: Deploy supply‑chain stress tests against scenarios that include crude price spikes and TEA price shocks. Negotiate multi‑year supply agreements with flexible volume bands and consider secondary sourcing geographies to avoid tariff friction.
-
Pursue focused M&A and JV activity: Given moderate concentration, acquisitive consolidation of regional specialists and VpCI innovators can rapidly expand capability sets and fill portfolio gaps. Target companies with proven end‑market traction and clear path to integration.
-
Commercialize system‑level solutions: Move from single‑product selling to system offers (e.g., rust prevention + lubricant + service) that increase customer switching costs and command higher margin capture.
-
Invest in regulatory and market intelligence: Build a rapid response cell to monitor chemical regulation, trade policy, and emerging end‑user standards. Early intelligence reduces rework and positions the company as a trusted partner to OEMs facing regulatory scrutiny.
-
Differentiate through sustainability metrics: Quantify carbon, VOC, and chemical hazard improvements on a per‑use basis and incorporate those metrics into sales collateral and distributor incentives.
Risks and leading indicators to watch in 2026
-
Regulatory escalation (REACH amendments, expanded PFAS regulation) that could require abrupt reformulation.
-
Raw material shock: energy price volatility or sudden TEA supply constraints that compress margins.
-
Trade policy shifts that create asymmetric cost bases between supplying regions.
-
Technological substitution: faster adoption of alternative corrosion‑management approaches (coatings, cathodic protection, smart inhibitors) that alter long‑run demand mixes.
Next steps: how to use the report for 2026 planning
For executive teams, this report serves as a strategic compass and an operational toolkit. Use the headline market sizing and CAGR to calibrate top‑line targets; deploy the supply‑chain cost models to set acceptable procurement KPIs; and apply the competitive scorecards to prioritize partnerships or M&A workstreams. The report is intentionally structured as a “trailer”—it demonstrates the rigor of our analysis and delivers immediate, actionable recommendations while reserving the full segmented datasets, scenario models, and supplier‑level financials for readers who access the full study.
To obtain the complete dataset—regional and application‑level forecasts, detailed segmentation tables, modelled scenario outputs, and the full set of supplier profiles—please visit our report page listed in the official release. PW Consulting is prepared to run custom workshops to translate the findings into a 90‑day action plan tailored to your organization’s risk appetite and growth ambitions.
For detailed analysis of this topic, please visit the official page: Antirusting Anti Rust Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


