



Category: market research
PW Consulting: Solar Mobile Light Tower Market to Rise from USD 315.5 Million in 2025 to USD 558.5 Million by 2032 on an 8.5% CAGR
By PW Consulting, 2026-07-01
Solar Mobile Light Tower Market: Strategic Preview for 2026 Decisions
As organizations recalibrate capital plans, supplier relationships, and sustainability roadmaps for 2026, the solar mobile light tower sector is poised to transition from niche adoption to mainstream infrastructure. PW Consulting’s latest market research—anchored on a 2025 base year and a 2026–2032 forecast horizon—quantifies that transition and translates it into action‑ready intelligence. This release offers a high‑level preview of the report’s strategic value while withholding the detailed segment tables and proprietary financial models to encourage stakeholders to consult the full study for implementation-grade data.
Solar Mobile Light Tower Market
Market Trajectory at a Glance
The solar mobile light tower market has expanded consistently through the 2020–2025 historical window and enters the forecast period with robust momentum. Our analysis identifies a compound annual growth rate (CAGR) of approximately 8.5% across the 2026–2032 forecast. The market value at the 2025 base year and the modeled path to 2032 reflect a durable structural shift driven by regulatory pressure, cost declines in core components, and changing on‑site operational requirements.
Solar Mobile Light Tower Market
For executives, the practical implication is clear: the market is large enough to justify strategic investment but remains sufficiently fragmented to reward decisive moves—whether through differentiated product offerings, optimized service models, or M&A to accelerate scale and technical capability.
Solar Mobile Light Tower Market
Why This Matters for 2026 Decision Cycles
-
Capital allocation and procurement: Procurement teams should revisit fleet replacement timelines and total cost of ownership (TCO) models in 2026. Increasing system autonomy, lower lifecycle fuel and maintenance costs, and improving battery chemistries mean that previously marginal paybacks can become attractive within typical replacement windows.
-
Product development and differentiation: Advances in photovoltaic efficiency, LiFePO4 battery systems, and high‑lumen LED optics enable OEMs to compete on autonomy, reliability, and lifecycle emissions. Prioritizing modularity—swappable batteries, plug‑and‑play telematics, and hybrid energy inputs—will unlock addressable segments that value uptime and low operational disruption.
-
Service models and circularity: After‑sales services (remote diagnostics, battery lifecycle management, and refurbishment pathways) will be decisive differentiators. Organizations that integrate predictive maintenance and circular‑economy practices into their go‑to‑market strategy can materially improve margin profiles and sustainability reporting outcomes.
-
Regulation and reputation risk: Tightening noise and emissions standards in construction, mining, and event permitting increase the non‑price value of silent, zero‑emission lighting. Firms that proactively transition can convert compliance obligations into competitive advantage.
Report Contents: Practical, Actionable, and Forward‑Looking
The full PW Consulting report is designed as a decision support tool for strategy, purchasing, and product teams. Key actionable deliverables include:
-
Market sizing and forecast model: A transparent financial model (base year 2025; forecast 2026–2032) that powers scenario analysis and sensitivity testing for price, battery cost decline, and component supply risk.
-
Commercial segmentation framework: Granular segmentation across product type, application, and region to identify high‑velocity growth pockets and underserved niches (note: detailed segmentation tables are reserved for the full report).
-
Unit economics and TCO templates: Practical worksheets to calculate fleet replacement economics under different duty cycles and regulatory regimes, including guidance on warranty structures and financing options.
-
Procurement and supplier playbook: Benchmarking of vendor capabilities, procurement levers, and recommended contract structures for fleet purchases, leases, and managed service agreements.
-
Scenario planning and risk register: Three near‑term scenarios (conservative/regulatory shock/accelerated adoption) with associated KPIs and contingency playbooks for supply chain interruptions, battery raw material volatility, and rapid policy shifts.
-
Commercial roadmaps: Go‑to‑market tactics for OEMs, rental companies, and end‑users to convert early interest into repeatable revenue, including bundling of telematics, energy storage services, and on‑site lighting design.
Competitive Landscape: Established OEMs and Emerging Specialists
The industry exhibits a mixture of multinational OEMs evolving product portfolios and regional players pushing cost‑competitiveness in high‑volume markets. Market concentration metrics indicate leading vendors capture meaningful—but not dominant—shares, leaving space for innovative entrants and consolidation plays.
-
Global incumbents: Long‑standing industrial equipment manufacturers have integrated solar and battery options into their mobile lighting portfolios to maintain relevance on large construction and mining contracts. These firms leverage brand trust, service networks, and financing capability to win enterprise deals.
-
Specialist providers: Companies focused exclusively on off‑grid solar lighting differentiate on product simplicity, ease of transport, and tighter price points. Their agility allows them to iterate rapidly on battery chemistries, mast designs, and user interfaces.
-
Rental and service operators: Rental fleets are a critical channel for adoption. Operators that integrate telematics and battery lifecycle services can extract higher utilization and customer stickiness, creating a durable demand pipeline for OEMs that supply to rental networks.
Representative manufacturers profiled in the full study include established multinationals and focused specialists. Each company profile evaluates product attributes (runtime, mast height, LED efficacy), go‑to‑market approach, service footprint, and recent product developments—enabling buyers to align procurement decisions to operational requirements rather than marketing claims.
Recent Market Signals and Technology Drivers
-
Product upgrades and new introductions: Leading vendors have announced product enhancements that extend runtime and expand hybrid capability—trends that reduce operational constraints in disaster response and extended remote deployments.
-
Regulatory tailwinds: Government and sectoral initiatives accelerating solar deployment underpin demand for solar‑based equipment. Public data shows rapid growth in solar installations over the past decade, creating favorable policy and procurement environments for zero‑emission alternatives.
-
Component innovations: Integration of higher‑efficiency photovoltaic modules, LiFePO4 (and advanced gel options where appropriate), and high‑lumen, energy‑efficient LEDs have collectively improved autonomy while lowering lifecycle costs.
Strategic Playbook for 2026
PW Consulting recommends a prioritized set of actions for industry participants preparing for 2026 decision cycles:
-
For OEMs: Invest in modular platform architectures that support hybridization and rapid component upgrades. Build longer warranty and battery‑replacement programs to address end‑user concerns over lifecycle costs.
-
For rental operators: Pilot managed‑service bundles that include remote monitoring, fast swap battery logistics, and refurbishment pathways. Use telemetry to move from time‑based to utilization‑based pricing.
-
For construction and mining buyers: Reassess fleet standards to include acoustic and emissions criteria. Initiate procurement trials that quantify on‑site productivity impacts of moving from diesel to solar mobile lighting.
-
For investors and acquirers: Target assets that combine product IP with service capability. The midmarket holds consolidation potential where scale and distribution can meaningfully compress unit economics.
Risks, Mitigations, and Monitoring Signals
Key risks that could influence 2026 outcomes include raw material and battery supply volatility, abrupt policy reversals in key markets, and slower than anticipated customer behavior change. The report contains a monitoring dashboard with leading indicators—such as battery price indices, permitting trend lines, and rental utilization rates—that corporate teams should track quarterly.
Conclusion and Next Steps
In 2026, decisions about fleet composition, contract structures, and product roadmaps will determine which companies capture the expansion of the solar mobile light tower market. PW Consulting’s full report provides the proprietary segmentation, competitive scorecards, financial models, and implementation checklists needed to convert strategic intent into measurable outcomes. This press release is a strategic preview intended to surface the report’s actionable themes while preserving confidentiality of the granular datasets and model outputs that power procurement and M&A decisions.
To access the complete dataset, vendor benchmark tables, and the downloadable TCO and scenario tools, please consult the full Solar Mobile Light Tower Market report available on our website.
For detailed analysis of this topic, please visit the official page: Solar Mobile Light Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digestive Enzyme Complex Market Poised for Breakout Growth — 7.21% CAGR Forecast Through 2032
By PW Consulting, 2026-07-01
Digestive Enzyme Complex Market: A 2026 Strategic Preview — Why This Report Will Shape Boardroom Decisions
As global demand for digestive enzyme complexes accelerates, commercial and clinical stakeholders face a near-term inflection point. PW Consulting’s new market study synthesizes historical performance (2020–2025), robust forecasting (2026–2032), and actionable strategy to help executives navigate supply, regulation, and product innovation. The core finding is straightforward: the market is expanding steadily — from roughly USD 775 million in 2020 to USD 1,096.9 million in 2025 — and is projected to grow at a compound annual growth rate (CAGR) of 7.21% through the 2026–2032 forecast window, reaching an estimated USD 1,785.7 million by 2032. This release serves as a concise strategic primer; the full report contains the granular inputs and scenario matrices required for near-term investment and operational decisions.
Digestive Enzyme Complex Market
Why 2026 Is a Pivotal Year for Digestive Enzyme Strategies
-
Market momentum and maturity: The market’s mid-single-digit-to-high-single-digit growth trajectory is driven by heightened consumer interest in gut health, expanding clinical usage of pancreatic enzyme replacement therapies (PERT), and ingredient innovation (plant and microbial enzymes). For 2026 planning cycles, companies must reconcile growth ambitions with supply-side realities and regulatory expectations.
Digestive Enzyme Complex Market -
Regulatory scrutiny and labeling: Prescription PERT products remain tightly regulated; oversight extends to enzyme characterization, source documentation, and manufacturing controls. These requirements will materially affect time-to-market and commercialization costs for new clinical and non-prescription formulations.
Digestive Enzyme Complex Market -
Supply chain fragility: A substantial portion of enzymatic starting material has historically relied on animal-sourced supply chains, which are exposed to geopolitical, animal-health, and traceability risks. Strategic procurement and vertical integration are rapidly moving from “nice-to-have” to “must-have” in board-level discussions.
What PW Consulting’s Digestive Enzyme Complex Report Delivers (Practical, Operational, and Strategic)
-
Proprietary forecasting model: A bottom-up demand model calibrated against historical market activity (2020–2025) and validated by supplier interviews and public filings. Scenarios quantify upside/downside cases tied to raw material shocks, regulatory shifts, and accelerated clinical adoption.
-
Go-to-market playbooks: Detailed commercial strategies for prescription and OTC channels, segmented by customer archetype (clinicians, practitioners, e-tail/retail), pricing levers, and promotional ROI assumptions that help prioritize pilot investments in 2026.
-
Supply and manufacturing blueprint: Facility capacity maps, contract manufacturing capability assessments, and a risk heatmap for porcine-derived supply chains — plus alternative sourcing pathways via plant and microbial fermentation.
-
Regulatory & quality readiness checklist: Practical steps for compliance with current FDA guidance on enzyme preparations, expected dossier requirements for clinical claims, and management of biologic/food supplement transitions.
-
Product innovation radar: A curated pipeline review highlighting enzyme combinations, novel delivery formats, and co-formulations with probiotics that are most likely to convert into commercial success in the 2026–2028 window.
-
M&A and partnership playbook: Target criteria for bolt-on acquisitions (ingredient IP, fermentation capacity, clinical evidence), plus opportunistic partnership frameworks for faster market entry.
Competitive Landscape — Who Matters and What Their Moves Mean
The industry exhibits a mix of specialist enzyme manufacturers, ingredient conglomerates, clinical product holders, and consumer brands. Market leadership is dispersed: a handful of legacy players hold meaningful scale, but the market remains sufficiently fragmented to allow nimble entrants to capture niche value.
-
Large pharmaceutical / clinical incumbents: Companies offering prescription PERT — exemplified by long-standing branded therapies — retain pricing power in clinical segments, but their growth hinges on ensuring API and finished-dose availability and on meeting tight regulatory standards for biologic-derived products. Supply announcements and capacity investments by major PERT suppliers materially influence market stability.
-
Ingredient and enzyme specialists: Firms focusing on lactase, protease, lipase and other core activities (including advanced fermentation providers) are positioned to convert R&D into scalable, higher-margin ingredient streams. Their ability to certify sources and deliver consistent activity units will determine commercial partnerships with consumer brands and nutraceutical formulators.
-
Contract manufacturers and B2B formulators: True manufacturers that can supply finished blends and custom formulas provide a strategic shortcut to market for brands without in-house capabilities. GMP-certified producers that offer co-development and regulatory support are increasingly attractive.
-
Consumer-focused brands: Established supplement players leverage brand trust and distribution for mid-market, plant-based, and value segments. Their success will depend on differentiated claims, clinical substantiation, and transparent sourcing.
Collectively, the competitive map shows opportunity for scale and specialization: incumbents can defend clinical channels through regulatory and supply advantages, while challengers can win consumer trust with ingredient transparency and targeted clinical evidence.
Recent Industry Developments and Strategic Implications (2024–2025 Signals)
-
Product innovation and channel expansion: New practitioner-grade enzyme-probiotic combinations have entered the market, reflecting a convergence between digestive enzymes and microbiome therapeutics. This trend signals a near-term premiumization opportunity for formulas that demonstrate measurable clinical outcomes.
-
Supply-side investments: Announcements by major suppliers to expand API or finished-dose capacity are early indicators of anticipated demand growth and of attempts to mitigate episodic shortages. These investments will influence pricing dynamics and sourcing strategies through the end of the decade.
-
Public procurement actions: Governmental steps to secure supply of clinically critical PERT products underscore the public health sensitivity of certain enzyme segments; companies active in these channels should plan for contract compliance, higher documentation burdens, and inventory commitments.
Regulatory and Raw-Material Realities — Constraints That Shape Strategy
-
Characterization and contamination controls: Regulators expect detailed source characterization and robust contaminant control regimes. These requirements increase the threshold to entry for novel enzyme sources and favor suppliers that can provide traceability and third-party certification.
-
Animal-sourced supply dependency: A significant fraction of established digestive enzymes are derived from animal tissues. This creates vulnerability to supply interruptions, ethical sourcing concerns, and potential market substitution toward plant and microbial alternatives — a dynamic that will influence both R&D prioritization and procurement strategies.
Actionable 2026 Playbook — What Boards and Growth Teams Should Do Next
-
Prioritize supply-security measures now: Lock in multi-sourced contracts, qualify alternative ingredient pathways, and evaluate strategic investments in fermentation or extraction capacity to reduce single-source dependency.
-
Invest in regulatory readiness: Fund targeted studies and build dossier templates aligned with FDA enzyme guidance and regional labeling expectations to shorten approval and launch timelines for new clinical and consumer products.
-
Differentiate via evidence: Accelerate clinical or real-world studies that demonstrate functional outcomes (e.g., symptom reduction, nutrient absorption) to justify premium pricing and placement in practitioner channels.
-
Pursue selective vertical integration: Consider bolt-on acquisitions that add fermentation capability, proprietary extraction technologies, or validated supply chains to capture margin and control quality.
-
Design modular product lines: Create platform formulations that can be localized by channel (prescription vs OTC vs direct-to-consumer) and compliant labeling while maintaining supply flexibility.
-
Prepare for M&A arbitrage: Monitor smaller specialists and niche brands with clinical assets or unique sourcing; acquisition multiples in the sector are likely to favor assets with verifiable traceability and documented activity profiles.
What This Preview Leaves Out (and Why You Should Read the Full Report)
In this strategic preview we deliberately maintain high-level visibility: we disclose the market’s historical scale and its forecast trajectory to 2032, and we identify the principal competitive and regulatory dynamics. What we do not publish here are the granular, proprietary segmentation matrices — including regional and application revenue breakdowns, fine-grain channel economics, and confidential supplier-level capacity schedules — that clients use to size investments, negotiate supply contracts, and model post-merger integration. Those elements live in the full PW Consulting report and in our interactive data tools, which power scenario simulations and board-ready decision packages.
How PW Consulting Can Help
-
Executive briefings and scenario workshops to translate the report’s insights into 90-day and 18-month action plans.
-
Custom due diligence support for M&A, joint ventures, and supplier qualification.
-
Supply-chain stress-testing and a tailored playbook for securing enzyme inputs and manufacturing continuity.
The digestive enzyme complex market presents a compelling growth arc through the decade, but 2026 will be the year that separates passive observers from decisive market-shapers. PW Consulting’s full Digestive Enzyme Complex Market report offers the quantified scenarios, supplier intelligence, and tactical playbooks that senior teams need to convert growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Digestive Enzyme Complex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pregnancy Tests Market Poised to Hit USD 2,716.46 Million by 2032, Expanding at a 4.85% CAGR
By PW Consulting, 2026-07-01
Pregnancy Tests Market — 2026 Strategic Outlook and Action Playbook
PW Consulting’s latest market intelligence on the global pregnancy tests market anchors 2025 as the base year and projects the industry through 2032. The market reached approximately USD 1,950 Million in 2025 and, under our central forecast (CAGR 4.85% for 2026–2032), is set to continue steady expansion. This release highlights the strategic implications of our findings for corporate decision-makers preparing budgets, R&D priorities, go-to-market plans, and M&A strategies for 2026 — without disclosing the granular segmentation that appears exclusively in the full report.
Pregnancy Tests Market
What the Report Provides — Practical, Transaction-Ready Intelligence
-
Actionable market sizing and a scenario-based forecast framework (base year 2025; forecast window 2026–2032) to stress-test investment cases against different macro trajectories.
Pregnancy Tests Market -
A regulatory roadmap that translates device-class rules (e.g., 510(k) pathways) into milestone schedules and resource requirements for product launches in regulated markets.
Pregnancy Tests Market -
Supplier and raw-material mapping: visibility into critical upstream inputs (notably monoclonal antibodies), their cost contribution to lateral-flow devices, and practical mitigation levers.
-
Channel playbooks and commercial pilots for retail, e-commerce, and professional channels — including diagnostic positioning, trade terms, listing timelines, and promotional models.
-
Competitive benchmarks and capability profiles for the market’s leading and challenger firms, together with an M&A heatmap and strategic partnership templates for scale and technology access.
-
Price and margin matrices, unit economics by generic product archetype, and a returns sensitivity model that supports go/no-go decisions for new SKUs and production investments.
-
Operational checklists for quality, regulatory compliance, and post-market surveillance to reduce time-to-market risk and minimize recall exposure.
Why This Intelligence Matters for 2026 Decisions
-
Timing: The market trajectory supports steady growth but is not immune to policy or supply shocks. 2026 is a pivotal year for embedding cost and regulatory resilience into product roadmaps.
-
Product strategy: Innovation is concentrated in higher-sensitivity and digital-readout formats. Firms that align R&D and commercialization calendars to the 510(k) lifecycle will accelerate first-mover advantages in sensitivity and user-experience upgrades.
-
Channel shift: E-commerce continues to change purchase behavior and inventory strategies. Brand owners and private-label manufacturers must adopt hybrid channel models that preserve margin while securing shelf and search visibility.
-
Supplier risk: Monoclonal antibodies used in hCG detection account for a material share of production cost in lateral-flow devices; securing diversified supply, long-term contracts, or vertical integration options is a near-term priority.
-
Regulatory and reimbursement realities: Home pregnancy tests are regulated devices in many jurisdictions and professional testing carries modest reimbursements — these constraints should inform price and channel choices rather than be treated as afterthoughts.
-
Demographics and demand: Macro fertility trends are reshaping geographic demand patterns and adoption rates of at-home testing, favoring convenience and early-detection messaging in developed markets while creating volume opportunities elsewhere.
Competitive Landscape: Leaders, Challengers, and Strategic Moves
The market exhibits moderate concentration at the top: the three largest competitors account for a substantial but not dominant portion of total revenue, and the top five capture just over half of industry sales. That structure creates room for specialist challengers and private-label scale players to win share through cost leadership, channel focus, or technical differentiation.
-
Procter & Gamble (Cincinnati, OH, USA) — P&G continues to invest in sensitivity and user experience enhancements; its recent launch of improved ultra-early products underscores a strategy of premiumization and channel breadth.
-
Swiss Precision Diagnostics (Geneva, Switzerland) — As a producer of advanced digital readout tests, the firm remains a standard-bearer for weeks-estimator functionality and tech-enabled UX. Licensing/contract manufacturing dynamics in this segment are highly strategic.
-
Abbott Laboratories / Alere (Chicago / Waltham, USA) — A combined capability set offering both professional and OTC product lines; Abbott’s reach into clinical workflows provides a complementary route-to-market to consumer channels.
-
Prestige Consumer Healthcare (Tarrytown, NY, USA) — Focused on high-sensitivity early-result positioning; brand strength in retail supports premium pricing in selected markets.
-
QuidelOrtho and OraSure — Firms focused on point-of-care and private-label solutions; their trade-show visibility and manufacturing breadth make them attractive partners for channel extension.
-
Chinese OEM/Export Players (examples include Recare, Nantong Egens, Wondfo) — These manufacturers supply bulk strips and consumables globally; recent regulatory clearances and certification activity have increased their addressable opportunity and made them central to cost-optimization strategies.
Recent market events reinforce these dynamics: premium product launches and packaging refreshes by market leaders, trade-show showcases of incremental product updates, and regulatory clearances for high-volume OEMs. Collectively, these moves raise the bar on both product performance and cost benchmarks.
2026 Strategic Playbook — Five Concrete Moves
-
Anchor R&D to regulated-schedule deliverables: Map your product pipeline to the 510(k) timeline and prioritize submissions that unlock clinical claims (earliest detection, digital readability). Late-stage pivots are costly.
-
Secure antibody supply and manufacturing agility: Negotiate multi-year supply agreements, qualify multiple antibody sources, and consider co-investment in reagent capacity to stabilize margins.
-
Channel-conditional commercialization: Differentiate product configurations by channel (e.g., premium digital units for pharmacies and simplified strips for private label/e-commerce), with clear PLAs and logistics playbooks for each.
-
Commercial partnerships and M&A: Given mid-tier concentration, inorganic moves (bolt-ons for capacity, technology, or distribution) can be accretive. Use our M&A heatmap to shortlist targets that fill capability gaps or price-cost weaknesses.
-
Operationalize quality and post-market surveillance: Invest in digital complaint systems and batch-traceability to reduce recall risk and accelerate regulatory reporting; these investments pay off by protecting brand equity and reimbursement streams.
Risk Matrix and Contingency Planning
-
Supply disruption: A concentrated antibody supply base or single-region manufacturing creates acute exposure; contingency plans should include safety stock policies and alternative sourcing triggers.
-
Regulatory tightening: Changes in device classification or additional clinical expectations can delay launches; scenario-planned capital and staffing buffers are essential.
-
Price compression: E-commerce commoditization and private-label competition will pressure ASPs; margin protection requires mix management and reduced variable costs.
-
Demographic shifts: Continued fertility declines in some regions will change unit growth profiles; diversify market exposure and tailor communications to preserve demand elasticity.
How to Use the Full Report in Your 2026 Planning Cycle
-
Board-ready slides: Use the enclosed investor-quality decks to justify capital allocation, with sensitivity analyses that mirror finance committee requirements.
-
Commercial playbooks: Deploy our channel-specific go-to-market templates to pilot new SKUs in a low-risk, measurable manner during the 2026 trade calendar.
-
M&A and sourcing diligence: Apply the supplier scorecards and M&A heatmap during target screening and vendor selection to reduce transaction risk.
-
Regulatory runbooks: Align product teams with milestone checklists and submission templates to prevent avoidable delays in regulated markets.
PW Consulting’s report is built to be operationally useful: it translates market projections into specific, budget-ready actions and an executable timetable for 2026. To preserve the value of the underlying market architecture and granular segmentation, we’ve intentionally limited disclosure in this release. The full report contains the detailed regional, product, and distribution splits, alongside unit economics and pricing matrices that are indispensable for transaction diligence and go-to-market execution.
Next Steps
-
For executive briefings, tailored scenario runs, or to license the full pregnancy tests market report (including the detailed segmentation tables and downloadable financial models), contact PW Consulting’s Industry Insights team. Our advisors will prioritize rapid, bespoke workstreams to inform your 2026 operating plan and investment decisions.
About PW Consulting: We specialize in translating complex healthcare markets into decision-ready strategies for corporate leadership, investors, and policy teams. Our market research blends primary fieldwork, regulator liaison, and financial modeling to produce prescriptive recommendations that accelerate value capture.
For detailed analysis of this topic, please visit the official page: Pregnancy Tests Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Cameras Market to Reach USD 455.0 Million by 2032, Growing at a 7.6% CAGR (Base Year 2025; 2026–2032 Forecast)
By PW Consulting, 2026-06-30
Industrial Cameras Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Intelligence
PW Consulting today publishes a forward-looking industry briefing that synthesizes our 2025 base-year market model and a robust forecast to 2032 for the global industrial cameras market. Built from a validated historical series (2020–2025) and scenario-tested assumptions for 2026–2032, the report equips executives with the commercial and operational levers they will need to act confidently in 2026. This release intentionally showcases the analytical depth of our work while withholding primary segment tables and granular regional shares to motivate direct engagement with the full report and underlying datasets.
Industrial Cameras Market
Market snapshot: scale, trajectory, and concentration
Using 2025 as the base year, our core forecast shows the market continuing to expand at a mid-single-digit compound annual growth rate (CAGR) of 7.6% through the 2026–2032 horizon. In absolute terms, the industry—measured in USD Million revenue—has moved from a clearly recoverable post‑pandemic baseline in the early 2020s to materially larger market sizes by the end of the forecast. The 2026 inflection reflects renewed capex cycles across factory automation, logistics automation, and data-capture applications; by 2032 the market is projected to be substantively larger than in 2025.
Industrial Cameras Market
Market concentration is notable: the top three suppliers account for a majority of sales, while the top five increase share materially, translating into a CR3 of 55.2% and CR5 of 67.8%. That structure creates both competitive pressures and strategic opportunities: incumbents gain margin and scale advantages, but focused challengers can win on specialization, software ecosystems, and channel strategies.
Industrial Cameras Market
What PW Consulting’s report delivers (practical, decision-ready resources)
- Closed-form market model (USD Million revenue, base year 2025) with high/central/low scenarios for 2026–2032—designed for board-level briefing decks and integration into financial planning systems.
- Actionable go-to-market playbooks for hardware OEMs, system integrators, and component suppliers that balance direct sales, distribution, and strategic partnerships.
- Technology roadmaps mapping sensor innovation (including low-light sCMOS and thermal modules), interface standards, and edge-compute integration—paired with R&D investment guidance tied to expected time-to-market shifts.
- Regulatory and supply-chain risk matrix covering export controls, critical minerals, and compliance pathways—complete with contingency triggers for sourcing and localization strategies.
- Competitive landscaping with vendor scorecards, capability matrices, and a curated list of potential M&A and JV targets ranked by fit and integration risk.
- Commercial diagnostics and pricing playbooks that translate market size and concentration dynamics into margin optimization tactics for 2026 procurement cycles.
Competitive landscape: what the established vendors are doing now
The market remains populated by a mix of global platform providers, specialist imaging companies, and systems vendors who embed cameras into larger automation stacks. Key incumbents continue to differentiate along three vectors: sensor & optics performance, platform software/integration, and global go-to-market reach.
- KEYENCE CORPORATION (Osaka, Japan) — continues to leverage tightly integrated hardware-software offerings and a direct-sales field force to command premium pricing in high-throughput semiconductor and electronics inspection. Their playbook favors system-level differentiation over component commoditization.
- Basler AG (Ahrensburg, Germany) — maintains a broad product portfolio across area and line-scan cameras and is investing in interface and ecosystem compatibility to protect industrial channel relationships in Europe and beyond.
- Teledyne Technologies (including FLIR IIS / Vision Solutions) — combines visible and thermal imaging capabilities, which creates unique solutions-selling options for robotics and quality assurance. Note: companies in this grouping are operating under heightened regulatory scrutiny in several jurisdictions, which is an active risk vector for buyers and partners.
- The Imaging Source (Bremen, Germany) — a high-volume, product-focused supplier emphasizing USB/GigE camera lines for repeatable production-line applications and rapid time-to-delivery advantages for OEMs.
- IDS Imaging Development Systems GmbH (Obersulm, Germany) — positions itself on developer friendliness and AI-enablement at the edge, offering modular camera systems with software toolkits that shorten integrator cycles for semiconductor and electronics inspection.
- TKH Group (TKH Vision, Eindhoven, Netherlands) — brings 2D/3D system integration experience and is a strong choice for customers seeking turnkey machine vision subsystems rather than component purchases.
- Cognex Corporation (Natick, Massachusetts, USA) — continues to integrate cameras tightly with its vision software stack, emphasizing application-specific performance and enterprise-grade support that appeals to high-reliability manufacturing.
For buyers, this means vendor selection is more than price competition: it is a holistic evaluation of support, software lifecycle, sensor roadmap, and supply-chain resilience. Our vendor scorecards quantify those trade-offs (available in the full report).
Dynamics & systemic risks shaping 2026 decisions
A confluence of regulatory and supply-chain events has reshaped the risk profile for the industry. Several developments warrant particular attention:
- Export-control dynamics and enforcement actions have increased commercial compliance costs and created near-term supplier uncertainty. Buyers and investors should assume higher due diligence requirements and potential re-routing costs in vendor contracts.
- Concentration risks in critical minerals and semiconductor inputs raise the probability of episodic supply shocks. Recent multilateral ministerial activity signals geopolitical will to rework these supply chains—but reconfiguration timelines extend beyond typical procurement cycles.
- Standards evolution is accelerating—example: the latest iteration of a leading high-speed machine-vision interface standard was released in mid-2026. Vendors that rapidly certify and integrate the new standard stand to lower integration friction with modern edge systems and robotics platforms.
- Product innovation continues apace: suppliers are commercializing ultra‑low-light sCMOS modules and hybrid visible/thermal sensors, providing new value in logistics and automated-inspection niches. Early movers gain both reference wins and IP advantages.
Strategic recommendations for 2026 corporate decision-makers
We designed the following recommendations to be executable within the 2026 planning cycle. Each recommendation aligns to the market model and risk scenarios contained in the full report.
- Re-balance supplier portfolios for resilience and optionality. Build layered sourcing strategies to mitigate critical input concentration. Prioritize dual-sourcing for high-risk components and negotiate cost pass-through clauses linked to geopolitical trigger events.
- Invest selectively in standards compliance and certification. Allocate budget to certify new interface standards and to validate interoperability with major robotics/PLC vendors—this reduces time-to-integration and is a high-return commercial investment.
- Prioritize product lineups by value elasticity, not volume alone. Use our market model to stress-test pricing strategies across component scarcity and demand shock scenarios; protect margins by differentiating through software, calibration services, and extended warranties.
- Stand up an M&A playbook focused on software and niche sensors. With market concentration favoring platform vendors, targeted acquisitions of AI-software players, edge-inference vendors, or specialized sensor makers can accelerate entry into adjacent automation segments with lower integration risk than greenfield builds.
- Embed compliance and localization into contract templates. Move from reactive to proactive compliance by elevating export-control checks into supplier scorecards and including localized supply commitments where strategic risk warrants.
- Monetize after-sales and data services. Create annuity streams via calibration-as-a-service, health monitoring, and model-updates for AI-based inspection. These services improve customer stickiness and smooth revenue cyclicality.
- Use scenario planning to inform capex and inventory strategy. Our three-tier scenarios highlight different inventory and production implications—use the central and downside scenarios to set conservative working capital limits while maintaining optionality for upside demand.
How to use this briefing—and where to find the full intelligence
This briefing is a directional summary intended for senior leadership and strategy teams preparing 2026 plans. The full PW Consulting Industrial Cameras Market Report contains the proprietary market model (USD Million unit), detailed vendor scorecards, product roadmaps, downloadable Excel models, and the full set of segment-level forecasts and regional allocations. To preserve the strategic value of those granular tables we have purposely omitted segment-level shares and dollar-by-dollar regional splits from this public summary.
If you are preparing sourcing contracts, technology roadmaps, investor materials, or an M&A screening shortlist for 2026 decisions, the full report provides the evidence base and ready-to-use tools that reduce execution risk and shorten decision cycles. Contact PW Consulting to request the comprehensive dataset, scenario workshop, and tailored advisory support.
For detailed analysis of this topic, please visit the official page: Industrial Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Functional Chewing Gum Market Poised to Grow at a 5.7% CAGR, New Insights Predict
By PW Consulting, 2026-06-30
Functional Chewing Gum Market 2026: Strategic Signal — PW Consulting Executive Brief
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present the executive brief accompanying our new Functional Chewing Gum Market report (base year: 2025; historical window: 2020–2025; forecast horizon: 2026–2032). This is a strategic preview intended to orient senior decision-makers on why 2026 demands sharper, more integrated choices across innovation, channel strategy, regulatory preparedness, and supply-chain design. The full report contains the proprietary, transaction-grade data and model outputs that underpin the conclusions summarized below.
Functional Chewing Gum Market
Market trajectory at a glance
-
The functional chewing gum market has moved from a niche wellness adjunct into a resilient mid-sized category. From our 2020 starting point through the 2025 base year the market expanded steadily; the 2025 market size—our base year—shows the category’s maturation as mainstream players scale their functional propositions.
Functional Chewing Gum Market -
Looking ahead, our forecast projects compound annual growth of 5.7% across 2026–2032 under the base-case scenario, with the market approaching a materially larger scale by the end of the forecast window. This trajectory is driven by recurring purchase behavior, new delivery formats, and broader acceptance of ingestible convenience formats as carriers for vitamins, stimulants, and oral-care actives.
Functional Chewing Gum Market -
Concentration dynamics matter: the category exhibits meaningful market share aggregation among a few global incumbents, reflecting high brand equity and route-to-retailer advantages. This concentration influences partner selection, pricing dynamics, and private-label opportunity sets for new entrants.
Why 2026 is a strategic inflection point
-
Macro momentum and commercial readiness: With steady growth in 2020–2025 and a clear, positive compound growth outlook, organizations face a trade-off in 2026: accelerate investment to capture scale-sensitive returns now, or adopt a wait-and-see posture that raises barriers to future entry.
-
Productization and delivery advances: Compressed-tablet gum, liquid-core formats, and encapsulation-enabled actives have moved from R&D pilots into scaled launches. These technologies materially affect bioavailability, flavor stability, and manufacturing economics — and therefore pricing and margin profiles.
-
Channel and consumer behavior shifts: On-the-go consumption and DTC/online channel growth are rewriting go-to-market playbooks. Retail buyers increasingly segment display and merchandising by benefit claim (e.g., energy, oral care, smoking cessation), altering shelf strategies.
-
Regulatory and ingredient pressure points: Nicotine or pharmaceutical claims are tightly regulated in key markets. Ingredient sourcing (e.g., xylitol, encapsulated probiotics, vitamins) and export controls create differentiated risk across supply chains and regions.
Competitive landscape — what leading players are doing
-
Global confectionery incumbents have transitioned from product extension toward platform strategies. Household-name manufacturers leverage existing global distribution to launch functional SKUs while protecting legacy margins through portfolio segmentation and co-branding arrangements.
-
Specialist and contract-development players are capitalizing on technology-led differentiation: firms offering compressed gum manufacturing, liquid-core delivery, and private-label capabilities are becoming strategic partners for brands seeking rapid scale without heavy capital investment.
-
Start-ups and naturals brands are carving premium niches, emphasizing clean-label ingredients, sustainability, and differentiated ingredient stories (e.g., tree-sap bases, pure xylitol formulations). Their agility pressures incumbents on NPD speed and narrative authenticity.
-
Recent commercial moves underscore the market’s maturation: strategic partnerships between established confectioners and herbal or nutraceutical specialists, in-flight and travel retail contracts that provide high-frequency sampling environments, and targeted product launches for caffeinated or performance-oriented formats.
Key market dynamics to model in 2026 planning
-
Ingredient economics: Some high-value actives require encapsulation or specialized processing, which increases COGS and affects price elasticity. Decision-makers should stress-test margin scenarios against volatile inputs and packaging costs.
-
Regulatory uncertainty: Products that cross the food–drug threshold (nicotine, certain vitamins at therapeutic levels) face divergent regulatory regimes. Regulatory pathway mapping must be integrated into product timelines and launch budgets early in 2026 planning.
-
Channel fragmentation: Traditional brick-and-mortar retailers remain important for reach, but online and travel retail deliver higher growth rates for certain performance formats. Channel-specific SKU strategies, pricing, and promotional mechanics are table stakes.
-
Supply-chain resilience and trade policy: Export controls and tariff regimes affect ingredient sourcing, particularly for specialized actives from Asia-Pacific suppliers. Diverse sourcing and nearshoring options should be part of scenario planning.
-
Consumer retention mechanics: Functional gum benefits create habitual purchase patterns. Brands that invest in refillable, subscription, or on-demand packaging capture higher lifetime value — but execution requires integrated fulfillment capabilities.
Strategic imperatives for 2026 corporate decision-making
-
Prioritize platform technologies that align with your margin target. Evaluate compressed gum and liquid-core approaches not only for consumer differentiation but for implications on manufacturing capex, COGS, and regulatory classification.
-
Build regulatory playbooks early. For any product with pharmacological claims or borderline actives, establish cross-functional regulatory, legal, and clinical pathways before committing to mass production.
-
Design channel-led product portfolios. Allocate SKUs by channel archetype (mass retail, travel, online/subscription) and test elasticities in controlled pilots rather than national rollouts.
-
Secure strategic supply partnerships. Locking in key inputs with tiered pricing or capacity agreements reduces volatility and accelerates time-to-market for seasonal launches.
-
Consider M&A and contract manufacturing strategically. If speed to shelf is essential, partnering with or acquiring CDMOs that specialize in functional gum formats often outperforms greenfield launches.
Operational playbook — three horizons
-
90-day actions: Complete a supply-chain heat map for critical actives; run a small-scale shelf test for one channel (e.g., travel retail or e-commerce) to validate merchandising and repeat purchase; initiate regulatory scoping for any new actives.
-
6–12 month actions: Execute one platform technology pilot (compressed or liquid-core), formalize at least one strategic supplier contract, and finalize a channel-segmented SKU architecture with pricing tests and promotional thresholds.
-
18–36 month actions: Scale successful pilots into prioritized markets, consider bolt-on acquisitions of CDMOs or niche brands to accelerate capability, and invest in subscription/fulfillment tech if the customer retention economics are validated.
What PW Consulting’s Functional Chewing Gum Market report delivers
-
Proprietary demand model calibrated to 2020–2025 historicals and forward-cast to 2032 with scenario variants around ingredient cost, regulation, and channel shifts (base-case CAGR: 5.7%).
-
Competitive matrix with capability maps for leading incumbents, specialist CDMOs, and challenger brands — including go-to-market footprints, R&D capabilities, and partnership archetypes.
-
Actionable commercial playbooks: SKU architecture templates, launch checklist, pricing sensitivity matrices, and retailer negotiation levers tailored to mass, travel, and digital channels.
-
Regulatory and ingredient risk dashboard, including export-control implications and classification guidance for borderline active claims in key jurisdictions.
-
Transaction support assets: diligence data rooms, target screens for M&A, and an LBO-style valuation stub for CDMOs and specialist IP owners.
Implications for buyers, manufacturers, and investors
-
Buyers/retailers: Expect SKU rationalization and greater price differentiation by benefit claim. Retailers that proactively curate functional assortments with clear benefit navigation will convert higher basket values.
-
Manufacturers: Invest in platform technologies that reduce unit costs over time and enable rapid reformulation. Contract development partners with proven compression or liquid-core capabilities are strategic assets.
-
Investors: The category offers predictable, repeat-purchase revenue and brand defensibility where incumbents scale quickly. Focus diligence on supply-side differentiation, regulatory clearance timing, and distribution exclusivities.
Closing perspective and next steps
The functional chewing gum market presents a compelling growth corridor through 2032. With a clear base-case CAGR of 5.7% and continued product and channel innovation, 2026 is the year to move from exploratory pilots to resource commitments that capture scale economics and consumer habituation. That said, success hinges on marrying product-technology choices with regulatory foresight and channel-led commercialization.
PW Consulting’s full report supplies the detailed market sizing, confidential segment-by-segment breakouts, and the proprietary models you need to translate this strategic outlook into an executable plan. For companies contemplating launches, partnerships, or transactions in 2026, the report functions as both a roadmap and a negotiation toolkit.
Contact PW Consulting to access the complete findings, scenario models, and our bespoke advisory offering tailored to the functional chewing gum ecosystem. Our analysts are prepared to run a customized 90-day diagnostic to prioritize investments and finalize go-to-market sequencing for 2026.
For detailed analysis of this topic, please visit the official page: Functional Chewing Gum Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts IoT MCU Market to Grow at a Robust 12.52% CAGR During 2026–2032
By PW Consulting, 2026-06-30
IoT Microcontroller (MCU) Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
PW Consulting today releases its authoritative market briefing on the IoT Microcontroller (MCU) sector, providing senior executives and investment committees with the strategic context required to make decisive moves in 2026. Anchored on a 2025 base year and a seven-year forecast horizon (2026–2032), the analysis explains why MCUs are shifting from a cost component to a strategic differentiator across consumer, industrial and automotive ecosystems.
IoT Microcontroller (MCU) Market
Why this report matters for 2026 decision-makers
-
Macro momentum: The IoT MCU market that PW Consulting tracked from 2020 through 2025 has entered a rapid expansion phase. Our forecast shows sustained growth into the next decade, with a projected compound annual growth rate (CAGR) of 12.52% across the 2026–2032 window. This trajectory implies that leaders must treat MCU strategy as central to product roadmaps, sourcing plans and security investments, not as a peripheral procurement decision.
IoT Microcontroller (MCU) Market -
Concentration dynamics: Market concentration is moderate — the top three vendors account for a meaningful portion of revenue, and the top five remain collectively influential. That mix creates an environment where tier-1 suppliers can set technical roadmaps and scale economics, yet opportunities remain for focused challengers with differentiated propositions.
IoT Microcontroller (MCU) Market -
Timing is critical: Our base-year vantage (2025) shows the market positioned for accelerated adoption in 2026. Companies that align product feature-sets, compliance programs and supply strategies in the coming 12 months will capture disproportionately higher value over the forecast period.
What the report delivers — operational, actionable intelligence
-
Practical decision templates: executable procurement playbooks, supplier risk scorecards, and BOM-level cost-sensitivity tables calibrated to volatile materials and regional supplier dynamics.
-
Technology roadmaps: comparative analysis of MCU architectures (energy-optimized cores, real-time controllers, and crossover edge-AI platforms) mapped to specific use-case performance and development-effort trade-offs.
-
Security and compliance matrix: end-to-end mapping of certification requirements (including automotive and critical infrastructure standards), and prescriptive steps to achieve compliance without derailing time-to-market.
-
Go-to-market playbook: product segmentation approaches, reference-software stacks, and partner ecosystems that reduce integration risk for device OEMs.
-
Investment and M&A dashboards: scenario models that stress-test valuation assumptions under different consolidation and price-competition scenarios.
Industry dynamics that will shape 2026 strategies
-
Security regulations are accelerating adoption of certified MCUs. Recent rollouts of automotive and IoT security compliance frameworks are not benign policy changes — they reshape supplier selection, vendor certification timelines and total cost of ownership. Organizations integrating connected vehicle or safety-critical capabilities must now bake certification pathways into product development milestones.
-
Pricing pressure from lower-cost suppliers is material and persistent. Independent analyses point to sustained price differentials among supply sources, which has direct implications for margin dynamics and sourcing choices. Buyers need robust scenario planning to balance cost savings against long-term supply-chain and regulatory risk.
-
Materials and labor volatility increase the value of resilient regional supply. The MCU value chain depends on hundreds of specialty materials with concentrated sources; this translates into spot risk for key components and underlines the commercial premium for diversified sourcing and locally assured capabilities.
-
Wireless, security and edge AI are converging at the silicon level. The market is transitioning from single-function MCUs to multifunction SoCs and crossover parts that bundle wireless stacks, security engines and machine learning accelerators — enabling new product capabilities but raising integration complexity.
Competitive landscape — who to watch and why
Our vendor analysis profiles leading and high-impact players across capability bundles, channel coverage and strategic intent. The competitive map shows established incumbents extending into adjacent value pools, and disruptive vendors driving aggressive price-performance moves.
-
Infineon Technologies AG — Infineon’s recent product initiatives underscore a deliberate move to combine ultra-low-power connectivity with strong security credentials. Their new tri-radio Wi‑Fi 7 MCU family and certified automotive/IoT compliance efforts exemplify how a platform-plus-certification strategy can protect higher-margin use cases.
-
NXP Semiconductors — The MCX Arm Cortex-M lineup and crossover i.MX RT parts position NXP at the intersection of edge AI and secure connectivity, making them a natural partner for OEMs that need a rapid route to deployable intelligence at the node.
-
STMicroelectronics — ST’s emphasis on secure, high-performance and ultra-low-power Cortex-based offerings aligns with industrial and smart-node requirements. Their product stack is tailored to customers prioritizing security primitives such as TrustZone.
-
Texas Instruments — TI’s low-power and real-time MCUs, combined with an established RTOS and wide-channel distribution, remain attractive for industrial endpoints where deterministic behavior and ecosystem support matter.
-
Renesas — Renesas continues to focus on ultra-low-power designs with security hardening, targeting metering, home and industrial segments that require long service lifecycles and cloud connectivity.
-
Microchip Technology — Microchip’s broadened Cortex-M family and production-ready edge AI solutions reflect a playbook of modular hardware plus full-stack software — attractive for sensor-node OEMs seeking short integration cycles.
-
Silicon Labs — With wireless SoCs supporting Bluetooth, Zigbee and Matter, Silicon Labs emphasizes low-power wireless stacks and developer tooling, enabling rapid deployments in smart home and constrained industrial applications.
-
Espressif Systems — Espressif’s integrated Wi‑Fi/Bluetooth and RISC‑V efforts continue to pressure price-performance thresholds, particularly for AIoT and multi-protocol use cases where software flexibility is essential.
-
Holtek Semiconductor — Holtek targets cost-sensitive applications with ultra-low-power 8/32-bit devices and wireless-enabled lines that suit consumer and small smart-device markets.
Notable product and compliance milestones (select recent developments)
-
Tier‑1 vendors introduced multi-radio, Wi‑7-capable IoT MCUs and expanded edge‑AI stacks in early 2026 — signaling a next phase of silicon-enabled functionality for node-level intelligence.
-
Key automotive and IoT MCUs have moved through updated certification steps in early 2026, raising the bar on supplier qualification timelines and forcing OEMs to integrate compliance planning into product calendars.
-
Several vendors announced production-ready full-stack edge AI offerings, shortening the path from prototype to high-volume deployment for AI-enabled endpoints.
Strategic implications — five actions for 2026
-
Embed compliance early: Treat certification timelines as a critical path item. Build supplier selection criteria around proven certification programs and maintain certification milestones in product Gantt charts.
-
Adopt a dual-source procurement posture: Balance cost advantages from lower-priced suppliers against geopolitical and regulatory risks. Our procurement playbook lays out threshold tests for where single sourcing is acceptable and where diversification is mandatory.
-
Prioritize platform-based architectures: Choose MCUs that offer an upgrade path — flexible wireless stacks, security acceleration and ML inference capabilities — to protect future feature introductions without repeated hardware redesigns.
-
Hedge on integration services: Secure software and middleware partnerships early. The performance differential in time-to-market increasingly comes from available reference firmware, security libraries and validated dev-kits.
-
Monitor consolidation windows: With mid-level concentration and ongoing margin pressure, strategic buyers and PE sponsors should prepare playbooks for bolt-on acquisition opportunities that accelerate access to differentiated IP or regional capacity.
Risk matrix and scenario planning — what the report hides (and why)
In keeping with PW Consulting’s “trailer” approach to public briefings, this release demonstrates the analytical depth underlying our conclusions — but intentionally omits granular subsegment tables, exact regional shares and proprietary vendor scorecards. These discrete datasets drive the modeled scenarios and vendor-level recommendations in the full report. Organizations that need executable numbers to populate procurement contracts, capital allocation models or M&A valuation decks should consult the complete dataset and interactive models available from PW Consulting.
How executives should use this report
Senior leaders in product, supply chain and corporate development will find the briefing useful to set cadence for 2026 initiatives: align R&D budgets to platform migration timelines; reconcile procurement contracts with exposure to concentrated materials; and prioritize security certifications that unlock regulated market segments. The full report provides the granular inputs and dynamic scenario models required to convert these strategic priorities into measurable KPIs.
Next steps
PW Consulting’s IoT Microcontroller (MCU) Market report is published with interactive tools, vendor scorecards, procurement playbooks and scenario models. To access the full intelligence package, including the confidential segmented datasets and downloadable financial models that informed the strategic recommendations summarized here, please visit our official report page or contact your PW Consulting account representative.
For detailed analysis of this topic, please visit the official page: IoT Microcontroller (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precious Metal Recycling Market to Grow from USD 19.63 Million in 2025 to USD 27.7 Million by 2032 at a 5.1% CAGR — Electronics & E‑Waste and Asia Pacific Lead
By PW Consulting, 2026-06-30
Precious Metal Recycling Market 2026 Strategic Brief — PW Consulting Releases In-Depth Industry Report
PW Consulting today publishes its latest market research brief on Precious Metal Recycling, designed specifically to inform executive decision-making for the 2026 planning cycle. Built on a 2025 base year and a historical review covering 2020–2025, the study delivers forward-looking scenarios for 2026–2032. At a macro level the market shows resilient expansion — rising from approximately USD 15.2 Million in 2020 to USD 19.6 Million in 2025, and projected to grow at a compound annual growth rate (CAGR) of 5.1% through the forecast horizon, approaching an estimated USD 27.7 Million by 2032. The report combines quantitative modeling with operational playbooks, regulatory mapping, and competitive diagnostics to convert market dynamics into executable strategies.
Precious Metal Recycling Market
What the report contains — pragmatic intelligence for operators and investors
-
Market sizing and scenario models: a base-case and two stress scenarios (price-driven and regulatory-constrained) for 2026–2032, with sensitivities for key feedstock inflows and metal price shocks.
Precious Metal Recycling Market -
Supply‑chain flow maps: origin-to-refinery routing analysis, loss points, and logistics constraints that govern recoverable yields across feedstock types.
Precious Metal Recycling Market -
Regulatory and trade risk atlas: jurisdiction‑level compliance obligations, waste shipment rules, and tariff events that alter trade flows and refinery economics.
-
Competitive and capability matrix: validated profiles and capability assessments for the leading refiners and regional specialists, enabling benchmarking across processing technology, feedstock breadth, and commercial terms.
-
Operational toolkits: due‑diligence checklists, assay validation protocols, supplier contract templates, and CAPEX/OPEX benchmarking to accelerate implementation.
-
M&A and partnership playbook: valuation levers, integration risks, and a shortlist of acquisition targets and JV archetypes aligned to scale recovery capacity or secure feedstock.
-
Commercial models and pricing playbooks: end-to-end margin build-ups, working-capital optimization tactics, and hedging frameworks for volatile metal prices.
Key market takeaways and implications for 2026 strategy
-
Steady structural growth with episodic volatility. The sector’s mid-single-digit CAGR (5.1%) masks material short-term swings driven by commodity price cycles and policy shocks. Executives should plan for a steady organic expansion path while maintaining tactical flexibility for sharp price moves that can materially compress or expand margins.
-
Fragmented incumbent landscape presents opportunity. Market concentration remains moderate — the largest three players account for under one-third of the market while the top five capture roughly one-third — indicating scope for consolidation, bolt-on acquisitions, and commercial alliances that can unlock scale economics and feedstock security.
-
Regulatory dynamics are a near-term differentiator. Recent regulatory activity (including recycling-specific waste regulations and evolving tariff regimes) is already reshaping feedstock routing and compliance cost. Firms that embed regulatory scenario planning and cross-border compliance capabilities into commercial models will avoid value destruction in 2026.
-
Feedstock routing and tariffs matter as much as technology. Trade and tariff uncertainty has tangible effects on where scrap is processed; changes to tariff lines and waste shipment rules can divert flows between major refineries and create localized supply squeezes. Supply‑chain resilience — through diversified origination, contractual offtake, and selective in-region capacity — will be essential.
-
Price shocks amplify strategic value of processing flexibility. When underlying metals spike, firms with flexible processing portfolios and high recovery yields capture disproportionate economics. Conversely, low-price intervals favor operators with low fixed costs and efficient logistics.
Competitive landscape — who matters and why
The market is served by a mix of global refiners, regional specialists, and vertically integrated chemical and catalyst businesses. Key players profiled in the report include:
-
Heraeus Precious Metals (Hanau, Germany) — a specialist in processing multi-material streams with a broad global refining footprint and rapid recovery capability. Their integrated recycling sites offer scale and process flexibility ( https://www.heraeus-precious-metals.com).
-
Globe Metal Recycling (Sainte‑Catherine, Canada) — focused on buying and recycling diverse scrap categories worldwide, including spent catalysts and industrial wastes ( https://globemetal.com).
-
Umicore Precious Metals Refining (Hoboken, Belgium) — notable for recovering value from complex waste streams across electronics and catalysts using innovative and proprietary processing routes ( https://www.umicore.com).
-
BASF Environmental Catalyst and Metal Solutions (ECMS) (Iselin, USA) — a full recycling business for PGM-containing catalysts with commercial models oriented to supplying recycled PGM back into the supply chain ( https://basf-catalystsmetals.com).
-
Johnson Matthey (London, UK) — a leading secondary PGM refiner with broad geographic refinery coverage and deep technology expertise ( https://www.matthey.com).
-
Sibanye‑Stillwater Recycling — incorporating Metallix and Reldan — demonstrates capability expansion across precious metals with process technologies designed to increase recycling throughput for multiple metals ( https://www.sibanyestillwater.com).
-
Mid‑States Recycling & Refining, Hensel Recycling, Prince & Izant and other regional operators provide complementary capacity and faster local turnarounds; these players are common targets for supply partnerships or bolt-on consolidation.
Recent corporate activity underscores the strategic focus on regional capacity: for example, Hensel Recycling is expanding operations in Asia (new Singapore site operational in early 2026) and relocating UK capacity to support throughput and proximity to Southeast Asia and India. Such moves matter because they shift logistical economics and shorten feedstock-to-refinery lead times.
Operational playbook — nine actions to prioritize in 2026
-
Translate scenario outputs into an actionable supply strategy: build a three-tier supplier map (core, strategic, contingency) and secure contractual terms that include assay verification and competitive settlement mechanics.
-
Invest selectively in recovery flexibility: prioritize process investments that raise yield on high‑value metals and shorten cycle time between intake and settlement.
-
Embed regulatory surveillance into commercial workflows: establish a regulatory trigger matrix to quantify the impact of changes (e.g., waste rules, tariff amendments) on routing costs and contractual liabilities.
-
Operationalize traceability and trust: deploy digital assay records and chain-of-custody proofs to reduce buyer uncertainty and enable premium pricing in closed-loop supply agreements.
-
Hedge price exposure tactically: combine short-dated hedges with structured recycling contracts that link settlements to benchmark prices with banded adjustments.
-
Accelerate feedstock diversification: increase feedstock sources across electronics, catalysts, industrial sludges, and emerging battery streams to smooth seasonal volatility.
-
Pursue selective M&A to secure feedstock or add high‑yield processing technologies, using a valuation framework focused on feedstock synergies and recovery uplift rather than revenue multiple alone.
-
Benchmark and reduce working capital: implement turn-key assay-to-settlement SLAs and inventory reduction targets to free capital for strategic investment.
-
Frame sustainability as commercial advantage: certify recycling flows, quantify carbon avoided, and use these metrics to access green procurement budgets and premium customers.
Why senior leaders should act now
2026 is a pivotal year: macro growth remains supportive, but episodic regulatory changes and trade uncertainty can rapidly alter where value accrues. Firms that wait risk paying a higher price for capacity, losing feedstock to competitors better positioned regionally, or facing balance-sheet shocks from metal-price swings. The PW Consulting report converts market-level forecasts into a near-term action agenda — from operational fixes that improve yield to strategic moves that lock in feedstock and scale.
How to use this brief
-
Board and investor briefings: extract scenario outputs and sensitivity ranges to stress-test capex proposals and M&A case studies.
-
Commercial planning: use the supply-chain maps and assay protocols to rewrite supplier terms and reduce settlement risk.
-
Regulatory engagement: translate the regulatory atlas into position papers and advocacy priorities in key jurisdictions.
-
Integration planning: adopt the M&A playbook to accelerate post‑deal capture of synergies in processing and origination.
Note on content scope: this public brief is intentionally selective. To preserve the commercial integrity of the analysis and to guide readers to our full suite, we have provided high‑confidence macro outcomes and executable frameworks while withholding the detailed segment-level tables, regional splits, and granular pricing ladders. The comprehensive report contains the full dataset, downloadable financial models, supplier scorecards, and detailed regional and application breakdowns.
To obtain the complete Precious Metal Recycling Market report and the supporting Excel model for immediate use in 2026 planning, please visit PW Consulting’s report page. Our team is available for tailored briefings and custom scenario runs to align the findings with your corporate planning cycle and investment timetables.
For detailed analysis of this topic, please visit the official page: Precious Metal Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Monocyanamide Market to Grow at a 4.34% CAGR During 2026–2032, New Report Finds
By PW Consulting, 2026-06-30
Monocyanamide Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
Executive summary
PW Consulting’s new Monocyanamide Market report (base year 2025, forecast period 2026–2032) provides the decision-grade intelligence chemical, agricultural, and electronics sector leaders need to make high-stakes choices in 2026. The global monocyanamide market has expanded steadily from an estimated USD 224.9 Million in 2020 to approximately USD 278.1 Million in 2025 and is projected to reach roughly USD 374.3 Million by 2032, progressing at a compound annual growth rate (CAGR) of 4.34% over the forecast window. These headline dynamics mask important operational, regulatory and quality-driven inflection points that will determine winners and laggards through 2026 and beyond.
Monocyanamide Market
Why this matters for 2026 strategy
- Demand is resilient but selective. Modest but steady volume growth underpins broad industry interest; however, end-users are increasingly differentiating on product grade (standard vs. electronic/pharmaceutical) and on downstream integration into higher-value specialty molecules.
- Supply-side concentration shapes negotiation leverage. The market displays high concentration among a few large suppliers. This structural reality amplifies the commercial and operational consequences of single-facility outages, strategic capex decisions, or product-grade investments by leading producers.
- Raw-material exposure is material to margins. A dominant portion of operating cost in monocyanamide manufacture is driven by calcium cyanamide and related upstream inputs—an exposure that translates volatility in upstream markets directly into margin pressure for producers and price risk for buyers.
- Quality and regulatory alignment are emerging differentiators. Demand for high-purity grades in electronics and pharmaceuticals is accelerating, and regulatory moves in some markets are amplifying the value of certified, lower-impurity supply chains.
Key market dynamics to track in 2026
- Price and cost signals: Short-cycle price indicators from the first quarter of 2026 show material per-ton pricing that traders and procurement teams should use as inputs to scenario models and hedging strategies. Given the upstream cost composition, even moderate swings in cyanamide-related raw materials can have outsized effects on producer economics.
- Capex and capacity timing: Several strategic investments announced by major non-Chinese producers will change grade-availability dynamics for electronic- and pharmaceutical-grade monocyanamide beginning in the second half of 2026. Executives should map supplier capex calendars into their sourcing timelines to avoid procurement mismatches.
- Regulatory and ESG pressure: Environmental controls on ammonia-related and cyanamide feedstocks, as well as tighter scrutiny of supply chains for critical electronic inputs, are likely to drive higher compliance costs and create selective advantages for producers that have invested in cleaner upstream profiles or local production near high-regulation markets.
- Geopolitical and trade-side noise: While no monocyanamide-specific tariffs emerged in 2025, broader trade measures and export controls in adjacent chemical sectors can create indirect supply-chain ripple effects. Buyers should stress-test supply networks under modest trade disruption scenarios.
Competitive landscape — what the data implies
The market’s concentration metrics indicate that the top three players account for a dominant share of supply, with the top five capturing an even larger share. This has several pragmatic implications:
Monocyanamide Market
- Margin management and premium positioning: Large integrated producers—especially those that can source or vertically integrate upstream calcium-cyanamide feeds—enjoy structural cost advantages. At the same time, suppliers that invest in purification and quality-certification can command premiums for electronic- and pharmaceutical-grade product lines.
- Supplier risk and diversification: The concentration profile increases the strategic value of diversified supply contracts, dual-sourcing agreements, and regional inventory hubs for buyers seeking continuity of supply.
- M&A and partnership windows: High concentration lowers the number of strategically meaningful acquisition targets but increases the potential strategic impact of bolt-on acquisitions that add grade capabilities or complementary downstream products.
Profiles and recent moves — strategic takeaways
Our supplier analysis highlights a mix of long-established Western producers and a large cohort of Chinese manufacturers supplying global markets. Notable observations include:
Monocyanamide Market
- AlzChem Group AG (Trostberg, Germany): A unique non-Chinese large-scale producer with substantial capacity at its Trostberg site and a focus on high-purity, electronic and pharmaceutical grades. Recent announcements—expanded downstream capacity for nitroguanidine (new plant commissioning targeted in H2 2026) and a capital expenditure program announced in early 2026 to improve electronic-grade purification—signal a strategic push to capture higher-margin specialty demand in Europe. Buyers targeting European electronic manufacturers should prioritize engagement with suppliers making such investments.
- Nippon Carbide Industries Co., Ltd. (Tokyo, Japan): With production experience dating back to the 1930s and an established portfolio covering polymer additives, epoxy curing, and pharmaceutical applications, this supplier represents a profile of long-term reliability and technical know-how—attributes prized by customers in regulated sectors.
- Large China-based cohort: A set of major Chinese manufacturers continues to supply bulk volumes and serves as the backbone of global commodity supply. Their roles are central to feedstock flows and price formation; however, buyers seeking higher-purity grades or regulatory alignment for critical electronics supply chains may face a differentiation trade-off between cost and conformity.
What our report delivers — practical, transaction-ready outputs
PW Consulting’s report is built for immediate operational use by procurement directors, corporate strategists, and M&A teams. Core deliverables include:
- Market-sizing and high-resolution trend models (2020–2032) with scenario stress-tests for demand, price and capex timing.
- Supply-chain maps and supplier risk heatmaps that integrate plant-level announcements and likely outage/maintenance windows—presented in a format that supports contract negotiation or hedging decisions.
- Price modeling templates that use current FOB benchmarks and upstream cost drivers to forecast short- and medium-term price bands for negotiation and budgeting.
- Actionable playbooks for procurement (dual-sourcing templates, inventory thresholds tied to regional lead times, supplier certification checklists for electronic/pharma grades).
- Strategic investment cases and ROI calculators for capex or M&A activity, including sensitivity to raw-material cost changes and regulatory cost projections.
To preserve the commercial integrity of supplier-specific strategies and to guide users to the correct tactical next steps, the report deliberately consolidates but does not publish detailed split-level revenue or percentage shares across regions and applications in this press announcement. Those granular matrices are included in the full report and are essential for transaction execution.
Action roadmap for 2026 — prioritized steps
- Q1 2026 — Price & exposure triage: Run immediate sensitivity checks against the Q1 2026 FOB price signals and your organization’s raw-material exposure. If gross margin sensitivity exceeds internal thresholds, prepare contingency procurement actions.
- Q2 2026 — Supply and quality lock-in: Negotiate dual-sourced contracts with explicit grade and delivery SLAs; prioritize suppliers with announced capex that align with your quality requirements for H2 2026 onward.
- Mid-2026 — Capex & partnership decisions: If pursuing backward integration or JV with upstream calcium-cyanamide producers, target agreements that de-risk at least 60–70% of production OPEX exposure to feedstock cost volatility (our report quantifies typical upstream cost profiles).
- Ongoing — Regulatory & ESG monitoring: Implement a regulatory watch leveraging our compliance matrix to flag changes that would materially alter local sourcing economics or require process investments.
KPIs senior leaders should monitor
- Quarterly FOB benchmark vs. internal cost-of-goods delta
- Percentage of procurement under dual- or multi-sourcing contracts
- Lead-time variance from top three suppliers
- Share of purchases contracted for certified electronic/pharma grades
- Supplier capex announcements vs. anticipated grade-availability windows
Conclusion — the strategic edge for 2026
In a market that is growing steadily but is structurally concentrated and sensitive to upstream raw-material dynamics, 2026 will be the year that separates transactional buyers from strategic, margin-protecting players. Executives who integrate supplier capex calendars, upstream cost exposure, and grade-differentiated demand into procurement and investment decisions will preserve margin and secure continuity in high-value downstream chains. PW Consulting’s Monocyanamide Market report provides the models, supplier intelligence, and execution playbooks to make those decisions with confidence.
Next steps
For access to the full dataset, supplier-level matrices, and our transaction-ready tools, please download the complete report from the PW Consulting website or contact our industry team for a bespoke briefing. Our analysts are prepared to run tailored scenario analyses that align the report’s findings with your 2026 operating and investment calendar.
For detailed analysis of this topic, please visit the official page: Monocyanamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Aerogel Market Poised to Grow at a 13.8% CAGR During 2026–2032
By PW Consulting, 2026-06-30
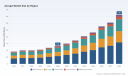
Aerogel Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive summary
PW Consulting’s latest Aerogel Market report (base year 2025; historical 2020–2025; forecast 2026–2032) maps a rapidly maturing sector that is transitioning from niche high‑tech use cases to broader industrial adoption. Our model indicates the global aerogel market will grow from an estimated USD 1.32 Billion in 2025 to roughly USD 3.62 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 13.8% across the forecast window. For executive teams planning capital allocation, product roadmaps, or M&A playbooks in 2026, this trajectory creates both time‑sensitive opportunities and strategic risks that require targeted, data‑driven responses.
Aerogel Market
Why 2026 is the inflection point
- Commercial scale-up is reaching a tipping point. Multiple producers have moved from pilot to full‑scale lines and blanket panel manufacture is beginning to reach the volumes required by energy, transportation and industrial insulation markets.
- Value migration beyond thermal insulation is accelerating. Aerogel formulations are being designed for EV battery safety, acoustic insulation, fire protection and lightweight structural uses, broadening total addressable markets for incumbent and new‑entrant manufacturers.
- Policy and procurement drivers are coalescing. Carbon accounting, stricter thermal performance regulations, and industrial decarbonisation targets are raising the procurement priority for high‑performance insulation, making 2026 a year of contract formation and supplier re‑ranking.
Data‑driven clarity — without giving away the farm
We present headline macro sizing and trajectory here to orient decision‑makers. The full report contains the granular segmentations, price decks, supplier scorecards and contract templates you need to execute. In this briefing we deliberately withhold discrete region‑ and application‑level percentage splits and individual product revenue lines to preserve the commercial value of the primary research; the detailed splits and downloadable financial models are available in the full PW Consulting report.
Aerogel Market
Key growth drivers and headwinds
- Demand pull from electrification: OEMs and tier‑ones seeking improved EV battery thermal management and fire prevention are committing to materials that balance thermal resistance with low mass and form factor flexibility.
- Industrial insulation replacement cycles: Asset owners in energy and process industries are pursuing retrofit programs where aerogel blankets and panels deliver lifecycle cost advantages despite higher upfront price points.
- Manufacturing scale and unit‑cost momentum: Recent capacity additions and continuous production innovations are compressing cost curves, improving availability, and enabling new configurations (monolithics, blankets, granules).
- Regulatory and trade complexity: Tariffs on silica precursors and specialized equipment, carbon border mechanisms, and rising scrutiny on embodied carbon are reshaping sourcing strategies and supplier risk profiles.
- Raw material and input volatility: While metallurgical silicon prices showed pockets of stability into late 2025, volatility remains — including measured upticks in silicone‑related indices in North America in 2026 — which can quickly affect margin for manufacturers with thin hedging strategies.
Competitive landscape — who matters and why
The aerogel industry today is a mixed structure of established specialty chemical and advanced materials firms plus agile pure‑play aerogel producers. Competitive advantage is being forged along three vectors: scale and cost of production, product form‑factor and performance, and go‑to‑market partnerships in adjacent value chains (e.g., EV battery systems, construction supply, energy OEMs).
Aerogel Market
- Aspen Aerogels, Inc. — A de facto commercial leader, Aspen has invested in flexible silica aerogel blankets and focused go‑to‑market channels in energy and EV battery applications. Their scale and field experience give them preferred supplier status in many industrial contracts.
- Cabot Corporation — Cabot’s continuous ambient‑condition particulate silica processes and experience in thermal management for batteries provide a differentiated materials approach suited for high‑volume, high‑consistency applications.
- Aerogel Technologies, LLC — With a portfolio spanning monolithics, panels and custom solutions, Aerogel Technologies competes on product breadth and engineered systems for scientific and industrial users.
- Armacell International — Armacell’s ArmaGel series targets industrial thermal and fire protection with global manufacturing footprints that accelerate project delivery for asset owners and EPCs.
- LG Chem Ltd. — Leveraging large‑scale plant operations, LG Chem targets the EV battery thermal barrier market with an emphasis on fire prevention and integration into battery module manufacturing.
- Alkegen — Alkegen’s recent commercialisation of its proprietary AlkeGel material and step‑ups in production capacity position it as an aggressive challenger in the EV safety segment.
- Svenska Aerogel, Green Earth Aerogel, Nano Technology Co., Active Aerogels, Resonac — These regional and technology‑specialist players are important for niche applications and local supply chains; their engineered formulations and partnerships can be decisive in specific tenders.
Recent market moves illustrate strategic posturing: Alkegen announced full‑scale commercial production for EV battery applications in mid‑2025; Armacell expanded manufacturing capacity in 2024 and launched a higher‑temperature product line in late 2024; partnerships such as the strategic distribution arrangement between Foli Aerogel and Aerogel Technologies in 2025 show the growing importance of channel plays. These events are not isolated — they are part of a pattern of capacity additions, product iterations, and route‑to‑market alignments that will define supplier hierarchies through 2026.
What PW Consulting’s report delivers — practical, executable content
Beyond headline sizing and forecasts, the full report is built as a toolkit for 2026 decision cycles. Highlights include:
- Decomposed market models (historical to 2025, base year 2025, detailed forecasts 2026–2032) with scenario variants and sensitivity to raw‑material, tariff and adoption‑speed assumptions.
- Supply‑side maps and a capacity tracker that connect production technology to unit costs, scale economics and likely commercialization timelines.
- Supplier due‑diligence templates, negotiation playbooks and RFP scorecards tailored for large procurement events (EPC, OEM, fleet electrification programs).
- Unit economics and component price decks (confidential appendices) for capex planning, break‑even analyses and contract pricing strategies.
- Regulatory impact matrices and embodied carbon scenario analyses, including potential consequences of carbon border adjustments and tightened European environmental standards.
- M&A and partnership heat maps identifying targets across technology, capacity and geography, plus near‑term integration risk checklists.
- Technology roadmaps that benchmark silica, polymer and carbon‑based aerogels against alternative thermal and fire safety solutions, with R&D priority recommendations.
- Interactive dashboards and downloadable financial models to stress‑test investment cases and prioritize use cases by ROI, time‑to‑market and strategic fit.
Strategic recommendations for 2026
- Prioritise supplier partnerships that combine scale with product validation in your end market. For OEMs and major energy companies, anchoring a preferred supplier relationship in 2026 will secure supply and price advantage as demand ramps.
- Adopt a dual track: secure short‑term off‑take and pilot projects while participating in equity or strategic investments to capture long‑term upside from capacity expansions. Where financial exposure is constrained, consider structured offtake with price collars.
- Factor regulatory and carbon considerations into sourcing decisions today. Hedging material and embodied‑carbon risk through diversified suppliers and pre‑qualified low‑carbon feedstock pathways will reduce procurement disruption risk from tariffs and CBAM‑style measures.
- Embed aerogel unit economics into product design early. For product teams (EV battery packs, industrial equipment, building components), small design shifts that reduce required material volume can materially alter total system cost and adoption probability.
- Use scenario and sensitivity analysis to plan capex: only greenlight large‑scale investments after stress‑testing against slower adoption and higher input‑cost outcomes; maintain agility with modular plant designs where possible.
Risks to monitor closely
- Input price volatility: short windows of silicone and silicon feedstock price movement can compress margins for vertically exposed suppliers without hedging strategies.
- Trade and regulatory shifts: tariff changes or stricter standards on embodied carbon could re‑order supply competitiveness and import flows.
- Concentration and customer power: growth will attract entrants, but procurement consolidation among large OEMs could concentrate negotiating power and pressure supplier pricing.
How to access the full intelligence
This release is intended as an executive‑level primer. The PW Consulting Aerogel Market report contains the confidential segment economics, supplier scorecards, downloadable models and tender templates necessary to operationalise a 2026 strategy. For access to the full dataset, primary interviews, and the interactive dashboards referenced above, visit PW Consulting’s Aerogel Market report page or contact our industry team for a briefing and tailored workshop.
In short, 2026 will be a defining year for organisations that wish to convert aerogel’s technical promise into commercial advantage. The choices made this year about partners, plant footprints, and product design will determine who captures the upside as the market scales toward our 2032 outlook.
For detailed analysis of this topic, please visit the official page: Aerogel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Clothing Market to Soar from USD 2.15 Billion in 2025 to USD 6.0 Billion by 2032, Backed by a 15.78% CAGR
By PW Consulting, 2026-06-30
PW Consulting: Strategic Brief — Smart Clothing Market Outlook and 2026 Playbook
The smart clothing market is entering a decisive phase. After a rapid five-year expansion (2020–2025), the industry reached approximately USD 2.15 Billion in 2025 and, under our central forecast, is projected to grow at a compounded annual growth rate (CAGR) of 15.78% through 2032 — reaching an estimated USD 6.0 Billion by the end of the forecast period. For executives planning budgets, partnerships, or M&A in 2026, these headline numbers are only the starting point: the competitive, regulatory, and cost dynamics that accompany this growth will determine winners and losers.
Smart Clothing Market
Why this PW Consulting report matters for 2026 decisions
-
Actionable risk reduction: The market is still structurally fragmented; leading firms do not command dominant shares, and regulatory clarity is a gating factor for medical and occupational use cases. Our report provides decision-ready risk matrices that translate regulatory and quality exposure into near-term capital and operating requirements.
Smart Clothing Market -
Investment sizing with return horizons: We translate high-level growth into scenario-based investment envelopes and payback timelines calibrated for realistic go-to-market ramps and pilot-to-scale conversion rates.
Smart Clothing Market -
Supplier and cost playbook: Given persistent production cost pressure, our report contains supplier maps, cost-build templates, and recommended sourcing strategies (including nearshoring, co-manufacturing, and platform partnerships) designed to compress time-to-profitability.
-
Commercial blueprints: For product, channel, and service design, the report includes modular GTM playbooks aligned with distinct buyer personas (enterprise occupational buyers, clinical trial purchasers, and consumer fitness adopters).
What the report contains — practical, field-tested deliverables
-
Raw and modeled datasets: Cleaned market time series (2020–2025) and scenario projections (2026–2032), plus proprietary adoption curves by use case and product archetype.
-
Financial models and investment checklists: CapEx/Opex templates, unit-economics worksheets, break-even and sensitivity models keyed to production cost drivers and service monetization paths.
-
Regulatory and compliance playbooks: Step-by-step guidance for navigation of medical device pathways (including U.S. FDA expectations where medical claims are intended), EU sustainability obligations, and recommended testing regimes aligned to industry standards.
-
Quality and test frameworks: Practical implementation guidance for IPC-8981-derived test methods, washability protocols, and connector reliability tests that reduce field-failure risk.
-
Supplier maps and manufacturing levers: A curated list of Tier-1 and Tier-2 e-textile suppliers, contract fabricators, and digital textile platforms, plus strategies for design-for-manufacture that materially reduce per-unit costs.
-
Go-to-market templates and pilot blueprints: Contract language, data governance models, and clinical trial design templates for buyer categories that require privacy-safe biometric data handling.
-
Competitive intelligence and M&A playbook: Target screening criteria, valuation heuristics, and integration checklists for acquiring capabilities (sensor IP, AI diagnostic stacks, manufacturing scale, or distribution).
Market dynamics that will shape 2026 outcomes
-
Regulatory bifurcation: Products that make medical claims face clear regulatory oversight; the U.S. FDA stance has already influenced product roadmaps and labeling strategies. Companies planning to sell into clinical or worker-safety contexts must budget for regulatory lifecycle costs and clinical validation.
-
Sustainability and end-of-life rules: New EU rules on unsold textiles and extended producer responsibility are coming into force — these materially affect inventory financing and returns policies for companies selling into European markets.
-
Quality and test standardization: The emergence of comprehensive e-textile test frameworks (e.g., IPC-8981) raises the bar for washability and connector reliability. Firms that internalize these standards in design-phase reduce warranty exposure and accelerate enterprise procurement approval.
-
Cost pressure and manufacturing economics: Historical production-cost benchmarks show unit-costs that constrain margin at low volumes. Achieving scale, adopting automated assembly, and rethinking electronics modularity are the primary levers to reach commercial viability.
-
Platformization of software and data: The competitive edge is increasingly about software ecosystems — AI diagnostic pipelines, digital biomarker libraries, and secure, multi-tenant device management. Hardware without a viable data strategy risks being relegated to low-margin component supplier status.
Competitive landscape — who to watch and why
The market hosts a mix of specialist hardware innovators, digital-platform players, and vertically integrated incumbents. Our competitive analysis focuses on capability vectors: regulatory clearance, manufacturing scale, platform strength, and domain specialization.
-
Hexoskin / Carre Technologies: With FDA 510(k) clearance for medical-grade ambulatory monitoring and a publicized move to commercialize AI diagnostic models, they represent a template for moving from sensor-product to regulated digital medical system. Their approach demonstrates how clinical validation and AI assets can unlock higher-value enterprise demand.
-
AiQ Smart Clothing Inc.: Known for conductive textile components and integrated apparel systems, their recent infrastructure consolidation and partnership access to a digital textile platform accelerate time-to-market and scalable manufacturing — a crucial combination for firms seeking faster iteration cycles.
-
Xenoma: Their work on durable, washable e-textile connectors and Printed Circuit Fabric reflects a pragmatic route to solve long-term reliability and assembly challenges. Validation of connector reliability reduces one of the most common failure modes in smart garments.
-
Sensoria: Focused on sports and gait analysis products, they exemplify a focused, vertical product strategy where sensor insights map directly to consumer performance outcomes — a lower-regulatory-risk pathway to monetization.
-
Wearable X and Myontec: These firms show differentiation via user experience (haptic guidance) and modality (EMG for muscle monitoring). They highlight how specialized sensing modalities can create defensible niche positions if paired with a strong software and content strategy.
Strategic plays we recommend for 2026
-
Regulatory-first product design: For any product that will assert health outcomes or safety benefits, plan for regulatory milestones from Day 1. Allocate budget to clinical validation and regulatory counsel; consider staged claims that start with wellness and progress to regulated claims.
-
Invest in quality and standards compliance early: Adopt IPC-8981 test methods during prototype cycles. Early alignment reduces rework costs and accelerates enterprise procurement approvals.
-
Build a software moat: Prioritize data-platform development, digital biomarkers, and analytics as core assets. Monetizable subscription services reduce dependence on hardware margin and improve customer lifetime value.
-
Optimize manufacturing path: Use our supplier maps to compare outcomes from co-manufacturing, licensing of textile electronics, or acquisition of a strategic fabric partner. Small productivity improvements and connector reliability gains have outsized effects on unit economics.
-
Partnership and ecosystem playbook: For faster scale, partner with digital textile platforms and established textile manufacturers. Platform deals can compress capex and shorten pilot cycles.
-
M&A as capability shortcut: Consider tuck-ins for sensor IP, validated clinical datasets, or manufacturing nodes to leapfrog multi-year organic scale efforts. Use our M&A checklist to stress-test post-acquisition integration risks.
Scenario planning — calibrating investment to growth prospects
At a 15.78% CAGR, the smart clothing market more than doubles from the 2025 base to our 2032 estimate. That pace creates sizable near-term opportunity, but it is not uniformly distributed across use cases or channels. Our report provides three investment scenarios (conservative, base, aggressive) that translate top-line growth into required R&D, pilot budgets, and commercialization spends for each risk profile. Each scenario is paired with expected payback horizons and break-even unit volumes so executives can tailor capital allocation to board risk tolerance.
What we recommend you do next (2026 checklist)
-
Complete a regulatory gap analysis for any product claims and budget for required clinical work.
-
Run a three-month supplier validation sprint focused on IPC-8981 test methods and connector reliability.
-
Pilot a service-led revenue model (SaaS + hardware) to measure incremental ARPU and stickiness.
-
Use our investment scenarios to set capital ask and milestones for the next 12–18 months.
PW Consulting’s Smart Clothing Market report is designed as a working tool for 2026 strategy cycles — not an academic exercise. It combines verified historical datasets, forward-looking financial models, and operational playbooks to reduce execution risk and accelerate commercial outcomes.
To access the full market breakdown (regional, product and application splits), detailed company profiles, our proprietary datasets, and the downloadable financial models referenced above, please visit the PW Consulting report landing page. The granular segment data and templates are intentionally reserved for the full report to preserve competitive value to clients and partners.
For detailed analysis of this topic, please visit the official page: Smart Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


