



Category: market research
PW Consulting: PVDF Market Hits $1.37B in 2025, Surging to $2.48B by 2032 on 8.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Polyvinylidene Difluoride Market 2026-2032
As global industries navigate a period of rapid technological transition, supply chain recalibration, and evolving regulatory landscapes, Polyvinylidene Difluoride (PVDF) has emerged as a critical enabler across energy storage, advanced chemical processing, and high-performance filtration. For executives, supply chain leaders, and R&D directors, understanding where this market is headed is no longer optional—it is foundational to capital allocation, capacity planning, and competitive positioning. Our latest comprehensive research delivers the strategic intelligence required to make informed decisions in 2026 and beyond.
Over the past half-decade, the PVDF sector has demonstrated remarkable momentum, driven by expanding demand from lithium-ion battery manufacturing, next-generation water treatment infrastructure, and specialized high-purity coatings. Historical trajectory data reveals a clear upward arc: the market generated approximately 800 million USD in 2020, gradually climbed past the 920 million USD threshold in 2022, crossed the 1,200 million USD milestone by 2024, and reached an estimated 1,372 million USD by 2025. This established baseline sets the stage for what analysts project will be a sustained growth phase. Looking ahead to the 2026-2032 forecast window, the market is expected to scale from roughly 1,497 million USD in 2026 toward nearly 2,479 million USD by the close of the decade. This trajectory translates to a compound annual growth rate of 8.8 percent, positioning PVDF as one of the most structurally resilient specialty polymer segments in the broader advanced materials landscape.
For enterprise leaders, these figures are more than retrospective benchmarks—they are strategic signals. An accelerating growth rate of this magnitude implies tightening supply-demand balances, heightened competition for qualified raw material streams, and an urgent need to secure reliable downstream partnerships before capacity constraints or pricing volatility erode margins. Companies that approach 2026 without a clear view of regional demand nodes, application-specific consumption patterns, and evolving cost structures risk reactive decision-making in a market that rewards foresight.
Decoding the Operating Environment: Dynamics Shaping 2026
No market strategy is complete without a granular understanding of the operational forces currently reshaping PVDF supply chains. Several intersecting dynamics are already influencing production economics and demand trajectories, and their cumulative impact will define competitive outcomes throughout the forecast period.
On the raw material front, the sector has faced notable supply pressure. A pronounced shortage of hydrogen fluoride during the second quarter of 2025 forced approximately ten percent production cuts across several Chinese PVDF plants, triggering a rapid elevation in global spot prices. Compounding this vulnerability is the broader chemical input environment: a twelve-fold surge in R-142B pricing between 2023 and 2024 pushed PVDF production costs upward by 18 to 25 percent, disproportionately squeezing smaller manufacturers with thinner balance sheets. Adding another layer of structural complexity, China currently controls over three-quarters of global VDF production capacity. Recent environmental clampdowns in Jiangsu and Shandong provinces have already driven 10 to 12 percent cost spikes on a quarter-on-quarter basis, underscoring how tightly coupled regional compliance enforcement is with global cost curves.
Simultaneously, regulatory evolution is introducing profound uncertainty and opportunity. Europe has moved closer to a potential blanket restriction on PVDF membranes following an updated dossier from the European Chemicals Agency (ECHA) that explores banning the manufacture of all per- and polyfluoroalkyl (PFAS) substances. While the final scope and timeline remain under active review, the mere trajectory of this regulatory conversation is already prompting downstream adopters to re-evaluate supplier diversification, material substitution pathways, and long-term procurement commitments. In markets where compliance timelines intersect with capital-intensive production cycles, anticipating regulatory inflection points is a decisive competitive advantage.
The strategic takeaway is clear: cost volatility, regional capacity concentration, and evolving chemical regulations are not peripheral concerns. They are central to pricing strategy, supplier negotiations, and geographical expansion planning. Companies that map these dynamics to their specific operational footprints will be positioned to manage risk proactively rather than react to margin compression after the fact.
Polyvinylidene Fluoride (PVDF) (PVDF Resin) Market
Mapping Competitive Forces and Industry Structure
The PVDF market exhibits a moderately concentrated competitive structure, with the top three players collectively commanding approximately 55 percent of market share and the leading five firms extending their combined presence to roughly 65 percent. This concentration pattern reflects decades of technical specialization, established fluoropolymer processing expertise, and long-term relationships with high-specification end users. Yet the landscape is far from static. The remaining market share is distributed across a mix of regional specialists, application-focused innovators, and emerging capacity builders, all of whom are actively carving out positions through targeted product development and strategic manufacturing investments.
Several established multinational and regional players define the current industry architecture. Arkema S.A., headquartered in Colombes, France, has been actively strengthening its PVDF footprint, most notably through its Kynar brand. In March 2026, Arkema announced a 20 percent capacity expansion at its Changshu site in China, with startup scheduled for 2028. This expansion is explicitly designed to support surging demand across lithium-ion batteries, energy storage systems, high-performance coatings, chemical processing, semiconductors, water filtration, and wire and cable applications. Solvay S.A., based in Brussels, Belgium, maintains a differentiated position through its advanced specialty polymer portfolio, leveraging deep formulation expertise and global technical service networks. Kureha Corporation, situated in Tokyo, Japan, brings longstanding fluoropolymer engineering heritage and a strong presence in high-purity industrial applications. Daikin Industries, Ltd., also headquartered in Osaka, Japan, continues to invest in fluorine chemistry capabilities that underpin high-performance membrane and coating solutions. In China, Shanghai Huayi 3F New Materials Co., Ltd. and Shanghai Ofluorine Chemical Technology Co., Ltd. represent rapidly scaling domestic players that are expanding their technical portfolios and aligning closely with regional demand surges, particularly in energy storage and industrial processing. Rounding out the competitive set, 3M Company, based in St. Paul, Minnesota, United States, applies its broad materials science platform to specialized PVDF-enabled solutions across filtration, electronics, and industrial coatings.
Recent corporate activity underscores how aggressively incumbents are positioning for the next demand cycle. Capacity additions, formulation upgrades, and regional manufacturing investments are no longer isolated R&D projects—they are strategic infrastructure plays designed to lock in supply preference with high-growth end markets. Understanding the timing, scale, and geographic focus of these moves is essential for any organization evaluating partnership opportunities, assessing competitive exposure, or planning its own capacity strategy.
Inside the Research: What Decision-Makers Will Find
A market report of this scope must do more than chart growth curves. It must translate macro trends into operational intelligence that can be actioned across procurement, product development, sales strategy, and investment planning. Our analysis is structured to deliver precisely that bridge between high-level market intelligence and day-to-day strategic execution.
The research framework begins with a robust historical reconstruction spanning 2020 through 2025, establishing baseline consumption patterns, pricing behavior, and demand composition before projecting forward across the 2026-2032 window. From there, the analysis segments the market across multiple structural dimensions, allowing readers to isolate the specific demand drivers, application growth rates, and product-type dynamics that matter most to their business models. Rather than presenting a single aggregate number, the report unpacks how different segments reinforce or diverge from the overall growth trajectory, enabling executives to identify where capital deployment will yield the strongest returns and where latent demand risks may be underestimated.
Beyond segmentation, the publication delivers a comprehensive competitive mapping exercise. It profiles the operating strategies of key market participants, evaluates recent capacity and investment announcements, and contextualizes each player’s positioning relative to regional demand centers and technical differentiation. This competitive layer is paired with a supply chain and cost structure assessment that traces input dependencies, highlights vulnerability nodes, and identifies where margin pressure is most acute. Given the raw material sensitivity documented in recent quarters, this dimension alone can materially improve procurement negotiation leverage and inventory planning accuracy.
The regulatory and compliance landscape receives dedicated analytical treatment as well. With evolving chemical governance frameworks intersecting with long-lived infrastructure and capital equipment decisions, the report maps potential policy trajectories, evaluates downstream substitution feasibility, and outlines strategic response pathways. For organizations operating in or selling into European markets, or for those dependent on PVDF-enabled membranes and coatings in regulated environments, this section provides a structured view of compliance risk rather than speculative headlines.
Finally, the research integrates demand-side application intelligence across energy storage, industrial piping and fittings, advanced coatings and membranes, and other high-value use cases. By connecting application growth signals to regional manufacturing footprints, raw material availability, and competitor capacity timelines, the report equips strategy teams to answer a far more valuable question than market size alone: which opportunities are defensible, which are commoditizing, and where should resources be concentrated in 2026 and the years immediately following?
Polyvinylidene Difluoride (PVDF) Market
Turning Market Intelligence into 2026 Competitive Advantage
The strategic value of this research lies in its ability to convert complex, fast-moving market signals into a coherent decision-making framework. In a segment where capacity expansions are being announced years in advance, where raw material cost spikes can compress margins within a single quarter, and where regulatory trajectories can reshape demand assumptions overnight, reactive planning is a structural disadvantage. Organizations that ground their 2026 strategies in verified market sizing, segmentation clarity, competitive intelligence, and dynamic supply chain analysis will enter the forecast period with significantly greater operational confidence.
For procurement leaders, the analysis highlights where long-term contracting, alternate sourcing architectures, and cost-indexing mechanisms can mitigate volatility exposure. For product and R&D teams, it clarifies which application domains are scaling fastest and which technical specifications are becoming table stakes versus differentiators. For commercial and corporate strategy functions, it surfaces where competitive concentration creates partnership opportunities, where regional demand imbalances may justify localized investments, and where regulatory developments may accelerate or decelerate adoption curves. In each case, the underlying market intelligence serves as a shared reference point, reducing internal disagreement and accelerating execution.
Access the Complete Strategic Analysis
The overview presented here reflects the analytical framework, directional market signals, and structural dynamics that define the current PVDF landscape. It is designed to establish the strategic context and demonstrate the depth of insight available to decision-makers who require more than headline figures. However, the full segmentation breakdowns, region-specific demand mapping, product-type growth trajectories, application-level consumption analysis, and detailed competitive profiles are reserved for the complete market research publication.
For organizations preparing capital allocation decisions, supplier negotiations, capacity evaluations, or market entry assessments in 2026, the complete dataset provides the precision necessary to move from directional confidence to executable strategy. We invite you to access the full report to obtain the comprehensive intelligence, granular segmentation detail, and forward-looking scenario analysis required to navigate the next phase of PVDF market evolution with clarity and strategic conviction.
For detailed analysis of this topic, please visit the official page: Polyvinylidene Difluoride (PVDF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Warehouse Robotics Market to Hit $19.3B by 2032, 16.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Warehouse Robotics Revolution: Strategic Intelligence for 2026 Decision-Makers
The warehouse robotics market is entering a decisive inflection point. As businesses confront escalating labor constraints, volatile consumer demand, and the operational imperative of round-the-clock fulfillment, automation has transitioned from experimental pilot programs to core infrastructure. Our newly released Warehouse Robotics Market research provides a rigorous, forward-looking assessment of this transformation, delivering the analytical granularity required for capital allocation, vendor evaluation, and long-term operational strategy. Set against a historical baseline spanning 2020 through 2025 and a comprehensive forecast window extending to 2032, this report equips executives with the macro and micro intelligence needed to navigate a rapidly consolidating ecosystem.
Market Trajectory: From Acceleration to Structured Growth
Over the past half-decade, the warehouse robotics sector has demonstrated a pattern of accelerated investment punctuated by brief normalization cycles. Historical revenue expansion between 2020 and 2025 reflects widespread adoption across e-commerce, third-party logistics, and heavy distribution networks. Following a period of market recalibration in the mid-2020s, momentum has firmly reasserted itself. The forecast period from 2026 through 2032 projects sustained expansion, with the market advancing from a baseline of 7,543.03 million USD in 2026 toward 19,305.49 million USD by the terminal forecast year. This trajectory translates to a compound annual growth rate of 16.8 percent, signaling that robotics-driven throughput is no longer a niche advantage but a baseline expectation for competitive fulfillment operations.
These figures are not abstract indicators. They represent a structural shift in how warehouses are designed, staffed, and scaled. Facilities that previously relied on manual picking and fixed conveyor pathways are now reconfiguring floor layouts around flexible automation nodes. The recurring investment pattern visible in the historical series underscores that buyers are moving past one-off deployments and toward phased, integrated automation architectures. For executives planning budget cycles in 2026, understanding the velocity and persistence of this growth curve is essential to aligning procurement timelines with real demand signals rather than speculative bottlenecks.
What the Report Delivers: Actionable Architecture for Strategy Teams
This research is structured to move beyond surface-level sizing and into the operational mechanics that determine deployment success. Rather than presenting a single aggregated figure, the analysis dissects the market across technology categories, functional applications, and geographic demand patterns. Decision-makers will find clearly mapped pathways linking each segment to specific operational outcomes, procurement considerations, and integration constraints.
- Technology and form-factor evaluation that distinguishes between established automated guided vehicle architectures and the rapidly scaling autonomous mobile robot segment, including guidance on where each solution class delivers the strongest return under different throughput and zoning requirements.
- Application-level breakdowns spanning transportation, picking and placing, palletizing and depalletizing, and packing, with analytical commentary on workflow integration, cycle-time implications, and the operational trade-offs that dictate segment prioritization.
- Regional demand mapping that contextualizes where investment intensity is concentrating, enabling supply chain leaders to align facility rollouts, vendor sourcing, and localized support strategies with prevailing deployment momentum.
- Concentration and competitive benchmarks that clarify market share dynamics among leading integrators and platform providers, helping procurement teams assess vendor dependency risk, partnership leverage, and long-term technology roadmaps.
Beyond structural segmentation, the report integrates technology roadmaps, deployment maturity curves, and total cost of ownership considerations. Readers will gain a working framework for evaluating whether a given automation topology aligns with their facility footprint, SKU complexity, peak-season volatility, and labor availability. This is not a static catalog of solutions; it is an analytical instrument designed to support scenario planning, vendor shortlisting, and capital sequencing.
Competitive Landscape: Platform Differentiation in a Consolidating Market
The vendor environment has matured into a spectrum of highly specialized platforms, each pursuing distinct architectural philosophies and target workflows. Several organizations have emerged as defining players whose technology choices are actively shaping procurement standards and deployment expectations.
Warehouse Robotics Market
Symbotic has built its market position around AI-powered end-to-end warehouse automation, coupling high-density storage, automated picking, and palletizing within a proprietary robotics ecosystem. Its emphasis on integrated workflow orchestration appeals to operators seeking to compress multiple manual stages into a single coordinated system. Locus Robotics, by contrast, has advanced a robots-to-goods fulfillment model anchored in AI-driven autonomous mobile robots and fully autonomous array configurations, targeting facilities that prioritize scalable, human-collaborative picking workflows.
Worldwide Warehouse Robots Market
Geek+ continues to expand its footprint with AMR-based warehouse robotics, robot arm picking stations, high-speed mobile platforms, and embodied intelligence frameworks purpose-built for e-commerce and B2B fulfillment. AutoStore differentiates through energy-efficient autonomous robotics designed for high-density storage and order fulfillment across retail, healthcare, and third-party logistics environments, where space optimization and retrieval speed are paramount. Addverb provides a broad automation toolkit spanning autonomous mobile robots, AS/RS systems, and integrated picking and packing solutions, positioning itself as a flexible partner for diverse distribution center configurations.
Vecna Robotics focuses on autonomous mobile robots engineered for horizontal transport, lifting, and conveying within human-centric warehouse layouts, making its technology particularly relevant for mixed-inventory facilities that must preserve operator interaction while increasing material movement efficiency. ForwardX Robotics brings autonomous forklifts and AMRs to warehouse and manufacturing material handling, addressing environments where heavy-load mobility and structured aisle navigation are critical. Ocado has built recognition around its On-Grid Robotic Pick technology and end-to-end fulfillment automation systems, emphasizing precision picking and scalable grocery and consumer goods operations. Exotec rounds out the landscape with Skypod AS/RS systems that integrate autonomous robotics for high-density, high-performance storage and retrieval.
These companies are not merely competing on hardware specifications. Recent product and deployment activity illustrates how quickly the competitive frontier is shifting. In early 2026, Locus Robotics introduced a fully autonomous Locus Array robots-to-goods fulfillment system that combines mobile robotics, integrated picking arms, and AI perception to support end-to-end workflows with reduced manual intervention. In the same period, Addverb unveiled the Trakr 2.0 high-order carousel automation system alongside three new warehouse robots and the Brisk interface at LogiMAT India 2026, signaling increased emphasis on storage automation and operational safety. Geek+ also introduced a robot arm picking station marketed as an end-to-end unmanned picking solution, along with an embodied intelligence platform aimed at expanding adaptive manipulation capabilities. Separately, Symbotic marked a significant deployment milestone by reaching one million robots deployed across fulfillment centers worldwide, reinforcing the scale at which AI-powered robotic warehouse systems are now operating.
For buyers, this level of activity carries both opportunity and risk. Differentiation is accelerating, but integration complexity, interoperability standards, and vendor roadmap stability are becoming equally important evaluation criteria. The report contextualizes these competitive movements so that procurement and operations leaders can assess not just what a vendor offers today, but how its trajectory aligns with a facility’s multi-year automation plan.
Industry Dynamics Shaping 2026 Procurement and Deployment
Technology capability is only part of the deployment equation. External cost pressures, regulatory evolution, and infrastructure considerations are actively reshaping project economics and timing. In 2025, rising steel and aluminum costs driven by tariff exposure increased the price of warehouse automation projects, compressing budget headroom for some operators and forcing trade-offs between scope and staging. By 2026, procurement teams are responding with more modular deployment strategies, phased capital releases, and stronger emphasis on lifecycle cost modeling rather than upfront price comparisons alone.
Regulatory and safety frameworks are also evolving in ways that influence system design and acceptance testing. The 2025 revision of ISO 10218-1 introduced technical changes reflecting marketplace developments and updated risk mitigation requirements for industrial robots, prompting engineering teams to revisit safeguarding architectures and integration protocols. At the same time, OSHA continues to operate without robotics-specific standards, instead requiring employers to eliminate recognized hazards under the General Duty Clause, which places a premium on site-specific risk assessments and documented safety processes. Fire protection guidance adds another layer of complexity: NFPA 13 sprinkler protection requirements for AS/RS systems remain under review because manufacturer-specific configurations in automated storage and retrieval create variability in hazard modeling and suppression planning.
Trade policy and regional industrial strategy are introducing further uncertainty. The EU industrial strategy and import tariffs on robotics components may raise short-term prices while simultaneously encouraging regional manufacturing and localized supply chains. For multinational operators, this means vendor selection cannot be reduced to performance specifications alone; sourcing geography, parts availability, service coverage, and tariff exposure now sit squarely within the strategic evaluation matrix.
Why This Research Matters for 2026 Strategy
The convergence of strong market growth, rapid product innovation, and shifting cost and regulatory conditions makes 2026 a pivotal planning year. Companies that treat warehouse robotics as a tactical purchase risk under-scoping integration requirements, overestimating deployment readiness, or locking into platforms that lack the scalability needed for future volume spikes. Companies that approach robotics through a structured intelligence framework can sequence investments more efficiently, match technology to workflow reality, and build vendor relationships around transparent performance expectations.
Our report is designed to support that decision-making process at multiple levels. Executive teams can use the market trajectory and concentration analysis to frame capital planning and risk posture. Operations leaders can leverage the segmentation and application analysis to prioritize automation nodes that deliver the fastest operational leverage. Procurement and engineering groups can draw on the competitive and regulatory context to refine vendor scorecards, integration checklists, and safety validation workflows.
The full dataset, segment-level modeling, vendor evaluation frameworks, and deployment scenario analysis are available in the complete report. For organizations preparing multi-quarter automation roadmaps or evaluating major systemintegrations in 2026, the detailed findings provide the evidentiary base needed to move from preliminary interest to confidently structured investment.
For detailed analysis of this topic, please visit the official page: Warehouse Robotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diabetes Drugs Market to Hit $117.7B by 2032, 6.5% CAGR Amid GLP-1 Growth
By PW Consulting, 2026-09-16
# The Diabetes Drugs Market in 2026: Navigating Growth, Innovation, and Strategic Complexity ## Executive Summary: Why Deep Intelligence Matters Now The global landscape for diabetes management is undergoing a seismic shift, driven by breakthrough therapies, evolving reimbursement models, and persistent supply chain vulnerabilities. For executives, investors, and strategic planners, relying on surface-level data is no longer sufficient. The decisions made in 2026 will dictate competitive positioning for the remainder of the decade. This article provides a high-level strategic overview of the market environment, illustrating the complexity and opportunity that define the sector today. However, true strategic advantage requires granular precision that goes beyond public headlines. Our comprehensive Diabetes Drugs Market research report delivers the specific segmentation volumes, competitive share analysis, and future trajectories necessary to optimize your portfolio and entry strategies. ## Market Trajectory and Scale: A Decade of Expansion The diabetes drugs market has demonstrated consistent resilience and growth over the past half-decade, establishing a robust foundation for the forecast period extending through 2032. Between 2020 and 2025, the market experienced significant expansion, with revenues rising from 51.0 billion USD to 75.9 billion USD. This historical performance underscores the inelastic demand for chronic care solutions and the rapid adoption of newer therapeutic classes. Looking forward, the market is projected to sustain a Compound Annual Growth Rate (CAGR) of 6.5 percent during the 2026 to 2032 forecast period. This trajectory suggests that the market will surpass the 100 billion USD milestone shortly after the turn of the decade, reaching approximately 117.7 billion USD by 2032. Such growth is not uniform; it is fueled by specific innovation waves and regional dynamics that require careful unpacking. While the top-line figures indicate a healthy sector, the distribution of this growth across drug classes, diabetes types, and geographic regions reveals critical niches where value is being created and captured. Understanding where the revenue streams are concentrating is vital for resource allocation, yet these specific breakdowns are detailed within our full proprietary dataset. ## The Innovation Engine: Drug Classes and Therapeutic Shifts The competitive battlefield is defined by the performance of distinct drug classes, each carrying different risk profiles, pricing power, and patient adherence rates. The market has seen a pronounced pivot toward incretin-based therapies, which have reshaped expectations for glycemic control and weight management. Conversely, traditional insulin markets remain foundational but face pressure from biosimilar competition and novel delivery mechanisms. Recent regulatory milestones highlight the pace of innovation. In March 2026, Novo Nordisk received FDA approval for Awiqli (insulin icodec-abae), a once-weekly insulin designed to improve glycemic control for type 2 diabetes. This approval represents a significant advancement in patient convenience and potentially adherence, disrupting the daily injection paradigm. Alongside such developments, the market landscape is being reshaped by key industry players who are leveraging distinct portfolios to capture share. Our report provides an in-depth profiling of the entities driving these changes. Leading manufacturers such as Novo Nordisk A/S, headquartered in Bagsværd, Denmark, continue to dominate with a strong lineup including Ozempic, Wegovy, and Rybelsus. Their strategy focuses heavily on the intersection of diabetes and obesity management. Similarly, Eli Lilly and Company, based in Indianapolis, Indiana, USA, is pushing the envelope with GLP-1 and GIP receptor agonists, including Mounjaro, Zepbound, and the investigational orforglipron, targeting both glycemic control and obesity-related metrics. Traditional insulin leaders remain relevant through formulation innovation. Sanofi, headquartered in Paris, France, maintains a strong presence with long-acting insulins like Lantus and Toujeo. Meanwhile, the SGLT2 inhibitor space is contested by developers like Boehringer Ingelheim, based in Ingelheim am Rhein, Germany, with products such as Jardiance, and Janssen Pharmaceuticals, located in Beerse, Belgium, offering Invokana for type 2 diabetes management. The interplay between these giants involves patent cliffs, pipeline Succession, and strategic partnerships that are meticulously analyzed in our full report to help you anticipate market share shifts. ## Geography and Patient Segmentation: Where the Revenue Lies Revenue distribution is not homogeneous across the globe. Certain regions exhibit higher purchasing power and faster adoption rates for premium therapies, while others offer volume growth potential driven by prevalence rates and improving healthcare infrastructure. The concentration of value in specific geographic zones creates distinct regulatory and pricing challenges for multinational strategies. Similarly, the patient base is segmented by diabetes type, with the vast majority of therapeutic spend directed toward Type 2 diabetes management, reflecting the global burden of metabolic syndrome. Type 1 diabetes, while smaller in terms of total revenue volume, represents a critical area for innovation in insulin delivery and immunosuppression therapies. The nuances of how these segments interact with drug class preferences—for instance, the preference for SGLT2 inhibitors in specific comorbidity profiles versus insulin dependence in advanced cases—require detailed modeling. Our research breaks down these segments to identify high-growth pockets that are often obscured in aggregate market figures. Access to the full segmentation data allows stakeholders to pinpoint exactly where their products fit within the current hierarchy of treatment guidelines. ## Market Concentration and Competitive Intensity The diabetes drugs market is characterized by a moderate level of concentration, suggesting room for niche players while maintaining strong barriers to entry for complex biologics and patented formulations. The top three companies hold a significant portion of the market share, collectively accounting for approximately 50 percent of revenue. Expanding the view to the top five players, the concentration rises to 65 percent. This structure indicates a market dominated by well-capitalized incumbents with extensive distribution networks and regulatory expertise. However, concentration does not imply stagnation. The remaining 35 percent of the market is highly competitive, with opportunities arising from generic entry, biosimilar development, and novel mechanisms of action. Strategic decisions regarding M&A, licensing, or organic pipeline development must account for this concentration risk. Entering a market segment dominated by the top five requires a differentiated value proposition, whether through superior clinical outcomes, cost efficiency, or delivery convenience. Our competitive landscape analysis dives deeper into the strategic moves of these key players, evaluating their R&D pipelines, litigation status, and global expansion strategies to provide a clear picture of the barriers and opportunities ahead. ## Supply Chain and Regulatory Dynamics: Navigating Risk in 2026 Beyond the clinical data and revenue projections, the operational environment for diabetes drugs is fraught with logistical and regulatory complexities. Supply chain resilience has emerged as a critical strategic pillar, particularly concerning the sourcing of key starting materials and active pharmaceutical ingredients (APIs). Recent analysis by the United States Pharmacopeia (USP) highlights a significant vulnerability: nearly half (48 percent) of key starting materials for drugs on the USP vulnerable medicines list are solely manufactured in a single country. This concentration poses acute and chronic risks to the supply of diabetes medications should disruptions occur. Furthermore, the USP emphasizes that upstream starting material sourcing bottlenecks could impact the availability of essential medicines. In the context of raw materials, 48 percent of global API Drug Master Files (DMFs) originate from India. This heavy reliance underscores the need for diversified sourcing strategies and robust contingency planning. Regulatory and reimbursement landscapes are also shifting dynamically. The Centers for Medicare & Medicaid Services (CMS) has introduced the GLP-1 Bridge model, providing access at a $50 copay for eligible Medicare beneficiaries with standardized coverage criteria. Additionally, the Medicare GLP-1 Bridge program offers eligible Part D beneficiaries $50 monthly access to certain GLP-1 medications beginning July 1, 2026. These initiatives are designed to improve patient access but introduce new variables for pricing strategy and demand forecasting. Stakeholders must understand how these reimbursement changes affect volume projections and manufacturer rebates. Our report synthesizes these regulatory developments with market demand models to predict how policy shifts will alter consumption patterns and profitability across different payer segments. ## Strategic Implications for Industry Stakeholders The convergence of robust market growth, therapeutic innovation, and supply chain fragility creates a complex decision matrix for 2026. Manufacturers must balance the urgency of launching new formulations against the risk of supply disruptions. Investors need to discern which drug classes will sustain premium pricing versus those facing imminent generic erosion. Policymakers and payers are grappling with the cost implications of widespread GLP-1 adoption while trying to expand access. To navigate this environment, organizations require more than just top-line growth numbers. They need a granular understanding of how segmentation splits interact with regional regulations, how competitive concentration affects pricing power, and how supply chain dependencies impact product availability. The data provided in public summaries often lacks the depth required to model these scenarios accurately. For instance, knowing the overall market size is useful, but understanding the specific revenue contribution of SGLT2 inhibitors versus GLP-1 receptor agonists in North America versus Asia Pacific is essential for regional market entry or expansion plans. ## Conclusion: The Value of Granular Intelligence The diabetes drugs market is poised for significant expansion through 2032, driven by a CAGR of 6.5 percent and evolving therapeutic standards. However, realizing value in this market requires precise intelligence. The interplay between major pharmaceutical players, regional demand variations, drug class performance, and regulatory policies creates a landscape where general knowledge is insufficient for competitive advantage. Our comprehensive Diabetes Drugs Market research report goes beyond the macro trends to provide the detailed segmentation data, competitive profiles, and strategic analysis necessary for informed decision-making. By uncovering the specific revenue splits, concentration metrics, and dynamic risk factors, this report equips stakeholders to mitigate risk and capitalize on growth opportunities with confidence. We invite you to explore the full findings to gain the actionable insights needed to thrive in this evolving sector.
Diabetes Drugs Market
Fertility Drugs Market
For detailed analysis of this topic, please visit the official page: Diabetes Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smoked Salmon Market Hits $541 Million in 2025, Projects 5.6% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Smoked Salmon Market Through 2032
The global smoked salmon industry stands at a critical inflection point. As supply chains mature and consumer preferences shift toward premium protein sources, understanding the trajectory of this market is no longer optional for stakeholders operating at scale. Our latest research publication delivers a comprehensive assessment of the sector, distilling twelve years of historical performance and forward-looking projections into an actionable intelligence framework. For executives planning capital allocation, product development, and geographic expansion in 2026, this report serves as the foundational reference for disciplined decision-making.
The value proposition of this study lies not merely in aggregation, but in synthesis. Where many market assessments stop at headline figures, this analysis traces the structural forces that will define competitive positioning over the next seven years. Readers who approach this document as a strategic compass rather than a static dataset will find a clear pathway through an environment characterized by both robust demand fundamentals and intensifying operational complexity.
Industry Trajectory and Structural Momentum
The market has demonstrated consistent expansion across the historical review window, recovering from mid-cycle fluctuations and establishing a higher baseline entering the forecast horizon. After reaching a valuation of 541.0 million USD in the base year of 2025, the sector moves into a projected growth phase that extends through 2032. The compound annual growth rate of 5.6 percent reflects a measured but durable expansion profile, one that rewards participants capable of balancing volume scale with margin discipline.
This trajectory is underpinned by several interlocking dynamics. Consumer demand continues to favor seafood protein as a cornerstone of modern dietary patterns, while retail and food service channels alike are expanding their premium cold-cut and prepared protein assortments. At the same time, the production ecosystem is responding to supply-side pressures ranging from raw material sourcing constraints to evolving regulatory expectations. The interplay between these demand-pull and supply-push forces creates a landscape where operational readiness, rather than market entry alone, determines which organizations capture disproportionate share.
Our forecast framework extends through 2032, tracing a path from the 587.32 million USD expected in 2026 to a projected 788.0 million USD by the terminal year of the analysis window. The progression is not a simple linear extrapolation; it incorporates the shifting weight of channel consumption, the maturation of regional supply networks, and the cadence of product innovation that will redefine value perception among end consumers. Executives who map their internal planning against this progression will be better positioned to synchronize capacity investments, inventory strategies, and go-to-market timing with the actual pace of market absorption.
Competitive Architecture and Strategic Positioning
The competitive landscape is defined by a concentration profile that rewards scale, brand equity, and channel relationships while leaving room for differentiated specialists to capture premium niches. According to the concentration metrics embedded in our analysis, the top three firms account for approximately 32 percent of the market, and the top five together command roughly 45 percent. This structure indicates a moderately consolidated arena where leading incumbents retain meaningful influence over pricing norms, supplier relationships, and category standards, yet where fragmentation below the top tier allows for opportunistic positioning by agile operators.
Across North America, Europe, and select international nodes, a diverse set of manufacturers is shaping the category. Long-established producers such as Acme Smoked Fish Corporation and Haifa Smoked Fish have built distribution footprints that span retail and foodservice, with private label partnerships and broad cold-smoked portfolios anchoring their relevance to large-scale buyers. Operators like Honey Smoked Fish Co., Boston Smoked Fish Co., and Forman & Field emphasize craftsmanship narratives, leveraging traditional smoking methods, local sourcing, and heritage positioning to command premium price points. Meanwhile, vertically integrated and export-oriented players including Bakkafrost Scotland, Trident Seafoods, and Suempol Sp. z o.o. balance volume production with geographic diversification, supplying fresh and smoked salmon variants across multiple destinations.
Recent corporate activity underscores the competitive intensity. In early 2026, Trident Seafoods expanded its smoked salmon line with a premium King Smoked Salmon offering, signaling a direct push into the higher-value tier. Around the same period, Echo Falls Seafoods, operating under Ocean Beauty Seafoods, unveiled flavor and retail packaging innovations for salmon caviar products at Seafood Expo North America, extending the category footprint beyond whole fillet formats. Natural Grocers entered the retail assortment landscape with a private-label Wild Smoked Salmon line featuring sockeye and coho varieties, certified under the Marine Stewardship Council and cold smoked in small batches at a seaside smokehouse. This launch illustrates how retailer-branded offerings continue to pressure branded manufacturers while also raising the bar for quality signaling and traceability.
Not all developments are expansionary. The category has also been shaped by product integrity events that reinforce the centrality of food safety as a strategic asset. In late 2025, both Haifa Smoked Fish and Acme Smoked Fish issued voluntary recalls related to potential Listeria contamination in cold-smoked products, with one involving a private label assortment tied to a major retailer. These episodes highlight the operational accountability that accompanies cold-smoked production, particularly under the FDA's Fish and Fishery Products Hazards and Controls Guidance, which mandates rigorous sanitation and environmental monitoring for Listeria in cold-smoked environments. For decision-makers, the strategic implication is clear: quality assurance infrastructure, supplier oversight, and rapid response capability are competitive differentiators, not merely compliance functions.
Demand Channels and Product Form Evolution
The consumption architecture of the market is distributed across retail and food service channels, each with distinct purchase drivers, format requirements, and price sensitivity profiles. Retail demand favors branded differentiation, convenient packaging, and clear quality credentials, while food service demand emphasizes consistency, portion control, and menu versatility. Our segmentation analysis examines how these channels interact with product types, revealing where margin opportunities concentrate and where volume-led strategies remain viable.
Within product form, cold-smoked and hot-smoked preparations serve different culinary applications and consumer experiences. Cold-smoked offerings generally align with appetizer, deli, and premium retail formats, where texture, aroma, and presentation are primary purchase drivers. Hot-smoked products, by contrast, often connect with ready-to-eat meal occasions and foodservice menus that prioritize warmth, robustness, and ease of preparation. The balance between these forms shapes production planning, smokehouse utilization, and the product innovation agenda of leading manufacturers.
Smoked Salmon Market
Innovation activity in recent months points to a broader category expansion beyond traditional fillet formats. Flavor experimentation, packaging refinement, and the introduction of derivative products such as salmon caviar indicate that manufacturers are seeking incremental growth through differentiation rather than relying solely on volume gains. Retailers and private label operators are simultaneously curating assortments that emphasize species variety, certification signals, and small-batch production narratives. This dual pressure from branded producers and retailer offerings is reshaping shelf strategy and menu integration across both channels.
Regulatory Environment and Trade Friction
Regulatory and trade conditions form a persistent layer of complexity in the smoked salmon market. U.S. import requirements and permitting regimes apply to many fishery products, including smoked salmon from certain origins, driven by disease and health standard considerations. These restrictions can influence sourcing strategies, lengthen lead times, and create volatility in cross-border supply planning. At a regional level, facility-level export constraints have also been observed, with indications that certain operations may face ongoing limitations on shipments to the United States into the first half of 2026. Such disruptions can cascade through downstream distribution networks, making geographic diversification and multi-origin sourcing strategically valuable.
On the domestic compliance side, the enforcement of the FDA's hazard controls guidance places cold-smoked production under continuous scrutiny for sanitation and environmental monitoring. This regulatory backdrop elevates the importance of validated process controls, supplier verification, and documentation rigor. For organizations evaluating capacity investments or supplier partnerships, the compliance burden is not a peripheral concern but a core determinant of operating risk and brand reputation. Our report integrates these regulatory considerations into the broader market framework, enabling readers to assess where friction is likely to persist and how leading operators adapt their operating models in response.
Strategic Relevance for 2026 Decision-Making
The strategic utility of this research for 2026 planning is rooted in its ability to connect macro momentum with operational reality. Executives facing capital allocation decisions can use the growth trajectory and concentration profile to calibrate expectations around market entry difficulty, share capture potential, and the realistic cadence of revenue scaling. Product and innovation teams can align their roadmaps with the observed direction of channel preferences, species and format diversification, and the certification and quality signals that increasingly influence purchase behavior. Supply chain and procurement leaders can benchmark their sourcing strategies against a backdrop of trade restrictions, multi-origin supply dynamics, and the heightened accountability surrounding cold-smoked safety controls.
This report is designed to support scenario-based thinking. Rather than presenting a single predetermined outcome, it structures the evidence so that leadership teams can test assumptions about pricing power, channel mix, capacity expansion, and geographic prioritization. The analysis examines how concentration dynamics affect competitive response times, how regulatory and trade conditions shape the cost and reliability of supply, and how product innovation cycles influence category perception and consumption frequency. Each of these dimensions is mapped to practical decision points, allowing subscribers to translate intelligence into planning inputs with precision.
In a market where the difference between effective and ineffective strategy often comes down to the quality of early-stage information, this study provides the granularity needed to move beyond broad assumptions. The macro outlook establishes the size and pace of the opportunity; the competitive and operational analysis reveals who is acting, how they are acting, and where the structural pressures are most acute; and the channel and product-form discussion clarifies where value creation is most defensible. Together, these elements form a decision-support foundation that is intended to be referenced repeatedly throughout the planning cycle, not merely read once and filed.
Smoked Meats Market
What This Study Delivers
Our methodology combines historical performance review with a seven-year forecast, anchored in a base year of 2025 and extending through 2032. The study examines total market size progression, growth rate assumptions, and the structural components that drive divergence across regions, product types, and applications. Segmentation is presented with the analytical depth required to understand relative scale and strategic relevance, while preserving the confidentiality of the finer breakdowns that constitute the full intelligence asset.
The competitive section profiles the companies that materially influence supply, pricing, and category direction, integrating recent developments such as new product introductions, private label expansions, packaging and flavor innovations, and product integrity events. These developments are contextualized within broader industry dynamics, including macro import patterns for seafood products, the weight and value share of salmon within those imports, and the specific regulatory requirements that shape production and trade. By weaving together company-level action with sector-level conditions, the report enables readers to interpret discrete events as part of a coherent strategic narrative.
Beyond the published segments, the complete study contains detailed regional and application-level breakdowns, type-specific evolution paths, company profiles with operational context, and scenario-oriented interpretation that supports targeted planning. These components are structured to answer the questions that executive teams repeatedly encounter: where growth is concentrated, which players are positioned to benefit, how regulatory and trade conditions alter the cost of participation, and what product and channel moves are most likely to resonate with demand. The report is therefore both an information resource and a planning instrument, intended for use in budgeting, sourcing strategy, product portfolio review, and competitive benchmarking.
Conclusion: Positioning for Durable Advantage
The smoked salmon market in 2026 is neither a nascent category nor a mature commodity play. It is a differentiated protein segment with steady growth characteristics, meaningful concentration among leading operators, and a competitive environment that increasingly rewards quality signaling, channel readiness, and operational discipline. The organizations that navigate the next phase most effectively will be those that treat intelligence as a strategic input rather than a retrospective summary.
This research publication has been designed to support that approach. It provides the scale and trajectory needed to frame opportunity, the competitive and regulatory context needed to manage risk, and the segmentation depth needed to prioritize action. For leaders shaping 2026 strategy, the value lies in using the analysis to pressure-test assumptions, align cross-functional plans, and identify the specific moves that convert market momentum into durable advantage. The full report extends far beyond the outline presented here, offering the complete dataset, company-by-company detail, and interpretive guidance necessary to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Smoked Salmon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasonic Cleaners Market to Hit $1.98B by 2032, 6.8% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Medical Ultrasonic Cleaners Market 2026-2032: A Executive Outlook
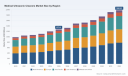
The global medical ultrasonic cleaners market stands at a critical inflection point as healthcare infrastructure modernization, stringent infection control mandates, and evolving regulatory frameworks reshape equipment procurement cycles. Over the 2026–2032 forecast horizon, the sector is projected to advance at a compound annual growth rate of 6.8 percent, translating into a trajectory from 1331.54 million USD in 2026 to 1980.92 million USD by 2032. This sustained expansion is not merely a function of volume replacement; it reflects a structural revaluation of decontamination workflows within sterile processing departments, operating rooms, and centralized instrument reprocessing facilities. For executives navigating medical device manufacturing, healthcare operations, or sterile supply chain management, the current market phase demands more than incremental procurement adjustments. It requires a disciplined, data-informed approach to technology adoption, regional deployment, and competitive positioning. Our newly released Medical Ultrasonic Cleaners Market research delivers precisely that analytical infrastructure, translating macro momentum into actionable enterprise strategy.
Market Trajectory and the 2026 Investment Thesis
Growth in the ultrasonic cleaning sector has accelerated decisively since 2020, when the market was valued at 987.65 million USD. By 2025, revenue had climbed to 1273.5 million USD, reflecting a compound expansion of roughly 6 percent annually across the historical record. The forecast period extends this momentum, with revenue projected to cross 1524.59 million USD in 2028, 1751.76 million USD in 2030, and 1913.12 million USD in 2031, before stabilizing at 1980.92 million USD in 2032. This trajectory is underpinned by three converging forces: the replacement of legacy manual decontamination protocols, the integration of ultrasonic technology into automated reprocessing lines, and the growing recognition of ultrasonic cavitation as a repeatable, validated method for contaminant removal on complex surgical and dental instrument geometries.
Medical Desktop Ultrasonic Equipment Market
For 2026 strategic planning, the most salient implication is that volume growth is increasingly tied to capability upgrades rather than baseline installation counts. Healthcare networks are reassessing capital expenditure priorities in light of labor constraints, throughput bottlenecks, and compliance documentation requirements. Ultrasonic systems that deliver programmable cycles, reproducible rinse profiles, and digital validation outputs are transitioning from optional enhancements to operational necessities. The research emphasizes that organizations which anchor their 2026 procurement roadmaps to process standardization, instrument throughput targets, and total cost of ownership modeling will capture disproportionate efficiency gains relative to peers pursuing ad hoc equipment rotation.
Core Report Architecture: From Data Layers to Decision Frameworks
The study is structured to support multi-functional decision-making across procurement, clinical operations, regulatory affairs, and market development. Rather than presenting isolated statistics, the analysis integrates demand-side drivers, supply-side capacity signals, and operational benchmarks into a cohesive planning environment. Key analytical modules include:
- Demand driver mapping across surgical, dental, laboratory, and medical device reprocessing workflows, with emphasis on throughput requirements, cycle validation expectations, and decontamination chain integration points.
- Product configuration analysis that distinguishes between benchtop, industrial, and specialized formats, linking tank capacity, frequency stability, and control architecture to use-case suitability and procurement risk.
- Regional deployment intelligence that evaluates healthcare spending patterns, manufacturing footprint expansion, and localized compliance expectations across major economic corridors without isolating granular share percentages.
- Competitive benchmarking that profiles product positioning, recent commercial moves, and strategic intent across the leading participants shaping category standards.
- Scenario-based modeling that allows leadership teams to test procurement timing, capacity expansion, and partnership strategies against shifting regulatory and reimbursement conditions.
This architecture is designed for execution. Procurement leaders can calibrate specification thresholds against validated deployment patterns. Clinical operations teams can align decontamination workflows with cycle reproducibility and purity expectations. Commercial teams can identify account segments where digital control upgrades, modular reconfiguration, or eco-friendly agent compatibility directly influence purchasing velocity. The report deliberately refrains from over-disclosing sub-segment percentages and localized valuation breakdowns within this executive preview; those layers remain fully accessible in the complete intelligence package, where the granularity supports precise territory planning and product-mix optimization.
Competitive Architecture and Strategic Orbital Moves
The competitive field is moderately concentrated, with the top three firms accounting for approximately 28.5 percent of category revenue and the top five expanding that footprint to roughly 35.2 percent. This concentration signals a market where scale, application specialization, and compliance readiness increasingly separate leaders from followers. Several manufacturers have moved aggressively to reinforce their positions through targeted product evolution, partnership formation, and regulatory alignment.
Crest Ultrasonics, headquartered in Trenton, New Jersey, has sharpened its focus on precision cleaning for surgical and medical instruments through healthcare-oriented product lines such as the Healthcare Pro Junior series, which incorporates multi-cycle wash and rinse capabilities alongside digital controls tailored for sterile processing environments. In September 2025, the company entered a strategic partnership with a leading hospital network to deliver customized ultrasonic cleaning solutions, a move that underscores the growing preference for networked deployments aligned to institutional workflow specifications.
Elma Schmidbauer GmbH, based in Singen, Germany, continues to advance modular ultrasonic cleaning platforms and has introduced eco-friendly InnoWave PCF models designed to support medical device instrument reprocessing and decontamination under evolving medical device regulation expectations. In July 2025, the company unveiled an eco-friendly ultrasonic cleaner utilizing biodegradable cleaning agents for medical applications, highlighting an industry-wide shift toward agent compatibility, waste stream management, and environmental compliance within sterile decontamination processes. Regulatory documentation reinforces that Elma Schmidbauer medical ultrasonic cleaners are positioned for instrument reprocessing in medical technology applications, with ultrasound cleaning systems expected to provide reproducible processes and the highest purity standards in medical device manufacturing.
Branson Ultrasonics, operating from Danbury, Connecticut, has reinforced its emphasis on digital control sophistication for surgical instrument cleaning. In August 2025, the company announced a new line of ultrasonic cleaners specifically for surgical instruments, incorporating advanced digital controls intended to enhance cleaning efficiency and support validation workflows. This product direction aligns with broader operating-room and sterile processing priorities around cycle repeatability, documentation readiness, and reduced manual intervention.
Ultrasonic Power Corporation, based in New Britain, Connecticut, manufactures industrial and medical-grade ultrasonic cleaners for pharmaceutical and medical applications, including custom systems engineered for precision part cleaning. Ultrasonic LLC, also United States-based, supplies machines designed for medical parts cleaning, handling small batches and complex components across healthcare and aerospace-related requirements. Together, these participants reflect a diversifying supplier base in which application specificity, custom configuration capability, and regulatory awareness increasingly influence purchasing decisions.
For enterprise strategists, these competitive signals carry clear implications. Supplier selection is no longer a function of unit price alone; it incorporates validation readiness, cycle programmability, compliance support, and compatibility with institutional decontamination chains. Organizations that evaluate vendors through a multi-criteria scorecard encompassing traceability, digital output quality, service response, and upgrade pathways will be better positioned to lock in operational resilience as category standards tighten.
Operational, Regulatory, and Labor Economics Shaping Procurement Behavior
Beyond competitive dynamics, the market is being reshaped by operational realities that directly influence specification priorities. High-capacity stainless steel tank models in the 5-liter to 8-liter range have become standard in medical ultrasonic cleaners for instrument pre-cleaning, reflecting a broader shift toward throughput-compatible hardware that can process reusable instrument sets efficiently at the front end of decontamination workflows. This hardware normalization reduces variability in cycle execution while supporting consistent exposure of instrument surfaces to cavitation activity.
Labor economics are also accelerating adoption. Ultrasonic cleaners deliver measurable labor savings by replacing manual cleaning methods for surgical instruments in sterile processing departments. As staffing pressures persist and training consistency becomes a recognized operational risk, automated or semi-automated cleaning cycles offer a practical lever for reducing variability, reducing rework, and improving instrument readiness before sterilization. Reimbursement and compliance structures further reinforce this direction. In practice, instrument cleaning equipment used in healthcare settings must support decontamination prior to autoclaving, and systems that align with established healthcare standards are increasingly favored during procurement reviews and quality audits.
Regulatory context adds another layer of strategic relevance. Medical technology applications are subject to evolving expectations around documentation, process reproducibility, and validation traceability. Organizations are therefore placing greater weight on equipment that supports repeatable cycles, verifiable rinse outcomes, and integration into broader quality management systems. In this environment, procurement decisions are increasingly evaluated not just on cleaning performance in isolation, but on how effectively a system supports downstream compliance and sterilization readiness.
Medical Ultrasonic Cleaners Market
Strategic Playbook for 2026 Enterprise Decision-Makers
Translating these dynamics into executable strategy requires a structured approach. The research outlines several priorities that resonate across healthcare networks, medical device manufacturers, and equipment distributors:
- Define instrument reprocessing targets first, then map equipment specifications to those targets. Throughput, cycle flexibility, and validation output should be treated as interdependent decision variables rather than separate purchasing dimensions.
- Embed total cost of ownership analysis into capital planning. Upfront pricing comparisons should be supplemented with assessments of labor displacement, rework reduction, maintenance expectations, and compliance documentation value.
- Align supplier evaluation with future regulatory and environmental expectations. Preference should be given to platforms that accommodate standardized cycle programs, digital record generation, and compatibility with evolving cleaning agent requirements.
- Treat regional deployment as a strategic variable. Healthcare infrastructure maturity, manufacturing presence, and localized service capacity influence implementation timelines and long-term support reliability, making geography a relevant component of procurement planning.
- Use competitive intelligence to anticipate category direction. Recent product launches, partnerships, and eco-friendly innovations signal where specification expectations are heading, enabling earlier internal alignment and reduced procurement friction.
These priorities are not generic best practices; they are derived from the observed intersection of demand-side operational pressures, supplier innovation cadence, and regulatory reinforcement within the ultrasonic cleaning category. Organizations that operationalize them early in the 2026 planning cycle will have a clearer path to procurement efficiency, reduced implementation risk, and stronger alignment with downstream sterilization and quality requirements.
The Complete Intelligence Layer: What Is Held Back and Why
This executive overview is intentionally structured as a strategic preview. The purpose is to establish analytical credibility, demonstrate sector fluency, and clarify how the full report supports decision-making without dispersing the most granular intelligence across public-facing formats. Core segmentation values, regional revenue distributions, application-level breakdowns, and product-type splits remain embedded in the complete study, where they can be cross-referenced against operational benchmarks, competitive profiles, and scenario models without dilution. That architecture allows procurement and strategy teams to apply precise figures to territory planning, product-mix evaluation, and vendor comparison without exposing sensitive analytical layers prematurely.
In practice, the full report provides the quantitative scaffolding required to convert directional momentum into specific procurement, expansion, and partnership decisions. The macro trajectory, competitive positioning, regulatory context, and operational drivers presented here form the strategic foundation; the detailed segmentation and valuation layers supply the execution-level precision. Together, they create a planning environment that supports both short-term purchasing calibration and multi-year capability roadmapping.
Closing Perspective: Positioning for Measured, High-Value Growth
The medical ultrasonic cleaners market is advancing along a clearly defined growth path, but the strategic opportunity lies less in the headline numbers than in the operational and regulatory conditions that are reshaping procurement logic. As the category moves from 1331.54 million USD in 2026 toward nearly 1980.92 million USD in 2032, the organizations that win will be those that convert that momentum into disciplined specification choices, validated workflow integration, and supplier relationships aligned with compliance, reproducibility, and efficiency goals. The complete Medical Ultrasonic Cleaners Market research is built to support precisely that outcome, offering the depth, structure, and benchmarking context required to move from informed awareness to decisive execution.
For detailed analysis of this topic, please visit the official page: Medical Ultrasonic Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coding Equipment Market Hits $6.75B in 2025, Projects CAGR of 6.12% to $10.27B by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Coding and Marking Equipment Market: Navigating Growth Through 2032
In an era where supply chain transparency, regulatory compliance, and packaging sustainability dictate competitive advantage, the coding and marking equipment market stands at a critical inflection point. Manufacturing leaders, procurement directors, and automation strategists are no longer asking whether to upgrade their marking infrastructure, but how to align capital allocation with a market that is expanding at a steady pace while simultaneously fragmenting under technological, regulatory, and material-cost pressures. Our latest comprehensive study on the Coding and Marking Equipment Market transforms raw trajectory data into a decision-ready framework, offering executives a clear line of sight into the operational and financial implications of the 2026–2032 forecast window.
The market’s historical foundation provides essential context for forward-looking strategy. Between 2020 and 2025, sector revenue climbed from approximately 5.0 billion USD to 6.75 billion USD, reflecting a period of accelerated line automation, heightened traceability mandates, and widespread adoption of advanced coding technologies across high-volume production environments. This momentum is projected to sustain itself through the end of the decade, with market valuation expected to reach 7.21 billion USD in 2026 and continue its upward trajectory toward 10.27 billion USD by 2032. The forecast period compound annual growth rate of 6.12 percent underscores a mature but structurally resilient industry, one whose expansion is increasingly driven not by volume alone, but by precision, compliance readiness, and lifecycle optimization.
For enterprise decision-makers, these figures represent more than a top-line growth narrative. They signal a shifting capital allocation landscape where legacy equipment refresh cycles, cross-platform compatibility, and total cost of ownership calculations must be recalibrated against a backdrop of evolving packaging substrates, tightening food-safety disclosures, and intensifying competitive consolidation. Our report translates these macro trends into actionable intelligence, enabling strategy teams to stress-test investment theses, benchmark regional performance vectors, and anticipate demand inflection points before they materialize in procurement cycles.
Decoding the Operational Architecture of the Analysis
The study is engineered for practitioners rather than passive observers. It maps the full lifecycle of coding and marking deployment, from technology selection and line integration to maintenance economics and compliance verification. Readers will encounter a methodical dissection of how different printing modalities interact with production throughput, substrate variability, and regulatory labeling requirements. The analysis places particular emphasis on the operational tradeoffs that procurement and engineering teams face daily: balancing ink-based continuity against laser permanence, evaluating thermal transfer durability under abrasive or temperature-fluctuating conditions, and aligning printer head lifecycle with line-speed targets and changeover frequency.
Beyond equipment taxonomy, the report integrates upstream cost dynamics that directly influence capital expenditure planning. Recent shifts in raw material pricing have compressed margins across packaging supply chains, creating ripple effects for coding system operators who must now weigh upfront hardware investments against ongoing consumables volatility. The analysis incorporates these material-cost pressures into scenario modeling, helping executives evaluate whether modular upgrades, ink-substitution strategies, or full-line conversions offer the most defensible path to sustained ROI. This practical orientation ensures that financial teams can align operational roadmaps with realistic cost curves rather than static vendor quotes.
Compliance architecture forms another critical pillar of the study. As labeling requirements become more granular and audit expectations more stringent, the functional scope of coding equipment has expanded beyond simple identifier placement. The report examines how verification workflows, third-party audit readiness, and automated inspection integration are reshaping procurement priorities. Organizations seeking to future-proof their packaging lines will find structured guidance on aligning coding capabilities with traceability mandates, nutrient-disclosure frameworks, and sustainability-driven substrate transitions.
Competitive Dynamics and Strategic Differentiation
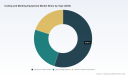
The market’s competitive architecture reflects both entrenched 리더십을 and continuous technological repositioning. The sector remains moderately concentrated, with the top three players collectively commanding roughly 45.8 percent of revenue and the top five firms controlling approximately 61.2 percent. This distribution indicates a landscape where scale advantages, service networks, and cross-vertical application expertise create meaningful barriers, yet leave sufficient headroom for specialized innovators and regional specialists to capture value through niche performance differentiation.
At the center of the competitive field are organizations that have built deep application fluency across high-demand verticals. Domino Printing Sciences, headquartered in Cambridge, United Kingdom, has maintained a strong focus on continuous inkjet, laser, and hybrid inkjet coding systems, with dedicated solutions engineered for high-speed traceability on cans, bottles, cartons, and cases. Its recent product cadence illustrates the pace of innovation shaping the market: in March 2026, the company introduced the Cx150i direct-to-box printer utilizing oil-based ink for more sustainable and accessible coding on food packaging, alongside the Ux360i UV Laser Coder designed for high-speed sustainable packaging applications in food and beverage lines. The same period saw the release of the Gx-Series PRO Printhead, built to support the industry’s transition toward 2D coding on food packaging. These developments were preceded by the October 2025 introduction of the Dx1060i CO2 Laser Coder and F-Series fibre lasers, which target permanent code generation on beverage cans, glass, and plastics.
Videojet Technologies, based in Auckland, New Zealand, continues to position its CIJ, TIJ, and laser coder portfolio around permanent, food-safe prints tailored for food and beverage packaging lines. Markem-Imaje, operating from Aubervilliers, France, offers thermal inkjet, continuous inkjet, and laser marking systems calibrated for product- and case-level coding within food and beverage environments. Matthews International Corporation, headquartered in Pittsburgh, Pennsylvania, supplies TIJ, laser, and labeling systems aimed at high-resolution and permanent coding applications, while ID Technology, based in Minneapolis, Minnesota, delivers thermal inkjet coders and integrated systems for direct marking on cans, jugs, and cartons.
The competitive field also includes significant contributions from industrial equipment manufacturers and compliance-adjacent service providers. Hitachi Industrial Equipment Systems, headquartered in Tokyo, Japan, manufactures laser and inkjet coding systems optimized for traceability in industrial food and beverage settings. SATO Holdings Corporation, also based in Tokyo, provides TIJ and thermal transfer coders focused on packaging identification and regulatory compliance. SGS, headquartered in Geneva, Switzerland, extends the ecosystem through third-party verification and audit services for coding and marking systems deployed in food and beverage packaging lines. Rounding out the roster, Gem Gravure, based in the United States, supplies regulation-quality coding equipment specifically engineered for food and beverage packaging applications.
For strategy teams, this competitive mosaic matters because vendor selection is no longer a straightforward equipment-procurement exercise. It is a multi-year partnership decision that encompasses service responsiveness, technology roadmaps, consumables availability, and compliance-support capabilities. The report provides a structured comparison framework that helps organizations evaluate not just hardware specifications, but the broader value chain resilience each supplier brings to high-volume, high-compliance production environments.
Regulatory and Material-Cost Pressures Redefining Market Dynamics
External forces are accelerating the strategic relevance of coding and marking infrastructure. Regulatory evolution is one of the most immediate drivers. In January 2025, the FDA proposed a rule requiring a front-of-package Nutrition Info box on most packaged foods, mandating clear display of saturated fat, sodium, and added sugars categorized as Low, Medium, or High. By April 2025, the agency finalized updates to the healthy nutrient content claim definition, tightening limits on added sugars, saturated fat, and sodium. These developments do not merely change label content; they reshape the precision, legibility, and verification demands placed on coding systems, particularly on high-speed lines where print quality, placement consistency, and audit-ready documentation must remain uncompromised.
Simultaneously, raw material dynamics are injecting cost volatility into packaging production and, by extension, into coding system planning. In 2026, PET, PP, and PS plastic sheet prices rose 15–30 percent due to energy costs and paraxylene supply constraints. Corrugated paperboard and paper packaging costs also increased amid higher pulp and energy prices for food packaging production. For coding and marking operators, these shifts affect substrate compatibility, ink adhesion performance, laser interaction with treated surfaces, and overall line-tuning requirements. Equipment that performs reliably on stable substrate profiles may require recalibration, consumables substitution, or complementary inspection modules when material characteristics fluctuate.
These intersecting pressures are reshaping market dynamics in ways that reward proactive planning. Organizations that treat coding infrastructure as a static cost center risk encountering deployment bottlenecks when regulatory label formats change or when substrate transitions alter print stability. Conversely, enterprises that align their equipment strategy with anticipated regulatory timelines and material-cost trajectories can convert compliance and packaging shifts into efficiency gains, reducing downtime, minimizing rework, and improving audit outcomes.
Why This Study Matters for 2026 Decision-Making
The value of this research lies in its translation of trajectory data into operational clarity. Enterprise leaders operating in 2026 must navigate a market that is simultaneously expanding, consolidating, and being reshaped by compliance mandates and input-cost volatility. Top-line growth figures alone cannot guide capital deployment; they must be paired with segmentation intelligence, competitive capability mapping, regulatory horizon scanning, and total-cost modeling that reflects real-world line conditions.
Coding and Marking Equipment Market
Our report delivers that integrated view. It helps strategy and operations teams identify where demand concentration is forming, which technology pathways align with upcoming packaging and labeling requirements, and how vendor portfolios differ in their capacity to support rapid changeover, substrate variability, and verification workflows. It also contextualizes market concentration dynamics, enabling organizations to evaluate whether partnership with a large-scale incumbent, a specialized technology provider, or a service-oriented verification partner best matches their risk tolerance and growth targets.
Crucially, the study is designed to support decisions that extend beyond the current fiscal year. With a forecast horizon stretching to 2032, executives gain a structured basis for multi-phase investment planning, technology refresh scheduling, and capacity alignment. Rather than reacting to equipment obsolescence or compliance gaps after they emerge, organizations can sequence upgrades, model consumables exposure, and stress-test vendor commitments against plausible regulatory and material-cost scenarios.
Accessing the Full Strategic Blueprint
The coding and marking equipment market is entering a phase where precision, compliance, and cost resilience will separate scalable operators from those burdened by reactive procurement. This study provides the analytical foundation needed to navigate that phase with confidence. It combines market trajectory mapping, technology and application segmentation, competitive profiling, and dynamic cost-and-regulation context into a single decision-support instrument.
Coding and Marking Systems and Solutions Market
To explore the complete segmentation breakdown, detailed vendor capability comparisons, scenario-based cost modeling, and region-specific growth vectors, we invite you to access the full report through our source page. The complete intelligence package is structured for immediate integration into capital planning, procurement strategy, and operational roadmapping, enabling your team to move from market awareness to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Coding and Marking Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Compact Construction Equipment Market to Reach $311M by 2032, Growing at 5.1% CAGR
By PW Consulting, 2026-09-16
Compact Construction Equipment Market: Strategic Intelligence for 2026 Decision-Makers
The compact construction equipment sector is entering a phase of transformative acceleration, driven by shifting labor dynamics, stringent regulatory frameworks, and rapid technological integration. For enterprise leaders, procurement strategists, and market development teams, the operational environment in 2026 demands more than surface-level awareness. It requires granular, forward-looking intelligence capable of informing capital allocation, product positioning, and competitive response. Our latest comprehensive research report on the Compact Construction Equipment Market delivers precisely this intelligence, translating historical trajectories and forward forecasts into actionable strategic playbooks for the 2026 fiscal landscape and beyond.
The Macro Trajectory: From Recovery to Sustained Expansion
Over the past half-decade, the compact equipment segment has demonstrated remarkable resilience, evolving from post-pandemic supply chain recalibration into a structurally expanding market. The addressable revenue base has grown consistently, reflecting sustained demand across construction, infrastructure, and specialized industrial applications. This growth trajectory is not merely cyclical; it is underpinned by fundamental shifts in how site work is executed, how fleets are optimized, and how operators are trained. With a projected compound annual growth rate of 5.1 percent across the forecast horizon extending to the early 2030s, the market is poised to surpass the 300 million dollar threshold, representing a meaningful expansion from its mid-2020s baseline.
This macro progression masks critical inflection points that will define competitive positioning throughout 2026 and the subsequent years. Understanding where volume is accumulating, how pricing power is shifting among equipment classes, and which operational bottlenecks are reshaping procurement cycles requires a disciplined analytical framework. Our report constructs that framework, offering enterprise teams a structured vantage point from which to evaluate market entry, product portfolio expansion, and commercial strategy.
Market Structure and Competitive Realities in 2026
The competitive architecture of the compact equipment landscape is defined by a concentrated yet highly dynamic environment. Leading manufacturers have entrenched strong market share, with the top three and top five players collectively commanding substantial portions of total industry revenue. This concentration reflects decades of brand equity, distribution network maturity, and service infrastructure investment. Yet, within this consolidated top tier, a wave of strategic repositioning is underway, particularly as electrification, smart automation, and regional market penetration converge to reshape competitive boundaries.
Established industrial leaders continue to leverage their scale, engineering heritage, and financing ecosystems to reinforce their standing. Their compact offerings span tracked loaders, skid steers, and mini excavators, each engineered for versatility across general construction, landscaping, utility work, and material handling. Financing incentives, including promotional terms structured through mid-2026, are actively deployed to stimulate fleet acquisition and lower procurement barriers for contractors and rental operators. At the same time, legacy manufacturers are recalibrating product roadmaps to address evolving operator expectations and compliance mandates.
Compact Construction Equipment Market
Construction Equipment Market
Simultaneously, emerging entrants and regional manufacturers are intensifying their competitive presence. Korean equipment groups, for instance, have been aggressively expanding their compact construction and demolition equipment portfolios, emphasizing hands-on demonstrations, customizable job-site configurations, and brand-led North American market entry strategies. These organizations are signaling long-term commitment through trade show participations, product unveilings, and operational demonstrations designed to capture the attention of procurement teams seeking differentiated value propositions.
Product Innovation and the Strategic Imperative of Electrification
Equipment innovation in the compact segment is no longer a peripheral development track; it is a central driver of commercial differentiation. Recent industry showcases have highlighted a clear pivot toward next-generation smart and automated compact equipment, with manufacturers unveiling concept platforms, enhanced operator-assist technologies, and streamlined mechanical architectures. Electrically powered models are increasingly prominent, reflecting both regulatory tailwinds and end-user demand for quieter, zero-emission site operations. Mini excavator lineups, in particular, have seen notable advancements in chassis engineering, control precision, and modular customization capabilities.
For corporate strategy teams, these product developments carry direct implications. Fleet electrification planning, service network readiness, battery lifecycle considerations, and operator training reconfiguration all intersect with procurement timing and total cost of ownership models. Our analysis dissects these innovation trajectories, mapping them against adoption curves, segment-specific demand patterns, and regional compliance timelines to help decision-makers anticipate where competitive advantage will be captured in the near term.
Regulatory Shifts, Labor Dynamics, and Supply Chain Headwinds
The operational environment for compact equipment operators is being reshaped by intersecting external forces. In Europe, the revised Construction Products Regulation has taken full effect, introducing stricter sustainability and digital compliance requirements that reverberate through equipment specifications, documentation, and certification workflows. Across North America, regional energy codes and space conditioning mandates are altering equipment specification standards, placing renewed emphasis on efficiency-aligned machinery and compliant operational configurations.
Concurrently, labor market realities continue to exert pressure on construction operations. Skilled labor shortages persist, accelerating the adoption of compact equipment that reduces training time, simplifies site workflows, and integrates automation features capable of compensating for workforce constraints. This labor-driven demand signal reinforces the strategic value of compact machinery as a productivity multiplier rather than a mere capacity substitute.
On the supply side, material cost volatility remains a persistent concern. Fluctuations in steel and aluminum pricing, influenced by tariff structures and trade tensions, continue to impact manufacturing margins, inventory planning, and lead-time reliability. At the same time, engineering adaptations such as the incorporation of high-strength steel and advanced alloys in booms and chassis are improving durability and extending service intervals, partially offsetting input cost pressures through performance gains. These interconnected dynamics require scenario-aware planning, and our report structures this complexity into clear strategic considerations for procurement, production, and distribution leadership.
What follows is a curated overview of the analytical depth contained within our full market research publication. The sections below illustrate how each dimension of the study is designed to support concentrated decision-making in 2026.
In-Depth Market Sizing, Segmentation, and Forecast Architecture
Our research constructs a multi-layered sizing and forecasting model that traces historical performance and projects forward market evolution across the defined forecast period. Rather than presenting a single top-line figure, the report decomposes market structure across equipment classifications, application domains, and geographic footprints, enabling stakeholders to identify where volume concentration is strongest and where growth acceleration is most pronounced. Each segmentation layer is examined through the lens of operational relevance, allowing readers to evaluate how product mix decisions, regional expansion initiatives, and application-specific demand signals will interact throughout the planning horizon.
The forecast architecture accounts for base-year baselines, historical trend calibration, and forward projections that incorporate demand elasticity, regulatory pacing, and technology adoption curves. By aligning forecast outputs with strategic planning cycles, enterprise teams can stress-test portfolio assumptions, evaluate market entry timing, and model revenue scenarios with greater precision. The complete segmentation datasets, regional volume distributions, application-level revenue splits, and equipment-class breakdowns are detailed within the full report, providing the quantitative foundation required for board-level presentations, capital planning, and commercial forecasting.
Competitive Intelligence and Strategic Move Analysis
Understanding competitive positioning requires more than a roster of key players. It demands a structured assessment of where manufacturers are deploying capital, how they are differentiating product lines, and which commercial tactics are reshaping buyer behavior. Our competitive analysis maps the strategic activity of leading organizations across the compact equipment ecosystem, examining product specialization, geographic focus, financing programs, and demonstration-driven market engagement.
Analysis covers organizations with broad compact equipment portfolios as well as those executing targeted regional expansions and product launches. The report evaluates how manufacturers are aligning their offerings with application-specific requirements, how they are leveraging trade events and hands-on demonstrations to accelerate adoption, and how new model introductions are influencing competitive pressure points. Recent product unveilings, trade show activations, and electrification-focused launches are contextualized within broader market dynamics, allowing readers to distinguish between tactical visibility and structurally significant strategic moves.
This competitive mapping is designed to support benchmarking, identify white-space opportunities, and inform partnership or distribution strategy decisions. Full competitive profiles, recent development timelines, product positioning summaries, and strategic implication analyses are documented comprehensively within the complete publication.
Operational Dynamics, Risk Factors, and Strategic Response Frameworks
Effective market strategy requires an integrated view of external pressures and internal capability adjustments. Our report synthesizes the most consequential operational dynamics shaping the compact equipment sector, translating regulatory, labor, and supply-chain developments into actionable response frameworks. Rather than treating these factors as isolated constraints, the analysis positions them as interconnected variables that collectively influence pricing strategy, inventory management, product specification decisions, and regional market prioritization.
Labor-driven productivity requirements, compliance deadlines, raw material cost exposure, and material innovation trends are examined as strategic inputs rather than background noise. The report outlines how organizations can structure procurement timing, service readiness, and product mix adjustments to navigate these pressures while preserving margin integrity and market responsiveness. Scenario-based considerations are embedded throughout, helping leadership teams prepare for divergent operating environments and make calibrated decisions under uncertainty.
Why This Research Matters for 2026 Strategic Planning
As market participants navigate a landscape defined by concentrated competition, accelerating product innovation, evolving compliance mandates, and persistent operational constraints, the cost of incomplete information is rising. Strategic decisions made in 2026 will have compounding effects on fleet positioning, regional growth trajectories, and competitive resilience through the remainder of the decade. Access to structured, forward-looking intelligence is therefore not a supplementary advantage but a foundational requirement.
Our Compact Construction Equipment Market research is engineered to serve as that foundation. It consolidates historical context, forecast modeling, competitive mapping, regulatory analysis, and operational dynamics into a unified decision-support resource. The complete report enables leadership teams to move beyond high-level market awareness and into precise, evidence-based strategy formulation. For organizations seeking to refine procurement roadmaps, evaluate product portfolio expansion, benchmark against rival moves, or identify high-opportunity segments and regions, the full publication provides the depth and clarity necessary to act with confidence.
The complete dataset, extended segmentation breakdowns, detailed competitive profiles, and forward scenario analyses are available in the full report. Explore the complete intelligence package to align your 2026 strategy with the structural realities shaping the compact construction equipment market.
For detailed analysis of this topic, please visit the official page: Compact Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Visual Effects Services Market to Reach $344.8M by 2032, Growing at 7.12% CAGR from 2026-2032
By PW Consulting, 2026-09-16
The Visual Effects Services Market in 2026: Strategic Intelligence for Enterprise Decision-Making
Navigating a Transformative Era in Visual Storytelling
The global Visual Effects Services Market has entered a defining phase where artistic ambition, technological acceleration, and financial engineering converge. As production pipelines evolve and audience expectations shift toward immersive, photorealistic storytelling, enterprises across film, television, gaming, and advertising must look beyond creative intuition and ground their strategies in rigorous market intelligence. This new research publication from PW Consulting provides a comprehensive, data-driven examination of the Visual Effects Services Market, offering executives a strategic blueprint for navigating the opportunities and pressures that will shape the industry through the end of the decade.
The market has demonstrated consistent momentum across the historical review period, reflecting sustained demand for high-end visual content and expanding investment in digital production capabilities. Our analysis traces this trajectory from 2020 through the base year of 2025, capturing the structural shifts that have redefined competitive positioning, service delivery models, and revenue generation across the sector. The data underscores a market that has not merely grown but fundamentally restructured itself around new workflows, platform diversification, and the integration of advanced computation into creative processes.
For enterprise leaders, the critical question is no longer whether visual effects will play a central role in content strategy, but how to allocate capital, select partners, and position operations in a landscape characterized by rapid technological change, evolving incentive frameworks, and intensifying competition for specialized talent. This research is designed to answer that question with precision, offering actionable intelligence that supports investment planning, vendor selection, geographic expansion, and long-term portfolio management.
Forecasting Framework: Aligning 2026 Decisions with the 2026–2032 Outlook
The forecast period covered in this report spans from 2026 through 2032, a window that coincides with pivotal developments in production technology, distribution economics, and regulatory incentives. By anchoring strategic planning in a disciplined forward-looking framework, organizations can anticipate demand shifts, assess the ROI of capability investments, and identify the inflection points where competitive advantage will be won or lost.
The report integrates historical demand patterns with forward projections to deliver a coherent view of market evolution. This approach enables decision-makers to stress-test assumptions against multiple scenarios, evaluate the timing of capacity expansions, and understand how macro-level growth translates into sector-specific opportunities. Rather than presenting growth as a monolithic trend, the analysis disentangles the underlying drivers—content volume, platform fragmentation, technological adoption, and regional production migration—to reveal where value is being created and how it is likely to redistribute over time.
Strategic alignment with this forecast horizon is essential for organizations that must commit resources today to capabilities that will mature over the next several years. Whether the objective is to internalize certain production functions, form strategic alliances with specialized vendors, or reallocate budget toward higher-value service tiers, the report provides the contextual foundation needed to make those choices with confidence. The emphasis throughout is on decision relevance: every dataset, every segmentation lens, and every competitive observation is framed to support operational and financial planning in the current fiscal cycle and beyond.
Report Architecture: Operational Depth Across Segments, Competition, and Dynamics
To support rigorous strategic analysis, this research is structured around a set of operational modules that together provide a complete picture of the market environment. The segmentation framework examines the market through multiple dimensions, allowing readers to isolate the demand characteristics, service configurations, and growth profiles that are most relevant to their specific business context. By analyzing the market across type-based and application-based lenses, the report illuminates how different service categories and end-use channels contribute to overall demand patterns and where structural advantages are emerging.
The regional dimension of the analysis adds further granularity, mapping how production activity, vendor ecosystems, and incentive environments vary across major geographic corridors. This regional perspective is particularly valuable for organizations evaluating location strategy, outsourcing partners, or international expansion, as it surfaces the interplay between local production capacity, talent availability, and policy support. Importantly, the report maintains a disciplined focus on strategic interpretation rather than exhaustive enumeration, ensuring that the data serves decision-making rather than overwhelming it.
Complementing the segmentation analysis is a detailed competitive landscape assessment that profiles the leading operators shaping the market. The research examines the positioning, capability strengths, and strategic moves of prominent firms, including Industrial Light & Magic, Weta Digital, Framestore, DNEG, Pixomondo, Animal Logic, Rodeo FX, Cinesite, Method Studios, Deluxe, Digital Domain, The Mill, and Scanline VFX. These profiles are not static company summaries; they are structured to reveal how each organization competes on technology, service breadth, artistic reputation, and operational scale, and how recent consolidation, investment, and partnership activity is reshaping the hierarchy.
The report also incorporates a dedicated dynamics module that captures the forces currently redefining market behavior. This includes an examination of labor cost structures and talent availability, with attention to median compensation levels and employment growth trajectories for visual effects artists and animators in the context of sustained demand across gaming, film, and television. The regulatory landscape receives equal attention, with analysis of incentive programs and policy initiatives that are actively influencing production location decisions and cost structures. Recent developments illustrate how these forces are unfolding in real time, including significant investment activity, acquisitions that consolidate animation and VFX operations, award-recognized creative campaigns, and organizational rebranding efforts that reflect evolving workflow integration.
By integrating these content streams, the report functions as both a reference document and a planning tool. Readers will find a clear path from high-level market context to granular operational insight, enabling them to draw connections between market structure, competitor behavior, and their own strategic priorities.
Competitive Intensity and Strategic Positioning in a Consolidating Landscape
The competitive environment in the Visual Effects Services Market is characterized by a combination of creative differentiation, technological capability, and ongoing consolidation. With a moderately concentrated market structure, the leading firms compete not only on artistic quality but also on their ability to deliver end-to-end solutions that span visual effects, animation, virtual production, and post-production support. This breadth of capability has become increasingly important as producers seek to streamline workflows, reduce integration risk, and maintain consistency across complex, multi-platform projects.
Several of the most prominent operators have pursued strategic moves that signal how they intend to strengthen their competitive position. Investment activity has provided selected companies with the capital to expand technology pipelines, deepen AI-driven workflows, and scale content production capacity. Acquisitions have been used to consolidate complementary capabilities, particularly where animation and visual effects operations can be integrated to offer more complete service offerings. At the same time, high-profile creative recognition continues to serve as a powerful differentiator, reinforcing brand equity and attracting premium client relationships.
For enterprise buyers and investors, this dynamic landscape raises important questions about vendor stability, service continuity, and the long-term implications of consolidation. The report addresses these concerns by evaluating how recent transactions and investments are likely to affect pricing, capacity, and service specialization. It also examines how firms are positioning themselves around emerging capability areas, including simulation, creature work, motion capture, immersive media, and AI-assisted production. Understanding these strategic vectors is essential for organizations that must select partners capable of supporting both current production needs and future content ambitions.
Regulatory and Cost Dynamics: Incentives, Labor, and Operational Strategy
Market behavior in the Visual Effects Services Market is increasingly shaped by the interaction between labor economics and policy incentives. On the labor side, specialized creative and technical roles command significant compensation, and employment growth in animation and visual effects is projected to remain positive over the coming decade, driven by ongoing demand across entertainment and interactive media. This sustained demand places pressure on talent availability and reinforces the strategic importance of workforce planning, retention, and productivity-enhancing technology adoption.
Worldwide CG Visual Service Market
At the same time, a range of incentive programs is actively reshaping where and how visual effects work is performed. Recent policy developments have expanded or clarified credit structures in key production markets, giving producers new options for optimizing cost structures while maintaining access to high-quality service providers. In some jurisdictions, tax credit frameworks have been updated to increase eligible spend or streamline application and audit processes, reducing administrative friction and making incentive capture more predictable. In others, advocacy efforts are pushing for standalone post-production incentives that would better align support with the specific economics of visual effects work.
Visual Effects Services Market
These dynamics create both opportunities and risks for enterprises. Advantages can be gained by aligning production footprints with favorable incentive environments, but such strategies must be balanced against considerations of talent quality, vendor capability, delivery timelines, and long-term relationship strength. The report provides a structured examination of these trade-offs, helping decision-makers evaluate how regulatory and cost factors should inform location strategy, vendor selection, and budget allocation. Rather than treating incentives as isolated financial benefits, the analysis situates them within the broader operational context in which content is produced and delivered.
Strategic Imperatives for 2026 and Beyond
As enterprises move through 2026, the most successful organizations will be those that treat visual effects not as a discretionary enhancement but as a core component of content strategy and operational planning. That shift requires a clear understanding of where the market is heading, which capabilities will command premium value, and how competitive and regulatory forces will influence cost and access over time. This research is designed to provide that understanding in a form that can be directly applied to investment decisions, partnership strategies, and organizational planning.
Among the strategic imperatives highlighted in the report are the need to evaluate vendor partners against long-term capability roadmaps rather than short-term project requirements, the importance of monitoring consolidation and investment activity for signals about market concentration and service availability, and the value of integrating incentive and labor considerations into location and sourcing decisions from the outset. The report also emphasizes the growing relevance of technology adoption, particularly where advanced workflows can improve efficiency, quality, and scalability without compromising artistic integrity.
For executives seeking to translate market intelligence into action, the full study offers a more detailed evidentiary base, including deeper segmentation analysis, competitive profiling, and scenario-based interpretation of demand drivers. The complete research package is available through the source publication, where readers can access the full range of data, analysis, and strategic recommendations that support enterprise decision-making across the 2026–2032 horizon.
In a market defined by rapid change and high creative stakes, disciplined intelligence is the foundation of confident strategy. This report provides the context, structure, and insight needed to make that strategy durable, responsive, and aligned with the realities of the Visual Effects Services Market as it enters its next phase of growth.
For detailed analysis of this topic, please visit the official page: Visual Effects Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI in Agriculture Market to Hit $13.9B by 2032, Growing at 22.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Harvest of Intelligence: Strategic Imperatives in the AI Agriculture Market (2026–2032)
Executive Preview: The Inflection Point for Agricultural Intelligence
The global agricultural sector is undergoing a structural transformation driven by artificial intelligence, shifting from incremental automation to foundational decision intelligence. As we move through 2026, the Artificial Intelligence (AI) in Agriculture market has crossed a critical adoption threshold. Recent market research indicates that the sector generated approximately $2.6 billion in revenue during the base year of 2025, reflecting a maturation phase where pilot deployments are rapidly transitioning into enterprise-grade agricultural operations. This trajectory is projected to accelerate through the end of the forecast period in 2032, with the market expanding to $13.9 billion. This represents a compound annual growth rate (CAGR) of 22.85%, signaling sustained capital allocation and accelerated commercialization across the agri-tech ecosystem.
Artificial Intelligence (AI) in Agriculture Market
For executive leadership, investors, and strategic planners, these aggregate figures represent more than macroeconomic momentum. They reflect a fundamental reordering of competitive advantage in food production. Organizations that treat AI as an operational utility rather than a discretionary technology investment are capturing disproportionate margins in yield optimization, input efficiency, and supply chain resilience. This market intelligence briefing outlines the strategic architecture of the AI agriculture landscape, equipped to guide resource allocation, partnership strategies, and risk mitigation in the 2026–2032 horizon.
Market Architecture and Growth Trajectory
The historical progression from 2020 to 2025 demonstrates a market that has consistently expanded despite macroeconomic headwinds and transitional supply chain constraints. Revenue climbed from $1.8 billion in 2020 to $2.6 billion by 2025, with minor cyclical fluctuations reflecting regional deployment pacing and platform maturity cycles. The forward-looking trajectory through 2032 indicates sustained expansion, with revenue scaling past $3.04 billion in 2026 and continuing to accelerate through the latter half of the forecast window.
This growth is underpinned by converging operational pressures and technological enablement. Agricultural operators are increasingly deploying AI to address structural labor constraints, input cost volatility, and climate-related yield unpredictability. The market is simultaneously being shaped by enterprise digitization initiatives, subsidies for precision technologies, and the standardization of agricultural machine learning datasets. Strategic decision-makers must recognize that the revenue expansion is not uniform across use cases or geographies; rather, it is concentrated in high-value application domains and regions with advanced digital infrastructure, creating distinct monetization pathways and competitive moats.
Core Application Domains and Technological Enablers
The AI agriculture ecosystem is organized around several foundational technological pillars and application segments that collectively drive value creation across the farm-to-market continuum. The dominant deployment patterns reflect a shift from isolated automation tools to integrated decision platforms that combine sensing, predictive modeling, and operational execution.
- Machine Learning continues to serve as the core analytical engine, enabling adaptive modeling for crop performance, input optimization, and risk forecasting across variable environmental conditions.
- Computer Vision has become critical for real-time field-level perception, supporting weed identification, crop health assessment, and automated guidance systems that reduce chemical usage and operational waste.
- Predictive Analytics is increasingly embedded in agronomic planning workflows, allowing growers and agribusinesses to anticipate weather impacts, soil conditions, and yield variability with greater temporal precision.
On the application side, Precision Farming remains the most extensively deployed category, integrating data-driven field management, variable-rate application, and equipment interoperability. Parallel growth is evident in Agriculture Robots and Livestock Monitoring, where AI-enabled automation addresses labor scarcity, animal welfare, and operational consistency. The strategic implication for enterprise buyers is clear: the highest near-term returns are emerging where AI is embedded directly into operational workflows rather than deployed as standalone analytics. Organizations evaluating market entry or capability expansion should prioritize integration depth, data interoperability, and measurable operational impact over feature breadth alone.
Competitive Landscape and Strategic Positioning
The market remains moderately fragmented, with a concentrated core of established players and a dynamic periphery of specialized innovators. Industry concentration metrics indicate that the top three competitors command approximately 24.6% of total market revenue, while the top five collectively account for 26.2%. This structure reflects an environment where scale advantages in data networks, platform ecosystems, and equipment integration coexist with niche differentiation in imaging, sensing, and agronomic intelligence.
Several incumbents and platform leaders define the current competitive architecture. John Deere continues to anchor its strategy in precision agriculture platforms that combine AI-driven autonomous equipment, computer vision for weed and crop identification, and centralized farm management data operations. Microsoft leverages its Azure FarmBeats ecosystem to unify machine learning, IoT sensing, drone imagery, and satellite data for precision farming insights and resource optimization. IBM contributes through its Watson Decision Platform for Agriculture, integrating AI, weather intelligence, and IoT streams to generate predictive crop health, soil, and weather insights. Bayer Crop Science extends its digital farming footprint via the Climate FieldView platform, applying AI-powered analytics for crop recommendations, risk management, and yield optimization. Trimble supports the space with AI-powered precision agriculture tools and connected solutions designed for machine guidance, data analysis, and operational efficiency.
Worldwide Agricultural Nanotechnology Market
Beyond the platform and equipment incumbents, a robust wave of specialized innovators is reshaping field-level intelligence. Valmont Industries applies integrated AI and machine learning to irrigation systems, crop monitoring, and anomaly detection through center-pivot technology. Taranis has built an AI-powered crop intelligence platform that uses machine learning and leaf-level imagery for disease detection, nutrient analysis, and agronomic recommendations. Gamaya combines hyperspectral imaging and remote sensing within an AI platform for crop health monitoring, yield prediction, and sustainability optimization. Ag Leader Technology focuses on precision farming technology for machine guidance, planting, and harvest optimization with integrated field operation data. Corteva Agriscience continues to expand digital tools and AI solutions for precision agriculture, including seed genetics and input recommendations.
Recent corporate activity underscores the velocity of this competitive evolution. In February 2026, John Deere announced its 2026 Startup Collaborator program, aligning with six ag-tech startups focused on AI, robotics, satellite analytics, and advanced sensing to strengthen precision farming capabilities. In October 2025, Taranis disclosed a strategic AI partnership with Syngenta Group to integrate generative AI-powered agronomic intelligence for crop advisors and growers. In July 2025, Gamaya merged with Terraview to unlock new opportunities for sustainable food systems through AI-powered agronomic intelligence. These moves reflect a broader pattern: incumbents are increasingly acquiring, partnering, or collaborating to accelerate data network effects, expand application coverage, and reduce time-to-market for advanced agronomic capabilities.
Industry Dynamics, Regulation, and Infrastructure Realities
Market expansion is not occurring in a vacuum. Strategic planners must account for an evolving regulatory and operational environment that directly shapes deployment economics and adoption pacing. Public-sector frameworks are increasingly directing how AI is governed, standardized, and integrated into agricultural operations. The USDA Fiscal Year 2025–2026 AI Strategy mandates ethical, transparent, and accountable governance for AI deployment in agricultural operations, establishing expectations for data use, model accountability, and operational oversight. In parallel, the European Union Coordinated Plan on Artificial Intelligence includes targeted implementation progress for AI applications in precision agriculture and intelligent spraying, indicating heightened attention to compliance, environmental outcomes, and technology verification in mature regulatory markets.
Standardization efforts are also gaining traction. The AgML framework is working to standardize agricultural machine learning datasets and benchmarks for AI model development and evaluation, an initiative that should reduce fragmentation in training data quality and improve cross-platform comparability. For enterprise buyers and technology developers alike, these standardization and governance trends create both operational clarity and new compliance obligations. Organizations that build governance-ready architectures and auditable model workflows will face lower regulatory friction and stronger stakeholder trust as adoption scales.
Infrastructure and labor dynamics further define the practical boundaries of market growth. IoT sensors and solar-powered connectivity systems require significant upfront investment in farm-level data collection infrastructure for AI applications, meaning that deployment economics can vary sharply by operation size, connectivity availability, and capital access. At the same time, AI integration is increasingly positioned as a structural response to labor shortages, automating weed identification, spraying, and harvest operations through computer vision and robotics. This dual pressure—higher upfront infrastructure cost alongside labor cost mitigation—creates a nuanced investment calculus. Strategic decision-makers should evaluate AI adoption not solely on technology capability, but on total cost of ownership, infrastructure readiness, and the scalability of automation benefits across seasons and field conditions.
Strategic Priorities for 2026 Decision-Making
The 2026–2032 forecast window rewards organizations that align AI strategy with operational reality, data readiness, and ecosystem positioning. Several priority axes emerge for leadership teams evaluating market participation, investment, or capability development.
- Prioritize workflow-embedded AI over standalone analytics. Solutions that integrate directly into planting, spraying, irrigation, and harvest decisions are more likely to deliver measurable return and stickier adoption.
- Assess infrastructure readiness before scaling deployment. Farm-level connectivity, sensor coverage, and data ingestion capacity will determine whether AI initiatives translate into repeated operational gains or remain constrained pilot programs.
- Monitor partnership and consolidation signals. The mix of startup collaboration programs, platform partnerships, and mergers indicates that capability gaps are increasingly being closed through ecosystem alliances rather than internal build-only strategies.
- Embed governance and data standards early. With regulatory expectations rising and dataset standardization advancing, organizations that adopt transparent, auditable AI practices will be better positioned for cross-market expansion and partner integration.
- Evaluate concentration risk and differentiation opportunities. While leading platforms hold meaningful share, the market remains open to specialized solutions in imaging, irrigation intelligence, livestock monitoring, and agronomic advisory. Targeted differentiation can create defensible positions even in a fast-scaling market.
How to Use This Intelligence
This overview is designed to establish the strategic frame for deeper operational planning. It highlights the direction of market growth, the structure of competition, and the regulatory and infrastructure realities that shape deployment outcomes. However, actionable market entry, investment allocation, and capability planning require granular segmentation, use-case-level revenue splits, regional deployment differentials, and competitive benchmarking that exceeds the scope of a high-level briefing.
For organizations that need precise allocation models, segment-level growth decomposition, application-specific adoption curves, and detailed competitor capability mapping, the complete market research report provides the structured intelligence necessary to convert strategic direction into executable plans. The full analysis isolates the segments, regions, and deployment models that matter most to your operating context, enabling decision-makers to move from directional confidence to specific, data-backed action.
Closing Perspective
The AI in Agriculture market has entered a phase where technological promise is being converted into operational impact at scale. The combination of sustained double-digit growth, expanding platform ecosystems, and intensifying competitive collaboration suggests that the decisive question for 2026 is no longer whether AI will reshape agricultural operations, but how quickly organizations can integrate it into the economics of production. Leaders who align strategy with workflow reality, data infrastructure, and governance readiness will be best positioned to capture value as the market advances toward 2032.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence (AI) in Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Optic Cable Assembly Market to Reach $11.13B by 2032 at 6.9% CAGR
By PW Consulting, 2026-09-16
Fueling High-Velocity Networks: The Strategic Imperative Behind the 2026 Fiber Optic Cable Assembly Market Outlook
As global digital infrastructure accelerates toward 2032, leaders across telecommunications, data center development, aerospace, and public-sector engineering are navigating a market defined by compounding demand, evolving regulatory frameworks, and intensifying competitive maneuvering. The Fiber Optic Cable Assembly Market has transitioned from a purely operational procurement category to a strategic leverage point for enterprises seeking bandwidth resilience, latency optimization, and future-proof connectivity architectures. Our newly released research offering provides a comprehensive, decision-oriented exploration of this landscape, mapping historical trajectories, forward-looking growth corridors, and the operational realities that will shape purchasing, positioning, and partnership strategies throughout the 2026–2032 forecast horizon.
For executives evaluating capacity planning, vendor consolidation, or geographic expansion in the coming fiscal year, the underlying market signals warrant close attention. Drawing on a rigorous analytical framework anchored in historical performance through 2025 and extending across the 2026–2032 forecast window, this research translates macro-level momentum into actionable strategic context. Rather than offering static snapshots, the study is designed to help leadership teams anticipate inflection points, stress-test assumptions, and align capital allocation with the structural drivers reshaping fiber connectivity value chains.
Decoding the Macro Trajectory: Why the Growth Curve Matters for 2026 Planning
The market has demonstrated consistent expansion across the historical review period, reflecting a steady escalation in demand for high-performance cable assemblies that support increasingly data-intensive networks. By the close of the base year, total market revenue had climbed to a substantial milestone, underscoring the durability of fiber-based connectivity as a foundational infrastructure layer. The forecast period projects continued upward momentum, with the overall market expected to advance at a compound annual growth rate of 6.9 percent through 2032. For strategists, this trajectory is more than a headline figure; it signals a sustained demand environment in which capacity missteps, overly conservative sourcing models, or delayed technology adoption can create competitive disadvantages that compound over multiple planning cycles.
Importantly, the growth profile reflects more than incremental volume increases. It encapsulates shifting end-user expectations around reliability, signal integrity, deployment speed, and lifecycle durability. As enterprises and public institutions push bandwidth requirements higher while tightening tolerance for failure points, the cable assembly segment sits at the intersection of physical-layer performance and strategic network design. Decision-makers evaluating product roadmaps, inventory strategies, and supply commitments in 2026 must therefore interpret growth not merely as a sizing exercise, but as an indicator of where performance specifications, qualification standards, and application-specific requirements will become increasingly binding.
Inside the Research: What Decision-Makers Will Find
This study is structured to support practical, executive-level decision-making rather than abstract market commentary. It delivers a layered analytical architecture that connects high-level sizing context with granular structural insights, enabling readers to isolate the drivers most relevant to their operating environment. The report examines the market through multiple strategic lenses, including:
- Structural segmentation analysis that clarifies how demand patterns diverge across cable assembly formats, end-use applications, and regional deployment realities, helping teams pinpoint where specification requirements and procurement cycles differ most sharply.
- Competitive positioning and profiling of leading and emerging participants, including operational footprints, product focus areas, and the strategic moves that are reshaping share dynamics and customer value propositions.
- Regulatory and standards-driven dynamics that assess how qualification frameworks, customs and trade policy developments, and infrastructure-era procurement practices are influencing sourcing risk, compliance planning, and regional competitiveness.
- Deployment and production context covering the operational prerequisites that distinguish high-precision assembly environments, including cleanroom-class manufacturing considerations, testing rigor, and the practical implications for lead times, customization, and reliability assurance.
- Recent event intelligence tied to corporate collaborations, product catalog evolution, major infrastructure rollouts, and regulatory updates, providing a real-time anchor for interpreting how the competitive and operating landscape is shifting on the ground.
Each section is designed to feed directly into commercial assessment, procurement strategy, and forward planning. The goal is not simply to show what the market has been, but to equip leadership with the context needed to evaluate where to invest, where to standardize, and where to differentiate in a segment that rewards both technical precision and strategic timing.
Competitive Landscape and Strategic Positioning Signals
The fiber optic cable assembly market remains structurally fragmented, with a top-three concentration that reflects meaningful but not dominant consolidation among leading manufacturers and solution providers. This competitive configuration creates a distinctive environment: large-scale incumbents can leverage established manufacturing capabilities, broad product portfolios, and long-standing customer relationships, while specialized players compete on precision, customization, qualification readiness, and application-specific engineering. For procurement leaders and strategy teams, the implication is clear. Vendor evaluation cannot be reduced to unit pricing alone; total value increasingly depends on qualification support, delivery predictability, design flexibility, and the supplier's ability to align with the technical and regulatory demands of the target deployment environment.
Several market participants illustrate the range of strategic postures now shaping the segment. Optical Cable Corporation has built its profile around military, tactical, and commercial enterprise fiber optic cable assemblies and connectivity solutions, spanning both pre-terminated and custom variants. In mid-2025, the company entered a strategic collaboration agreement with Lightera, LLC, including an investment component, aimed at expanding offerings for data center and enterprise applications. That move signals a deliberate pivot toward higher-growth infrastructure end-markets and reflects a broader industry pattern in which traditional manufacturers are reinforcing capabilities where bandwidth demand and deployment velocity are most acute.
Diamond SA exemplifies the precision-engineering orientation that increasingly differentiates suppliers serving demanding use cases. Based in Switzerland, the company specializes in high-precision fiber optic interconnects and assemblies and maintains cleanroom production environments tailored to enterprise, space, and other stringent applications. In a market where signal integrity and contamination control can directly affect qualification success, this production philosophy highlights the operational premium attached to controlled-assembly environments. Meanwhile, L-com Global Connectivity continues to emphasize ruggedized and pre-terminated fiber optic cable assemblies, patch cords, and custom connectivity solutions for networking and industrial applications, reinforcing the importance of durability and field-readiness in industrial and critical-infrastructure settings.
Cable Assembly Market
On the distribution and customization side, Fiber Instruments Sales, Inc. provides a broad catalog of fiber optic cable assemblies, including fusion-spliced and field-installable options, bridging manufacturing output with practical deployment flexibility. fiberone, llc has similarly emphasized customer-specific design in its custom multi-fiber cable assemblies, adjusting lengths, breakouts, and pulling eyes to meet precise project requirements. Recent activity from fiberone, llc in early 2026, including an updated product catalog and refreshed emphasis on customer-specific designs, illustrates how tailored specification support remains a competitive differentiator for projects where off-the-shelf configurations are insufficient. Taken together, these profiles show a market in which competitive advantage is being constructed through a blend of manufacturing discipline, application specialization, partnership strategy, and responsiveness to project-level engineering requirements.
Regulatory Currents, Trade Realities, and Deployment Economics
Strategic sourcing in fiber optic cable assemblies cannot be separated from the regulatory and policy environment shaping cross-border trade, safety qualification, and public infrastructure procurement. One of the most consequential developments for safety-critical deployments came from the Nuclear Regulatory Commission, which issued Regulatory Guide RG 1.257 in August 2025. The guide addresses the qualification of fiber-optic cables, connections, and optical fiber splices for use in safety systems within production and utilization facilities. For organizations operating in or supplying to regulated environments, this type of guidance directly affects validation pathways, documentation expectations, and the burden of demonstrating long-term reliability under defined operating conditions.
Trade policy remains another critical variable. Implementation of Section 301 tariffs on optical fiber cables from China continues to impose a 25 percent additional duty, and industry commentary submitted to BIS in late 2025 noted that these measures remain in effect without coverage under Section 232 tariffs. For sourcing teams, the practical consequence is a persistent cost and supply-chain consideration that can influence origin decisions, inventory timing, and supplier diversification strategies. Executives evaluating total landed cost, qualification continuity, and geopolitical exposure must factor these duties into scenario planning rather than treating them as transient conditions.
At the infrastructure level, fiber deployment economics remain highly project-dependent. Recent cost-plot updates from U.S. Department of Transportation ITS KRS, including revisions to roadside telecommunications fiber optic cable installation costs, highlight the sensitivity of project budgets to installation context, geography, and operational constraints. Public-sector and private infrastructure programs alike must contend with cost variability that can reshape feasibility assessments and phased rollout plans. In parallel, legislative interest in fiber infrastructure security has continued to gain visibility, including the introduction of the Bipartisan Strategic Subsea Cables Act of 2026, which proposes expanded U.S. government engagement around subsea fiber-optic cable security, maintenance, and repair. While subsea systems represent a distinct layer of the broader connectivity ecosystem, the policy direction reinforces a widening recognition of fiber infrastructure as a strategic asset worthy of heightened oversight and coordinated response frameworks.
These overlapping forces illustrate why the market cannot be understood through sizing alone. Regulatory qualification, tariff exposure, installation cost variability, and infrastructure security priorities all influence how quickly projects move, which suppliers are eligible, and how procurement teams balance cost efficiency with resilience. The research incorporates these dynamics as active variables in the market outlook, helping readers connect policy and operational realities to commercial planning.
Why 2026 Is a Decision Pivot Point
The current forecast window places unusual importance on early-cycle decisions. With market value projected to rise materially from the 2026 base estimate toward the end of the decade, organizations that define their sourcing architectures, qualification strategies, and application focus early are better positioned to manage cost structures, secure supply continuity, and align product capabilities with the most attractive demand pools. Conversely, teams that defer structural decisions risk entering a more crowded, more regulated, and more cost-sensitive environment with less flexibility.
Several practical imperatives follow from this outlook. First, demand planning should be anchored in application-specific requirements rather than aggregate volume alone. The growth trajectory is being shaped by differing needs across telecom and datacom environments, broadcasting and CATV deployments, military and aerospace specifications, power and new energy applications, healthcare installations, and other specialized use cases. Each of these segments carries its own performance thresholds, qualification expectations, and purchasing rhythms, making segmented insight essential for accurate forecasting and effective product positioning.
Fiber Optic Cable Assembly Market
Second, supply-chain strategy should account for both performance assurance and policy exposure. Cleanroom-class production environments, precision assembly practices, and rigorous testing protocols are not merely operational details; they are increasingly central to winning qualification-sensitive work and differentiating from lower-spec alternatives. At the same time, tariff structures and sourcing origins can materially affect total cost and supply predictability, requiring scenario-based procurement planning rather than single-path sourcing assumptions.
Third, competitive strategy should recognize that the market rewards a blend of scale, specialization, and adaptability. Some participants compete by expanding into high-growth data center and enterprise segments through collaboration and investment. Others compete by deepening precision manufacturing and application-specific engineering. Still others compete through catalog breadth, distribution reach, or customization capability. Understanding where a company’s own strengths align with these competing logics is essential for positioning, partnership selection, and long-term share capture.
From Intelligence to Action: What the Full Study Enables
The overview presented here is intended to demonstrate the analytical rigor and strategic relevance of the full report, while deliberately preserving the deeper segmentation data, quantification detail, and comparative frameworks that justify the complete study. Enterprise teams that rely on a high-level summary alone risk missing the structural nuance that determines where growth is concentrated, how competitive pressure is distributed, and which operational requirements will most influence sourcing outcomes in specific deployment contexts.
The complete research offering expands on every dimension introduced here, providing the detailed market sizing breakdown, segmentation insight, and competitive profiling required to support precise planning. It enables readers to move from general market confidence to targeted decision support by revealing how demand is distributed across cable assembly types, application areas, and regional dynamics, and by placing those patterns in the context of recent corporate moves, regulatory developments, and infrastructure activity. For organizations preparing budgets, product strategies, qualification roadmaps, or expansion plans for 2026, that level of detail is not optional; it is the difference between reactive planning and strategically informed execution.
The market is expanding, but expansion alone does not create advantage. Advantage is created by understanding where the growth is structurally grounded, which requirements will become non-negotiable, and how competitive and regulatory forces will reshape the cost and capability equation over the next several years. Our full market research is designed to deliver exactly that level of intelligence. We invite decision-makers to access the complete study to obtain the comprehensive segmentation data, comparative analysis, and forward-looking strategic context needed to translate this market outlook into concrete, high-confidence action throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


