



Category: market research
Worldwide Oblong Container Market: Beyond the 4.28% CAGR and Hidden Regional Shifts
By PW Consulting, 2026-09-18
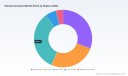
Strategic Trends and Commercial Opportunities in the Worldwide Oblong Container Market
Market Overview and Core Challenges
The worldwide oblong container market has evolved into a structurally significant segment within the broader rigid packaging industry, driven by consistent demand across consumer goods, industrial applications, and pharmaceuticals. With a total market valuation reaching approximately 1,251 million USD in 2025 and projected to advance toward 1,678 million USD by 2032, the segment reflects a compound annual growth trajectory of roughly 4.28 percent. This growth is not a simple continuation of historical expansion but rather a response to converging pressures in material economics, regulatory mandates, and application-specific performance requirements. The market has demonstrated measured resilience through cyclical demand shifts, with notable valuation stability between 2021 and 2023 before a reacceleration in recent years.
Despite this favorable trajectory, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, rising resin and metal input volatility is compressing margins for mid-tier producers and forcing earlier design-phase decisions around material substitution. Second, fragmented regulatory frameworks across major economies are accelerating the need for standardized sustainability attributes, creating compliance complexity for companies operating across multiple jurisdictions. Third, application differentiation is intensifying as end-use sectors demand containers that balance ergonomics, dispensing precision, chemical compatibility, and recyclability, narrowing the window for generic, low-differentiation product offerings. These pressures are not merely operational hurdles; they are redefining entry barriers and rewarding firms that can integrate material science, regulatory foresight, and application engineering into a single value proposition.
Worldwide Oblong Jar Market
Key Drivers Reshaping the Market
Technological innovation is no longer a peripheral advantage in this segment; it is becoming a core determinant of market share. Advances in blow molding precision, multi-layer coextrusion, and dispensing integration are enabling oblong containers that meet stricter performance criteria without proportionally increasing material weight. For manufacturers targeting personal care, household, and pharmaceutical applications, this translates into containers that can support airless mechanisms, controlled dosing, and improved barrier properties while maintaining the familiar oblong footprint preferred for shelf presence and user handling. The ability to embed functionality directly into container architecture reduces secondary packaging needs and aligns with broader sustainability objectives, creating a compounding benefit for brands seeking to meet both performance and environmental targets.
Regulatory pressure is simultaneously accelerating material transition timelines. In Europe, packaging regulations are establishing recycled content thresholds for plastic packaging that will effectively require redesigned oblong formats by the end of the decade. Parallel requirements in parts of the United States are mandating post-consumer recycled material adoption for rigid plastic containers, while extended producer responsibility frameworks in several states are shifting financial responsibility for end-of-life recovery toward producers. These developments are not isolated compliance events; they are restructuring the economics of container procurement. Companies that adopt recyclability-by-design principles and secure reliable recycled resin streams early are positioned to reduce future reformulation risk and avoid rushed transitions that often accompany late-stage regulatory deadlines.
Demand-side behavior is also shifting the competitive center of gravity. Consumer brands and industrial buyers increasingly evaluate packaging decisions through a combined lens of sustainability performance, supply reliability, and application compatibility. In the chemicals and solvents space, oblong containers must deliver chemical resistance, secure closure systems, and compatibility with industrial handling. In automotive and lubricant applications, containers are expected to support branding durability, safe transport, and efficient dispensing. Food and beverage, personal care, and pharmaceutical buyers are prioritizing material consistency, contamination control, and dispensing precision. This diversification of requirements is increasing the premium on engineered container solutions rather than commodity-style supply, pushing market value toward suppliers that can demonstrate application-specific competency.
Supply chain and cost structure dynamics complete the driver set. The cost of primary materials such as HDPE and PET has experienced measurable volatility, with HDPE resin averaging around 1,450 USD per metric ton in late 2025 and PET resin prices moving upward by roughly 8 percent year-over-year due to supply chain constraints. These fluctuations affect not only direct material costs but also the relative attractiveness of alternative material pathways and regional sourcing models. At the same time, production footprint decisions are being influenced by proximity to end markets, energy costs, and logistics resilience. Suppliers that can balance regional responsiveness with scale efficiency are gaining leverage, especially as buyers prioritize continuity of supply in addition to price competitiveness.
- Material innovation is moving from optional differentiation to baseline expectation, particularly where recycled content, lightweighting, and dispensing integration converge.
- Regulatory mandates are shifting procurement cycles toward longer planning horizons, rewarding early compliance and transparent material traceability.
- Application-specific requirements are raising the value of engineered oblong containers, reducing the share of purely commodity-oriented supply.
- Input cost volatility is reshaping sourcing strategies, increasing the importance of regional supply resilience and resin mix flexibility.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated structure in which a limited group of established players accounts for a substantial share of revenue, while regional specialists and application-focused suppliers compete on differentiation rather than scale alone. Leading companies are pursuing distinct strategic positions that reflect their material competencies, end-use focus, and integration depth. Berry Global has reinforced its presence in oblong HDPE and PET containers for personal care, household, and pharmaceutical packaging, with recent product introductions emphasizing recycled content integration for personal care applications. Amcor has focused on custom oblong plastic bottles and jars for beauty, food, and healthcare use, showcasing recyclable designs optimized for hot-fill processes at major industry events. These moves reflect a broader emphasis on recyclability and application engineering rather than volume-only competition.
AptarGroup has built advantage around dispensing and closure integration, supplying oblong dispensing containers and pumps that work with rigid packaging for cosmetics and pharmaceuticals. This positioning allows the company to participate in value creation beyond the container body itself, where dispensing functionality, user experience, and dosing precision directly influence brand preference. Gerresheimer has concentrated on oblong glass and plastic primary packaging for pharmaceuticals, including vials and bottles, an area where regulatory compliance, material purity, and dimensional consistency are especially critical. Silgan has extended its portfolio across oblong metal and plastic containers through its plastics operations, targeting personal care and household products where durability and shelf-ready presentation matter. Albea has carved out a recognizable role in skincare and cosmetics packaging by supplying oblong airless and pump-enabled plastic containers, an approach that ties container geometry to product protection and dispensing performance.
What distinguishes these leaders is not simply product breadth but the alignment of capability with regulatory and demand trends. Companies that combine material expertise, dispensing or closure integration, and application-specific validation are better positioned to support customer transitions toward recycled content, recyclable formats, and enhanced end-use functionality. This alignment is also shaping competitive dynamics: larger players are expanding integration across container bodies, closures, and dispensing systems, while application specialists are seeking partnerships or niche scale to serve sectors with stringent performance requirements. New entrants face meaningful hurdles in raw material access, process engineering, and compliance readiness, but targeted entry remains possible in high-value subsegments where dispensability, barrier properties, or pharmaceutical-grade consistency create defensible positioning. Consolidation is likely where overlapping capabilities and regional footprints create cost or capability synergies, while fragmentation will persist where end-use customization demands small-batch engineering and close customer collaboration.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the oblong container market will likely be shaped by three interconnected trends. The first is the mainstreaming of recycled content and recyclability as procurement prerequisites. As recycled content expectations rise and regional rules tighten, oblong container designs that can accommodate post-consumer resin without compromising strength, clarity, or dispensing performance will gain preference. Commercial opportunity will accrue to suppliers that can provide validated material blends, transparent traceability, and consistent lot-to-lot quality, especially in personal care, household, and pharmaceutical applications where aesthetics and functional reliability are both important.
The second trend is the continued convergence of container geometry with dispensing and closure systems. Oblong formats are well suited to ergonomics and shelf presentation, but their value will increasingly depend on how effectively they integrate pumps, airless mechanisms, and closure technologies. This will favor suppliers that can offer coordinated container-plus-dispensing solutions rather than standalone vessels. For brands, this integration can reduce development risk, improve user experience, and support premium positioning in categories such as skincare, cosmetics, and specialty chemicals. The commercial opportunity lies in co-developed solutions that shorten time to market while meeting sustainability and performance targets simultaneously.
The third trend is regional supply realignment driven by material economics, regulatory geography, and logistics considerations. As resin pricing fluctuates and producer responsibility frameworks expand, buyers will place greater emphasis on supply continuity, regional manufacturing proximity, and compliance readiness. Suppliers with diversified production footprints and flexible material portfolios will be better equipped to manage cost shocks and meet jurisdiction-specific requirements. At the same time, consolidation may accelerate among players with overlapping capabilities, while application-specific niches remain open to focused specialists. The main risk is that rapid regulatory or input-cost changes could outpace product development cycles, forcing reactive redesigns and temporary margin pressure for companies with less flexible architectures.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product portfolios with the direction of regulation and demand. This means investing in designs that can accommodate recycled content, ensuring compatibility with recyclable formats, and strengthening dispensing or closure integration where end-use applications justify it. Companies should also evaluate resin mix flexibility and regional sourcing options to reduce exposure to input volatility, while prioritizing application validation that supports customer adoption in higher-value segments.
PW Consulting
For investors, the most relevant signal is the widening gap between commodity-oriented container supply and engineered, application-integrated solutions. Capital allocation should favor businesses that demonstrate measurable progress in recycled content readiness, regulatory compliance, and functional integration, especially where those capabilities are tied to defensible end-use relationships. Monitoring M&A activity and capacity realignment will also help identify where scale synergies are being created versus where niche differentiation remains the stronger value driver.
For procurement and sourcing leaders, the imperative is to treat container selection as a multi-year strategic decision rather than a transactional purchase. Evaluating suppliers on recycled content capability, regulatory preparedness, dispensing integration, and supply resilience will reduce exposure to future reformulation and compliance risk. Longer-term partnerships with suppliers that can support coordinated design, material traceability, and application testing will typically deliver more stable outcomes than short-cycle price optimization alone.
For decision makers seeking deeper segmentation data, regional detail, and tailored scenario planning, the complete research report provides expanded breakdowns across material pathways, application categories, and competitive positioning. It also includes structured guidance for assessing investment timing, procurement strategy, and product development priorities in relation to evolving regulatory and cost dynamics.
Worldwide Bulk box Market
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soft Tissue Repair Mesh Market: 5 Strategic Shifts Reshaping Growth to $6.68B by 2032
By PW Consulting, 2026-09-18
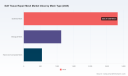
Strategic Trends and Commercial Opportunities in the Global Soft Tissue Repair Mesh Market
Market Landscape and Core Challenges
The global soft tissue repair mesh market has demonstrated resilient expansion over the past five years, establishing itself as a critical component within the broader surgical devices sector. Valued at approximately 4.5 billion USD in 2025, the market has recovered from a period of stagnation and litigation-driven caution that characterized the early 2020s. Historical trajectories indicate a steady climb from roughly 3.37 billion USD in 2020, reflecting an industry that has successfully navigated regulatory headwinds to return to a growth trajectory. Looking ahead, the market is projected to expand at a compound annual growth rate of 5.81 percent through 2032, suggesting a mature yet evolving landscape where value creation depends on innovation rather than volume alone.
Despite this positive outlook, the industry stands at a significant inflection point defined by heightened scrutiny and shifting clinical preferences. One of the primary challenges involves the complex regulatory environment surrounding product safety and transparency. While mesh products for hernia repair generally maintain Class II classification, specific applications such as transvaginal pelvic organ prolapse have faced severe restrictions due to long-term safety concerns. This dichotomy creates a fragmented market where manufacturers must differentiate rigorously between product categories to avoid reputational spill-over effects. The increased demand for transparency is reshaping how products are labeled and marketed, forcing companies to provide more clinically relevant mechanical data on packaging to facilitate safe use.
Furthermore, the market concentration remains high, with the top few players commanding a significant share of total revenue. This consolidation poses barriers to entry for smaller innovators while simultaneously pressuring incumbent leaders to maintain portfolios that satisfy diverse surgical needs. A second critical challenge lies in the reimbursement landscape. Payment rates for procedures involving mesh implantation vary widely based on complexity and setting, creating economic pressure on healthcare providers. These reimbursement constraints influence procurement decisions, often favoring cost-effective synthetic options over premium biological alternatives unless clinical outcomes clearly justify the added expense. Consequently, manufacturers face the dual challenge of proving superior clinical efficacy while navigating tight hospital budgets.
Finally, the supply chain for raw materials and manufacturing capacity remains a point of vulnerability. As demand shifts toward specialized composite and hybrid meshes, the ability to scale production without compromising quality becomes a strategic differentiator. These challenges collectively suggest that future growth will not be uniform across all segments but will instead favor companies that can balance regulatory compliance, clinical evidence, and economic efficiency.
Key Drivers of Market Change
Several fundamental factors are propelling the soft tissue repair mesh market forward, transforming it from a commodity-driven space into one defined by technological differentiation. The most prominent driver is technological innovation in material science. There is a marked shift away from traditional heavyweight synthetics toward lightweight, composite, and bioresorbable options. Manufacturers are increasingly developing meshes that integrate with host tissue more effectively, reducing foreign body responses and chronic pain. For instance, the recent regulatory clearance for electrospun fiber matrices highlights the industry's movement toward advanced structures that mimic natural tissue properties. This innovation is not merely about material composition but also about structural design, such as macroporous configurations that allow for better tissue ingrowth while maintaining mechanical strength.
Regulatory dynamics are simultaneously acting as both a constraint and a catalyst. While the FDA has tightened oversight on specific high-risk applications, the pathway for hernia repair meshes remains well-defined under the 510(k) clearance process. However, the recent draft guidance recommending standardized package labeling indicates a push toward greater transparency. This regulatory evolution forces companies to invest more heavily in clinical data generation and labeling compliance. Rather than hindering growth, this environment tends to favor larger, well-resourced organizations that can absorb the costs of compliance and clinical trials. It effectively raises the barrier to entry, consolidating the market around players who can demonstrate robust safety profiles and provide clear usage guidelines.
On the demand side, the aging global population and the rising prevalence of conditions requiring soft tissue reconstruction are driving volume. Hernia repair remains the dominant application, supported by consistent surgical rates across developed and developing regions. However, there is growing interest in pelvic organ prolapse and breast reconstruction, provided safety concerns are adequately addressed through improved product design. Surgeons are increasingly seeking solutions that reduce recurrence rates and minimize complications, which drives demand for higher-performance meshes. This shift in surgeon preference influences procurement policies, pushing hospitals to adopt products that offer long-term cost savings through reduced revision surgeries, even if the upfront device cost is higher.
Supply chain and cost structures also play a pivotal role. The pressure to reduce healthcare costs globally encourages the adoption of efficient manufacturing processes and cost-effective synthetic materials. Yet, the rise of biological and hybrid meshes suggests a premium segment is emerging for complex cases where synthetic options are contraindicated. Companies are responding by optimizing their supply chains to support diverse product lines, ranging from mass-market synthetics to specialized biologics. This dual approach allows manufacturers to capture volume in standard procedures while maintaining margins in specialized applications. The interplay between reimbursement rates and device pricing continues to shape adoption patterns, with economic factors often determining the speed at which new technologies penetrate the market.
Worldwide Hernia Mesh Devices Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large diversified medical device conglomerates and specialized niche players. The market concentration is significant, with the top three companies holding a substantial portion of total revenue. This structure implies that competitive advantage is often derived from portfolio breadth and global distribution networks rather than single-product superiority. Leading players such as Johnson & Johnson and Medtronic leverage their extensive surgical portfolios to offer comprehensive solutions, integrating meshes with fixation devices and surgical tools. Their strategy focuses on maintaining market leadership through continuous product iteration and strong relationships with surgical communities. For these giants, the ability to offer a range of options—from synthetic to composite—allows them to address various clinical scenarios while mitigating risk associated with any single product line.
Specialized manufacturers employ different strategic maneuvers. Companies like BD, formerly associated with Bard, focus on expanding portfolios that include bioresorbable options like Phasix, catering to surgeons seeking long-term safety without permanent implantation. Recent commercial launches of absorbable hernia patches highlight a strategy centered on innovation in material absorption rates and handling characteristics. Similarly, companies like TELA Bio and Organogenesis focus on regenerative medicine and reinforced tissue matrices. Their value proposition lies in providing alternatives for patients where synthetic meshes pose higher risks, thereby capturing a premium segment willing to pay for biologic properties. These players often invest heavily in clinical evidence to support reimbursement claims and differentiate themselves from standard synthetic offerings.
The landscape is also evolving through strategic partnerships and acquisitions. Larger entities often acquire innovative smaller firms to gain access to novel technologies or specific market segments without developing them internally. This trend accelerates the integration of new materials like electrospun fibers into established product lines. Meanwhile, the regulatory environment acts as a filter. Recent FDA actions regarding pelvic organ prolapse meshes have reshaped the competitive field, removing certain products from the market and redirecting demand toward safer alternatives. This dynamic benefits companies with strong compliance records and diversified portfolios that are not overly exposed to high-risk applications. The result is a market where stability and trust are becoming as valuable as technological features.
PW Consulting
New entrants face a challenging path. While the 510(k) pathway provides a mechanism for market access, the reputational risks associated with mesh products require careful positioning. Success for new players often depends on identifying underserved niches, such as specific anatomical repairs or regions with growing surgical volumes. The presence of established global players means that pricing pressure is inevitable, pushing innovators to demonstrate clear clinical advantages that command premium pricing. Overall, the competitive dynamics suggest a market moving toward consolidation among top players while allowing room for specialized innovators who can navigate regulatory complexity and prove distinct clinical value.
Future Trends and Commercial Implications
Looking toward the next three to five years, several trends are likely to define the trajectory of the soft tissue repair mesh market. First, the differentiation between synthetic and biological meshes will become more nuanced. Rather than a binary choice, hybrid and composite meshes are expected to gain prominence, offering a balance of mechanical strength and biocompatibility. This trend creates opportunities for manufacturers who can successfully engineer materials that degrade at controlled rates while providing sufficient support during the healing phase. The commercial implication is a shift in R&D focus toward material science that can justify premium pricing through reduced long-term complications.
Second, regulatory transparency will continue to intensify. The move toward standardized labeling and clearer communication of mechanical properties suggests that future market access will depend heavily on how well a product's performance is documented and communicated. Companies that proactively align with these regulatory shifts will gain trust among surgeons and procurement teams. This environment may slow the adoption of unproven innovations but will strengthen the position of established products with robust data packs. For investors, this signals a preference for assets with clear regulatory pathways and strong intellectual property protection around material composition and labeling data.
Third, regional dynamics will play an increasingly important role. While mature markets drive revenue through high-value products, emerging regions offer volume growth driven by increasing surgical access. However, reimbursement constraints in developed markets may push cost-sensitive innovations toward emerging economies. A potential risk lies in the variability of regulatory standards across regions, which can complicate global launches. Companies must balance the need for standardized products with the flexibility to adapt to local reimbursement and clinical preferences. The uncertainty surrounding long-term safety data for certain applications remains a persistent risk, potentially impacting adoption rates if new safety signals emerge. Success in this environment requires agility in product positioning and a deep understanding of local market nuances.
Worldwide Inguinal Hernia Repair Mesh Market
Strategic Actions for Decision Makers
For manufacturers, the priority should be to strengthen clinical evidence packages that support both safety and cost-effectiveness. Investing in data that demonstrates reduced revision rates or faster recovery times can justify premium positioning and align with value-based care initiatives. Companies should also monitor regulatory guidance closely to ensure labeling and marketing materials meet evolving transparency standards, reducing the risk of compliance issues.
Investors evaluating opportunities in this sector should focus on companies with diversified portfolios that are not overly reliant on high-risk applications. Technologies that offer unique material properties or clear pathways to reimbursement are more likely to sustain growth. Due diligence should include a thorough assessment of regulatory clearance status and the strength of intellectual property surrounding material innovations.
Procurement leaders and healthcare providers need to balance cost considerations with long-term patient outcomes. Selecting meshes that offer proven safety profiles and align with reimbursement structures can optimize procedure costs over time. Engaging with suppliers who provide comprehensive training and data support can also improve surgical consistency and outcomes. Access to detailed segmentation data and customized market intelligence is essential for navigating these complex decisions effectively.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Tissue Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Low Vision Devices Market: Home Care Leads the $1.1B Growth Trajectory
By PW Consulting, 2026-09-18
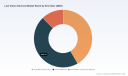
Navigating the Global Low Vision Devices Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The worldwide market for low vision devices has entered a phase of sustained expansion, driven by demographic shifts and rapid advancements in assistive technology. Valued at approximately 685.5 million USD in 2025, the market has demonstrated consistent growth over the past five years and is projected to reach 1,115.2 million USD by 2032, reflecting a compound annual growth rate of 7.2 percent. This trajectory signals more than incremental demand; it indicates a structural transformation in how vision impairment is managed across clinical, home, and rehabilitation settings. As the global population ages and chronic conditions affecting visual acuity become more prevalent, the commercial relevance of low vision solutions continues to rise across both developed and emerging economies.
Despite this favorable headline trajectory, the industry operates within a landscape of persistent structural challenges. The first challenge lies in reconciling clinical prescription pathways with real-world adoption barriers. Many low vision devices meaningfully improve daily functioning, yet end users often face fragmented access to specialized fitting, training, and follow-up care. The second challenge centers on reimbursement architecture. Public and private health programs frequently cover rehabilitation services and assistive technology instruction, but direct device procurement remains inconsistently covered. This mismatch can slow purchase cycles, shift cost burden toward patients, and complicate forecasting for manufacturers. The third challenge is fragmentation within the product ecosystem. Optical aids, electronic video magnifiers, software-driven applications, and wearable systems serve overlapping clinical needs, yet user experience, compatibility, and service expectations vary significantly across categories and channels.
The market is also undergoing a credibility test as technology claims accelerate faster than reimbursement structures and clinical integration models. Devices that deliver clearer performance benefits are entering the field, but adoption depends on more than hardware capability. It requires clinician confidence, caregiver education, and durable support ecosystems. For commercial stakeholders, the implication is clear: success will depend less on isolated product launches and more on how effectively companies reduce friction across prescription, training, reimbursement navigation, and long-term usability.
Key Demand Drivers Shaping the Market
Technological innovation is the most visible force reshaping the low vision market. Electronic video magnifiers and AI-enabled wearables are no longer competing solely on magnification strength; they are increasingly differentiating through contrast optimization, text recognition, voice interaction, and portability. Head-mounted and handheld systems are closing the gap between clinical functionality and everyday convenience, allowing users to move beyond stationary reading tasks into navigation, workplace use, and independent living. The rise of software and application-based support has also broadened the addressable use case set, enabling integration with mobile platforms, remote configuration, and personalized visual profiles. In practical terms, this means device value propositions are shifting from magnification alone to functional independence, which expands adoption potential beyond traditional eye care channels.
Policy and regulatory dynamics are shaping the pace and confidence of innovation. Device classifications under medical device frameworks create structured pathways for many electronic and optical aids, while certain lower-risk optical magnifiers remain exempt from premarket notification requirements. This regulatory stratification matters commercially because it influences time-to-market, documentation burden, and the ability to scale across jurisdictions. At the same time, growing attention to accessibility standards and vision rehabilitation support is reinforcing the legitimacy of low vision technology as a healthcare priority rather than a niche assistive category. The increasing visibility of breakthrough designations and clinical trial activity for advanced visual restoration and augmentation approaches further underscores how seriously the innovation pipeline is being taken by regulators and investors.
Demand-side behavior is evolving as clinical awareness and user expectations change simultaneously. Eye care professionals are increasingly prescribing low vision technology alongside rehabilitation services, particularly when patients face progressive conditions or functional limitations that affect reading, mobility, and work. At the same time, end users are seeking devices that fit seamlessly into daily routines rather than requiring specialized setups or constant assistance. Home healthcare environments are playing a growing role in this shift, as patients and caregivers prioritize tools that can be used independently, maintained easily, and adapted to changing visual needs. This behavioral change favors solutions that combine ease of use with demonstrable functional gains, especially when supported by training and follow-up guidance.
Supply chain and cost structure factors are introducing both pressure and strategic differentiation. Components supporting high-resolution displays, sensing, battery efficiency, and AI processing have become more central to product performance, which increases sensitivity to sourcing stability, quality control, and manufacturing complexity. At the same time, the cost of delivering device-supported rehabilitation has become a critical commercial variable. When device pricing, service expectations, and reimbursement uncertainty combine, manufacturers that offer stronger service models, clearer clinical value narratives, and adaptable product tiers can gain an advantage in procurement discussions. In this environment, cost efficiency is not simply a margin issue; it is a market-access issue.
Competitive Landscape and Leading Strategies
The competitive field in low vision devices is broad, active, and increasingly differentiated by technology orientation and go-to-market style. HumanWare has built a strong reputation around electronic video magnifiers and portable assistive devices designed for reading and daily independence, reflecting a focus on practical usability and sustained user support. Eschenbach Optik GmbH represents the high-precision optical tradition, emphasizing magnifiers, telescopic devices, and illuminated hand and stand magnifiers for professional and everyday use. Vispero, through its VFO Group, offers a broader low vision portfolio that includes CCTV and video magnifiers alongside a range of optical and electronic aids, an approach that allows it to address multiple use cases within a single ecosystem. Enhanced Vision concentrates on electronic video magnifiers with features such as text-to-speech and high-contrast imaging, positioning itself around rehabilitation-oriented functionality. Optelec develops portable and desktop video magnifiers and electronic aids, supporting both low vision and broader vision support applications.
The landscape also includes companies advancing more immersive or intelligent device forms. OrCam Technologies has pushed into AI-powered wearable devices that convert visual information into audio feedback, giving users real-time text reading and object and face recognition capabilities. This direction reflects a broader shift from passive magnification toward active visual assistance. eSight Corp. has focused on electronic eyewear and head-mounted systems that enhance functional vision through advanced imaging, appealing to users seeking hands-free and mobility-friendly solutions. Zoomax Technology produces a range of portable, handheld, and desktop video magnifiers with AI integration and tablet-based systems, illustrating how regional manufacturing strength can align with feature-rich product development. Other contributors, including LVI Low Vision International, Aumed Group Corp., Ocutech, Inc., ZEISS, IrisVision Global, and HIMS Inc., extend the competitive base across optical specialization, bioptic and telescopic design, filter and contrast-control optics, headset-based magnification with voice and OCR capabilities, and broader assistive technology offerings.
Across this set of players, strategic differentiation is emerging around four dimensions. The first is product architecture, where manufacturers choose between optical precision, electronic magnification, wearable augmentation, or software-enabled support. The second is user experience, where portability, intuitive controls, training requirements, and real-world task coverage increasingly influence purchase decisions. The third is regulatory and reimbursement positioning, where companies that proactively align with classification pathways and prescription workflows can reduce friction in clinical adoption. The fourth is ecosystem readiness, where service, fitting support, and follow-up usability become competitive assets rather than secondary operations.
Night Vision Devices Market
The market structure is evolving along two complementary paths. Consolidation is becoming more attractive for players seeking broader portfolios, stronger distribution, and improved ability to serve end users across care settings. Simultaneously, the field remains open to new entrants that bring fresh technology approaches, particularly in wearable AI, intelligent image processing, and integrated digital support. This combination of consolidation pressure and innovation-driven entry suggests that competitive advantage will increasingly depend on how well companies combine technical capability with practical clinical and consumer adoption strategies.
Future Trends and Strategic Outlook
Over the next three to five years, one of the clearest trends will be the continued migration from standalone magnification hardware toward integrated, intelligent assistance. Devices will likely become more adaptive, more connected, and more capable of supporting daily functions beyond reading, including object identification, orientation support, and digital workflow interaction. This trend expands the commercial opportunity beyond traditional low vision segments into broader accessibility-oriented use cases, especially where usability and independence are prioritized.
A second trend will be increasing pressure on reimbursement and access pathways to catch up with product innovation. As devices become more clinically meaningful and more technologically advanced, stakeholders will likely push harder for clearer coverage logic, stronger rehabilitation integration, and better alignment between prescribed services and device purchase models. Companies that invest early in evidence generation, clinician education, and reimbursement navigation will be better positioned to convert innovation into durable demand.
A third trend will be portfolio and channel convergence. The line between optical aids, electronic magnifiers, software support, and wearable systems will continue to blur as users seek flexible solutions that adapt to changing vision levels and living environments. This creates opportunities for manufacturers to design modular product strategies, cross-sell across care settings, and build offerings that support both clinical use and home-based independence.
Still, uncertainty remains. Regulatory pathways can affect launch timing and documentation requirements. Reimbursement inconsistency can slow volume growth, especially in segments where device cost is highly visible. In addition, rapid feature escalation can raise expectations and complicate clinical integration if support, training, and interoperability are not addressed with equal seriousness. The market’s upside is significant, but it will be captured by organizations that can translate technology leadership into practical adoption.
Strategic Actions for Decision Makers
For device manufacturers, the priority should be aligning product roadmaps with adoption friction rather than feature count alone. That means investing in usability, training support, clinician-facing evidence, and reimbursement-friendly positioning as core commercial capabilities. Differentiating through ecosystem strength: fitting, service, compatibility, and long-term user engagement can be as important as the next technical enhancement.
PW Consulting
For investors, the most compelling opportunities are likely to sit at the intersection of intelligent assistance, wearable form factors, and rehabilitation integration. Due diligence should focus not only on technical novelty, but also on regulatory readiness, reimbursement exposure, channel access, and the ability to scale support infrastructure. Companies that can demonstrate real-world functional value and clear access pathways are better positioned for sustained traction.
Assistive Technologies for Visual Impairment Market
For procurement and care-program leaders, the practical opportunity is to treat low vision devices as part of a broader rehabilitation strategy rather than isolated purchases. Selecting solutions with stronger training support, clearer outcome expectations, and compatibility with home healthcare or clinic-based workflows can improve adoption consistency and long-term value. Structured evaluation across clinical benefit, usability, service model, and reimbursement fit will reduce downstream implementation risk.
Detailed segmentation data, company-level positioning, and region-specific commercial dynamics can sharpen these decisions further, especially for teams evaluating product entry, partnership structures, or investment theses in a market that is expanding quickly but remains operationally complex.
For detailed analysis of this topic, please visit the official page: Worldwide Low Vision Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Heavy-Duty Wear Protection Materials Market: Asia Pacific Dominance and 5.85% Growth Redefining 2032
By PW Consulting, 2026-09-18
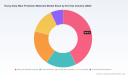
Strategic Shifts and Commercial Opportunities in the Global Heavy-Duty Wear Protection Materials Market
Market Status and Core Challenges
The global heavy-duty wear protection materials market has demonstrated resilient growth over the past five years, expanding from approximately $1.38 billion in 2020 to an estimated $1.85 billion in 2025. This trajectory reflects a compound annual growth rate of 5.85 percent through 2032, with revenue projections reaching $2.75 billion by the end of the forecast horizon. Such expansion underscores a structural shift: wear protection is no longer treated as a routine maintenance commodity but as a strategic operational lever that directly impacts asset longevity, downtime reduction, and total cost of ownership across heavy industries.
Beneath these headline figures, several structural tensions are reshaping how organizations evaluate and deploy wear-resistant solutions. First, the market is experiencing a pronounced performance-versus-cost optimization challenge. Operators in mining, cement, and power generation face mounting pressure to extend maintenance intervals while avoiding excessive upfront capital expenditure. This has accelerated demand for engineered hybrid materials that balance abrasion resistance, impact tolerance, and installability, forcing procurement teams to evaluate lifecycle economics rather than unit pricing alone.
Wear Resistant Steel Market
Second, raw material volatility and supply chain fragmentation continue to test margin stability. Advanced ceramics, high-alloy steels, and engineered polymers rely on energy-intensive processing and geographically concentrated feedstock networks. Fluctuations in energy costs, logistics bottlenecks, and regional manufacturing capacity constraints have introduced unpredictability into lead times and pricing structures. Companies that depend on single-source sourcing or rigid specification frameworks are encountering disproportionate exposure to these disruptions.
Third, the regulatory and sustainability agenda is altering material selection criteria. Environmental evaluations of cast wear protection alloys increasingly compare traditional cobalt-, nickel-, and iron-based formulations against lower-impact iron aluminide and alternative composite approaches. While performance requirements in extreme abrasion and high-temperature environments remain non-negotiable, procurement specifications are gradually incorporating lifecycle carbon considerations, recycling pathways, and compliance documentation into vendor qualification processes. These converging pressures are pushing the market past a transition point where incremental material upgrades are being replaced by systematic engineering and sourcing redesigns.
Key Drivers Shaping Market Dynamics
Technological innovation remains the most visible catalyst for market evolution. Material science advancements have shifted the performance ceiling for abrasion-resistant solutions, particularly in ceramic and composite segments. Alumina and silicon carbide continue to serve as primary feedstocks for advanced ceramics deployed in heavy-duty linings, delivering exceptional hardness and thermal stability in high-wear environments. Simultaneously, engineered polymer systems, including polyurethane-based liners and ceramic-filled epoxy coatings, have expanded the solution envelope for applications where spray-applied repair, conformability, and rapid reinstatement are critical. The result is a broader toolkit that enables engineers to match material architecture to specific wear mechanisms rather than applying uniform protective layers across dissimilar operating conditions.
PW Consulting
Policy and regulatory developments are reinforcing this technical diversification. Environmental scrutiny around alloy composition, energy-intensive manufacturing, and end-of-life material handling is influencing both product design and procurement standards. Industry evaluations increasingly compare conventional hardfacing alloys with sustainable iron aluminide alternatives, especially where regulatory reporting, emissions tracking, and responsible sourcing requirements are tightening. This does not eliminate high-performance alloys from consideration, but it encourages specification teams to document environmental impact alongside mechanical performance, gradually shifting vendor selection toward suppliers with transparent material credentials and validated sustainability pathways.
Demand-side behavior is changing as well. Operators are prioritizing predictive maintenance and condition-based replacement strategies over reactive repairs. In mining and mineral processing, cement and construction, and power generation, equipment downtime carries steep production penalties, making wear protection a direct contributor to operational continuity. This mindset favors materials and installation methods that reduce intervention frequency, simplify field repair, and integrate with monitoring programs. Companies are also demanding more consistent performance data, accelerated testing results, and application-specific validation rather than relying solely on generic laboratory benchmarks.
Supply chain and cost structure shifts are amplifying these demand-side expectations. Regionalization of manufacturing, nearshoring of service capabilities, and greater emphasis on inventory resilience are reshaping how wear protection products reach end users. Lead-time reliability, localized technical support, and adaptable product formats are becoming competitive differentiators alongside raw material pricing. At the same time, the need to maintain high wear resistance in steel, cement, and power plant environments has sustained strong demand for materials that can withstand severe abrasion without frequent replacement. Organizations that can combine material performance with responsive supply and installation support are capturing disproportionate share in applications where downtime costs dominate procurement decisions.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a concentration of specialized material suppliers and industrial solution providers, with the top three players accounting for roughly a third of total market revenue and the top five representing just under half. This structure reflects a market where technical credibility, application-specific engineering, and installed-base relationships matter as much as scale. Leading organizations are competing on differentiated value propositions rather than on product commoditization alone.
Several strategic archetypes are emerging among incumbent players. One group emphasizes advanced ceramic and refractory expertise, positioning high-hardness alumina, silicon carbide, and zirconia-toughened formulations as the default choice for extreme abrasion and thermal stress. These suppliers typically focus on engineered linings, custom shapes, and stringent quality control to serve demanding sectors such as mining, cement, and power generation. Their advantage lies in material science depth, repeatable performance in severe environments, and the ability to tailor formulations to specific wear profiles.
A second archetype centers on composite, coating, and hardfacing solutions designed for repair, retrofit, and rapid field application. Polyurethane liners, chrome carbide overlay plates, ceramic-filled epoxy systems, and hardfacing alloys address applications where installability, impact resistance, and on-site reinstatement are prioritized over monolithic ceramic performance. Companies in this segment often compete through application engineering, field service coverage, and the ability to extend equipment life without full component replacement. Their differentiation comes from bridging the gap between laboratory-grade material performance and practical operational deployment.
A third strategic orientation integrates wear protection into broader equipment ecosystems. The strongest players combine proprietary liner technologies with equipment design, wear monitoring guidance, and maintenance planning. By embedding wear solutions into chutes, hoppers, mills, and conveying systems, they create switching costs and long-term service relationships. This model is particularly effective in mining and mineral processing, where wear patterns are predictable enough to support engineered upgrades that reduce recurring replacement cycles.
Wear Plate Market
Market evolution is moving toward selective consolidation and capability expansion. Larger industrial suppliers are acquiring or partnering with specialized material formulators to broaden their application coverage and geographic reach. At the same time, smaller firms with niche formulations, regional service footprints, or proprietary installation methods continue to compete by serving high-value applications where customization outweighs scale advantages. New entrants are most likely to succeed where they bring genuine material innovation, validated field data, or digitally enabled service models that shorten diagnostic and replacement cycles. The overall trend is fragmentation at the application level combined with consolidation at the strategic level, as buyers increasingly prefer partners who can deliver consistent performance across multiple assets and sites.
Future Trend Forecasts
Over the next three to five years, one defining trend will be the acceleration of hybrid and engineered composite wear systems. Monolithic solutions will remain necessary for the most extreme environments, but many applications will shift toward layered or blended architectures that combine ceramic hardness, polymer toughness, and steel reinforcement where appropriate. This approach enables more precise matching to abrasion, impact, and thermal conditions while reducing installation complexity and enabling partial repairs rather than full component swaps. Commercial opportunity lies with suppliers that can standardize modular system designs, provide clear performance comparison frameworks, and support faster field reinstatement.
A second trend will be the growing integration of wear protection decisions into lifecycle and sustainability planning. Procurement and engineering teams are expected to weigh material composition, manufacturing energy intensity, repairability, and end-of-life handling alongside traditional performance metrics. This creates openings for vendors that can supply lower-impact alloy alternatives, recyclable composite formats, or coatings that extend service life with reduced material input. The risk is that sustainability requirements may outpace standardized testing and reporting norms, creating uneven compliance burdens for suppliers operating across multiple jurisdictions. Companies that move early to document environmental performance and align specifications with operational realities will be better positioned to navigate evolving expectations.
A third trend is the shift toward predictive wear management and service-integrated offerings. As condition monitoring, sensor data, and maintenance analytics become more accessible, wear protection will increasingly be specified as part of a broader uptime strategy rather than as a standalone material purchase. Suppliers that combine durable materials with installation expertise, replacement forecasting, and site-specific wear mapping will capture stronger customer retention. The principal uncertainty is the pace at which smaller operators adopt data-driven maintenance practices and whether labor constraints and skill gaps limit the speed of more advanced wear management deployments.
Strategic Recommendations for Decision Makers
Manufacturers and material suppliers should prioritize application-specific validation and lifecycle-oriented messaging. Investing in field data, comparative performance documentation, and modular system designs will help differentiate offerings in a market where buyers are scrutinizing total cost of ownership rather than unit price. Expanding regional service capability and technical support can also reduce exposure to supply chain volatility while strengthening customer retention.
Investors should look for participants with defensible technical positioning, diversified end-use exposure, and the ability to integrate material performance with service or equipment ecosystems. Companies that can navigate raw material constraints, incorporate lower-impact material options without compromising performance, and capture recurring maintenance demand are likely to deliver more resilient growth than those competing solely on commodity pricing.
Procurement and operations leaders should evaluate wear protection suppliers based on installed performance, repairability, and responsiveness rather than catalog specifications alone. Establishing clear wear mechanism profiles for critical assets, standardizing qualification criteria that include environmental and maintenance considerations, and building relationships with suppliers capable of supporting predictive replacement cycles can materially reduce unplanned downtime. For organizations seeking deeper segmentation data, regional demand patterns, competitive benchmarking, and tailored sourcing or investment scenarios, accessing a comprehensive market study provides the granularity needed to convert these strategic themes into executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy-Duty Wear Protection Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Container Vans Market: Why 4.35% CAGR and Asia Pacific Growth Redefine Future Returns
By PW Consulting, 2026-09-18
The Worldwide Container Vans Market: Navigating Growth, Geopolitics, and Industrial Transformation Through 2032
The global container vans market has evolved from a cyclical, commodity-driven sector into a strategically critical component of international trade and logistics infrastructure. Over the past five years, the market has demonstrated resilience amid shifting trade patterns, supply chain reconfiguration, and tightening environmental standards. Measured in USD across the baseline year of 2025 and extending through the forecast horizon to 2032, the industry reflects a steady, structurally anchored trajectory. Revenue figures spanning the historical period from 2020 through 2025 reveal a market that absorbed the turbulence of pandemic-era disruptions, rebound in global freight volumes, and gradually stabilized into a more predictable growth environment. Entering the forecast window, the market is expanding at a compound annual growth rate of approximately 4.35 percent, with total revenue values projected to cross the mid-point of the next decade at a scale that underscores the enduring role of standardized containerized transport in global commerce.
This expansion is not merely a function of increased freight tonnage. It reflects deeper structural shifts in how goods move across maritime routes, inland corridors, and multimodal gateways. The container van has become the foundational unit of intermodal efficiency, enabling seamless transfers between ocean carriers, rail networks, and trucking fleets. Yet, beneath the headline growth trajectory, the industry is navigating a period of pronounced transition. Capacity utilization patterns, regional trade realignments, and the economics of manufacturing consolidation are reshaping competitive dynamics. Stakeholders across the value chain are confronting a landscape where scale, cost discipline, and specification differentiation increasingly determine long-term positioning.
Several interrelated challenges define the current inflection point. First, the sector operates under intense cost pressure tied to the volatility of core input materials. The economics of container production remain tightly coupled to steel pricing, and fluctuations in metallurgical markets transmit directly into manufacturing margins, pricing strategies, and order book planning. Second, the industry must reconcile sustained demand growth with evolving compliance and safety requirements that govern structural performance, load ratings, and international approval standards. Containers that fail to meet recognized testing protocols or safety certifications face exclusion from global service networks, making regulatory alignment a non-negotiable operational baseline. Third, the market is experiencing a gradual divergence in demand profiles across application areas. The core volume driver remains firmly anchored in maritime shipping, where standardized units enable high-throughput port operations and dense vessel utilization. At the same time, land transport corridors are generating incremental demand for durable, road-compliant units that support inland distribution and cross-border logistics, while storage and modular construction applications create niche but meaningful utilization pathways for surplus and repurposed inventory. These overlapping pressures require operators to balance volume ambitions with cost control, compliance rigor, and application-specific engineering.
Key Forces Propelling Market Evolution
The trajectory of the container vans market is being shaped by a set of reinforcing drivers that extend well beyond simple freight volume growth. Understanding these forces is essential for decision-makers seeking to align capacity planning, procurement strategy, and investment priorities with where the market is actually heading.
Technological innovation and manufacturing precision have become central to competitive differentiation. While the fundamental design of the container van remains anchored in ISO-compliant geometry, advances in fabrication workflows, material utilization, and quality assurance are reshaping cost structures and product consistency. High-volume producers have progressively integrated more controlled welding processes, automated inspection routines, and tighter tolerance management to reduce structural variability and improve durability under repeated loading cycles. These improvements matter because container vans are subject to harsh operational environments, including salt exposure, stacking pressure, and repeated handling across congested terminal operations. Manufacturers that can deliver more consistent structural performance while containing unit costs are better positioned to secure long-term supply agreements with shipping lines and freight forwarders that prioritize reliability and reduced maintenance downtime.
Policy and regulatory frameworks continue to impose discipline on the market, but they also function as a filter that rewards operational maturity. International standards governing testing, structural integrity, and load ratings establish a common technical language for container performance, enabling interoperability across global shipping networks. Safety approval regimes administered through national authorities reinforce this baseline by ensuring that units in international service meet defined structural and handling requirements. For manufacturers and operators alike, compliance is not a peripheral activity; it is an integral part of market access. The implication is that regulatory alignment increasingly rewards scale producers with established certification pipelines and repeatable quality systems, while raising the barrier for entrants that lack the institutional capacity to manage documentation, testing, and audit traceability efficiently.
Demand-side behavior is shifting in ways that extend beyond headline trade growth. The continued expansion of e-commerce and complex multinational supply chains has reinforced the need for standardized, rugged, and easily transferable container units that support rapid modal switching. Buyers are increasingly attentive not only to acquisition cost but also to lifecycle performance, including resistance to corrosion, structural fatigue, and handling wear. At the same time, shipping lines and logistics providers are evaluating container fleets through a broader operational lens, weighing factors such as stackability, space optimization on vessel cells, and the ability to maintain service reliability under variable port conditions. These preferences gradually elevate the importance of specification quality and consistency over pure price competition, particularly in segments where operational downtime or cargo integrity carries high financial risk.
Supply chain and cost structure dynamics represent the most immediate pressure point. Steel remains the dominant raw material in container van production, and the economics of manufacturing are closely linked to steel price behavior and regional availability. In the recent operating environment, steel pricing in major industrial markets has reflected the combined influence of infrastructure demand, energy input costs, and trade flow patterns, sustaining moderate volatility into the near term. Because new production costs track these material inputs closely, manufacturers face a continuous challenge in managing margin stability while preserving competitive pricing for volume customers. This dynamic is magnified by the concentration of manufacturing capacity in key production regions, which can amplify the impact of localized demand swings, logistics bottlenecks, or input scarcity. The resulting environment favors operators with disciplined procurement strategies, diversified sourcing options, and the ability to pass through or absorb cost fluctuations without disrupting order fulfillment.
Competitive Landscape and Strategic Positioning
The competitive architecture of the container vans market is characterized by a high degree of concentration among established manufacturers with broad production scale, global distribution reach, and strong integration with shipping and logistics networks. This concentration is not accidental; it reflects the capital intensity of container manufacturing, the importance of certification and compliance infrastructure, and the value that large buyers place on dependable supply and uniform specification quality.
Several major producers illustrate the dominant strategic models in the market. Large-scale manufacturers headquartered in China have built global leadership by emphasizing high-volume output of ISO-compliant dry van and specialized units, supported by multiple production facilities designed to serve international intermodal demand. Their advantage lies in the ability to combine scale, breadth of product range, and efficient cost structures while maintaining close links to port infrastructure and shipping line procurement cycles. Other significant players have pursued similar strategies with varying degrees of specialization, expanding their offerings across dry freight, special-purpose, and container van products to capture demand across both standard and differentiated applications. Meanwhile, select European-linked producers have positioned around higher-specification and refrigerated container vans, emphasizing quality, durability, and integration with broader logistics operations. This specialization matters because reefer and high-performance units typically command different procurement logic, with greater emphasis on thermal performance, equipment reliability, and lifecycle service support.
PW Consulting
Differentiation in this market is increasingly defined by three overlapping dimensions. The first is scale and supply reliability. Large buyers prioritize manufacturers who can meet sustained order volumes without disruption, particularly when fleet replacement cycles and network expansion plans require predictable delivery schedules. The second is specification performance and compliance maturity. Operators that can demonstrate consistent structural integrity, standardized testing alignment, and robust safety approval processes gain an advantage in segments where service continuity and cargo protection are critical. The third is application-specific engineering and product breadth. As demand evolves across maritime shipping, land transport, and storage or modular construction use cases, manufacturers with the ability to tailor unit configurations while preserving core standardization can capture value beyond undifferentiated volume competition.
The market structure also shows signs of gradual evolution. Consolidation pressures remain relevant where scale economies, certification overhead, and global distribution requirements favor larger, well-capitalized producers. At the same time, segmentation continues to create space for focused players that serve specific application niches or regional demand pockets. New entry remains challenging due to the combination of material cost exposure, compliance burden, and the importance of entrenched buyer relationships, but it is not impossible for producers that bring clear cost advantages, specialized engineering capabilities, or strategic alignment with emerging logistics corridors. The overall direction points toward a landscape where competitive advantage is less about isolated unit pricing and more about the integration of manufacturing discipline, product reliability, and customer-specific service model alignment.
Forward Outlook: Three Trends Shaping the Next Era
The next three to five years are likely to be shaped by a combination of demand momentum, cost discipline, and operational specialization. Several trends stand out as particularly consequential for strategic planning.
Steady growth anchored in intermodal standardization. Global trade activity and e-commerce-driven logistics complexity are expected to continue supporting demand for standardized container vans that enable efficient movement across sea, rail, and road. The market’s projected compound growth trajectory reflects this foundational role rather than speculative expansion. The opportunity here lies not simply in volume but in capturing demand from corridors and customer segments where reliability, turnaround speed, and fleet consistency deliver measurable operating advantages.
Cost volatility as a permanent management challenge. Because production economics remain closely linked to steel pricing and manufacturing concentration patterns, material cost volatility is likely to persist as a central operational concern. The strategic response will increasingly involve procurement diversification, inventory and order timing optimization, and pricing frameworks that protect margin without eroding customer relationships. Companies that treat input cost management as a core capability rather than a periodic reaction will be better positioned to navigate fluctuations without sacrificing competitiveness.
Specification and application differentiation gaining relative importance. As maritime shipping continues to anchor the largest share of demand, growth opportunities will also emerge from land transport intensifications and storage or modular construction utilization. These segments create incremental value for units with specific durability characteristics, handling resilience, or configuration flexibility. Over time, the market is likely to reward manufacturers and buyers who can match product attributes to application requirements rather than relying on uniform, lowest-common-denominator procurement. This shift creates opportunities for targeted product development, more precise fleet planning, and stronger supplier-customer alignment around operational objectives.
Worldwide Container Dumper Market
These trends carry embedded uncertainty. Trade policy shifts, port congestion dynamics, energy and input cost shocks, and the pace of logistics network modernization can all alter regional demand patterns and procurement timing. Similarly, any acceleration in regulatory expectations around safety, testing, or lifecycle performance would raise the operational bar for market participation. Decision-makers should therefore treat the medium-term outlook as directional rather than deterministic, using scenario planning to evaluate how shifts in trade flows, material costs, and compliance requirements might affect capacity deployment and sourcing choices.
Container Leasing Market
Strategic Implications for Key Stakeholders
For manufacturers and producers, the priority is to reinforce the strategic value of scale, compliance maturity, and specification consistency. Investing in process control, quality traceability, and application-aligned product breadth can strengthen positioning with buyers who increasingly assess total operational value rather than unit price alone. Proactive management of material cost exposure and delivery reliability should be treated as central competitive capabilities, especially in an environment where input volatility and concentration amplify margin risk.
For investors and capital allocators, the market presents a profile of steady structural demand combined with concentration and cost sensitivity. Opportunities are most compelling where operators demonstrate durable manufacturing efficiency, broad product capability, and the ability to serve high-value segments such as refrigerated or higher-specification container vans. At the same time, exposure to raw material volatility and regional demand cyclicality warrants disciplined due diligence on cost management, customer concentration, and the resilience of order pipelines across different trade environments.
For procurement leaders and logistics operators, the strategic emphasis should shift from transactional price comparison toward fleet performance, service continuity, and specification fit. Aligning container procurement with actual operational requirements across maritime, land, and storage or modular use cases can reduce downstream risk and improve total cost outcomes. Building stronger visibility into supplier production capacity, certification standing, and material sourcing strategy can also improve resilience when demand spikes or input markets become unsettled.
For executives seeking to act on these dynamics with precision, detailed segmentation data, pricing context, regional demand patterns, and company-level benchmarks provide the kind of granular intelligence that supports targeted capital allocation, sourcing strategy, and product planning. A comprehensive market report can help translate the broad structural trends outlined here into decision-ready detail tailored to specific segments and operational priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Container Vans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Uncooled Infrared Detector Housing Market: Why 8.11% CAGR Reshapes Competition
By PW Consulting, 2026-09-18
Navigating the Global Uncooled Infrared Detector Housing Market: Strategic Shifts and Commercial Pathways
Market Landscape and Core Challenges
The worldwide market for uncooled infrared detector housings has entered a phase of sustained expansion, driven by the broader adoption of thermal imaging across defense, industrial, and commercial sectors. Revenue has grown consistently from the early 2020s through the base year of 2025, with the trajectory pointing toward a robust forecast window extending to 2032. At the heart of this growth is the continuous reduction in size, weight, power, and cost (SWaP-C) requirements, which has made uncooled microbolometer technology viable for an expanding range of applications. The sector's compound annual growth rate reflects both organic demand pull and structural improvements in packaging and integration methodologies, positioning housings not merely as protective enclosures but as critical enablers of performance, reliability, and miniaturization.
Worldwide Microbolometer Infrared Detector Market
Despite the positive momentum, the industry confronts a set of interconnected challenges that will shape competitive outcomes over the next several years. The first revolves around the tension between performance thresholds and supply chain accessibility. As applications demand lower noise-equivalent temperature difference (NETD) values and higher resolution formats, packaging architectures must preserve thermal stability, mechanical resilience, and signal integrity while accommodating tighter dimensional constraints. This creates a technical bottleneck for manufacturers that cannot simultaneously optimize vacuum integrity, material compatibility, and high-volume yield. The second challenge stems from regulatory and export control dynamics. Performance-based restrictions on certain detector classes have introduced additional qualification cycles and constrained the flow of advanced components across borders, forcing suppliers to navigate divergent compliance regimes depending on end-use and destination markets. The third challenge is the pressure on cost structures amid intensifying competition. As wafer-level and ceramic packaging approaches mature, incumbents and new entrants alike must reconcile the economics of high-precision manufacturing with the expectation of lower unit costs, particularly in price-sensitive commercial and consumer-adjacent segments.
These pressures are not merely operational; they redefine how value is captured in the housing segment. Suppliers that treat packaging as a commodity risk margin erosion, while those that integrate housings with detector design, thermal management, and application-specific qualification can command premium positioning. The market's concentration among leading players underscores the importance of scale, technical know-how, and long-term qualification relationships. Yet the same concentration also signals opportunity for differentiated entrants that can address regional demand nuances, leverage localized production, or offer packaging solutions that reduce integration friction for system integrators. For decision-makers, the central question is no longer whether the market is growing, but which packaging pathways, qualification strategies, and geographic footprints will determine competitiveness in an environment where performance, cost, and compliance must be balanced simultaneously.
Key Drivers Reshaping the Market
Technology Innovation and Packaging Architecture Evolution
The most consequential driver is the ongoing evolution of packaging technologies that directly determine detector performance, durability, and integration cost. Ceramic packaging has emerged as a preferred pathway for many uncooled infrared detectors because it combines mechanical robustness with design flexibility, enabling miniaturization without sacrificing reliability. Optimized ceramic structures have demonstrated the ability to reduce material volume and overall footprint while preserving mechanical integrity under demanding vibration and shock conditions, making them suitable for mobile, airborne, and field-deployed systems. At the same time, wafer-level vacuum packaging is gaining traction for high-volume production of entry-level and mid-tier thermal imaging modules. By moving vacuum encapsulation closer to the wafer process, suppliers can significantly lower assembly complexity and integration cost, supporting mass deployment in applications where SWaP-C is the dominant selection criterion. The coexistence of ceramic and wafer-level approaches reflects a broader segmentation logic: high-performance and mission-critical use cases continue to favor robust ceramic carriers, while volume-driven commercial applications increasingly adopt wafer-level formats to achieve cost thresholds that unlock new market pockets.
Policy, Export Controls, and Compliance as Strategic Variables
Regulatory and export control environments are increasingly shaping technology roadmaps and supply chain decisions. Performance-based thresholds on detector sensitivity and related specifications have introduced compliance considerations into packaging qualification, influencing which architectures can be supplied to specific end-use markets and geographies. For manufacturers, this means that packaging strategies must account not only for technical performance but also for the documentation, traceability, and qualification pathways required in defense, homeland security, and certain industrial deployments. These dynamics can lengthen qualification cycles and narrow the pool of eligible suppliers for advanced applications, reinforcing the value of established relationships and proven reliability records. At the same time, the evolving policy landscape encourages regional diversification, as system integrators seek to de-risk supply by qualifying multiple packaging sources and maintaining flexibility across different compliance regimes.
Demand-Side Shifts Across Application Verticals
Demand is expanding beyond traditional defense and security applications into industrial thermography, advanced driver-assistance systems, and a growing set of commercial imaging solutions. Automotive ADAS is a particularly influential driver, as thermal imaging is increasingly evaluated for low-visibility detection and pedestrian recognition in safety-critical contexts. This application trajectory pushes packaging requirements toward compact form factors, thermal stability under vehicular conditions, and cost profiles compatible with volume production. Industrial and thermography applications, meanwhile, reward housings that support consistent performance across varied environmental conditions and that can be integrated into portable or fixed inspection systems with minimal re-engineering. In security and surveillance, the trend favors smaller, lower-power modules that can be embedded into networked camera platforms, drones, and mobile monitoring solutions. Together, these demand shifts are broadening the base of end-users and forcing packaging suppliers to develop application-tailored variants rather than relying on a single standardized offering.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are intensifying as multiple manufacturing hubs expand capabilities in metal, ceramic, and wafer-level packaging. In Asia-Pacific, domestic production lines for vanadium oxide-based uncooled detectors across multiple packaging formats have supported more competitive pricing and shorter lead times for regional system integrators. This localization trend is reinforced by the desire to reduce exposure to cross-border constraints and to align supply with regional demand growth. However, cost competitiveness must be balanced against reliability and qualification expectations, particularly where applications require proven mechanical and thermal performance. Suppliers that can demonstrate high-yield manufacturing, consistent vacuum integrity, and robust test protocols are better positioned to protect margins even as unit prices face downward pressure. The broader effect is a market in which scale, process control, and application-specific validation are becoming the primary levers for commercial success, rather than packaging alone as a discrete component sale.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established defense-linked suppliers, regional specialists, and packaging-focused manufacturers that serve the broader uncooled detector ecosystem. Leonardo DRS stands out for its work in leadless chip carrier and wafer-level vacuum packaging for uncooled vanadium oxide long-wave infrared microbolometers, supporting high-resolution formats for both defense and commercial thermal imaging. Its strategic positioning emphasizes proven packaging reliability and the ability to scale sophisticated architectures for demanding applications, including ongoing development toward higher-resolution focal plane arrays. This approach reflects a broader pattern among top-tier suppliers: differentiation comes from integrating packaging expertise with detector performance roadmaps and from maintaining qualification depth in mission-critical use cases.
Global Sensor Technology, associated with Wuhan Guide Infrared, illustrates a volume-and-flexibility strategy. By offering metal, ceramic, and wafer-level packages across multiple resolutions, the company targets high-volume production with an emphasis on SWaP-C optimization and integration into thermal modules. Its recent introduction of ceramic-packaged uncooled infrared detectors using mainstream technology highlights a push toward improved reliability and cost performance, reinforcing the idea that packaging choices are increasingly tied to application economics. For commercial and industrial customers, this type of multi-format capability can reduce integration risk and provide a path to cost-down without abandoning performance requirements.
European and Israeli suppliers contribute additional differentiation through high-performance formats and compact pixel pitch technologies. Lynred has expanded its uncooled microbolometer portfolio with ceramic packaging options for aerospace, defense, and industrial applications, and its move toward smaller pixel pitch architectures signals a focus on resolution and portability for advanced thermal imaging. SCD complements this landscape with low SWaP-C ceramic-packaged detectors aimed at military, homeland security, and industrial deployments, emphasizing form factors and performance attributes suited to specialized end-use scenarios. These players illustrate how regional technology strengths and application histories shape packaging strategies, with a shared emphasis on reliability, performance consistency, and the ability to support higher-resolution or smaller-format trends.
In South Korea, i3system manufactures uncooled infrared detectors for commercial and military thermal imaging, including formats designed for security, surveillance, and night vision systems. Its footprint demonstrates how regional champions can serve both domestic demand and export markets by aligning packaging and detector capabilities with application-driven requirements. Meanwhile, specialized packaging suppliers such as Hebei Sinopack and Hefei Shengda focus on ceramic and electronic packaging components tailored to uncooled infrared focal plane detectors, supporting night vision, security, and monitoring applications. Their role highlights an important structural dynamic: the housing and packaging segment is not served only by detector manufacturers, but also by suppliers whose core competency lies in precision packaging, thermal management, and mechanical integration. Kyocera adds another dimension with ceramic packages and lids for optical and infrared sensors, including surface-mount designs that replace traditional can-style packages. Its emphasis on miniaturization and thermal management reflects an industry-wide shift toward form factors that simplify integration and support higher packaging density.
Taken together, the competitive landscape is evolving along three axes. First, consolidation of capability is occurring among suppliers that can combine detector know-how, vacuum packaging expertise, and qualification depth, especially for higher-resolution and defense-adjacent applications. Second, segmentation is intensifying as ceramic, wafer-level, and metal packaging each find distinct footholds depending on performance, volume, and cost priorities. Third, new entry opportunities exist for companies that can deliver packaging solutions reducing integration friction, supporting regional supply resilience, or enabling cost thresholds for emerging commercial applications. For system integrators and end-product manufacturers, the implication is clear: supplier selection is increasingly a strategic decision that affects not only component cost, but also qualification timelines, application fit, and long-term flexibility across performance tiers and geographies.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most important trends will be the continued migration toward smaller pixel pitches and higher-resolution formats in uncooled microbolometer families. As packaging architectures adapt to these tighter geometries, housings will need to preserve thermal stability, vacuum integrity, and mechanical resilience at reduced scales. This trend creates commercial opportunity for suppliers that can deliver compact, high-reliability packages suitable for portable and high-resolution thermal imaging, where size and performance are jointly decisive. It also raises the bar for process control, because yield and consistency become more sensitive as formats shrink and packing density increases.
A second trend is the widening of volume-driven commercial applications, particularly where SWaP-C thresholds open new adoption pathways. Wafer-level vacuum packaging and optimized ceramic designs are well positioned to support high-volume production and lower integration costs, making thermal imaging more accessible for security, industrial, and certain consumer-adjacent use cases. The commercial opportunity here lies in packaging solutions that standardize interfaces, simplify module integration, and reduce qualification burden for platform manufacturers seeking to deploy thermal imaging at scale. Suppliers that can provide repeatable, cost-effective housings with predictable performance will be better positioned to capture demand in these expanding segments.
A third trend is the growing importance of regional supply resilience and compliance-aware sourcing. As export controls and performance-based restrictions influence which components can be supplied to specific markets, system integrators and OEMs will increasingly pursue multi-source strategies and regional qualification pathways. This creates opportunity for packaging suppliers with localized production, flexible compliance documentation, and the ability to support different end-use regimes. At the same time, uncertainty remains. Regulatory shifts, raw material and process cost volatility, and the risk of quality or yield challenges in advanced packaging formats can all affect timing and margin. The companies that navigate this environment most effectively will be those that treat packaging not as a static enclosure, but as a strategic interface between detector performance, application economics, and supply chain risk management.
Strategic Recommendations for Decision-Makers
For packaging and detector manufacturers, the priority is to align packaging roadmaps with the performance-versus-cost curve that different applications demand. This means investing in process maturity for both ceramic and wafer-level pathways, strengthening vacuum integrity and mechanical validation, and developing application-specific variants that reduce integration effort for system builders. Companies should also evaluate where miniaturization, pixel pitch reductions, and higher-resolution formats create openings for differentiated housings, and where volume economics require a more standardized, cost-optimized approach. Building qualification depth and documentation rigor will be especially valuable where compliance cycles and performance thresholds shape purchasing decisions.
Infrared Detector Market
For investors, the most promising signals lie in suppliers that combine scalable manufacturing with clear application focus and compliance-aware supply strategies. Attention should be paid to firms that can demonstrate yield consistency, multi-format capability, and the ability to serve both specialized and volume markets without compromising reliability. Regional production momentum, particularly where domestic lines support cost-competitive supply while maintaining qualification relevance, is another important indicator of resilience. In a market where concentration is meaningful but segmentation is deepening, capital allocation should favor businesses with defensible process expertise and clear pathways to integration into high-growth application verticals.
For procurement and strategic planning teams, supplier selection should extend beyond unit price to include integration complexity, qualification timelines, mechanical and thermal reliability, and the ability to support future format changes. Diversifying across packaging types and geographies can reduce exposure to regulatory and supply disruptions, while standardizing interfaces where possible can lower total system cost. Engaging early with packaging suppliers on application requirements, test protocols, and anticipated resolution or form-factor evolution can shorten integration cycles and improve long-term flexibility. For organizations that need detailed segmentation data, regional revenue splits, and tailored sourcing or investment scenarios, the full market research report provides the deeper quantitative foundation and customized context required to translate these strategic directions into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Uncooled Infrared Detector Housing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Block Air Fresheners Market 2026: Why 5.2% CAGR Signals Major Shifts
By PW Consulting, 2026-09-18
Navigating Growth and Transformation in the Global Block Air Fresheners Market
The worldwide block air fresheners market has demonstrated consistent expansion, with market size reaching USD 650.0 Million in 2025 and a compound annual growth rate of 5.2% projected through 2032. This trajectory reflects a sector that has evolved from basic odor masking to a more sophisticated hygiene and ambiance solution embedded across commercial, residential, and specialized industrial environments. Historical data indicates steady growth from USD 504.47 Million in 2020, highlighting resilience even amid supply chain disruptions and shifting consumer priorities. The market's expansion is not merely a function of population growth or real estate development; it is increasingly driven by heightened awareness of indoor air quality, professional hygiene standards, and the strategic role of scent in customer experience and operational efficiency.
Despite this positive momentum, the industry faces structural challenges that demand strategic attention. First, regulatory fragmentation continues to complicate product formulation and compliance, particularly as jurisdictions tighten restrictions on chemical ingredients and packaging waste. Second, raw material volatility, especially in fragrance oils and polymer derivatives, introduces margin pressure and pricing uncertainty for manufacturers operating on thin production cycles. Third, the market is experiencing a paradigm shift in consumer and procurement expectations, with growing demand for biodegradable, non-toxic, and performance-verified solutions that align with broader sustainability mandates. These dynamics create both friction and opportunity, compelling companies to rethink formulation pipelines, supply chain resilience, and value proposition design.
Key Drivers Reshaping the Market Landscape
Technological Innovation and Formulation Advancements
Innovation in block air freshener technology has moved beyond incremental scent duration improvements to include controlled-release mechanisms, enzymatic action, and material science optimizations. Extended-release formulations that maintain consistent fragrance output over multiple weeks are reducing replacement frequency and lowering total cost of ownership for high-traffic environments. Simultaneously, the integration of bio-based carriers and enzymatic additives is addressing hygiene concerns while minimizing environmental impact. These advancements allow manufacturers to differentiate on performance rather than price alone, creating room for premium positioning in commercial and institutional channels where reliability and compliance are prioritized.
Scent Machines Market
Regulatory Pressure and Compliance as a Competitive Lever
Regulatory frameworks are increasingly shaping product architecture and market access. Stricter chemical restrictions, particularly around phthalates and certain synthetic additives, are forcing reformulation across major markets. At the same time, packaging regulations and waste reduction targets are accelerating the shift toward recyclable and reduced-material designs. Companies that proactively align with these requirements are not only mitigating compliance risk but also gaining credibility with procurement teams and facility managers who evaluate vendors against environmental and safety criteria. In this context, regulatory adaptation has become a strategic differentiator rather than a back-office compliance exercise.
Demand-Side Shifts in Commercial and Consumer Behavior
Demand patterns are being reshaped by two converging forces. In commercial and institutional settings, facility operators are prioritizing hygiene solutions that reduce maintenance labor, minimize odor complaints, and support wellness-focused environments. This is especially evident in hospitality, healthcare, education, and transportation sectors where visitor perception and sanitation standards directly influence reputation and occupancy. In residential segments, consumers are increasingly selective about ingredients, favoring products perceived as safer for households with children, pets, or sensitivities. The rise of biodegradable and plant-based block formats reflects this sentiment, with growth trajectories indicating that sustainability preferences are translating into actual purchase behavior rather than remaining niche aspirations.
Carbon Block Market
Supply Chain Realignment and Cost Structure Dynamics
Cost structures in the block air freshener market are being influenced by raw material price movements, freight volatility, and geographic sourcing decisions. Fragrance oil pricing has experienced upward pressure due to supply constraints in key producing regions, while transoceanic shipping costs have introduced additional variability for imported inputs and finished goods. These factors are prompting manufacturers to diversify supplier bases, evaluate regional production footprints, and explore formulation adjustments that reduce dependency on volatile inputs. At the same time, companies with stronger procurement capabilities and inventory planning models are better positioned to absorb shocks and maintain competitive pricing without sacrificing margin integrity.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of global consumer goods conglomerates, specialized hygiene suppliers, and regional manufacturers with strong distribution networks. Leading players maintain advantage through brand recognition, broad distribution reach, and ongoing investment in product performance and compliance. However, the competitive field is not static. Differentiation is increasingly tied to formulation credibility, regulatory readiness, and the ability to serve professional hygiene channels with tailored solutions rather than relying solely on consumer-facing brand equity.
Strategic positioning among top participants reveals several distinct approaches. Some companies emphasize extended-release performance and professional-grade formats designed for high-traffic washrooms and institutional facilities, targeting procurement teams that value reduced maintenance frequency and consistent output. Others are advancing sustainability-led product lines, introducing recyclable packaging and biodegradable block formats to align with procurement policies and consumer expectations. A third cohort focuses on niche hygiene applications, leveraging specialized formulations and regional distribution strengths to serve commercial washroom markets with targeted solutions. These divergent strategies indicate a market where breadth and depth can coexist, but long-term advantage will depend on executing a clear value proposition rather than competing across all dimensions simultaneously.
Recent industry activity underscores how companies are translating strategy into action. Extended-fragrance-release urinal blocks have been introduced to reduce replacement cycles in commercial settings, reflecting a focus on operational efficiency and total cost management. Professional-grade block air fresheners have been showcased at major hygiene and facility management events, signaling sustained attention to institutional procurement channels and specifier relationships. Recyclable packaging initiatives for toilet rim blocks have rolled out in European markets, aligning product design with regional waste reduction expectations. In parallel, enzymatic urinal block formulations have entered the market with an emphasis on eco-friendly hygiene performance, illustrating how bio-based technology is moving from concept to commercial deployment. These moves suggest that innovation is being directed toward three overlapping priorities: durability and service frequency, environmental compliance, and hygiene efficacy.
Market structure is evolving along multiple axes. Consolidation remains plausible as larger players seek to strengthen regional coverage, acquire specialized formulation capabilities, or integrate downstream distribution advantages. At the same time, fragmentation persists in local and regional segments where cost competitiveness, responsiveness, and channel relationships matter as much as global brand presence. New entrants and smaller specialist firms are finding opportunities in sustainability-focused formulations, professional hygiene niches, and regions where imported alternatives face freight or compliance headwinds. The net effect is a landscape where scale provides distribution and procurement leverage, but specialization and regulatory fluency increasingly determine which players capture premium segments and high-trust commercial accounts.
Future Outlook: Trends Shaping the Next 3–5 Years
Over the next several years, the block air freshener market is likely to be shaped by three interrelated trends. First, performance-plus-sustainability product architectures will become a baseline expectation rather than a differentiator. Formulations that combine extended release, reduced environmental impact, and verified hygiene benefits will be favored in procurement decisions, especially where facility operators must justify spending against measurable outcomes. This creates opportunity for manufacturers that can substantiate claims with consistent performance data and transparent ingredient and packaging profiles.
Second, regional demand centers will continue to diverge in pace and preference. Higher-growth regions will see expanding commercial infrastructure, rising hygiene standards, and increasing adoption of professional-grade block solutions, while mature markets will focus more on reformulation, packaging transitions, and channel optimization. Companies that can adapt product portfolios to local regulatory requirements and procurement cultures will be better positioned to capture growth without relying on a single global playbook. This regional responsiveness will matter as much as overall market expansion, because localization increasingly influences both compliance speed and customer acceptance.
Third, supply chain resilience will become a strategic priority rather than a tactical concern. Input price variability, logistics fluctuations, and regulatory shifts will continue to test margin stability and product availability. Organizations that invest in diversified sourcing, demand forecasting, and formulation flexibility will be more capable of maintaining consistent supply and competitive pricing. The risk side of this outlook includes the possibility that raw material constraints or freight disruptions could compress margins faster than pricing actions can offset, and that regulatory changes could outpace reformulation cycles for smaller players with limited R&D bandwidth. In addition, any reputational incidents tied to product performance or ingredient safety can quickly influence procurement confidence, making quality control and transparent communication essential safeguards.
Strategic Implications for Decision Makers
For manufacturers, the priority is to align product development with the dual demands of performance reliability and compliance readiness. Investing in extended-release or enzymatic formulations, evaluating recyclable or reduced-waste packaging, and securing resilient raw material sourcing can strengthen margin stability and market access. Companies should also assess whether their portfolio is sufficiently positioned for professional hygiene channels, where procurement criteria often emphasize lifecycle cost, service frequency, and documented safety compliance over retail-style brand appeal alone.
PW Consulting
For investors, the market offers opportunities in companies that demonstrate clear differentiation through formulation technology, regulatory agility, and channel specialization. Attention should be directed toward players with credible sustainability transitions, strong commercial-institutional penetration, and the operational discipline to manage input cost volatility. Given ongoing freight and raw material uncertainty, due diligence should extend beyond top-line growth assumptions to include supply chain robustness, reformulation capacity, and regional exposure.
For procurement and facility management teams, the most effective purchasing strategies will increasingly weigh total lifecycle value rather than unit price alone. Evaluating fragrance longevity, replacement frequency, hygiene performance, ingredient restrictions, and packaging end-of-life implications can reduce hidden operational costs and align procurement with organizational sustainability goals. Building supplier relationships that provide transparency on formulation changes and regulatory compliance will also help mitigate risk in long-term contracts.
As the market matures and competitive distinctions narrow around sustainability, performance, and compliance, decision makers benefit from access to detailed segment-level data and scenario-based guidance. A comprehensive research report can provide the granular view needed to assess regional demand patterns, formulation shifts, pricing dynamics, and competitor movements with greater precision. For organizations looking to translate market momentum into informed strategy, deeper intelligence offers a practical foundation for product planning, investment prioritization, and procurement decisions in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Block Air Fresheners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mazindol Tablet Market: Why 4.12% CAGR and Asia Pacific Weight Drive 2032 Billion>
By PW Consulting, 2026-09-18
Navigating the Global Mazindol Tablet Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Core Challenges
The worldwide Mazindol tablet market has entered a phase of measured expansion, anchored by steady demand in niche therapeutic areas and a recognized role for appetite suppression in obesity management. Market size data across recent years reflects a trajectory that moved from approximately $191 million in 2020 to a base of $235 million in 2025, with forward estimates projecting growth toward $312 million by 2032. This path corresponds to a compound annual growth rate of 4.12% over the 2026–2032 forecast window, indicating that while expansion is not explosive, it is structurally durable. The valuation reached in 2025 establishes a starting point for planning, and the incremental growth curve suggests that value creation will depend less on volume surges and more on formulation differentiation, indication extension, and regional availability improvements.
Kamstrup et al. (2017) noted the sizeable drop in bioavailability of oral mazindol 2 mg relative to the reference standard, highlighting pharmacokinetic considerations that continue to inform formulation choices.
The size of the market is underpinned by multiple application streams, with obesity management representing the dominant share of revenue, followed by more specialized use cases in narcolepsy treatment and clinical research. Dosage strength distribution shows that mid-strength and higher-strength presentations account for a meaningful portion of sales, reflecting formulation strategies that balance efficacy, tolerability, and dosing convenience. In regional terms, Asia Pacific and Latin America together constitute a substantial share of the market, while Europe, North America, and the Middle East and Africa provide smaller but strategically important contributions. This geographic pattern reflects the intersection of authorized manufacturing footprints, local availability, and clinical practice norms.
PW Consulting
Concentration is pronounced. The market structure is dominated by a limited number of authorized manufacturers and specialized developers, with top players holding a meaningful share of total revenue. The market concentration profile—characterized by a high share held by the leading manufacturers and a robust share captured by the top five—underscores the importance of manufacturing authorization, regulatory standing, and formulation IP in shaping commercial outcomes.
Key Challenges and Inflection Points
One central challenge lies in the regulatory classification of mazindol as a controlled substance. In the United States, mazindol is categorized as a Schedule IV controlled substance, which shapes how formulations can be developed, marketed, and distributed. This classification introduces procedural complexity and influences the pace at which new entrants can scale, while also affecting reimbursement pathways and prescriber behavior in certain territories.
A second inflection point concerns availability and the legacy status of the original branded product. The original branded mazindol (Sanorex, Mazanor) was discontinued in the United States and European markets around the late 1990s to early 2000s for commercial reasons, and limited availability has persisted in select markets such as Mexico, Central America, Japan, and Argentina. At the same time, the FDA has determined that mazindol tablets (1 mg and 2 mg) were not withdrawn from sale for reasons of safety or effectiveness, a determination that supports the possibility of generic approvals under appropriate regulatory pathways. This combination of historical discontinuation and a permissive regulatory stance creates both an opening for reformulation and a need to navigate fragmented availability.
Finally, there is a supply chain concentration risk that warrants attention. Certain developers rely on single third-party manufacturing arrangements for drug substance and drug product, which can affect continuity, quality oversight, and time-to-market. As the market expands and more stakeholders evaluate mazindol-based programs, resilience in sourcing and manufacturing relationships becomes a strategic differentiator rather than a back-office concern.
2. Key Drivers of Market Change
Technological Innovation and Formulation Breakthroughs
Formulation technology is a primary engine of value creation in this market. Extended-release and modified-release approaches are reshaping the therapeutic proposition by smoothing plasma exposure, improving tolerability, and enabling once-daily dosing regimens. Patent-protected multilayer tablet architectures for immediate-release and sustained-release combinations illustrate how intellectual property can be aligned with clinical differentiation rather than serving only as a defensive moat. In parallel, peer-reviewed scientific contributions continue to broaden understanding of mazindol’s multifaceted mechanisms, reinforcing the case for broader therapeutic exploration beyond historical appetite-suppression uses. These scientific advances support formulation programs that are designed for specific indications and patient profiles, rather than treating the molecule as a commodity.
Policy and Regulatory Environment
Regulatory clarity and controlled-substance policy are shaping how the market can grow. The determination that branded mazindol tablets were not withdrawn for safety or effectiveness reasons creates an enabling backdrop for abbreviated new drug applications and potential generic entry over time. At the same time, the Schedule IV classification means that any scale-up in availability must account for handling, prescribing, and distribution requirements that vary by jurisdiction. Government authorization for manufacture as a psychotropic substance in select countries adds another layer: in those markets, the ability to produce and supply depends on regulatory standing and compliance, which can become a competitive advantage for established, authorized manufacturers.
Demand-Side Shifts
Demand is influenced by evolving clinical and patient perspectives on weight management and sleep disorders. In obesity management, the broader therapeutic landscape is moving toward multi-modal and sustained approaches, which elevates interest in molecules with established appetite-modulating profiles, especially when paired with formulations that support adherence. In narcolepsy and related hypersomnolence conditions, there is growing attention to agents that can address daytime sleepiness while fitting into long-term management plans. For clinical research, mazindol continues to serve as a reference molecule in studies of appetite regulation, stimulant mechanisms, and related pharmacology, sustaining a smaller but consistent demand stream. Together, these demand patterns favor stakeholders who can present credible clinical narratives, appropriate dosing options, and reliable supply.
Supply Chain and Cost Structure Dynamics
Cost structure dynamics are increasingly tied to manufacturing authorization, formulation complexity, and supply resilience. Where manufacturers hold GMP capabilities and authorized status, they can capture value through both branded and generic pathways, particularly in markets where availability has historically been limited. Conversely, reliance on single-source manufacturing arrangements can compress flexibility and elevate risk, especially when programs advance toward later-stage clinical use or commercialization. Over the forecast period, stakeholders are likely to place greater emphasis on dual-sourcing strategies, quality systems, and regional manufacturing footprints that reduce lead-time and continuity risk. For investors and commercial teams, the cost equation is not solely about API price; it also includes the expense of regulatory navigation in controlled-substance markets and the operational cost of maintaining consistent availability in fragmented territories.
Worldwide Armodafinil Market
These drivers connect to recent market developments that illustrate how strategy and execution are converging. Patent protection extending beyond September 2038 for certain mazindol ER formulations and their uses in ADHD, sleep disorders, and opioid dependence signals a long-duration IP strategy aimed at securing exclusivity for differentiated products. In parallel, planning activity around late-stage clinical programs for mazindol ER in narcolepsy indicates that developers are preparing for potential indication expansion into sleep medicine. Complementary scientific publication activity further supports the narrative that mazindol’s mechanism and therapeutic potential are being revisited with contemporary rigor. For authorized manufacturers in Latin America, maintaining compliant production of mazindol and related substances provides continuity in markets where availability is valued, while historical originator experience remains relevant as a reference point for regulatory determinations and generic pathway discussions.
3. Competitive Landscape and Leading Strategies
The competitive landscape is defined by a small set of authorized manufacturers and specialized developers, each pursuing a distinct strategic position. One group comprises Argentine manufacturers with authorized production status for mazindol as listed in UNODC reports on narcotic and psychotropic substances. Their positioning is anchored in regulatory authorization and regional manufacturing capability, which supports continuity of supply in markets where authorized production and local availability matter. A second group is represented by a Brazilian manufacturer with mazindol API production and GMP capabilities, offering an upstream value position that can support both domestic and export-oriented supply chains. A third group includes a Swiss-based developer focused on extended-release formulations and indication expansion, with platforms targeting narcolepsy/idiopathic hypersomnia and ADHD, as well as internal-release and sustained-release multilayer tablet architectures and potential applications in opioid dependence. The historical originator, based in Switzerland, remains relevant as a reference point even though its branded product was discontinued in major markets, with its legacy influencing regulatory determinations and the broader commercial conversation.
Strategic Positioning and Differentiation
Differentiation is emerging along several axes. Formulation IP is one of the clearest levers. Patent protection for extended-release formulations and their uses provides a long-duration competitive advantage, particularly when paired with late-stage development planning in narcolepsy. This positions developers to build defensible franchises around specific dosing regimens and indications, rather than competing solely on molecule-level equivalence. A second axis is regulatory standing. Authorized manufacturers that are explicitly listed for mazindol or related psychotropic substance manufacture have an advantage in markets where authorization is a prerequisite for lawful production and distribution. A third axis is scientific credibility. Peer-reviewed publication activity that revisits mechanism and therapeutic potential can strengthen the basis for indication expansion and support dialogue with clinicians, regulators, and partners. Finally, manufacturing and quality capability—GMP compliance for API production and controlled manufacturing arrangements for drug substance and product—underpins both reliability and the ability to support later-stage programs.
Evolving Market Structure: Consolidation, Fragmentation, and New Entry
The market is likely to evolve through a combination of consolidation around authorized players and selective fragmentation driven by formulation and indication strategy. Because the molecule is a controlled substance and availability has historically been uneven, the number of entities that can credibly enter is naturally constrained. This favors incumbents that already hold authorization, IP, or clinical data. At the same time, the FDA’s determination that branded tablets were not withdrawn for safety or effectiveness reasons preserves a potential pathway for generic competition in certain markets where appropriate approvals can be secured. That pathway introduces fragmentation risk over the longer term, particularly if multiple generic sponsors pursue authorized generics or regionally targeted launches. New entry will most likely come from players that can combine regulatory navigation, formulation differentiation, and supply resilience, rather than from undifferentiated volume plays. For investors, this suggests that value will accrue to companies that can articulate a clear clinical and commercial rationale, protect it with IP where available, and execute reliably in a controlled-substance environment.
Within this landscape, one practical implication is that competitive advantage is less about raw market share and more about optionality. The companies that can sustain authorized production, advance differentiated formulations, and keep multiple indication and market pathways open are better positioned to capture growth as availability improves and clinical uses broaden. Conversely, stakeholders that depend on a single manufacturing relationship or lack clear regulatory positioning face more constrained upside and higher continuity risk.
4. Future Outlook: Trends and Opportunities (2026–2032)
Trend 1: Gradual Value Growth Through Formulation and Indication Expansion
Over the next several years, the market is expected to grow at a measured pace consistent with the 4.12% CAGR projected across the 2026–2032 period. Rather than dramatic acceleration, the more likely path is steady value accumulation driven by differentiated formulations, expanded clinical narratives, and improved availability in select markets. For commercial teams, this implies that growth will be won through product design and clinical positioning as much as through reach. Opportunities will emerge for stakeholders who can align extended-release or modified-release designs with adherence and tolerability expectations, and who can support indication exploration in sleep disorders and related areas.
Trend 2: Regional Availability and Authorized Manufacturing as strategic Moats
Authorized manufacturing status and regional availability are likely to remain powerful differentiators. In markets where mazindol has maintained limited availability or where authorized production is a prerequisite, manufacturers with the right regulatory standing can secure durable demand. Opportunities may also arise as generic pathways become more accessible in jurisdictions where the regulatory backdrop allows, particularly if new entrants can demonstrate bioequivalence or therapeutic equivalence under the appropriate frameworks. At the same time, regional regulatory variation will continue to shape where and how products can be made available, making local compliance and distribution expertise a critical enabler.
Trend 3: Controlled-Substance Management as a Strategic Capability
As activity increases around formulation development, clinical programs, and potential generic entry, the ability to manage controlled-substance requirements will become more central to commercial execution. This includes handling, prescribing, and distribution considerations that differ by jurisdiction, as well as the operational discipline needed to maintain continuity when supply chains are concentrated. Stakeholders that treat controlled-substance compliance as a strategic capability—rather than a regulatory overhead—are better positioned to reduce interruption risk and build trust with prescribers, payers, and partners. Opportunities here include dual-sourcing strategies, quality system investment, and clear documentation of manufacturing authority and compliance.
Potential uncertainties should be acknowledged. Clinical outcomes from late-stage programs, regulatory decisions regarding indications and generic pathways, and shifts in controlled-substance policy could influence the pace and shape of growth. In addition, supply concentration and regional availability constraints could affect continuity if not actively managed. These factors do not change the structural outlook, but they highlight the importance of scenario planning and flexible execution.
Worldwide Danazol Market
5. Strategic Recommendations for Decision Makers
For Manufacturers and Developers
Prioritize formulation differentiation backed by durable IP where possible, especially in extended-release and multilayer architectures that support indication-specific use. Align development programs with clinical areas where medical need is clear and where adherence and tolerability can be meaningfully improved. Invest in manufacturing resilience by diversifying sourcing where feasible and strengthening quality systems, since continuity will increasingly differentiate credible programs from fragile ones. Maintain regulatory positioning that reflects authorized manufacturing status and controlled-substance obligations, as these will influence market access in important territories.
For Investors
Focus on companies with clear optionality across formulations and indications, supported by IP, clinical data, or authorized manufacturing standing. Assess supply chain concentration and regulatory positioning as core risk factors, not peripheral issues. Favor business models that can sustain value through a controlled-substance environment and that have credible pathways to indication expansion or regional availability improvements. In a market growing at a moderate CAGR, returns are likely to come from differentiated execution rather than broad volume assumptions.
For Procurement and Supply Chain Leaders
Evaluate supplier authorization status, GMP capability, and manufacturing resilience before committing to long-term supply arrangements. Where possible, build redundancy into sourcing for drug substance and drug product, and confirm documentation that supports compliance in controlled-substance markets. Consider regional availability constraints when planning inventory and demand forecasting, especially in markets where access has been historically limited. Proactive supplier qualification can reduce interruption risk and support more stable planning.
For stakeholders seeking to move from high-level trend awareness to detailed, segment-level planning, granular data on regional performance, dosage strength splits, application-specific dynamics, competitive positioning, and scenario-based forecasts can materially sharpen strategy. Access to a full structured research set enables more precise prioritization of markets, formulations, and partner options, and helps align commercial plans with the regulatory and supply realities that shape this market.
For detailed analysis of this topic, please visit the official page: Worldwide Mazindol Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Wafer Geometry System Market: 8.5% CAGR Ignites a New Competitive Playbook
By PW Consulting, 2026-09-18
Navigating the Global Wafer Geometry System Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide wafer geometry system market has demonstrated sustained expansion over the past half-decade, evolving from a niche metrology segment into a critical enabler of advanced semiconductor manufacturing. Valued at approximately 680.45 million USD in 2020, the market climbed to 949.23 million USD by 2024 and reached an estimated 1005.0 million USD in 2025. Forward projections indicate the sector will expand to 1779.0 million USD by 2032, reflecting a compound annual growth rate of 8.5 percent across the 2026 to 2032 forecast period. This trajectory underscores a structural shift where precision geometry measurement is no longer a secondary quality check but a foundational requirement for device performance, yield optimization, and process control.
The Asia Pacific region continues to represent the dominant share of global market activity, driven by dense manufacturing clusters, aggressive capacity expansion, and rapid adoption of advanced node technologies. North America and Europe maintain substantial but comparatively smaller footprints, often concentrated in high-value metrology innovations, specialized substrate markets, and integrated equipment ecosystems. The market remains highly consolidated, with the top three participants capturing roughly 82.4 percent of total revenue and the top five holding approximately 91.15 percent. Such concentration reflects the capital-intensive nature of metrology hardware, the importance of customer qualification cycles, and the technical barriers associated with sub-nanometer measurement accuracy across diverse substrates.
Despite the favorable growth outlook, the industry faces several interconnected challenges that are reshaping competitive dynamics. First, the transition toward three-dimensional device architectures, wider-bandgap semiconductors, and increasingly complex patterned wafers places unprecedented demands on metrology precision. Geometry systems must now resolve nanoscale topography, stress-induced warping, and multi-layer deformation without compromising throughput. Traditional measurement paradigms are struggling to keep pace with device complexity, forcing vendors to rethink sensor architectures, inspection speeds, and data integration capabilities.
Second, the market is navigating pronounced supply chain and input cost volatility. Fluctuations in raw material availability, combined with tightening export controls on critical minerals and semiconductor manufacturing equipment, are disrupting procurement timelines and increasing operational uncertainty. Restrictions affecting materials such as gallium, germanium, graphite, rare earths, tungsten, antimony, bismuth, and magnesium have introduced cost pressure and sourcing complexity across substrates and ancillary components. At the same time, regulatory adjustments extending certain equipment authorizations and refining direct product rules have created a moving compliance landscape that equipment manufacturers must continuously monitor.
Third, demand-side dynamics are exhibiting cyclical tension. Global silicon wafer shipments experienced a modest contraction before rebounding, signaling that capacity planning and procurement strategies remain sensitive to macroeconomic conditions, inventory cycles, and regional investment timing. For wafer geometry system suppliers, this volatility complicates forecasting, lengthens sales cycles, and requires more flexible commercial models. Companies that can align their product roadmaps with substrate economics, regional investment patterns, and evolving quality requirements will be better positioned to convert market growth into durable revenue streams.
Key Drivers Shaping Market Expansion
Technological innovation remains the most powerful engine behind market growth, particularly as device manufacturers push into advanced logic, high-density memory, and power semiconductor segments. Geometry metrology is increasingly integrated into process flows where thickness uniformity, bow, warp, total thickness variation, and nanotopography directly influence lithographic focus budgets, etch uniformity, and packaging reliability. The shift from bare wafer inspection to patterned wafer geometry analysis reflects a broader industry recognition that shape and stress characteristics must be monitored throughout fabrication, not just at initial substrate receipt. Vendors investing in dual-sided measurement, high-speed wavefront or capacitive sensing, and automated handling are gaining traction because they reduce variability and enable in-line feedback loops.
Policy and regulatory developments are simultaneously redefining market boundaries and access patterns. Extensions of temporary general licenses and authorizations for semiconductor manufacturing equipment items have provided short-to-medium-term continuity for cross-border equipment deployment, but they also signal a sustained emphasis on controlled technology transfer. Refinements to foreign-produced direct product rules and targeted controls on specific equipment categories have added compliance complexity for multinational vendors and customers alike. For participants in the wafer geometry space, these dynamics create both friction and opportunity. Companies that can offer regionally adaptable configurations, maintain robust qualification documentation, and support customers through evolving export control requirements are finding it easier to secure long-term engagements in fragmented markets.
Demand-side behavior is shifting as chipmakers and substrate producers realign capacity around technological priorities rather than pure volume growth. Advanced packaging, silicon carbide and gallium nitride applications, and high-bandwidth memory development are driving demand for specialized geometry monitoring on non-silicon and patterned substrates. In parallel, manufacturers are placing greater emphasis on yield enhancement and defect reduction, viewing metrology as a cost-saving lever rather than a compliance expense. This mindset change supports higher adoption of automated geometry systems that can deliver consistent measurements across large lots, integrate with process control software, and reduce reliance on offline laboratory checks.
Supply chain and cost structure changes are reinforcing the need for measurement flexibility and platform modularity. Variability in substrate availability, shifting wafer shipment volumes, and regional cost differentials are encouraging vendors to design systems that can accommodate multiple substrate types, diameters, and process stages without extensive retooling. Capacitive sensing approaches, for example, have gained attention because they allow non-contact measurement of thickness, total thickness variation, bow, warp, flatness, resistivity, and film stress across sliced, lapped, and etched substrates. Such versatility helps equipment owners maximize utilization across product mix changes and reduces the financial risk associated with substrate cycle swings.
Recent product introductions illustrate how vendors are responding to these drivers. The launch of a new wafer geometry monitoring product line using capacitive sensing for thickness, total thickness variation, bow, warp, flatness, resistivity, and film stress on semiconductor substrates demonstrates a clear emphasis on multi-parameter, non-contact measurement for a broad range of substrate conditions. This type of platform addresses a practical pain point: customers want a single measurement architecture that can support multiple process steps and substrate states while maintaining accuracy and throughput. In a market where qualification cycles are long and integration requirements are stringent, offerings that reduce footprint complexity and expand parameter coverage tend to resonate strongly with fabrication and substrate engineering teams.
Competitive Landscape and Leading Strategies
The market’s concentrated structure has fostered a competitive environment where incumbents rely on measurement accuracy, platform breadth, and deep customer integration, while challengers differentiate through speed, novel sensing modalities, and targeted substrate segments. Leading participants have built their positions around metrology systems capable of handling both bare and patterned wafers across diverse materials, including silicon, silicon carbide, and gallium nitride. Their value proposition often extends beyond hardware to include software-driven data interpretation, automation compatibility, and process-specific calibration support. In advanced memory and logic manufacturing, geometry systems that can characterize shape, stress, warp, and nanotopography are increasingly evaluated on their ability to fit into high-volume 생산라인 environments without disrupting cycle time.
Strategic differentiation is evident across several dimensions. Some vendors emphasize established capacitive gauge platforms and manual-to-automated system options that serve both semiconductor and photovoltaic process flows, appealing to customers seeking reliability, broad parameter coverage, and incremental automation upgrades. Others focus on high-speed wavefront phase imaging for blank and patterned 300mm wafers, targeting applications where rapid topography, warp, bow, and in-plane displacement measurement can support tighter process control. A third group concentrates on precision bare wafer geometry metrology and sorting systems designed for wafer manufacturers who need consistent thickness, total thickness variation, bow, and warp measurements across high-throughput production lines. Meanwhile, electron beam-based verification systems have found a niche in advanced NAND, DRAM, and logic manufacturing, where pattern and geometry inspection demand high-accuracy validation and detailed structural feedback.
These divergent approaches reflect a broader market evolution toward segmentation by substrate type, device architecture, and process stage. Rather than competing solely on vertical integration, companies are increasingly building specialized capabilities that align with particular customer workflows. This specialization can create defensible positions in complex applications where measurement physics, substrate handling, and data integration must be carefully matched to fabrication requirements. At the same time, the presence of established multinational players and regionally anchored suppliers contributes to a landscape where qualification trust, service networks, and long-term support matter as much as instrument specifications.
Consolidation and selective new entry are shaping the next phase of competition. The high concentration among top players suggests that scale advantages in R&D, global support, and customer onboarding remain important. Yet the market also leaves room for focused entrants that bring differentiated measurement methods, stronger software ecosystems, or superior handling of emerging substrates. Customers are likely to continue favoring suppliers that can demonstrate repeatable accuracy, reduce integration risk, and evolve with changing device roadmaps. For vendors, the strategic imperative is to balance platform breadth with application depth, ensuring that systems can adapt to new geometry challenges without forcing customers into costly process redesigns.
International trade dynamics and regional investment patterns are further influencing competitive positioning. As equipment authorizations and export control refinements continue to evolve, suppliers with flexible deployment models and strong regional compliance capabilities may gain an advantage in navigating cross-border procurement. In parallel, customers are increasingly evaluating total cost of ownership through the lens of measurement reliability, throughput, and downstream yield impact, which rewards vendors that can translate technical performance into clear operational benefits.
Future Outlook and Emerging Opportunities
Over the next three to five years, the wafer geometry system market is likely to be shaped by three interrelated trends. First, multi-parameter metrology will become the default expectation rather than a premium feature. As device complexity rises, customers will increasingly seek systems that capture geometry, stress, and material-related parameters within a unified workflow, reducing measurement handoffs and improving process feedback. This shift favors platform architectures that can scale across bare and patterned wafers while maintaining high accuracy and throughput.
Second, automated integration and data connectivity will separate high-growth deployments from legacy installations. Geometry systems that interface smoothly with factory automation, support inline decision-making, and provide structured data for process control will command stronger demand. The commercial opportunity lies not only in instrument sales but in enabling yield optimization, reducing re-measurement cycles, and supporting advanced packaging and wide-bandgap manufacturing workflows. Vendors that can demonstrate measurable operational impact will be better positioned to expand within existing customer bases and enter new facilities.
Third, regional capacity shifts and regulatory evolution will continue to influence market access and product configuration. Fluctuations in substrate volumes, alongside policy adjustments affecting equipment deployment, will reward suppliers that can offer adaptable solutions and maintain consistent qualification support across markets. At the same time, export controls on critical minerals and equipment-related authorizations introduce uncertainty around sourcing and deployment timing, making resilience and flexible supply strategies increasingly valuable.
These trends carry tangible commercial implications, but they also introduce risks. Rapid technology changes can shorten product lifecycles, while regulatory uncertainty may delay procurement decisions. Substrate cycle volatility can pressure demand in the short term, and highly concentrated competition can compress margins for suppliers that lack differentiated capabilities or strong service networks. Companies that monitor these signals closely and align their investment and product strategies accordingly will be better prepared to capture growth while managing downside exposure.
Strategic Guidance for Decision-Makers
For wafer and semiconductor manufacturers, the priority is to treat geometry metrology as an integrated process enabler rather than an isolated inspection step. Evaluating systems against actual workflow requirements, substrate mix, and automation compatibility can reveal opportunities to improve yield consistency and reduce downstream variability. Manufacturers should also build flexibility into metrology planning, ensuring that selected platforms can accommodate new materials, patterned structures, and evolving device architectures without major re-qualification overhead.
For investors and strategic planners, the market’s steady growth trajectory and concentrated structure suggest that differentiation in sensing technology, software integration, and substrate specialization will be key value drivers. Tracking product introductions, regional capacity announcements, and regulatory updates can provide early signals about where demand will intensify and which application segments will command premium attention. Companies with adaptable platforms and strong qualification support are likely to capture disproportionate benefit from capacity expansion in advanced memory, logic, and wide-bandgap segments.
For procurement and technology leaders, the focus should be on total cost of ownership and long-term support reliability. Multi-parameter capability, measurement speed, and integration readiness often matter more than headline specifications, especially when production environments require consistent performance across varied substrate states. Engaging early with suppliers on roadmap alignment and qualification requirements can shorten deployment timelines and reduce operational risk.
Detailed segmentation data, company-level benchmarking, and region-specific outlooks can help decision-makers refine these priorities and translate market dynamics into actionable plans. For a fuller view of market sizing, application and type splits, regional nuances, and competitive benchmarks, the complete PW Consulting report provides expanded datasets and tailored recommendations for specific operating contexts.
PW Consulting
Worldwide Wafer Thickness Measuring System Market
Worldwide Overlay Metrology System Market
For detailed analysis of this topic, please visit the official page: Worldwide Wafer Geometry System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Metal Mesh Sleeve Composite Compensator Market: Why 5.38% CAGR Redefines 2032
By PW Consulting, 2026-09-18
Global Metal Mesh Sleeve Composite Compensator Market: Strategic Trends and Commercial Opportunities (2026–2032)
The worldwide market for metal mesh sleeve composite compensators has entered a phase of steady, structurally driven expansion. Valued at 412.28 million USD in 2025, the sector is projected to reach 594.96 million USD by 2032, reflecting a compound annual growth rate of 5.38 percent over the forecast horizon. This trajectory follows a measured recovery from the 2020 baseline of 311.45 million USD, with particularly notable acceleration between 2022 and 2025 as industrial operators prioritized thermal management solutions amid volatile energy environments and infrastructure modernization programs. The growth is not merely cyclical; it reflects a fundamental shift in how high-temperature fluid systems, combustion exhaust networks, and precision piping assemblies are engineered to accommodate expansion, vibration, and alignment tolerances.
Despite the positive trajectory, the industry faces several structural friction points that will define competitive outcomes over the next cycle. First, standardization and certification complexity continue to fragment procurement cycles across jurisdictions. Pressure equipment directives, mechanical engineering associations, and regional safety frameworks impose divergent testing, documentation, and material traceability requirements, lengthening qualification timelines and increasing non-recurring engineering costs for suppliers seeking multi-market footprints. Second, the raw material backbone of metal mesh sleeves and bellows remains tightly coupled to stainless steel pricing dynamics and specialty alloy availability. Grades such as 304, 316, and 321 are routinely specified for corrosion resistance and high-temperature flexibility, yet their cost volatility introduces margin uncertainty, particularly for manufacturers operating on fixed-price contracts or long-lead procurement agreements. Third, the market exhibits a moderate concentration profile, with the top three players accounting for roughly 18 percent of revenue and the top five reaching just over 28 percent. This leaves substantial room for regional specialists and new entrants, but also means that incumbents must continuously defend position through engineering differentiation rather than scale alone. The transition from commoditized sleeve assemblies to integrated, application-engineered compensator systems is reshaping how value is captured and how customers evaluate total cost of ownership.
PW Consulting
Key Drivers Reshaping the Market
Technological Innovation and Material Engineering
Advancements in composite architecture and metallic reinforcement are redefining performance envelopes for expansion compensation. Multi-layer fabric composites and PTFE-lined configurations have become baseline expectations in corrosive and high-cycle environments, while elastomer-integrated designs are gaining traction where dynamic vibration damping and rapid thermal response are critical. Engineers are increasingly specifying compensators that combine metal mesh sleeves with precision-wound bellows, internal sliding sleeves, and reinforced gasket interfaces to manage axial, lateral, and angular movements without compromising sealing integrity. The ability to tailor layer composition, mesh density, and liner thickness to specific pressure-temperature regimes allows suppliers to move up the value chain, offering application-specific solutions rather than catalog components. This engineering granularity is particularly valuable in sectors where unplanned downtime carries heavy economic consequences, pushing procurement teams to prioritize reliability and lifecycle performance over unit price.
Worldwide Braided Sleeving Market
Regulatory and Standards Environment
Compliance frameworks are acting as both a barrier to entry and a catalyst for professionalization. Expansion joints and composite compensators must align with pressure equipment directives, ASME guidance, and EJMA conventions for design, fabrication, and inspection. These standards are not static; they evolve as operators and regulators place greater emphasis on documented material traceability, weld integrity, fatigue testing, and installation verification. Suppliers that invest early in standardized qualification protocols, digital documentation trails, and third-party validation tend to shorten customer approval cycles and reduce project risk for engineering contractors. Conversely, manufacturers that rely on regional homologation alone face lengthening sales cycles when bidding on cross-border infrastructure programs. The regulatory environment is also pushing consolidation of technical support functions, as end users increasingly expect a single point of accountability for design review, field installation guidance, and ongoing maintenance advisories.
Demand-Side Shifts Across Industrial Sectors
Demand is being pulled by several overlapping operational priorities. Power generation facilities are expanding and upgrading turbomachinery and heat recovery networks, where precise thermal expansion management and vibration isolation directly affect asset reliability. Chemical and petrochemical operators are extending service life in corrosive fluid handling and high-temperature reactor piping, favoring compensators that combine metal reinforcement with chemically resistant liners. Marine and shipbuilding programs, including LNG-capable vessel construction and retrofit campaigns, require flexible connections that withstand cyclic loading, saline exposure, and compact spatial constraints. Aerospace and defense applications add another layer of specificity, demanding lightweight, high-integrity compensators for engine test rigs, ground support piping, and specialized fluid systems. HVAC and construction segments contribute steady, distributed demand, particularly in large commercial and industrial building networks where thermal movement must be absorbed without compromising pressure stability.
Supply Chain and Cost Structure Dynamics
The cost architecture of composite compensators is increasingly shaped by material sourcing strategies, manufacturing localization, and production efficiency. Stainless steel grades form the structural core of metal mesh sleeves and bellows, making input cost management a strategic priority. Manufacturers are responding by diversifying alloy suppliers, securing long-term mill agreements, and optimizing cut-and-form cycles to reduce scrap and labor intensity. At the same time, regionalization of production is accelerating as customers seek shorter lead times, lower freight exposure, and closer engineering collaboration. This does not necessarily mean full decentralization; rather, it favors a hybrid model where core metallurgical and testing capabilities remain concentrated, while finishing, assembly, and technical support are positioned closer to key demand clusters. The net effect is a supply base that is more responsive but also more complex to coordinate, rewarding companies with robust quality systems and integrated design-to-delivery workflows.
Competitive Landscape and Strategic Positioning
The competitive field is defined by a mix of established European specialists, globally operating engineering groups, and regionally anchored manufacturers with expanding footprints. Witzenmann GmbH occupies a prominent position in flexible metal elements, offering a broad portfolio of metal expansion joints and bellows with internal sleeves designed for pipeline compensation across industrial, energy, and plant engineering applications. Its differentiation rests on system-level engineering depth, broad configuration flexibility, and long-standing relationships with engineers who specify compensators as part of integrated piping designs rather than isolated components. EagleBurgmann similarly competes on application breadth, supplying axial, tied, and clamshell expansion joint designs with bellows and protective sleeves for power generation, petrochemical, and heavy industry piping systems. Its strategic emphasis on ruggedized designs and field-proven configurations aligns with operators prioritizing reliability in demanding thermal and pressure environments.
Teadit Group has reinforced its market presence through application-focused knowledge sharing, including guidance on maintenance programs for metallic and non-metallic expansion joints and technical articles on using expansion joints to elevate heat exchanger performance under thermal cycling. This content-driven approach supports a positioning strategy centered on lifecycle value, customization, and engineering partnership rather than price competition. The company's EJMA membership and focus on refining, petrochemical, power, and mining applications further anchor its credibility in sectors where documentation and standardized design practices carry significant weight. BOA Group complements the landscape with stainless steel expansion joints across standard, industrial, and special series, serving engine, shipbuilding, rail, and industrial piping compensation needs. Its ability to scale up to large nominal diameters while maintaining structured product families gives it relevance in infrastructure and mobile equipment programs where spatial and load constraints vary widely.
On the materials- and application-specific side, Mersen contributes Armylor PTFE bellows and compensators, often reinforced with metal elements, targeting highly corrosive chemical and pharmaceutical piping systems where chemical resistance and sealing stability are paramount. This specialization illustrates how material science can create defensible niches even within a broadly engineered product category. A cohort of manufacturers based in China, including Sunny Steel Enterprise, TongYong Bellows, Haoyin Bellows, and Wenda Metal Hose, has expanded the supply base for sleeve compensators, metal compensators, and metal mesh sleeve assemblies used in hot fluid pipelines, vibration reduction, and specialized flexible connections including LNG-related applications. These producers typically compete on configuration availability, lead-time responsiveness, and cost efficiency, while increasingly investing in stainless steel construction quality and application documentation to meet the expectations of more discerning buyers.
Recent operational and knowledge-development activity underscores how competition is evolving. In late 2025, Teadit published maintenance guidance and heat exchanger performance expertise, signaling a broader industry shift toward educational engagement and lifecycle support as differentiators. In early 2026, Comdiflex highlighted ongoing production of compensators incorporating metal rings or wire for structural strength in gaskets and expansion components, reflecting continuous refinement in reinforcement design. These developments point to a market where competitive advantage is increasingly derived from engineering credibility, documentation maturity, and the ability to reduce installation and maintenance risk for end users. The landscape is neither fully consolidated nor fragmented beyond recovery; it is stratified, with premium engineering players competing on performance and total cost of ownership, while regional manufacturers compete on responsiveness, configuration breadth, and price. New entrants can gain traction by targeting underserved application niches, modularizing complex designs for faster configuration, or offering hybrid material solutions that bridge corrosion resistance and structural durability.
Worldwide Micro Perforated Sleeves Market
Future Trends and Strategic Implications
Over the next three to five years, the market is likely to be shaped by three interlinked trends. First, application-engineered customization will become the default expectation in higher-value segments. As power, chemical, marine, and aerospace programs demand tighter control over thermal movement, vibration damping, and corrosion performance, suppliers that can rapidly map operating conditions to compensator architecture will capture disproportionate share. This shifts commercial negotiations from unit pricing toward specification alignment, testing evidence, and lifecycle support. Second, regulatory and standards harmonization efforts, even if incremental, will compress qualification timelines for suppliers that already operate with mature documentation and testing practices. Companies that treat compliance as a design input rather than a post-production checkbox will secure faster market access and stronger position in cross-border tenders. Third, supply chain resilience will increasingly influence procurement decisions. Buyers will favor suppliers that can demonstrate stable alloy sourcing, predictable lead times, and localized technical support, especially for projects where installation windows are tight and rework is costly. This favors organizations that balance centralized engineering mastery with regionally distributed assembly and service capability.
These trends create clear commercial opportunities. Manufacturers can expand margins by moving toward specification-led selling, bundling design review, installation guidance, and maintenance advisories with core compensator sales. Investors can look for companies that combine material expertise with modular production platforms, since such setups allow faster response to specification changes without sacrificing quality. Procurement teams can reduce project risk by prioritizing suppliers with documented fatigue and corrosion performance data, clear standards alignment, and established field support, rather than selecting solely on initial price. At the same time, uncertainty persists. Raw material price swings, divergent regional certification requirements, and shifting end-user project pipelines can compress margins or delay adoption. Over-engineering for one application class while neglecting others may also leave suppliers exposed if demand rotates toward different sectors more quickly than anticipated.
Actionable Guidance for Decision-Makers
Manufacturers should treat metal mesh sleeve composite compensators as a platform for engineering differentiation rather than a commodity output. Investing in modular design libraries, material-grade flexibility, and documented testing protocols will shorten configuration cycles and improve win rates in specification-driven bids. Strengthening technical content and maintenance guidance also builds trust with engineering teams who increasingly evaluate total cost of ownership across the asset life. Investors should prioritize organizations that demonstrate scalable production without sacrificing metallurgical control, alongside a clear route to higher-margin segments such as chemical processing, power generation, and specialized marine or aerospace piping. Procurement and engineering leaders should standardize evaluation criteria around standards alignment, fatigue and corrosion evidence, installation support, and supply continuity, ensuring that specification choices reduce downstream operational risk rather than simply minimizing upfront cost.
For those seeking a deeper view of segment dynamics, regional breakdowns, material-grade trends, and company-level positioning, a detailed research study can provide the granularity needed to convert these high-level insights into procurement plans, capacity decisions, and investment theses. The full report extends the analysis with structured segmentation data, competitive benchmarking, and tailored guidance for manufacturers, investors, and buyers navigating this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Mesh Sleeve Composite Compensator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


