



Category: market research
PW Consulting: Digital Refractometers Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Digital Refractometers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global digital refractometers market is at an inflection point. After expanding from a mid‑three‑figure USD base in 2020 to USD 215.0 Million in 2025, the market is projected to grow at a compound annual growth rate (CAGR) of 6.98% across the forecast window, reaching an estimated USD 344.8 Million by 2032. That trajectory reflects steady demand from food & beverage quality control, regulated laboratory workflows, and process automation in pharmaceutical and chemical manufacturing. For corporate leaders planning investments, partnerships, or go‑to‑market pivots in 2026, this study distills the commercial, regulatory and competitive signals that will determine winners and losers.
Digital Refractometers Market
Why this study matters for 2026 strategic choices
We designed the Digital Refractometers Market report to be a decision tool, not an academic exercise. In 2026, management teams will be evaluating resource allocation across R&D, channel expansion, and compliance investments against a backdrop of moderate, but differentiated growth. The market’s steady CAGR masks important structural dynamics — regulatory runway for clinical applications, reimbursement changes in niche healthcare segments, and an industry structure that remains concentrated among a few incumbents — that materially affect M&A valuation, product roadmaps, and commercial cadence.
Digital Refractometers Market
Report scope — practical deliverables for executives
- Proprietary market sizing and forecasting model built on 2020–2025 historicals with scenario outputs through 2032, enabling rapid what‑if analysis for pricing, volume, and share assumptions.
- Technology and product taxonomy that distinguishes handheld, benchtop and inline process architectures and maps them to buyer needs and validation requirements.
- Regulatory and reimbursement playbook that consolidates global device classifications and recent policy shifts affecting clinical and blood‑bank use cases.
- Commercial playbooks with go‑to‑market options (direct, distributor, OEM), pricing levers, and packaging strategies including service, calibration and consumable attachments.
- Competitive heatmaps and vendor scorecards that evaluate technical capability, regulatory clearances, channel reach and innovation velocity.
- M&A and partnership scenarios with valuation sensitivities and integration checklists for roll‑up strategies.
- Operational risk register and supply‑chain mitigation templates to protect launches against component shortages and quality issues.
Each element contains actionable templates — slide‑ready frameworks, vendor shortlists, and validation checklists — designed to accelerate 90‑day and 12‑month plans. Note: this preview purposefully omits granular regional and application splits and detailed revenue shares; those are available in the full report.
Digital Refractometers Market
Key market dynamics shaping 2026 plays
- Regulatory clarity is a growth enabler. Refractometers intended for clinical measurements benefit from a clear regulatory pathway: in the U.S., many clinical refractometer uses fall under Class I 510(k) exempt classifications. That lowers barriers to market entry for validated devices and encourages OEM investment in clinical models.
- Reimbursement shifts create targeted demand pockets. Recent policy changes (for example, legislation authorizing reimbursement for certain total protein tests in licensed blood centers) have created a tangible commercial runway for devices tailored to blood bank and plasma center workflows.
- Data integrity and compliance are must‑have features. Demand for devices and software that support audit trails, electronic signatures and FDA 21 CFR Part 11 compliance is rising among regulated labs and pharmaceutical manufacturers, making integrated connectivity and validated software differentiators.
- Service and recurring revenue are strategic levers. As instruments commoditize, aftermarket calibration, certification, and software subscriptions become decisive margins drivers.
- Concentration and channel dynamics favor scale. With a high market concentration among top vendors, smaller players must seek niche clinical validations, strategic distribution partners, or value‑adding services to differentiate.
Competitive landscape — interpreting market concentration
The market exhibits notable concentration: the top three players account for the large majority of industry revenues, and the top five control an even greater share. This structure creates both barriers and opportunities. Incumbents enjoy scale advantages in manufacturing, compliance and global distribution, but they can be slow to pursue niche clinical or software‑centric innovations that smaller, more agile firms can exploit.
Highlighted players and strategic positioning:
- Atago Co., Ltd. (Tokyo) — Strengths: broad handheld and benchtop portfolio with clinical models and regulatory clearances that facilitate adoption in clinical and veterinary environments. Strategic implications: acquisition targets or OEM partnerships for companies seeking an immediate clinical foothold.
- Anton Paar GmbH (Graz) — Strengths: laboratory‑grade refractometers and pharma‑compliant platforms (validated for regulatory frameworks). Strategic implications: attractive partner for process‑control and high‑precision laboratory applications, particularly where Part 11 and GMP traceability are required.
- Bellingham + Stanley / Xylem Analytics (United Kingdom) — Strengths: product lines with explicit compliance features for regulated labs. Strategic implications: strong channel and systems integration capability for customers prioritizing validated electronic records.
- MISCO Refractometer (Solon, OH) — Strengths: handheld clinical scales aimed at hospitals and veterinary customers. Strategic implications: niche clinical play with established distribution in North American healthcare facilities.
- Reichert Technologies (AMETEK) (Depew, NY) — Strengths: clinical refractometer brands focused on medical and veterinary diagnostics. Strategic implications: solid installed base and service network for aftermarket monetization.
For 2026, decision‑makers should evaluate these vendors not just on device specs, but on their validation libraries, software roadmaps, OEM partnerships and service ecosystems — factors that drive adoption in regulated environments.
Three pragmatic commercial plays for 2026
- Incumbent play — defend and extend: Invest in validated software features (audit trails and Part 11), expand service contracts, and pursue targeted clinical approvals. Prioritize long‑tail revenue from calibration and consumables to offset hardware margin pressure.
- Challenger play — specialize and collaborate: Focus on a narrowly defined clinical or process niche (e.g., blood bank protein testing enabled by recent reimbursement policy). Pursue co‑development with clinical partners to build evidence and seek targeted regulatory clearances rather than broad, costly programs.
- Investor play — roll‑up and integrate: Acquire complementary manufacturers and consolidate distribution to build scale. Supplement hardware with software and service assets to increase recurring revenue multiples and de‑risk cyclical hardware demand.
Risk profile and mitigations
- Regulatory reversals or reclassification — Mitigation: maintain active regulatory monitoring, engage early with notified bodies and regulators, and design modular validation packages that can be repurposed across geographies.
- Reimbursement uncertainty — Mitigation: pursue pilot programs with payors and clinical networks to establish real‑world evidence and accelerate local reimbursement adoption.
- Component shortages and cost inflation — Mitigation: dual‑source critical components, qualify alternative suppliers, and consider near‑shoring for high‑risk subassemblies.
- Price erosion from low‑cost manufacturers — Mitigation: pivot to differentiated features (connectivity, validated software, bundled services) and lock in long‑term service agreements.
How PW Consulting’s analysis translates into 90‑day and 12‑month actions
From our experience advising instrument manufacturers and distributors, the highest ROI actions in year one are pragmatic and low friction: update product validation language and documentation to support regulated buyers; pilot a subscription‑based calibration service in two major markets; and negotiate OEM partnerships that expand clinical channel reach without large capex. Over 12 months, firms should aim to convert at least one pilot into a commercial agreement with a blood bank, clinical laboratory chain, or pharmaceutical process partner to validate demand and justify broader investment.
What we are intentionally withholding in this public preview
To preserve the “trailer” nature of this preview — designed to demonstrate rigor while driving access to the full study — we have summarized macro trends, regulatory pivots and competitive implications but have withheld the detailed quantitative splits by region, by device type and application, company‑level revenue shares, and line‑item pricing models. The full report contains the granular tables, downloadable models and vendor financial benchmarks necessary to execute acquisition diligence, product pricing decisions and market entry plans.
Next steps
For leadership teams preparing budgets and strategic roadmaps in 2026, this study is an essential input: it combines validated market forecasting, regulatory mapping, competitor intelligence and executable commercial playbooks. To obtain the full dataset, vendor scorecards, and scenario models referenced here, access the complete Digital Refractometers Market report and the accompanying Excel decision‑support models through our publication page.
For detailed analysis of this topic, please visit the official page: Digital Refractometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polyvinyl Alcohol (PVA) Films: Strategic Outlook for 2026 — A PW Consulting Preview
As global manufacturers, brand owners, and investors prepare bids, alliances, and capital allocations for 2026, understanding where the Polyvinyl Alcohol (PVA) films market is heading has moved from helpful to imperative. PW Consulting’s latest market study — anchored on a 2025 base year and a seven-year forecast through 2032 — synthesizes market sizing, technology trajectories, regulatory shocks, and commercial playbooks into an actionable intelligence package. This preview outlines the strategic value of that study for 2026 decision-makers, highlights the major forces shaping the PVA films ecosystem, and signals the commercial moves that will separate winners from followers next year.
Polyvinyl Alcohol (PVA) Films Market
Market Snapshot — What the Numbers Tell Us
PVA films is a mid-sized specialty polymer market with meaningful growth momentum. From a historic base (2020–2025) the market climbed from mid-three-hundreds to just under USD 500 million in 2025 (PW Consulting base year). Our model forecasts the market expanding at a compound annual growth rate of approximately 5.5% for 2026–2032, driven by both volume growth and a premiumization trend toward specialty, certified, and performance-differentiated grades. By 2032 the market is projected to surpass the high hundreds of millions (USD, revenue unit: Million), reflecting sustained adoption in end-markets that prize water-solubility, reduced microplastic risk, and application-specific functionality.
Polyvinyl Alcohol (PVA) Films Market
Two high-level structural facts are especially relevant for 2026 planning. First, the PVA films industry is consolidated: the top three global players control roughly two-thirds of the market, and the top five hold well over four-fifths. Second, price sensitivity remains material: raw-material oscillations and trade-policy shifts can materially compress margins in commoditized grades while providing margin upside for certified, traceable, and specialty variants.
Polyvinyl Alcohol (PVA) Films Market
Key Demand Drivers and Market Dynamics
-
Sustainability legislation and brand commitments: New regulatory efforts — notably nation-level single-use plastic restrictions and regional policies aimed at plastic waste reduction — are accelerating the migration toward water-soluble and biodegradable delivery forms. Consumer-packaged-goods (CPG) brands and chemical formulators are fast-tracking qualification programs for PVA films as a route to compliant and marketable product formats.
-
Performance premiumization: End-users are demanding higher-performance PVA films (optical clarity, controlled dissolution profiles, low foaming, and tailored hydrolysis levels) for sensitive applications such as detergent pods, agrochemical delivery, and specialty industrial uses. This bifurcates the market into value-added specialty streams and lower-margin commodity segments.
-
Input-cost volatility and feedstock tightness: The cost of vinyl acetate monomer (VAM) and related intermediates has been volatile — for example, VAM spot prices spiked materially in 2025 following upstream ethylene and acetic acid rallies, and PVA regional prices saw a notable uptick in early 2026. Such swings affect contract negotiation, pass-through strategies, and the attractiveness of vertical integration or long-term offtake agreements.
-
Trade and tariff environment: Resurgent protectionist measures and tariff restorations in 2025 have introduced greater friction into global supply chains. For companies that rely on cross-border sourcing of resin, films, or machinery, nearshoring and regional capacity expansion are now strategic levers.
-
Technology and certification as differentiators: Certifications (e.g., low-carbon traceability schemes), novel coating or barrier technologies, and controlled hydrolysis chemistries are creating entry barriers and value premiums. Buyers are increasingly willing to pay for supply-chain transparency and certified lower-carbon inputs.
What the Full Report Contains — Practical, Executable Intelligence
-
Top-down and bottom-up market sizing (historical 2020–2025; forecast 2026–2032), with scenario runs for low/mid/high growth.
-
Detailed price-cost modeling that isolates feedstock, energy, and conversion contributions to margin under varying input-price scenarios.
-
Segment and application dashboards (regional demand drivers, grade-level performance requirements). Note: this preview intentionally omits the granular splits that are included in the paid study to preserve the unique commercial value of the full dataset.
-
Supplier matrix and capability assessment (manufacturing footprints, capacity maps, technology specializations, certification status).
-
Regulatory scenario analysis and fast-track compliance playbooks for major jurisdictions.
-
Commercial go-to-market playbooks for brand owners and film manufacturers, including pricing strategies, innovation roadmaps, and channel models.
-
M&A and partnership screening — a prioritized list of targets and strategic rationale for consolidation, verticalization, or capability-acquisition moves.
-
Risk heatmap and mitigation levers: supply disruptions, raw-material shocks, and demand-pull failures, with contingent action plans.
Competitive Landscape — Who’s Shaping the Market
The PVA films sector is populated by several well-capitalized incumbents and a cohort of regional specialists. Leading specialty chemical groups and dedicated PVA film houses are investing in both capacity and capability — expanding lines for optical-use films, water-soluble delivery systems, and certified low-carbon product lines. Recent strategic moves illuminate the trajectory:
-
Large integrated players have announced capacity expansions and product partnerships to capture demand from packaging and construction. These investments aim to lock in scale advantages and secure long-term supply to large converters and brand owners.
-
Manufacturers with sustainability-focused portfolios have pursued certification schemes and regional manufacturing footprints to capture premium demand for traceable, lower-carbon films.
-
Regional champions — particularly in Asia and Europe — continue to compete on tailored product solutions, price, and proximity to downstream converters, while emerging players emphasize customer intimacy and rapid customization.
Our competitive profiles in the report include leadership maps, capability scoring, and likely strategic options for each major player — from capacity redeployment to selective partnerships with CPGs and agrochemical formulators. The full study also tracks recent public moves such as capacity announcements, sustainability certifications, and targeted product launches that will reverberate through 2026 purchasing cycles.
Strategic Implications for 2026 — What Companies Should Do Now
-
Prioritize grade-mix optimization: Reassess product portfolios to tilt toward specialty, certified, and higher-margin grades. A commodity-heavy stance is vulnerable to feedstock volatility; premium grades offer margin insulation and strategic stickiness with customers.
-
Secure input-cost flexibility: Negotiate multi-year supply contracts, consider hedging for key feedstocks, and evaluate backward coordination where economically viable. Even modest reductions in feedstock exposure materially improve margin resilience.
-
Accelerate certification and traceability efforts: Investment in recognized sustainability certifications and verified sourcing can unlock shelf-space and RFP advantages with multinational customers and public-sector tenders.
-
Reconfigure supply chains for agility: Build optionality through regional production nodes or co-manufacturing arrangements to mitigate tariff and logistics shocks. Nearshoring or local partnerships in key demand corridors reduce lead times and political risk exposure.
-
Adopt a differentiated commercial model: Use value-based pricing for specialty products, bundle formulations or application engineering services, and create performance warranties for dissolution profiles where appropriate.
-
Scan for consolidation and capability buys: Given the market’s concentration dynamics, opportunistic M&A can secure capability gaps (e.g., optical films, ISCC-certified production, regional logistics hubs) more cheaply than greenfield builds in 2026.
Risk and Opportunity — Reading the Near-Term Signals
2025–2026 has proven that a single external shock (commodity rally, tariff change, or regulatory pivot) can quickly reshuffle competitive advantage. The key inference for 2026 planning is that optionality and speed of execution are as valuable as long-term strategy. Firms that can rapidly pivot capacity, secure low-cost feedstock basins, and credibly demonstrate sustainability outcomes will capture the disproportionate share of upside as premium demand grows.
Conversely, players that remain product- or regionally-constrained without certification or customer-lock mechanisms risk margin compression and displacement by certified, regionalized competitors.
How PW Consulting Helps You Act in 2026
-
We build tailored scenario models that quantify the P&L impact of feedstock swings, tariff shocks, and demand shifts for your portfolio.
-
We map the competitor moves that matter, translating public announcements into probabilistic forecasts of capacity, pricing, and customer outreach.
-
We deliver prioritized action plans — from procurement hedges to M&A targets and go-to-market scripts — that are designed for rapid execution in 2026 procurement cycles.
Next Steps — Where to Find the Full Intelligence
This preview has outlined the high-level market trajectory, the primary dynamics to watch, and the strategic implications for 2026. For buyers, producers, and investors ready to translate these insights into concrete actions, the full PW Consulting report includes the granular segmentation, scenario-tailored financial models, supplier-level benchmarking, and executable playbooks that are intentionally withheld from this teaser. Access to the complete study will enable you to quantify trade-offs, price propositions, and capacity investments with precision.
In a market where consolidation and certification are creating durable value pools, 2026 is a year for decisive moves. Use robust data and scenario planning to protect margins, accelerate into specialty streams, and build supply-chain options before competitors lock the preferred channels. PW Consulting’s full PVA films study provides the data backbone and strategic templates to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Polyvinyl Alcohol (PVA) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Aluminium Extrusions Market to Reach USD 368.3M by 2032 at 8% CAGR
By PW Consulting, 2026-07-12
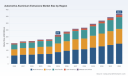
Automotive Aluminium Extrusions Market — Strategic Preview for 2026 Decision-Making
As automotive manufacturers and suppliers reset product roadmaps and capital plans for a post‑pandemic, electrified future, aluminium extrusions occupy a decisive position in the race to deliver lighter, safer and more energy‑efficient vehicles. PW Consulting’s forthcoming Automotive Aluminium Extrusions Market research — base year 2025, forecasting through 2032 — synthesizes the macro trajectory and the competitive dynamics firms must internalize to make confident 2026 investments.
Automotive Aluminium Extrusions Market
Why this research matters for 2026
-
Timing: With the study’s base year anchored in 2025 and a forecast window beginning in 2026, the analysis maps directly onto the investment horizon of many OEM and Tier‑1 capital projects, procurement contracts, and localization initiatives.
Automotive Aluminium Extrusions Market -
Market momentum: The global market shows a clear recovery and structural expansion — growing from approximately USD 153 million in 2020 to USD 215 million in 2025, and forecast to reach about USD 368 million by 2032 at a compound annual growth rate of 8.0%. This growth profile creates a runway for capacity investments, alloy development, and downstream integration.
Automotive Aluminium Extrusions Market -
Decision relevance: The report translates market growth into actionable choices — where to site capacity, which alloy platforms to prioritize, how to balance recycled content with mechanical performance, and how to reshape sourcing strategies in the face of supply concentration.
What’s changing in the market — dynamics that will shape 2026 plans
-
Electrification is accelerating aluminium demand: OEMs increasingly specify aluminium extrusions for EV structural frames and battery enclosures to achieve the twin goals of lightweighting and crash performance. This is not a marginal trend — industry research indicates aluminium content per vehicle is accelerating and will materially exceed early‑2020 levels as automakers reengineer platforms around battery packs.
-
Higher extrusion content per vehicle: Engineering trends and supplier designs have pushed extrusion content upward — historical estimates show a rise from roughly 35 pounds per vehicle in 2020 toward nearly 45 pounds by 2025, with modern vehicle architectures often containing around 50 pounds of extrusions in front‑end and roof structures. These per‑vehicle gains multiply quickly across global vehicle build plans.
-
Supply‑side consolidation and concentration: The market exhibits notable concentration at the top. The three largest suppliers control a substantial share of the market, and the top five command an even higher cumulative share. For procurement and risk managers, that concentration translates into both negotiating leverage and potential single‑point vulnerabilities.
-
Decarbonization and circularity: Low‑carbon and recycled aluminium is a competitive imperative. Leading suppliers are investing in closed‑loop recycling, low‑emission smelting, and alloy development targeted at retaining mechanical performance while lowering embodied carbon per kilogram.
-
Design complexity and integration: As multi‑material vehicles proliferate, extrusions are no longer standalone parts; they are engineered into hybrid assemblies, cast‑to‑extrusion joins, and adhesive‑integrated structural modules. Suppliers that can offer engineering services and validated assembly solutions win share more rapidly.
What the report contains — practical, transaction‑ready intelligence
-
Market sizing and scenario forecasts (2026–2032): Base‑year grounding plus three demand scenarios calibrated to EV penetration, aluminium price pathways, and vehicle production forecasts.
-
Value‑chain mapping and cost stacks: From billet sourcing to extrusion, heat treatment, finishing and machining — with pragmatic levers to reduce unit costs and carbon intensity.
-
Technology and alloy roadmaps: Comparative analysis of the 6xxx and 7xxx alloy families, high‑strength tempering routes, and secondary operations that affect part performance in crash and fatigue.
-
Buyer playbooks: Procurement frameworks, hedging approaches for aluminium feedstock, and supplier scorecards tailored for OEMs and Tier‑1s.
-
Operational diagnostics: Plant capacity planning templates, OEE benchmarks, and recommendations for ramp sequencing when converting legacy lines to higher‑precision extrusion workflows.
-
Risk registers: Supply concentration assessment, geopolitical scenarios, and near‑term raw material disruption matrices with mitigation options.
-
Deal and partnership playbooks: M&A valuation heuristics, JV structuring principles for local content programs, and cross‑border supply‑chain strategies.
Competitive landscape — strategic profiles and implications
The market features a mix of integrated upstream producers, specialist extruders, and regional champions. PW Consulting’s competitive analysis highlights strategic posture, capability gaps, and partnership vectors for the players that matter to OEMs and Tier‑1s.
-
Constellium SE (France) — Advanced extrusion systems and tailored structural components. Strength: engineering depth and program integration for structural integrity and sustainable mobility. Strategic implication: Constellium is a go‑to for OEMs seeking co‑development of crash‑relevant profiles and aluminium‑heavy architectures.
-
Novelis Inc. (United States) — Focus on high‑strength recycled alloys. Strength: closed‑loop recycling and rolled products that complement extrusion ecosystems. Strategic implication: Novelis’s emphasis on recycled content increasingly aligns with OEM ESG mandates, making it an attractive upstream partner for low‑carbon supply chains.
-
Norsk Hydro ASA (Norway) — Low‑carbon and recycled extrusion platforms. Strength: green aluminium credentials and supply integration. Strategic implication: Buyers with strict Scope 3 targets should prioritize contracts offering low‑emission aluminium claims validated by lifecycle analysis.
-
Kaiser Aluminum Corporation (United States) — High‑strength extrusion capabilities for EV battery frames and crash‑absorbing components. Strength: niche technical capability in high‑performance alloy systems. Strategic implication: Kaiser is well positioned to serve segments where mechanical performance and dimensional precision cannot be compromised.
-
UACJ Corporation (Japan) — Precision fabrication and tightly controlled process engineering. Strength: high‑volume, high‑precision production for body structures. Strategic implication: Asian OEMs and global platforms requiring tight dimensional and surface standards will favor UACJ’s offerings.
-
Arconic Corporation (United States) — Lightweight and corrosion‑resistant extrusion solutions. Strength: broad systems integration and multi‑material design support. Strategic implication: Arconic’s service breadth makes it a strong Tier‑1 candidate for global programs requiring coordinated materials engineering.
-
Bonnell Aluminum (United States) — IATF‑16949 certified supplier with OEM presence. Strength: certification pedigree and supplier reliability for mainstream automotive production. Strategic implication: Procurement teams will consider Bonnell for high‑volume closures and body‑in‑white integration where quality systems are non‑negotiable.
-
ETEM Gestamp Aluminium Extrusions (Bulgaria) — Crash‑relevant profiles and machined parts for OEMs and Tier‑1s. Strength: European footprint and tailored crash‑management designs. Strategic implication: Localized supplies for European programs and short lead‑time needs favor ETEM’s model.
-
Press‑Metal Aluminium Holdings Berhad (Malaysia) — Regional supplier for body‑in‑white components. Strength: competitive cost base and regional integration. Strategic implication: Cost‑sensitive programs and regional content policies make Press‑Metal a logical partner in Asia and adjacent markets.
-
Gränges AB (Sweden) — Extruded profiles for transportation applications. Strength: niche expertise in transport and finishing services. Strategic implication: Gränges is attractive for customers prioritizing surface engineering and downstream finishing standards.
Strategic takeaways for executives planning in 2026
-
Prioritize alloy and process flexibility: Given the pace of EV adoption and regulatory pressure on embodied carbon, firms must be capable of switching alloy mixes and heat‑treatment routes without costly line changeovers.
-
Embed carbon transparency into sourcing: Contracts with traceable recycled content and verified emissions data will increasingly be a procurement differentiator, not just a marketing advantage.
-
De‑risk supply concentration: With the top suppliers controlling a significant share of capacity, parallel sourcing, strategic stockpiles, and regional qualification pipelines are prudent tactics.
-
Make engineering services a commercial lever: Suppliers that offer co‑design, crash simulation, and assembly validation can capture part value and accelerate OEM time‑to‑market.
-
Plan capacity with scenario discipline: Use the report’s scenario forecasts to stress‑test capex decisions against EV adoption curves, aluminium price volatility, and geopolitical supply shifts.
How this preview intentionally withholds core segmentation
This article is designed as a strategic trailer: it highlights the market’s scale, growth trajectory and the practical levers that leaders must evaluate in 2026. To preserve the commercial utility of the full analysis, we have intentionally omitted the detailed segmentation matrices and the granular regional and application‑level splits that underpin supplier targeting, plant siting, and M&A valuation models. Those detailed matrices — including regional demand distribution, application mixes, and alloy‑level revenue breakdowns — are included in the full PW Consulting report and are essential for transaction execution and program qualification.
Next steps — how executives should use this intelligence
-
Procurement chiefs: Use the market concentration signals and supplier profiles to redesign sourcing strategies and hedge feedstock exposure.
-
Product and engineering leads: Validate alloy choices and extrusion content against the report’s scenario outputs before finalizing platform redesigns.
-
Strategy and corporate development teams: Leverage the report’s M&A playbook and valuation heuristics when screening acquisition targets or forming JVs to secure local content.
-
Operations and plant managers: Apply the operational diagnostics and ramp sequencing templates to reduce time‑to‑qualified production and mitigate rework rates.
For procurement contracts, capex decisions, and platform engineering that will be locked in during 2026, decision quality demands both a clear view of the macro growth curve and access to the granular segmentation that determines unit economics. PW Consulting’s full Automotive Aluminium Extrusions Market report provides that end‑to‑end intelligence — including the regional, application and alloy‑level breakdowns required to finalize supplier selections, capacity allocations and acquisition targets. Contact PW Consulting to access the complete dataset, detailed scenario models, and the supplier due‑diligence annex that underpins our recommendations.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Extrusions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Footwear Market to Reach USD 455.8 Million by 2032 at 6.4% CAGR
By PW Consulting, 2026-07-12
Military Footwear Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As defense planners recalibrate sourcing policies and OEMs reposition manufacturing footprints, the global military footwear market is entering a phase of steady, policy-driven growth. Our PW Consulting baseline places 2025 as the report's base year (historical window 2020–2025) and models the market through 2032. The market is expected to expand at a compound annual growth rate (CAGR) of 6.4% across the 2026–2032 forecast period, rising from roughly USD 296 million in 2025 to a forecast in the mid‑400s (USD million) by 2032. Market concentration remains low-to-moderate (CR3 ≈ 24.6%, CR5 ≈ 36.5%), underlining a fragmented supplier landscape with meaningful opportunities for scale-driven consolidation and niche specialization.
Military Footwear Market
Why this study matters for 2026 corporate strategy
Two forces converged in late 2024–2026 to reshape the operating logic of military footwear suppliers: regulation-driven reshoring and an intensifying procurement discipline from defense logistics authorities. The inclusion of the BOOTS Act as an amendment in the FY2026 National Defense Authorization Act, the U.S. Army Footwear Certification Program’s stricter certification and inspection cadence, and active Defense Logistics Agency (DLA) engagement (industry webinars and committee meetings in 2025 and a presolicitation for recruit athletic footwear in early 2026) create a new baseline of compliance, traceability, and domestic-content expectations. For strategy teams, these are not academic changes — they directly affect unit economics, capital planning, and go-to-market choices for 2026 and beyond.
Military Footwear Market
What the macro numbers tell you — and what they don’t
-
Growth trajectory: A 6.4% CAGR through 2032 signals reliable demand growth driven by modernization programs, training throughput, and expanding non-traditional procurements (e.g., specialized athletic footwear for recruit and resilience programs).
Military Footwear Market -
Scale and headroom: With 2025 market size near USD 296 million and a projected rise into the mid‑400s by 2032, the market is large enough to absorb strategic investment but small enough that focused investments in domestic capacity or differentiation can materially alter competitive position.
-
Fragmentation: CR3 and CR5 metrics highlight a market where top suppliers are important but not dominant; opportunities exist both for consolidation and for agile challengers to capture contract-led share.
Regulatory and procurement dynamics that will shape 2026 decisions
-
Mandatory domestic content: Implementation of the BOOTS Act and sustained enforcement of the Berry Amendment mean procurement favors 100% U.S.-manufactured footwear with domestic materials for many categories. Expect higher landed costs for compliant suppliers but better protection from foreign competition in DoD channels.
-
Certification and inspection: The U.S. Army Footwear Certification Program imposes prescriptive quality and inspection regimes with two‑year certification cycles and mid‑cycle reviews. Suppliers must invest in process controls, test laboratories, and traceable Bill-of-Material systems to avoid disqualification.
-
DLA engagement and pipelines: The Defense Logistics Agency’s 2025 industry webinars and October committee meeting, plus the February 2026 presolicitation for recruit athletic footwear, signal ongoing alignment between procurement planners and manufacturers — a practical avenue for suppliers to shape requirements but also a reminder that procurement calendars will increasingly drive production planning.
-
Labor and cost pressure: Berry-compliance elevates labor and material costs relative to offshore alternatives. Competitive strategies must therefore shift from low-cost sourcing to productivity, automation, and total-cost-of-ownership value propositions.
Supply chain and manufacturing imperatives
For 2026 operational plans, five manufacturing and supply-chain priorities rise to the top:
-
Certify early, inspect often — make compliance a design constraint. Investments in quality management systems and audit readiness will shorten lead times during procurement cycles and reduce contract risk.
-
De-risk through capacity partnerships — contract manufacturing in the U.S., modular lines, and shared-capacity arrangements can provide the domestic sourcing ribbon without full greenfield capex. Recent facility expansions by domestic OEMs illustrate the capital intensity and timeline of scaling made-in‑America capacity.
-
Automate selectively — automation and advanced assembly reduce the labor delta to offshore options; targeted automation for sole assembly, cutting, and finishing generates outsized productivity benefits.
-
Material strategy and supplier integration — securing U.S.-sourced leather, textiles, and polymer compounds requires multi-year supplier agreements and near-shore backup suppliers to satisfy certification traceability.
-
Service and lifecycle economics — offering rebuilds, sole replacement, and condition-based maintenance programs turns footwear into a lifecycle service, which can align with procurement budgets focused on total cost of ownership.
Product and commercial strategy — beyond the boot
Winning in 2026 will be less about single-product pricing and more about portfolio logic and program alignment:
-
Modularity: Platforms that share last patterns, midsoles, and upper modules reduce SKUs while enabling role-specific variants for training, operational use, or parade applications.
-
Data-enabled value propositions: Embed sensor-ready components or lifecycle tracking to support condition-based replacement programs favored by logistics managers.
-
Performance and sustainability: Lightweight, durable materials and demonstrable lifecycle environmental improvements will influence both civilian resale channels and non-combat procurement lines.
-
Commercial channels and dual-use strategies: Maintain civilian product lines to smooth demand cyclicality and capture economies of scale, while aligning select SKUs to defense certification standards to shorten conversion times when contracts arise.
Competitive landscape: capabilities to watch
The market is populated by established domestic manufacturers with deep relationships to DoD procurement and newer global brands that increasingly adapt lines for Berry compliance. Key company archetypes to watch include:
-
Legacy domestic suppliers with government legacy contracts and institutional knowledge — companies with long histories of supplying U.S. services typically excel at compliance, traceability, and program continuity.
-
Regional specialty brands that combine European technical footwear expertise with U.S. supply arrangements — these players often lead on product innovation and tactical performance metrics.
-
Mid-market manufacturers scaling domestic capacity — recent capacity investments by several U.S.-headquartered manufacturers illustrate a strategic bet on long-term procurement certainty under Berry and legislative preferences.
While we profile representative suppliers in the full report, the salient competitive insight for 2026 is this: incumbency and compliance matter as much as product performance. With CR3 and CR5 indicating fragmentation, there is room for both consolidation and focused challengers that pair domestic production with operational agility.
Scenario triggers and short-term decision checkpoints for 2026
-
Regulatory enforcement schedule: Track BOOTS Act implementing guidance and any amendments to Berry interpretive guidance; supplier qualification timelines must align with those rulings.
-
Procurement pipelines and solicitations: Monitor DLA and service branch RFP calendars; the presolicitation for recruit athletic footwear is a template for recurring program opportunities.
-
Certification cadence: Prepare for mid-cycle inspections under the Army Footwear Certification Program; failing an inspection can remove a supplier from pools for months.
-
Capital availability and M&A windows: Given market fragmentation, watch for strategically timed acquisitions of manufacturing platforms or raw-material suppliers to purchase near-term scale and compliance credentials.
Recommended 90–180 day action plan for executives
-
Compliance sprint: Complete a gap analysis against the Army Footwear Certification Program and initiate corrective action for traceability and BOM controls.
-
Capacity hedging: Negotiate short-term shared-capacity agreements with U.S. partners to secure domestic production slots while evaluating any greenfield investments.
-
Commercial alignment: Map current product lines to likely procurement categories (including recruit and athletic lines) and designate a fast-track SKU list for certification.
-
M&A screen: Run a rapid screen for target acquisitions that add certified capacity, U.S.-sourced materials, or logistics capability with minimal integration risk.
-
Bid readiness: Align costing models to reflect Berry-driven labor and materials premiums and develop lifecycle-based commercial offers that highlight TCO advantages.
What’s in the full PW Consulting report (practical modules)
-
Market sizing and validated forecast models (2020–2032) with downloadable time-series data and scenario toggles.
-
Regulatory and procurement landscape matrix with implementation timelines and audit checklists.
-
Detailed company profiles and capability maps including production footprints, compliance credentials, and strategic moves.
-
Supply-chain risk model and cost-to-compliance simulation to quantify domestic production impacts on margin and cash flow.
-
Go-to-market playbook for prime contractors and subcontractors, including bid‑build templates, value-based pricing models, and lifecycle service propositions.
-
M&A and partnership playbook with a prioritized target list and integration KPIs for acquiring capacity or materials security.
The report intentionally refrains from publishing detailed segmented shares and contract-level datapoints in this preview. Those granular datasets, procurement timelines, and interactive models are available in the full research package and are designed to be used directly in board-level decision frameworks and bid preparation.
Conclusion — the strategic horizon for 2026
For executives and procurement leaders, 2026 is a year to convert regulatory certainty into strategic advantage. The market’s steady growth and procurement policy tilt toward domestic content create a window where the right investments in compliance, capacity, and lifecycle offerings can yield outsized returns. Given the market’s fragmentation, disciplined M&A and capability-led partnerships can accelerate scale and compliance credentials faster than organic build alone. Use the next six months to lock compliance, secure capacity, and validate product portfolios against certification requirements — the full PW Consulting report provides the data, scenarios, and operational templates to make those decisions with precision.
For detailed analysis of this topic, please visit the official page: Military Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrasonic Flaw Detector Market Set to Expand at 7.8% CAGR Through 2032
By PW Consulting, 2026-07-12
Ultrasonic Flaw Detector Market: Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
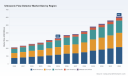
Between 2020 and 2025 the global market for ultrasonic flaw detectors moved from an early‑maturing niche toward a predictable growth phase, driven by stronger demand for non‑destructive testing across heavy industry, transport and energy sectors. Using 2025 as the base year, our research places the market at roughly USD 333 million and models a clear upward trajectory through the 2026–2032 forecast window, with a compound annual growth rate (CAGR) of 7.8% that sees the market roughly double in scale by the end of the period. This combination of steady organic demand and pockets of rapid adoption (phased‑array, digital workflows, service models) creates a set of high‑leverage strategic choices for suppliers, integrators and investors in 2026.
Ultrasonic Flaw Detector Market
Why this matters for 2026 decision cycles
- Investment timing: The projected mid‑to‑late decade acceleration means product roadmaps and capital allocation plans begun in 2026 will capture the most commercially attractive portion of the cycle.
- Go‑to‑market focus: Buyers increasingly prefer integrated hardware + software inspection solutions and service contracts; vendors who can bundle calibration, training and digital reporting will win share and margin.
- Regulatory and procurement risk: Heightened standardization around calibration and phased‑array verification is changing procurement checklists — compliance will be table stakes for enterprise contracts.
Forces shaping supply, demand and returns
Our analysis groups the dynamics into four influencing layers:
Ultrasonic Flaw Detector Market
- Technology: Phased‑array ultrasonic testing and interpretive software continue to migrate from specialized labs into routine field inspection. Portable devices are evolving into software‑centric instruments with cloud‑enabled data management and automated analysis pipelines.
- Standards and regulation: Recent updates to calibration and verification standards — including new emphasis on equipment traceability and reference block accuracy — change buyer evaluation criteria and extend sales cycles for non‑compliant offerings. UNE‑EN ISO 22232‑1 and related ISO updates are shaping RFP language and acceptance testing practices.
- Supply chain and components: Piezoelectric transducer technology remains the dominant sensor architecture; our sector analysis shows bulk piezoelectric segments capturing the lion’s share of related sensor demand by 2026, a structural factor that keeps unit costs down but concentrates raw‑material exposure in a few supplier lines.
- Operational economics: Adoption of automated inspection workflows reduces technician dependency, shortens on‑site time and lowers training burden. That same automation shifts value from hardware unit sales to software licenses, data services and recurring calibration/maintenance revenues.
Competitive landscape — who matters and why
The market is neither a monopoly nor highly fragmented: the leading vendors command meaningful share, but mid‑tier and regional suppliers remain important partners for field service and low‑cost segments. Top incumbent brands combine global channel reach with recognized hardware platforms; smaller vendors compete on price, service agility and local relationships.
Ultrasonic Flaw Detector Market
- Waygate Technologies (Houston, USA) — A platform leader with broad portable and phased‑array portfolios (Mentor UT family, Krautkramer models). Strengths: deep enterprise relationships in energy and heavy industry, advanced phased‑array capabilities and validated calibration workflows. Strategic implication: incumbency advantage in large industrial tenders but exposure to price competition at the base of the market.
- Evident Scientific / Olympus IMS (Waltham, USA) — Offers conventional and phased‑array systems (EPOCH, OmniScan series) with strong software ecosystems for data capture and analysis. Strengths: integration of hardware and analytics; preferred by service providers focused on complex inspections. Strategic implication: prime target for partnerships where software differentiation is the sales hinge.
- Sonatest (Pune, India) — Competes on portable and phased‑array products designed for field use (WAVE, Veo3, Sitescan lines). Recent product documentation updates in 2025 sharpen its product claims and channel collateral. Strengths: agile product refresh cycles and competitive pricing. Strategic implication: an effective challenger for growth in emerging markets and service fleets.
- Danatronics (USA) — Specialist in compact portable detectors (ECHO FD, Echo Pro), with a 2025 product launch emphasizing simplified user workflows. Strengths: focused product set with rapid time‑to‑market. Strategic implication: attractive acquisition target for larger firms wanting entry into specific portable segments.
- SIUI (Shantou, China) — Offers compact, cost‑effective portable detectors tailored for general industry. Strengths: low‑cost manufacturing and wide distribution in price‑sensitive markets. Strategic implication: continuing price pressure at the low end; necessity for western OEMs to upgrade service and compliance offerings to defend margins.
- NDT Systems Inc., Zetec Inc., Elcometer — These vendors add depth across legacy digital systems, high‑performance UT equipment and ergonomically designed handhelds. Strengths: niche specialization and strong aftermarket/service presence. Strategic implication: consolidation candidates or strategic partners for service expansion.
Market concentration is moderate: the top three vendors capture less than half of total revenue, and the top five capture just over half. That structure leaves room for targeted M&A and regional plays while preserving substantial opportunity for differentiated product and service strategies.
Strategic playbook for 2026
For executives preparing 2026 plans, the following moves translate the market outlook into action:
- Prioritize software and data services: Reallocate R&D budgets from incremental hardware refinements into analytics, cloud reporting and AI‑assisted defect calling. Even modest subscription revenue can materially improve long‑term value capture.
- Invest in compliance and verification: Ensure product roadmaps and factory calibration workflows comply with evolving standards. Winning enterprise deals increasingly hinges on transparent calibration traceability.
- Secure piezoelectric supply lines: Evaluate multi‑sourcing, long‑term purchase agreements or vertical partnerships for transducer supply to dampen component volatility and avoid single‑source risk.
- Design a hybrid go‑to‑market: Combine global OEM branding with local service partners to reach price‑sensitive segments without eroding margin in premium accounts. Use training and certification programs as lock‑in mechanisms.
- Hunt for tuck‑ins that add service revenue: Identify mid‑tier vendors with strong field service footprints or complementary software capabilities — these are the most accretive M&A targets for revenue growth and faster ARR conversion.
- Repackage offerings for OPEX buyers: Create inspection‑as‑a‑service and managed‑inspection programs tailored to oil & gas, aerospace and manufacturing customers that prefer predictable operating expenditures.
What PW Consulting’s full study delivers — operational and executable
This research is designed to be a practical toolkit for 2026 decision‑makers rather than a high‑level narrative. Deliverables include:
- Comprehensive market sizing and trajectory model (2020–2032) with scenario toggles — base, upside, downside — accessible as an interactive spreadsheet so finance teams can re‑run forecasts under alternative assumptions.
- Go‑to‑market playbooks for three archetypes (OEMs, service integrators, financial sponsors) including customer segmentation frameworks, price/value matrices and channel economics.
- Competitive benchmarking dashboard mapping product feature sets (portable vs stationary, phased‑array capability, software integrations), route‑to‑market strengths and aftermarket footprints for the eight core vendors profiled.
- Regulatory and compliance matrix that translates standards (calibration, verification, traceability) into product and process requirements, acceptance checklists and suggested certification timelines.
- Supply‑chain heat map and cost‑sensitivity analysis focused on transducer inputs and electronics — with practical mitigation options (buffer inventory, dual‑sourcing, supplier partnerships).
- M&A shortlist and valuation frameworks for acquisitive players — including suggested integration playbooks to convert hardware sales into recurring service revenue.
- 90/180/365‑day tactical action plan designed to accelerate wins in core accounts, deploy pilots of automated inspection workflows, and prioritize certification investments required by large buyers.
Practical first steps for executives in 2026
Short list of immediate actions to translate insight into results:
- Run a gap analysis between your product calibration processes and the latest standards; select a short list of corrective investments with clear ROI timelines.
- Launch a pilot that bundles inspection hardware with standardized cloud reporting and a subscription analytics tier; measure uplift in customer retention and bid conversion rates.
- Negotiate transducer supply options with at least two suppliers and model the P&L impact of tiered pricing scenarios across expected unit volumes.
- Identify one mid‑tier service firm with strong regional presence and evaluate a partnership or bolt‑on acquisition to accelerate service revenue and field coverage.
Conclusion — what this intelligence enables
For boards and executive teams planning allocations and strategic moves in 2026, the ultrasonic flaw detector sector presents a rare combination: steady, predictable growth at the market level combined with tactical inflection points at the product, service and regulatory layers. The winners will be those who convert hardware credibility into recurring data and service revenue, align product roadmaps to tightened calibration standards, and secure resilient component supply while defending premium accounts against low‑cost entrants.
Next step
PW Consulting’s full Ultrasonic Flaw Detector Market report includes the detailed tables, interactive models and segment‑level intelligence required to underwrite 2026 investments and M&A decisions. For access to the complete dataset, scenario models and proprietary company profiles, please visit our report page and request the executive briefing package.
For detailed analysis of this topic, please visit the official page: Ultrasonic Flaw Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
EMP Filters Market to Hit USD 196.2M by 2032 at 9.5% CAGR - PW Consulting
By PW Consulting, 2026-07-12
Electromagnetic Pulse (EMP) Filters Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
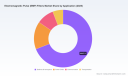
As governments and critical-infrastructure operators move from awareness to deployment, the market for Electromagnetic Pulse (EMP) and High-altitude Electromagnetic Pulse (HEMP) filters has entered a sustained growth phase. Our analysis shows the global market expanding from roughly USD 65 million in 2020 to about USD 104 million in 2025, with a compound annual growth rate of 9.5% projected through the 2026–2032 forecast horizon. By 2032 the market is expected to approach the USD 200 million range. For executives planning 2026 capital allocations, procurement strategies, and technology partnerships, this trajectory signals an inflection: EMP protection is no longer a niche defence line-item but an operationally material element of resilience planning.
Electromagnetic Pulse (EMP) Filters Market
Why this matters for decisions in 2026
-
Threat environment is changing. Intentional electromagnetic interference (IEMI), non‑nuclear EMP events and targeted transient attacks are now recognized vectors against networked systems. Organizations that treat EMP protection as a point-in-time compliance exercise risk costly rework or service interruptions.
Electromagnetic Pulse (EMP) Filters Market -
Standards and testing are differentiating factors. Military-grade specifications such as MIL-STD-188-125-1A remain the benchmark for point-of-entry protection in high-risk assets; meanwhile, civilian attenuation requirements differ materially. Procurement teams must match attenuation profiles and independent acceptance testing to the actual threat model rather than default to “military-grade” premiums.
Electromagnetic Pulse (EMP) Filters Market -
Market economics favour quick movers. The submarket is growing at a near‑double‑digit CAGR, which translates into expanding supplier activity, product launches, and distributor partnerships. Firms that establish credible supplier relationships, validation processes and deployment pilots in 2026 will secure preferred access to constrained capacity and specialized engineering services.
Market dynamics and demand drivers
Three structural forces are driving the EMP filters market:
-
Critical‑infrastructure hardening: Power utilities, telecom operators and defense agencies are budgeting for layered protection as part of resilience programs. The shift to decentralized energy, electrified transport, and dense telecommunications nodes increases both exposure and the number of points requiring protection.
-
Technology and product evolution: Suppliers are delivering broader portfolios—ranging from low-voltage point-of-use filters and filtered connectors to now-commercial medium‑voltage HEMP filters designed for substation and distribution-level protection. This extends the applicability of EMP protection beyond tactical platforms into utility-scale assets.
-
Certification and trust: Independent acceptance testing by accredited labs and adherence to recognized standards are table-stakes. Buyers are increasingly demanding documented performance (insertion loss, pulse handling, and acceptance testing) and traceable certification to de‑risk procurement and lifecycle support.
Competitive landscape — what to watch
The supplier base exhibits meaningful specialization: dedicated EMP/HEMP filter manufacturers, connector and interconnect specialists, and systems integrators that pair filters with shielding and transits. Market concentration is moderate: the three largest suppliers account for a material share of revenue and the top five firms consolidate a clear majority of market value, which creates both competitive pressure and partnership opportunities.
Strategic implications by supplier archetype:
-
Specialist filter manufacturers (example capabilities): These vendors focus on high‑insertion‑loss, military‑grade filters and transportable solutions. Their strengths include in-depth testing, legacy defense procurement relationships, and rapid response engineering for bespoke configurations—critical when attenuation requirements or transient profiles fall outside commodity specifications.
-
Connector and interconnect manufacturers: Firms that integrate filter elements into connectors and planar arrays bring advantages where space, weight and MIL‑DTL form‑factors matter. For airborne and ruggedized applications, these suppliers reduce system-level integration risk.
-
System integrators and shielding specialists: Vendors that combine filters with shielded racks, cable transits and enclosure systems are winning large, turnkey procurements for hospitals, data centres and SCIF-grade installations. Their value proposition is integration and lifecycle assurance rather than component-level price.
Recent vendor activity underscores the market’s momentum: some suppliers introduced medium-voltage HEMP filters for utility applications, others launched integrated EMP protection suites for critical operations, and certain niche manufacturers expanded channel coverage through distribution agreements in new geographies. For buyers, these developments mean an expanding vendor set but also the need to validate new product claims against independent test reports and field acceptance data.
Regulation, standards and technical realities
-
Standards set performance expectations but do not eliminate buyer due diligence. MIL‑STD‑188‑125‑1A remains a reference for point-of-entry protection in high-threat environments, including requirements for high insertion loss across wide frequency bands. Civilian HEMP use-cases, however, often require different attenuation profiles; matching requirement to asset criticality reduces over‑engineering and unnecessary CAPEX.
-
Certification pathways matter. Practitioners should require independent acceptance testing and chain‑of‑custody documentation. Vendors that can demonstrate verified performance through accredited third-party labs earn a procurement premium and reduce program risk.
What the PW Consulting report contains (practical value for 2026)
The full PW Consulting market study is organized to convert insight into actionable steps. Highlights include:
-
Validated market sizing and growth forecasts (2020–2032) with scenario analyses that stress-test demand under alternative threat, regulatory and technology adoption paths.
-
Vendor profiles and capability matrices that evaluate certification status, testing capacity, product breadth, and aftermarket service—presented as a buyer’s decision framework for shortlisting suppliers.
-
Procurement playbooks: specification checklists, acceptance-testing requirements, suggested contractual guardrails (including repair/replace SLAs, spare parts provisioning and obsolescence management).
-
Technology assessment: attenuation performance trade-offs, connectorized versus point‑of‑entry solutions, and system-level integration considerations for grid, communications and secure facilities.
-
Supply‑chain map and risk register: lead‑time sensitivity, single-source exposures, and mitigation strategies for constrained components and test-lab throughput.
-
Investment and M&A compass: screening criteria for acquiring niche manufacturers, partnering with integrators, or establishing distribution partnerships in growth geographies.
Actionable recommendations for 2026 planning
-
Align threat model to attenuation specification. Rather than defaulting to the highest attenuation spec, define asset criticality and disturbance scenarios to determine whether military‑grade attenuation or civilian HEMP performance is appropriate.
-
Run pilot deployments on medium-voltage feeders and high-risk points of entry. Recent commercial availability of medium‑voltage HEMP filters enables pilots at substations; a 2026 pilot program positions utilities to validate performance and develop installation standards before broader rollouts.
-
Standardize acceptance testing in procurement contracts. Require documented third‑party tests and field acceptance signatures; include clause for periodic re‑testing after major firmware/hardware changes in the protected systems.
-
Design for layered protection and lifecycle support. Combine filter technology with physical shielding, sealing solutions for cable transits and connectorized filtering where space‑constrained integration matters.
-
Adopt supplier diversification plus strategic partnerships. The market’s concentration suggests a limited set of proven suppliers for certain performance levels; use dual‑sourcing and distribution partnerships to secure capacity while negotiating technical transfer and local support arrangements.
-
Embed EMP considerations into capex planning. Treat EMP protection as a resilience investment tied to asset availability targets; use the market’s growth profile to negotiate multi‑year pricing and service agreements.
How PW Consulting can accelerate your 2026 program
This preview highlights the strategic choices decision-makers face next year—selection of technical profiles, supplier risk management, pilot planning, and budget prioritization. The full PW Consulting study contains the granular segmentation, regional and application-level modelling, vendor scorecards and price curves needed to translate these recommendations into procurement schedules and investment cases. To access the detailed breakdowns, scenario outputs and supplier dossiers that inform an actionable 2026 roadmap, please consult the complete report and supporting annexes.
Decision-makers who treat EMP protection as a strategic resilience discipline in 2026—not an afterthought—will convert rising market momentum into durable operational advantage.
For detailed analysis of this topic, please visit the official page: Electromagnetic Pulse (EMP) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electron Beam Resists Market Poised for 6.5% CAGR Through 2032
By PW Consulting, 2026-07-12
Electron Beam Resists Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
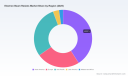
PW Consulting’s new Electron Beam Resists Market study delivers a market-centric, execution-ready intelligence package calibrated to the calendar year 2026. At the macro level, the market has expanded from roughly USD 280 million in 2020 to about USD 355 million in 2025 and is projected to continue its upward trajectory, reaching an estimated USD 544 million by 2032. This trajectory implies mid-single-digit compound annual growth across the forecast horizon (the model uses a 6.5% CAGR for 2026–2032), driven by continued investment in high-resolution patterning for semiconductors, advanced storage media, and emerging nanofabrication processes.
Electron Beam Resists Market
Why this report matters for decisions in 2026
- Make capital-allocation choices with confidence: the report translates forecast ranges into capital- and capacity-planning thresholds for R&D, production scale-up, and contract manufacturing.
- Prioritise product and developer chemistry investments: we show where HSQ-like chemistries and PMMA derivatives are likely to capture incremental value, and where formulation breakthroughs will re-shape adoption curves.
- De-risk supply and procurement: the research quantifies exposure to raw-material cost swings and minimum-order constraints and provides mitigation playbooks for 12–36 month procurement cycles.
- Inform M&A and partner screening: the competitive analysis and vendor scorecards isolate acquisition targets and strategic partnerships most likely to accelerate entry into advanced lithography segments.
What the research delivers — operational, decision-grade content
- Validated historical market sizing (2020–2025) and high‑granularity forecasting (2026–2032) with upside/downside scenarios tied to device demand, research funding, and regulatory shifts.
- Commercial segmentation by technology class, application family, and go-to-market channel (including channel economics and buyer behavior matrices).
- Supply‑chain stress-testing: vendor concentration maps, raw-material sourcing risk scores, lead-time elasticities, and minimum-order sensitivity models.
- Technology deep dives: performance envelopes for HSQ-based, PMMA, and hybrid resist chemistries, including process compatibility and resolution metrics.
- Competitive playbooks: vendor scorecards, pricing matrices, and capability gaps for incumbents and scale-up challengers.
- Regulatory and environmental impact assessment: developer chemistry pathways, waste management constraints, and compliance timing for major jurisdictions.
- Commercial due diligence toolkits: integration checklists, synergy calculators, and two-way earn-out model templates for potential acquisitions.
Market dynamics shaping the 2026 strategic agenda
Several structural and tactical forces will determine winners and losers over the next 24–36 months. First, demand remains anchored in semiconductor patterning and next‑generation data storage — both of which require sustained improvements in resolution, line edge roughness, and process latitude. Parallel growth pockets are emerging in nanoimprint lithography and specialized research markets, creating opportunities for premium pricing on high‑performance formulations.
Electron Beam Resists Market
Second, formulation innovation is accelerating. Recent product introductions demonstrate that commercially viable HSQ alternatives and optimized PMMA derivatives are reaching reproducible sub‑5 nm performance in production‑oriented workflows. These advances compress the timeline for adoption by foundries and advanced research fabs, increasing the premium for resist vendors that can demonstrate process robustness across temperature and storage conditions.
Electron Beam Resists Market
Third, regulatory and sustainability pressures are re-shaping process chemistry choices. A notable example is the industry move toward safer developer chemistries: choline‑based developers, presented publicly in 2025, are positioned as less hazardous and more biodegradable alternatives to traditional alkaline developers. For manufacturers and OEMs, this trend will influence procurement specifications, customer acceptance criteria, and potentially production footprint decisions in jurisdictions with tightening chemical controls.
Finally, raw-material economics matter more than ever. For certain HSQ-style formulations recently commercialized, raw‑material production costs were reported in the upper four‑digit dollar range per liter with minimum order quantities that effectively set a one‑liter commercial unit and limited shelf life to about six months. That profile creates working‑capital and inventory risks for smaller buyers while motivating larger-scale purchasers to pursue volume contracts or backward integration.
Competition and technology briefs — who to watch
- Allresist GmbH (Germany) : A focused developer and manufacturer of multiple e‑beam resist chemistries. Recent milestones include the commercial launch of a new HSQ‑category product in late 2025 that demonstrated repeatable sub‑5 nm line widths across extended sample storage conditions, and public presentation of a choline‑based developer as a safer alternative to legacy alkaline developers. Allresist’s incremental innovations — including compatibility adjustments for conductive resists used on insulating substrates — make it a technology leader in application‑specific formulations.
- EM Resist Ltd (United Kingdom) : Specialist supplier of high‑resolution HSQ negative-tone resists and positive‑tone PMMA variants. The company introduced a higher concentration HSQ formulation in early 2025 and is active in niche nanofabrication research channels, a profile that makes it both a partner for early adopters and a potential acquisition target for larger chemical houses seeking high‑resolution capabilities.
- Kayaku Advanced Materials (United States) : A broad supplier with established PMMA and mr‑EBL series resist lines targeting microelectronics and research markets. Kayaku’s scale and distribution footprint position it well for customers seeking supply security and global logistics, especially as minimum order quantities and shelf life considerations increasingly differentiate suppliers.
Market structure and consolidation outlook
The sector exhibits moderate concentration: the largest three firms account for a meaningful share of market revenue, and the top five increase that concentration materially. That structure creates a dual dynamic. On the one hand, incumbent vendors can leverage scale to absorb raw-material input volatility and to underwrite product development. On the other hand, mid‑tier and specialist suppliers exploit niche process advantages and faster innovation cycles to capture value in high‑margin applications. The competitive landscape therefore supports both bolt‑on M&A for established chemical groups and organic growth plays for agile formulators partnering with foundries and research labs.
Strategic plays for companies making 2026 decisions
- Procurement and supply: lock in multi‑year agreements for critical precursors, evaluate contract manufacturing partnerships to reduce MOQ exposure, and model inventory buffers that reflect six‑month shelf‑life constraints on some HSQ precursors.
- R&D and product positioning: prioritize formulations that balance resolution with process latitude and environmental compliance; accelerate validation trials with a small set of strategic fabs to shorten qualification cycles.
- Go‑to‑market and commercial partnerships: co‑develop application notes and process recipes with leading academic and industrial users to reduce adoption friction and create visible performance references.
- M&A and alliances: target specialist HSQ and developer chemistry teams for bolt‑on acquisitions where IP and process know‑how are the primary assets; for larger players, invest in vertical integration of high‑cost precursors that present supply risk.
- Regulatory and ESG risk mitigation: proactively transition to developer chemistries with lower occupational and environmental hazards, anticipate customer specification shifts, and incorporate compliance timelines into product launch calendars.
How PW Consulting’s deliverables translate into boardroom actions
Our report is structured to transform market insight into executable decisions. Each chapter ties forecast outputs to a specific governance action: capital-expenditure thresholds for manufacturing expansion, vendor selection rules for procurement, deal‑structuring templates for M&A, and a regulatory roadmap that links product design to compliance milestones. The suite includes downloadable financial models (sensitivity-tested), supplier heatmaps, vendor scorecards, and scenario playbooks that allow commercial teams to quantify trade-offs in minutes rather than weeks.
Next steps — where to find the depth
This article highlights the strategic contours and decision levers that matter for 2026. For operational leaders needing the underlying datasets — including regional and application splits, vendor-level revenue and pricing assumptions, technology performance matrices, and full scenario model workbooks — the complete PW Consulting report provides the granular tables, charts, and model files required to translate strategy into execution. Access to the full dataset includes custom briefing sessions and a one‑day workshop option to calibrate the findings to your portfolio or transaction thesis.
In an environment where chemistry choices, raw‑material economics, and regulatory shifts are converging to re‑price differentiation, the right intelligence — timely, specific, and operational — becomes a competitive weapon. PW Consulting’s Electron Beam Resists Market study is designed to be that weapon for 2026 decision-makers.
For detailed analysis of this topic, please visit the official page: Electron Beam Resists Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Anchors Market to Reach USD 4.64B by 2032 at 3.42% CAGR
By PW Consulting, 2026-07-12
Concrete Anchors & Fasteners Market — Strategic Briefing for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, actionable introduction to our full Concrete Anchors & Fasteners Market study. This briefing distills the structural forces, competitive dynamics, and decision levers that will matter most for capital allocation, sourcing, product strategy, and M&A through 2026 — while preserving the detailed, proprietary segmentation and scenario outputs for subscribers of the full report.
Concrete Anchors/Fasteners Market
Why this market matters in 2026
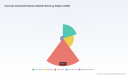
Concrete anchors and fasteners sit at the intersection of construction activity, infrastructure renewal, industrial installation, and building-code evolution. After a steady recovery in the early 2020s, the global market achieved an estimated size of USD 3.65 Billion in the base year 2025 and is forecast to grow to approximately USD 4.64 Billion by 2032 — a compound annual growth rate of about 3.42% across the 2026–2032 forecast horizon. That trajectory reflects structural demand from commercial and industrial capex, selective residential resilience, and public-sector infrastructure programs.
Concrete Anchors/Fasteners Market
For corporate leadership, 2026 is a year for translating macro certainty into tactical advantage: locking supply chains against raw-material volatility, optimizing channel footprints as installer buying patterns shift, and positioning product portfolios for tightening regulatory acceptance criteria in post-installed anchors.
Concrete Anchors/Fasteners Market
High-level market dynamics you must plan for
- Demand continuity with pockets of premiumization. Market growth is moderate and uneven: routine repair, refurbishment, and retrofit work underpin baseline demand while specific segments demonstrate willingness to pay for certified, higher-value solutions (e.g., systems with extended performance warranties or specialty chemical anchors).
- Raw-material pressure and cost management. Carbon steel remains the primary raw material used across the category. Price volatility in carbon steel is a persistent input risk that flows through supplier margins and buyer procurement decisions — making hedging, supplier diversification, and design-for-material-efficiency core 2026 priorities.
- Regulatory and code-driven gatekeeping. Post-installed anchors increasingly must meet qualification standards (notably ACI 355.2 for mechanical anchors and ACI 355.4 for adhesive anchors, as referenced by the 2024 International Building Code). Companies that can articulate certified test protocols, provide supporting documentation, and internalize compliance costs will win a disproportionate share of specification-driven tenders.
- Commercial dynamics: distribution/installer influence. The buyer base remains fragmented at the installer level but consolidated upstream among OEMs and large distributors. Go-to-market sophistication — from technical sales to installer training and on-site specification support — is now a differentiator, not just a cost center.
- Product innovation is manufacturing + install efficiency. Recent launches emphasize speed, repeatability, and lowered rework risk. A March 2026 product introduction — a reusable template system for rapid anchor-bolt placement — exemplifies the category’s move toward time-saving installation aids that reduce labor variability and schedule risk on foundation and slab works.
What the full report provides (practical, execution-focused)
PW Consulting’s comprehensive study was designed for executives who need more than market numbers — they need executable playbooks. Key deliverables include:
- Executive summary with investment and go/no-go thresholds tied to growth scenarios for 2026–2032.
- Market-sizing and historical trend analysis validating the USD 3.65 Billion base and the 3.42% CAGR through 2032, with sensitivity to macro construction cycles.
- Regulatory impact matrix mapping ACI/IBC acceptance pathways by anchor type, including an actionable compliance checklist for product teams and certifying laboratories.
- Raw-material risk models and procurement response playbooks that quantify the P&L impact of carbon-steel price swings and present hedging and contract structures.
- Channel and route-to-market playbooks for distributor partnerships, national account engagement, and installer ecosystem development — including margin and service-level benchmarks.
- Commercial pricing and value-capture frameworks that reconcile installer willingness-to-pay with differentiated product features (mechanical vs. adhesive systems, installation aids, and testing services).
- Competitive landscaping with strategic profiles of the leading global OEMs and regional challengers, plus an M&A screening tool calibrated to market concentration and synergies.
- Case studies and three-year implementation roadmaps for capex deployment, manufacturing footprint optimization, and product-line rationalization.
Competitive landscape — who matters and why
The market combines global OEMs, specialist manufacturers, and regional brands that leverage local manufacturing and distribution. The competitive set includes longstanding engineering-led players focused on system performance and certification, global distributors offering breadth, and nimble regional manufacturers that compete on lead times and “made-in” credentials.
- Hilti Corporation — engineering-centric, premium positioning, strong in system warranties and installer training programs.
- Simpson Strong-Tie — deep anchoring systems expertise, broad product mix across mechanical and adhesive arenas, strong U.S. specification relationships.
- ITW Construction Products (Red Head) — historical strength in adhesive anchors and chemical systems; integrated distribution partnerships.
- MKT Fastening LLC — U.S.-manufactured focus, attractive for buyers prioritizing local supply and rapid delivery.
- fischer fixings & Würth Group — European engineering and distribution scale, with emphasis on steel fixings and heavy-duty anchors.
- Powers Fasteners — recognized for wedge anchors and contractor-oriented solutions; close ties to professional installer channels.
- Rawlplug — growth through product breadth across screw, mechanical, and chemical anchors; gains where modular performance matters.
- Concrete Fastening Systems & Cobra Anchors — regional specialists that compete on product availability, U.S. sourcing credentials, and price-performance.
Collectively, leading OEMs command material share at the global level, but the market still rewards regional agility, certification accessibility, and channel intimacy. Recent product introductions that reduce on-site labor or rework demonstrate how innovation can shift specification preferences faster than raw capacity investments.
Strategic implications and recommended 2026 actions
- Procurement & Supply Chain: Establish multi-tier contracts with steel suppliers, include indexation clauses linked to industrial steel benchmarks, and pilot inventory pooling with key distributors to reduce lead-time spikes.
- Product & R&D: Prioritize product variants that simplify installation and reduce inspection risk. Invest in certification kits and field demonstration resources to accelerate spec acceptance under ACI/IBC pathways.
- Go-to-market: Rebalance sales compensation to reward specification wins and training programs. Create installer accreditation programs to lock in repeat usage for higher-margin systems.
- M&A & Portfolio Moves: Target regional manufacturers with complementary footprint or proprietary installation aids rather than purely volume plays. Use our M&A screening tool to size accretion potential under three putative integration scenarios.
- Risk Management: Integrate raw-material price scenarios into product pricing models and tender bids. Maintain a dedicated compliance resource to track ACI updates and provide rapid route-to-compliance for new products.
How this brief should be used in boardroom decisions
Use this briefing as the strategic framing for three board-level decisions in 2026:
- Approval of a 12–24 month capex plan to expand capacity for higher-margin, certified anchor systems.
- Mandate to procurement to execute layered supply agreements and pilot distributor consignment models in two strategic regions.
- Greenlight for a bolt-on acquisition or partnership that accelerates installation-aid capabilities or broadens certified product portfolios.
Next steps — where to find the detailed evidence
This article purposefully highlights the strategic themes and operational implications while withholding the granular segmentation and regional/application breakdowns that underpin model-driven recommendations. The full PW Consulting report contains those detailed charts, quantitative segmentation, sensitivity tables, and the proprietary M&A screening dataset you’ll need to translate strategy into action.
For access to the complete dataset, scenario outputs, and a tailored briefing for your executive team, please consult the PW Consulting market page or contact your account director. Subscribers will receive the full dossier including appendices on methodology, primary interviews, and the regulatory compliance checklist that maps directly to ACI 355 series requirements.
PW Consulting remains available to facilitate a 90-minute executive workshop where we can: validate assumption sets against your operations, prioritize immediate tactical moves for 2026, and map a 36-month transformation program for product, channels, and supply chain resilience.
For detailed analysis of this topic, please visit the official page: Concrete Anchors/Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Asia‑Pacific Holds 52.8% of the Urea Market — Outlook to 2032
By PW Consulting, 2026-07-12
Urea Market 2026: Navigating a Low-Growth, High-Volatility Landscape — Strategic Insights from PW Consulting
As companies set strategy for 2026, choices made this year will determine competitive positioning across the urea value chain for the rest of the decade. Our new market study — anchored on a 2025 base year and projecting through 2032 — shows a mature global market expanding at a modest compound annual growth rate (CAGR) of 3.1% from 2026 to 2032. The market size recorded in 2025 stands at USD 82.62 Million (revenue unit: Million). Under our base forecast, the market rises to USD 104.41 Million by 2032. These headline metrics frame a story of steady demand underpinned by core agricultural consumption, but punctuated by intermittent supply shocks, input-cost volatility and a fast-accelerating sustainability agenda.
Urea Market
Why this study matters for 2026 decision-makers
-
Timing: 2026 is a pivot year. Feedstock markets that eased in 2025 have shown renewed volatility, regulatory pressure on fertilizers is intensifying, and technology pathways for low-emissions urea are entering early commercialization. Strategic moves made now — investments, sourcing shifts, product repositioning — will capture value or lock in rising cost exposure.
Urea Market -
Precision: The study translates headline growth into actionable scenarios for capex prioritization, product-mix optimization, and commercial hedging. We map the implications of a 3.1% CAGR onto unit economics and cash flow sensitivities across six operational archetypes (co-located ammonia-urea complexes, seafreight exporters, mid-scale inland producers, toll processors, specialty formulators, and controlled-release innovators).
Urea Market -
Risk-to-reward clarity: The report integrates near-term disruptions and medium-term structural shifts to create decision-ready matrices — helping executives balance short-term profitability with long-term strategic resilience.
Market dynamics shaping strategy in 2026
-
Feedstock and cost volatility: Ammonia remains the dominant input and a primary driver of urea cost curves. Recent months have delivered mixed signals — production costs fell meaningfully in some markets late in 2025, yet ammonia prices rebounded into late-2025. At the same time, liquid sulfur moved sharply higher within a year, exerting upward pressure on production costs where sulfur feed is integral to routes or logistics. These movements increase the importance of flexible sourcing, long-term offtakes and hedging frameworks for producers and large buyers.
-
Supply shocks and trade flow sensitivity: The industry continues to exhibit sensitivity to localized energy and infrastructure disruptions. A major exporter experienced a temporary halt to operations in early 2026, underlining the risk of concentrated production footprints. Our modelling shows short interruptions have outsized effects on regional freight and spot pricing — a reminder that geographic and logistical diversification matter even in a modest-growth market.
-
Regulatory and trade headwinds: Trade policy moves in key markets are already reshaping commercial flows. Import barriers and targeted tariffs introduce margin risk for seaborne suppliers and elevate the value of regionalized supply. Simultaneously, regulatory scrutiny around emissions and nutrient runoff is fueling demand for premium and stabilized products, which command a price differential and require different go-to-market capabilities.
-
Product and technology inflection: 2025–2026 saw credible progress on product-level emissions claims and new application formats. Manufacturers and technology suppliers verified emissions reductions from stabilized urea formulations, and several markets scaled nano-urea production for concentrated application formats. Separately, green ammonia-to-urea routes are moving from pilot to early commercial stages with selective off-takers already contracting low-carbon volumes. These trends create a bifurcated market: commodity urea with tight margin management, and premium segments driven by sustainability and agronomic performance.
Competitive landscape — direction without the proprietary detail
The industry is neither atomized nor monopolized. Market concentration is moderate: the largest global players collectively hold a substantial share of seaborne flows and capacity, but national champions and regional producers maintain significant local dominance. This creates room for both scale-driven exporters and agile regional specialists.
-
Large integrated fertilizers and ammonia majors are leveraging scale and feedstock integration to defend margins. Their strategies emphasize reliability of supply, incremental low-carbon product offerings and control over seaborne logistics.
-
Regionally focused companies and traders compete on customer intimacy, service models and tailored product mixes (e.g., enhanced-efficiency fertilizers for specialty cropping systems).
-
Newer entrants and portfolio players are targeting premium niches — controlled-release, stabilized products, nano-formulations — where technical differentiation can translate to higher margins and customer stickiness.
Our full company profiles include detailed financial and operational benchmarking across the peer set, including plant footprints, product portfolios, recent capital projects and strategic priorities. For example, leaders in Europe and North America are advancing low-carbon urea routes and enhanced-efficiency formulations, while Gulf-region producers continue to dominate seaborne export capabilities. Major publicly listed players and state-backed groups all feature in the competitive map, and our scorecards evaluate them on scale, feedstock security, decarbonization readiness, and commercial agility.
What’s included in the PW Consulting urea study (practical toolkit)
-
Integrated forecast model (2026–2032) — top-line market trajectories and scenario variants that stress-test demand and supply under different oil, ammonia and trade assumptions.
-
Cost and margin curve analyses — plant-level cost buckets, feedstock sensitivities, and break-even maps for different operational archetypes.
-
Supply-side inventory — a validated register of major production assets (operational status, technology route, ownership structure), plus a pipeline tracker for announced projects and commissioning windows.
-
Policy & regulatory scenarios — trade-policy shocks, emissions pricing, and nutrient management regimes modelled for commercial impact through 2032.
-
Product segmentation playbooks — go-to-market guidance for commodity, stabilized and specialty urea products, including pricing strategy, channel design, and agronomic validation requirements.
-
Company scorecards and M&A decision framework — tailored diligence checklists, valuation sensitivities and integration blueprints for both bolt-on and transformational deals.
-
Operational resilience & procurement protocols — actionable measures to reduce exposure to feedstock swings and logistical disruptions, including contract templates and shortlists of risk-mitigation partners.
Strategic actions for corporate leaders in 2026
-
Stress-test your portfolio against at least three cost scenarios: commodity-soft, feedstock-shock, and premium-adoption. Use the study’s scenario engine to quantify bottom-line sensitivity and inform capex gating decisions.
-
Prioritize feedstock security: lock in long-term ammonia supply or consider co-investment in upstream capacity where scale economics justify. For trading and merchant businesses, diversify shipping and storage footprints to mitigate short interruptions that can cascade into spot price spikes.
-
Define a clear product stratification strategy. Maintain competitive pricing in the commodity core, while selectively expanding stabilized and enhanced-efficiency offerings where agronomic data and local regulation support a premium.
-
Make decarbonization decisions commercial. Select pilot customers and long-term offtakers for low-carbon urea volumes; structure offtake agreements and price premia based on verified emissions reduction claims.
-
Use M&A selectively. Small, targeted acquisitions can accelerate entry into specialty segments or improve route-to-market in high-value regions. Larger transactions should be justified by feedstock synergies or the ability to capture seaborne supply economics.
-
Embed geopolitics into procurement. Tariff and trade barriers are no longer rare events; model tariff scenarios and quantify the elasticity of your trading routes to rapid policy shifts.
Signal events and near-term monitors
-
Operational continuity at large export hubs — any extended outage can reshape spot spreads and create short-term arbitrage opportunities.
-
Ammonia cost trajectory and sulfur market behavior — these are the principal levers on the cost curve; procurement teams must have live-tracking and hedging playbooks.
-
Regulatory approvals for stabilized and nano-formulations — verification of emissions or agronomic claims materially affects premium potential and market acceptance.
-
New commissioning waves in target markets — domestic production expansion can compress imports and change regional pricing dynamics.
Closing — the value proposition of the full report
Our 2026 urea market study is designed as a decision accelerator. It combines rigorous forecasting with hands-on tools — models, scorecards, procurement playbooks and scenario generators — so executives can move from insight to action within weeks, not months. This article outlines the strategic contours and immediate implications; the full report contains the granular datasets, segmented forecasts, and company-level metrics required for transaction-level or operational planning.
For teams preparing budgets, negotiating offtake agreements, evaluating decarbonization investments, or sizing M&A targets, the difference between a prudent and a transformative decision in 2026 will be the quality of the market intelligence behind it. PW Consulting’s full study gives you that edge.
Access to the full dataset, regional and application splits, plant-level profiles and the interactive forecast model is available on our report landing page — where the detailed numbers and tools required to execute on the strategies above are provided to subscribers and clients.
For detailed analysis of this topic, please visit the official page: Urea Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Continuous Emission Monitoring Systems (CEMS) Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
As regulatory scrutiny and corporate net-zero commitments intensify, the global Continuous Emission Monitoring Systems (CEMS) market has entered a multi-year growth phase. Our analysis, anchored on a 2025 base year and a comprehensive historical window (2020–2025), shows the market expanding at a compound annual growth rate (CAGR) of 9.4% through the 2026–2032 forecast horizon. From a market size of roughly USD 2.25 Billion in 2025, projected trajectories point to a materially larger installed base and service economy by 2032, driven by regulatory upgrades, technology substitution, and increasing demand for multi-pollutant, data-integrated solutions.
Continuous Emission Monitoring Systems (CEMS) Market
Why this research matters in 2026
- Regulatory inflection points: 2026 is not business as usual. Major compliance frameworks are being modernized—most notably the US EPA's ECMPS 2.0 rollout and revisions to European industrial emissions guidance—that will materially affect reporting, data format requirements, and the permissible measurement ranges for CEMS. These changes create both compliance risk and procurement opportunity windows.
- Technology parity and differentiation: Laser-based techniques, FTIR, hybrid analyzers, and improved particulate sensing are converging toward higher fidelity, lower maintenance, and expanded multi-species capability. Vendors that translate these technical advances into lower total cost of ownership (TCO) and simpler regulatory acceptance will capture share.
- Services and data monetization: As installations proliferate, the aftermarket—calibration, remote diagnostics, software updates, and data assurance—will represent an increasingly valuable margin pool. Buyers must evaluate OPEX impacts alongside capital costs.
- Supply chain and integration risk: CEMS is no longer plug-and-play; it sits at the intersection of field instrumentation, local control systems, and enterprise data platforms. Procurement decisions in 2026 must incorporate integration roadmaps and cyber-physical risk assessments.
What the PW Consulting CEMS study delivers
This report is designed for executives who must convert regulatory change and technology trends into investment-grade decisions during 2026. It provides actionable, operational intelligence across the entire investment timeline—from initial vendor shortlisting to multi-site rollout and aftermarket optimization.
Continuous Emission Monitoring Systems (CEMS) Market
- Proven market-sizing and forecast methodology with sensitivity scenarios reflecting regulatory acceleration and slower adoption paths.
- Clear articulation of near-term demand drivers and inhibitors, including an up-to-date regulatory matrix and compliance timelines affecting procurement cycles.
- Technology decision frameworks that translate instrument-level performance into plant-level KPIs: measurement accuracy, drift, calibration cadence, spare-parts footprint, and integration effort.
- Practical TCO models and deployment cost envelopes that allow finance teams to compare models across procurement, leasing, and service-centric contracting strategies.
- Vendor evaluation scorecards and RFP templates tailored for different buyer archetypes (large utility, mid-sized industrial, engineering service provider).
- Implementation playbooks and failure-mode checklists drawn from field deployments and supplier audits to minimize first-year performance risk.
Industry dynamics shaping 2026 decisions
- Policy and standard updates: The upcoming ECMPS 2.0 release (scheduled for Q1 2026) and tightened European compliance thresholds are accelerating replacement cycles for legacy systems and expanding the addressable market for high-fidelity, multi-gas analyzers.
- New product momentum: Recent product introductions—such as a hybrid laser-paramagnetic analyzer released in early 2026—indicate a vendor shift toward hybrid platforms that balance sensitivity with operational robustness. These launches are meaningful because they shorten the technology adoption lag for end-users who prioritize regulatory defensibility.
- Consolidation and concentration: Market concentration metrics show a moderate consolidation: the leading three vendors account for nearly half of industry revenues, and the top five approach roughly two-thirds. This structure informs competitive dynamics—scale matters for service coverage and software ecosystems, but niche specialists remain strategically important for bespoke or hard-to-measure pollutants.
- Cross-industry demand: Beyond the obvious utility and heavy-industrial buyers, demand pockets are emerging where multi-component, low-drift measurement capability matters—these include process industries, waste-to-energy, and large industrial complexes pursuing integrated emissions and energy optimization programs.
Competitive landscape: strategic takeaways for buyers and investors
We profile established global leaders, specialist instrument builders, and emerging systems integrators. The vendor universe shows differentiated positions along product breadth, regulatory pedigree, and aftermarket/service capability.
Continuous Emission Monitoring Systems (CEMS) Market
- ABB Ltd. (Zurich, Switzerland) — Recognized for its hardware breadth and compliance-focused offerings, ABB’s multi-component platforms deliver certified low-range measurement capability. Strategic buyers should engage ABB when project requirements prioritize regulatory defensibility and broad multi-gas coverage.
- Siemens AG (Munich, Germany) — With a process-analytics orientation, Siemens competes on systems integration and alignment with industrial control architectures. Their strength lies in marrying analytics to plant automation for operations-led emissions management.
- Emerson Electric Co. (St. Louis, USA) — Emerson’s recent introduction of a hybrid laser-paramagnetic analyzer underscores a push toward hybrid architectures that increase measurement scope while reducing maintenance. Emerson is a strong candidate where hybrid performance and supplier lifecycle support are decision criteria.
- Teledyne Technologies Inc. (Los Angeles, USA) — Teledyne’s component-level expertise—particularly in particulate monitors and high-performance gas modules—makes it a vital partner for OEMs and EPCs designing bespoke systems or upgrades.
- HORIBA, Ltd. (Kyoto, Japan) — Focused on integrated CEMS with robust software stacks, HORIBA is frequently selected by buyers seeking turnkey stack-gas monitoring with strong data processing capabilities.
- Thermo Fisher Scientific Inc. (Waltham, USA) — A go-to for compliance-critical analyzers in jurisdictions with strict EPA-aligned requirements, Thermo Fisher combines regulatory legacy with broad field acceptance.
- SICK AG (Waldkirch, Germany) — SICK’s particulate monitoring pedigree and integrated system offerings suit projects where dust measurement and continuity of reporting are central.
- DURAG GROUP (Hamburg, Germany) — Known for advanced dust and gas analyzers and industry-focused systems, DURAG is a fit for complex installations requiring specialized measurement chains.
- ENVEA Group (Paris, France) — ENVEA’s multi-pollutant stacks, including dioxins and mercury capability, position the company in niches with elevated regulatory complexity.
- Fuji Electric Co., Ltd. (Tokyo, Japan) — Fuji’s multi-component, real-time CEMS offerings are attractive for process industries seeking broad flue-gas visibility.
- Gasmet Technologies Oy (Helsinki, Finland) — FTIR specialists like Gasmet provide simultaneous multi-gas and VOC analysis that is particularly useful in complex-species monitoring and fugitive emissions screening.
- AMETEK, Inc.; IMR Environmental; M&C TechGroup; California Analytical Instruments — These firms occupy important niches: compliance analyzers, environmental monitoring, continuous process monitoring, and regionally focused gas analyzer expertise. They are commonly used in hybrid procurement strategies where OEM-supply is combined with specialist integration.
Strategic implications for 2026 execution
- Align procurement with regulatory timelines: Given the timing of ECMPS 2.0 and similar updates, staged procurement that prioritizes high-risk sites and regulatory hot spots will protect compliance while smoothing capex profiles.
- Prioritize TCO and service networks: The choice between a lower-capex instrument and a service-rich supplier will often be decided by the site’s ability to perform on-site calibration and the criticality of uninterrupted data streams. Factor lifecycle service availability into vendor scoring.
- Design for data integration: Contracts should include data-format and API requirements, cyber-security provisions, and provisions for third-party validation to reduce lock-in risk and ensure auditability.
- Use pilots to de-risk technology adoption: Pilot deployments of hybrid or FTIR systems on representative stacks reduce uncertainty and reveal operational integration costs not obvious in vendor literature.
- Consider M&A and partnership screening: For investors, the moderate concentration in the market suggests opportunities to consolidate regional specialists or to back service platform plays that aggregate data across portfolios.
How to convert this intelligence into 90-day actions
- Run a rapid compliance gap assessment across your asset base, prioritizing sites with imminent reporting changes or known measurement blind spots.
- Initiate vendor shortlists using the scorecards in this report, conducting RFIs that request lifecycle cost models and integration case studies rather than list prices.
- Launch 3–6 month pilots for at least two different technology approaches (e.g., hybrid vs. FTIR) to validate TCO assumptions under operational conditions.
- Negotiate service-level agreements that include data integrity clauses, spare parts turnaround times, and remote diagnostics—then incorporate them into your capital planning.
Closing – a pragmatic invitation
For executives who must build defensible 2026 budgets, select the right CEMS partners, or evaluate acquisition targets, this PW Consulting study provides the analytical scaffolding and operational tools to turn regulatory and technology change into competitive advantage. The analysis above intentionally highlights strategic signals and supplier positioning while withholding the granular segment-level tables and proprietary vendor scoring that are central to competitive procurement. To access the full segmentation, supplier scorecards, methodology, and downloadable RFP templates, please visit our report page for the complete dataset and tailored briefings.
For detailed analysis of this topic, please visit the official page: Continuous Emission Monitoring Systems (CEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


