



Category: market research
PW Consulting: Variable Optical Attenuators Market to Reach USD 2,039M by 2032 at 9.8% CAGR
By PW Consulting, 2026-07-12
Variable Optic Attenuators Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a strategic primer designed to orient executive teams, corporate development groups, and product planners to the critical inflection points shaping the Variable Optic Attenuators (VOA) market as they prepare plans for 2026. This preview synthesizes the quantitative market trajectory, the technology and supply‑chain forces at play, and the competitive moves that will determine who captures value in the next wave of optical networking and sensing investments. It intentionally highlights analytical depth while reserving detailed segment-level figures for the full market study — a deliberate “trailer” to encourage deeper read‑through of our complete report.
Variable Optic Attenuators Market
Macro snapshot: growth profile and market scale
Through methodical modeling using a 2025 base year and a historical window that spans 2020–2025, PW Consulting projects the VOA market to continue expanding robustly through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 9.8%. The industry has moved from early recovery into structural growth driven by several converging trends in telecommunications, data centers, sensing and test equipment. By 2026 the market steps into a new growth band that accelerates investment in higher‑precision and integrated attenuation solutions, and by the latter part of the forecast horizon the market crosses the multi‑billion dollar threshold (USD, revenue unit: Million). This is not a fad: the growth path is broad‑based across use cases and geographies, even as competitive intensity and supplier strategies differ by sub‑segment.
Variable Optic Attenuators Market
Why this matters for 2026 strategy
- Timing of capital allocation: With near‑double‑digit CAGR, VOAs are transitioning from commodity peripherals toward higher‑margin, system‑integrated components. Product roadmaps and R&D budgets in 2026 should reallocate toward MEMS, PIC‑compatible VOAs, and embedded power‑metering capabilities to capture outsized returns.
- Supply‑chain and sourcing playbooks: MEMS chips and specialized fiber materials remain critical inputs with concentrated supply routes. Procurement teams must implement multi‑tier sourcing, buffer strategies, and supplier development programs in 2026 to hedge geopolitical and tariff risk.
- M&A and partnership timing: Given the market’s measured consolidation (moderate top‑tier share concentration), 2026 is an opportune window for strategic tuck‑ins and technology acquisitions that close gaps in electrostatic MEMS, LNOI/PIC integration, or multi‑channel attenuator capabilities.
- Regulatory and compliance readiness: New reliability testing standards and rising tariff noise necessitate compliance and scenario planning. Certification investments in 2026 can serve as points of differentiation.
What the full PW Consulting report delivers (practical, actionable content)
The full study is built for operators and investors who need executable intelligence, not just descriptive charts. Key deliverables include:
Variable Optic Attenuators Market
- Granular market model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario‑based sensitivity runs that isolate demand drivers and tariff/regulatory shocks.
- Demand drivers map and use‑case deep dives (telecom evolution, data centers, fiber sensing, test & measurement), aligned to procurement and product requirements by customer archetype.
- Supply‑chain heat maps and supplier dependency diagnostics highlighting critical inputs (MEMS chips, specialty fiber) and recommended dual‑sourcing architectures.
- Vendor benchmarking and scorecards combining technology, product breadth, manufacturing footprint, and commercialization strength — tailored for buy/sell/partner decisions.
- Go‑to‑market playbooks for suppliers in three tiers: incumbent OEMs, emerging MEMS/PIC startups, and precision test‑equipment providers — including channel strategies and value‑pricing tactics.
- Regulatory and standards matrix with action plans to align product validation to emerging test/qualification frameworks and to anticipate tariff scenarios.
- M&A screening framework with prioritized targets and valuation multipliers adjusted for integration risk and supply‑chain exposure.
Competitive landscape — strategic positions and implications
The VOA competitive set remains populated by specialized instrumentation firms, MEMS innovators, and optical components houses. Our analysis profiles a cross‑section of vendors to illustrate how capability sets map to end‑market demand:
- Santec Corporation (Japan): Known for high‑accuracy, repeatable modules optimized for transport networks and lab validation. Their recent wins in 400G/800G network supply chains underscore strength in carrier engagements and large‑volume qualification processes.
- VIAVI Solutions (United States): Broad portfolio across field, lab, and manufacturing applications. Their modular approaches and field‑ready devices make them a go‑to for operators requiring ruggedization and test‑automation integration.
- EXFO (Canada): Differentiates with precise multi‑channel attenuators and self‑adjusting mode features — attractive for manufacturing and automated test environments where channel count and repeatability matter.
- OZ Optics (Canada) and Thorlabs (United States): Serve the experimental, lab, and niche industrial segments with compact, rugged, and cost‑efficient offerings that prioritize flexibility and speed to deploy.
- Quantifi Photonics (MATRIQ) & Sercalo: MEMS‑centric players offering fast attenuation speeds, low insertion loss, and hermetic packaging — well positioned as MEMS becomes the dominant actuator technology for embedded VOAs.
- Lumentum Holdings (United States): With a recent introduction of an Electrostatic MEMS VOA (ESVOA), they signal a move toward high‑speed, integrable devices aligned to agile photonic components strategies.
- Optilab (United States): Focused on programmable, high‑resolution modules tailored for lab testing and DWDM/EDFA scenarios — important for customers seeking repeatable calibration and automation features.
Strategic implication: buyers should map vendor strengths to their critical use cases (speed, insertion loss, channel count, environmental ruggedness, and integration with PICs or automated testbeds). Suppliers should prioritize clear value props (e.g., integrated power metering, hermetic MEMS packaging, multi‑channel scalability) to move beyond price competition.
Recent industry developments and their strategic import
- New product introductions: The ESVOA announcement from a major component house signals commercial momentum for electrostatic MEMS that balance speed and integrability — a capability that will be table stakes for high‑speed network and PIC applications.
- Academic breakthroughs: Demonstrations of VOAs on thin‑film lithium niobate (LNOI) platforms point to medium‑term disruption: compact, low‑loss PIC‑compatible attenuators could rework product architectures and drive consolidation between photonic foundries and attenuator vendors.
- Large contracts: Carrier procurement of wide‑range VOA modules for next‑generation 400G/800G deployments validates the demand pull for high‑dynamic‑range and carrier‑grade qualification.
- Standards and regulation: The publication of new reliability testing standards for VOAs and the reintroduction of tariff uncertainty are governance dynamics that will reshape qualification cycles and sourcing strategies.
Risk profile and scenario considerations
Key risks that should be embedded into 2026 planning:
- Geopolitical and tariff volatility: Heavy reliance on Asian‑sourced MEMS components creates susceptibility to trade policy shifts. Scenario planning in our full report quantifies revenue impacts under alternate tariff and localization assumptions.
- Technology substitution: PIC‑based attenuators and advances in LNOI threaten to displace discrete MEMS VOAs in some applications. Roadmaps should therefore balance product lifecycles and optionality toward photonic integration.
- Standards and qualification: New IEC testing standards increase time‑to‑market for suppliers without structured testing and certification pipelines, advantaging incumbents with robust validation infrastructures.
- Supply‑chain concentration: Single‑source dependencies for MEMS chips or specialized fibers create downstream production and margin risk unless addressed proactively.
Recommended 2026 playbook (prioritized actions)
- Immediate (0–12 months): Freeze dual‑sourcing strategies for MEMS inputs, establish tariffs contingency pricing, and fast‑track compliance to the latest reliability standards.
- Near term (12–24 months): Invest or partner in MEMS and PIC integration capabilities, add embedded telemetry (e.g., in‑built power metering) to differentiate, and pilot multi‑channel product variants for manufacturing partners.
- Medium term (24–36 months): Execute targeted M&A for niche MEMS or LNOI competencies, consolidate vendor relationships where scale advantage exists, and deploy field trials with anchor customers to validate integrated solutions.
Closing: how PW Consulting helps
Our full Variable Optic Attenuators Market report provides the quantitative backbone and executable frameworks to convert the strategic takeaways above into board‑level decisions. It contains the complete market model (2020–2025 historic, 2026–2032 forecasts), segment and regional breakdowns, vendor scorecards, acquisition target lists, and scenario simulations that translate market growth and shocks into P&L and balance‑sheet impacts. If you are positioning for product launches, negotiations with carriers, or evaluating strategic M&A in 2026, the detailed intelligence in the complete study will supply the data‑driven confidence and operational playbooks you need.
To access the full set of segment‑level forecasts, regional splits, and the vendor due‑diligence matrices that we intentionally withhold here, please visit our report page or contact PW Consulting’s advisory desk for a tailored briefing and model access.
For detailed analysis of this topic, please visit the official page: Variable Optic Attenuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wireless Broadband to hit USD 404M by 2032 at 13.5% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Wireless Broadband Market — Strategic Outlook for 2026
As organizations recalibrate connectivity strategies in an era defined by private 5G, fixed wireless access, and spectrum reshuffling, PW Consulting’s Wireless Broadband Market study is designed to inform the high-stakes decisions you will make in 2026. The market’s macro trajectory is clear: having expanded from roughly USD 96.7 million in 2020 to USD 168.0 million in 2025, the sector is expected to continue a sustained growth path — reaching an estimated USD 195.3 million in 2026 and accelerating to about USD 404.0 million by 2032 at a compound annual growth rate (CAGR) of 13.5% over the forecast horizon. This briefing explains why those headline numbers matter for strategy, what the research delivers, and how to translate insight into action — while intentionally reserving the report’s granular segment-level intelligence for the full publication.
Wireless Broadband Market
Why this study is strategically material for 2026
-
Investment timing and capital allocation: With a mid-teens CAGR and clear inflection points across 2026–2032, executives need market-backed scenarios to prioritize capex vs. opex, spectrum investments, and infrastructure rollouts.
Wireless Broadband Market -
Vendor and partner selection: The ecosystem spans global infrastructure vendors, CPE manufacturers, and service providers; nuanced vendor profiles and competitive dynamics determine negotiation leverage and partnership architectures.
Wireless Broadband Market -
Regulatory-driven opportunities and risks: Policy changes and auctions scheduled in 2026 materially affect access to spectrum and deployment economics for utilities, enterprise campuses, and service providers.
-
Use-case prioritisation: From critical communications to remote monitoring and consumer FWA, selecting which applications to prioritize determines technology roadmaps and monetization strategies.
Reading the macro numbers — what the trajectory implies
The market’s expansion from 2020–2025 and the projected doubling through the early 2030s reflect several converging forces: accelerated private and public 5G deployments, broader adoption of Fixed Wireless Access (FWA) in underserved geographies, and densification through small cells and mmWave trials. The uplift between the 2025 base year and 2026 indicates that near-term catalysts — including spectrum reallocations, successful operator mid-band deployments, and enterprise trials — are already translating into commercial momentum. For strategic planners, the 13.5% CAGR signals both robust addressable demand and intensifying competitive pressure, requiring earlier clarity on go-to-market models and differentiated service propositions.
What this report delivers — practical, decision-ready outputs
-
Robust market sizing and trend maps (historical 2020–2025; forecast 2026–2032), with scenario variants to stress-test conservative, base, and aggressive adoption paths.
-
Probability-weighted forecasts and a sensitivity toolkit to quantify how spectrum availability, permitting reforms, or a major vendor win/loss could change outcomes.
-
Actionable go-to-market frameworks for operators, system integrators, and enterprise IT teams — including market-entry checklists, partner archetypes, and procurement playbooks.
-
Investment-grade vendor dossiers and a competitive scorecard that synthesizes capabilities across radio, core, CPE, systems integration, and managed services.
-
Deployment case studies and trial summaries that translate technical performance into commercial KPIs and total cost of ownership (TCO) models.
-
Regulatory impact assessment and an advocacy roadmap that links policy shifts to practical deployment pathways for critical infrastructure and enterprise campuses.
-
Risk matrices, adoption inhibitors, and mitigation strategies for supply chain constraints, interoperability gaps, and security/operational resilience.
Note: The full report contains the detailed regional, type, and application splits that underlie the headline forecasts. Those granular datasets and proprietary segment models are intentionally not disclosed in this preview and are available in the full publication.
Competitive landscape — positioning and implications
The market shows a moderate level of concentration, with the top three players accounting for a meaningful portion of commercially-active deployments and the top five nearing half of the competitive footprint. This structure creates room for both scale-driven incumbents and specialist challengers to capture value through differentiation.
-
Ericsson (Stockholm) : Strong in 5G FWA hardware, radio and core. Recent mmWave extended-range trials and strategic private 5G partnerships demonstrate Ericsson’s push to convert proof-of-concept momentum into enterprise-grade offerings. Expect Ericsson to continue leveraging operator relationships to scale FWA and private network projects across both consumer and enterprise verticals.
-
Nokia (Espoo) : Focused on CPE and network platforms for both residential and enterprise deployments. Nokia’s recent private 5G deployment for a municipal utility underscores its positioning in grid modernization and industrial verticals — an area where long-term service and lifecycle revenue can be captured.
-
Huawei Technologies (Shenzhen) : Offers integrated RAN and core platforms globally. While market access varies by geography, Huawei’s breadth of product capability keeps it competitive where regulatory conditions allow, particularly in large-scale infrastructure projects.
-
Cisco Systems (San Jose) : Targets enterprise use cases with private 5G platforms and integrated IoT services. Cisco’s strength in networking and enterprise services positions it to hybridize wireless and wired ICT architectures for large enterprises.
-
Major US operators — T-Mobile US, Verizon, AT&T : These operators have operational 5G FWA offerings and continue to use mid-band spectrum to densify capacity. Recent large-scale site upgrades and spectrum deployments indicate an ongoing strategic bet on consumer and small-business fixed-wireless monetization.
-
Inseego (San Diego) : Focused on CPE devices for FWA. Device manufacturers like Inseego are critical enablers of deployment economics and user experience — areas where differentiation impacts adoption speed and churn.
Strategic takeaway: incumbent vendors will continue to compete on scale, ecosystem breadth, and operator relationships, while smaller specialists and systems integrators will win by focusing on verticalized solutions and integration-led services.
Regulatory and market dynamics you must factor into 2026 plans
-
Policy shifts: The reclassification of broadband internet access and subsequent regulatory clarity reduced one axis of uncertainty, but new rulemaking and auction timelines create fresh decision points for spectrum-dependent strategies.
-
Spectrum access: Expansions of access in bands like 900 MHz for utilities and the imminent AWS-3 auction (commencing June 2, 2026) materially influence private network feasibility and long-haul wireless economics.
-
Permitting and infrastructure: Federal proposals to streamline tower and small cell permitting accelerate deployment timelines for densification strategies, improving the business case for mmWave and small-cell heavy architectures.
-
Operational readiness: Utilities and critical infrastructure actors are being explicitly enabled via regulatory channels — making energy/utility verticals attractive early-adopter targets for private wireless solutions.
Use cases and technology enablers to prioritize
Operational planners should prioritize solutions that map clearly to near-term monetizable use cases: critical communications, remote monitoring and surveillance, and enterprise connectivity for distributed sites. Technology enablers — private 5G, mmWave extended-range, advanced CPE, and integrated edge compute — should be evaluated not as isolated line items but as bundled platforms that convert performance into measurable business outcomes (reliability, latency, security, and TCO).
How to use the report in 90 days
-
Week 1–2: Align executive stakeholders on macro scenarios and validate which adoption path (conservative/base/aggressive) matches your risk appetite.
-
Week 3–6: Use the vendor scorecards and procurement playbooks to shortlist partners and test commercial models with realistic ROIs from the report’s financial templates.
-
Week 7–12: Run a pilot informed by the deployment case studies, measure against the report’s KPIs, and commit to scale or iterate based on performance and regulatory developments.
Next step — get the full intelligence
This briefing has surfaced the strategic levers and market context that should shape 2026 decisions. For procurement-grade models, full regional and application-level splits, vendor benchmarking detail, and the proprietary scenario engine that underpins the forecast, access to the complete report is required. PW Consulting’s full Wireless Broadband Market study provides those datasets and actionable tools to convert the market’s growth trajectory into defensible, revenue-generating strategy.
For detailed analysis of this topic, please visit the official page: Wireless Broadband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AFM Probe Market 2026 Strategic Preview — What C‑Suites Need to Know
Executive snapshot
Atomic force microscope (AFM) probes are a foundational consumable across semiconductor R&D, materials science and an expanding set of life‑science applications. Our latest PW Consulting preview, anchored on a 2025 base year and a historical window spanning 2020–2025, shows a market that expanded from roughly USD 179.3 Million in 2020 to USD 242.0 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 7.85% through the 2026–2032 forecast window — reaching approximately USD 405.0 Million by 2032. The market displays high concentration at the top (CR3 ≈ 72.5%, CR5 ≈ 88.0%), a factor with immediate strategic consequences for supply, pricing and M&A planning in 2026.
AFM Probe Market
Why this report matters for 2026 decision cycles
-
Procurement and supply‑chain resilience: Growth and concentration create both supply risk and leverage. Buyers must decide whether to centralize spend with incumbent leaders to secure priority manufacturing capacity or to diversify across smaller niche suppliers to reduce single‑source exposure.
AFM Probe Market -
Product roadmap and R&D prioritization: The market’s steady CAGR and technology trajectory mean investments in probe design (e.g., wear‑resistant coatings, ultra‑sharp tips, liquid‑compatible bioprobes) will likely yield compounded returns through higher ASPs and differentiated applications.
AFM Probe Market -
M&A and strategic partnerships: High concentration combined with targeted capability gaps (e.g., ultra‑high purity electrical probes, bespoke biological probes, diamond‑coatings) creates fertile ground for bolt‑on acquisitions and exclusive supply agreements.
-
Commercial models and pricing: Consumable economics and the absence of direct reimbursement pathways for probes (they are consumables within capital AFM systems, not billable items) force suppliers to focus on value‑added features, subscription and bundled instrument‑consumable models.
What the PW Consulting AFM Probe study delivers (practical deliverables)
-
Top‑level market sizing and validated growth trajectories (2020–2025 historical; 2026–2032 forecast) with scenario-driven sensitivity to price declines, substitution and volume expansion.
-
Technology and product roadmap that maps probe types (including wear‑resistant and diamond‑coated tips, high‑aspect ratio probes, and soft contact probes for liquids) to likely application adoption curves.
-
Supplier capability benchmarking: factory capabilities (e.g., clean‑room nanofabrication, in‑house R&D), product line breadth, specialty materials expertise, and distribution reach — actionable for sourcing RFPs and partner selection.
-
Supply‑chain risk heat map covering critical inputs (e.g., high‑purity platinum, platinum‑iridium alloys, diamond coatings, specialized carbon whisker structures), single‑point failure exposures and mitigation levers, including inventory and dual‑sourcing strategies.
-
Commercial playbooks: pricing frameworks, channel strategies, and procurement templates calibrated for 2026 negotiation cycles and CAPEX refresh plans.
-
M&A and partnership candidate shortlists, including rationale tied to capability gaps, integration risk and likely deal multiples in a highly consolidated sub‑market.
-
Regulatory and operational guidance for life‑science adoption: practical notes on liquid environment compatibility, handling protocols and lab infrastructure considerations that reduce integration friction for biological imaging programs.
Competitive landscape — who matters and why
The industry is dominated by a small set of specialist providers and several focused niche players. The full report contains a detailed vendor scorecard; here we surface strategic positioning and capability signals that matter to corporate buyers and investors.
-
Bruker Corporation (Billerica, MA): Operates vertically integrated nanofabrication capacity (Class‑100 clean rooms) and a broad portfolio spanning performance and value probes — a natural counterparty for customers seeking scale, consistency and integration with AFM instrument platforms.
-
NanoWorld AG (Neuchâtel): A leader in high‑precision cantilevers and probes, with a strong orientation toward biological and life‑science imaging — making them a go‑to for labs moving toward living‑cell AFM workflows or high‑speed liquid imaging.
-
NANOSENSORS™ (Switzerland): Specializes in probes optimized for low thermal drift and biological applications, including soft tapping and rounded tips for cell imaging — a supplier to watch for customers prioritizing delicate sample interaction and repeatability.
-
Adama Innovations (Israel): Focused on diamond‑coated, wear‑resistant ultra‑sharp tips, addressing high‑resolution topography and conductive imaging needs — attractive for customers with heavy throughput or abrasive sample sets.
-
NuNano Ltd. (UK): Provides bespoke silicon probes via direct channels and partners; their expanded distribution agreements (notably added SPARK series to major instrument eStores in 2024) broaden access to specialized probe types.
-
Rocky Mountain Nanotechnology (Utah): Niche specialist in ultra‑high purity platinum and platinum‑iridium probes for electrical modes and nanoprobing — a critical upstream supplier for high‑precision electrical AFM applications. Notably, Park Systems announced a strategic acquisition in April 2026, signaling further vertical integration in electrical probe supply.
Recent technology and commercial inflection points (selected)
-
Distribution expansion: NuNano’s 2024 distribution deal broadened access to certain silicon probe series via major instrument eStores and regional offices — an example of how channel plays accelerate adoption without immediate manufacturing scale‑up.
-
Fabrication innovation: A 2025 publication described a batch fabrication method enabling ultra‑sharp probes with novel handle geometries, indicating potential for scale‑economics improvements in high‑end probe production and a likely price‑performance squeeze over the medium term.
-
M&A: The 2026 Park Systems acquisition of Rocky Mountain Nanotechnology highlights supplier consolidation around specialty materials for electrical modes and a move by instrument OEMs to secure upstream inputs.
Market dynamics that will shape winning strategies in 2026
-
Materials and input cost sensitivity: Innovations such as diamond coatings, EBD carbon whiskers (used to create tall, sub‑2 nm tips for biological topography), and ultra‑high purity Pt/Pt‑Ir all introduce cost and sourcing considerations that influence margin profiles by probe subtype.
-
Application environment constraints: Biological AFM is increasingly performed in liquid environments with minimal sample prep. This drives demand for soft contact probes with very low force constants and fluid‑compatible geometries — suppliers who master these specifications can command preference among life‑science labs.
-
Commercial framing: Because probes are consumables within capital instruments (and not reimbursable as standalone clinical items), go‑to‑market strategies must emphasize instrument‑ecosystem compatibility, lifecycle cost and workflow integration rather than fee‑for‑service models.
-
Consolidation and access dynamics: High CR3/CR5 concentration suggests incumbents will retain pricing power for differentiated probe classes, but niche innovators and fabrication advances will periodically disrupt margins and open specialization opportunities.
Practical recommendations for corporate leaders in 2026
-
Sourcing: Implement a two‑track supplier strategy — secure capacity with top incumbents for baseline needs, while piloting secondary suppliers for specialized probes (diamond‑coated, high‑aspect ratio, bio‑optimized) to build optionality.
-
R&D alignment: Prioritize co‑development agreements for probes that reduce sample damage in liquid environments and extend tip lifetime for high‑throughput applications — these features shorten total cost of ownership and drive customer lock‑in.
-
M&A and partnerships: Target bolt‑ons that close capability gaps (e.g., ultra‑pure electrical probes, bespoke bio probes), especially where incumbents show limited focus on a growing sub‑application.
-
Commercial models: Test subscription and bundled consumable programmes with instrument sales to capture recurring revenue and reduce buyer churn; emphasize calibration standards and traceable quality as differentiators.
-
Intelligence posture: Monitor fabrication research outputs and material supply constraints closely; small advances in probe fabrication can quickly shift competitive dynamics and margin pools.
How to read this preview — and where to go next
This preview is designed as a high‑signal executive brief: it presents the macro growth trajectory, concentration metrics and strategic implications needed to inform 2026 planning cycles while intentionally withholding the granular segment‑level tables, regional splits and unit‑price decks to preserve the consultative value of the full study. The full PW Consulting AFM Probe Market report contains the operational annexes decision‑makers use to execute — including supplier scorecards, product feature matrices, segment revenue build‑ups, regional demand models and actionable playbooks for procurement, R&D and M&A.
Closing — timing and next steps
The AFM probe market is neither a niche hobby nor a commodity curtain‑call: it sits at the intersection of instrument ecosystems, material science advances and application adoption in biology and electronics. With a multi‑year CAGR approaching 8% and clear concentration among leading providers, 2026 is a hinge year for locking in supply, accelerating product differentiation and positioning for consolidation. PW Consulting’s full report converts the directional insights summarized here into executable plans — from specific supplier selection criteria to modeled ROI for co‑development and M&A — enabling leaders to move from strategy to measurable action.
For detailed analysis of this topic, please visit the official page: AFM Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coke Market to Reach USD 357.54 Million by 2032, 3.5% CAGR
By PW Consulting, 2026-07-12
Coke Market 2026: A Strategic Preview for Boardroom Decisions
As Senior Strategy Advisor and Lead Industry Analyst at PW Consulting, I present this executive preview of our Coke Market 2026 research. The aim is to surface the precise strategic choices that will matter to leadership teams in 2026, while reserving the granular segment-level data for the full report. This “trailer” highlights the study’s diagnostic depth, decision-ready frameworks, and the key risk/return levers that should drive allocation of capital, commercial priorities, and operational programs over the coming planning cycle.
Coke Market
Headline market signal
The Coke Market demonstrated consistent expansion through the early 2020s, increasing from roughly USD 218 million in 2020 to USD 285 million in the base year 2025. Our forecast models project a continuation of steady growth at a 3.5% compound annual growth rate across the 2026–2032 horizon, taking the market to approximately USD 358 million by 2032. That trajectory reflects a maturing category with structural tailwinds—population and income growth in selective markets, product portfolio innovation, and resilient branded demand—tempered by persistent margin pressure from packaging and commodity cost volatility.
Coke Market
Why this research matters to 2026 decision-makers
-
Portfolio prioritization: The report isolates which product-format-investment combinations are likely to deliver step-change returns versus those that primarily defend share. For management teams balancing innovation funding and cost rationalization, the difference is material to IR messaging and capital allocation.
Coke Market -
Channel and SKUs strategy: With varying recovery patterns across off-premise, foodservice, and convenience channels, our frameworks guide SKU rationalization, pack-size optimization, and channel-specific promotional tactics to improve gross margin per point of distribution.
-
Packaging and sustainability investment planning: Given increasing regulatory and customer scrutiny, the research lays out an actionable roadmap for packaging redesign, rPET targets, and recycling partnerships—prioritized by payback and regulatory exposure.
-
Supply chain and commodity risk mitigation: Scenario-ready cost curves and hedging playbooks address aluminum, PET, CO2, and sweetener risk—helping procurement and finance leaders stress-test budgets and set rolling hedging policies.
-
M&A and bottler engagement: We map where capacity gaps, distribution whitespaces, or adjacent product capabilities could be closed faster through targeted deals or strategic partnerships with independent bottlers.
Market dynamics shaping strategic choices
-
Regulatory pressure and labeling: Jurisdictions are advancing taxes, mandatory front-of-pack disclosures, and limitations on added-sugar products. These measures create asymmetric impact across flavor and pack formats and will force faster portfolio reformulation and labeling investments.
-
Packaging cost and tariffs: New tariffs and commodity swings materially increase unit packaging costs. Our models show that even modest tariff-driven uplifts can compress category EBIT unless offset by pack redesign, sourcing diversification, or price architecture changes.
-
Consumer price sensitivity: Elevated inflation has increased price elasticity in many consumer cohorts, accelerating downtrading to value formats and private label in price-sensitive channels. Pricing architecture and promotion discipline will be decisive for 2026 gross margins.
-
Sustainability as a commercial filter: Leading bottlers and brand owners are converting sustainability commitments (e.g., rPET targets, recyclable-by-design packaging) into sourcing and merchandising advantages. Early movers capture retailer shelf premium and reduce regulatory tail risk.
-
Distribution complexity: The Coca‑Cola system delivered extensive unit case volume in 2025, underscoring the strategic importance of bottler relationships. Independent bottlers remain critical control points for execution, innovation trials, and local pricing tactics.
Competitive landscape — concentration and strategic posture
The Coke Market is concentrated, with top firms commanding the majority of channel accessibility and brand equity. This concentration creates both barriers to entry and tactical windows: established players benefit from scale in procurement and route-to-market, while nimble independents can pilot packaging or pricing models faster at a regional level.
-
The Coca‑Cola Company (Atlanta) remains the architectural brand owner, licensing concentrates and orchestrating global marketing. Its system-wide unit case volume in 2025 underscores its leverage over national and cross-border distribution.
-
Large bottlers—such as Coca‑Cola FEMSA, Coca‑Cola Europacific Partners, Coca‑Cola HBC, Arca Continental, and Swire Coca‑Cola—operate as semi-autonomous commercial engines. They balance local execution with adherence to global brand rules, and they are primary vectors for innovations and packaging pilots.
-
Recent initiatives illustrate strategic priorities: mini-can expansion into convenience stores, recyclable multipack trials replacing plastic film with glue-dots and cardboard handles, and progress toward design-for-recyclability and rPET content targets. These examples reflect a dual focus on convenience-led growth and sustainability-driven cost avoidance.
Practical contents of the full report (what you will unlock)
-
Segmented demand and supply forecasts by region, flavor and application with scenario variants and elasticities (note: detailed segment tables and numeric splits are available in the full study).
-
Price and margin sensitivity models with commodity pass-through mechanics and recommended hedging thresholds for procurement.
-
Competitive playbooks for brand owners and bottlers: commercialization sequencing, co-investment templates, and pilot evaluation scorecards.
-
Packaging optimization library: design options, estimated capex and opex impacts, and retail shelf implications—ranked by payback and regulatory alignment.
-
Regulatory and tariff impact matrix with near-term compliance priorities and longer-term policy watchlist to be monitored by government affairs teams.
-
M&A opportunity map and valuation multiples by strategic rationale (capacity, distribution, category adjacency), plus integration checklists focused on cost synergies and route-to-market uplift.
-
Practical templates: executive dashboards, GTM test protocols, and a 12–36 month implementation roadmap customized for enterprise, bottler and retail partners.
Actionable strategic implications for 2026
-
Rebalance SKU portfolios toward high-margin, sustainability-aligned formats. Short-term SKU pruning should free investment for scalable pack innovations that reduce per-unit material intensity.
-
Lock in packaging supply through multi-year agreements and diversified sourcing to blunt tariff and commodity shocks; consider indexed pass-through clauses that protect margin while maintaining competitiveness.
-
Coordinate with key bottlers on joint pilots: speed-to-market for mini and convenience formats, retailer pack innovations, and shared sustainability investments deliver asymmetric advantage at lower cost.
-
Embed consumer price sensitivity analytics into promotion planning: shift from broad discounting to targeted, measurable promotions that protect base price architecture.
-
Operationalize sustainability claims: set near-term, verifiable targets (e.g., percentage rPET, recoverability by design) and align procurement and packaging teams to ensure claims translate to lower regulatory and reputational risk.
-
Prepare M&A and partnership playbooks: use the report’s opportunity map to prioritize acquisitions or alliances that fill distribution gaps, add cold-chain capacity, or acquire adjacent beverage competencies.
How to use this preview in your 2026 planning cycle
Use the insights here to focus your Board and Executive team conversations—identify which operational levers to stress-test in your 2026 budget process. The full report converts each high-level recommendation into executable steps with financial implications, scenario-tested outcomes, and a prioritized implementation timeline suitable for a Q1 strategic review.
Closing and next step
This preview is intentionally selective: it surfaces the market trendline, competitive dynamics and the decision levers that matter most in 2026, while reserving the segmented forecasts and granular commercial matrices for the full PW Consulting report. For teams making capital allocation, pricing and sustainability trade-offs this year, the complete study provides the detailed data and the ready-made operational frameworks required to convert insight into measurable outcomes. Contact PW Consulting to access the full Coke Market 2026 study and the accompanying implementation toolkits.
For detailed analysis of this topic, please visit the official page: Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrasonic Dissector Market to Reach USD 675.5M by 2032 at 10.5% CAGR
By PW Consulting, 2026-07-12
Ultrasonic Dissector Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Chief Industry Analyst, I present a concise, strategy‑first briefing derived from our full Ultrasonic Dissector Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This briefing synthesizes the macro evolution of the market, the competitive dynamics shaping supplier advantage, and the practical levers executives must pull in 2026 to convert growth potential into defensible revenue streams.
Ultrasonic Dissector Market
Why this study matters for 2026
Ultrasonic dissector technologies—already demonstrating robust clinical utility across general surgery, gynecology and other specialties—are moving from niche adoption to scale commercial deployment. PW Consulting’s market model shows the industry expanding from USD 210.5 Million in 2020 to USD 346.6 Million in 2025, with a baseline forecast that the market will reach USD 675.5 Million by 2032 at a compound annual growth rate (CAGR) of 10.5% over the 2026–2032 period. These macros matter because they quantify not only demand growth but also the pace at which product portfolios, channel strategies and regulatory investments must accelerate.
Ultrasonic Dissector Market
For leadership teams evaluating capital allocation in 2026, the strategic value of this study is threefold:
Ultrasonic Dissector Market
- It translates market momentum into actionable growth targets calibrated to realistic adoption curves and clinical pathways.
- It flags structural risks—supply chain, regulatory, and competitive concentration—so management can pre‑empt value erosion.
- It provides a pragmatic roadmap for go‑to‑market sequencing and partnership priorities that protect margins while scaling sales.
What the full report delivers (practical, operator‑grade tools)
- Market sizing and validated growth scenarios: a base case and two alternative scenarios derived from adoption rates, reimbursement sensitivity, and device substitution dynamics.
- Methodology transparency: raw assumptions, data sources, and a reproducible bottom‑up model calibrated to historical 2020–2025 performance and key event timelines.
- Commercial playbooks: segmented GTM approaches for integrated hospital systems, ambulatory surgical centers, and robotics OEM partnerships—complete with sales force staffing models and expected ramp timelines.
- Regulatory and reimbursement matrix: country‑level filing strategies, dossier requirements, and timelines to expected market access (base year 2025 regulatory landscape incorporated).
- Supply chain and margin stress tests: vendor dependency mapping (notably piezoelectric transducer exposure), alternate supplier options, and contingency cost models.
- Competitive benchmarking and M&A heatmap: capability gaps, likely consolidation targets, and takeout valuation ranges under multiple integration scenarios.
- Investment memo templates and board‑ready slide decks: concise materials to support 2026 funding rounds, partnership negotiations, or internal capital approvals.
Note: this preview intentionally omits granular segmentation figures (regional and application splits) to preserve the commercial value of the full dataset available in the complete report.
Market dynamics shaping strategy in 2026
- Robust demand trajectory. The market’s multi‑year growth (CAGR 10.5%, 2026–2032) supports investments in commercialization, clinical evidence generation, and selective capacity expansion. Executives should treat this as a window of opportunity to gain share before the market reaches mid‑cycle maturity.
- Concentration and competitive pressure. Top players control a meaningful share of the market (CR3 ≈ 62%; CR5 ≈ 75%). This concentration amplifies the value of differentiated clinical claims, preferred hospital contracting, and interoperable platform partnerships.
- Supply chain volatility. Component pressures—most notably on piezoelectric transducers in 2025—compressed supplier margins and pushed lead times. Companies that secured multi‑source agreements or forward contracts in 2025 found themselves better positioned in 2026.
- Regulatory complexity. Regulatory status varies by device and manufacturer; some offerings faced approval constraints in major geographies as recently as April 2026, creating uneven go‑to‑market terrain. A surgical device’s commercial trajectory now depends as much on regulatory pathway execution as on clinical performance.
Competitive landscape — what to watch
Incumbent surgical energy and device companies and fast‑maturing challengers are pursuing divergent tactics. Representative examples include:
- Medtronic (Minneapolis, MN, USA) — market credibility through established platforms (e.g., Sonicision™ curved jaw cordless systems and newer models focused on vessel coagulation). Their playbook prioritizes platform integration, global distribution scale, and post‑market evidence collection to defend share.
- Saints Sages Surgical Co., Ltd. (Shanghai Zhangjiang Science City, China) — aggressive product commercialization with the SanAgile Ultrasonic Dissector System launched at SAGES 2025. Their strategy emphasizes cost competitiveness, OEM supply agreements, and leveraging regional manufacturing advantages.
- CMR Surgical — expanded energy offerings by adding an ultrasonic dissector to its Versius Plus portfolio (product launch December 2024), signaling a strategy of surgical system OEMs integrating proprietary energy tools to lock in clinical workflows.
Implication: incumbents will double down on platform depth and global access; challengers will lean on price and rapid local adoption. For 2026 strategic planning, it is imperative to map which competitors are likely to pursue price‑based penetration versus capability‑based differentiation.
Actionable recommendations for 2026 executives
- Prioritize regulatory readiness and modular filings. Given uneven approval status across geographies, structure regulatory programs that allow phased market entry—start with jurisdictions offering faster review and scalable reimbursement, while preparing dossiers for larger markets.
- Hedge supply‑side risk now. Lock supplier agreements or qualify alternate transducer sources. Even modest price pressure on a critical BOM item can erode gross margin rapidly as volumes scale.
- Invest in targeted clinical evidence. Build a 12–24 month evidence plan emphasizing endpoints that purchasers care about: OR time savings, device‑driven reduction in thermal spread, and improved patient throughput. Real‑world evidence tied to cost per case will accelerate hospital adoption.
- Choose GTM partners strategically. For firms without an installed surgical systems channel, prioritize partnerships with robotics OEMs and ISV integrators; for incumbents, invest in reseller and direct hospital contracting where lifetime revenue from disposables justifies initial discounts.
- Adopt a two‑track pricing strategy. Use premium pricing for differentiated, evidence‑backed offerings and targeted lower‑price SKUs for high‑volume sites where procurement is price sensitive.
- Scan M&A selectively. With the market reasonably concentrated, bolt‑on acquisitions that fill capability gaps (clinical evidence, disposables manufacturing, regional distribution) can accelerate scale more predictably than greenfield expansion.
Risk map and mitigation
- Regulatory delays. Mitigation: staggered filings; expedited clinical protocols; engage payers early.
- Component shortages & input price rises. Mitigation: dual sourcing, strategic inventory, and pass‑through pricing clauses.
- Competitive price pressure. Mitigation: differentiate via integrated platforms, bundled service contracts, and outcome‑linked pricing pilots.
- Reimbursement uncertainty. Mitigation: health‑economics models demonstrating total cost of care improvements and targeted negotiations with high‑volume accounts.
How to use this study in board and investor conversations
The full PW Consulting report converts market growth metrics into investment grade narratives. Prepare three slide decks from the study for 2026 stakeholders:
- Investment thesis: emphasize TAM growth, runway to scale, and defensibility via regulatory and clinical moats.
- Commercial blueprint: show phased market entry, expected ROI on clinical studies, and break‑even scenarios under conservative adoption curves.
- Risk & mitigation playbook: quantify impact of supply and regulatory shocks and present contingency costs and timing.
Closing — the strategic choice for 2026
We are at an inflection point. The Ultrasonic Dissector market has moved beyond early adopter dynamics into a phase where clinical proof, distribution muscle, and supply resilience will determine the winners. With the market more than doubling from mid‑cycle levels in the coming decade under our base case, 2026 is the year to convert intent into irreversible capability: secure supplies, accelerate filings, and field the clinical data that turns preference into procurement.
For a full breakdown of segmentation, regional demand curves, and downloadable models (including the interactive scenario dashboard and board‑ready investment memos), consult the full Ultrasonic Dissector Market report. The detailed segment matrices and company‑level data are intentionally reserved for the report to preserve their commercial utility.
For detailed analysis of this topic, please visit the official page: Ultrasonic Dissector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MALDI-TOF Mass Spectrometer Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I prepared this market briefing to orient senior executives, corporate development teams, and institutional buyers on why our 2026 MALDI-TOF Mass Spectrometer Market study is a practical must-read for near-term strategy. The market is both mature in core clinical applications and rapidly evolving at the intersection of diagnostics, research, and environmental analysis. Our study synthesizes historical performance (2020–2025), establishes a rigorously modeled 2026–2032 forecast horizon, and translates those inputs into actionable decision frameworks that preserve optionality while accelerating value capture.
MALDI-TOF Mass Spectrometer Market
Headline market context — growth, scale, and concentration
Key quantitative takeaway: the global MALDI-TOF market shows a sustained recovery and expansion phase. From a documented base in 2020, the market rose steadily through 2025 and is forecast to continue growing through 2032 at a compound annual growth rate (CAGR) of 6.98%. In practical terms, this trajectory underpins a multi-year runway for suppliers and service partners to scale revenues, invest in adjacent workflows (software, consumables, and assays), and pursue international reimbursement and regulatory strategies.
MALDI-TOF Mass Spectrometer Market
Market concentration is moderate: the leading three vendors account for a meaningful share of market revenue, while the top five widen that reach further — a structure that creates oligopolistic dynamics for instrument pricing but open fields for differentiated consumables, software, and application-specific service models.
MALDI-TOF Mass Spectrometer Market
Why this study matters for 2026 strategy
- Risk‑calibrated investment planning: The report’s 2026–2032 forecast (base year 2025) and scenario stress-tests quantify upside and downside cases tied to reimbursement shifts, regulatory milestones, and capital procurement cycles. This enables CFOs and portfolio managers to align CAPEX commitments to probabilistic revenue pathways rather than single-point estimates.
- Commercial prioritization: Rather than a static market map, our assessment layers competitive positioning, product maturity, and service economics so commercial leads can prioritize segments where early margin expansion is plausible within the next 18–36 months.
- Regulatory and reimbursement playbooks: The report translates regulatory changes and reimbursement signals into tactical actions — from timeline-driven CE-IVD adoption in EU markets to the operational implications of newly established CPT codes in the U.S. — helping market participants accelerate clinical acceptance while managing compliance risk.
- M&A and partnership intelligence: By combining market size trajectories with concentration metrics and vendor profiles, corporate development teams can identify acquisition sweet spots — bolt-on service providers, niche consumables manufacturers, and software firms that materially improve lifetime customer value.
What the report contains — practical deliverables
- Comprehensive market sizing and validated historical series (2020–2025) with a 2026–2032 forecast model and sensitivity scenarios.
- Vendor benchmarking and competitive scorecards that go beyond product lists to evaluate go-to-market models, installed base health, service economics, and channel strategies.
- Regulatory and reimbursement impact matrix with country-level milestones, expected adoption curves, and decision triggers for market entry or withdrawal.
- Consumables and services economics: unit economics, margin pools, and sample throughput models that convert instrument sales into recurring revenue forecasts.
- Procurement playbooks for hospitals, public agencies, and private labs — including specification checklists, validation timelines, and total cost of ownership (TCO) templates calibrated to realistic throughput bands.
- M&A heatmaps and integration checklists oriented to scale efficiencies in manufacturing, R&D, and service delivery.
- Appendices with methodology, primary interview transcripts, and a gated dataset for clients who require the raw figures behind segmentation and scenario inputs.
Competitive landscape — what to watch among incumbent and emerging suppliers
Our analysis profiles established instrument vendors and emergent specialists, assessing not only product roadmaps but also business model resilience (services, reagents, and software). Key players covered include:
- Bruker Corporation — A market stalwart with a strong clinical portfolio focused on systems tailored to microbiology and translational research. Their installed base in clinical settings makes them central to any interoperability or lifecycle service play.
- bioMérieux — A leader in clinical microbiology with product positioning that leverages rapid microbial ID workflows. Expect continued emphasis on validated clinical assays and laboratory automation partnerships.
- SCIEX — A player emphasizing advanced MALDI-TOF/TOF capabilities for proteomics, tissue imaging, and specialized surface profiling. Their offerings are attractive to translational and academic research customers willing to pay for high-end analytical performance.
- JEOL Ltd. — Focused on imaging and broad analytical applications; their spiral TOF architectures and instrumentation variants are positioned toward research and specialized industrial analytics.
- Shimadzu Corporation — A broad-spectrum supplier whose product range targets routine laboratory workflows. Notably, Shimadzu’s MALDI-8000 Series earned an industry-first environmental certification in 2025, an early indicator that sustainability credentials are becoming a commercial differentiator.
- Agena Bioscience — A niche player with platforms optimized for nucleic acid analysis and genetic testing; attractive as a bolt-on for molecular diagnostics routes-to-market.
Our vendor profiles look beyond product specs to analyze installed-base dynamics, service revenue potential, strategic partnerships, and provenability — i.e., how effectively an OEM can demonstrate clinical utility and cost-savings to hospital procurement committees.
Regulatory, reimbursement, and procurement dynamics shaping 2026
- Reimbursement shifts: The establishment of dedicated CPT codes for MALDI-TOF-based pathogen identification in the U.S. removes a historical billing barrier and is expected to accelerate hospital adoption where ROI is demonstrable.
- Regulatory inflection points: Full implementation of the EU IVDR framework and national approvals (e.g., new clinical assay panels in Japan) create both hurdles and commercial opportunities; vendors with CE-IVD or equivalent-clearance roadmaps will gain first-mover adoption in regulated clinical environments.
- CapEx signals: Public-sector procurement forecasts and bench-top procurement cycles (including government forecasts for replacement/maintenance spend) indicate windows where enterprise sales teams should intensify RFP engagement.
- Operational economics: Consumable spend is non-trivial for busy clinical labs and should be included in TCO assessments. Our study provides ranges and sensitivity models to help procurement teams quantify recurring spend and to help vendors design consumables bundles that improve retention.
Strategic imperatives for 2026
- Design for recurring revenue: Instrument sellers who sharpen their consumables, software, and service bundles will materially outpace those relying on one-time equipment sales. Our modeling shows sizable margin lift from even modest consumable attach rates.
- Regulatory-first commercialization: Prioritize clinical validations and CE-IVD/IVDR alignment in your product roadmap. Where reimbursement pathways exist, be ready with health-economic dossiers demonstrating shortened time-to-result and cost-per-diagnosis benefits.
- Channel and partnership engineering: Build partnerships across lab automation vendors, clinical informatics platforms, and regional distributors to lower adoption friction. Consider service franchises or certified third-party maintenance as a competitive lever in regions with price-sensitive purchasing.
- Sustainability as competitive edge: Certifications and lower lifecycle environmental impact are increasingly visible procurement criteria. Early adopters of certified “green” hardware or consumables will convert new buyer segments in public institutions and pharmaceutical partners.
- M&A selective playbook: Target acquisitions that accelerate access to recurring revenue (reagents, software) or fill critical gaps in assay libraries and clinical validations.
Uncertainties and scenario planning
Key upside drivers include faster-than-expected adoption in high-throughput clinical labs and expanded reimbursable indications. Downside risks include protracted regulatory timelines in major markets, material-cost inflation impacting consumable margins, and competitive pressure from alternative analytical platforms. Our report provides scenario layers that map these risks to P&L impacts across multiple timelines.
Next steps — how to use this briefing in 2026 planning
This briefing is intended to orient your executive team and set priorities for strategic planning cycles. For teams preparing 2026 budgets, procurement strategies, or M&A pipelines, our full study contains the granular segmentation tables, vendor financial proxies, and a gated dataset required to finalize investment memos and RFP responses.
PW Consulting’s full report couples the qualitative insights summarized here with the detailed figures that matter in boardroom decisions — from unit economics and regional adoption curves to product-level forecasts and sensitivity analyses. To access the full dataset, vendor scorecards, and the procurement playbooks referenced above, please consult the report page on our site.
For detailed analysis of this topic, please visit the official page: MALDI-TOF Mass Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber-Coupled SLED Market to Reach USD 265M by 2032 (7.45% CAGR)
By PW Consulting, 2026-07-12
Fiber-Coupled SLED Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
As PW Consulting’s lead industry analyst, I present an evidence-backed overview of the fiber-coupled superluminescent diode (SLED) market tailored to executives and product strategists preparing for 2026. The market has demonstrated steady expansion, growing from approximately USD 150.0 Million in 2020 to USD 195.0 Million in the 2025 base year. Our forecast horizon (2026–2032) models a continuation of this trend, with the market projected to expand at a compound annual growth rate (CAGR) of 7.45%, reaching roughly USD 265.0 Million by 2032. These headline figures quantify a clear commercial runway for suppliers, integrators, and downstream system OEMs—but they only tell part of the story. The purpose of this briefing is to translate that macro trajectory into the discrete strategic choices that will matter in 2026, while preserving the proprietary granularity that lies within our full report.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Why 2026 is a pivotal planning year
-
Technology inflection: Optical coherence tomography (OCT), advanced fiber sensing and certain metrology applications are maturing in parallel with multi-SLED and tunable broadband innovations. Companies that lock in technology leadership or differentiated supply now can capture outsized share as system integration accelerates over the next two to three years.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Supply-chain tightening and regulatory shifts: New export control regimes and critical-mineral licensing introduced by key suppliers are already changing sourcing economics and valid routes to market. Procurement strategies established in 2026 will materially affect lead times and margin profiles through 2027–2029.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Consolidation window: Market concentration metrics indicate a moderate incumbent advantage—top-three vendors control a meaningful but non-dominant portion of revenue, and top-five concentration increases that share materially. This creates both acquisition targets for scale players and white-space opportunities for innovative niche entrants.
Market trajectory and what the top-line numbers conceal
The market’s steady growth—evidenced by a rise from USD 150.0 Million in 2020 to USD 195.0 Million in 2025 and a forecast path to roughly USD 265.0 Million by 2032 at a 7.45% CAGR for 2026–2032—masks divergent microtrends that will decide winners and losers. Pricing ranges for single SLED diodes vary by wavelength, fiber type and customization, and we observe transaction price bands from approximately USD 673 to USD 2,624 per diode in typical industry datasets. Standard lead times clustered around five weeks create a planning cadence for OEMs building to production ramps.
But unit economics, integration complexity, and service-level expectations differ sharply by end-market. Organizations that interpret the headline market growth without overlaying technology roadmaps, regulatory risk matrices, and supplier resilience scenarios will misallocate capital. Our work stresses that the aggregate expansion is necessary but not sufficient to inform product investment, M&A, or channel strategy.
Supply chain and regulatory dynamics — actionable implications
-
Material dependencies: Fiber-coupled SLED devices remain dependent on compound semiconductor materials—InGaAs, InP and GaAs—and their associated supply chains. This creates vectors of risk (single-source substrates, specialty wafer processing) that translate to lead-time and cost volatility for system integrators.
-
Export controls and licensing: Recent policy changes instituted by major material-exporting jurisdictions have introduced licensing requirements for components that use certain Chinese-sourced materials or production technologies. These regulatory shifts are not binary; they create a sliding scale of compliance cost and approval delay that should be stress-tested across procurement scenarios.
-
Price and procurement strategy: Given the observed price dispersion, buyers can improve margin capture by redesigning product specifications to accept alternate fiber terminations, modular SLED assemblies, or multi-sourcing strategies. Conversely, suppliers can protect ASPs by bundling optical engines with calibration and software, reducing direct comparability.
Competition and consolidation — interpreting recent moves
The competitive topology is a mix of diversified photonics suppliers, specialist SLED vendors, and agile start-ups focused on spectral engines. Notable players include established component houses and innovators offering both stock and custom fiber-coupled SLED sources. Recent corporate activity underscores two simultaneous dynamics: strategic consolidation among scale players, and capability-driven partnerships targeting high-value applications such as OCT.
-
Portfolio expansion: Strategic acquisitions and partnerships—highlighted by moves to broaden photonics portfolios and co-develop OCT-focused SLED sources—signal that access to combined optical subsystems and integration capabilities is a priority for market leaders.
-
Innovation-driven entrants: A cohort of specialist firms is commercializing ultrawide-spectrum optical engines, multi-SLED modules and tunable broadband sources. Their ability to deliver differentiated spectral characteristics and tighter system integration can outcompete commodity diode suppliers on total system value.
-
Concentration insight: Market concentration measurements show the top three vendors controlling a meaningful slice of the market while the top five raise that share noticeably—evidence of moderate concentration and an active M&A runway. For buyers and investors, that means predictable supplier selection environments but also opportunities to consolidate value through targeted acquisitions.
What PW Consulting’s full report delivers (practical, executable content)
-
Granular market model: A reproducible forecasting model (2026–2032) with sensitivity scenarios for policy disruption, raw-material shocks and accelerated adoption cases. The public summary here shares top-line CAGR and market endpoints; the full model contains the build-up by product architecture, channel and end-use.
-
Competitive playbooks: Vendor capability maps, product-differentiation matrices, and go-to-market playbooks that prioritize high-margin applications and define switching barriers for system OEMs.
-
Supply-chain stress tests: Scenario analyses that quantify the operational and P&L impact of export controls, semiconductor substrate shortages, and single-source suppliers—plus mitigation roadmaps (dual-sourcing, strategic inventories, licensing strategies).
-
M&A and partnership targets: A curated shortlist of acquisition and alliance candidates by capability cluster (broadband engines, tunable sources, integrated spectral modules), with valuations and synergy estimates modeled under three commercial cases.
-
Procurement and engineering playbooks: Tactical recommendations to trim lead time, reduce cost per system, and accelerate time-to-market—covering spec harmonization, design-for-sourcing, and post-quantum compliance checklists.
Strategic recommendations for 2026
-
Invest in spectral differentiation, not commoditization: Focus R&D and product-management resources on ultra-broadband and tunable SLED engines where integration complexity and IP can sustain premium pricing and create switching costs.
-
Operationalize supply-chain resilience: Implement multi-tier sourcing, qualify alternative wafer suppliers, and establish legally vetted sourcing protocols to navigate new licensing requirements. Build a six- to nine-month buffer for critical components during transitional regulatory periods.
-
Pursue bolt-on M&A or technology partnerships: For incumbents seeking scale, target companies with complementary optical engine technologies or software-enabled calibration services that raise total system value and lower buyer commoditization risk.
-
Adopt a value-based commercial approach: Shift from per-diode pricing to outcome-based offers (e.g., calibrated spectral engines, service-level guarantees for OCT systems) to capture more of the system integration value.
-
Embed regulatory scenario planning into capital allocation: Incorporate licensing timelines and potential export restrictions into investment approvals and supply contracts; stress-test business cases with conservative procurement lead times.
Conclusion and next steps
The fiber-coupled SLED market presents a compelling growth trajectory from a compositional and financial perspective, but success in 2026 will be decided by actions taken now on supply chain resilience, product differentiation, and strategic partnerships. Our full PW Consulting study decodes the microstructure beneath the macro figures—providing the granular segmentation, vendor scorecards, and scenario models necessary to make confident capital, product and M&A decisions.
For executives preparing 2026 budgets and commercial roadmaps, the core takeaways are straightforward: treat the headline CAGR and market expansion as directional impetus, but allocate resources to mitigate supply-side risk, lock in spectral differentiation, and pursue targeted consolidation where it accelerates access to high-value applications. Accessing the complete report provides the operational playbooks and data-driven build-ups that translate those strategic priorities into executable programs.
How to obtain the full analysis
PW Consulting’s comprehensive fiber-coupled SLED market study contains the detailed segmentation, vendor-level profiles, and executable recommendations necessary for board-level decisions in 2026. Contact our team to request the full report, which includes the models and supporting annexes excluded from this preview to preserve comparative advantage for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial RTU Market: 4.2% CAGR to USD 1,060.39M by 2032; Asia Pacific $326.77M
By PW Consulting, 2026-07-12
Industrial Remote Terminal Unit (RTU) Market — Strategic Outlook for 2026 Enterprise Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, strategy-first briefing that frames our full Industrial Remote Terminal Unit (RTU) Market study for executives planning decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the research while deliberately withholding granular segment datapoints and proprietary tables to guide readers to the full report for detailed validation.
Industrial Remote Terminal Unit (RTU) Market
Market trajectory at a glance — what the numbers imply
The RTU market has shown steady expansion through the early 2020s and continues on a modest growth trajectory. Our base-year assessment for 2025 places the global market near USD 801 million, rising at a compound annual growth rate (CAGR) of approximately 4.2% over the 2026–2032 forecast window, reaching just over USD 1.06 billion by 2032. Historical trend analysis shows sustained recovery and investment cycles since 2020, reflecting a combination of legacy-system refreshes, targeted digitalization in industrial verticals, and increasing portfolio mixes that include edge-enabled and wireless-capable RTUs.
Industrial Remote Terminal Unit (RTU) Market
Why this matters for 2026: the market size and mid-single-digit CAGR indicate an environment where disciplined prioritization of capex and differentiated product/service strategies win. Large incumbents and focused specialists alike will chase incremental growth—creating selective opportunity windows for strategic buyers, system integrators, and technology partners.
Industrial Remote Terminal Unit (RTU) Market
Market structure and competitive dynamics — fragmentation with platform concentration
The market is structurally fragmented: the share held by the largest three and five firms is modest, signaling ample room for regional specialists, system integrators, and component vendors to compete. This fragmentation creates strategic consequences:
- Price and specification competition remain intense at the low end, favoring scale players and contract manufacturers.
- At the high end, platform interoperability, cybersecurity, and lifecycle services are primary differentiators.
- M&A and partnership playbooks are the likely medium-term levers for top-tier players to accelerate access to niche capabilities and regional footprints.
Key market participants we track include global automation and control leaders, telecom and communications specialists, industrial computing vendors, and regional RTU manufacturers and integrators. The following qualitative profiles summarize the strategic postures we see in the market (this is an analytical snapshot, not an exhaustive vendor scorecard).
- ABB (Zurich): Leverages broad grid and automation franchises to position RTUs within larger distribution and substations solutions; focus on system-level integration and lifecycle services.
- General Electric (Schenectady): Integrates RTUs into broader asset management and industrial digitalization offers, emphasizing analytics and legacy modernization pathways.
- Schneider Electric (Rueil‑Malmaison): Uses EcoStruxure and system-level offerings to bind RTUs into energy management and process-automation value propositions.
- Honeywell (Charlotte): Positions RTUs as part of its process automation and remote monitoring suites, strong in regulated industries requiring proven safety and compliance traces.
- Siemens (Munich): Offers RTUs within grid automation and industrial digitalization stacks, with emphasis on interoperability and engineering tools.
- Emerson (St. Louis): Focuses on process industries and integration with DCS platforms; competitive where lifecycle services and vendor-managed solutions are required.
- Rockwell Automation (Milwaukee): Competes via control-system integration and scalable automation architectures suited to North American process and discrete markets.
- Motorola Solutions (Chicago): Brings communications and ruggedized networking strengths—relevant where mission-critical remote communications are a core requirement.
- Advantech & Moxa (Taipei): Position as industrial-computing and IIoT gateway specialists that translate RTU data into edge compute and connectivity solutions.
- Yokogawa (Tokyo): Integrates RTUs with DCS and process-control expertise, strong in long-cycle capital projects.
- Red Lion (York) & Fanox (Barcelona): Niche specialists in protocol conversion, remote monitoring, and protection components—important partners for retrofit programs.
- Arteche, Iskra Sistemi, SEL, Dongfang Electronics: Regional and technical specialists providing measurement, protection, and rugged RTU solutions tailored to local grid and industrial standards.
- INTECH Process Automation, Kalki Communication Technologies: Systems integrators and communications specialists that convert vendor stacks into working field deployments at scale.
Strategically, incumbents lean on platform integration and services to expand TAM per customer, while smaller vendors compete on price, agility, and regional compliance expertise. Expect an uptick in alliances pairing global platforms with regional integrators over the next 18–24 months.
Demand drivers and headwinds — shaping priorities in 2026
- Digitalization & IIoT adoption: Edge analytics, remote asset management, and data-driven O&M are primary demand drivers. RTUs that natively support secure edge processing and common industrial protocols gain procurement preference.
- Asset modernization: Utilities and industrial operators with long tail of legacy RTUs will pursue staged refreshes to balance reliability and ROI.
- Cybersecurity mandates: Regulatory and insurer expectations force RTU purchases to include hardened communication stacks and patch-management guarantees.
- Wireless uptake vs. wired reliability: Wireless RTUs unlock lower-install-cost remote monitoring, but mission-critical applications still demand deterministic wired options; product roadmaps must accommodate both.
- Supply chain & materials volatility: Semiconductor supply-chain constraints, and the rising compliance and cost pressures around sustainable packaging and materials, affect lead times and TCO modeling.
Note on regulatory context: broader environmental and packaging regulations in major markets are increasingly relevant to hardware vendors’ supply chains. For example, recent EU and UK directives and taxes on packaging and recycled-content requirements have raised supplier compliance burdens and, in some cases, near-term cost exposure for plastic enclosures and packaging. In Europe, recycled-PET pricing has been higher than virgin PET through 2020–2025 in certain categories—an issue that hardware procurement teams should model into total lifecycle costs and supplier audits.
Strategic playbook for 2026 — recommended actions
- Adopt a two-speed procurement model: fast pilots for wireless/edge RTU use cases and long-lead tender tracks for mission-critical wired deployments.
- Prioritize interoperability and lifecycle services in vendor selection to reduce obsolescence risk and lower long-term TCO.
- Embed cybersecurity and patch-management SLAs into procurement contracts; require supplier transparency on supply-chain resilience.
- Design retrofit-first architectures where practical—use vendor-agnostic protocol gateways and edge compute nodes to extend legacy asset life while enabling phased data enrichment.
- Maintain an M&A/partnership watchlist: regional integrators and niche technology providers offer rapid capability fills for cloud/edge analytics and communications.
- Model regulatory cost exposure linked to packaging and materials compliance as part of capex justification for new hardware rollouts.
What the PW Consulting RTU report delivers (practical content)
Our full study is built for immediate operational use by procurement, OT/IT architects, and corporate strategy teams. Highlights include:
- Market sizing and 2020–2032 forecast with scenario variants and sensitivity to key drivers (base-year 2025 anchoring).
- Segmentation frameworks (by product type, application, and region), plus addressable-market maps for prioritizing growth plays — note: granular segment tables are available in the full report.
- Vendor benchmarking across technical, commercial, and delivery dimensions (capability heatmaps and RFP-ready supplier shortlists).
- Go-to-market playbooks: retrofit vs greenfield decision trees, pilot designs, and integration checklists.
- Financial tools: TCO and ROI templates for procurement justification, and capital planning scenarios under different obsolescence/maintenance assumptions.
- Risk matrix and mitigation playbook covering supply chain, regulatory, and cybersecurity exposures.
- Primary research annex: interview summaries with buyers, integrators, and vendor product leads, plus methodology notes and data sources.
Closing — why use this insight in 2026
By 2026, typical enterprise agendas will combine tighter capital discipline with an increased need to extract operational value from existing assets. The RTU market’s modest growth yet fragmented supplier landscape means that a targeted strategy—combining selective capex, supplier rationalization, and partnerships for analytics and cybersecurity—will generate outsized returns versus blanket replacement programs.
This briefing provides the strategic spine; the full PW Consulting RTU Market report supplies the granular segmentation, interactive models, and vendor-level benchmarking necessary to operationalize these recommendations. We intentionally withheld detailed subsegment tables and proprietary mappings here to ensure readers consult the full dataset for procurement and investment-grade decisions.
To access the comprehensive dataset, vendor scorecards, and downloadable decision tools, please consult the full PW Consulting report and supporting digital workbook.
For detailed analysis of this topic, please visit the official page: Industrial Remote Terminal Unit (RTU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Impact Crusher Market 2026: Strategic Preview for Decision‑Makers
Introduction — Why this preview matters for 2026 planning
As organizations reset capital allocation, supply‑chain priorities, and product‑mix strategies for 2026, an accurate read on the impact crusher market is no longer optional. PW Consulting’s latest market study (base year 2025, forecast 2026–2032) synthesizes demand trajectories, regulatory headwinds, input‑cost volatility, and vendor positioning to convert noise into actionable choices. This preview highlights the study’s strategic takeaways while preserving the granular sub‑segment intelligence that we reserve for the full report—intentionally positioning this piece as a high‑trust trailer that equips executives to prioritize next steps, not to replace the full dataset and scenario models.
Impact Crusher Market
Market trajectory and macro context
The impact crusher market has moved from a niche replacement cycle into a phase of steady, investment‑grade growth. After recovering through the early 2020s, the market reached an estimated USD 86.2 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% across the 2026–2032 forecast window. By 2026 the market is expected to exceed USD 90 Million, with continued expansion through the late 2020s driven by infrastructure activity, recycling mandates, and equipment fleet renewals in mining and aggregates operations.
Impact Crusher Market
For corporate leadership, two far‑reaching implications follow: first, predictable top‑line growth validates multi‑year product development and aftermarket investments; second, the rate of growth is modest enough that competitive advantage will accrue to firms who combine operational excellence, aftermarket capture, and regulatory compliance—rather than to those relying solely on rapid top‑line expansion.
Impact Crusher Market
What is changing beneath the headline numbers
- Shift from pure throughput to lifecycle economics: Buyers increasingly evaluate crushers on total cost of ownership (TCO), factoring energy consumption, wear‑part longevity, uptime, and modularity for multi‑site redeployment.
- Mobility and configurability premium: Mobile and semi‑mobile platforms with faster set‑up, simplified transportability, and modular screening/secondary crushing options are commanding procurement attention in contract tendering and rental markets.
- Sustainability and emissions compliance: Equipment that enables recycling and reduces fleet emissions is being prioritized in public projects and large private contractors’ procurement frameworks.
Regulatory, material‑cost and safety dynamics that will shape 2026 decisions
Procurement, product engineering, and aftermarket strategies must be stress‑tested against a trio of external dynamics that are material to margins and project timelines.
- Standards and compliance: Mobile crushers are increasingly governed by ISO 21873‑1 terminology and commercial requirements; design, testing, and labeling processes must reflect these standards to secure bids and pass regulatory audits.
- Wear‑part specifications: ASTM A128 specifications for austenitic manganese steel affect materials sourcing and supplier qualification. Companies that lock in compliant alloy supply lines and offer validated wear‑part warranties will secure a pricing and availability advantage.
- Input‑cost volatility: Manganese ore prices are linked to broader steel and infrastructure cycles; recently prices moved lower month‑over‑month (to roughly CNY 32.25/mtu in June 2026), but longer‑term demand drivers—urbanization and energy technologies—support price upside risk. Sourcing strategies and hedging policies should be revisited now, not later.
- Workplace and emissions safety: MSHA and regional mobile equipment emission rules are tightening in key markets. Compliance capability (documentation, testing, retrofit paths) is a differentiator in public tenders and long‑term supply contracts.
Competitive landscape — who matters and why
The impact crusher market sits in a moderately concentrated competitive structure. The top three players collectively command a meaningful share of the market, and the top five extend that footprint further—creating both consolidation opportunities and niche openings for specialist players. For decision‑makers, the dynamic is clear: incumbents with broad portfolios are focusing on uptime, modularity, and lifecycle services, while niche and regional manufacturers are leveraging agility and local service networks.
Key vendor behaviors we observed in 2026 that will inform procurement and partnership strategies:
- Product line refreshes with transportability and configurability improvements — exemplified by a major OEM’s launch of a new horizontal impact series designed for easier road transport and site configuration, showcased at a major UK trade show in mid‑2026.
- Rotor and materials engineering advances — a leading Austrian manufacturer introduced next‑generation mobile impact units with rotors engineered for 17–25% higher inertia, paired with automated control systems to increase uptime for aggregate producers.
- Scale and capacity pushes — another OEM debuted a high‑capacity mobile impact crusher capable of headline feed sizes and throughput that target large quarry operations and aggressive recycling programs; these launches signal that vendors are pushing both ends of the market: high throughput and high mobility.
Representative companies demonstrating these strategic postures include global OEMs and specialist mobile‑plant vendors. Their recent product moves and regional positioning illustrate three distinct competitive playbooks: full‑spectrum OEMs pushing integrated systems and services; European mobile specialists emphasizing rotor and control innovation; and North American track‑specialists focusing on on‑site crushing and rental market needs. Each playbook has implications for procurement (e.g., bundling vs. best‑of‑breed), service partnerships, and aftermarket capture.
Report contents — what the full study delivers (practical, operational, and tactical layers)
PW Consulting’s full Impact Crusher Market report provides layered intelligence designed for commercial, product, and strategic planning teams. Highlights include:
- Market sizing and validated time series (2020–2025) and deterministic scenarios for 2026–2032 with sensitivity to commodity cycles and infrastructure spend.
- Scenario modeling (base, upside, downside) that quantifies impacts of regulatory changes, manganese price shocks, and accelerated recycling mandates on market demand and margin pools.
- Competitive diagnostic including vendor profiles, recent product introductions, technology scorecards (mobility, energy efficiency, modularity), and go‑to‑market vectors for each vendor archetype.
- Procurement playbook: decision matrices to evaluate buy vs. rent vs. lease, total cost of ownership calculators, and a supplier‑selection checklist that aligns with ISO and ASTM compliance requirements.
- Aftermarket and services roadmap: prioritized opportunities for spare‑parts margins, predictive maintenance programs, retrofit offerings, and digital‑services monetization pathways.
- Commercial annex: tender language templates, sample specification bundles, and a pricing framework to benchmark capital and spare‑parts offers against market medians.
Note: The report contains detailed regional, type, and application-level splits and unit economics that we do not publish in this preview. Those granular tables and interactive dashboards are available exclusively in the full report to preserve the competitive value of the segment-level intelligence.
Strategic recommendations for 2026 — five high‑impact moves
- Prioritize lifecycle economics in RFPs. Move procurement evaluation away from headline throughput metrics and toward validated uptime, wear‑part life, and energy usage under customer‑relevant duty cycles.
- Lock in compliant materials suppliers. Given ASTM and ISO alignment and the sensitivity to manganese pricing, create multi‑year agreements or option‑based contracts with qualified alloy suppliers to stabilize aftermarket margins.
- Modularization and retrofit pathways. Invest in modular secondary crushing and screening options, and design retrofit kits that enable existing fleets to meet evolving emissions and safety regulations without full replacement.
- Aftermarket service packages as a revenue lever. Build or partner for predictive maintenance, fleet telematics, and guaranteed‑uptime contracts—these convert installed base into repeatable revenue and higher margin streams.
- Scenario‑based capex timing. Use the report’s scenario outputs to time significant capital deployments: accelerate in upside infrastructure scenarios, but stage purchases through rental partnerships when downside commodity risk is elevated.
Closing — how to use this preview
This preview is intended to orient executive priorities and identify the critical questions to ask in 2026 planning cycles: where to invest in R&D, how to structure supply agreements, which supplier archetypes to partner with, and how to monetize installed fleets. If your organization is evaluating procurement strategies, product roadmaps, or aftermarket growth targets, PW Consulting’s full report provides the model outputs, segment‑level splits, and supplier scorecards needed to translate these strategic recommendations into executable plans.
For access to the complete dataset, downloadable dashboards, and the supplier benchmarking annex (including the regional, application, and type‑level breakdowns that underpin our recommendations), please consult the full Impact Crusher Market report on our website.
For detailed analysis of this topic, please visit the official page: Impact Crusher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silage Corn Seed Market to Reach USD 344.8 Million by 2032 at 7.21% CAGR
By PW Consulting, 2026-07-12
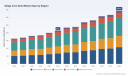
Silage Corn Seed Market — Strategic Preview for 2026 Decision-Makers
As global dairy and livestock systems face mounting pressure to improve feed efficiency, lower production costs, and mitigate climate risk, the silage corn seed market stands at a strategic inflection point. Our latest PW Consulting study — built on a 2020–2025 historical base and forward-looking to 2032 — shows the market expanding at a compound annual growth rate of 7.21%. The research synthesizes macro sizing, scenario-driven forecasts, supplier positioning, cost and regulatory shocks, and practical playbooks that companies must adopt to convert growth into profitable share gains in 2026 and beyond.
Silage Corn Seed Market
Why this report matters for 2026
-
Timing: 2026 is the first full planning year after multiple 2025 product launches and regulatory updates that materially affect seed development, risk management, and field economics. Boards and commercial leaders must translate these near-term changes into 3–5 year plans now.
Silage Corn Seed Market -
Market trajectory: The market’s steady historical growth combined with an above-average forecast trajectory implies both continued demand and heightened competitive intensity. Strategic moves in R&D, channel coverage, and pricing executed in 2026 will disproportionately shape outcomes for the remainder of the decade.
Silage Corn Seed Market -
Concentration dynamics: Market concentration at the top tier remains high, creating asymmetric opportunities. Established leaders can leverage scale and trait portfolios, while challengers can win by narrowing focus and exploiting gaps in innovation or service.
What the PW Consulting report delivers (practical, executable content)
-
Robust market architecture: a clear articulation of demand drivers, cost pressures, and adoption levers across the value chain, with modeled scenarios that stress-test pricing, yield, and trait-penetration assumptions.
-
Actionable commercial playbooks: segmented go-to-market options for seed houses and distributors, including prioritized channel investments, differentiated product messaging for dairy vs. beef systems, and farm-level ROI calculators to increase adoption.
-
R&D and product strategy guidance: a diagnosis of trait gaps and breeding priorities (e.g., digestibility, drought tolerance, BMR variants, and gene-edited traits), recommended investment pacing, and partnership archetypes for co-development or licensing.
-
M&A and partnership scorecards: framework for evaluating targets by asset type (germplasm, trait stack, distribution footprint), with sensitivity analyses showing how different deal structures affect short- and long-term return profiles.
-
Commercial risk matrix: regulatory and insurance shifts, supply-chain fragilities, and farm economics translated into contingency playbooks for price shocks, seed shortages, or rapid trait adoption.
Competitive landscape — what to watch in 2026
The market is dominated by a small number of global R&D leaders with deep hybrid pipelines, broad distribution networks, and the capital to commercialize advanced trait packages. That said, a vibrant mid-market and regional specialist cohort remain strategically important — both as customers (through licensing or distribution partnerships) and as acquisition targets.
-
Bayer CropScience: Continues to push breeding advances and has moved into gene editing for drought resilience. Expect Bayer to lean into trait differentiation and stewardship programs that help translate genetic advances into demonstrable on-farm value.
-
Corteva Agriscience: With a broad hybrid portfolio and strong channel relationships, Corteva’s pathway to growth emphasizes integrated trait stacks and farm-centric data services that increase stickiness across the growing season.
-
Syngenta: Focused on digestibility-optimized lines and energy-efficient hybrids; Syngenta’s near-term bets will be on partnerships and co-branded products that accelerate adoption in dairy-intensive geographies.
-
KWS, Limagrain, Brevant, Maizex, Hybrid85 and other regional players: These firms compete on niche specialization — forage-centric breeding, non-GMO portfolios, or value pricing and direct shipping. Their agility and local knowledge make them credible challengers in defined segments.
Recent 2025–early-2026 developments reflect this dynamic: new hybrid launches across multiple firms, drought-tolerant gene-edited lines coming to market, and distribution partnerships that increase route-to-farm reach. Taken together, these signals point to faster product turnover and a higher premium on commercialization excellence.
Cost, regulation and operational dynamics shaping 2026 choices
-
Input cost pressure: Field-level economics are shifting. For 2026, industry averages show a step-up in per-acre planting costs compared with 2025. Management teams must account for this when designing price-pack structures and farmer financing offers.
-
Insurance and regulatory flux: The USDA Risk Management Agency’s updated standards and new pilot insurance programs approved in late 2025 change the risk calculus for both farmers and seed firms. Companies should model the impact of these programs on adoption risk and stocking strategies.
-
Seed unit economics: Kernel-level breeding and scaling efficiencies, including cost per 1,000-kernel metrics in major production geographies, are now core inputs to pricing models and inventory decisions.
Strategic implications and recommended 2026 priorities
Companies that treat 2026 as a pivot year — aligning portfolio, go-to-market, and capital allocation decisions to a mid-term (2028–2030) value capture view — will outperform. Below are prioritized actions for executive teams.
-
Prioritize product-to-market velocity. Compress the commercialization funnel for proven trait packages by reallocating marketing and trial resources toward the highest-response geographies and channels. Fast-follower models that shorten shelf-to-farm time will capture disproportionate share.
-
Rebalance pricing and packaging. With farm-level planting costs elevated, experiment in 2026 with conditional pricing (e.g., performance rebates, split-payment structures, bundled agronomic services) to reduce perceived adoption risk while protecting margins.
-
Make targeted R&D bets plus external leverage. Divide R&D spend between core long-lead breeding and near-term gene-editing or trait-acceleration investments. Complement internal work with structured licensing and co-development to derisk time-to-market.
-
Strengthen distribution economics. Reassess distributor incentives and direct-to-farm capabilities; investments in digital ordering, logistic optimization, and seed-finance products can materially increase farmer loyalty and margin capture.
-
Use M&A strategically. Pursue tuck-ins that enhance trait breadth or regional coverage, and consider bolt-on acquisitions that instantly upgrade commercial capacity rather than purely germplasm consolidation.
-
Plan for regulatory and insurance permutations. Build scenario models that incorporate the updated crop-insurance standards and pilot programs, and design commercial offers that align with farmer risk-management choices.
How this preview is designed to spark action — and what is reserved for the full study
This article is intentionally structured as a strategic “trailer”: it surfaces the key directional forces, competitive moves, and executive-level recommendations that should shape 2026 planning. The full PW Consulting Silage Corn Seed Market report contains the granular inputs and proprietary models that drive these conclusions — including regional demand curves, type- and application-level adoption scenarios, company benchmarking scorecards, investor-ready financials, and downloadable ROI tools for field trials.
Concretely, the full study provides:
-
Model spreadsheets that allow users to run their own sensitivity tests against price, yield, and trait-penetration assumptions.
-
Detailed competitor dossiers and GTM mapping that uncover white-space opportunities within and between geographic clusters.
-
Step-by-step commercialization templates for launching new hybrid lines, including trial design, farmer engagement, and distributor incentive mechanics.
Final note to executives
As the silage corn seed market scales, the window to secure advantaged positions narrows. 2026 will reward companies that combine disciplined capital allocation, sharper commercialization, and flexible risk-management solutions for farmers. Our research quantifies the market’s trajectory, unpacks the near-term shocks, and prescribes the operational moves that convert macro growth into durable competitive advantage. For teams preparing budgets, M&A pipelines, or product roadmaps for 2026, this study is the strategic backbone that turns insight into implementation.
PW Consulting remains available to walk leadership teams through a tailored briefing of our findings, run custom scenarios on your portfolio, and co-develop a 90–180 day execution plan aligned to your ambition in this evolving market.
For detailed analysis of this topic, please visit the official page: Silage Corn Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


