



Category: market research
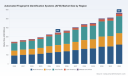
Automated Fingerprint Identification Systems (AFIS): Strategic Imperatives for 2026 — A PW Consulting Preview
As governments, border agencies, financial institutions and large enterprises reassess identity infrastructure in the wake of rising security needs and renewed investment cycles, AFIS remains central to identity assurance strategies. This preview distills the strategic value of PW Consulting’s forthcoming AFIS Market report — framed for C-suite and procurement leaders making decisions in 2026 — and highlights actionable themes while deliberately omitting the granular segment-level figures that sit behind our full analysis.
Automated Fingerprint Identification Systems (AFIS) Market
Why this analysis matters for 2026 decision-makers
-
Timing: 2026 is a pivot year. With the base year of our study set at 2025 and a forecast horizon to 2032, organizations launching procurements or platform migrations in 2026 must balance near-term operational needs with a multi‑year technology roadmap.
Automated Fingerprint Identification Systems (AFIS) Market -
Investment discipline: The AFIS market is growing at a steady compound annual growth rate (CAGR) of 7.5% in our forecast window. That growth rate implies meaningful technology refresh cycles and recurring procurement opportunities for both vendors and system integrators. Buyers who lock into immutable architectures risk higher switching costs mid‑cycle.
Automated Fingerprint Identification Systems (AFIS) Market -
Strategic trade-offs: Leaders must make three critical choices in 2026 — prioritize cloud-native scalability vs. on-premise control, invest in multimodal expansion (e.g., palmprint/latent support) vs. deepening fingerprint accuracy, and select vendors with demonstrated integration or certification pathways relevant to their use case.
Market trajectory — headline figures and interpretation
Our market sizing, presented in USD (Million), shows a consistent upward trajectory from the historical period through the forecast horizon. The market grew from a mid‑two‑hundreds base in 2020 to USD 348.0 Million in 2025 (base year). Projections extend to 2032, where AFIS revenues reach a substantially larger footprint under the modeled scenario. This expansion is underpinned by the 7.5% CAGR noted above and reflects both organic replacement cycles and new deployments across public and private sectors.
For executives, the implication is clear: procurement windows in 2026 will intersect with a market that is expanding but also consolidating around differentiated technology stacks and partnerships. Recognizing where the market is on this growth curve is essential to negotiation strategy, total cost of ownership (TCO) modeling, and risk assessment for multi‑year programs.
Drivers, inhibitors and near-term inflection points
-
Drivers: Rising cross‑border mobility and an emphasis on secure digital identities push demand for AFIS capabilities at borders and in law enforcement; financial and commercial adoption of strong biometric authentication adds incremental volumes; and a pivot to cloud and hybrid architectures elevates software and services revenue.
-
Technology accelerants: Advances in algorithmic matching, AI-enhanced latent print identification, and multi‑biometric fusion are improving match rates and operational throughput. These advances change the calculus for legacy vendors and create upgrade pathways for existing deployments.
-
Inhibitors: Data privacy regimes, procurement cycles, interoperability challenges with legacy enrollment databases, and capital constraints in certain public budgets can slow implementation. Cybersecurity and data sovereignty considerations will also shape whether agencies choose cloud, edge, or on-premise models.
-
Inflection points to watch in 2026: certifications and compliance milestones (e.g., national or international acceptance of new algorithmic standards), major national ID or border programs moving into procurement, and the emergence of cloud‑native ABIS/AFIS offerings reaching enterprise readiness.
Technology and product trends shaping supplier selection
-
Cloud-native vs. legacy: Cloud ABIS/AFIS options reduce time-to-deploy and improve horizontal scaling, but they introduce choices around data residency and latency. We advise a staged migration approach for centralized databases and a hybrid model for mission‑critical border operations.
-
Algorithm differentiation: Vendors now market algorithmic boosts (e.g., AI-enhanced matching and latent print capabilities) as a central differentiator. Procurement teams should request matched performance metrics on representative datasets rather than vendor-supplied claim sheets.
-
Hardware-software co‑development: FBI/National standards certified scanners and integrated livescan devices continue to matter. For high-volume sites, throughput and certification compatibility are as important as algorithmic quality.
-
Multimodal extension: Fingerprint systems that are architected to ingest palmprints, facial templates or latent traces offer better long‑term value. Vendors promoting modularity and API-first architectures reduce lock‑in risk.
Competitive landscape — what to look for among leading providers
The AFIS vendor ecosystem is a mix of long-standing incumbents and agile regional specialists. Market concentration metrics indicate that the top three vendors account for a substantial portion of global revenues, with the top five increasing that footprint further — a structure that favors established players but leaves room for niche and regional challengers. Key archetypes we focus on in our analysis include:
-
Global system integrators with deep law‑enforcement pedigree: Companies known for mature AFIS/ABIS platforms, strong algorithm portfolios, and long track records with national programs. These providers are often selected where certification and field-proven scalability are paramount.
-
Cloud and AI-first vendors: Providers emphasizing cloud-native ABIS platforms, elastic matching farms, and AI-enhanced latent identification. They appeal to financial institutions, large-scale civil registries, and agencies prioritizing rapid scaling.
-
Hardware-centric firms: Manufacturers that bundle certified livescan scanners, turnkey appliances and scanner‑software stacks. Their value lies in delivering end‑to‑end, certified solutions with predictable operational profiles.
-
Regional specialists: Local vendors that excel at meeting country‑specific compliance, language and operational needs. For many governments, these suppliers provide a pragmatic balance between capability and on‑the‑ground support.
Our competitive profiles examine, among others, the technical strengths and strategic positioning of major vendors active in AFIS: suppliers offering integrated AFIS/ABIS platforms with advanced matching engines; companies delivering cloud and AI-enhanced services for both public and private customers; firms focusing on certified scanner hardware and livescan management; and regional players advancing multimodal and forensic offerings. Each profile assesses product maturity, certification posture, go‑to‑market focus, partnership ecosystems and probable competitive moves through 2026.
What our full report delivers — operationally actionable intelligence
PW Consulting’s full AFIS Market report is built for practitioners and strategists. It combines quantitative market models, scenario-based forecasts and vendor due diligence into a toolkit you can use within procurement, product planning or corporate development. Highlights include:
-
A validated market model (base year 2025; forecast 2026–2032) that explains which demand pools and purchasing behaviors drive the topline and where growth premium is most likely to accrue.
-
Use-case driven buyer personas and decision frameworks to align requirements across security, privacy and IT stakeholders — helping to write informed RFPs and evaluation criteria.
-
A vendor assessment toolkit that synthesizes capability matrices, certification checklists and third-party validation steps — enabling faster, lower‑risk procurement cycles.
-
Migration playbooks for hybrid, cloud and on‑premise strategies — with phased TCO and integration risk considerations tailored for 2026 program timelines.
-
Scenario stress-tests covering regulatory shocks, major national ID projects and rapid adoption of AI latent‑matching to show upside and downside paths for market participants.
Note: In order to preserve the integrity of competitive positioning and to encourage dialogue with decision-makers, the full report retains detailed segment break‑outs by region, type and application — those granular datasets and strategic recommendations are available exclusively with the complete publication.
Actionable recommendations for executive teams in 2026
-
For buyers: Treat AFIS purchases as platform decisions, not product buys. Require API openness, roadmap guarantees for algorithm upgrades and clearly defined data residency commitments. Negotiate performance-based SLAs tied to matching accuracy and throughput.
-
For vendors: Differentiate on integration velocity and certification pathways. Cloud‑native offerings should emphasize secure hybrid deployment patterns and a clear migration route for legacy customers.
-
For investors and M&A teams: Look for targets with strong algorithm IP, proven government references and modular product architecture. Regional specialists with sticky public sector contracts can be consolidation candidates.
-
For systems integrators and consultancies: Build cross-domain competencies (biometrics, cybersecurity, data governance) and position as orchestration partners for multi-vendor deployments.
How to use this preview
Consider this article a strategic orientation guide ahead of procurement and planning sessions in 2026. Use the high‑level market trajectory, growth assumptions and strategic themes here to: align stakeholder priorities, benchmark RFP timing against market cycles, and identify which vendor archetypes to prioritize for deeper diligence.
For readers ready to move beyond the preview: PW Consulting’s full AFIS Market report provides the necessary datasets, supplier evaluations and implementation playbooks to operationalize a 2026‑era AFIS strategy. It is designed to be directly usable in vendor selection, negotiation and roadmap planning — while containing the granular segmentation and financial models that underpin the strategic recommendations presented above.
Contact PW Consulting to access the full report and a tailored briefing session to translate these insights into an executable 2026 plan for your organization.
For detailed analysis of this topic, please visit the official page: Automated Fingerprint Identification Systems (AFIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold Mix Asphalt Additives Market to Grow at 4.92% CAGR (2026–2032)
By PW Consulting, 2026-07-12
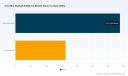
Cold Mix Asphalt Additives Market — Strategic Preview for 2026 Decision-Makers
PW Consulting's new market study on Cold Mix Asphalt Additives positions this segment as a quietly strategic inflection point for materials suppliers, pavement contractors, public works agencies, and investors in 2026. This preview outlines the study’s practical value for near-term corporate decisions, highlights the structural forces reshaping the competitive landscape, and signals where executive teams should concentrate scarce attention and capital. To preserve the report’s commercial integrity this article demonstrates analytical depth while intentionally omitting the granular segment-level tables and region-by-application splits contained in the full report—visit PW Consulting’s Cold Mix Asphalt Additives research page for the complete dataset and vendor scorecards.
Cold Mix Asphalt Additives Market
Why this market matters in 2026
-
Performance meets policy: Cold mix solutions lower the technical and environmental barriers to asphalt rehabilitation, enabling pavement work outside narrow hot‑mix windows and in remote or low-infrastructure settings.
Cold Mix Asphalt Additives Market -
Macro growth with tactical implications: The market has grown steadily from the 2020 base through the 2025 reference year and is forecast to expand across the 2026–2032 horizon at a compound annual growth rate of 4.92% (forecast period). In absolute terms the sector’s scale moves from mid‑hundreds (USD Million, base year 2025) toward a materially larger market by 2032—enough to justify dedicated product lines, supply‑chain investments, and targeted M&A for companies with regional reach or specialty chemistries.
Cold Mix Asphalt Additives Market -
Fragmentation and the premium opportunity: Concentration metrics show a market that is neither a monopoly nor fully commoditized (CR3 ≈ 37.5%, CR5 ≈ 45.2%). This structure creates a two‑track playbook: incumbent suppliers must defend formulation IP and logistics while emerging players can capture premium bio-based or performance-differentiated niches.
What the PW Consulting study delivers (practical contents)
-
Actionable market sizing and near-term forecasts calibrated to a 2025 base year and the 2026–2032 projection window, with scenario sensitivity around raw‑material volatility and regulation-driven adoption curves.
-
Supply‑chain maps and cost‑to-serve models that quantify margin sensitivity to petrochemical feedstock swings, emulsifier availability, and packaging/logistics tradeoffs—tools that allow procurement and finance teams to stress‑test contracts under realistic commodity scenarios.
-
Go‑to‑market playbooks tailored to three corporate archetypes (global chemical majors, regional formulators, and specialized bio‑additive challengers). Each playbook includes channel strategies, sample pricing ladders, and proof‑of‑value messaging for municipal and contractor buyers.
-
Regulatory compliance and risk playbook aligned to multi‑jurisdictional standards (EU REACH, California Proposition 65 analogs, and core Commonwealth frameworks), including a stepwise testing roadmap and estimated time/cost to registration by market.
-
Technology scouting and product roadmaps that evaluate polymer‑modification, bio‑based chemistries, and carbon‑sequestering innovations against durability, workability, and lifecycle‑cost metrics used by municipalities and national agencies.
-
Vendor benchmarking and an M&A target shortlist based on technology fit, geographic coverage, and scalability. The report includes a confidential scoring matrix used by corporate development teams to prioritize diligence targets.
Market dynamics you must factor into 2026 planning
-
Energy and emissions calculus: Cold mix approaches deliver substantial operational benefits versus conventional hot‑mix processes—independent studies show ambient‑temperature application can reduce energy consumption by roughly 35–50% and lower emissions by approximately 40–60%. For organizations evaluating total cost of ownership and sustainability commitments, those reductions materially affect procurement decisions, grant eligibility, and eligibility for green infrastructure funds.
-
Raw‑material volatility: Petrochemical feedstock and crude price swings directly influence the cost base for emulsifiers, amine anti‑stripping agents, and petroleum‑derived adhesion promoters. The net effect is asymmetric risk for formulators with high oil‑based input intensity and limited hedging capability; companies with diversified feedstocks or bio‑based options face less margin stress.
-
Regulatory lift and friction: Green procurement mandates in Europe, North America, and Oceania create demand pull for low‑emission cold mixes—but statutory regimes like REACH and California Proposition 65 also raise non‑trivial compliance costs. Cross‑border product launches must now budget for toxicology dossiers and extended testing timelines, which can extend commercial rollouts by quarters and increase go‑to‑market costs for smaller innovators.
-
Price vs. preference premium for sustainability: Bio‑based alternatives command a market premium—roughly on the order of mid‑teens to low‑twenties percent—reflecting both higher input costs and willingness‑to‑pay by public project owners that prioritize lifecycle emissions. Capturing that premium requires validated EPDs, field performance data, and third‑party certification in many jurisdictions.
Technology and innovation themes
-
Polymer modification is mainstreaming: Polymer‑modified cold additives are improving viscosity control and moisture resistance, enabling higher reclaimed asphalt pavement (RAP) incorporation without sacrificing early strength.
-
Bio‑based formulations are moving from demo to deployment: Recent product launches demonstrate commercialized polymer‑modified, bio‑derived additive systems capable of high RAP content and reduced VOCs—an important proof point for procurement teams that must reconcile sustainability targets with durability requirements.
-
Carbon‑sequestration adjuncts: Novel additions such as biochar show potential to sequester CO₂ within pavements while maintaining traffic durability—opening an adjacent value stream for suppliers able to validate long‑term carbon permanence.
Competitive snapshot — what leading vendors are doing
-
Arkema SA (Courbevoie, France) — Arkema’s ColdGrip® portfolio targets adhesion and moisture resistance by displacing water and promoting bond strength in cold patch applications. Their approach combines applied polymer chemistry with adhesion promoters to extend field service life, which is persuasive for municipal maintenance crews focused on patch longevity. Arkema’s global footprint and application engineering capability make them a credible incumbent for large contracts that demand technical support and supply continuity. (See company resources: https://www.arkema.com)
-
Cargill (Minneapolis, MN, USA) — Cargill’s Anova cold mix additives emphasize polymer‑modified, bio‑based formulations enabling high RAP incorporation, low VOC profiles, and year‑round application flexibility. Their emphasis on bio‑sourcing and supply reliability aligns with government buyers seeking lower‑emission solutions without sacrificing constructability. Cargill’s move into polymer-modified bio‑additives reflects commodity players capturing more value by layering formulation expertise on raw material supply. (See company resources: https://www.cargill.com)
Recent market signals and what they imply
-
Product innovation is accelerating: In mid‑2025 multiple vendors announced new formulations—ranging from polymer‑enhanced bio‑based additives to biochar‑infused mixes that claim CO₂ sequestration. These launches indicate an emergent bifurcation: performance‑first solutions that prioritize durability and logistics, and sustainability‑first solutions that leverage higher‑value procurement channels.
-
Procurement is becoming prescriptive: Public agencies increasingly require documented lifecycle emissions and validated product performance data, which raises the bar for entrants. The combination of green procurement preferences and regulatory compliance obligations amplifies the advantage of vendors who can invest in testing and certification up front.
Strategic implications and recommended next steps for 2026
-
Secure formulation IP or partnerships now. With mid‑single digit market CAGR and growing public procurement incentives, owning a differentiated chemistry—or a reliable licensing channel—will separate margin makers from volume players.
-
Invest in regulatory readiness. Budget for REACH/Proposition‑65 style dossiers and accelerated field trials where you want to compete; the time to first contract is increasingly gated by third‑party validation, not just price.
-
Hedge feedstock risk and de‑commoditize inputs. Consider dual‑sourcing strategies and incremental adoption of bio‑derived intermediates to reduce exposure to crude oil volatility while preserving cost competitiveness.
-
Pursue a two‑track product portfolio: one line optimized for low cost and rapid availability for contractor networks; a parallel premium line with certified sustainability claims aimed at municipal and green‑infrastructure budgets.
-
Use the PW Consulting vendor scorecard and M&A shortlist to prioritize inorganic deals that either fill regional distribution gaps or bring complementary chemistries into the fold.
How to use the full PW Consulting study
Executives preparing 2026 budgets should use the report to stress‑test scenarios across three vectors: cost volatility, regulatory timelines, and procurement demand elasticity for sustainability attributes. The study’s practical tools—cost‑to‑serve models, regulatory checklists, product roadmaps, and a confidential vendor scoring matrix—are designed to convert market intelligence into investment decisions within 60–120 days.
This article provides a high‑resolution view of the forces and decisions that will shape the cold mix additives landscape in 2026. For the complete dataset, segmented forecasts, confidential vendor scorecards, and downloadable decision tools, consult the full PW Consulting Cold Mix Asphalt Additives Market report. PW Consulting’s proprietary appendices contain the granular regional and application splits and the underlying assumptions that corporate strategy, procurement, and M&A teams will require to finalize action plans.
For detailed analysis of this topic, please visit the official page: Cold Mix Asphalt Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Drug Market to Reach USD 6,831.9M by 2032 with 6.2% CAGR
By PW Consulting, 2026-07-12
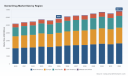
Dental Drug Market 2026 — Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a succinct, actionable preview of our new Dental Drug Market study — a practitioner's guide for boards, corporate strategy teams, and private capital preparing decisions in 2026. Anchored on a 2025 base year and a robust 6.2% compound annual growth rate (CAGR) through the near-term forecast, this research translates macro momentum into decision levers you can operationalize today. The purpose of this preview is to outline the strategic value of the full report: we will demonstrate analytical depth and signal the most consequential implications for 2026 moves while intentionally withholding the granular segment tables and proprietary data sets to direct you to the full study for transaction-level intelligence.
Dental Drug Market
Why this study matters in 2026
-
Market scale and trajectory: The dental drug market reached a substantial scale in 2025 (base year) and is poised to expand at a mid-single-digit CAGR. That combination of size and steady growth makes the sector a target for both incremental product strategies and transformative M&A plays.
Dental Drug Market -
Strategic inflection points: Shifts in payer dynamics, regulatory cost structures, and concentrated supplier footprints are creating differentiated winners and losers. Timing and sequencing of investment — not just capability — will determine whether incumbents defend margins or new entrants capture share.
Dental Drug Market -
Decision urgency: For commercial leaders planning product launches, for supply-chain leaders sizing capacity, and for investors underwriting private deals, 2026 is a preparatory year: structural changes in pricing and regulation will begin to materialize in ways that affect IRR and time-to-market.
Core dynamics shaping 2026 strategy
-
Regulatory and payer pressure: The implementation of negotiated prices under new drug-pricing programs has begun to change the pricing baseline for outpatient pharmaceuticals. While these initial negotiations target select drugs, the precedent shifts negotiation leverage among payers and manufacturers. Separately, higher regulatory filing costs and agency fee schedules have raised the fixed-cost threshold for bringing novel dental therapeutics through a formal drug-approval route. Together, these forces raise breakeven timelines for innovation and prioritize product platforms with clear reimbursement pathways.
-
Supply chain and raw-material sensitivity: The dental drug value chain depends on specialized APIs and contract-manufacturing know-how for tasks such as cartridge filling and sterility assurance. Sourcing pressure for key anesthetic APIs and concentrated filling capacity create single-point risks that can quickly affect availability and price. Manufacturers who invest in redundant sourcing, local/nearshore capacity, or backward integration will gain negotiating leverage and stability.
-
Labor and operational specialization: Beyond chemical inputs, this segment relies on trained labor for high-precision manufacturing and clinic-level administration (e.g., cartridge handling, injectable protocols). Wage inflation and skills shortages in production and QC can materially alter unit economics and time-to-scale in emerging geographies.
-
Clinical and product mix evolution: Therapeutic demand centers on pain management, infection control, and procedural adjuncts. Local anesthetics continue to be the single-largest therapeutic category by usage; however, clinical demand for non-opioid analgesics and minimally invasive local-delivery modalities is accelerating. Product innovation is therefore a mix of formulation refinement, delivery convenience, and procedural integration.
Competitive landscape — who to watch and why
The market displays moderate concentration: the top-three companies account for a meaningful share of industry revenues, and the top-five increase that concentration modestly. This structure creates a mix of scale advantages and white-space opportunities for specialists.
-
Septodont Holding (Saint-Maur-des-Fossés, France) — a long-established leader in local and topical anesthetics with global distribution; their recent strategic investment and board participation in a development-stage analgesic specialist signals an explicit move to broaden their pipeline and accelerate injectable innovation.
-
Dentsply Sirona (Charlotte, NC, USA) — integrates pharmacologic adjuncts into broader dental workflows, creating cross-selling opportunities between devices and drug consumables; their product strategy emphasizes clinical interoperability.
-
Henry Schein (Melville, NY, USA) — a distribution powerhouse whose catalog breadth and channel reach make it a vital partner for commercial rollouts; the 2025/2026 catalog refresh expanded anesthetic assortments and demonstrates ongoing channel-led product shaping.
-
Ultradent Products, 3M, Centrix, Pierrel, Huons, Normon, and several agile specialists — each occupies distinct strategic positions: innovation-oriented formulation houses, large industrial players with adjacent oral-care portfolios, regional manufacturers with cost-advantaged production, and niche developers focused on opioid-sparing analgesics. These firms are the primary targets for bolt-on acquisitions, supply agreements, and co-development partnerships.
-
Balanced Pharma Inc. (North Carolina, USA) — a small but strategically important innovator focused on novel dental injectables and opioid-alternative analgesics; strategic backing from larger incumbents has amplified their visibility as an M&A and licensing candidate.
Recent developments with immediate strategic impact
-
Strategic investments and board realignments among incumbents and innovators are accelerating access to differentiated injectable therapies. These moves reduce technical execution risk for novel formulations and signal a near-term uptick in licensing activity.
-
Major distributors are refreshing assortments to capture higher-margin product families and to support bundled procedural offerings — a trend that increases the premium on streamlined SKUs and clinician-friendly packaging.
-
Payer and regulatory changes are shifting pricing benchmarks and increasing the importance of early health-economics evidence generation to secure formulary positioning.
What PW Consulting’s full report delivers — practical, transaction-ready content
Our objective was to produce work that is not merely descriptive but operational. The study contains granular tools you can adopt immediately to inform 2026 decisions. Highlights of deliverables include:
-
Executive dashboards with scenario-based revenue trajectories (base, upside, downside) driven by our 6.2% CAGR assumption and stress-tested for regulatory, reimbursement, and supply shocks.
-
Actionable market-entry playbooks for biologics/formulations vs. generics, including go-to-market sequencing, recommended channel partners, and targeted pricing strategies.
-
Commercial diligence templates: customer segmentation logic, salesforce sizing, list-versus-net pricing sensitivity analyses, and a retailer/distributor negotiation scorecard.
-
Regulatory-impact mapping: timeline implications of current fee and filing environments, recommended evidence packages for expedited payer conversations, and cost models for clinical programs under current agency fee structures.
-
Supply-chain risk matrix and sourcing playbook, including supplier concentration indices, contract-manufacturing scorecards, and recommended nearshoring thresholds to secure continuity for high-priority SKUs.
-
Competitive benchmarking and M&A playbook: capability heatmaps for the leading firms, valuation multiples observed in recent transactions, and a prioritized list of acquisition and partnership targets by strategic objective.
-
Customizable financial model (editable) that integrates unit economics, channel mix, and price erosion curves — built for scenario runs around payer-negotiation outcomes and manufacturing-cost shocks.
How to use this research in 2026 planning
-
Corporate strategy: Use the study’s scenario framework to test inorganic vs. organic growth at multiple price-pressure thresholds. Prioritize investments into product platforms that either protect gross margin through differentiation or materially reduce cost-per-dose via manufacturing scale.
-
Commercial teams: Leverage the go-to-market playbooks to rationalize SKUs, develop distributor partnerships, and design clinician adoption incentives tied to measurable procedural outcomes.
-
R&D and portfolio leaders: Reallocate resources to formulation advances and delivery systems that reduce clinic time, improve safety, and facilitate payer coding — all of which accelerate reimbursement and adoption.
-
Private equity and corporate development: Apply PW’s M&A playbooks and valuation sensitivities to accelerate deal sourcing and to structure earn-outs and milestone payments tied to regulatory and commercial inflection points.
What we intentionally withhold in this preview — and why
To preserve the commercial value of the study for decision-makers, we are not disclosing the full segmentation tables, region-by-region allocations, or product-level revenue splits in this preview. The full report contains proprietary market-calibration data, segment-by-segment forecasting models, and detailed price and volume assumptions that are indispensable for transaction diligence and will be made available through our report portal or consulting engagements.
Final recommendations for 2026 executives
-
Prioritize supply security and alternative sourcing for anesthetic APIs and cartridge-filling capacity; these areas represent the quickest route to stabilizing margin volatility.
-
Accelerate partnerships or minority investments in development-stage innovators that offer opioid-sparing analgesics or clinician-friendly delivery systems; these assets will be highly sought after as payers focus on outcome-based arrangements.
-
Recalibrate launch and pricing playbooks to reflect higher regulatory overhead and payer negotiation risk; embed real-world evidence generation into early commercialization plans.
-
For investors, focus on targets with defensible manufacturing footprints, strong distributor relationships, and modular product platforms that can be rapidly scaled across multiple geographies.
PW Consulting’s full Dental Drug Market report provides the data, models, and playbooks that turn these recommendations into executable programs. For access to the detailed tables, segment models, and a guided briefing with our strategy team, please visit the full report page or contact our client services desk to schedule a 2026 planning workshop.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
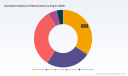
Epoxidized Soybean Oil (ESBO) Market: Strategic Primer for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a concentrated strategic primer to frame your 2026 planning for the Epoxidized Soybean Oil (ESBO) value chain. This briefing synthesizes our independent market sizing, competitive landscaping, and risk matrix to show where commercial advantage will be won — while reserving the granular segment-level forecasts and model outputs for the full study.
Epoxidized Soybean Oil Market
Why ESBO deserves executive attention in 2026
- ESBO is at the intersection of commodity agriculture and specialty chemicals: it is a bio-based additive with direct sensitivity to soybean oil availability, commodity price cycles, and shifting regulatory regimes tied to plastics and fuels.
- Our base-year market sizing (2025) anchors strategy decisions: the global ESBO market sits just below a half‑billion USD in revenue (2025 base), and our forecast path — underpinned by a 7.58% compound annual growth rate — points to a material scaling opportunity through the 2026–2032 horizon.
- Structural change is underway. Demand dynamics are being reshaped by PVC formulation shifts, sustainability-driven procurement, biofuel policy impacts on feedstock flows, and targeted trade remedies. These forces create both margin pressure and differentiation opportunities for producers, distributors and downstream formulators.
What the 2026 strategic landscape looks like (high level)
- Growth momentum: After steady expansion over 2020–2025, the ESBO market accelerates into the forecast period supported by stronger demand in traditional plasticizer and stabilizer applications plus broadened uptake in specialty uses. Our scenario models show the market roughly doubling in scale from the early 2020s over the medium term under the baseline case.
- Supply-side concentration: The sector exhibits moderate concentration among leading producers and integrated agribusinesses, creating oligopolistic dynamics for sourcing and premium product positioning. Competitive advantage will accrue to firms that combine feedstock control, technical grade differentiation, and route-to-market strength.
- Volatility vectors: Raw material availability (soybean oil), regulatory shifts (trade probes and food-contact rules), and renewable diesel policy are primary sources of near-term upside/downside risk. Commercial teams should assume episodic price swings and intermittent trade restrictions when stress-testing 2026 plans.
How PW Consulting’s ESBO research supports board-level decisions
Our full study is built for executives who must convert market intelligence into defensible action. We structure the work around four decision-use modules:
Epoxidized Soybean Oil Market
- Market Sizing & Scenario Forecasting — transparent methodology, baseline and alternate-path scenarios, and sensitivity to feedstock price and regulatory shocks.
- Commercial Due Diligence — supplier and buyer scorecards, channel economics, margin waterfall analysis, and a pricing playbook designed to navigate volatility while protecting market share.
- Portfolio & Product Strategy — product differentiation levers (e.g., food-contact certification, Kosher status, high-IV/heat-stable grades), licensing and co-development frameworks for formulators, and premiumization pathways for specialty ESO variants.
- M&A and Capex Roadmap — target screens for strategic acquisitions (vertical integration, regional converters, niche specialty players), greenfield vs brownfield build templates, and payback scenarios under multiple commodity-price regimes.
Each module contains executable outputs: decision matrices, model kits, playbooks, and a prioritized action list to be operationalized in 90-, 180- and 360-day horizons.
Epoxidized Soybean Oil Market
Competitive dynamics — what leading firms are doing
The competitive landscape is shaped by a mix of global specialty chemical suppliers, agrichemical/agribusiness integrators, regional manufacturers, and distributors. Across this set, three strategic postures prevail:
- Scale + feedstock control (vertical integration): Large agribusinesses that integrate soybean crushing into their operations can shield margins when crude oil or biodiesel policy diverts feedstock. These firms often have the flexibility to prioritize internal offtake or participate in spot markets selectively.
- Specialty differentiation: Chemical suppliers that combine certification credentials (food-contact, Kosher), tailored formulations, and heat-stable/high-performance grades aim to capture value above commodity ESBO levels. Recent product promotions and launches underscore the importance of technical depth to win formulation share in PVC and niche end-uses.
- Channel & services play: Distributors and toll manufacturers emphasize logistics, packaging flexibility (drums/totes/bulk), and rapid technical support. For many end users, sourcing stability and timely product qualification are as critical as unit price.
Notable recent moves reinforce these themes: capacity upgrades and modernization projects have expanded output capability; new ESBO variants focused on improved compatibility or thermal stability have been launched; and product promotions highlight food-safe and renewable credentials as a commercial differentiator. These developments indicate the market is maturing from a commodity-buyer environment toward one where technical and certifiable product attributes command premium access to certain channels.
Key commercial implications for 2026 planners
- Hedge feedstock risk strategically: Given the tight linkage to soybean oil supply, procurement teams should layer contracts (long-term offtake, index-linked clauses, and option-based hedges) and explore direct sourcing partnerships to manage price exposure and availability.
- Invest in product credentials: Certification (food-contact, Kosher) and demonstrable performance (heat stability, compatibility) accelerate adoption in regulated end markets. R&D and regulatory investment are high-leverage moves that improve price realization and reduce churn.
- Prepare for regulatory theater: Ongoing trade investigations and local content scrutiny require an agile compliance function and contingency sourcing plans. Rapid re-routing capability and tariff mitigation strategies can be decisive during episodic market shocks.
- Deploy selective downstream integration: CPF (capacity, flexibility, footprint) analysis suggests selective M&A or JV activity — particularly in regions with demand growth or where logistics create a competitive moat — can be accretive to margin and resilience.
- Differentiate through service: For converters and formulators, reliable supply, technical service, and packaging flexibility often trump the lowest-cost offer. Sales models should align around value selling rather than strict commodity procurement pitches.
Risk map: what to watch through 2026
- Raw-material pressure: Changes in soybean oil allocation (e.g., diversion to biofuel mandates) can tighten availability and lift prices; procurement teams must stress-test models for multiple feedstock-disruption scenarios.
- Trade and anti-dumping actions: Recent investigations in certain jurisdictions have already impacted flows; expect episodic protectionist measures that re-route trade lanes and alter landed cost math.
- Regulatory & sustainability standards: Evolving plastics regulation and increasing demand for renewable/traceable feedstocks create both barriers and premium opportunities; firms that fail to document chain-of-custody will see limited access to higher-value contracts.
- Technology and substitution risk: New plasticizer chemistries or formulations that reduce reliance on ESBO could emerge; continual product innovation is therefore essential to maintaining relevance.
What the full PW Consulting report contains (practical deliverables)
- Comprehensive market model with transparent assumptions, scenario toggles, and downloadable model artifacts for board use.
- Supply-chain heat maps and supplier scorecards highlighting capacity, technical capability, and strategic fit for potential partners or acquisition targets.
- Regulatory tracker and tariff scenarios tailored to priority markets, plus playbooks for rapid response to trade remedies or import restrictions.
- Commercial levers playbook: pricing frameworks, contract templates, logistics optimization, and SKU rationalization guidance.
- M&A screening dossier with high-probability targets, valuation benchmarks, and integration risk checklists.
Note: The full report contains granular regional and application-level forecasts, detailed split analytics, and company-level volume/price matrices. In keeping with this primer’s “trailer” design, those detailed segment outputs are intentionally withheld here to channel readers to the source study for the complete intelligence package.
Next steps for executives
- Use the headline market sizing and CAGR outlook in this primer to calibrate top-line targets and stress scenarios for 2026 budgeting cycles.
- Commission a rapid commercial due diligence (4–6 week sprint) if you are considering capacity investment, a JV, or an acquisition in the ESBO chain — the timing is right to capture first-mover advantages before premium segments harden.
- Initiate cross-functional workshops (procurement, R&D, regulatory, sales) to define a 180-day plan focused on feedstock resilience, product-certification upgrades, and targeted customer pilots.
For teams ready to translate these insights into actionable plans, PW Consulting offers the full ESBO market study along with bespoke advisory engagements to operationalize the recommendations. Our models and playbooks are built to be immediately integrated into 2026 capital allocation and commercial strategies.
Closing
ESBO is no longer merely a commodity intermediate — it is a strategic lever for formulators, a hedged commodity for agribusinesses, and a focal point for sustainability claims across plastics and packaging. With a clearly defined market trajectory and identifiable risk corridors, 2026 is the year to move from reactive sourcing to strategic positioning. PW Consulting’s full report gives you the maps and decision toolkits to do precisely that.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patrol Boats Market to Grow to USD 63.8 Million by 2032 at 6.7% CAGR
By PW Consulting, 2026-07-12
Patrol Boats Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision‑grade preview of our Patrol Boats Market research — a practical briefing intended to align executive choices with the market dynamics that will matter most through 2026 and beyond. This note signals the strategic value and immediate applicability of the full report while preserving the detailed segment intelligence that we reserve for licensed access.
Patrol Boats Market
Executive snapshot
The global patrol‑boats market has experienced a structural softening across the early 2020s, followed by a clear inflection beginning in 2026. After peaking in the prior decade, total industry revenue contracted between 2020 and 2025 before stabilizing at a base‑year value in 2025. From that base, our forecast anticipates a sustained recovery through 2032, with the market expanding at a compound annual growth rate (CAGR) of 6.7% during the 2026–2032 forecast window and reaching materially higher absolute levels by 2032.
Patrol Boats Market
For procurement leaders, investors and OEM executives, this pattern matters: budget cycles that were deferred or compressed during the downturn are re‑entering the planning horizon, while new mission sets and modular technologies are reshaping procurement criteria. Understanding the timing and shape of that recovery is the primary strategic dividend of this research.
Patrol Boats Market
Why this research matters for 2026 decisions
- Procurement timing and scale: The 2026 inflection creates narrow windows for order placement if organizations want to lock earlier production slots and favorable pricing before a deeper recovery lifts demand and input costs.
- Capability redefinition: Patrol craft are no longer one‑dimensional platforms. Law enforcement, coast guard and expeditionary forces now demand boats configured for hybrid missions — from high‑end interdiction to humanitarian SAR — pushing OEMs to offer configurable modularity rather than single‑purpose models.
- Supply‑chain and localization risks: Recent deliveries and international partnerships underscore a trend toward regional manufacturing footprints that shorten lead times and mitigate trade barriers. These decisions affect total cost of ownership and long‑term sustainment obligations.
- Competitive positioning and consolidation levers: The market’s competitive structure favors scale in engineering, repeatable production and aftermarket services. Buyers and investors must assess vendor roadmaps for product‑platform continuity and integration of mission systems.
Market trajectory — what the numbers tell us (high‑level)
Historical performance (2020–2025) shows a contraction in absolute market revenue driven by fiscal retrenchment, delayed programs, and a temporary softening of non‑defense demand. The 2025 base year reflects that trough. Importantly, the forecast horizon (2026–2032) models a multi‑year rebound underpinned by renewed defense modernisation, coast guard recapitalisation programs, and rising civil search‑and‑rescue and law‑enforcement needs. The projected CAGR of 6.7% is not uniform — the recovery features episodic procurement spikes tied to sovereign programs and offshore security initiatives — but it is sufficiently robust to alter strategic choices on capacity investments, alliance formation and product development roadmaps.
Structural dynamics and demand drivers
- Mission diversification: Patrol craft must now balance speed, endurance and mission modularity. Vessels optimized for interdiction operate against different requirements than those tasked with extended offshore presence or special‑forces insertion. Buyers increasingly specify modular payload interfaces, rapid reconfiguration, and integrated C4ISR packages.
- Technological inflection points: Advances in materials, propulsion and small‑boat launch systems are lowering life‑cycle costs and improving survivability. Examples in the market include rapid‑deploying masts for sensor packages and stabilized collars for RIB platforms that extend sea‑state operability. Diesel‑waterjet combinations and catamaran hull forms are delivering demonstrable increases in top‑end speed and offshore stability.
- Regulatory and operational context: Coast guard and maritime police force profiles are shifting toward multi‑day coastal patrols, stern‑launch RHIB capability, and interoperability with unmanned surface vehicles. These operational requirements are influencing vendor designs and insistence on modularity and sustainment‑friendly architecture.
- Sustainment and total cost of ownership (TCO): Buyers now evaluate TCO across an extended lifecycle horizon that includes crew training, depot repair infrastructures and interoperability of mission systems. The cost calculus is moving decisions away from lowest‑price toward best‑value suppliers who can guarantee availability and rapid parts provisioning.
Competitive landscape — what to watch
The market is shaped by a mix of specialized builders and regional champions that emphasize speed, customization and mission fit. Several leading suppliers exemplify the capabilities suppliers must bring to win in 2026‑era procurements:
- Metal Shark Boats (Jeanerette, LA): A custom aluminum vessel builder emphasizing high‑speed, seaworthy platforms for military and law‑enforcement missions. Recent activity demonstrates strong program execution — including multiple deliveries to national and state government units and completion of a multi‑vessel programme for the U.S. Navy — and the strategic use of international manufacturing partnerships to localize supply and accelerate delivery.
- MetalCraft Marine (Watertown, NY): Known for high‑speed interceptor designs and patented rapid‑hinging mast systems that materially reduce mast‑deployment time for sensor payloads. Their product focus suits agencies needing rapid reaction capability with reduced crew overhead.
- Moose Boats (Vallejo, CA): Specializes in aluminum catamaran and monohull platforms that combine high top‑end speeds with government contracting credentials, making them competitive for domestic law‑enforcement programmes and harbour security assignments.
- Swiftships (Morgan City, LA): Offers a range of steel, aluminum and composite craft scaled for both commercial and military roles — an advantage for countries seeking interoperable fleets and localized sustainment options.
- Zodiac Milpro (Paris): A market leader in RIB and inflatable response craft, delivering modular responder platforms with design features that improve operation in heavy seas and rapid intervention contexts.
- Aresa Shipyard (Arenys de Mar): Provides armored and special‑forces craft tailored to high‑threat littoral operations — a niche that has seen renewed interest as asymmetric threats and coastal incursions rise.
Recent vendor developments — including cross‑border deliveries, government program completions, and partner appointments for regional manufacturing — illustrate a market where execution speed and geopolitical agility matter as much as product capability. These developments should inform bids, partnership decisions and M&A diligence.
Operational implications for buyers and suppliers
- For procuring agencies: Early engagement with OEMs to lock configuration baselines and support packages will preserve program flexibility and reduce schedule risk. Consider contracting for platform commonality across mission sets to reduce training and spare parts inventories.
- For OEMs: Invest in modular open‑architecture interfaces and aftermarket capabilities (training, spare parts, mission‑package swaps). Regional manufacturing partners can shorten lead times and increase program wins in jurisdictions with localization requirements.
- For investors and private equity: The recovery window makes capabilities in rapid production scaling, systems integration, and sustainment particularly attractive. Target acquisitions should be evaluated not only on current backlog but on repeatability of delivery and the ability to convert small‑lot military programs into higher‑volume civilian sales.
Strategic playbook — three immediate moves for 2026
- Map mission‑to‑platform economics: Build decision matrices that compare platform types across lifecycle costs for specific mission profiles (interdiction, SAR, special operations). The best near‑term bets will be those that minimize conversion friction between roles.
- Localize selectively: Use strategic partnerships in priority regions to mitigate tariff and procurement preferences. Partnerships that include licensed production, skills transfer and local content commitments materially increase win rates for government tenders.
- Prioritize aftermarket differentiation: Move from one‑time sales to subscription‑style service contracts for spare parts, training and mission‑package swaps. This shifts buyer calculus from acquisition price to predictable lifecycle spend — and creates defensible recurring revenue for suppliers.
Report contents — practical tools included
The full PW Consulting patrol‑boats report is built as an operational toolkit for executives who must act in 2026. Highlights include:
- Market sizing and validated forecast models (2020–2032) with sensitivity scenarios tied to defence budgets and civil procurement cycles.
- Program‑level vendor scorecards and capability matrices that capture production capacity, modularity, sustainment footprint and export credentials.
- Procurement playbooks for end users: RFP templates, evaluation weightings, and risk allocation language optimized for modular patrol craft.
- TCO calculators and sustainment modelling templates that quantify trade‑offs between hull materials, propulsion choices and depot infrastructures.
- Deal screening tools for investors: integration risk checklists, commercial‑to‑military conversion frameworks, and a shortlist of strategic targets ranked by synergy and defensibility.
- Actionable annexes covering regulatory considerations, interoperability checklists, and recommended contract clauses for transfer of technology and localization.
Note: The full report contains detailed regional, type and application splits and vendor market‑share matrices that are intentionally omitted here to preserve the value of the licensed analysis.
How to use this preview
Treat this briefing as the strategic layer that should sit above program‑level decision‑making. Use our high‑level findings to:
- Accelerate alignment between procurement, legal and operational stakeholders before RFP release.
- Identify candidates for strategic partnerships or bolt‑on acquisitions that improve delivery predictability and aftersales revenue.
- Calibrate negotiation strategies with suppliers around lead times, localization commitments and aftermarket guarantees.
Next steps
If your organization is preparing procurement cycles, investor diligence, or product investments in 2026, the full PW Consulting Patrol Boats Market report delivers the granular intelligence and executable templates you need. Our licensed package includes proprietary splits, vendor rankings, and scenario tables that convert the macro trajectory outlined here into specific procurement and investment actions.
For access to the complete dataset, vendor scorecards and the operational toolset, contact PW Consulting to arrange a briefing and secure your copy of the full study.
For detailed analysis of this topic, please visit the official page: Patrol Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Combine Harvesters Market Poised for 4.5% CAGR, Reaching USD 180M by 2032
By PW Consulting, 2026-07-12
Combine Harvesters Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Combine Harvesters Market study is designed as a strategic compass for executives, investors, and policy teams making critical decisions in 2026. Built on a transparent base year of 2025, a historical window from 2020–2025, and a forward-looking forecast through 2032, the research synthesizes primary-market interviews, manufacturer intelligence, and an econometric forecasting engine. At the macro level, the market expanded from USD 120.0 Million in 2020 to USD 145.0 Million in 2025 and is modelled to reach USD 180.0 Million by 2032, reflecting a compound annual growth rate of 4.5% across the forecast horizon. That steady, mid-single-digit growth masks critical inflection points—technology adoption, policy incentives, and shifting farm economics—that will determine winners and losers over the coming investment cycles.
Combine Harvesters Market
Why this study matters for 2026
-
Timing capital allocation. In an environment where OEMs and distributors are prioritizing digital and autonomy investments, precise, defensible market sizing and forward scenarios allow CFOs and corporate development teams to time CAPEX and M&A more effectively.
Combine Harvesters Market -
Designing profitable product roadmaps. Product leaders will find our mapped buyer journeys, feature willingness-to-pay curves, and operational cost profiles invaluable when balancing hardware complexity, software services, and aftermarket revenue strategies.
Combine Harvesters Market -
Mitigating supply and service risk. Dealers and tier-one suppliers can use our supplier risk matrix and field-service clustering to protect uptime and optimize parts inventory across diverse geographies and crop cycles.
-
Translating policy into market opportunity. With public programs and subsidy schemes influencing upgrade cycles, strategy teams can quantify which incentive structures accelerate replacement and which only reallocate demand.
What the report delivers — practical, transaction-ready outputs
-
Robust market model: Annual historicals (2020–2025) and dynamic scenario forecasts (2026–2032) that support sensitivity testing across price, adoption, and macroeconomic inputs.
-
Commercial segmentation framework: A replicable taxonomy that separates platform type, power class, and application use cases—built to be fed into go-to-market and product planning tools. (Core split datapoints are summarized in the full report to preserve segmentation granularity.)
-
Competitive heat maps: Comparative analysis across product capability (autonomy, throughput, fuel efficiency), brand positioning, distribution reach, and service economics—enabling M&A screening and partnership targeting.
-
Buyer economics and TCO models: Operator-level total cost of ownership scenarios under different utilization and labor-cost assumptions, plus cross-validated field survey inputs for maintenance and lifecycle cost drivers.
-
Scenario playbooks: Four executable market scenarios—Baseline, Technology Acceleration, Policy-Driven Uptake, and Downturn Resilience—each with tactical checklists for OEMs, lessors, and dealers.
-
Deal toolkit: Valuation multiples by capability cluster, integration risk checklists, and three near-term acquisition targets selected based on capability gaps, distribution fit, and aftermarket synergies.
Competitive landscape — reading the footprints of incumbents
The combine harvester market remains led by a mix of global OEMs that combine deep manufacturing scale with growing software and services businesses. Our competitive analysis focuses on strategic positioning rather than raw unit counts, allowing clients to assess where value creation will come from in the next five years.
-
John Deere (Moline, Illinois, United States) — Known for its high-integrated S-Series and X9 machines, Deere’s recent product highlights emphasize automation and operator-assist systems. The company is actively commercializing machine-sync and autopilot features, which create pathways to recurring software revenue and differentiated field productivity metrics.
-
CLAAS KGaA mbH (Harsewinkel, Germany) — CLAAS continues to leverage heritage models while scaling production and brand momentum. Milestones in production demonstrate manufacturing depth, and design continuity positions CLAAS to capitalize on premium segments and special edition releases that reinforce dealer relationships.
-
CNH Industrial N.V. (Amsterdam, Netherlands) — CNH’s high-power CR-series machines target large-scale operations and contractors. Their strategy emphasizes throughput and operating efficiency, which serves well in markets where consolidation of farm acreage and contractorization are accelerating.
-
AGCO Corporation (Duluth, Georgia, United States) — With brands such as Massey Ferguson and Gleaner, AGCO pursues a multi-brand approach to cover distinct channel segments, pairing global OEM capability with regional distribution expertise.
-
Kubota Corporation (Osaka, Japan) — Kubota’s strength in crop-specific solutions (notably in rice- and wheat-dominant regions) and investments in unmanned/autonomous prototypes position the company well in markets where labor constraints drive a premium for automation.
These OEMs are not just competing on metallurgy and horsepower. The strategic battlegrounds are increasingly software-integrated services, dealer experience, financing solutions, and parts availability. Our provider profiles include links to primary product pages and offer a concise view of each company’s strategic intent, R&D focus, and go-to-market mechanics.
Market dynamics shaping strategic choices in 2026
-
Technology and autonomy: Ongoing advances in sensor fusion, machine control, and AI-based harvesting support are altering the economics of labor and throughput. OEMs that move from one-off autonomy features to subscription-grade operational services position themselves to capture higher lifetime value per machine.
-
Labor pressures and service models: Persistent labor gaps in harvesting operations are driving demand for higher automation and new service models—custom-harvesting contractors, equipment-as-a-service, and pay-per-hour harvesting all look more viable under current farm labor dynamics.
-
Policy and subsidy levers: Public programs that incentivize eco-friendlier equipment upgrades are active levers in many markets. Strategic planning must therefore incorporate policy timing and eligibility rules to predict replacement cycles accurately.
-
Aftermarket economics: With field uptime critical to operator economics, dealers who optimize parts logistics and predictive maintenance programs can materially improve fleet utilization—and create differentiated, recurring margin streams.
-
Capital intensity and financing: High-capex assets require flexible ownership models. OEMs and captive finance arms that develop compelling lease and insurance offerings win share by reducing the adoption barrier for smaller operators.
Recent signals and what they imply
-
Market demand volatility: Industry sales reporting has recently signaled a sharp year-on-year sales contraction in certain retail channels. This underscores two realities: (1) inventory and dealer network management must be dynamic; and (2) short-term unit demand swings can mask structural growth in services and retrofit markets.
-
OEM product movements: High-profile product showcases emphasize small-property and rugged-terrain capabilities with integrated autopilot—indicating a deliberate push by tier-one players into smaller-acreage segments and more complex operating environments.
-
Manufacturing milestones: Production volume milestones reaffirm scale advantages but also highlight the importance of capacity planning and supplier diversification as manufacturers pursue both legacy and next-gen platforms.
How to use the report for immediate 2026 plays
-
For strategic planning: Use the scenario models to stress-test five-year product roadmaps against combinations of technology adoption rates and policy shifts. Identify the "minimum viable feature set" that secures aftermarket revenue without overloading initial hardware cost.
-
For commercial teams: Leverage our buyer segmentation and regional dealer mapping to rebalance inventory and prioritize field trials where adoption barriers are lowest and subsidy capture is highest.
-
For M&A and partnerships: Apply the deal toolkit and valuation ranges to rapidly screen targets that fill capability gaps in autonomy, precision agronomy, or distribution reach.
-
For operations and supply chain: Implement the supplier risk matrix and parts-availability scenarios to reduce downtime exposure and optimize spare-parts stocking across critical nodes.
Closing perspective
The combine harvester market in 2026 is at a crossroads: the headline growth is stable, but structural change is accelerating underneath. Executives who combine disciplined market models with targeted investments in software, service, and distribution will be best-placed to convert mid-single-digit market growth into outsized returns. PW Consulting’s Combine Harvesters Market study provides the layered, actionable insight you need to make those choices with confidence—while preserving the granular, proprietary segmentation and financial models that drive high-quality dealmaking and product planning.
To access the complete dataset, subsegment unpacking, and our customizable forecasting model, please visit the PW Consulting report page. Our team is available to translate the findings into a tailored strategic workshop or actionable M&A shortlist specific to your portfolio.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DNA Microarray Market to Reach USD 4,007.4M by 2032 at 8.91% CAGR
By PW Consulting, 2026-07-12
DNA Microarray Market — 2026 Strategic Preview for Corporate Decision-Makers
Executive teaser
As companies set priorities for 2026, the DNA microarray market offers a renewed strategic frontier. After steady recovery and reinvestment from 2020–2025, the market reached an estimated USD 2,215.0 million in 2025. Our modeled baseline—reflecting technological maturation, regulatory clarifications and evolving clinical utility—projects the sector to expand at a compound annual growth rate (CAGR) of approximately 8.91% through 2032, reaching roughly USD 4,007.4 million by the end of the forecast horizon. This trajectory signals meaningful reward for correctly timed investments, but it also requires granular, operationally actionable insight to convert macro tailwinds into repeatable commercial outcomes.
DNA Microarray Market
Why this preview matters for 2026 decisions
-
Investment prioritization. With mid-single-digit-to-high-single-digit CAGR dynamics, firms must choose between accelerating product development, pursuing inorganic consolidation, or prioritizing margin improvement through automation and higher-value diagnostic assays. Timing and scale matter: the next 12–18 months will crystallize winners.
DNA Microarray Market -
Commercial positioning. Clinical adoption curves, payer recognition and laboratory workflow modernization are re-shaping where and how microarrays capture value. Commercial strategies that align with new CPT-reimbursement pathways and automated workflows will gain disproportionate share.
DNA Microarray Market -
Regulatory and reimbursement clarity. Recent and pending regulatory actions—when translated into clear coverage policies—can rapidly reorder demand. Executives who weave regulatory intelligence into go-to-market planning will avoid costly rework.
Market dynamics shaping the near-term playbook
-
Clinical expansion and diagnostic differentiation. Microarrays are being repositioned from purely research tools toward clinically actionable diagnostics—especially where methylation profiling, high-density SNP panels and multiplex autoimmune assays offer diagnostic or prognostic differentiation. New payer-recognized codes and defined clinical criteria are accelerating that reorientation.
-
Regulatory quality and standardization. Initiatives such as the FDA’s MAQC/SEQC programs continue to raise the bar for data quality in regulatory and commercial submissions. Market access strategies must now incorporate robust analytical validation aligned with these programs to pass payer and regulator scrutiny.
-
Automation and throughput. Vendors are investing heavily in automation platforms to reduce per-sample costs and to enable tighter integration with laboratory information systems. Automation partners and platform compatibility will be decisive in procurement decisions by high-volume labs and reference networks.
-
Reimbursement inflection points. New CPT codes effective 1 October 2024 introduced granular categorization for certain methylation and high-density SNP services; contemporaneously, policy updates have clarified payment limits on duplicate testing. These dynamics create both upside for novel, clearly differentiated assays and downside for commoditized offerings.
-
Consolidation potential. The market presents moderate concentration: the top three players command meaningful share but do not create insurmountable barriers. This structural openness invites targeted acquisitions, partnerships and vertical integration plays—especially around assay IP, automation, and clinically validated panels.
Competitive landscape: capabilities and strategic implications
Understanding vendor roadmaps is essential to strategy. Three incumbent vendors shape supply-side dynamics, and a set of emerging diagnostic-focused entrants is accelerating clinical validation activity.
-
Illumina, Inc. — Illumina continues to leverage deep assay expertise and a strong brand in population genomics. Its Infinium genotyping and methylation arrays remain a go-to for high-resolution genotyping and epigenomic profiling. For strategic planners, Illumina represents both a stable supply partner for high-throughput applications and a competitive benchmark for platform-level integration and assay validation rigor.
-
Agilent Technologies, Inc. — Agilent’s SurePrint and GenetiSure Dx platforms emphasize customizability and clinical diagnostics integration. Their positioning favors labs seeking tailored arrays or combined CGH+SNP solutions for constitutional and diagnostic workflows. Companies pursuing niche diagnostic differentiation or clinical laboratory partnerships should view Agilent as a preferred collaborator for assay customization and regulatory support.
-
Thermo Fisher Scientific, Inc. — Thermo Fisher brings legacy array technology and an expanding automation portfolio. The rollout of next-generation microarray analyzers and automated systems (notably recent launches of integrated automation platforms) underscores a push to combine throughput, ease-of-use, and pharmacogenomics-ready content. For market entrants, Thermo Fisher represents both a competitor at scale and a potential OEM/partner for labs prioritizing automated, validated workflows.
In parallel, smaller diagnostics-focused vendors have pursued regulatory clearance for disease-specific multiplex arrays; several notable 510(k) submissions in 2025 demonstrate accelerated clinicalization of microarray-based assays for autoimmune and other specialized indications. These entrants are increasing pricing and access pressure in select clinical pockets.
Recent developments that change 2026 tactics
-
Active 510(k) filings for disease-targeted multiplex arrays signal growing regulatory commitment among smaller innovators to enter clinical markets—an inflection that requires incumbents to defend downstream clinical relationships and payers to adapt coverage criteria.
-
Major vendors’ product launches of next-generation analyzers and automation platforms compress total cost of ownership and create new procurement dynamics. Buyers will increasingly evaluate platform economics across throughput, assay menu, and laboratory integration costs.
-
Reimbursement updates and clarified rules around duplicate testing are shifting diagnostic economics. Companies must align clinical utility dossiers to secure favorable coverage and avoid marginalization by payer policies that limit payment for redundant testing.
What the full PW Consulting report delivers (operationally focused)
The full report is designed as a decision-ready toolkit for 2026 initiatives. Highlights include:
-
A transparent market model with base-year calibration (2025) and scenario-modeled forecasts to 2032, enabling sensitivity testing around adoption curves, pricing, and regulatory outcomes.
-
Actionable segmentation frameworks (by product-type, application and geography) with commercial implications—note: the public preview intentionally withholds proprietary segment-level tables; subscribers receive full split tables and interactive modeling worksheets.
-
Competitive profiles and capability maps for incumbent and emerging vendors, including platform roadmaps, assay pipelines and likely strategic moves over 12–24 months.
-
Reimbursement and regulatory playbooks that translate CPT and coverage dynamics into launch sequencing, evidence-generation milestones and pricing guardrails.
-
Commercial templates: go-to-market playbooks, lab-partnership term sheets, and procurement negotiation guides tailored to high-volume reference labs and hospital networks.
-
M&A and partnership heatmaps that identify attractive target archetypes (assay IP, automation enablers, clinical-lab networks) and provide valuation guardrails under multiple exit scenarios.
-
Primary research appendix: interview summaries from lab directors, payers and KOLs, plus methodological notes on how we harmonized clinical adoption signals with vendor shipment data.
How to use this intelligence in 2026 (practical playbook)
-
Prioritize investments based on optionality: favor platforms and assays that are either payer-favorable or extendable into adjacent high-margin clinical indications.
-
Lock down automation and integration early: reduced per-sample cost and LIS connectivity are decisive procurement criteria for large lab networks.
-
Sequence evidence generation to match reimbursement milestones: design clinical validation studies that feed directly into coverage dossiers and CPT-aligned coding strategies.
-
Reassess pricing and bundling models in response to duplicate-testing policies: create clear value statements for unique assays and avoid competing on commoditized SKU features.
-
Consider targeted M&A to accelerate clinical annotation and assay IP capture, rather than generic capacity buys; buyers that pair platform scale with differentiated content win share faster.
Risk and sensitivity considerations
-
Regulatory or payer delays: slower-than-expected coverage decisions can compress near-term revenue and extend payback horizons for new assay launches.
-
Technological substitution: sequencing-based approaches continue to encroach on some microarray use-cases; the strategic imperative is to identify defensible niches where arrays deliver faster, cheaper or better clinical signal.
-
Supply chain concentration: dependence on specific reagent or consumable suppliers creates execution risk—diversification or secure-supply contracts are prudent mitigants.
Conclusion — the strategic imperative for 2026
The DNA microarray market is at an inflection where validated clinical utility, automation-enabled economics and clarified reimbursement pathways can create outsized returns for well-positioned players. With the market roughly doubling from its 2025 baseline to 2032 under our central forecast, the window to build defensible scale and capture value is narrow but clear. Executives must combine program-level clinical evidence with platform-level automation and payer-aligned commercialization to convert macro growth into durable share. PW Consulting’s full report supplies the granular segment tables, vendor revenue benchmarks and playbooks you’ll need to execute that strategy—our public preview intentionally limits certain proprietary splits to preserve the tactical utility of the licensed deliverable.
For the complete dataset, interactive models, and vendor scorecards to support board-level and operating-plan decisions in 2026, access the full PW Consulting DNA Microarray Market report.
For detailed analysis of this topic, please visit the official page: DNA Microarray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydraulic Bolt Tensioner Market: USD 304.3M by 2032 at 5.5% CAGR | PW Consulting
By PW Consulting, 2026-07-12
Hydraulic Bolt Tensioner Market — Strategic Imperatives for 2026
As capital allocation, maintenance strategies, and supply-chain resilience become decisive factors in industrial competitiveness, hydraulic bolt tensioners have moved from being a niche capital-good to an operational lever across energy, heavy industry, and renewables. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical behavior (2020–2025) and a seven-year outlook (2026–2032) to illuminate where procurement chiefs, OEM product strategists, and private equity investors should place their bets. The market has expanded from roughly USD 163.15 Million in 2020 to USD 211.10 Million in 2025 and is forecast to reach approximately USD 304.27 Million by 2032, implying a steady compound annual growth rate of about 5.5% through the forecast horizon.
Hydraulic Bolt Tensioner Market
Why this report matters to decision-makers in 2026
- Capital budgeting: Understand realistic revenue and replacement cycles for bolting equipment to prioritize CAPEX vs. rental decisions in 2026–2027.
- Product strategy: Translate macro growth and sector dynamics into product roadmaps — when to invest in subsea stainless upgrades, wind-turbine single-stage designs, or lighter topside models.
- Procurement optimization: Use the analysis to design supplier panels and inventory policies that reduce downtime risk without creating stranded inventory in a transitioning energy mix.
- M&A and partnership scouting: Identify attractive entry points in a market with moderate concentration where specialist technology providers and service platforms remain target-rich.
- Regulatory and standards compliance: Integrate standards risk into TCO models so flange-joint integrity programs meet ISO/ASTM requirements while minimizing rework.
Market trajectory and interpretation
The hydraulic bolt tensioner market’s measured expansion — from ~USD 163 million in 2020 to ~USD 211 million in 2025, with a projected climb to ~USD 304 million by 2032 — signals a mature but still-evolving market. A 5.5% CAGR reflects steady replacement demand, adoption in new applications (notably renewable energy foundations and industrial high-pressure joints), and incremental gains from product innovation. For 2026 planning, this trajectory implies predictable baseline demand; the material upside will be determined by technology differentiation, aftermarket service models, and the pace of sectoral shifts such as accelerated wind-farm buildouts or offshore decommissioning cycles.
Hydraulic Bolt Tensioner Market
Key dynamics shaping near-term strategy
- Standards and compliance: Continued enforcement of bolt and fastener standards (e.g., ISO and ASTM frameworks) is raising minimum performance thresholds. Buyers must bake compliance testing and certification into procurement cycles to avoid costly rework or liability exposure.
- Application-driven product needs: Wind-turbine foundation tensioning and subsea bolting present distinct engineering constraints — from restricted workspace to corrosion-resistant materials — requiring suppliers to offer targeted single-stage or multi-stage solutions and compatible pumps.
- Materials and cost pressure: High-strength stainless steels and corrosion-resistant coatings for subsea units materially increase component costs; design-for-cost and total-cost-of-ownership (TCO) thinking should guide vendor selection and lifecycle planning.
- Labor and safety optimization: Designs that reduce manual handling — spring-return, auto-retract, and quick-fit release mechanisms — materially lower exposure and on-site man-hours, altering the ROI calculus for higher-priced, ergonomically advanced equipment.
- Service and rental economics: As the installed base grows, aftermarket services (calibration, certification, repair) and rental fleets become valuable levers to manage uptime without committing to full ownership across geographically distributed sites.
What the PW Consulting report delivers (practical content)
- Robust market sizing and trend matrices covering 2020–2032, with scenario-sensitive forecasts and sensitivity ranges so planners can stress-test budgets under different demand shocks.
- Operational playbooks: procurement frameworks, rental vs. purchase decision trees, recommended spare-part inventories, and inspection/certification cadences tied to regulatory expectations.
- Product strategy toolkit: component-cost drivers, design trade-offs (single-stage vs. multi-stage), and prioritized feature sets for wind, subsea, topside, and industrial end‑users.
- Competitive benchmarking and supplier scorecards focused on capability, geographic reach, aftermarket presence, and product breadth — designed for both sourcing teams and corporate development professionals.
- M&A and partnership playbooks: valuation proxies, integration risk checklists, and a short list of capability gaps that make for compelling bolt-on targets.
- Case studies and failure-mode analyses that translate into maintenance schedules, inspection protocols, and training curricula for field technicians.
Competitive landscape — who matters and why
The market displays moderate concentration (CR3 ≈ 35%, CR5 ≈ 45%), meaning leading vendors capture meaningful share but there remains ample room for specialists and regional players. Strategic positioning is heterogeneous: some firms excel in system breadth and global aftermarket services; others compete on niche innovations and price performance.
Hydraulic Bolt Tensioner Market
- HYTORC (United States) — Recognized for a broad portfolio that spans topside, subsea, and wind single-stage models with flexible adapters. Strength: modularity and broad bolt-size coverage for industrial and field service fleets.
- TorqLite (United States) — Competes on application-specific designs: spring-return tensioners, dedicated wind-turbine models, and subsea variants with protective finishes. Strength: product variants tailored to maintenance workflows and ergonomics.
- Tritorc (India) — Industrial-focused, with heavy-duty pneumatic and high-pressure axial systems; recent catalog and design updates (May 2025) improve technical transparency on load-cell accuracy and pump outputs, strengthening credibility for oil & gas clients.
- Atlas Copco (Sweden) — Global OEM with integrated pumps and tensioning systems; depth in wind and topside solutions and a robust service organization that supports multinational projects.
- Hydratight (United Kingdom) — Known for flange-focused tensioners and extensive accessories; strong in regulated hydrocarbon environments where flange integrity protocols are stringent.
- Hi-Force (United Kingdom) — Diverse portfolio including subsea quick-fit release tensioners and manual-return models with overstroke protection; competitive in sectors that emphasize safety interlocks and maintenance speed.
- FPT Fluid Power Technology (Italy) — Engineering-driven, offering single- and multi-stage systems for specialized flange types and serial hydraulic connections — attractive to OEMs needing custom interfacing.
- Technotorc (India) — Producer of multi-stage tensioners for heavy industrial and construction use-cases; cost-competitive for high-volume, less-regulated applications.
- WREN Hydraulics (United States) — Focuses on ultra-high-pressure tools within a broader bolting-services portfolio; positions well where extreme preload capabilities are required.
Recent vendor activity underscores competitive differentiation beyond price. Example: Tritorc’s 2025 catalog and technical guidance updates (May 2025) raise transparency on measurement accuracy and subsea suitability — a commercial differentiator when buyers demand quantifiable performance guarantees. Additionally, new wind-focused introductions (e.g., Halyard Tensioner 32, Feb 2025) point to continued innovation driven by renewable-energy engineering constraints.
Implications for procurement, product, and M&A strategies in 2026
- Prioritize supplier capabilities over unit price in regulated or high-risk sectors. Require documented compliance with applicable ISO/ASTM standards and insist on traceable calibration and maintenance histories for rented and purchased tools.
- Modularize equipment fleets to capture cross-application value: adapters and multi-stage options can reduce total fleet size while increasing mission flexibility.
- Capitalize on aftermarket services: vendors with strong service networks command price premiums and reduce operational risk — consider revenue-share or managed-service models to align incentives.
- Design for lifecycle cost: quantify the labor savings of spring-return and auto-retract designs in TCO models; in many cases, lower man-hour exposure offsets higher upfront capital cost within 18–36 months.
- Use M&A selectively to acquire capability gaps (e.g., subsea corrosion-resistant manufacturing or wind-specific tensioner IP) rather than chasing pure volume consolidation in an only moderately concentrated market.
How to use this intelligence in 90 days
- For procurement teams: implement a compliance-based RFP addendum, mandate field-trial periods for new tech, and run a rental vs. purchase sensitivity analysis tied to downtime-cost assumptions.
- For product leaders: shortlist three feature investments (e.g., corrosion-resistant finishes, quicker adapter interfaces, digital preload verification) and cost-justify them with reduced OPEX and service-call reductions.
- For investors and corporate development: map targets against the capability gaps identified in the report and prioritize deals that accelerate service penetration or unlock adjacent end-markets (wind, subsea, heavy industrial).
PW Consulting’s Hydraulic Bolt Tensioner Market report is designed as an actionable briefing for 2026: it blends macro sizing and CAGR context with vendor-level intelligence, regulatory constraints, and operational playbooks. For readers seeking the granular segmentation, supplier scorecards, and downloadable decision tools that power tactical procurement and M&A moves, the full report and accompanying datasets are available on the PW Consulting portal. Accessing the complete intelligence will convert the directional insights above into executable 12–36 month plans tailored to your portfolio and geographies of interest.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Calcium Sulfate Market to Reach USD 385.32M by 2032 at 4.2% CAGR
By PW Consulting, 2026-07-12
Calcium Sulfate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare budgets and capital plans for 2026, the calcium sulfate market presents a blend of steady growth, supply-side disruption and regulatory momentum that will shape strategic choices across industrial, agricultural and specialty segments. PW Consulting’s forthcoming full report — grounded in five years of historical tracking (2020–2025) and a seven‑year forecast horizon (2026–2032) — quantifies that backdrop and translates it into actionable options for producers, consumers, investors and policy-facing stakeholders.
Calcium Sulfate Market
Market at a Glance: Macro Trajectory and Competitive Texture
Our market model places 2025 as the base year. The global calcium sulfate market expanded from approximately USD 235.2 Million in 2020 to USD 288.9 Million in 2025, and PW Consulting projects the market to reach roughly USD 385.3 Million by 2032, representing a compound annual growth rate (CAGR) of about 4.2% across the 2026–2032 forecast period (values in USD Million). This steady compound growth reflects a balance of mature end‑use demand in construction and industrial applications, incremental gains in agriculture and food/pharmaceutical uses, and growing momentum for specialty and value‑added derivatives.
Calcium Sulfate Market
Concentration metrics in our competitive assessment show a moderately consolidated industry: the top three firms account for around 58% of identifiable market share, while the top five reach roughly 62%. That structure creates both stability and pressure points: established players have pricing influence and distribution reach, but mid‑sized and niche innovators can exert outsized local influence through product specialization or targeted logistics improvements.
Calcium Sulfate Market
Why This Matters for 2026 Decision Cycles
-
Capex and capacity planning: With a predictable mid‑single‑digit growth path, capital investments should prioritize flexibility and product mix optimization over large, inflexible greenfield bets. Timing of new capacity must be aligned with feedstock trends and regulatory developments to avoid stranded assets.
-
Supply security and feedstock strategy: Shifts in synthetic gypsum availability — linked to the accelerated retirement of coal‑fired power plants in several markets — are altering feedstock economics and increasing the strategic value of vertically integrated sources and recycled streams.
-
Regulatory and value‑chain repositioning: Emerging guidance on handling and reuse (for example, national environmental agencies encouraging agricultural and industrial reuse of flue gas desulfurization gypsum) is creating new commercial pathways but also increasing compliance and documentation burdens.
-
Margin capture and product differentiation: As base demand remains steady, growth in margins will come from higher‑value grades, blended fertilizers, specialty food/pharma‑grade products and service‑based propositions (quality assurance, customized logistics, technical support).
What the PW Consulting Report Delivers (Practical, Transaction‑Ready Content)
The full PW Consulting market study is built for decision makers who need to act in 2026. Highlights of the deliverables include:
-
Robust market sizing and forecast models: Five years of historicals (2020–2025) and seven years of forecast outputs (2026–2032) with scenario toggles for demand elasticity, price stress and feedstock constraints.
-
Value‑chain mapping and cost stack analysis: Farm to factory mapping, typical unit economics for different product forms, and sensitivity tables for raw‑material price swings and logistics cost shocks.
-
Commercial playbook for market entry and expansion: Channel strategies, tender participation templates, sample offtake and distribution contract clauses, and go‑to‑market scorecards for prioritizing regional investments.
-
Regulatory impact assessment and compliance checklist: Actionable steps to convert regulatory shifts — such as guidance to encourage reuse of gypsum streams — into commercial opportunities while limiting liabilities.
-
Competitive intelligence and benchmarking tools: Confidential profiles, performance benchmarks and strategic positioning matrices for incumbent and emerging players, along with an M&A heat map identifying targets and acquirers likely to move in 2026.
-
Supply disruption scenarios: Triggers and lead times tied to feedstock scarcity (e.g., decline in synthetic gypsum availability), logistics constraints and policy changes; mitigation playbooks for each scenario.
Note: This preview intentionally withholds the granular segment breakdowns and regional/application tables that are included in the paid report. Those segmented data, price curves and downloadable models are essential for transaction diligence and are available through PW Consulting’s full deliverable.
Competitive Landscape — Strategic Implications from Company Profiles
Our qualitative and quantitative assessment of market participants highlights diverse strategic postures:
-
CB Minerals (Mamaroneck, NY): A diversified supply base spanning dihydrate, hemihydrate and anhydrous forms, with sourcing from multiple countries. Their blended product availability and cross‑market footprint make them a logical partner for industrial customers seeking reliability and product breadth. Strategic implication: direct competitors and offtakers should expect a strong focus on logistics and blended SKU convenience from CB Minerals.
-
The Kish Company (Mentor, OH): Positioned as a supplier and processor of calcium sulfate for industrial extension and additive markets. Their processing expertise suggests they can capture margin through tailored particle sizing and surface treatment. Strategic implication: companies targeting industrial formulations should prioritize technical collaboration to lock in co‑development advantages.
-
Hebei Xingtai Shuanghua Gypsum Products (Xingtai, China): A manufacturer/exporter with competencies in food‑grade and pharmaceutical applications. Their product mix targets higher‑value end uses that require stringent quality controls. Strategic implication: firms seeking to expand into food and pharma markets must invest in regulatory certifications and traceability systems to compete.
-
SUL4R‑PLUS (Illinois, USA): An emerging, agriculture‑focused player producing granular calcium sulfate fertilizer blends. A recent strategic move — the April 2025 opening of a 100,000‑ton annual capacity facility in Marissa, Illinois — underscores the near‑term growth potential in agri‑blends and the competitive advantage from proximity to key agricultural zones. Strategic implication: agribusiness buyers and regional distributors should re‑evaluate supply contracts and distribution footprints to capitalize on lower delivered costs and customized blend capabilities.
These profiles, combined with PW Consulting’s benchmarking metrics, reveal where competitive advantage rests — product breadth and logistics for large suppliers, technical customization for mid‑size processors, and targeted agricultural or specialty focus for niche entrants.
Regulatory and Feedstock Dynamics: Near‑Term Disruption and Opportunity
Two regulatory and raw‑material trends warrant immediate attention in 2026 planning:
-
Regulatory guidance driving reuse: National environmental authorities in several countries have issued guidance to encourage the safe reuse of flue gas desulfurization (FGD) gypsum in agriculture and industry. Companies that can demonstrate robust sampling, certification and traceability will be positioned to capture this stream as a lower‑cost input — but compliance costs and reputational risk must be managed.
-
Decline in synthetic gypsum availability: Accelerated retirements of coal‑fired generation have already started to reduce synthetic gypsum volumes in some markets, tightening what had been an abundant secondary feedstock. The supply contraction amplifies the value of owned deposits, recycling infrastructure and long‑term offtake agreements.
Recommended Strategic Moves for 2026
For executives formulating 2026‑era strategy, PW Consulting recommends a measured portfolio of actions that balance resilience and growth:
-
Secure feedstock diversity: Negotiate multi‑source offtake agreements, explore partnerships with utilities and cement plants for recycled streams, and assess modest investments in beneficiation to widen acceptable feedstock types.
-
Prioritize higher‑margin applications: Allocate R&D and certification budgets toward food and pharmaceutical grades, specialty agricultural blends and engineered gypsum products that command price premiums and more stable demand.
-
Invest in logistical efficiency: Given the bulk nature of product flows, micro‑optimizations in terminal positioning, rail/road contracts and packaging can yield outsized margin improvements.
-
Monitor and shape regulation: Engage proactively with regulators on reuse protocols and material standards to both reduce compliance risk and open new markets for reclaimed gypsum.
-
Prepare M&A and alliance playbooks: With a moderately concentrated market structure, bolt‑on acquisitions and joint ventures can rapidly expand geographic coverage or add specialty capabilities — but due diligence must include our scenario stress tests for feedstock volatility.
Risk Triggers and Early‑Warning Signals
Key triggers to watch in 2026 that should prompt tactical shifts include:
-
Announcements of large coal plant decommissions or changes in power‑sector FGD management that would further skew synthetic gypsum flows.
-
New or revised national rules on gypsum reuse that materially change compliance timelines, handling costs or allowable applications.
-
Rapid capacity additions from low‑cost producers targeting agricultural blends in specific regions, which could compress regional spreads.
-
Logistics disruptions (port congestion, freight rate spikes) that affect delivered costs for bulk commodities.
Next Steps — How PW Consulting Supports 2026 Decisions
PW Consulting’s full Calcium Sulfate Market report provides the segment‑level data, regional demand matrices, pricing curves and executable playbooks that trading desks, corporate strategy teams and private equity investors need to finalize 2026 commitments. If your objectives include contract negotiation, capacity planning, or opportunity screening for M&A, our models — which include downloadable scenario toggles and a confidential supplier shortlist — will materially shorten your decision cycle and reduce execution risk.
For readers of this preview: this briefing highlights the levers and risks that will define competitive advantage in 2026, but the granular segmentation, supplier‑level benchmarking and financial models that enable binding decisions are reserved for the full PW Consulting deliverable. Contact PW Consulting to access the complete dataset and transaction toolkit.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plating Equipment Market Poised for 6.5% CAGR to USD 279.35M by 2032
By PW Consulting, 2026-07-12
Plating Equipment Market — A 2026 Strategic Outlook for Industrial Leaders
As capital allocation rounds intensify and supply-chain fragilities persist, boards and executive teams face a pivotal set of choices in 2026 for the plating equipment sector. PW Consulting’s latest market study — anchored on a 2025 base year, with historical analysis across 2020–2025 and forecasts for 2026–2032 — translates industry complexity into a pragmatic decision framework. The global market grew from roughly USD 137 Million in 2020 to USD 182 Million in 2025 and is projected to expand to about USD 198.01 Million in 2026, following a compound annual growth rate (CAGR) of 6.5% across the forecast interval and reaching approximately USD 279.35 Million by 2032. This report is designed not as a catalog of numbers alone, but as a strategy dossier: mapping where value pools will form, how competitive dynamics will shift, and what operational playbooks are required to capture upside while mitigating regulatory and commodity risks.
Plating Equipment Market
Why this report matters for 2026 decisions
-
Capital allocation with conviction — With the market expanding at mid-single-digit CAGR, equipment OEMs and large end-users must prioritize investments that accelerate automation and sustainability rather than incremental capacity alone. The report quantifies payback horizons under realistic adoption curves, enabling CFOs to compare CAPEX scenarios rigorously.
Plating Equipment Market -
Risk-adjusted supply chain planning — Commodity and geopolitical shocks are no longer tail risks. Our analysis integrates real-world indicators — from copper anode price spikes tied to EV battery demand to export controls affecting critical magnetics and components — translating them into procurement and inventory strategies for 2026.
Plating Equipment Market -
Regulatory preparedness as a competitive edge — New effluent and wastewater treatment standards (e.g., updated EPA limitations effective 2025) reshape the economics of plating installations. Early movers who retrofit or adopt low-waste chemistries can avoid retrofit costs and gain market access faster.
-
Talent and automation trade-offs — Labor constraints are driving OEMs and processors toward robotic integration and selective plating technologies. Our scenarios show how automation can compress unit costs and reduce compliance exposure, but they also identify where human expertise remains irreplaceable.
What the report contains — practical, deployable intelligence
-
Transparent market sizing and forecast methodology: detailed base-year reconciliations and sensitivity runs that stress-test demand against copper price, regulatory tightening, and end-market cycles (automotive, electronics, aerospace, jewelry, and industrial segments).
-
Scenario modeling: three calibrated futures (Base, Accelerated Automation, and Regulatory Shock) with implied demand curves, margin impacts, and capital requirements. Each scenario includes suggested tactical responses for 90-day and 12-month horizons.
-
Competitive benchmark & capability matrix: comparative analysis of major solution providers, including integrated chemistry‑plus‑equipment firms, specialist brush- and selective-plating vendors, turnkey systems integrators, and service-driven suppliers. Profiles capture strategic positioning, technological strengths, go‑to‑market models, and aftermarket footprints.
-
Procurement and CAPEX playbooks: decision trees for selecting between retrofit vs. greenfield configurations, TCO calculators in USD Million terms, and contract structures that align OEM incentives with long-term performance.
-
Regulatory and environmental compliance toolkit: step-by-step guidance for wastewater treatment upgrades, chemical substitution strategies, and emissions monitoring — including vendor shortlists and estimated implementation timelines.
-
Investor diligence pack: tailored synopses for private equity and strategic buyers covering market concentration, exit multiples under different scenarios, and integration risks for bolt-on acquisitions.
Competitive landscape: incumbents, challengers, and tactical moves
The plating equipment ecosystem remains moderately fragmented — market concentration metrics show top-three and top-five firm shares that permit both scale advantages and niche opportunities. Several archetypes dominate strategic thinking:
-
Integrated chemistry + equipment leaders: Firms that combine plating chemistries with turnkey equipment can accelerate customer adoption of lower-waste processes and lock-in aftermarket chemical sales. These players invest in platform-level R&D and leverage trade events to showcase integrated offerings — recent industry activity includes prominent participations at JPCA and SUR/FIN where integrated PCB and advanced packaging solutions were highlighted.
-
Selective and brush plating specialists: Companies concentrating on on-site repair, selective plating, and brush systems sustain strong relationships with maintenance-heavy end-users (aerospace repair, critical industrial components). Their value lies in service models and rapid deployment capabilities.
-
Turnkey systems integrators and automation players: Automation-focused OEMs are introducing new fixture designs (for example, recent launches of advanced barrel geometries) and robotics integrations to address labor shortages and throughput demands for high-mix manufacturers.
-
Vertical-focused suppliers: Smaller firms continue to win in jewelry and specialty markets through gold and decorative plating kits, leveraging domain-specific knowledge and responsiveness.
Representative company examples profiled in the study include leading integrated chemistry and turnkey providers, global specialty-chemistry and brush plating leaders, and regional equipment suppliers and integrators. The report synthesizes public announcements and proprietary intelligence — such as trade show showcases and product launches — and translates them into strategic implications for customers and competitors alike.
Industry dynamics that will shape winners in 2026
-
Environmental regulation: Manufacturers that pre-empt EPA-style effluent rules and invest in low-waste chemistries will avoid future compliance penalties and gain preferential status with OEM customers requiring secured supply chains.
-
Commodities and component availability: Spikes in copper and constraints in rare-earth dependent components (driven by export controls) will favor suppliers with diversified sourcing, substitution roadmaps, and recycling programs.
-
Labor and automation: Skilled labor shortages increase the ROI on robotic plating cells and selective automation; however, companies must balance capital intensity with flexible capacity to serve high-mix clients.
-
Service and aftermarket: As lead times extend for new equipment, aftermarket services, retrofits, and chemical supply contracts become reliable revenue engines; service-centric business models will outpace pure hardware players in margin resilience.
Actionable playbook for executives — immediate and strategic moves
-
For OEMs and contract platers: Initiate a 90-day audit of wastewater and chemical usage tied to a 12-month retrofit plan for low-waste processes. Price in commodity hedging for critical inputs and negotiate longer-term chemical supply agreements to stabilize margins.
-
For equipment manufacturers: Prioritize modular automation platforms and software-enabled service offerings; deploy a second-source strategy for components exposed to export controls and run scenario tests against copper price surges.
-
For investors: Use the report’s scenario outputs to stress-test exit multiples under regulatory and commodity shock models. Target acquisitions that provide service or chemistry lock-ins rather than pure hardware plays.
-
For policymakers and large buyers: Encourage standards alignment and provide incentives for adoption of low-waste chemistries; coordinate with suppliers to pilot technology demonstrators that de-risk broader procurement programs.
What sets PW Consulting’s study apart
This analysis is not an aggregation of public filings; it combines field interviews, supplier capability scoring, regulatory mapping, and a proprietary demand model calibrated to historical market transitions (2020–2025). Our forecast series (2026–2032) is presented in multiple realistic scenarios and is accompanied by downloadable CAPEX/TCO tools denominated in USD Million to help executives run deterministic sensitivity analyses. Critically, the full report includes granular segment-level forecasts, regional supply maps, and transaction comparables that we have intentionally reserved for report subscribers to preserve competitive advantage.
Next steps — how to use this insight in 2026
Leaders who treat 2026 as an execution year rather than a wait-and-see period will capture disproportionate share gains. Use the report to (1) prioritize retrofit and automation projects with quantified ROI thresholds, (2) secure supply contracts and diversification plans for volatile inputs, and (3) identify acquisition targets that shift revenue mix toward recurring services. For teams preparing investment committees or board briefings, the study supplies slide-ready scenario outputs and a checklist of regulatory and operational triggers to monitor month-by-month.
To access the complete dataset, segment-level forecasts, vendor scorecards, and the CAPEX modeling toolkit, consult the full Plating Equipment Market report on PW Consulting’s portal. The executive briefing provided here is deliberately calibrated to convey strategic depth while preserving the detailed actionable intelligence available to subscribers.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


