



Category: market research
PW Consulting: Blockchain Finance Market to Hit $126.88B by 2032, Growing at 26.94% CAGR
By PW Consulting, 2026-09-16
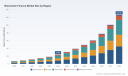
Blockchain Finance Market: Strategic Intelligence for the 2026 Enterprise
The convergence of traditional finance and distributed ledger technology has crossed a critical threshold. What began as experimental pilots and niche cryptocurrency transactions has evolved into a structured financial infrastructure supporting regulated assets, institutional settlements, and enterprise-grade tokenization. For corporate strategists, treasury leaders, and investors navigating the 2026 landscape, understanding the trajectory of the blockchain finance market is no longer optional. It is a prerequisite for capital allocation, risk management, and competitive positioning.
PW Consulting's latest comprehensive market research delivers the analytical rigor required to make informed decisions in this rapidly maturing sector. This report synthesizes historical performance, forward-looking projections, structural segmentation, and competitive intelligence into a single strategic framework. Below, we outline the market's current trajectory, the operational realities shaping deployment, and the regulatory architecture that will define execution over the next several years.
Macro Trajectory and the Investment Horizon
The blockchain finance market has demonstrated sustained expansion across the historical evaluation window, accelerating from foundational levels in the early 2020s to a materially larger operational footprint by 2025. Our tracking of revenue generation across the sector shows a consistent upward curve, with the market surpassing multiple inflection points as institutional participation deepened and tokenized asset infrastructure matured.
Looking ahead through the 2026–2032 forecast horizon, the market is projected to follow a steep growth trajectory, reflecting compounding adoption across payment networks, capital market tokenization, and decentralized financial infrastructure. The compound annual growth rate encoded in our baseline forecast underscores the velocity at which blockchain-native financial services are scaling relative to conventional analogues. This is not a speculative curve. It is a projection anchored in adoption patterns, regulatory clarity, and the structural migration of financial workflows onto distributed platforms.
For enterprise decision-makers, this trajectory carries two immediate implications. First, the window for establishing competitive presence in high-growth segments is narrowing as infrastructure providers consolidate market share. Second, the revenue potential embedded across transaction rails, asset management, and cross-border settlement warrants serious evaluation against internal digital transformation roadmaps and liquidity strategy. Organizations that map their capabilities to the segments experiencing the strongest tailwinds will be better positioned to capture disproportionate share as the market expands toward the decade's end.
Structural Segmentation and Operational Realities
Blockchain finance does not grow as a monolith. Deployment patterns, transaction volumes, and protocol preferences vary significantly across use cases, geographies, and technical architectures. Our report dissects these structural layers to help leaders isolate the opportunities most relevant to their strategic mandate.
Transaction Types and Capital Flows
Payment and settlement activity continues to dominate transaction volume, with peer-to-peer transfers and cross-border payment solutions capturing substantial portions of market activity. Cryptocurrency lending and supply chain finance represent adjacent but structurally distinct categories, each requiring specialized risk frameworks, counterparty diligence, and regulatory compliance postures. The distribution of transaction types reflects where blockchain delivers the clearest operational advantages: speed of settlement, reduced intermediary friction, and programmable financial logic.
Protocol Ecosystems and Infrastructure Choices
The protocol landscape reveals a clear hierarchy of adoption. Bitcoin remains the most extensively utilized network by transaction volume within the broader market, while Ethereum continues to anchor a significant portion of tokenized asset activity and decentralized financial applications. Enterprise-oriented frameworks, including Hyperledger and Ripple, serve specialized institutional use cases where permissioned structures, interoperability requirements, and regulatory alignment take precedence over open public-network deployment. Understanding the protocol mix is essential for technology procurement, risk assessment, and long-term infrastructure planning.
Application Domains and Enterprise Deployment
Digital asset management stands as the largest application category, reflecting the institutional demand for custody, portfolio infrastructure, and asset servicing across both native digital assets and tokenized representations of traditional instruments. Trade finance and digital identity solutions constitute meaningful secondary pillars, each addressing structural inefficiencies in legacy processes. The breadth of application adoption signals that blockchain finance is no longer confined to speculative trading environments. It is being embedded into core financial operations where transparency, auditability, and settlement certainty carry measurable commercial value.
Geographic Distribution and Regional Dynamics
Market activity spans multiple regions, with mature financial centers in North America and Europe maintaining substantial share alongside rapidly expanding activity across Asia Pacific. Emerging regions, including Latin America and the Middle East and Africa, represent smaller but strategically important footholds where blockchain-based financial services address specific gaps in legacy infrastructure, cross-border liquidity, and financial inclusion. Regional divergence in regulatory posture, banking integration, and technology adoption creates distinct entry strategies for organizations evaluating geographic expansion.
Competitive Landscape: Positioning Among Core Players
The competitive environment in blockchain finance is defined by a blend of incumbent financial institutions extending into digital infrastructure, technology-native platforms building capital market utilities, and payment networks scaling institutional settlement capabilities. Our report profiles the dominant participants shaping the market's architecture and outlines the strategic moves that are redefining competitive boundaries.
Societe Generale-FORGE has established a focused presence in regulated digital asset issuance, leveraging public blockchain networks for the deployment of stablecoin instruments backed by institutional custody arrangements. Their approach illustrates how traditional banking entities are bridging balance-sheet credibility with blockchain execution layers, a model that carries relevance for organizations evaluating partnership structures and regulated digital currency infrastructure.
Figure Technology Solutions operates as a blockchain-native capital marketplace designed for the origination, funding, and trading of tokenized assets and real-world assets. By constructing an end-to-end marketplace around asset tokenization, the company addresses a structural need for liquidity, distribution, and secondary market functionality that traditional infrastructure has struggled to deliver at scale. Their trajectory reflects the broader institutional push toward asset digitization as a capital markets modernization strategy.
DeFi Technologies bridges traditional capital markets and decentralized finance through financial technology platforms that integrate exchange-traded product structures and treasury solutions. Their positioning highlights a growing intersection where institutional investors seek regulated exposure to digital asset ecosystems without abandoning familiar investment wrappers. This convergence plays an important role in broadening access and establishing institutional-grade entry points into decentralized financial markets.
Ripple continues to anchor its strategy around cross-border payment networks and institutional banking solutions built on its underlying ledger infrastructure. The company's emphasis on settlement efficiency and institutional interoperability positions it as a key participant in the enterprise payment and liquidity management segment, where transaction speed and counterparty trust remain decisive factors.
Recent developments among these and adjacent market participants reinforce the pace of structural change. The launch of regulated stablecoin instruments on public blockchains with institutional reserve custodians, the authorization of major post-trade infrastructure providers to offer tokenization services, and the emergence of public companies natively issuing equity instruments on blockchain all point toward the normalization of digital asset workflows within regulated financial ecosystems. These milestones are not isolated experimentations. They represent compounding steps toward a reconfigured financial infrastructure.
Regulatory Architecture and Market Dynamics
Regulatory evolution is the single most powerful force shaping blockchain finance deployment in 2026. For years, market participants navigated fragmented guidance and jurisdictional uncertainty. That environment is now being replaced by defined frameworks that establish boundaries for stablecoin issuance, securities classification, and crypto-asset service provision.
In the United States, the establishment of a federal regulatory framework for stablecoins marked a foundational shift, providing clearer operating parameters for issuers and users of regulated digital currency instruments. Subsequent regulatory clarifications addressing the application of federal securities laws to crypto assets and transactions have further reduced ambiguity for institutional participants seeking to structure compliant offerings. These developments do not eliminate risk, but they convert an environment of uncertainty into one where compliance strategy can be designed with greater precision.
Across the Atlantic, the Markets in Crypto-Assets regulation has entered its full application phase, representing the first comprehensive regulatory framework for crypto-assets at scale. Its technical standards and service provider requirements create a structured operating environment that influences not only European market participants but also global organizations seeking to align their product design and compliance infrastructure with internationally recognized standards. The Bank for International Settlements has recognized this framework's significance, reinforcing its role as a reference point for cross-border regulatory coordination.
Blockchain Finance Market
These regulatory developments carry direct operational consequences. Organizations entering blockchain finance markets must now account for licensing pathways, reserve and custody requirements, disclosure obligations, and jurisdictional variance in treatment of digital assets. The market's growth trajectory will increasingly favor participants that integrate regulatory foresight into product design rather than treating compliance as a downstream constraint. Strategic advantage will accrue to those who can align innovation with demonstrable regulatory legitimacy.
Strategic Implications for 2026 Decision-Making
The data and dynamics captured in this research translate into several actionable strategic considerations for enterprise leaders evaluating blockchain finance in 2026.
Worldwide Blockchain Insurance Market
- Asset and liquidity strategy: The scale of digital asset management activity and the expansion of tokenized instrument infrastructure suggest that treasury, custody, and investment operations should reassess exposure to blockchain-based instruments as both an efficiency lever and a diversification tool.
- Capital markets modernization: Tokenization of real-world assets and the emergence of blockchain-native marketplaces indicate that origination, distribution, and secondary trading workflows may be restructured around programmable infrastructure. Early movers in pilot design and partnership formation can influence standards and capture liquidity advantages.
- Payment and settlement optimization: Cross-border payment and peer-to-peer transfer volumes underscore persistent demand for faster settlement and reduced intermediary friction. Organizations with international cash flow requirements should evaluate blockchain-based rails against conventional correspondent banking cost structures and operational risk profiles.
- Regulatory-aligned product design: With clearer frameworks emerging for stablecoins, securities treatment, and crypto-asset services, product roadmaps should incorporate compliance architecture from inception. The cost of retrofitting regulatory alignment is materially higher than designing within an informed regulatory perimeter.
- Competitive positioning: Concentration patterns in the market indicate that a limited set of participants is capturing a disproportionate share of activity. This suggests that late entrants may face increasing barriers to differentiation unless they target underserved segments, specialized use cases, or distinct jurisdictional opportunities.
What the Full Study Delivers
This overview provides the strategic context. The complete PW Consulting Blockchain Finance Market report delivers the operational intelligence required to convert context into decision-ready plans. The study includes detailed segmentation analysis, historical revenue tracking, forward forecasts calibrated across multiple dimensions, protocol-level evaluations, application-domain depth, and regional deployment patterns. It examines competitive positioning with structured company profiles, recent development tracking, and partnership and product-launch timelines that reveal how market leaders are executing. It also integrates the regulatory and infrastructure cost context that shapes deployment economics and risk exposure.
To access the complete dataset, segmentation breakdowns, competitive profiles, and forecast scenarios that support granular strategic planning, we invite you to explore the full report at the source page. The complete intelligence package is designed for executive teams, investment committees, and strategy functions that require precise market structure, credible forward projections, and actionable competitive context to guide 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Blockchain Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FPGA Market Hits $11.73B in 2025, Projected 10.5% CAGR to $23.6B by 2032
By PW Consulting, 2026-09-16
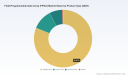
Navigating the FPGA Inflection Point: Strategic Intelligence for Enterprise Decision-Making in 2026 and Beyond
The global semiconductor landscape is undergoing a profound structural transformation, and within it, the Field-Programmable Gate Array (FPGA) market stands at a critical inflection point. For enterprise technology leaders, procurement strategists, and innovation officers, FPGAs have evolved from niche reconfigurable components into foundational enablers of adaptive compute across artificial intelligence, edge processing, telecommunications infrastructure, and high-reliability defense systems. Yet the sheer velocity of technological advancement, coupled with shifting regulatory frameworks and supply chain realignments, has rendered legacy forecasting models insufficient. This gap between market volatility and the demand for actionable intelligence is precisely why our newly published FPGA Market Research Report has been commissioned and structured. Designed as a strategic decision-support instrument rather than a static data repository, this study maps the trajectory of the FPGA ecosystem from 2026 through 2032, equipping organizations with the contextual depth and analytical rigor required to allocate capital, manage supply exposure, and position product portfolios ahead of competitive cycles.
The Strategic Imperative: Why 2026 Demands a New Analytical Lens
Market history provides the necessary baseline for forward-looking strategy, but 2026 introduces variables that fundamentally alter the planning horizon. The sector’s measured compound annual growth rate of 10.5 percent reflects more than aggregate expansion; it signals a reallocation of investment toward architectures that prioritize flexibility, power efficiency, and cryptographic resilience. Over the past five years, the industry has consistently scaled its value creation, with revenue climbing steadily to an estimated 11.73 billion United States dollars in the 2025 base year and projected to cross the 12.73 billion mark as 2026 takes shape. Looking further downstream, the forecast horizon extends to 23.6 billion dollars by 2032, indicating that the coming years will not merely continue historical momentum but rather accelerate it as system architects embed hardware programmability deeper into AI inference pipelines, advanced communication stacks, and mission-critical platforms.
However, macroeconomic growth curves alone do not dictate enterprise strategy. The strategic value of this research lies in its refusal to treat the market as a monolith. Regional dynamics, product architecture selection, and application-specific adoption curves diverge significantly, and companies that apply uniform assumptions across their operations risk misallocating engineering resources or underestimating procurement constraints. By deliberately synthesizing historical performance data with forward-looking scenario modeling, our report enables decision-makers to anticipate inflection zones where supply constraints, design complexity, or competitive repositioning will create asymmetric advantages. The objective is not to overwhelm stakeholders with fragmented metrics but to distill complex market behaviors into strategic action pathways that can be operationalized within existing product roadmaps, procurement frameworks, and partnership strategies.
Field-Programmable Gate Array (FPGA) Market
Market Architecture and Forward Trajectory: Decoding the Growth Curve
The structural composition of the FPGA market reveals how demand segments are evolving and where enterprise exposure is most concentrated. Product architecture remains a defining variable in both procurement strategy and engineering roadmapping. The market environment continues to be anchored by established platforms that dominate deployment volume, while alternative architecture families serve specialized reliability, security, or power-efficiency niches. Each architecture type carries distinct implications for design lifecycle management, software ecosystem compatibility, and geopolitical supply exposure. Organizations evaluating vendor portfolios must therefore assess not only performance benchmarks but also the long-term viability of toolchains, legacy migration pathways, and the strategic alignment of each architecture with their projected deployment environments.
Application segmentation further underscores the broadening scope of FPGA utilization. Telecommunications, data center infrastructure, consumer electronics, automotive systems, industrial automation, and military or aerospace programs each impose unique performance, certification, and lifecycle requirements. As processing workloads migrate toward disaggregated architectures and domain-specific acceleration, the programmable fabric has become a strategic layer for bridging fixed silicon limitations with evolving algorithmic demands. The interplay between these verticals is increasingly bidirectional: breakthroughs in data center acceleration architectures frequently inform edge deployment optimizations, while stringent environmental and reliability standards in industrial or aerospace sectors drive innovations that eventually cascade into broader commercial applications.
Concentration dynamics add a critical dimension to competitive and procurement strategy. The market remains highly consolidated, with the top three players collectively commanding three-quarters of total industry revenue and the top five reaching approximately eighty-five percent. High concentration implies that partnership negotiations, licensing terms, roadmap alignment, and supply allocation privileges are disproportionately influenced by interactions with a small cohort of dominant suppliers. For enterprises without direct leverage over these ecosystems, the strategic response involves diversified sourcing architectures, co-development arrangements, and early engagement with emerging platform providers that may offer alternative value propositions in targeted application domains. Long-term planning therefore requires a nuanced understanding of which suppliers will dominate next-generation architectural transitions and which will retreat into niche segments as consolidation accelerates.
Competitive Dynamics and Recent Strategic Moves
The competitive landscape is defined by both established scale players and specialized innovators pursuing differentiated architecture strategies. AMD, operating through its Xilinx lineage, continues to anchor high-performance adaptive compute with its Versal architecture and UltraScale+ platforms, targeting AI-adjacent workloads, data center acceleration, and embedded compute scenarios. Intel’s Altera division has reinforced its commitment to the edge and communications segments through Agilex series platforms optimized for high-speed throughput and compact embedded deployments. These two ecosystem behemoths exert structural influence on toolchain standardization, strategic pricing expectations, and downstream design migration pathways, making their product announcements highly consequential for enterprise planning.
Smaller but increasingly influential players are carving out defensible positions by focusing on power efficiency, security hardening, and domain-specific reliability. Lattice Semiconductor has expanded its footprint in low-power and mid-range applications while embedding cryptographic agility into its FPGA families, a move that directly addresses emerging security guidance from government and industrial regulators. Microchip Technology maintains a strong positioning in radiation-hardened and high-assurance environments, supporting defense and space architectures that demand both electromagnetic compatibility and resistance to side-channel vulnerabilities. Efinix continues to advance compact, low-power architectures targeting edge AI and real-time processing workloads, while QuickLogic emphasizes antifuse and radiation-tolerant platforms alongside embedded FPGA intellectual property for specialized defense and industrial deployments. Each of these companies is actively shaping the market through targeted product launches, strategic contracting, and roadmap commitments that redefine what programmable silicon can deliver in constrained or highly regulated environments.
The speed of recent corporate activity illustrates how rapidly the competitive frontier is moving. Early in 2026, Intel unveiled its Agilex 3 family, emphasizing optimized power-performance-size tradeoffs for embedded and edge deployments, with software support cycles and production timelines already established. Later that year, AMD announced next-generation Kintex UltraScale+ devices with substantially expanded memory bandwidth and extended availability horizons, signaling a deliberate push toward long-lifecycle industrial and embedded applications. These announcements were preceded by a series of strategic milestones throughout 2025, including Lattice’s introduction of its post-quantum cryptography-ready FPGA family and QuickLogic’s award of a significant defense contract to advance radiation-hardened technology under trusted microelectronics programs. Together, these developments demonstrate that competition is no longer limited to raw logic density or clock speed; it increasingly centers on cryptographic readiness, supply assurance, software maturity, and alignment with government or industry assurance frameworks.
Structural Shifts Shaping Industry Dynamics
Market growth does not occur in a vacuum. The FPGA sector is simultaneously navigating regulatory evolution, material supply volatility, and assurance-driven procurement mandates that will alter sourcing strategies and design methodologies. In early 2025, government defense authorities released updated security guidance specifically directed at FPGA deployments, emphasizing cryptographic key management, hardware security module compliance, and integrated cryptographic libraries within design flows. Such guidance transforms security from an optional hardening step into a foundational design requirement, with direct implications for vendor evaluation, architecture selection, and lifecycle maintenance. A subsequent revision of best practice documentation further codifies expectations around authentication, auditability, and reproducible build environments, reinforcing the need for supply chain traceability and design process discipline.
Geopolitical and material constraints are introducing parallel pressures. Semiconductor manufacturing dependencies on concentrated raw material sources have become a strategy-informing reality. A substantial share of global silicon production and the overwhelming majority of certain low-purity gallium requirements originate from a single geographic region, and export control actions implemented during late 2024 and early 2025 triggered significant price escalation for gallium-dependent supply chains. While not every architecture depends equally on constrained inputs, enterprises with diversified component sourcing needs or long-duration program commitments must incorporate material availability risk into supplier qualification criteria and inventory planning. This is particularly relevant for platforms pursuing extended availability windows, where procurement continuity across multiple product generations becomes a strategic differentiator.
Defense and space program dynamics are also accelerating specialized FPGA development. The progression into advanced phases of radiation-hardened research contracts signals sustained institutional commitment to securing domestically assured microelectronics for current and future mission architectures. As these programs mature, the resulting technology transfer pathways will influence commercial-grade reliability expectations, testing methodologies, and architectural feature sets, creating downstream benefits that may eventually diffuse into broader industrial deployments. For enterprises operating in or adjacent to regulated environments, tracking the intersection of assurance mandates, material constraints, and architectural innovation is essential to maintaining procurement resilience and avoiding unexpected compliance bottlenecks.
Inside the Report: What Decision-Makers Will Gain
Our research methodology was designed to convert market complexity into executable strategy. Rather than presenting isolated data tables or retrospective summaries, the report is structured around decision-centric analysis that connects market sizing, segmentation behavior, competitive positioning, and environmental dynamics into a coherent strategic framework. Decision-makers will find detailed profiling of core suppliers, including their architectural emphasis, target application domains, recent product milestones, and strategic posture relative to market concentration. This enables procurement teams, corporate strategists, and engineering leadership to evaluate supplier roadmaps against internal deployment timelines, compliance requirements, and long-term availability objectives.
The segmentation analysis is organized to illuminate growth distribution across regions, product architectures, and end-use applications without obscuring the underlying structural drivers. Regional dynamics are examined through the lens of infrastructure investment cycles, adoption maturity, and supply chain proximity, while application-based analysis focuses on workload intensity, certification requirements, and the rate at which programmable acceleration is displacing or complementing alternative silicon solutions. Combined with historical tracking from 2020 through 2025 and a forecast window extending to 2032, these layers allow organizations to calibrate investment timing, prioritize internal capability development, and model multiple adoption scenarios under differing supply or regulatory conditions.
A substantial portion of the report is devoted to operationalizing intelligence. Readers will encounter practical frameworks for evaluating design-tool compatibility, assessing post-quantum readiness, anticipating material-driven cost volatility, and structuring supplier engagement strategies in a highly concentrated market. Regulatory developments, certification expectations, and government-backed research activities are integrated directly into the analysis of market dynamics rather than treated as peripheral commentary, ensuring that compliance and assurance considerations are addressed as strategic variables rather than administrative afterthoughts. By aligning market data with execution-oriented guidance, the study functions as a planning reference that can be applied across capital allocation, sourcing strategy, engineering roadmapping, and partnership development.
Programmable Logic Controller (PLC) Market
Why Act Now: Aligning Intelligence with 2026 Decision Cycles
The window for proactive positioning is narrowing. As product portfolios evolve, toolchain ecosystems mature, and assurance requirements become more explicitly codified, organizations that defer strategic assessment risk finding themselves locked into architectures or supplier relationships misaligned with the next growth phase. The FPGA market’s trajectory suggests that programmable acceleration will remain embedded in the core infrastructure of emerging computing workloads, making early intelligence-gathering and supplier alignment a durable competitive advantage rather than a temporary tactical exercise.
This report is engineered to support that advantage. It provides the contextual map, the competitive intelligence, and the structural analysis necessary to turn market signals into disciplined decision-making. However, the full depth of segmentation behavior, detailed supplier positioning, regional nuance, and scenario-based growth pathways is preserved within the complete research deliverable, where interactive analysis, extended vendor profiling, and decision frameworks are available for teams seeking to operationalize the findings directly within their planning workflows. For executives evaluating 2026 capital deployment, supply strategy, product roadmap alignment, or partnership engagement, the comprehensive report offers the intelligence foundation required to act with precision in a market that rewards foresight.
For detailed analysis of this topic, please visit the official page: Field-Programmable Gate Array (FPGA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Pump Brake Market to Hit $344.8M by 2032, 5.8% CAGR
By PW Consulting, 2026-09-16
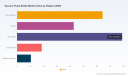
Navigating the 2026 Vacuum Pump Brake Market: Strategic Intelligence for OEMs and Tier 1 Suppliers
The global automotive braking ecosystem is undergoing a structural reconfiguration. With hydraulic and pneumatic architectures giving way to electrified brake boosters, vacuum pump brake technologies are entering a decisive growth phase. For procurement directors, R&D leads, and competitive intelligence teams, understanding this trajectory is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and product roadmap alignment. The 2026 editions of our Vacuum Pump Brake Market study are designed to translate macroeconomic momentum into actionable operational guidance.
Over the historical window from 2020 through 2025, the sector has demonstrated consistent upward traction, reflecting both fleet modernization and the incremental electrification of brake assistance systems. That momentum carries directly into the forecast horizon, establishing a multi-year growth corridor that will shape sourcing strategies, capacity planning, and partnership models. The strategic question facing executives today is not whether to engage with this shift, but how to position portfolios, negotiate with manufacturers, and mitigate regulatory exposure while the market re-rates itself around electrification, consolidation, and compliance.
This article serves as an advance briefing on the scope, analytical framework, and competitive intelligence embedded in our latest Vacuum Pump Brake Market report. It outlines the structural forces reshaping demand, introduces the competitive landscape and recent industry developments, and clarifies the practical decision-support tools available to subscribers. Core valuation splits, detailed matrix breakdowns, and granular regional matrices are intentionally reserved for the full dataset to preserve the analytical integrity of the deliverable.
Structure and Scope of the Research Deliverable
A high-quality industry assessment must bridge the gap between high-level market indicators and the granular, operation-ready intelligence that engineering and procurement teams actually use. Our Vacuum Pump Brake Market study is built on that premise. Rather than delivering a single macro figure, the report distributes context across a structured architecture designed to support segmentation, scenario planning, source evaluation, and risk mapping.
The analytical backbone rests on a rigorously tracked historical series paired with a forward-looking projection window. Trailing data captures the maturation curve of vacuum-assisted braking installations, while the forecast horizon extends through the next several model lifecycle cycles, allowing strategists to test capacity decisions, sourcing flexibility, and portfolio pivots against realistic adoption pathways. The revenue framing is standardized in USD millions, ensuring comparability across geographies and product categories while maintaining a consistent valuation baseline for executive review.
Beyond the headline growth trajectory, the report dissects the market through engineered segmentation lenses that reflect how vehicle manufacturers and suppliers actually think about product design, sourcing, and performance differentiation. The type dimension distinguishes between mechanical and electric architectures, capturing the functional divergence that increasingly drives specification decisions. The application lens separates passenger vehicles from commercial vehicles, a split that matters because demand elasticity, duty cycles, warranty exposure, and procurement cycles differ substantially across those segments. Regional breakdowns further contextualize where demand is concentrating and where nearshoring, tariff exposure, or local content requirements may alter sourcing logic.
Each segment view is integrated with cross-referencing modules so that readers can trace how architectural preference, vehicle class, and geographic rollout interact. This is essential for teams evaluating supplier fit, component compatibility, and aftermarket service footprints. Rather than presenting isolated slices, the study constructs a connective analytical grid that supports multi-variable decision-making.
Competitive Landscape: Who Shapes the Vacuum Pump Brake Ecosystem
Market positioning in this space is defined less by aggregate size than by specialization, certification readiness, OEM relationships, and speed of adaptation to electrification mandates. Several manufacturers have differentiated themselves through targeted product lines, volume reliability, and long-term integration with vehicle platforms. Understanding that competitive fabric is central to evaluating both threat and opportunity.
In South Korea, a cluster of specialist manufacturers has built durable positions around electric and mechanical vacuum pump production for brake systems. One player, headquartered in Incheon, focuses on electric motor-driven vacuum pumps designed for brake booster assistance in electric vehicles. Its production cadence for one-ton class models and multi-decade track record supplying Korean EV OEMs signal a mature, volume-oriented manufacturing base. Another Korean manufacturer, based in Gyeongju, produces parallel-electric and mechanical vacuum pump series tailored for passenger cars and hybrid applications. Its emphasis on BLDC and DC motor variants underscores the ongoing tension between efficiency optimization and cost discipline in mainstream vehicle architectures. A third South Korean manufacturer has become a notable supplier within the domestic electric vehicle ecosystem, producing variants scaled for sedans, SUVs, RVs, and light commercial bodies. Its integration into major OEM brake system assemblies and established quality certifications illustrate how regional specialization can translate into embedded platform placement.
Beyond East Asia, North American and European names maintain relevance through different value propositions. A United States-based supplier with original equipment manufacturing capability focuses on plug-and-play vacuum pump replacements for premium and performance brands, positioning around compatibility, warranty assurance, and service-channel reliability. Meanwhile, European innovation activity points toward electrification-driven brake system upgrades that align with emissions reduction objectives, highlighting how traditional suppliers are adapting product lines to meet shifting regulatory and performance expectations.
Vacuum Pump Brake Market
On the broader manufacturing side, Chinese producers continue to expand their vacuum pump and booster system capabilities. Several facilities concentrate on commercial vehicle brake power boosters and vacuum pump assemblies, reflecting the commercial fleet segment’s ongoing need for robust, cost-efficient braking support hardware. At the product level, CE-certified brake booster units and vacuum booster series for Japanese vehicle platforms indicate that export-oriented production is increasingly structured around compliance, interchangeability, and model-specific fitment.
What unites these competitors is not uniform scale, but differentiated positioning. Some compete on volume reliability and OEM integration. Others compete on certification readiness, part interchangeability, or electrification-specific motor architectures. A few compete primarily on commercial vehicle durability and cost. For buyers and strategists, the competitive map is less about identifying a single dominant leader and more about recognizing where switching costs, technical lock-in, and supply continuity may shape sourcing choices.
Recent Industry Developments Redefining the Curve
The vacuum pump brake market does not evolve in a vacuum. Supply chains, safety exposure, and product launches are intersecting in ways that alter both near-term procurement and long-term engineering priorities. Several events in the recent cycle illustrate why this sector deserves heightened strategic attention.
Product launch activity continues to reflect the dual pressure of electrification and cost efficiency. Recent introductions of electric vacuum pump series for passenger vehicles emphasize consistent vacuum delivery and manufacturing efficiency, signaling that suppliers are trying to reconcile performance stability with margin discipline. At the same time, European language around new electric vacuum pump introductions has explicitly connected brake system electrification with emissions reduction, reinforcing the regulatory tailwind behind electric booster technology.
Exhibition and trade activity also indicate that the supply base remains active and increasingly export-oriented. Recent automotive maintenance and parts exhibitions in China featured multiple brake vacuum pump exhibitors showcasing electric fuel and brake pump systems. For sourcing teams, these events are not merely marketing showcases; they are practical indicators of supplier readiness, product breadth, and regional manufacturing momentum.
At the same time, the market is not immune to quality and liability exposure. A class-action filing in U.S. federal court has alleged that a major automaker failed to fully warn owners about a brake vacuum pump defect capable of causing sudden loss of power assist in certain models. Whether or not a given company is directly involved, events of this nature matter to the broader market because they reshape warranty assumptions, recall management practices, parts traceability expectations, and the reputational calculus that OEMs apply when qualifying suppliers. They also elevate the value of supplier quality systems, documentation consistency, and testing rigor as strategic differentiators rather than administrative checkboxes.
Strategic Lens: What This Means for 2026 Decision-Making
For automotive executives, the practical takeaway is that vacuum pump brake technology is moving from a mature accessory category into a more strategically sensitive component of the vehicle safety and electrification architecture. The implications span sourcing, product planning, and risk management.
Vacuum Pumps Market
First, the pace of electrification is reshaping specification logic. Mechanical and electric vacuum pump architectures serve different vehicle strategies, and the choice between them increasingly affects energy efficiency, system integration complexity, and long-term service expectations. Teams evaluating supplier portfolios need to weigh not only current part fitment, but also how rapidly each manufacturer can pivot its motor architecture, certification readiness, and production line flexibility as platform requirements evolve.
Second, geographic demand distribution creates sourcing trade-offs. Where demand is building, local content considerations, logistics resilience, and tariff exposure may influence whether buyers prioritize regional suppliers, export-oriented manufacturers, or multi-sourced arrangements. The competitive landscape includes both entrenched OEM-integrated players and broader manufacturing ecosystems capable of serving multiple vehicle classes and export markets. Choosing among them requires clarity on volume stability, part interchangeability, and compliance posture.
Third, quality and liability dynamics are now part of supplier evaluation rather than downstream incident management. Recent litigation language around brake vacuum pump defects underscores how quickly perceived reliability gaps can translate into consumer risk exposure and regulatory attention. For procurement and quality teams, that means the value of robust process control, documented testing, and recall readiness is rising in the hierarchy of supplier selection criteria.
The full report translates these themes into a structured set of decision frameworks. It provides a consistent historical baseline and forecast series so readers can test growth assumptions, align capacity planning, and map demand concentration. It organizes the segmentation views that matter for engineering and sourcing teams without forcing them into simplified averages. It profiles competitors with enough operational context to support like-for-like evaluation. And it embeds recent developments within the broader demand, regulation, and quality narrative so that strategic teams can anticipate disruption rather than react to it.
Why This Study Matters for 2026
As the market expands through the forecast horizon, the difference between reactive sourcing and proactive portfolio strategy will increasingly come down to information quality and analytical discipline. Vacuum pump brake demand will not grow uniformly across vehicle classes, architectures, or regions. The companies that gain advantage will be those that understand where concentration is forming, which suppliers have credible scale or specialization, and how regulatory and safety developments may alter both specification and sourcing behavior.
The full Vacuum Pump Brake Market report is built for that environment. It equips teams with a coherent narrative, a structured segmentation architecture, competitive profiles, and forward-looking scenario context. Readers who engage with the complete dataset will be better positioned to evaluate supplier resilience, time product transitions, and allocate resources with confidence in a market that is simultaneously maturing and electrifying.
For detailed analysis of this topic, please visit the official page: Vacuum Pump Brake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive eCall Market Hits $1B in 2025, Projected to Triple by 2032 at 12.5% CAGR
By PW Consulting, 2026-09-16
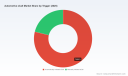
Navigating the Next Wave of Automotive eCall: Strategic Insights for 2026 Decision-Makers
The automotive emergency call landscape is undergoing a structural transformation that demands immediate attention from OEMs, tier suppliers, and regulatory strategists. As vehicle connectivity evolves from legacy networks to packet-switched 4G and 5G architectures, the eCall ecosystem is no longer a compliance checkbox but a core component of occupant safety, aftermarket integration, and cross-border emergency response. Our latest market research on the Automotive eCall Market provides a rigorous, data-backed framework for navigating this transition through 2032. Built on historical tracking from 2020 through a forward-looking forecast window of 2026 to 2032, the study translates macroeconomic momentum, regulatory sequencing, and supplier innovation into actionable intelligence for enterprise planning.
The industry has already crossed a decisive inflection point. From an estimated 560 million USD in 2020, the global market expanded to 1,000 million USD by 2025, reflecting sustained investment in in-vehicle emergency systems, regulatory alignment, and network modernization. The trajectory accelerates from here, with the market projected to reach approximately 1,121.56 million USD in 2026 and continue its climb toward roughly 2,274.04 million USD by 2032. This growth path is underpinned by a compound annual growth rate of 12.5 percent across the forecast horizon, signaling durable demand rather than a temporary regulatory bump. For leadership teams mapping capital allocation, product roadmaps, and compliance portfolios, these figures establish the baseline scale of opportunity and the cost of inaction.
Regulatory Sequencing and the Legacy Network Risk
The dynamics shaping eCall adoption cannot be separated from the regulatory calendar. European Commission frameworks have introduced a phased approach to next-generation emergency calling, creating both certainty and transitional friction. Commission Delegated Regulation (EU) 2024/1180 mandates that new M1 and N1 vehicle types be equipped with 112-based eCall in-vehicle systems capable of operating over packet-switched networks such as 4G and 5G beginning 1 January 2026. This requirement reorients system design away from circuit-switched legacy dependencies and pushes the industry toward faster, data-rich emergency workflows.
Automotive eCall Market
At the same time, the regulatory timeline has been calibrated to give manufacturers breathing room. Commission Delegated Regulation (EU) 2025/1871 defers the mandatory application of the new eCall standards EN 17184:2024 and EN 17240:2024 to 1 January 2027. This adjustment reflects a pragmatic recognition of engineering lead times, supply chain readiness, and the need for validation cycles before full-scale compliance. For enterprises, the layered timeline creates a strategic window: early movers can align product architectures to next-generation specifications while de-risking certification, and late movers face a compressed retrofit environment as legacy systems age into obsolescence.
The legacy network dimension adds urgency. As several EU member states advance shutdowns of 2G and 3G infrastructure, approximately 64 million vehicles face potential loss of emergency call functionality without coordinated mitigation. This exposure does not merely affect aftermarket service providers; it impacts fleet operators, leasing companies, insurance models, and OEM brand reputation. Mitigation strategies increasingly require hybrid communication designs, network-agnostic fallback logic, and lifecycle planning that extends beyond the vehicle's initial homologation date. Our study analyzes how these regulatory and network transitions intersect, helping stakeholders prioritize where to invest, when to phase out legacy dependencies, and how to structure compliance roadmaps without disrupting production schedules.
Market Structure, Concentration, and Growth Drivers
The eCall market is not a monolithic pool of demand. It is shaped by vehicle-type mix, trigger mechanisms, regional deployment intensity, and the concentration of competitive capability. The total addressable opportunity reflects a market where passenger vehicles and commercial fleets generate distinct adoption curves, and where automatically initiated emergency calls account for the dominant share of system activity relative to manually initiated calls. These structural patterns influence how suppliers design hardware and software, how testing organizations validate interoperability, and how OEMs plan service architecture across regions.
Concentration dynamics further sharpen the competitive picture. The market remains moderately consolidated, with the top three players accounting for 42.5 percent of share and the top five reaching 58.2 percent. This distribution indicates a landscape where a limited number of technologically advanced firms hold visible influence over standards readiness, test infrastructure, and hybrid system integration, while still leaving meaningful room for regional specialists and component suppliers to compete on cost, customization, and service coverage. Understanding this concentration profile is essential for procurement teams evaluating supplier resilience, for investors assessing competitive moats, and for executives considering partnerships or acquisitions in the emergency connectivity space.
Growth momentum is reinforced by several operational realities. Vehicle connectivity is becoming a baseline expectation rather than a premium feature, emergency response institutions are increasingly integrated with digital PSAP workflows, and manufacturers are compressing development cycles to meet evolving standards. The result is a market where volume expansion is tied to engineering reliability, certification velocity, and the ability to deliver consistent performance across heterogeneous network environments. These are precisely the conditions where comprehensive market intelligence delivers leverage: revealing where demand is genuinely durable, where margin pressure is likely to intensify, and where technical differentiation will determine share gains.
Competitive Landscape and the Test-and-Certification Frontier
The companies leading the eCall space are not only shipping products; they are actively shaping the validation environment that determines how quickly the industry can transition to next-generation standards. Three organizations illustrate the breadth of strategic activity now unfolding.
Keysight Technologies, Inc.
Headquartered in Santa Rosa, California, Keysight has moved decisively into the certification layer for hybrid eCall systems aligned to the EN 18052:2025 standard. The company develops and certifies test solutions that enable dynamic switching between legacy and next-generation eCall networks, a capability that directly supports interoperability across mixed connectivity environments. In June 2026, Keysight achieved DEKRA validation for Hybrid eCall certification to the EN 18052:2025 standard, reinforcing regulatory readiness and cross-system compatibility for in-vehicle emergency platforms. For OEMs and tier suppliers, such certification milestones shorten the path to compliance while reducing uncertainty around hybrid operation during the network transition period.
Rohde & Schwarz GmbH & Co. KG
Based in Munich, Rohde & Schwarz has built a strong position in verification and test infrastructure for next-generation eCall functionality. The company verified NG eCall implementation on the Qualcomm Snapdragon Auto 5G Modem-RF in line with EN 17240:2024, including PSAP simulation, as documented in a July 2025 press release. This work demonstrates end-to-end validation across modem, RF, and emergency call workflows, and it underscores the growing importance of integrating communications silicon with emergency service architecture. Rohde & Schwarz also offers test solutions spanning hybrid and next-generation eCall compliance, positioning the firm as a key enabler for manufacturers seeking to confirm performance before homologation.
LG Electronics Inc.
From Seoul, LG Electronics has expanded its role as an integrated supplier of hybrid emergency call solutions. Starting in 2025, LG began supplying hybrid emergency call systems designed for reliable communication across 2G, 3G, 4G, and 5G networks, embedding emergency call capability directly into vehicle platforms. This approach reflects a practical response to the legacy-to-next-generation transition: rather than treating network evolution as a separate engineering problem, LG's integration model aims to preserve emergency functionality while future-proofing the communication path. As manufacturers seek unified supply partners, such integration breadth becomes a differentiator in cost planning, validation complexity, and service continuity.
Taken together, these developments highlight a competitive arena where value is increasingly created at the intersection of hardware integration, modem and RF verification, and certification alignment. The firms that can deliver standards-compliant, network-resilient solutions with repeatable test coverage will influence not just individual vehicle programs, but the broader pace of industry migration toward packet-switched emergency calling.
What the Report Covers: Practical Intelligence for Execution
This research study is structured for decision-makers who need more than high-level forecasts. It connects market sizing with the operational realities of system design, validation, regulatory adoption, and supplier selection. The report is intended to support executive planning, product strategy, compliance roadmapping, and competitive positioning across the 2026 to 2032 horizon.
Readers will find an integrated view of the market that ties historical performance to forward projections, interprets growth through structural drivers rather than headline numbers alone, and maps competitive activity to the standards and testing infrastructure now shaping the industry. The study goes beyond generic trend statements to examine how automatically initiated and manually initiated eCall models distribute across the market, how passenger car and commercial vehicle segments differ in adoption intensity, and how regional deployment patterns influence supplier strategy and compliance prioritization. It also contextualizes market concentration, identifying where scale advantages matter, where specialized capabilities create entry points, and where partnership strategies can accelerate time to market.
Equally important, the report translates regulatory developments into execution-relevant implications. It examines how the EU's phased standards timeline interacts with network shutdown risks, what hybrid system architectures can mitigate legacy exposure, and how certification milestones such as DEKRA validation and EN 17240 verification affect product readiness. The analysis is designed to help teams answer practical questions: which technical capabilities are becoming table stakes, which validation activities should be prioritized now versus deferred, and how to structure supply and engineering plans so that compliance is achieved without sacrificing program velocity.
To ensure relevance for operational teams, the report links market intelligence to supplier evaluation, procurement strategy, and risk management. It examines how leading test and integration providers are positioning for next-generation compliance, what that means for component sourcing and system integration, and where enterprises should focus diligence when assessing partners for eCall hardware, software, and validation services. By anchoring these discussions in a 2025 base year and a detailed 2026 to 2032 forecast, the study provides a coherent framework for scenario planning, investment justification, and executive alignment.
Automotive Escape Tools Market
Why This Research Matters for 2026 Decisions
The 2026 planning cycle is not an ordinary annual reset. It arrives at the convergence of regulatory mandates, network modernization, and supplier capability maturation. For OEMs, the question is no longer whether eCall systems need to evolve, but how quickly hybrid and next-generation architectures can be deployed without disrupting homologation, cost targets, or service continuity. For tier suppliers and technology providers, the opportunity lies in delivering validated, standards-aligned solutions that reduce integration risk and accelerate certification. For commercial fleet operators and service organizations, the challenge is managing legacy exposure across large vehicle populations while preparing for packet-switched emergency workflows.
In this environment, strategic advantage comes from clarity. Decision-makers need a reliable view of the market's overall scale and growth trajectory, a grounded understanding of how regulatory timing reshapes development priorities, and a realistic picture of where competitive capability is concentrating. The forecast growth from approximately 1,121.56 million USD in 2026 to roughly 2,274.04 million USD by 2032, at a compound annual growth rate of 12.5 percent, sets the scale of the opportunity. The regulatory calendar, Legacy network risks, and certification milestones define the sequence of execution. The concentration profile and supplier activity shape the competitive response.
Our Automotive eCall Market research brings these elements together in a single, structured intelligence asset. It is designed to support strategic planning across engineering, compliance, procurement, and commercial functions, and it provides the context needed to evaluate investments, partnerships, and product roadmaps with confidence. For organizations preparing to act in 2026 and beyond, the study offers the analytical foundation to move from reactive compliance to proactive market positioning.
To access the full segmentation analysis, regional deployment context, complete forecast tables, and detailed company profiles, please visit the source page for the complete report. The comprehensive dataset and operational breakdowns are available there, enabling deeper diligence and more precise planning across your eCall strategy.
For detailed analysis of this topic, please visit the official page: Automotive eCall Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TMP Market to Hit $346M by 2032, 6.5% CAGR Amid 2025 Base of $235M
By PW Consulting, 2026-09-16
Navigating the Trimethylolpropane Market Outlook 2026–2032
As industrial supply chains recalibrate after years of volatility, the Trimethylolpropane (TMP) market stands at a pivotal inflection point. PW Consulting's latest comprehensive market research offers a rigorous, data-driven examination of the sector, designed specifically to equip executive teams with the strategic intelligence necessary for informed decision-making throughout the 2026–2032 forecast horizon. This overview outlines the analytical framework, competitive intelligence, and forward-looking dynamics embedded within our study, while highlighting why precise, granular market mapping has become indispensable for capital allocation, procurement strategy, and long-term product portfolio planning.
Strategic Imperatives in a Maturing Specialty Chemical Landscape
Trimethylolpropane continues to serve as a foundational building block across multiple high-value industrial applications, ranging from advanced polyurethane systems to performance coatings, synthetic lubricants, and specialty resins. Over the past five years, the sector has transitioned from a period of reactive price stabilization into a phase defined by structural demand shifts, regional capacity realignments, and increasingly stringent environmental compliance frameworks. Against this backdrop, superficial market summaries no longer suffice. Organizations require a granular understanding of how feedstock cost trajectories, regional regulatory divergence, and manufacturer-level capacity adjustments interact to shape pricing behavior and supply reliability.
Our research synthesizes historical performance metrics, forward-looking demand modeling, and structural market analysis into a single decision-support architecture. By anchoring the analysis in verifiable historical data and extending projections through the 2032 horizon, the study enables stakeholders to stress-test investment theses, evaluate sourcing alternatives, and anticipate where competitive pressure is likely to intensify. The emphasis throughout is on actionable clarity: identifying which applications will absorb incremental volume, which regional corridors will dictate pricing trends, and how established producers are repositioning their operational footprints to capture margin resilience.
Macro Trajectory and Forecast Architecture
The historical record reveals a sector characterized by steady, compound growth underpinned by diversified end-use demand. Between 2020 and 2025, the global TMP market expanded from an estimated 180.0 million USD to a base-year valuation of 235.0 million USD, reflecting consistent year-over-year gains despite periodic feedstock disruptions and logistics bottlenecks. Looking ahead, our forecast model projects the market will continue its upward trajectory, reaching approximately 243.3 million USD in 2026 and progressing toward 346.0 million USD by the close of the 2032 forecast window. This expansion corresponds to a projected compound annual growth rate of 6.5 percent, a figure that encapsulates both underlying volume growth and the gradual pass-through of compliance-driven formulation changes.
It is important to recognize that aggregate figures only tell part of the story. The forecast architecture dissects this growth across multiple structural dimensions, mapping how demand concentration, supply-side capacity additions, and regional procurement patterns jointly determine which submarkets will outperform or lag. Our methodology isolates these interactions without relying on static assumptions, instead incorporating scenario sensitivity around feedstock availability, regulatory adaptation timelines, and manufacturer capacity utilization rates. Stakeholders who access the full report will find detailed breakdown tables, regional deployment mappings, and application-level volume projections that translate the headline CAGR into operational planning parameters.
Competitive Landscape and Capacity Realignment
The TMP producer ecosystem is defined by a concentration of established chemical manufacturers operating across multiple geographies, with a noticeable tilt toward integrated production models and targeted capacity enhancements. Market concentration metrics indicate a moderately fragmented environment, where leading players hold meaningful but not dominant aggregate shares. This structure fosters both regional price competition and strategic differentiation through specialty-grade formulation, supply reliability, and technical service capabilities.
Key participants continue to shape market dynamics through geographic footprint optimization and targeted production investments. European and North American operations maintain strong positions in high-specification coatings and lubricant applications, while Asian manufacturing hubs have expanded their relevance in polyurethanes, alkyd resin systems, and industrial coating supply chains. Companies such as LANXESS AG, Perstorp Holding AB, OXEA GmbH, Mitsubishi Gas Chemical Company, Inc., Chang Chun Group, BASF SE, Polioli SpA, Hubei Yihua Group Co., Ltd., Jilin Petrochemical Company, and Baichuan Chemical Industrial collectively illustrate the breadth of active participation across the value chain.
Capacity decisions have become particularly consequential. Recent operational developments underscore how individual producer strategies can ripple through regional availability and pricing behavior. Perstorp Holding AB completed a capacity expansion at its Swedish facility, adding significant annual TMP-equivalent output to support growing demand for paints, lacquers, synthetic lubricants, and polyol intermediates. BASF SE announced process enhancements at its Ludwigshafen site, improving yield efficiency and reducing specific energy consumption, a move that reinforces the importance of integrated production economics in specialty chemical manufacturing. Meanwhile, LANXESS AG implemented a substantial global price adjustment in early 2026, reflecting the compounding effect of elevated energy and raw material costs on producer margins. These events are not isolated; they form part of a broader pattern in which manufacturers balance volume growth, cost discipline, and regional supply commitments.
Our full competitive analysis maps each major participant's operational footprint, product grade emphasis, and recent strategic actions, then contextualizes them within regional supply balances and procurement preferences. The report deliberately avoids simplistic rankings, instead offering a nuanced assessment of where supplier reliability, technical support, and formulation compatibility will determine long-term contract outcomes.
Demand-Side Drivers and Application Evolution
TMP demand is shaped by a combination of volume-driven applications and specification-sensitive use cases. Polyurethane systems and performance coatings remain central demand anchors, but the composition of that demand is shifting. Formulators are increasingly prioritizing waterborne systems and low-emission architectures, driven by regulatory pressure and buyer sustainability expectations. These formulation transitions influence not only how much TMP is required, but also the grade consistency, purity thresholds, and technical assistance that downstream buyers expect from suppliers.
Trimethylolpropane (TMP) Market
Coatings applications continue to represent a substantial share of consumption, with industrial, automotive, and construction segments each exhibiting distinct growth rhythms. Polyurethane-related usage similarly spans multiple industrial pathways, from elastomers and sealants to specialty foam systems and synthetic lubricant intermediates. The report breaks down how these application landscapes interact with regional manufacturing capacity and feedstock procurement patterns, allowing readers to identify where incremental volume is most likely to materialize and which grade specifications will command premium positioning. Rather than presenting static application splits, our analysis evaluates how substitution risk, formulation innovation, and regulatory adaptation will reshape demand intensity over the forecast period.
Trimethylolpropane Trioleate Market
Regulatory Pressure, Feedstock Economics, and Pricing Sensitivity
The operational environment for TMP producers and consumers alike is increasingly defined by intersecting regulatory and raw-material dynamics. In Europe, evolving VOC directives have tightened emission thresholds, raising compliance costs for coating producers and accelerating adoption of waterborne formulations that rely more heavily on TMP-based architectures. At the same time, EU deforestation-related scrutiny and REACH compliance frameworks have intensified due diligence requirements for imported material, particularly affecting procurement strategies that depend on Chinese-origin supply. These regulatory layers do not merely add administrative overhead; they alter lead-time expectations, qualification cycles, and the relative attractiveness of regional sourcing alternatives.
Raw-material conditions have equally influenced market behavior. Feedstock inputs such as formaldehyde and n-butyraldehyde remain central to production economics, and their cost trajectories directly affect manufacturer pricing decisions. Recent price movements in Northeast Asia reflect this sensitivity: benchmark levels moved upward between late 2025 and early 2026, supported by steady demand from alkyd resins, polyurethane coatings, and synthetic lubricants. Producers have responded with selective price adjustments, while buyers weigh the trade-off between spot exposure and longer-term contractual stability. Our report examines these dynamics through a structured lens, separating short-term price noise from structural cost drivers, and identifying where procurement teams can best position themselves against volatility.
A critical element of the analysis is the interplay between compliance-driven formulation changes and price acceptance. As end-use industries adapt to stricter environmental standards, certain TMP grades and derivative formats gain functional importance, creating pockets of demand resilience even when broader macro conditions fluctuate. Understanding which applications exhibit this resilience, and which remain exposed to substitution or cost-down pressure, is essential for both producers planning capacity allocation and buyers negotiating supply agreements.
What the Full Report Delivers
The complete PW Consulting market research package extends well beyond the macroeconomic and competitive themes summarized here. Decision-makers who access the full study will find a structured set of analytical tools designed for practical use:
- Historical market sizing and forward projections calibrated across the full forecast horizon, enabling baseline planning and scenario testing
- Regional and application-level market maps that reveal where volume growth, pricing tension, and capacity availability are most likely to converge
- Supplier profiling and competitive positioning analysis that connects operational footprints with recent capacity, process, and pricing actions
- Feedstock, regulatory, and compliance overlays that translate policy and cost developments into procurement and sourcing implications
- Strategic recommendations for capacity planning, contract structuring, grade selection, and regional supply diversification
Each section is built to be referenced directly in board-level discussions, sourcing reviews, and investment committee materials. Rather than offering generic commentary, the report anchors every insight in quantitative structure and verifiable industry movement, allowing stakeholders to move quickly from understanding to action.
Using This Intelligence for 2026 Decision-Making
The 2026 outlook for TMP is not simply a question of whether demand will rise or fall. It is a question of where growth will concentrate, how suppliers will manage cost pass-through, and which procurement strategies will preserve margin and supply continuity in a more regulated, more regionally differentiated environment. Companies that rely on aggregated headlines risk misjudging regional availability, over-committing to single-source supply, or underestimating the cost of compliance-driven formulation transitions.
PW Consulting's research is designed to reduce that uncertainty. By combining historical rigor, forward-looking modeling, and detailed competitive and regulatory context, the study gives strategists, procurement leaders, and product planners a shared factual base for prioritization. Whether the objective is to evaluate new capacity commitments, renegotiate supply contracts, assess regional sourcing shifts, or prepare for emerging compliance requirements, the full report provides the granularity needed to move with confidence.
For executives seeking a complete view of the TMP market through 2032, including detailed segmentation, regional deployment analysis, supplier-level competitive mapping, and scenario-based procurement guidance, the full market research report is available now. Access the comprehensive study to transform high-level market signals into targeted, defensible strategy for the year ahead and beyond.
For detailed analysis of this topic, please visit the official page: Trimethylolpropane (TMP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Butt Fusion Machines Market to Hit $0.29B by 2032, 4.32% CAGR
By PW Consulting, 2026-09-16
Industrial Butt Fusion Machines Market: Strategic Intelligence for 2026 Decision-Making
Navigating a Consolidated Landscape Defined by Precision, Digital Integration, and Material Dynamics
As industrial infrastructure demands continue to prioritize leak-free, high-integrity piping systems, the Industrial Butt Fusion Machines Market remains a critical enabler across utility, energy, and chemical sectors. Our latest market research delivers a comprehensive, forward-looking assessment of this specialized equipment arena, calibrated to guide corporate strategy through 2026 and beyond. The study is structured not merely as a historical retrospective but as a decision architecture that aligns procurement planning, product development, competitive positioning, and geographic expansion with verifiable market mechanics. By synthesizing multi-year historical tracking with a disciplined forecast window through 2032, the report equips executives with the contextual clarity needed to allocate capital, differentiate offerings, and respond to evolving technical standards.
The market’s trajectory reflects a broader industrial shift toward automation, traceable weld documentation, and diameter-flexible machine architectures. Over the historical review period spanning 2020 through 2025, the sector navigated an environment characterized by fluctuating raw material pricing, varying municipal procurement cycles, and the gradual adoption of digitally enabled fusion equipment. This period laid the foundation for a measured, yet structurally positive, growth path. The research captures these dynamics and translates them into actionable frameworks, allowing stakeholders to distinguish between cyclical pricing noise and durable demand shifts.
Macro Trajectory and Forecast Architecture: What 2026 Executes for Long-Range Planning
A core value of this research lies in its disciplined forecast architecture. The study establishes a forecast horizon from 2026 through 2032, anchored against a recent reference year and supported by a consistent historical dataset. Across the projection window, the market is positioned for a compound annual growth rate of 4.32%, signaling a steady and calculable expansion rather than a speculative surge. This level of growth implies that operators, investors, and suppliers must plan with precision: incremental volume gains will depend on successful deployment of advanced machine classes, alignment with regional infrastructure programs, and the ability to navigate raw material cost variability.
The revenue trajectory across the forecast horizon points toward gradual but compounding market scaling, with total industry revenue progressing into a higher range by the close of the decade. For leadership teams, the strategic implication is that timing matters as much as scale. Early positioning in semi-automated and fully automated platforms, along with service and data-recording ecosystems, becomes a differentiator when growth is distributed across a broad equipment continuum rather than concentrated in a single product breakthrough. The report maps this progression in a manner that supports scenario planning, allowing executives to test sensitivity around pricing, adoption pace, and application-led demand without relying on superficial indicators.
Electrofusion Fittings Market
Segmentation Architecture: Understanding Where Value and Volume Converge
A defining feature of the Industrial Butt Fusion Machines Market is its segmentation across multiple operational dimensions. Rather than presenting isolated percentages, the report contextualizes each segment through its functional relevance to buyers and manufacturers. By machine type, the market distinguishes among automatic, semi-automatic, and manual butt fusion equipment. This classification is not simply descriptive; it signals how various end users balance throughput requirements, labor availability, and site conditions. Automatic platforms tend to anchor high-volume industrial deployments where repeatability and weld-record traceability are paramount. Semi-automatic variants address mid-range projects with a need for flexibility and operator oversight, while manual configurations remain relevant for specialized or constrained installations where portability and lower upfront cost dominate purchasing logic.
By application, the research examines how core end-use environments shape equipment requirements and purchasing cycles. Oil and gas operations continue to demand robust fusion solutions for pressure-critical piping, often favoring machines capable of handling larger diameters and ensuring rigorous documentation. Water supply networks depend on reliable fusion for municipal and regional distribution infrastructure, where consistency across long pipeline runs and field serviceability are decisive. Chemical applications place emphasis on material compatibility and welded joint integrity across corrosive or high-purity service conditions. The report details how these application streams influence machine specification, maintenance expectations, and aftermarket service demand, giving suppliers a clearer picture of where operational value is created over the equipment lifecycle.
On the regional front, the study evaluates how geographic demand clusters and infrastructure priorities create distinct market environments. Instead of reducing each territory to a single numeric share, the report analyzes regional demand drivers, competitive intensity, import and distribution patterns, and the role of localized service support. This approach allows readers to understand where equipment demand is likely to be volume-led, where technical customization dominates, and where export-oriented manufacturing strategies may create pricing pressure. In practice, this means stakeholders can better align product portfolios, distribution partnerships, and service footprints with the realities of each region’s procurement culture and infrastructure agenda.
Industrial Butt Fusion Machines Market
Competitive Dynamics: A Focused Field of Specialized Manufacturers
The competitive environment is characterized by a modest level of concentration, reflecting a market where specialized engineering capability, measurement precision, and application-specific reliability remain decisive advantages. The research examines the landscape through the lens of established manufacturers that have built reputations on machine performance, weld documentation, and breadth of pipe material compatibility. These firms span North America, Europe, Asia, and other regions, each competing through differentiated machine architectures, digital integration, and service ecosystems.
Key competitors evaluated in the study include firms such as McElroy Manufacturing, Inc., recognized for premium automatic and semi-automatic butt fusion machines designed for HDPE and PE piping, with digital weld recording capabilities and track-mounted platforms suited for demanding field conditions. Georg Fischer Piping Systems Ltd. is assessed for its automated and portable fusion equipment supporting pressure piping systems across water, gas, and industrial contexts. Ritmo S.p.A. is examined for its emphasis on high-productivity track-mounted and workshop-based machines covering HDPE, PP, and other thermoplastics. Fusion Group Limited contributes to the analysis as a supplier of precision butt fusion equipment for PE pipe and fittings in industrial and municipal projects. Rothenberger USA LLC and Hurner Welding Technology GmbH are reviewed for their manual, semi-automatic, and automatic machine offerings and workshop or on-site solutions for thermoplastics up to large diameters. WIDOS Wilhelm Dommer Söhne GmbH and KraussMaffei Technologies GmbH round out the evaluation as manufacturers of plastic welding machinery and butt fusion systems oriented toward pressure pipe applications. Additional players, including Wuxi Baoda Plastic Pipe Welding Equipment Co., Ltd., SWT Plastic Welding, Leister Technologies AG, Plasson Ltd., Worldpoly Pty Ltd, and Nupi Americas, Inc., are assessed for their contributions to multi-angle, portable, and industrial-grade fusion equipment portfolios. This competitive mapping is designed to provide relative positioning insight, not just product lists, enabling strategic benchmarking around automation levels, diameter coverage, documentation technology, and regional service reach.
Recent Developments and Operational Signals Shaping 2026 Strategy
Market momentum is not driven by forecasts alone; it is continuously reshaped by product launches, trade-channel activity, material cost behavior, and equipment pricing signals. The report integrates recent operational developments to give decision-makers a current picture of how the competitive field is moving. In mid-to-late 2025, new product catalog releases and showcase activity brought renewed attention to hydraulic butt fusion machines for water, gas, mining, and petrochemical applications. Trade show participation and technical demonstrations further illustrate how manufacturers are communicating advanced thermoplastic welding solutions and buyer guidance, reinforcing the importance of visibility and specification support in procurement cycles.
On the materials side, polyethylene pricing behavior remains a relevant variable for machine utilization, project budgeting, and pipe procurement. Recent price movements have reflected shifts in regional supply dynamics and import competition, with European HDPE markets experiencing steady softening in late 2025 due to competitive imports from Asia and the Middle East. These material fluctuations do not change the fundamental demand for fusion equipment, but they do influence project economics and the pace at which operators invest in higher-capacity or higher-automation machines. The report contextualizes such input-cost behavior so that market participants can separate short-term commodity movements from durable equipment demand.
At the equipment level, recent industry signals underscore how pricing ranges and product innovation interact. For example, automatic butt fusion machines in the 315 mm to 630 mm size range were observed at average selling price levels ranging broadly in 2025, reflecting the premium associated with larger-diameter, higher-throughput platforms. This matters because price dispersion across machine classes shapes buyer expectations, financing decisions, and competitive differentiation. Simultaneously, the introduction of independently powered track-mounted machines for large-diameter oil and gas applications demonstrates how manufacturers are expanding machine capability to serve more technically demanding installation environments. The report connects these developments to purchasing logic, showing how feature sets and power architecture affect total cost of ownership and site deployment efficiency.
Report Structure and Practical Content for Executive Use
Beyond high-level market orientation, this research is designed as an operational reference. The report introduces a structured view of segmentation logic, historical performance patterns, and forecast assumptions, allowing readers to interrogate demand drivers rather than simply accept summary figures. It includes detailed discussion of how machine type, application, and regional context interact in real purchasing environments, enabling more precise go-to-market planning and product positioning. The analysis also addresses competitive behavior, including how dominant firms maintain relevance through automation, documentation tools, and service coverage, and where smaller or regionally focused manufacturers can compete on specialization, lead time, or application-specific configuration.
In addition, the study incorporates market concentration indicators to provide a realistic view of competitive structure. With a moderately concentrated field, the research explains the strategic significance of scale, technical reputation, and the ability to support large-diameter or digitally integrated platforms. This is especially useful for companies evaluating partnership opportunities, acquisition targets, import pathways, or regional expansion, because it clarifies where market influence is distributed and where entry barriers remain tied to technical credibility and service reliability. The report’s practical orientation extends to purchase considerations, operational deployment factors, and the ways in which weld-record data and machine control architectures are becoming part of the broader value proposition in industrial piping projects.
Why This Research Matters for 2026 Decisions
The strategic value of this report comes from its ability to convert complex market mechanics into decision-ready intelligence. For manufacturers, it supports product roadmap choices by clarifying where automation, portability, and documentation features are most valued. For distributors and service providers, it highlights where regional demand patterns and machine-class preferences create opportunities for targeted inventory, training, and field support. For investors and corporate planners, it offers a forecast-consistent view of how the market is likely to expand and where competitive advantage will be earned through differentiation rather than volume alone.
By maintaining a disciplined balance between macro trajectory and operational detail, the study helps stakeholders avoid overreliance on fragmented indicators and instead base decisions on a connected understanding of type, application, region, and competitive behavior. It also prepares readers to interpret raw material movements, equipment pricing dispersion, and product launch activity as part of a larger market system rather than isolated events.
Accessing the Full Strategic Intelligence
This introduction outlines the scope and analytical direction of the research, but the complete dataset, scenario framing, and detailed segmentation discussion reside in the full report. To obtain the comprehensive market intelligence needed for precise 2026 planning across equipment strategy, regional deployment, competitive benchmarking, and demand forecasting, readers are encouraged to access the complete report directly through the source page. The full version delivers the depth required to convert market awareness into executable corporate strategy.
For detailed analysis of this topic, please visit the official page: Industrial Butt Fusion Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Family Entertainment Market Hits $182.3M in 2025, 5.45% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Future of Family and Indoor Entertainment: Navigating the 2026 Landscape
The global Family/Indoor Entertainment Centres market stands at a pivotal inflection point as we move through 2026. Against a backdrop of shifting consumer priorities, rising operational costs, and aggressive physical expansion by market leaders, strategic clarity is no longer optional. This newly released market research report delivers a comprehensive, data-driven foundation for decision-makers operating in or adjacent to the family entertainment ecosystem. By synthesizing historical performance, forward-looking projections, competitive intelligence, and operational benchmarks, the study equips executives, investors, and site-selection teams with the analytical rigor required to allocate capital, design experiential offerings, and defend market share in an increasingly crowded arena.
The sector has demonstrated remarkable resilience over the past half-decade. Drawing on verified historical records and carefully modeled trajectories, the market has evolved from a baseline of approximately $145.35 million in 2020 to a projected $182.3 million in 2025. The forward window extends through 2032, with revenue forecasts charting a steady climb toward $262.7 million by the terminal year. This expansion is underpinned by a compound annual growth rate of 5.45 percent across the forecast horizon, a figure that reflects sustained demand for structured, family-oriented leisure experiences even as discretionary spending patterns continue to recalibrate. The trajectory underscores a fundamental truth: experiential entertainment is transitioning from a discretionary luxury to a normalized component of household recreation budgets.
Macro Market Trajectory and Growth Architecture
Understanding the shape of this growth requires more than headline numbers. The report dissects the revenue curve across multiple temporal layers, beginning with the historical reconstruction from 2020 through 2025 and extending into a granular forecast spanning 2026 to 2032. Each year is contextualized within broader economic signals, seasonal visitation patterns, and capital deployment cycles. The analysis reveals that momentum is not evenly distributed; rather, it concentrates around specific operational models, geographic clusters, and experiential formats that consistently outperform peer configurations. By isolating the structural drivers behind the 5.45 percent CAGR, the study enables stakeholders to distinguish between temporary cyclical strength and durable secular expansion.
Revenue projections are anchored to realistic assumptions about foot traffic, per-visit spend, and operational scalability. Internal benchmarks indicate that families typically allocate between $12 and $22 at individual location-based entertainment venues, with an average spend nearing $25 when admission, gaming, food and beverage, retail, and equipment rentals are combined. This per-transaction economics framework is critical because it exposes the leverage points where design, pricing, and ancillary monetization converge. The report maps these dynamics across the forecast period, allowing operators to model sensitivity scenarios around ticket pricing, promotional cadence, and ancillary attach rates without relying on broad industry averages that obscure site-level reality.
Consumer Experience Drivers and Behavioral Segmentation
The heart of the family indoor entertainment proposition lies in how guests experience the venue. The research categorizes consumer engagement through experience intensity, revealing a clear hierarchy in how different guest profiles translate into revenue and loyalty. Full-experience environments, which integrate multi-attraction layouts, sustained dwell time, and comprehensive dining or retail components, command the largest share of market value. Half-experience configurations, which balance active play with selective amenities, represent a substantial secondary tier, while no-experience or entry-level formats capture a smaller but strategically relevant segment of the market.
Parallel to experience depth, the report examines attitude-driven demand. Consumer sentiment clusters into highly interested, interested, and not interested cohorts, each requiring distinct site design, marketing messaging, and operational pacing. The highly interested segment drives repeat visitation and word-of-mouth amplification, while the moderately interested group responds strongly to seasonal programming, group bookings, and value-added passes. By aligning venue architecture and promotional calendars with these behavioral strata, operators can avoid the common pitfall of designing for an undifferentiated mass audience and instead engineer experiences that convert interest into recurring revenue.
Regional demand patterns further shape the opportunity set. Market value is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with each geography presenting distinct visitation frequency norms, labor cost structures, and competitive density. The analysis does not treat these regions as monolithic blocks; instead, it examines how local consumption habits, real estate economics, and regulatory environments interact with the core entertainment model. For instance, North American households tend to visit family entertainment centers three to five times per year, prioritizing shared experiential leisure over material goods. This frequency baseline becomes a critical input for staffing models, inventory planning, and loyalty program design.
Competitive Landscape and Strategic Positioning
The competitive architecture of the sector is defined by a mix of highly scaled incumbents and regionally focused challengers, all competing on experience density, brand recognition, and operational efficiency. Dave & Buster's, headquartered in Coppell, Texas, has built a formidable presence through large-scale indoor entertainment centers that combine extensive arcade gaming, full-service dining, sports bar environments, and family-oriented attractions across North America. Its recent expansion cadence, including a major new location in King of Prussia, Pennsylvania, opened in May 2026 with over 100 arcade games, integrated dining, and the creation of 150 new jobs, signals a deliberate strategy of market deepening and brand reinforcement in high-traffic suburban corridors.
Urban Air Adventure Parks, based in Bedford, Texas, pursues a distinctly active-play orientation. Its indoor adventure parks center on climbing walls, trampoline networks, inflatable features, and structured active play zones designed to attract families seeking physical engagement rather than passive entertainment. The company's continued footprint growth, including a newly signed lease for an Owings Mills, Maryland facility expected to open in early 2027, reflects confidence in the durability of motion-centric family experiences and the willingness of consumers to pay for structured activity-based leisure.
Chuck E. Cheese, also headquartered in Irving, Texas, maintains its status as an iconic family entertainment brand by fusing arcade gaming, pizza dining, and birthday party venues into a tightly integrated experience model. Its May 2026 product launch introduced ten new arcade games alongside a 2026 Summer Fun Pass offering unlimited visits, a move that underscores the brand's focus on repeat engagement, seasonal campaign alignment, and family-centric programming. Main Event Entertainment, located in Coppell, Texas, competes through multi-activity indoor centers that layer bowling, laser tag, arcade games, and team-building experiences into a single destination. Its expansion pipeline, including a new Huntsville location unveiled in May 2026, a Brownsville center planned for July 2026, and a Greensboro grand opening, illustrates a methodical approach to geographic penetration and multi-attraction differentiation.
Scene75 Entertainment Centers, operating from Dayton, Ohio, rounds out the competitive field with large indoor venues that combine go-karts, laser tag, arcade gaming, bouncing areas, and full dining under one roof. This breadth of offering positions Scene75 as a destination-style player that competes on variety and dwell time. Collectively, these companies illustrate the spectrum of operational philosophies currently shaping the market, from arcade-and-dining dominance to active-play specialization and multi-activity integration.
Market Concentration and Structural Efficiency
A critical dimension of strategic planning is understanding how concentrated the market truly is and what that implies for new entrants, site acquisition, and competitive response. The report quantifies concentration through standard industry metrics, revealing that the top three players account for approximately 26.5 percent of market revenue, while the top five capture roughly 34.2 percent. This moderate concentration indicates a fragmented landscape with room for regional leaders and well-executed niche concepts, but it also signals that scaled operators retain meaningful advantages in purchasing power, brand recognition, and multi-site operational learnings.
The concentration profile has direct implications for capital deployment. Operators evaluating expansion must weigh the benefits of scale-driven cost efficiencies against the risks of market saturation in established corridors. The study provides a framework for assessing whether a given submarket is dominated by a single experiential format or remains open to differentiated concepts. By mapping concentration patterns alongside regional demand intensity, the report helps decision-makers identify corridors where competitive white space still exists and where brand positioning can be established before saturation intensifies.
Family/Indoor Entertainment Centres Market
Operational Economics and Profitability Levers
Operational discipline separates sustainable operators from those that chase foot traffic without securing margin. Industry benchmark data continues to show that employee payroll represents the largest expense category for family entertainment centers, making labor scheduling, cross-training, and peak-hour staffing efficiency central to profitability. The report integrates these cost realities into its strategic analysis, demonstrating how venue layout, attraction mix, and service design directly influence labor intensity per guest hour. Venues that optimize throughput without sacrificing experience quality consistently outperform peers on margin, even when facing similar revenue levels.
Profitability benchmarks further contextualize the operating environment. Approximately one-third of facilities report revenue exceeding $1 million, with an average profit margin of 14.8 percent across the sector. These figures are not aspirational; they are achievable outcomes of disciplined site selection, pricing architecture, and operational orchestration. The research breaks down how ancillary revenue streams, group bookings, birthday party packages, and seasonal promotions contribute to margin expansion, enabling operators to move beyond top-line growth and focus on value capture. By aligning labor models with visitation patterns and designing pricing structures that protect attach rates, operators can convert per-visit spend into durable profitability.
Party Costumes Market
What the Full Research Delivers
This report is engineered for execution, not observation. It provides a structured intelligence package that translates market dynamics into actionable planning inputs across strategy, operations, finance, and expansion functions. The full document includes:
- A complete historical reconstruction and forward forecast with year-by-year revenue trajectories, enabling scenario modeling under multiple demand and cost assumptions.
- Experience-level and attitude-level segmentation analysis that maps guest engagement intensity to revenue contribution, visitation frequency, and operational design requirements.
- Regional demand distribution and competitive density profiling that supports site selection, market entry timing, and format localization decisions.
- Competitive profiling of leading operators, including business model differentiation, recent expansion and product-launch activity, and strategic positioning cues.
- Operational benchmark integration covering labor cost structures, revenue thresholds, profit margin ranges, and per-visit spend dynamics that inform pricing, staffing, and ancillary monetization strategies.
- Market concentration metrics and structural readouts that clarify scale advantages, fragmentation risk, and the conditions under which new concepts can achieve defensible positioning.
- Actionable strategic recommendations for capital allocation, experiential design, promotional cadence, and geographic expansion sequencing through the 2032 horizon.
Each section is designed to feed directly into planning cycles. The historical reconstruction anchors expectations, the forecast window supports budgeting and expansion scheduling, the segmentation analysis guides venue architecture and marketing targeting, and the competitive and concentration readouts inform positioning and risk assessment. Together, these components create a decision-ready intelligence platform rather than a passive market summary.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment demands more than intuition. Consumer habits continue to favor shared experiential leisure, but families are also more deliberate about where they allocate limited discretionary budgets. Operators that succeed will be those that design for repeat engagement, manage labor intensity intelligently, and position their offerings against clearly defined competitive alternatives rather than against an abstract market average. The report's combination of macro trajectory, segmentation depth, competitive tracking, and operational benchmarking provides the evidentiary base required to make those choices with confidence.
For executives, the study functions as a strategic compass. It clarifies where growth is structurally supported, which experiential formats align with high-intent guest segments, how labor and ancillary revenue interact to shape margin, and where competitive concentration leaves space for differentiated concepts. For investors and corporate development teams, it offers a disciplined framework for evaluating expansion timing, site economics, and brand positioning in a market that rewards operational precision as much as creative concepting.
Conclusion
The Family/Indoor Entertainment Centres market is expanding along a measurable, multi-year trajectory, but the opportunity is not uniformly accessible. Success in 2026 and beyond will belong to organizations that translate market data into operational design, pricing strategy, staffing models, and expansion sequencing. This research report exposes the underlying architecture of that opportunity, from historical performance and forward forecasts to experience segmentation, competitive behavior, and concentration dynamics. It is built to support real decisions: where to invest, how to design, whom to target, and how to sustain margin in a competitive, labor-sensitive environment.
The complete analysis, including the full dataset, segmentation breakdowns, regional profiles, competitive tracking, and strategic recommendations, is available through the full report download. Stakeholders seeking to align their 2026 planning with a rigorous, forward-looking market view are encouraged to access the complete intelligence package and integrate its findings into capital allocation, site strategy, and experiential design decisions.
For detailed analysis of this topic, please visit the official page: Family/Indoor Entertainment Centres Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Building Market Hits $111B in 2025, Projected to Reach $298.3B by 2032 at 15.2% CAGR
By PW Consulting, 2026-09-16
Unlocking the 2032 Horizon: Strategic Intelligence for the Smart Building Revolution
The trajectory of the global commercial real estate and infrastructure sectors has fundamentally shifted. As we move through 2026, the smart building market is no longer a niche segment of facility management but a central pillar of corporate sustainability, operational efficiency, and tenant experience strategies. For C-suite executives, investors, and industry stakeholders, understanding the velocity and direction of this transformation is critical for capitalizing on emerging opportunities and mitigating regulatory risks.
PW Consulting has synthesized extensive primary and secondary research to deliver a comprehensive Smart Building Market study, covering the historical performance from 2020 through 2025 and providing a robust revenue forecast from 2026 to 2032. This article serves as a strategic overview of the intelligence contained within our latest report, demonstrating why this analysis is an indispensable tool for navigating the next seven years of market evolution.
The numbers tell a compelling story of rapid acceleration. From a market size of US 46.0 Billion in 2020, the industry has expanded dramatically to reach an estimated US 111.0 Billion in 2025. This growth underscores the pent-up demand and the urgent adoption of automation technologies following the global shifts in work patterns and energy consciousness over the past few years. As we look forward, the momentum shows no signs of slowing. The total market revenue is projected to cross the US 130.12 Billion mark in 2026, continuing its ascent toward a transformative milestone of nearly US 298.3 Billion by 2032.
Driving this expansion is a compound annual growth rate (CAGR) of 15.2 percent over the forecast period. For strategy teams, this metric signals that smart building technologies are entering a phase of mainstream maturity where scale becomes as important as innovation. However, raw market size and growth rates are only the starting point. The true value of the PW Consulting study lies in decoding the underlying dynamics, competitive pressures, and technological standards that will determine which players thrive and which are left behind in this hyper-competitive environment.
The Anatomy of Market Acceleration
The surge from 2020 to 2025 was characterized by a rapid digitalization of building operations, driven by the need for remote monitoring, energy cost volatility, and heightened occupant health expectations. The jump from US 76.01 Billion in 2023 to US 91.93 Billion in 2024, followed by the breakout to US 111.0 Billion in 2025, reflects a decisive market shift. Organizations are moving beyond pilot projects to enterprise-wide deployments.
Looking ahead to the 2026-2032 forecast horizon, the growth trajectory suggests a market that is consolidating around integrated platforms. The revenue jump from US 130.12 Billion in 2026 to US 149.86 Billion in 2027, and the subsequent climb to US 224.76 Billion by 2030, indicates that adoption will deepen across diverse building portfolios. By 2032, when the market is anticipated to reach US 298.3 Billion, the definition of a smart building will have expanded to encompass fully autonomous energy management, predictive maintenance ecosystems, and seamless occupant interaction layers. Our analysis deconstructs these phases to identify the inflection points where investment yields the highest return.
Segmentation Insights and Strategic Allocation
While the aggregate market figures provide the macro context, the allocation of revenue across different dimensions reveals where the battle for market share is being fought. Our research dissects the market into key components, building types, and geographic regions to highlight concentration and opportunity.
A significant majority of current market activity is concentrated within the Solutions segment, accounting for the lion's share of revenue generation compared to Services. This dominance indicates that the market is prioritizing software platforms, automation engines, and integrated control systems over standalone consulting or maintenance services. The value is shifting toward intellectual property and scalable digital products. However, our report also provides a granular look at how the services component is evolving, particularly in areas such as integration support and lifecycle management, which remain essential for successful deployment.
In terms of building typologies, the market is no longer solely dominated by one sector. Commercial properties continue to drive substantial volume, reflecting the high density of enterprise deployments. Yet, residential and industrial applications are emerging as high-growth vectors. The residential segment is seeing a wave of upgrades driven by consumer demand for energy efficiency and home automation, while the industrial sector is leveraging smart building controls for safety, compliance, and operational resilience. Our study quantifies the interplay between these segments, helping clients identify cross-sector synergies and market gaps.
Building Management System Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains a powerhouse of adoption, fueled by mature infrastructure and strong enterprise investment. Europe is undergoing a regulatory-led transformation, while Asia Pacific presents rapid urbanization and digital leapfrogging opportunities. Latin America and the Middle East and Africa represent emerging frontiers with distinct growth drivers. The report avoids superficial generalizations, offering a nuanced view of regional maturity levels, investment climates, and specific adoption barriers that vary by location. By understanding these regional weights, multinational corporations can tailor their market entry or expansion strategies with precision.
Competitive Landscape: Titans and Disruptors
The smart building ecosystem is populated by a mix of established industrial giants, technology enablers, and specialized innovators. Market concentration data reveals that a core group of players holds significant sway, with the top three competitors collectively commanding more than half of the market revenue, while the top five extend their influence further. This level of concentration suggests that while barriers to entry exist, competitive intensity remains high as incumbents vie for dominance in platform ecosystems.
At the forefront of this landscape are companies that have built comprehensive portfolios spanning hardware, software, and analytics. Siemens AG continues to leverage its integrated building automation capabilities, utilizing platforms like Desigo CC and Building X to unify HVAC, lighting, security, and fire systems. Their focus on energy optimization and remote control positions them as a critical partner for large-scale infrastructure projects. Similarly, Johnson Controls International plc has reinforced its leadership through the OpenBlue smart building platform and Metasys building management system, integrating AI-driven analytics and cloud services to drive portfolio optimization and enhance occupant experience.
Schneider Electric SE contributes to the competitive fray with its EcoStruxure Building Operation platform, offering integrated control across HVAC, power, lighting, and access for commercial and campus buildings, backed by BACnet certification to ensure interoperability. ABB Ltd. counters with its ABB Cylon and i-bus KNX platforms, focusing on building automation, energy management, and HVAC controls, while also exploring integration opportunities within broader smart ecosystems such as SmartThings.
The landscape also includes major technology and industrial players adapting their core competencies to the built environment. Honeywell International Inc. is deploying AI and IoT solutions for predictive maintenance, security, and energy optimization, adding a layer of intelligence to traditional building controls. Cisco Systems, Inc. provides the foundational networking infrastructure and cybersecurity solutions necessary to support connected smart building systems and the proliferation of IoT devices, recognizing that connectivity is the backbone of the smart building. IBM Corporation brings its strength in cloud computing, AI, and analytics to building management, offering predictive insights that transform raw data into actionable strategy.
Regional and specialized players are also making their mark. Hitachi, Ltd. focuses on automation and control systems tailored for energy management and environmental monitoring, addressing the growing need for sustainability in Asian and global markets. Legrand SA rounds out the competitive field with its expertise in electrical installation and smart building solutions, delivering value through lighting, access, and automation technologies that enhance both functionality and user experience.
Recent developments illustrate how these companies are competing for mindshare and wallet share. In April 2025, Johnson Controls released a commissioned Forrester study quantifying up to 155 percent ROI and 10 percent energy savings from its OpenBlue platform across a composite customer model. This type of evidence-based marketing underscores the industry's shift toward demonstrating tangible financial returns to justify capital expenditures. Our report analyzes such developments to help clients benchmark vendor claims against market realities.
Regulatory Tailwinds and Industry Standards
The smart building market is operating within a dynamic regulatory environment that acts as both a catalyst and a constraint. In Europe, the revised Energy Performance of Buildings Directive (EU/2024/1275) entered into force on 28 May 2024, with a transposition deadline of 29 May 2026 for EU countries. This directive mandates significant improvements in building energy efficiency and promotes the deployment of building automation and control systems (BACS). Furthermore, EU countries are required to submit draft national building renovation plans by 31 December 2025 and final plans by 31 December 2026. The European Commission's adoption of a support package offering practical guidance to EU countries for transposing these requirements, including specific BACS mandates, signals a tightening regulatory framework that will drive demand for compliant solutions.
The industry is also responding to the need for harmonization and interoperability. Standardization efforts such as CEN/TR 18081:2024 specify the requirements of hardware and functions for products and systems for the control and management of HVAC in smart building automation. This standard, alongside the development of open international standards like KNX, LonWorks, and BACnet for BACS, is crucial for ensuring interoperability in smart building systems. As noted in recent academic research, these standards mitigate the risk of vendor lock-in and facilitate the integration of multi-vendor environments. Our study evaluates the impact of these regulatory and standardization trends on market growth, procurement cycles, and technology selection criteria.
Why This Study Matters for 2026 Decision-Making
In an era of information overload, clarity and actionable intelligence are the ultimate competitive advantages. The PW Consulting Smart Building Market report is designed for decision-makers who require more than high-level estimates. It provides a detailed map of the market landscape, enabling stakeholders to:
- Identify high-growth segments and geographic regions where investment can yield superior returns.
- Understand the competitive positioning of key players and anticipate shifts in market share.
- Align product development and go-to-market strategies with regulatory timelines, such as the EU building renovation plan deadlines and BACS requirements.
- Evaluate the financial impact of technologies by referencing independent studies and industry benchmarks.
- Navigate the complexities of interoperability and integration by leveraging insights on standards like KNX, BACnet, and CEN/TR 18081.
Our forecast model is built on a rigorous methodology that accounts for historical performance, current market indicators, and forward-looking variables. The revenue projections from 2026 to 2032 are not merely extrapolated trends but reflect a deep understanding of the drivers, restraints, and opportunities that will shape the industry. For investors, this means a clearer view of valuation metrics and risk factors. For technology vendors, it means validated demand signals for R&D prioritization. For facility owners and operators, it means a roadmap for phased modernization that aligns with budget cycles and compliance mandates.
The market concentration data, showing significant revenue held by leading players, also highlights the importance of differentiation. New entrants and established players alike must find unique value propositions, whether through superior analytics, niche application focus, or unbeatable integration capabilities. Our report includes profiling of key companies, detailing their core offerings, strategic moves, and areas of focus, providing a reference point for competitive analysis and partnership opportunities.
Smart Building Market
Conclusion: Your Gateway to Market Mastery
The smart building market stands at the intersection of technology, sustainability, and urban development. With projections pointing to a near tripling of market size by 2032, the decisions made in 2026 will have lasting implications for portfolio performance, operational resilience, and brand reputation. The PW Consulting Smart Building Market study offers the comprehensive intelligence needed to navigate this complex terrain with confidence.
We invite you to explore the full depth of our research. The complete report contains detailed segmentation data, competitive benchmarking matrices, regional analysis, and strategic recommendations that go beyond the scope of this overview. Don't rely on fragmented insights; equip your organization with the authoritative data and strategic context required to lead in the smart building era. Access the full report to unlock the detailed intelligence that will define your success over the next seven years.
For detailed analysis of this topic, please visit the official page: Smart Building Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Pruning Shears Market Hits $215M in 2025, Poised for 5.2% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Green Cut: Strategic Imperatives in the Global Electric Pruning Shears Market Through 2032
The agricultural and landscaping equipment sectors are undergoing a profound transformation, driven by the urgent need for operational efficiency, labor optimization, and sustainability compliance. At the forefront of this shift is the Electric Pruning Shears Market, a segment that has evolved from a niche innovation to a critical component of modern horticultural management. Our latest market intelligence report offers a comprehensive roadmap for stakeholders aiming to capitalize on the projected growth trajectory spanning from 2026 to 2032. As enterprises allocate capital for the upcoming fiscal year, understanding the nuanced dynamics of this market is no longer optional—it is a strategic necessity.
Market Trajectory and Growth Outlook
The financial footprint of the electric pruning shears market has demonstrated consistent resilience and expansion over the past half-decade. Our analysis tracks the market journey from a robust baseline in 2025, with readings hitting approximately 215.0 Million USD in base year revenue. This establishes a solid foundation for the forecast period extending through 2032, where the market is anticipated to reach significantly higher valuation milestones, crossing the 340 Million USD threshold by the end of the forecast window.
This upward trajectory is underpinned by a Compound Annual Growth Rate (CAGR) estimated at 5.2% over the forecast horizon. Such growth signals more than just incremental improvement; it indicates a structural shift in how pruning tasks are executed across both commercial and residential sectors. For enterprise leaders, this 5.2% CAGR represents a stable yet dynamic environment where early movers can secure significant market share before saturation occurs in mature segments. The historical data from 2020 to 2025 reveals a pattern of steady acceleration, suggesting that the drivers of demand are systemic rather than cyclical, rooted in technological adoption and regulatory pressure.
Key Growth Catalysts
Several intrinsic factors are fueling this expansion. First, the rigorous labor constraints in agriculture and landscaping have made efficiency a priority, pushing operators toward high-performance electric solutions that offer precision and reduced physical strain. Second, the push toward sustainability and organic farming practices aligns perfectly with the low-impact nature of electric pruning tools, which often complement broader environmental compliance strategies. Third, advancements in battery technology and motor efficiency have addressed earlier concerns regarding runtime and power, making these tools viable for extended professional use. These converging trends create a fertile ground for sustained investment and product development.
Detailed Segmentation Analysis and Market Drivers
Our report dissects the market into critical dimensions that influence purchasing decisions and product development roadmaps. By categorizing the market through type, application, and geography, we provide clients with the granularity needed to refine their strategic positioning without exposing every tactical detail in the summary view. The segmentation data reveals distinct preferences that vary by use case, highlighting where value is being generated and where competitive intensity is highest.
In terms of product type, the market shows a clear divergence between cordless and corded options. Cordless electric pruning shears currently command a significant portion of the market, reflecting the industry's strong preference for mobility, reduced noise, and ease of use in diverse terrains. Corded models remain relevant in specific stationary or high-power applications, but the momentum clearly favors wireless convenience. This shift is not merely about convenience; it is about enabling workflows that were previously impractical with tethered equipment. The adoption of brushless motor technology has further enhanced the appeal of cordless units, offering longer life and higher efficiency.
When examining applications, the data underscores the dominance of high-value agricultural sectors. Vineyards and orchards represent the primary demand centers, where precision cutting is essential for yield optimization and plant health. These sectors demand tools capable of handling substantial branch diameters while maintaining ergonomic standards for prolonged use. Landscaping follows as a significant secondary application, driven by residential and commercial grounds maintenance needs. Each segment presents unique requirements regarding cut capacity, battery life, and durability, and our analysis maps these requirements against available product offerings to identify gaps and opportunities.
Geographically, market distribution reflects the varying stages of technological adoption and economic activity across regions. Certain established markets demonstrate higher penetration rates, while emerging regions exhibit rapid growth potential as infrastructure and awareness improve. Understanding these regional nuances is vital for companies planning export strategies or localized manufacturing. The report provides context on how regulatory environments, labor costs, and agricultural practices differ by region, influencing the rate of adoption for electric pruning tools.
Technology and Product Advancement Trends
The competitive landscape is being reshaped by continuous innovation in core technologies. Lithium-ion battery advancements have been a game-changer, extending runtime to six to ten hours per charge in professional models while keeping tool weights under 800 grams. This improvement directly addresses one of the historical barriers to adoption: battery anxiety and user fatigue. Furthermore, the integration of smart features is beginning to emerge, with some manufacturers exploring connectivity options that allow for performance monitoring, battery health tracking, and user customization via mobile applications. These technological leaps are raising the bar for what constitutes a competitive product, pushing the entire market toward higher standards of performance and user experience.
Competitive Landscape and Strategic Initiatives
The market features a diverse array of players, from specialized Swiss precision manufacturers to global power tool giants and value-oriented brands. Our report delves deep into the profiles, capabilities, and strategic moves of key competitors, including Felco SA, STIHL Group, Makita Corporation, Worx, DeWalt, RYOBI, Craftsman, and Pellenc SA. Understanding the positioning of these entities is critical for assessing threat levels, identifying partnership opportunities, and benchmarking product development efforts.
Felco SA continues to lead in the niche of high-precision electric pruning shears, leveraging its heritage of iconic designs. The company recently unveiled the FELCO 2e electric successor to its legendary model, featuring patented CUT SHIELD technology and enhanced battery efficiency. This release reinforces Felco's commitment to precision and durability, targeting users who demand the highest standards of cutting performance and reliability. Similarly, STIHL Group has maintained its aggressive posture in the cordless battery pruning segment. At CES 2026, the company launched the GTA 30 battery-powered pruner, boasting 400W cutting power tailored for residential and DIY applications. This launch expands STIHL's reach beyond professional arborists into the consumer and light commercial markets, demonstrating a strategy of capturing demand across multiple user tiers.
Makita Corporation has also made significant strides with its 18V LXT brushless cordless pruning shears. The introduction of the DUP181Z brushless pruning shear in the 18V LXT line underscores Makita's focus on high-efficiency precision cutting, appealing to professionals who require seamless integration with existing battery ecosystems. This ecosystem lock-in strategy is a common theme among major tool manufacturers, and our analysis examines how it influences customer retention and competitive dynamics. On the value side, brands like Worx and RYOBI are competing with lightweight, affordable options. Worx focuses on its 20V PowerShare brushless pruning shears, emphasizing ergonomic, one-handed operation for branch trimming. RYOBI leverages its 18V ONE+ HP brushless line for quick, trigger-powered cutting of light pruning tasks, targeting users who prioritize ease and versatility.
DeWalt and Craftsman round out the competitive field with robust offerings designed for durability and high capacity. DeWalt's 20V MAX cordless pruning shears, such as the DCPR320 series, advertise high cut counts per charge, positioning the brand for shrub trimming and branch clipping applications. Craftsman's V20 cordless pruning shears offer substantial cut capacity and reliable performance, appealing to general contractors and serious DIY enthusiasts. The presence of these well-funded brands introduces intense price and feature competition, pressuring smaller players to differentiate through specialization or superior service. Additionally, specialized players like Pellenc SA have commercialized advanced series, such as the C3X series with integrated batteries and NFC connectivity, signaling a trend toward smart, connected tools in the professional segment.
Regulatory and market alerts also shape the competitive environment. Recent product safety alerts, such as the recall issued for Moore Electric Pruning Shears, highlight the importance of quality control and compliance. For market participants, these events serve as reminders of the risks associated with supply chain vulnerabilities and the necessity of rigorous testing. Companies that can maintain high safety standards and avoid such pitfalls can leverage compliance as a competitive advantage, building trust with institutional buyers and risk-averse procurement teams.
Regulatory Tailwinds and Macro-Economic Factors
Beyond product and competitive factors, the market is heavily influenced by regulatory frameworks and macro-economic conditions that are reshaping demand. In Europe, the EU Farm to Fork Strategy targets 25% organic farming by 2030, a policy directive that drives the adoption of precision, low-impact tools like electric pruning shears in major agricultural nations including France, Germany, Spain, and Italy. This regulatory push encourages farmers to invest in equipment that aligns with organic and sustainable practices, creating a sustained demand stream for compliant tools.
Furthermore, there is a growing regulatory focus on reducing occupational musculoskeletal disorders among agricultural and landscaping workers. This has accelerated the procurement of ergonomic electric pruning shears, as employers seek to mitigate health risks and improve worker retention. The EU Common Agricultural Policy 2023-2027 includes horticultural equipment subsidies that support technology adoption for electric pruning shears, effectively lowering the barrier to entry for many operators. These subsidies not only boost sales volumes but also encourage the transition from manual or gas-powered tools to electric alternatives.
Worldwide Power Shears Market
On the operational side, electric pruning shears are delivering tangible labor savings in commercial orchards and vineyards. Professional models now enable up to 2000+ cuts per charge, significantly reducing the manpower required for pruning tasks and allowing for faster completion of seasonal work. This labor reduction is particularly valuable in regions facing labor shortages or rising wage costs. The combination of subsidy support and demonstrated ROI through labor savings creates a compelling business case for adoption, ensuring that demand is driven by both compliance and economic rationality.
Strategic Conclusion and Recommendations for 2026
As enterprises evaluate their strategic priorities for 2026 and beyond, the Electric Pruning Shears Market presents a landscape rich with opportunity but demanding of careful navigation. The projected growth, anchored by a solid CAGR and supported by favorable regulatory and technological trends, suggests that the market will continue to expand and evolve. However, success will depend on more than just participating; it will require a nuanced understanding of segment-specific needs, competitive differentiation, and the ability to anticipate shifts in consumer and institutional behavior.
For manufacturers, the emphasis should be on balancing innovation with reliability. The market is rewarding products that offer extended battery life, ergonomic design, and sufficient cut capacity, but it is also sensitive to quality and safety standards. Investment in R&D should focus on maintaining competitive edges in battery efficiency, motor performance, and user interface, while ensuring that supply chains remain robust and compliant. For distributors and retailers, understanding the varying needs of application segments—from high-end vineyards to residential landscaping—is essential for inventory optimization and targeted marketing. Partnerships with brands that have strong ecosystem compatibility or unique value propositions may yield strategic advantages.
For agricultural and landscaping businesses, the procurement decision should extend beyond unit price to total cost of ownership, including labor savings, maintenance, and lifecycle durability. The availability of subsidies and the potential for improved worker health outcomes should be factored into the investment rationale. As the market matures, differentiation will increasingly come from service, support, and the ability to integrate tools into broader operational workflows.
This market intelligence report serves as a foundational resource for making informed decisions in this dynamic environment. By providing deep insights into market size, segmentation nuances, competitive dynamics, and regulatory influences, the study equips stakeholders with the knowledge necessary to identify high-potential avenues and mitigate risks. We invite you to explore the full report for a comprehensive analysis, including detailed data tables, forecasting models, and strategic recommendations tailored to specific business objectives. The future of pruning is electric, and those who act with foresight will define the next era of horticultural efficiency.
Electric Pruning Shears Market
For detailed analysis of this topic, please visit the official page: Electric Pruning Shears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: English Language Learning Market to Hit $344.8M by 2032, 6.98% CAGR from $215M in 2025
By PW Consulting, 2026-09-16
Strategic Intelligence for the ELT Sector: Why the 2026 Language Learning Market Report Is Essential for Executive Decision-Making
The English Language Learning market is undergoing a structural transformation that few organizations are equipped to navigate with confidence. Between historical fluctuations and compound growth trajectories, the sector has moved from fragmented experimentation to consolidated demand patterns. For corporate leaders, investors, and institutional strategists operating in 2026, surface-level market headlines are no longer sufficient. What matters is a disciplined reading of how technology adoption, regulatory shifts, learner behavior, and competitive positioning intersect to shape revenue pipelines, product roadmaps, and regional expansion strategies.
PW Consulting has prepared a comprehensive research study designed specifically for decision-makers who require actionable intelligence rather than generic market summaries. This article outlines the strategic architecture of that research, demonstrates how macro-level market dynamics inform 2026 planning cycles, and explains why the granular segmentation, competitive profiling, and scenario-based analysis contained in the full report are critical for organizations seeking durable advantage in a rapidly evolving sector.
The 2026 Market Context: Growth With Complexity
Over the past half-decade, the English Language Learning sector has progressed from a post-pandemic recovery phase into a more mature expansion cycle. The market reached an estimated 205.57 million USD in 2024, advanced to 215.0 million USD in 2025, and is projected to continue its upward path through the 2026-2032 forecast window. This trajectory reflects sustained demand across professional upskilling, academic preparation, migration-driven language acquisition, and enterprise training programs. Yet the headline trajectory alone masks the strategic tensions that matter most to executives.
A compound annual growth rate of 6.98 percent during the forecast period signals healthy expansion, but growth at this pace rarely distributes evenly across products, geographies, or buyer segments. The real strategic question for 2026 is not whether the market is growing, but where value is concentrating, which distribution channels are capturing disproportionate share, and how the mix between institutional procurement and individual self-directed spending is reshaping customer acquisition economics. Organizations that treat the market as monolithic risk misallocating capital toward channels or product formats that may be structurally disadvantaged in the next cycle.
The full research study breaks down these dynamics with a level of segmentation precision that allows leadership teams to distinguish between broad sector tailwinds and specific commercial opportunities. Rather than relying on generalized growth narratives, the report maps how structural demand drivers interact with format preferences, regional purchasing environments, and application-type adoption patterns, giving strategists a practical framework for prioritizing investments and adjusting go-to-market assumptions.
What the Research Delivers: Operational Content for Decision-Makers
This study is constructed as a decision-support instrument, not an academic survey. Its architecture is designed to help executives, product leaders, and market-entry teams answer concrete questions about positioning, resource allocation, and competitive exposure. The report integrates both historical reconstruction and forward-looking scenario analysis so that readers can test strategic assumptions against a range of plausible market outcomes.
The core content areas include:
- A detailed market sizing and trajectory analysis that reconstructs past performance and extends the outlook across the full forecast horizon, enabling leaders to benchmark internal expectations against sector-wide momentum.
- A multi-dimensional segmentation framework that separates the market by region, product type, and end-user application, allowing teams to evaluate where demand is most structurally supported and where growth may be more volatile or contingent on external factors.
- A competitive landscape assessment that profiles major participants, examines their strategic orientations, and identifies how differing business models—digital-first platforms, blended academy models, assessment-driven offerings, and enterprise-focused programs—compete for the same learner pools.
- An analysis of market concentration and consolidation signals, helping stakeholders assess whether the sector is fragmenting toward niche specialization or consolidating around platforms that can combine content, technology, and distribution at scale.
- A regulatory and policy environment review that places recent institutional changes within the broader context of language education governance, student support frameworks, and multilingual service guidance, all of which can influence procurement behavior, compliance requirements, and program design assumptions.
In addition to these structural analyses, the report incorporates recent industry developments that directly affect planning assumptions. Signals ranging from federal administrative adjustments to regional program guidance are evaluated for their potential impact on institutional funding flows, learner demand patterns, and the operating environment for service providers. This contextual layer is essential for organizations that need to anticipate how policy recalibration may alter demand concentration or shift purchasing authority within education and enterprise channels.
The full document is organized to support rapid executive consumption as well as deeper cross-functional alignment. Strategists can use it to pressure-test market-entry theses, product leaders can use it to assess whether existing feature sets align with emerging buyer expectations, and finance teams can use the segmentation structure to refine revenue forecasts with more defensible assumptions about where growth is most likely to materialize.
Competitive Landscape: How Strategic Positioning Is Evolving
The English Language Learning market is contested by a diverse set of players whose strategic postures differ not only in scale but in underlying value propositions. The research evaluates the competitive environment through the lens of commercial model, distribution reach, learner engagement strategy, and institutional vs. individual orientation. This approach matters because competition in the sector is increasingly defined by how effectively companies integrate content quality, technology-enabled personalization, assessment infrastructure, and brand trust across distinct buyer segments.
Several large, established organizations anchor the market with multi-layered offerings that span curriculum, assessment, and proficiency certification. Pearson, based in London, competes through a broad suite of English Language Teaching courseware, assessment services, and proficiency testing solutions that address institutions, governments, and individual learners. Its positioning reflects an orientation toward structured institutional procurement and credibility-driven evaluation tools, making it a relevant benchmark for organizations assessing how assessment and credentialing capabilities influence purchasing decisions.
English Language Learning Market
International immersion and cultural-exchange-focused operators occupy a different strategic space. EF Education First, headquartered in Baar, Switzerland, has built its identity around immersive English programs and cross-cultural learning experiences. Berlitz, operating from the United States, emphasizes immersive instruction built around its signature teaching method, serving individuals, businesses, and government clients. These companies illustrate how experiential and instructor-mediated models continue to compete against purely digital approaches, particularly in segments where outcomes depend heavily on speaking confidence, cultural familiarity, or enterprise credibility.
The digital learning frontier is represented by a cluster of platform-driven companies with distinct user acquisition and engagement strategies. Duolingo, based in Pittsburgh, has popularized mobile and web-based bite-sized lessons that lower the barrier to habitual practice for English and other languages. Rosetta Stone, headquartered in Harrisonburg, Virginia, focuses on immersive computer-assisted learning with speech recognition capabilities that aim to strengthen pronunciation and listening proficiency. Babbel, based in Germany, pursues online subscription-based lessons structured around scientific learning methods for English. Wall Street English, with its base in Italy, differentiates through guaranteed-results course models supported by coaches and teachers, blending digital convenience with human accountability.
In parallel, network-based and infrastructure-oriented providers shape the operational environment for institutions and training centers. inlingua International, headquartered in Switzerland, operates through blended and online language training centers, while Sanako Corporation, based in Finland, focuses on language lab software and hardware that support classroom pronunciation and speaking-skill development. These offerings matter because they influence the technical backbone available to institutions seeking to standardize instruction, track learner progress, and scale language practice in structured settings.
Taken together, these competitive profiles reveal a market in which advantage is increasingly tied to the ability to combine scalable technology with credible outcomes signaling. The research explores how different players are attempting to capture value across the Learner journey—acquisition, practice, assessment, certification, and institutional adoption—and where overlaps in target segments create pressure on pricing, retention, and differentiation. The complete report provides deeper comparisons of business-model resilience, channel dependencies, and the strategic implications of recent product and market developments, without reducing the analysis to simple market-share statements.
Why This Report Matters for 2026 Strategy
Strategic decisions made in 2026 will be judged not by whether they aligned with last year’s assumptions, but by whether they anticipated how the market is reorganizing itself around format preferences, buyer motivation, and regulatory reality. A growth environment of this nature rewards organizations that can distinguish durable demand from temporary hype, and that can identify which customer segments are expanding their willingness to pay for structured learning, assessment, or enterprise-language solutions.
The report is designed to support that kind of judgment. It enables leadership teams to evaluate whether current expansion plans reflect genuine segment traction or simply broad sector optimism. It helps product and operations leaders assess whether their offerings are aligned with the channels and application types that are capturing the most sustainable demand. It also provides investors and corporate strategy teams with a structured way to think about concentration risk, competitive response patterns, and the likelihood that certain subsegments may consolidate faster than others.
Equally important, the research places recent policy and institutional developments in context so that executives can incorporate regulatory uncertainty into scenario planning rather than treating it as an external distraction. Shifts in federal administrative structures, changes in language-access guidance, and state-level adjustments to English learner program frameworks can all influence demand visibility, procurement timelines, and program-design constraints. Organizations that integrate these variables into strategic planning are better positioned to manage risk and identify emerging opportunities before competitors do.
Online Language Learning Market
The full study goes further than the overview presented here. It supplies the segmentation detail, company-level profiling, and forward-looking analysis needed to convert market awareness into concrete action. For teams that require defensible assumptions about where growth is concentrated, which business models are most exposed, and how the competitive field is likely to evolve, the complete research package provides the depth necessary to support board-level discussion, investment committee review, and cross-functional planning cycles.
Conclusion: Moving From Market Awareness to Strategic Precision
The English Language Learning market in 2026 is not simply expanding; it is reconfiguring. Demand continues to grow, but the strategic value of that growth depends on how precisely organizations can interpret segmentation signals, competitive behavior, and policy-driven changes in the operating environment. PW Consulting’s English Language Learning Market research is built to help executives make that interpretation with confidence, offering a structured, evidence-based foundation for decisions that will shape growth, positioning, and resilience over the coming years.
Organizations that want to move beyond high-level market narratives and into the detail that supports concrete strategy should review the complete report. The full analysis provides the segmentation clarity, competitor context, and forward-looking assessment needed to turn market movement into informed strategic action.
For detailed analysis of this topic, please visit the official page: English Language Learning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


