



Category: market research
Color Coated Steel Market: How 4.86% CAGR and Asia Pacific's Lead Redefine Revenue Paths
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Color Coated Steel Market
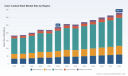
The color coated steel market is navigating a period of structural transition. Between 2020 and 2025, global revenue grew from $183.0 million to $238.0 million, reflecting steady demand across construction, manufacturing, and consumer applications. The trajectory points toward $330.71 million by 2032, implying a compound annual growth rate of 4.86 percent. This expansion is neither uniform nor frictionless. Regional imbalances, regulatory reconfiguration, and material cost volatility are reshaping how value is created and captured across the value chain. For executives and investors, the opportunity lies not in chasing aggregate growth, but in positioning operations and portfolios around the structural forces that will determine competitive advantage over the next five years.
The market remains moderately concentrated, with three firms accounting for roughly 55 percent of revenue and five firms controlling approximately 62 percent. This concentration masks significant fragmentation at the regional and application levels, particularly among processors and fabricators who serve localized construction and industrial demand. The operating environment is also being redefined by policy shifts and material economics that differ sharply across jurisdictions. The following analysis examines the core challenges, demand drivers, competitive dynamics, and emerging trends that will shape strategic decisions in the color coated steel sector.
Market Landscape and Critical Inflection Points
The period from 2020 through 2025 demonstrates resilient demand, but the growth path is uneven. Revenue crossed the $220 million threshold in 2023 before a slight contraction in 2024, followed by recovery in 2025. This pattern reflects the sensitivity of coated steel demand to construction cycles, import policy volatility, and the timing of large project pipelines. The forecast horizon through 2032 indicates that growth will increasingly be driven by application diversification, coating technology upgrades, and regional supply realignment rather than by uniform volume expansion.
Steel Roofing Market
Several structural challenges are converging at once.
- Policy and trade friction are compressing arbitrage opportunities. Tariff escalations and anti-dumping actions are narrowing the traditional cost advantages of cross-border sourcing. Import-dependent supply chains face higher landed costs and greater planning uncertainty, while domestic producers confront both protection and the pressure to justify scale investments.
- Material cost volatility is reshaping margin structures. The zinc galvanizing layer that provides the essential corrosion barrier accounts for approximately 8 to 12 percent of total production cost, with pricing influenced by global commodity exchanges. Fluctuations in zinc and substrate costs directly affect coating economics, especially for producers operating on thin service-center margins.
- Regulatory mandates are accelerating formulation change. Environmental requirements around chromate-free and ultra-low-VOC coating systems are moving from optional best practice to compliance baseline in key markets. This shifts the competitive conversation from price-per-ton to performance durability, compliance documentation, and downstream certification readiness.
These forces are not isolated. Trade policy influences where capacity is built, material costs determine which coating chemistries remain economically viable, and environmental regulations raise the bar for product qualification. The net effect is a market that rewards operators with flexible production systems, transparent compliance records, and the ability to serve application-specific performance requirements rather than generic commodity volumes.
Key Demand Drivers Reshaping the Market
Growth is being pulled by a combination of technology, policy, demand-side behavior, and supply chain economics. Each driver reinforces the others, creating a landscape where differentiation is increasingly tied to capability depth rather than scale alone.
Coating technology and performance differentiation. Advances in resin systems and surface engineering are expanding the addressable use cases for color coated steel. Polyester-based formulations continue to anchor high-volume construction and consumer applications due to cost efficiency and adequate durability. At the same time, higher-performance chemistries are gaining traction where exposure conditions, aesthetic requirements, and service life expectations justify premium pricing. The practical impact is a market that is segmenting by performance tier rather than by commodity classification. Producers who can demonstrate measurable improvements in weather resistance, color retention, and formability are capturing share in application segments where failure costs are high.
Policy and regulatory reconfiguration. Trade and environmental policy are becoming central to competitive positioning. The United States increased Section 232 tariffs on steel from 25 percent to 50 percent in mid-2025, a move intended to reduce import dependence and stimulate domestic capacity investment. In parallel, the European Union's carbon border adjustment mechanism for iron and steel became fully operational at the end of 2025, imposing carbon-related costs on imported products. Brazil's foreign trade authority also announced definitive anti-dumping tariffs in early 2026 on pre-painted steel from India and China, with rates spanning a wide per-tonne range. These measures alter the economics of inter-regional trade and push buyers and suppliers to reconsider sourcing geography, inventory strategy, and contract structures.
Demand-side behavior and application expansion. Construction remains the largest demand anchor, but the character of demand is evolving. Residential and commercial building activity, infrastructure renewal, and retrofit programs continue to support volume, while specification requirements increasingly emphasize durability, corrosion protection, and environmental compliance. Beyond construction, consumer goods and automotive applications provide additional demand layers that value consistent finish quality, weight efficiency, and formability. The presence of multiple application streams reduces dependence on any single cycle and creates opportunities for suppliers who can align coating systems with specific end-use performance criteria.
Supply chain structure and cost dynamics. The cost stack for color coated steel is sensitive to substrate availability, coating raw materials, and energy intensity. The zinc layer, which serves as the critical anti-corrosion component, introduces commodity-linked cost variability. At the same time, regional production footprints are being reassessed in response to tariff and carbon policy. Some operators are prioritizing closer-to-market coil processing and finishing to reduce exposure to trade friction, while others are investing in integrated capabilities to protect margin and improve qualification speed. Supply chain resilience is becoming a commercial differentiator, particularly for buyers who require consistent lead times and documented compliance across multiple SKUs.
Competitive Landscape and Strategic Positioning
The competitive field spans manufacturers, processors, and traders across North America, India, and South Korea, with distinct strategic postures emerging by region and business model. Companies are not competing solely on price; they are competing on qualification breadth, coating system versatility, compliance readiness, and the ability to support downstream fabrication and assembly requirements.
In North America, a group of active manufacturers and processors has built positions around pre-painted and color coated steel coils for construction, building panels, garage doors, and service canopy applications. Several of these firms emphasize specific resin platforms, including PVDF-based systems and weather-resistant polyester coatings, to align with architectural and industrial specification requirements. The regional focus reflects both the tariff environment and the importance of responsive service, short lead times, and localized technical support for fabricators and building product manufacturers.
India hosts a dense set of manufacturers and exporters with varying capacities and coating portfolios. Some operators focus on large-scale production and broad geographic reach, exporting across multiple continents. Others differentiate by offering a wide range of colors, embossed patterns, and coating systems such as RMP, SMP, PU, and PVDF to serve roofing, cladding, and industrial applications. The combination of domestic demand growth and export orientation creates a competitive environment where scale, standard compliance, and coating versatility are key advantages.
South Korean participants include integrated manufacturers and traders offering pre-painted coils and sheets across multiple coating types, including silicon polyester, PVDF, and high-polymer systems. Several firms maintain substantial annual production capacity and emphasize product standards compliance and appliance-grade finish quality. Their positioning reflects the region's strength in process precision and the importance of meeting specification requirements for downstream manufacturers in construction and consumer durable segments.
Across these regions, several strategic patterns are evident.
- Differentiation through coating systems and compliance. Leading participants are building reputations around specific resin platforms, color consistency, and adherence to international standards. This matters because downstream buyers increasingly require documented performance, VOC compliance, and corrosion resistance data as part of procurement decisions.
- Regionalization of supply as a risk management tool. Tariff and carbon policy are encouraging closer alignment between production, processing, and end markets. Operators with flexible regional footprints can reduce exposure to trade volatility and respond faster to specification changes.
- Capacity and qualification as barriers. In segments where reliability, certification, and throughput matter, capacity scale and process control create meaningful barriers. At the same time, niche processors can compete effectively by specializing in high-specification applications or by offering rapid customization for local fabricators.
The market structure suggests continued divergence. Large integrated players will continue to compete on scale, standard compliance, and export reach, while regional processors and specialists will compete on service speed, coating flexibility, and application-specific performance. Consolidation is possible where scale and compliance costs favor larger operators, but fragmentation can persist where localized service and specification support remain critical to winning business.
Forward Outlook: Three Trends to Watch
Looking ahead to the 2026 through 2032 horizon, three trends are likely to shape where value concentrates and where risk accumulates.
Coil Coatings Market
Trade and carbon economics will continue to rewire sourcing maps. The combination of higher steel tariffs in certain markets, operational carbon border mechanisms in others, and targeted anti-dumping actions will keep inter-regional arbitrage under pressure. Over the next few years, buyers and suppliers will likely place greater weight on nearby processing capacity, inventory buffering, and contract structures that can absorb policy variability. For producers, this environment rewards transparency around carbon intensity and the ability to offer compliance-ready documentation alongside product quality. The commercial opportunity lies in serving buyers who need predictable sourcing under changing policy conditions.
Performance-tier segmentation will intensify. As formulators advance chromate-free and ultra-low-VOC systems and as end markets raise durability expectations, the market will increasingly separate into performance tiers. Commodity-grade volumes will remain important, but growth and margin will be more concentrated in applications that demand long service life, high weather resistance, and strict environmental compliance. Suppliers with validated coating systems, clear test data, and application engineering support will have an advantage in specification-driven segments such as architectural cladding, infrastructure, and corrosion-sensitive industrial uses.
Material cost management will become a strategic capability rather than an operational detail. With zinc-linked costs representing a meaningful share of the production cost base, effective raw material procurement, coating formulation optimization, and waste reduction will directly influence profitability. Operators that can align coating selection with application requirements while controlling input costs will be better positioned to maintain margins through commodity cycles. This is particularly relevant for processors serving price-sensitive construction and consumer segments, where small cost advantages can translate into competitive share gains.
PW Consulting
These trends carry risk. Policy directions can shift faster than capacity decisions, and carbon compliance costs may rise as mechanisms mature. Formulation mandates can increase production complexity and require reformulation investment. Demand in construction-linked applications remains sensitive to interest rates, project finance conditions, and regional economic cycles. Participants who overestimate the stability of current trade and demand patterns risk building capacity or sourcing commitments that become suboptimal if conditions change.
Actionable Guidance for Decision Makers
Different roles in the value chain face different priorities, but several strategic moves are broadly relevant.
For manufacturers and processors. Prioritize coating flexibility and compliance documentation as core capabilities. The ability to offer multiple resin systems, demonstrate VOC and chromate compliance, and provide clear performance data will increasingly determine access to specification-driven demand. Where possible, align production and finishing capacity with the markets you serve most frequently to reduce exposure to trade and logistics volatility. In parallel, treat raw material cost management as a strategic lever, integrating supplier relationships, formulation optimization, and yield improvement into a single margin-protection plan.
For investors. Focus on operators with differentiated positioning rather than undifferentiated volume exposure. Companies with strong certification records, application-specific coating expertise, and regional supply alignment are better placed to navigate policy and cost volatility. Assess exposure to carbon-related costs, tariff sensitivity, and the proportion of revenue tied to performance-tier applications versus commodity-grade volume. In markets where consolidation is plausible, look for signs of scale advantage in compliance, process control, and export readiness; in more fragmented settings, look for specialists with durable local relationships and technical service depth.
For procurement and specification teams. Build sourcing strategies that assume continued policy and cost variability. Diversify between domestic and regional supply options where feasible, validate compliance documentation before award, and include coating performance and environmental requirements explicitly in specifications. Where lead time and availability matter, consider the trade-offs between lowest landed cost and supply resilience, especially for applications where re-specification or replacement carries high downstream cost.
The color coated steel market is moving from a phase where aggregate volume growth was the primary narrative to one where policy, performance, and cost structure determine who wins share and where margin is earned. Navigating this environment requires granular understanding of regional dynamics, coating system capabilities, and the evolving requirements of downstream applications. Detailed segmentation data, company-level benchmarks, and scenario-based sourcing analysis can sharpen these decisions significantly. For decision makers who need to move beyond high-level trends into market-specific sizing, competitive mapping, and tailored strategy options, the full research report provides the deeper dataset and structured analysis necessary to support investment, capacity, and procurement choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Color Coated Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Car Chargers Market: Strategic Trends and Commercial Opportunities
The electric vehicle charging infrastructure sector has shifted from a niche sustainability initiative to a core component of global transportation and energy systems. Over the past half-decade, the market has demonstrated consistent momentum, with revenue scaling from approximately 12.5 billion USD in 2020 to 34.8 billion USD by 2025. Projections through 2032 place the sector on a trajectory toward 143.1 billion USD, supported by a compound annual growth rate of roughly 22.5 percent. This expansion reflects more than incremental adoption; it signals a structural realignment in how electricity is distributed, consumed, and monetized across mobility networks.
USB Car Chargers Market
For executives and investors, the numbers themselves tell only part of the story. The real value lies in understanding what is accelerating deployment, what is constraining it, and where competitive advantages are being forged. The charging ecosystem no longer operates as a standalone hardware play. It intersects with grid capacity, fleet electrification timelines, consumer payment expectations, and increasingly stringent domestic sourcing rules. Companies that treat charging infrastructure as a systems integration challenge rather than a transactional equipment sale are beginning to capture disproportionate margins and market share.
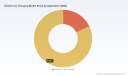
Several inflection points are reshaping the landscape. First, the gap between residential and commercial deployment is widening in strategic importance. While home charging remains foundational for individual vehicle owners, commercial and public charging networks are becoming the primary battleground for scale, utilization rates, and recurring revenue models. Second, the technology mix is bifurcating between slower alternating current solutions and higher-power direct current systems, each serving distinct use cases and requiring different grid interconnections, permitting pathways, and maintenance frameworks. Third, market concentration remains moderate, with the top three players holding a combined share near 35 percent and the top five approaching 42 percent. This fragmentation suggests room for consolidation, but also indicates that regional specialization, software differentiation, and partnership ecosystems matter more than pure manufacturing volume.
Key Drivers Shaping Market Trajectory
Technology Innovation and Performance Thresholds
Charging hardware is evolving from a relatively static product category into a performance-optimized platform. Direct current fast charging continues to advance in power output and thermal management, enabling shorter dwell times for medium- and heavy-duty fleets, ride-hailing operations, and highway corridor deployments. At the same time, alternating current chargers are gaining intelligence through embedded load-balancing algorithms, energy monitoring, and integration with home energy management systems. The practical effect is a market where throughput, reliability, and software responsiveness increasingly determine utilization rather than mere charger availability.
Recent industry activity illustrates this shift. Tritium has been advancing its DC fast charging portfolio through modular platforms designed for ultra-fast public and fleet scenarios, emphasizing scalability and serviceability in high-traffic environments. ZEROVA has focused on high-power commercial and fleet applications, pushing hardware capable of delivering substantial charging capacity in constrained spaces. These developments reflect a broader industry realization that charger specifications must align with operational realities: fleet turnaround windows, peak demand pricing, and site electrical constraints. Companies that design for modular upgrades, remote diagnostics, and predictable uptime are reducing total cost of ownership for operators and improving session completion rates.
Policy and Regulatory Dynamics
Government procurement standards, utility make-ready programs, and domestic content rules are actively shaping where and how infrastructure gets deployed. In the United States, federal-aid projects face evolving Buy America requirements that have prompted discussions about raising domestic content thresholds for EV charger components. Proposed adjustments would increase the required share of domestic component costs, with comment periods and implementation guidance continuing to mature through early and mid-2026. For projects obligated after certain dates, charger compliance frameworks are aligning more closely with general manufactured products rules, which changes how suppliers structure supply chains and document sourcing.
At the state and utility level, interoperability and hardware conformance standards are gaining enforcement traction. Certain public service commission programs have begun requiring ISO 15118-3 hardware conformance for level 2 chargers, signaling a move toward standardized communication protocols that support smoother plug-and-charge experiences, billing transparency, and grid integration. These rules do more than set technical baselines; they influence which products can participate in subsidized programs, how quickly deployments can clear regulatory review, and which manufacturers have the compliance infrastructure to scale across jurisdictions.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing the economics of charging networks. Individual consumers increasingly prioritize ease of payment, session reliability, and predictable pricing over raw charger count. Fleet operators and commercial property managers, meanwhile, are evaluating charging infrastructure through the lens of operational continuity, energy cost management, and vehicle utilization schedules. This divergence is pushing vendors to offer more segmented solutions: residential and light commercial options that emphasize installation simplicity and smart energy features, versus high-throughput public and fleet systems built for repeated high-power cycles.
The commercial application segment has become particularly important in revenue terms, reflecting the growing role of workplace charging, retail destinations, logistics hubs, and fleet depots. As more organizations electrify portions of their vehicle assets, charging infrastructure is no longer a peripheral amenity; it is part of the operational backbone. That shift raises the stakes for uptime, remote monitoring, and service response times. It also encourages companies to bundle hardware with network services, energy management tools, and site-level load optimization, creating value beyond the initial equipment sale.
Supply Chain Structure and Cost Dynamics
Hardware manufacturing, component sourcing, and installation capacity remain central to market execution. Domestic content expectations, semiconductor and power electronics availability, and regional manufacturing footprints all influence lead times and pricing stability. Suppliers that can maintain consistent quality while navigating changing procurement rules are gaining an advantage in federally supported and utility-sponsored programs. At the same time, the cost structure of charging deployments is increasingly tied to electrical upgrades, civil works, and network connectivity rather than the charger unit alone. This reality rewards companies that offer streamlined installation pathways, interoperable components, and financing or turnkey models that reduce project friction.
Recent collaboration activity highlights how the industry is adapting to these supply-side realities. Nayax and Tritium announced a global partnership designed to simplify payment enablement for EV chargers. By connecting hardware providers with payment and transaction infrastructure, such arrangements aim to reduce one of the persistent operational pain points: fragmented payment experiences that complicate utilization and revenue reconciliation. In parallel, deployment partnerships are expanding physical networks in targeted corridors. Kempower and Blink Charging, for example, moved forward with a multi-site DC fast charging expansion along the U.S. East Coast, leveraging high-power hardware to strengthen coverage in high-traffic regions. These types of initiatives reflect a market that is increasingly comfortable combining hardware, software, and site development expertise rather than pursuing isolated product launches.
Competitive Landscape and Leading Strategies
The competitive field spans established network operators, hardware specialists, energy technology companies, and regional manufacturers. ChargePoint has built a presence around charging stations and network management solutions spanning home, commercial, and fleet applications, positioning itself around software-enabled session management and broader ecosystem connectivity. Enphase has moved into bidirectional charging, supporting vehicle-to-home and vehicle-to-grid integration that links electric vehicles more tightly with distributed energy resources. This direction points toward a future where chargers function not only as energy consumers but as controllable assets within broader home and grid energy flows.
Other manufacturers are differentiating through durability, compatibility, and targeted use cases. Grizzl-E has emphasized rugged level 2 chargers with multiple connector compatibilities and a domestic manufacturing footprint, participating actively in regional industry events to reinforce brand visibility and dealer relationships. Emporia Energy has focused on smart level 2 chargers with load-balancing and energy monitoring, appealing to users who want visibility into consumption and coordination with household electrical loads. EVOIQO and Apex Charger have concentrated on practical level 2 offerings with flexible installation options and connector-specific designs, addressing residential and light commercial buyers who value straightforward specifications and deployment simplicity.
In the higher-power segment, Tritium and ZEROVA illustrate distinct approaches to fast charging. Tritium’s platform orientation emphasizes modular DC fast charging for public and fleet contexts, while ZEROVA has targeted high-power commercial and fleet applications with substantial output capabilities. The strategic implication is that fast charging is not a single market but a set of segmented requirements: corridor hubs, fleet depots, retail fueling equivalents, and destination sites all place different demands on power delivery, canopy design, electrical service, and maintenance models.
The market structure is evolving through a mix of consolidation, partnership, and specialization. Moderate concentration at the top suggests that scale alone has not yet produced a dominant monopoly-style landscape. Instead, competitive advantage is being built through several overlapping strategies. One is ecosystem integration, where charging hardware is paired with network software, payment services, and energy management features. Another is regional proximity and supply chain resilience, which matters more as domestic content expectations and program eligibility rules tighten. A third is application-specific engineering, where winners design products for clearly defined operational profiles rather than attempting to serve every segment with a single platform.
Trade presence and targeted partnerships are also becoming more important as a signal of execution capability. Grizzl-E’s participation in major industry exhibitions, for instance, reflects the continued relevance of in-person demonstrations, dealer engagement, and hands-on product visibility in a market where installation partners and fleet buyers want to assess build quality, compatibility, and support structures directly. Meanwhile, payment enablement partnerships and multi-site deployment agreements indicate that the industry is moving toward integrated operating models, where hardware reliability, transactional smoothness, and geographic coverage are treated as interconnected commercial priorities.
Forward Outlook: Three Strategic Trends for the Next Three to Five Years
The next phase of market development will likely be defined by integration, standardization, and utilization economics rather than raw charger count alone.
The first trend is the rise of smarter, more interoperable charging networks. As hardware conformance expectations and communication protocols become more firmly embedded in program rules and consumer expectations, chargers that support smooth plug-and-charge interactions, reliable payment processing, and utility-readable data will gain preference. This creates opportunities for manufacturers and service providers that can deliver consistent interoperability across sites and reduce the operational friction that currently depresses utilization in some networks. The commercial opportunity lies in recurring software, maintenance, and energy-management revenue, not just hardware turnover.
The second trend is the continued divergence between residential and commercial deployment pathways. Home charging will remain essential for private vehicle owners, but commercial and public charging will drive a growing share of strategic investment, especially where fleets, high-traffic destinations, and corridor travel converge. Businesses that can optimize commercial sites for load management, peak demand avoidance, and high session throughput will be better positioned to convert infrastructure into dependable operating margins. For residential and light commercial players, the opportunity is in simplifying installation, expanding connector compatibility, and offering intelligent energy features that align with consumer interest in cost visibility and home energy coordination.
The third trend is supply chain and compliance reshaping procurement winners. As domestic content expectations evolve and manufactured product rules become more explicitly aligned with program requirements, suppliers with transparent sourcing, adaptable bill-of-materials strategies, and documentation readiness will face fewer deployment delays. This is especially relevant for federally supported and utility-sponsored programs, where eligibility can determine whether a project moves forward on schedule. Companies that treat compliance as a design and supply-chain function rather than a late-stage paperwork exercise will likely secure more consistent access to capital-intensive deployment pipelines.
PW Consulting
These trends carry risks that decision makers should monitor. Grid capacity and interconnection timelines can constrain site readiness, particularly in areas with rapid deployment interest. Utilization risk remains real in locations where traffic patterns, pricing structures, or payment friction limit session frequency. Regulatory timelines can shift as agencies refine content requirements and program guidance, altering project economics with limited lead time. Finally, hardware reliability and service response continue to influence customer experience and operator reputation; in a market where networks are compared session by session, uptime gaps can translate quickly into lost share.
Actionable Implications for Decision Makers
Different stakeholders face different priority sets, but several strategic moves are broadly relevant.
For hardware and network providers, the priority is to align product roadmaps with operational realities rather than aggregate specifications. That means designing for modular servicing, predictive diagnostics, connector compatibility, and payment interoperability, while also ensuring that supply chains can withstand evolving domestic content expectations. Companies should evaluate whether they compete primarily on hardware performance, network services, energy integration, or geographic coverage, and then build the partnerships necessary to reinforce that position. A clear application focus, supported by reliable installation and service pathways, tends to outperform broad but shallow product portfolios in a market where uptime and user experience drive repeat utilization.
Electric Vehicle Charging App Market
For investors, the opportunity lies in distinguishing between companies that are building durable operating models and those that are relying on short-term subsidy tailwinds or hardware-only economics. Favor businesses that demonstrate recurring revenue potential through software, maintenance, energy management, or transaction services, and that show evidence of compliance readiness and supply chain resilience. Pay attention to deployment partnerships and payment integrations, since these often signal a move toward integrated commercialization rather than standalone product sales. Also weigh regional exposure carefully; markets with strong utility programs, clear procurement rules, and established installation ecosystems will generally outpace fragmented environments where permitting and electrical upgrades slow project velocity.
For commercial buyers and fleet operators, the focus should be on total cost of ownership, session reliability, and site-level energy management rather than sticker price alone. Evaluate charger platforms based on expected utilization profiles, downtime history, remote monitoring capabilities, and the availability of service support in your operating region. Consider how load-balancing, scheduled charging, and potential bidirectional capabilities could reduce demand charges or improve energy flexibility. Engage early with electrical planners and installation partners, because site readiness and interconnection timelines often determine project success more than the choice of charger brand. Where possible, prefer solutions that simplify payment and reporting, since transaction friction frequently undermines utilization and complicates reconciliation across multiple sites.
Why Detailed Intelligence Matters Now
The charging market is moving from rapid qualitative expansion into a more demanding phase where execution quality, regulatory alignment, and utilization economics determine commercial outcomes. In that environment, broad headlines are helpful for orientation but insufficient for planning. Segment-level deployment patterns, regional program eligibility, compliance timelines, and competitor positioning all influence which strategies will hold up under scrutiny. Decision makers who need to prioritize regions, applications, technology paths, or partnership structures benefit from more granular data than a high-level market narrative can provide.
A deeper research resource can help translate these dynamics into specific choices: where to allocate capital, which product segments offer the strongest risk-adjusted opportunity, how regulatory shifts may alter project timelines, and which competitive moves are likely to reshape category leadership. For organizations already operating in the space, that level of detail supports pricing, capacity planning, and go-to-market execution. For those evaluating entry or expansion, it reduces the risk of committing to segments where utilization, compliance, or supply-chain friction is underpriced.
The market trajectory suggests continued scale, but scale alone does not guarantee profitable execution. The companies and investors that perform best over the next several years will be those that treat charging infrastructure as an integrated systems business, align their strategies with evolving rules and user expectations, and base their decisions on segment-level evidence rather than aggregate projections. Detailed research reports can provide the subcategory breakdowns, regional comparisons, and competitive tracking necessary to turn these strategic signals into concrete operational plans and investment committees’ decisions.
For detailed analysis of this topic, please visit the official page: Electric Car Chargers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Shot Blasting Machines Market: Why 6.32% CAGR and Automation Shift Commercial Dynamics
By PW Consulting, 2026-09-21
Shot Blasting Machines Market: Strategic Trends and Commercial Opportunities
The global shot blasting machines market is undergoing a structural transformation defined by automation, digital integration, and shifting end-use priorities. With a projected compound annual growth rate of 6.32 percent and an expanding revenue trajectory from approximately $1.5 billion in 2025 toward over $2.3 billion by 2032, the sector reflects sustained industrial demand for surface preparation, cleaning, and finishing solutions. Growth is not merely a function of volume; it is increasingly shaped by how manufacturers align equipment capabilities with stricter cleanliness standards, labor constraints, and operational efficiency targets. Understanding where momentum is building, and which forces are reshaping competitive positioning, is essential for executives evaluating capital deployment, product strategy, or procurement direction.
Market Landscape and Core Challenges
The market has moved through a period of steady expansion, recovering from earlier cyclical softness and reaccelerating as industrial throughput improved across multiple regions. Revenue figures have climbed consistently year over year, supported by replacement cycles, capacity additions in casting and forging, and broader investments in surface treatment infrastructure. This trajectory signals a market that is stabilizing around higher baseline demand, yet one that is also entering a more demanding operational environment where incremental efficiency gains matter as much as unit sales.
Several forces are creating friction and opportunity at the same time. First, the link between surface preparation quality and downstream performance is becoming more visible across metal-intensive industries. Cleanliness, profile consistency, and blast repeatability now carry direct implications for coating adhesion, corrosion resistance, and component life. That makes shot blasting less of a commodity service and more of a controlled process step, raising expectations for equipment precision and documentation.
PW Consulting
Second, labor availability and skill constraints are altering how plants use existing equipment. In several major markets, shortages of experienced metalworking technicians are limiting utilization rates and increasing the cost of manual interventions. This dynamic is pushing organizations to favor machines that reduce operator dependency, simplify changeovers, and maintain output even with thinner skilled-labor pools.
Third, material and consumable volatility is forcing a sharper focus on total cost of ownership. Abrasive media usage, dust handling, and wear-part replacement directly affect operating economics. When media prices fluctuate and alternative materials compete for adoption, manufacturers are increasingly evaluating blast systems not only by purchase price but by consumption control, recovery efficiency, and integration with broader material management practices. These challenges are not purely restrictive; they are also helping separate operators who treat blast cleaning as a cost center from those who treat it as a process capability that can be optimized.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technology maturation, regulatory pressure, demand-side behavior, and supply-side cost dynamics. These drivers are interacting, not operating in isolation.
Technology Innovation and Process Control
The most visible shift is the move from standalone mechanical systems toward connected blast platforms that provide visibility into media consumption, wheel wear, and process consistency. Intelligent monitoring and data-linked controls are making it easier to balance output quality with consumable usage. For operators, that means fewer unplanned interruptions, more predictable cleaning results, and stronger alignment between surface preparation and downstream workflow. The practical value is not just automation itself, but the ability to standardize results across shifts, batches, and product mixes.
Alongside connectivity, equipment design continues to evolve around throughput, ergonomics, and serviceability. Machines are being configured to handle a wider range of part geometries and throughput requirements while reducing manual handling. That is especially relevant where mixed production schedules or shorter runs demand flexible equipment rather than rigid high-volume lines. The market is increasingly rewarding systems that combine repeatability with practical adaptability.
Regulatory and Standards Pressure
Regulatory expectations around worker exposure, dust control, and surface cleanliness are strengthening the case for more controlled blast environments. Filtrations, containment, and protective features are becoming central to equipment selection rather than peripheral add-ons. In parallel, widely referenced surface cleanliness standards are pushing structural fabricators and metal processors toward more consistent automated preparation methods.
Cast Steel Shot & Grit Market
The commercial consequence is twofold. Equipment that can demonstrate reliable compliance and cleaner outputs gains a qualitative advantage in bid-sensitive environments. At the same time, buyers are less willing to treat blast capacity as interchangeable, since cleanliness and handling requirements increasingly influence qualification decisions. This is expanding the premium on engineered systems that integrate dust management, media recovery, and controlled blast intensity into a cohesive process.
Demand-Side Shifts in End-Use Industries
End-use demand is becoming more segmented and performance-driven. Automotive and aerospace remain influential, but the nature of demand is shifting toward consistent surface quality, tighter throughput expectations, and components that must meet demanding service environments. Foundries and metal processors continue to rely on shot blasting for casting cleaning and scaling removal, but they are also weighing equipment against broader line efficiency and inspection readiness. Construction, rail, shipbuilding, and other industrial applications contribute to demand in their own ways, particularly where heavy components, infrastructure materials, or repaired assets require dependable surface treatment.
A notable change is that buyers increasingly view blast equipment as part of a broader quality and throughput system. That means machine selection is more closely tied to downstream finishing, coating, inspection, and rework reduction. The implication is that performance claims grounded in process control, media efficiency, and repeatable outcomes are becoming more persuasive than broad equipment descriptions alone.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping purchasing logic. Raw material swings, regional production differences, freight variability, and service-part availability all influence the delivered economics of shot blasting equipment. As a result, buyers are paying more attention to system-level operating costs, including media life, wheel wear, filtration load, and maintenance downtime. This is particularly important in environments where machines run frequently and downtime carries disproportionate production penalties.
Shot Peening Machine Market
At the same time, regional manufacturing footprints are becoming strategically relevant. Localized support, faster parts availability, and proximity to end markets can reduce operating risk. In several cases, expanding production capacity in or near high-growth regions is being used to improve service response and strengthen competitive positioning. This points to a market where hardware capability still matters, but responsiveness and execution may differentiate suppliers as much as product specifications.
Competitive Landscape and Leading Strategies
The competitive field is diversified, with global players, regional specialists, and application-focused manufacturers coexisting across different machine types, technologies, and service models. Market concentration remains moderate, indicating that share is distributed across a broad set of participants rather than resting with a small group of dominant incumbents. That structure leaves room for differentiation through technology, application expertise, regional presence, and aftermarket support.
Strategic Positioning of Leading Players
Several companies illustrate distinct strategic arcs within the market. International manufacturers with broad portfolios are emphasizing integrated solutions that span wheel blast and air blast systems, batch and continuous processes, and industrial surface preparation across multiple end markets. Their positioning tends to rely on a wide application base, global service networks, and established product ranges that can be adapted to varied customer requirements.
Other players have leaned toward engineering depth and digital-enabled process control. Smart platform capabilities, real-time wear monitoring, and integration with plant systems are being used to position equipment as a productivity and quality enabler rather than a standalone cleaning device. This strategy is particularly relevant for customers seeking consistent output and lower consumable waste in demanding production environments.
Regional and specialized manufacturers continue to play an important role by focusing on specific machine configurations, material types, or local support expectations. Their advantage often lies in responsiveness, customization, and close alignment with regional fabrication or foundry practices. For buyers prioritizing shorter lead times, local service, or application-specific tuning, these suppliers can be highly competitive.
Recent Moves Shaping the Landscape
Recent activity highlights where competition is intensifying. The rollout of IoT-linked blast platforms with analytics for abrasive media consumption and wheel wear points to a market that is moving toward data-informed operation. Demonstrations combining live performance testing, augmented reality, and optimization sessions indicate growing interest in practical efficiency gains rather than product novelty alone. Participation in international trade events and facility expansion in high-growth regions further suggests that manufacturers are investing in visibility, capacity, and localized support to capture demand more effectively.
Taken together, these developments suggest a competitive environment in which differentiation is increasingly built on three layers: core machine reliability, process intelligence, and service responsiveness. Companies that can align those layers with customer operating priorities are better positioned to capture share in a market where specifications alone are no longer a sufficient advantage.
Consolidation, Fragmentation, and New Entry
The market is not trending toward rapid monopoly-style consolidation. Instead, it appears to be evolving through selective consolidation at the service and technology levels while remaining broad at the product level. Larger players may pursue complementary capabilities, regional reach, or application coverage, but fragmentation persists because blast cleaning requirements vary widely by part type, material, throughput, and labor context. New entrants can still find opportunity by serving niche applications, offering lower-cost configurations, or focusing on fast regional support. However, long-term credibility tends to depend on consistent performance, parts availability, and the ability to demonstrate measurable savings in media usage, downtime, and rework.
Future Trends to Watch
Over the next three to five years, several trends are likely to define how the market evolves and where commercial value accumulates.
- Process intelligence becomes standard rather than exceptional. Connected monitoring, consumables analytics, and integration with plant systems will increasingly be expected in higher-value installations. The commercial opportunity lies in reducing total operating cost, improving consistency, and making blast performance easier to manage across shifts and product variations.
- Automation and labor-efficient designs gain preference. As skilled-worker constraints persist in several regions, equipment that reduces manual intervention, simplifies setup, and supports steady utilization will be favored. This trend creates opportunities for manufacturers who can prove that their machines maintain output with fewer dependent labor inputs.
- Compliance and cleanliness become stronger purchase criteria. Regulatory expectations and surface quality requirements will continue to push buyers toward equipment with better containment, filtration, and repeatable surface preparation. Suppliers that can tie equipment capabilities to documentation, consistency, and risk reduction will have an advantage in qualified and bid-sensitive environments.
These trends are not risk-free. Technology integration can raise upfront complexity and require training, data management, and support infrastructure that smaller users may find difficult to absorb. Material price volatility can still disrupt operating budgets, especially when alternative media options shift demand patterns. And if regional economic conditions slow capital investment, demand may become more replacement-driven than expansion-driven, which would reward reliability and service more than new unit sales. Capital intensity, installation constraints, and the need for practical process adaptation also mean that the strongest opportunities will likely accrue to players who can pair advanced functionality with implementable, site-specific solutions.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to move beyond equipment selection as a purely mechanical decision. Investments should be evaluated against total operating cost, cleanliness consistency, service accessibility, and integration with existing production workflows. The most resilient product and capacity strategies are likely to emphasize flexible configurations, measurable consumable efficiency, and support models that help customers sustain utilization. Companies that can demonstrate how blast performance reduces downstream rework or improves coating readiness will find stronger commercial traction than those competing mainly on headline specifications.
For investors, the attractive question is not simply whether demand will continue to grow, but which business models can convert growth into durable margins. Preference should be given to organizations with clear aftermarket revenue streams, repeatable installation and service processes, and credible differentiation in efficiency or compliance-related capabilities. It is also worth watching how regional expansion, localized support, and digital-enabled offerings reshape competitive dynamics, since these factors can influence both market share and long-term return profiles.
For procurement and operations leaders, the practical focus should be on total cost of ownership and process reliability. Selection criteria should include media consumption behavior, wear-part accessibility, filtration and containment readiness, changeover simplicity, and the supplier’s ability to support consistent utilization. Where possible, buyers should seek performance evidence tied to their own part types and throughput conditions rather than relying on generic capability claims. Aligning blast equipment with downstream quality requirements and labor realities can materially reduce operating risk.
Strategic decisions in this market are best made with detailed segmentation, regional nuance, and application-specific benchmarks in view. A targeted view of machine types, technology preferences, operational modes, end-use demand, and regional dynamics can clarify where investment, procurement, or partnership opportunities are most likely to pay off. For decision makers seeking a deeper breakdown of market size by segment, regional trajectories, competitive positioning, and scenario-based demand outlooks, the full PW Consulting report provides the supporting detail needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Shot Blasting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Refrigeration Equipment Market: Why Asia Pacific and Ammonia Redefine the 4.9% CAGR Outlook
By PW Consulting, 2026-09-21
The Industrial Refrigeration Equipment Market: Navigating the Next Wave of Growth and Transformation
The industrial refrigeration equipment market is entering a structurally distinct phase. Over the 2020 to 2025 period, the market expanded from approximately $17.87 billion to $22.70 billion, reflecting a compound trajectory that has outpaced many adjacent industrial segments. The forecast period through 2032 points to continued expansion, with revenue projected to reach roughly $31.73 billion, translating to a compound annual growth rate of 4.9 percent. These figures represent more than incremental capacity additions; they signal a market transitioning from steady replacement cycles to a demand profile shaped by regulatory mandates, refrigerant transitions, and capital expenditure patterns that favor higher-efficiency, lower-emission architectures.
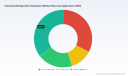
Beneath the headline growth lies a landscape that is simultaneously fragmented in execution and increasingly concentrated in strategic influence. The market continues to operate with a moderate concentration profile, where the top three participants command roughly 38 percent of total revenue and the top five approach 46 percent. This structure suggests that while regional specialists, engineering firms, and component suppliers retain meaningful share, scale players and technology-focused incumbents are widening their influence through integrated system offerings, expanding service footprints, and partnerships that reduce project risk for end users. For executives and investors, the implication is clear: the market is large enough to sustain multiple business models, yet selective enough that differentiation in technology, compliance readiness, and service economics will increasingly determine who captures disproportionate value.
Market Context and Strategic Challenges
The current market environment is defined by a collision of long-cycle infrastructure demand and fast-moving regulatory and technological change. Three challenges stand out as particularly consequential for companies operating across the industrial refrigeration value chain.
First, the refrigerant transition has moved from a compliance topic to a design constraint that influences equipment architecture, component selection, and total cost of ownership. Natural refrigerant platforms, especially carbon dioxide and ammonia, are increasingly central to new installations and major retrofits. However, the shift is not uniform. Different applications impose different safety, efficiency, and operating-pressure requirements, and the pace of adoption varies by region, sector, and capital budget. Equipment manufacturers and system integrators are therefore being asked to support a broader portfolio of solutions while maintaining engineered reliability across diverse operating conditions.
Second, cost pressure on inputs is reshaping project economics. Tariff actions affecting steel and aluminum imports have pushed up the cost of compressors, condensers, and structural frameworks. In industrial refrigeration, where systems often represent large capital projects with long payback expectations, material cost volatility can alter bid dynamics, compress margins, and delay commitment cycles. The challenge is not simply higher input prices, but managing the ripple effects through supply agreements, lead-time planning, and value engineering without compromising durability or energy performance.
Third, the market is navigating a complex and evolving standards environment. Regulatory provisions targeting high-global-warming-potential refrigerants, combined with energy efficiency priorities and updated safety standards, are raising the bar for system design and operation. For operators, this means more scrutiny on refrigerant choice, maintenance practices, and lifecycle performance. For suppliers, it means that product differentiation is increasingly tied to compliance readiness, documentation, training, and the ability to support customers through transitions rather than simply shipping hardware.
These challenges should not be read only as headwinds. They are also reshaping the basis of competition. Companies that can offer lower-risk transitions, stronger energy performance, and more predictable project execution are finding greater leverage with customers who must balance operational continuity with regulatory and sustainability obligations.
Core Drivers Shaping the Market
Several forces are working in Concert to reshape demand, pricing, and competitive positioning across industrial refrigeration. The most consequential can be grouped into technology, policy, demand-side behavior, and supply-side cost structures.
Technology Innovation and the Rise of Natural Refrigerant Systems
The most visible technical shift is the acceleration of carbon dioxide and ammonia-based solutions in commercial and industrial applications. Recent industry activity highlights how rapidly these platforms are moving from specialized niches into broader mainstream consideration. At AHR Expo 2026, for example, the exhibition floor featured a strong showing of CO2-based products, including condensing units, transcritical and subcritical compressor technologies, and specialized valves and fittings designed for natural refrigerant systems. This level of visibility matters because it signals that suppliers are not only advancing individual components but also building out integrated ecosystems around refrigerants that require distinct engineering approaches.
For the market, the practical implication is that equipment roadmaps are increasingly aligned with refrigerant performance curves, system controls, and safety architecture. Companies that can combine compressors, heat exchangers, valves, and controls into coherent, application-specific solutions are better positioned to reduce integration risk and improve system reliability. At the same time, component-level innovation remains essential. Specialized fittings, check valves, and ball valves for high-pressure CO2 environments illustrate how seemingly narrow product categories can become critical enablers of broader adoption.
Policy and Regulatory Pressure as a Market Catalyst
Policy is no longer a peripheral factor. In the United States, EPA Technology Transitions provisions under the AIM Act have established a schedule that bans HFC refrigerants with a GWP above 700 in new industrial process refrigeration chillers starting January 1, 2026, with additional phased limits tightening to a GWP of 300 for certain cold storage applications. Broader EPA rules effective at the same date prohibit high-GWP refrigerants across new commercial and industrial refrigeration systems. These timelines create a concrete forcing function for equipment selection and replacement planning.
In parallel, energy efficiency is becoming a more prominent policy target. Industrial refrigeration compressors have been identified by the U.S. Department of Energy as a priority category for energy efficiency standards, reflecting the scale of energy consumption in food and pharmaceutical manufacturing. This matters because it links refrigerant policy with operational cost policy. Customers are increasingly asked to optimize for both environmental compliance and energy consumption, which elevates the strategic importance of high-efficiency compressors, improved heat exchange design, and controls that adapt to load variability. Updated industry standards, such as revised industrial refrigeration guidelines incorporating the latest ISO and safety requirements, further reinforce the direction of travel toward more formalized design and operational practices.
Demand-Side Change Across Food, Pharmaceutical, and Industrial End Markets
Demand is being reshaped by more than regulatory compliance. Cold chain reliability, production quality, and operational resilience have become priority concerns across multiple end-use sectors. In food and beverage operations, temperature control remains foundational to product quality and safety, but customers also care about throughput, redundancy, and energy intensity. In pharmaceutical applications, precision and reliability are paramount, and refrigeration systems are increasingly viewed as part of a broader quality and compliance infrastructure rather than isolated mechanical assets. Chemical processing and other industrial uses add further complexity, where refrigeration may be tied to process conditions, batch consistency, and facility-level efficiency goals.
Road Transport Refrigeration Equipment Market
A notable demand-side dynamic is the shift toward lifecycle thinking. Buyers are increasingly looking beyond first cost and considering the broader economics of refrigerant choice, maintenance requirements, service availability, and expected energy consumption over the life of the system. This does not eliminate price sensitivity, but it does change the criteria by which solutions are evaluated. Suppliers that can articulate and deliver on total cost of ownership, including compliance and service considerations, are better positioned to compete in capex-heavy and mission-critical environments.
Supply Chain Dynamics and Cost Structure Sensitivity
The cost environment remains an important driver of market behavior. Tariff-related increases on steel and aluminum have affected key structural and mechanical components, adding uncertainty to project planning and procurement. In an industry where lead times, sourcing reliability, and build quality all affect customer confidence, input cost volatility can have outsized effects on quoting, scheduling, and margin management.
At the same time, supply chain dynamics are encouraging greater attention to sourcing strategy and design flexibility. Some manufacturers are revisiting material specifications, supplier diversification, and inventory buffers to reduce exposure. Others are using system architecture choices to optimize cost and performance simultaneously, for example by balancing component consolidation against redundancy and serviceability. These adjustments are not merely defensive; they can become sources of advantage when executed with discipline and transparency.
Competitive Landscape and Leading Strategies
The competitive field in industrial refrigeration equipment is diverse, spanning commercial and industrial unit manufacturers, compressor specialists, component suppliers, and project-oriented system integrators. Rather than a single dominant model, the market rewards different forms of differentiation depending on the customer segment and application.
Several companies illustrate the range of strategic positions now in play. Heatcraft Refrigeration Products focuses on unit coolers, condensers, and evaporators for commercial and industrial refrigeration applications, positioning around core components that are widely specified across multiple system architectures. Magna Industrial Refrigeration provides industrial refrigeration equipment, components, and solutions, including unit coolers for commercial and industrial use, reflecting a strategy centered on breadth of product availability and application coverage. NDL Industries emphasizes high-pressure CO2 fittings, valves, check valves, and three-way valves for industrial refrigeration and natural refrigerant systems, illustrating how a component-focused specialist can play a vital role in enabling refrigerant transitions.
PW Consulting
On the compressor and system side, Danfoss, Copeland, and Bock GmbH represent technology-driven positions that emphasize solutions for low-temperature and transcritical CO2 applications, along with compressor platforms tailored to industrial cold storage and process cooling. These players are competing not just on hardware, but on the ability to offer engineered solutions that simplify adoption of natural refrigerants and support specific performance targets. Frigo Mekanik represents a complementary model, specializing in project design, manufacturing, and turnkey installation of industrial refrigeration cooling systems. This approach highlights the continuing importance of integration capability, especially where site-specific constraints, local service requirements, and project execution risk are significant.
Recent industry activity reinforces the direction of these strategies. The IIAR Natural Refrigeration Conference and Heavy Equipment Expo featured exhibitors such as Magna Industrial Refrigeration by Heatcraft, underscoring continued engagement with industrial refrigeration and natural refrigerant safety and equipment. Meanwhile, Frigo Mekanik’s participation in the HVACR Egypt Expo 2026 points to the regional expansion of project-oriented players seeking exposure to international demand and project pipelines. On the event calendar, RETA’s national conference continues to provide a focused forum for industrial refrigeration systems and components, reinforcing the importance of concentrated industry gatherings in shaping technology diffusion, standards awareness, and supply chain relationships.
Worldwide Compression Refrigeration Machine Market
The competitive trends that emerge from this landscape are best described as selective integration paired with targeted specialization. Larger players are broadening their offerings to reduce customer friction across specification, installation, and service, while specialized suppliers are deepening their role in critical subsystems that become differentiators in natural refrigerant applications. The market is not necessarily moving toward a single consolidated model; instead, it is evolving toward ecosystems in which components, compressors, controls, and project capabilities are combined in ways that reduce total risk for the buyer. In that environment, companies that can demonstrate compliance readiness, reliable performance under changing refrigerant regimes, and strong service economics are likely to capture a disproportionate share of high-value projects.
Forward Outlook: Trends and Opportunities for 2026 to 2030
Looking ahead, the market is likely to be shaped by a small number of reinforcing trends that translate into defensible commercial opportunities for well-positioned players.
One major trend is the continued mainstreaming of natural refrigerant solutions in new builds and retrofits. As regulatory deadlines take effect and customer expectations around environmental performance rise, CO2 and ammonia platforms will see increasing specification in a wider range of applications. The commercial opportunity lies not just in selling equipment, but in helping customers manage the engineering, safety, and operational implications of these systems. Suppliers that can standardize design approaches, simplify commissioning, and provide robust field support will be better positioned to scale adoption without eroding reliability.
A second trend is the tightening link between refrigerant policy and energy efficiency. As efficiency standards and compliance requirements reinforce one another, end users will increasingly look for solutions that reduce both emissions exposure and operating cost. This creates opportunities around high-efficiency compressors, improved heat transfer designs, advanced controls, and integrated monitoring that supports optimization over time. The upside is especially significant in sectors with high utilization and sensitive temperature requirements, where even modest efficiency improvements can translate into meaningful operational savings.
A third trend is the growing importance of service, lifecycle support, and standards-based execution. As systems become more specialized and regulations more detailed, the value of post-sale support rises. Customers will increasingly favor partners that can help with maintenance planning, technician training, spare parts availability, and compliance documentation. This shift favors companies that treat service not as an afterthought, but as a core part of the commercial proposition. It also raises the stakes for component and equipment suppliers to design for maintainability and to align their offerings with updated industry standards and safety practices.
These trends are not without risk. The pace of adoption may vary by region and application, and customers may delay capital decisions if cost pressures, interest rates, or project timelines become unfavorable. Material cost volatility can continue to complicate bidding and margin planning. In addition, technological transitions can create temporary friction, especially where engineering expertise, trained labor, or supply availability lag behind product availability. Companies should therefore treat natural refrigerant leadership as a long-term play that requires disciplined execution, not simply a product-line expansion.
Strategic Implications for Decision Makers
The most useful way to approach this market is to align strategy with the forces that are most likely to determine purchasing decisions and competitive outcomes over the next several years. The following recommendations are intended to separate signal from noise and focus action where it matters most.
For equipment manufacturers and system integrators, the priority is to reduce the friction of transition. This means developing and communicating clear pathways for natural refrigerant adoption, strengthening integration across components and controls, and reinforcing service and training capabilities that lower customer risk. Where material cost pressure is persistent, value engineering and supply chain resilience should be treated as strategic capabilities rather than transactional tasks. Differentiation will increasingly come from how well a company helps customers navigate compliance, efficiency, and reliability together.
For investors and strategic partners, the opportunity is to identify businesses whose value is tied to durable shifts rather than short-cycle demand. Indicators of resilience include exposure to applications with high uptime requirements, strong positions in components or subsystems essential to natural refrigerant systems, and service models that generate recurring value beyond initial equipment sales. It is also worth watching how companies adapt to cost volatility and whether they can convert regulatory pressure into differentiated offerings rather than treating it as a compliance burden.
For procurement leaders and end-user organizations, the focus should be on total cost and transition risk. Specifying equipment with an eye toward lifecycle energy performance, refrigerant compliance, service availability, and ease of maintenance can reduce exposure to future regulatory changes and operating cost escalation. Where capital projects are planned, early engagement with suppliers on system architecture, standards alignment, and local support can improve execution certainty and reduce the likelihood of costly rework or delayed commissioning.
For all of these audiences, timely access to detailed market data can sharpen decision-making. Segment-level dynamics, regional demand patterns, competitive moves, and regulatory timelines all influence how opportunities should be prioritized. A focused view of these variables helps turn broad market growth into a more actionable plan, especially when decisions involve capital intensity, long service life, and compliance-sensitive technologies.
Closing Perspective
The industrial refrigeration equipment market is large, expanding, and increasingly governed by structural forces that reward clarity of strategy. Growth to the mid-2030s is expected to remain steady, but the more important story is how that growth is being shaped by refrigerant transitions, efficiency priorities, input cost pressures, and the rising importance of service and integration. Companies that can combine technical strength with compliance readiness, project reliability, and lifecycle value will be best positioned to convert market expansion into durable advantage. For executives, investors, and procurement leaders, the practical task is to use these signals to prioritize where to invest, where to differentiate, and where to reduce risk before the next wave of regulatory and demand-side change fully settles in.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Jet Engines Market: Why 6.5% CAGR and Civil Aviation’s 53% Share Redefine Growth
By PW Consulting, 2026-09-21
Strategic Fronts in the Jet Engines Market: Navigating Growth, Technology, and Geopolitical Complexity
The global jet engines market is entering a phase defined by the intersection of sustained demand recovery, accelerating technological evolution, and heightened geopolitical friction. Revenue for the segment reached USD 78.9 billion in 2025 and is projected to expand to USD 122.34 billion by 2032, translating to a compound annual growth rate of approximately 6.5% across the 2026–2032 forecast window. These figures reflect a market that has moved past the immediate disruptions of the early 2020s and is now being shaped by long-cycle fleet investment, regulatory pressure on emissions, and shifting supply-chain configurations. For executives and capital allocators, understanding where value will concentrate requires looking beyond headline growth and examining the structural forces that are redefining competitive advantage in propulsion.
Trajectory and Structural Dynamics
The market’s expansion over the 2020–2025 period was uneven but steadily positive, moving from roughly USD 64.78 billion in 2020 to the current 2025 baseline. Growth is now supported by a broad backlog of commercial aircraft deliveries, renewed military modernization programs, and the gradual replacement of aging powerplants with higher-thrust, more fuel-efficient configurations. The market remains moderately fragmented at the top, with the top three firms accounting for about 24.6% of revenue and the top five reaching approximately 26.2%. This concentration level indicates that durable pricing power and aftermarket control are still influenced by a small set of incumbents, even as specialized suppliers and regional players gain relevance in components, accessories, and dedicated platform programs.
Key Challenges and Inflection Points
Three structural challenges are redefining how value is captured across the jet engines market. First, the tension between near-term cost pressures and long-cycle innovation is intensifying. Engine development requires multi-year investment with uncertain returns, while operators and airlines are simultaneously sensitive to fuel costs and total operating expense. This creates a delicate balance where manufacturers must deliver measurable efficiency gains without destabilizing unit economics or delivery timelines. Second, the regulatory and trade environment is becoming more fragmented. Export-control measures now extend to certain civil aircraft parts when there is a risk of military end-use, and tariff frameworks have introduced new complexity for engine and aircraft trade flows. Supply commitments increasingly need to account for jurisdictional restrictions, license requirements, and sourcing adjustments. Third, the aftermarket is becoming a strategic battleground. As new engine families enter service, the long-term service, repair, and overhaul ecosystem will determine a meaningful share of lifecycle profitability, particularly for narrow-body and regional platforms that operate in high-cycle environments.
Core Drivers Reshaping Demand and Value Creation
The market’s direction is being shaped by forces that cut across technology, regulation, demand behavior, and cost architecture. Each driver interacts with the others, creating opportunities for firms that can align product strategy with changing operating realities.
Technology Innovation as a Competitive Lever
Efficiency and emissions performance are no longer secondary attributes; they are central to platform selection and long-term fleet economics. Next-generation engine programs are increasingly built around higher bypass ratios, advanced materials, and architectures that reduce fuel burn and carbon intensity. CFM International’s RISE program, for example, has matured technologies aimed at reducing net carbon emissions by up to 20% for the next-generation CFM engine targeted for mid-2030s entry. This kind of forward-looking development matters because it signals a shift from incremental upgrades to platform-level architectural change. For manufacturers, the implication is clear: differentiation will depend on the ability to demonstrate credible performance improvements that reduce operating costs while meeting evolving environmental expectations. For buyers, the practical question is whether near-term configuration choices will hold up under future regulatory and fuel-price scenarios.
Policy, Regulatory and Trade Dynamics
Policy is becoming a more direct factor in engine market economics. In early 2026, U.S. export-control measures under the EAR began requiring licenses for certain civil aircraft parts and components destined for China when there is a risk of military end-use. Earlier, U.S. authorities paused certain exports of aircraft and semiconductor technology, including jet-engine components, to China in response to Beijing’s restrictions on critical minerals. At the same time, the Trump administration imposed new tariffs on aircraft and engines in 2025, with exemptions for USMCA-compliant aerospace components from Canada and targeted measures against selected Chinese end-users. These developments do not simply change trade flows; they reshape sourcing strategies, after service coverage, and the relative attractiveness of different manufacturing locations. Companies that can design flexible supply chains and maintain compliance assurance will have an advantage in preserving program continuity and customer confidence.
Demand-Side Shifts in Civil and Military Aviation
Demand is being driven by two reinforcing trends. In civil aviation, airline fleets are moving toward more efficient narrow-body and regional platforms, supported by sustained travel demand and a desire to reduce operating costs. In military aviation, modernization programs continue to require propulsion solutions that balance performance, survivability, and long-term sustainment. The market structure reflects this dual demand: civil aviation represents the majority of revenue, while military aviation remains a substantial and technologically demanding segment. For suppliers, this split suggests that growth is unlikely to come from a single path. Commercial programs reward scale, reliability, and low total cost of ownership, while defense and specialized platforms reward capability, customization, and secure production relationships. Firms that can manage both worlds without diluting execution quality are likely to maintain stronger strategic positioning.
Supply Chain and Cost Architecture
Cost dynamics remain a defining constraint. Global average jet fuel price fell 11.4% week-on-week to $141.64 per barrel, with U.S. Gulf Coast prices at $3.30 per gallon as of early June 2026. Even with this near-term relief, fuel continues to be a major operating expense, and volatility keeps efficiency on the agenda. At the same time, engine-makers are investing in site expansion and new manufacturing capacity to support output and complex part production. Safran, for example, expanded operations in Le Creusot to manufacture complex parts for Rafale engines, and Williams International began building a new $1 billion turbine engine factory in Florida. These investments suggest that capacity, precision manufacturing, and localized production are becoming as important as design leadership. For procurement teams and investors, the relevant insight is that the cost structure of propulsion is increasingly tied to manufacturing footprint, supply resilience, and the ability to manage long-lead inputs without sacrificing quality.
Competitive Landscape and Strategic Positioning
The market’s competitive structure is shaped by a small number of engine families, collaborative ventures, and a layered supplier base. Differences in platform focus, aftermarket control, and geopolitical exposure create distinct strategic positions rather than a single race to the bottom on price.
Leading Companies and Differentiated Advantages
GE Aerospace remains a central force in commercial turbofans, designing, manufacturing, and servicing a broad portfolio that includes CF34, CF6, the CFM LEAP family, CFM56, GEnx, and GE9X, alongside military engines for narrow-body, wide-body, and business aviation. Its breadth across multiple aircraft categories gives it scale and the ability to serve both high-volume and premium long-haul segments. Pratt & Whitney focuses on large commercial turbofans such as the GTF family, PW1000G, PW4000, and PW6000, powering platforms including the Airbus A320neo family, A220, and Embraer E-Jets. Its strategy is closely tied to narrow- and regional-jet adoption, making reliability and engine-family support important differentiators. Rolls-Royce positions itself strongly in wide-body propulsion through the Trent family, including Trent XWB, Trent 7000, Trent 900, Trent 500, and Trent 800 for aircraft such as the Boeing 787 and A350. This wide-body emphasis gives it a distinct role in long-haul operations where thrust requirements and mission profiles differ from single-aisle work.
Safran Aircraft Engines and CFM International illustrate the strategic value of joint-venture structures and platform concentration. CFM International, a 50/50 GE Aerospace–Safran JV, produces the LEAP and CFM56 narrow-body turbofans for the Airbus A320neo family and Boeing 737 MAX. Safran contributes the LEAP-1A/B/C single-aisle turbofans and brings additional reach into military programs. The JV model supports scale and resource sharing while concentrating risk and reward on dominant narrow-body platforms. MTU Aero Engines adds a complementary layer by focusing on component manufacturing and support for Pratt & Whitney GTF family engines and PW4000 engines, while also participating in next-generation fighter engine development. This positions MTU as a critical supplier and technology partner rather than a single-brand original equipment manufacturer. Tusaş Engine Industries supports indigenous jet engines and engine parts or modules for UAVs, commercial, and military aircraft, alongside assembly and component production for international programs. Its profile reflects a growing regional capability set that is especially relevant where sovereignty, defense readiness, and local content requirements shape procurement. Williams International rounds out the landscape with the FJ33/FJ44 business jet turbofan family, serving general aviation and business aircraft platforms. This specialization in business aviation creates a focused niche where product range, service responsiveness, and platform fit matter more than mass-market volume.
Recent Developments and Strategic Implications
Recent company actions show how the competitive field is shifting in practice. In May 2026, SSAMC became the first CFM LEAP Premier MRO Provider in China, and in April 2026, IAG and CFM signed a new LEAP Premier MRO license agreement. These moves underscore the importance of controlled aftermarket expansion and the strategic value of service authorizations in key geographies. In January 2026, Safran expanded operations in Le Creusot to manufacture complex parts for Rafale engines, reinforcing defense-oriented capacity. In February 2026, Safran launched the European Clean Aviation TAKE OFF project with partners, pointing toward collaborative decarbonization efforts that may influence future engine architectures and supporting ecosystems. Tusaş Engine Industries showcased national aviation engines at SAHA 2026 in May 2026, aligning with regional demand for sovereign propulsion capabilities. Williams International’s new $1 billion turbine engine factory in Florida, announced in April 2026, reflects continued investment in business aviation manufacturing capacity. Together, these developments highlight three recurring themes: the expanding importance of MRO ecosystems, the continued layering of defense and commercial production needs, and the strategic use of facility investment to support both volume and specialized output.
Emerging Structural Trends in Competition
The competitive landscape is not simply consolidating or fragmenting; it is becoming more layered. On one hand, integrated engine families and JV structures continue to concentrate value in capable incumbents with strong platform positions and aftermarket capability. On the other hand, specialized suppliers, regional manufacturers, and platform-specific entrants are gaining relevance in components, modules, UAVs, and defense programs. For the market as a whole, this means competition is increasingly multidimensional. Some firms will compete on scale, fuel efficiency, and global support networks. Others will compete on customization, regional access, and secure production relationships. New entrants are unlikely to displace the largest engine franchises quickly, but they can create meaningful influence in niches where local content, sovereign requirements, or specialized missions shape purchasing decisions. The strategic question for incumbents is whether they can preserve platform leadership while accommodating new suppliers and navigating trade-sensitive sourcing. For smaller players, the opportunity lies in demonstrating differentiated technical value and reliable execution in selected programs.
Diesel Engines Market
Forward Outlook: Where Value Is Likely to Concentrate
Looking across the 2026–2032 horizon, three trends are likely to shape commercial outcomes and define where strategic advantage can be built.
Efficiency as a Default Requirement, Not an Optional Upgrade
As next-generation engine technologies mature and environmental expectations tighten, efficiency will move from a competitive differentiator to a baseline requirement. CFM International’s RISE program is one example of how propulsion roadmaps are being structured around materially lower carbon emissions for mid-2030s entry. This matters commercially because efficiency improvements affect fuel costs, maintenance profiles, and fleet planning over long asset lives. For manufacturers, the opportunity is to turn technology roadmaps into credible product narratives and delivery commitments. For operators and financiers, the opportunity is to align platform selection with future operating conditions rather than only current economics. The uncertainty is timing: technology maturation, certification pathways, and airline fleet cycles do not always move in sync, and early positioning can carry commitment risk if deployment schedules shift.
Geopolitically Aware Supply Chains and Aftermarket Coverage
Trade policy, export controls, and tariff structures are now part of the market’s operating environment. License requirements for certain civil parts destined for China when military end-use risk exists, combined with broader export pauses and targeted tariffs, mean that engine supply and service coverage need to be mapped against jurisdictional rules. This creates a strategic premium for firms that can maintain resilient sourcing, qualify alternative supply paths, and offer customers predictable service continuity. Over the next few years, we can expect more attention to regional MRO capacity, localized production for sensitive platforms, and structured compliance management as part of customer value propositions. The risk is that overly rigid supply designs reduce flexibility, while overly simplified assumptions about trade rules create disruption when regulations change. The balance will favor companies that treat geopolitical exposure as a managed variable rather than a background condition.
Aftermarket Control as a Profitability Anchor
As new engine families accumulate service hours, the aftermarket will increasingly determine lifecycle economics. Service agreements, MRO provider designations, and license relationships are becoming more visible strategic tools. Recent MRO agreements involving CFM and regional providers show how engine-makers are building service presence in important markets. This trend is likely to continue because aftermarket revenue can be more stable and recurring than new-engine delivery cycles, especially for high-utilization narrow-body fleets and long-serving military platforms. For competitive positioning, the ability to provide reliable, authorized support can reinforce customer lock-in and improve total-value perception. The risk is that aftermarket expansion can become uneven if service capacity, parts availability, or regulatory access does not keep pace with engine placement, especially in complex or trade-sensitive regions.
Rocket Engine Market
Actionable Guidance for Decision-Makers
The jet engines market offers strong long-cycle growth, but capturing value requires decisions that reflect technology timing, trade complexity, and aftermarket strategy rather than relying on demand growth alone.
For Manufacturers, Program Leaders, and Suppliers
Align product roadmaps with the efficiency expectations that are now reshaping platform selection. This means investing not only in performance claims, but in certification progress, serviceability, and demonstrable operating-cost reduction. Build supply strategies that can tolerate export-control and tariff friction without disrupting core programs. Where possible, diversify critical component sources and maintain clear compliance pathways for cross-border movement of parts and technical data. For component suppliers and specialized manufacturers, identify niches where sovereign content, defense readiness, or dedicated platform support create structural demand, and focus on execution reliability and qualification speed.
For Investors and Corporate Strategy Teams
Evaluate propulsion exposure with a focus on lifecycle economics, not only unit sales. Engine programs with strong aftermarket potential, durable platform adoption, and manageable trade exposure are likely to offer more predictable value than those dependent on narrow delivery windows. Pay attention to where capacity investments are being made and how service coverage is expanding, because these signals often precede shifts in competitive strength. Be attentive to concentration risk and to the fact that market leadership may be unevenly distributed across civil and military segments, regions, and engine types. A portfolio view that distinguishes between high-volume narrow-body exposure, wide-body specialization, and defense-linked production can provide better clarity on where returns are most likely to materialize.
For Procurement, Fleet Planners, and Operating Companies
Treat propulsion selection as a multi-period decision. Engine efficiency, fuel-price exposure, support availability, and compliance complexity should all be weighed together, because a lower acquisition cost can be offset by higher operating expense or service constraints over time. When evaluating options, prioritize vendors that can demonstrate reliable local or regional support, clear licensing and trade readiness, and stable parts and MRO pathways. In trade-sensitive contexts, structure sourcing and service plans to reduce disruption risk, including contingency arrangements for spare parts, repair capacity, and technical support. Where specialized platforms or UAVs are involved, consider whether indigenous or regional capability offers strategic value beyond pure cost comparison.
PW Consulting
Why Deeper Intelligence Matters Now
The market is moving on several axes at once: technology roadmaps are advancing, trade and export conditions are shifting, and aftermarket relationships are becoming more strategically important. These changes alter which combinations of platform, geography, and supplier capability will generate the strongest returns. Broad market sizing and high-level segmentation can identify direction, but they do not show where specific opportunities are likely to open or where exposure may be concentrated. Detailed forecasts by engine family, application, region, pricing trajectory, and program-level service dynamics are needed to turn strategic themes into operational decisions. For that reason, teams evaluating investments, production plans, or procurement strategies should pair this high-level view with a more granular research asset that maps the segments, company developments, and regional dynamics in greater depth. A full research report can provide the decomposed data and customized assumptions required to test scenarios, prioritize initiatives, and compare competitive positioning across the most relevant segments.
For detailed analysis of this topic, please visit the official page: Jet Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ear Wash Station Market: Beyond the 4.65% CAGR Story—Key Shifts Explained
By PW Consulting, 2026-09-21
The Eye Wash Station Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for emergency eye wash stations has entered a phase of measured, steady expansion. From 2020 through 2025, total market revenue climbed from approximately USD 300.0 million to USD 435.0 million, reflecting a compound trajectory that underscores the essential nature of workplace safety infrastructure. Looking ahead to the 2026–2032 forecast horizon, the market is projected to grow at a CAGR of 4.65 percent, reaching an estimated USD 596.0 million by 2032. This growth profile is not explosive, but it is structurally resilient. Emergency first-aid equipment sits at the intersection of regulatory compliance, industrial activity levels, and organizational risk management priorities. As long as those foundational drivers remain intact, the market maintains a predictable revenue floor alongside pockets of incremental upside.
Behind the headline numbers, however, lie structural shifts that demand attention from manufacturers, distributors, procurement leaders, and investors. The market is no longer moving purely on compliance-driven replacement cycles. It is being reshaped by evolving technical expectations, tightening performance standards, supply chain recalibration, and shifting application profiles across high-exposure industries. Understanding these dynamics is essential for anyone positioning themselves in the safety equipment space.
Current Market Landscape and Critical Challenges
The eye wash station market operates as a mature but still evolving segment within the broader workplace safety equipment ecosystem. Revenue growth over the past half-decade has been supported by steady industrial output, ongoing laboratory expansion, and consistent investment in occupational health infrastructure. Rather than experiencing abrupt cyclical swings, the market reflects the incremental nature of compliance upgrades, facility build-outs, and periodic modernization programs. The forecast period through 2032 suggests continued expansion, but at a pace that rewards companies with disciplined product planning, strong service networks, and clear differentiation rather than those relying solely on volume-driven commoditization.
Three core challenges and inflection points are shaping how participants navigate the market today.
Compliance complexity and specification drift. Emergency eyewash requirements are not static checklists. Regulatory frameworks and recognized standards continue to refine expectations around water temperature, flow consistency, activation speed, and maintenance protocols. For manufacturers and specifiers alike, this creates a moving target: products must satisfy baseline compliance while also aligning with installation practices, testing routines, and user training expectations that vary by facility type, region, and internal safety policies. The challenge is not simply meeting a standard once; it is designing systems that remain compliant over their service life under real operating conditions.
Total cost of ownership versus upfront purchase price. Many procurement decisions still default to initial cost, even though the operational footprint of an eyewash station can be substantial. Plumbed systems involve plumbing integration, water quality management, and ongoing testing programs. Self-contained units reduce infrastructure dependence but require cartridge or solution replacement, inventory management, and scheduled service. Combination units and higher-performance configurations add complexity and cost. Organizations increasingly need to evaluate installed cost, maintenance burden, downtime risk, and compliance documentation rather than treating eyewash stations as discrete commodity purchases.
Uneven adoption across facility types and geographies. While large industrial operators and accredited laboratories tend to have mature safety programs, smaller facilities, newer industrial zones, and certain emerging market environments may lag in standardization. This creates a bifurcated market where some segments demand advanced features and frequent replacement cycles, while others remain price-sensitive or delay investment until regulatory inspection or incident-driven reassessment forces action. Participants must therefore balance portfolio scope: offering accessible entry-level solutions while preserving higher-margin options for performance-conscious buyers.
These challenges also represent the market's pressure points for innovation. Companies that reduce compliance uncertainty, simplify maintenance, or make total cost easier to quantify are better positioned to capture specification wins and retain end users over time.
Key Drivers Shaping the Market
The market's trajectory is being pulled by several interconnected forces. Individually, each matters; together, they define where growth is likely to concentrate and where competitive advantage will be earned.
Eye Anatomical Model Market
Technical innovation and performance differentiation
One of the most significant drivers is the ongoing push toward better flushing performance, faster activation, and more predictable user experience. Innovative rinsing technologies, improved flow distribution, and ergonomic actuation mechanisms are becoming meaningful differentiators, especially in environments where seconds matter and the margin for error is small. Products designed to deliver consistent dual-eye coverage, tepid water delivery, and intuitive activation address both compliance goals and practical usability concerns. In laboratory and healthcare-adjacent settings, compact footprints, easy integration with existing wall or bench configurations, and reduced risk of cross-contamination during use are also shaping purchasing preferences.
For manufacturers, the strategic implication is clear: technical features are increasingly tied to specification decisions. Product leadership now extends beyond build quality into performance reliability, ease of testing, and the ability to document compliance over time. This elevates the importance of engineering discipline, validation data, and post-sale support in competitive positioning.
Regulatory expectations and standards enforcement
Regulatory frameworks continue to anchor demand for emergency eyewash infrastructure. Occupational safety requirements mandate suitable facilities for immediate flushing where eyes or body may be exposed to harmful corrosive materials. In practice, this creates a baseline obligation for employers operating in at-risk environments and pushes safety equipment from optional courtesy infrastructure into essential compliance assets.
At the same time, recognized performance and installation guidance continues to sharpen expectations around continuous flow, tepid water delivery, minimum flush duration, and simultaneous eye coverage. Manufacturers and facility managers must therefore consider not only whether a unit exists, but whether it performs correctly under required conditions and can be maintained accordingly. This dynamic reinforces demand for compliant products and services, while also raising the stakes for installation, testing, and recordkeeping practices. In effect, regulation is not only stimulating purchase volume; it is also increasing the cost of non-compliance and rewarding organizations that treat eyewash readiness as an integrated program rather than a point purchase.
Demand-side behavior and organizational risk culture
Buyer behavior is shifting from reactive compliance toward proactive risk management. In chemical-intensive industries, pharmaceutical operations, electronics manufacturing, and oil and gas facilities, the consequences of inadequate first-aid readiness are visible and potentially severe. As a result, safety equipment is increasingly evaluated through the lens of incident mitigation, employee protection, and operational continuity rather than solely regulatory checking.
This cultural shift influences purchasing in several ways. Facilities are more likely to standardize across sites, prefer combination units in high-risk zones, and invest in products that simplify inspection and maintenance workflows. Laboratory environments, in particular, often prioritize immediate accessibility and space-efficient designs that support rapid deployment without disrupting sensitive workflows. In parallel, growing awareness of worker welfare and safety branding can make higher-specification units more attractive, especially where organizations are trying to signal a strong safety culture to staff, auditors, or partners.
Supply chain structure and regional manufacturing dynamics
Cost structure and supply resilience are becoming more prominent in purchasing and product strategy. Manufacturers must navigate raw material pricing, component availability, shipping volatility, and the operational requirements of maintaining consistent quality across different production locations. At the same time, regional sourcing options are shaping buyer considerations around lead times, customization, and support responsiveness.
This environment favors companies that can balance scale with flexibility. For some buyers, domestically produced or well-supported regional products offer perceived advantages in documentation, service proximity, and specification familiarity. For others, competitive pricing and broader portfolio availability from international manufacturers create attractive alternatives, especially in price-sensitive segments or fast-growing industrial markets. The result is a more varied competitive field in which differentiation often comes from a combination of product reliability, service access, and the credibility of compliance support rather than price alone.
Competitive Landscape and Leading Strategies
The market features a diverse set of participants spanning established manufacturers, safety-focused brands, laboratory specialists, distributors, and international producers. This diversity reflects the broad application base of emergency eyewash equipment and the different ways customers evaluate solutions. The presence of multiple competent suppliers also means that competitive advantage depends heavily on execution: product design, compliance alignment, service coverage, and go-to-market clarity.
Parts Washer Market
Strategic positioning among leading participants
Several companies illustrate the range of successful strategic approaches in the market.
Haws Corporation has built a strong identity around flushing performance and application-specific engineering. Its emphasis on advanced rinsing technology for industrial, laboratory, and healthcare settings positions it as a solution provider for buyers who prioritize performance consistency and specialized use cases. This approach helps the company compete on specification quality rather than solely on price, particularly in environments where superior flushing performance is directly tied to safety outcomes.
Guardian Equipment Company is widely recognized for emergency eyewash and shower equipment that covers wall-mounted, pedestal-mounted, and combination configurations. Its alignment with ANSI/ISEA Z358.1 and OSHA expectations gives buyers a straightforward compliance narrative, which is valuable in procurement environments where standardization and audit readiness matter. The breadth of mounting options and unit types also supports flexibility across facility layouts and risk zones.
Bradley Corporation focuses on industrial emergency eyewash stations, safety showers, and combination units with customizable features for high-risk chemical exposure areas. This positions the company well in environments where exposure risk is significant and where specifiers want solutions that can be adapted to specific operational conditions. Customization capability can be a decisive factor when standard off-the-shelf configurations do not fully match site requirements or when facilities seek to consolidate safety equipment specs across complex installations.
Speakman Company offers plumbed and portable eyewash stations along with replacement parts and safety showers. This combination of product supply and parts availability supports longer-term customer relationships by addressing the maintenance and replacement cycle. For many end users, ongoing service access and parts availability are as important as the initial purchase, especially when compliance testing and operational readiness must be sustained over time.
Haws Safety Products under Honeywell brings the recognizable Fendall® brand into industrial and laboratory settings with eye wash stations and cartridges designed for immediate flushing. The brand and cartridge-based approach can resonate with buyers looking for predictable performance, simplified resupply, and familiarity across multiple sites. In laboratory contexts especially, compact cartridge-based solutions may offer a practical balance between readiness and infrastructure demands.
Hughes Safety Company designs ANSI-compliant eyewash stations, self-contained units, and emergency showers for global industrial and workplace use. Its international orientation and compliance-focused portfolio make it relevant for organizations operating across multiple jurisdictions or seeking a consistent safety equipment standard across global facilities. For multi-site enterprises, that consistency can reduce specification fragmentation and simplify training and maintenance programs.
LOC Scientific targets laboratory eye wash station units designed for immediate emergency rinsing and compliance in research and industrial labs. By concentrating on laboratory-specific needs, it addresses a segment where accessibility, space constraints, and rapid response expectations are particularly acute. Niche focus can be a strong competitive lever when the end user environment has distinct operational requirements and when general-purpose products do not fit as cleanly.
Unicare stands out as a pioneer manufacturer based in India, producing eye/face wash stations and safety showers with in-house engineering for industrial and laboratory applications. This reflects the growing relevance of regional manufacturing capability and self-contained engineering resources. For buyers in emerging industrial markets or those seeking localized supply and support, such providers can offer attractive combinations of price, responsiveness, and application understanding.
EyewashDirect.com operates as a distributor and provider of eyewash stations, safety showers, and repair parts from leading manufacturers. Its role highlights the continued importance of distribution channels in this market. Many buyers prefer consolidated sourcing, technical guidance, and access to multiple brands when specifying safety equipment. Distributors that can combine product breadth with compliance-oriented support often serve as important intermediaries between manufacturers and end users.
Sysbel Manufacturing, based in China, supplies laboratory and industrial eye wash systems, including emergency eyewash solutions for chemical splash protection. Its presence underscores the growing influence of international manufacturers in both laboratory and industrial segments, particularly where cost competitiveness, export capability, and expanding portfolio range align with buyer needs.
How the competitive structure is evolving
The market is neither highly concentrated nor fragile. The competitive share distribution suggests room for multiple winners, with leadership determined by product relevance, service quality, and specification influence rather than by scale alone. Over time, three evolutionary patterns are likely to persist.
Consolidation through capability, not just acquisition. Some tightening may occur as larger platforms strengthen their safety portfolios or as distributors integrate broader product lines. However, meaningful consolidation will likely be driven by the desire to offer more complete compliance, service, and specification support rather than by eliminating competition purely for market share.
Segmentation by application and performance tier. As buyers become more sophisticated, the market will continue to differentiate between baseline compliance units and higher-performance or specialized solutions. Manufacturers that can clearly articulate why a given design is better suited to a specific environment—chemical processing areas, laboratory benches, outdoor sites, or multi-hazard work zones—will have stronger positioning.
Entry and expansion from regional and international suppliers. New and expanding suppliers can gain traction by offering competitive alternatives in specific geographies or application niches. This creates both opportunity and pressure for incumbents to defend specification relationships, demonstrate reliable performance, and maintain strong service networks.
Future Trends and What They Mean for Opportunities
Over the next three to five years, the eye wash station market is likely to be shaped by trends that blend compliance, technology, and operational practicality. These trends are not speculative shifts; they are extensions of current pressures and buyer priorities.
Trend 1: Compliance-as-program instead of compliance-as-equipment
Emergency eyewash readiness will increasingly be treated as an ongoing operational program rather than a one-time installation decision. That means greater emphasis on testing routines, documentation, activation reliability, solution or cartridge management, and user training. For suppliers, this opens opportunities in service, replacement parts, inspection support, and products designed to make compliance easier to sustain. For buyers, it argues for selecting equipment and partners that reduce administrative and maintenance friction over the asset lifecycle.
Trend 2: Performance features become default purchasing criteria
As the market matures, features that improve flushing effectiveness, speed of access, temperature control, and ease of use are likely to move from differentiators to expected attributes in many segments. This will reward manufacturers with clear engineering advantages and penalize those competing only on price in specification-driven environments. The commercial opportunity lies in translating technical performance into practical outcome language that resonates with safety managers, facility engineers, and procurement teams.
Trend 3: Broader application diversification and regional growth paths
Demand will continue to spread across chemical, pharmaceutical, electronics, oil and gas, and other industrial or laboratory environments, but the pace and mix will vary. In some regions, expanding industrial activity and laboratory build-outs will support stronger volume growth. In others, replacement cycles and compliance upgrades will be the main driver. This unevenness creates targeted opportunities: companies that align product portfolios with high-exposure segments and regional demand patterns can capture disproportionate relevance in the markets that matter most to them.
PW Consulting
Potential risks and uncertainties
Several uncertainties deserve attention. Regulatory expectations or interpretation can shift, affecting specification requirements and maintenance burdens. Economic cycles may pressure capital spending, particularly among smaller operators or in segments where safety equipment competes with more immediate operational priorities. Supply chain disruptions or input cost volatility can affect margins and delivery reliability. In addition, if buyers over-emphasize lowest initial cost, the market may experience pressure on quality differentiation and service investment. Companies that depend on a narrow product range or on a single geography may also face greater exposure if demand patterns shift unexpectedly.
Strategic Actions for Decision Makers
Different participants should approach the market with different priorities, but several actionable themes apply across roles.
For manufacturers and product developers, clarity of application focus is essential. Rather than competing broadly on volume alone, define where your design advantages actually matter—whether that is flushing performance, laboratory compactness, combination-unit flexibility, cartridge-based resupply, or serviceability. Invest in the documentation, validation, and support materials that help specifiers justify selection during procurement reviews. In parallel, treat maintenance and parts availability as part of the product story, because long-term compliance depends on them.
For investors and strategic planners, the market offers steadier demand characteristics than many discretionary industrial categories, but the best opportunities are likely to come from companies with defensible positioning in specification-driven segments. Look for participants that can demonstrate consistent compliance alignment, meaningful product distinction, and reliable routes to end users through distribution, service, or direct enterprise relationships. Capital allocation should favor structures that can withstand pricing pressure while still investing in performance and support.
For procurement teams and facility operators, the strongest buying decisions will come from evaluating total ownership impact rather than unit price alone. That includes installation requirements, testing burden, water quality considerations, cartridge or solution replacement logistics, replacement part availability, and the consistency of the solution across multiple sites. Where possible, standardize specifications to reduce training and maintenance complexity, and ensure that selected units genuinely match the exposure profile of each zone rather than defaulting to a single model across all areas.
Across all of these roles, timely and detailed market intelligence matters because the eye wash station market is not driven by a single force. It is shaped by overlapping regulation, technical expectations, application needs, and regional dynamics. Decisions made without a clear view of those layers can lead to over-investment in the wrong product tier, missed specification opportunities, or insufficient attention to service and compliance sustainability. The broader market trajectory is constructive, but the real value lies in understanding where growth is concentrated, which product attributes are becoming non-negotiable, and how competitive advantage is being earned on the ground.
Conclusion
The eye wash station market is expanding along a stable, compliance-anchored path, with growth reinforced by industrial activity, laboratory demand, and the continued institutionalization of workplace safety programs. Yet the most important developments are not simply the headline revenue figures. They are the shifts in how products are specified, maintained, and justified; the increasing importance of performance and usability; and the growing influence of service, distribution, and regional manufacturing in shaping buyer choices. Participants that treat eyewash readiness as a long-term operational commitment—and build products, bundles, and relationships accordingly—are best positioned to benefit from the market's next phase of growth.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Karl Fischer Titrators Market: Strategic Trends and Commercial Opportunities Through 2032
The Karl Fischer titration market has entered a phase of sustained expansion, driven by tightening quality standards, evolving regulatory expectations, and the growing need for precise moisture determination across critical industrial and life sciences applications. Valued at approximately $230 million in 2025, the market has grown consistently from its 2020 baseline, reflecting a compound annual growth rate of 5.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $335 million, underscoring a steady but structurally shifting demand profile. This trajectory is not merely a function of incremental adoption; it reflects a broader transformation in how organizations approach analytical chemistry, compliance, and operational efficiency. The market's resilience amid macroeconomic fluctuations suggests that moisture analysis has transitioned from a optional quality control step to an embedded requirement across regulated and high-stakes production environments.
Yet expansion alone does not capture the strategic reality facing manufacturers, investors, and procurement leaders. The market is navigating several inflection points that will determine which players capture disproportionate value and which face margin compression or relevance erosion. Understanding these dynamics requires moving beyond headline growth figures and examining the underlying technological, regulatory, and competitive forces reshaping the landscape.
PW Consulting
Market Landscape and Core Challenges
A Market Shaped by Concentration and Capability Gaps
The Karl Fischer titrators market remains moderately concentrated, with the top three participants capturing roughly 70 percent of total revenue and the leading five firms accounting for approximately 85 percent. This concentration reflects the high technical barriers to entry, the importance of reagent ecosystems, and the entrenched procurement relationships within pharmaceutical, chemical, and regulated manufacturing environments. While concentration typically signals stability, it also masks underlying fragmentation in application-specific needs, regional adoption curves, and the widening gap between legacy benchtop systems and next-generation automated or connected platforms. Organizations that continue to treat Karl Fischer titration as a commoditized measurement tool risk underestimating the strategic weight of calibration integrity, data traceability, and operator workflow optimization.
Challenge 1: Balancing Precision with Operational Efficiency
One of the most persistent tensions in the market is the trade-off between measurement precision and throughput. Traditional titration workflows, while highly accurate, often require skilled operators, manual reagent handling, and frequent titer verification. In high-volume environments, these requirements translate into labor intensity, inconsistent turnaround times, and elevated risk of human error. The pressure to increase sample throughput without compromising compliance-grade accuracy is pushing laboratories and production teams to reevaluate their instrumentation strategies. Companies that fail to integrate automation, sample handling, or streamlined calibration routines will find their solutions increasingly misaligned with the operational tempo of modern quality and process labs.
Challenge 2: Regulatory Complexity and Data Integrity Expectations
The regulatory environment surrounding moisture analysis has become more demanding, particularly in pharmaceutical and biotechnology applications where data integrity, auditability, and instrument validation are non-negotiable. Compliance with frameworks such as FDA 21 CFR Part 11 andGood Manufacturing Practice expectations requires more than accurate titration results; it demands secure data handling, version-controlled methods, and traceable calibration records. At the same time, emerging cybersecurity and resilience requirements, including the EU Cyber Resilience Act, are extending compliance obligations into laboratory equipment ecosystems that were historically treated as isolated analytical tools. For manufacturers and end users alike, this creates a dual burden: maintaining analytical rigor while implementing stronger software governance, access controls, and remote diagnostic safeguards.
Challenge 3: Reagent Stability and Supply Chain Reliability
Moisture titration depends heavily on reagent quality and consistency, yet standard solvents and titration reagents introduce operational variability that can quietly erode measurement confidence. Methanol-based solvents used in volumetric Karl Fischer titration, for example, exhibit gradual titer degradation that necessitates regular verification and corrective adjustments. Approximately a 5 percent titer decrease per year is typical, meaning that laboratories must build routine titer checks into their workflows or risk systematic measurement drift. This reality complicates cost planning, increases consumable management overhead, and underscores the importance of reagent formulation innovation. In an era where supply chain volatility can disrupt laboratory operations, the ability to standardize reagent performance and reduce frequent titer corrections is becoming a meaningful differentiator rather than a logistical footnote.
Laboratory Water Purifier Market
Key Drivers Reshaping the Market
Technological Innovation and the Shift Toward Intelligent Titration
Technological advancement is the most visible force propelling market evolution. The industry is moving beyond standalone titration units toward integrated systems that combine faster detection algorithms, automated sample introduction, and smarter calibration logic. Recent product introductions illustrate this shift clearly. In mid-2024, a major analytical instrumentation provider launched a volumetric Karl Fischer titrator featuring a fast-forecasting amperometric algorithm alongside an oven autosampler designed for high-throughput water analysis. The combination of improved signal processing and automated sample handling directly addresses the throughput-versus-precision tension described earlier. A few months later, another manufacturer extended its titrator lineup by upgrading control firmware and electrode systems to improve measurement stability, highlighting how incremental engineering refinements can yield meaningful gains in repeatability and operator confidence.
By early 2025, the trend toward intelligence and remote support became even more pronounced when a leading Swiss instrumentation firm released a titration platform integrating AI-based calibration and remote diagnostics. This move signals a broader industry recognition that instrumentation value is increasingly defined by software-enabled accuracy, predictive maintenance, and reduced downtime rather than mechanical design alone. In parallel, a major scientific instrumentation company introduced a portable Karl Fischer moisture analyzer with wireless connectivity and ruggedized construction for field applications, expanding the addressable use cases beyond controlled laboratory environments into on-site production, logistics, and remote quality checks. These developments collectively point to a market where analytical performance, connectivity, and deployment flexibility are converging.
Regulatory and Compliance Pressures as Adoption Accelerators
Regulatory expectations are not merely constraints; they are powerful adoption drivers. In regulated industries, the requirement for validated methods, documented data integrity, and instrument traceability encourages organizations to upgrade from informal or aging titration setups to compliant, auditable systems. The emphasis on data security and operational resilience is also reshaping procurement criteria. As laboratory operations face updated GMP expectations and broader cybersecurity mandates, buyers are increasingly prioritizing instruments that support secure data handling, controlled user access, and firmware or software update pathways that do not compromise validated states. This regulatory momentum benefits manufacturers that design compliance into their platforms from the outset, while creating friction for those relying on retrofitted or opaque software architectures.
Evolving Demand Patterns Across Regulated and Process Industries
Demand is being shaped by a combination of quality intensification and broader application expansion. In pharmaceutical and biotechnology environments, moisture specification control remains critical for product stability, formulation integrity, and process validation, sustaining steady demand for high-precision titration solutions. In the chemical industry, moisture monitoring influences reaction control, catalyst performance, and product grading, reinforcing the need for reliable titration across both laboratory and process-adjacent settings. Food and beverage applications, while smaller in relative terms, continue to drive adoption where moisture content affects shelf life, sensory properties, and regulatory compliance. Beyond these core segments, additional application areas contribute to demand diversification, including specialized industrial testing and routine quality assurance workflows.
What matters strategically is not just the existence of these application segments, but the changing expectations within them. End users increasingly want solutions that reduce hands-on time, simplify reagent management, and integrate cleanly into existing laboratory or production data environments. The organizations winning adoption are those that align instrumentation capabilities with practical workflow outcomes rather than competing solely on specification sheets.
Supply Chain, Consumables, and Cost Structure Dynamics
Cost structures in the Karl Fischer titrators market are influenced by both hardware economics and ongoing consumable requirements. Instrument pricing remains important, but total cost of ownership is increasingly defined by reagent consumption, titer verification frequency, maintenance intervals, and the operational cost of downtime. The stability of standard methanol solvents and the recurring need for titer checks illustrate how consumable behavior can affect laboratory budgeting and staffing. At the same time, efforts to develop more stable or eco-friendly titration reagents are gaining traction. A notable partnership in mid-2025 between a major instrument manufacturer and a leading chemical producer focused on co-developing eco-friendly titration reagents for Karl Fischer applications, signaling that reagent innovation is becoming a strategic pillar rather than a back-end supply detail. For end users, better reagent stability translates into fewer corrective checks and more predictable consumable planning; for manufacturers, it opens avenues for differentiated reagent ecosystems and longer service intervals.
Competitive Landscape and Strategic Positioning
Established Leaders and Their Differentiation Plays
The competitive field is anchored by a mix of globally established analytical instrumentation firms and specialized manufacturers with strong regional or application-specific footprints. One of the leading Swiss providers has built its position around a broad portfolio spanning volumetric and coulometric platforms, including models designed for liquid, solid, and gaseous sample types. Its recent emphasis on AI-assisted calibration and remote diagnostics reflects a strategy centered on reducing operational uncertainty and extending service reach beyond the laboratory door. By embedding intelligence into calibration and support workflows, the company aims to reinforce trust in measurement results while lowering the hidden costs of troubleshooting and repeat analysis.
A major U.S.-based instrumentation player has pursued a parallel but distinct path, focusing on automatic titration systems and high-precision moisture analysis workflows. Its product lineup includes volumetric and coulometric options, complemented by oven autosampling capabilities that support higher throughput and broader sample handling. The strategic logic here is clear: by pairing precise titration chemistry with automation and robust application support, the company addresses the needs of laboratories that must handle larger sample volumes while maintaining compliance-grade data quality. This automation-led positioning is particularly relevant in environments where operator time and method consistency are under pressure.
Another prominent European analytics group has strengthened its presence through automatic titration platforms engineered for both volumetric and coulometric water determination, with connectivity-oriented design elements such as integrated interface sockets for expanded system integration. This connectivity focus aligns with the broader industry movement toward instruments that can sit within larger analytical or laboratory data ecosystems rather than functioning as isolated devices. Meanwhile, a Japanese manufacturer has carved out a recognizable position through dedicated moisture titration series and proprietary reagent formulations, emphasizing precision and application-specific reliability. Its product range spans coulometric and volumetric models designed for automated moisture analysis, reinforcing the importance of matched reagent-instrument systems in delivering consistent results.
Moisture Analyzer Market
U.S.-based specialty manufacturers have also maintained meaningful positions, particularly where application focus sharpens competitive advantage. One company has concentrated on coulometric titrators for petroleum, petrochemical products, oils, and solvents, an application segment where moisture control is tightly linked to product quality and processing efficiency. Another major water analysis and instrumentation supplier offers automatic Karl Fischer titrators suited to both laboratory and process applications, reflecting the value of versatile platforms that can bridge analytical and near-process environments. A further U.S. provider emphasizes customizable volumetric titration setups for laboratory moisture analysis, appealing to organizations that prioritize flexibility in method configuration and sample handling.
In Japan, another electronics and instrumentation manufacturer has contributed to the market with moisture titrators supported by dedicated reagent systems designed for industrial sample analysis, underscoring the continued relevance of regional engineering expertise and application-tuned reagent chemistry. At the same time, Chinese manufacturers have been expanding their presence with cost-competitive titrator platforms that combine practical specifications with upgraded firmware and electrode systems. Recent updates from one Chinese manufacturer highlighted improved measurement stability through firmware and electrode enhancements, illustrating how emerging competitors are moving beyond price competition toward capability refinement. Another Chinese firm has promoted titrator solutions with defined polarization current and repeatability characteristics, appealing to buyers who need predictable performance at accessible price points.
Market Evolution: Consolidation, Differentiation, and New Entry Points
The competitive landscape is evolving along three concurrent paths. First, established leaders are deepening differentiation through software, automation, and service connectivity rather than hardware novelty alone. The most valuable platforms are increasingly those that reduce operator burden, improve calibration confidence, and support secure, auditable data practices. Second, application specialization remains a viable and often underappreciated route to competitive strength. Companies that tailor their titration platforms, reagents, and workflow support to specific industries or sample types can build durable demand even in a concentrated market. Third, new and expanding entrants are challenging the assumption that advanced titration capabilities are the exclusive domain of large multinational firms. By improving measurement stability, offering practical specifications, and targeting cost-sensitive segments, these players are widening the competitive field and pressuring incumbents to justify premium positioning through demonstrable workflow and compliance benefits.
For buyers and investors, this evolution means that competitive advantage is less about brand familiarity and more about fit: fit between instrument capabilities and sample workflows, fit between reagent systems and verification frequency, and fit between software architecture and regulatory or cybersecurity expectations. The organizations that can articulate and deliver that fit will be best positioned to defend share and expand into adjacent application areas.
Forward Outlook: Three Strategic Trends to Watch
Trend 1: Intelligence and Remote Support as Standard Expectations
Over the next three to five years, AI-assisted calibration, predictive diagnostics, and remote support capabilities are likely to transition from differentiators to baseline expectations in the Karl Fischer titrators market. The recent introduction of platforms featuring AI-based calibration and remote diagnostics, alongside firmware and electrode upgrades aimed at measurement stability, indicates that the industry is already moving in this direction. For manufacturers, this trend creates opportunities to design instruments that reduce downtime, simplify maintenance planning, and improve result consistency across operators and sites. For end users, the commercial implication is clear: instrumentation that supports fewer interruptions, more reliable calibration states, and faster issue resolution can lower the hidden costs of moisture analysis and improve laboratory throughput. The principal risk is that intelligence features become commoditized quickly, shifting the competitive battleground toward data security, integration depth, and long-term service economics rather than feature presence alone.
Trend 2: Compliance and Cybersecurity as Procurement Filters
Regulatory and cybersecurity requirements will increasingly shape purchasing decisions, particularly in regulated industries and multi-site laboratory environments. Compliance with data integrity expectations and broader resilience mandates is pushing organizations to evaluate instruments not only on analytical performance but also on software governance, user access control, validation support, and update management. This trend favors manufacturers that have built compliance-friendly architectures and can provide clear documentation and support pathways. It also creates a practical opportunity for vendors to bundle instrumentation with services that help laboratories maintain validated states while adapting to evolving security requirements. The uncertainty lies in the pace and variability of regulatory interpretation across regions, which may lead to uneven adoption timelines and divergent compliance expectations that complicate global deployment strategies.
Trend 3: Reagent Innovation and Field-Ready Deployment Expanding Use Cases
Two related developments are likely to broaden the market's application base and change how moisture analysis is deployed. First, reagent innovation focused on improved stability and environmental profile is gaining momentum, with partnerships aimed at co-developing eco-friendly titration reagents signaling a longer-term shift in consumable strategy. If these efforts translate into reduced titer drift and more predictable handling, they can lower the operational burden of routine verification and improve cost predictability for end users. Second, the expansion of portable and ruggedized moisture analysis tools with wireless connectivity is extending Karl Fischer-based measurement into field and process-adjacent settings. This opens opportunities in industries where sample transport to a central laboratory creates delays or where on-site decisions depend on rapid moisture data. The commercial opportunity for manufacturers lies in building platforms that combine dependable analytical performance with practical field usability and consumables that hold up under varied operating conditions. The risk is that broader deployment also exposes instruments to more demanding environments, increasing the importance of robustness, training, and support infrastructure.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Positioning should increasingly revolve around workflow outcomes rather than isolated specifications. Investments in automation, smarter calibration logic, electrode and firmware stability, and secure software architecture are likely to yield stronger competitive returns than incremental hardware changes alone. Equally important is the reagent and consumables strategy: improving reagent stability, offering clearer titer management guidance, and aligning reagent formulations with instrument performance can reduce customer friction and create defensible ecosystem advantages. Manufacturers should also prepare for compliance-driven procurement by ensuring that documentation, data handling, and update processes support auditable, validated operations without imposing disproportionate administrative burden on end users.
For Investors and Strategic Planners
The market's growth trajectory is steady, but value creation will be uneven. The most attractive opportunities are likely to emerge where technology, compliance readiness, and application fit intersect. Investors and planners should look beyond top-line growth and assess which companies are building durable advantages through software-enabled reliability, reagent ecosystem strength, and service models that reduce total cost of ownership. Interest in field-deployable and connected moisture analysis also suggests that adjacent use cases may expand demand beyond traditional laboratory settings. At the same time, concentration in the market means that competitive disruptions are more likely to come from capability upgrades by emerging players or from application-specific specialization than from broad-based price wars. Monitoring firmware, electrode, and reagent innovations, as well as partnerships that reshape consumable offerings, will provide early signals of shifting competitive dynamics.
For Procurement and Operations Leaders
Procurement decisions should weigh total cost of ownership more heavily than initial purchase price. Key evaluation criteria should include calibration and titer management burden, automation and sample handling capabilities, data integrity and software governance features, reagent stability expectations, and the vendor's ability to support validated or regulated environments. Where moisture analysis is tied to high-volume workflows or compliance-critical applications, instruments that reduce operator intervention and improve measurement repeatability can deliver meaningful operational savings over time. Procurement teams should also consider deployment context: laboratory-bound systems, process-adjacent setups, and field applications have different robustness, connectivity, and support requirements, and matching the platform to the environment can prevent underperformance and unnecessary service costs.
The Karl Fischer titrators market is entering a period in which analytical precision, operational efficiency, and compliance readiness must advance together. Organizations that treat moisture analysis as a strategic workflow rather than a routine test will be better positioned to capture the value of upcoming technological and regulatory shifts. For those seeking a more detailed breakdown of segmentation dynamics, regional adoption patterns, application-specific demand drivers, and competitive benchmarks to support internal planning, the full research report provides a deeper evidence base and tailored scenario guidance.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
VCI Anti Rust Paper Market: Why 4.8% CAGR and Hidden Applications Reshape 2032 Outlook
By PW Consulting, 2026-09-21
The VCI Anti Rust Paper Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and the Road Ahead
The global VCI anti rust paper market has demonstrated consistent expansion over the past half decade, moving from approximately 78.25 million USD in 2020 to an estimated 98.2 million USD in 2025. This trajectory reflects a compound annual growth rate of 4.8 percent, with projections indicating the market will cross the 136 million USD threshold by 2032. The growth is not merely a function of incremental volume increases but rather a structural shift in how manufacturers, logistics providers, and industrial distributors approach asset protection during storage and transit. Corrosion prevention has evolved from a compliance afterthought into a strategic component of supply chain resilience, quality assurance, and total cost of ownership calculations. Beneath these headline figures lies a market with concentrated positioning and distinct regional and sectoral imbalances. A handful of established players command the majority of market share, with the top three firms accounting for roughly 62.5 percent and the top five reaching 78.2 percent of total revenue. This concentration signals a mature competitive landscape where differentiation, rather than scale alone, determines winners. At the same time, regional demand patterns reveal divergent growth drivers, with developed markets focusing on regulatory compliance and technical performance while emerging economies prioritize cost-effective corrosion protection for expanding metalworking and packaging sectors. Understanding these underlying dynamics is essential for decision makers evaluating market entry, capacity expansion, or supplier relationships.
Structural Challenges Shaping the Market
Several intersecting challenges are forcing the industry to recalibrate its growth assumptions and operational strategies. Recognizing these friction points early allows executives to build more resilient business models rather than reacting defensively when pressures intensify.
One of the most pressing challenges is the tightening regulatory environment around chemical formulations. Environmental and safety directives in major markets are progressively restricting amine-based volatile corrosion inhibitors and phthalate-based plasticizers commonly used in VCI film and paper products. Compliance is no longer a static checkbox; it requires continuous reformulation, testing, and documentation. Companies operating with legacy chemistries face escalating scrutiny, while those that proactively transition to nitrite-free, renewable, and fully repulpable formulations are positioning themselves to capture procurement mandates from increasingly sustainability-conscious buyers.
A second challenge stems from cost inflation across raw material inputs and logistics channels. Amine chemistry feedstocks and transportation expenses have exerted sustained pressure on margin structures for VCI packaging materials. In an environment where end users are highly price-sensitive and alternative barrier solutions remain available, suppliers must balance cost pass-through with value demonstration. The burden falls on manufacturers to articulate how advanced VCI paper reduces total lifecycle costs through reduced damage, lower warranty claims, and extended storage life, rather than competing solely on unit price.
A third structural challenge involves the heterogeneity of end-use requirements. Metal packaging, machinery and equipment, and other industrial applications each impose distinct performance criteria, exposure conditions, and regulatory expectations. A formulation that performs adequately for ferrous metal storage may not satisfy multi-metal protection requirements or extended duration needs. This fragmentation complicates standardization and increases the cost of tailored product development. Companies that fail to align product architectures with specific application profiles risk losing share to competitors offering more precise fit-for-purpose solutions.
Core Drivers Catalyzing Market Evolution
The market's continued expansion is being propelled by a combination of technological innovation, regulatory realignment, shifting demand behaviors, and supply chain restructuring. Each driver reinforces the others, creating compounding effects that reward early movers and penalize laggards.
Technology and chemistry innovation remains the most decisive differentiator. Recent advancements in vapor-phase corrosion inhibition have enabled formulations that deliver extended protection without compromising recyclability or repulpability. The development of VCI nanotechnology on renewable kraft substrates illustrates how performance and sustainability can converge rather than compete. Products that combine expandable cushioning with active corrosion inhibition represent a step change in functional packaging, addressing both mechanical protection and long-term metal preservation within a single consumable. These innovations reduce the need for multiple packaging layers, simplify handling, and improve protection consistency across complex part geometries.
Policy and regulatory pressure is accelerating the transition toward compliant chemistries across key markets. Regulatory frameworks are increasingly mandating nitrite-free formulations and pushing for biodegradable and safer chemical profiles in VCI papers. In parallel, air quality and emission standards are raising compliance costs for amine-based chemistries, making reformulation an operational necessity rather than a discretionary initiative. Companies that treat regulatory evolution as a strategic signal rather than a compliance expense are building portfolios with longer regulatory half-lives and broader geographic applicability.
Demand-side behavior shifts are reshaping procurement priorities. Industrial buyers are placing greater weight on lifecycle performance, environmental footprint, and vendor reliability when selecting corrosion protection solutions. The emphasis has moved beyond immediate cost to include total cost of ownership, risk mitigation, and alignment with corporate sustainability commitments. This shift is particularly pronounced among operators managing high-value machinery, sensitive electronic components, and long-duration storage scenarios, where corrosion-related failures carry significant financial and reputational consequences. Procurement teams are consequently favoring suppliers that can demonstrate consistent performance, transparent chemistry, and documentation supporting waste reduction and material recovery.
Supply chain and cost structure changes are influencing sourcing strategies and manufacturing footprints. Volatility in raw material pricing and freight costs has prompted buyers to diversify suppliers, shorten supply lines where feasible, and prefer partners with localized production or regional distribution capabilities. At the same time, manufacturers are investing in process efficiencies and formulation optimization to absorb input cost pressures without eroding margins. The result is a market where responsiveness, reliability, and formulation flexibility are becoming as important as base pricing.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a core group of specialized manufacturers whose strategic approaches illuminate the pathways to sustained advantage. While market concentration remains high, the nature of competition is shifting from broad product availability toward targeted technical value, regulatory readiness, and application-specific performance.
Cortec Corporation has built its positioning around renewable, recyclable, and fully repulpable VCI chemistry applied to kraft paper substrates. Its coated VCI papers are designed for both ferrous and non-ferrous metal protection across storage and shipping contexts. The strategic emphasis on a circular-material profile aligns with procurement teams seeking to reduce waste streams and simplify end-of-life handling while maintaining active corrosion inhibition.
Daubert Cromwell has focused on nitrite-free formulations and compliance-oriented product lines, including VCI papers aligned with recognized military specifications for multi-metal corrosion protection. This compliance-centric posture appeals to sectors where documentation, standardization, and chemical safety are non-negotiable, such as defense, aerospace-adjacent supply chains, and regulated industrial manufacturing.
ZERUST Solutions offers VCI kraft papers and reinforced or poly-coated variants that provide vapor-phase protection for ferrous metals. The breadth of substrate options enables coverage across different handling conditions and exposure profiles, allowing the company to address varied industrial requirements without fragmenting its core technology.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Intertape Polymer Group emphasizes extended-duration protection, with nitrite-free VCI saturated kraft papers that support multi-metal protection over long storage intervals. The ability to specify protection duration is a meaningful commercial lever in logistics-heavy environments where parts may remain in transit or warehousing for extended periods.
Antirusting Anti Rust Agents Market
Armor Protective Packaging has combined nanotechnology-enabled corrosion inhibition with renewable kraft substrates, including expandable cushioning formats that integrate mechanical protection and VCI function. Its recent collaborative launch of an expandable VCI paper concept underscores a broader industry move toward multi-functional packaging that reduces material complexity while improving performance.
Rust-X has concentrated on durability attributes such as tear and puncture resistance through super laminated VCI papers. For operations handling heavy, irregular, or high-abrasion metal components, mechanical robustness is a critical purchase criterion, and this focus differentiates the offering in applications where standard paper formats may be prone to failure.
PW Consulting
Across these players, several strategic themes emerge. First, differentiation is increasingly rooted in chemistry transparency, regulatory alignment, and sustainability credentials rather than price alone. Second, product architectures are becoming more application-specific, with reinforcement, coating, and saturated formats tailored to distinct handling and exposure conditions. Third, the market is experiencing incremental convergence between mechanical protection and active corrosion inhibition, reducing the need for layered packaging and improving total system performance.
The evolutionary trend in market structure points toward selective consolidation and continued specialization. Established players with strong technical portfolios and regulatory readiness are well positioned to absorb niche capabilities or expand into adjacent format segments. At the same time, new entrants may find opportunity in highly targeted niches, such as formulations for specific metal alloys, biodegradable variants, or region-specific compliance packages. Broad, undifferentiated entry is less viable in a market where performance validation and regulatory familiarity carry substantial weight.
Forward Outlook: Three Trends to Watch
Looking ahead across the next three to five years, several trends are likely to shape investment, sourcing, and product strategy in the VCI anti rust paper market.
Accelerated reformulation toward compliant, renewable chemistries will intensify as regulatory scrutiny deepens and buyer sustainability requirements become more explicit. Companies that proactively retire higher-risk chemistries and develop nitrite-free, biodegradable, or fully repulpable solutions will gain preferential access to procurement cycles in regulated and sustainability-focused segments. The commercial opportunity lies not only in compliance but in the ability to market a clear environmental and safety narrative that reduces buyer risk and aligns with corporate responsibility goals. The associated risk is execution lag; firms that delay reformulation may face sudden exclusion from bids that specify chemical restrictions or biodegradability criteria.
Multi-functional packaging will continue to gain share as operators seek to simplify material stacks and improve protection consistency. Integrating cushioning, barrier properties, and vapor-phase corrosion inhibition into a single paper-based solution reduces handling complexity and can lower total packaging cost even when per-unit pricing is higher. This trend opens opportunities for manufacturers that can combine mechanical robustness with active inhibition and for buyers who can rationalize SKU counts and supplier relationships. The risk is that over-functionalization may increase cost or compromise recyclability if substrate choices are not carefully managed, so technical validation remains essential.
Regional divergence in demand and compliance requirements will create both fragmentation and arbitrage opportunities . Mature markets will continue to emphasize regulatory conformity, documentation, and lifecycle performance, while faster-growing regions will balance performance with affordability and supply reliability. Suppliers with flexible formulation platforms, localized distribution, and the ability to tailor products to regional regulatory baselines will be better positioned to capture cross-market growth. The uncertainty lies in the pace and symmetry of regulatory adoption across jurisdictions, which can shift competitive advantage quickly if one region moves ahead of others in restricting specific chemistries.
Strategic Considerations for Decision Makers
For manufacturers and product developers, the priority is to align formulation roadmaps with regulatory trajectories and application-specific performance needs. Investing in nitrite-free, renewable, and repulpable chemistries while maintaining protection duration and mechanical robustness will expand addressable demand and reduce regulatory exposure. Equally important is building validated documentation and testing protocols that allow procurement teams to verify performance claims and meet internal sustainability thresholds. Companies that can articulate a clear link between chemistry, protection performance, and end-of-life handling will be better equipped to justify value to buyers who are increasingly scrutinizing total cost rather than unit price. For investors, the market rewards businesses with defensible technical differentiation and resilient compliance postures. Concentration in the top tier suggests that competitive advantage is often tied to formulation IP, regulatory readiness, and application breadth rather than scale alone. Due diligence should therefore emphasize chemistry portfolios, reformulation capability, certification and documentation strength, and the ability to serve multi-metal and extended-duration requirements. Capital allocation toward companies with clear pathways to compliant, multi-functional products and regional flexibility is likely to offer more durable exposure than bets on undifferentiated capacity expansion. For procurement and supply chain leaders, the focus should shift from transactional price comparison to total value evaluation. Evaluating VCI paper suppliers against criteria such as multi-metal compatibility, protection duration, mechanical durability, chemical compliance, and recyclability can reduce downstream risk and improve consistency across storage and shipping operations. Diversifying supply sources while prioritizing vendors with strong regulatory alignment and transparent chemistry reduces vulnerability to reformulation disruptions and regional compliance shifts. Negotiations are more effective when underpinned by performance specifications that reflect actual exposure conditions rather than generic packaging requirements. The pace of regulatory change, input cost volatility, and evolving buyer expectations means that static market assumptions quickly become outdated. Decision makers benefit from continuously updated intelligence on formulation shifts, competitive moves, and regional compliance baselines to avoid misaligned sourcing or investment choices. Detailed segment-level data, company-level profiling, and scenario analysis can sharpen planning and reveal where to concentrate resources for the highest return.
Completing the full analysis provides access to granular segment breakdowns, regional demand profiles, competitive benchmarking, and forward scenarios that extend beyond the directional view presented here. For teams evaluating market entry, supplier selection, formulation investment, or portfolio strategy, that additional depth supports more precise prioritization and reduces the uncertainty inherent in a rapidly evolving corrosion protection market.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Airbag Market to Hit $29.79B by 2032: Decoding the 7.25% CAGR Growth and Asia Pacific's Dominance Shift
By PW Consulting, 2026-09-21
Navigating the Airbag Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global airbag market has entered a maturation phase characterized by steady expansion, technological diversification, and shifting regulatory pressures. Valued at approximately $18.28 billion in 2025, the sector has grown consistently from $12.93 billion in 2020, reflecting a compound annual growth rate of 7.25 percent through 2032. This trajectory is not merely a function of rising vehicle production; it signals a structural realignment in how occupant and external safety are engineered, regulated, and commercialized. For executives, investors, and procurement leaders, the next seven years will reward those who align product strategy with evolving safety expectations, supply chain resilience, and regional regulatory divergence.
Beneath the headline growth figures lies a market exhibiting pronounced concentration and regional asymmetries. The top three suppliers capture roughly 62.8 percent of revenue, while the top five account for 74.5 percent, indicating an environment where scale, established automaker relationships, and integrated component capabilities create durable moats. At the same time, the market’s composition reveals where value creation is accelerating: frontal systems remain the largest category, side airbags command significant share, and knee/curtain configurations are expanding as vehicle architectures grow more complex. On the application side, passenger vehicles dominate revenue generation, commercial vehicles represent a stable but slower-growing segment, and electric vehicles are carving out a distinct growth corridor as platform designs and battery-related safety considerations reshape module requirements. Understanding these structural patterns is essential before evaluating the forces that will shape competitive positioning through the end of the decade.
Market Landscape and Core Challenges
The airbag market’s expansion is anchored in a multi-year upward trajectory, but growth alone does not guarantee profitability or strategic advantage. Several structural frictions are forcing suppliers and automakers to recalibrate how they design, source, and deploy safety systems.
Regulatory Fragmentation and Compliance Complexity
Safety regulations are no longer converging globally; they are diverging in ways that complicate platform standardization. In the United States, the Department of Commerce’s January 2025 final rule on connected-vehicle information and communications technology supply chains has introduced new compliance pathways for components tied to vehicle electronics and embedded safety systems. While the rule targets ICTS sourcing, its ripple effects extend to airbag control units, sensing integration, and supplier qualification processes, particularly for companies with cross-border manufacturing footprints. This regulatory layer adds cost and timeline uncertainty, especially for suppliers navigating dual requirements across North American, European, and Asian markets.
Raw Material Volatility and Cost Structure Pressures
Airbag manufacturing remains sensitive to polymer and chemical input pricing. Nylon 6,6, a critical material for airbag fabric and structural components, experiences periodic price fluctuations driven by production capacity shifts and downstream demand dynamics. Ascend Performance Materials’ ongoing support of nylon 6,6 production for airbag applications underscores how tightly woven the material supply chain is. When feedstock costs move, suppliers must decide whether to absorb margin compression, renegotiate tier agreements, or accelerate material substitution programs. The companies that treat material strategy as a continuous optimization exercise rather than a periodic sourcing task will preserve competitiveness during cyclical price swings.
Waste Management and Recall-Related Liability
End-of-life handling and recall scenarios introduce operational and reputational risk that is often underestimated in top-line planning. Hazardous airbag waste falls under RCRA hazardous waste regulations, and the U.S. EPA’s October 2025 interim final rule on safe management of recalled airbags adds conditional exemptions and procedural requirements that affect how manufacturers, dealers, and recyclers manage inventory and field returns. For suppliers, this means that compliance does not end at the point of sale; it extends into reverse logistics, documentation, and cooperative recall response. Firms that build these processes into their operating models reduce exposure to regulatory friction and strengthen customer trust during safety interventions.
Taken together, these challenges point to a market where scale alone is insufficient. Growth will increasingly be captured by organizations that can manage regulatory complexity, stabilize input costs, and integrate safety with broader mobility ecosystems rather than treating airbags as isolated passive components.
Key Drivers Shaping Market Dynamics
The market’s forward trajectory is being pulled by three interconnected forces: technology innovation that expands the definition of protection, regulatory and policy shifts that raise baseline expectations, and demand-side behavior that blends occupant safety with external collision mitigation. A fourth driver, supply chain restructuring around cost and resilience, is determining who can profitably scale new configurations.
Technology Innovation and the Expansion of Protection Boundaries
Airbag technology is moving beyond traditional occupant compartments into external protection, specialty applications, and smarter deployment logic. Autoliv’s April 2026 launch of a second-generation cyclist-pedestrian protection airbag illustrates this shift. By covering a larger area to improve head protection during external collisions, the product reorients airbag value propositions around vulnerable road users and vehicle-to-environment interactions. Similarly, Daicel’s May 2026 wearable airbag, developed with NIIST and the Sony Acceleration Platform, extends automotive safety technology into elderly fall mitigation. These launches are not isolated product news; they signal that safety technology portfolios are becoming more modular and application-agnostic, creating pathways to non-automotive revenue streams and cross-market brand leverage.
Policy and Regulatory Pressure Raising Baseline Safety Expectations
Regulators continue to tighten occupant protection expectations, and vehicle safety ratings increasingly influence purchase decisions. The introduction of Volvo Trucks’ industry-first standard integrated side curtain airbag in February 2026, recognized as a HDT 2025 Top 20 Product, demonstrates how regulatory and rating-driven pressure can push advanced configurations from optional features to standard equipment in commercial segments. When flagship players normalize a technology, the threshold for competitor adoption rises, and procurement teams must plan for broader specification coverage across fleets. Policy momentum therefore operates as both a compliance requirement and a competitive cascade, accelerating adoption curves that might otherwise lag behind passenger-car segments.
Demand-Side Shifts in Consumer and Fleet Behavior
Buyers are increasingly treating safety as a differentiated purchase criterion rather than a standardized expectation. In passenger vehicles, this translates into demand for more comprehensive curtain, knee, and side configurations as cabin layouts evolve and seating positions change. In commercial vehicles, fleet operators are prioritizing driver protection and total cost of ownership, which makes standard safety packages more attractive when they reduce incident-related downtime and insurance exposure. Electric vehicles add another layer: platform architectures, battery placement, and weight distributions alter deployment zones and module placement logic, prompting suppliers to adapt designs to EV-specific packaging constraints. As a result, demand is no longer uniform across vehicle types; it is fragmenting by use case, platform, and operational profile.
Worldwide Belt Type Fall Protection Airbag Market
Supply Chain and Cost Structure Realignment
The supply base is responding to material volatility, geographic sourcing constraints, and the need for faster engineering feedback loops. Suppliers that integrate inflator technology, fabric engineering, and module assembly under coordinated development cycles can reduce lead-time variability and better manage cost transitions. At the same time, regulatory actions around ICTS and connected systems are encouraging regionalization and dual-sourcing strategies, particularly for electronics-adjacent safety components. The practical implication is that cost leadership is increasingly derived from integration, regional presence, and engineering responsiveness rather than sheer procurement volume alone.
These drivers converge on a single insight: the airbag market is expanding not just because more vehicles are being sold, but because protection is becoming broader in scope, more standardized at higher performance levels, and more dependent on integrated engineering capability.
Competitive Landscape and Strategic Positioning
The market’s concentration profile favors incumbent suppliers with global footprints, established automaker partnerships, and multi-product capabilities across inflators, modules, and complementary restraint systems. A review of the leading players shows how different strategic postures are being used to defend share and capture growth.
Incumbent Scale and Integrated Capabilities
Autoliv’s positioning as the world’s largest automotive safety supplier gives it broad exposure across airbags, seatbelts, and passive safety systems, enabling coordinated engineering across restraint categories. This scale supports platform sharing, global volume leverage, and the ability to introduce advanced external-protection concepts such as the cyclist-pedestrian airbag. Joyson Safety Systems occupies a similarly broad mobility safety position, extending beyond automotive into non-automotive markets, which diversifies revenue and creates cross-application learning loops. ARC Automotive focuses more narrowly on inflators for a wide range of airbag types, a specialization that makes it a critical component partner and allows it to influence deployment performance at a foundational level. Daicel brings chemical and plastics expertise to inflators, pyro-fuses, and related safety technologies, positioning it at the intersection of material science and safety performance.
Regional and Ecosystem-Embedded Players
Toyota Boshoku and Hyundai Mobis illustrate how supplier strength can be amplified by close ties to vehicle platforms. Toyota Boshoku’s interior systems capabilities and Hyundai Mobis’s module and safety technology portfolio benefit from group-aligned development cycles, which can shorten validation timelines and improve packaging fit. Nihon Plast and Toyoda Gosei add depth in safety components and interior/safety integration, while ZF Friedrichshafen and Continental contribute broader automotive technology portfolios that include occupant protection systems alongside seating and chassis-related competencies. These players demonstrate that differentiation is not limited to volume; it can also come from platform alignment, component specialization, and technology adjacency.
Strategic Differentiation and Competitive Evolution
The competitive evolution in this market is moving along two tracks. On one track, consolidation and partnership activity reinforce the advantages of scale, global service networks, and multi-component integration. On the other, differentiation is increasingly found in application expansion, such as external protection and wearable safety concepts, and in the ability to adapt to commercial vehicle standardization and EV packaging requirements. New entrants face a steep climb unless they bring a defensible technology niche, a distinctive material or inflator advantage, or a strong regional relationship model. The more probable competitive dynamic is continued concentration at the top, layered with selective specialization where performance, application scope, or regional compliance create meaningful separation.
For decision-makers, the practical takeaway is that supplier selection and partnership strategy should account for more than unit price. Engineering collaboration, regional compliance readiness, inflator and module integration depth, and the ability to support nonstandard configurations are becoming decisive factors in long-term value capture.
Forward Outlook: Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value is created and where risk accumulates.
Trend One: External and Vulnerable-Road-User Protection Becomes a Commercial Priority
External protection concepts are moving from experimental to productized, as evidenced by cyclist-pedestrian airbag developments and broader attention to vehicle-to-environment interactions. This trend opens opportunities in advanced module designs, sensing-adjacent integration, and region-specific safety packaging. The commercial upside lies in differentiated safety claims, rating advantages, and potential regulatory alignment in markets that increasingly weigh external impact performance. The uncertainty is execution: external protection requires careful validation, packaging trade-offs, and cost discipline to avoid becoming a low-volume niche.
Trend Two: Standard Safety Packages Expand in Commercial and Specialty Segments
Commercial vehicle adoption of integrated side curtain airbags as standard equipment suggests a broader shift toward baseline protection in segments historically treated as optional. This creates demand visibility and volume stability for suppliers that can meet durability, service, and fleet-level specification requirements. The opportunity is in scalable module architectures, simplified service interfaces, and fleet-oriented documentation and support. The risk is margin pressure if standardization triggers price competition without accompanying engineering or service differentiation.
Automotive Airbags Market
Trend Three: EV- and Platform-Specific Safety Architectures Drive Customization Demands
Electric vehicle platforms continue to alter interior packaging, weight distribution, and component placement, which in turn affects airbag deployment zones and module form factors. Suppliers that can adapt quickly to platform-specific constraints will capture premium positioning and repeat business across model cycles. The upside is a shift from commoditized replacement logic to engineered safety integration, where value is tied to packaging efficiency and validation speed. The uncertainty is platform volatility: rapid EV redesign cycles can compress supplier development windows and increase engineering cost if not managed with early engagement and flexible module strategies.
Across these trends, the consistent commercial thread is that airbag value will increasingly be defined by integration, application breadth, and responsiveness to vehicle architecture changes rather than by component volume alone. Organizations that treat safety systems as part of a broader vehicle architecture and mobility-solution context will be better positioned to convert growth into durable margin.
Actionable Implications for Decision-Makers
-
For manufacturers and suppliers: Prioritize integration across inflators, fabrics, and module engineering to reduce lead-time variability and improve cost control during material price swings. Invest in external-protection and specialty application capabilities where validation pathways are achievable and regional demand signals are strengthening. Build reverse-logistics and recall-readiness processes into the operating model to manage waste regulation exposure and maintain customer confidence during field actions.
-
For investors: Focus on suppliers with durable automaker relationships, multi-product restraint exposure, and the ability to extend safety technology into adjacent applications. Evaluate exposure to regulatory-driven standardization in commercial vehicles and to EV-specific packaging adaptation, as these can shape volume visibility and engineering intensity. Monitor concentration dynamics and regional compliance readiness, since ICTS-related rules and material sourcing constraints can influence margin stability and geographic mix.
-
For procurement teams and fleet operators: Treat safety specifications as strategic levers rather than fixed checkboxes. Standard packages can improve fleet safety profiles and reduce incident-related operational friction, but they should be weighed alongside service support, regional compliance alignment, and supplier capability to handle nonstandard configurations. Engage early with suppliers on EV and commercial-platform requirements to secure packaging feasibility and validation timelines before specification lock-in.
The strategic value of these decisions depends on the granularity of the underlying data. Regional revenue distribution, type-level growth differentials, application-specific penetration patterns, and competitive share movements can materially change sourcing, investment, and product-planning choices. Detailed segmentation, forward volume assumptions, and company-level positioning are most useful when aligned to specific vehicle programs, geographic commitments, and margin targets. For teams that require that level of precision, a full research report can provide the supporting breakdowns and scenario detail needed to translate these market-level insights into operational planning.
The airbag market is not simply growing; it is being redefined by broader protection concepts, standardization pressure in commercial segments, and platform-specific adaptation in electric vehicles. Participants that align engineering, compliance, and application strategy with these shifts will be better positioned to convert market expansion into sustained competitive advantage.
PW Consulting
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ceramic Ink Market: How 5.79% CAGR and Asia Pacific Demand Reshape Growth
By PW Consulting, 2026-09-21
Navigating the Ceramic Ink Market: Strategic Trends and Commercial Opportunities Through 2032
The global ceramic ink market has entered a phase of steady, technology-driven expansion. Valued at approximately 2.71 billion USD in 2020, the segment climbed to 3.59 billion USD by 2025, and forward projections indicate a trajectory toward 5.32 billion USD by 2032. This growth reflects a compound annual rate of 5.79 percent across the forecast horizon. While the absolute numbers signal a mature, resilient market, the underlying composition tells a more nuanced story. Regional demand is increasingly concentrated in high-volume manufacturing corridors, functional formulations are outpacing decorative variants in both volume and margin potential, and ceramic tile applications continue to dominate downstream consumption. For decision-makers, the headline growth rate matters less than the structural shifts that will determine which players capture disproportionate value in the next cycle.
Worldwide Specialty Ink Market
The market is not expanding uniformly. Growth is being pulled forward by regions with heavy ceramic production footprints, while mature markets are shifting from volume-driven expansion toward premiumization and regulatory compliance. Functional inks, which enable advanced surface properties beyond aesthetics, now represent the larger revenue share and are expected to retain their lead as technical specifications tighten across construction, packaging, and consumer goods verticals. Decorative inks remain critical for design differentiation, but their growth trajectory is increasingly tied to digital printing adoption rather than traditional manual or mechanical decoration methods. On the application side, ceramic tiles account for the largest consumption base, followed by glass printing and food container printing. Each vertical carries distinct performance requirements, regulatory exposures, and cost sensitivities, which means aggregated market figures can obscure pockets of volatility and opportunity.
Structural Headwinds and Inflection Points
Despite the positive top-line outlook, the industry faces a narrow set of challenges that will shape competitive positioning over the coming years. First, environmental and emissions regulations are tightening across key export and domestic markets, particularly in Europe and increasingly in Southeast Asia. Manufacturers are being asked to deliver formulations that maintain performance while reducing volatile organic compounds, odor, and hazardous substances. This is not a compliance checkbox; it is a reformulation burden that affects raw material sourcing, process control, and validation cycles. Companies that treat sustainability as an afterthought will face margin compression and delayed time-to-market, while those that design low-emission architectures early can convert regulatory pressure into a defensible product advantage.
Second, the technical bar for ink performance is rising as digital decoration systems become more capable and more widely deployed. Inorganic pigment-based ceramic inks must withstand fine milling, precise dispersion, and high-temperature firing conditions that can exceed 1250 degrees Celsius in tile production. This requires tighter supplier coordination, consistent batch quality, and formulation stability across varying line speeds and substrate types. As digital printing moves from pilot lines to high-throughput production environments, even minor inconsistencies in viscosity, particle size distribution, or adhesion can translate into elevated rejection rates and operational downtime. The inflection point here is clear: ink is no longer a commoditized consumable but a critical process enabler whose performance directly affects overall equipment effectiveness.
Third, supply chain localization is becoming a strategic necessity rather than a logistical preference. Ceramic manufacturing clusters in Southeast Asia, particularly in Vietnam and Indonesia, are expanding capacity and attracting both machinery and ink suppliers seeking closer proximity to end users. At the same time, procurement teams are increasingly sensitive to lead times, freight volatility, and currency exposure. The result is a market where regional responsiveness, localized technical support, and flexible inventory models are gaining importance alongside product performance. Organizations that remain dependent on distant, inflexible supply structures risk slower reaction times and weaker customer intimacy in fast-moving production markets.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Formulation Breakthroughs
Technology is the most visible driver of market evolution, and its influence is accelerating across both product design and production integration. The shift toward low-emission digital inks is a case in point. Recent product announcements highlight formulations that reduce harmful emissions and volatile organic compounds by up to 50 percent compared with standard eco-inks, while also introducing almost no-smelling components to lower environmental impact in factory environments. These advances are not merely cosmetic improvements; they reflect a broader engineering push to reconcile high-temperature durability with workplace safety and regulatory expectations. For manufacturers, this means ink selection increasingly involves trade-offs between adhesion, color consistency, firing tolerance, and emissions profile, all of which must be validated on specific production lines.
Ceramic Package Market
At the same time, inorganic pigment-based ceramic inks continue to demand sophisticated milling and dispersion processes to remain compatible with extreme firing conditions. This technical complexity creates a barrier to entry that favors incumbents with deep formulation expertise and testing infrastructure. It also raises the value of application engineering, because the same ink can behave differently depending on printhead configuration, substrate preparation, and kiln parameters. The commercial implication is that differentiation is moving upstream into R&D capability, quality control rigor, and customer-facing technical support. Companies that can demonstrate repeatable performance across diverse digital decoration setups are better positioned to command premium pricing and longer contract tenure.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. European REACH compliance and broader environmental impact reduction goals are pushing ink suppliers to redesign formulations and document material safety more comprehensively. This has already prompted notable product launches focused on low-VOC architectures, signaling that compliance is becoming a product development priority rather than a reactive adjustment. In parallel, regional manufacturing expansion in Southeast Asia is shaping a new regulatory landscape where local content expectations, environmental standards, and export requirements intersect. Ink producers and distributors that proactively align their portfolios with these evolving standards can reduce the risk of market access delays and position themselves as preferred partners for manufacturers seeking globally acceptable output.
The regulatory dimension also affects downstream demand. Tile manufacturers and homeware producers facing stricter emissions criteria in their own operations are increasingly inclined to select inks that simplify their compliance burden. This creates a pull effect where ink specifications are evaluated not only on print quality but also on the broader environmental footprint of the decorated product. As a result, regulatory alignment is becoming a commercial differentiator, especially in markets where export competitiveness depends on meeting diverse destination-country requirements.
Demand-Side Shifts in Consumer and Industrial Behavior
Demand is being reshaped by the broader adoption of digital decoration in high-volume ceramic production. In markets with massive tile output, digital ink adoption is accelerating as producers seek greater design flexibility, shorter changeover times, and more consistent repeatability across batches. This shift is not limited to luxury or custom segments; it is increasingly relevant in standard production lines where manufacturers want to respond faster to fashion cycles and regional preference variations without sacrificing throughput. The net effect is a rising appetite for ink systems that can support frequent design changes while maintaining line stability.
On the decorative side, consumer expectations continue to push for richer patterns, more realistic textures, and tighter color matching across product families. These expectations place additional pressure on ink color fidelity and gloss control. Meanwhile, functional requirements are expanding beyond aesthetics into areas such as surface durability, hygiene compatibility, and specialized coatings for containers and glass applications. The demand story is therefore bifurcating: volume-driven tile markets want reliability and speed, while design-sensitive and functional applications want performance precision. Ink manufacturers that can serve both poles with a coherent portfolio and clear application guidance are likely to capture a broader share of wallet.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as raw material inputs, energy considerations, and logistics complexity interact with formulation intensity. Inorganic pigment-based inks require fine milling and dispersion, which means that processing quality and material consistency have direct implications for yield and cost per fired unit. Any disruption in pigment supply, solvent availability, or specialized additives can ripple through the value chain and affect both pricing and delivery reliability. At the same time, the trend toward localized production in Southeast Asia is altering the cost calculus by reducing transport distances for certain markets while introducing new operational requirements around regional quality assurance and technical staffing.
This shifting cost environment rewards suppliers that can balance formulation sophistication with manufacturing efficiency. It also rewards buyers who evaluate total cost of ownership rather than unit price alone. In practice, that means factoring in waste reduction, printhead compatibility, cleaning frequency, firing stability, and rework rates. Ink that appears cheaper on a per-liter basis may underperform when measured against line efficiency and finished-product quality. As procurement teams become more sophisticated in this assessment, suppliers with transparent performance data and strong application support gain an advantage in price negotiations.
Competitive Landscape and Leading Strategies
Incumbents with Technical Depth and Regional Reach
The market features a mix of specialized ink manufacturers, global equipment-linked ink providers, and ceramic machinery groups that also supply inks and glazes. Sicer S.p.A. stands out for its focus on digital inks tailored to ceramic tile decoration, including low-emission formulations and custom series designed for specific decoration workflows. Its recent emphasis on low-emission digital inks achieving up to 50 percent VOC reduction illustrates how a focused manufacturer can turn environmental pressure into a product story. A.T. Inks, based in India, positions itself as a large-scale producer of inorganic pigment-based ceramic inkjet inks for wet-on-wet tile printing up to 1250 degrees Celsius firing. Its scale and formulation orientation make it relevant for high-volume producers seeking reliable pigment performance under extreme firing conditions.
NUtec Digital Ink operates with a broader digital ink portfolio spanning UV-cured, solvent, and water-based systems, supporting ceramic printing and homeware applications. This multi-technology footprint allows it to serve customers with varied process preferences and substrate requirements. EFI brings long-standing formulation expertise in eco-solvent and water-based ceramic inks for digital tile decoration, which positions it as a partner for producers already embedded in its equipment ecosystem or seeking proven compatibility. KEDA Industrial Group, as a ceramic machinery supplier, showcases inks and glazes alongside equipment at industry events, reinforcing an integrated value proposition that appeals to manufacturers looking to streamline supplier relationships and align ink selection with machine capability.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along three axes: formulation specialization, regulatory readiness, and application ecosystem support. Formulation specialization matters because high-temperature durability, color consistency, and printhead compatibility are not trivial to achieve at scale. Regulatory readiness matters because low-emission and low-VOC positioning is increasingly tied to market access and customer procurement criteria. Application ecosystem support matters because digital decoration success depends on more than the ink bottle; it depends on line integration, maintenance practices, and troubleshooting responsiveness. Suppliers that combine these elements can move beyond transactional selling and into solution-level relationships.
Recent industry developments reinforce this direction. The launch of new low-VOC ceramic ink lines to reduce environmental impact demonstrates a clear regulatory and sustainability response. The opening of new manufacturing facilities in Vietnam for Southeast Asia operations reflects the localization theme and the desire to serve emerging ceramic clusters with shorter supply chains. Trade show participation and product announcements continue to be important signaling mechanisms, particularly in regions where face-to-face technical engagement and live demonstrations influence procurement decisions. Taken together, these moves indicate that competitive advantage is being built through a combination of product engineering, geographic responsiveness, and visible commitment to compliance and customer support.
Evolution of the Market Structure
The market is not heading toward a simple monopoly or a fragmented free-for-all. It is more likely to evolve through selective consolidation among suppliers seeking broader portfolios and geographic coverage, alongside continued specialization by niche players who serve specific printing technologies, verticals, or regional needs. New entrants may appear, but the technical barriers around high-temperature performance, dispersion quality, and application validation will remain significant. As a result, the most disruptive threats may not come from isolated ink startups but from integrated equipment-ink-material combinations that simplify adoption for tile manufacturers and homeware producers. The competitive logic is shifting from product-only competition to process-level relevance, where ink is evaluated as part of a larger digital decoration system.
Forecasting the Next 3–5 Years
Trend 1: Low-Emission and Compliant Formulations Will Become Baseline Expectations
Over the next few years, low-emission and low-VOC architectures will transition from premium differentiators to baseline requirements in many markets. This shift will be driven by regulatory momentum, workplace safety expectations, and downstream customer preferences for cleaner production processes. Ink suppliers that treat this as a one-time reformulation exercise may find themselves repeatedly catching up, while those that build compliance and emissions reduction into their core formulation philosophy can offer a more stable value proposition. The commercial opportunity lies in packaging compliance with performance, so that customers do not have to choose between environmental goals and print quality.
PW Consulting
Trend 2: Digital Integration Will Deepen the Value Chain
Digital decoration will continue to expand beyond high-end segments into broader production volumes, especially in regions with large-scale ceramic output. As this happens, ink will become more tightly coupled with printer configuration, substrate preparation, and firing profiles. The result will be greater demand for integrated solutions, technical validation services, and application-specific tuning. This trend favors suppliers that can support line trials, provide repeatable setting parameters, and help customers reduce trial-and-error cycles. It also raises the stakes for equipment-ink compatibility, which may encourage closer cooperation between ink manufacturers and printer makers.
Trend 3: Regional Manufacturing Hubs Will Reshape Supply and Demand Patterns
Southeast Asia’s ceramic manufacturing clusters will continue to influence where ink capacity is located, how quickly new products reach end users, and how suppliers compete on responsiveness. Localized production and support can shorten feedback loops, improve service levels, and reduce exposure to long-haul logistics disruptions. At the same time, regional expansion introduces challenges around quality consistency, talent development, and coordination across multiple markets with different regulatory and customer expectations. The strategic opportunity is to build regional presence that is not merely logistical but technically credible, with local teams capable of supporting formulation queries, line optimization, and compliance documentation.
Associated Risks and Uncertainties
These trends carry meaningful uncertainties. Regulatory requirements may diverge across regions, creating compliance complexity for globally distributed portfolios. Raw material availability and energy cost fluctuations can pressure margins, especially for formulations that depend on specialized pigments and dispersion processes. Demand may also shift faster than expected if digital adoption accelerates in some markets while lagging in others, leaving suppliers with uneven capacity utilization. Finally, competition from integrated equipment-ink offerings could compress standalone ink pricing in certain segments, particularly where customers prioritize convenience and system compatibility over independent supplier choice. Companies that monitor these signals closely and maintain flexible product and supply strategies will be better positioned to adapt.
Actionable Recommendations for Decision-Makers
For Manufacturers and Production Leaders
Evaluate ink selection as a process decision rather than a consumable purchase. Prioritize trial data that reflects your actual line speeds, substrates, and firing conditions, and compare total cost of ownership across performance, waste, rework, and maintenance. If environmental compliance is becoming more important to your customers or your own operations, ask suppliers for clear documentation on emissions profiles, material safety, and validation support. Where digital decoration is expanding, invest in application engineering relationships that can help stabilize settings and reduce changeover friction. A disciplined evaluation framework will help avoid false economies from low-cost inks that underperform in production.
For Investors and Strategy Teams
Look for value creation at the intersection of formulation strength, regulatory readiness, and regional service capability. Companies that can demonstrate low-emission performance without sacrificing firing durability, and that maintain credible technical support in growth markets, are likely to earn stronger customer loyalty and more defensible margins. Pay attention to integration signals as well: partnerships or product alignments between ink suppliers and equipment providers may reveal where the market is heading in terms of bundled solutions and channel power. In parallel, track capacity expansion in Southeast Asia and the associated localization of supply chains, since these moves can influence both competitive intensity and regional demand trajectories.
For Procurement and Sourcing Professionals
Broaden evaluation criteria beyond unit price to include consistency, compatibility, and compliance readiness. Request performance evidence tied to high-temperature firing and digital print workflows, and verify that suppliers can support repeat orders with stable specifications. Consider multi-supplier or region-specific sourcing strategies if your production footprint spans multiple markets with different regulatory or logistics conditions. Where possible, negotiate for clear application support and issue resolution timelines, since responsiveness during line problems often matters more than marginal price differences. A well-structured sourcing approach can reduce operational risk while preserving flexibility as production needs evolve.
The ceramic ink market is moving through a period where growth is real but uneven, and where competitive advantage depends on how well companies align product performance with regulatory expectations, digital production realities, and regional demand patterns. The organizations that will benefit most are those that treat ink as a strategic input, build evidence-based procurement and investment decisions, and stay attentive to the intersection of formulation science, compliance, and market localization. For leaders who need a more granular view of segment dynamics, regional breakdowns, application-level demand splits, and company-level positioning beyond the trends outlined here, the full research report provides the detailed segmentation data and customized analysis required to translate these insights into concrete plans.
For detailed analysis of this topic, please visit the official page: Ceramic Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


