



PW Consulting: AC-DC EPS Market to Hit $9.83B in 2025, Growing at 5.3% CAGR to 2032
By PW Consulting, 2026-09-16
Powering the Next Decade: Strategic Intelligence for the AC-DC External Power Supply Market
The AC-DC External Power Supply (EPS) market is undergoing a structural transformation. From consumer electronics to industrial automation and healthcare devices, external power supplies remain the critical link between grid electricity and modern equipment. As regulatory frameworks tighten and efficiency requirements escalate, understanding the trajectory of this market is no longer optional for enterprise decision-makers. This article outlines the strategic value of our latest market research report, designed to equip stakeholders with the foresight needed to navigate the 2026-2032 forecast period and beyond.
Market Trajectory and Growth Dynamics
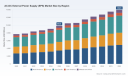
The global AC-DC EPS market has demonstrated consistent expansion over the past half-decade. Historical data from 2020 through 2025 reveals a market that has grown from approximately 7,700 million USD to nearly 9,830 million USD, reflecting a compound annual growth rate that underscores steady demand accumulation across multiple end-use sectors. Looking ahead, the forecast period from 2026 to 2032 projects a sustained CAGR of 5.3 percent, with revenue expected to approach 13,923 million USD by the end of the forecast horizon.
This growth is not merely a function of volume expansion. It represents a convergence of technological innovation, regulatory compliance pressures, and shifting application demands. The base year of 2025 serves as a critical inflection point, with the market crossing the 9,800 million USD threshold and setting the stage for accelerated adoption of high-efficiency, compact power solutions. Enterprises that understand the underlying drivers of this trajectory will be better positioned to allocate capital, plan product roadmaps, and identify partnership opportunities.
However, aggregate figures tell only part of the story. The true strategic value lies in dissecting the market across multiple dimensions—power output ranges, application verticals, and geographic regions—each of which presents distinct growth vectors, competitive intensities, and risk factors. Our report provides this granular dissection, enabling stakeholders to move beyond headline numbers and develop nuanced, segment-specific strategies.
Key Industry Dynamics Shaping the Landscape
Several macro-level forces are reshaping the competitive environment for AC-DC external power supplies. Understanding these dynamics is essential for anticipating market shifts and positioning products or investments accordingly.
- Regulatory Compliance压力 : Efficiency standards continue to evolve globally. The U.S. Department of Energy's Level VI requirements, ENERGY STAR Program Requirements for Single Voltage External AC-DC Power Supplies, and the EU Ecodesign framework (2025/2052) are mandating higher efficiency thresholds. Manufacturers must ensure their products meet these criteria to remain eligible for key markets. Additionally, Natural Resources Canada has implemented energy efficiency standards for single-voltage external AC-DC power supplies effective 2025, further expanding the compliance landscape. ENERGY STAR Partner Commitments also require manufacturers to adhere to strict eligibility criteria including efficiency testing protocols.
- Raw Material Volatility : Copper prices fluctuated within an 8,500 to 10,200 USD per ton range in 2025, driving bill of materials costs for power supply components up by nearly one-fifth. This volatility introduces margin pressure and necessitates strategic sourcing decisions, supplier diversification, and potentially redesigned architectures that optimize material usage.
- Technology Innovation : The adoption of wide-bandgap semiconductors such as silicon carbide (SiC) and gallium nitride (GaN) is enabling higher efficiency, reduced thermal losses, and miniaturization. Recent product launches from leading manufacturers demonstrate this shift, with GaN-based solutions and wide-range AC-DC modules entering the market at various power levels.
- Application Diversification : While consumer electronics remain a significant demand driver, industrial, automotive, healthcare, and telecommunications applications are expanding their share of the market. Each vertical imposes unique requirements around reliability, efficiency, form factor, and environmental durability, creating specialized niches that reward targeted engineering and market positioning.
Competitive Landscape: Key Players and Strategic Positioning
The AC-DC EPS market is characterized by a concentrated competitive structure. The top three firms command approximately 65 percent of market revenue, while the top five collectively hold around 80 percent. This concentration reflects the scale advantages, established customer relationships, and engineering capabilities that leading players have cultivated over time. However, the presence of numerous specialized manufacturers and regional players ensures that competition remains dynamic, particularly in segments where customization, rapid innovation, or cost optimization are paramount.
AC-DC External Power Supply (EPS) Market
Our report provides detailed profiles of the key companies shaping this landscape, examining their product portfolios, geographic reach, application focus, and recent strategic moves. Among the profiled firms are TDK-Lambda Americas, COSEL USA, Bel Fuse Inc., XP Power, Murata Manufacturing Co., Mean Well Enterprises Co. Ltd., FSP Technology Inc., Sparkle Power Incorporated, Advanced Energy Industries Inc., P-DUKE Technology Co. Ltd., Phihong USA, Acopian Power Supplies, and Pico Electronics.
These companies represent a diverse array of strategic positions. Some focus on high-performance solutions for medical and industrial applications, leveraging advanced technologies like SiC and GaN to deliver efficiency gains and compact form factors. Others emphasize broad portfolios spanning desktop and wall-plug adapters alongside enclosed AC-DC supplies for industrial and ITE applications. Several manufacturers have established strong presences in harsh-environment and factory automation segments, offering configurable and ruggedized solutions. The geographic spread of headquarters and manufacturing capabilities—from the United States and Japan to Taiwan and the United Kingdom—adds another layer of strategic consideration for supply chain resilience and market access.
Worldwide External Power Supplies (EPS) Market
Recent product launches and technological announcements provide valuable signals about where competitive intensity is building. In early 2026, multiple firms introduced new product lines emphasizing efficiency, power density, and application-specific optimization. These developments underscore the pace of innovation and the importance of monitoring competitor roadmaps to anticipate market shifts and identify whitespace opportunities. Our report captures these recent developments and contextualizes them within broader competitive trends.
Report Scope and Actionable Insights
This market research report is designed to serve as a comprehensive decision-support tool. It goes beyond descriptive market sizing to deliver actionable intelligence across multiple dimensions. Key components of the report include:
- Historical and Forecast Revenue Analysis : Detailed revenue breakdowns for the 2020-2025 historical period and the 2026-2032 forecast period, enabling trend analysis and growth rate validation at both aggregate and segment levels.
- Segmentation by Output Power : Analysis of market share and growth trajectories across power output ranges, from low-power solutions up to 10W through higher-power segments reaching 101W-400W. Each range presents distinct application profiles and competitive dynamics.
- Segmentation by Application : Deep dives into the major application verticals driving demand, including consumer electronics, industrial, automotive, healthcare, telecommunications, and others. The report examines the unique requirements, growth catalysts, and competitive intensity within each vertical.
- Segmentation by Region : Geographic revenue distribution and growth outlooks that help stakeholders assess market maturity, penetration opportunities, and regional regulatory considerations across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Company Profiles and Competitive Benchmarking : In-depth profiles of key market participants, covering their strategic focus, product offerings, recent developments, and positioning within specific segments. This enables competitive mapping and identification of potential partnership or acquisition targets.
- Regulatory and Technology Landscape : Synthesis of the evolving efficiency standards, energy certification requirements, and material cost dynamics that influence product design, compliance costs, and time-to-market decisions.
The report is structured to support multiple use cases. Product managers can leverage segment-level data to prioritize development resources and refine feature specifications. Supply chain and procurement teams can use geographic and cost dynamics insights to optimize sourcing strategies. Strategic planners and investors can rely on the forecast models and competitive analysis to evaluate market entry opportunities, partnership scenarios, and long-term growth potential.
Strategic Value for 2026 Decision-Making
As enterprises navigate the 2026 business environment, the AC-DC EPS market presents both opportunities and complexities. The combination of steady market growth, regulatory evolution, raw material volatility, and rapid technological advancement demands a data-driven approach to strategy formulation. This report is built to address those demands by providing:
- Forward-Looking Visibility : The 2026-2032 forecast period offers a clear window into expected market trajectories, helping organizations align investment cycles, capacity planning, and product launch calendars with anticipated demand patterns.
- Segment-Specific Intelligence : Rather than relying on aggregate market figures, decision-makers can drill into the segments most relevant to their business, understanding the competitive intensity, growth rate, and application requirements that define each space.
- Competitive Context : With a concentrated market structure and active innovation pipelines, knowing where key players are focusing their efforts is critical. The report maps competitor capabilities and recent developments to help identify gaps, overlaps, and potential areas for differentiation.
- Risk and Compliance Awareness : Regulatory requirements and material cost fluctuations can significantly impact product economics and market access. The report integrates these factors into the analysis, enabling proactive risk management and compliance planning.
The strategic questions facing organizations in this market are numerous. Which power output ranges offer the most attractive growth-to-competition ratios? How will regulatory changes reshape the competitive hierarchy over the forecast period? Where are the geographic markets with the strongest expansion potential, and what barriers exist to entry? How are technology shifts like wide-bandgap semiconductors altering product specifications and customer expectations? Our report provides the foundational data and analytical framework to address these questions with confidence.
Accessing the Full Intelligence
This article has outlined the strategic context and structural components of the AC-DC External Power Supply Market research report. The market is positioned for continued growth, driven by expanding application demands, efficiency-driven innovation, and a competitive landscape that rewards both scale and specialization. However, the full value of this research lies in the detailed segment breakdowns, comparative analysis, and forward-looking models that go beyond the high-level overview presented here.
Organizations seeking to make informed decisions in 2026 and beyond should consider accessing the complete report, which contains the granular revenue data, segment-level growth rates, regional distributions, application splits, and company-specific profiles necessary to build robust, evidence-based strategies. The combination of historical validation, forecast modeling, and competitive intelligence provides a comprehensive foundation for navigating the market's evolving dynamics.
For stakeholders ready to deepen their understanding and translate market intelligence into actionable strategy, the full report offers the depth, precision, and contextual analysis required to stay ahead in a competitive and rapidly changing landscape.
For detailed analysis of this topic, please visit the official page: AC-DC External Power Supply (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Agritourism Market Hits USD 9.01 Billion in 2025, Forecasts 11.9% CAGR to 2032
By PW Consulting, 2026-09-16
Agritourism Market Outlook 2026: Capitalizing on the Experience Economy via Strategic Intelligence
The convergence of agricultural production and experiential travel has evolved from a niche diversification tactic into a structural growth engine for rural economies. As hospitality consumers increasingly seek authenticity, provenance, and direct connection to land-based operations, agritourism has matured into a standalone commercial discipline. Our latest market research synthesizes historical trajectories, forward-looking demand signals, and competitive positioning to equip executive teams with the institutional intelligence required to navigate this rapidly shifting landscape. With the global market expanding from 5.8 billion USD in 2020 to a projected 10.43 billion USD in 2026, and an anticipated compound annual growth rate of 11.9 percent through 2032, the sector presents both remarkable expansion potential and complex operational trade-offs. Leaders who base capital allocation, partnership strategies, and market entry decisions on fragmented or retrospective data risk misjudging regional regulatory friction, consumer preference volatility, and the pace of infrastructure development. This analysis outlines how a disciplined, data-driven framework transforms uncertainty into executable strategy.
Executive Snapshot: Macro Trajectory and Structural Shifts
The agritourism sector has demonstrated consistent upward momentum over the past half-decade, reflecting a broader consumer migration toward localized, immersive, and mission-aligned travel. Revenue streams have expanded across direct-to-consumer farm interfaces, curated educational programming, and recreational event models, creating a diversified commercial ecosystem that rewards operators capable of balancing agricultural functionality with hospitality-grade service standards. The baseline forecast indicates continued acceleration, yet the pace and profitability of growth will vary significantly depending on regional tourism infrastructure, municipal zoning frameworks, seasonal capacity utilization, and the degree to which operators can integrate value-added processing into their visitor experience. Market concentration metrics further signal an industry in consolidation, where established players hold disproportionate share while emergent regional operators compete by specializing in high-touch experiences, targeted demographic segments, or hybrid agricultural-servitization models. Understanding where scale advantages concentrate, and where agile niche execution can outpace incumbents, is essential for portfolio planning and competitive benchmarking.
Report Architecture: How This Study Maps to Operational Decision-Making
A market intelligence briefing only delivers strategic value when it translates high-level trends into operational levers. This study is designed around that translation layer, moving systematically from macro sizing to actionable execution pathways. The research framework encompasses historical performance baselines, multi-year forecast modeling across primary commercial vectors, and a granular assessment of the competitive landscape. It evaluates how distinct experiential formats are monetized, how hospitality expectations are reshaping traditional farm operations, and how regulatory environments influence site development, liability exposure, and partnership viability. Readers will find structured sections covering demand drivers, consumer segmentation behaviors, capital deployment considerations, and the operational requirements of scaling agritourism from seasonal add-on activity to a year-round revenue architecture. The report deliberately avoids superficial market commentary and instead focuses on the mechanics of growth: visitor acquisition channels, experience design optimization, service capacity constraints, and the financial modeling required to sustain occupancy and repeat visitation. By anchoring analysis in measurable market signals rather than aspirational narratives, the study provides a repeatable methodology for stress-testing strategic options across different risk profiles and capital environments.
Agritourism Market
Competitive Landscape: Benchmarking Established Operators and Sector Archetypes
Agritourism is not a homogenous market. It operates as a layered ecosystem where luxury hospitality brands, specialized tour operators, educational programming providers, and regional farm consortia compete on different value propositions. Leading operators illustrate the strategic diversity available within the sector. High-end integrated resorts demonstrate how agricultural land can be positioned as a premium hospitality asset, combining working farm operations with curated culinary journeys, outdoor programming, and multi-day accommodation models that command elevated per-guest valuations. By contrast, escorted agricultural tour providers focus on connective infrastructure, linking international and domestic visitors to producer networks, rural tourism operations, and behind-the-scenes farming experiences that emphasize authenticity and direct producer engagement. Specialist tour firms extend this model further by offering inspection-oriented and bespoke itineraries designed for associations, professional audiences, and organizations seeking structured exposure to agricultural systems. Custom group travel providers layer programming around rural site visits for professionals, students, and sector enthusiasts, while dedicated agri-technical and educational tour operators build repeatable B2B and institutional channels through association partnerships and organizational programming.
These archetypes reveal distinct strategic postures. Luxury and integrated hospitality models compete on exclusivity, service depth, and land-based brand narrative. Tour and facilitation operators compete on access, logistics reliability, and curated producer relationships. Educational and institutional operators differentiate through content authority, program design, and repeatable group frameworks. Each model carries its own growth requirements, staffing demands, risk profile, and margin structure. Executive teams evaluating entry or expansion must assess where their organizational capabilities align within these competitive clusters, which consumer segments justify premium pricing, and which operational components can be sourced through partnerships rather than built in-house. The competitive analysis in this report maps these dynamics in detail, outlining positioning strategies, brand differentiation paths, and the implications of operating at different points along the experience spectrum.
Regulatory Friction and Structural Dynamics Shaping Deployment Timelines
Growth in agritourism is increasingly mediated by policy environments, land-use frameworks, and liability architectures. Regulatory signals are no longer peripheral; they directly affect site development schedules, operational scope, insurance cost structures, and the feasibility of scaling visitor-facing activities on agricultural land. Recent guidance published by regional agricultural authorities has begun to establish clearer baselines for value-added processing and agritourism operations, signaling a move toward more formalized compliance expectations. At the same time, local planning proposals addressing gatherings on farmland demonstrate how municipal priorities can reshape allowable visitor experiences, parking logistics, event frequency, and nighttime operations. Executive teams planning capital deployment must treat regulatory analysis as a core planning variable rather than a post-investment compliance task. Strategic advantage increasingly belongs to organizations that map jurisdictional variance early, incorporate permitting lead times into rollout roadmaps, and design flexible experience modules that can adapt to changing land-use parameters without sacrificing core revenue logic. On the policy side, broader legislative frameworks influencing program eligibility and income classification have begun altering the economics of farm-based diversification, particularly for operators heavily reliant on direct marketing and visitor revenue. These developments highlight the importance of scenario planning, where growth strategies account not only for demand-side opportunity but also for the administrative cadence and compliance cost embedded in different jurisdictions.
Operations Momentum and the Institutionalization of Agritourism
The sector is also maturing through organized industry activity that is accelerating knowledge transfer, peer benchmarking, and professionalization. Anniversary conventions, regional tourism workshops, and inaugural global conferences are creating venues where operators exchange practical insights on product development, seasonal planning, partnership formation, and experience economy integration. These gatherings reflect a broader shift from ad hoc farm diversification to coordinated industry building, where operators invest in staff training, guest journey design, and repeatable program structures rather than relying solely on informal rural charm. Alongside event-based momentum, select operators are launching dedicated retreat-style offerings that emphasize working-farm immersion, animal engagement, heritage storytelling, and natural setting experiences. Such launches underline the growing commercial appeal of multi-day stays and curated agricultural immersion, reinforcing the need for operators to think beyond day-visit revenue models.
Federal and regional economic data further support the migration toward experience-led farm revenue. Agritourism and recreational service income have expanded materially over the past decade, with meaningful participation spread across counties and median outcomes indicating broad-based, not merely outlier-driven, adoption. This trajectory suggests durable structural demand rather than a temporary travel cycle effect. Yet scale remains uneven. Margin quality, seasonality management, and the ability to convert first-time visitors into repeat guests continue to differentiate high-performing operators from those that merely capture transient foot traffic. The strategic question is therefore not whether demand exists, but how organizations build the operational discipline required to monetize it consistently across weather cycles, staffing constraints, and shifting consumer expectations.
Translating Market Intelligence into 2026 Decision-Making
For executives entering 2026, the practical challenge is prioritization under uncertainty. Capital can be allocated toward destination development, experience packaging, marketing acquisition, partnership expansion, or regulatory navigation, but each path carries different payback horizons and risk exposures. The strategic value of a comprehensive market study lies in its ability to compress that decision space by clarifying where growth is most defensible, which formats align with target demographics, and where competitive white space remains under-monetized. Organizations that build strategy on partial information often overinvest in visible but saturated demand channels while underweighting the operational complexity of service delivery, permitting, and year-round occupancy. Conversely, leaders who ground their planning in sector-specific sizing, segmentation dynamics, and competitive benchmarking can sequence investments more effectively, aligning capability building with the customer segments and experience formats most likely to sustain revenue resilience.
The report accompanying this article is designed to support that disciplined approach. It consolidates historical performance signals, forecast trajectories, competitive archetypes, and structural dynamics into a unified reference framework. By focusing on the mechanics of growth rather than isolated statistics, it enables leadership teams to evaluate entry timing, partnership strategy, experience portfolio design, and regional expansion with greater confidence. Agritourism is increasingly a strategic business discipline rather than a secondary farm activity, and the organizations that treat it accordingly will be better positioned to convert experiential demand into durable commercial advantage.
Strategic Conclusion and Next Steps
The agritourism market is moving into a phase where differentiation, operational precision, and regulatory fluency determine competitive outcomes more than raw destination appeal alone. The projected expansion curve through 2032 underscores the magnitude of the opportunity, while the competitive and regulatory context underscores the need for careful execution. Executive teams seeking to convert this opportunity into measurable performance should treat market intelligence as an active planning instrument, integrating sizing context, segmentation logic, competitor positioning, and policy dynamics into a coherent investment thesis. The full study provides the depth required to pressure-test those decisions across multiple growth scenarios and operational assumptions. We invite leadership teams, investors, and strategy functions to engage with the complete research package to align their 2026 planning with the market realities shaping this sector.
Worldwide Culinary Tourism Market
For detailed analysis of this topic, please visit the official page: Agritourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plastic Cards Market to Reach $414.97 Million by 2032, Growing at 6.98% CAGR from 2025
By PW Consulting, 2026-09-16
Navigating the Plastic Cards Market: Strategic Intelligence for 2026 and Beyond
The global plastic cards market stands at a pivotal juncture in 2026. As digital transformation accelerates across financial services, identity management, and consumer loyalty programs, physical smart cards and traditional plastic credentials continue to evolve rather than disappear. For executives, investors, and supply chain strategists, understanding the trajectory of this market requires more than surface-level forecasts. It demands rigorous, data-backed intelligence that connects historical performance, regional dynamics, competitive positioning, and emerging sustainability mandates into a coherent decision-making framework.
Our latest market research publication on the Plastic Cards Market delivers precisely that intelligence. Designed as a strategic companion for 2026 planning cycles, the report synthesizes a comprehensive historical baseline spanning 2020 through 2025 and extends a detailed revenue trajectory through 2032. By grounding forward-looking analysis in audited historical data and validated industry signals, the study equips decision-makers with the clarity needed to allocate capital, refine product roadmaps, and anticipate regulatory shifts before they become market constraints.
Historical Trajectory and the 2026 Inflection Point
Over the past half-decade, the plastic cards sector has demonstrated consistent resilience and measured expansion. Revenue across the global market progressed from a baseline of approximately $213.23 million in 2020, climbing steadily through successive years to reach $278.68 million by 2025. This historical arc reflects more than incremental growth; it reveals underlying structural demand driven by payment infrastructure modernization, government identification initiatives, and the persistent need for secure, tactile credentialing systems.
Entering 2026, the market projects an initial revenue figure of $285.5 million, signaling a continuation of established growth patterns. More importantly, the forecast horizon extending to 2032 maps a clear upward trajectory, culminating in an estimated $414.97 million by the terminal forecast year. This progression underscores a compound annual growth rate of 6.98 percent across the 2026 to 2032 window. For strategic planners, this CAGR is not merely a statistical output; it serves as a quantitative anchor for capacity planning, inventory forecasting, and investment prioritization. The data indicates that demand will not plateau but will instead accelerate in specific high-value corridors, even as broader macroeconomic conditions fluctuate.
Crucially, the report deliberately withholds granular percentage splits and absolute dollar allocations across individual regions, application verticals, and card types within the publicly accessible preview. This intentional framing ensures that stakeholders recognize the breadth of the analytical model without diluting the commercial value of the full dataset. Decision-makers who require precise regional weightings, application-specific revenue breakdowns, and type-segment penetration rates are directed toward the complete intelligence package, where these parameters are mapped with surgical precision to support localized strategy development.
Competitive Architecture and Concentration Dynamics
The plastic cards manufacturing landscape is characterized by a pronounced concentration of market share among established producers. The report identifies that the top three players collectively command a 68.0 percent share of total market revenue, while the top five firms extend their influence to 78.0 percent. This level of concentration carries significant implications for procurement strategy, pricing power, and supply chain resilience. Organizations that rely on plastic credentials for payment, access control, or government compliance must understand how supplier consolidation affects lead times, customization capabilities, and long-term contractual stability.
The competitive ecosystem spans both North American and European production hubs, with several foundational manufacturers defining industry benchmarks. Custom Plastic Card Company, headquartered in Pompano Beach, Florida, has operated since 1983 as one of the largest North American producers of blank and printed PVC cards, RFID credentials, gift and membership cards, and associated magnetic products. NewGuard Plastic Cards, LLC, based in Rocky Mount, Virginia, holds the position of North America's largest manufacturer of blank plastic cards, adhering strictly to ISO/ANSI standards and utilizing exclusively US-sourced raw materials, while also expanding into composite, eco-friendly, and technology-enabled card formats. The 2024 acquisition of Allegheny Card Solutions by NewGuard, finalized in November 2024, further broadened its portfolio across plastic, composite, eco, and technology card categories, signaling an aggressive consolidation strategy within the blank and specialty card segment.
Other notable producers reinforce the fragmented yet highly specialized nature of the broader market. CardPrinting.com, operating from the United States since 1996, focuses on custom PVC and laminated plastic card printing, delivering gift, loyalty, RFID, ID cards, and plastic key tags. Perfect Plastic Printing Corporation emphasizes compliant production, secure personalization, and sustainability across personalized debit, credit, and secure card formats. Continental BizMag maintains direct quality control through domestic PVC card production in its South Florida wholesale facility. Print Robot operates a 55,000-square-foot US factory dedicated to membership, gift, and business card manufacturing. Across the Atlantic, Variuscard in Austria brings over fifty years of experience to chip, RFID, smart, loyalty, gift, and ID card production, maintaining 100 percent Austrian manufacturing. Polskie Karty sp z o.o. serves as a leading direct producer in Poland and Europe, leveraging an advanced technology park for custom printed plastic cards.
The full report delves into operational profiles, production capacities, regional footprint advantages, and strategic positioning for each key company. Rather than presenting static corporate summaries, the analysis evaluates how these manufacturers respond to customization demands, compliance requirements, and sustainability mandates, enabling buyers and investors to map supplier capabilities against specific procurement or partnership criteria.
Industry Dynamics: Sustainability, Sourcing, and Regulatory Alignment
No strategic assessment of the plastic cards market in 2026 is complete without addressing the accelerating influence of sustainability mandates and raw material sourcing shifts. The industry is undergoing a measurable transformation as manufacturers, material suppliers, and end-users realign around environmental performance, supply chain transparency, and regulatory compliance.
Material innovation has emerged as a primary driver of competitive differentiation. Klöckner Pentaplast has advanced its SecondLife card films by increasing recycled content from 25 percent to 100 percent across both PVC and PET options, achieving a 65 percent reduction in CO2 emissions and a 65 percent reduction in landfill impact. This scale of material transition signals that recycled substrates are moving from pilot initiatives to mainstream production standards. Simultaneously, the International Card Management Association continues to advance sustainability frameworks through its EcoLabel Program and member-led initiatives focused on recycled content integration and reduced environmental impact, creating an industry-wide benchmark that manufacturers and buyers alike must navigate.
Supply chain localization and raw material security are equally critical themes. NewGuard Plastic Cards has transitioned to fully US-sourced raw materials for its blank plastic card production to meet ISO/ANSI standards, reflecting a broader move toward domestic sourcing resilience and compliance assurance. On the demand side, Bank of America reported in September 2024 that 80 percent of its plastic cards utilize post-consumer recycled plastic, illustrating how major financial institutions are embedding sustainability into procurement specifications at scale. The ICMA Expo 2025 further reinforced these trends, showcasing partnerships and exhibits centered on sustainable plastic card solutions, including recycled PVC laminates and advanced chip card technologies.
The report's Dynamics section synthesizes these developments into actionable strategic observations. Rather than treating sustainability as a peripheral compliance exercise, the analysis positions it as a core determinant of supplier eligibility, cost structure evolution, and consumer-facing brand positioning. Organizations that integrate material innovation timelines, regulatory trajectories, and procurement policy shifts into their 2026 planning will be better equipped to manage risk and capture emerging value pools.
Report Architecture: Operational Intelligence for 2026 Decision-Making
The research publication is structured to translate macro-level market intelligence into operational relevance. It begins with a comprehensive market overview that anchors the forecast period in historical performance, establishing the quantitative baseline necessary for scenario modeling. From there, the report progresses through segmentation analysis that explores how different card types, application verticals, and regional markets interact to shape revenue distribution. While the publicly accessible preview highlights the overall market scale and projected CAGR, the complete report unpacks the underlying segmentation architecture, enabling users to identify which corridors present the highest growth potential, where demand is stabilizing, and how product mix strategies should adapt.
A dedicated competitive landscape section maps the operational footprint, production capabilities, and strategic moves of key market participants. This analysis extends beyond corporate profiles to examine consolidation patterns, production localization trends, and the competitive implications of scale versus specialization. The recent acquisition activity, such as NewGuard's expansion through Allegheny Card Solutions, is evaluated within the broader context of market concentration and supplier diversification strategies.
Plastic Cards Market
Additionally, the report incorporates a forward-looking dynamics component that tracks material innovation, sustainability standardization, regulatory alignment, and procurement policy evolution. These elements are cross-referenced with manufacturing capabilities and end-user adoption patterns, providing a multi-dimensional view of how external pressures will reshape supply chains, cost structures, and product specifications through 2032.
Importantly, the research is designed for practical deployment. Executive summaries, data tables, and segmentation frameworks are organized to support capital allocation decisions, supplier evaluation workflows, product development prioritization, and regional expansion assessments. The full dataset, accessible through the complete report, provides the precise regional weightings, application-level revenue breakdowns, and type-segment performance metrics required for granular strategic planning.
Plastic Bag Market
Strategic Imperatives for 2026
As organizations enter the 2026 planning cycle, several strategic imperatives emerge from the market intelligence. First, supplier concentration demands a deliberate approach to procurement diversification and contract structuring. With a significant share of market revenue concentrated among a limited number of manufacturers, buyers must evaluate supplier resilience, customization capacity, and compliance assurance rather than relying solely on price benchmarking.
Second, sustainability is no longer optional. The transition toward high-recycled-content substrates, the expansion of EcoLabel-aligned production, and the embedding of post-consumer recycled materials into major financial institution card programs indicate that environmental performance will increasingly influence supplier selection and product eligibility. Organizations that proactively align their card specifications with sustainability trajectories will reduce future procurement friction and strengthen brand positioning.
Third, the forecast horizon through 2032 highlights the importance of forward-looking capacity and investment planning. The projected growth trajectory suggests that demand will continue to expand across multiple application corridors, requiring stakeholders to anticipate production scalability, technology integration, and regional demand shifts rather than reacting to near-term volume changes alone.
The complete Plastic Cards Market research report provides the detailed segmentation data, competitive analysis, and dynamics mapping necessary to operationalize these imperatives. By accessing the full intelligence package, decision-makers can extract region-specific revenue allocations, application-level demand patterns, and type-segment performance metrics that transform high-level forecasts into actionable strategy.
For executives, procurement leaders, and industry analysts seeking to navigate the plastic cards market with precision in 2026 and beyond, this research delivers the structured, data-anchored insight required to make informed, forward-compatible decisions.
For detailed analysis of this topic, please visit the official page: Plastic Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silyl Modified Polymer Market Hits $1.1B in 2025, Projected 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Silyl Modified Polymer Market in 2026
In the rapidly evolving landscape of advanced materials, Silyl Modified Polymers (SMP) have emerged as a cornerstone technology for high-performance sealants, adhesives, and coatings. As we enter 2026, enterprises across construction, automotive, and industrial sectors face a critical juncture. The convergence of shifting supply chains, regulatory pressures, and demand for durable, isocyanate-free solutions demands more than off-the-shelf market data. It requires a granular, forward-looking intelligence framework. PW Consulting's latest Silyl Modified Polymer Market report is designed to serve as that framework, translating historical trends into actionable 2026 strategic decisions.
This market study is not merely a compilation of figures. It is a strategic tool engineered to de-risk capital allocation, optimize product mix, and identify white-space opportunities. By integrating a robust quantitative baseline with qualitative assessment of competitive maneuvers and macroeconomic headwinds, the report offers a complete intelligence picture. Below, we outline the strategic architecture of this research and why it is indispensable for corporate planning in the current fiscal year.
Market Trajectory and the 2026 Inflection Point
Understanding where the market has been is essential to validating where it is going. Our analysis tracks revenue growth from 2020 through 2025, establishing a baseline of resilience and expansion. In 2020, the global market for silyl modified polymers recorded revenue of USD 850.0 Million. Through the subsequent five-year period, the sector demonstrated consistent upward momentum, absorbing supply shocks and capitalizing on increasing substitution rates from traditional adhesive technologies. By the base year of 2025, market revenue had climbed to USD 1.1 Billion, reflecting a compound annual growth rate that underscores sustained commercial adoption.
Looking forward to the forecast period spanning 2026 to 2032, the trajectory indicates continued expansion, though with notable variability that demands careful interpretation. While early forecast years project steady growth, the medium-term outlook suggests that market velocity will be influenced by raw material volatility and regional capacity adjustments. Specifically, the forecast grows to a projected USD 1,197.74 Million in 2026, before navigating intermediate fluctuations that reflect the complex interplay of investment cycles and demand normalization. By 2032, the market is anticipated to reach a substantial scale, highlighting the long-term structural appeal of SMP technology.
For corporate strategists, these macro-trends are not just benchmarks; they are inputs for scenario planning. The shift from historical stability to a forecast period characterized by dynamic variables means that static budgeting is insufficient. Decision-makers must understand the drivers behind the growth rate—a 5.5% CAGR over the forecast horizon—and the specific conditions that could accelerate or decelerate this pace. Our report deconstructs these drivers without oversimplifying them, providing the nuance required for robust 2026 planning.
Segmentation Insights: Beyond the Aggregate
Aggregate market size tells only half the story. The true strategic value lies in understanding how value is distributed across types, applications, and geographies. However, sharing every percentage split in a preview would diminish the premium nature of the full intelligence package. Instead, we highlight the structural composition that defines the competitive battlefield.
The market is fundamentally anchored by two primary polymer architectures. Polyether-based variants continue to command a significant share of global revenue, driven by their balance of flexibility and weatherability. Polyurethane-based formulations represent the second major pillar, often selected for specific mechanical properties or compatibility requirements. A smaller but strategically important category encompasses other specialized types that serve niche high-performance needs. The interplay between these types dictates formulation strategies for end-users and pricing power for suppliers.
On the application side, the construction sector remains a dominant consumption center, leveraging SMP technology for sealants and coatings that require long-term durability and low maintenance. The automotive sector follows as a critical growth engine, particularly as vehicle architectures evolve toward lightweighting and electric mobility, where bonding solutions must meet increasingly stringent safety and thermal standards. General industry and other application verticals complete the demand picture, each with unique procurement cycles and technical specifications.
Geographically, the market exhibits a multi-polar demand structure. While mature economies in North America and Europe maintain steady consumption levels supported by infrastructure maintenance and regulatory compliance, the Asia Pacific region reflects the dynamic growth of manufacturing capacity and urbanization. Latin America and the Middle East and Africa represent smaller but emerging pockets of opportunity, often tied to specific project pipelines rather than broad-based consumption. Our report maps these regional nuances in detail, helping firms align their distribution and production footprints with actual demand centers rather than assumptions.
Competitive Landscape: Incumbents and Differentiators
The SMP market is characterized by a mix of specialized chemical producers and large-scale material solutions providers. Market concentration metrics indicate that the top three players hold approximately 35% of the revenue share, while the top five possess around 48%. This moderate concentration suggests a market where scale matters, but differentiation through technology and regional service capability can secure significant positions for mid-tier players.
Several key companies define the operational and technological baseline for the industry:
N Methoxymethyl N Trimethylsilylmethylbenzylamine Market
- Kaneka Corporation , based in Osaka, Japan, stands as a foundational player. The company is recognized for its Kaneka MS Polymer™ technology, an original isocyanate-free base resin designed for high-performance moisture-cure sealants, adhesives, and coatings. Kaneka's legacy in this space sets a technical benchmark for purity and performance consistency.
- Risun Polymer International Co., Ltd. , headquartered in Huai'an, Jiangsu, China, operates as a leading manufacturer of Silane Terminated Polyether (STP/SMP) polymers. By combining polyurethane and silicone features, Risun addresses the needs of sealant, adhesive, and coating formulators seeking versatile performance profiles, particularly within the Asian manufacturing ecosystem.
- CAPLINQ Corporation , located in Ottawa, Canada, produces the BS-7000 and BS-2000 Series SMP adhesives. These products are engineered for industrial, mass-transit, and electric vehicle applications, with a specific focus on primerless bonding and compliance with standards such as EN45545. This focus on regulated, high-stakes applications highlights the specialized end-game for SMP adoption.
- Bostik (Arkema) , with headquarters in Paris, France, supplies SMP-based sealants and adhesives for construction, transportation, and marine uses. With global manufacturing capabilities and adherence to Buy America compliance, Bostik illustrates how multinational presence and regulatory navigation are critical components of market competitiveness.
- W. R. Meadows, Inc. , based in Hampshire, Illinois, USA, manufactures AIR-SHIELD SMP self-adhering vapor-permeable air barrier membranes and HS-1 SL hybrid sealants. Their use of silyl-modified polymer technology demonstrates the material's versatility in building envelope solutions and specialized sealing applications.
Beyond these profiles, the competitive environment is shaped by strategic moves that are not always visible in headline financials. Our report analyzes capacity expansions, technical partnerships, and regional positioning strategies that allows clients to anticipate competitor behavior. In a market where brand trust and technical support often decide procurement decisions, understanding the operational footprint of these players is vital.
Industry Dynamics: Raw Material Pressures and Regulatory Shifts
No market analysis is complete without integrating the external forces that reshape cost structures and availability. As of late 2025 and early 2026, several dynamics are directly impacting the SMP value chain.
Raw material pricing has become a focal point for procurement teams. In December 2025, US silane prices climbed due to high demand and limited availability, a trend reported by ChemAnalyst. This pressure on precursor costs ripples through the formulation economics of SMP products, potentially squeezing margins for manufacturers who cannot pass through price adjustments quickly. Conversely, Polydimethylsiloxane antifoam emulsion prices showed a stable to marginally soft trend in Q1 2026, suggesting that not all silicone-derived inputs are moving in tandem. This divergence requires precise input cost tracking rather than blanket assumptions.
Furthermore, supply chain distortions originating from the Middle East continue to influence global pricing structures. In March 2026, WACKER announced a price increase for its silicone-based product range effective April 1, 2026, citing energy and raw materials market distortions and supply-chain disruptions linked to regional conflicts. This move, reported by Adhesives & Sealants Industry, underscores the vulnerability of the broader silicone ecosystem to geopolitical and energy market shocks. For SMP producers and consumers, such announcements are leading indicators of potential cost volatility and sourcing challenges.
These dynamics create a complex operating environment. Companies must balance the need for stable supply against the risk of cost inflation. The report integrates these factors into a "Dynamics" section that models potential scenarios, helping clients stress-test their 2026 procurement and pricing strategies against realistic external shocks.
What the Full Report Delivers for 2026 Decision-Making
The preview provided here offers a high-level view of the market structure and the forces at play. However, executing a successful strategy in 2026 requires depth. The complete PW Consulting Silyl Modified Polymer Market report is structured to provide immediate operational utility across multiple functions:
- Detailed Segmentation Revenue and Volume Analysis: While this preview omits specific regional and application splits, the full report delivers precise revenue and volume breakdowns by region, type, and application. This enables precise TAM/SAM/SOM calculations and allows R&D to align product development with the highest-value segments rather than chasing aggregate growth.
- Competitive Benchmarking and Strategy Maps: Beyond company profiles, the report includes analysis of recent developments, product launches, and strategic shifts. Clients gain insight into where competitors are investing, which applications they are targeting, and how they are responding to raw material pressures.
- Supply Chain and Cost Structure Modeling: Integrating raw material trends like the silane price movements and silicone price adjustments, the report offers frameworks for understanding cost pass-through capabilities and margin resilience. This is critical for pricing strategy and vendor negotiations.
- Regulatory and Compliance Landscape: With players navigating standards like EN45545 and Buy America compliance, the report maps the regulatory terrain across key markets. This helps quality and regulatory teams anticipate compliance costs and certification timelines.
- Forecasting and Scenario Planning: The forecast data is presented with sensitivity analysis, allowing planners to model best-case, base-case, and stress scenarios. This supports capital investment decisions, inventory management, and long-term capacity planning.
Conclusion: The Cost of Uncertainty vs. The Value of Precision
The silyl modified polymer market in 2026 is defined by opportunity tempered by volatility. Demand fundamentals remain strong, anchored by construction durability needs and automotive innovation. Yet, raw material fluctuations, geopolitical supply disruptions, and competitive maneuvering create an environment where intuition alone is not enough.
PW Consulting's market research is designed to replace uncertainty with precision. By revealing the structural composition of demand, the competitive DNA of key players, and the critical dynamics shaping costs, the report empowers leadership teams to make informed, confident decisions. The macro numbers tell the story of growth; the deep-dive segmentation and company intelligence tell the story of how to capture it.
Silyl Modified Polymer Market
For organizations ready to move beyond surface-level trends and secure a competitive edge in the SMP market, the full report provides the comprehensive intelligence necessary to navigate the year ahead. The strategic advantage belongs to those who understand not just the size of the market, but the mechanics of its movement.
For detailed analysis of this topic, please visit the official page: Silyl Modified Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Fibre Rope Market to Hit $2,610M by 2032, Driven by 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Navigation in a High-Growth Synthetic Fibre Rope Market: A 2026 Decision-Maker's Brief
The synthetic fibre rope sector stands at a critical inflection point. As global industrial operations demand higher performance, greater durability, and increasingly sustainable load-bearing solutions, the market has evolved from a commodity-adjacent category into a technology-driven ecosystem. Our recently published market research on the Synthetic Fibre Rope Market delivers a comprehensive, forward-looking intelligence framework designed specifically for executive teams planning capital allocation, supply chain restructuring, and competitive positioning across the 2026–2032 horizon.
This article serves as a strategic preview of the full study. It outlines the macroeconomic trajectory, highlights the operational and competitive dimensions covered in depth, and explains why the report's analytical architecture is calibrated to support high-stakes decision-making in the current year. The objective is not to replicate existing trade summaries, but to equip strategists, procurement leaders, and corporate planners with the conceptual scaffolding required to assess where the market is heading, who will shape its contours, and which structural variables will define profitability in the next cycle.
The Trajectory: Why 2026 Matters for Capital Allocation
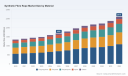
The global synthetic fibre rope market has demonstrated consistent expansion over the past half-decade, with total revenue growing from approximately 1,347 million USD in 2020 to an estimated 1,688 million USD in 2025. The forecast period extends through 2032, with projected revenue reaching roughly 2,610 million USD by the final forecast year. This trajectory reflects a compound annual growth rate of 6.5 percent, a figure that may appear moderate on its own but carries substantial structural implications when viewed through the lens of industrial demand intensity, raw material volatility, and regional capacity reconfiguration.
Synthetic Fibre Rope Market
For executives evaluating 2026 investment priorities, the key insight is not simply that the market is expanding, but that the composition of that expansion is shifting. High-performance synthetic variants are capturing incremental share in applications where failure risk, weight sensitivity, or corrosion resistance justify premium pricing. Meanwhile, conventional grades continue to anchor high-volume, cost-sensitive segments. Understanding which end-use categories are driving volume versus value, which materials are experiencing input-cost pressure, and how regional manufacturing footprints are adapting to logistics and sustainability mandates requires a granular view that only a structured market study can provide. The report dissects these layers systematically, enabling leadership teams to separate cyclical noise from durable demand shifts.
Inside the Research: Analytical Architecture and Operational Utility
The study is organized around a multi-dimensional analytical framework designed to translate complex market signals into actionable intelligence. Rather than presenting static snapshots, the research maps the interplay between material technology, application requirements, regional dynamics, and competitive behavior across the forecast window. The structure is deliberately built for cross-functional use: procurement teams can benchmark input exposure, R&D groups can evaluate material substitution pathways, sales leadership can align territory strategies with regional demand intensities, and corporate development teams can assess partnership, acquisition, or capacity-expansion opportunities.
Core analytical components include:
- Material-level performance and cost dynamics. The report examines how different synthetic families are positioned across performance tiers, weight-to-strength profiles, chemical resistance characteristics, and price sensitivity thresholds. It tracks how premium-grade materials compete against established conventional options, particularly in segments where total cost of ownership, not unit price, determines adoption.
- Application-driven demand mapping. End-use requirements vary dramatically across marine, industrial, energy, construction, and specialized technical sectors. The study evaluates the distinct performance criteria, procurement cycles, and regulatory environments shaping demand in each application cluster, helping readers anticipate where volume growth will be most concentrated and where specification upgrades will drive mix improvement.
- Regional market structure and supply chain considerations. Demand intensity, manufacturing presence, logistics constraints, and local regulatory frameworks differ meaningfully across geographies. The report contextualizes these differences to support localization decisions, import/export strategy, and regional partnership selection without reducing the analysis to oversimplified share rankings.
- Competitive positioning and strategic group analysis. The study profiles the operational focus, technological orientation, and market footprint of leading participants, enabling readers to understand where differentiation is being created, how certification and compliance capabilities affect purchasing decisions, and which collaborative or consortium-based initiatives are reshaping industry standards.
- Pricing context and input-cost exposure. Given the substantial cost differentials between synthetic and natural alternatives, as well as between conventional and high-performance synthetics, the research provides pricing context that helps procurement and finance teams model inventory exposure, capital expenditure sensitivity, and supplier negotiation leverage.
The full report goes further by integrating these dimensions into a coherent forecast model, allowing decision-makers to test assumptions around volume growth, material substitution, and regional expansion under varying macroeconomic and regulatory scenarios.
Competitive Landscape: incumbents, Specialists, and Standards Bodies
The synthetic fibre rope market is characterized by a blend of established manufacturers, technology-focused specialists, and regional producers with deep application expertise. Industry concentration is meaningful: the three largest participants account for approximately 62.5 percent of market revenue, while the top five collectively represent around 75.0 percent. This concentration shape has strategic implications. It suggests that pricing power, specification influence, and relationship-driven procurement remain significant in many end-use segments, while simultaneously leaving room for agile specialists to capture niche positioning through performance innovation, certification strength, or application-specific engineering support.
Several companies exemplify the competitive diversity shaping the sector today. Samson Rope Technologies, based in the United States, has built a reputation around high-performance synthetic ropes spanning polyester, nylon, and high-modulus polyethylene, with emphasis on lifting, rigging, marine, and safety applications. Teufelberger Holding AG, headquartered in Austria, supplies fiber ropes and high-performance synthetic rope solutions across marine, forestry, arborist, and industrial contexts. Lanex, operating from the Czech Republic, maintains a traditional manufacturing base serving marine, yachting, rescue, military, and industrial applications. Yale Cordage, also U.S.-based, focuses on advanced braiding techniques and high-tech synthetic rope systems for energy, marine, medical, and research environments. Unirope, based in Canada, emphasizes certified lifting and rigging synthetic rope products aligned with ISO 9001 and LEEA standards. Cortland Limited serves energy, subsea, marine, medical, and research sectors with high-tech ropes, slings, and strength members. In Europe, Oliveira has combined fiber rope and steel wire rope production since the early nineteenth century and remains active in EUROCORD, while COTESI and BADINOTTI, both Italian producers, participate in the same European association and serve industrial and marine applications.
These profiles matter because competitive advantage in this market is rarely determined by volume alone. Procurement teams in marine, energy, construction, and industrial settings often weigh certification credibility, technical support capacity, material consistency, and supply reliability alongside price. The report examines how such differentiators are translating into market positions and where consolidation, collaboration, or technology licensing may alter the landscape over the forecast period.
Recent Developments Shaping Strategic Assumptions
Several recent industry movements reinforce the need for updated decision frameworks in 2026. Price-environment observations from early 2026 indicate that synthetic ropes typically command substantial premiums over natural fiber alternatives, with cost ranges per meter varying widely by material class. Polypropylene and polyester remain positioned at lower price points relative to high-performance options, while ultra-high-molecular-weight polyethylene and similar advanced fibers occupy a significantly higher cost band. For large-scale operators managing substantial rope inventories across utility, marine fleet, or construction operations, these differentials have direct implications for working capital intensity and inventory strategy.
On the innovation and sustainability front, a notable product partnership announced in April 2026 brought together a high-tech rope producer and a protective materials specialist to develop a green synthetic rope manufactured in the United States. This type of collaboration signals growing investor and customer interest in reducing the environmental footprint of synthetic load-bearing products without sacrificing performance, and it underscores how regional manufacturing claims can become part of the value proposition in certain procurement contexts.
At the industry-organizational level, EUROCORD continues to serve as a focal point for synthetic rope producers in Europe and beyond. Recent annual meetings and newsletter activity have drawn participation from multiple established manufacturers, with emphasis on standards, industry updates, and collective positioning on material availability and sustainability. This institutional activity matters because standards alignment, quality expectations, and regulatory awareness increasingly influence specification decisions in marine, industrial, and energy applications. The study incorporates these dynamics to help readers understand how advocacy, standardization, and consortia participation can affect both competitive behavior and procurement requirements over time.
In parallel, broader material-market context indicates that fossil-based synthetic feedstocks have seen volume increases, alongside heightened attention to the availability and sustainability trajectory of biobased alternatives. For rope manufacturers and downstream buyers alike, this signals that input sourcing strategies, supplier diversification, and material substitution roadmaps will remain central to cost management and reputational positioning.
What the Full Study Enables
The complete research publication is designed to convert the themes outlined above into a practical decision-support toolkit. Readers can expect detailed baseline estimates, forward projections, and structured segmentation analysis that illuminate where growth is accumulating and how value is migrating across materials, applications, and regions. The study also provides competitive profiles, recent strategic developments, and industry-institution activity that help map the evolving rules of competition. Importantly, it frames pricing and input-cost dynamics in a way that supports scenario planning rather than static assumptions, recognizing that synthetic rope procurement is frequently a balance between performance assurance, total cost of ownership, and supply resilience.
For organizations making 2026 decisions on capacity, supplier selection, product development, regional entry, or market expansion, the report offers a consolidated reference point that reduces reliance on fragmented sources and ad hoc estimates. It is structured to be referenced by multiple functions simultaneously, with enough depth to support board-level narrative building and enough operational specificity to inform procurement, sales, and engineering planning.
Conclusion: Positioning for the Next Cycle
The synthetic fibre rope market is growing, but more importantly, it is re-composing. Growth is not uniformly distributed across materials, applications, or regions, and the premium-versus-value dynamic is reshaping both supplier strategy and buyer evaluation criteria. In this environment, the strategic question is no longer simply whether to participate, but how to position for the segments, specifications, and supply-chain configurations that will generate the most durable returns through 2032.
Synthetic Concrete Fibers Market
The full market research provides the depth, structure, and forward framing required to answer that question with confidence. For executives seeking to align capital, procurement, and competitive strategy with the next phase of market development, the study offers a rigorous starting point for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Synthetic Fibre Rope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Prosthetic Foot Market Hits $830M in 2025, Projecting 6.4% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Prosthetic Foot Market (2026–2032)
The prosthetic foot market stands at a critical inflection point. Beyond the first prosthetic foot enabling basic ambulation, modern solutions are now engineered to restore high-impact mobility, adapt to variable terrains, and seamlessly integrate with the user’s biomechanical profile. As healthcare systems evolve, reimbursement frameworks tighten, and demographic shifts accelerate demand, stakeholders require more than surface-level market summaries. They need a precise, forward-looking intelligence framework that translates macro trends into actionable commercial and clinical strategies. The forthcoming Prosthetic Foot Market research delivers exactly that: a rigorous, evidence-based roadmap designed to inform capital allocation, product portfolio decisions, and go-to-market positioning through 2032.
Macro Trajectory: How Structural Shifts Are Reshaping the Market
Over the past half-decade, the prosthetic foot sector has demonstrated steady, compounding growth, recovering strongly from pandemic-era supply and demand disruptions and entering a phase of sustained expansion. From a baseline established in 2020, the market has tracked a consistent upward curve, crossing the 700-million threshold by 2023 and accelerating toward an estimated 830 million in 2025. Forward projections indicate that this momentum will carry the market well past the one-billion milestone during the late 2020s, ultimately approaching a valuation near 1.27 billion by 2032. The compound annual growth rate underpinning this trajectory sits at 6.4 percent, a figure that reflects not only rising prevalence of limb loss conditions but also the broadening adoption of advanced prosthetic technologies, improved reimbursement accessibility, and an expanding pipeline of active, mobility-focused end users.
This growth is not uniform across product categories or patient demographics, and that uneven distribution holds vital strategic implications. Advanced microprocessor-controlled prosthetic feet are capturing an increasing share of clinical preference, driven by superior gait symmetry, fatigue reduction, and adaptability to complex environments. Yet mechanical feet remain foundational, sustaining broad volume across diverse payer environments and activity-level classifications. Meanwhile, the demand base is bifurcating: adult users continue to anchor core volume, while pediatric and adolescent segments are growing as early-intervention protocols mature and long-term mobility outcomes gain prominence in clinical guidelines. Understanding how these demand streams interact—and where margin pools actually concentrate—requires granular, segment-level analysis that goes far beyond headline numbers.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Makers
This study is built for practitioners who must make time-sensitive, resource-intensive decisions in a highly regulated, technology-intensive market. Rather than offering retrospective summaries, the report anchors its analysis in a structured forecast architecture covering the 2026–2032 horizon, calibrated against a transparent historical baseline spanning 2020 through 2025. The methodology is intentionally designed to support scenario planning, portfolio rationalization, and competitive positioning with precision.
Readers will find a multidimensional dissection of demand drivers, sales channels, and end-use adoption patterns, with particular attention to how activity-level classifications shape product-mix economics. The analysis unpacks the interplay between rehabilitation trajectories, payer policies, and prosthetic design requirements, enabling manufacturers, distributors, and service providers to anticipate where volume and value will shift next. Pricing architectures, reimbursement sensitivity, and component-level substitution dynamics are examined to clarify which product formats carry durable margin resilience and which face structural compression under evolving payer scrutiny.
Equally important, the research supplies the operational scaffolding needed to translate market signals into execution. Demand forecasts are mapped against realistic penetration ceilings, capacity considerations, and regional procurement behaviors. Strategic questions—such as whether to prioritize modular design ecosystems, where to concentrate advanced-technology commercialization efforts, and how to align clinical education campaigns with payer-aligned prescribing patterns—are addressed through a lens of commercial realism rather than theoretical optimism.
Competitive Arena: Where Leaders Are Winning—and Where the Gaps Remain
The competitive landscape is defined by a concentrated set of established players, each leveraging differentiated engineering philosophies, clinical relationships, and geographic footprints. Market concentration underscores this reality, with the top three firms collectively representing a substantial share of total revenue, and the top five extending that dominance even further. This structure rewards companies that can combine product reliability, clinical validation, and responsive commercialization while penalizing those that rely on undifferentiated volume plays.
Ottobock SE & Co. KGaA continues to reinforce its position through a dual-track portfolio that pairs mechanical strength with intelligent adaptation. Its Taleo and Evanto mechanical prosthetic feet target active users who demand durability and predictable energy transfer, while its microprocessor-controlled offerings extend the company’s reach into higher-complexity mobility scenarios. This balance allows Ottobock to serve both cost-sensitive and performance-oriented procurement pathways without diluting brand coherence.
Össur hf has built its reputation on dynamic, terrain-responsive design, and its current lineup reflects that philosophy with precision. The Proprio Foot, Pro-Flex family, Balance Foot, and Cheetah series are engineered to address variable walking conditions and high-activity demands. By emphasizing gait adaptability and user confidence across uneven surfaces, Össur positions itself squarely in the performance segment where functional outcomes often dictate purchasing decisions.
Blatchford Limited takes a different route, focusing on high-impact resilience and modular engineering. Its BladeXT e-carbon foot and Echelon series are oriented toward users who push beyond routine ambulation, requiring robust load handling and responsive energy return. The emphasis on active and high-demand user profiles gives Blatchford a clear niche in markets where clinical protocols prioritize return-to-activity outcomes.
College Park Industries contributes to the competitive mix with a focus on biomechanically tuned dynamic feet. The Soleus and Trustep lines highlight energy return and hydraulic modeling, meeting the needs of users who require smoother gait transitions and durable daily-use performance. This orientation appeals to clinicians seeking reliable, functionally versatile options across a broad activity spectrum.
Fillauer LLC strengthens the field with performance-oriented modular solutions. Its Aeris Performance line, alongside bio-attributed PVC shell designs, speaks to an expanding appetite for customizable, modular foot systems that can be adapted to individual residual limb characteristics and activity requirements. This modularity-centric approach aligns with broader industry trends favoring adaptability and component-level servicing.
WillowWood Global LLC has moved to deepen its market relevance through both product engineering and partnership strategy. Its MetaShock dynamic feet and modular component sets are designed for users operating at K3 and K4 activity levels, while its December 2025 strategic partnership with Click Medical signals a clear push toward user-specific prosthetic solutions. Such collaborations reflect a wider industry shift toward personalized fitting workflows and integrated care models.
Worldwide 3D Printed Prosthetic Hands Market
Streefedered KG rounds out the competitive picture with modular systems built for customization. Its Vari-Flex line and modular foot configurations cater to practitioners who value flexible component selection and patient-specific tuning, reinforcing the market’s ongoing emphasis on individualized mobility solutions. Endolite adds further depth with its broad portfolio of components and feet engineered for varied amputation levels, supporting clinical teams that require scalable, level-appropriate solutions across diverse patient populations.
The strategic implication for stakeholders is clear: pricing power, channel access, and clinical adoption will increasingly favor companies that can integrate product differentiation with reimbursement alignment and service scalability. Firms that treat these dimensions as separate workstreams will find themselves outmaneuvered by competitors who treat them as a unified commercial architecture.
2026 Reimbursement Realities: Why Policy Is Now a Product Strategy Variable
One of the most consequential developments shaping near-term decision-making is the reconfiguration of payer coding and reimbursement pathways. In March 2026, the Centers for Medicare & Medicaid Services announced final determinations for lower extremity prosthetics, including the introduction of a new HCPCS code, L5992. Effective April 1, 2026, this code is designated for replacement of foot shells in modular or non-solid ankle cushion heel prosthetic feet and is separately payable at a rate of 127.11 dollars. The same determinations clarify that foot covers remain included within base foot component codes and are not separately payable.
For manufacturers, distributors, and prosthetic service providers, this is not merely a compliance update. It is a structural input into product economics, service-model design, and portfolio prioritization. Separately payable foot-shell replacement creates a distinct revenue touchpoint that can influence how modular systems are positioned, how service contracts are structured, and how clinical teams approach long-term component maintenance. At the same time, the explicit exclusion of foot covers from separate reimbursement reinforces the importance of base-component pricing discipline and value communication.
These reimbursement dynamics interact directly with broader market concentration and product-mix trends. In a market where a limited number of firms already command the majority of revenue, reimbursement shifts can accelerate consolidation advantages, reward companies with clearer modular articulation, and pressure players whose economics depend on blended, less-transparent pricing. Companies that fail to map reimbursement changes onto their product architecture risk mispricing innovation, misaligning sales incentives, or under-serving the maintenance needs that drive long-term patient retention.
Where Strategic Focus Should Land in 2026
As the market advances toward the 2032 horizon, the most successful organizations will be those that treat product development, reimbursement intelligence, and commercial execution as tightly coupled systems. Several strategic priorities stand out.
First, segmentation precision must move from retrospective reporting to forward-looking portfolio design. Volume concentration across adult and pediatric populations, and across mechanical and microprocessor-controlled categories, will shape where R&D dollars produce the strongest commercial returns. Companies that can identify the highest-value intersection of activity level, reimbursement compatibility, and clinical preference will deploy capital more efficiently than those pursuing blanket expansion.
Second, reimbursement navigation is now a core competitive capability. The L5992 pathway, along with broader payer scrutiny on component-level billing, demands that commercial teams understand not just price points but the operational logic of claims, coverage rules, and service cycles. Alignment between clinical messaging, product documentation, and reimbursement architecture will differentiate firms that can secure consistent procurement from those that face repeated reimbursement friction.
Third, partnership and modularity strategies will increasingly determine market agility. The recent WillowWood–Click Medical collaboration illustrates a broader pattern: the market is moving toward more individualized fitting, integrated service delivery, and component ecosystems that reduce friction across the patient journey. Firms that can embed themselves in these workflows—through engineering compatibility, distribution relationships, or joint solution design—will be better positioned to capture sustained demand.
Prosthetic Foot Market
Finally, competitive positioning will hinge on the ability to communicate differentiated clinical value without overpromising on outcomes that payers and clinicians will scrutinize. High-impact designs, terrain-adaptive mechanics, and microprocessor intelligence each solve real user problems, but their commercial success depends on clear reimbursement alignment, credible clinical evidence, and service models that sustain performance over time. In a concentrated market, reputation and reliability can be as decisive as feature sets.
Why the Full Report Matters Now
The prosthetic foot market is no longer defined solely by volume growth. It is being reshaped by reimbursement architecture, product modularity, competitive concentration, and the accelerating expectation that prosthetic solutions should support high-function, real-world mobility. The 6.4 percent CAGR and multi-year revenue trajectory signal opportunity, but opportunity without segmentation insight, reimbursement literacy, and competitive clarity can easily translate into misallocated investment or missed positioning windows.
This research was designed to close that gap. It provides the analytical depth required to evaluate where demand is genuinely expanding, which product and service architectures are most resilient under current payer conditions, and how leading players are structuring their portfolios to defend or extend market share. The macro numbers offer direction; the segment-level dynamics, competitive profiles, and reimbursement-sensitive economics offer the precision needed to act.
Organizations preparing product launches, portfolio reviews, capacity planning, or regional market entry in 2026 will find the full report essential for stress-testing assumptions and prioritizing moves with the highest strategic payoff. Complete segmentation breakdowns, forward scenario analysis, and detailed competitive benchmarking are available in the full study. Readers seeking the complete intelligence framework, including the granular data necessary to translate these market signals into execution-ready plans, are encouraged to access the full report through the source page.
For detailed analysis of this topic, please visit the official page: Prosthetic Foot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lymphedema Pneumatic Compression Market Hits $1.29B in 2025, Poised for 7.0% CAGR
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Pneumatic Compression Devices for Lymphedema Market in 2026 and Beyond
The global landscape for pneumatic compression devices designed for lymphedema management is undergoing a structural transformation. As healthcare systems shift from reactive acute care to proactive chronic disease management, the demand for non-invasive, home-enabled therapeutic interventions has accelerated. Our latest research on the Pneumatic Compression Devices for Lymphedema Market provides a rigorous, data-grounded framework for executives, investors, and clinical strategy teams to navigate this growth trajectory with precision. This article sets the stage for the full report, outlining the macro forces, competitive realities, regulatory shifts, and strategic imperatives that will define decision-making through 2032.
A Market Reshaped by Volume, Velocity, and Value
The historical trajectory of this market tells a clear story of steady, compounding expansion. Between 2020 and 2025, global revenue climbed from approximately 925 million USD to nearly 1,300 million USD, reflecting a consistent upward curve driven by rising prevalence of chronic venous insufficiency, increased oncology survivorship rates, and broader adoption of conservative compression therapies as first-line interventions. The momentum does not slow in the forecast period. Projected to reach roughly 1,400 million USD in 2026, the market is positioned to accelerate further, with forward estimates indicating a climb toward 2,070 million USD by 2032. This trajectory translates to a compound annual growth rate of approximately 7 percent across the full forecast horizon, a pace that outstrips many adjacent durable medical equipment segments and underscores a durable demand cycle rather than a cyclical surge.
Pneumatic Compression Devices for Lymphedema Market
The growth is not merely a function of more units sold. It reflects a fundamental repositioning of pneumatic compression within clinical workflows. Hospitals, outpatient clinics, and home care environments each play distinct roles in the patient journey, yet the segmentation of revenue across these settings reveals an increasingly balanced ecosystem. Similarly, the product landscape continues to differentiate along the lines of segmented and non-segmented architectures, each addressing different clinical protocols and patient compliance profiles. The full report deconstructs these dynamics in depth, mapping how clinical efficacy, reimbursement alignment, and manufacturing economics intersect to shape where value accrues.
Competitive Architecture: Specialization, Differentiation, and Clinical Credibility
The supplier landscape is defined by a focused set of manufacturers that have built commercial and clinical moats around specific compression methodologies, garment engineering, and patient-access pathways. Rather than a commoditized price war, the market rewards companies that can demonstrate differentiated pressure profiles, ease of home use, and robust supporting evidence. Our competitive analysis profiles the leading participants and examines how their product strategies align with emerging reimbursement and clinical guidelines.
- Bio Compression Systems has established a strong foothold in the sequential compression segment with its Sequential Circulator line, emphasizing non-peristaltic pumping technology and multi-chamber garments tailored for lymphedema and chronic venous insufficiency. Their positioning reflects a long-standing focus on reproducible pressure delivery and clinical familiarity.
- Mego Afek, through its Lympha-Press and Lympha-Press Optimal systems, offers pneumatic compression pumps and garments that target lymphedema, venous insufficiency, and related conditions. The company’s international footprint and modular garment design position it to serve both clinical and home-based pathways across diverse reimbursement environments.
- Tactile Medical has carved out a distinctive presence in the home care segment with its Flexitouch and Flexitouch Plus advanced intermittent pneumatic compression systems. By pairing sophisticated compression sequencing with patient-centric garment engineering, the company addresses the compliance and usability challenges that often determine long-term adherence in at-home therapy.
- Neomedic’s Powerpress Unit Sequential Circulator continues to serve as a clinically oriented option for lymphedema and edema management, with distribution and product focus aligned to providers seeking reliable, prescription-grade compression solutions.
- Huntleigh Healthcare brings a broad diagnostics and care portfolio to the space, with its LymphAssist Professional and Hydroven 12 intermittent pneumatic compression systems and multi-chamber garments. Their presence highlights the intersection of diagnostic-led clinical decision-making and therapeutic device deployment.
- EEZCare Medical, through its EzLymph and EzLymph M pneumatic compression pumps, reflects the growing geographic diversification of the supply base, expanding manufacturing and distribution capacity to serve regional demand while maintaining clinical functionality.
- Koya Medical operates at the edge of the traditional pneumatic category with its Dayspring non-pneumatic active compression device, illustrating how adjacent technologies are expanding the broader conversation around chronic edema and lymphedema management. Its differentiated modality serves as a reminder that competitive pressure in this market extends beyond direct pneumatic substitutes to alternative compression philosophies.
The report does not stop at company descriptions. It examines how these players compete on clinical documentation, service networks, DME channel partnerships, and product line extensions. Concentration metrics indicate that while incumbents hold meaningful share, the market remains sufficiently open to well-positioned entrants that can align product performance with payer expectations and provider workflows.
Worldwide Mobile Whole Body Pressure Therapy Apparatus Market
Regulatory, Reimbursement, and Clinical Evidence: The Inflection Points That Matter
The commercial trajectory of pneumatic compression devices for lymphedema is inseparable from the policy and clinical environment. In 2026, decision-makers must operate within a tightening but clarifying framework of coverage criteria, device classification, and evidence expectations. Medicare’s national coverage architecture continues to anchor much of the reimbursement landscape, with coverage pathways tied to documented therapeutic need and conservative management prerequisites. All FDA-cleared pneumatic compression devices for lymphedema are regulated as Class II devices under a defined product code, and maintaining ISO 13485 certification remains a baseline requirement for quality management across manufacturers. These structural requirements shape not only market entry but also ongoing compliance, distributor relationships, and contracting risk.
The reimbursement code framework adds further granularity to commercial planning. Coverage under the durable medical equipment benefit relies on distinct HCPCS codes differentiated by segmental and gradient characteristics. This coding structure directly influences how devices are positioned, priced, and prescribed, and it creates natural segmentation in purchasing behavior. Payers increasingly assess clinical appropriateness through prior authorization and utilization management reviews. Recent activity signals a more active oversight environment: Medicare began initiating prior-authorization reviews for pneumatic compression devices effective in mid-April 2026, a policy shift with immediate operational implications for providers, DME suppliers, and device manufacturers alike.
At the same time, clinical evidence is strengthening the long-term rationale for intermittent pneumatic compression in lower extremity lymphedema management. Updated clinical directives and community care guidance have reinforced the role of sustained compression therapy where conservative measures alone are insufficient. Major payers have also revisited their coverage criteria, with recent guideline reviews updating clinical utilization parameters for pneumatic compression pumps. Together, these developments create a dual dynamic: heightened administrative scrutiny paired with stronger clinical endorsement for appropriate patient populations.
Why This Report Matters for 2026 Decision-Making
For executives planning capacity, pricing, channel strategy, and clinical positioning, the strategic question is no longer whether the market is growing, but where the growth is most defensible and how to capture it. This research is designed to translate macro momentum into actionable intelligence. It provides a structured view of historical performance, forward projection, and the operational levers that determine commercial outcomes in a market sensitive to reimbursement rules, clinical adoption, and product differentiation.
The report is built for practical use. It examines the full revenue arc across the forecast period, identifies the structural drivers behind the projected 7 percent compound growth, and situates that growth within the interplay of segmented and non-segmented device architectures. It maps the distribution of demand across home care, hospital, and clinic settings without reducing the story to a single channel narrative, because real-world adoption is shaped by referral pathways, DME logistics, and clinical protocols that vary by setting. It also breaks down regional performance in a way that highlights where mature demand, emerging adoption, and pricing dynamics create distinct strategic opportunities.
Equally important, the analysis integrates the competitive landscape with regulatory and reimbursement realities. It shows how prior authorization requirements, DME coding structures, coverage determinations, and quality certification expectations influence purchasing behavior, channel economics, and market entry timing. For device manufacturers, this means understanding which product features are most likely to satisfy payer and provider criteria. For distributors and DME providers, it means anticipating administrative burden and aligning service models accordingly. For investors, it means separating durable expansion from short-term policy noise.
What You Will Find Inside
- A complete historical and forecast revenue trajectory with the analytical context behind the growth curve, including the forces shaping the 2026 base and the acceleration path through 2032
- A detailed segmentation review across device type, care setting, and geography, with interpretation of how each segment’s economics and adoption drivers differ
- A competitive profile of the core participants, with emphasis on product architecture, clinical positioning, distribution strategy, and differentiation relative to adjacent modalities
- A synthesized analysis of regulatory and reimbursement dynamics, including device classification, coding structure, coverage prerequisites, prior authorization developments, and clinical evidence trends
- Strategic implications for product strategy, channel design, market entry, and pricing in a market where clinical credibility and reimbursement alignment increasingly determine commercial success
The full report delivers the complete dataset, scenario analysis, and segment-level interpretation needed to move from awareness to action. It also includes the most current policy and clinical developments as they evolve, ensuring that strategy is anchored to the operational reality of 2026 rather than outdated assumptions.
Positioning for the Next Phase of Growth
The Pneumatic Compression Devices for Lymphedema Market is entering a phase where scale matters, but precision matters more. Companies and investors that understand the interplay between clinical evidence, reimbursement architecture, competitive differentiation, and care-setting economics will be better equipped to allocate resources and shape long-term positioning. The macro forecast points to a market approaching the 2 billion USD threshold by the end of the forecast window, but the strategic value lies in understanding how that total is constructed and where competitive advantage can be built within it.
This research is intended as a decision-grade resource: rigorous enough to support executive planning, detailed enough to inform product and commercial strategy, and current enough to reflect the fast-moving policy environment. For teams evaluating product portfolios, market entry, partnership structures, or investment exposure, the full market report provides the foundation required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pneumatic Compression Devices for Lymphedema Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Speed Reducers Market to Hit $18.79B by 2032, Growing at 8.4% CAGR
By PW Consulting, 2026-09-16
Strategic Outlook 2026: Navigating the Speed Reducers Market Landscape
Executive Summary
The global industrial landscape is undergoing a profound transformation, driven by automation, efficiency mandates, and supply chain realignments. At the heart of these mechanical systems lie speed reducers, critical components that ensure precise torque control and operational reliability across diverse sectors. As we move deeper into 2026, understanding the trajectory of this market is no longer optional for strategic planners; it is a necessity. This article serves as a precursor to our comprehensive market research report, offering a high-level view of the forces shaping the industry while highlighting the depth of intelligence available to stakeholders who seek a competitive edge.
The speed reducers market has demonstrated remarkable resilience and growth over the past half-decade. Based on our analysis, the market value reached approximately 10,681.55 million USD in 2025, building upon a steady historical trajectory from 2020. The momentum shows no signs of slowing, with projections indicating a climb toward 18,786.21 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.4 percent during the forecast period of 2026 to 2032. Such figures suggest more than mere inflation; they point to genuine industrial uptake and technological integration that demands attention from C-suite executives and investment committees alike.
Speed Reducers Market
Market Trajectory and Macro-Economic Drivers
Understanding the historical context is vital for validating future projections. The market valuation has consistently escalated from 7,136.54 million USD in 2020 to the 2025 baseline. This upward curve reflects broader industrial health, yet the forecast period introduces new variables. The growth from 11,235.94 million USD in 2026 to over 18,000 million USD by 2032 implies a significant acceleration in demand. This is not merely a continuation of past trends but suggests a shift in how power transmission systems are valued and utilized in modern engineering contexts.
Several macroeconomic factors are fueling this expansion. The push for energy efficiency in manufacturing plants requires machinery that minimizes power loss during transmission. Speed reducers play a pivotal role here, converting high-speed motor output into high-torque, low-speed application requirements. Furthermore, the ongoing modernization of legacy infrastructure in developed economies, coupled with rapid industrialization in emerging markets, creates a dual-engine growth scenario. However, navigating this landscape requires more than top-line numbers; it requires an understanding of where the value is concentrated and how risks are distributed.
Competitive Landscape and Corporate Intelligence
The market structure is characterized by a moderate level of concentration, indicating a mix of dominant players and specialized niche providers. Our analysis indicates that the top three companies hold a significant portion of the market share, while the top five extend this influence further. This concentration suggests that while there is room for innovation, scale and established distribution networks remain critical advantages. The competitive field is global, featuring legacy manufacturers from Europe and North America alongside agile innovators from Asia.
Prominent entities such as SEW-Eurodrive, headquartered in Bruchsal, Germany, continue to set standards in integrated drive systems. Their focus on combining helical, worm, and bevel-helical reducers with electric motors highlights a trend toward simplification and ease of integration for industrial automation. Similarly, Sumitomo Heavy Industries in Tokyo maintains a strong foothold in heavy-duty sectors, supplying large speed reducers and cycloidal units for mining and steel applications. These companies represent the established backbone of the industry, providing reliability for high-load environments.
On the precision front, Nidec Corporation and Harmonic Drive LLC are pivotal. Nidec Shimpo's focus on planetary and cycloidal reducers for robotics and machine tools aligns with the broader automation surge. Harmonic Drive, based in Peabody, Massachusetts, specializes in strain-wave technology, catering to the stringent requirements of medical equipment and precision machinery. Meanwhile, North American manufacturers like Bonfiglioli, ABB Baldor, Boston Gear, and Nord Drivesystems offer comprehensive solutions ranging from standard components to custom-industrial packages. Companies like Winsmith and Broadwind focus on heavy-duty custom assemblies, ensuring that specific torque and load requirements are met without compromise.
Recent activity among these key players underscores the dynamic nature of the sector. In early 2026, Winsmith announced a new line of aluminum round and square speed reducers, signaling a shift toward lightweight materials and modular housing designs. Participation in major trade events such as IPTEX GRINDEX and AISTech by entities like Regal Rexnord and various gear specialists demonstrates the industry's commitment to showcasing metal industry solutions and high-speed epicyclic units. These developments are not isolated; they are signals of strategic pivots toward material innovation and specific industry vertical solutions.
Segmentation Dynamics: Type and Application
To make informed decisions, one must look beyond the aggregate number. The market is divided by technology type, with gear reducers historically commanding the largest share due to their versatility and durability. Worm wheel reducers, planetary gears, cycloid reducers, and harmonic drives each serve distinct operational niches. For instance, while planetary gears offer high efficiency and compactness suitable for robotics, cycloid reducers are preferred for heavy-duty shock load resistance. Understanding the share and growth potential of each type is crucial for product portfolio planning.
Application sectors also drive demand diversity. The industrial sector remains the primary consumer, reflecting the broad use of speed reducers in general machinery and automation. However, significant volume is also generated by the food industry, mining industry, and construction industry. Each sector imposes unique constraints. Food processing requires hygiene-compliant materials and sealing, mining demands extreme durability under abrasive conditions, and construction needs mobility and ruggedness. A strategic supplier must align its product engineering with these specific application demands. Our research delves into the revenue contribution and growth rates of each application segment, identifying where the highest margins and fastest growth intersect.
Regional Insights and Supply Chain Considerations
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific represents a massive volume hub, driven by manufacturing capacity and local industrial growth. North America and Europe remain critical for high-value, precision applications and aftermarket services. Latin America and the Middle East and Africa offer emerging opportunities tied to infrastructure projects. However, regional performance is not just about sales volume; it is about supply chain resilience.
The cost of raw materials remains a primary concern. High-grade cast iron, steel forgings, and specialized alloys constitute a significant majority of the manufacturing cost for speed reducers. Volatility in these inputs can compress margins significantly. Strategic procurement and vertical integration are becoming differentiators. Companies that secure stable supply lines for critical alloys or invest in additive manufacturing for complex gear components may gain a cost advantage. Furthermore, logistics and localization strategies are evolving to mitigate geopolitical risks and reduce lead times for customers in critical regions.
Regulatory Frameworks and Technical Standards
Compliance is another layer of complexity defining the 2026 landscape. Technical standards ensure interoperability and safety, but they also act as barriers to entry for non-compliant manufacturers. The American Gear Manufacturers Association (AGMA) continues to provide essential classifications for designing and maintaining reliable power transmission systems. Adherence to these standards is often a prerequisite for tendering in large industrial projects.
Beyond general manufacturing standards, specific operational regulations are coming into force. The ISO 15016:2025 specification for the assessment of speed and power performance by analysis of speed trial data entered into force on May 1, 2026. This regulation impacts how performance is validated, particularly in marine and mobile applications. Additionally, MEPC.403(83) requires EEDI-relevant speed trials for newbuilding vessels to utilize ISO 15016:2025 or specific recommended procedures from the same date. For companies supplying reducers to marine or offshore sectors, alignment with these updated specifications is immediate and critical. Failure to comply can result in exclusion from key contracts or regulatory penalties.
Strategic Implications for 2026 Decision Makers
The convergence of growth, competition, and regulation creates a complex decision matrix for 2026. For investors, the 8.4 percent CAGR presents an attractive entry point, but due diligence must extend beyond top-line growth to assess the competitive positioning of individual firms. For manufacturers, the focus must shift to differentiation through material innovation, such as the aluminum housing trends noted in recent product launches, and precision enhancements in planetary and harmonic technologies.
Procurement leaders face the challenge of balancing cost against reliability. With raw material costs representing a large fraction of manufacturing expenses, supplier stability is as important as unit price. Partners with robust supply chains and adherence to evolving ISO and AGMA standards offer lower risk profiles. Additionally, the regional distribution of revenue suggests that a multi-region strategy may be necessary to hedge against localized economic downturns or supply disruptions.
RV Reducer Market
Conclusion: The Value of Complete Intelligence
The speed reducers market in 2026 is a landscape of opportunity tempered by technical and regulatory complexity. While the macro indicators point to a robust expansion toward nearly 19 billion USD by 2032, the real strategic value lies in the nuances. Which specific technology type is outperforming in the robotics sector? Which region is seeing the fastest adoption of high-efficiency worm reducers? How do the latest regulatory changes specifically impact offshore gear supply contracts?
This article has outlined the framework of the market, highlighting the key players, the regulatory environment, and the macroeconomic drivers. However, actionable strategy requires granular data. Our full market research report provides the detailed segmentation analysis, historical volume data, company profiles, and competitive benchmarking necessary to transform these insights into execution. To access the complete intelligence required for precise planning and investment decisions in this evolving sector, we invite you to explore the full study. The depth of data available there will empower your team to navigate the 2026 landscape with confidence.
For detailed analysis of this topic, please visit the official page: Speed Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


