



PW Consulting: Wallichinine Market Climbs to USD 5.2 Million in 2025, Poised for 4.2% CAGR Through 2032
By PW Consulting, 2026-07-13
Wallichinine Market 2026 Strategic Preview — PW Consulting Industry Brief
Executive summary
As life‑science companies, specialty chemical suppliers, and institutional investors prepare their 2026 plans, the Wallichinine market presents a classic niche-growth challenge: limited absolute dollar scale yet strategically disproportionate importance for specific R&D and procurement decisions. PW Consulting’s latest market research shows that the Wallichinine market reached roughly USD 5.2 Million (base year 2025) after steady expansion from the early 2020s, and is forecast to grow at a compound annual growth rate (CAGR) of approximately 4.2% through 2032, reaching an estimated USD 6.9 Million by the end of the forecast horizon. This preview highlights the implications of that trajectory for corporate strategy in 2026 while preserving the proprietary, segment‑level detail available in the full report.
Wallichinine Market
Why Wallichinine matters for 2026 corporate decisions
-
Research intensity over absolute volume: Wallichinine’s primary market is research use — pharmaceutical research, academic and clinical studies — rather than large‑scale commercial deployment. That makes supplier selection, purity control, and regulatory positioning disproportionately important relative to market size.
Wallichinine Market -
Procurement and continuity risk: Raw material sourcing (Wallichinine is predominantly isolated from Piper species) and single‑sourcing exposure can create brittle supply chains for organizations that depend on consistent, high‑purity material for sensitive assays. Procurement teams that optimize supplier diversification in 2026 can avoid outsized disruption costs.
Wallichinine Market -
Scientific inflection points: Emerging preclinical findings — for example, studies indicating activity as a PAF antagonist and potential reversal of ABCB1‑mediated multidrug resistance — mean that unexpected demand spikes or specification changes could arise quickly if translational research advances. Strategic monitoring of the scientific pipeline is therefore a 2026 imperative.
-
Regulatory clarity for RUO products: The supply chain for Wallichinine is explicitly positioned for research use only (not approved for human or veterinary therapeutic use). Companies that act on this market must ensure labeling, contractual terms, and compliance processes are tightly aligned to avoid regulatory or liability exposure.
Market trajectory and what the numbers mean
The market’s modest absolute scale masks two useful planning signals. First, historical growth from the low‑millions in 2020 to roughly USD 5.2 Million in 2025 reflects steady, research‑driven demand that survived episodic macro volatility. Second, the forecasted ~4.2% CAGR to 2032 implies predictable, incremental expansion rather than explosive commercialization — a landscape suited to targeted strategic moves (e.g., quality‑of‑supply differentiation, value‑added services, or focused alliances) rather than broadscale capacity expansion.
For procurement and R&D leaders, this means 2026 decisions should prioritize supplier quality, availability guarantees, and technical support rather than volume discounts alone. For investors and M&A teams, the market’s trajectory suggests value will accrue to companies that can lock in premium positions in high‑purity offerings, technical validation services, and rapid regulatory compliance for RUO pathways.
Supply chain and dynamics — practical considerations for 2026
-
Raw material sourcing: Wallichinine is primarily isolated from the stems of Piper wallichii and related Piper species. That botanical dependency introduces agricultural, seasonal, and geopolitical variables into sourcing strategies that procurement must model explicitly in 2026.
-
Purity segmentation: Market demand is concentrated around high‑purity grades for reference standards and sensitive assays. Buyers should require certificate of analysis (COA) consistency, stability data, and batch traceability as part of standard procurement terms.
-
Service expectations: Leading suppliers differentiate through documentation (method of isolation, spectral data), customized packaging and sizes for small‑batch research use, and rapid turnaround for urgent assay requirements. Expect these service elements to be decisive in 2026 negotiations.
-
Regulatory positioning: All players in the supply chain currently position Wallichinine strictly for research use only. Companies entering adjacent areas (e.g., translational studies that approach clinical contexts) must plan for regulatory consultation and enhanced QA/QC pathways well in advance.
Competitive landscape — who to watch
The Wallichinine supply ecosystem combines specialist manufacturers, life‑science reagent suppliers, and distributors. The competitive field is moderately concentrated: a small group of established vendors command meaningful influence over quality standards, reference‑grade supply, and commercial relationships. Strategic 2026 engagement should therefore prioritize a select set of due‑diligence activities rather than broad market scans.
-
Pharmaffiliates (India) — Known for supplying high‑purity Wallichinine as reference standards and life‑science reagents. Their emphasis on analytical documentation and reference standard services makes them a primary partner choice for labs needing traceable, validated material.
-
ChemFaces (China) — A natural products manufacturer offering high‑purity isolates derived from Piper species. Their upstream access to botanical sources and integrated isolation processes is an advantage for customers prioritizing supply chain transparency and cost‑effective high‑purity material.
-
Adooq Bioscience (USA) — A distributor/supplier that provides Wallichinine in multiple pack sizes for research use. Their strengths lie in logistics flexibility and customer service models tailored to academic and small‑scale industrial buyers.
-
BioBioPha Co., Ltd. (China) — A biochemical supplier with a focus on natural compounds; relevant for buyers seeking regional supply alternatives and catalogue breadth.
-
Alfa Chemistry (USA) and MedKoo Biosciences (USA) — Western suppliers that combine regulatory awareness and established distribution channels into research institutions; useful partners for organizations prioritizing compliance and traceability.
In 2026, competitive advantage will accrue to suppliers that can demonstrate: (1) consistent analytical verification tied to internationally recognized methods; (2) supply continuity plans for botanical raw materials; and (3) a clear compliance posture for research‑use distribution.
What the PW Consulting Wallichinine report delivers (operational, actionable content)
Our full study is intentionally crafted as a practitioner’s toolkit to support operational decisions in 2026. Highlights include:
-
Proprietary market model with historical series and scenario‑based forecasts (base year 2025; forecast 2026–2032) to support budgeting and volume planning.
-
Supplier due‑diligence framework and scorecard templates to operationalize quality, traceability, and responsiveness assessments.
-
Go‑to‑market playbooks for suppliers targeting pharmaceutical research vs. academic buyers, including pricing architecture, pack‑size strategies, and technical service offerings.
-
Procurement playbook for buyers: contracting language, COA requirements, contingency planning, and short‑list criteria for single‑source vs. multi‑source strategies.
-
Regulatory and compliance checklist specific to RUO positioning, labeling, and cross‑border transfer requirements.
-
Technology and scientific watchlist capturing preclinical advances (e.g., PAF antagonism, ABCB1 MDR reversal) that could trigger demand volatility.
-
Risk matrix and mitigation options covering botanical supply, geopolitical exposure, and specification drift.
-
Executive‑level M&A and partnership map highlighting logical strategic targets and the valuation drivers buyers should prioritize.
Strategic recommendations for 2026 decision‑makers
-
For suppliers: Invest selectively in high‑purity validation and customer‑facing technical documentation. These investments yield premium positioning in a market where trust and traceability matter more than scale.
-
For buyers (academic and industrial): Adopt a two‑tier sourcing strategy — primary trusted supplier(s) with contractual continuity clauses plus a validated alternate to protect against botanical or logistical shocks.
-
For investors and corporate development: Look for targets that own upstream botanical sourcing, proprietary isolation know‑how, or differentiated analytical capabilities. These are the value drivers that support margin expansion in a steady‑growth market.
-
For R&D managers: Maintain close coordination with procurement and regulatory functions. If a project’s translational pathway moves beyond RUO expectations, preemptive regulatory engagement will save time and cost downstream.
Risk scenarios to model in 2026
-
Supply interruption: A localized crop failure or export restriction could cause short‑term scarcity. Scenario planning should quantify the premium buyers would reasonably pay for continuity and identify substitution thresholds.
-
Scientific breakthrough: If translational validation accelerates, demand could shift from RUO channels toward larger‑scale, regulated supply needs — a dramatic shift for a market that currently remains research‑focused.
-
Regulatory tightening: Stricter RUO definitions or cross‑border compliance requirements could increase compliance costs and favor larger suppliers with established quality systems.
How to use this preview — and where to find more
This brief is designed as a strategic “trailer” that highlights the decision levers and operational playbooks necessary for effective 2026 planning while preserving the granular segmentation, supplier scorecards, and proprietary datasets that underpin our conclusions. The full PW Consulting Wallichinine Market report contains the detailed models, supplier scorecards, and downloadable procurement templates referenced here — including regional and application breakdowns, price‑trend matrices, and a validated vendor watchlist.
For teams building 2026 budgets, supplier tender schedules, or M&A target lists, the full report will convert the high‑level implications in this brief into executable plans. Visit PW Consulting’s report page to access the complete study, data appendices, and a customizable Excel model to stress‑test scenarios against your specific demand profile.
Closing perspective
Wallichinine exemplifies a class of specialty compounds where strategic foresight, supplier governance, and scientific monitoring matter more than sheer market scale. In 2026, organizations that translate the modest but stable market growth into disciplined procurement, validated supplier partnerships, and proactive scientific surveillance will capture the upside while insulating projects from supply and regulatory shocks. PW Consulting’s full report equips decision‑makers with the models and playbooks necessary to do exactly that.
For detailed analysis of this topic, please visit the official page: Wallichinine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Transmitter Market to Expand at 5.4% CAGR, Reaching USD 5.55 Billion by 2032
By PW Consulting, 2026-07-13

Smart Transmitter Market 2026 Strategic Intelligence: PW Consulting Executive Brief
PW Consulting’s latest Smart Transmitter Market research report delivers the strategic vantage point executives need to make high‑stakes 2026 decisions with confidence. Built from an exhaustive review of historical performance (2020–2025), primary interviews with OEMs, end users and channel partners, and scenario-driven forecasting for 2026–2032, this briefing highlights how the global smart transmitter ecosystem is evolving — and what market leaders must do now to preserve margin, accelerate digital value capture, and mitigate near‑term supply risks.
Smart Transmitter Market
Why this report matters for 2026 planning
-
Actionable foresight: The report translates macro forecasts into decision-ready pathways — from capex prioritization to product roadmaps and aftermarket monetization models — without drowning readers in raw sub‑segment tables. We show where dollars will be deployed and the commercial levers that move ROI faster.
Smart Transmitter Market -
Regulatory and standards readiness: New and revised standards are changing procurement and validation cycles across process industries. This research decodes the operational impacts so procurement, compliance and R&D teams can preempt enforcement and accelerate time‑to‑compliance.
Smart Transmitter Market -
Competitive clarity: A practical competitor playbook correlates technology differentiators, channel strategies and M&A vectors with commercial outcomes to expose where consolidation will concentrate value.
Market trajectory at a glance
Our top‑line view: the global smart transmitter market demonstrated steady expansion through the mid‑2020s and is poised for continued growth as industrial digitalization and process optimization initiatives scale. In numerical terms, the market measured approximately USD 3,842.5 Million in the 2025 base year and is forecast to progress to roughly USD 5,552.6 Million by 2032. Across the 2026–2032 forecast window the market carries a compound annual growth rate (CAGR) of about 5.4%.
Importantly, the near term is non‑linear: supply‑chain constraints, project timing and macroeconomic headwinds create year‑to‑year fluctuations that affect vendor order books, inventories and pricing behavior. The report surfaces those inflection points and maps out three realistic scenarios (conservative, base, and upside) to help executives stress‑test decisions against plausible market paths.
Market structure and concentration
The smart transmitter market retains a moderately concentrated vendor landscape. Our analysis places the combined share of the top three suppliers in a mid‑40s percentage range, with the five largest vendors accounting for a clear majority of revenues. This structure creates both opportunity and risk: scale plays (pricing power, channel breadth, global service footprints) are rewarded, but nimble innovators can capture pockets of premium value in software-enabled services and specialized sensors.
Competitive landscape — what to watch in 2026
-
Emerson Electric Co. (United States) — Strengths in process automation and deep protocol compatibility (HART, Fieldbus and wireless). Strategic focus: integration of transmitter data into enterprise control systems and lifecycle services.
-
ABB Ltd. (Switzerland) — Recent product activity includes a refreshed high‑performance pressure transmitter portfolio. Strategic focus: accuracy‑driven differentiation for heavy industrial and utility segments.
-
Yokogawa Electric Corporation (Japan) — Emphasizes diagnostics and measurement integrity for process industries; strength in digital protocol support and field diagnostics.
-
Honeywell International Inc. (United States) — Prioritizes IIoT connectivity and predictive maintenance in its transmitter suites; growing play in value‑added services.
-
Siemens AG (Germany) — Leverages system integration capabilities to bind transmitters into broader automation ecosystems.
-
Endress+Hauser Group (Switzerland) — Focus on advanced field interfaces (Bluetooth, Ethernet‑APL) and calibration services to lock in long‑life installed bases.
-
WIKA, Schneider Electric and a range of specialized regional players — Provide competitive depth: differentiated product engineering, local service networks and targeted channel models.
For buyers and investors, the takeaway is clear: product performance alone is no longer sufficient. Value capture occurs where device accuracy, digital interoperability, services (calibration, predictive analytics), and lifecycle contracting converge.
Standards, regulation and supply dynamics shaping 2026 decisions
-
Standards and test procedures — Updates such as the new test procedures for industrial pressure transmitters and revisions to measurement management system requirements are increasing validation overhead for manufacturers and purchasers alike. Embedding compliance into product development and calibration workflows will be table stakes.
-
Interface and interoperability — Emerging and active field communications (including industrial Ethernet variants designed for field devices) are accelerating the demand for devices supporting fast digital communication and standardized device data descriptions.
-
Component availability — Semiconductor export controls and allocation pressures continue to influence lead times and BOM costs. Manufacturers must balance vertical integration, multi‑sourcing and product modularity to reduce exposure.
-
Cybersecurity and lifecycle risk — With greater connectivity comes increased attack surface; procurement teams must insist on device‑level security assurances as part of vendor SLAs.
Practical strategic playbook for 2026
Below are prioritized moves PW Consulting recommends to vendors, buyers and investors preparing for 2026:
-
For OEMs: Accelerate modular platform development that allows scalable feature licensing (diagnostics, analytics, digital twin connectors) while optimizing BOMs for chip scarcity. Establish prioritized compliance roadmaps for new test and measurement standards to shorten customer qualification cycles.
-
For system integrators and EPCs: Champion interoperability early in project lifecycles by specifying devices with standardized digital descriptors and native support for industrial Ethernet field protocols. Use total cost of ownership (TCO) models that incorporate calibration and lifecycle services to benchmark bids.
-
For end‑users (asset owners): Create a device governance framework: map criticality of transmitters to business KPIs, mandate secure connectivity and lifecycle support clauses, and prioritize predictive maintenance pilots to quantify serviceable value.
-
For investors and M&A teams: Target assets that combine sensing hardware with recurring software or service revenue, and consider bolt‑on acquisitions to broaden digital service portfolios and tighten installed‑base economics.
Report contents — what’s inside (practical, not exhaustive)
-
Executive synthesis and scenario forecasts (2026–2032) with stress‑tested outcomes for capex and procurement cycles.
-
Vendor landscaping: strategic profiles, product roadmaps, channel footprints and a capability‑to‑value matrix for rapid benchmarking.
-
Go‑to‑market playbooks for product managers and commercial teams, including pricing levers, service bundling strategies and aftermarket models.
-
Supply‑chain resilience prescriptions: BOM risk heatmaps, alternative sourcing pathways, and semiconductor mitigation strategies.
-
Operational checklists aligned to the latest standards and regulatory developments to accelerate compliance and reduce qualification timelines.
-
Case studies and validated TCO models demonstrating measurable uplift from digitalization and predictive maintenance pilots.
Note: This briefing intentionally surfaces high‑value insights and actionable recommendations while withholding granular regional, application and per‑type breakdowns reserved for licensed access. The full report contains detailed sub‑segment tables, regional demand models, vendor revenue splits and downloadable data sets essential for procurement modeling and investment valuation.
KPIs and decision triggers for 2026
-
Time to compliance: percentage of product portfolio validated against newly updated test standards within 12 months.
-
Service attach rate: recurring revenue as a share of device sales (target uplift through diagnostics & calibration contracts).
-
Lead‑time variance: reduction in average delivery lead time through diversified sourcing and strategic component stockpiles.
-
Installed‑base monetization: average revenue per installed device through software and lifecycle services.
How to use this intelligence
Procurement teams should use the findings to reframe vendor qualification, moving beyond capex price focus to lifecycle value. Product leaders will find the technology and standards analysis indispensable for prioritizing R&D spend. Investors can apply the market concentration insights and scenario forecasts to refine thesis timelines and valuation multiples.
Next steps — where to get the full intelligence
PW Consulting’s full Smart Transmitter Market report is the only source in the market that couples granular, validated market data with actionable playbooks and compliance checklists tailored for 2026 decision cycles. For access to the complete dataset, vendor scorecards, and downloadable models, visit PW Consulting’s report page or contact our research team to arrange a briefing and licensing options.
Prepared by: PW Consulting — Senior Strategic Advisory & Industry Analysis. Our research methodology combines proprietary survey data, interviews with leading OEMs and end users, and rigorous bottom‑up modeling to ensure clients can act with commercial precision in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Smart Transmitter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Road Construction Services Market Set to Grow at 7.51% CAGR Through 2032 as Asia Pacific Dominates
By PW Consulting, 2026-07-13

Road Construction Services Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
The global Road Construction Services market stands at a critical inflection point as firms set strategies for 2026. PW Consulting’s latest market research positions the overall market at approximately USD 1,240.82 Billion in 2025, expanding to roughly USD 1,332.32 Billion in 2026 and tracking toward continued growth through the forecast window (2026–2032) at a compounded annual growth rate (CAGR) of 7.51%. By 2032 the market is projected to exceed USD 2,000 Billion — a dynamic backdrop that demands timely, actionable choices from investors, contractors, equipment suppliers, and public-sector planners.
Road Construction Services Market
What this report delivers — practical, decision-grade outputs
- Executive playbooks for near-term bid and procurement strategy that reconcile margin preservation with aggressive backlog capture in inflationary environments.
- Scenario-based financial models (base, stress, upside) that translate macro growth into project-level investment thresholds, IRR sensitivities, and working-capital implications.
- Labor and materials sensitivity matrices that model the P&L impact of wage pressure, input-price shocks, and tariff regimes on typical road construction contracts.
- Contract and risk-allocation templates tailored for design-build, EPC and PPP arrangements, with annotated negotiation levers that preserve cashflow under cost escalation.
- Technology and fleet upgrade roadmaps, prioritizing digital tendering, asset-management telematics, and mechanization pathways to offset rising labor costs.
- Regulatory and procurement guidance for public agencies to accelerate renewals, maintenance programs, and concession structures while protecting budgetary outcomes.
Market dynamics and implications for 2026 decision-making
The headline growth trajectory masks important operational headwinds and structural drivers. Our analysis synthesizes macro growth with near-term industry "noise" to surface the decisions that will define winners and losers in 2026:
Road Construction Services Market
- Labor scarcity and wage inflation: North American and select other markets are projecting acute shortfalls in skilled trades. For example, the U.S. construction sector faces a multihundred-thousand-worker gap by 2026, and construction wages rose materially year-over-year in 2025. For contractors, this elevates the strategic importance of workforce planning, modularization, and automation investments that reduce crew-hour exposure.
- Material-price volatility and tariff risk: Nonresidential construction input prices surged sharply in early 2026, and steel/aluminum tariffs implemented across 2025–2026 have amplified cost unpredictability. Structural-steel cost inflation alone added double-digit pressure during 2025 — a direct margin risk for bridge-heavy programs. Procurement teams must shift from ad hoc buying to hedged, indexed contracts and vendor partnerships that pass through limited, predefined cost adjustments.
- Procurement and financing dynamics: Public-sector stimulus, maintenance backlogs, and road-safety mandates continue to underpin demand. However, funding profiles and concession structures are shifting — requiring contractors and investors to model extended payment cycles, availability-based payments, and hybrid financing solutions.
- Consolidation and competition: While headline growth creates volume, market concentration remains low — the top three and five players account for a modest share of global activity — signaling a fragmented marketplace. This structure favors regional champions, niche specialists, and acquisitive firms seeking scale in target corridors.
Competitive landscape — what the major players signal for 2026
The vendor landscape spans global integrated contractors, national heavy-civil specialists, and engineering-driven delivery firms. Prominent names active across major portfolios include large state-backed engineering contractors, multinational infrastructure groups, and established heavy-civil firms. Recent public moves illustrate strategic patterns:
Road Construction Services Market
- Contract awards in developed markets demonstrate a willingness by governments to accelerate large-capacity expansions and renewals, with incumbents and consortiums capturing long-duration EPC scopes.
- Strategic corporate initiatives — business-plan articulations and backlog disclosures — show leading contractors repositioning for growth through backlog optimization, selective international expansion, and service-line diversification.
- Engineering and design firms are winning statewide and framework agreements that convert advisory capability into recurring delivery pipelines, underlining the value of integrated program-management capability.
Strategically, the low headline market concentration (a fragmented supplier base) means that scale is not the only route to advantage. Firms with differentiated delivery models — e.g., superior risk-transfer contracting, embedded digital tools, or fleet modernization — can leapfrog larger competitors in targeted segments. Our competitive profiles analyze each major player’s geographic posture, capital structure, alliance patterns, and demonstrated capability to deliver turnkey road projects under inflationary stress.
Strategic imperatives for executives making decisions in 2026
Actionable choices fall into four pragmatic buckets. Firms that prioritize these will be positioned to protect margins, accelerate backlog, and harvest long-term value from the growth cycle.
- De-risk procurement and contracting: Implement index-linked material clauses, adopt dual-sourcing for critical inputs, and insist on staged acceptance criteria in long-duration contracts to minimize cost-to-complete exposure.
- Embed labor resilience: Rapidly scale apprenticeship and cross-training programs, deploy mechanization in labor-intensive tasks, and explore labor-sharing consortiums for regional projects to smooth peak demand.
- Invest in measurable productivity: Prioritize telematics, machine-control systems, and predictive maintenance to increase utilization and reduce downtime — investments that pay back most rapidly where wage inflation is highest.
- Pursue selective M&A and partnerships: Target bolt-on acquisitions that add geographies or technology, and form alliances with material suppliers to secure capacity and price transparency.
- Revise financial planning: Stress-test project pipelines against material and wage shocks, maintain higher working-capital buffers, and structure financing to align with availability-based revenue where possible.
- Engage public clients on pragmatic policy solutions: Advocate for procurement designs that allow adaptive pricing, quick-release contingency funding for emergency repairs, and longer-term concession models that improve lifecycle outcomes.
Decision-making tools in the PW Consulting report
The report is designed to be an execution companion — not an abstract overview. Key tools include:
- Interactive scenario spreadsheets that translate market CAGR and macro volatility into project-level cashflow outcomes, with toggles for tariff exposures and wage inflation paths.
- Contract drafting checklists and risk-allocation templates mapped to three common delivery models (design-bid-build, design-build/EPC, PPP), each with clause-level language to protect margin and schedule.
- CapEx/Opex replacement models for fleet renewal decisions, showing payback under alternate labor-cost trajectories and fuel/energy assumptions.
- Stakeholder engagement playbooks for public—private dialogues, including example concession structures and government-friendly performance metrics that reduce funding friction.
How to use these insights in 90/180/365-day plans
- 90 days: Rebaseline active tenders for realistic input-cost assumptions; implement mandatory material-index clauses; prioritize bids with favorable payment profiles.
- 180 days: Launch a workforce resilience program; pilot mechanization on two high-hour projects; secure key supplier agreements to lock in capacity.
- 365 days: Execute targeted M&A or alliance to shore up regional scale; roll out digital asset-management across the fleet; transition a share of revenue to availability-based contracts.
Why PW Consulting’s Road Construction Services study matters for 2026
Growth is robust at the market level, but the pathway from volume to profit is narrow and reliant on managing input volatility, regulatory shifts, and human-capital constraints. Our report couples the macro view (market size and a 7.51% CAGR over the forecast window) with granular decision tools that allow executives to translate forecasted expansion into resilient execution strategies. The fragmented competitive landscape further amplifies opportunity: firms that sequence investments wisely and adopt disciplined contracting will consolidate advantage.
Next steps and access to the full intelligence
This article highlights the strategic framing and practical outputs available in PW Consulting’s full Road Construction Services Market report. To preserve the tactical value of our segment-level models, granular regional splits, and downloadable scenario files, those detailed tables and proprietary forecasting models are available exclusively in the full report package and via our client portal. Organizations preparing capital budgets, bid strategies, or procurement reforms for 2026 should request the complete report and a tailored briefing with a PW Consulting senior analyst.
For detailed analysis of this topic, please visit the official page: Road Construction Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oil Tank Sight Glasses Market to Expand at a 6.45% CAGR — 2025 Report Forecasts Strong Growth Through 2032
By PW Consulting, 2026-07-13
Oil Tank Sight Glasses Market — Strategic Outlook for 2026
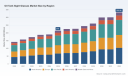
PW Consulting’s latest market study on Oil Tank Sight Glasses provides a decisive, executive-grade briefing for leaders preparing capital, product and M&A decisions in 2026. Grounded in a meticulous historical reconstruction (2020–2025) and a multi-scenario forecast through 2032, the report quantifies a steady industry expansion—from an estimated USD 142.35 Million in 2020 to USD 215.0 Million in 2025—and projects continued growth at a compound annual growth rate (CAGR) of 6.45% across the 2026–2032 forecast window. Under our base scenario the market reaches roughly USD 225.41 Million in 2026 and climbs toward USD 332.99 Million by 2032.
Oil Tank Sight Glasses Market
Why this market matters to corporate decision-makers in 2026
- Predictable, capital-light growth: The mid-single-digit CAGR signals an industry with steady replacement and retrofit demand rather than boom-and-bust cycles—ideal for strategic investments in product differentiation, aftermarket services and selective capacity increases.
- Consolidation and partnership opportunity: Market concentration metrics show meaningful room for scale plays. The three- and five-firm concentration ratios indicate that leading vendors capture a material share of value, but a fragmented mid-market still exists—creating an attractive environment for bolt-on acquisitions and strategic alliances.
- Regulatory and standards-driven purchasing: Specification references such as API and DIN standards drive procurement behavior in upstream and process sectors. Compliance and certification matter more than ever when buyers evaluate suppliers.
- Material and systems innovation: Advances in glass chemistry and high-performance polymers, and the integration of condition monitoring, are reshaping product roadmaps and aftermarket propositions.
Key trends shaping the market
- Standards and safety as demand multipliers: API 610’s guidance and DIN norms for sight glass discs mean that equipment replacement cycles are often triggered by regulatory audits and reliability programs—creating predictable windows of opportunity for compliant suppliers.
- Materials evolution: Borosilicate glass remains the industrial reference for thermal and chemical resistance, while technopolymers and engineered copolyesters are expanding use cases where impact resistance and weight reduction matter. Suppliers that can offer certified material options across that spectrum win specification reviews.
- From component to service: Customer procurement is moving from one-off buys toward service-led models (inspection-as-a-service, spares-as-a-contract). This trend increases lifecycle revenues and raises total addressable serviceable market per installed asset.
- Digital augmentation: Condition-monitoring pods and electronic sensors—often paired with advanced sight-glass designs—are enabling predictive maintenance and creating cross-sell opportunities with OEMs and end-users.
What the PW Consulting report delivers (practical, decision-ready content)
- Proven market-sizing and forecast models (2020–2032) with transparent assumptions, sensitivity analyses and alternative scenarios to stress-test your business plan.
- Commercial playbooks for product managers and sales leaders: specification-mapping, tender response templates, and price-band benchmarks (confidential datasets reserved for report subscribers).
- Supplier and component risk assessment: lead-time analyses, single-source dependency mapping and mitigation checklists for procurement teams.
- Go-to-market strategies for OEMs vs aftermarket specialists, including channel economics and recommended distributor incentive structures.
- Regulatory impact matrix (API/DIN/ATEX) and a step-by-step compliance roadmap to accelerate approvals and shorten sales cycles.
- M&A and partnership evaluation toolkit: target scoring criteria, integration risk templates and quick financial screens to prioritize bolt-on acquisitions.
- Technology scouting and product roadmap recommendations that align materials engineering with digital monitoring capabilities.
Competitive landscape — practical implications for 2026
The market’s leading suppliers range from global industrial OEMs to specialist niche manufacturers. Our competitive analysis synthesizes public profiles, product focus and recent market activity to help you craft a defensible response—either as a supplier planning expansion or as a buyer rationalizing your vendor list.
Oil Tank Sight Glasses Market
- Alfa Laval (Lund, Sweden): Strengths lie in hygiene-focused sight glass solutions and deep channel access to food, beverage and biopharma sectors. Their emphasis on borosilicate-based inline and tank sight products means they are well-positioned where distortion-free clarity and regulatory pedigree matter. Strategic implication: if your exposure includes hygienic process markets, expect Alfa Laval to compete on certified performance and service uptime.
- Douglass (Nashville, USA): A specialist with focused capability in tank-level and flow observation for industrial fluids. Their depth in sight-glass equipment for oil and gas niches makes them a logical partner or acquisition target for companies seeking to strengthen direct field-installation competence.
- Luneta (USA): Notable for 3D oil sight glasses and condition-monitoring pods using high-clarity copolyesters. Their product set signals a clear move toward integrating mechanical sighting with digital condition monitoring—an area buyers will prize for predictive maintenance strategies.
- Elesa (Monza, Italy): Offers a broad materials portfolio (technopolymer, aluminum, brass, stainless steel) and temperature/ATEX-capable options for hydraulic and industrial systems. Elesa demonstrates how material and compliance breadth can be converted into specification wins in regulated environments.
- Des-Case (USA): Focused on visual oil analysis and BS&W bowl solutions; recent catalog updates underscore a continued play on contamination-detection and oil-quality monitoring—an area tightly coupled with API-driven maintenance regimes.
- Zight / United Glass LLC (USA) and GREATGLAS, Inc. (USA): Specialists in borosilicate tubular and circular gauge glasses; these firms are suppliers of engineered glass components for higher-pressure service. They form the critical upstream supply layer for many OEMs.
- PresSure Products Company (PPC) (USA): A full-range manufacturer of sight glasses and flow indicators, PPC competes on breadth and availability—an effective position for aftermarket and general industrial channels.
Strategic takeaway: leaders should anticipate selective consolidation and competitive bundling (hardware + monitoring services). Where scale matters—specifically in channels serving process and heavy industries—the market favors vendors that combine certified materials, reliable logistics and integrated service offerings.
Oil Tank Sight Glasses Market
Supply chain and materials considerations for 2026
- Borosilicate supply resilience: Given its dominant role for high-temperature and chemically aggressive applications, securing qualified borosilicate supply (and qualified fabricators) should be flagged as a strategic procurement priority.
- Alternate material qualification: Where weight, impact resistance or speed-to-market matter, technopolymers and engineered copolyesters provide viable alternatives—but they require validated endurance testing and, in some cases, additional certification to be accepted in regulated segments.
- Lead times and inventory strategy: Component lead times and finish machining create windows where build-to-stock vs build-to-order decisions materially affect cash and service levels. We recommend a tiered inventory strategy linked to installed-base criticality.
Technology and product innovation opportunities
- Integrated sensing: The convergence of sight-glass hardware with electronics (condition-monitoring pods) opens recurring revenue via SaaS-enabled diagnostics and predictive maintenance contracts.
- Advanced coatings and glasses: Anti-fouling, scratch-resistant and enhanced-transparency coatings are differentiators in markets where visual clarity equals diagnostic value.
- Modular designs: Standardized mounting and modular retrofit kits reduce installation friction and accelerate aftermarket growth.
Actionable recommendations for 2026
- Prioritize certification-led product upgrades: Allocate R&D spend to meet API/DIN and ATEX requirements in priority verticals—this shortens spec cycles and increases win rates.
- Move up the value chain: Bundle sight glasses with condition monitoring and service contracts to increase lifetime customer value.
- De-risk supply: Qualify at least two borosilicate fabricators and one polymer alternative supplier for each key product family.
- Targeted M&A and partnerships: Use the mid-market fragmentation to acquire complementary technology (sensor integration) or to secure regional aftermarket distribution.
- Commercialize retrofit kits: Fast-to-install retrofit kits are a capital-light path to aftermarket penetration and recurring revenue.
How to use the report
Executives should use the report as a playbook: plug our forecast and sensitivity runs into your 2026 planning, apply the supplier risk matrix to procurement decisions, and adapt the go-to-market templates to shorten tender cycles. The full report also contains the granular segmentation, regional demand maps, price-band tables and a ranked vendor scorecard that underpin the strategic recommendations summarized here—information available only in the subscriber edition.
For access to the complete dataset, supplier scorecards, downloadable financial models and the full list of segment-level forecasts (including regional and application splits), please consult the PW Consulting Oil Tank Sight Glasses Market report on our website or contact your PW advisor to request the subscriber package.
For detailed analysis of this topic, please visit the official page: Oil Tank Sight Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Skin Measurement Instruments Market Poised to Expand at an 8.24% CAGR, Fueling the Next Wave of Cosmeceutical Innovation
By PW Consulting, 2026-07-13

Skin Measurement Instruments Market — Strategic Briefing for 2026
PW Consulting’s latest market intelligence on Skin Measurement Instruments synthesizes five years of historical performance (2020–2025) and a forward-looking 2026–2032 forecast to equip executives, investors, and clinicians with the actionable insight needed to make decisive moves in 2026. The global market has expanded from approximately USD 685 million in 2020 to roughly USD 1,022 million in 2025, and our base-case projection points to continued robust growth (CAGR 8.24%) through the forecast window, with the market approaching USD 1.78 billion by 2032. This briefing highlights strategic implications, competitive vectors, regulatory inflection points, and the practical content you will find in the full report — while reserving the full, segment-level intelligence for report subscribers.
Skin Measurement Instruments Market
Executive snapshot
-
Historical coverage: 2020–2025 (base year 2025). Forecast horizon: 2026–2032.
Skin Measurement Instruments Market -
Market scale and momentum: market more than doubled in valuation across the decade pathway embedded in our model; measured growth is underpinned by a sustained CAGR of 8.24% through 2032.
Skin Measurement Instruments Market -
Market structure: mid-level concentration — our concentration metrics indicate the top three and top five vendors capture meaningful pools of value, leaving ample room for vertical challengers, regional specialists, and platform-enabling players.
-
Segmentation: the market is multi-modal (contact sensors, TEWL, dielectric/TDC, imaging, spectroscopic and multi-parameter platforms) and serves distinct end markets (cosmetic R&D, dermatology, academic research, point-of-sale/retail consultation). Detailed splits and segment-level forecasts are available in the paid report.
Why this matters for 2026 decision-making
-
Regulatory momentum is lowering barriers to market in the United States: a recent reclassification of certain optical diagnostic devices and electrical impedance spectrometers to Class II (with special controls) enables a 510(k) pathway for many instruments, accelerating commercialization timelines and altering product development roadmaps.
-
Reimbursement and hospital outpatient payment changes for CY 2026 are shifting how skin-related procedures and adjunct technologies are billed. These coding and APC adjustments influence hospital purchasing behaviour and the downstream demand for capital imaging systems versus portable point-of-care instruments.
-
Convergence of clinical-grade imaging and AI analytics is creating a two-speed market: high-capability capital equipment for clinics and research, and validated portable devices for point-of-care and consumer-facing use. Each requires distinct regulatory, clinical-evidence, and go-to-market playbooks.
Key market dynamics driving near-term growth
-
Evidence-driven claims and regulatory scrutiny are compelling cosmetics and device manufacturers to invest in validated measurement systems and robust clinical protocols.
-
AI-enabled image analysis and 3D mapping are expanding the value proposition of imaging platforms from simple visualization to quantifiable decision-support tools for clinicians and consumer advisers.
-
Portability and non-invasive measurement technologies (including dielectric constant methods and TEWL measurement) are enabling new clinical workflows and at-home monitoring — creating recurring revenue opportunities via software and services.
-
Channel evolution: aesthetic clinics and specialty dermatology practices are increasingly purchasing capital imaging systems to differentiate offerings, while retail and personalized beauty consultation channels adopt lower-cost, turnkey analyzers supported by cloud analytics.
-
Standardization pressures (ISO, CE, 510(k) pathways) are driving consolidation among vendors who can demonstrate compliance and strong clinical documentation.
Competitive landscape — who matters and strategic implications
-
Courage + Khazaka electronic GmbH (Köln, Germany) — recognized for gold-standard probes and modular multi-probe systems used in laboratory and clinical research. Strategic implication: incumbency in validated measurement creates high switching costs for R&D customers; challengers must match traceability and calibration regimes or own niche clinical endpoints to compete.
-
Delfin Technologies (Finland) — strong in portable, peer-reviewed devices (including TDC/lymphedema diagnostics and layered hydration meters). Strategic implication: validated portability paired with cited evidence makes Delfin an attractive partner for telehealth and managed-care pilots.
-
Canfield Scientific, Inc. (Parsippany, NJ) — leader in VISIA® and VECTRA® 3D imaging; recently launched a next-gen VISIA that integrates AI-driven facial analysis (March 2026). Strategic implication: the leader’s product refresh sets a bar for 3D + AI feature sets and will reframe competitive expectations for consultation and procedural planning tools.
-
FotoFinder Systems GmbH — specialist in dermatology imaging and AI lesion assessment; acquisition-led expansion into handheld solutions extends reach into point-of-care. Strategic implication: combining total-body mapping with handheld follow-up tools is a winning play for longitudinal dermatology workflows.
-
Emerging and specialized providers (Cortex Technology, Callegari, Bomtech, 3Gen/DermLite, HEINE, Michelson Diagnostics, DermaSensor) — collectively, these vendors create a vibrant ecosystem spanning dermatoscopy, OCT, spectroscopy, and salon/professional analyzers. Strategic implication: partnerships and modular integrations (hardware + SaaS) will be critical to scale distribution and clinical validation affordably.
What the full PW Consulting report delivers (practical, operational items)
-
Granular market model (historical & forecast) by technology tier, application, and channel — with scenario and sensitivity analysis to stress-test pricing, adoption rates, and regulatory timelines.
-
Competitive matrix and vendor scorecards with capability mapping, go-to-market footprints, product roadmaps, M&A activity trackers, and vendor financial proxies.
-
Regulatory playbook and submission templates tailored to US (510(k)), EU (CE/MDR), and key APAC jurisdictions, plus a stepwise clinical-evidence generation plan aligned to intended claims.
-
Reimbursement and procurement mapping, including hospital outpatient APC implications and payer engagement strategies for clinical-grade devices.
-
Actionable GTM blueprints for manufacturers, distributors, and clinic operators: pricing archetypes, channel economics, sales-force segmentation, and service/consumable revenue levers.
-
M&A and partnership shortlist with play-by-play rationale: tuck-in vs. platform buy, capability vs. market-access targets, and integration risk benchmarks.
-
Primary research appendices: interview summaries with clinicians, procurement officers, and R&D heads; methodological notes; and downloadable data tables (note: detailed segment tables require subscription).
Actionable 90–180 day priorities for 2026
-
For device manufacturers: accelerate regulatory readiness for the 510(k) pathway where applicable; prioritize clinical studies that support both safety and differentiated efficacy claims; and architect modular hardware that can host cloud analytics and subscription services.
-
For investors and corporate development: focus diligences on imaging + AI platforms with defensible datasets and OEM relationships; seek targets that close capability gaps (spectroscopy, OCT, or strong clinical trial portfolios) rather than only revenue scale.
-
For dermatology and aesthetic operators: evaluate ROI for capital imaging upgrades versus portable validated systems; design bundled service offerings (diagnostics + treatment + follow-up analytics) to capture higher lifetime value.
-
For cosmetics R&D teams: form early-stage co-development and measurement partnerships with vendors able to provide traceable, validated endpoints to shorten product claim cycles.
-
For distributors: invest in field-service capabilities and outcome-focused training to reduce churn and increase consumables/analytical-subscription attach rates.
M&A and partnership signals — where consolidation makes sense
The market’s mid-level concentration and distinct technology adjacencies create attractive consolidation corridors: (1) horizontal roll-ups to aggregate regional share and calibration standards; (2) vertical integration pairing hardware leaders with AI/software analytics providers to capture higher-margin services; and (3) bolt-on clinical evidence houses to accelerate claim substantiation. Buyers should prioritize integration targets with clean regulatory histories and modular architectures to minimize technical debt.
Concluding perspective and next steps
2026 is a strategic inflection point for skin measurement instruments: regulatory changes accelerate market entry in major geographies, AI-enabled imaging redefines clinical utility, and service-first business models unlock recurring revenue. PW Consulting’s report provides the playbook required to translate these trends into executable 12–36 month plans. For vendors, payers, and clinical operators preparing capital allocation, R&D prioritization, or M&A activity in 2026, the report delivers the evidence base and decision frameworks necessary to act with confidence.
To access the full dataset, vendor benchmarks, and proprietary scenario models that underpin the insights summarized here, visit the PW Consulting report page or contact our industry practice lead for a briefing and sample executive dashboard.
For detailed analysis of this topic, please visit the official page: Skin Measurement Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Low Fat Soya Flour Market to Grow from USD 586.39 Million in 2025 to USD 865.54 Million by 2032 at a 5.72% CAGR (2026–2032)PW Consulting: Oat Flakes Market Forecast to Reach USD 9,411.39 Million by 2032
By PW Consulting, 2026-07-13

Low Fat Soya Flour Market 2026: Strategic Insights for Executives — A PW Consulting Briefing
As global food manufacturers, ingredient traders, and investment committees plan capital allocation and product roadmaps for 2026, Low Fat Soya Flour is shifting from a niche functional ingredient to a strategic building block for protein fortification, plant-based product innovation, and cost-efficient formulation. PW Consulting’s new market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes commercial intelligence, supply-chain dynamics, and competitive positioning to convert market trends into clear, executable corporate choices.
Low Fat Soya Flour Market
Executive snapshot
The low fat soya flour market recorded steady expansion through 2020–2025, rising from roughly USD 452 million in 2020 to USD 586 million in 2025. Our base-year assessment (2025) and forward-looking scenario analysis project the market to reach approximately USD 865 million by 2032, reflecting a compound annual growth rate of ~5.72% across the 2026–2032 forecast window. Market concentration is moderate — the top three players account for c.38.5% of market revenues and the top five roughly 52.2% — leaving room for regional specialists, co-ops and niche ingredient innovators to capture share.
Low Fat Soya Flour Market
Why 2026 is a decision inflection point
-
Supply-side reconfiguration: Recent capacity investments and new entrants have altered bottlenecks in key crushing and flour-processing corridors. Executives must decide in 2026 whether to secure long-term off-take, invest in captive processing, or pursue tolling arrangements to stabilize supply.
Low Fat Soya Flour Market -
Product architecture: Low-fat variants (high-protein, low residual fat) are becoming baseline specs in bakery, meat analogs, and fortified beverages. Formulation choices made in 2026 will lock-in cost and label attributes for multi-year product cycles.
-
Risk management: Agricultural input volatility, shifting crush rates and trade classification changes are compressing margins for downstream manufacturers; 2026 is the window for hedging, sourcing diversification and contractual innovation.
Market dynamics and contextual drivers
-
Demand composition: Protein-fortification and plant-based product development remain the primary growth engines. Consumer preference for high-protein, lower-fat formulations underpins steady off-take across bakery, meat alternatives and nutrition segments.
-
Raw material and crush trends: In early 2026 soybean meal prices displayed regional variation, with CIF reference points near USD 316/MT in the U.S. during February. Concurrently, USDA lifted the 2025/26 U.S. soybean crush forecast to a record 2.61 billion bushels, indicating a structural increase in processing throughput that will influence meal and flour availability.
-
Regulatory context: Low-fat soya flour continues to fall under established international tariff classification (HS Code 12081000), which has implications for cross-border pricing, duty planning and preferential tariff utilisation in multi-jurisdiction sourcing strategies.
-
Innovation and product launches: The market is seeing higher-protein soy flours and ultra-high-protein variants targeted at sustainable protein propositions; these introduce new formulation options but also require commercial validation and supply assurances.
Competitive landscape — strategic positions
Our competitive analysis profiles global processors, regional specialists, and co-operatives to show tactical options for partners and competitors.
-
Cargill, Incorporated (Minneapolis) — Offers branded defatted/low-fat soy flours (e.g., Prolia®) with ~50% protein positioning for bakery, snacks and meat applications. Cargill’s strength lies in integrated supply chains, formulation support, and established food-industry relationships that reduce time-to-market for co-developed concepts.
-
Archer Daniels Midland (ADM, Chicago) — ADM is a large-capacity global processor with a broad portfolio including non-GMO options, enabling scale contracts and consistent quality for multinational food companies. Their value proposition centers on secure supply and program-level sourcing.
-
Tiger Soy, LLC (Mexico, Missouri) — A regional specialist focusing on reduced-fat and low-fat, non-GMO and gluten-free lines sourced from local farmers. Their advantage is traceability and fast-cycle custom batches for mid-size food manufacturers.
-
Soy Austria Produktions GmbH (Austria) — European producer of non-GMO semi-defatted flours, positioned to serve premium ingredient requirements and regional certification demands.
-
Agricultural Cooperative BACEX (Vojvodina) — A cooperative model that offers competitive cost structures and direct farmer linkage, attractive for buyers seeking origin differentiation and price resiliency in Eastern Europe.
-
Bic Services (Netherlands), Seasons International (India), CHS Inc. and Bunge — Each brings distinct strengths: specialty ingredient development, export capacity, cooperative member supply integration, and global crushing/processing networks respectively. These companies enable varied commercial strategies from local bespoke supply to global program buying.
Recent strategic moves shaping the supply picture
-
Facility expansions among processors (e.g., a new plant in Kansas that materially increases crush and ingredient throughput) are relieving capacity tightness in certain corridors and create new arbitrage opportunities for buyers willing to re-route logistics.
-
Product innovation (for example, launches of ultra-high protein soy flours) is broadening the addressable set of formulations for plant-based and fortified foods, but also raises quality-control and specification hurdles that buyers must validate before scaling.
What PW Consulting’s report delivers — practical outputs for 2026 decisions
We built the study as a decision-support toolkit, not an academic exercise. Key deliverables include:
-
Verified market sizing and a scenario-capable financial model (2026–2032) that allows users to run custom price, volume and margin scenarios linked to input-cost and crush-rate assumptions.
-
Supply-chain maps and supplier scorecards (quality, capacity, certification, ESG exposure) that convert competitive intelligence into shortlist recommendations for long-list/short-list selection.
-
Go-to-market playbooks for ingredient companies and food manufacturers: three pragmatic routes — defend (scale & integrate), niche (formulation-led differentiation), and partner (co-development & supply contracts).
-
Contracting templates and risk mitigations for 2026 negotiations (indexed off-take clauses, flex-buys, multi-sourcing guardrails, and logistics contingency plans).
-
M&A and CapEx decision heuristics, including an invest/defend framework calibrated to market concentration metrics and regional processing economics.
-
Regulatory and trade implications — compliance checklists and tariff planning tied to international codes and common certification pathways.
How corporate leaders should use these insights in 2026
-
Procurement: Reassess sourcing strategy to balance cost and continuity. Consider partial vertical integration or strategic tolling partnerships where feedstock risk and freight volatility threaten margins.
-
R&D and innovation: Prioritise pilot programs that leverage high-protein, low-fat variants for label-differentiated launches. Use the report’s formulation risk matrix to shorten validation cycles.
-
Commercial strategy: Align pricing and promotional plans with projected market growth and competitor capacity expansions. Where concentration is moderate, targeted partnerships or exclusivity in regional supply can create defensible advantages.
-
Investors & Boards: Use the scenario model to stress-test returns for capacity investments versus contract acquisition. The market’s mid-single-digit CAGR and the identified concentration profile will shape expected IRR horizons and exit options.
Trailer — what we intentionally withhold here
To ensure strategic value for subscribers and prospective clients, this briefing highlights the analytical architecture and executive implications while withholding granular breakdowns of revenue by region, type and application. The full report contains the detailed segment-level modellings, supplier-by-capacity tables, and downloadable Excel scenario files that underpin the recommendations summarized above.
Concluding guidance
2026 is the moment to convert market momentum into structural advantage. Whether the objective is to secure low-cost protein inputs, launch higher-margin plant-based SKUs, or evaluate strategic M&A into processing, the choices made this year will determine cost structures and differentiation for the next investment cycle. PW Consulting’s Low Fat Soya Flour study equips decision-makers with a repeatable playbook — a mixture of data, supplier intelligence, scenario tools and negotiation templates — designed to accelerate confident, risk-calibrated action.
To access the full dataset, segment analyses, and proprietary modelling tools that support these recommendations, visit the PW Consulting report page and download the complete Low Fat Soya Flour Market report.
For detailed analysis of this topic, please visit the official page: Low Fat Soya Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Intellectual Property Translation Services Market to Grow at 6.5% CAGR, Reaching USD 6.5 Billion by 2032 (USD 4.18B in 2025)
By PW Consulting, 2026-07-13

IP Translation Services Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As corporations accelerate global IP filing, enforcement and commercialization strategies, the market for Intellectual Property (IP) translation services is entering a phase of sustained, predictable growth. PW Consulting’s forthcoming market research highlights that the industry — measured on a consistent, USD-million revenue basis with 2025 as the base year — has expanded steadily through the 2020–2025 review window and is projected to continue on a compound annual growth rate (CAGR) of approximately 6.5% across the 2026–2032 forecast horizon. This preview frames why 2026 represents a pivotal inflection year for corporate procurement, vendor strategy, and technology investment in IP translation.
Intellectual Property Translation Services Market
Why 2026 matters
Buyers and providers face converging pressures in 2026: increasing cross-border filing volumes, heightened regulatory scrutiny around data privacy and localization, and a rapid shift from manual workflows to AI-assisted processes. Our analysis shows that the market’s baseline size in 2025 provides sufficient scale to support continued vendor investment in tooling and domain-specialist labor while still leaving room for differentiated service models. For corporate decision-makers, 2026 is the year to translate strategic intent into procurement actions — locking in partnerships, defining SLAs that reflect hybrid human/AI workflows, and building internal capabilities to validate translated outputs for prosecution, litigation and technical transfer.
Intellectual Property Translation Services Market
Market trajectory and macro drivers
Reviewing the historical series (2020–2025) alongside the 2026–2032 forecast reveals three enduring macro drivers:
Intellectual Property Translation Services Market
- Volume growth tied to international filings and portfolio maintenance — as multinationals expand filing footprints, translation throughput becomes a recurring operational cost and a gating factor for timely filings.
- Technology adoption — AI-assisted engines and pre-translation content reuse tools are reducing effort per word, changing pricing dynamics and creating new product bundles that combine translation, terminology management and IP-specific QA.
- Risk and compliance pressures — data protection regimes and IP office requirements force higher standards for secure handling, secure storage and auditable workflows, increasing both compliance overhead and value capture for certified providers.
Together these drivers explain why the market is forecast to grow consistently at roughly 6.5% CAGR: demand is structural, and the industry is professionalizing rather than commoditizing. Organizations that treat translation as a strategic, risk-managed capability will extract disproportionate value — faster national-phase entries, lower prosecution friction, and better evidence preservation for cross-border enforcement.
What the full report delivers (practical, operational outputs)
PW Consulting’s full report is designed as a playbook for procurement, legal operations and IP strategy teams. It avoids high-level platitudes and focuses on executable assets, including:
- Vendor selection scorecards tailored for distinct buying personas (corporate IP counsel, patent operations, external law firms), with weighted criteria that capture accuracy, security certifications, linguistic domain depth and integration capability.
- Template RFPs and contract clauses that address data protection (DPA language, retention/deletion windows, encryption expectations), acceptance testing protocols and liability allocation for translation errors affecting prosecution or litigation outcomes.
- Total cost of ownership (TCO) models that incorporate per-word effort trends, expected reductions from content reuse, revision cycles and post-translation legal review costs — enabling scenario analysis for centralized vs. decentralized sourcing.
- Implementation playbooks for hybrid workflows — detailing how to blend machine output, terminology management, and specialist post-editors while maintaining ISO/ISO-equivalent security and audit trails.
- Operational KPIs and QC checklists that counsel teams can embed in intake portals to reduce scope ambiguity and downstream rework.
Competitive landscape — how to read vendor differentiation
The market remains fragmented by design: a mix of specialist translation houses, legal-tech enabled platforms, and large IP services firms. Market concentration is modest, with the combined shares of the top three and top five providers indicating ample room for regional and niche specialists to compete. The competitive set we track includes established global players and specialist boutiques. Key patterns to watch:
- Scale + domain depth: Some incumbents pair ISO-certified workflows with deep subject-matter teams that support national-phase entry and European validations — a strong proposition for large filers seeking certainty and auditability.
- AI-enabled productivity plays: Several vendors are embedding AI at the authoring and pre-translation stages to identify content reuse and reduce scope before human effort is applied — shifting cost drivers from raw linguist time to platform subscriptions and integration services.
- Platform integrations: Providers that can expose connectors into IP management systems and law-firm toolchains are lowering friction for programmatic procurement and invoice reconciliation.
- Quality assurance positioning: Boutique providers emphasize certified translators and sector-specialist reviewers for high-stakes filings and litigation support, whereas larger providers scale with blended teams and standardized QA pipelines.
In short, selection is less about “best” and more about “fit”: choose vendors according to risk tolerance, internal review capabilities, and the degree to which your organization prioritizes speed versus absolute linguistic forensic defensibility.
Recent strategic moves that signal direction
Market participants are making targeted moves that shed light on priorities for 2026:
- Proprietary AI for pre-translation scoping — for example, a leading global provider recently secured IP protection for a system that predicts translation effort during authoring, surfacing reuse opportunities that reduce downstream cost and turnaround.
- Integration-first product launches — platform vendors are delivering connectors that integrate translation workflows directly into IP management systems, enabling end-to-end visibility from docketing to translated deliverable.
- Public-sector translation advances — translation tools deployed by multilateral IP organizations are expanding language coverage and daily throughput, raising the baseline quality and accessibility of machine outputs for public prior art searches.
Regulatory, security and cost considerations
Three non-negotiables require attention in vendor and program design:
- Data protection and certification: Legal translation firms must comply with GDPR and relevant national privacy regimes. Providers with ISO 27001-aligned controls, documented DPAs, and strict retention policies reduce enterprise exposure to regulatory penalties.
- Cost volatility and labor dynamics: Patent translation cost-per-word remains a practical lever for budgeting and negotiation. While machine assistance is compressing unit costs in some workflows, national-phase and litigation-grade translations still demand specialist human review — influencing baseline budget expectations.
- Standards alignment: Adherence to established IP documentation standards and WIPO recommendations facilitates cross-border acceptance and reduces rework when filings or evidence cross jurisdictions.
Risk scenarios and mitigation playbook
Leaders should stress-test translation programs against three primary risk scenarios:
- Regulatory breach: Ensure DPAs, encryption-in-transit/at-rest, and pseudonymization procedures are contractually mandated; define breach remediation timelines and responsibilities.
- Quality failure impacting prosecution: Institute acceptance testing and a defined remediation pipeline; create contractual incentives for repeat accuracy on standard claim structures and claim charts.
- Vendor lock-in or integration failure: Maintain exportable terminology and TM assets, require API-based access to translation memories, and establish off-ramp clauses with knowledge-transfer obligations.
How to use the full PW Consulting report in 90 days
For leadership teams preparing 2026 budgets and vendor roadmaps, the full report functions as an executable toolkit:
- 30 days — conduct a gap assessment using our vendor scorecards and security checklist to validate current suppliers.
- 60 days — issue a targeted RFP using the included templates, run acceptance tests, and simulate TCO for 3 vendor scenarios (status quo, hybrid AI-enabled, and in-sourced specialist model).
- 90 days — finalize contracts with SLAs tied to quality and security KPIs, deploy integration pilots with high-volume filers, and operationalize translation memory sharing and terminology governance.
Conclusion — strategic posture for 2026
IP translation is no longer a transactional, line-item service; it is a strategic capability that impacts filing speed, enforcement success and global commercialization. With steady market growth and accelerating technology adoption, 2026 is the moment for firms to translate strategic intent into procurement discipline, secure data governance and investment in hybrid human/AI workflows. PW Consulting’s comprehensive report provides the due-diligence, operational templates and competitive intelligence required to make those decisions confidently.
Next steps
For the full dataset, vendor scorecards, and implementation materials referenced in this preview, visit our report landing page to download the complete Intellectual Property Translation Services Market report and supporting toolkits. PW Consulting’s advisory team is available for bespoke briefings and sourcing clinics tailored to corporate IP, legal operations and law-firm needs.
For detailed analysis of this topic, please visit the official page: Intellectual Property Translation Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Controller Mapper Software Market Poised for 8.4% CAGR During 2026–2032, New Report Reveals
By PW Consulting, 2026-07-13

Controller Mapper Software Market — Strategic Imperatives for 2026 (PW Consulting)
Executive snapshot
PW Consulting’s new Controller Mapper Software Market report is the definitive operational playbook for executives, product leaders, and investors planning decisions in 2026 and beyond. Built on a rigorous historical review (2020–2025) and a forward-looking forecast (2026–2032), the study blends quantitative market sizing with hands‑on strategic workstreams — vendor playbooks, go‑to‑market models, interoperability matrices, and regulatory checklists — to convert market intelligence into immediate action. This release serves as a “trailer”: it surfaces the critical implications you need to prioritize right now while preserving the granular segmentation that drives transaction‑level decisions for subscribers.
Controller Mapper Software Market
Market momentum: scale, growth and structure
The controller mapper software market has moved from niche utility to strategic platform over the last half‑decade. Our topline sizing shows the market expanding from roughly USD 243.6 million in 2020 to about USD 364.6 million in 2025, with the first forecast year landing near USD 386.4 million. Under the baseline forecast, the market is expected to continue a steady expansion to the end of the projection window in 2032 — reaching an overall market scale materially larger than today — with an average compound annual growth rate of 8.4% over the 2026–2032 period. These macro dynamics reflect multiple tailwinds: broader gaming and eSports monetization, enterprise and industrial input customizations, accessibility and assistive‑tech adoption, and the growing need for cross‑platform input standardization in cloud and hybrid environments.
Controller Mapper Software Market
Competitive structure is mixed: concentration metrics indicate an industry with a handful of influential vendors but a substantial long tail. The top three companies account for a meaningful, but not dominant, share of industry revenue, while a broader set of commercial and open‑source projects sustain rapid feature innovation and price competition. This fragmentation creates both opportunities for consolidation and persistent execution risk for incumbents.
Controller Mapper Software Market
What the PW Consulting report contains (practical, executable deliverables)
- Executive brief and investment thesis — clear decision frameworks for M&A, partnership, and greenfield investments tailored to 2026 budget cycles.
- Market sizing & forecast methodology — transparent assumptions, sensitivity cases, and scenario runs (base, upside, downside) for CFOs and planning teams.
- Buyer persona maps and procurement triggers — profiles for consumer, competitive gamer, enterprise automation, and accessibility buyers with purchase criteria and SLA expectations.
- Product taxonomy and feature matrix — canonical definitions for mapping, emulation, macro systems, virtual controller layers, haptics, and cloud APIs; comparative scoring for capability gaps.
- Vendor scorecards and go‑to‑market playbooks — operational KPIs, pricing approaches, distribution strategies (direct, platform stores, OEM bundling), and partner ecosystems.
- Interoperability & compatibility matrix — prioritized OS/controller pairings, maintenance effort estimates, and test automation blueprints to de‑risk releases.
- Regulatory & accessibility compliance checklist — practical steps to meet GDPR data‑handling expectations and accessibility standards that influence product design and procurement.
- M&A and integration checklist — due diligence templates emphasizing technical debt, community fork risk, license clarity, and talent continuity.
- Cost and talent model — benchmarking of primary operational expenses, with emphasis on specialized software engineering effort required to track controller and OS evolution.
- Scenario playbooks for 2026 decisions — short, medium, and long horizon options with KPIs and expected ROI ranges for each strategic path.
Competitive landscape — profiles and strategic implications
The report profiles the ecosystem from commercial incumbents to community‑led projects, each playing a distinct role in market dynamics:
- reWASD — a commercially oriented remapping and emulation platform focused on comprehensive controller support, advanced macros, and virtual device emulation. Strategic implication: premium feature sets and enterprise licensing present a licensing path for players seeking predictable revenue beyond consumer one‑time sales.
- Free Colors, Ltd. (JoyToKey) — long‑standing mapping utility that has evolved with frequent updates and pragmatic UX improvements. Strategic implication: established footprint among power users; product maturity and small, focused R&D teams can outmaneuver larger organizations on release cadence.
- Xpadder — a resilient utility with a strong legacy user base and scripting/automation capabilities. Strategic implication: legacy wallets and strong profile tooling make it a natural candidate for OEM bundling or white‑label partnerships.
- AntiMicroX — an active open‑source project delivering cross‑platform graphical mapping and macro functions. Strategic implication: the open‑source layer accelerates innovation and sets functional expectations; commercial vendors should plan for integration or differentiation rather than ignoring community projects.
- DS4Windows (community forks) — focused on PlayStation controller compatibility for Windows via virtual Xbox controller emulation; community stewardship ensures quick fixes and platform adaptiveness. Strategic implication: community stewardship can both complement and undercut commercial offerings; mitigations include hybrid licensing and contributor programs.
- ControllerBuddy — an open‑source specialist that targets high‑precision applications such as flight simulators, demonstrating the value of niche vertical focus. Strategic implication: vertical specialization creates defensible positions that attract enthusiast communities and enterprise users with specific needs.
Recent signals and why they matter for 2026 plans
- Accelerating community cadence — notable releases and updates in late 2025 and early 2026 from major community projects demonstrate the speed of feature iteration outside traditional corporate R&D cycles. The recent maintenance and enhancement cadence suggests that community projects will continue to set baseline expectations for compatibility and feature parity.
- Commercial quality improvements — ongoing bug‑fix releases and usability improvements among commercial vendors indicate maturing product management practices and a shift toward subscription and enterprise feature sets.
- Platform and OS dependencies — recent updates highlight persistent maintenance burdens tied to OS updates and controller firmware changes, reinforcing the need to budget for continuous compatibility engineering.
- Regulatory and accessibility pressures — GDPR adherence when processing input telemetry and growing accessibility requirements are shifting product roadmaps from nice‑to‑have to compliance mandates; this produces a feature‑led differentiation opportunity for vendors that invest early.
Actionable strategic priorities for 2026 decision‑makers
- Prioritize interoperability and test automation. Make compatibility matrices and automated regression suites contractual deliverables for any acquisition or partner integration.
- Design monetization with dual engines: consumer freemium to capture network effects + enterprise/vertical licensing for predictable revenue. Evaluate subscription economics against one‑time license pricing in light of lifecycle support costs.
- Treat accessibility as market‑making. Investing in assistive features and compliance will broaden TAM and reduce procurement friction with enterprise and public‑sector buyers.
- Adopt a build‑vs‑buy decision rubric that emphasizes technical debt, community fork risk, and maintenance velocity rather than simple cost arbitrage.
- Embed data‑privacy by design. Ensure telemetry, profiling, and consent flows meet regional privacy regimes to avoid downstream legal and reputational risk.
- Plan for people: allocate specialized engineering FTE for controller/OS monitoring, compatibility validation, and firmware triage as a recurring operating expense.
- Use M&A to buy capability, not just customers. Target deals that add vertical specialization, test‑automation assets, or unique community access, and require contractual contributor continuity where community projects are involved.
Why this report is strategically valuable in 2026
Decision cycles in 2026 demand more than trend summaries — they require executable roadmaps. Our report translates the market’s macro trajectory (sustained mid‑single‑digit to low‑double‑digit growth under baseline scenarios) into clear operating actions: what to acquire, what to build, how to price, and how to organize for continuous compatibility. For boards, the study provides diligence templates that shorten time to transaction and reduce integration surprises. For product teams, it connects competitive feature matrices with prioritized engineering backlogs. For investors, it distills risk factors and exit scenarios across a fragmented competitive set where the top handful of players are influential but far from monopolistic.
Access and next steps
This release is an executive‑level extract designed to show the report’s strategic value while preserving subscription‑level granularity: full regional and application splits, company revenue comparisons, and the complete scenario dataset are available in the comprehensive report. PW Consulting clients and subscribing organizations can obtain the full dataset, model files, and bespoke advisory sessions to convert findings into 2026 operational plans.
For enquiries about licensing the full Controller Mapper Software Market report, bespoke briefings, or to schedule a workshop to convert the study into a 90‑day implementation plan, please contact PW Consulting’s Market Intelligence team through our official channels.
For detailed analysis of this topic, please visit the official page: Controller Mapper Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


