



PW Consulting: Oil & Gas Drones Market to Reach USD 103.8B by 2032 at 19.12% CAGR
By PW Consulting, 2026-07-13
Oil & Gas Drones Market — Strategic Outlook for 2026 Decision-Makers
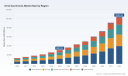
As energy companies accelerate digital transformation of field operations, unmanned aerial systems (UAS) have moved from niche pilots to enterprise-grade inspection, monitoring, and emergency-response platforms. Our latest PW Consulting market study provides the strategic intelligence executives need to make defensible investments in 2026 and beyond. At a macro level, the oil & gas drones market has transitioned from a fragmented, project-driven spend to a predictable, high-growth market: global revenue reached USD 30,501.38 Million in the report base year (2025) and is forecast to exceed USD 103,803.52 Million by 2032, reflecting a compound annual growth rate (CAGR) of 19.12% over the forecast period. Market concentration remains modest (CR3 ~22.15%, CR5 ~34.20%), underlining continued room for new entrants and differentiation.
Oil Gas Drones Market
Why this research matters for 2026 strategic choices
-
Timing is decisive: 2026 is a pivot year where regulatory clarity, maturing sensor stacks, and demonstrated ROI from early adopters converge — creating a narrow window to lock in advantageous commercial terms and operational baselines.
Oil Gas Drones Market -
Capital allocation decisions hinge on credible scenario modeling. Our study translates the market’s high-level growth path into investment scenarios tailored to asset-heavy operators, mid-tier service providers, and technology vendors.
Oil Gas Drones Market -
Procurement and vendor strategy must balance performance, supply-chain resilience, and regulatory compliance; the report gives procurement teams the framework they need to avoid “platform lock” while securing service-level guarantees.
Market trajectory and executive takeaways
The historical growth trend from 2020 through 2025 shows rapid adoption across pipeline patrols, offshore asset monitoring, leak detection, and emergency response workflows. The market scaled from documented levels in 2020 to USD 30,501.38 Million in 2025. Under our central forecast, the market expands to USD 36,361.66 Million in 2026 and accelerates through the late 2020s to cross USD 100 billion by 2032. This magnitude and speed of expansion justify treating UAS as core operational infrastructure rather than optional field technology.
From a decision-making perspective, three macro implications are immediate:
-
Shift from CapEx experiments to recurring, integrated Opex models (managed services, data subscriptions, and SLA-backed inspection contracts).
-
Prioritize platforms and sensors that enable multi-mission use; flexibility drives utilization rates and shortens payback.
-
Embed regulatory and security risk into procurement criteria — compliance capabilities materially affect deployable scope and timelines.
What the report contains — practical, operational, and commercial tools
This research is intentionally tactical. Rather than high-level forecasts alone, the report is a playbook for implementation teams and C-suite sponsors. Key deliverables include:
-
Operational playbooks for safe, compliant UAS deployment covering flight authorization, BVLOS enablement strategies, and hazardous-material handling under new guidance.
-
Procurement templates and vendor evaluation matrices that score platforms by mission fit (e.g., thermal, LiDAR, chemical/gas sensing), endure requirements, and supply-chain risks.
-
Data architecture and analytics blueprints for integrating aerial data into existing asset integrity and SCADA systems, including recommended formats, retention policies, and ML-ready pipelines.
-
Financial models (CapEx/Opex scenarios) with sensitivity analyses for utilization rates, service vs. buy decisions, and accelerated ROI pathways for scale deployments.
-
Regulatory compliance checklists and suggested lobby/engagement strategies for jurisdictions with evolving UAS rules and critical-infrastructure restrictions.
-
Actionable case studies and “lessons learned” from early enterprise rollouts — highlighting what reduced operational downtime, lowered inspection costs, and improved safety outcomes.
Competitive landscape — how vendors are positioning and what it means for buyers
The vendor ecosystem blends established UAV OEMs, specialist analytics firms, and service integrators. Each archetype brings distinct strengths and constraints that matter to 2026 buyers:
-
Platform-centric incumbents (e.g., DJI Enterprise) deliver mature multirotor systems with expansive payload ecosystems. Their advantage is end-to-end hardware availability and large install bases — attractive for rapid scaling but sensitive to supply-chain and jurisdictional restrictions.
-
Specialist manufacturers and sensor integrators (e.g., Flyability, Acecore Technologies, Microdrones) differentiate on mission-specific capabilities such as confined-space inspection robustness, modular LiDAR integration, and high-performance airframes for harsh environments.
-
Service-first players (e.g., Terra Drone, Cyberhawk Innovations) offer managed inspection programs and analytics-as-a-service, reducing up-front CapEx for operators that prefer outcome-based contracts.
-
Autonomy and software leaders (e.g., Skydio, PrecisionHawk) compete on flight autonomy, obstacle avoidance, and data-processing platforms that accelerate actionable insight generation.
-
Tactical UAS suppliers and long-endurance vendors (e.g., AeroVironment, Insitu/Boeing) are focused on remote, persistent surveillance use-cases where range and endurance trump short-range agility.
For buyers, the recommendation is to adopt a “best-of-breed assembly” approach: lock down the mission-critical payload and analytics stack, while keeping airframe selection flexible where possible. Given the current concentration ratios, partnerships and regional ecosystems will determine long-term total-cost and service quality.
Regulatory context and industry dynamics — the 2026 reality
Regulatory shifts in late 2024–2026 materially change program design and procurement windows. Notable context for 2026 planning includes:
-
PHMSA’s recent integration guidance (published April 2026) explicitly recognizes UAS for pipeline right-of-way patrols — creating operational pathways for wide-area patrol programs backed by a compliance framework.
-
FAA and PHMSA’s November 2025 guidance clarifies risk-based transport of hazardous materials by UAS, enabling new logistics and emergency-response use cases previously constrained by ambiguity.
-
U.S. contractors face restrictions (effective December 22, 2025, guidance) on using covered foreign entities on federally funded projects — an important procurement constraint that affects sourcing, warranty, and support expectations.
-
State-level rules, such as Florida’s statute restricting drone operations near critical infrastructure (2025 updates), create patchwork governance that requires tailored operational playbooks per region.
These regulatory changes are both an accelerant and a filter: they increase addressable use-cases while raising the bar for compliance, documentation, and vendor traceability. Companies that move early with compliant, auditable programs will secure competitive advantage and regulatory goodwill.
Strategic implications and five immediate actions for 2026
-
Establish a cross-functional “UAS Center of Excellence” that unites operations, HSE, legal, and procurement to standardize policies and scale capability.
-
Run a 12-month pilot portfolio that includes at least two mission archetypes (e.g., pipeline ROW patrol and offshore platform thermography) to validate operational workflows and data handoffs.
-
Implement dual-sourcing and vendor contingency clauses focused on firmware provenance, parts availability, and export/compliance constraints to mitigate supply and regulatory risk.
-
Adopt a data-first approach: require vendors to deliver ML-ready datasets and open APIs to avoid vendor lock-in and accelerate analytics maturity.
-
Translate regulatory developments into executable flight-authority maps and compliance playbooks by jurisdiction — keep these updated and use them as procurement pass/fail gates.
How to use PW Consulting’s full report
The executive brief you are reading is a strategic primer. The full PW Consulting Oil & Gas Drones Market study supplies the granular tools operational teams require to execute. Subscribers will receive:
-
Detailed segmentation across use-cases and airframe types, with proprietary scenario-based demand curves and sensitivity to sensor adoption rates (note: detailed segment tables are held in the full report to preserve proprietary modeling).
-
Vendor assessment scorecards with methodical scoring across performance, regulatory compliance, support footprint, and total cost of ownership.
-
Ready-to-use flight operations templates, procurement RFP language, and contractual clauses for warranties, data ownership, and cybersecurity obligations.
-
Customized roadmap workshops and executive briefings to convert market intelligence into a 12–36 month implementation plan aligned with your asset and regulatory footprint.
Closing — why act now
2026 represents an operational inflection point for oil & gas companies and their service ecosystems. The convergence of favorable regulation for specific applications, rapid capability advances in autonomy and sensing, and a multi-billion-dollar growth trajectory means that early, well-governed deployments yield outsized returns — operational resilience, safety improvements, and measurable cost reductions. PW Consulting’s study is designed to be immediately actionable for teams that must move from pilot to program with confidence.
For the full market segmentation, vendor scorecards, and hands-on templates that operationalize these insights, refer to the complete PW Consulting Oil & Gas Drones Market report.
For detailed analysis of this topic, please visit the official page: Oil Gas Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rative Dentistry Market to grow 6.51% CAGR to USD 32.42B by 2032
By PW Consulting, 2026-07-13
Rative Dentistry Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a succinct yet rigorous preview of our Rative Dentistry Market research — calibrated to inform board-level decisions and corporate strategy for 2026. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory headwinds and practical implications executives must account for when allocating capital, designing product roadmaps, and shaping go-to-market plays. It purposefully demonstrates analytical depth while reserving the granular segment-by-segment tables and split forecasts for the full report.
Rative Dentistry Market
Why this study matters for 2026
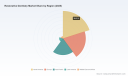
The restorative dentistry market is on a clear growth path: our work uses 2025 as the base year and projects performance through 2032 under a structured forecasting framework. The market reached approximately USD 20.85 billion in 2025 and is modeled to expand at a compound annual growth rate of 6.51% across the 2026–2032 forecast window, reaching an expected market size above USD 32 billion by 2032. That pace points to durable volume expansion and pricing upside driven by material science advances, digital workflow penetration, and broader systemic incentives for oral health integration.
Rative Dentistry Market
For executives, this macro picture frames three enduring strategic questions for 2026:
Rative Dentistry Market
- Where on the value chain should we concentrate investment to capture the fastest-growing pockets (materials, digital systems, implants, or consumables)?
- How aggressively should we pursue inorganic growth given competitive concentration and mid-market consolidation opportunity?
- What operational changes are required to mitigate raw-material volatility and regulatory complexity while accelerating clinical adoption?
Market trajectory: what the headline numbers conceal
The headline CAGR and market totals validate that restorative dentistry remains an investable, innovation-rich segment. Yet beneath this steady growth lie three structural shifts that materially alter competitive playbooks:
- Material innovation: Next-generation bioactive composites and ion-releasing fillers are shifting clinical preference toward solutions that actively support remineralization and reduce secondary caries risk. Early launches and clinical data have begun to rebase value propositions from “fit and finish” toward demonstrable biological benefit.
- Digitalization and same‑day workflows: The maturation of CAD/CAM systems and chairside restoratives has compressed procedure timelines and increased the economic value of integrated platforms that bundle hardware, software and consumables.
- Policy and reimbursement tailwinds: Emerging incentives to integrate oral health screening into broader care pathways (for example, a new Medicare-related incentive structure in the U.S.) are creating additional referral and utilization levers for restorative services.
These forces interact: innovative materials increase procedure value, digital workflows lower delivery cost and time, and reimbursement incentives expand addressable demand. For decision-makers, the combined effect magnifies returns for strategically timed investments in product and channel capabilities.
Competitive landscape — concentrated but open to moves
The market exhibits a mid-level concentration profile: our metrics indicate that the top three players capture a meaningful share, and the top five further consolidate nearly half of market revenue. That configuration produces a landscape where global champions maintain scale advantages while a long tail of specialist and regional players create pockets of dislocation and opportunity.
- Dentsply Sirona: A global leader pairing comprehensive restorative portfolios with CAD/CAM systems and broad consumable lines. Recent product launches in bioactive composites and a solid financial outlook signal continued investment in integrated restorative solutions.
- 3M: Strong in advanced direct restorative materials and bonding systems; recognized for durable, aesthetic composites and cement technologies.
- Straumann Group: Deep expertise in implant and digital restorative workflows; recent annual disclosures emphasize digital and regenerative product launches that strengthen end-to-end restorative propositions.
- Ivoclar Vivadent, GC, Zimmer Biomet, Envista (Kerr/Nobel), and select specialist suppliers: Each holds differentiated capabilities — from high‑aesthetic ceramics and bioactive glass ionomers to implant systems and prosthetic platforms — creating a competitive mosaic where partnerships and selective M&A are logical strategic tools.
Executives facing growth or defense decisions should evaluate three levers: scale (to defend pricing and distribution), differentiation (material or digital-led), and platform orchestration (connectivity between clinics, labs and suppliers). Our qualitative and quantitative profiling in the full report maps these levers to near-term commercial outcomes, but we reserve detailed segment-level share tables for subscribers.
Operational and regulatory dynamics that will shape 2026 actions
Operational resilience matters more than ever. Key dynamics we modeled and stress-tested include:
- Raw material cost volatility: The composites supply chain is sensitive to synthetic monomer and specialty filler pricing. Procurement strategies should combine longer-term supply contracts, multi-sourcing and pass-through pricing mechanisms embedded in distributor agreements.
- Quality and compliance: ISO 13485-aligned quality management systems remain a gating item for major market access and for supporting rapid regulatory filings. Companies without robust QMS risk delayed launches and shortened commercial windows.
- Environmental and clinical standards: Policies encouraging the use of amalgam separators and the broader push toward mercury-free restorative alternatives are reshaping product developmental priorities and facility investments.
- Reimbursement & incentives: The addition of oral health incentives into broader payment programs (notably in the U.S.) creates new justification for investments in screening-enabled restorative pathways and cross-referral systems between medical and dental providers.
These operational inputs feed directly into capital allocation decisions. For example, allocating R&D spend to bioactive, fluoride-releasing or low-shrinkage chemistries should be balanced against investments in regulatory capacity and clinical evidence generation to accelerate reimbursement capture.
Practical, action-oriented outputs inside the report
PW Consulting’s full study is designed as a decision toolkit rather than a static market narrative. Key deliverables include:
- A top-down market model with scenario analyses (base, upside and downside) through 2032, enabling sensitivity testing across price, penetration and adoption curves.
- Proprietary competitive heat maps and capability matrices that score rivals on product breadth, digital integration, clinical evidence and distribution strength.
- Go-to-market playbooks for incumbents and new entrants: channel optimization, lab-clinic partnerships, and differentiated service bundles that increase lifetime value per patient.
- Regulatory and reimbursement roadmaps tailored to major markets, with tactical checklists to accelerate product approvals and payer engagement.
- M&A and partnership screening: target archetypes, valuation benchmarks, and integration risk matrices reflecting prevailing market concentration dynamics.
Each module is accompanied by executable annexes — for example, negotiation templates for supplier contracts, sample clinical economic models, and a phased rollout plan for implementing chairside CAD/CAM capabilities across multi-site clinic groups.
Investment and M&A implications for 2026
Given the market’s growth profile and concentration metrics, strategic options that consistently emerge from our analysis are:
- Build-or-buy decisions favoring bolt-on acquisitions that add a technical differentiator (e.g., bioactive chemistries or proprietary digital integration) rather than generic volume plays.
- Selective vertical integration into critical consumables to protect margins and ensure supply continuity, combined with partnerships for capital-intensive hardware.
- Portfolio optimization where firms rationalize lower-growth commodity lines to free resources for high-margin, innovation-led products and digital services.
Private equity and corporate strategists will find the market structure conducive to platform plays that combine a strong channel partner with differentiated proprietary technology; our report includes candidate profiles and diligence checklists for these opportunities.
What this preview deliberately withholds — and why
To preserve the value of the research as a strategic asset, this introduction intentionally avoids publishing the detailed regional, product-type and end-user splits that underpin our modeling and scenario outputs. Those granular split metrics — which include region- and application-level growth drivers, price elasticity estimates, and sub-segment revenue projections — are available in the full report and associated data pack. Withholding segment-level tables is intended to protect the commercial sensitivity of the analysis and to provide an incentive for stakeholders to engage directly with the full deliverables.
How to use this intelligence in your 2026 planning cycle
Leaders should treat this research as both a forecasting engine and a decision-support library. Immediate steps we recommend before committing capital in 2026:
- Run the report’s scenario models against your internal pipeline to see how product launches and pricing moves change enterprise value under conservative and aggressive adoption assumptions.
- Prioritize short-term investments in regulatory capacity and clinical evidence generation for any bioactive or novel restorative product you plan to commercialize within 18–24 months.
- Revisit procurement and hedging strategies for critical resin and filler inputs; convert spot exposures into contracted supply where possible to stabilize margins.
- Map potential M&A targets using the capability matrices in the report to identify the fastest routes to product differentiation and geographic scale.
Closing perspective
Restorative dentistry in 2026 is not a market of marginal improvements; it is a sector in which material science, digital workflows and changing care economics converge to reshape where value will accrue. The market’s steady CAGR and expanding total size create a favorable backdrop, but success will be determined by choices around differentiation, operational discipline and evidence-backed commercialization. PW Consulting’s full Rative Dentistry Market study translates these strategic imperatives into operational plans — the deeper data, segment-level forecasts, and executable annexes are contained in the report and supplementary data packs.
For boards, investment committees, and corporate strategy teams preparing 2026 plans, this preview sets the strategic frame. To access the complete market model, competitor scorecards, and tactical playbooks referenced here, please consult PW Consulting’s full research release.
For detailed analysis of this topic, please visit the official page: Rative Dentistry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Liquid-Cooled Cable Market to Reach USD 2,385M by 2032 (23.01% CAGR)
By PW Consulting, 2026-07-13
Flexible Liquid-Cooled Cable Market: Strategic Briefing for 2026 Decision-Makers
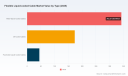
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused industry briefing designed to translate the Flexible Liquid-Cooled Cable market’s rapid expansion into actionable decisions for 2026. This market — sized and modeled on a 2025 base year with a historical window from 2020–2025 and a forecast horizon through 2032 — is no longer a niche engineering curiosity. It is a critical enabling technology for ultra-fast EV charging, high-power data centers, and heavy industrial heating equipment. Our model shows the global market advancing from early-stage commercial volumes in 2020 to a materially larger, commercially investable market in 2025 and accelerating further into the early 2030s, with a compound annual growth rate (CAGR) of 23.01% through the 2026–2032 forecast period (values in USD Million).
Flexible Liquid Cooled Cable Market
Why this matters for 2026 strategy
Three strategic inflection points make 2026 pivotal:
Flexible Liquid Cooled Cable Market
- Demand convergence: Megawatt-class EV charging and continued scaling of data center and industrial power density have synchronized technical requirements — high sustained current, thermal management, ergonomic handling — that only liquid-cooled flexible cables can realistically satisfy at scale.
- Commercial readiness: Mature product variants and multiple supplier classes (from specialized custom fabricators to global cable OEMs) create a viable supplier ecosystem. The market concentration metrics indicate that a relatively small group of established players command meaningful share, but there is room for consolidation and new entrants with differentiated IP or channel strategies.
- Standards and safety momentum: Recent certifications and emerging standards for high-power liquid-cooled systems are reducing buyer risk and accelerating deployment of ultra-fast charging and megawatt-class installations.
Macroeconomic snapshot (what the numbers tell us)
Our market sizing and scenario work (base year 2025; historical 2020–2025; forecast 2026–2032; currency: USD; revenue unit: Million) reveal a compound trajectory that turns this technology from specialized spend into a high-growth industrial market. The model quantifies a strong post-2025 acceleration driven by charging infrastructure rollouts, data center refresh cycles, and industrial electrification programs. For commercial leaders, this is both an investment signal and a timing issue: address supply chain, product certification, and field-service readiness in 2026 to capture leadership positions as volumes scale.
Flexible Liquid Cooled Cable Market
What the full report delivers (practical, executable content)
- Market sizing and validated forecasts, including historical reconciliation and three forecast scenarios (base, fast-adoption, and constrained-supply) to stress-test capex and demand assumptions.
- End-to-end value-chain maps (materials, components, subassembly, finished cables, installation/field service) and supplier tiering to support sourcing strategies and contract structuring.
- Technology and regulatory matrix: comparative analysis of cooling media (water-glycol, oil, fluorinated liquids), conductor and hose materials, connector interfaces, and compliance pathways across IEC/UL/ISO frameworks.
- Supplier scorecards and capability heatmaps for manufacturing, customization, lead times, and IP position — configured for use in RFP evaluation or M&A target screening.
- Commercial playbooks for OEMs, charging network operators, and EPC firms outlining partnership models, margin structures, and installation-service bundling strategies.
- Risk and mitigation frameworks covering raw-material volatility (copper exposure), quality control, warranty and liability, certification timelines, and field service logistics.
- Five transactable growth pathways: licensing/IP partnerships, vertical integration, contract manufacturing scale-up, platform-driven service offerings (e.g., charging-as-a-service), and strategic M&A priorities.
Competitive landscape — who to watch
The vendor environment is heterogeneous, spanning small specialized fabricators that serve high-current industrial furnaces to global cable firms focused on EV high-power charging ecosystems. Our competitive analysis synthesizes product architecture, manufacturing footprint, go-to-market approach, and strategic intent so buyers and investors can prioritize engagement and sourcing.
- Specialized industrial fabricators (examples: firms focused on water-cooled leads for furnaces and induction equipment). These players excel at custom designs, fast turnaround, and legacy relationships in heavy industry. Their strengths are technical customization and service-led value, and they are often first responders for retrofit and repair work.
- EV charging-focused innovators and traditional cable OEMs transitioning to liquid-cooled solutions. These competitors pursue system-level integration (cable + connector + cooling loop), certification pathways, and ergonomics for public and commercial charging sites. They are driving standards adoption and partnering with charger OEMs for turnkey deployments.
- Regional players with specialized capabilities (high-section cables, swiveling terminals, tailored connectors) that serve geographic industrial clusters and can scale with the right capital or distribution partnerships.
Notable vendors profiled in the report include small and midsized specialists that dominate high-current industrial niches and larger global OEMs that are actively productizing liquid-cooled cable systems for EV HPC deployments. Each is profiled for product lines, strategic partnerships, recent developments, and typical lead times — enabling targeted procurement and alliance strategies.
Recent market signals and regulatory tailwinds
- Product integrations and platform launches by charger OEMs and cable makers are turning proof-of-concept into fielded systems. Collaborative product integrations with major charging platforms signal that the technology stack is moving from pilot to commercial deployment.
- Companies continue to refine product safety, ergonomics, and thermal performance while maintaining compatibility with connector standards and safety frameworks. Recent certifications supporting higher power thresholds materially reduce buyer risk for megawatt-class installations.
- Raw material and component design choices — primarily high-conductivity copper conductors, protective high-temp hoses, and carefully engineered coolant circuits — remain determinative for both performance and cost. Procurement strategies must therefore incorporate copper sourcing and alternate-material contingency plans.
Strategic implications and recommended moves for 2026
We distill the strategic agenda into pragmatic, prioritized actions that hinge on your role (OEM, network operator, investor, EPC, or supplier):
- For OEMs and Tier-1 suppliers: accelerate platform certification and ergonomics optimization now. Partners who hold connector and liquid-management expertise will unlock early market share as installations scale. Protect IP around thermal-management assemblies and connector-cooling interfaces.
- For charging network operators and site hosts: pilot megawatt-capable deployments with clear O&M contracts. Specify certified liquid-cooling systems to lower technical debt and warranty exposure. Negotiate spare-part and field-service SLAs tied to uptime metrics.
- For investors and M&A teams: prioritize targets offering either differentiated IP (coolant circulation, swivel terminals, connector integration) or established industrial relationships and manufacturing capacity. The market’s concentration shows opportunity for consolidation to accelerate path-to-scale.
- For suppliers and contract manufacturers: invest in modular manufacturing lines and quality processes to reduce lead times. Build certification roadmaps (IEC/UL/ISO) and demonstrate repeatable manufacturing quality — these become binary buying criteria for large-scale integrators.
- For procurement and supply-chain teams: hedge copper exposure and lock long-lead items (high-temp hoses, specialty connectors) via multi-year agreements or strategic inventory to avoid build-up lag when demand surges.
Risk map and near-term watch list
- Certification delays and evolving safety standards remain the principal regulatory risk; mitigate by partnering with certified component suppliers and funding pre-certification testing.
- Supply bottlenecks for electrolytic copper and specialty polymer hoses can introduce schedule slippage; active supplier development and dual-sourcing are essential.
- Field-service and operational readiness — connectors, swivel terminals, and coolant maintenance — are recurring operational risks that must be priced into offering models.
Closing: how PW Consulting can accelerate your 2026 plan
Our full Flexible Liquid-Cooled Cable Market study provides the quantitative detail, supplier scorecards, and decision-grade models needed to move from strategy to execution. The report includes granular scenario outputs, supplier bench-strength matrices, and downloadable financial models tailored for capex planning, RFP assessments, and M&A diligence.
In this briefing I’ve highlighted why 2026 is a turning point and where executives must focus: certification-ready product platforms, supplier and materials risk mitigation, and commercially viable service models for deployment and maintenance. The market’s growth trajectory (high double-digit CAGR through the forecast period) creates a narrow window for scale advantages. For executives planning capital allocation, procurement lead-time commitments, or partnership strategies in 2026, the full report delivers the segmented, actionable intelligence you need to lock in advantage — including detailed regional and application breakdowns, vendor scoring, and cost models reserved for the report subscribers.
Contact PW Consulting to access the full study and the decision-support toolkit that converts this market growth into defensible, high-return actions in 2026.
For detailed analysis of this topic, please visit the official page: Flexible Liquid Cooled Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fertility ELISA Kits Market to Top USD 1,021.3M in 2026 at 6.12% CAGR
By PW Consulting, 2026-07-13
Fertility ELISA Test Kit Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our forthcoming Fertility ELISA Test Kit Market report. This briefing translates the report’s core macro findings into actionable strategic levers for executives planning investments, product strategies, regulatory programs, and go‑to‑market moves in 2026. It demonstrates the depth of our analysis while intentionally withholding the granular segment tables and model outputs that subscribers will access on the report page.
Fertility Elisa Test Kit Market
Headline market trajectory — what matters to 2026 planning
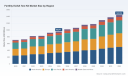
The global fertility ELISA test kit market has exhibited steady expansion through the 2020–2025 period and reached a definitive base in 2025. Our model indicates a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Concretely, the market expanded meaningfully during the historical window and is projected to approach roughly USD 1.44 billion by 2032 — a trajectory that creates a predictable runway for mid‑sized investments, selective product launches, and consolidation plays.
Fertility Elisa Test Kit Market
Why this trajectory is strategically relevant in 2026:
Fertility Elisa Test Kit Market
- Predictability at the macro level enables multi‑year regulatory and manufacturing investments with a reasonable ROI horizon.
- Moderate growth rather than hypergrowth favors disciplined, differentiated product strategies (e.g., premium assays, service bundles, automation) rather than aggressive volume plays only.
- Stability in the base market size supports M&A transactions aimed at capability certainty (assay panels, manufacturing scale, or distribution reach) rather than pure market share capture.
Market structure and competitive intensity — concentration and opportunity
The market exhibits a mid‑level concentration: the top three players account for just under two‑fifths of market share, while the top five collectively control a little over half. This constellation creates a mixed competitive environment: established incumbents command important clinical and distribution footprints, but meaningful share remains available to specialized entrants and regional players.
Strategic implications:
- Incumbent players can leverage scale and regulatory dossiers to defend pricing and channel access; challengers must therefore rely on superior clinical differentiation, lower total cost of ownership, or targeted clinical partnerships to accelerate adoption.
- Private equity and corporate M&A strategies can be value‑accretive by acquiring niche assay portfolios or localized manufacturing to plug capability gaps for larger players seeking near‑term growth.
Competitive landscape: capabilities that determine winners
Our competitive assessment focuses on firms that demonstrate distinct assay portfolios, regulatory positioning, and commercial breadth across fertility and endocrine testing:
- Ansh Labs (Webster, TX) — Notable for immunoassay specialization and monoclonal antibody platforms applied to AMH testing. Their mix of RUO and CE‑marked products illustrates a staged regulatory commercialization approach and a clinically respected assay lineage relevant to ovarian reserve and IVF outcome assessment.
- DRG International (Springfield, NJ) — A producer of classic competitive binding and immunoassays such as estradiol and other steroid hormone tests. Their product set and assay formats make them a logical partner for labs and clinics that require validated hormone monitoring during ovulation induction and menstrual dysfunction management.
- Monobind Inc. (Lake Forest, CA) — Offers broad IVD ELISA menus including FSH, LH, prolactin, and beta‑hCG, enabling lab consolidation of assay workflows. Monobind’s IVD breadth is a strategic asset where buyers prefer a single‑vendor test menu for endocrine and reproductive panels.
- Sure Bio‑Tech (USA) — Export‑oriented supplier with compliance to GMP/ISO 13485 and CE marking; positions itself as a cost‑competitive source for routine fertility assays while emphasizing manufacturing compliance and international distribution.
Each profile above reflects technology choice (e.g., monoclonal antibody specificity vs. competitive binding formats), regulatory footprints (RUO, CE, pathways to FDA clearance), and commercial focus (specialist assay developer vs. broad IVD supplier). Our full report maps these dimensions against adoption vectors in clinics, hospitals, and diagnostic laboratories to identify realistic near‑term champions and acquisition targets.
Regulatory, quality, and reimbursement environment — constraints and accelerants
Three non‑negotiable externalities will shape winners and losers in 2026:
- Regulatory pathways: Fertility ELISA kits — especially those intended to inform clinical decisions like menopausal status or ovarian reserve — are subject to formal regulatory review (e.g., FDA clearance or de novo authorization for specified claims) and CE marking for European commercialization. The intended use claim is often the gating factor for both clinical adoption and commercial reimbursement potential.
- Quality systems: ISO 13485 compliance and GMP practice are baseline requirements for market access and large‑scale distribution; suppliers that can demonstrate robust manufacturing traceability and lot consistency command higher trust with laboratory buyers and institutional procurement teams.
- Reimbursement and coding: Fertility hormone assays typically flow through established clinical laboratory coding structures rather than a dedicated fertility ELISA code. That creates both simplicity (standard lab reimbursement processes) and complexity (lack of fertility‑specific reimbursement premiums), requiring suppliers to make compelling health‑economic and workflow arguments to justify premium pricing.
Where the practical value lies — what the full report delivers
PW Consulting’s full report is engineered as a practitioner’s toolkit for 2026 strategy execution. Subscribers will receive:
- Market sizing and validated forecast model (2020–2032) with driver‑level sensitivity and scenario outputs that allow executives to stress‑test investment cases.
- Competitive benchmarking matrix linking assay technology, regulatory status, manufacturing capacity, and commercial channels to identify defensible niches and M&A targets.
- Regulatory pathway playbooks (FDA, CE, and selected APAC pathways), including typical timelines, documentation checklists, and cost‑rate assumptions for product launches and intended‑use expansions.
- Go‑to‑market frameworks for three archetypal players — incumbent large IVD, specialty assay developer, and a scaled distributor — with tailored pricing, channel, and partnership strategies to maximize adoption in clinics and labs.
- Operational readiness assessments for scaling manufacturing (capacity planning, QC automation, raw material sourcing) and supply chain risk matrices addressing critical reagent and antibody supplier concentration.
- Investment and M&A decision tools: valuation comparables, synergy templates, and integration checklists focused on assay portfolio consolidation and cross‑selling opportunities.
To honor the “trailer” approach of this preview, we are intentionally omitting the granular segment breakdowns (by region, product type, and end‑user) and the underlying financial model that supports our forecasts. These are available with subscription to the complete report and come with an interactive model file.
Action agenda for 90 days and 12 months — prioritized moves
For executives looking to translate insight into action in 2026, prioritize the following:
- 90‑day moves: finalize regulatory gap analyses for any pipeline assays with clinical claims; initiate targeted partnership discussions with IVF clinic networks for pilot validations; perform a quick win supply‑chain audit focused on critical antibody sources.
- 12‑month initiatives: allocate budget for regulatory submissions aligned with prioritized intended uses, execute at least one channel partnership (e.g., national distributor or reference lab), and evaluate acquisition targets that deliver either complementary assay panels or manufacturing scale to compress time‑to‑market.
Concluding counsel — the competitive posture for 2026
The fertility ELISA kit market in 2026 is neither a winner‑take‑all battlefield nor a stagnant commodity patch. It is a growth market with moderate concentration, technical entry barriers, and clear regulatory gating. Firms that combine clinical differentiation (assay specificity/precision), credible regulatory strategy, and disciplined commercial execution will capture disproportionate value. Companies that treat this market as a simple volume play will face margin pressure and payer scrutiny.
PW Consulting’s complete Fertility ELISA Test Kit Market report equips leaders with the granular segmentation, model files, and execution playbooks needed to make high‑confidence decisions. For the full dataset, regional and product splits, and downloadable financial model, visit our report page — the granular intelligence there is designed to immediately inform board‑level investment deliberations and commercial operating plans for 2026.
For detailed analysis of this topic, please visit the official page: Fertility Elisa Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Retardant Additives Market to Reach $13.26B by 2032 at 4.95% CAGR
By PW Consulting, 2026-07-13
Fire Retardant Additives Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
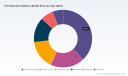
As companies prepare investment and commercial plans for 2026, the fire retardant additives market is entering a period defined by steady expansion, regulatory tightening, and material-technology rebalancing. Our base-year assessment (2025) pegs total global revenue at approximately USD 9.45 billion, with a mid-single-digit compound annual growth rate (CAGR) of about 4.95% across the 2026–2032 forecast horizon. By the end of the forecast window the market is expected to be roughly one-third larger than the 2025 base, driven by ongoing substitution toward halogen-free chemistries, rising performance requirements in electronics and transportation, and recovery in construction activity in several major markets.
Fire Retardant Additives Market
Why this matters for 2026 planning
-
Capital allocation: Forecasted mid-single-digit growth informs capacity planning and brownfield/greenfield CAPEX timing. Investors and operations teams need to weigh modest demand growth against localized raw-material and regulatory risks that can affect margins and payback horizons.
Fire Retardant Additives Market -
Product strategy: Demand is moving decisively toward non-halogenated solutions and synergistic systems. Companies that can quickly demonstrate regulatory-compliant performance while managing cost-to-formulate will capture premium share in selective applications.
Fire Retardant Additives Market -
M&A and partnerships: Market concentration metrics indicate a clear top-tier influence but meaningful room for consolidation and specialist plays. Strategic bolt-ons that fill portfolio gaps (e.g., polymeric phosphorus grades, engineered fillers, or application-specific masterbatches) remain attractive.
Market trajectory & interpretive lens
The trajectory from 2020 through the 2025 base year shows recovery and rebalancing following pandemic-era disruptions. The modest but persistent CAGR through 2032 reflects a market driven less by commoditized volume expansion and more by structural shifts: regulatory-driven reformulations, electrification and miniaturization in electronics, and higher safety specifications in building codes and automotive interiors. For 2026 decision-makers, the key inference is that revenue pools will grow, but value will cluster around differentiated chemistries, formulation services, and regulatory assurance capabilities rather than undifferentiated filler supply alone.
Key demand & supply dynamics to watch
-
Regulatory pressure is a primary near-term determinant. Recent European restrictions under chemical authorisation frameworks and jurisdictional labelling requirements in places like California have accelerated reformulation timelines for several legacy brominated and chlorinated systems. This creates both compliance costs and commercial openings for halogen-free alternatives.
-
Raw-material volatility remains elevated. Supply-side constraints and production discipline in feedstock chains have periodically pushed prices higher and tightened availability for critical inputs such as mineral fillers and bromine intermediates. Buyers will need scenario-based cost models to stress-test formulations and customer economics under price shocks.
-
Trade and tariff noise has raised sourcing complexity. Recent adjustments to import duties on certain supplier-origin products require firms to reassess nearshoring, dual-sourcing, and transfer-price impacts when constructing supply strategies for 2026.
-
Application-level demand is diversifying: electronics and electrical segments are demanding higher-performance thin-film and polymeric solutions; transportation is prioritizing low-smoke, low-toxicity systems for EV battery enclosures and interiors; construction continues to require cost-efficient, code-compliant fillers and intumescent systems. Winning requires product configurability across these distinct value pools.
Competitive landscape — what the leaders are doing
The market exhibits a moderately consolidated structure: the top three firms control a meaningful share of global revenue, while the top five capture a clear majority of market value, leaving room for specialized players to thrive. Competitive dynamics are a mix of scale-driven commodity supply and innovation-led niche plays.
-
Clariant AG (Muttenz, Switzerland) — Deep portfolio strength in phosphorus-based and halogen-free flame retardants used across plastics, textiles and coatings. Recent product introductions demonstrate a push to win polyolefin conversion projects where regulatory compliance and processability matter.
-
BASF SE (Ludwigshafen, Germany) — Strong engineering-plastics position and coatings expertise; a player to watch for integrated solutions combining char-forming intumescent systems with polymeric co-additives for high-performance applications.
-
Lanxess AG (Cologne, Germany) — Focused on phosphate esters and formulations for foams and polyurethanes; a reliable channel to mattress, furniture and insulation segments where comfort and flame safety intersect.
-
Albemarle Corporation (Charlotte, NC, USA) — Major bromine-based supplier with scale in electronics and construction materials; strategic response to bromine supply constraints and price swings will determine regional competitiveness.
-
ICL Group Ltd (Tel Aviv, Israel) — Expanding capacity in phosphorus flame retardants; a contender for wire & cable and textile markets seeking polymeric and polymer-bound chemistries.
-
Huber Engineered Materials (Atlanta, GA, USA) — Specialist in fillers such as alumina trihydrate and magnesium hydroxide; value proposition centers on technical-support-driven substitution opportunities in composites and polymers.
-
FRX Polymers (Chelmsford, MA, USA) — Innovation-led supplier of oligomeric phosphorus-based polymers targeting high-performance thermoplastics, electronics and transportation applications.
-
Thor Specialties (Speyer, Germany) — Broad, application-focused offerings for textiles and specialty papers; plays to regulated markets where certification services are important.
-
Rio Tinto (London, UK) — Upstream provider of magnesium-hydroxide feedstocks; supply economics and mine-level reliability will affect downstream margin models.
-
Dow Inc. (Midland, MI, USA) — Integrated chemicals player with synergist and additive portfolios for polyolefins and styrenics; competitive advantage where polymer-additive interaction engineering is required.
Recent corporate actions—product launches, capacity expansions, and focused new-grade releases—underscore two strategic behaviors: (1) leaders are investing selectively in halogen-free and polymeric systems, and (2) specialist vendors are leveraging technical differentiation to capture routes-to-market in electronics and transport. The market concentration statistics suggest meaningful advantages for scale players (integration, global reach) while leaving growth pathways for innovation-centric companies.
Industry headwinds and accelerants
-
Regulatory accelerants: New listings and listings-related labelling requirements have compressed acceptable chemical choices in certain jurisdictions, intensifying demand for compliant alternatives and driving testing and certification spend.
-
Supply-side headwinds: Spot supply tightness for mineral fillers and halogen feedstocks in specific quarters has increased procurement risk. Procurement teams should model dual-sourcing and inventory strategies into 2026 budgets.
-
Price dynamics: Raw-material volatility favors manufacturers with hedging, tolling partnerships, or vertically integrated feedstock access. Commercial teams should quantify pass-through elasticity across key customer segments.
What the PW Consulting report delivers — practical content for 2026 action
The full Fire Retardant Additives Market report is constructed as a decision-support toolkit for corporate leaders and investors. Key deliverables include:
-
Demand and revenue forecast models (2026–2032) with scenario sensitivity to raw-material cost shocks and regulatory adoption curves.
-
Commercial playbooks for conversion from legacy halogen systems to halogen-free and polymeric phosphorus solutions, including margin impact templates and customer negotiation levers.
-
Supplier scorecards and a vetted short-list for strategic partnerships, joint development agreements, and tolling options.
-
Regulatory impact matrices and a monitoring calendar keyed to major jurisdictions, including compliance cost estimates and reformulation lead times.
-
Detailed competitor dossiers with capability maps, recent moves, and likely next steps by product line and region (note: granular subsegment shares and confidential price schedules are reserved for full subscribers).
-
Raw-material cost models and stress tests, including contract-renewal negotiation guides and hedging options for critical feedstocks.
-
M&A target profiles and integration checklists for roll-up strategies aimed at acquiring specialty chemistries or formulation capabilities.
Seven strategic imperatives for 2026
-
Prioritize halogen-free product platforms where customer upgrade cycles and regulatory timelines align; accelerate pilot projects with top-tier OEMs in electronics and transportation.
-
Invest in formulation services and regulatory-certification capabilities as a commercial differentiator—customers increasingly value 'end-to-end' validated solutions.
-
Hedge supply risk through diversified raw-material sourcing, commercial inventory cushions for critical inputs, and selective upstream partnerships.
-
Use scenario planning to quantify margin sensitivity to commodity swings and tariff fluctuations; build price-escalation clauses into long-term contracts where feasible.
-
Explore bolt-on acquisition targets that deliver specific application know-how (e.g., thin-film phosphorus polymers, intumescent coatings, specialty fillers) rather than general scale alone.
-
Differentiate with sustainability and circularity narratives (e.g., lower-toxicity formulations, recyclability-friendly designs) that resonate with procurement teams under ESG mandates.
-
Embed rapid-response formulation teams to shorten lead times for customers facing sudden regulatory changes or component shortages.
How to use this analysis in 2026 decision cycles
For C-suite and business-unit leaders, this analysis should be treated as both a market map and an active playbook. Use the forecast and scenario outputs to set realistic capacity expansion profiles and to stress-test existing supply contracts. For product and commercial teams, the recommended playbooks will accelerate win rates in conversion projects. For corporate development, the report’s target-screening approach reduces diligence time by highlighting capability gaps and valuation sensitivities specific to flame-retardant chemistries.
Next steps — where to get the full intelligence
This introduction highlights the strategic contours you need for 2026 planning, while preserving the detailed subsegment economics, contractual templates, and confidential supplier benchmarking that power executable programs. PW Consulting’s full Fire Retardant Additives Market report contains the granular models and annexes required to operationalize the imperatives above. To access the comprehensive datasets, scenario workbooks, and vendor scorecards, please visit PW Consulting’s report page or contact our industry practice lead for a tailored briefing and sample extracts.
For detailed analysis of this topic, please visit the official page: Fire Retardant Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial GBL Market to Hit USD 4,435.2 Million in 2025
By PW Consulting, 2026-07-13
Industrial-Grade Gamma-Butyrolactone (GBL): Strategic Outlook for 2026 — A PW Consulting Market Primer
Executive snapshot
As global manufacturing rebounds and battery, electronics and specialty chemical supply chains reposition for 2026, industrial-grade gamma-butyrolactone (GBL) has shifted from a niche solvent to a strategic commodity in multiple high-value value chains. Our PW Consulting analysis frames this shift with rigorous time-series market sizing, demand-driver mapping and supplier-level intelligence designed to inform near-term procurement, capacity and M&A decision-making.
Industrial Grade Gamma Butyrolactone Gbl Market
Market snapshot — growth trajectory and concentration
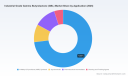
Between 2020 and 2025, the industrial-grade GBL market experienced steady expansion, and our base-year assessment (2025) places the global market above the mid‑billion‑dollar mark. From the base year, our forecast through 2032 anticipates continued growth underpinned by battery and electronics demand, industrial cleaning and specialty solvent applications — a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window. By the end of the forecast horizon the market is projected to materially exceed current levels, reflecting both structural volume growth and product-premium adoption.
Industrial Grade Gamma Butyrolactone Gbl Market
Market concentration is meaningful: the top three players control a substantial share of the market, and the top five further consolidate supply. This level of concentration implies that supplier strategy — from feedstock sourcing to capacity discipline and product stewardship — will exert outsized influence on pricing and availability in 2026.
Industrial Grade Gamma Butyrolactone Gbl Market
Why this matters for 2026 decision-makers
- Procurement resilience: Buyers in battery, capacitor, electronics and specialty coatings need deterministic procurement strategies. Given concentration dynamics and recent supplier pricing actions, locking in flexible offtake terms, multi-sourcing where feasible, and indexed contracts will reduce exposure to episodic price moves and spot volatility.
- Capital allocation for producers: Investment decisions in new or debottlenecked GBL capacity must be justified against predictable downstream demand vs. potential feedstock volatility. Our scenarios quantify payback sensitivities across conservative and accelerated demand paths for 2026–2029.
- Product & portfolio strategy: High-purity grades and sustainability-linked product variants are moving from differentiators to table-stakes in certain end markets. Manufacturers and formulators should adopt tiered product strategies tied to traceability, PCF (product carbon footprint) disclosures and specs demanded by electronics and pharma customers.
- Regulatory compliance and market access: Evolving controls across major jurisdictions influence supply chain design, documentation and transport logistics. Firms must incorporate regulatory scenario planning into 2026 sourcing and distribution models to avoid timedelivery and compliance penalties.
Key market dynamics shaping 2026
- Downstream pull from energy storage and electronics: Demand growth tied to lithium-ion battery electrode chemistries and high-value electronics continues to be a primary structural driver for industrial-grade GBL. Suppliers integrated into BDO/THF/GBL chains are better positioned to capture this pull, provided they align capacity with quality and sustainability requirements.
- Feedstock and cost transmission: 1,4‑Butanediol (BDO) remains the primary upstream feedstock; its regional price trajectories and availability materially influence GBL margins and tactical pricing. Producers with integrated or hedged access to BDO enjoy a competitive advantage during periods of feedstock tightness.
- Supplier actions and capacity moves: Recent supplier behavior signals both discipline and selective expansion. For example, one leading producer completed a measured capacity ramp to serve high‑purity demand in electronics and EV supply chains, while another announced a global price adjustment for derivative solvents in response to feedstock pressures. These moves underscore a market balancing act between meeting premium demand and preserving margin.
- Sustainability & product stewardship: Sustainability claims and lifecycle disclosures are escalating from marketing to procurement criteria. Several major players are publishing PCF and value‑chain sustainability updates, which affect bid competitiveness for customers with net‑zero roadmaps.
What the PW Consulting report delivers — practical, actionable intelligence
This publication is structured to be a working tool for managers, not an academic exercise. Highlights include:
- Proven market-sizing methodology with transparent assumptions and reconciled historicals for 2020–2025 and an explicit, stress-tested forecast for 2026–2032.
- Demand-driver decomposition linking industrial end uses, purity tiers and substitute dynamics to volume trajectories — presented as scenario outputs rather than raw segment tables to preserve commercial sensitivity.
- Supply-mapping by plant, technology route and vintage, including an availability-risk index that rates facilities for feedstock exposure, regulatory risk and expansion lead times.
- Price-dynamics model that simulates margin outcomes under differing BDO cost pathways and utilization shocks — intended for CFOs and commodity managers to stress-test procurement terms.
- Competitive benchmarking and playbooks: supplier scorecards, value‑chain integration matrices and tactical recommendations for vertical players, chemical distributors and formulators.
- Regulatory & compliance compendium covering major frameworks and actionable steps for compliance, classification and cross-border logistics in 2026.
- M&A and partnership screens identifying criteria, screening thresholds and an early‑warning list of mid‑cap assets and technologies that fit acquisition profiles for strategic buyers.
Competitive landscape — selected profiles and implications
The GBL market is served by a mix of integrated global majors, regional specialists and specialty chemical houses. Key players exhibit differing strategic rhythms:
- Integrated majors — global chemical groups with BDO-to-GBL integration emphasize supply reliability and can offer sustainability-anchored variants. Their strategic advantage rests on feedstock integration, regulatory expertise and the ability to serve high‑spec end markets.
- Specialty producers — several regional manufacturers focus on high‑purity grades and niche technical service. Their agility and customer intimacy make them preferred partners in fast-moving electronics and pharmaceutical supply chains.
- Value-focused players — companies with broad derivatives portfolios compete on cost and scale, often impacting commodity-grade segments and available spot volumes during tight markets.
Recent company developments illustrate these dynamics: a major producer completed a targeted capacity increase at a strategic plant to service high‑purity demand; another supplier implemented a global pricing adjustment for BDO derivatives in response to upstream pressures; and several firms have accelerated sustainability disclosures across the BDO/THF/GBL value chain. These actions have immediate implications for contract negotiations, spot market behavior and supplier selection in 2026.
Regulatory and risk landscape
- Regulatory frameworks in key jurisdictions continue to tighten controls on precursors and restricted chemicals. Buyers and logisticians must ensure robust documentation, classification and handling protocols to avoid delays and potential sanctions.
- Export/import licensing rules and product-specific exemptions in certain markets change the economics of cross-border trade; firms should maintain a dynamic compliance register and integrate regulatory scenarios into supply‑chain planning.
- Environmental, health and safety (EHS) compliance and process safety investments remain non‑negotiable. Suppliers with demonstrable EHS performance can reduce total cost of ownership for major customers.
How to use this analysis in 2026 planning
- Procurement teams: adopt a two-tier contracting approach — strategic long-term agreements for critical volumes plus a disciplined spot policy tied to our price-model outputs.
- Corporate strategy & M&A: use the supplier scorecards and acquisition screens to prioritize targets that add feedstock integration, high‑purity capability or sustainability credentials.
- Plant and operations: apply the supply‑risk index when scheduling turnarounds and negotiating tolling arrangements; assess debottleneck options against short‑cycle demand scenarios.
- R&D and product management: align product roadmaps to purity and sustainability tiers where willingness to pay is rising, especially in electronics and battery applications.
Conclusion — the strategic window for 2026
GBL has moved into a strategic category for firms exposed to high‑value electronics, battery and specialty chemical markets. The combination of demand-side momentum, concentrated supply and an evolving regulatory backdrop creates a narrow window for decisive action in 2026. Whether the priority is securing feedstock‑linked capacity, refining procurement strategy, or executing bolt-on M&A, the right intelligence can materially change outcomes.
PW Consulting’s Industrial-Grade GBL Market study delivers the actionable evidence and scenario tools required to make those choices with conviction — while preserving the granular, commercially sensitive segment data for subscribers. For access to full segment-level analytics, plant-by-plant mappings, and the interactive price/margin model, visit our report page and request the comprehensive dataset and executive workshop tailored to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Industrial Grade Gamma Butyrolactone Gbl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Melanin Market 2026: Strategic Primer for Decision-Makers
As companies finalize budgets and mid-term strategies for 2026, a focused understanding of the melanin market—its structural drivers, opportunity vectors, and regulatory fault lines—will be a differentiator. PW Consulting’s Melanin Market study synthesizes historical performance, a 2026–2032 forecast, and actionable playbooks to support commercial, R&D, and M&A decisions. This article serves as a trailer: it distills the high-level strategic takeaways and methodological rigour behind the full report while intentionally omitting granular segment tables to prompt readers to consult the primary research for detailed allocations and figures.
Melanin Market
Why Melanin Matters to 2026 Strategy
-
Cross-sector relevance: Melanin is no longer a niche biochemical. It has migrated from laboratory reagents into cosmetics, biomedical therapies, and emergent bio-electronics applications—creating cross-industry demand dynamics that require integrated commercial thinking.
Melanin Market -
Predictable expansion with complexity: The market exhibits steady compound growth underpinned by both traditional consumption and new technological use-cases. PW Consulting’s baseline shows a compound annual growth rate (CAGR) of 5.82% over the forecast window, reflecting both organic adoption and incremental use-cases in adjacent sectors.
Melanin Market -
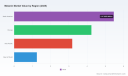
Concentration and fragmentation: The market is partially consolidated—our concentration metrics (CR3 ~42.2%, CR5 ~56.4%) indicate meaningful scale advantages for top players, while a long tail of specialized producers and reagents suppliers continue to serve niche research and formulation needs.
Macro Snapshot (Context, Not a Spreadsheet)
From 2020 through 2025, the total market demonstrated resilient expansion, and our forecast to 2032 anticipates continued growth driven by the confluence of cosmetic innovation, biomedical translation, and material science applications. The report documents year-on-year movements across 2020–2025 and provides a detailed 2026–2032 scenario set to help leaders stress-test investments against demand variability and regulatory shocks. For organizations planning capital allocation or new product timelines in 2026, this macro trajectory is the bedrock input for sizing and phasing decisions.
What the Full Report Contains (Practical, Executable)
-
Data backbone: Harmonized time series (2020–2025) and a transparent forecasting methodology for 2026–2032, with sensitivity testing under alternate demand and regulatory scenarios.
-
Market architecture: Layered segmentation by region, product type, and application—presented with interactive slicers in the companion dashboard so users can model “what-if” mixes without redoing the analytics.
-
Supply-chain heatmaps: Supplier footprints, bottlenecks, and raw-material exposure analyses—built from trade flows, customs data, and proprietary supplier interviews—highlight where single-node risks and substitution pathways exist.
-
Regulatory and standards playbook: Step-by-step guidance for certifying natural and synthetic melanin for cosmetic and pharmaceutical uses, including recommended testing panels, audit templates, and a benchmarking matrix against major regulatory regimes.
-
Commercial scorecards and go-to-market blueprints: Pricing sensitivity models, channel economics for B2B and B2C pathways, and four archetypal GTM roadmaps (licensing, direct supply, co-development, platform-embedded) with milestone KPIs for the first 24 months.
-
Technology and R&D roadmap: Comparative analysis of extraction, biosynthesis, and chemical synthesis routes with CAPEX/OPEX back-of-envelope models, time-to-market estimates, and recommended partnership profiles.
-
Investment and M&A playbook: Deal screening templates, valuation comparables, and integration checklists tailored to the melanin value chain, from reagent suppliers to finished-formulation players.
-
Risk register and mitigation playbook: Scenario-driven risk matrices (regulatory, sourcing, reputational), insurance considerations, and agile contingency plans to minimize revenue disruption.
Competitive Landscape—Who Matters and Why
The melanin ecosystem is diverse: it includes specialist producers of natural extracts, manufacturers of synthetic reference materials, global distributors serving life sciences, and fast-moving ingredient houses that package bioactive formulations for cosmetics. Below are strategic profiles of representative players and what their positioning implies for 2026 action.
-
BIOFOUNT (Beijing / Amsterdam) —Scale + vertical focus. With production capacity targeted at high-purity lines, BIOFOUNT exemplifies players seeking to capture pharmaceutical-grade demand. For partners, they offer supply security; for competitors, they signal rising technical thresholds for entry.
-
The Innovation Company (Dreux) —Natural ingredient commercialization. Its Creanatural Sepia Melanin demonstrates how natural-origin branding and specific functionalities (UV absorption, antioxidant) can drive adoption in premium cosmetics segments—useful context for positioning and premiumization strategies.
-
Biosynth (Staad) —Standards and research reagents. Companies like Biosynth are critical nodes for reproducibility and preclinical work; their role as reference material providers accelerates translational timelines for therapeutics and advanced materials.
-
AdooQ BioScience, Thermo Fisher, MilliporeSigma, Spectrum Chemical, BOC Sciences —Distribution and standardization. These firms supply the research and industrial base with high-purity materials and analytical-grade reagents, representing channels that new entrants must navigate for lab-to-market validation.
-
Hubei Xinkang —Bulk chemical supplier. Its focus on volume supply highlights the cost-competitive segment of the value chain and underlines the substitution risk between high-purity and commodity-grade routes.
Strategic implication: incumbents with integrated capabilities—from synthesis to regulatory dossiers—are best placed to capture value in regulated end-markets. Niche innovators can succeed by pairing technical differentiation with channel partnerships that lower commercialization friction.
Recent Market Signals and Their Strategic Meaning
-
Product innovation spike: 2026 and late-2025 product launches indicate two parallel trends—formulas that modulate melanin biology (e.g., anti-gray hair, pigmentation modulators) and digital personalization platforms trained on melanin-rich skin datasets. Players should prepare for combined product–platform competition where ingredient attributes are embedded into software-driven personalization.
-
Regulatory friction: A significant share of producers report certification hurdles for natural melanin in pharmaceutical uses, while a non-trivial fraction of shipments experienced delays due to mismatched regional standards. This is not a niche compliance headache—it directly affects time-to-revenue and inventory economics.
-
Raw material availability: Environmental and land-use constraints have materially limited access to some plant-based precursors. Expect continued upward pressure on certain natural-extract input costs and a widening role for biosynthetic substitutes.
-
Standards momentum in China: Recent national-level activity focused on cosmetic raw material safety signals regulatory tightening and creates both risk and opportunity for suppliers that can achieve certification early.
2026 Playbook — Four Practical Moves for Firms
-
Lock in supply optionality: Diversify precursor and finished-goods sources across synthesis routes (chemical, biosynthesis, sepia/biomass) and vendor tiers. Prioritize conditional contracts that allow volume flexibility to respond to demand bursts.
-
Invest in regulatory capital: Translate certification effort into commercial advantage. Firms that standardize testing regimens and pre-certify batches for multiple jurisdictions will shorten sales cycles and command premium terms.
-
Partner across the value chain: Co-development with cosmetic formulators and universities, licensing agreements with platform players, and distribution pacts with established reagent houses accelerate market access without full vertical build-out.
-
Differentiate through application depth: Target high-value verticals—advanced biomedical applications and bio-electronics—where doubling down on purity and traceability yields disproportionate margins compared with commodity markets.
What We Recommend Executives Do Next
-
Use the PW Consulting scenario toolkit to stress-test planned product launches against the regulatory and raw-material scenarios laid out in the full report.
-
Commission a short-form supply-chain due diligence for any new supplier from markets with known certification misalignment; our appendices include templates that reduce time-to-complete.
-
Prioritize partnerships with distribution leaders or standards providers if your route-to-market depends on rapid clinical, cosmetic, or analytical adoption.
Final Note — Why This Report Matters for 2026
Decisions made in 2026—around where to allocate R&D dollars, whether to integrate production, and how to structure regulatory roadmaps—will define competitive positioning for the rest of the decade. PW Consulting’s Melanin Market report supplies both the high-level growth thesis (a mid-single-digit CAGR and a clear trajectory from 2025 levels to 2032) and the granular, actionable frameworks companies need to capture disproportionate share. This article previews our findings and the practical playbooks included in the full study; for the complete dataset, interactive slicers, and downloadable due-diligence templates, please consult the full report.
For detailed analysis of this topic, please visit the official page: Melanin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Tailgate Radar Market to Grow at 8.65% CAGR to 2032
By PW Consulting, 2026-07-13
Electric Tailgate Radar Market — Strategic Briefing for 2026
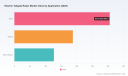
This briefing distills the strategic implications of PW Consulting’s forthcoming Electric Tailgate Radar Market study and explains why procurement, product, and corporate strategy teams should prioritise the report when making decisions in 2026. The study consolidates five years of historical performance (2020–2025), uses 2025 as the base year, and projects the market across a 2026–2032 forecast horizon. At a compound annual growth rate (CAGR) of 8.65%, the market trajectory and concentration dynamics present both clear opportunities and specific risks for OEMs, Tier‑1 suppliers, semiconductor vendors, and investors.
Electric Tailgate Radar Market
Executive snapshot: what this briefing conveys
- Macro view: the electric tailgate radar market has more than doubled since 2020 and is on a steady growth path into 2032 (base year 2025, forecast period 2026–2032), driven by feature demand, cost declines, and regulatory alignment for mmWave operation.
- Why it matters in 2026: component availability, standards compliance, and the competitive supplier landscape will determine which OEM programs secure reliable, scalable hands‑free tailgate experiences.
- What PW Consulting’s full report delivers: actionable procurement playbooks, vendor scorecards, technology roadmaps, and scenario-based financial models designed for near-term sourcing and multi‑year product planning.
Market trajectory and the investment case
The broader market has expanded materially from the early 2020s into 2025 and is forecast to continue growing through 2032. This expansion is underpinned by three converging forces: consumer preference for convenience and perceived luxury, OEM standardisation of perimeter sensing for safety and regulatory compliance, and incremental cost reductions in millimetre-wave (mmWave) components and integration platforms. For decision‑makers, the headline numbers — including the 8.65% CAGR embedded in our forecast — quantify the scale of opportunity and justify near-term investment in integration, testing, and procurement pipelines.
Electric Tailgate Radar Market
Crucially, the market is not homogeneous. Adoption curves differ by vehicle architecture, regional regulatory timetables, and OEM platform strategies. That heterogeneity creates differentiated earnings potential for component suppliers and integration partners — and it is deliberately where the tactical value of PW Consulting’s study becomes most usable: to translate macro growth into programme-level decisions without overexposure to commoditisation risk.
Electric Tailgate Radar Market
Regulatory and supply‑chain environment (implications for 2026)
- Standards and frequency compliance: Updated regulatory frameworks for radar operation (including recent UN ECE and regional telecom authority updates) have clarified permissible bands and interoperability expectations for 79 GHz implementations. For vehicle programmes launching in 2026 and beyond, alignment with these standards is a gating factor for cross‑market rollouts.
- Functional safety expectations: Industry guidance reinforces ISO 26262 requirements for obstacle detection systems; ASIL‑B compliance is now a common expectation for radar sensors used in power tailgate obstacle mitigation. Programmes that treat functional safety as an afterthought will face integration delays and certification bottlenecks.
- Semiconductor supply dynamics: Supply‑chain normalisation has improved lead times for mmWave radar chips in early 2026, reducing component lead times materially versus the constrained years that preceded it. This change improves the feasibility of multi‑sourcing strategies and shortens new program ramp timelines.
Competitive landscape — what matters when choosing partners
The vendor landscape combines established automotive suppliers, specialist radar vendors, and semiconductor incumbents. Market concentration metrics reveal moderate consolidation: the top three firms capture a meaningful portion of sales, while the top five increase that share further, creating a marketplace where technical differentiation and program relationships matter more than pure scale alone.
- Tier‑1 integrators: Suppliers with electro‑mechanical system expertise and proven production ramps — particularly those offering turnkey electric tailgate drives and sensor integration — are best positioned to win vehicle content. Their value proposition is the consolidation of mechanics, control electronics, and validated sensor interfaces, which shortens OEM validation cycles.
- Radar specialists and module providers: Companies focused on mmWave sensing bring specialized detection algorithms and compact form factors that matter for packaging and false‑trigger robustness. Their competitive edge is product maturity in real‑world foot‑gesture detection and reduced nuisance activations in complex rear bumper environments.
- Semiconductor and IC suppliers: Chip providers enable system differentiation through advancements in signal processing, low‑power operation, and integration density. Their roadmaps constrain or enable product features; selection of an IC family is a multi‑year commitment for integrators and OEMs alike.
To illustrate the strategic positioning that matters (without disclosing proprietary dynamics), consider these vendor archetypes represented in the market: specialised radar companies that supply compact 79 GHz kick sensors optimized for hands‑free gestures; Tier‑1s that provide integrated power tailgate systems with validated radar interfaces; and semiconductor firms offering mmWave SoCs and radar front‑ends enabling feature differentiation. Recent market activity underlines these archetypes: a series production order for a 79 GHz kick sensor demonstrates OEM readiness for high‑frequency mmWave solutions; trade show showcases highlight integrators revealing hybrid sensor stacks combining UWB and radar; and SoC advancements continue to boost the performance envelope for contactless control.
Report contents — practical outputs for 2026 decision cycles
The full PW Consulting Electric Tailgate Radar Market study is structured to move teams from insight to action. Key deliverables include:
- Market sizing and forecast (2020–2032) with scenario variants tied to component cost curves and regulatory horizons.
- Vendor scorecards and procurement playbooks that evaluate suppliers across technical fit, production readiness, safety compliance, and commercial terms.
- Integration checklists and test protocols for radar kick sensor systems, including guidance on ASIL‑level testing, EMC/EMI strategies, and environmental validation.
- Supply‑chain resilience frameworks and dual‑sourcing decision matrices reflecting the improved but still fragile semiconductor environment.
- Go‑to‑market and product roadmap templates for OEMs considering platform‑level adoption versus optional content strategies.
- Financial models and TCO calculators that convert market forecasts into programme‑level revenue and margin projections under conservative and aggressive uptake scenarios.
Strategic playbook — 6 pragmatic moves for 2026
- Lock in standards compliance early: require suppliers to evidence UN/region‑specific frequency conformity and ISO 26262 artefacts during RFQs to avoid downstream re‑work.
- Prioritise integration partners with validated production ramps: choose vendors who can demonstrate series production orders or equivalently rigorous pilot programmes.
- Adopt hybrid sensing roadmaps: combine radar with UWB or proximity sensors selectively to optimise user experience and reduce false activations in complex rear‑end geometries.
- Mitigate single‑source risk: build dual‑sourcing strategies for critical mmWave components while negotiating volume de‑risk clauses tied to lead‑time improvements.
- Embed safety early: require ASIL‑level validation gates and obstacle detection failure mode analyses in supplier contracts to accelerate homologation and reduce recall risk.
- Use pilot programmes to de‑risk UX: short, instrumented pilot runs in diverse climatic and regulatory environments uncover edge cases that lab tests miss and protect brand experience at launch.
Why PW Consulting’s research is essential for 2026 decision‑making
Procurement and product leaders face a narrow window in 2026 to lock design choices and supplier commitments that will govern platform roadmaps through the late 2020s. The combination of steady market growth, evolving standards for mmWave operation, and improved component availability creates an environment where early but well‑informed investments yield sustained advantage. PW Consulting’s study converts macro signals — the measured CAGR and aggregate market size trajectory — into concrete vendor comparisons, risk matrices, and cost scenarios that materially reduce execution risk.
Importantly, this briefing purposefully omits the granular regional, type, and application split tables that underpin the full analysis. Those segment‑level datasets, supplier program timelines, and downloadable procurement templates are available only in the complete report — the content prospective buyers tell us delivers immediate ROI by shortening procurement cycles and improving launch predictability.
Closing: immediate next steps
Teams preparing for 2026 program decisions should prioritise three actions this quarter: (1) secure access to the full market study and vendor scorecards, (2) schedule cross‑functional workshops to align safety, procurement, and systems engineering on ASIL and frequency compliance requirements, and (3) commence pilot validations with at least two radar or hybrid sensor suppliers to validate real‑world gesture reliability and integration timelines.
PW Consulting’s Electric Tailgate Radar Market study is designed to be the single operational reference for those actions — marrying market sizing, regulatory context, supplier intelligence, and executable procurement collateral into a compact package for 2026 decision cycles.
For a guided walkthrough of the report’s practical modules and the vendor playbooks, request access through our publication page. Our research team can provide a tailored briefing that maps the analysis directly to your product roadmaps and sourcing calendar.
For detailed analysis of this topic, please visit the official page: Electric Tailgate Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


