



PW Consulting: Fuel Vapor Canisters Market to grow at 3.42% CAGR through 2032
By PW Consulting, 2026-07-13
Automotive Fuel Vapor Canisters Market — Strategic Preview for 2026 Decisions
Executive trailer: what this preview delivers
As original equipment manufacturers (OEMs), Tier‑1 suppliers, aftermarket specialists and private‑equity investors plan for the critical 2026 decision window, the Automotive Fuel Vapor Canisters market presents a mix of steady growth, regulatory-driven technology demand and concentrated supplier economics. This preview synthesizes the macro trajectory (historical performance and base‑case forecast through 2032), the regulatory inflection points that will shape product specifications, and the supplier dynamics that matter when allocating R&D, procurement and M&A capital. The aim is to show the analytical depth that informs PW Consulting’s full study while intentionally withholding the granular segmentation tables and line‑item forecasts that are available in the full report.
Automotive Fuel Vapor Canisters Market
Market snapshot: scale, rhythm and near‑term outlook
Between 2020 and 2025 the market expanded modestly, reflecting the interaction of vehicle parc dynamics, tightening evaporative‑emission regulations, and the continued role of combustion powertrains in global mobility. In 2025 the global market reached approximately USD 2.95 billion. Under PW Consulting’s baseline modelling — which incorporates regulatory timelines, OEM cycle plans and material‑supply assumptions — the market is expected to grow at a compound annual growth rate of about 3.42% through the 2026–2032 forecast window, reaching an estimated market size north of USD 3.7 billion by 2032. This is a growth profile of steady, regulation‑anchored demand rather than explosive expansion, and it implies different strategic priorities than markets driven primarily by disruptive technology adoption.
Automotive Fuel Vapor Canisters Market
Why 2026 is a strategic inflection
- Regulatory alignment and product specifications: New evaporative emission test procedures and running‑loss standards adopted by major regulators have a phase‑in cadence that centers on 2026–2028. These standards do more than tighten acceptable emissions — they prescribe test protocols, working‑capacity criteria and size/pressure thresholds that materially affect canister designs, media formulations and system packaging.
- OEM program timing: Vehicle program development cycles mean that specification freezes and supplier selection decisions made in 2026 influence model years launching through the late 2020s. Suppliers that can demonstrate compliance at program sign‑off stand to win multi‑year content partnerships.
- Supply chain tightening for activated carbon: The adsorbent media at the heart of most canisters is subject to feedstock variability and capacity bottlenecks. Securing validated media—both in performance and in sustainable sourcing—becomes a procurement priority as OEMs push for validated high‑capacity media to meet new testing regimes.
What the PW Consulting report contains (practical, decision‑grade content)
The full study is built to support capital allocation, product roadmaps and commercial negotiation through:
Automotive Fuel Vapor Canisters Market
- Proprietary market sizing and a clear, auditable forecast model (2026–2032) that ties unit volumes to vehicle production scenarios, regulatory adoption curves and technical upgrades in canister design.
- Technology and test‑protocol gap analysis that maps regulatory requirements (e.g., running loss, butane working capacity and breakthrough criteria) to product attributes — media capacity, flow characteristics, purge strategies and canister sizing constraints.
- Procurement playbooks for activated carbon and composite housings: supplier scorecards, risk heatmaps and inventory/contract structures to mitigate feedstock and freight volatility.
- Go‑to‑market recommendations for OEMs and aftermarket players, including channel segmentation, warranty risk assessment and pricing sensitivity under different regulatory and fuel blend scenarios (gasoline, ethanol blends, LPG and methanol variants).
- Deal rationales for M&A and JV candidates, including financial thresholds, integration pitfalls and a framework for valuing proprietary media formulations or modular canister platforms.
Concrete tools include a scenario‑driven forecast workbook, supplier negotiation checklists and regulatory compliance matrices — all designed for immediate operational use by procurement, engineering and corporate development teams.
Competitive landscape: who matters and why
The market is commercially concentrated: a limited set of established suppliers dominate global content for activated carbon canister systems while a mix of aftermarket specialists and materials producers shape the complementary value chain. The players profiled in the study illustrate the strategic choices facing buyers and investors:
- PHINIA Inc. — A specialist with deep expertise in modular carbon canisters and integrated OBD/evaporative solutions. PHINIA’s long product lineage and modular approach make it a natural partner for OEMs that require flexible tank‑size support and fuel‑blend compatibility.
- A. Kayser Automotive Systems GmbH — A market leader in activated carbon canister systems, with full systems capability (valves, ventilation and purge lines). Kayser’s systems depth positions it to capture engineering content beyond the canister itself, which raises competitive barriers to smaller suppliers.
- MAHLE GmbH — An OEM‑grade supplier with integrated fuel management platforms. MAHLE’s scale and engineering resources allow it to drive system integration wins where thermal and packaging constraints must be solved across powertrain architectures.
- Standard Motor Products, Inc. (SMP) — A dominant aftermarket player with an expansive EVAP program and recent program and product expansions in 2025–2026. SMP’s aggressive coverage on late‑model applications underscores aftermarket growth opportunities and the importance of spares availability for in‑service fleets.
- MotoRad — Focused on EVAP canisters for replacement and service markets; a reminder that aftermarket channel strategies and warranty economics can support differentiated pricing and margin profiles versus OEM supply.
- Ingevity Corporation — A leading activated carbon producer whose hardwood‑based media is widely used in automotive EVAP systems. Media suppliers like Ingevity influence technical capability, validation timelines and, crucially, raw material availability.
Recent public moves — for example, SMP’s program expansions announced in mid‑2025 and early‑2026 — signal the aftermarket’s proactive response to fleet replacement needs and late‑model coverage. Regulatory updates (notably CARB’s 2022 adoption of new evaporative test procedures) functionally elevate the technical bar for all suppliers and accelerate qualification timelines for media and modules.
Regulatory & material dynamics that will shape supplier economics
- Test protocols become product drivers: Rules that define working‑capacity (for example, butane loading and 2‑gram breakthrough criteria), stabilization cycling and purge protocols create engineering targets. Suppliers that invest in test‑bench validation and can provide OEMs with documented compliance will command a premium in supplier selection.
- Feedstock and capacity risk for activated carbon: High‑capacity, durable adsorbent media is not a commoditized input in automotive EVAP contexts. Variability in feedstocks and converting capacity can create multi‑quarter qualification lead times; buyers should consider multi‑sourcing, inventory buffer strategies and strategic contracts with performance clauses.
- Design complexity and system integration: As evaporative regimes broaden to cover running loss, diurnal and hot‑soak emissions, canister solutions increasingly need multi‑layer media, high‑flow passages and integrated control valves. Suppliers with systems capability (canister + valves + lines + OBD integration) extract higher content per vehicle and create switching costs.
Practical strategic moves for executives in 2026
- For OEMs and Tier‑1s: Fast‑track canister validation projects tied to regulatory deadlines; prioritize suppliers that can demonstrate test‑bench data under the adopted protocols. Incorporate performance‑based contracting with media suppliers (e.g., warranty‑linked adsorption metrics) to de‑risk compliance.
- For suppliers and materials firms: Differentiate on validated media performance and systems integration capability. Consider modular platforms that allow tuning of media volumes and purge strategies across vehicle programs to increase addressable content without reinventing packaging.
- For aftermarket players: Leverage late‑model coverage expansions and warranty repair trends to build recurring revenue streams. Strengthen logistics and SKU rationalization to reduce time‑to‑repair for high‑utilization fleets.
- For investors and M&A teams: Target bolt‑on acquisitions that add validated media capacity, systems integration know‑how or regional manufacturing footprint in high‑volume OEM hubs. Avoid assets that are long on product but lack documented compliance to the latest test procedures.
Risk matrix — what could upset the base case
- Accelerated EV adoption in specific markets: Faster‑than‑expected electrification in key regions would reduce demand for ICE canisters and compress the market sooner than modelled.
- Feedstock shocks: Disruptions in activated‑carbon feedstock or conversion capacity could spike prices and materially affect supplier margins and qualification timelines.
- Regulatory variance: Divergent test interpretations or delayed implementation in major markets can create asymmetric adoption and inventory build cycles; this favors suppliers with geographic diversification.
Conclusion — the 2026 decision agenda
For organizations making strategic commitments in 2026, the fuel vapor canister market requires a focused, evidence‑based approach: prioritize validated technical compliance, secure media supply under performance guarantees, and evaluate partnerships that raise system‑level content rather than simply component supply. The market’s steady growth and regulatory anchoring create predictable opportunity — but converting that into durable commercial advantage hinges on execution across engineering validation, procurement design and channel strategy.
Next step
PW Consulting’s full Automotive Fuel Vapor Canisters Market report provides the detailed segmentation, supplier scorecards, scenario financials and downloadable forecast model needed to operationalize the recommendations above. To access the proprietary tables, regional and application splits, and the complete forecast workbook, please consult the report brief on our website or contact our industry team for a demonstration.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Rescue Drone Market Insights — Projected 12.45% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Emergency Rescue Drone Market: Strategic Brief for 2026 Decision-Makers
Executive teaser
As public safety agencies, humanitarian organizations, and defense customers accelerate adoption of unmanned systems for life-saving missions, the Emergency Rescue Drone market has moved from niche proof-of-concept deployments into mainstream operational planning. Our new PW Consulting market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—quantifies that acceleration, demonstrates the economic runway (12.45% CAGR through the forecast), and translates that macro momentum into immediate, executable actions for procurement, operations, and strategic investment in 2026.
Emergency Rescue Drone Market
Why this study matters for 2026
Three converging forces will make 2026 a pivotal year for organizations that plan to field, partner around, or invest in emergency rescue drones: regulatory normalization (notably enabling Drone-as-First-Responder workflows), supply-chain hardening for government and public-safety procurements, and rapid technology maturations in autonomy, sensing, and system integration. PW Consulting’s report synthesizes market-size trajectory (historic growth through 2020–2025 and a robust projection to 2032, in USD Million) with operational case studies and procurement-grade decision tools so that leadership teams can make defensible, time-sensitive choices this year.
Emergency Rescue Drone Market
Macro snapshot (what the numbers tell you)
- Market momentum: The market more than doubled over the 2020–2025 historical window, and the study’s baseline and forecasts—expressed in USD Million, base year 2025—show sustained, high-single to low-double-digit expansion into the early 2030s.
- Growth driver profile: Adoption is being driven by maturity in autonomous navigation, integration of thermal/EO payloads for SAR, and institutional programs (e.g., Drone-as-First-Responder) that convert pilot projects into standardized mission sets.
- Industry structure: Concentration metrics indicate a market with meaningful incumbent influence but open spaces for specialized entrants — CR3 and CR5 metrics in the study quantify this balance and help frame partnership versus build decisions.
What the report contains — practical, procurement-ready deliverables
This is not a conceptual white paper. PW Consulting’s Emergency Rescue Drone Market study is a playbook for action. Highlights of the deliverables:
Emergency Rescue Drone Market
- Validated market-sizing model (USD Million) spanning 2020–2032, with scenario-based sensitivities tied to regulatory shifts and technology adoption curves.
- Procurement scorecards and vendor comparison templates designed for governmental purchasing officers and NGO tech leads (criteria include NDAA compliance risk, autonomy maturity, payload modularity, sustainment costs, and lifecycle replacement schedules).
- Operational deployment playbooks for Drone-as-First-Responder (DFR) prepositioning, including site-selection heuristics, maintenance cadences, and staffing models informed by our field interviews and simulation workstreams.
- CapEx/Opex modeling tools for program managers that convert performance specs into budget forecasts and ROI timelines under multiple mission profiles (urban SAR, disaster logistics, medical supply delivery).
- Supplier due-diligence dossier templates, including red-team checklists for supply-chain security, NDAA-compliance verification paths, and component lineage mapping (critical for government programs).
- Technology roadmaps and integration blueprints identifying where autonomy, multi-spectral sensing (thermal + EO), BVLOS enablers, and hybrid airframes will change total cost of ownership.
- M&A and partnership heatmaps showing where strategic acquisitions, licensing, or OEM partnerships make sense depending on your corporate objectives.
Note: In keeping with the “trailer” approach of this executive brief, detailed segment-level tables and vendor scoring matrices are reserved for the full report.
Competitive landscape — who matters and why
The market is shaped by a mix of specialized innovators and established aerospace contractors. Our competitor analysis focuses on operational readiness, product differentiation, and procurement fit for public-safety and defense customers.
- BRINC Drones (Seattle, WA; https://brincdrones.com) — Tactical specialization and mission-first engineering are BRINC’s distinguishing strengths. Their product suite targets indoor and confined-space rescue with features like two-way communications and unconventional payloads (e.g., glass-breaking capability). Recent strategic moves—facility expansion and a next-generation response drone announced in March 2026—signal capacity scaling and renewed focus on 24/7 DFR programs.
- Skydio (San Mateo, CA; https://www.skydio.com) — Skydio’s leadership in autonomy and obstacle avoidance makes them a preferred partner for complex-environment SAR missions. Their autonomy stack and thermal integrations reduce operator workload and speed time-to-victim in cluttered urban canyons.
- AeroVironment (Arlington, VA; https://www.avinc.com) — As a legacy tactical UAS provider, AeroVironment brings field-proven ISR and VTOL platforms that match defense procurement cycles and rapid-deployment doctrines. They are a natural partner for programs where interoperability with larger ISR architectures is required.
- Draganfly (USA/Canada; https://draganfly.com) — Manufacturing and payload specialization for North American customers is Draganfly’s differentiator. For agencies that prioritize domestic production and supply-chain traceability, they offer a familiar procurement profile.
- ZenaDrone (USA; https://www.zenadrone.com) — Focused on long-range, mission-tailored platforms with robust telemetry and thermal payloads, ZenaDrone positions itself for extended patrol and casualty-evacuation support scenarios where range and link reliability are critical.
- Ascent Aerosystems (USA; https://www.ascentaerosystems.com) — Compact, robust coaxial designs aimed at public safety and defense missions. Their engineering approach emphasizes durability and ease of integration into existing emergency workflows.
Our competitive profiles include SWOTs, procurement-fairness risk maps, and partner-fit worksheets to help you align vendor capabilities with operational objectives.
Regulatory and supply-chain dynamics that will shape procurement in 2026
- Compliance is not optional: NDAA requirements and similar supply-chain-security frameworks are now core gating factors for many government and public-safety procurements. The report offers a compliance matrix and vendor verification playbook.
- FAA DFR enablement: Streamlined processes for Drone-as-First-Responder programs are lowering operational barriers. Organizations planning mass rollout should prioritize interface standards, prepositioned-station strategies, and emergency waiver pipelines described in the DFR playbook.
- Component constraints: Mission-critical components—batteries and power systems that meet NDAA or government sourcing rules—are supply chokepoints. Our procurement roadmap includes sourcing strategies, inventory buffer models, and recommendations for second-source qualification.
Strategic implications and recommended actions for 2026
Time matters. The following phased actions are designed to convert market insight into competitive advantage within 90–360 days.
- 0–90 days: Conduct a rapid-gap assessment using our vendor scorecard to rationalize current pilot programs. Prioritize NDAA risk remediation and secure spare-part contracts for critical batteries and sensors.
- 90–180 days: Select up to two vendor pilots with complementary capabilities (e.g., a high-autonomy platform + a long-range VTOL) and run standardized operational validation scripts at representative sites. Use our CapEx/Opex templates to lock in TCO comparisons.
- 180–360 days: Scale DFR deployments by establishing prepositioned stations, operational SOPs, and a regional maintenance hub. Reassess partnerships for manufacturing scale—BRINC’s capacity expansion is a case in point of suppliers moving to meet institutional demand.
- Strategic hedge: Maintain a flexible supplier set and pursue software-first architectures that allow payload and autonomy modules to be swapped without hardware re-procurement. This reduces obsolescence risk as sensing and autonomy improve rapidly.
Investment and M&A signals to watch
The study flags three investor and corporate signals that correlate strongly to future value creation: (1) suppliers securing government-standard certifications and NDAs; (2) demonstrable field metrics from DFR pilots (reduction in response times, improved victim detection rates); and (3) scaling of manufacturing footprint to meet multi-jurisdictional procurements. For financial sponsors, targets that combine strong autonomy IP and government-compliant supply chains are the highest-probability exit candidates over the forecast window.
Closing — what to expect in the full report
This brief demonstrates the strategic urgency and actionable pathways for organizations planning to operationalize emergency rescue drones in 2026. The full PW Consulting report delivers the underlying models (USD Million market sizing, scenario variants), procurement-ready tools, and detailed vendor scorecards that we have intentionally summarized here. For program managers, procurement officers, and corporate strategists, the full dataset and templates will convert insight into executable plans.
Next steps
- Access the full report to retrieve the granular benchmarking tables, vendor scorecards, and downloadable CapEx/Opex models.
- Engage PW Consulting for a tailored workshop to apply the playbooks to your operational environment and accelerate 2026 rollout decisions.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Fuel & Oil Filters Market Poised for 5.25% CAGR
By PW Consulting, 2026-07-13
Fuel, Fuel Oil & Aircraft Aerospace Filters: Strategic Outlook for 2026 Decision‑Making
Executive summary
PW Consulting’s latest Market Research on Fuel, Fuel Oil & Aircraft Aerospace Filters provides a pragmatic, decision‑ready view for corporate leaders preparing strategy and capital allocation plans in 2026. The market has progressed from a compact base in the early 2020s to a mature, capital‑intensive niche: global revenues rose from the low hundreds of millions (USD Million) in 2020 to approximately 179.65 in the report base year, 2025, and the market is projected to continue expanding through the 2026–2032 forecast window at a compound annual growth rate of roughly 5.25%. By 2032 the market is expected to exceed the mid‑hundreds (USD Million), driven by a mix of regulatory pressure, fuel composition shifts and fleet modernization.
Fuel Fuel Oil Aircraft Aerospace Filters Market
This introduction outlines why that trajectory matters for 2026 strategic choices—R&D priorities, supply chain hedging, M&A screening, aftermarket and fleet support models—and previews how our full report arms executives with the granular inputs they need to act. The intent here is to demonstrate the analytical depth and actionable framing of the full study while reserving the detailed segment-level breakdowns for report subscribers.
Fuel Fuel Oil Aircraft Aerospace Filters Market
Market outlook: dynamics shaping 2026–2032
Three structural forces are re‑shaping the aerospace fuel filtration landscape as companies set strategy for 2026:
Fuel Fuel Oil Aircraft Aerospace Filters Market
- Fuel compositional change and regulation: Policy initiatives accelerating Sustainable Aviation Fuel (SAF) penetration—ReFuelEU Aviation’s minimum SAF blend requirements, for example—are altering filter performance and qualification needs. SAF’s current production economics (commonly several times costlier than conventional jet fuel) create a transition period in which mixed fuel streams and variable contaminant profiles increase technical complexity for filtration designs.
- Technical standards and safety expectations: Established standards such as EI 1581 that prescribe two‑stage filtration and water separation remain central to certification and procurement. At the same time, new water barrier and coalescer technologies are being adopted in response to both regulatory pressure and operational lessons from contamination events.
- Aftermarket and operational risk awareness: Incidents such as DEF (Diesel Exhaust Fluid) contamination and crystallization events have elevated operator sensitivity to filter maintenance, traceability and last‑chance filter design—translating into higher demand for validated, PMA‑certified replacements, diagnostics and fleet support services.
These drivers collectively underpin the steady market growth we model: a continuation of the post‑pandemic recovery and replacement cycles, amplified by the technical investments required to manage SAF‑related challenges and to meet evolving regulatory baselines.
Why 2026 is an inflection year for corporate strategy
For executives mapping 2026 initiatives, three strategic levers should be prioritized:
- Product architecture and qualification roadmaps: The phase‑out of legacy monitoring technologies and the adoption of next‑generation water barrier/coalescer systems create an immediate product modernization imperative. Firms that accelerate EI‑compliant qualification and demonstrate SAF compatibility will capture a larger share of retrofit and OEM replacement spend.
- Service‑led growth and lifecycle economics: With fleets focused on uptime and certification risk, companies positioned to offer validated fleet support, traceability, predictive maintenance analytics, and PMA replacement programs will command better margins and more stable recurring revenue.
- Supply chain and raw material risk mitigation: Filter media and specialist components are increasingly exposed to supply constraints and pricing pressure tied to broader materials markets. Procurement strategies that diversify media suppliers, secure long‑lead components and build strategic buffer inventories will reduce program risk in the 2026 procurement cycle.
Competitive landscape: what the players are doing now
The competitive field combines established filtration specialists, diversified aerospace systems houses and focused PMA vendors. Key names covered in the full study include Parker Hannifin Corporation, Donaldson Company, Inc., Pall Corporation, Porvair Filtration Group, Safran, Eaton Corporation, Tempest Aero Group, Chase Filters & Components, Global Filtration and Norman Filter Company. Each firm exhibits a distinct positioning across product depth, qualification capability, aftermarket reach and geographic coverage.
- Parker Hannifin Corporation (Cleveland, Ohio): A legacy provider of aviation fuel filtration systems, Parker’s product roadmap reflects a deliberate shift away from some legacy EI‑qualified monitors toward newer water barrier technologies. The company’s choices presage opportunities for competitors and for partners that can fill transitional gaps in monitoring and end‑of‑line diagnostics.
- Donaldson Company, Inc. (Minneapolis, Minnesota): Donaldson’s completion of the Facet Filtration acquisition in 2026 expands its mission‑critical filtration portfolio for aviation. This deal is strategically significant because it accelerates Donaldson’s route to broader cartridge and system capabilities tailored to aviation fuel and fluid handling.
- Pall Corporation (Port Washington, New York): Pall continues to supply high‑performance filters compatible with emerging fuel blends and remains deeply embedded with major OEMs and fleet operators; recent fleet support engagements demonstrate the competitive advantage of long‑standing OEM relationships when operators prioritize proven supply continuity.
- Other specialist providers: European and North American filtration specialists (Porvair, Tempest Aero, Chase, Norman and PMA specialists such as Global Filtration) maintain critical niche strengths—customization, rapid prototyping, certification agility and aftermarket responsiveness—that make them attractive partners for OEMs and MROs managing tight turnaround windows.
In the full report we map these suppliers against multiple decision criteria—technology readiness, SAF compatibility, aftermarket service model, certification track record and supply‑chain resilience—so you can rapidly shortlist partners, identify potential acquisition targets and plan procurement partnerships without re‑creating baseline research.
Report content: practical outputs for 2026 decisions
PW Consulting’s full study is organized to translate market intelligence into action. Highlights of the operational deliverables include:
- Proprietary market sizing and forecast model covering 2020–2032 with scenario levers for SAF adoption rates, regulatory timelines and replacement cycles—built to be used as an input for capital planning and sensitivity analysis.
- Competitive benchmarking and supplier playbooks that show where incumbents have technical advantages, where consolidation pressure is likely, and where PMA/reseller models can capture profitable aftermarket share.
- Regulatory and standards matrix linking compliance steps (e.g., EI 1581 criteria) to product qualification milestones and test program requirements.
- Risk heatmaps for supply chain exposures, raw material scarcity, and contamination events—paired with mitigation options and a prioritized list of tactical interventions for 12–24 month horizons.
- M&A screening toolkit and valuation sensitivities for targets that could accelerate technology gaps, aftermarket capabilities or regional reach.
These tools were designed specifically for leadership teams that need to translate 2026 budgets into concrete deliverables: short‑term product investments, mid‑term service model redesign and longer‑term inorganic growth plays.
Practical scenarios and recommended plays
To orient decision‑makers, the full study outlines three pragmatic scenarios and corresponding plays:
- Conservative (compliance first): Prioritize qualification of existing product lines to meet SAF‑adjusted test regimes; emphasize service contracts and inventory buffers.
- Proactive (technology leadership): Invest in next‑gen water barrier/coalescer R&D, accelerate certification for mixed‑fuel environments and pursue bolt‑on acquisitions to fill media technology gaps.
- Opportunistic (aftermarket capture): Scale PMA programs, build predictive maintenance offerings, and target rapid OEM‑agnostic replacement kits for fleets with high variability in fuel quality.
Each play includes expected P&L impacts, capex/timing considerations and a risk matrix tailored to 2026 operational realities. The optimal mix for any company depends on its current positioning along the product/service spectrum and its tolerance for certification investment timelines.
Regulatory and operational watchlist for 2026
Executives should monitor three high‑impact items through 2026:
- SAF policy and procurement rules at major hubs—changes in blend mandates or airport supply requirements can accelerate retrofit cycles.
- Standards updates (e.g., EI 1581 interpretations) that influence test protocols and acceptance criteria for two‑stage and water separation systems.
- Contamination incident trends and safety alerts (for example, DEF‑related crystallization cases) that shift operator procurement toward validated, traceable filtration solutions.
Next steps and how PW Consulting helps
The market’s steady growth—anchored by a multi‑year CAGR of roughly 5.25% and a clear path from a 2025 base to material gains by 2032—creates real options for suppliers, OEMs and service providers in 2026. The choice is not binary: firms can combine product qualification, aftermarket expansion and targeted M&A to both defend and expand revenue pools. PW Consulting’s full report provides the detailed segmental splits, regional and application breakdowns, supplier scorecards and executable roadmaps necessary to finalize budgets and move from strategy to execution.
For executives ready to convert this diagnostic into a one‑page executive action plan, or to receive the full dataset and interactive forecasting model, our subscription page and advisory team are prepared to provide curated briefings and bespoke scenario runs.
For detailed analysis of this topic, please visit the official page: Fuel Fuel Oil Aircraft Aerospace Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Pet Deworming Market to hit USD 4,976M by 2032 at 6.75% CAGR
By PW Consulting, 2026-07-13
Home Pet Deworming Medicine Market — Strategic Briefing for 2026 Decision-Makers
As pet ownership and preventative care deepen across mature and emerging markets, the home pet deworming medicine market is moving from a fragmented, product-led niche into a strategic battleground for innovation, channel differentiation and supply-chain resilience. PW Consulting’s new study — anchored on a 2025 base year and forecasting through 2032 — frames the market not only as a steady-growth commercial opportunity but as a focal point for tactical portfolio choices and operational hedging in 2026. This briefing highlights the study’s strategic value, summarizes the practical intelligence inside, and sketches the high-impact actions executives should prioritize this year.
Home Pet Deworming Medicine Market
Market at a Glance: The Big Picture You Need Now
From 2020 through the 2025 base year the global home pet deworming market expanded materially, reflecting higher pet populations, increased preventive care spend and greater OTC availability. Our top-line model puts 2025 industry revenue at roughly USD 3,150 million (USD Million base). The market is forecast to grow at a compound annual growth rate (CAGR) of about 6.75% through the 2026–2032 horizon, reaching roughly USD 4,976 million by 2032 under the central scenario. That growth trajectory signals durable demand while leaving room for substantive share shifts among formulation types, channels and therapeutic positioning.
Home Pet Deworming Medicine Market
Competitive structure is moderately concentrated: the top-three firms collectively control under half of market share (CR3 ~48.2%), and the top-five firms account for around 62.4% (CR5 ~62.4%). In practice, this means global leaders set benchmarks for brand, pricing and distribution, but meaningful openings remain for specialized players, private-label entrants and regional champions.
Home Pet Deworming Medicine Market
Why this report matters for 2026 planning
- Actionable go-to-market signals: The study dissects channel economics (vet clinics, retail, online, club stores, and direct-to-consumer telehealth), helping you prioritize routes that deliver the fastest payback on marketing spend and margin protection.
- Product strategy refinement: We map where innovation and reformulation (palatability, combination APIs, multi-parasite coverage) materially influence adoption and repeat purchase — essential when shelf space and recommendation slots are limited.
- Regulatory and supply-chain risk ranking: With API production concentrated in Asia Pacific and fresh generic approvals reshaping price points, the report outlines supplier diversification and inventory strategies to avoid margin erosion and stockouts.
- M&A and partnership screening: Our framework identifies mid-cap targets and capability gaps that would yield rapid scale, from manufacturing continuity to DTC fulfillment proficiency.
- Scenario planning for pricing and reimbursement dynamics: We model downside and upside scenarios (including regulatory shifts and generic entry) and quantify impacts on revenue and gross margin, enabling CFOs to stress-test 2026 budgets.
What’s inside — practical, deal-ready deliverables
The full PW Consulting report is deliberately tactical. It combines quantitative modeling with qualitative diagnostics to produce deliverables you can use in boardrooms and investor decks, including:
- Top-down and bottom-up market sizing and a transparent forecast model for 2026–2032 (editable Excel models included).
- Demand drivers and elasticity estimates by formulation class and channel, plus consumer willingness-to-pay matrices for premium versus value propositions.
- Competitive landscaping with capabilities maps, product pipelines, brand positioning and recommended counter-strategies for each competitor archetype.
- Supply-chain heatmap identifying single-source risks, API concentration risks, and short/medium-term mitigation playbooks.
- Regulatory tracker and compliance checklist tailored to the US FDA labelling and OTC frameworks, with implications for labeling, claim substantiation and marketing controls.
- Commercial playbooks: tailored sales/marketing activation plans for veterinarians, retailers and DTC channels with projected ROI timelines.
- M&A shortlists and valuation heuristics for bolt-on acquisitions, plus integration roadmaps focused on SKU rationalization and channel consolidation.
- Risk & mitigation register and three alternative market scenarios to support capital allocation and contingency planning in 2026.
Competitive dynamics — who matters and why
The market combines global animal-health majors, specialist veterinary firms and consumer-focused OTC brands. Key players we profile in depth include Zoetis, Merck Animal Health, Elanco, Virbac, PetIQ and several European specialists such as Boehringer Ingelheim, Ceva and Dechra. Also relevant are consumer-facing and distribution-focused companies like Central Garden & Pet (Farnam) and Durvet.
- Global leaders leverage R&D scale, established veterinary relationships and broad distribution networks to defend premium pricing and secure formulary preference.
- Regional specialists and private-label manufacturers win on agility: faster time-to-market for palatable formats, competitive pricing, and flexible channel partnerships.
- Over-the-counter brands and channel specialists are increasingly important as pet owners self-treat more frequently, supported by telehealth and online pharmacy growth.
Recent industry developments underline these dynamics. Early 2026 saw regulatory movement with approval activity around fenbendazole generics, expanding the pool of cost-competitive solutions and potentially compressing prices in certain segments. Earlier, regulatory flexibility had enabled emergency authorizations for novel therapeutic uses, demonstrating the speed at which regulatory events can re-shape clinician and consumer behavior.
Supply-side watchlist — where to focus procurement and sourcing
API sourcing and manufacturing economics matter. Fenbendazole and other common APIs are primarily produced in Asia Pacific, which supports low-cost formulation but also concentrates geopolitical and operational risk. Our supply-chain assessment quantifies the impact of API concentration on lead times, cost curves and allowable safety stock — crucial inputs for procurement targets and contract negotiations in 2026.
Opportunities and threats — a CEO’s quick checklist for 2026
- Opportunity: Capture underserved DTC demand by bundling dewormers with subscription-based parasite-control programs and telehealth follow-up.
- Opportunity: Differentiate via palatability and convenience — chewables and spot-on innovations can lift adherence and repeat purchases.
- Threat: Generic entrants and growing private-label penetration can compress category ASPs; strategic price-defense and premium layering will be essential.
- Threat: Regulatory shifts or label restrictions can rapidly alter permissible claims; continuous compliance monitoring is non-negotiable.
- Opportunity: Targeted M&A to secure manufacturing redundancy or digital distribution capability can outpace organic growth.
Strategic playbook — prioritized moves for 2026
- Short term (0–6 months): Lock down API supply contracts with tiered volume commitments, and run SKU rationalization to improve fill rates and reduce working capital.
- Medium term (6–18 months): Pilot DTC subscription bundles and loyalty programs in selected geographies where online pet-pharma adoption is highest; concurrently, negotiate exclusive retail or vet-clinic placements for new formulations.
- Long term (18+ months): Invest in formulation R&D (palatability, combination therapies) and consider bolt-on acquisitions that deliver either manufacturing resilience or digital fulfillment competence.
Why executives should read the full report
This briefing outlines the contours of opportunity and risk but intentionally leaves the segment-level granularities, regional allocation matrices, and proprietary pricing elasticity tables for the full report — because those data points are the levers you’ll use to re-write sales targets, revise 2026 capex and prioritize acquisition targets. PW Consulting’s complete package delivers the models, sourcing lists, and competitor playbooks you need to operationalize the strategies summarized here.
Final takeaways
The home pet deworming market offers steady headline growth and a fertile ground for strategic repositioning in 2026: from channel-led disruption and product innovation to supply-chain arbitrage and targeted M&A. With market revenue at roughly USD 3.15 billion in 2025 and a mid-single-digit CAGR to 2032, companies that align product portfolios, secure API continuity, and execute disciplined commercial plays will convert forecast growth into sustainable market leadership. PW Consulting’s full report equips leadership teams with the forecasts, playbooks and risk mitigations required to make those choices with confidence.
Contact PW Consulting to access the complete dataset, editable forecasting model and the competitive intelligence annex that underpin this briefing.
For detailed analysis of this topic, please visit the official page: Home Pet Deworming Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bio-Based Polyamides to Reach USD 6.00B by 2032 at 15.02% CAGR
By PW Consulting, 2026-07-13
General Bio-Based Polyamide Market — Strategic Briefing for 2026 Decision Makers
As sustainability moves from compliance checkbox to strategic differentiator, bio-based polyamides have shifted from niche curiosity to boardroom agenda item. PW Consulting’s latest General Bio Based Polyamide Market study synthesizes the commercial, technological, and regulatory drivers that will shape supplier economics, product roadmaps, and procurement strategies in 2026 and beyond. This briefing outlines the strategic value of that research for executives evaluating investments, sourcing frameworks, product innovation, and M&A — while preserving the granular segment tables and company-level volumes for subscribers who follow through to the full report.
General Bio Based Polyamide Market
Why this market matters in 2026
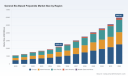
The global market has accelerated sharply in the first half of the decade. Total industry revenues expanded from roughly USD 1.12 billion in 2020 to about USD 2.25 billion by the report base year of 2025, reflecting strong demand from automotive, textiles, consumer electronics and engineering plastics applications. Our baseline forecast anticipates continued rapid expansion through the 2026–2032 horizon, with the market tracking a compound annual growth rate (CAGR) of approximately 15.0% and reaching an estimated USD 6.0 billion by 2032 under the central scenario.
General Bio Based Polyamide Market
For executives, that growth number is not just a headline — it is the basis for sizing new plant investments, prioritizing supplier partnerships, and quantifying the revenue opportunity for bio-attributed product lines versus legacy fossil-derived polyamides.
General Bio Based Polyamide Market
How PW Consulting’s study supports 2026 decisions
- Market sizing with actionable fidelity — our top-down and bottoms-up modelling reconciles reported company shipments, announced capacity expansions and feedstock availability to produce a defensible revenue curve through 2032. These models are scenario-enabled so you can stress-test assumptions around feedstock disruption, certification adoption, and policy shifts.
- Supply chain risk mapping — we map feedstock origins (including castor-oil based value chains and alternative bio-based monomers), logistics chokepoints, and supplier integration strategies. That analysis is calibrated to recent volatility patterns in key intermediates to support hedging, contract terms and local versus global sourcing decisions.
- Commercial playbooks — the report includes go-to-market templates for OEMs, compounders and converters: product positioning by performance and sustainability attributes, pricing premium frameworks, channel economics, and sample commercial clauses for off-take contracts and mass-balance claims.
- Regulatory and certification matrix — a practical tool linking regional regulations (including EU programs promoting renewable content) to required documentation, third-party certification options (mass-balance versus bio-attribution), and grant/incentive opportunities that materially change project IRRs.
- Technology and application readiness — technical benchmarking across resin families, additive and compounding options, processing notes (injection, extrusion, 3D printing powders), and field performance trade-offs (moisture uptake, thermal performance, abrasion, etc.) to inform material selection in product development cycles.
- Investment and M&A screeners — a prioritized list of strategic acquisitions, minority stakes, and JV structures, including financial heuristics and sensitivity analyses to support capital allocation decisions under different market-growth and feedstock-cost scenarios.
Key dynamics that will determine winners and losers
- Feedstock architecture and control — castor-derived chemistries remain a foundational feedstock pathway for many bio-based polyamides. Producers that secure upstream integration, resilient sourcing contracts, or credible alternative monomer supplies will reduce margin volatility and protect product availability during supply shocks.
- Certification and carbon accounting — buyers and capital markets increasingly demand verifiable claims. Mass-balance approaches and ISCC PLUS certification are already mainstream tools for product differentiation; companies with transparent LCA data and low production carbon footprints will command premium positioning.
- Technology split between drop-in versus performance-differentiated grades — some bio-based polyamides provide near drop-in processing characteristics for existing PA6/PA66 platforms; others offer distinct low-moisture or biodegradation properties that enable new applications. Portfolio managers must decide whether to prioritize volume capture or premium niche leadership.
- Price volatility in intermediates — certain derivatives tied to renewable feedstocks have shown significant short-term price swings. Pricing mechanisms, indexation clauses and inventory strategies can materially impact gross margins on multi-year contracts.
- Market structure — the sector shows a moderate level of concentration: the top three suppliers together control roughly half of the market, while the top five control a noticeably larger share. This structure supports continued premiumization by established players, but leaves room for focused specialists and regional champions to win by capability or cost advantage.
Competitive landscape — thematic profiles (actionable perspectives)
The competitive field is composed of large integrated chemical groups, specialty polymer houses, and focused biotech entrants. Our report includes detailed strategic profiles, but the following high-level themes summarize current positioning:
- Integrated value-chain leaders — firms that operate castor oil-to-resin chains and have invested in downstream capabilities reduce feedstock exposure and accelerate new grade commercialization. They can offer transparent LCAs and often lead on cost and reliability.
- Performance polymer incumbents — established engineering polymer producers are converting existing R&D and compounding expertise into bio-based variants to protect customer relationships in automotive and industrial segments.
- Bio-molecule innovators — companies commercializing odd-carbon diamine chemistries or alternative monomers enable differentiated fiber and resin properties attractive to textiles and specialty engineering markets.
- Compounders and formulators — firms that combine bio-resins with fillers, flame retardants and reinforcements are critical go-to-market partners for OEMs that require validated processing and performance.
Recent, market-moving developments
- Early 2026: A leading PA11 producer brought a new transparent bio-based polyamide capacity online in Singapore, substantially increasing available grades for eyewear, medical and electronics applications and demonstrating the commercial viability of higher-clarity bio-resins.
- Mid-2025: A major specialty resin house launched an expanded mass-balanced PA6 portfolio, fully ISCC PLUS certified, signaling accelerated adoption of mass-balance supply chains among industrial buyers aiming for rapid carbon footprint improvement.
- Late-2024 / ongoing: Verified production carbon footprints as low as ~1.3 kg CO2e/kg for certain castor-based PA11 chains (achieved through renewable electricity and process efficiency measures) have reset buyer expectations about the emissions profile available from bio-based alternatives.
Risks, mitigants and strategic options for 2026
- Raw material concentration risk — dependence on a narrow set of renewable feedstocks increases exposure to climatic, agronomic and price shocks. Mitigants include multi-sourcing strategies, investment in upstream processing, offtake agreements with indexed pricing, and diversification into alternative monomers.
- Certification and greenwashing risk — inconsistent claims across suppliers can lead to buyer pushback and reputational damage. Require third-party verification, align contract language on mass-balance accounting, and audit supplier LCAs.
- Technology adoption lag — engineering teams may face a multi-quarter validation curve when switching materials. Mitigate through co-development agreements, sample programs, and supplier-backed testing guarantees.
- Competitive price pressure — as volumes scale, pricing will normalise. Leaders should lock in premium segments where proprietary grades, integrated supply, or certification provide defensible margins.
How to use the full PW Consulting study
- Run the report’s scenario tool with your company’s raw-material exposure assumptions to quantify EBITDA at risk under alternative feedstock price paths.
- Align product roadmaps with the report’s technical compatibility matrix to shorten time-to-market for bio-based replacements in critical platforms.
- Leverage the provided M&A screeners to identify targets that enhance feedstock control, certification capability or route-to-market in priority regions.
- Use the included procurement playbook to design long-term offtake and hedging contracts that balance cost certainty with sustainability claims.
PW Consulting’s General Bio Based Polyamide Market study is deliberately structured as a decision-support toolkit for executives allocating capital and operational attention in 2026. We provide transparent market totals, forward growth rates, concentration metrics, supplier-by-strategy analysis, and scenario-enabled financial models — while preserving the detailed segment tables, region/application splits, and company volumes behind the report portal to ensure subscribers receive the full, auditable dataset.
Next steps
If your priorities for 2026 include securing supply, accelerating product replacements, or evaluating strategic investments in bio-based polyamides, the full report will supply the granular segmentations, supplier volumes and pricing curves required to convert strategy into executable plans. Visit the report page to access the dataset, interactive models and the supplier deck that underpins the analysis.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Grade Power Supplies to Reach USD 2,151.6M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-13
Medical Grade Power Supplies Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but deep preview of our forthcoming Medical Grade Power Supplies Market study. This briefing is written as a strategic primer for executive teams preparing 2026 plans—highlighting the macro trajectory, structural dynamics, competitive moves, regulatory inflection points, and the practical intelligence our full report delivers. We intentionally show methodological depth and directional conclusions while withholding segment-level granularity to preserve the value of the full report.
Medical Grade Power Supplies Market
Market at a Glance — The Macro Trajectory
The global medical-grade power supplies market has moved from a post‑pandemic recovery phase into a structurally growing market characterized by steady demand from diagnostic imaging, patient monitoring, and an expanding at‑home medical device base. Our base-year calibration (2025) and historical series (2020–2025) underpin a forecast through 2032 that assumes moderate but resilient expansion: a mid-single-digit compound annual growth rate (CAGR) of approximately 5.8% from 2026 across the forecast horizon. Under our central scenario the total market expands meaningfully by 2032, reflecting both replacement cycles in hospital estates and an increasing share of power-intensive devices in ambulatory and home-care settings.
Medical Grade Power Supplies Market
Why This Matters for 2026 Strategic Planning
- Procurement & Sourcing Strategy: The market’s steady growth and supplier concentration dynamics imply that procurement teams should shift from transactional buying to supplier portfolio optimization—balancing reliability, compliance, and cost predictability across multi-year contracts.
- R&D and Product Roadmapping: Regulatory tightening and EMC requirements raise technical entry thresholds. Firms that front-load investment in isolation topologies, leakage-current minimization, and EMC shielding will shorten time-to-market for 2026 product launches.
- M&A and Partnership Playbooks: Market concentration and specialized capabilities create fertile ground for bolt-on acquisitions and strategic alliances focused on certification expertise and application‑specific designs.
- Go‑to‑Market Timing: Regulators and reimbursements influence adoption curves—understanding both is essential to time launches, especially for products that depend on hospital procurement cycles or durable medical equipment (DME) reimbursements.
Key Dynamics Shaping 2026 Decisions
- Regulatory Tightening: Medical power supplies must meet modern safety and risk management requirements—including updated IEC 60601-1 editions and mandatory risk management per ISO 14971. EMC standards have been tightened in the latest IEC 60601-1-2 4th edition, raising immunity thresholds and increasing test complexity for suppliers and OEMs alike.
- Supply‑chain Input Pressure: Component-level constraints remain a near-term cost and reliability issue. For example, high‑purity copper foil costs increased materially in 2024, stressing transformer margins and encouraging design optimization or dual-sourcing strategies.
- Reimbursement & End‑market Economics: Certain device classes continue to benefit from defined reimbursement pathways—an example is the HCPCS code covering power supplies for specific therapeutic devices. Where reimbursement exists, unit economics can support higher product development and certification costs.
- Quality & Safety Events: Recent Class II recalls tied to capacitor failures underscore the reputational and regulatory risks of component selection. Risk mitigation via supplier qualification, accelerated life testing, and traceable BOMs is now non‑negotiable.
Competitive Landscape — Who Matters and Why
The competitive field is a mix of long-established power specialists, diversified electronics conglomerates, and regional OEMs that serve vertical niches. Competitive intensity is moderate and characterized by technology-driven differentiation rather than pure price competition—though commoditization pressure exists at lower power bands.
Medical Grade Power Supplies Market
- Advanced Energy / Artesyn / SL Power (Advanced Energy group): These units combine high‑power capabilities and compliance breadth—supplying AC‑DC and DC‑DC platforms certified to contemporary IEC safety editions. Recent expansions include higher-wattage models and parallelable architectures that target imaging and surgical suites.
- XP Power: Focused on external/internal modular supplies, XP emphasizes margin‑accretive features such as 2xMOPP isolation and product families tailored for home healthcare and laboratory instruments. Their 2025 product introductions reflect a push into higher-density imaging applications.
- MEAN WELL & Delta Electronics: These manufacturers play a volume-to-value role—offering BF-class insulation and broad product portfolios for ventilators, infusion pumps, and bed systems. Certification updates and product refreshes in 2025 indicate active pursuit of clinical OEMs.
- TDK‑Lambda & Cosel: Japanese incumbents continue to compete on EMC performance, compact chassis solutions, and custom OEM designs—leveraging deep technical certifications and local market trust.
Collectively, top players account for a meaningful share of supply capacity, with the market exhibiting moderate concentration—enough that strategic decisions around partnerships, IP ownership, and factory footprint have material implications for access and margins.
Recent Industry Moves (Strategic Implications)
- Product introductions through 2025 show a clear trend: higher power density at certified isolation levels, and external modules tailored for imaging and ultrasound—indicating OEM demand for turnkey certified blocks that accelerate device certification.
- Certification updates and product expansions highlight the industry’s response to the newest IEC editions—firms that invested early in compliance are now converting that investment into commercial momentum.
- Supply‑side cost shocks (e.g., copper foil) and component reliability incidents place a premium on supply chain resilience—buyers should expect pass-throughs and periodic lead‑time volatility into 2026.
What the Full PW Consulting Report Contains (Practical Tools for 2026)
Our full market study is structured to be immediately operational for leadership teams. Key deliverables include:
- Top‑down market sizing and bottom‑up validation (base year 2025), with scenario-based forecasts through 2032 calibrated to regulatory and reimbursement pathways.
- Supply chain maps and a component risk heatmap that quantifies exposure to critical inputs, single‑source suppliers, and lead‑time sensitivities.
- Certification and compliance tracker (including IEC editions, EMC testing requirements, and emerging cybersecurity expectations) that links regulatory timelines to product release calendars.
- Commercial playbooks: go‑to‑market templates for new product introductions, distributor strategies, and OEM channel economics.
- Competitive intelligence dossiers for the leading suppliers, including capability matrices, recent product pipelines, and recommended counter‑moves.
- Acquisition target shortlist and valuation cushions (qualitative and quantitative) built from public filings, product breadth, and certification IP.
- Supplier scorecards and procurement KPIs designed to move procurement from tactical buying to strategic supplier relationship management.
Note: detailed segment‑level tables and regional/application splits are intentionally excluded from this preview; the full report contains the complete, attributable tables and interactive dashboards.
Actionable Strategic Recommendations for 2026
- Prioritize Certified Blocks for Faster Time‑to‑Market: For device OEMs targeting hospital tenders or regulated home-care markets, procure pre‑certified modules where feasible to reduce project risk and shorten approval timelines.
- Build Redundancy into Critical BOMs: Dual‑sourcing critical passive components and qualifying alternate transformer vendors will mitigate near‑term cost and supply shocks.
- Invest in EMC & Leakage Testing Early: Embedding EMC mitigation and leakage‑current control into early design reduces costly rework when testing to the latest IEC 60601‑1-2 benchmarks.
- Make Certification a Strategic Asset: Firms that own test suites, compliance documentation, and recognized test partners translate certification speed into commercial advantage—consider strategic partnerships or acquisitions to acquire these capabilities.
- Monitor Reimbursement Pathways: Where reimbursement is available, design trade-offs that increase device robustness and lengthen field life can be justified by improved unit economics.
How to Use This Preview
Consider this article a strategic framework: it identifies the market direction, the levers that matter for 2026, and the operational capabilities that separate leaders from followers. For teams preparing budgets, product roadmaps, or M&A lists, the full PW Consulting study provides the actionable tables, supplier-level data, and scenario models you will need to finalize plans.
Closing — The Strategic Edge for 2026
Medical power supplies sit at the intersection of safety, reliability, and regulatory complexity. Our market model—anchored on a 2025 base and a multi‑year forecast through 2032—shows a market expanding at roughly a mid‑single-digit CAGR. That growth masks important heterogeneity: some subsegments are seeing accelerated demand due to procedural digitization and home-care decentralization, while certification and component risk create barriers and opportunities in equal measure.
Executives who treat power supplies as a strategic component—rather than a commoditized box—will unlock faster product approvals, steadier margins, and lower regulatory risk. To access the full dataset, modeled scenarios, and our supplier scorecards that translate these insights into executable 2026 plans, request the complete PW Consulting Medical Grade Power Supplies Market report.
For detailed analysis of this topic, please visit the official page: Medical Grade Power Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Defense Asset Management Software to Reach USD 3,432.7M by 2032 (8.45% CAGR)
By PW Consulting, 2026-07-13
Defense Asset Management Software Market — Strategic Brief for 2026 Decision-Makers
As the world’s defense organizations accelerate platform sustainment, interoperability, and digitization, software that manages military assets is shifting from administrative tool to operational imperative. PW Consulting’s new market study — built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon — quantifies that transition and translates it into actionable guidance for executives planning procurement, integration, and sustainment strategies in 2026.
Defense Asset Management Software Market
High-level market trajectory
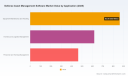
Our base-year analysis (2025) and forward modeling show a market expanding at a compound annual growth rate of 8.45% across the forecast window. In practical terms, the market nearly doubles in scale from the mid-2020s into the early 2030s, driven by a convergence of programmatic modernization, regulatory pressure, and a wave of cloud- and AI-enabled product enhancements. This trajectory creates three categories of opportunity for defense stakeholders: immediate (risk reduction and compliance), medium-term (operational readiness and lifecycle cost reduction), and strategic (digital continuity and force transformation).
Defense Asset Management Software Market
Why this research matters for decisions in 2026
-
Procurement windows are compressing. The DoD’s Software Modernization Implementation Plan (FY25–26) creates new procurement dynamics—enterprise licensing, SaaS Authority to Operate (ATO) pathways, and FinOps disciplines—that materially change total cost of ownership and vendor selection criteria.
Defense Asset Management Software Market -
Operational requirements are evolving beyond maintenance schedules to include AI-enabled readiness forecasting, multi-domain asset visibility, and data fusion across logistics and operations. Programs such as the US Air Force’s Next-Generation AOC initiatives will demand asset management capabilities that integrate into mission-level decisioning.
-
Security and compliance are non-negotiable. CMMC 2.0 asset management practices, DLMS requirements for logistics data, and DCMA IT asset management directives mean implementation teams must treat software adoption as a combined technology-and-policy program.
Key strategic implications for 2026 planning
-
Favor composable architectures that can meet both operational and regulatory needs. Vendors that provide modular EAM/ALM (Enterprise Asset Management / Asset Lifecycle Management) components—capable of running securely on approved cloud enclaves or on-premise stacks—significantly reduce integration risk during contract execution.
-
Account for specialized labor as a material line item. Implementation, integration, and ongoing sustainment require personnel with security clearances and domain experience; these human costs frequently exceed basic software license spend and should be scoped early in procurement.
-
Design procurement around SaaS ATO and enterprise licensing opportunities. Where possible, leverage emerging DoD enterprise agreements and FinOps practices to accelerate deployment and reduce duplication of license management across programs.
-
Prioritize interoperability with logistics and standards frameworks. Compliance with logistics standards and the ability to transform non‑compliant legacy data are decisive capabilities for vendors competing for defense contracts.
-
Build AI and data integration into the business case, not as an afterthought. Recent vendor releases and pilot programs signal that asset health prediction, readiness scoring, and automated maintenance orchestration will be differentiating features during the next procurement cycle.
What’s in the full PW Consulting study (practical deliverables)
- Validated market-sizing using our 2020–2025 historical base and scenario-driven forecasts through 2032, including sensitivity models for technology adoption and regulatory shifts.
- A buyer’s playbook: procurement checklists, sample RFP language tailored for defense acquisition, SaaS ATO roadmaps, and a FinOps workbook for total-cost-of-ownership calculations.
- Implementation tooling: phased migration templates (on-premise to cloud, hybrid patterns), integration patterns for logistics standards, and security-control mappings aligned to CMMC/DLMS/DCMA guidance.
- Vendor evaluation materials: methodology and scorecards for capability, compliance, scalability, and sustainment; red-team considerations for supply chain and cybersecurity risk.
- Case studies and use cases demonstrating runway reductions in maintenance downtime, improvements in mission-availability metrics, and cost-to-service improvements under alternative deployment scenarios.
Competitive landscape — how to read the market
The competitive field is functionally segmented into three groups: large enterprise software vendors, defense primes and systems integrators, and specialized niche vendors. Our CR metrics identify a market with meaningful scale concentration at the top but substantial room for specialized players to win program-specific business. That structure produces predictable outcomes:
-
Enterprise incumbents (e.g., global ERP and EAM providers) bring broad lifecycle capabilities, deep integration stacks, and established enterprise licensing models conducive to large-scale, cross-domain deployments. Their value is strongest where defense organizations seek a single-source backbone for asset lifecycle, finance, and procurement integration.
-
Defense primes and systems integrators embed asset-management capability inside platform sustainment offers, often combining software with logistics engineering, depot modernization, and long-term sustainment contracts—an attractive model for platform-centric programs requiring tight lifecycle control.
-
Specialist vendors deliver rapid, feature-rich offerings focused on fleet management, MRO, or DoD contractor compliance and often provide faster time to capability for specific asset classes. These vendors are frequently the innovators in niche functional capability—AI-enabled diagnostics, complex parts tracking, or defense-grade inventory control.
For 2026, decision-makers should expect vendor competition to center on three axes: compliance-first readiness (ATO, CMMC), integration depth (ERP/PLM/logistics standards), and productized AI capabilities for predictive maintenance and readiness forecasting.
Recent programmatic and product developments that matter
-
Policy-level momentum from the DoD’s Software Modernization Plan is reshaping enterprise purchasing behavior—encouraging SaaS adoption under clearly defined security and licensing constructs.
-
Operational programs—such as next-generation command center initiatives—are creating new requirements for data fusion between asset management and mission systems, accelerating demand for interoperable solutions.
-
Vendors are responding: we have observed targeted releases and AI-enhancements aimed at defense asset management, signaling a near-term product cycle focused on predictive analytics and operational integration.
Risk factors and mitigations
-
Regulatory misalignment: procurement that does not account for SaaS ATO, CMMC, and DLMS interoperability risks project delays. Mitigation: pre-ATO discovery, inclusion of compliance milestones in contracts, and use of a regulatory mapping annex in Statements of Work.
-
Underestimated integration costs: legacy data and non‑standard inventory codes can balloon implementation efforts. Mitigation: early data health audits and budgeted transformation sprints.
-
Talent scarcity: cleared, domain-experienced staff are scarce and costly. Mitigation: hybrid staffing models, strategic use of specialist vendors, and investment in vendor‑provided managed services where appropriate.
A recommended decision framework for 2026
-
Define a succinct, measurable mission outcome (e.g., platform availability, depot throughput, fleet readiness) and map required functional capabilities to that outcome before engaging vendors.
-
Shortlist vendors using a layered evaluation: compliance gating, reference-based functional scoring, integration effort estimate, and sustainment economics over a 7–10 year horizon.
-
Run a focused pilot aligned to an operationally meaningful objective and scaled to expose integration, people, and regulatory risks within 6–12 months.
-
Institutionalize FinOps and license-governance within acquisition and sustainment teams to capture efficiency gains from enterprise agreements and shared services.
-
Lock in data stewardship and transformation standards to guarantee continuity as systems evolve and platforms are modernized.
Closing — how PW Consulting’s study supports your 2026 roadmap
Our research equips leaders with the market sizing and trend context necessary to prioritize investments, the procurement and technical playbooks required to execute quickly and compliantly, and vendor evaluation tools to make defensible vendor choices. We intentionally presented a high-resolution view of market direction, competitive positioning, policy tailwinds, and operational levers while reserving granular regional and application-level segment data, vendor scorecards, and the full set of financial tables for the full report. Those granular data sets are designed to plug directly into program-level business cases and procurement documentation.
For teams planning strategic acquisitions, upgrades, or large-scale sustainment programs in 2026, the study provides both the quantitative foundation and the practical, step-by-step guidance to convert market momentum into program success—while ensuring compliance, manageability, and measurable operational improvement.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Built-In Electric Curtains Market at USD 3,248.5M in 2025; 10.51% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Built-In Electric Curtains Market — A 2026 Strategic Preview for Decision‑Makers
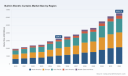
PW Consulting’s latest market research on Built‑In Electric Curtains frames the next investment cycle for product managers, procurement leads, real‑estate developers and systems integrators. Anchored on a 2025 base year and projecting through 2032, the study quantifies a high‑growth landscape: the market expands at a compound annual growth rate (CAGR) of 10.51% over the forecast window. Our topline sizing shows a multi‑year climb from the early 2020s into a substantially larger market by the end of the decade (figures in USD Million). This preview synthesizes the strategic implications you need to act in 2026 while intentionally holding back detailed sub‑segment tables — those are reserved for the full report.
Built In Electric Curtains Market
Why built‑in electric curtains matter now
-
Smart‑home and intelligent building adoption is shifting specification patterns. Stakeholders are moving away from add‑on retrofit motors toward fully integrated, recessed or track‑based systems that preserve interior design while delivering automation and energy‑management benefits.
Built In Electric Curtains Market -
Technology convergence (low‑power wireless standards, local bridging, cloud services and software ecosystems) is transforming curtain systems from discrete mechanical products into platform opportunities — unlocking recurring revenue through services, updates and integrated building control.
Built In Electric Curtains Market -
Cost dynamics and regulation are compressing time‑to‑market for new designs. Raw‑material duties and component import tariffs increase landed costs for motors and aluminum extrusions; safety standards (notably ANSI/WCMA A100.1‑2022) further influence product form factors and customer acceptance.
Market trajectory — what the numbers signal for strategy
The market’s 10.51% CAGR reflects a combination of accelerating demand in premium residential and commercial segments, growing retrofit activity in retrofit‑heavy regions, and stronger specification for integrated systems in new construction. From a strategic perspective, that growth rate creates three simultaneous imperatives for business leaders entering 2026:
-
Scale to capture volume while protecting margin — growth will reward players who can manage supply‑chain cost inflation and offer differentiated integration capabilities.
-
Differentiate through software and services — the hardware commodity risk rises unless firms bundle persistent value (control platforms, analytics, maintenance plans).
-
Manage regulatory and trade exposure — tariffs on motors, fabrics and aluminum extrusions, and safety standards eliminating free‑hanging cords, require product redesign and more agile sourcing.
What the full PW Consulting report delivers (practical, actionable)
This research is designed as a decision‑support toolkit for 2026 and beyond. Key deliverables include:
-
A validated market model with annual sizing (base 2025) and granular forecasts to 2032, including scenario analyses that stress tariffs, raw‑material cost swings and adoption curves for wireless platforms.
-
Go‑to‑market playbooks for three archetypes: OEM suppliers, branded system integrators, and channel/installer networks. Each playbook contains recommended product roadmaps, pricing levers, and channel incentive structures.
-
Supply‑chain diagnostics and mitigation templates: cost‑build models (motor, track, electronics, fabric), supplier concentration mapping, and contingency plans for duties and logistics disruptions.
-
Regulatory and standards tracker with practical compliance checklists (including ANSI/WCMA A100.1‑2022 implications) to accelerate safe‑to‑ship timelines.
-
Detailed competitive profiles and SWOTs for market participants, plus M&A and partner scouting lists for acquisition or alliance strategies.
-
Case studies on built‑in installations across residential, hospitality and institutional sites demonstrating OPEX impacts, installation workflows and specification language templates for architects and consulting engineers.
Note: this preview intentionally avoids publishing the detailed regional, power‑source and end‑use splits. Those core segmentation matrices and the revenue tables that many practitioners require are available exclusively in the full report.
Competitive landscape — practical takeaways
-
Market structure: The market displays a moderate concentration with top‑three players holding a substantial share and top‑five further extending reach. This dynamic creates a two‑tier opportunity: large platform players will continue to dominate high‑spec projects, while nimble challengers can win in retrofit, mid‑market and regional channels.
-
Player archetypes and strategic moves:
-
Platform integrators: Companies with deep system control capabilities focus on bundled lighting/shading ecosystems and premium residential/commercial specifications. Their competitive edge is integration with building automation platforms and channel relationships with designers.
-
Component specialists & OEMs: Providers of motors and tracks maintain margin by selling into both branded systems and white‑label channels; securing OEM contracts and scale manufacturing is core to their playbook.
-
B2B smart window suppliers: Newer entrants leveraging modern interoperability stacks (e.g., Matter/Thread) and rechargeable motor designs emphasize clean integrations and faster installer experiences.
-
-
Notable companies to watch: Established leaders bring scale and integration depth, while specialized track and motor manufacturers control critical component roadmaps. Recent product launches — for example, a 2025 introduction of a Matter bridge and showroom suite by a smart window covering B2B brand — illustrate how interoperability and customer experience are now front‑and‑center in product roadmaps.
Regulatory and cost headwinds — how they influence 2026 decisions
-
Tariffs and import duties: Motor components, fabrics and aluminum extrusions face import levies that can add materially to landed costs. Pricing strategies must account for potential 10–25% tariff exposures on specific components depending on origin and customs classification.
-
Standards and safety: ANSI/WCMA A100.1‑2022 and similar regional safety requirements accelerate the normalization of motorized solutions in place of hazardous free‑hanging cords; product development teams must embed compliance early to avoid late‑stage redesigns.
-
Raw‑material duties and supply risk: Additional duties on aluminum and tubular components increase production costs for integrated tracks, making near‑shoring and supplier diversification strategic priorities.
Priority actions for 2026 — a tactical roadmap
-
Secure your component supply chain: Lock multi‑year agreements with motor and extrusion suppliers, include tariff‑pass‑through clauses and evaluate local assembly to mitigate import duties.
-
Design for standards and retrofit: Revisit mechanical designs to meet ANSI/WCMA requirements and reduce installation time; create retrofit kits that minimize structural work in the field.
-
Invest in interoperability: Accelerate support for open ecosystems and bridges (Matter/Thread, Zigbee integrations) to be chosen by system integrators and smart‑building specifiers.
-
Develop a service monetization plan: Pilot subscription models for remote diagnostics, preventive maintenance and software feature tiers tied to installations.
-
Model scenario P&Ls: Run sensitivity analyses for tariff shocks, aluminum price spikes and slower adoption to inform pricing, inventory and new product launch timelines.
-
Plan selective partnerships and M&A: Where time to capability matters, pursue minority stakes or distribution deals with regional installers, or acquire niche track/motor specialists to internalize margin and IP.
Using this preview — next steps
This article is a curated preview designed to inform 2026 strategic planning. For commercial teams, the report is a playbook: it contains the full revenue matrices, regional and end‑use splits, channel economics and supplier lists that operationalize the recommendations above. For product leaders, the report includes design impact analyses and compliance roadmaps. For M&A and corporate development teams, it contains target scouting and valuation sensitivities tied to the sector’s growth profile.
PW Consulting’s full Built‑In Electric Curtains Market report is the source of the detailed segmentation, vendor scorecards and downloadable modeling assets referenced here. To access the full intelligence package and data tables required to convert the strategic priorities above into executable plans, please visit our report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


