



PW Consulting: Remote Proctoring Solutions Market to grow at 15.7% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Remote Proctoring Solutions Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As organizations plan budgets and procurement strategies for 2026, remote proctoring has moved from a tactical response to pandemic-era constraints to a persistent, strategic capability across higher education, professional certification, government testing, and large-scale corporate assessment programs. PW Consulting’s new market study (base year 2025; historical window 2020–2025; forecast 2026–2032) projects continued robust expansion: the market moves from an estimated USD 390 million in 2025 toward a USD 700‑plus million outcome by 2032 under a mid‑teens compound annual growth rate (CAGR 15.7%).
Remote Proctoring Solutions Market
Why this matters for 2026 strategy
- Risk and reputation now sit alongside cost and capacity. High‑stakes assessors must weigh technical integrity, legal defensibility, candidate experience, and geopolitical data constraints when selecting a platform.
- Technology choices made in 2026 will lock in vendor relationships and integration patterns for several years. With a pronounced growth trajectory, procurement windows present both risk (vendor lock) and opportunity (favorable pricing and co‑innovation terms).
- Regulatory and adversarial pressures are tightening concurrently. New rules and sophisticated synthetic‑media threats mean that platform selection should be treated as a strategic architecture decision—not a point purchase.
Market dynamics that will shape vendor and buyer strategies in 2026
Three themes will dominate boardroom conversations and RFPs in 2026.
Remote Proctoring Solutions Market
- Security vs. accessibility tradeoffs. Buyers must reconcile broader access goals (e.g., remote licensing, expanded candidate pools) with increasingly stringent security expectations from regulators and professional bodies.
- AI as both solution and threat. Automated proctoring and behavioral analytics reduce cost per seat, but the same ML advances enable more realistic synthetic attacks. Defenses that combine algorithmic detection with human adjudication become the de‑facto standard for defensibility.
- Regulatory fragmentation and data sovereignty. Major platforms now universally present GDPR/FERPA/CCPA compliance pathways; buyers will prioritize granular data residency controls, encryption standards, and audit trail capabilities when procurement stakes are high.
Selected recent shocks and policy moves
- Policy tightening for high‑stakes professional exams: In April 2026 NCARB announced operational constraints for online delivery of ARE 5.0 that become effective June 1, 2026—most notably, mandatory use of mobile devices as a secondary camera and restrictions on permitted delivery platforms. Such edicts force buyers and vendors to rapidly adapt exam workflows and support toolchains.
- Anti‑spoofing innovations: A May 2026 release of a commercial deepfake detection module that leverages GAN artifact analysis highlights the accelerating arms race between synthetic media and detection systems. Procurement teams must now evaluate not only the presence of AI detectors but their update cadence and transparency.
- Program expansions: Regulatory bodies exploring remote administration of previously in‑person exams (e.g., plans for remote NCLEX testing) signal new addressable demand and stricter acceptance criteria for proctoring evidence.
Competitive landscape — positioning and strategic implications
The market presents a mixed structure: a handful of established providers with specialized capabilities and many niche or regional players. Market concentration remains modest (CR3 ~28.5%; CR5 ~32.8%), indicating room for consolidation and continued opportunity for differentiated entrants.
Remote Proctoring Solutions Market
- Meazure Learning (ProctorU) : A pioneer in live human proctoring focused on high‑stakes certification and licensing. Strengths include robust human review workflows and long experience in defensible chain‑of‑custody practices—important where auditability is paramount.
- Honorlock : Known for hybrid AI + on‑demand live intervention and behavioral analytics tailored to higher education and mid‑stakes assessments. Its model is attractive to institutions seeking a balance between scalability and human oversight.
- PSI Services : Enterprise‑grade portfolio with strong penetration in government and licensing markets. PSI’s platform breadth supports complex delivery modes and testing‑center integration—valuable where exam ecosystem interoperability matters.
- Turnitin / ExamSoft : Focused on academic integrity, coupling assessment delivery with AI‑based cheating indicators and identity verification. Particularly relevant for large universities that emphasize content similarity and learning analytics.
- Proctorio : Automated, high‑volume offering with features such as browser lockdown and eye‑tracking. Suited to cost‑sensitive, scale‑oriented deployments—but buyers should stress test defences against evolving synthetic threats.
- Examity , Talview , Proctor360 , and Proctortrack : Each occupies differentiated niches—ranging from configurable hybrid solutions and enterprise assessment platforms to continuous identity verification and hardware‑assisted environmental security.
- Integrity Advocate : Distinguishes itself with mandatory human review on every AI flag and a no‑install browser approach, positioning for clients that prioritize defensible human adjudication and minimal candidate friction.
What the PW Consulting report provides (practical, action‑oriented content)
This study is structured to support procurement, product, and risk teams as they make near‑term commitments and design multi‑year roadmaps. Highlights include:
- Market sizing, historical tracing (2020–2025), and scenario forecasts (2026–2032) with sensitivity analysis for upside/downside adoption cases.
- Vendor benchmarking matrices: capabilities, deployment footprints, review processes, ML model update cadence, incident response SLAs, and privacy & data‑sovereignty features.
- Use‑case decision trees and procurement scorecards tailored to four archetypal buyers (high‑stakes certification boards, public universities, enterprise talent assessment teams, and government licensing bodies).
- Operational playbooks: pilot design, candidate support models, integrated identity verification flows, and human‑in‑the‑loop escalation protocols.
- Legal & compliance checklist: contract clauses for audit logs, raw footage retention policies, cross‑border transfer risk mitigations, and defensibility standards in the event of contested results.
- M&A and partner landscape: acquisition targets that accelerate capabilities (deepfake detection, secure browsers, hardware accessories), and a short list of potential bolt‑on plays for incumbent platforms.
- ROI and TCO models, including break‑even analyses for live vs. automated proctoring mixes, plus scenario modeling templates to stress test cost/performance tradeoffs.
How buyers should approach procurement in 2026
PW Consulting recommends a three‑track approach for organizations planning decisions in 2026:
- Immediate (0–6 months): Shore up operational controls around identity verification, data residency, and candidate support. Run a focused pilot that stresses synthetic‑media scenarios and multi‑device constraints introduced by new regulatory requirements.
- Medium (6–18 months): Negotiate flexible contracting that preserves pathways for technology swaps and feature upgrades (e.g., module licensing for anti‑deepfake detection). Require transparency on model training data, update frequency, and human review thresholds.
- Strategic (18–36 months): Define a target architecture for assessment delivery across modalities (in‑person, remote hybrid, remote automated) and budget for co‑development with preferred vendors to embed vendor capabilities into broader credentialing ecosystems.
Where vendors will win in 2026
Winning suppliers will demonstrate four competencies:
- Defensible evidence chains—robust, tamper‑resistant audit logs and human review pipelines suitable for legal scrutiny.
- Adaptive detection—rapid ingestion of new threat signatures (including synthetic media) and transparent validation metrics for false‑positive/false‑negative tradeoffs.
- Interoperability—APIs and standards support for LMS, registration systems, and certification platforms to reduce friction and integration costs.
- Customer success at scale—proven operational playbooks for candidate onboarding, accessibility accommodations, and 24/7 support.
What we intentionally withhold in this briefing (and why)
In line with our “trailer” approach: this briefing surfaces directionally important numbers and competitive dynamics but intentionally omits segment‑level tables and region/application share figures. Those granular splits, vendor scorecards, and downloadable financial models are included in the full PW Consulting report and interactive dashboard—materials that procurement and product teams will need to operationalize decisions and contract negotiations.
Next steps and call to action
For teams making FY‑2026 budget allocations, the next step is a short diagnostic: map your assessment portfolio to the four archetypes in our report, run a three‑month synthetic‑threat pilot against your shortlisted vendors, and require each vendor to produce a defensibility dossier (human review logs, model validation results, and data retention practices). PW Consulting’s full market study provides the vendor scorecards, RFP templates, contractual language, and TCO models to convert that diagnostic into procurement decisions with confidence.
Access the full report to obtain the detailed segment analytics, vendor scorecards, risk matrices, and downloadable scenario models that will underpin defensible 2026 decisions.
For detailed analysis of this topic, please visit the official page: Remote Proctoring Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ellagic Acid Market to grow at 6.65% CAGR - USD 275M (2025) to USD 425M (2032)
By PW Consulting, 2026-07-12
Ellagic Acid Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, strategy-first preview of our full Ellagic Acid Market study — a decision-ready briefing tailored for corporate leaders preparing plans for 2026. The market for ellagic acid (USD, revenue unit: Million; base year: 2025) is on a sustained expansion path: our model forecasts growth from the 2025 baseline to the end of the 2032 horizon at a compound annual growth rate (CAGR) of 6.65%. That trajectory reflects evolving end-market demand, shifting supply dynamics, and an intensifying regulatory and certification environment that will shape supplier advantage and commercial returns in the coming 18–36 months.
Ellagic Acid Market
Why this matters for 2026 planning
-
Predictability meets disruption: The underlying growth (mid-single-digit CAGR) affords companies enough runway to invest, but structural supply and regulatory volatility raises execution risk — meaning traditional capacity expansions alone will not guarantee commercial success in 2026.
Ellagic Acid Market -
Premiumization is a margin lever: Higher-purity grades and certification-backed products are capturing buyer preference and commanding meaningful premiums. Firms that can credibly deliver pharma-grade purity or certified organic/Non‑GMO product streams will unlock differentiated pricing power.
Ellagic Acid Market -
Supply resilience is strategic: Raw material concentration and climate exposure are real. Pomegranate peel — the predominant commercial feedstock — varies significantly in active content and has been affected by droughts in key producing regions, which has translated into pronounced cost swings. Securing raw material pathways will be a top procurement priority in 2026.
What the PW Consulting report delivers (practical value)
-
Validated market sizing and a transparent demand model (base year 2025, forecast 2026–2032) that converts macro trends into revenue scenarios and break-even timelines for new investments.
-
Actionable segmentation intelligence across product forms, applications and regional demand pockets — presented as market-weighted demand drivers and opportunity matrices (note: detailed regional/application splits are reserved for the full document).
-
Supplier scorecards and an M&A target shortlist: operational metrics, certification status, quality systems, and integration risk assessments to accelerate buy-side diligence.
-
Commercial playbooks and contract templates for offtake, tolling and captive supply arrangements — enabling rapid deployment of sourcing strategies to mitigate raw-material shocks.
-
Regulatory and quality roadmap: step-by-step requirements to obtain ISO/GMP/Halal certifications and REACH registration considerations for intermediates such as pomegranate extract formulations.
-
Price and margin sensitivity models that tie raw material inflation and purity mix to P&L outcomes under alternative marketing strategies (private label vs. ingredient branding; food-grade vs. pharma-grade focus).
Market dynamics shaping competitive advantage
-
Feedstock concentration and climate risk — operational impact: Pomegranate peel is the primary commercial feedstock and contains high concentrations of ellagitannins that are processed to ellagic acid. Drought-driven yield reductions in several producing countries have materially tightened supplies and created volatility in raw-material pricing. Companies with diversified sourcing or vertical integration into peel processing demonstrate clear first-mover resilience.
-
Certification and quality escalation — commercial impact: International buyers increasingly require ISO, GMP and Halal certifications. Suppliers that invested early in quality management systems now attract longer-term contracts and premium customers in regulated regions.
-
Regulatory overlay — compliance as a gatekeeper: REACH registration and similar regulatory frameworks are non-trivial compliance items for many formulations; treating regulatory readiness as a product feature (and a cost line) is necessary for access to the most valuable buyers.
-
Purity segmentation — margin differentiation: Pharmaceutical-grade material above very-high purity thresholds commands substantial premiums versus lower-grade, food‑industry material. A deliberate product-tier strategy — from research-grade to pharma-grade — is a direct route to improved portfolio margins.
Competitive landscape: positioning and implications
The market is characterized by a mix of specialized botanical-extract houses, regional processors, and global life-science suppliers. A few themes emerge from our company-level review:
-
Specialist extractors and regional scale players: Several established botanical-extract manufacturers offer bulk ellagic acid in multiple grades and leverage low-cost raw material access. These firms compete on cost, certifications and export logistics. Their value lies in scale, supply continuity and price competitiveness for food- and supplement-grade demand.
-
Quality-focused European and US players: A subset of suppliers differentiates through higher-spec products, regulatory compliance (including REACH attention) and technical documentation. These firms are preferred partners for European and North American buyers demanding traceability and SDS/Hazard communication updates.
-
Research- and reagent-grade suppliers: Global life-science distributors offer high-purity ellagic acid for R&D and industrial use, filling a premium niche that supports small-volume, high-margin business lines.
Notable supplier developments illustrate these dynamics: a European producer recently updated safety data and product documentation to reflect evolving regulatory expectations, while multiple Asian manufacturers are expanding organic and GMP-capable production lines to win nutraceutical and pharmaceutical business.
Strategic imperatives for 2026
-
Secure diversified feedstock contracts: Move beyond spot buying. Structured multi-year offtake contracts with staggered delivery, coupled with limited vertical investment in peel-processing capacity, will reduce margin volatility and improve supply predictability.
-
Invest in certification and traceability: Prioritize ISO/GMP/traceability investments — these are market access enablers in key buyer geographies and will convert to higher order sizes and longer contract tenors.
-
Define a purity-tiered commercial strategy: Adopt a two-track approach — protect margins via pharma/high-purity channels while maintaining volume by serving stable supplement/food applications with commodity grades.
-
Operationalize a climate-risk playbook: Implement supplier audits, develop alternate sourcing corridors, and consider feedstock hedging or inventory buffering informed by our supply-stress simulations.
-
Pursue focused M&A or joint ventures: The market concentration indicators show room for consolidation that can deliver procurement synergies and certification-ready capacity. Target companies should add complementary geography, certified capacity or proprietary extraction know-how.
Risk matrix — what keeps CFOs awake
-
Raw-material inflation and availability: Episodic drought and constrained peel supply can raise input costs and compress margins if not hedged or contractually managed.
-
Regulatory non‑compliance: Missing REACH or GMP expectations closes off the most lucrative buyer segments and can lead to retroactive supply interruptions.
-
Product liability and documentation gaps: SDS and technical data currency are now procurement gatekeepers in many advanced markets — lagging updates can disqualify suppliers.
How PW Consulting can accelerate your 2026 agenda
-
Fast-track diagnostics: We offer a bespoke two-week supply-chain stress test and certification gap analysis that translates market benchmarks into an executable 90-day plan.
-
M&A and commercial diligence: Use our proprietary supplier scorecard and valuation overlay to prioritize targets and structure earn-outs tied to certification milestones.
-
Commercial readiness: Access our contract templates, pricing playbooks and go-to-market positioning frameworks tailored for food, nutraceutical and pharmaceutical customers.
Final note — invest with insight
The ellagic acid market presents a classic strategic inflection: a steady top-line growth profile (6.65% CAGR in our 2026–2032 forecast) coupled with elevated execution complexity. Companies that treat quality, regulatory readiness and feedstock resilience as strategic assets — not just operational costs — will capture disproportionate value as the market continues to mature. Our complete report contains the detailed regional and application splits, full supplier profiles, price-curves and the granular scenario models required to operationalize the recommendations above.
Request the full report to obtain the proprietary demand model, supplier scorecards and the granular data that underpins these recommendations. In the current cycle, access to precise segmentation and supplier-level intelligence is the differentiator between cautious participation and market leadership.
For detailed analysis of this topic, please visit the official page: Ellagic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Alarm Equipment Market Set for 6.8% CAGR Through 2032
By PW Consulting, 2026-07-12
Fire Alarm Equipment Market 2026: Strategic Imperatives for Decision‑Makers
As organizations recalibrate capital allocation and product roadmaps for 2026, a clear line of sight into the fire alarm equipment market is no longer optional — it is strategic. PW Consulting’s latest market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes macro trajectories, regulatory inflection points, competitor action, and practical go‑to‑market playbooks that corporate leaders, investors, and procurement chiefs must use to shape near‑term choices and durable advantage.
Fire Alarm Equipment Market
Market trajectory: a growth arc that demands attention
The global market has expanded steadily, moving from approximately USD 270 Million in 2020 to USD 345 Million in 2025 (base year). Our forecast anticipates continued momentum into the 2026–2032 window, with the market expected to reach roughly USD 378.6 Million in 2026 and move toward USD 545.2 Million by 2032, representing a compound annual growth rate (CAGR) of about 6.8% over the forecast period. These headline numbers conceal granular dynamics — rising retrofit activity, accelerating adoption of connected addressable and intelligent systems, and growing service and software revenues — that will define winners and laggards.
Fire Alarm Equipment Market
Why 2026 is a strategic hinge year
-
Regulatory acceleration: NFPA 72 (2025 edition) provisions come into force in 2026, introducing mandatory cybersecurity requirements, tighter smoke‑detector testing protocols, and new battery handling/listing rules. These are not marginal compliance items; they create technology requirements, procurement constraints, and new maintenance workflows that will influence product specifications and recurring revenue models.
Fire Alarm Equipment Market -
Technology convergence: The market is transitioning from hardware‑centric fixtures to systems that integrate edge detection, cloud telemetry, and lifecycle analytics. Recent launches and product updates signal vendor moves to embed gateways, LTE/5G telemetry, and user platforms into the control plane — making software strategy a core determinant of value capture.
-
Service and labor dynamics: NFPA‑aligned qualified inspection and testing procedures increase labor intensity and create opportunity for premium maintenance offerings and certification‑driven service models. At the same time, certified technician supply is tightening, forcing channel and vendor rethink on training and automation.
Competitive landscape: concentrated but contested
The market exhibits moderate concentration: the top three players account for just under half of market sales, and the top five approach six in ten on aggregate (CR3 ≈ 49%, CR5 ≈ 59%). This structure favors established OEMs with scale, distribution, and aftermarket reach, but leaves meaningful room for specialist innovators and regional champions to exploit niches.
-
Scale incumbents: Companies such as Johnson Controls and Honeywell continue to leverage full‑stack portfolios — from control panels to integrated life‑safety systems — and are accelerating cloud and gateway offers to win enterprise installations and multisite managed services.
-
Systems integrators and automation majors: Siemens and Carrier are pushing intelligent detection and modular life‑safety architectures, often bundling fire detection with building automation and energy management to raise switching costs.
-
Component and notification specialists: Companies like Gentex, System Sensor, and Potter maintain defensible positions in notification appliances and detector technologies; they are critical partners for OEMs focused on product differentiation.
-
Regional and niche players: Mircom, Napco, Hochiki America, Bosch’s fire division, and a set of European specialists (Zettler, Schrack Seconet, CWS) exploit local standards, channel partnerships, and compliance know‑how to compete effectively against global brands.
Recent vendor moves illustrate strategic shifts that will play out in 2026: Johnson Controls' introduction of cloud‑connected gateways and user platforms, and NAPCO’s rollout of addressable control panels with LTE/5G transmission, both point to accelerated vendor investment in remote monitoring, secure telemetry, and mobile‑first user experiences. Potter’s active participation at sector trade shows underscores the continuing importance of relationship‑driven channel engagement.
Regulatory and standards shockwaves: implications for product and procurement
-
Cybersecurity as a line item: NFPA 72’s 2025 edition makes cybersecurity a functional requirement. Procurement teams must now include security validation and firmware lifecycle commitments in RFPs, and operations must budget for vulnerability management and secure provisioning.
-
Battery policy and traceability: New UL listing enforcement for rechargeable batteries and mandatory 'best by' date tracking on smoke detector batteries increase BOM scrutiny and inventory controls. Vendors that cannot demonstrate compliant battery sourcing and lifecycle tracking will face installation blockages.
-
Inspection and workforce impact: More rigorous NFPA 72‑aligned testing increases both the frequency and complexity of maintenance visits, elevating the commercial value of certified training programs and remote self‑diagnostics.
Key risks and supply constraints to model in 2026 planning
-
Component availability: Listed battery components, semiconductor sensors, and RF modules are chokepoints. Buyers should model lead times and dual‑source critical components.
-
Labor scarcity: Certified technicians are becoming a scarce resource in major markets; outsourcing or building training academies is a strategic hedge.
-
Cyber risk and liability: Connected gateways introduce new attack surfaces and insurer scrutiny; cybersecurity features should move from marketing to contractual warranties and SLAs.
-
Regulatory enforcement variance: Local enforcement and product listing expectations differ by market; standardization workstreams and regional compliance playbooks are needed for rollouts.
What the PW Consulting report delivers — practical, actionable, and purchase‑ready
Our study intentionally balances authoritative market synthesis with hands‑on tools executives use to act quickly in 2026. Highlights include:
-
Granular market model and scenarios: A transparent, auditable market sizing model (USD Million basis, 2020–2032) with upside/downside scenarios reflecting regulatory acceleration, technology adoption rates, and macro shocks.
-
Strategic segmentation playbooks: Actionable GTM and product strategies across types (conventional, addressable, intelligent), channel routes, and application classes — with ROI cases for retrofit vs greenfield approaches. (Note: the full segmentation tables and regional splits are deliberately reserved for the full report.)
-
Competitive benchmark and capability matrix: Comparable capability scoring across the leading suppliers, including product portfolios, cloud and edge capabilities, distribution strength, and aftermarket services.
-
Regulatory compliance matrix: Mapped NFPA 72 changes to product and service implications, with vendor checklists and procurement contract language you can insert into RFPs today.
-
Supply‑chain risk heatmap: Component concentration, single‑sourcing exposures, and recommended mitigation priorities (inventory buffers, second‑source qualification, and strategic contract language).
-
Monetization and pricing playbooks: Bundling strategies for hardware, cloud subscriptions, and inspection services to lift gross margin and extend customer lifetime value.
-
M&A and partnership screen: A prioritized list of capability targets (software gateways, notification specialists, regional installers) with integration checklists and sample valuation heuristics.
2026 decision agenda — recommended priorities for executives
-
Procurement and Specification: Update RFPs to demand UL‑listed battery components, firmware update policies, and minimum cybersecurity features. Build contractual milestones tied to NFPA‑compliant delivery.
-
Product and R&D: Fast‑track cloud‑gateway integration, secure provisioning, and remote diagnostics. Prioritize addressable/intelligent capabilities where lifecycle service revenues can be captured.
-
Service and Talent: Invest in certified training programs and remote testing tools to offset technician shortages and monetize inspection cycles.
-
Channel and Partnerships: Create preferred integrator programs with incentives for compliance‑ready installs; consider telco partnerships for LTE/5G telemetry and resilient connectivity.
-
M&A and Portfolio Optimization: Target tuck‑ins that accelerate software, analytics, or notification appliance portfolios; use earnouts tied to interoperability and compliance milestones.
Final synthesis: how to convert market insight into defensible outcomes
For decision‑makers, the 2026 operating environment is defined by three converging forces: regulatory mandates that raise technical thresholds, technology shifts that commoditize legacy hardware while creating software margins, and service dynamics that reward certification and recurring revenue. The headline market growth (CAGR ≈ 6.8% to 2032) confirms demand expansion, but the real profit pools will flow to vendors and buyers who execute on secure, connected offerings and who can operationalize compliance and service delivery at scale.
PW Consulting’s full report delivers the data, models, vendor scorecards, and executable playbooks you need to make those choices with confidence. This introduction is a strategic preview; for the full segmentation tables, downloadable model, and vendor benchmarking matrices that underpin these recommendations, please access the complete study on our site.
For detailed analysis of this topic, please visit the official page: Fire Alarm Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roofing Adhesives Market — Strategic Outlook for 2026 Decision-Makers
Executive preview
As companies plan capital allocation, R&D roadmaps, and go-to-market moves for 2026, the roofing adhesives market presents a blend of steady expansion and regulatory-driven disruption. Our latest PW Consulting study—anchored on a 2025 base year, with historical coverage from 2020–2025 and forecasts through 2026–2032—quantifies this trajectory and translates it into actionable options for manufacturers, distributors, specifiers, and investors.
Roofing Adhesives Market
Why this market matters in 2026
The market has grown from approximately USD 225 million in 2020 to about USD 290 million by 2025, and our forecast implies continued steady expansion at a compound annual growth rate of 5.6% across the upcoming planning horizon. By 2026 the market is projected to pass the USD 300 million threshold and is expected to approach the mid‑hundreds by the end of the 2032 forecast window. That combination of durable size, predictable growth, and ongoing product differentiation makes roofing adhesives a pragmatic arena for strategic investment—even as regulatory momentum and technology shifts reshape specification criteria.
Roofing Adhesives Market
Key structural themes shaping 2026 decisions
- Regulatory and standards acceleration:
Across North America and Europe, tighter VOC limits, updated test standards and more prescriptive ecolabels are raising the bar for formulation and documentation. Notable changes include recent revisions to ecolabel standards for commercial adhesives, stricter regional VOC requirements that many California projects default to, and updated ASTM practices covering time‑to‑failure and uplift testing. These are no longer compliance items only for environmental teams—they materially change product roadmaps, testing budgets, and time‑to‑market for new formulations.
Roofing Adhesives Market - Materials and product innovation:
Expect further acceleration toward low‑VOC, solvent‑free, bio‑based and equipment‑efficient systems. Recent product introductions and plant expansions demonstrate suppliers are prioritizing sprayable canisters, solvent-free hybrids, and adhesives with significant bio‑based content while preserving performance targets such as wind uplift and long‑term creep resistance. Competitive advantage increasingly rests on marrying performance with clear environmental and contractor‑ease attributes.
- Channel and execution economics:
Distribution partnerships and regional production footprint decisions matter more than ever. Manufacturers are optimizing channel partnerships and on‑the‑ground service (training, specification support, and fast shipping) to win fully adhered specifications. Notably, strategic collaborations and capacity expansions are reshaping availability and local cost structures—affecting tender competitiveness and contractor adoption curves.
- Market concentration and consolidation potential:
The roofing adhesives market displays a moderate level of concentration among leading global players. This creates a twofold strategic implication: established players can extract scale benefits from R&D and compliance investments, while well‑targeted acquisitions or partnerships provide a viable route for mid‑tier players and private capital to accelerate capability build‑out and market access.
Competitive dynamics — how the field lines up
The competitive set combines large global chemical and specialty adhesives companies, building‑materials groups, and focused regional players. Global formulators with integrated R&D and broad manufacturing footprints are pushing portfolio strategies that cover single‑ply membranes, modified bitumen and insulation bonding. Technical specialists are differentiating on contractor productivity and sustainability credentials. Regional and system providers emphasize specifier relationships, warranty compatibility and distribution depth.
- Full‑portfolio global players: These firms leverage broad product families across resin classes and roof systems, using global scale to fund testing, certification and localized manufacturing.
- Technical innovators: Suppliers focused on next‑generation application formats (equipment‑free canisters, sprayable, low‑VOC hybrids) are converting specification trials into repeat business by reducing on‑roof labor cost and improving installation reliability.
- System integrators and regional specialists: Companies with deep relationships with membrane and insulation manufacturers or strong contractor networks can command premium positioning through bundled warranties and specification convenience.
Recent market signposts (examples for 2025–early‑2026)
- Product launches emphasizing low‑VOC and solvent‑free chemistries and equipment‑friendly formats signal a near‑term industry tilt toward contractor productivity and environmental compliance.
- Production capacity expansions and strategic distribution partnerships indicate leading firms are reducing lead times and localizing supply to serve large specification markets more reliably.
- Regulatory updates—particularly ecolabel clarifications and regional VOC rules—are forcing reformulation timelines and creating certification costs that will favor players with scale or differentiated technical capabilities.
Concrete implications for 2026 strategy
- For manufacturers:
Prioritize formulation platforms that can be quickly adapted to meet tightened VOC/eco‑label thresholds and maintain mechanical benchmarks (wind uplift, creep). Invest in equipment‑friendly formats that lower contractor labor time and make total installed cost a visible selling point. Consider selective capacity expansions or contract manufacturing in priority regions to shorten lead times and reduce freight and inventory exposure.
- For distributors and channel partners:
Differentiate through specification support and contractor training. Bundled solutions—adhesive + warranty + installation training—will win in competitive bids where performance and compliance are jointly evaluated by owners and specifiers.
- For specifiers and large end users:
Update procurement templates to incorporate both environmental compliance (e.g., updated ecolabels and regional VOC limits) and contractor efficiency metrics. Require documented compliance pathways to new standards and prefer suppliers that offer installation‑ready packaging and warranty support.
- For investors and corporate development teams:
With the market expanding at an approximate mid‑single digit CAGR and moderate concentration among leaders, opportunistic M&A can bring differentiated chemistries or channel access into a larger platform at attractive multiples. Focus targets should combine proprietary, low‑VOC or equipment‑efficient chemistries with established distribution relationships.
Report coverage — what PW Consulting delivers to inform 2026 choices
The full study provides a practical toolkit to turn insight into action. Key deliverables include: a transparent forecasting model spanning 2026–2032; a granular segmentation framework by resin family, application, and geography; a regulatory and standards matrix tied to commercialization timelines; product benchmarking against performance and sustainability KPIs; supply‑chain maps and raw material risk assessments; company profiles with capability heatmaps; and commercial playbooks tailored for manufacturers, distributors, and private equity.
Importantly, while this preview outlines strategic themes and macro trajectories, the report reserves core segmented analytics and proprietary company estimates—data that enable precise prioritization and transactional diligence—for the full publication.
How to use these insights in your 2026 planning cycle
- Update product roadmaps to incorporate low‑VOC/solvent‑free and bio‑content targets with hard milestones tied to certification timelines.
- Stress‑test supply chains for raw materials subject to regulatory scrutiny and identify qualified second‑source partners.
- Quantify the economics of changing packaging and application systems (e.g., canisters, sprayable, pressure‑sensitive) in pilot projects with key contractor partners.
- Make targeted investments in specifier engagement and warranty packages that translate environmental compliance into procurement advantages.
- For acquirers: prioritize targets with both differentiated chemistries and existing distribution linkages in high‑growth end markets.
Closing perspective
The roofing adhesives market in 2026 is neither a high‑risk frontier nor a mature commodity space—it's a pragmatic growth category at the intersection of performance engineering, sustainability regulation, and contractor economics. The projected market expansion and the moderate concentration of leading firms create clear pathways for value creation through product differentiation, targeted capacity decisions, and channel innovation. PW Consulting’s full report turns these strategic pathways into executable plans—complete with the numerical granularity and company‑level diagnostics executives need to commit capital and mobilize teams in 2026.
For access to the full dataset, segmented forecasts, and the detailed competitive and regulatory dossiers that underpin these recommendations, visit PW Consulting’s roofing adhesives market page to license the complete report and modeling tools.
For detailed analysis of this topic, please visit the official page: Roofing Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Asia Pacific Leads Screw Jacks Market with USD 128.95M; 4.38% CAGR to 2032
By PW Consulting, 2026-07-12
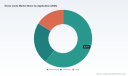
Screw Jacks Market 2026: Strategic Intelligence Briefing for Decision-Makers
As organizations prepare budgets and strategic priorities for 2026, the Screw Jacks market presents a textbook combination of steady expansion, episodic input-cost volatility, and evolving commercial models. This briefing distills PW Consulting’s latest research into the practical intelligence executives need to act decisively—while preserving the granular segmentation and scenario models available in the full report.
Screw Jacks Market
Market snapshot: steady growth, selective disruption
The global screw jacks market has demonstrated resilient expansion through the 2020–2025 period, increasing from an aggregate market base in 2020 to a larger base by the 2025 report year. Our forecast through 2032 projects continuation of this trajectory under a compound annual growth rate of approximately 4.38%, reaching a materially larger market by 2032. Two facts matter for 2026 planning: growth is reliable but not runaway, and the shape of value capture is shifting toward engineered solutions, aftermarket services, and electrified actuation.
Screw Jacks Market
Why this matters for 2026 decision cycles
-
Capital allocation: With moderate, predictable top-line growth, capital deployed into differentiated product lines (electric actuation, high-precision systems, or modular ex-stock offerings) typically yields higher ROIC than investments that chase commodity positions.
Screw Jacks Market -
Supply-chain hedging: The industry continues to feel raw-material and energy-cost swings. Procurement strategies that increase visibility and secure continuity—inventory buffers, strategic hedges, and local sourcing—will reduce production and delivery risk in 2026.
-
M&A and portfolio moves: The market concentration metrics in our study indicate a mixed landscape—leading players secure sizeable shares while room remains for regional specialists and technology-focused entrants. This supports selective bolt-on M&A to acquire niche capabilities or distribution reach.
Key market dynamics shaping 2026 strategies
-
Electrification and precision: Demand for electric screw jacks and precision screw-drive systems is accelerating in segments where automation, repeatability, and remote control are table stakes. Companies that combine mechanical robustness with controls integration will be favored by OEMs seeking simplified supply chains.
-
Modularity and availability: As some players move to ex-stock models and platformized modular offerings, buyers increasingly expect short lead times and configurability. The commercial value of “in-stock” modular kits—especially for uptime-critical industrial clients—will be a key differentiator in tender processes.
-
Aftermarket and services: With screw jacks embedded into larger systems, lifecycle services (inspection packages, rapid-replacement programs, and retrofit kits) offer margin and relationship advantages. Building out service capability is a pragmatic route to margin expansion in 2026.
-
Input-cost pressure: Steel and related raw material cost trends have shown upward movement in recent periods, adding cost and pricing complexity. Procurement and engineering teams that prioritize material efficiency, alternate alloys, or process redesign will protect margins.
Competitive landscape: capabilities to watch
Our competitive analysis surveys global suppliers ranging from precision-drive specialists to heavy-load system providers. Several patterns emerge that should guide competitor-mapping and partner-selection in 2026:
-
Platform leaders (e.g., manufacturers with broad tonnage ranges and standardized product lines) maintain wins in heavy industrial and infrastructure projects by offering proven reliability and scale supply. They compete on delivery capacity and certifications for large installations.
-
Precision and aerospace specialists are differentiating through integrated actuation and high-accuracy screw drives—appealing to applications where positional tolerance and repeatability are non-negotiable.
-
Niche pioneers focus on modularity, ex-stock models, and configurators that reduce lead time. These entrants convert downtime risk into commercial opportunity by promising rapid replacements or local spares availability.
-
Service-first providers are monetizing aftermarket opportunities with inspection contracts, refurbishment, and field support—turning single-sale relationships into multi-year revenue streams.
Representative players examined in the report include firms known for their heavy-duty ActionJac offerings and linear-motion portfolios, ball- and worm-screw specialists with varied machine and ball screw systems, precision screw-drive makers for high-accuracy motion, and suppliers prioritizing modular or ratchet designs for heavy-duty lifting. Each has a clear strategic posture—scale and capacity, precision electromechanics, modular availability, or service-led monetization—and the competitive map in our full analysis shows how these positions cluster geographically and by end-market focus.
Recent developments that will influence 2026 tactics
-
Manufacturers expanding ex-stock and platform services are altering buyer expectations around lead time and uptime risk. Strategies that ignore availability risk ceding high-value aftermarket contracts to fast-fulfill competitors.
-
Visibility at trade venues continues to matter—suppliers showcasing integrated linear-motion and actuator systems influence OEM specifications and early-stage design decisions.
-
Raw-material and energy cost trends persist as an operational risk. Teams must balance short-term price recovery with longer-term pricing discipline and value communication to customers.
Actionable playbook for 2026 (select priorities)
-
Product strategy: Prioritize a two-track approach—(1) reinforce platform reliability in commodity-heavy, high-load applications; (2) accelerate development and go-to-market for electric and precision screw-drive variants where ASPs and margins justify R&D and certification spend.
-
Commercial model: Pilot ex-stock and modular bundles in one or two high-opportunity regions or verticals to validate inventory economics and lead-time elasticity before broader rollout.
-
Aftermarket expansion: Design fixed-price maintenance and rapid-replacement offerings for strategic accounts—measure impact through customer churn reduction and service-margin uplift.
-
Procurement and operations: Implement rolling hedging or supplier diversification strategies for key steel inputs; consider design changes that maintain performance while reducing raw material intensity.
-
Partnerships and M&A: Target acquisitions that add complementary actuation controls, field-service footprints, or configurator technology. Prioritize deals that close capability gaps and shorten go-to-market timelines.
-
Digital enablement: Invest in an after-sales portal, digital configurator, and predictive-maintenance analytics to raise switching costs and capture higher lifetime value.
How PW Consulting’s report supports 2026 decision-making
The full study is structured to convert market insight into executionable plans. Highlights include:
-
Market-sizing and reliable trend models that cover the historical 2020–2025 period and present base-year (2025) benchmarking with scenario-based forecasts through 2032—enabling CAPEX and revenue-planning under conservative, base, and accelerated adoption cases.
-
Competitive dashboards that profile leading and niche suppliers by capability, channel coverage, technology focus, and aftermarket strength—designed to accelerate competitor due diligence in M&A and partnership assessment.
-
Procurement risk matrices and input-cost sensitivity analyses, including stress tests for raw-material price swings and contingency playbooks for sourcing and inventory tactics.
-
Playbooks for product architecture decisions, pricing frameworks, and service-pack design—each anchored in customer willingness-to-pay analysis and procurement behavior observed across multiple end markets.
-
A prioritized list of strategic moves with estimated timeline and resource intensity—intended to help leadership teams create a 12–24 month plan that balances near-term operational resilience with medium-term capability building.
What the briefing intentionally omits—and why
In keeping with PW Consulting’s “trailer” approach, this briefing surfaces the macro trajectory, competitive themes, and decision-focused recommendations you need for 2026 planning, while withholding the granular split tables and proprietary segment-by-region or application-level shares contained in the full report. Those segmentation matrices and exact regional/application allocations are purpose-designed to inform bidding strategies, channel commitments, and valuation models—and are therefore available through the full study to paying subscribers and licensed clients.
Next steps for leaders
-
Use this briefing to align executive priorities for 2026: pick one near-term operational hedge (procurement/reduction in lead time) and one near-term commercial experiment (ex-stock pilot or service package test).
-
Commission a rapid competitor deep-dive if you are considering M&A: our profiles and benchmarking templates reduce discovery time and uncover integration risks specific to screw-jack technologies and service capabilities.
-
Request the full PW Consulting Screw Jacks Market report for the segmentation matrices, supplier scorecards, and the scenario-modeled financials required to finalize budgets, bids, and acquisition diligences.
For organizations that need to translate steady medium-term growth into competitive advantage in 2026, the right mix of product differentiation, availability, and service monetization will determine winners and laggards. PW Consulting’s full study provides the empirical foundation and execution toolset to select and sequence those moves with confidence—contact us to access the complete analysis and the downloadable resources that accompany it.
For detailed analysis of this topic, please visit the official page: Screw Jacks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Private Tutoring Market Poised for 4.75% CAGR (2026–2032)
By PW Consulting, 2026-07-12
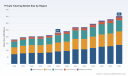
Private Tutoring Market — 2026 Strategic Preview
Why this preview matters for 2026 decision-makers
As organizations plan investments, partnerships, and product strategies for 2026, the private tutoring market presents a distinct blend of steady expansion and structural change. Our PW Consulting base-year assessment (2025) observes that the market has expanded meaningfully since 2020 and — under conservative assumptions — is projected to grow at a 4.75% compound annual growth rate through the 2026–2032 forecast window. Translating that trajectory into practical planning: the market that stood at the low hundreds of million USD five years ago is on a path to mid-hundreds of million USD by the end of the forecast horizon. That macro trend creates predictable demand pressure while leaving plenty of room for differentiated players to capture outsized returns.
Private Tutoring Market
This preview highlights the strategic implications of that growth path without disclosing the full tables, subsegment splits and granular regional allocations that are contained in the complete PW Consulting Private Tutoring Market report. Think of this as the strategic trailer: enough evidence of rigor to act, but intentionally not the proprietary datasets that power investment-grade decisions.
Private Tutoring Market
Market dynamics that will determine winners in 2026
- Demand stabilization with pockets of acceleration.
After a period of rapid digital adoption and episodic policy shocks, demand is maturing. Growth is driven by persistent parental and institutional willingness to invest in learning outcomes, with the fastest commercial potential concentrated where convenience, measurable outcomes, and accredited quality intersect.
Private Tutoring Market - Labour economics are a structural constraint.
Median annual tutor wages highlight the cost component for many operating models. Labour cost dynamics will determine pricing bands, margin levers and the attractiveness of automation or platform-mediated scale for different business models.
- Regulation remains a strategic risk and a moat.
Decades-long policies in multiple jurisdictions have limited or constrained teacher-provided private tutoring, and landmark interventions — most notably regulatory shockwaves in certain large markets — demonstrate how quickly operating landscapes can shift. Regulatory foresight and compliance capability are prerequisites for scalable expansion.
- Data privacy and tutor quality certification are buyer-deciding factors.
Institutional buyers and more sophisticated parents increasingly select providers on demonstrable privacy compliance and verified tutor credentials. Firms that embed these features into their product proposition enjoy higher conversion and retention.
- AI and product innovation are the new oxygen.
AI-driven personalization, automated lesson diagnostics, and guided practice engines materially raise per-student outcomes while enabling higher utilization of tutor time. Recent vendor launches demonstrate how quickly feature gaps can be closed by focused investment.
Competitive landscape — what we evaluated
Our analysis synthesizes public disclosures, proprietary interviews, and primary market modeling to profile a broad cross-section of incumbents and challengers. The market displays moderate concentration: the top three firms command a meaningful share of revenue, and the top five firms approach half of the market — a structure that rewards scale and differentiated distribution.
- Digital-first platforms: Companies that built marketplace or platform models have advantages in matching efficiency, variable cost structures, and data capture. They compete on matching algorithms, platform trust signals, and monetization architectures.
- Franchise and center-based operators: These players continue to capture demand where local trust and hands-on delivery matter. Expansion strategies are often franchise-led and can deliver rapid unit growth where brand, training, and local marketing are strong.
- Test-prep and admissions specialists: Brands with reputation in high-stakes testing leverage premium service lines and bundled offerings to secure higher ARPU (average revenue per user) customers.
- Hybrid operators: Firms combining in-person centers with online delivery are experimenting with dual-channel economics to optimize tutor utilization and market reach.
We evaluated leading participants across these archetypes — including global platform providers, established franchise networks, and specialist test-prep firms — to extract strategic patterns. Each profile in the full report contains an assessment of go-to-market, monetization, unit economics, recent strategic moves and an M&A posture snapshot.
Recent developments that matter for 2026 planning
- Significant franchise acceleration by franchise-led educators signals renewed appetite for physical expansion where unit economics support it.
- AI-enabled product launches from marketplace incumbents demonstrate how personalization and learner analytics are being embedded into core propositions.
- Ownership changes at established online tutoring providers illustrate both strategic repositioning and the continued investor interest in scalable digital tutoring assets.
What the full PW Consulting report delivers (practical, operational, decision-ready)
The full report is designed for boards, corporate strategy teams, private equity sponsors, and product leaders who need executable guidance. Key deliverables include:
- Market sizing & conservative-to-optimistic forecasts by year (base-year 2025 and forecast 2026–2032) with sensitivity analyses.
- Segment economics and pricing benchmarks (institutional vs consumer channels), with modeled LTV:CAC and break-even timelines for representative business models.
- Go-to-market playbooks for three archetypes: platform marketplaces, franchised centers, and integrated hybrid operators — each with tactical KPIs, channel budgets, and pilot templates.
- Regulatory risk matrix and mitigation pathways tailored to priority expansion markets.
- Product feature prioritization framework emphasizing AI personalization, compliance controls, and measurement systems that drive renewals.
- M&A screening tools and an actionable shortlist methodology that identifies targets by revenue profile, margin expansion potential, and integration risk.
- Operational playbooks for tutor recruitment, certification programs, and quality assurance that align with institutional purchasing criteria.
- Scenario planning playbooks with trigger-based decision rules for accelerating or pausing expansion under regulatory, macroeconomic, or competitive stress.
To preserve the strategic value of our proprietary work—and to serve as a call to action for stakeholders seeking transaction-ready intelligence—we do not reproduce detailed subsegment tables or regional/application percentage breakdowns in this preview. Those granular insights, including full-year-by-year tables and downloadable models, are available in the complete PW Consulting publication.
Strategic actions for 2026 — where to focus
- Prioritize product levers that increase measurable outcomes:
Invest in AI-driven lesson personalization, outcome tracking dashboards, and tutor enablement tools that demonstrably lift test scores or course completion. These are the features that convert higher-value buyers and justify premium pricing.
- Embed compliance and credentialing into the commercial proposition:
Develop audit-ready privacy controls and tutor certification pathways. Institutional buyers increasingly treat these as pre-requisites, not differentiators.
- Choose an expansion mode that fits economics:
Franchise expansion can scale presence quickly where local brand matters; marketplaces scale faster with lower capital intensity. Hybrid approaches can unlock incremental reach but require disciplined integration to avoid margin erosion.
- Design M&A to buy capabilities, not just customers:
Targets that bring proprietary curriculum, validated outcome data, or superior local operations are more accretive than acquisitive plays that only increase topline volume.
- Measure the right KPIs:
Track tutor utilization, repeat-purchase rate, LTV:CAC by channel, average session yield, and a regulatory-risk index. These metrics should feed a quarterly dashboard used by the leadership team to pivot quickly.
- Run focused growth experiments:
Pilot bundles (micro-subscriptions, outcomes guarantees, school co-delivery) in 1–2 markets before scaling — use clearly defined decision gates tied to unit economics improvement.
Conclusion — the opportunity and the ask
The 2026 strategic horizon for private tutoring is one of measured opportunity: predictable overall growth, evolving buyer sophistication, and clear technological pathways to improve outcomes and margins. Success will accrue to firms that combine rigorous outcome measurement, disciplined unit economics, and regulatory foresight.
PW Consulting’s full Private Tutoring Market report contains the detailed tables, regional and application splits, company scorecards, and downloadable financial models necessary to operationalize these recommendations. For boards, PE investors and growth teams preparing 2026 plans, that level of granularity will be essential — and it is intentionally gated to ensure our clients receive transaction-grade intelligence.
Next steps
- Contact PW Consulting to request the full report and the accompanying financial models for scenario testing.
- Use the preview insights above to prioritize a short list of pilots and an M&A screening hypothesis for Q1 2026.
- Adopt the KPIs enumerated here as the core of your weekly growth and compliance dashboard.
For detailed analysis of this topic, please visit the official page: Private Tutoring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
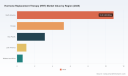
Hormone Replacement Therapy (HRT) Market: Strategic Outlook for Corporate Decision‑Making in 2026
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused, executive‑level preview of our new HRT market study — a practical intelligence product built for companies making portfolio, commercial, manufacturing, and M&A decisions in 2026. This introduction lays out the strategic implications that flow from the market’s trajectory, regulatory inflection points and competitive dynamics, while deliberately withholding the granular segment tables and product‑level financials that subscribers will find in the full report.
Hormone Replacement Therapy (HRT) Market
Macro picture: where the HRT market is now and where it’s headed
Using 2025 as the base year and tracking historical performance from 2020–2025, our modeling shows the global HRT market has expanded steadily in recent years and is positioned for sustained growth over the coming decade. The market grew from a modest base in 2020 to a larger, more commercially meaningful size by 2025, and our forecast through 2032 anticipates continued expansion at a compound annual growth rate (CAGR) of approximately 6.98% over the 2026–2032 period. Under PW Consulting’s scenarios, the market continues to benefit from improved access, evolving clinical guidance, and an active product pipeline that includes both hormonal and non‑hormonal therapeutic options.
Hormone Replacement Therapy (HRT) Market
These topline dynamics are the essential inputs for 2026 planning cycles — informing revenue run‑rates, capacity investments, pricing strategy and M&A valuation multiples. The full report contains the year‑by‑year market figures and scenario sensitivities used to stress‑test business plans; this preview focuses on what those numbers mean for strategic choices this year.
Hormone Replacement Therapy (HRT) Market
Why 2026 is an inflection year
- Regulatory and safety re‑profiling: Late‑2025 actions by the U.S. regulator — including approval of a generic version of a long‑standing conjugated estrogen product and removal of broad black‑box warnings for menopausal HRT formulations — materially change the safety narrative and the economics of the category. Those changes accelerate adoption in some patient cohorts and invite payors to reconsider coverage policy and cost‑effectiveness thresholds.
- Non‑hormonal entrants: Approval of a novel non‑hormonal agent for menopausal vasomotor symptoms in late 2025 expands treatment choice and redefines therapeutic positioning. Companies must now model cross‑elasticities between hormonal and non‑hormonal options when forecasting uptake and pricing.
- Generics and price pressure: The first generic approvals for legacy branded HRTs in decades create immediate competitive pressure on brand volumes, margins and formulary positions. At the same time, generics improve affordability and may expand addressable patient populations.
- Supply constraints and operational risk: Early‑2026 shortages of multiple estradiol transdermal patch suppliers illustrate that demand growth and manufacturing complexity can create acute availability risk. Companies with manufacturing flexibility or contract manufacturing relationships can translate scarcity into strategic advantage; those without must prepare contingency plans.
- Localized reimbursement shifts: State‑level coverage mandates for menopausal therapies that came into force in 2026 create patchworks of access that commercial teams must navigate — changing market entry sequencing and reimbursement dossiers.
Strategic implications for 2026 corporate planning
- Portfolio prioritization: Reassess launch sequencing and lifecycle investments with three lenses — clinical differentiation (safety/efficacy), payor access (coverage & prior authorization risk) and manufacturing resilience. Where regulatory actions de‑risk safety perceptions, re‑allocate promotional dollars to volume capture and adherence programs; where generics are imminent, accelerate differentiated formulations or delivery systems.
- Pricing and contracting: Expect dual pressures: downward list‑price pressure from generics and upward rebate/contracting pressure from payors seeking budget predictability. Build flexible pricing playbooks that include indication‑tiering, performance‑based agreements for symptomatic outcomes, and volume hedging in supply contracts.
- Manufacturing & supply chain strategy: Shortages in patch supply in early 2026 are a practical warning. Invest in capacity buffering, dual‑sourcing, and finished‑product inventory for critical SKUs. Evaluate near‑term investments in manufacturing scale only when backed by scenario‑specific demand forecasts and ROI thresholds in our model.
- M&A and partnership screening: The market’s moderate concentration and mixed incumbency create M&A arbitrage opportunities — from acquiring transdermal platform specialists to in‑licensing non‑hormonal assets. Prioritize targets that deliver immediate manufacturing capacity, differentiated delivery technology, or clear payor value propositions.
- Regulatory & market access preparedness: Update labeling strategies and real‑world evidence (RWE) plans to capitalize on the removal of broad safety warnings and to defend brand positioning against generics. Payers will increasingly request RWE that demonstrates symptom control, QoL benefits, and health‑economic outcomes.
- Commercial model recalibration: Hybrid channels (specialty clinics, primary care, telehealth) are reshaping access. Reallocate field force and digital spend to capture touchpoints where menopausal care is now being delivered, and design education programs for clinicians and patients aligned with the new safety narrative.
Competitive landscape: positioning and tactical moves
The HRT landscape comprises a mix of large integrated pharmaceutical companies, specialty manufacturers and aggressive generic producers. Market concentration metrics indicate a market that is neither highly consolidated nor atomized — the top three firms account for a material share but a long tail of players remain competitive. This structure favors differentiated branded products with strong clinical evidence and cost‑efficient generics competing on price and supply reliability.
- Global pharmaceutical leaders with established HRT portfolios (including major firms based in the United States and Europe) retain advantages in brand recognition, distribution networks and clinical legacy assets.
- Generic and specialty manufacturers hold critical roles in affordability and access; their operational reliability is now a procurement criterion for health systems and payors.
- New non‑hormonal entrants complicate prescribing algorithms and create headwinds for commoditized hormonal products — but also expand the treatment paradigm for patients who cannot or prefer not to take hormones.
Specific firms profiled in our research include leading multinational therapy originators, prominent generic manufacturers, and niche patch/route‑of‑administration specialists. Each profile in the full report contains an actionable assessment: revenue exposure to imminent generic erosion, pipeline roadmaps, manufacturing footprint, supply risk scores and suggested competitive countermeasures.
What the PW Consulting HRT Market report delivers — practical content for 2026 decisions
- Rigorous market sizing and forecasting model (2020–2025 history, 2026–2032 scenarios) with scenario toggles for regulatory shifts, generic entry timing and non‑hormonal uptake.
- Commercial playbooks: launch sequencing, pricing & contracting templates, payor negotiation scripts and patient support program blueprints tailored to HRT subsegments.
- Supply chain and manufacturing risk matrix with mitigation roadmaps — capacity build vs. contract manufacturing tradeoffs analyzed under multiple demand scenarios.
- Competitor and product intelligence dossiers covering clinical profiles, manufacturing capabilities, recent approvals and regulatory events; actionable SWOTs and likely moves for each major player.
- Regulatory tracker and policy impact assessment — including the late‑2025 FDA actions and state‑level reimbursement mandates — with quantified impacts on demand and price.
- M&A and partnership screening tool that ranks targets by strategic fit, valuation sensitivity and integration complexity.
- Real‑world evidence (RWE) playbook and health economic models to support coverage negotiations and formulary positioning.
Note: Consistent with our “preview” approach, this introduction highlights the frameworks and strategic implications of our analysis while withholding the granular segment tables (route of administration, gender and regional splits), product‑level revenue streams, and downloadable financial models. These are available only in the full report and client portal.
How to use this research in your 2026 decision cycle
- Board and investor briefings: use the topline forecasts and scenario summaries to set realistic top‑line expectations and capital allocation plans.
- Operating plan refresh: feed our demand scenarios into your FY‑2026 manufacturing, procurement and commercial budgets to stress‑test capacity and cash flow.
- Portfolio and R&D prioritization: re‑score projects by commercial viability under new safety and access dynamics; accelerate those with payor‑friendly outcomes or durable differentiation.
- M&A diligence: apply our target screening outputs to prioritize partners and acquisition candidates that reduce supply risk or provide differentiated delivery platforms.
- Market access campaigns: adopt the RWE and pricing templates to accelerate formulary wins and state‑level reimbursement approvals.
In short, our HRT market study is designed to be immediately operational — not just descriptive. It aligns quantitative forecasts with tactical playbooks so that commercial, supply, regulatory and corporate development teams can act with clarity in 2026.
Next steps and access
If your team is prioritizing market share defense, margin protection, manufacturing resilience or inorganic growth in HRT during 2026, PW Consulting’s full report supplies the detailed segmentations, product‑by‑product financials, and downloadable scenario models you will need. The full study also contains the proprietary segmentation breakouts and the exact route‑of‑administration, gender and regional forecasts that underpin the strategic recommendations summarized here — data we withhold in this preview to preserve the report’s commercial value.
Visit our HRT Market research page to access the comprehensive report, schedule a briefing with our analysts, or request a customized workshop that maps the findings directly to your portfolio and operating plan.
For detailed analysis of this topic, please visit the official page: Hormone Replacement Therapy (HRT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BPO Business Analytics Market to Reach USD 55B by 2032 at 14.2% CAGR
By PW Consulting, 2026-07-12
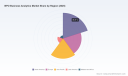
BPO Business Analytics Market: Strategic Imperatives for 2026
As enterprises sharpen their focus on operational resilience and customer intimacy, BPO Business Analytics has moved from a back-office efficiency play to a board-level strategic lever. This PW Consulting briefing introduces our full market research (base year 2025; forecast 2026–2032) and explains why the findings will materially affect vendor selection, sourcing strategy, and investment priorities in 2026. Below we surface the high-level trajectories, competitive dynamics, regulatory headwinds, and actionable priorities—while deliberately reserving the granular segment tables for the full report to encourage deeper engagement with our datasets and models.
BPO Business Analytics Market
Executive snapshot
-
The global BPO Business Analytics market expanded rapidly through the early 2020s—growing from a multi-billion USD market in 2020 to an estimated USD 22.0 Billion in 2025—and is on a path to approximately USD 55.0 Billion by 2032, reflecting a compound annual growth rate (CAGR) of about 14.2% over the forecast period.
BPO Business Analytics Market -
Market concentration is modest: the top three providers account for roughly a quarter of market value, and the top five capture just over a third, indicating sustained opportunity for both large-scale integrators and nimble specialists.
BPO Business Analytics Market -
For 2026 planning cycles, this implies an expanding supplier ecosystem, rapidly evolving product portfolios, and heightened need for disciplined vendor due diligence.
Why this research matters for enterprise decisions in 2026
-
Budget allocation: With near-term budgets pressured by macro uncertainty, procurement teams must justify investments in analytics-enabled BPO by linking spend to measurable financial and non-financial KPIs. Our study provides the ROI frameworks and benchmarking protocols buyers need to model multi-year payoff curves.
-
Vendor selection and partnership design: As vendors shift from transactional outsourcing to co-managed models anchored in analytics, enterprises must evaluate not only cost and scale but data governance, cloud integration, and AI model stewardship. The report profiles capability gaps and partnership archetypes that will influence RFP structures in 2026.
-
Risk and compliance: Increasing regulatory complexity—GDPR, HIPAA, and sector-specific rules—changes the calculus around nearshore vs. offshore delivery, anonymization techniques, and contractual safeguards. Our operational checklists and compliance decision trees are built to inform 2026 contracting and service-level negotiations.
Macro trajectory and what it signals
The market’s expansion—from the early 2020 baseline through a pronounced 2020–2025 acceleration to USD 22.0 Billion, and continuing to a projected USD 55.0 Billion by 2032—signals three structural shifts:
-
Analytics embedded into standard BPO offerings: Analytics is no longer an add-on; it is becoming embedded across process layers and delivery footprints.
-
AI and automation as differentiators: Investments increasingly prioritize predictive and prescriptive analytics tied to automation to reduce cycle times and escalate outcomes.
-
Platformization and partnerships: Cloud-native stacks and strategic cloud partnerships are reshaping how analytics capabilities are bundled with BPO services.
For corporate planners, the implication is clear: 2026 is a year to convert pilots into governed scale, and to embed analytics KPIs into outsourcing contracts rather than treating them as separate initiatives.
Dynamics, constraints and the “noise” shaping decisions
-
Regulatory pressure increases operational complexity. Data protection regimes such as GDPR—and sector-specific controls—raise the cost and process overhead for analytics outsourcing. We model the margin impacts and supply-chain remedies (e.g., tokenization, sovereign clouds) in the full report.
-
Labor market tightness and cost arbitrage stay relevant. Providers are formalizing hybrid delivery architectures—mixing onshore governance, nearshore escalation hubs, and offshore analytics teams—to manage cost and continuity. We quantify trade-offs in our scenario analyses.
-
Data quality and integration bottlenecks are the practical constraint to analytics ROI. The firms that win in 2026 will excel at end-to-end data orchestration—not merely at model-building.
What the full report delivers (practical, decision-ready content)
Our research is structured for immediate operational use by sourcing, finance, and technology leadership. Key inclusions:
-
Actionable use-case playbooks that map analytics capabilities to business outcomes and typical time-to-value for BPO engagements.
-
Vendor capability heatmaps and maturity scoring across data management, model governance, automation, vertical expertise, and cloud partnerships.
-
Contract and SLA templates with embedded metrics, penalty frameworks, and governance checkpoints tailored to analytics-led BPO.
-
Implementation roadmaps and an Analytics Center of Excellence (CoE) blueprint to migrate from pilot to pervasive deployment within 12–24 months.
-
Financial models and sensitivity analyses for build vs. buy vs. hybrid sourcing decisions, including headcount delta, run-rate savings, and reinvestment timelines.
-
Regulatory compliance matrices and operational controls for cross-border data flows and sectoral requirements.
-
A concise M&A and partnership playbook highlighting when to partner with a specialist, when to acquire capabilites, and how to structure joint offerings with cloud providers.
Competitive landscape — how to read the vendor field
The vendor universe is best understood in three clusters, each with distinct implications for enterprise buyers:
-
Global systems integrators and tier-1 BPOs (e.g., Accenture, Capgemini, Cognizant, IBM, TCS). These players compete on end-to-end transformation capability, strong cloud alliances, and the ability to embed analytics into large-scale BPO contracts. They are the default choice for complex, cross-border programs where governance and integration risk are paramount.
-
Analytics-first and process-specialist firms (e.g., EXL, Fractal, Genpact, WNS). These vendors bring domain-rich predictive models and verticalized analytics assets—useful when outcomes require deep process nuance, such as finance, healthcare, or supply chain optimization.
-
Contact-center and experience specialists (e.g., Teleperformance, Concentrix, Sitel, Alorica). Their advantage lies in high-volume interaction analytics, speech/text intelligence, and real-time CX optimization—critical when customer experience metrics are the core KPI.
Across the spectrum, we observe active productization: several vendors launched or upgraded AI analytics platforms through 2025 (notable examples include major platform releases and strategic partnerships announced in mid-to-late 2025). These moves accelerate de-risking of enterprise adoption but also heighten the importance of integration and change management capability.
Strategic recommendations for 2026 planning
-
Prioritize outcome-linked commercial models: Move away from pure FTE pricing toward outcome- and value-sharing models that align incentives around predictive accuracy, automation yield, and cost-to-serve reductions.
-
Establish a vendor segmentation and tiering framework: Use a two-step RFP where the first stage validates data governance and cloud posture, and the second stage pilots the analytics use-case at scale.
-
Invest in a Federated Analytics CoE: Blend centralized standards (model governance, tooling, data security) with embedded analytics talent in the business units to accelerate adoption.
-
Lock in regulatory controls early: Require vendors to demonstrate privacy-by-design, anonymization tooling, and jurisdictional data residency options as part of baseline compliance criteria.
-
Plan for talent scarcity: Prioritize vendor partnerships that provide managed analytics talent or robust automation that reduces reliance on scarce senior data scientists.
-
Adopt phased scaling: Pilot in high-value workflows (e.g., collections, claims triage, or procurement analytics), instrument the outcomes, and then scale with contractual incentives tied to measured performance.
Short checklist for procurement and technology leaders (next 90 days)
-
Map three priority use cases where analytics can deliver measurable cash or NPS improvement within 12 months.
-
Run a quick vendor capability vetting using a 12-point governance checklist (data residency, model explainability, cloud integration, SLA measurables).
-
Secure pilot budget and define success gates that convert pilots into enterprise-wide programs upon meeting pre-agreed ROI thresholds.
-
Negotiate clauses for data portability and IP reuse to avoid long-term lock-in as platforms evolve.
Methodology and how to use the full study
The full PW Consulting study combines primary interviews, supplier financial analysis, client-side surveys, and bottom-up TAM modelling calibrated to observed vendor revenues (base year 2025) and forward-looking adoption curves through 2032. For procurement and strategy teams, the report should be used both as an input to annual planning cycles and as an evolving decision-support tool. We provide dynamic worksheets and scenario models in the full package to tailor the findings to your organization’s size, vertical exposure, and risk appetite.
Conclusion and next steps
The BPO Business Analytics market presents a window of strategic leverage in 2026—where carefully structured pilots, disciplined vendor selection, and strong governance can translate into disproportionate advantage. Our research quantifies that opportunity at a market level (noting the expansion from the early 2020s through USD 22.0 Billion in 2025 and the projected USD 55.0 Billion by 2032 at a 14.2% CAGR), and offers the playbooks, contract language, and benchmarking tools to act now.
We have intentionally summarized actionable insights here while withholding full granular segmentation and proprietary vendor scoring details to preserve the research’s decision-making value. Access the complete PW Consulting BPO Business Analytics Market report to obtain the full datasets, region- and application-level breakdowns, vendor heatmaps, and downloadable implementation tools designed to guide your 2026 strategy.
For detailed analysis of this topic, please visit the official page: BPO Business Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


