



PW Consulting: Chelating Agents Market Set for 6.1% CAGR to Reach $344.8 Million by 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Chelating Agents Market Through 2032
The global chelating agents market stands at a critical inflection point. Based on comprehensive historical analysis from 2020 through 2025 and forward-looking forecasts extending to 2032, the market has demonstrated a trajectory of robust, compound annual growth. For executive leadership teams, procurement directors, and strategic planners, the question is no longer whether demand will expand, but how organizations can position themselves to capture value amidst shifting regulatory tides, raw material volatility, and an increasingly bifurcated product landscape defined by traditional performance versus emerging sustainability mandates. Our latest market research report offers the granular intelligence required to navigate this complexity, transforming macro-level economic signals into actionable strategic roadmaps for the 2026 fiscal year and beyond.
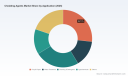
The historical data outlines a market that has steadily accelerated its revenue generation. Reviewing the performance from a base of approximately $163.15 million in 2020, the sector climbed consistently through successive years, reaching $170.07 million in 2021, $172.94 million in 2022, $185.51 million in 2023, and $206.85 million in 2024. Entering the most recent reporting year of 2025, the market total was valued at $215.0 million. This established foundation sets the stage for the forecast period beginning in 2026, where the market size is projected to surge to $236.38 million, followed by projected valuations of $247.57 million in 2027, $257.16 million in 2028, $284.71 million in 2029, $297.93 million in 2030, $312.61 million in 2031, and ultimately reaching $344.8 million by 2032. This trajectory, underpinned by a robust compound annual growth rate (CAGR) of 6.1% across the forecast horizon, signals sustained structural demand. For decision-makers, this growth represents both a significant opportunity for market share expansion and a rising risk of supply chain disruption if capacity investments and procurement strategies are not meticulously aligned with forecasted consumption patterns.
Chelating Agents Market
Chelants Market
However, relying solely on top-line revenue figures is insufficient for sophisticated strategic planning. The true competitive advantage lies in decoding the intricate segmentation dynamics that drive these numbers. Our research dissects the market across multiple critical dimensions, specifically analyzing regional consumption patterns, the evolving dichotomy between application-specific performance chemistries, and the distinct categorization by product nature. While the overall economic signal is strong, the distribution of value is not uniform. Understanding where demand is intensifying, which product archetypes are gaining traction, and how industrial, commercial, and consumer applications are diverging is paramount.
In the realm of geographic consumption, distinct regional economic profiles dictate varied growth drivers. Certain established markets maintain heavy reliance on mature industrial ecosystems, while high-growth regions are accelerating adoption due to expanding manufacturing bases, urban infrastructure development, and stringent environmental compliance requirements. The ability to align supply chain logistics and distribution networks with these disparate regional consumption velocities is a key differentiator. Similarly, the analysis of how demand is partitioned across core verticals reveals critical interdependencies. End-use sectors are the ultimate arbiters of volume. Traditional industrial applications continue to anchor volume, yet we are observing a marked acceleration in segments where water remediation, advanced cleaning formulations, and chemical processing are driving incremental growth. The report delves deep into these application-specific volumes, providing the granular breakdown necessary to identify which sectors offer the highest margin potential and which are susceptible to commoditization pressures. Furthermore, the categorization by product nature presents a strategic crossroads: the market remains anchored by non-biodegradable variants that dominate current volume, yet the share attributable to biodegradable alternatives is expanding at a significantly faster pace, propelled by regulatory pressure and brand owner sustainability commitments. Understanding the precise revenue mix and the elasticity of demand between these two archetypes is essential for portfolio optimization.
The Competitive Architecture: Navigating a Consolidated yet Dynamic Landscape
The chelating agents market is characterized by a moderately concentrated competitive structure. With the top three players accounting for a significant portion of market share and the top five controlling over half of total industry revenue, the landscape is dominated by multinational chemical giants with deep integration capabilities. However, the market remains contestable, with regional specialists and innovators driving disruption through niche product development, cost-competitive manufacturing, and sustainable chemistry alternatives. Our report provides a detailed competitive profiling of the key entities shaping the market trajectory, enabling clients to benchmark their strategic positioning against the moves of the industry's most influential players.
BASF SE, headquartered in Ludwigshafen, Germany, remains a foundational pillar of the global supply chain. As a leading producer of the Trilon® EDTA-series chelating agents, BASF provides comprehensive solutions spanning home care, industrial cleaning, agriculture, and broad industrial applications. The company's extensive product portfolio and brand recognition in the EDTA space make it a benchmark for performance and reliability. In a telling recent development that highlights the cost pressures ravaging the industry, BASF announced in June 2026 a price increase effective July 1, 2026, or as existing contracts allow, raising prices by $0.33 per kilogram for a broad select of its Trilon® chelating agents portfolio in North America. This adjustment affects liquid and solid forms of Trilon B, Trilon BD, Trilon BS, Trilon BX, Trilon C, Trilon CA Food Grade, Trilon D, Trilon G, and Trilon NA Food Grade. The rationale, as stated in BASF's official press release, points to an unrelenting convergence of cost drivers: continued increases in key raw material inputs, spiraling energy costs, and persistent logistics inflation, compounded by ongoing supply chain volatility. For customers and competitors alike, this move is a stark indicator of the margin compression facing traditional chemistry and the necessity for robust hedging strategies and supply diversification.
Dow Inc., based in Midland, Michigan, United States, maintains a formidable presence through its VERSENE™ EDTA and acid chelating agents. Dow's portfolio is engineered for broad pH metal ion control, serving critical functions in detergents, food processing, and complex industrial systems. Their ability to deliver consistent performance across widely varying pH environments positions them as a preferred supplier for applications where process chemistry precision is non-negotiable. Meanwhile, Nippon Shokubai Co., Ltd., operating from Osaka, Japan, distinguishes itself through innovation in high-performance polymeric chelating agents. Their AQUALIC™ line exemplifies this technological focus, targeting detergents, water treatment, and paper/pulp applications. This specialization allows Nippon Shokubai to command premium positioning in segments where efficiency and specific material interactions are valued over commoditized pricing.
On the Asian manufacturing front, Shandong IRO Chelating Chemical Co., Ltd., headquartered in Zaozhuang, Shandong, China, has established itself as a manufacturer of a remarkably full-spectrum chemistry catalog. Their production capabilities encompass the full EDTA-series, DTPA-series, NTA-series, and organophosphine chelating agents. This breadth enables Shandong IRO to serve a vast array of downstream markets including detergents, agriculture, textiles, and food applications, often providing a cost-competitive alternative to western incumbents and catering to the rapid industrialization demands of the Asia Pacific region. In the sustainability corner, two European players stand out for their strategic pivot toward bio-based solutions. Jungbunzlauer, based in Basel, Switzerland, is a recognized producer of biodegradable fermentation-based chelating agents, specifically citrates and gluconates. Their expertise is highly relevant for sensitive applications such as food, beverage, and personal care formulations, where natural origin and safety profiles are paramount. Complementing this, Nouryon, headquartered in Amsterdam, Netherlands, is a manufacturer of advanced biodegradable chelating agents including GLDA, MGDA, IDS, and HBED. These next-generation chemistries are engineered for demanding applications in agriculture, detergents, and industrial processes, offering performance profiles that can rival traditional EDTA while addressing the biodegradability gaps that are increasingly drawing regulatory scrutiny.
The strategic implications of this competitive map are profound. BASF's recent pricing maneuver serves as a case study in the vulnerability of supply chains dependent on petrochemical derivatives and energy-intensive production routes. It underscores the value of contracts with long-term price stabilization clauses and the potential for suppliers of alternative chemistries to gain traction as buyers seek to mitigate cost risk. The divergence between BASF/Dow's commodity-scale EDTA focus and the specialized offerings of Nippon Shokubai, Jungbunzlauer, and Nouryon highlights the market's polarization. Buyers must now evaluate not just price per kilogram, but the total cost of performance, including regulatory compliance costs, consumer perception risks, and the operational flexibility offered by different chemical architectures. Our report dissects these competitive dynamics, analyzing market share concentrations, strategic partnerships, capacity expansions, and the product launch trajectories that will define market winners and losers over the forecast period.
Actionable Intelligence for 2026 Decision-Making
A market research report is only as valuable as its applicability to real-world business challenges. Our Chelating Agents Market study is designed as an executive toolkit, providing the operational intelligence required to make informed decisions in procurement, R&D, M&A, and market entry. The report structure moves beyond descriptive analytics to deliver prescriptive insights. Key components include:
- Detailed Value Chain Mapping: An end-to-end analysis of the supply ecosystem, from key raw material precursors like formaldehyde, sodium cyanide, and ethylene diamine to the manufacturing processes, logistics networks, and downstream consumption loops. This mapping identifies critical bottlenecks, sub-tier supplier dependencies, and points of leverage where supply disruptions or cost pass-through mechanisms are most likely to impact margins.
- Regulatory and Sustainability Deep-Dive: A comprehensive review of the evolving regulatory landscape across major jurisdictions. This includes an assessment of restrictions on EDTA usage in certain household detergents in the European Union and other regions, the growing emphasis on aquatic toxicity profiles, and the incentives driving the adoption of readily biodegradable alternatives. The report evaluates the timeline for regulatory enforcement and its projected impact on demand substitution across different regions and applications.
- Technology and Formulation Trends: An evaluation of emerging chelating technologies and formulation science. This covers the development of hybrid chelants, synergistic blends, and the integration of chelating agents into concentrated and solid detergent formats. Understanding these technical shifts is crucial for product developers aiming to future-proof their formulations against performance degradation or regulatory non-compliance.
- Procurement and Negotiation Intelligence: Drawing on the cost pressure signals exemplified by BASF's recent announcement, the report provides a framework for analyzing supplier pricing power, raw material exposure indices, and the negotiation levers available to buyers. It helps procurement teams anticipate price volatility cycles and structure contracts that balance supply security with cost control.
- Segmentation-Specific Growth Models: While the aggregate market data provides the macro context, this report unlocks the specific regional and application-level drivers. The segmentation data reveals how demand is ordered across the top-five regions, the interplay between type-based consumption of non-biodegradable versus biodegradable chemistries, and the volume distribution across key application verticals. This level of detail is essential for allocating marketing resources, targeting plant expansion, and identifying white-space opportunities in underserved niches.
The Path Forward: Translating Data into Advantage
The chelating agents market of 2026 is not merely a reflection of past industrial activity; it is a complex system influenced by the interplay of chemical engineering, environmental policy, global supply chain resilience, and shifting consumer expectations. The headline growth figures, while impressive, are a composite of divergent underlying forces. Some segments will thrive on volume and cost efficiency, while others will be propelled by performance differentiation and the urgent need for sustainable alternatives. Organizations that treat this market with a one-size-fits-all strategy risk being blindsided by localized disruptions, margin erosion, or regulatory headwinds.
Access to the complete intelligence contained in this report is the bridge between reactive management and proactive strategy. The data on regional consumption velocities, the precise revenue contributions of each product type, and the application-specific volume forecasts allow planning teams to model multiple scenarios with confidence. The competitive profiles provide the context to anticipate competitor moves, whether that involves BASF's pricing adjustments to protect margins or Nouryon's push into bio-based agriculture solutions. The industry context, highlighted by raw material and energy cost dynamics, equips stakeholders with the foresight to manage risk proactively.
We invite you to explore the full scope of this analysis. The insights presented here are a glimpse into a comprehensive body of work designed to empower your executive team with the clarity and depth needed to lead in a dynamic market environment. By leveraging the detailed segmentation data, the granular competitive assessments, and the forward-looking scenario analyses provided in the full report, you can transform the 6.1% CAGR growth trajectory into a tailored strategic advantage. To access the complete dataset, regional and application breakdowns, and the full suite of strategic recommendations, please visit our source page to download the full study. Equip your organization with the intelligence required to navigate the complexities of the chelating agents market and capture the value that lies ahead.
For detailed analysis of this topic, please visit the official page: Chelating Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ozone Analyzer Market to Reach $422.64M by 2032 at 6.0% CAGR
By PW Consulting, 2026-09-16
Executive Preview: Navigating the Ozone Analyzer Market in 2026 and Beyond
The global landscape for environmental monitoring and industrial safety is undergoing a significant transformation. As regulatory frameworks tighten and industrial processes become increasingly automated, the demand for precise gas detection and water quality assurance has never been more critical. At PW Consulting, we have compiled a comprehensive strategic analysis of the Ozone Analyzer Market, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 to 2032.
This article serves as an executive preview of our latest research. It outlines the macroeconomic trajectory, the shifting competitive terrain, and the regulatory forces shaping the industry. However, to ensure that our clients make decisions based on the most granular and actionable data, we have intentionally reserved specific segmentation breakdowns and detailed financial models for the full report. This preview establishes the strategic context, demonstrating why access to the complete intelligence suite is vital for 2026 planning.
Market Trajectory and Macroeconomic Context
The ozone analyzer sector is experiencing steady expansion, driven by heightened awareness of environmental compliance and the adoption of ozone-based disinfection technologies. Our analysis tracks market performance from historical baseline years through the current forecast horizon. The data indicates a consistent upward trend in revenue, reflecting both increased unit sales and a shift toward higher-value monitoring solutions.
For the base year 2025, the market established a significant valuation benchmark, setting the stage for accelerated growth in the coming years. The trajectory suggests that by 2032, the total market revenue will reach new heights, underpinned by a compound annual growth rate that underscores the sector's resilience. This growth is not merely linear; it reflects structural changes in how industries monitor ozone concentrations, moving from manual sampling to integrated, real-time digital monitoring systems.
Understanding the aggregate market size is only the first step. The true value for enterprise decision-makers lies in understanding the velocity of this growth across different technological and geographic vectors. While the overall top-line figures indicate a healthy market, the dispersion of value across different segments reveals where the highest margins and fastest adoption rates are occurring. Our full report dissects these layers to identify high-opportunity zones without exposing the company to the risks of generalized industry data.
Technological Segmentation and Application Drivers
The market is diversified across various technological methodologies and end-use applications. In terms of technology, UV photometric methods continue to hold substantial weight due to their precision and regulatory acceptance. Electrochemical solutions also represent a significant portion of the market, particularly where cost-effectiveness and portability are prioritized. The balance between these technologies is shifting as industries demand higher sensitivity and lower maintenance overhead.
Application-wise, the demand is broad but concentrated in specific sectors. Water treatment remains a cornerstone driver, with the Drinking Water Industry and Sewage & Industrial Process Water sectors accounting for a substantial share of adoption. However, growth is also notable in the Cosmetics and Pharmaceutical Industries, where ozone is used for sterilization and process purity. Environmental and Health Industries further contribute to the demand landscape, focusing on ambient air quality monitoring.
Strategic Note: While the broad categories are visible, the specific revenue contribution of each segment varies significantly by region and by vendor capability. Identifying which application segment offers the highest return on investment in a specific geographic territory requires the detailed segmentation matrices provided in the full PW Consulting study. General industry averages often mask local disparities that can make or break a product launch strategy.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of established multinational corporations and specialized niche players. Market concentration indicates a moderate level of consolidation, with the top five competitors holding a significant share of the total market revenue. This structure suggests that while there is room for innovation and entry, scale and regulatory certification are becoming increasingly important barriers to entry.
Ozone Generator Market
Key players are differentiating themselves through technology specialization and regulatory compliance. For instance, Teledyne API focuses on UV absorption analyzers such as the Model T400 and T703 series, which are EPA-approved for regulatory compliance. Similarly, 2B Technologies offers ambient and industrial UV-based ozone monitors certified as Federal Equivalent Methods (FEM), making them critical vendors for air quality and generator monitoring sectors.
Other notable entities include Aeroqual, known for portable and fixed ozone gas sensors for perimeter and indoor air quality applications, and HORIBA, which utilizes NDUV technology for ambient ozone monitors in air quality control. Acoem provides precise ambient air ozone measurements with the Serinus 10 analyzer, while BMT MESSTECHNIK GmbH specializes in high-concentration ozone analyzers with temperature and pressure compensation for industrial settings.
In the water treatment space, Hach integrates portable and process ozone analyzers with water treatment monitoring systems, whereas Sailhero targets marine and environmental ozone monitoring instruments. Thermo Fisher Scientific contributes instruments for environmental and laboratory air quality testing, and Eco Sensors focuses on environmental ozone sensors for air quality monitoring. IN USA, Inc. offers UV absorption ozone analyzers for high-concentration gaseous phase monitoring in safety and industrial applications, and Ozone Solutions Inc. provides monitoring systems for semiconductor, water, and industrial applications.
Strategic Note: Evaluating the specific market share and growth rate of each of these competitors requires the detailed competitor benchmarking section of our report. Knowing who leads the market is different from knowing which player is gaining share in high-growth segments like semiconductor manufacturing or pharmaceutical sterilization.
Regulatory Dynamics and Industry Developments
Regulatory frameworks are a primary catalyst for market demand. The U.S. Environmental Protection Agency (EPA) has implemented regulations that promote the use of ozone for disinfection, enhancing market growth in related monitoring solutions. Furthermore, the EPA is supplementing proposals to clarify the intended scope under the Protection of Stratospheric Ozone listing of substitutes. These regulatory actions create a compliance imperative for industries, driving the need for accurate, certified monitoring equipment.
Beyond regulation, industry standards are evolving. Trends in the ozone aging tester market emphasize ISO and ASTM standards for automation and certification in testing solutions. This shift toward standardized, automated testing increases the reliability of data and encourages the adoption of advanced analyzers that can integrate with broader quality management systems.
Recent industry activity also signals shifting dynamics. In May 2025, RainHarvest Systems launched new Pro Series and M Series ozone generator lines with integrated monitoring capabilities for water purification applications. Such product launches indicate a trend toward integrated systems where generation and monitoring are coupled, reducing installation complexity and improving reliability for end-users.
Strategic Value of the 2026-2032 Forecast Period
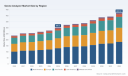
The forecast period from 2026 to 2032 represents a critical window for strategic investment. The market is expected to grow from a valuation of approximately 324.23 Million USD in 2026 to over 422.64 Million USD by 2032. This growth trajectory offers opportunities for capacity expansion, M&A, and product portfolio optimization. However, capturing this value requires precise timing and segmentation strategy.
Early movers who can align their product offerings with emerging regulatory requirements in North America, Europe, and Asia Pacific will gain a competitive advantage. The regional divergence in growth rates means that a one-size-fits-all strategy is inefficient. Some regions may prioritize ambient air quality monitoring due to urban pollution concerns, while others may focus on industrial process water due to manufacturing expansion.
Ozone Analyzer Market
Our full report provides the necessary depth to tailor strategies to these regional nuances. It includes detailed analysis of supply chain dynamics, pricing trends, and technology adoption curves that are not visible in high-level summaries. For executives planning capital allocation in 2026, understanding these granular drivers is essential to mitigate risk and maximize ROI.
Report Contents and Operational Utility
The PW Consulting Ozone Analyzer Market study is designed for operational utility. It goes beyond macro trends to provide actionable intelligence. The report covers:
- Detailed Segmentation Analysis: Breakdown by type, application, and region with historical and forecast data to identify high-growth pockets.
- Competitive Benchmarking: Profiled assessments of key market players, including their strategic moves, product portfolios, and regional footprints.
- Regulatory Impact Assessment: Analysis of how current and upcoming EPA regulations and ISO/ASTM standards affect demand and compliance costs.
- Market Concentration Metrics: Insights into CR3 and CR5 dynamics to understand competitive intensity and pricing power.
- Risk Factors and Opportunities: Identification of potential market headwinds and strategic avenues for growth.
Each section is crafted to answer specific strategic questions. For product managers, the segmentation data informs R&D priorities. For sales leaders, the regional breakdowns guide territory planning. For investors, the growth projections and competitive landscape assessments support valuation and due diligence processes.
Conclusion: The Case for Deep Intelligence
The Ozone Analyzer Market is poised for sustained growth, driven by regulatory tailwinds, technological advancements, and expanding industrial applications. However, the complexity of the market landscape means that surface-level data is insufficient for high-stakes decision-making. The difference between a successful market entry and a missed opportunity often lies in the details of segmentation performance and competitor positioning.
This preview highlights the structural elements of the market and the strategic importance of the 2026-2032 period. Yet, the specific data points that enable precise targeting and risk assessment are contained within the full PW Consulting report. We invite stakeholders to access the complete study to gain the comprehensive intelligence required to lead in this evolving sector. By leveraging deep-dive insights, enterprises can align their strategies with the most lucrative opportunities and navigate the regulatory complexities with confidence.
For detailed analysis of this topic, please visit the official page: Ozone Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Vacuum Pump Market to Hit $3.04B by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
The Automotive Vacuum Pump Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is navigating a structural transformation defined by electrification, stringent emissions regulations, and evolving safety architectures. At the intersection of braking performance, engine management, and thermal integration, the automotive vacuum pump market has emerged as a critical subsystem category. This report provides a comprehensive, decision-ready analysis of market trajectory, competitive positioning, and technology migration patterns across the forecast period from 2026 to 2032.
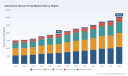
Our baseline assessment situates the market within a broader historical context spanning 2020 through 2025. Over this six-year window, the global market advanced from 1,520.0 million USD to a projected 1,950.0 million USD in 2025, reflecting sustained adoption of electric vacuum pumping solutions, integration into brake-by-wire architectures, and demand from hybrid and electric vehicle platforms. Looking forward, the forecast window projects continued expansion, with the market reaching 2,121.39 million USD in 2026 and progressing toward 3,043.56 million USD by 2032. This trajectory implies a compound annual growth rate of 6.5 percent, underscoring a market that is not merely growing in absolute terms but is also evolving in capability, supplier concentration, and application complexity.
For executive teams, product planners, procurement leaders, and investment analysts, these figures are not isolated statistics. They represent a signal of where value is moving within the powertrain and chassis subsystems landscape. The market is no longer defined by a linear replacement cycle. Instead, it is being reshaped by regulatory mandates, electrified brake architectures, and the need for on-demand vacuum generation in engine-off and start-stop conditions. Understanding this shift is essential for 2026 planning cycles, supplier negotiations, platform allocation decisions, and long-term portfolio strategy.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will be judged against how well organizations anticipated the convergence of electrification, braking safety, and emissions compliance. The automotive vacuum pump market is no longer a peripheral component category. It sits at the core of brake assist reliability, hybrid energy management, and advanced driver assistance functionality. This research is designed to help leaders cut through short-term noise and focus on durable structural drivers.
The study translates market growth into actionable intelligence. Rather than presenting numbers in isolation, the analysis ties valuation trends to product substitution patterns, architecture shifts, and supplier capability profiles. Decision-makers can use this framework to assess where demand is most likely to intensify, which performance attributes will differentiate winning products, and how supplier ecosystems are consolidating or expanding around key vehicle programs. The report also supports scenario planning by linking technology deployment logic to real-world operational requirements such as low-noise operation, thermal load management, and rapid vacuum buildup during engine-off phases.
Equally important, the report provides context for regulatory and safety developments that influence purchasing and engineering priorities. On-demand vacuum generation has become a relevant factor in meeting CO2 reduction targets, supporting downsized engine architectures, and ensuring brake assist continuity in hybrid and electric applications. At the same time, market participants have had to respond to field performance concerns, including notable recall actions that highlighted the importance of robust vacuum pump reliability in certain brake assist conditions. These events reinforce the strategic value of better data, tighter quality oversight, and more resilient supplier selection.
What the Report Delivers in Practice
This market research is built for operational use. It goes beyond headline figures and provides a structured foundation for product planning, competitive benchmarking, and market entry evaluation. The study is organized to support practical decision-making across multiple functional areas:
- Market sizing and forecast logic that connects historical performance with forward-looking demand assumptions across the 2026 to 2032 period
- Technology segmentation analysis that examines how different pump architectures are positioned across vehicle categories and subsystem requirements
- Application-level demand mapping that identifies where vacuum pumps are most critical within brake systems, engine management, HVAC systems, and emission control domains
- Regional demand context that highlights where volumes are developing and how regional vehicle mix, electrification pace, and OEM sourcing strategies shape opportunity
- Competitive landscape profiling that evaluates major incumbents and emerging contributors by technology focus, geographic footprint, and program relevance
- Recent product and deployment developments that track how suppliers are translating engineering intent into market-facing launches and modular platform strategies
- Regulatory and safety context that frames how compliance requirements and field performance issues influence design priorities and sourcing confidence
The report is intentionally constructed to support both strategic and tactical use cases. Product planners can assess where to allocate development resources. Procurement teams can better understand concentration risk and alternative sourcing options. Commercial teams can identify which applications and regions are likely to generate the strongest demand momentum. Investors and analysts can use the framework to interpret supplier commentary, program wins, and technology migration signals with greater precision.
Competitive Landscape and Technology Leadership
The competitive structure of the market reflects a concentrated but diversified supplier base. Market concentration metrics indicate that the top three participants account for approximately 25.8 percent of market revenue, while the top five participants represent about 35.2 percent. This structure suggests that while scale incumbents remain influential, there is meaningful room for specialist suppliers, regional players, and technology-focused entrants to compete on performance, integration, and program access.
Several European and Asian suppliers are defining the current pace of innovation. Continental AG has been advancing electric vacuum pump solutions for brake systems in passenger cars, commercial vehicles, and hybrid applications, with integration pathways into zone control and brake-by-wire architectures. Robert Bosch GmbH has expanded its electric vacuum pump platform across global SUV programs that rely on brake-by-wire for stable vacuum independent of engine operation, while also supporting modular deployments with adaptive control and regenerative braking compatibility. MAHLE GmbH has focused on high-efficiency electric vacuum pumps with integrated thermal management modules suited to 48V mild-hybrid and electric vehicle architectures.
Valeo SA supplies electric vacuum pumps for brake assist and emissions control in micro-hybrid and electric vehicles, including OEM supply relationships with major Asian manufacturers. Hella GmbH & Co. KGaA provides electric vacuum pump solutions for power brake boosters, including auxiliary and diaphragm-type models for hybrid and internal combustion engine braking systems. Rheinmetall Automotive AG, through its Pierburg division, supplies high-efficiency electric vacuum pumps for hybrid passenger vehicles, optimized for low noise, rapid buildup, and on-demand operation during engine-off phases.
From an Asia-Pacific and emerging-market perspective, Denso Corporation develops diaphragm-type electric vacuum pumps for hybrid and internal combustion engines with adaptive control intended to improve braking and fuel efficiency. Aisin Seiki Co., Ltd. supplies electric vacuum pumps for automotive brake systems integrated with advanced driver assistance and efficiency-related systems. Ningbo Tuopu Group Co., Ltd. produces electric vacuum pumps as part of intelligent brake systems, supporting mass production and OEM supply for passenger and commercial vehicles. Youngshin Precision Co., Ltd. manufactures electric vacuum pumps for automotive braking systems with an emphasis on quality and global OEM supply. Johnson Electric develops electric vacuum pumps for automotive applications including brake assist and hybrid systems. Advik Hi-Tech Pvt Ltd manufactures and supplies advanced electric vacuum pumps for passenger cars and commercial vehicles, including 48V ABS-related applications for hybrid and electric use.
The competitive picture is not static. Recent activity through early 2025 shows how supplier roadmaps are being executed in practice. In January 2025, Advik Hi-Tech unveiled a broader range of automotive components, including advanced electric vacuum pumps for passenger cars and commercial vehicles. Also in January 2025, Robert Bosch GmbH expanded deployment of its electric vacuum pump platform across multiple global SUV programs using brake-by-wire for stable vacuum independent of engine operation. In March 2025, Continental AG unveiled a high-performance electric vacuum pump for passenger internal combustion engines in Europe, featuring adaptive vacuum control for power efficiency and regenerative braking support. In April 2025, Pierburg under Rheinmetall Automotive launched an electric vacuum pump in Germany designed to reduce CO2 emissions and enhance hybrid and brake systems. In the same month, Denso Corporation launched a diaphragm-type electric vacuum pump in Asia-Pacific with adaptive vacuum control for hybrid and internal combustion engines to improve braking and fuel efficiency.
Vacuum Pumps Market
These developments matter because they demonstrate a shift from generic component supply toward application-specific optimization. Suppliers are increasingly designing for engine-off reliability, low parasitic loss, noise reduction, and integration with electrified brake and chassis control systems. That shift has direct implications for sourcing strategy, validation requirements, and long-term supplier partnerships.
Demand Drivers and Market Dynamics
The market's forward momentum is anchored in several reinforcing dynamics. First, electrification and hybridization continue to reshape vacuum requirements. In hybrid and electric vehicles, vacuum can no longer be assumed from a running engine in all operating conditions. Electric vacuum pumps enable on-demand brake vacuum generation, which supports brake assist performance and helps vehicle programs comply with CO2 reduction targets while maintaining safe and predictable braking behavior in downsized and electrified powertrains.
Second, brake-by-wire and advanced driver assistance deployment are increasing the importance of stable vacuum management during engine-off and start-stop events. In 2025, deployments of electric vacuum pumps in brake-by-wire systems have provided stable vacuum for advanced driver assistance functionality during those transitions. This is not merely an efficiency consideration; it is a safety and architecture consideration that influences which pump technologies are selected for next-generation vehicle programs.
Third, integration into 48V mild-hybrid architectures has created new design priorities. Electric vacuum pumps in these systems can reduce thermal load and parasitic losses while maintaining brake booster performance. At the same time, high-efficiency electric vacuum pumps for hybrid passenger vehicles are being optimized for low-noise operation and pulse-width-modulated control to minimize energy draw during intermittent engine phases. These engineering refinements indicate a market that is moving toward higher-performance, more tightly integrated solutions rather than commoditized replacements.
Fourth, safety and reliability scrutiny remains an important market factor. Field events such as the NHTSA recall action in August 2025, which addressed vacuum pump failure that could reduce brake assist performance under specific conditions, highlight the consequences of performance variability in critical brake systems. For sourcing and engineering teams, this reinforces the need for thorough validation, robust quality processes, and supplier selection criteria that account not only for cost and volume, but also for long-term durability and system-level reliability.
These dynamics collectively shape the market's next phase. Demand is not simply increasing; it is becoming more selective. Vehicle programs are increasingly evaluating vacuum pump solutions in the context of electrified braking architectures, thermal constraints, acoustic targets, and regulatory expectations. Suppliers that can demonstrate adaptive control, low energy consumption, rapid vacuum buildup, and integration-ready packaging are better positioned to participate in higher-value programs.
Where the Market Appears to Be Heading
Based on the trajectory documented in this study, the market is likely to continue expanding as vehicle electrification deepens and brake architectures become more dependent on electronically managed vacuum support. Growth is expected to be distributed across multiple application domains, with brake systems and engine management remaining central demand anchors while HVAC and emission control applications contribute additional volume and differentiation opportunities. The relative importance of electric vacuum pumps is expected to rise as hybrid and electric vehicle content increases and as braking safety requirements become more tightly integrated with advanced driver assistance and chassis control logic.
Regional variation will continue to influence market outcomes. Vehicle mix, electrification pace, OEM sourcing preferences, and regulatory exposure differ materially across regions, and these differences shape where demand scales most quickly and which supplier capabilities are most valued. The report examines these regional patterns without reducing them to simplistic rankings. Instead, it situates each region within the broader context of vehicle production, technology adoption, and program timing.
The competitive environment is also likely to evolve through a combination of consolidation, technology specialization, and program-level competition. Incumbents with strong brake system integration and global OEM relationships will continue to play a leading role, while regional and specialist suppliers may gain traction where they can demonstrate differentiated performance in noise, efficiency, packaging, or application-specific control. The market concentration structure suggests that scale matters, but it does not guarantee advantage unless supported by product relevance and reliability.
How to Use This Research in 2026 Planning
This report is intended to support concrete decisions rather than generic market awareness. In 2026, organizations can use the findings to align product roadmaps with demand where it is most likely to grow, assess supplier portfolios against performance and integration requirements, and anticipate how regulation and safety expectations will shape validation and sourcing criteria. The study also supports more disciplined interpretation of supplier announcements, program wins, and technology launches by placing them in a broader market context.
Automotive Vacuum Pump Market
For teams comparing opportunities across applications or regions, the report provides a structured basis for evaluating where vacuum pump demand is most strategically relevant and which technology attributes are gaining importance. For teams managing supplier relationships, it offers a framework for assessing concentration, differentiation, and program readiness. For analysts and investors, it provides a market narrative that connects sizing, growth, and competitive action to underlying automotive trends rather than short-term cycles.
Conclusion
The automotive vacuum pump market is entering a phase in which growth and technology transformation are intertwined. Historical expansion from 2020 through 2025 and the projected path toward 2032 indicate a market that is responding to electrification, brake system modernization, and emissions-driven design constraints. The market is not simply getting larger; it is becoming more performance-sensitive, more application-specific, and more dependent on supplier capability in areas such as adaptive control, thermal integration, and reliability under engine-off conditions.
This report translates that complexity into a usable strategic framework. It combines market sizing, segmentation logic, competitive profiling, and recent industry developments with the regulatory and safety context that influences sourcing and engineering decisions. For organizations preparing for 2026 and beyond, the value of the study lies in its ability to connect market movement with decision-relevant insight.
For the complete dataset, detailed segmentation analysis, regional demand breakdowns, application-level valuation, and full supplier profiles, please access the full report through the source page. The executive summary presented here is designed to demonstrate the scope and analytical depth of the study while preserving the proprietary segmentation and directional intelligence that support informed commercial, engineering, and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Vacuum Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Respiratory Humidifying Equipment Market Hits $7B in 2025, Poised for $11.6B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Respiratory Humidifying Equipment Market: Navigating the 2026 Decision Landscape
The respiratory humidifying equipment market stands at a critical inflection point. As healthcare systems worldwide recalibrate around patient outcomes, supply chain resilience, and sustainable procurement, the devices that deliver optimal airway hydration have evolved from routine clinical accessories to strategically decisive assets. For executives, procurement leaders, and medical technology strategists, the weeks leading into 2026 demand more than generalized market briefings. They require structurally sound, forward-looking intelligence capable of informing capital allocation, R&D prioritization, competitive positioning, and regulatory compliance roadmaps.
Our latest comprehensive study, Respiratory Humidifying Equipment Market, is engineered to meet that exact requirement. Spanning a rigorous historical retrospective from 2020 through 2025 and projecting systematically across the 2026–2032 forecast horizon, the analysis translates complex clinical, regulatory, and commercial signals into actionable executive guidance. This overview outlines the strategic architecture of the report, demonstrates how macroeconomic and tactical data are synthesized, and clarifies the executive decisions the study is designed to support.
Executive Context: Why the Market Now Demands Precision Intelligence
The structural drivers shaping respiratory humidification are no longer confined to incremental clinical adoption. They intersect with regulatory recalibration, reimbursement architecture, material science breakthroughs, and consolidation pressures within the medical device supply chain. Organizations that continue to rely on fragmented market snapshots or backward-looking incident reports risk misallocating development budgets, underestimating compliance timelines, and misreading competitive velocity.
Respiratory Humidifying Equipment Market
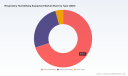
The research is grounded in a disciplined quantitative foundation. Tracking the market’s progression from approximately 5,200 million USD in 2020 to a 2025 baseline of 7,000 million USD, the study documents a trajectory defined by sustained clinical demand, technology maturation, and gradual geographic expansion. The forecast period extends to 2032, reflecting a compound annual growth rate of 7.75 percent. By anchoring analysis in this extended horizon, the report enables decision-makers to evaluate not only near-term operational impacts but also multi-year capacity planning, product portfolio evolution, and strategic partnership timing. Importantly, the narrative treats top-line magnitude and growth velocity as directional compasses rather than isolated metrics, always threading them into the operational conditions that actually determine commercial execution.
Report Architecture: Operational Intelligence Over Abstract Market Commentary
A distinguishing feature of this study is its emphasis on execution-ready content. Rather than cataloguing broad trends, the analysis dissects the operational levers that determine procurement cycles, product roadmaps, and pricing architecture. The report integrates rigorous segmentation perspectives across product architecture, clinical environment, and geographic deployment, while deliberately preserving analytical depth that supports scenario modeling and internal stakeholder alignment.
Worldwide Active Humidifier Devices Market
Product Architecture and Clinical Deployment Dynamics
The study examines how humidifier design philosophies are diverging across clinical workflows. Active heated systems, passive condensation-management configurations, and ancillary accessory categories are analyzed not merely as discrete revenue pools, but as responses to distinct clinical demands, sterilization requirements, and integration constraints. The research explores how product architecture decisions influence procurement frequency, service intensity, and total cost of ownership across acute care, extended-stay facilities, and decentralized care environments.
Equally critical is the report’s treatment of application pathways. By mapping how humidification technologies are deployed across institutional settings, long-term care environments, homecare programs, and specialized respiratory support contexts, the analysis identifies where adoption velocity is being accelerated by workflow integration, reimbursement alignment, or care-delivery restructuring. This application-level perspective helps organizations anticipate where channel strategy, clinical validation, and service infrastructure must be synchronized to capture durable demand.
Geographic Exposure and Regional Commercial Architecture
Market opportunity is not uniformly distributed, and neither is the operational complexity of capturing it. The research builds a regional framework that examines how healthcare infrastructure maturity, procurement governance, regulatory cadence, and distribution ecosystems shape market penetration. By evaluating how different regions absorb product introductions, navigate sterilization and maintenance logistics, and respond to reimbursement mechanisms, the report enables firms to prioritize market-entry sequencing, localization investments, and partnership strategies with greater precision.
Competitive Architecture: Positioning in a Concentrated but Dynamic Field
Concentration in the respiratory humidifying equipment market is substantial, with the three largest participants collectively commanding a dominant share and the top five consolidating an even broader portion of total revenue. Yet concentration does not equate to stagnation. The field remains tactically active, with incumbents upgrading integrated humidification platforms, challengers pursuing regulatory clearances, and component specialists expanding sustainable material capabilities.
The report provides a structured evaluation of the companies defining this competitive environment. Profiles extend beyond descriptive summaries to examine each organization’s product philosophy, integration strategy, geographic footprint, and recent commercial moves. The analysis covers firms with distinct strategic identities: organizations anchoring their position in advanced heated humidification systems for hospital and homecare respiratory support; manufacturers focused on mechanical ventilation gas humidification and patient respiratory support components; suppliers of active heated humidifiers and breathing systems for hospital respiratory care; developers of heated humidification systems for clinical respiratory support; ventilator-integrated humidifier manufacturers serving ICU and respiratory applications; providers of CPAP and NIV humidification systems for sleep and respiratory therapy; companies embedding humidification within BiPAP and ventilator ecosystems; suppliers of humidifiers tailored to intensive care and neonatal respiratory care; firms integrating humidification with adult and pediatric ventilator platforms; developers of respiratory humidification circuits and accessories oriented toward sustainable care; and manufacturers of respiratory care humidification solutions designed for both hospital and homecare environments.
Recent company-level developments illustrate the contours of this competitive dynamism. In late 2025, one manufacturer announced a next-generation humidifier designed to minimize condensate for advanced respiratory support, signaling continued emphasis on workflow efficiency and airway management. Around the same period, a separate medical company secured regulatory clearance for a respiratory humidifier unit, reinforcing the importance of compliance milestones in sustaining commercial momentum. Meanwhile, a component and circuit specialist advanced a series of sustainability-focused milestones, including the launch of a bioplastic-based breathing circuit and humidification component showcased at a major industry trade fair, alongside multiple certifications intended to strengthen quality standards and sustainable innovation credentials within respiratory humidifying equipment. These developments are not presented as isolated announcements; they are interpreted as indicators of how product differentiation, regulatory timing, and material sustainability are converging into competitive advantage.
Market Dynamics: The Operational Forces Shaping Commercial Execution
Commercial outcomes in this sector are increasingly determined by the interplay of regulation, reimbursement, material economics, and infrastructure realities. The report treats these forces not as background context but as primary variables in the competitive equation.
Regulatory and Standards Evolution
The regulatory environment is tightening the operational boundaries within which humidification devices are designed, validated, and deployed. Updated safety and performance specifications are redefining compliance expectations for respiratory humidifiers in medical settings. At the same time, guidance emphasizing proper disinfection, performance testing, and sterilization control standards reinforces the clinical and legal importance of documented hygiene protocols. For manufacturers and procurement organizations alike, these measures alter development timelines, validation burdens, and lifecycle management expectations, making regulatory readiness a strategic asset rather than an administrative task.
Reimbursement Architecture and Commercial Access
Reimbursement structures directly influence adoption speed and procurement predictability. Specific billing codes continue to serve as the operational mechanism for reimbursement of respiratory humidifiers and heated humidifiers under Medicare policies. Understanding how these code categories function, where they facilitate access, and where they create administrative friction is essential for forecasting demand stability and designing commercially viable product configurations. The study examines these reimbursement pathways as enablers or constraints on segment-level growth, especially in settings where cost justification must withstand structured review.
Material Economics, Sterilization, and Procurement Cycles
Material selection and processing costs have become decisive factors in both product design and procurement behavior. Elevated raw material costs intersect with the demand for biocompatible, sterilizable materials featuring antimicrobial coatings, influencing not only production economics but also replacement cycles and service frequency. In parallel, sterilization and maintenance costs remain a persistent constraint, particularly for smaller hospitals and homecare adoption, where operational budgets are tighter and service infrastructure is less centralized. The report analyzes how these cost pressures affect purchasing intervals, product longevity expectations, and the competitive appeal of systems that reduce total lifecycle burden.
Strategic Implications for 2026 Decision-Making
For organizations operating in or entering this market, 2026 is a year of structural choices. Should product strategy prioritize integration with mechanical ventilation and critical care platforms, or expand into decentralized respiratory support and homecare ecosystems? How should R&D resources be divided between performance enhancement, condensate management, and sustainable material adoption? Where should commercial teams concentrate regulatory preparation, reimbursement alignment, and distribution partnerships to minimize time-to-value?
The research is designed to support these decisions through scenario-based interpretation rather than static snapshots. By combining historical trajectory, forward demand projections, segmentation logic, competitor movement analysis, and operational constraint mapping, the study enables leaders to stress-test assumptions. Companies can evaluate how product launches, regulatory updates, certification milestones, and reimbursement clarity may shift competitive positions. Procurement leaders can better anticipate where sterilization, maintenance, and material constraints will influence supplier selection. Strategy teams can identify which geographic and application opportunities warrant earlier investment versus more cautious monitoring.
The report also recognizes that market advantage increasingly depends on anticipating secondary effects. A new product announcement may matter less for its headline presence than for what it reveals about rival engineering priorities. A certification achievement may signal not just compliance status but readiness to expand into regulated channels. A standards update may reshape procurement specifications long before a purchasing cycle formally opens. By reading these signals together, executives can convert market complexity into timing advantage.
How to Use This Study for Enterprise Planning
The study is structured to serve multiple internal audiences without diluting analytical precision. Executive leadership can use the forecast horizon and macro growth trajectory to frame capital allocation and portfolio review. Product and engineering teams can leverage the segmentation architecture, material considerations, and standards developments to prioritize feature roadmaps and manufacturing requirements. Commercial and market access teams can draw on the competitive landscape, reimbursement context, and application-level deployment analysis to refine channel strategy and pricing logic. Regulatory and quality teams can integrate the compliance and sterilization expectations into planning calendars and documentation workflows.
To preserve the strategic integrity of the analysis while ensuring operational relevance, the full report moves beyond directional commentary into detailed segmentation splits, revenue breakdown structures, regional deployment profiles, product-type contributions, application-level demand distribution, and company-specific performance indicators. Those datasets form the quantitative backbone required for board-level reviews, investor communications, go-to-market planning, and competitive benchmarking.
Closing Perspective
The respiratory humidifying equipment market is being reshaped by the convergence of clinical performance expectations, regulatory rigor, reimbursement discipline, and sustainability-driven product innovation. In that environment, strategic decisions made in 2026 will set the trajectory for the remainder of the decade. Organizations that rely on incomplete market narratives risk reacting late to compliance shifts, misreading competitive intent, and underpositioning against evolving procurement economics.
This study provides the depth, structure, and forward orientation necessary to move from reactive awareness to deliberate strategy. By translating historical momentum, forecast growth, competitive maneuvers, and operational constraints into a unified executive framework, it equips decision-makers to align product, commercial, and compliance strategies with the realities of the market ahead. The full intelligence set—segment-level breakdowns, regional deployment figures, application distribution detail, and company-specific indicators—completes the analytical picture required for high-stakes planning.
For leaders seeking to secure a decisive informational advantage, the complete report is available through our official market research portal, where the full dataset, segmentation detail, and competitive profiles can be reviewed in their entirety and integrated directly into enterprise strategy workflows.
For detailed analysis of this topic, please visit the official page: Respiratory Humidifying Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Camellia Oil Market to Hit $321.07M by 2032 at 9.1% CAGR
By PW Consulting, 2026-09-16
The Camellia Oil Market: Strategic Imperatives for 2026 and Beyond
The global camellia oil landscape stands at a critical inflection point. As consumer preferences shift toward premium, health-oriented edible oils and functional cosmetic ingredients, market participants face a complex matrix of supply chain restructuring, regulatory evolution, and intensifying regional competition. Our newly published Camellia Oil Market research provides executives with the analytical framework needed to navigate this transition with confidence. The study does not merely track historical performance; it constructs a forward-looking decision architecture calibrated for corporate strategy through 2032.
For leadership teams evaluating expansion, acquisition, or product positioning in 2026, the timing of this intelligence is decisive. Structural supply investments, cross-border certification milestones, and technology-driven consolidation are reshaping competitive boundaries faster than traditional market signals can capture. A disciplined, data-grounded view of trajectory, segmentation dynamics, and player positioning is no longer optional; it is foundational to capital allocation and go-to-market design.
Market Trajectory and the Architecture of Growth
Historical data paints a clear picture of sustained expansion. Between 2020 and 2025, total market revenue progressed from approximately 113.4 million USD to 175.7 million USD, reflecting consistent year-over-year appreciation driven by widening adoption in food applications, rising demand for plant-based cosmetic formulations, and improved extraction and branding capabilities across producing regions. The momentum carries decisively into the forecast window. Starting from an estimated 185.6 million USD in 2026, the market advances through a series of compounding steps, reaching 202.8 million USD in 2027, 233.0 million USD in 2028, and continuing upward to 253.1 million USD in 2029, 271.1 million USD in 2030, 292.8 million USD in 2031, and 321.1 million USD by 2032. This pathway corresponds to a compound annual growth rate of 9.1 percent across the 2026 to 2032 forecast period.
Such a rate signals more than incremental expansion. It reflects the convergence of multiple reinforcing forces: maturing consumer appreciation for cold-pressed and single-origin oils, broadening cosmetic formulations leveraging favorable regulatory assessments, and supply-side scaling that reduces unit costs while improving grade consistency. Yet trajectory alone does not dictate strategy. The strategic value lies in understanding which segments and channels capture disproportionate share of this growth, how regional demand patterns diverge, and where capacity, certification, and distribution bottlenecks may create asymmetric advantages for well-positioned operators.
Segmentation Dynamics Without Surface-Level Simplification
The market’s internal structure reveals distinct value pools rather than a uniform growth curve. Demand is distributed across food, cosmetics, and other applications, each with different procurement cycles, pricing sensitivities, and quality thresholds. Edible use remains anchored by traditional culinary consumption and emerging premium positioning, while cosmetic applications benefit from growing formulation diversity and recently expanded safety recognition that eases entry into international personal care channels. The other applications segment captures niche industrial and specialty uses that, while smaller, often command higher margins and longer contract horizons.
Camellia Oil Market
Product differentiation further shapes competitive outcomes. Extra virgin and pure camellia oil categories serve different buyer expectations. The former emphasizes minimal processing, sensory quality, and traceability, aligning with premium retail and gift-channel demand. The latter supports broader functional and blending applications where consistency and scale are prioritized. Understanding the interplay between these product streams, their pricing architectures, and the manufacturing capabilities required to serve them is essential for companies deciding whether to compete on terroir and certification or on volume and cost efficiency.
Regional patterns add another layer of strategic nuance. Production and consumption are not evenly distributed, and supply chain geography heavily influences margin structure, logistics cost, and responsiveness. Some markets function primarily as demand centers with strong import dependence for specialty grades, while others combine cultivation, processing, and export orientation within integrated corridors. The report maps these regional contributions and demand intensities without reducing them to static percentage snapshots, instead emphasizing relative scale, growth direction, and the strategic implications of geographic concentration for sourcing, distribution, and market entry timing.
Competitive Landscape: Integrated Players and Emerging Consolidation
The player base reflects a concentration of vertically integrated producers, especially among leading Chinese manufacturers that coordinate cultivation, processing, refining, and branded sales. Firms such as Hunan Yamei Camellia Oil Co., Ltd. emphasize organic and premium edible positioning with end-to-end control from cultivation to processing. Hunan Jinhao Camellia Oil Co., Ltd. pursues a comparable vertical model, offering fresh-pressed oils and high-end edible products supported by ISO9001 and CNAS accreditation. In Jiangxi Province, multiple enterprises extend the integrated chain with differentiated emphases. Jiangxi YouNiBao Agricultural Science And Technology Co., LTD supplies across multiple provinces with a focus on organic certification and export-grade edible oils. Jiangxi Tianyuan Camellia Oil Co., Ltd. and Jiangxi Wufeng Camellia Oil Co., Ltd. concentrate on single-origin and terroir-differentiated oil, expanding cold-pressing capacity and securing organic and non-GMO certifications targeting premium channels.
Worldwide Wolfberry Oil Market
Other participants complement this landscape with specialized functions. Jiangxi Golden Deer Oil Co., Ltd. operates with an export orientation, maintaining cold-pressing lines certified to international food safety standards and developing partnerships across Japan, South Korea, Singapore, Australia, and the United States. Jiangxi Youjia Oils and Grains Co., Ltd. focuses on refining and packaging, leveraging extensive domestic distribution and growing export operations for bulk ingredients. Hunan Jiufeng Agricultural Development Co., Ltd. represents another vertically integrated model, spanning oil-tea cultivation, raw material processing, pressing, refining, and branded sales, anchored by partnerships with numerous cooperatives.
Market concentration metrics indicate that the top three competitors command roughly 40 percent of revenue, while the top five reach approximately 45 percent. This level of concentration suggests meaningful but not insurmountable consolidation, leaving room for differentiated entrants, regional specialists, and channel-focused operators to compete on quality, certification, or distribution strength. The strategic question for 2026 is not only who leads today, but which capabilities will determine leadership by the end of the forecast period.
Industry Dynamics Shaping the 2026 Decision Environment
Recent developments illustrate how quickly structural change is materializing. Production capacity in China has expanded materially, with annual output reaching approximately 1.1 million metric tons, an increase of about 53 percent since 2020 following a three-year expansion of hundreds of thousands of hectares under a dedicated action plan. This expansion aligns with planting area reaching roughly 75 million mu by the end of 2025, with Hunan Province leading at over 1.58 million hectares and contributing substantial yield. Such scale alters the supply base, improves availability of graded material, and intensifies competition for export and premium-channel positioning.
At the same time, corporate activity signals a shift toward technology-enabled supply chain integration. A recent preliminary acquisition agreement involving a major group and a vertically integrated producer underscores interest in building AI-driven supply chain capabilities around camellia oil production. Parallel industry events have highlighted intelligent harvesting technology and promotional efforts to strengthen camellia oil’s standing as a distinct edible oil category. These moves indicate that operational efficiency, traceability, and category elevation are becoming central competitive battlegrounds.
Regulatory and certification progress is equally consequential. A favorable safety review for camellia oleifera seed oil in cosmetic applications has expanded access to European personal care markets, lowering a historic barrier and opening new formulation opportunities. Simultaneously, clarified quality benchmarks for exports and continued policy support for planting expansion are shaping both supply reliability and market access. For international buyers and exporters, these developments affect conformance requirements, sourcing strategy, and the credibility of premium claims.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is designed as a working instrument rather than a static overview. It connects macro trajectory with segment-level logic, regional demand patterns, and competitive positioning to support concrete decisions in product strategy, sourcing, pricing, and market entry. The report provides:
- A consolidated market size and forecast series that situates current performance within a multi-year growth path and highlights inflection points relevant to capacity planning and investment timing
- Segment-level analysis across product types and application categories that explains relative scale, demand drivers, and the operational implications of serving premium versus volume-oriented channels
- Regional demand and supply context that helps identify where procurement, distribution, and market development efforts are likely to yield the strongest return, without reducing complex geography to decontextualized shares
- A structured competitive assessment of leading manufacturers, including their integration models, certification postures, export orientation, and premium-market positioning, enabling benchmarking and threat assessment
- An integrated view of regulatory, certification, and capacity-expansion developments that affect export readiness, formulation access, and supply reliability
- Strategic scenario framing that links market dynamics to actionable choices in brand architecture, channel selection, partnership design, and technology adoption
Throughout, the report emphasizes decision utility over data volume. Executives will find not only what is changing, but how to interpret those changes in relation to margin goals, risk exposure, and competitive positioning through 2032.
Why 2026 Demands a Disciplined Intelligence Baseline
The coming year will reward organizations that can align product-grade strategy with real demand traction, match sourcing and certification capabilities to target markets, and anticipate consolidation and technology adoption that may redefine cost and speed advantages. Companies that treat camellia oil as a generic commodity risk misreading premiumization trends, regulatory openings, and regional concentration effects. Those that invest in a precise, forward-looking view can better prioritize capacity, refine channel mix, and structure partnerships for durable advantage.
The complete research contains the full segmentation detail, regional breakdowns, competitive benchmarking, and forecast architecture necessary to move from directional awareness to executable strategy. To access the complete dataset, segment-level breakdowns, and full competitive profiles, refer to the source page for the Camellia Oil Market study.
For detailed analysis of this topic, please visit the official page: Camellia Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Machine Vision Camera Market Hits $2.88 Billion in 2025, Projected 8.3% CAGR to 2032
By PW Consulting, 2026-09-16
Industrial Machine Vision Camera Market: Strategic Intelligence for 2026 Enterprise Decision-Making
Executive Context: The Imperative for Precision Intelligence
In the rapidly evolving landscape of industrial automation, machine vision has transitioned from a supportive technology to a central pillar of operational excellence. As we navigate the mid-2020s, the industrial machine vision camera market is undergoing a period of significant transformation. Shaped by technological standardization, shifting trade dynamics, and aggressive adoption of AI-driven inspection, the sector is defined by both complex headwinds and unprecedented upside. For enterprise stakeholders, moving beyond surface-level market narratives is no longer optional. It requires granular, forward-looking intelligence that translates market trajectories into actionable investment and operational strategies.
PW Consulting's latest comprehensive research on the Industrial Machine Vision Camera Market delivers exactly that depth. Built upon a rigorous historical foundation and a disciplined forecast horizon, this report equips strategic leaders with the analytical clarity required to navigate 2026 and the decade beyond. Rather than presenting a static snapshot, the analysis constructs a dynamic framework for understanding how competitive forces, technological inflection points, and supply-chain realities will converge across the forecast period.
Macro Trajectory and Structural Growth Architecture
The historic performance of the industrial machine vision camera sector demonstrates a clear and sustained expansion curve. Across the historical window spanning 2020 through 2025, the market advanced from a baseline of approximately 1,945 million USD to an estimated 2,880 million USD in the most recent full-year assessment. This progression reflects the compounding effect of manufacturing digitization, escalating quality assurance standards, and the integration of vision capabilities into smart production ecosystems. The compound annual growth rate of 8.3 percent underscores the market's resilience and its capacity to outpace broader industrial equipment spending in multiple regions.
Looking toward the forward-looking window extending through 2032, the trajectory indicates continued acceleration. Projected revenue climbs steadily from the 2026 baseline, crossing successive thresholds as adoption scales across industries and technological capabilities mature. By the end of the forecast horizon, the sector is positioned to approach a substantially higher valuation, driven by the compounding demand for high-resolution imaging, embedded vision architectures, and integrated intelligence at the edge. For enterprise planners, this growth architecture is not merely a revenue projection; it represents a structural shift in how industrial value is created, monitored, and optimized.
The growth narrative is anchored by a bifurcated technology landscape. Area scan architectures continue to command substantial share, reflecting their versatility in high-speed inspection, dimensional measurement, and assembly verification. Line scan configurations maintain their critical role in continuous web processing, surface inspection, and high-throughput material handling. Understanding the strategic deployment patterns, performance trade-offs, and pricing dynamics between these technology streams is essential for aligning procurement strategies with operational requirements across diverse production environments.
2026 Market Dynamics: Standards, Supply Constraints, and Trade Realities
The current market environment is defined by a convergence of regulatory, technical, and logistical forces that demand nuanced strategic interpretation. One of the most consequential developments for system architects and procurement leaders is the approval of GigE Vision Version 3.0 by the Association for Advancing Automation in April 2026. This standard update incorporates RoCEv2 technology, enabling high-speed image streaming capabilities reaching 400 Gbps and beyond. For enterprises designing next-generation inspection lines, logistics tracking systems, or real-time process monitoring architectures, this represents a generational leap in data throughput. However, realizing the operational benefits of these bandwidth capabilities requires synchronized investments in network infrastructure, compute architecture, and software stack optimization. Our analysis delineates the realistic adoption timelines and infrastructure prerequisites required to translate this technical leap into measurable throughput gains.
Simultaneously, the industry continues to consolidate measurement rigor through the evolution of EMVA1288, which has been promoted to full international standard status as ISO 24942 and unified under Version 4.1. For engineering and quality teams, standardized camera and sensor characterization eliminates ambiguity in performance benchmarking. Yet, the operational implications extend further: standardized measurement protocols influence vendor selection criteria, drive competitive differentiation around verifiable performance metrics, and reshape procurement evaluation frameworks. The report examines how enterprises are adjusting technical qualification processes to leverage the new standard for supply-chain transparency and performance assurance.
Trade policy remains an active determinant of cost structures and sourcing strategies. The imposition of 25 percent US tariffs on Chinese-origin lenses, contrasted against substantially lower duties on most other machine vision components, has created an asymmetric cost landscape that demands deliberate component-level sourcing optimization. Enterprises that treat vision systems as monolithic procurement packages face heightened exposure to tariff-driven cost inflation. Conversely, organizations that pursue modular sourcing strategies and regional diversification can mitigate exposure while preserving technical performance. The research maps the strategic pathways available to balance cost efficiency with supply reliability in the current tariff environment.
Compounding these trade dynamics are persistent supply-chain constraints affecting image sensors and optical components. These constraints continue to influence production timelines for industrial machine vision systems, creating lead-time variability that can disrupt line integration schedules and capacity ramp-up plans. Strategic procurement and inventory architecture have therefore become critical competitive differentiators. Our analysis evaluates the evolving supplier ecosystem, identifies the capacity allocation patterns that influence lead-time predictability, and provides guidance on structuring procurement commitments to preserve operational continuity without sacrificing agility.
Competitive Landscape: Strategic Profiling and Ecosystem Positioning
The competitive architecture of the industrial machine vision camera market is characterized by a mix of established system integrators, specialized camera manufacturers, and critical sensor technology providers. Industry concentration metrics indicate that the three largest players collectively account for approximately 25 percent of market revenue, while the top five expand that share to roughly 35 percent. This structure reflects a market that is neither fully consolidated nor highly fragmented, but rather one where scale, technological differentiation, and application-specific expertise determine competitive advantage.
Cognex Corporation, headquartered in Natick, Massachusetts, remains a defining presence in the sector. Its portfolio of industrial machine vision cameras, barcode readers, and complete vision systems supports automated inspection, defect detection, and robotic guidance across broad manufacturing verticals. The company's strength lies in its ability to deliver integrated, application-tuned solutions that reduce system integration complexity for end-users operating at scale.
Basler AG, based in Ahrensburg, Germany, has built a reputation for manufacturing industrial machine vision cameras that emphasize premium sensors, robust connectivity options including USB 3.0, GigE, and CoaXPress, and a comprehensive range of area scan, line scan, 3D, and embedded models. For automation engineers seeking reliability and interface flexibility across demanding deployment scenarios, Basler's product architecture provides a compelling foundation.
Teledyne FLIR, operating from Wilsonville, Oregon, extends the competitive field into advanced thermal and multispectral imaging territory. Its capabilities in inspection, quality control, and non-contact measurement provide distinctive value in applications where conventional visible-spectrum imaging is insufficient. This positions the company at the intersection of traditional machine vision and specialized sensing modalities.
In the Asia-Pacific competitive axis, Omron Corporation, based in Kyoto, and Keyence Corporation, headquartered in Osaka, represent powerful contenders. Omron's smart cameras and software platforms are engineered for precision inspection, measurement, and tight integration into automated production lines. Keyence focuses on high-performance cameras and measurement systems optimized for high-speed defect detection, dimensioning, and assembly verification, with particular penetration in electronics and automotive manufacturing environments.
The European specialist tier includes Allied Vision Technologies in Thalwil, Switzerland, which emphasizes high-resolution sensors and flexible interfaces for robotics, logistics, and quality assurance applications; IDS Imaging Development Systems in Obersulm, Germany, which has established itself in robust cameras, sensors, and systems optimized for machine integration and real-time industrial imaging tasks; and JAI A/S in Rødovre, Denmark, whose product emphasis on high sensitivity and versatile connectivity supports food inspection, semiconductor, and biomedical applications.
At the component level, Sony Semiconductor Solutions, headquartered in Tokyo, supplies industrial-grade image sensors and machine vision cameras leveraging advanced CMOS and related technologies for high-resolution, low-light industrial inspection. Meanwhile, SICK AG in Waldkirch, Germany, integrates AI-enabled vision sensors and cameras for automated defect detection, sorting, and process monitoring, reflecting the broader market shift toward intelligent, algorithm-driven inspection at the sensor and camera level.
Industrial Cameras Market
Strategic positioning within this landscape requires more than recognizing brand presence. It demands a granular understanding of how each competitor's product roadmaps, connectivity strategies, application focus, and partnership ecosystems align with specific enterprise requirements. The report maps these alignments and provides the analytical basis for vendor evaluation, partnership structuring, and technology roadmap planning.
Report Architecture: Operational Content and Decision-Readiness
The research is designed for direct integration into corporate planning workflows. Its architecture balances macro-level strategic framing with the operational detail required by engineering, procurement, and commercial teams. Core coverage includes comprehensive market sizing and forward projections anchored in a disciplined historical baseline and a clearly defined forecast horizon. The analysis decomposes the market across technology architectures, application environments, and regional demand patterns. Critically, the report avoids superficial aggregation and instead examines the structural drivers that differentiate growth trajectories across segments.
Beyond quantitative sizing, the report delivers operational instruction in several high-value areas. It profiles the competitive positioning of leading firms, evaluates recent product releases, standard updates, and trade show activity, and interprets their implications for procurement timing and technology adoption. The inclusion of recent developments, such as the Phoenix 28×28 mm camera release by LUCID Vision Labs in March 2026, the VISION Show 2026 exhibition plans for IMAGO Technologies and Active Silicon, and the ongoing EMVA certification processes tied to the unified ISO-standardized characterization method, ensures that decision-makers are grounded in near-term market activity rather than backward-looking summaries.
The study also provides structured evaluation frameworks for assessing vendor viability, technology readiness, and total cost of ownership across different deployment contexts. For enterprises planning capacity expansion, technology refresh cycles, or supplier diversification, these frameworks translate market complexity into actionable selection criteria. The report's treatment of trade exposure, supply-chain lead-time variability, and standardization-driven procurement evolution gives procurement and operations leaders the context needed to build resilient sourcing strategies.
Industrial Machine Vision Camera Market
Strategic Value for 2026 Enterprise Decision-Making
The industrial machine vision camera market in 2026 is no longer a commodity procurement category. It is a strategic technology domain where performance differentiation, integration velocity, and supply resilience directly influence production quality, throughput, and operational cost. Enterprises that rely on fragmented market intelligence risk misaligning technology investments with actual adoption trajectories, overpaying for components exposed to tariff volatility, or underestimating the infrastructure requirements needed to exploit next-generation connectivity standards.
This research was constructed to eliminate those blind spots. By combining rigorous historical analysis with forward-looking scenario framing, it enables enterprises to prioritize technology roadmaps, calibrate procurement strategies, and align internal engineering capacity with market realities. The analysis is particularly relevant for organizations evaluating high-bandwidth imaging deployment, navigating component-level tariff exposure, standardizing performance qualification processes, or restructuring supplier relationships in response to persistent sensor and optics supply constraints.
The complete research deliverable provides the full segmentation architecture, regional demand structures, application-specific revenue breakdowns, technology adoption curves, and competitive benchmarking data necessary to convert market insight into executable strategy. To access the complete intelligence package, including detailed segmentation, competitive positioning matrices, and actionable procurement guidance tailored to 2026 planning cycles, visit the source page and obtain the full report. In a market where timing, precision, and supply resilience define competitive advantage, comprehensive intelligence is not an optional enhancement; it is a strategic prerequisite.
For detailed analysis of this topic, please visit the official page: Industrial Machine Vision Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Popcorn Market Hits $7.5B in 2025, Poised for 6.85% CAGR Through 2032
By PW Consulting, 2026-09-16
Popcorn Market Strategic Outlook 2026: Navigating Growth, Innovation, and Regulatory Shifts
The global popcorn market stands at a critical inflection point as we move through 2026. What was once viewed as a stable snack category with predictable seasonal patterns has evolved into a dynamic landscape shaped by shifting consumer preferences, intensifying regulatory scrutiny, and rapid innovation in packaging and product formats. For executive teams, category managers, and strategic planners, the ability to anticipate these forces is no longer optional. It is a competitive necessity. Our latest market research publication, the Popcorn Market Analysis, is designed to provide the analytical rigor and forward-looking perspective required to make informed decisions in this evolving environment.
Market Trajectory and Macro Growth Context
Historical data underscores the category resilience and steady expansion that have characterized the popcorn sector over the past half-decade. Between 2020 and 2025, global revenue climbed from USD 5.0 billion to USD 7.5 billion, reflecting a compound trajectory that has outpaced many adjacent packaged food segments. The forecast period extending through 2032 projects continued upward momentum, with market value expected to reach USD 11.69 billion by the close of the forecast window. This growth path is anchored by a forecasted compound annual growth rate of 6.85 percent, a figure that signals sustained demand expansion rather than a temporary cyclical surge.
The scale of this expansion carries direct implications for capital allocation, capacity planning, and channel strategy. Companies that treat popcorn as a legacy commodity risk underestimating the structural shifts driving volume and value migration. The research delves into the underlying demand drivers, consumption frequency patterns, and format preferences that are reshaping the category baseline. Rather than presenting a static snapshot, the analysis maps the inflection points where strategic intervention can yield outsized returns. Readers seeking granular regional breakdowns, format-level revenue contributions, and channel-specific growth differentials will find those details within the full report, where the data is structured to support precise scenario modeling and investment prioritization.
Competitive Landscape and Strategic Positioning
Incumbent Players and Portfolio Architecture
The market remains characterized by a relatively concentrated competitive structure, with the top three players commanding a combined share that reflects the durable influence of established brands and vertically integrated supply chains. The top five competitors collectively hold a substantial majority of category revenue, creating a landscape where scale, distribution access, and brand equity function as powerful barriers to entry. Several incumbent organizations continue to anchor the market through well-recognized microwave and ready-to-eat portfolios.
Peanuts Market
ConAgra Brands, headquartered in Chicago, Illinois, remains a defining presence through its Orville Redenbacher's and Act II lines, brands that have long set consumer expectations for taste, texture, and convenience in the microwave segment. American Pop Corn Company, based in Iowa, sustains its market position through the Jolly Time brand, which spans both kernel and microwave offerings and carries significant retail penetration. Snyder's-Lance, operating under the Pop Secret brand, continues to compete aggressively in the microwave space with a focus on flavor innovation and tangency with broader snacking trends.
Beyond the branded microwave players, specialized and vertically integrated producers occupy strategic niches. Weaver Popcorn Company, operating from Illinois, supplies bulk popcorn kernels tailored for commercial, theater, and gourmet applications, serving a channel that underpins much of the out-of-home consumption experience. Princeton Popcorn Company, also based in the United States, has built its reputation on mushroom and specialty popcorn varieties, emphasizing a differentiated product architecture that appeals to premium and niche positioning. These operators illustrate how the competitive field is not monolithic; rather, it is stratified across value, premium, specialty, and ingredient-supply tiers, each with distinct margin profiles and growth vectors.
Recent Operational Events and Risk Signaling
The competitive environment is not static, and 2026 has already produced operational events that carry strategic lessons. Food safety and quality control remain paramount, as evidenced by a series of voluntary recalls that have surfaced in recent months. Jonco Industries, Inc. initiated a voluntary recall of certain consumer-sized white cheddar seasoning products in May 2026 due to potential Salmonella contamination, a reminder that seasoning and flavor systems introduce distinct risk vectors beyond the kernel itself. In April 2026, Prospector Popcorn, LLC conducted a voluntary recall of its Belgian Chocolate Toffee Popcorn due to potential contamination, highlighting the vulnerabilities that can accompany specialty flavor extensions and co-manufacturing arrangements.
Associated Food Stores expanded the scope of risk awareness in May 2026 by initiating a recall of 6,480 containers of Red Button Movie House Buttered Popcorn for possible foreign material contamination, an event that underscores the importance of supply chain visibility and traceability across private-label and licensed movie-theater formats. These incidents, drawn from FDA and industry recall notices, are not isolated anomalies; they are stress tests that reveal where quality systems, supplier qualifications, and recall readiness must be strengthened. The full research report maps these events within a broader risk management framework, offering structured guidance on how to assess vendor resilience, build redundancy into flavor and packaging supply chains, and align quality assurance protocols with the realities of scale and speed.
Simultaneously, product innovation continues to push the category forward. In April 2026, Gold Medal Products Co. announced the launch of ReadyServe Jr., a compact self-serve popcorn dispenser targeted at sports bars, convenience stores, and entertainment venues. This development signals a deliberate push to capture out-of-home and on-the-go consumption occasions with hardware-enabled distribution models. The research evaluates such innovations not merely as product launches but as strategic bets that reshape channel economics, consumer interaction points, and the boundary between packaged goods and equipment-based concession solutions.
Regulatory and Supply Chain Dynamics
The 2026 decision environment is being reshaped as much by regulatory and input-side factors as by consumer demand. On the raw material front, US corn production reached 1.23 billion metric tons in the 2024/2025 season, providing a robust feedstock base for popcorn kernel supply. This scale of agricultural output supports stable input availability, but it also invites scrutiny of price volatility, crop quality consistency, and the geographic concentration of supply. The report examines how kernel sourcing strategies intersect with processor margins, contract structures, and the risk of regional supply disruptions.
Regulatory change is equally consequential. In May 2025, the US FDA proposed a front-of-package nutrition labeling rule that would require simplified indicators for saturated fat, sodium, and added sugars on most packaged foods, including popcorn. For a category that spans lightly seasoned kernels, butter-flavored microwave bags, and indulgent ready-to-eat formats, this proposal has direct implications for packaging design, product reformulation, and consumer communication. The research explores how leading players are modeling the potential impact on shelf placement, brand perception, and the relative competitiveness of healthier versus indulgent segments.
Packaging regulation is advancing on multiple fronts. As of January 2025, PFAS-containing grease-proofing substances used in food contact packaging no longer hold effective FDA food contact notifications, altering the compliance landscape for microwave popcorn bags and other coated packaging formats. At the state level, jurisdictions such as Louisiana and Texas enacted 2025 laws requiring PFAS restrictions in food packaging materials, creating a patchwork of requirements that complicates multi-state distribution and sourcing. In Europe, the Packaging and Packaging Waste Regulation entered force in 2025, mandating recyclable packaging with labeling for recycling and reusability on food products, including popcorn. These overlapping requirements introduce cost, design, and timeline pressures that directly affect product roadmaps and supplier selection. The full report provides a structured analysis of how these regulations interact with product formats, regional rollout strategies, and the economics of packaging transitions.
Popcorn Market
Demand Architecture and Channel Evolution
Understanding where and how popcorn is purchased is essential for any strategy that aims to capture growth efficiently. The category is distributed across a mix of retail and convenience channels, each with distinct consumer behavior, margin structures, and promotional dynamics. Supermarkets and hypermarkets represent the largest distribution conduit, reflecting the category's role as a staple pantry and impulse snack within the broader grocery basket. Convenience stores contribute a meaningful share, driven by grab-and-go consumption, solitary snacking occasions, and the channel's sensitivity to flavor innovation and pack size optimization. Online retail, while smaller in absolute terms, continues to expand as e-commerce penetration deepens and consumers increasingly use digital channels for replenishment and discovery.
Format preferences further complicate the demand picture. Ready-to-eat popcorn and microwave popcorn each serve distinct usage occasions, with different expectations around convenience, portion control, flavor variety, and preparation experience. The research disentangles these format-driven behaviors and examines how they interact with channel selection, pricing architecture, and promotional effectiveness. Rather than treating format and channel as independent variables, the analysis models their intersection to reveal where white space exists for line extensions, pack rationalization, and channel-specific assortment strategies. Detailed segmentation contributions and region-level revenue distributions are provided in the complete report, enabling teams to prioritize the markets and formats that align with their specific growth objectives.
Strategic Implications for 2026 Decision-Making
The 2026 landscape demands a strategy that is simultaneously ambitious and disciplined. Growth is available, but it is increasingly distributed across formats, channels, and regional dynamics that reward precision over broad-stroke assumptions. Several strategic priorities emerge from the research framework.
- Align product portfolios with regulatory trajectories. Front-of-package labeling, PFAS restrictions, and packaging recyclability mandates are not distant contingencies; they are active forces shaping packaging costs, reformulation timelines, and shelf positioning. Companies that integrate regulatory forecasting into portfolio planning will reduce exposure and capture first-mover advantages in compliant design.
- Strengthen supply chain resilience and quality assurance. The recall events of early 2026 illustrate the cost of vulnerability in seasoning systems, specialty flavor extensions, and foreign-material controls. Strategic investment in supplier qualification, traceability, and recall readiness should be treated as a margin protection and brand trust imperative.
- Exploit channel and format intersections. The largest demand pools are not uniform. Supermarket, convenience, and online channels each reward different pack sizes, flavor profiles, and pricing strategies. Ready-to-eat and microwave formats serve different occasions and require distinct innovation and merchandising approaches. Segmentation-aware planning enables more efficient resource allocation.
- Monitor competitive signaling from incumbents and niche players. The concentration of revenue among leading brands does not eliminate disruption risk. Vertical integrators, specialty variety producers, and equipment-enabled concession innovations can alter channel economics and consumer expectations. Continuous competitive intelligence is necessary to distinguish temporary noise from structural shifts.
- Ground decisions in scenario-based forecasting. The forecast period through 2032 projects a market trajectory that supports long-term investment, but the path is influenced by input costs, regulatory timing, and consumer response to labeling and packaging changes. Scenario modeling that stress-tests assumptions across these variables improves the quality of capital and inventory decisions.
What the Full Research Delivers
This article serves as a strategic preview, but the complete Popcorn Market research publication provides the depth required for execution-level planning. The report integrates historical performance data, forecasted market sizing, and structured segmentation analysis across regions, product types, and distribution channels. It includes detailed profiles of key market participants, an evaluation of recent operational events and their implications for quality and supply chain management, and a regulatory and raw material context that maps the forces shaping cost structures and compliance timelines.
Beyond data presentation, the research translates analysis into actionable frameworks. Readers will find scenario models that connect market growth to strategic choices, channel and format assessments that support assortment and pricing decisions, and competitive landscape mapping that clarifies positioning opportunities and threat vectors. The objective is to equip decision-makers with a coherent view of where growth is concentrated, where risk is accumulating, and where intervention can create durable advantage.
For teams preparing 2026 planning cycles, the full report is designed to function as a reference point for capital allocation, product roadmap prioritization, channel strategy, and risk mitigation. We invite you to access the complete publication to explore the segmentation breakdowns, regional revenue distributions, and detailed competitive and regulatory analyses that underpin the strategic recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Popcorn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Interrupter Market Hits 2.78B in 2025, Driven by 4.16% CAGR to 3.7B by 2032
By PW Consulting, 2026-09-16
Navigating the Vacuum Interrupter Market: Strategic Intelligence for 2026 and Beyond
The global vacuum interrupter market stands at a critical inflection point. As grid modernization accelerates and renewable energy integration reshapes medium-voltage infrastructure, equipment manufacturers, utility planners, and investment committees require more than surface-level forecasts. They need defensible, scenario-ready intelligence that connects macroeconomic tailwinds to operational decision-making. Our latest Vacuum Interrupter Market research report delivers exactly that—a structured, data-grounded framework designed to guide capital allocation, product roadmapping, and competitive positioning through 2032.
This article previews the analytical architecture of the study, outlines the operational insights embedded within, and clarifies why 2026 represents a make-or-break window for stakeholders operating across the medium-voltage switching ecosystem. Core granular data points remain intentionally reserved for the full report, ensuring that procurement leaders, product managers, and strategy directors receive a verified signal before committing to deep-dive purchasing decisions.
Market Trajectory: Reading the Curve Beyond Headline Numbers
Historical tracking from 2020 through the base year of 2025 reveals a market that has matured through cycles of infrastructure investment, supply chain recalibration, and shifting deployment priorities. The trajectory shows consistent expansion, with measured annual valuations progressing from early-2020s baselines toward a 2025 footing in the high two-billion-dollar range. Looking forward, the forecasting window spans 2026 to 2032, during which the market is projected to advance toward a valuation approaching the mid-three-billion-dollar threshold.
The implied compound annual growth rate across the forecast horizon sits at 4.16 percent, a pace that signals steadiness rather than explosive disruption. For strategic planners, this profile matters because moderate, predictable expansion typically rewards players who optimize supply reliability, certification readiness, and regional service coverage over those chasing speculative volume spikes. The growth curve also underscores a structural reality: vacuum interrupter demand is increasingly tied to upgrade cycles in existing substations, expansion of ring-main networks, and the replacement of aging switching components in distribution networks.
Vacuum Isolators Market
Readers should note that overall market sizing tells only part of the story. The full report decomposes this trajectory across multiple analytical dimensions, allowing decision-makers to isolate the segments most relevant to their portfolios. Those granular breakdowns—by geography, application, and voltage class—are deliberately withheld here to preserve the integrity of the paid intelligence and to encourage a targeted evaluation of the complete dataset.
Structural Dynamics Shaping Demand and Supply
Several interlocking forces are redefining the operating environment for vacuum interrupter manufacturers and buyers. First, grid modernization initiatives continue to accelerate across mature and emerging power networks alike. As utilities replace legacy air-insulated and oil-based switching equipment, vacuum interrupters have emerged as a preferred solution for their sealed architecture, reduced maintenance burden, and compatibility with compact substation footprints.
Second, the integration of renewable generation is creating new switching node requirements. Distributed solar, wind aggregation points, and hybrid grid-edge installations demand interruption technology that can handle frequent cycling, maintain dielectric recovery, and align with modern protection schemes. These trends are pushing medium-voltage switchgear manufacturers to reevaluate component specifications, particularly for applications where operational reliability must be maintained under variable load profiles and fault conditions.
Third, regulatory and standards-driven compliance remains a non-negotiable gatekeeper. Vacuum interrupters are certified according to IEC, ANSI, and GB standards for reliable operation in medium-voltage applications, while product specifications must meet or exceed IEEE, UL/CSA, IEC, JEC, and GB/DL expectations, supported by ISO 9001 and ISO 14001 certification in many 조달 environments. Independent verification also plays a central role: IEC 62271-100 type test reports from accredited laboratories verify vacuum interrupter performance for fault currents up to 40 kA. For procurement teams, this means that supplier evaluation is as much about documentation and test evidence as it is about quoted unit economics.
On the supply side, material costs introduce a persistent constraint. The high cost of copper chromium alloy contacts in vacuum interrupters for high-voltage applications serves as a primary restraining factor on market expansion, influencing both pricing strategy and margin management for OEMs and component suppliers. This cost dynamic interacts with production scale, metallurgy capabilities, and yield discipline, making process optimization a strategic differentiator rather than a back-office concern.
Competitive Landscape: Scale, Specialization, and Geographic Footprints
The competitive set in this market spans global electrical conglomerates, regional switchgear specialists, and component-focused manufacturers. The report provides a structured competitive scan that goes beyond simple company listings, examining how each player positions itself across voltage classes, end-use applications, and certification frameworks. Market concentration metrics underscore the importance of incumbency: the top three firms account for roughly 50 percent of market share, while the top five collectively represent about 65 percent, indicating a landscape where established players retain substantial influence but where focused niche competitors can still secure defensible positions.
A representative cross-section of the competitive field illustrates the breadth of strategic postures currently in play. ABB produces vacuum interrupters and embedded poles for medium-voltage applications up to 40.5 kV, drawing on over 40 years of experience with certifications aligned to IEC, ANSI, and GB standards. Eaton offers custom vacuum interrupter solutions for circuit breakers and switchgear, meeting IEEE, IEC, and GB/DL requirements with a heritage rooted in electrical circuit protection. Siemens develops proprietary vacuum interrupters optimized for medium-voltage components, engineered as hermetically sealed units for reliable switching in grid applications.
In Asia, Mitsubishi Electric manufactures vacuum interrupters ranging from 1.5 kV to 84 kV for vacuum circuit breakers, load switches, and contactors, with total production exceeding 3.5 million units. Meidensha has operated as a pioneer since 1965, producing vacuum interrupters from 3.3 kV to 145 kV with long operating life up to 250,000 cycles and IEC/ANSI/GB certifications. Schneider Electric provides vacuum interrupters in medium-voltage switchgear, including Shunt Vacuum Interrupter technology for grid modernization and renewable integration. Toshiba operates advanced vacuum metallurgy facilities supporting vacuum interrupters used in railway traction and high-cycle industrial switching applications.
Further broadening the field, CG Power and Industrial Solutions supplies vacuum interrupters within its medium-voltage electrical equipment portfolio for power distribution and industrial uses. LS Electric manufactures vacuum interrupters integrated into switchgear systems for medium-voltage applications. Fuji Electric produces vacuum interrupters for circuit breakers and contactors certified to international standards. At the regional and specialized end of the spectrum, Shone Vacuum Electrical Apparatus focuses on high-quality vacuum interrupter production and sales with R&D emphasis on advanced materials and strict quality control for domestic and export markets. Xi'an XD High Voltage Apparatus develops and manufactures high-voltage apparatus including vacuum interrupters for power transmission and distribution. Changshu Switchgear Manufacturing produces switchgear components including vacuum interrupters for electrical equipment applications. Beijing Beiyi Electric concentrates on research and production of vacuum interrupters with advanced processes for power plants and substations. GLVAC offers vacuum interrupters as core components for vacuum switches in power equipment systems.
This competitive diversity matters because procurement strategies increasingly depend on application fit, certification alignment, and supply continuity rather than price alone. The full report maps these profiles against segment relevance, enabling readers to benchmark supplier options against their specific voltage, cycling, and compliance requirements.
Recent Developments Signaling the Pace of Change
Market movement is not abstract; it is visible in product releases, production milestones, and partnership activity. In the first quarter of 2026, Schneider Electric launched the Ringmaster AirSeT medium-voltage switchgear featuring a Shunt Vacuum Interrupter mechanism with three-position ring operation, SCADA connectivity, and a 30-year design life. This launch reflects a clear industry push toward longer service life, smarter connectivity, and modular substation architectures.
On the production and scale side, ABB reached a cumulative delivery milestone of 7 million vacuum interrupters from its factory in Ratingen, Germany, underscoring the importance of manufacturing credibility and long-running process maturity in a market where reliability is a core selling point. Meanwhile, in mid-2025, General Electric entered a strategic partnership with a leading renewable energy developer for co-development of advanced vacuum interrupter technologies, signaling how incumbents are beginning to align R&D directly with the needs of renewable-heavy grid environments.
Vacuum Interrupter Market
These events are not isolated headlines; they are indicators of where capability investments are flowing. The report situates such developments within a broader trend analysis, helping readers separate marketing momentum from structural adoption signals.
What the Report Delivers: An Operational Toolkit for 2026 Decisions
The study is structured to support concrete decisions rather than general orientation. It combines market sizing, forecast modeling, segmentation analysis, competitive profiling, and regulatory context into a single decision-support framework. Key components include:
- Macro market sizing and forecast pathways anchored to a defined historical window and a forward outlook through 2032, expressed in USD billion terms.
- Segment-level analysis across regional demand patterns, application categories, and voltage-class distributions, designed to help readers identify where growth is concentrated and where substitution risk may arise.
- Competitive profiling of major manufacturers, including headquarters, product scope, certification posture, and operational scale indicators.
- Regulatory and standards context covering IEC, ANSI, GB, IEEE, UL/CSA, JEC, and GB/DL expectations, alongside ISO certification relevance and type-test verification for fault current performance.
- Supply-side constraints and enablers, including material cost dynamics, metallurgy considerations, and production scale implications for margin and availability.
- Recent corporate developments—product launches, milestones, and partnerships—that illustrate how incumbents and challengers are repositioning for medium-voltage grid modernization.
Importantly, the report is built for scenario use. Readers can isolate the segments that match their product lines, regional targets, or procurement programs and then stress-test assumptions around growth pace, competitive pressure, and compliance requirements. This modularity is particularly valuable for teams building multi-year capacity plans or evaluating entry and expansion opportunities in medium-voltage switchgear and protection equipment markets.
Why 2026 Is a Decision Pivot
The forecast period begins in 2026, and that timing is strategically meaningful. At a projected 2026 valuation approaching 2.95 billion USD, the market is moving from a phase of steady historical growth into a period where policy-driven infrastructure spending, renewable integration mandates, and substation upgrade cycles begin to compound. For manufacturers, this is the moment to align production capacity, certification portfolios, and regional distribution with the segments most likely to absorb incremental volume. For distributors and system integrators, it is the moment to secure supply commitments and differentiate on service reliability rather than commodity pricing. For investors and corporate strategy teams, it is the moment to separate durable growth narratives from short-term procurement timing effects.
The market’s moderate CAGR suggests that winners will not be determined by speculative overbuild, but by precision: the ability to match voltage-class coverage, application-specific performance, and standards compliance to the right geographies and customer programs. The full report provides the segmentation granularity required to make those matches with confidence.
Reserved Intelligence and How to Use It
In keeping with the analytical purpose of this preview, detailed regional splits, application-level values, and voltage-class proportions are not disclosed here. These figures are central to the report’s commercial value because they enable tailored planning for specific product lines and market-entry strategies. The full study makes those breakdowns available in a structured format, allowing stakeholders to benchmark against their own pipeline assumptions and to refine procurement or production plans accordingly.
Leaders evaluating this market for 2026 planning should treat the preview as a confidence check. If the macro trajectory, competitive breadth, standards environment, and recent product and partnership signals align with your internal assumptions, the full report offers the precise segment intelligence needed to convert strategy into execution. If gaps remain, the complete dataset provides the reference points required to recalibrate.
Closing Perspective
The vacuum interrupter market is not experiencing a sudden rupture; it is undergoing a calculated evolution shaped by grid modernization, renewable integration, compliance rigor, and material-cost discipline. That evolution favors organizations that can read the market at the segment level, match technology capability to application need, and build supply credibility over time. The full Vacuum Interrupter Market research report is designed to support exactly that posture, offering a comprehensive, forecast-anchored, and competitively detailed foundation for 2026 decision-making.
For strategic teams ready to move from directional understanding to actionable planning, the complete report provides the reserved segmentation, competitive depth, and scenario-ready structure necessary to make informed commitments in a market where reliability, certification, and timing increasingly determine outcomes.
For detailed analysis of this topic, please visit the official page: Vacuum Interrupter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


