



PW Consulting: Spunbond Nonwoven Market to Reach $26.58 Billion by 2032, 6.1% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Spunbond Nonwoven Fabrics Market: Navigating Growth Amid Regulatory and Supply Chain Shifts in 2026
Executive Overview
The spunbond nonwoven fabrics sector is entering a defining growth phase, driven by sustained demand across hygiene, medical, automotive, filtration, and industrial applications. As manufacturers and converters plan for 2026 and beyond, the market is characterized by a resilient demand trajectory, evolving material economics, and a rapidly tightening regulatory horizon. This introduction outlines the strategic rationale behind our latest market research, demonstrating how a granular, forward-looking analysis can convert macro trends into executable decisions for sourcing, capacity investment, compliance planning, and competitive positioning.
Over the past six years, the industry has expanded from a baseline of approximately 13.06 billion USD in 2020 to 17.56 billion USD in 2025, reflecting a compound annual growth rate of 6.1 percent through the 2026-2032 forecast horizon. In 2026, the market is projected to reach 18.22 billion USD, with expansion continuing toward 26.58 billion USD by 2032. These headline figures underscore a market that is not merely growing, but transforming in terms of product portfolios, regional dynamics, and value chain complexity. The question for decision makers is no longer whether the spunbond nonwoven fabrics market will expand, but how to capture share, manage cost volatility, and align operations with regulatory and sustainability mandates that are reshaping competitive rules.
Our newly released market research is designed to answer that question. It provides an integrated view of demand drivers, segment trends, regional momentum, competitive strategies, and the regulatory and raw material variables that will influence margins and availability in 2026 and beyond. The report functions as both a market map and an operating playbook, enabling executive teams to stress test assumptions, prioritize investments, and anticipate inflection points before they become industry consensus.
Market Trajectory and Structural Signals
The historical evolution of the spunbond nonwoven fabrics market reveals a steady, broad-based expansion rather than a single-cycle surge. From 2020 through 2025, growth was supported by robust post-pandemic hygiene demand, continued medical and filtration applications, and the gradual penetration of spunbond materials into automotive interiors, geotextiles, and agricultural uses. The forecast period extends this narrative, projecting acceleration in select end-use categories while challenging players to manage input cost exposure and regional competitiveness.
Several structural signals are particularly relevant for 2026 planning. First, demand is increasingly bifurcated by performance and sustainability requirements. High-loft and specialized spunbond grades are gaining traction where lightweighting, breathability, and filtration efficiency matter, while conventional commodity volumes remain critical for hygiene and base medical applications. Second, regional growth patterns are diverging as regional demand bases, trade policy, and local capacity build-out alter relative competitiveness. Third, raw material dynamics are reshaping cost structures: polypropylene feedstock prices rose 25.74 percent year-over-year by March 2026, reflecting petroleum market dynamics that directly affect spunbond nonwoven production costs and converter margins.
These forces require a decision framework that goes beyond top-line growth estimates. Companies must evaluate where demand is structurally durable versus cyclically sensitive, how regional capacity additions will affect supply availability and pricing, and which material and regulatory variables will most impact unit economics. The research provides these answers through demand-side segmentation, supply-side capacity analysis, and scenario-based considerations that link macro trajectory to operational choices.
Meltblown PP Nonwoven Fabric Market
What the Research Delivers
This report is built for practitioners who need actionable intelligence rather than generic market commentary. It combines a comprehensive market assessment with operational depth, allowing teams to translate industry-wide momentum into segment, regional, and application-specific strategies. Key content areas include:
- A detailed market sizing and forecast framework spanning historical performance and a multi-year outlook, enabling leaders to benchmark internal plans against industry trajectory and evaluate the timing of capacity or product launches.
- Segment-level analysis across material types and application categories, with a focus on the drivers of demand intensity, substitution risk, and pricing dynamics that differentiate commodity and specialty spunbond nonwoven fabrics.
- A regional perspective that maps growth momentum, supply conditions, and competitive intensity across major markets, helping firms assess where to expand, source, or reposition their commercial footprint.
- Competitive landscape profiling of leading manufacturers and suppliers, including strategic focus areas, application strengths, and recent capacity and investment activity that influence market balance.
- Market structure indicators that illuminate concentration and the degree of fragmentation or consolidation, supporting channel strategy, negotiation leverage, and partnership decisions.
- Regulatory and sustainability analysis covering carbon-related mechanisms, product stewardship rules, chemical compliance expectations, and recycled content pressures that are reshaping material choices and import competitiveness.
- Supply chain and cost considerations, including raw material price behavior, tariff exposure, and conversion constraints, with implications for sourcing strategy and margin protection.
Throughout the report, findings are presented in a way that supports scenario planning. Readers can assess how changes in feedstock costs, regulatory timelines, or regional capacity additions might alter demand distribution, competitive positioning, and return profiles. This approach is particularly valuable for 2026 decisions, where the combination of strong demand and heightened external uncertainty rewards preparation over reaction.
Competitive Landscape: Strategic Focus Across Leading Players
The spunbond nonwoven fabrics market is shaped by a mix of global integrators and specialized manufacturers, each pursuing distinct application strengths and regional priorities. The report profiles leading companies whose activities illustrate the strategic diversity now defining the sector.
Berry Global Group, Inc., headquartered in Evansville, Indiana, USA, operates as a major producer and supplier of spunbond nonwoven fabrics primarily for hygiene, medical, and industrial applications. Its scale and broad application footprint make it a central reference point for understanding how integrated players manage volume demand while developing specialized grades. Freudenberg Performance Materials SE, based in Weinheim, Germany, is a leading manufacturer focused on filtration, automotive, and industrial markets, reflecting the importance of performance-grade spunbond materials in technical applications where functional differentiation matters more than pure cost competition.
Spunbond Nonwoven Fabrics Market
Kimberly-Clark Corporation, headquartered in Irving, Texas, USA, is a key producer for hygiene and consumer products, with a strong presence in end-markets where brand strength, consistent quality, and supply reliability are critical. Ahlstrom-Munksjö Oyj, based in Helsinki, Finland, manufactures sustainable spunbond nonwoven fabrics for medical and hygiene applications, positioning sustainability attributes as part of product value rather than a separate compliance exercise. Mogul Nonwovens, in Gaziantep, Turkey, produces spunbond nonwoven fabrics for automotive, filtration, and hygiene markets, illustrating how regional manufacturers can serve diversified demand while remaining responsive to regional cost and sourcing conditions.
Toray Industries, Inc., in Tokyo, Japan, supplies high-performance spunbond nonwoven fabrics for automotive interiors and filtration, reinforcing the role of advanced material engineering in premium applications. Fitesa S.A., headquartered in Simpsonville, South Carolina, USA, is a global manufacturer serving hygiene, medical, and industrial uses, with an emphasis on scale and breadth of application coverage. Sandler AG, in Halberstadt, Germany, produces spunbond nonwoven fabrics for filtration and technical textiles, aligning with the growing demand for engineered nonwovens in specialized end-uses.
Asahi Kasei Corporation, also based in Tokyo, Japan, provides spunbond nonwoven fabrics for hygiene, medical, and filtration applications, combining material expertise with demand across both consumer-facing and technical markets. PFNonwovens Holding s.r.o., in Prague, Czech Republic, focuses on hygiene and medical products, highlighting how regional players can build defensible positions in high-consistency end-markets. Together, these companies demonstrate that competitive advantage in spunbond nonwoven fabrics is increasingly defined by application specialization, regional responsiveness, sustainability credentials, and the ability to manage capacity and input-cost volatility.
Recent Developments and Capacity Dynamics
Capacity expansion and capital deployment are central themes in the current market environment, and several recent moves illustrate how competitors are positioning for the forecast period. In February 2025, Avgol Nonwovens unveiled a new high-speed, high-capacity flexible multiple beam spunbond production line at its Mocksville, NC facility following a 100 million USD investment, delivering additional spunbond nonwoven capacity and high-loft products. This move signals not only volume expansion but also a focus on differentiated, higher-value structures.
In May 2025, Kimberly-Clark Corporation announced a 2 billion USD investment over five years in its North America business, including major expansion for polypropylene spunbond nonwoven fabric production with a 50 percent capacity increase. This is a strong indicator of confidence in sustained demand and an emphasis on securing supply for key end-markets. Also in May 2025, Spunweb Group acquired two advanced polypropylene spunbond production lines, increasing capacity by approximately 53 percent, from 12,240 MTPA to 18,740 MTPA. The transaction underscores how consolidation of production capability can rapidly alter regional supply dynamics and competitive standing.
These developments matter for 2026 planning because capacity additions do not simply shift volume; they reshape lead times, regional availability, and pricing leverage across segments. Where new capacity is directed toward high-loft or specialized grades, it may ease bottlenecks in premium applications while intensifying competition in standard grades. Where expansion is concentrated in particular regions, it can alter relative import dependence and shift the economics of local conversion versus imported material. The report analyzes these dynamics in greater detail, helping firms anticipate where competitive pressure will intensify and where supply security will become a strategic differentiator.
Regulatory and Supply Chain Forces Reshaping the Market
Market growth alone does not determine profitability or strategic success; the regulatory and supply chain backdrop is equally important. Several developments are recalibrating competitiveness and material strategy in the spunbond nonwoven fabrics sector. On the regulatory front, the EU Carbon Border Adjustment Mechanism and Packaging and Packaging Waste Regulation are recalibrating import competitiveness for polypropylene nonwoven fabrics in Europe. At the same time, REACH and SVHC compliance requirements for polypropylene resins are driving development of sustainable and bio-based alternatives in spunbond nonwoven manufacturing. In parallel, European Union and North American environmental regulations on plastic waste are compelling a shift toward recycled content in spunbond nonwoven fabrics.
Trade policy is also introducing uncertainty. Section 122 tariffs on polypropylene imports create uncertainty for North American converters in the spunbond nonwoven market, adding a variable that can affect landed costs and sourcing flexibility. Combined with the 25.74 percent year-over-year rise in polypropylene feedstock prices by March 2026, these factors place renewed importance on procurement strategy, formulation alternatives, and product design choices that can reduce exposure to input volatility.
Why This Research Matters for 2026 Decisions
In a market expanding toward 26.58 billion USD by 2032 with a 6.1 percent CAGR across the forecast period, the margin between participation and leadership will be defined by how well companies align strategy with the forces shaping supply, demand, and regulation. The spunbond nonwoven fabrics market is not simply getting larger; it is becoming more segmented, more policy-sensitive, and more dependent on operational agility. Companies that can match capacity decisions to durable end-use demand, manage raw material exposure, and anticipate regulatory change will be better positioned to protect margins and capture share.
This research provides the structure needed to make those choices with confidence. It synthesizes market sizing, segment behavior, competitive moves, and external pressures into a coherent decision framework, allowing leadership teams to evaluate where to invest, where to consolidate, where to differentiate, and where to hedge. Given the pace of recent capacity expansion and the evolving regulatory landscape, 2026 is a pivotal year for establishing a durable competitive position. The full report delivers the detailed segmentation, regional momentum, application trends, and competitive intelligence necessary to turn market growth into strategic advantage.
To access the complete analysis and the specific data behind these market-wide trends, please visit the source page for the full publication and supporting materials.
For detailed analysis of this topic, please visit the official page: Spunbond Nonwoven Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Market to Hit $5.33 Billion by 2032, Growing at 4.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Automotive Door Handles Market: Navigating Growth, Regulation, and Technological Disruption Through 2032
The automotive door handle has evolved from a passive mechanical latch into a sophisticated interface for vehicle access, security, ergonomics, and increasingly, digital identity. As OEMs push toward seamless smart entry, wireless charging integration, and aerodynamic flush-designed exteriors, the door handle subsystem has become a strategic battleground where mechanical engineering, mechatronics, and regulatory compliance intersect. For procurement leaders, product developers, and competitive intelligence teams, understanding the trajectory of this component market is no longer optional—it is a prerequisite for resilient supply chain planning and differentiated vehicle architecture decisions.
Our latest Automotive Door Handles Market research delivers a comprehensive, data-grounded assessment of the industry, calibrated for decision-makers operating on 2026 planning cycles. Rather than offering static snapshots, this report maps the structural forces reshaping revenue pools, competitive positioning, and engineering roadmaps across the forecast horizon. The following overview highlights the strategic dimensions stakeholders can expect, while preserving the full analytical granularity for the complete intelligence package.
Market Sizing and Trajectory: Reading the Growth Curve Beyond Aggregate Figures
The global automotive door handles market has demonstrated consistent expansion over the past five years, driven by rising vehicle production volumes, premiumization trends, and the steady migration toward electronically assisted access systems. Historical revenue progression from 2020 through 2025 reflects a resilient demand base, supported by both passenger vehicle refresh cycles and commercial fleet renewals. The market has now crossed a meaningful scale threshold, and the forward trajectory suggests continued growth with a compound annual growth rate of 4.5 percent throughout the 2026 to 2032 forecast period.
This growth profile is not uniform. Revenue expansion is being shaped by a combination of volume-driven regions, shifting vehicle mix toward electrified platforms, and the premium pricing power associated with integrated mechatronic handle systems. The report dissects these momentum drivers across multiple analytical lenses, helping readers separate cyclical production effects from structural shifts in component value. By anchoring regional and application-level analysis within a unified framework, the study clarifies where demand is accumulating, which vehicle segments are absorbing higher-value handle configurations, and how total addressable revenue is expected to compound as platforms mature.
Because the door handle market sits at the intersection of commodity mechanical parts and increasingly sophisticated electronic subsystems, understanding the aggregate growth trajectory is only the starting point. The full research unpacks the revenue composition behind these headline figures, giving stakeholders a calibrated view of where margin pools are forming and where price competition is intensifying.
Report Scope and Actionable Analytical Framework
This study is designed as an operationally useful reference for strategy, sourcing, and product planning functions. It moves beyond descriptive market narratives to provide structured intelligence that can be directly embedded into investment appraisals, supplier evaluation matrices, and platform development timelines.
Key capabilities embedded in the report include:
- A forward-looking market model spanning the 2026 to 2032 period, with historical baselines that contextualize post-2025 momentum and enable scenario-based revenue planning.
- Segment-level analysis across handle architecture types, vehicle application categories, and geographic demand centers, allowing readers to identify where value is concentrating and where supply requirements are diversifying.
- Competitive profiling of leading manufacturers, mapping product portfolios, technology orientations, and strategic moves that are reshaping supply relationships and OEM qualification dynamics.
- Regulatory and materials watchpoints, including design mandates, sustainability requirements, and manufacturing process shifts that are altering cost structures and engineering choices.
- Strategic synthesis tied to practical decision levers: supplier diversification, platform-commonization trade-offs, mechatronic integration timing, and regional compliance readiness.
The report is structured so that each analytical layer can be used independently or read together for a consolidated market assessment. For organizations evaluating new sourcing commitments, platform specification decisions, or market entry strategies, the work functions as both a benchmark and a planning tool, translating macro trends into specific operational implications.
Competitive Landscape: Who Is Shaping the Next Generation of Door Handle Systems
The door handle market is characterized by a concentrated group of sophisticated Tier suppliers with deep OEM relationships, multiplexed product architectures, and increasing emphasis on mechatronic integration. Rather than competing solely on unit cost, leading players are differentiating through system-level value: flush-mounted aesthetics, passive entry and sensor integration, power closure functionality, and fastening solutions that simplify assembly while preserving structural integrity.
Automotive Door Handles Market
Among the firms profiled, Huf Hulsbeck & Fürst GmbH & Co. KG stands out for its broad portfolio of rotational flush, parallel deployable, flap flush, and fixed handle designs, augmented by integrated mechatronic passive entry and sensor technologies. Its positioning reflects a market leader’s playbook: offering OEMs a complete spectrum of access solutions while pushing electronic intelligence into the handle subsystem itself. Magna International Inc. approaches the market from a module-integration perspective, delivering door module assemblies and SmartAccess systems that bundle mechanical and electronic handle functions with actuators, regulators, and controls. This systems-level offering aligns well with OEMs seeking reduced interface complexity and coordinated module performance.
Kiekert AG contributes a complementary strength in side door locking systems, power closing actuators, and mechatronic solutions that directly support door handle operation and access comfort. Aisin Seiki Co., Ltd. brings advanced door handle systems, keyless entry modules, and power closure components to major automakers, with a clear focus on integrated entry control technologies. U-Shin Ltd. extends the competitive field with outside and inside handles, lock sets, and power closure systems emphasizing flush and smart access designs tailored to Asian and global OEMs. WITTE Automotive GmbH adds specialized expertise in exterior handles, classic bow handles, and flush-mounted solutions supported by advanced fastening systems, while Minda VAST Access Systems Pvt. Ltd. represents the growing capability base in vehicle access systems and mechatronic solutions serving Indian and export-oriented supply chains.
Recent corporate activity underscores how quickly the strategic center of gravity is shifting. In April 2025, Magna showcased advanced SmartAccess technologies and integrated door modules at industry events, emphasizing mechatronic handle solutions as a focal point of its access strategy. In May 2025, Huf announced a major strategic partnership with Sodecia to strengthen supply chain capacity and accelerate innovation in door handle systems. Then, in August 2025, WITTE Automotive collaborated with trinamiX on a concept car featuring integrated facial authentication and automatic door opening without a physical handle, eliminating traditional handles in the B-pillar area for next-generation vehicle designs. These moves illustrate a landscape where partnerships, concept demonstrations, and module-level integration are becoming as important as base component performance.
Regulatory and Materials Dynamics: The Hidden Cost and Design Shifts Reshaping the Market
One of the most consequential forces in the door handle sector is regulatory intervention, particularly where safety mandates intersect with design philosophies that have been trending toward concealed or fully electronic operation. Starting January 1, 2027, China will require manual release hardware on all electric door handles for vehicles sold domestically, ensuring emergency opening from both sides of the car. This mandate effectively restricts hidden or electronic-only handle designs on new vehicles from that date, pushing traditional mechanical handles or hybrid designs onto models that had been moving toward fully concealed access mechanisms.
The practical implications are multifaceted. For manufacturers, the requirement adds cost and engineering complexity, because mechanical release hardware must be integrated without undermining the intended aesthetics or packaging goals of flush and smart-access designs. For OEMs, it introduces a compliance constraint that can alter exterior styling strategies, interior access logic, and component sourcing plans. For suppliers, it reinforces the need for hybrid solutions that satisfy both regulatory expectations and consumer-facing design ambitions. The report examines how such mandates reshape segment economics and influence the pace at which fully electronic concepts can scale in regulated markets.
Automotive Door Handle Sensors Market
At the same time, the wider adoption of flush-mounted door handles in a substantial share of new global vehicle models in 2025 is driving demand for specialized surface coatings and precision injection molding. These requirements are not purely cosmetic; they support aerodynamic integration, consistent exterior finish quality, and long-term durability under varied environmental exposure. As flush designs become more common, the manufacturing bar rises, and suppliers that can deliver tight tolerance, stable surface performance, and efficient production throughput gain a clearer competitive edge.
Sustainability pressure is also entering the supplier qualification process. New OEM requirements for ESG compliance and sustainable materials are increasing expectations for lower-carbon production processes across door handle manufacturing. This trend is pushing suppliers to evaluate material choices, energy intensity, and process efficiency with greater scrutiny, especially as vehicle programs extend their lifecycle assessments and component-level carbon accounting becomes more embedded in procurement decisions.
Strategic Implications for 2026 Decision-Making
For organizations planning in 2026, the door handle market presents a layered set of strategic questions. The first concerns technology timing: how aggressively should programs pursue fully integrated mechatronic handles, and where should hybrid or mechanically backed designs remain the priority to balance compliance, cost, and user experience? The second concerns supply resilience: with market concentration leaning toward a limited group of capable global suppliers, how should OEMs and Tier customers structure qualification pipelines, dual-sourcing strategies, and regional supply coverage? The third concerns design-for-regulation: how can product architectures accommodate emerging mandates without locking in obsolescence or sacrificing aerodynamic and aesthetic objectives?
The report provides the analytical scaffolding needed to answer these questions with greater confidence. By linking market size evolution, segmentation patterns, competitive activity, and regulatory developments into a single decision-oriented framework, it helps stakeholders prioritize where to invest, where to monitor, and where to intervene. Whether the objective is securing stable supply for high-volume programs, positioning for premium access features, or assessing the commercial viability of next-generation handle concepts, the study is built to support structured, evidence-based action.
The complete market intelligence package goes further still, offering detailed segmentation analysis, company-level profiles, recent development tracking, and forward demand modeling that cannot be fully reproduced in a summary format. For teams that need to translate industry momentum into procurement strategy, product roadmaps, or competitive positioning, the full report provides the depth required to move from broad market awareness to precise, executable insight.
For detailed analysis of this topic, please visit the official page: Automotive Door Handles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gantry/Cartesian Robots Market to Hit $5.9 Billion by 2032 at 9.4% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Next Decade: Unlocking Value in the Gantry and Cartesian Robots Market
Executive Overview: A Market at the Inflection Point
The global landscape for industrial automation is undergoing a fundamental transformation, driven by the relentless pursuit of efficiency, precision, and adaptability in manufacturing environments. At the heart of this shift lies the Gantry and Cartesian Robots market, a sector poised for robust expansion over the coming years. Our latest comprehensive market study, covering the historical period from 2020 to 2025 and forecasting through 2032, provides a critical roadmap for stakeholders navigating this evolving terrain. With a projected compound annual growth rate indicating sustained momentum, the market is expected to grow from an estimated valuation in the base year to nearly double that figure by the end of the forecast period. This trajectory underscores the essential role these robotic systems play in modernizing supply chains, optimizing production lines, and enabling high-precision applications across diverse industries.
For enterprise leaders, investors, and operational strategists, understanding the nuances of this growth is not merely an academic exercise but a strategic imperative. The transition from the historical data of the past five years to the forward-looking projections for 2026 and beyond reveals a market that is maturing in technology yet remains dynamic in its competitive structure. This article serves as a strategic preview of our full research publication, highlighting the key drivers, competitive forces, and operational dynamics that will define decision-making in 2026. While we outline the broader contours of opportunity here, the specific granular data required for precise capacity planning and investment allocation is detailed within the full report.
Market Trajectory and Growth Dynamics
The historical performance of the market demonstrates a consistent upward trend, reflecting the increasing adoption of automated solutions in sectors ranging from logistics to precision manufacturing. Data from the historical window shows a steady accumulation of revenue, setting a strong foundation for the forecast period. As we move into 2026, the growth narrative is supported by several macroeconomic and technological factors. The demand for automated material handling and processing is accelerating, fueled by the need to mitigate labor shortages and enhance operational throughput.
Worldwide Dual Arm Cooperative Robot (Dual Arm Cobot) Market
Our analysis indicates that the market valuation is expected to climb steadily, reaching significant milestones by 2032. This expansion is not uniform across all facets of the industry; rather, it is driven by specific advancements in mechanical design, control systems, and integration capabilities. The forecast period presents varied opportunities depending on the specific type of coordinate automation employed and the application landscape it serves. Companies that can align their product development and go-to-market strategies with these growth vectors will be best positioned to capture market share. Furthermore, the consolidation of market power remains a key area of focus; our data suggests a competitive landscape where top players hold a significant, though not monopolistic, portion of the total revenue, indicating room for specialized entrants and niche innovators to thrive alongside established giants.
Competitive Landscape and Strategic Positioning
The ecosystem surrounding Gantry and Cartesian Robots is populated by a diverse array of global players, each leveraging distinct technological advantages and regional strengths. Understanding the positioning of these key entities is crucial for benchmarking and strategic planning. Our report provides detailed profiles and comparative analyses of major contributors to the market, offering insights into their product philosophies and operational focus.
- igus (Germany): Recognized for their focus on maintenance-free solutions, specifically utilizing drylin plastic linear robots and gantry systems. Their offering is often positioned for cost-effective pick-and-place and palletizing tasks where reducing lubrication and maintenance overhead is a priority.
- Yamaha Motor Co., Ltd. (Japan): A significant player in factory automation, known for the XY-X series Cartesian robots. Their portfolio includes both moving arm and gantry types designed for high-performance environments, emphasizing reliability and speed in industrial settings.
- Festo (Germany): Specializes in ready-to-install Cartesian robots and 3D gantries based on linear and slide drives. Their approach often integrates advanced control technologies, aiming to simplify deployment for complex automation tasks.
- IAI Automation (Japan): Focuses on compact solutions, offering 2- to 6-axis Cartesian robots utilizing linear drives and parallel kinematics. This highlights a market segment driven by the need for flexibility and space efficiency without sacrificing multi-axis capability.
- Güdel Group AG (Switzerland): Known for heavy-load handling capabilities, with series such as the FP-5 and gantryRobot. Their systems are engineered for high precision in applications requiring the movement of several tonnes, catering to heavy industry demands.
- Dunkermotoren (Germany): Leverages ServoTube linear motors in their gantry systems. This technology is particularly relevant for high-speed packaging and electronics assembly, where rapid acceleration and precise positioning are critical.
- Physik Instrumente (PI) USA (USA): Targets high-precision sectors with modular XY/Z and XYZ gantries. Utilizing air bearings and linear motors, their solutions are tailored for semiconductor manufacturing and additive processes like 3D printing.
- Janome Industrial Equipment (Japan): Provides standard Cartesian robots aimed at cost-effective industrial handling, representing a segment of the market focused on accessible automation for general purpose tasks.
- Nordson EFD (USA): Offers 3-axis Cartesian systems specifically optimized for adhesive dispensing and material handling, demonstrating how application-specific needs drive product differentiation.
- Promation (USA): Focuses on tabletop Cartesian robots for soldering and electronics assembly, addressing the needs of smaller footprint operations and delicate manufacturing processes.
Recent developments among these players signal the direction of the market. In late 2025, Yamaha Motor Co., Ltd. established a joint venture with Taiwanese partner TOYO Automation, signaling a strategic shift to transfer production of single-axis and Cartesian robots to expand lineups and reduce lead times starting in 2026. Similarly, advancements in application scope were highlighted when the International Federation of Robotics featured Güdel's FP-5 gantry robot in a 3D concrete printing case study in late 2025, showcasing the crossover of industrial robotics into construction. By mid-2026, Festo introduced an AI-based gripper solution compatible with Cartesian systems, aiming to enable faster deployment for mixed-product handling without imposing brand lock-in. Additionally, industry presence at events like the Automate trade show in Chicago highlighted by companies such as Rollon in mid-2026 reinforces the focus on linear motion components and gantry-compatible systems as foundational elements of the automation ecosystem.
Operational Challenges and Market Drivers
Raw Material Volatility and Cost Pressures
One of the critical dynamics shaping the market economics is the fluctuation in raw material costs. Since 2022, prices for essential components such as steel and rare-earth magnets have experienced significant volatility, with year-on-year fluctuations ranging between 8 and 15 percent. This instability exerts direct margin pressure on manufacturers, particularly affecting the cost structures of linear guides and ball screws which are fundamental to gantry and Cartesian systems. Our analysis suggests that these raw material cost variations have compressed gross margins by a notable margin in the standard-grade segments since 2022. Navigating this environment requires strategic sourcing and potentially redesigning systems for material efficiency, a topic explored in depth within the full report.
Regulatory Standards and Safety Compliance
The deployment of heavy industrial robots, including gantry systems, is subject to increasingly strict regulatory standards and safety requirements, particularly in North America. These regulations impose significant restraints and compliance costs on the deployment of such systems. Furthermore, updated safety standards introduced in 2025, including revisions to ISO and ANSI protocols, now require comprehensive risk assessments for collaborative applications involving gantry robot cells. Compliance with these evolving standards is not optional but a prerequisite for market entry and operation in key regions. The report details the implications of these regulatory shifts on installation timelines, system design, and total cost of ownership.
Energy Efficiency and Sustainability
In response to operational cost pressures and broader sustainability goals, manufacturers are increasingly integrating energy-efficient designs into robotic systems. The goal is to minimize power consumption during intensive operations, such as heavy material handling. This trend is influencing product design at the component level, pushing vendors to develop motors and drives that offer high performance with lower energy footprints. For end-users, selecting systems with superior energy efficiency metrics can translate into substantial long-term operational savings, making this a key criterion in procurement decisions.
Gantry/Cartesian Robots Market
Segmentation Insights: Type, Application, and Region
The market is diversified across multiple dimensions, each offering unique growth opportunities and challenges. Our research breaks down the market by Type, Application, and Region, providing a multi-faceted view of where value is being generated. While specific percentage splits and absolute values for each segment are reserved for the detailed dataset in the full report, the functional overview reveals distinct strategic zones.
In terms of Type, the market ranges from simpler single-axis configurations to complex multi-axis gantry systems. Each axis configuration serves different complexity levels in automation tasks. The demand varies based on the precision required and the spatial freedom needed for the operation. Similarly, the Application segment covers a broad spectrum of industrial activities. Handling remains a cornerstone application, but specialized uses such as Palletizing, Welding, and other niche processes drive specific demand curves. The report analyzes how the adoption rates differ across these applications, influenced by factors such as cycle time requirements, payload capacities, and integration complexity.
Geographically, the market exhibits varying maturity levels and growth rates across regions such as North America, Europe, and Asia Pacific, among others. Each region presents a unique combination of regulatory environment, labor cost dynamics, and industrial base characteristics. Understanding the specific demand drivers in each geography is essential for companies looking to expand their footprint or optimize their supply chain logistics. The comprehensive regional analysis in our study provides the context needed to assess market entry barriers and potential return on investment in different territories.
Strategic Outlook for 2026 and Beyond
As we look toward the remainder of the decade, the Gantry and Cartesian Robots market is set to evolve through a combination of technological innovation and adaptive business models. The data points covered in this preview illustrate a market with strong fundamental growth, yet one that is sensitive to external pressures like material costs and regulatory compliance. Success in this environment will depend on a company's ability to innovate within constraints and to identify high-value niches where precision and reliability command a premium.
The integration of AI and smart gripping solutions, as seen in recent product launches, points toward a future where Cartesian systems are more adaptable to mixed-product lines without extensive reprogramming. This flexibility is likely to be a major differentiator. Furthermore, the expansion of applications into new sectors, such as construction demonstrated by recent case studies, suggests that the addressable market may be broader than traditionally defined. For strategists, this implies the need to look beyond conventional manufacturing boundaries when assessing growth potential.
However, realizing the full potential of these opportunities requires access to precise, actionable data that goes beyond high-level trends. Decision-makers need detailed segmentation data, competitive benchmarking, and scenario analysis to formulate robust strategies. The high-level figures and trends presented in this article are intended to highlight the significance of the market and the breadth of our analysis. They serve as an invitation to delve deeper into the specifics that will underpin your 2026 planning.
Accessing Comprehensive Intelligence
To fully leverage the insights discussed and secure a competitive advantage, we invite you to access the complete Gantry/Cartesian Robots Market research report. The full publication contains the exhaustive data sets, including specific revenue projections by type and application, detailed regional breakdowns, and in-depth company profiles that are referenced here. It also provides a thorough examination of the supply chain dynamics, risk factors, and technological roadmaps that will influence the market through 2032.
Investing in this level of strategic intelligence allows your organization to move from reactive planning to proactive opportunity capture. Whether you are evaluating vendor partnerships, assessing market entry, or optimizing internal automation strategies, the granular data within our report provides the foundation for informed decision-making. We encourage you to visit our source web page to obtain the complete report and equip your leadership team with the detailed intelligence necessary to navigate the complexities of the global automation market.
For detailed analysis of this topic, please visit the official page: Gantry/Cartesian Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thyristors Market Hits $1,461M in 2025, Driven by 4.1% CAGR to 2032
By PW Consulting, 2026-09-16
Powering Critical Infrastructure: The Strategic Imperative of the Global Thyristors Market Outlook 2026–2032
In the architecture of modern electricity, few components are as quietly indispensable as the thyristor. From grid stabilization to high-power industrial drives, these semiconductor switches dictate the reliability of systems that societies and economies depend on daily. As we enter 2026, the thyristors market stands at a decisive inflection point, shaped by evolving power demands, supply chain recalibrations, and accelerating deployment in renewable energy and mobility. For executives navigating capital allocation, product roadmaps, and sourcing strategies, the difference between reactive planning and competitive advantage lies in rigorous, forward-looking intelligence.
This insight introduces our latest thyristors market research, a comprehensive study designed to equip decision-makers with the analytical depth required to act confidently across the 2026–2032 forecast horizon. Rather than offering static snapshots, the report translates macroeconomic signals, technology shifts, and competitive maneuvers into actionable strategic frameworks.
Market Trajectory: From Recovery to Sustained Expansion
The global thyristors market has demonstrated consistent growth over the past half-decade, reflecting the ongoing electrification of industrial processes, the modernization of power transmission networks, and the proliferation of power electronics across consumer and automotive applications. Historical data from 2020 through 2025 reveals a market that has steadily expanded, reaching approximately USD 1,461.0 Million in 2025. This trajectory underscores not only demand resilience but also the component's entrenched role in mission-critical power control environments.
Looking ahead, the forecast period from 2026 to 2032 projects a robust expansion pathway, with the market anticipated to reach approximately USD 1,936.5 Million by 2032. This growth corresponds to a compound annual growth rate of 4.1 percent, a pace that signals steady, structurally supported demand rather than a short-lived cyclical spike. The implication for strategic planners is clear: thyristor-enabled solutions are being woven more deeply into long-cycle infrastructure and industrial automation investments, creating multi-year revenue visibility for suppliers and system integrators alike.
Yet, headline figures only tell part of the story. The real strategic value lies in understanding where growth concentrates, which applications drive incremental volume, and how regional dynamics influence sourcing and localization. Our analysis unpacks these layers without oversimplifying them, giving leaders a nuanced map of opportunity rather than a single aggregated number.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
Our thyristors market study is structured to address the practical questions that arise in boardrooms, engineering reviews, and procurement discussions. The report provides a multidimensional view of the market, combining quantitative forecasting with qualitative analysis of technology roadmaps, demand catalysts, and competitive positioning. Key areas of coverage include:
- Macro-market sizing and growth projections across the base year and forecast horizon, anchored in a transparent methodology that allows for scenario testing.
- Segment-level analysis by product type, application, and geographic region, illuminating which categories are expanding fastest and why.
- Demand driver assessment covering grid modernization, industrial automation, renewable integration, e-mobility, and power conversion needs.
- Supply-side dynamics, including manufacturing capacity trends, raw material trajectories, lead-time behavior, and cost structure sensitivities.
- Competitive landscape profiling that maps the strategic moves of leading incumbents and emerging challengers across the value chain.
- Technological and regulatory context, highlighting how material availability, wafer economics, and policy shifts affect downstream planning.
The objective is not to overwhelm with data but to distill complexity into decision-ready formats. Executives can use the study to evaluate market entry assumptions, benchmark regional exposure, refine product portfolio priorities, and anticipate supply continuity risks. For procurement and operations leaders, the report surfaces practical indicators that inform contracting, inventory strategy, and supplier diversification.
Competitive Landscape: Establishing Position in a Concentrated Arena
The thyristors market is characterized by a notably concentrated competitive structure, with a small group of established players commanding a substantial share of total revenue. This concentration has important strategic implications. It suggests that scale, technological breadth, application-specific expertise, and long-standing customer relationships remain powerful moats. At the same time, it signals that competitive differentiation increasingly comes from portfolio completeness, performance in extreme operating conditions, and the ability to support specialized end markets.
Leading participants reflect a diverse set of strategic orientations. Some competitors focus on high-power solutions spanning thyristors, GTOs, IGCTs, and diodes, serving grid, traction, renewables, and e-mobility applications with broad current and voltage ranges. Others specialize in bipolar thyristor discs and pulse-power devices manufactured in-house, emphasizing low thermal resistance and high-voltage capability for demanding industrial and pulsed-power environments. Additional players concentrate on mission-critical power modules for aerospace, defense, and space applications, or on discrete SCR and TRIAC devices for motor control, lighting, heating, and general industrial systems.
The field also includes semiconductor manufacturers integrating thyristors and related modules into broader power conversion and automotive portfolios, alongside specialists providing SCR thyristors and AC switches for industrial and consumer power control. Discrete device producers serving alternative energy, lighting, and industrial use cases further round out the landscape, while companies focused on power discrete thyristors and TRIACs address automotive, consumer, and industrial power management needs. Collectively, these players demonstrate that the market is not monolithic; it is a mosaic of overlapping capabilities, each shaped by distinct technological strengths and customer segments.
Importantly, competitive dynamics are not static. Recent developments illustrate how capital commitments and policy support can reshape production capacity and innovation pacing. For example, a significant funding agreement finalized in mid-2026 provides targeted investment to expand domestic manufacturing and R&D for power modules, including thyristors. Such moves matter because they influence regional supply resilience, cost trajectories, and the speed at which new capabilities reach the market. In a concentrated environment, even a single major capacity or R&D announcement can alter bargaining dynamics and competitive expectations across the value chain.
Industry Dynamics: Lead Times, Raw Materials, and Cost Signals
Beyond company-level activity, broader industry dynamics are shaping how organizations plan for 2026 and beyond. One critical factor is lead-time behavior for discrete components. In the second quarter of 2025, lead times for discrete components, including thyristors, held steady or increased slightly, reaching approximately 26 weeks. For sourcing teams and system designers, this is more than a logistical statistic; it affects inventory buffers, project timelines, and the feasibility of just-in-time models in high-reliability applications. The persistence of extended lead times reinforces the importance of supplier collaboration, demand forecasting accuracy, and multi-source strategies where technically feasible.
Worldwide Thyristor Protectors Market
On the materials side, silicon wafer shipments rose 5.4 percent in 2025, with new record shipments forecast for 2028. This trend is supportive for the supply of foundational inputs used in thyristor production, helping to moderate certain cost pressures over the medium term. However, material availability does not automatically translate into stable end-device economics. Upstream costs remain sensitive to node-specific manufacturing economics and specialized wafer pricing. In 2026, advanced-node wafer costs increased by 3 to 10 percent, with 2 nm wafers reaching approximately USD 30,000 per wafer. While thyristor technologies do not uniformly depend on leading-edge nodes, these broader semiconductor cost dynamics influence overall material expense expectations, capital investment decisions, and pricing strategies across the power semiconductor ecosystem.
Together, these dynamics highlight a market where planning must account for both demand-side momentum and supply-side friction. Effective strategy requires a holistic view: aligning product roadmaps with likely lead-time envelopes, evaluating how wafer and material trends affect cost assumptions, and monitoring capital investments that could alter regional supply balances. The report integrates these factors to help leaders stress-test their assumptions under realistic operating conditions.
Strategic Takeaways for 2026 and Beyond
As organizations set priorities for the coming years, several strategic themes emerge from the market landscape:
- Demand durability is anchored in infrastructure and industrial use cases. The thyristors market's growth is closely tied to long-cycle investments in power transmission, industrial automation, and renewable integration. Teams should evaluate how these durable demand streams align with their sales coverage, service capabilities, and product support models.
- Portfolio breadth and application specialization create differentiation. With a concentrated competitive field, firms that can combine high-power capabilities, thermal performance, and application-specific support are better positioned to defend margins and capture complex requirement sets.
- Supply continuity is a strategic variable, not just an operational concern. Lead-time persistence and material cost movements require proactive planning, including scenario-based inventory policies, supplier diversification, and close monitoring of capacity investments.
- Regional context matters for sourcing and market access. Different regions present distinct demand profiles and supply dynamics. Understanding where demand is intensifying and how local production or policy initiatives may evolve can inform market prioritization and risk management.
- Capital and policy developments can shift competitive expectations. Major funding commitments and domestic production expansions can affect cost structures, lead times, and supplier relationships. Keeping pace with such developments helps organizations anticipate changes rather than react to them.
Why This Research Matters Now
The 2026–2032 outlook period is not a routine forecast window; it is a planning horizon in which today's assumptions will shape tomorrow's competitive position. The thyristors market is expanding at a measured but meaningful pace, supported by broad-based application demand and an increasingly strategic view of power electronics across industries. In this environment, theorganizations that excel will be those that pair market awareness with disciplined execution: selecting the right segments, anticipating supply constraints, and aligning product and sourcing strategies with where value is actually created.
Our study is designed to support exactly that kind of decision-making. It offers the analytical rigor required to justify investment choices, the segmentation detail needed to prioritize resources, and the competitive context necessary to understand where pressure points and opportunities lie. Most importantly, it is built to be practical—translating complex market forces into clear implications for product planning, procurement, sales strategy, and risk management.
Thyristors Market
Explore the Full Intelligence
The information summarized here is intended to provide a credible preview of the depth and direction of our research. Many of the most actionable insights—the detailed segmentation values, region- and application-level breakdowns, company-specific strategic assessments, and scenario-based projections—are reserved for the full report. Those details are essential for translating high-level trends into precise operational decisions, and they are available in the complete study.
To access the full thyristors market research, including comprehensive sizing, segmentation analysis, competitive profiles, and forward-looking strategic recommendations for 2026 and beyond, please visit the report page on our website. There you will find the complete dataset and analysis needed to support confident, evidence-based decisions in a market where timing, positioning, and supply awareness matter more than ever.
For detailed analysis of this topic, please visit the official page: Thyristors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Sunglasses Market Hits $14.45B in 2025, Set for 4.59% CAGR Through 2032
By PW Consulting, 2026-09-16
The Strategic Imperative: Navigating the Luxury Sunglasses Market in 2026
The global accessory landscape is undergoing a subtle but profound transformation. Within this shift, the Luxury Sunglasses Market stands out as a beacon of resilience and sustained growth. For brand leaders, investors, and supply chain strategists, understanding the nuance of this sector is no longer optional; it is a critical component of long-term portfolio management. As we move through 2026, the intersection of timeless design, technological integration, and complex regulatory environments defines the operational terrain.
PW Consulting's latest comprehensive market research offers a detailed map of this terrain. This report is not merely a collection of statistics; it is a strategic toolkit designed to inform decision-making across product development, regional expansion, and competitive positioning. By analyzing historical trajectories and forecasting future trends, we provide the intelligence necessary to capitalize on emerging opportunities while mitigating the risks inherent in a fragmented market.
The following insights outline the current state of the industry and demonstrate why access to granular data is the ultimate competitive advantage in the coming fiscal years.
Macro Growth Trajectory and Market Valuation
The financial architecture of the luxury eyewear sector reveals a steady upward trend. Our analysis covers historical performance from 2020 through the base year of 2025, extending with precision into the forecast period of 2026 to 2032. This longitudinal view allows stakeholders to contextualize recent volatility against long-term growth patterns.
In 2025, the global market reached a valuation of approximately 14.45 billion USD. Looking ahead, the market is projected to expand to 14.95 billion USD in 2026, continuing its climb toward nearly 19.78 billion USD by 2032. This expansion reflects a Compound Annual Growth Rate (CAGR) of 4.59 percent over the forecast period. While these headline figures indicate healthy momentum, the drivers behind this growth are multifaceted, influenced by consumer behavior shifts, economic conditions, and product innovation.
For executives, the implication is clear: the market is large enough to support diverse strategies but competitive enough to demand precise execution. The steady CAGR suggests that organic growth is achievable, but capturing market share requires more than passive participation. It requires an understanding of where value is being created and how supply chain constraints might alter profitability margins.
The Competitive Landscape: Consolidation and Innovation
The luxury sunglasses sector is characterized by a moderate to high level of concentration. Our research indicates that the top three players hold a significant portion of the market revenue, while the top five firms command an even larger share. This concentration highlights the dominance of major conglomerates that manage multiple licensed and owned brands, though niche players continue to carve out premium positions through craftsmanship and brand heritage.
Several key companies define the current competitive hierarchy:
- EssilorLuxottica (Paris, France): As a market leader, this entity controls a vast portfolio including Ray-Ban, Oakley, and licensed luxury brands such as Tom Ford, Oliver Peoples, and Dolce & Gabbana. Their strategy blends mass appeal with high-end licensing.
- Marcolin Group (Italy): A crucial player in the production and distribution of designer luxury sunglasses, notably holding strong associations with Tom Ford eyewear.
- De Rigo Rem (Italy): Specializes in manufacturing and licensing luxury eyewear, with notable presence in brands like Police and Lozza.
- Safilo Group (Italy): Known for producing licensed luxury sunglasses for prestigious houses such as Gucci, maintaining strong ties to fashion heritage.
- Garrett Leight (United States): Represents the artisanal end of the market, designing and selling handcrafted luxury sunglasses with a focus on premium materials.
- Oliver Peoples (United States): Under EssilorLuxottica ownership, this brand continues to offer premium luxury sunglasses, leveraging its independent heritage within a larger corporate structure.
Strategic activity among these players is intensifying. For example, in March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana, securing development, production, and worldwide distribution rights for prescription frames and sunglasses. Simultaneously, they unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses handmade in Japan. These moves signal a dual strategy: consolidating established luxury licenses while pushing the boundaries of material and fashion collaborations. Furthermore, the expansion of AI glasses portfolios, such as new Ray-Ban Meta optical styles for prescription wearers, indicates a convergence of wearable technology and traditional luxury aesthetics.
Market Dynamics and Regulatory Headwinds
No strategic plan is complete without accounting for external forces. The operational environment in 2026 is shaped by significant regulatory developments, particularly regarding trade policy. Recent updates from The Vision Council highlight substantial shifts in duty rates affecting the optical industry.
Imports of optical products from China have faced updated duty rates, with sunglasses encountering combined rates reaching 154.5 percent. This figure includes base duties, Section 301 tariffs, and reciprocal tariffs enacted in 2025. Such levels drastically impact landed costs and require immediate adjustments in pricing strategies and sourcing logic. In response to these pressures, major industry participants like EssilorLuxottica have implemented price increases in the US market to offset tariff impacts on imports from China and Thailand.
However, the regulatory landscape remains fluid. A 90-day pause on newly implemented country-specific reciprocal tariff increases was announced by the US Administration for countries that have not retaliated, effective April 2025. While this pause offers temporary relief, the underlying trade tensions suggest that supply chain diversification is no longer just a best practice but a necessity for risk mitigation. Companies relying heavily on single-source manufacturing hubs face elevated exposure, making the case for nearshoring or multi-regional production capabilities more compelling than ever.
Segmentation Insights: Where Value Resides
Understanding the composition of the market is vital for targeted investment. Our report dissects the market across three primary dimensions: Region, Type, and Application. While the aggregate numbers tell a story of growth, the segmentation data reveals where the profitability engines are located.
The market is distributed across major geographic zones, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct consumer behaviors. For instance, mature markets in Europe and North America continue to drive volume through established luxury channels, while Asia Pacific represents a dynamic zone of growing affluence and brand consciousness. Navigating these regional differences requires more than a one-size-fits-all approach; it demands localized marketing strategies and distribution partnerships that resonate with specific cultural nuances.
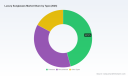
Product type segmentation further illustrates the evolution of consumer preference. The market is divided between Polarized, Non-polarized, and Other Types. The performance of polarized lenses reflects a growing demand for functional luxury, where eye protection and visual clarity are prioritized alongside style. Meanwhile, the non-polarized segment maintains a stronghold in fashion-forward contexts where aesthetics take precedence.
Application-based segmentation highlights the dual identity of luxury sunglasses. The Fashion application dominates the landscape, underscoring the role of eyewear as a critical accessory in personal style and identity. Sports and Other applications, while smaller in relative value, represent high-growth niches where performance materials and specialized designs command premium pricing. Recognizing the balance between these applications allows brands to allocate R&D resources effectively, ensuring they meet the demands of both the runway and the racecourse.
Luxury Sunglasses Market
The Strategic Value of Granular Intelligence
Headline figures and company profiles provide the context, but the true power of this research lies in the details that are not immediately visible. Strategic decisions regarding pricing elasticity, channel mix, and inventory management require access to specific volume data, share percentages, and trend velocity metrics.
For example, knowing the exact revenue split between regions helps determine where to prioritize expansion capital. Understanding the precise share of polarized versus non-polarized types informs product roadmap prioritization. Identifying the specific growth rate of the fashion application segment versus sports allows for nuanced marketing budget allocation. This report provides those specific data points, enabling clients to move beyond general assumptions to evidence-based planning.
Furthermore, the interplay between tariff structures and segmentation is critical. A tariff impact might affect one region or product type more severely than another. Only with detailed data can a company model these scenarios accurately and prepare contingency plans. The inclusion of recent developments, such as specific partnership extensions and product launches, also provides a benchmark for evaluating competitor aggression and innovation cycles.
The market concentration data served as a warning and an opportunity. For new entrants or smaller brands, the high concentration among the top players suggests high barriers to entry in mainstream luxury. However, the persistence of niche brands like Garrett Leight shows that differentiation through material quality and brand storytelling remains a viable path. The research helps identify the white spaces where concentration is lower and potential for disruption exists.
Looking Ahead: Actionable Intelligence for 2026 and Beyond
As we progress through 2026, the Luxury Sunglasses Market will continue to be shaped by the tension between heritage and innovation. Brands must honor the craftsmanship that defines luxury while integrating new technologies and adapting to regulatory shifts. The forecast period extending to 2032 offers a long-term view, allowing companies to plan beyond quarters and focus on sustainable growth.
Sunglasses Market
The data indicates that the market will continue to expand, reaching nearly 20 billion USD by the early 2030s. However, capturing this value requires agility. Supply chain resilience, pricing strategy adjustments, and brand differentiation are the pillars of success in this environment. Companies that rely on outdated assumptions about trade flows or consumer preferences risk margin erosion and loss of relevance.
PW Consulting's Luxury Sunglasses Market Research is designed to equip stakeholders with the clarity needed to navigate these complexities. By providing a comprehensive view of market size, segmentation, competitive dynamics, and regulatory impacts, we enable leadership teams to make informed choices. The insights contained within this report are not just observations; they are the foundation for strategy.
To fully leverage this intelligence, stakeholders must access the complete dataset. The intersection of macro trends and micro-segmentation data reveals the specific pathways to growth that headline numbers cannot show. We invite decision-makers to explore the full report to unlock the detailed analytics required to outmaneuver competitors and secure a dominant position in the evolving luxury eyewear landscape.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rainscreen Cladding Market Hits $169.2B in 2025, Projected to Hit $293.76B by 2032 at 8.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Rainscreen Cladding Market: Strategic Intelligence for 2026 and Beyond
The global construction industry stands at a critical juncture where aesthetic ambition must be reconciled with rigorous safety standards, material cost volatility, and evolving regulatory frameworks. Rainscreen cladding systems have emerged as a cornerstone of modern architectural design, offering critical benefits in moisture management, thermal insulation, and fire safety. For executives, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a necessity for capitalizing on growth opportunities while mitigating systemic risks.
PW Consulting's latest comprehensive research on the Rainscreen Cladding Market provides a definitive roadmap for navigating these complexities. This study is designed to empower decision-makers with actionable intelligence, moving beyond surface-level observations to deliver a granular analysis of market drivers, competitive dynamics, and financial forecasts. As we look toward the forecast period extending to 2032, the data reveals a landscape defined by robust expansion, technological innovation, and shifting geopolitical pressures.
Market Trajectory and Financial Outlook
The historical performance of the rainscreen cladding sector underscores its resilience and growing importance in the built environment. Between 2020 and 2025, the market demonstrated consistent upward momentum, driven by a resurgence in construction activity and an heightened focus on building envelope performance. The total market revenue climbed from approximately $114.09 billion in 2020 to an estimated $169.2 billion in 2025. This growth trajectory reflects a compound annual growth rate that signals strong underlying demand across multiple verticals.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is anticipated to reach $181.66 billion in 2026, accelerating toward a projected value of $293.76 billion by 2032. This growth is underpinned by a CAGR of 8.2 percent, indicating that the sector will significantly outpace general construction market averages in many regions. However, realizing this potential requires a nuanced understanding of the forces shaping supply chains, material selection, and regional adoption rates. Our report dissects these variables, offering a clear view of where value is being created and where vulnerabilities lie.
Rainscreen Cladding Market
Product segmentation and Material Shifts
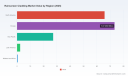
A critical component of strategic planning lies in understanding the divergence in material preferences and application demands. The market is segmented by type into Metal, Fiber Cement, Composite Material, and Ceramic solutions. Metal cladding continues to hold a dominant position, reflecting its versatility and durability, though it faces pressure from raw material cost fluctuations. Fiber Cement and Composite Material segments show substantial uptake, particularly where cost-efficiency and aesthetic flexibility are prioritized. Ceramic solutions, while smaller in volume, are gaining traction in high-end architectural projects demanding specific thermal and fire-resistant properties.
Application-wise, the Residential sector commands the largest share of demand, fueled by urbanization and a shift toward modern, energy-efficient housing designs. Commercial applications follow closely, driven by corporate office builds and retail expansions that prioritize facade branding and weather protection. Institutional and Industrial segments also contribute significantly, often governed by stricter compliance requirements that favor specialized cladding systems. The report provides a deep dive into how these segments interact with regional economic conditions and regulatory environments, allowing stakeholders to identify high-growth niches without exposing themselves to oversaturated or declining sub-markets.
Competitive Landscape: Leaders and Strategic Moves
The market structure is characterized by a mix of established multinational corporations and specialized regional providers. Our analysis identifies key players such as Kingspan Group plc, Rockwool International A/S, Cladding Corp, Alucobond, and Sotech Optima Company as pivotal actors influencing market direction. These companies are not merely competing on price; they are engaging in aggressive innovation and strategic positioning to capture market share.
Kingspan Group plc, headquartered in Ireland, remains a formidable force with its extensive portfolio of ventilated and non-ventilated rainscreen facades and insulation boards. In August 2025, the company announced a new range of eco-friendly rainscreen cladding products meeting stringent environmental standards, signaling a shift toward sustainability as a key differentiator. Similarly, Rockwool International A/S, based in Denmark, has strengthened its position by expanding production capacity in Europe with a new manufacturing facility in September 2025. This move aims to support rising demand for their BBA-approved stone wool insulation boards used in ventilated and sealed rainscreen systems, addressing both performance and supply reliability.
In the Americas, Cladding Corp, located in Camden, New Jersey, continues to serve as a vital provider of drained and back-ventilated systems for terracotta, fiber cement, ceramic, and porcelain panels, offering full engineering support that appeals to complex project requirements. Alucobond, operating from Germany, has focused on innovation in aluminum composite panels designed for pressure-equalized systems. Their strategic partnership with a leading architectural firm in July 2025 highlights a focus on developing innovative cladding solutions for high-rise buildings, where performance and aesthetics intersect. Meanwhile, Sotech Optima Company in the United Kingdom has launched the Optima BrickTech system in February 2025, a fully non-combustible rainscreen system offering the look of traditional brickwork with modern cladding performance, directly responding to fire safety concerns while maintaining design integrity.
The report delves deeper into the competitive dynamics, analyzing market concentration metrics such as CR3 and CR5 percentages to illustrate the balance of power. While these figures indicate a degree of consolidation among top players, there remains significant opportunity for agile competitors who can navigate local regulations and supply chain disruptions effectively.
Industry Dynamics: Regulatory and Economic Headwinds
No strategic assessment is complete without a rigorous examination of the external forces reshaping the market. The regulatory environment has become increasingly stringent, particularly regarding fire safety. In the UK, the government has implemented a complete ban on Metal Composite Material with unmodified polyethylene core in rainscreen cladding for all new buildings under the revised Approved Document B of the Building Regulations. This regulation, coupled with the requirements of the Building Safety Act which mandates stricter testing and certification following the Grenfell Tower inquiry, has fundamentally altered material preferences in the region. Similarly, local building codes in states such as California and New York increasingly mandate non-combustible materials for buildings over four stories, favoring metal and stone wool rainscreen systems.
Worldwide Wall Cladding Market
Economic factors also play a decisive role. Raw material cost volatility presents a significant challenge. Aluminum prices rose by over 30 percent from December 2024 into 2025, while steel prices increased nearly 17 percent, directly raising costs for architectural metal cladding components. These pressures are compounded by trade policy shifts. The US Environmental Protection Agency imposed a 50 percent import tariff on aluminum and steel products under Section 232 tariffs, effective April 2026, increasing costs for imported rainscreen cladding materials. These dynamics create a complex cost environment where pricing strategies, supply chain localization, and material substitution become critical success factors. Our research analyzes how these headwinds impact margins and advises on mitigation strategies.
Scope of Comprehensive Analysis
PW Consulting's Rainscreen Cladding Market report is engineered to provide end-to-end visibility for strategic planning. The study encompasses a detailed analysis of market size and growth forecasts, segmented by region, type, and application, allowing stakeholders to benchmark their performance against broader industry trends. It includes a thorough examination of the competitive landscape, profiling key companies with insights into their product portfolios, recent developments, and strategic initiatives.
Beyond quantitative data, the report offers qualitative insights into market dynamics, including the impact of regulatory changes, raw material price fluctuations, and technological advancements. It provides a review of historical performance from 2020 to 2025 to contextualize current market conditions and validate forecasting models. The forecast period through 2032 is analyzed with scenario-based projections to account for potential disruptions. Additionally, the research explores supply chain structures, identifies barriers to entry, and highlights emerging trends such as the integration of living wall systems and eco-friendly materials. This holistic approach ensures that readers gain a 360-degree view of the market, enabling informed decisions on product development, market entry, partnership formation, and investment allocation.
Strategic Imperatives for 2026 and Beyond
As the market moves into 2026, the convergence of growth opportunities and regulatory constraints demands a proactive stance. Companies must balance the push for innovative, sustainable products with the need to manage rising input costs and navigate complex compliance landscapes. The ban on certain composite materials in key regions necessitates a re-evaluation of product lines, while tariffs on metals require supply chain resilience and potential localization strategies. The expansion of capacity by major players like Rockwool underscores the importance of securing reliable supply channels, while product launches focused on non-combustibility and eco-friendliness highlight the shifting priorities of architects and developers.
This report serves as an essential tool for organizations aiming to thrive in this evolving environment. By leveraging the data-driven insights and strategic analysis provided, stakeholders can identify high-value segments, anticipate regulatory shifts, and align their portfolios with market demands. Whether you are a manufacturer seeking to expand your footprint, a distributor looking to optimize your inventory, or an investor evaluating market potential, this research delivers the depth and precision required to navigate the future of rainscreen cladding with confidence. The detailed forecasts, competitor benchmarks, and dynamic analysis contained within are designed to transform uncertainty into actionable strategy.
For a complete understanding of the global rainscreen cladding market, including detailed regional breakdowns, application-specific growth rates, and financial modeling, we invite you to access the full report. The data presented here offers a strategic overview, but the full intelligence package provides the granular detail necessary to execute with precision. Explore the findings in depth to secure your competitive advantage in a market poised for significant transformation.
For detailed analysis of this topic, please visit the official page: Rainscreen Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radar Level Transmitters Market Hits $606.11M in 2025, Forecasting $894M by 2032 at 5.69% CAGR
By PW Consulting, 2026-09-16
Radar Level Transmitters Market 2026: Strategic Intelligence for Industrial Automation Leaders
The industrial automation landscape is undergoing a profound transformation, driven by stringent regulatory frameworks, the integration of IoT-enabled diagnostics, and a persistent demand for precision in hazardous environments. For stakeholders operating within the process industries, understanding the trajectory of level measurement technology is no longer optional—it is a critical component of capital allocation and operational resilience. PW Consulting is pleased to introduce our comprehensive market research study on the Radar Level Transmitters Market, designed specifically to equip decision-makers with the foresight required to navigate the period from 2026 through 2032.
This report serves as a strategic compass. While the broader industrial sector faces volatility, the radar level transmitter segment demonstrates a resilient growth trajectory grounded in technological maturation and regulatory compliance. Our analysis moves beyond surface-level observations to unpack the underlying mechanics of market expansion, competitive positioning, and the shifting value chain. By leveraging historical data from 2020 to 2025 and projecting forward, we provide a clear picture of where revenue opportunities will concentrate and how technology adoption curves are likely to unfold.
Executive Summary: Market Trajectory and Growth Dynamics
The global market for radar level transmitters has established itself as a cornerstone of modern process instrumentation. Based on historical performance from 2020 through 2025, the market has shown consistent upward momentum, reflecting the broader industrial shift away from traditional gauging methods toward non-contact and advanced guided wave solutions. The market revenue, measured in USD Million, has evolved significantly over the last half-decade, moving from a baseline of 425.0 in 2020 to an estimated 606.11 in 2025.
This historical growth sets the stage for the forecast period. As we look toward 2026, the market is positioned at an estimated 622.3, indicating a continuation of positive momentum. Over the long-term forecast horizon ending in 2032, the market is projected to reach 894.0. This expansion is underpinned by a compound annual growth rate (CAGR) of 5.69 percent during the forecast period. Such a rate suggests steady, sustainable growth rather than speculative bubbles, making this sector attractive for long-term investment and operational planning.
Worldwide Electronic Transmitters Market
The growth is not uniform across all segments. The transition from legacy technologies to 80 GHz radar solutions is a primary driver. For instance, recent industry developments highlight a surge in product launches and certifications tailored to specific regulatory needs. In April 2025, SKE launched its new 80 GHz SKE series radar level transmitter, featuring integrated molding technology aimed at improved performance. Similarly, Emerson launched the Rosemount 1208 wireless non-contacting radar level transmitter in October 2025, focusing on simplified installation for utility and process applications. These launches indicate a market trend toward wireless connectivity, compact design, and ease of integration.
Furthermore, the competitive landscape is characterized by moderate concentration. With a CR3 of 28.5 percent and a CR5 of 53.4 percent, the market remains accessible to a variety of players while maintaining strong leadership from established multinational corporations. This balance suggests that while market leaders hold significant sway, there is ample space for specialized innovators to capture niche segments through differentiation in frequency, certification, or connectivity.
Regulatory Tailwinds and Industry Dynamics
One of the most critical aspects of our analysis focuses on the external forces reshaping demand. Regulation is no longer just a compliance hurdle; it is a market accelerator. In Europe, for example, regulations mandating advanced overfill protection have prompted operators to replace ultrasonic gauges with 80 GHz radar solutions. This shift is not merely technical but operational, as radar offers superior performance in challenging conditions such as vapor, dust, and turbulence.
Simultaneously, methane-emission rules in Europe require tighter tank-gauging accuracy. This regulatory pressure is driving the adoption of 80 GHz radar sensors that can meet these stringent accuracy standards, thereby reducing leaks and environmental impact. In the United States, certification agencies have cleared W-band (76-81 GHz) sensors for process use. This clearance is driving scale economies and eroding price premiums, making advanced technology more accessible to a broader range of industrial clients.
Safety certifications remain a pivotal differentiator. VEGA achieved MCERTS Class 1, WRAS, and Ex ia ATEX certifications for VEGAPULS smart compact radar level sensors in August 2025. This achievement enables use in UK water, wastewater, and hazardous applications, opening up specific verticals that require rigorous safety validation. Similarly, SKE 80 GHz radar level sensors received TÜV NORD SIL2/SIL3 certification, reinforcing the importance of functional safety in critical process industries. These certifications are not just badges; they are prerequisites for entry into regulated markets, and our report details how these compliance landscapes affect market penetration strategies.
Competitive Landscape and Strategic Positioning
The radar level transmitter market is contested by a robust mix of global automation giants and specialized instrumentation firms. The competitive environment is defined by innovation in frequency modulation, wireless connectivity, and integration with broader process control systems. Our report provides an in-depth profiling of key companies that are shaping this landscape, analyzing their product portfolios, strategic moves, and regional strengths.
Radar Level Transmitters Market
Among the leaders, Emerson Electric Co. continues to strengthen its position with the Rosemount series, including the 3408 and 5408 models for liquids, solids, and interface measurement. Their focus on smart diagnostics and wireless options aligns with the industry's move toward Industry 4.0. Endress+Hauser Group maintains a strong foothold with its Micropilot and FMR series 80 GHz radar level transmitters, particularly noted for high precision and hygienic certifications suitable for process liquids, slurries, and solids.
Siemens AG competes with the SITRANS series, emphasizing advanced signal processing and IoT integration for industrial process monitoring. ABB Ltd. supplies both guided wave and non-contact models, including the LWT series, which are critical for total and interface level measurement in harsh environments. VEGA Grieshaber KG remains a key player with the VEGAPULS series, offering 80 GHz radar level sensors with Bluetooth connectivity and compact design, catering specifically to water, wastewater, and hazardous applications.
Other significant contributors include KROHNE Messtechnik GmbH, which introduced the OPTIWAVE 1500 series in October 2025 with expanded models 1520 and 1540, further diversifying their liquid and solids measurement capabilities. Honeywell International Inc. includes radar level transmitters in its broader automation portfolio, while Yokogawa Electric Corporation manufactures solutions tailored for the chemical, oil, and gas industries. Ametek, Inc., through Magnetrol International, offers Pulsar and other radar level transmitters for liquids, slurries, and solids, leveraging its reputation for bulk solids measurement.
The market also includes regional specialists and niche providers such as Automation Products Group (APG) with its TRUE ECHO series explosion-proof pulse radar level transmitters for hazardous locations, and Nivelco Process Control Ltd., which released its 2026 product catalog featuring new PiloTREK WP–200 and WT–300 compact 80 GHz FMCW radar level transmitters. Companies like KOBOLD Instruments, FINE-TEK Co., Ltd., WIKA Alexander Wiegand SE & Co. KG, and Pepperl+Fuchs SE round out the competitive field, each bringing specific strengths in installation ease, sensor portability, or specific industrial verticals. This diversity ensures that while the market is concentrated, it remains dynamic and responsive to varied customer needs.
Product Segmentation and Application Trends
Understanding how the market splits across technology types and applications is vital for targeting sales efforts and procurement strategies. The market is primarily divided into contact and non-contact technologies. Non-contact solutions, including Pulsed Radar and FMCW Radar, continue to gain favor due to their versatility and reduced maintenance requirements compared to contact methods. Guided Wave Radar remains essential for specific interface measurements where precision is paramount.
In terms of application, the demand spans across liquids, slurries, interfaces, and solids. The handling of solids represents a significant portion of the use cases, driven by industries such as mining, cement, and bulk chemical storage. Liquids and slurries remain the traditional stronghold, particularly in oil and gas, water and wastewater, and pharmaceutical sectors. Our report dissects these segments to reveal which combinations of type and application are yielding the highest growth margins.
Recent developments suggest a convergence in technology capabilities. The introduction of 80 GHz sensors across multiple brands—such as KROHNE, VEGA, SKE, and Nivelco—indicates a standardization of high-frequency technology as the benchmark for performance. This standardization allows buyers to compare specifications more easily but also raises the bar for performance across the board. Integration into process control systems is another key trend, with manufacturers ensuring their transmitters communicate seamlessly with PLCs and SCADA systems, reducing engineering time and installation costs.
Strategic Recommendations for 2026 Decision Makers
As enterprises plan their capital expenditures and technology roadmaps for 2026 and beyond, several strategic imperatives emerge from our analysis. First, regulatory compliance should be viewed as a procurement criterion rather than an afterthought. With methane-emission rules and overfill protection mandates tightening, selecting transmitters that already hold necessary certifications like ATEX, SIL, and MCERTS can mitigate project delays and operational risks.
Second, the shift toward wireless and IoT-integrated solutions offers an opportunity to reduce lifecycle costs. The launch of products like the Rosemount 1208 wireless transmitter highlights the industry's direction. Investing in infrastructure that supports wireless connectivity can simplify installation in remote or hazardous locations, where cabling is costly and dangerous.
Third, supply chain resilience and vendor stability are crucial. With a CR5 of 53.4 percent, the top five players hold a majority share, providing a level of stability and support capacity that smaller vendors may struggle to match. However, the presence of agile specialists means that for niche applications, partnering with vendors who offer specialized engineering support can yield better operational outcomes than relying solely on generic large-scale solutions.
Finally, staying abreast of technological standardization is key. As 80 GHz becomes the norm for high-performance applications, legacy 26 GHz systems may face obsolescence pressure in critical environments. Procurement teams should evaluate existing installed bases against these emerging standards to plan for phased upgrades that maintain accuracy and compliance without unnecessary capital waste.
Accessing Comprehensive Market Intelligence
This article provides a strategic overview of the Radar Level Transmitters Market, highlighting the macro-economic trends, regulatory drivers, and competitive shifts that define the landscape. However, the full depth of our research extends far beyond these high-level insights. For organizations seeking to make data-backed decisions regarding market entry, expansion, or procurement, the granular details are essential.
Our complete market research report offers detailed segmentation analysis, historical data tables, and forecast models that quantify growth across specific regions and application verticals. We provide exhaustive company profiles, analyzing strategic moves, product launch timelines, and financial positioning of the key players. Furthermore, the report includes an assessment of market concentration, pricing dynamics, and the specific impact of regulatory changes on supply and demand curves.
To leverage this intelligence for your strategic planning, we invite you to access the full Radar Level Transmitters Market Research report. The comprehensive dataset within will empower your team to identify untapped opportunities, benchmark against competitors, and align your technology investments with the projected market trajectory through 2032. Do not rely on fragmented information when precise intelligence is available. Engage with the full study to secure a competitive advantage in the evolving industrial automation sector.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flooring Underlayment Market to Reach $2.7B by 2032 with 4.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for a Resilient Floor: Inside the 2026 Flooring Underlayment Market Outlook
The flooring underlayment market is entering a decisive phase of commercial maturity, where incremental growth hides complex structural shifts. For executives navigating procurement, product development, or channel strategy in 2026, surface-level demand signals are no longer sufficient. What matters now is the interaction between raw-material volatility, regional manufacturing footprints, warranty-driven performance standards, and the quiet consolidation shaping competitive positioning. Our newly released market research distills these forces into an actionable framework, giving leadership teams a reliable basis for capital allocation, pricing discipline, and portfolio planning through the end of the decade.
The numbers tell a story of steady expansion rather than explosive disruption. Between 2020 and 2025, the global market climbed from roughly $1.53 billion to $1.94 billion, reflecting a cumulative push built on residential renovation, commercial retrofit programs, and a broader shift toward performance-oriented floor systems. Heading forward, the forecast period from 2026 to 2032 points to continued upward momentum, with the market trajectory implying a compound annual growth rate of 4.8 percent. That pace is significant not because it is dramatic, but because it is durable: it signals an industry where growth is increasingly tied to specification quality, installer behavior, and material innovation rather than simple volume replacement.
Yet durable growth creates a more demanding decision environment. A market expanding at this speed still remains structurally fragmented at the top. Concentration metrics indicate that the three largest players account for approximately 42.5 percent of revenue, while the top five hold around 58.2 percent. In practical terms, that means scale advantages exist, but they are not yet absolute. Regional demand patterns, application-specific requirements, and material preferences continue to create differentiated opportunity zones. Our research maps these zones without reducing them to oversimplified rankings, allowing decision-makers to see where intensity is rising and where margins are most exposed.
The strategic value of this report lies in its operational focus. Rather than stopping at top-line forecasts, it integrates the market numbers with the mechanics that actually shape profitability: raw-material input dynamics, regulatory and warranty constraints, labor and installation practices, and the pricing pressures emerging from trade and transportation costs. These are the variables that determine whether a company can convert demand into margin. In 2026, that conversion is anything but automatic.
What the Research Delivers
This study is designed as a decision-grade reference for executives who need to anticipate shifts before they become visible in quarterly results. The analysis combines historical performance tracking with forward-looking scenarios, allowing readers to test assumptions against a structured baseline. The report examines how demand is forming across residential, commercial, and industrial applications, and it evaluates how material types are competing for share in increasingly specification-driven environments.
Beyond segmentation, the research digs into the operational realities that separate resilient operators from those simply riding market growth. It assesses how manufacturers are responding to raw-material cost sensitivity, especially where polyethylene-based foam remains central to dominant product categories and pricing tracks closely with crude oil movements and refinery capacity conditions. It also examines how recycled rubber and natural cork formulations are being rebalanced after the supply disruptions of 2022 and 2023, enabling a number of producers to revisit capacity expansion with greater confidence.
Equally important, the report addresses the commercial constraints that define product viability. Underlayment performance is not merely a technical question; it is a warranty question. For resilient flooring, manufacturers commonly require underlayment to remain within strict thickness limits, often capping total build at around 3 millimeters to prevent stress on locking joints and avoid voiding warranties. This constraint shapes product design, installation guidance, and competitive differentiation in ways that many market summaries overlook. Our analysis places these limitations in context so that strategy teams can evaluate where performance claims are credible and where they risk creating downstream friction.
Flooring Underlayment Market
The research also incorporates the cost pressures that are reshaping sourcing and import planning. Tariffs are increasing expenses tied to imported foam materials, rubber components, and cork, while transportation surcharges continue to influence landed costs. For companies operating across multiple regions, these pressures do not simply raise prices; they alter the economics of channel selection, inventory positioning, and supplier diversification. By mapping these dynamics alongside regional demand intensity, the report helps leaders identify where cost absorption is feasible and where it is not.
Competitive Landscape: Scale, Specialization, and Recent Moves
The competitive environment reflects a blend of broad-capability incumbents and smaller specialists competing on acoustics, moisture control, sustainability, and application-specific performance. The market is not defined by a single product philosophy. Instead, it is shaped by manufacturers who are pursuing different answers to the same core question: how to deliver sound reduction, moisture protection, and installation reliability without breaking warranty constraints or exposing the buyer to excessive cost volatility.
Several companies illustrate the strategic range now visible in the sector. MP Global Products, based in Norfolk, Nebraska, has built recognition around acoustic fiber underlayments marketed under the QuietWalk brand for hardwood, laminate, and vinyl flooring. Its emphasis on noise reduction, moisture protection, and recycled content reflects a broader industry push toward environmentally conscious formulations that still meet performance expectations in residential and commercial settings. Leggett & Platt Flooring Products remains a major U.S. force in carpet cushion and hard-surface underlayment, offering foam, rubber, and other formulations tailored to laminate, vinyl, and engineered wood applications. Its breadth positions it as a supplier that can address multiple floor types within a single procurement relationship.
Pak-Lite, Inc. occupies a distinctive niche as a large private-label manufacturer of floating wood and laminate flooring underlayment in North America, with customized products structured around IIC, STC, and Delta performance ratings. That rating-centered approach matters because it aligns product selection with measurable acoustic outcomes, an increasingly important factor for specification-driven projects. Wise Flooring Products LLC, in Old Hickory, Tennessee, focuses on recyclable, American-made underlayment for residential and commercial applications, reinforcing a domestic-production value proposition that resonates in certain procurement environments. FloorMuffler contributes a portfolio spanning XLPP foam, rubber, and recycled-fiber underlayments, including product lines such as FloorMuffler UltraSeal, Natura, and FloorMat, all oriented toward sound insulation and moisture protection beneath vinyl, laminate, and hardwood.
Regional manufacturing presence is also expanding the field. Cyg Tefa, based in Vietnam, supplies high-density IXPE foam underlayment for luxury vinyl plank, laminate, and wood flooring, with an emphasis on soundproofing and moisture resistance. Hubei Xiangyuan New Material Technology Inc. operates as a professional manufacturer offering multiple underlayment types for different flooring applications, reflecting the broader diversification of Asian material supply capacity. RSP Industries, Inc. rounds out the competitive picture as a manufacturer of acoustic underlayment products, adding another voice to a market where sound performance is becoming a primary purchase criterion.
Roofing Underlying Materials Market
Recent activity in 2026 underscores how actively companies are trying to reshape category expectations. In May 2026, Floordi introduced F-Shield Underlayment, a premium acoustic solution intended to improve floor stability, enhance acoustic comfort, and add moisture protection for modern flooring systems. The launch signals continued investment in higher-performance formulations rather than basic cushioning. In April 2026, MP Global Products promoted its range of eco-friendly acoustic underlayments, emphasizing recycled material usage alongside noise reduction and moisture control. Earlier, in January 2026, Cyg Tefa showcased advanced IXPE and XPE foam underlayment solutions at Vietbuild Hanoi 2025, highlighting soundproofing, moisture resistance, and suitability for LVP, laminate, and wood flooring, with reported interest from manufacturers and distributors.
These moves matter because they reveal where the market is trying to earn higher margins: through better acoustic performance, stronger moisture management, and clearer sustainability storytelling. They also show that competition is no longer confined to price per square foot. As specifiers and installers become more attentive to warranty compatibility and long-term floor stability, companies that can credibly demonstrate performance across multiple criteria are better positioned to defend pricing and win repeat business.
Market Dynamics Shaping 2026 Decisions
The operational context of the underlayment market is being reshaped by a small number of powerful forces. Raw-material sensitivity remains one of the most important. Polyethylene foam continues to serve as a primary input for the dominant foam-based underlayment category, which means pricing exposure is closely linked to crude oil swings and refinery capacity constraints. In a market growing at a mid-single-digit pace, input volatility can quickly alter the profitability of otherwise successful product lines. Companies that rely on a narrow material base face greater risk than those with diversified formulations or stronger hedging and sourcing strategies.
At the same time, supply chain normalization is creating new strategic room. Recycled rubber and natural cork remain common in underlayment formulations, and the stabilization of supply after the disruptions of 2022 and 2023 has allowed some manufacturers to move more confidently toward capacity expansion. That shift is not merely operational; it has strategic implications for lead times, regional fulfillment, and the ability to support product launches with reliable inventory. In practical terms, normalized supply can become a competitive advantage when paired with the right application focus.
Regulatory and warranty constraints are equally important. Underlayment must meet manufacturer warranty requirements for resilient flooring, and those requirements often include strict limits on total thickness, typically capping build at about 3 millimeters to avoid excessive stress on locking joints and the risk of voiding warranties. This reality limits the scope for oversized product claims and pushes differentiation toward material density, acoustic ratings, moisture behavior, and installation consistency. For strategy teams, it means that the most defensible product narratives are those aligned with accepted installation parameters rather than speculative performance extremes.
Trade exposure is another pressure point. Tariffs are increasing costs for imported foam materials, rubber components, and cork used in underlayment production, while transportation surcharges add further complexity to landed-cost calculations. These effects vary by sourcing footprint, but they consistently influence the relative attractiveness of domestic production, regional sourcing, and inventory buffering. Companies that treat these costs as static will likely misjudge margin durability. Those that incorporate them into scenario planning will be better prepared to adjust pricing, revise supplier mixes, or shift demand toward less exposed product lines.
Labor and installation dynamics also deserve attention. In the U.S. market, moisture mitigation systems and installer-focused innovation are influencing labor requirements for floor prep and underlayment installation. This matters because installation friction can determine adoption rates just as much as product specification. If a solution is technically strong but difficult to deploy consistently across job sites, its commercial advantage may be limited. Conversely, installer-friendly designs can improve throughput, reduce rework, and strengthen end-user satisfaction, all of which support repeat demand and specification lock-in.
How to Use This Research in 2026
The report is structured to support several high-value decisions at once. For product and innovation teams, it provides a baseline for assessing which performance attributes are gaining commercial weight and where claims must remain closely aligned with warranty and installation constraints. For sourcing and operations leaders, it connects material volatility and trade exposure to practical choices about supplier diversity, inventory posture, and regional fulfillment. For commercial and sales leadership, it helps explain why the market is increasingly rewarding specification credibility, acoustic performance, and moisture management over simple cost positioning.
Most importantly, the research is built to support scenario-based planning. A market expanding at a 4.8 percent CAGR over the 2026 to 2032 forecast period is not a market where a single strategy will remain optimal for long. Different regions, applications, and material types will respond unevenly to cost pressures, demand shifts, and competitive launches. The report helps leadership teams anticipate that unevenness, identify where concentration and fragmentation intersect, and evaluate which moves are likely to strengthen positioning versus merely preserve share.
This overview is intended as a strategic preview, not a complete substitute for the full analysis. The underlying report contains the detailed segmentation structures, competitive benchmarking, and operational insights needed to translate market direction into executable plans. For organizations preparing budgets, expansion choices, or product roadmaps for the remainder of the decade, that deeper intelligence is where uncertainty becomes manageable and strategy becomes durable.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


