



PW Consulting Safety Glasses Market Reaches USD 225.5M in 2025, Growing at 4.05% CAGR
By PW Consulting, 2026-09-16
Strategic Foresight in Eye Protection: Navigating the Safety Glasses Market Through 2032
Executive Introduction
The safety glasses market stands at a critical intersection of regulatory evolution, material innovation, and operational safety prioritization. As we move through the mid-2020s, enterprises across industrial, construction, and manufacturing sectors face mounting pressure to align procurement strategies with updated compliance frameworks and shifting demand patterns. This article introduces PW Consulting latest comprehensive market research on the Safety Glasses Market, designed to equip decision-makers with the strategic intelligence required for 2026 planning and beyond. Rather than offering surface-level demand estimates, our analysis dissects the underlying structural drivers, competitive positioning, and compliance dynamics that will shape purchasing decisions, product development roadmaps, and regional expansion strategies over the next seven years.
For procurement leaders, product managers, and corporate strategists, the question is no longer whether the market will grow, but how to capture margin, mitigate supply chain volatility, and future-proof inventory against evolving safety standards. Our latest research delivers a granular, forward-looking view of the landscape, translating macro trends into actionable intelligence tailored for enterprise-level decision-making.
Market Trajectory and Structural Drivers
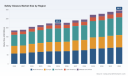
Over the historical period from 2020 to 2025, the global safety glasses market has demonstrated steady expansion, reflecting sustained investment in occupational health, manufacturing output, and construction activity. Total market revenue has progressed from approximately 185.2 million USD in 2020 to an estimated 225.5 million USD by 2025, underscoring consistent demand absorption across mature and emerging ecosystems. Looking ahead, our forecast model projects the market to reach roughly 227.7 million USD in 2026, with continued expansion through 2032, culminating in an estimated 296.5 million USD.
This trajectory translates to a compound annual growth rate of 4.05 percent across the 2026 to 2032 forecast horizon. While the percentage may appear moderate at first glance, the strategic implication lies in the compounding effect on mid-to-high-tier product categories, where premium coatings, ballistic-rated frames, and prescription-compatible designs command stronger margins and longer replacement cycles. The 4.05 percent CAGR signals a market transitioning from volume-driven commodity sales toward value-driven performance specifications, demanding that buyers and suppliers recalibrate sourcing strategies accordingly.
Several structural drivers underpin this momentum. First, the ongoing renewal of occupational safety standards is reshaping certification requirements, pushing manufacturers and buyers to update product lines and compliance documentation. Second, industrial automation and advanced manufacturing workflows continue to introduce new hazard profiles, requiring eyewear that balances impact resistance with optical clarity and long-wear comfort. Third, construction sector expansions in multiple regions sustain baseline demand, while specialty applications, from chemical processing to radiation-prone environments, create differentiated demand pockets that reward niche engineering. Together, these forces create a market where strategic procurement and product positioning determine competitive advantage.
Competitive Landscape and Enterprise Positioning
The market exhibits a moderately fragmented but increasingly competitive structure, with top-tier players consolidating influence through brand recognition, certification portfolios, and coating technology leadership. Our concentration analysis indicates that the top three companies command approximately 35.5 percent of market revenue, while the top five players collectively account for roughly 52.3 percent. This distribution suggests that while scale players hold meaningful share, substantial opportunities remain for specialized manufacturers that can differentiate through ergonomic design, ANSI-aligned testing performance, and rapid catalog refresh cycles.
Among the leading enterprises shaping the landscape, Wiley X has established a strong reputation for ballistic and industrial safety glasses featuring advanced lens coatings engineered for high-impact and chemical resistance. Its positioning appeals to sectors where occupational hazards exceed standard impact thresholds, making its product lines particularly relevant for defense-adjacent, heavy manufacturing, and high-risk industrial buyers. Bollé Safety, based in France, emphasizes anti-fog and anti-scratch performance through its PLATINUM-coated portfolio, aligning with workplaces where temperature fluctuations, humidity, and particulate exposure degrade visual clarity and worker compliance. The company certification emphasis under ANSI Z87.1 and OSHA frameworks reinforces its relevance for compliance-sensitive procurement.
uvex Safety Group continues to expand its footprint with high-quality safety glasses and goggles that meet ANSI/ISEA Z87.1 standards, including prescription and specialized models. Its German engineering heritage and broad product breadth allow it to serve both general industry and specialized environments, while its ongoing participation in major trade platforms underscores its commitment to visible market engagement and product refreshes. MCR Safety, headquartered in the United States, focuses on ANSI Z87.1-compliant eye protection with military-grade and UV-blocking options, targeting industrial applications where prolonged outdoor exposure or high-intensity lighting conditions demand enhanced filtration and durable frame construction. Its recently updated catalog reflects a strategic push toward latest styles, advanced coatings, and ANSI Z87+ impact-rated options, indicating responsiveness to buyer preferences for both aesthetics and certified performance.
Honeywell and MSA Safety represent substantial industrial safety ecosystems, offering comprehensive safety glasses and goggles certified to ANSI Z87.1 for workplace impact, chemical, and splash protection, along with prescription options suited to general industry and construction. Their scale, distribution reach, and integration with broader PPE portfolios make them key reference points for enterprise buyers seeking streamlined vendor relationships. Essilor, through its prescription safety eyewear partnerships, bridges optical precision with compliance, working alongside frame manufacturers to deliver ANSI Z87.1 and OSHA-compliant prescription safety glasses that address a persistent pain point in jobs requiring corrected vision without sacrificing protection standards.
Radians Safety has gained attention for its GLYF™ and ballistic-rated safety eyewear compliant with ANSI Z87.1, emphasizing comfort and debris protection. Its recent product introductions, including ballistic-rated Crossfire BOLO™ eyewear showcased at major safety expos, illustrate how mid-tier players can gain momentum through targeted innovation and event-driven visibility. Meanwhile, Day Sun Industrial Corp. from Taiwan contributes ANSI Z87.1 and CE-certified safety glasses with anti-scratch and UV protection for industrial use, highlighting the continued role of cross-regional manufacturers in balancing cost efficiency with certified performance.
For enterprise strategists, this competitive environment demands a dual lens: evaluating incumbents on certification reliability, coating durability, and supply consistency, while monitoring emerging entrants that can rapidly iterate on lens technology, frame ergonomics, and ballistic-rated options. Our report maps these positioning dynamics in detail, helping buyers and suppliers identify where consolidation pressure is most intense and where white space remains for differentiated offerings.
Safety Glasses Market
Regulatory Dynamics and Compliance-Led Demand
Regulatory evolution is one of the most consequential forces shaping near-term procurement and product strategy. The Vision Council published ANSI/ISEA Z87.1-2025 in January 2026, marking the sixth revision of the voluntary consensus standard for occupational eye and face protection devices. This revision establishes updated criteria for testing, marking, and use across a broad range of occupational hazards, with a clear emphasis on harmonization with global standards and performance for diverse workplace conditions, including chemical and radiation exposure.
OSHA 1910.133 continues to anchor workplace requirements by mandating that safety glasses comply with recognized ANSI/ISEA standards. The current framework references earlier editions while also accepting the 2025 revision for hazard protection involving impact, radiation, and liquid splash. Equally important, OSHA mandates side shields for flying debris protection in general industry, reinforcing the operational relevance of frame design choices that balance coverage, peripheral visibility, and wearer compliance. The Z87 Committee on Safety Standards for Eye Protection developed the 2025 revision, which is then codified by OSHA for workplace requirements, creating a direct link between consensus testing protocols and enforceable employer obligations.
For buyers and product planners, these dynamics introduce both risk and opportunity. On the risk side, legacy inventory that does not align with updated marking, testing, or side-shield expectations may face procurement disqualification or compliance scrutiny. On the opportunity side, companies that proactively refresh catalogs with ANSI Z87.1-2025-aligned specifications can strengthen their value proposition to safety managers, reduce audit exposure, and position themselves as preferred vendors in compliance-driven tenders. Our research unpacks how these regulatory shifts interact with regional enforcement patterns, certification timelines, and manufacturer readiness, enabling enterprises to sequence product transitions and sourcing decisions with confidence.
What the Report Delivers for Decision-Makers
PW Consulting Safety Glasses Market research is structured to convert complex market signals into operational clarity. The report goes beyond headline figures to provide a practical toolkit for 2026 strategy formulation, procurement alignment, and competitive benchmarking. Below is a high-level overview of the actionable content included in the full study.
- Market sizing and trajectory analysis that traces historical performance and forecast pathways, giving leaders a clear baseline for demand planning and investment timing.
- Segment-level breakdowns across material types, application environments, and regional demand structures, enabling precise alignment between product portfolios and end-market requirements without oversimplifying complexity.
- Competitive benchmarking that evaluates major players on technology emphasis, certification alignment, product breadth, and market engagement, helping procurement teams compare vendor options against operational priorities.
- Regulatory impact assessment that maps ANSI/ISEA Z87.1-2025 updates and OSHA requirements to purchasing decisions, certification documentation, and product transition planning.
- Innovation and product lifecycle indicators that highlight coating advancements, ballistic-rated options, prescription-compatible designs, and comfort-driven ergonomics influencing repeat purchase behavior.
- Strategic implications for sourcing, inventory planning, and regional expansion, with guidance on where margin pressure is likely to intensify and where differentiated specifications can support premium positioning.
Each section is designed to support different internal stakeholders. Procurement leaders gain a clearer framework for evaluating supplier consistency, compliance readiness, and total cost of ownership. Product and innovation teams receive context on where coating technology, frame materials, and specialized models are gaining traction. Executives and strategy teams can use the forward-looking analysis to stress-test expansion plans, assess competitive exposure, and coordinate cross-functional safety procurement with broader operational goals.
Why This Research Matters for 2026 Strategy
The 2026 planning cycle demands more than a static snapshot. Market participants must reconcile steady overall growth with shifting demand composition, evolving compliance expectations, and intensifying competition among both global incumbents and specialized manufacturers. A 4.05 percent CAGR over the forecast period may appear measured, yet the underlying composition of growth, which materials lead, which applications expand fastest, and which regions absorb new capacity, will determine whether companies capture value or merely participate in the market.
One of the most important strategic takeaways is that compliance is becoming a differentiator, not just a baseline. As ANSI/ISEA Z87.1-2025 gains deployment and OSHA continues to reference updated standards, buyers are increasingly likely to favor product lines with clear certification alignment, documented testing, and updated marking protocols. Manufacturers that anticipate these expectations can shorten sales cycles and reduce friction in regulated procurement environments. At the same time, enterprises that delay portfolio alignment may face rising replacement costs and narrowing supplier options as legacy SKUs are phased out.
Another critical dimension is the growing importance of wearability and coating performance in sustaining compliance. Anti-fog, anti-scratch, and chemical-resistant coatings directly influence whether workers consistently use provided eyewear, which in turn affects incident rates, liability exposure, and safety program effectiveness. This makes product selection a strategic safety decision rather than a purely cost-driven purchase. Our report examines how these performance attributes correlate with demand patterns and competitive positioning, giving leaders a firmer basis for specification decisions.
Finally, the concentration profile of the market suggests that scale advantages matter, but they do not tell the full story. With the top five companies accounting for just over half of market revenue, a meaningful share of demand continues to flow to specialized providers that can serve distinct application requirements, offer prescription-compatible options, or deliver ballistic-rated performance. For buyers, this means vendor diversification can be strategically valuable when paired with rigorous compliance and quality evaluation. For suppliers, it means that targeted innovation and certification clarity can unlock share even in a moderately consolidated landscape.
Navigating the Opportunity with Precision Intelligence
As the safety glasses market advances through its forecast period, the organizations that outperform will be those that integrate demand forecasting, compliance readiness, and competitive intelligence into a single decision framework. PW Consulting latest research is built to support that integration. It provides the structural understanding needed to interpret market movement, the segment-level detail required to align product and procurement strategy, and the competitive context necessary to evaluate supplier options with confidence.
The full report expands on every dimension introduced here, delivering the depth required for 2026 planning and the forward view needed to anticipate 2027 through 2032 shifts. Readers seeking complete regional breakdowns, application-level demand structures, material-type segmentation, and enterprise-specific benchmarking will find those detailed insights accessible through the full study. This article serves as a strategic preview, outlining the market logic, compliance forces, and competitive dynamics that make the complete research essential for informed decision-making.
For executives, procurement leaders, and industry strategists committed to aligning safety procurement with operational performance and regulatory reality, the next step is clear: move from macro awareness to segment-level precision. The complete PW Consulting Safety Glasses Market research provides that precision, equipping your team with the intelligence needed to act decisively in 2026 and position your organization for durable advantage through 2032.
Sunglasses Market
For detailed analysis of this topic, please visit the official page: Safety Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Cs Beam and Hydrogen Maser Clocks Market Hits USD 40M in 2025, Projects 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Precision Timing Revolution: Strategic Insights into the Cs Beam and Hydrogen Maser Atomic Clocks Market (2026–2032)
In an era where nanosecond precision dictates the reliability of global navigation, telecommunications, financial trading, and critical infrastructure, atomic clock technology has evolved from a specialized scientific instrument into a strategic asset class. The Cs beam and hydrogen maser atomic clocks market stands at a pivotal inflection point as nations, defense contractors, and telecommunications operators confront mounting threats from GNSS disruptions, space-based timing degradation, and escalating cybersecurity vulnerabilities. This comprehensive market intelligence study, anchored in historical performance from 2020 through 2025 and projecting forward to 2032, provides decision-makers with the analytical rigor required to navigate a highly concentrated yet rapidly commercializing landscape. By examining macro trajectory, competitive dynamics, technological substitution patterns, and regulatory catalysts, this report equips strategic planners, procurement leaders, and investment committees with actionable foresight for 2026 and beyond.
Market Trajectory and Structural Foundations
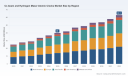
The market has demonstrated consistent expansion over the historical review period, climbing from 25.0 million USD in 2020 to an estimated 40.0 million USD in 2025. This growth trajectory reflects a compound annual growth rate of approximately 6.98 percent across the forecast window extending through 2032, with revenue projections indicating a continued upward arc driven by next-generation timing infrastructure, sovereign GNSS resilience initiatives, and the proliferation of precision-dependent applications in telecommunications and space exploration. The forecast period reveals a market that is scaling steadily rather than experiencing volatile spikes, underscoring the deliberate, engineering-intensive nature of atomic clock deployment and the long lifecycle characteristics of primary reference timing systems. By 2032, total market revenue is expected to surpass 60 million USD, illustrating sustained institutional and commercial demand for frequency standards that deliver unparalleled long-term stability and traceability to international timekeeping frameworks.
Several structural factors underpin this expansion. First, the growing deployment of optical cesium beam architectures and enhanced hydrogen maser platforms is broadening the addressable market beyond traditional national metrology laboratories and defense enterprises into commercial data centers, power grid synchronization networks, and next-generation telecommunications infrastructure. Second, the industry’s shift toward sovereign timing capabilities has accelerated procurement cycles, as governments and critical infrastructure operators seek to reduce reliance on vulnerable satellite-based timing signals. Third, the maturation of manufacturing ecosystems and the establishment of dedicated production lines for high-performance hydrogen masers are gradually improving supply chain reliability, reducing lead times, and expanding the commercial viability of these precision instruments. Together, these drivers create a durable growth foundation that strategic stakeholders can leverage to align product roadmaps, capacity planning, and partnership strategies.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate-to-high concentration profile, with the top three participants collectively commanding a significant share of total revenue and the top five firms accounting for approximately half of the overall market. This concentration reflects the capital-intensive nature of precision timing research, the stringent certification requirements associated with primary frequency standards, and the long-standing intellectual property positions held by established players. However, the competitive environment is not static. Recent corporate developments underscore a sharp focus on manufacturing scalability, product diversification, and strategic deployment of atomic clock systems in high-stakes operational contexts.
- Microchip Technology Inc., headquartered in Chandler, Arizona, continues to reinforce its leadership in cesium beam frequency standards and active hydrogen maser solutions. The company’s MHM-2020 active hydrogen maser and 5071B cesium beam frequency standard have become reference architectures for metrology, telecommunications, and satellite applications requiring accuracies at the 5×10⁻¹³ level. In April 2026, the company inaugurated a new manufacturing facility in Tuscaloosa, Alabama, purpose-built to expand MHM-2020 production capacity, reduce delivery lead times, and address rising demand for independent timing systems in national infrastructure protection programs.
- Oscilloquartz SA, based in Neuchâtel, Switzerland, has extended its footprint through the OSA 3230 series of optical cesium beam atomic clocks and hydrogen maser solutions engineered for enhanced short-term stability via its ESTU module. The firm serves telecommunications, defense, and precision timing customers seeking compact, high-reliability architectures that bridge the performance gap between legacy cesium systems and premium hydrogen masers.
- Safran Electronics & Defense, operating from Paris, France, has emerged as a decisive player in spaceborne and ground-based atomic clock deployments. The Space Hydrogen Maser (SHM) powered the ESA ACES atomic clock ensemble aboard the International Space Station, achieving record stability for global timekeeping and deep-space applications. In September 2025, an all-European maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions and signaling a broader push toward sovereign timing sovereignty in deep-space communications.
- Adtran Inc., headquartered in Huntsville, Alabama, has strengthened its positioning through the integration of Oscilloquartz optical cesium beam clocks with ESTU modules, delivering hydrogen-maser-comparable short-term stability for data centers, power utilities, and defense PNT (positioning, navigation, and timing) applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, cost-effective optical cesium beam solutions with a 10-year lifespan and improved holdover capabilities designed to support telecom and infrastructure modernization efforts.
These developments reflect a competitive environment characterized by parallel strategies: vertical expansion into dedicated manufacturing capacity, cross-company technology integration, space mission validation, and product launches targeting cost-sensitive yet performance-critical segments. For buyers and partners, this landscape presents both consolidation opportunities and fragmentation risks. Organizations that map the competitive dynamics with precision can anticipate supply shifts, evaluate vendor lock-in exposure, and identify collaborative pathways that align with long-term timing resilience objectives.
Industry Dynamics: Regulation, Certification, and Technological Substitution
The market’s trajectory is increasingly shaped by regulatory milestones, standardization activities, and certification events that redefine performance benchmarks and procurement criteria. A notable catalyst occurred in April 2025, when the National Institute of Standards and Technology certified the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard, calibrated against hydrogen masers to improve UTC traceability and metrology applications. This certification effectively signals the transition away from legacy HP 5071A models in national metrology laboratories and establishes a new reference baseline that influences downstream procurement specifications across government and commercial sectors.
Simultaneously, the ESA ACES mission’s selection of Safran’s Space Hydrogen Maser in April 2025 underscores the strategic importance of exceptional short-term frequency stability for spaceborne applications. The deployment of an all-European maser active hydrogen maser at the New Norcia deep-space ground station in September 2025 further illustrates how certification and mission validation are converging to support sovereign deep-space tracking and GNSS resilience. These events are not isolated achievements; they represent structural shifts in how timing infrastructure is evaluated, deployed, and protected against environmental and geopolitical disruptions.
On the commercial side, Adtran’s June 2025 launch of Oscilloquartz optical cesium beam clocks with ESTU modules demonstrates a deliberate push to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a more accessible cost profile. This product evolution reflects a broader industry dynamic: the compression of performance gaps between cesium beam and hydrogen maser technologies, driven by module-level enhancements, improved holdover characteristics, and extended operational lifespans. As these dynamics mature, procurement teams must reassess the traditional dichotomy between cost and stability, particularly when evaluating deployment scenarios that demand rapid recovery from signal loss, long-duration holdover, or stringent synchronization tolerances.
Cs beam and Hydrogen Maser Atomic Clocks Market
What This Research Delivers: Operational Intelligence for 2026 Decision-Making
This market research study is designed as a decision-support toolkit rather than a static data summary. It provides a multi-layered examination of the Cs beam and hydrogen maser atomic clocks market, translating complex technical, commercial, and regulatory interdependencies into structured intelligence that can be operationalized across strategy, procurement, R&D, and investment functions. The report integrates historical performance data, forecast modeling, segment-level analysis, and competitive profiling to deliver a comprehensive view of market directionality and actionable differentiation points.
Core Analytical Components
- Macro market sizing and forecast modeling that contextualizes historical growth from 2020 through 2025 and projects revenue expansion through 2032, enabling scenario-based planning for capacity allocation, investment prioritization, and demand forecasting.
- Segment-level evaluation across technology types and regional markets, offering insight into how cesium beam and hydrogen maser architectures are positioned relative to one another, where adoption momentum is concentrating, and which demand drivers are most influential in shaping procurement strategies.
- Competitive profiling of incumbent and emerging participants, including corporate headquarters, product portfolios, accuracy and stability specifications, application footprints, and recent strategic developments that signal shifts in manufacturing scale, technology roadmaps, and market emphasis.
- Regulatory, certification, and standardization tracking that maps the impact of metrology lab transitions, space mission deployments, ground station operations, and product certifications on downstream procurement requirements and vendor qualification criteria.
- Market concentration and structural analysis that evaluates the implications of top-three and top-five share distribution for pricing dynamics, supply chain resilience, and partnership opportunities in a market where incumbency and certification heritage carry significant weight.
- Application-driven demand assessment that connects timing performance requirements to end-use environments—including telecommunications synchronization, defense PNT resilience, power grid stability, data center infrastructure, satellite operations, and deep-space communications—enabling stakeholders to align product strategy with real-world operational constraints.
Each component is constructed to support practical decision-making. Procurement leaders can use the segmentation and competitive profiling modules to evaluate supplier qualification criteria, benchmark performance specifications, and anticipate supply continuity risks. R&D and product management teams can leverage the regulatory and certification tracking sections to align development roadmaps with evolving metrology standards and space mission validation pathways. Strategy and corporate development functions can draw on the concentration analysis, regional demand signals, and technology substitution dynamics to identify partnership targets, geographic expansion priorities, and investment allocation frameworks.
Strategic Imperatives for 2026 and Beyond
As the market advances toward 2032, several strategic imperatives emerge for organizations operating within or adjacent to the precision timing ecosystem. First, sovereign timing resilience is transitioning from a policy aspiration to an operational requirement, and organizations that proactively align their timing infrastructure with independent, high-stability atomic clock solutions will be better positioned to mitigate GNSS disruption risks and comply with evolving national security and critical infrastructure mandates. Second, the convergence of optical cesium beam enhancements and hydrogen maser performance characteristics is reshaping the value proposition across price-performance tiers, requiring buyers and suppliers alike to reassess specification thresholds, total cost of ownership, and lifecycle support commitments. Third, manufacturing capacity expansions and dedicated production lines are gradually improving supply reliability, but lead time management, component sourcing, and qualification lead times remain critical considerations for deployment planning.
Fourth, space mission validation and deep-space ground station deployments are establishing new reference points for performance and reliability, creating pull-through effects that influence terrestrial procurement specifications and vendor evaluation criteria. Fifth, market concentration implies that strategic partnerships, long-term supply agreements, and dual-sourcing strategies may be necessary to balance performance requirements with supply chain resilience. Organizations that integrate these imperatives into their planning cycles will be better equipped to navigate a market that rewards technical precision, regulatory alignment, and strategic foresight in equal measure.
Conclusion: From Insight to Action
The Cs beam and hydrogen maser atomic clocks market is defined by its technical rigor, its growing strategic importance, and its steady expansion from specialized metrology and defense applications into broader commercial and infrastructure domains. The historical performance from 2020 through 2025 establishes a credible growth baseline, while the forecast through 2032 signals a market that continues to scale in response to sovereign timing initiatives, space mission deployments, telecommunications modernization, and critical infrastructure synchronization requirements. Competitive dynamics remain shaped by incumbency, certification heritage, and manufacturing scale, yet recent facility expansions, product launches, and mission validations demonstrate that the landscape is actively evolving.
For executives, procurement leaders, and strategic planners, the imperative is clear: precision timing is no longer a backend technical consideration but a front-line resilience priority. This market research study provides the structured intelligence required to translate that priority into informed decisions—whether those decisions involve vendor selection, technology roadmap alignment, geographic demand assessment, or investment prioritization. To access the full segmentation analysis, regional demand breakdowns, detailed competitive profiles, and forecast scenario modeling that underpin these strategic conclusions, stakeholders are invited to explore the complete report on our platform, where the complete intelligence is available to support your 2026 planning cycle and beyond.
Rubidium Atomic Clock Market
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Food Service Equipment Market Hits $41.47B in 2025, Poised for 7% CAGR Through 2032
By PW Consulting, 2026-09-16
The Strategic Value of the 2026 Food Service Equipment Market Intelligence Report
As the global foodservice industry navigates a period of structural transformation, equipment procurement has evolved from a tactical expense to a strategic lever. The latest comprehensive study by PW Consulting on the Food Service Equipment Market offers decision-makers a rare, data-grounded compass for navigating the forecast window from 2026 through 2032. Built on a rigorous historical baseline spanning 2020 to 2025 and calibrated to forward-looking demand indicators, this research translates macroeconomic momentum, competitive realignments, and operational cost pressures into actionable intelligence tailored for executives, supply chain planners, and capital allocation teams.
For 2026 enterprise strategy, the market conversation has shifted decisively toward resilience, efficiency, and capital optimization. The industry is operating under a dual narrative: sustained revenue expansion coexisting with intensifying margin scrutiny, labor cost escalation, and raw material volatility. Our report captures this complexity without oversimplifying it, providing the structural clarity required to time investments, prioritize categories, and anticipate competitor moves. Rather than presenting a static snapshot, the analysis maps the trajectory of market growth, identifies concentration patterns, and outlines the operational and regulatory forces that will dictate procurement velocity over the next seven years.
Macro Trajectory: Mapping the Growth Arc and Capital Allocation Window
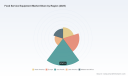
The historical record demonstrates a clear and accelerating expansion pattern. Between 2020 and 2025, the global market for foodservice equipment advanced from approximately 29.6 billion USD to 41.5 billion USD, reflecting consistent demand recovery, channel stabilization, and an expanding base of commercial kitchen operators. More importantly, the forecast period from 2026 to 2032 positions the market on a sustained upward trajectory, with projected revenue reaching 44.5 billion USD in 2026 and continuing to climb toward the mid-60 billion USD range by 2032.
This growth curve is not merely a function of volume recovery; it reflects structural demand drivers that favor deliberate, phased investment. The forecast period coincides with a phase in which labor economics, energy compliance expectations, and operational throughput requirements increasingly influence equipment specification decisions. For 2026 decision-makers, this trajectory carries two immediate implications. First, it validates a medium-to-long-term capital planning horizon rather than opportunistic purchasing. Second, it signals that the most consequential procurement decisions will be those that balance upfront cost with downstream efficiency, maintenance predictability, and regulatory alignment.
The compounding annual growth rate embedded in the forecast underscores a market that continues to expand at a meaningful pace even as operators tighten capital discipline. That combination creates a strategic tension that the report addresses directly: how to capture growth opportunities without overextending operational budgets or misreading regional and segment-level demand signals. The analysis is structured to help executives differentiate between broad market momentum and the narrower pockets of acceleration that should drive category-specific investment.
Competitive Architecture: Concentration, Positioning, and Strategic Implications
One of the most valuable elements of the report is its dissection of the competitive landscape. The market is not fragmented in a way that rewards undifferentiated pricing competitions; instead, it exhibits meaningful concentration among manufacturers that combine scale, brand breadth, and category specialization. The data indicates that the top three players collectively account for 38.5 percent of the market, while the top five represent 52.6 percent. Such concentration shapes channel dynamics, pricing agency, and the strategic weight of partnerships, service networks, and product roadmaps.
The competitive field includes organizations with distinctly different strategic postures. Some manufacturers compete on broad portfolio coverage and multi-brand architecture, spanning ranges, ovens, refrigeration, dishwashing systems, and ancillary kitchen infrastructure. Others differentiate through category leadership, leveraging deep engineering focus on specific equipment classes such as combi-steam ovens, ice production systems, beverage equipment, or heavy-duty mixing and cooking platforms. A third competitive vector is corporate ownership and consolidation activity, which influences product integration, regional distribution reach, and strategic prioritization across North America, Europe, and Asia Pacific.
Food Service Equipment Market
Recent developments highlight the pace and direction of competitive maneuvering. Mid-2025 product launches have targeted cost-conscious operators with refreshed refrigeration offerings, while facility expansions and experiential customer centers have reinforced service, demonstration, and specification support capabilities. Partnerships with institutional bodies have opened grant-assisted upgrading pathways for school meal kitchens, reflecting a broader pattern in which manufacturers increasingly align product strategy with public-sector and community nutrition programs. Leadership transitions in major multinational operations point to renewed focus on North American execution and portfolio alignment. Meanwhile, trade show demonstrations of energy-recovery systems illustrate the growing prominence of operational efficiency as a competitive differentiator rather than a compliance afterthought.
For 2026 strategy teams, this competitive architecture matters because it determines the realistic set of procurement alternatives, negotiation leverage, and vendor dependency risks. The report does not simply list competitors; it evaluates how portfolio scope, ownership structures, and recent strategic moves influence market behavior. That perspective allows buyers and investors to interpret supplier announcements with greater contextual accuracy and to anticipate which firms are likely to expand capacity, reprice offerings, or redirect innovation investment.
Operational and Regulatory Forces Reshaping Procurement Logic
Market size and competitive structure tell only part of the story. The real strategic value of the report emerges in its treatment of the forces that alter equipment selection criteria, total cost of ownership, and deployment timing. One of the most prominent is the labor cost trajectory in food services and drinking places. Rising average hourly earnings between 2025 and early 2026 have intensified the operational case for labor-saving equipment, automated food preparation, and holding solutions that reduce hands-on station time. In this environment, equipment is increasingly evaluated not only for throughput and durability but also for its contribution to workforce productivity and shift scalability.
Food Processing Equipment Market
Parallel to this, raw material dynamics continue to influence manufacturing economics. Volatility in steel and aluminum markets affects the cost structure of equipment components and, by extension, the pricing stability and lead-time predictability that operators rely on when planning capital projects. The report situates these material pressures within a broader procurement rhythm, helping organizations anticipate where cost variability may be absorbed by manufacturers, passed through to buyers, or mitigated through design engineering and supply chain adjustments.
Regulatory expectations also form a critical layer of the strategic landscape. ENERGY STAR certification and similar energy-efficiency frameworks have become practical gateways to utility incentives and compliance with evolving efficiency standards for dishwashers, ice machines, fryers, and other commercial kitchen assets. At the same time, equipment must satisfy electrical safety, gas safety, pressure vessel, and food contact material requirements to secure market access. These requirements are not static checkboxes; they shape product roadmaps, specification guidelines, and the cost-benefit calculus of choosing one equipment category over another.
The report also addresses reimbursement pathways that affect institutional demand. In the school nutrition segment, for example, equipment grants tied to USDA meal program upgrades can meaningfully offset capital costs for kitchen modernization projects. Recognizing where grant mechanisms, incentive structures, and compliance requirements intersect enables operators and contractors to design procurement plans that align with available financial support and regulatory timelines. For 2026 planning, this is especially relevant because public-sector and institutional budgets often move on different calendar cycles than commercial operators, and misreading those cycles can lead to missed windows or suboptimal specification choices.
What the Report Delivers: Operational Content for 2026 Decision-Making
This study is engineered for practical use rather than abstract commentary. It integrates historical performance, forward forecasts, competitive context, and market dynamics into a single framework that can be directly applied to budgeting, sourcing, and investment planning. The report content is organized to support several high-value decisions.
First, it provides a structured view of the market by type, application, and geography, allowing readers to identify where demand is concentrated and how segment-level priorities differ. Rather than presenting uncontextualized splits, the analysis interprets these dimensions in relation to operational realities, such as the differing equipment intensity of full-service restaurant environments versus quick-service formats, and the implications of institutional, catering, and hospitality use cases for equipment specification and replacement cycles.
Second, the report examines the competitive set with enough granularity to inform vendor selection and partnership strategy. It profiles leading manufacturers across multiple categories and geographies, noting their core product competencies, brand footprints, and recent strategic actions. This enables readers to map competitors not as isolated names but as participants in a competitive system defined by portfolio breadth, specialization, regional execution, and corporate ownership.
Third, the study incorporates the latest industry developments and regulatory signals that influence near-term planning. Product launches, facility investments, partnership activity, leadership transitions, and trade show initiatives are evaluated for their strategic relevance, while regulatory, material, and labor-market facts are integrated into the broader demand narrative. The goal is to equip decision-makers with the context needed to distinguish transient noise from durable trend shifts.
Fourth, the report addresses total cost of ownership considerations that often get overlooked in category-level discussions. Energy efficiency eligibility, labor productivity impact, maintenance expectations, and compliance readiness all have implications for long-term operating expense. By connecting these factors to market structure and procurement behavior, the analysis helps organizations evaluate equipment decisions with a fuller financial lens. For 2026 strategy, that lens is essential because capital availability, operational efficiency, and regulatory alignment increasingly converge in the same purchasing decision.
Finally, the report is designed to be referenced, not merely read. Its structure supports scenario planning, category prioritization, and procurement scheduling. Whether an organization is evaluating a kitchen modernization program, planning a multi-site rollout, assessing vendor consolidation opportunities, or modeling category growth under different labor and energy assumptions, the research provides the framing necessary to reduce uncertainty and improve decision quality.
How to Use This Intelligence for 2026 Planning
The most effective use of this report is to align market intelligence with an organization's procurement calendar, capital constraints, and operational goals. For manufacturers and distributors, the analysis supports product portfolio prioritization, geographic focus, and competitive positioning. For operators and contractors, it informs specification strategy, replacement-cycle timing, and energy-efficiency investment decisions. For investors and market entrants, it clarifies concentration dynamics, growth concentration, and the practical barriers created by regulatory and supply-chain requirements.
Because the study deliberately abstracts away segment-level percentage detail and specific regional or application amounts in this overview, the complete dataset remains essential for precise planning. The published version provides the granular breakdowns, comparative context, and working-level detail required to translate strategic direction into operational execution. Decision-makers who rely only on summary-level figures risk missing the segment-specific signals that determine where and when capital should be deployed.
Conclusion: A Deliberate Framework for a Changing Market
The Food Service Equipment Market in 2026 is not simply expanding; it is being reshaped by labor economics, energy compliance, raw material variability, and a competitive landscape in which concentration and specialization both matter. The PW Consulting market research is designed to help organizations navigate that environment with confidence by combining historical rigor, forward forecast discipline, and practical competitive analysis into a single decision-support resource.
The report offers the breadth and depth needed to inform capital allocation, procurement strategy, and competitive positioning without overloading readers with uncontextualized data. Its true value lies in helping organizations distinguish durable growth from temporary momentum and to align equipment strategy with the operational realities that will define the next several years. For those preparing for 2026 and beyond, the complete report provides the detailed segment and regional intelligence required to move from strategic direction to informed execution.
For detailed analysis of this topic, please visit the official page: Food Service Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: POCT Market Hits $215M in 2025, Projects $377.98M by 2032 at 8.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Point-of-Care Testing Landscape: Strategic Insights for 2026 and Beyond
The global healthcare delivery model is undergoing a fundamental structural shift, moving diagnostics from centralized laboratories to the patient's side. As we enter 2026, Point-of-Care Testing (POCT) is no longer merely a convenience but a critical infrastructure component for resilient health systems. PW Consulting's latest comprehensive market research provides a definitive roadmap for stakeholders navigating this high-growth environment. This analysis synthesizes historical performance with forward-looking projections to underscore the strategic imperative of understanding this market's trajectory.
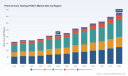
The market has demonstrated remarkable resilience and growth over the past half-decade. Valued at approximately 163 million USD in 2020, the industry navigated volatility before establishing a robust upward trend. By 2025, the market size stabilized around 215 million USD, setting the stage for accelerated expansion. Our forecast period, spanning from 2026 to 2032, indicates a compound annual growth rate of 8.5 percent. This growth suggests the market could approach close to 378 million USD by the end of the decade, driven by aging demographics, the prevalence of chronic diseases, and the enduring demand for rapid diagnostic results.
Lateral Flow POC Reader Market
Strategic Value for Enterprise Decision-Making
For executives and investors, understanding the aggregate numbers is only the first step. The true value of this research lies in dissecting the underlying drivers that will dictate capital allocation and product development strategies in 2026. The transition to decentralized testing is creating new value chains, altering reimbursement landscapes, and reshaping competitive dynamics. Our report moves beyond surface-level statistics to offer actionable intelligence on where value is being created and how market share is being contested.
Decision-makers need to anticipate regulatory shifts that could alter compliance costs and market access. Similarly, understanding the concentration of power among top-tier vendors is essential for assessing supplier risk and partnership opportunities. The following sections detail the operational depth included in the full study, designed to mitigate risk and identify high-probability growth avenues.
Operational Scope and Analytical Depth
This market research is constructed to serve as a practical toolkit for strategy formulation. It bridges the gap between high-level market sizing and on-the-ground commercial execution. Readers will find granular analysis covering the entire ecosystem, from manufacturing inputs to end-user adoption patterns.
-
Technology Segmentation Analysis: The report categorizes the market by testing type, including glucose monitoring, infectious disease testing, cardiometabolic testing, and other emerging categories. We analyze the adoption curves and technological maturity of each segment to predict future revenue mix shifts.
-
End-User Application Drivers: Special attention is given to the settings where testing occurs, such as hospital bedside, physician offices, and home self-testing environments. Understanding the unique procurement cycles and regulatory requirements of each application is vital for market entry strategies.
-
Regional Market Dynamics: We examine performance across key geographic territories, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This analysis highlights varying levels of market maturity and infrastructure readiness without limiting the scope to static regional snapshots.
-
Supply Chain and Manufacturing Insights: The study evaluates the operational capabilities required to scale POCT devices and consumables, considering reagent stability, device portability, and connectivity requirements.
Competitive Landscape and Key Player Strategies
The POCT market is characterized by a mix of established diagnostics giants and specialized innovators. Our analysis provides detailed profiles of the core companies shaping the industry, evaluating their product portfolios, strategic positioning, and recent market activities. The competitive intensity is notable, with a significant portion of revenue concentrated among the top firms, indicating high barriers to entry and strong brand loyalty.
Major Incumbents and Product Portfolios
Leaders in the space are leveraging diverse technological platforms to capture share across multiple testing categories. Abbott Laboratories, headquartered in Abbott Park, Illinois, continues to strengthen its position with the i-STAT system and the ID NOW rapid molecular platform, alongside the Alinity i for various markers. These offerings span cardiac, infectious, and metabolic testing, providing a broad suite for clinical settings.
F. Hoffmann-La Roche Ltd, based in Basel, Switzerland, is focusing on molecular precision with the cobas liat system. Their recent activities highlight a push toward multiplex testing capabilities at the point of care, enabling rapid detection of multiple targets simultaneously. Siemens Healthineers AG from Erlangen, Germany, offers comprehensive solutions for blood gas, cardiac, and routine testing, utilizing high-throughput analyzers that bridge the gap between central lab efficiency and point-of-care speed.
Danaher Corporation, located in Washington, D.C., leverages its subsidiary strengths through Cepheid GeneXpert and Beckman Coulter platforms. These tools address molecular and immunoassay needs, catering to complex diagnostic requirements in varied care settings. QuidelOrtho Corporation in San Diego, California, maintains a strong presence with Sofia fluorescent analyzers and QuickVue lateral flow tests, focusing on rapid immunoassay POCT for infectious diseases. Becton, Dickinson and Company (BD), based in Franklin Lakes, New Jersey, provides the Veritor system and other rapid diagnostic platforms, covering both molecular and immunoassay tests to support decentralized testing initiatives.
bioMérieux SA, headquartered in Marcy-l'Étoile, France, contributes with the BIOFIRE and VITEK 2 systems, emphasizing rapid molecular and automated solutions for critical care environments. Thermo Fisher Scientific Inc., from Waltham, Massachusetts, rounds out the key player list with rapid diagnostic and molecular test solutions tailored for infectious diseases and clinical POCT applications.
Point-of-Care Testing (POCT) Market
Recent Strategic Moves and Regulatory Milestones
Market velocity is often dictated by regulatory approvals and strategic consolidations. Our report tracks these events to provide context on market readiness. In early 2025, Roche received FDA clearance with a CLIA waiver for cobas liat STI multiplex panels, expanding the utility of their platform for point-of-care use in sensitive testing scenarios. Later that year, in July 2025, BD received FDA 510(k) clearance for the BD Veritor System for SARS-CoV-2 rapid point-of-care testing, transitioning from emergency use authorization to standard clearance, which signals a maturation in the regulatory pathway for respiratory diagnostics.
Strategic consolidation is also reshaping the landscape. In June 2025, QuidelOrtho announced its intent to acquire LEX Diagnostics, contingent on U.S. FDA clearance for the VELO respiratory POCT system. This move included plans to discontinue the Savanna platform, indicating a strategic pivot toward next-generation respiratory testing technologies. Additionally, independent developments such as SEKISUI Diagnostics launching new rapid diagnostic tools for RSV detection in professional healthcare settings during May 2025 highlight the ongoing innovation pipeline beyond the major conglomerates.
Regulatory Dynamics and Industry Standards
The operational environment for POCT is heavily influenced by regulatory frameworks that ensure test accuracy and reliability. A significant update occurred in January 2025, when full effects of CLIA regulatory updates for point-of-care testing went into place. These updates included enhanced proficiency testing requirements with a performance range of plus or minus 8 percent for analytes like hemoglobin A1C. Such regulations directly impact device validation, quality control protocols, and the cost structure for providers implementing POCT solutions.
Understanding these regulatory nuances is critical for any organization planning to introduce new tests or expand existing ones. Our research details how these compliance requirements affect different testing types and regions, offering guidance on navigating the approval processes and maintaining operational compliance without stifling innovation. The interplay between regulatory bodies and market innovation defines the pace at which new technologies can be deployed to patients.
Market Concentration and Future Outlook
The competitive structure of the POCT market suggests a consolidated environment where scale and technological breadth are key advantages. Our data indicates a concentration ratio among the top three and top five firms that underscores the dominance of established players. This concentration influences pricing power, supply chain negotiations, and the ability to invest in R&D for next-generation platforms.
Looking toward 2032, the trajectory points toward increased integration of digital health solutions with physical testing devices. Connectivity, data interoperability, and automated result reporting will likely become standard expectations rather than differentiators. The growth from 228 million USD in 2026 to nearly 378 million USD by 2032 represents not just revenue expansion but a transformation in how healthcare data is generated and utilized.
Investors and corporate strategists must consider how these long-term trends align with their portfolios. The shift toward home self-testing and physician office-based testing continues to rise, challenging traditional hospital-centric models. Each segment presents unique challenges regarding reimbursement, user education, and device usability. Our full report provides the segmented data necessary to model these scenarios accurately.
Unlock the Full Intelligence
This overview serves as a strategic preview of the comprehensive intelligence available in PW Consulting's full Point-of-Care Testing Market Report. While the macro trends and competitive dynamics outlined here provide a strong foundation, the detailed segmentation data, specific regional revenue estimates, and granular application breakdowns are essential for precise planning. The specific numerical splits across regions, testing types, and applications reveal the nuanced opportunities that aggregate data obscures.
Access to the complete dataset allows stakeholders to benchmark their internal targets against market realities, identify underserved niches, and anticipate competitor moves with greater accuracy. The detailed profiles of key companies, including specific product positioning and recent development timelines, offer a clear view of the battlefield. For procurement teams, the insights into supplier concentration and regulatory requirements inform risk management strategies.
To leverage these insights for your 2026 planning cycle, we invite you to access the full report web page. There you will find the complete quantitative models, deep-dive case studies, and actionable recommendations tailored to drive growth in the evolving POCT landscape. Do not rely on partial data for critical strategic decisions; obtain the complete intelligence package to secure a competitive advantage in this high-growth market.
The window for strategic positioning in the Point-of-Care Testing market is open, but the landscape is shifting rapidly. Armed with the right intelligence, organizations can navigate regulatory changes, capitalize on technological advancements, and capture value in a market poised for significant expansion. PW Consulting remains committed to providing the clarity needed to turn market complexity into strategic opportunity.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
P.W. Consulting Reveals Feminine Care Sanitary Napkin Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Sanitary Napkin for Feminine Care Market Through 2032
The global feminine hygiene sector stands at a critical inflection point. As consumer expectations evolve and regulatory frameworks mature, decision-makers require more than headline figures. They need a structured, evidence-based view of how the sanitary napkin for feminine care market will compound, where competitive pressure will concentrate, and which operational capabilities will separate resilient players from the rest. The newly released PW Consulting market study translates a decade of historical performance and a seven-year forward trajectory into a decision-ready toolkit for 2026 strategy planning.
This overview outlines the analytical architecture of the report, demonstrates how the macro trajectory anchors strategic planning, and previews the competitive and regulatory dimensions that will shape portfolio choices, manufacturing footprints, and go-to-market investments. Detailed segment valuations, regional breakdowns, and company-level scenario models are reserved for the full dataset, ensuring that executives who engage with the complete study gain exclusive access to the full intelligence stack.
Market Trajectory and the Strategic Baseline for 2026
The sanitary napkin for feminine care market has navigated a clear growth corridor over the past half-decade. Historical tracking from 2020 through 2025 shows a steady climb in absolute revenue, reflecting sustained demand, incremental product innovation, and broader distribution penetration across mature and emerging channels. This historical arc establishes the baseline against which forward-looking assumptions are stress-tested in the forecast window extending to 2032.
The forward trajectory projects continued expansion at a compound annual growth rate of 6.98 percent across the forecast period. Such a rate signals more than incremental volume accumulation; it points to structural tailwinds that reward companies able to align product architecture, supply chain agility, and compliance readiness with shifting consumer preferences. For 2026 planning teams, the key implication is that growth will not accrue uniformly. Revenue will concentrate around specific value propositions, manufacturing capabilities, and regional execution quality, making segmentation intelligence indispensable for capital allocation.
PW Consulting’s analysis converts this trajectory into a planning framework. Instead of treating the forecast as a single line item, the study maps how different product architectures, application contexts, and operational models contribute to the cumulative outcome. This approach allows leadership teams to test sensitivity around pricing, mix shifts, capacity utilization, and regulatory compliance costs without relying on blunt averages. The result is a clearer picture of where margin potential exists and where execution risk is most likely to erode returns.
Because the market’s expansion is coupled with tightening oversight and intensifying brand competition, the strategic question for 2026 is no longer whether the sector will grow, but how to position within that growth. The report is built to answer that question through disciplined segmentation, competitive benchmarking, and scenario planning that can be operationalized across commercial, procurement, and regulatory functions.
What the Report Delivers: Architecture of Actionable Intelligence
A market study earns its place in the executive workflow only when it converts data into decisions. The PW Consulting report is organized around practical deliverables that support strategy formulation, investment prioritization, and risk management. The content is designed to be referenced directly in planning cycles rather than read once and shelved.
Core Analytical Components
- Historical market reconstruction that ties observed performance from 2020 to 2025 to the assumptions driving the forecast through 2032
- Segment-level assessment of product-type dynamics and application contexts, enabling a precise reading of where demand intensity and competitive overlap are highest
- Market concentration analysis that quantifies how revenue is distributed across leading players and what that implies for entry barriers, pricing power, and partnership strategy
- Competitive profiling of key enterprises, including headquarters positioning, brand portfolios, and recent strategic moves that signal future capability builds
- Regulatory and standards monitoring that tracks classification, testing expectations, labeling guidance, quality management alignment, and emerging global standardization activity
- Scenario-ready framing that lets teams evaluate how shifts in compliance cost, raw material strategy, channel mix, and brand positioning could alter outcomes within the forecast horizon
Each component is interlinked. Historical performance informs segment assumptions; segment dynamics clarify competitive positioning; competitive positioning shapes partnership and private-label decisions; and regulatory trajectory defines the compliance ceiling that every manufacturer must accommodate. By presenting these layers together, the report gives executives a coherent map rather than isolated data points.
Importantly, the study preserves analytical rigor without overwhelming the reader with raw tables. Narrative interpretation accompanies the numbers so that teams can understand not only what the figures are, but why they matter and how they should influence resource allocation. For confidentiality and commercial focus, granular regional shares and application-level monetary splits are disclosed in the full report, ensuring that subscribers receive the depth required for precise planning while this overview maintains the strategic preview format.
Competitive Landscape: Convergence, Differentiation, and Strategic Moves
The sanitary napkin for feminine care market is shaped by a mix of global multinationals, regional specialists, and manufacturing partners serving private-label and OEM/ODM channels. The competitive field reflects differing strategic priorities: some companies compete through brand heritage and broad distribution, others through product technology and softness claims, and still others through cost-efficient manufacturing and regulatory readiness for specific markets.
Key Enterprise Positioning
- Kimberly-Clark Corporation, based in Irving, Texas, maintains a prominent brand presence through Kotex sanitary napkins and panty liners, with distribution and partnership activity that extends into essential-care initiatives
- Unicharm Corporation, headquartered in Ehime, Japan, competes through the Sofy line of sanitary napkins and panty liners, reinforcing its position in markets where comfort, fit, and consumer trust are decisive purchase drivers
- Kao Corporation, located in Tokyo, Japan, advances the Laurier brand and has emphasized product refinements aimed at improving softness and breathability, aligning innovation with everyday usage expectations
- Hengan International Group Company Limited, operating from Jiangxi, China, manages brands such as Space7 and Anerle, reflecting a portfolio approach that targets value-conscious and mid-tier consumer segments
- Family Cares Group, based in Fujian, China, produces Ecolivia sanitary napkins and maintains quality-system and registration credentials that support traceability and compliance-oriented positioning
- Premier Care Industries, headquartered in Winnipeg, Manitoba, Canada, manufactures sanitary napkins and liners under the Bodyform brand for private-label and national-equivalent channels, highlighting the strategic role of contract and brand-transfer models
- Ontex Group NV, based in Aalst, Belgium, participates across feminine hygiene sanitary napkins and liners, with a footprint that supports multi-market execution and product range breadth
- Haoyue Personal Care Co., Ltd., from Hangzhou, Zhejiang, China, operates in the OEM/ODM space, serving as a manufacturing partner for brands that require flexible production and specification customization
The competitive story is not simply a ranking of scale. It is a study in how companies allocate effort across brand building, product engineering, channel access, and manufacturing efficiency. In this market, a player with strong brand recognition may still face pressure if regulatory expectations rise or if a competitor secures a meaningful advantage in comfort, absorbency, or cost structure. Likewise, manufacturers serving private-label and OEM/ODM customers have a different risk profile: they must align with client specifications, quality expectations, and compliance documentation while maintaining production reliability.
Recent Strategic Signals
Recent activity among leading participants illustrates how the competitive field is being shaped in real time.
- In October 2025, Kimberly-Clark Corporation expanded global partnerships with Baby2Baby, Plan International, Project HOPE, and UNICEF to advance essential care for women and girls, signaling a broader corporate commitment that intersects with brand visibility and social-impact positioning
- In April 2024, Unicharm Corporation entered a strategic partnership with Kao Corporation, a move that underscores how collaboration can reshape distribution leverage, product development velocity, and market access
- In 2024, Kao Corporation introduced advanced Ultra-Soft Technology in Laurier products, enhancing softness and breathability, an example of product-level differentiation intended to reinforce consumer preference in a crowded category
These developments matter because they show where competitors are investing attention. Partnerships can accelerate reach and credibility. Product innovations can shift purchase criteria. Regulatory and quality milestones can define who is eligible to compete in more demanding channels. The report uses these signals to build a living picture of competitive momentum rather than a static list of players.
Tampons Market
Regulatory Evolution and Quality Infrastructure as Strategic Variables
Regulatory dynamics are no longer peripheral to commercial strategy in feminine care. They influence product design, testing protocols, labeling clarity, quality management systems, and market access. For 2026 and beyond, compliance readiness is a competitive variable, not just a legal checkbox.
Classification and Testing Expectations
Sanitary napkins are classified by the FDA as Class II medical devices, and in October 2025 the agency issued draft guidance for performance testing and labeling. The guidance includes recommendations for pads to ensure safe absorption and to provide clear directions for use. This development points to an environment where substantiation, transparency, and consistent product performance are increasingly central to market acceptance.
Sanitary Napkin for Feminine Care Market
Quality Management Alignment
Effective February 2, 2026, the FDA QMSR incorporates ISO 13485:2016 into 21 CFR Part 820, extending its relevance to menstrual products including sanitary napkins. For manufacturers, this alignment raises the importance of documented quality processes, traceable controls, and system-level consistency. Companies that already operate mature quality frameworks will face a different adaptation burden than those building compliance capability from the ground up.
Certification and Standards Momentum
Standards activity is also advancing. ISO/TC 338 is developing global standards for single-use menstrual pads, including sanitary napkins, with expected completion in December 2026. In parallel, certain manufacturers maintain ISO 9001:2015 certification and FDA establishment registration credentials that support export readiness and buyer confidence. These elements collectively indicate that the market is moving toward more formalized expectations around product consistency and documentation.
Strategically, the implication is clear. Product claims, absorption performance, and user instructions will be judged against a more defined oversight environment. Supply chains, manufacturing sites, and product-development timelines must account for the time and cost of validating performance and maintaining compliant quality systems. The report integrates these regulatory currents into the forward assessment so that strategy teams can anticipate operational impact rather than react after the fact.
How to Use This Study for 2026 Decision-Making
The value of a market study lies in its deployment. For 2026 planning, the PW Consulting research is structured to support several concrete uses.
Portfolio and Product Strategy
Leadership teams can use the segmentation architecture to determine where to reinforce existing offerings, where to introduce product refinements, and where to avoid overinvestment in crowded or low-differentiation positions. The forward trajectory and segment interpretation help frame whether resources should tilt toward comfort and breathability, absorption reliability, sustainability positioning, or channel-specific packaging and sizing.
Competitive and Partnership Planning
The competitive profiles and recent moves provide a basis for assessing partnership opportunities, private-label potential, and brand-transfer dynamics. Companies evaluating collaboration can better understand which partners bring distribution strength, which bring product technology, and which bring manufacturing flexibility. This is particularly relevant in a market where OEM/ODM capabilities and national-equivalent branding both play meaningful roles.
Compliance and Operational Readiness
With evolving guidance, QMSR alignment, and international standards development, the study gives teams a structured basis for compliance planning. Product, quality, and regulatory functions can use the framework to anticipate documentation needs, testing expectations, and system updates, thereby reducing the risk of late-stage remediation.
Scenario and Investment Planning
Because the forecast spans to 2032, executives can test investment horizons against multiple assumptions. Capacity expansion, geographic focus, brand investment, and compliance spending can all be evaluated in the context of a compounding market trajectory rather than a single-year snapshot. That longer lens helps distinguish short-lived opportunities from durable structural growth.
Why the Full Dataset Matters
This overview has intentionally presented the strategic scaffold while reserving the detailed segment magnitudes, regional distributions, and application-level monetary splits for the complete report. That design reflects how executive intelligence should work: enough transparency to establish credibility and demonstrate analytical depth, while preserving the full economic granularity that drives precise planning.
Subscribers to the full study gain access to the complete segmentation values, market concentration detail, competitive profiling, and scenario framing needed to convert the 6.98 percent compound trajectory and the broader 2020-to-2032 arc into actionable investment decisions. For teams responsible for 2026 budgeting, channel strategy, product roadmaps, or regulatory readiness, the full dataset provides the resolution required to move from directional confidence to specific commitment.
Closing Perspective
The sanitary napkin for feminine care market is expanding within a context defined by consumer-refinement pressure, intensifying brand and manufacturing competition, and a maturing regulatory environment. Growth is real, but its value will be captured by organizations that can align product differentiation, compliance discipline, and competitive positioning with a clear view of where demand and margin will concentrate.
PW Consulting’s study is designed to make that alignment practical. It connects historical evidence, forward projections, competitive behavior, and regulatory direction into a single planning framework. For executives preparing 2026 decisions, the report offers both the strategic narrative and the operational detail needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Sanitary Napkin for Feminine Care Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Microcrystalline Wax Market to Hit $1.93B by 2032 at 4.15% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Microcrystalline Wax Market (2026–2032)
The global microcrystalline wax sector is entering a phase of recalibration. As industries from personal care to industrial adhesives demand more specialized, sustainable, and supply-chain-resilient materials, stakeholders must look beyond headline figures to understand the structural forces shaping value creation over the coming decade. Our latest Microcrystalline Wax Market research study delivers the analytical rigor required to position portfolios, pricing strategies, and sourcing models ahead of the curve.
This article previews the strategic architecture of that study, outlining how macro-trajectory data, competitive positioning, and regulatory fault lines intersect to form a decision framework for enterprise leaders in 2026 and beyond. Detailed segment-level figures, regional revenue breakdowns, and granular application splits are reserved for the full report, where they can be evaluated alongside scenario models and actionable benchmarks.
A Decade of Measured Expansion: What the Trajectory Tells Us
The microcrystalline wax market has demonstrated consistent growth across the reference period, expanding from a baseline valuation of approximately USD 1,134 million in 2020 to an estimated USD 1,425 million in 2025. That progression reflects underlying demand diversification rather than a single dominant catalyst. Over the forecast window spanning 2026 through 2032, the market is projected to advance at a compound annual growth rate of 4.15%, translating into a forward valuation trajectory that reaches upward of USD 1.9 billion by the close of the period.
These headline metrics serve as orientation points rather than endpoints. The real strategic value lies in unpacking what drives variance around the trend line: feedstock cost dynamics, cross-application substitution patterns, regional trade rerouting, and the pace at which sustainability mandates reshape procurement specifications. The study maps these forces into a unified analytical model, enabling clients to test how changes in one variable—say, crude oil benchmark movement or a new import restriction—cascade through volume assumptions, margin structures, and sourcing priorities.
Importantly, the growth path is not uniformly linear. The forecast period captures intervals of recalibration where supply-side constraints and regulatory interventions temporarily alter the pace of expansion. Understanding where those inflection points occur, and how incumbents versus challengers respond, is central to building resilient operating strategies in 2026.
Report Architecture: From Macro Context to Execution-Ready Intelligence
The research is designed as a practical decision-support instrument rather than a static data compendium. It combines market sizing, structural segmentation, competitive intelligence, and regulatory tracking into a single navigable framework. The following components illustrate the scope and operational orientation of the study:
- Market Sizing and Forward Modeling: Historical performance from 2020 through 2025 is reconstructed to establish a defensible baseline, then extended through 2032 using scenario-conditioned projections. The modeling approach isolates sensitivity to feedstock pricing, demand elasticity across application families, and trade-flow adjustments, giving users a basis for internal forecasting rather than reliance on a single point estimate.
- Structural Segmentation Analysis: The study disaggregates the market across type, application, and region to expose where volume and value concentrate, where growth rates diverge, and where substitution risk is most pronounced. Rather than presenting percentages in isolation, the analysis pairs each segmentation dimension with qualitative drivers—performance requirements, regulatory exposure, formulation trends, and procurement norms—so that readers can interpret shifts within a commercial context.
- Competitive Landscape and Strategic Profiles: Eight core enterprise profiles are developed with attention to product architecture, capacity orientation, application coverage, and recent commercial moves. Each profile highlights how a player positions itself within the value chain and where it is investing to capture differentiated demand.
- Regulatory and Trade Dynamics Tracking: Because mineral waxes sit at the intersection of commodity sourcing and cross-border compliance, the report integrates an active watchlist of policy developments. Coverage extends from targeted import restrictions and forced-labor enforcement actions to tariff subheadings and carbon-footprint disclosures, each mapped to potential procurement and routing implications.
- Cost and Feedstock Context: The analysis embeds raw-material dynamics—including refinery throughput constraints, crude benchmark movement, and derivative price volatility—into the demand-and-supply narrative. This linkage helps explain why price trends in specific quarters diverge from the broader growth trajectory and how that divergence affects negotiation leverage, inventory strategy, and contract design.
- Application-Level Demand Interpretation: Cosmetics and personal care, candles, adhesives, packaging, rubber, and other end-use segments are examined through the lens of formulation requirements, quality standards, and purchasing cycles. The goal is to show where microcrystalline wax functions as a performance-critical input versus a commoditized additive, and how that distinction shapes pricing power and switching behavior.
By integrating these layers, the study moves beyond descriptive market snapshots to provide a structured basis for capacity planning, product-mix decisions, supplier diversification, and market-entry evaluation.
Competitive Landscape: Positioning Among Established Players and Emerging Pressures
The market exhibits meaningful concentration, with the top three firms collectively representing a substantial share of revenue and the top five extending that footprint further. Such concentration does not imply homogeneity, however. Incumbents differentiate through grade specialization, compliance certification, geographic coverage, and the ability to supply customized physical forms and purity levels. The report profiles a cross-section of leading participants to illustrate how strategy diverges even within a consolidated field.
ExxonMobil Corporation anchors its microcrystalline wax offering around the Prowaxx™ family, spanning fully refined, semi-refined, and slack grades directed at packaging, adhesives, construction, personal care, and rubber applications. The breadth of grade availability supports customers who require consistent performance across varied melting ranges and oil-content specifications. Recent 2025 activity, including the launch of a high-purity microcrystalline wax line for specialty plastics and coatings, signals continued investment in higher-specification segments where formulation precision and surface-protection performance carry premium value.
Sasol Limited has emphasized differentiated, lower-impact materials through its SASOLWAX LC Spray portfolio, including micronized grades designed for coatings, inks, plastics, and specialty manufacturing. The introduction of grades featuring a notably reduced product carbon footprint aligns with buyer requirements in markets where sustainability documentation increasingly influences specification decisions. This positions Sasol at the intersection of performance consistency and environmental reporting, a combination that is gaining relevance in procurement cycles across Europe and other regulated import markets.
Calumet Specialty Products Partners L.P. maintains a strong orientation toward intermediate and microcrystalline waxes, with a significant proportion of capacity oriented toward hard grades used in industrial adhesives, packaging, and consumer products. The emphasis on hard-grade capacity is strategically meaningful because it addresses applications where hardness, brittleness resistance, and adhesion characteristics are central to product performance. Calumet’s profile illustrates how capacity allocation decisions can reinforce a company’s relevance in specific end-use clusters.
Sonneborn LLC leverages its Multiwax™ line, including U.S. FDA-compliant grades, to serve personal care, topical formulations, food packaging, and hot melt adhesives. Compliance readiness and grade consistency are central value propositions in categories where regulatory documentation and batch-to-batch repeatability are non-negotiable. In personal care and food-adjacent applications, such attributes often function as gatekeeping requirements before price or logistical considerations come into play.
The International Group, Inc. (IGI Wax) differentiates through dedicated microcrystalline wax production and blending flexibility, offering bulk liquid, granule, pellet, or slab forms for cosmetics, food-grade, industrial, and coatings applications. Form-factor versatility supports customers who integrate wax into diverse manufacturing workflows and require tailored handling characteristics. This operational flexibility can reduce friction in sourcing relationships where application engineers value supply consistency and specification tuning.
Sinopec Corporation brings substantial production and supply capability, including downstream distribution and small-package delivery to markets such as Europe. Its scale and integrated posture enable it to act across multiple points in the value chain, supporting both industrial users and distributors seeking reliable volume and geographic reach. In an environment where trade restrictions and routing complexity are increasing, the ability to manage cross-border logistics and package sizing can be a meaningful differentiator.
Paramelt B.V. positions its microcrystalline waxes around sustainability and bio-based alternatives in coatings, adhesives, and plastics. This orientation reflects a broader industry shift in which buyers evaluate not only functional performance but also the environmental narrative of material inputs. Paramelt’s focus suggests a strategic bet on the accelerating relevance of sustainable specification language in downstream formulation decisions.
Kahlwax GmbH concentrates on industrial-grade microcrystalline wax for plastics, rubber, and specialty manufacturing. Its profile highlights the importance of application-tailored industrial grades where processing conditions, thermal behavior, and compatibility with polymer matrices drive selection. In such contexts, technical support and grade consistency often weigh as heavily as unit pricing.
Together, these profiles reveal a competitive environment in which scale, grade breadth, compliance readiness, sustainability positioning, and form-factor flexibility all serve as potential sources of advantage. The full report assesses how these attributes map to market share dynamics, regional presence, and responsiveness to recent commercial developments.
Regulatory Fault Lines and Feedstock Volatility: The 2026 Operating Environment
Strategic planning in 2026 must account for an unusually active policy and cost environment. Several developments have begun to reshape the risk calculus for microcrystalline wax procurement, distribution, and formulation.
Trade Restrictions and Enforcement Scope
Regulatory measures in key import markets have expanded the scope of scrutiny applied to mineral waxes. Amendments associated with Canada’s Special Economic Measures Act, effective from mid-2025, explicitly bring paraffin wax, micro-crystalline petroleum wax, and slack wax within the scope of targeted import and trade restrictions. For organizations with North American supply chains or customer bases, this introduces additional compliance mapping and potential rerouting considerations that can affect lead times, documentation burdens, and supplier eligibility.
In parallel, enforcement actions in the United States have extended to mineral waxes within proposed duty frameworks and forced-labor-related import measures. Tariff subheadings covering other mineral waxes, including microcrystalline wax, carry specified duty rates that feed directly into landed-cost calculations. Proposed additional ad valorem rates associated with enforcement actions further complicate procurement modeling, especially for buyers sourcing from regions exposed to trade scrutiny. These measures do not necessarily change underlying demand, but they alter the cost and feasibility of particular sourcing paths.
Feedstock Pressure and Price Trend Dynamics
On the cost side, rising crude oil benchmarks and refinery constraints have placed upward pressure on microcrystalline wax pricing. In the first quarter of 2026, average prices increased across global markets as feedstock expenses climbed, illustrating how quickly margin and pricing assumptions can shift when upstream conditions tighten. This type of movement matters not only for cost accounting but also for contract structuring, inventory timing, and the negotiation of pass-through mechanisms.
Compounding this dynamic, broader geopolitical disruption in the Middle East has affected chemical feedstock flows, contributing to price volatility in naphtha, LPG, and natural gas derivatives. Because these inputs influence wax production costs and related derivative markets, the effect can ripple through the value chain in uneven ways, creating pockets of pressure that differ by region, grade, and supply route.
Why These Dynamics Matter Strategically
Regulatory and cost developments rarely operate in isolation. A tariff adjustment can change the relative attractiveness of one sourcing corridor; a feedstock surge can accelerate the search for alternative grades or formulation adjustments; a compliance expansion can narrow the pool of eligible suppliers in a given market. Our research integrates these threads into a coherent operating-risk map so that clients can anticipate interactions rather than react to them sequentially.
Strategic Takeaways for 2026 Decision-Makers
The convergence of steady long-term demand growth, concentrated competition, and a volatile regulatory and feedstock environment creates a clear mandate for structured intelligence. Several strategic priorities emerge from the study’s analytical design:
Micronized Wax Market
- Stress-test sourcing assumptions against policy exposure. Trade restrictions, duty structures, and enforcement actions can change the effective cost and availability of specific grades from specific origins. Scenario analysis should incorporate compliance mapping as a core variable rather than a peripheral legal issue.
- Align grade strategy with application criticality. In segments where microcrystalline wax functions as a performance enabler—adhesives, personal care, food-adjacent packaging, specialty coatings—grade consistency, purity, and compliance documentation can outweigh narrow price comparisons. In more commoditized uses, procurement leverage and logistics efficiency may dominate. Understanding this distinction helps prioritize where to defend specifications and where to optimize cost.
- Evaluate sustainability positioning as a procurement input. Lower-carbon-footprint grades and bio-based alternatives are increasingly relevant in buyer evaluations. Even where regulatory mandates are not yet universal, sustainability documentation can influence supplier selection, especially in export-oriented and compliance-intensive markets.
- Build flexibility into inventory and contract design. Feedstock-driven price movement and trade-related supply disruption argue for a deliberate approach to inventory buffers, contract terms, and supplier diversification. Flexibility is particularly valuable when price spikes are associated with temporary constraints rather than permanent structural shifts.
- Track capacity orientation, not just revenue. Competitors’ capacity allocation choices—such as emphasis on hard grades, micronized formats, or FDA-compliant lines—signal where they intend to compete and where they may be less responsive to certain customer needs. These structural signals can inform supplier selection and competitive positioning.
What the Full Study Provides
This overview establishes the strategic frame; the complete Microcrystalline Wax Market report delivers the underlying detail required to operationalize it. The full study includes comprehensive sizing and forecast modeling, segmentation analysis across type, application, and region, extended competitive profiles with recent development tracking, regulatory and trade mappings tied to commercial impact, and cost-context analysis that connects feedstock dynamics to pricing behavior.
Importantly, the complete report preserves analytical integrity by presenting segmentation detail—regional contributions, application-level valuations, and type-level splits—within interpretive context rather than as isolated figures. That approach allows decision-makers to see not only where value sits today, but how shifts in formulation, regulation, and sourcing economics are likely to redistribute it through 2032.
For enterprise leaders responsible for sourcing strategy, product development, capacity planning, or market-entry evaluation, the study offers a structured path from macro trajectory to actionable insight. The market is expanding, but the value of that expansion will accrue to organizations that can interpret its drivers with precision and act on them before the next round of policy or cost shocks changes the landscape.
Microcrystalline Wax Market
For detailed analysis of this topic, please visit the official page: Microcrystalline Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paraffin Wax Market Hits $9.65B in 2025, Forecasts 5.6% CAGR to $14.13B by 2032
By PW Consulting, 2026-09-16
Paraffin Wax Market Intelligence Report: Strategic Forecasts and Competitive Dynamics 2026–2032
The global paraffin wax market stands at a pivotal inflection point as industries navigate shifting regulatory frameworks, evolving material specifications, and intensifying competitive pressures. Our latest market research deliverable provides executives, procurement leaders, and strategic planners with a comprehensive, data-anchored foundation for navigating the 2026 landscape and beyond. This introduction outlines how the study translates macro trajectories into actionable intelligence, positioning decision-makers to capture growth while mitigating structural risks across supply chains, product development, and geographic expansion.
Market Trajectory and Long-Term Growth Architecture
Historical performance across the 2020–2025 cycle demonstrates consistent demand expansion, with revenue progressing from roughly 7.35 billion USD at the start of the period to 9.65 billion USD by the 2025 baseline. This steady ascent reflects sustained utilization across traditional and specialized channels, underpinned by incremental capacity adjustments and broadening downstream adoption. Our forward-looking model extends through 2032, projecting a compound annual growth rate of 5.6 percent that lifts market revenue toward 14.13 billion USD by the final forecast year.
Forecast intervals for 2026 through 2030 illustrate a measured but uninterrupted climb, with each successive period capturing incremental value creation driven by refined manufacturing outputs, medical and laboratory-grade adoption, and packaging-related consumption. The trajectory is neither linear nor uniform across categories, which is precisely why our analytical framework isolates the structural drivers that will determine which participants secure margin resilience and which face compression from commoditization or compliance overhead.
Structural Segmentation: Where Value and Complexity Intersect
The market’s composition is shaped by three interlocking dimensions—product refinement thresholds, geographic distribution networks, and end-use deployment patterns. Fully refined and semi refined variants each command substantial share, yet their operational implications diverge sharply when evaluated against purification standards, melting-point stability, and downstream processing requirements. The residual category further reflects niche utilization pathways that often depend on specialized formulation parameters.
Geographic revenue concentration reveals mature demand centers alongside emerging corridors that are gradually scaling procurement volumes. Advanced industrial ecosystems continue to anchor baseline consumption, while regions in early-stage capacity building and import-dependent supply structures present differentiated growth risks and partnership opportunities. Application demand inherits this same structural complexity, with traditional usage streams maintaining broad volume presence, packaging-related requirements expanding through regulatory and sustainability mandates, and cosmetics and personal care segments leveraging refined waxes for formulation stability and user experience enhancements.
Our segmentation analysis deliberately avoids superficial percentage breakdowns in favor of a systematic evaluation of substitution thresholds, compliance friction points, and regional procurement behaviors. These outputs equip leadership teams with the granularity necessary to prioritize resource allocation, calibrate capacity commitments, and identify the applications or locations where competitive moats can be constructed before saturation accelerates.
Competitive Landscape and Strategic Positioning
The market’s competitive architecture reflects a blend of specialized medical-grade suppliers, histology-focused consumables manufacturers, and broader industrial producers that influence pricing, availability, and technical standard-setting across the value chain. A set of established entities illustrates the bifurcated nature of current competition. Companies such as WR Medical Electronics Co., Epredia, Polysciences Inc., CellPath Ltd., Poth Hille & Co. Ltd., Citotest Scientific Co. Ltd., and Biosharp each occupy distinct nodes within the ecosystem, balancing formulation precision, laboratory compatibility, and distribution reach.
The medical and laboratory-focused segment demonstrates particular intensity as procurement teams increasingly prioritize traceability, standardized documentation, and adherence to quality management expectations. Suppliers in this space differentiate not merely through volume, but through grade consistency, application compatibility, and the ability to support regulated workflows without introducing contamination risk or processing delays. Meanwhile, broader refining and chemical enterprises continue to shape availability dynamics by aligning upstream process modernization with specialty wax output, effectively influencing both cost structures and supply reliability for downstream converters and end manufacturers.
Our competitive analysis maps product portfolio breadth, geographic servicing capabilities, and strategic realignment activities to expose where consolidation pressure is likely to intensify. The report details how firms are positioning their refinement capabilities, laboratory-grade portfolios, and compliance documentation against buyer expectations, and identifies the structural advantages that separate market leaders from price-takers in multi-source procurement environments.
Recent Industry Developments Reshaping Market Momentum
Recent operational and product-level moves underscore the market’s transition toward higher specification demands and more disciplined supply practices. Product delivery activity in the medical-grade space has highlighted the importance of reliable cross-border fulfillment for hospital pathology departments and third-party testing laboratories, reinforcing the need for logistics consistency and batch traceability. Concurrently, major refining and petrochemical organizations have advanced facility upgrades and modernization initiatives designed to expand specialty wax output, signaling supply-side investment in higher-value production streams rather than bulk commodity routing alone.
Product portfolio expansions have also targeted low-carbon and specialized application pathways, reflecting buyer sensitivity to sustainability considerations in packaging and medical device contexts. Parallel catalog and specification updates within the therapeutic and professional-use segment demonstrate continued alignment with recognized quality and regulatory expectations, ensuring that refill options and device-compatible inputs maintain compatibility with established compliance standards. These developments collectively illustrate a market in which technical differentiation, documentation rigor, and capacity alignment increasingly determine commercial outcomes.
Paraffin Wax Market
Worldwide Paraffin Phase Change Material (PCM) Market
Regulatory, Material, and Operational Dynamics
Market behavior cannot be separated from the compliance environment and operating cost structures that shape procurement decisions. Paraffin wax applications used in occupational therapy and related therapeutic settings operate within defined classification frameworks that distinguish first-aid heat treatments from procedures requiring formal medical recordkeeping, influencing how providers structure procurement and usage protocols. At the same time, any paraffin wax destined for medical device consumables or histology workflows must satisfy international quality and traceability expectations, with ISO 13485 serving as a critical benchmark for documentation, quality control, and supply chain accountability.
Material cost and operational considerations further complicate segment economics. Facilities engaged in medical-grade or histology-related utilization must account for sanitization protocols, disposable liner requirements, and routine replacement cycles, all of which contribute to total cost of ownership beyond base material pricing. Medical-grade paraffin wax itself is characterized by elevated purity, stable melting behavior, and favorable permeability, attributes that directly support tissue embedding, slide preparation, and cellular pathology workflows. These technical and compliance factors interact with procurement strategy, making specification clarity and supplier qualification decisive variables in vendor selection and long-term contracting.
Strategic Decision Framework for 2026 and Beyond
Translating market intelligence into competitive advantage requires a structured approach that aligns market trajectory with internal capability and risk tolerance. Our report is designed to support that translation across three core planning dimensions. First, it delivers a decision-grade forecast architecture that connects baseline momentum to multi-year projections, enabling leadership teams to evaluate capacity timing, inventory positioning, and regional prioritization with greater confidence. Second, it breaks down segmentation complexity in a way that reveals substitution pathways, specification sensitivity, and demand concentration patterns without relying on superficial splits that obscure operational realities.
Third, the study incorporates competitive and developmental intelligence to help organizations anticipate supplier behavior, gauge consolidation risk, and identify partnership or sourcing opportunities before shift patterns become fully priced into the market. Combined with regulatory and operating-cost context, this provides a practical basis for scenario planning across procurement, product development, and market-entry decisions. In an environment where quality documentation, traceability, and application compatibility increasingly determine commercial viability, the ability to distinguish structural growth from temporary fluctuation is a strategic necessity.
Report Scope and Analytical Coverage
This research deliverable is structured to support both executive briefing and operational planning. It integrates historical performance, forward projections, segmentation logic, competitive profiling, and recent development tracking into a single analytical framework that can be applied across strategy, procurement, and business development functions. The study includes detailed examination of refinement categories, application pathways, and regional demand dynamics, along with supplier positioning that highlights differentiation drivers, compliance alignment, and distribution reach.
It also incorporates development tracking across facility modernization, portfolio expansion, product delivery activity, and specification updates, allowing readers to connect discrete events with broader market momentum. Operational and regulatory context is embedded throughout, ensuring that market sizing and competitive assessment are interpreted within the practical constraints that shape end-use requirements and total cost considerations. The result is a comprehensive reference document designed to support high-stakes decisions in a market where precision, traceability, and strategic timing increasingly define competitive outcomes.
Organizations seeking to align near-term sourcing and product decisions with longer-horizon growth trajectories will find the full dataset, segmentation architecture, and competitive mapping essential to disciplined planning. This report provides the analytical foundation required to convert market momentum into defensible strategy throughout the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capsule Filling Machines Market to Reach $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence Brief: Capsule Filling Machines Market 2026–2032
Executive Overview
The global capsule filling machines market stands at a critical inflection point as manufacturers navigate tightening regulatory frameworks, evolving product formats, and intensifying capacity demands across pharmaceutical, nutraceutical, and cosmetic sectors. Our latest market research delivers a comprehensive, forward-looking intelligence framework designed specifically for executive decision-makers, procurement leaders, and business development strategists operating within the 2026–2032 forecast horizon.
Drawing on a rigorous historical analysis spanning 2020 through 2025, the study establishes a clear trajectory of sustained expansion. The market has consistently demonstrated resilient growth, with the base year valuation reflecting steady industrial adoption and cross-sector formulation complexity. As we project forward, the forecast period captures a measured but unmistakable acceleration, anchored by a compound annual growth rate of 6.98 percent. By 2032, the sector is positioned to reach a substantially elevated revenue threshold, underscoring the strategic imperative for stakeholders who must align capital expenditure, technology procurement, and regional deployment strategies with verifiable market signals rather than speculative assumptions.
This research is crafted as a decision-enabling instrument. It translates macro-level momentum into actionable intelligence, mapping the structural forces that will define competitive positioning, supply chain resilience, and operational scalability throughout the remainder of the decade.
Market Dynamics & Regulatory Architecture
Regulatory compliance has evolved from a baseline operational requirement to a central driver of equipment specification, vendor selection, and facility design. Pharmaceutical manufacturers continue to operate under stringent current Good Manufacturing Practice mandates that dictate sanitary design, routine calibration protocols, inspection schedules, and maintenance rigor. Dietary supplement and nutraceutical formulators face parallel expectations, with quality management and food safety certifications now serving as non-negotiable prerequisites for market access. Equipment suppliers must demonstrate conformance across multiple certification standards to maintain eligibility for regulated production environments, and procurement teams increasingly evaluate vendor documentation as a primary filter before technical evaluation begins.
Beyond product-grade regulations, equipment transactions themselves are shaped by compliance reporting obligations that affect cross-border procurement cycles, import-export workflows, and domestic supply arrangements. Electronic reporting requirements for specific equipment categories have matured into standardized administrative processes that procurement and logistics teams must integrate into their acquisition timelines. Equipment safety, operator protection, and sanitation protocols further dictate facility layout considerations, environmental controls, and validation workflows. The cumulative effect is a procurement environment where regulatory readiness directly influences total cost of ownership, deployment speed, and long-term operational continuity.
Simultaneously, market concentration remains relatively moderate, indicating a fragmented but actively consolidating competitive field. This structure rewards organizations that can differentiate through dosing precision, format versatility, validation support, and service responsiveness. The research examines how these dynamics shape purchasing behavior, upgrade cycles, and strategic partnerships across production scales, from high-throughput commercial lines to specialized multi-format operations.
Segmentation Intelligence & Structural Shifts
The market is defined by three interrelated segmentation dimensions that collectively determine equipment performance requirements, capital allocation patterns, and end-use deployment logic. The research deconstructs each dimension to reveal how purchasing priorities are shifting and where hidden risk or opportunity may reside.
Equipment Type Architecture
The type-based breakdown captures the balance between fully automated throughput systems, semi-automated hybrid configurations, and manual-scale units. As formulation complexity increases and batch variability demands tighter control, procurement decisions are increasingly influenced by throughput targets, changeover flexibility, and integration with downstream packaging and quality control workflows. The study analyzes how these type-level preferences differ across production volumes and how manufacturers evaluate automation roadmaps relative to labor constraints, validation burdens, and aggregation of multiple fill formats within a single line.
Application-Driven Demand Patterns
Demand across pharmaceutical, nutraceutical, and cosmetic applications continues to diverge in terms of speed, precision tolerance, material compatibility, and compliance documentation. Pharmaceutical applications remain the most demanding in terms of validation, repeatability, and regulatory traceability. Nutraceutical and supplement production has expanded the relevance of formats that support powders, pellets, tablets, mini-tablets, and multi-fill configurations. Cosmetic applications increasingly intersect with broader encapsulation requirements, bringing additional material-handling considerations into equipment selection. The report examines how these application-specific requirements influence technology roadmaps and how manufacturers position their equipment portfolios to capture cross-application demand without compromising compliance or throughput.
Regional Growth Architecture
Regional analysis within the study reveals how geographic demand concentration, manufacturing footprints, and regulatory environments shape deployment strategies. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region each present distinct procurement rhythms, capacity expansion priorities, and localization considerations. The research maps these regional dynamics to help stakeholders anticipate where demand is intensifying, where competitive pressure is building, and where supply chain alignment may require localized service, support, or sourcing strategies. Detailed regional valuations and split-level figures are reserved for the full dataset, where they are presented with the granularity required for territory-specific planning.
Competitive Landscape & Strategic Positioning
The competitive environment is shaped by a diverse set of global and regional manufacturers, each emphasizing distinct technological strengths, compliance credentials, and application coverage. The research profiles leading participants and evaluates how their equipment families, product launches, and market messaging align with prevailing buyer priorities.
Syntegon Technology continues to emphasize high-volume pharmaceutical and nutraceutical production through precision dosing and throughput-oriented capsule filling platforms, reinforcing its positioning for large-scale, validated production environments. IMA Group maintains a strong presence with rotary and suction bowl systems engineered for advanced dosing flexibility and high-speed operation, appealing to manufacturers seeking throughput maximization with adjustable fill control. MG2 S.r.l. has expanded its relevance through multi-format support spanning powders, pellets, tablets, mini-tablets, and capsule-in-capsule applications, while maintaining strong compliance alignment for regulated markets. ACG Worldwide focuses on integrated solutions that prioritize simplicity, safety, and efficiency for pharmaceutical and nutraceutical use, targeting operational reliability and deployment practicality. Harro Höfliger Verpackungsmaschinen GmbH addresses high-efficiency pharmaceutical production lines with integrated capsule filling and packaging system perspectives, supporting end-to-end line optimization. Qualicaps Co., Ltd. provides encapsulation technology solutions for global pharmaceutical manufacturers, reinforcing the importance of technical partnership and application-specific engineering. Torpac Inc. and Index Capsule Fillers continue to serve pharmaceutical and nutraceutical segments with equipment and service offerings that emphasize regional availability and operational support. Capsugel, operating under the Lonza Group, contributes specialized expertise in hard capsule filling and drug delivery-focused encapsulation systems. Dott Bonapace reinforces the automatic capsule filling segment for pharmaceutical and supplement production with dedicated machine families. Finetech Pharmaceutical Equipment and Feton International Ltd. represent important contributions from Asian manufacturing bases, with Finetech advancing semi-automatic and hybrid-automation configurations and Feton covering both industrial and laboratory-scale capsule filling equipment for pharmaceuticals and supplements.
Recent product activity underscores the speed at which vendor portfolios are evolving. Finetech Pharmaceutical Equipment introduced new technology for its NJP-1200 capsule filling equipment to improve precision and efficiency in pharmaceutical manufacturing. MG2 S.r.l. launched the Experta model within its E Series, emphasizing human-centered design, advanced dosing combinations, and weight control systems. MG2 also debuted the IN-CAP SE automatic capsule filling machine at a major trade fair, highlighting support for multiple fill types with strong compliance alignment and practical throughput characteristics for targeted application segments. These developments illustrate how vendors are responding to demand for controlled weight consistency, format versatility, operator ergonomics, and faster integration into modern production environments.
The report situates these company-level movements within a broader competitive framework, allowing readers to assess where differentiation is emerging, where service and validation capabilities may become deciding factors, and how vendor concentration may shift over the forecast period.
Report Architecture & Decision Utility
This market research is structured to support both strategic planning and operational execution. The study integrates historical performance analysis, forward-looking forecasts, segmentation evaluation, competitive profiling, regulatory context, and recent market developments into a unified intelligence package. Readers will find detailed coverage of market sizing across the historical window and forecast horizon, equipment type distributions, application-level demand behavior, and regional deployment patterns. The report also maps the competitive field through company profiles, recent product activity, and strategic positioning analysis, enabling procurement and business development teams to benchmark vendor options against operational requirements.
Capsule Filling Equipment Market
Beyond quantitative coverage, the research provides interpretive frameworks for evaluating equipment selection criteria, compliance readiness, total cost of ownership considerations, and deployment risk. It examines how automation adoption interacts with validation demands, how format flexibility influences multi-product operations, and how regional demand variations shape sourcing and service strategies. The analysis is designed to support capital planning, vendor shortlisting, regional expansion decisions, and technology roadmap development across pharmaceutical, nutraceutical, and cosmetic manufacturing organizations.
Strategic Implications for 2026 Decision-Makers
For leaders making capital allocation, procurement, and expansion decisions in 2026, the market research offers several strategic advantages. First, it converts broad growth momentum into structured evidence that can support internal business cases and investment approvals. Second, it clarifies how regulatory expectations now influence not only product manufacturing but also equipment acquisition, documentation, and long-term compliance sustainability. Third, it reveals how vendor innovation is reshaping buyer expectations around dosing control, format versatility, line integration, and operational ergonomics. Fourth, it provides a competitive map that helps organizations anticipate supplier differentiation strategies and evaluate where service, support, and validation capabilities may become decisive in multi-vendor evaluations.
The research is particularly relevant for manufacturers planning capacity upgrades, multi-format expansion, compliance hardening, or regional sourcing shifts. It also supports suppliers and investors seeking to understand where demand intensity, technology differentiation, and competitive pressure are likely to converge over the next several years.
Conclusion
The capsule filling machines market is advancing through a period defined by regulatory rigor, format diversification, and sustained demand expansion. Organizations that approach procurement and strategy with granular, forward-looking intelligence will be better positioned to manage compliance exposure, optimize throughput, and align equipment investments with long-term production objectives. This report delivers the analytical depth required to make those decisions with confidence.
Capsule Filling Machines Market
For complete market sizing, segmentation breakdowns, company-level assessments, regulatory mappings, and forecast tables, please access the full study on the PW Consulting research portal. Detailed quantitative data and comprehensive segmentation splits are available in the complete report.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


