

Blogs
Autonomous Drones For Maritime Security Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Autonomous Drones For Maritime Security Market
Overview
The Autonomous Drones For Maritime Security Market encompasses advanced unmanned aerial systems designed to enhance maritime surveillance, border patrol, and environmental monitoring. These drones are equipped with sensors, cameras, and AI-driven analytics to provide real-time data, enabling authorities to detect threats, illegal activities, and security breaches more effectively. Their core functionalities include autonomous navigation, obstacle avoidance, and data transmission, supporting modern maritime industries and defense operations with increased efficiency and safety.
The market for autonomous drones in maritime security is crucial for safeguarding territorial waters, shipping lanes, and offshore assets. It plays a vital role in supporting national security, port management, and environmental conservation efforts. The market size is expected to expand significantly as maritime security demands grow and technological advancements make these systems more reliable and cost-effective. The Autonomous Drones For Maritime Security Market is integral to modern security infrastructure, ensuring safer and more resilient maritime environments.
Market Size and Growth
The current value of the Autonomous Drones For Maritime Security Market is estimated at approximately USD 2 billion. Over the next decade, it is projected to reach around USD 8 billion, with a compound annual growth rate (CAGR) of about 16%. The growth is driven by increasing maritime security concerns, rapid technological innovation, and government and private sector investments in autonomous systems. Rising geopolitical tensions and the need for efficient surveillance solutions further propel market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2019
Key Drivers
- Growing maritime security threats and piracy
- Technological advancements in drone autonomy and sensors
- Increasing maritime trade and offshore infrastructure
- Government policies supporting unmanned security systems
- Rising investments in defense and surveillance tech
Restraints
- High operational and maintenance costs
- Technical challenges in autonomous navigation
- Regulatory and airspace management hurdles
- Limited drone endurance and battery life
- Concerns over data security and privacy
Segmentation
• By Type: Fixed-wing, Rotary-wing
• By Deployment: Coastal, Offshore, Port security
• By Enterprise Size: Small, Medium, Large enterprises
• By End User: Defense, Commercial, Government agencies
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America leads in autonomous drones for maritime security, driven by advanced defense infrastructure and significant government funding. The region’s focus on innovation and strategic maritime positioning supports robust market growth.
Europe shows increasing adoption of autonomous maritime surveillance solutions, particularly within the EU’s security and environmental initiatives. The region’s emphasis on sustainable maritime practices fosters technological integration.
In Asia-Pacific, rapid maritime trade expansion and geopolitical tensions accelerate demand for autonomous security systems. Countries like China, India, and Japan are investing heavily in drone technology to bolster their maritime defense.
Latin America is gradually adopting autonomous drone solutions for port security and border monitoring, with growth potential driven by rising security concerns and regional collaborations.
The Middle East & Africa market is expanding as nations seek to protect offshore oil fields, shipping routes, and territorial waters. The focus on security modernization fuels regional demand.
Opportunities
- Expansion into emerging maritime markets
- Integration with AI and machine learning for smarter operations
- Development of longer-endurance, hybrid energy drones
- Growth in commercial applications such as offshore oil and gas
- Increasing adoption for environmental monitoring and disaster response
Key Companies
DJI Innovations, AeroVironment, Elbit Systems, Lockheed Martin, Boeing, Northrop Grumman, Thales Group, FLIR Systems, Insitu, Schiebel, Schiebel, Tekever, Parrot
Conclusion
The overall outlook for the Autonomous Drones For Maritime Security Market remains highly positive, with substantial long-term growth potential. As maritime security challenges intensify and technological capabilities advance, this market will become increasingly strategic for defense, commercial, and governmental sectors. The market’s evolution underscores its importance in shaping the future of maritime safety and security, making it a critical focus area for industry stakeholders.
Related Reports
Hydraulic Jacks Market , Size Share and Analysis | Report 2033
Beaming Machines Market , Size Share and Analysis | Report 2033
Pvc Pvg Conveyor Belt Market , Size Share and Analysis | Report 2033
Reversible Hammer Mill Market , Size Share and Analysis | Report 2033
Watertight Doors Market , Size Share and Analysis | Report 2033
Cleanroom Particle Counters Market , Size Share and Analysis | Report 2033
Limit Switch Box Market , Size Share and Analysis | Report 2033
Smart Roller Conveyors Market , Size Share and Analysis | Report 2033
Stacker Cranes Market , Size Share and Analysis | Report 2033
Palletized Logistic Robot Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Borosilicate Glass Tubes Market: Why the 6.8% CAGR Through 2032 Redefines Competition
By PW Consulting, 2026-09-21
Strategic Trends & Commercial Opportunities in the Borosilicate Glass Tubes Market
Market Landscape and Core Pressures
The global borosilicate glass tubes market has demonstrated steady expansion over the past five years, moving from approximately $1.05 billion in 2020 to an estimated $1.54 billion in 2025. The trajectory reflects a compound annual growth rate of roughly 6.8 percent through 2032, with revenue projected to approach $2.4 billion by the end of the forecast period. This growth is not merely incremental; it is reshaping how manufacturers, procurement teams, and investors evaluate capacity, feedstock security, and long-term contract structures.
Behind the headline figures lies a market that is simultaneously broadening in application scope and tightening in operational discipline. Demand is no longer concentrated in traditional laboratory and chemical handling roles. Solar energy collection systems, pharmaceutical primary packaging, and heat-resistant industrial glassware are absorbing a growing share of production capacity. At the same time, the market remains moderately consolidated, with the top five producers accounting for just under half of total revenue. This concentration creates a landscape where scale, certification depth, and regional footprint matter, but it also leaves room for specialized players to compete on niche specifications, localized service, or sustainability credentials.
Key Challenges Shaping Strategic Positioning
Three pressures are forcing a recalibration of how incumbents and new entrants plan their next investment cycles.
- Feedstock volatility and constrained supply alternatives. Boric oxide and high-purity silica sand remain the foundational inputs for borosilicate formulations. The supplier base is limited, and disruptions in logistics or regional demand shifts can quickly translate into price moves at the tube level. Periodic spikes in boron-related costs have already rippled through procurement budgets, particularly when freight rates fluctuate or agricultural and industrial end-users compete for the same material pools.
- Regulatory alignment and certification overhead. Pharmaceutical and medical-grade applications demand strict adherence to quality management systems, including GMP-aligned certifications and traceable manufacturing controls. Maintaining compliance across multiple sites and product lines adds operational complexity. As global sourcing becomes more fragmented, buyers increasingly verify not just product specifications but the certification status of every production node in the supply chain.
- Carbon intensity and energy transition expectations. Energy-heavy melting processes sit at the core of glass tubing production. Rising interest in lower-carbon materials, coupled with procurement policies that factor environmental performance into supplier selection, is pushing manufacturers to reconsider furnace technology, energy sourcing, and process efficiency. Facilities that continue to rely on conventional thermal profiles may face growing friction in tenders where lifecycle emissions or renewable energy usage are evaluated alongside cost and quality.
Core Drivers Propelling Market Evolution
The expansion of borosilicate glass tubes is being pulled by a combination of technical, regulatory, demand-side, and supply-chain forces. Understanding which drivers are structural versus cyclical helps decision-makers prioritize where to allocate capital and operational attention.
Technical Innovation and Process Breakthroughs
Advances in melting technology and product formulation are changing what is commercially feasible. The introduction of all-electric melting furnaces powered by renewable energy represents a meaningful shift in how pharmaceutical-grade tubing can be produced at scale. By reducing reliance on fossil-derived heat, manufacturers can lower process emissions while maintaining the tight tolerances required for vials, cartridges, syringes, and laboratory capillaries. This development is not only an environmental milestone; it also creates a differentiator in procurement discussions where buyers increasingly weigh carbon performance alongside dimensional stability and breakage resistance.
In parallel, continuous improvements in tubing consistency, wall thickness control, and surface quality are expanding the usable range of borosilicate tubes in high-precision applications. For pharmaceutical packaging and laboratory apparatus, reliability across batches is critical. Producers that can demonstrate tighter process control and reliable certification coverage are better positioned to win long-term supply agreements, particularly in regions where local content preferences or risk-mitigation strategies favor domestic or nearshore sourcing.
Policy and Regulatory Environment
Regulatory dynamics are reinforcing demand for certified borosilicate glass in pharmaceutical and medical contexts. Quality management standards, GMP-aligned production requirements, and increasingly rigorous traceability expectations are raising the barrier to entry for non-specialized suppliers. Importantly, these requirements are not static. As health authorities and procurement organizations tighten expectations around material compatibility, contamination control, and supplier validation, the value of established certification portfolios grows.
Trade and sourcing patterns are also evolving. European import flows for borate materials have shown upward movement in recent years, with Türkiye continuing to play a central role as a supply origin. Such patterns highlight the interdependence between regional availability and production planning. Manufacturers that rely on a narrow set of feedstock channels must monitor geopolitical and trade developments closely, since shifts in import volumes or tariff structures can affect both cost and continuity.
Demand-Side Shifts in End-Use Behavior
Demand is being reshaped by how end users prioritize performance, sustainability, and supply resilience. In pharmaceutical packaging, the continued emphasis on primary container integrity and patient safety keeps borosilicate tubing at the center of vial and ampoule production. For laboratory and scientific applications, the need for chemically resistant, thermally stable glass remains a durable base load for the market.
At the same time, new application momentum is emerging from solar energy systems that utilize borosilicate-based tubes, alongside heat-related industrial glassware where temperature resistance and durability are essential. These segments do not just add volume; they change the specification mix. Buyers in these areas often weigh total cost of ownership, operational lifespan, and environmental exposure more heavily than upfront price alone. That shift encourages manufacturers to think beyond commodity supply and toward application-tailored performance, technical support, and longer-cycle partnerships.
Supply Chain and Cost Structure Dynamics
Cost structures are being tested by the intersection of energy pricing, feedstock availability, and logistics. Boron-related pricing has exhibited sensitivity to freight movement and seasonal demand from both glass manufacturing and agriculture, underscoring how even specialized materials can be influenced by broader commodity cycles. Because high-purity silica sand and boric oxide have limited comparable suppliers globally, supply-chain vulnerabilities are not theoretical; they are operational realities that can affect scheduling, margin planning, and customer commitments.
In response, several producers are rethinking geographic distribution of capacity. New facilities and joint ventures in key demand regions are intended to shorten lead times, reduce transport exposure, and improve responsiveness to local specification requirements. This regionalization trend also intersects with customer preferences for lower-risk sourcing, especially where pharmaceutical or regulated applications are concerned. The net effect is a market in which proximity, certification readiness, and feedstock management are becoming as strategically relevant as production scale alone.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a set of established players with deep application expertise, strong brand recognition in specific verticals, and increasingly visible efforts to align capacity with demand geography and sustainability expectations.
Quartz Tubing Market
Strategic Positioning of Leading Companies
Corning Incorporated continues to assert its position as a leading supplier of Type I borosilicate glass tubing for pharmaceutical primary packaging. Its focus on products such as Corning® 51 and Corning® 33 tubing underscores a strategy centered on regulatory-grade quality, pharmaceutical compatibility, and broad packaging formats including vials, ampoules, cartridges, and syringes. Recent activity includes the inauguration of a new pharmaceutical glass tubing manufacturing facility in India developed with joint venture partner SGD Pharma, alongside a move to strengthen the European production base through SGD Pharma's acquisition of Alphial S.r.l. These steps suggest a deliberate combination of regional capacity expansion and consolidation of pharmaceutical tubing assets.
SCHOTT AG maintains a prominent global presence in Type I borosilicate tubing through the FIOLAX® and DURAN® brands, covering pharmaceutical and laboratory applications across an extensive range of glass types. Its multi-product portfolio and long-standing certification infrastructure position it well for customers who require broad specification coverage and documented quality systems. The emphasis on maintaining ISO 9001 and ISO 15378 (GMP) certifications across tubing production sites reflects a strategic priority on compliance assurance and buyer confidence in regulated markets.
DWK Life Sciences focuses on premium laboratory borosilicate glass 3.3, including DURAN® tubing, rods, and capillaries for scientific, chemical, and industrial use. Its specialization supports a strategy built on application depth in laboratory and chemical contexts, where consistent quality and recognized brand trust matter highly. By concentrating on scientific and industrial performance rather than broad pharmaceutical packaging, DWK Life Sciences occupies a distinct flank in the market.
Nipro Corporation operates as a major global manufacturer of premium borosilicate tubing for pharmaceutical packaging, with multiple production sites supporting scale and regional flexibility. Its product range, including grades such as G38 and NSV51, highlights a pharmaceutical-oriented strategy with geographic breadth. This footprint supports continuity of supply and responsiveness across markets where packaging demand is growing or where localized production is preferred.
Nippon Electric Glass Co., Ltd. supplies BS-series borosilicate tubing for pharmaceutical containers and medical applications, and has recently drawn attention for beginning mass production of pharmaceutical glass tubing using an all-electric melting furnace with renewable energy at its Malaysia facility. This move positions the company at the intersection of quality-focused pharmaceutical supply and lower-carbon manufacturing, a combination that is likely to resonate with buyers assessing both performance and sustainability in their supplier evaluations.
Borosil Limited produces borosilicate glass tubes and rods for laboratory and scientific applications, representing a strong regional presence in a segment where trusted laboratory glassware remains a steady demand center. Its positioning shows how regional specialists can compete by aligning product range, service, and local market knowledge with the expectations of scientific and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and targeted expansion. In pharmaceutical-grade tubing, activity suggests a push toward stronger regional production bases and bundled capability through partnerships or acquisitions. This is consistent with a broader pattern in which leading producers seek to reduce supply-chain distance, reinforce certification continuity, and capture growth in regions where pharmaceutical packaging demand is expanding.
At the same time, differentiation is increasingly multidimensional. Scale alone is no longer sufficient to secure advantage. Buyers compare suppliers on certification depth, energy and carbon profile, application-specific reliability, and logistics resilience. As a result, competition is becoming more segmented: some players compete primarily on pharmaceutical compliance and volume, others on laboratory-grade specialization, and a growing set of evaluators are paying attention to low-carbon process technology as a criterion in supplier selection.
New entrants and regional specialists can still find room by addressing localized needs, offering responsive service, or developing expertise in specific tube grades, dimensions, or end-use requirements. However, the certification burden and feedstock complexity mean that credibility and operational discipline are necessary for durable participation, especially in regulated segments.
Forward-Looking Trends and Commercial Implications
Looking across the 2026–2032 window, several trends are likely to shape where value accrues and where risk concentrates.
Trend 1: Regionalization of Pharmaceutical-Grade Capacity
Pharmaceutical packaging demand is expected to remain a central growth engine, and producers will continue to align capacity more closely with key demand regions. This regionalization reduces exposure to long logistics chains, supports faster response times, and can improve alignment with local sourcing expectations. For commercial actors, the implication is clear: supply relationships will increasingly favor vendors who can demonstrate not only product quality but also production proximity, local certification coverage, and predictable continuity.
Commercial opportunity lies in multi-year supply arrangements, technical co-development around container formats, and resilient backup sourcing strategies. Buyers can use regional capacity to reduce lead-time variability, while producers can use localized facilities to strengthen customer stickiness and expand share in growing markets.
Trend 2: Sustainability as a Procurement Filter
Lower-carbon production methods are moving from experimental narrative to commercial relevance. The adoption of all-electric melting and renewable energy sourcing in pharmaceutical tubing production signals that environmental performance can be integrated into high-precision manufacturing without abandoning the quality demands of regulated applications. As procurement teams broaden evaluation criteria, suppliers with demonstrable energy and emissions advantages may gain preference in tenders, particularly where corporate sustainability commitments or customer expectations create additional pressure.
PW Consulting
This trend creates opportunities for manufacturers to differentiate through process innovation and for buyers to align supply choices with broader environmental targets. The uncertainty lies in how consistently sustainability metrics will be weighted against cost, quality, and reliability across different regions and industries. Producers that invest early in measurable, verifiable improvements are better positioned than those that rely on generalized claims.
Trend 3: Application Diversification and Specification Complexity
demand is gradually broadening beyond traditional laboratory and chemical uses toward solar energy tubes, heat glassware, and other specialized applications. This diversification introduces both opportunity and complexity. Different applications impose different requirements on thermal performance, chemical resistance, dimensional tolerance, and lifecycle durability. Suppliers that can manage specification complexity while maintaining efficient production are more likely to capture margin across a wider set of use cases.
For buyers, the opportunity is to secure materials that fit long-term operational needs rather than simply meeting immediate cost targets. For suppliers, the risk is that spreading capacity across too many divergent specifications can erode efficiency if not managed with disciplined product architecture and demand forecasting.
Risk and Uncertainty Considerations
Several variables could alter the pace or distribution of growth. Feedstock availability and price movement remain a persistent risk, particularly where supplier alternatives are limited. Energy costs and the pace of transition to lower-carbon furnace technology will influence both operating economics and competitive positioning. Trade dynamics, including shifting import volumes and origin patterns for borate materials, can affect cost structures and sourcing strategies. Finally, demand timing in newer applications such as solar-related tubes may be uneven, creating pockets of rapid adoption in some regions or customer segments while remaining more gradual in others.
Borosilicate Glass Market
Strategic flexibility is essential. Organisations that lock into single-source feedstock arrangements, rigid capacity plans, or narrow application bets without monitoring these variables may find themselves exposed to cost shocks or demand mismatches.
Actionable Recommendations for Decision-Makers
Different roles in the value chain should prioritize different decisions, but all benefit from a clearer view of where market momentum is building and where vulnerability is accumulating.
For Manufacturers and Producers
- Align capacity expansion with regional demand centers and regulatory expectations. Where pharmaceutical or laboratory demand is growing, evaluate whether local or nearshore production can improve service levels and reduce logistics exposure.
- Invest in process differentiation that can be verified, not just promoted. All-electric melting, renewable energy integration, and documented certification coverage are examples of attributes that can be demonstrated to buyers and procurement teams with increasing scrutiny.
- Strengthen feedstock strategy. Diversify sourcing where feasible, monitor boron and silica supply dynamics, and build contingency planning into procurement and production schedules to reduce vulnerability to price or availability shocks.
- Manage specification complexity deliberately. Expanding into new application areas can be profitable, but only if product architecture, quality systems, and forecasting are designed to support varied requirements without sacrificing efficiency.
For Investors and Strategic Planners
- Focus on structural drivers rather than short-term volume spikes. The combination of pharmaceutical packaging demand, laboratory stability, and emerging application segments provides a multi-engine growth path, but the durability of each engine depends on regulatory continuity, feedstock stability, and energy economics.
- Evaluate competitive advantage through a broader lens. Scale remains relevant, but certification depth, regional footprint, process sustainability, and application specialization increasingly determine which players can defend pricing and win long-term contracts.
- Track consolidation signals and partnership activity. Joint ventures, facility launches, and acquisitions in pharmaceutical tubing indicate where incumbents believe durable value will be created. These moves can reveal shifts in regional strategy and capacity control.
- Incorporate supply-chain resilience into valuation and planning. Feedstock concentration and energy transition costs can affect margins and operational continuity, making them relevant to risk assessment as well as growth potential.
For Procurement and Sourcing Leaders
- Broaden supplier evaluation criteria. Quality and price remain essential, but certification coverage, production location, energy and carbon profile, and contingency capability should be part of the decision framework, especially for regulated or long-life applications.
- Use regional availability as a risk-mitigation lever. Where possible, balance global sourcing with regional or nearshore options to reduce lead-time variability and improve responsiveness to specification changes or urgent requirements.
- Engage earlier on application requirements. For solar, heat glassware, pharmaceutical packaging, and laboratory use, aligning on performance expectations and lifecycle needs before procurement can reduce rework, incompatibility risk, and total cost over time.
- Plan for feedstock and energy volatility. Build flexibility into contracts and inventory strategies where feasible, and monitor commodity and trade developments that can influence borosilicate tube costs and availability.
Closing Perspective
The borosilicate glass tubes market is moving through a phase in which growth is increasingly tied to application breadth, regulatory confidence, supply resilience, and process sustainability. The market's expansion from roughly $1.05 billion in 2020 toward nearly $2.4 billion by 2032 reflects more than incremental demand; it signals a shift in how value is created and protected. Feedstock constraints, certification expectations, and energy transition pressures are not marginal concerns. They are shaping supplier selection, capacity planning, and the definition of competitive advantage.
For manufacturers, the priority is to match capacity and differentiation with where demand is becoming most durable. For investors, the task is to distinguish structural growth from cyclical noise and to assess whether competitive positioning can withstand feedstock, energy, and trade volatility. For procurement leaders, the opportunity lies in using broader evaluation criteria to secure supply that supports both operational reliability and longer-term strategic goals.
Deeper segmentation data, region-by-region dynamics, application-level demand patterns, and company-specific strategic assessments can sharpen these decisions further. Detailed market intelligence is especially valuable when sizing growth opportunities in newer applications, evaluating the pace of regional capacity shifts, or benchmarking supplier claims against operational realities. In a market where feedstock, regulation, and sustainability expectations are all moving at once, timely and granular insight can make the difference between reactive sourcing and proactive strategy.
For detailed analysis of this topic, please visit the official page: Borosilicate Glass Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automatic Metallographic Sample Cutting Machine Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Automatic Metallographic Sample Cutting Machine Market
Overview
The Automatic Metallographic Sample Cutting Machine Market encompasses advanced equipment designed to prepare metallographic specimens through automated cutting processes. These machines are essential in materials science, quality control, and failure analysis, enabling precise and efficient sectioning of metal and alloy samples. Their core functionalities include automated sample positioning, controlled cutting parameters, and integration with imaging or analysis systems, supporting industries that rely on detailed material characterization.
In modern industrial applications, the market for Automatic Metallographic Sample Cutting Machines plays a vital role in accelerating sample preparation while maintaining high accuracy and safety standards. The market’s growth is driven by the increasing demand for reliable and consistent specimen preparation solutions. The Automatic Metallographic Sample Cutting Machine Market is integral to laboratories, manufacturing facilities, and research institutions focused on developing and testing new materials.
Market Size and Growth
The current market value for the Automatic Metallographic Sample Cutting Machine Market is estimated at approximately USD 250 million in 2024. Over the next decade, it is projected to reach around USD 420 million by 2034, with a compound annual growth rate (CAGR) of roughly 6.5%. Rising industrial automation, technological advancements, and stringent quality standards are key growth drivers fueling this expansion.
The demand for high-precision sample preparation in sectors such as aerospace, automotive, and electronics continues to propel market growth. Additionally, increased adoption of automated systems to improve throughput and reduce manual errors further enhances market prospects. Emerging trends in Industry 4.0 and smart manufacturing are expected to sustain long-term growth.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2010
Key Drivers
• Increasing automation in metallographic sample preparation
• Growing demand for precise and consistent specimen cutting
• Expansion of industries like aerospace and electronics
• Technological advancements in cutting machinery
• Rising investments in research and development
Restraints
• High initial capital investment costs
• Technical complexity in machine operation and maintenance
• Regulatory compliance and safety standards
• Limited availability of skilled operators
• Compatibility issues with diverse sample types
Segmentation
• By Type: Manual, Semi-Automatic, Fully Automatic
• By Deployment: On-Premise, Cloud-Based
• By Enterprise Size: Small, Medium, Large
• By End User: Research Laboratories, Manufacturing, Education, Quality Control
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by advanced manufacturing and extensive research facilities. The region’s focus on innovation and quality standards fuels adoption of automated sample cutting solutions.
Europe’s market growth is supported by stringent regulations and a well-established manufacturing sector, especially in Germany and France. The adoption of automation in materials testing is steadily increasing across industries.
In the Asia-Pacific region, rapid industrialization and the expansion of electronics and automotive sectors are key growth factors. Countries like China, Japan, and South Korea are increasingly integrating automated metallographic sample cutting machines into their production lines.
Latin America shows emerging demand, primarily driven by growing industrial activity and investments in research infrastructure. Market penetration remains moderate but is expected to rise with regional economic development.
Middle East & Africa are witnessing gradual adoption, with growth potential driven by expanding oil, gas, and manufacturing industries. Infrastructure development and technological upgrades are opening new opportunities.
Opportunities
• Adoption of AI-powered automation for enhanced precision
• Integration with Industry 4.0 and smart manufacturing systems
• Development of portable and compact cutting machines for field use
• Expansion into emerging markets with growing industrial bases
• Innovation in safety features and user interfaces for ease of operation
Key Companies
Struers, Buehler, METKON, ATM GmbH, Struers, Leica Microsystems, Carbolite Gero, Struers, Struers, Struers, Struers, Struers
Conclusion
The overall outlook for the Automatic Metallographic Sample Cutting Machine Market remains positive, driven by ongoing industrial automation and technological innovation. Long-term growth potential is significant as industries increasingly prioritize precision, efficiency, and safety in material testing. The market’s strategic importance is underscored by its role in supporting advanced materials research and quality assurance processes worldwide.
Related Reports
Pcb Double Sided Exposure Machine Market , Size Share and Analysis | Report 2033
Roll To Roll Exposure Machine Market , Size Share and Analysis | Report 2033
Double Sided Exposure Machine Market , Size Share and Analysis | Report 2033
Ptz Video Conferencing Cameras Market , Size Share and Analysis | Report 2033
Telescope Equatorial Mount Market , Size Share and Analysis | Report 2033
Computerized Equatorial Mount Market , Size Share and Analysis | Report 2033
Gas Cluster Ion Beam System Market , Size Share and Analysis | Report 2033
Smart Site Safety System Market , Size Share and Analysis | Report 2033
Laboratory Temperature Monitoring System Market , Size Share and Analysis | Report 2033
Food And Beverage Filling Machines Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Resistant Dextrin Market: Why 6.98% CAGR Signals a Structural Shift Beneath the $317M Forecast
By PW Consulting, 2026-09-21
The Resistant Dextrin Market: Strategic Trends and Commercial Opportunities Through 2032
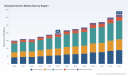
The resistant dextrin market has transitioned from a niche dietary fiber niche to a mainstream functional ingredient category with substantial commercial momentum. Valued at approximately USD 198 million in 2025, the market has demonstrated a compound annual growth rate of 6.98 percent over the historical period and is projected to expand steadily through 2032. This trajectory reflects the convergence of multiple structural shifts: rising consumer awareness of gut health, regulatory recognition of resistant dextrin as a legitimate dietary fiber, and manufacturing innovations that enable broader application across food, beverage, and nutraceutical formats. For executives and investors navigating this landscape, the market presents meaningful opportunities alongside distinct competitive and operational risks that require careful strategic positioning.
Understanding where this market is heading requires looking beyond aggregate revenue figures. The underlying dynamics involve evolving formulation requirements, shifting supply chain cost structures, and an increasingly polarized competitive field where differentiation hinges on clinical validation, regulatory approvals, and application-specific performance. This analysis examines the current market structure, the forces driving change, the competitive landscape, and the strategic implications for stakeholders across the value chain.
Market Landscape and Structural Challenges
The market's expansion over the past several years has been anything but linear. Historical data reveals periods of contraction followed by renewed growth, underscoring the influence of external shocks and demand elasticity. After a moderate decline in 2022, the market rebounded strongly through 2025 and is forecast to accelerate notably in the latter half of the projection period. This pattern suggests that the category is sensitive to macroeconomic conditions, raw material pricing, and the pace of regulatory developments, yet maintains a resilient long-term growth trajectory driven by fundamental demand shifts.
Several structural challenges define the current inflection point for resistant dextrin.
Supply Chain Volatility and Input Cost Pressure
The cost environment for key raw materials has introduced significant uncertainty into margin planning. Corn starch, a primary feedstock for most resistant dextrin production, experienced a sharp price escalation in mid-2025, reaching record levels that placed upward pressure on manufacturing costs across the value chain. For producers operating on thin margins or competing in price-sensitive segments, this volatility complicates inventory management, long-term contracting, and pricing strategies. Companies that fail to implement hedging mechanisms, diversify feedstock sources, or pass through costs effectively risk compressing profitability during periods of sustained input inflation.
Regulatory Fragmentation and Claim substantiation Requirements
While resistant dextrin enjoys growing regulatory acceptance, the path to commercialization remains uneven across jurisdictions and application categories. Regulatory recognition of specific fiber types, permissible health claims, and labeling requirements differ across regions and continue to evolve. In this environment, manufacturers must invest in clinical substantiation and regulatory navigation to secure approvals and defend market access. The increasing emphasis on evidence-backed positioning means that companies without robust clinical data or established regulatory relationships face a higher barrier to entry, particularly in healthcare and nutraceutical segments where claim substantiation is a prerequisite rather than an optional differentiator.
Application-Specific Formulation Constraints
Resistant dextrin is not a one-size-fits-all ingredient. Functional performance varies by source material, processing method, solubility profile, and compatibility with different formulation environments. Food and beverage developers face constraints related to taste modification, texture impact, stability under processing conditions, and interaction with other ingredients. These technical considerations limit the speed at which resistant dextrin can be adopted across new applications and create opportunities for suppliers who can provide application support, customized formats, and formulation guidance. The gap between generic availability and application-ready solutions represents both a challenge and a strategic lever for differentiation.
Key Drivers Shaping Market Dynamics
The growth trajectory of resistant dextrin is propelled by a combination of technological, regulatory, demand-side, and supply chain factors. Each driver carries distinct implications for market participants.
PW Consulting
Technological Innovation and Product Differentiation
Advances in enzymatic processing, starch modification, and purification techniques have expanded the range of resistant dextrin grades available to formulators. Manufacturers now offer variations in fiber content, solubility, particle size, and functional properties that enable tailored solutions for specific applications. These innovations support broader adoption by addressing formulation challenges that previously limited use in sensitive matrices such as low-pH beverages, baked goods, and clear-liquid formats.
Beyond physical properties, the emphasis on clinical validation has become a central dimension of product differentiation. Independent verification of prebiotic activity and gut health benefits through recognized certification programs has emerged as a credibility marker that resonates with both consumers and purchasing managers. Recent certification achievements by leading suppliers demonstrate how clinical evidence can be translated into marketable claims that support premium positioning and facilitate adoption in health-oriented formulations. These developments signal a shift from commodity-driven competition to evidence-based differentiation, where the strength of scientific backing increasingly determines market access and pricing power.
Regulatory Progress and Recognition Expansion
The regulatory environment has been a meaningful tailwind for resistant dextrin adoption. Recognition by major regulatory bodies as a valid dietary fiber, alongside expanded Generally Recognized as Safe status for additional food categories, has reduced ambiguity for formulators and accelerated inclusion in new products. Expanded approvals covering reduced-calorie beverages and other application areas illustrate how regulatory clarity can unlock growth by lowering development risk and enabling faster time-to-market.
Resistant Starch Market
At the same time, the regulatory landscape continues to reward companies that proactively engage with authorities and maintain comprehensive dossiers. Suppliers with established regulatory histories and documented safety profiles are better positioned to support customers through the approval process and navigate emerging requirements. As regulatory scrutiny around health claims and ingredient transparency intensifies, this capability becomes a strategic asset that compounds over time, creating a moat around well-prepared market participants.
Consumer and Enterprise Demand Shifts
Demand for functional ingredients with digestive health benefits has moved from a fringe concern to a mainstream purchasing driver. Consumers increasingly associate gut health with broader wellness outcomes, influencing food and beverage selection across categories. This shift has prompted manufacturers to incorporate fiber and prebiotic ingredients into everyday products, not just specialized health supplements. The result is a broader application footprint for resistant dextrin, spanning everyday beverages, bakery items, confectionery, dairy alternatives, and convenience foods.
On the enterprise side, brands face pressure to deliver products that align with clean-label expectations, sugar reduction goals, and functional benefits without compromising sensory quality. Resistant dextrin offers advantages in this context, including solubility, neutral flavor profiles in certain grades, and compatibility with nutritional goals such as fiber enrichment and calorie management. As product development cycles shorten and consumer expectations rise, ingredient suppliers that can provide technical support, co-development services, and rapid prototyping capabilities gain a competitive edge in securing inclusion in new formulations.
Supply Chain Structure and Cost Dynamics
The supply chain for resistant dextrin is shaped by the availability and pricing of starch feedstocks, the geographic distribution of manufacturing capacity, and logistics considerations. Production is concentrated among established players with integrated starch processing capabilities or long-standing supplier relationships, while emerging manufacturers seek to enter the market through cost-competitive positioning or regional focus. This structure creates both stability and vulnerability.
Record raw material prices illustrate how input cost fluctuations can ripple through the value chain, affecting producer margins, supplier pricing, and ultimately end-product economics. Companies that operate with flexible sourcing strategies, forward contracting, or diversified feedstock portfolios are better equipped to manage these dynamics. Conversely, reliance on single-source inputs or inflexible contract terms heightens exposure to price shocks. Over time, cost structure resilience will likely become a more prominent factor in supplier selection, particularly for large-volume buyers seeking supply security alongside competitive pricing.
Competitive Landscape and Strategic Positioning
The resistant dextrin market is characterized by a mix of established multinational ingredient suppliers and specialized manufacturers, with a notable degree of concentration among leading players. This concentration reflects the technical and regulatory barriers to entry, as well as the importance of scale, application expertise, and regulatory track records in securing market share.
Maltodextrin Market
Leading Players and Strategic Differentiation
Several companies occupy prominent positions by leveraging distinct strengths. Global ingredient manufacturers with broad portfolios and established relationships across food, beverage, and pharmaceutical channels benefit from scale, regulatory experience, and the ability to support customers across multiple markets. These players often differentiate through comprehensive technical service, co-development capabilities, and the credibility that comes with long-standing regulatory recognition.
Specialized producers have carved out positions by focusing on specific formats, source materials, or certification-backed claims. Companies offering resistant dextrin derived from corn or tapioca, with options spanning powder, liquid, and agglomerated formats, address varied formulation needs and enable customers to select grades suited to their application constraints. The availability of non-GMO, kosher, and other quality certifications further expands market access, particularly in segments where these attributes carry significant purchasing weight.
Increasingly, the competitive battleground is shifting toward evidence-based positioning. Suppliers that invest in clinical substantiation and secure independent verification of functional benefits are able to command stronger brand recognition and support customer claims with defensible data. This trend favors companies with the resources to conduct or commission clinical research and the regulatory expertise to translate findings into approved claims and certification status.
Market Consolidation and Emerging Entrants
The market structure suggests ongoing consolidation pressure, driven by the economies of scale associated with production, regulatory investment, and global distribution. Larger players are well positioned to absorb input cost volatility, fund application research, and expand capacity in response to demand growth. At the same time, regional manufacturers and distributors can find opportunities by serving localized demand, offering cost-advantaged products, or focusing on niche segments where broader players may not prioritize investment.
New entrants face meaningful hurdles. Establishing regulatory recognition, building clinical credibility, and securing consistent feedstock supply require capital and time. However, partnerships with established producers, contract manufacturing arrangements, and focused geographic strategies can provide pathways for incremental market participation. The presence of distributors and bulk suppliers that aggregate products from multiple producers also adds a layer of intermediation, which can benefit end-users seeking simplified sourcing while introducing additional considerations around quality control and supply traceability.
Forward Outlook: Trends and Opportunities (2026–2032)
Looking ahead, several trends are likely to shape the resistant dextrin market over the next several years, each carrying distinct commercial implications.
Accelerated Adoption in Everyday Food and Beverage Formats
As regulatory recognition expands and formulation capabilities improve, resistant dextrin is poised to move further into mainstream food and beverage applications. Categories that were once considered challenging for fiber enrichment, such as clear beverages, confectionery, and shelf-stable products, are becoming more accessible as ingredient grades and processing techniques evolve. This broadening application base supports volume growth and creates opportunities for suppliers who can demonstrate application-specific performance and provide formulation support that reduces development friction.
For brands, the opportunity lies in leveraging resistant dextrin to meet multiple objectives simultaneously: fiber enrichment, sugar reduction, texture management, and functional benefits. Success in this environment depends on selecting grades that align with product requirements and on communicating benefits in ways that resonate with target consumers without overstepping regulatory boundaries.
Evidence-Based Positioning as a Core Competitive Lever
The emphasis on clinical evidence and independent certification is expected to intensify. As consumers and purchasing managers become more sophisticated about ingredient claims, suppliers with verified functional benefits and documented safety profiles will hold an advantage in securing inclusion in premium and health-oriented products. Certification programs that evaluate prebiotic function and other claimed benefits provide third-party validation that can differentiate products in crowded markets and support premium pricing where justified.
This trend also introduces risk for companies that rely on generic positioning without substantive clinical backing. As the category matures, differentiation will increasingly depend on the credibility of functional claims and the quality of supporting data, making investment in research and regulatory documentation a strategic priority rather than an optional enhancement.
Supply Chain Resilience and Sourcing Strategy Recalibration
Input cost volatility and the concentration of feedstock supply are likely to drive recalibration of sourcing strategies across the value chain. Buyers and producers alike will place greater emphasis on supply security, long-term contracting, feedstock diversification, and regional capacity considerations. These dynamics may encourage investment in additional production capacity in key markets, as well as closer collaboration between ingredient suppliers and end-product manufacturers to manage risk and ensure consistent availability.
For market participants, the strategic implication is clear: resilience in supply chain design will increasingly influence competitiveness. Companies that build flexibility into sourcing, maintain transparent quality systems, and develop contingency plans for input disruptions will be better positioned to sustain operations and customer relationships through periods of volatility.
Potential Risks and Uncertainties
Despite the favorable long-term outlook, risks remain. Regulatory shifts, including changes to fiber recognition criteria or health claim requirements, could alter market access conditions. Raw material cost fluctuations may compress margins for players without effective risk management. Competitive intensity could increase as new entrants attempt to capture share through price competition, potentially pressuring returns in segments where differentiation is weaker. Additionally, consumer trends are subject to change, and categories that appear promising today may face headwinds if broader wellness preferences shift or if alternative ingredients gain traction.
Navigating these uncertainties requires continuous monitoring of regulatory developments, input market conditions, and competitive activity. Strategic agility, grounded in accurate intelligence, will be essential for capitalizing on opportunities while mitigating downside exposure.
Strategic Implications for Decision-Makers
The resistant dextrin market presents distinct considerations for manufacturers, investors, and procurement professionals. Each group faces different priorities and time horizons, but all stand to benefit from a clear understanding of market dynamics and a proactive approach to positioning.
For Ingredient Manufacturers and Formulators
- Invest in application-specific value propositions. Differentiate beyond basic fiber content by demonstrating performance in target matrices, offering multiple formats, and providing technical support that reduces customer development time.
- Strengthen regulatory and clinical credibility. Proactively pursue regulatory recognition for new applications, maintain comprehensive safety documentation, and consider independent verification of functional claims to support differentiation and customer confidence.
- Build supply chain resilience. Evaluate feedstock sourcing options, consider forward contracting or diversification strategies, and assess how input cost volatility may affect margins under different scenarios.
For Investors and Strategic Capital Allocators
- Assess differentiation quality, not just scale. Evaluate companies based on their regulatory track records, clinical substantiation, application expertise, and ability to command premium positioning rather than volume alone.
- Monitor consolidation dynamics and capacity investments. Track which players are expanding capacity, entering new geographies, or securing certifications, as these moves often signal strategic intent and can reshape competitive balance.
- Consider downstream integration and partnership models. Opportunities may exist in companies that offer integrated solutions, co-development services, or distribution models that simplify sourcing for end-users, particularly as demand broadens across applications.
For Procurement and Sourcing Professionals
- Prioritize supply security alongside cost. Evaluate suppliers on feedstock flexibility, production capacity, quality certifications, and contingency capabilities, recognizing that input volatility can affect availability and pricing over time.
- Leverage application support in supplier selection. Suppliers that provide formulation guidance, technical service, and co-development resources can reduce time-to-market and improve product outcomes, adding value beyond the ingredient itself.
- Stay informed on regulatory and claim developments. Understanding evolving recognition status and certification options enables more confident product positioning and helps avoid compliance risks associated with unsupported claims.
Conclusion
The resistant dextrin market is at a point where fundamental demand drivers, regulatory progress, and technological capability are aligning to support sustained growth. The projected expansion through 2032 reflects not only increasing volume but also the broadening of applications and the deepening of competitive differentiation around evidence, format flexibility, and supply reliability. For stakeholders across the value chain, the path to capturing value lies in understanding these dynamics in detail and acting with strategic precision.
Aggregate market figures provide a useful baseline, but the real strategic complexity resides in segment-level dynamics, regional regulatory variations, application-specific performance requirements, and the evolving cost structure of feedstock supply. Accessing granular data on subsegments, competitive benchmarks, and scenario-based forecasts can materially improve decision quality, whether the objective is product development, capacity planning, investment allocation, or sourcing strategy. Deeper intelligence enables more confident navigation of a market that is simultaneously expanding and becoming more competitive.
For detailed analysis of this topic, please visit the official page: Resistant Dextrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Artificial Blood Vessel Market: How 5.38% CAGR Redefines Growth Trajectories to 2032
By PW Consulting, 2026-09-21
The Artificial Blood Vessel Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape: Scale, Momentum, and Structural Challenges
The artificial blood vessel market has entered a phase of steady, compounding growth. The overall market size reached approximately $2.38 billion in 2025, expanding from $1.83 billion in 2020 at a compound annual growth rate of 5.38 percent. The trajectory points toward $3.45 billion by 2032, with the forecast period from 2026 through 2032 reflecting a consistent upward slope. This expansion is not accidental; it reflects a convergence of clinical necessity, material science advancement, and shifting procurement dynamics across healthcare systems.
Despite the encouraging headline numbers, the market faces structural headwinds that will define competitive outcomes over the next several years. Three challenges stand out as particularly consequential for decision-makers.
First, reimbursement fragmentation remains a persistent drag on adoption velocity. Advanced graft technologies, particularly tissue-engineered and bioengineered variants, carry unit costs that far exceed conventional synthetic alternatives. Without consistent, transparent payment pathways across payers and procedures, volume adoption lags behind clinical approval. The gap between regulatory clearance and real-world utilization is where many promising products stall.
Second, the supply chain for specialized vascular materials is vulnerable to cost volatility and manufacturing complexity. Certain polymer-based and biologic grafts require tightly controlled production environments, validated sterilization processes, and cold-chain logistics. Any disruption in raw material availability or scaling bottlenecks can compress margins and delay hospital deliveries. Companies that treat these operational constraints as strategic risks rather than back-office issues are better positioned to protect market share.
Third, clinical preference and procedural heterogeneity create uneven adoption patterns. Not all vascular indications demand the same performance profile. Hemodialysis access, peripheral artery disease interventions, aortic reconstruction, and trauma revascularization each carry distinct hemodynamic, durability, and handling requirements. A product optimized for one pathway does not automatically translate across others. Decision-makers must recognize that broad market growth can coexist with highly segmented demand realities.
The market concentration profile reflects a moderately consolidated environment. The top three players hold a combined share of approximately 35.2 percent, while the top five reach roughly 42.5 percent. This structure suggests that incumbents retain meaningful scale advantages in reimbursement negotiations, clinical education, and distribution reach. At the same time, the remaining share dispersion leaves room for differentiated entrants, particularly those bringing breakthrough technology or targeted clinical value propositions to underserved indications.
Key Drivers: What Is Propelling Change
Technology Innovation and Clinical Performance Shift
Material science and bioengineering are reshaping the performance envelope of vascular grafts. Traditional synthetic materials have long served as workhorse solutions, but next-generation options are expanding what clinicians can achieve in complex anatomy and high-risk patient populations. Acellular tissue-engineered vessels, cryopreserved allografts, and collagen-based grafts each address different unmet needs, from reduced thrombogenicity to better endothelialization potential and improved handling in contaminated fields.
The commercial signal from recent product milestones is instructive. Humacyte Global advanced its acellular tissue-engineered vessel, Symvess, through FDA approval for use in adults as a vascular conduit for extremity arterial injury when urgent revascularization is needed and autologous vein is not feasible. The approval pathway, executed via Biologics License Application, reflects a shifting regulatory recognition of engineered tissue products as viable conduits in trauma and reconstruction settings. The product subsequently received priority designation for vascular trauma treatment from the U.S. Secretary of Defense, underscoring a dual commercial and defense-relevant use case. In May 2025, Symvess was submitted for a New Technology Add-On Payment with a potential start for discharges on October 1, 2025, and was priced at $29,500 per unit. Notably, that list price compares against the inflated 2024 cost equivalent of autologous vein harvest, estimated at approximately $37.45 per minute. The economics argument is not abstract; it is being quantified in procedural time, complication risk, and downstream resource utilization.
For manufacturers, the implication is clear: performance differentiation must be paired with economic justification. A graft that reduces harvest time, lowers re-intervention risk, or simplifies operative workflow can command premium positioning if the value story is coherent across the care pathway.
Policy and Regulatory Environment as a Catalyst and Gatekeeper
Regulatory design and reimbursement architecture increasingly determine which innovations reach scale. Approval pathways for biologics and tissue-engineered devices are becoming more defined, but they remain demanding. Companies that secure priority designations, navigate biologic licensing frameworks, and proactively engage payment mechanisms stand to compress the time between clearance and commercial uptake.
The Humacyte trajectory illustrates this dynamic in practice. Beyond the FDA approval and defense designation, the planned marketing authorization application for Symvess in Israel, announced in January 2026, signals an intent to broaden geographic access after establishing a U.S. foothold. International expansion is rarely a simple replication exercise; it requires alignment with local regulatory expectations, payer structures, and clinical adoption patterns. Still, the company's sequential moves suggest a deliberate strategy: validate in a high-value domestic market, secure payment recognition, then pursue regional authorizations where unmet need and procurement readiness intersect.
For the broader market, policy momentum around vascular trauma, dialysis access, and peripheral revascularization is likely to sustain regulatory attention. The challenge is that reimbursement reforms often lag product innovation. Executives should monitor where add-on payment mechanisms, coverage with evidence development pathways, and national pricing dialogues are evolving, because these are the levers that convert clinical differentiation into volume growth.
Demand-Side Shifts in Clinical Practice and Patient Populations
Demand is being propelled by both epidemiological trends and procedural evolution. Rising prevalence of peripheral artery disease, expanding dialysis populations, and increasing complexity of aortic and peripheral reconstructions are widening the addressable base for vascular grafts. At the same time, surgeons are seeking alternatives to autologous vein harvest in scenarios where donor tissue is unavailable, unsuitable, or associated with excessive operative burden.
This shift is not uniform across indications. Hemodialysis access continues to drive consistent volume, particularly where arteriovenous graft salvage and lower extremity bypass options are needed. Peripheral artery disease interventions benefit from grafts that can accommodate challenging distal targets. Aortic and peripheral reconstructive procedures increasingly favor materials with predictable handling and durable patency characteristics. The common thread is a growing preference for solutions that reduce procedural complexity while maintaining or improving clinical outcomes.
Vascular Graft Market
From a commercial standpoint, this means market growth is being pulled by specific clinical workflows rather than a single generalized demand surge. Companies that map their product portfolios to procedure-level economics and surgeon decision criteria are more likely to convert adoption interest into repeat utilization.
Supply Chain and Cost Structure Realignment
Cost structures in the artificial blood vessel market are being redefined by material inputs, manufacturing intensity, and logistics requirements. Conventional synthetic grafts benefit from mature production ecosystems, while advanced biologics and engineered tissues carry higher unit costs and more complex upstream dependencies. The resulting margin profile is diverging across product categories, and procurement teams are increasingly scrutinizing total cost of care rather than sticker price alone.
This environment favors organizations that can manage the full operational chain with discipline. Reducing variability in raw material sourcing, standardizing sterilization and packaging, and anticipating cold-chain or specialized storage needs are not mere cost-center activities; they are competitive differentiators. When unit economics are under pressure, reliability and scalability become the difference between sustainable market presence and episodic, margin-eroding sales.
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field is defined by companies with distinct clinical footprints and strategic priorities. Rather than competing on a single dimension, leaders are building portfolios and positioning statements around specific use cases, material platforms, and procedural contexts.
Humacyte Global has concentrated on acellular tissue-engineered vessels, with Symvess as its flagship offering for extremity arterial injury when autologous vein is not feasible. The company's strategic posture emphasizes regulatory validation, payment recognition, and targeted trauma and reconstruction applications. By pursuing FDA approval through a biologic pathway, securing a defense-related priority designation, and engaging NTAP processes, Humacyte is attempting to anchor a premium-priced technology in a reimbursement framework that acknowledges its differentiated cost and clinical profile. The planned 2026 authorization application in Israel extends this playbook internationally, indicating a phased geographic rollout rather than simultaneous global expansion.
Artivion operates in the cryopreserved allograft space, with CryoArtery Aortoiliac Artery and CryoArtery Femoral Artery positioned for below-knee revascularization and peripheral vascular repair. Its differentiation rests on the use of preserved biological tissue for scenarios where synthetic options are less favorable, particularly in complex peripheral reconstructions. The cryopreserved allograft angle requires robust tissue handling, preservation logistics, and surgeon familiarity, but it opens access to patient populations where matching biological properties to the repair site matters.
PW Consulting
LeMaitre Vascular offers the Artegraft Collagen Vascular Graft, a bovine carotid artery product used for hemodialysis access, AV graft salvage, and lower extremity bypass. Its positioning emphasizes a collagen-based biological graft in a segment where access durability and salvage options are clinically important. Participation in upcoming investor conferences in June 2026 suggests continued attention to capital markets and strategic communications alongside product activity. In a market where dialysis access remains a steady volume driver, a biologically derived graft with a defined salvage and access role can maintain relevance, especially when hospitals seek alternatives to synthetic access options in selected patients.
B. Braun Melsungen AG brings warp-knitted polyester vascular prostheses through its Silver Graft and Silver Graft Helix lines, targeting aortic and peripheral reconstructive procedures. Its strength lies in established synthetic manufacturing capabilities, broad distribution, and product lines designed for reconstructive consistency. In many healthcare systems, such polyester-based prostheses serve as reliable defaults for aortic and peripheral repair, benefiting from surgeon familiarity, inventory stability, and procurement economics. The strategic challenge for incumbents of this type is to sustain utilization while anticipating the slow but real migration toward advanced materials in select indications.
Terumo Medical Corporation has been building around bioengineered vascular grafts within a broader innovative product portfolio for vascular surgery. Its approach reflects an integrated device company posture, where vascular grafts complement a wider surgical offering and benefit from cross-portfolio distribution, clinical support, and procurement relationships. For a company of this scale, vascular grafts can function as both a stand-alone growth avenue and a reinforcing element within a broader vascular surgery ecosystem.
Man-made Vascular Graft Market
Market structure is evolving along several axes. Consolidation pressure exists where scale advantages in reimbursement, education, and distribution favor larger platforms. At the same time, fragmentation persists because different product technologies address different clinical niches, and breakthrough entrants can capture meaningful share in targeted areas without displacing incumbents across the entire market. New entrants with tissue-engineered, bioengineered, or biologically derived platforms are most likely to succeed when they pair regulatory and payment readiness with a clear procedural value proposition. The middle ground, where companies offer incremental improvements without a compelling clinical or economic story, is the most vulnerable to margin compression and share erosion.
Future Outlook: Three Trends Shaping 2027 to 2032
Trend One: Premium, Engineered Grafts Gain Traction Where Economics Can Be Defended
Over the next three to five years, advanced grafts are likely to expand beyond early adoption clusters into broader procedural use, but not uniformly. The commercial ceiling for premium-priced solutions will be set by the ability to demonstrate value in procedural time savings, reduced complications, and lower downstream costs. Indications where autologous alternatives carry high harvest burden, where contamination risk makes biocompatible options attractive, or where re-intervention costs are material will be the most receptive.
The commercial opportunity lies in building indication-specific evidence packages and payment narratives. Companies that can quantify the total care pathway impact, rather than defend list price in isolation, will be better positioned to secure utilization in hospitals and integrated delivery networks. The risk is overreliance on regulatory milestones without parallel progress on reimbursement and real-world evidence, which can leave even approved products with constrained volume trajectories.
Trend Two: Regional Divergence and Strategic Geographic Expansion
Market growth will not be geographically even. Regions with mature reimbursement systems, established vascular surgery volumes, and procurement frameworks that recognize advanced device economics will adopt more quickly. Areas where access to vascular care is expanding but payment pathways are less developed may show slower volume conversion despite rising procedural need.
This divergence creates two distinct strategic opportunities. First, companies with strong domestic positions can pursue measured international expansion where authorization processes, clinical demand, and procurement readiness align. Second, manufacturers that anticipate regional reimbursement gaps can design market access strategies that include evidence generation, pilot programs, and payer engagement tailored to local structures. The downside is that uncoordinated geographic expansion can dilute resources and create fragmented launch execution, especially when regulatory and payment systems differ substantially from one market to the next.
Trend Three: Consolidation of Distribution and Service, Alongside Niche Innovation
The market is likely to see continued tension between scale-oriented consolidation and niche innovation. Larger platforms may pursue distribution, service, and portfolio synergies that reduce selling costs, improve hospital support, and strengthen procurement positioning. In parallel, smaller or more specialized innovators can capture value by targeting unmet needs in trauma, dialysis access, distal revascularization, or biologic graft alternatives.
For decision-makers, this implies a market where broad portfolios and narrow, high-value technologies can both thrive, but under different playbooks. Scale players must protect relevance by maintaining clinical credibility and supply reliability. Specialist entrants must justify premium positioning with clear clinical and economic differentiation. The risk for both is complacency: incumbents that assume synthetic defaults will remain unchallenged may lose select indications, while entrants that underestimate reimbursement complexity may struggle to convert innovation into sustained revenue.
Actionable Guidance for Decision-Makers
The artificial blood vessel market is expanding with moderate but dependable momentum, and the most consequential decisions will be shaped by how well organizations align product strategy, market access, and operational execution. A few priorities stand out across stakeholder groups.
- For manufacturers, the priority is to design indication-specific value propositions that connect clinical performance to procedural economics. Where a graft reduces harvest burden, simplifies handling, or lowers re-intervention likelihood, that story must be supported by evidence and communicated in terms that resonate with surgeons, hospital administrators, and procurement teams. Equally important is operational discipline: supply reliability, manufacturing scalability, and logistics readiness should be treated as core commercial capabilities rather than operational afterthoughts.
- For investors, the most durable opportunities are likely to be found where regulatory progress is matched by reimbursement engagement and geographic rollout discipline. A product with approval, payment recognition, and a defined expansion path offers a stronger risk-adjusted profile than one relying on clinical promise alone. Attention should also be paid to differentiation durability: technologies that can defend premium pricing through demonstrable total-cost advantages are better positioned than those competing solely on novelty.
- For procurement and clinical decision-makers, the focus should be on evaluation frameworks that capture total cost and outcomes rather than unit price alone. Where advanced grafts reduce operative time, lower complication risk, or address cases where autologous options are impractical, they may offer value that is not visible in a sticker-price comparison. Building institutional familiarity through targeted education and procedure-level evaluation can improve adoption decisions and reduce reliance on default product choices.
The market is large enough, and the product landscape varied enough, that a single generalized strategy will not fit all players. The organizations that will capture disproportionate value are those that combine clinical clarity, payment readiness, operational reliability, and a disciplined view of where advanced grafts truly outperform defaults. Because reimbursement pathways, regulatory rhythms, and regional procurement dynamics continue to evolve, timely access to granular segmentation data, company-level tracking, and tailored scenario analysis can materially improve capital allocation and commercial planning. For decision-makers seeking a deeper, more customized view of pricing dynamics, regional variation, and segment-specific opportunity sets, the full research report provides the supporting detail and structured analysis needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Artificial Blood Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Animal Electric Shock Stimulation Device Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Overview
The Animal Electric Shock Stimulation Device Market is centered on devices designed to deliver controlled electrical impulses to animals, primarily for training, behavior modification, or therapeutic purposes. These devices are integral to modern veterinary practices, animal training programs, and research institutions, providing a non-invasive means to influence animal behavior or assess neuromuscular responses.
The purpose of these devices is to enhance animal management efficiency while ensuring humane treatment. They support industries such as livestock management, pet training, and biomedical research, by offering core functionalities like adjustable shock intensity, remote operation, and safety features. The Animal Electric Shock Stimulation Device Market plays a crucial role in advancing animal care and training technologies.
Market Size and Growth
The current market value of the Animal Electric Shock Stimulation Device Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 2.3 billion, reflecting a compound annual growth rate (CAGR) of roughly 8%. Growth is driven by increasing adoption in veterinary and animal training sectors, alongside technological advancements that improve device safety and efficacy.
Rising demand for humane training solutions and expanding research activities in animal behavior are key growth drivers. Additionally, regulatory developments favoring ethical treatment are influencing market expansion, supporting long-term growth prospects.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2060
Key Drivers
• Rising awareness of humane animal training methods
• Growing adoption in veterinary and research sectors
• Technological innovations enhancing device safety
• Increasing demand for remote and automated devices
• Expanding applications in livestock management
Restraints
• Regulatory restrictions on shock device usage
• High costs of advanced device models
• Operational challenges in ensuring humane treatment
• Technical limitations in device customization
• Limited acceptance in certain regions due to ethical concerns
Segmentation
• By Type
- Handheld Devices
- Fixed Devices
- Wearable Devices
• By Deployment
- Veterinary Clinics
- Animal Training Centers
- Research Laboratories
- Livestock Farms
• By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
• By End User
- Veterinary Professionals
- Animal Trainers
- Researchers
- Livestock Managers
• By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Insights
North America leads the Animal Electric Shock Stimulation Device Market, driven by high animal welfare standards and technological adoption. The region’s focus on research and development supports steady growth, with increasing use in pet training and veterinary care.
Europe exhibits significant demand, especially within animal welfare regulations and ethical training practices. Stringent laws encourage innovation and adoption of advanced, humane devices across countries like Germany and the UK.
In Asia-Pacific, rapid industrialization and expanding livestock sectors boost demand for animal management tools. Growing awareness and technological penetration are fueling market growth, particularly in China and India.
Latin America shows moderate adoption, primarily in livestock management and research applications. Economic development and increasing animal welfare awareness are expected to drive future demand.
The Middle East & Africa region is emerging as a niche market, with growth driven by livestock modernization and research initiatives. Limited regulatory restrictions currently influence adoption rates.
Opportunities
• Expansion in emerging markets with increasing livestock populations
• Integration of IoT and AI for smarter device functionality
• Development of humane, multi-functional stimulation devices
• Adoption in precision livestock farming and bio-robotics
• Growing industry focus on ethical animal training solutions
Key Companies
Ani-Sci
Dogtra
PetSafe
Olympic Kennel Club
ToughBuilt
Pet Trainer Inc.
Innotek
Dogtra Co. Ltd.
Julius-K9
Dogtra International
Electro-Impulse Devices
VetTech Solutions
Conclusion
The Animal Electric Shock Stimulation Device Market demonstrates strong long-term growth potential, driven by technological advancements and increasing demand for humane animal management solutions. Its strategic importance lies in supporting sustainable and ethical practices across veterinary, research, and livestock industries. The market’s evolution presents substantial opportunities for innovation and expansion, making it a vital segment within the broader animal care technology landscape.
Related Reports
Cameralink Industrial Cameras Market , Size Share and Analysis | Report 2033
Marine Mooring Bollard Market , Size Share and Analysis | Report 2033
High Temperature Resistant Polyurethane Sealing Ring Market , Size Share and Analysis | Report 2033
Autonomous Drones For Maritime Security Market , Size Share and Analysis | Report 2033
Pu Polyurethane Turning Seals Market , Size Share and Analysis | Report 2033
Pole Chainsaws Market , Size Share and Analysis | Report 2033
Automatic Metallographic Sample Cutting Machine Market , Size Share and Analysis | Report 2033
Optical Fiber Coloring System Market , Size Share and Analysis | Report 2033
Frame Tv Market , Size Share and Analysis | Report 2033
Fiber Coloring Rewinding Machines Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Yucca Mohave Extract Market: Why 5.75% CAGR and 78% CR5 Redefine 2032 Outlook
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Yucca Mohave Extract Market
The Yucca Mohave Extract market has entered a phase of structural expansion, characterized by steady revenue growth across a diverse set of downstream applications. Based on the 2025 baseline and forward projections through 2032, the sector is positioned to advance at a compound annual growth rate of 5.75%. Revenue climbed from 81.15 million in 2020 to 106.3 million in 2025, with the trajectory expected to reach 156.98 million by the end of the forecast window. This pace reflects more than cyclical demand recovery; it signals a maturing value chain where botanical extracts are increasingly integrated into mainstream wellness, nutrition, and specialty industrial formulations.
For executives and investors, the growth profile matters less as an isolated metric and more as a signal of where capital, production capacity, and product development are flowing. The market’s expansion is not uniform across all formats or end uses, and the underlying dynamics reveal clear entry points for companies that can align sourcing, compliance, and application expertise with shifting buyer expectations. At the same time, the sector faces a set of operational and strategic pressures that will separate resilient operators from those dependent on commodity-style positioning.
The following analysis maps the current market environment, identifies the forces shaping demand and supply, examines how leading companies are positioning themselves, and outlines the trends most likely to define the next three to five years. The objective is to provide decision-makers with a practical framework for evaluating where value is being created and where exposure should be managed.
Market Snapshot and Core Challenges
The market’s size and growth path indicate a sector that has moved beyond early adoption and is now scaling within established distribution channels. The upward arc from 2020 through 2025 was not linear, with a modest contraction in one recent year before the 2025 rebound. That pattern suggests a market responding to supply availability, pricing adjustments, and procurement cycles rather than one driven purely by end-market enthusiasm. Looking ahead, the forecast implies that growth will increasingly depend on product standardization, broader application penetration, and the ability of suppliers to maintain consistent quality at scale.
Worldwide Sugar Beet Juice Extract Market
Three challenges stand out as critical to navigating the next phase of expansion.
Supply Consistency and Botanical Variability
Yucca Mohave extract is rooted in a specific botanical source, and variability in raw material quality can cascade through extraction yields, active content consistency, and final product performance. Companies operating at higher volumes must manage harvest timing, regional sourcing differences, and post-harvest handling to avoid inconsistencies that undermine customer trust. In categories such as dietary supplements and food ingredients, buyers increasingly expect batch-to-batch reliability and documented potency, which places pressure on suppliers to invest in traceability and process control.
Regulatory and Quality Assurance Complexity
As yucca-derived ingredients move further into regulated and semi-regulated spaces, documentation and manufacturing standards are becoming competitive differentiators rather than compliance overhead. Buyers in pharmaceuticals, nutraceuticals, and food applications are paying closer attention to sourcing integrity, extraction methods, and certification status. Suppliers that can demonstrate robust quality systems and transparent ingredient provenance are better positioned to enter higher-value channels, while those relying on less formal assurance may face barriers to expansion.
Competitive Concentration and Margin Pressure
The market remains relatively concentrated among established participants, which creates both stability and tension. Concentrated supply can support consistent market intelligence and long-term buyer relationships, but it also raises the stakes for differentiation. As more manufacturers introduce powdered, liquid, and encapsulated formats, price competition can intensify in commodity-adjacent segments. Companies that compete primarily on volume without distinct technical or application advantages may find margins squeezed, especially when raw material or processing costs fluctuate.
Key Drivers Shaping Market Direction
The market’s trajectory is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers do not operate in isolation; they interact to determine which product formats gain traction, which applications expand fastest, and which suppliers are able to command premium positioning.
Technological Innovation in Extraction and Standardization
Extraction and processing methods continue to influence product performance and commercial flexibility. Different approaches can affect purity, solubility, color, taste profile, and active content consistency, all of which matter to downstream formulators. Suppliers that invest in refined extraction processes and standardized outputs are better equipped to serve customers who need predictable ingredient behavior in complex formulations. This is especially relevant in liquid and powder formats, where application performance can dictate repeat purchasing and product line expansion.
Recent operational developments underscore how quality-focused improvements are becoming part of the competitive narrative. For example, certification achievements that strengthen excipient-grade manufacturing and quality assurance contribute to greater buyer confidence in yucca-derived saponin ingredients. In parallel, capacity expansion by producers seeking to meet rising demand reflects the industry’s move toward scaling while attempting to preserve quality standards. These moves are not merely operational; they signal a market in which performance assurance and manufacturing credibility are becoming central to growth.
Policy and Regulatory Environment as an Enabler and Filter
Regulatory expectations are increasingly influencing market access. In sectors where ingredients are incorporated into health-oriented products or food and beverage formulations, documentation, safety substantiation, and manufacturing discipline can determine whether a supplier is eligible for certain buyer shortlists. Rather than acting as a single barrier, the regulatory environment is functioning as a filter that rewards transparency and consistent quality. This trend benefits suppliers that have invested early in compliant production practices and creates a steeper path for those attempting to enter higher-trust channels without comparable systems.
At the same time, regional differences in regulatory expectations and market norms can create uneven adoption curves. Suppliers with multi-market exposure often gain an advantage by aligning product documentation and format choices with the requirements of each destination market, enabling them to capture demand across a wider set of buyer types.
Maca Extract Market
Shifting Demand-side Behavior Across End Uses
Demand is being shaped by broader consumer and industrial preferences for plant-derived ingredients, functional benefits, and cleaner formulation profiles. In dietary supplements and food and beverage applications, buyers are looking for ingredients that can support label clarity, consumer familiarity, and formulation compatibility. In cosmetics and related personal care uses, there is growing interest in botanical inputs that fit emerging positioning around natural-origin ingredients and sensory or functional performance. Pharmaceutical-adjacent interest adds another layer, where standardization and documentation become especially important.
This diversified demand base is one reason the market can sustain growth even when one application category slows. The broader pattern suggests that yucca extract is transitioning from a narrower specialty input toward a more versatile ingredient portfolio. The commercial implication is that suppliers with application breadth can better balance volume and margin, while those overly dependent on a single end-use segment may be more exposed to category-specific volatility.
Supply Chain and Cost Structure Dynamics
Cost structures in botanical extract markets are influenced by raw material sourcing, harvesting logistics, processing intensity, and the scale of production. Because yucca Mohave extract depends on a geographically specific plant source, supply chains must manage both biological variability and transportation and processing costs. As demand increases, suppliers that can secure reliable sourcing commitments and optimize extraction efficiency are more likely to protect margins during periods of input cost pressure.
The cost equation also intersects with format strategy. Liquid and powder products can require different handling, packaging, and logistics considerations, which affects total delivered cost and customer adoption. Companies that can align format offerings with practical supply chain advantages often gain an edge in price-sensitive segments while still preserving room for premium offerings in more demanding applications.
Competitive Landscape and Leading Strategies
The market features a mix of regional specialists, vertically oriented processors, and ingredient suppliers with broader botanical portfolios. This mix creates a landscape where competitive advantage often comes from a combination of source access, extraction capability, application knowledge, and certification or quality positioning. The companies that stand out are not necessarily the largest in every dimension, but those that have constructed a defensible niche through one or more of these levers.
Strategic Positioning Among Core Participants
Several participants illustrate the different ways companies are competing in this space.
- Some manufacturers emphasize high-quality liquids and powders produced from yucca schidigera sourced for food, beverage, and animal feed use, with an emphasis on cold-pressed and application-specific formulations.
- Other U.S.-based suppliers focus on large-scale provision of pure extracts and dried powders, linking production to southwestern harvesting and processing for animal feed and nutraceutical markets.
- A further group operates as suppliers and manufacturers of food-grade plant extract raw materials for food, feed, and nutraceutical applications, often competing on standardization and supply reliability.
- Certain participants provide spray-dried, fiber-related, and extract-based products for food, feed, and industrial uses, broadening the scope of potential end markets.
- Manufacturers in Asia have entered with powder and liquid offerings targeted at healthcare products, food supplements, cosmetics, and animal nutrition, reflecting a growing international supply presence.
- Some producers highlight experience in alcohol and water extraction processes for pharmaceutical, dietary supplement, and food-grade applications, using process diversity as a point of differentiation.
- Leading processors with integrated extraction and distribution capabilities connect harvesting in the southwestern U.S. and Baja Mexico to downstream supply, reinforcing control over source-to-product flow.
- Larger specialty ingredient providers contribute standardized botanical extracts for food, beverage, and pharmaceutical uses, often leveraging broader formulation support and global distribution networks.
- Formulators focused on liquid yucca schidigera extract for aquaculture and premium animal feed illustrate how application specialization can open niche but valuable demand channels.
- Suppliers of dry plant extracts for biostimulant and plant growth applications show the market’s reach beyond human nutrition into agricultural and industrial uses.
This range of profiles indicates that the market is not defined by a single business model. Instead, success often depends on aligning sourcing access, processing capability, and application focus in a way that matches the expectations of a specific buyer group.
Differentiation and Evolving Market Structure
Differentiation is increasingly tied to credibility, consistency, and application readiness. Certification achievements and quality-system improvements are becoming meaningful signals in premium channels, especially where buyers need documented manufacturing discipline for excipient or ingredient-grade use. Capacity expansion also matters, but only when it is paired with quality control and demand alignment; otherwise, added volume can increase exposure to pricing pressure without strengthening long-term positioning.
Industry developments from recent periods reinforce this pattern. Certification milestones in excipient manufacturing highlight how quality assurance can enhance a supplier’s eligibility for more demanding applications. Capacity expansion initiatives reflect efforts to capture rising demand, but they also imply that competitive advantage will depend on whether the added capacity is absorbed by differentiated products or by commoditizing segments.
Looking at the broader structure, the market appears to be moving through a combination of consolidation and segmentation. Established suppliers with strong regional access and multi-format capabilities are likely to retain advantages in core channels, while new and expanding entrants may pursue differentiation through specific applications, geographic reach, or price-competitive formats. The result is a landscape where buyers have more options but also face a wider variance in quality, documentation, and application support.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Opportunities
Based on current market dynamics and the trajectory of demand, three trends are likely to shape the next three to five years.
Trend One: Broader Application Integration With Higher Documentation Expectations
As yucca extract continues to appear across dietary supplements, food and beverage, cosmetics, and pharmaceutical-adjacent uses, buyers will likely demand more consistent documentation and product standardization. This trend creates commercial opportunity for suppliers that can offer not just volume, but formulation-ready ingredients with clear specifications and dependable quality. Companies that invest in technical support, application compatibility, and transparent sourcing will be better positioned to move into higher-value partnerships.
The risk here is that documentation and quality expectations may outpace the capabilities of some producers, especially those operating with less formalized systems. Suppliers that cannot meet rising assurance requirements may find themselves limited to lower-margin channels or more price-sensitive buyers.
Trend Two: Format Strategy as a Margin and Channel Differentiator
Liquid, powder, capsule, tablet, and other formats are not interchangeable from a commercial standpoint. Each format carries different processing, packaging, logistics, and customer adoption considerations. Over time, competitive advantage may increasingly come from selecting the right format mix for the intended end market rather than offering the broadest possible portfolio by default. Formulators and procurement teams will likely favor suppliers that can align format choice with performance needs and supply chain practicality.
This creates opportunities for companies that can tailor product forms to specific use cases, especially where solubility, handling, dosage form, or sensory characteristics influence repeat purchasing. The downside is that format diversification without clear application logic can increase operational complexity and dilute focus.
Trend Three: Regional Sourcing Themes and Multi-market Access
Because the raw material basis is geographically anchored, regional sourcing narratives and supply reliability will remain strategically important. Buyers in multiple markets may respond differently depending on local preferences, regulatory expectations, and price sensitivity. Suppliers with access to consistent harvests and the ability to serve multiple downstream geographies may gain flexibility in matching supply to demand cycles. At the same time, companies in emerging supply regions may expand their presence by offering competitive cost structures and targeted application support.
The opportunity lies in designing sourcing and distribution strategies that can accommodate both concentrated demand in established regions and faster growth in developing markets. The uncertainty is that botanical sourcing can be affected by harvest variability, environmental conditions, and logistics disruptions, which means multi-source planning and inventory discipline will remain important.
Actionable Recommendations for Decision-Makers
The strategic implications vary by role, but several priorities are broadly relevant.
For Manufacturers and Ingredient Suppliers
- Prioritize standardization and quality documentation as core commercial assets, especially if expansion into food, nutraceutical, or pharmaceutical-adjacent channels is a goal.
- Align format strategy with real application demand rather than pursuing indiscriminate product-line expansion, and use format choices to differentiate on handling, solubility, or performance where it matters most.
- Evaluate sourcing and processing investments with an eye toward batch consistency and cost resilience, since these factors increasingly determine margin durability under volume growth.
For Investors
- Assess companies based on their ability to combine source access, processing discipline, and application relevance, rather than on top-line growth alone.
- Watch for indicators of quality-tier migration, such as certification progress, capacity expansion paired with demand absorption, and movement into higher-trust application segments.
- Consider exposure to format concentration and end-use dependency, since these can influence both upside and downside under changing buyer preferences.
For Procurement and Supply Chain Leaders
- Use specification clarity, documentation, and supplier quality systems as selection criteria, not just price, to reduce variability risk in downstream production.
- Build sourcing options that account for regional supply realities and format-specific logistics, especially when demand spans multiple applications or markets.
- Track supplier developments in capacity, certification, and application support, as these can affect long-term reliability and negotiation leverage.
For decision-makers seeking a deeper, more customized view of segmentation, regional dynamics, format-level demand shifts, and company-specific positioning, the full research report offers a more granular breakdown of the market and tailored strategic implications. Detailed data and segment-level analysis can support more precise planning for capacity allocation, product development, sourcing strategy, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Yucca Mohave Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Fuel Cell Gas Diffusion Layer Market Hits $2B, 5 Shifts Reshaping Growth Through 2032
By PW Consulting, 2026-09-21
Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Trends and Commercial Opportunities Through 2032
The hydrogen economy has graduated from pilot programs and regulatory mandates to a phase where material science and component reliability directly determine commercial viability. At the heart of every proton exchange membrane fuel cell lies the gas diffusion layer, a deceptively thin component that governs water management, reactant transport, electrical conductivity, and long-term durability. While often treated as a commodity within fuel cell stacks, the gas diffusion layer market has matured into a strategically distinct segment where performance trade-offs, supply chain resilience, and sustainability credentials increasingly separate winners from the rest. Market trajectory data from 2020 through 2032 point to a sustained expansion from approximately 700 million USD in 2020 to the 2 billion USD threshold in 2025, with continued growth projected at a compound annual growth rate of 13.18 percent through the 2026 to 2032 window, reaching the 4 billion USD mark by 2032. This trajectory reflects more than demand pull; it signals a structural shift in how hydrogen technologies are engineered, manufactured, and scaled across automotive, stationary, and emerging portable applications.
The current landscape is defined by accelerating adoption in heavy-duty mobility and distributed power, yet it is simultaneously pressured by material complexity, regulatory divergence, and concentrated manufacturing know-how. The industry is not simply searching for cheaper substrates; it is recalibrating the performance envelope to support higher current densities, colder start-up conditions, longer stack lifetimes, and tighter environmental standards. Understanding where the market is heading requires looking past headline sizing and into the operational realities that shape procurement, R&D prioritization, and competitive positioning.
Market Landscape and Core Challenges
Sizing the Opportunity Without Losing Sight of the Complexity
The hydrogen fuel cell gas diffusion layer market has expanded from roughly 700 million USD in 2020 to about 2 billion USD in 2025, with projections indicating further growth to 2.27 billion USD in 2026 and a steady climb toward 4 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 13.18 percent, reflecting cumulative demand from fuel cell electric vehicles, stationary power systems, and a broadening set of specialized applications. The expansion is not uniform across segments or geographies. Asia Pacific continues to anchor a substantial portion of volume, driven by manufacturing scale and policy-backed deployment, while North America and Europe contribute strongly through technology-intensive applications and stringent durability requirements. Carbon-based substrates remain the dominant material family, with carbon paper securing the largest share of the market, supported by carbon cloth and a smaller but strategically important pool of alternative formats. Automotive applications lead demand, followed by stationary power generation and portable power segments that, while smaller in absolute terms, provide valuable entry points for differentiated product strategies.
Beyond the numbers, the market is defined by a high degree of concentration. A relatively small group of established players commands a dominant share of total revenue, reflecting the technical barriers associated with fiber architecture, microporous layer formulation, and hydrophobic treatment consistency. This concentration gives incumbents an advantage in qualification cycles and volume supply, but it also exposes the market to fragility when disruption arrives in the form of material substitution, regulatory pressures, or regional trade dynamics.
Key Challenges and Inflection Points
The first challenge is performance versus durability trade-offs under real operating conditions. Gas diffusion layers must balance effective gas transport with water removal and electron conduction, all while enduring mechanical compression, thermal cycling, and chemical exposure over thousands of hours. As stack designs push higher power density and faster load acceptance, the tolerance for inconsistency narrows. Any mismatch in thickness uniformity, pore distribution, or hydrophobic treatment can manifest as localized flooding, mass transport losses, or accelerated degradation. The market is therefore shifting from acceptable baseline performance toward application-tuned solutions, which increases complexity in both manufacturing and qualification.
The second challenge is the material sustainability and regulatory environment. Traditional gas diffusion layers rely heavily on carbon fiber paper or cloth treated with perfluorinated hydrophobic agents such as PTFE to manage water repellency. While effective, these chemistries face increasing scrutiny in certain markets, and supply chains are being tested by environmental policy direction, potential trade barriers, and the broader push toward circular material strategies. This is not merely an environmental narrative; it is a sourcing risk and a design constraint. Manufacturers and system integrators must now consider whether existing material choices will remain viable under future regulatory frameworks, and whether alternative hydrophobic approaches can deliver equivalent performance without compromising cost or lifecycle expectations.
The third challenge is supply chain concentration and geopolitical exposure. Because a limited number of suppliers and specialized raw material streams support the sector, regional trade constraints and component-level bottlenecks can disrupt lead times and pricing. For program planners and procurement teams, the implication is clear: single-source dependency is increasingly risky, and qualification strategies need to account for geographic diversification and alternative material pathways without sacrificing stack performance.
Together, these challenges create a market inflection point. Demand is strong enough to justify investment, but the value is shifting toward suppliers and system integrators who can manage durability, regulatory compliance, and supply resilience simultaneously. The question is no longer whether the market will grow, but which players can turn material innovation and supply chain strategy into durable competitive advantage.
Key Drivers Shaping the Market
Technology Innovation as a Performance Multiplier
Material and process innovation remains the most powerful driver of market evolution. The gas diffusion layer is moving from a standardized component toward a performance-critical enabler of stack efficiency and system cost. Research and development activity is increasingly focused on tuning fiber architecture, optimizing microporous layer distribution, and refining hydrophobic treatments to reduce mass transport losses while preserving mechanical integrity. Equally notable is the emergence of fluorine-free hydrophobic approaches that explore interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These alternatives are not simply substitutes; they represent a broader push to decouple water management performance from perfluorinated chemistry, potentially lowering long-term regulatory exposure while opening new performance windows.
In parallel, production innovation is gaining strategic relevance. Pilot lines using recycled carbon fibers have been introduced to reduce raw material waste, with some programs targeting reductions in waste by up to 40 percent. This matters because GDL manufacturing is sensitive to fiber quality, fiber alignment, and treatment consistency. The ability to preserve performance while expanding recycled content can improve cost structures and supply flexibility, while also responding to customer and regulatory expectations around circularity. In practical terms, material innovation is no longer confined to the lab; it is becoming a commercial lever that influences qualification success, total stack cost, and long-term supply viability.
Policy and Regulatory Direction as a Deployment Accelerator
Policy remains a foundational driver, but its influence is evolving from general hydrogen support to more specific requirements around durability, sourcing, and environmental compatibility. Public incentives, zero-emission vehicle mandates, and hydrogen infrastructure programs continue to stimulate demand across mobility and stationary power. At the same time, regional policy divergence is shaping procurement strategies. In Europe, the push for green energy policies and the possibility of trade barriers for certain GDL materials are encouraging supply chain localization and material differentiation. In the United States and China, trade constraints on critical components can affect availability and cost, making regional capability and supplier diversification more valuable than ever.
For commercial decision-makers, the policy environment is not just about volume; it is about compliance risk and time-to-market. Stack developers that design with regulatory trajectory in mind can reduce the probability of late-stage redesigns, whereas those dependent on materials or chemistries facing future restrictions may face higher qualification costs and shorter product lifecycles. Policy is therefore a demand driver, but also a design constraint that shapes the strategic value of material choice.
Demand-Side Shifts Toward Reliability and Total Cost
Demand behavior is maturing on both the consumer and enterprise sides. In automotive applications, the focus has moved beyond proving feasibility to optimizing total cost of ownership, stack longevity, and cold-start reliability. Fleets and OEMs increasingly evaluate fuel cell components not by unit price alone but by their impact on maintenance intervals, degradation rates, and system uptime. In stationary power generation, demand is influenced by grid resilience needs, backup power requirements, and the desire for low-emission distributed generation. Portable power applications, while smaller, contribute to a broader commercial ecosystem where reliability and specific performance characteristics can justify differentiated products.
This shift changes how gas diffusion layers are valued. A GDL that is marginally more expensive but improves water management under dynamic load or extends stack life can be commercially superior to a lower-cost alternative that introduces performance variability. As a result, demand-side behavior is rewarding suppliers that can provide application-specific optimization, consistent quality, and evidence of durability under real operating conditions.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by the interaction of material specialization, regional production capability, and cost pressure. Carbon fiber-based substrates remain central, yet the cost structure of these materials is sensitive to precursor availability, processing efficiency, and the degree of customization required by fuel cell manufacturers. As volumes scale, there is increasing pressure to improve throughput, reduce waste, and standardize dimensions and treatment protocols without sacrificing performance. At the same time, demand for resilience is encouraging dual-sourcing, geographic diversification, and greater transparency into material provenance.
The cost conversation is therefore moving from unit price to total economic value. Suppliers that can offer stable lead times, reproducible quality, and material strategies aligned with future regulatory expectations gain leverage even if their nominal pricing is not the lowest. Conversely, initiatives that reduce waste, increase recycled content, or streamline treatment steps can create meaningful cost advantages while also strengthening sustainability positioning. In this environment, supply chain strategy is a competitive differentiator rather than a back-office concern.
Competitive Landscape and Leading Strategies
Incumbents and the Architecture of Advantage
The market features a mix of specialized material suppliers, broader industrial composites players, and application-oriented distributors, with a clear tilt toward a concentrated group of established leaders. Companies such as SGL Carbon, Toray Industries, Freudenberg Group, AvCarb LLC, Caplinq Corporation, Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG each occupy distinct positions in the value chain, balancing scale, specialization, and customer proximity.
SGL Carbon remains a notable leader in carbon paper and carbon cloth gas diffusion layers, with product families built around microporous layer and PTFE treatment for PEM hydrogen fuel cells. Its strategic advantage is rooted in material expertise, manufacturing discipline, and the ability to support qualification programs with consistent product performance. Recent capacity expansion activity has also signaled a forward-looking approach to sustainability, including pilot production using recycled carbon fibers to reduce raw material waste. This combination of performance credibility and supply-side innovation helps reinforce its position in a market where qualification cycles and reliability matter as much as unit economics.
Toray Industries brings a strong composites and advanced materials heritage, with carbon paper GDL products supporting both PEM fuel cells and water electrolyzers. Its presence across hydrogen-related applications gives it broader exposure to the hydrogen ecosystem and an ability to align material development with adjacent technology demand. Participation in industry exhibitions and technical exchanges has reinforced its focus on communicating product capability for PEM fuel cell and electrolyzer use, emphasizing the link between material performance and system-level outcomes.
Freudenberg Group contributes a broad fuel cell gas diffusion layer portfolio spanning carbon cloth and paper types. Its advantage often lies in systems-level thinking and application breadth, which can support differentiated offerings for specific operating environments. AvCarb LLC and Caplinq Corporation occupy more specialized positions in the North American market, with product lines that include carbon cloth and carbon paper-based GDLs and conductive plastic alternatives. These companies often compete on responsiveness, customization, and the ability to serve research, pilot, and production needs with flexible supply.
Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG round out a diverse competitive field. Some focus on carbon fiber cloth and felt-based diffusion layers, others on porous substrates or mesh-based configurations, and some on distribution and broader component availability. Their presence illustrates that the market is not monolithic; there is room for both generalized scale players and specialized suppliers, depending on application requirements, volume, and regional service expectations.
Differentiation and Strategic Positioning
The competitive edge in this market is increasingly multidimensional. Performance consistency and durability remain foundational, but differentiation now also depends on material sustainability, supply resilience, and application-specific engineering support. Leaders tend to combine several of the following capabilities:
Hydrogen and Fuel Cells Market
- Advanced control over fiber structure and microporous layer uniformity to support predictable electrochemical performance
- Hydrophobic treatment strategies that balance water management with regulatory and sustainability considerations
- Production flexibility that enables both standardized high-volume products and tailored solutions for demanding applications
- Supply chain transparency and geographic or sourcing diversification to reduce exposure to trade and material constraints
- Technical engagement with stack developers and system integrators to align material properties with real operating conditions
In practical terms, this means the most resilient players are not necessarily those with the simplest cost structure, but those that can translate material know-how into reliability, compliance readiness, and customer-specific value.
Evolution of the Competitive Structure
The market is likely to experience both consolidation and fragmentation pressure over the next several years. On one hand, scale advantages in material production, qualification support, and global supply can favor larger incumbents and encourage integration across the component value chain. On the other hand, niche applications, regional demand pockets, and material innovation pathways create opportunities for specialized entrants and for suppliers that can move faster on sustainability-driven redesigns. New entrants that bring fluorine-free hydrophobic concepts, improved recycled content strategies, or novel porous architectures may find traction in specific performance segments, especially where incumbents are constrained by legacy chemistry or older production lines.
Worldwide Bipolar Plate Fuel Cell Market
At the same time, distributors and multi-brand providers will continue to play a useful role in lowering entry barriers for research teams, pilot programs, and smaller-scale deployments. However, the strategic center of gravity remains with suppliers that can support volume production with consistent quality and a credible path through changing regulatory and sustainability expectations. The market is thus evolving from a relatively narrow competition around material type into a broader contest over reliability, compliance, and supply resilience.
Future Trends and Commercial Opportunities
Trend One: Performance-Tailored GDL Design Becomes the Norm
As stack requirements diverge by application, the market is moving toward more application-tuned gas diffusion layers rather than one-size-fits-all substrates. Automotive stacks with high dynamic load cycles, stationary systems with long-duration operating profiles, and specialized portable units each impose distinct water management, compression, and durability demands. Suppliers that can configure pore structure, thickness, and treatment characteristics to match these profiles will be better positioned to capture value. The commercial opportunity lies in moving from transactional component supply to engineered solution partnerships, where performance data, validation support, and lifecycle outcomes become part of the commercial proposition.
Trend Two: Sustainability-Driven Material Redesign Gains Commercial Weight
Regulatory direction and customer expectations are increasing the strategic importance of fluorine-free hydrophobic approaches and recycled or lower-waste production methods. Material redesign is not only an environmental initiative; it is a risk management and differentiation lever. Suppliers that can demonstrate equivalent or superior performance with alternative chemistries or improved material efficiency can open access to customers seeking to reduce future compliance exposure and improve sustainability narratives. The opportunity is to align R&D with market-facing requirements early, so that material alternatives are commercially viable when needed rather than arriving too late to influence program decisions.
Trend Three: Regionalization and Supply Diversification Become Structural Requirements
Given the concentration of expertise and material streams, regional demand growth will increasingly encourage localized supply capabilities, dual sourcing, and more resilient qualification pathways. Trade dynamics and component-level constraints can stretch lead times or complicate sourcing, making geographic diversification a pragmatic hedge. For suppliers, the commercial opportunity is to build regional service depth, maintain reproducible quality across sites, and offer credible alternatives when program planners seek to reduce single-source exposure. For buyers, the opportunity is to secure performance without locking into fragile supply arrangements.
Risks and Uncertainties to Factor Into Planning
Despite the positive trajectory, several uncertainties warrant attention. Material substitution may take longer than anticipated if alternative hydrophobic chemistries or new fiber architectures struggle to meet durability and cost thresholds at scale. Policy divergence could create uneven demand across regions, with some markets accelerating while others face compliance or trade complications that slow deployment. Supply chain disruptions affecting carbon fiber precursors, treatment chemicals, or specialized manufacturing equipment can create cost and timing volatility. In addition, if fuel cell adoption in certain segments underperforms relative to expectations, even a strong overall market can hide segment-level weakness that affects supplier revenue mix. Decision-makers should therefore treat momentum as real but conditional, and design strategies that can adapt to changes in regulation, material availability, and application demand.
PW Consulting
Strategic Recommendations for Decision-Makers
For Manufacturers and Material Suppliers
Prioritize performance consistency and durability evidence as the basis for commercial differentiation. As qualification cycles lengthen and application requirements diversify, the ability to demonstrate reproducible behavior under real operating conditions becomes a decisive advantage. At the same time, invest early in material innovation that addresses sustainability and regulatory trajectory, including fluorine-free hydrophobic options and waste-reducing production approaches. Building flexibility into product architecture and manufacturing processes will allow faster response to changing customer needs and reduce the risk of being locked into legacy chemistries.
For Investors and Strategic Partners
Focus on companies and technologies that combine material expertise with supply resilience and a credible path through regulatory change. The most attractive opportunities are likely to sit at the intersection of performance reliability, sustainability alignment, and regional supply capability. In diligence, look beyond near-term revenue and assess whether a supplier can sustain quality, support qualification, and adapt material strategies as policy and customer expectations evolve. Portfolio exposure to hydrogen applications should also account for segment variability, since automotive, stationary, and portable demand can follow different adoption rhythms.
For Procurement and System Integrators
Treat gas diffusion layer sourcing as a strategic decision rather than a commodity purchase. Evaluate suppliers on quality consistency, application fit, lead-time reliability, and alignment with future regulatory expectations. Where possible, diversify sourcing and establish qualification pathways that allow alternative materials or regions to be introduced without disrupting program timelines. The goal is to secure stack performance while reducing exposure to single-source dependency and material chemistry risk.
The strategic significance of the hydrogen fuel cell gas diffusion layer market is growing alongside its size. Demand momentum is clear, but long-term value will accrue to those who manage the intersection of performance, sustainability, and supply resilience with discipline. For decision-makers who need deeper segmentation, competitive benchmarking, regional demand detail, and scenario-based planning data, the full PW Consulting market research report provides the structured, granular intelligence needed to translate these trends into concrete business decisions.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Water Filters Market 2026: Why a 7.7% CAGR and 84.2M Revenue Change Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Water Filters Market
The global water filters market stood at approximately USD 50.0 million in 2025, continuing a steady expansion trajectory from USD 35.15 million in 2020. Over the historical period of 2020 to 2025, the sector demonstrated consistent growth, reflecting heightened awareness of water quality and increasing adoption of point-of-use treatment solutions. Looking ahead to the forecast period of 2026 to 2032, the market is projected to reach USD 84.2 million by the end of the forecast window, translating to a compound annual growth rate of 7.7 percent. This growth profile suggests a market that is maturing but still capable of expansion, driven by technological refinement, regulatory evolution, and shifting consumer expectations. For decision makers, the key question is not whether the market will grow, but which segments, geographies, and strategic positioning will capture disproportionate value as the landscape evolves.
Core Dynamics and Structural Challenges
A defining feature of the current market is its relatively fragmented structure. The top three players account for roughly 28.5 percent of total revenue, while the top five hold around 36.2 percent. This concentration level indicates that no single entity dominates the entire value chain, leaving room for specialized players, regional champions, and new entrants to compete on product differentiation, certification strength, and channel strategy. At the same time, fragmentation can pressure margins and create complexity in standardizing quality and compliance across diverse product portfolios. The industry is at a inflection point where brand trust, certification credibility, and supply chain reliability increasingly differentiate winners from laggards, rather than scale alone.
Three structural challenges shape the near-term outlook. First, regulatory tightening around contaminant reduction claims is raising the bar for product validation. Standards governing PFAS, heavy metals, and aesthetic performance are becoming more rigorous, requiring manufacturers to invest in testing, documentation, and continuous reformulation. Second, raw material cost volatility is compressing margins for certain filter technologies, particularly those dependent on activated carbon, where supply constraints and input price movements have become more pronounced. Third, consumer and commercial buyers are increasingly sophisticated, demanding clearer evidence of performance, water efficiency, and total cost of ownership rather than relying solely on brand familiarity. Together, these forces reward companies that can align innovation with credible certification and transparent value propositions, while exposing those that compete primarily on price without differentiated performance.
Key Drivers Shaping Market Trajectory
Technology Innovation and Certification-Led Differentiation
Technology advancement remains a central engine of growth, but the nature of innovation is shifting from basic filtration capability to targeted contaminant reduction and system efficiency. Reverse osmosis continues to represent the largest technology segment by revenue share, reflecting its broad applicability across residential and light commercial settings where comprehensive contaminant removal is valued. Ultrafiltration and activated carbon solutions also hold meaningful positions, serving use cases where taste, odor, chlorine, particulate, and specific chemical reductions are priorities. The market is increasingly rewarding products that combine multiple treatment stages, intelligent monitoring, and validated performance claims.
Certification dynamics are amplifying the impact of technical innovation. In November 2025, guidance from the EPA reinforced stricter test protocols for the NSF/ANSI 53 standard related to PFAS reduction in point-of-use water filters, requiring certified products to meet elevated contaminant reduction claims for PFOA and PFOS. This shift raises the competitive stakes for manufacturers that can demonstrate verified performance, while simultaneously creating a barrier for products that cannot substantiate their claims. More recently, in April 2026, NSF published its Annual Review and Impact Report 2025, outlining strategic priorities for water filtration standards and certifications for 2026. These developments signal a market where certification is not merely a compliance checkbox but a strategic asset that influences procurement decisions, retail placement, and customer trust.
Policy, Standards, and Regional Regulatory Divergence
Regulatory and standards activity is not uniform across regions, creating both complexity and opportunity. In addition to the tightened PFAS protocols in North American contexts, 2026 saw the NSF/ANSI 42 standard for aesthetic effects revised to require higher minimum recovery rates for water efficiency in certified water filters. This adjustment reflects a broader emphasis on water conservation and system efficiency, encouraging designs that reduce waste while maintaining performance. For manufacturers, the implication is clear: water efficiency is becoming a competitive dimension alongside contaminant reduction, especially in markets where utility costs, sustainability expectations, and resource constraints are rising.
Standards development is also expanding geographically. The launch of the NSF P535 Drinking Water Treatment Units – Filtration protocol for the Chinese market introduced verification for reduction claims covering lead, mercury, chromium, PFOA, PFOS, and BPA in domestic point-of-use systems. This kind of regional standards expansion helps formalize quality expectations in markets with growing middle-class demand and increasing public attention to drinking water safety. At the same time, divergent standards across regions increase the compliance burden for globally oriented product lines, favoring companies that can modularize development, align testing early in the design cycle, and treat regional certification as a core element of market entry strategy rather than a late-stage adaptation.
Air Filters Market
Demand-Side Shifts in Residential, Commercial, and Industrial Settings
Demand trends are evolving across application environments, though the residential segment continues to account for the largest share of market revenue. In homes, the driver is not only perceived taste improvement but also heightened concern about contaminants that are more difficult to detect without testing, including PFAS and certain heavy metals. Consumers are increasingly willing to pay for certified performance and are more attentive to filter replacement cycles, ease of maintenance, and the credibility of contaminant reduction claims. This shift pushes retailers and brands to communicate technical performance in accessible terms while maintaining rigorous certification backing.
Commercial and industrial applications, while smaller in aggregate revenue share, remain strategically important because they often involve higher volume, recurring replacement demand, and more stringent specification requirements. Facilities managers, hospitality operators, and light commercial users are increasingly integrating water treatment into broader sustainability and operational efficiency agendas. In these contexts, total cost of ownership, service reliability, and documentation of performance can matter as much as upfront price. The commercial and industrial segments therefore provide a pathway for differentiated offerings that combine certified filtration with service models, monitoring capabilities, and application-specific configuration.
Supply Chain, Raw Material Costs, and Input-Side Pressure
Supply-side dynamics are an increasingly important part of the market story. In the first quarter of 2026, activated carbon raw material prices in the United States averaged approximately USD 2,204 per metric ton, up from prior quarters due to constraints in coconut shell charcoal supply. For product lines reliant on activated carbon, this kind of input pressure can affect cost structures, pricing flexibility, and margin stability. The challenge is not simply short-term cost fluctuation but the need to manage supply resilience, validate alternative media where appropriate, and ensure that cost changes do not undermine the perceived value of certified performance.
Companies that proactively address input volatility through supplier diversification, formulation efficiency, and transparent communication tend to be better positioned to maintain consistency in product availability and performance claims. In a market where trust is closely tied to consistency, supply chain reliability becomes a strategic differentiator. This is especially true as end users and procurement teams become more aware of the operational consequences of filter performance variation, replacement frequency, and unexpected downtime in commercial settings.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive set spans a range of business models, from retail-focused pitcher and dispenser brands to under-sink and whole-home system providers, and from diversified industrial suppliers to specialized filtration manufacturers. Their profiles illustrate how differentiation is being built across product format, certification emphasis, and channel strategy.
PW Consulting Automotive & Machinery Research Center
- Brita, headquartered in Menden, Germany, remains an active provider of pitcher, dispenser, and bottle water filters certified for taste, odor, and contaminant reduction, with a dominant position in retail volume sales. Its strength lies in everyday consumer accessibility, brand familiarity, and a product ecosystem that aligns with high-frequency replacement behavior.
- A.O. Smith Corporation, based in Auburn, Alabama, is an active manufacturer of under-sink and countertop reverse osmosis and carbon-based water filters, marketing the Aquasana and Pureit brands. Its positioning connects higher-performance treatment technologies with multi-brand portfolios that can address different customer segments and price points.
- Culligan International, located in Northbrook, Illinois, is an active provider of under-sink, pitcher, and whole-home water filtration systems with certified contaminant reduction. Its breadth across home water treatment formats supports a service-oriented model and a strong presence in installed solutions.
- Aquasana, headquartered in Middleburg Heights, Ohio, is an active manufacturer of under-sink and countertop water filters certified to NSF standards for heavy metals, chlorine, and PFAS reduction. Its emphasis on certified contaminant reduction aligns directly with the growing consumer focus on verifiable health-related performance.
- 3M Company, based in Saint Paul, Minnesota, is an active supplier of under-sink and point-of-use water filters and cartridges certified for reduction of volatile organic compounds, chlorine, and particulates. Its heritage in engineered materials and filtration media supports a technical credibility narrative in point-of-use applications.
- iSpring Water Systems LLC, in Atlanta, Georgia, is an active manufacturer of reverse osmosis and sediment/carbon water filter systems certified to NSF/ANSI standards. Its focus on certified RO and multi-stage systems reflects the ongoing demand for comprehensive home treatment solutions.
- Coway Co. Ltd., headquartered in Seongnam, South Korea, is an active provider of countertop, under-sink, and pitcher water purifiers and filters certified for health-related contaminants. Its presence illustrates the global nature of competition and the rising importance of certified performance in Asian and export markets.
- Pentair plc, located in Apopka, Florida, is an active supplier of residential and commercial water filtration systems and cartridges for point-of-use treatment. Its scope across residential and commercial applications positions it to capture demand in both everyday consumer settings and higher-specification commercial environments.
- ZeroWater, headquartered in Wilmington, Delaware, is an active provider of pitcher, dispenser, and faucet-mounted water filters certified to NSF/ANSI 58 for TDS reduction. Its emphasis on total dissolved solids reduction highlights how specific performance claims can anchor brand identity and consumer adoption.
Differentiation, Consolidation, and the Role of New Entrants
The competitive landscape is shaped less by a single dominant champion and more by overlapping spheres of advantage. Some players compete primarily on retail reach and convenience, others on certified contaminant reduction and technical documentation, and still others on installed systems and service relationships. The most resilient strategies tend to combine several of these elements: a clear performance claim, credible certification, reliable supply, and a channel approach that matches the product format to the buying journey.
Market concentration data suggests there is room for both consolidation and continued specialization. Larger players can leverage scale in procurement, testing, and distribution, while smaller or regional specialists can win by focusing on narrow application needs, localized certification, or distinctive product designs. At the same time, the evolving standards environment may encourage consolidation among companies that cannot sustain the cost and complexity of ongoing compliance and reformulation. New entrants are most likely to succeed when they address a specific unmet need, such as a highly targeted contaminant reduction claim, improved water efficiency, smart monitoring, or a service-led commercial model, rather than attempting to compete broadly on price in saturated retail formats.
Forward Outlook: Three Strategic Trends for the Next 3-5 Years
Trend 1: Certification as Commercial Currency
Over the next several years, certified performance is likely to become an even stronger commercial differentiator. As standards tighten around PFAS, heavy metals, and water efficiency, buyers in both consumer and commercial channels will increasingly rely on certification as a shorthand for trust. Products that can clearly document validated reduction claims, replacement consistency, and testing rigor will gain an advantage in retail, e-commerce, and specification-driven procurement. The commercial opportunity lies in turning certification into a visible part of the value proposition rather than a back-office requirement, using it to support pricing discipline, channel selection, and brand positioning. The risk is that certification without clear consumer communication or without consistent product execution becomes a costly compliance burden with limited commercial return.
Refrigerator Water Filters Market
Trend 2: Efficiency, Resource Sensitivity, and System Design
Water efficiency and resource-conscious design are expected to gain prominence as part of a broader sustainability and operating-cost agenda. Revisions to aesthetic and efficiency standards, combined with growing attention to water use in homes and facilities, will encourage product designs that reduce waste and improve recovery rates without compromising contaminant reduction. For manufacturers, this creates an opportunity to innovate around system architecture, filter life, and replacement economics. For commercial buyers, efficiency features can support broader sustainability goals and reduce total cost of ownership. The uncertainty is that efficiency requirements can increase design complexity and testing costs, particularly for smaller suppliers, potentially tilting the field toward companies with stronger engineering and compliance capabilities.
Trend 3: Regional Standardization and Market Formalization
The expansion of regional protocols, such as the newly launched NSF P535 filtration protocol for the Chinese market, points toward a future in which more markets formalize drinking water treatment expectations. As standards become more defined, demand in those markets may become more accessible to certified suppliers while also raising the entry barrier for products that cannot meet local verification requirements. This trend creates opportunities for companies that can navigate regional certification early and build local credibility, especially in high-growth regions where safety concerns and purchasing power are both rising. The counter-risk is regulatory fragmentation: differing test methods, claim language, and certification pathways can increase the cost of multi-region offerings and require more sophisticated product management.
Actionable Guidance for Decision Makers
For Manufacturers and Brand Leaders
Prioritize certification strategy as a core element of product development, not a final-stage approval step. Align engineering, claims language, and testing timelines early so that product launches can be supported by credible, up-to-date certifications. In parallel, evaluate input exposure across filter media and components, especially where activated carbon and other constrained materials play a central role. Diversifying supply, improving media utilization, and designing for consistent replacement performance can help protect margins and maintain trust. Finally, consider how product formats map to customer buying behavior: everyday retail products benefit from strong brand familiarity and clear, simple performance messaging, while installed and commercial solutions gain from documented performance, service reliability, and efficiency credentials.
For Investors and Strategic Allocators
Focus on business models that combine defensible certification, recurring replacement economics, and resilient supply chains. The most attractive opportunities are likely to emerge where companies can demonstrate differentiated contaminant reduction claims supported by recognized standards, while also managing input volatility and regional compliance complexity. In fragmented markets, scalable distribution, strong consumer trust, and the ability to expand into adjacent formats or service-led commercial offerings can create meaningful value. At the same time, attention should be paid to companies that depend heavily on price competition without clear performance differentiation, since tightening standards and input cost pressures may erode the economics of that approach over time.
For Procurement and Channel Decision Makers
Treat certification and documented performance as primary selection criteria, especially where contaminant reduction, water efficiency, and replacement consistency matter to end users or facility operations. Evaluate total cost of ownership rather than initial unit price alone, including replacement frequency, availability, service support, and compliance status. For commercial buyers, request evidence of testing and certification that matches the specific contaminants and use conditions relevant to the site. For retail and distribution partners, prioritize products that communicate performance clearly and can sustain consistent supply, since stockouts or inconsistent quality can quickly erode consumer confidence in a category where trust is central.
Closing Perspective
The water filters market is moving through a phase in which growth is supported by rising awareness, regulatory maturation, and continued product innovation, but value capture is increasingly tied to credibility, efficiency, and supply resilience. The combination of tighter contaminant reduction standards, expanded regional protocols, and input cost dynamics is reshaping the basis of competition. Companies that treat certification, water efficiency, and supply chain reliability as strategic assets are better positioned to convert market growth into durable advantage. For leaders seeking to act with confidence in a market that is both expanding and re-segmenting, detailed segment-level data, regional nuance, and tailored scenario analysis can make the difference between broad exposure and targeted opportunity. The full research report provides deeper segmentation data, regional detail, and customized strategic guidance for those looking to translate these trends into specific commercial decisions.
For detailed analysis of this topic, please visit the official page: Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The KNX Products Market: Strategic Trajectories and Commercial Imperatives
The KNX products market represents a mature yet rapidly evolving segment within the broader building automation ecosystem. As buildings worldwide transition from passive structures to intelligent, interconnected environments, KNX-certified solutions have solidified their position as a benchmark protocol for integrated control systems. The market has demonstrated consistent growth over the past half-decade, expanding from approximately 127.0 million USD in 2020 to an estimated 164.19 million USD in 2025. Projections indicate this trajectory will accelerate through the end of the decade, with the market reaching roughly 180.25 million USD in 2026 and climbing to 338.0 million USD by 2032. This expansion reflects a compound annual growth rate of approximately 10.94 percent, signaling that demand is not merely sustaining but compounding as architectural, technological, and regulatory forces converge.
Such growth is not uniform across all vectors. The market's composition reveals a balanced but increasingly specialized demand structure, where sensors command the largest share of product allocation, followed by actuators, system devices, and ancillary product categories. Application-wise, lighting control remains the dominant use case, with HVAC control, energy management, shutter and blind control, and access and security systems forming a tightly interwoven secondary tier. Geographically, the market has historically been anchored in Europe, which accounts for the largest revenue share, while North America, Asia Pacific, Latin America, and the Middle East and Africa each contribute distinct but growing portions of total demand. The competitive arena remains moderately fragmented, with the top three players commanding roughly 24.0 percent of market revenue and the top five collectively holding about 36.0 percent. This concentration suggests a landscape where established incumbents retain substantial influence but where differentiation, regional adaptation, and technological refinement continue to create openings for strategic positioning.
Key Challenges and Inflection Points
Despite the favorable growth outlook, the KNX products market is navigating several structural challenges that will shape competitive outcomes over the next several years. The first challenge lies in protocol harmonization and interoperability expectations. While KNX enjoys strong recognition as a standardized, open protocol, building owners and system integrators increasingly expect seamless connectivity across heterogeneous ecosystems, including IP-based networks, cloud platforms, and proprietary IoT extensions. Manufacturers that treat KNX as a standalone control layer without addressing cross-protocol bridging risk losing relevance in projects where unified dashboards, remote accessibility, and data interoperability are non-negotiable requirements.
A second challenge emerges from the tension between standardization and customization. KNX-certified devices offer reliability and compatibility advantages, but many high-value commercial and luxury residential projects demand bespoke integration scenarios, localized regulatory compliance, and aesthetic differentiation. Suppliers must balance the efficiency of standardized product lines with the flexibility required for specialized deployments. Over-indexing on either extreme can erode margins or reduce market reach.
Third, the market faces an inflection point around skills and installation capacity. As KNX solutions expand from advanced residential projects into broader commercial, institutional, and multi-family environments, the availability of trained integrators and electricians becomes a bottleneck. The protocol's technical rigor is an asset for system performance, but it also raises the barrier to rapid deployment. Companies that invest in simplified configuration tools, stronger partner enablement, and clearer commissioning workflows are better positioned to scale adoption without compromising quality.
Key Drivers of Market Change
Technological Innovation and Protocol Evolution
Technology advancement is the most visible driver reshaping the KNX products market. The convergence of traditional KNX bus architecture with IP connectivity and IoT-enabled extensions is widening the addressable use cases for sensors, actuators, and system devices. Recent industry activity underscores this direction. In March 2026, the KNX Association showcased its member ecosystem at Light + Building, where multiple companies presented the latest KNX IoT and intelligent energy management solutions. This exhibition signaled a clear strategic emphasis: KNX is evolving beyond isolated control functions toward integrated energy intelligence, remote management, and data-aware building operations.
For manufacturers, this shift is not merely a feature upgrade. It reframes the value proposition of KNX-certified devices from static control components to enablers of measurable energy performance and operational insight. Sensors that once served localized detection functions are now being positioned as inputs for broader automation logic, while actuators and system devices are increasingly designed to interface with centralized analytics and demand-response strategies. Companies that embed connectivity, software-friendly interfaces, and upgrade pathways into their hardware portfolios are likely to capture disproportionate share in projects where building owners prioritize future-proofing over lowest initial cost.
Policy and Regulatory Momentum
Regulatory pressure is a powerful accelerant for KNX adoption, particularly in regions with aggressive building decarbonization targets. Policy frameworks are increasingly tying building performance to measurable energy outcomes, and automation systems have become essential instruments for compliance and optimization. The EU Energy Performance of Buildings Directive, for example, highlights that buildings account for approximately 40 percent of EU energy consumption and 36 percent of energy-related CO2 emissions. This regulatory context creates direct demand for control systems capable of monitoring, balancing, and reducing consumption across lighting, HVAC, shading, and security functions.
Within this environment, KNX-certified products are gaining relevance because they align with established energy performance assessment standards. Certified products can enable up to 50 percent energy savings in building automation when deployed in accordance with top Energy Performance Class requirements under EN 15232. This capacity is not a marginal benefit; it is becoming a core procurement rationale for public tenders, large-scale commercial developments, and retrofit programs where compliance and documented efficiency gains carry financial and reputational weight. For suppliers, regulatory tailwinds are most valuable when paired with clear documentation, certification transparency, and application guidance that helps project teams translate compliance goals into system design choices.
Smart Building Market
Demand-Side Shifts in Building Ownership and Operations
Demand patterns are also changing as building owners and facility operators reevaluate the role of automation in total cost of ownership. The traditional purchase logic centered on hardware price is giving way to a broader assessment that includes energy savings, comfort, maintenance predictability, and integration with corporate sustainability commitments. In residential segments, buyers are increasingly treating smart control not as a premium add-on but as a baseline expectation for new developments and high-end renovations. In commercial environments, operational resilience and energy cost control are driving facility managers to favor systems that can centralize control across multiple subsystems without creating vendor lock-in.
This shift has implications for product mix and go-to-market strategy. Lighting control remains the largest application area, but demand is increasingly cross-linked with HVAC control, energy management, and access and security workflows. Buyers are less interested in isolated subsystems and more interested in coherent environments where shading, climate, illumination, and security can respond to occupancy patterns and external conditions in a coordinated manner. As a result, suppliers offering integrated yet modular KNX portfolios are better aligned with how projects are being specified and evaluated.
Supply Chain and Cost Structure Considerations
Supply chain dynamics continue to influence competitive positioning, particularly for hardware-heavy product categories. The market's reliance on sensors, actuators, and system devices means that component availability, manufacturing efficiency, and logistics stability directly affect time-to-market and margin preservation. While the sector has not faced the same level of disruption as some consumer electronics segments, cost volatility and lead-time variability remain practical concerns for both producers and integrators. The companies most effectively managing these pressures are those that combine disciplined sourcing with product architectures that allow regional adaptation without excessive rework.
Cost structures are also being reshaped by the growing importance of software-supported configuration, remote diagnostics, and service-enabled offerings. As building automation becomes more data-centric, the economic value of a KNX product is increasingly tied to the surrounding ecosystem: documentation quality, integration support, training, and post-installation service. Manufacturers that treat these elements as part of the core offering, rather than as after-sales extras, can differentiate more effectively in a market where hardware specifications alone are becoming less sufficient as a competitive moat.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field in the KNX products market features a broad set of established manufacturers, many of whom anchor their KNX offerings in certified actuators, sensors, and control devices spanning lighting, heating, ventilation, and security applications. German and French firms feature prominently in this landscape, reflecting the deep integration of KNX within European building culture and procurement norms. Companies such as ABB AG through its BUSCH-JAEGER and STOTZ-KONTAKT units, Albrecht Jung GmbH & Co. KG, 4ba GmbH, Berker, B.E.G. Brück Electronic GmbH, Busch-Jaeger, Gira, Hager Group, MDT Technologies, Theben AG, and Siemens AG represent a strong presence of organizations with well-defined automation portfolios and established distribution relationships.
Beyond these, the landscape includes Legrand and Schneider Electric from France, Somfy from France, and a wider circle of specialists and regional players such as Eelectron, HDL Automation, IPAS GmbH, Lime International, STEINEL, Urmet, Weinzierl Engineering, Zennio Avance y Tecnologia S.L., and GVS. While their individual product emphasis varies, the collective profile suggests a market where many manufacturers compete on similar foundational capabilities: KNX certification, application breadth, and reliability. Differentiation therefore tends to emerge through brand strength, regional channel reach, design language, integration partnerships, and the ability to support complex project requirements end to end.
PW Consulting
Leading incumbents are increasingly distinguishing themselves not just by what they sell, but by how they enable deployment. Stronger technical documentation, expanded accessory ecosystems, integration with planning tools, and more intuitive commissioning processes can reduce friction for integrators and specifiers. In practice, this means that a manufacturer's strategic advantage may depend as much on its support infrastructure and partner network as on the specifications of individual devices. In a market where the top five players collectively hold around 36.0 percent of revenue, sustained leadership will likely belong to those who convert certification and product range into repeatable project wins and long-term specification loyalty.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape appears poised for selective consolidation and parallel specialization. On one hand, the moderate concentration levels indicate room for continued fragmentation, especially in regional markets where local service, compliance knowledge, and distributor relationships remain decisive. On the other hand, the increasing complexity of connected building projects favors larger portfolios, stronger R&D resources, and broader international support capabilities. This dynamic may encourage consolidation among mid-tier players seeking scale, while also creating space for niche specialists who excel in particular application areas such as lighting control, shading, or energy management.
New entrants and adjacent players are also likely to influence the market, especially where KNX intersects with IoT platforms, smart metering, and remote building management. The competitive threat is not necessarily direct displacement of KNX devices, but rather the expansion of expectations around what those devices must connect to and communicate with. Companies that can position KNX as the dependable field-level backbone within a broader digital architecture are likely to preserve and extend their relevance. Conversely, players that fail to adapt to cross-platform expectations may find their products confined to narrower, more price-sensitive segments.
Future Trends and Commercial Opportunities
Trend 1: Energy Intelligence as a Core Product Dimension
Over the next three to five years, energy management is expected to transition from a supporting application to a central design driver for KNX product strategies. Regulatory pressure, operating cost sensitivity, and corporate sustainability commitments are aligning to make measurable energy performance a priority in both new builds and retrofits. KNX systems that can coordinate lighting, HVAC, shading, and security while feeding usable data into building-level energy oversight will likely see stronger specification rates. The commercial opportunity lies in developing product combinations and configuration models that make energy outcomes easier to design, validate, and maintain. Suppliers that can demonstrate credible savings pathways and align their portfolios with recognized performance classes will have an advantage in tender processes and high-value projects.
Trend 2: Greater Emphasis on Interoperability and Remote Management
A second trend is the growing expectation that KNX deployments should integrate smoothly with broader digital building environments. This includes IP-based communication, cloud-connected monitoring, and interfaces that allow facility teams to manage multiple sites or subsystems from unified platforms. The commercial opportunity is not simply to add connectivity features, but to reduce the operational burden of KNX integration. Products that are easier to commission, easier to monitor, and easier to expand will appeal to integrators and building owners alike. This trend also creates opportunities for service-oriented models, where ongoing diagnostics, firmware management, and configuration support become part of the value chain rather than peripheral activities.
Trend 3: Regional Acceleration and Application Diversification
The third trend concerns the geographic and application broadening of demand. While Europe remains the strongest revenue base, regions such as Asia Pacific, North America, Latin America, and the Middle East and Africa are contributing increasing shares as building modernization programs, premium residential development, and commercial automation projects expand. At the same time, application demand is spreading beyond lighting control into HVAC control, shutter and blind control, energy management, and access and security control. The commercial opportunity here is twofold: manufacturers can pursue regional adaptation strategies that reflect local building norms, and they can develop application-focused bundles that mirror how projects are actually specified. Companies that treat regional growth as a replication of the European playbook may underappreciate the importance of local integration practices, certification expectations, and procurement channels.
Risks and Uncertainties
These opportunities are accompanied by meaningful uncertainties. One risk is that rapid software-centric innovation could shift value toward platform providers and integrators, compressing hardware margins if manufacturers are unable to justify premium pricing through differentiated performance or services. Another is regulatory variation: while some regions are tightening building performance requirements, others may move more slowly or prioritize different compliance mechanisms, creating uneven demand growth. A third risk relates to execution complexity. As products become more connected and application combinations more intricate, the potential for installation errors, commissioning delays, and support burdens increases. Companies that expand their portfolios without strengthening the corresponding enablement and service infrastructure may find that growth brings operational drag rather than profitable scale.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize building portfolios that combine KNX certification credibility with clear pathways for connectivity, energy management, and integration support. Rather than treating IoT capabilities as optional add-ons, they should be designed into the product architecture from the outset so that devices can function as dependable field-level components within broader digital building strategies. Equally important is the enablement ecosystem: planning tools, configuration guidance, commissioning support, and partner training can determine whether a strong product lineup translates into repeat specification and successful project outcomes. In a market where concentration remains moderate, differentiation through deployment ease and application coherence can be as important as hardware specifications.
For Investors and Strategic Capital
Investors should evaluate opportunities with attention to companies that can bridge hardware reliability and software-enabled value creation. The most attractive positions may be found where firms can demonstrate durable certification advantages, strong regional channel relationships, and the ability to serve cross-application demand such as lighting, HVAC, and energy management in a coordinated way. Capital allocation should also account for the growing importance of service, training, and integration support as margin contributors. In a market growing at a double-digit CAGR, value capture will increasingly depend on whether a company can convert demand growth into specification loyalty and repeatable project execution rather than one-time product sales.
For Procurement and Integration Leaders
Procurement and integration teams should approach KNX selection with a broader project lens. The lowest unit price may not deliver the best outcome if it increases commissioning complexity, limits future expandability, or weakens energy performance alignment. Evaluation criteria should include certification transparency, compatibility with planned energy management goals, ease of integration with existing or anticipated building platforms, and the quality of supplier support. Given the increasing importance of compliance and operational efficiency, procurement decisions should weigh how well a chosen product set can support documented performance goals over the building lifecycle. Early engagement with suppliers that can provide clear application guidance and integration pathways can reduce project risk and improve long-term value.
Conclusion
The KNX products market is entering a phase where growth is being reinforced by regulatory pressure, technological extension, and shifting expectations around energy performance and interoperability. The market's expansion from roughly 127.0 million USD in 2020 to an projected 338.0 million USD by 2032 reflects more than incremental demand; it reflects a structural realignment in how buildings are specified, commissioned, and operated. Sensors, actuators, and system devices remain foundational, but their commercial value is increasingly tied to how effectively they support lighting control, HVAC control, energy management, shading, and security within integrated environments.
IO-Link Market
For companies operating in this space, the strategic question is no longer whether KNX remains relevant, but how to position within a market that is becoming more connected, more performance-driven, and more application-integrated. The leaders who gain durable advantage will likely be those who combine certified product excellence with stronger enablement, clearer energy-performance alignment, and the ability to serve regional and application diversity without losing coherence. Detailed segment-level data, company-level comparisons, and customized strategic guidance can help decision makers convert these trends into concrete plans. For those seeking a deeper operational view of segmentation, competitive positioning, and forward demand pathways, the full research report provides a more granular foundation for strategy development.
For detailed analysis of this topic, please visit the official page: KNX Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com